


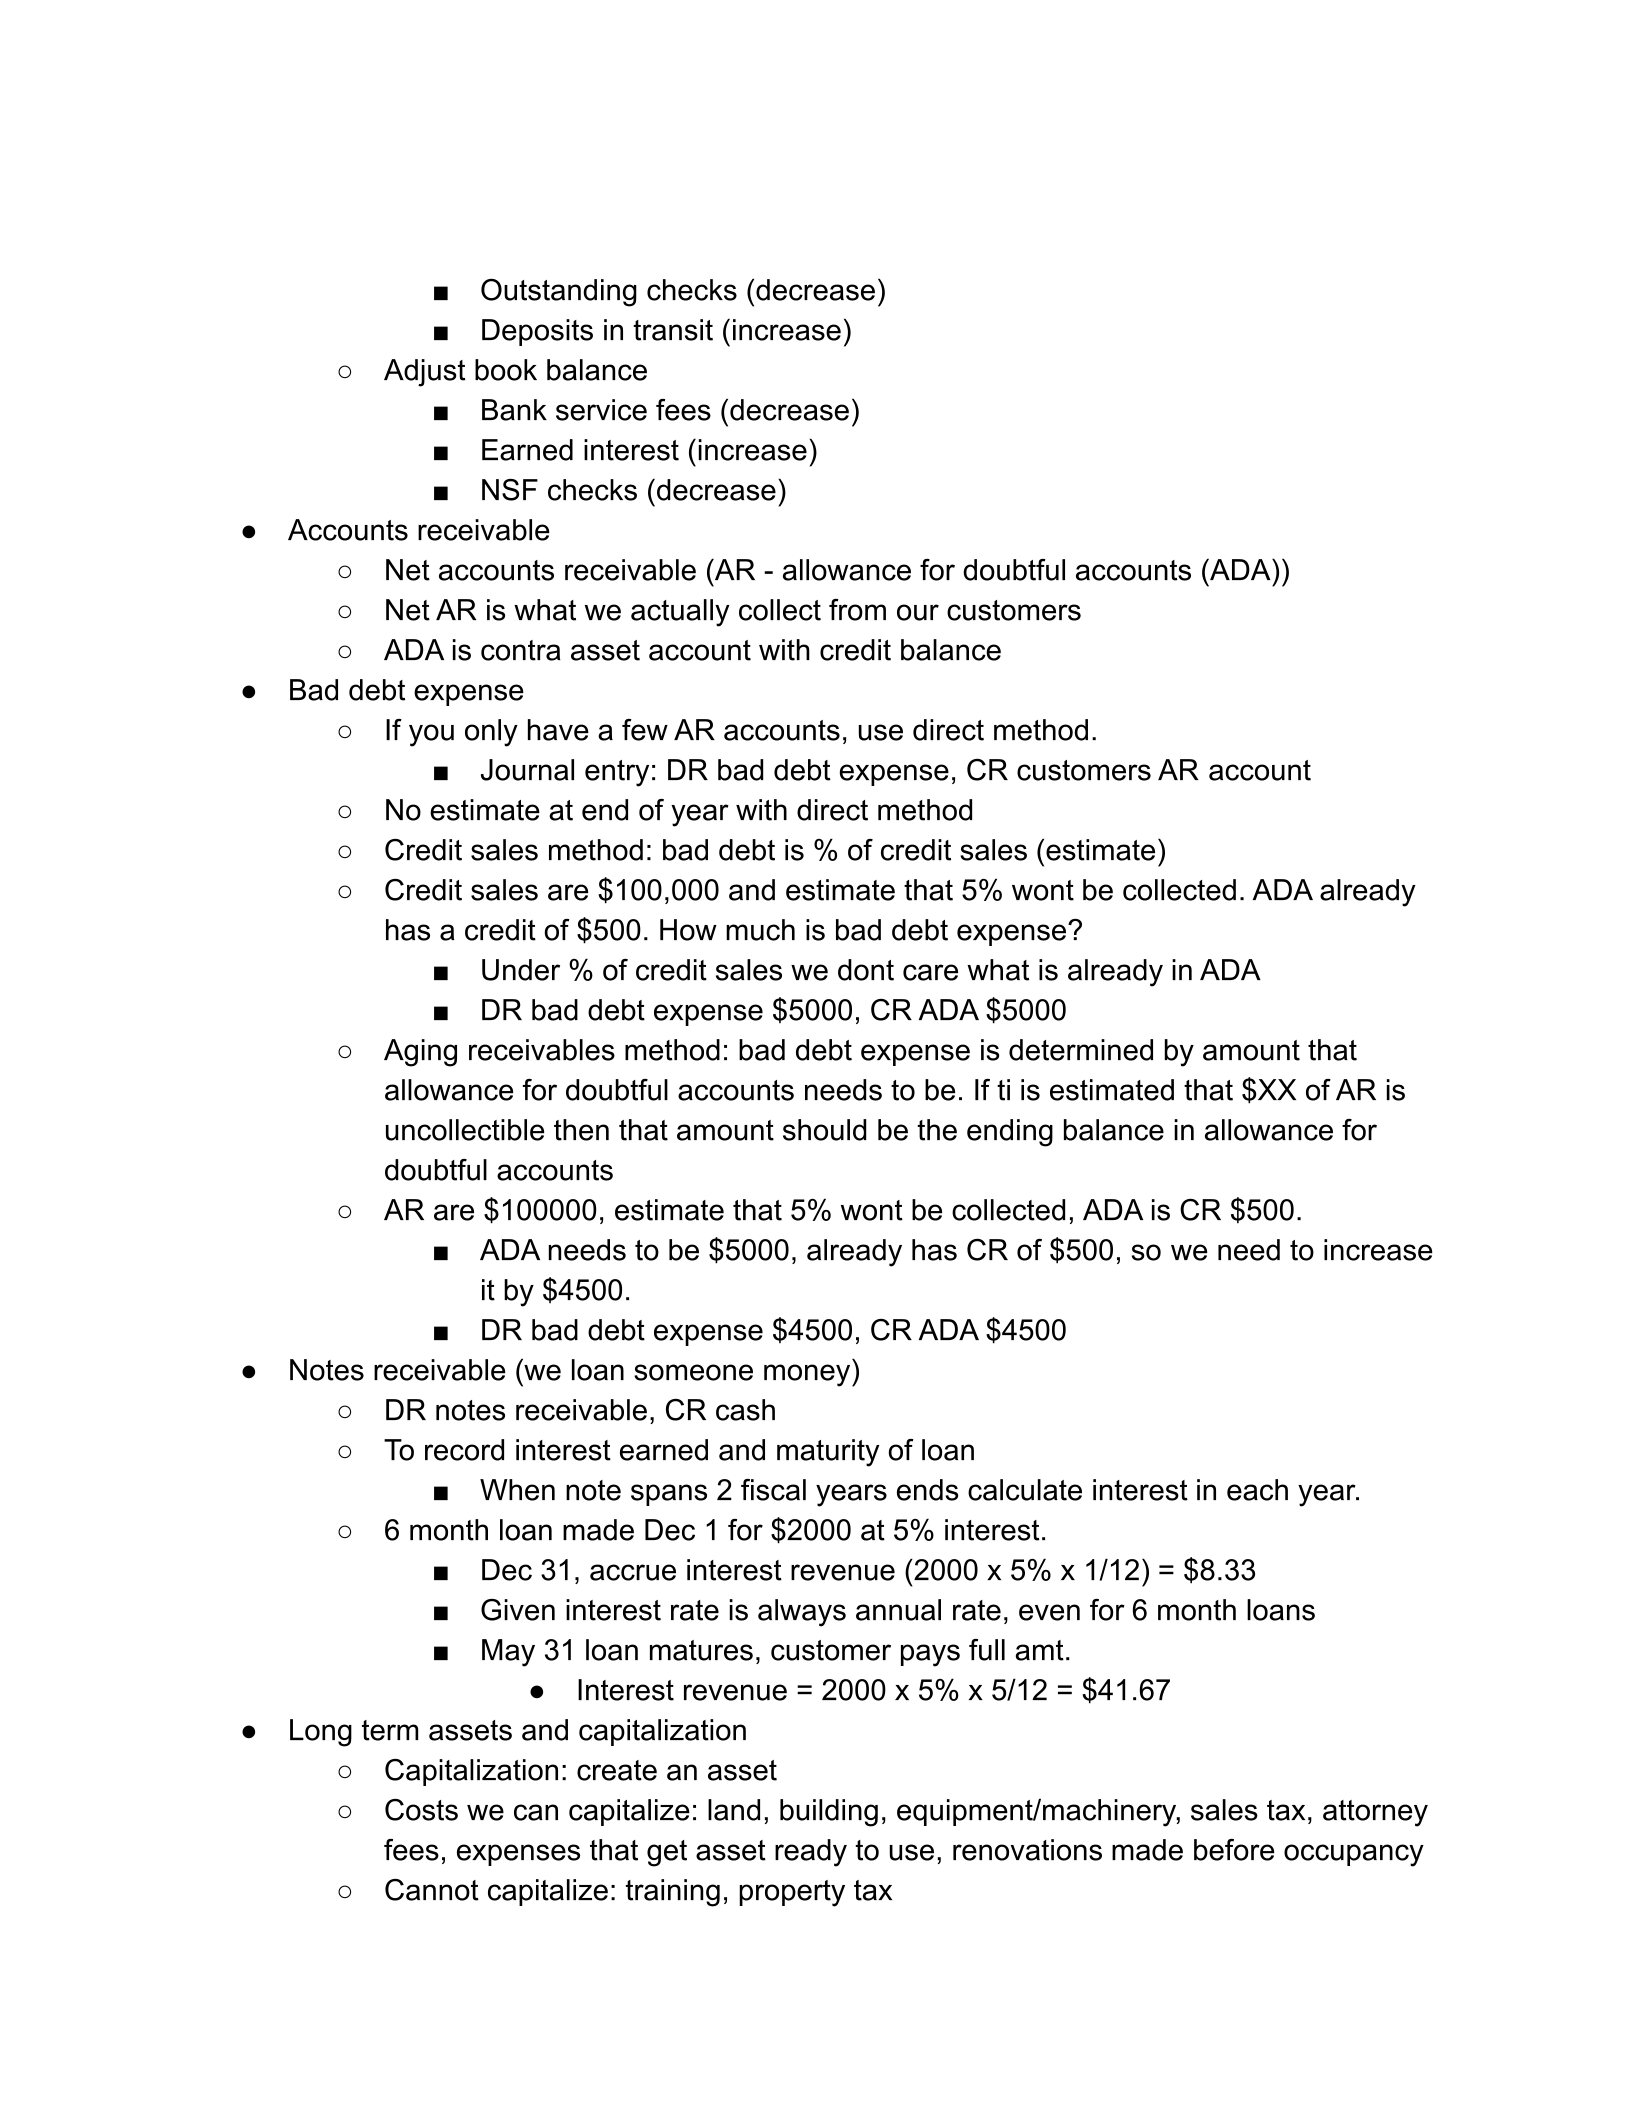
■ Outstanding checks (decrease)
■ Deposits in transit (increase)
○ Adjust book balance
■ Bank service fees (decrease)
■ Earned interest (increase)
■ NSF checks (decrease)
● Accounts receivable
○ Net accounts receivable (AR - allowance for doubtful accounts (ADA))
○ Net AR is what we actually collect from our customers
○ ADA is contra asset account with credit balance
● Bad debt expense
○ If you only have a few AR accounts, use direct method.
■ Journal entry: DR bad debt expense, CR customers AR account
○ No estimate at end of year with direct method
○ Credit sales method: bad debt is % of credit sales (estimate)
○ Credit sales are $100,000 and estimate that 5% wont be collected. ADA already
has a credit of $500. How much is bad debt expense?
■ Under % of credit sales we dont care what is already in ADA
■ DR bad debt expense $5000, CR ADA $5000
○ Aging receivables method: bad debt expense is determined by amount that
allowance for doubtful accounts needs to be. If ti is estimated that $XX of AR is
uncollectible then that amount should be the ending balance in allowance for
doubtful accounts
○ AR are $100000, estimate that 5% wont be collected, ADA is CR $500.
■ ADA needs to be $5000, already has CR of $500, so we need to increase
it by $4500.
■ DR bad debt expense $4500, CR ADA $4500
● Notes receivable (we loan someone money)
○ DR notes receivable, CR cash
○ To record interest earned and maturity of loan
■ When note spans 2 fiscal years ends calculate interest in each year.
○ 6 month loan made Dec 1 for $2000 at 5% interest.
■ Dec 31, accrue interest revenue (2000 x 5% x 1/12) = $8.33
■ Given interest rate is always annual rate, even for 6 month loans
■ May 31 loan matures, customer pays full amt.
● Interest revenue = 2000 x 5% x 5/12 = $41.67
● Long term assets and capitalization
○ Capitalization: create an asset
○ Costs we can capitalize: land, building, equipment/machinery, sales tax, attorney
fees, expenses that get asset ready to use, renovations made before occupancy
○ Cannot capitalize: training, property tax
● Bank reconciliations
○ Adjust bank balance:
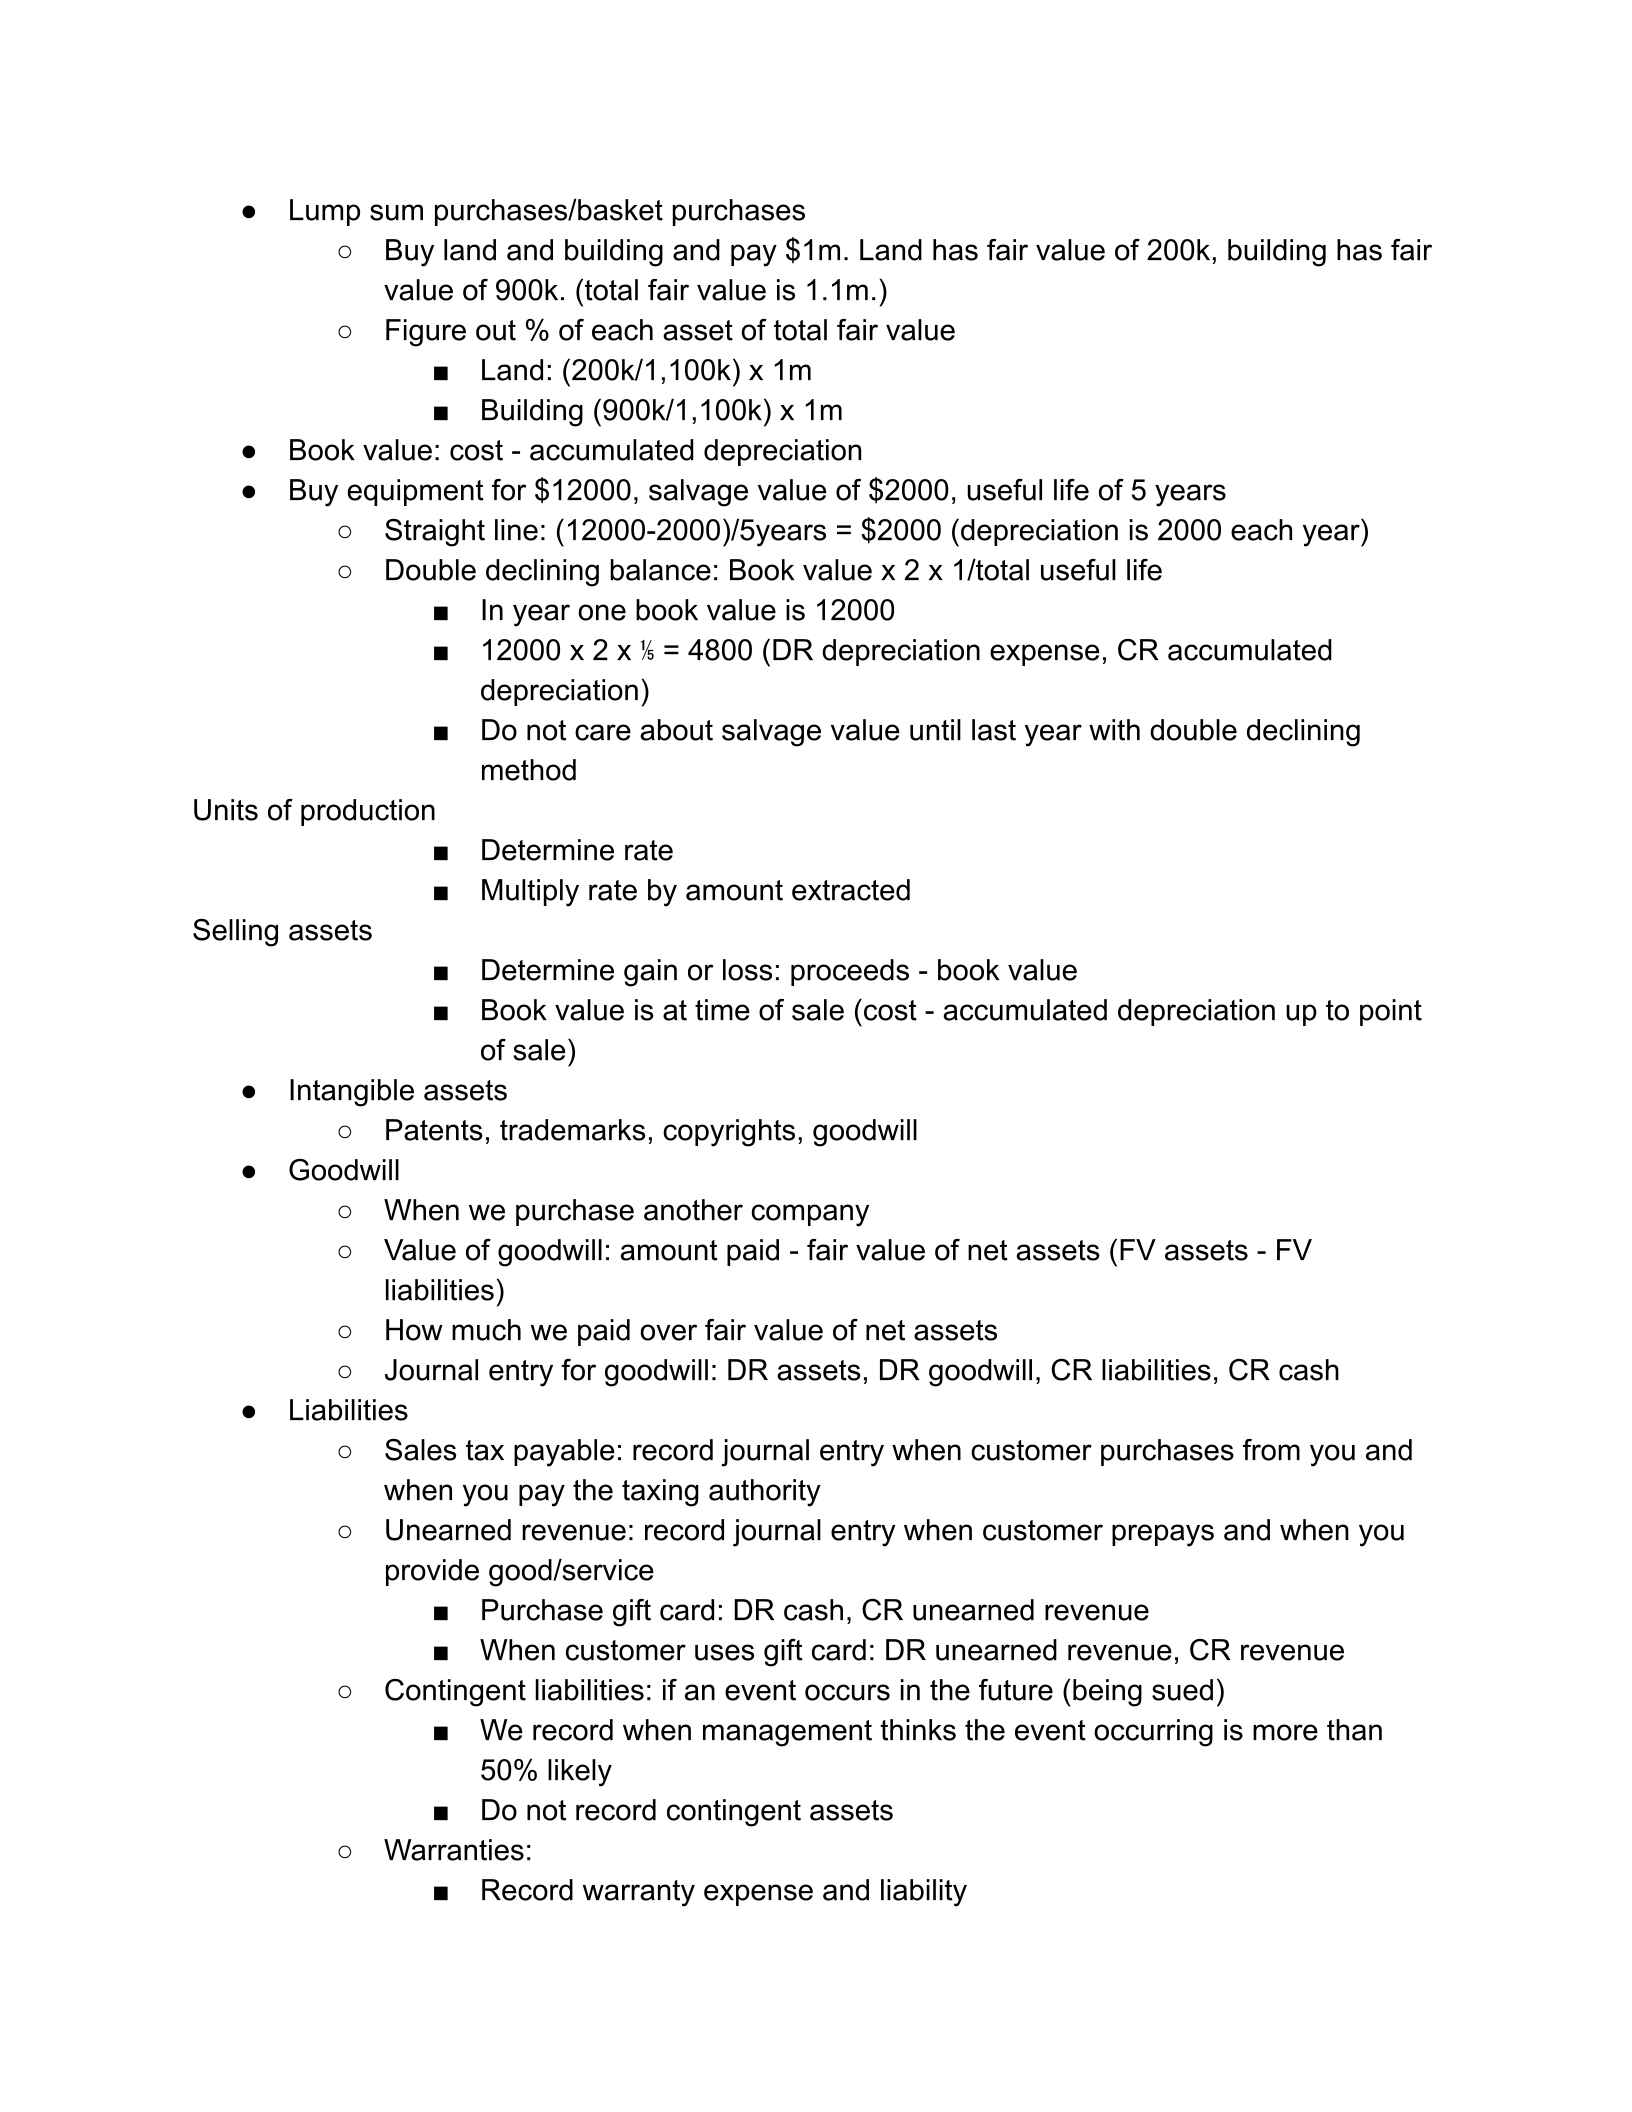
● Lump sum purchases/basket purchases
○ Buy land and building and pay $1m. Land has fair value of 200k, building has fair
value of 900k. (total fair value is 1.1m.)
○ Figure out % of each asset of total fair value
■ Land: (200k/1,100k) x 1m
■ Building (900k/1,100k) x 1m
● Book value: cost - accumulated depreciation
● Buy equipment for $12000, salvage value of $2000, useful life of 5 years
○ Straight line: (12000-2000)/5years = $2000 (depreciation is 2000 each year)
○ Double declining balance: Book value x 2 x 1/total useful life
■ In year one book value is 12000
■ 12000 x 2 x ⅕ = 4800 (DR depreciation expense, CR accumulated
depreciation)
■ Do not care about salvage value until last year with double declining
method
Units of production
■ Determine rate
■ Multiply rate by amount extracted
Selling assets
■ Determine gain or loss: proceeds - book value
■ Book value is at time of sale (cost - accumulated depreciation up to point
of sale)
● Intangible assets
○ Patents, trademarks, copyrights, goodwill
● Goodwill
○ When we purchase another company
○ Value of goodwill: amount paid - fair value of net assets (FV assets - FV
liabilities)
○ How much we paid over fair value of net assets
○ Journal entry for goodwill: DR assets, DR goodwill, CR liabilities, CR cash
● Liabilities
○ Sales tax payable: record journal entry when customer purchases from you and
when you pay the taxing authority
○ Unearned revenue: record journal entry when customer prepays and when you
provide good/service
■ Purchase gift card: DR cash, CR unearned revenue
■ When customer uses gift card: DR unearned revenue, CR revenue
○ Contingent liabilities: if an event occurs in the future (being sued)
■ We record when management thinks the event occurring is more than
50% likely
■ Do not record contingent assets
○ Warranties:
■ Record warranty expense and liability
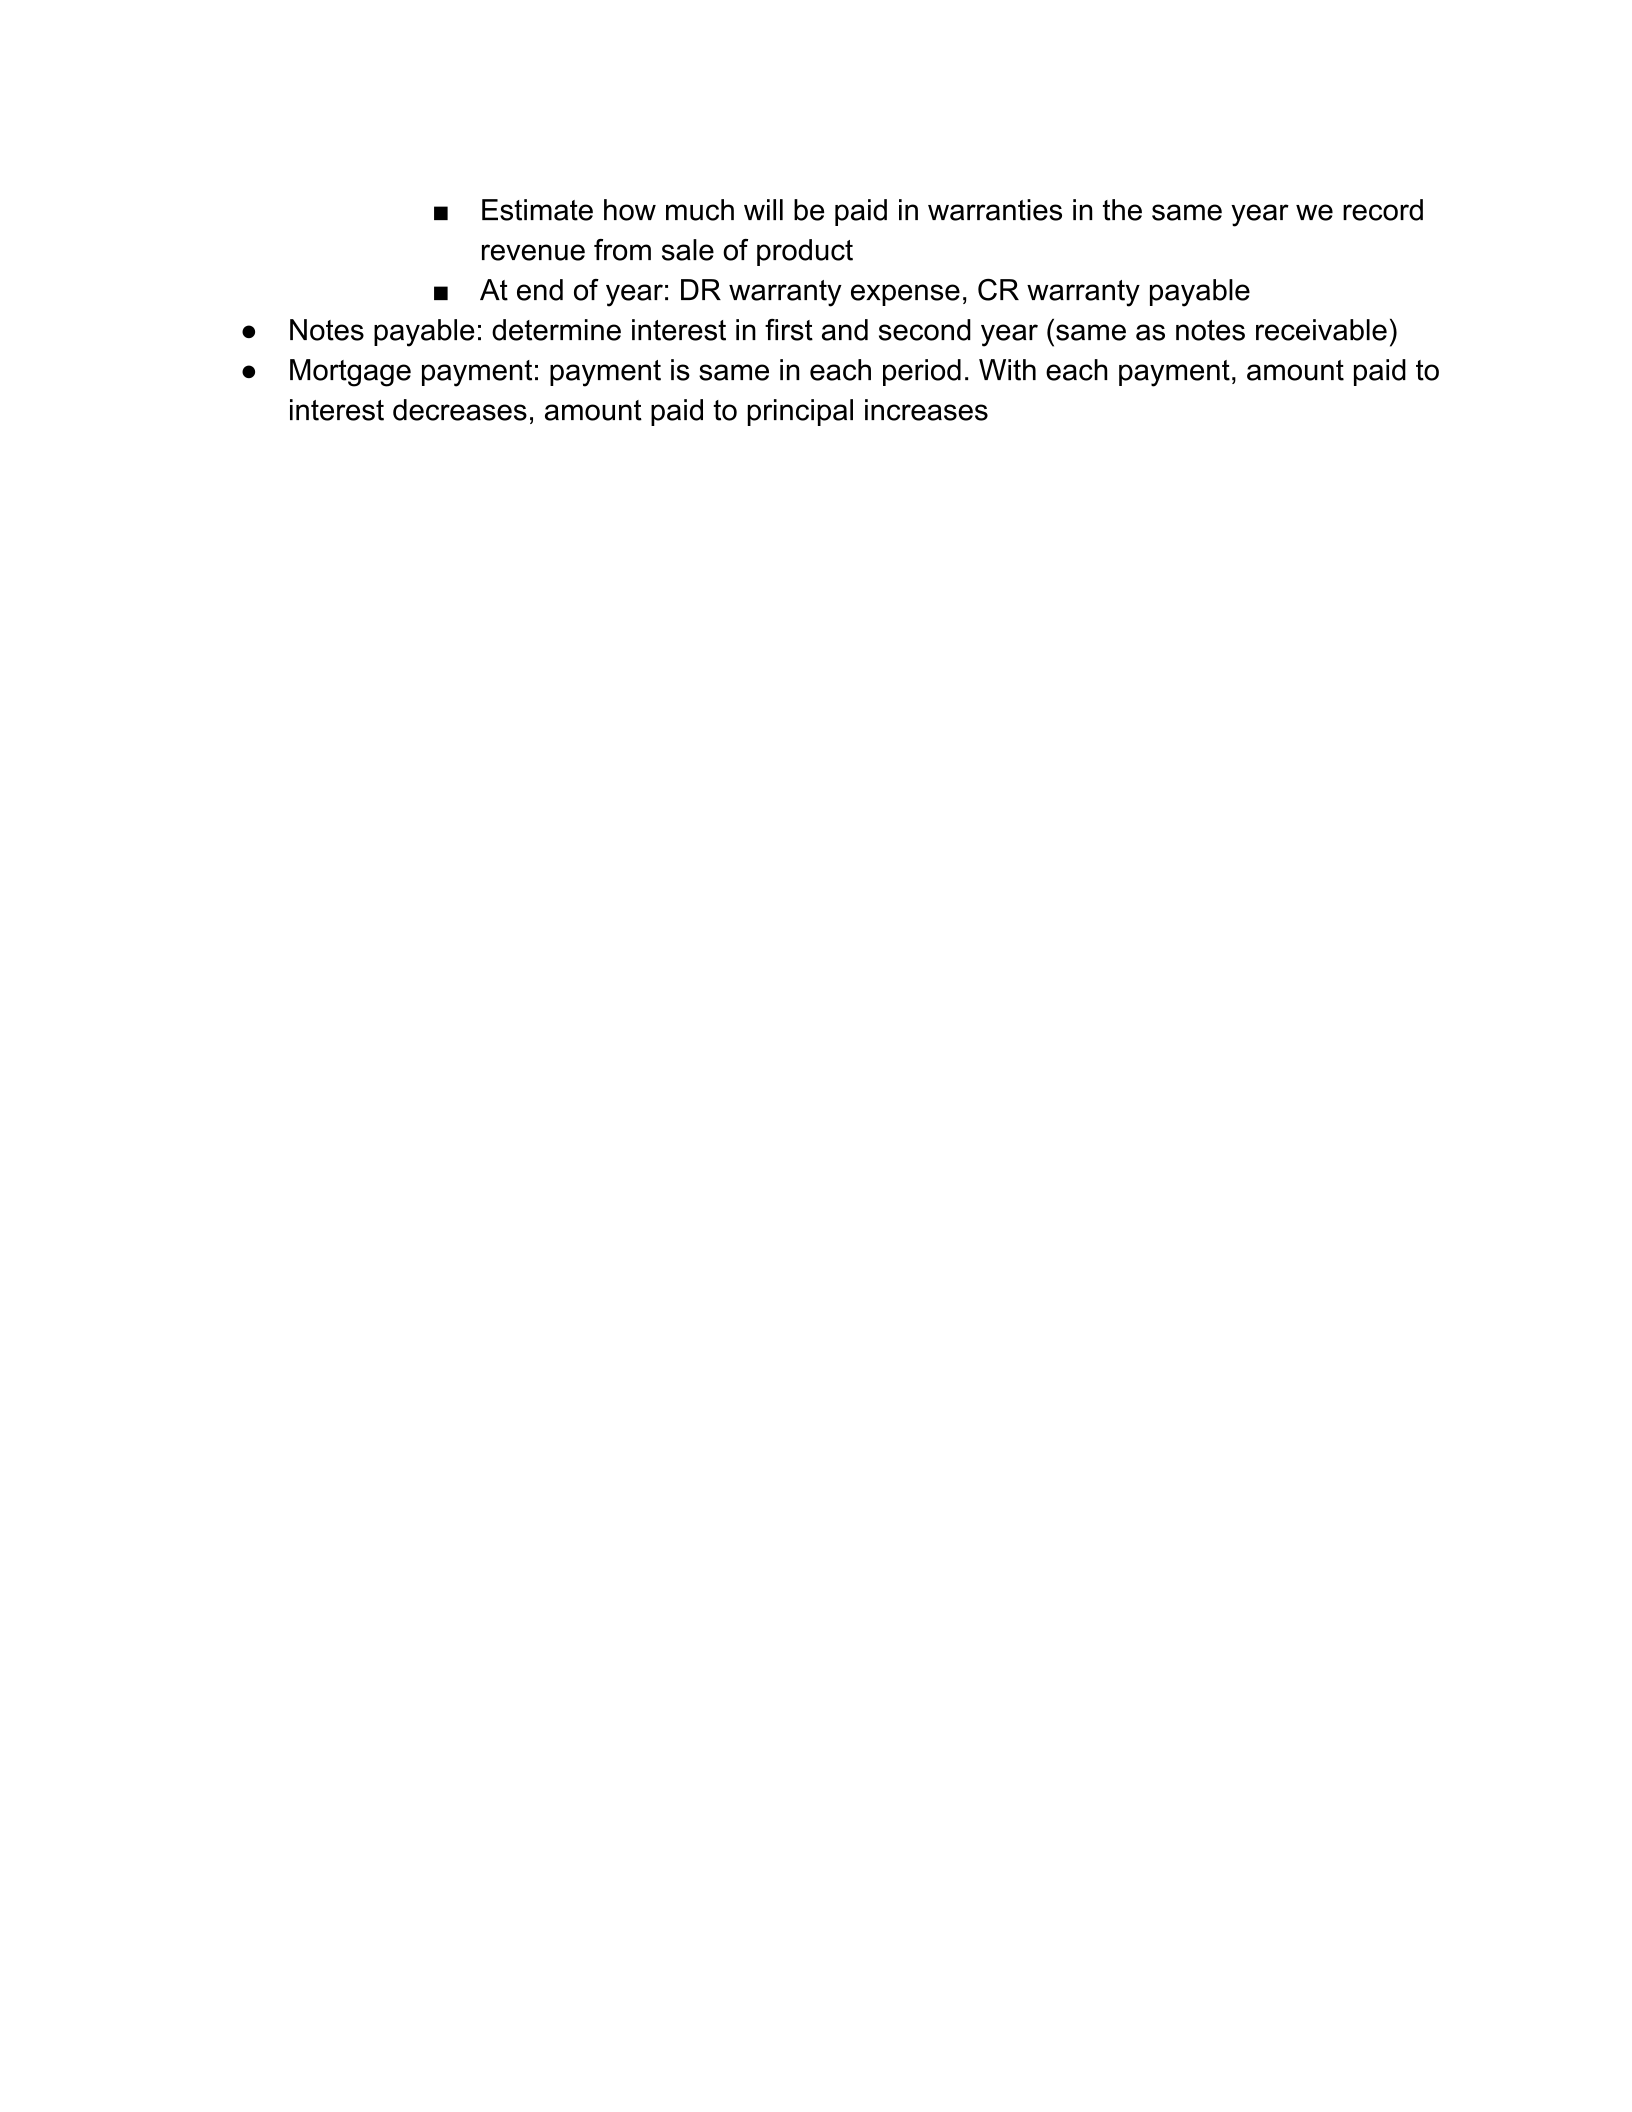
■ Estimate how much will be paid in warranties in the same year we record
revenue from sale of product
■ At end of year: DR warranty expense, CR warranty payable
● Notes payable: determine interest in first and second year (same as notes receivable)
● Mortgage payment: payment is same in each period. With each payment, amount paid to
interest decreases, amount paid to principal increases
Powered by TCPDF (www.tcpdf.org)

