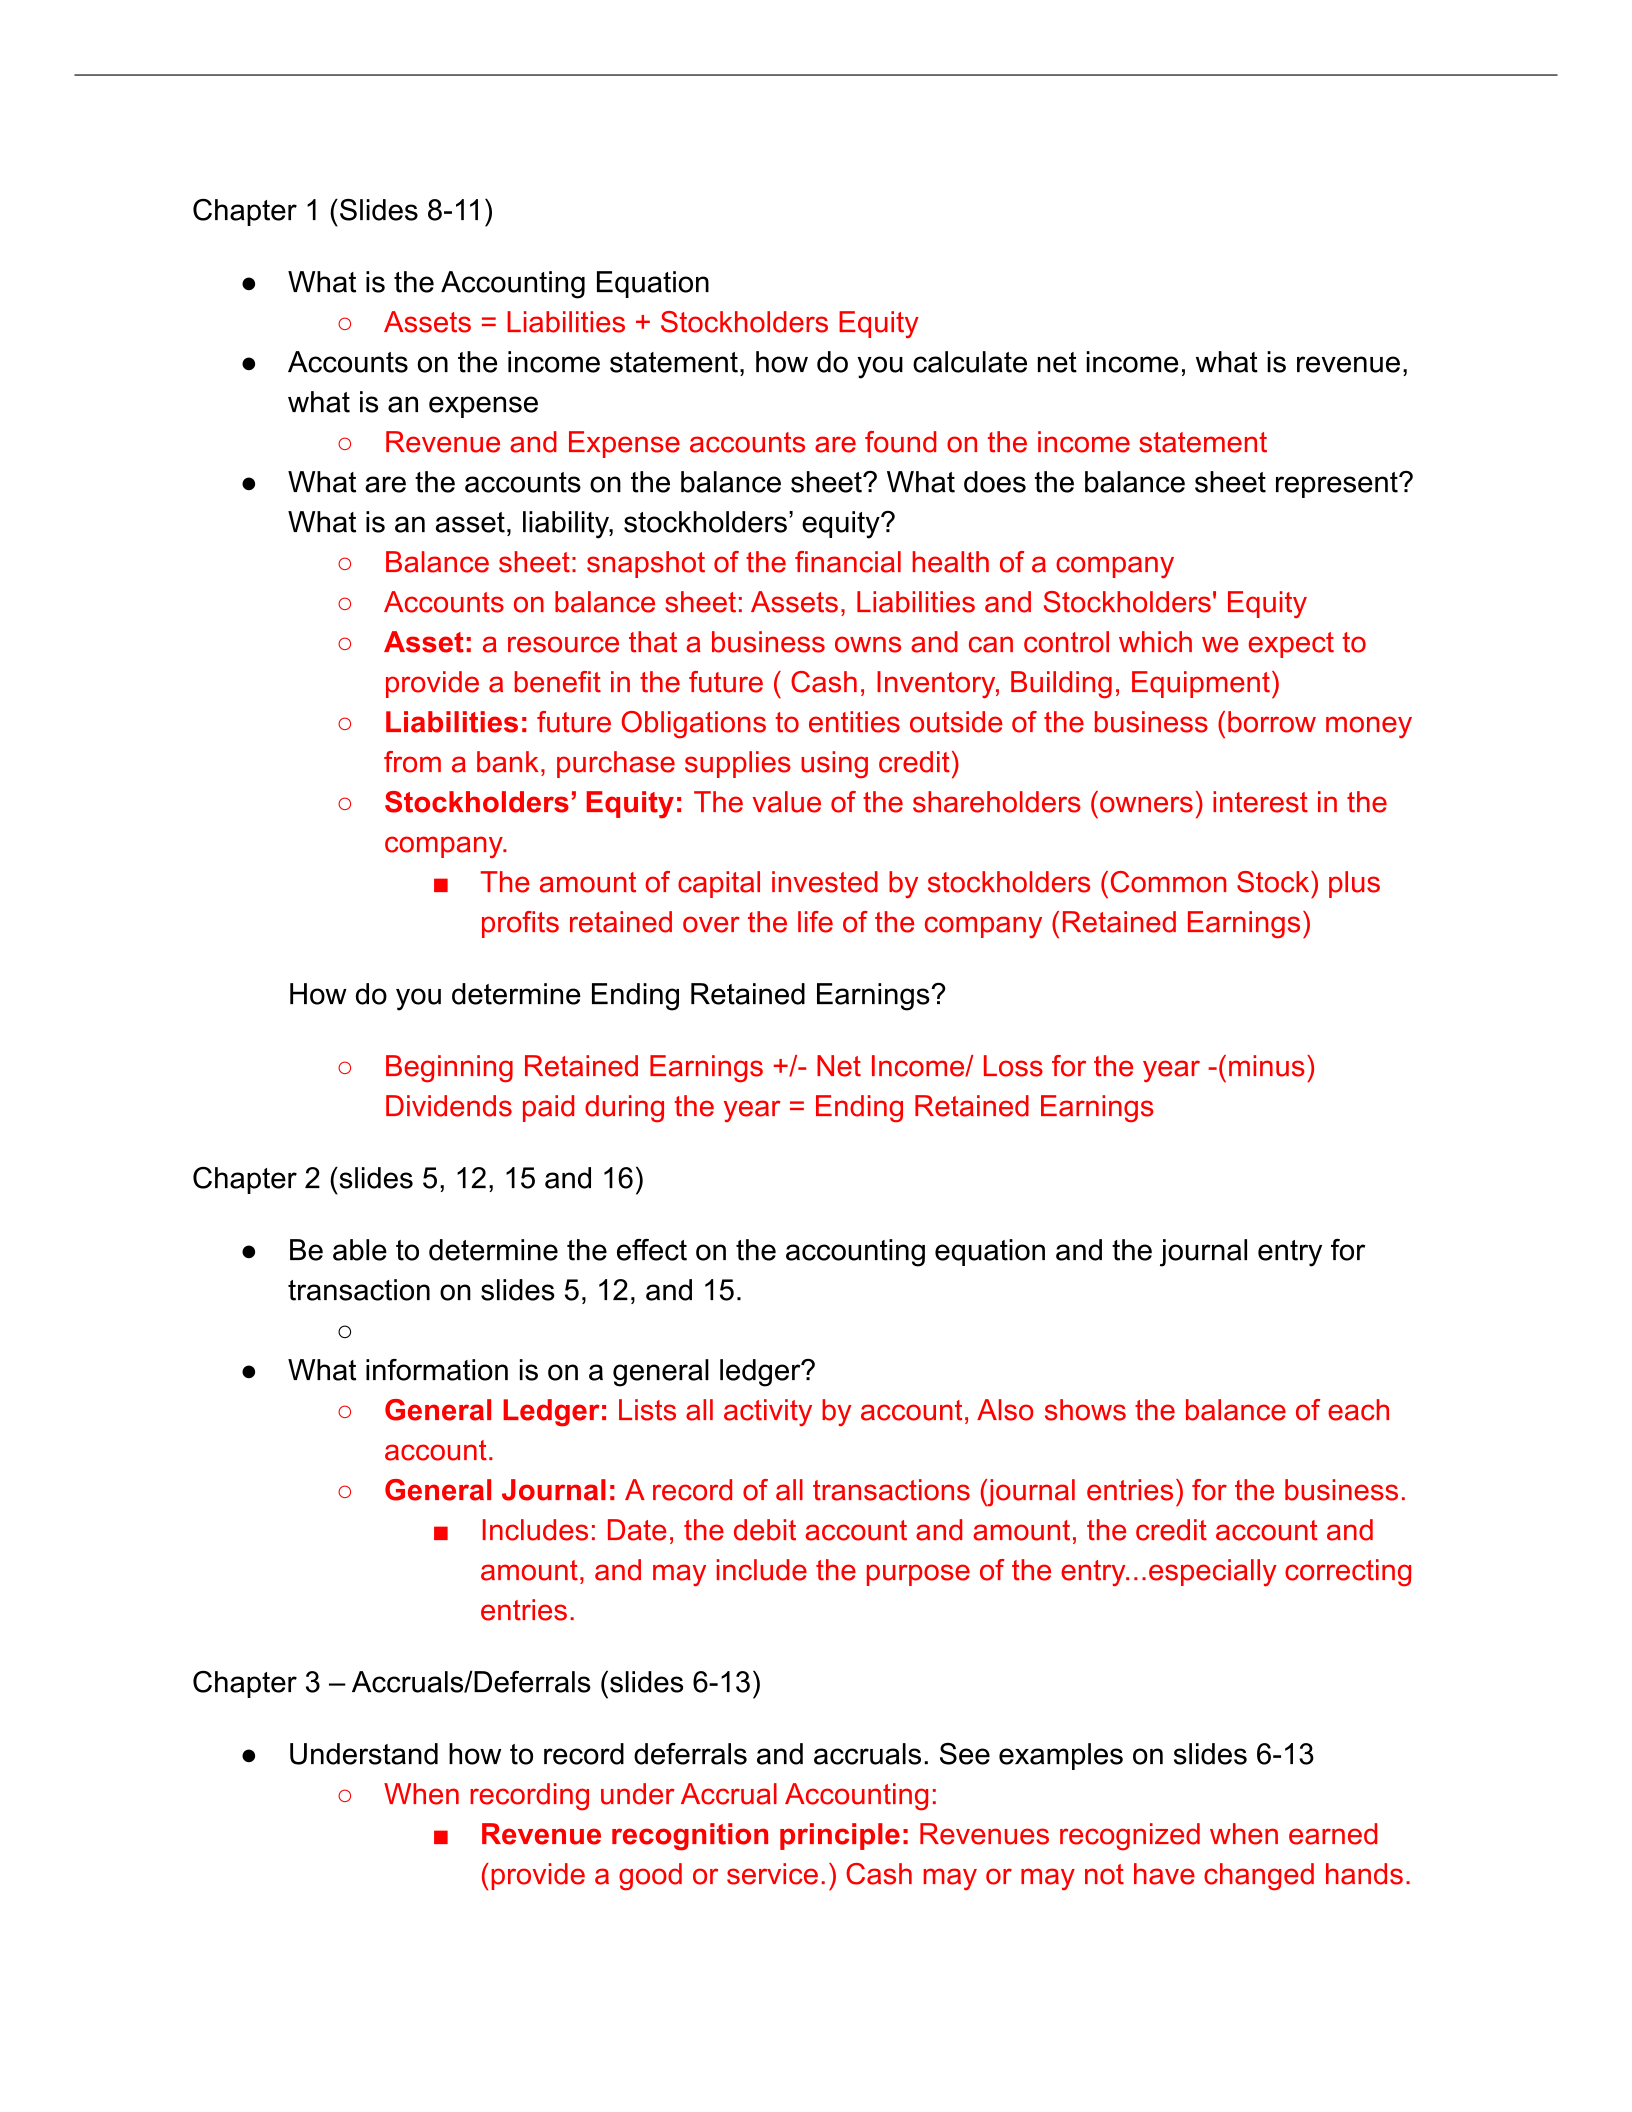
Chapter 1 (Slides 8-11)
● What is the Accounting Equation
○ Assets = Liabilities + Stockholders Equity
● Accounts on the income statement, how do you calculate net income, what is revenue,
what is an expense
○ Revenue and Expense accounts are found on the income statement
● What are the accounts on the balance sheet? What does the balance sheet represent?
What is an asset, liability, stockholders’ equity?
○ Balance sheet: snapshot of the financial health of a company
○ Accounts on balance sheet: Assets, Liabilities and Stockholders' Equity
○Asset: a resource that a business owns and can control which we expect to
provide a benefit in the future ( Cash, Inventory, Building, Equipment)
○Liabilities: future Obligations to entities outside of the business (borrow money
from a bank, purchase supplies using credit)
○ Stockholders’ Equity: The value of the shareholders (owners) interest in the
company.
■ The amount of capital invested by stockholders (Common Stock) plus
profits retained over the life of the company (Retained Earnings)
How do you determine Ending Retained Earnings?
○ Beginning Retained Earnings +/- Net Income/ Loss for the year -(minus)
Dividends paid during the year = Ending Retained Earnings
Chapter 2 (slides 5, 12, 15 and 16)
● Be able to determine the effect on the accounting equation and the journal entry for
transaction on slides 5, 12, and 15.
○
● What information is on a general ledger?
○ General Ledger: Lists all activity by account, Also shows the balance of each
account.
○ General Journal: A record of all transactions (journal entries) for the business.
■ Includes: Date, the debit account and amount, the credit account and
amount, and may include the purpose of the entry...especially correcting
entries.
Chapter 3 – Accruals/Deferrals (slides 6-13)
● Understand how to record deferrals and accruals. See examples on slides 6-13
○ When recording under Accrual Accounting:
■ Revenue recognition principle: Revenues recognized when earned
(provide a good or service.) Cash may or may not have changed hands.
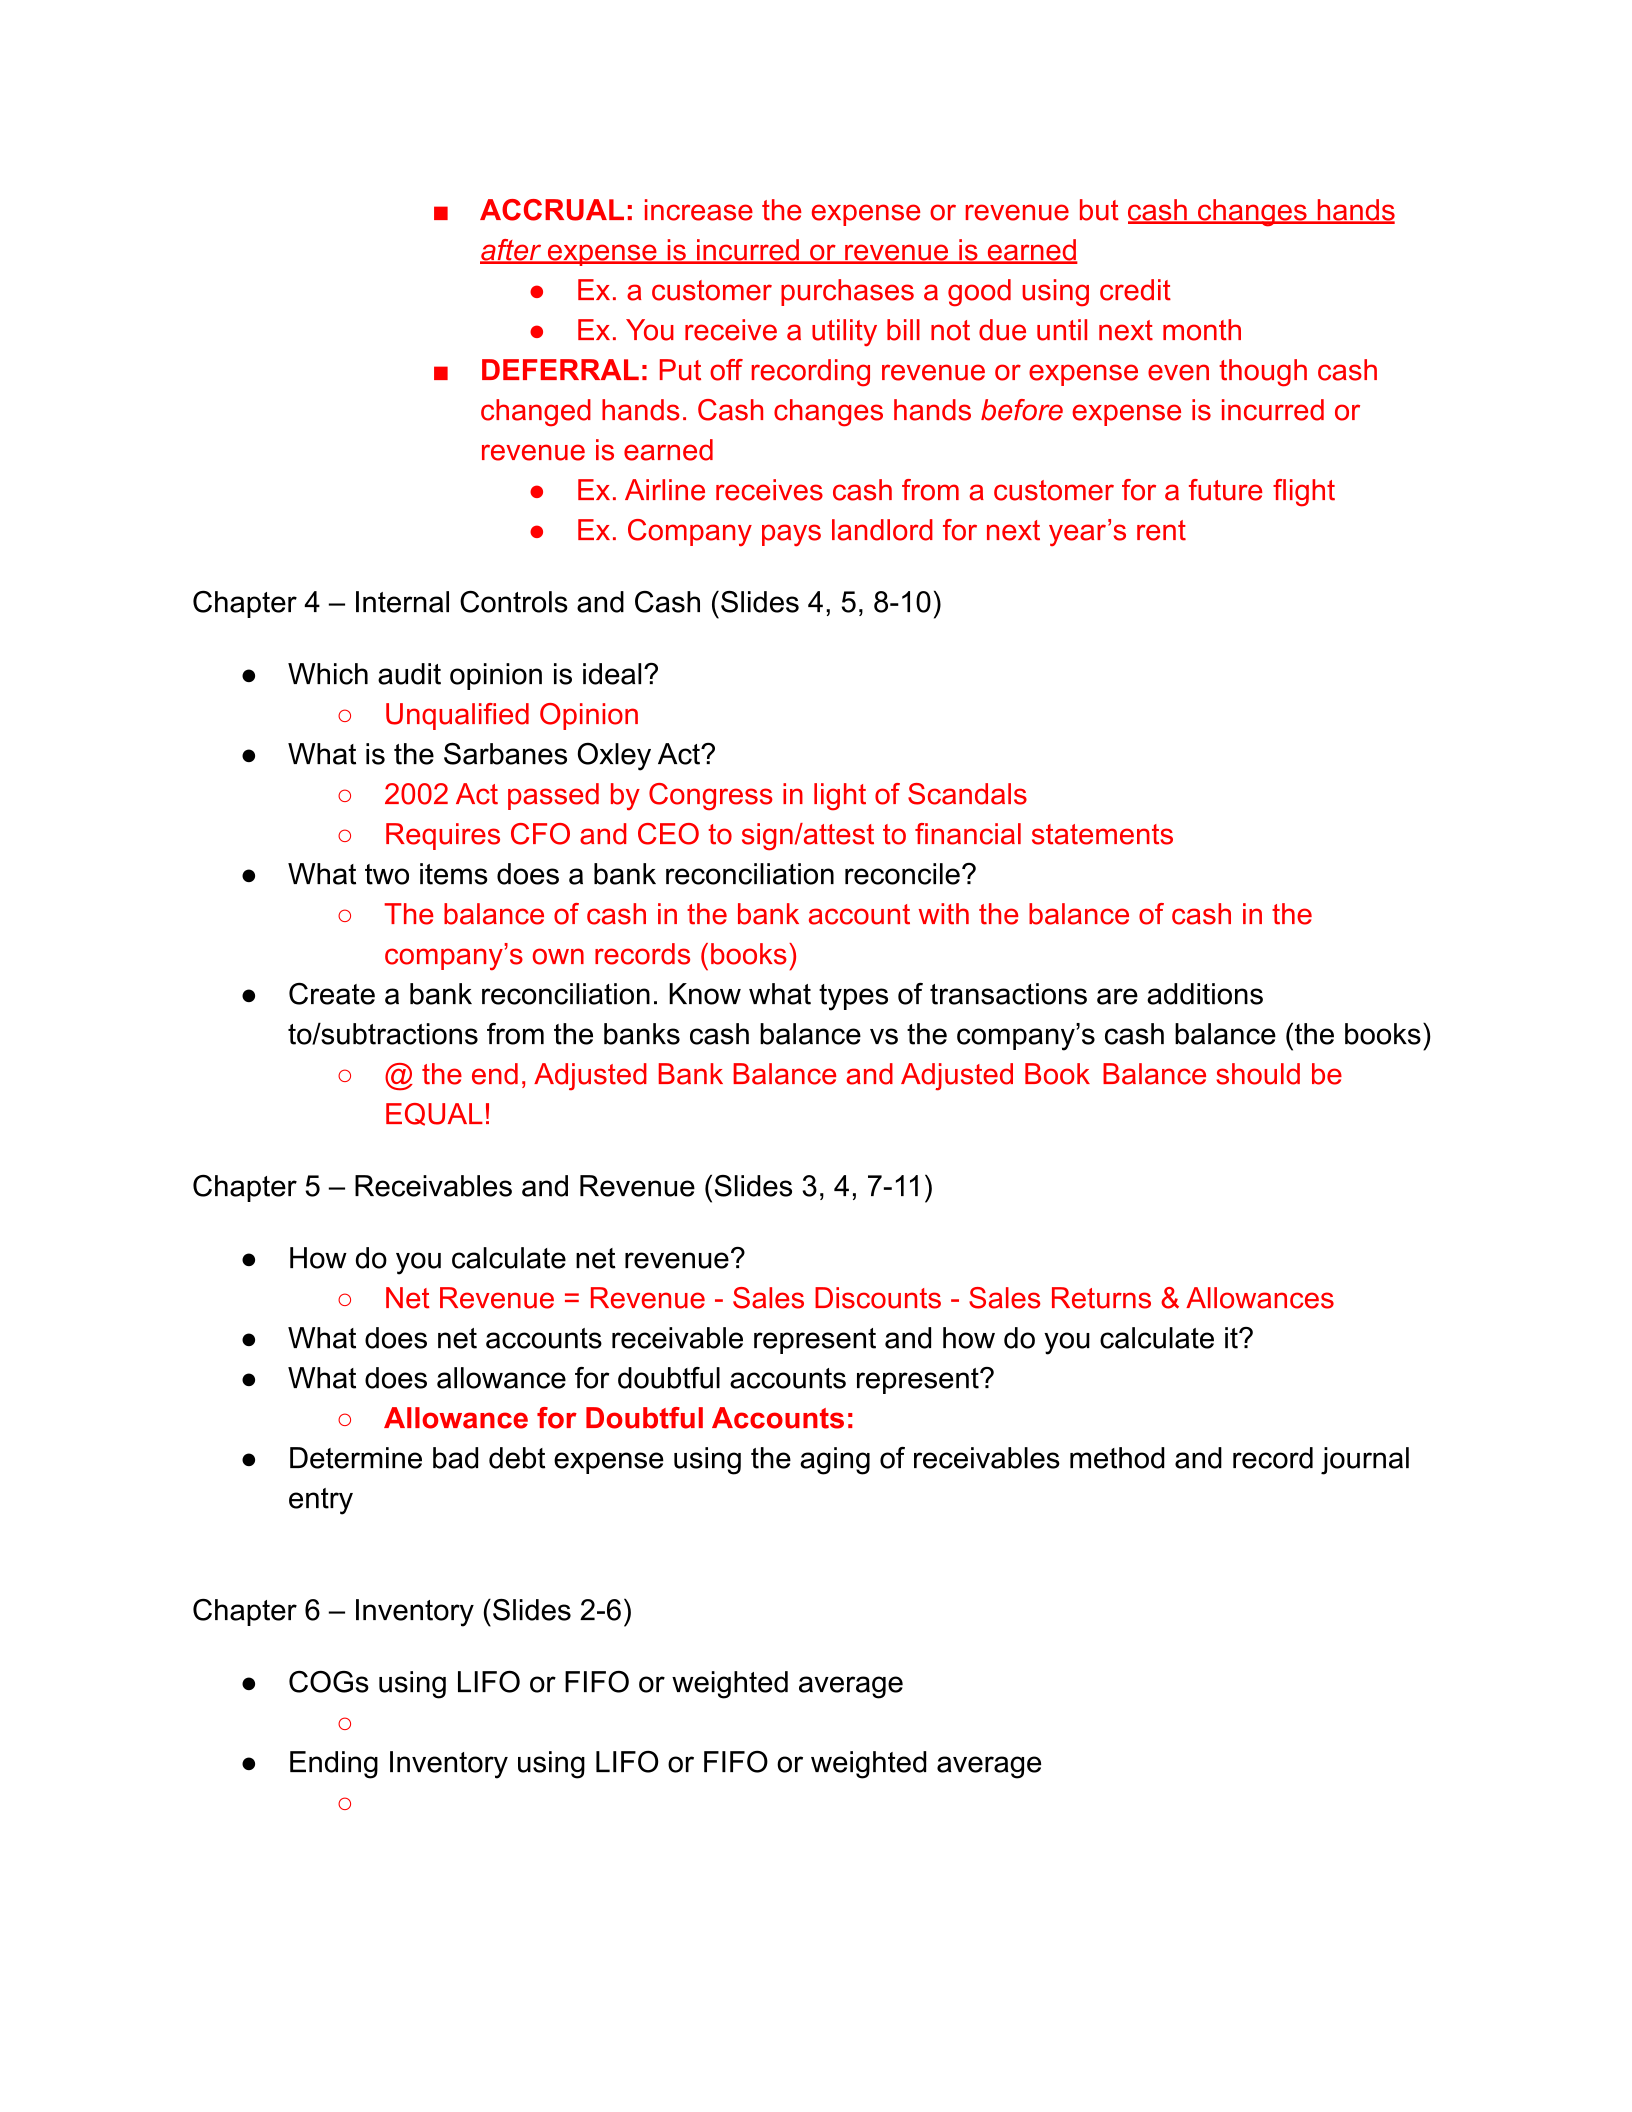
■ ACCRUAL: increase the expense or revenue but cash changes hands
after expense is incurred or revenue is earned
● Ex. a customer purchases a good using credit
● Ex. You receive a utility bill not due until next month
■ DEFERRAL: Put off recording revenue or expense even though cash
changed hands. Cash changes hands before expense is incurred or
revenue is earned
● Ex. Airline receives cash from a customer for a future flight
● Ex. Company pays landlord for next year’s rent
Chapter 4 – Internal Controls and Cash (Slides 4, 5, 8-10)
● Which audit opinion is ideal?
○ Unqualified Opinion
● What is the Sarbanes Oxley Act?
○ 2002 Act passed by Congress in light of Scandals
○ Requires CFO and CEO to sign/attest to financial statements
● What two items does a bank reconciliation reconcile?
○ The balance of cash in the bank account with the balance of cash in the
company’s own records (books)
● Create a bank reconciliation. Know what types of transactions are additions
to/subtractions from the banks cash balance vs the company’s cash balance (the books)
○ @ the end, Adjusted Bank Balance and Adjusted Book Balance should be
EQUAL!
Chapter 5 – Receivables and Revenue (Slides 3, 4, 7-11)
● How do you calculate net revenue?
○ Net Revenue = Revenue - Sales Discounts - Sales Returns & Allowances
● What does net accounts receivable represent and how do you calculate it?
● What does allowance for doubtful accounts represent?
○ Allowance for Doubtful Accounts:
● Determine bad debt expense using the aging of receivables method and record journal
entry
Chapter 6 – Inventory (Slides 2-6)
● COGs using LIFO or FIFO or weighted average
○
● Ending Inventory using LIFO or FIFO or weighted average
○
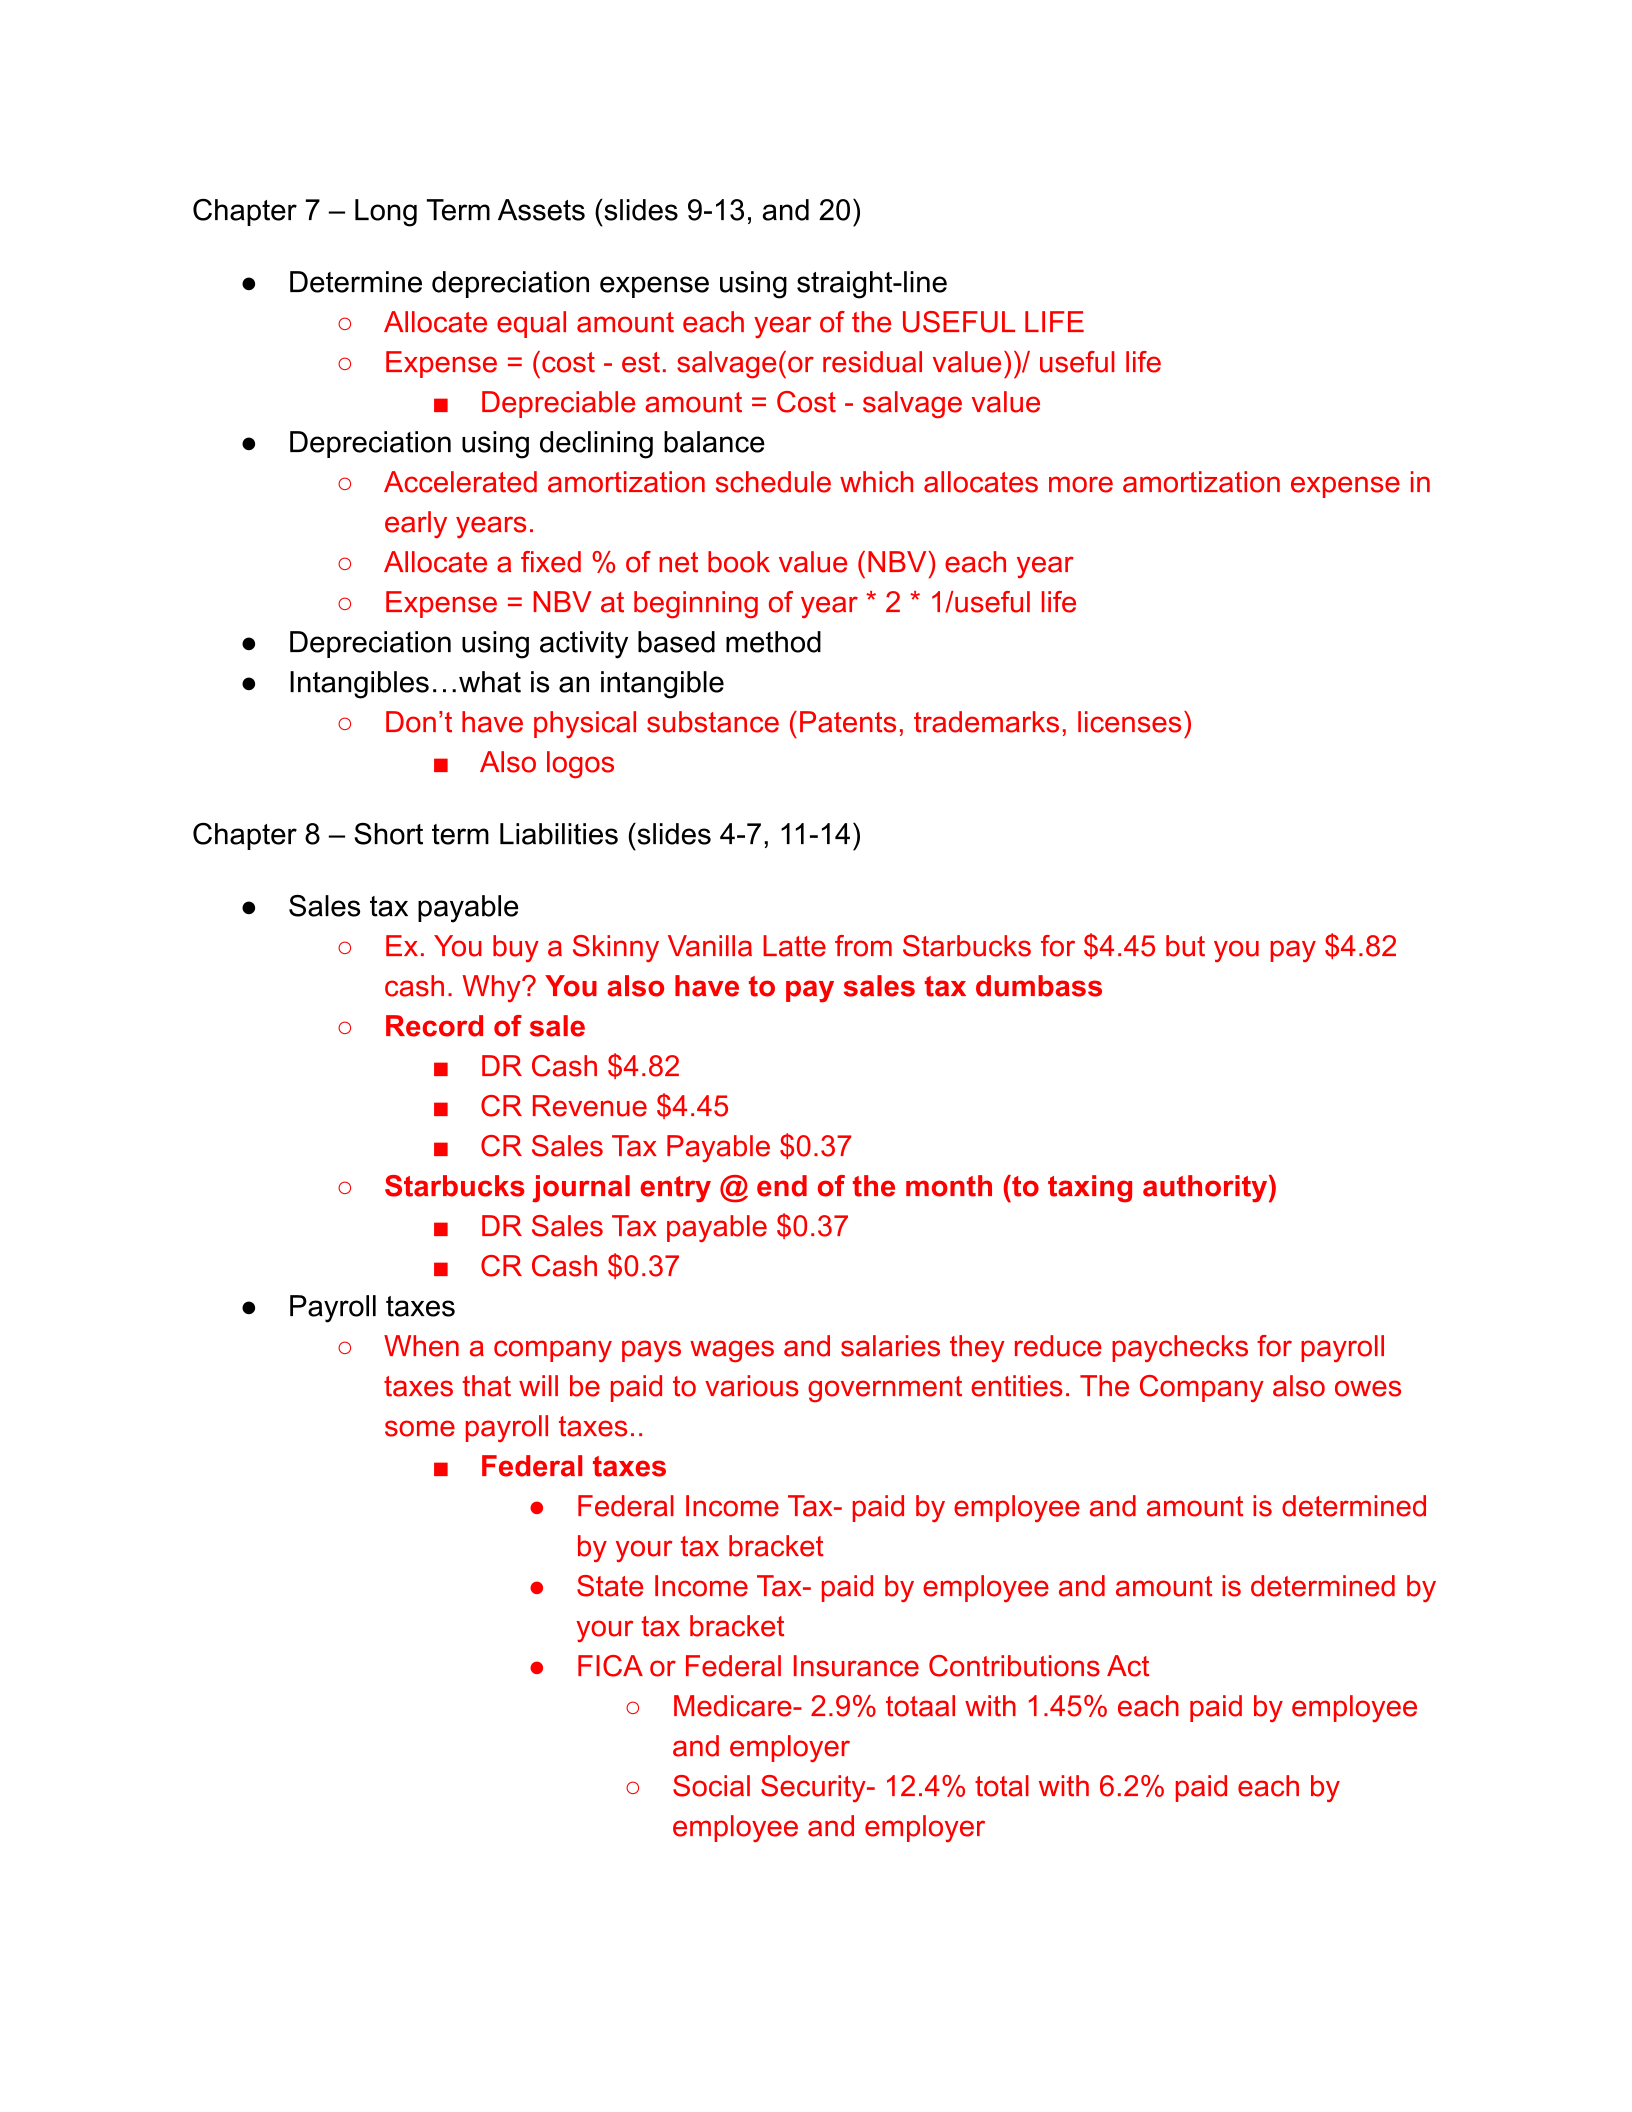
Chapter 7 – Long Term Assets (slides 9-13, and 20)
● Determine depreciation expense using straight-line
○ Allocate equal amount each year of the USEFUL LIFE
○ Expense = (cost - est. salvage(or residual value))/ useful life
■ Depreciable amount = Cost - salvage value
● Depreciation using declining balance
○ Accelerated amortization schedule which allocates more amortization expense in
early years.
○ Allocate a fixed % of net book value (NBV) each year
○ Expense = NBV at beginning of year * 2 * 1/useful life
● Depreciation using activity based method
● Intangibles…what is an intangible
○ Don’t have physical substance (Patents, trademarks, licenses)
■ Also logos
Chapter 8 – Short term Liabilities (slides 4-7, 11-14)
● Sales tax payable
○ Ex. You buy a Skinny Vanilla Latte from Starbucks for $4.45 but you pay $4.82
cash. Why? You also have to pay sales tax dumbass
○ Record of sale
■ DR Cash $4.82
■ CR Revenue $4.45
■ CR Sales Tax Payable $0.37
○ Starbucks journal entry @ end of the month (to taxing authority)
■ DR Sales Tax payable $0.37
■ CR Cash $0.37
● Payroll taxes
○ When a company pays wages and salaries they reduce paychecks for payroll
taxes that will be paid to various government entities. The Company also owes
some payroll taxes..
■ Federal taxes
● Federal Income Tax- paid by employee and amount is determined
by your tax bracket
● State Income Tax- paid by employee and amount is determined by
your tax bracket
● FICA or Federal Insurance Contributions Act
○ Medicare- 2.9% totaal with 1.45% each paid by employee
and employer
○ Social Security- 12.4% total with 6.2% paid each by
employee and employer
●Short term note payable how much interest expense do you record in each year if the
loan spans two fiscal periods? (slide 9)
Chapter 9 – Long term liabilities (slides 4-6, 8, and 9)
● Determine the interest expense and the amount of principle from a mortgage payment
and also the remaining mortgage payable balance after the payment
● Bonds
● If stated rate = market rate, bond is issued at PAR
● If stated rate is > market rate, bond is issued at a PREMIUM
■ Investors will receive high interest payments so will be willing to pay more
than the face value of the bond.
● If stated rate is < market rate, bond is issued at a DISCOUNT
● when stated rate is higher/lower than market rate issued at premium/discount
● when bond is sold at 102 vs 97 how much does bond sell at?
Chapter 10 – Stockholders Equity (slides 4, 6- 8, 10-13, 14-16)
● Record sale of stock with and without par
○
● Record journal entries for the declaration and date of payment for dividends
● Record journal entry to purchase Treasury stock? What is it? Does it increase or
decrease stockholders equity?
Chapter 11 – Cash flow statement (slides 4-7, 10-13)
● What does each category in the cash flow statement represent? (slide 3)
● Examples of increases and decreases in each category
● What does the change in cash flow reconcile to on the balance sheet?
● What does the operating section start with?
Chapter 12 – Financial statement analysis (slides 5, 6, 8, 10, 17, 18)
● What is a discontinued Operation?
● How do you calculate a % change?
● How do you calculate a trend %?
● What are the calculations when performing vertical analysis?
● common size income statement?