


Explain why an Interest Rate Swap (assume LIBOR as the floating rate) with quarterly settlement (assume 90 days per quarter) can be viewed as a strip of Eurodollar futures contracts. (Note: A strip is a sequence of ED futures with successive expirations
 navingolyan
(a) Explain why an Interest Rate Swap (assume LIBOR as the floating rate) with quarterly
settlement (assume 90 days per quarter) can be viewed as a strip of Eurodollar futures
contracts. (Note: A strip is a sequence of ED futures with successive expirations)
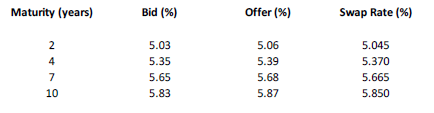
(b) The following table gives the bid and offer fixed rates in the swap market and the
corresponding swap rates
Maturity (years) Bid (%) Offer (%) Swap Rate (%)
2 5.03 5.06 5.045
4 5.35 5.39 5.370
7 5.65 5.68 5.665
10 5.83 5.87 5.850
(i) Suppose that Company X can invest for 4 years at 4.5%. Recommend a floating
rate, can it swap this fixed rate into?
(ii) Company Y can invest for 10 years at LIBOR minus 50 basis points.
Recommend a fixed rate, can it swap this floating rate into?
 8 years ago
Purchase the answer to view it


