


Diversification of the Family Business
LAW 6003 - Business Law
University of Cincinnati
October 25, 2024

Foreword
Analysis of family businesses, as well as research into
issues that may not only be unique to the family
business concept such as diversification, succession and
corporate governance, to name a few is not a new
practice, but rather a well established practice from
both, an academic as well as a practical perspective.
Within this study, the main aim is to establish the effect
of previously mentioned processes with specific
emphasis upon diversification in the family businesses,
as well as the resulting effect or effects, brought about
by such strategic decision making and diversification
processes.
A combination of primary and secondary research
helped assessing these effects, as well as the
consequences whether based on a positive or negative
outcome, in addition to the various findings or inactions
that were brought about by the primary research
sampling, on the managerial level and the strategic
direction of the companies concerned.
Based upon the fact that a family business concept is
quite often a private or closely held affair, market
research proves to be somewhat difficult in obtaining
adequate contribution and clear responses in certain
areas. However, the sampling within the primary

research data is deemed to be sufficient in establishing
an overall commonality or differences where applicable.
Specific issues pertaining to the sampling laid out
according to the findings, with the summary providing
an insight into lessons learned from the diversification
process, as well as processes that become necessary on
a post-diversification basis, have had to be
implemented by the companies concerned to ensure
continuity, succession, governance and adherence to
the legal and operational frameworks where applicable.
Executive Summary
The rationale of the study was to analyze how does the
decision to diversify family businesses impact the long-
standing family business, providing the current
formation/structure of the business from a legal
perspective, as well as thoughts and impressions of the
business ownership to the process of diversification,
based upon the overall negative or positive result of
pursuing such strategic decisions.
Although an average market response was received, the
size and response of the sampling is sufficient to
establish a certain median within the questions posed,
and in turn, displaying sufficient results and patterns.
On the basis of post-analysis, a number of interesting
issues surfaced which could have been included within

the primary data collection phase, such as that of
succession. However, a significant amount of research
has already been conducted on this topic and is
expanded upon both in the secondary data discussion,
as well as the lessons learned, which can, furthermore,
be stressed and considered by family businesses in their
planning, not only for continuity but to achieve
sustainability as well. These issues are further
investigated by that of corporate governance or the lack
thereof, of which is highlighted within the document in
hand.
Hypothesis Statement
What are the effects of the previously mentioned
processes with specific emphasis upon diversification in
family businesses and the effects due to the strategic
decision making and diversification processes?
Tools Used in Research
For this study, a web based survey has been designed
using Survey Monkey. Survey Monkey helps not only in
designing a survey with multiple options, but it also
allows the user to send the survey to respondents by
email. User can also publish the designed survey on
networking sites like Facebook, etc. Another good
feature offered by Survey Monkey is the result
evaluation by the mean of graphical presentation and

charts. These features helped a lot in evaluating survey
results in the best possible way.
Introduction
This study involves analysis of family businesses, as well
as the research over the issues that may not only be
unique to the family business concept such as
diversification, succession and corporate governance.
Investigation not only involves the academic aspect of
the topic but would also explore the practical
perspective of the same. This study aims to establish the
effects of previously mentioned processes with specific
emphasis upon the diversification in family businesses,
as well as the resulting effect or effects of the strategic
decision making and the diversification processes.
The research side of this paper involves both, the
primary and secondary data so that the effects of
research and its implementation are assessed in the
best possible way. This study also involves analysis of
the consequences for the companies to rectify the
managerial level and strategic direction of the
companies concerned.
Literature Review
This section of the dissertation involves review of
several term papers, researches, articles and journal,
etc. As discussed above, this study involves primary and

secondary data. Primary data is the unprocessed data,
obtained via research. While secondary data is
processed data, this could be a term paper, dissertation,
article, journal, blog or any other piece of work that is
written by someone and is based on some research.
Methodology of any study involves two main sections.
The first one is the literature review while the other one
is the real research.
Summary of the Secondary Data
Secondary data of this study involves the relevant
literature that is obtained and accessed via published
journal articles, books and other available media items.
All papers that have been utilized in this study are not
only relevant to the diversification process and its
impact upon the family business, but also to numerous
other factors that come into play, as the business
progresses in the form of growth, expansion, as well as
the resource management and ultimate issues that
affect the continuity of the business, which is somewhat
more prevalent within the family business
circumstances.
Additional factors that also engage a role within the
business itself is the family relationship dynamic and
how these dynamics play out within a business
environment, whereby the family members may or may

not associate their familial relationships within the
business environment.
These factors are mostly discussed and investigated in
the analysis, however, the literature has been analyzed
with certain elements and conditions that came into
light which require further exploration as they play a
role within the specifics of the family owned and or
controlled businesses under scrutiny.
Additional research possibilities and opportunities exist
albeit on a secondary basis, via the internet, as well as
published sources. The information that is highlighted
here is selected in accordance with boundaries of the
diversification process and the impact upon a family
owned company, more importantly on well established
family businesses, as per the research subject matter.
One has to furthermore bear in mind that the family
business is subject to additional “phenomena”, that may
not be relevant to other companies, such as succession
strategies, as well as the handling of internal family
affairs and the resulting benefits or disadvantages
thereof.
A number of statistics regarding the family business are
well worth mentioning here, in order that one may gain
an understanding of the large contribution that family
businesses across the world actually provide within

their respective locations. With respect to the additional
research into the family business or organization, the
family owned and controlled businesses are in fact the
predominant form of business within the United States,
yet a remarkably low level of research into these entities
has been conducted, and furthermore, the authors
claim that the ownership and management of the firms
are widely separated (Phan & Butler 2008), which as
revealed within the primary market research is not the
case. The respondents within the study revealed that
some sort of involvement whether via management or
leadership had continued within the organization in one
form or another.
A Look at “The Top One Hundred Oldest Family
Businesses”
A closer look at the family business reveals that many
companies that are now publicly listed may well have
started off as a family business. O’Hara provides in his
analysis of the top one hundred oldest family
businesses, a variety of geographically located
companies that operate in just diverse sectors and
fields. In terms of these companies many internationally
recognized brands and names are represented, the likes
of which include that of Reidel Glassmakers, Villeroy &
Boch, Taittanger, and Antinori. Interestingly, analysis of

the descriptions of the companies as well as their
development reveals that many of these companies
underwent some sort of diversification from product
offering expansion, to geographical diversification to
that of mergers and acquisitions, to create companies
that are established in modern day economies. A brief
analysis of O’Hara’s data and research is pertinent due
to the relevancy of the topic at hand; it further provides
an insight into the international viewpoint of the family
business as well as location and subsequent
developments of these very old family owned
businesses (O’Hara n.d).
The geographic dispersion of these companies is
interesting as one will realize a trend in countries which
have the most representation of these companies. The
illustration below reflects the geo-location, by country
of some of the world’s oldest family owned companies.
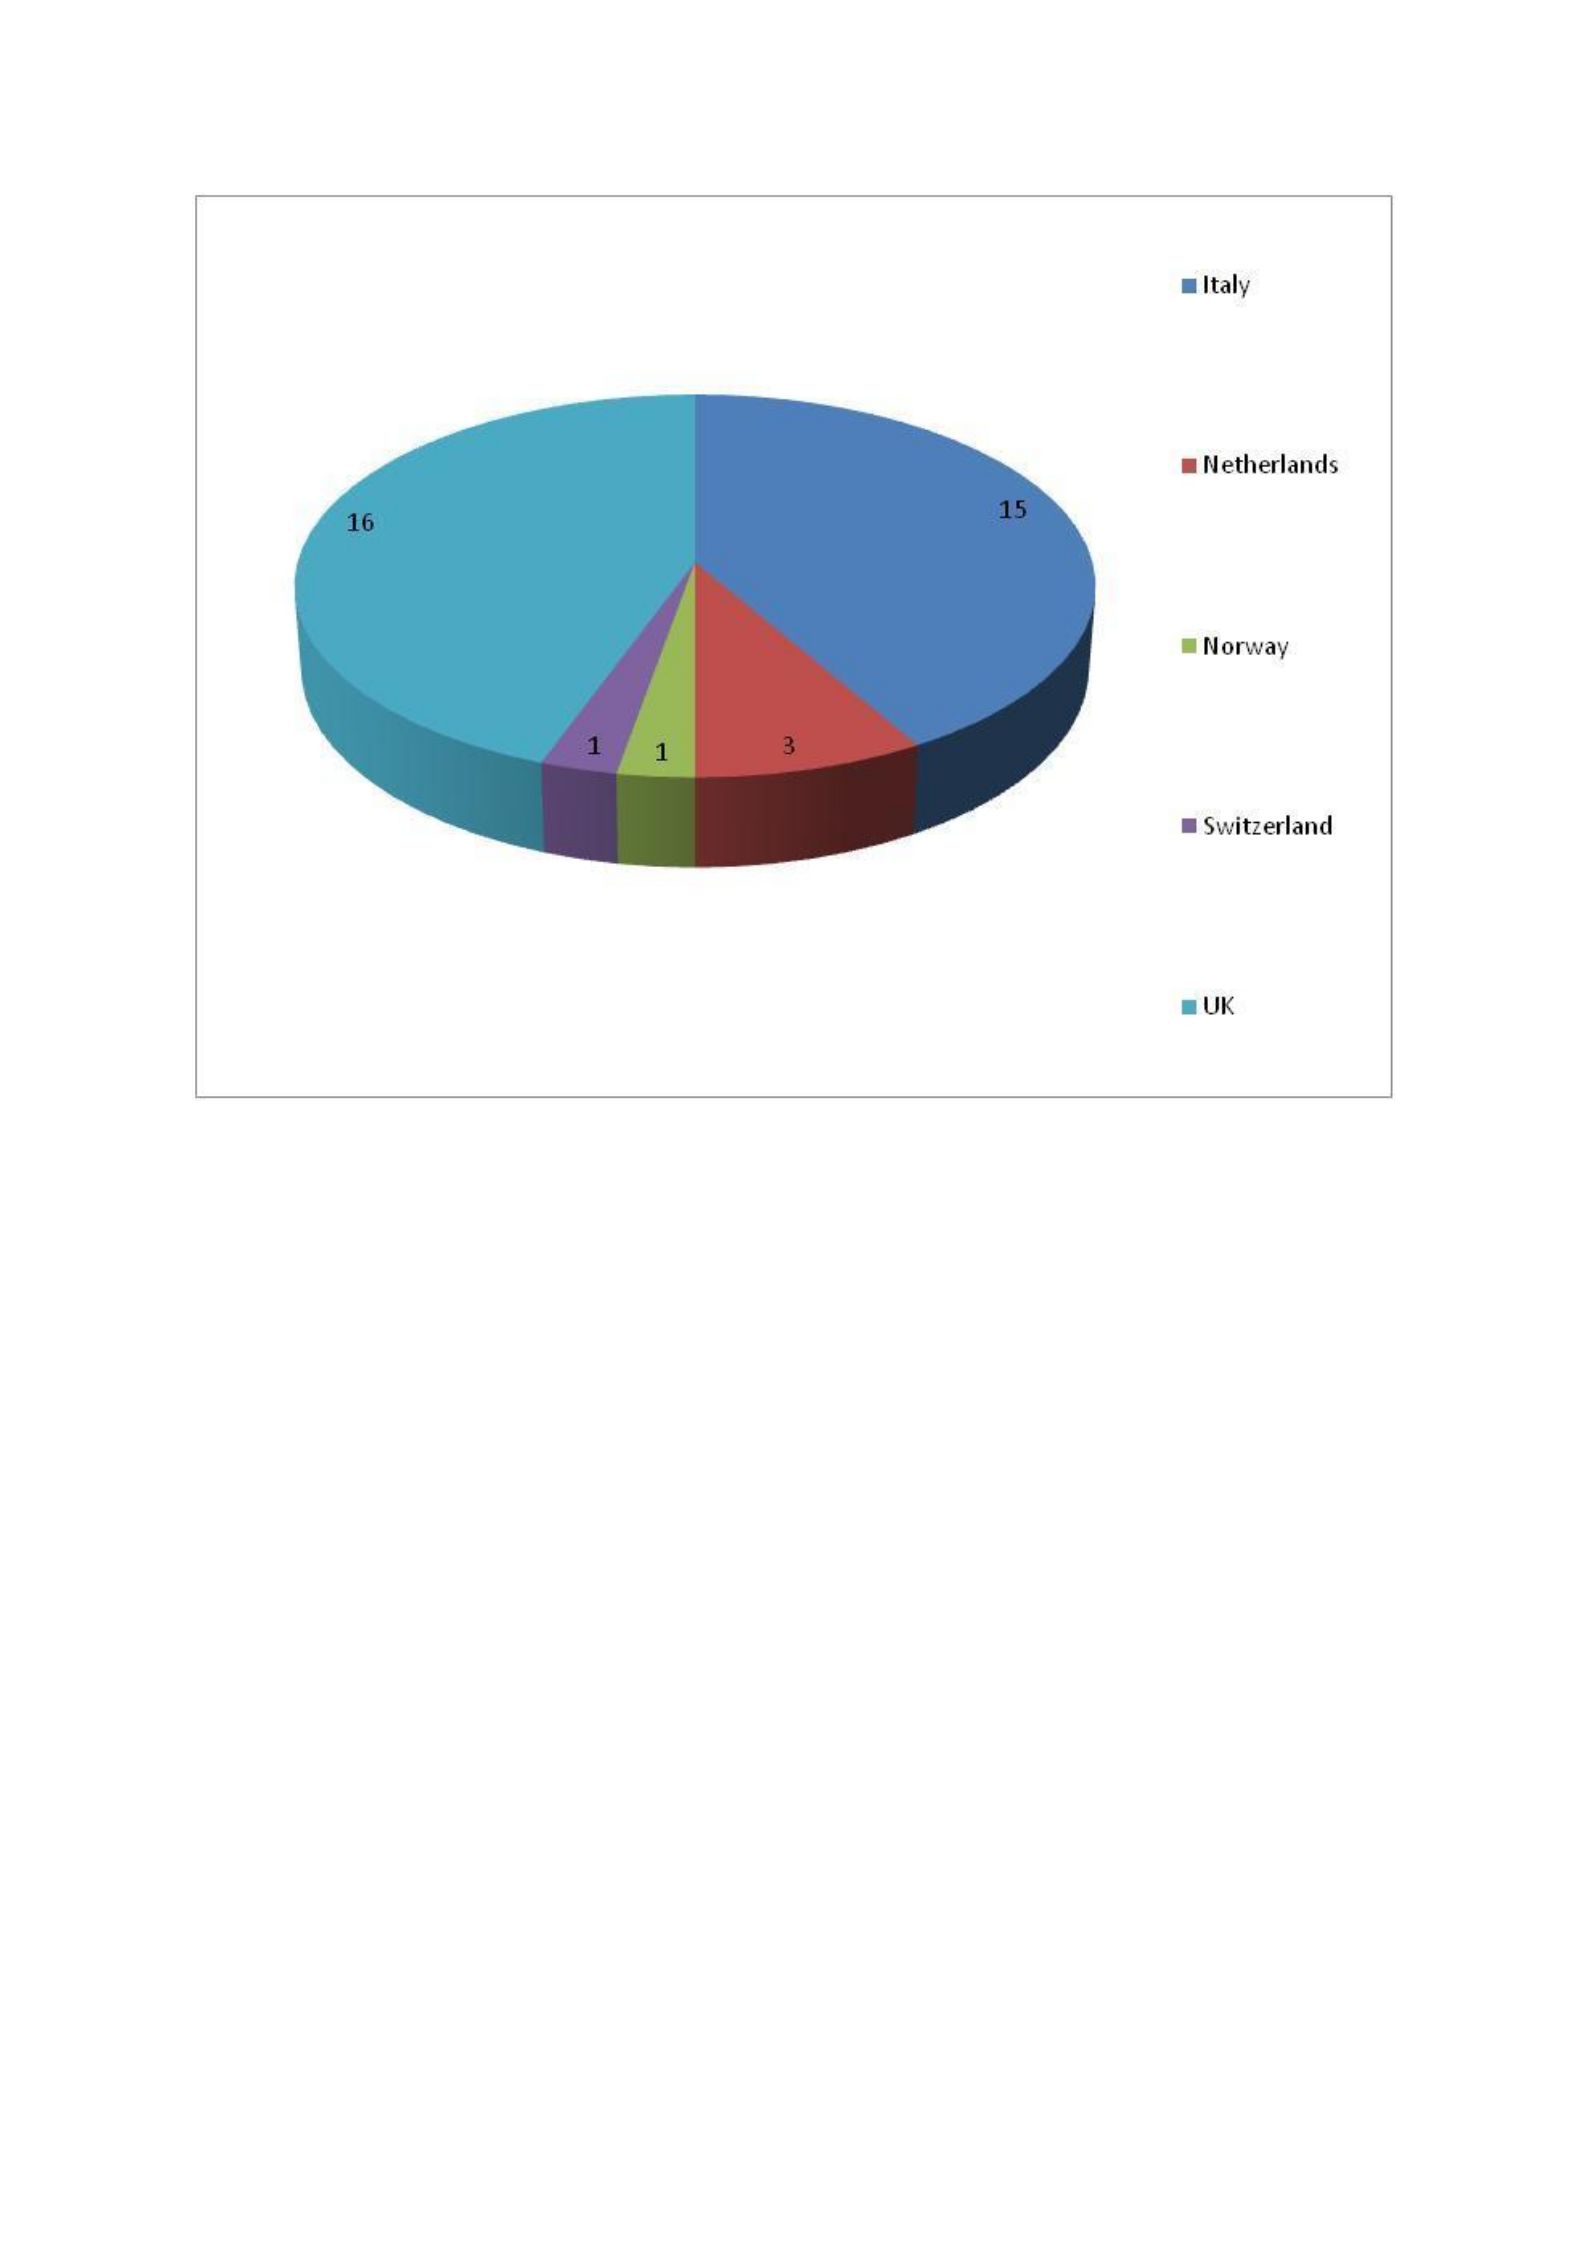
Figure 1: Country location of Top 100 Oldest Family
Owned Businesses.
The top position in terms of location is jointly held at
Sixteen percent of the top one hundred, and
represented by France, the United Kingdom and the
United States, which are each represented by sixteen
companies each. The fourth and fifth countries in terms
of representation within the data are those of Italy and
Germany, making up fifteen and fourteen percent or
companies respectively. Hence the top five countries, in
terms of the world’s top one hundred oldest family
businesses make up no less than seventy seven percent
of the top one hundred.

The average age of the top one hundred oldest family
businesses is calculated at 383.1 years old, of which only
32% of the companies is in fact older than that median.
The oldest known family business is one thousand four
hundred and 31 years old, and remains within their core
business of construction to this very day. The business
is currently run by the fortieth generation, with
involvement of later generations currently working
within the company.
In terms of analyzing these companies who have or have
not undergone some sort of diversification over long
histories, it reveals that 31 percent of the selection has
undergone a process or strategy decision that meets
with the broader definition of diversification. The figure
below represents the makeup of the percentages of the
companies which have undergone such strategic
processes.
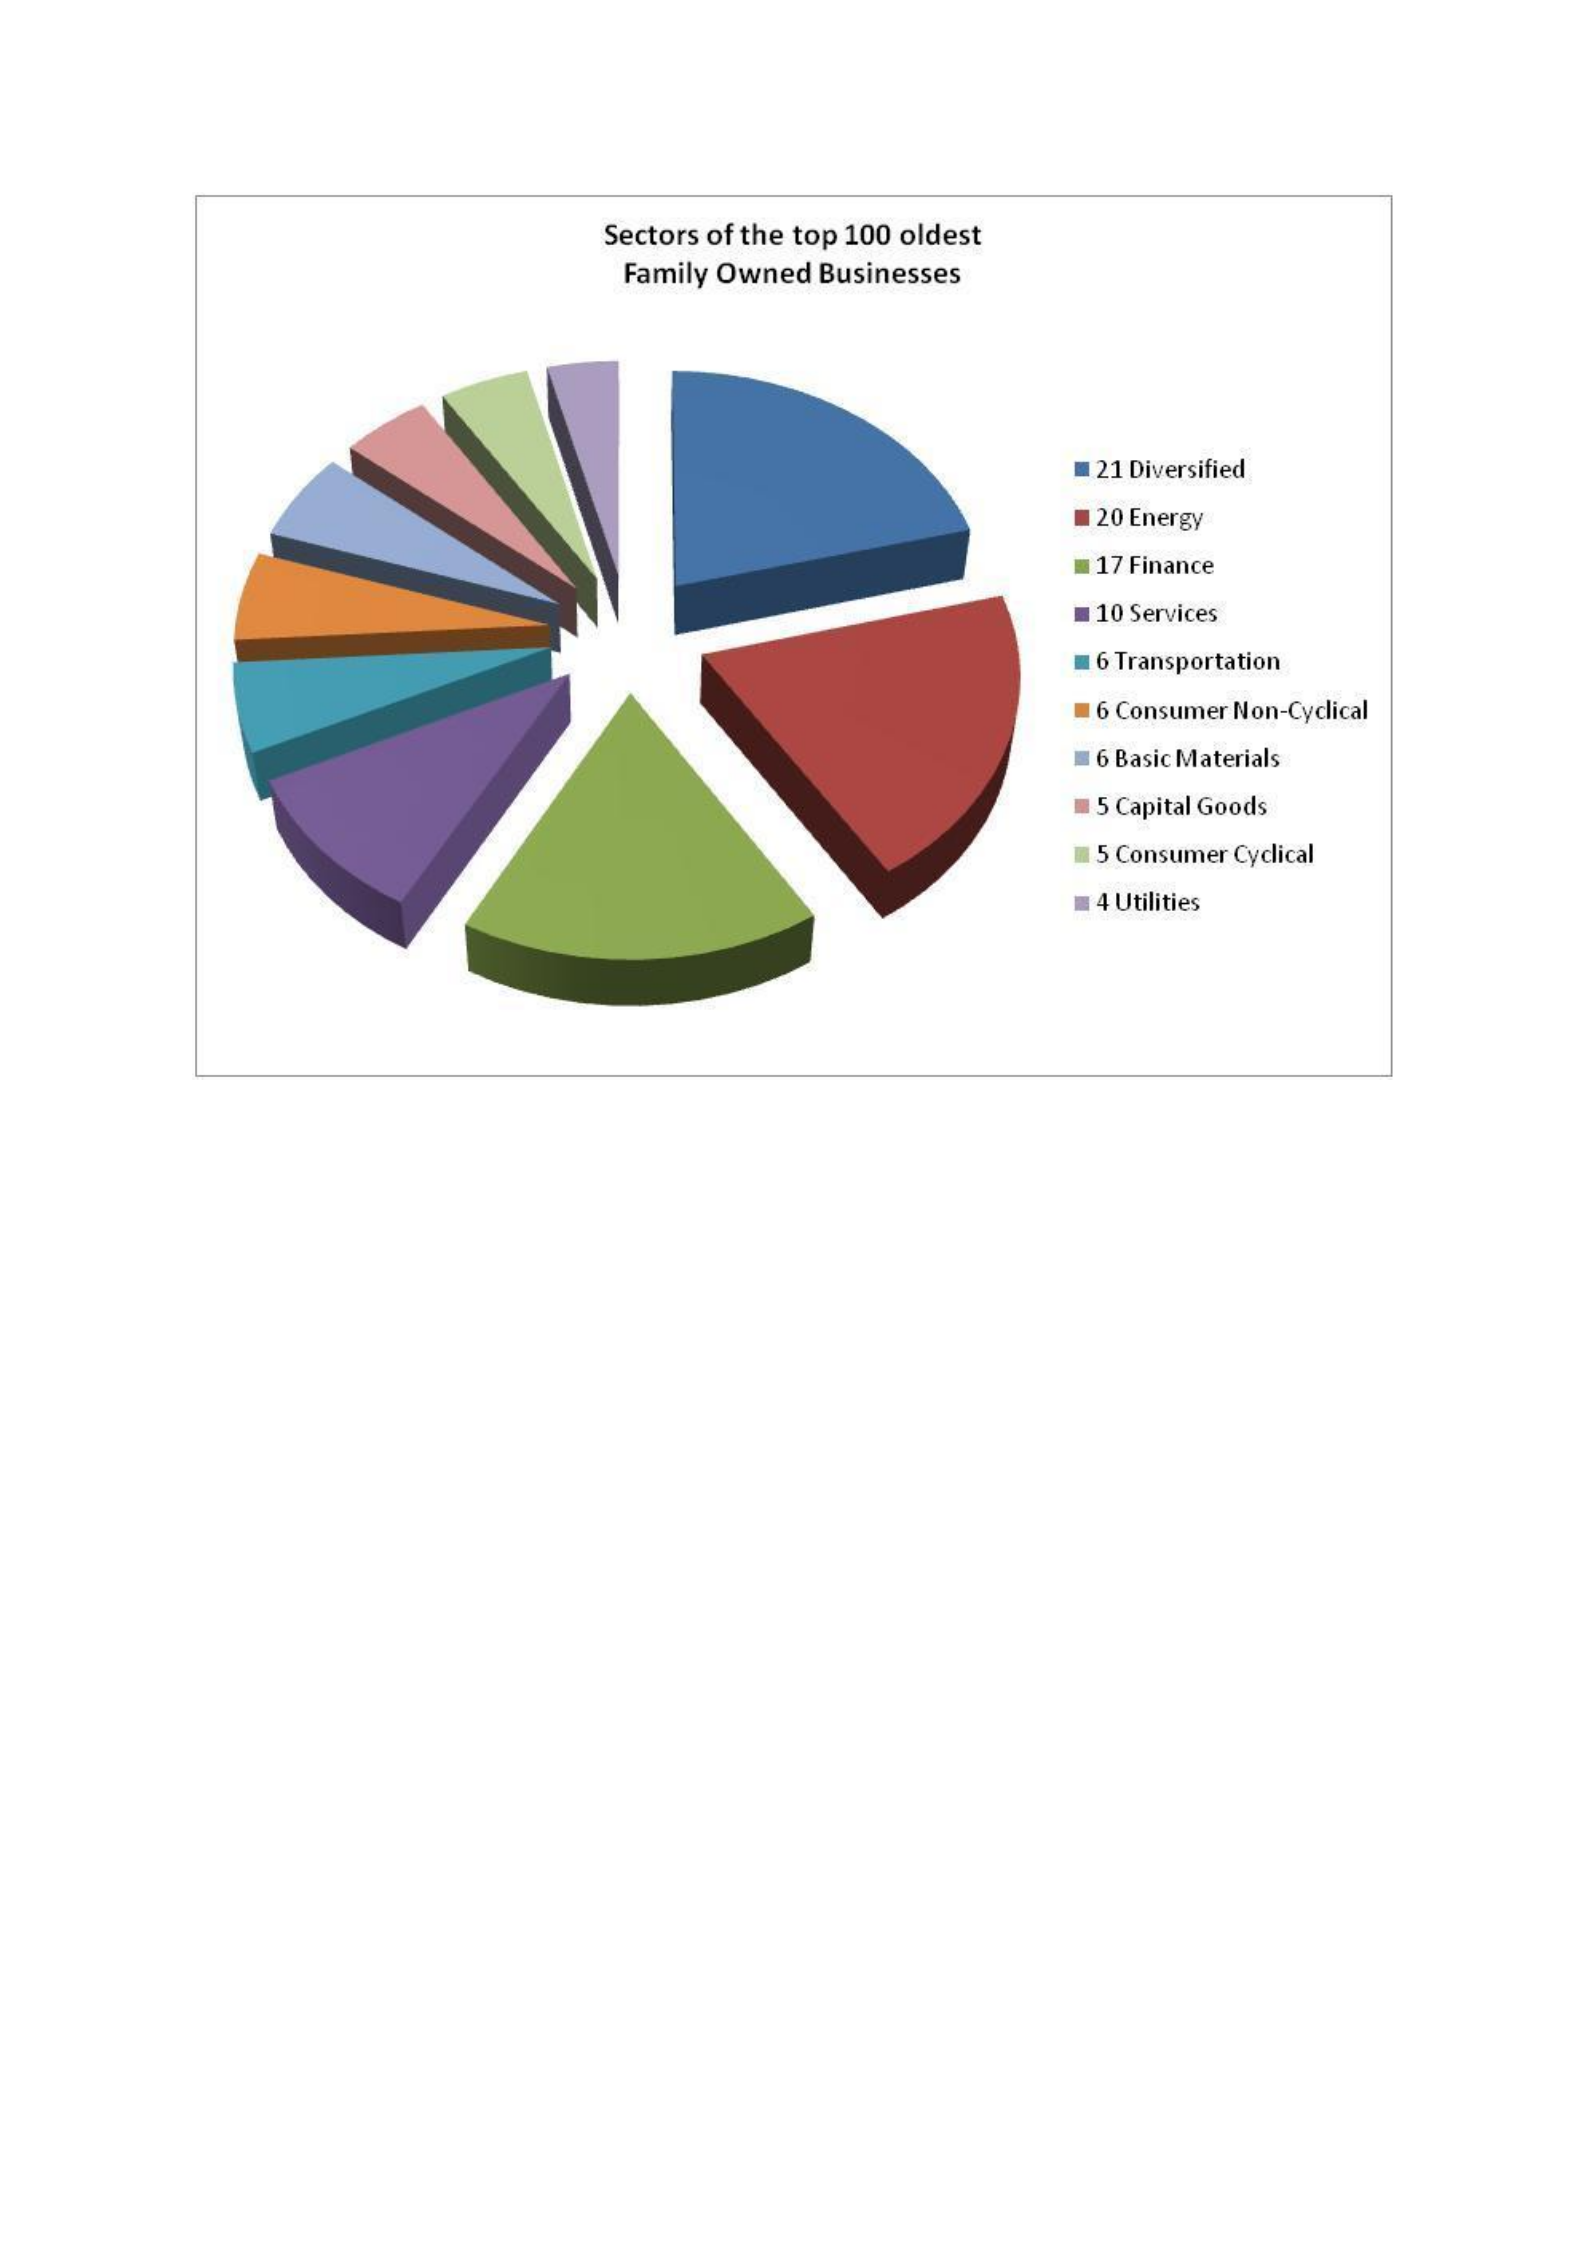
Figure 2: Diversification Analysis of Top 100 Oldest
Family Owned Businesses.
What the above figure may reveal is that a non
diversification strategy may well provide the basis for
longevity of the company concerned, as the proof lies
literally within the figures represented above. This may
be seen as those companies retaining focus have
survived both issues of market and economy volatility
as well as the issues of succession, which play a vital role
within family business. In the case of the remaining
thirty one percent that have revealed some sort of
diversification, include the processes of acquisitions,
mergers, product line expansion as well as complete

product differentiation into different sectors
completely. Although the complete diversification out
of their core business area and expertise was limited to
less than five percent of the entire top one hundred list,
which was represented by companies leaving a specific
sector and entering into a completely new sector.
In terms of the analysis of the actual diversification
process, and whether the business remained within
their core business activities, compared to that of
mergers and geo-location and so forth the following
figure represents a breakdown of the variety of
diversification decisions.
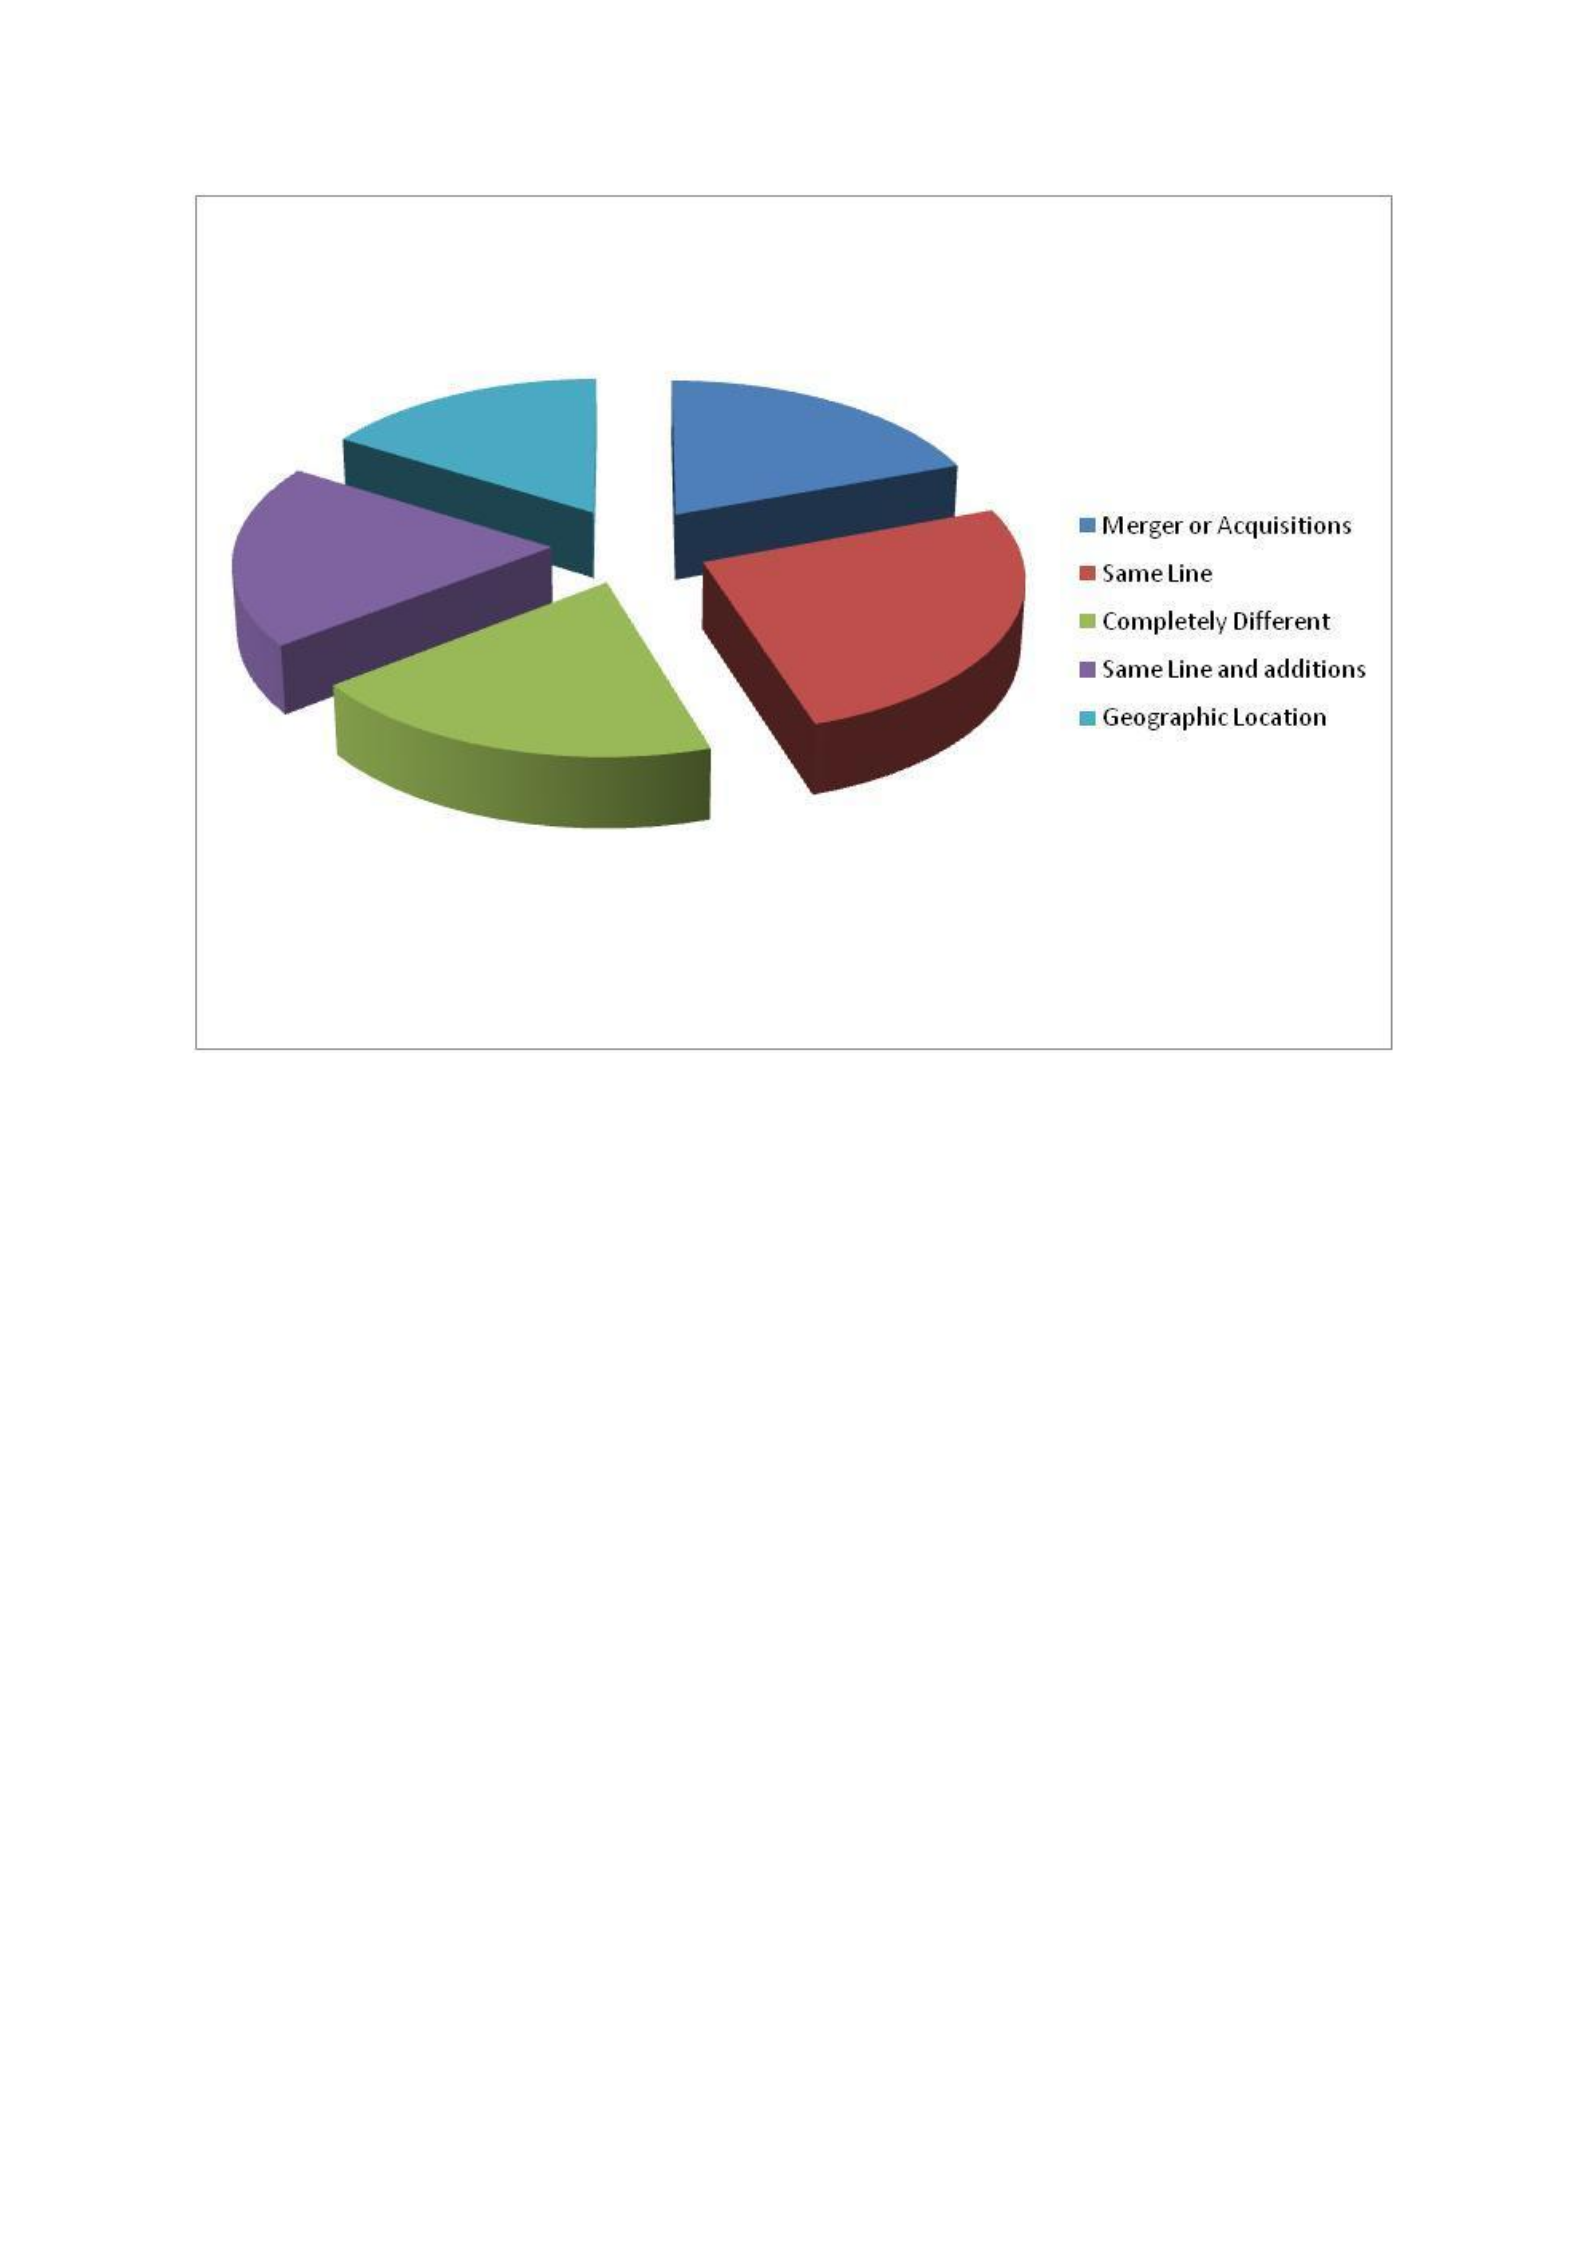
Figure 3: Post Diversification Analysis of the Businesses
that have chosen to diversify.
The areas into which the companies chose to diversify
in terms of the above named classifications were led by
that of diversifying within the same line via product
expansion or service offering within the original core
business activities, represented by no less than 25,81%
of the analyzed 31% of top one hundred oldest family
owned companies. The merger/acquisition, complete
different activity and same line/with additions all shared
the second top classification at 19.35% each, whilst the
geographic location was the least represented process,

at 16.13% or 5 companies of the thirty one diversifying
companies analyzed.
Based on the fact that the companies chose to expand
upon or diversify within their core business operations
lead one to believe that this may well be the most
popular choice within this specific data. However, as will
be revealed by specific authors, this follows the
academic thought of remaining within the company’s
core business activity to ensure success within the
diversification process. However, the fact that a large
majority of the analyzed data here, shared by the
second position in terms of diversification processes or
options, leads one to believe that this practice in all
intensive purposes negates the writings and thoughts of
authors, as per a saying, “innovative efforts that take
the existing business out of its own field are rarely
successful” (Druker 1985, p. 160); and by considering
the data above and as per the Appendices attached, the
proof lies in proven ability of these top one hundred
oldest family companies proving this may be challenged
and is not necessarily as accurate as one might be led to
believe.
Although the oldest company to have elected the
strategic diversification, only did so in 1936, in which
instance, they elected to merge with a competing

company. At that time, the company concerned, being
that of Baroviers, had attained the age of six hundred
and 41 years old. The merger took place between two
families, being the Barovier and the Toso families, in
Italy, to create the Barovier & Taso who are the creators
of magnificent glass products and decorative pieces.
Though, this could be seen as diversification within the
same business sector the most notable of these top one
hundred companies and specifically those that have
diversified might be the Italian company of Torrini
Firenze which diversified from an armory or armor
producer to that of a goldsmith. One of the most diverse
companies that are well worth mentioning is that of
John Brooke & Sons, which is now four hundred and
sixty eight years old, and having started in the fabric
business is now currently involved entrepreneurial
development, something of a far cry from their founding
activities.
The basis for analysis of these figures was to provide an
insight into what one might view as the very long
standing business, highlighting the diversified
companies versus those that did not diversify, and
whilst the majority did not elect to take this route, all of
these companies are still in operation.

Considering the various academic views of
diversification, such as that of Drucker (1985) who claim
that broad diversification may lead to an unfocused
business model that may well not ensure success to the
business concerned, one has to consider the research
presented here, in that respect, quite a few of the
respondents diversified outside their core business
interests, and yet achieved success and what appears to
be sustainability based upon the average age of the
business (Chandler 2003). This fact taken in conjunction
with the views of Rumelt in Strategy, structure, and
economic performance (Rumelt 1974), who suggested
that the “broadly diversified corporation was a superior
strategy to being more focused” (Thomas, Pettigrew &
Whittington 2000, p. 79), who further stated that from
a financial perspective.
The more closely diversified business, displayed higher
profitability (Thomas, Pettigrew & Whittington 2000, p.
80). These views are essentially contradictory, yet the
factual results, as presented within the study, reveal
that the element of both financial performance, as well
as business survival, within the sampling was achieved
in both the closely and wider diversified businesses
analyzed. Moores & Barrett provide that the
diversification concern is in fact one of the most
important strategies or part thereof within a company’s

development (Moores & Barrett 2002, p. 158). And
furthermore, will lead to increase participation by
management, in this case mostly family members, in
budgetary control and preparation (Moores & Barrett
2002, p. 100).
The larger proportion of the sampling further states that
their initial decisions regarding the diversification was
based on opportunities that were available within the
marketplace at the time, with many taking advantage of
such opportunity to contribute more towards the
company and the family’s revenue streams at the time.
Academic theory inclusively related to the writings of
the authors mentioned above seems to be somewhat
ambiguous. Their contradictory views are held with the
diversification that it should be in a more focused or
closer role in relation to the businesses core activities,
in which it is claimed that higher profitability will ensue
the closer such diversification is. However, from a
strategic perspective, as stated above, it has been
suggested that a wider diversification is in fact a
superior strategy (Rumelt 1974). The sampling analyzed
revealed that the majority of respondents pursue the
wider diversification option, with those that diversified
more closely also achieved success within their
respective sectors. This is proven by the fact that

companies surveyed are still in existence to this day, and
continue with their diversified operations and most of
the businesses are being controlled by the second
generation already, some of which going on to the third
even fourth generation involvement level. Therefore,
provided the management strategies and leadership
remain intact and suitable for the relevant business. It
appears that success is not only achievable but,
sustainable regardless of how closely or widely the
business chooses to diversify within or outside their
core business sector.
Diversification Process
According to Hess, the family and the business provide
for an extremely dynamic environment, when operated
together, in which the business and the family overlap,
and based upon the fact that each is changing in its own
right due to growth, or even within the instance of this
analysis within the diversification process. The family
dynamics make it in fact a lot more difficult to manage
a family business, as compared to a non family business
(Edward 2006, pp. 25-55). The result is that many issues
are integrated into the business structure than would
have been in a non family business environment, which
creates the challenges and potential problems that
come along with the family business management and

subsequent analysis thereof. Hence regardless of
whether or not the family business undergoes any
diversification, one is forced to consider the familial
factor that comes into play in the management of the
business especially during times of change.
In analyzing diversification, there are two important
trends in the diversification process, according to the
significant historical events (Grant 2005). These events
were seen as Post-War diversification and Post-1980s
refocusing. The Post-War diversification process
heralded an important phase within the corporate
world and can be viewed as an “important source of
corporate growth” across all sectors. Within this time, a
period of significant decline in single business
companies was revealed, whilst the number of
diversified companies in both related and unrelated
sectors increased steadily in a variety of geographical
locations across the world, the 1960s and 1970s
considered the height of the so-called diversification
boom, which naturally led on to the post 1980s
refocusing trend (Palmberg 2002, pp. 129-148). Many of
the diversification processes came about due to an
increase in that a variety of management techniques
and processes, together with the newly found “science
of management” which in all encouraged businesses to

take on additional business units or divisions, which is
nothing less than diversification.
The issue of growth of companies, rather than that of
significant profitability was another contributing factor
of this diversification trend (Palepu 1981, p. 19). But in
the 1980s, the realization for the necessity of
profitability became prevalent and although the
diversification trend of the preceding decades slowed
down significantly, but practice of acquisitions
continued which meets with the definition of
diversification, although according to Grant, this
represented an unrelated diversification (Grant 2005,
pp. 447-448). Considering the average age of the
respondent companies surveyed, this period coincides
with many of the companies’ strategic diversification
efforts, and is further confirmed by many of the various
sectors within which these businesses now operate, and
are truly diverse as detailed.
The refocusing efforts of the 1980s as well as the
resultant affects upon performance of the company
(Cantwell, Gambardella & Granstrand 2004, p. 33). Their
studies indicated that manufacturing productivity
increased within the United States in this time, whilst
analysis within the stock market returns of companies
that had diversified, had revealed a positive growth

within the stock returns and market sentiment of these
companies, and more specific to the sampling within
this study was that “other studies also show that
internally controlled firms with large-block ownership
by corporate insiders show a better performance”
(Cantwell, Gambardella & Granstrand 2004, pp. 28-30).
This correlates with the sampling within which those
companies that had chosen to go the public listed
company route, whilst retaining majority ownership and
control would be viewed within this sector and would
show positive market sentiment as described above.
As stated, the process of diversification is often a
strategic decision within which the company stands to
not only reduce their exposure to a specific market, but
may consider such diversification as an additional form
of revenue, which was clearly indicated by the
researched and surveyed companies. The choice of
which route to follow and how exactly to go about such
diversification is arguably as diverse as the sectors
within which the companies that were surveyed
operate. Hess further provides that motivating factors
behind the diversification process include that of
consolidation of industry, market shrinkage or
shareholders, or the company itself requiring additional
capital for further expansion opportunities. These
expansion opportunities may take the form of a variety

of different strategies from investments, to acquisitions
or mergers, geographical expansion or that of product
line expansion. Although diversification process should,
in fact, focus upon the addition of product lines within
the business current area of expertise to maximize
existing infrastructure and expertise within their field of
operation, this will in effect avoid any dilution of any
positive traits of the organization concerned (Chandler
2003).
Primary research indicated that although a small
amount of respondents remain specifically within their
niches, those that did remain there in sought to add
value in their immediate supply chain; the balance of
respondents diversified away from their core business,
and in one specific instance even ceased to operate
within their initial core business area. The precious
studies imply that the diversifying business, going away
from the original core activities will in all likelihood not
succeed compared to those remaining close to their
fields of expertise (Druker 1985). To the contrary, the
research has revealed the opposite of be true, where
companies diversified into a variety of specialized fields
and continue to function to this very day. An individual,
as with a closely held family business is in a vulnerable
position without seeking out a diversification strategy
(Jurinski & Zwick 2002).

However, in the face of volatility, as provided by Grant,
should a business elect to diversify from such volatility
to escape these market conditions, they would be
foolish to believe that any business operates within an
ideal world situation or environment. The strategies of
the company concerned should rather be seen as a
guidance of what the business wishes to achieve, as well
as an aide in achieving those goals and objectives, whilst
providing for sufficient preparation to face adversity,
volatility and risk. The only guarantee that exists is that
of the calculated risk of such product or geographical
analysis and market research in planning for the
diversification process and activities (Grant 2005, pp.
147-148). Hence the volatility issue does not really
appear to be a feasible factor in the decision making
process, but rather an informed acceptance and
resultant exposure to the risk thereof that has the
accompanying reward of the diversification strategy and
implementation thereto associated.
From the perspective of geographical diversification,
the company has the opportunity of alternative geo-
targeting, in terms of existing product lines, as well as
new product offerings, and the election of such a
strategy will, furthermore, result in growth within the
company itself (Channon 1999, p. 78). Hence, by
venturing away from where the company originally

started operation, the company stands to realize
additional growth opportunities, by virtue of the
increased size of the market being sought after. This
does not ever take away from the added cost in terms
of logistics that will be required to deliver such product
to these new geographical locations, which needs to be
analyzed prior to undertaking such a strategic direction.
The company may seek to establish representation in
the alternative geographic areas, which in all likelihood
would represent a significant capital investment,
realizing the issue of whether or not to seek internal or
external funding or financing for such growth.
The geographic diversification is more often than not
influenced by social and political factors that further
need to be taken into account prior to undergoing such
strategic processes. Regions that are influenced by
religion may play a role in specific products, such as that
of alcoholic beverages in predominantly Muslim
countries as an example and would Therefore, require
the specific analysis and investigation in terms the
expansion into such a market that may be adversely
affected thereby. Navarro provides that beyond the
business unit diversification strategy, the geographical
diversification strategy may not be solely motivated by
that of any hedging initiative, but rather that of
achieving greater economies of scale, whilst providing

opportunity to “deploy core managerial and production
skills across a broader range of opportunities” (Navarro
2006, p. 11), which in essence indicates the experience
sought after by company leadership in providing to and
dealing with alternative markets with respect to their
products and services, gaining market share as well as
invaluable experience in dealing within these varied
geographical areas, each influenced by their respective
socio-political infrastructure.
Financing of the diversification processes may well
prove to be more of a challenge for the family business,
due to the fact that it is not an exposure of risk to
external shareholders, or stakeholders, but rather to
that of the business owners which in this instance is
represented by family members themselves
(Poutziouris & Smyrnios 2006). Furthermore, research
by the author suggests that issues of autonomy within
the business will also play a determinant role, beyond
that of the acceptance of the risk associated by such a
strategy and to the family members themselves. It quite
appropriately to add here that “there is typically no
clear demarcation line between business concerns and
family concerns since the family business is typically the
vehicle that fuels the family’s current income and future
wealth, and business results directly affect the family
(Jurinski & Zwick 2002, p. 11), which concurs with

Poutziouris in that the exposure may well be greater to
the family business (Poutziouris & Smyrnios 2006), and
the ownership as compared to that of the corporate or
publicly listed company. Although within the primary
research, some of the businesses were publicly listed
companies, due to be allocated shareholding the family
still retained large portions of ownership, if the majority
share, in which case such exposure and the potential
resultant effect upon the family and the business would
still be realized in this instance.
The extent to which the business diversifies would be
for all intensive purposes up to the risk tolerance level
of the family concerned. Within the research, one of the
respondents indicated that the family had diversified
into no less than twenty-seven separate companies, and
into a variety of different fields and disciplines. This may
be construed as an undisciplined diversification
strategy, in that once a company succeeds in a specific
field the owners thereof would like to “try one’s talents
in new industries or geographical areas” (Gersick &
Davis 1997, p. p189), specifically under that of the
holding company.
Although this methodology or strategy may provide
many benefits to the family concerned, specifically, in
terms of the extended family such as that of cousins, as

well as providing a basis for internationalization, there
are disadvantages to the specific strategy, as provided
by the author in “if the process is not carefully evaluated
and controlled” (Gersick & Davis 1997, p. 190) which has
been represented in a number of studies in which
“broad diversification can distract the company from its
successful enterprises and dilutes needed investment in
profitable ventures” (Gersick & Davis 1997, p. 198).
Once again reiterating the diluting effect of a too broad
a diversification strategy. Interestingly, enough Gersick
further provides that business owners are often left at
odds as to how to manage or deal with the original
founding business, in which many instances the family is
merely attached to this company for entirely
sentimental reasons. In many instances, the original
business has either passed its maturity stage, or is no
longer profitable or viable to retain and the most
prudent course of action would be to deal with it
accordingly, Although this may prove to be somewhat
of an emotional challenge, based upon the involvement
by the family over the years.
An important aspect of analysis of the company, instead
of post-diversification strategy and performance, which
can be performance analyzed based upon sectors within
which the businesses had become operational or having
diversified into (Cantwell, Gambardella & Granstrand

2004). Although the interpretation of relationships
between diversification and performance seem to be
somewhat controversial, due to conflicting evidence, as
well as diversification processes and timing which would
naturally skew the results (Santalo & Becerra 2006). As
revealed in the research a number of respondents took
advantage of market opportunities, and Therefore,
entering the market with the right time enabling a
significant growth phase which was uninhibited by any
major barriers to entry, that essentially did not exist at
that time are prevalent today. This is confirmed by the
‘mixed response’ of the positive or negative nature of
the diversification decision and process as revealed by
the primary research data.
Additional factors of diversification, which may or may
not be conscious decisions in terms of such a strategy
include that of the technological diversification within a
company, in the process within which the variety of
sectors update their existing infrastructure in order to
realize the benefits of improved technology and
processes, regardless of the sector within which they
operate. Within this process of modernization a large
degree of training, as well as significant capital
investment is more than often required in order to meet
the investment requirements. This may not be
considered as a strategic diversification, with in the

initial phases thereof however, considering the overall
impact upon the organization both from a capital
intensive as well as productivity perspective such
changes can very well be regarded as diversifying.
The controls of the diversification process is best
described by Porter in terms of the competitive
advantage analysis of the business, as provided in
Porter’s “Better Off Test”, and specifically pertaining to
that of business unit diversification (Grant 2005, p. 254),
although this can be applied in essence to a
geographical strategy too. In essence the better off
analysis provides that the business stands to gain from
such a strategy and is in a better off position, both
financially and operationally than prior to undertaking
any strategic decisions or movements within the desired
direction, as identified by any market analysis or
research. The consideration of suitability of pursuing
any such move will be affected by the financial
resources immediately available to the family business
or family members involved within the company,
alternatively the associated risk of seeking external
funding will become apparent, with the potentiality of
loss of autonomy becoming a determining factor.
In the event of survival of the business, as represented
by the respondents the family members may be faced

with the opportunistic options of increasing revenue
streams, which is represented by the diversification of
the business interests in terms of the fields and markets
within which they operate, or the alternative of a
quickly diminishing market, for whatever reason
realizing the demise of the family business concern. The
latter represented by one of the respondents within the
study, in that failing the process of diversification, the
company would no longer be viable or even in
operation. In as far as the research panel goes, there
were no specific mentions made of acquisitions or
mergers in terms of the respondents and hence the
optimization of any merged or acquired units does not
come into play here but rather the efficiency within
which the business unit diversification has taken place
or been taken advantage of.
Facilitation of the diversification process can take place
by means of a variety of financial means by which the
family members will decide the loss of autonomy, in the
case of a publicly listed company in which majority
shares are not retained, or alternatively by means of
internal funding by private fundraising. The private
fundraising exercise will entail additional exposure of
personal finance standings to financial institutions in the
form of private loans or investments from personal
sources, or the acquisition of financing based upon the

financial standing of the family members themselves.
This will increase the risk exposure to the personal
members of the family at an opportunity cost of the
consideration of the loss of autonomy, and hence
careful thought and strategic planning is required in
either of the routes under consideration in terms of the
financing possibilities of such a strategic determination.
Thereby the reduction of risk from a business exposure
and operation perspective is transferred to the
individual members of the family in the case of private
financing, whilst the public listing of the company would
in all likelihood result in sufficient capital for
development, reduction of risk to personal family
members but the loss in complete autonomy of control
of the business.
Beyond the perspectives described above Navarro
provides that the business leadership unit seek
diversification, whether it be from a family business or
publicly owned perspective, for the purposes of hedging
against business cycle risks and associated elements,
where outsourcing and ‘off shoring’ are factored into
the business unit and geographical diversification
possibilities or options, quite aptly quoted by Navarro in
Jurgen Strube’s statement of “the challenge is not to
avoid business cycles but to manage in such a way that
[the business units] will perform, on average, well”

(Navarro 2006, p. 151); which is in essence is what many
businesses strive to achieve, this is represented by the
fact that a business remains within operation by
profiting from the business environment, despite the
associated loss that may come along with the markets
and business cycles, provided the business is profiting it
remains a viable opportunity for the owners thereof.
Scott provides further insight in his analysis of
diversified firms versus those companies that did not
diversify, on a so-called purposive basis, as well as the
resultant behavior of the relevant companies (Scott
1993). In terms of purposive the author provides that
the companies took advantage of opportunities within
their core areas of expertise and the major differences
revealed from the study revealed that the purposively
diversified company conducted more research and
development than that of the non diversified
companies. This would result in an additional
expenditure cost for the company, and whilst this
research is consistently undertaken the diversified
company would in all likelihood continue with such
strategy based upon their research efforts (Malerba,
Lissoni & Breschi 2002, pp. 69-87). This represents the
issue that once the primary diversifying strategy is
undertaken, this will lead to further diverse markets and
product offerings (Scott 1993, p. 125).

This research is confirmed by the primary data within
this study, specifically with the proportion of
respondents that indicated additional opportunities
that were undertaken by the companies, resulting
widely diverse structures, mostly managed from a
central holding company or the family unit itself. With a
small percentage of the researched companies widely
diversifying, the majority of respondents seemed to stay
within their respective markets, in the broader sense of
the sector concerned. To a large degree, this does
confirm Scott’s research, in that once the initial
diversification strategy has been undertaken the
company continues to seek out opportunities, albeit by
research and development or whichever means
necessary in order to realize whether or not any
competitive advantage can be established for the
company, and whether such opportunity will represent
growth potential for the company concerned. It appears
that the risk associated with such strategic decisions is
lessened, in the eyes of the diversifying business or
family members, once the initial step has been taken in
such a strategic decision.
In terms of further analysis on the research and
development perspective, as provided by Scott,
Villalonga & Amit provide the following “family and
nonfamily firms also differ significantly in their

investment policies. Family firms have relatively higher
capital expenditures but slightly lower R&D
expenditures (Yang 2010). They are also less prone to
being diversified than are their nonfamily counterparts.
Consistent with their diversification profile, family firms’
stock returns show higher levels of risk, both systematic
and idiosyncratic. This pattern contrasts with the
conventional wisdom that families may be inclined to
diversify their firms to make up for their lack of personal
diversification” (Villalonga & Amit 2004). This is
somewhat contradictory to what Scott provides.
However, this is not the only area of contradiction that
has been revealed by the study and research within the
family business and related diversification issues. The
authors here provide that valuation studies by two
separate groups, in terms of Tobin’s q was higher for
family firms than non family firms in one study and in a
separate study by different academics the opposite was
found to be true. This arises as to which of the
information or data is the more reliable and more
importantly which is the more relevant or which should
be taken as more accurate.
The consideration of company legal structure appears
to be confirmed, within our study, with that of Phan &
Butler who provide “alternative mechanisms of control
over the governance of the firm often utilized to retain

influence of critical strategic decisions and guide the
firm during times of crisis” (Phan & Butler 2008, p. 7); in
that regardless of whether the company with the
sampling took on the legal structure of limited liability
company or public company, it was done in such a way
that control was in fact retained by the family via a
mechanism of majority shareholding retention by the
family within either form or structure of the companies,
as mentioned. The authors furthermore confirm,
together with the findings of the surveyed companies
that the original family ethic is retained within the
business, in terms of leadership and management of the
company in “a strong culture of regard for the
preference of the founder or founding family may be
enough to influence the decision making process of
hired managers and independent directors” (Phan &
Butler 2008, p. 7). However, according to Moores &
Barrett, the structure of the family firms affect both “the
content and the form of controls” of the organization
itself, inevitably when any structural change occurs, so
well all the controls albeit from an operational, or
profitability perspective, with many of the
responsibilities vesting with management (Moores &
Barrett 2002, p. 136).
Bearing in mind that family businesses account for
between 80 and 90% of all businesses in the United

States and 75% of businesses in the United Kingdom, as
well as 80% of businesses in the Philippines (Johnston
n.d.), to name but a few of the available geographical
statistics; the realization, not only of the contribution of
these businesses, but to the extent to which these
businesses occur one has to consider the fact that such
control as mentioned above is prevalent across these
quoted statistics. This implies that such family values
and ethics are carried through to these businesses
which account for such a large percentage of economies
across the world.
Tying in with that of Phan & Butler’s views, is that
regardless of company legal structure or formation
these companies are under the control of the founder
or founding family and operate accordingly their terms
of strategy and critical business decisions. In terms of
analyzing the family business, one should also not
consider the business to be that of a small operation,
that may be working from home or a small office or
warehouse somewhere, as provided by Johnson (2004)
“37% of Fortune 500 companies or family owned while
60% of publicly listed companies are family controlled”
(Gersick & Davis 1997). Study provides that on an
international basis between 65 and 80% of all
worldwide business enterprises are owned or managed
by families (Gersick & Davis 1997, p. 2). Such control

would arguably be in the form of majority shareholding,
by the family concerned that has been confirmed within
the sampling.
The above serves to confirm that regardless of company
structure, within the sampling, control over the various
diversified business units was ultimately retained by the
family in concern.
The various motivational issues behind that of the
diversification of family business, is confirmed by the
sampling’s response of increasing business strength,
which leads directly or indirectly to increase
profitability, which ultimately provides a greater
revenue stream to the business and family ownership
unit. The academic measure of the diversification
process while that of Michael Porter’s “essential tests”
was not specifically and directly addressed with the
sampling (Granados 2004, p. 8). However, two of
Porter’s tests were revealed in the responses by the
sampling, being that of the attractiveness test as well as
the cost of entry test.
A large proportion of the sampling indicates that
opportunities within the economic market presented
themselves, which is a direct indication of the
attractiveness test, as the management and ownership
of the business that time realized inherent value in

taking up such an opportunity at the time of
diversification. One of the respondents specifically
mentioned that entry into one of their diversified
markets, would not be possible to date due to the cost
of entry, and on a retrospective basis such
diversification had not capitalized on the cost of entry
into their chosen diversified field, and would therefore,
be justified in terms of such strategic decision at the
time. Grant (2005) specifically stated the company
being “better off” based upon profit generation, either
via mergers or acquisitions, this issue did not affect the
sampling in this case, as no specific mention has been
made of an acquisition or merger drive from any of the
companies within the sampling. However, such
diversification and strategic decisions were based upon
a more generic and internal process than that described
by Grant, Therefore, such theory not being applicable to
the sampling surveyed.
The issue of resources of the family business from a
financial perspective was not directly addressed by the
respondents. However, from the provision of responses
with respect to the company structure, one might
assume that such financial resources were generated
from internal sources or via traditional funding sources
such as that of financing houses, or banks. This is with
the exception of the publicly listed respondents,

represented by just over 22.72% of the sampling, in that
they had elected the public company route. In all
likelihood the publicly traded company is a mechanism
to generate sufficient financing to fund such expansion
activities, and once again the control was retained via
majority shareholding of the now publicly traded
company, coinciding with that of the statistics as quoted
by Johnson (2004) above.
The balance of the companies, within the sampling did
not specifically claim internal funding or loans via banks
or similar institutions. However, the inference of a
limited liability company, being that of a privately
owned company, is that of self or internal funding, in
essence not wanting to open the company up to too
much external influence. However, whilst protecting the
interests of the family members via such a legal
company structure, from a liability perspective. Rising of
external capital may well be more expensive, as
provided by Grant (2005). However, once again based
on the fact that these businesses are still in operation,
regardless of the means of how and where such
financing was obtained, attests to the fact that the
necessary funding was indeed obtained and allocated
efficiently to ensure the apparent success presented
within the study. For those respondents who elected
the public company route, one may surmise that the

capital requirements were too vast for self funding and
therefore, the need for such listing was made in order
to meet capital requirements within the diversification
drive.
An alternative form of growth, being that of mergers
and acquisitions was not highlighted in the primary
data, which in fact coincides with Davies (2006) who
provides that family firms preferred the organic growth
aspect, based upon the fact that most families work
within a family controlled businesses as a form of
working on the inheritance factors, by implementing a
merger or acquisition strategy the inherent risk is
represented by the addition of an unwanted culture
being brought into the business. Therefore, the issue of
diversification or other alternative organic growth
seems to be much preferable to the family owned and
or controlled enterprise. This change in culture is
neither desired by entrepreneurs nor family businesses
(Ravensburg 2009, p. 13). Furthermore, based on the
fact that the entire sampling seems to represent an
entrepreneurial spirit, in addition to the fact that these
are family owned businesses, such change in culture is
ultimately undesirable (Davies 2006, p. 98).
Human resources requirements become important
once the company begins to grow, and in the case of

diversification, a number of elements have to be
decided upon by the controlling family, who may well
retain control will have to start delegating and so called
letting go of certain functional activities within the
business (Rowley & Abdul-Rahman 2007). Naturally the
need for an increased workforce is presented upon such
growth, and along with such an increase within the
human resource element is the requirement of efficient
and effective management according to the strategic
goals of the company concerned. The sampling provided
a number of possible solutions or elected procedures,
which included the outsourcing of the human resource
management function, as well as the establishment of
specific specialized companies for each business unit,
whilst retaining an oversight via the holding company,
which in turn held the control in the various individual
companies.
Beyond the management of human resources within
the now diversified firm, as well as an aspect that
touches upon the structure of the firm, business risk
becomes inherent in the business environment, where
something might go wrong within the delivery of a
product or service to the end user or customer, in which
instance the customer may sue the company (Sadgrove
2005). This insight provides for the formation of the
limited liability company and the public company, which

provides some protection for the shareholders.
However, this is not the be all and end all of risk
management, which filters through to the human
resource element, as well as the issue of business
continuity, in the event of legal action being brought
against the company due to the action or inaction of
employees, management or leadership of the company.
The human resource element of the family business is
further extended to include the fact that the family
dynamic as well as the corporate structure becomes
intertwined within the corporation itself, with this being
coupled with the concept of succession, a number of
possibly difficult business decisions and issues may arise
from this closely bound relationship (Raghavan et al.
2005, pp. 4235 – 4265).
Succession planning, as provided by Gersick (1997), is
often blamed and labeled as such in the event of family
conflict within the business unit, it is furthermore a field
of expertise that is more often sought than not to be
dealt with on an external or consultancy based basis.
Gersick (1997) and Poutziouris (2006) further provide
that extensive literature exists on the succession
planning and implementation phases, with two
opposing forces becoming prevalent during both the
planning and implementation phases. These forces

include from the senior level, in not wanting to let go
and from the junior level of not wanting to wait for the
succession implementation. Gersick further provides
that the distinction between succession and continuity
must be drawn, with the senior generation more often
than not becoming concerned with the issue of
continuity rather than that of succession, with an
amount of confusion being represented in this ‘senior
opposing force’.
Specifically pertaining to the issue of succession, within
our sampling it appears that all of the respondents
involved seem to have dealt with the primary steps of
succession with the involvement of the second, and in
some instances the third generation. The median of
generations within the sampling was slightly over the
second-generation, represented by an average
population of 1.6 generations that were involved in the
family business. Therefore, one will notice that these
primary steps have been taken, due to the involvement
of additional generations, with the remaining issue of
the senior generation having to “let go” when the time
arises. However, due to the fact that the majority of the
businesses within the sampling are relatively young,
represented by a median of 15 to 17 years lifespan, one
would expect that such specific “letting go” phase is yet
to come. This is further confirmed by the sampling’s

acknowledgement of the fact that numerous
generations are currently still actively involved within
the leadership structures of the relevant businesses.
Relevant research into family ownership of a business
that has undergone the diversification process and
publicly listed as a result, Villalonga & Amit (2006) have
found via relevant data collected that the value of the
company is enhanced in the event of the founding
family member serving as the prime leader of the
company, such as the Chairman or the Chief Executive
Officer. In the event of descendants taking up such a
position the value of the firm is reduced. This issue
further raises the importance of the succession
management and planning in order to retain the value
of the firm, as well as retain investor confidence where
applicable, as the founding member cannot serve the
company in perpetuity and will have to at some point
relinquish control of the company in question.
Another pertinent issue is that of the diversification of
investments by the family business. Investments may
refer to the reserve capital in the company, which may
form the basis of income for the ownership or family in
the case of volatile economic conditions or market
slumps. According to Schmid, Ampenberger, Kaserer &
Achleitner the research based upon family and non

family business pertaining to the use of cash hedging
instruments as a form of diversification revealed that
the family owned business was less likely to use the cash
hedging option than that of a non family business which
provides that the company from a non family held basis
may well be less risk conscious or possess a higher
threshold for risk taking initiative than that of the family
held or owned business (Schmid, Kaserer & Ann-Kristin
2008).
Methodology
Methodology of this study involves two phases. First
phase is the literature review that has already been
discussed above. Literature review involves taking help
to bring all pros and cons of your topic in to light. It
involves referring to the researches of others so that to
assess and evaluate the findings of other papers (Kerr
2000, pp. 6-10). Literature review is the backbone of any
dissertation as it discloses the clear picture of one’s
topic. Researcher summarizes the points and then move
on to the next stage, i.e. the real or practical side of any
study. Therefore, the second phase of the methodology
involves research. As discussed above, literature review
involves secondary data that are also called the
processed data. While the unprocessed data that a

researcher collects himself using various methods while
researching, is called the primary data.
Collection of Primary Data
Prior to the collection of data and submission of the
question, specific definitions to which the surveyed
sampling should adhere are provided below, as well as
a description of the questionnaire design and
submission process.
Definition of Terms
The following definitions are relevant to the subject
being researched here, and for the purpose of clarity
and understanding specific definitions must be
accepted for the research and analysis of the
diversification effect upon family businesses. The Family
business is defined in a number of ways. However, there
seems to be an overriding central theme, which is
represented in the following definition, which will be
accepted for the purpose of this study: “a business
actively owned or managed by a member of a family, in
which other family members may or may not actively
participate in the management thereof. However, the
majority ownership rests within the mentioned family.”
This provides the starting point of analyzing how a
family owned business is affected by the decision and
process of diversification, duly defined below.

The definition of diversification that needs to be
accepted here is based upon the fact that it is the very
decision or process that is central to understanding
what the changes are and which that are effected, how
these changes affect the company, the stakeholders, as
well as the strategic position and future of the company
concerned. Therefore, for the purpose of this analysis
the definition of diversification that will be accepted is
as follows: “diversification is the decision, and resultant
process, of risk reduction which can involve the addition
of products, services, clients as well as markets and
locations to the company undergoing or intending to
undergo such diversification. This process can be
motivated via both seasonal and economic fluctuations
within the company’s sector, and may further be a
strategic invasion into a specific and defined market.”
This definition may also extend to the investment of
surplus funds that may be available to the company as a
form of income generation or security, generated in the
times of substantial excess gains or profits made by the
company.
The analysis of the family owned business that intends
to be undergoing or has undergone the diversification
decision and process will be conducted via a primary
and secondary research objective. Within this research
a questionnaire has been designed and dispatched to

numerous family owned companies, randomly selected
and both geographically and sector differentiated,
referring to their physical location and their primary or
core business activity respectively. In order to obtain as
wide a research result as possible, thirty questionnaires
were forwarded to family owned businesses. The results
and analysis are thereby provided within the following
sections of this paper, together with the discussion of
the questions contained within the questionnaire.
A number of issues regarding the results that have been
highlighted from the research will be discussed with
reference to theoretical or academic literature as well
as to commercial or “real life” examples; this will be
conducted due to the fact that within the so-called real
world events, they do not necessarily occur in the way
in which one may wish events to occur, or according to
the ideal world scenarios that are often referred to
within academic literature. Therefore, the analysis and
findings will be able to provide an insight into the actual
process, as well as highlight potential advantages,
disadvantages and problems that companies may incur
along the diversification journey.
The conclusion will be supported by the analysis of the
research and will aim to identify possible routes or
elements of success that are provided by the research,

as well as possibly form a frame of reference for future
companies, in which they may realize the true effects of
diversification from both a negative and positive impact
upon the family business.
Research – Questionnaire design
The questionnaire forwarded to the family business,
which forms the basis for the primary research
methodology, consists of total 25 questions; the entire
questionnaire is attached to Annexure A.
The questionnaire was designed using a web based tool
Survey Monkey and was sent on an anonymous basis, to
a geographical diverse audience, to gauge whether the
geographical location does or does not affect the family
business in such a process, and if so to what extent such
geographical positioning is relevant. This may be specific
to country laws or practices, as well as any possible
significant cultural influences that may well be relevant
to the business itself.
In order to establish the relevancy to the business being
interviewed, the question is set to ascertain whether or
not the respondent considered their business as being a
family business. This is important in establishing the
relevancy of the questionnaire to the business being
interviewed, with another question confirming the level
of ownership and / or control within a specific family or

not. These questions serve to qualify the respondent
businesses in accordance with the accepted definition,
as highlighted above. The question pertains to the
length of operation of the business, which is required to
establish to what effect and extent the change was,
which further serves to highlight the positive results of
diversification in assuming that such a process or
decision was in fact directly responsible for the
company still being in operation to this day. The
preceding question is supported by the question in
establishing which generation is now running the family
business, Therefore, supporting the length of operation
of the company.
The core business or activities of the business in
question serves to highlight or confirm the necessity of
the diversification in terms of the current economy, or
the state of the economy as it was in the instance of the
decision or process being undertaken or initiated. This
serves to establish how macro or micro economic
factors are relevant to the business regardless of size or
structure, with the question pertaining to the structure
of the company serving to establish any unique issues or
consistency in type of business structure relevant to the
family business. This in line with the ‘international’
distribution of the questionnaire is to provide an

underlying commonality of the formation and structure
of the family business or the lack thereof.
Additional business interests on the part of the family in
question may also be indicative of the diversification of
the business, which may have come about to the need
to extend or expand the business interest, in which
instance the reduction of risk may have been deemed to
be more effective on the establishment of an additional
business, instead of changing the existing business or
structure as well as the core competencies. This may be
reflected in the alternative or additional business being
wholly owned by the business in question, in which
instance such a business entity could well be envisaged
as a diversification effort on the part of the business.
The 8th question serves as confirmation of the preceding
statement, and determines the level of such
diversification interest.
The primary motivation for the diversification process
and the decision will provide an insight as to whether or
not the company’s survival depends upon the process of
diversification, or whether the company is seeking the
mentioned invasion into profitable markets. Whether or
not the company ownership made the diversification
move due to market or product maturity will be
reflected in the response of this question, which adds to

the analysis of motivation of the process and decision.
The following question extends further to analyze the
market position of the company immediately prior to
the extension of the company, in the form of their
diversification process.
The next question seeks to establish whether or not the
diversification process ceased after the initial process
itself, or whether or not the company continued to
evolve in line with its initial realization of diversification,
which serves to prove whether or not the initial process
served as a catalyst for the continued expansion of the
company.
Organizational structure is analyzed from the
perspective of whether or not the company would have
had to take on additional financing or partners, which is
represented in the twelfth question. Answers to this
question will provide whether the majority of
respondents in our sampling needed to facilitate
structural change or not, as well as highlighting the need
for external financing to enhance the process or even
enable the company to conduct such changes as were
necessary at the time of diversification. An important
factor on both the structure and control of the company
has been claimed by many authors, the questions
pertaining to this is to establish whether or not such

changes have occurred within respondent companies
and to which extent. Responses within this area further
motivate the concept of how drastically the decision
impacted upon the company and to what extent these
changes have impacted within the physical control and
management of the company.
Many family owned businesses are often seen as more
flexible due to the fact that any organizational changes
or decisions pertaining thereto can be decided upon
more quickly and with less so-called red tape or
bureaucratic processes than that of the listed company.
Hence, any changes within the business after the
diversification will be reflected in the ability or inability
of the company maintaining such flexibility or autonomy
within the company during the decision making
processes.
Ascertaining the impact of corporate governance is
deemed to establish whether or not this issue was in
fact considered at the time of diversification, and seeks
to establish whether or not the management or
ownership of the company has considered the impact
thereof on the now diversified business. The distinction
between whether or not such governance is a
prerequisite or actually an asset to the business serves
to establish the positive impact or benefits arising from

the necessity of corporate governance, or whether the
practice thereof is deemed to adversely affect the
company. In many instances the corporate governance
issue will be a new policy or practice for the family
business, which would now in the post diversification
phase have to implement this practice and these
stipulated regulations.
The view of overall negative or positive impact of the
process must be established in order to retrospectively
measure the success of such processes and decisions, in
order to establish potential future strategic moves for
the company, or within other family businesses. It may
serve as a frame of reference for future business
decisions in difficult markets or even those markets that
are seen as saturated. The question regarding the core
business perspective thereof may also serve to establish
whether or not the company still maintains such core
business, or perhaps if the decision to diversify may
have led the business into a different product or service
offering that leads them away completely or even
partially from their original core business practice.
Quantitative vs. Qualitative within the research
process
The process that has been undertaken in establishing a
sampling within the family business ‘sector’ is based

upon that of a quantitative approach in obtaining the
insight as well as to the effects and what has led up to
the mentioned process of diversification. Whilst one
may determine that the actual diversification process,
which is highlighted within the research forms part of a
qualitative subject or process, as these decisions may or
may not be guided by market forces with respect to
diversifying.
The methodology of the surveys sent to the
respondents can be classified as an online methodology,
as the questionnaire was forwarded to the respondents
via email, as per the format in Appendix A.
A total of thirty questionnaires were forwarded to
known family businesses via colleagues, friends and
family. The questionnaires contained the questions
discussed above, and form the basis of analysis of how
diversification affected the family owned businesses,
and to what extent this process and decision affected
the concern, as well as what has essentially become of
the business on a post diversification basis. Further
insight into the family business with respect to which
trade sector the business belongs to, as well as issues
such as age and generations involved within the
business that serves to establish whether or not any sort
of trends exist in regard to this process and decision.

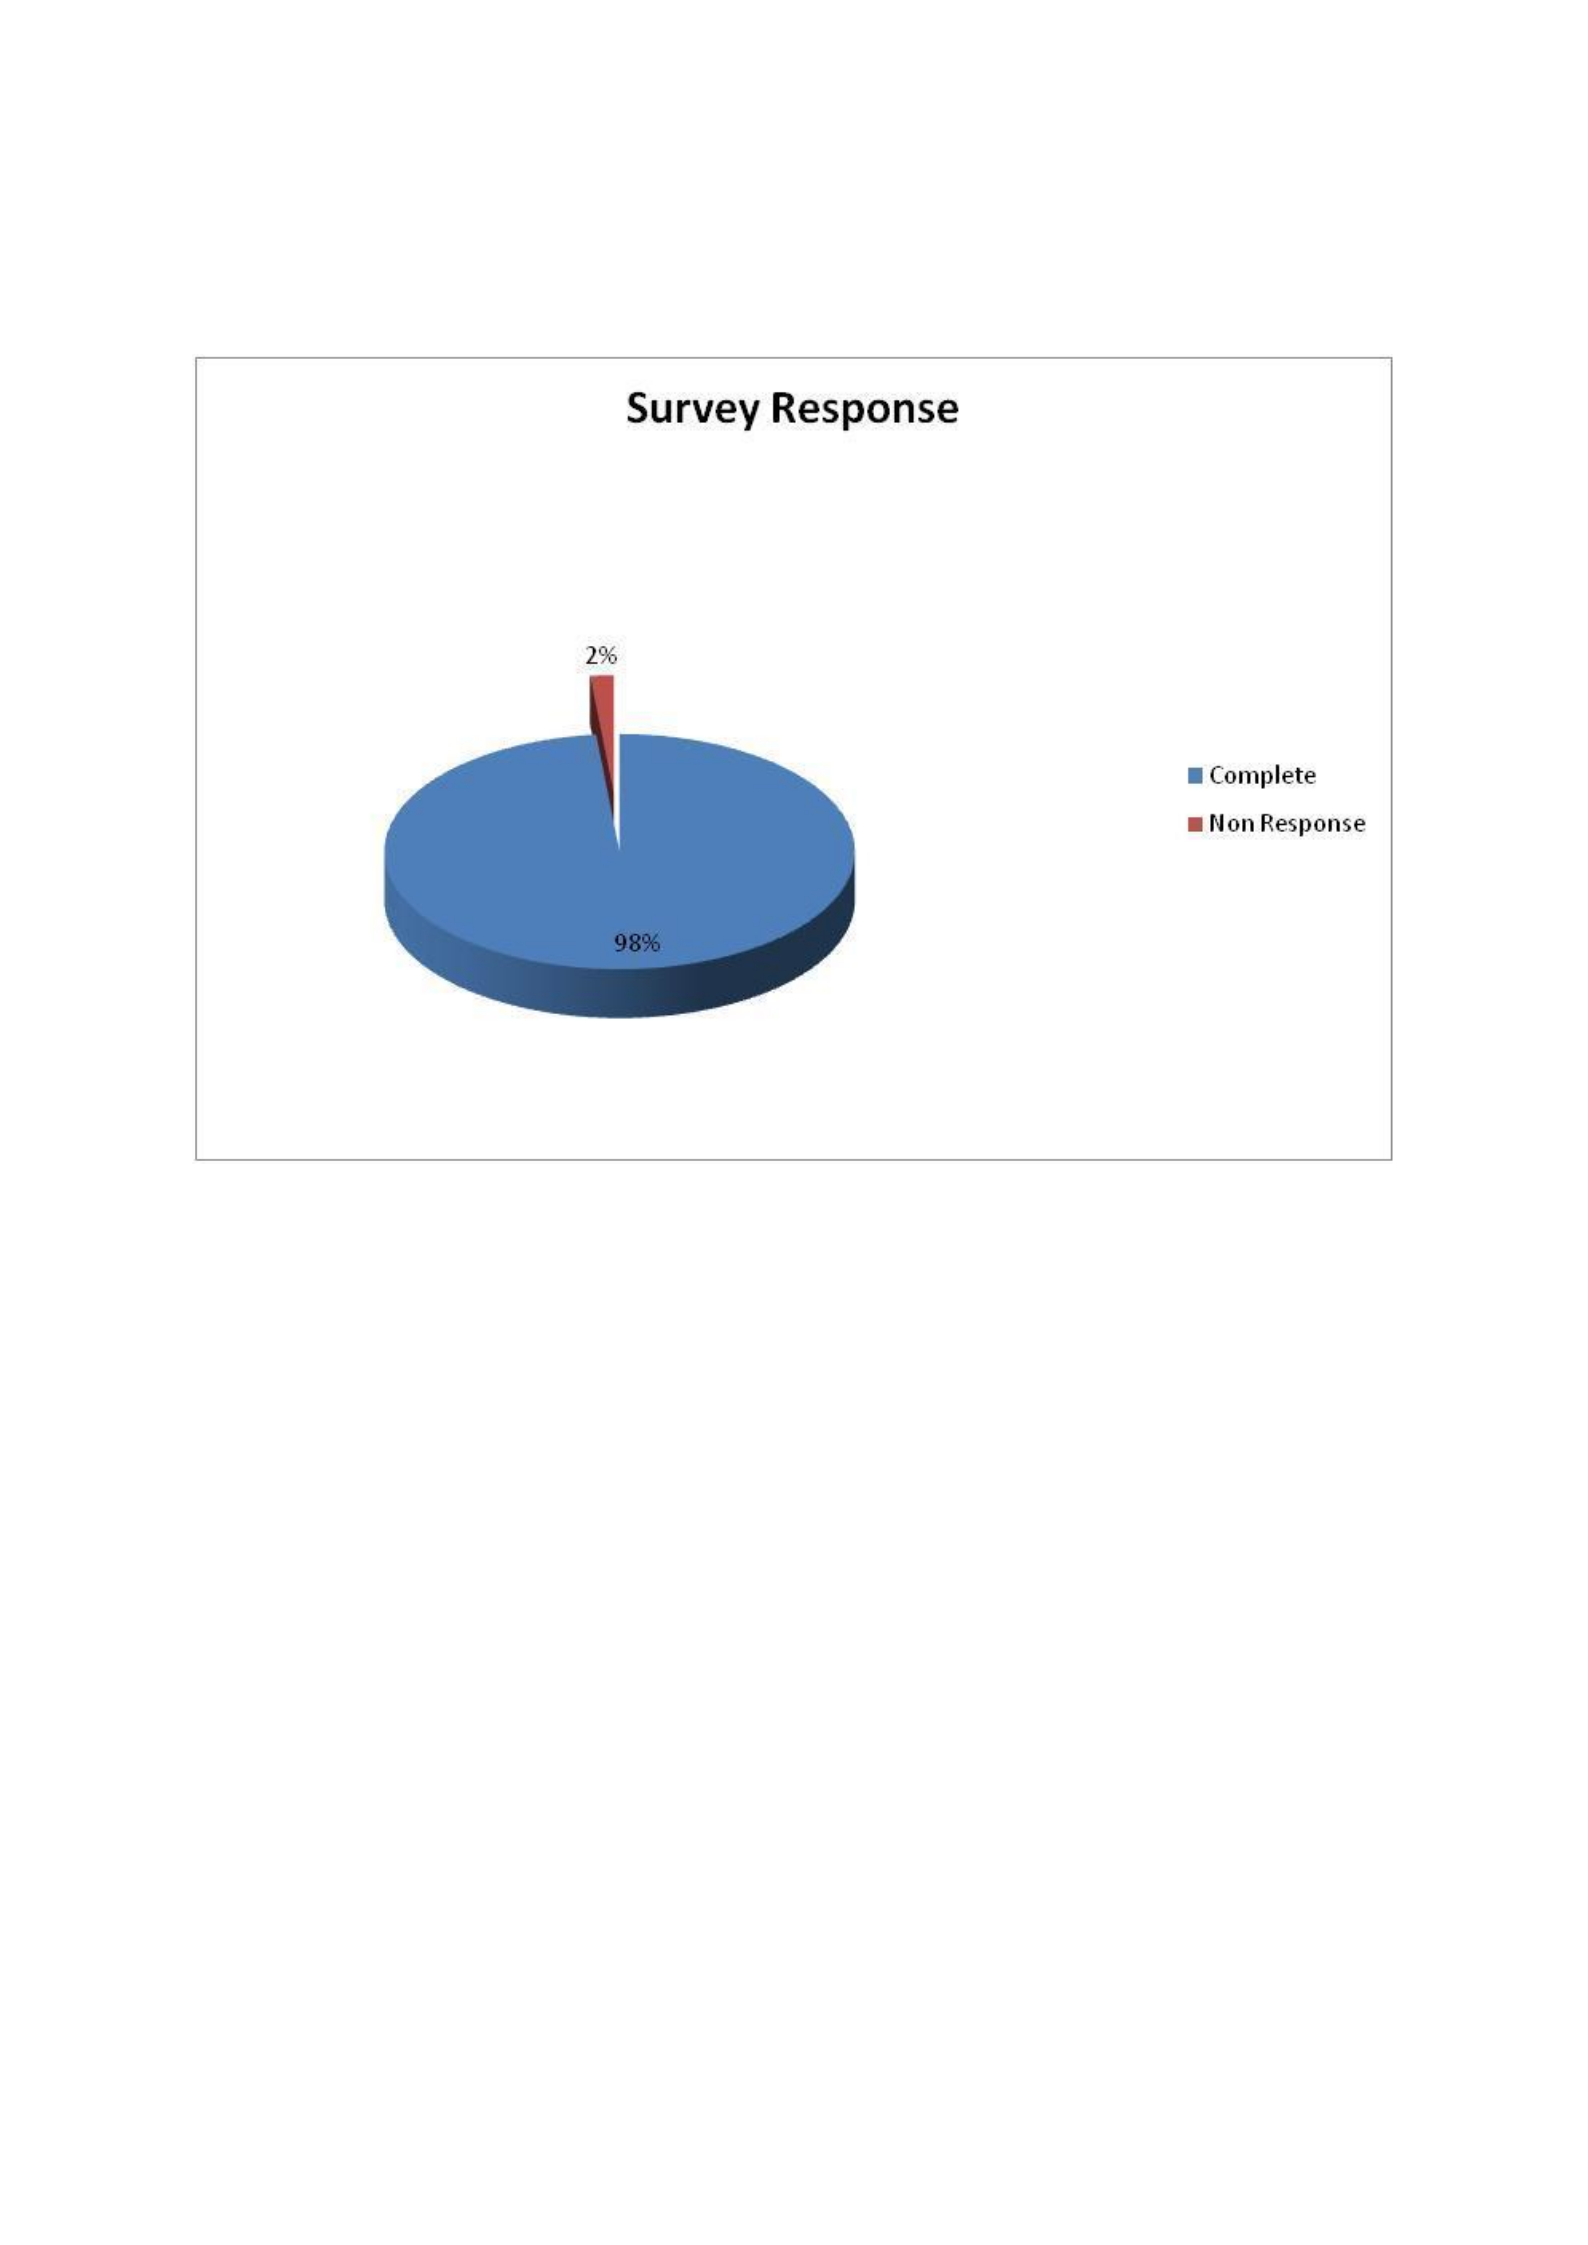
Of the submitted questionnaires only twenty two
questionnaires were returned, which represents a
73.33% response ratio, the balance of questionnaires
and the reasons for non completion were stated as the
people who were approached were too busy with their
daily management activities and obligations to
complete the requested information. In addition to this,
four respondents stated that they were not prepared to
provide answers due to concerns of confidentiality
issues, despite the assurance that none of the
information would be published and was for analytical
purposes only. The sentiment as previously described is
confirmed by Poutziouris who provides that “given the
private nature of most family businesses, accurate
information about them is not readily available” (2006
p. 56), which provides some sort of confirmation as to
the expressed wish to not participate within the
presented study.
Yu & Cooper (1983) provide that although numerous
research exercises have been undertaken to improve
response rates in an attempt to reduce non-response
bias. However, although these approaches have been
suggested “little is known about their relative
effectiveness” (Yu & Cooper 1983). Hence, based upon
the reasons for non-response of the mentioned selected
sampling, it is a suitable justification that the responses
received are in fact sufficient for the analysis herein
contained.
Figure 4: Completed vs. Non Response for Online
Surveys.
The 98% response rate is higher than the “market
standard” of 50% and above, considering the nature and
“niche” of this specific analysis, the representative
sample is deemed to be sufficient, due to the variety of
responses, sectors and structures as per the completed
questionnaires that have been received. The sampling
represents businesses that are deemed to satisfy the
family business definition, as per the outlined definition
of terms, as well as having undergone a diversification
decision and resultant process, with the exception of

one respondent. Therefore, for the purposes of this
analysis the sampling is considered 98% within the
family business definition and the respondents or the
sampling have undergone some sort of diversification
within their respective business life cycle.
Findings
Findings of this study are based on two phases, the
literature review and the research part.
Analysis of Literature Review
The following discussion is based on analysis of
academic, as well as statistical information specifically
pertaining to the family businesses and their
involvement within society and the economy in general,
in order to get an understanding of how the family
businesses impacted upon, via mentioned issues such as
diversification, corporate governance and so forth.
Cater (2006) specifically provides that the duality of the
success of a family business is dictated by both family
life and business life, which is compounded by the
family business unit, which in turn adds a degree of
complexity, to the already complex nature of business
with the possibility of family relationships affecting the
work environment. Cater further provides that one of
the leading topics in research and family businesses is
that of succession, which may be confirmed by the

degree of involvement by the number of generations as
highlighted in the sampling collected. One of the key
points highlighted by Cater is in fact that 70% of family
businesses actually fail to successfully implement a
succession of policy from the first to the second
generation, representing a massive loss to the economy.
Considering the family business has survived the
diversification process, but stands to fail in the
succession process would truly represent such a loss,
after many years of survival both pre-and post-
diversification. In addition to the recent statistics
provided, of the 70% of the failure rate, should the
business reach the succession stage from second to
third generation only 12% of these businesses
successfully implement such a change over with
succession from third generation to fourth possessing a
mere 3% success rate. Cater’s research further coincides
with that of the primary doctor represented here, in
that the average lifespan of the family business is
quoted as 25 years, less than the median of 33.41 years
as represented in the research. This may indicate that
the various businesses surveyed in the sampling may
well not be around within the next few years, unless a
concerted effort and well-managed succession plan is
put into place.

Based upon the mentioned statistics, of 60 to 85% of all
businesses on an international level being under family
ownership or control the issue of succession suddenly
appears to be of vital importance within this form of
ownership and control. Regardless of successful
leadership and strategic decisions a family that controls
its business units should be in a position to implement a
viable and sustainable succession within their ranks, all
efforts within their business sectors regardless of
whether diversification strategies were undertaken or
not, it would in fact all be a waste of time.
Moores & Barrett (2002) not only confirm the issue of
succession, as described by Cater, but further delve into
the growth dynamic of the family business, which in
essence is associated with that of diversification as it is
described throughout the study. Such internal issues are
further exasperated by that of external pressure, such
as changing technology, government incentives (or the
lack thereof), customer preferences and opinion which
are then carried over to the structure of the firm; in that
questions of workload management, structure and
ownership begin arising placing added pressure on both
the business and family unit respectively. Moores &
Barrett claim this to be the context of the business, and
further state that the company “whether family owned
or not – needs to engineer its internal situation to best

fit its external environment” (2002 p.13); these issues
effectively referred to as contingency plans have been
greatly researched by what the academic world refers
to as organizational theorists.
Managing all through the internal situation, as well as
the external environment and any business decisions
pertaining to these elements are according to what the
authors referred to as strategies, which in this study
refers directly to the process and decision of
diversification, the allocation of resources and the
resultant business units and companies created from
these processes. Kuratko & Hodgetts also make mention
of what they term as, “Forcing Events” which can be
likened to that of death, illness, abrupt departure, legal
problems, business decline and financial difficulties. The
authors furthermore claim that the family business, and
the family itself “seldom has a contingency plan in
dealing with” the aforementioned forcing events; these
issues further exasperate the issue of succession, as well
as the future efficacy of the leaders of the business
(Kuratko 2008, p. 491). One will Therefore, realize that
besides the “normal” succession of procedure within
the family business, these contingency plans need to be
incorporated in the event of the mentioned forcing
events occurring, whilst furthermore implementing

suitable succession programs or policies to ensure the
continuity of the growing concern.
Coinciding with the some of the wider diversification
examples contained sampling Moores & Barrett confirm
that “these family firms operate in a greater number of
markets and have to take account of more areas of
development.” (Moores & Barrett 2002, p. 134). This
may well represent an agreement with respondents
from the survey, who stated that upon undergoing the
diversification process focus was taken away from the
original core business because of the need for attention
on their respective ventures and opportunities that
were taken at the time. The authors further provide that
the strategy of diversification “represent distractions
from their core business” which does in fact coincide
with representative sampling within the data analysis.
In contrast to the issues of succession as already
described Weidenbaum provides a perspective on the
Chinese Family Business, which may well be
represented by more of a private ownership than that
of a publicly traded company, although this coincides
with the sampling majority within the study; from a
succession basis the author provides that “succession
typically runs through the family group, rather than
depending upon seniority.” (Weidenbaum 1996).

Further expanding upon the difference between the
family business and the non-family business, Kuratko &
Hodgetts (2008) provide that the overlap between
family and business will vary between each family
business concerned. However, this was not entirely
revealed within the sampling, but rather the strengths
of individual family members were deployed into
specific areas where upon the content family member
displayed sufficient skills in terms of the management
and leadership of the sector concerned, no real
evidence was provided that family issues were brought
into the business and rather a more holistic process of
leadership within the family seems to have been
displayed by the sampling.
With further relevance to the succession issue, a
number of strategies exist, as highlighted by Kuratko &
Hodgetts and specifically that of early entry strategy and
delayed entry strategy, with each strategy having their
respective advantages and disadvantages. The fact that
a secondary or tertiary generation has become involved
in the business does not necessarily indicate that the
business has proceeded successfully with a succession
program, and has provided by the authors one of the
main issues that the successor will have to address is
that of gaining credibility amongst employees of the
firm, and their ability or inability to do so. In addition to

this the authors provide that the founding generation
normally prefer a succeeding generation, or the
succeeding leadership to actually work outside the firm
where there may learn, and make mistakes prior to
taking over the leadership of the company concerned.
These issues were not confirmed by primary data, based
upon current statistics of the family businesses that
succumb to failure within the succession process, it is
well worth noting, specifically with respect to the
mentioned early and late entry strategies.
Although these strategies may have specific advantages
or disadvantages respectively, it would really depend
upon the family concerned as to the encouragement of
the involvement of the succeeding generation. Some of
the advantages of the early entry strategy include a
more intimate relationship with the business and
employees, specific skills pertaining to the relevant
business are developed, achievement of credibility
ensues; on the other hand the advantages pertaining to
delay entry include a more objectively judged scenario
of the successor by the employees, success of self-
confidence and achievement development, overall
business perspective is widened by the successor. The
disadvantages for these respective strategies include
from an early entry perspective, being that of the
aforementioned opposing force of relinquishing control

to the successor, mistakes viewed as incompetence, and
limited overall business knowledge and experience. The
delayed entry strategy disadvantages are described as
key business strategies, and success factors specific to
the family business may be lacking, outside business
“habits, or patterns” may conflict with that of the family
systems, including values and ethics, resentment
amongst employees may occur with implementation of
the successor from within the family, instead of that of
a long serving employee (Kuratko 2008, p. 492). Based
upon the primary data analysis, supported by the
involvement of multiple generations and in addition to
the lifespan media and identified within the analysis, the
majority of successful involvement within the business
in all likelihood appears to be that of the early stage
entry strategy, in which entire generations have been
involved and continue to be involved in the family
businesses as described.
Based on the issues described previously mentioned
authors one might expect that a possible problem in the
succession will be in all likelihood caused by the two
mentioned opposing forces, based on the fact that it
appears the succeeding generation has been deployed
within the business on an early entry strategy basis,
whilst these opposing forces of letting go by the senior
generation, and impatience or waiting there for by the

younger generation may be the two, or either of, factors
that may contribute to the failure of the succession
process when the time comes about. As previously
stated with successful succession it may well occur that
these very businesses surveyed within the primary data,
may no longer be in existence in the next few years,
based upon the previously mentioned issues as well as
the median average age is revealed in the primary data
analysis.
Beyond issues already discussed, and a further point of
interest that is well worth mentioning and discussing is
that of corporate governance and the impact thereof
upon the diversified family businesses in particular. In
regard to the specific primary data research it did not
seem that corporate governance carried much weight
amongst the respondents, and seemed to be an issue
that was meant to be adhered to, and not a vital tool
that it could well be used for. Davies (2006) defines
corporate governance as a system by which companies
are directed and controlled, with directors being
responsible for such governance, which in turn raises
the issue of accountability in terms of the leadership of
the company concerned (Davies 2006, p. 3). In addition
to this definition Morck (2005) provides that a number
of authors claim the issue of governance emanated

from that of bankers to ensure repayment of financing
by companies (Morck 2005, p. 52).
Morck further provides that different countries have
different sets of rules and regulations in terms of the
corporate governance practice. However, within the
study it should be highlighted that the issue of
governance is more focused upon the management,
control and leadership of the company for the purpose
of continuity and sustainability of the family business
concerned, and how management and ownership relate
to each other, which is in line with previously discussed
issues of succession and so forth. The issue of corporate
governance does not come without related problems,
as Morck provides that with the different structures in
place issues become relevant in terms of allocation of
control, funds and so forth; but as stated a more
transparent and sustainable “rule structure” should be
implemented within the family business environment,
beyond that of any legal requirement adherence, to
ensure the survival of the business, for the benefit of the
family and the economy as a whole.
Aronoff & Ward provide that the organization of the
company’s board of directors, in the family business is
often underestimated by the controlling family
themselves, with respect to the potential contribution

that such board members can bring about. In addition
to this, authors provide that some might criticize the
privately held company, and family control as a
convenient way to channel director fees to family
members, which may well be the case as represented by
the primary data in which it was revealed that board
members are in fact family members (Ward & Aronoff
1996, p. 30); alternatively the authors state that
examples exist with family members which have openly
agreed that the appointment of outside board
members, meaning those that have no ties with the
family besides that of the directorship of the family
controlled business, has in fact provided significant
improvements to the business, specifically for those
business owners that are truly interested in the
perpetuity of the business concerned. This contributes
to the many mentioned succession and continuity
issues, thereby revealing how corporate governance is
interrelated with one of the primary potential failure
issues of the family business, being that of succession is
described.
Beyond the issue of good governance aiding in the
succession and continuity of the business, in terms of
present-day operations Aranoff & Ward confirmed that
all their governance is somewhat of an abstract concept,
this concept can go a long way in assisting the family

unit in terms of “smooth decision making, cohesiveness,
effective conflict resolution and freedom from political
warfare” which all aide in the development of a “healthy
and sustainable” family business (Ward & Aronoff 1996,
p. 53); with two distinctive approaches pointing to the
governance of the family and to that of the business on
two different levels. This is confirmed by Davies (2006)
who provides that the “importance of proper
governance within the family, and separately for the
business, is emerging strongly” (Davies 2006, p. 95); this
does not appear to be the case within the primary data,
as the vast majority of respondents hardly commented
on the need of such governance, as well as only a couple
believing that such governance was a tool for
optimization, as described above.
The governance issue will also spill over into the
interests of non family stakeholders that are within the
business, being that of employees. Herewith the issues
of discrimination are raised, as the astigmatism
attached to the family is that the employee may never
specifically progress within the company, due to such
non family involvement. On the other hand, the level of
ethics, the culture and the environment created by the
family may well perhaps counter any such perceptions,
but the governance is sure to establish a set of rules that
can make the employee more comfortable in terms of

not being discriminated against. One of the respondents
within the primary data, specifically stated that the
employment and human resource function was
attended by an external consultant, which coincides
with the view of Davies (2006), in which “it is becoming
accepted practice for appointments to be subject to
competitive interview with external monitoring”
(Davies 2006, p. 102).
This construes the fact that due to external pressure the
popularity of such a process is becoming more
acceptable to the family that has to adhere to such a
practice in order to remain attractive to potential
employees as well as the within the human resource
market, which requires the addition or augmentation of
the workforce within the expansion and growth phases
of the family business. Davies further echoes of other
authors in “effective corporate governance is the key
instrument for developing and sustaining excellence”
whilst “families are realizing that they can continue as
owners of their companies only by separating direction
from ownership” (Davies 2006, p. 95) which further
highlights the central theme as raised in accordance
with corporate governance affecting the continuity,
sustainability and effectively the future of the company
in question.

Furthermore, if one likens the separation of ownership
from that of direction as stated, and according to the
primary data, even those companies that selected the
public company, retained such ownership, together
with directorships on the board represents a possible
contradiction to the theories and literature herein
presented. This is where one has to question the
sustainability of the companies surveyed within the
primary data selection, as well as the true motivation
behind whether or not the company ownership does
indeed seek perpetuity for the companies in question.
Davies provides that a way around the governance issue
is that those families, who have family councils,
naturally extend into the governance area within
business, providing a set of rules and regulations that
govern the actions and or inactions of the company
concerned.
Based upon responses received from the respondents
within the survey, and specifically pertaining to that of
the issues of corporate governance, and in comparison
to the original family values and controls, a
predominant trend within the survey indicate that the
original family values and core ethics have filtered down
throughout the lifespan of the family business
concerned. These values have been installed as rules
and guidelines for the corporation, and provided these

are in line with the interests of both external and
internal stakeholders then such corporate governance is
no longer as much of an issue in this instance. However,
if these values and core family beliefs are solely for the
purpose for the well-being of the family inheritance,
then the perpetuity, continuity and sustainability of the
business comes under question. Once again some of the
responses were somewhat limited, due to be as
mentioned closely held family business issues, and
Therefore, many of the responses are deemed to infer
certain circumstances and situations, based upon
responses to specific and other questions with regards
to be corporate governance, control and beliefs of the
family members controlling the businesses in question.
From an external point of view, and then according to
Davies (2006) the issue of corporate governance goes
beyond that of ensuring the previously described
sustainability and excellence within the company,
regardless of whether it is family owned and controlled
or not, but furthermore builds reputation in the eyes of
the prospective customers, and possibly suppliers too,
Therefore, governance goes further with the
potentiality of directly affecting the bottom line.
According to the author, and specific to the field of
governance, the reputation of the organization extend
further into the social and ecological responsibilities of

the firm, and although these factors receive significant
media attention within the modern day society, the
author believes they form an integral part of the
reputation of any organization (p. 105). These issues
would be specific to manufacturing concerns, as well as
construction companies that work closely with the
environment, and are only truly represented by 18% of
the sampling during contact.
The balance of the respondents was predominantly
involved with in the service sector, as what one may
determine who is being a third-party or middlemen. This
does not alleviate from the social responsibilities that
the family business should consider in their daily
business operations. This reputation is furthermore,
somewhat of an intangible aspect of the corporation.
However, it is deemed to be “the identity of that
organization in the eyes of others.” (Davies 2006 p.105)
Although this issue has become known as corporate
social responsibility many organizations have in fact
embraced it as a brand building component within their
overall strategy and business operation. An example of
this is that the McDonald’s Corporation, although this is
not a family run enterprise, who publish a socially
responsible report inclusive of the suppliers, as well as
the overall supply chain, that they use annually in the
deliverance of their products to the consumer. Surely

the cost of such “marketing” is a mere fraction of the
overall benefits obtained by the organization by such
practice, which further adds to the reputation of the
company is a conscious service provider, as well as
employer, which will go towards the sustainability of the
company as a whole. One should not expect to meet the
standards of such multinational corporations. However,
social initiatives within the communities within which
they operate can certainly add to the reputation of the
organization, adding to the localized brand equity,
within the region in which they operate.
Aronoff & Ward (1996) in agreement with Davies
maintained that issues of governance should serve
stakeholders [both internal and external] in order to
meet the goals as defined by the stakeholders and
management of the company (Ward & Aronoff 1996, p.
53). Thereby in addressing the needs and goals of the
stakeholders the reputation of the company can
increase, arguably contributing to the longevity of the
firm.
Despite the fact that no specific mention of financing
was made within the sampling, the issue of governance
goes further in establishing reputation with financiers
and banks. As previously stated where Morck (2005)
provides that bankers and financing institutions utilize

traditional corporate governance as a measure of
repayment and to ensure that corporate borrowers
repay their debts, provides an insight into the “minds”
of the people that may provide financing for the growth
of the family business. Exemplary conduct within the
governance issues will serve the company in application
for such financing, considering the fact that financiers
take this into account in terms of the granting of credit
facilities or even the financing of such expansion.
The issue of corporate governance differs on an
international level, with a specific respondent within the
sampling claiming that such governance, although being
a requirement is difficult to implement, based upon the
market and society within which the specific respondent
operates. The geographical location is not known.
However, this sector within which they operate is that
of travel and tourism, which was accordingly grouped
into the hospitality sector. One may find it difficult to
understand as to why such governance would be
difficult to implement within the industry, without a full
understanding of the environment within which the
specific respondent operates in. Unfortunately one
encounters a variety of corruption issues within specific
geographical locations, whereby many successes or
failures hinge upon the fact of whether or not the

individual or company concerned is willing to engage in
such corruption with officials.
Morck further provides that such official corruption
“retards economic development”. However, the
engagement there in is represented by a “raising the
return to investment in political connections above that
to investing in ordinary business projects” (Morck 2005,
p. 89). The history of corruption in certain societies,
which further continues to exist, has almost become
second nature to economies, so much so that it is
expected. This issue is beyond the scope of the study,
but has a relevance upon governance as well as the
future of the company, based upon the fact that if the
company had engaged in such corruption to reach a
successful level in which they operate today, in all
likelihood such corruption would most likely have to
continue in order to ensure an ongoing level of success
to which the family members and organization have
become accustomed to.
Analysis of the Real Research Findings
Using web based tool, offered by Survey Monkey,
results are graphically evaluated. Real research of this
study involves a survey that contains 25 questions.
Analysis of the survey findings are as under:
What is your role/position?
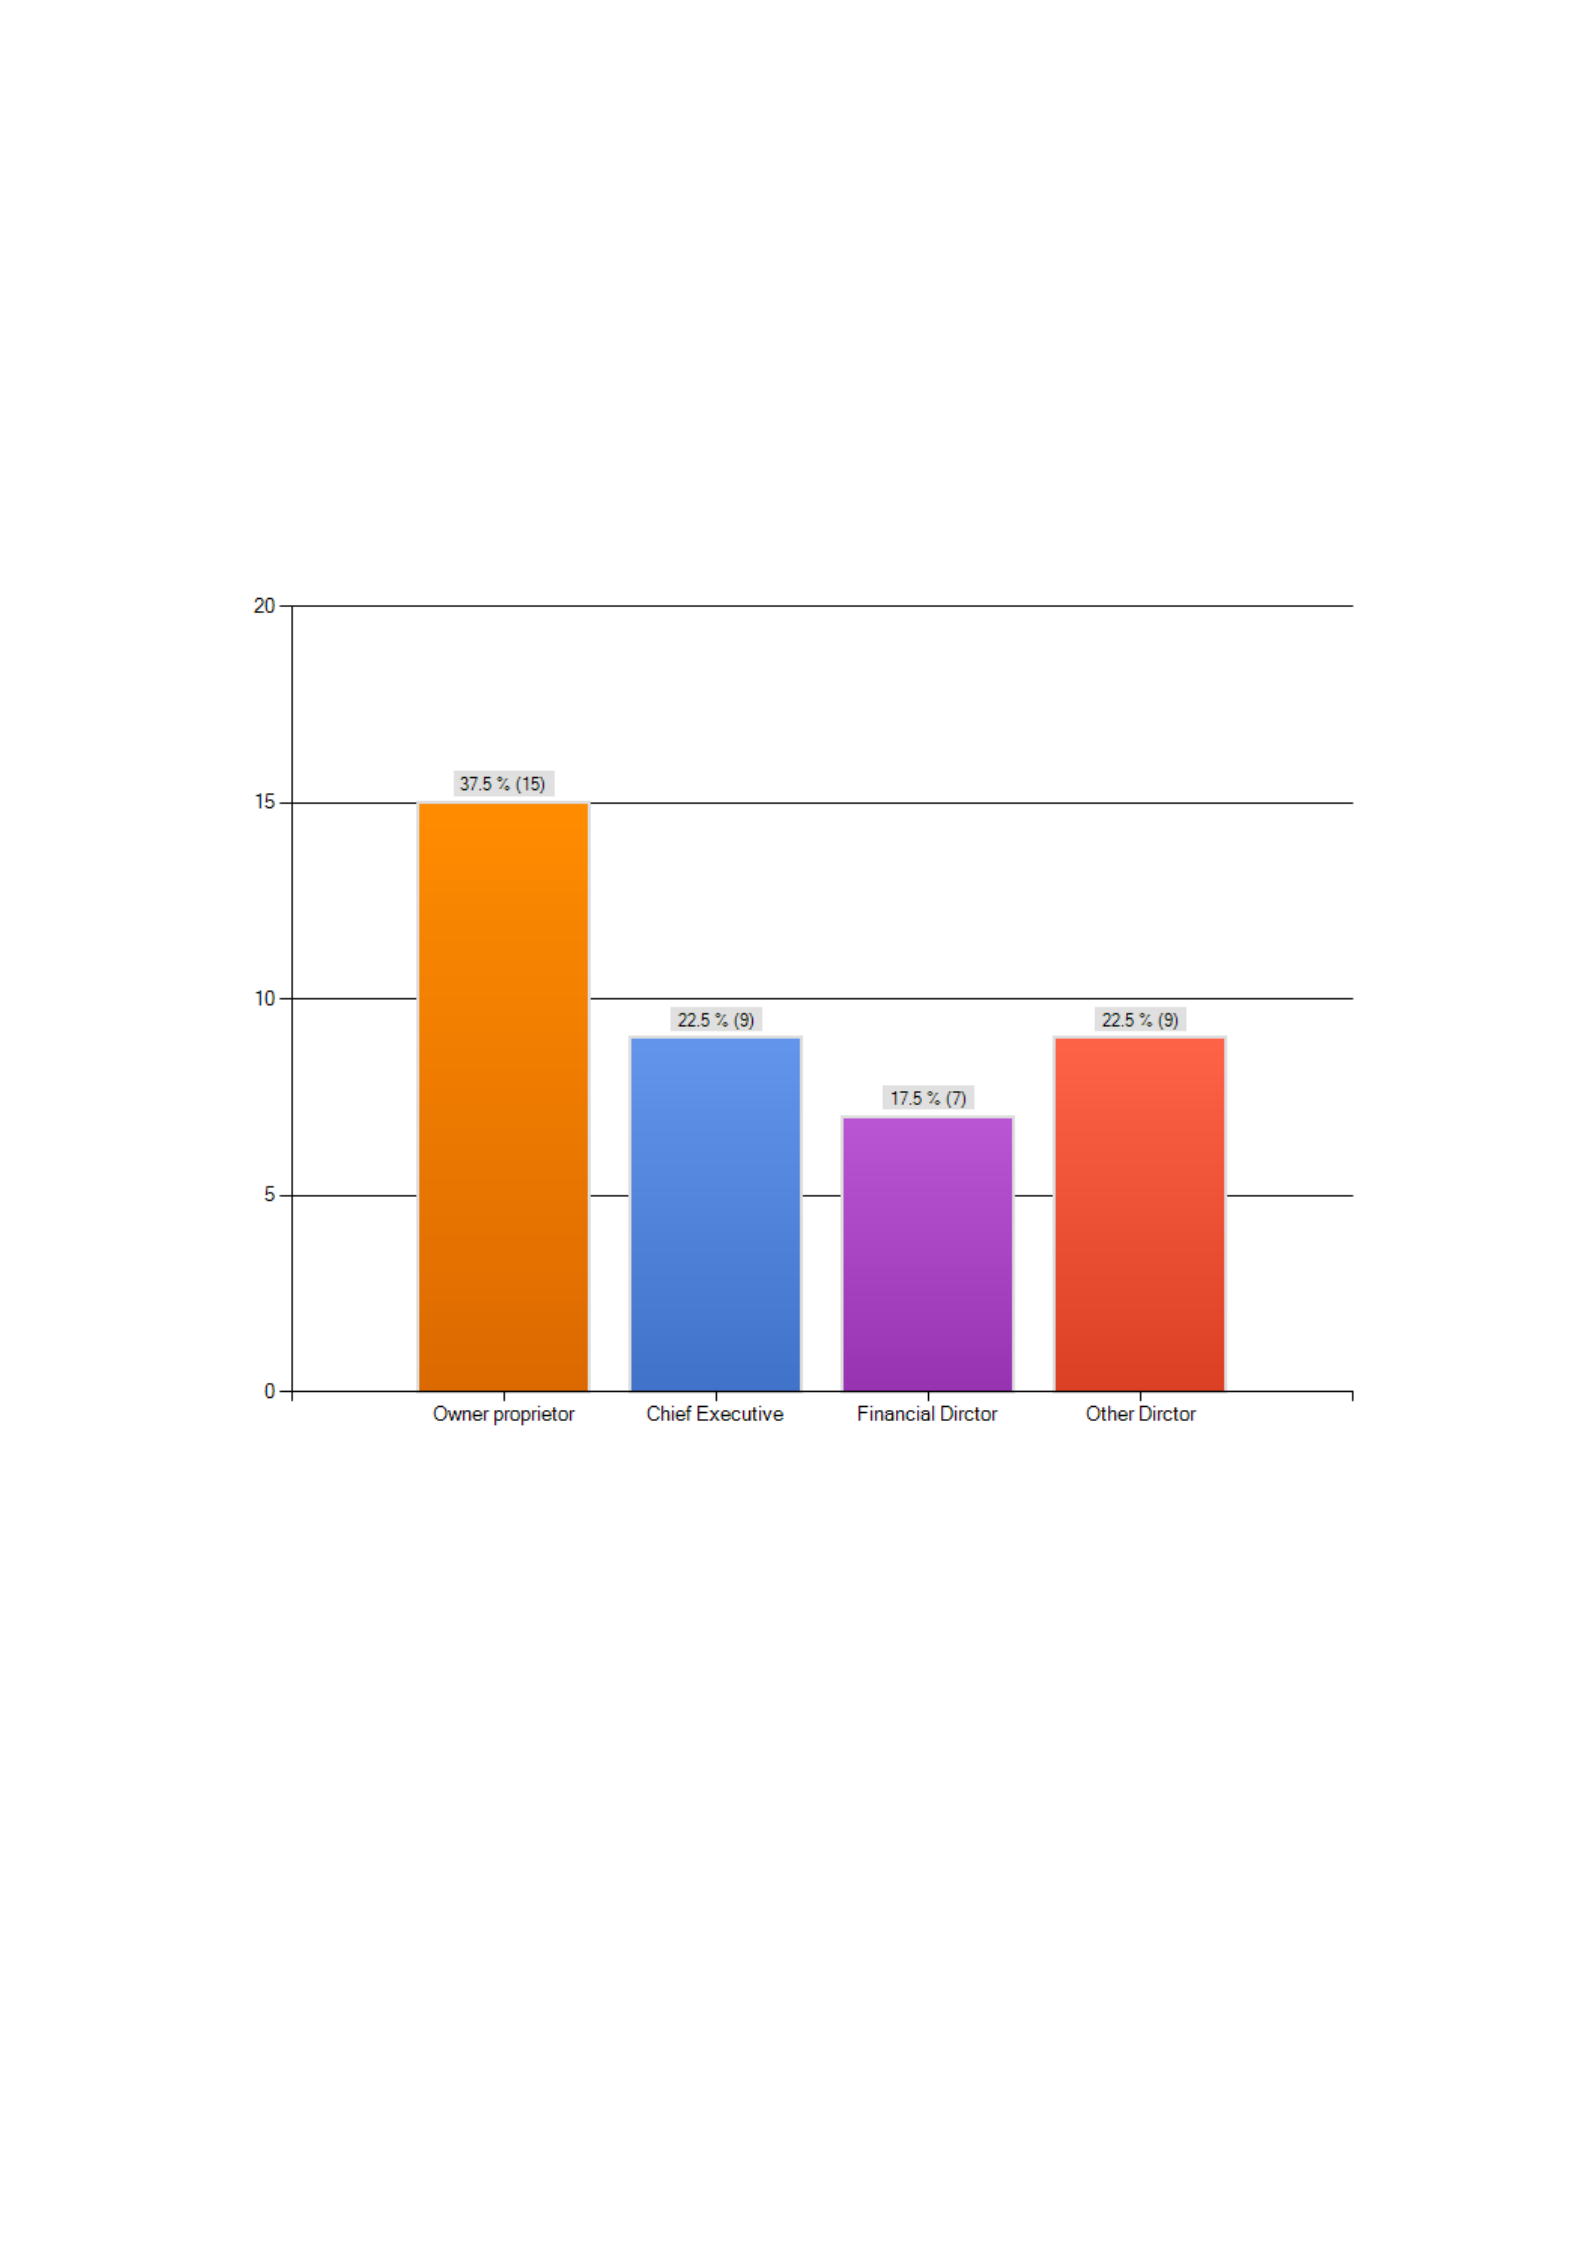
This question has been applied on a sample of 40
participants so that to know the role of each
respondent, participating in this study’s survey. Below is
the graphical presentation of the responses received in
answer of Q1.
Figure 5: Role of Survey Participants.
For the survey, we only selected the executive level
participants. Above graph illustrate that out of 40
participants, the majority with total 15 participants are
the owners / proprietors of their family businesses.
However, second big chunk is of Chief Executive Officers
with total number as 9. Besides, 7 Financial Directors
participated while the remaining 9 are different other
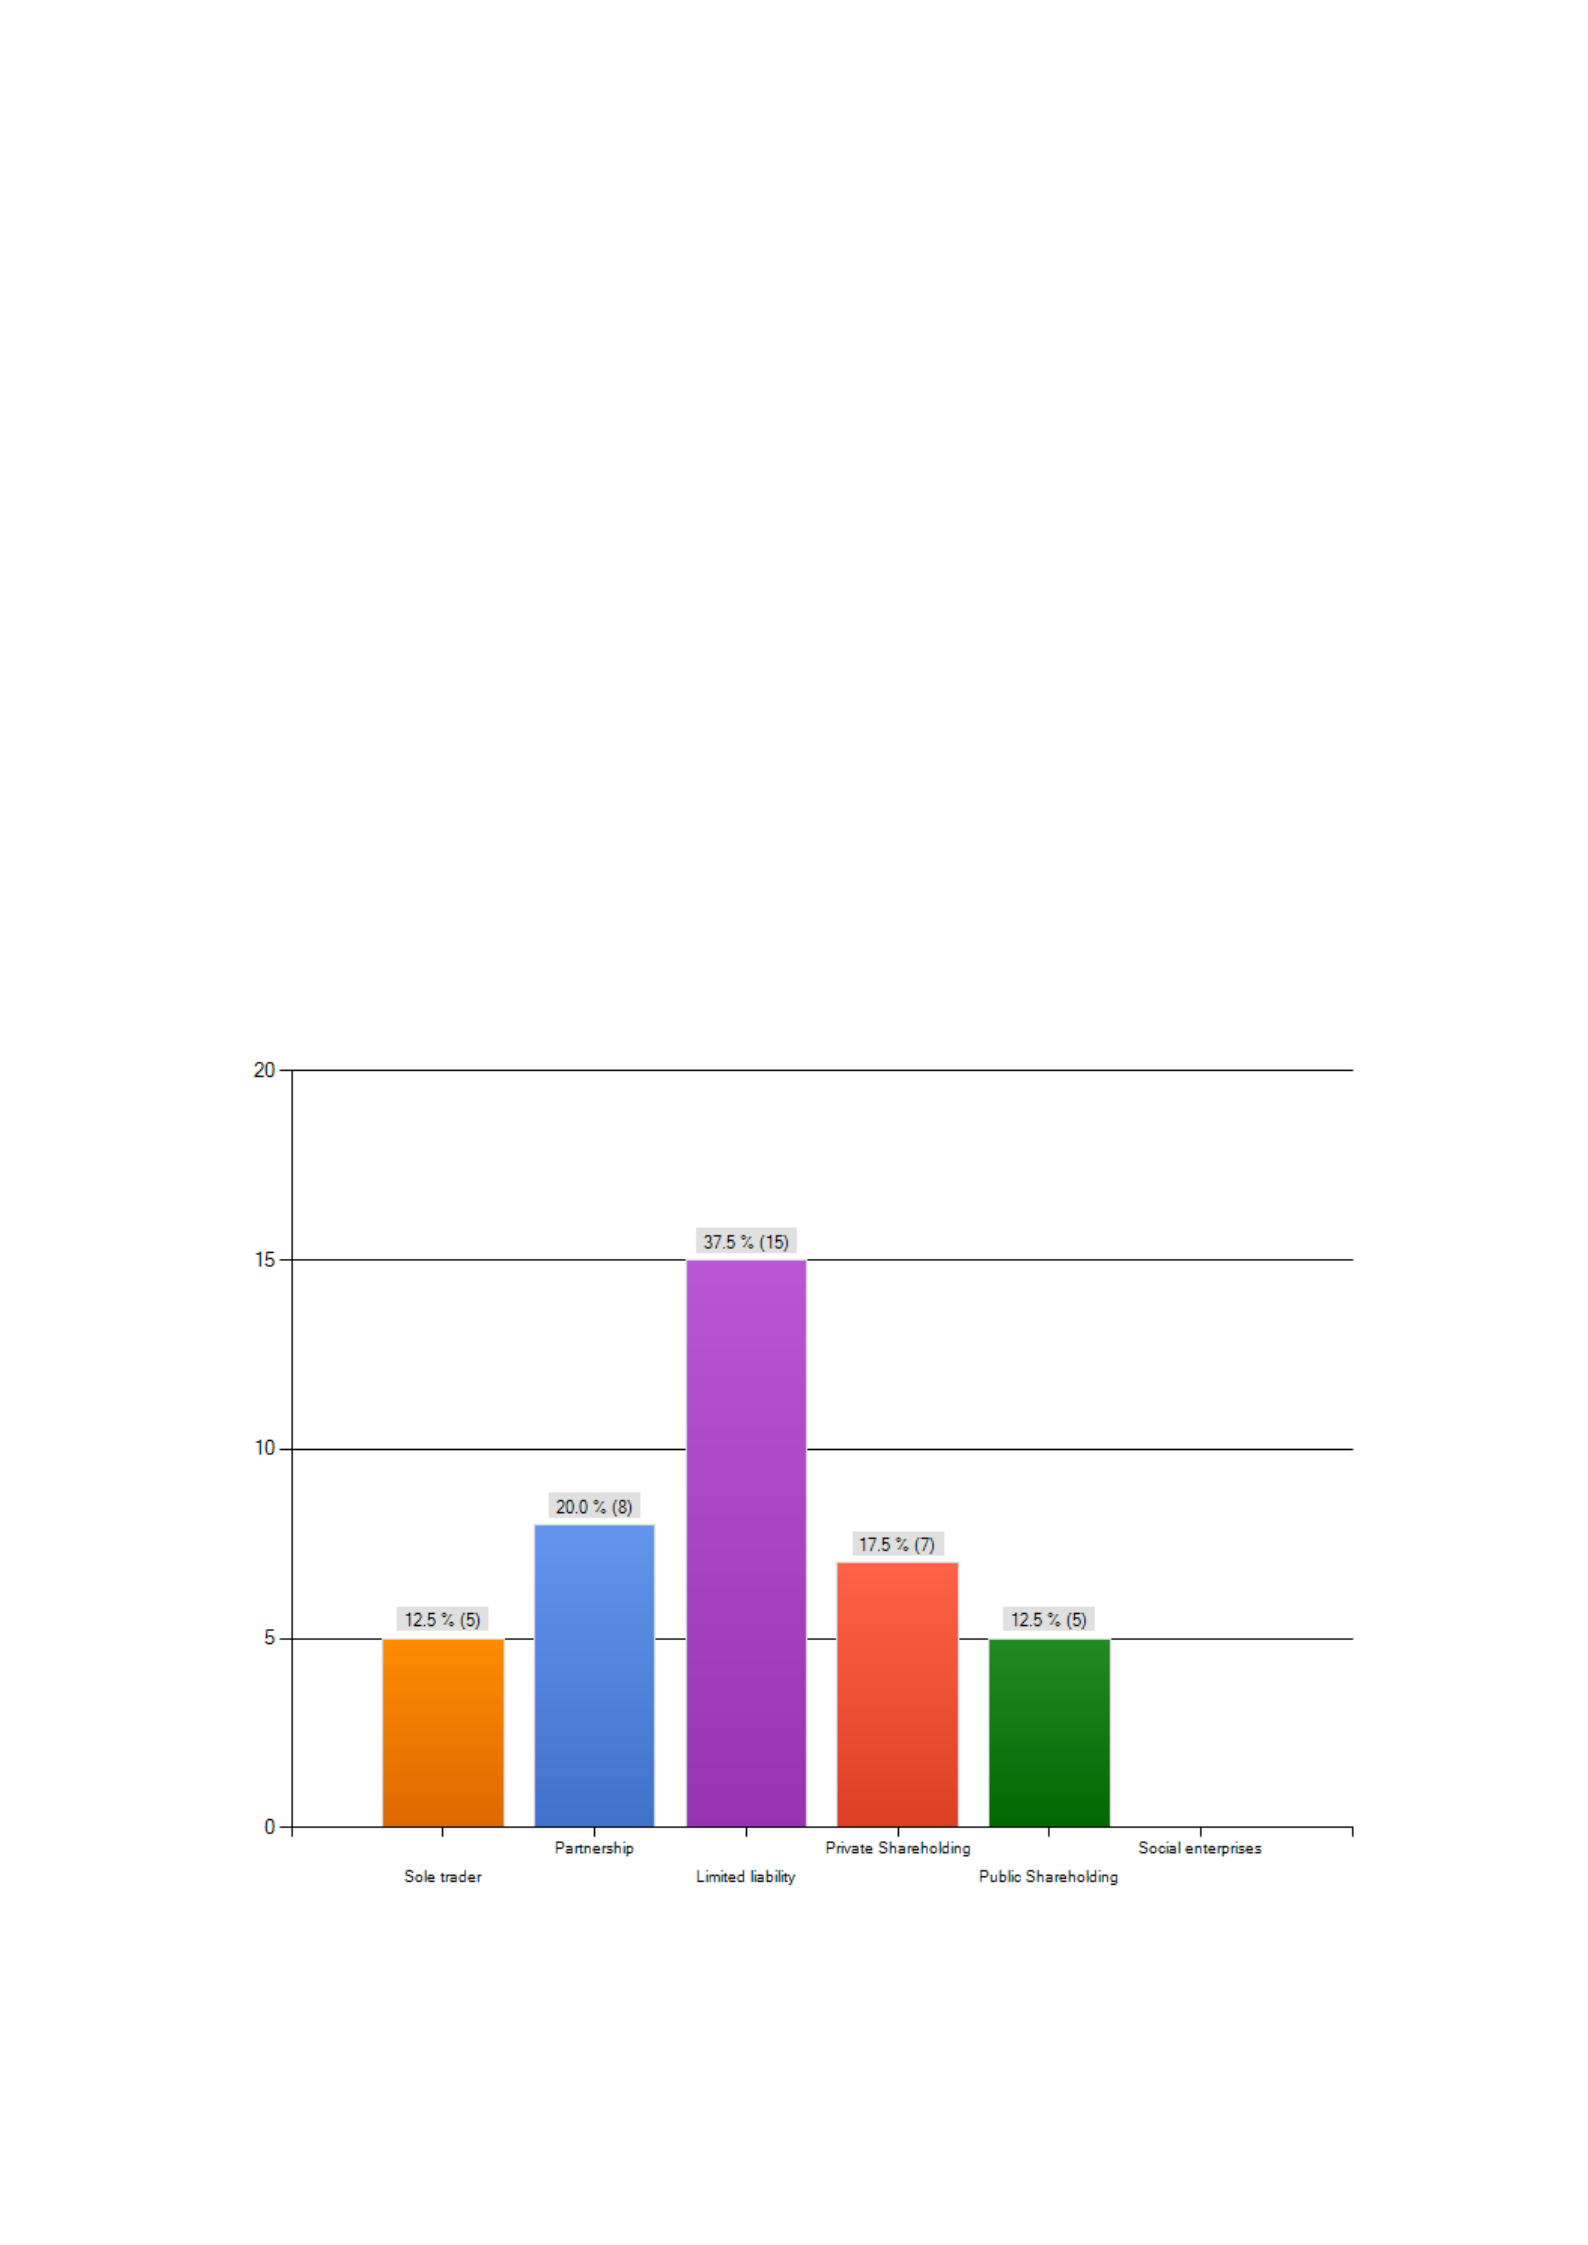
directors. Q1 results indicate that the majority of the
survey participants are the owners of the companies.
The percentages of Q1 for the owner/proprietor, Chief
Executive Officers, Financial directors and other
Directors are 37.5%, 22.5%, 17.5% and 22.5%
respectively.
What is the company’s legal structure?
Q2 is another basic question to identify the contribution
of each legal structure of companies owned by the
participants of this survey. Below is the graphical
presentation of Q2.
Figure 6: Company Legal Structure of Participants.

Above graph illustrates that the majority participants
(15 participants out of 40) with 37.5% of the total
population belong to the companies with limited
liability. The second big chunk is of 8 participants with
20% of the population belongs to the partnership
businesses. Third big chunk is of 7 participants with
17.5% of the total population belongs to the private
shareholding firms while the other two chunks contain
5 participants with 12.5% of the total population each
belong to the sole traders and the public shareholding
businesses. Q2 results clearly indicate that most of our
participants belong to the limited liability businesses.
How long has the business been in operation?
For this survey, it was taken quite seriously to only
include businesses that have been operating for at least
5 years or so. However, only a few participants are from
the businesses that have been operating between 1 to
9 years. For more illustration, below is the graphical
presentation.
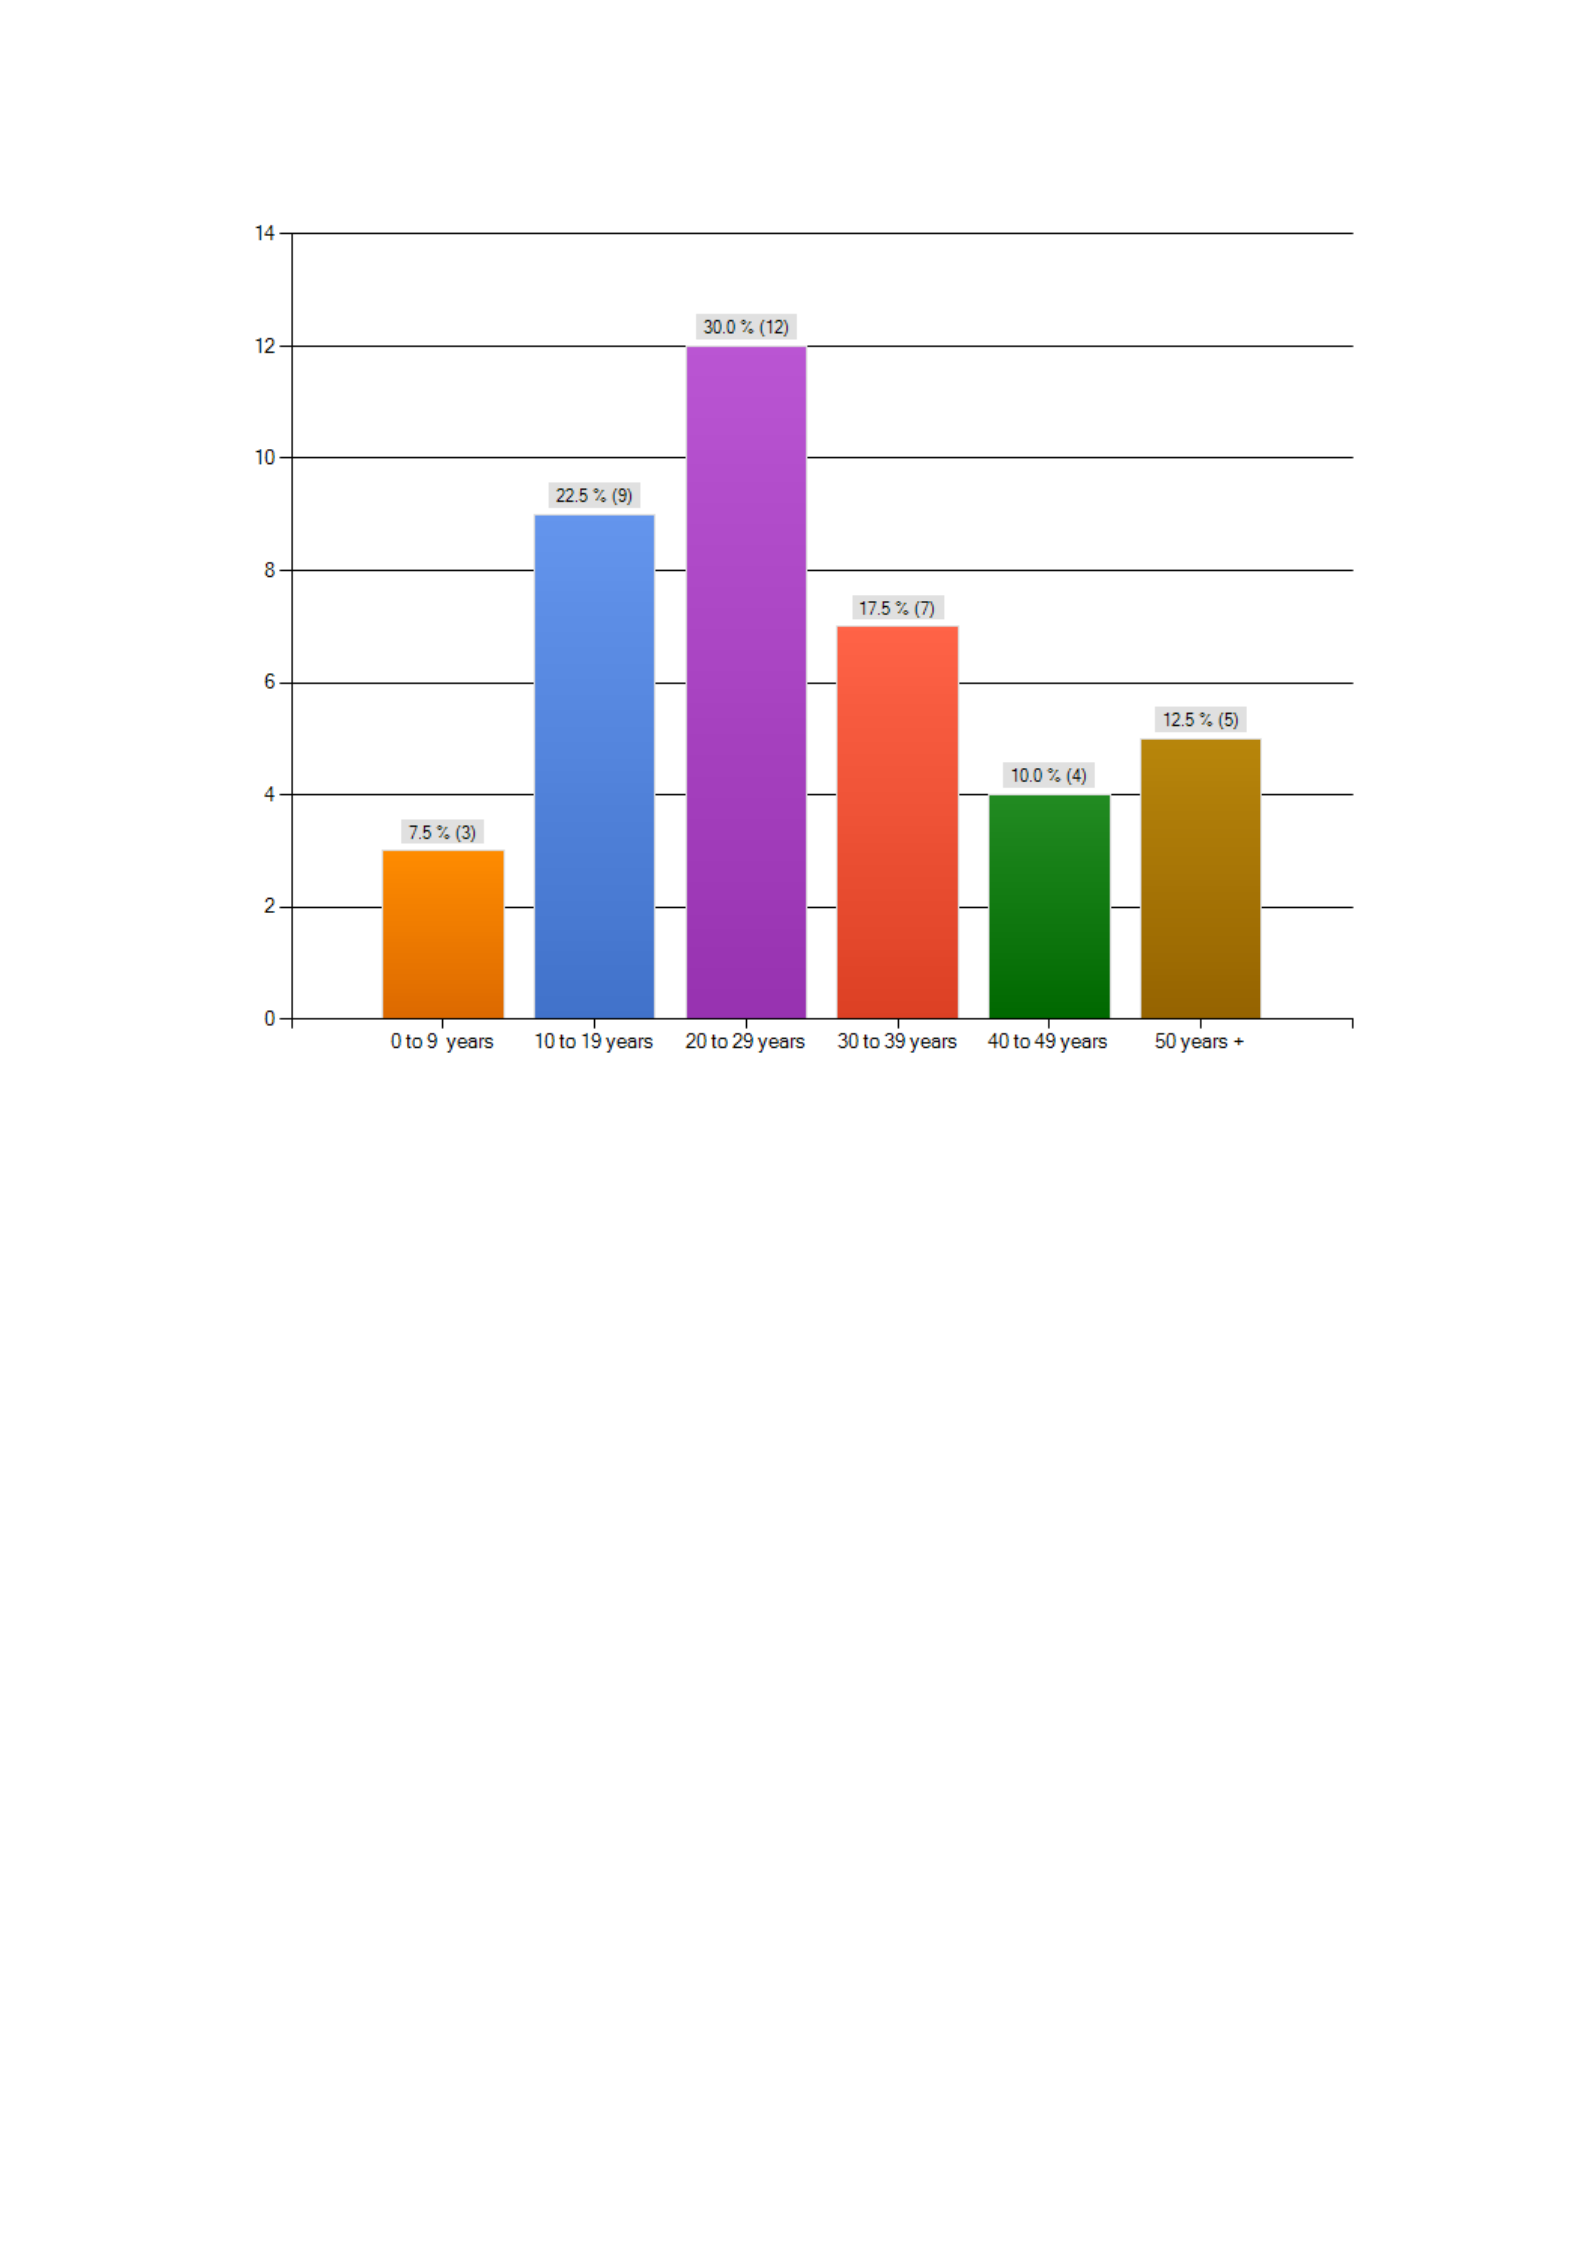
Figure 7: Years in Business.
Above graph indicates clearly that the major chunk of 12
participants with 30% of the total participants is from
the family businesses that are operational since 20 to 29
years. Second big chunk refers to 9 participants who
operate businesses operating in market since 10 to 19
years. Third big chunk contains total 7 participants who
own businesses that are in market since 30 to 29 years.
Fourth chunk contains participants of companies that
are as old as 50 years or above. Fifth big chunk refers to
4 participants (10% of the population) who are in
business since 40 to 49 years. While, the smallest
classification or chunk refers to the participants who

own companies that are in business since 9 years or less.
Above illustration reveals that participants are taken
from stable companies that have been operating since
quite long now. Choosing participants from companies
which were established in different years is significant
because considering companies that have been
operating since similar tenors might not add value to the
findings and it could also influence the findings.
Would you consider your business as being that of a
family owned business?
Since our topic is all about the impact of diversification
on family business, therefore, it was quite necessary to
take special care while choosing participants from the
family owned businesses. However, below graph
reveals if the participants of this survey belong to the
family owned businesses.
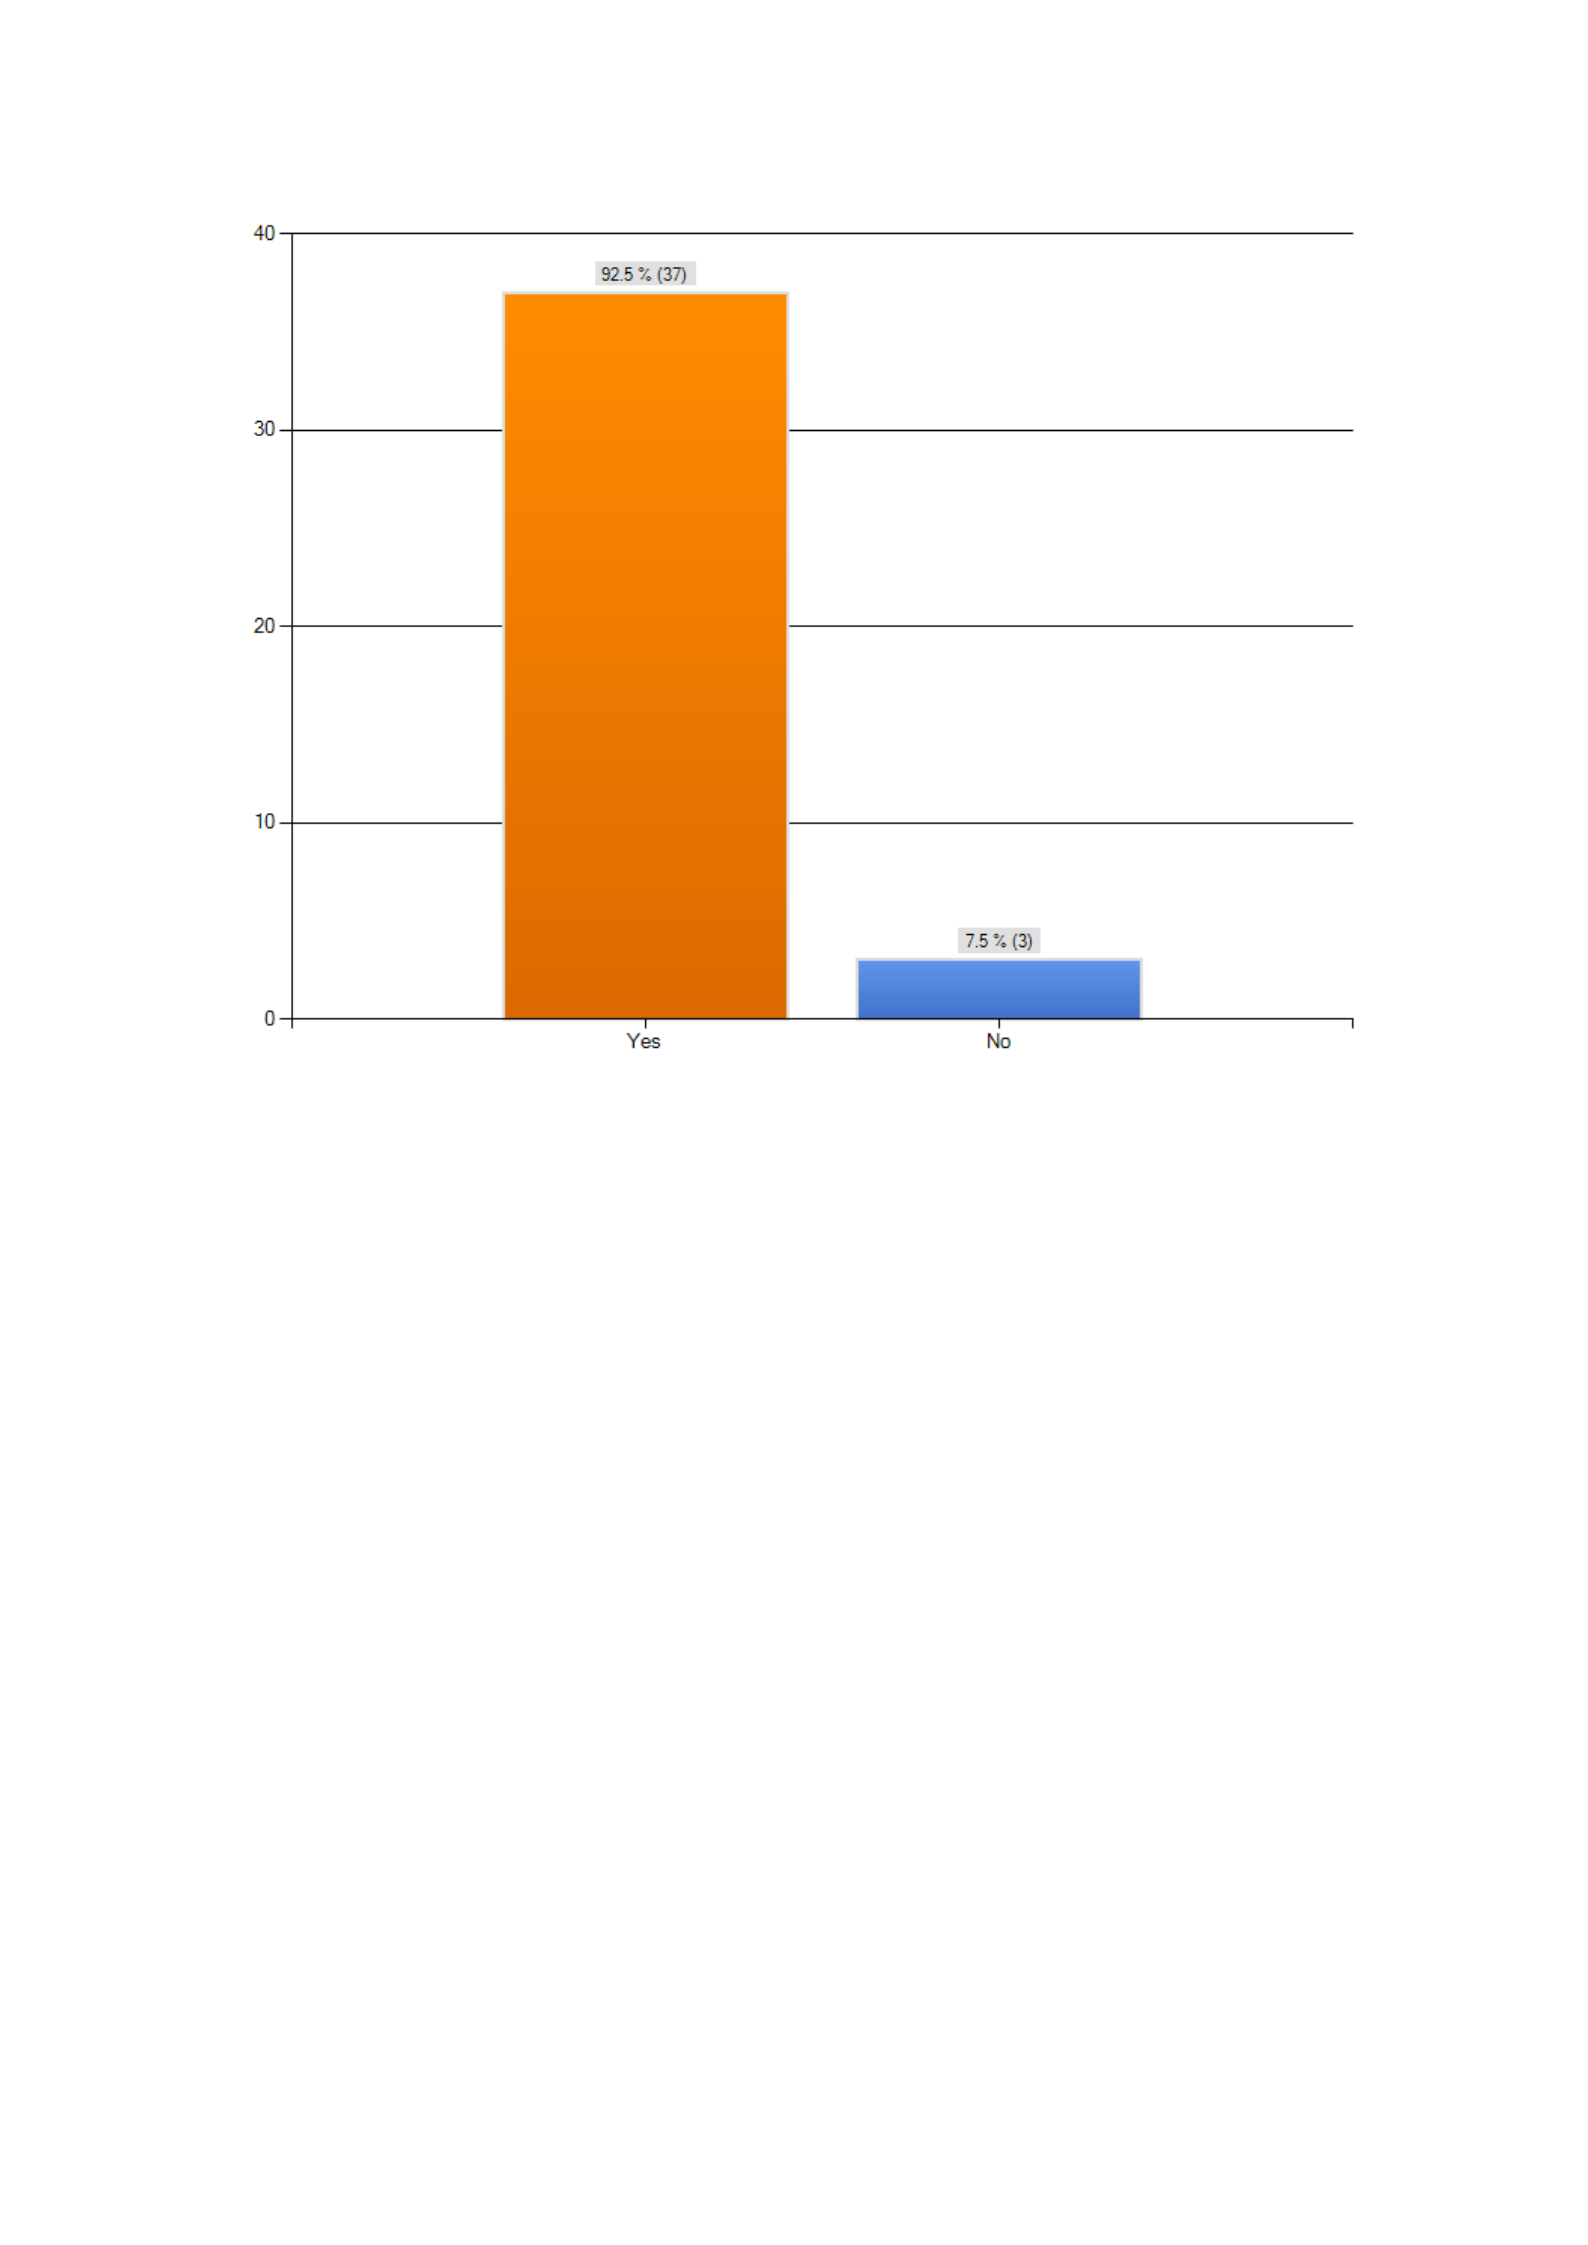
Figure 8: Family Owned Businesses Analysis.
Above graph indicates that 37 participants out of 40
participants belong to the family owned businesses
while only 3 out of 40 participants declared that their
businesses not as the family owned businesses.
Therefore, majority with 92.5% of the total participants
reveals that requirement of choosing the right
participants has been met satisfactorily.
What is your historical core business?
This question is to make sure if participants are from
different businesses as if a major chunk is taken from
same nature of businesses, this might affect the findings
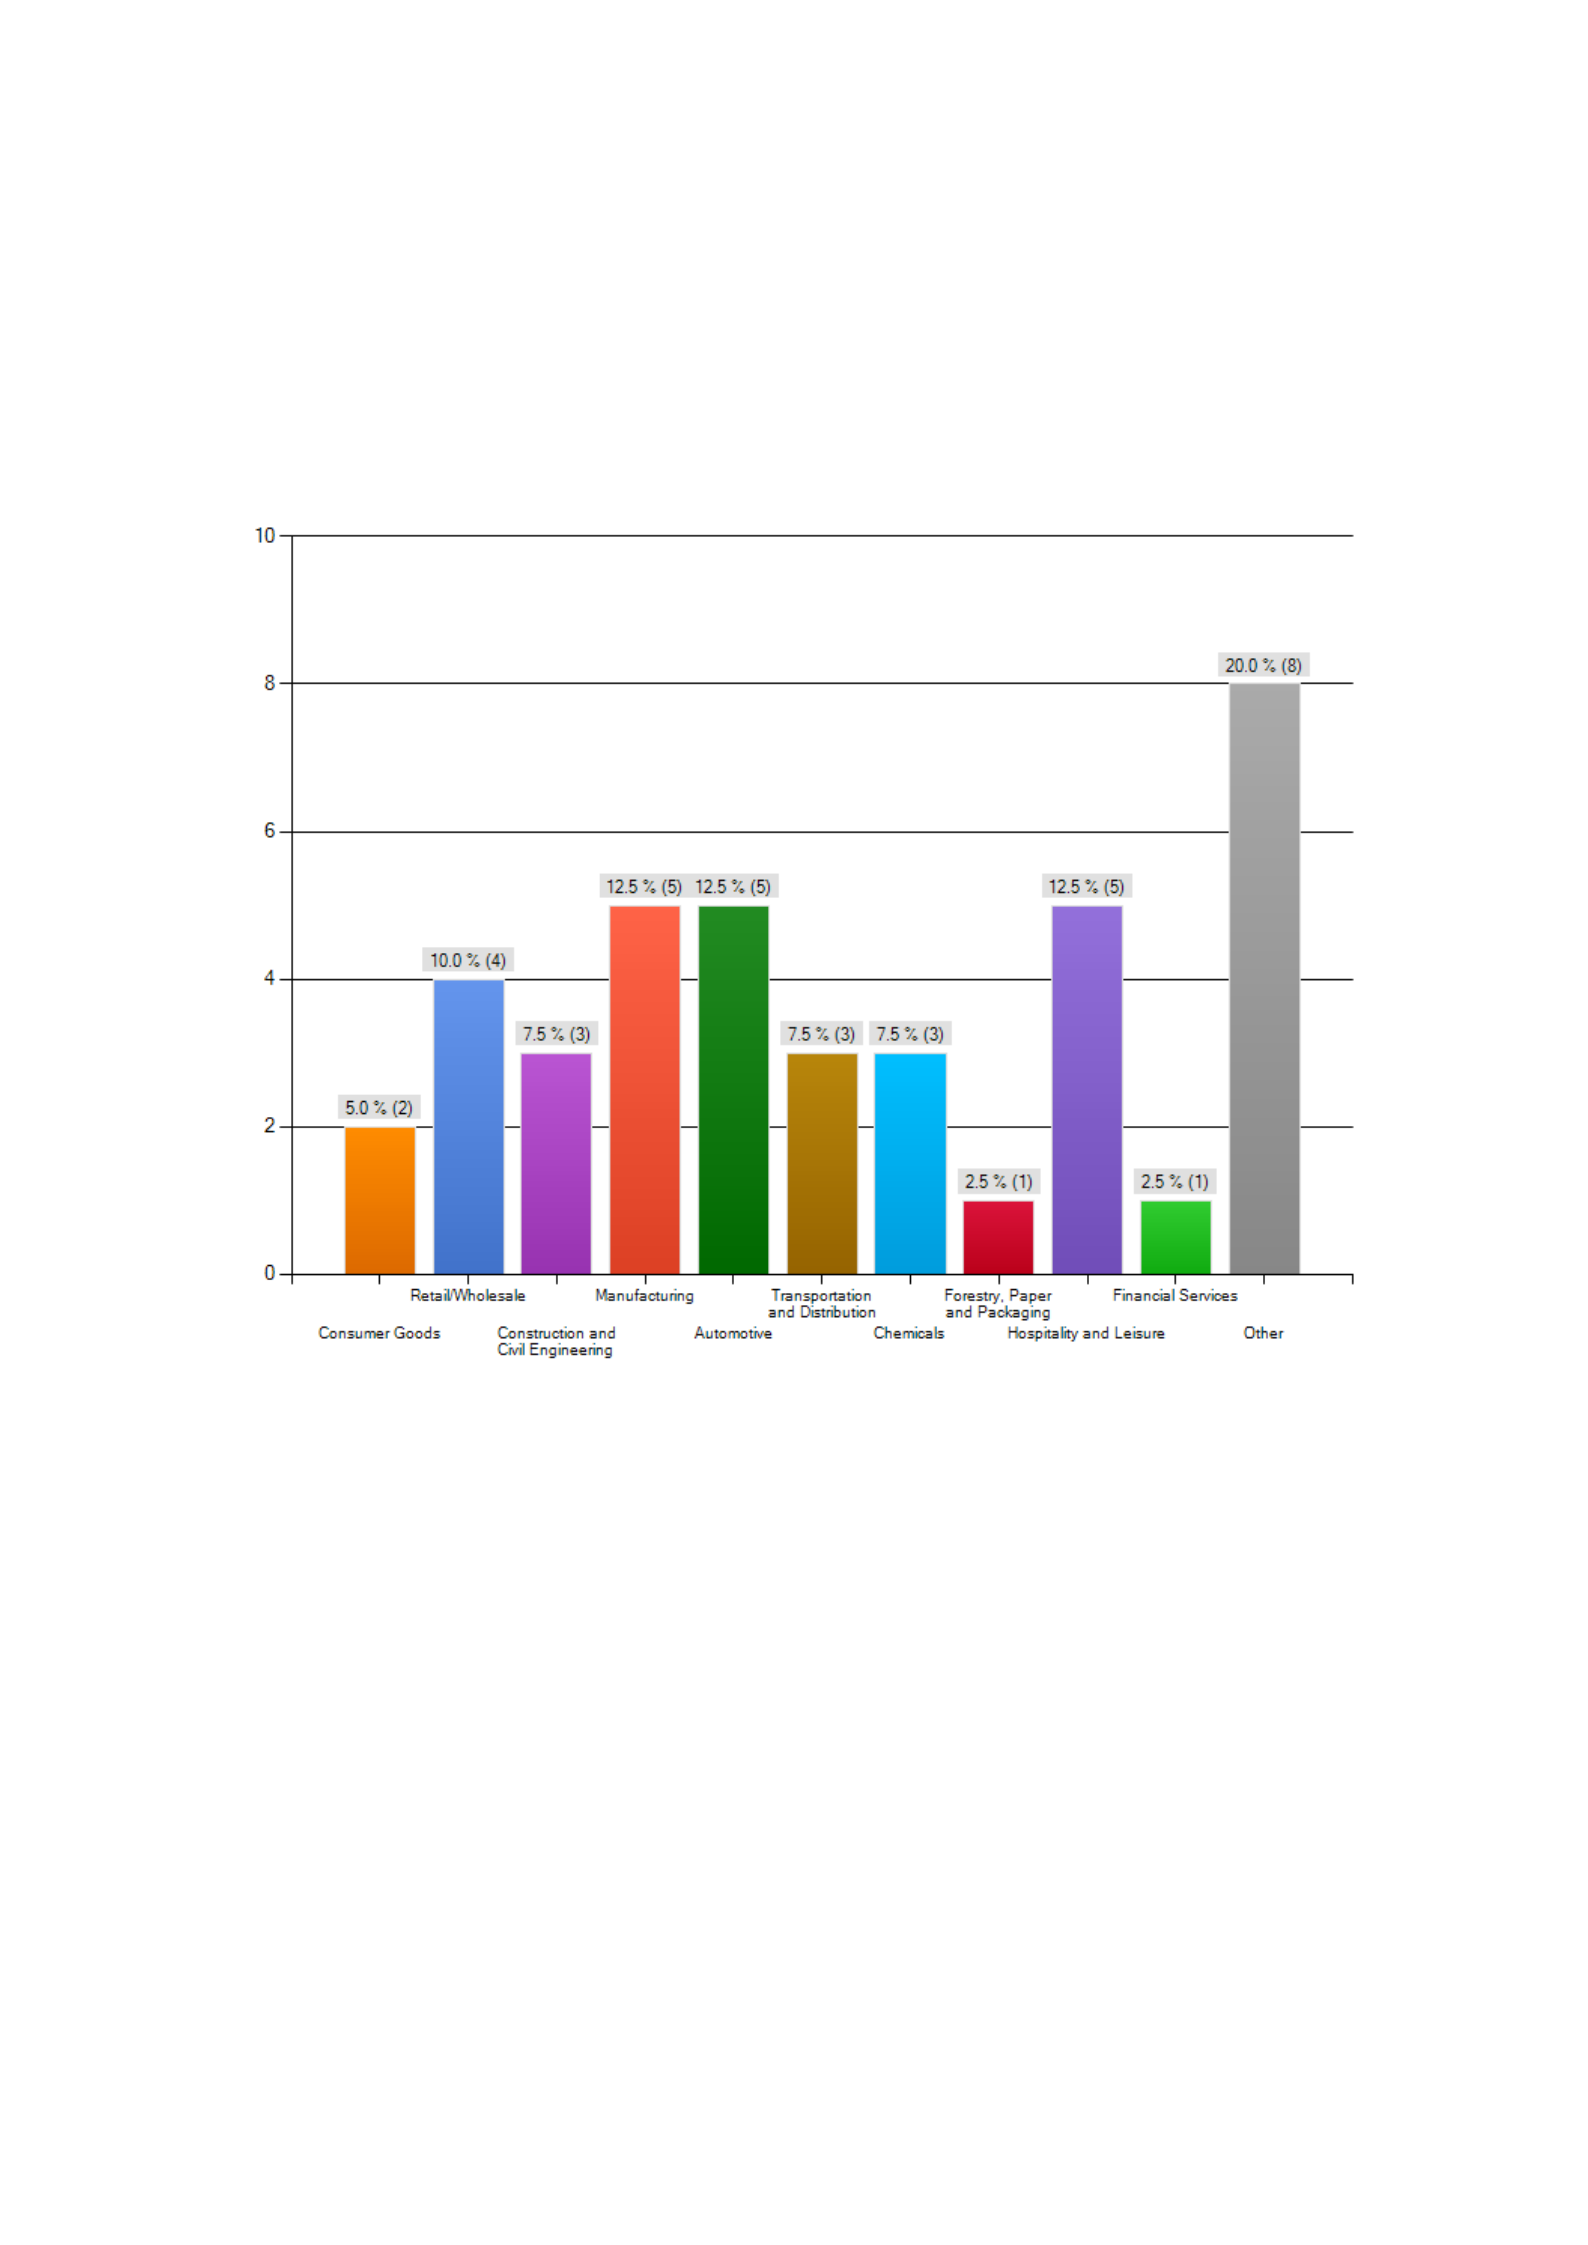
so it is necessary to choose participants from various
fields. Below graph represents Q5 findings that would
help in assessing if participants are chosen correctly for
this survey.
Figure 9: Historical Core Business.
Above graph represents that participants of this survey
are taken from various fields with different historical
core business including consumer goods, retail
wholesale, construction and civil engineering,
manufacturing, automotive, transportation and
distribution, forestry paper and packaging, hospitality
and leisure, financial services and a few others.
Questionnaire was sent to executives from various fields
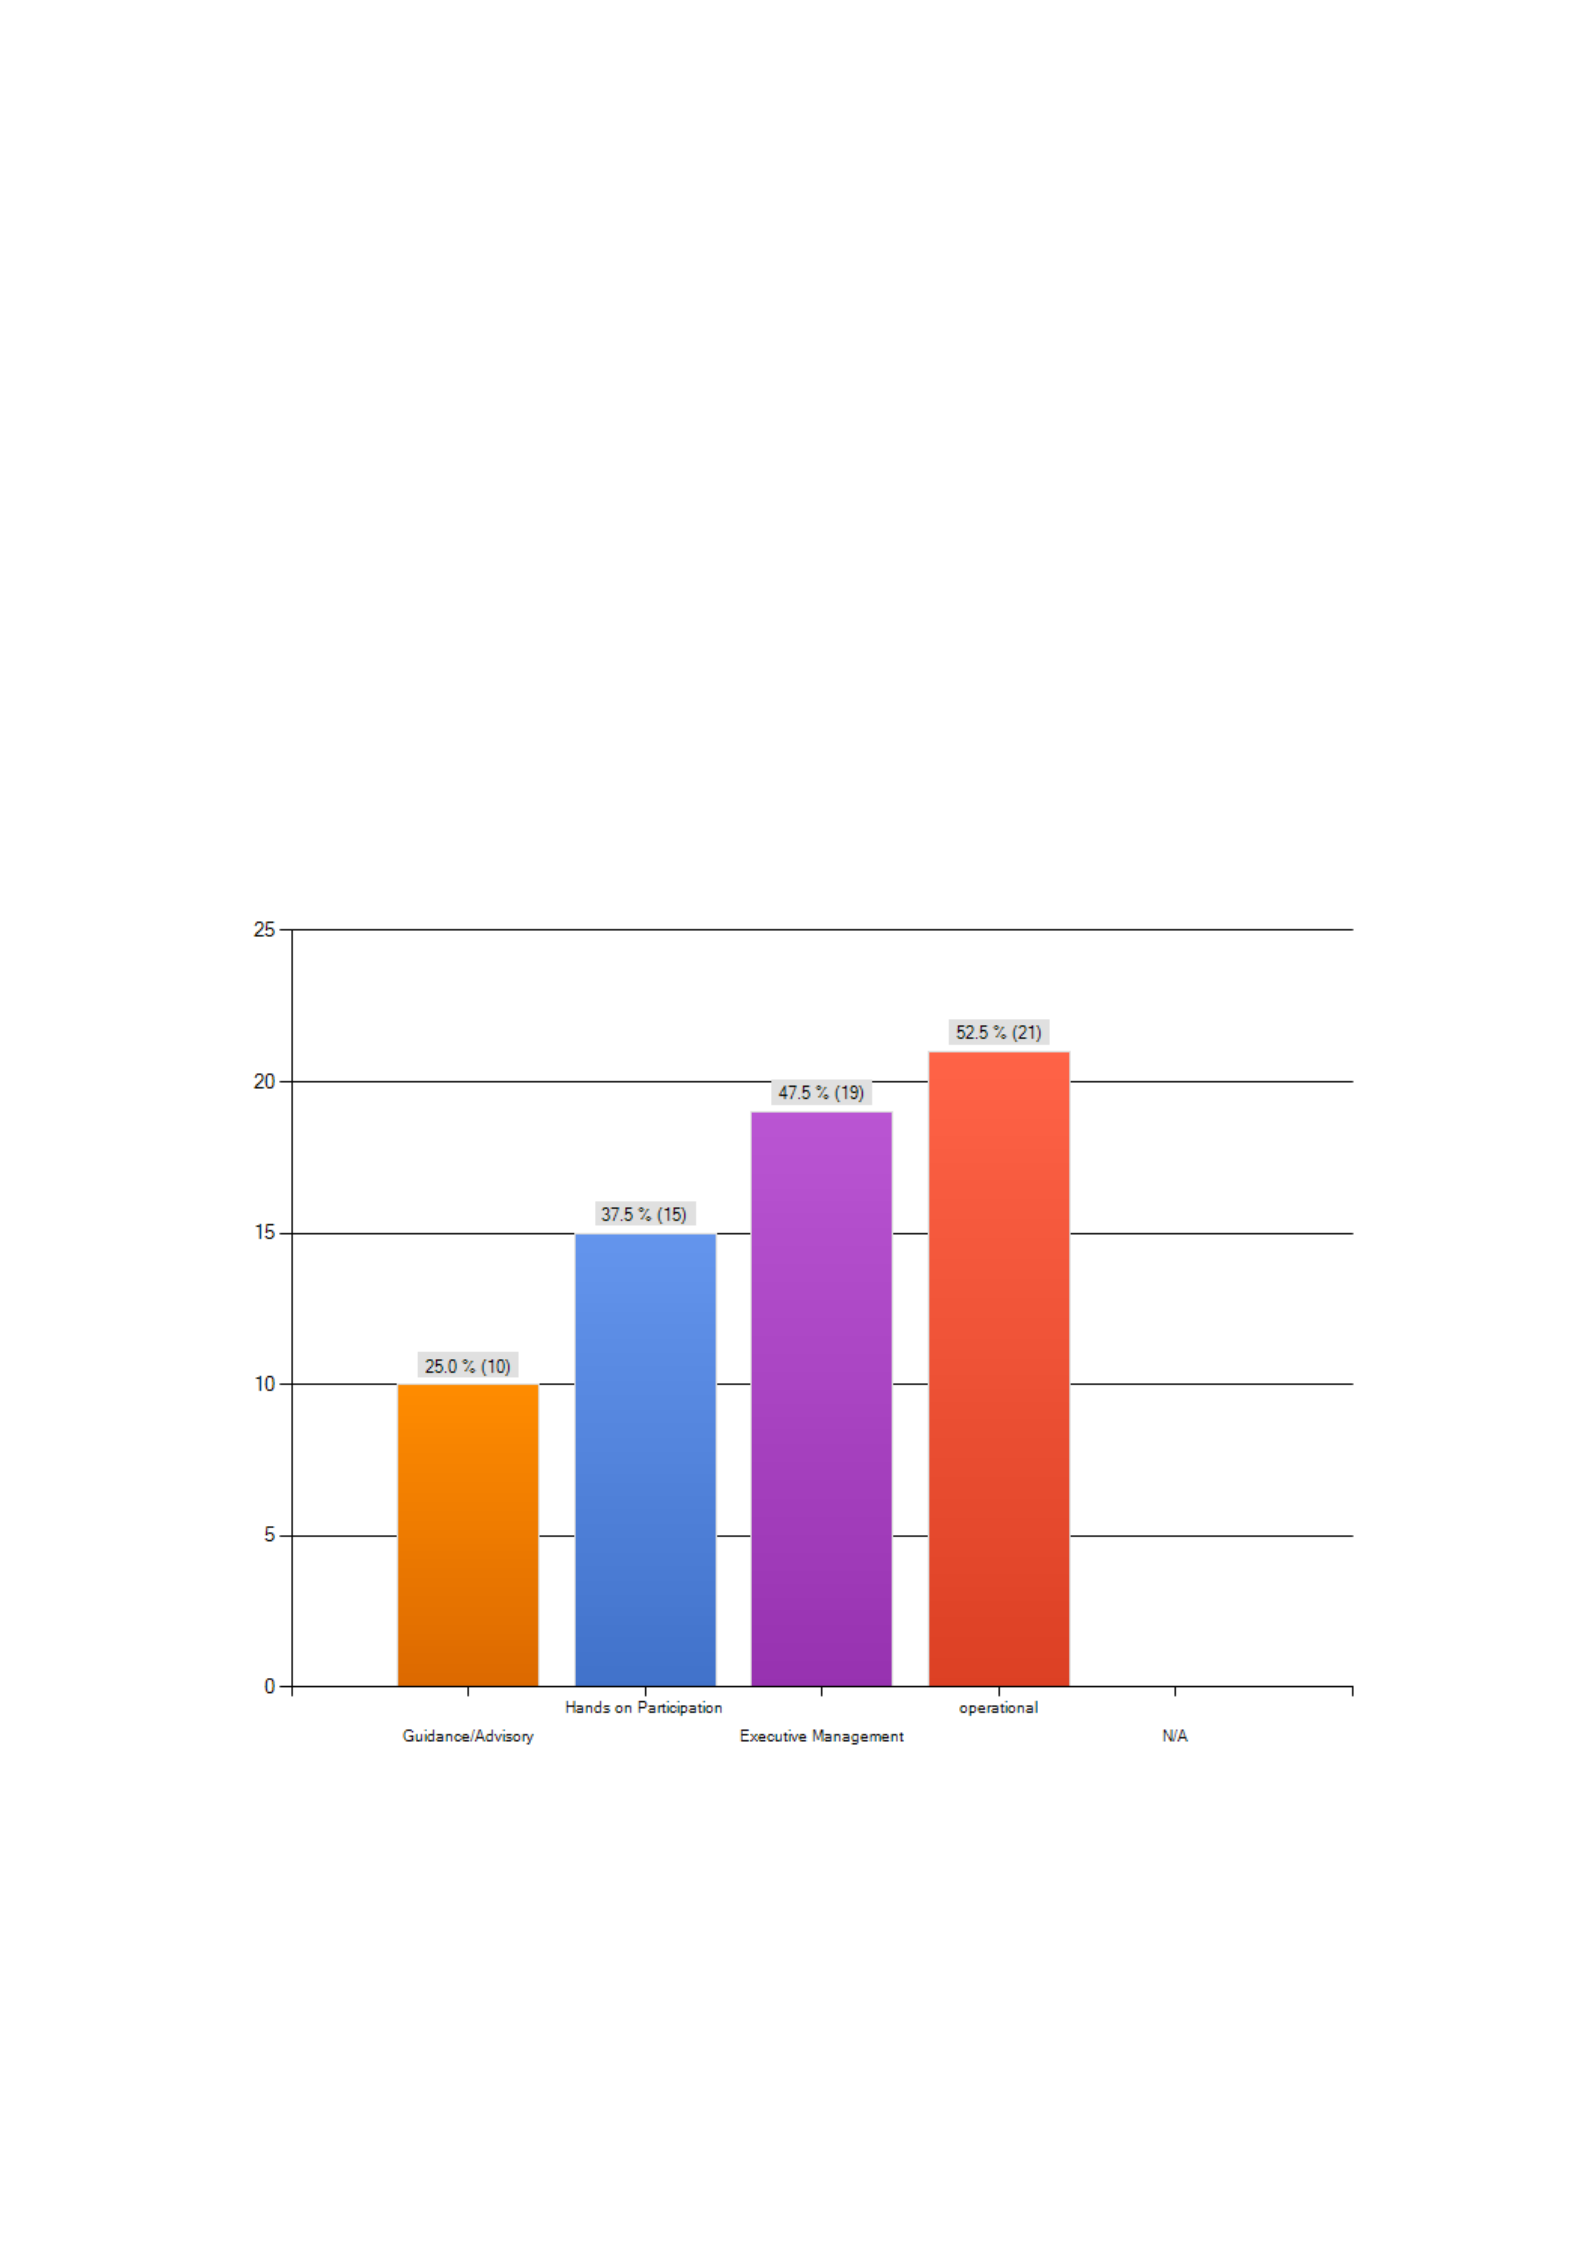
to ensure the required balance. Above graph indicates
that the task of choosing participants for this survey has
been accurately performed.
What participation level does family members have in
the business?
For any family business assessment, it is of vital
importance that the participations of other family
members are identified. Answers of Q6 as graphically
presented below.
Figure 10: Participation Level.
Above graph represents the findings of Q6. It indicates
that most of the participants (21 out of 40) with 52.5%

of the total population, personally participate in the
operations of the family owned businesses. This is a
good sign. Results indicate that second big chunk of 19
participants, out of 40 participants; with 47.5% of the
total population hold the positions of senior
management or executive management. Third big
chunk of 15 participants with percentage of 37.5 hold
are those who hand on participation while the smallest
chunk of 10 participants are those who act as seniors
and provide guidance and advisory assistance to the
operational executives of the family owned businesses.
These participants are mostly the seniors who actually
initiated businesses but when they turn senior citizens,
they relax and only provide advisory assistance to the
existing management. However, for this survey, most of
the participants are either operational or the executive
management.
What is your current generation / how many
generations have been involved in running / operating
/ managing the family owned business?
This question aims to find out the existing generations
involved in running/managing/operating the family
owned businesses. This is to check the participation of
first/second/third or the fourth generations at present
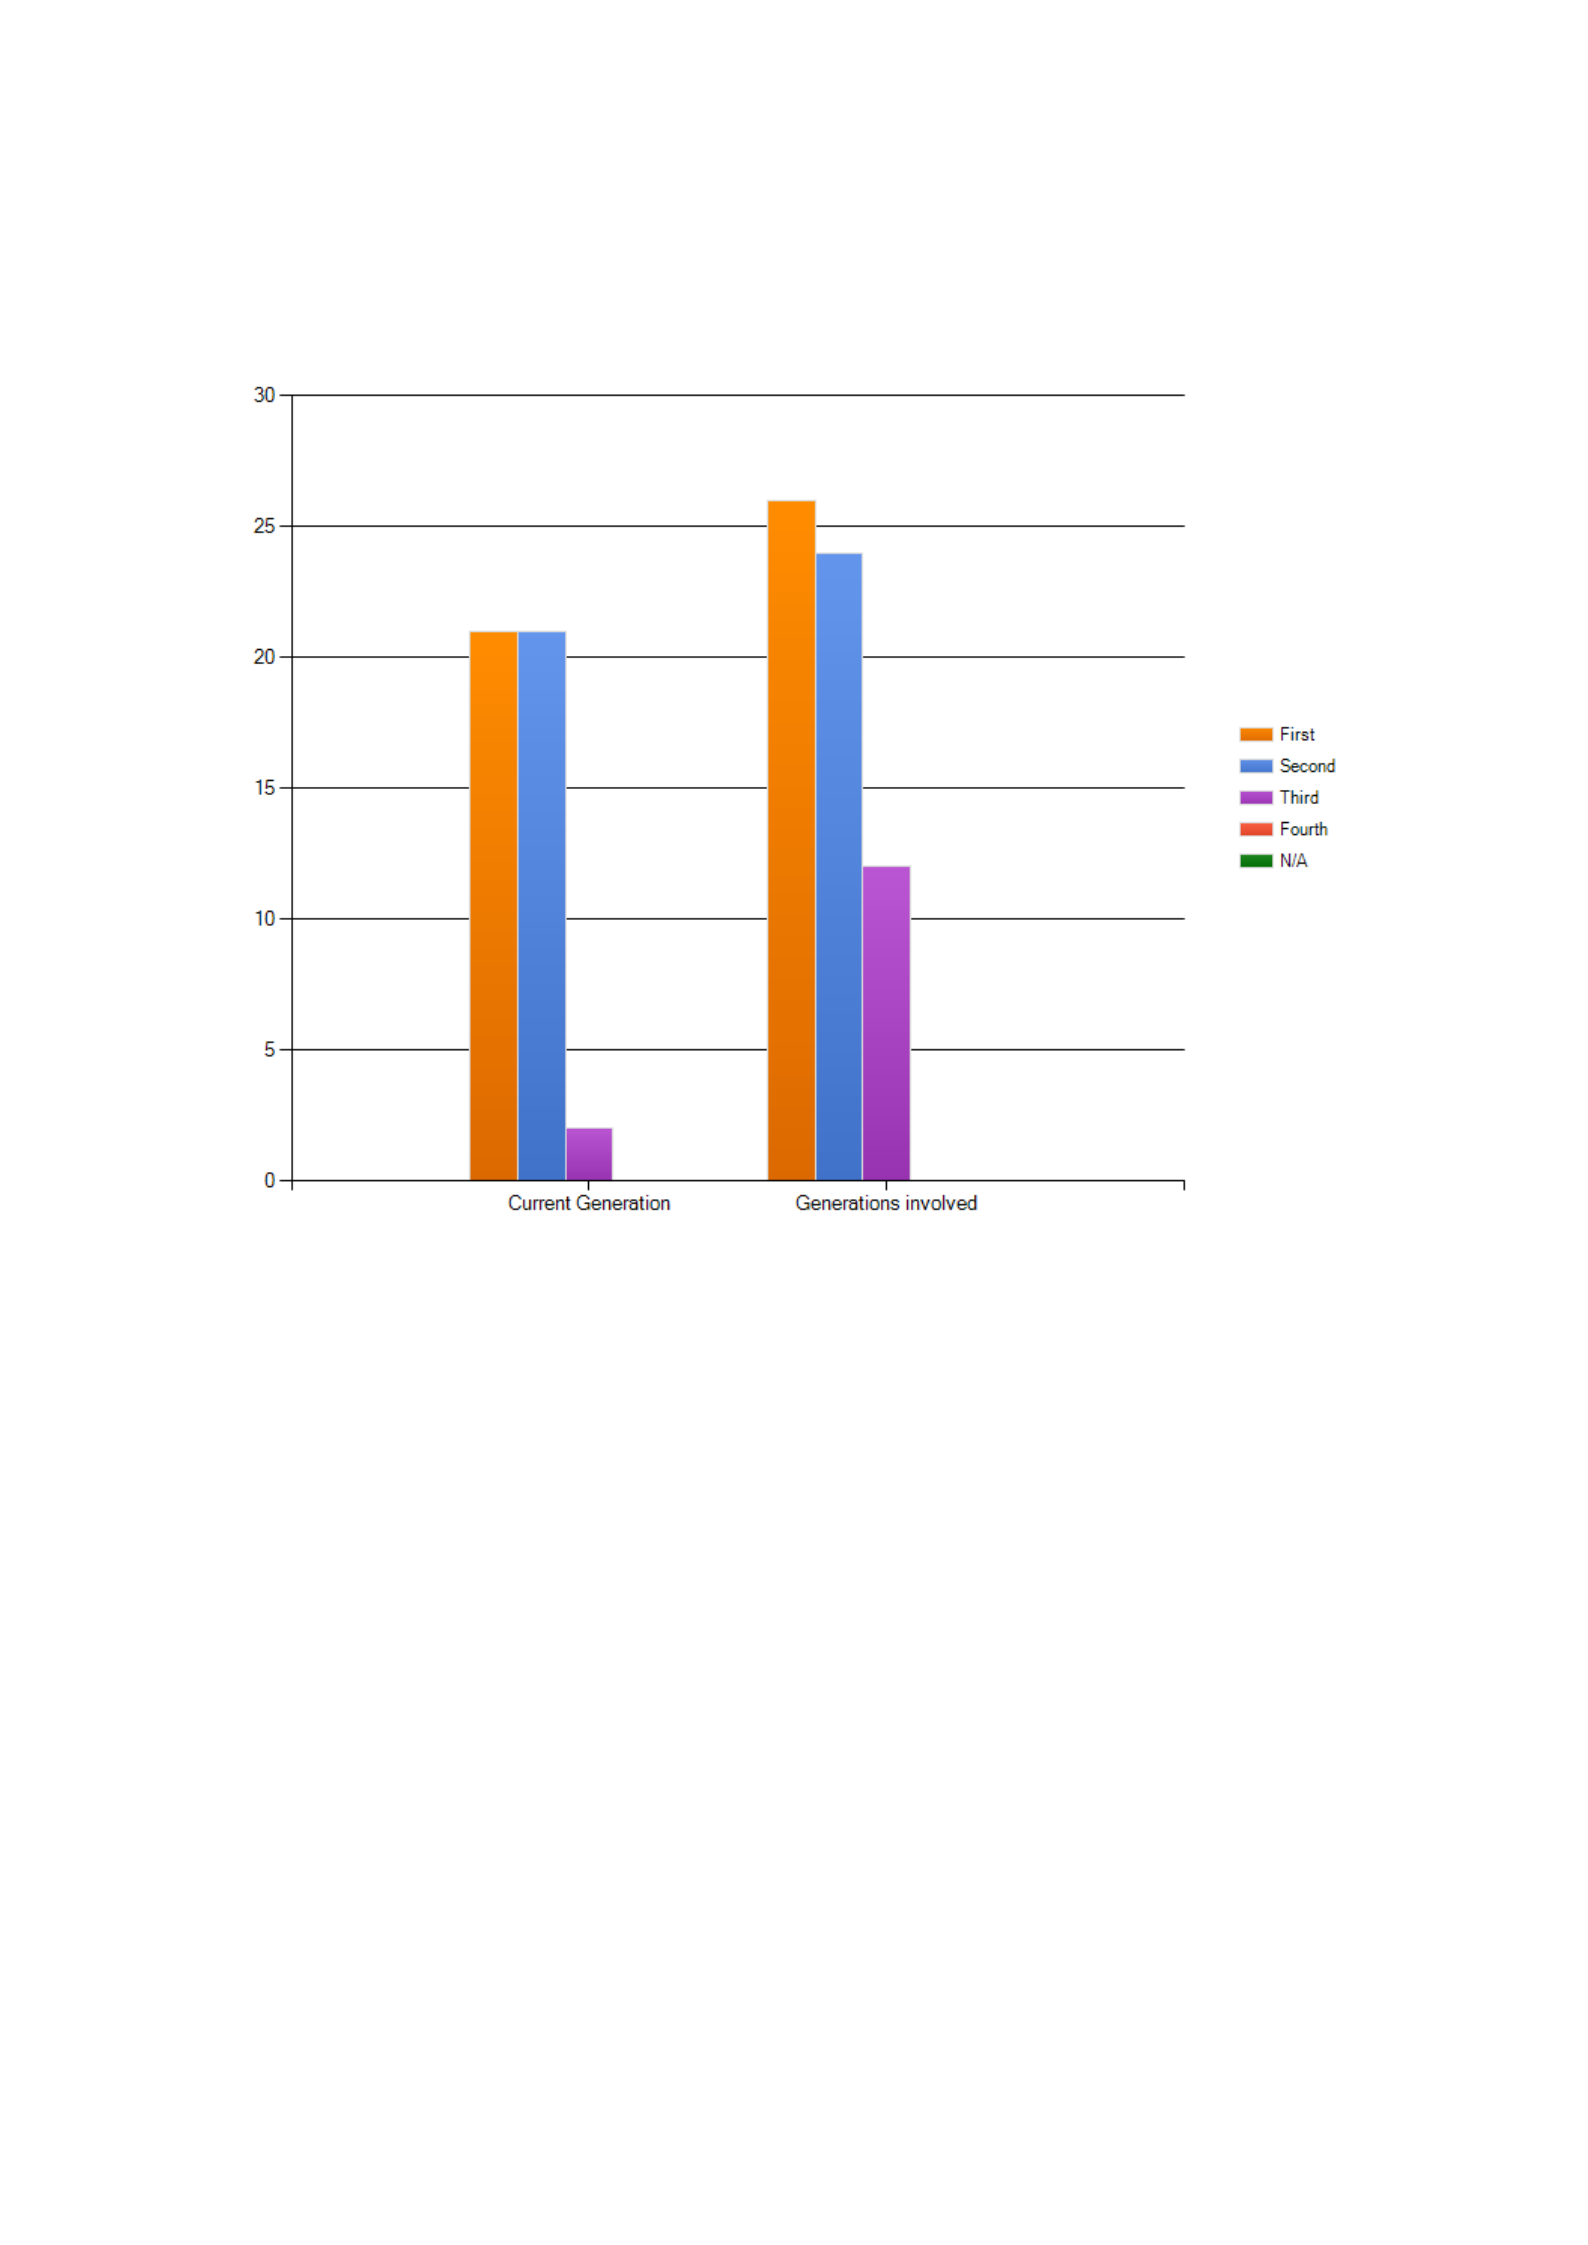
in their family owned businesses. Below is the graphical
presentation of Q7 results.
Figure 11: Involvement of Generations.
Above graph illustrate that the third generations of all
our selected participants’ businesses are not
significantly participating in any operational role of their
family owned businesses. The percentage of fourth
generation is 0%; the participation of third generation is
5% in the current execution. However, the participation
of first and second generations is equal, active and
significant in the current executing/operational roles of
their family owned businesses.

Second part of Q7 indicates the generations involved in
overall establishment of their family owned businesses.
Surprisingly, results illustrate that majority of the
individuals involved in the establishment of their family
businesses belong to the first generation. With a little
difference, the second major chunk is of the individuals
from the second generation involved in the
establishment. However, the third generation
contribution also seems active in the establishment of
related family owned businesses.
Do you expect a change of hands (generation) will
occur? And if yes, when?
This question has been included to see if the change in
executing generation is expected. Below is the graphical
presentation of Q8.
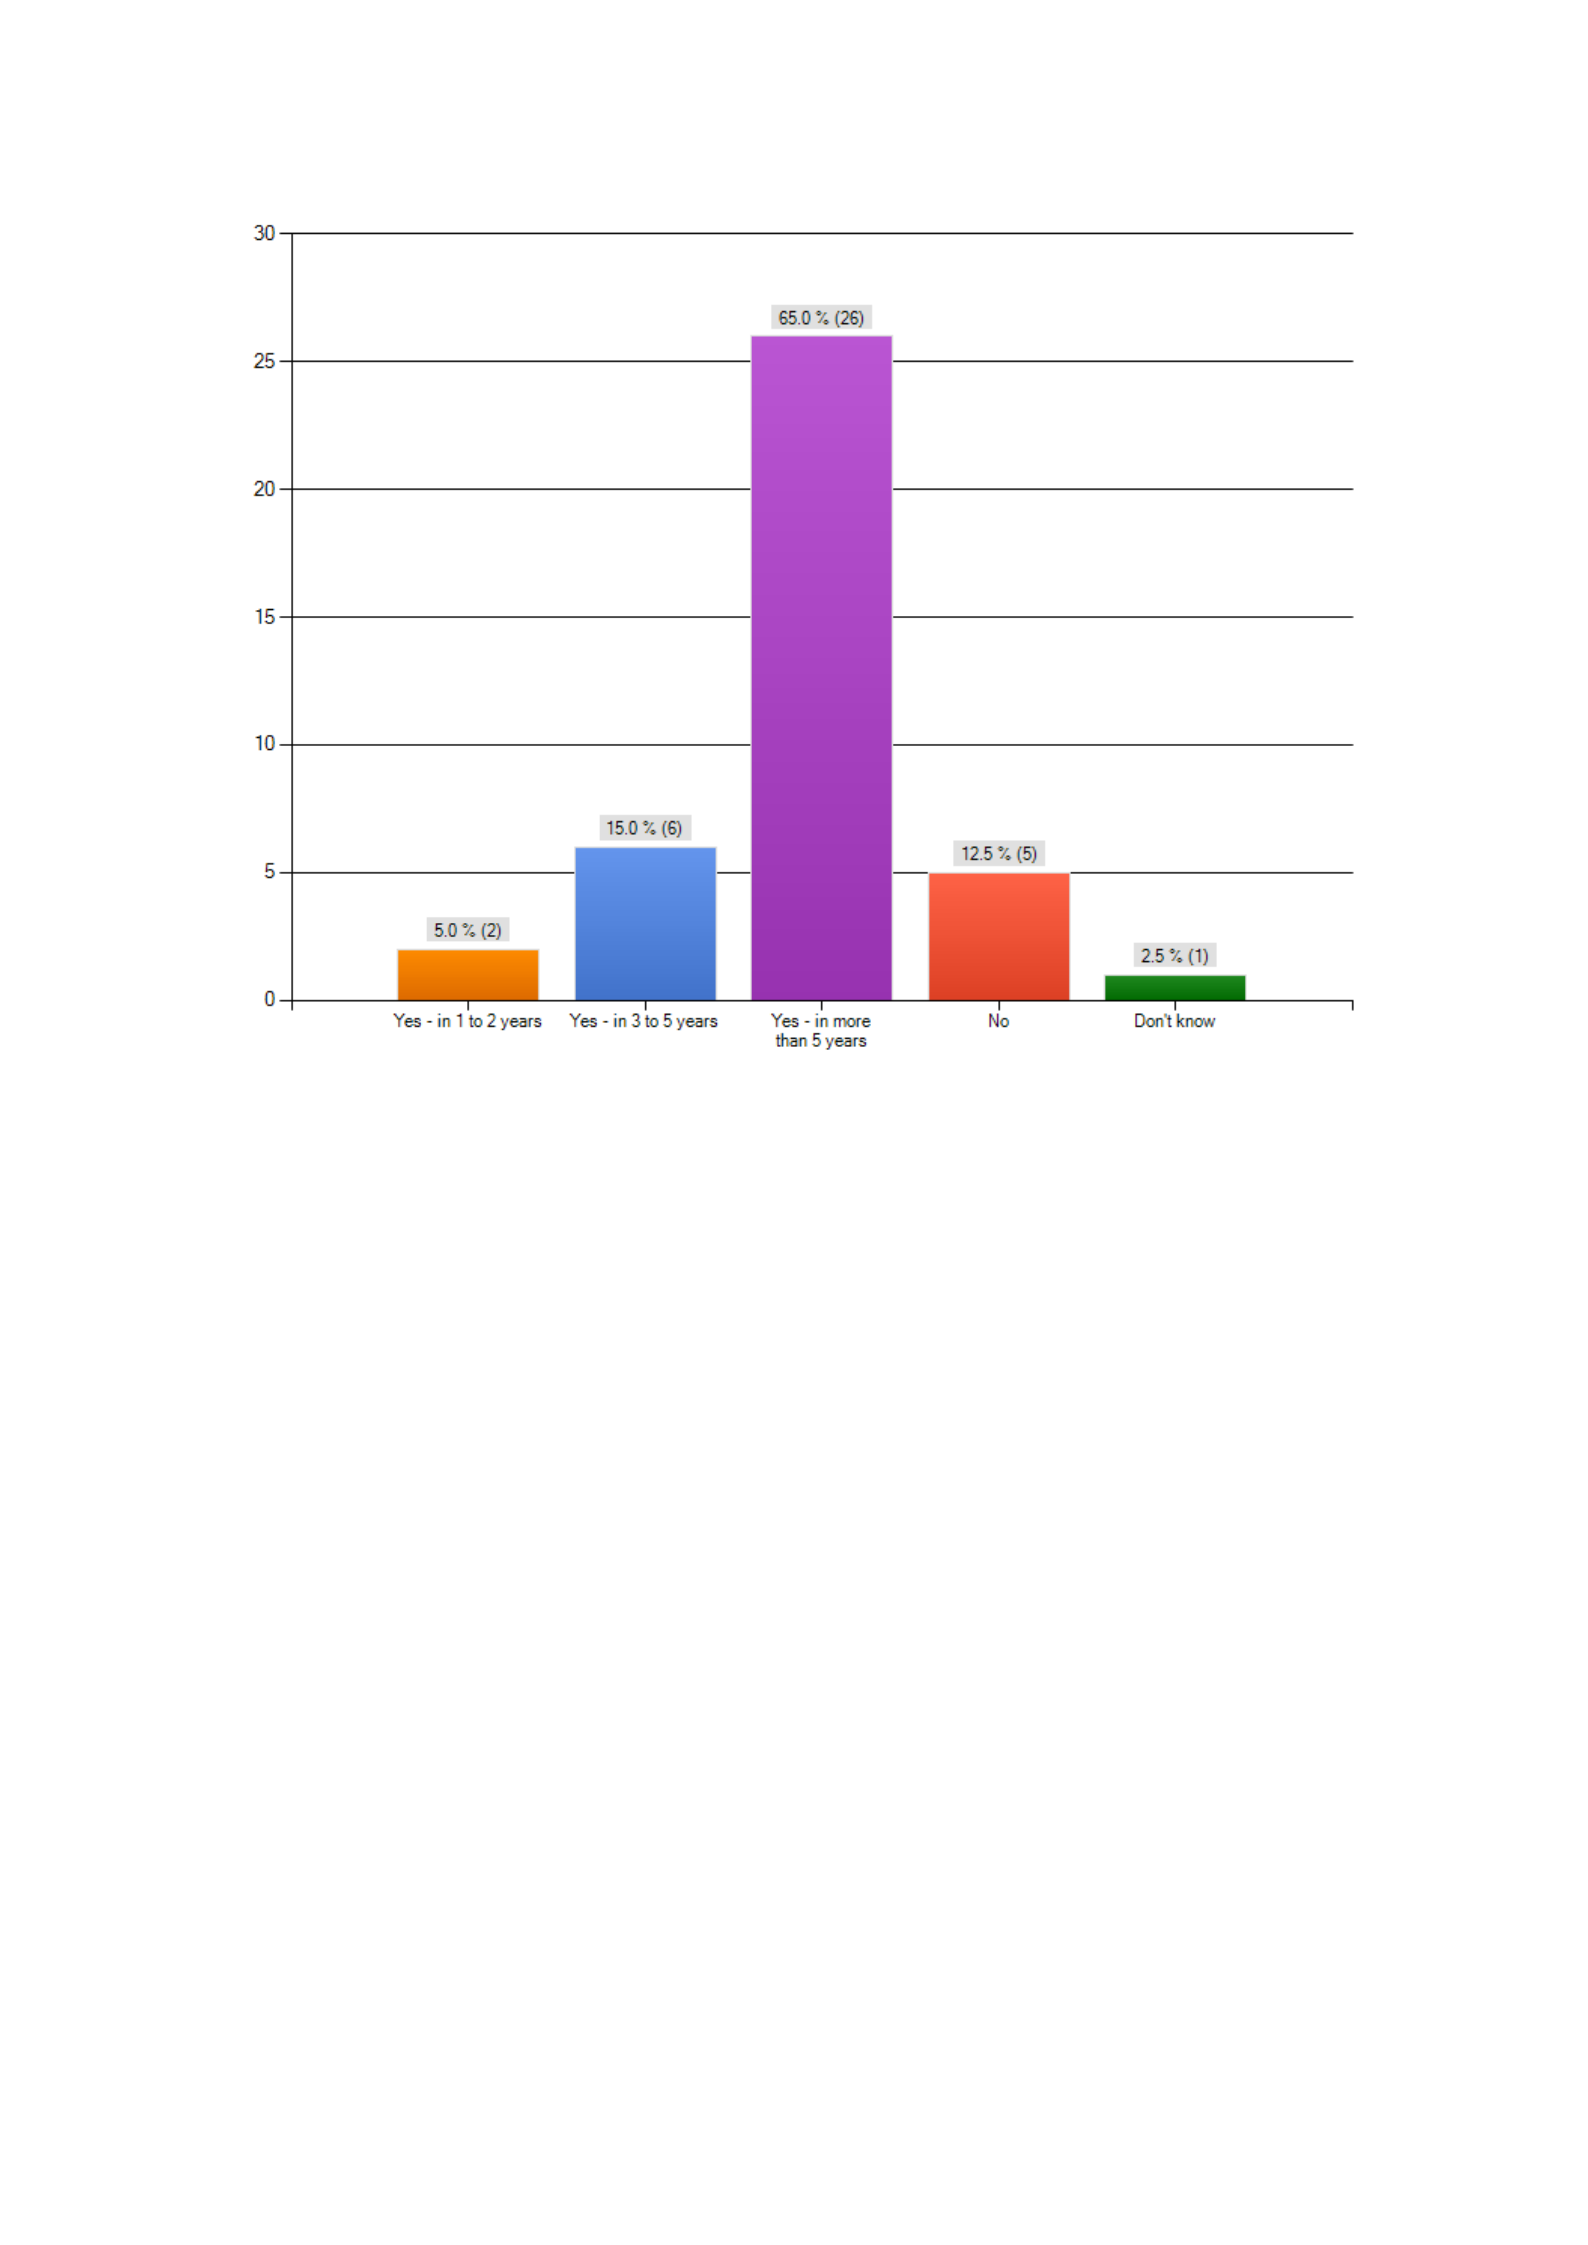
Figure 12: Expected Change of Hands.
Above graph shows that most of the participants (26 out
of 40) with 65% of the total population believe that the
change is expected in five years or more. 6 participants
out of 40 with 15% of the population believe that
change is possible in next three to five years. However,
12.5% participants (5 out of 40) believe that change is
not expected at all. Two participants think that change
is possible in next one to two years. While only one
participant refused to answer and ticked the option
of don’t know. Results clearly indicate that though it is a
family owned business, change is expected in five years
or more. This also means that current generation is

quite involved in business affairs and participants
(representing population) do not think that they are
exhausted yet or it’s a time to pass on the charge to the
next generation. They still tend to finalize and execute
the system for next 5 years or so, depending upon their
willingness and depending upon their perception of
assuming the next generation as ready to take the
charge. As normally, it takes time to once finalize to
transfer the system to the next generation, and even if
seniors think to transfer, they still need to work hard on
training the next generation by working with them for a
few years.
Would you consider your company as diversified?
This question is to test if the participants are from the
companies that are diversified. This question has also
been tested on the same population of 40 participants.
Responses are as under:
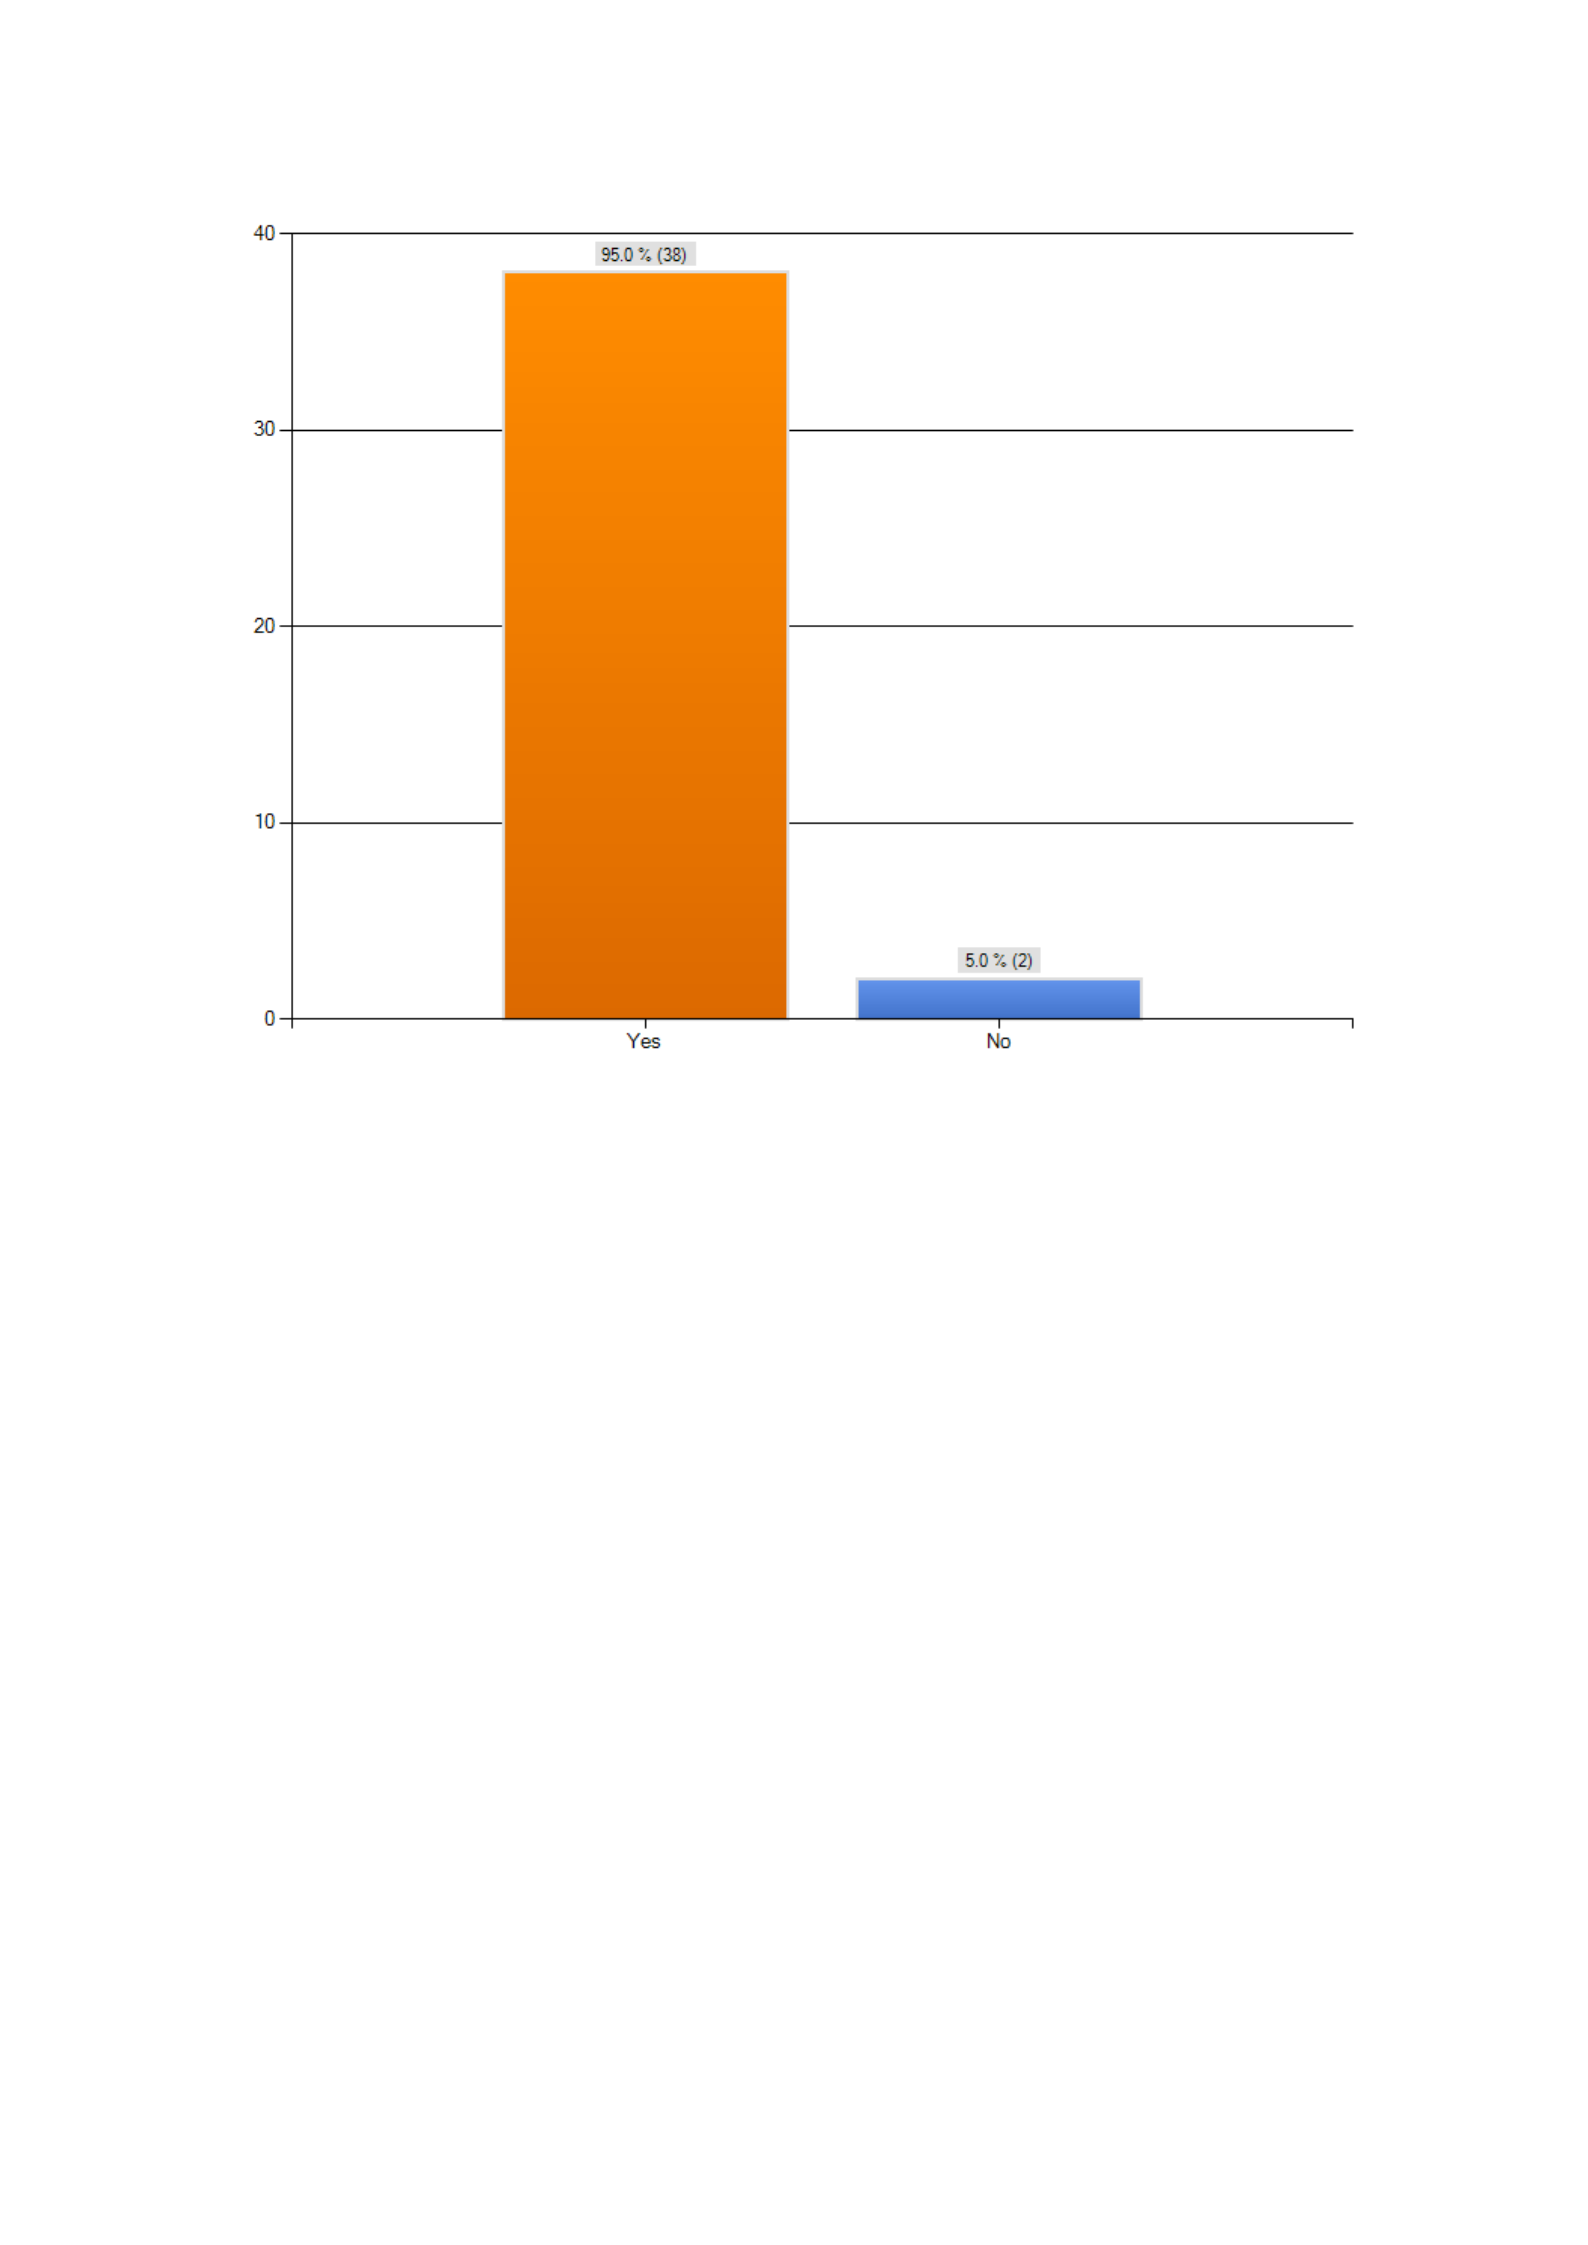
Figure 13: Diversification Status.
Above chart illustrates that 38 out of 40 participants
(95% of the total population) declare their businesses as
diversified. Only 2 participants negatively responded to
Q9. Results of Q9 clearly illustrate that majority
participants are well selected for this study as the topic
revolves around the diversified family owned
businesses.
Do you own or operate any other businesses?
In order to verbally cross check if the participants of this
survey own any other business, Q10 has been tested
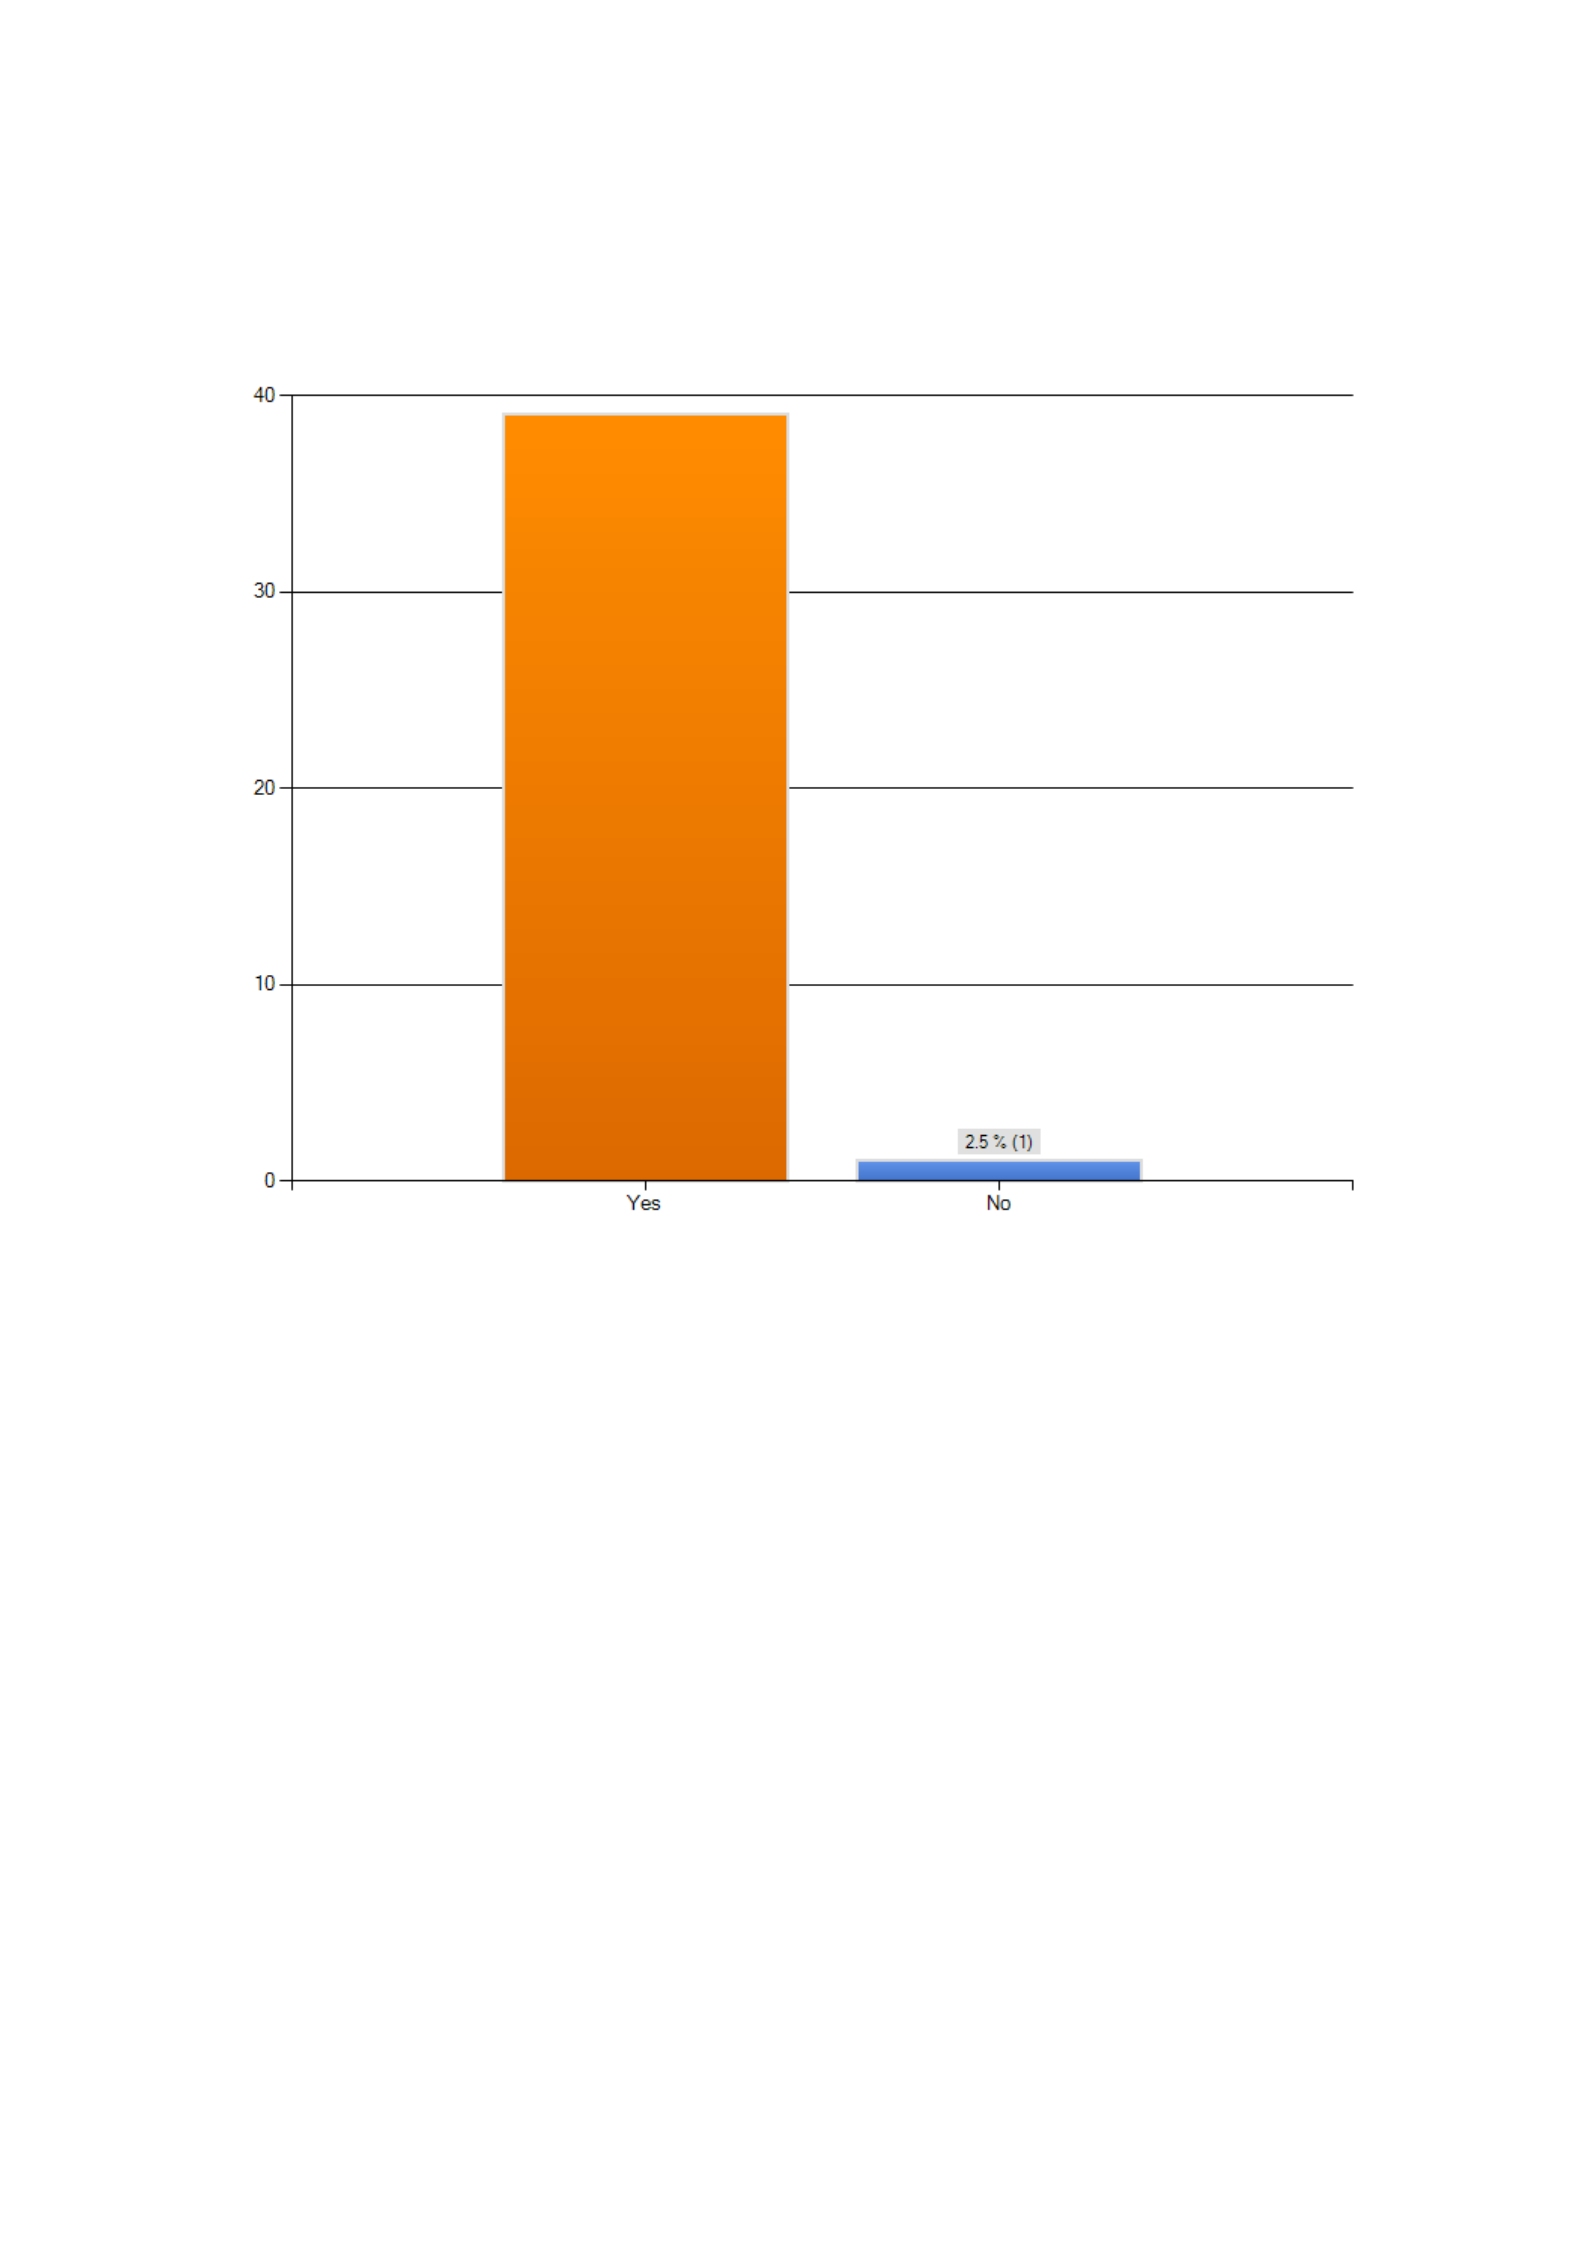
over the population of 40 participants. Below is the
graphical presentation of Q10.
Figure 14: Status of Other Owned Businesses.
Out of 40 participants, 39 participants declared that
they own other businesses as well. Only one participant
replied in negative. This indicates that most of the
participants own other businesses too.
What level of control do you have on the other
businesses?
In order to identify the participants’ level of control, Q11
has been tested over the same population. The results
are graphically presented below:
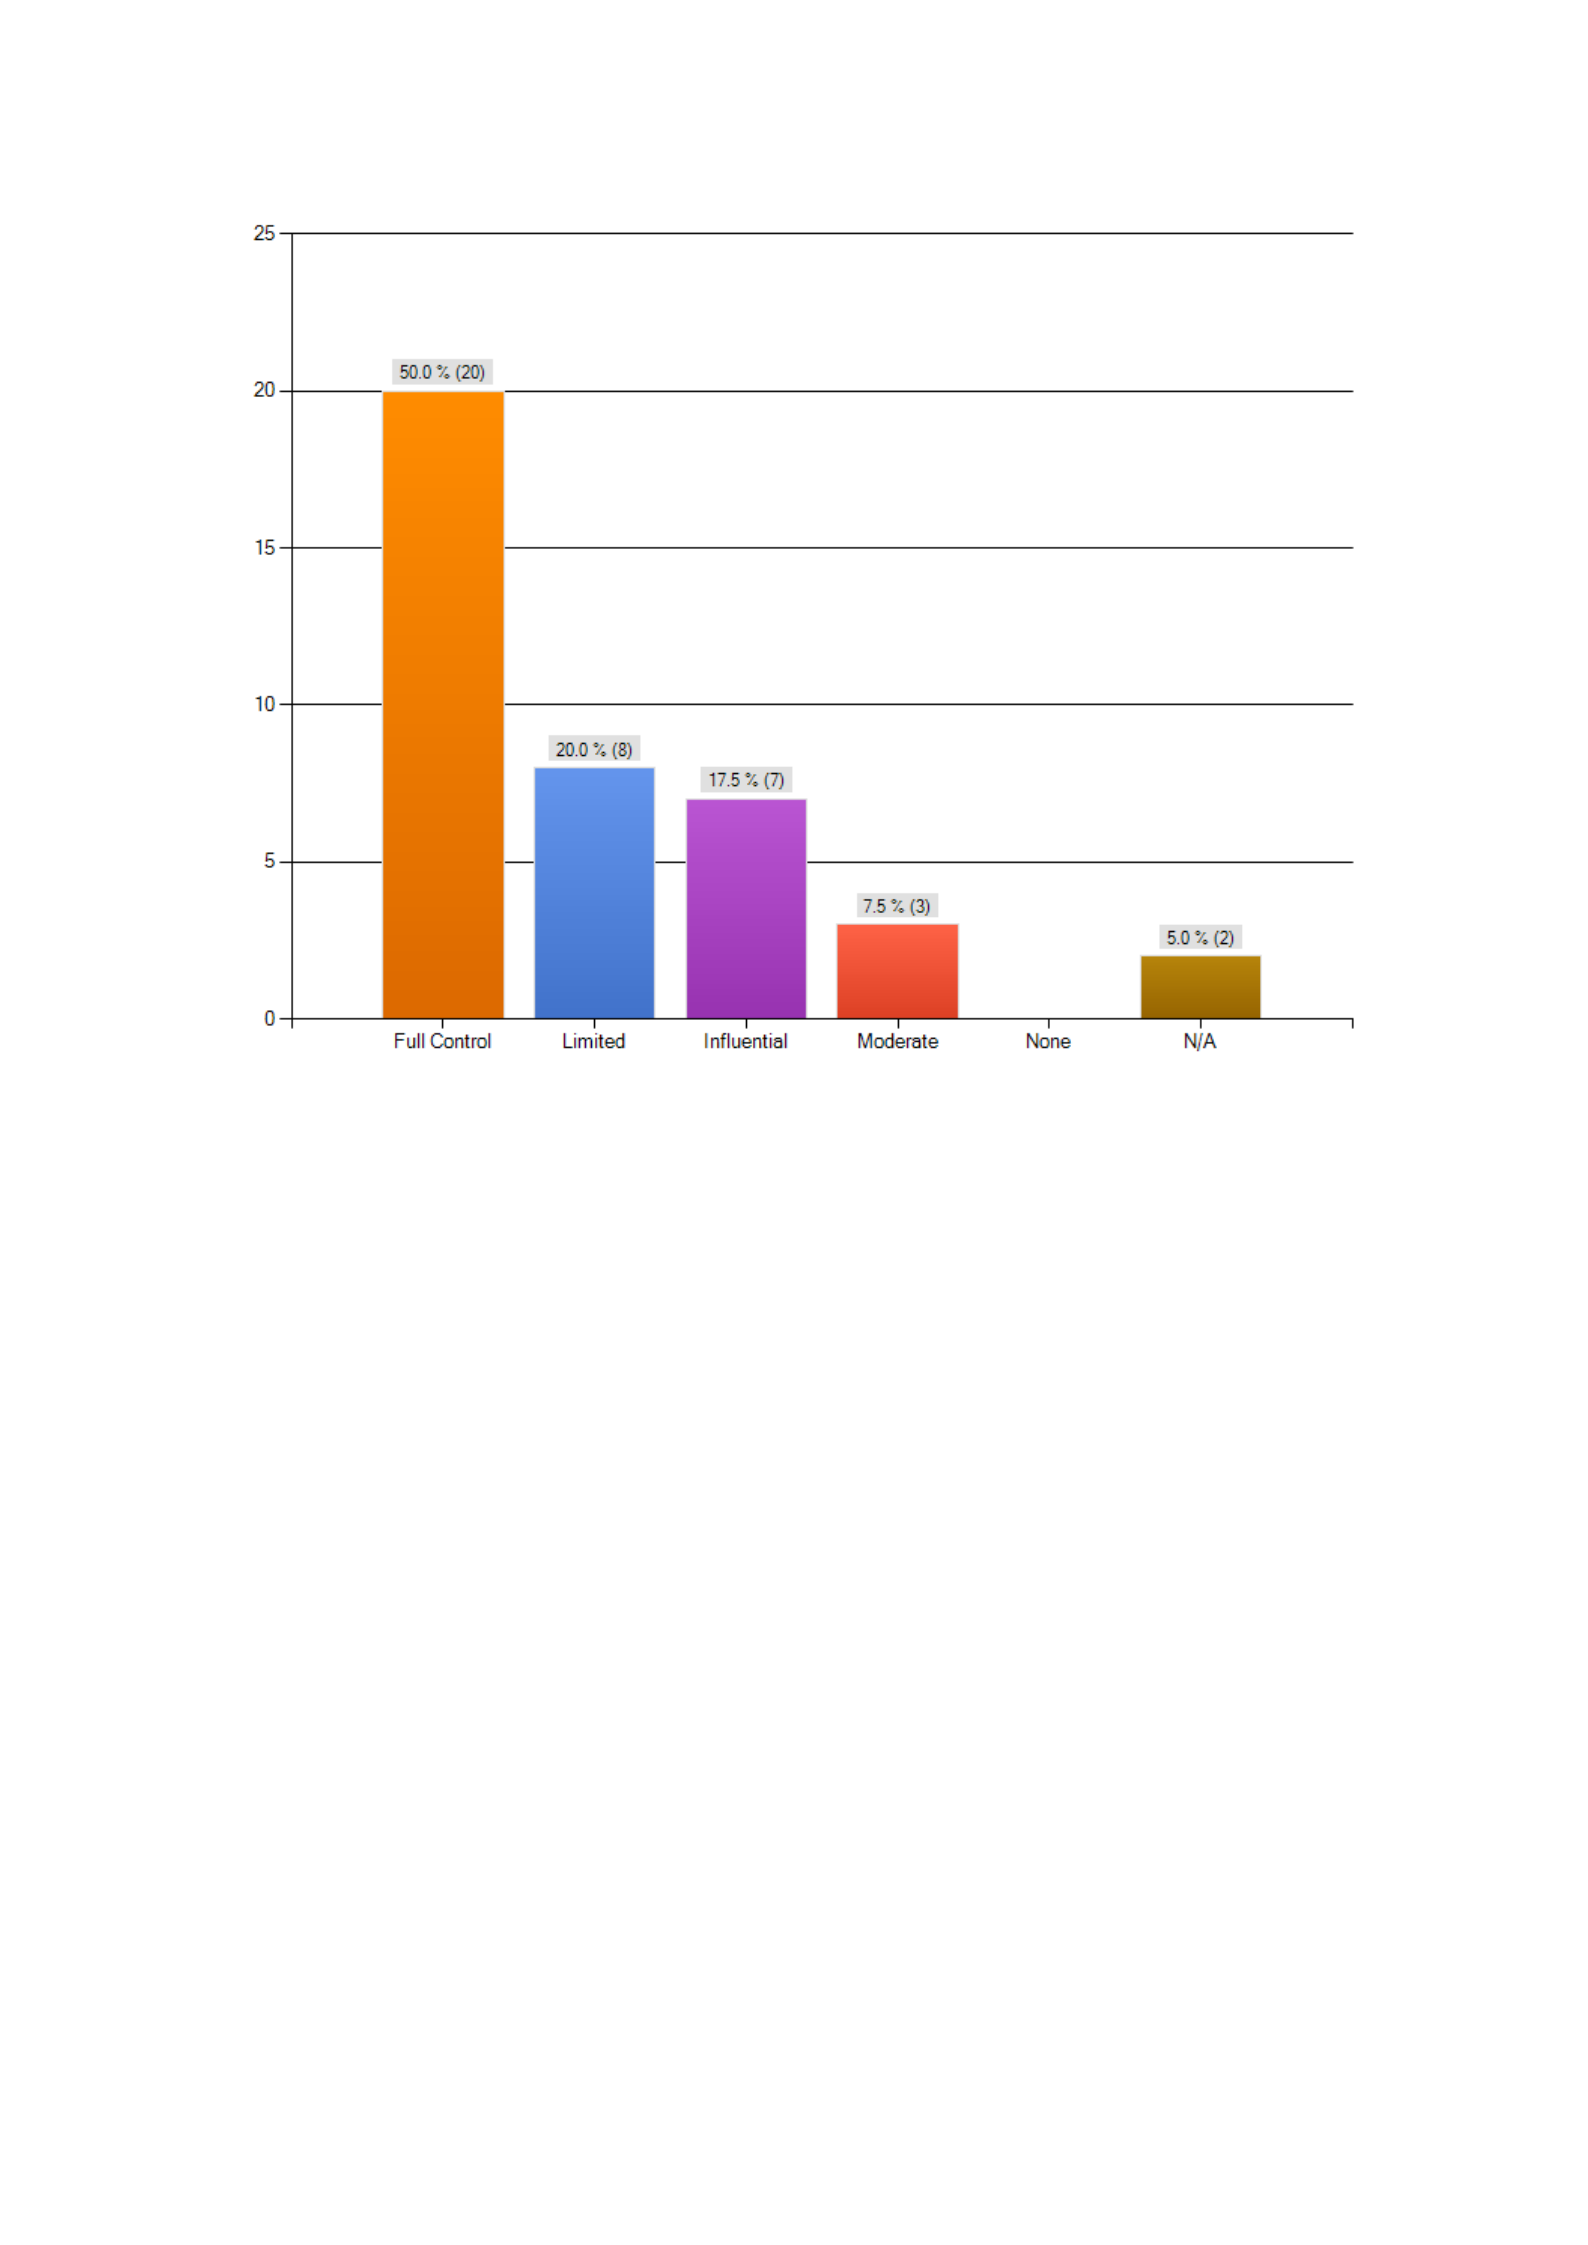
Figure 15: Level of Control.
Q11 results clearly indicate the influence of participants
on their other businesses. Above graph clearly shows
that around 50% of the population, total 20 participants
have complete control over the decision making of their
businesses. Second big chunk of 8 participants with 20%
of the total population have limited control and
influence over the overall decision making of their other
businesses. 7 participants with around 17.5% of the
population stated that they do not have the complete
power but their suggestions are influential. 2
participants with 5% of the population refused to
comment while no one selected the option of none. Q11

results clearly indicate that being senior directors or
executives, they have certain limits to influence the
decisions. However, 50% of the executives (mostly the
sole traders) have 100% control over the overall
decisions of their businesses. Q11 clearly indicates that
after all, their suggestions matter a lot and they can play
a vital role in taking decisions for the positive or
negative future of their companies. The influence is
there and cannot be neglected.
What was the primary motivation for diversification?
Diversification is considered for some reason. There
could be several reasons for looking forward to move
with diversification in businesses. Q12 results would
help a lot in identifying the most common motivation
for diversification. Findings are graphically presented
below to present a better picture:
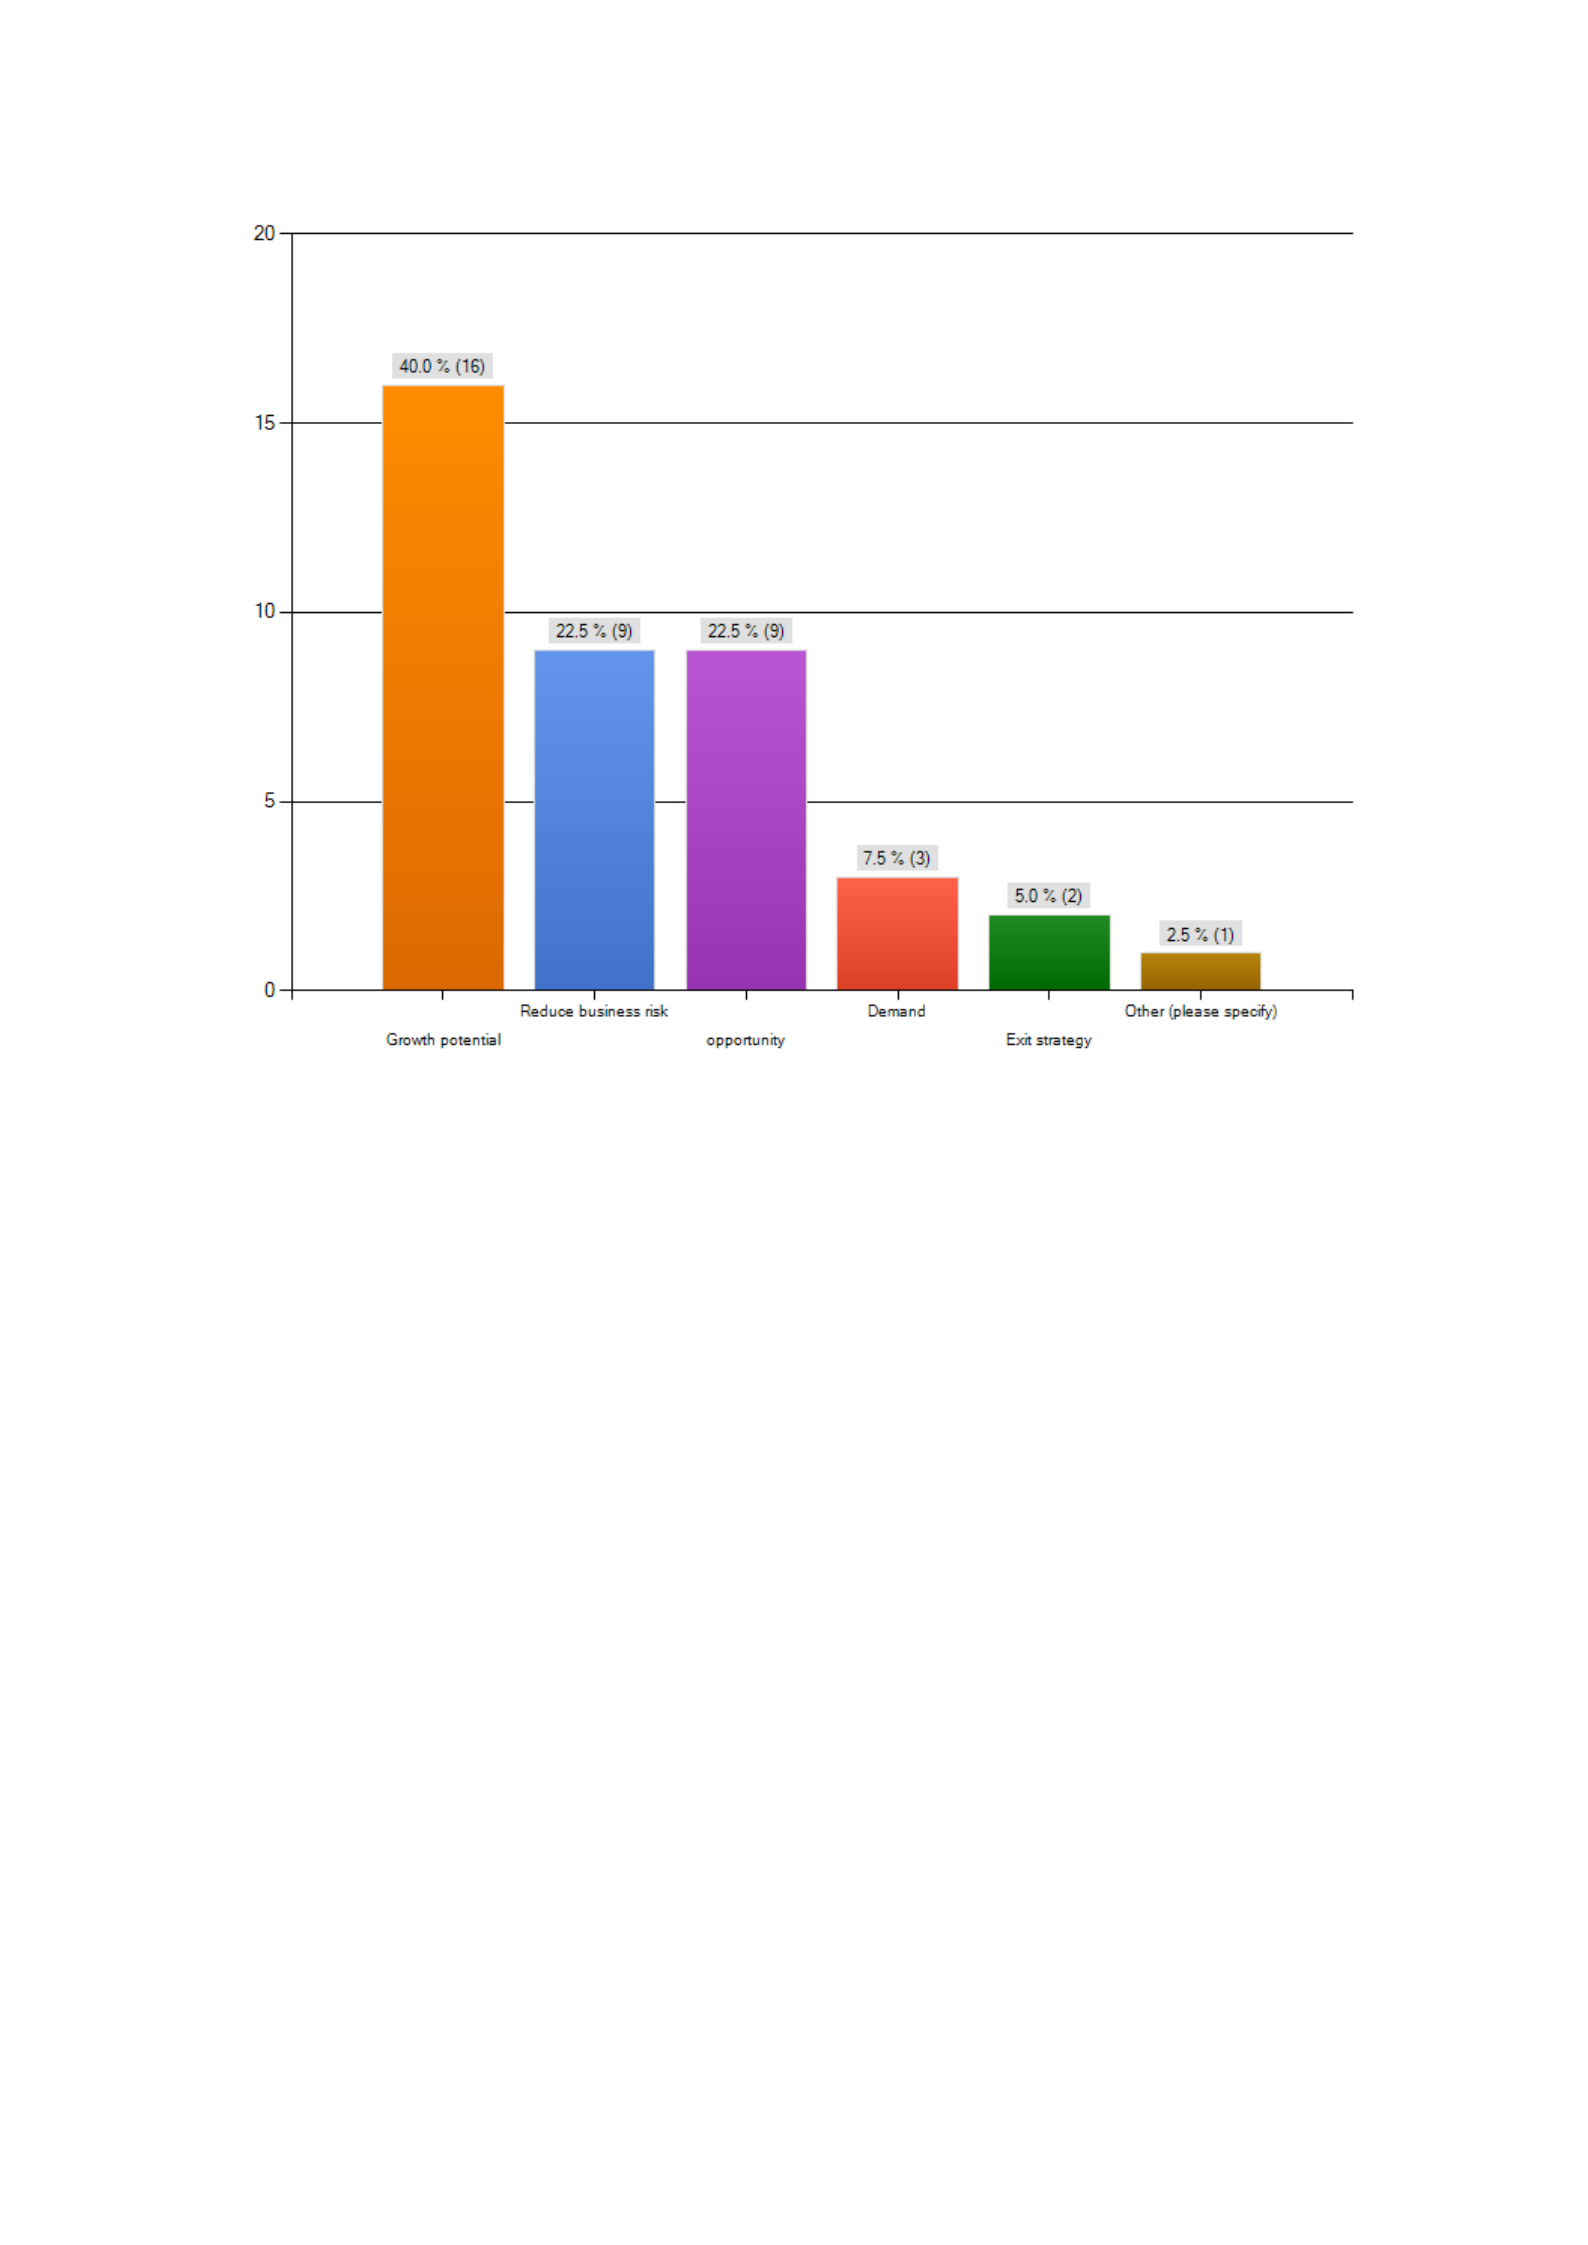
Figure 16: Primary Motivation for Diversification.
Above graph reveals that 16 out of 40 participants, with
40% of the total population, considered diversification
for the growth potential. 9 participants with 22.5%
considered diversification to reduce business risk.
Again, 9 participants with 22.5% declared that they
considered diversification by considering it an
opportunity. 3 participants with 7.5% of the total
population though it was a market demand that led
them going for diversification. Two participants with 5%
of the total population took it as the exit strategy while
only one participant with 2.5% of the population ticked
the option of other but did not specify exactly.

The results of Q12 indicate that majority went for
diversification by taking it as the growth potential. With
this result, we can assume the trend of diversification is
adopted for the sake of business growth.
Would you consider at the time of diversification, that
your core business reached maturity?
Another aspect of diversification could be the maturity
of one’s core business. At many places while reviewing
the literature, it has been found that one of the reasons
to go for diversification could be the maturity of one’s
core business. However, to test it practically, Q13 has
been designed and tested over the same population.
The results are graphically presented as under:
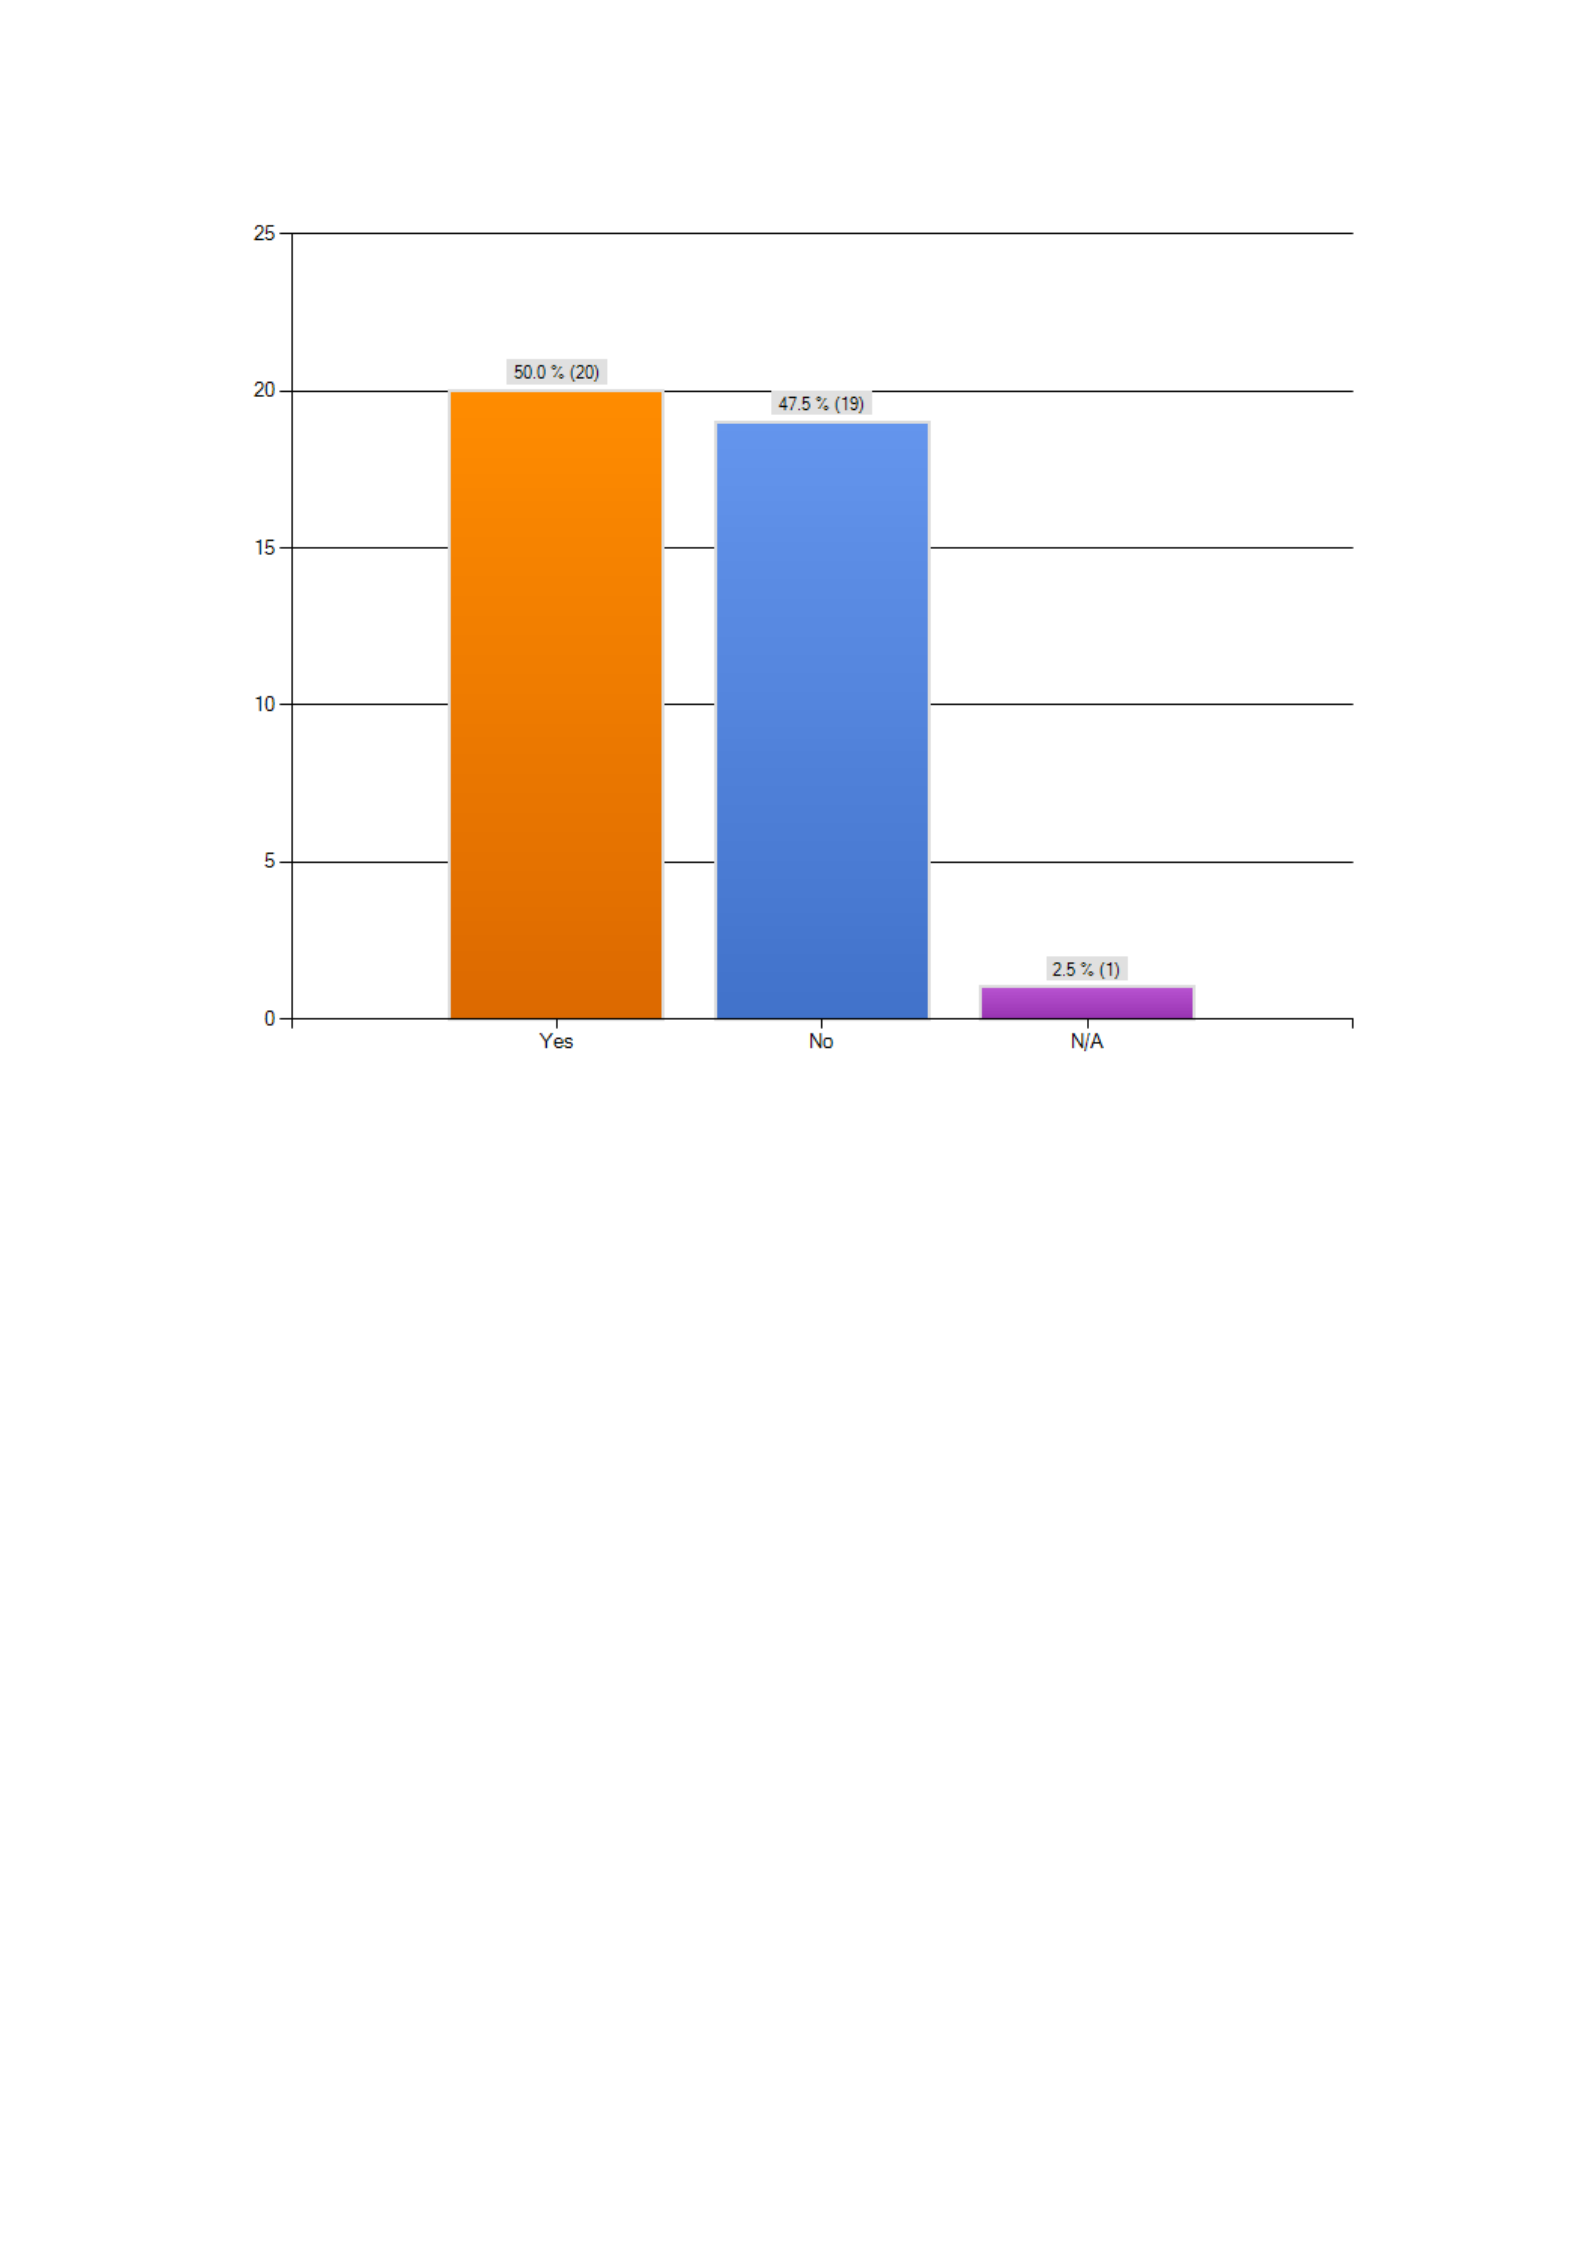
Figure 17: Maturity Status of Core Businesses.
Above graph indicated that 20 out of 40 participants,
50% of the total population agreed with the fact that
they considered diversification as their core business
reached maturity. 1 participant (2.5%) refused to
comment while 19 participants denied Q13. This seems
a tough fact to analyze as there is just a difference of
one point from yes to no. However, for Q13, it is not
wrong to say accept the statement that due to core
business reached maturity, diversification is considered.
If your answer to the above is yes, on that stage what
was your market position or market share in relation
to the core business?
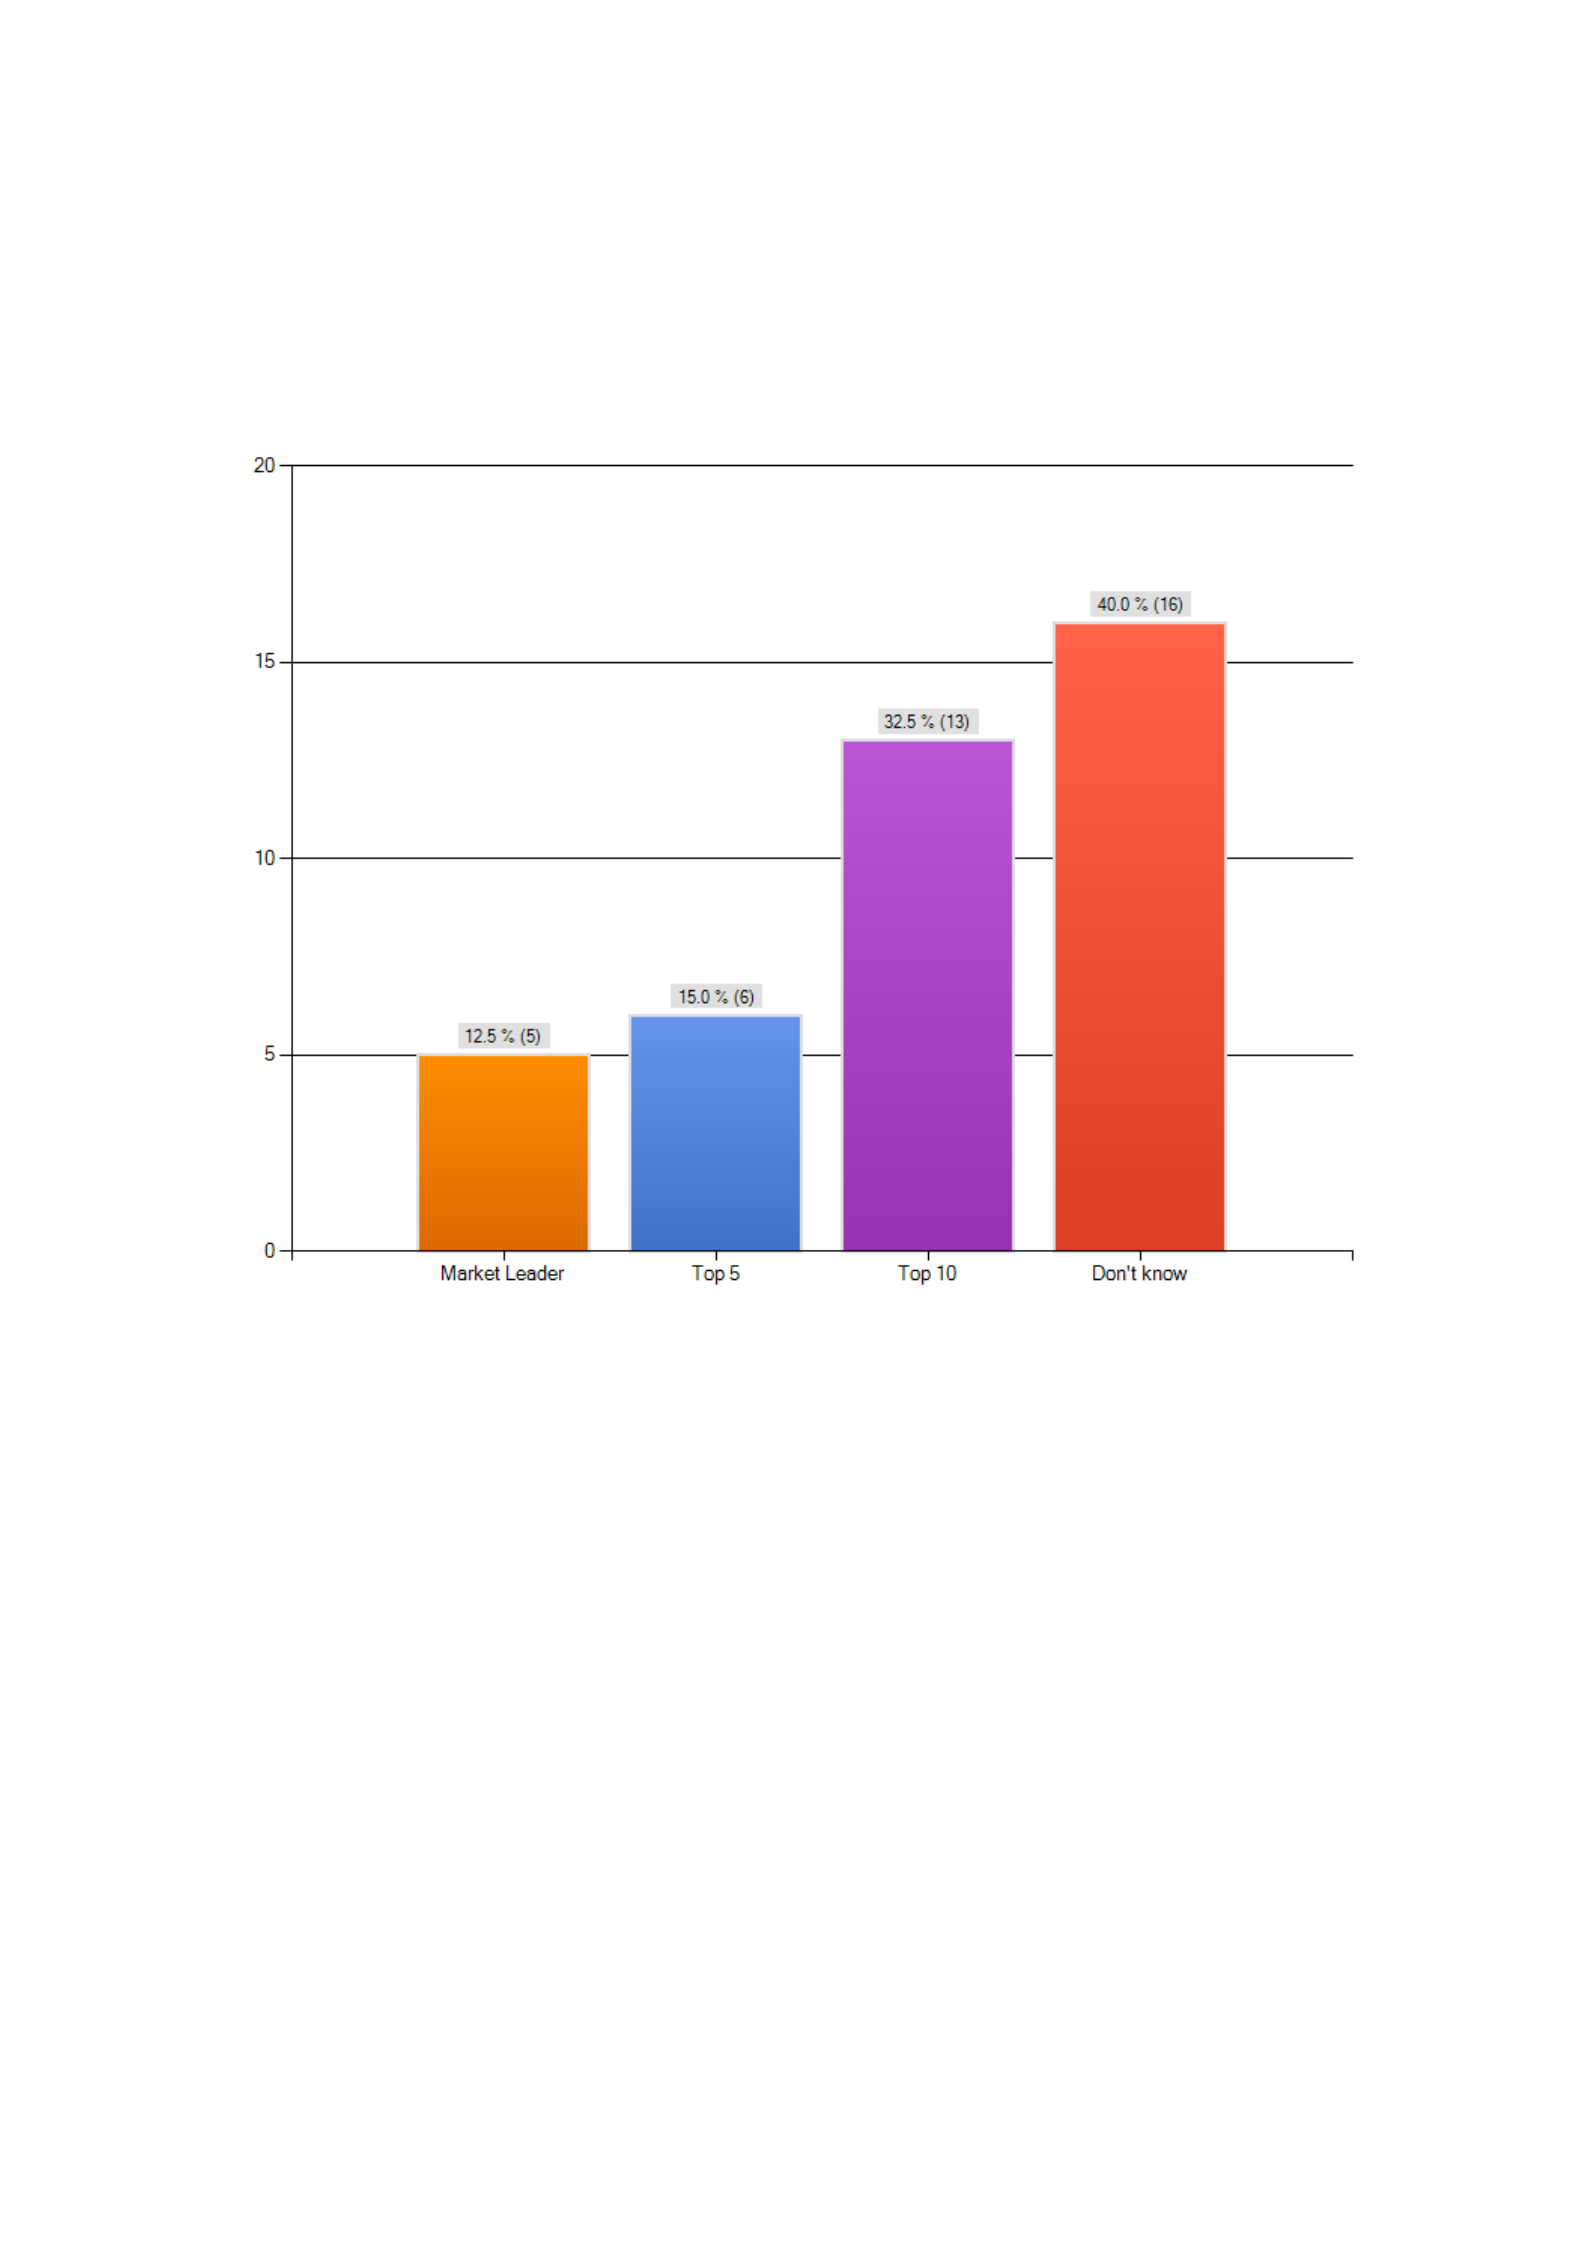
Q14 would help in assessing the reason of diversification
up to some extent. Below is the graphical presentation
of Q14 results:
Above graph indicates that participants who considered
diversification are mostly under impression that there
companies are not in top ranking. Only five participants
with 12.5% declared their companies as the market
leaders. 15% with only 6 participants declared to be in
top 5. The majority selected don’t know option that is a
confusing feedback. Above results clearly indicate that
due to fall in revenue and market status, participants
considered diversification because they think that their
core businesses reached maturity.
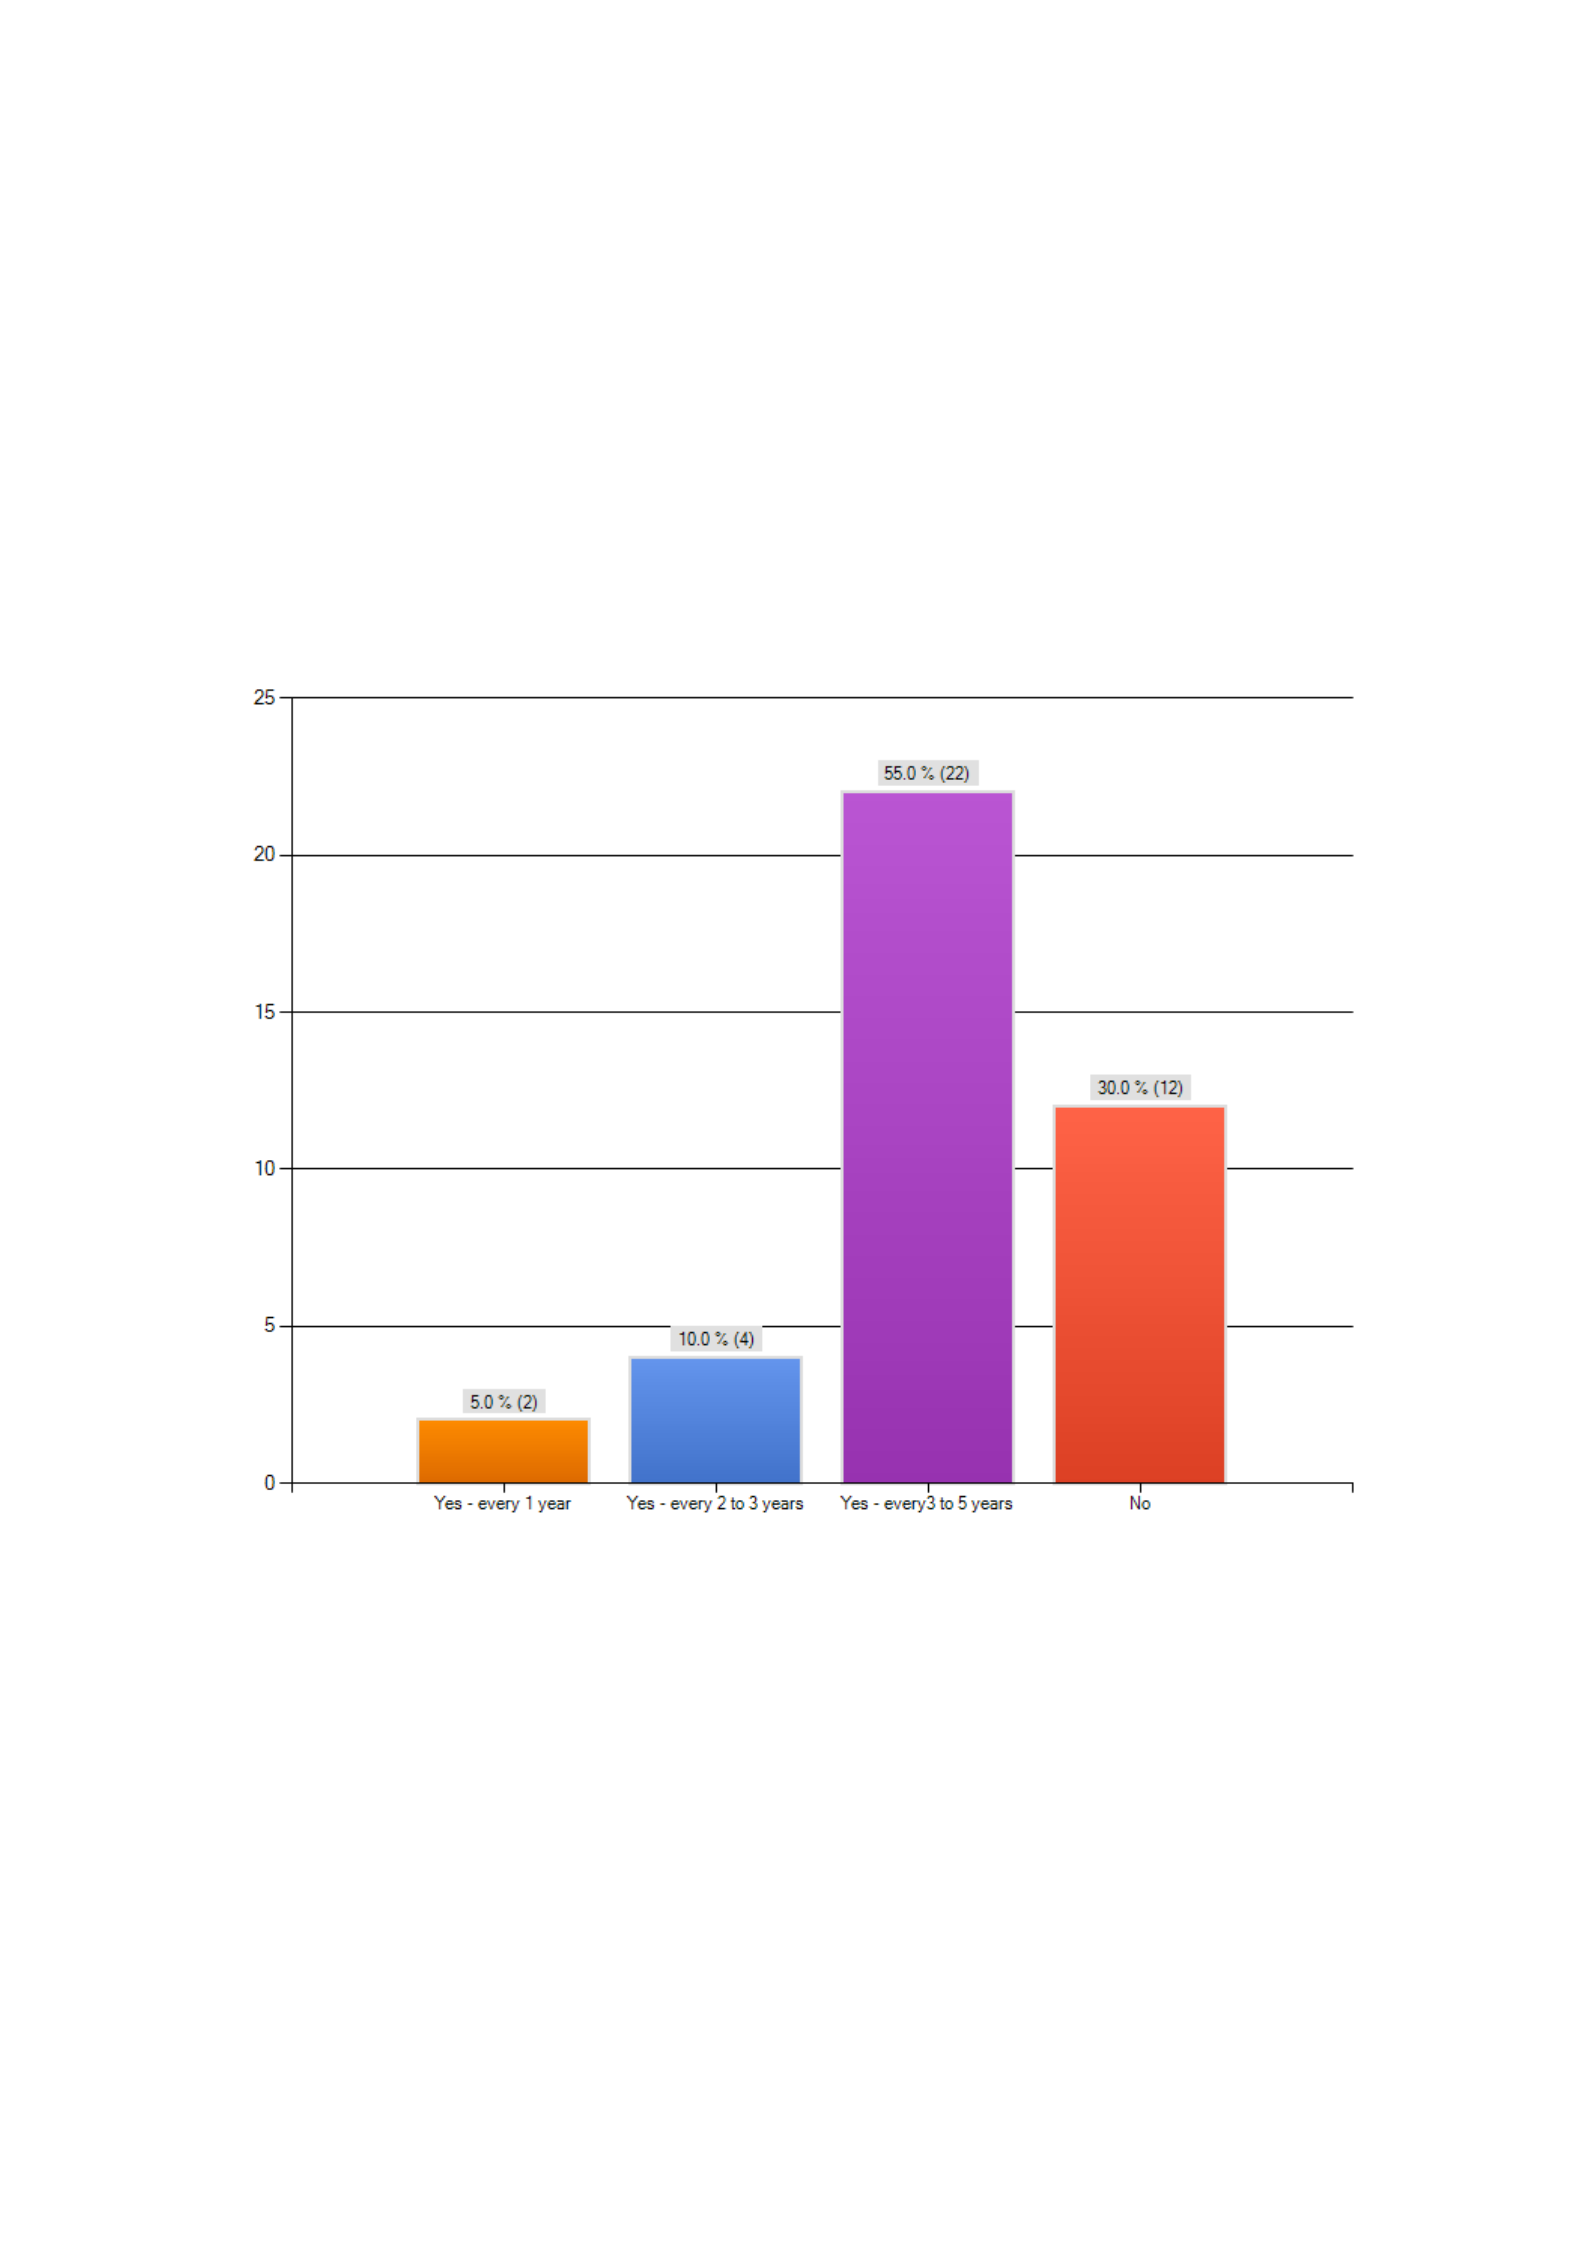
Once diversified, did the process of diversification
continue to take place and if yes in which frequency?
After diversification for the first time, process of
diversification begins to take place. To check its
frequency, this question has been designed. Below are
the results.
Figure 19: Continuation Process of Diversification.
Above graph shows the trend of majority cases. 22 out
of 40 participants stated that once diversified,
diversification process takes place in every 3 to 5 years.
12 participants stated that it is not necessary that once
diversified, diversification begins to take place. 4

participants stated that diversification takes place every
2 to 3 years, while only 2 participants (5%) stated that it
occurs every 1 year. However, results influence us to
believe that once diversified, diversification begins to
take place every 3 to 5 years.
Did the diversification process leads to organizational
structure change and if yes how?
The process of diversification influences the
organizational structure. However, in large
organizations, change is not observed as such. Q16 has
been tested over the same 40 participants. Results are
graphically presented below:
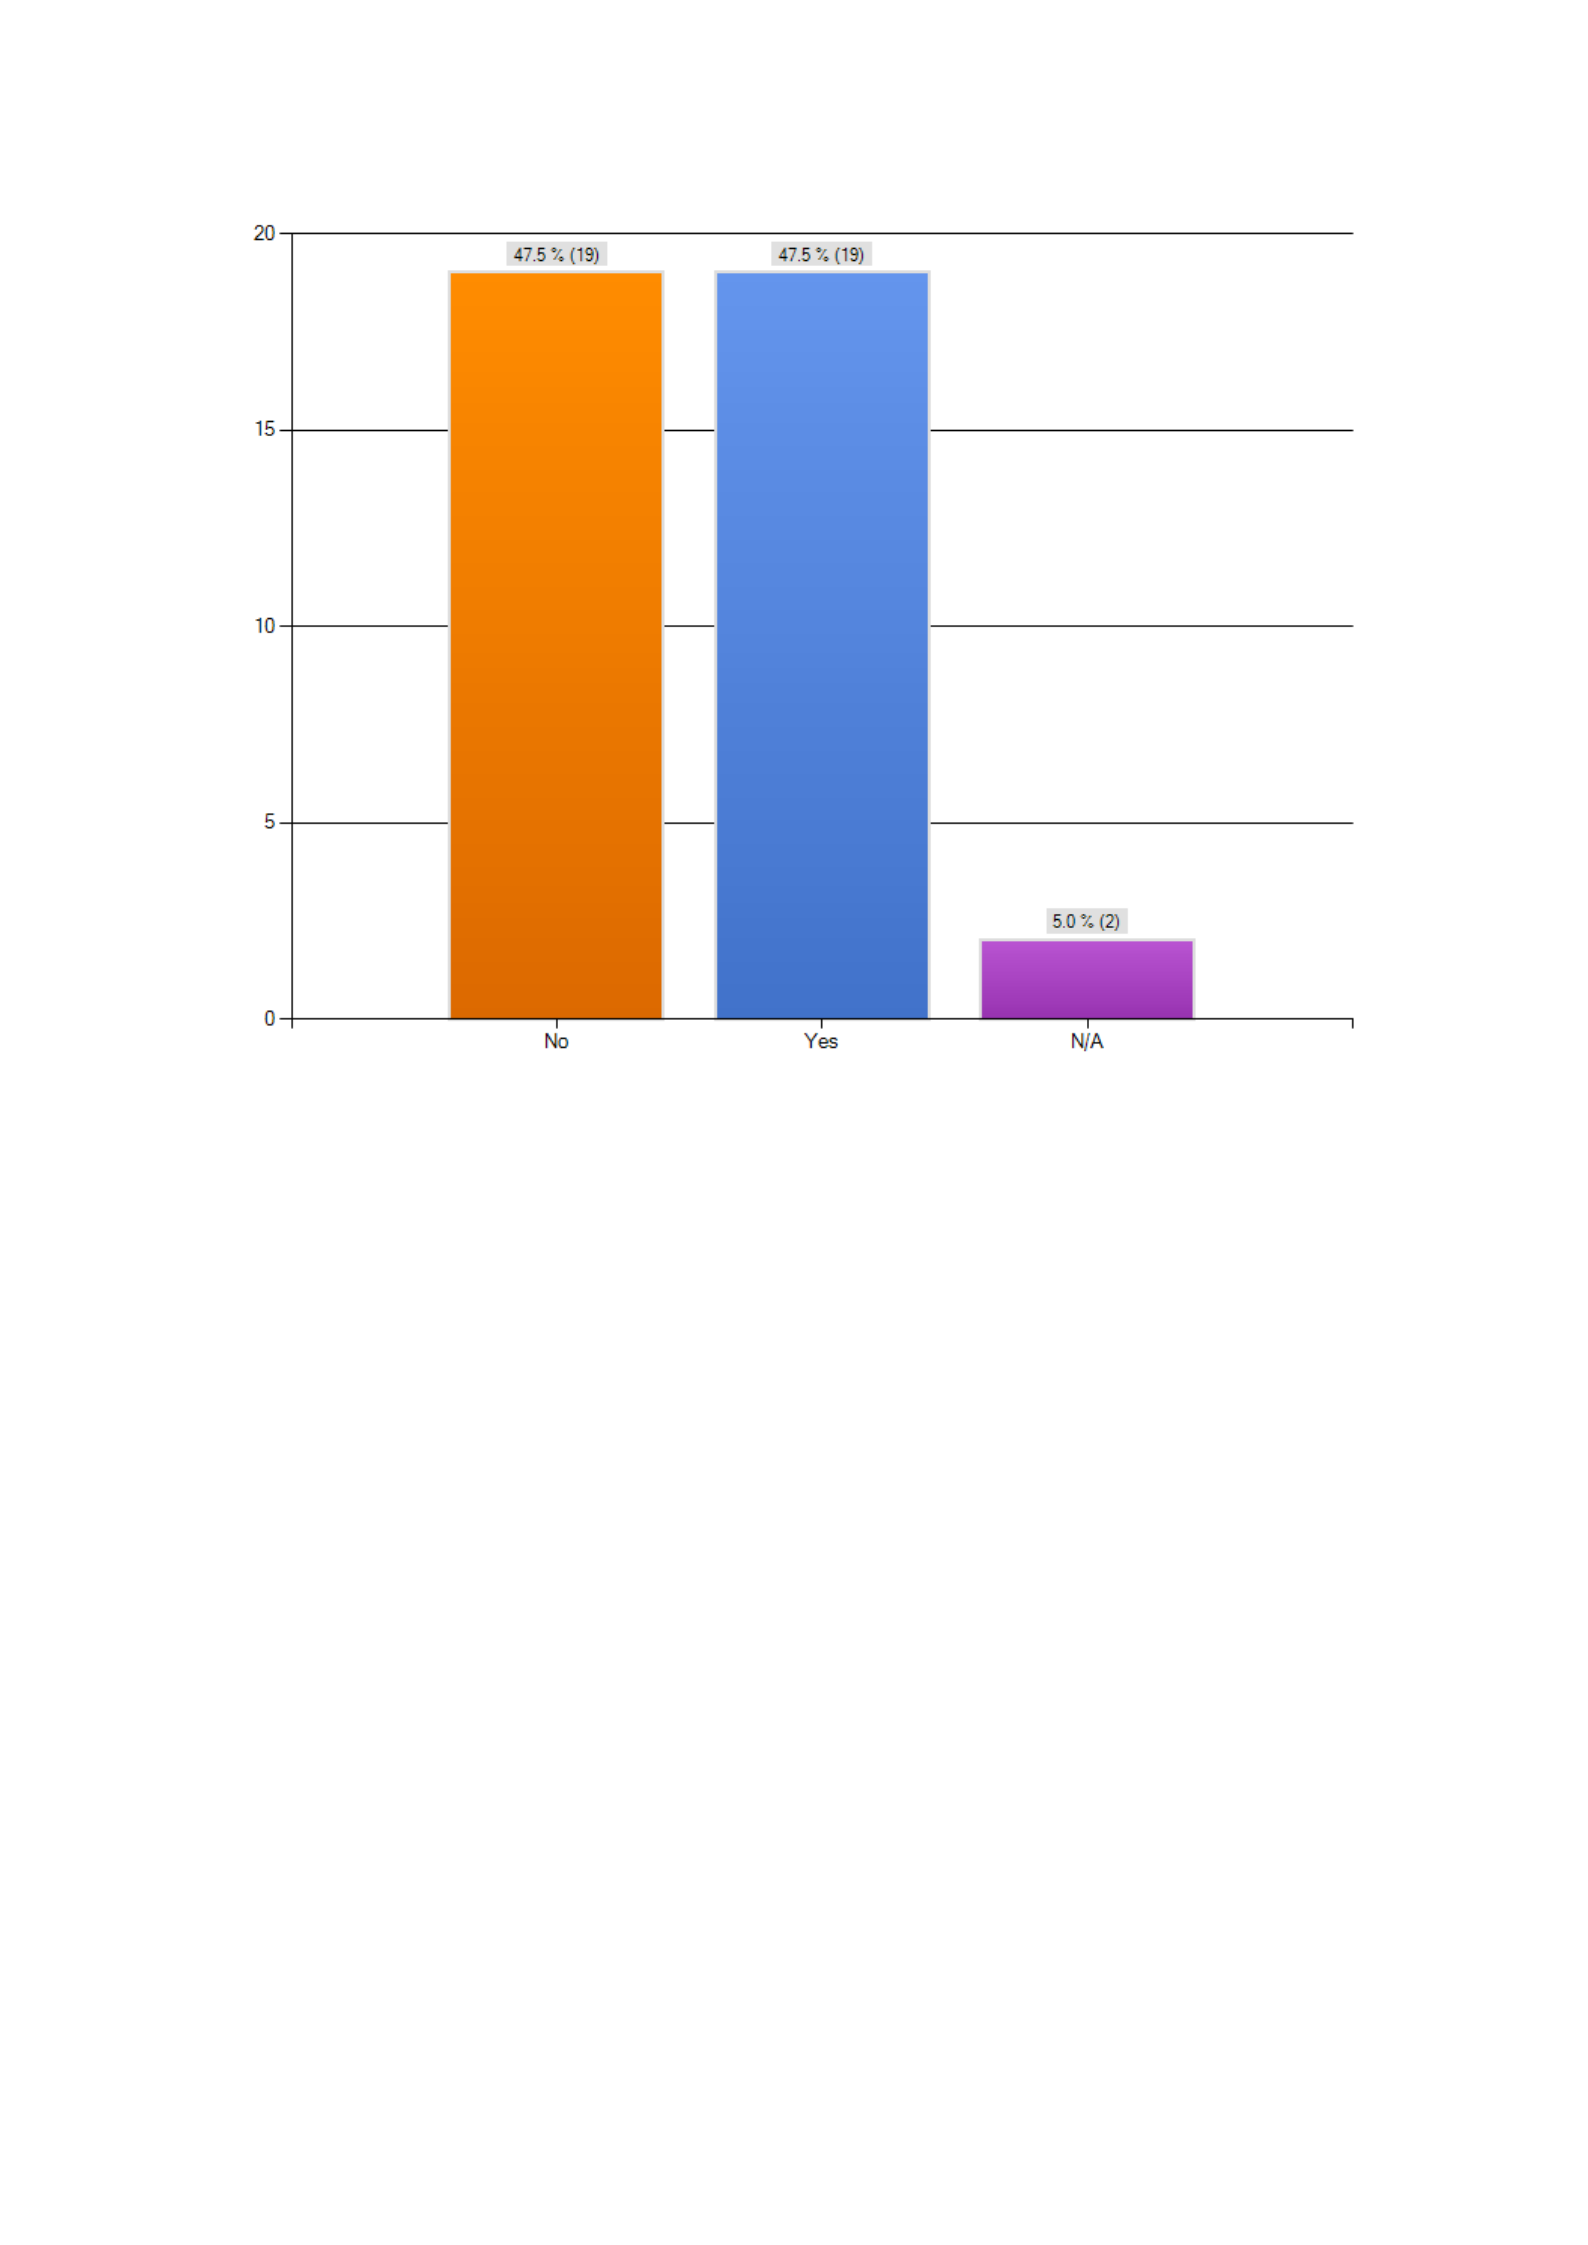
Figure 20: Change Organizational Structure.
Above results do not present a clear picture as out of 40
participants, 2 participants refused to answer anything.
Out of remaining 38 participants, surprisingly, 19
participants chose the option of Yes, and 19 participants
selected the option No. Literature review indicates that
up to some extent, diversification does impact the
organizational structure but processes in the large
organizations do not really lead to the change in
organizational structure. However, in research part of
this study, we cannot really say anything as results are
neural.
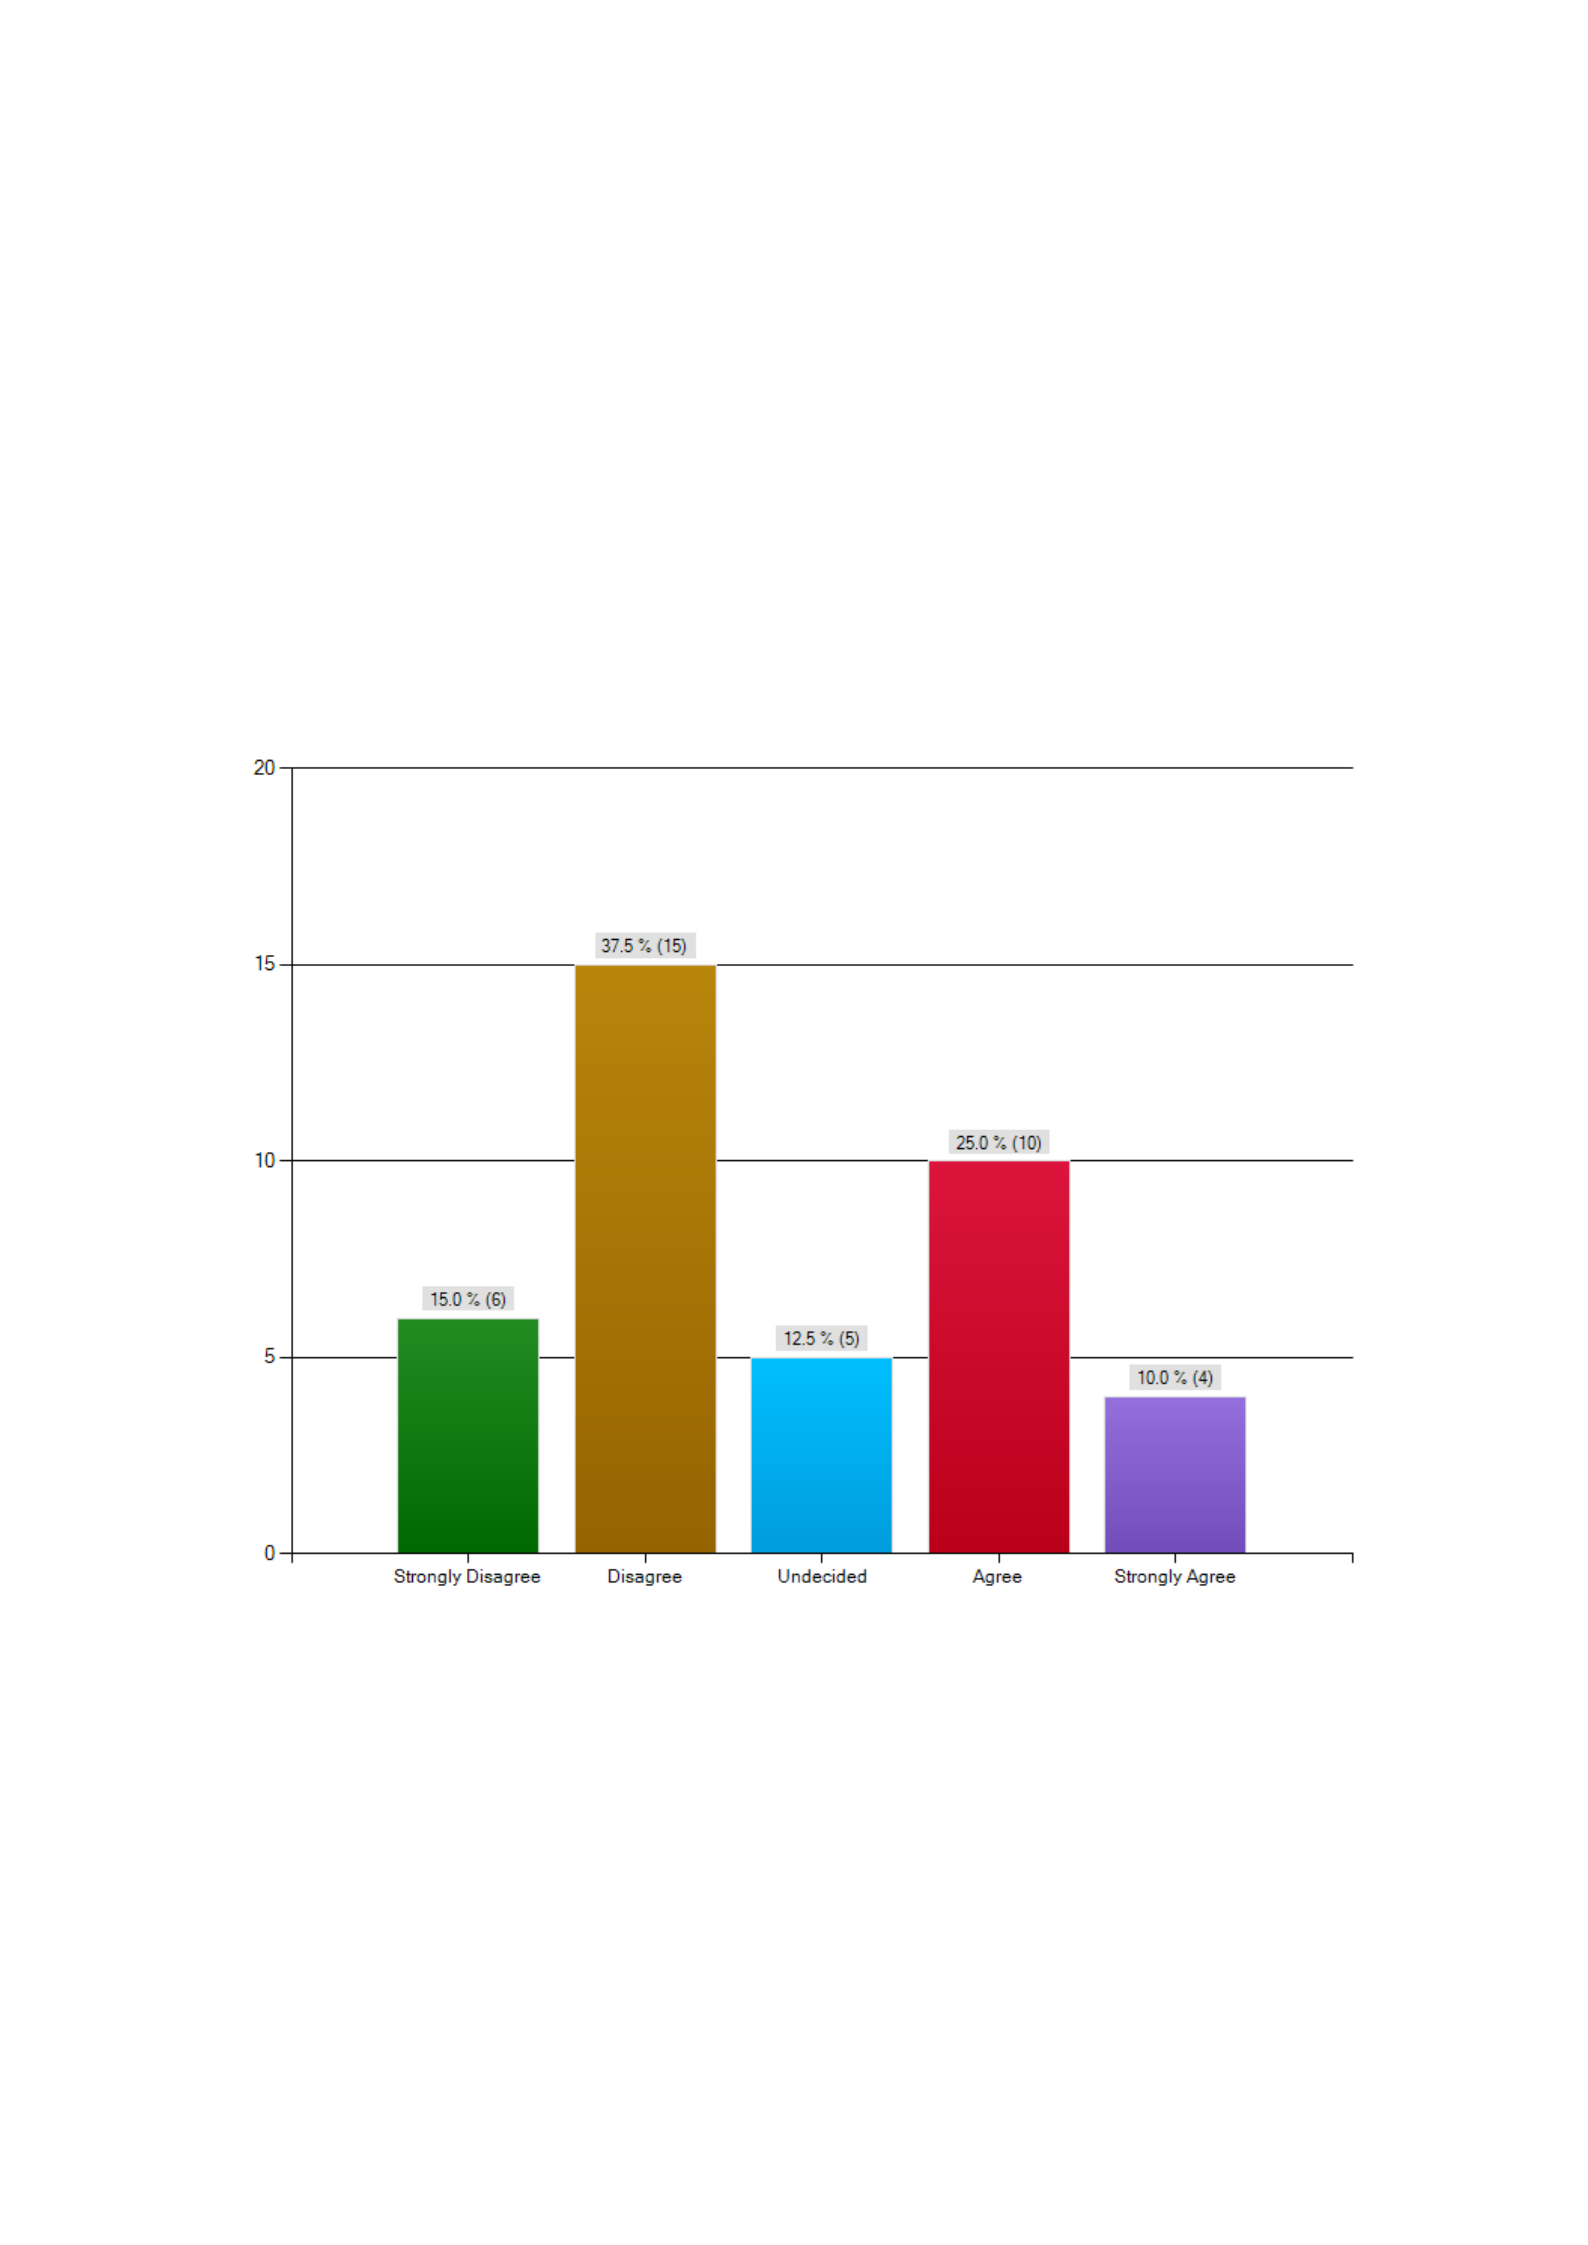
Do you believe that the “larger organization” has
affected the internal controls and flexibility of the
business?
As an organization grows, internal control is affected so
as the flexibility. To test this point, Q17 has been tested
on the same population of 40 participants. Below are
the results:
Figure 21: Effects of Internal Controls in Large
Organization.
In reply to Q17, surprisingly, 15 out of 40 participants
(37.5% of the total population) selected the option
of disagree. 10 out of 40 participants (25% of the

population) ticked the option of agree, 6 participants
(15% of the population) ticked strongly disagree, 5
participants (12.5% of the total population) did not
comment, 4 participants with 10% of the population
ticked strongly agree option. Results are surprisingly
proving Q17 to be wrong. With Q17 results, it has been
rejected to accept that the “larger organization” affects
the internal control and flexibility of the business
With added business what are the main internal
pressures your company currently or will be facing: 1=
extremely concerned, 5 = not at all concerned?
Q18 analyzes various internal areas of concern for the
family owned businesses to check the level to which
participants are concerned about each of the below
factors:
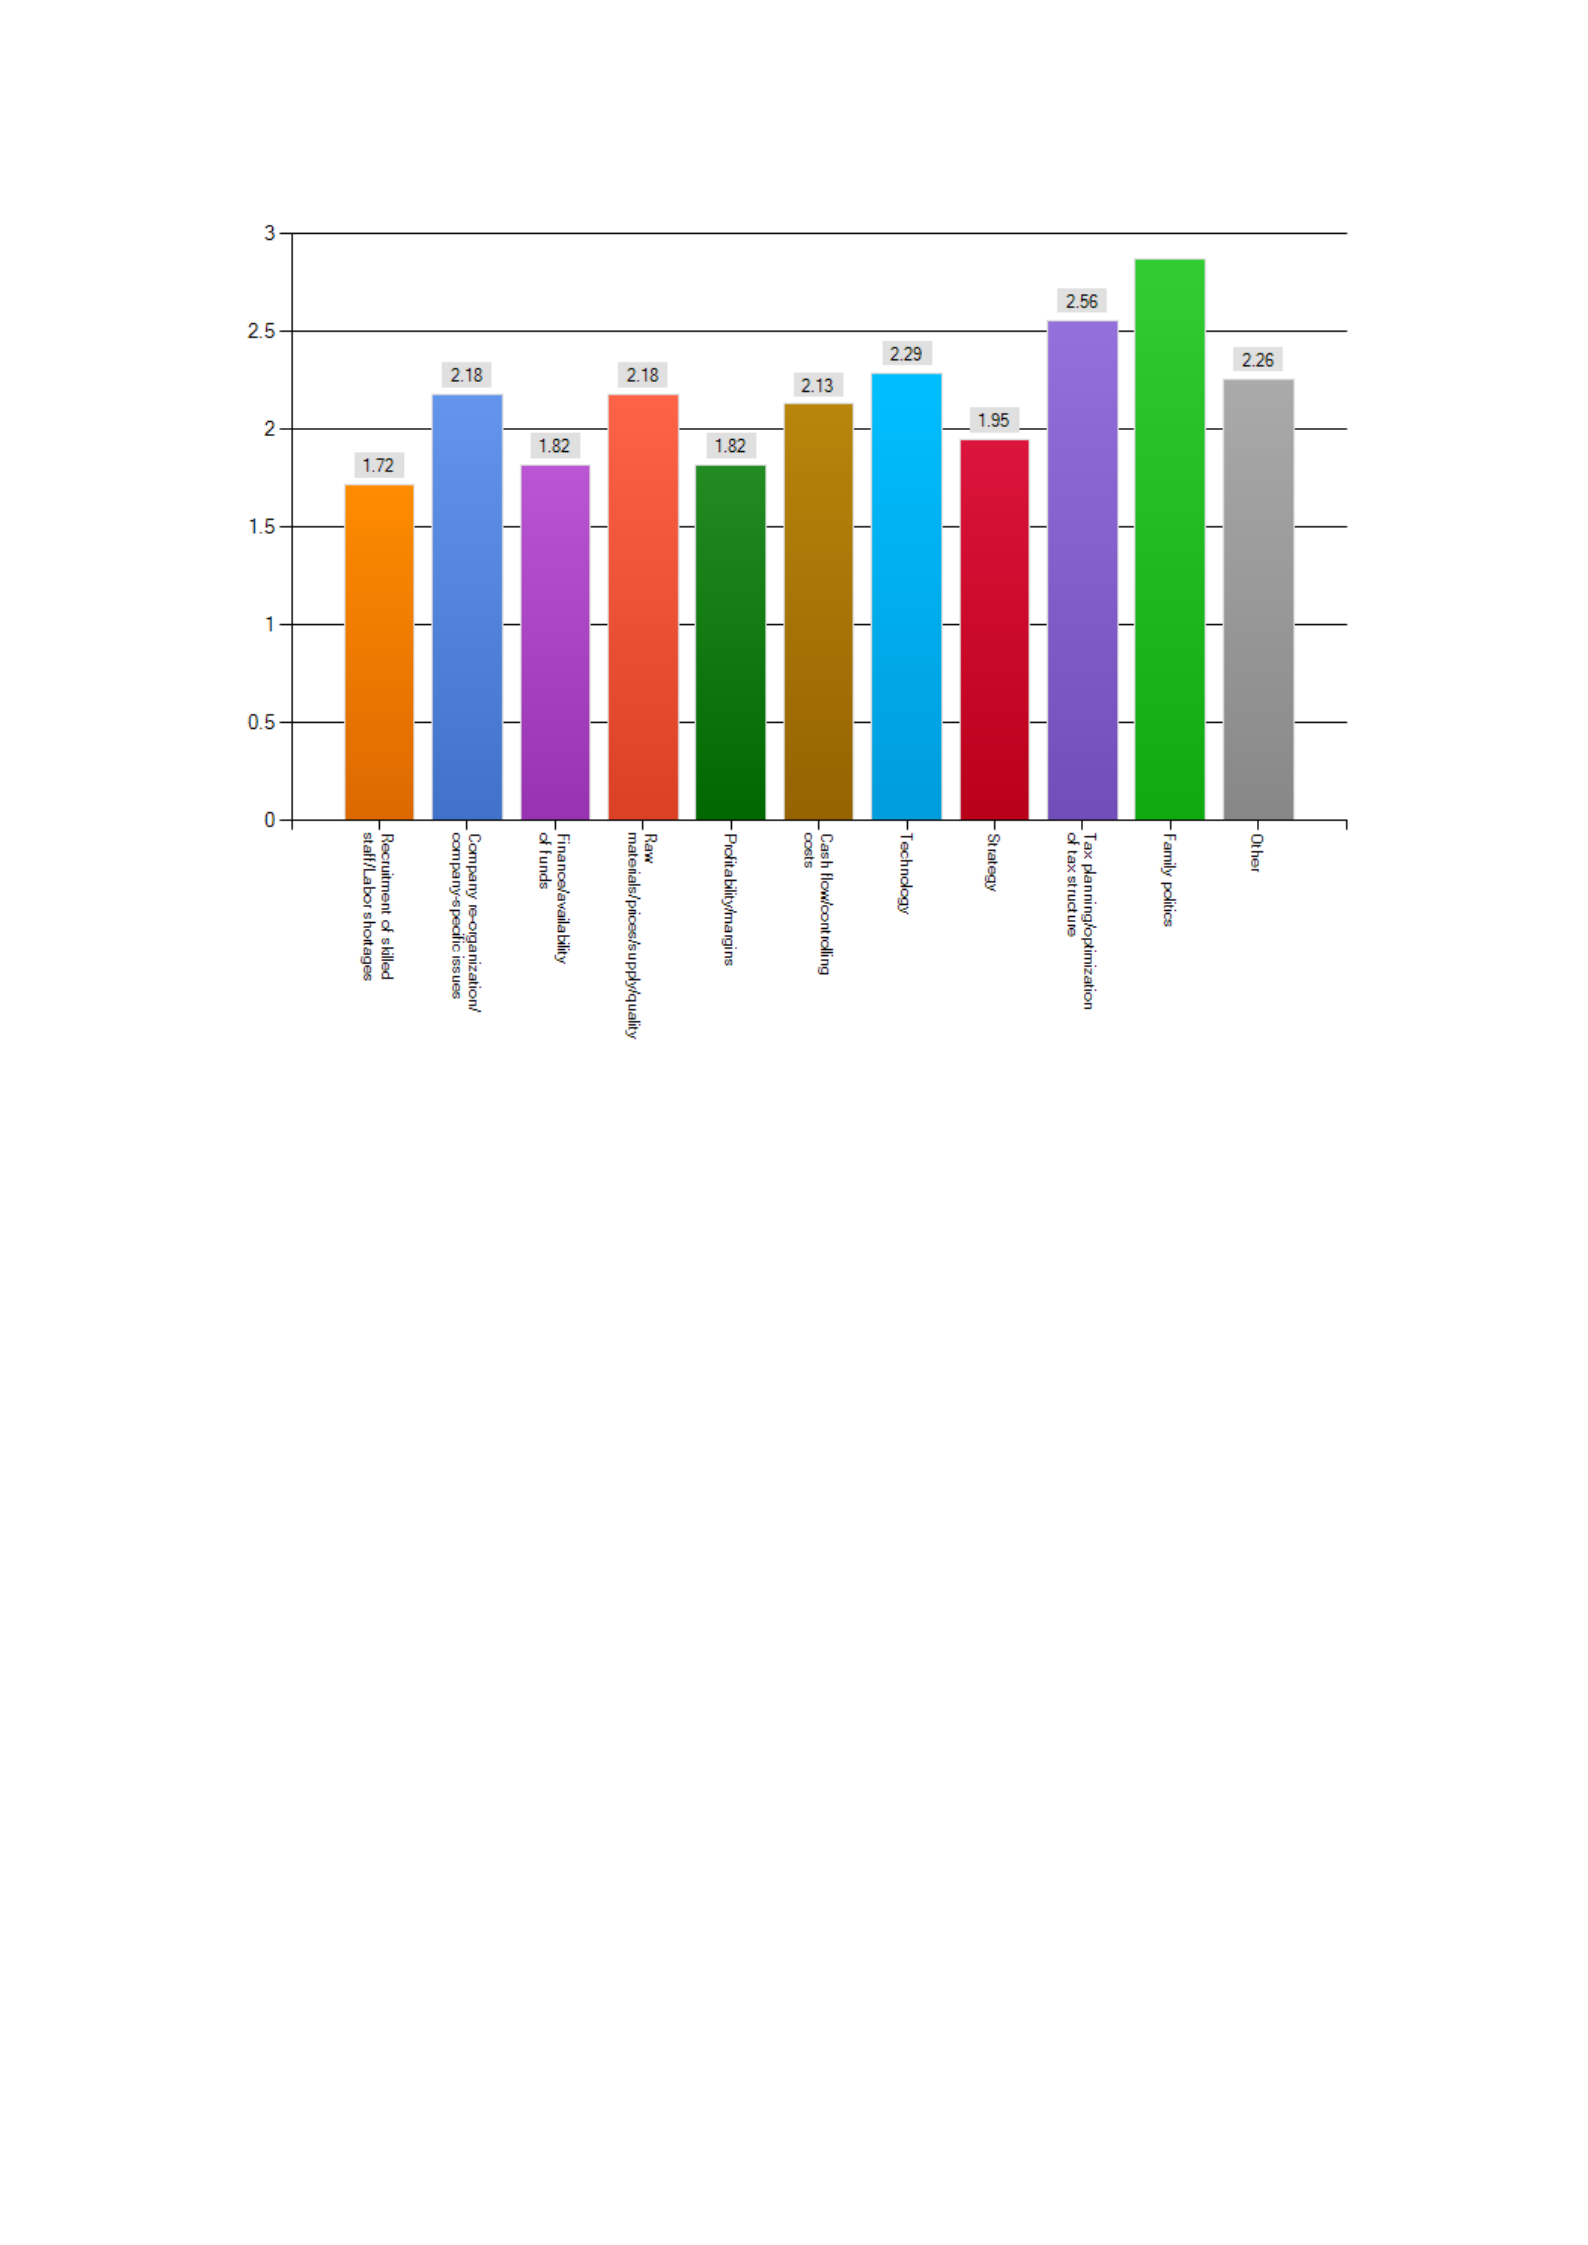
Figure 22: The Main Internal Pressures on Companies.
There are different aspects of concern for any family
business, such as family politics, tax planning, strategy,
technology, operating costs, profitability, raw material
availability / quality, financial soundness, company
recognition and labor issues. Above graph clearly
illustrate that taking an average, all these factors are
important and participants are concerned. However,
due to the nature of core business, a few factors might
not be important for one party than another.
Please rate the level of concern you have regarding the
following external factors your company is currently
facing or will face in the near future: 1= extremely
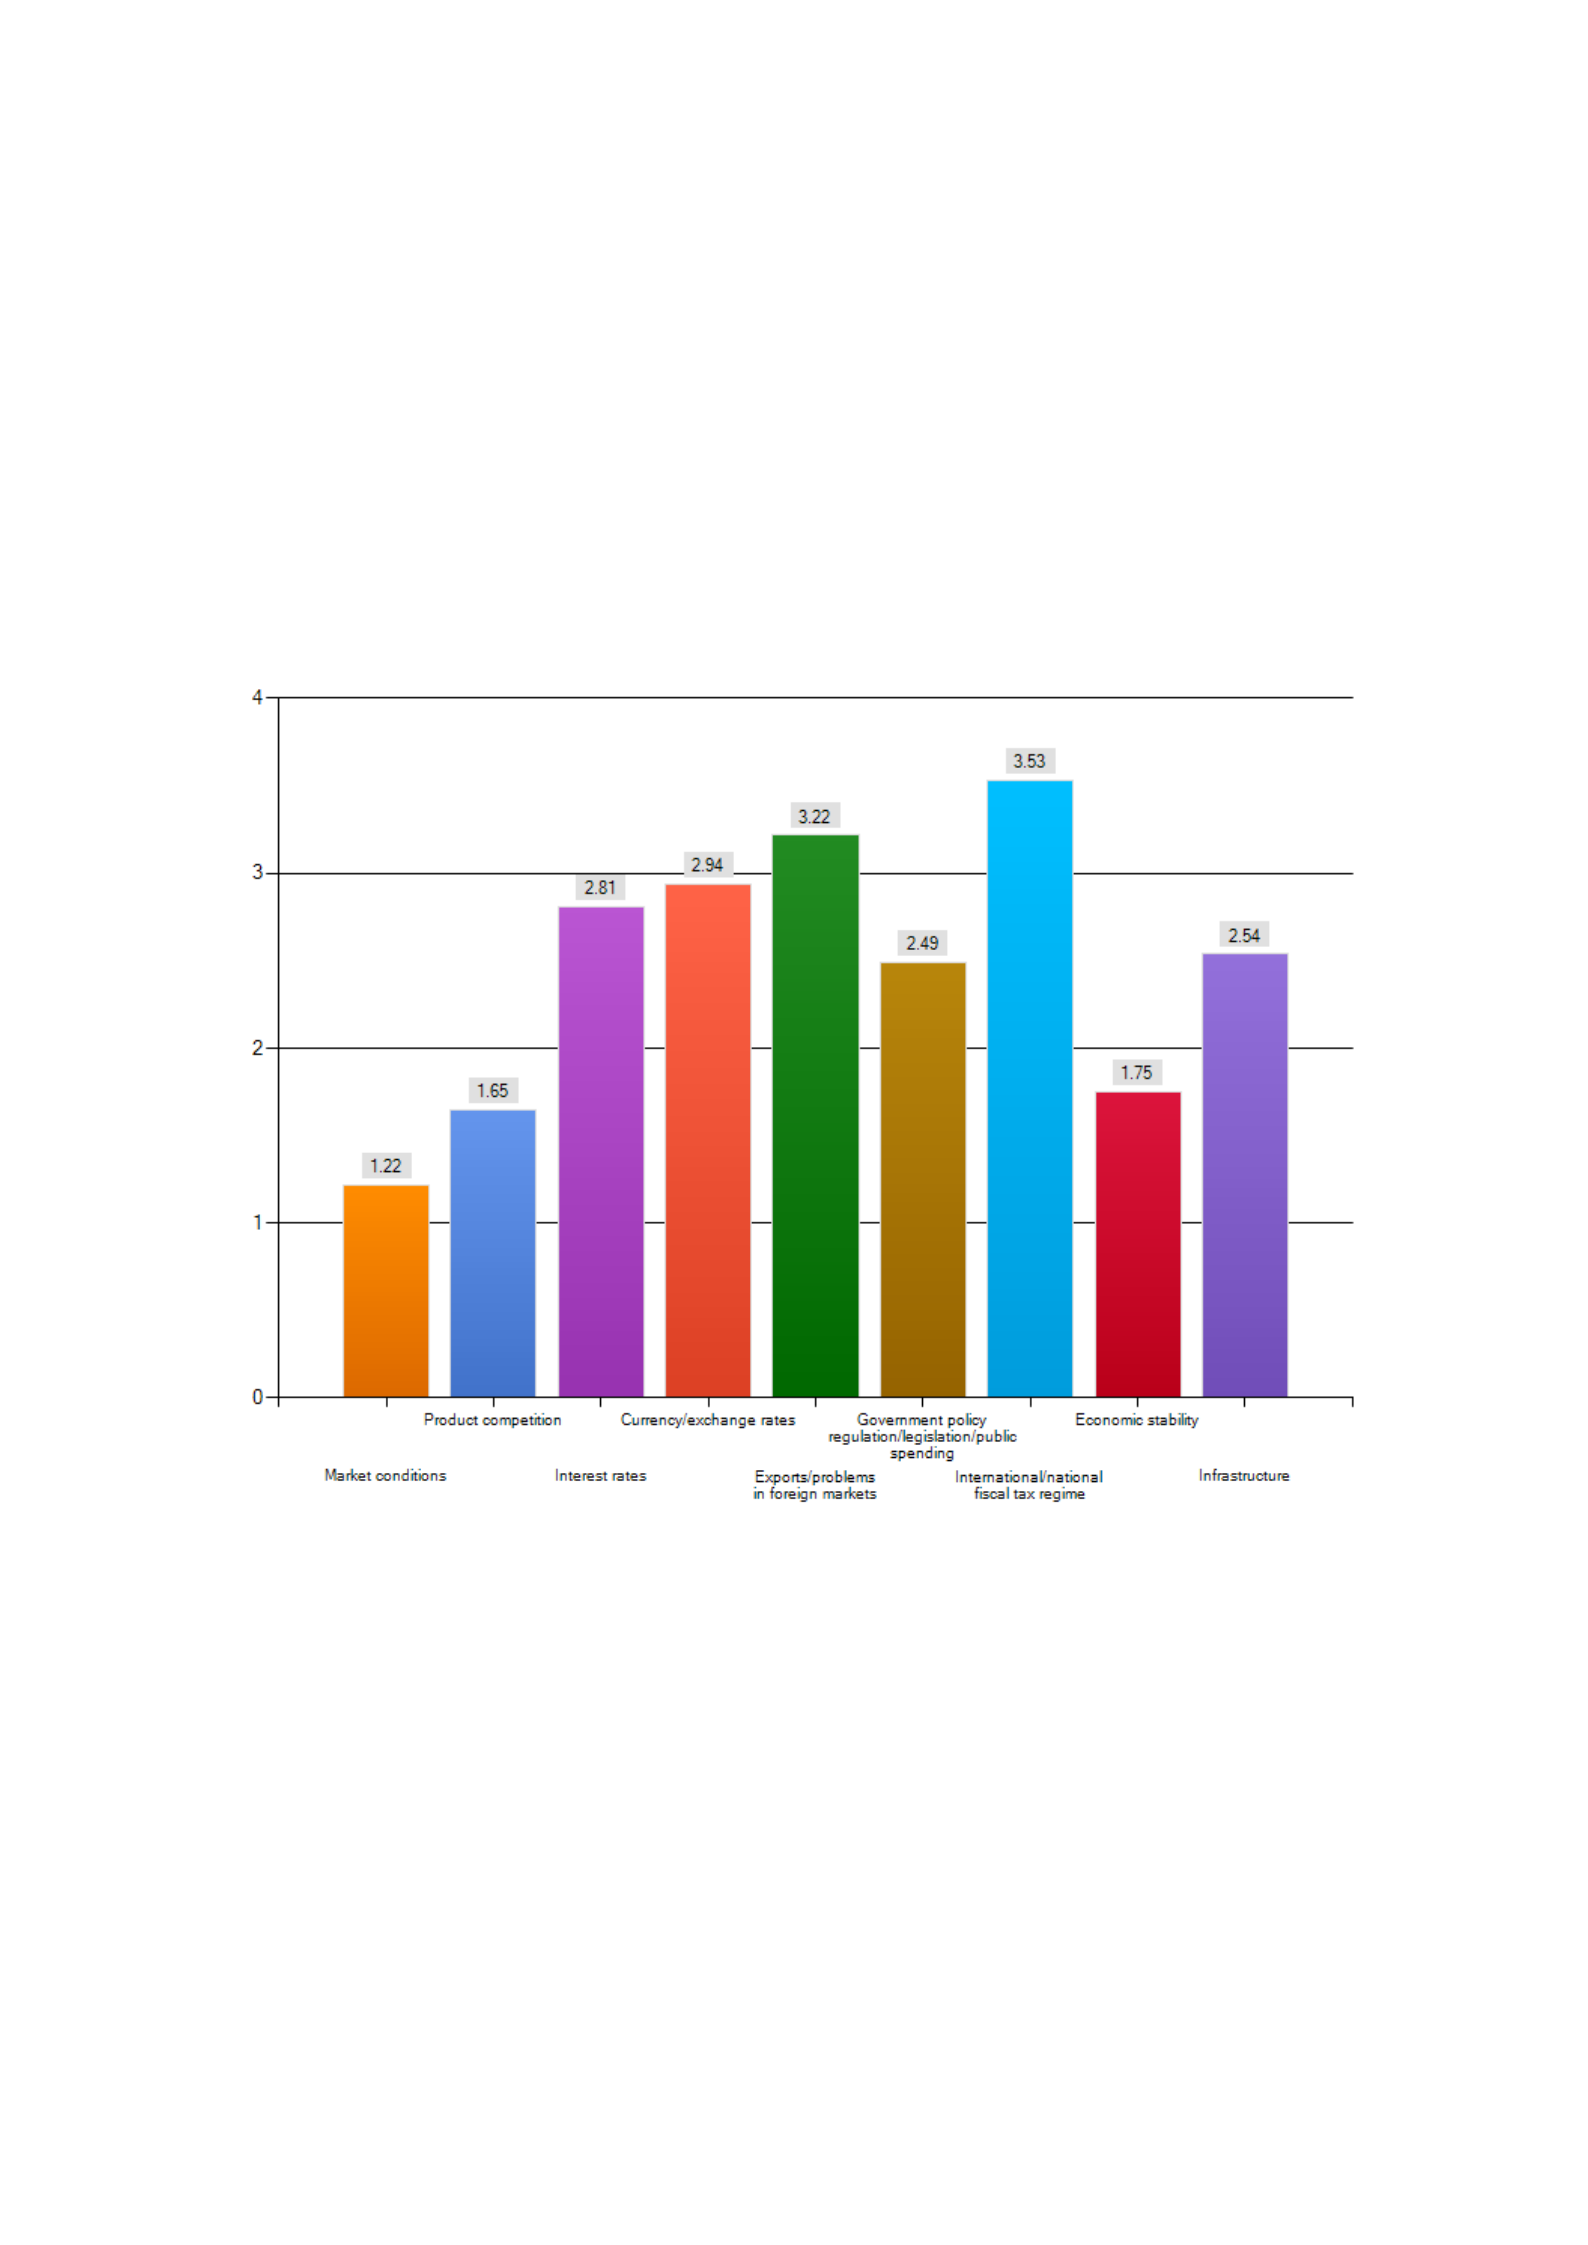
concerned, 5 = not at all concerned or will be facing: 1=
extremely concerned, 5 = not at all concerned?
Q19 analyzes the various external areas of concern for
the family owned businesses to check the level to which
participants are concerned about each of the below
factors:
Figure 23: Level of Concern you have Regarding the
Following External factors.
Market conditions, product competition, interest rates,
currency exchange rate, export problems, government
policies, public spending, international/national fiscal
tax regime, economy stability and infrastructure are

also the areas where participants are concerned.
However, depending on the nature of business, a few
points that matter to company A might not be an area
of concern for company B. The participants’ feedbacks
illustrate a mix picture where average of all factors are
somewhat important but the areas of
international/national tax regime, export problems,
infrastructure and the currency exchange rates are the
common concerns in most of the cases.
Retrospectively would you consider the diversification
process as having been an option available or an
element of business survival/ was the decision to take
opportunity of market demand or more from a
strength building perspective, in relation to your
competitors?
Results are as under:
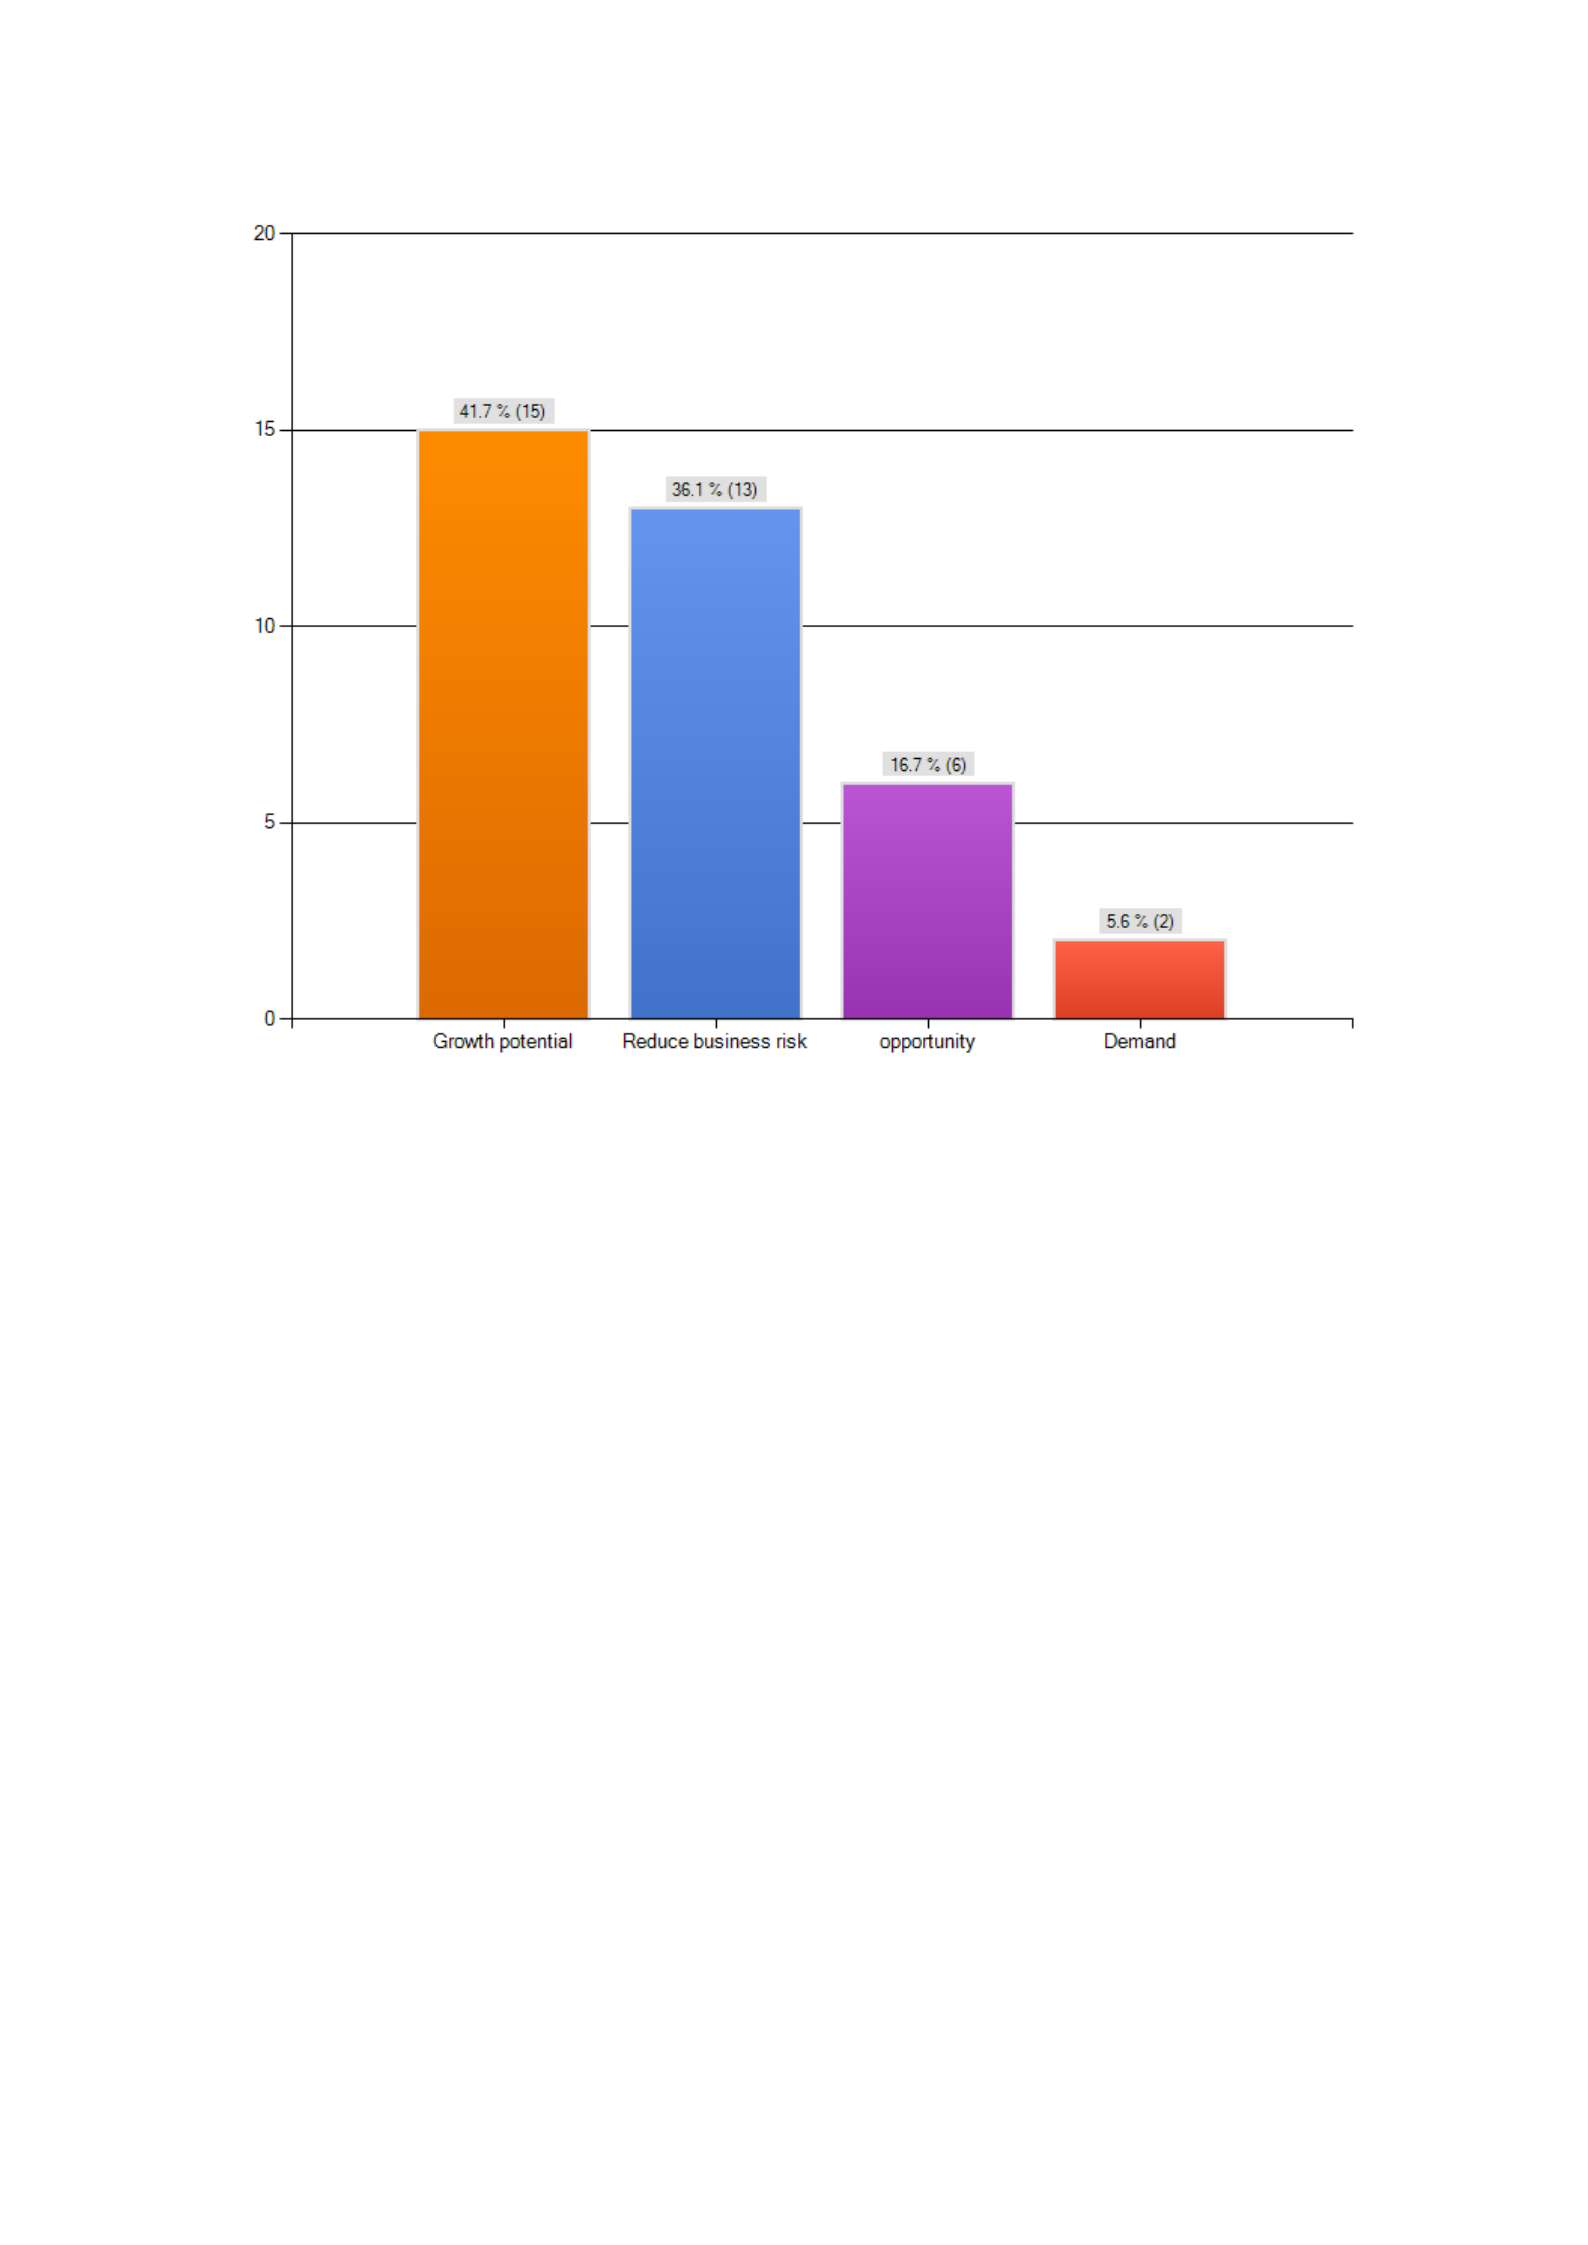
Figure 24: Motivation for Diversification.
The results illustrate that the decision of diversification
was taken by the participants as an opportunity from a
strength building perspective, in relation to the
competitors for the growth potential, reduction of
business risk, opportunity or demand. However, most of
the participants emphasized on the growth potential as
total 15 out of 40 participants (41.7%) ticked the option
of growth potential, 13 participants selected the option
of reduce business risk option, 6 participants (16.7%)
ticked opportunity option and only two participants
(5.6%) ticked the option of demand.
Do you have a succession plan in place?
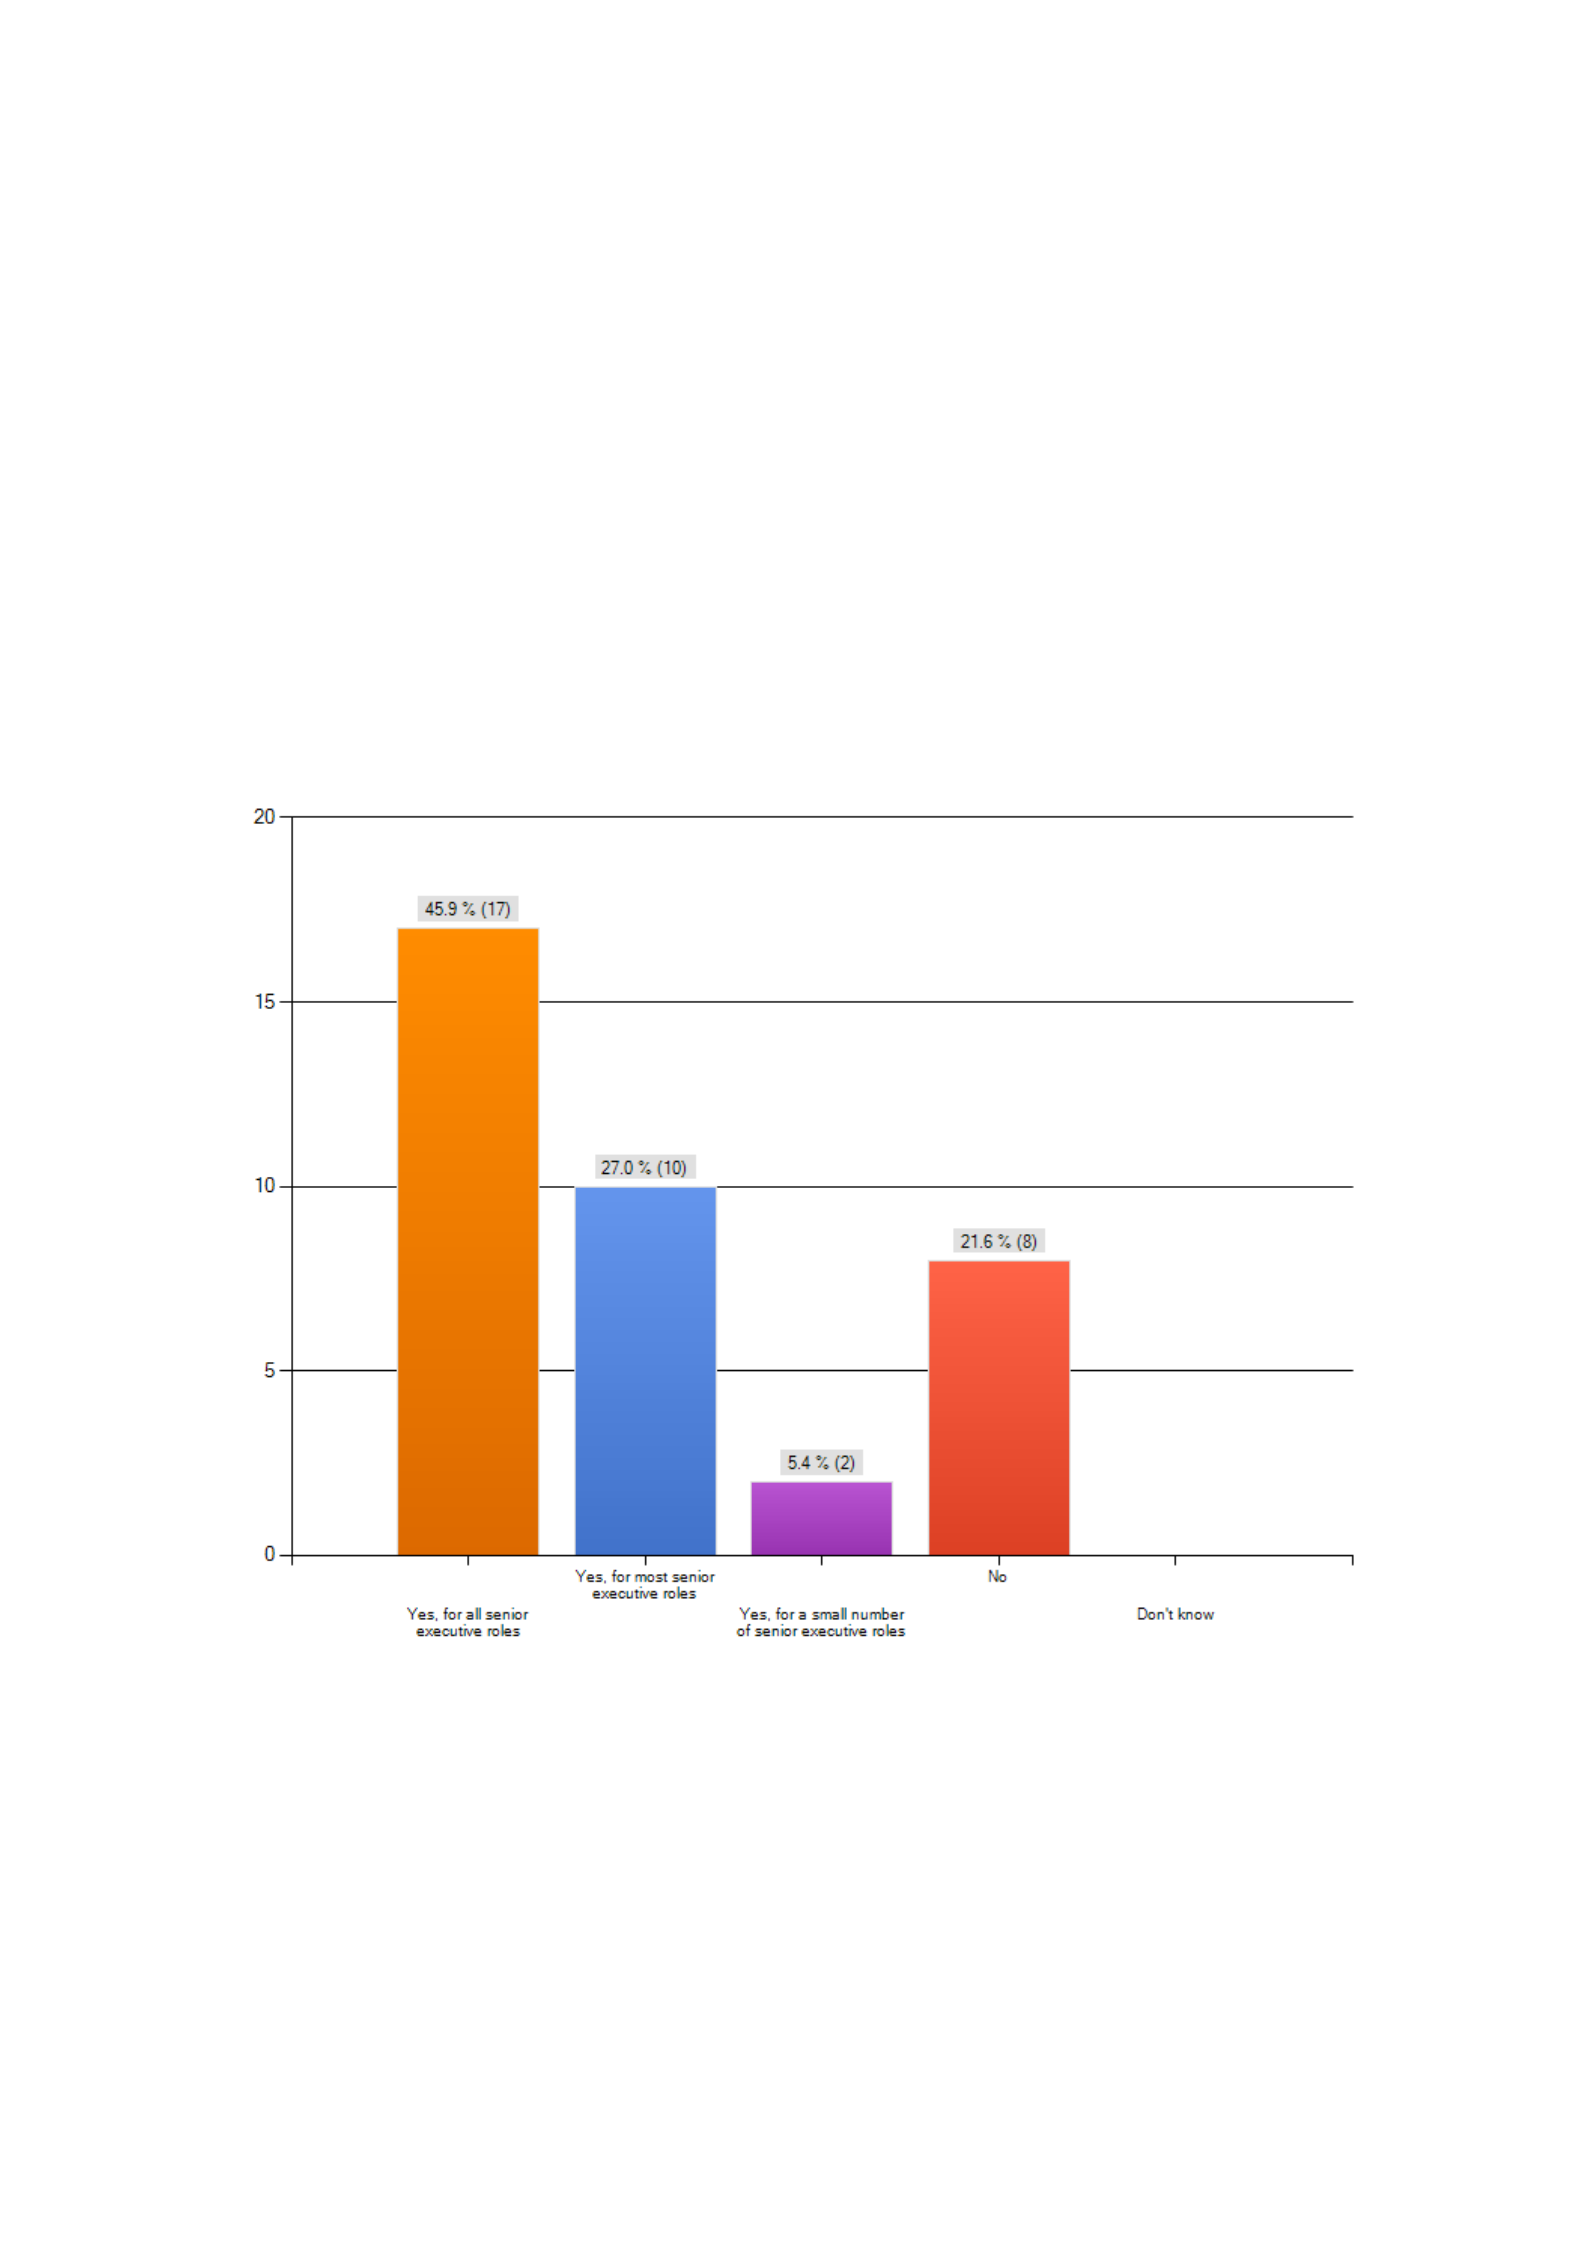
Succession plan is taken as something quite important
in large organizations. Formally or informally,
succession plans are observed even in small businesses.
As for this survey, participants are taken from different
core businesses with different roles and business legal
structures, Q21 would help in identifying if the
succession plan practice is adopted in most of the cases.
Results of Q21 are graphically presented below.
Figure 25: Status of Succession Plan.
Above graph illustrates that 45.9% of the total
population 17 out of 40 participants) responded that
they do have succession plan for all senior roles. 27% of
the total population (10 out of 40 participants) stated

that they have the succession plan for most of the senior
executive roles. 2 participants (5.4% of the total
population) stated that they do have succession plan for
small number of senior executive roles, while 8
participants out of 40 (21.6) declared that they do not
have any succession plan. Q21 reveals the importance
of succession plan with three fourth of the total
population having succession plans for different roles.
Majority companies have succession plan for all senior
roles while a few have for small number of senior
executives.
Do you consider the company as it is today, as being
the same family business holding the same culture and
ethics or a merely a corporation controlled by
members of one family?
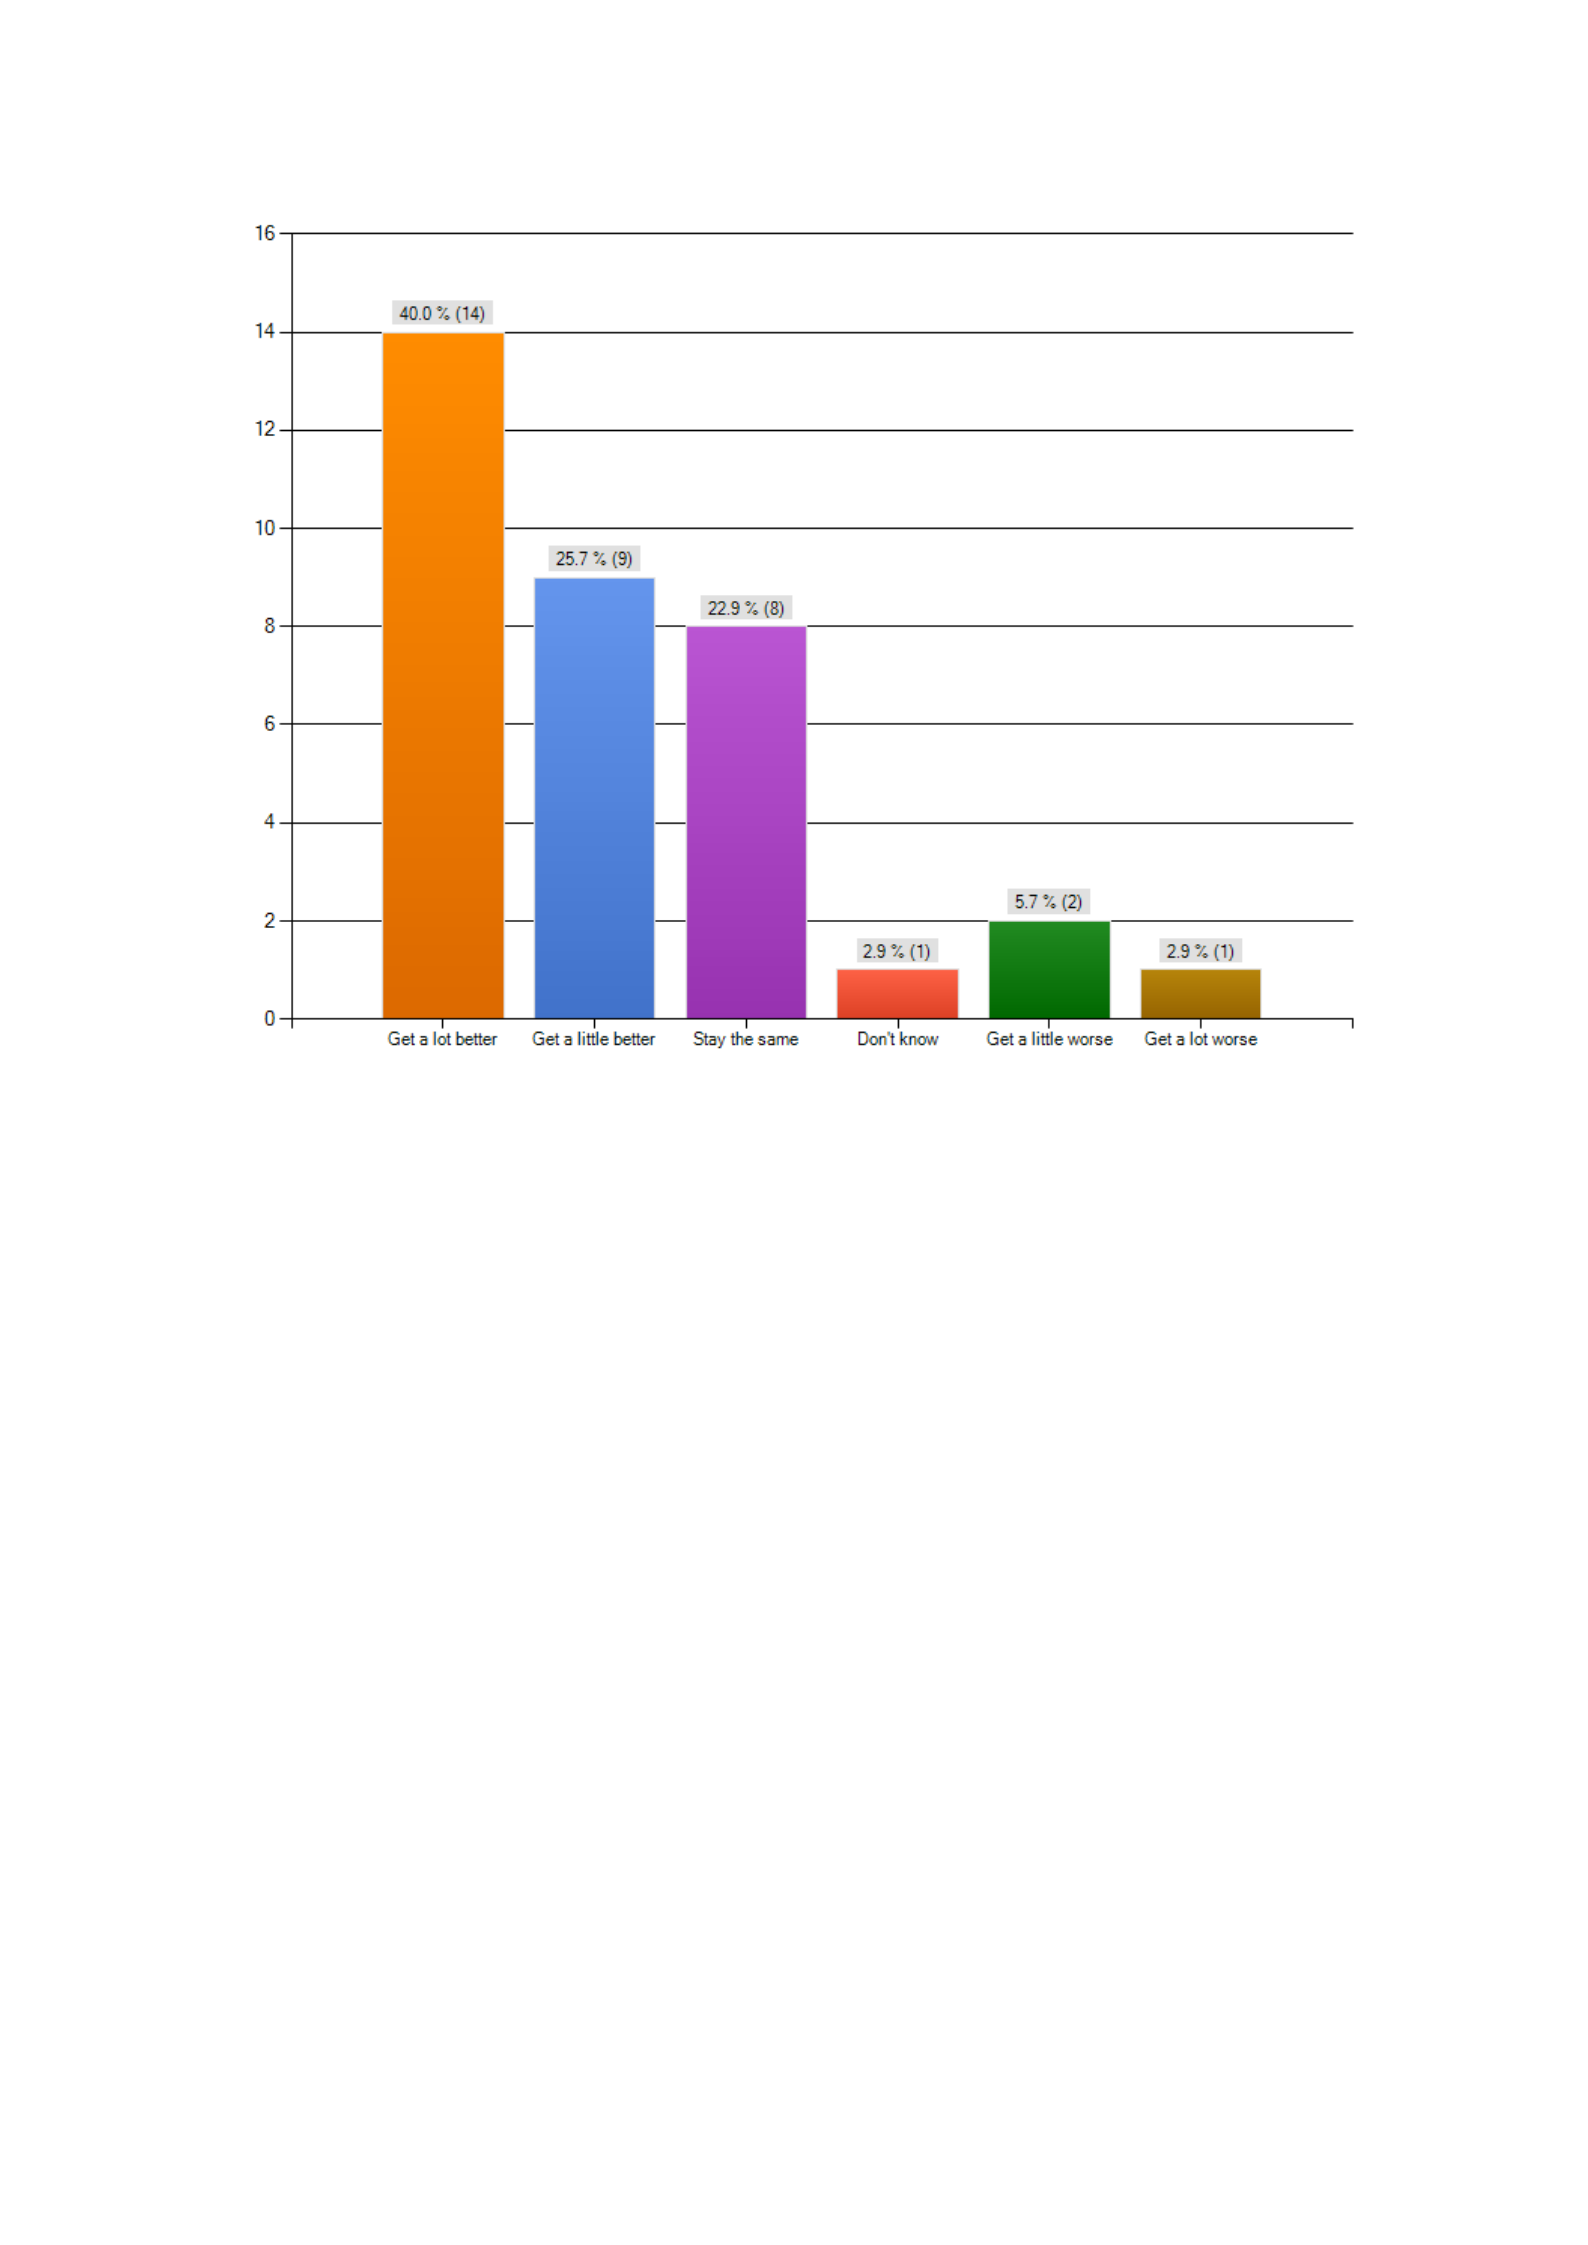
Figure 26: Recommendation for the System.
Considering all practices, strategies, structures and
family politics etc, when participants were asked to
comment if they want it to get a lot better than it is
today, to get it a little better, to stay the same, to get a
little worse or to get a lot worse. Expectedly, results
indicate that most of the participants (14 out 40
participants with percentage of 40% of the total
population) believe that it is needed to get a lot better
than what it is now. 25.7% (9 participants out of 40)
believe that it need to get a little better, 22.9% (8
participants out of 40) want it to stay the same with no
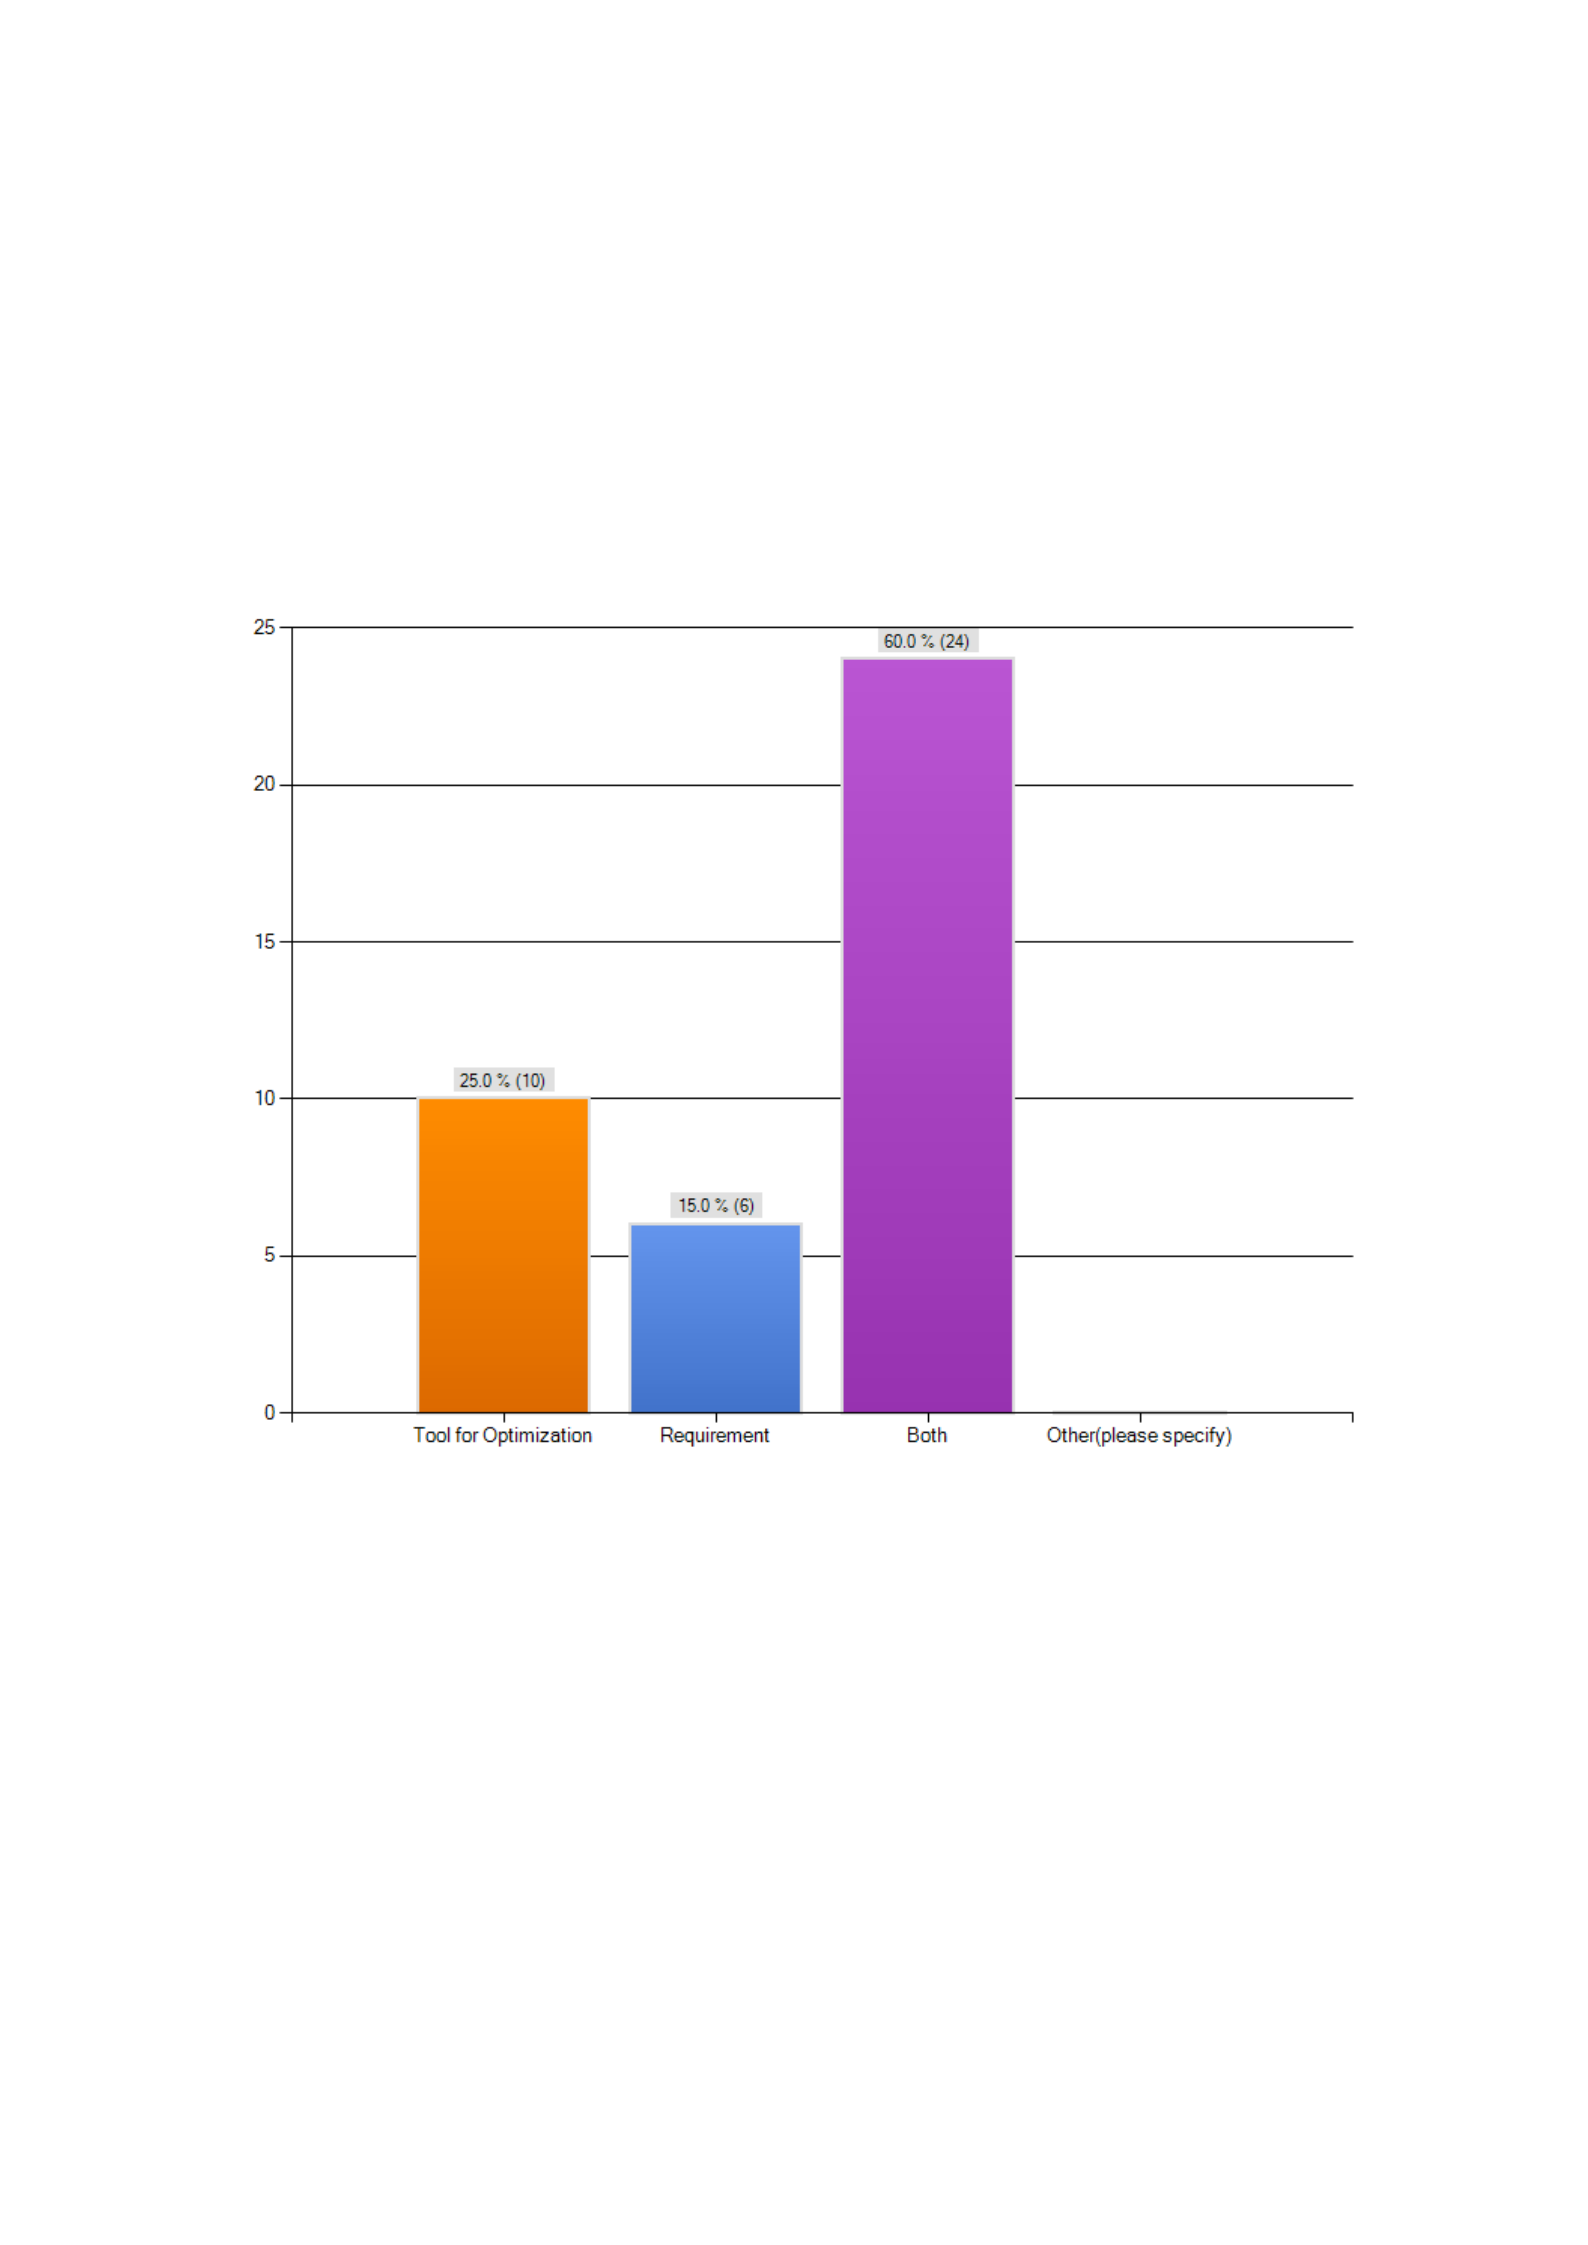
change. Results indicate that companies need to
improve a lot more than current state.
In your opinion, is corporate governance a tool for
optimization or a requirement in the age of
diversification?
Figure 27: Corporate Governance.
Q23 is one of the most important question of this survey
as it is to test if the corporate governance a tool for
optimization or a requirement in the age of
diversification. Tool for optimization and requirement
both are required so this question was to test it
practically. 24 out of 40 participants (60% of the total

population) take both as equally important. However,
10 participants (25%) selected the option of tool for
optimization and 6 participants with 15% of the total
population ticked the option of requirement. Results
clearly show that most of the participants consider both
sides as important so this has been proven that tool for
optimization and requirement both are the important
aspects.
If and with corporate governance in place, how would
you rate the influential power of ‘Family Concept’
(owners) with respect to that of ‘business rules’
(management) in controlling the business:
To run any business formally to receive good results,
companies must have corporate governance in place.
However, family concepts might influence the corporate
decisions. To test this, Q24 has been designed. Below is
the graphical presentation of Q24 results:
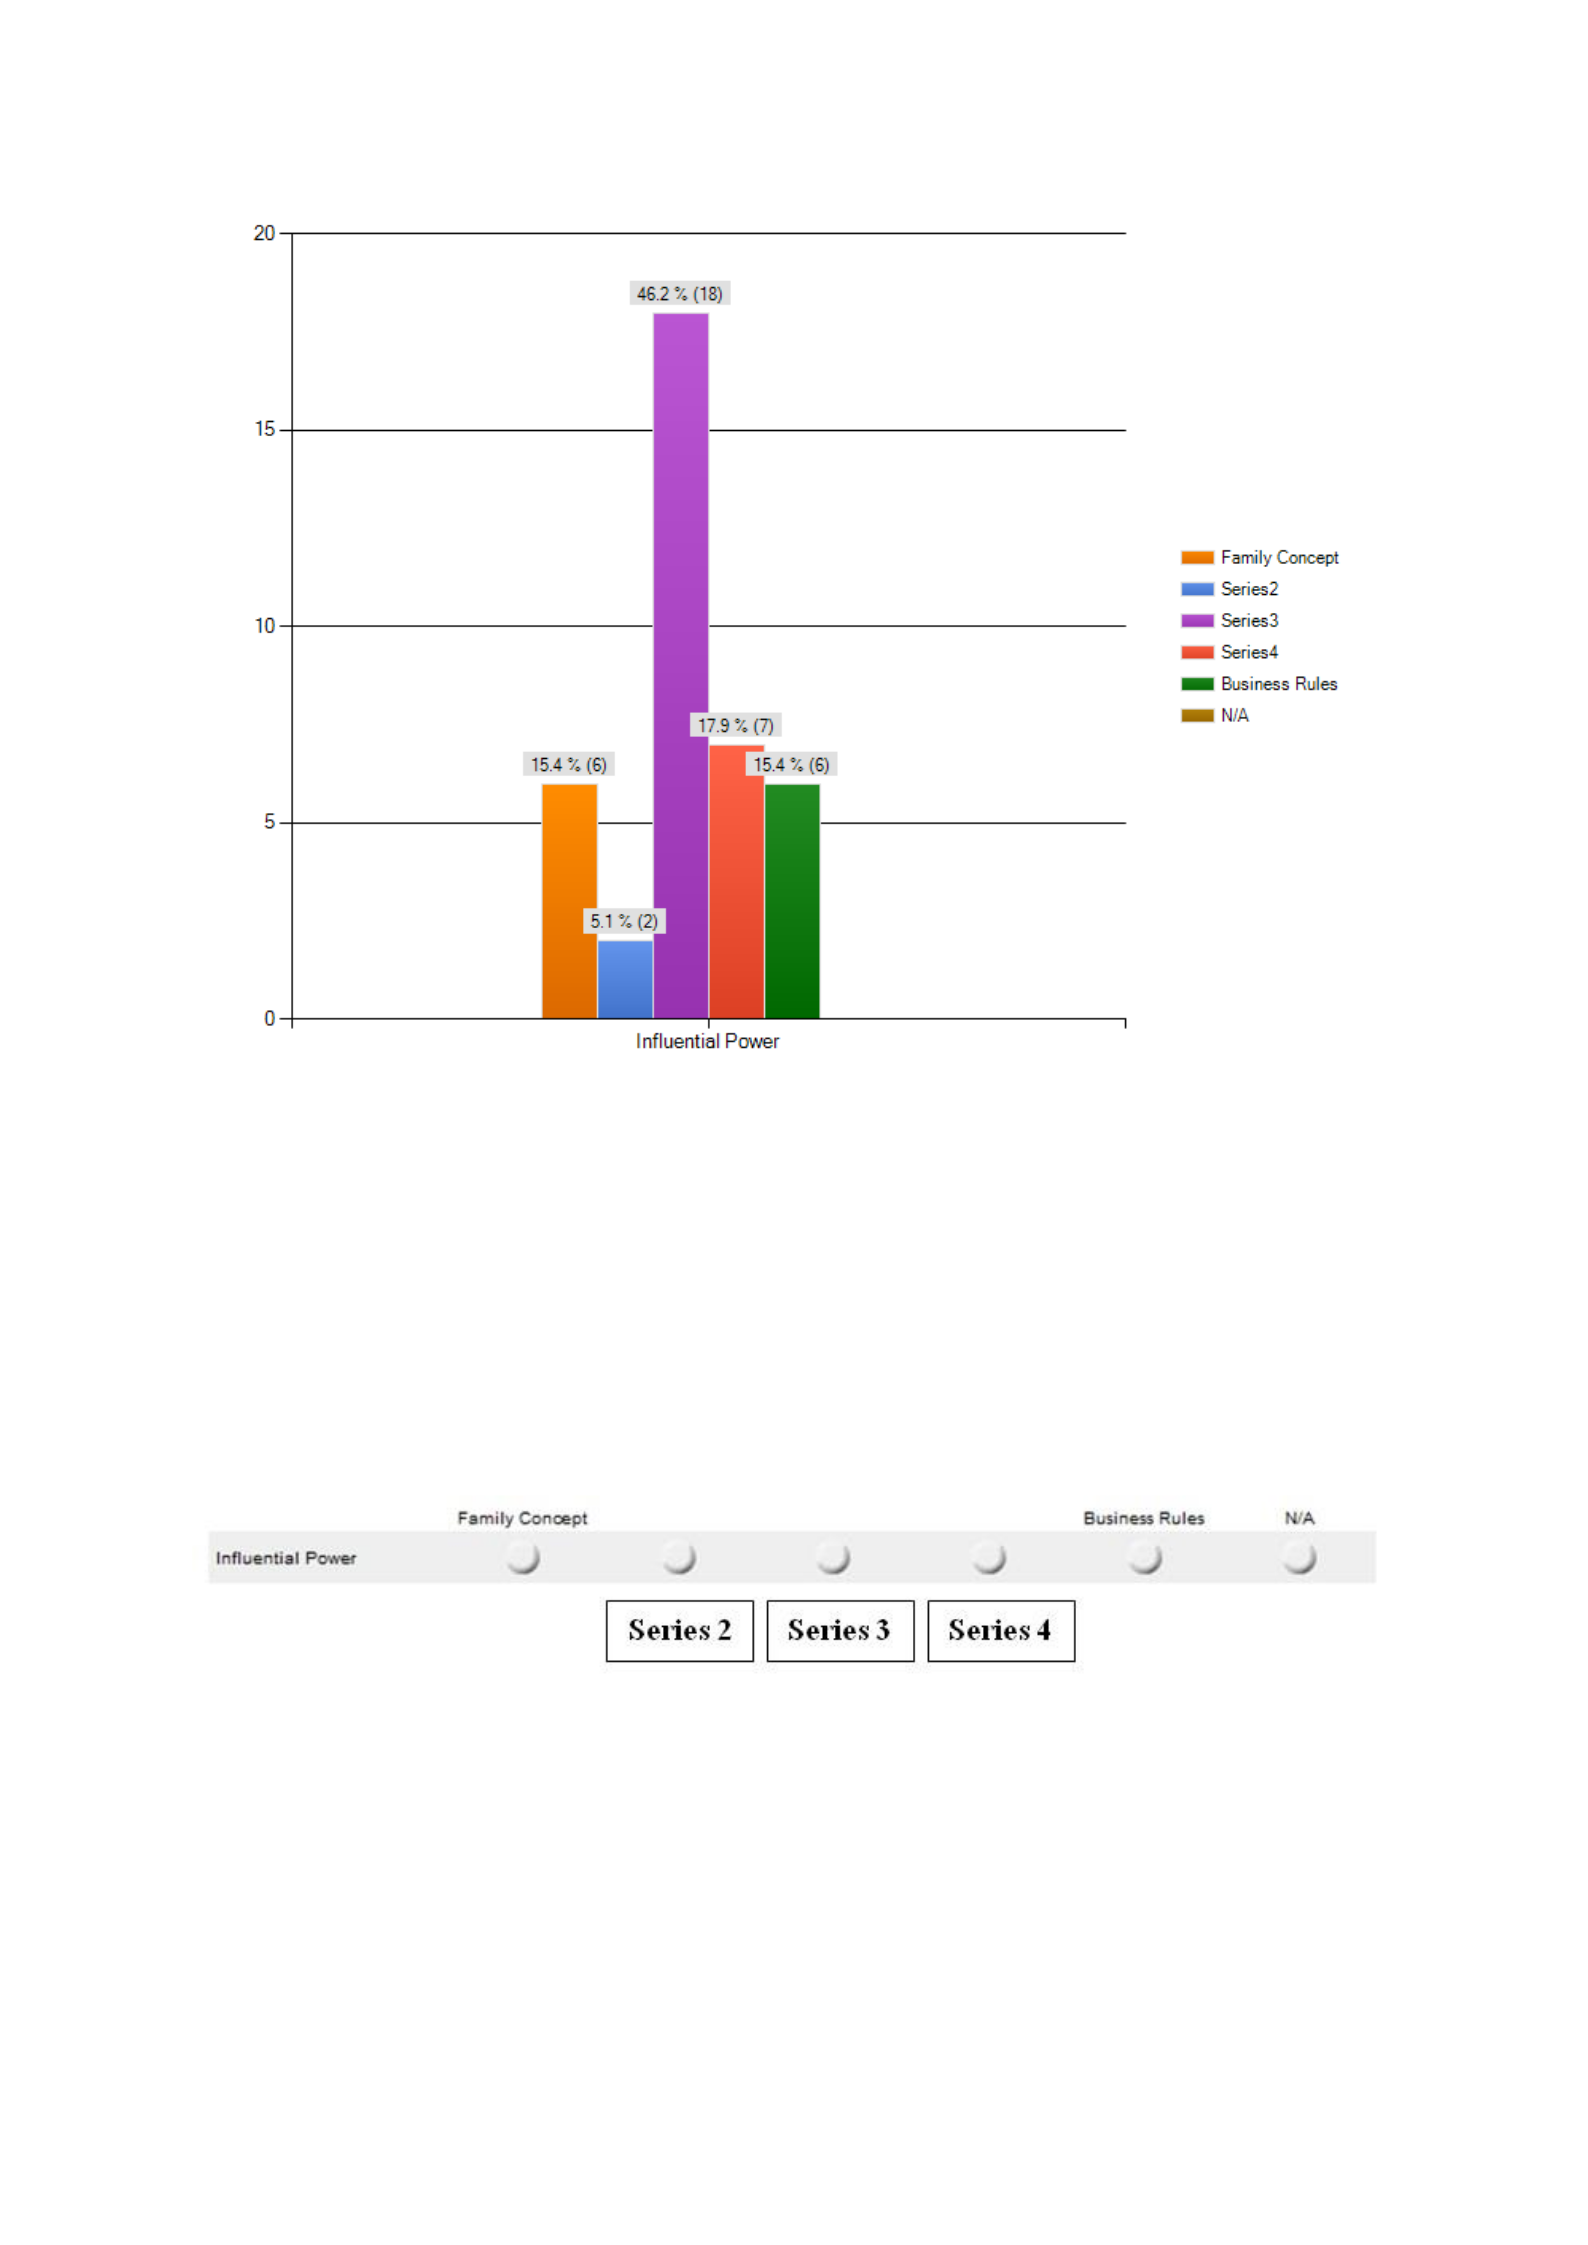
Figure 28: Influential Power of ‘Family Concept’ w.r.t
‘business rules’.
Series 2,3,4 refer to the extent to which participants’
decisions are influenced by the family concept and the
business rules.
Above graph illustrates that participants do accept and
realize the importance of corporate governance in their
business decisions and execution. However, family
concept also influence the operations and decisions
naturally. The results are dramatically 100% as per the

expectations. Majority of the participants (46.2% of the
population, 18 out of 40 participants) chose series 3,
that means their business decisions are equally
influenced by the family concept and the business rules.
Other series are even less than half of series 3. After
testing Q24, we accept that business decisions of family
owned diversified businesses are equally influenced by
the family concept and the business rules.
From your experience, did the diversification decision
and resulting process have a positive or a negative
impact on the core business?
The very last question of our survey and the most
important part of testing is to assess what exactly our
participants perceived regarding the results of their
diversification decision. They are the ones who actually
practically went through all advantages and
disadvantages that their core businesses faced as result
of their diversification decision. Probably, they can
better evaluate the situation and its consequences than
any other researchers. Below is the graphical
presentation of Q25 results.
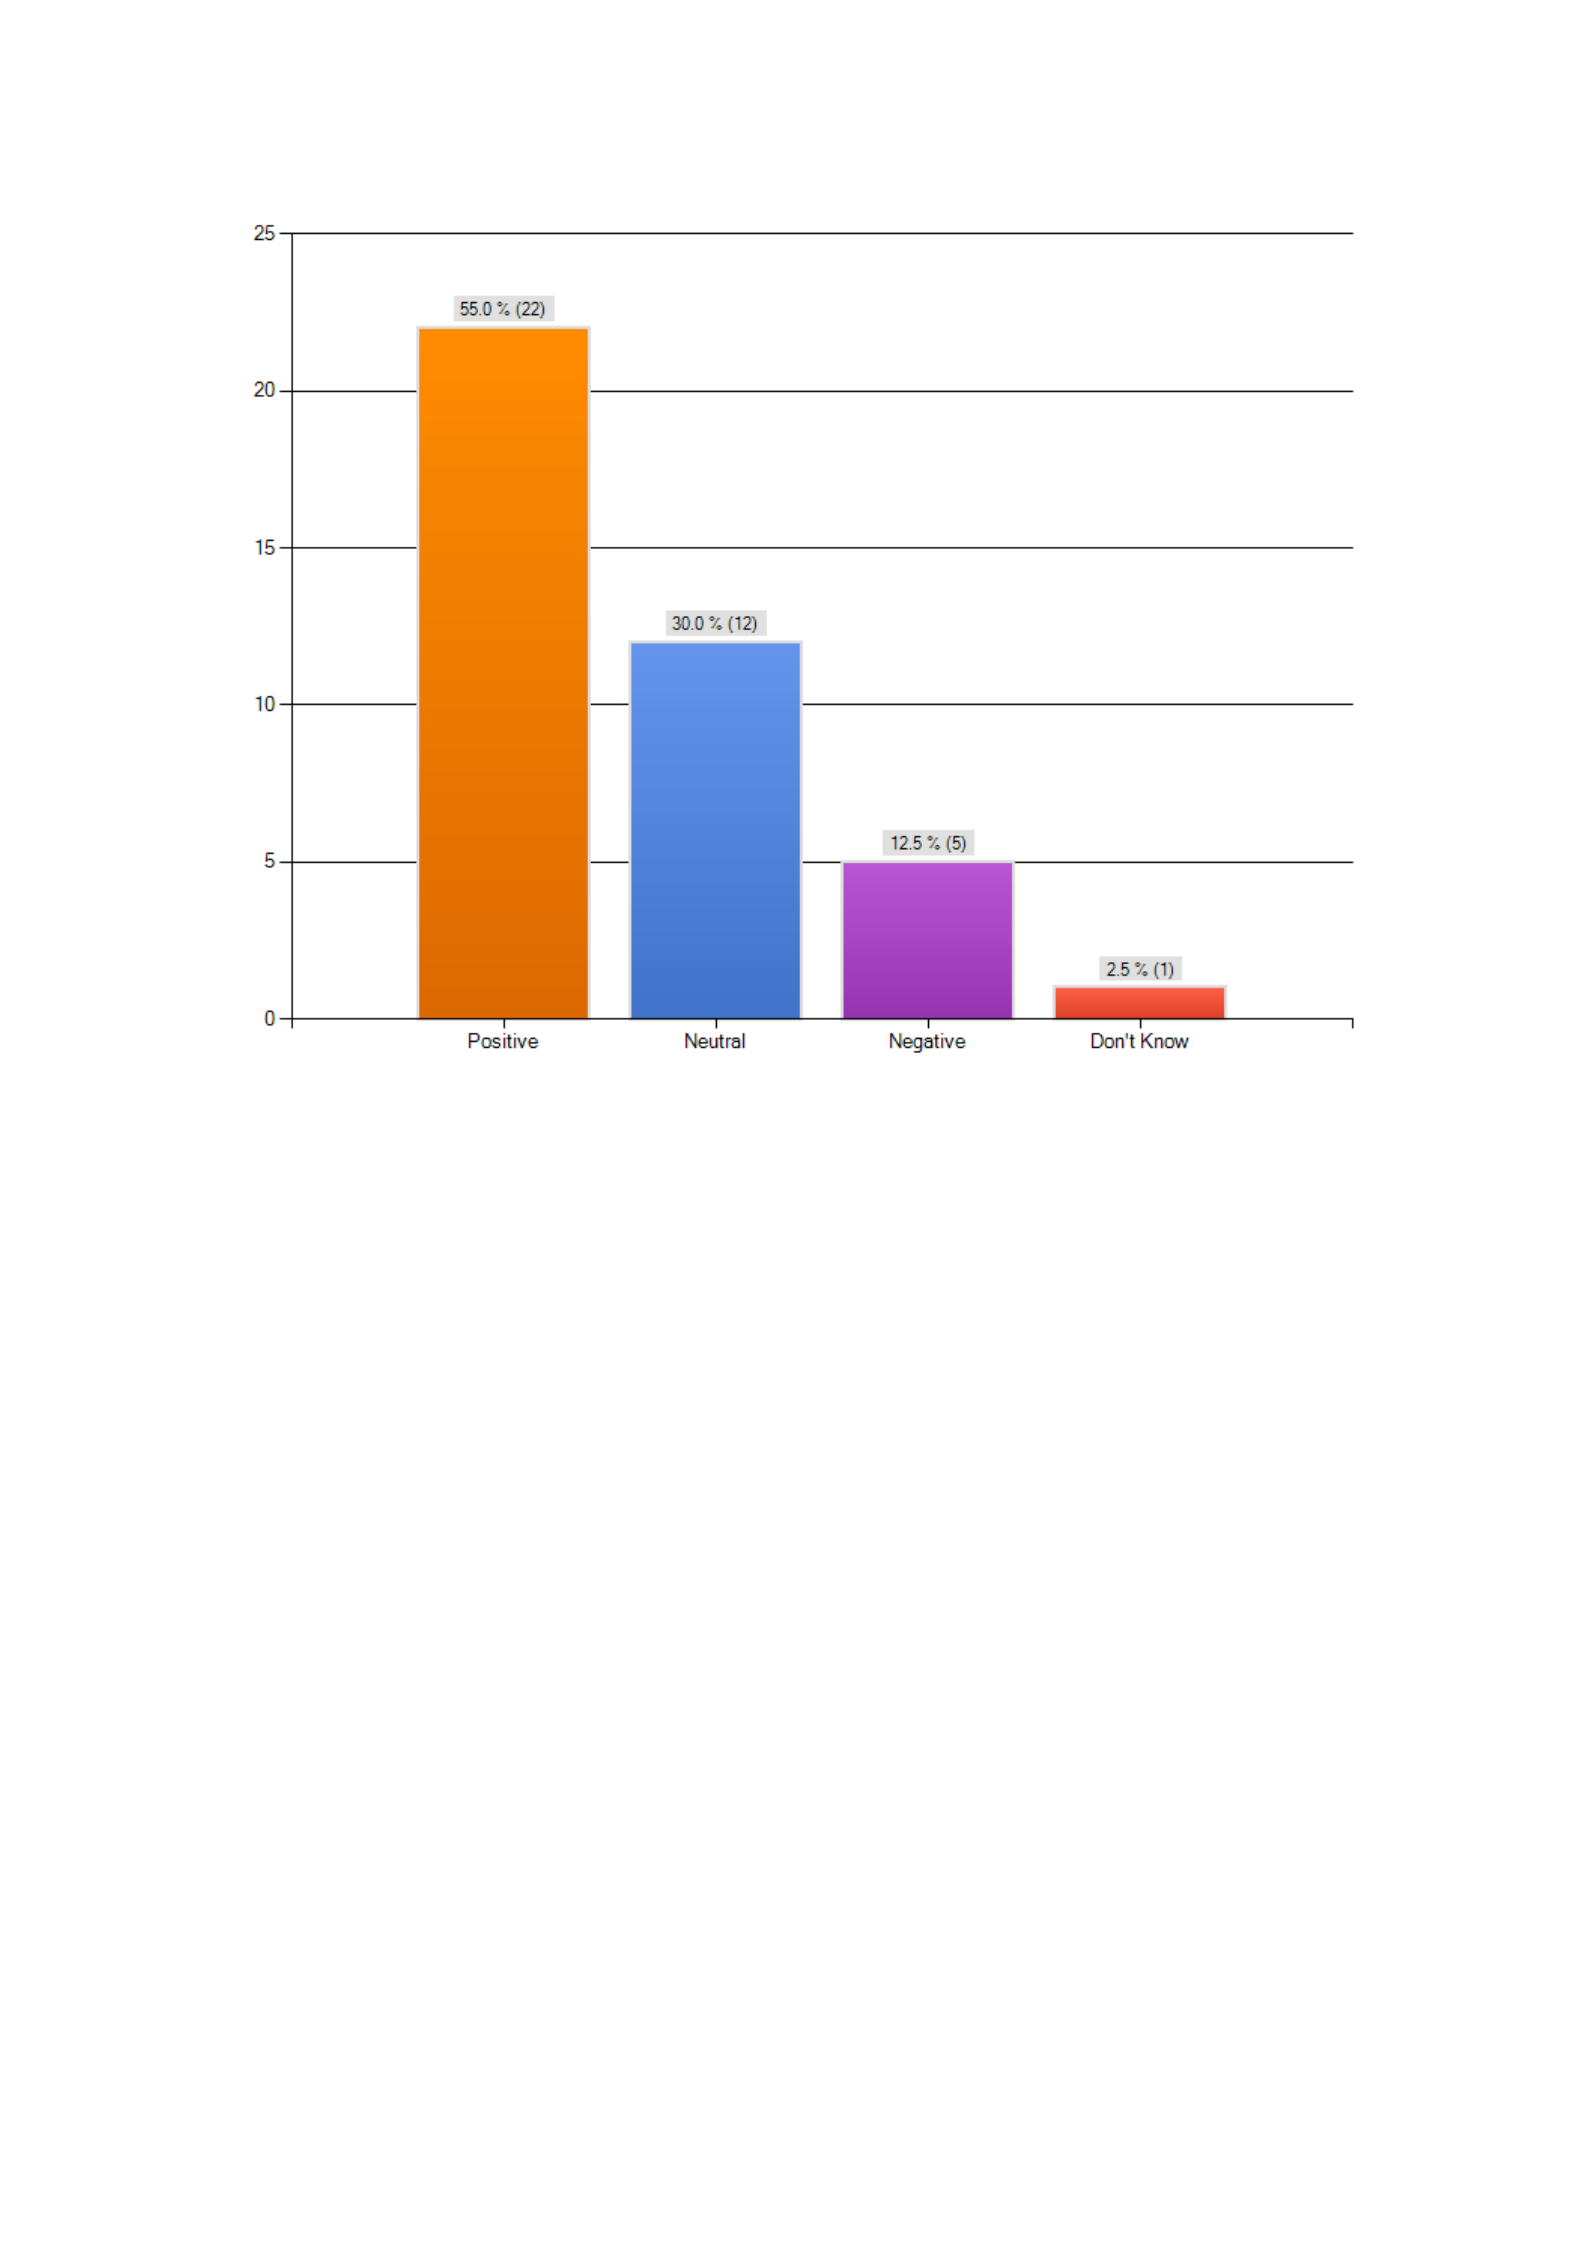
Figure 29: Feedback on Diversification.
Above results reveal that afterall, when summing up all
pros and cons, participants think that diversification is
not a bad decision to take. They believe that in the end,
results obtained are positive. 55% of the total
participants (22 participants out of 40) declared that
diversification decision is proven to be positive. 30% of
the population (12 participants) believes that if it was
not positive than also not negative. However, 5
participants (12.5%) declared that they regret their
decision while one could not actually assess if it was
positive or negative. Results clearly prove that the

diversification decision impacted positively on their core
businesses.
Discussion
The analysis of the data presented within the sampling
is not to establish whether or not the diversification
decision and process was the right or wrong move for
the company from a financial perspective, represented
by concrete figures; rather the analysis takes form of the
identification of specific patterns and general
developments, from the perspective of a family
business. With addition of the analysis of sectors, the
reasoning therefore, is to establish whether these
businesses engaging in specific sectors were more likely
to opt for a diversification opportunity, whether it be
based out of necessity or for reasons specific to that
sector or due to the fact that the family business is
represented by a more flexible and/or an opportunistic
or entrepreneurial drive. The analysis furthermore,
addresses each question in depth seeking out any
specific general or major consistencies across the
sampling, in order to understand how the strategic
decisions and planning therefore, have affected the
business on a post diversification basis. The analysis
revealed that additional issues such as that of
succession and continuity most definitely needs further

thought on the part of the business that wishes to
create a sustainable and long-term future.
Management of the companies in their current forms,
with respect to the involvement of the families
concerned revealed that the majority of the businesses
are merely guided by existing family members, with a
low level of participation in the actual daily operations
and running of the business concerned alone. Of the
families that are still involved with the businesses 52.5%
are solely involved in running the business in terms of
daily operations, and with 25% of businesses are solely
maintaining more of an oversight role from a guidance
perspective. Interestingly, the businesses sample
showed effective participation in both the aspect of
guidance and direct involvement of the managerial and
operational duties.
Hence, the entire sampling is still seen as being involved
in the business in one way or another although the post
diversification situation seems to reveal that the
majority of companies that have undergone such a
process has resulted in an involvement of the actual
workings of the business on a daily basis and guidance
in a different context, which translates to an effect on
the autonomy of the business after such a process and
decision being realized to the extent that such

autonomy is in fact reduced accordingly. This may well
be confirmed by the company structure that the
business is currently represented by, and based upon
the specific sampling, 37.5% are Limited Liability
Corporations, or the equivalent with the remaining 30%
being that of a public or private holding company.
Therefore, the structure of the company, of which the
LLC appears to be the most popular is represented
within this majority and is based upon the company
ownership also being protected in their private
capacities by such company structure. In addition to
these possibilities of changing the company structure to
suit the needs of the company in the diversification
process, this may well be undertaken due to the fact of
adding additional partners or shareholders to meet the
requirements of financing such a diversification process
and expanding the business albeit on a product offering
or on a geographical basis.
Business Age and Generation Involvement Analysis
An important aspect of the research reveals the average
age of the businesses surveyed. The importance of this
is to reveal that the businesses that have undergone
diversification have been in operation for more than 3
decades, and according to some of the responses, had
the company not undergone any diversification, the
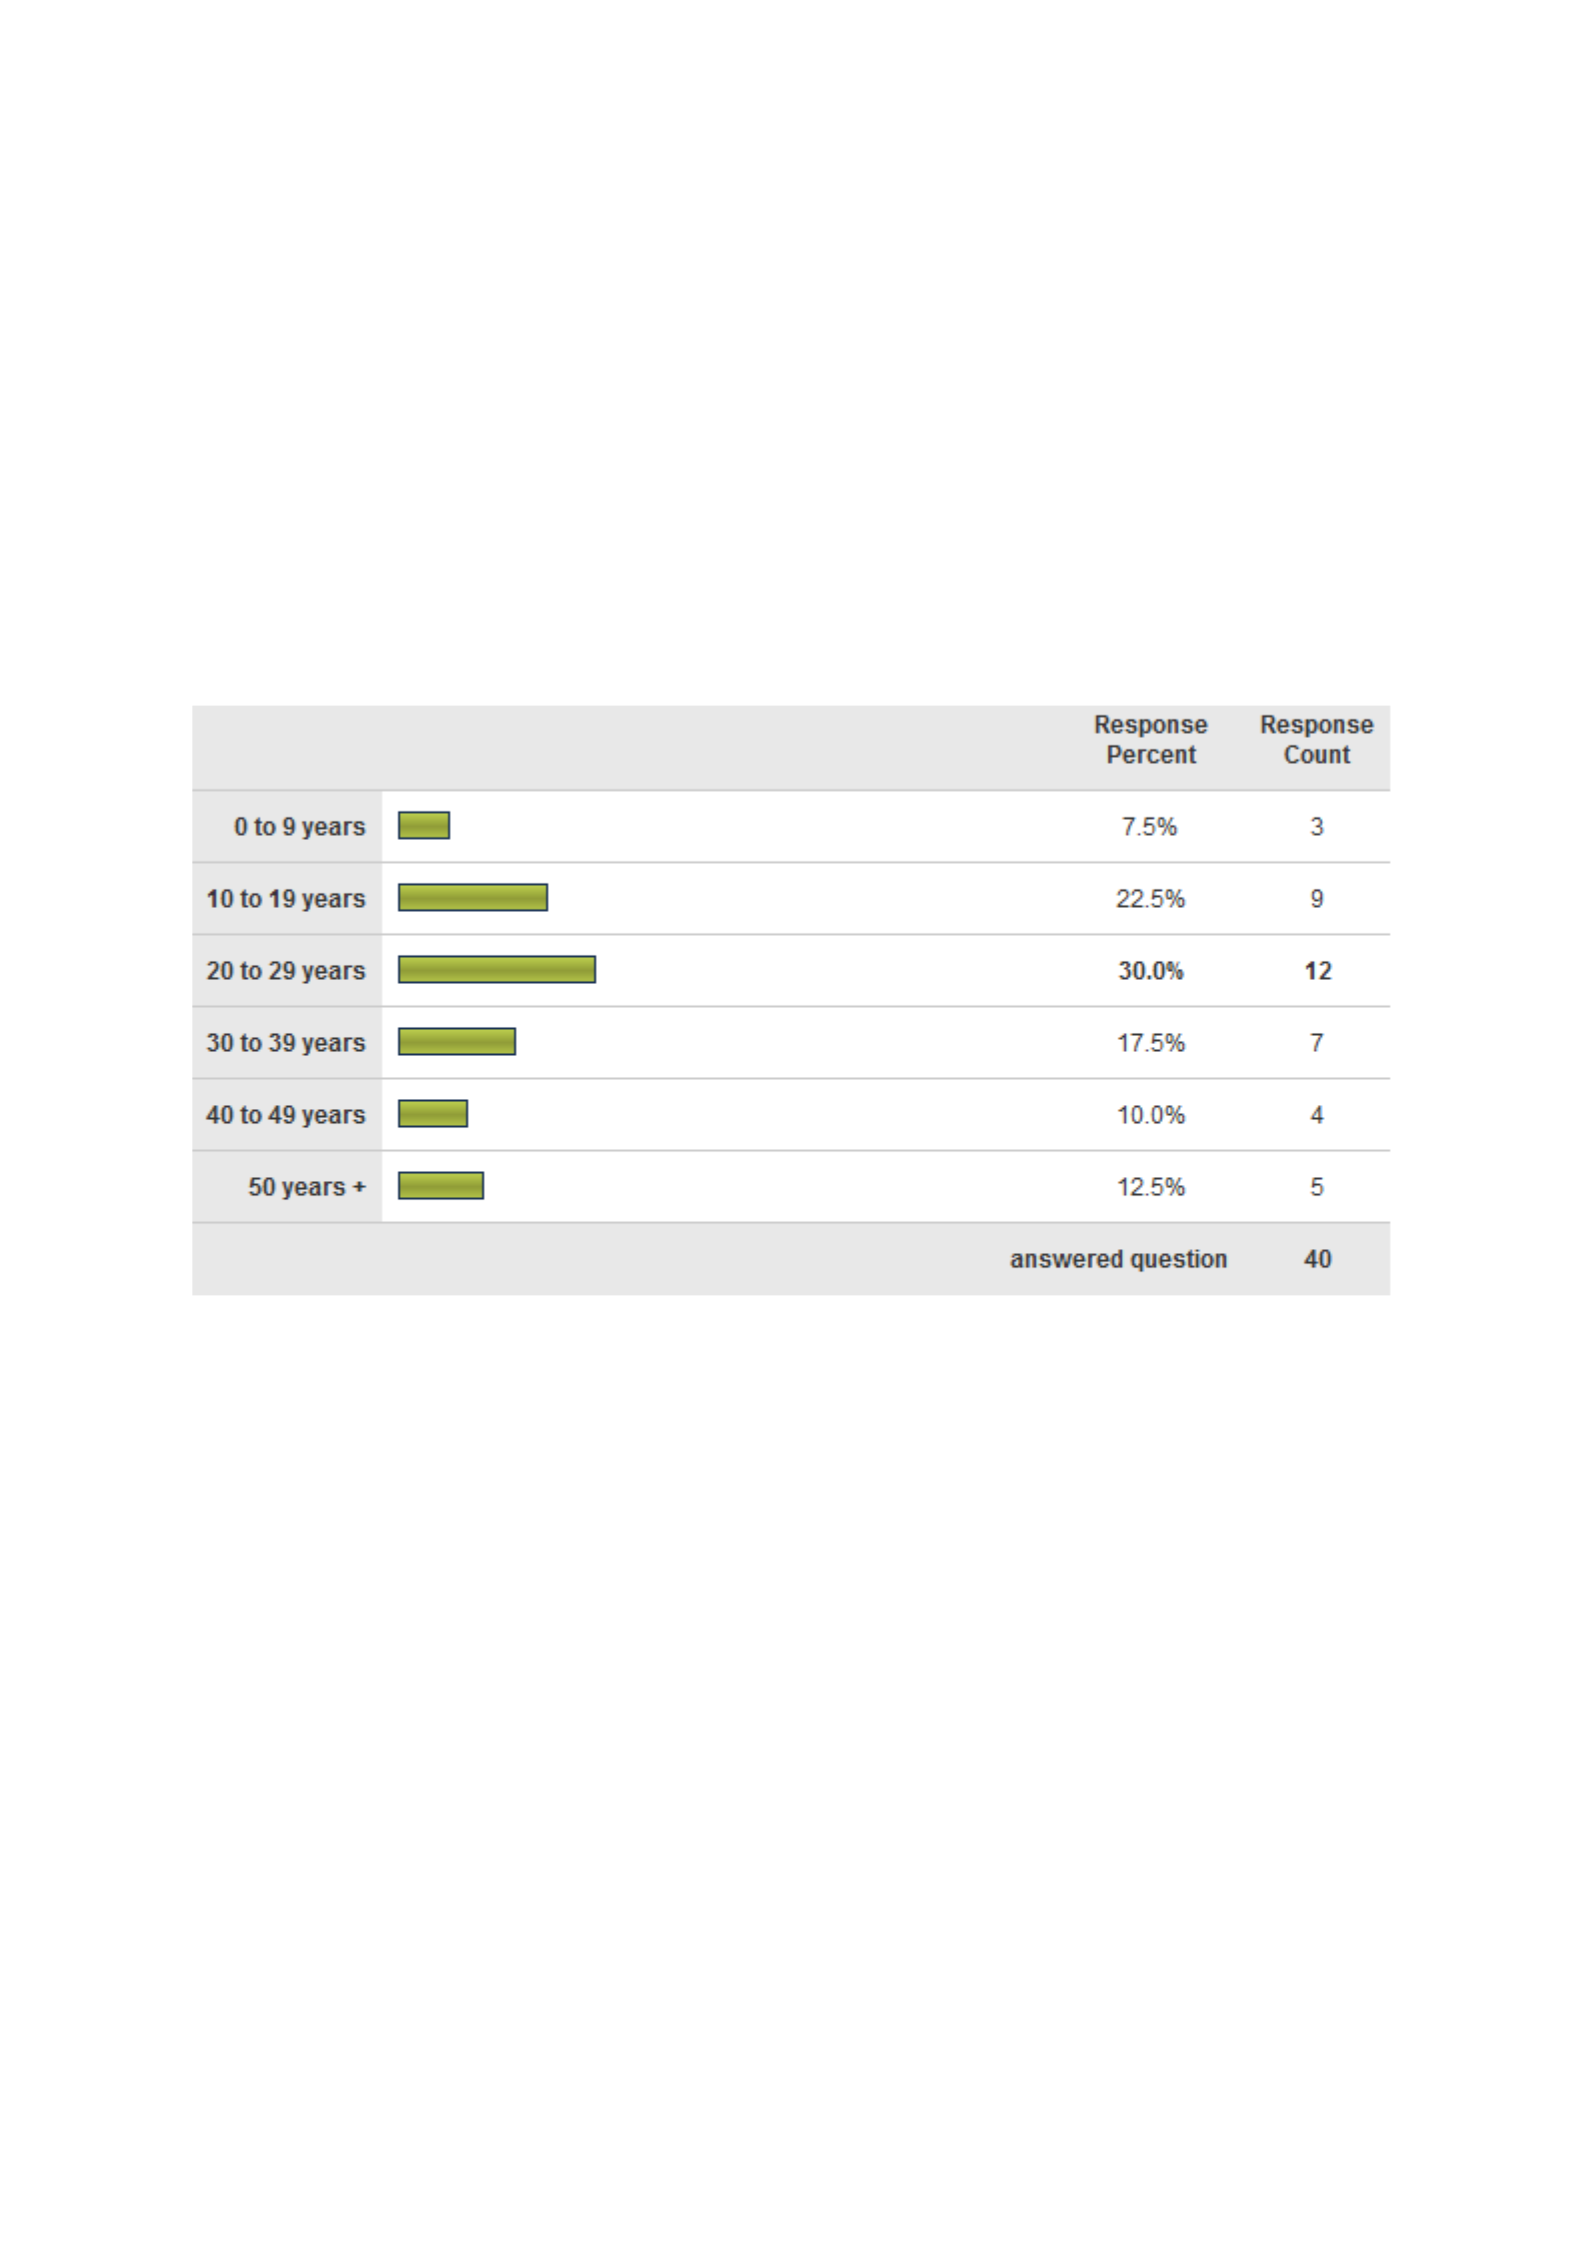
entity may well have ceased to exist rendering the
company null. Hence the choice of diversification could
signal the survival or the need to survive via this
decision, and had the decision not been made the
company would no longer be in existence today.
Analysis of the various business, represented below,
reveal the following relevant data:
Figure 30: Business Age Analysis of Sampling.
The average response percent is 16.7%; the median of
our collected sample is 15 years. The above analysis
serves to highlight the fact that only 45.45% of the
sampling are above the average business age of 52.41
years, with the balance being represented by 30% of
business respondents being below the median age. One
may translate this issue of diversification into possible
globalization issues and opportunities that have arisen
over the short to medium term, in that the younger

business may well have had greater opportunities to
take advantage of such globalization, in which a
diversification process and decision must have been
undertaken, as compared to the older companies who
might be more established and unwilling to engage in
such diversification.
The sampling used here, with specific reference to the
age of the business is lower than that indicated by
Poutziouris (2006) in analysis of various nationalities
and the average age of the family businesses, such as in
Japan the median is 145.22 years, whereas in China the
median of the family business age is 52, and in the
United States it is quoted as being lower than that. The
sampling revealed that the average age as at the
present time is 16.67% years which can be translated as
being just below 35.75% younger than that of the
median of Chinese family businesses, and almost 77%
younger than that of the Japanese median, as reported
by Poutziouris.
The issue of how many generations has been involved in
the business further serves to confirm the lifespan of
the business to present dates, and although this may
serve as a confirmation issue, it does raise another point
which although beyond the scope of this paper, is well
worth mentioning. The issue of succession within the

family business is just as an important factor to the
success of the business and plays a vital role in terms of
the decision making process and future success and
longevity of the business. Cater provides that the family
business is faced with additional family issues that need
to be taken into account to ensure the future of the
business, whilst also dealing with external factors and
situations (Cater 2006).
In dealing with the family issues notice must be given to
the satisfaction of the older generation whilst preparing
the younger generation for succession and to take the
leadership and control of the business into account. The
sampling in this analysis revealed that a median of 1.67
generations have been involved within the defined
family business indicating that the second or third
generation is currently involved with or has been
involved in the management and control of the
company concerned. It is important to imply that the
sampling conforms to a longer standing representative
sampling in terms of the involvement of the
generations, as well as the age or lifespan of the
business. Cater further indirectly provides that
succession in the family business is arguably more vital
to the success of entity than the process of
diversification, and therefore, such succession factors
and attention to this topic needs further insight and

analysis. Specific research figures provided by Cater
include the fact that “only 30% of all family firms survive
the succession from the first to the second generation,
only 12% survived the succession to the third
generation, and only 3% survived beyond the third
generation.” These quoted figures serve to highlight the
importance of the preparation of succession regardless
of diversification being undertaken.
Sector Analysis
The reasoning behind the analyzing of the sectors within
which the sampling was obtained is to establish whether
or not diversification is more relevant to specific sectors
or whether it is a relatively widespread phenomenon
across all industries.
According to the respondents, a wide variety of sectors
are represented here. However, specific attention
should be given to the automotive, manufacturing,
Hospitality and Leisure sectors here, in which over
12.5% of respondents is operational in this field. The
actual naming of these sectors as well as the percentage
breakdown of the respondents is reflected in Table 2
below:
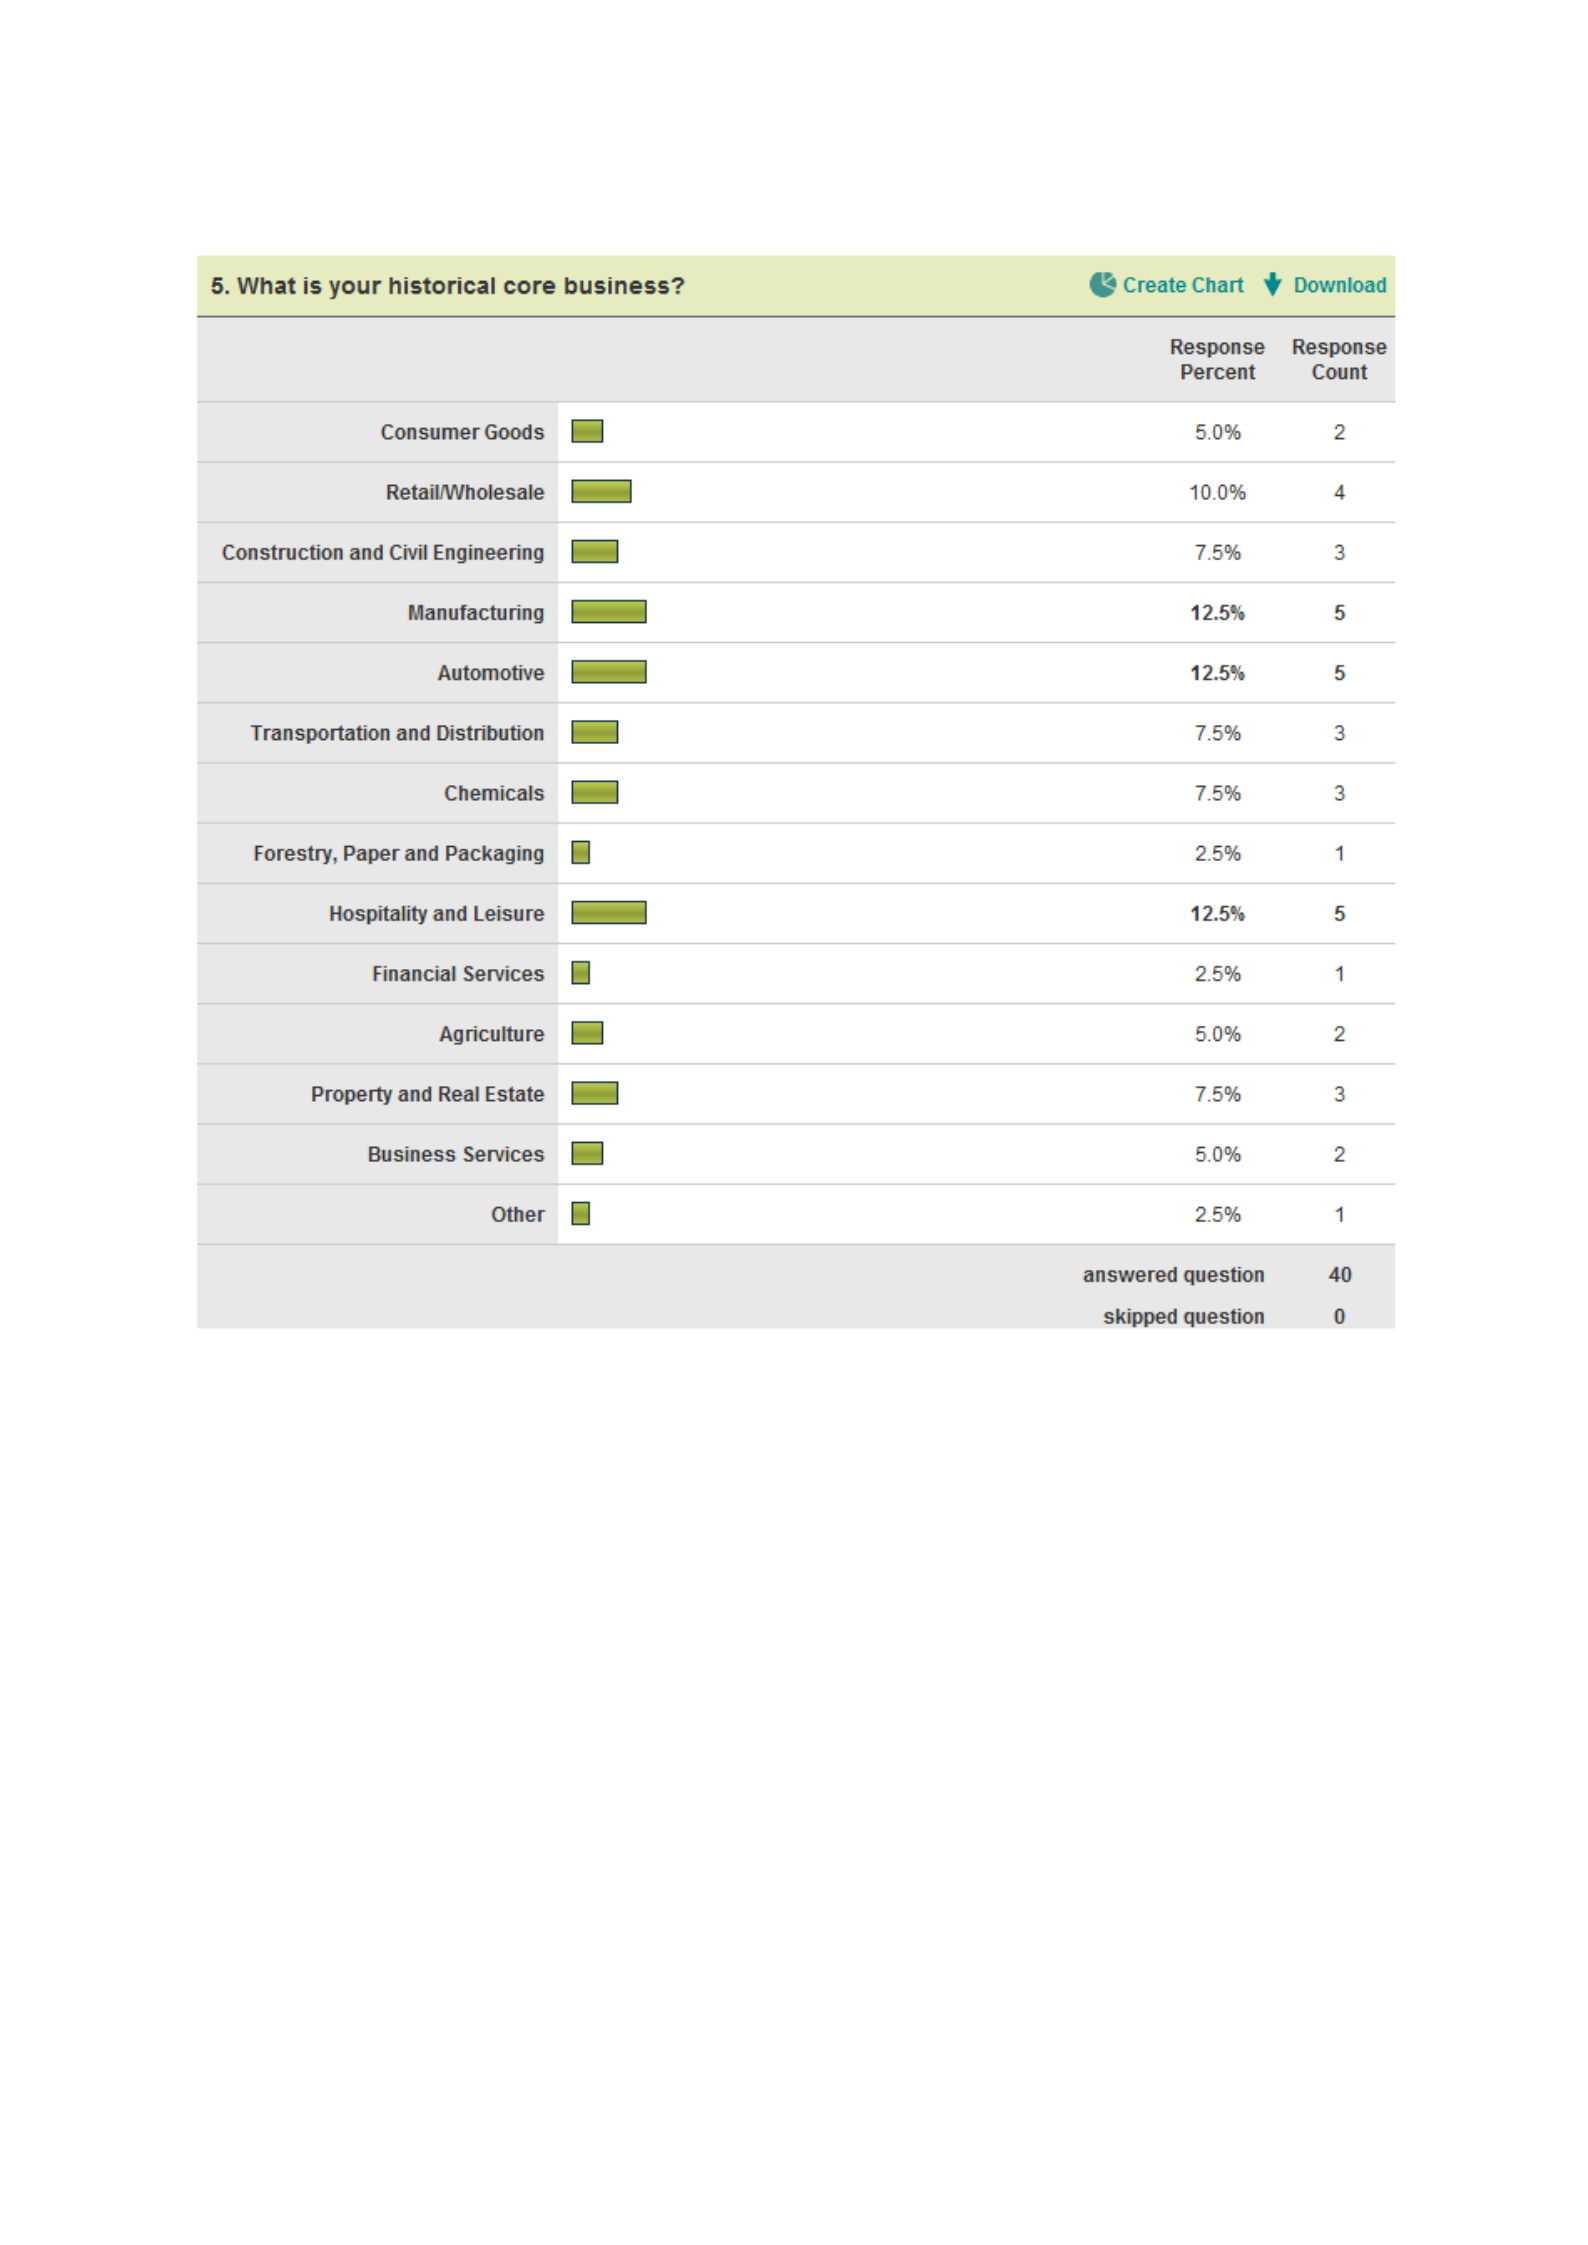
Figure 31: Sector Representation of Respondents and
Sampling.
The figures highlighted above further support that the
automotive and hospitality industries may also
relatively open to the need of diversification for survival
or profit maximization for the family business. Upon
analysis of the responses of whether or not the market
had reached maturity, which may have served as the
motivation for diversification, the vast majority of the
respondents has provided that the maturity of their

respective markets had in fact not been realized, and it
was rather from an opportunistic perspective that the
decision of diversification was taken. The exception
within the sampling was that of the two respondents
which had not undergone any sort of diversification, as
well as another single respondent who stated that their
original core business had become enviable for them,
and therefore, the diversification process had been
undertaken out of necessity for survival and continuity
of the business itself.
At the time of diversification, a number of external
factors have been quoted as facilitating the process and
motivating the need to take up the additional
opportunities, as they had become available at the time
of the decision. The fact that the majority of
respondents have answered that the diversification
process and decision was more of an opportunistic
move will Therefore, create a conclusion that the tool of
diversification itself is not primarily that of a survival
‘mechanism’ but rather a tool for optimization and
maximization of the business and its potential profits
and returns. This does not however, take away from the
fact that it can be based on survival needs alone, as is
represented by five of the respondents within the
sampling.

It should also be noted that although some of the
sectors may well overlap from a macroeconomic
definition, these sectors are deemed to be sufficiently
different to warrant separate analysis and
categorization, as per Table 2 above.
A further interesting fact revealed on the analysis of the
questionnaires, and specifically relating to the
businesses that have undergone diversification,
represented by 39 of the 40 respondents or the
equivalent of 97.5% of family businesses who
participated in the study have additional business
interests outside their core, all original business sector.
This raises the point that perhaps the diversification
process further acts as a catalyst for the family business
or small business owner in realizing the value of
diversifying their investments across a variety of sectors
to reduce exposure to external forces that are relevant
to specific sectors.
Control and Shareholding Interest
Although this area may overlap slightly with that of the
previously mentioned question of involvement in the
business, it is somewhat different, it represents the
ownership of the entity under question, and serves to
reveal the involvement of external stakeholders from a
partnership, investor roles in the structure of the

company and how it has taken in the form of structure.
This area of analysis further reveals to what extent the
original family ownership unit is still involved in terms of
the oversight and leadership of the family business, as
well as any other external decision-makers with
stakeholders as mentioned.
In addressing the ownership factor of the companies
and sampling, regardless of the legal structure the
majority of respondents are either wholly owned or a
majority shareholding is held by the original family,
which once owned the business. Therefore, the
conclusion can be drawn that despite any diversification
within the business itself, control and majority
ownership was retained across the spectrum of the
sampling, with all companies remaining under the
control of the family concerned. This may be translated
into the fact that upon deciding to undergo such
diversification the company is contained within the
sampling did not elect for external funding, such as the
incorporation of the partners, but may have funded the
diversification process generically or via traditional
financing mechanisms, such as bank loans or personal
investment from within the family. Another key factor
realized from the analysis of the specific control
question, realizes the fact that the companies
concerned have retained their leadership and oversight

of the families concerned, albeit by a managerial or
directorship channel.
Diversification Motivation
Analyzing the reasons for diversification within the
sampling, highlighted the fact that many of the
businesses surveyed had not achieved maturity within
their core market, but had rather identified
opportunities either related or unrelated to their core
market, into which the companies had entered. It
appears that the motivation had been primarily growth
potential. However, up to some extent; it is also a case
of survival or an opportunity. Companies diversify
within their core market or into sub-sectors of their core
market, claiming that a more holistic approach, in terms
of logistics and the supply chain within their respective
markets had offered an opportunity to not only reduce
costs, but rather add to the company revenue, as well
as forming a reliable base within which each business
unit could operate on a successful basis. Another two of
the businesses surveyed did however; stipulate that the
motivation for their decision-making process,
specifically in the automotive market, was to counter
the instability being experienced within the sector at the
time. In addition to stabilizing their revenue streams the
decision was undertaken to seek out alternative

business opportunities to guard against future possible
market fluctuations, in an effort to stabilize overall
income across the automotive market, as well as the
new sector in which they chose to operate at the time,
which is that of financing and related activities.
The primary motivation for having undergone
diversification in whichever of the sectors mentioned
above is apparently that of the addition of revenue, as
well as an alternative source of revenue to the
companies concerned, therefore, motivating the
opportunistic or entrepreneurial underlying spirit
evident within the family businesses surveyed.
With the exception of the company that confirmed their
core business was no longer viable, the majority of
companies had achieved relatively high market
positions, in relation to their core business, which
further supports the fact of the opportunistic nature of
the diversification process as described above.
According to the respondents, 32.5% enjoyed a top ten
positions within their market, at the very least within
their regional markets; and in considering this market
position, it motivates the conclusion of entrepreneurial
decisions, as well as taking advantage of opportunities
presented at the time and therefore, motivating the
decisions and processes of diversification within their

companies. Even the single company claiming that their
core business was no longer viable, had enjoyed a top
four positions, the necessity for such diversification had
proven to be not only viable but, essential for the family
business to continue as a going concern.
Continued Diversification
In order to establish whether the diversification process
was a once off or a continued process within the
sampling, the question was posed as to whether the
process had continued or was a once off decision and
process. Their responses indicated that majority with
50% of the participants believe that once diversification
take place, it occurs every three to five years. 30%
doesn’t call it necessary to experience it ever after once.
One may interpret this as an equal representation
between those that continued diversification and those
that did not providing an equal amount of companies
representing each decision. Of those companies that
continued the diversification process, these companies
diversified into different sectors away from their core
business model or market, whilst some diversified
within their area of specialization. This fact may
represent a true diversification and risk reduction, in
seeking opportunities outside their existing businesses,

whilst encouraging additional revenue streams from
alternative sources.
Organizational Structure
The fact as to whether diversification can or does lead
to the changing of the organizational structure is
important in relation to possible changes in the
shareholding and ownership, as well as ultimate control
of the company itself and more importantly by whom.
Such structural change may be brought about by the
fact that the company may well have needed to raise
funds to facilitate the process of diversification, or
perhaps even the acquisition of necessary intellectual
capital or related expertise.
A total of 47.5% of the sampling indicate that the
organization did in fact undergo structural changes, but
not due to the necessity of raising funds or acquisition
of mentioned expertise. Rather, the approach of the
organizational change was in order to increase
efficiency in terms of management of the various
sectors of the family organization, including that of the
newly diversified operations. Although a majority of
limited liability companies are represented within the
sampling, this decision had been made from more of a
control and oversight perspective than that of having to
undergo such structural change in the diversification

process, and is more reflective of a rationalization effect
from a management perspective.
Of the companies that underwent such structural
change, and went the public listed company route,
which is represented by 12.5% percent of the sampling
the family maintains control over the company, despite
public listing and occupy positions as board members,
whilst retaining majority shares within the company
itself. Therefore, if one considers the process of publicly
listing a company is primarily motivated for the purpose
of raising funds for the growth of the business the
mentioned percentage of the sampling confirms that
less than a third of the companies surveyed required
such financing, and even in the incidence of acquiring
the necessary funds for expansion and diversification,
control was still retained by the family concerned. This
was achieved via the retention of a majority
shareholding, which in turn provides the family the
opportunity to install board members as according to
their majority vote, which in this instance maintains that
family influence on of the original organization.
One may furthermore, conclude that by conducting the
restructuring, or structuring of the new entity in such a
manner the issue of autonomy or less autonomy within
the family operated or owned business is overcome by
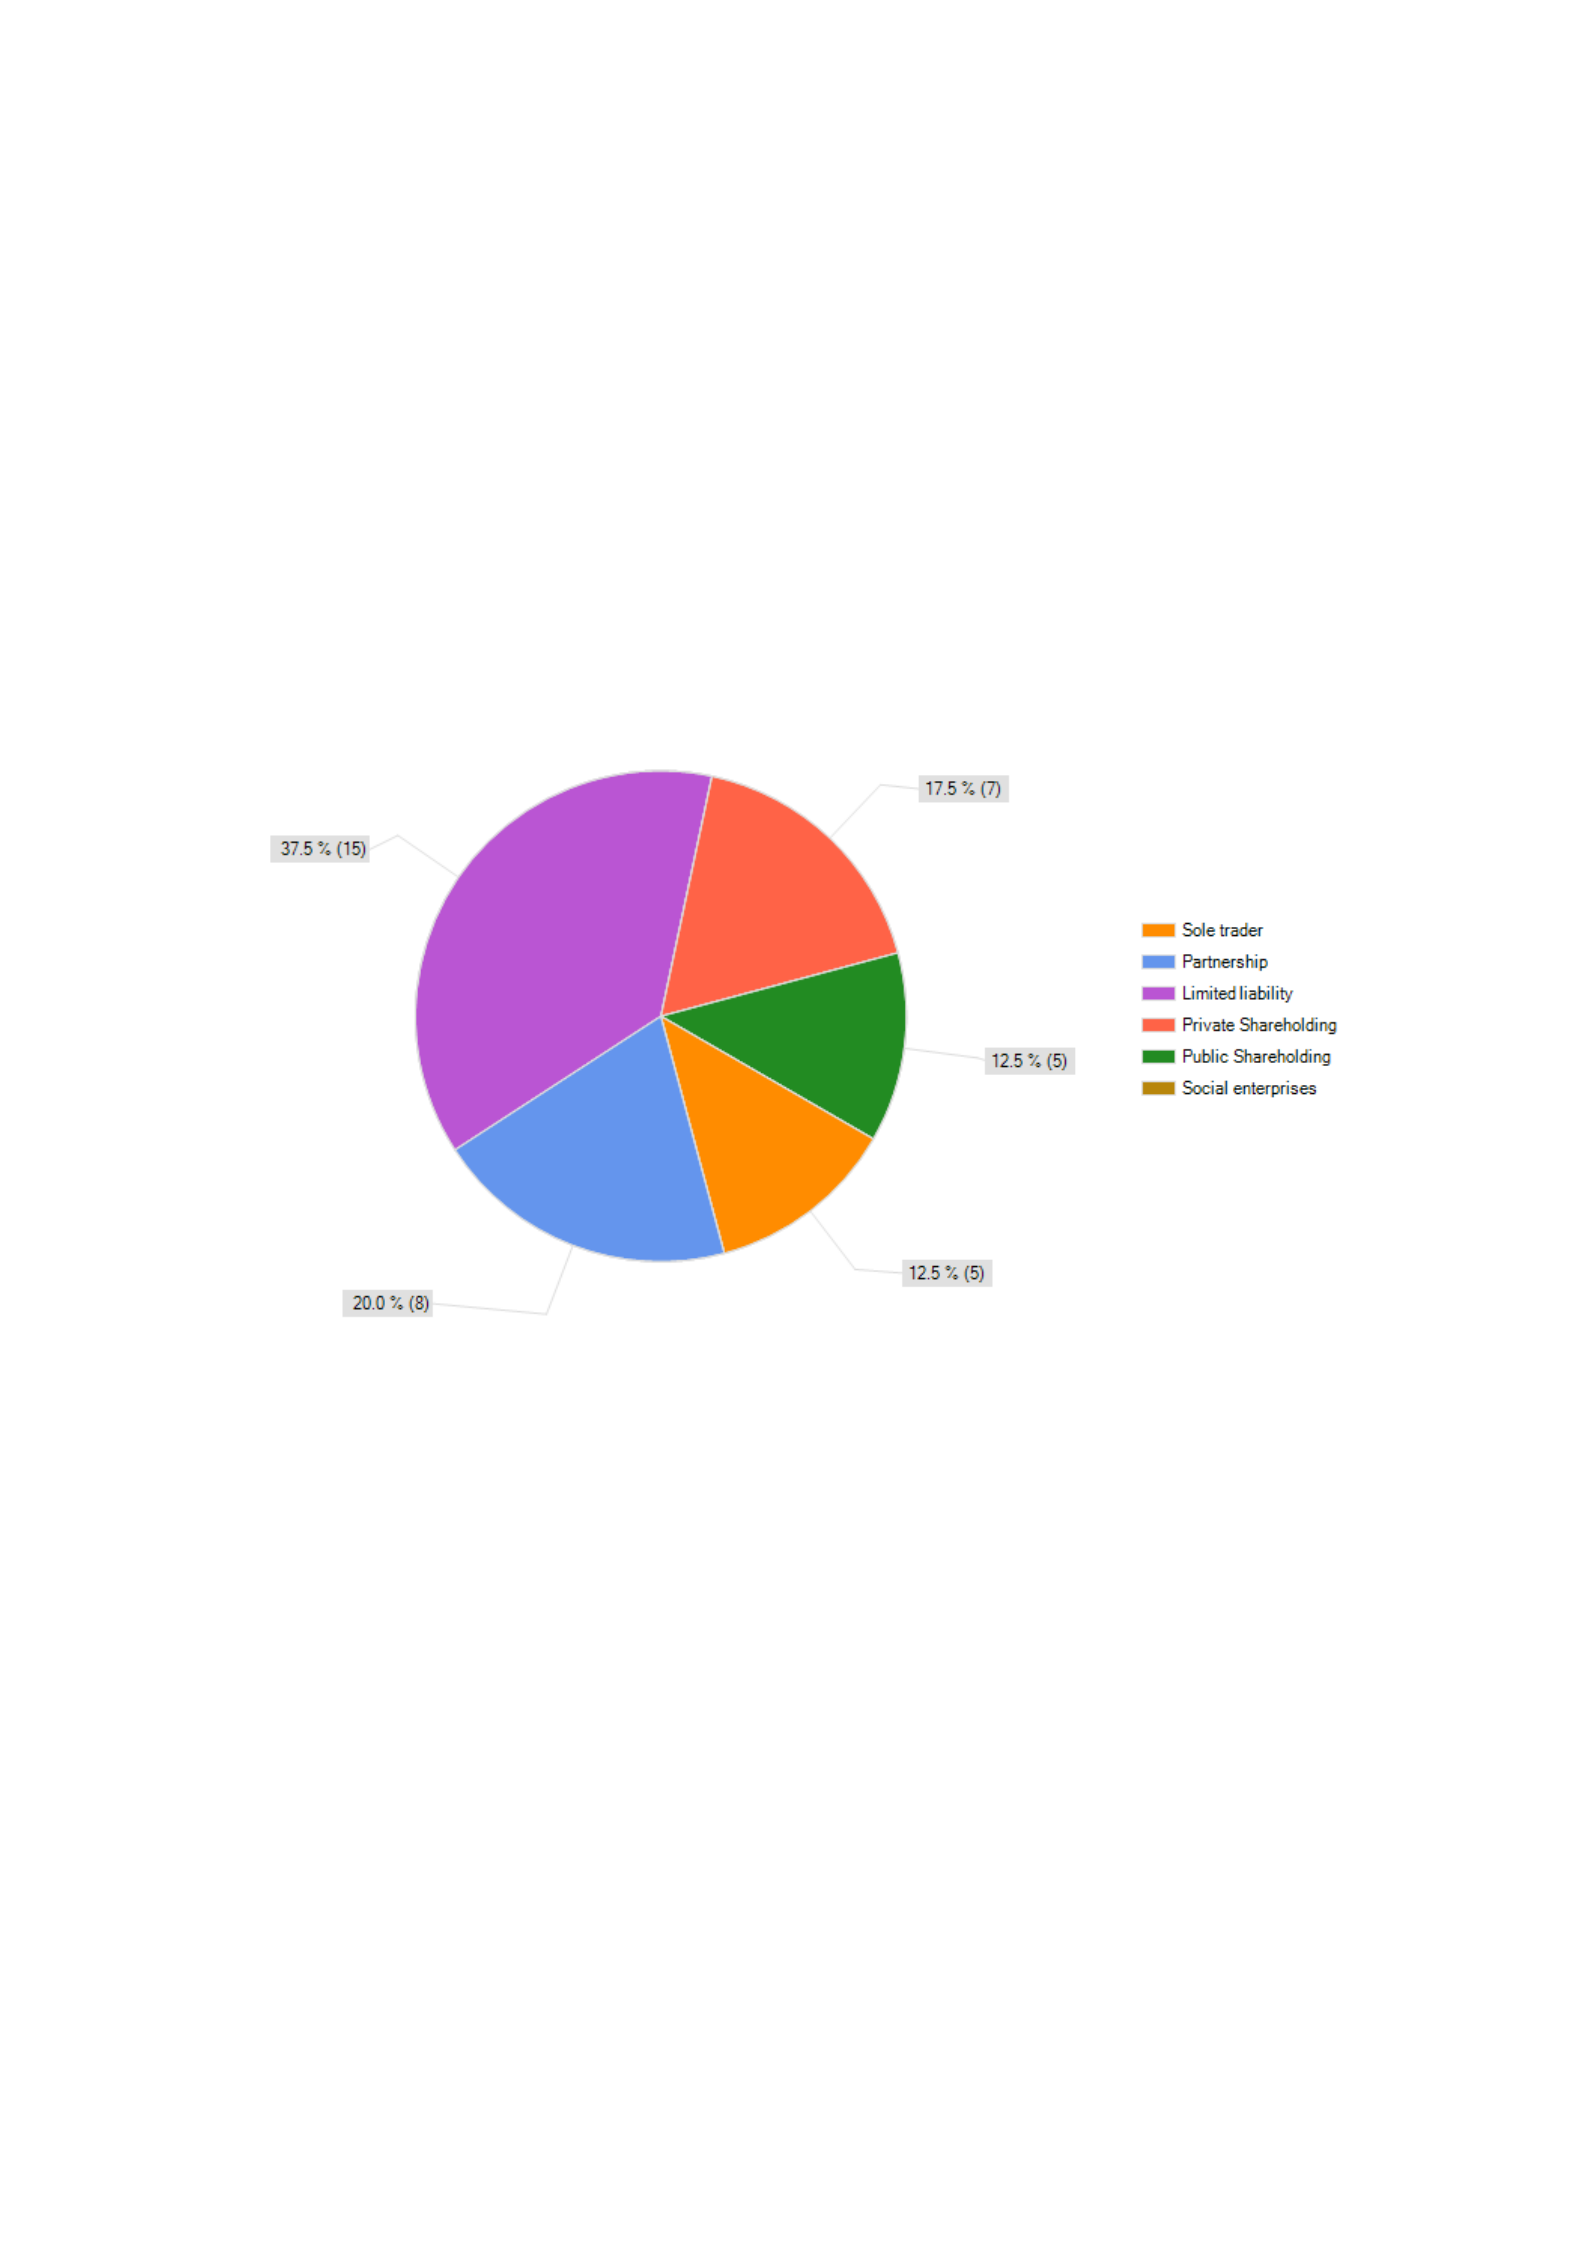
a majority shareholding strategy, which although the
company has to abide by a specific corporate
governance rules and related items, this process serves
to maintain the actual control in terms of the strategic
directions of the company concerned.
Figure 32: Company Structure on a Post Diversification
Basis.
Figure 30 above serves to illustrate the nature of the
business or company structure on a post diversification
basis. Each company structure has its own merits, and
as previously discussed according to the sampling the
manner in which the companies who elected the plc
route still retained majority shareholding which in turn

facilitated or facilitates greater control with acquiring
the necessary financing for the expansion or
diversification process. The limited liability company
route, although arguably similar to that of the plc
without the public offering of shares in the company,
still offers protection to the owners and shareholders
within reason, the corporate governance issues may not
be as pertinent to that of the plc type of company. The
limited liability company option furthermore offers
more flexibility in terms of the setting up of the
company structure itself, as well as the allocation of
ownership portions or shares.
In the process of establishment of an alternative
company, the issue of autonomy is once again raised, as
well as the flexibility that is associated with such
organizational structure. In terms of the sampling of
family businesses that have undergone such change, no
negative aspects of the flexibilities of the companies
were provided, but rather a more positive insight into
the controls of the company have been revealed by the
entire sampling. Therefore, 100%, or an unanimous vote
in terms of the positive effect of such structural change,
and specific to the controls perspective was provided by
the sampling, which suggests that although companies
may experience some sort of apprehension in terms of
the perceived change in control and flexibility, this

apprehension is unfounded as reported by the response
from the market research provided.
Management of Diverse Units
The management of the diverse business units requires
necessary analysis in the determination of whether the
business units have been separated in terms of
management and how the company intends to manage
these divisions. This further serves to confirm the nature
of strategic decisions and management, whether it
emanates from a central decision making unit or
whether each business or sector is responsible for their
own activities in terms of marketing, promotion, and
human resources and so forth. As with any strategic
expansion of a company a number of factors will add to
the management issues and pressure associated with
such management practices accordingly, which in turn
needs to be managed either externally or internally.
The sampling revealed a number of different strategies
that have been undertaken via the individual companies
from the perspective of the various functions and
management issues. Although the majority of
respondents indicated that such diversification had in
fact contributed to the added pressures of management
and control, a number of different strategies were
employed to address the situation of management and

control of the various business units and internal
processes.
One of the respondents indicated that family members
were put in position to manage and control the various
aspects within the business, whilst over a few of
respondents used external suppliers and providers to
manage certain aspects of the business, such as
marketing and human resources, while maintaining
control within the business from a management
perspective amongst family members and employees.
The majority of respondents indicated that systems and
policies defined by family shareholders were
implemented within the organization to ensure smooth
running an effective control on a post diversification
basis, while 47.5% of the population indicated no
changes on their organizational structure. Many of
these decisions, systems and policies stemmed from the
initial ethics of the family organization and were carried
through into the new business entity, regardless of
structure, size and number of employees. This seems to
have further contributed to the company’s survival and
success in maintaining the original ethics and
entrepreneurial drive behind the company itself, based
upon the majority response of the sampling.

The use of outsourcing has alleviated specific pressures
within which the family members deemed to be better
suited to external management, which although
remaining under the control of the family business and
stakeholders appear to be more streamlined in being
dealt with by the relevant professionals concerned.
Retrospective Diversification Analysis and Impact upon
Business Culture
The reasoning behind retrospective analysis of the
diversification process is to establish whether the
respondent concerned conducted such a process on a
strategic business option or based upon survival of the
business unit itself. Analysis of the decision of
diversification search confirmed the necessity of such
process, or whether the entrepreneurial drive or spirit
serves as the motivation thereof. Although this question
has been touched upon earlier within the questionnaire,
one may consider this line of questioning as a control
measure to fully confirm motivating factors of the
process. It furthermore serves to illustrate the positive
impact of such decisions in terms of the strength of the
business, which one can analyze retrospectively to form
the basis of future expansion and related business
decisions, in terms of the overall business strategy and
direction.

In terms of sampling, a number of respondents
confirmed an increase in market share, or business
strength based upon their decision of expansion and
diversification, both within the relevant business sector
in terms of their core business market share, as well as
an increased strength from a revenue perspective via
diversification into alternative sectors. Sixteen of the
respondents, or 40% of the sampling stated that
business survival had been a motivating factor, with two
of the businesses stating that their core field of
expertise had subsequently ceased to exist, hence
justifying the diversification decision and process. 22.5%
called it an opportunity. 7.5% reasoned it for the sake of
demand. The remaining 22.5% stated that the
motivation behind such decision retrospectively was to
reduce business risk.
As previously stated the primary motivation within the
sampling of the family businesses, pertaining to the
reasoning and motivation of such strategic decisions in
terms of the company’s future is driven by the
opportunities presented in the market, and could once
again be attributed to the entrepreneurial spirit of the
family business with respect to taking up such
opportunities. Furthermore, the fact that the reasoning
behind the diversification is consistent with the directly
presented reasoning previously discussed confirms this

mentioned motivation and establishes the
opportunistic manner in which the family business
operates within the sampling of businesses.
Corporate Governance and Control
The issue of corporate governance and control is
specifically relevant to the family business that has
undergone structural change and may have resulted in
a loss of the initial family values and ethics that are
prevalent in the family business due to possible changes
effected in order to adhere to corporate governance
requirements as stipulated by any relevant legal
framework. Butler & Phan provide that “family
dominance in the corporate governance structure may
strengthen the ability of the corporation to coordinate
on decision-making and hence have an impact in
strategic interactions with external stakeholders.” (2008
p.10) These places the family controlled enterprise in a
possibly stronger position than that of corporations that
such family dominance and involvement.
With respect to the sampling of family businesses which
participated in the study, around 10 respondents agreed
that corporate governance is an effective tool for
optimization of the business, represented by 25% of the
sampling. 6 participants (15%) saw such governance as
a requirement that had to be attended by the business

concerned in terms of operational procedures and
adherence to regulations, Therefore, not utilizing the
issue of governance as an optimization mechanism for
the company, but rather seen as a necessity for
compliance. The majority of 24 participants with 60% of
the population called corporate governance a tool for
optimization or a requirement in the age of
diversification both.
Poutziouris provides that the issue of corporate
governance should be seen as the promotion of the
company, or the stakeholders or both (2006 p.322),
which should be seen by the family business owners and
management as a positive tool and not that of an issue
of necessity.
Whether corporate governance has taken over from the
initial family business ethic, culture and concept would
contribute to the feeling that autonomy has in fact been
lost within the expansion process or that of
diversification, and hence it would be specifically
relevant to the overall feelings or belief of the family
unit of whether or not such expansion had facilitated
the loss of such autonomy. Within the sampling over,
many respondents agreed to the fact that the family
unit, together with the original culture and ethic still
manages the company accordingly, within the defined

rules and issues of corporate governance, and
Therefore, do not attribute any major change to the
management of a going concern to that of corporate
governance. Based on the fact that of those companies
interviewed, who are more prone to such corporate
governance, family members are appointed to the
board of the company concerned, and as Poutziouris
provides that the accountability of these board
members should be the central theme of corporate
governance and not that of the structure itself (2006 p.
322.).
Based on the findings of the surveys, regardless of
company structure and whether or not the issue of
corporate governance is seen as an optimization
mechanism that born out of necessity for adherence,
the family unit together with the original ethics, culture
and internal controls seem to dominate across the
entire sampling.
Diversification – Positive or Negative
The view of whether the diversification process was
positive or negative is to provide an insight as to
whether or not the risk or perceived risk of following
such a path in terms of business strategy did in fact
achieve the goals and objectives of the initial decision of
such a process, and whether or not the family business

as it stands today is in a better or worse off profession
and position as a result of such actions, or in actions.
The figure above highlights the perceived positive
impact of the respondents within the survey,
represented by the majority of the respondents
specifying that the overall impact was in fact positive.
Interestingly enough 55% of the respondents found that
the diversification process was positive, 30% found it as
neutral and only 12.5% found it negative to their
businesses. However, one did not participate in above
three options. However, this was offset by the success
achieved in those specific sectors and thereby
contributing to the positive effect of such
diversification. The 12.5% that found the process to be
negative shared similar views to those responses that
found that both positive and negative simultaneously, in
that their attention and efforts were diverted away
from the original business. One respondent is
represented in the 2.5% as being not applicable due to
the fact that the business had not undergone any
diversification but, had undergone expansion in their
core business. 55% responded that diversification had
positive results.
Conclusion

In conclusion of the analysis of the questionnaires,
sufficient response was provided by the respondents, in
compliance with the line of questioning providing an
insight into what the family companies had undergone
in terms of a diversification decision and resulting
process. Findings were further confirmed via control
questions, with the majority of decisions being
motivated by strengthening, revenue generation or
opportunistic benefits and beliefs behind the
diversification process. It is furthermore apparent that
the family ethic and control survived the diversification
process, and are instilled in the new company regardless
of the legal structure or family level involvement.
The issue of the autonomy is apparently also been dealt
with via the allocation of shares in specific amounts and
by specific structures to ensure that majority control
and leadership remains with the family concerned. It
appears that the majority of the respondents had
facilitated such diversification via their own funding
mechanisms, as the majority of respondents indicated a
limited liability company structure, implying that such
financing was obtained on an internal basis or via banks,
but not by offering shares within the company on a
public basis. The exception to the rule within the
respondents was a single company, which although they
elected to publicly list their company, the majority

shareholding was retained by the family concerned,
with the overall control vesting within the family by the
appointment of family members to the board of
directors. Regardless of actual involvement within the
company on a post-diversification basis, the original
family members still retained some level of control or
involvement, albeit from a supervisory or oversight
basis.
Lessons Learned
Contradiction with the Theory
Based upon the primary part of the research that clears
indication of the majority of businesses diversifying was
due to that of favorable market conditions, and
entrepreneurial risk and reward type action, whereby
the family businesses were taking advantage of
opportunities that presented them within the market.
This type of entrepreneurial action, according to
Drucker (1985) should in fact not be confused, or
classified within the same field as innovation, as the
author claims that such action of taking the business out
of its core field of expertise is normally unsuccessful.
However, the actual responses of the sampling indicate
that this is not the case. On the one hand, such
innovation is claimed to be unsuccessful, whilst primary
data reveal that the businesses are still thriving to this

day, with interested stakeholders being satisfied with
the growth, expansion and continuance of their relevant
businesses. One has to now consider that although
according to the academic side of the argument, in
terms of such innovative actions resulting in successful
business practice, the actual primary research data
indicate the opposite, which is represented in the fact
that the business continues to operate today.
Involvement of Generations
Although within the sampling the majority of the
businesses surveyed seem to be satisfied with market
position and growth of the business, together with the
physical involvement of a number of generations of the
family, it is expected that issue such as succession and
continuity are due to arise. This is said to do that, but
the involvement of multiple generations indicate that
the company is still largely under the leadership and
control the original generation, and although the
involvement of the secondary, and in certain instances
tertiary generations have been encouraged and
implemented, the fact that the original generation is still
involved in the leadership of the business points to what
mentioned authors described as one of the opposing
forces still in control of the business, referring to the
original generation. This founding generation in all

likelihood has concerns of the continuity of the
business, as described by the authors, and whilst these
family businesses run the risk of becoming one of the
statistics of succession failure, as previously described,
then suitable succession planning and implementation
needs to be effected as soon as possible. Whether or
not the secondary opposing force of the younger
generation becoming impatient or tired of waiting, was
not revealed within the sampling; however, it has
highlighted within the secondary research of the
organizational theorist, and it is indeed well worth
noting.
Corporate Governance as a Tool for Optimization
Corporate governance, although it may not be a
requisite for a privately owned firm, is well worth
encouraging within the family business to be used as a
tool for optimization, inclusive of the management of
resources, from all perspectives including that of human
resources, financial resources and management
resources. Such governance creates a perception
amongst external stakeholders, in more ways than one
might be led to believe. Typical of this issue is that of the
generational demographic, of what the marketing
fraternity referred to as generation Y, where they seek
out employers, producers and service providers with

strong ethics and solid track records, this is an
implication upon the perception of the business
regardless of whether it is family owned and controlled
or publicly listed. Therefore, the issue of corporate
governance cannot only be used as a management tool,
but marketing and branding tool as well. These factors
further contribute to the continuity of the family
business, over and above the issues of succession,
diversification and sound management and leadership
whilst providing a sound framework for the
management of various resources within the family
owned and controlled business.
The Need For Effective Management Controls
There is no doubt that the respondents within the
survey realize the need for effective management
controls, as was witnessed by the majority of responses
indicating that specific legal structures were required in
order for the business to progress accordingly. Despite
the fact that the governance issues are seen as a pre-
requisite, this has doubtfully been implemented across-
the-board of the sampling. Based upon the fact that
average, or median generations operational within the
sampling is that of 1.67 generations, the sampling
reveals that perhaps the businesses are fairly young,
further indicated by an average age of almost 17 years.

This raises speculation of the succession issue again,
despite the fact that legal entities have been structured
correctly, such as the limited liability companies and the
public companies is provided by respondents in the
study. The mere creation of a legal entity does not
ensure the sustainability of the company, and as
described a wide variety of issues, inclusive of attitudes
must be addressed with respect to the succession
process, as well as that of the governance issues
mentioned and discussed. The recognition of the need
of legal structures in order to protect the families
concerned is recognized and a valid step forward, with
the next step being that of ensuring mentioned
sustainability and continuity.
Impact on Family Business
Furthermore, based upon the contribution that family
businesses actually provide to the economy as a whole,
combined with the fact that between 92.5% of all
companies are family owned and/or operated, perhaps
national legislators should seek to educate family
members, currently controlling businesses as to the
issues specifically pertaining to corporate governance,
including social responsibility, as well as that of
succession and continuity in order that the succession
success ratio increases thereby reducing the possible

downfall of established businesses on a post-succession
basis. In a study conducted by KPMG and Family
Business Australia, government regulation and
employee issues were contained in the top four
challenges faced by family business, which are
highlighted in the above in terms of instead of a
regulation based environment, the government should
seek to provide greater encouragement and or
initiatives for the family business, perhaps for those
who adhere to specific corporate governance issues,
which in turn may well address the other challenge of
employee issues as expressed in their research and
survey response (Family Businesses 2008). Hence, issues
such as that of governance may well go a long way in not
only promoting social responsibility, succession,
continuity that filters through to issues of human
resources and ultimately financial aspects of the
company too.
Diversification in Family Businesses
One of the most predominant issues that bear
highlighting here is the contradictory evidence provided
by various authors as well as that is revealed within both
the primary and secondary data analysis and research.
This could be attributed to the private nature of the
family held business, or that of the vastly diverse areas

within which these family businesses operate. Based
upon the significant taxation that many of these
companies are exposed to at some point it is without
doubt understandable as to the very nature of the
retention of private information and the lack of
willingness displayed by many respondents within this
study.
Entrepreneurial Trait And Opportunistic Perspective
In closing the sampling reveals that many of these family
businesses, together with the founding family members
display a specific entrepreneurial trait in the taking up
of opportunities as presented by the marketplace at the
time and although a variety of academic authors and so-
called organizational theorists may well describe certain
issues such as innovation and entrepreneurial-ism
should not be confused or even likened, as in the case
of Drucker (1985), the fact that these businesses
represented in the sampling continue to operate and
have continued to diversify and grow, whether it be
from an organic or externally funded basis, tends to
negate the views of authors such as these.
Granted there are specific, and extremely relevant case
studies that exist and which highlights issues of
succession, continuity and sustainability which may well
be lacking from the perspective of the sampling, or due

to the inadequate information provided; the
opportunistic nature of the sampling has enabled these
corporations all companies whichever the case may be
to maintain levels of success and growth, whether it be
from an innovative or opportunistic perspective, which
in many views is construed as being that of an
entrepreneurial nature. Families work for the well-being
of the family unit, as well as inheritance of the family as
a whole, as previously stated; with these family units
choose to do so in an opportunistic level, innovative
level or by virtue of the fact that these people are
entrepreneurial minded it does not have to satisfy any
theoretical decision or definition is described by
organizational theorists. Naturally provided actions of
the family unit within the ambit of the relevant
legislated requirements in the way in which they choose
to pursue success should not have to adhere to any
theoretical or academic definition specifically in
diversity.
Impact of Diversification
All indication towards the decision of diversification has
proven to be positive, and has resulted in this success of
the family businesses surveyed, so much so that one of
the respondents has progressed to twenty-seven
separate businesses under control from first deciding to

diversify. Whether one views that as an entrepreneurial
move or that of innovation is irrespective as it has
undoubtedly contributed to the revenue stream of the
family and the businesses under management and
control.
Internal and External Factors
External factors that affect the family business, as well
as that of any other business do not discriminate in
effect these businesses on an even basis. However, the
family business has internal factors that are inherent to
the family business due to the dynamic of the family
relationship, which should not be allowed to negatively
affect the daily operations of the family business,
although this may well be easier said than done. The
most important factor that has been highlighted here is
arguably that of a route forward with respect to
succession it would be the primary recommendation
towards any family business in ensuring the success and
longevity of the business in question.
Overall Perception
Many areas of research have been conducted within the
family business context, many of which refer specifically
to that of succession. However, one may believe once
again at the theoretical aspect as presented by the
theorists may prove to be a little more difficult to

implement learning practical or real life situations,
based upon the years and efforts put into the family
business by the founding members. The second
opposing force which has been quoted, half that of the
succeeding generation that will always play a role in that
in all likelihood this succeeding generation does not
have a real sense of sacrifice that was required when the
founding members originally built up a family business.
These perceptions contribute to the primary or
preceding generation, in that they may well believe this
succeeding generation lacks appreciation and the
commitment required in order to ensure success of a
business that they, the founding generation worked so
hard to build up and make succeed.
Bibliography
Cantwell, J, Gambardella, A & Granstrand, O 2004, The
economics and management of technological
diversification, Routledge, London.
Cater, JJ 2006, LONG LIFE IN THE FAMILY FIRM: AN
EXPLORATORY STUDY OF BUSINESS, Louisiana State
University.
Chandler, AD 2003, Strategy and structure: chapters in
the history of the American, Beard Books, Washington.

Channon, DF 1999, The Blackwell encyclopedic
dictionary of strategic management, Blackwell
Pubishers, Massachusetts.
Davies, A 2006, Best practice in corporate governance:
building reputation and sustainable , Gower Publishing
Limited, Burlington.
Druker, PF 1985, Innovation and entrepreneurship:
practice and principles, New York.
Edward, DH 2006, The Successful Family Business: a
Proactive Plan for Managing the Family and the
Business, Praeger Publishers, United States of America.
Gersick, KE & Davis, JA 1997, Generation to generation:
life cycles of the family business, Congress Cataloging-in-
Publication Data, United States.
Granados, ER 2004, Preservation of Competitive
Advantages by Aligning Capabilities to Firm’s Strategy,
IESE, Barcelona, Web.
Grant, RM 2005, Contemporary strategy analysis,
Blackwell Publishing, Oxford.
Johnston, SE, ‘The Family Business: Statistics, Profiles
and Peculiarities’.
Jurinski, J & Zwick, GA 2002, Transferring interests in the
closely held family business, Philadelphia, PA, American

Law Institute-American Bar Association Committee on
Continuing Professional Education.
Kerr, EA 2000, Quality of care for general medical
conditions: a review of the literature, RAND, Arlington.
KPMG and Family Business Australia Survey of Family
Businesses 2008, Web.
Kuratko, DF 2008, Entrepreneurship: Theory, Process,
and Practice, 8th edn, South-Western College Pub.
Malerba, F, Lissoni, F & Breschi, S 2002, ‘Knowledge-
relatedness in firm technological
diversification’, Research Policy, vol 32, no. 1.
Moores, K & Barrett, M 2002, Learning family business:
paradoxes and pathways, Ashgate Publishing Limied,
Aldershot, Hampshire, England, Reprinted in 2004.
Morck, RK 2005, A History of Corporate Governance
around the World: Family Business Groups to
Professional Managers, University of Chicago Press,
Chicago.
Navarro, P 2006, A well-timed strategy managing the
business cycle for competitive, Tim Moore, Pearson
Education Inc.
O’Hara, WT n.d, ‘The World’s Oldest Family
Companies’, Management for Family Business.

Palepu, KG 1981, Diversification and Profit Performance
in the Food Processing Industry, Cambridge University
Press, Massachusetts, United States.
Palmberg, C 2002, ‘Technological systems and
competent procurers—the transformation of Nokia and
the Finnish telecom industry
revisited?’, Telecommunications Policy, vol 26, no. 3-4,
pp. 129-148.
Phan, HC & Butler, JE 2008, ‘Theoretical Development
and Future Research in Family Business’, Research in
Entrepreneurship and Management, p. 3.
Poutziouris, P & Smyrnios, K 2006, Handbook of
research on family business, Edward Elgar Publishing
Limited, Northampton.
Raghavan, UN, Greaves, M, Kumara, S & Surana, A 2005,
‘Supply-chain networks: a complex adaptive systems
perspective’, International Journal of Production
Research, vol 43, no. 20, pp. 4235 – 4265.
Ravensburg, NG 2009, Enterprise future lies in
cooperation – Entrepreneur Cooperatives in Africa, Web.
Rowley, C & Abdul-Rahman, S 2007, The Management
of Human Resources in Malaysia: Locally-owned
Companies and Multinational Companies, Web.

Rumelt, RP 1974, Strategy, Structure, and Economic
Performance., Division of Research, Graduate School of
Business Administration, Harvard University, Boston.
Sadgrove, K 2005, The Complete Guide to Business Risk
Management, 2nd edn, Gower Publishing, Ltd.,
Burlington.
Santalo, J & Becerra, M 2006, Competition from
Specialized Firms and the Diversification-Performance
Linkage, Web.
Schmid, T, Kaserer, M & Ann-Kristin, A 2008, Family
Firms, Agency Costs and Risk Aversion-Empirical
Evidence from Diversification and Hedging Decisions,
CEFS Working Paper No. 2008-13.
Scott, JT 1993, Purposive diversification and economic
performance, Cambridge University Press, New York,
Cambridge, England.
Thomas, H, Pettigrew, AM & Whittington, R
2000, Handbook of Strategy and Management , Paul
Chapman, London.
Villalonga, B & Amit, R 2004, ‘How Do Family Ownership,
Control, and Management Affect Firm Value?’, Journal
of Financial Economics, pp. 80, 385, Web.
Ward, JL & Aronoff, CE 1996, Family Business
Governance: Maximizing Family and Business Potential

(Family business leadership series), Family Enterprise
Publisher, Marietta.
Weidenbaum, M 1996, The Chinese Family Business
Enterprise, California.
Yang, M-L 2010, The Impact of Controlling Families and
Family CEOs on Earnings Management, National Chung
Cheng University, Taiwan.
Yu, J & Cooper, H 1983, ‘A Quantitative Review of
Research Design Effects on Response Rates to
Questionnaires’, Journal of Marketing Research, vol 20,
no. 1, pp. 36-44.
Appendix-A
The following questions are for the purposes of a
Master’s Dissertation solely for academic purposes. All
questions are asked in the strictest confidence, with
answers remaining strictly confidential. Only the results
of the answers will be presented as a group or trend
analysis and therefore, confidentiality is assured. Thank
you for participating within this study. Should you
require any clarification please contact.
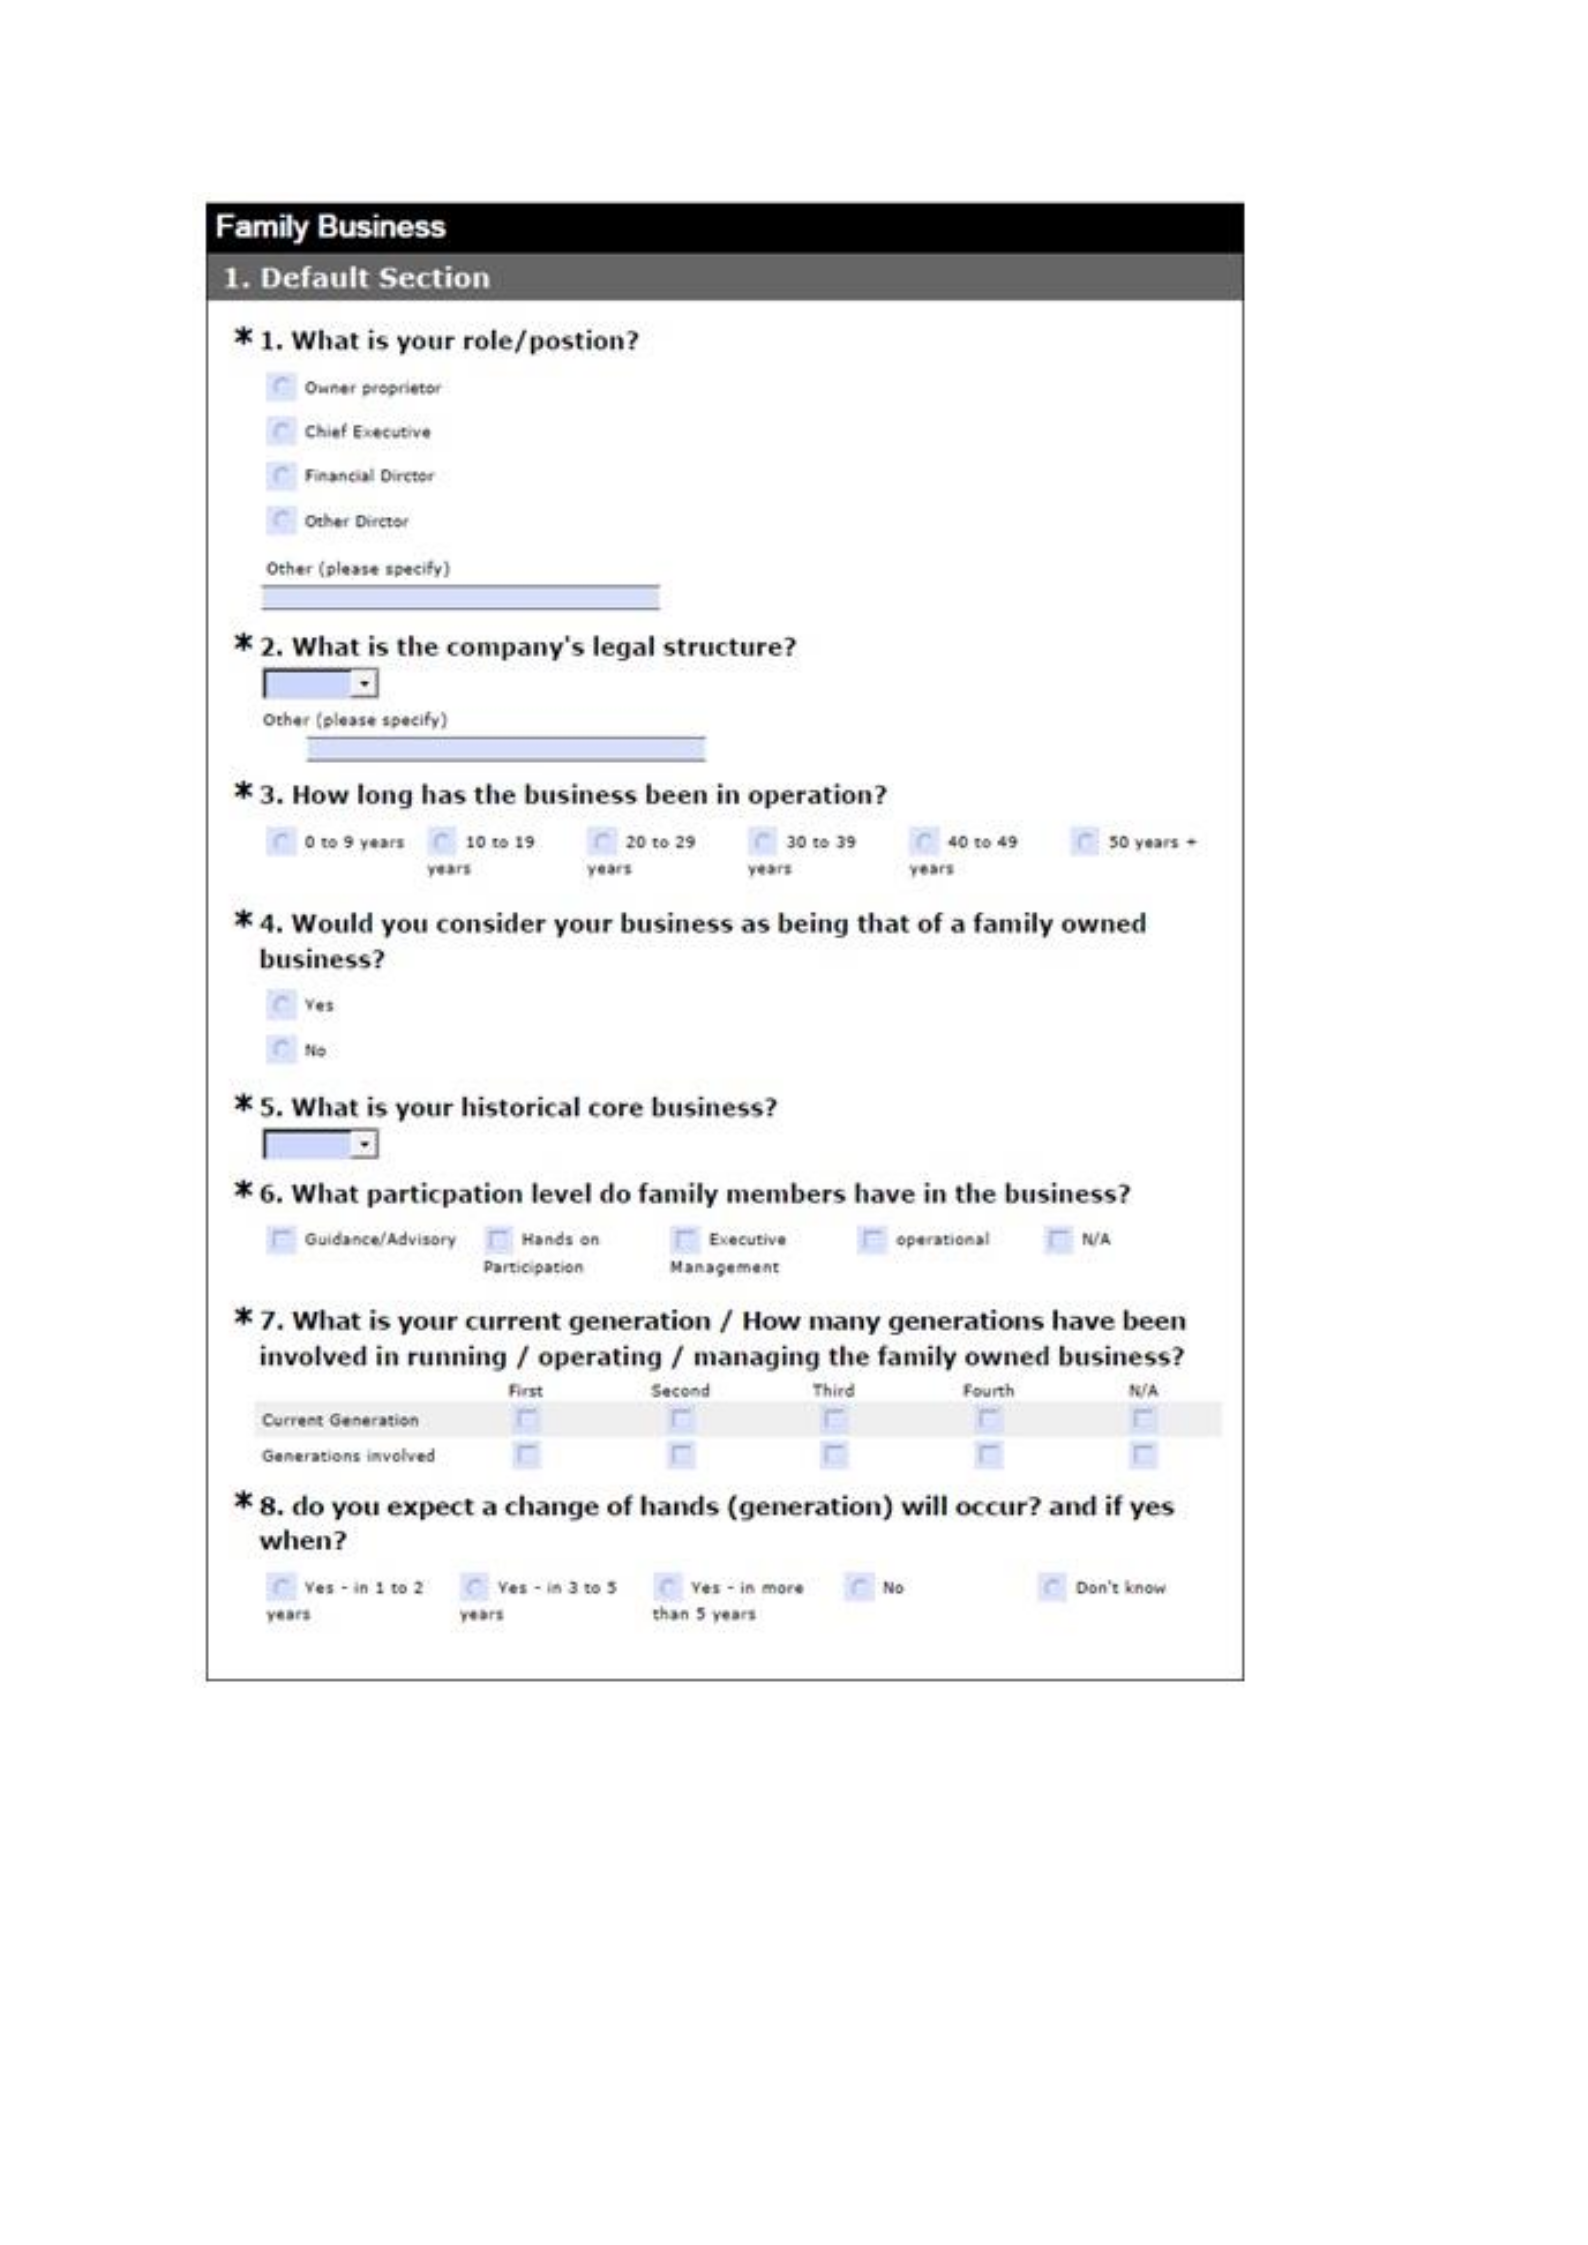
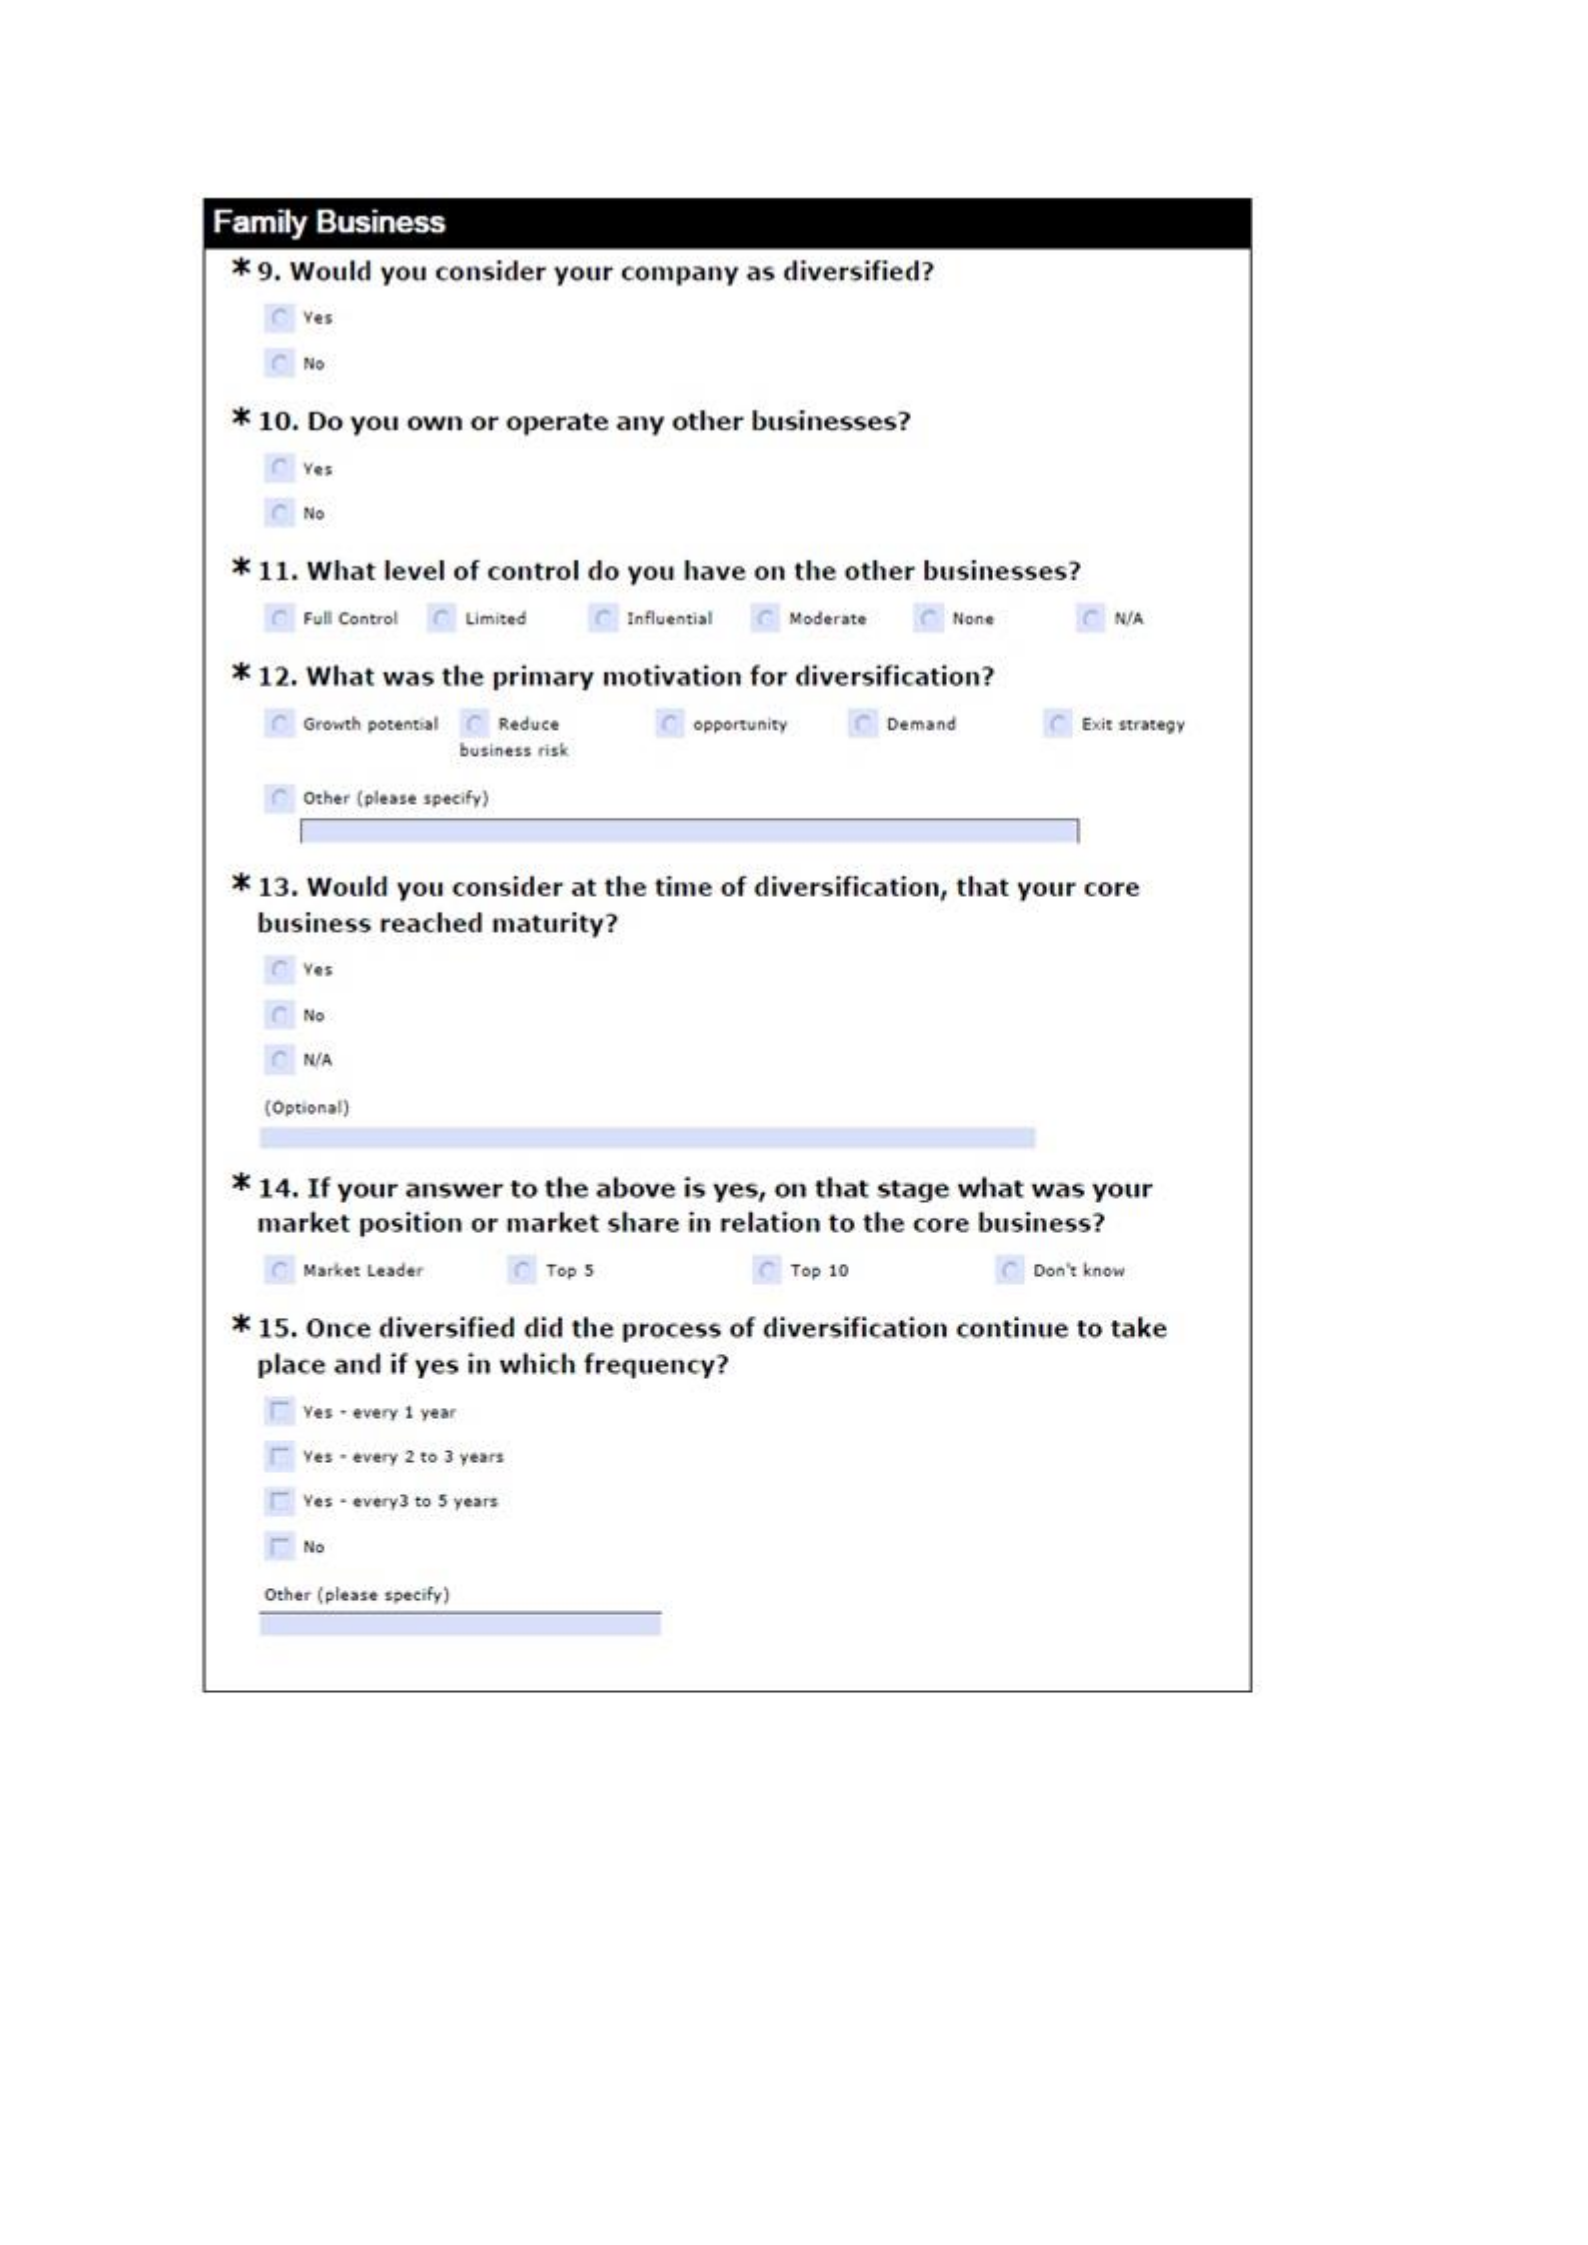
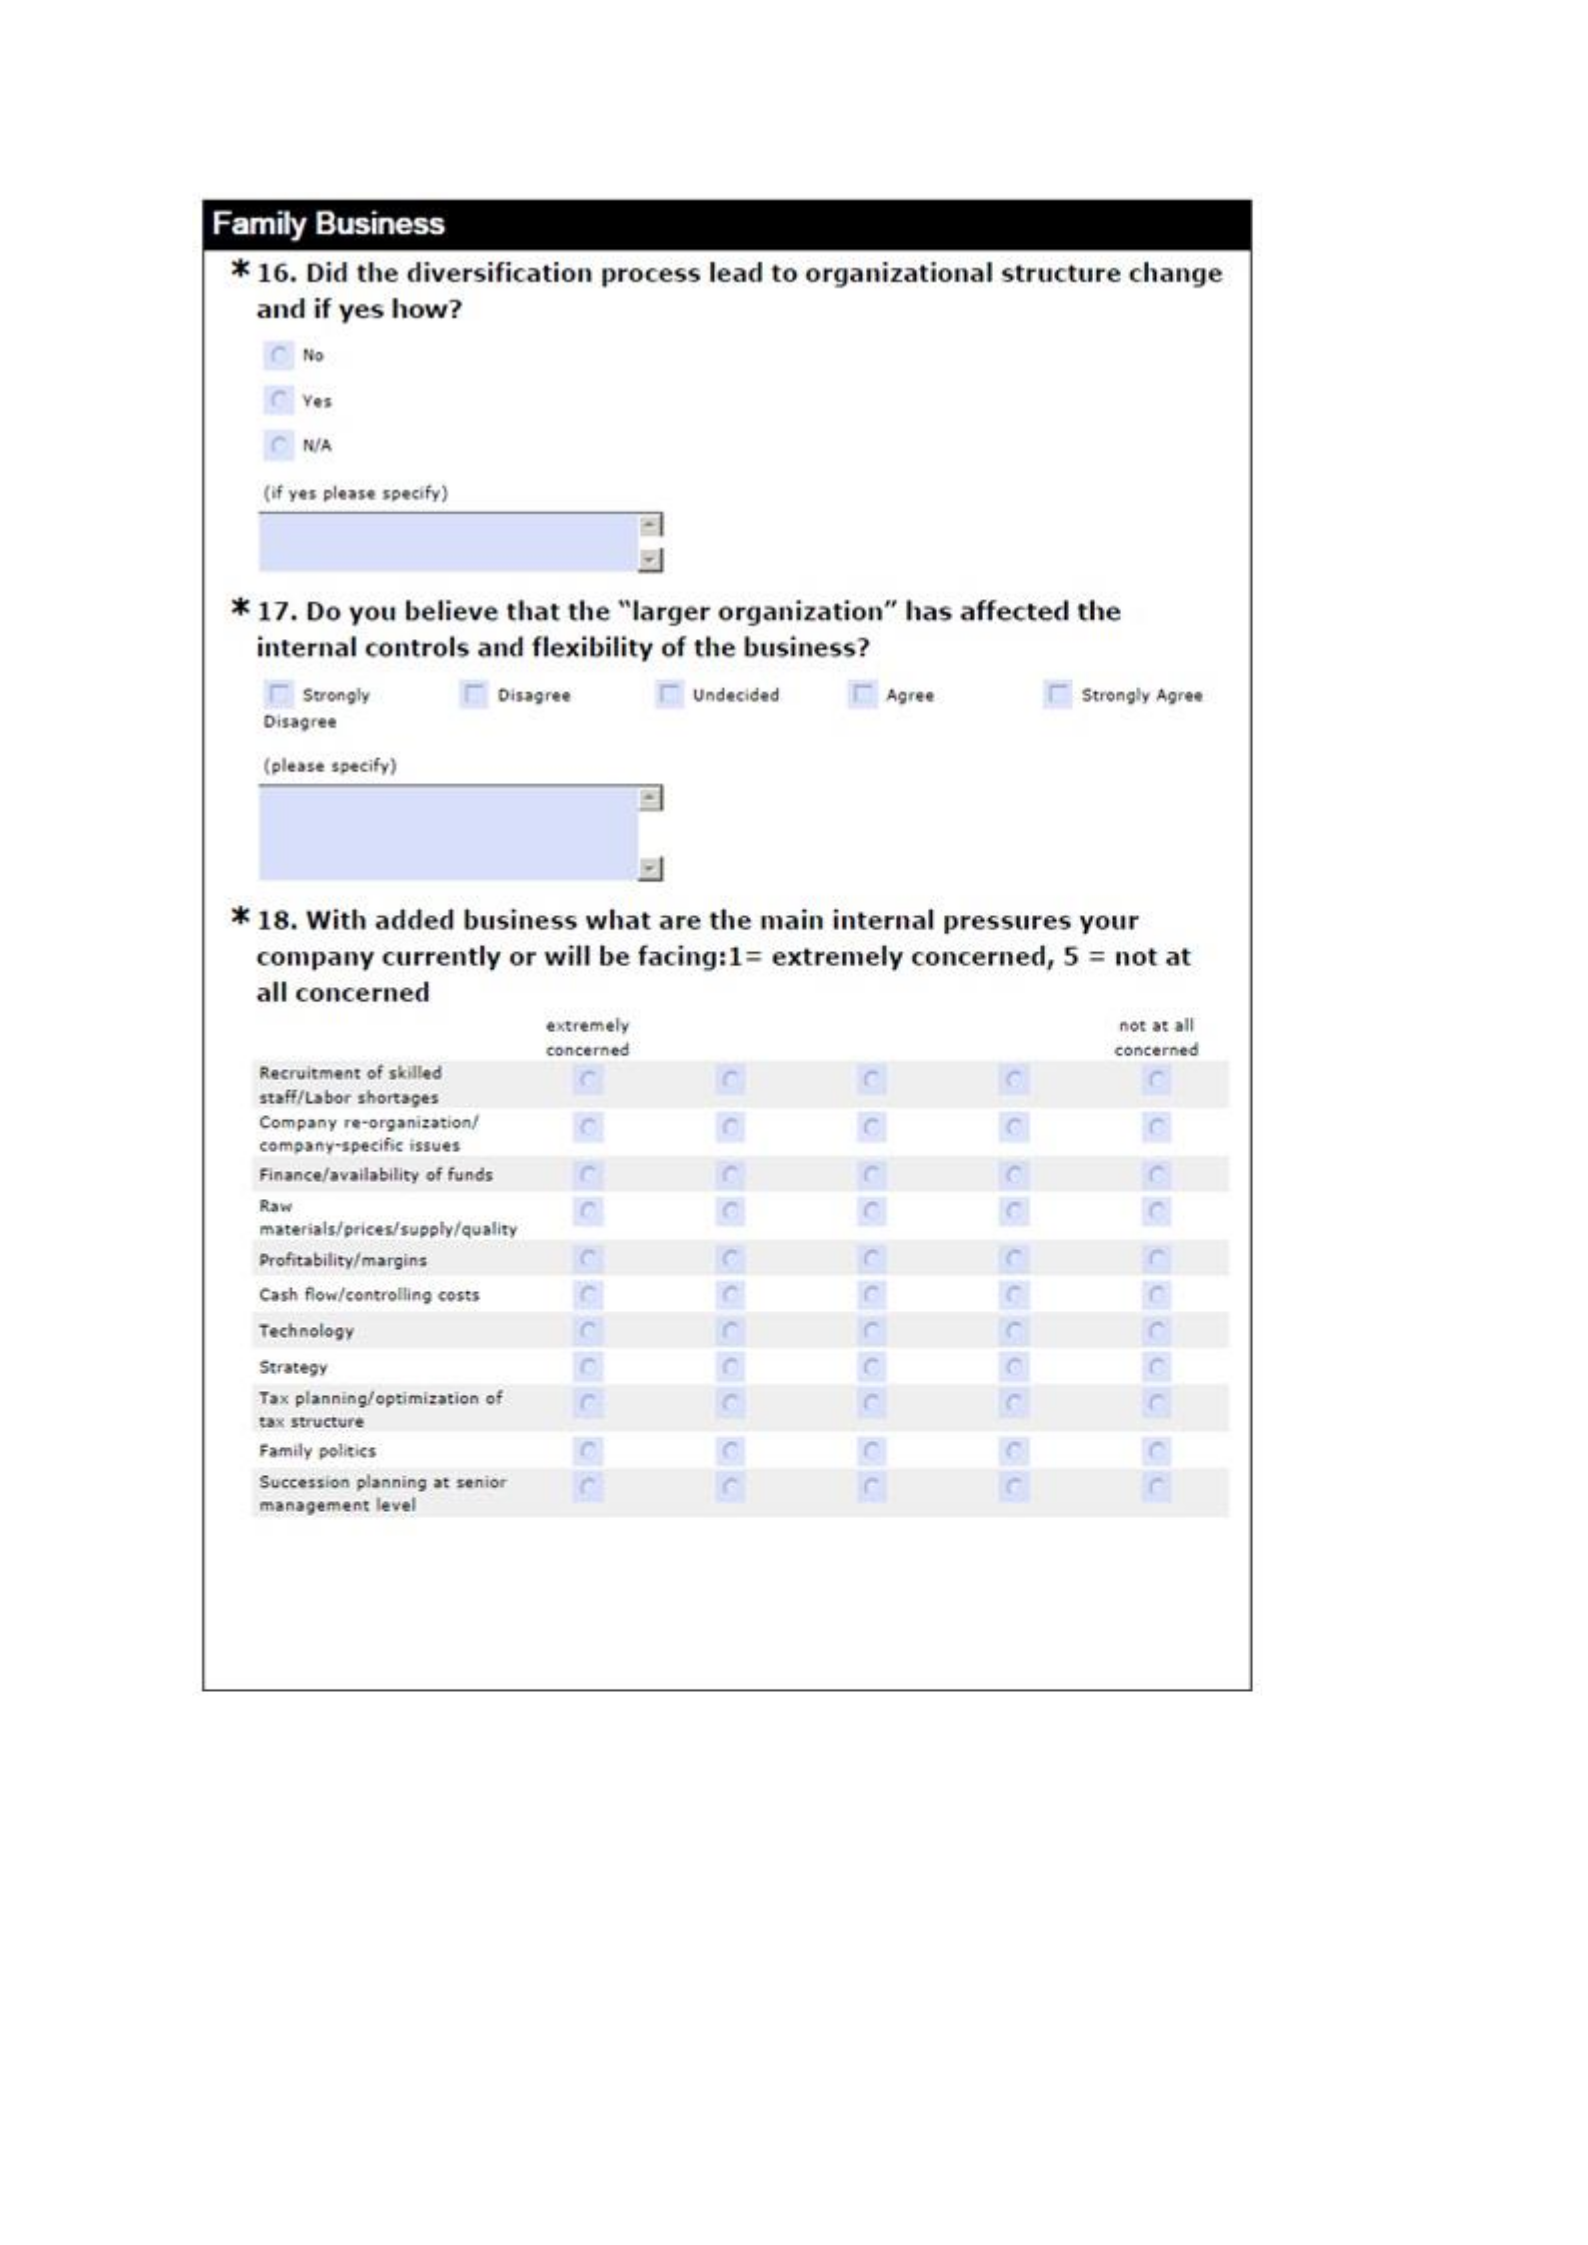
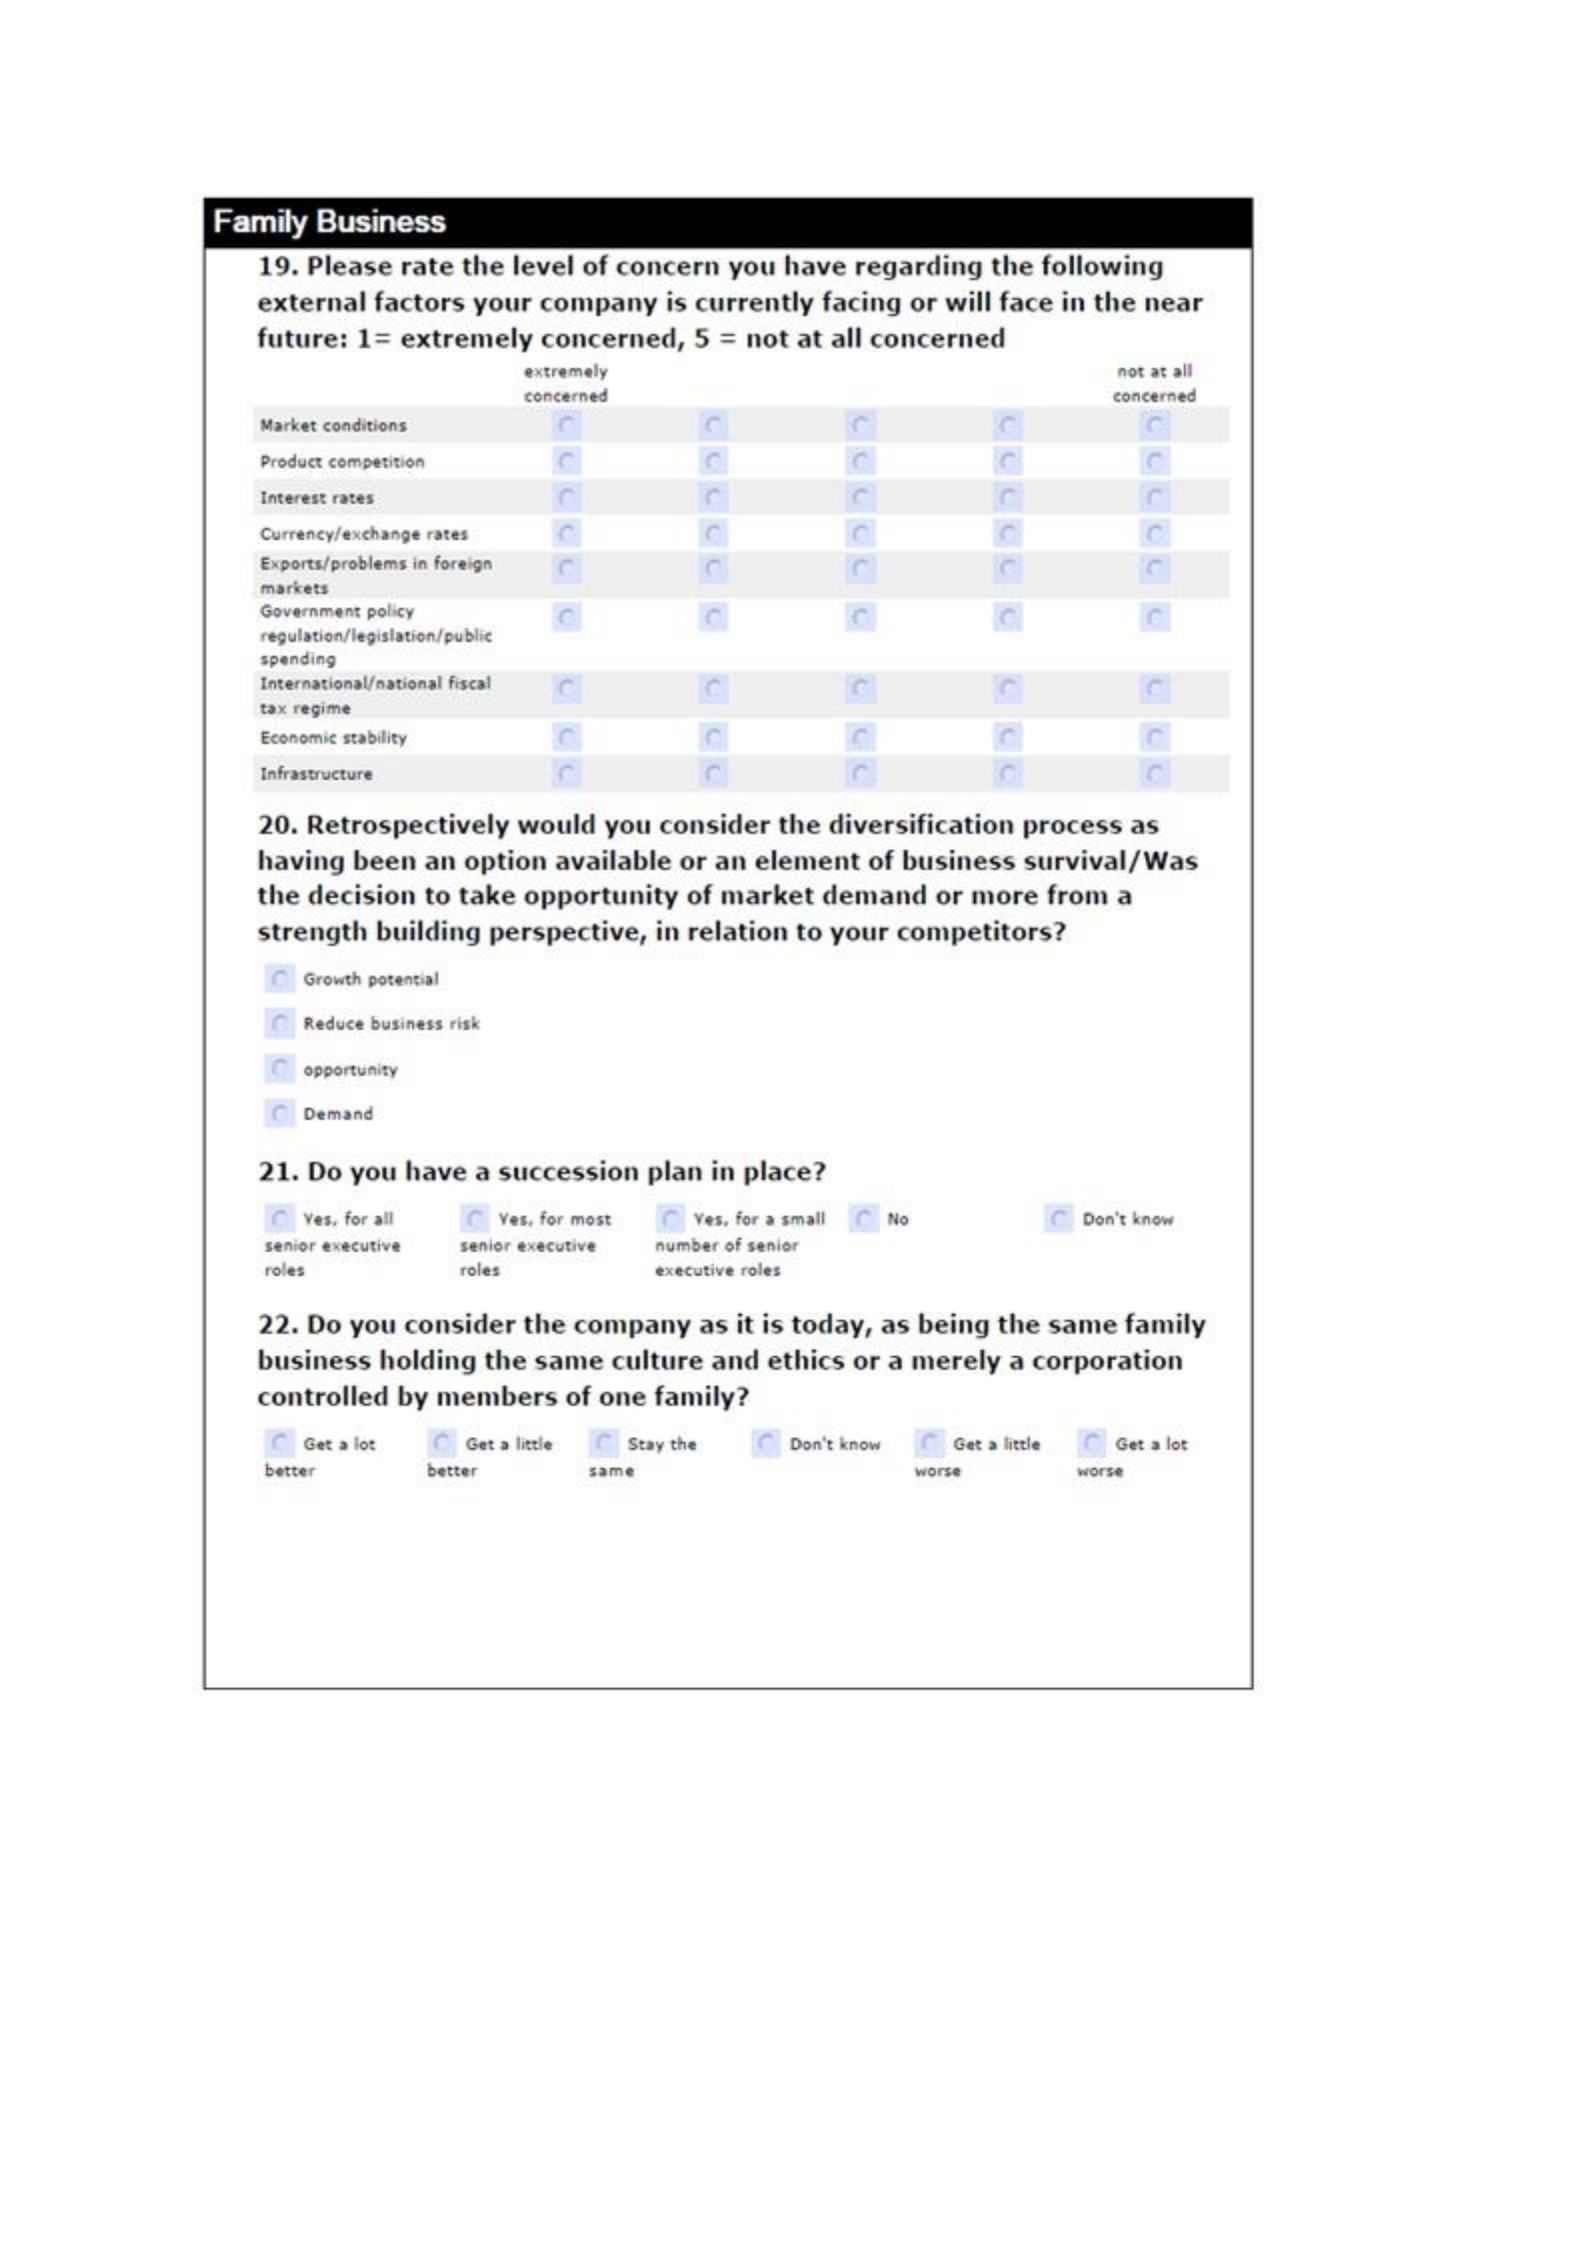
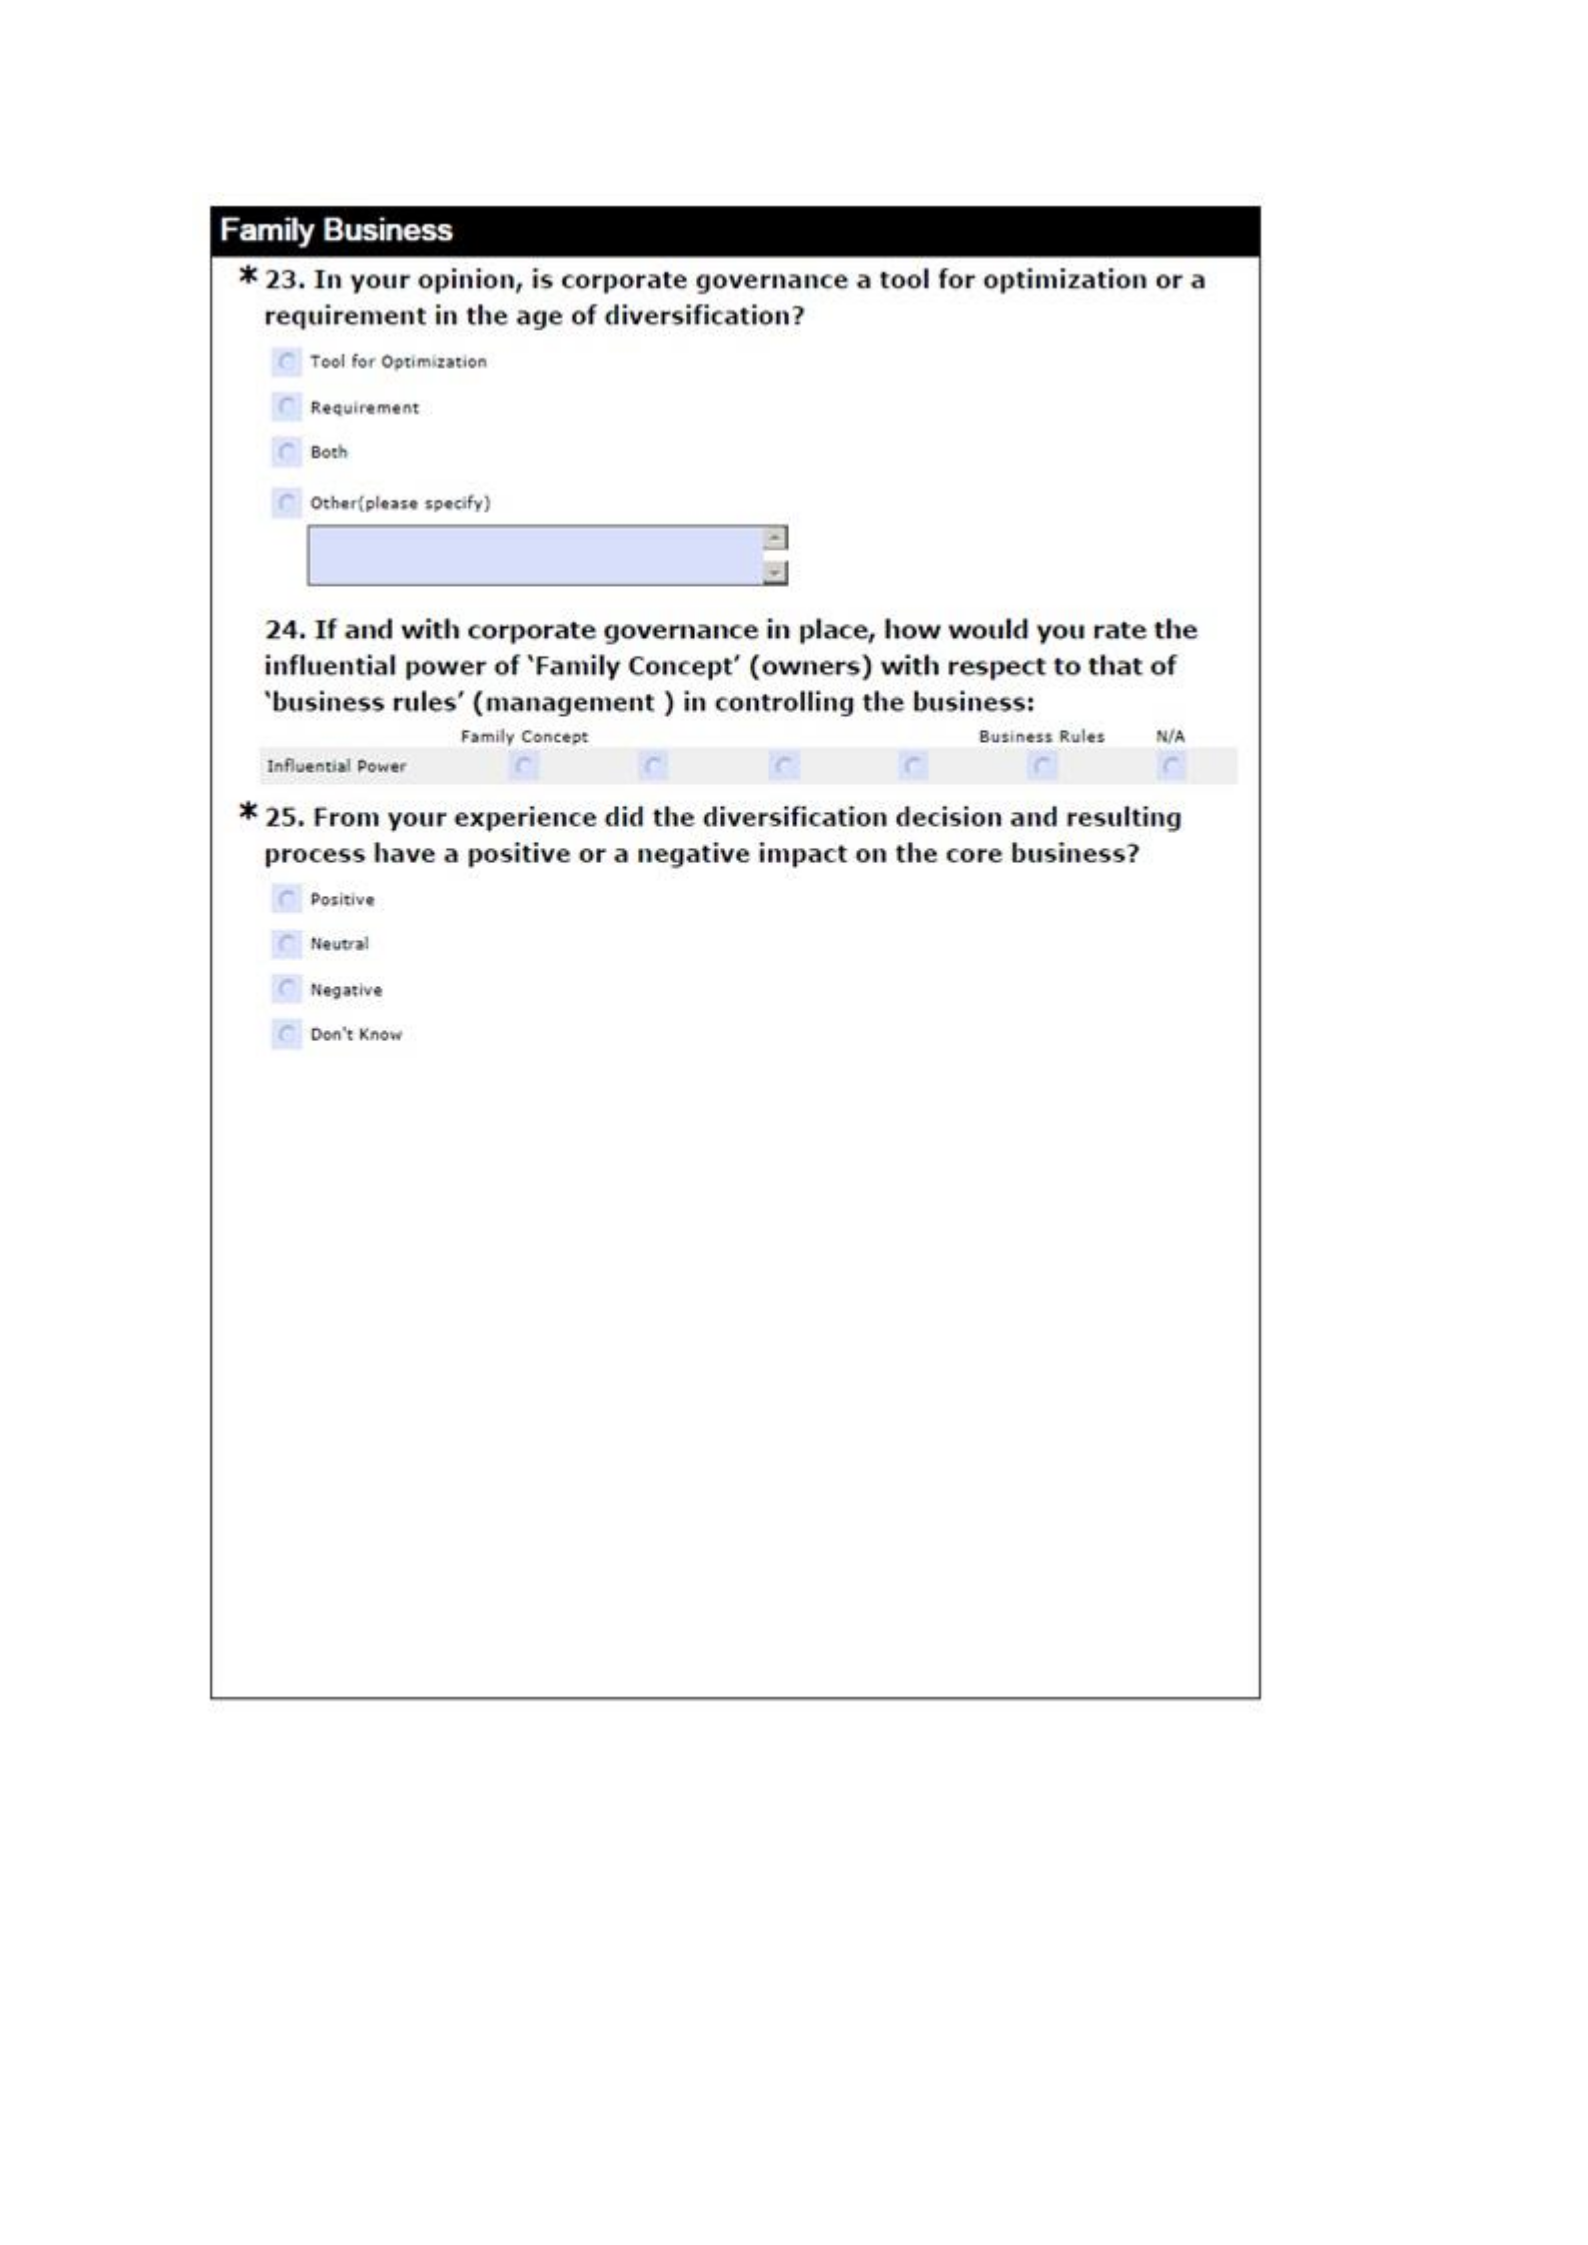
Appendix-B
Appendix – Table of The Top 100 Oldest Companies,
indicating origin or geo location, year founded, age,
average age, as well as notes on diversification.
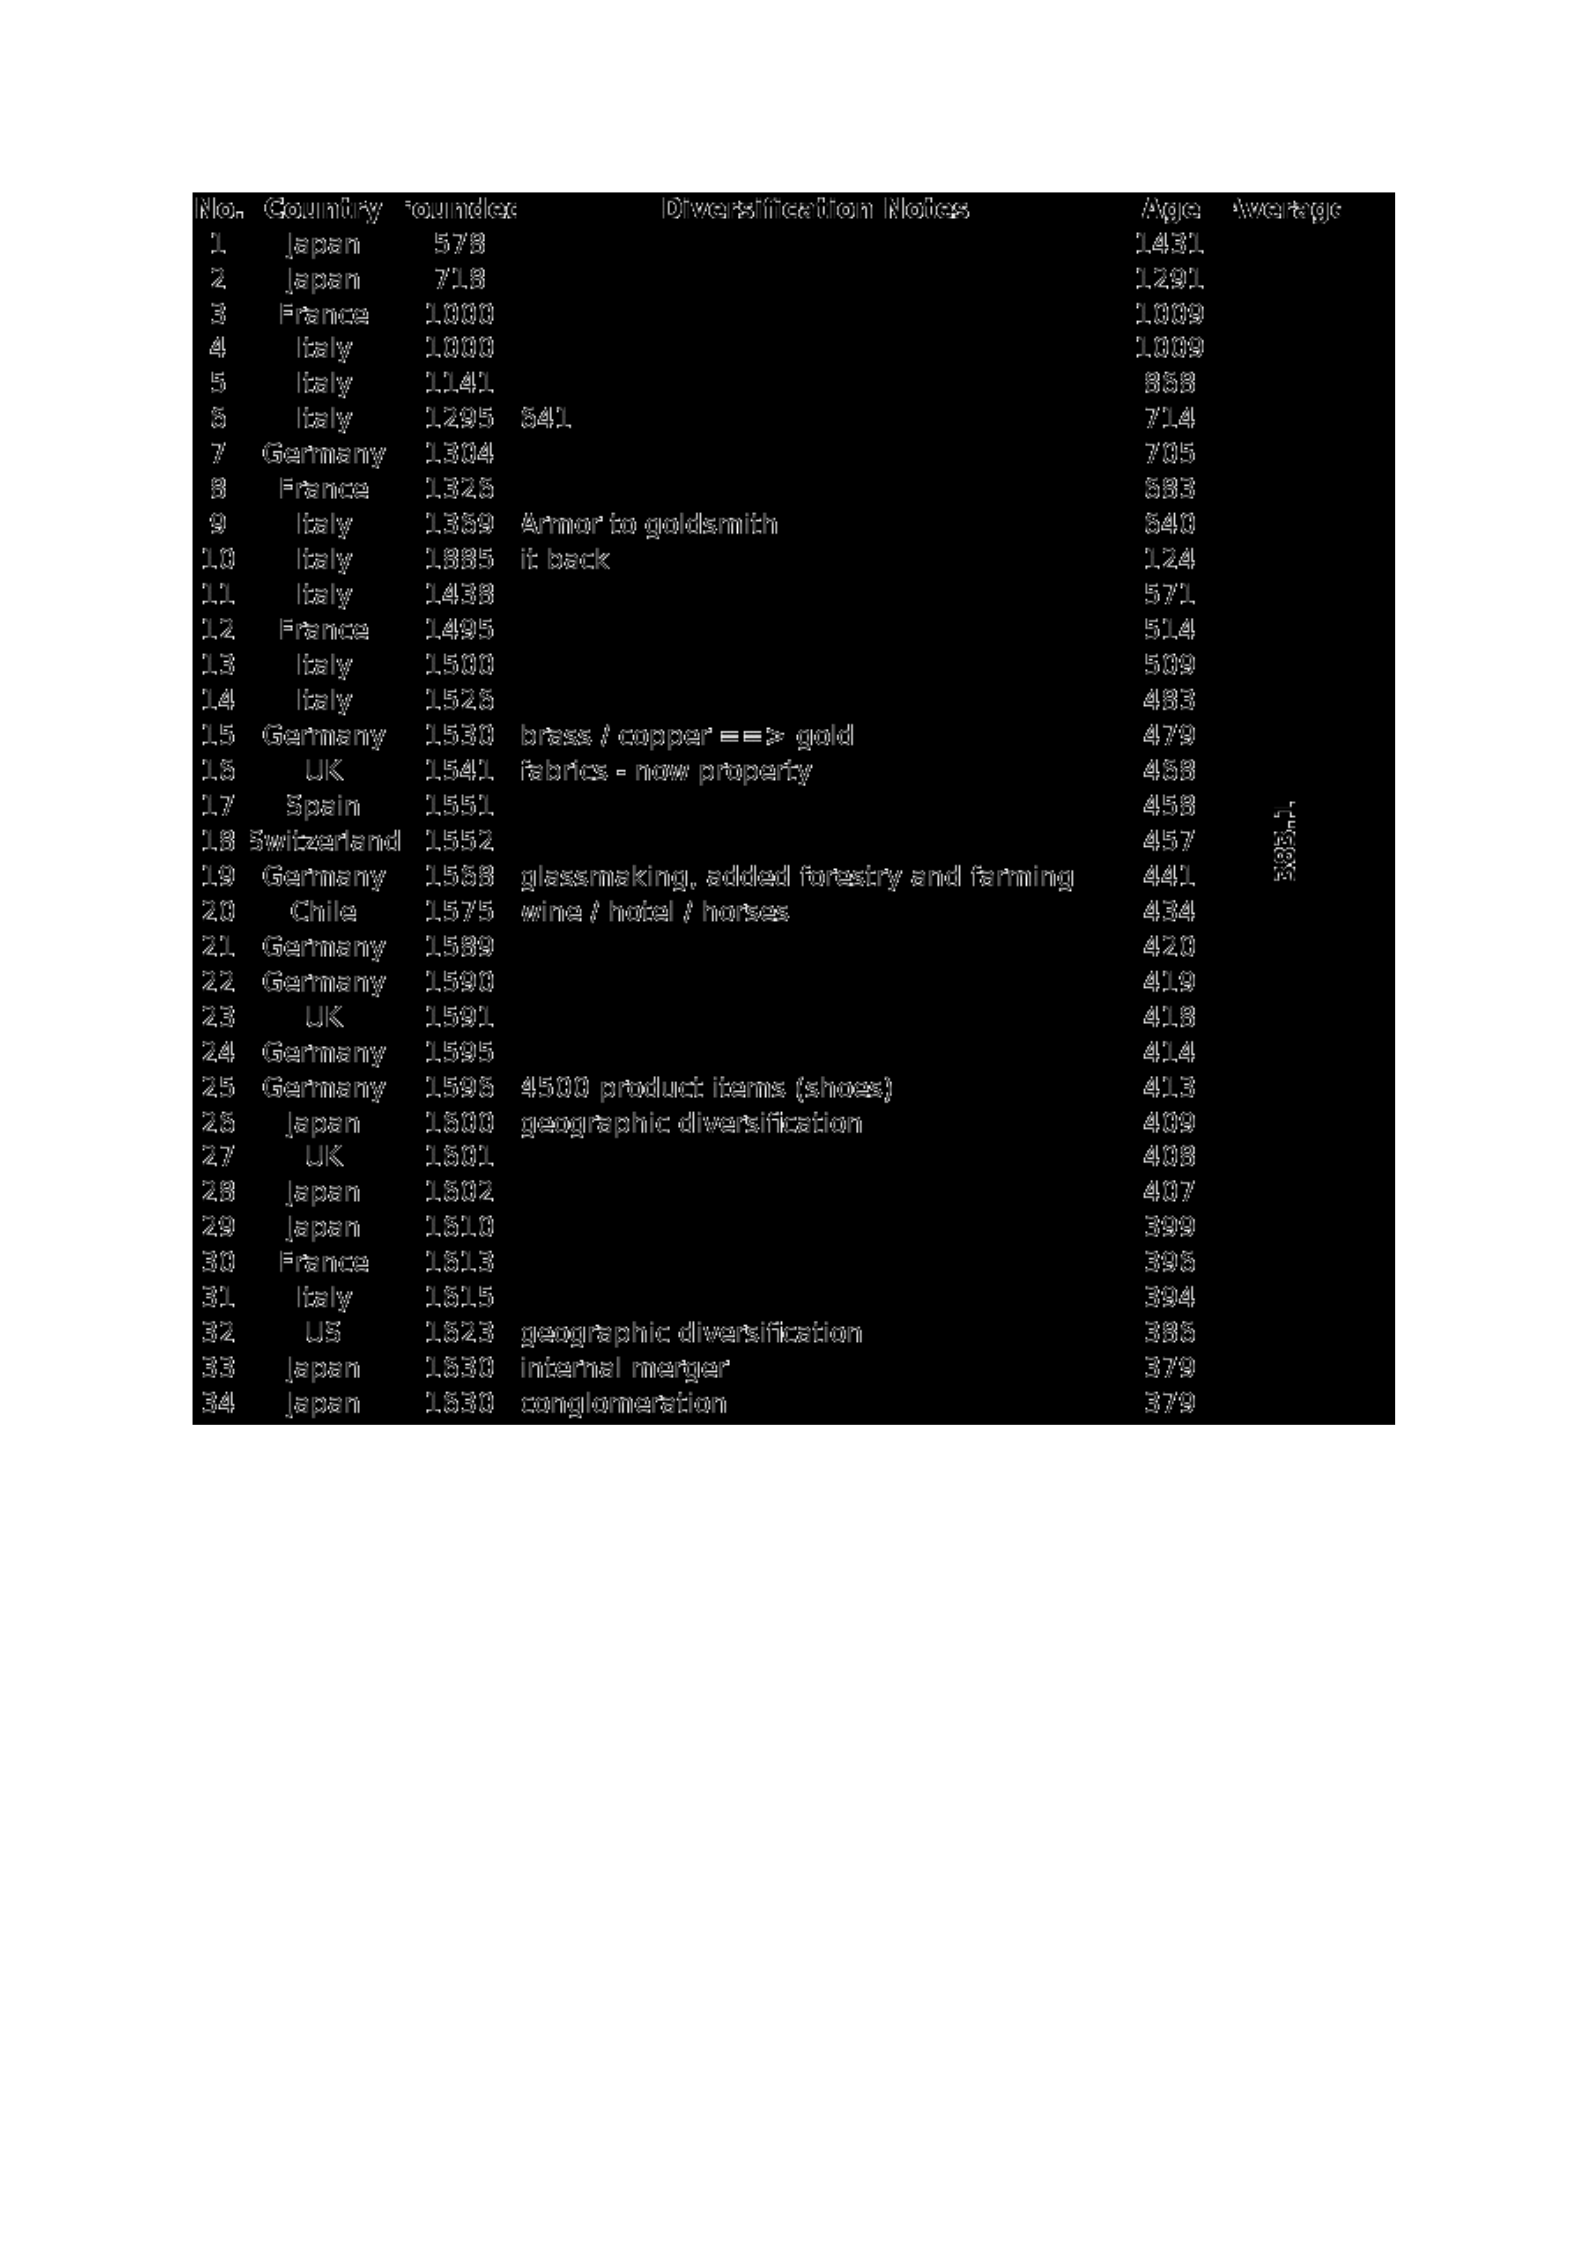
(Based upon research of O’Hara).
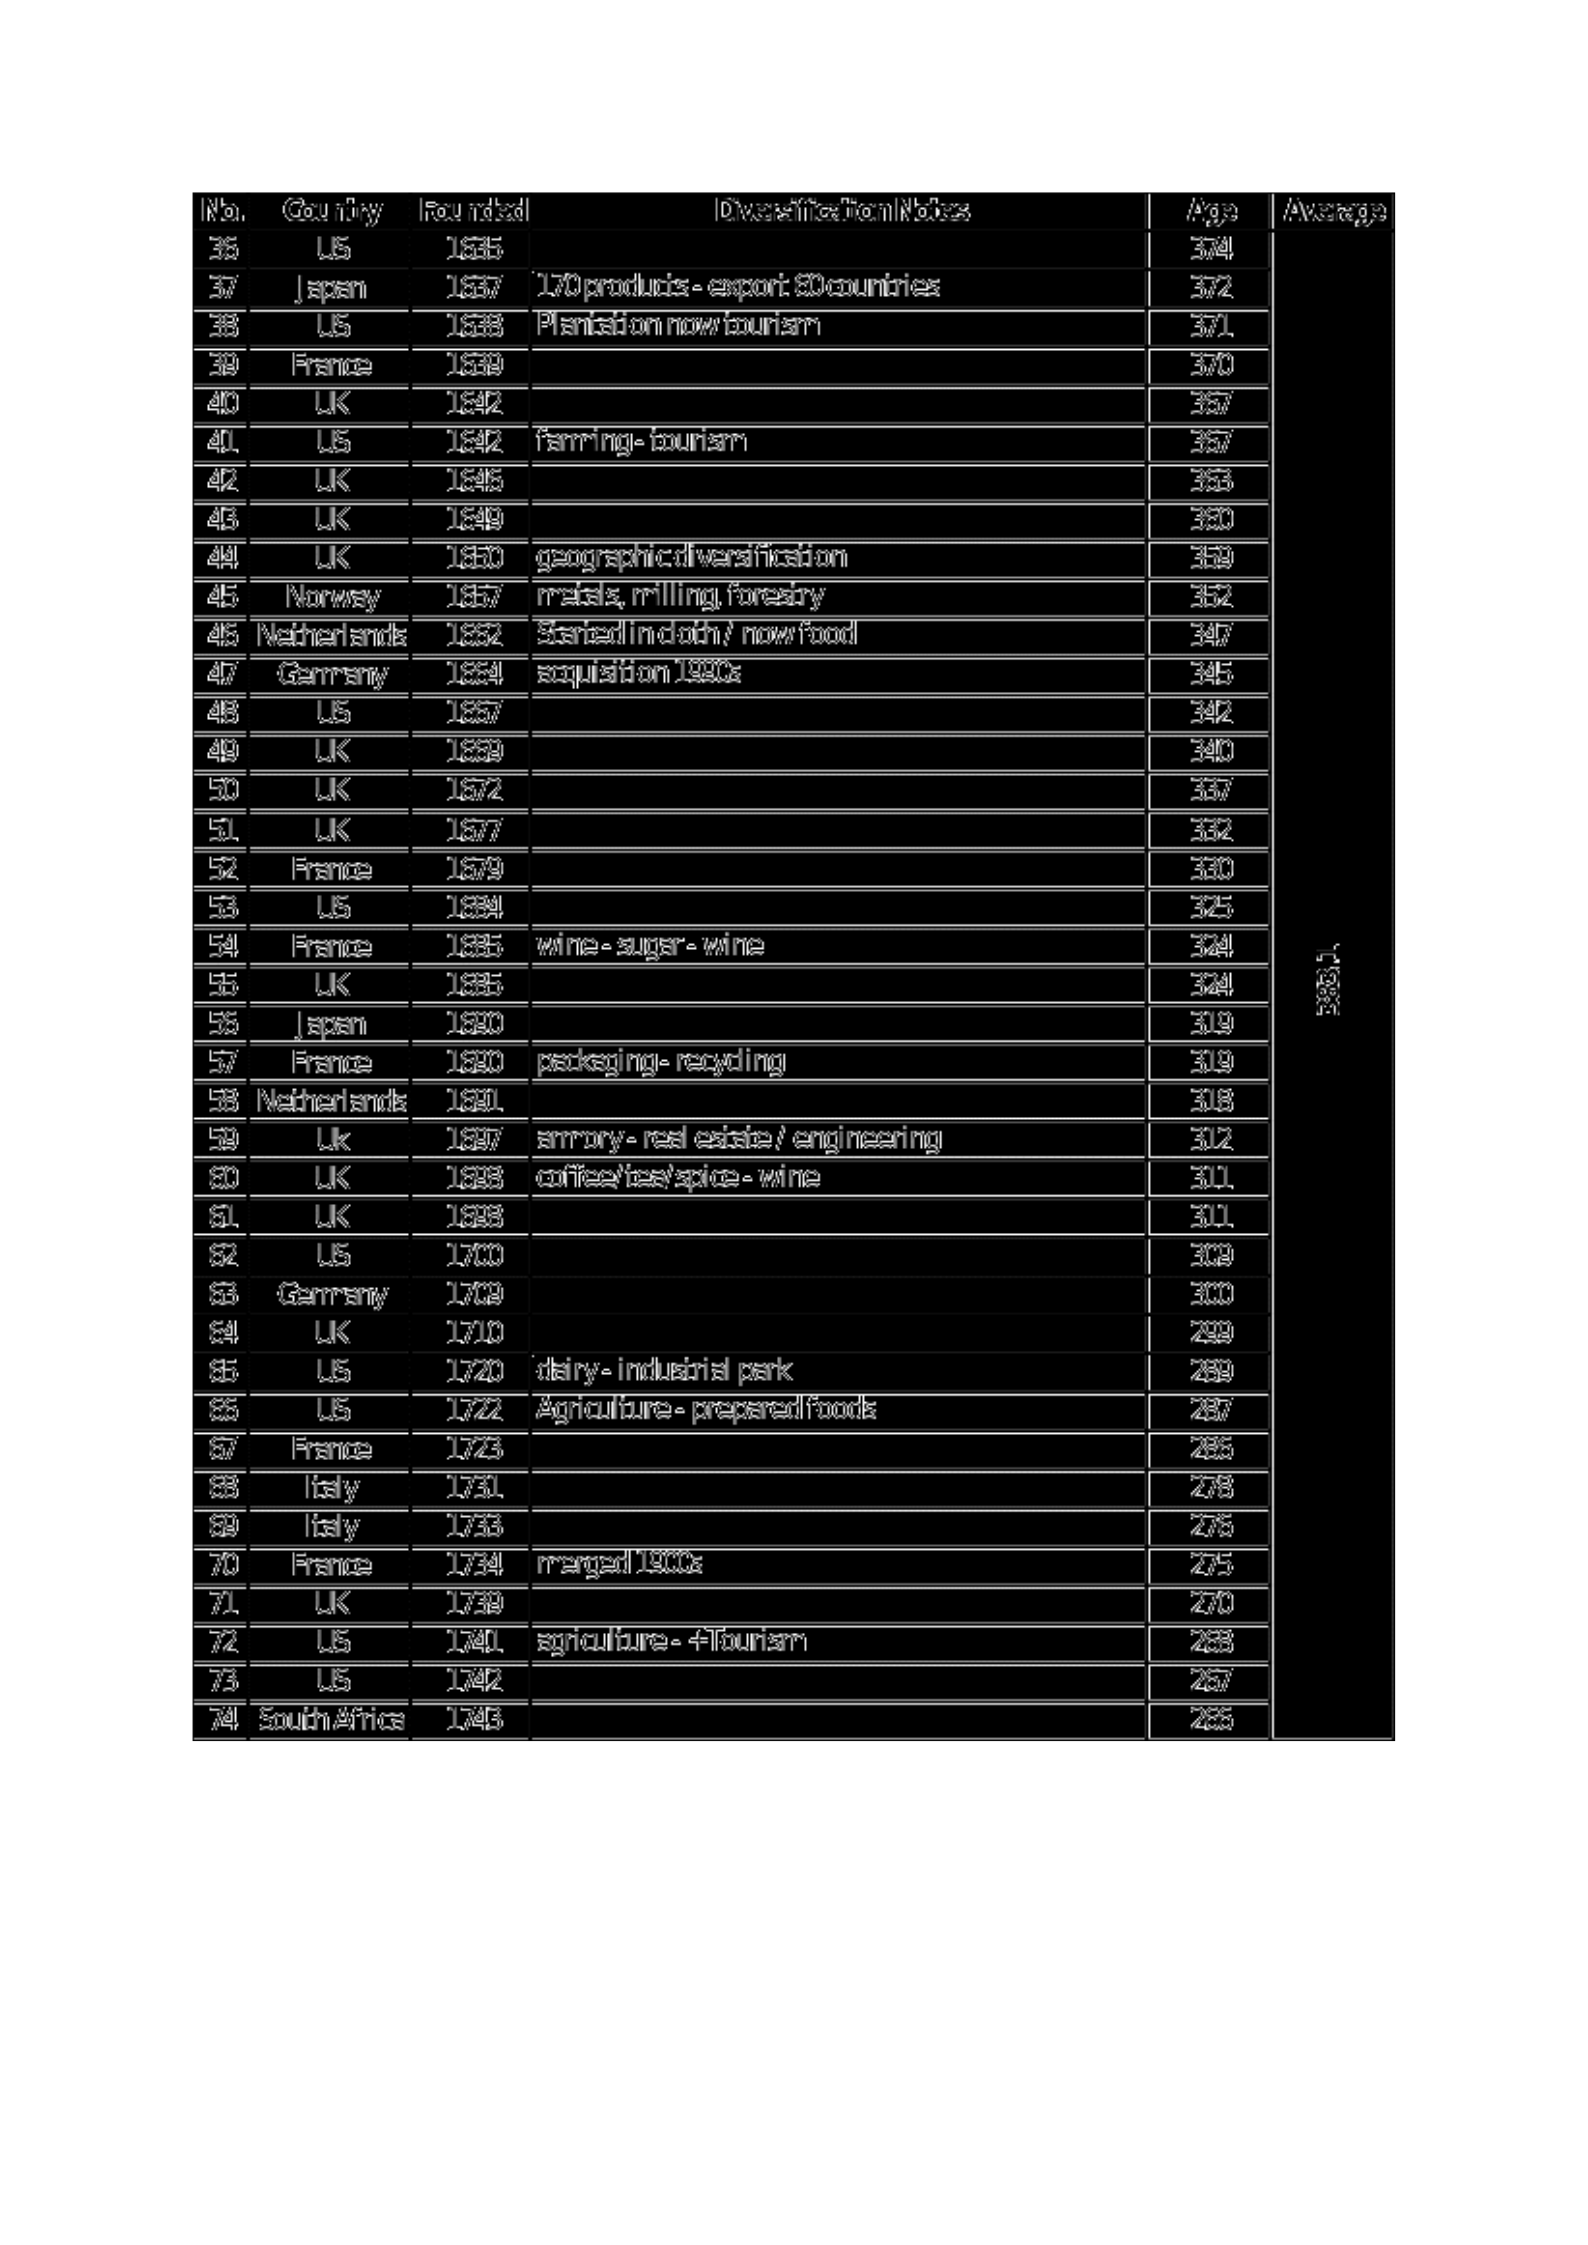
(Based upon research of O’Hara).
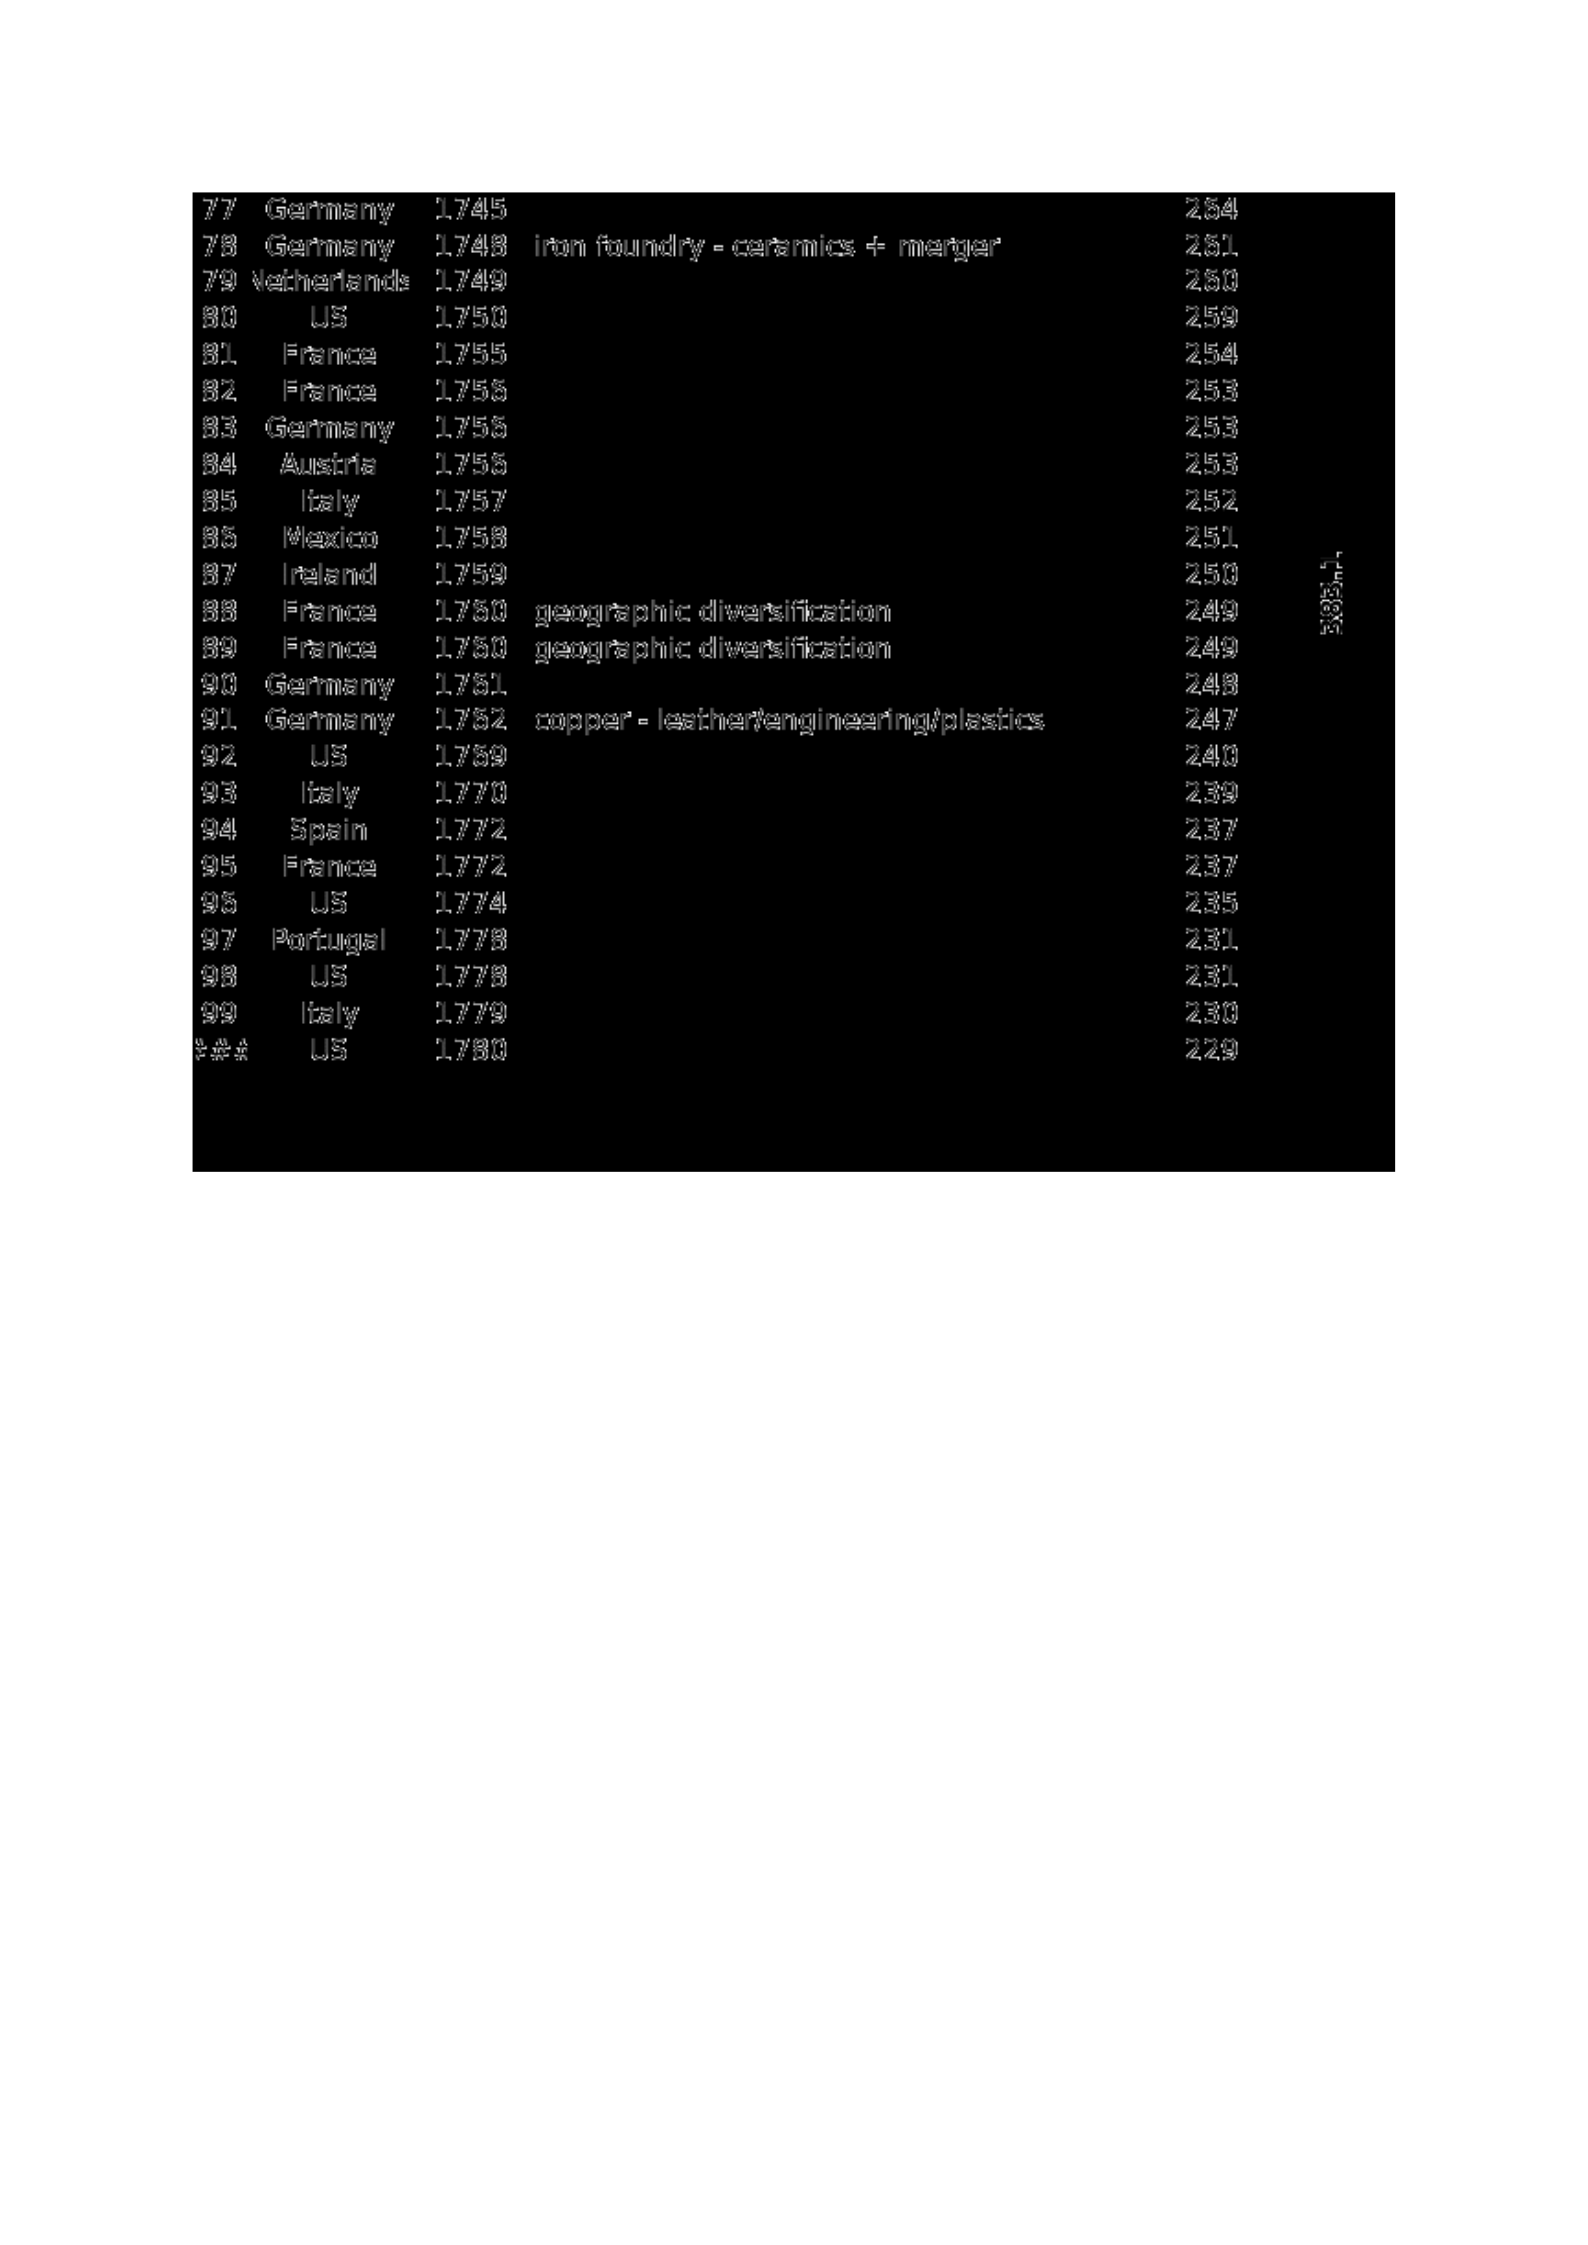
(Based upon research of O’Hara).

