The Sunk-Cost Effect on
Investments Essay
In this article, the author analyzes
such a concept as the sunk cost
effect, namely the continuation of
investments that do not work. The
reason for this is previous
investments that cannot be
reimbursed. Three experiments were
carried out in the article, which show
the level of sunk cost effect
depending on the perspective from
which it was analyzed. In other
words, the analysis of the impact also
included the study of some
additional aspects, such as human
nature, intentions, and background

causes. The authors found that the
effect of sunk costs is less if the cost
decision leads to negative
consequences for others. In other
words, it is a process of interaction
between sunk costs and aspects of
the ethics of caution. In another
experiment, a sunk cost effect was
observed in one person who
followed another decision-maker.
Finally, by conducting a third
experiment, the authors confirmed
the hypothesis of a decrease in the
impact of sunk costs in the case of
negative consequences for other
people. It was done by using more
powerful statistical methods to test

the hypothesis. The authors found a
possible reason for this effect, which
lies in differently placed priorities.
Thus, the author’s assumption is that
violation of the basic aspects of the
ethics of care eliminates bias in
decision-making. Therefore,
prioritizing ethical violations
overshadows the sunk cost effect,
making it less significant for the
person.
Finally, the conclusions drawn in the
work will help to understand better
the decision-making process in the
aspect of significant investments. It
will help to analyze how various
external factors influence the

investor’s thinking and why in some
cases, there is a sunk cost effect.
Reference
Hamzagic, Z., Derksen, D., Matsuba,
M. C., & Bernstein, D. (2020). Harm to
others reduces the sunk-cost
effect. Memory & Cognition, 49, 544-
556.
Investment Sale: The Cash Flows
Essay
Yes, the cash flows of selling an
investment should factor in the tax
impact from the sale. This is because
paying taxes on profits means
handing up cash to the government.
Both cash inflows and outflows

should be taken into consideration if
one is to arrive at an accurate
accounting of the profits made from
the sale of an investment. This is so
as the company’s cash flow will
inevitably decrease due to the sale’s
tax consequences. The expected
profit of the business cannot be
accurately predicted without
factoring in the tax ramifications of
selling the venture (Reimers, 2011). If
stakeholders in a company want to
know whether selling an investment
is a good idea from a cash flow
perspective, they need to know how
much money will be made once taxes
are taken out. Yes, I contend that

dividends and interest should be
factored into the cash flows from
financing endeavors. This is because
dividends, while not assured, will be
paid out in the likelihood that the
firm will have a successful year. Since
interest payments and dividends
received can affect net income, they
may be considered operating cash
flows. When a company’s results are
consistently beyond projections, the
management will begin issuing
dividends (Yeo, 2018). Therefore, it
makes the most sense to include
interest and dividend income in
operating activities because it is
directly related to current-year
operating profits. Cash flow from
investing operations of a firm
comprises dividend and interest
income generated from the
company’s investments. Cash flows
from interest and dividends can be
categorized as operational, investing,
or financing as long as the
categorization is maintained from
one period to the next.
References
Reimers, J. (2011). Financial
accounting: A business process
approach (3rd ed.). Pearson.
Yeo, H. J. (2018). Role of free cash
flows in making investment and
dividend decisions: The case of the
shipping industry. The Asian Journal
of Shipping and Logistics, 34(2), 113-
118. Web.
Explaining Investment Types to a
Layman Report
Introduction
The investing environment may be
quite dynamic and constantly
changing. However, over the long
run, individuals who take the time to
comprehend the fundamental ideas
and the many asset classes stand to
benefit greatly. A person who wants
to invest has many places where they
can put their money. It is crucial to
consider the different investment
kinds thoroughly. Stocks, bonds, and

cash equivalents are the three main
categories into which investments
are often divided. Within each
category, there are several distinct
kinds of investments. The purpose of
this work was to inform readers of
the current investing options.
Bonds
An investment reflecting a loan from
a lender to a borrower is called a
bond. An example of a government
bond is a treasury bill; a convertible
bond represents a corporate one (CFI
Team, 2022). In a typical bond, a
private sector company agency may
be the issuer, and in exchange for
borrowing the lender’s funds, the

lender will pay the lender a specified
interest rate. In companies that
utilize bonds to fund operations,
acquisitions, or other initiatives,
bond rates are often determined by
interest rates (Ammer et al., 2019).
As a result, they are actively traded
when the Central Bank raises interest
rates or when there is a monetary
stimulus phase.
Stocks
Shares of stock provide shareholders
the opportunity to profit from a
company’s growth through
payments and price rises in the stock.
The most widely used ones are
common, growth, and preferred

stocks (Smith et al., 2022). In the case
of bankruptcy, shareholders would
be entitled to certain assets, but they
do not really own them (Siegel,
2021). Ordinary stock owners have
the ability to vote at shareholders’
meetings. Investors with preferred
shares do not have voting rights, but
they get investment returns before
common shareholders.
Cash Equivalents
Treasury bills issued by the US
government, bank deposits, bankers’
admissions, corporate papers, and
other money market products are
examples of financial assets. These
financial products frequently feature

minimal risk, a market with a high
level of liquidity, and short
maturities. Other examples of cash
equivalents are commercial papers,
treasury notes, and money market
funds (Examples of cash equivalents,
n.d.). Accountants may also use a
company’s capability to generate
future cash flows to judge whether it
would be wise to invest in a particular
company because it shows how a
corporation can pay its obligations
over a short period of time.
About Planning and Writing the
Report
One should constantly remind
oneself of one thing when preparing

and writing an informative report for
an uneducated and uninformed
receiver, especially if the topic is
multifaceted, like accounting and
finance. This thing is the fact that “an
uninformed audience is one that
does not share the same set of
knowledge as the presenter” (How to
present, 2020, para. 17). The report
begins with a smooth introduction to
the topic of investments with
attention-grabbing statements that
these are very profitable if the
individual with money knows how to
manage them.
Conclusion
The introduction also contains a
short list of sub-topics, for the client
to get the first insight. The client
explores the topic for the first time,
so only the basic, traditional
investing methods are included,
described, and explained in the
educative report. Complex
accounting and financial terminology
are missing for the same reason.
Specific information is taken from
academic scientifically-produced
sources and topic-specific and
reputable websites.
References
Ammer, J., Claessens, S., Tabova, A.,
& Wroblewski, C. (2019). Home
country interest rates and
international investment in US
bonds. Journal of International
Money and Finance, 95, 212-227.
Web.
Managers Exploiting Investor’s
Irrationalities Essay
Investors are often irrational when
making decisions on how to spend
their money. For instance, they may
retain shares in stocks that are no
longer profitable. As such, one of the
prerequisites for market timing in
behavioral corporate finance is that
irrational investors control security
prices (Baker & Wurgler, 2013). I
think managers take advantage of

such investors and are cautious to
please them to prevent the logical
ones from causing competition and
arbitraging prices. Notably, it is only
when informed investors compete to
correct mispricing that security
prices can embed fundamental
values.
Furthermore, managers have several
advantages that help them to
identify mispricing before the
investors. For instance, corporate
leaders better understand their firms
and any abnormally high returns
occurring due to illegal or legal
errands. In addition, managers can
manufacture data through

controlling earnings or bribing
analysts to provide favourable data
(Baker & Wurgler, 2013). For
example, they can ask the external
auditors to omit some records so that
the financial data present the
company as having a good overall
performance. The investor may not
easily discover the tricks the
managers use in the financial records
and then make wrong decisions.
In conclusion, I believe that for a
financial market to operate
efficiently, all publicly available
information should reflect the
security process. The rationale is that
there is always a direct correlation
between the monetary data
conveyed in the market and how
resources are allocated. Noteworthy,
the investors rely on such content to
make decisions on places they can
place their money. Shrewd managers
can take advantage of the correlation
by either revealing less information
about the financial records or
creating data through manipulation.
Moreover, they keep irrational
investors close so that they can
continue influencing the security
prices.
Reference
Baker, M. P., & Wurgler, J.
(2013). Behavioral corporate finance:
An updated survey. In G.
Constantinides, M. Harris & R. Stulz
(Eds.). Handbook of the Economics of
Finance (pp. 357–424). Elsevier
Science B.V. Retrieved from Social
Science Research Network (SSRN):
Web.
Decision on Refinancing a Mortgage
Essay
Refinancing a mortgage may be
viable decision for a wide variety of
reasons. For instance, one may
decide to refinance to reduce the
overall interest paid to the loaner
even at the cost of increased monthly
payments. It is beneficial to look at
the decision-making process based

on an example. Assume that a person
needs to make a refinancing decision
of a $100,000 mortgage of 15 years
for 7% interest rate. After one year,
the person receives a chance to
refinance the mortgage with a 5.5%
interest rate for 15 years. One should
consider refinancing if the monthly
payment decreases and if the
payback period of the closing cost is
reasonable (Treece, 2022).
Calculation provided below
demonstrate how the decision can be
made using quantitative analysis. It is
also crucial to determine the payback
period of the closing cost. The
breakeven point can be calculated by
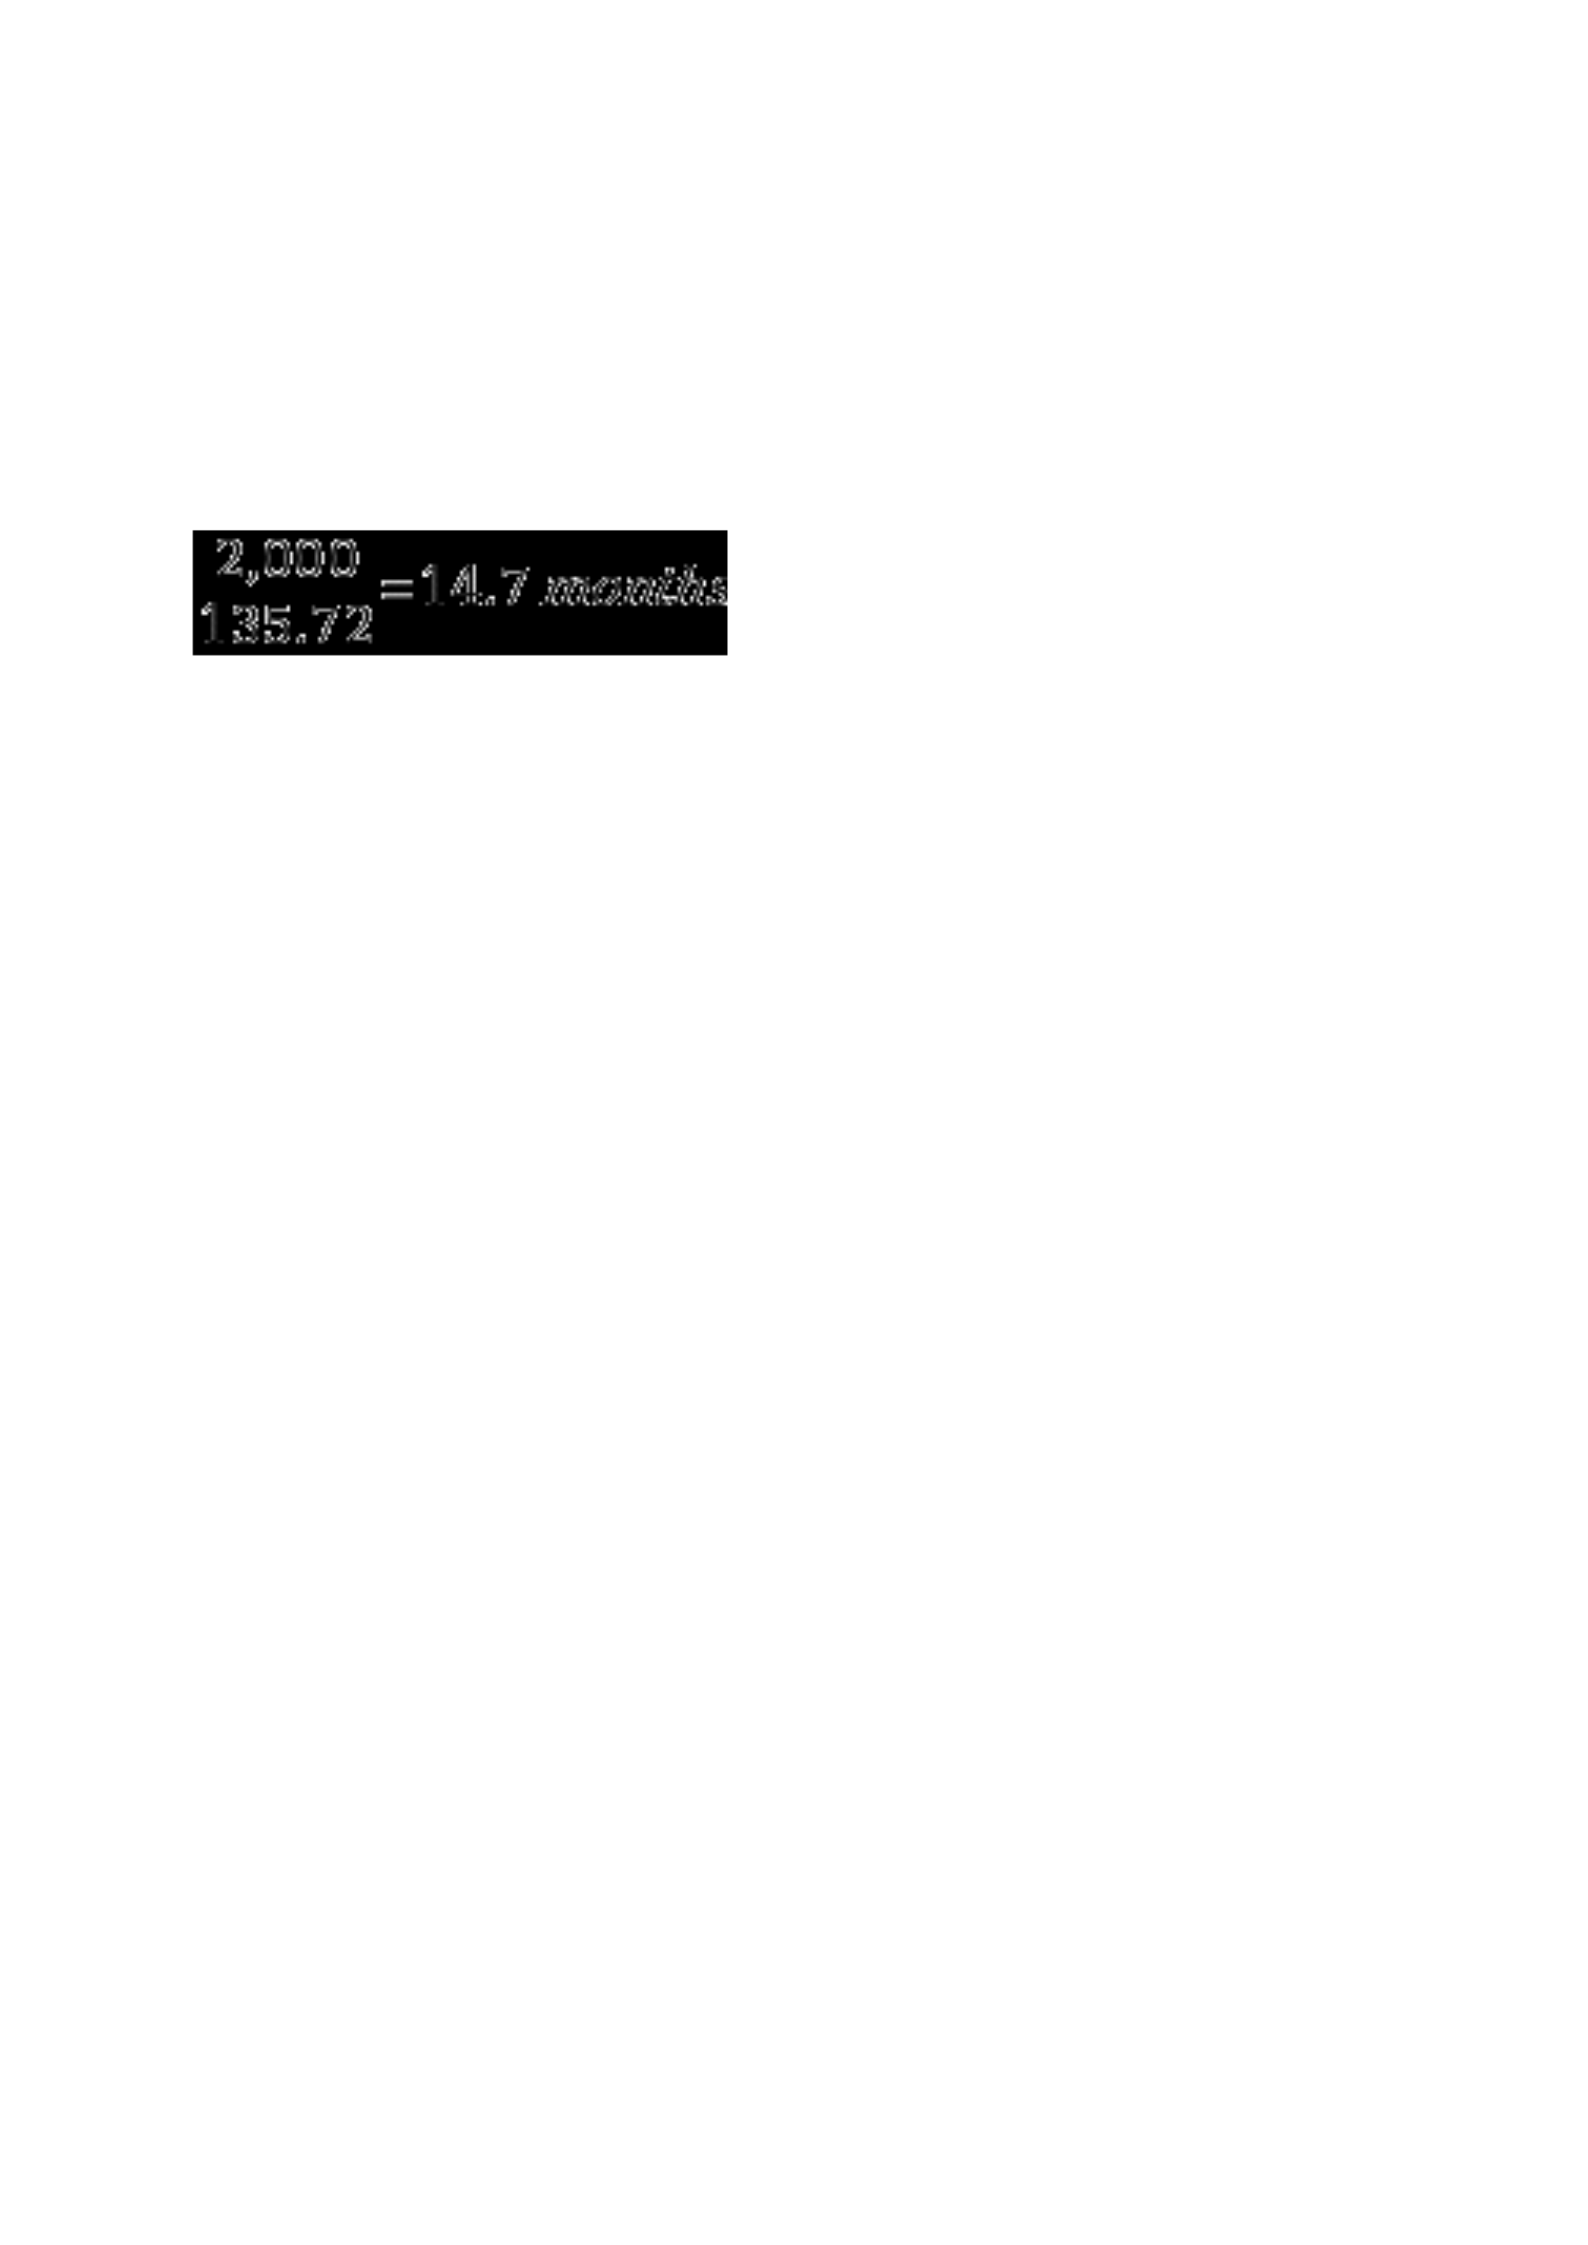
dividing the closing cost by monthly
savings. The breakeven point is
calculated below:
Thus, it is clear that the person
should refinance the mortgage, as
the monthly savings will be $135.72,
which will cover the closing cost of
the current mortgage 15 months.
However, there are some non-
quantitative factors that should be
considered. The first qualitative
factor that should be considered is
the period that the owner will hold
on to the property. The reason why it
matters is due to the ability to benefit
from decreased monthly payments.

For instance, in the case discussed
above it would be incorrect to
refinance the mortgage if the person
expects to hold on to the property for
less than 15 months, as the person
would be unable to benefit from
decreased interest rates.
Considering individual capacity of
paying back the loan is another
qualitative factor to be considered in
the process of ensuring that financing
the loan has been reached at. This is
justified by the fact that mortgage
lenders are always motivated to
know individual ability of financing
the mortgage in the event the
application process goes through. It

is always prudent to considered
changes in the interest rates which
have a significant impact in
determining how refinancing the
mortgage is to be done
(Parameswaran, 2011). For example,
if the economy is poor, Federal
Reserve Bank lowers interest rates
with the intention of encouraging
investing, maintaining normal
process of lending and preventing
chances of inflation occurring within
the economy.
Another crucial factor that
contributes to the decision-making
process is personal preference. A
decision-maker needs to feel that it is

acceptable to stay I debt for another
year (Parameswaran, 2011). Thus,
psychological factors may have a
significant role in the decision-
making process.
References
Parameswaran, S.
(2011). Fundamentals of financial
instruments: Stocks, bonds, foreign
exchange, and derivatives. Hoboken,
NJ: John Wiley & Sons.
Treece, K. (2022). Mortgage
Refinance Calculator: Should I
Refinance My Home?
Martingale Asset Management HBS:
Investment Essay

Introduction
Martingale Asset Management is a
quantitative value-oriented
investment management firm based
in Boston, Massachusetts. The firm’s
investment process is centered on
technology and data analysis, which
gives them an edge in investing. To
assess Martingale’s effectiveness in
managing 130/30 funds, investors
should consider the firm’s
performance history, market
conditions, risk tolerance, and
investment goals. Before making any
investment decisions, thorough due
diligence should be conducted.
Issues to Consider

Investors should consider several
factors when deciding whether to
invest in a 130/30 fund. Firstly, as
stated in the HBS case “Martingale
Asset Management” (Greenwood &
Viceira, 2011), they should assess the
investment manager’s experience
and expertise in managing such
funds. William Jacques, the CIO of
Martingale Asset Management, was
experienced in managing minimum-
variance strategies within a 130/30
fund framework. Secondly, investors
should evaluate the market
conditions impacting the fund’s
performance. As mentioned in the
article “Investing for Impact”

(Chowdhry et al., 2018), the
performance of a 130/30 fund is
influenced by market conditions such
as volatility and liquidity. Hence,
prospective investors should
consider these market conditions
before deciding to invest in a 130/30
fund. Thirdly, investors should
consider the risk-return trade-off and
whether the fund aligns with their
investment goals. According to the
research paper titled
“Implementation Matters” (Davies et
al., 2019a), loosening limitations can
enhance the probable yields of
factor-based approaches. However,
investors should weigh the benefits

of higher returns against the risk of
higher volatility.
Martingale’s Edge in Investing and
Performance Results
Based on the information provided in
the case, Martingale has an edge in
investing due to its quantitative
value-oriented investment approach
and use of technology and data
analysis in its investment process.
The firm’s chief investment officer,
William Jacques, was preparing to
present the backtesting and real-
time results of a new minimum-
variance strategy within the
framework of a 130/30 fund. The
outcome of the performance

evaluation was auspicious, indicating
that Martingale possesses both the
experience and proficiency in
administering 130/30 funds.
However, as Jacques notes, there is
still some uncertainty about whether
the results are a fluke of the data or a
reflection of a true market anomaly,
which highlights the importance of
conducting due diligence and
evaluating the firm’s performance
over a more extended period before
making an investment decision.
According to Chowdhry et al. (2018),
“Investors should consider the track
record of the fund manager, their
investment philosophy, and their

approach to managing risk when
evaluating the suitability of a fund for
their investment portfolio” (p. 865).
Investors should scrutinize
Martingale’s investment philosophy
and risk management strategies
before investing in a 130/30 fund.
The Growing Trend and Associated
Risks
The popularity of 130/30 funds is not
just a passing fad but a trend gaining
momentum. They have been gaining
popularity among investors as they
offer the potential for higher returns
compared to traditional long-only
investment mandates. This is
because 130/30 funds allow fund

managers to take short positions in
stocks that they believe will
underperform while holding long
positions in stocks that they believe
will outperform. This added flexibility
has the potential to increase returns
for investors. Nevertheless, as with
any investment option, 130/30 funds
come with inherent risks that
potential investors should consider
before reaching a conclusion. For
example, short selling risks unlimited
losses if the stock price rises instead
of falling. Additionally, taking short
stock positions may result in higher
transaction costs and taxes than

traditional long-only investment
mandates.
Benefits of Low-Volatility Strategies
By implementing a low-volatility
strategy within a 130/30 fund
structure, investors can achieve
higher returns than traditional long-
only investment mandates while
reducing the risk of significant losses
(Chowdhry et al., 2018). The 130/30
fund structure allows for a higher
degree of flexibility and the potential
to increase returns by taking short
positions in overvalued securities
and going long on undervalued
securities (Davies et al., 2019a). As
noted by Jacques in the case, the

performance results of Martingale’s
minimum-variance strategy were
very encouraging (Greenwood &
Viceira, 2011). However, investors
should always conduct their due
diligence and assess the firm’s track
record before making an investment
decision.
Suitability of Low-Volatility
Strategies
Low-volatility strategies are
appropriate for investors who
prioritize capital preservation and
steady returns and have a low-risk
tolerance. These strategies are
particularly suitable for investors
close to retirement or those with a

short investment horizon. The
130/30 structure balances potential
returns and risk management,
making it an attractive option for
low-risk investors. Chowdhry et al.
(2018) argue that the popularity of
low-volatility strategies has grown
due to their appeal to investors who
prioritize “the preservation of capital
and stable returns.” This makes them
particularly suitable for investors
close to retirement or those with a
short investment horizon. However,
as with any investment strategy,
investors need to consider the trade-
off between risk and return (Davies
et al., 2019a). The 130/30 structure

may offer higher returns than
traditional long-only investment
mandates, but it comes with higher
associated risks (Davies et al.,
2019b). Therefore, investors should
carefully assess their investment
goals and risk tolerance before
investing in a 130/30 fund or any
other low-volatility strategy
(Chowdhry et al., 2018). Low-
volatility strategies are appropriate
for investors who prioritize capital
preservation and steady returns and
have a low-risk tolerance.
Conclusion
In conclusion, investing in a 130/30
fund or a low-volatility strategy

requires careful consideration of
several vital factors. Firstly, the
investment manager’s experience
and expertise, as well as their use of
technology and data analysis, should
be evaluated by investors. Secondly,
market conditions play a significant
role in the performance of a 130/30
fund, and investors should be aware
of the factors that may impact
performance. Finally, investors must
understand their risk tolerance and
investment goals and assess whether
the risk-return trade-off aligns with
these goals.
Investments: Aspects of the Hedge
Funds Report

Introduction
It is well acknowledged that bias may
result in inefficient market prices
when it is used to make business and
financial decisions. This leaves the
potential for smart investments that
can take advantage of inefficiencies
in the market and investing process.
Hedge fund investments demand a
large minimum investment or net
capital from certified investors,
despite being viewed as a hazardous
alternative investment option (Liang
et al., 2022). Simultaneously, it is
essential to take into account a high-
potential approach that prioritizes

consistent returns and modest entry
barriers.
Discussion
The fundamental concept that can
have significant benefits is to
establish a small-size stock-focused
hedge fund. This is anticipated to
succeed since small-cap stocks
sometimes go unnoticed by
institutional investors, which causes
them to be undervalued (Sorensen &
Lancetti, 2020). Large investors
sometimes pass over small-size
stocks because they are thought to
be riskier, and these equities are
typically undervalued as a result
(Baker & Wurgler, 2012). Hedge

funds that are ready to take on
greater risk now have more options.
Since small-cap companies have the
potential to produce substantial
returns, success with this strategy is
anticipated.
The trading approach of this hedge
fund would be to purchase
inexpensive small-cap companies
and hold them for a protracted
period of time. Building a portfolio
should include selecting a diverse
collection of stocks with a small
capitalization that has the potential
to provide large profits (Liang et al.,
2022). The portfolio will be
frequently reviewed as part of the

rebalancing process, and
modifications will be made as
needed. The hedge fund can profit
from a potential revaluation of these
assets by purchasing and holding
these shares for a long time (Jena et
al., 2021). The process of developing
a hedge fund’s portfolio will attempt
to diversify its assets so that it is not
too exposed to any stock. By
regularly rebalancing the portfolio,
the hedge fund will be able to take
advantage of inexpensive stocks and
keep the portfolio’s diversification.
The lack of information and liquidity
in the stock market with a small
capitalization are two factors that

can theoretically lead to inefficiency.
Small-cap equities are less widely
recognized than larger-cap stocks,
and as a result, they are not as
actively traded, which results in
continued inefficiency. This can be
profitable for the hedge fund but will
require assessing liquidity and
information distribution (Sorensen &
Lancetti, 2020). It is crucial to
examine how funds function and
ascertain how long their superior
performance lasts in order to look
into inefficiencies (Canepa et al.,
2020). Thus, hedge funds might
provide better returns due to the lack
of knowledge and liquidity.

Because it is a risky investment, other
investors have not taken advantage
of this chance. Small-cap stocks are
harder to trade because they are less
liquid and more volatile than larger-
cap companies. These investments
are overlooked in the market due to
biases in business decisions and a
lack of transparency in different
sectors (Jena et al., 2021). These
equities are frequently undervalued
because of their more significant risk.
Hedge funds can, however, benefit
from the heightened risk by earning
larger returns. Due to the significant
risk involved, this opportunity would
not be accessible to regular

investors. Although they frequently
have a substantial investment
opportunity, they are frequently less
reliable and may not be lucrative.
Small-cap stocks are harder to trade
because they are less liquid and more
volatile than larger-cap companies
(Baker & Wurgler, 2012). Hedge
funds can, however, benefit from the
heightened risk by earning larger
returns.
The past success of small-cap stocks
serves as evidence that the
technique can work and be
profitable. Since small-cap
companies outperformed large-cap
stocks over the long run, this

approach is anticipated to generate
positive returns. Due to small-cap
companies consistently beating
large-cap stocks, this approach is
anticipated to produce substantial
returns. This dominance results from
the frequent undervaluation of
small-cap stocks (Sorensen &
Lancetti, 2020). This demonstrates
that this particular trading strategy
can deliver impressive results.
Data and empirical studies above
show that the trading method
performs better than other options.
Small-cap firms have outperformed
large-cap stocks historically,
therefore, investing in them is likely

to provide strong returns. It is clear
that trading tactics are more
effective when statistics and real-
world research are used. Historically,
small-size firms have outperformed
large-cap equities in terms of long-
term performance (Canepa et al.,
2020). This dominance results from
the frequent undervaluation of
small-cap stocks. As a result, this
approach could result in greater
returns for investors, potentially
leading to superior performance.
Conclusion
Overall, finding the correct kind of
investment is challenging for this
form of hedge fund. Although this

disadvantage makes it challenging to
take sizable commitments from
institutional investors while
maintaining performance, it can be
seen that the lack of scalability makes
it feasible to secure competitive
pricing on which to survive. While a
small equity-focused hedge fund will
never be able to match the profits of
a large, diversified corporation, it
may produce volatility and offer
steady returns.
References
Baker, M., & Wurgler, J. (2013).
Behavioral corporate finance: An
updated survey. In Constantinides, G.
& Harris, M. (Eds.) Handbook of the
economics of finance (pp. 357-424).
Elsevier.
Canepa, A., González, M., & Skinner,
F. S. (2020). Hedge fund strategies: A
non-parametric
analysis. International Review of
Financial Analysis, 67(1), 101436.
Web.
Jena, S. K., Tiwari, A. K., Dash, A., &
Aikins Abakah, E. J. (2021). Volatility
spillover dynamics between large-,
mid-, and small-cap stocks in the
time-frequency domain: Implications
for portfolio management. Journal of
Risk and Financial Management,
14(11), 531. Web.