


Investment Strategy and Loan Approvement
Abstract
Investment decisions are the most common decisions
that are normally made by organizations. Getting funds
approved is the second most important activity for a
company wishing to raise credit facilities to assist them
make investment. Investments may be international
expansion or acquisition of assets for diversification
purposes which will assist the company in growth. This
involves setting of strategies and always choosing or
setting a strategy of investment that is acceptable to the
loan provider. Investments are made under conditions
of uncertainty where the future is not known and is
uncertain but companies follow those uncertain routes.
This calls for proper decision making in the provision
of credit facilities.

The study was set in a commonwealth bank of
Australia and bank of America ; An American bank
one a multinational bank while the earlier is an
Australian bank that has successfully entered the
international market with her presence felt in Australia.
Both offer business loans for expansion in various
countries. In my study have to identify and strategies
implemented by each bank, their risk analysis process
and how the risk is calculated before a loan is given
and the effect of the strategy to its market
competitiveness.
Every Bank executive and managers wants to move
forward should take this study serious. The main
purpose of businesses is the maximization of goals. In
order for banks to achieve these goals in this era of
corporate sustainability, fraudsters and corrupt loan

there is need to move towards best methods of
assessing the credit facility and come up with criteria
to use issue of loans. Banks need to develop strategies
that will lead them to grater heights in the world stage
market.
Therefore, to accommodate the rapid changes
occurring in the business and banking world, quick
decisions about loan approving strategies are made and
well communicated.. This study is paramount to the
banks understudy because the research will assist in
decision-making.
Introduction
The speedy processing of credit facilities in banks are
very vital especially when banks need to keep

customers satisfied to bank with them and increase
market share but reduce risk of losing funds. In the
recent past banks have embarked on quick credit
facility processing so as to get and maintain more
customers into their banks. This is because they want
to win market share (to have a large market share). The
key to improving on profits is to get more clients, win
the market share, keep the existing customers by
making them to be loyal and then benefits will
definitely increase by day. However, customer’s
loyalty and large market shares do not bring in profits
to the banks always and this need to be checked
thoroughly.
For example, we have prestigious customers who are
on their segments. Banks have divided customers into
segments, which have customers who have similar

needs and are worth broadly in the same economic
value. Under these propositions, we have the prestige
proposition. Non prestige customers have large
amounts of money invested in banks but they do not
always bring in profits because they have large costs
which are associated with them because they need
personalized banking, they also need special attention
and on the other hand they might demand special
services which are additional costs to the bank. So for
the past years, companies have decided to embark on
quick loan credit facility processing because they have
realized that this service and value are intrinsically
linked and the way you handle a customer means a lot
and this is how the bank will get more and more
clients.

Banks have tried to differentiate themselves for
competitors through providing better customer service.
Consistent delivery of superior loan service requires
the careful design and execution of a whole system of
activities that include people, technology and good
processes. This will lead to more revenue from
customers who will be impressed with services
provided. To do this, banks embarked on creating loans
and financial strength of their customers can be sought
through monthly statements. After this, they enhanced
the customer’s profitability before advancing any
credit facilities. This is the analysis of the value bought
in by the customer against the cost of loans facility
issued to the customer owns.
So each customers cost and revenue is known to
measure whether the customer is a loyal customer who

has no profits to the bank or whether he is a long-term
profitable customer who needs nurturing so that the
bank can give the customer the nurturing he deserves
that issue quick loan facility. They should also need to
know about short-term customers who need to be
exploited before they pull out. This will all lead to the
quick credit facility issuance that will keep the
customer in the business.
Background of study
Banks have also embarked on segmentation of their
customers into different value propositions according
to the profitability of customers, which influences
credit facilities. This is when the 80-20% profit
generation against customers arises from. Banks
customer segments have people with similar needs and
worth broadly in the same economic value, earn almost

similar income etc. They are given a combination of
services, products, prices and branding which fit them.
This is called managing customers according to
segments. Banks also compute the lifetime value or
profitability of customers through forecasting and use
of strategies like introducing new products that will fit
the customers in future. Banks can also modify existing
products to fit customers in a particular way hence
making them satisfied and this will lead to increased
revenue.
Banks should also try to come up with strategies that
are directly related to how they know the credit
worthiness to increase the rate at which credit is
processed so as to solve their needs. Customer
understanding is vital because a good strategy is that
which is related to the improvement of bank products,

whether asset products like loans or liability products
where bank entrust their money to the customer. This
means banks should come up with strategies aimed at
particular target customers to understand their
investment strategies. This type of strategy is
persuasive in that it explains to customers why they
should take credit facilities. it also shows that the credit
facilitates depends on other factors not only the
investment strategy
Banks can also pick on the behavior based
segmentation strategy and this involves looking at past
and present relationship of the customer and the bank
before giving loans or any other credit facilitates.
Banks should look at how long a client has been in the
bank.

Has the client been on and off-has he ever left the bank
for another bank and back? They should also look at
the value of customers in terms of how much money
the customer has in the bank or how much he has
borrowed or he is willing to borrow. Segmentation of
clients is important in banks because customers are
given a bundle of benefits that have been used.
Geographic- should be also be used and is where the
banks take into account the geographical boundaries
and this majorly assists the bank in staffing and
opening of new branches and also to assess market
potential. They have also been using psychographic
segmentation that deals with customer lifestyle, tastes
and preferences, why customer want a particular
product instead of the other.

The demographic segmentation deals with dividing
customers according to age, stage in life cycle etc. and
it helps banks to design production for all types of
people depending on their age, income, etc. this also is
another factor that is considered in according credit
facilitates.
Apart from the behavior based segments, the bank can
also adopt segmentation, depending on what the bank
wants and not what customers want, banks have
different value propositions that it wishes to give
customers hence it will segment its products according
to its value propositions and as customers take them
they automatically fall to segments. The banks have
three major objectives and these are get deposits and
minimize the cost of funds producing quality credit
balances at maximum spread income and to generate

free income and reduce services expenses. This leads
to the following four segments. There are those people
who want to invest others want to borrow, others want
convenience and on others are fast limited customers.
These segments can be used as a basis for the bank to
develop long-term strategies, to attract customers to the
different segments.
As much as strategies are good, bank should avoid
using one strategy for all products or marketing
applications effective segments or marketing
applications effective segments. A strategy will vary
according to what are the marketing objectives. In the
case of attracting new customers who have no history
with the bank. The bank will come up with a wedge
product strategy where they give customers of other
banks a chance to sample some of its products or

services for the time being and this will enable them to
cross-sell more profitable products to them and create a
long lasting relationship with them. This is done by
direct marketing for example they can send letters to
customers requesting them to try products or phone
calls.
In making existing customers to be more profitable, the
bank should study their behavior carefully and give
them the most appropriate product or service that can
turn a marginally customers, their lifestyle and the
amounts of cash they handle and the needs comes from
good data management. When the bank can use the
data it has to identify best ways in available banks,
database can enable them to know which customers are
profitable, marginally profitable and unprofitable.

Apart from keeping existing customers, banks also
need get more and more customers by prospecting well
and turning these prospects to potential customers. The
methods we have seen that are employed here is the
direct mail methods and telephone calls. Geographical
prospects can also be employed by use of strategic
positioning of new branches at areas where trade is
high and directing advertisements to such areas to lure
more customers into the banks customer base,
whichever the method, banks have realized that CRM
is very important because it concerns more on
customer satisfaction rather than products.
Most banks then have realized that in order to
understand customers well and this information is in
the banks database. There should be therefore good
management of data that gives information about the

customers and whether they are profitable or not. For
good data management, banks should ensure that:
1. They have relevant and accurate
data(information) about the customers,
2. Develop daily, weekly, yearly etc analysis of
customers’ profitability and
3. Develop tactics on these segments that modify
behaviors of both customers and employees to
increase sales and revenue while lowering costs.
Banks should ensure good data management by careful
collection of customer data, turning this data into
knowledge and then using this knowledge to develop
strategies and tactics to modify behavior of both
employees and customers and prospects to improve
long-term profits.

Banks should realize that just aiming at having a large
market share is not enough to generate profits. They
should also ensure that they do good customer relations
management in order to achieve good results. This is
by understanding their customer needs well and then
the bank will match the customers with available
products to ensure maximum customer satisfaction.
They should also manage customers well by
segmenting them into useful segments based on
profitability so as to give them beneficial value
prepositions that will make them have good long-term
relationship with the bank and hence increase the
profitability.
Using the information kept will determine the approve
of the loan facilities although there are other factors

which are related with the strategies of the loan seeker
but they are less influential as compared to banks own
information.
Statement of the Problem
Making a decision, how to give loans to customers and
how it should be done with the support of the
management is difficult and had to believe. The
conventional analysis of customers investment strategy
has looked simply at efficiency of customer awarding
of a loan as compared to the efficiency of banks to
detect the losses that will be incurred using risk
analysis : if the cost of risk analysis is greater than the
cost of administering within the bank, then banks needs

to change the method of assessing the customer credit
worthiness.
Transaction cost analysis does not, however, provide
the complete answer. In the first place, customer credit
facilities strategies are not simply accept or reject
choices—there are wide varieties of ways in which a
bank can structure credit facilities to attract customers
to product. Secondly, the most critical long-run
consideration is the development of banks capability to
award credit quickly. If a bank is to sustain competitive
advantage, it must restrict itself to those activities
where it possesses the capabilities that are superior to
those of the other banks that perform those activities.
The most difficult issues arise where there are linkages
between customers’ investment strategy and banks risk
analysis strategies.

Ultimately, investment decisions revolve around two
key questions. First, which activities will we undertake
for profitability and attract sponsorship? Second, how
do convince the bank to attract their credit facilities
and increase our profitability?
Purpose of the Study
The objectives of this study is
To identify the strategies implemented by banks
to attract credit facilities and how they are
developed.
How customer investment strategy and banks
risks assessment affects the rate of loan issuance.
Assess the relative merits of the strategies and
loan transactions in organizing customer loan

processing and related activities and understand
the circumstances that influence their
comparative advantages.
Identify a range of possible factors that influence
among banks and related firms loan processing.
Identify scenarios of various strategies affecting
loan issuance.
Explain why some types of strategies and related
activities are integrated within a single bank,
whereas others are performed by separate banks.
Identify the critical considerations pertinent to
make-or-buy decisions and the extent to which a
bank should adopt.
To achieve the objectives I will go through case studies
of two banks whereby the concept of customer

relationship and product development strategies are in
use.
The scope of the study
To understand investment strategies and strategies that
relate loan issuing of to their customers, services and
diversification for banks, a comprehensive analysis is
carried out to ascertain the various needs of customers
in the banking sector in relation loans approval. This
research project is on two banks. In carrying out this
project, certain constraints will inhibit effective study,
firstly due to short deadline period to finish this write,
time factor will render certain aspects not to be
examined in details. Secondly, the study assumes that
effective and efficient management and application of
loan approval strategies are the determinant of
performance and greater market position of banks.

This due to the fact that if customers don not have
money the banks will be doing badly.On the other
hand, in economic reality, there are features that affect
performance and market position of banks and
companies such as Capital deployment, employee’s
motivation, organizational structure, organization
capacity, supply chain management and technology.
However, this study does not consider these factors.
This study also assumes that all strategies applied by
two banks are geared towards increasing speed of loans
approval in terms of increasing the market share. It
also assumes that they are ready to implement are
customer friendly strategies that increase the market
share. Nevertheless, this is not the case in the real
strategic management situation in as these strategies
are often separated and could be use for survival.
Significance/Importance of the Study

My research study will be of great value to future
researchers, management of banks, investors, educators
and others because:
To highlight the important role that investment
strategies play on the bank’s market share and
customers satisfaction.
It highlights how customer investment strategies
are made and how they strategies affect the bank
market share.
It helps the management in making strategic
decision-making.
Determine the risk preference function for the
centre of the bank
Determine which risk measure(s) are compatible
with this risk preference function

Assess the relevance of coherency for the
internal risk measure(s)
Assess the impact of the structure of the
compensation payment function on portfolio
selection and incentive-compatibility
Identify how agency problems impact on the
performance measurement framework
Design a solution to deal with agency problems
Evaluate how bank-wide factors impact on the
decisions of managers and the assessment of
their performance.
Research Questions
The key questions for the research were set as follows:
how does the target credit rating of the bank
influence portfolio selection and pricing?

When might a higher solvency standard
beneficial to a banking firm?
should hurdle rates adjust in line with changes in
the target credit rating of a bank?
Which credit rating implemented by the two
banks and they how have they developed them?
What are the advantages of each form of form
strategies?
What are possible relationships among vertically
related banks and, including spot market
transactions and strategic alliances?
What is the relationship between the investment
strategies?
What loans approval strategy is favorable to
bank board members?
What is in house policy and what is it used for?

Are the policies of the two banks different from
those of competitors?
Assumptions regarding the hurdle rate, and in
particular, whether it should adjust to reflect changes in
leverage, are critical to determining the optimal credit
rating for a bank. This in turn impacts on pricing
decisions and the market value of credit portfolios, and
consequently, the risk-adjusted performance measures
of portfolios under the control of managers. A loan
pricing model was constructed to test the impact of
changes in the target credit rating of a bank on the
pricing of its loans.
The decision of a bank to increase its solvency
standard increases the minimum interest rate on its
loans in order to achieve the required hurdle rate on
capital assigned to the loans. Offsetting this upward
pressure is the impact of the reduced funding costs

arising from the higher credit rating. If retail deposit
rates are insensitive to an upgrade in the credit rating
of bank debt securities, we find that the benefits to a
bank from increasing its target credit rating rest with
the extent to which the cost of wholesale funds falls
relative to the increase in the price of bank loans.
Research Hypothesis
The following hypothesis will guide the research:
H1. On average, behavior segmentation in loan
approval will be similar all the banks and the
sample will be a true representative.
H2. The investment strategy of the loan seekers
will be positive or negative depending on the
motive and the customer management embraced.

H3. On average, risk of the investment of the
bank customers will be more powerful predictors
of customer relationship management.
H4. All banks makes choices of the credit facility
management without the banking sector
regulator interfering.
H5. Bank customers of banks are aware of the
loan application rules and willing to served by
them.
H6. Risk assessment depends on the policies of
the banks.
H7AThe ideas underlying the problem-solving
task to be solved is understood by key players in
the industry.
Loan approval is very powerful in shaping the banks
profitability and the investor’s success. The result

obtained can not be ignored it should be used to make
some few changes in the banking sector and investors
strategies. Banks are an important sector in the circular
flow of money in any economy and thus the beginning
of economic development of a country. Therefore it is
an important sector that should be managed with care.
Limitation of the Study
This research project is on a session of the project. In
carrying out this project, certain constraints will inhibit
effective study:
1. Time factor will render certain aspects not to be
investigated in details because of the deadline
period to finish this thesis,
2. The study assumes that effective and efficient
management and application of investment
strategies are the sole determinant of loan

approval. However, in economic reality, there
are features that affect loan approval such as
Capital deployment, employee’s motivation,
organizational structure, organization capacity,
supply chain management and technology.
3. My study also assumes that the all loan approval
strategies will be applied by banks and they are
geared towards increasing market share banks.
Delimitation of the Study
The researcher is a student, he will be carrying out the
research with the trust that managements will co-
operate.
The research will be carried out by a full time student
thus having enough time for coverage of the topic.
The researcher will access the banks with easy because
of he is an insider that is he works in the baking sector.

Definition of Terms
The terms that are in use in this thesis are defined in
the context in which they are being used in this
research and they are as follows:
Strategy:Strategy is the direction and scope of
an organization over the long term, which
achieves advantage in a changing environment
through the configuration of resources and
competencies with the aim of fulfilling
stakeholders’ expectations.
Market share:This refers to the total sales of a
bank divided by the total sales of other firms for
a specified product –market. It may be
calculated on the basis of actual sales or forecast
sales.

Intended strategy:This is an expression of
desired strategic direction deliberately
formulated or planned by managers.
Overview Summary
This section gives a general outline of the main parts of
this Thesis. It will have an abstract and five chapters
written and each chapter will contain the following.
Abstract
The final report will begin with an abstract that will
summarize the topic, the findings and the importance.
Executive Summaries
This will summarize all the chapters and the
conclusion reached.
Chapter I

The chapter will have introduction, which will explain
issues surrounding the topic and the importance of the
study. Then there will be background information that
will cover topic and the banks under study , it will also
provide with an overview of the study, purpose of the
study, research question, research hypothesis,
limitation and delimitation, Significant of the study and
definition of the terms used.
Chapters 2
This chapter covers literature relating to the topic
under study and in my case this will cover an
introduction, literature review, Collection of theories
and secondary sources and Criticism of secondary
sources

Chapter Three
In this chapter the researcher will explain the
methodology used that is the Research Approach, the
Research Design and discussion of its quality, validity
and reliability, , The Target company, Procedure,
Instruments for data and continuous prose collection
and data analysis technique.
Chapter 4
This chapter contains empirical data presentation,
which is made up of the strategies implemented by
banks and their market situation.
Chapter 5
This will be the last chapter. It will contain summary of
the findings recommendations and conclusion.
Literature Review
Introduction

This is a literature review of investment strategy, risks
associated with investments and standards set out for
loan issuance. The literature consolidates information
from various literatures written by various groups,
scholars and central bank. The thesis will differentiate
between the capital budgeting decisions of companies,
cost of capital, risks associated with loans and other
related issues. Analysis on credit facilities will be
carried out and this will be in form of scholarly written
documents,.
Collection of theories and secondary sources
The researcher will use books available in the
University for the Collection of literature. The
computer laboratory in the university and personal
computer in the house has contributed greatly in the
success of my project through the access of scholarly

written documents available in the internet. Therefore,
the process of gathering data from articles, journals and
books is done primarily by the use of university
material. The research on internet was done through
funnel manner by using key worse such as cost of
capital, credit worthiness and issuance of loans. The
World Bank and reserve bank facilities that have been
used will also be acknowledged.
In addition, the government and other state documents
have been used intensively as supplementary sources
during the search of information for this project.
Factors influencing capital decision
In any manufacturing organization, the largest dollar
investment maintained is in fixed assets. Fixed assets
are necessary for production and without them their

will be no production. Each firm maintains fixed assets
depending on their nature of production processes.
Because of change in techno lodge and competition,
organization make capital expenditure specifically to
acquire, replace, or modernize fixed assets or gain a
less tangible benefit over along period of time.
Capital Budgeting
This is the overall process of generating, evaluating,
selecting and following up on capital expenditure
alternatives. In most cases, firms are affected by the
amounts available for this process and the type of the
proposal they are undertaking into consideration.
Because of this constraint, firms opt to undertake those
projects which maximize their benefits in the long run.
They can also rank the proposals according to the
predetermined criterion and choose the best depending
on their returns to the company. Further a company can

limit its funds such that only those proposals that yield
high return in the long run will be accepted whereas it
can accept all the projects considered if its funds are
unlimited.
Availability of funds
This affects capital budgeting because if a firm has to
incur any capital expenditure it must have some funds
to use. Therefore it affects the decision process making
environment of the management as to how much to
spend. Some firms have unlimited funds for investment
hence making the process even cheaper but others have
limited funds meaning that the amounts for capital
expenditure is fixed normally specified in the company
annual budget. Where there are unlimited funds the
company accepts all projects that yield gains higher
than the predetermined level. If it is limited, the
organization ranks the proposals and chooses the best.

Firms use cash flows to measure their ability to acquire
the proposed assets or pay bills
Type of the Project
The firm has to establish the best project from a
number of different proposals available. This is
difficult because any project undertaken must be
capable of bringing high returns to the organization in
the long run. Some projects are independent such that
acceptance of one project does not eliminate the
consideration of the others. Whereas others are
mutually exclusive meaning that in allocating funds to
these projects, the firm has to rank them according to
the long term gains.
The cost of the new projects

This is the outlay of the intended fixed asset and
normally the purchase price is definite. The firm must
consider its available funds for purchasing this new
asset. This is done by measuring its net cash flows
which is called net investment. If the company is not
replacing an existing asset and does not incur any
installation cost, then the purchase price is equal to the
net investment.
Installation costs
These are extra costs incurred to make the machine
into operation and all this must be recognized by the
firm and capitalized. This is because they are part of
the initial cost and they should be capitalized.this will
enhance accuracy of determining depreciation.

Loans
A loan is an arrangement whereby the lender, which
may be a commercial bank or commercial finance
company, receives control of the pledged collateral.
This arrangement provides the lender with the ultimate
degree of security.
Lending procedures
In the case of a loan, the lender selects the collateral
that is acceptable as collateral for the loan. Once the
collateral has been selected, the lender takes or hires to
physically take possession of the collateral.
Terminal warehouses (inventory loan)
A terminal warehouse is one located in the
geographical vicinity of the borrower. It is a central
warehouse that is used to store the merchandise of
various customers. A terminal warehouse is normally

used by the lender when the inventory used as security
is easily transported and can be delivered to the
warehouse relatively inexpensively. When the goods
arrive at the warehouse designated by the lender the
warehousemen checks the merchandise in. he lists each
item received on a warehouse receipt, noting the
quantity, serial or lot numbers, and the estimated value.
Once the warehouseman has checked in all the
merchandise, he forwards the warehouse receipt to the
lender, who then files a lien on all the items listed on
the receipt.
Field warehouses
Under a field warehouse arrangement, the lender hires
a field warehousing company to actually set up a
warehouse on the borrower’s premises or lease part of
the borrower’s warehouse. There are a number of
companies in the united states that specialize in

establishing field warehouses for a fee. The procedures
followed by the field warehousemen are quite similar
to those followed by the terminal warehousemen. Once
they have isolated the inventory to be used as
collateral, they check it in, listing the items and their
characteristics on the warehouse receipt, files a lien on
the pledged collateral. A field warehouse may take the
form of a fence around a stock of raw materials located
outdoors, it may consist of a rope-off section of the
lender’s warehouse, or it may actually be a warehouse
constructed by the warehousing company on the
lender’s premises, which have been leased by the
warehousing company.
Regardless of whether a terminal or field warehouse is
established, the ware housing company places a guard
over the inventory. Public warehouses always have a
guard; under a field warehousing arrangement, a guard

is stationed by the warehoused collateral. The guard or
warehouseman is not permitted to release the collateral
without authorization from the lender. In other words,
the lender has complete control over the inventory used
to collateralize the loan. Only upon written approval of
the lender can any portion of the secured inventory be
released.
The loan agreement
The actual lending agreement will specifically state the
requirements for the release of inventory. As in the
case of other secured loans, the lender accepts only
collateral believed to be readily marketable and
advances only a portion of the collateral’s book value.
The types of collateral normally found most acceptable
for warehouse receipt loans are canned foods, lumber,
refined products, and basic metal stocks. The loan
agreement typically provides for the release of certain

pledged items upon receipt of partial repayments of the
loan. The lien on the released merchandise is, of
course, removed.
Although most warehouse receipts are nonnegotiable,
some are negotiable, which means that they may be
transferred by the lender to other parties. If the lender
wants to remove a warehouse receipt loan from his
books, he can sell a negotiable warehouse receipt to
another party, who then replaces the original lender in
the agreement. In some instances the ability to transfer
a warehouse receipt to another party may be desirable.
The cost of warehouse receipt loans
The specific costs of warehouse receipt loans are
generally higher than those of nay other secured
lending arrangements due to the need to hire and pay a
third party (the warehousing company) to guard and
attend to the collateral. The basic interest charged on

warehouse receipt loans is higher than that charged on
unsecured loans. It generally ranges from 3 to 5 percent
above the prime rate. In addition to the interest charge,
the borrower must absorb the costs of warehousing by
paying the warehouse fee, which is generally between
1 and 3 percent of the amount of the loan. These
charges vary depending upon the size of the loan and
other factors. In some instances the firm’s marginal
warehousing costs are small since they have to
warehouse the inventory anyway. The borrower is
normally required to pay the insurance costs on
warehoused merchandise.
Whenever warehouse receipt loans are arranged, it is
important for the lender to select a reputable
warehousing company. The warehousing company as
his agent is responsible for seeing that the collateral
pledged is actually in the warehouse. There have been

instances in the past where receipts against nonexistent
collateral. If this happens, and the borrower defaults on
the loan, the lender is in the same position as an
unsecured creditor.
The main features and complexities of capital
budgeting
Capital budgeting involves the decision making for
long-term projects or investments for company. It
involves the for following decision making model:
1. identification of objectives;
2. search for investment opportunities;
3. identify states of nature;
4. list possible outcomes;
5. Measure payoffs;
6. select investment projects;

7. obtain authorization and implement projects;
8. review capital investment decisions.
The effects of inflation on future cash flows and the
required rate of return
Always the discount rate of return has required rate of
return on a risk less investment plus the risk premium
that is associated with the project risk. Inflation affects
both the risk free rate and the risk premium. In order
for one to incorporate inflation in the future, cash
flows, the interest rate has to be adjusted for inflation.
Fisher proposed the following formula for adjusting the
required rate of return.
(1+nominal rate of return)= (1 + real rate of interest) x
(1 +expected rate of inflation)

Using the above rate of return as an example and the
inflation rate of is 8%. then applying the fisher
equation it would be
(1+0.0925)(1+0.08)= 1.1799
The nominal rate of return then it would be 17.99%.
This means the shareholders who were earning at 9.25
for every 100 before inflation for the time value of
money will now earn 17.99 for every 100. if the return
is less than that then they will be loosing.
Inflation also affects the future cash flows. Take for
instance; assume that you expect a cash flow of 1000
in one year’s time the rate of inflation remains at 8% as
used above. The expected cash flow will be 1080
instead of the expected. However, the investors will
not better off than when receiving 1000 without
inflation
Capital budgeting under uncertainty of cash flows
Uncertainty exists where there are several possible
outcomes, but there is little previous information or
statistical evidence to enable the possible outcomes to
be predicted. There many methods of handling
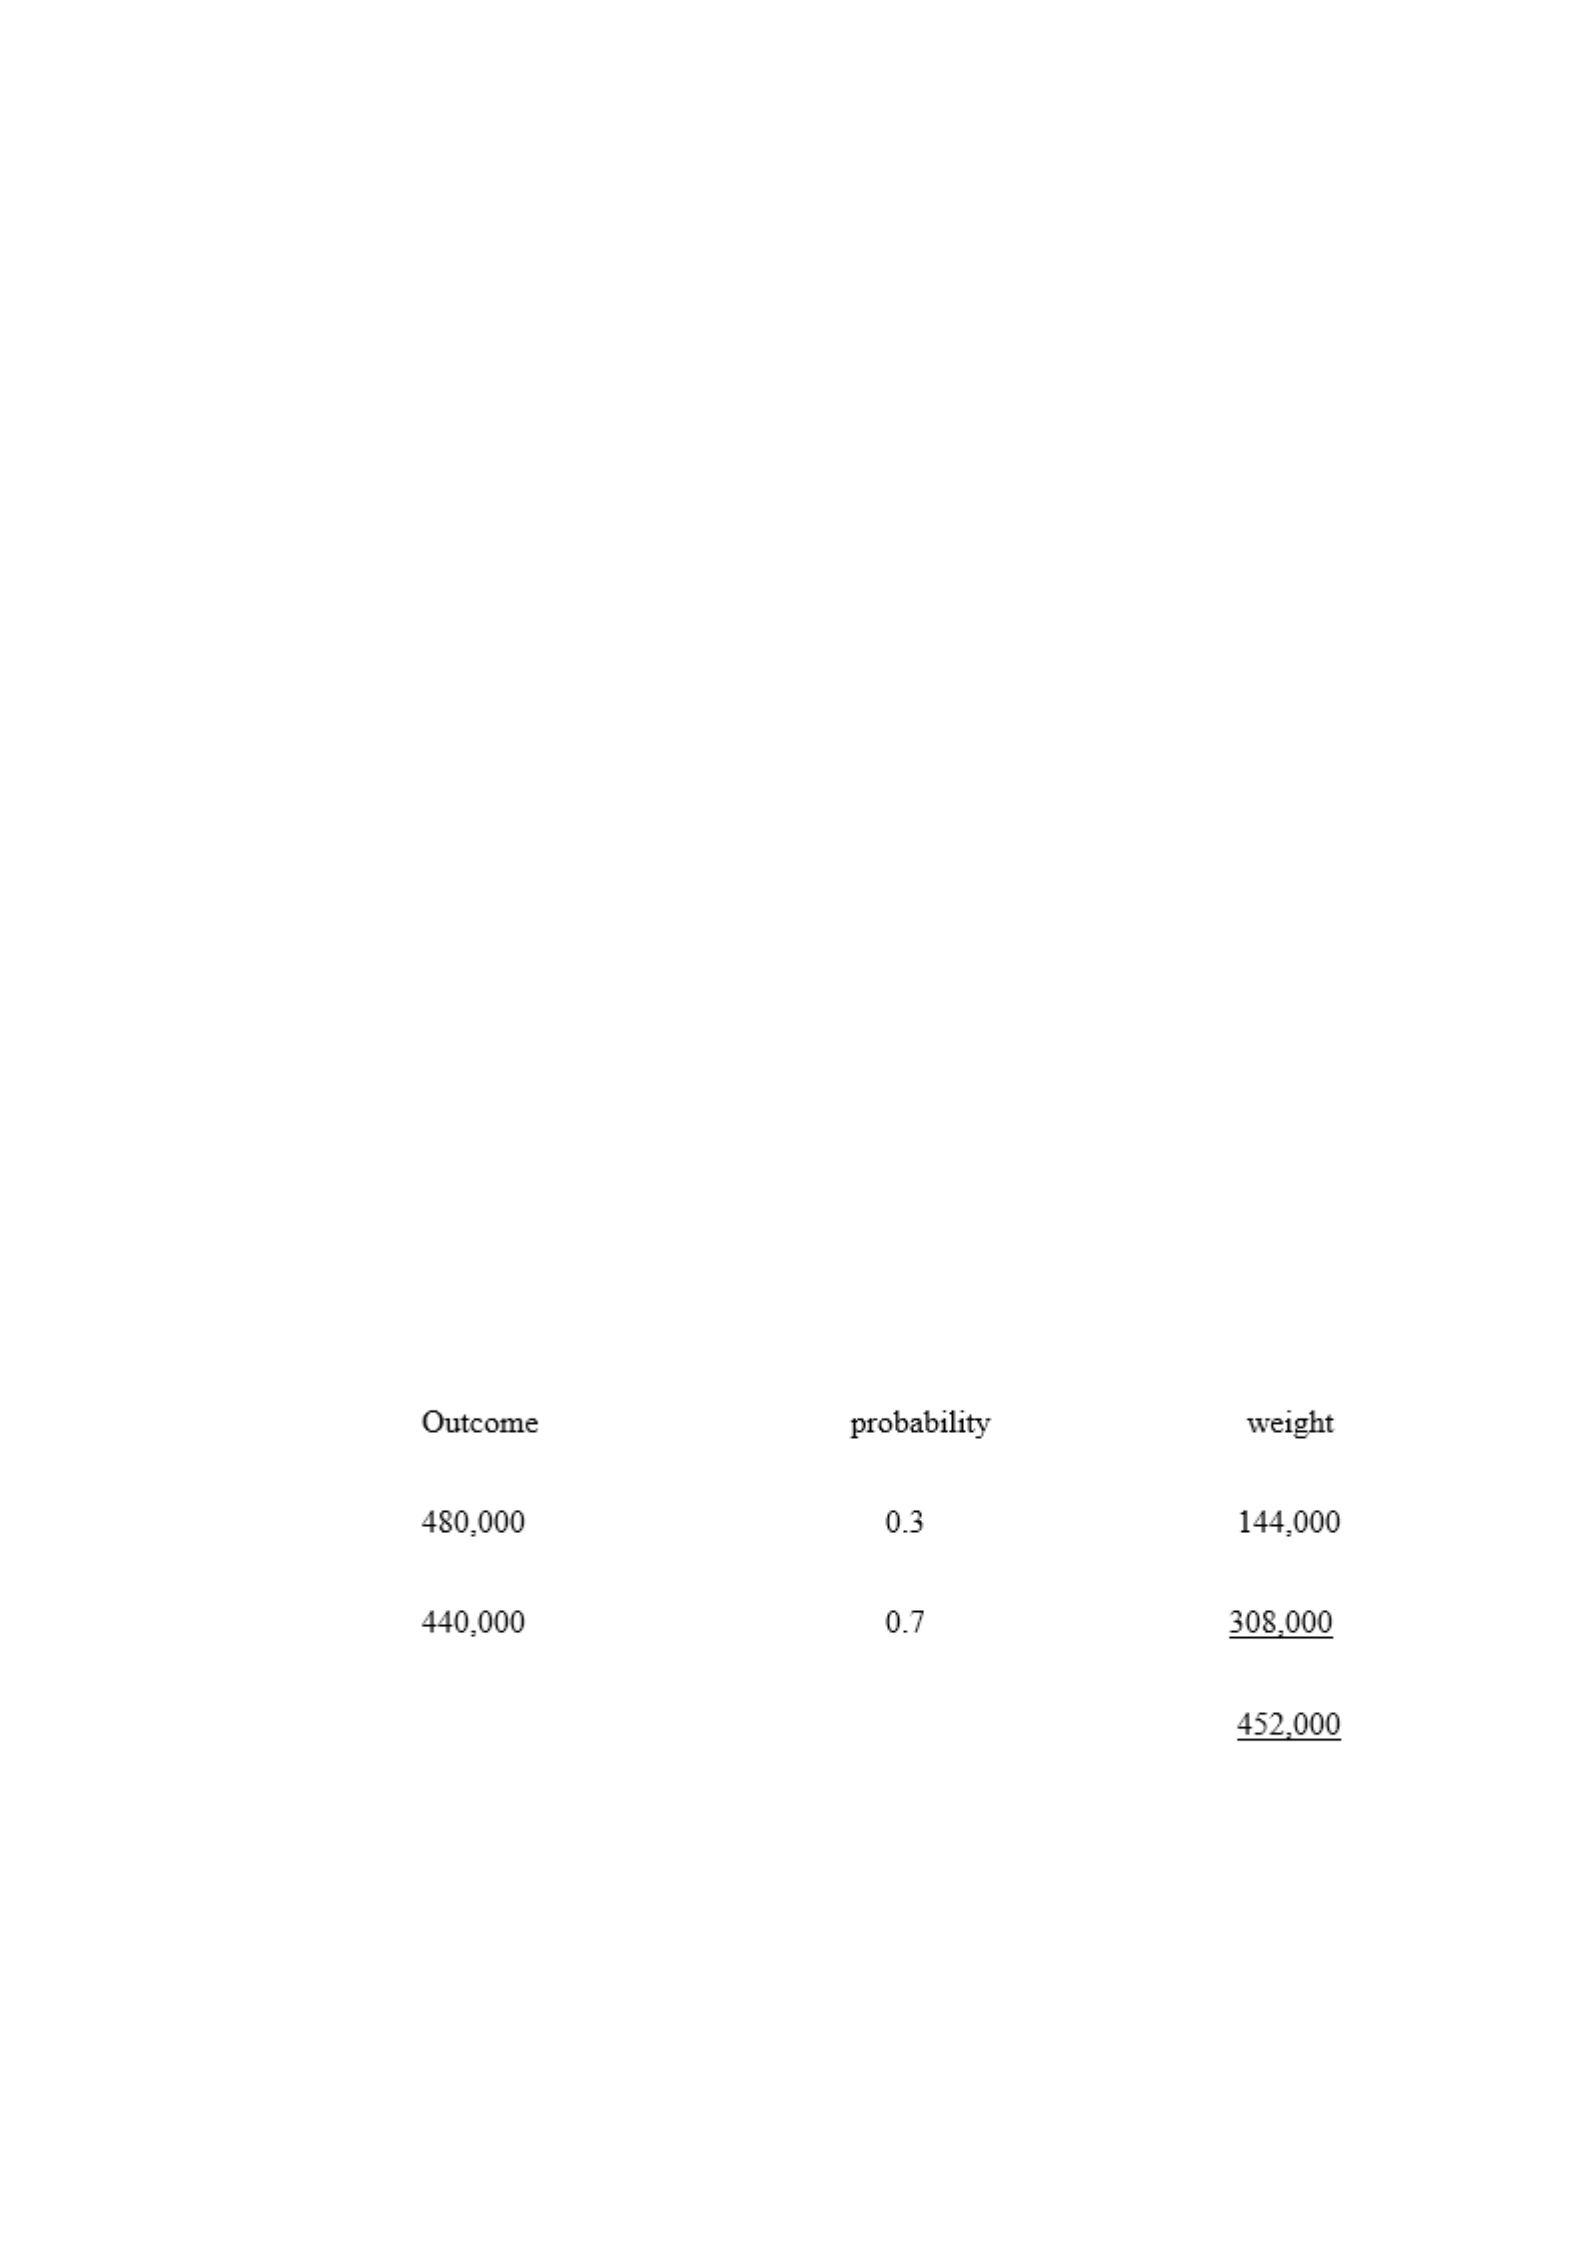
uncertainty this includes (1) probabilities; this is the
likelihood that an event is will occur for example using
the above data given and assuming that the
probabilities of having 440,000 per year is 70% and
probability of having 500,000 is 30%.
Then the cash flows will be as follows

The cash flows that will be subjected to measure NPV
analysis will be 452,000.
From the probabilities that some cash is likely to be
earned then standard deviations is used to measure
dispersion of the probabilities.
Investment risk
Assessing the risk attitude of bank owners is more
contentious. When limited liability and the regulatory
safety net are taken into consideration, bank
shareholders may be risk-seeking and have a convex
risk preference function. If a bank carries significant
franchise value, however, owners may prefer that the
bank acts in a risk-averse manner in order to preserve
the associated benefits. In this case the objective
function for the bank would be concave. This also
assumes that the owners are concerned with total bank
risk, and not just systemic risk.245 On the assumption

that the value of the franchise to bank owners exceeds
the value of the option associated with limited liability,
we make the assumption that bank owners will also be
risk-averse.
Consequently it was concluded that the bank risk
preference function should possess the characteristics
of non-satiety, risk-aversion and a preference for
positive skewness in the distribution of returns.
Stochastic dominance is used as the methodology to
rank portfolios in accordance with the risk preferences
of the centre. The key to using stochastic dominance
criteria is that the methodology allows portfolios to be
ranked without having to specify the exact form of the
investor utility function – different orders of stochastic
dominance correspond to different classes of utility
function. Third-order stochastic dominance (TSD)
criteria embody non-satiety, risk aversion and a

preference for positive skewness in the distribution of
returns. This makes it the most applicable criteria for
risk-ordering portfolios given our conclusions
regarding the characteristics of the risk preference
function of the centre.
It was found that the lower partial moment of orderAn=
2 (LPM2) provides a measure of risk that is consistent
with the risk preference function of the centre. More
specifically, portfolios that dominate by TSD criteria
are decreasing in risk according to the LPM2 risk
measure. The quadratic power function in this measure
means large deviations from the loss threshold receive
a greater penalty than smaller deviations in the risk
measure – consistent with a risk-averse attitude to
losses and a preference for positive skewness in the
distribution of returns.

Methodology
Introduction
The intention of research is to identify factors that
influence issuance of loans to individuals and how
individuals get past against them. The research looks at
strategies that are implemented by banks. The research
is based on two companies, the bank of America and
the common wealth bank of Australia.
Research Methodology
The main objective of this dissertation is to identify
how the chosen research methodology will match the
main objective of the dissertation question and how it
will be achieved. Essentially, there are two types of
research methodology; they are qualitative and

quantitative research. While the quantitative research is
carried out through obtaining primary data such as
questionnaire, qualitative research is a research that is
conducted through interviews and observations.
Therefore, the method enables a researcher to explore
the details of individual perceptions over phenomena.
Research Approach
The research approach that develops the methodology
explained below is based on descriptive research
theory and inductive reasoning. This is important to
develop the foundation by which the research will be
designed, conducted and consequently analyzed.
Firstly, it is important to establish the research
approach in order to create a significant qualitative
methodology. The research approach undertakes a
specific design that is “the overall strategy chosen to
obtain the information required answering the research

question” (Ghauri and Gronhaug p 47, 2002). The
research approach will review the types of research
design and data collection methods. The research
approach is built on logical relations and not just
beliefs.
Descriptive research is used when the research
question is understood (Ghauri and Gronhaug 2002). In
the research approach, the data measurements are
dependent on the obtainment of required information
and the quality of the information. The outcome of the
research, therefore, is dependent on the measurement
procedures used in the collection of the data, and this
in turn is dependent on the types of data collection
(Ghauri and Gronhaug p 47 2002).
This is an important concept of qualitative research,
where the description is either inductive or deductive.
Inductive research begins with a question and seeks to

describe it, and deductive research begins with the
problem by working backwards to the answers.
Therefore, this research uses the inductive approach to
build the theory from the data gathered to explore
possible conclusions towards credit facilities factors.
Collection of Theories and Secondary Sources
The researcher has collected information from various
literature reviews, which are available at internet
scholarly books, journals and newspapers. Theses
materials used are not sufficient to add something new
to the subject, which has been extensively researched.
Research Method
There are many approaches to this research being a
case study. Case studies are always investigated using
two-research method, Qualitative and Quantitative.
Quantitative approach involves the collection of

figures and facts in a form of tables and graphs.
Qualitative involves measuring people’s attitude,
behaviors and opinions. One can note that a person’s
perceptions opinions and attitudes cannot be measured
using quantitative technique. I.e. you cannot assign a
figure to somebody’s attitude of something.
Researchers have written that qualitative method of
collecting data or information is through observation,
interviews and analysis in a narrative manner. In this
case, quantitative analysis will not benefit us much as
compared to qualitative analysis.
The researcher is going to use qualitative method of
research in analyzing the strategies or factors adopted
by group common wealth bank of Australia and bank
of America. We shall also look using the same method
affect the issuance of loans. Therefore, in my final
report, I am producing an analysis for the two.

Data Collection
Data collection was carried out through internet search
engines and interviews. The researcher is a student
with authority in the university to target the two banks
to get insight of credit facilities given out by banks,
although the interview will be very difficult. Other
considerations have been made for this quantitative
method but the result is to interpret the information as
it was seen visible through interviews. I shall use
questioners I carrying out this important research.
For, me to carry out the test interviews possible and
bring an employee of one of the company; I have
selected the best option possible for my colleagues. I
have also use conventional interviews, which are
interview through internet for common wealth bank of
Australia and Australian bank. Although I gathered
information sufficient for me to make decisions, I

realized that face-to-face interview is more appropriate
as compared to telephone and internet. This is because
face-to-face interviews are easier since the questions
can be rephrased if the respondent does not understand
the question. However, in the internet and telephone
the respondent can choose to ignore the questions.
Quality Criteria
I shall explore whether there is a quality criteria for the
qualitative method used. This will be possible if we
give in depth analysis to give the findings a degree of
truth and validate them.
Validity
The validity of this investigation is achieved if it
measures what was intended for. The valuables should
be able to measure what the research intended to do.
Validity can be characterized by internal and external

validities. In this case, we are not going to use
laboratory measures.
Quality criteria
The purpose of this section is to establish the stance
used in the qualitative approach to this Study. In doing
so, the reader will better comprehend the degree of
truth that this dissertation has In addition, validate the
findings.
Validity
The validity of a study is achieved if it measures what
it was intended for, that is variables measure what the
research was intended to measure with little or no
error. This is characterized by internal and external
validity, which varies between types of research; field
experiments (research done in natural environment)

and lab experiment (done in contrived or artificial
environment). In lab experiments, the researcher
controls the setting, in which the research is been
conducted, may influence the variables, while
observing the changes or no changes in variables. Due
to the ability to control and eliminate certain variables
or conditions that may have a profound effect on the
outcomes of the research, would likely improve the
validity of the research. On the other hand, in field
experiments, the researcher retains control over the
independent variables but conducts the research in a
natural setting, without control over environmental
influences.
Internal validity describes or accounts for all factors,
including those that are not directly specified in the
theory being tested, but might affect the outcome of the
study. That is, it usually concerns the soundness of the

research being carried out. External validity on the
other hand refers to the generalization of the research,
which is the ability of the conclusions
To be validly extended from the specific environment
in which the research study is conducted to similar real
world situations.
The research for this thesis could be considered as a
field research (survey) as it is carried out in a particular
company in the real world. The literature on this
survey was got from an interview on human beings of
the company thus; we cannot influence their responses
in any significant way. To ensure for both internal and
external validity, we believe to have used the most
accurate and up-to-date literature, the right and relevant
questions asked during the interview (face-to-face
interview), the most feasible data collection method
utilized and the tools used to analyze the data are also

considered to be the most appropriate in this situation.
Therefore, this thesis is considered accurate and hence
produces valid results. Thus, we assume that the
overall validity of the results is considered high.
However, we would argue that the internal validity of
this thesis is relatively high but the same cannot e said
for its external validity. The reason for this position is
discussed under the degree of generalization.
Reliability
The aim of any researcher we believe is to use a given
procedure and reach a conclusion that will be
applicable in any given environment. The primary
objective should be that if a later investigation
followed exactly the same procedure as described by
an earlier investigator and conducted the same study all
over again; this later investigator should be able to
arrive at the same findings and conclusions.

Thus, the study could be considered highly reliable.
However, due to the very nature of human beings, a
100% reliability (especially regarding External
validity) cannot be guaranteed for this thesis, as errors
might occur in the course of writing down answers
during the interview or in coding answers due to
human nature. In this study, the errors were minimized
as one interviewer poses the questions and the other
concentrates in writing down responses. Immediately
after each interview, the two interviewers sat together
to discuss and document the final responses. With all
these measures put in place to minimize error, we
believe that the results of this study could be regard as
reliable.
Degree of generalization
Generalization is the applicability of results of a
research study to other settings. Probability sample is

only what justifies that inference can be made about
the population but this is not a guarantee as the results
from the sample cant be generalized because of the risk
of random and
Systematic errors in the sample. In case studies, it is
not important to make generalization of the study but
to explain what is the situation of that company in that
particular situation and there is no problem if the
results cannot be generalized. This is so because no
two companies can be the same, thereby case studies in
general do not return appropriate information for
generalization but in optimal case, can produce a rough
guideline/understanding of how theories are practically
applicable. Thus, our findings from the study can be
considered as Guidelines for companies implementing
certain strategies to gain growth in their market
Choice of Case Study

The research problem is that the investment strategies
adopted by bank of America influence decisions to
receive credit facilities as compared to strategies
required by common wealth bank of Australia. I shall
have to explore the complex and different perspectives
on how investment strategies are developed and
implemented by common wealth bank of Australia.
Therefore, I have used scientific study methods to
understand how these strategies have been
implemented and how to assist the bank. It is because
of this perspective that I decided to choose bank of
America and common wealth bank of Australia with
different approaches to expansion from different parts
of the world i.e. developed and developing.
Background of bank of America
Bank of America is the largest bank in the world which
resulted from the merger of two major banks in the US.

They have expanded into various economies of the
world and have created themselves a name in the
banking sector with few issues remaining unsolved.
Being one of the largest banks in the world, it was
incorporated in the United States of America for the
purpose of providing banking services to the American
society. The company has expanded to almost all
countries of the world through strategic alliances,
takeovers, and mergers as methods of diversification.
Bank is a public traded company and for years, this
company has moved to many countries geographically
and they have had products and services improved to
the level of online banking for the world. The owners
and their families run the management of the bank and
its activities influence decisions of many economies of
the world. They provide highly valuable services to the
world. At the present the company issues credit

facilities after assessing the riskiness of the client’s
information. This has strengthened their market share
through providing loan facilities to companies or
individuals who have stable financial records..
Background of Commonwealth bank of Australia
The common wealth bank of Australia was
incorporated in Australia as moved to various parts of
the world and they represent interests of Australia to
many places. The bank has a good credit facility policy
which ought to be emulated by many banking
institutions while issuing credit facilities.
Results
Assume the is approached by a customer to finance a
project it risk will be analyzed as followed
COST OF CAPITAL : Cost of capital for retaining
KeA= D1A/POA+ g

PoA= 35 D1A= 3.25 g = 5%
KeA= 3.25/ 35 +5% = 14.3%
= 14.3%
Cost of capital for common stock
KeA= D1A/POA– f + g
PoA= 35 D1A= 3.25 g = 5% f= 2
KeA= 3.25 +5% = 14.8%
35-2 = 14.8%
Cost of capital for preferred stock
KpA= D1/ PO – f
PoA= 102 D1A= 6% of 100 f= 4
KpA= 6 = 6.1%
102-4 = 6.1%
Cost of capital for debt

PdA=CF+ interest/(1- Kd)n
PdA– CF = interest PdA– 1000
(1- Kd)nACF —( 1000-20- 20)= 960
1000 – 960 = 6.5% X1000
(1- Kd)10
40 (1- KD)A10A= 65
(1- KD)A10A= 65/40
10 log (1- KD) =log 1.625
log (1- KD) =log 1.625/10
log (1- KD) =0.21085/10
log (1- KD) = log 1.0497
1- KDA= 1.0497
KdA=5%
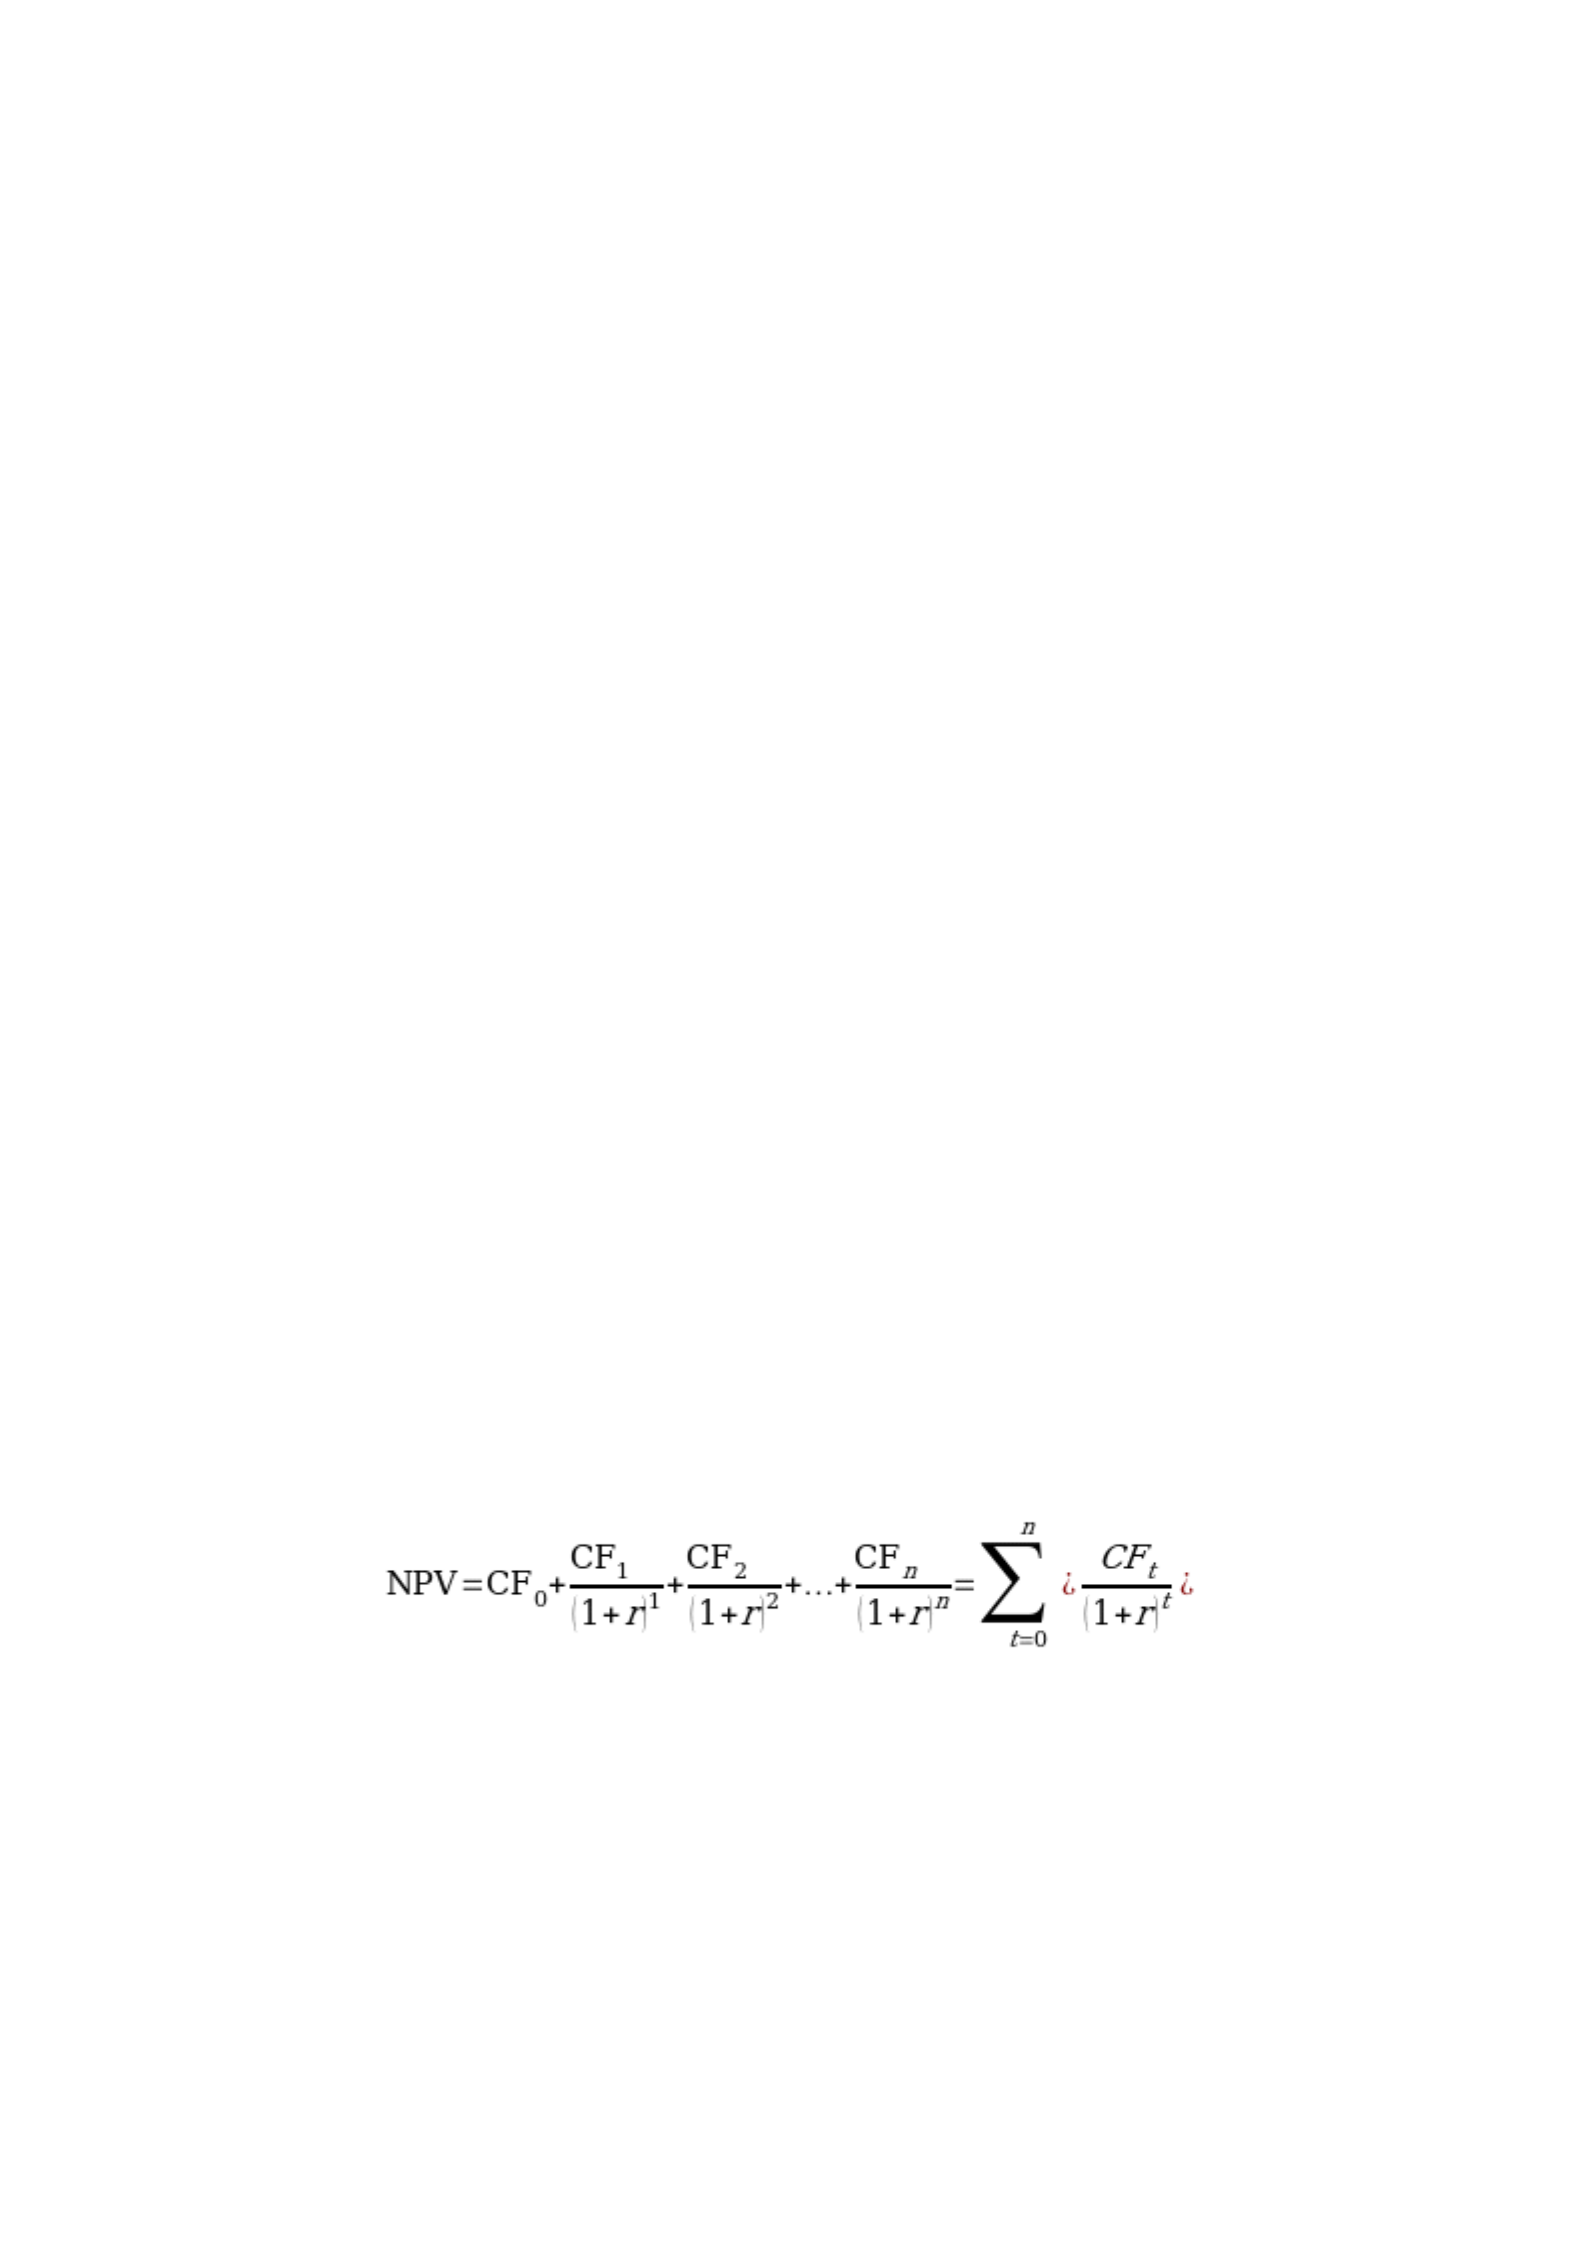
WACC = wdrd(1-T)A+ wprpA+ wkerkeAWACC= 0X 5%( 1-
0.4) + 0 X 6.1% + 599,300/699,300 X 14.8% +
100,000/ 699,300 X 14.3%= 14.7%
The project Initial Investment
Cost of purchase of a new machine = 14 million
Cost of installation = 1 million
Increase in account receivable = 1.5 million
Inventory increase = 2 million
Account payable = (1 million )
Disposable value of old machine = (3.5 million)
Initial Investment 14 million
Therefore NPV = (1,000,000)+ 440,000 + 440,000
+440,000 +440,000 + 440,000

(1.0925)1A(1.0925)A2A(1.0925)3A(1.0925)4A(1.0925)5
(1,000,000) + 402,746 + 368,646+ 337,433+ 308,863+
282,712
= 700,400
Analysis
Assumptions regarding the hurdle rate, and in
particular, whether it should adjust to reflect changes in
leverage, are critical to determining the optimal credit
rating for a bank. This in turn impacts on pricing
decisions and the market value of credit portfolios, and
consequently, the risk-adjusted performance measures
of portfolios under the control of managers. A loan
pricing model was constructed to test the impact of
changes in the target credit rating of a bank on the
pricing of its loans.

The decision of a bank to increase its solvency
standard increases the minimum interest rate on its
loans in order to achieve the required hurdle rate on
capital assigned to the loans. Offsetting this upward
pressure is the impact of the reduced funding costs
arising from the higher credit rating. If retail deposit
rates are insensitive to an upgrade in the credit rating
of bank debt securities, we find that the benefits to a
bank from increasing its target credit rating rest with
the extent to which the cost of wholesale funds falls
relative to the increase in the price of bank loans.
A number of scenarios are employed to measure the
impact of bank-wide decisions on target credit rating
and funding mix on the pricing of bank loans. As the
bank increases its target credit rating, there is a
significant divergence between the change required in
the cost of wholesale funds to maintain unchanged loan

rates and empirical data on bank credit spreads. This
divergence narrows, however, as the credit quality of
the bank loan book increases and the proportion of
retail deposits falls. The divergence also narrows
considerably when the hurdle rate on capital is allowed
to adjust to reflect changes in bank leverage.
Further, our model shows that a bank can gain from
increasing its solvency standard, in the sense that the
cost of funds falls more than the increase in loan
prices, when the regulatory capital requirement for the
loan exceeds the economic capital requirement.
This occurs when banks make loans to high credit-
quality borrowers, because capital ‘capacity’ enables
the bank to realize a reduction in funding costs without
an offsetting increase in economic capital, and hence
an increase in loan interest rates. Our analysis shows
that the benefits of changes in credit rating are

contingent upon assumptions regarding changes in the
hurdle rate in response to changes in leverage.
This is also relevant at the level of managers, where
performance on portfolios is measured by the RORAC
against the bank hurdle rate. In chapter four we found
that a fixed hurdle rate for pricing bank assets is not
consistent with a constant probability of default when
bank returns are less than perfectly correlated with the
return on the market portfolio. We argued that the
internal hurdle rate should capture the additional costs
to investors associated with bank-specific risks. If the
contributors of economic capital to the bank perceive
that bank leverage is governed by minimum regulatory
requirements, then a case might be established for a
constant hurdle rate. However as banks target higher
solvency standards, and the gap between economic
capital and regulatory capital widens, the contributors

of capital should be willing to accept a lower required
return in response to lower bank leverage.
Recommendations and Conclusion
Most organizations and individuals seek loan facilities
for investment. However, all these organizations that
seek loan facilities face risks of various magnitudes.
From the perspective of a bank, each individual or
entity seeking a loan has a risk and it differs from one
entity to another because of differences in
fundamentals. For a bank to give an individual the
loan, they must be ready to transform the risk, price it
and monitor the risk to ensure that their money is given
to the right person. Investment policy or investment
strategy of an organization will assist them get loan
facilities depending on the loan facility they intend to
give.

Therefore before the bank advances credit facilities,
they have a responsibility of managing their credit
facility, market the company’s products and manage
the operational risk associated with the loan. The
company is charged with the responsibility of ensuring
that the risk associated with giving loans is properly
managed. It may be simple but accompanying risk
must be captured in order to ensure that loans are
issued to people who have provided all information
needed to estimate the amount of risk involved in issue
of loans.
The information about investment strategy is important
as it will assist the bank or the credit facility provider
to estimate the risk associated with the loan. You
cannot dismiss the investment strategy as a way of
assisting an organization or individual in receiving a
loan facility or facilitating the quick process of the loan

facility. Then much in the same way as the business
operates, the bank will have a reduced risk. Businesses
operated by individual owners have high risks
compared to business operated by a group of partners.
The information provided by each person will be the
reasons for the money and of course the bank or a
lending institution cannot issue money to a business
with a poor investment strategy. For example, a
company wanting to investment in a factory to produce
new products in the market will stand a better chance
of getting credit facilities as compared to a company
with a strategy to invest in a company which is
producing products saturated in the market.
The bank will have to calculate the expected risk of the
investment opportunity available and estimate the
profit of the investment proposed by the loan seeker.
The risk will be allocated the available capital and

other resources within the organization. This will
provide the bank with the required rate for lending
money. If the rate is lower than the proposed, then the
project will not be risky and the bank will not provide
the loan. First, the loan interest rate must be higher.
Therefore, provides best opportunities of the
investment. If the investment strategy is not sound and
bearing in mind the supply of capital is limited, the
task is reduced, that is investing in those opportunities
that have high returns.
There are many factors that determine the getting of a
loan from a banking facility. As identified, these
factors are crucial and necessary for the loan facilities.
Unfortunately, most banks do not use these facilities in
issuing of loans. The center of the bank charged with
responsibilities of issuing loans at item find themselves
looking at other issues which are irrelevant in issuance

of loans. However, almost all apart from the few cases,
bank loans are issued based on the facts. There is no
universally accepted means of measuring risks of the
loan seeker from the perspective of the bank. The
literature reviewed show that the amount of
information provided by the clients influences issuance
of loans. The literature further shows ha banks view
risk based on the information provided.
Although market prices determine the loan to be
issued, risk is also considered. According to Domar
and Musgrave, the banks view risks as the probability
of losing their money while Savage (1951) argued that
risk is making wrong investment choice and Roy
(1952) describes risk as the perception about the future
cash inflows. There are many writers and scholars who
have viewed risks from the perspective of the bank as
terms of variability of the expected amount from the

loan seeker. The unavailability of a standard way of
understanding risk based on the information provided
from the client and no proper objectives stating how
risk is measured then banks will rely on the
information provided. This information provided will
revolve around your investment strategy. Therefore, it
is necessary for the person seeking credit facilities to
draw up proper information relating to risk investment
strategy to assist him get credit facilities.
Companies who are faced with lack of information on
how to measure risk describe it or spread it will find
themselves making wrong investment decisions in not
getting credit facilities. Therefore, they should be able
to come up with strategies that will assist them get
credit facilities and other institutions. Therefore, the
credit facility provider requirements implicitly involve
a notion of risks as determined by bank regulators that

is the free interest arte security setters who are the
government arm sets the minimum risk before issuing
loan facilities. There are credit risks which are set out
by bank regulators and these determine whether the
loan seeker will get credit facility.
Therefore it is common knowledge that the cost of
capital of the firm in question will determine the
amount of loan that will be provided. If the company
has a high cost of capital, the probability of getting a
loan becomes low because this company will not be
bale to raise money that will sustain the interest that
accrue on the loan. To avoid technical defaults, banks
will avoid such a client.
Banks will use the perspective which identifies risks as
a probability that the client will not be bale to pay and
there is a risk of this client getting out of business thus
determines the economic capital requirement of that

firm before raising funds. Investment strategy is
affected by great rating by the bank and credit
worthiness.
There is a problem with the above mentioned method
since solvency follows a company after they have
failed to deliver the part of the agreement. This is why
the companies or an individual seeking credit facilities
need to disclose the loan provider the purpose of the
loan, proposed method on how it will be paid back and
the thresh hold. There fore there is another standard of
measure that assists the company to get credit facilities.
This measure is the measure of solvency. This implies
that the risk measured using the ability of the firm to
pay the loan does not capture the potential losses which
will be incurred upon failure by the company to honor
their agreements.

Viewed from one perspective, that is from the bank’s
point of view, the risk is greater if the financial
statements of the company reflects poor profitability
and performance. The challenge is in the hands of the
bank to ensure that there is relevant measure for risk of
the client’s information provided. The methods used
should be recognized method for risk measurement.
This requires the ability of the bank to decentralize her
activities in issuance of loans. If the bank’s credit
facility is not decentralized, then the loan will not be
forthcoming as quick as industrialized areas.
Take for example Commercial bank of Australia
discussed in this case and Bank of America who have
decentralized their facilities and another bank in the
third world which has failed to decentralize. The third
world bank will take long to issue credit facility and it

will be riskier for that bank since the credit facility
offered is not properly decentralized.
The question that arises from the above two examples
is whether the creditor or the person seeking the credit
facility is risk averse or risk taker. This is another that
well determines the issuance of loan.

References
Beidleman, C. ed. (1987)Athe handbook of
international investing. Chicago: probus publishing.
Bierman. H (1996) “Investing in junk bonds.”AJournal
Portfolio Management.
Bicksler and Thorp E., “The capital growth model: An
empirical investigation,‘”AJ. Financial and
Quantitative Anal.
Black, F(1981); “The ABC’s of business
cycles”Afinancial analysts Journal.
Booth J., and D. Officer (1985). “Expectations, interest
rates, and commercial bank stocks.”A“journal of
financial researchA(spring 1985), pp.51 -58.
Brick, J.R..H.K.Baker, and J. A. Haslem.(1986);
EdsAFinancial Markets Instruments and concepts. 2d
ed. Redston Publishing.

Cox, J,.J. Ingersoll, and S. Ross( 1981);. A Re –
examination of Traditional Hypothesis about the Term
Structure of Interest rates. “Journal of finance.
Fabozzi F.J. Bond makers (1993);AAnalysis and
Strategies. Englewood Cliffs, N J.: prentice Hall.
Federal reserve bank of Richmond,(1990);Ainstruments
of the money market. 8thAed. Richmond: federal
reserved bank of Richmond.
Krutzmer, P. (1992)“Monetary vs. Fiscal policy: new
evidence on an old debate. “economic review, federal
reserve bank of kansasa city.
Nyemira, M.P and G. Fredman. (1991); “An evaluation
of the composite index of leading indicators for
signaling turning points in business and growth cycles.
“Abusiness economics.

Sprinkel,B. (1971;AMoney and Markets: A Monetarists
view, Homewood, III.: Richard D. Irwin. The
handbookAof fixed income securities, 3d ed.
Homewood, II.: Business one Irwin, 1991.
First Boston Corp. handbook of securities of the United
States Government and federal agencies 35thAed. New
York :first boston corp.,1990.
Ibboston, R,G., and L,B. Siegel. (1991); “The. World
bond market; market values yields, and returns.
‘Ajournal of fixed – income.
Van Horne, J.C. (1983);AFinancial market rates and
flows.A4thAed. Englewood cliffs, N.J.: Prentice Hall.
Wilson, R.S and F.J Fabozzi (1990);.AThe New
corporate bond market. Chicago: probus publishing.
Yago Glenn (1991);.AJunk bonds. New York: oxford
university press.

Latane H, “Criteria for choice among risk ventures,” J.
Politic. Economy, vol. 67, pp. 144-155,1959.
Thorp E., (1969); “Optimal gambling systems for
favorable games,”ARev.Internat. Statist., vol. 37, pp.
273-293, 1969.
-, “Portfolio choice and the Kelly criterion,”ABusiness
Econom.Statist. Proc. Amer. Stat. Assoc., pp. 215-224.
Williams J, (1936) “Speculation and the carryover,”
Quart. J. Econom.,vol. 50, pp. 436-455, 1936.
Kelly J, (1956) “A new interpretation of information
rate,” Bell Syst.Tech. J., pp. 917-926, 1956.
H. Latane,(1959) “Criteria for choice among risk
ventures,” J. Politic.Economy, vol. 67, pp. 144-
155,1959.

N. Hakansson and T. Liu, “Optimal growth portfolios
when yields are serially correlated,” Rev. Econom.
Statist., pp. 385-394, 1970.
N. Hakansson, “Capital growth and the mean-variance
approach toportfolio selection,” J. Financial and
Quantitative Anal., vol. VI, pp.517-557,197l.
R. Bell and T. Cover, “Competitive optimality of
logarithmic investment,” Math. of O.R., vol. 5, no. 2,
pp. 161-166, 1980.
-, “Competitive portfolio selection,” in preparation.
K. Arrow, Essays in Theov of Risk Bearing.
Amsterdam: North Holland, 1974.
S. Kullback, Information Theoql and Statistics. New
York: Dover,1959.

