


3
Problem Statement
Retirement plans in the workplace are a form of recognition and reward. Plan
sponsors of retirement plans must also account for the risks associated with such plans.
The threat of litigation related to the reasonableness of fees and the best interest of plan
participants has increased, hence an increase organizational risk preparation for due
diligence is appropriate (Ferreraand & Schleppegrell, 2015; Pratt, 2016). More than 100
new 401(K) plan complaints were filed between 2016-2017, the highest 2-year total since
2008-2009 (Mellman & Sanzenbacher, 2018). The general business problem is the
growing fiduciary liability leaders realize associated with workplace retirement plans.
The specific business problem is that some business leaders lack the guidance of
strategies to minimize the risk of workplace retirement plans for their organization.
Purpose Statement
The purpose of this qualitative multiple case study was to explore the strategies
stakeholders presented to business leaders to minimize the organizational risk of
workplace retirement plans. Employers receive guidance in this area through several
stakeholders associated with the retirement plan operation. Ten business leaders
responsible for retirement plan operations represent the participant base. The 10 business
leaders represent a national geographic footprint as well as a different subset of industries
in which the plans operate. The Edelman Trust Barometer is an annual global study of
trust among institutions; in 2018, 72% of respondents indicated they trust employers
while the benchmark of trust in U.S. financial services declined by 23%(Edelman, 2018).
My study, related findings, and conclusions are the initial phases of research in which

4
risk mitigation occurs through a maximization of trust. The implication for positive social
change suggests employers use inherent trust to increase the trust of financial products.
By limiting the distrust in financial service firms using workplace retirement plans,
business leaders could extend the trust of employers to financial services alleviated while
protecting the retirement preparedness activities of consumers.
Nature of the Study
The research study was a qualitative exploration of the organizational risk
associated with workplace retirement plans through a multiple case study design.
Through an explorative exercise, I investigated the problem through a holistic lens. The
investigation of a problem through a holistic lens is a practice Cronin (2014) described as
beneficial in qualitative studies in which individuals, groups, activities, or phenomena are
highlighted. A quantitative study allows the researcher to test a hypothesis given a set of
standards, to elicit facts through hard percentages or numbers (Barnham, 2015). In the
case of organizational risk mitigation, such factual data was in its infancy. A deeper
understanding applying a qualitative method was preferred, limiting the viability of
quantitative and mixed methods approaches.
Yin (2017) espoused the value of case study design through an ability to address
complexity and contextual conditions, among other methods such as survey or
experimental research. A case study design approach is well documented to provide a
framework for a researcher analytic or conceptual generalization which defines the basis
of the case to a broader population of related cases (Yin, 2017). My study was not an
exploration of the lived experience or individual essence of risk so phenomenological

5
strategies would not be prudent. Narrative or ethnographic studies are adequate to study
the shared, unique, or environmental experiences associated with individual retirement
(Yates & Leggett, 2016) but such findings were out of scope for my research and
analysis. My ability to adapt to the enhanced experience of unique situations through
interviewing, an idea discussed by Cronin as a function of the case study approach was
more beneficial.
Research Question
What guidance is provided by stakeholders to formulate strategies business
leaders use to minimize the organizational risk of workplace retirement plans?
Interview Questions
1. How do you minimize the organizational risk of the workplace retirement plan?
2. What strategies do you use to minimize the organizational risk of the workplace
retirement plan?
3. What tools and resources minimize the organizational risk of the workplace
retirement plan?
4. How were you advised on the fiduciary liability associated with your
organizational workplace retirement plan?
5. What steps has your organization taken to minimize fiduciary liability?
6. How is an organizational risk of retirement plans communicated to managers and
directors of the organization?
7. What are your top three resources used to mitigate organizational risk of
workplace retirement plans?

6
8. What approaches or strategies toward organizational risk of retirement plans that
have not been discussed that may be important to this study?
Conceptual Framework
Leader-member exchange (LMX) theory is a framework that originated in 1975
through the works of Dansereau, Graenm, and Haga (Northouse, 2016). As an evolution
of vertical dyad linkage (VDL) theory, LMX theory practitioners expand upon the
interactional relationship between leaders and followers. Two potential interactional
outcomes of the LMX approach include in-group and out-group behaviors, a factor in
how to manage engaged and disengaged members (Northouse, 2016). Facets of LMX
theory research identifies a causal relationship to positive employee behaviors such as job
satisfaction, commitment, creativeness, positive citizenship behavior, and alignment to
reward systems (McCleskey, 2014; Northouse, 2016). Another, LMX is a prescriptive
model among leaders and followers. A prescriptive model in that the content delivered to
leaders evolves naturally, is trainable, can be developed over time, and may apply to
various levels of an organization.
The mitigation of risk within workplace retirement plans must account for the
discovery of strategies to identify risk as well as implementing such findings. Workplace
retirement plans operate as an elective employee benefit, participation is not required but
an optional benefit provided by employers; I used a conceptual framework that addresses
activities which extend beyond normal job responsibilities. LMX is a prescriptive model,
the results of my research and analysis may apply to businesses of all sizes and varying
levels of leadership experience.

7
Operational Definitions
401(k): A 401(k) participants (employees) can elect to defer receiving a portion of
salary, which is instead contributed on their behalf, before taxes, to the 401(k) plans
(DOL, 2019). Employees who participate in 401(k) plans assume responsibility for
retirement income by contributing part of their salary and, in many instances, by directing
their own investments (Ali & Frank, 2019; Cumbie, Ice, & Krishman, 2018).
Defined contribution plan: A defined contribution plan enables the employee, the
employer, or both contributions to the employee's individual account under the plan,
sometimes at a set rate (DOL, 2019). The employee will ultimately receive the balance
within accounts, although, the value of the account will fluctuate due to the changes in the
value of the investments (Ali & Frank, 2019; Cumbie, Ice, & Krishman, 2018; DOL,
2019).
Defined benefit: A defined benefit plan promises a specified monthly benefit at
retirement (DOL, 2019). The plan may state this promised benefit as an exact dollar
amount or it may calculate a benefit through a plan formula that considers such factors as
salary and service (Ali & Frank, 2019; DOL, 2019; EBRI, 2017; Vanderhei, 2013).
ERISA: The Employee Retirement Income Security Act of 1974 (ERISA) is a
federal law that requires plans to provide participants with plan information including
important information about plan features and funding; sets minimum standards for
participation, vesting, benefit accrual and funding; provides fiduciary responsibilities for
those who manage and control plan assets; requires plans to establish a grievance and
appeals process for participants to get benefits from plans; gives participants the right to

8
sue for benefits and breaches of fiduciary duty; and, if a defined benefit plan is
terminated, guarantees payment of certain benefits through a federally chartered
corporation (Costin, 2018, DOL, 2019).
Goal efficacy: Goal efficacy is a concept that describes the design of goal.
Includes a person’s belief in their ability and how such abilities will lead to success or
failure (Weiner & Doescher, 2008). If a person believes in a higher likelihood of failure,
they are less likely to exert effort.
Plan sponsors: Plan sponsors are business leaders who act in fiduciary capacity
for their organizations (Guerriero, 2017). Plan Sponsors may be synonymous with
employers, business leaders, sponsors, fiduciaries, or owner.
Retirement Plan Committee: Members of an organization who serve in an
advisory capacity to ensure there is varying voices in the overall process and decision to
select a plan (Geller, 2015).
Assumptions, Limitations, and Delimitations
Assumptions
Researchers are limited by the human nature of knowledge, research is not
valuefree or neutral (Kirkwood & Price, 2013). As a researcher, I assumed that all
participants will answer questions honestly. When discussing the implementation of
workforce retirement plans, organizational risk assessment, and the dyadic relationship
between an organization and its employees, my assumption was that respondents answer
to their best capabilities. Various platforms permit the use of a workforce retirement plan:
for this study, an assumption that corporations use defined contribution plans, or 401(k)

9
was made. Assuming a 401(k) as the program of choice, the risk is assessed based on the
presence of mutual fund investments as funding vehicles for retirement savings. Unlike
individually managed IRA, 401(k) investments within the plan features are selected by
the employer for the benefit of the employee inferring fiduciary responsibility (ERISA).
Limitations
As described by Brutus, Aguinis, and Wassmer (2012), citing the 1993 work of
Campion, researchers must acknowledge the realistic limitations and weaknesses of the
research present. Given the limited time frame of an initial study, I was limited by how
in-depth discussions of financial literacy of business leaders and participants.
Acknowledging the additional factors of suboptimal use of workplace retirement plans
such as financial education, retirement confidence, and risk aversion was prudent. Several
factors may cause a participant in a retirement plan to think as if they are ill-equipped to
make retirement plan decisions. An individual may not have a proper degree of financial
literacy to experience comfort with the decision. Given one’s earnings and potential
future earnings, the individual may not possess a confidence that retirement is a viable
option. My research, analysis and findings do not represent a medium to assess the
organizational risk associated with these specific acts, in its place the results of my
research and analysis hope to address the holistic nature of organizational risk.
Delimitations
Faulty language may lead to faulty conclusions which makes it difficult to
compare one set results to another normative set. In the example of my research and
analysis, the research was used to frame the appropriate scope and boundary of my study.

10
Delimitations address the scope of workplace retirement plans and organizational risk
explored in my study. The scope of my study was to explore the assessment of
organizational risk associated with workplace retirement plans. Within the scope of study
I addressed an understanding the fiduciary liability, the external litigious environment,
and the potential for losses associated with fiduciary breaches and practices to mitigate
such risk. My analysis did not compare defined contribution plans versus other plan
types, address individual retirement plans such as IRAs or address retirees within the
scope of my research findings.
Significance of the Study
Some business leaders have noticed an increase in organizational risk associated
with workplace retirement plans (Mellman & Sanzenbacher, 2018). The results from this
study may allow leaders to identify and mitigate risk based on exposure originating from
the investment offering. Exposure includes Index and Stable Value fund claims, the offer
of guaranteed benefit funds in which fixed rates adjust unilaterally, and the offer of
alternative investments outside of traditional asset classes (Rachal, Rumeld, & Chirinos,
2017). Finally, the expanding scope of fiduciary liability under the Department of Labor
(DOL) new fiduciary standards that would require further oversight of fiduciary breaches
(Pratt, 2016).
Contribution to Business Practice
Given the rise fiduciary litigation, the explorative case study results are beneficial
to the larger business community. The business community may apply the results of my
research findings to safeguard a process in which employees’ choice of funds

11
acknowledges individual best interests, an assessment of the clarity and commonality of
fiduciary responsibility among business leaders was present, and a proper due diligence
assessment of workplace retirement plan organizational risk was available. Identifying the
appropriate elements of risk mitigation can be valuable as a tool to incorporate best
practices into the business community.
Implications for Social Change
The Edelman trust barometer is an annual global study of trust among institutions;
in the latest iteration of the study, 2018, 72% of respondents indicated they trust
employers while the benchmark of trust in U.S. financial services declined by 23%
(Edelman, 2018). My analysis, related findings, and context provide a pathway for
employers to use inherent trust to increase the trust of financial institutions. By limiting
the distrust in financial service firms using workplace retirement plans, business leaders
could extend the trust of employers to financial services alleviated while protecting the
retirement preparedness activities of consumers.
A Review of the Professional and Academic Literature The literature
review was organized thematically to describe the fiduciary responsibility of retirement
plans, the risks associated with fiduciary responsibility, and the actions of leaders in
mitigating such risks. The review was an attempt to validate the efficacy of workplace
retirement plans by addressing decision-making barriers that result in fiduciary breaches.
The search strategy of my research study was to assess existing literature on fiduciary
liability associated with workplace retirement programs. The framework of the search
strategy was twofold; first to describe the component issues of workplace retirement

12
programs and the keywords, or synonyms, to denote the breadth of the topic. Second to
use databases and research types that fulfill the outcome of the underlying research.
Component issues included but delimited to organizational risk, fiduciary
responsibility, corporate risk mitigation, and workplace retirement programs. Keywords
included the most common terms in retirement and leadership discussions (fiduciary
liability, fiduciary responsibility, fiduciary breach, ERISA, best interest standard, DOL
ruling, financial education, financial literacy, financial capability, retirement, retirement
preparedness, retirement confidence, leadership, employee engagement, ethical
leadership, and leader-member exchange theory). The databases included peer-reviewed
materials available on various platforms (Thoreau Multi-Database, Academic Search
Complete, ProQuest Central, Sage Journals, EBRI.org, Bureau of Labor Statistics, and
Google Scholar). The type of research includes research reports, articles, dissertations,
journals, blogs, books, bibliographies, webinars, and interviews.
To ensure alignment to fiduciary responsibility changes during 2015-2018, the
hook and anchor of my final study are based on statistics within a 5-year period.
Scholarly rigor necessitates peer-reviewed sources to answer the research question as well
as exploring the existing information available; databases that include peer-reviewed
sources are used facilitate information gathering. The databases included peer-reviewed
materials available on various platforms (Thoreau Multi-Database, Academic Search
Complete, ProQuest Central, Sage Journals, EBRI.org, Bureau of Labor Statistics, and
Google Scholar). Using the practice of chain searching, evaluating the citations of
existing research for personal use, ensures a good chance of achieving 60% (or at least

13
85% of total sources) different peer-reviewed sources through the literature review. My
literature review was constructed based on the work of 61 scholarly peer-reviewed
articles, nine of which are no more than 5 years old to achieve the 85% requirement.
The body of research about behavioral finance has primarily focused on the
relationship between consumers and economic decisions they make, in which behavior is
said to be predictably irrational. A similar body of work has gained traction, behavioral
governance, in which the focus of research delves into the decision-making of business
leaders, partners, and other stakeholders whose decisions influence more than just the
individual (Lew & Sinkovics, 2013). Trone is a well-known advocate of fiduciaries for
his framework of behavioral governance and participation in DOL fiduciary legislation
hearings (Pasztor, 2016). I incorporated Trone’s framework of behavioral governance
includes leadership, stewardship, and governance. The similar language will ensure
commonality while expanding on the amalgamation of leadership theories it is based on.
In one aspect this research exploration was an extension of several theories which
are trustworthy behavior is drawn from social and relational norms in the business world.
Outside factors that are ignored in strategic thinking spurred the research of shared value
theory, in which solving societal issues may be advantageous for business and
communities alike. Several scholars have spoken to the efficacy of models that in parallel
support business efficiency and societal influences such Kramer and Pfitzer (2016) and
De Los Reyes Jr., Scholz, and Smith (2017), which outside factors influence decision
making within organizations. business leaders may find solutions in the benefits of
behavioral governance through the lens of leader-member exchange. Given the dyadic

14
relationship between leaders and staff to achieving goals beyond job duties, aspects of
behavioral governance can be used interchangeably.
Thematic elements of behavioral governance are captured in the work of some
scholars. Some scholars address behavioral sciences in leadership scenarios; specifically
Okoye’s (2013) research about the risks of leadership personalities, as well as, Garoui and
Jarboui (2014) work on corporate governance and the role of behavioral sciences. The
work Herciu and Ogrean (2014), Young and Thyil (2014), and Lew and Sinkovics (2013)
discussed cross industry stakeholder relationships.
The work of Garoui and Jarboui (2014), Okoye (2013) and the addition of a
baseline understanding of various leadership theories was how I framed the Trone version
of behavioral governance, three-dimensional, governance, stewardship, and leadership.
Governance addresses the system of laws, regulations, or corporate policies (Young &
Thyil, 2014). Stewardship describes the passion and discipline to judge wisely and
objectively; with a pro-organizational view (Glinkowska & Kaczmarek, 2015). Finally,
leadership addresses the capacity to engagement of others with integrity (Northouse,
2016). The best way to discuss strategies for behavioral governance was to do so within
an easy to follow context; describing behavioral governance through the lens of fiduciary
liability was a relatable example.
The dimension of governance reflects the existing legislation which dictates
retirement plan administration. A synopsis of existing literature on the history of the
fiduciary liability, and the influence of 2015-2017 DOL (2014) guidance further defining
fiduciary responsibility was the first theme of the review. The background was important

15
to understand the basis of the research study, which was to explore the ways to mitigate
the risk of fiduciary breaches for business leaders. A fair amount of cases of fiduciary
misconduct have arisen, leading to an increase in cases filed and cases settled.
Stewardship, in the lens of fiduciary liability, addresses the plight of business
leaders to wisely and objectively make decisions regarding the retirement plan
considering a litigious environment (Glinkowska & Kaczmarek, 2015). A review of
existing literature on the due diligence process of retirement plan selection; including
search criteria, and selected plan feature details are a secondary theme of the review.
Stewardship reflects both the strategy of business leaders and the communication of the
strategy. The synopsis also includes an overview of retirement plan communication
theories.
The ways in which a new understanding of fiduciary liability requires a new form
of leadership was the final theme of the review. The reason to view fiduciary liability
through the lens of behavioral governance was to assist business leaders and build trust in
decisions in business leaders. The review concludes with an overview of leader-member
exchange theory as a leadership development guideline.
Scope of Fiduciary Liability
Business leaders operate in an uncertain environment in matters of financial
responsibility. The uncertainty derives from outstanding questions in the litigation of
fiduciary breaches, including the scope of investigations (Costin, 2018), the "lawyer
generated" nature of fiduciary litigation (Musick, 2019), and the enforcement of
arbitration in breach litigation (Faucer & Rudolph, 2018). Business leaders also face

16
internal conflicts that may impact decision making. Several factors may obstruct business
leader decision making; As denoted by Robinson (2019), the influence of the dual role of
fiduciary/participants, the scope of personal liability, and the varying acts resulting in a
breach are only a few considerations of business leaders. In isolation, fiduciary decisions
may be manageable, in which deliberation and prudence are probable. Fiduciary
responsibility is not an isolated incident. In reality, business leaders face multifaceted,
complex decisions, which several are ill-informed to address.
Musick estimates that litigants file one new ERISA case in district court each
week (2019). The filings lead to investigations by the DOL, in which, regardless of the
reason for opening an extensive investigation into plan administration, management, and
operations should be expected (Geller, S.M. 2019). The cases are increasingly brought by
the plaintiff's attorney's targeting ERISA plans, not by plan participants themselves,
pointing to an external threat (Musick, 2019). Attorneys have followed the direction of
court decisions in such matters. The Supreme Courts' recent decisions on arbitration
provisions, commonly associated with employment contracts and guidelines of the
Federal Arbitration Act (FAA) concerning ERISA, are enforceable to preclude class
action lawsuits (Costin, 2018). The decisions of the court are a trend predicated on
canons, the legal version of "rules of thumb" (Costin, 2018).
The courts are not the only entity to use the "rules of thumb," business leaders
may face internal conflicts based on the ability to make decisions under duress or a lack
of information. Business leaders must juggle dual competing roles; in which plans require
fiduciaries and often fiduciaries are also employees (Musick, 2019). Fiduciaries maintain

17
personal liability, which as ERISA explicitly references, noting fiduciaries "shall be
personally liable to make good" losses resulting from a fiduciary breach (Musick, 2019).
Examples of potential violations include using incorrect data for plan determinations like
eligibility, which depends on accurate age and hours worked, failure to maintain a fidelity
bond or failure to make timely deposits (Geller, S.M. 2019). Violations of an
administrative or operational manner may occur when fiduciaries are unaware of plan
governance practices and become aware as the result of an investigation (Geller, S.M.
2019).
Business leaders have protections, even in an uncertain environment of fiduciary
liability. Geller (2019) discusses recommendations to minimize risk in the current
environment are both practical and broad-reaching. Fiduciaries charged with plan
governance should establish a well-structured process on informed decision-making,
reporting, benchmarking, and adherence to plan terms. Organizations should determine
which plan-related roles have fiduciary status, develop a fiduciary selection process, and
train selected fiduciaries on potential civil and criminal liability. Organizations can also
look to case law applications of deference to protecting fiduciaries in meaningful ways, as
outlined by Faucer and Rudolph (2018). The U.S. Supreme Court has held that plan who
expressly grant plan officials discretionary authority to determine eligibility and terms of
the plan have given fiduciaries the benefit of the doubt(Faucer & Rudolph, 2018;
Musick, 2019).
As shown in the work of Costin (2018), Faucer and Rudolph (2018), Geller
(2019), and Musick (2019) business leaders are given the benefit of the doubt in courts

18
and have access to multiple risk mitigation strategies. The existing literature also
acknowledges some fiduciaries are unaware of the full scope of their liability. As a result,
the fiduciary environment if complex but capable to navigate with appropriate guidance.
Efficacy of Workplace Retirement Plans
Workplace retirement plans are a mainstay of mid to large organizations within the
United States. The concept of retirement is synonymous with pensions, a term used long
ago in middle English, since the introduction of the first U.S. pension in 1875 by the
American Express Company (Workplace Flexibility, 2010, p. 1). Defined benefit, another
name for pension, replaced a portion of workers income throughout non-working years,
the introduction of retirement began at the establishment of Social Security in 1935 (Sass,
2018; SSA, 2018). From 1935 until approximately 1985 the defined benefit and the
process of receiving the defined benefit, retirement, existed analogously as a construct for
lifelong saving converted into lifelong income (Guerriero, 2017). The idea of retirement
is not new, as the idea of fiduciary is also not new, but a change to the communication of
retirement has created a new set of problems.
The proxy of retirement has changed from approximately 1980 until present day
as the popularity of defined contribution plans, commonly referred to as a 401(k), has
grown without a likelihood of changing in the immediate future (EBRI, 2017; Munnell,
2018; Munnell, Hou, & Sanzenbacher, 2018; Sass, 2018; SSA, 2018). The shift toward
401(k) has also led to new views of risk management associated toward workplace
retirement plans. Limitations of the average American consumer cover a wide array of
factors.

19
Adel and Mariem, (2013); Ambuehl, Bernheim, and Lusardi (2016); Forte, (2014)
and Tisdell, (2014) shared the view of Garcia (2013) that behavioral sciences play a
significant role in financial decision making. English (2014), as well as, Lusardi,
Michaud, and Mitchell (2017) shared the view of Merton (2014) that a misalignment
existed in investment communication between advisors and consumers. Multiple authors
described a view of participant engagement occurred at the intersection of several
disciplines, such as aspects of financial education, behavioral economics, and fiduciary
liability (Akabas, Bell, Collins, & Gold, 2014; Hyoyoun & Wook, 2013; Kim, 2013;
Papaoikonomou, Ryan, & Ginieis, 2011; Rhee, 2013). Several factors are at play
regarding how participants prepare for retirement, in the same vein fiduciaries should be
aware that fiduciary responsibility contiains multiple factors as well.
My exploration of organizational risk was based on participant engagement;
identifying implementable strategies of mitigating fiduciary liability. The approach was a
niche in the existing research in which Pearl and Daley (2016), Polyak (2016), and
Mellman and Sanzenbacher (2018) discussed the increased fiduciary liability among
businesses. In a heightened sense of oversight for financial decisions consumers are
illequipped to make, employers have few solutions. Retirement plans in the workplace
were a form of recognition and reward; as of late inequality in retirement savings among
consumers and the increased threat of litigation from consumers perpetuates
organizational risk.

20
History of ERISA
The seminal legislative prescription for fiduciary liability is the ERISA. The act
outlines fiduciary responsibility through a description of the duties associated with a
fiduciary (DOL, 2019). The administrative duties include operating the plan for the
exclusive purpose of providing benefits to participants and assuming the risk and
expenses of administering the plan (DOL, 2019). Business leaders also have a
stewardship responsibility to understand an employee base well enough to make
decisions in a like capacity, characterized in a similar fashion and with similar aims of
prudent man (DOL, 2019). An explicit investment duty of diversifying investment assets
to limit risk is outlined within the legislation. The entire process occurs in a fully
transparent manner.
ERISA outlines the fiduciary duties as a prescription of adherence to a common
standard. Fiduciary duties may apply to administrative actions, as well as, investment
decisions related to selection (Guerriero, 2017). Plan sponsors outsource the investment
decisions to industry professionals, in which fiduciary liability persists through existing
financial professional legislation (Guerriero, 2017). Some financial professionals adhere
to fiduciary responsibility through designation or certification. The fiduciary provisions
of the Investment Company Act of 1940 (1940 Act) and the standard of care required
under the Securities and Exchange Act of 1933 (1934 Act). ERISA is a framework that
requires adherence in order to meet compliance obligations. The scope of fiduciary
responsibility is codified into several laws enacted as early as 1934. The context of

21
nuance of how to adhere to compliance obligations is also changing and fiduciary
responsibility must be viewed through a new lens.
The guidelines of fiduciary liability are largely legislative. As a result, the
definition and responsibilities of a fiduciary is framed within legislation: ERISA, the
Investment Company Act of 1940, the Securities & Exchange Act of 1933, and Pension
Protection Act are among the more commonly known (EBRI, 2017). Oversight extends
among several entities including the DOL and Internal Revenue Service (IRS). Oversight
of financial professionals expands to include the State Insurance Regulators, Financial
Institution Regulatory Authority (FINRA), and Securities & Exchange Commission
(SEC; Guerriero, 2017).
Guerriero (2017) summarized the various aspects of oversight and duties into a
palatable explanation of governance. Two factors of fiduciary duty that significant to the
discussion of organizational risk include the assignment of the fiduciary status and the
penalties for breaching fiduciary liability. An individual can become a fiduciary by
performing fiduciary functions, or fiduciary duties are imposed through the course of
serving the plan. Business leaders have additional exposure as ERISA section 409
specifies plan fiduciaries can be held personally liable for losses attributed to a breach
(Guerriero, 2017).
The governance of a retirement plan has changed significantly since workplace
retirement programs in 1974. For example, in 1974 plan sponsors could adhere to 75% of
the fiduciary duty as a function of running business, with the remaining 25% executed
through a manageable and predictable money manager (Bonestroo, 2017; Guerriero,

22
2017; and Swisher, 2017). In 2018, more likely than not, a plan sponsor was able to
adhere to fiduciary responsibility 25% of running the business and outsourcing the
remaining 75% (Mellman & Sanzenbacher, 2018). The reversion of fiduciary governance
spotlights the significance of reviewing how business leaders have adapted to the new
paradigm. What guidance has been afforded to fiduciaries to account for recent changes
in their overall responsibility? Fiduciaries need a new way to conceptualize their
responsibility, one that considers their linear history of responsibility while infusing new
elements of organizational risk.
Definition of Organizational Risk
Organizational risk of workplace retirement plans continues to evolve; a function
of business leadership is to stay abreast of such changes and assess the organizational
influence. The DOL (2019) definition of a fiduciary defined all financial professionals
who work with retirement plans, provide advice for retirement plans, and, trustees of
retirement plan as automatic fiduciaries. In an analysis of retirement legislation from
1974 to 2017, Guerriero (2017) described a linear evolution of organizational risk in
retirement plans. One significant difference from 1974 to 2017 is the framework.
Avoidance of fiduciary status as a practice in 1974 has evolved to disclosure and
transparency of all entities who are fiduciaries (Guerriero, 2017). As the shift toward
defined contribution plans persists, 2015-2017 legislation has changed to account for the
oversight and consumer protections of an investment-oriented product (Guerriero, 2017).
Fiduciaries may lack to guidance and strategies to protect themselves from personal

23
liability. The shift towards investment-oriented products infuses elements of suitability
and risk that fiduciaries must account for and mitigate.
Guerriero (2017) acknowledged the organizational risk of workplace retirement
plans continued to evolve. some authors have offered insights into the changing landscape
of fiduciary responsibility, ways in which employers can stay abreast of additional
changes, and react accordingly regardless of the challenges that may exist (Bartlett, 2016;
Cerrone & Hirschhorn, 2016; Geller, 2015; Swisher, 2017). Investment decisions are
normally out of the purview of plan sponsors, employers specifically focus on the areas
they can reasonably assess. Bartlett (2016) synthesized a common theme of client
communications, a long-standing method of determining the appropriate way to share
information. Geller (2015) described another common theme, the retirement plan
committees, who ensure varying voices in the overall decision to select a plan. The
mitigation of fiduciary responsibility was a common objective of employers, in which I
use the work of Swisher to synthesize the best practices.
Bartlett (2016) identified client communications as an area of awareness for
employers under the new DOL Fiduciary Rule. Client expectations have shifted from
phone calls and letters to electronic mediums like email and text messaging. As
technology has created efficiencies in communicating among various stakeholders,
privacy of such information has become paramount. A meeting conducted in person was
acceptable via video conferencing or through a webinar. As financial decisions increase in
depth, clients seek event-driven communication; targeted communication around goals
like retirement, marriage, or college savings are more advantageous and in the best

24
interest of the client (Bartlett, 2016). An employer accounts for the appropriate
communication method, based on the needs of employees and providers’ delivery
method, to meet a fiduciary standard.
Geller (2015) focused the argument of employer strategies, in which employers
who have workplace retirement plans, or those thinking of enacting a plan, often used
committees to ensure a plans’ prudent management. Geller addressed the aspects of the
DOL’s fiduciary rule that employers should consider in deciding on a retirement provider.
Retirement plan committees should be aware of DOL initiatives, ensure appropriate due
diligence, understand methods of revenue sharing, and align to an investment policy
statements (Geller, 2015).
As described by Swisher (2017), employers who embrace the fiduciary business
model follow the fiduciary principles and processes, more so than simply showing
compassion about employees. Fiduciary responsibility has shifted from avoidance to
transparency; employers must prepare for a new and changing paradigm (Swisher) that
includes changes to retirement committees, participant communication methods, and the
financial professionals through which they interact. Organizational risk, considering
2015-2017 changes to the DOL’s fiduciary classification, has changed the way employers
prudently managed workplace retirement plans since 1974. The employer is asked to
embrace fiduciary responsibility as opposed to avoiding such responsibility.
Workplace retirement plans are similar in nature to other forms of risk a
corporation must manage. The communication methods, use of technology, method of
financial education and overall suitability concerns are a sampling of what fiduciaries

25
must account for. An all inclusive process that accounts for the varying elements of
compliance and meeting savings needs of employers is a responsbility fiduciaries must
account for. The question of how to infuse such changes may be addressed through the
application of LMX theory.
Application of LMX theory through Governance dimension
The history of ERISA, organizational risk of retirement plans, and the present-day
liability necessitate an organizational culture in which those giving directions, and those
following directions optimize responsibilities. Through the lens of behavioral governance,
ensuring such alignment exists is a function of the governance dimension. As laws and
procedures in 2018 exist for governance, the prescriptive model of LMX theory which
was an intriguing aspect of assessing leader and follower behavior. LMX theory research
identifies a causal relationship to positive employee behaviors such as job satisfaction,
commitment, creativeness, positive citizenship behavior, and alignment to reward systems
(McCleskey, 2014; Northouse, 2016;).
Arif, Kashif, Sindhu, and Zahid (2017) correlated the conceptual framework of
LMX theory to change management within organizations. Given the 2015-2017 changes
to fiduciary definitions and liability of breach that has proceeded, a leadership approach
inclusive of change management aspects would aid business leaders. As Don Trone
described in DOL hearings, five years of experience plus additional training is the
baseline to determine the new best interest standard (Pasztor, 2016). Arif et al.(2017)
offered a viewpoint of LMX theory in change management; in which organizational
change emphasizes the need for people to alter values and perspectives to align with the

26
organizational perspective. Under such a premise, special emphasis is placed on the roles
of leaders and members, and the interactions between members and leaders (Arif et al.,
2017).
To increase the probability of change success, understanding the change process is
a series of actions, procedures, communications, and regular meetings (Arif et al., 2017).
Understanding the roles at play and the interaction between the roles is a precept of the
change process. These findings were important because of the ability to relate the dyadic
relationship to procedures and communication in fiduciary and employee interactions.
The ability of leaders to use LMX theory as a prescription for incorporating change
throughout an organization is one of the benefits that stands out among other leadership
theories.
Assessing the Efficacy of Fiduciary Responsibility in Retirement Plans
A fundamental question of workplace retirement plan organizational risk was why
fiduciary standards exist and the ramifications of breaching the fiduciary status.
Secondary to the question of why fiduciary standards exist was what acts, requirements,
or actions by plan fiduciaries? Finally, fiduciary liability can be assigned to an individual
as well as a group, in either case, what was the scope of fiduciary responsibility regarding
risk assessment and risk mitigation?
The responsibilities of a plan fiduciary are robust and nuanced. Compliance is
essential to avoid fiduciary breaches which have become more commonplace. As Geller
(2015) acknowledged in vary sentiments from meta-analysis of qualitative studies, the

27
DOL has established aggressive litigation and audit initiatives that impose personal
liability on plan fiduciaries for the failure to monitor the reasonableness of plan expenses
paid with plan assets. A liability quantified by Bonestroo (2017) based on data from the
Employee Benefits Securities Administration (EBSA); in which 2002 civil investigations
in 2016 - closed with 67.7 % resulting in monetary or corrective action, an average
penalty of $500,000.
Fiduciary standards exist to ensure adherence to the fiduciary principles that
underpin professional relationships among the average consumer, a thought articulated by
Aikin (2016) that described why fiduciary responsibility is important. A simpler rationale
of the decision-making sponsors must make, whether equipped with the proper expertise
or not, is offered by Bonestroo (2017) whose meta-analysis of qualitative research due
diligence exhibited by plan fiduciaries is outlined in Figure 1. Some employers fall into
three categories; plan sponsors may have the expertise, may not have the expertise and
seek guidance, or are completely unaware of actions that may cause compliance issues.
Further refining the decision-making, where applicable the plan sponsor may deem it
necessary to hire an individual to assist with fiduciary duties or receive education on the
specific roles and responsibilities of a fiduciary. The standards of prudence and loyalty
underpin the responsibility of plan sponsors to act in a manner that adheres to the best
interests of employees.
28
Figure 1: Decision making with or without expertise
Plan sponsors may not know the level of fiduciary responsibility required to
administer a workplace retirement plan. Existing research offers a roadmap in navigating
the fiduciary landscape. Over time best practices have emerged in the compliance and
administration of retirement plans. A helpful guideline and framework for employers is
the Bonestroo (2017) research in this area of fiduciary liability. The four thematic
elements of the work of Bonestroo are; a sense of awareness of fiduciary responsibility,
transparency in the decision-making, clarification of the roles, and the best practices.
Awareness. Employers should be aware of general requirements and fiduciary
requirements of sponsoring a plan.
Transparency. An audit trail of the named and unnamed fiduciaries of the plan
exists, including the personal liability of plan fiduciaries.
Expertise of fiduciary
May have
May not have
and seeks
guidance
completely
unaware of
impact of actions
Lack of expertise
Hire or contract
an invidual for
fiduciary duties
receive education
on the specific
roles and
responsibilities
Decision must reflect
prudence loyalty
29
Clarification. An understanding of the administrative tasks, educational materials,
plan documentation, and documented procedures is explained to plan fiduciaries.
Best Practices. An outline of the common mistakes fiduciaries make is made
available to plan fiduciaires.
Transparency is a multi-faceted theme, the inclusion company stock or a
retirement plan committee add additional layers of transparency. Using the framework of
Bonestroo (2017) as a base and layering additional disclosures outlined by Burch (2017)
for the inclusion of company stock and Geller (2015) when decisions are made by a
retirement committee. As Figure 2 depicts, the work of Bonestroo, Burch, and Geller to
address transparency is multi-disciplined but aligned toward the common goal of
transparency.
Figure 2. Interrelationship of transparency activities
401(k) committees
should make fiduciary
decisions concerning
the plan as experts
would, with the same
care, skill, prudence,
and diligence under the
circumstances
placing investment
savvy non-insiders as
ERISA fiduciaries and
removing insider ERISA
fiduciaries to reduce
insider trading concerns
An audit trail of the
named and unnamed
fiduciaries of the plan
exists, including the
personal liability of plan
fiduciaries
evaluating plan
documents, other
governing plan
documents, and
investment policy
statements to remove
ambiguity related to
investment in employer
stock

30
Business leaders who offer employer stock in retirement plans require additional
information. Requirements to evaluate plan documents, governing plan documents, and
investment policy statements to remove ambiguity related to investment in employer
stock (Burch, 2017) represent some of the requirements sponsors face. Employers should
consider placing investment non-insiders as ERISA fiduciaries and removing insider
ERISA fiduciaries to reduce insider trading concerns (Burch, 2017).
Retirement plan or 401(k) committees should make fiduciary decisions
concerning the plan as experts would, with the same care, skill, prudence, and diligence
under the circumstances (Geller, 2015). Members should systematically conduct due
diligence on all plan investment at regular intervals to ensure continued appropriateness,
and the level of diligence must be reasonable and appropriate under the circumstances. As
a result, ensuring an audit trail of communicating, and acknowledging the communication
of responsibilities was prudent.
Retirement Plan Committees must outline a process to effectively and
competitively bid recordkeeping services and limit the payment of revenue sharing from
the plan service provider. A reasonable plan cost was hard to estimate because of the
ambiguity associated with describing plan fees. Carosa (2013) identified a common
narrative in the public policy of retirement plans; in which most regulators will indicate
the cost of paying too many fees without ever indicating a reasonable fee amount. The
cost of a retirement plan varies, but insufficient data to arrive a reasonable benchmark.
According to the Brightscope Inc. database of retirement plan tax filings, the
average cost for more than 50,000 plans provides insight into the employer costs (Carosa,

31
2013). Retirement plans with assets over $100 million signified total plan costs averaging
0.49% (Carosa, 2013). Plans with assets totaling $10-$100 million incurred total plan
costs on average of .87% (Carosa, 2013). Finally, the segment of plans under $10 million
reported total plan cost averages of 1.41% (Carosa, 2013). Fiduciaries are responsible for
determining the suitability and reasonableness of fees as part of their due diligence
process.
Communication of Retirement Plans
Kim (2013) found an inadequacy among 42% of working households
preparations for retirement. Another 47% rated future retirement income adequate (Kim,
2013). Thirty-eight million working-age households do not have access to a retirement
account, whether in an employer-sponsored 401(k) type plan, or an IRA (Rhee, 2013).
The average working household has no retirement savings. The collective retirement
savings gap among working household’s age 25-64 ranges from $6.8 to $14 trillion
depending on the financial measure (Rhee, 2013).
Workplace retirement programs are a multi-faceted vehicle for employers. The
objective is to reduce employer costs for employee retirement, mitigate fiduciary liability,
take advantage of tax benefits, and engage employees in purposeful retirement planning.
Employers must weigh the benefits of offering a retirement program against the potential
liabilities associated with the program (Bonestroo, 2017). One way to mitigate liabilities
lies in the communication program to employees.
Weiner and Doescher (2008) defined a succinctly organized framework promoting
retirement programs which described two approaches, structural and communication best

32
practices. The structural approach is used to create the ideal conditions given policy and
legislation to achieve retirement savings (Weiner & Doescher, 2008). The
communications approach is behavior oriented, enabling a change knowledge and
perceptions to increase engagement for retirement savings (Weiner & Doescher, 2008).
The benefits and consequences to each approach are numerous, from an organizational
risk perspective assessing each approach based on fiduciary compliance and employee
engagement.
The structural approach was a prudent framework to assess compliance. The
structural approach alters the conditions associated with retirement savings; for example,
the advantages of pre-tax benefits or income contributions limits may act as a lever to
increase retirement savings or limit the pre-tax savings of high-income earners. In the
view of academics and government agencies, a compliant plan design under ERISA
specifications allows employers to enjoy a host of tax benefits (DOL, 2019; IRS, 2019).
The design of retirement plans permits pre-tax savings, tax-deferred growth, and tax
deductions on the part of employers and employees. The tax treatment applies to all
participants, in which, defined contribution plans do not discriminate in favor of highly
compensated employees (DOL, 2019; IRS, 2019).
From a regulatory view there are guidelines for classifying employees outside of
the scope of my research. Classifications of employees regarding IRS status were outside
of the scope of my research; for example, highly compensated defined as an individual
making above $115,000 has no bearing on the research question. Similarly, an important
employee classified as someone with ownership status or decision-making authority, and

33
greater than $150,000 in compensation (IRS, 2019) has no bearing on the research
question. The structural approach also encompasses plan design architecture, which
allows an employer to build a retirement plan based on the businesses’ specific needs.
The structural approach is more quantitative based, ripe with documentation to mitigate
liability and based on an abstract view of the needs of participants in favor of compliance
on behalf of the employer.
Some authors have acknowledged the educational gap between knowing and
doing such as Forte, (2014) and Tisdell, (2014). The gap persists as 2015-2017 data has
concluded that steps to narrow this gap globally have been inadequate (EBRI, 2017). The
communications approach seeks to change both the knowledge and perception of savings,
retirement, investments, and decision-making to positively influence retirement savings
(Weiner & Doescher, 2008). To change knowledge of financial matters education has
been used in various forms of enrollment support to guidance through tools and resources
(Forte, 2014; Tisdell, 2014). Education alone has not been able to change perceptions, in
instances an infusion of behavior modification and education may yield positive results.
Financial Education and the method of delivery may offer insights into how to
mitigate risk for organizations. Tisdell (2014) found that certain assumptions within a
definition of financial education that influence the output of education. One was the
assumption of a capitalist economy. The embracing of capitalism occurs in several
countries including the United States, Canada, Germany, China, Japan, and India, yet the
ideology of capitalism is different, even among those who embrace it. As Tisdell
acknowledged the notion that a capitalist economy does not serve the interest of

34
lowincome, poor, or diverse socio-cultural communities is seldom addressed. The
influence of individuals from adverse downstream effects of programs that embrace
capitalism is a challenging environment for those who can benefit the most from
education programs.
The role of social experience, and sociocultural issues influence the
decisionmaking of consumers. Forte (2014) expanded upon the narrative of socio-
economic influences on financial decision making through a discussion of the way adult
learners and educators must account for the race, ethnicity, gender, socio-economic class,
education, sexual orientation, age, language, and ability of the audience. Forte (2014) and
Tisdell (2014) had a common opinion, (in line with the work of Vygotsky 1978; Choules,
2007; Freire, 1971 and Freire & Macedo, 1995), that social experience shapes the ways of
thinking and interpreting the world, referred to the perception of money within the family
unit, and emotional support for financial issues.
The current state of education programs perpetuate a misconception that a
consumer presented with financial knowledge will; spend less, save more, strengthen the
economy, and do personal bests to prevent another financial collapse (English, 2014).
Regardless of age, gender, or race; individuals failed to save enough for retirement,
overinvest in risky or overly safe assets, fail to take advantage of certain tax benefits, and
chose to remain outside of the formal financial sector entirely (Garcia, 2013). By failing
to acknowledge the process of becoming educated, leaders are unaware of the bottlenecks
within the process. Such bottlenecks are inherently risky as leaders fail to see how the

35
challenges of education transition into financial literacy and subsequent changes in
behavior.
Ambuehl et al. (2016) conducted research into the role financial education plays
in several areas participant decision-making that offer insights into how an organization
may mitigate risk. Lusardi et al. (2017) explored the role of financial education in
widening the gap of wealth inequality. Clark, Lusardi, and Mitchell (2015) described the
influence of limited education on long-term retirement preparation behavior. Clark et al.
explained the gaps in financial literacy skills that will need to be filled to avoid pitfalls
based on such limitations. The correlation between financial education and risk, the
factors outlined by Lusardi et al.(2017) show interconnected role of education.
The theme of behavioral economics is an infusion of psychology and economics
to explain participant behavior. A near-universal conclusion of participant behavior is
uniqueness; in which consumer decision-making were based on a combination of
heuristics when making complex decisions adoption (Hyoyoun & Wook, 2013;
Papaoikonomou et al., 2011). Advancements in behavioral sciences, and a consensus
among scholars in this area, highlight the need for an understanding of the way decisions
were made. Further to education, retirement plan communication programs must also
understand ways to nudge retirement savings behavior (Akabas et al., 2014; Hyoyoun &
Wook, 2013; Kim, 2013; Papaoikonomou et al., 2011; Rhee, 2013).
An irrational decision is seen more often as rationale given a set of variables (Adel
& Mariem, 2013). The correlation between decision making and literacy rates persisted
throughout the research. For example, Copeland (2013) and VanDerhei (2013) noted most

36
consumers are unprepared and lack confidence in the ability to retire. Similarly, in works
of Brown and Graf (2013), and Castro-Gonzalez (2013) unprepearedness was a common
theme as their research validated financial literacy rates below acceptable comprehension
levels.
The organizational risk of the workplace should account for the behaviors and
situations that lead a consumer to make decisions, as the ramifications of these decisions
may lead to litigation depending on the losses incurred by the consumer. For example, the
complexity of financial decisions resulted in challenges for consumers, deficiencies in
both preparation and capacity to optimize accounts (Akabas et al., 2014; Kim, 2013;
Rhee, 2013). Low confidence in the ability to retire and to have enough money to last
through retirement caused limited or conservative savings participation, highlighting the
issue retirees faced most often (EBRI, 2017).
The communications approach emphasizes the individual, the behavior, and how
to nudge behavior to optimize retirement savings (Weiner & Doescher, 2008). Used
independently the communications approach, and structured approaches have shown
several inconsistencies in attainment of, influence, and knowledge required to achieve a
goal. When combined with the structural approach, a framework that addresses structure
and communication strategies provide employers possess two methods of engagement for
workplace retirement plans. Engagement plays an important role in the workplace
retirement plan. Engagement serves two purposes; first, as a conduit toward application.
Unless an employee base is actively involved in the retirement plan, a company cannot
fully capitalize on tax advantages of the program. Second, considering a healthy

37
participation, employers can use engagement as a tool to assess the reasonableness of
costs associated with establishing a plan.
The conversation of organizational risk is a one regarding expenses regulated by
the employer. In some instances, a growing financial burden excluding the prospects of
litigation. Employer expenses have continued to rise, measuring the effectiveness of
retirement programs remain challenging (EBRI, 2017). An abundance of information was
available about the retirement phenomenon the United States faces; in business
decisionmaking, a retirement program is one factor in a suite of employee benefits and
benefits costs.
Application of LMX Theory through Stewardship Dimension
The efficacy of workplace retirement plans, and how utility is communicated
highlights the plight of business leaders to wisely and objectively make decisions. A
number of factors including the growing influence of behavioral sciences, low levels of
financial literacy, and misaligned communication campaigns give credence to LMX
theory as an approach. Factors that manifest from an innate understanding of individuals
are a function of stewardship; the work of Lloyd, Boer, and Voelpel (2017), as well as,
Omilion-Hodges and Baker (2017) are prescriptive models to apply.
Lloyd et al. (2017) highlighted the importance of listening in the creation of
potential for long-lasting, strong partnerships. Specifically, the listening aspect of the
dyadic relationship is a factor in leader-employee relationships that may influence
workrelated attitudinal and behavioral outcomes. The work of Matta, Scott, Koopman,
and

38
Conlon (2015) described similar findings by notating the meaningful effects of employee
motivation and behavior. These findings were important because of the behavioral aspects
associated with the risk of organizational workplace retirement plans. Omilion-Hodges
and Baker (2017) described the advantages of LMX by highlighting relationships are a
byproduct of effective communication exchanges, concrete and continuous. Designating
communication as the central driver of effective exchanges between leaders and members,
Omilion-Hodges and Baker (2017) suggested that such communication exchanges occur by
working together to accomplish organizational tasks. LMX research validates member
advantages through higher levels of autonomy and job satisfaction. Such advantages also led
to corporate profitability in the form of team effectiveness and higher job performance
(Omilion-Hodges & Baker,
2017).
Alleviating Fiduciary Responsibility
The neoclassical approach toward retirement savings uses a structural approach to
increase participation and meet retirement plan compliance. As discussed, this approach
includes optimizing the tax benefits, and plan design elements to boost participation. The
approach did little to change behavior, instill confidence, or, increase the knowledge base
of employees (Weiner & Doescher, 2008). Employers may also use resources based on
the precepts of behavioral science to influence cognitive aspects of retirement planning
and to mitigate fiduciary liability.
Weiner and Doescher (2008) developed a framework for promoting retirement
savings infusing classical approaches and behavioral sciences. One aspect of this

39
approach is the concept of Goal Efficacy which is the combination of an individual’s
selfefficacy and the response efficacy. In other words, the perceived ability is the sum of
(a) one’s assessment of an ability and (b) the likelihood of success for an act using the
ability. Based on findings, a person must think that the positive consequences of acting
outweigh the costs. If a person’s self-efficacy is so low that the individual does not think
engagement in an act is feasible, effort will be minimal. When self-efficacy is low,
increasing the benefits from acting (higher returns, more money) will not result in a
higher likelihood of acting.
Participants of retirement programs must determine whether saving is possible;
where possible represents the belief that saving will result in maintaining current
standards of living throughout retirement. The goal efficacy approach is a framework for
leaders to understand the behavior of employees in answering the savings question. Goal
efficacy is a premise which assumes if a person does not believe they can save, does not
know how to save, or does not believe that saving they will maintain current lifestyles,
they will not act or even attempt to act. Upon assessing a consumer’s ability, and the
likelihood of success, if the consumer confidence is low there is a failure to act.
Goal Efficacy
Applying the classical approach of Weiner and Doescher (2008), the achievement
of participant saving occurs through the accessibility of educational resources, and
automatic defaults of the most common product features. In the short-term, such a
practice would change the statistics of the retirement plan optimization, yet, would do
very little to change behavior. In the context of goal efficacy, nudge concepts are used as

40
determinants to limit subjective judgment. There are four concepts which have proven to
be successful;
The communication of effective attainment among business leaders. The
experience of past successful performance of a similar task increases the perception of
achieving a task. Business leaders should understand the logistics of long term saving
when considering retirement savings. The research and results highlight the effacacy of
the concept through the use of stewarship behaviors. Tasks to encourage non-savers to
begin saving small amounts of money on a regular basis and over time, encouraging them
to increase the level of saving. Citations?
The influence of a vicarious experience to enhance engagement. The
observation of similar individuals succeeding at a similar task increases confidence.
Business leaders should understand the need to communicated the achievement of goals.
As discussed in the presenation of findings, stewardship activities were essential to this
concept. Enhancing engagement through communication of how others with similar jobs,
employers, and life circumstances are saving creates confidence in others. Citations?
The effect of persuasive messages in communicating. A marketing-oriented
message that communicate that the individual can meet an objective. Business leaders
should understand, and my research validates the understanding, that increasing an
employee’s confidence is as important as providing access to resources. Incorporating
messages that convey confidence in the individual’s ability to save enough money to
reach either a retirement goal or similar goal creates confidence in others to achieve the
same (Weiner & Doescher, 2008).

41
The sway of heuristics and bias among business leaders. The mental short cuts,
or rules of thumbs, people use when making judgments under uncertainty is a
consideration of future behavior. People save in various ways; business leaders must
understand the nuance of culture and diversity on behavior. A lack of personal
experiences or experiences by others who share a viewpoint may create communication
barriers. As noted by scholars, individuals who experience such communication barriers
may have trouble saving (Garcia, 2013; Hyoyoun & Wook, 2013; Tisdell, 2014).
Application of LMX Theory through Leadership Dimension
Engagement techniques for workplace retirement plans use two approaches; a
structural and communication (Weiner & Doescher, 2008). The foundation of the
structural approach includes public policy and legislation; the approach aims to ensure
compliance by applying the classical approaches of education and automation to increase
plan participation (Weiner & Doescher, 2008). Sponsors may favor the approach to
mitigate low engagement, allowing fiduciaries to meet compliance obligations through
transparency and documentation. The communication approach is behavior-oriented; in
which the utility of marketing and persuasion approaches are implored to increase
participation (Weiner & Doescher, 2008). sponsors may favor the communication
approach for those with high engagement. Ideally, plan sponsors would benefit from a
blend of the two approaches ensuring an offering satisfies the needs of those highly
engaged as well as those who may not be engaged.
Employers warrant a viable framework for change if the findings of my research prove
to be advantageous. Scholars have applied concepts and practices of LMX in empirical

42
studies. The results of experimentation have shown the framework of leadermember
Exchange (LMX) theory may be a viable and prudent option (Arif et al., 2017; Cropanzano,
Dasborough, & Weiss, 2017; Lee & Chae, 2015; Lu & Sun, 2016; Lloyd et al., 2017; Matta et
al., 2015; Newman, Schwarz, Cooper, & Sendjaya, 2017; OmilionHodges & Baker, 2017).
The correlation of the leader/follower dynamic is like the dynamic of the fiduciary/employee
dynamic, further discussions of the relationship refers to fiduciary/employee. A correlation
exists between the engaged and disengaged employee and the in-group and out-group
concepts of LMX theory. Several aspects of LMX theory show the viability of the framework
as a conduit of change management.
Researchers of LMX theory have provided evidence of employee motivation and
positive behavior, increased communication, enhanced listening, mediation of
organizational change, influence of organizational culture, organizational citizenship
behavior, organizational policy formation, and socio-emotional behaviors (Arif et al.,
2017; Cropanzano et al., 2017; Lee & Chae, 2015; Lu & Sun, 2016; Lloyd et al., 2017;
Matta et al., 2015; Newman et al., 2017; Omilion-Hodges & Baker, 2017). Researchers
have conducted studies in which results have shown that LMX theory serves as a conduit
for job resources and social support, addresses diversity and cultural communication
differences, and offers perspectives on the individual, the dyadic relationship as well as
the collective group (Lee & Chae, 2015; Lu & Sun, 2016). LMX theory is a framework
that originated in 1975 through the works of Dansereau, Graenm, and Haga (Northouse,
2016),

43
The benefits of LMX include easing communication differences and varying
perspectives of individual participants, insight into the perspective of a collective group,
identify the influence of higher quality relationships, and identify ways to increase levels
of trust. When analyzing the data, I used themes categorized by similar segments to
convey the results as a best practices summary. Two potential interactional outcomes of
the LMX approach are in-group and out-group behaviors; a factor of how to manage
engaged and disengaged members (Northouse, 2016). Facets of LMX theory research
identifies a causal relationship to positive employee behaviors such as job satisfaction,
commitment, creativeness, positive citizenship behavior, and alignment to reward systems
(McCleskey, 2014; Northouse, 2016). LMX also serves as a prescriptive model among
leaders and followers. A prescriptive model because the content delivered to leaders
evolves naturally, is trainable, can be developed over time, and may apply to various
levels of an organization (McCleskey, 2014).
Cropanzano et al. (2017) acknowledged the success of LMX theory in studying
organizational leadership. The favorable employee responses of better performance and
organizational citizenship behaviors allowed for more focus on the significance of the
dyadic relationships. Denoting the influence of higher quality relationships increasing
levels of trust, respect, and liking, employers would ideally seek this behavior.
Specifically, increasing trust of all higher quality relationships was what makes LMX an
ideal framework in which mitigating risk was a desired outcome. The research of
Cropanzano et al. (2017) is an insightful analysis of the employee behavior; in which
low-quality relationships exist within the organization, research emphasizes the feeling of

44
deprivation and unfairness which may imply a moral judgment. These findings are
important because of the liability associated with retirement plan participants who also
experience deprived and unfair, and how to change such emotions.
LMX theory was a suitable framework for Governance and Stewardship
discussions, nonetheless the framework was as insightful for the Leadership dimension.
Several researchers have found LMX to serve as a conduit for desired group behaviors.
Lee and Chae (2015) found the LMX framework improved job resources and social
support flows, each of which affects career-related outcomes in performance and
promotion. Newman et al. (2017) encouraged organizational citizenship behavior from
employees. Lu and Sun (2016) found LMX facilitated job performance through enhanced
self-efficacy and self-esteem. Because of aspects of the framework LMX derived from
organizational identification theory, a leader’s treatment of employees would be
interpreted as that of the organizations whether favorable or unfavorable.
Transition
Section 1 was an introduction to workplace retirement plans and concepts related
to transitioning from the workplace into sustained income through savings is not a new
concept. The concepts of pensions have existed for centuries, closer to 2015-2017
legislation of ERISA has served as a guide for fiduciary compliance. The present-day
reality of employers must address the need to offer workplace retirement plans with the
organizational risk associated with the product offering. Employers can assess the
organizational risk of retirement plans based on the retirement communications approach,
the resources available to mitigate risk, or a combination of both, once risk was assessed

45
a framework to espouse the best practices of limiting organizational liability offers the
best opportunity for employers to codify such practices into corporate culture. Section 1
of the study included the background and rationale for the assessment of organizational
risk, the subsequent sections outline the process of developing a methodology to assess
organizational risk of retirement plans and the conclusions uncovered in the
developmental process.

46
Section 2: The Project
The process of constructing a study to explore organizational risk associated with
retirement plans included an analysis of the rigor associated with the project. In the
following section, the scope of the study is outlined to include the research methodology
and design, validation and transferability of data, segmentation of participants for my
research as well as logistical information about the data collection and analysis. Section 2
of the study provides a framework to align the structural process of conducting my
research to the underlying intent of discovery indicated in Section 1.
Purpose Statement
The purpose of this qualitative multiple case study was to explore the strategies
business leaders used to minimize the organizational risk of workplace retirement plans.
Business leaders responsible for the operation of retirement plans represent the optimum
sample participant base. An optimal base of 10 stakeholders represents a national
geographic footprint as well as a different subset of industries in which the plans operate.
The Edelman trust barometer is an annual global study of trust among institutions; in the
latest iteration of the study, 2018, 72% of respondents indicated they trust employers,
while the benchmark of trust in U.S. financial services declined by 23% points (Edelman,
2018). My research, related findings, and context provide a pathway for employers to use
inherent trust to increase the trust of financial institutions. By limiting the distrust in
financial service firms using workplace retirement plans, business leaders could extend
the trust of employers to financial services alleviated while protecting the retirement
preparedness activities of consumers.

47
Role of the Researcher
Fink (2000) described an architectural design of data collection which includes
thematizing, designing, interviewing, analyzing, verifying, and reporting. Thematizing
allowed me to answer several questionsof what was going to be studied, why, and how to
complete the research. Designing relates to the methodical process of planning and
preparation. Interviewing was the process of constructing the interview guide and
conducting the formal interviews of my study. Analyzing was the result of naming and
categorizing of the results through close examination of data. Verifying was a process in
which generalizability, reliability, and validity of findings results in the final reporting. To
ensure reliability and validity of my study, the framework outlined by Fink was an
established process that defines the process of data collection from inception to
conclusion.
The Belmont principles are outlined in a seminal document produced by the U.S.
Department of Health and Human Services in 1979 (Bromley, Mikesell, Jones, &
Khodyakov, 2015; Cascella & Aliotta, 2014; Hammer, Eckardt, & Barton-Burke, 2016).
Ensuring the tenets of the Belmont report were met is a process that begins when
designing a study (Hammer et al., 2016) and is an integral part of the entire study adheres
to the trust-based obligations that are foundational aspects of research ethics (Bromley et
al., 2015). Researchers using quantitative and qualitative studies must adhere to Belmont
principles; researchers of qualitative studies are more likely to engage participants and the
ethical considerations of human subjects (Cascella & Aliotta, 2014). The tenets of the

48
Belmont report include respect of persons, beneficence, and justice to describe the
interaction between myself and research subjects or participants (Hammer et al., 2016).
Respect for persons outlines the informed consent process. To adhere to this
principle the informed consent document must be comprehensible, meaning free of
perplexing legalese, available in multiple languages, and graspable (Cascella & Aliotta,
2014). The tenet beneficence is a description of the experimental nature of a study. In
general, researchers of a study seek to maximize benefits of the research project while
minimizing harm to the subject (Bromley et al., 2015). Last, the tenet, justice, is an
interpretation of how the researchers views a study significance and ensures the research
study was nonexploitative and fair among participants (Bromley et al., 2015). When
engaging human subjects, researchers adhering to the justice principle should ensure
persons with communications disorders should have an equal opportunity to participate in
research, independent of education, race, ethnicity, and socio-economic class (Cascella &
Aliotta, 2014).
The focus of my study was to provide the perspective of strategies stakeholders
use to mitigate organizational risk. The scope of my study did not infer a form of
treatment, nor did I aim to correct a behavior; as a result, I maintained a separation
between practice and research to avoid conflict or bias. The ethical considerations for the
research met the protocol of the Belmont report by adhering to the context of respect for
persons, beneficence, and justice.
The criteria for participation in my study also infers a degree of justice in which
each business leader equally shares responsibility to make decisions in the best interest of

49
the client, the employer, or plan sponsor. I used a documented acknowledgement for each
participant to confirm his or her informed consent to participate in my study. Participation
in my study was voluntary; any and all risks were outlined to make an informed decision
regarding participation. A listing of the criteria used for selection of the participant
sample appears within the content of Section 2. The process of participation was
understood to be voluntary and if desired, participants could withdraw at their discretion.
Bazzano (2014) described the process of Epoche as one in which the view of
world, self, or others is afresh. The process outlined enables me to remove potential bias
of the population, by learning a situation anew through the perspectives of participants.
The use of open-end questions ascribes to the insights of Chenail (2011) to create an
environment that allows for the insiders’ perspective to take center stage.
Participants
Employers seek retirement plan providers using financial intermediaries or
directly through the retirement plan provider. A plans sponsor engages in a due diligence
process to compare the investment options, educational resources, plan features and plan
design elements of multiple providers prior to a decision (Bonestroo, 2017). Upon a
favorable decision, the management installation and conversion of plan assets into a new
workplace retirement plan by a plan provider relationship manager begins the retention
process (Bonestroo, 2017). The relationship manager, retirement committee members,
third party administrators, and organizational representatives represent a group of
stakeholders to make appropriate plan decisions. The stakeholder represents a valued
partner in the origination or takeover of a retirement plan. Stakeholders analyze the

50
previous plan or current needs, fill the gaps with services and resources of the provider,
and ensure the plan is established to follow applicable regulations.
To be eligible for participation in my study, stakeholders met certain criteria.
Ninety-four participants responded to a screening survey for the candidate pool. The
candidates met criteria of participating in at least one conversion or installation of a
retirement plan, a tenure longer than 1 year, and an understanding of the term’s fiduciary
and organizational Risk. In addition to meeting my study criteria, a significant amount of
the 94 participants were employed full time (92%) and have a tenure of greater than 5
years (61%). The participant baseline was a person who is asked their opinion (95.1%),
who generally has an opinion or point of view on a subject (85%), who offers their advice
in great detail (90%), and who enjoys exchanging ideas with people (90%).
This study was an exploration of organizational risk in which I leveraged the
expertise of the business leaders. The stakeholders are in an advantageous position to
describe the approach to assessing organizational risk and communicating potential
solutions to plan sponsors. The stakeholders are in the unique position of answering the
primary research question of my study “What guidance of strategies to minimize the
organizational risk of workplace retirement plans do stakeholders present?”
To answer the research question, I used definitions and process described by
Asiamah, Mensah, and Oteng-Abayie (2017) to define a study population through the
hierarchical specification of general, target, and accessible populations. The general
population shares one area interest; the target population was comprised of those whose
participation aligns with the research goal, assumption or context, and the accessible

51
population which was comprised of a sample population who may or may not participate
from which data was collected by surveying either all its members or a sample drawn
from it (see Asiamah et al., 2017). The framework was not unique as a similar framework
by Fritz and Morgan (2010) used different terms; the iterative process calls for the
refinement of the target population by the accessible population, the selected sample, and
conclude with the actual sample.
Asiamah et al. (2017) used a collection of best practices, easy to understand
context, and process orientation which was ideally suited for my research. The general
population included business leaders among all employers with workplace retirement
plans, a single attribute of interest was they had workplace retirement plans. Upon further
refinement, the target population included employers with workplace retirement plans,
who work with stakeholders for ongoing maintenance and compliance, greater than 100
employees, who used defined contribution plans, and purchased through a national plan
provider. Further refinement resulted in the sample population for my study denoted as
the accessible population.
As described by Baskarada (2014), the unit of analysis is an essential aspect of the
case study was for otherwise the entire study may be invalidated. In my case, the unit of
analysis was the role of the business leader. Stakeholders are best equipped to describe
how options to minimize retirement plan organizational risk. The stakeholders possess a
better understanding of the best and worst cases of risk assessment conversations.
Access to the pool of stakeholders was provided by the market research and
recruiting firm Dynata. Dynata is a provider of online panels and recruitment of

52
participants for various studies; in this capacity I use their expertise in recruitment to
secure the participant base. As with other studies and focus groups, the basis of the
relationship between me and participant was the premise that the participants for this
study were adding useful insights to the inner workings of organizational retirement
plans.
Research Method and Design
Research Method
The research study was a qualitative exploration of the organizational risk associated
with workplace retirement. Several scholars (e.g. Applebaum, 2012; Barnham,
2015; Connelly, 2010; Cronin, 2014; Tuohy, Cooney, Dowling, Murphy, & Sixsmith,
2013) described the appropriateness of qualitative methodologies in retirement plan
oriented research. Applebaum (2012) denoted the fit of qualitative studies based on
existing research into retirement plan management, in which quantitative methodology
would focus on the data elements the qualitative focus seeks to understand the why and
how of phenomena. The mode of research was deductive in which I narrowly focused on
the business problem as opposed to the contrarian view, inductive, which was more
openended and abstract in nature (see Tuohy et al., 2013). Under this view, quantitative
methodologies which were abstract and vague would not be suitable to address a specific
business problem.
The strategy to obtain an answer to the research question uses opinion-oriented
research, in which data collection occurs through the survey, interviews, or brainstorming
(Connelly, 2010). A quantitative study would allow me to test a hypothesis given a set of

53
standards, to elicit facts through hard percentages or numbers (seeBarnham, 2015). By
using a qualitative methodology I investigated the problem through a holistic lens.
Research Design
Case studies were an appealing design to explore the organizational risk of
workplace retirement plans. Case studies seek to act as a form of discovery or act as form
validation, in either case, the result of the case study was to further clarify the stated
research question (Yin, 2017). Yin (2017) described the value of case study design
through an ability to address complexity and contextual conditions, among other methods
such as survey or experimental research. A case study can act as a method of discovery
uncovering the causes of organizational risk. Conversely, case studies can be used to
validate an assumption or opinion. The design contrasted most often with case study is
experimentation; my study would not be an ideal selection since in experimentation the
researcher controls the variables of the case, in which case studies allow the phenomena
studied to occur in a natural setting (Hammersley, 2004).
As noted in the work of Lokke and Sorensen (2014), building upon the work of
Cavaye (1996), case study research can be applied in various forms including positivist or
interpretivist, deductive or inductive, and quantitative or qualitative. An advantage of the
case study, regardless of form, was the ability to assist in the support of a theory building
(Lokke & Sorensen, 2014). When describing the theoretical research paths for case
studies Lokke and Sorensen cited the work of Flyvberg, in which case studies identify
real-life situations and test against phenomena producing an aspect of social life as they
unfold. The concepts of phenomenology were used to construct questions, the case study

54
design, which concludes with a way of conceptualizing, categorizing, and ordering the
retirement plan decision-making process was preferable.
Crowe et al. (2011) described aspects of a case study design that provide a
narrower definition of the type of case study used for my research. Naturalistic describes
the exploration of a phenomenon in its natural context (Crowe et al., 2011), the
phenomenon in this situation identifies the retirement plan management process. The
management process was explored in multiple cases. Similar to the approach described by
Crowe et al., multiple cases imply a collective case study design. If a study were larger in
scope a social survey might be appropriate, to gather large amounts of information from
multiple cases, the narrow scope nature of my study highlights the advantage of case
study design (see Hammersley, 2004).
The benefits of the case study design to initiate research extend to the concluding
results of case studies. Turner and Danks (2014) highlighted a focal point of process
improvement, in which benefits can arise through successfully completing a case study.
Given the assumption that researchers seek to understand the dynamics within a single
setting and phenomena originating from a discipline that is complex or paradoxical
(Turner & Danks, 2014), the design sets the foundation for identifying best practice
recommendations within the existing process. To ensure the proper design in gathering
process information Turner and Danks suggested a format of Benbasat, Goldstein and
Mead that I applied in which the examination of phenomena occurs in its natural setting,
the collection of data occurs by multiple means, examination occurs among multiple
entities and no indication manipulation of experimental controls occurred.

55
Population and Sampling
Considering the scale of the general population I used a convenience sample. The
convenience sample was an approach common among qualitative studies which are less
demanding, affordable, easy, and the subjects are readily available (Etikan, Musa, &
Alkassim, 2016; Oppong, 2013; Robinson, 2014). Using the guidance of Oppong, the
approach used matched similar qualitative studies in which the main objective is to
collect information from participants who were accessible to me. In contrast to random
sampling, which involves some sort of random selection of the population members, each
member of the population has a known and equal probability of being selected. Similar to
the approach described by Etikan et al. (2016), the most suitable participants to answer
the underlying research question were preferred.
Similar types of nonprobability sampling techniques have advantages but are
unlikely to be feasible given the scale of the general population. For example, using a
purposive sampling, which a researcher decides what needs to be known and sets out to
find the subject, was not ideal because the choice of participants could not be deliberate
given the criteria (Etikan et al., 2016). Considering the size of a general population of all
U.S. employers with workplace retirement plans, a hierarchical approach which refines
the general population to an accessible sample pool was more viable.
One disadvantage of convenience sampling was the inherent risk of bias. As the
primary researcher my professional experiences in retirement plan management,
operations and design could not manifest in the study. As Robinson discussed
convenience sampling biases and probabilities are not quantified and unpredictable

56
(2014). The risk of gathering poor quality data affecting research outcomes is possible
(Etikan et al., 2016; Robinson, 2014), hence, I chose a third-party for participant
screening to minimize the risk. Considering my study was exploratory in nature, a
consideration that the conclusions drawn from my research may validate the approach or
provide examples of gaps in the approach that can be revisited in subsequent studies.
The framework of the hierarchical specification for my study was used to classify
general, target, and accessibility in the following manner. The general population
included business leaders of all employers with workplace retirement plans, a single
attribute of interest was they have workplace retirement plans. I further refinemed the
target population to employers with workplace retirement plans and more than 100
employees who work with stakeholders for ongoing maintenance and compliance and use
defined contribution plans purchased through a national plan provider.
Once I provided the participant criteria, the target population of employers
responsible for one plan installation or conversion, to the service generating the
participant pool I was able to begin the process outlined in Figure 3.
57
Figure 3. Population and sampling process
Case studies are appropriate for exploratory exercises to establish baselines for
phenomena (Baskarada, 2014; Boddy, 2016). Rich information can be attained through as
little as one case study in lieu of multiple studies or multifaceted studies (Baskarada,
2014). Data saturation occurs when repetitive information is no longer possible, my
findings indicate the case study was an appropriate framework to provide rich context
from a single case (Morse, 2004). Ideally, saturation entails collecting data from subjects
capable of providing insight within a scale that infers generalizability (Litt, 2010; Morse,
2004). The approaches of theoretical saturation are typically an approach of grounded
theory, the same principles apply in any qualitative research in which the data collected as
part of a process that is exploratory in nature (Litt, 2010; Morse, 2004).
Output of viable
candidates for study (94)
Refine participant sample
based on consent
acknowledgement
Thirty four candidates
based on meeting study
criteria.
Separate list into pilot
group and final group,
random selection.
Distribute consent forms
to pilot and final groups
Conduct pilot interviews,
refine, clarify
Conduct final interviews
Interview question
completion will took place
independent of the
observers.
Interviews took place via
web conference using
Zoom conference services
to enhance accessibility
and convenience.

58
I used a pilot study to determine plausibility of data saturation based on the
questions, validating or changing to ensure saturation during the final study. Boddy
(2016) described instances in which sample sizes as low as 10 and no higher than 30 are
appropriate to determine saturation. Boddy has indicated multiples of 10 subjects are
appropriate for a minimum sample participant base. A fact conferred by Baskarada (2014)
who indicated a minimum of between 10-12 subjects or units for a minimum sample in
exploratory cases. Mason (2010) has noted qualitative studies of smaller project sample
sizes, consisting of at least 25 participants, are sufficient as little net new information
occurs by interviewing more than 20 people. My pilot study was an interview with 10
relationship managers responsible for the provider to plan sponsor relationships and on-
going support for retirement plans. I developed the research questions on my own; I did
not have a pre-existing question format to answer my research questions. Instead, I used
the pilot study to serve as a form of reliability and validity with a set of standard research
questions.
Pilot Study Research Questions.
1. In what ways, have you supported the employer-sponsored retirement plan so that
employees are saving?
2. How do you minimize the organizational risk of retirement plans for Plan
Sponsors?
3. What strategies do you use to minimize the organizational risk of retirement
plans?

59
4. What tools and resources minimize the organizational risk of workplace
retirement plans?
5. How do you advise plan sponsors on their fiduciary liability associated with your
organizational workplace retirement plan?"
6. What steps help to mitigate fiduciary liability among plan sponsors?
7. How is an organizational risk of retirement plans communicated to managers and
directors of the organization?"
8. What are your top three resources used to mitigate organizational risk of
workplace retirement plans?"
9. What approaches or strategies towards organizational risk of retirement plans that
have not been discussed that may be important to this study?
Open-end questions were used as follow up, for example “does this question make
sense to you?” and “Do you understand the terms used?” to refine the interview protocol.
Checkboxes to acknowledge comprehension of the terms “fiduciary” and “organizational
risk” were added to the screening questions based on the pilot study questions.
Ethical Research
The context and compliance of Belmont Principles infer more than consent being
graspable, free from perplexing jargon and legalese, and available in the participant's
language. As several scholars have ascribed, the consenting process should explicitly
describe the relationship between the participant and research throughout a study
(Bromley et al., 2015; Cascella & Aliotta, 2014; Hammer et al., 2016). Specifically,
Bromley et al. (2015) inferred that in its simplest form Belmont ascribes that individual

60
becomes a subject by consenting to provide data, the process was task focused centering
on completing activities to generate data, and once the data collection was complete the
subject role and relationship with the researcher ends.
Participants in the interview portion of my study consented through a consent
agreement prior to the beginning of the interview. The consent agreement denoted that, as
conducted, the interview was part of a doctoral study, participation was voluntary, and
results were only to be used to supplement academic findings throughout existing
research. A pilot study, using a ten-person sample of participants, was provided with a
similar consent form, differing only in the expectation in which results are to be used to
revise interview questions.
The general population of my study included business leaders among all
employers with workplace retirement plans. Ninety-four business leaders met the criteria
of belonging to employers with workplace defined contribution retirement plans, with
greater than 100 employees, who work with stakeholders for ongoing maintenance and
compliance, and purchased through a national plan provider. Thirty-one participants
consented to participation in the study; the process of consenting, documenting responses
to the research questions (see Appendix A), and agreeing to an interview (see Appendix
B) resulted in a final sample of 13 business leaders. Incentives were not used to entice
behavior; the participation in my study was on a voluntary, participatory basis with a full
right to withdraw at any time in the process. In the consent form language, a statement
that the data was maintained in a secure location for at least 5 years to protect the rights
of participants appeared.

61
The participant received a description of the research and the scope of
participation in the research study. The participant was made aware of potential risks,
associated with participation in my study, and potential benefits resulting from the
research study. The participant received language that describes the protection of
confidentiality. The participant received language that addressed the voluntary nature of
my study and the process of withdrawal from the research study. The participant received
the contact information for myself and university affiliate.
The identity of participants, direct supervisors of participants, and companies
related to my study were not be revealed in any publication resulting from this study.
Participants were identified through number assignment correlated to participation in the
project. The responses to interview questions and the retention of the consent form were
maintained under a secured URL for at least 5 years from the date of the interview.
Data Collection Instruments
I was primary data collection for my exploratory case study. As a researcher, I
used semi-structured interviews to collect information that was used to answer the
primary research question. Documents that were used in the pursuit of data collection, or
obtaining approval, are in the appendix section of the study. As a first-time researcher of
this scale it was imperative to test the efficacy the process using a pilot study.
My interview protocol matches that of Castillo-Montoya (2016) in which the
process was a four-phase framework which includes; (1) ensuring interview questions
align to with research questions, (2) constructing inquiry-based conversations, (3)
receiving feedback on interview protocols, and (4) piloting the interview protocol.

62
Aligning the interview questions with research questions increases the utility of the
interview questions validating necessity (Castillo-Montoya, 2016).
I used a single case study, in which eight interview questions were asked of
subjects to uncover the process stakeholders use to minimize the organizational risk of
retirement plans. The eight questions, which were follow-up or clarifying in nature, have
been constructed to uncover the process of minimizing risk. This framework allows for
saturation in a manner similar to the deductive process described by Boddy (2016) as
highly informative and meaningful when discussing management and medical research.
The instrument of data collection was multi-faceted; as discussed, I am one
component as the researcher who serves as the conduit of data collection, the second was
using the survey delivery system SurveyMonkey to collect participant responses. A
matrix using a Microsoft Excel spreadsheet, IBM SPSS Statistic Software and NVivo
version 12 software to use to segment and further analyze the responses. I found the IBM
SPSS Statistic Software to be compatible with spreadsheets from multiple stakeholders
and format friendlier than Microsoft Excel. The Microsoft Excel spreadsheet, IBM SPSS
Statistic Software and NVivo version 12 software served as the collection source of pilot
study and final study data. The spreadsheet, found in Appendix A, contains one tab for the
pilot study, followed by a master slide to aggregate all responses, then individual slides to
capture the question by question response of participants.
The interview protocols also serve the purpose of enhancing reliability and
validity; as described by Asiamah et al. (2017) and was the essence of every study. The
protocols allowed me the opportunity to see if the sample was fit for purpose, defined by

63
Catania, Dolcini, Orellana, and Narayanan (2015) as validating whether the sample was
appropriate for the purposes of a study. The two methods of validation I used were a pilot
study and interview transcription, the process and rationale for the two methods were
outlined the following section on data collection techniques. The protocols increased the
quality of data obtained through research interview, provided me with a shared language
outlining the steps of the protocol, and ensured congruency of my study (Castillo-
Montoya, 2016).
Data Collection Technique
In a similar fashion to the protocol suggested by Chenail (2011), I incorporated a
pilot study, which allows for the opportunity to refine aspects of my methodology. I used
the pilot study to address important logistics related to my research. Specifically, to
administer the questions in the same way as in the main study, to ask the subjects for
feedback to identify ambiguities, to challenge questions, and to record the time taken to
complete the interview (Chenail, 2011). I used the results of the pilot study to decide
whether the process was reasonable and provides a better record of participants time
commitments in the IRB protocol, and last, to discard ambiguous questions.
Three observations from the pilot phase influenced the final study. I sensed that the
focus on relationship managers might lead to biased results. Responses to questions about
reducing the risk of fiduciary responsibility were highly weighted toward proprietary
products. In cases which a response was not product-oriented, the content was vague and
ambiguous. Second, campaigning was the primary source of engagement with the
participant base. My initial attempts to discuss strategy were bogged in proprietary

64
product discussions instead of rationale and reasoning. The digital distribution of
educational resources or best practices was the primary source of risk mitigation guidance
offered. Last, the focus on relationship managers did not offer the perspective of business
leaders faced with personal liability. The questions were written to understand how risk
was communicated; however, the benefit of understanding risk from the perspective of
personal liability would be more impactful.
As a result of the pilot phase, I made significant changes to my study. I changed
the audience to reflect the perspective of a business leader rather than a stakeholder. By
targeting business leaders, there would be a limited likelihood of a proprietary product
solution. Second, I developed the research questions to provide a first-person perspective
as opposed to a second-hand account. The change was advantageous to represent
decision-making under particular duress. I used open-end and follow up questions to
better understand the reasoning for decisions as opposed to the effect of the decision.
As discussed in the protocol described by Castillo-Montoya (2016), the process
allowed me to ensure alignment questions within my study, receive feedback regarding
the interview protocol, and pilot the interview protocol. The pilot study was conducted
following successful approval of the IRB and prior to the formal research study.
The pilot study provided several important insights in regard to accessibility of
participants and their objectivity. My initial target population was relationship managers,
the representative of the plan provider or plan administrator who assists the business
leader. Attaining an acceptable sample size proved to be difficult. A representative
comfortable with completing the letter of cooperation (Appendix C) to access employees

65
made the process of arriving at an ideal sample size both challenging and time
consuming. Individuals were chosen by the employer, and it was clear from the responses
that employees were not comfortable describing details other than available resources
within the organization. As a result of the pilot; I changed the participant base to
stakeholders who were business leaders in a fiduciary capacity, widened the scope to
include Dynata for a nationwide panel, and added screening and descriptive data criteria.
Data collection using interviews was ideal given the scope of exploration
(Houghton, Murphy, Shaw, & Casey, 2015; Jamshed, 2014; Rimando et al., 2015).
Online or paper survey would not permit the rich detail captured in an interview format.
General observation would posit a better understanding of the phenomena in the natural
setting, though, the context and nuance of the phenomena would be difficult to interpret
(Jamshed, 2014). Likewise, alternative techniques like site visit or video recording would
not allow the interaction between to researcher and participant to better understand
context and nuance (Houghton et al., 2015). I used the pilot test to provide rich in detail
responses using a technique best suited for context and nuance.
Documenting the pilot study results occurs in the interview protocol matrix (see
Appendix A) tab identified for the pilot study. Prior to input within the matrix, as with the
final study, I used a NVivo version 12 transcription service of the interview to avoid the
infusion of research bias into the responses. Inquiry-based conversations refer to the
process of asking questions that specifically relate to the research study. I used a
semistructured qualitative approach for interview questions, comprised of open-end
questions to enhance the interaction between researcher and subject. Based on the form of

66
questions, I used a naturalized approach of transcription; a process which allows for what
was said, how words were said, also including contextual language through the recording
of interview session (Azevedo et al., 2017).
Prior to conducting formal interviews, I ensured the feedback protocols attain the
information sought in the interview process. The best way to test this validation was
through the pilot study process which I conducted prior to the formal study. After the pilot
study, I found that through a refinement process the final study meets the second
component of the interview protocol by constructing an inquiry-based conversation. I
input information from the pilot study into the matrix and transpose this information,
refinement or follow up questions, into the master tab of the formal study. The pilot study,
transcription of the pilot study, and conclusions of the pilot study reside in the interview
protocol matrix prior to the formal study.
To begin the data collection process, I worked with the market research firm
Dynata to develop screening questions and descriptive data appropriate for the study.
Upon selecting screening questions and demographic data, Dynata used their online panel
of participants to recruit 100 potential business leaders to participate in my study. Over
seven days, Dynata ran a campaign to recruit participants. After the campaign, 94
qualified participants were sent to me via email.
SurveyMonkey was used to gather screening information and demographic data
on participants, as well as short-form responses to research questions. The final questions
of the screener survey asked if the participant would like to participate in a research study
conducted by the researcher and provided with my email contact information. Upon

67
consent, participants were routed to a new page to read and consent to the voluntary
nature of my study by checking a box. The participant was not able to proceed if they
choose to participate. I did not offer incentives to participate in my study. Dynata, used a
form of incentive to recruit the original participant base. The method of incentive was
based on Dynata and included in the total cost of using their service.
Contact was initiated with business leaders by email. Ninety-four prospects were
sent an email with a link to participate in the study. Ten of the prospect email addresses
were undeliverable, leaving the contacted pool of 84 business leaders. In response to the
email request, 13 business leaders consented and participated in the short form responses.
I conducted a follow up with the 13 Business leaders who participated in short-form
responses and indicated they were available for a 30 minute follow up interview. Five of
the 13 business leaders agreed to a follow-up interview, three of the five business leaders
attended the scheduled appointment and participated in a transcribed interview.
The interviews were conducted via Zoom video/audio conference software.
Personal phone numbers were not used; instead, participants dialed into a standard
conference call number. Two recording devices were used to capture interviews; first,
Zoom conference call software has an embedded recording capability; as part of their
services, the conference call recording. A secondary recording source was Garage band
software, simultaneously recording through the audio output. The method of the
conference call for interaction limits the effectiveness of tools like a cell phone, a
personal recording device, and a form of a transcription pen. Garage band was used to

68
convert the transcribed interviews into mp3 files, which were subsequently transcribed
using a NVivo version 12 transcription service.
To achieve triangulation, I used a combination of literature review, interviews,
and member checking. Member checking was achieved by providing an aggregate of
responses in a thematic hierarchy. A word cloud export of the transcribed interview to
ensure the essence of the conversation was accurate. Interviewees were emailed a pdf of
the interview word cloud and asked to provide any feedback within five days to ensure
accuracy, however, no feedback was provided.
The data collection process and use of the interview protocol matrix had several
advantages. One advantage was the ability to identify gaps in the alignment of interview
questions to the purpose of my study as described by Castillo-Montoya (2016). Changing
the audience and scope of questions allowed for a better data collection process. I used
the guidance of Azevedo et al., (2017) in two aspects of my study. First, the construction
of an inquiry-based conversation, the transcription of the conversation, and thematic
analysis in NVivo version12 shows authenticity in the interaction between researcher and
participant that is captured in the collection process. Next, I used a digital transcription
service, through NVivo for member checking, as a tool to limit misunderstandings and
biases. In instances, the use of human transcription has an inherent likelihood the same
interview may be transcribed in different ways by different people (Azevedo et al., 2017).
Data Organization Technique
The maintenance of interview data occurs in an interview protocol matrix. The
matrix I chose uses the labels of the interview protocol, the refinements of questions or
69
follow up questions, the raw data transcription, and subsequent final study results as
illustrated in Figure. 4. The matrix contains the aspects described by Yujin (2011);
including issues or barriers to recruitment, the Epoche process, reflections of me from a
situational perspective, and modifying interview questions. The raw data retention occurs
in a secure URL cloud-based database for a period of five years from the conclusion of
my study. After five years the raw, paper and electronic, data will be deleted and will not
be archived.
Figure. 4 Data labels
As a researcher, avoiding bias and setting aside the inclination of such biases to
influence thinking was paramount. This practice is referred to as an Epoche process,
which I used in the following way. The purpose of the research study was not to associate
an opinion, whether favorable or unfavorable, of fiduciary responsibility. Second, the
Interview
Responses
Screener
Questions Themes Raw Data
Transcription
Final Study
Results
Reflection
Journal

70
research study was not a determination of the full scope of risk associated with retirement
plans. The purpose was to begin a process of understanding, how workplace retirement
plans have evolved and if such an evolution was aligned with standard risk management
practices.
The research questions were process of discovery, using semi-structured
interviews to hear from those closely aligned to the retirement plan process. The
questions were segmented to understand how risk was communicated, how risk was
mitigated and the understanding of risk among stakeholders. Once data had been
collected the responses were aggregated under the themes of governance, stewardship and
leadership. Throughout the process my views were not infused into the responses, I have
limited the ability to nudge an opinion, and upon the conclusion of data collection I report
out the findings. While all biases cannot be erased, the process avoids or reduces the
likelihood of adverse bias or focus.
Several methods of capturing, interpreting, and analyzing the data collected in a
qualitative study have been identified by previous scholars (Carter, Bryant-Lukosius,
DiCenso, Blythe, & Neville, 2014; Cleary, Horsfall, & Hayter, 2014; Morse, & Coulehan,
2015). I chose a combination of transcription within NVivo version 12 and other forms of
data organization. A reflective journal is the documentation of thinking in a critical and
analytical way about research in progress until conclusion (Outlaw &
Rushing, 2018). I note the overall impression of organizational risk at the participant
level, observations of why questions were refined or to conduct follow up, feedback
gathered from participants, and process logistics. I feel this information was helpful in the

71
data analysis section as a baseline of research insights to compare to themes identified in
final study. Alternative approaches included labeling systems and research log, which
were more common in experimental and clinical studies (Morse, & Coulehan, 2015). As
the participants in my study were providing commentary on expertise, labeling and
research logs would not be the best method. In the case of my research, I used NVivo
version 12 technology to capture the essence of the data and arranged in a way that easily
identifies commonalities as prescribed in existing literature (Cleary et al., 2014).
Data Analysis
As a researcher, the argument that a method was appropriately scoped to reach an
outcome was a top priority to address in the findings. conceptualizing the qualitative
process to that of the more familiar quantitative process was advantageous. I am an
advocate the benefits of qualitative research methods, in which word cloud visuals and
thematic hierarchical pictures, as opposed to numbers, are used to describe situations. The
alternative approach offers a degree of precision in description and stringency throughout
the interview analysis process and interpretation. Such precision, in essence, as to
replicate in qualitative interviews the exactness of quantitative measurements.
Quantitative methods allow a researcher to reach conclusions based on granular detail, the
qualitative process allows a researcher to reach conclusions through saturation, whether
granular or thematic.
The benefits of LMX include easing communication differences and varying
perspectives of individual participants, insight into the perspective of a collective group,
identify the influence of higher quality relationships, and identify ways to increase levels

72
of trust. In analyzing the data, I used themes categorized by similar segments to convey
the results as a best practices summary.
The audit process contained two phases; a categorical depiction of data collected,
and the process of intellectual interpretation (Carcary, 2009). The categorical information
included raw data, data reduction and reconstruction, analysis and process notes, and
preliminary development information. The process of intellectual research included a
depiction of a starting philosophical position, questioning the positivist position, consider
alternatives, search for a philosophical stance, interpreting the evidence, and the
distillation of new theory from the body of research. The important issue in qualitative
research was achieving a congruence of understanding, in which, confirmability occurs
either within the context of the research or, context to which the research findings were to
be applied. Qualitative research possesses several unique characteristics that were
difficult to fit perfectly into the positivist paradigm of quantitative studies.
The qualitative researcher can also provide vivid and rich detail through a
naturalistic paradigm in which the unique characteristics of phenomena may be present.
One challenge is the possibility for the interpretation of data to be skewed by a single
researcher. To the extent that single interpretation can skew the overall results of a study, I
shared the results of my analysis with two reviewers, relationship managers in the
retirement plan industry with more than 25 years of combined experience, prior to full
submission. The reviewers were individuals familiar with the retirement industry and
research methodology, allowing for the member checking function to be served

73
mitigating bias. The reviewers agreed with the use of terminology, context of the
problem, and potential interest of business community.
Member checking is form of feedback or validation; in which the final stage of the
interview is to view an aggregation of the responses in word cloud and thematic hierarchy
chart. I incorporated this step as a check if the appearance of a disconnect between a
response and the interpretation. The process to took 10 days at the conclusion of final
participant interviews.
NVivo version 12 software was used for data collection and thematic analysis. The
combination of document storage, data analysis tools, and simple coding methods were
contributing factors in using NVivo version 12. Alternative software such as HubSpot,
MAXQDA, or Microsoft Excel, in my view, were inadequate for collecting the various
types of data and thematizing my dataset. A Codebook supplement guide containing the
themes, labels, and instances to validate the efficacy of research was provided.
The first layer of analysis was to develop a persona of the participant pool,
descriptive information of their experience, role, comprehension of terms, and binary
responses to screening questions. I used SPSS software for the first layer, given the data
point form of responses. In the initial layer, all business leaders in the pool of 94
contributed a short form response describing their last retirement plan provider
interaction. I collected the information in NVivo version 12 as a standalone data set for
use in the overall analysis.
The second layer of analysis was to use NVivo version 12 software to identify
themes from existing literature, short-form responses, and interview transcriptions. For

74
example, I categorized a preferred fiduciary approach based on the themes of Structured,
Communication, or a blend of the two approaches from existing literature. Further
analysis included an overview of organizational risk based on business leaders who were
advised on fiduciary liability, about the communication of risk, and the strategies to
minimize risk.
Another layer of analysis was the interviews that capture three perspectives of
fiduciary liability and organizational risk. The perspectives of an ERISA attorney,
manufacturing business leader, and a senior executive fiduciary. The final analysis was to
identify best practices and align with a communication format for the business leader
audience.
Reliability and Validity
Reliability
Member checking is a process of participant involvement to check and to confirm
the ideas and responses captured during the interview process (Birt, Walter, Scott, Cavers,
& Campbell, 2016; Harvey, 2015). The member checking process has several advantages;
as indicated by Harvey (2015), the process was a form of verification and confirmation of
the response accuracy. Similarly, Birt et al. (2016), described the process as a form of
respondent or participant validation that involve the participants or focus groups. Member
checking exists in various forms which are dependent on the theoretical issues and
methods implored. For example, various approaches toward re-engaging the sample
participant base including returning verbatim transcripts, subsequent interviews using the
transcript, or an interview of all participants using the analysis of the single participant

75
data (Birt et al., 2016) exist. Focus groups can be used to compare the results among a
group of individuals, or member checking through a synthesis of analyzed data
(Birt et al., 2016; Harvey, 2015).
My approach in analyzing the collected data was to use a member checking
process with synthesized analyzed data. To ensure transparency to the business leader
population the consent process acts as a form of reciprocity, in which the results and
conclusions captured in my work provide valuable information plan sponsors and the
providers of risk management services. The results may offer valuable training
opportunities for stakeholders in this space. The member checking approach of
synthesized analyzed data validate and confirm accuracy for the reliability of my study
and identify training opportunities for the business leaders.
Validity
The business leader was best equipped to answer the central question of my study;
a narrowly focused exploration of how provider/plan sponsor conversations were guided
by stakeholders to mitigate organizational risk of retirement plan programs, and, the
products and services to mitigate such risks. Given the narrow scope, stakeholders and the
lens in which the discussion of organizational risk occurs allows for credibility as a
participant in the research study. As described by Baskarada (2014) the case study design
and expertise of the participant base was ideal for generalizations which transform tacit
knowledge into explicit knowledge, a process in which the stakeholders were uniquely
equipped to provide insight.

76
The conclusions documented in my study also lend to its transferability, as the
conversation of organizational risk was assessable from the perspective of the business
leaders receiving the information, the participant in the retirement plan in consideration of
the best interest, or the financial professional responsible for investment decisions. As
discussed in the purpose of the study; the current climate of fiduciary breaches, and
organizational liability born from 2015-2017 fiduciary guidance, were central themes to
the decision of conducting my study now with the business leader group as participants.
The member checking approach of using synthesized data serves two purposes;
first the confirmability of my study was assessed by confirmation or corroboration of the
leadership team of the stakeholders reviewing the synthesized data. The second was the
aspect of data saturation, in which literature reviews, interviews and transcription of the
interviews represent methodological triangulation of my study. As Morse (2004)
described the data collection and validation was an outcome of inquiry to develop
concepts further and clearly describe the connection to other concepts. An extended
discussion of organizational risk to include the perspective of another stakeholder would
be ideal, however the scope of my study was best suited to articulate the change
management process of addressing such risks with the leader-member exchange
framework as described by Arif et al. (2017) and Newman et al. (2017).
Transition and Summary
The objective of this qualitative multiple case study was to reveal the strategies
presented to business leaders by stakeholders to minimize the organizational risk of
workplace retirement plans. My study was an exploration of organizational risk in which

77
I leveraged the expertise of the stakeholders as the primary participants. I used a
qualitative methodology in which I investigated the problem through a holistic lens in
which individuals, groups, activities or phenomena effected by workplace retirement
plans were captured. Specifically, I used the design of case studies to act as a form of
discovery or act as form validation of the efficacy of the research problem. Considering
the scale of the general population I used a convenience sample, an approach common
among qualitative studies which are less demanding, affordable, easy and the subjects are
readily available to arrive at the desired number of participants.
My interview protocol matches that of Castillo-Montoya (2016) in which the
process was a four-phase framework which includes; (1) ensuring interview questions
align to with research questions, (2) constructing inquiry-based conversations, (3)
receiving feedback on interview protocols and (4) piloting the interview protocol. Last,
interpreting the collected data occurred through several methods of capturing, interpreting
and analyzing the data collected in a qualitative study. The rigor of the framework and
data collection served as the basis for Section 3 which highlight the results of my
research.
Section 3: Application to Professional Practice and Implications for Change
Introduction
The objective of this qualitative multiple case study was to explore the strategies
stakeholders presented to business leaders to minimize the organizational risk of
workplace retirement plans.
78
Presentation of the Findings
Findings indicated named fiduciaries were aware of their responsibility through
previous experience, inference as a business leader, or through a third-party consultant.
Business leaders were aware of their limited understanding and feel comfortable seeking
the guidance of a third party, or indemnification through a product for fiduciary risk
mitigation. Business leaders successively communicate the risk to other stakeholders of
the organization. The communication of risk occurs at a meeting or training for to
communicate risk. As shown in Figure 5, the communication to stakeholders was a
threestep process.
Figure 5. Fiduciary communication
The remaining portion of Section 3 is a presentation of this research in a two-part
process; Part 1 is a thematic analysis of interview data collected among ten business
leaders of varying industries and Part 2 is a secondary analysis of follow up interviews
with specific business leaders to add context to their responses. Throughout the analysis, I
Fiduciary
•Experience or Inference
•3rd Party Stakeholders
Meeting or Training

79
will align the findings to similar research identified in the literature review to synthesize
the relevant themes of risk mitigation for workplace retirement plans.
Analysis of Findings
Concerning the initial interview data, two major themes emerged. These themes
were the strategies used to minimize organizational risk, an area comprised of 31 of 66
risks coded thematically and the communication approach among stakeholders for
awareness of fiduciary responsibility, which accounts for 25 of the 66 coded responses.
As illustrated in Figure 6, business leader strategies to minimize organizational risk
include investment compliance as a top of mind, followed by plan compliance; however,
business leaders were also comfortable allocating fiduciary duties to committees or third
parties. In the interviews, my data coding indicated investment compliance as the most
referenced strategy. Investment-oriented risk strategy coding includes investment
selection, investment price, or suitability. Plan compliance was the second form of risk
mitigation, in which coding includes references to match, testing, or administrative
guidance. Where business leaders could not explicitly articulate an investment or plan
compliance strategy, the alternative approach was to create a separation between the
fiduciary and potential conflicts.
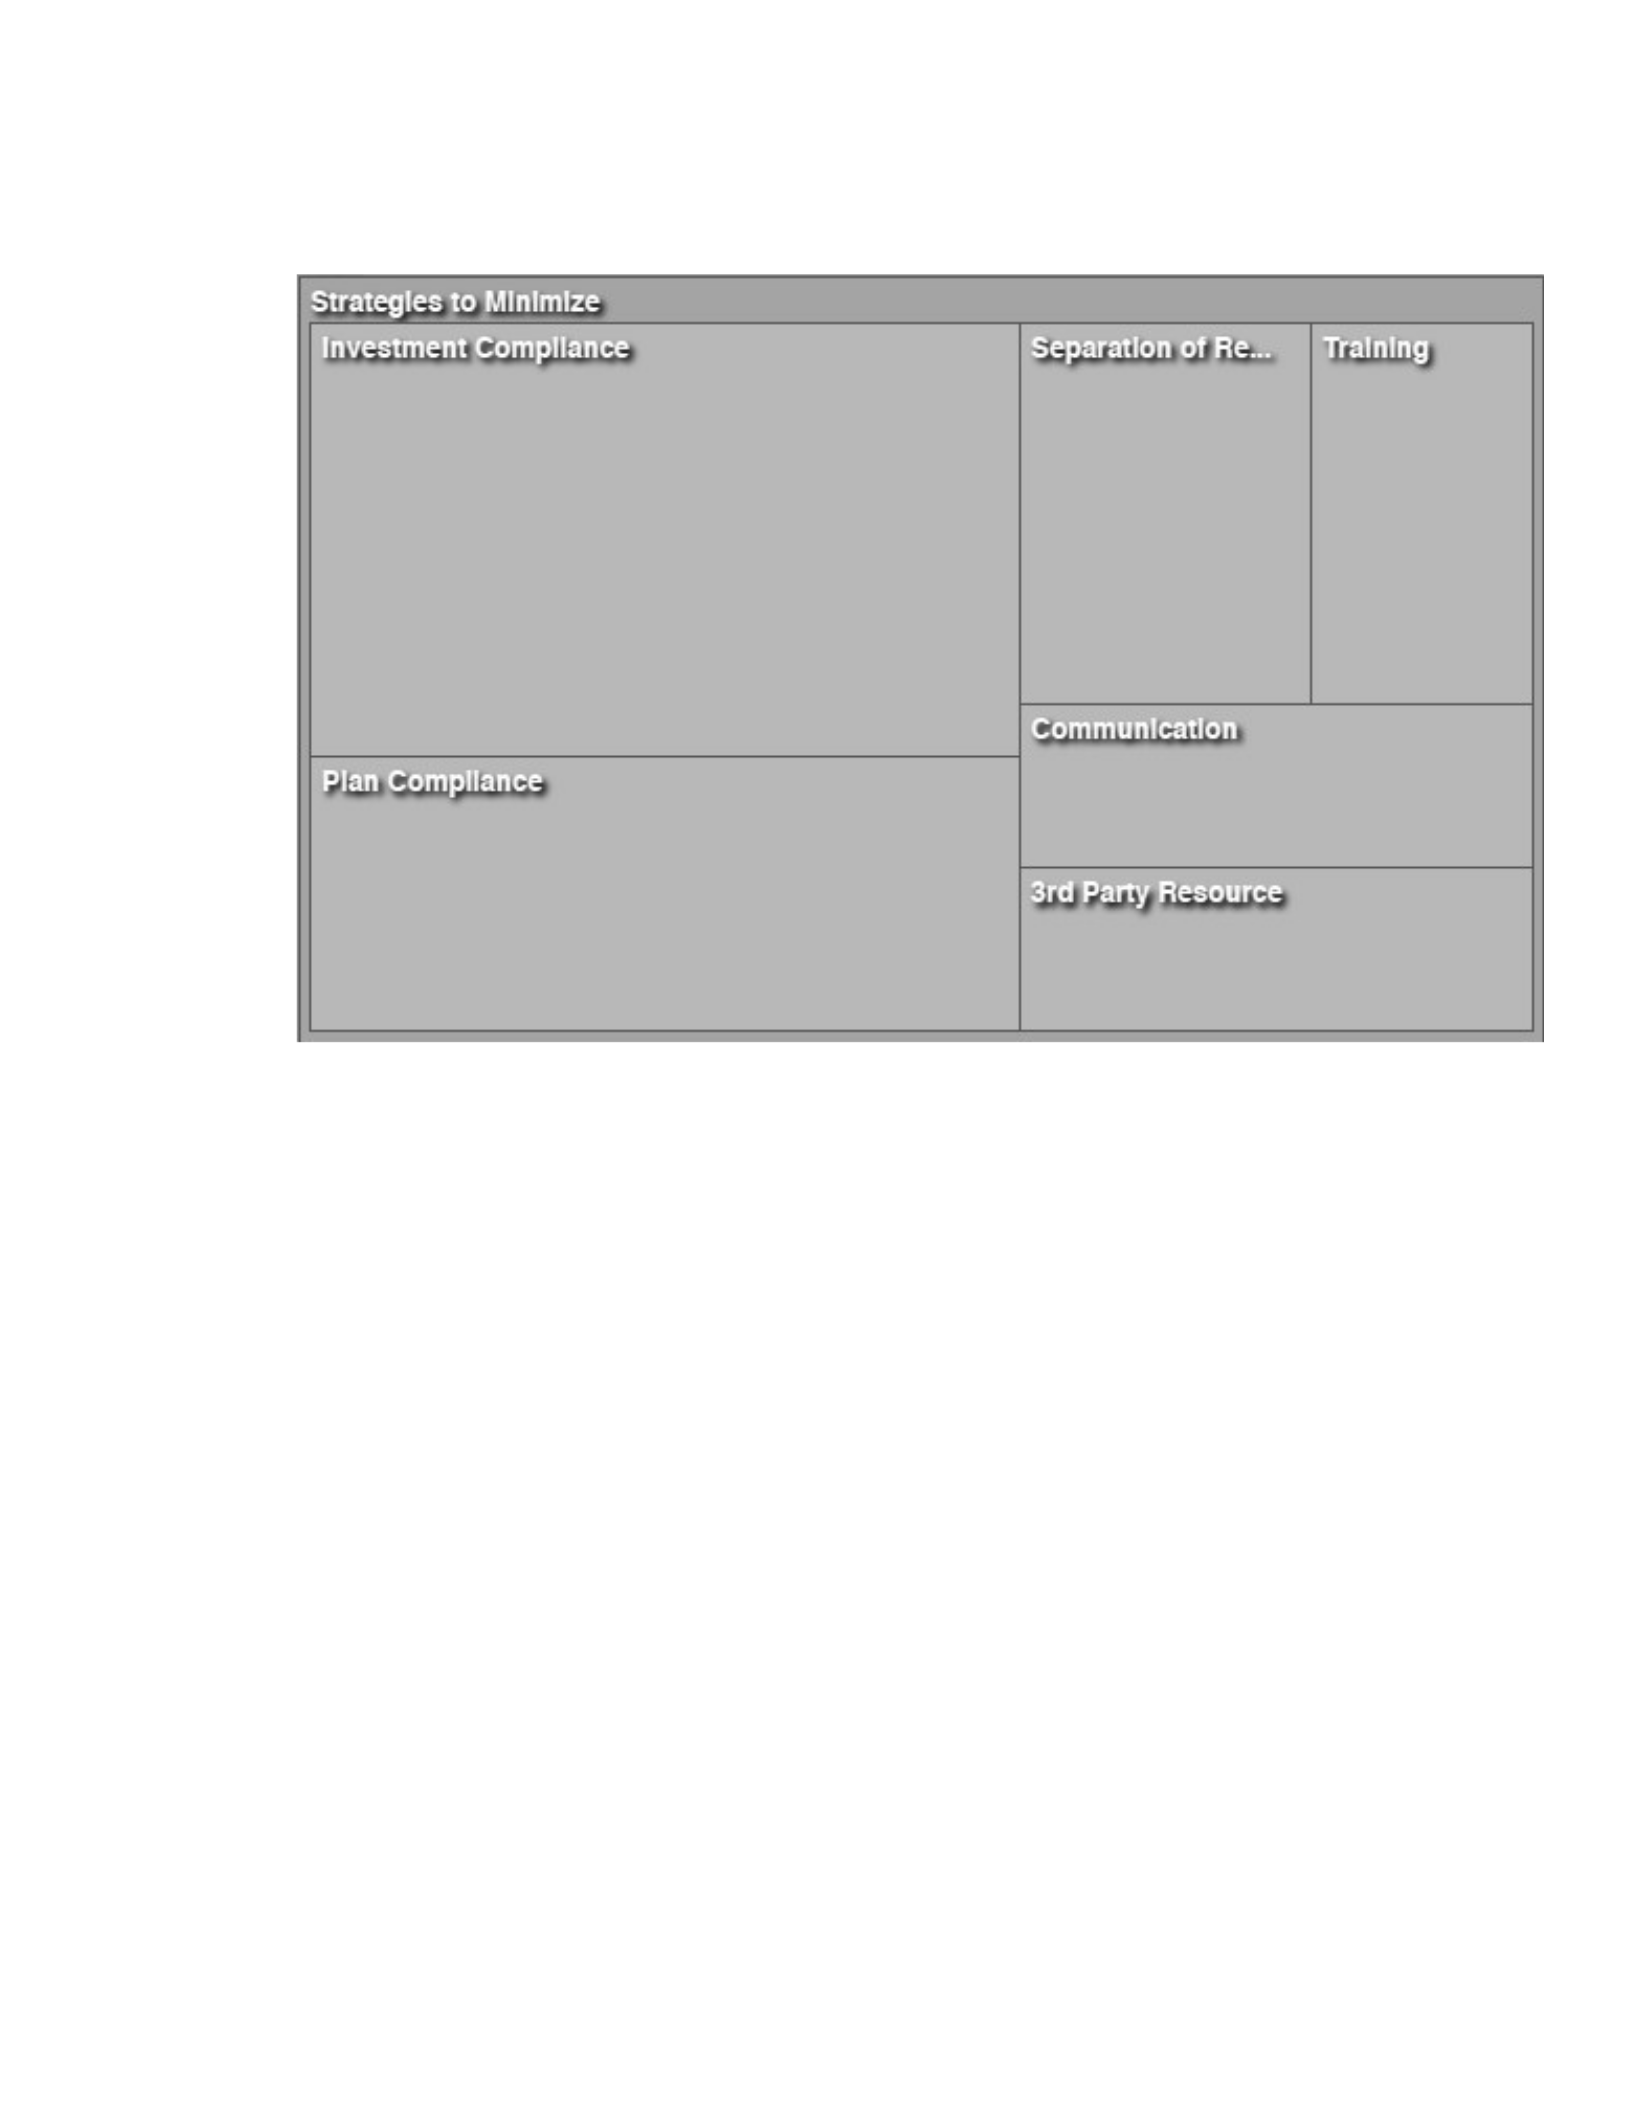
80
Figure 6. Strategies to minimize risk
To mitigate self-dealing, Geller (2015) described a vehicle to mitigate personal
liability, the retirement plan committee, in which members ensure diverse voices were
present in the overall decision to select plans and programs. As Geller surmised a
retirement plan committee’s awareness of DOL initiatives, the appropriateness of a due
diligence process, understanding of revenue sharing methods, and alignment to an
investment policy statement were imperative. Retirement plan committees should make
fiduciary decisions concerning the plan as experts would, with the same care, skill,
prudence, and diligence under the circumstances (Geller, 2015).
Separation of duty was a commonality among interviewees. My research showed
that business leaders use separation of duty as a mitigation strategy for fiduciary breach

81
penalties. Based on interview feedback, the predominant vehicle to segment fiduciary
duty was the committee. Some business leaders indicated committees conduct due
diligence on all plan investment at regular intervals to ensure continued appropriateness,
and the level of diligence was reasonable and appropriate under the circumstances.
Similar research by Geller (2015) surmised that committees outline a process to
effectively and competitively bid recordkeeping services and limit the payment of
revenue sharing from the plan service provider. Business leaders were consistent in
ensuring an audit trail of communicating, based on the documentation referenced themes,
and acknowledging the communication of responsibilities. Although the phrasing varies
between investment committee, 401K committee, and fiduciary committee, my research
showed business leaders implore a similar strategy consistent with the expectations of the
committee and align to baseline activities of Geller.
The hierarchy of themes in Figure 7 depicts the principal setting for
communicating the organizational risks of retirement plans which influence fiduciaries
and stakeholders occurred at training or meeting for this purpose. Method of
communication, meetings, or training for this purpose occurred 15 times out of 25 coded
responses on communication. The closest comparative method was electronic
documentation or directly through a third party, each with three coded references. As
shown in the thematic hierarchy chart for risk, references for investment compliance and
training or meeting were visibility significant.
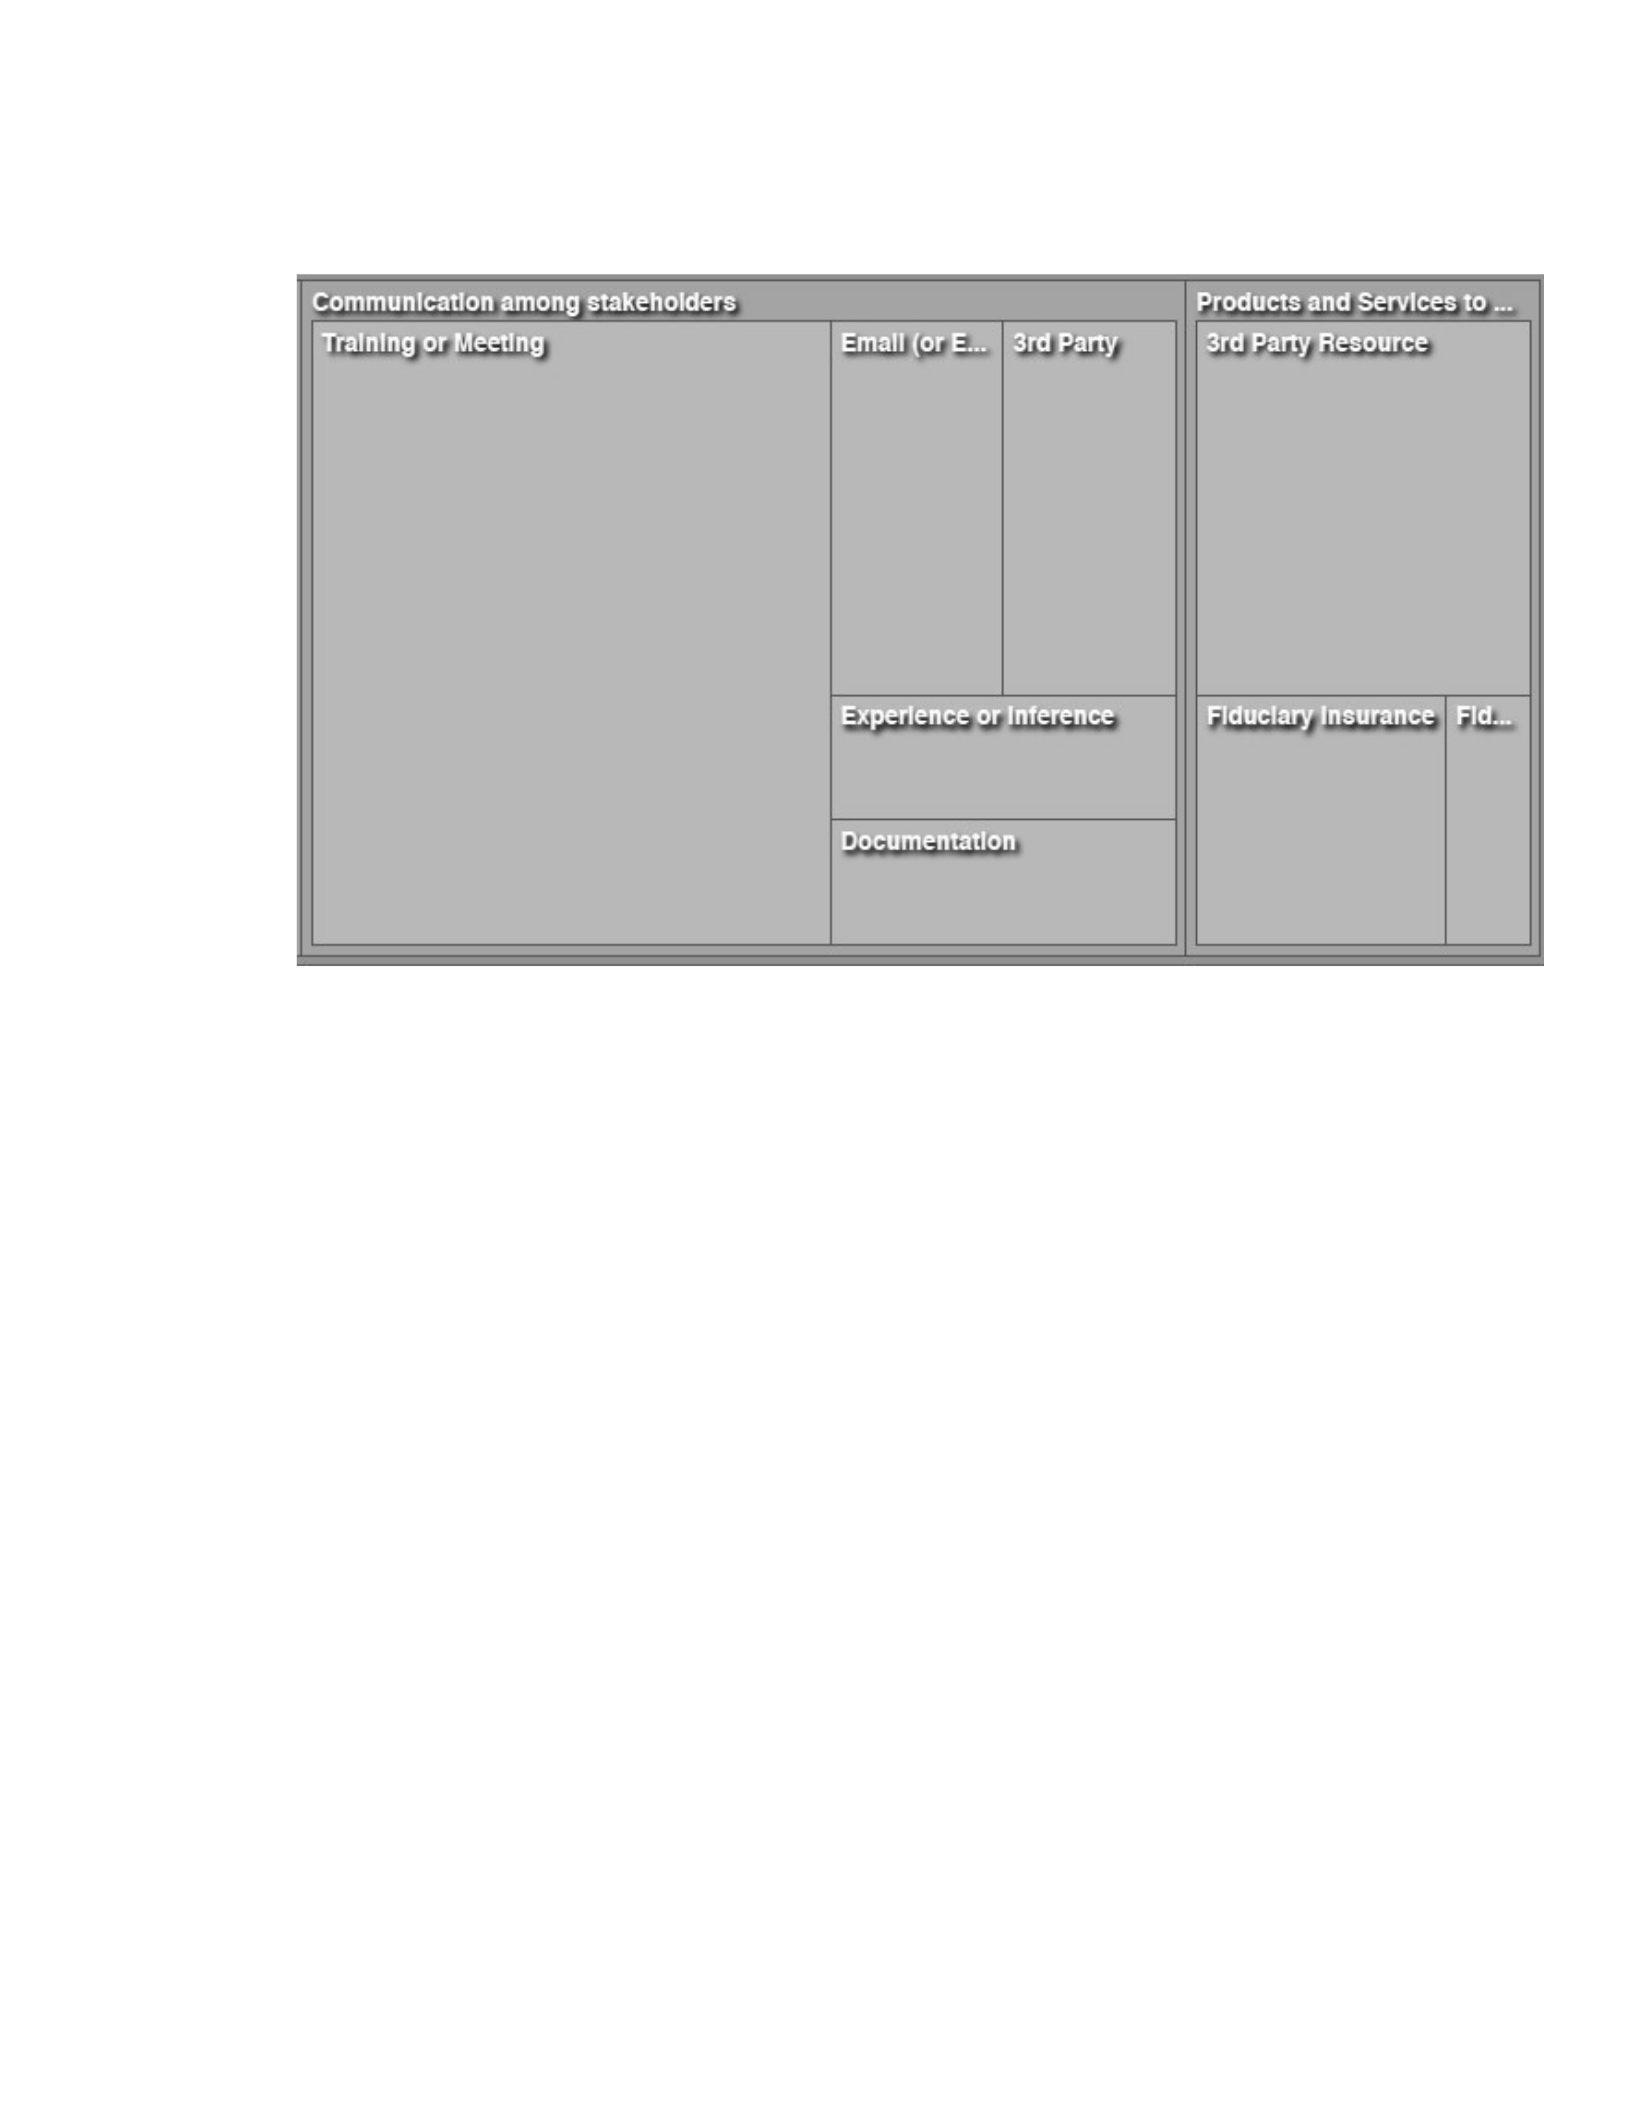
82
Figure 7. Stakeholder communication
It seems as if products were available to minimize the risk to organizations as well
as a personal liability; however, they were often neglected. Fidelity bonds are a
requirement and protect the organization against the harmful acts of fiduciaries; however,
the product was seldom mentioned. Similarly, fiduciary insurance was available as
optional coverage to alleviate the personal liability of fiduciaries, often paid for by the
firm; however, as with fidelity bonds, it was seldom mentioned.
An ERISA attorney interviewed as a business leader was able to add valuable
context in this area.
But it's interesting when my clients get audited how many of them don't have a
fidelity bond because they're just unaware of the requirements. I think in general
there certainly is of some awareness, but I think many clients need to be educated

83
about that because they just you know they just don't know. I mean the insurance
company, or you know an investment company calls them up to say we can set it
up. But they don't tell about all these regulatory issues. And one of them is the
fidelity bond. So, I would say that that's something people need to be educated on.
Bonestroo (2017) posited that business leaders who may not understand fiduciary
responsibility will fall into three segments: (a) those who possess the required expertise,
(b) those who seek guidance in which expertise does not exist, and (c) those who were
unaware of the influence of their actions/decisions. The findings of my research align
with Bonestroo. My research indicated that those unaware of the actions made references
that may likely represent a potential conflict. Through thematic coding illustrated in
Figure 8, business leader coding aligned to Bonestroo; those who seek guidance
accounted for a significant weighting of business leaders aware of their responsibility
with six coded responses. Business leaders sought the guidance of an expert more often,
with one possessing expertise in ERISA. Furthermore, when counseled, guidance was
about investments or plan compliance.
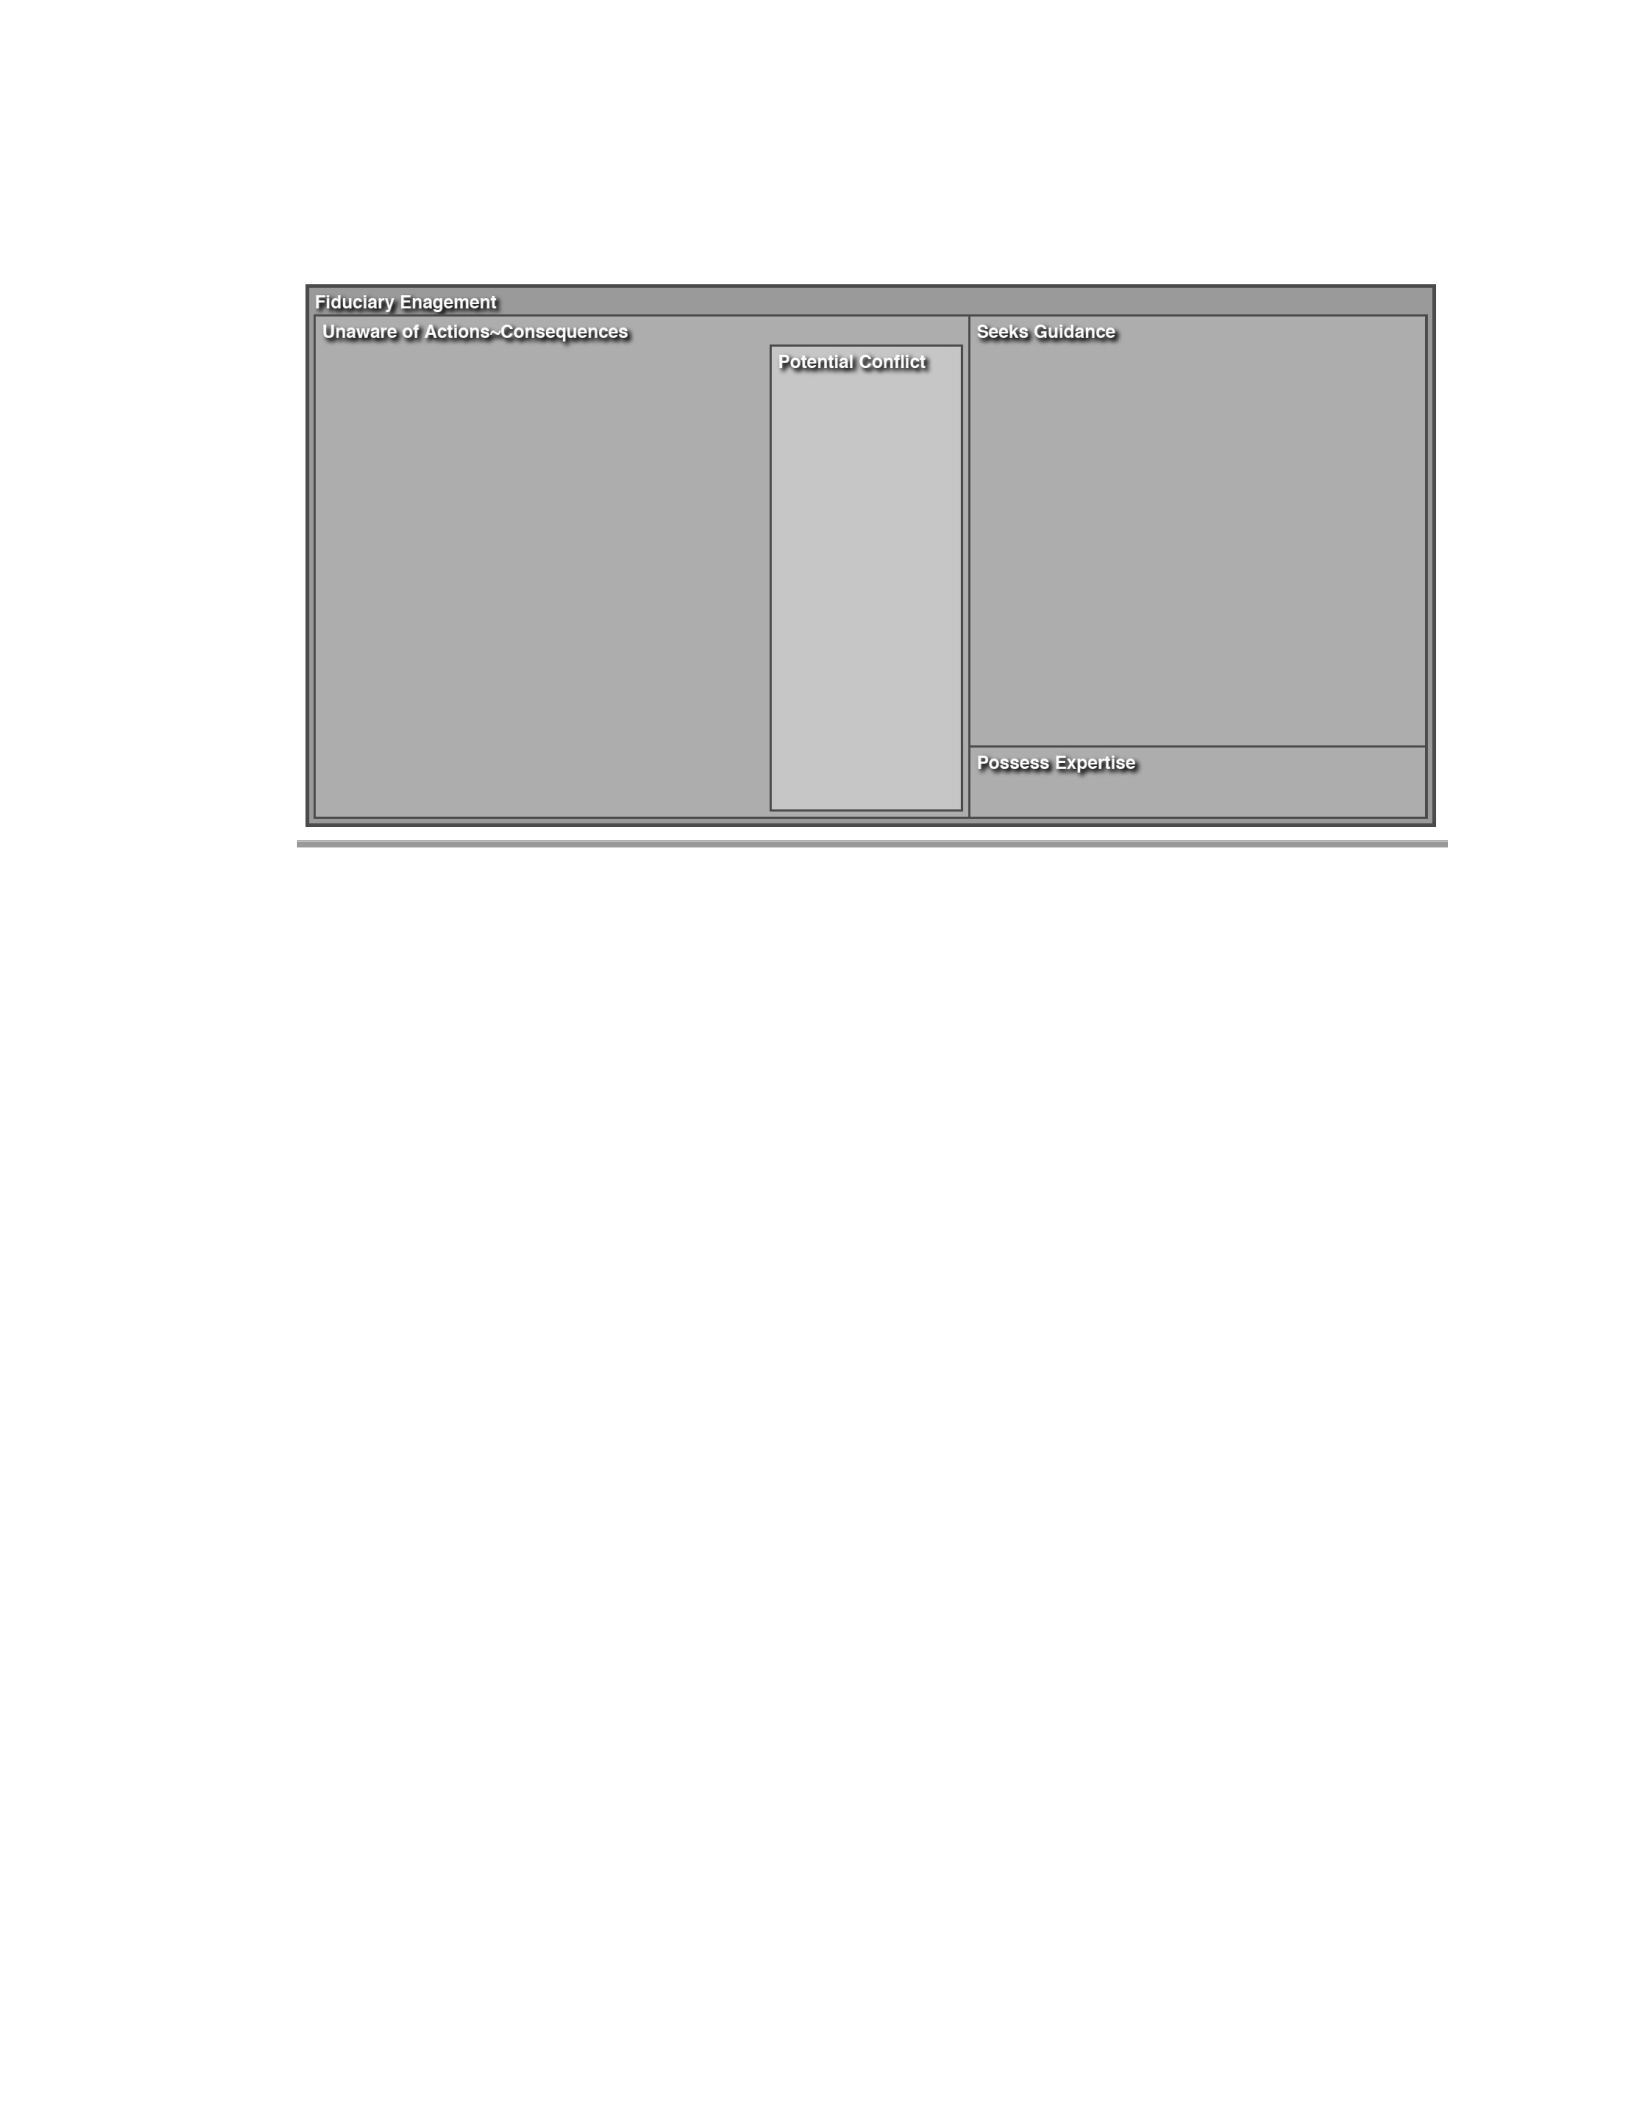
84
Figure 8. Fiduciary Engagement
Behavioral Governance
Behavioral governance is a body of work in which the focus of research delves
into the decision making of business leaders. Lew and Sinkovics (2013) expanded the
scope understanding to the decision making of leaders; which extends to partners and
other stakeholders whose decisions influence more than just the individual. Trone used a
connotation of behavioral governance which includes governance, leadership, and
stewardship, to segment aspects of fiduciary liability (Pasztor, 2016). The findings of this
research will aim to communicate organizational risks of retirement plans in an
informative and solution-oriented manner. Hence, to maintain consistency of
communication in fiduciary responsibility to business leaders, the behavioral governance
framework was applied in the presentation of results.

85
Governance
The governance of a retirement plan has changed significantly since programs
pre-ERISA in the early 1970s (Bonestroo, 2017; Guerriero, 2017; Swisher, 2017).
Governance represents the adherence among business leaders to stated fiduciary
responsibilities. As defined contribution plans have gained in popularity from 2000-2015,
workplace retirement programs are a multi-faceted decision-making process for
employers. My data shows that the objectives of workplace retirement plans are
multilayered to mitigate fiduciary liability, leverage internal and external relationships,
and engage employees in purposeful retirement planning. Similar research carried out by
Bonestroo (2017) found comparable results in which retirement programs reduce
employer costs for employee retirement, mitigate fiduciary liability, take advantage of tax
benefits, and engage employees in purposeful retirement planning.
The findings of my research show evidence that business leaders were aware of,
counseled on, and further communicate internally to stakeholders the personal nature of
fiduciary responsibility and the penalties associated with a breach. Research conducted by
Guerriero (2017) and Bonestroo (2017) found that business leaders who act as fiduciaries
have additional exposure as ERISA Section 409 specifies plan fiduciaries can be held
personally liable for losses attributed to a breach. An analysis of Section 409 breaches
found personal liability from a fiduciary breach incurs an average penalty of $500,000
(Bonestroo, 2017). My findings, illustrated in Figure 9, show a preference of business
leader to hear and communicate fiduciary responsibilities in meetings or training for that
purpose. Similar research by Guerriero (2017) found that fiduciary duty is a twofactor
86
system of how a fiduciary is assigned and the penalties for breaching fiduciary liability.
My findings add further context showing that the communication of assignment of
fiduciary duty and penalties associated with a breach occur at meetings or training for that
purpose.
Figure 9. Communication only Interviewees seemed to be conflicted between what was a
compassion and giving approach towards risk mitigation and the penalties associated with
the breadth of fiduciary responsibility. The conflict in some instances led to a new or
innovative approach, while other times, documentation and transparency were preferred.
Business leaders have a similar theme as they describe the best interest of the
employees/participants in the decision-making process.
Senior Executive Interview. You know I would just tell you as the president I
still have this concern about whether our employees are investing. You know I'm

87
still not totally convinced our employees have a clear understanding of the level
of investment that might be required to support a retirement that might be 25 or
30 years. So, you know it's something we continue to talk about in terms of
further furthering this financial wellness program in terms of education. I would
say that's my major concern. And so, I want to make sure it's not as if the
employees have not been presented with the information.
Manufacturing Leader Interview. We have some highly paid employees and
then we have across the board [workers]. There are not many things that are like
working on production for a lot of our highly paid employees. But if you're a new
employee and natural you're not highly paid so we're trying to do is not penalize
the highly paid employees from contributing to their plan and encouraging the
lower paid employees to start practicing. So that's kind of a long-winded way of
saying we need increased participation to eliminate risk.
ERISA Attorney Interview. I mean, there's a lot covered by the prohibited
transaction rules and I need to be aware and I need to have my clients aware when
I do that I mean for my own plan but certainly for my clients who are in similar
positions I need them to understand just how broad the reach of the self-dealing
rules are.
Given the varying experience of the senior executive, manufacturing leader, and ERISA
attorney the plight of employees in regard to their sophistication and likelihood of
successful outcome is palpable. Business leaders appear to understand their role in
assisting employees achieve their retirement goals. The business leaders do not offer

88
guidance outside of the expertise, yet each one articulates an understanding of what must
be done to assist their participants.
My findings are similar to comparative findings by Swisher (2017), in which
employers who embrace the fiduciary business model follow fiduciary principles and
processes, do so by more than merely showing compassion about employeesnecessitating
a process of documentation. An ERISA attorney discussed the significance of
documentation.
What fiduciary responsibilities and the way of risk to what risk requires a lot of it
is process, process, process. It's so important that you document what you've done
what your reasoning was why you came to that conclusion. I mean it's so
important to put this in the decisions you made the person the process that you
went through the consultants that you brought in needs to be documented. And
that is extremely important.
Adherence to fiduciary responsibility is more than providing a retirement plan to
employees. In addition to following the stated rules, fiduciaries must understand the
consequence of stated rules on participants. As the ERISA attorney says, understanding
the decisions of fiduciaries and the impact on participants is a pivotal fiduciary
responsibility. The ability of a fiduciary to back up an action through documentation of
reasoning is a mitigation technique the is rare but essential.
Swisher (2017) also noted a shift in fiduciary responsibility from avoidance to
transparency; in which employers must prepare for a new and changing paradigm that
includes changes to retirement committees, participant communication methods, and the
89
financial professionals through which they interact. A business leader in the
manufacturing sector made a specific reference to avoidance.
We're all about avoidance. In other words, you’re avoiding risk and you ask good
questions and you project for the future. That’s really what our meetings are all
about now. We get compliance reports, we get all the testing, we know exactly
where we're at. We can see where we've been and see where we're going.
Business leaders exhibited similar behaviors to those outlined in the works
Bonestroo, 2017; Guerriero, 2017; and Swisher, 2017. In terms of fiduciary responsibility,
the business leaders articulated the depth and breadth of fiduciary responsibility, the
difficulty in assessing conflicts of interests from accepted business practices and staying
abreast of new insights in fiduciary responsibility to remain in compliance. In terms of
personal responsibility, the business leader's awareness was unequivocal in the personal
nature of fiduciary responsibility. As depicted in Figure 10, the business leaders possess
the ability to articulate personal liability, describe in general terms their fiduciary
responsibility, and have access to resources to minimize organizational risks. Resources
to minimize organizational risk may be required, like with a fidelity bond, or optional as
in the case of fiduciary insurance.
Figure 10. Governance best practices
Governance Best Practices
90
Fiduciary Responsibility
Process
Fiduciary Fidelity
Insurance Bond
Leadership
While governance represents the ability to adhere to stated fiduciary
responsibilities, leadership addresses how business leaders approach the management of
fiduciary responsibility. Similar research carried out by Weiner and Doescher (2008), and
Bonestroo (2017) show that employers were likely to use a structural approach, a
communication approach, or a blend of the two encapsulating situational decisionmaking
for fiduciary responsibility management. Bonestroo supported the belief that business
leaders would benefit from a blend of two approaches ensuring an offering satisfies the
needs of those highly engaged as well as those who may not be engaged
(2017).
The communications approach emphasizes the individual, the behavior, and how
to nudge behavior to optimize retirement savings (Weiner & Doescher, 2008). The
communication approach is behavior-oriented; in which the utility of marketing and
persuasion approaches were implored to increase participation and may favor those with
high engagement (Weiner & Doescher, 2008). Conversely the structural approach alters

91
the conditions associated with retirement savings; for example, the advantages of pre-tax
benefits or income contributions limits may act as a lever to increase retirement savings
or limit the pre-tax savings of high-income earners. Business leaders in a blended model
would use a form decision making, in which aspects may include general understanding
requirements, understanding of the concepts well enough to communicate to others, the
most appropriate audit trail, and an understanding of common mistakes fiduciaries make.
Bonestroo (2017), in similar research, used the themes of awareness, transparency,
clarification, and best practices to illustrate a comparable decision-making process.
The efficacy of the structural approach outlined by Weiner and Doescher (2008) was
evident in terms of how business leaders communicated organizational risk. References to
the structural approach accounted for 16 of the 41 overall references on fiduciary
management approach (Codebook p.2). As shown in Figure 11, business leaders infer
plan design elements as triggers for increasing retirement savings and participation, with
a focus on employee fairness. Coding of structural elements included three forms;
matching contributions, outsourcing administrative functions to a third party, and
involving an investment consultant to increase savings, participation, or engagement.
Figure 11. Interview 2 themes
92
When using a blended approach, my research suggested that business leaders,
shown in Figure 12, skew towards possessing a general understanding of fiduciary
aspects and feeling comfortable communicating their fiduciary responsibilities. General
understanding of fiduciary aspects includes a general sense of; documentation,
relationship management, or communication to account for fiduciary management
activities. However; the transparency practices, in which leaders communicate their
decision-making, show responses in which some business leaders articulate potential
selfdealing conflicts. For example, one business leaders stated strategy “I minimize risk
through choosing the right options for my employees.” Alternatively, choosing a
proprietary fund company “(W)e use vanguard only” or basing the investment selection
on non-expert suggestions because “all my friends use them and no complaints or high
fees.”
Figure 12. Fiduciary approach
93
Blended
• Structural • Base • Conflict of Interest
• Communication Undertanding • Risk
• Blended • Communication
• Transparency
Best practices identified in Figure 13 indicate themes of fiduciary responsibility,
and avoiding the perception of self-dealing, and the efficacy of separation of duties as a
resource to minimize risk were evident. Whether through inference, experience, guidance,
or counsel, business leaders exhibit similar behaviors to those outlined in the works
Bonestroo, 2017; Guerriero, 2017; and Swisher, 2017.
Figure 13. Leadership best practices
Fiduciary Approach Transparency
Seperation of
Duties
Perception of
conflict Documentation Communication

94
Stewardship
Business leaders have a stewardship responsibility to understand an employee
base well enough to make decisions in a like capacity, characterized in a similar fashion
and with similar aims of the prudent man. Stewardship describes the passion and
discipline to judge wisely and objectively; with a pro-organizational view (Glinkowska &
Kaczmarek, 2015). Stewardship, in the lens of fiduciary liability, addresses the plight of
business leaders to wisely and objectively make decisions regarding the retirement plan
considering a litigious environment. Stewardship reflects both the strategy of business
leaders and the communication of the strategy.
Two themes in stewardship were evident based on the findings of this research;
one, a communication fiduciary management approach was likely to result in positive
employer and employee behaviors. Two, stewardship behaviors embedded within the
communications approach were an effective risk mitigation strategy. Transformative
leadership styles were likely to result in higher employee engagement, increase savings
rates, and lead to higher impact relationships in comparison to transactional leadership
styles. My data shows that stewardship behaviors among leaders were used more often to
increase savings and participation rate than plan design elements solely.
In interviews, business leaders who used the communication approach to manage
fiduciary responsibility exhibit more stewardship behaviors. In analyzing interview data,
the communications approach was used least often when compared to a structural
approach or a blended approach. However, the stewardship activities within the approach
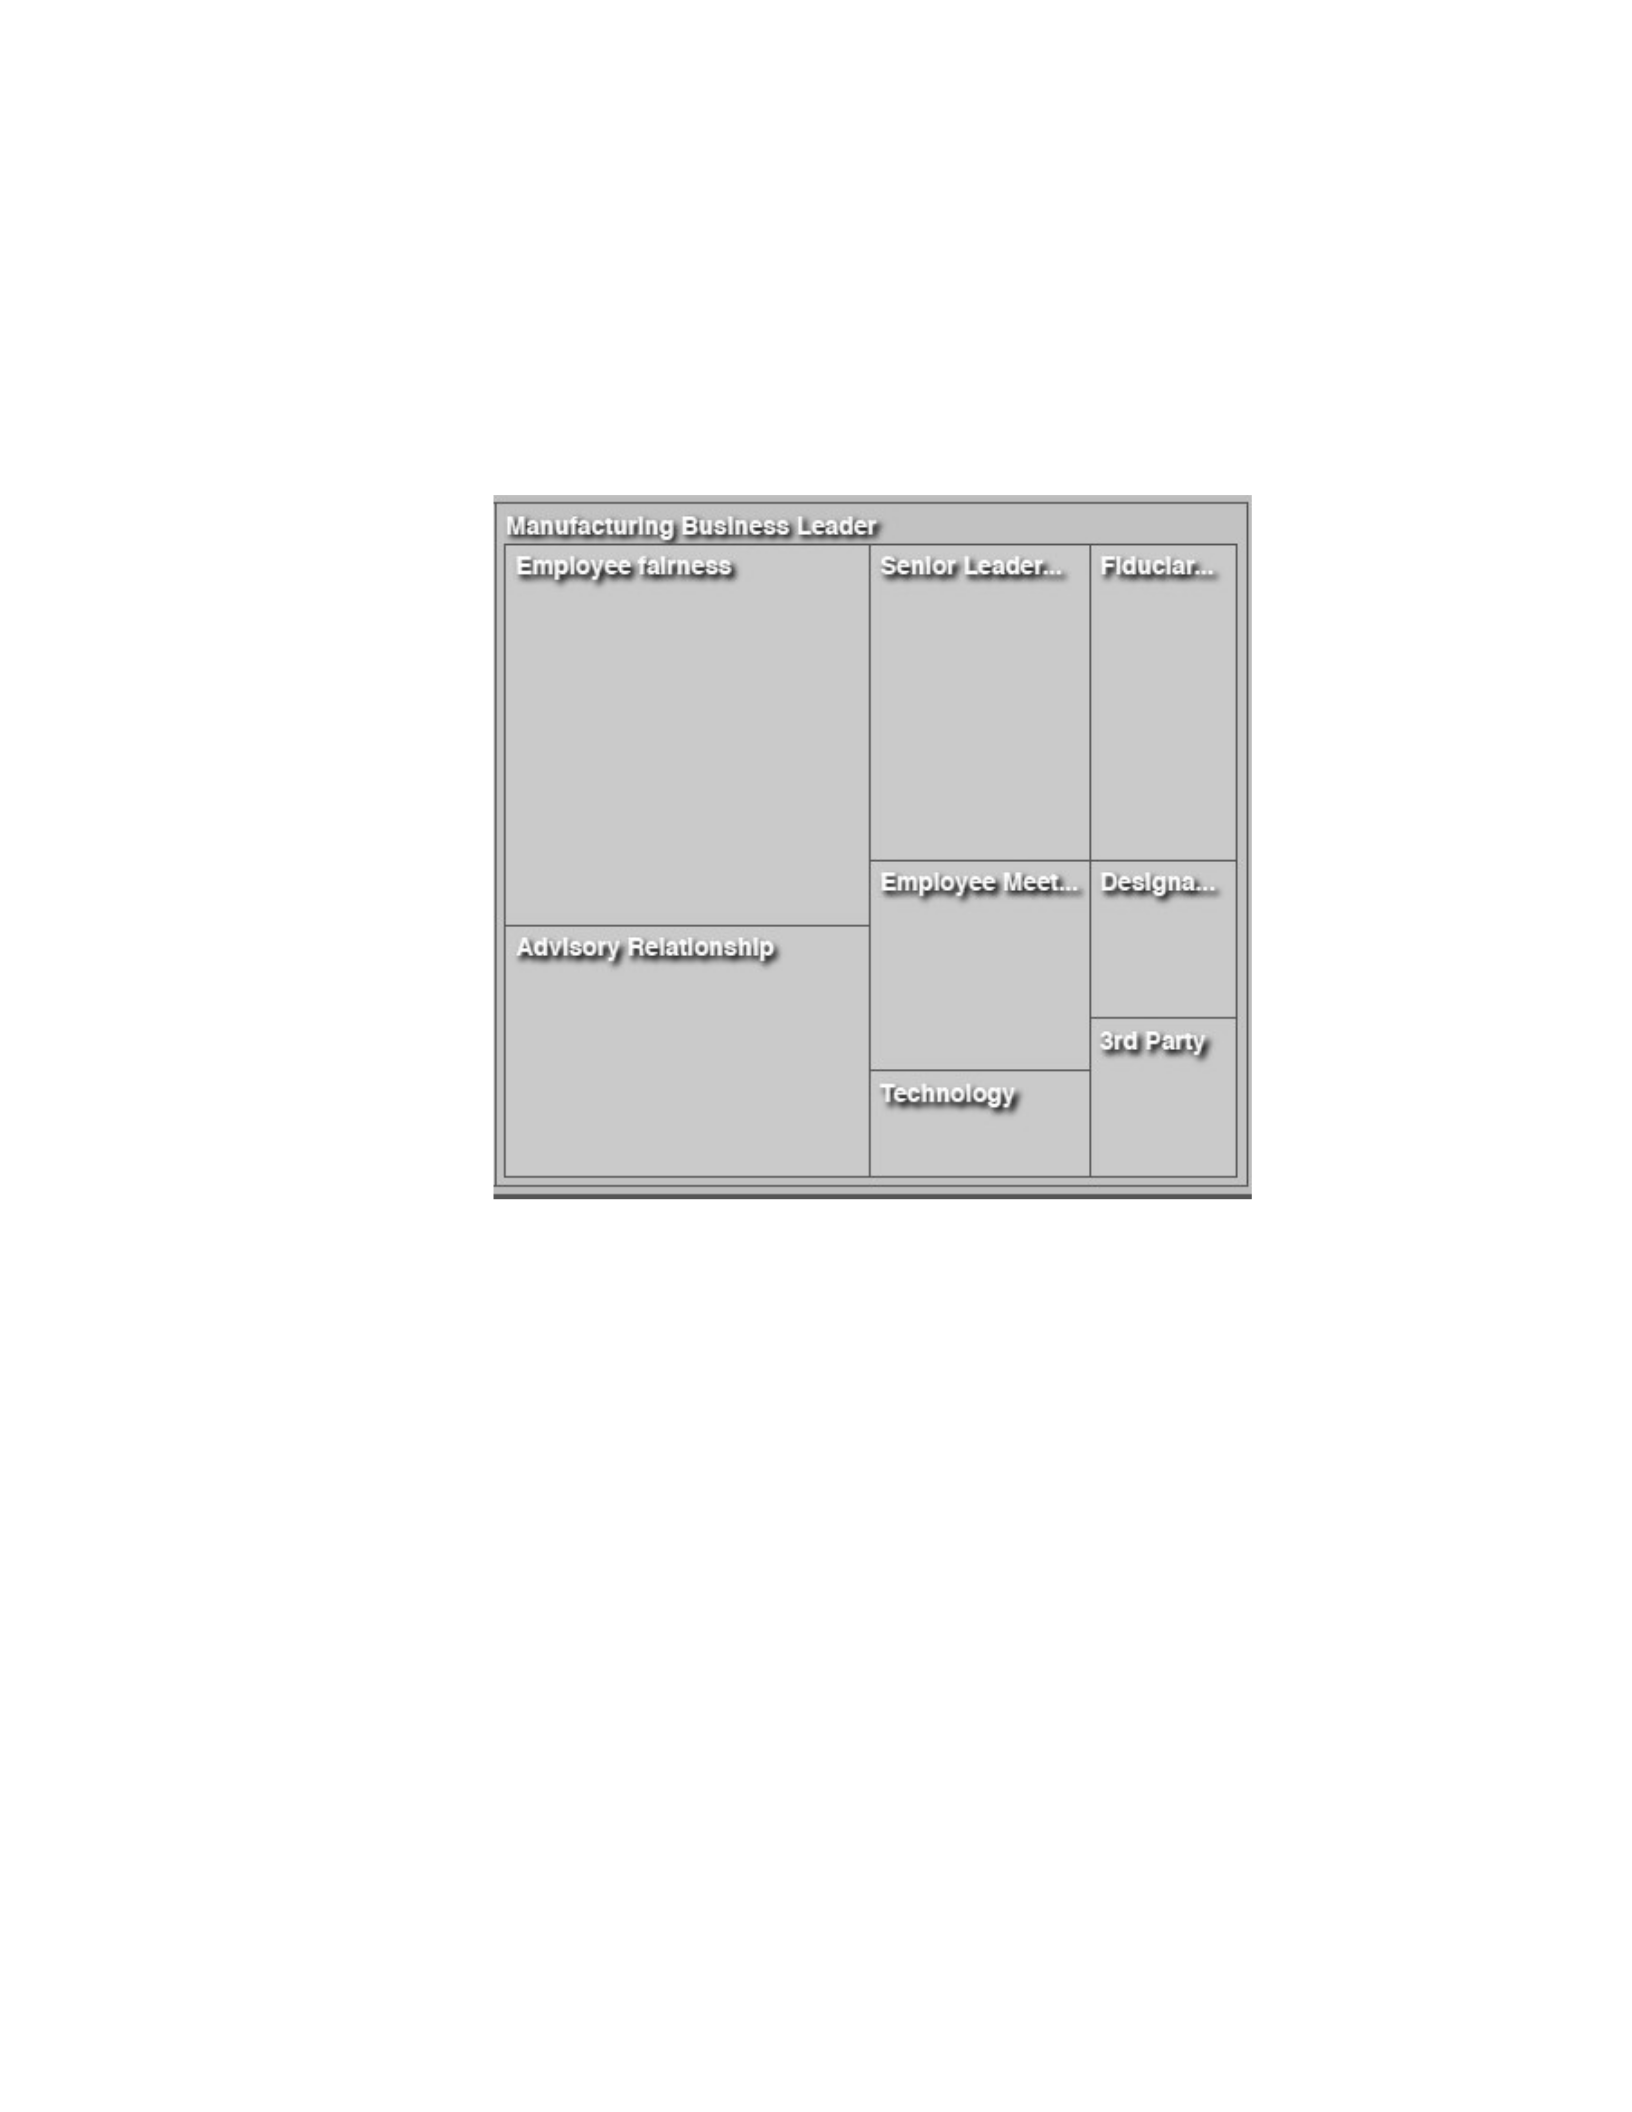
95
increased engagement, senior leadership participation, education for employees, and
communication among stakeholders.
Figure 14. Manufacturing leader
Business leader activities under the communications approach align with the
benefits of LMX theory in areas which influence compliance and engagement. In
beneficial areas, responses from business leaders' equal areas in which the use of LMX
has been advantageous. The themes depicted in Figure 14 of employee fairness, senior
leadership involvement, fiduciary responsibility, employee meetings, and utilizing
advisory relationships for employee engagement were palpable in interviews.
LMX Theory
The findings of my research have aligned existing literature with the real-life
practices of business leaders to determine a transferable best practice. The LMX theory is

96
a prescriptive model of change management to incorporate stewardship, through the
communications approach, into the fiduciary management process. Where similar
activities have shown positive changes in employee engagement, high impact
partnerships, and savings rate while minimizing risk and increasing trust. Given the
20152017 changes to fiduciary definitions and liability of breach that has proceeded, a
leadership approach inclusive of change management aspects would aid business leaders.
Arif et al. (2017) offered a viewpoint of LMX theory in change management; in which
organizational change emphasized the need for people to alter values and perspectives to
align with the organizational perspective. Under such a premise, particular emphasis was
placed on the roles of leaders and members, and the interactions between members and
leaders (Arif et al., 2017). Structural or blended approach leaders may likely use LMX
theory to transition to a communications approach, in which incremental stylistic changes
between leaders and followers were possible. Among the benefits of LMX approaches
studied, easing communication differences and varying perspectives of individual
participants is a top advantage in organizations with diverse employee bases. The
influence of higher-quality relationships in increasing levels of trust and engagement on
leaders who use a structural approach only would ideally represent the desired changed
behavior.
My research has identified four several areas of change management to facilitate
the process; easing communication differences, collective group insights, the influence of
high-quality relationships, and increasing trust.

97
Easing communication differences. Include staff members with dual
responsibility for retirement plan engagement among employees — participation of
senior leadership in retirement plan education meetings.
Perspective/insight of collective group. Understanding the income differences
among participants to remain in plan compliance while helping educate employee base —
for example, a business leader who understands the savings and engagement of new
employees versus tenured employees.
Capacity for high-quality relationships. The capacity to articulate the value of
an excellent partnership to help engage the participant base. Ensure a synergy among the
provider, third party administrator, financial representative, and business leaders to help
employees achieve goals.
Ways to increase trust. Ensuring that individuals with expertise are in positions
in which they can make meaningful decisions. Allowing the building trust with
employees, through education and wellness, to minimize organizational risk.
To increase the probability of change success, understanding the change process
as a series of actions, procedures, communications, and regular meetings to understand
the roles at play and the interaction between the roles is a precept of the change process.
The findings of this study provide a framework in identifying positive-oriented behavior
from approaches in fiduciary management. For example, business leaders use of plan
design elements as triggers for increasing retirement savings and participation, is a
potential transferable practice that is beneficial to business leaders. Structural or blended
approach business leaders articulated plan design elements of several forms; matching

98
contributions, outsourcing administrative functions to a third party, involving an
investment consultant with the intent to increase savings, participation, or engagement.
Alternately, communication approach business leaders use employee engagement, high
impact partnerships, increasing trust as triggers for increasing retirement savings and
participation.
Cropanzano et al. (2017) acknowledged the success of the LMX theory in
studying organizational leadership. Arif et al. (2017) offered a viewpoint of LMX theory
in change management; in which organizational change emphasizes the need for people
to alter values and perspectives to align with the organizational perspective. The
favorable employee responses of better performance and organizational citizenship
behaviors allowed for more focus on the significance of the dyadic relationships.
Increasing trust of all higher-quality relationships is what makes LMX an ideal
framework in which mitigating risk is the desired outcome.
Applications to Professional Practice
Fiduciary breach litigation categorized as self-dealing rose between 2015-2018,
what is surprising was that the rise occurred at a time when global trust in employers was
72%. Attorney firm rewards from fiduciary breaches became a form of revenue, as the
risk to public image and class action nature of lawsuits increase the likelihood of
settlement. My research indicated the plausibility of an environment in which class action
suits are possible.
Based on my sample of participants, several aspects of their feedback could be
considered red flags. Half of respondents offered somewhat negative feedback on the last

99
interaction with their provider, few were positive, and most business leaders were neutral
at best. In discussing the improvements, the responses related to communication, which
the information was either complex or the representatives were not aware of specific plan
details, occurred frequently.
Communication also represents a problem for business leaders, in an interview of
ten business leaders, multiple comments could be perceived as a conflict. Further,
business leaders may be unaware of mandated and optional resources to alleviate
organizational risk and personal liability, or they were aware and use the resources
infrequently. My findings imply business leaders operate in an uncertain environment;
given this uncertainty fidelity insurance and documentation of processes should be a
standard practice among fiduciaries.
Fiduciary Insurance
The fiduciary responsibilities and breaches of such accountability are hard to
quantify and manage. The potential personal liability in combination with ambiguity of
common best practices in fiduciary responsibility is an intimidating responsibility. As
with other forms of risk, indemnity is valuable. Business leaders and organizations can
mitigate some risk through the use of fiduciary insurance or fidelity bond.
Documentation of Processes and Decision-Making
Accumulating the best practices of fiduciary responsibility has been somewhat of
a Rorschach test. Fiduciary responsibility is in the eyes of the beholders, the outside
consultant or the plans record keeper. Business leaders should have the capacity to

100
articulate why they made certain decisions, why they chose not to make others, and have
documented evidence of the process for each form of risk.
Implications for Social Change
The Edelman Trust Barometer is an annual global study of trust among
institutions; in the latest iteration of the Study, 2018, 72% of respondents indicated they
trust employers while the benchmark of trust in U.S. financial services declined by 23
percent. Litigation of the largest public and private institutions under the precept of
failing to ensure the best interests of their participants on face seems contrary to the
global perspective of employers. Yet, as of 2019, it was happening and on the rise through
the lens fiduciary litigation. Diluting trust in employers to ensure the best interests of
those under their care affects individuals, families, communities and foundation of how
most consumers earn of living.
My study, related findings, and context provide a pathway for employers to use
inherent trust to increase the trust of financial institutions. By limiting the distrust in
financial service firms using workplace retirement plans, business leaders could extend
the trust of employers to financial services alleviated while protecting the retirement
preparedness activities of consumers. In fact, building trust was a common theme in the
transcribed interviews denoting without trust in the provider, advisor, or company would
be averse to participant trust. The manufacturing business leader captured the essence of
the relationship between trust and risk when describing his companies approach towards
employee education.

101
Are you familiar with the book Being Trusted? It's basically trying to repair and
rebuild bridges and rebuild trust. I talked about it one time here in our company,
we basically have an internal university and what we found was that we did not
have a lot of trust issues. Where we did have trust issues we would take the
opportunity to rebuild that kind of thing and we thought this is great. Set a
precedent in the world. You know this is great. Let's go ahead and build upon that.
Let's make sure that we've got our employees trust. And likewise let's be friends
with our various traders our associates. And that way we can have the trust with
them and so we'll ask them very direct questions. We think that trust and
transparency and those kind of things goes a long way.
The discussions reinforce the idea of employers being a source a trust. The
business leaders expressed their intentions and fears for their employees while trying to
provide the best outcome. Financial Wellness programs, matching contributions,
educational resources and an awareness of the plight of employees are small examples of
how business leaders I interviewed instill trust in the organization through their efforts
outside of the product resources and materials.
Recommendations for Action
As discussed earlier, the benefits of LMX include easing communication
differences and varying perspectives of individual participants, insight into the
perspective of a collective group, identify the influence of higher quality relationships,
and identify ways to increase levels of trust. The correlation of the leader/follower
dynamic was like the dynamic of the fiduciary/employee dynamic, further discussions of

102
the relationship refers to fiduciary/employee. A correlation exists between the engaged
and disengaged employee and the in-group and out-group concepts of LMX theory.
Throughout the data collection and analysis phase similarities to the LMX
framework were easy to identify. Business leaders who recognize the differences in their
employee bases and adjust their communication were easing communication difference of
varying perspectives. Through the lens of business leaders in various industries,
commonalities were present allowing for insight into a collective group. In their own
words, business leaders describe the changes in communication, engagement, and overall
relationship has led to favorable results like higher participation or savings. An alternative
approach is the efficacy of the retirement communications approach of Weiner and
Doescher (2008), a framework for promoting retirement savings infusing classical
approaches and behavioral sciences. Specifically, in the aspect of Goal Efficacy, in which
examples of effective attainment, shared vicarious experiences and persuasive messaging
were used by business owners to minimize organizational risk. However, I felt areas of
improvement from my research were needed that are important to add.
Risk Management Alignment
Ensure the risk management strategy of the workplace retirement plan aligns to
the risk management program for the organization. Placing risk management functions of
all types under one umbrella ensures proper alignment of resources.
Retirement Plan Policy
Similar to an investment policy statement, create a retirement policy statement
that describes the due diligence process of selecting a retirement plan provider and how

103
the resources are used. Articulate the goals of the plan from the business leader
perspective and how they will influence the participants.
Internal Leader Communication Plan
Ensure the is a plan in place to communicate internally to middle management.
Describe the organizational risks and ways to mitigate.
Recommendations for Further Research
As described by Brutus, et al. (2012)-citing the work of Campion
(1993)researchers must acknowledge the realistic limitations and weaknesses of the
research present. Acknowledging the additional factors of suboptimal utilization of
workplace retirement plans such as financial education, retirement confidence, and risk
aversion are prudent. Several factors may cause a participant in a retirement plan to think
as if they are ill-equipped to make retirement plan decisions. Further research examining
the
confidence of participants in their retirement decisions may add context to what
constitutes “ill-equipped”.
As Fan (2013) described in a study, faulty language may lead to faulty conclusions
which makes it difficult to compare one set results to another normative set. The scope of
my study was to explore the assessment of organizational risk associated with workplace
retirement plans. I chose the specific niche of defined contribution, 401(k), plans. An
expanded scope to include other forms of retirement plans represents an additional
opportunity for further research. Exploring the communication of organizational risk for
defined benefit, pension, plans or small business IRA’s like a SIMPLE IRA or SEP IRA

104
may be good comparative studies. Last, further research into additional sectors may be
advantageous. Retirement plans for non-profit organizations, school systems, and health
care organizations are referred to as 403(b) plans. Further research as a comparative study
for 403(b) plans and 401(k) plans would represent an opportunity for further research.
Reflections
One of the more challenging aspects of the research study was to create a tangible
social impact as a result of the work. Business leaders use products and services provided
by financial services firms to assist employees in their savings. As a result, I could not
think of a topic that would be worthwhile to study than retirement plan services.
However, what I found was both frustrating and hopeful, creating the perfect opportunity
for social impact. The frustration lies in the prevalence of information readily available to
business leaders and their stakeholders that goes unused. As shown in my literature
review; the breadth of fiduciary responsibility and suggestions for avoidance, in addition
to the guidance outlined in ERISA, warrants a concise standard for business leaders to
follow. Hence the hope. Small and incremental changes towards mitigating a fiduciary
breach are possible, available, and ready to be interpreted. My research was a collection
of insights and palatable discussions, digestible into conversations that can aid business
leaders. The aid is to highlight business leader’s ability to protect their organization while
providing a secure retirement and opportunities for financial wellness among their
employees.

105
Conclusion
A rise in self-dealing fiduciary breach litigation at a time when global trust in
employers was high captured my interest. A research question was chosen to understand
how business leaders formulate strategies to minimize organizational risk, as well as, how
to communicate such strategies to other stakeholders. This study outlines the perspective
of business leaders who act as fiduciaries. Their objectives for workplace retirement plans
are multilayered; business leaders hope to mitigate fiduciary liability, leverage internal
and external relationships, and engage employees in purposeful retirement planning.
Business leaders possess the ability to articulate personal liability, describe in
general terms their fiduciary responsibility, and have access to resources to minimize
organizational risks. These leaders were aware of, counseled on, and further communicate
internally to stakeholders, the personal nature of fiduciary responsibility and the penalties
associated with a breach. Business leaders who act as fiduciaries were aware of their
responsibility through previous experience, inference as a business leader, or through a
third-party consultant.
Business leaders use separation of duty as a mitigation strategy for fiduciary
breach penalties. Fiduciary responsibility may be spread among several in the
organization because a fiduciary status encompasses acts that may signify fiduciary acts.
Considering the scale of fiduciary responsibility, business leader strategies to minimize
organizational risk include investment compliance as a top of mind, followed by plan
compliance; however, business leaders were also comfortable allocating fiduciary duties

106
to committees or third parties. In my analysis, the predominant vehicle to segment
fiduciary duty was the committee.
Business leaders were consistent in ensuring an audit trail of communicating, based
on the documentation referenced themes, and acknowledging the communication of
responsibilities. Similar to comparative findings by Swisher (2017), in which employers
who embrace the fiduciary business model follow fiduciary principles and processes, do
so by more than merely showing compassion about employees-necessitating a process of
documentation. The principal setting for communicating the organizational risks of
retirement plans which influence fiduciaries and stakeholders occurred at training or
meeting for this purpose. Themes of fiduciary responsibility, benchmarking, and the
efficacy of committees and resources to minimize risk were evident. Whether through
inference, experience, guidance, or counsel, business leaders exhibit similar behaviors to
those outlined in the works Bonestroo, 2017; Guerriero, 2017; and Swisher, 2017.
In terms of management of fiduciary responsibility, the efficacy of the structural
approach outlined by Weiner and Doescher (2008) was evident in terms of how business
leaders communicate organizational risk. When using a blended approach, business
leaders skew towards possessing a general understanding of fiduciary aspects and feeling
comfortable communicating their fiduciary responsibilities. Two themes in stewardship
were evident based on the findings of this research; one, a communication fiduciary
management approach was likely to result in positive employer and employee behaviors.
Two, stewardship behaviors embedded within the communications approach were an
effective risk mitigation strategy. Transformative leadership styles were likely to result in

107
higher employee engagement, increase savings rates, and lead to higher impact
relationships in comparison to transactional leadership styles. My data showed that
stewardship behaviors among leaders were used more often to increase savings and
participation rate than plan design elements solely.
An area of concern for business leaders was risk exposure and to protect
fiduciaries from penalties associated with a breach. Products were available to minimize
the risk to organizations as well as a personal liability; however, they often neglected.
Fidelity Bonds are a requirement and protect the organization against the harmful acts of
fiduciaries; however, the product seldom mentioned. Similarly, fiduciary insurance was
available as optional coverage to alleviate the personal liability of fiduciaries, often paid
for by the firm, however as with fidelity bonds were seldom mentioned.
References
Adel, B., & Mariem, T. (2013). The impact of overconfidence on investors’ decisions.
Business and Economic Research (BER), 3(2), 53-75. doi:10.5296/ber.v3i2.4200
Aikin, B. F. (2016). Why the Fiduciary Standard exists? Journal of Financial
Planning, 29(8), 17-19. Retrieved from www.onefpa.org
Akabas, S., Bell, S., Collins, B., & Gold, A. (2014). A diversity of risks: The challenge of
retirement preparedness in America; Economic Policy Program; Retrieved from
http://bipartisanpolicy.org/sites/default/files/BPC%20Retirement%20Security%20
Personal%20Savings.pdf
Ali S. & Frank, H. (2019). “Retirement planning decisions: choices between Defined

108
Benefit and Defined Contribution plans.” American Review of Public
Administration 49, (2), 218–35. Retrieved from
https://journals.sagepub.com/home/arp
Ambuehl, A., Bernheim, D., & Lusardi, A. (2016). The effect of financial education on
the quality of decision making. Economics of Education Review Retrieved from
http://gflec.org
Applebaum, M. (2012). Phenomenological Psychological research as science. Journal of
Phenomenological Psychology, 43(1), 36-72. doi:10.1163/156916212X632952
Arif, M., Kashif, U., Sindhu, M., & Zahid, S. (2017). Role of leader-member exchange
relationship in organizational change management: mediating role of
organizational culture. International Journal of Organizational Leadership 6(1),
32. Retrieved from http://aimijournal.com/Jg/0/d09bbfae-ea92-4d65-b205-
76fbf8c1ad58
Asiamah, N., Mensah, H. K., & Oteng-Abayie, E. F. (2017). General, target, and
accessible population: demystifying the concepts for effective sampling.
Qualitative Report, 22(6), 1607-1621. Retrieved from https://tqr.nova.edu
Azevedo, V., Carvalho, M., Fernandes-Costa, F., Mesquita, S., Soares, J., Teixeira, F., &
Maia, Â. (2017). Interview transcription: conceptual issues, practical guidelines,
and challenges. Revista de Enfermagem Referência, 4(14), 159-167. Retrieved
from http://www.scielo.mec.pt/scielo.php?script=sci_serial&pid=0874-
0283&lng=en
Barnham, C. (2015). Quantitative and qualitative research. International Journal of

109
Market Research, 57(6), 837-854. doi:10.2501/IJMR-2015-070
Bartlett, A. R. (2016). A New era in client communications after the fiduciary rule.
Journal of Financial Service Professionals, 70(6), 47-54. Retrieved from
https://national.societyoffsp.org/page/aboutjfsp
Baskarada, S. (2014). Qualitative case study guidelines. Qualitative Report, 19(40),
1-18. Retrieved from http://nsuworks.nova.edu/tqr/vol19/iss40/3
Bazzano, M. (2014). On becoming no one: Phenomenological and empiricist
contributions to the person-centered approach. Person-Centered & Experiential
Psychotherapies, 13(3), 250-258. doi:10.1080/14779757.2013.804649
Birt, L., Walter, F., Scott, S., Cavers, D., & Campbell, C. (2016). Member checking: A
tool to enhance trustworthiness or merely a nod to validation? Qualitative Health

