


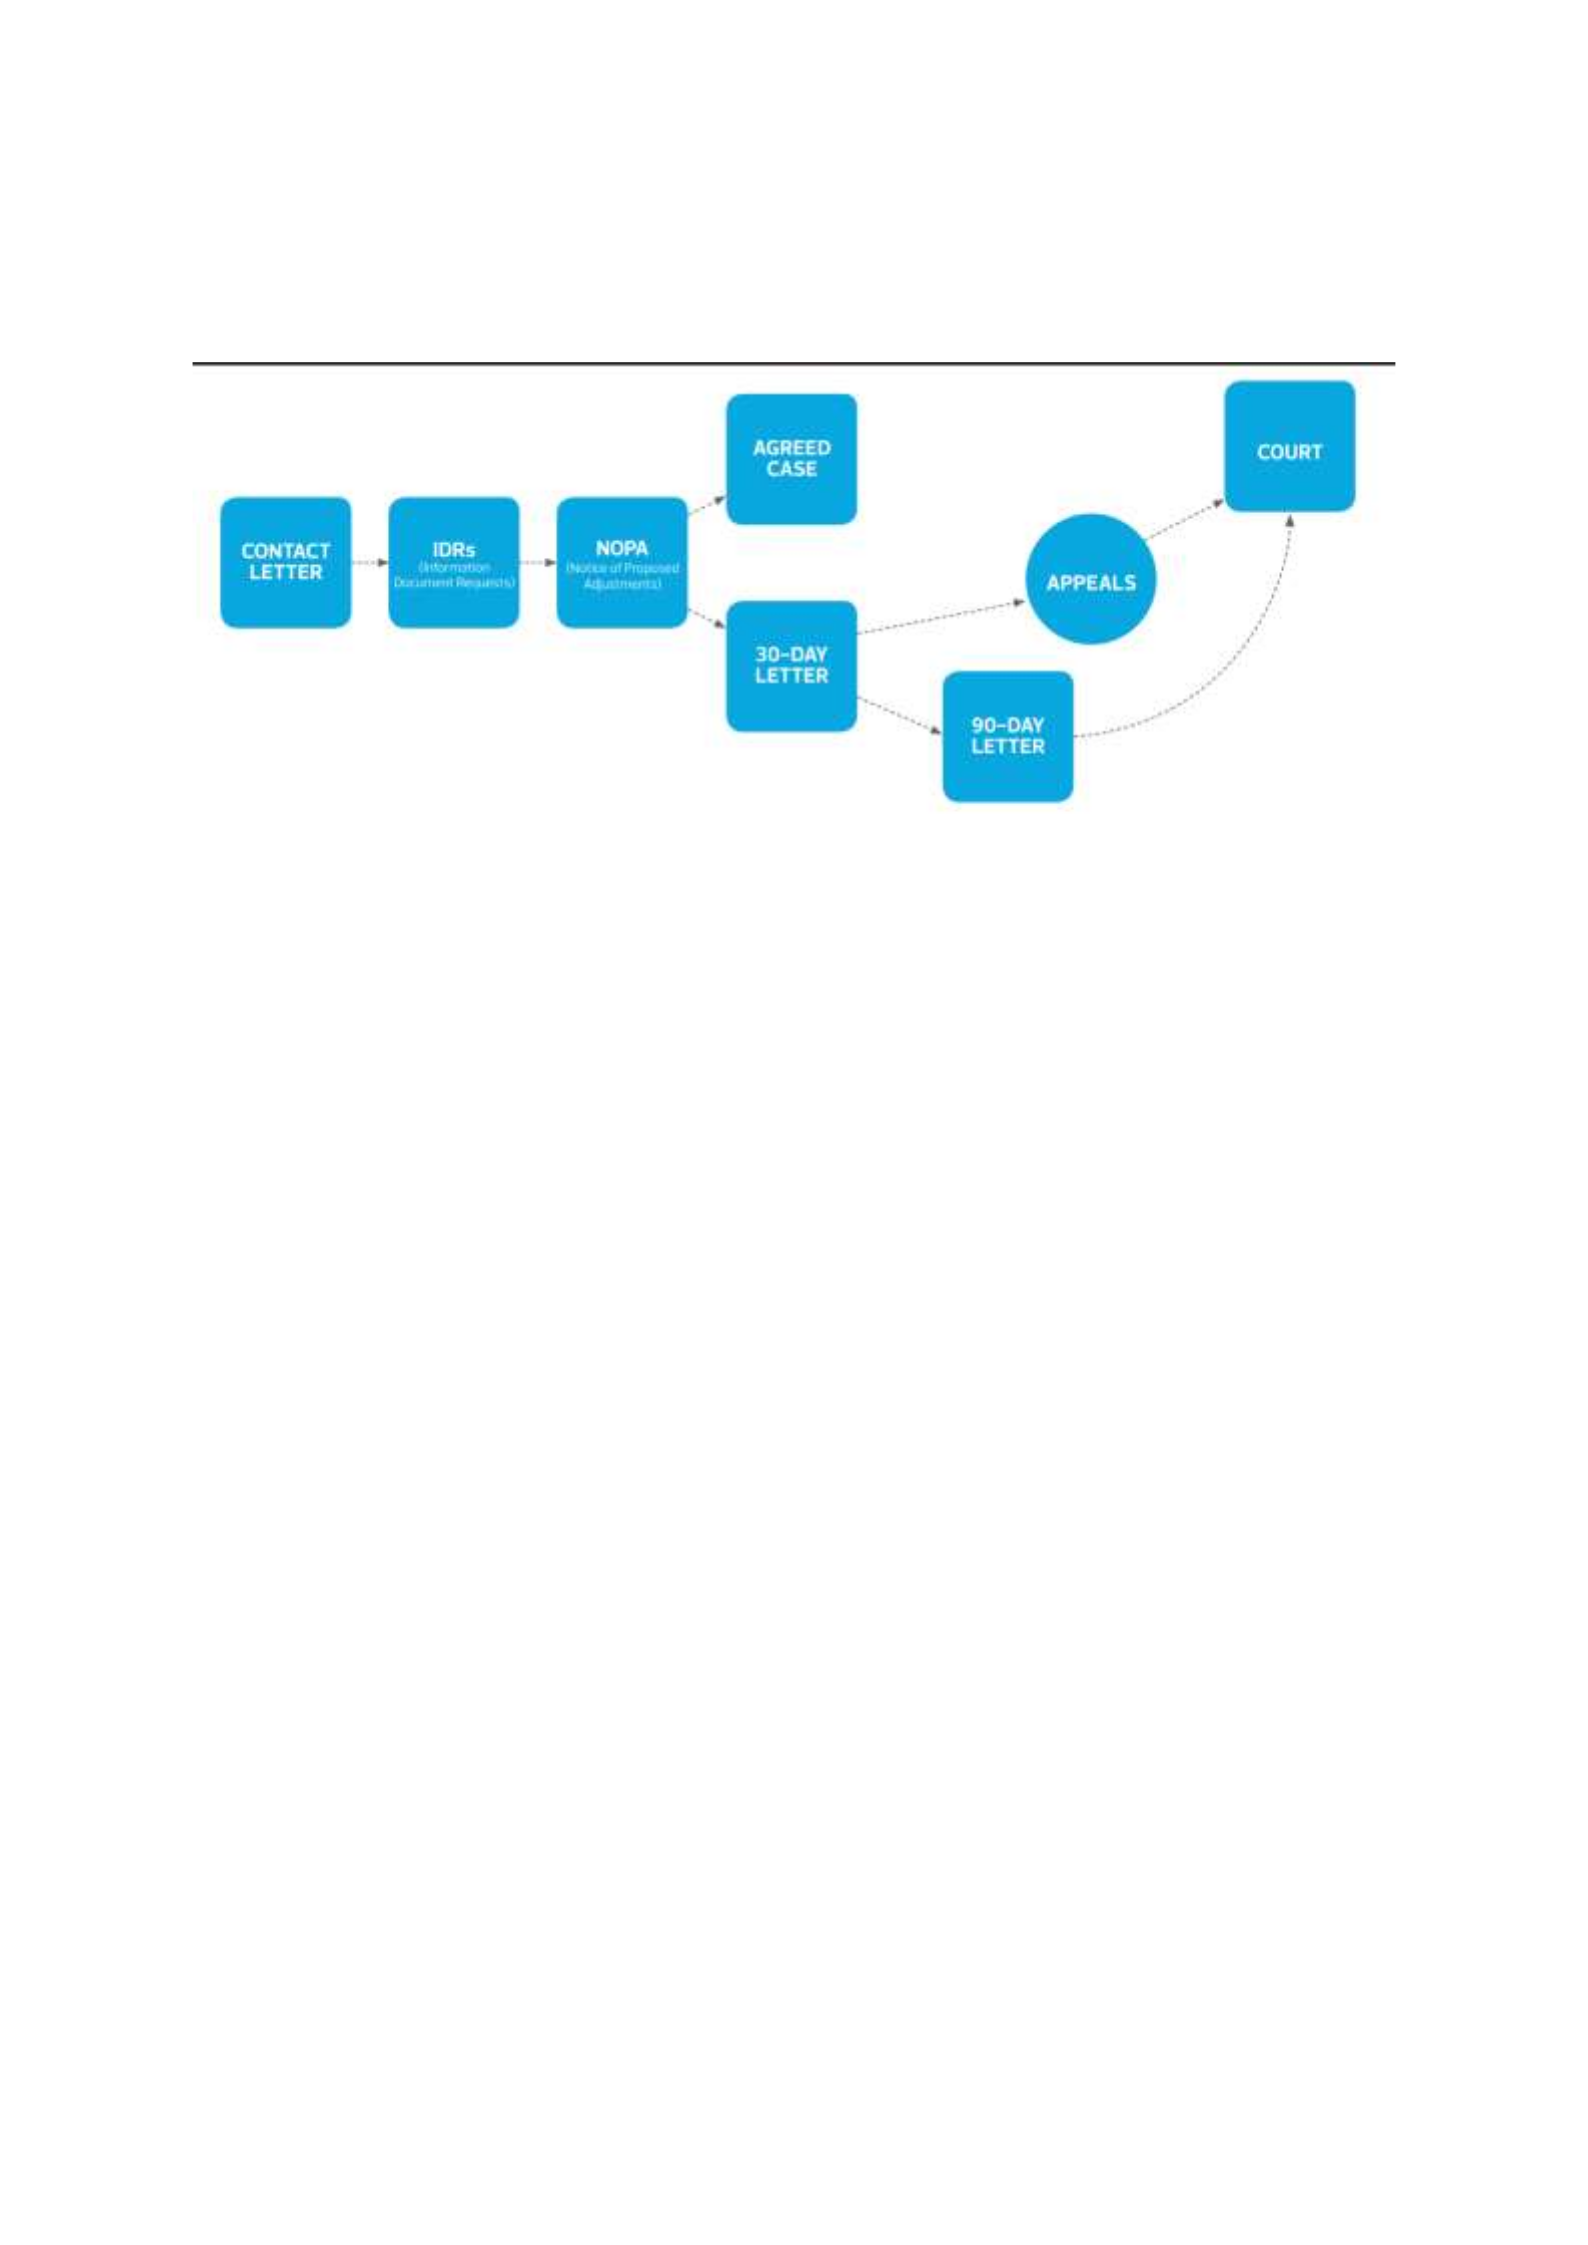
An issuance of a Notice of Proposed Adjustment is a part of the IRS audit process,
which consist of the following steps:
An initial contact letter that a taxpayer receives explains that his/her tax return was
selected for an audit and contains a list of the specific items reported on the tax return that
are being questioned by the IRS, with a request that the taxpayer provides documentation
to support the identified items. The primary method of obtaining information for the IRS
is through issuing Form 4564, Information Document Request (IDR). IDRs are required to
be issue-focused and contain a statement of the issue. However, IDRs issued at the
beginning of an examination to request basic books and records and general information
about a taxpayer’s business are not subject to the requirement to state an issue (Sec.
4.46.4.2(2)). As the case progresses, the IRS may issue additional IDRs. As Sec.
4.46.4.7(1) states, IDRs encourage collaboration between the taxpayer and the IRS to
discuss and determine the necessary information for proper issue development. In simple
words, IDRs are used by the revenue agents to understand the taxpayer’s position and
develop factual record. For this discussion, I am going to assume the taxpayer submitted
the documentation and the revenue agent completed the field examination. The next step
in the audit is a Notice of Proposed Adjustments (Form 5701), which represents the IRS’s
view of the facts and its analysis of the issue (“we disagree with your position
because…”). The form includes the following: tax year at issue, adjustment amount,
account or tax return line, IRC section as a primary authority, and a summary of proposed
adjustment(s). Form 5471 also contains the taxpayer’s anticipated response date.
Consequently, the taxpayer has an opportunity to explain his/her position and present any
additional legal authorities to support the case. Per Sec. 4.46.4.13.3(1), the taxpayer’s
response should describe in detail the legal position on which the taxpayer relies.
References
Sec. 4.46.4.2(2)
Sec. 4.46.4.7(1)
Sec. 4.46.4.13.3(1)
IRS Audit Survival Guide: Navigate the IRS examination process. (n.d.). RSM. Retrieved
from
a https://www.hbepc.org/assets/Councils/HoustonBusiness-TX/library/nt-tax-all-
0817_tax-audit-survival-guide_e-book.pdf
• image_91737476821689033575599.png
(74.31 KB)

