


ACC 696
Introduction
T standar tha are in f gov accoun and financial
pr vary fr nation to another.
IFRS GAAP are the two major standar tha a adhe
by nations across the globe when c to financial reporting
SEC to shift from GAAP to IFRS in the future
A ev of IFRS GAAP is in the present .
Rules-Based Versus Principles-Based
Accounting
P -based accoun
P -based utiliz principles ev s to c the balance sheets
inc st of or .
I has guidelines that mus f while cr financial
R -based
R -based accoun re a encompassing a series rules tha
be stric follow while preparing financial s (S & W , 2021).
T approach companies mak c betw e pr in
simple manner.
Principles
-based
accounting
Rules
-based accounting
The principles
-based
accounting method is
based on the principles
that have been
established by the
Financial Accounting
Standard Board
The rules
-based
accounting is based on
predefined rules and
guidelines, which are
designed with minimum
complexity.
It offers high flexibility while
accounting, but the
complexity might increase
when computations
increase.
It is not as flexible as the
principles
-based
accounting method, but it
has less complexity.
It lacks consistency as no
strict rules are in place.
The method is more
consistent due to the
existence of a definite set
of rules.
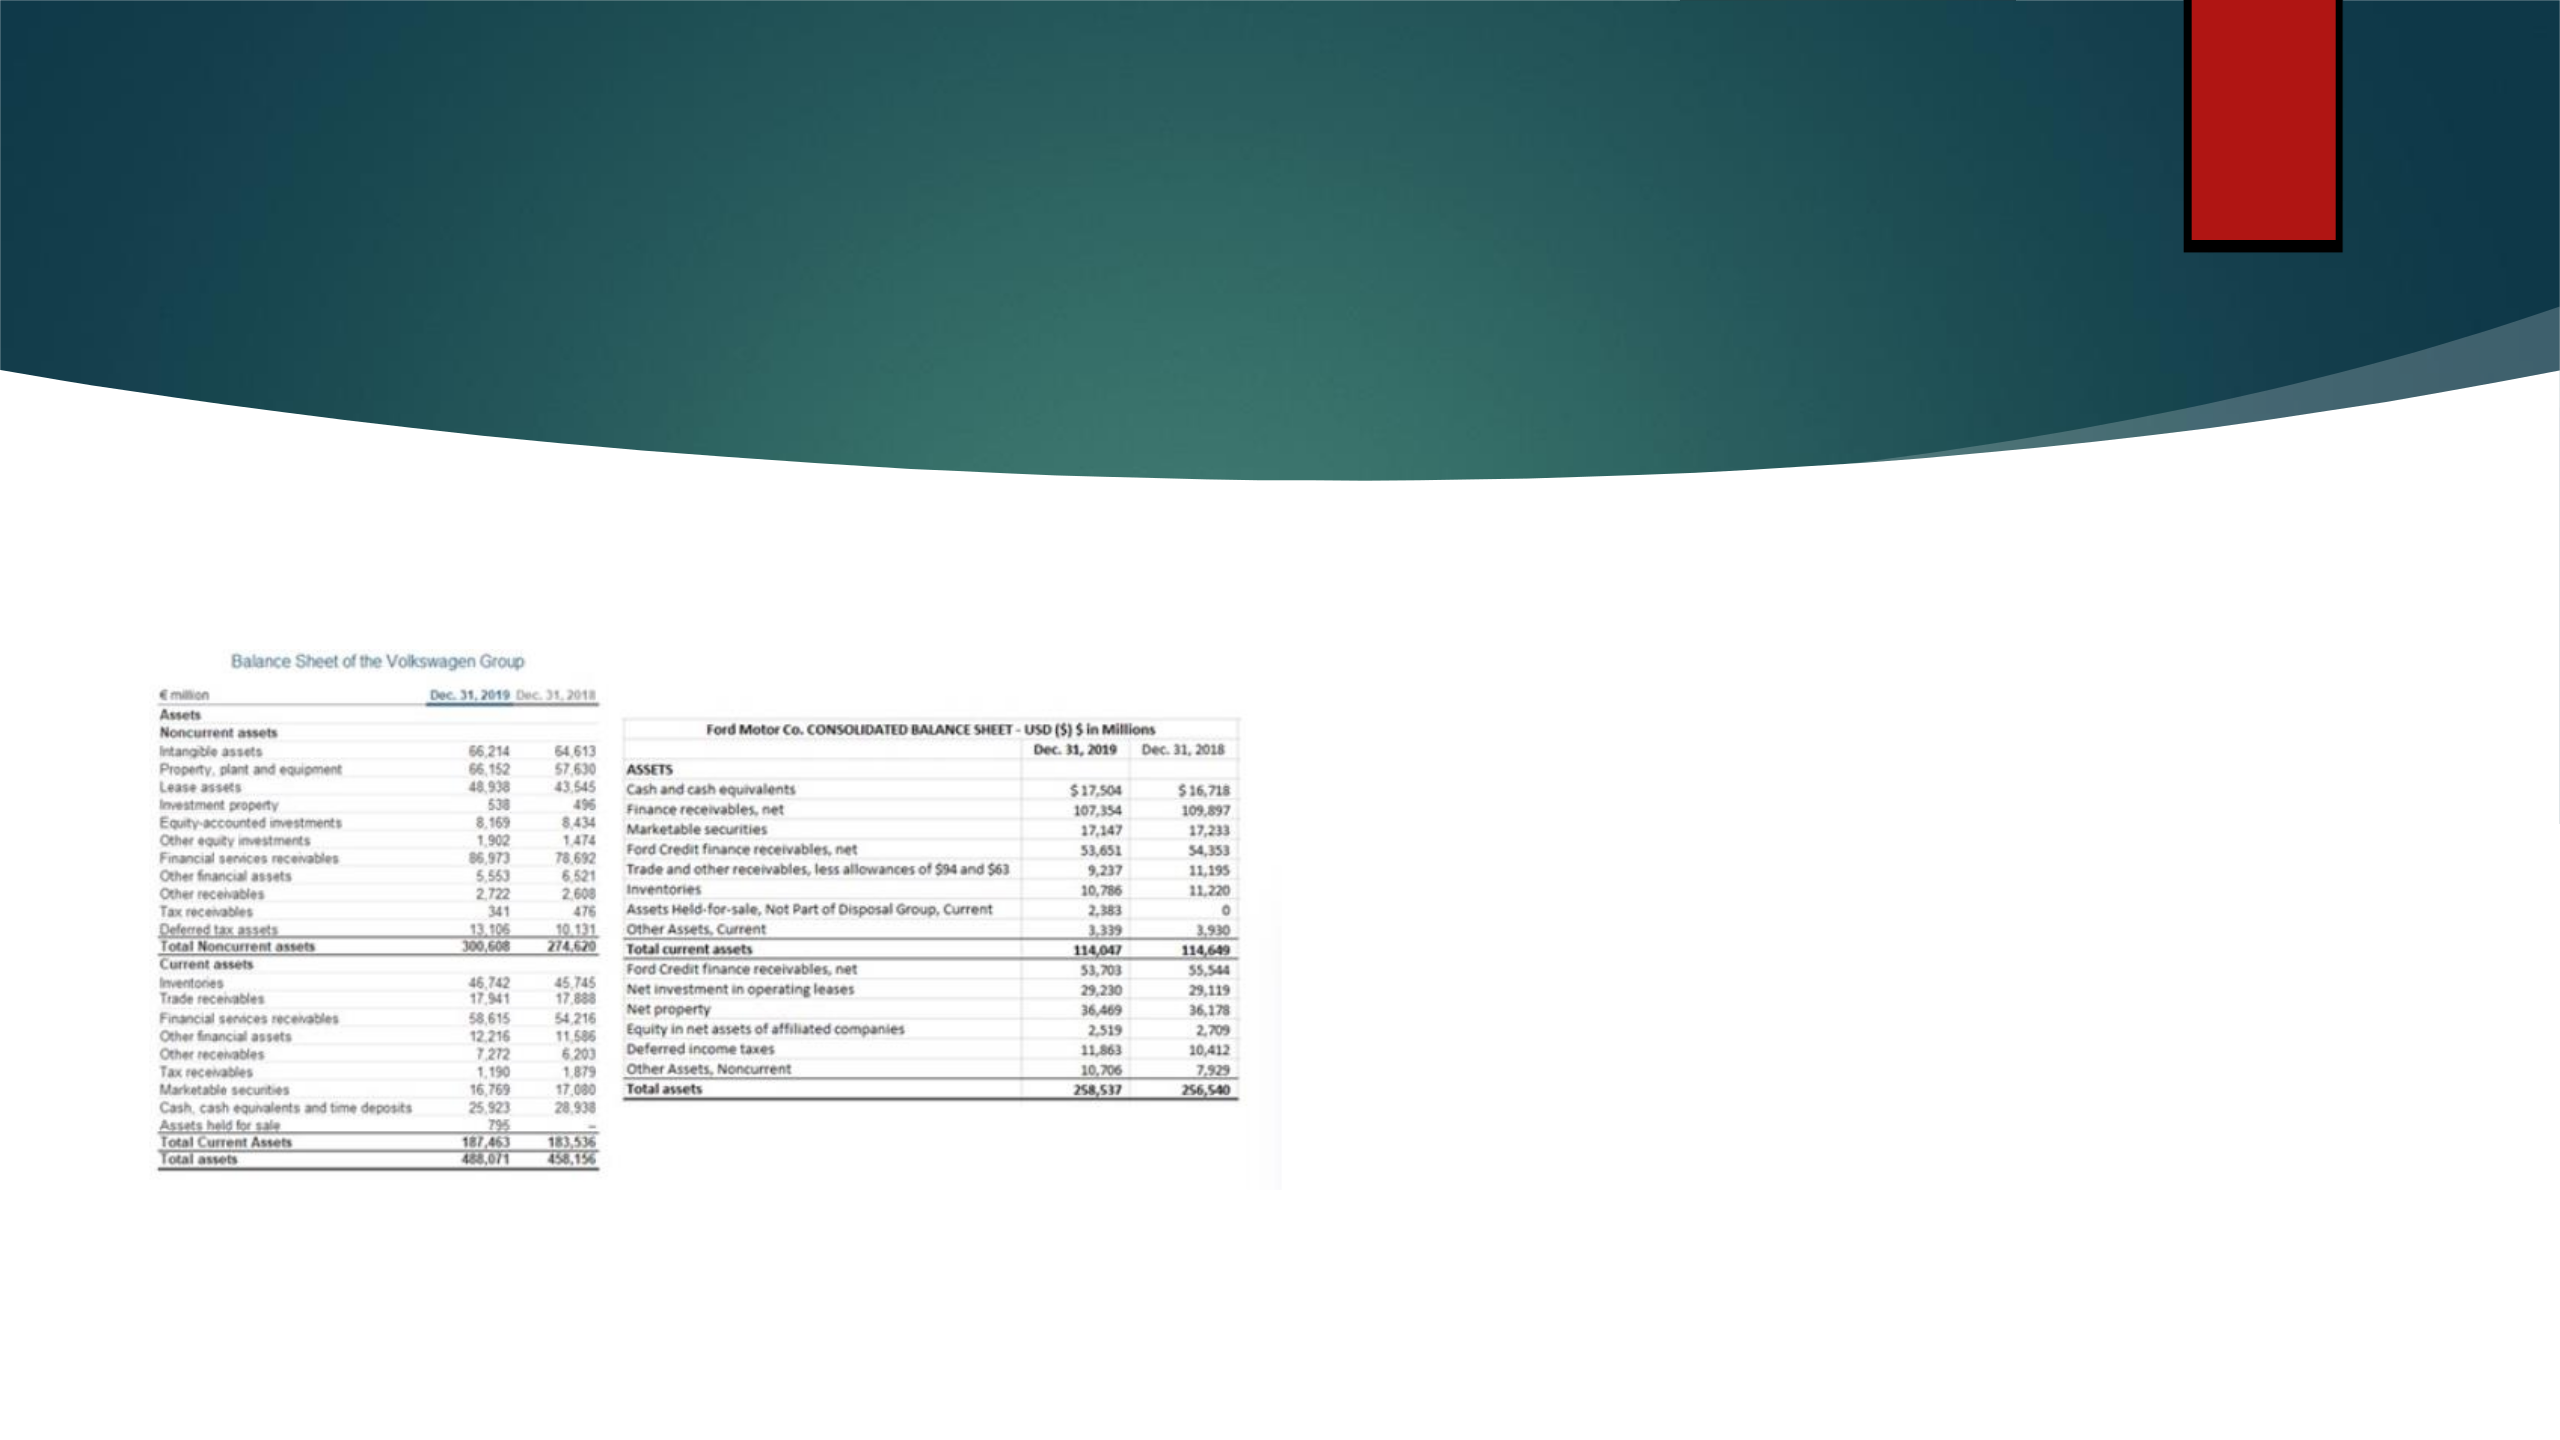
GAAP and IFRS Scenarios
Under the Generally Accepted Accounting
Principles, the assets are listed in the
decreasing order of liquidity. Thus the
current assets are captured before the non-
current assets.
In International Financial Reporting
Standards, assets are recorded in increasing
order of liquidity, and thus, non-current
assets appear before current assets (US
GAAP vs. IFRS. Wall Street Prep, 2022).
C ..
Recognition of accounting elements –R&D
Under GAAP, all the research and development costs are expensed out except capitalized
software costs as well as motion picture development.
In IFRS, the research costs are also expensed out, but it allows the capitalization of development
costs as long as specific criteria are met.
Airbus –The company capitalizes on development costs amounting to several euros, which are
recognized either as intangible assets or development activities relating to the construction of
specific tools (Financial statements - Airbus. airbus, 2021).
Boeing - The research and development encompasses costs that are incurred for experimenting,
testing and designing along with bids as well as proposal efforts.
Contd..
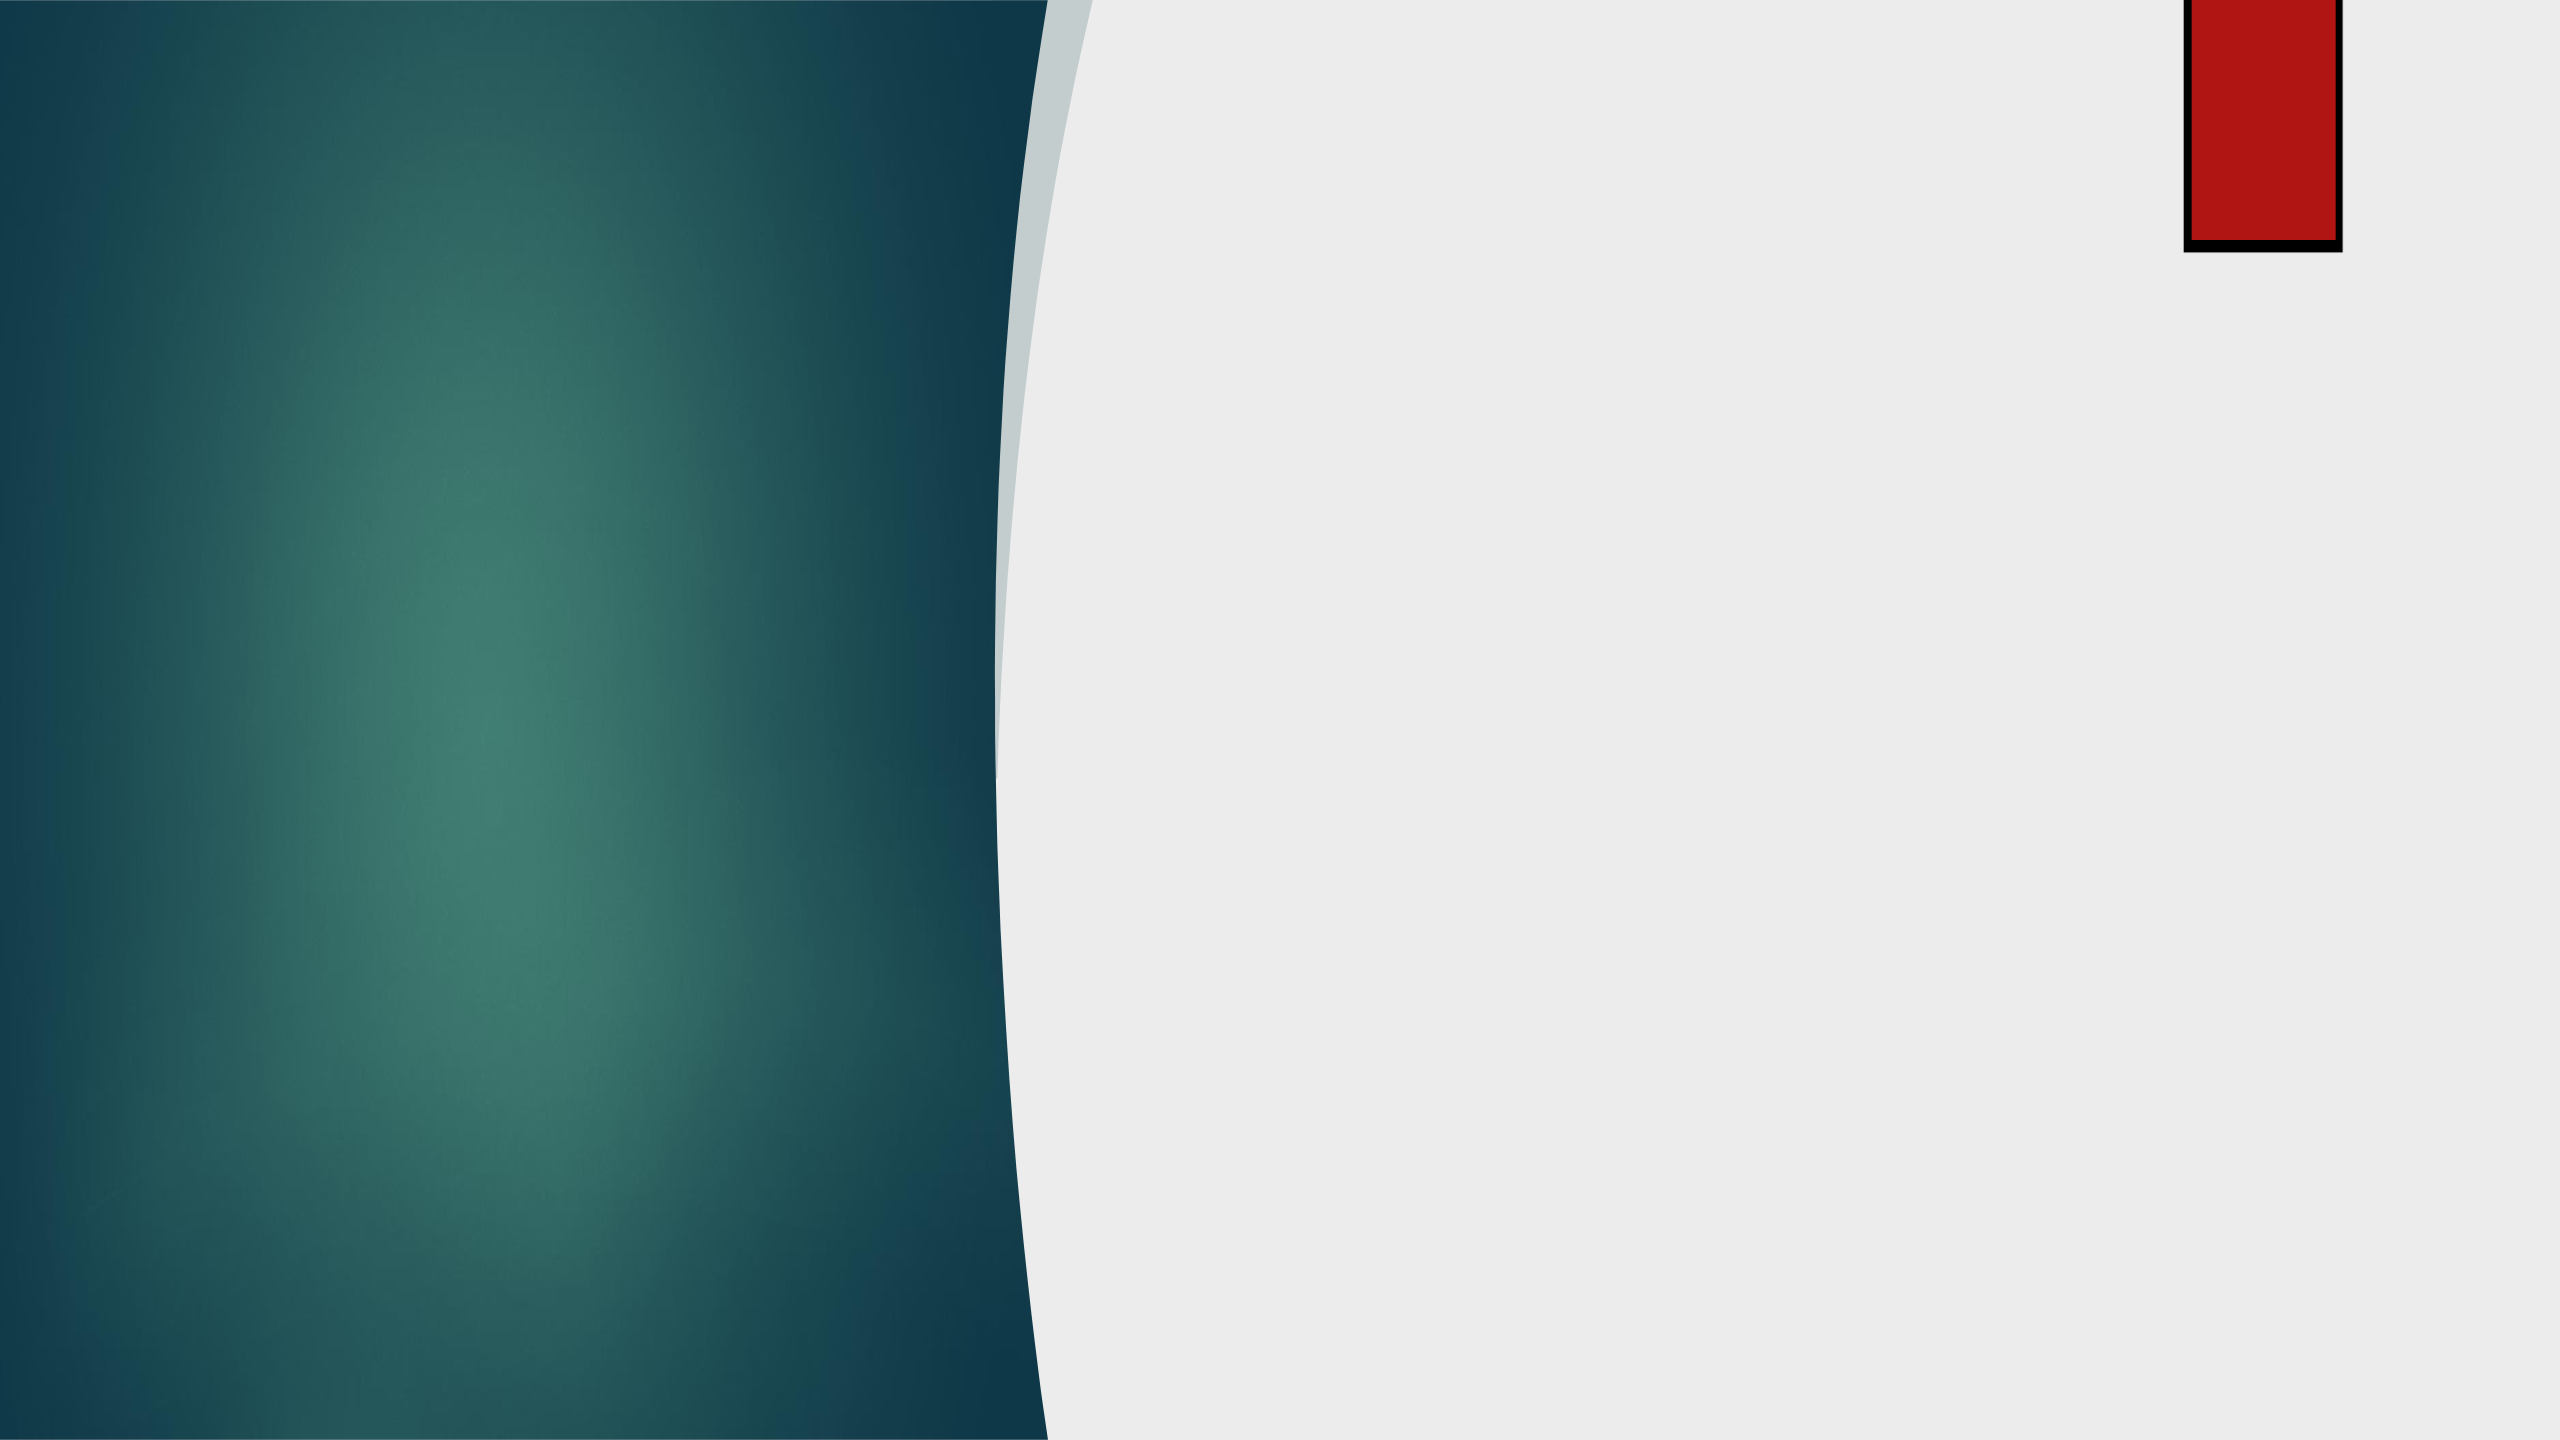
Lease
There exist a number of similarities between GAAP
and IFRS while handling leases.
According to the Leases standard, effective from
2019, leases for more than 12 months must be
reported in the balance sheet as ‘Right for Use
Assets under GAAP as well as IFRS (Group balance
sheet. Tesco PLC, 2021).
While GAAP distinguishes between operating and
financial leases, there is no such distinction under
IFRS.
G
C
G
- C
Several laws and regulations have been adopted that make it
mandatory for business organizations to adopt the best
corporate practices while operating globally and domestically
(Lorange et al., 2006).
However, a number of challenges may arise in the context of
global corporate governance.
Some of the major challenges in the context of global
corporate governance include:
Convergence as well as divergence of corporate best
practices (Bhasa, 2004)
High possibility of malpractices and fraudulent practices
Lack of adherence to suitable standards
C ..
According to the Organisation for Economic Cooperation and Development
(OECD), in the globalized era, corporate governance can create value for a diverse
range of stakeholders. Good corporate governance must be in place so that an
environment of trust, accountability, and transparency can be established.
In the contemporary corporate world, some of the major concerns that arise
relating to global corporate governance revolve around financial and accounting
practices (Corporate governance. OECD, 2021).
Elements like a rise in cross-border ownership, lack of adherence to appropriate
accounting principles, etc., increase the possibility of fraudulent activities in
terms of reporting and accounting.
GAAP or IFRS –Personal Conclusion
T pr change fr Gener Accepted Accounting P (GAAP)
I Financial Reporting St (IFRS) is a smart mov .
A GAAP is a rules-based accounting , mor well-defined and
as compared t the IFRS me , which is based on
.
A SEC f the GAAP method, it is able to f a specific set of rules that
it to carry out its accounting and financial reporting functions in a
.
Contd..
S of the major benefits of GAAP that can w in fa of the SEC terms of
accounting and financial functions include:
A to f the futur
H consis and limi complexity
A in business spen
V f shareholder
C ..
Out of the two accounting standards that are available, GAAP is a more practice
option that the SEC must consider.
However, there is also an opportunity to converge some of the elements so that a
uniformity can be established.
The harmonization of both IFRS and U.S. GAAP is an option that can help to
establish a single centralized set of Global Accounting Standards that companies
can adopt (Fosbre et al., 2009).
C
A comparison between International Financial Reporting Standards (IFRS) and
Generally Accepted Accounting Principles (GAAP) has been made.
As GAAP is a rules-based accounting method whereas IFRS is a principles-based
accounting method, the former is more consistent and methodical.
Thus it has been concluded that the SEC must not move from GAAP to IFRS as its
consistency may get adversely affected.
References
B , M. P. (2004). G corporate governance:
. C Governance: T internati business .
C governance. OECD. (2021). R S 29, 2022,
://www. .org/corpor /
F , A. B., K , E. M., & F , P. B. (2009). T globalization accounting
: IFRS . US GAAP. G J B R ,3(1), 61-71.
F - A . . (2021). R S 29, 2022,
://www. .com/sites/ /files/jlcbta136/ /2021-07/A -Financial-
S -2020-L.N.
G sheet. T PLC. (2021). R S 29, 2022,
://www. .com/investors/r -results-and- /financial-
/group-ba -sheet/
G -Tomaszewski, S., & S , V. (2020). C Impact I F
R S US Generally A A Principles. J of
G Aw ,1(1), 7.
IFRS 15: R contract c . P C. (2021). R S 29,
2022, https:// .pwc.com/ /en/services/ / / -15.html
L , P., S , U., N , F., W , J., & G , B. (E .). (2006). M
corporate . J W & Sons.
US GAAP . IFRS. W Street P . (2022, S 14). R S 29,
2022, https:// .w .com/kno /u - - - - -
-exa -pdf-che -sheet/
S , S. F., & W , A. (2021). P -Based R -Based A
S : A R -Enforceability T .

