


ACC 696 1
Final Project Submission
ACC696
SNHU

2
ACC 696
Contents
I. Background ............................................................................................................................. 3
II. Ethical Violations .................................................................................................................. 3
III Theoretical Models ............................................................................................................... 6
IV External Influences and International Accounting Standards ............................................... 8
V. Ethical Framework .............................................................................................................. 11
Conclusion ............................................................................................................................... 15
References ................................................................................................................................ 16

3
ACC 696
I. Background
cd transferred and manipulated assets between the accounts. All these activities were
done without the consent and knowledge of the customers (Cruz, Bien Justine, 2018).
The main rationale for choosing the Wells Fargo Scandal is that it is a scandal of the
bank of the United States that is a popular example of ethical violation. Another reason for
choosing the situation and the Company is that its unethical sales practices or sales integrity
violation is an important topic in recent times.
A number of ethics violations were discovered in the case of the Wells Fargo scandal.
One of the important ones is the sales integrity violation. The Company has violated the
responsibility of treating the customers with utmost fairness. Moreover, the bank has also gone
against its own vision, and value statements that states Wells Fargo continuously strives to
“set the standard among the world’s great companies for integrity and principled
performance.” The Company also states that “We value what’s right for our customers in
everything we do.” The value of honest practices in business has been violated by the financial
institution of the United States (Welch, 2022).
II. Ethical Violations
a) The main participants who committed the violation in the case of the Wells Fargo scandal
are the employees of the bank and the management. The management of the bank was too
aggressive and had framed impractical sales goals for the employees. Meeting the
performance goals set by the management was challenging for the employees. In order to meet
the goals, they created fake accounts of the existing customers of the bank. The fake accounts
were opened for free, but the information of the customers was used without consent. It
enabled the employees of Wells Fargo to meet their sales goals.

4
ACC 696
In this case, the ethical responsibility of professional accountants is to ensure that the
employees of Wells Fargo perform their professional duties and responsibilities with the
highest integrity (Ethics and The Accounting Profession. Ethics and the Accounting
Profession, 2020). They are also responsible for ensuring that the employees discharge their
responsibilities free of any conflicts of interest. Maintaining the confidentiality of the
information of the customers is another important ethical responsibility of professional
accountants.
The ethical violation case of the Wells Fargo scandal affected the stakeholders in a
number of ways. Many of the employees who were involved in the ethical violation were
removed from their jobs. The executives of the bank were panned as well as punished
publicly. The management of Wells Fargo lost the trust of the customers in the United States.
b) A number of principles of the AICPA Codes of Professional Conduct were violated in the
Wells Fargo Scandal. One of the codes that were violated was integrity. Integrity is considered
to be at the core of professional recognition (Jenkins et al., 2020). By employing dishonest
means in order to meet the sales target, the employees of Wells Fargo violated the integrity
principle. Another principle that was compromised in the Wells Fargo scandal was the
objectivity principle. Due to conflicts of interest, the employees of the bank were unable to
discharge their professional responsibilities. The confidentiality principle of the AICPA Codes
of Professional Conduct was also violated. The confidentiality of the information of the
customers of the bank was not maintained by the employees.
(i) Independence in fact, as well as appearance, is vital in order to maintain professional
autonomy and esteem in the profession. It is important for professionals to maintain
independence when carrying out their roles and responsibilities within professional
boundaries. The professionals need to be independent in fact as well as in appearance to avoid

5
ACC 696
the impairment of the professionals in rendering the assigned responsibilities (Jenkins et al.,
2020). It ensures that the professionals carry out their functions without any kind of bias or
conflict of interest.
(ii) The main participants of the Wells Fargo scandal did not adhere to the ethical and moral
principles of the AICPA Codes of Professional Conduct. The sales integrity was compromised
by the employees as well as the management of the bank. The employees created unauthorized
bank accounts for the existing customers and did not carry out their responsibilities in an
ethical manner.
(iii) The main stakeholders of the Wells Fargo scandal did not maintain objectivity. According
to the principle of objectivity, professionals should not allow any kind of bias, undue influence
of others, or conflict of interest to override business and professional judgments (Sonnerfeldt
& Loft, 2018). However, the need to meet the sales target of the Company, influenced the
employees of Wells Fargo and affected their professional and business judgments negatively.
c) The ethical violations of Wells Fargo had several implications in different aspects of the
business.
(i) In terms of legal aspects, Wells Fargo and many of the executives were panned and
punished publicly.
(ii) In terms of the social aspect, the reputed bank lost the trust of many of its customers. The
customers felt that they were deceived by Wells Fargo. The ethical violation negatively
affected the reputation of the bank.
(iii) In terms of the economic aspect, Wells Fargo has to pay a sum of USD 142 million to the
customers on account of its actions (Sonnerfeldt & Loft, 2018).

6
ACC 696
(d) Yes, Wells Fargo has a code of conduct. According to the Code of conduct of the
Company, it is its responsibility to act with integrity and honesty. However, they have violated
this ethics component of their Code of conduct (Sonnerfeldt & Loft, 2018). The employees of
the Company have not been honest in communicating with the customers and behaving in an
ethical manner. All of these have significantly affected the trust of the customers in the
prestigious bank of the United States. The Code of conduct of Wells Fargo also states that they
protect and keep the data and information of the customers confidential (Sonnerfeldt & Loft,
2018). However, this element has also been compromised by the employees.
After analyzing the background and ethical violation of Wells Fargo company, it has been
identified that the employees of the Company have compromised the codes of conduct and the
ethical principles that have resulted in affecting their brand image. In the next part of the
research, the major focus will be on the theoretical model that will explain the violation of
ethical models in organizational settings. It has also highlighted how the ethical models are
effectively used by Wells Fargo company to produce better outcomes and decisions.
III Theoretical Models
a. Violation of ethical models
In the case of the Wells Fargo scandal, a number of ethical models were violated, such as
the utilitarian ethical model and virtue ethics theory. According to the utilitarian ethical model,
an action can be considered to be ethical if it maximizes the benefits for others or minimizes
the harm that is caused to others (Quinton, 1973). Instead of focusing on self-interest, the
ethical model urges individuals to take into consideration the interests of others as they could
be impacted by one’s actions (Quinton, 1973). In the Wells Fargo context, utilitarianism was
violated, and the employees created millions of fake customer accounts in order to meet the
sales goals. Instead of ethically and rationally dealing with the pressure that the top
management was creating to achieve the business target, the employees resorted to

7
ACC 696
malpractices so that they could fulfill unrealistic expectations. Due to their unethical actions,
the customers on whose behalf fake accounts were created were at the receiving end. They
were unnecessarily charged fees for the services that they had not used or opted for. c c
The virtue ethics theory states that an action is right if a virtuous individual would carry it
out under similar circumstances. It primarily lays emphasis on moral virtue and the strength f
one’s character. The role of virtue is of paramount importance in integrating the best practices
in a professional setting (Berg, 2020). In the case of Wells Fargo, the employees and the
management failed to show a strength of character as the employees resorted to unethical
practices to meet the sales goal and the top executives of the organization intimidated their
subordinates to achieve the unrealistic sales targets. Both of them failed to carry out their
duties in a virtuous manner, and they failed to strive towards the common good, due to which
the major accounting issue arose (Akrivou & Fernández, 2021).
b. Application of ethical models for better decisions and outcomes
In order to prevent the major accounting scandal from taking place, the proper application
of the ethical model would have played a key role since it would have helped to produce better
decisions and outcomes. The duty-based ethical model, which is also known as the
deontological ethical approach, could have been adopted. It emphasizes the personal will as
well as the intentions of an individual while making ethical decisions (Brown University. A
Framework for Making Ethical Decisions | Science and Technology Studies, 2021). Instead of
focusing on the consequences, it would have enabled the organization, including the top
executives and the staff members, to focus on their intentions while performing their duties.
By adopting the ethical model, the management would have realized that its intentions were
self-centered, and the staff would have realized that its actions were unprofessional and could
harm the customers of the business. The duty-based ethical model by Kant could have

8
ACC 696
encouraged them to act in a more responsible and accountable manner while progressing
toward the business goals and objectives. c
The utilitarian ethical model could have been adopted in the context of Wells Fargo so that
the management and staff of the organization would focus on maximizing the benefits of
others instead of focusing on their self-interest. By adhering to the ethical model, the
possibility of violating it could have been averted, and responsible and ethical decisions could
have been taken instead of merely focusing on achieving the sales target. It would have guided
the organization, including the top executives and their subordinates, to make ethical
decisions, specifically the decisions that could have consequences for a large number of
people (Berg, 2020).
IV External Influences and International Accounting Standards
a. Impact of regulatory activities on the ethics of the case
Regulatory activities play a critical role in molding the ethical approach that is adopted by
organizations while carrying out their business activities and functions. The regulations, rules,
and legislation serve as key instruments that organizations must adhere to so that they
sustainably conduct their business activities in an ethical and responsible manner.
Organizations have a responsibility to adhere to appropriate regulations that have been
introduced at the industrial level. The regulatory activities influence the policies that are
adopted by companies to support ethical practices and behaviour (Hodges & Steinholtz, 2017).
In the case of Wells Fargo, there were violations of rules, regulations and laws relating to
accounting, internal accounting controls and auditing functions (Fargo, 2019, p .9). Due to the
breach of regulations, malpractice by employees was going on for a considerable time within
the organization without the knowledge of the customers. As the workforce of the
organization did not stick to the appropriate regulations while performing their respective

9
ACC 696
roles and responsibilities, the unethical practice escalated, and millions of fake savings and
checking were created on behalf of the customer and clients of the company (Kelly, 2022).
b. Impact of international accounting standards on the ethics of the case
International accounting standards have the potential to significantly influence the ethical
practices that are adopted by business entities while achieving business goals and objectives.
The ‘International Ethics Standards Board for Accountants’ (IESBA) is a global body that is
responsible for developing and promoting ethical standards that professional accountants, as
well as auditors, need to adhere to. The fundamental objective is to promote good ethical
practice in the organizational landscape by integrating ethics. The auditor that was responsible
for carrying out the auditing of Wells Fargo when the malpractice was going on was KPMG.
KPMG failed to prevent or disclose the fraud activities that were going on in Wells Fargo. Due
to the inability of the auditor to adhere to international accounting standards to ensure the
integrity and authenticity of the financial activities of the bank, several lawmakers raised
questions relating to KPMG’s quality of audit (Lynch, 2017). The lack of compliance with
international accounting standards contributed to the escalation of the situation, which
affected hundreds and thousands of customers of the Wells Fargo organization. As
international accounting standards were disregarded, the ethical dimension was adversely
affected in the case of the Wells Fargo organization.
c. Impact of emerging technologies on the ethics of the case
In the digitalized era of the 21st century, new and emerging kinds of technologies can play
an instrumental role in influencing the ethical approach that is adopted by business entities
while working towards their business goals and objectives. As new technologies are entering
the modern business landscape, they are raising serious ethical questions relating to diverse
areas such as security, privacy, the confidentiality of users, transparency, accountability, etc.

10
ACC 696
Brey has stated that emerging technologies give rise to a host of ethical challenges due to the
high degree of uncertainty and unpredictability.
Several emerging technologies are in their nascent stage, such as Artificial Intelligence (AI),
Machine Learning (ML), etc. However, they have shown the promise to revolutionize
different kinds of work environments such as education, healthcare, retail, manufacturing, etc.
In spite of being full of promise and potential, they also increase the level of risk that may arise
for business organizations as well as customers, among other stakeholders. Some of the
critical ethical issues that have the potential to diminish the effectiveness of emerging
technologies for business are related to the issues of autonomy, justice, responsibility and
accountability, well-being, etc. (Hodges & Steinholtz, 2017). In order to address these ethical
issues, business entities need to act in a responsible manner while integrating emerging
technologies into their business processes so that ethical behavior can be given high priority.
However, in the case of Wells Fargo, the managers abused emerging technology and, instead
of focusing on ethics, created fake customer accounts to achieve their sales targets. The
autonomy of the customers was lost as they did not have a say when fake accounts were
created on their behalf by the employees to achieve sales targets. Due to the existence of gaps
in ethical practices, the organization was able to leverage emerging technologies and carry on
with its unethical business practices until they were discovered..
After analyzing the impact of international accounting standards, regulatory activities, and
emerging technologies on the ethics of the case, it has been identified that the ethical
dimension was adversely affected in the case of the Wells Fargo organization. However, the
negative consequences can be eradicated by following the potential ethical framework at the
organizational level. The next part of the research highlighted the proposed ethical framework
for the Wells Fargo organization and mentioned some internal controls to produce more
ethical behavior at the organizational level.

11
ACC 696
V. Ethical Framework
a) Propose
An ethical framework is essential for a business organization, which is nothing but a
perspective that is helpful for reasoning the course of actions that can offer the best moral
outcome. It has been observed that many individuals simply follow things that they feel are
best at the time and do not prefer to use a reasoning process, which results in an ethical
violation. Thus, it becomes essential for all business organizations to follow reflexive and
ethical principles (What are ethical frameworks, 2021). In the present case of Wells Fargo,
some of the ethical violations have been observed including the sales integrity violation,
violated the responsibility of treating the customers, the bank gone against its own value and
vision statements. Thus, it is significant for the Company to propose an ethical framework to
set up an appropriate standard of conduct to maintain professional accounts and enhance the
decision-making process, as well as create a higher level of ethical values. Thus, the researcher
has proposed an ethical framework that includes the involvement of management in the
process and ensures the availability of company resources to employees that can help them to
make ethical choices.
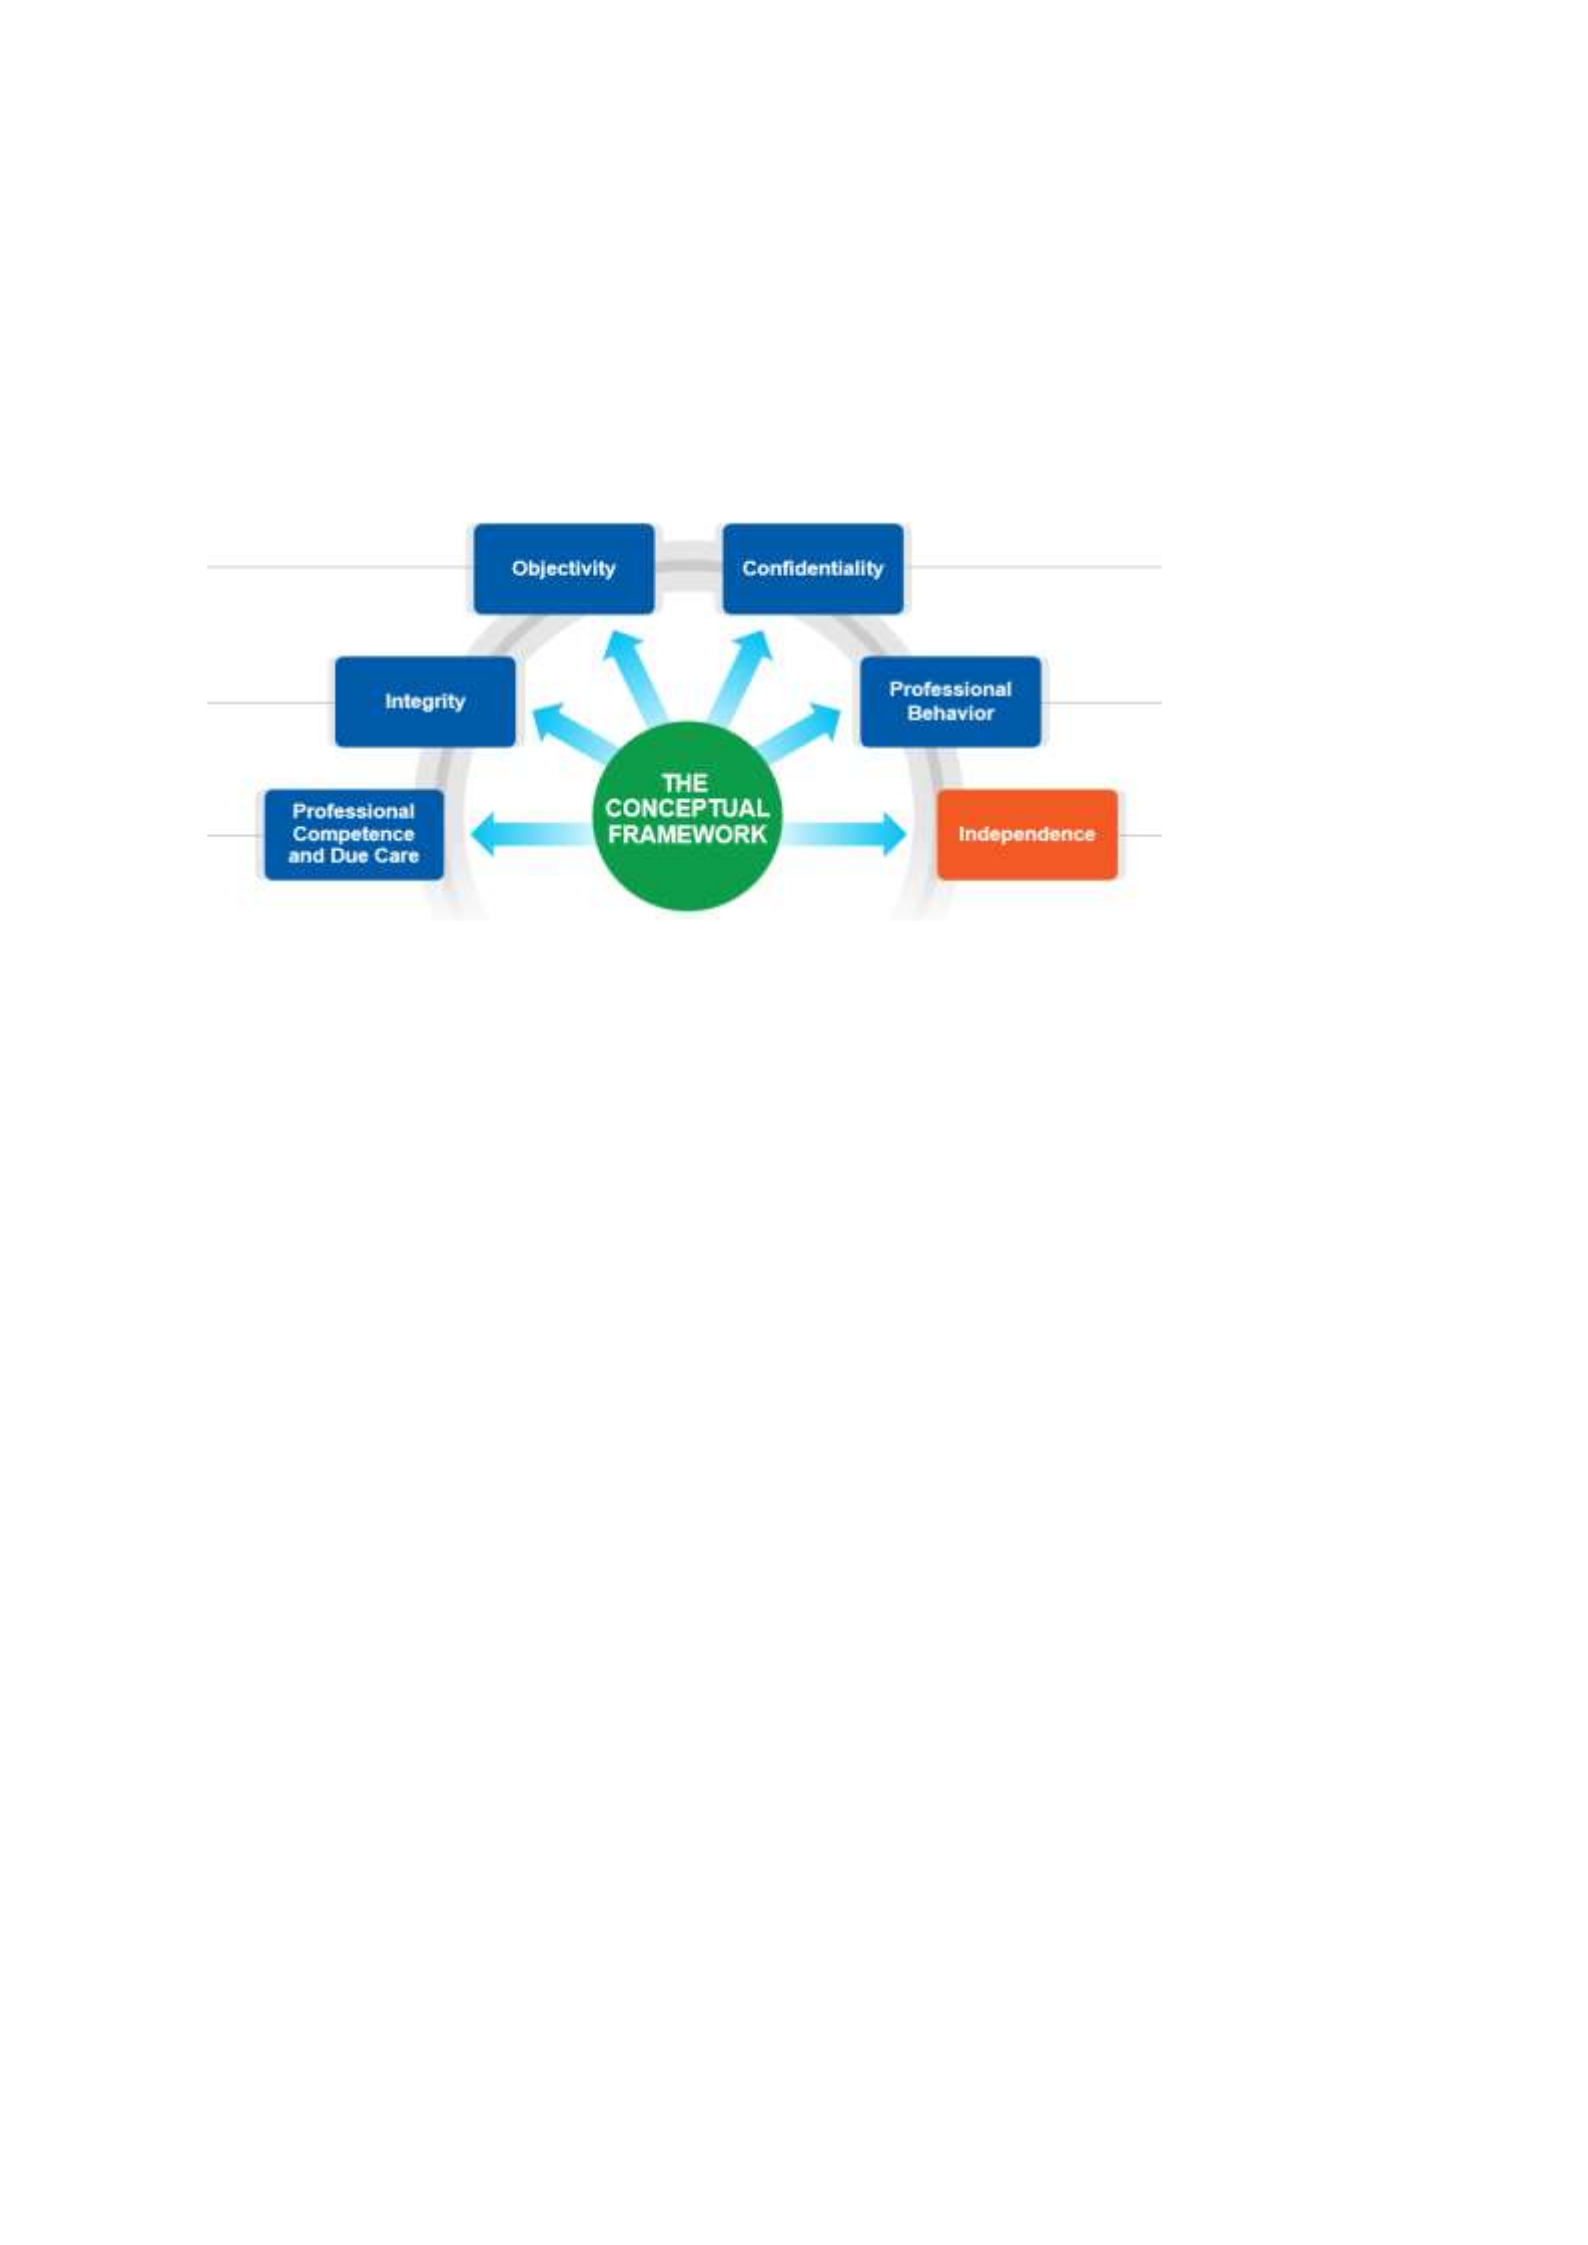
According to the IFAC report, an enhanced conceptual framework involves the fundamental
principles within the Code, including objectivity, integrity, confidentiality, professional
behaviour, independence, and professional competence and due care. These principles with
the Code can help to reflect the recognition of its public interest responsibility in the
profession and to establish the behaviour standard expected of a professional accountant (The
International Code of Ethics for professional accountants: Key areas of focus for smes and
SMPS, 2021). In the present case of Wells Fargo, the selection of such ethical framework can
be beneficial for the settings of an appropriate standard of conduct to maintain the professional
accounts and enhance the decision-making process. The Company must follow the five
12
ACC 696
fundamental principles of ethics, such as objectivity, integrity, confidentiality, professional
behaviour, and professional competence and due care, so that future growth can be predicted
well for the Wells Fargo company.
Figure-1: A proposed ethical framework for Wells Fargo company
c
Source: (The International Code of Ethics for professional accountants: Key areas of focus for
smes and SMPS, 2021)
• Integrity
An honest and straightforward behaviour of a professional accountant should be maintained in
all business and professional relationships. Here, the use of integrity term explains that all the
team members of an organization must not be associated with any kind of misleading
information. In the present context of Wells Fargo, the employees need to maintain integrity
within the work culture so that ethical violations can be reduced in the Company and better
productivity can be expected. The following integrity can also help the Company to generate a
higher level of ethical values in terms of growing sales. Likely, the sales integrity violation of
Wells Fargo could have been avoided.
• Objectivity
A professional accountant must not go for a compromise in the business or professional
judgments because of the conflict of interest, biasness, or undue influence of others. Here, the

13
ACC 696
team members of the organization must appear to be independent if undertaking the
engagement of assurance. For instance, the Wells Fargo company needs to maintain
objectivity so that professional accountants and the office staff should never compromise in
the judgment because of a conflict of interest, biasness, or undue influence of others. Likely,
the Company can ensure the better involvement of the management in the process.
• Confidentiality
A professional accountant must maintain and respect the confidentiality of information, which
is the most crucial factor in maintaining business and professional relationships. They should
not disclose any confidential information to third parties without any specific and proper
authority. The professional staff can share confidential data with a professional or legal right
or duty to disclose. This principle of ethics supports that the organization acquired confidential
information as a result of business and professional relationships should not be used by third
parties or professional accountants for their personal advantage (Morley et al., 2020). In the
present context of wells Fargo, the professional accountants and other staffs needs to follow
such kinds of ethical principle so that confidentiality of information can be maintained at the
organization level and nobody can take advantage of these confidential data for their personal
use. The following Company needs to ensure that disclosure of confidential data is only
possible with legal rights. As a result, it can help the Company to maintain the confidentiality
of data.
• Professional Competence and Due Care
Another important fundamental principle of ethics is professional competence and due care.
This principle helps to maintain and attain the professional skills and knowledge at the level
that needs to make sure that an employing organization or client receives competent
professional service on the basis of professional and current technical standards and relevant

14
ACC 696
legislation. Moreover, this principle ensures the Company must act diligently in accordance
with applicable professional and technical standards. In the present context of Wells Fargo, it
is essential to ensure professional competence and due care so that the professional skills and
knowledge of the employees can be attained and maintained. As a result, Wells Fargo
company can ensure that competent professional services are provided to the clients and the
organization. Moreover, the implementation of such kind of ethical framework helps to
maintain the current technical standards and relevant legislation that can influence
organizational performance by encouraging and influencing the potential skills of the
employees. It has been observed that settings of such appropriate standards and the inclusion
of higher levels of ethical values can help the following organization in making more ethical
choices.
• Professional Behavior
A professional accountant must comply with the relevant rules and regulations and the laws of
the organization. They must try to avoid such actions that discredit their profession and
maintains professional behavior. According to Yosoff, professional behavior is considered to
be the behavior reflection of professionalism (Yusoff, 2009). For instance, Wells Fargo has
experienced ethical issues and ethical violations because of the negligence and not
maintenance of the professional behavior in the work sector. Thus, it is crucial to implement
such ethical principles at the Company so that professional behavior can be shaped by giving
proper training to the employees. This can result in improving the employees' performance at
the workplace, and the maintenance of professional behavior can ensure the reduction of
ethical violations.
Overall, the management will be involved in the whole ethical framework to ensure the perfect
implementation of the five ethical principles such as integrity, objectivity, professional

15
ACC 696
competence and due care, professional behavior, and confidentiality. The company resources
must include providing ethics training, offering protective mechanisms, communicating
ethical expectations etc., to help the employees to do more ethical choices.
b) Internal control
Yes, the researcher found that internal controls can be better utilized to generate more ethical
behavior in the organizational context. It has been identified that the ethical culture is
considered to be the foundation of effective and efficient internal controls. Every professional
accountant needs to understand that internal controls are very important and best practice to
make sure compliance with regulations and applicable laws and to make sure the presence of
system balances and checks to detect transactions that are inappropriate. The internal controls
are helpful in making various policies and procedures by the management towards the job of
the employees and their appropriate behavior at the workplace. In the present case of Wells
Fargo, it is crucial for the management, board of directors, and other personnel to design the
internal control process effectively to provide reasonable assurance in terms of reliability of
financial reporting, accurate, reliable, and timely information, and compliance with applicable
laws, contracts, regulations, procedures, and policies. Here, a plan by corporate governance
can be an appropriate way to provide internal control at the organizational level, as good
corporate governance can result in the best ethical business practices and shows better
financial viability.
Conclusion
The popular Wells Fargo company has committed a number of ethics violations that include
sales integrity violation, the violation of the responsibility of treating the customers with the
utmost fairness, and many more. This has resulted in affecting its reputation in the market.
Thus, it becomes essential for the Company to implement the proposed ethical framework that

16
ACC 696
includes integrity, objectivity, professional competence and due care, professional behavior,
and confidentiality so that ethical violence can be reduced in the upcoming years.
Additionally, the research also highlights that the Company should have internal controls over
ethical behavior so that better outcomes can be expected in the future.
References
Akrivou, K., & Fernández González, M. J. (2021). Beyond personalist virtue ethics:
transcendental anthropology and its implications for interpersonal communication.
Frontiers in Communication: Organisational Psychology, 6.
Brown University. A Framework for Making Ethical Decisions | Science and Technology
Studies. (2021). Retrieved October 7, 2022, from
https://www.brown.edu/academics/science-and-technology-studies/framework-making-
ethical-decisions
Berg, H. (2020). Virtue ethics and integration in evidence-based practice in psychology.
Frontiers in Psychology, 11, 258.

17
ACC 696
Cruz, Bien Justine. (2018). Wells Fargo: An article based analysis.
10.13140/RG.2.2.18452.65924.
Ethics and The Accounting Profession. Ethics and the Accounting Profession. (2020).
Retrieved September 15, 2022, from https://www.illumeo.com/blogs/illumeo-customer-
success/2020/10/22/ethics-accounting-profession
Fargo, W. (2019) Our code of ethics and business conduct: Living our vision, values & goals.
Hodges, C., & Steinholtz, R. (2017). Ethical business practice and regulation: a behavioural
and values-based approach to compliance and enforcement (Vol. 6). Bloomsbury
Publishing.
Kelly, J. (2022, April 14). Wells Fargo forced to pay $3 billion for the bank's fake account
scandal. Forbes. Retrieved October 7, 2022, from
https://www.forbes.com/sites/jackkelly/2020/02/24/wells-fargo-forced-to-pay-3-billion-
for-the-banks-fake-account-scandal/
Jenkins, J. G., Popova, V., & Sheldon, M. D. (2020). Monitoring the accounting profession
under the AICPA code of professional conduct: An analysis of state board of
accountancy participation. Journal of Accounting and Public Policy, 39(3), 106742.
Lynch, S. N. (2017, April 25). Lawmakers question quality of KPMG's Wells Fargo Audits.
Reuters. Retrieved October 7, 2022, from https://www.reuters.com/article/wells-fargo-
kpmg-idUSL1N1HX1YX
Morley, J., Floridi, L., Kinsey, L., & Elhalal, A. (2020). From what to how: an initial review of
publicly available AI ethics tools, methods and research to translate principles into
practices. Science and engineering ethics, 26(4), 2141-2168.

18
ACC 696
Mitra, R. (2019). Utilitarianism: An Ethical Decision Making Approach.
10.13140/RG.2.2.30208.99843
Quinton, A. (1973). Utilitarian ethics. Springer.
Sonnerfeldt, A., & Loft, A. (2018). The changing face of ethics–Developing a Code of Ethics
for Professional Accountants from 1977 to 2006. Accounting History, 23(4), 521-540.
The International Code of Ethics for professional accountants: Key areas of focus for smes and
SMPS. (2021, June 29). Retrieved October 21, 2022, from
https://www.ifac.org/knowledge-gateway/building-trust-ethics/discussion/international-
code-ethics-
professional#:~:text=The%20fundamental%20principles%20within%20the,of%20its%
20public%20interest%20responsibility
Welch, J. (2022). Wells Fargo: a corporate recovery model to bank on. Journal of Business
Strategy, (ahead-of-print).
What are ethical frameworks? (2021). Retrieved October 21, 2022, from
https://aese.psu.edu/teachag/curriculum/modules/bioethics-1/what-are-ethical-
frameworks#:~:text=Ethical%20frameworks%20are%20perspectives%20useful,is%20b
est%20at%20the%20time
Yusoff, M. S. B. (2009). Professional behaviour: what does it means?. Education in Medicine
Journal, 1(1).

