


The public company I chose to research is Bristol Myers Squibb Company (BMY). I chose this
company because my mother has worked for BMY the past 25 years and in those years her pay
has increased 5 times her original hired annual pay. Giovanni Caforio is the CEO of BMY and his
annual salary for 2021 was $1.7 million with additional stock awards, Non-equity Incentive Pay
Compensation, and other compensations his total compensation for 2021 was $19.7 million. This is
133 times the median employees pay for 2021. The CEO makes 158 times my mother’s annual
salary which I found rather interesting. The CEO entire compensation breakdown by percentage is
Salary - 10%, Annual Incentive - 14%, Market Share Units - 30%, and Performance Share Units -
46%. The Performance Shares are only applying to Vice President and above. In the company’s
Proxy Statement (Schedule 14A) they state that a thorough Risk Assessment of Compensation
Policies and Practices was conducted by the Compensation and Management Development
Committee. They stated, “Based on this review, the Committee concluded that our material
compensation policies and practices are not reasonably likely to have a material adverse effect on
the company. On a global basis, our compensation policies and practices contain many design
features that mitigate the likelihood of inducing excessive or inappropriate risk-taking behaviour.”
(SEC.gov 2022) This committee annually evaluates the incentive programs to determine if the
incentive pay encourages excessive or inappropriate risk-taking.
In my opinion, there are a few benefits to compensating executives with stock or the option to
purchase stock. This allows the company to share ownership with the employees, which in turn
aligns the executive and shareholder interests. Performance shares allows for the business to
evaluate the performance of the executive before shares are awarded. This is beneficial to the
executive as well as the company. The costs however are very significant. It may be very difficult
to set performance targets and in a down market the shares quickly become valueless. “The main
goal in granting stock options is, of course, to tie pay to performance—to ensure that executives
profit when their companies prosper and suffer when they flounder. Many critics claim that, in
practice, option grants have not fulfilled that goal. Executives, they argue, continue to be
rewarded as handsomely for failure as for success.” (Harvard Business Review, 2014) This is
prominent in BMY because even with the pandemic the CEO has continued to receive $13+ million
in shares in each of the last 3 years.
AS 2110: Identifying and Assessing Risks of Material Misstatement sections 10, 10a, and 11 would
be the best way to audit executive compensation. “Required audit procedures include reading
employment and compensation contracts with executive officers and reading proxy statements.”
(SQ 2013) Utilizing these standards will assist the auditor in determining if there is any chance of
fraud and material misstatements. BMY auditors are required to look at these items which is why
the Proxy Statement (Schedule 14A) is so lengthy and detailed.
Walmart for this discussion primarily due to my love/hate relationship with the retail giant. I
cannot deny that they are a one-stop shop for anything from pharmaceutical needs to groceries
and even automotive and professional hair care services. They indeed do have everything. It's the
limited cashiers, super long lines, and as of late, in the Neighbourhood Markets, it is strictly Self-
checkout. Not to mention its reputation for poor employee compensation. This leads to the point
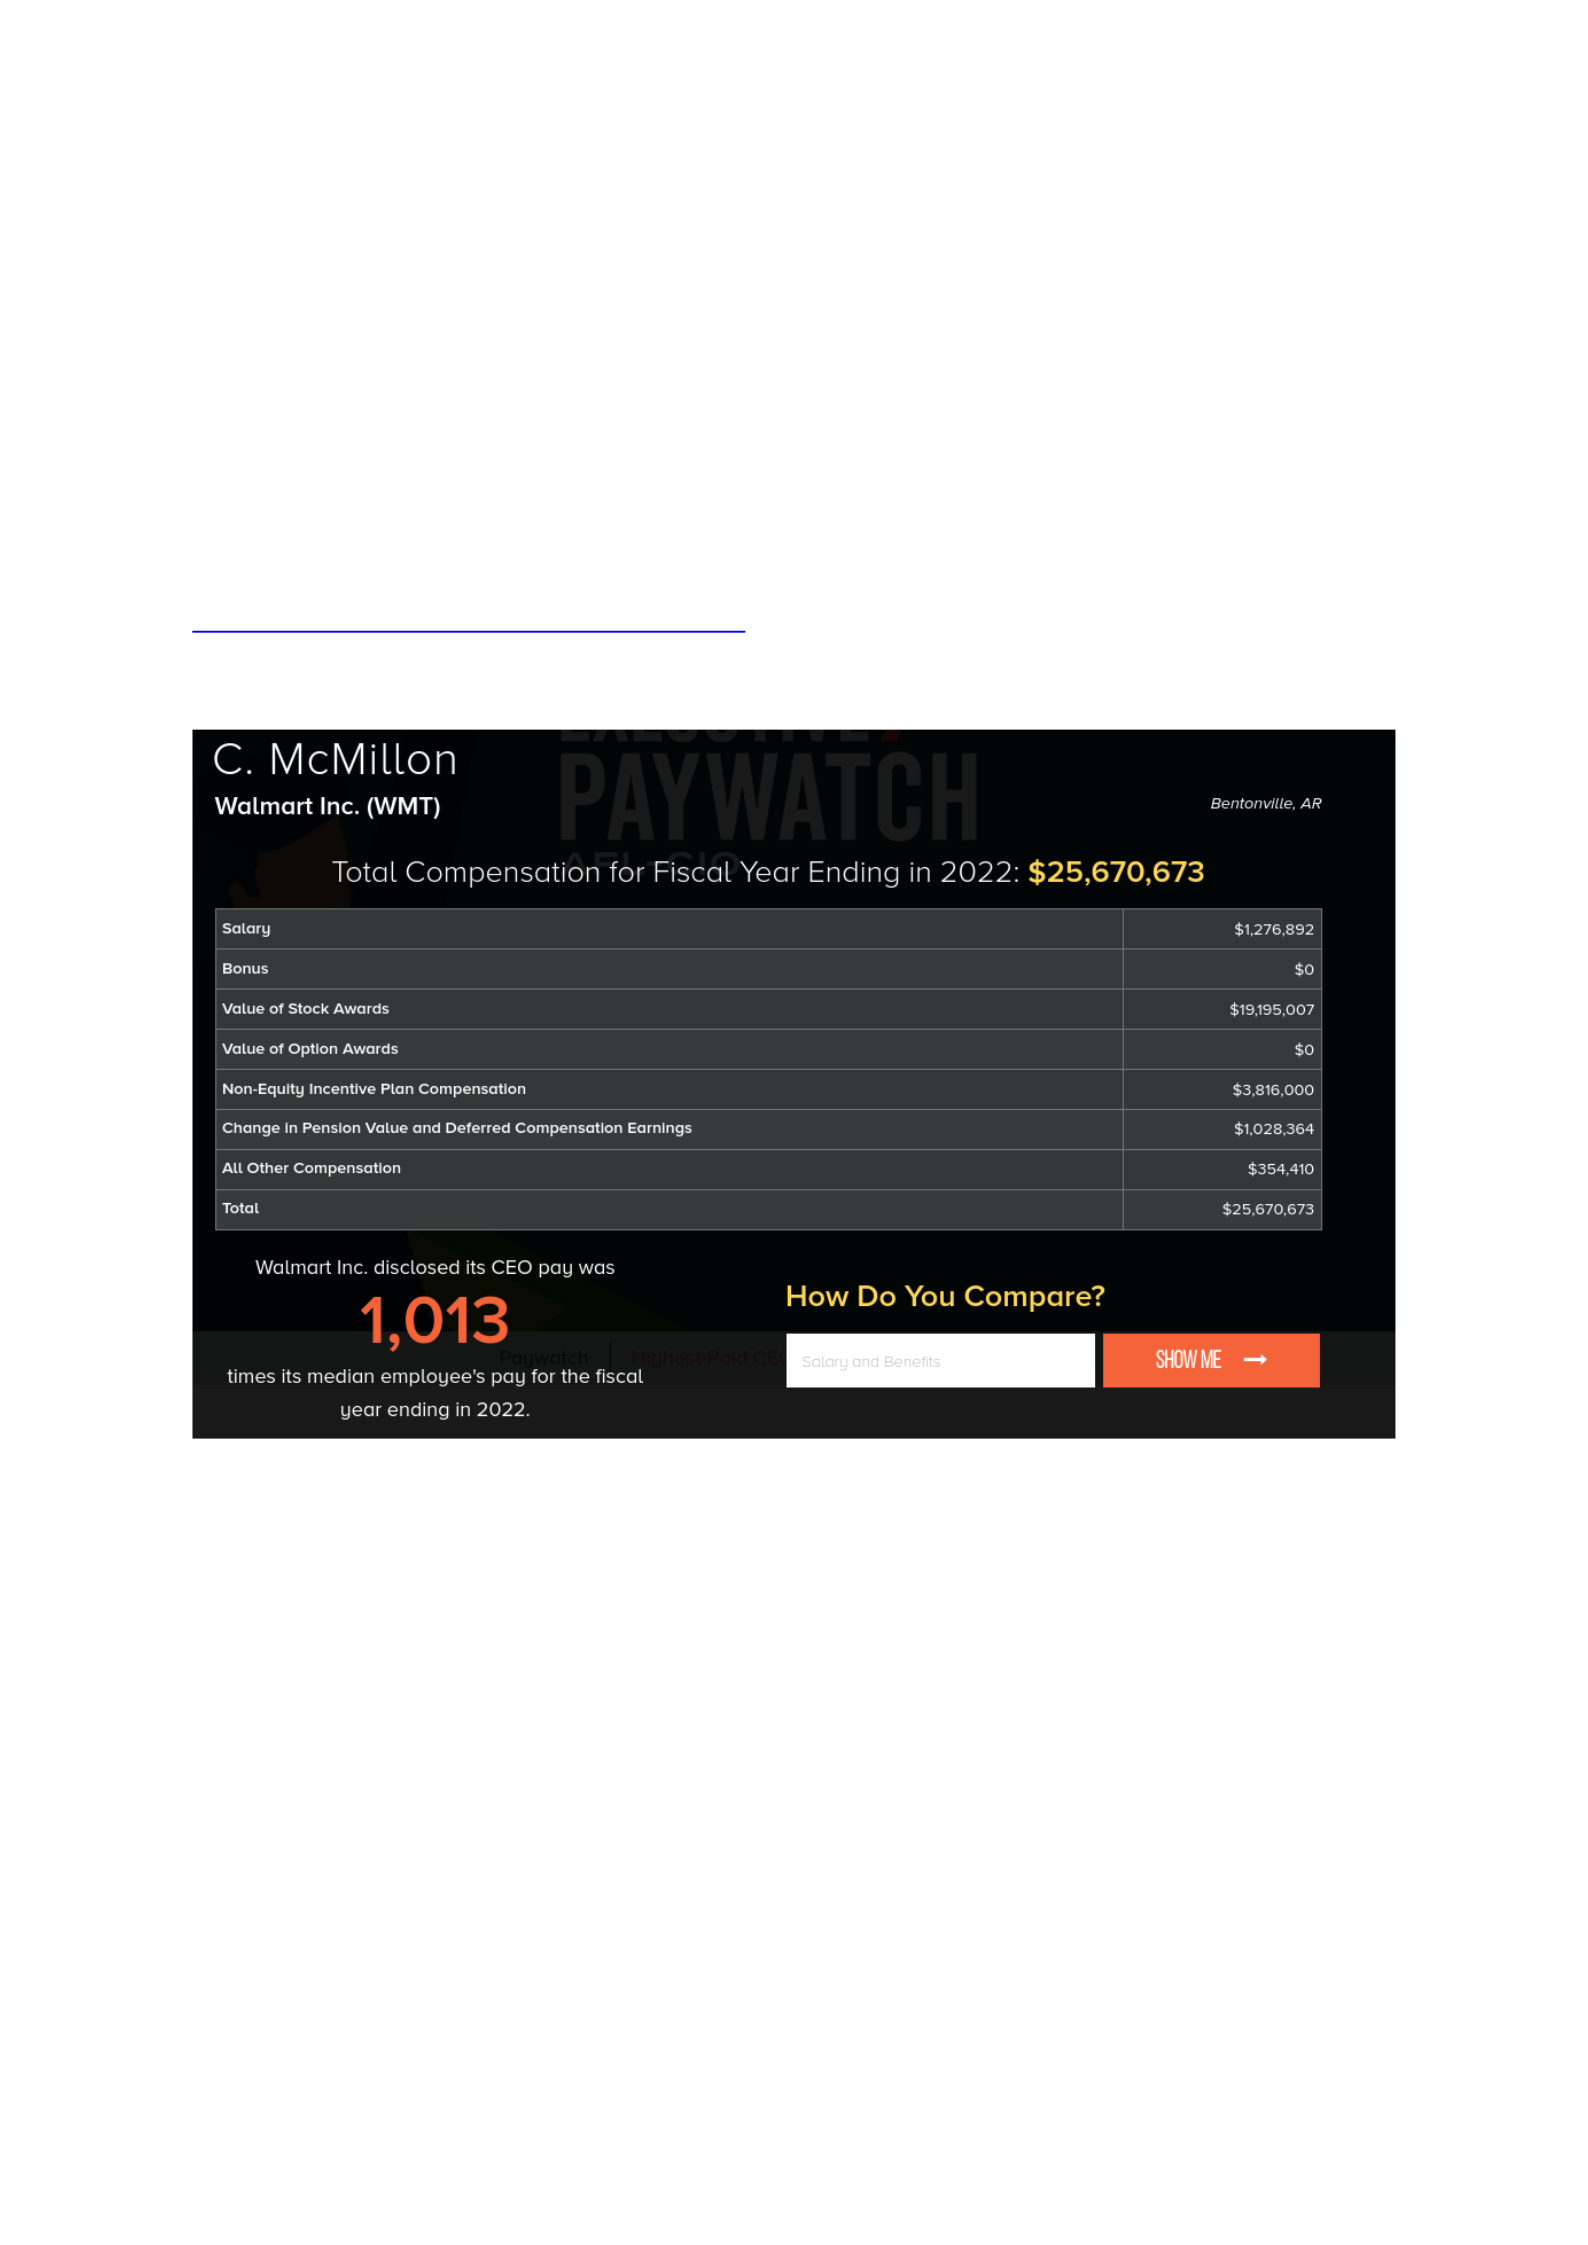
of this discussion; in a recent filing with the US Securities and Exchange Commission, Walmart
disclosed that CEO Doug McMillon’s compensation for the fiscal year ending 2022 is $25,670,673.
As you can see from the chart below, his pay is 1013 times the median employees pay for that
fiscal year. This discrepancy places the retail giant among companies with the widest pay gap
between the CEO and an essential employee. It is noteworthy to mention that in the "case of
Walmart -- a publicly traded and 'pay for performance' firm -- a significant portion of CEO
compensation is in the form of stock grants that are not realized until the company meets certain
goals." while I do believe and understand that individuals holding an executive position do hold
the weight of an entire company on their shoulders and should be rewarded; I do not believe that
their compensation should be so grossly excessive to that of the people that work on the frontline.
Many of these frontline workers who were once deemed "essential" are not being compensated
with a living wage. The average starting wage in US corporate-owned companies, such as Walmart,
is $10 an hour. Studies have shown that Walmart was one of the top four employers of SNAP and
Medicaid beneficiaries in every state. Meanwhile, "CEO pay continues to be very high and has
grown far faster in recent decades than typical worker pays; exorbitant CEO pay means that the
fruits of economic growth are not going to ordinary workers."
https://aflcio.org/paywatch/highest-paid-ceos
Being that Walmart is a "pay based on performance" firm, auditing the revenue process would be
the best course of action to reduce the likelihood of material misstatements and or fraud would
be PCAOB AS 2401 #12 consideration of fraud in financial statement audit, which states "for many
companies, revenue is one of the largest accounts in the financial statements and is an important
driver of the companies operating results. In audits under PCAOB standards, revenue typically is a
significant account, often involving significant risks that warrant special audit consideration."
References
Butler-Young, S. (2018). Pondering the Pay Gap: Inside Walmart's CEO-to-worker compensation
comparison. FN: Footwear News, 74(14), 8.
Messier, W. Glover, S. Prawitt, D. (2019). Auditing & Assurance Services: A Systematic Approach
11th Edition. McGraw Hill Education.
Rosenberg, E. (2020, November 18). Walmart and McDonald's have the most workers on food
stamps and Medicaid, new study shows. The Washington Post.
Proxy Statement Pursuant to Section 14(a) of the Securities Exchange Act of 1934. Sec.gov. (n.d.).
Retrieved September 29, 2022, from
https://www.sec.gov/Archives/edgar/data/14272/000114036122010987/ny20002084x1_def14a.ht
m#tRAOCP
What you need to know about stock options. Harvard Business Review. (2014, August 1).
Retrieved September 29, 2022, from https://hbr.org/2000/03/what-you-need-to-know-about-stock-
options
Highest-paid CEOS: AFL-CIO. AFL. (n.d.). Retrieved September 29, 2022, from
https://aflcio.org/paywatch/highest-paid-ceos
As 2110: Identifying and assessing risks of material misstatement. Default. (n.d.). Retrieved
September 29, 2022, from https://pcaobus.org/oversight/standards/auditing-
standards/details/AS2110
Messier, W. Glover, S. Prawitt, D. (2019). Auditing & Assurance Services: A Systematic Approach
11th Edition. McGraw Hill Education.
image_39192120121664473990220.png
(97.84 KB)

