


VENTURE CAPITAL AND PRIVATE EQUITY
1 1. LIMITED ACCESS TO CAPITAL FOR STARTUPS
Problem 1. A startup is seeking funding from venture capitalists for their new business. They
have estimated their initial capital requirement to be $500,000 for equipment, marketing, and salaries.
The venture capitalist has offered to invest the full amount in exchange for a 20
a) How much equity will the startup owner retain after the investment?
b) If the business grows and requires an additional $300,000 in funding in the future, how much
equity will the owner have to give up if the venture capitalist maintains their 20
c) What is the total valuation of the company after the second investment?
Solution 1.
a) The venture capitalist is investing $500,000 for a 20
$500,000 = 0.20 ×X
Solving for X:
X=$500,000
0.20 = $2,500,000
Therefore, the startup owner will retain 100% −20% = 80% of the equity in the company after
the investment.
b) If an additional $300,000 is invested while maintaining the 20
$300,000 = 0.20 ×Y
Solving for Y:
Y=$300,000
0.20 = $1,500,000
The startup owner will now have 100% −20% = 80% of the equity in the company after the
second investment.
c) The total valuation of the company after the second investment is Y= $1,500,000.
2 2. RISK MANAGEMENT IN VENTURE CAPITAL INVESTMENTS
Problem 2. You are a venture capitalist considering investing in two startups. Startup A has a
70
a) Calculate the expected return for both startups.
b) Which startup would you choose to invest in based on expected return alone?
Solution 2.
a) The expected return for an investment can be calculated as the probability of success multi-
plied by the profit in case of success, minus the probability of failure multiplied by the loss in case
of failure.
Let’s calculate the expected return for each startup:
For Startup A: Expected return = (0.3 * $1,000,000) - (0.7 * $200,000) = $300,000 - $140,000
= $160,000
For Startup B: Expected return = (0.5 * $800,000) - (0.5 * $150,000) = $400,000 - $75,000 =
$325,000
b) Based on expected return alone, Startup B has a higher expected return of $325,000 com-
pared to Startup A’s expected return of $160,000. Therefore, if you were to choose based on
expected return alone, you would choose to invest in Startup B.
Certainly! Here is a numerical problem on Venture Capital and Private Equity for you:
3 3. INVESTOR DIVERSIFICATION IN PRIVATE EQUITY
Problem 3. A venture capital investor has a portfolio of investments in three startups, with the
following initial amounts invested and expected returns:
Startup A: Investment of $100,000 with an expected return of $150,000 Startup B: Investment of
$200,000 with an expected return of $250,000 Startup C: Investment of $150,000 with an expected
return of $180,000
Assuming all three investments are uncorrelated, calculate the total expected return, standard
deviation, and coefficient of variation for the investor’s portfolio.
Solution 3.
a) To find the total expected return, we simply sum up the expected returns of each individual
investment:
Total Expected Return = $150,000 + $250,000 + $180,000 = $580,000
b) Next, to calculate the standard deviation of the portfolio, we need to find the variance of the
portfolio first. Since the investments are uncorrelated, we can use the following formula for the
variance of a portfolio of two assets:
Variance of Portfolio = w2
A∗V ar(A) + w2
B∗V ar(B) + w2
C∗V ar(C)
Where: wA, wB, wC=weightsofinvestmentsA, B, Cintheportfolio(sumofweights = 1)V ar(A), V ar(B), V ar(C) =
varianceofinvestmentsA, B, C
Given the investments are uncorrelated, the variance of each investment is equal to its expected
return:
Var(A) = $150,000 Var(B) = $250,000 Var(C) = $180,000
Let’s calculate the variance: Variance of Portfolio = (100,000/450,000)2∗150,000+(200,000/450,000)2∗
250,000 + (150,000/450,000)2∗180,000
Variance of Portfolio = 83,333.33
Then, the standard deviation is the square root of the variance:
Standard Deviation = √83,333.33 ≈$288.67
c) Finally, the coefficient of variation (CV) is calculated by dividing the standard deviation by the
expected return:
Coefficient of Variation = $288.67 / $580,000 Coefficient of Variation 0.0004986, or approxi-
mately 0.04986
I. Problem: Due Diligence in Venture Capital
A venture capital firm is considering investing $500,000 in a startup company. During the due
diligence process, they discover that the company’s financial projections are as follows:
- Year 1: Revenue of $200,000, Expenses of $150,000 - Year 2: Revenue growth of 20%,
Expenses growth of 10%
Calculate the Net Income for each year and determine the company’s Net Income Margin in
Year 2.
Solution:
a) Net Income for Year 1:
Net Income = Revenue - Expenses
Net Income = $200,000 −$150,000 = $50,000
b) Net Income for Year 2:
Revenue in Year 2 = $200,000 ×1.20 = $240,000
Expenses in Year 2 = $150,000 ×1.10 = $165,000
Net Income = Revenue - Expenses
Net Income = $240,000 −$165,000 = $75,000
c) Net Income Margin in Year 2:
Net Income Margin = NetIncome
Revenue ×100
Net Income Margin = $75,000
$240,000 ×100
Net Income Margin = 75
240 ×100 = 31.25%
Therefore, the company’s Net Income Margin in Year 2 is 31.25%.
4 5. LACK OF TRANSPARENCY IN PRIVATE EQUITY INVESTMENTS
Problem 5. A Venture Capital firm invested 500,000 in a startup in exchange for 20% equity
ownership. After a few years, the startup gets acquired for 5times its initial valuation. If the firm
decides to exit their investment, what is the total cash they receive from the acquisition?
Solution 5. Let’s first calculate the initial valuation of the startup when the Venture Capital firm
invested:
Initial Valuation = Investment Amount
Equity Ownership =500,000
0.20 = 2,500,000
After the acquisition, the startup is acquired for 5times its initial valuation:
Acquisition Price = 5×Initial Valuation = 5 ×2,500,000 = 12,500,000
Since the Venture Capital firm owns 20% equity in the startup, their cash from the acquisition
would be:
Cash from Acquisition = Equity Ownership ×Acquisition Price = 0.20 ×12,500,000 =2,500,000
Therefore, the Venture Capital firm would receive 2,500,000 in cash from the acquisition of the
startup.
I.
5 6. VALUATION DIFFICULTIES IN EARLY-STAGE STARTUPS
Problem 6. You are a venture capitalist looking to invest in a promising early-stage startup.
The startup is seeking $500,000 in funding in exchange for a 20
a) What is the pre-money valuation of the startup based on the given information?
b) If you decide to invest the requested amount, how many shares will you receive?
c) What is the price per share you will pay for this investment?
Solution 6.
a) The pre-money valuation of the startup can be calculated as follows:
Pre-money valuation =Post-money valuation −Amount of funding
Pre-money valuation = $2.5M−$500K= $2M
b) To calculate the number of shares you will receive, we first need to find the value of each
share. The value of each share can be calculated as:
Post-money valuation =Pre-money valuation ×(1 + Equity stake)
$2.5M= $2M×(1 + 0.20)
$2.5M= $2M×1.20
$2.5M= $2.4M
Now, the value per share is $2.4 million. Therefore, the number of shares you will receive is:
Amount of funding
Value per share =$500K
$2.4M=500
2400 =5
24
c) The price per share you will pay for this investment is the same as the value per share, which
is $2.4 million.
6 7. THE IMPACT OF INDUSTRY TRENDS ON VENTURE CAPITAL FUNDING
Problem 7. The venture capital firm XYZ is considering investing in two different industries:
Tech and Biotech. The expected return on investment (ROI) for Tech is 20% with a standard
deviation of 5%, while the expected ROI for Biotech is 15% with a standard deviation of 8%. The
correlation between the two industries is 0.4. If XYZ invests $1 million in Tech and $2 million in
Biotech, calculate the expected ROI of the portfolio and the standard deviation of the portfolio’s
ROI.
Solution 7. Let Xbe the ROI in Tech and Ybe the ROI in Biotech. The expected ROI of a
portfolio is given by the weighted average of the expected ROIs of the individual investments:
E(Rp) = w1E(R1) + w2E(R2)
where w1and w2are the weights of the investments and E(R1)and E(R2)are the expected ROIs
of Tech and Biotech, respectively.
Given: - E(R1) = 20%,E(R2) = 15% -w1= $1,000,000/$3,000,000 = 1
3,w2= $2,000,000/$3,000,000 =
2
3
E(Rp) = 1
3(20%) + 2
3(15%) = 18.33%
The variance of the portfolio is calculated as:
V ar(Rp) = w2
1V ar(R1) + w2
2V ar(R2)+2w1w2Cov(R1, R2)
where V ar(R1)and V ar(R2)are the variances of the individual investments and Cov(R1, R2)is
the covariance between the investments.
Given: - V ar(R1) = (0.05)2,V ar(R2) = (0.08)2,Cov(R1, R2)=0.4(0.05)(0.08)
V ar(Rp) = 1
32
(0.05)2+2
32
(0.08)2+ 2 1
32
3(0.4(0.05)(0.08))
V ar(Rp)≈0.00042833
Therefore, the standard deviation of the portfolio’s ROI is:
σ=qV ar(Rp)≈√0.00042833 ≈0.0207 = 2.07%
Hence, the expected ROI of the portfolio is approximately 18.33%, and the standard deviation
of the portfolio’s ROI is approximately 2.07%.
7 8. INVESTOR EXIT STRATEGIES IN PRIVATE EQUITY DEALS
Problem 8.
A private equity investor invested $1 million in a startup company with the following projected
cash flows over the next five years:
Year 1: $200,000 Year 2: $300,000 Year 3: $400,000 Year 4: $500,000 Year 5: $600,000
Assuming a desired Internal Rate of Return (IRR) of 20% per annum, calculate the exit value
required at the end of Year 5 to achieve the target return for the investor.
Solution 8.
To calculate the exit value required at the end of Year 5, we need to find the Present Value (PV)
of the cash flows and then determine the exit value that would give an IRR of 20%.
The PV of the cash flows can be calculated using the formula:
P V =CF1
(1 + r)1+CF2
(1 + r)2+CF3
(1 + r)3+CF4
(1 + r)4+CF5+ExitV alue
(1 + r)5
Where: CFi= Cash flow at the end of Year i r = 0.20 (IRR) ExitV alue = Exit value at the end
of Year 5
Substitute the given values into the formula:
P V =200,000
(1 + 0.20)1+300,000
(1 + 0.20)2+400,000
(1 + 0.20)3+500,000
(1 + 0.20)4+600,000 + ExitV alue
(1 + 0.20)5
P V =200,000
1.20 +300,000
1.202+400,000
1.203+500,000
1.204+600,000 + ExitV alue
1.205
P V ≈166,666.67 + 225,000 + 250,000 + 277,777.78 + 600,000 + ExitV alue
1.48
P V ≈919,444.45 + 600,000 + ExitV alue
1.48
Since the total initial investment is $1,000,000 at the start, the exit value at the end of Year 5
should be such that the total PV equals the total initial investment:
1,000,000 = 919,444.45 + 600,000 + ExitV alue
1.48
1,000,000 −919,444.45 = 600,000 + ExitV alue
1.48
80,555.55 = 600,000 + ExitV alue
1.48
119,200 ≈600,000 + ExitV alue
ExitV alue ≈119,200 −600,000
ExitV alue ≈ −480,800
Therefore, the exit value required at the end of Year 5 to achieve the target return for the investor
is approximately $480,800 *negative value indicates a loss*.
I.
8 9. REGULATORY COMPLIANCE IN VENTURE CAPITAL AND PRIVATE EQUITY
Problem 9. A Venture Capital firm is considering investing in a startup. The firm’s management
fee is 2% of committed capital, and they charge a 20% carried interest (profit share) on returns
exceeding an 8% preferred return hurdle rate. If the firm raises a fund of 100 million from limited
partners and invests 80
Solution 9.
a) The management fee can be calculated as 2% of the committed capital. Therefore, manage-
ment fee = 0.02 ×100 million = 2 million.
b) The profit share or carried interest is calculated on the returns exceeding the preferred return
hurdle rate. The total profits from the startup investment are 80
Therefore, the profit share = 20
Therefore, the carried interest payable by the startup is 14.4million.
Thus, the management fee payable by the startup is 2million and the carried interest payable
is 14.4million.
I.
9 10. COMPETITION FOR QUALITY DEALS IN THE VENTURE CAPITAL MARKET
Problem 10. In a competitive venture capital market, investors are evaluating two investment
opportunities. Opportunity A requires an investment of 500,000andisexpectedtoyieldareturnof1,000,000
with a probability of success of 30
a) Calculate the expected value of each investment opportunity.
b) Calculate the expected value of the two opportunities if investors can only choose one of
them.
c) Analyze which investment opportunity seems more attractive based on the expected values
calculated in parts (a) and (b).
Solution 10.
a) The expected value of an investment opportunity is calculated by multiplying the return by
the probability of success.
For Opportunity A: Expected value = 1,000,000 ∗0.30 =300,000
For Opportunity B: Expected value = 1,200,000 ∗0.40 =480,000
b) To calculate the expected value of the two opportunities if investors can only choose one, we
compare the expected values of both opportunities.
Choosing between A and B, Opportunity B has a higher expected value of 480,000comparedtoOpportunityA′s300,000.
c) Based on the expected values calculated in parts (a) and (b), Opportunity B seems more
attractive as it offers a higher expected return on investment compared to Opportunity A.
10 11. MANAGING PORTFOLIO COMPANIES IN PRIVATE EQUITY INVESTMENTS
Problem 11. A private equity firm has invested $5 million in a portfolio company and acquired
a 20% stake. After a successful year, the portfolio company’s valuation has increased by 30%.
a) What is the new valuation of the portfolio company?
b) Calculate the new value of the private equity firm’s stake in the portfolio company.
c) If the private equity firm decides to exit its investment by selling its stake, how much profit
would they make if the exit price per share is 25% higher than the original valuation?
Solution 11.
a) The new valuation of the portfolio company after a 30% increase can be calculated as:
New Valuation =Original Valuation ×(1 + Increase %)
New Valuation = $5,000,000 ×(1 + 0.30)
New Valuation = $5,000,000 ×1.30
New Valuation = $6,500,000
Therefore, the new valuation of the portfolio company is $6,500,000.
b) The new value of the private equity firm’s stake in the portfolio company can be calculated
as:
New Value of Stake =New Valuation ×Stake %
New Value of Stake = $6,500,000 ×0.20
New Value of Stake = $1,300,000
Therefore, the new value of the private equity firm’s stake in the portfolio company is $1,300,000.
c) If the exit price per share is 25% higher than the original valuation, then the exit price per
share would be:
Exit Price Per Share =Original Valuation ×(1 + 0.25)
Exit Price Per Share = $5,000,000 ×1.25
Exit Price Per Share = $6,250,000
The profit the private equity firm would make upon exit can be calculated as:
Profit =Exit Price Per Share ×Stake % −Investment
Profit = $6,250,000 ×0.20 −$5,000,000
Profit = $1,250,000 −$5,000,000
Profit = $250,000
Therefore, if the private equity firm exits its investment at an exit price 25% higher than the
original valuation, they would make a profit of $250,000.
11 Venture Capital and Private Equity
Problem: You are a venture capitalist considering investing in a startup. The startup has
projected cash flows for the next 5 years as follows:
Year 1: $100,000 Year 2: $150,000 Year 3: $200,000 Year 4: $250,000 Year 5: $300,000
If the discount rate is 10%, calculate the present value of these cash flows.
Solution: To calculate the present value of the cash flows, we need to discount each cash flow
using the formula:
P V =CF
(1 + r)t
where: P V = Present Value CF = Cash Flow in that year r= Discount Rate t= Time period in
years
Let’s compute the present value of each cash flow and sum them up:
a) For Year 1:
P V1=100,000
(1 + 0.10)1=100,000
1.10 = $90,909
b) For Year 2:
P V2=150,000
(1 + 0.10)2=150,000
1.21 = $123,966
c) For Year 3:
P V3=200,000
(1 + 0.10)3=200,000
1.331 = $150,289
d) For Year 4:
P V4=250,000
(1 + 0.10)4=250,000
1.4641 = $170,866
e) For Year 5:
P V5=300,000
(1 + 0.10)5=300,000
1.6105 = $186,410
Now, summing up all the present values:
P V = $90,909 + $123,966 + $150,289 + $170,866 + $186,410 = $722,440
Therefore, the present value of the cash flows is $722,440.
12 13. THE ROLE OF TECHNOLOGY IN DISRUPTING VENTURE CAPITAL AND PRIVATE
EQUITY
Problem 13. A venture capital firm invests $1,000,000 in a startup with a promised return of
25% annually over 5 years. However, after the first year, the startup faces challenges and the return
drops to −10% annually for the remaining 4 years. Calculate the net present value (NPV) of the
investment if the discount rate is 15%.
Solution 13. a) To calculate the NPV of the investment, we need to find the present value of
the expected cash flows from the investment.
The initial investment is $1,000,000.
After the first year, the return is 25%, so the cash flow at the end of year 1 will be: $1,000,000 ×
1.25 = $1,250,000
For the remaining 4 years, the return is −10% annually. The cash flows for years 2 to 5 are
calculated as follows:
Year 2: $1,250,000 ×0.90 = $1,125,000 Year 3: $1,125,000 ×0.90 = $1,012,500 Year 4:
$1,012,500 ×0.90 = $911,250 Year 5: $911,250 ×0.90 = $820,125
b) Now, we calculate the present value of these cash flows using the discount rate of 15%.
The present value (PV) of each cash flow is calculated using the formula: P V =CF
(1+r)n, where
CF is the cash flow, ris the discount rate, and nis the period.
PV of Year 1 cash flow: ($1,250,000)
(1+0.15)1= $1,086,957.61
PV of Year 2-5 cash flows: ($1,125,000)
(1+0.15)2= $873,573.64 ($1,012,500)
(1+0.15)3= $718,331.05 ($911,250)
(1+0.15)4=
$566,638.49 ($820,125)
(1+0.15)5= $453,157.44
c) Finally, we calculate the NPV by summing up the present values of the cash flows and sub-
tracting the initial investment.
NP V =P VY ear1+P VY ear2+P VY ear3+P VY ear4+P VY ear5−$1,000,000 NP V = $1,086,957.61+
$873,573.64 + $718,331.05 + $566,638.49 + $453,157.44 −$1,000,000 NP V = $1,698,658.23 −
$1,000,000 NP V = $698,658.23
Therefore, the net present value (NPV) of the investment is $698,658.23.
13 Venture Capital and Private Equity
Problem 1.
A venture capital firm is considering investing $1,000,000 in a startup. The firm expects the
startup to be valued at $3,000,000 in 3 years if they invest. If the firm requires a return of 25% per
year on their investment, what percentage ownership should they demand in the startup?
Solution 1.
Let xbe the percentage ownership the venture capital firm should demand in the startup.
The present value of the investment should equal the initial investment of $1,000,000. The
future value of the investment in 3 years should be $3,000,000.
Using the concept of Compound Interest formula:
1,000,000 = 3,000,000
(1 + 0.25)3×x
Solving for x, we get:
x=1,000,000
3,000,000/1.952 = 0.6513 = 65.13%
Therefore, the venture capital firm should demand a 65.13% ownership in the startup.
14 15. FUNDRAISING CHALLENGES FOR VENTURE CAPITAL FIRMS
Problem 15. A Venture Capital firm is looking to raise a new fund of 100 million. They plan to
charge a 2% management fee and a 20% carry fee on any profits generated from investments. If
the firm expects to generate 30% returns on investments over the lifetime of the fund, calculate the
total fees earned by the Venture Capital firm over the fund’s lifetime.
Solution 15. a) The total management fee can be calculated as:
Management Fee =Fund Size ×Management Fee Rate = 100 million ×0.02 = 2 million
b) The total carry fee can be calculated as:
Carry Fee =Return ×Carry Fee Rate = (100 million ×0.30) ×0.20 = 6 million
c) Therefore, the total fees earned by the Venture Capital firm over the fund’s lifetime would be:
Total Fees =Management Fee +Carry Fee = 2 million + 6 million = 8 million
15 16. BALANCING RISK AND REWARD IN PRIVATE EQUITY INVESTMENTS
Problem 16. ABC Ventures is considering investing in a startup company. The expected return
on this investment is 15
Solution 16. a) The Sharpe ratio is calculated as follows:
Sharpe ratio =Rp−Rf
σp
Where: - Rpis the expected return on the investment (15- Rfis the risk-free rate (5- σpis the
standard deviation of the investment (20
Substitute the values into the formula:
Sharpe ratio =0.15 −0.05
0.20 =0.10
0.20 = 0.5
Therefore, the Sharpe ratio for this investment is 0.5.
I can definitely help with that. Let’s work on a numerical problem related to Venture Capital and
Private Equity under the given subtopic.
16 17. IMPACT OF ECONOMIC DOWNTURNS ON VENTURE CAPITAL AND PRIVATE EQ-
UITY
Problem 17. During an economic downturn, a venture capital fund decides to invest 100,000inastartupcompanywithanexpectedreturnof30
Solution 17. Let’s first calculate the expected return after 5 years:
Expected return after 5 years = $100,000 ×(1 + 0.30)5
= $100,000 ×(1.30)5
= $100,000 ×2.8561
= $285,610
Now, the actual return turns out to be 10
Actual return after 5 years = $285,610 ×(1 −0.10)
= $285,610 ×0.90
= $257,049
Therefore, the total amount the venture capital fund will receive after 5 years is $257,049.
I’m glad to help with that! Here is a numerical problem related to Venture Capital and Private
Equity:
17 Venture Capital and Private Equity
Problem:
A venture capital firm invests $1,000,000 in a startup with an agreed 20% equity stake. The
startup later gets acquired for $10,000,000. How much profit does the venture capital firm make
from this investment?
Solution:
First, let’s calculate the value of the equity stake acquired by the venture capital firm:
Equity Stake Value =Investment Amount ×Equity Stake (%)
100
Equity Stake Value = $1,000,000 ×20
100 = $200,000
Then, we can find the profit made by the venture capital firm from the acquisition:
Profit =Acquisition Amount −Equity Stake Value −Investment Amount
Profit = $10,000,000 −$200,000 −$1,000,000 = $8,800,000
Therefore, the venture capital firm makes a profit of $8,800,000 from this investment.
I. Problem 1: Investor Equity Stake Calculation
A venture capital firm invests $1 million in a start-up company in exchange for a 20
Solution 1: Let Vbe the pre-money valuation of the company. The equity stake can be calcu-
lated using the formula:
Equity Stake =Investment Amount
Pre-money Valuation +Investment Amount ×100%
Substitute the values given:
20% = 1,000,000
V+ 1,000,000 ×100%
Solving for V:
V+ 1,000,000 = 1,000,000
20%
V+ 1,000,000 = 5,000,000
V= 4,000,000
Therefore, the pre-money valuation of the company is $4 million.
II. Problem 2: Preferred Stock Liquidation Preference
A venture capitalist invests $2 million in a start-up with a 2x liquidation preference. The company
sells for $5 million. How much money does the venture capitalist receive?
Solution 2: The venture capitalist will first receive back the $2 million invested due to the 2x
liquidation preference. The remaining amount will be divided pro-rata among all shareholders.
Since the company sells for $5 million, the remaining $3 million will be distributed among share-
holders based on their ownership percentage. The venture capitalist owns 2
5of the company ($2
million out of the $5 million total investment).
Therefore, the venture capitalist will receive:
$2,000,000 (liquidation preference)+2
5×$3,000,000 (remaining amount) = $2,000,000+$1,200,000 = $3,200,000
The venture capitalist will receive $3.2 million from the sale.
III. Problem 3: Internal Rate of Return (IRR) Calculation
A private equity firm invests $500,000 in a company and receives the following cash flows:
$100,000 in year 1, $200,000 in year 2, and $300,000 in year 3. Calculate the internal rate of
return for this investment.
Solution 3:
The IRR is the discount rate that makes the net present value (NPV) of all cash flows equal to
zero. Setting up the equation:
0 = −500,000 + 100,000
(1 + r)1+200,000
(1 + r)2+300,000
(1 + r)3
Using a financial calculator or software, solving the above equation gives r≈19.73%.
Therefore, the internal rate of return for this investment is approximately 19.73
18 20. GENDER AND DIVERSITY ISSUES IN VENTURE CAPITAL AND PRIVATE EQUITY.
Problem 20. In a venture capital firm, the distribution of investment decisions made by the
partners is as follows:
•40% of investment decisions are made by male partners
•30% of investment decisions are made by female partners
•30% of investment decisions are made by partners who identify as non-binary
If there are a total of 50 investment decisions made in a year by the venture capital firm, de-
termine the number of investment decisions made by each group (male, female, and non-binary
partners).
Solution 20. Let’s denote:
•Number of investment decisions made by male partners as x
•Number of investment decisions made by female partners as y

•Number of investment decisions made by non-binary partners as z
From the information given in the problem:
x= 0.40 ×50 = 20 (investment decisions by male partners)
y= 0.30 ×50 = 15 (investment decisions by female partners)
z= 0.30 ×50 = 15 (investment decisions by non-binary partners)
Therefore, the number of investment decisions made by each group are as follows:
•Male partners: 20 investment decisions
•Female partners: 15 investment decisions
•Non-binary partners: 15 investment decisions
For Startup A: Expected return = (0.3 * $1,000,000) - (0.7 * $200,000) = $300,000 - $140,000
= $160,000
For Startup B: Expected return = (0.5 * $800,000) - (0.5 * $150,000) = $400,000 - $75,000 =
$325,000
b) Based on expected return alone, Startup B has a higher expected return of $325,000 com-
pared to Startup A’s expected return of $160,000. Therefore, if you were to choose based on
expected return alone, you would choose to invest in Startup B.
Certainly! Here is a numerical problem on Venture Capital and Private Equity for you:
3 3. INVESTOR DIVERSIFICATION IN PRIVATE EQUITY
Problem 3. A venture capital investor has a portfolio of investments in three startups, with the
following initial amounts invested and expected returns:
Startup A: Investment of $100,000 with an expected return of $150,000 Startup B: Investment of
$200,000 with an expected return of $250,000 Startup C: Investment of $150,000 with an expected
return of $180,000
Assuming all three investments are uncorrelated, calculate the total expected return, standard
deviation, and coefficient of variation for the investor’s portfolio.
Solution 3.
a) To find the total expected return, we simply sum up the expected returns of each individual
investment:
Total Expected Return = $150,000 + $250,000 + $180,000 = $580,000
b) Next, to calculate the standard deviation of the portfolio, we need to find the variance of the
portfolio first. Since the investments are uncorrelated, we can use the following formula for the
variance of a portfolio of two assets:
Variance of Portfolio = w2
A∗V ar(A) + w2
B∗V ar(B) + w2
C∗V ar(C)
Where: wA, wB, wC=weightsofinvestmentsA, B, Cintheportfolio(sumofweights = 1)V ar(A), V ar(B), V ar(C) =
varianceofinvestmentsA, B, C
Given the investments are uncorrelated, the variance of each investment is equal to its expected
return:
Var(A) = $150,000 Var(B) = $250,000 Var(C) = $180,000
Let’s calculate the variance: Variance of Portfolio = (100,000/450,000)2∗150,000+(200,000/450,000)2∗
250,000 + (150,000/450,000)2∗180,000
Variance of Portfolio = 83,333.33
Then, the standard deviation is the square root of the variance:
Standard Deviation = √83,333.33 ≈$288.67
c) Finally, the coefficient of variation (CV) is calculated by dividing the standard deviation by the
expected return:
Coefficient of Variation = $288.67 / $580,000 Coefficient of Variation 0.0004986, or approxi-
mately 0.04986
I. Problem: Due Diligence in Venture Capital
A venture capital firm is considering investing $500,000 in a startup company. During the due
diligence process, they discover that the company’s financial projections are as follows:
- Year 1: Revenue of $200,000, Expenses of $150,000 - Year 2: Revenue growth of 20%,
Expenses growth of 10%
Calculate the Net Income for each year and determine the company’s Net Income Margin in
Year 2.
Solution:
a) Net Income for Year 1:
Net Income = Revenue - Expenses
Net Income = $200,000 −$150,000 = $50,000
b) Net Income for Year 2:
Revenue in Year 2 = $200,000 ×1.20 = $240,000
Expenses in Year 2 = $150,000 ×1.10 = $165,000
Net Income = Revenue - Expenses
Net Income = $240,000 −$165,000 = $75,000
c) Net Income Margin in Year 2:
Net Income Margin = NetIncome
Revenue ×100
Net Income Margin = $75,000
$240,000 ×100
Net Income Margin = 75
240 ×100 = 31.25%
Therefore, the company’s Net Income Margin in Year 2 is 31.25%.
4 5. LACK OF TRANSPARENCY IN PRIVATE EQUITY INVESTMENTS
Problem 5. A Venture Capital firm invested 500,000 in a startup in exchange for 20% equity
ownership. After a few years, the startup gets acquired for 5times its initial valuation. If the firm
decides to exit their investment, what is the total cash they receive from the acquisition?
Solution 5. Let’s first calculate the initial valuation of the startup when the Venture Capital firm
invested:
Initial Valuation = Investment Amount
Equity Ownership =500,000
0.20 = 2,500,000
After the acquisition, the startup is acquired for 5times its initial valuation:
Acquisition Price = 5×Initial Valuation = 5 ×2,500,000 = 12,500,000
Since the Venture Capital firm owns 20% equity in the startup, their cash from the acquisition
would be:
Cash from Acquisition = Equity Ownership ×Acquisition Price = 0.20 ×12,500,000 =2,500,000
Therefore, the Venture Capital firm would receive 2,500,000 in cash from the acquisition of the
startup.
I.
5 6. VALUATION DIFFICULTIES IN EARLY-STAGE STARTUPS
Problem 6. You are a venture capitalist looking to invest in a promising early-stage startup.
The startup is seeking $500,000 in funding in exchange for a 20
a) What is the pre-money valuation of the startup based on the given information?
b) If you decide to invest the requested amount, how many shares will you receive?
c) What is the price per share you will pay for this investment?
Solution 6.
a) The pre-money valuation of the startup can be calculated as follows:
Pre-money valuation =Post-money valuation −Amount of funding
Pre-money valuation = $2.5M−$500K= $2M
b) To calculate the number of shares you will receive, we first need to find the value of each
share. The value of each share can be calculated as:
Post-money valuation =Pre-money valuation ×(1 + Equity stake)
$2.5M= $2M×(1 + 0.20)
$2.5M= $2M×1.20
$2.5M= $2.4M
Now, the value per share is $2.4 million. Therefore, the number of shares you will receive is:
Amount of funding
Value per share =$500K
$2.4M=500
2400 =5
24
c) The price per share you will pay for this investment is the same as the value per share, which
is $2.4 million.
6 7. THE IMPACT OF INDUSTRY TRENDS ON VENTURE CAPITAL FUNDING
Problem 7. The venture capital firm XYZ is considering investing in two different industries:
Tech and Biotech. The expected return on investment (ROI) for Tech is 20% with a standard
deviation of 5%, while the expected ROI for Biotech is 15% with a standard deviation of 8%. The
correlation between the two industries is 0.4. If XYZ invests $1 million in Tech and $2 million in
Biotech, calculate the expected ROI of the portfolio and the standard deviation of the portfolio’s
ROI.
Solution 7. Let Xbe the ROI in Tech and Ybe the ROI in Biotech. The expected ROI of a
portfolio is given by the weighted average of the expected ROIs of the individual investments:
E(Rp) = w1E(R1) + w2E(R2)
where w1and w2are the weights of the investments and E(R1)and E(R2)are the expected ROIs
of Tech and Biotech, respectively.
Given: - E(R1) = 20%,E(R2) = 15% -w1= $1,000,000/$3,000,000 = 1
3,w2= $2,000,000/$3,000,000 =
2
3
E(Rp) = 1
3(20%) + 2
3(15%) = 18.33%
The variance of the portfolio is calculated as:
V ar(Rp) = w2
1V ar(R1) + w2
2V ar(R2)+2w1w2Cov(R1, R2)
where V ar(R1)and V ar(R2)are the variances of the individual investments and Cov(R1, R2)is
the covariance between the investments.
Given: - V ar(R1) = (0.05)2,V ar(R2) = (0.08)2,Cov(R1, R2)=0.4(0.05)(0.08)
V ar(Rp) = 1
32
(0.05)2+2
32
(0.08)2+ 2 1
32
3(0.4(0.05)(0.08))
V ar(Rp)≈0.00042833
Therefore, the standard deviation of the portfolio’s ROI is:
σ=qV ar(Rp)≈√0.00042833 ≈0.0207 = 2.07%
Hence, the expected ROI of the portfolio is approximately 18.33%, and the standard deviation
of the portfolio’s ROI is approximately 2.07%.
7 8. INVESTOR EXIT STRATEGIES IN PRIVATE EQUITY DEALS
Problem 8.
A private equity investor invested $1 million in a startup company with the following projected
cash flows over the next five years:
Year 1: $200,000 Year 2: $300,000 Year 3: $400,000 Year 4: $500,000 Year 5: $600,000
Assuming a desired Internal Rate of Return (IRR) of 20% per annum, calculate the exit value
required at the end of Year 5 to achieve the target return for the investor.
Solution 8.
To calculate the exit value required at the end of Year 5, we need to find the Present Value (PV)
of the cash flows and then determine the exit value that would give an IRR of 20%.
The PV of the cash flows can be calculated using the formula:
P V =CF1
(1 + r)1+CF2
(1 + r)2+CF3
(1 + r)3+CF4
(1 + r)4+CF5+ExitV alue
(1 + r)5
Where: CFi= Cash flow at the end of Year i r = 0.20 (IRR) ExitV alue = Exit value at the end
of Year 5
Substitute the given values into the formula:
P V =200,000
(1 + 0.20)1+300,000
(1 + 0.20)2+400,000
(1 + 0.20)3+500,000
(1 + 0.20)4+600,000 + ExitV alue
(1 + 0.20)5
P V =200,000
1.20 +300,000
1.202+400,000
1.203+500,000
1.204+600,000 + ExitV alue
1.205
P V ≈166,666.67 + 225,000 + 250,000 + 277,777.78 + 600,000 + ExitV alue
1.48
P V ≈919,444.45 + 600,000 + ExitV alue
1.48
Since the total initial investment is $1,000,000 at the start, the exit value at the end of Year 5
should be such that the total PV equals the total initial investment:
1,000,000 = 919,444.45 + 600,000 + ExitV alue
1.48
1,000,000 −919,444.45 = 600,000 + ExitV alue
1.48
80,555.55 = 600,000 + ExitV alue
1.48
119,200 ≈600,000 + ExitV alue
ExitV alue ≈119,200 −600,000
ExitV alue ≈ −480,800
Therefore, the exit value required at the end of Year 5 to achieve the target return for the investor
is approximately $480,800 *negative value indicates a loss*.
I.
8 9. REGULATORY COMPLIANCE IN VENTURE CAPITAL AND PRIVATE EQUITY
Problem 9. A Venture Capital firm is considering investing in a startup. The firm’s management
fee is 2% of committed capital, and they charge a 20% carried interest (profit share) on returns
exceeding an 8% preferred return hurdle rate. If the firm raises a fund of 100 million from limited
partners and invests 80
Solution 9.
a) The management fee can be calculated as 2% of the committed capital. Therefore, manage-
ment fee = 0.02 ×100 million = 2 million.
b) The profit share or carried interest is calculated on the returns exceeding the preferred return
hurdle rate. The total profits from the startup investment are 80
Therefore, the profit share = 20
Therefore, the carried interest payable by the startup is 14.4million.
Thus, the management fee payable by the startup is 2million and the carried interest payable
is 14.4million.
I.
9 10. COMPETITION FOR QUALITY DEALS IN THE VENTURE CAPITAL MARKET
Problem 10. In a competitive venture capital market, investors are evaluating two investment
opportunities. Opportunity A requires an investment of 500,000andisexpectedtoyieldareturnof1,000,000
with a probability of success of 30
a) Calculate the expected value of each investment opportunity.
b) Calculate the expected value of the two opportunities if investors can only choose one of
them.
c) Analyze which investment opportunity seems more attractive based on the expected values
calculated in parts (a) and (b).
Solution 10.
a) The expected value of an investment opportunity is calculated by multiplying the return by
the probability of success.
For Opportunity A: Expected value = 1,000,000 ∗0.30 =300,000
For Opportunity B: Expected value = 1,200,000 ∗0.40 =480,000
b) To calculate the expected value of the two opportunities if investors can only choose one, we
compare the expected values of both opportunities.
Choosing between A and B, Opportunity B has a higher expected value of 480,000comparedtoOpportunityA′s300,000.
c) Based on the expected values calculated in parts (a) and (b), Opportunity B seems more
attractive as it offers a higher expected return on investment compared to Opportunity A.
10 11. MANAGING PORTFOLIO COMPANIES IN PRIVATE EQUITY INVESTMENTS
Problem 11. A private equity firm has invested $5 million in a portfolio company and acquired
a 20% stake. After a successful year, the portfolio company’s valuation has increased by 30%.
a) What is the new valuation of the portfolio company?
b) Calculate the new value of the private equity firm’s stake in the portfolio company.
c) If the private equity firm decides to exit its investment by selling its stake, how much profit
would they make if the exit price per share is 25% higher than the original valuation?
Solution 11.
a) The new valuation of the portfolio company after a 30% increase can be calculated as:
New Valuation =Original Valuation ×(1 + Increase %)
New Valuation = $5,000,000 ×(1 + 0.30)
New Valuation = $5,000,000 ×1.30
New Valuation = $6,500,000
Therefore, the new valuation of the portfolio company is $6,500,000.
b) The new value of the private equity firm’s stake in the portfolio company can be calculated
as:
New Value of Stake =New Valuation ×Stake %
New Value of Stake = $6,500,000 ×0.20
New Value of Stake = $1,300,000
Therefore, the new value of the private equity firm’s stake in the portfolio company is $1,300,000.
c) If the exit price per share is 25% higher than the original valuation, then the exit price per
share would be:
Exit Price Per Share =Original Valuation ×(1 + 0.25)
Exit Price Per Share = $5,000,000 ×1.25
Exit Price Per Share = $6,250,000
The profit the private equity firm would make upon exit can be calculated as:
Profit =Exit Price Per Share ×Stake % −Investment
Profit = $6,250,000 ×0.20 −$5,000,000
Profit = $1,250,000 −$5,000,000
Profit = $250,000
Therefore, if the private equity firm exits its investment at an exit price 25% higher than the
original valuation, they would make a profit of $250,000.
11 Venture Capital and Private Equity
Problem: You are a venture capitalist considering investing in a startup. The startup has
projected cash flows for the next 5 years as follows:
Year 1: $100,000 Year 2: $150,000 Year 3: $200,000 Year 4: $250,000 Year 5: $300,000
If the discount rate is 10%, calculate the present value of these cash flows.
Solution: To calculate the present value of the cash flows, we need to discount each cash flow
using the formula:
P V =CF
(1 + r)t
where: P V = Present Value CF = Cash Flow in that year r= Discount Rate t= Time period in
years
Let’s compute the present value of each cash flow and sum them up:
a) For Year 1:
P V1=100,000
(1 + 0.10)1=100,000
1.10 = $90,909
b) For Year 2:
P V2=150,000
(1 + 0.10)2=150,000
1.21 = $123,966
c) For Year 3:
P V3=200,000
(1 + 0.10)3=200,000
1.331 = $150,289
d) For Year 4:
P V4=250,000
(1 + 0.10)4=250,000
1.4641 = $170,866
e) For Year 5:
P V5=300,000
(1 + 0.10)5=300,000
1.6105 = $186,410
Now, summing up all the present values:
P V = $90,909 + $123,966 + $150,289 + $170,866 + $186,410 = $722,440
Therefore, the present value of the cash flows is $722,440.
12 13. THE ROLE OF TECHNOLOGY IN DISRUPTING VENTURE CAPITAL AND PRIVATE
EQUITY
Problem 13. A venture capital firm invests $1,000,000 in a startup with a promised return of
25% annually over 5 years. However, after the first year, the startup faces challenges and the return
drops to −10% annually for the remaining 4 years. Calculate the net present value (NPV) of the
investment if the discount rate is 15%.
Solution 13. a) To calculate the NPV of the investment, we need to find the present value of
the expected cash flows from the investment.
The initial investment is $1,000,000.
After the first year, the return is 25%, so the cash flow at the end of year 1 will be: $1,000,000 ×
1.25 = $1,250,000
For the remaining 4 years, the return is −10% annually. The cash flows for years 2 to 5 are
calculated as follows:
Year 2: $1,250,000 ×0.90 = $1,125,000 Year 3: $1,125,000 ×0.90 = $1,012,500 Year 4:
$1,012,500 ×0.90 = $911,250 Year 5: $911,250 ×0.90 = $820,125
b) Now, we calculate the present value of these cash flows using the discount rate of 15%.
The present value (PV) of each cash flow is calculated using the formula: P V =CF
(1+r)n, where
CF is the cash flow, ris the discount rate, and nis the period.
PV of Year 1 cash flow: ($1,250,000)
(1+0.15)1= $1,086,957.61
PV of Year 2-5 cash flows: ($1,125,000)
(1+0.15)2= $873,573.64 ($1,012,500)
(1+0.15)3= $718,331.05 ($911,250)
(1+0.15)4=
$566,638.49 ($820,125)
(1+0.15)5= $453,157.44
c) Finally, we calculate the NPV by summing up the present values of the cash flows and sub-
tracting the initial investment.
NP V =P VY ear1+P VY ear2+P VY ear3+P VY ear4+P VY ear5−$1,000,000 NP V = $1,086,957.61+
$873,573.64 + $718,331.05 + $566,638.49 + $453,157.44 −$1,000,000 NP V = $1,698,658.23 −
$1,000,000 NP V = $698,658.23
Therefore, the net present value (NPV) of the investment is $698,658.23.
13 Venture Capital and Private Equity
Problem 1.
A venture capital firm is considering investing $1,000,000 in a startup. The firm expects the
startup to be valued at $3,000,000 in 3 years if they invest. If the firm requires a return of 25% per
year on their investment, what percentage ownership should they demand in the startup?
Solution 1.
Let xbe the percentage ownership the venture capital firm should demand in the startup.
The present value of the investment should equal the initial investment of $1,000,000. The
future value of the investment in 3 years should be $3,000,000.
Using the concept of Compound Interest formula:
1,000,000 = 3,000,000
(1 + 0.25)3×x
Solving for x, we get:
x=1,000,000
3,000,000/1.952 = 0.6513 = 65.13%
Therefore, the venture capital firm should demand a 65.13% ownership in the startup.
14 15. FUNDRAISING CHALLENGES FOR VENTURE CAPITAL FIRMS
Problem 15. A Venture Capital firm is looking to raise a new fund of 100 million. They plan to
charge a 2% management fee and a 20% carry fee on any profits generated from investments. If
the firm expects to generate 30% returns on investments over the lifetime of the fund, calculate the
total fees earned by the Venture Capital firm over the fund’s lifetime.
Solution 15. a) The total management fee can be calculated as:
Management Fee =Fund Size ×Management Fee Rate = 100 million ×0.02 = 2 million
b) The total carry fee can be calculated as:
Carry Fee =Return ×Carry Fee Rate = (100 million ×0.30) ×0.20 = 6 million
c) Therefore, the total fees earned by the Venture Capital firm over the fund’s lifetime would be:
Total Fees =Management Fee +Carry Fee = 2 million + 6 million = 8 million
15 16. BALANCING RISK AND REWARD IN PRIVATE EQUITY INVESTMENTS
Problem 16. ABC Ventures is considering investing in a startup company. The expected return
on this investment is 15
Solution 16. a) The Sharpe ratio is calculated as follows:
Sharpe ratio =Rp−Rf
σp
Where: - Rpis the expected return on the investment (15- Rfis the risk-free rate (5- σpis the
standard deviation of the investment (20
Substitute the values into the formula:
Sharpe ratio =0.15 −0.05
0.20 =0.10
0.20 = 0.5
Therefore, the Sharpe ratio for this investment is 0.5.
I can definitely help with that. Let’s work on a numerical problem related to Venture Capital and
Private Equity under the given subtopic.
16 17. IMPACT OF ECONOMIC DOWNTURNS ON VENTURE CAPITAL AND PRIVATE EQ-
UITY
Problem 17. During an economic downturn, a venture capital fund decides to invest 100,000inastartupcompanywithanexpectedreturnof30
Solution 17. Let’s first calculate the expected return after 5 years:
Expected return after 5 years = $100,000 ×(1 + 0.30)5
= $100,000 ×(1.30)5
= $100,000 ×2.8561
= $285,610
Now, the actual return turns out to be 10
Actual return after 5 years = $285,610 ×(1 −0.10)
= $285,610 ×0.90
= $257,049
Therefore, the total amount the venture capital fund will receive after 5 years is $257,049.
I’m glad to help with that! Here is a numerical problem related to Venture Capital and Private
Equity:
17 Venture Capital and Private Equity
Problem:
A venture capital firm invests $1,000,000 in a startup with an agreed 20% equity stake. The
startup later gets acquired for $10,000,000. How much profit does the venture capital firm make
from this investment?
Solution:
First, let’s calculate the value of the equity stake acquired by the venture capital firm:
Equity Stake Value =Investment Amount ×Equity Stake (%)
100
Equity Stake Value = $1,000,000 ×20
100 = $200,000
Then, we can find the profit made by the venture capital firm from the acquisition:
Profit =Acquisition Amount −Equity Stake Value −Investment Amount
Profit = $10,000,000 −$200,000 −$1,000,000 = $8,800,000
Therefore, the venture capital firm makes a profit of $8,800,000 from this investment.
I. Problem 1: Investor Equity Stake Calculation
A venture capital firm invests $1 million in a start-up company in exchange for a 20
Solution 1: Let Vbe the pre-money valuation of the company. The equity stake can be calcu-
lated using the formula:
Equity Stake =Investment Amount
Pre-money Valuation +Investment Amount ×100%
Substitute the values given:
20% = 1,000,000
V+ 1,000,000 ×100%
Solving for V:
V+ 1,000,000 = 1,000,000
20%
V+ 1,000,000 = 5,000,000
V= 4,000,000
Therefore, the pre-money valuation of the company is $4 million.
II. Problem 2: Preferred Stock Liquidation Preference
A venture capitalist invests $2 million in a start-up with a 2x liquidation preference. The company
sells for $5 million. How much money does the venture capitalist receive?
Solution 2: The venture capitalist will first receive back the $2 million invested due to the 2x
liquidation preference. The remaining amount will be divided pro-rata among all shareholders.
Since the company sells for $5 million, the remaining $3 million will be distributed among share-
holders based on their ownership percentage. The venture capitalist owns 2
5of the company ($2
million out of the $5 million total investment).
Therefore, the venture capitalist will receive:
$2,000,000 (liquidation preference)+2
5×$3,000,000 (remaining amount) = $2,000,000+$1,200,000 = $3,200,000
The venture capitalist will receive $3.2 million from the sale.
III. Problem 3: Internal Rate of Return (IRR) Calculation
A private equity firm invests $500,000 in a company and receives the following cash flows:
$100,000 in year 1, $200,000 in year 2, and $300,000 in year 3. Calculate the internal rate of
return for this investment.
Solution 3:
The IRR is the discount rate that makes the net present value (NPV) of all cash flows equal to
zero. Setting up the equation:
0 = −500,000 + 100,000
(1 + r)1+200,000
(1 + r)2+300,000
(1 + r)3
Using a financial calculator or software, solving the above equation gives r≈19.73%.
Therefore, the internal rate of return for this investment is approximately 19.73
18 20. GENDER AND DIVERSITY ISSUES IN VENTURE CAPITAL AND PRIVATE EQUITY.
Problem 20. In a venture capital firm, the distribution of investment decisions made by the
partners is as follows:
•40% of investment decisions are made by male partners
•30% of investment decisions are made by female partners
•30% of investment decisions are made by partners who identify as non-binary
If there are a total of 50 investment decisions made in a year by the venture capital firm, de-
termine the number of investment decisions made by each group (male, female, and non-binary
partners).
Solution 20. Let’s denote:
•Number of investment decisions made by male partners as x
•Number of investment decisions made by female partners as y

•Number of investment decisions made by non-binary partners as z
From the information given in the problem:
x= 0.40 ×50 = 20 (investment decisions by male partners)
y= 0.30 ×50 = 15 (investment decisions by female partners)
z= 0.30 ×50 = 15 (investment decisions by non-binary partners)
Therefore, the number of investment decisions made by each group are as follows:
•Male partners: 20 investment decisions
•Female partners: 15 investment decisions
•Non-binary partners: 15 investment decisions
For Startup A: Expected return = (0.3 * $1,000,000) - (0.7 * $200,000) = $300,000 - $140,000
= $160,000
For Startup B: Expected return = (0.5 * $800,000) - (0.5 * $150,000) = $400,000 - $75,000 =
$325,000
b) Based on expected return alone, Startup B has a higher expected return of $325,000 com-
pared to Startup A’s expected return of $160,000. Therefore, if you were to choose based on
expected return alone, you would choose to invest in Startup B.
Certainly! Here is a numerical problem on Venture Capital and Private Equity for you:
3 3. INVESTOR DIVERSIFICATION IN PRIVATE EQUITY
Problem 3. A venture capital investor has a portfolio of investments in three startups, with the
following initial amounts invested and expected returns:
Startup A: Investment of $100,000 with an expected return of $150,000 Startup B: Investment of
$200,000 with an expected return of $250,000 Startup C: Investment of $150,000 with an expected
return of $180,000
Assuming all three investments are uncorrelated, calculate the total expected return, standard
deviation, and coefficient of variation for the investor’s portfolio.
Solution 3.
a) To find the total expected return, we simply sum up the expected returns of each individual
investment:
Total Expected Return = $150,000 + $250,000 + $180,000 = $580,000
b) Next, to calculate the standard deviation of the portfolio, we need to find the variance of the
portfolio first. Since the investments are uncorrelated, we can use the following formula for the
variance of a portfolio of two assets:
Variance of Portfolio = w2
A∗V ar(A) + w2
B∗V ar(B) + w2
C∗V ar(C)
Where: wA, wB, wC=weightsofinvestmentsA, B, Cintheportfolio(sumofweights = 1)V ar(A), V ar(B), V ar(C) =
varianceofinvestmentsA, B, C
Given the investments are uncorrelated, the variance of each investment is equal to its expected
return:
Var(A) = $150,000 Var(B) = $250,000 Var(C) = $180,000
Let’s calculate the variance: Variance of Portfolio = (100,000/450,000)2∗150,000+(200,000/450,000)2∗
250,000 + (150,000/450,000)2∗180,000
Variance of Portfolio = 83,333.33
Then, the standard deviation is the square root of the variance:
Standard Deviation = √83,333.33 ≈$288.67
c) Finally, the coefficient of variation (CV) is calculated by dividing the standard deviation by the
expected return:
Coefficient of Variation = $288.67 / $580,000 Coefficient of Variation 0.0004986, or approxi-
mately 0.04986
I. Problem: Due Diligence in Venture Capital
A venture capital firm is considering investing $500,000 in a startup company. During the due
diligence process, they discover that the company’s financial projections are as follows:
- Year 1: Revenue of $200,000, Expenses of $150,000 - Year 2: Revenue growth of 20%,
Expenses growth of 10%
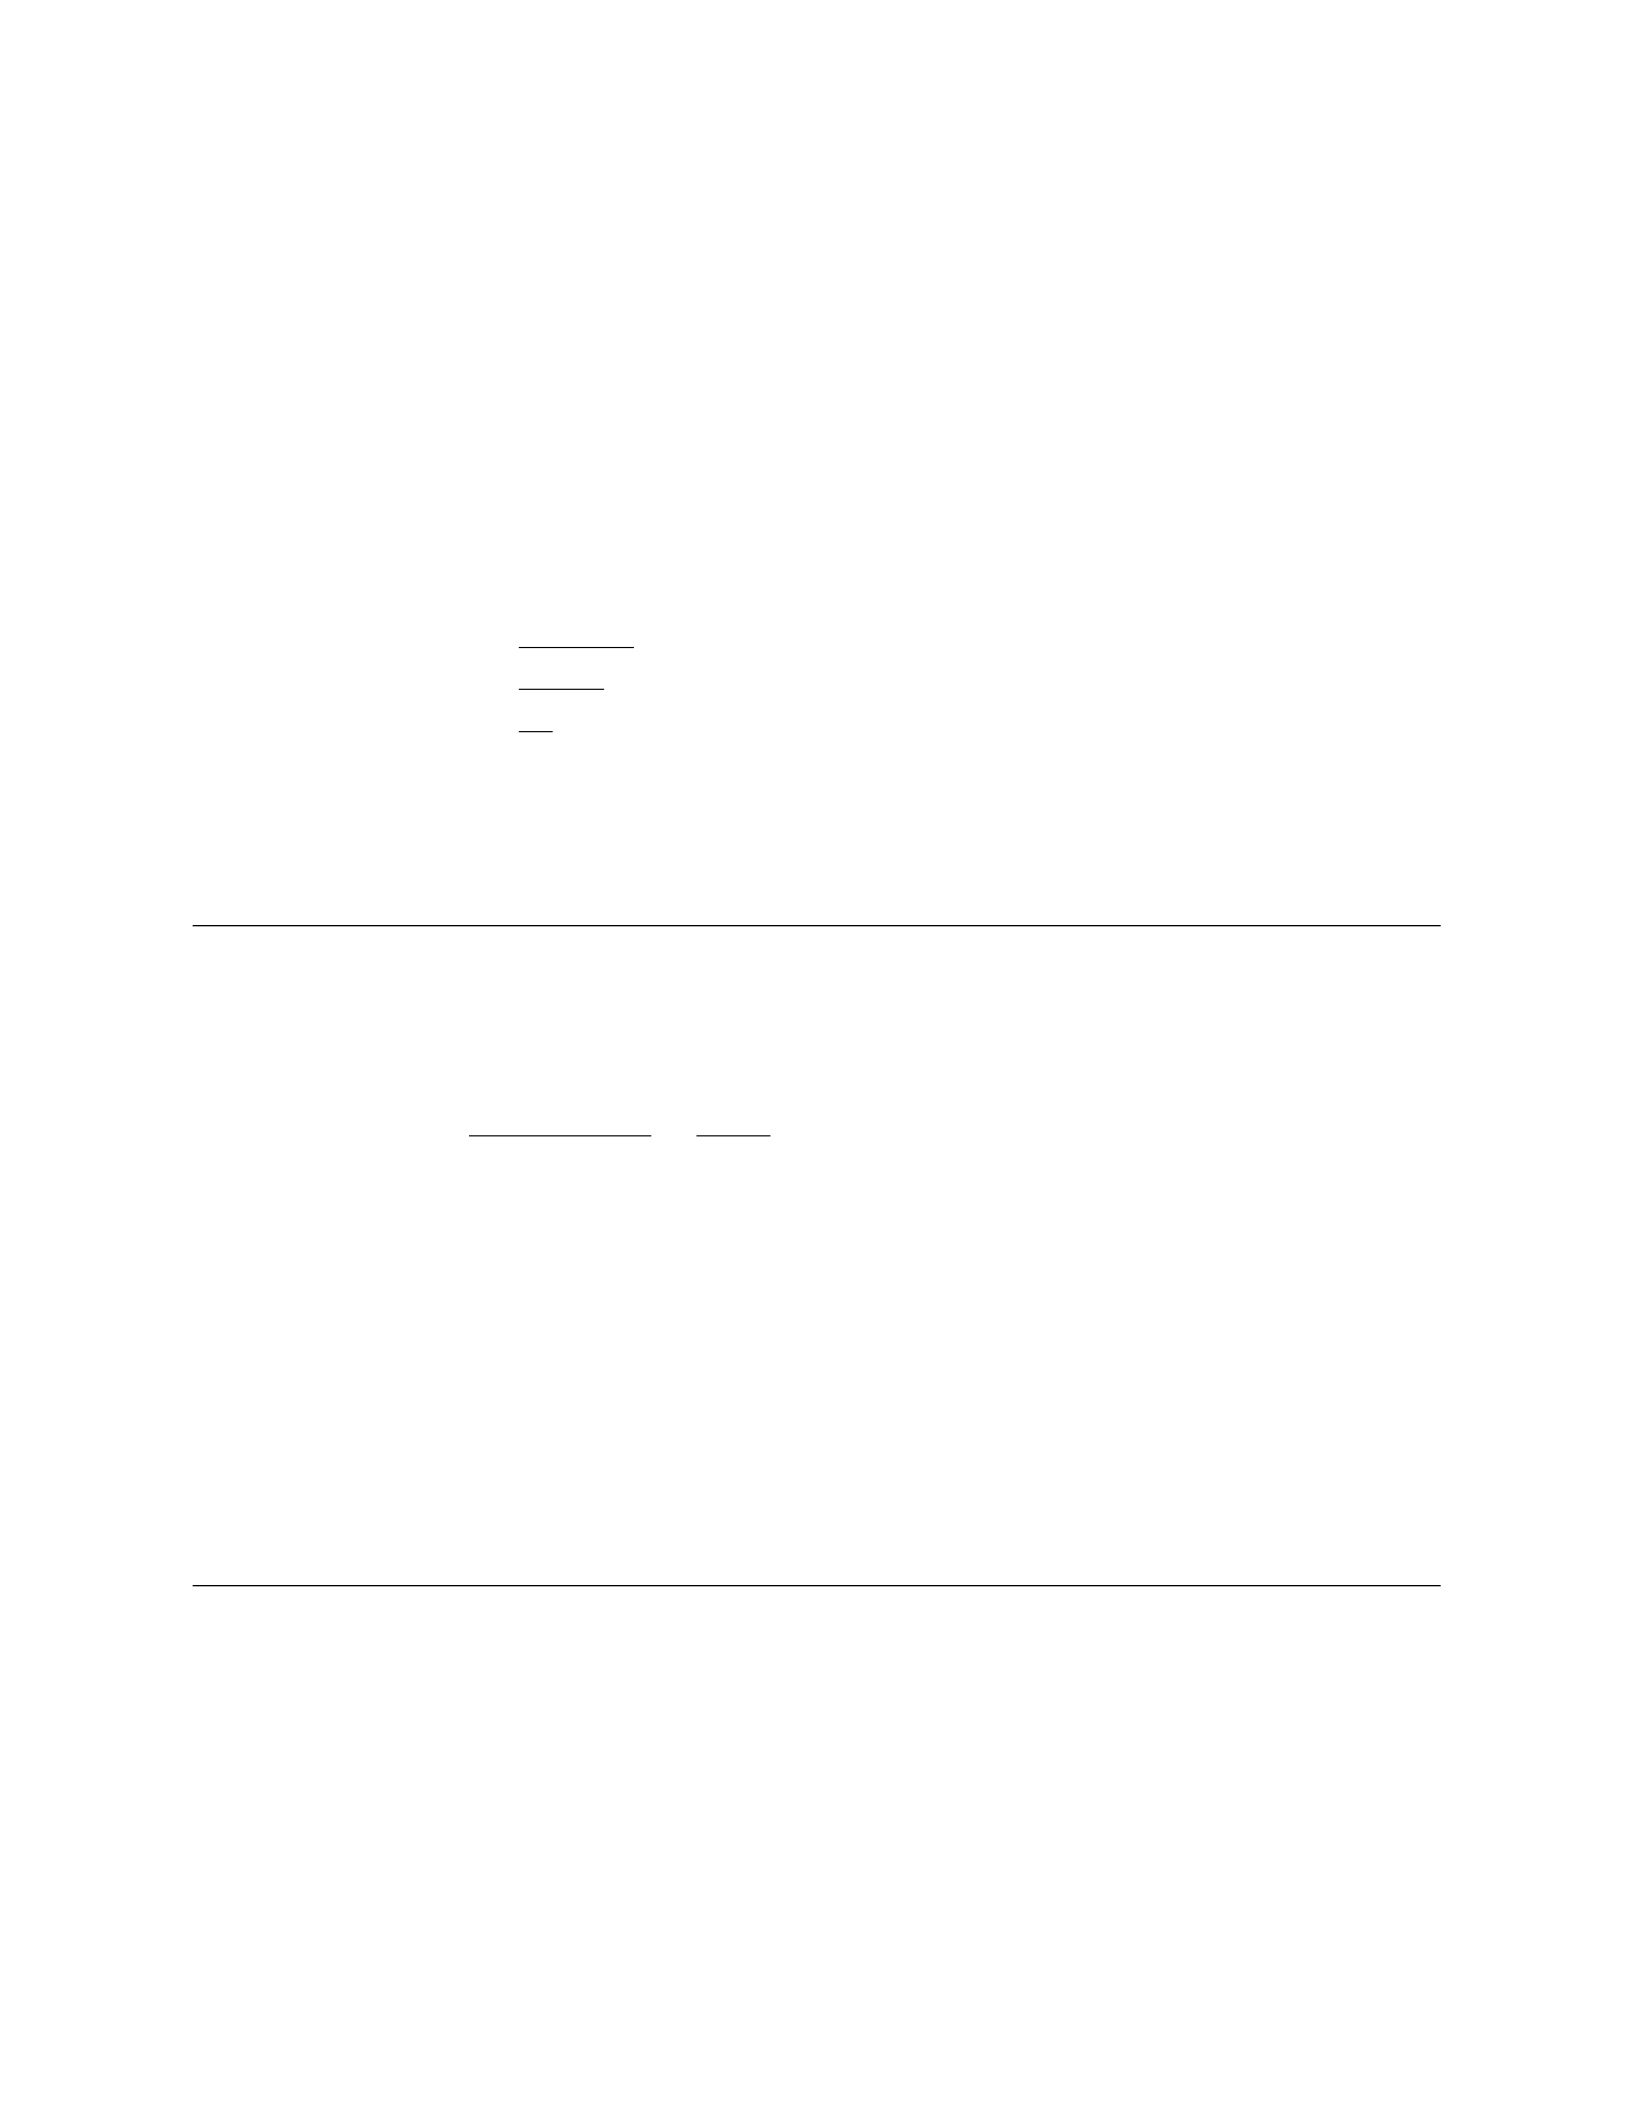
Calculate the Net Income for each year and determine the company’s Net Income Margin in
Year 2.
Solution:
a) Net Income for Year 1:
Net Income = Revenue - Expenses
Net Income = $200,000 −$150,000 = $50,000
b) Net Income for Year 2:
Revenue in Year 2 = $200,000 ×1.20 = $240,000
Expenses in Year 2 = $150,000 ×1.10 = $165,000
Net Income = Revenue - Expenses
Net Income = $240,000 −$165,000 = $75,000
c) Net Income Margin in Year 2:
Net Income Margin = NetIncome
Revenue ×100
Net Income Margin = $75,000
$240,000 ×100
Net Income Margin = 75
240 ×100 = 31.25%
Therefore, the company’s Net Income Margin in Year 2 is 31.25%.
4 5. LACK OF TRANSPARENCY IN PRIVATE EQUITY INVESTMENTS
Problem 5. A Venture Capital firm invested 500,000 in a startup in exchange for 20% equity
ownership. After a few years, the startup gets acquired for 5times its initial valuation. If the firm
decides to exit their investment, what is the total cash they receive from the acquisition?
Solution 5. Let’s first calculate the initial valuation of the startup when the Venture Capital firm
invested:
Initial Valuation = Investment Amount
Equity Ownership =500,000
0.20 = 2,500,000
After the acquisition, the startup is acquired for 5times its initial valuation:
Acquisition Price = 5×Initial Valuation = 5 ×2,500,000 = 12,500,000
Since the Venture Capital firm owns 20% equity in the startup, their cash from the acquisition
would be:
Cash from Acquisition = Equity Ownership ×Acquisition Price = 0.20 ×12,500,000 =2,500,000
Therefore, the Venture Capital firm would receive 2,500,000 in cash from the acquisition of the
startup.
I.
5 6. VALUATION DIFFICULTIES IN EARLY-STAGE STARTUPS
Problem 6. You are a venture capitalist looking to invest in a promising early-stage startup.
The startup is seeking $500,000 in funding in exchange for a 20
a) What is the pre-money valuation of the startup based on the given information?
b) If you decide to invest the requested amount, how many shares will you receive?
c) What is the price per share you will pay for this investment?
Solution 6.
a) The pre-money valuation of the startup can be calculated as follows:
Pre-money valuation =Post-money valuation −Amount of funding
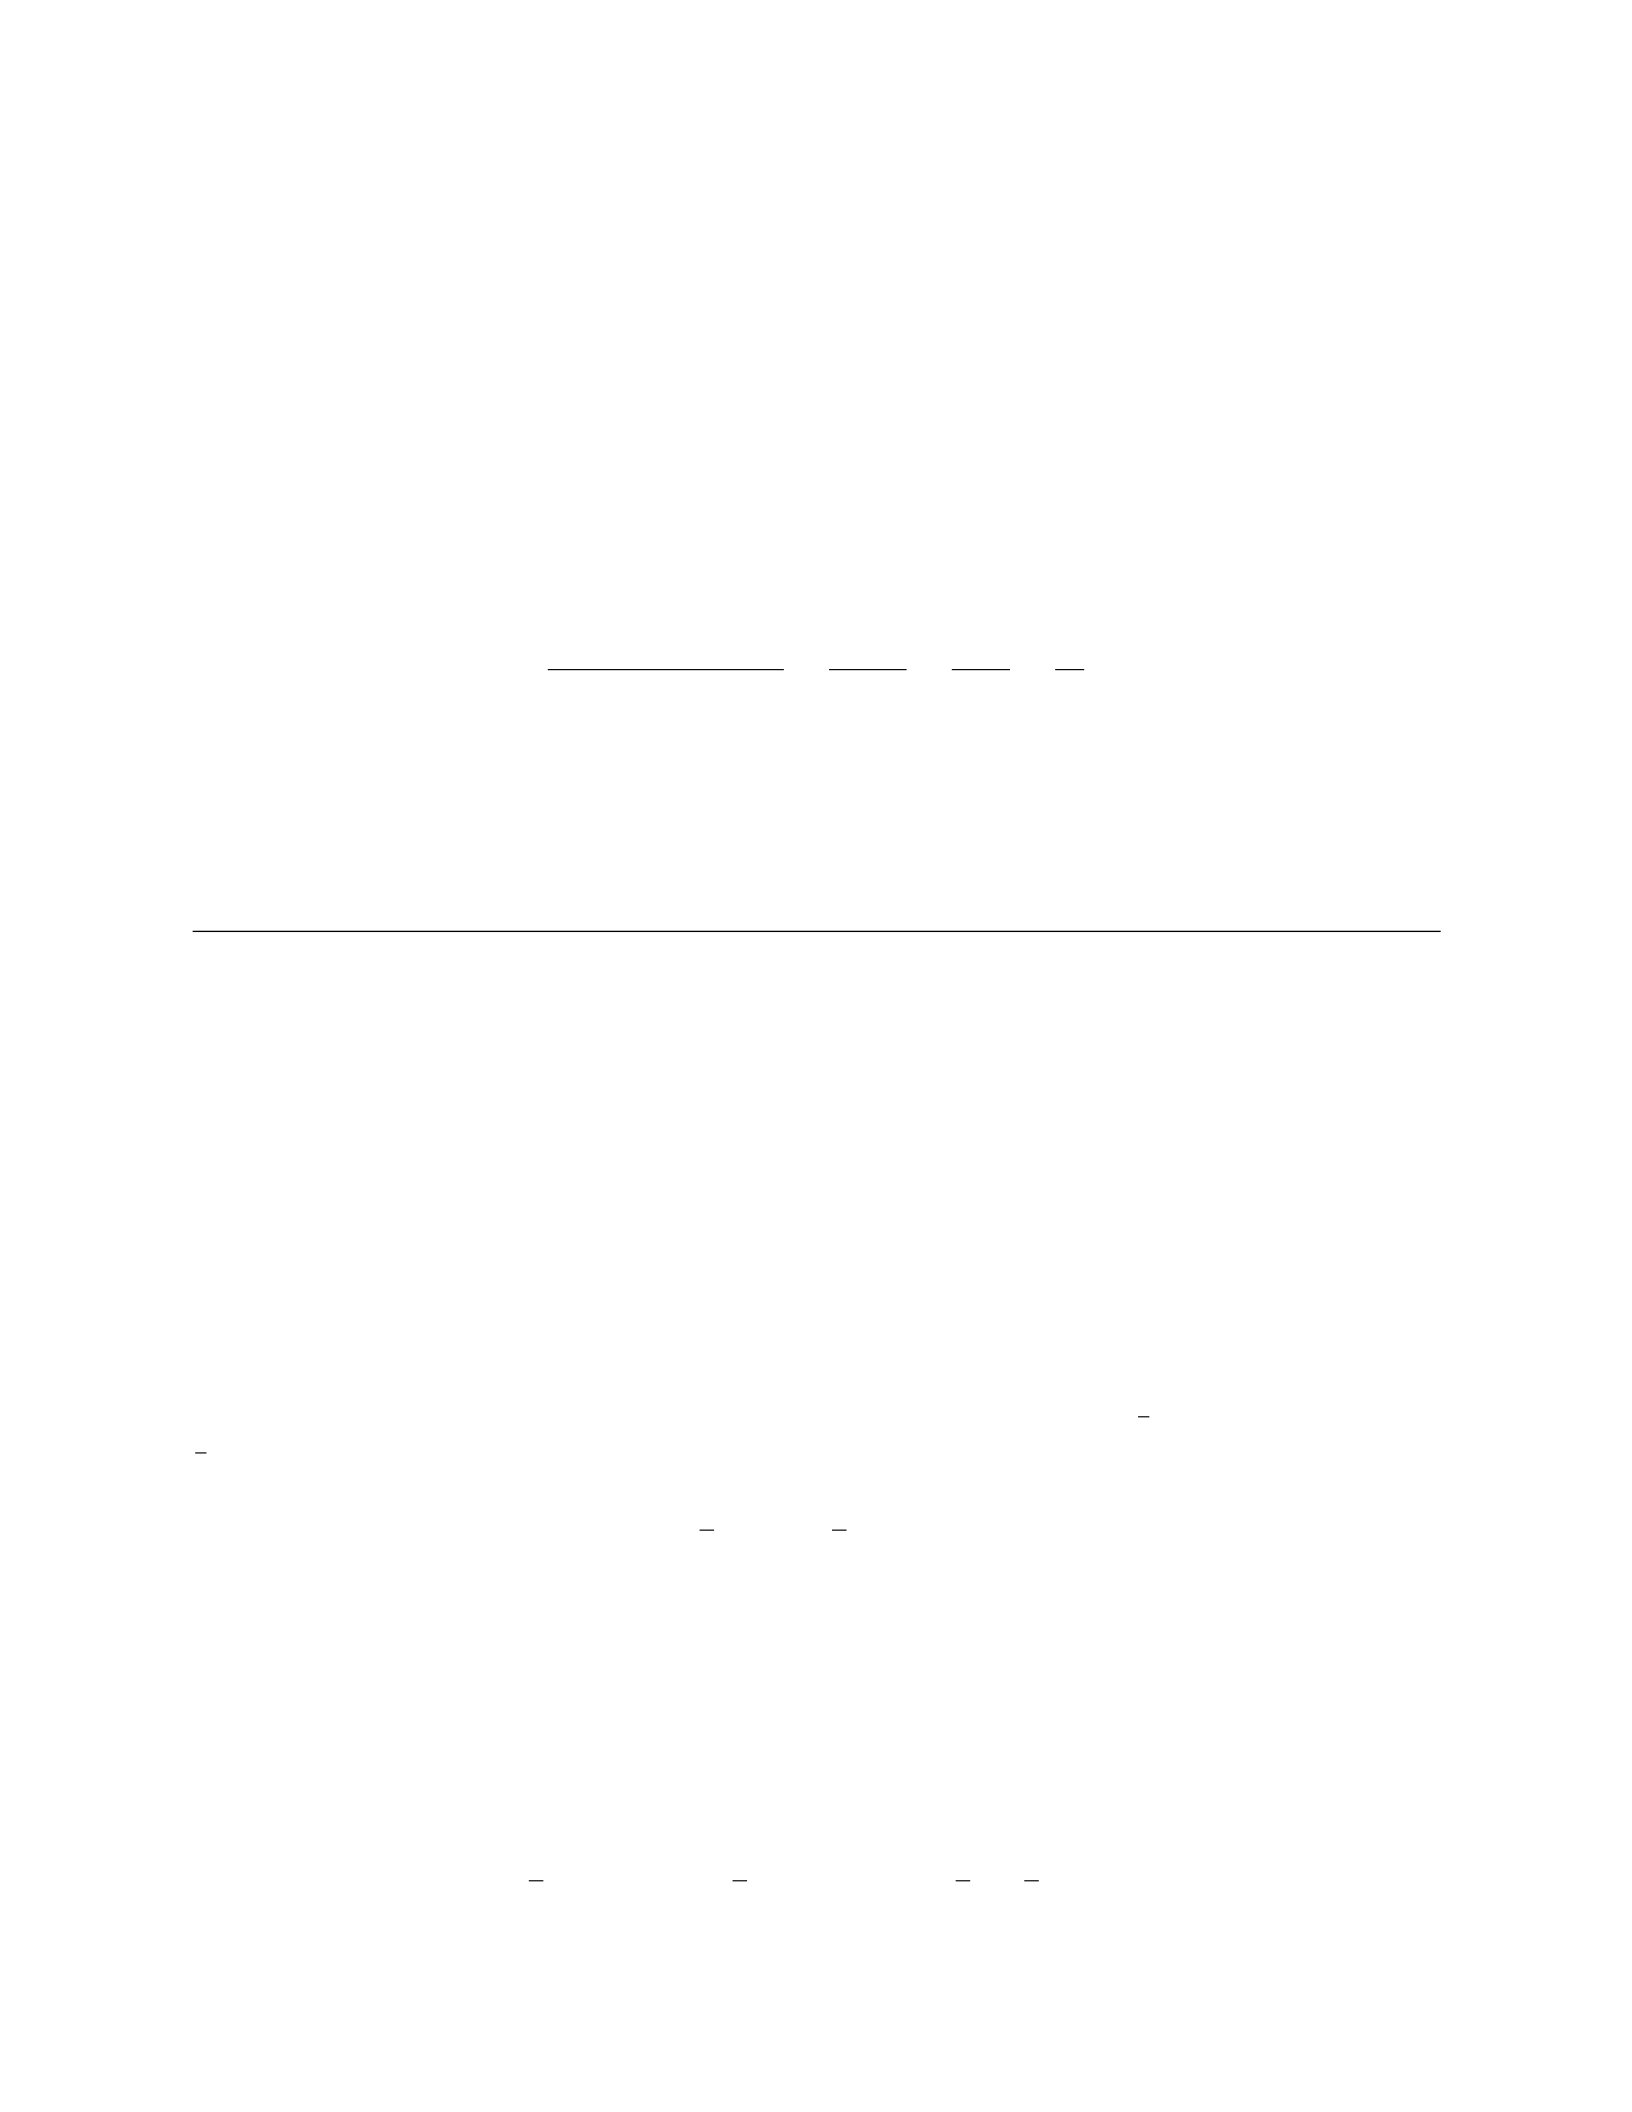
Pre-money valuation = $2.5M−$500K= $2M
b) To calculate the number of shares you will receive, we first need to find the value of each
share. The value of each share can be calculated as:
Post-money valuation =Pre-money valuation ×(1 + Equity stake)
$2.5M= $2M×(1 + 0.20)
$2.5M= $2M×1.20
$2.5M= $2.4M
Now, the value per share is $2.4 million. Therefore, the number of shares you will receive is:
Amount of funding
Value per share =$500K
$2.4M=500
2400 =5
24
c) The price per share you will pay for this investment is the same as the value per share, which
is $2.4 million.
6 7. THE IMPACT OF INDUSTRY TRENDS ON VENTURE CAPITAL FUNDING
Problem 7. The venture capital firm XYZ is considering investing in two different industries:
Tech and Biotech. The expected return on investment (ROI) for Tech is 20% with a standard
deviation of 5%, while the expected ROI for Biotech is 15% with a standard deviation of 8%. The
correlation between the two industries is 0.4. If XYZ invests $1 million in Tech and $2 million in
Biotech, calculate the expected ROI of the portfolio and the standard deviation of the portfolio’s
ROI.
Solution 7. Let Xbe the ROI in Tech and Ybe the ROI in Biotech. The expected ROI of a
portfolio is given by the weighted average of the expected ROIs of the individual investments:
E(Rp) = w1E(R1) + w2E(R2)
where w1and w2are the weights of the investments and E(R1)and E(R2)are the expected ROIs
of Tech and Biotech, respectively.
Given: - E(R1) = 20%,E(R2) = 15% -w1= $1,000,000/$3,000,000 = 1
3,w2= $2,000,000/$3,000,000 =
2
3
E(Rp) = 1
3(20%) + 2
3(15%) = 18.33%
The variance of the portfolio is calculated as:
V ar(Rp) = w2
1V ar(R1) + w2
2V ar(R2)+2w1w2Cov(R1, R2)
where V ar(R1)and V ar(R2)are the variances of the individual investments and Cov(R1, R2)is
the covariance between the investments.
Given: - V ar(R1) = (0.05)2,V ar(R2) = (0.08)2,Cov(R1, R2)=0.4(0.05)(0.08)
V ar(Rp) = 1
32
(0.05)2+2
32
(0.08)2+ 2 1
32
3(0.4(0.05)(0.08))
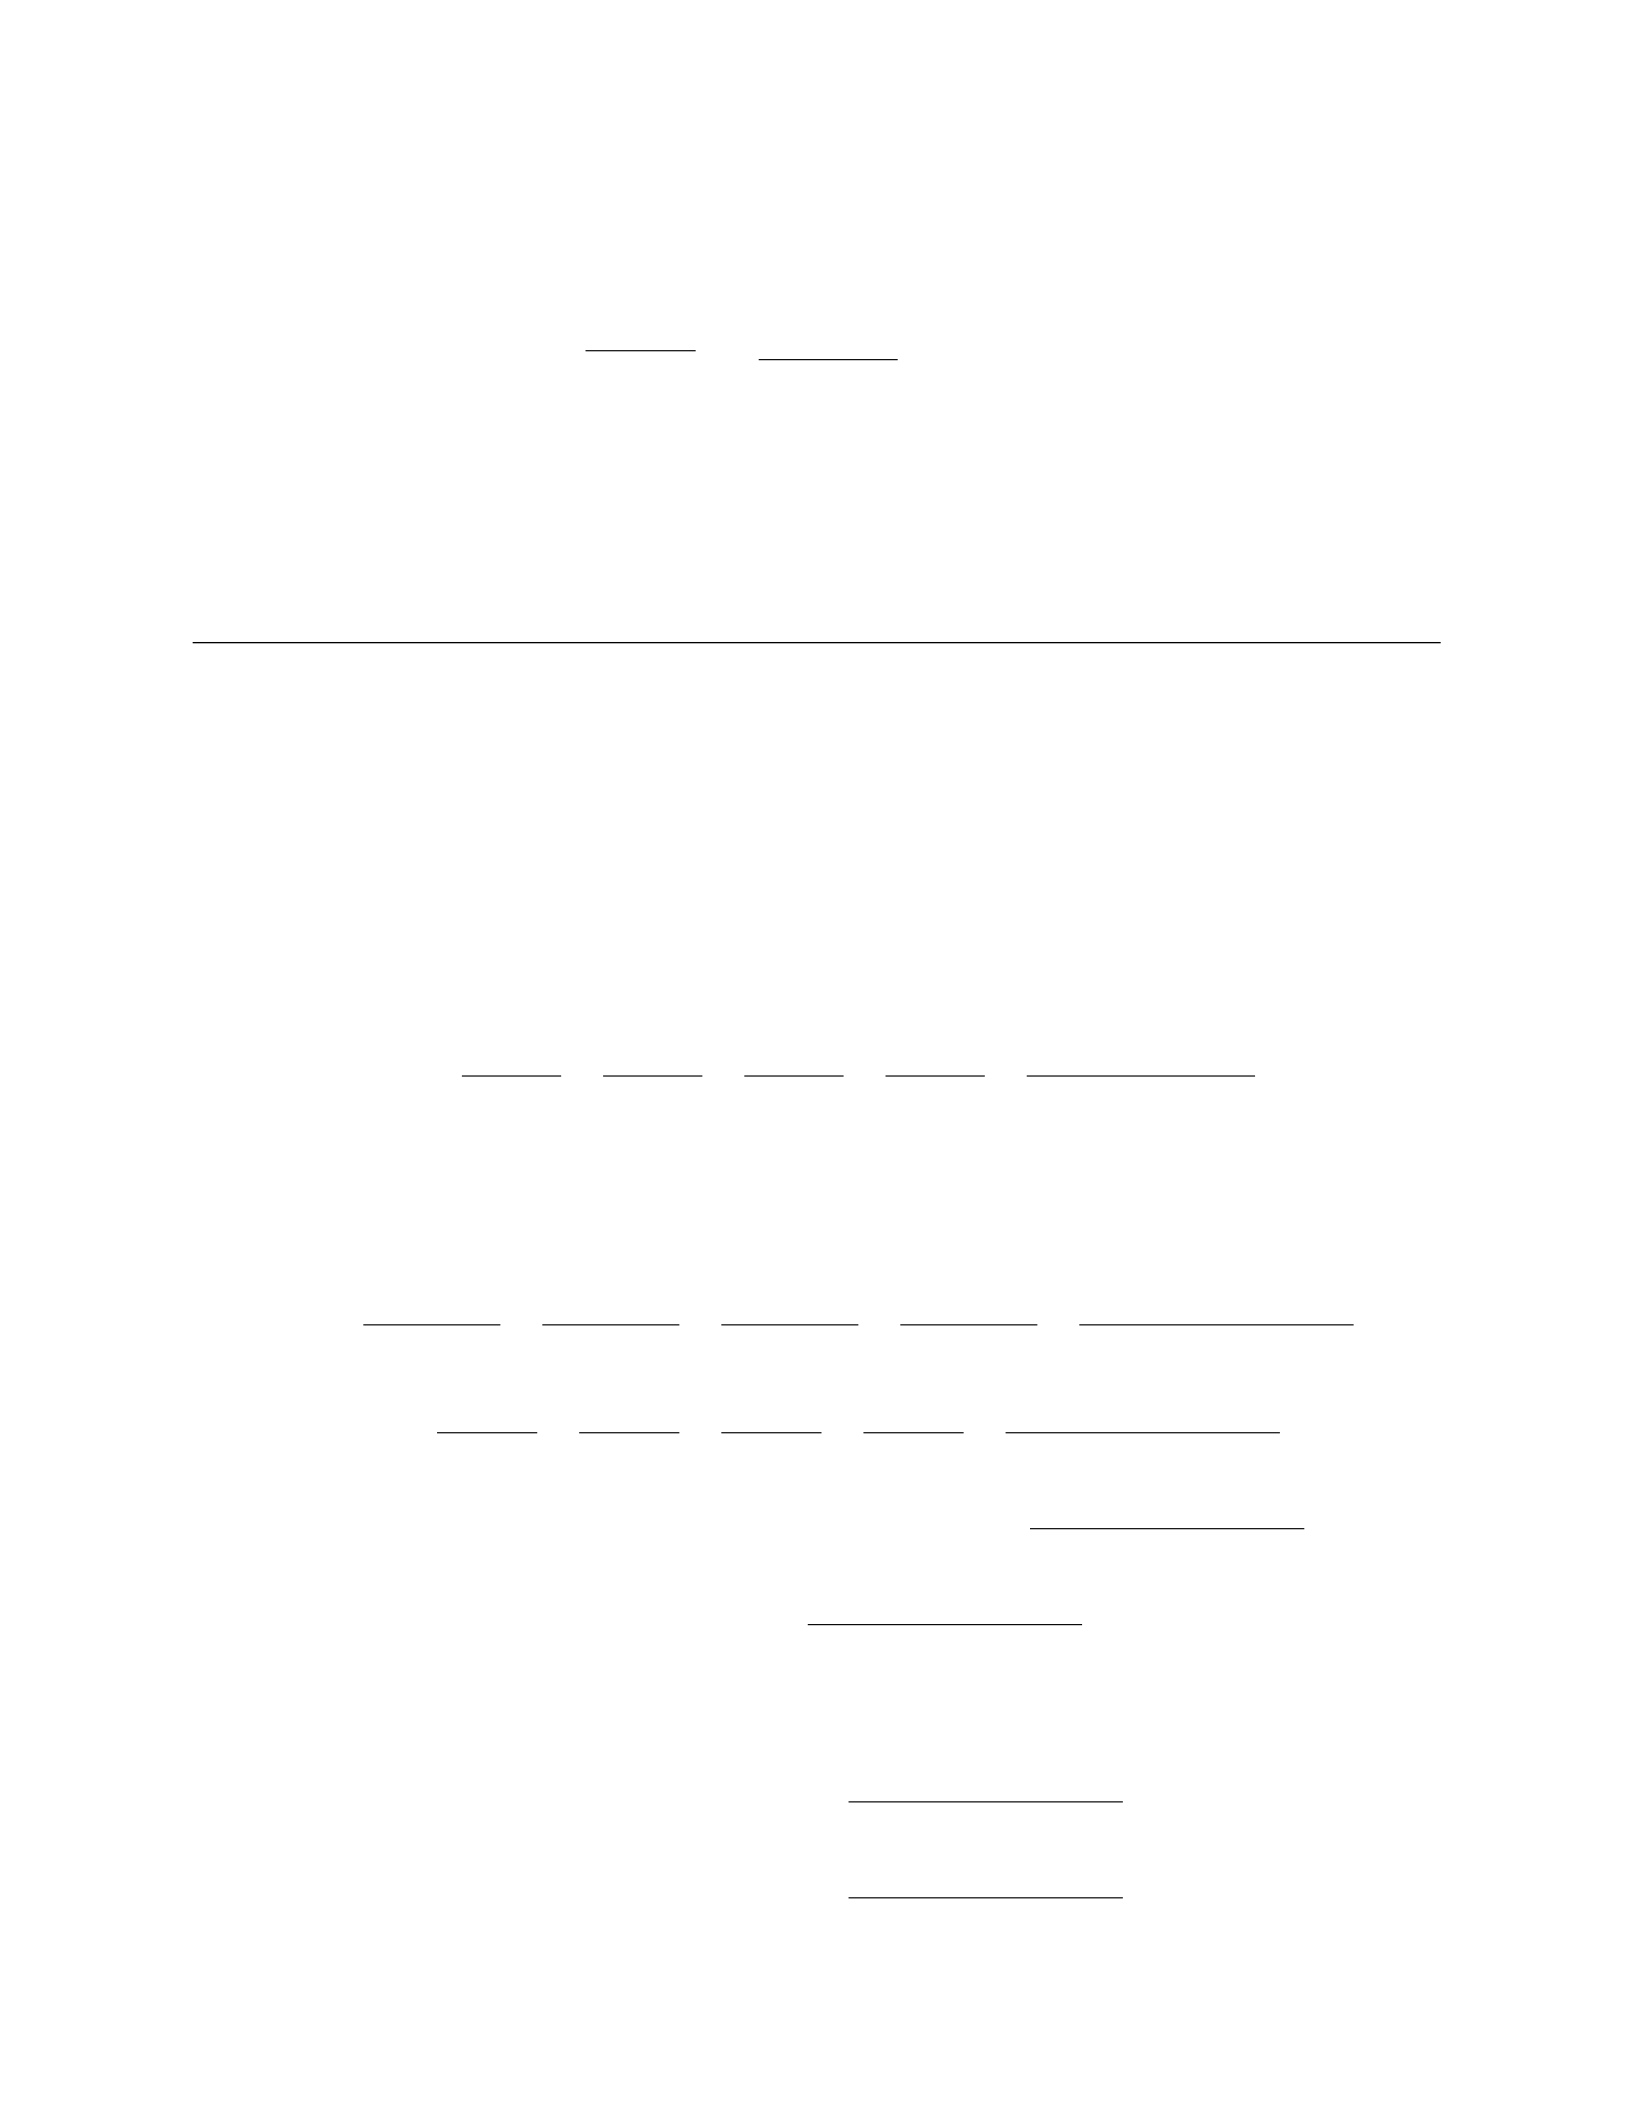
V ar(Rp)≈0.00042833
Therefore, the standard deviation of the portfolio’s ROI is:
σ=qV ar(Rp)≈√0.00042833 ≈0.0207 = 2.07%
Hence, the expected ROI of the portfolio is approximately 18.33%, and the standard deviation
of the portfolio’s ROI is approximately 2.07%.
7 8. INVESTOR EXIT STRATEGIES IN PRIVATE EQUITY DEALS
Problem 8.
A private equity investor invested $1 million in a startup company with the following projected
cash flows over the next five years:
Year 1: $200,000 Year 2: $300,000 Year 3: $400,000 Year 4: $500,000 Year 5: $600,000
Assuming a desired Internal Rate of Return (IRR) of 20% per annum, calculate the exit value
required at the end of Year 5 to achieve the target return for the investor.
Solution 8.
To calculate the exit value required at the end of Year 5, we need to find the Present Value (PV)
of the cash flows and then determine the exit value that would give an IRR of 20%.
The PV of the cash flows can be calculated using the formula:
P V =CF1
(1 + r)1+CF2
(1 + r)2+CF3
(1 + r)3+CF4
(1 + r)4+CF5+ExitV alue
(1 + r)5
Where: CFi= Cash flow at the end of Year i r = 0.20 (IRR) ExitV alue = Exit value at the end
of Year 5
Substitute the given values into the formula:
P V =200,000
(1 + 0.20)1+300,000
(1 + 0.20)2+400,000
(1 + 0.20)3+500,000
(1 + 0.20)4+600,000 + ExitV alue
(1 + 0.20)5
P V =200,000
1.20 +300,000
1.202+400,000
1.203+500,000
1.204+600,000 + ExitV alue
1.205
P V ≈166,666.67 + 225,000 + 250,000 + 277,777.78 + 600,000 + ExitV alue
1.48
P V ≈919,444.45 + 600,000 + ExitV alue
1.48
Since the total initial investment is $1,000,000 at the start, the exit value at the end of Year 5
should be such that the total PV equals the total initial investment:
1,000,000 = 919,444.45 + 600,000 + ExitV alue
1.48
1,000,000 −919,444.45 = 600,000 + ExitV alue
1.48
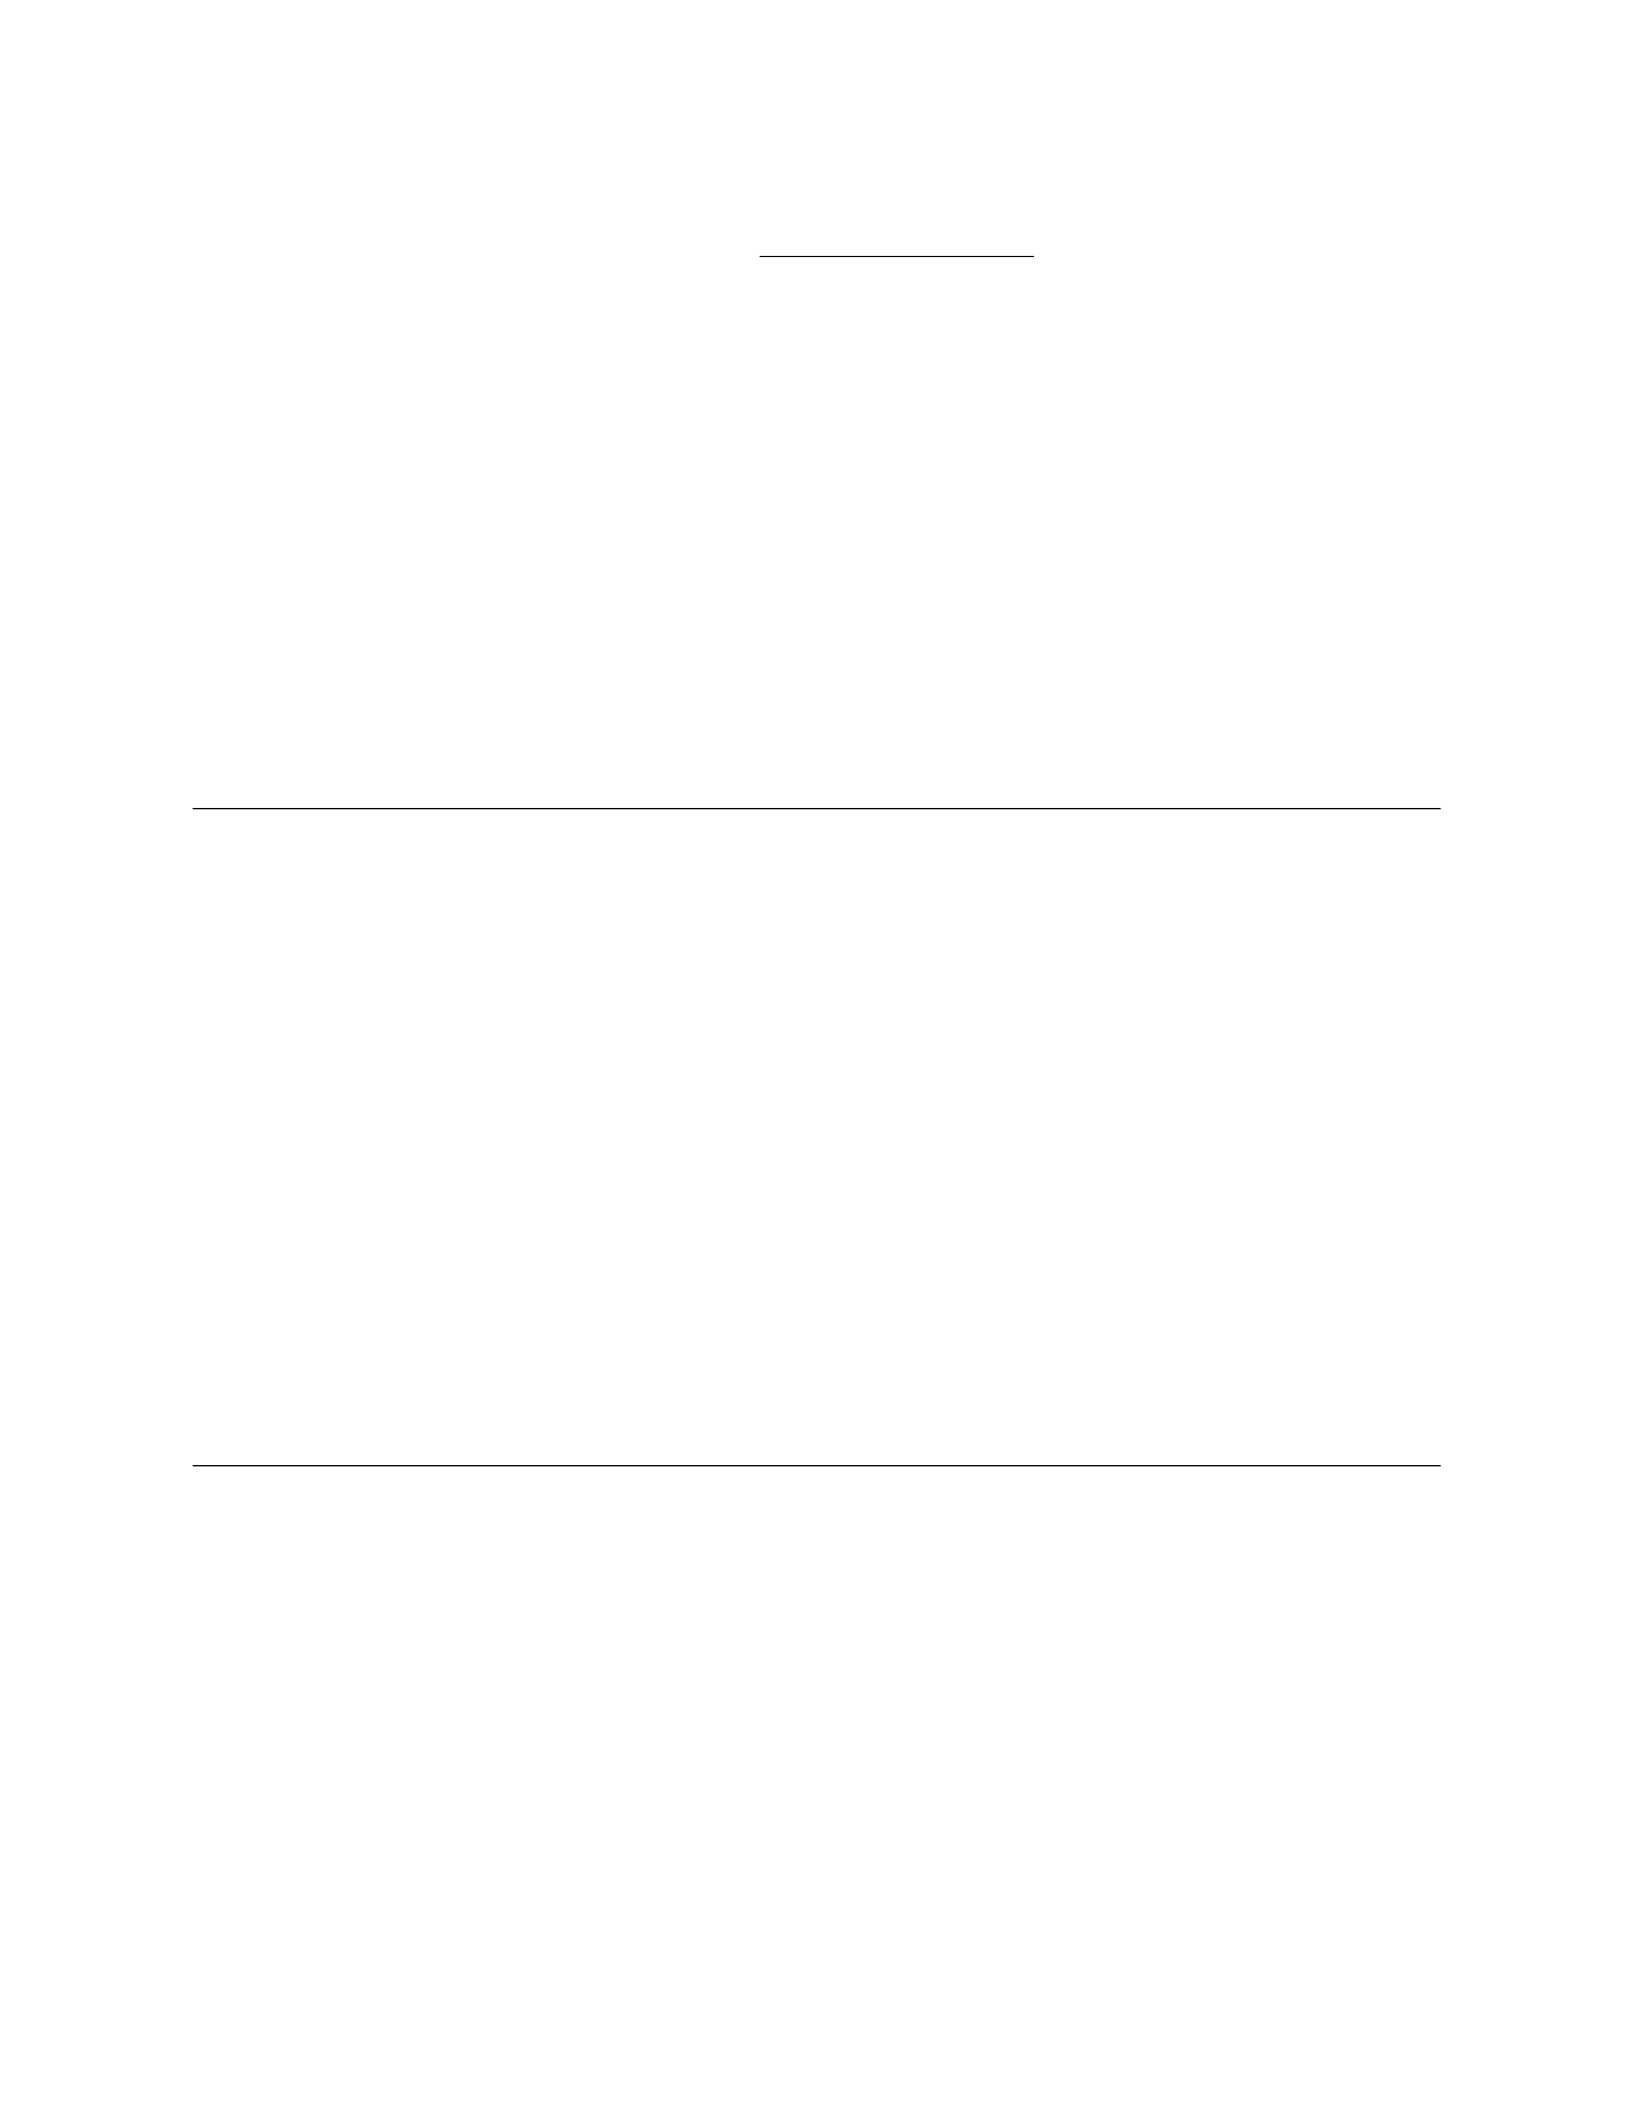
80,555.55 = 600,000 + ExitV alue
1.48
119,200 ≈600,000 + ExitV alue
ExitV alue ≈119,200 −600,000
ExitV alue ≈ −480,800
Therefore, the exit value required at the end of Year 5 to achieve the target return for the investor
is approximately $480,800 *negative value indicates a loss*.
I.
8 9. REGULATORY COMPLIANCE IN VENTURE CAPITAL AND PRIVATE EQUITY
Problem 9. A Venture Capital firm is considering investing in a startup. The firm’s management
fee is 2% of committed capital, and they charge a 20% carried interest (profit share) on returns
exceeding an 8% preferred return hurdle rate. If the firm raises a fund of 100 million from limited
partners and invests 80
Solution 9.
a) The management fee can be calculated as 2% of the committed capital. Therefore, manage-
ment fee = 0.02 ×100 million = 2 million.
b) The profit share or carried interest is calculated on the returns exceeding the preferred return
hurdle rate. The total profits from the startup investment are 80
Therefore, the profit share = 20
Therefore, the carried interest payable by the startup is 14.4million.
Thus, the management fee payable by the startup is 2million and the carried interest payable
is 14.4million.
I.
9 10. COMPETITION FOR QUALITY DEALS IN THE VENTURE CAPITAL MARKET
Problem 10. In a competitive venture capital market, investors are evaluating two investment
opportunities. Opportunity A requires an investment of 500,000andisexpectedtoyieldareturnof1,000,000
with a probability of success of 30
a) Calculate the expected value of each investment opportunity.
b) Calculate the expected value of the two opportunities if investors can only choose one of
them.
c) Analyze which investment opportunity seems more attractive based on the expected values
calculated in parts (a) and (b).
Solution 10.
a) The expected value of an investment opportunity is calculated by multiplying the return by
the probability of success.
For Opportunity A: Expected value = 1,000,000 ∗0.30 =300,000
For Opportunity B: Expected value = 1,200,000 ∗0.40 =480,000
b) To calculate the expected value of the two opportunities if investors can only choose one, we
compare the expected values of both opportunities.
Choosing between A and B, Opportunity B has a higher expected value of 480,000comparedtoOpportunityA′s300,000.
c) Based on the expected values calculated in parts (a) and (b), Opportunity B seems more
attractive as it offers a higher expected return on investment compared to Opportunity A.
10 11. MANAGING PORTFOLIO COMPANIES IN PRIVATE EQUITY INVESTMENTS
Problem 11. A private equity firm has invested $5 million in a portfolio company and acquired
a 20% stake. After a successful year, the portfolio company’s valuation has increased by 30%.
a) What is the new valuation of the portfolio company?
b) Calculate the new value of the private equity firm’s stake in the portfolio company.
c) If the private equity firm decides to exit its investment by selling its stake, how much profit
would they make if the exit price per share is 25% higher than the original valuation?
Solution 11.
a) The new valuation of the portfolio company after a 30% increase can be calculated as:
New Valuation =Original Valuation ×(1 + Increase %)
New Valuation = $5,000,000 ×(1 + 0.30)
New Valuation = $5,000,000 ×1.30
New Valuation = $6,500,000
Therefore, the new valuation of the portfolio company is $6,500,000.
b) The new value of the private equity firm’s stake in the portfolio company can be calculated
as:
New Value of Stake =New Valuation ×Stake %
New Value of Stake = $6,500,000 ×0.20
New Value of Stake = $1,300,000
Therefore, the new value of the private equity firm’s stake in the portfolio company is $1,300,000.
c) If the exit price per share is 25% higher than the original valuation, then the exit price per
share would be:
Exit Price Per Share =Original Valuation ×(1 + 0.25)
Exit Price Per Share = $5,000,000 ×1.25
Exit Price Per Share = $6,250,000
The profit the private equity firm would make upon exit can be calculated as:
Profit =Exit Price Per Share ×Stake % −Investment
Profit = $6,250,000 ×0.20 −$5,000,000
Profit = $1,250,000 −$5,000,000
Profit = $250,000
Therefore, if the private equity firm exits its investment at an exit price 25% higher than the
original valuation, they would make a profit of $250,000.
11 Venture Capital and Private Equity
Problem: You are a venture capitalist considering investing in a startup. The startup has
projected cash flows for the next 5 years as follows:
Year 1: $100,000 Year 2: $150,000 Year 3: $200,000 Year 4: $250,000 Year 5: $300,000
If the discount rate is 10%, calculate the present value of these cash flows.
Solution: To calculate the present value of the cash flows, we need to discount each cash flow
using the formula:
P V =CF
(1 + r)t
where: P V = Present Value CF = Cash Flow in that year r= Discount Rate t= Time period in
years
Let’s compute the present value of each cash flow and sum them up:
a) For Year 1:
P V1=100,000
(1 + 0.10)1=100,000
1.10 = $90,909
b) For Year 2:
P V2=150,000
(1 + 0.10)2=150,000
1.21 = $123,966
c) For Year 3:
P V3=200,000
(1 + 0.10)3=200,000
1.331 = $150,289
d) For Year 4:
P V4=250,000
(1 + 0.10)4=250,000
1.4641 = $170,866
e) For Year 5:
P V5=300,000
(1 + 0.10)5=300,000
1.6105 = $186,410
Now, summing up all the present values:
P V = $90,909 + $123,966 + $150,289 + $170,866 + $186,410 = $722,440
Therefore, the present value of the cash flows is $722,440.
12 13. THE ROLE OF TECHNOLOGY IN DISRUPTING VENTURE CAPITAL AND PRIVATE
EQUITY
Problem 13. A venture capital firm invests $1,000,000 in a startup with a promised return of
25% annually over 5 years. However, after the first year, the startup faces challenges and the return
drops to −10% annually for the remaining 4 years. Calculate the net present value (NPV) of the
investment if the discount rate is 15%.
Solution 13. a) To calculate the NPV of the investment, we need to find the present value of
the expected cash flows from the investment.
The initial investment is $1,000,000.
After the first year, the return is 25%, so the cash flow at the end of year 1 will be: $1,000,000 ×
1.25 = $1,250,000
For the remaining 4 years, the return is −10% annually. The cash flows for years 2 to 5 are
calculated as follows:
Year 2: $1,250,000 ×0.90 = $1,125,000 Year 3: $1,125,000 ×0.90 = $1,012,500 Year 4:
$1,012,500 ×0.90 = $911,250 Year 5: $911,250 ×0.90 = $820,125
b) Now, we calculate the present value of these cash flows using the discount rate of 15%.
The present value (PV) of each cash flow is calculated using the formula: P V =CF
(1+r)n, where
CF is the cash flow, ris the discount rate, and nis the period.
PV of Year 1 cash flow: ($1,250,000)
(1+0.15)1= $1,086,957.61
PV of Year 2-5 cash flows: ($1,125,000)
(1+0.15)2= $873,573.64 ($1,012,500)
(1+0.15)3= $718,331.05 ($911,250)
(1+0.15)4=
$566,638.49 ($820,125)
(1+0.15)5= $453,157.44
c) Finally, we calculate the NPV by summing up the present values of the cash flows and sub-
tracting the initial investment.
NP V =P VY ear1+P VY ear2+P VY ear3+P VY ear4+P VY ear5−$1,000,000 NP V = $1,086,957.61+
$873,573.64 + $718,331.05 + $566,638.49 + $453,157.44 −$1,000,000 NP V = $1,698,658.23 −
$1,000,000 NP V = $698,658.23
Therefore, the net present value (NPV) of the investment is $698,658.23.
13 Venture Capital and Private Equity
Problem 1.
A venture capital firm is considering investing $1,000,000 in a startup. The firm expects the
startup to be valued at $3,000,000 in 3 years if they invest. If the firm requires a return of 25% per
year on their investment, what percentage ownership should they demand in the startup?
Solution 1.
Let xbe the percentage ownership the venture capital firm should demand in the startup.
The present value of the investment should equal the initial investment of $1,000,000. The
future value of the investment in 3 years should be $3,000,000.
Using the concept of Compound Interest formula:
1,000,000 = 3,000,000
(1 + 0.25)3×x
Solving for x, we get:
x=1,000,000
3,000,000/1.952 = 0.6513 = 65.13%
Therefore, the venture capital firm should demand a 65.13% ownership in the startup.
14 15. FUNDRAISING CHALLENGES FOR VENTURE CAPITAL FIRMS
Problem 15. A Venture Capital firm is looking to raise a new fund of 100 million. They plan to
charge a 2% management fee and a 20% carry fee on any profits generated from investments. If
the firm expects to generate 30% returns on investments over the lifetime of the fund, calculate the
total fees earned by the Venture Capital firm over the fund’s lifetime.
Solution 15. a) The total management fee can be calculated as:
Management Fee =Fund Size ×Management Fee Rate = 100 million ×0.02 = 2 million
b) The total carry fee can be calculated as:
Carry Fee =Return ×Carry Fee Rate = (100 million ×0.30) ×0.20 = 6 million
c) Therefore, the total fees earned by the Venture Capital firm over the fund’s lifetime would be:
Total Fees =Management Fee +Carry Fee = 2 million + 6 million = 8 million
15 16. BALANCING RISK AND REWARD IN PRIVATE EQUITY INVESTMENTS
Problem 16. ABC Ventures is considering investing in a startup company. The expected return
on this investment is 15
Solution 16. a) The Sharpe ratio is calculated as follows:
Sharpe ratio =Rp−Rf
σp
Where: - Rpis the expected return on the investment (15- Rfis the risk-free rate (5- σpis the
standard deviation of the investment (20
Substitute the values into the formula:
Sharpe ratio =0.15 −0.05
0.20 =0.10
0.20 = 0.5
Therefore, the Sharpe ratio for this investment is 0.5.
I can definitely help with that. Let’s work on a numerical problem related to Venture Capital and
Private Equity under the given subtopic.
16 17. IMPACT OF ECONOMIC DOWNTURNS ON VENTURE CAPITAL AND PRIVATE EQ-
UITY
Problem 17. During an economic downturn, a venture capital fund decides to invest 100,000inastartupcompanywithanexpectedreturnof30
Solution 17. Let’s first calculate the expected return after 5 years:
Expected return after 5 years = $100,000 ×(1 + 0.30)5
= $100,000 ×(1.30)5
= $100,000 ×2.8561
= $285,610
Now, the actual return turns out to be 10
Actual return after 5 years = $285,610 ×(1 −0.10)
= $285,610 ×0.90
= $257,049
Therefore, the total amount the venture capital fund will receive after 5 years is $257,049.
I’m glad to help with that! Here is a numerical problem related to Venture Capital and Private
Equity:
17 Venture Capital and Private Equity
Problem:
A venture capital firm invests $1,000,000 in a startup with an agreed 20% equity stake. The
startup later gets acquired for $10,000,000. How much profit does the venture capital firm make
from this investment?
Solution:
First, let’s calculate the value of the equity stake acquired by the venture capital firm:
Equity Stake Value =Investment Amount ×Equity Stake (%)
100
Equity Stake Value = $1,000,000 ×20
100 = $200,000
Then, we can find the profit made by the venture capital firm from the acquisition:
Profit =Acquisition Amount −Equity Stake Value −Investment Amount
Profit = $10,000,000 −$200,000 −$1,000,000 = $8,800,000
Therefore, the venture capital firm makes a profit of $8,800,000 from this investment.
I. Problem 1: Investor Equity Stake Calculation
A venture capital firm invests $1 million in a start-up company in exchange for a 20
Solution 1: Let Vbe the pre-money valuation of the company. The equity stake can be calcu-
lated using the formula:
Equity Stake =Investment Amount
Pre-money Valuation +Investment Amount ×100%
Substitute the values given:
20% = 1,000,000
V+ 1,000,000 ×100%
Solving for V:
V+ 1,000,000 = 1,000,000
20%
V+ 1,000,000 = 5,000,000
V= 4,000,000
Therefore, the pre-money valuation of the company is $4 million.
II. Problem 2: Preferred Stock Liquidation Preference
A venture capitalist invests $2 million in a start-up with a 2x liquidation preference. The company
sells for $5 million. How much money does the venture capitalist receive?
Solution 2: The venture capitalist will first receive back the $2 million invested due to the 2x
liquidation preference. The remaining amount will be divided pro-rata among all shareholders.
Since the company sells for $5 million, the remaining $3 million will be distributed among share-
holders based on their ownership percentage. The venture capitalist owns 2
5of the company ($2
million out of the $5 million total investment).
Therefore, the venture capitalist will receive:
$2,000,000 (liquidation preference)+2
5×$3,000,000 (remaining amount) = $2,000,000+$1,200,000 = $3,200,000
The venture capitalist will receive $3.2 million from the sale.
III. Problem 3: Internal Rate of Return (IRR) Calculation
A private equity firm invests $500,000 in a company and receives the following cash flows:
$100,000 in year 1, $200,000 in year 2, and $300,000 in year 3. Calculate the internal rate of
return for this investment.
Solution 3:
The IRR is the discount rate that makes the net present value (NPV) of all cash flows equal to
zero. Setting up the equation:
0 = −500,000 + 100,000
(1 + r)1+200,000
(1 + r)2+300,000
(1 + r)3
Using a financial calculator or software, solving the above equation gives r≈19.73%.
Therefore, the internal rate of return for this investment is approximately 19.73
18 20. GENDER AND DIVERSITY ISSUES IN VENTURE CAPITAL AND PRIVATE EQUITY.
Problem 20. In a venture capital firm, the distribution of investment decisions made by the
partners is as follows:
•40% of investment decisions are made by male partners
•30% of investment decisions are made by female partners
•30% of investment decisions are made by partners who identify as non-binary
If there are a total of 50 investment decisions made in a year by the venture capital firm, de-
termine the number of investment decisions made by each group (male, female, and non-binary
partners).
Solution 20. Let’s denote:
•Number of investment decisions made by male partners as x
•Number of investment decisions made by female partners as y

•Number of investment decisions made by non-binary partners as z
From the information given in the problem:
x= 0.40 ×50 = 20 (investment decisions by male partners)
y= 0.30 ×50 = 15 (investment decisions by female partners)
z= 0.30 ×50 = 15 (investment decisions by non-binary partners)
Therefore, the number of investment decisions made by each group are as follows:
•Male partners: 20 investment decisions
•Female partners: 15 investment decisions
•Non-binary partners: 15 investment decisions
For Startup A: Expected return = (0.3 * $1,000,000) - (0.7 * $200,000) = $300,000 - $140,000
= $160,000
For Startup B: Expected return = (0.5 * $800,000) - (0.5 * $150,000) = $400,000 - $75,000 =
$325,000
b) Based on expected return alone, Startup B has a higher expected return of $325,000 com-
pared to Startup A’s expected return of $160,000. Therefore, if you were to choose based on
expected return alone, you would choose to invest in Startup B.
Certainly! Here is a numerical problem on Venture Capital and Private Equity for you:
3 3. INVESTOR DIVERSIFICATION IN PRIVATE EQUITY
Problem 3. A venture capital investor has a portfolio of investments in three startups, with the
following initial amounts invested and expected returns:
Startup A: Investment of $100,000 with an expected return of $150,000 Startup B: Investment of
$200,000 with an expected return of $250,000 Startup C: Investment of $150,000 with an expected
return of $180,000
Assuming all three investments are uncorrelated, calculate the total expected return, standard
deviation, and coefficient of variation for the investor’s portfolio.
Solution 3.
a) To find the total expected return, we simply sum up the expected returns of each individual
investment:
Total Expected Return = $150,000 + $250,000 + $180,000 = $580,000
b) Next, to calculate the standard deviation of the portfolio, we need to find the variance of the
portfolio first. Since the investments are uncorrelated, we can use the following formula for the
variance of a portfolio of two assets:
Variance of Portfolio = w2
A∗V ar(A) + w2
B∗V ar(B) + w2
C∗V ar(C)
Where: wA, wB, wC=weightsofinvestmentsA, B, Cintheportfolio(sumofweights = 1)V ar(A), V ar(B), V ar(C) =
varianceofinvestmentsA, B, C
Given the investments are uncorrelated, the variance of each investment is equal to its expected
return:
Var(A) = $150,000 Var(B) = $250,000 Var(C) = $180,000
Let’s calculate the variance: Variance of Portfolio = (100,000/450,000)2∗150,000+(200,000/450,000)2∗
250,000 + (150,000/450,000)2∗180,000
Variance of Portfolio = 83,333.33
Then, the standard deviation is the square root of the variance:
Standard Deviation = √83,333.33 ≈$288.67
c) Finally, the coefficient of variation (CV) is calculated by dividing the standard deviation by the
expected return:
Coefficient of Variation = $288.67 / $580,000 Coefficient of Variation 0.0004986, or approxi-
mately 0.04986
I. Problem: Due Diligence in Venture Capital
A venture capital firm is considering investing $500,000 in a startup company. During the due
diligence process, they discover that the company’s financial projections are as follows:
- Year 1: Revenue of $200,000, Expenses of $150,000 - Year 2: Revenue growth of 20%,
Expenses growth of 10%
Calculate the Net Income for each year and determine the company’s Net Income Margin in
Year 2.
Solution:
a) Net Income for Year 1:
Net Income = Revenue - Expenses
Net Income = $200,000 −$150,000 = $50,000
b) Net Income for Year 2:
Revenue in Year 2 = $200,000 ×1.20 = $240,000
Expenses in Year 2 = $150,000 ×1.10 = $165,000
Net Income = Revenue - Expenses
Net Income = $240,000 −$165,000 = $75,000
c) Net Income Margin in Year 2:
Net Income Margin = NetIncome
Revenue ×100
Net Income Margin = $75,000
$240,000 ×100
Net Income Margin = 75
240 ×100 = 31.25%
Therefore, the company’s Net Income Margin in Year 2 is 31.25%.
4 5. LACK OF TRANSPARENCY IN PRIVATE EQUITY INVESTMENTS
Problem 5. A Venture Capital firm invested 500,000 in a startup in exchange for 20% equity
ownership. After a few years, the startup gets acquired for 5times its initial valuation. If the firm
decides to exit their investment, what is the total cash they receive from the acquisition?
Solution 5. Let’s first calculate the initial valuation of the startup when the Venture Capital firm
invested:
Initial Valuation = Investment Amount
Equity Ownership =500,000
0.20 = 2,500,000
After the acquisition, the startup is acquired for 5times its initial valuation:
Acquisition Price = 5×Initial Valuation = 5 ×2,500,000 = 12,500,000
Since the Venture Capital firm owns 20% equity in the startup, their cash from the acquisition
would be:
Cash from Acquisition = Equity Ownership ×Acquisition Price = 0.20 ×12,500,000 =2,500,000
Therefore, the Venture Capital firm would receive 2,500,000 in cash from the acquisition of the
startup.
I.
5 6. VALUATION DIFFICULTIES IN EARLY-STAGE STARTUPS
Problem 6. You are a venture capitalist looking to invest in a promising early-stage startup.
The startup is seeking $500,000 in funding in exchange for a 20
a) What is the pre-money valuation of the startup based on the given information?
b) If you decide to invest the requested amount, how many shares will you receive?
c) What is the price per share you will pay for this investment?
Solution 6.
a) The pre-money valuation of the startup can be calculated as follows:
Pre-money valuation =Post-money valuation −Amount of funding
Pre-money valuation = $2.5M−$500K= $2M
b) To calculate the number of shares you will receive, we first need to find the value of each
share. The value of each share can be calculated as:
Post-money valuation =Pre-money valuation ×(1 + Equity stake)
$2.5M= $2M×(1 + 0.20)
$2.5M= $2M×1.20
$2.5M= $2.4M
Now, the value per share is $2.4 million. Therefore, the number of shares you will receive is:
Amount of funding
Value per share =$500K
$2.4M=500
2400 =5
24
c) The price per share you will pay for this investment is the same as the value per share, which
is $2.4 million.
6 7. THE IMPACT OF INDUSTRY TRENDS ON VENTURE CAPITAL FUNDING
Problem 7. The venture capital firm XYZ is considering investing in two different industries:
Tech and Biotech. The expected return on investment (ROI) for Tech is 20% with a standard
deviation of 5%, while the expected ROI for Biotech is 15% with a standard deviation of 8%. The
correlation between the two industries is 0.4. If XYZ invests $1 million in Tech and $2 million in
Biotech, calculate the expected ROI of the portfolio and the standard deviation of the portfolio’s
ROI.
Solution 7. Let Xbe the ROI in Tech and Ybe the ROI in Biotech. The expected ROI of a
portfolio is given by the weighted average of the expected ROIs of the individual investments:
E(Rp) = w1E(R1) + w2E(R2)
where w1and w2are the weights of the investments and E(R1)and E(R2)are the expected ROIs
of Tech and Biotech, respectively.
Given: - E(R1) = 20%,E(R2) = 15% -w1= $1,000,000/$3,000,000 = 1
3,w2= $2,000,000/$3,000,000 =
2
3
E(Rp) = 1
3(20%) + 2
3(15%) = 18.33%
The variance of the portfolio is calculated as:
V ar(Rp) = w2
1V ar(R1) + w2
2V ar(R2)+2w1w2Cov(R1, R2)
where V ar(R1)and V ar(R2)are the variances of the individual investments and Cov(R1, R2)is
the covariance between the investments.
Given: - V ar(R1) = (0.05)2,V ar(R2) = (0.08)2,Cov(R1, R2)=0.4(0.05)(0.08)
V ar(Rp) = 1
32
(0.05)2+2
32
(0.08)2+ 2 1
32
3(0.4(0.05)(0.08))
V ar(Rp)≈0.00042833
Therefore, the standard deviation of the portfolio’s ROI is:
σ=qV ar(Rp)≈√0.00042833 ≈0.0207 = 2.07%
Hence, the expected ROI of the portfolio is approximately 18.33%, and the standard deviation
of the portfolio’s ROI is approximately 2.07%.
7 8. INVESTOR EXIT STRATEGIES IN PRIVATE EQUITY DEALS
Problem 8.
A private equity investor invested $1 million in a startup company with the following projected
cash flows over the next five years:
Year 1: $200,000 Year 2: $300,000 Year 3: $400,000 Year 4: $500,000 Year 5: $600,000
Assuming a desired Internal Rate of Return (IRR) of 20% per annum, calculate the exit value
required at the end of Year 5 to achieve the target return for the investor.
Solution 8.
To calculate the exit value required at the end of Year 5, we need to find the Present Value (PV)
of the cash flows and then determine the exit value that would give an IRR of 20%.
The PV of the cash flows can be calculated using the formula:
P V =CF1
(1 + r)1+CF2
(1 + r)2+CF3
(1 + r)3+CF4
(1 + r)4+CF5+ExitV alue
(1 + r)5
Where: CFi= Cash flow at the end of Year i r = 0.20 (IRR) ExitV alue = Exit value at the end
of Year 5
Substitute the given values into the formula:
P V =200,000
(1 + 0.20)1+300,000
(1 + 0.20)2+400,000
(1 + 0.20)3+500,000
(1 + 0.20)4+600,000 + ExitV alue
(1 + 0.20)5
P V =200,000
1.20 +300,000
1.202+400,000
1.203+500,000
1.204+600,000 + ExitV alue
1.205
P V ≈166,666.67 + 225,000 + 250,000 + 277,777.78 + 600,000 + ExitV alue
1.48
P V ≈919,444.45 + 600,000 + ExitV alue
1.48
Since the total initial investment is $1,000,000 at the start, the exit value at the end of Year 5
should be such that the total PV equals the total initial investment:
1,000,000 = 919,444.45 + 600,000 + ExitV alue
1.48
1,000,000 −919,444.45 = 600,000 + ExitV alue
1.48
80,555.55 = 600,000 + ExitV alue
1.48
119,200 ≈600,000 + ExitV alue
ExitV alue ≈119,200 −600,000
ExitV alue ≈ −480,800
Therefore, the exit value required at the end of Year 5 to achieve the target return for the investor
is approximately $480,800 *negative value indicates a loss*.
I.
8 9. REGULATORY COMPLIANCE IN VENTURE CAPITAL AND PRIVATE EQUITY
Problem 9. A Venture Capital firm is considering investing in a startup. The firm’s management
fee is 2% of committed capital, and they charge a 20% carried interest (profit share) on returns
exceeding an 8% preferred return hurdle rate. If the firm raises a fund of 100 million from limited
partners and invests 80
Solution 9.
a) The management fee can be calculated as 2% of the committed capital. Therefore, manage-
ment fee = 0.02 ×100 million = 2 million.
b) The profit share or carried interest is calculated on the returns exceeding the preferred return
hurdle rate. The total profits from the startup investment are 80
Therefore, the profit share = 20
Therefore, the carried interest payable by the startup is 14.4million.
Thus, the management fee payable by the startup is 2million and the carried interest payable
is 14.4million.
I.
9 10. COMPETITION FOR QUALITY DEALS IN THE VENTURE CAPITAL MARKET
Problem 10. In a competitive venture capital market, investors are evaluating two investment
opportunities. Opportunity A requires an investment of 500,000andisexpectedtoyieldareturnof1,000,000
with a probability of success of 30
a) Calculate the expected value of each investment opportunity.
b) Calculate the expected value of the two opportunities if investors can only choose one of
them.
c) Analyze which investment opportunity seems more attractive based on the expected values
calculated in parts (a) and (b).
Solution 10.
a) The expected value of an investment opportunity is calculated by multiplying the return by
the probability of success.
For Opportunity A: Expected value = 1,000,000 ∗0.30 =300,000
For Opportunity B: Expected value = 1,200,000 ∗0.40 =480,000
b) To calculate the expected value of the two opportunities if investors can only choose one, we
compare the expected values of both opportunities.
Choosing between A and B, Opportunity B has a higher expected value of 480,000comparedtoOpportunityA′s300,000.
c) Based on the expected values calculated in parts (a) and (b), Opportunity B seems more
attractive as it offers a higher expected return on investment compared to Opportunity A.
10 11. MANAGING PORTFOLIO COMPANIES IN PRIVATE EQUITY INVESTMENTS
Problem 11. A private equity firm has invested $5 million in a portfolio company and acquired
a 20% stake. After a successful year, the portfolio company’s valuation has increased by 30%.
a) What is the new valuation of the portfolio company?
b) Calculate the new value of the private equity firm’s stake in the portfolio company.
c) If the private equity firm decides to exit its investment by selling its stake, how much profit
would they make if the exit price per share is 25% higher than the original valuation?
Solution 11.
a) The new valuation of the portfolio company after a 30% increase can be calculated as:
New Valuation =Original Valuation ×(1 + Increase %)
New Valuation = $5,000,000 ×(1 + 0.30)
New Valuation = $5,000,000 ×1.30
New Valuation = $6,500,000
Therefore, the new valuation of the portfolio company is $6,500,000.
b) The new value of the private equity firm’s stake in the portfolio company can be calculated
as:
New Value of Stake =New Valuation ×Stake %
New Value of Stake = $6,500,000 ×0.20
New Value of Stake = $1,300,000
Therefore, the new value of the private equity firm’s stake in the portfolio company is $1,300,000.
c) If the exit price per share is 25% higher than the original valuation, then the exit price per
share would be:
Exit Price Per Share =Original Valuation ×(1 + 0.25)
Exit Price Per Share = $5,000,000 ×1.25
Exit Price Per Share = $6,250,000
The profit the private equity firm would make upon exit can be calculated as:
Profit =Exit Price Per Share ×Stake % −Investment
Profit = $6,250,000 ×0.20 −$5,000,000
Profit = $1,250,000 −$5,000,000
Profit = $250,000
Therefore, if the private equity firm exits its investment at an exit price 25% higher than the
original valuation, they would make a profit of $250,000.
11 Venture Capital and Private Equity
Problem: You are a venture capitalist considering investing in a startup. The startup has
projected cash flows for the next 5 years as follows:
Year 1: $100,000 Year 2: $150,000 Year 3: $200,000 Year 4: $250,000 Year 5: $300,000
If the discount rate is 10%, calculate the present value of these cash flows.
Solution: To calculate the present value of the cash flows, we need to discount each cash flow
using the formula:
P V =CF
(1 + r)t
where: P V = Present Value CF = Cash Flow in that year r= Discount Rate t= Time period in
years
Let’s compute the present value of each cash flow and sum them up:
a) For Year 1:
P V1=100,000
(1 + 0.10)1=100,000
1.10 = $90,909
b) For Year 2:
P V2=150,000
(1 + 0.10)2=150,000
1.21 = $123,966
c) For Year 3:
P V3=200,000
(1 + 0.10)3=200,000
1.331 = $150,289
d) For Year 4:
P V4=250,000
(1 + 0.10)4=250,000
1.4641 = $170,866
e) For Year 5:
P V5=300,000
(1 + 0.10)5=300,000
1.6105 = $186,410
Now, summing up all the present values:
P V = $90,909 + $123,966 + $150,289 + $170,866 + $186,410 = $722,440
Therefore, the present value of the cash flows is $722,440.
12 13. THE ROLE OF TECHNOLOGY IN DISRUPTING VENTURE CAPITAL AND PRIVATE
EQUITY
Problem 13. A venture capital firm invests $1,000,000 in a startup with a promised return of
25% annually over 5 years. However, after the first year, the startup faces challenges and the return
drops to −10% annually for the remaining 4 years. Calculate the net present value (NPV) of the
investment if the discount rate is 15%.
Solution 13. a) To calculate the NPV of the investment, we need to find the present value of
the expected cash flows from the investment.
The initial investment is $1,000,000.
After the first year, the return is 25%, so the cash flow at the end of year 1 will be: $1,000,000 ×
1.25 = $1,250,000
For the remaining 4 years, the return is −10% annually. The cash flows for years 2 to 5 are
calculated as follows:
Year 2: $1,250,000 ×0.90 = $1,125,000 Year 3: $1,125,000 ×0.90 = $1,012,500 Year 4:
$1,012,500 ×0.90 = $911,250 Year 5: $911,250 ×0.90 = $820,125
b) Now, we calculate the present value of these cash flows using the discount rate of 15%.
The present value (PV) of each cash flow is calculated using the formula: P V =CF
(1+r)n, where
CF is the cash flow, ris the discount rate, and nis the period.
PV of Year 1 cash flow: ($1,250,000)
(1+0.15)1= $1,086,957.61
PV of Year 2-5 cash flows: ($1,125,000)
(1+0.15)2= $873,573.64 ($1,012,500)
(1+0.15)3= $718,331.05 ($911,250)
(1+0.15)4=
$566,638.49 ($820,125)
(1+0.15)5= $453,157.44
c) Finally, we calculate the NPV by summing up the present values of the cash flows and sub-
tracting the initial investment.
NP V =P VY ear1+P VY ear2+P VY ear3+P VY ear4+P VY ear5−$1,000,000 NP V = $1,086,957.61+
$873,573.64 + $718,331.05 + $566,638.49 + $453,157.44 −$1,000,000 NP V = $1,698,658.23 −
$1,000,000 NP V = $698,658.23
Therefore, the net present value (NPV) of the investment is $698,658.23.
13 Venture Capital and Private Equity
Problem 1.
A venture capital firm is considering investing $1,000,000 in a startup. The firm expects the
startup to be valued at $3,000,000 in 3 years if they invest. If the firm requires a return of 25% per
year on their investment, what percentage ownership should they demand in the startup?
Solution 1.
Let xbe the percentage ownership the venture capital firm should demand in the startup.
The present value of the investment should equal the initial investment of $1,000,000. The
future value of the investment in 3 years should be $3,000,000.
Using the concept of Compound Interest formula:
1,000,000 = 3,000,000
(1 + 0.25)3×x
Solving for x, we get:
x=1,000,000
3,000,000/1.952 = 0.6513 = 65.13%
Therefore, the venture capital firm should demand a 65.13% ownership in the startup.
14 15. FUNDRAISING CHALLENGES FOR VENTURE CAPITAL FIRMS
Problem 15. A Venture Capital firm is looking to raise a new fund of 100 million. They plan to
charge a 2% management fee and a 20% carry fee on any profits generated from investments. If
the firm expects to generate 30% returns on investments over the lifetime of the fund, calculate the
total fees earned by the Venture Capital firm over the fund’s lifetime.
Solution 15. a) The total management fee can be calculated as:
Management Fee =Fund Size ×Management Fee Rate = 100 million ×0.02 = 2 million
b) The total carry fee can be calculated as:
Carry Fee =Return ×Carry Fee Rate = (100 million ×0.30) ×0.20 = 6 million
c) Therefore, the total fees earned by the Venture Capital firm over the fund’s lifetime would be:
Total Fees =Management Fee +Carry Fee = 2 million + 6 million = 8 million
15 16. BALANCING RISK AND REWARD IN PRIVATE EQUITY INVESTMENTS
Problem 16. ABC Ventures is considering investing in a startup company. The expected return
on this investment is 15
Solution 16. a) The Sharpe ratio is calculated as follows:
Sharpe ratio =Rp−Rf
σp
Where: - Rpis the expected return on the investment (15- Rfis the risk-free rate (5- σpis the
standard deviation of the investment (20
Substitute the values into the formula:
Sharpe ratio =0.15 −0.05
0.20 =0.10
0.20 = 0.5
Therefore, the Sharpe ratio for this investment is 0.5.
I can definitely help with that. Let’s work on a numerical problem related to Venture Capital and
Private Equity under the given subtopic.
16 17. IMPACT OF ECONOMIC DOWNTURNS ON VENTURE CAPITAL AND PRIVATE EQ-
UITY
Problem 17. During an economic downturn, a venture capital fund decides to invest 100,000inastartupcompanywithanexpectedreturnof30
Solution 17. Let’s first calculate the expected return after 5 years:
Expected return after 5 years = $100,000 ×(1 + 0.30)5
= $100,000 ×(1.30)5
= $100,000 ×2.8561
= $285,610
Now, the actual return turns out to be 10
Actual return after 5 years = $285,610 ×(1 −0.10)
= $285,610 ×0.90
= $257,049
Therefore, the total amount the venture capital fund will receive after 5 years is $257,049.
I’m glad to help with that! Here is a numerical problem related to Venture Capital and Private
Equity:
17 Venture Capital and Private Equity
Problem:
A venture capital firm invests $1,000,000 in a startup with an agreed 20% equity stake. The
startup later gets acquired for $10,000,000. How much profit does the venture capital firm make
from this investment?
Solution:
First, let’s calculate the value of the equity stake acquired by the venture capital firm:
Equity Stake Value =Investment Amount ×Equity Stake (%)
100
Equity Stake Value = $1,000,000 ×20
100 = $200,000
Then, we can find the profit made by the venture capital firm from the acquisition:
Profit =Acquisition Amount −Equity Stake Value −Investment Amount
Profit = $10,000,000 −$200,000 −$1,000,000 = $8,800,000
Therefore, the venture capital firm makes a profit of $8,800,000 from this investment.
I. Problem 1: Investor Equity Stake Calculation
A venture capital firm invests $1 million in a start-up company in exchange for a 20
Solution 1: Let Vbe the pre-money valuation of the company. The equity stake can be calcu-
lated using the formula:
Equity Stake =Investment Amount
Pre-money Valuation +Investment Amount ×100%
Substitute the values given:
20% = 1,000,000
V+ 1,000,000 ×100%
Solving for V:
V+ 1,000,000 = 1,000,000
20%
V+ 1,000,000 = 5,000,000
V= 4,000,000
Therefore, the pre-money valuation of the company is $4 million.
II. Problem 2: Preferred Stock Liquidation Preference
A venture capitalist invests $2 million in a start-up with a 2x liquidation preference. The company
sells for $5 million. How much money does the venture capitalist receive?
Solution 2: The venture capitalist will first receive back the $2 million invested due to the 2x
liquidation preference. The remaining amount will be divided pro-rata among all shareholders.
Since the company sells for $5 million, the remaining $3 million will be distributed among share-
holders based on their ownership percentage. The venture capitalist owns 2
5of the company ($2
million out of the $5 million total investment).
Therefore, the venture capitalist will receive:
$2,000,000 (liquidation preference)+2
5×$3,000,000 (remaining amount) = $2,000,000+$1,200,000 = $3,200,000
The venture capitalist will receive $3.2 million from the sale.
III. Problem 3: Internal Rate of Return (IRR) Calculation
A private equity firm invests $500,000 in a company and receives the following cash flows:
$100,000 in year 1, $200,000 in year 2, and $300,000 in year 3. Calculate the internal rate of
return for this investment.
Solution 3:
The IRR is the discount rate that makes the net present value (NPV) of all cash flows equal to
zero. Setting up the equation:
0 = −500,000 + 100,000
(1 + r)1+200,000
(1 + r)2+300,000
(1 + r)3
Using a financial calculator or software, solving the above equation gives r≈19.73%.
Therefore, the internal rate of return for this investment is approximately 19.73
18 20. GENDER AND DIVERSITY ISSUES IN VENTURE CAPITAL AND PRIVATE EQUITY.
Problem 20. In a venture capital firm, the distribution of investment decisions made by the
partners is as follows:
•40% of investment decisions are made by male partners
•30% of investment decisions are made by female partners
•30% of investment decisions are made by partners who identify as non-binary
If there are a total of 50 investment decisions made in a year by the venture capital firm, de-
termine the number of investment decisions made by each group (male, female, and non-binary
partners).
Solution 20. Let’s denote:
•Number of investment decisions made by male partners as x
•Number of investment decisions made by female partners as y

•Number of investment decisions made by non-binary partners as z
From the information given in the problem:
x= 0.40 ×50 = 20 (investment decisions by male partners)
y= 0.30 ×50 = 15 (investment decisions by female partners)
z= 0.30 ×50 = 15 (investment decisions by non-binary partners)
Therefore, the number of investment decisions made by each group are as follows:
•Male partners: 20 investment decisions
•Female partners: 15 investment decisions
•Non-binary partners: 15 investment decisions
For Startup A: Expected return = (0.3 * $1,000,000) - (0.7 * $200,000) = $300,000 - $140,000
= $160,000
For Startup B: Expected return = (0.5 * $800,000) - (0.5 * $150,000) = $400,000 - $75,000 =
$325,000
b) Based on expected return alone, Startup B has a higher expected return of $325,000 com-
pared to Startup A’s expected return of $160,000. Therefore, if you were to choose based on
expected return alone, you would choose to invest in Startup B.
Certainly! Here is a numerical problem on Venture Capital and Private Equity for you:
3 3. INVESTOR DIVERSIFICATION IN PRIVATE EQUITY
Problem 3. A venture capital investor has a portfolio of investments in three startups, with the
following initial amounts invested and expected returns:
Startup A: Investment of $100,000 with an expected return of $150,000 Startup B: Investment of
$200,000 with an expected return of $250,000 Startup C: Investment of $150,000 with an expected
return of $180,000
Assuming all three investments are uncorrelated, calculate the total expected return, standard
deviation, and coefficient of variation for the investor’s portfolio.
Solution 3.
a) To find the total expected return, we simply sum up the expected returns of each individual
investment:
Total Expected Return = $150,000 + $250,000 + $180,000 = $580,000
b) Next, to calculate the standard deviation of the portfolio, we need to find the variance of the
portfolio first. Since the investments are uncorrelated, we can use the following formula for the
variance of a portfolio of two assets:
Variance of Portfolio = w2
A∗V ar(A) + w2
B∗V ar(B) + w2
C∗V ar(C)
Where: wA, wB, wC=weightsofinvestmentsA, B, Cintheportfolio(sumofweights = 1)V ar(A), V ar(B), V ar(C) =
varianceofinvestmentsA, B, C
Given the investments are uncorrelated, the variance of each investment is equal to its expected
return:
Var(A) = $150,000 Var(B) = $250,000 Var(C) = $180,000
Let’s calculate the variance: Variance of Portfolio = (100,000/450,000)2∗150,000+(200,000/450,000)2∗
250,000 + (150,000/450,000)2∗180,000
Variance of Portfolio = 83,333.33
Then, the standard deviation is the square root of the variance:
Standard Deviation = √83,333.33 ≈$288.67
c) Finally, the coefficient of variation (CV) is calculated by dividing the standard deviation by the
expected return:
Coefficient of Variation = $288.67 / $580,000 Coefficient of Variation 0.0004986, or approxi-
mately 0.04986
I. Problem: Due Diligence in Venture Capital
A venture capital firm is considering investing $500,000 in a startup company. During the due
diligence process, they discover that the company’s financial projections are as follows:
- Year 1: Revenue of $200,000, Expenses of $150,000 - Year 2: Revenue growth of 20%,
Expenses growth of 10%
Calculate the Net Income for each year and determine the company’s Net Income Margin in
Year 2.
Solution:
a) Net Income for Year 1:
Net Income = Revenue - Expenses
Net Income = $200,000 −$150,000 = $50,000
b) Net Income for Year 2:
Revenue in Year 2 = $200,000 ×1.20 = $240,000
Expenses in Year 2 = $150,000 ×1.10 = $165,000
Net Income = Revenue - Expenses
Net Income = $240,000 −$165,000 = $75,000
c) Net Income Margin in Year 2:
Net Income Margin = NetIncome
Revenue ×100
Net Income Margin = $75,000
$240,000 ×100
Net Income Margin = 75
240 ×100 = 31.25%
Therefore, the company’s Net Income Margin in Year 2 is 31.25%.
4 5. LACK OF TRANSPARENCY IN PRIVATE EQUITY INVESTMENTS
Problem 5. A Venture Capital firm invested 500,000 in a startup in exchange for 20% equity
ownership. After a few years, the startup gets acquired for 5times its initial valuation. If the firm
decides to exit their investment, what is the total cash they receive from the acquisition?
Solution 5. Let’s first calculate the initial valuation of the startup when the Venture Capital firm
invested:
Initial Valuation = Investment Amount
Equity Ownership =500,000
0.20 = 2,500,000
After the acquisition, the startup is acquired for 5times its initial valuation:
Acquisition Price = 5×Initial Valuation = 5 ×2,500,000 = 12,500,000
Since the Venture Capital firm owns 20% equity in the startup, their cash from the acquisition
would be:
Cash from Acquisition = Equity Ownership ×Acquisition Price = 0.20 ×12,500,000 =2,500,000
Therefore, the Venture Capital firm would receive 2,500,000 in cash from the acquisition of the
startup.
I.
5 6. VALUATION DIFFICULTIES IN EARLY-STAGE STARTUPS
Problem 6. You are a venture capitalist looking to invest in a promising early-stage startup.
The startup is seeking $500,000 in funding in exchange for a 20
a) What is the pre-money valuation of the startup based on the given information?
b) If you decide to invest the requested amount, how many shares will you receive?
c) What is the price per share you will pay for this investment?
Solution 6.
a) The pre-money valuation of the startup can be calculated as follows:
Pre-money valuation =Post-money valuation −Amount of funding
Pre-money valuation = $2.5M−$500K= $2M
b) To calculate the number of shares you will receive, we first need to find the value of each
share. The value of each share can be calculated as:
Post-money valuation =Pre-money valuation ×(1 + Equity stake)
$2.5M= $2M×(1 + 0.20)
$2.5M= $2M×1.20
$2.5M= $2.4M
Now, the value per share is $2.4 million. Therefore, the number of shares you will receive is:
Amount of funding
Value per share =$500K
$2.4M=500
2400 =5
24
c) The price per share you will pay for this investment is the same as the value per share, which
is $2.4 million.
6 7. THE IMPACT OF INDUSTRY TRENDS ON VENTURE CAPITAL FUNDING
Problem 7. The venture capital firm XYZ is considering investing in two different industries:
Tech and Biotech. The expected return on investment (ROI) for Tech is 20% with a standard
deviation of 5%, while the expected ROI for Biotech is 15% with a standard deviation of 8%. The
correlation between the two industries is 0.4. If XYZ invests $1 million in Tech and $2 million in
Biotech, calculate the expected ROI of the portfolio and the standard deviation of the portfolio’s
ROI.
Solution 7. Let Xbe the ROI in Tech and Ybe the ROI in Biotech. The expected ROI of a
portfolio is given by the weighted average of the expected ROIs of the individual investments:
E(Rp) = w1E(R1) + w2E(R2)
where w1and w2are the weights of the investments and E(R1)and E(R2)are the expected ROIs
of Tech and Biotech, respectively.
Given: - E(R1) = 20%,E(R2) = 15% -w1= $1,000,000/$3,000,000 = 1
3,w2= $2,000,000/$3,000,000 =
2
3
E(Rp) = 1
3(20%) + 2
3(15%) = 18.33%
The variance of the portfolio is calculated as:
V ar(Rp) = w2
1V ar(R1) + w2
2V ar(R2)+2w1w2Cov(R1, R2)
where V ar(R1)and V ar(R2)are the variances of the individual investments and Cov(R1, R2)is
the covariance between the investments.
Given: - V ar(R1) = (0.05)2,V ar(R2) = (0.08)2,Cov(R1, R2)=0.4(0.05)(0.08)
V ar(Rp) = 1
32
(0.05)2+2
32
(0.08)2+ 2 1
32
3(0.4(0.05)(0.08))
V ar(Rp)≈0.00042833
Therefore, the standard deviation of the portfolio’s ROI is:
σ=qV ar(Rp)≈√0.00042833 ≈0.0207 = 2.07%
Hence, the expected ROI of the portfolio is approximately 18.33%, and the standard deviation
of the portfolio’s ROI is approximately 2.07%.
7 8. INVESTOR EXIT STRATEGIES IN PRIVATE EQUITY DEALS
Problem 8.
A private equity investor invested $1 million in a startup company with the following projected
cash flows over the next five years:
Year 1: $200,000 Year 2: $300,000 Year 3: $400,000 Year 4: $500,000 Year 5: $600,000
Assuming a desired Internal Rate of Return (IRR) of 20% per annum, calculate the exit value
required at the end of Year 5 to achieve the target return for the investor.
Solution 8.
To calculate the exit value required at the end of Year 5, we need to find the Present Value (PV)
of the cash flows and then determine the exit value that would give an IRR of 20%.
The PV of the cash flows can be calculated using the formula:
P V =CF1
(1 + r)1+CF2
(1 + r)2+CF3
(1 + r)3+CF4
(1 + r)4+CF5+ExitV alue
(1 + r)5
Where: CFi= Cash flow at the end of Year i r = 0.20 (IRR) ExitV alue = Exit value at the end
of Year 5
Substitute the given values into the formula:
P V =200,000
(1 + 0.20)1+300,000
(1 + 0.20)2+400,000
(1 + 0.20)3+500,000
(1 + 0.20)4+600,000 + ExitV alue
(1 + 0.20)5
P V =200,000
1.20 +300,000
1.202+400,000
1.203+500,000
1.204+600,000 + ExitV alue
1.205
P V ≈166,666.67 + 225,000 + 250,000 + 277,777.78 + 600,000 + ExitV alue
1.48
P V ≈919,444.45 + 600,000 + ExitV alue
1.48
Since the total initial investment is $1,000,000 at the start, the exit value at the end of Year 5
should be such that the total PV equals the total initial investment:
1,000,000 = 919,444.45 + 600,000 + ExitV alue
1.48
1,000,000 −919,444.45 = 600,000 + ExitV alue
1.48
80,555.55 = 600,000 + ExitV alue
1.48
119,200 ≈600,000 + ExitV alue
ExitV alue ≈119,200 −600,000
ExitV alue ≈ −480,800
Therefore, the exit value required at the end of Year 5 to achieve the target return for the investor
is approximately $480,800 *negative value indicates a loss*.
I.
8 9. REGULATORY COMPLIANCE IN VENTURE CAPITAL AND PRIVATE EQUITY
Problem 9. A Venture Capital firm is considering investing in a startup. The firm’s management
fee is 2% of committed capital, and they charge a 20% carried interest (profit share) on returns
exceeding an 8% preferred return hurdle rate. If the firm raises a fund of 100 million from limited
partners and invests 80
Solution 9.
a) The management fee can be calculated as 2% of the committed capital. Therefore, manage-
ment fee = 0.02 ×100 million = 2 million.
b) The profit share or carried interest is calculated on the returns exceeding the preferred return
hurdle rate. The total profits from the startup investment are 80
Therefore, the profit share = 20
Therefore, the carried interest payable by the startup is 14.4million.
Thus, the management fee payable by the startup is 2million and the carried interest payable
is 14.4million.
I.
9 10. COMPETITION FOR QUALITY DEALS IN THE VENTURE CAPITAL MARKET
Problem 10. In a competitive venture capital market, investors are evaluating two investment
opportunities. Opportunity A requires an investment of 500,000andisexpectedtoyieldareturnof1,000,000
with a probability of success of 30
a) Calculate the expected value of each investment opportunity.
b) Calculate the expected value of the two opportunities if investors can only choose one of
them.
c) Analyze which investment opportunity seems more attractive based on the expected values
calculated in parts (a) and (b).
Solution 10.
a) The expected value of an investment opportunity is calculated by multiplying the return by
the probability of success.
For Opportunity A: Expected value = 1,000,000 ∗0.30 =300,000
For Opportunity B: Expected value = 1,200,000 ∗0.40 =480,000
b) To calculate the expected value of the two opportunities if investors can only choose one, we
compare the expected values of both opportunities.
Choosing between A and B, Opportunity B has a higher expected value of 480,000comparedtoOpportunityA′s300,000.
c) Based on the expected values calculated in parts (a) and (b), Opportunity B seems more
attractive as it offers a higher expected return on investment compared to Opportunity A.
10 11. MANAGING PORTFOLIO COMPANIES IN PRIVATE EQUITY INVESTMENTS
Problem 11. A private equity firm has invested $5 million in a portfolio company and acquired
a 20% stake. After a successful year, the portfolio company’s valuation has increased by 30%.
a) What is the new valuation of the portfolio company?
b) Calculate the new value of the private equity firm’s stake in the portfolio company.
c) If the private equity firm decides to exit its investment by selling its stake, how much profit
would they make if the exit price per share is 25% higher than the original valuation?
Solution 11.
a) The new valuation of the portfolio company after a 30% increase can be calculated as:
New Valuation =Original Valuation ×(1 + Increase %)
New Valuation = $5,000,000 ×(1 + 0.30)
New Valuation = $5,000,000 ×1.30
New Valuation = $6,500,000
Therefore, the new valuation of the portfolio company is $6,500,000.
b) The new value of the private equity firm’s stake in the portfolio company can be calculated
as:
New Value of Stake =New Valuation ×Stake %
New Value of Stake = $6,500,000 ×0.20
New Value of Stake = $1,300,000
Therefore, the new value of the private equity firm’s stake in the portfolio company is $1,300,000.
c) If the exit price per share is 25% higher than the original valuation, then the exit price per
share would be:
Exit Price Per Share =Original Valuation ×(1 + 0.25)
Exit Price Per Share = $5,000,000 ×1.25
Exit Price Per Share = $6,250,000
The profit the private equity firm would make upon exit can be calculated as:
Profit =Exit Price Per Share ×Stake % −Investment
Profit = $6,250,000 ×0.20 −$5,000,000
Profit = $1,250,000 −$5,000,000
Profit = $250,000
Therefore, if the private equity firm exits its investment at an exit price 25% higher than the
original valuation, they would make a profit of $250,000.
11 Venture Capital and Private Equity
Problem: You are a venture capitalist considering investing in a startup. The startup has
projected cash flows for the next 5 years as follows:
Year 1: $100,000 Year 2: $150,000 Year 3: $200,000 Year 4: $250,000 Year 5: $300,000
If the discount rate is 10%, calculate the present value of these cash flows.
Solution: To calculate the present value of the cash flows, we need to discount each cash flow
using the formula:
P V =CF
(1 + r)t
where: P V = Present Value CF = Cash Flow in that year r= Discount Rate t= Time period in
years
Let’s compute the present value of each cash flow and sum them up:
a) For Year 1:
P V1=100,000
(1 + 0.10)1=100,000
1.10 = $90,909
b) For Year 2:
P V2=150,000
(1 + 0.10)2=150,000
1.21 = $123,966
c) For Year 3:
P V3=200,000
(1 + 0.10)3=200,000
1.331 = $150,289
d) For Year 4:
P V4=250,000
(1 + 0.10)4=250,000
1.4641 = $170,866
e) For Year 5:
P V5=300,000
(1 + 0.10)5=300,000
1.6105 = $186,410
Now, summing up all the present values:
P V = $90,909 + $123,966 + $150,289 + $170,866 + $186,410 = $722,440
Therefore, the present value of the cash flows is $722,440.
12 13. THE ROLE OF TECHNOLOGY IN DISRUPTING VENTURE CAPITAL AND PRIVATE
EQUITY
Problem 13. A venture capital firm invests $1,000,000 in a startup with a promised return of
25% annually over 5 years. However, after the first year, the startup faces challenges and the return
drops to −10% annually for the remaining 4 years. Calculate the net present value (NPV) of the
investment if the discount rate is 15%.
Solution 13. a) To calculate the NPV of the investment, we need to find the present value of
the expected cash flows from the investment.
The initial investment is $1,000,000.
After the first year, the return is 25%, so the cash flow at the end of year 1 will be: $1,000,000 ×
1.25 = $1,250,000
For the remaining 4 years, the return is −10% annually. The cash flows for years 2 to 5 are
calculated as follows:
Year 2: $1,250,000 ×0.90 = $1,125,000 Year 3: $1,125,000 ×0.90 = $1,012,500 Year 4:
$1,012,500 ×0.90 = $911,250 Year 5: $911,250 ×0.90 = $820,125
b) Now, we calculate the present value of these cash flows using the discount rate of 15%.
The present value (PV) of each cash flow is calculated using the formula: P V =CF
(1+r)n, where
CF is the cash flow, ris the discount rate, and nis the period.
PV of Year 1 cash flow: ($1,250,000)
(1+0.15)1= $1,086,957.61
PV of Year 2-5 cash flows: ($1,125,000)
(1+0.15)2= $873,573.64 ($1,012,500)
(1+0.15)3= $718,331.05 ($911,250)
(1+0.15)4=
$566,638.49 ($820,125)
(1+0.15)5= $453,157.44
c) Finally, we calculate the NPV by summing up the present values of the cash flows and sub-
tracting the initial investment.
NP V =P VY ear1+P VY ear2+P VY ear3+P VY ear4+P VY ear5−$1,000,000 NP V = $1,086,957.61+
$873,573.64 + $718,331.05 + $566,638.49 + $453,157.44 −$1,000,000 NP V = $1,698,658.23 −
$1,000,000 NP V = $698,658.23
Therefore, the net present value (NPV) of the investment is $698,658.23.
13 Venture Capital and Private Equity
Problem 1.
A venture capital firm is considering investing $1,000,000 in a startup. The firm expects the
startup to be valued at $3,000,000 in 3 years if they invest. If the firm requires a return of 25% per
year on their investment, what percentage ownership should they demand in the startup?
Solution 1.
Let xbe the percentage ownership the venture capital firm should demand in the startup.
The present value of the investment should equal the initial investment of $1,000,000. The
future value of the investment in 3 years should be $3,000,000.
Using the concept of Compound Interest formula:
1,000,000 = 3,000,000
(1 + 0.25)3×x
Solving for x, we get:
x=1,000,000
3,000,000/1.952 = 0.6513 = 65.13%
Therefore, the venture capital firm should demand a 65.13% ownership in the startup.
14 15. FUNDRAISING CHALLENGES FOR VENTURE CAPITAL FIRMS
Problem 15. A Venture Capital firm is looking to raise a new fund of 100 million. They plan to
charge a 2% management fee and a 20% carry fee on any profits generated from investments. If
the firm expects to generate 30% returns on investments over the lifetime of the fund, calculate the
total fees earned by the Venture Capital firm over the fund’s lifetime.
Solution 15. a) The total management fee can be calculated as:
Management Fee =Fund Size ×Management Fee Rate = 100 million ×0.02 = 2 million
b) The total carry fee can be calculated as:
Carry Fee =Return ×Carry Fee Rate = (100 million ×0.30) ×0.20 = 6 million
c) Therefore, the total fees earned by the Venture Capital firm over the fund’s lifetime would be:
Total Fees =Management Fee +Carry Fee = 2 million + 6 million = 8 million
15 16. BALANCING RISK AND REWARD IN PRIVATE EQUITY INVESTMENTS
Problem 16. ABC Ventures is considering investing in a startup company. The expected return
on this investment is 15
Solution 16. a) The Sharpe ratio is calculated as follows:
Sharpe ratio =Rp−Rf
σp
Where: - Rpis the expected return on the investment (15- Rfis the risk-free rate (5- σpis the
standard deviation of the investment (20
Substitute the values into the formula:
Sharpe ratio =0.15 −0.05
0.20 =0.10
0.20 = 0.5
Therefore, the Sharpe ratio for this investment is 0.5.
I can definitely help with that. Let’s work on a numerical problem related to Venture Capital and
Private Equity under the given subtopic.
16 17. IMPACT OF ECONOMIC DOWNTURNS ON VENTURE CAPITAL AND PRIVATE EQ-
UITY
Problem 17. During an economic downturn, a venture capital fund decides to invest 100,000inastartupcompanywithanexpectedreturnof30
Solution 17. Let’s first calculate the expected return after 5 years:
Expected return after 5 years = $100,000 ×(1 + 0.30)5
= $100,000 ×(1.30)5
= $100,000 ×2.8561
= $285,610
Now, the actual return turns out to be 10
Actual return after 5 years = $285,610 ×(1 −0.10)
= $285,610 ×0.90
= $257,049
Therefore, the total amount the venture capital fund will receive after 5 years is $257,049.
I’m glad to help with that! Here is a numerical problem related to Venture Capital and Private
Equity:
17 Venture Capital and Private Equity
Problem:
A venture capital firm invests $1,000,000 in a startup with an agreed 20% equity stake. The
startup later gets acquired for $10,000,000. How much profit does the venture capital firm make
from this investment?
Solution:
First, let’s calculate the value of the equity stake acquired by the venture capital firm:
Equity Stake Value =Investment Amount ×Equity Stake (%)
100
Equity Stake Value = $1,000,000 ×20
100 = $200,000
Then, we can find the profit made by the venture capital firm from the acquisition:
Profit =Acquisition Amount −Equity Stake Value −Investment Amount
Profit = $10,000,000 −$200,000 −$1,000,000 = $8,800,000
Therefore, the venture capital firm makes a profit of $8,800,000 from this investment.
I. Problem 1: Investor Equity Stake Calculation
A venture capital firm invests $1 million in a start-up company in exchange for a 20
Solution 1: Let Vbe the pre-money valuation of the company. The equity stake can be calcu-
lated using the formula:
Equity Stake =Investment Amount
Pre-money Valuation +Investment Amount ×100%
Substitute the values given:
20% = 1,000,000
V+ 1,000,000 ×100%
Solving for V:
V+ 1,000,000 = 1,000,000
20%
V+ 1,000,000 = 5,000,000
V= 4,000,000
Therefore, the pre-money valuation of the company is $4 million.
II. Problem 2: Preferred Stock Liquidation Preference
A venture capitalist invests $2 million in a start-up with a 2x liquidation preference. The company
sells for $5 million. How much money does the venture capitalist receive?
Solution 2: The venture capitalist will first receive back the $2 million invested due to the 2x
liquidation preference. The remaining amount will be divided pro-rata among all shareholders.
Since the company sells for $5 million, the remaining $3 million will be distributed among share-
holders based on their ownership percentage. The venture capitalist owns 2
5of the company ($2
million out of the $5 million total investment).
Therefore, the venture capitalist will receive:
$2,000,000 (liquidation preference)+2
5×$3,000,000 (remaining amount) = $2,000,000+$1,200,000 = $3,200,000
The venture capitalist will receive $3.2 million from the sale.
III. Problem 3: Internal Rate of Return (IRR) Calculation
A private equity firm invests $500,000 in a company and receives the following cash flows:
$100,000 in year 1, $200,000 in year 2, and $300,000 in year 3. Calculate the internal rate of
return for this investment.
Solution 3:
The IRR is the discount rate that makes the net present value (NPV) of all cash flows equal to
zero. Setting up the equation:
0 = −500,000 + 100,000
(1 + r)1+200,000
(1 + r)2+300,000
(1 + r)3
Using a financial calculator or software, solving the above equation gives r≈19.73%.
Therefore, the internal rate of return for this investment is approximately 19.73
18 20. GENDER AND DIVERSITY ISSUES IN VENTURE CAPITAL AND PRIVATE EQUITY.
Problem 20. In a venture capital firm, the distribution of investment decisions made by the
partners is as follows:
•40% of investment decisions are made by male partners
•30% of investment decisions are made by female partners
•30% of investment decisions are made by partners who identify as non-binary
If there are a total of 50 investment decisions made in a year by the venture capital firm, de-
termine the number of investment decisions made by each group (male, female, and non-binary
partners).
Solution 20. Let’s denote:
•Number of investment decisions made by male partners as x
•Number of investment decisions made by female partners as y

•Number of investment decisions made by non-binary partners as z
From the information given in the problem:
x= 0.40 ×50 = 20 (investment decisions by male partners)
y= 0.30 ×50 = 15 (investment decisions by female partners)
z= 0.30 ×50 = 15 (investment decisions by non-binary partners)
Therefore, the number of investment decisions made by each group are as follows:
•Male partners: 20 investment decisions
•Female partners: 15 investment decisions
•Non-binary partners: 15 investment decisions
For Startup A: Expected return = (0.3 * $1,000,000) - (0.7 * $200,000) = $300,000 - $140,000
= $160,000
For Startup B: Expected return = (0.5 * $800,000) - (0.5 * $150,000) = $400,000 - $75,000 =
$325,000
b) Based on expected return alone, Startup B has a higher expected return of $325,000 com-
pared to Startup A’s expected return of $160,000. Therefore, if you were to choose based on
expected return alone, you would choose to invest in Startup B.
Certainly! Here is a numerical problem on Venture Capital and Private Equity for you:
3 3. INVESTOR DIVERSIFICATION IN PRIVATE EQUITY
Problem 3. A venture capital investor has a portfolio of investments in three startups, with the
following initial amounts invested and expected returns:
Startup A: Investment of $100,000 with an expected return of $150,000 Startup B: Investment of
$200,000 with an expected return of $250,000 Startup C: Investment of $150,000 with an expected
return of $180,000
Assuming all three investments are uncorrelated, calculate the total expected return, standard
deviation, and coefficient of variation for the investor’s portfolio.
Solution 3.
a) To find the total expected return, we simply sum up the expected returns of each individual
investment:
Total Expected Return = $150,000 + $250,000 + $180,000 = $580,000
b) Next, to calculate the standard deviation of the portfolio, we need to find the variance of the
portfolio first. Since the investments are uncorrelated, we can use the following formula for the
variance of a portfolio of two assets:
Variance of Portfolio = w2
A∗V ar(A) + w2
B∗V ar(B) + w2
C∗V ar(C)
Where: wA, wB, wC=weightsofinvestmentsA, B, Cintheportfolio(sumofweights = 1)V ar(A), V ar(B), V ar(C) =
varianceofinvestmentsA, B, C
Given the investments are uncorrelated, the variance of each investment is equal to its expected
return:
Var(A) = $150,000 Var(B) = $250,000 Var(C) = $180,000
Let’s calculate the variance: Variance of Portfolio = (100,000/450,000)2∗150,000+(200,000/450,000)2∗
250,000 + (150,000/450,000)2∗180,000
Variance of Portfolio = 83,333.33
Then, the standard deviation is the square root of the variance:
Standard Deviation = √83,333.33 ≈$288.67
c) Finally, the coefficient of variation (CV) is calculated by dividing the standard deviation by the
expected return:
Coefficient of Variation = $288.67 / $580,000 Coefficient of Variation 0.0004986, or approxi-
mately 0.04986
I. Problem: Due Diligence in Venture Capital
A venture capital firm is considering investing $500,000 in a startup company. During the due
diligence process, they discover that the company’s financial projections are as follows:
- Year 1: Revenue of $200,000, Expenses of $150,000 - Year 2: Revenue growth of 20%,
Expenses growth of 10%
Calculate the Net Income for each year and determine the company’s Net Income Margin in
Year 2.
Solution:
a) Net Income for Year 1:
Net Income = Revenue - Expenses
Net Income = $200,000 −$150,000 = $50,000
b) Net Income for Year 2:
Revenue in Year 2 = $200,000 ×1.20 = $240,000
Expenses in Year 2 = $150,000 ×1.10 = $165,000
Net Income = Revenue - Expenses
Net Income = $240,000 −$165,000 = $75,000
c) Net Income Margin in Year 2:
Net Income Margin = NetIncome
Revenue ×100
Net Income Margin = $75,000
$240,000 ×100
Net Income Margin = 75
240 ×100 = 31.25%
Therefore, the company’s Net Income Margin in Year 2 is 31.25%.
4 5. LACK OF TRANSPARENCY IN PRIVATE EQUITY INVESTMENTS
Problem 5. A Venture Capital firm invested 500,000 in a startup in exchange for 20% equity
ownership. After a few years, the startup gets acquired for 5times its initial valuation. If the firm
decides to exit their investment, what is the total cash they receive from the acquisition?
Solution 5. Let’s first calculate the initial valuation of the startup when the Venture Capital firm
invested:
Initial Valuation = Investment Amount
Equity Ownership =500,000
0.20 = 2,500,000
After the acquisition, the startup is acquired for 5times its initial valuation:
Acquisition Price = 5×Initial Valuation = 5 ×2,500,000 = 12,500,000
Since the Venture Capital firm owns 20% equity in the startup, their cash from the acquisition
would be:
Cash from Acquisition = Equity Ownership ×Acquisition Price = 0.20 ×12,500,000 =2,500,000
Therefore, the Venture Capital firm would receive 2,500,000 in cash from the acquisition of the
startup.
I.
5 6. VALUATION DIFFICULTIES IN EARLY-STAGE STARTUPS
Problem 6. You are a venture capitalist looking to invest in a promising early-stage startup.
The startup is seeking $500,000 in funding in exchange for a 20
a) What is the pre-money valuation of the startup based on the given information?
b) If you decide to invest the requested amount, how many shares will you receive?
c) What is the price per share you will pay for this investment?
Solution 6.
a) The pre-money valuation of the startup can be calculated as follows:
Pre-money valuation =Post-money valuation −Amount of funding
Pre-money valuation = $2.5M−$500K= $2M
b) To calculate the number of shares you will receive, we first need to find the value of each
share. The value of each share can be calculated as:
Post-money valuation =Pre-money valuation ×(1 + Equity stake)
$2.5M= $2M×(1 + 0.20)
$2.5M= $2M×1.20
$2.5M= $2.4M
Now, the value per share is $2.4 million. Therefore, the number of shares you will receive is:
Amount of funding
Value per share =$500K
$2.4M=500
2400 =5
24
c) The price per share you will pay for this investment is the same as the value per share, which
is $2.4 million.
6 7. THE IMPACT OF INDUSTRY TRENDS ON VENTURE CAPITAL FUNDING
Problem 7. The venture capital firm XYZ is considering investing in two different industries:
Tech and Biotech. The expected return on investment (ROI) for Tech is 20% with a standard
deviation of 5%, while the expected ROI for Biotech is 15% with a standard deviation of 8%. The
correlation between the two industries is 0.4. If XYZ invests $1 million in Tech and $2 million in
Biotech, calculate the expected ROI of the portfolio and the standard deviation of the portfolio’s
ROI.
Solution 7. Let Xbe the ROI in Tech and Ybe the ROI in Biotech. The expected ROI of a
portfolio is given by the weighted average of the expected ROIs of the individual investments:
E(Rp) = w1E(R1) + w2E(R2)
where w1and w2are the weights of the investments and E(R1)and E(R2)are the expected ROIs
of Tech and Biotech, respectively.
Given: - E(R1) = 20%,E(R2) = 15% -w1= $1,000,000/$3,000,000 = 1
3,w2= $2,000,000/$3,000,000 =
2
3
E(Rp) = 1
3(20%) + 2
3(15%) = 18.33%
The variance of the portfolio is calculated as:
V ar(Rp) = w2
1V ar(R1) + w2
2V ar(R2)+2w1w2Cov(R1, R2)
where V ar(R1)and V ar(R2)are the variances of the individual investments and Cov(R1, R2)is
the covariance between the investments.
Given: - V ar(R1) = (0.05)2,V ar(R2) = (0.08)2,Cov(R1, R2)=0.4(0.05)(0.08)
V ar(Rp) = 1
32
(0.05)2+2
32
(0.08)2+ 2 1
32
3(0.4(0.05)(0.08))
V ar(Rp)≈0.00042833
Therefore, the standard deviation of the portfolio’s ROI is:
σ=qV ar(Rp)≈√0.00042833 ≈0.0207 = 2.07%
Hence, the expected ROI of the portfolio is approximately 18.33%, and the standard deviation
of the portfolio’s ROI is approximately 2.07%.
7 8. INVESTOR EXIT STRATEGIES IN PRIVATE EQUITY DEALS
Problem 8.
A private equity investor invested $1 million in a startup company with the following projected
cash flows over the next five years:
Year 1: $200,000 Year 2: $300,000 Year 3: $400,000 Year 4: $500,000 Year 5: $600,000
Assuming a desired Internal Rate of Return (IRR) of 20% per annum, calculate the exit value
required at the end of Year 5 to achieve the target return for the investor.
Solution 8.
To calculate the exit value required at the end of Year 5, we need to find the Present Value (PV)
of the cash flows and then determine the exit value that would give an IRR of 20%.
The PV of the cash flows can be calculated using the formula:
P V =CF1
(1 + r)1+CF2
(1 + r)2+CF3
(1 + r)3+CF4
(1 + r)4+CF5+ExitV alue
(1 + r)5
Where: CFi= Cash flow at the end of Year i r = 0.20 (IRR) ExitV alue = Exit value at the end
of Year 5
Substitute the given values into the formula:
P V =200,000
(1 + 0.20)1+300,000
(1 + 0.20)2+400,000
(1 + 0.20)3+500,000
(1 + 0.20)4+600,000 + ExitV alue
(1 + 0.20)5
P V =200,000
1.20 +300,000
1.202+400,000
1.203+500,000
1.204+600,000 + ExitV alue
1.205
P V ≈166,666.67 + 225,000 + 250,000 + 277,777.78 + 600,000 + ExitV alue
1.48
P V ≈919,444.45 + 600,000 + ExitV alue
1.48
Since the total initial investment is $1,000,000 at the start, the exit value at the end of Year 5
should be such that the total PV equals the total initial investment:
1,000,000 = 919,444.45 + 600,000 + ExitV alue
1.48
1,000,000 −919,444.45 = 600,000 + ExitV alue
1.48
80,555.55 = 600,000 + ExitV alue
1.48
119,200 ≈600,000 + ExitV alue
ExitV alue ≈119,200 −600,000
ExitV alue ≈ −480,800
Therefore, the exit value required at the end of Year 5 to achieve the target return for the investor
is approximately $480,800 *negative value indicates a loss*.
I.
8 9. REGULATORY COMPLIANCE IN VENTURE CAPITAL AND PRIVATE EQUITY
Problem 9. A Venture Capital firm is considering investing in a startup. The firm’s management
fee is 2% of committed capital, and they charge a 20% carried interest (profit share) on returns
exceeding an 8% preferred return hurdle rate. If the firm raises a fund of 100 million from limited
partners and invests 80
Solution 9.
a) The management fee can be calculated as 2% of the committed capital. Therefore, manage-
ment fee = 0.02 ×100 million = 2 million.
b) The profit share or carried interest is calculated on the returns exceeding the preferred return
hurdle rate. The total profits from the startup investment are 80
Therefore, the profit share = 20
Therefore, the carried interest payable by the startup is 14.4million.
Thus, the management fee payable by the startup is 2million and the carried interest payable
is 14.4million.
I.
9 10. COMPETITION FOR QUALITY DEALS IN THE VENTURE CAPITAL MARKET
Problem 10. In a competitive venture capital market, investors are evaluating two investment
opportunities. Opportunity A requires an investment of 500,000andisexpectedtoyieldareturnof1,000,000
with a probability of success of 30
a) Calculate the expected value of each investment opportunity.
b) Calculate the expected value of the two opportunities if investors can only choose one of
them.
c) Analyze which investment opportunity seems more attractive based on the expected values
calculated in parts (a) and (b).
Solution 10.
a) The expected value of an investment opportunity is calculated by multiplying the return by
the probability of success.
For Opportunity A: Expected value = 1,000,000 ∗0.30 =300,000
For Opportunity B: Expected value = 1,200,000 ∗0.40 =480,000
b) To calculate the expected value of the two opportunities if investors can only choose one, we
compare the expected values of both opportunities.
Choosing between A and B, Opportunity B has a higher expected value of 480,000comparedtoOpportunityA′s300,000.
c) Based on the expected values calculated in parts (a) and (b), Opportunity B seems more
attractive as it offers a higher expected return on investment compared to Opportunity A.
10 11. MANAGING PORTFOLIO COMPANIES IN PRIVATE EQUITY INVESTMENTS
Problem 11. A private equity firm has invested $5 million in a portfolio company and acquired
a 20% stake. After a successful year, the portfolio company’s valuation has increased by 30%.
a) What is the new valuation of the portfolio company?
b) Calculate the new value of the private equity firm’s stake in the portfolio company.
c) If the private equity firm decides to exit its investment by selling its stake, how much profit
would they make if the exit price per share is 25% higher than the original valuation?
Solution 11.
a) The new valuation of the portfolio company after a 30% increase can be calculated as:
New Valuation =Original Valuation ×(1 + Increase %)
New Valuation = $5,000,000 ×(1 + 0.30)
New Valuation = $5,000,000 ×1.30
New Valuation = $6,500,000
Therefore, the new valuation of the portfolio company is $6,500,000.
b) The new value of the private equity firm’s stake in the portfolio company can be calculated
as:
New Value of Stake =New Valuation ×Stake %
New Value of Stake = $6,500,000 ×0.20
New Value of Stake = $1,300,000
Therefore, the new value of the private equity firm’s stake in the portfolio company is $1,300,000.
c) If the exit price per share is 25% higher than the original valuation, then the exit price per
share would be:
Exit Price Per Share =Original Valuation ×(1 + 0.25)
Exit Price Per Share = $5,000,000 ×1.25
Exit Price Per Share = $6,250,000
The profit the private equity firm would make upon exit can be calculated as:
Profit =Exit Price Per Share ×Stake % −Investment
Profit = $6,250,000 ×0.20 −$5,000,000
Profit = $1,250,000 −$5,000,000
Profit = $250,000
Therefore, if the private equity firm exits its investment at an exit price 25% higher than the
original valuation, they would make a profit of $250,000.
11 Venture Capital and Private Equity
Problem: You are a venture capitalist considering investing in a startup. The startup has
projected cash flows for the next 5 years as follows:
Year 1: $100,000 Year 2: $150,000 Year 3: $200,000 Year 4: $250,000 Year 5: $300,000
If the discount rate is 10%, calculate the present value of these cash flows.
Solution: To calculate the present value of the cash flows, we need to discount each cash flow
using the formula:
P V =CF
(1 + r)t
where: P V = Present Value CF = Cash Flow in that year r= Discount Rate t= Time period in
years
Let’s compute the present value of each cash flow and sum them up:
a) For Year 1:
P V1=100,000
(1 + 0.10)1=100,000
1.10 = $90,909
b) For Year 2:
P V2=150,000
(1 + 0.10)2=150,000
1.21 = $123,966
c) For Year 3:
P V3=200,000
(1 + 0.10)3=200,000
1.331 = $150,289
d) For Year 4:
P V4=250,000
(1 + 0.10)4=250,000
1.4641 = $170,866
e) For Year 5:
P V5=300,000
(1 + 0.10)5=300,000
1.6105 = $186,410
Now, summing up all the present values:
P V = $90,909 + $123,966 + $150,289 + $170,866 + $186,410 = $722,440
Therefore, the present value of the cash flows is $722,440.
12 13. THE ROLE OF TECHNOLOGY IN DISRUPTING VENTURE CAPITAL AND PRIVATE
EQUITY
Problem 13. A venture capital firm invests $1,000,000 in a startup with a promised return of
25% annually over 5 years. However, after the first year, the startup faces challenges and the return
drops to −10% annually for the remaining 4 years. Calculate the net present value (NPV) of the
investment if the discount rate is 15%.
Solution 13. a) To calculate the NPV of the investment, we need to find the present value of
the expected cash flows from the investment.
The initial investment is $1,000,000.
After the first year, the return is 25%, so the cash flow at the end of year 1 will be: $1,000,000 ×
1.25 = $1,250,000
For the remaining 4 years, the return is −10% annually. The cash flows for years 2 to 5 are
calculated as follows:
Year 2: $1,250,000 ×0.90 = $1,125,000 Year 3: $1,125,000 ×0.90 = $1,012,500 Year 4:
$1,012,500 ×0.90 = $911,250 Year 5: $911,250 ×0.90 = $820,125
b) Now, we calculate the present value of these cash flows using the discount rate of 15%.
The present value (PV) of each cash flow is calculated using the formula: P V =CF
(1+r)n, where
CF is the cash flow, ris the discount rate, and nis the period.
PV of Year 1 cash flow: ($1,250,000)
(1+0.15)1= $1,086,957.61
PV of Year 2-5 cash flows: ($1,125,000)
(1+0.15)2= $873,573.64 ($1,012,500)
(1+0.15)3= $718,331.05 ($911,250)
(1+0.15)4=
$566,638.49 ($820,125)
(1+0.15)5= $453,157.44
c) Finally, we calculate the NPV by summing up the present values of the cash flows and sub-
tracting the initial investment.
NP V =P VY ear1+P VY ear2+P VY ear3+P VY ear4+P VY ear5−$1,000,000 NP V = $1,086,957.61+
$873,573.64 + $718,331.05 + $566,638.49 + $453,157.44 −$1,000,000 NP V = $1,698,658.23 −
$1,000,000 NP V = $698,658.23
Therefore, the net present value (NPV) of the investment is $698,658.23.
13 Venture Capital and Private Equity
Problem 1.
A venture capital firm is considering investing $1,000,000 in a startup. The firm expects the
startup to be valued at $3,000,000 in 3 years if they invest. If the firm requires a return of 25% per
year on their investment, what percentage ownership should they demand in the startup?
Solution 1.
Let xbe the percentage ownership the venture capital firm should demand in the startup.
The present value of the investment should equal the initial investment of $1,000,000. The
future value of the investment in 3 years should be $3,000,000.
Using the concept of Compound Interest formula:
1,000,000 = 3,000,000
(1 + 0.25)3×x
Solving for x, we get:
x=1,000,000
3,000,000/1.952 = 0.6513 = 65.13%
Therefore, the venture capital firm should demand a 65.13% ownership in the startup.
14 15. FUNDRAISING CHALLENGES FOR VENTURE CAPITAL FIRMS
Problem 15. A Venture Capital firm is looking to raise a new fund of 100 million. They plan to
charge a 2% management fee and a 20% carry fee on any profits generated from investments. If
the firm expects to generate 30% returns on investments over the lifetime of the fund, calculate the
total fees earned by the Venture Capital firm over the fund’s lifetime.
Solution 15. a) The total management fee can be calculated as:
Management Fee =Fund Size ×Management Fee Rate = 100 million ×0.02 = 2 million
b) The total carry fee can be calculated as:
Carry Fee =Return ×Carry Fee Rate = (100 million ×0.30) ×0.20 = 6 million
c) Therefore, the total fees earned by the Venture Capital firm over the fund’s lifetime would be:
Total Fees =Management Fee +Carry Fee = 2 million + 6 million = 8 million
15 16. BALANCING RISK AND REWARD IN PRIVATE EQUITY INVESTMENTS
Problem 16. ABC Ventures is considering investing in a startup company. The expected return
on this investment is 15
Solution 16. a) The Sharpe ratio is calculated as follows:
Sharpe ratio =Rp−Rf
σp
Where: - Rpis the expected return on the investment (15- Rfis the risk-free rate (5- σpis the
standard deviation of the investment (20
Substitute the values into the formula:
Sharpe ratio =0.15 −0.05
0.20 =0.10
0.20 = 0.5
Therefore, the Sharpe ratio for this investment is 0.5.
I can definitely help with that. Let’s work on a numerical problem related to Venture Capital and
Private Equity under the given subtopic.
16 17. IMPACT OF ECONOMIC DOWNTURNS ON VENTURE CAPITAL AND PRIVATE EQ-
UITY
Problem 17. During an economic downturn, a venture capital fund decides to invest 100,000inastartupcompanywithanexpectedreturnof30
Solution 17. Let’s first calculate the expected return after 5 years:
Expected return after 5 years = $100,000 ×(1 + 0.30)5
= $100,000 ×(1.30)5
= $100,000 ×2.8561
= $285,610
Now, the actual return turns out to be 10
Actual return after 5 years = $285,610 ×(1 −0.10)
= $285,610 ×0.90
= $257,049
Therefore, the total amount the venture capital fund will receive after 5 years is $257,049.
I’m glad to help with that! Here is a numerical problem related to Venture Capital and Private
Equity:
17 Venture Capital and Private Equity
Problem:
A venture capital firm invests $1,000,000 in a startup with an agreed 20% equity stake. The
startup later gets acquired for $10,000,000. How much profit does the venture capital firm make
from this investment?
Solution:
First, let’s calculate the value of the equity stake acquired by the venture capital firm:
Equity Stake Value =Investment Amount ×Equity Stake (%)
100
Equity Stake Value = $1,000,000 ×20
100 = $200,000
Then, we can find the profit made by the venture capital firm from the acquisition:
Profit =Acquisition Amount −Equity Stake Value −Investment Amount
Profit = $10,000,000 −$200,000 −$1,000,000 = $8,800,000
Therefore, the venture capital firm makes a profit of $8,800,000 from this investment.
I. Problem 1: Investor Equity Stake Calculation
A venture capital firm invests $1 million in a start-up company in exchange for a 20
Solution 1: Let Vbe the pre-money valuation of the company. The equity stake can be calcu-
lated using the formula:
Equity Stake =Investment Amount
Pre-money Valuation +Investment Amount ×100%
Substitute the values given:
20% = 1,000,000
V+ 1,000,000 ×100%
Solving for V:
V+ 1,000,000 = 1,000,000
20%
V+ 1,000,000 = 5,000,000
V= 4,000,000
Therefore, the pre-money valuation of the company is $4 million.
II. Problem 2: Preferred Stock Liquidation Preference
A venture capitalist invests $2 million in a start-up with a 2x liquidation preference. The company
sells for $5 million. How much money does the venture capitalist receive?
Solution 2: The venture capitalist will first receive back the $2 million invested due to the 2x
liquidation preference. The remaining amount will be divided pro-rata among all shareholders.
Since the company sells for $5 million, the remaining $3 million will be distributed among share-
holders based on their ownership percentage. The venture capitalist owns 2
5of the company ($2
million out of the $5 million total investment).
Therefore, the venture capitalist will receive:
$2,000,000 (liquidation preference)+2
5×$3,000,000 (remaining amount) = $2,000,000+$1,200,000 = $3,200,000
The venture capitalist will receive $3.2 million from the sale.
III. Problem 3: Internal Rate of Return (IRR) Calculation
A private equity firm invests $500,000 in a company and receives the following cash flows:
$100,000 in year 1, $200,000 in year 2, and $300,000 in year 3. Calculate the internal rate of
return for this investment.
Solution 3:
The IRR is the discount rate that makes the net present value (NPV) of all cash flows equal to
zero. Setting up the equation:
0 = −500,000 + 100,000
(1 + r)1+200,000
(1 + r)2+300,000
(1 + r)3
Using a financial calculator or software, solving the above equation gives r≈19.73%.
Therefore, the internal rate of return for this investment is approximately 19.73
18 20. GENDER AND DIVERSITY ISSUES IN VENTURE CAPITAL AND PRIVATE EQUITY.
Problem 20. In a venture capital firm, the distribution of investment decisions made by the
partners is as follows:
•40% of investment decisions are made by male partners
•30% of investment decisions are made by female partners
•30% of investment decisions are made by partners who identify as non-binary
If there are a total of 50 investment decisions made in a year by the venture capital firm, de-
termine the number of investment decisions made by each group (male, female, and non-binary
partners).
Solution 20. Let’s denote:
•Number of investment decisions made by male partners as x
•Number of investment decisions made by female partners as y

•Number of investment decisions made by non-binary partners as z
From the information given in the problem:
x= 0.40 ×50 = 20 (investment decisions by male partners)
y= 0.30 ×50 = 15 (investment decisions by female partners)
z= 0.30 ×50 = 15 (investment decisions by non-binary partners)
Therefore, the number of investment decisions made by each group are as follows:
•Male partners: 20 investment decisions
•Female partners: 15 investment decisions
•Non-binary partners: 15 investment decisions
For Startup A: Expected return = (0.3 * $1,000,000) - (0.7 * $200,000) = $300,000 - $140,000
= $160,000
For Startup B: Expected return = (0.5 * $800,000) - (0.5 * $150,000) = $400,000 - $75,000 =
$325,000
b) Based on expected return alone, Startup B has a higher expected return of $325,000 com-
pared to Startup A’s expected return of $160,000. Therefore, if you were to choose based on
expected return alone, you would choose to invest in Startup B.
Certainly! Here is a numerical problem on Venture Capital and Private Equity for you:
3 3. INVESTOR DIVERSIFICATION IN PRIVATE EQUITY
Problem 3. A venture capital investor has a portfolio of investments in three startups, with the
following initial amounts invested and expected returns:
Startup A: Investment of $100,000 with an expected return of $150,000 Startup B: Investment of
$200,000 with an expected return of $250,000 Startup C: Investment of $150,000 with an expected
return of $180,000
Assuming all three investments are uncorrelated, calculate the total expected return, standard
deviation, and coefficient of variation for the investor’s portfolio.
Solution 3.
a) To find the total expected return, we simply sum up the expected returns of each individual
investment:
Total Expected Return = $150,000 + $250,000 + $180,000 = $580,000
b) Next, to calculate the standard deviation of the portfolio, we need to find the variance of the
portfolio first. Since the investments are uncorrelated, we can use the following formula for the
variance of a portfolio of two assets:
Variance of Portfolio = w2
A∗V ar(A) + w2
B∗V ar(B) + w2
C∗V ar(C)
Where: wA, wB, wC=weightsofinvestmentsA, B, Cintheportfolio(sumofweights = 1)V ar(A), V ar(B), V ar(C) =
varianceofinvestmentsA, B, C
Given the investments are uncorrelated, the variance of each investment is equal to its expected
return:
Var(A) = $150,000 Var(B) = $250,000 Var(C) = $180,000
Let’s calculate the variance: Variance of Portfolio = (100,000/450,000)2∗150,000+(200,000/450,000)2∗
250,000 + (150,000/450,000)2∗180,000
Variance of Portfolio = 83,333.33
Then, the standard deviation is the square root of the variance:
Standard Deviation = √83,333.33 ≈$288.67
c) Finally, the coefficient of variation (CV) is calculated by dividing the standard deviation by the
expected return:
Coefficient of Variation = $288.67 / $580,000 Coefficient of Variation 0.0004986, or approxi-
mately 0.04986
I. Problem: Due Diligence in Venture Capital
A venture capital firm is considering investing $500,000 in a startup company. During the due
diligence process, they discover that the company’s financial projections are as follows:
- Year 1: Revenue of $200,000, Expenses of $150,000 - Year 2: Revenue growth of 20%,
Expenses growth of 10%
Calculate the Net Income for each year and determine the company’s Net Income Margin in
Year 2.
Solution:
a) Net Income for Year 1:
Net Income = Revenue - Expenses
Net Income = $200,000 −$150,000 = $50,000
b) Net Income for Year 2:
Revenue in Year 2 = $200,000 ×1.20 = $240,000
Expenses in Year 2 = $150,000 ×1.10 = $165,000
Net Income = Revenue - Expenses
Net Income = $240,000 −$165,000 = $75,000
c) Net Income Margin in Year 2:
Net Income Margin = NetIncome
Revenue ×100
Net Income Margin = $75,000
$240,000 ×100
Net Income Margin = 75
240 ×100 = 31.25%
Therefore, the company’s Net Income Margin in Year 2 is 31.25%.
4 5. LACK OF TRANSPARENCY IN PRIVATE EQUITY INVESTMENTS
Problem 5. A Venture Capital firm invested 500,000 in a startup in exchange for 20% equity
ownership. After a few years, the startup gets acquired for 5times its initial valuation. If the firm
decides to exit their investment, what is the total cash they receive from the acquisition?
Solution 5. Let’s first calculate the initial valuation of the startup when the Venture Capital firm
invested:
Initial Valuation = Investment Amount
Equity Ownership =500,000
0.20 = 2,500,000
After the acquisition, the startup is acquired for 5times its initial valuation:
Acquisition Price = 5×Initial Valuation = 5 ×2,500,000 = 12,500,000
Since the Venture Capital firm owns 20% equity in the startup, their cash from the acquisition
would be:
Cash from Acquisition = Equity Ownership ×Acquisition Price = 0.20 ×12,500,000 =2,500,000
Therefore, the Venture Capital firm would receive 2,500,000 in cash from the acquisition of the
startup.
I.
5 6. VALUATION DIFFICULTIES IN EARLY-STAGE STARTUPS
Problem 6. You are a venture capitalist looking to invest in a promising early-stage startup.
The startup is seeking $500,000 in funding in exchange for a 20
a) What is the pre-money valuation of the startup based on the given information?
b) If you decide to invest the requested amount, how many shares will you receive?
c) What is the price per share you will pay for this investment?
Solution 6.
a) The pre-money valuation of the startup can be calculated as follows:
Pre-money valuation =Post-money valuation −Amount of funding
Pre-money valuation = $2.5M−$500K= $2M
b) To calculate the number of shares you will receive, we first need to find the value of each
share. The value of each share can be calculated as:
Post-money valuation =Pre-money valuation ×(1 + Equity stake)
$2.5M= $2M×(1 + 0.20)
$2.5M= $2M×1.20
$2.5M= $2.4M
Now, the value per share is $2.4 million. Therefore, the number of shares you will receive is:
Amount of funding
Value per share =$500K
$2.4M=500
2400 =5
24
c) The price per share you will pay for this investment is the same as the value per share, which
is $2.4 million.
6 7. THE IMPACT OF INDUSTRY TRENDS ON VENTURE CAPITAL FUNDING
Problem 7. The venture capital firm XYZ is considering investing in two different industries:
Tech and Biotech. The expected return on investment (ROI) for Tech is 20% with a standard
deviation of 5%, while the expected ROI for Biotech is 15% with a standard deviation of 8%. The
correlation between the two industries is 0.4. If XYZ invests $1 million in Tech and $2 million in
Biotech, calculate the expected ROI of the portfolio and the standard deviation of the portfolio’s
ROI.
Solution 7. Let Xbe the ROI in Tech and Ybe the ROI in Biotech. The expected ROI of a
portfolio is given by the weighted average of the expected ROIs of the individual investments:
E(Rp) = w1E(R1) + w2E(R2)
where w1and w2are the weights of the investments and E(R1)and E(R2)are the expected ROIs
of Tech and Biotech, respectively.
Given: - E(R1) = 20%,E(R2) = 15% -w1= $1,000,000/$3,000,000 = 1
3,w2= $2,000,000/$3,000,000 =
2
3
E(Rp) = 1
3(20%) + 2
3(15%) = 18.33%
The variance of the portfolio is calculated as:
V ar(Rp) = w2
1V ar(R1) + w2
2V ar(R2)+2w1w2Cov(R1, R2)
where V ar(R1)and V ar(R2)are the variances of the individual investments and Cov(R1, R2)is
the covariance between the investments.
Given: - V ar(R1) = (0.05)2,V ar(R2) = (0.08)2,Cov(R1, R2)=0.4(0.05)(0.08)
V ar(Rp) = 1
32
(0.05)2+2
32
(0.08)2+ 2 1
32
3(0.4(0.05)(0.08))
V ar(Rp)≈0.00042833
Therefore, the standard deviation of the portfolio’s ROI is:
σ=qV ar(Rp)≈√0.00042833 ≈0.0207 = 2.07%
Hence, the expected ROI of the portfolio is approximately 18.33%, and the standard deviation
of the portfolio’s ROI is approximately 2.07%.
7 8. INVESTOR EXIT STRATEGIES IN PRIVATE EQUITY DEALS
Problem 8.
A private equity investor invested $1 million in a startup company with the following projected
cash flows over the next five years:
Year 1: $200,000 Year 2: $300,000 Year 3: $400,000 Year 4: $500,000 Year 5: $600,000
Assuming a desired Internal Rate of Return (IRR) of 20% per annum, calculate the exit value
required at the end of Year 5 to achieve the target return for the investor.
Solution 8.
To calculate the exit value required at the end of Year 5, we need to find the Present Value (PV)
of the cash flows and then determine the exit value that would give an IRR of 20%.
The PV of the cash flows can be calculated using the formula:
P V =CF1
(1 + r)1+CF2
(1 + r)2+CF3
(1 + r)3+CF4
(1 + r)4+CF5+ExitV alue
(1 + r)5
Where: CFi= Cash flow at the end of Year i r = 0.20 (IRR) ExitV alue = Exit value at the end
of Year 5
Substitute the given values into the formula:
P V =200,000
(1 + 0.20)1+300,000
(1 + 0.20)2+400,000
(1 + 0.20)3+500,000
(1 + 0.20)4+600,000 + ExitV alue
(1 + 0.20)5
P V =200,000
1.20 +300,000
1.202+400,000
1.203+500,000
1.204+600,000 + ExitV alue
1.205
P V ≈166,666.67 + 225,000 + 250,000 + 277,777.78 + 600,000 + ExitV alue
1.48
P V ≈919,444.45 + 600,000 + ExitV alue
1.48
Since the total initial investment is $1,000,000 at the start, the exit value at the end of Year 5
should be such that the total PV equals the total initial investment:
1,000,000 = 919,444.45 + 600,000 + ExitV alue
1.48
1,000,000 −919,444.45 = 600,000 + ExitV alue
1.48
80,555.55 = 600,000 + ExitV alue
1.48
119,200 ≈600,000 + ExitV alue
ExitV alue ≈119,200 −600,000
ExitV alue ≈ −480,800
Therefore, the exit value required at the end of Year 5 to achieve the target return for the investor
is approximately $480,800 *negative value indicates a loss*.
I.
8 9. REGULATORY COMPLIANCE IN VENTURE CAPITAL AND PRIVATE EQUITY
Problem 9. A Venture Capital firm is considering investing in a startup. The firm’s management
fee is 2% of committed capital, and they charge a 20% carried interest (profit share) on returns
exceeding an 8% preferred return hurdle rate. If the firm raises a fund of 100 million from limited
partners and invests 80
Solution 9.
a) The management fee can be calculated as 2% of the committed capital. Therefore, manage-
ment fee = 0.02 ×100 million = 2 million.
b) The profit share or carried interest is calculated on the returns exceeding the preferred return
hurdle rate. The total profits from the startup investment are 80
Therefore, the profit share = 20
Therefore, the carried interest payable by the startup is 14.4million.
Thus, the management fee payable by the startup is 2million and the carried interest payable
is 14.4million.
I.
9 10. COMPETITION FOR QUALITY DEALS IN THE VENTURE CAPITAL MARKET
Problem 10. In a competitive venture capital market, investors are evaluating two investment
opportunities. Opportunity A requires an investment of 500,000andisexpectedtoyieldareturnof1,000,000
with a probability of success of 30
a) Calculate the expected value of each investment opportunity.
b) Calculate the expected value of the two opportunities if investors can only choose one of
them.
c) Analyze which investment opportunity seems more attractive based on the expected values
calculated in parts (a) and (b).
Solution 10.
a) The expected value of an investment opportunity is calculated by multiplying the return by
the probability of success.
For Opportunity A: Expected value = 1,000,000 ∗0.30 =300,000
For Opportunity B: Expected value = 1,200,000 ∗0.40 =480,000
b) To calculate the expected value of the two opportunities if investors can only choose one, we
compare the expected values of both opportunities.
Choosing between A and B, Opportunity B has a higher expected value of 480,000comparedtoOpportunityA′s300,000.
c) Based on the expected values calculated in parts (a) and (b), Opportunity B seems more
attractive as it offers a higher expected return on investment compared to Opportunity A.
10 11. MANAGING PORTFOLIO COMPANIES IN PRIVATE EQUITY INVESTMENTS
Problem 11. A private equity firm has invested $5 million in a portfolio company and acquired
a 20% stake. After a successful year, the portfolio company’s valuation has increased by 30%.
a) What is the new valuation of the portfolio company?
b) Calculate the new value of the private equity firm’s stake in the portfolio company.
c) If the private equity firm decides to exit its investment by selling its stake, how much profit
would they make if the exit price per share is 25% higher than the original valuation?
Solution 11.
a) The new valuation of the portfolio company after a 30% increase can be calculated as:
New Valuation =Original Valuation ×(1 + Increase %)
New Valuation = $5,000,000 ×(1 + 0.30)
New Valuation = $5,000,000 ×1.30
New Valuation = $6,500,000
Therefore, the new valuation of the portfolio company is $6,500,000.
b) The new value of the private equity firm’s stake in the portfolio company can be calculated
as:
New Value of Stake =New Valuation ×Stake %
New Value of Stake = $6,500,000 ×0.20
New Value of Stake = $1,300,000
Therefore, the new value of the private equity firm’s stake in the portfolio company is $1,300,000.
c) If the exit price per share is 25% higher than the original valuation, then the exit price per
share would be:
Exit Price Per Share =Original Valuation ×(1 + 0.25)
Exit Price Per Share = $5,000,000 ×1.25
Exit Price Per Share = $6,250,000
The profit the private equity firm would make upon exit can be calculated as:
Profit =Exit Price Per Share ×Stake % −Investment
Profit = $6,250,000 ×0.20 −$5,000,000
Profit = $1,250,000 −$5,000,000
Profit = $250,000
Therefore, if the private equity firm exits its investment at an exit price 25% higher than the
original valuation, they would make a profit of $250,000.
11 Venture Capital and Private Equity
Problem: You are a venture capitalist considering investing in a startup. The startup has
projected cash flows for the next 5 years as follows:
Year 1: $100,000 Year 2: $150,000 Year 3: $200,000 Year 4: $250,000 Year 5: $300,000
If the discount rate is 10%, calculate the present value of these cash flows.
Solution: To calculate the present value of the cash flows, we need to discount each cash flow
using the formula:
P V =CF
(1 + r)t
where: P V = Present Value CF = Cash Flow in that year r= Discount Rate t= Time period in
years
Let’s compute the present value of each cash flow and sum them up:
a) For Year 1:
P V1=100,000
(1 + 0.10)1=100,000
1.10 = $90,909
b) For Year 2:
P V2=150,000
(1 + 0.10)2=150,000
1.21 = $123,966
c) For Year 3:
P V3=200,000
(1 + 0.10)3=200,000
1.331 = $150,289
d) For Year 4:
P V4=250,000
(1 + 0.10)4=250,000
1.4641 = $170,866
e) For Year 5:
P V5=300,000
(1 + 0.10)5=300,000
1.6105 = $186,410
Now, summing up all the present values:
P V = $90,909 + $123,966 + $150,289 + $170,866 + $186,410 = $722,440
Therefore, the present value of the cash flows is $722,440.
12 13. THE ROLE OF TECHNOLOGY IN DISRUPTING VENTURE CAPITAL AND PRIVATE
EQUITY
Problem 13. A venture capital firm invests $1,000,000 in a startup with a promised return of
25% annually over 5 years. However, after the first year, the startup faces challenges and the return
drops to −10% annually for the remaining 4 years. Calculate the net present value (NPV) of the
investment if the discount rate is 15%.
Solution 13. a) To calculate the NPV of the investment, we need to find the present value of
the expected cash flows from the investment.
The initial investment is $1,000,000.
After the first year, the return is 25%, so the cash flow at the end of year 1 will be: $1,000,000 ×
1.25 = $1,250,000
For the remaining 4 years, the return is −10% annually. The cash flows for years 2 to 5 are
calculated as follows:
Year 2: $1,250,000 ×0.90 = $1,125,000 Year 3: $1,125,000 ×0.90 = $1,012,500 Year 4:
$1,012,500 ×0.90 = $911,250 Year 5: $911,250 ×0.90 = $820,125
b) Now, we calculate the present value of these cash flows using the discount rate of 15%.
The present value (PV) of each cash flow is calculated using the formula: P V =CF
(1+r)n, where
CF is the cash flow, ris the discount rate, and nis the period.
PV of Year 1 cash flow: ($1,250,000)
(1+0.15)1= $1,086,957.61
PV of Year 2-5 cash flows: ($1,125,000)
(1+0.15)2= $873,573.64 ($1,012,500)
(1+0.15)3= $718,331.05 ($911,250)
(1+0.15)4=
$566,638.49 ($820,125)
(1+0.15)5= $453,157.44
c) Finally, we calculate the NPV by summing up the present values of the cash flows and sub-
tracting the initial investment.
NP V =P VY ear1+P VY ear2+P VY ear3+P VY ear4+P VY ear5−$1,000,000 NP V = $1,086,957.61+
$873,573.64 + $718,331.05 + $566,638.49 + $453,157.44 −$1,000,000 NP V = $1,698,658.23 −
$1,000,000 NP V = $698,658.23
Therefore, the net present value (NPV) of the investment is $698,658.23.
13 Venture Capital and Private Equity
Problem 1.
A venture capital firm is considering investing $1,000,000 in a startup. The firm expects the
startup to be valued at $3,000,000 in 3 years if they invest. If the firm requires a return of 25% per
year on their investment, what percentage ownership should they demand in the startup?
Solution 1.
Let xbe the percentage ownership the venture capital firm should demand in the startup.
The present value of the investment should equal the initial investment of $1,000,000. The
future value of the investment in 3 years should be $3,000,000.
Using the concept of Compound Interest formula:
1,000,000 = 3,000,000
(1 + 0.25)3×x
Solving for x, we get:
x=1,000,000
3,000,000/1.952 = 0.6513 = 65.13%
Therefore, the venture capital firm should demand a 65.13% ownership in the startup.
14 15. FUNDRAISING CHALLENGES FOR VENTURE CAPITAL FIRMS
Problem 15. A Venture Capital firm is looking to raise a new fund of 100 million. They plan to
charge a 2% management fee and a 20% carry fee on any profits generated from investments. If
the firm expects to generate 30% returns on investments over the lifetime of the fund, calculate the
total fees earned by the Venture Capital firm over the fund’s lifetime.
Solution 15. a) The total management fee can be calculated as:
Management Fee =Fund Size ×Management Fee Rate = 100 million ×0.02 = 2 million
b) The total carry fee can be calculated as:
Carry Fee =Return ×Carry Fee Rate = (100 million ×0.30) ×0.20 = 6 million
c) Therefore, the total fees earned by the Venture Capital firm over the fund’s lifetime would be:
Total Fees =Management Fee +Carry Fee = 2 million + 6 million = 8 million
15 16. BALANCING RISK AND REWARD IN PRIVATE EQUITY INVESTMENTS
Problem 16. ABC Ventures is considering investing in a startup company. The expected return
on this investment is 15
Solution 16. a) The Sharpe ratio is calculated as follows:
Sharpe ratio =Rp−Rf
σp
Where: - Rpis the expected return on the investment (15- Rfis the risk-free rate (5- σpis the
standard deviation of the investment (20
Substitute the values into the formula:
Sharpe ratio =0.15 −0.05
0.20 =0.10
0.20 = 0.5
Therefore, the Sharpe ratio for this investment is 0.5.
I can definitely help with that. Let’s work on a numerical problem related to Venture Capital and
Private Equity under the given subtopic.
16 17. IMPACT OF ECONOMIC DOWNTURNS ON VENTURE CAPITAL AND PRIVATE EQ-
UITY
Problem 17. During an economic downturn, a venture capital fund decides to invest 100,000inastartupcompanywithanexpectedreturnof30
Solution 17. Let’s first calculate the expected return after 5 years:
Expected return after 5 years = $100,000 ×(1 + 0.30)5
= $100,000 ×(1.30)5
= $100,000 ×2.8561
= $285,610
Now, the actual return turns out to be 10
Actual return after 5 years = $285,610 ×(1 −0.10)
= $285,610 ×0.90
= $257,049
Therefore, the total amount the venture capital fund will receive after 5 years is $257,049.
I’m glad to help with that! Here is a numerical problem related to Venture Capital and Private
Equity:
17 Venture Capital and Private Equity
Problem:
A venture capital firm invests $1,000,000 in a startup with an agreed 20% equity stake. The
startup later gets acquired for $10,000,000. How much profit does the venture capital firm make
from this investment?
Solution:
First, let’s calculate the value of the equity stake acquired by the venture capital firm:
Equity Stake Value =Investment Amount ×Equity Stake (%)
100
Equity Stake Value = $1,000,000 ×20
100 = $200,000
Then, we can find the profit made by the venture capital firm from the acquisition:
Profit =Acquisition Amount −Equity Stake Value −Investment Amount
Profit = $10,000,000 −$200,000 −$1,000,000 = $8,800,000
Therefore, the venture capital firm makes a profit of $8,800,000 from this investment.
I. Problem 1: Investor Equity Stake Calculation
A venture capital firm invests $1 million in a start-up company in exchange for a 20
Solution 1: Let Vbe the pre-money valuation of the company. The equity stake can be calcu-
lated using the formula:
Equity Stake =Investment Amount
Pre-money Valuation +Investment Amount ×100%
Substitute the values given:
20% = 1,000,000
V+ 1,000,000 ×100%
Solving for V:
V+ 1,000,000 = 1,000,000
20%
V+ 1,000,000 = 5,000,000
V= 4,000,000
Therefore, the pre-money valuation of the company is $4 million.
II. Problem 2: Preferred Stock Liquidation Preference
A venture capitalist invests $2 million in a start-up with a 2x liquidation preference. The company
sells for $5 million. How much money does the venture capitalist receive?
Solution 2: The venture capitalist will first receive back the $2 million invested due to the 2x
liquidation preference. The remaining amount will be divided pro-rata among all shareholders.
Since the company sells for $5 million, the remaining $3 million will be distributed among share-
holders based on their ownership percentage. The venture capitalist owns 2
5of the company ($2
million out of the $5 million total investment).
Therefore, the venture capitalist will receive:
$2,000,000 (liquidation preference)+2
5×$3,000,000 (remaining amount) = $2,000,000+$1,200,000 = $3,200,000
The venture capitalist will receive $3.2 million from the sale.
III. Problem 3: Internal Rate of Return (IRR) Calculation
A private equity firm invests $500,000 in a company and receives the following cash flows:
$100,000 in year 1, $200,000 in year 2, and $300,000 in year 3. Calculate the internal rate of
return for this investment.
Solution 3:
The IRR is the discount rate that makes the net present value (NPV) of all cash flows equal to
zero. Setting up the equation:
0 = −500,000 + 100,000
(1 + r)1+200,000
(1 + r)2+300,000
(1 + r)3
Using a financial calculator or software, solving the above equation gives r≈19.73%.
Therefore, the internal rate of return for this investment is approximately 19.73
18 20. GENDER AND DIVERSITY ISSUES IN VENTURE CAPITAL AND PRIVATE EQUITY.
Problem 20. In a venture capital firm, the distribution of investment decisions made by the
partners is as follows:
•40% of investment decisions are made by male partners
•30% of investment decisions are made by female partners
•30% of investment decisions are made by partners who identify as non-binary
If there are a total of 50 investment decisions made in a year by the venture capital firm, de-
termine the number of investment decisions made by each group (male, female, and non-binary
partners).
Solution 20. Let’s denote:
•Number of investment decisions made by male partners as x
•Number of investment decisions made by female partners as y

•Number of investment decisions made by non-binary partners as z
From the information given in the problem:
x= 0.40 ×50 = 20 (investment decisions by male partners)
y= 0.30 ×50 = 15 (investment decisions by female partners)
z= 0.30 ×50 = 15 (investment decisions by non-binary partners)
Therefore, the number of investment decisions made by each group are as follows:
•Male partners: 20 investment decisions
•Female partners: 15 investment decisions
•Non-binary partners: 15 investment decisions

For Startup A: Expected return = (0.3 * $1,000,000) - (0.7 * $200,000) = $300,000 - $140,000
= $160,000
For Startup B: Expected return = (0.5 * $800,000) - (0.5 * $150,000) = $400,000 - $75,000 =
$325,000
b) Based on expected return alone, Startup B has a higher expected return of $325,000 com-
pared to Startup A’s expected return of $160,000. Therefore, if you were to choose based on
expected return alone, you would choose to invest in Startup B.
Certainly! Here is a numerical problem on Venture Capital and Private Equity for you:
3 3. INVESTOR DIVERSIFICATION IN PRIVATE EQUITY
Problem 3. A venture capital investor has a portfolio of investments in three startups, with the
following initial amounts invested and expected returns:
Startup A: Investment of $100,000 with an expected return of $150,000 Startup B: Investment of
$200,000 with an expected return of $250,000 Startup C: Investment of $150,000 with an expected
return of $180,000
Assuming all three investments are uncorrelated, calculate the total expected return, standard
deviation, and coefficient of variation for the investor’s portfolio.
Solution 3.
a) To find the total expected return, we simply sum up the expected returns of each individual
investment:
Total Expected Return = $150,000 + $250,000 + $180,000 = $580,000
b) Next, to calculate the standard deviation of the portfolio, we need to find the variance of the
portfolio first. Since the investments are uncorrelated, we can use the following formula for the
variance of a portfolio of two assets:
Variance of Portfolio = w2
A∗V ar(A) + w2
B∗V ar(B) + w2
C∗V ar(C)
Where: wA, wB, wC=weightsofinvestmentsA, B, Cintheportfolio(sumofweights = 1)V ar(A), V ar(B), V ar(C) =
varianceofinvestmentsA, B, C
Given the investments are uncorrelated, the variance of each investment is equal to its expected
return:
Var(A) = $150,000 Var(B) = $250,000 Var(C) = $180,000
Let’s calculate the variance: Variance of Portfolio = (100,000/450,000)2∗150,000+(200,000/450,000)2∗
250,000 + (150,000/450,000)2∗180,000
Variance of Portfolio = 83,333.33
Then, the standard deviation is the square root of the variance:
Standard Deviation = √83,333.33 ≈$288.67
c) Finally, the coefficient of variation (CV) is calculated by dividing the standard deviation by the
expected return:
Coefficient of Variation = $288.67 / $580,000 Coefficient of Variation 0.0004986, or approxi-
mately 0.04986
I. Problem: Due Diligence in Venture Capital
A venture capital firm is considering investing $500,000 in a startup company. During the due
diligence process, they discover that the company’s financial projections are as follows:
- Year 1: Revenue of $200,000, Expenses of $150,000 - Year 2: Revenue growth of 20%,
Expenses growth of 10%
Calculate the Net Income for each year and determine the company’s Net Income Margin in
Year 2.
Solution:
a) Net Income for Year 1:
Net Income = Revenue - Expenses
Net Income = $200,000 −$150,000 = $50,000
b) Net Income for Year 2:
Revenue in Year 2 = $200,000 ×1.20 = $240,000
Expenses in Year 2 = $150,000 ×1.10 = $165,000
Net Income = Revenue - Expenses
Net Income = $240,000 −$165,000 = $75,000
c) Net Income Margin in Year 2:
Net Income Margin = NetIncome
Revenue ×100
Net Income Margin = $75,000
$240,000 ×100
Net Income Margin = 75
240 ×100 = 31.25%
Therefore, the company’s Net Income Margin in Year 2 is 31.25%.
4 5. LACK OF TRANSPARENCY IN PRIVATE EQUITY INVESTMENTS
Problem 5. A Venture Capital firm invested 500,000 in a startup in exchange for 20% equity
ownership. After a few years, the startup gets acquired for 5times its initial valuation. If the firm
decides to exit their investment, what is the total cash they receive from the acquisition?
Solution 5. Let’s first calculate the initial valuation of the startup when the Venture Capital firm
invested:
Initial Valuation = Investment Amount
Equity Ownership =500,000
0.20 = 2,500,000
After the acquisition, the startup is acquired for 5times its initial valuation:
Acquisition Price = 5×Initial Valuation = 5 ×2,500,000 = 12,500,000
Since the Venture Capital firm owns 20% equity in the startup, their cash from the acquisition
would be:
Cash from Acquisition = Equity Ownership ×Acquisition Price = 0.20 ×12,500,000 =2,500,000
Therefore, the Venture Capital firm would receive 2,500,000 in cash from the acquisition of the
startup.
I.
5 6. VALUATION DIFFICULTIES IN EARLY-STAGE STARTUPS
Problem 6. You are a venture capitalist looking to invest in a promising early-stage startup.
The startup is seeking $500,000 in funding in exchange for a 20
a) What is the pre-money valuation of the startup based on the given information?
b) If you decide to invest the requested amount, how many shares will you receive?
c) What is the price per share you will pay for this investment?
Solution 6.
a) The pre-money valuation of the startup can be calculated as follows:
Pre-money valuation =Post-money valuation −Amount of funding
Pre-money valuation = $2.5M−$500K= $2M
b) To calculate the number of shares you will receive, we first need to find the value of each
share. The value of each share can be calculated as:
Post-money valuation =Pre-money valuation ×(1 + Equity stake)
$2.5M= $2M×(1 + 0.20)
$2.5M= $2M×1.20
$2.5M= $2.4M
Now, the value per share is $2.4 million. Therefore, the number of shares you will receive is:
Amount of funding
Value per share =$500K
$2.4M=500
2400 =5
24
c) The price per share you will pay for this investment is the same as the value per share, which
is $2.4 million.
6 7. THE IMPACT OF INDUSTRY TRENDS ON VENTURE CAPITAL FUNDING
Problem 7. The venture capital firm XYZ is considering investing in two different industries:
Tech and Biotech. The expected return on investment (ROI) for Tech is 20% with a standard
deviation of 5%, while the expected ROI for Biotech is 15% with a standard deviation of 8%. The
correlation between the two industries is 0.4. If XYZ invests $1 million in Tech and $2 million in
Biotech, calculate the expected ROI of the portfolio and the standard deviation of the portfolio’s
ROI.
Solution 7. Let Xbe the ROI in Tech and Ybe the ROI in Biotech. The expected ROI of a
portfolio is given by the weighted average of the expected ROIs of the individual investments:
E(Rp) = w1E(R1) + w2E(R2)
where w1and w2are the weights of the investments and E(R1)and E(R2)are the expected ROIs
of Tech and Biotech, respectively.
Given: - E(R1) = 20%,E(R2) = 15% -w1= $1,000,000/$3,000,000 = 1
3,w2= $2,000,000/$3,000,000 =
2
3
E(Rp) = 1
3(20%) + 2
3(15%) = 18.33%
The variance of the portfolio is calculated as:
V ar(Rp) = w2
1V ar(R1) + w2
2V ar(R2)+2w1w2Cov(R1, R2)
where V ar(R1)and V ar(R2)are the variances of the individual investments and Cov(R1, R2)is
the covariance between the investments.
Given: - V ar(R1) = (0.05)2,V ar(R2) = (0.08)2,Cov(R1, R2)=0.4(0.05)(0.08)
V ar(Rp) = 1
32
(0.05)2+2
32
(0.08)2+ 2 1
32
3(0.4(0.05)(0.08))
V ar(Rp)≈0.00042833
Therefore, the standard deviation of the portfolio’s ROI is:
σ=qV ar(Rp)≈√0.00042833 ≈0.0207 = 2.07%
Hence, the expected ROI of the portfolio is approximately 18.33%, and the standard deviation
of the portfolio’s ROI is approximately 2.07%.
7 8. INVESTOR EXIT STRATEGIES IN PRIVATE EQUITY DEALS
Problem 8.
A private equity investor invested $1 million in a startup company with the following projected
cash flows over the next five years:
Year 1: $200,000 Year 2: $300,000 Year 3: $400,000 Year 4: $500,000 Year 5: $600,000
Assuming a desired Internal Rate of Return (IRR) of 20% per annum, calculate the exit value
required at the end of Year 5 to achieve the target return for the investor.
Solution 8.
To calculate the exit value required at the end of Year 5, we need to find the Present Value (PV)
of the cash flows and then determine the exit value that would give an IRR of 20%.
The PV of the cash flows can be calculated using the formula:
P V =CF1
(1 + r)1+CF2
(1 + r)2+CF3
(1 + r)3+CF4
(1 + r)4+CF5+ExitV alue
(1 + r)5
Where: CFi= Cash flow at the end of Year i r = 0.20 (IRR) ExitV alue = Exit value at the end
of Year 5
Substitute the given values into the formula:
P V =200,000
(1 + 0.20)1+300,000
(1 + 0.20)2+400,000
(1 + 0.20)3+500,000
(1 + 0.20)4+600,000 + ExitV alue
(1 + 0.20)5
P V =200,000
1.20 +300,000
1.202+400,000
1.203+500,000
1.204+600,000 + ExitV alue
1.205
P V ≈166,666.67 + 225,000 + 250,000 + 277,777.78 + 600,000 + ExitV alue
1.48
P V ≈919,444.45 + 600,000 + ExitV alue
1.48
Since the total initial investment is $1,000,000 at the start, the exit value at the end of Year 5
should be such that the total PV equals the total initial investment:
1,000,000 = 919,444.45 + 600,000 + ExitV alue
1.48
1,000,000 −919,444.45 = 600,000 + ExitV alue
1.48
80,555.55 = 600,000 + ExitV alue
1.48
119,200 ≈600,000 + ExitV alue
ExitV alue ≈119,200 −600,000
ExitV alue ≈ −480,800
Therefore, the exit value required at the end of Year 5 to achieve the target return for the investor
is approximately $480,800 *negative value indicates a loss*.
I.
8 9. REGULATORY COMPLIANCE IN VENTURE CAPITAL AND PRIVATE EQUITY
Problem 9. A Venture Capital firm is considering investing in a startup. The firm’s management
fee is 2% of committed capital, and they charge a 20% carried interest (profit share) on returns
exceeding an 8% preferred return hurdle rate. If the firm raises a fund of 100 million from limited
partners and invests 80
Solution 9.
a) The management fee can be calculated as 2% of the committed capital. Therefore, manage-
ment fee = 0.02 ×100 million = 2 million.
b) The profit share or carried interest is calculated on the returns exceeding the preferred return
hurdle rate. The total profits from the startup investment are 80
Therefore, the profit share = 20
Therefore, the carried interest payable by the startup is 14.4million.
Thus, the management fee payable by the startup is 2million and the carried interest payable
is 14.4million.
I.
9 10. COMPETITION FOR QUALITY DEALS IN THE VENTURE CAPITAL MARKET
Problem 10. In a competitive venture capital market, investors are evaluating two investment
opportunities. Opportunity A requires an investment of 500,000andisexpectedtoyieldareturnof1,000,000
with a probability of success of 30
a) Calculate the expected value of each investment opportunity.
b) Calculate the expected value of the two opportunities if investors can only choose one of
them.
c) Analyze which investment opportunity seems more attractive based on the expected values
calculated in parts (a) and (b).
Solution 10.
a) The expected value of an investment opportunity is calculated by multiplying the return by
the probability of success.
For Opportunity A: Expected value = 1,000,000 ∗0.30 =300,000
For Opportunity B: Expected value = 1,200,000 ∗0.40 =480,000
b) To calculate the expected value of the two opportunities if investors can only choose one, we
compare the expected values of both opportunities.
Choosing between A and B, Opportunity B has a higher expected value of 480,000comparedtoOpportunityA′s300,000.
c) Based on the expected values calculated in parts (a) and (b), Opportunity B seems more
attractive as it offers a higher expected return on investment compared to Opportunity A.
10 11. MANAGING PORTFOLIO COMPANIES IN PRIVATE EQUITY INVESTMENTS
Problem 11. A private equity firm has invested $5 million in a portfolio company and acquired
a 20% stake. After a successful year, the portfolio company’s valuation has increased by 30%.
a) What is the new valuation of the portfolio company?
b) Calculate the new value of the private equity firm’s stake in the portfolio company.
c) If the private equity firm decides to exit its investment by selling its stake, how much profit
would they make if the exit price per share is 25% higher than the original valuation?
Solution 11.
a) The new valuation of the portfolio company after a 30% increase can be calculated as:
New Valuation =Original Valuation ×(1 + Increase %)
New Valuation = $5,000,000 ×(1 + 0.30)
New Valuation = $5,000,000 ×1.30
New Valuation = $6,500,000
Therefore, the new valuation of the portfolio company is $6,500,000.
b) The new value of the private equity firm’s stake in the portfolio company can be calculated
as:
New Value of Stake =New Valuation ×Stake %
New Value of Stake = $6,500,000 ×0.20
New Value of Stake = $1,300,000
Therefore, the new value of the private equity firm’s stake in the portfolio company is $1,300,000.
c) If the exit price per share is 25% higher than the original valuation, then the exit price per
share would be:
Exit Price Per Share =Original Valuation ×(1 + 0.25)
Exit Price Per Share = $5,000,000 ×1.25
Exit Price Per Share = $6,250,000
The profit the private equity firm would make upon exit can be calculated as:
Profit =Exit Price Per Share ×Stake % −Investment
Profit = $6,250,000 ×0.20 −$5,000,000
Profit = $1,250,000 −$5,000,000
Profit = $250,000
Therefore, if the private equity firm exits its investment at an exit price 25% higher than the
original valuation, they would make a profit of $250,000.
11 Venture Capital and Private Equity
Problem: You are a venture capitalist considering investing in a startup. The startup has
projected cash flows for the next 5 years as follows:
Year 1: $100,000 Year 2: $150,000 Year 3: $200,000 Year 4: $250,000 Year 5: $300,000
If the discount rate is 10%, calculate the present value of these cash flows.
Solution: To calculate the present value of the cash flows, we need to discount each cash flow
using the formula:
P V =CF
(1 + r)t
where: P V = Present Value CF = Cash Flow in that year r= Discount Rate t= Time period in
years
Let’s compute the present value of each cash flow and sum them up:
a) For Year 1:
P V1=100,000
(1 + 0.10)1=100,000
1.10 = $90,909
b) For Year 2:
P V2=150,000
(1 + 0.10)2=150,000
1.21 = $123,966
c) For Year 3:
P V3=200,000
(1 + 0.10)3=200,000
1.331 = $150,289
d) For Year 4:
P V4=250,000
(1 + 0.10)4=250,000
1.4641 = $170,866
e) For Year 5:
P V5=300,000
(1 + 0.10)5=300,000
1.6105 = $186,410
Now, summing up all the present values:
P V = $90,909 + $123,966 + $150,289 + $170,866 + $186,410 = $722,440
Therefore, the present value of the cash flows is $722,440.
12 13. THE ROLE OF TECHNOLOGY IN DISRUPTING VENTURE CAPITAL AND PRIVATE
EQUITY
Problem 13. A venture capital firm invests $1,000,000 in a startup with a promised return of
25% annually over 5 years. However, after the first year, the startup faces challenges and the return
drops to −10% annually for the remaining 4 years. Calculate the net present value (NPV) of the
investment if the discount rate is 15%.
Solution 13. a) To calculate the NPV of the investment, we need to find the present value of
the expected cash flows from the investment.
The initial investment is $1,000,000.
After the first year, the return is 25%, so the cash flow at the end of year 1 will be: $1,000,000 ×
1.25 = $1,250,000
For the remaining 4 years, the return is −10% annually. The cash flows for years 2 to 5 are
calculated as follows:
Year 2: $1,250,000 ×0.90 = $1,125,000 Year 3: $1,125,000 ×0.90 = $1,012,500 Year 4:
$1,012,500 ×0.90 = $911,250 Year 5: $911,250 ×0.90 = $820,125
b) Now, we calculate the present value of these cash flows using the discount rate of 15%.
The present value (PV) of each cash flow is calculated using the formula: P V =CF
(1+r)n, where
CF is the cash flow, ris the discount rate, and nis the period.
PV of Year 1 cash flow: ($1,250,000)
(1+0.15)1= $1,086,957.61
PV of Year 2-5 cash flows: ($1,125,000)
(1+0.15)2= $873,573.64 ($1,012,500)
(1+0.15)3= $718,331.05 ($911,250)
(1+0.15)4=
$566,638.49 ($820,125)
(1+0.15)5= $453,157.44
c) Finally, we calculate the NPV by summing up the present values of the cash flows and sub-
tracting the initial investment.
NP V =P VY ear1+P VY ear2+P VY ear3+P VY ear4+P VY ear5−$1,000,000 NP V = $1,086,957.61+
$873,573.64 + $718,331.05 + $566,638.49 + $453,157.44 −$1,000,000 NP V = $1,698,658.23 −
$1,000,000 NP V = $698,658.23
Therefore, the net present value (NPV) of the investment is $698,658.23.
13 Venture Capital and Private Equity
Problem 1.
A venture capital firm is considering investing $1,000,000 in a startup. The firm expects the
startup to be valued at $3,000,000 in 3 years if they invest. If the firm requires a return of 25% per
year on their investment, what percentage ownership should they demand in the startup?
Solution 1.
Let xbe the percentage ownership the venture capital firm should demand in the startup.
The present value of the investment should equal the initial investment of $1,000,000. The
future value of the investment in 3 years should be $3,000,000.
Using the concept of Compound Interest formula:
1,000,000 = 3,000,000
(1 + 0.25)3×x
Solving for x, we get:
x=1,000,000
3,000,000/1.952 = 0.6513 = 65.13%
Therefore, the venture capital firm should demand a 65.13% ownership in the startup.
14 15. FUNDRAISING CHALLENGES FOR VENTURE CAPITAL FIRMS
Problem 15. A Venture Capital firm is looking to raise a new fund of 100 million. They plan to
charge a 2% management fee and a 20% carry fee on any profits generated from investments. If
the firm expects to generate 30% returns on investments over the lifetime of the fund, calculate the
total fees earned by the Venture Capital firm over the fund’s lifetime.
Solution 15. a) The total management fee can be calculated as:
Management Fee =Fund Size ×Management Fee Rate = 100 million ×0.02 = 2 million
b) The total carry fee can be calculated as:
Carry Fee =Return ×Carry Fee Rate = (100 million ×0.30) ×0.20 = 6 million
c) Therefore, the total fees earned by the Venture Capital firm over the fund’s lifetime would be:
Total Fees =Management Fee +Carry Fee = 2 million + 6 million = 8 million
15 16. BALANCING RISK AND REWARD IN PRIVATE EQUITY INVESTMENTS
Problem 16. ABC Ventures is considering investing in a startup company. The expected return
on this investment is 15
Solution 16. a) The Sharpe ratio is calculated as follows:
Sharpe ratio =Rp−Rf
σp
Where: - Rpis the expected return on the investment (15- Rfis the risk-free rate (5- σpis the
standard deviation of the investment (20
Substitute the values into the formula:
Sharpe ratio =0.15 −0.05
0.20 =0.10
0.20 = 0.5
Therefore, the Sharpe ratio for this investment is 0.5.
I can definitely help with that. Let’s work on a numerical problem related to Venture Capital and
Private Equity under the given subtopic.
16 17. IMPACT OF ECONOMIC DOWNTURNS ON VENTURE CAPITAL AND PRIVATE EQ-
UITY
Problem 17. During an economic downturn, a venture capital fund decides to invest 100,000inastartupcompanywithanexpectedreturnof30
Solution 17. Let’s first calculate the expected return after 5 years:
Expected return after 5 years = $100,000 ×(1 + 0.30)5
= $100,000 ×(1.30)5
= $100,000 ×2.8561
= $285,610
Now, the actual return turns out to be 10
Actual return after 5 years = $285,610 ×(1 −0.10)
= $285,610 ×0.90
= $257,049
Therefore, the total amount the venture capital fund will receive after 5 years is $257,049.
I’m glad to help with that! Here is a numerical problem related to Venture Capital and Private
Equity:
17 Venture Capital and Private Equity
Problem:
A venture capital firm invests $1,000,000 in a startup with an agreed 20% equity stake. The
startup later gets acquired for $10,000,000. How much profit does the venture capital firm make
from this investment?
Solution:
First, let’s calculate the value of the equity stake acquired by the venture capital firm:
Equity Stake Value =Investment Amount ×Equity Stake (%)
100
Equity Stake Value = $1,000,000 ×20
100 = $200,000
Then, we can find the profit made by the venture capital firm from the acquisition:
Profit =Acquisition Amount −Equity Stake Value −Investment Amount
Profit = $10,000,000 −$200,000 −$1,000,000 = $8,800,000
Therefore, the venture capital firm makes a profit of $8,800,000 from this investment.
I. Problem 1: Investor Equity Stake Calculation
A venture capital firm invests $1 million in a start-up company in exchange for a 20
Solution 1: Let Vbe the pre-money valuation of the company. The equity stake can be calcu-
lated using the formula:
Equity Stake =Investment Amount
Pre-money Valuation +Investment Amount ×100%
Substitute the values given:
20% = 1,000,000
V+ 1,000,000 ×100%
Solving for V:
V+ 1,000,000 = 1,000,000
20%
V+ 1,000,000 = 5,000,000
V= 4,000,000
Therefore, the pre-money valuation of the company is $4 million.
II. Problem 2: Preferred Stock Liquidation Preference
A venture capitalist invests $2 million in a start-up with a 2x liquidation preference. The company
sells for $5 million. How much money does the venture capitalist receive?
Solution 2: The venture capitalist will first receive back the $2 million invested due to the 2x
liquidation preference. The remaining amount will be divided pro-rata among all shareholders.
Since the company sells for $5 million, the remaining $3 million will be distributed among share-
holders based on their ownership percentage. The venture capitalist owns 2
5of the company ($2
million out of the $5 million total investment).
Therefore, the venture capitalist will receive:
$2,000,000 (liquidation preference)+2
5×$3,000,000 (remaining amount) = $2,000,000+$1,200,000 = $3,200,000
The venture capitalist will receive $3.2 million from the sale.
III. Problem 3: Internal Rate of Return (IRR) Calculation
A private equity firm invests $500,000 in a company and receives the following cash flows:
$100,000 in year 1, $200,000 in year 2, and $300,000 in year 3. Calculate the internal rate of
return for this investment.
Solution 3:
The IRR is the discount rate that makes the net present value (NPV) of all cash flows equal to
zero. Setting up the equation:
0 = −500,000 + 100,000
(1 + r)1+200,000
(1 + r)2+300,000
(1 + r)3
Using a financial calculator or software, solving the above equation gives r≈19.73%.
Therefore, the internal rate of return for this investment is approximately 19.73
18 20. GENDER AND DIVERSITY ISSUES IN VENTURE CAPITAL AND PRIVATE EQUITY.
Problem 20. In a venture capital firm, the distribution of investment decisions made by the
partners is as follows:
•40% of investment decisions are made by male partners
•30% of investment decisions are made by female partners
•30% of investment decisions are made by partners who identify as non-binary
If there are a total of 50 investment decisions made in a year by the venture capital firm, de-
termine the number of investment decisions made by each group (male, female, and non-binary
partners).
Solution 20. Let’s denote:
•Number of investment decisions made by male partners as x
•Number of investment decisions made by female partners as y

•Number of investment decisions made by non-binary partners as z
From the information given in the problem:
x= 0.40 ×50 = 20 (investment decisions by male partners)
y= 0.30 ×50 = 15 (investment decisions by female partners)
z= 0.30 ×50 = 15 (investment decisions by non-binary partners)
Therefore, the number of investment decisions made by each group are as follows:
•Male partners: 20 investment decisions
•Female partners: 15 investment decisions
•Non-binary partners: 15 investment decisions
For Startup A: Expected return = (0.3 * $1,000,000) - (0.7 * $200,000) = $300,000 - $140,000
= $160,000
For Startup B: Expected return = (0.5 * $800,000) - (0.5 * $150,000) = $400,000 - $75,000 =
$325,000
b) Based on expected return alone, Startup B has a higher expected return of $325,000 com-
pared to Startup A’s expected return of $160,000. Therefore, if you were to choose based on
expected return alone, you would choose to invest in Startup B.
Certainly! Here is a numerical problem on Venture Capital and Private Equity for you:
3 3. INVESTOR DIVERSIFICATION IN PRIVATE EQUITY
Problem 3. A venture capital investor has a portfolio of investments in three startups, with the
following initial amounts invested and expected returns:
Startup A: Investment of $100,000 with an expected return of $150,000 Startup B: Investment of
$200,000 with an expected return of $250,000 Startup C: Investment of $150,000 with an expected
return of $180,000
Assuming all three investments are uncorrelated, calculate the total expected return, standard
deviation, and coefficient of variation for the investor’s portfolio.
Solution 3.
a) To find the total expected return, we simply sum up the expected returns of each individual
investment:
Total Expected Return = $150,000 + $250,000 + $180,000 = $580,000
b) Next, to calculate the standard deviation of the portfolio, we need to find the variance of the
portfolio first. Since the investments are uncorrelated, we can use the following formula for the
variance of a portfolio of two assets:
Variance of Portfolio = w2
A∗V ar(A) + w2
B∗V ar(B) + w2
C∗V ar(C)
Where: wA, wB, wC=weightsofinvestmentsA, B, Cintheportfolio(sumofweights = 1)V ar(A), V ar(B), V ar(C) =
varianceofinvestmentsA, B, C
Given the investments are uncorrelated, the variance of each investment is equal to its expected
return:
Var(A) = $150,000 Var(B) = $250,000 Var(C) = $180,000
Let’s calculate the variance: Variance of Portfolio = (100,000/450,000)2∗150,000+(200,000/450,000)2∗
250,000 + (150,000/450,000)2∗180,000
Variance of Portfolio = 83,333.33
Then, the standard deviation is the square root of the variance:
Standard Deviation = √83,333.33 ≈$288.67
c) Finally, the coefficient of variation (CV) is calculated by dividing the standard deviation by the
expected return:
Coefficient of Variation = $288.67 / $580,000 Coefficient of Variation 0.0004986, or approxi-
mately 0.04986
I. Problem: Due Diligence in Venture Capital
A venture capital firm is considering investing $500,000 in a startup company. During the due
diligence process, they discover that the company’s financial projections are as follows:
- Year 1: Revenue of $200,000, Expenses of $150,000 - Year 2: Revenue growth of 20%,
Expenses growth of 10%
Calculate the Net Income for each year and determine the company’s Net Income Margin in
Year 2.
Solution:
a) Net Income for Year 1:
Net Income = Revenue - Expenses
Net Income = $200,000 −$150,000 = $50,000
b) Net Income for Year 2:
Revenue in Year 2 = $200,000 ×1.20 = $240,000
Expenses in Year 2 = $150,000 ×1.10 = $165,000
Net Income = Revenue - Expenses
Net Income = $240,000 −$165,000 = $75,000
c) Net Income Margin in Year 2:
Net Income Margin = NetIncome
Revenue ×100
Net Income Margin = $75,000
$240,000 ×100
Net Income Margin = 75
240 ×100 = 31.25%
Therefore, the company’s Net Income Margin in Year 2 is 31.25%.
4 5. LACK OF TRANSPARENCY IN PRIVATE EQUITY INVESTMENTS
Problem 5. A Venture Capital firm invested 500,000 in a startup in exchange for 20% equity
ownership. After a few years, the startup gets acquired for 5times its initial valuation. If the firm
decides to exit their investment, what is the total cash they receive from the acquisition?
Solution 5. Let’s first calculate the initial valuation of the startup when the Venture Capital firm
invested:
Initial Valuation = Investment Amount
Equity Ownership =500,000
0.20 = 2,500,000
After the acquisition, the startup is acquired for 5times its initial valuation:
Acquisition Price = 5×Initial Valuation = 5 ×2,500,000 = 12,500,000
Since the Venture Capital firm owns 20% equity in the startup, their cash from the acquisition
would be:
Cash from Acquisition = Equity Ownership ×Acquisition Price = 0.20 ×12,500,000 =2,500,000
Therefore, the Venture Capital firm would receive 2,500,000 in cash from the acquisition of the
startup.
I.
5 6. VALUATION DIFFICULTIES IN EARLY-STAGE STARTUPS
Problem 6. You are a venture capitalist looking to invest in a promising early-stage startup.
The startup is seeking $500,000 in funding in exchange for a 20
a) What is the pre-money valuation of the startup based on the given information?
b) If you decide to invest the requested amount, how many shares will you receive?
c) What is the price per share you will pay for this investment?
Solution 6.
a) The pre-money valuation of the startup can be calculated as follows:
Pre-money valuation =Post-money valuation −Amount of funding
Pre-money valuation = $2.5M−$500K= $2M
b) To calculate the number of shares you will receive, we first need to find the value of each
share. The value of each share can be calculated as:
Post-money valuation =Pre-money valuation ×(1 + Equity stake)
$2.5M= $2M×(1 + 0.20)
$2.5M= $2M×1.20
$2.5M= $2.4M
Now, the value per share is $2.4 million. Therefore, the number of shares you will receive is:
Amount of funding
Value per share =$500K
$2.4M=500
2400 =5
24
c) The price per share you will pay for this investment is the same as the value per share, which
is $2.4 million.
6 7. THE IMPACT OF INDUSTRY TRENDS ON VENTURE CAPITAL FUNDING
Problem 7. The venture capital firm XYZ is considering investing in two different industries:
Tech and Biotech. The expected return on investment (ROI) for Tech is 20% with a standard
deviation of 5%, while the expected ROI for Biotech is 15% with a standard deviation of 8%. The
correlation between the two industries is 0.4. If XYZ invests $1 million in Tech and $2 million in
Biotech, calculate the expected ROI of the portfolio and the standard deviation of the portfolio’s
ROI.
Solution 7. Let Xbe the ROI in Tech and Ybe the ROI in Biotech. The expected ROI of a
portfolio is given by the weighted average of the expected ROIs of the individual investments:
E(Rp) = w1E(R1) + w2E(R2)
where w1and w2are the weights of the investments and E(R1)and E(R2)are the expected ROIs
of Tech and Biotech, respectively.
Given: - E(R1) = 20%,E(R2) = 15% -w1= $1,000,000/$3,000,000 = 1
3,w2= $2,000,000/$3,000,000 =
2
3
E(Rp) = 1
3(20%) + 2
3(15%) = 18.33%
The variance of the portfolio is calculated as:
V ar(Rp) = w2
1V ar(R1) + w2
2V ar(R2)+2w1w2Cov(R1, R2)
where V ar(R1)and V ar(R2)are the variances of the individual investments and Cov(R1, R2)is
the covariance between the investments.
Given: - V ar(R1) = (0.05)2,V ar(R2) = (0.08)2,Cov(R1, R2)=0.4(0.05)(0.08)
V ar(Rp) = 1
32
(0.05)2+2
32
(0.08)2+ 2 1
32
3(0.4(0.05)(0.08))
V ar(Rp)≈0.00042833
Therefore, the standard deviation of the portfolio’s ROI is:
σ=qV ar(Rp)≈√0.00042833 ≈0.0207 = 2.07%
Hence, the expected ROI of the portfolio is approximately 18.33%, and the standard deviation
of the portfolio’s ROI is approximately 2.07%.
7 8. INVESTOR EXIT STRATEGIES IN PRIVATE EQUITY DEALS
Problem 8.
A private equity investor invested $1 million in a startup company with the following projected
cash flows over the next five years:
Year 1: $200,000 Year 2: $300,000 Year 3: $400,000 Year 4: $500,000 Year 5: $600,000
Assuming a desired Internal Rate of Return (IRR) of 20% per annum, calculate the exit value
required at the end of Year 5 to achieve the target return for the investor.
Solution 8.
To calculate the exit value required at the end of Year 5, we need to find the Present Value (PV)
of the cash flows and then determine the exit value that would give an IRR of 20%.
The PV of the cash flows can be calculated using the formula:
P V =CF1
(1 + r)1+CF2
(1 + r)2+CF3
(1 + r)3+CF4
(1 + r)4+CF5+ExitV alue
(1 + r)5
Where: CFi= Cash flow at the end of Year i r = 0.20 (IRR) ExitV alue = Exit value at the end
of Year 5
Substitute the given values into the formula:
P V =200,000
(1 + 0.20)1+300,000
(1 + 0.20)2+400,000
(1 + 0.20)3+500,000
(1 + 0.20)4+600,000 + ExitV alue
(1 + 0.20)5
P V =200,000
1.20 +300,000
1.202+400,000
1.203+500,000
1.204+600,000 + ExitV alue
1.205
P V ≈166,666.67 + 225,000 + 250,000 + 277,777.78 + 600,000 + ExitV alue
1.48
P V ≈919,444.45 + 600,000 + ExitV alue
1.48
Since the total initial investment is $1,000,000 at the start, the exit value at the end of Year 5
should be such that the total PV equals the total initial investment:
1,000,000 = 919,444.45 + 600,000 + ExitV alue
1.48
1,000,000 −919,444.45 = 600,000 + ExitV alue
1.48
80,555.55 = 600,000 + ExitV alue
1.48
119,200 ≈600,000 + ExitV alue
ExitV alue ≈119,200 −600,000
ExitV alue ≈ −480,800
Therefore, the exit value required at the end of Year 5 to achieve the target return for the investor
is approximately $480,800 *negative value indicates a loss*.
I.
8 9. REGULATORY COMPLIANCE IN VENTURE CAPITAL AND PRIVATE EQUITY
Problem 9. A Venture Capital firm is considering investing in a startup. The firm’s management
fee is 2% of committed capital, and they charge a 20% carried interest (profit share) on returns
exceeding an 8% preferred return hurdle rate. If the firm raises a fund of 100 million from limited
partners and invests 80
Solution 9.
a) The management fee can be calculated as 2% of the committed capital. Therefore, manage-
ment fee = 0.02 ×100 million = 2 million.
b) The profit share or carried interest is calculated on the returns exceeding the preferred return
hurdle rate. The total profits from the startup investment are 80
Therefore, the profit share = 20
Therefore, the carried interest payable by the startup is 14.4million.
Thus, the management fee payable by the startup is 2million and the carried interest payable
is 14.4million.
I.
9 10. COMPETITION FOR QUALITY DEALS IN THE VENTURE CAPITAL MARKET
Problem 10. In a competitive venture capital market, investors are evaluating two investment
opportunities. Opportunity A requires an investment of 500,000andisexpectedtoyieldareturnof1,000,000
with a probability of success of 30
a) Calculate the expected value of each investment opportunity.
b) Calculate the expected value of the two opportunities if investors can only choose one of
them.
c) Analyze which investment opportunity seems more attractive based on the expected values
calculated in parts (a) and (b).
Solution 10.
a) The expected value of an investment opportunity is calculated by multiplying the return by
the probability of success.
For Opportunity A: Expected value = 1,000,000 ∗0.30 =300,000
For Opportunity B: Expected value = 1,200,000 ∗0.40 =480,000
b) To calculate the expected value of the two opportunities if investors can only choose one, we
compare the expected values of both opportunities.
Choosing between A and B, Opportunity B has a higher expected value of 480,000comparedtoOpportunityA′s300,000.
c) Based on the expected values calculated in parts (a) and (b), Opportunity B seems more
attractive as it offers a higher expected return on investment compared to Opportunity A.
10 11. MANAGING PORTFOLIO COMPANIES IN PRIVATE EQUITY INVESTMENTS
Problem 11. A private equity firm has invested $5 million in a portfolio company and acquired
a 20% stake. After a successful year, the portfolio company’s valuation has increased by 30%.
a) What is the new valuation of the portfolio company?
b) Calculate the new value of the private equity firm’s stake in the portfolio company.
c) If the private equity firm decides to exit its investment by selling its stake, how much profit
would they make if the exit price per share is 25% higher than the original valuation?
Solution 11.
a) The new valuation of the portfolio company after a 30% increase can be calculated as:
New Valuation =Original Valuation ×(1 + Increase %)
New Valuation = $5,000,000 ×(1 + 0.30)
New Valuation = $5,000,000 ×1.30
New Valuation = $6,500,000
Therefore, the new valuation of the portfolio company is $6,500,000.
b) The new value of the private equity firm’s stake in the portfolio company can be calculated
as:
New Value of Stake =New Valuation ×Stake %
New Value of Stake = $6,500,000 ×0.20
New Value of Stake = $1,300,000
Therefore, the new value of the private equity firm’s stake in the portfolio company is $1,300,000.
c) If the exit price per share is 25% higher than the original valuation, then the exit price per
share would be:
Exit Price Per Share =Original Valuation ×(1 + 0.25)
Exit Price Per Share = $5,000,000 ×1.25
Exit Price Per Share = $6,250,000
The profit the private equity firm would make upon exit can be calculated as:
Profit =Exit Price Per Share ×Stake % −Investment
Profit = $6,250,000 ×0.20 −$5,000,000
Profit = $1,250,000 −$5,000,000
Profit = $250,000
Therefore, if the private equity firm exits its investment at an exit price 25% higher than the
original valuation, they would make a profit of $250,000.
11 Venture Capital and Private Equity
Problem: You are a venture capitalist considering investing in a startup. The startup has
projected cash flows for the next 5 years as follows:
Year 1: $100,000 Year 2: $150,000 Year 3: $200,000 Year 4: $250,000 Year 5: $300,000
If the discount rate is 10%, calculate the present value of these cash flows.
Solution: To calculate the present value of the cash flows, we need to discount each cash flow
using the formula:
P V =CF
(1 + r)t
where: P V = Present Value CF = Cash Flow in that year r= Discount Rate t= Time period in
years
Let’s compute the present value of each cash flow and sum them up:
a) For Year 1:
P V1=100,000
(1 + 0.10)1=100,000
1.10 = $90,909
b) For Year 2:
P V2=150,000
(1 + 0.10)2=150,000
1.21 = $123,966
c) For Year 3:
P V3=200,000
(1 + 0.10)3=200,000
1.331 = $150,289
d) For Year 4:
P V4=250,000
(1 + 0.10)4=250,000
1.4641 = $170,866
e) For Year 5:
P V5=300,000
(1 + 0.10)5=300,000
1.6105 = $186,410
Now, summing up all the present values:
P V = $90,909 + $123,966 + $150,289 + $170,866 + $186,410 = $722,440
Therefore, the present value of the cash flows is $722,440.
12 13. THE ROLE OF TECHNOLOGY IN DISRUPTING VENTURE CAPITAL AND PRIVATE
EQUITY
Problem 13. A venture capital firm invests $1,000,000 in a startup with a promised return of
25% annually over 5 years. However, after the first year, the startup faces challenges and the return
drops to −10% annually for the remaining 4 years. Calculate the net present value (NPV) of the
investment if the discount rate is 15%.
Solution 13. a) To calculate the NPV of the investment, we need to find the present value of
the expected cash flows from the investment.
The initial investment is $1,000,000.
After the first year, the return is 25%, so the cash flow at the end of year 1 will be: $1,000,000 ×
1.25 = $1,250,000
For the remaining 4 years, the return is −10% annually. The cash flows for years 2 to 5 are
calculated as follows:
Year 2: $1,250,000 ×0.90 = $1,125,000 Year 3: $1,125,000 ×0.90 = $1,012,500 Year 4:
$1,012,500 ×0.90 = $911,250 Year 5: $911,250 ×0.90 = $820,125
b) Now, we calculate the present value of these cash flows using the discount rate of 15%.
The present value (PV) of each cash flow is calculated using the formula: P V =CF
(1+r)n, where
CF is the cash flow, ris the discount rate, and nis the period.
PV of Year 1 cash flow: ($1,250,000)
(1+0.15)1= $1,086,957.61
PV of Year 2-5 cash flows: ($1,125,000)
(1+0.15)2= $873,573.64 ($1,012,500)
(1+0.15)3= $718,331.05 ($911,250)
(1+0.15)4=
$566,638.49 ($820,125)
(1+0.15)5= $453,157.44
c) Finally, we calculate the NPV by summing up the present values of the cash flows and sub-
tracting the initial investment.
NP V =P VY ear1+P VY ear2+P VY ear3+P VY ear4+P VY ear5−$1,000,000 NP V = $1,086,957.61+
$873,573.64 + $718,331.05 + $566,638.49 + $453,157.44 −$1,000,000 NP V = $1,698,658.23 −
$1,000,000 NP V = $698,658.23
Therefore, the net present value (NPV) of the investment is $698,658.23.
13 Venture Capital and Private Equity
Problem 1.
A venture capital firm is considering investing $1,000,000 in a startup. The firm expects the
startup to be valued at $3,000,000 in 3 years if they invest. If the firm requires a return of 25% per
year on their investment, what percentage ownership should they demand in the startup?
Solution 1.
Let xbe the percentage ownership the venture capital firm should demand in the startup.
The present value of the investment should equal the initial investment of $1,000,000. The
future value of the investment in 3 years should be $3,000,000.
Using the concept of Compound Interest formula:
1,000,000 = 3,000,000
(1 + 0.25)3×x
Solving for x, we get:
x=1,000,000
3,000,000/1.952 = 0.6513 = 65.13%
Therefore, the venture capital firm should demand a 65.13% ownership in the startup.
14 15. FUNDRAISING CHALLENGES FOR VENTURE CAPITAL FIRMS
Problem 15. A Venture Capital firm is looking to raise a new fund of 100 million. They plan to
charge a 2% management fee and a 20% carry fee on any profits generated from investments. If
the firm expects to generate 30% returns on investments over the lifetime of the fund, calculate the
total fees earned by the Venture Capital firm over the fund’s lifetime.
Solution 15. a) The total management fee can be calculated as:
Management Fee =Fund Size ×Management Fee Rate = 100 million ×0.02 = 2 million
b) The total carry fee can be calculated as:
Carry Fee =Return ×Carry Fee Rate = (100 million ×0.30) ×0.20 = 6 million
c) Therefore, the total fees earned by the Venture Capital firm over the fund’s lifetime would be:
Total Fees =Management Fee +Carry Fee = 2 million + 6 million = 8 million
15 16. BALANCING RISK AND REWARD IN PRIVATE EQUITY INVESTMENTS
Problem 16. ABC Ventures is considering investing in a startup company. The expected return
on this investment is 15
Solution 16. a) The Sharpe ratio is calculated as follows:
Sharpe ratio =Rp−Rf
σp
Where: - Rpis the expected return on the investment (15- Rfis the risk-free rate (5- σpis the
standard deviation of the investment (20
Substitute the values into the formula:
Sharpe ratio =0.15 −0.05
0.20 =0.10
0.20 = 0.5
Therefore, the Sharpe ratio for this investment is 0.5.
I can definitely help with that. Let’s work on a numerical problem related to Venture Capital and
Private Equity under the given subtopic.
16 17. IMPACT OF ECONOMIC DOWNTURNS ON VENTURE CAPITAL AND PRIVATE EQ-
UITY
Problem 17. During an economic downturn, a venture capital fund decides to invest 100,000inastartupcompanywithanexpectedreturnof30
Solution 17. Let’s first calculate the expected return after 5 years:
Expected return after 5 years = $100,000 ×(1 + 0.30)5
= $100,000 ×(1.30)5
= $100,000 ×2.8561
= $285,610
Now, the actual return turns out to be 10
Actual return after 5 years = $285,610 ×(1 −0.10)
= $285,610 ×0.90
= $257,049
Therefore, the total amount the venture capital fund will receive after 5 years is $257,049.
I’m glad to help with that! Here is a numerical problem related to Venture Capital and Private
Equity:
17 Venture Capital and Private Equity
Problem:
A venture capital firm invests $1,000,000 in a startup with an agreed 20% equity stake. The
startup later gets acquired for $10,000,000. How much profit does the venture capital firm make
from this investment?
Solution:
First, let’s calculate the value of the equity stake acquired by the venture capital firm:
Equity Stake Value =Investment Amount ×Equity Stake (%)
100
Equity Stake Value = $1,000,000 ×20
100 = $200,000
Then, we can find the profit made by the venture capital firm from the acquisition:
Profit =Acquisition Amount −Equity Stake Value −Investment Amount
Profit = $10,000,000 −$200,000 −$1,000,000 = $8,800,000
Therefore, the venture capital firm makes a profit of $8,800,000 from this investment.
I. Problem 1: Investor Equity Stake Calculation
A venture capital firm invests $1 million in a start-up company in exchange for a 20
Solution 1: Let Vbe the pre-money valuation of the company. The equity stake can be calcu-
lated using the formula:
Equity Stake =Investment Amount
Pre-money Valuation +Investment Amount ×100%
Substitute the values given:
20% = 1,000,000
V+ 1,000,000 ×100%
Solving for V:
V+ 1,000,000 = 1,000,000
20%
V+ 1,000,000 = 5,000,000
V= 4,000,000
Therefore, the pre-money valuation of the company is $4 million.
II. Problem 2: Preferred Stock Liquidation Preference
A venture capitalist invests $2 million in a start-up with a 2x liquidation preference. The company
sells for $5 million. How much money does the venture capitalist receive?
Solution 2: The venture capitalist will first receive back the $2 million invested due to the 2x
liquidation preference. The remaining amount will be divided pro-rata among all shareholders.
Since the company sells for $5 million, the remaining $3 million will be distributed among share-
holders based on their ownership percentage. The venture capitalist owns 2
5of the company ($2
million out of the $5 million total investment).
Therefore, the venture capitalist will receive:
$2,000,000 (liquidation preference)+2
5×$3,000,000 (remaining amount) = $2,000,000+$1,200,000 = $3,200,000
The venture capitalist will receive $3.2 million from the sale.
III. Problem 3: Internal Rate of Return (IRR) Calculation
A private equity firm invests $500,000 in a company and receives the following cash flows:
$100,000 in year 1, $200,000 in year 2, and $300,000 in year 3. Calculate the internal rate of
return for this investment.
Solution 3:
The IRR is the discount rate that makes the net present value (NPV) of all cash flows equal to
zero. Setting up the equation:
0 = −500,000 + 100,000
(1 + r)1+200,000
(1 + r)2+300,000
(1 + r)3
Using a financial calculator or software, solving the above equation gives r≈19.73%.
Therefore, the internal rate of return for this investment is approximately 19.73
18 20. GENDER AND DIVERSITY ISSUES IN VENTURE CAPITAL AND PRIVATE EQUITY.
Problem 20. In a venture capital firm, the distribution of investment decisions made by the
partners is as follows:
•40% of investment decisions are made by male partners
•30% of investment decisions are made by female partners
•30% of investment decisions are made by partners who identify as non-binary
If there are a total of 50 investment decisions made in a year by the venture capital firm, de-
termine the number of investment decisions made by each group (male, female, and non-binary
partners).
Solution 20. Let’s denote:
•Number of investment decisions made by male partners as x
•Number of investment decisions made by female partners as y

•Number of investment decisions made by non-binary partners as z
From the information given in the problem:
x= 0.40 ×50 = 20 (investment decisions by male partners)
y= 0.30 ×50 = 15 (investment decisions by female partners)
z= 0.30 ×50 = 15 (investment decisions by non-binary partners)
Therefore, the number of investment decisions made by each group are as follows:
•Male partners: 20 investment decisions
•Female partners: 15 investment decisions
•Non-binary partners: 15 investment decisions

