


REAL OPTIONS AND INVESTMENT ANALYSIS
1 1. STRATEGIC DECISION-MAKING UNDER UNCERTAINTY
Problem 1. An investment project has two possible outcomes: success and failure, with prob-
abilities of 0.6 and 0.4 respectively. The project’s expected cash flows are $100 million in the
success state and $20 million in the failure state. The risk-adjusted discount rate for the project is
10%. Calculate the project’s Expected Net Present Value (ENPV) and advise whether the project
should be undertaken.
Solution 1.
The Expected Net Present Value (ENPV) of the project is calculated as follows:
EN P V = (psuccess ×CFsuccess +pfailure ×CFfailure)/(1 + r)
Where:
psuccess = 0.6(probability of success)
CFsuccess = $100 million (cash flow in success state)
pfailure = 0.4(probability of failure)
CFfailure = $20 million (cash flow in failure state)
r= 0.10 (risk-adjusted discount rate)
EN P V = (0.6×$100 + 0.4×$20)/(1 + 0.10)
EN P V = ($60 + $8)/1.10
EN P V = $68/1.10
EN P V = $61.82 million
Since the ENPV of the project is positive ($61.82 million), it indicates that the project is expected
to generate value and should be undertaken.
2 2. VALUATION OF REAL OPTIONS
Problem 2. An oil company is considering investing in a new drilling project. The initial invest-
ment required is $1,000,000. The company has the option to abandon the project if the price of oil
remains low. The current price of oil is $50 per barrel, and if oil prices remain low, the projected
cash flows for the next three years will be $200,000,$250,000, and $300,000, respectively. If the
price of oil increases, the projected cash flows will be $400,000,$450,000, and $500,000 over the
next three years. The risk-free rate is 4%.
a) Calculate the value of the real option to abandon the project.
b) Determine the net present value (NPV) of the project without considering the real option.
c) Calculate the net present value (NPV) of the project with the real option included.
Solution 2.
a) The value of the real option to abandon the project can be calculated using the binomial
option pricing model. The option to abandon is equivalent to a put option. Using the risk-neutral
valuation approach, the value of the option can be found by working backwards from the final year.
Let’s denote: - S0= $50 (price of oil at time t= 0) - X= $200,000 (cash flow if oil prices remain
low) - R= 1.04 (risk-free rate) - T= 3 years (time to expiration)
The value of the option to abandon is:
V3=1
1.04 0.5×Vu
4+Vd
4
1.04 + 0.5×X
where Vu
4= 0 since if the price of oil increases, the company will not abandon the project.
Therefore:
V3=1
1.04 0.5×0 + Vd
4
1.04 + 0.5×200,000
Given that Vd
4= 0, we can calculate:
V3=1
1.04 0.5×0
1.04+ 0.5×200,000=1
1.04 ×0.5×192,307.69 = $92,746.91
Therefore, the value of the real option to abandon the project is $92,746.91.
b) The NPV of the project without the real option is calculated as the present value of the
expected cash flows minus the initial investment:
NP V =200,000
1.04 +250,000
(1.04)2+300,000
(1.04)3−1,000,000 = 535,725.89
c) The NPV of the project with the real option included is the sum of the NPV without the option
and the value of the option:
NP V = 535,725.89 + 92,746.91 = 628,472.80
3 3. TIMING OF INVESTMENTS
Problem 3. A company is considering investing in a new project. The initial investment cost
is $500,000. The project is expected to generate cash flows of $200,000 per year for the next 5
years. The company’s cost of capital is 10%. If the company decides to delay the investment by
one year, the initial investment cost will decrease to $450,000, but the annual cash flows will also
decrease to $180,000 per year for the next 5 years. Should the company invest now or delay the
investment for one year?
Solution 3. Let’s first calculate the net present value (NPV) of the project if the company invests
now and if it delays the investment by one year.
a) NPV of investing now: The NPV of investing now can be calculated as follows:
NP Vnow =−500,000 + 200,000
1.10 +200,000
(1.10)2+200,000
(1.10)3+200,000
(1.10)4+200,000
(1.10)5
NP Vnow =−500,000 + 200,000
1.10 +200,000
(1.10)2+200,000
(1.10)3+200,000
(1.10)4+200,000
(1.10)5
NP Vnow =−500,000 + 181,818.18 + 165,289.26 + 150,263.87 + 136,603.52 + 124,184.11
NP Vnow = $157,158.94
b) NPV of delaying the investment by one year: The NPV of delaying the investment by one
year can be calculated as follows:
NP Vdelayed =−450,000 + 180,000
1.10 +180,000
(1.10)2+180,000
(1.10)3+180,000
(1.10)4+180,000
(1.10)5
NP Vdelayed =−450,000 + 163,636.36 + 148,760.33 + 135,236.66 + 122,942.42 + 111,766.74
NP Vdelayed = $131,342.11
c) Conclusion: Comparing the two options, investing now yields an NPV of $157,158.94, while
delaying the investment by one year yields an NPV of $131,342.11. Therefore, the company should
invest in the project now as it provides a higher NPV.
4 4. FLEXIBILITY IN PROJECT DEVELOPMENT
Problem 4. A company is considering investing in a new project that has the following cash
flows for the next 3 years:
•Year 1: −1,000 (investment cost)
•Year 2: 500
•Year 3: 800
The company has the option to abandon the project after year 1 with a salvage value of 300.
The risk-free rate is 5%.
a) Calculate the net present value (NPV) of the project without the abandonment option.
b) Calculate the NPV of the project with the abandonment option.
c) Determine whether the company should exercise the abandonment option or not.
Solution 4.
a) The NPV of the project without the abandonment option is calculated by discounting the cash
flows at the risk-free rate:
NP V =−1,000 + 500
1.05 +800
1.052=−1,000 + 476.19 + 756.14 = 232.33
Therefore, the NPV of the project without the abandonment option is 232.33.
b) To calculate the NPV of the project with the abandonment option, we need to consider the
salvage value if the project is abandoned after year 1. The NPV with the abandonment option is:
NP V =−1,000 + 300 + 500
1.05 +800
1.052=−1,000 + 300 + 476.19 + 756.14 = 532.33
So, the NPV of the project with the abandonment option is 532.33.
c) Comparing the NPVs, we see that the NPV with the abandonment option is greater than the
NPV without the abandonment option. Therefore, the company should exercise the abandonment
option if the project’s cash flows are as predicted.
5 5. UNCERTAINTY IN PROJECT OUTCOMES
Problem 5. A company is considering investing in a new project that has two possible out-
comes: success or failure. The probabilities of success and failure are estimated to be 0.6 and
0.4, respectively. If the project is successful, the company expects to earn $500,000, but if it fails,
they will lose $200,000. The initial investment required for the project is $100,000. Calculate the
expected net present value (NPV) of the project.
Solution 5. The expected NPV of the project is calculated as the sum of the expected cash
flows discounted to the present value at the appropriate rate.
a) Expected Cash Flows: The expected cash flow from a successful project is $500,000 and
from a failed project is -$200,000.
Expected cash flow = (Probability of success * Cash flow from success) + (Probability of failure
* Cash flow from failure) Expected cash flow = (0.6 * $500,000) + (0.4 * -$200,000) Expected cash
flow = $300,000 - $80,000 Expected cash flow = $220,000
b) NPV Calculation: NPV = Expected cash flow / (1 + r)twhere, r =discountrate, t =timeperiod, inthiscase, t =
0
Given that the initial investment is $100,000 and the expected cash flow is $220,000, the NPV
can be calculated as:
NPV = (Expected cash flow - Initial investment) / (1 + r)tNP V = ($220,000 −$100,000)/(1 +
r)0NP V = $120,000
Therefore, the expected net present value (NPV) of the project is $120,000.
6 6. INVESTMENT DECISION UNDER COMPETITION
Problem 6. A company is considering expanding its production capacity to meet the increasing
demand for its product. There are two options available: Option A involves investing $400,000 to
increase capacity by 10,000 units annually for the next 5 years. Option B requires an investment
of $600,000 for a capacity increase of 15,000 units annually for the next 5 years.
The company’s estimated revenue per unit is $50, and the variable cost per unit is $20. The
discount rate is 10%. The company operates in a competitive market where the demand is uncer-
tain. Based on the current information, the company forecasts the demand for the next 5 years to
have the following probabilities:
Demand Level Probability
Low 0.2
Medium 0.5
High 0.3
a) Calculate the NPV for each option.
b) Determine the value of the real options present in this investment decision.
Solution 6.
a) The Net Present Value (NPV) for each option is calculated as follows: Let’s denote: - R= $50
(revenue per unit) - C= $20 (variable cost per unit) - IA= $400,000 (investment for Option A) -
IB= $600,000 (investment for Option B) - d= 10% (discount rate)
For Option A:
NP VA=
5
X
t=1
[(R−C)×Demandt×10,000] −IA
NP VA= [(50 −20) ×10,000 ×0.2 + (50 −20) ×10,000 ×0.5 + (50 −20) ×10,000 ×0.3]−400,000
NP VA= (30 ×10,000 ×0.2 + 30 ×10,000 ×0.5 + 30 ×10,000 ×0.3) −400,000
NP VA= (60,000 + 150,000 + 90,000) −400,000 = 300,000 −400,000 = −100,000
For Option B:
NP VB=
5
X
t=1
[(R−C)×Demandt×15,000] −IB
NP VB= [(50 −20) ×15,000 ×0.2 + (50 −20) ×15,000 ×0.5 + (50 −20) ×15,000 ×0.3]−600,000
NP VB= (30 ×15,000 ×0.2 + 30 ×15,000 ×0.5 + 30 ×15,000 ×0.3) −600,000
NP VB= (90,000 + 225,000 + 135,000) −600,000 = 450,000 −600,000 = −150,000
Therefore, the NPV for Option A is -$100,000 and for Option B is -$150,000.
b) To determine the value of the real options present in this investment decision, we would
need to consider the flexibility in the decision-making over the 5-year period based on the market
conditions. Real options analysis would allow the company to make optimal decisions in response
to the changing market conditions, such as the ability to expand further, contract, or delay expan-
sion. The value of the real options in this case would be the additional value generated by having
flexibility in decision-making compared to a static investment analysis.
It is important to note that the value of real options can be complex to quantify and may require
more detailed analysis based on specific scenarios and assumptions.
7 7. OPTIMAL INVESTMENT STRATEGIES
Problem 7. ABC Corporation is considering investing in a new project that will require an initial
investment of $500,000. The project is expected to generate cash flows of $150,000 in the first
year, $200,000 in the second year, and $300,000 in the third year. The risk-free rate is 4%. The
firm’s cost of capital is 12% and the project’s beta is 1.5. The current stock price is $50. Calculate
the Net Present Value (NPV) and the Real Options Value (ROV) of the project.
Solution 7. a) Calculate the Net Present Value (NPV):
The NPV calculation involves discounting the cash flows of the project at the firm’s cost of
capital. The formula for NPV is:
NP V =
3
X
t=1
CFt
(1 + r)t−Initial Investment
Where:
CFt:Cash flow in year t
r:Cost of capital
Substitute the given values into the formula:
NP V =150,000
(1 + 0.12)1+200,000
(1 + 0.12)2+300,000
(1 + 0.12)3−500,000
= 150,000/1.12 + 200,000/1.2544 + 300,000/1.4049 −500,000
= 133,928.57 + 159,544.29 + 213,143.16 −500,000
= $6,616.02
Therefore, the Net Present Value (NPV) of the project is $6,616.02.
b) Calculate the Real Options Value (ROV):
The Real Options Value (ROV) incorporates the value of managerial flexibility in decision mak-
ing. The formula for ROV is:
ROV =NP V + (Stock P rice ×β×N P V )
Where:
Stock P rice :Current stock price
β:Beta of the project
NP V :Net Present Value
Substitute the given values into the formula:
ROV = 6,616.02 + (50 ×1.5×6,616.02)
= 6,616.02 + 4,974.015
= $11,590.03
Therefore, the Real Options Value (ROV) of the project is $11,590.03.
8 8. REAL OPTIONS AND RISK MANAGEMENT
Problem 8. A company is considering investing in a project that has an initial cost of $1,000,000.
The project is expected to generate $400,000 in revenue in the first year, with a 30
a) Calculate the expected present value (EPV) of the project.
b) Determine the real option value (ROV) of the project.
Solution 8.
a) The EPV of the project can be calculated using the expected cash flow and discounting it
back to present value.
For the successful scenario (30
P V =400,000
1+0.03 =400,000
1.03 ≈$388,349.51
For the unsuccessful scenario (70The present value is zero as there is no revenue.
P V = 0
Therefore, the EPV of the project is:
EP V = 0.3×$388,349.51 + 0.7×$0 = $116,504.85
b) To determine the real option value (ROV) of the project, we need to calculate the value of the
option to continue the project given that it is successful.
The cash flow for each year in the successful scenario is given by:
CFt= 400,000 ×(1.05)t
The present value of the cash flows can be calculated using the risk-free rate of 3
P Vt=400,000 ×(1.05)t
(1 + 0.03)t=400,000 ×(1.05)t
1.03t
For simplicity, let’s consider a perpetuity formula to find the present value of expected cash
flows after year 1:
P V∞=400,000 ×(1.05)
0.03 −0.05 =400,000 ×1.05
−0.02 ≈ −$21,000,000.00
Therefore, the ROV of the project is positive (since the project should be continued) and is
approximately $21,000,000.00.
9 9. REAL OPTIONS IN TECHNOLOGY INVESTMENTS
Problem 9. A technology company is considering investing in a new project that will cost
$500,000 upfront. The project is expected to generate cash flows of $200,000 in one year with a
60% chance, and $100,000 with a 40% chance. The risk-free rate is 5%, and the company uses a
discount rate of 10% for risky projects. The company has the option to abandon the project in one
year if the cash flows are not satisfactory.
a) Calculate the present value of the project without the option to abandon it.
b) Calculate the project’s value if the company has the option to abandon it in one year.
c) Determine the value of the abandonment option.
Solution 9.
a) The present value of the project without the option to abandon it can be calculated by dis-
counting the expected cash flows at the discount rate of 10%:
P V =200,000 ×0.6
1.10 +100,000 ×0.4
1.10 = $145,454.55 + $36,363.64 = $181,818.19
Therefore, the present value of the project without the option to abandon it is $181,818.19.
b) To calculate the project’s value with the option to abandon it, we need to consider the option
to abandon the project in one year if the cash flows are not satisfactory. We use the risk-neutral
probabilities to estimate the expected cash flow and discount it back at the risk-free rate:
E(CF ) = 200,000 ×0.6 + 100,000 ×0.4 = $160,000
P V =160,000
1.05 = $152,380.95
Therefore, the project’s value with the option to abandon it in one year is $152,380.95.
c) The value of the abandonment option is the difference between the present value of the
project without the option to abandon it and the project’s value with the option to abandon it:
Abandonment Option = $181,818.19 −$152,380.95 = $29,437.24
Therefore, the value of the abandonment option is $29,437.24.
10 10. REAL OPTIONS IN NATURAL RESOURCE EXPLORATION
Problem 10. A mining company is considering opening a new mine in a mineral-rich region.
The company has the option to delay the opening of the mine for two years to allow for more
exploration and better market conditions. The initial investment cost for opening the mine now is
$10 million. If the company delays the opening, it would incur exploration costs of $2 million per
year for the two-year period. The present value factor for each year is 0.909.
a) Calculate the net present value (NPV) of opening the mine now.
b) Calculate the net present value (NPV) of delaying the opening for two years and incorporating
the exploration costs.
c) Discuss whether it is financially advantageous for the company to delay the mine opening
based on the NPV calculations.
Solution 10.
a) The NPV of opening the mine now can be calculated using the formula:
NP V =−InitialInvestment +XN etCashF lowt
(1 + r)t
Given that the initial investment is $10 million, the annual net cash flow from the mine operation
is expected to be $5 million, and the discount rate is 10
NP V =−10 + 5(0.909) + 5(0.909)2
NP V =−10 + 4.545 + 4.132 = −10 + 8.677 = −1.323
Therefore, the NPV of opening the mine now is -$1.323 million.
b) The NPV of delaying the mine opening can be calculated by considering the exploration costs
for two years:
NP V =−InitialInvestment +XExplorationCostst
(1 + r)t
The exploration costs for year 1 and year 2 are $2 million each. So, the NPV of delaying the
opening for two years is:
NP V =−2(0.909) −2(0.909)2=−1.818 −1.818 = −3.636
Therefore, the NPV of delaying the mine opening is -$3.636 million.
c) Comparing the NPVs, we see that delaying the mine opening results in a higher negative
NPV (-$3.636 million) compared to opening the mine now (-$1.323 million). Therefore, from a
financial perspective, it is not advantageous for the company to delay the mine opening.
11 11. CAPITAL BUDGETING WITH REAL OPTIONS
Problem 11. ABC Corporation is considering an investment in a new project. The initial cost
of the project is $500,000. The project is expected to generate cash flows of $150,000 per year for
the next 5 years. The risk-free rate is 4% and the project’s beta is 1.2. The strike price for the real
option to abandon the project is $400,000. Calculate the Net Present Value (NPV) of the project
with and without the real option to abandon.
Solution 11.
a) First, let’s calculate the NPV of the project without the real option to abandon:
The NPV formula is:
NP V =−C0+
n
X
t=1
CFt
(1 + r)t
Where: - C0= $500,000 (initial cost of project) - CFt= $150,000 for all years 1 to 5 - r= 4%
(risk-free rate)
Substitute these values into the formula:
NP V =−$500,000 + $150,000
1.04 +$150,000
(1.04)2+$150,000
(1.04)3+$150,000
(1.04)4+$150,000
(1.04)5
Calculating the above expression gives:
NP V =−$500,000 + $144,230.77 + $138,888.89 + $133,951.10 + $129,404.77 + $125,229.48
NP V =−$500,000 + $671,705.01
NP V = $171,705.01
Therefore, the NPV of the project without the real option to abandon is $171,705.01.
b) Now, let’s calculate the NPV of the project with the real option to abandon:
The real option to abandon adds an extra Pto cash flow in year 2. The value of this real option
can be calculated as:
P=Max(0, K −V2)
Where: - K= $400,000 (strike price to abandon) - V2= $500,000 + $150,000
1.04 = $630,769.23 (value
of the project in year 2)
P=Max(0,$400,000 −$630,769.23)
P=Max(0,−$230,769.23) = $0
Therefore, there is no value in exercising the real option to abandon the project in year 2. The
NPV remains $171,705.01.
Thus, the NPV of the project with and without the real option to abandon remains the same at
$171,705.01.
12 12. REAL OPTIONS IN REAL ESTATE INVESTMENTS
Problem 12.
A real estate developer is considering the purchase of a parcel of land for $500,000. The
developer has the option to build either residential units or commercial units on the land. The
expected cash flows associated with each type of development are as follows:
•Residential units: $300,000 in the first year, $200,000 in the second year, and $100,000 in
the third year.
•Commercial units: $400,000 in the first year, $250,000 in the second year, and $150,000 in
the third year.
The developer has the right to delay the development decision by one year. If the developer
chooses to wait, the cost of the land will remain the same and the expected cash flows will also
remain the same. The risk-free rate is 5%.
a) Determine the net present value (NPV) of developing residential units immediately.
b) Determine the net present value (NPV) of developing commercial units immediately.
c) Calculate the value of the option to delay the development decision by one year.
Solution 12.
a) To find the NPV of developing residential units immediately, we need to discount the expected
cash flows back to present value. The NPV can be calculated using the formula:
NP V =
3
X
t=1
CFt
(1 + r)t−Initial Cost
Where CFtis the cash flow in year t,ris the risk-free rate, and the initial cost is $500,000.
Plugging in the values for residential units:
NP V =300,000
(1 + 0.05)1+200,000
(1 + 0.05)2+100,000
(1 + 0.05)3−500,000
NP V = 285,714.29 + 181,405.90 + 83,305.95 −500,000
NP V = $50,426.14
Therefore, the NPV of developing residential units immediately is $50,426.14.
b) Similarly, the NPV of developing commercial units immediately can be calculated as:
NP V =400,000
(1 + 0.05)1+250,000
(1 + 0.05)2+150,000
(1 + 0.05)3−500,000
NP V = 380,952.38 + 235,449.74 + 131,724.89 −500,000
NP V = $248,127.01
Therefore, the NPV of developing commercial units immediately is $248,127.01.
c) To calculate the value of the option to delay, we need to find the NPV of waiting for one year
and compare it to the NPV of immediate development.
The NPV of waiting for one year is the same as the NPV of immediate development because
the land cost and cash flows remain the same.
Therefore, the value of the option to delay the development decision by one year is $0.
13 13. REAL OPTIONS IN PHARMACEUTICAL INVESTMENTS
Problem 13. A pharmaceutical company is considering investing in the development of a new
drug. The initial investment is $5 million, and the expected cash flows from the drug over the next
5 years are as follows (in millions of dollars):
Year Expected Cash Flow
1 2
2 3
3 4
4 4
5 5
The company has the option to abandon the project at the end of year 2. The risk-free rate is
5% and the company’s cost of capital is 10%.
a) Calculate the Net Present Value (NPV) of the project without the option to abandon.
b) Calculate the NPV of the project with the option to abandon after year 2.
Solution 13.
a) The NPV of the project without the option to abandon can be calculated using the formula:
NP V =−5 + 2
(1 + 0.05) +3
(1 + 0.05)2+4
(1 + 0.05)3+4
(1 + 0.05)4+5
(1 + 0.05)5
NP V =−5 + 2
1.05 +3
(1.05)2+4
(1.05)3+4
(1.05)4+5
(1.05)5
Calculating this gives:
NP V =−5+1.9048 + 2.7232 + 3.7891 + 3.4185 + 3.2164 = 9.0519 million
Therefore, the NPV of the project without the option to abandon is $9.05 million.
b) The NPV of the project with the option to abandon after year 2 can be calculated by comparing
the NPV of continuing the project with the NPV of abandoning it after year 2.
At the end of year 2, the expected cash flows from the project are $4 million and $5 million in
years 3 and 4 respectively.
To calculate the NPV of the project if abandoned after year 2:
NP Vabandon =−5 + 2
(1 + 0.05) +3
(1 + 0.05)2+4
(1 + 0.05)3= 7.7232 million
If the project is continued after year 2, the cash flows in years 3 and 4 would be $4 million and
$4 million respectively. Calculating the NPV in this case:
NP Vcontinue =−5 + 2
(1 + 0.05) +3
(1 + 0.05)2+4
(1 + 0.05)3+4
(1 + 0.05)4= 8.7891 million
Comparing the two options, the NPV of continuing the project after year 2 is higher, so the
company should continue with the project.
14 14. REAL OPTIONS IN RENEWABLE ENERGY PROJECTS
Problem 14. You are evaluating an investment in a renewable energy project with the following
parameters:
- Initial investment cost: 200,000 −Expectedannualcashflowsforthenext5years :50,000 - Dis-
count rate: 10- Estimated salvage value at the end of year 5: 20,000
The project also has a real option to expand its capacity in year 3 by investing an additional
100,000.T heexpandedprojectisexpectedtogenerateadditionalannualcashf lowsof30,000 for the re-
maining 3 years.
a) Calculate the NPV of the initial investment without considering the expansion option.
b) Determine the NPV of the expanded project considering the expansion option.
Solution 14.
a) To calculate the NPV of the initial investment without considering the expansion option, we
need to discount the expected cash flows over the next 5 years and subtract the initial investment
cost:
NP V =−200,000 + 50,000
1.10 +50,000
(1.10)2+50,000
(1.10)3+50,000
(1.10)4+50,000 + 20,000
(1.10)5
NP V =−200,000 + 50,000
1.10 +50,000
(1.10)2+50,000
(1.10)3+50,000
(1.10)4+70,000
(1.10)5
Calculating the NPV, we get:
NP V =−200,000 + 45,454.55 + 41,322.31 + 37,565.74 + 34,150.67 + 40,772.27
NP V = $ −4383.46
Therefore, the NPV of the initial investment without considering the expansion option is −4383.46.
b) To determine the NPV of the expanded project, we need to consider the additional cash flows
from year 3 onwards as well as the expansion cost. The expanded project’s cash flows will be:
NP V =−200,000+50,000
1.10 +50,000
(1.10)2+(30,000−100,000)×1
(1.10)2+(30,000−100,000)×1
(1.10)3+(30,000−100,000)×1
(1.10)4+50,000 + 20,000
(1.10)5
NP V =−200,000 + 45,454.55 + 41,322.31 + 21,818.18 + 18,926.53 + 16,296.85 + 40,772.27
NP V = $15,409.48
Therefore, the NPV of the expanded project considering the expansion option is −15,409.48.
I. Real Options and Investment Analysis
Problem 1. A company is considering investing in a new project with an initial cost of $1,000,000.
The project is expected to generate cash flows of $400,000 in the first year, $500,000 in the second
year, and $600,000 in the third year. The company has the option to abandon the project after the
first year. The risk-free rate is 5%. Should the company invest in this project?
Solution 1. Given: Initial investment (C): $1,000,000 Cash flows: year 1 = $400,000, year 2 =
$500,000, year 3 = $600,000 Risk-free rate (r): 5
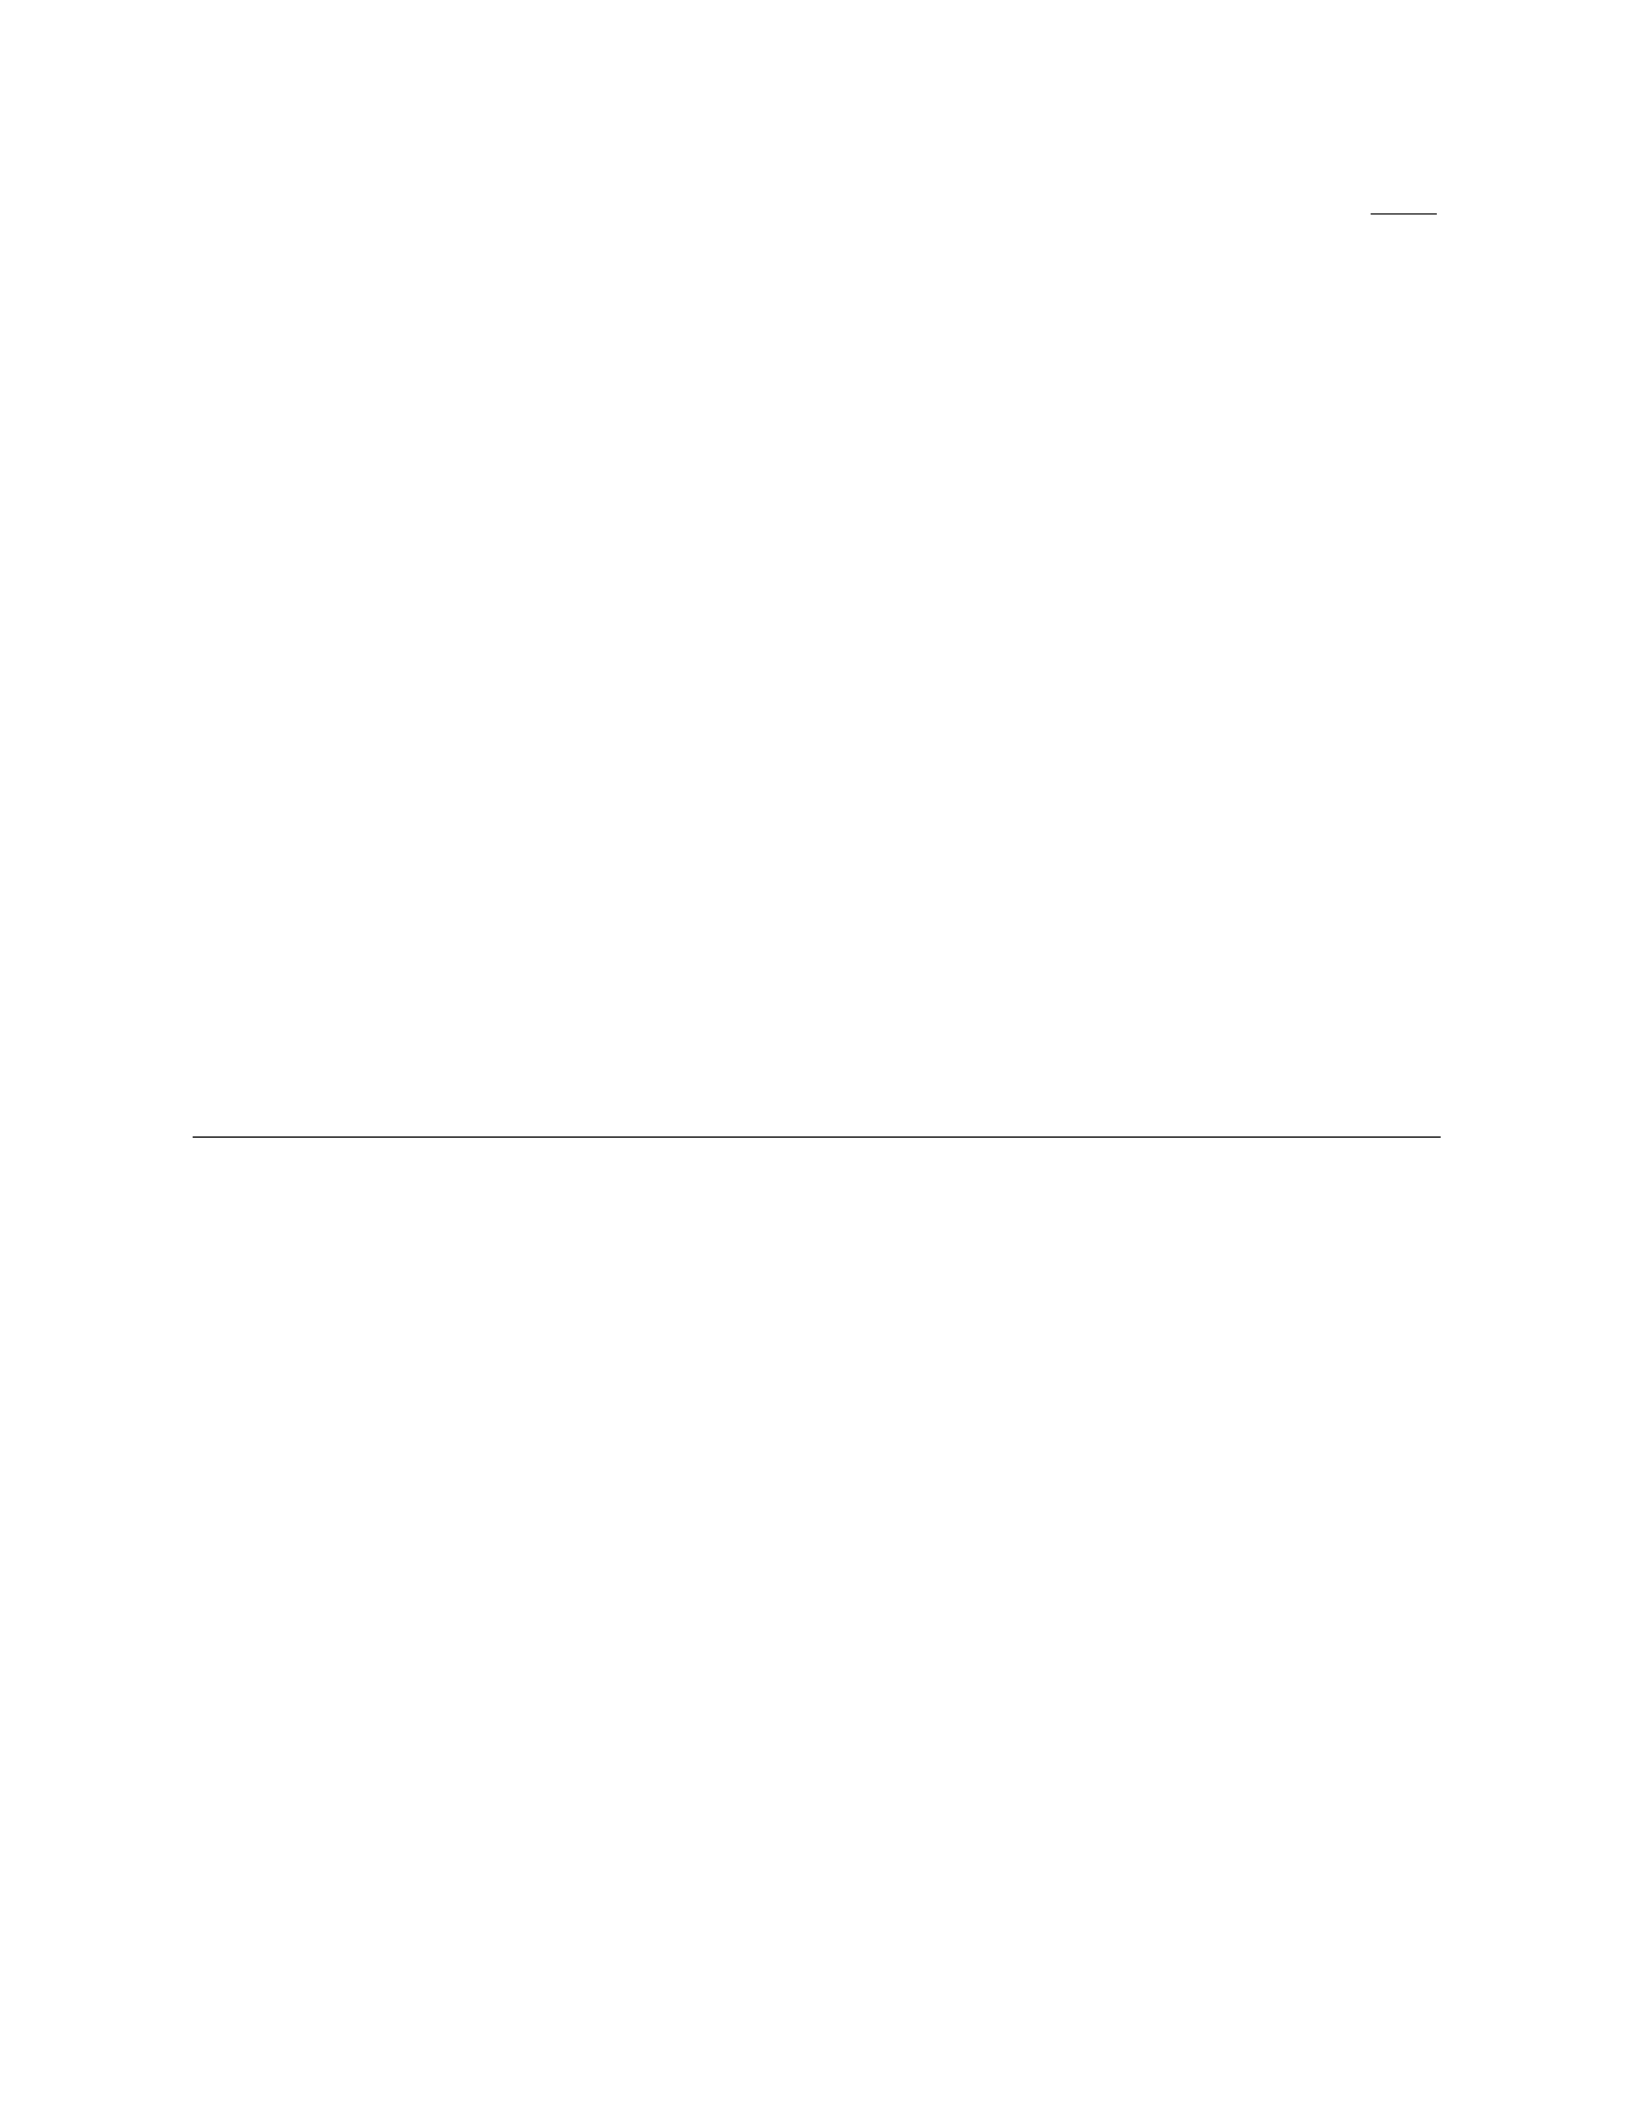
The Net Present Value (NPV) of the project can be calculated as follows: NPV = -C + PCFt
(1+r)t
NPV = -$1,000,000 + $400,000/(1+0.05)1+ $500,000/(1 + 0.05)2+ $600,000/(1 + 0.05)3
NPV = -$1,000,000 + $380,952 + $454,851 + $497,618.85 NPV = $333,421.85
The NPV of the project is positive, which indicates that the project is expected to generate a
return greater than the required rate of return. Therefore, the company should invest in this project.
Problem 2. A company is evaluating an investment in a project that requires an initial outlay
of $800,000. The cash flows from the project are expected to be $300,000 in year 1, $400,000 in
year 2, and $500,000 in year 3. The company has the option to expand the project at the end of
year 1 at an additional cost of $200,000. If the expansion is undertaken, the expected cash flows
in year 4 would be $600,000. Should the company invest in the project and expand in year 1 if the
opportunity arises? Assume a discount rate of 8
Solution 2. Given: Initial investment (C): $800,000 Cash flows: year 1 = $300,000, year 2 =
$400,000, year 3 = $500,000, year 4 (if expanded) = $600,000 Expansion cost: $200,000 Discount
rate (r): 8
Calculate the NPV if the project is undertaken without expansion: NPV = -$800,000 + $300,000/(1+0.08)1+
$400,000/(1 + 0.08)2+ $500,000/(1 + 0.08)3NP V =−$800,000 + $277,777.78 + $308,641.98 +
$340,136.66NP V = $126,556.42
Calculate the NPV if the project is expanded in year 1: NPV = -$800,000 + $300,000/(1+0.08)1+
$400,000/(1+0.08)2+$500,000/(1+0.08)3+$600,000/(1+0.08)4−$200,000NP V =−$800,000+
$277,777.78 + $308,641.98 + $340,136.66 + $387,096.77 −$200,000NP V = $513,652.21
Comparing the two NPVs, it is more beneficial for the company to invest in the project and
expand in year 1 if the opportunity arises, as it yields a higher NPV.
15 Real Options and Investment Analysis
Problem:
A company is considering acquiring a competitor in the same industry. The current market
value of the competitor is $50 million. The company believes that if it acquires the competitor, it
can implement a growth strategy that has a 60% chance of increasing the value of the acquired
firm to $80 million and a 40% chance of decreasing the value to $30 million. If the growth strategy
is successful, the company can generate additional cash flows of $20 million per year for the next
5 years. The risk-free rate is 4%.
a) Calculate the value of the real option to acquire the competitor.
b) Determine the optimal timing to exercise the real option if the company can only exercise it
once.
Solution:
a) Let’s first calculate the expected value of the acquired firm:
E[V]=0.6×$80 million + 0.4×$30 million
= $48 million + $12 million
= $60 million
The present value of the expected cash flows from the growth strategy can be calculated as:
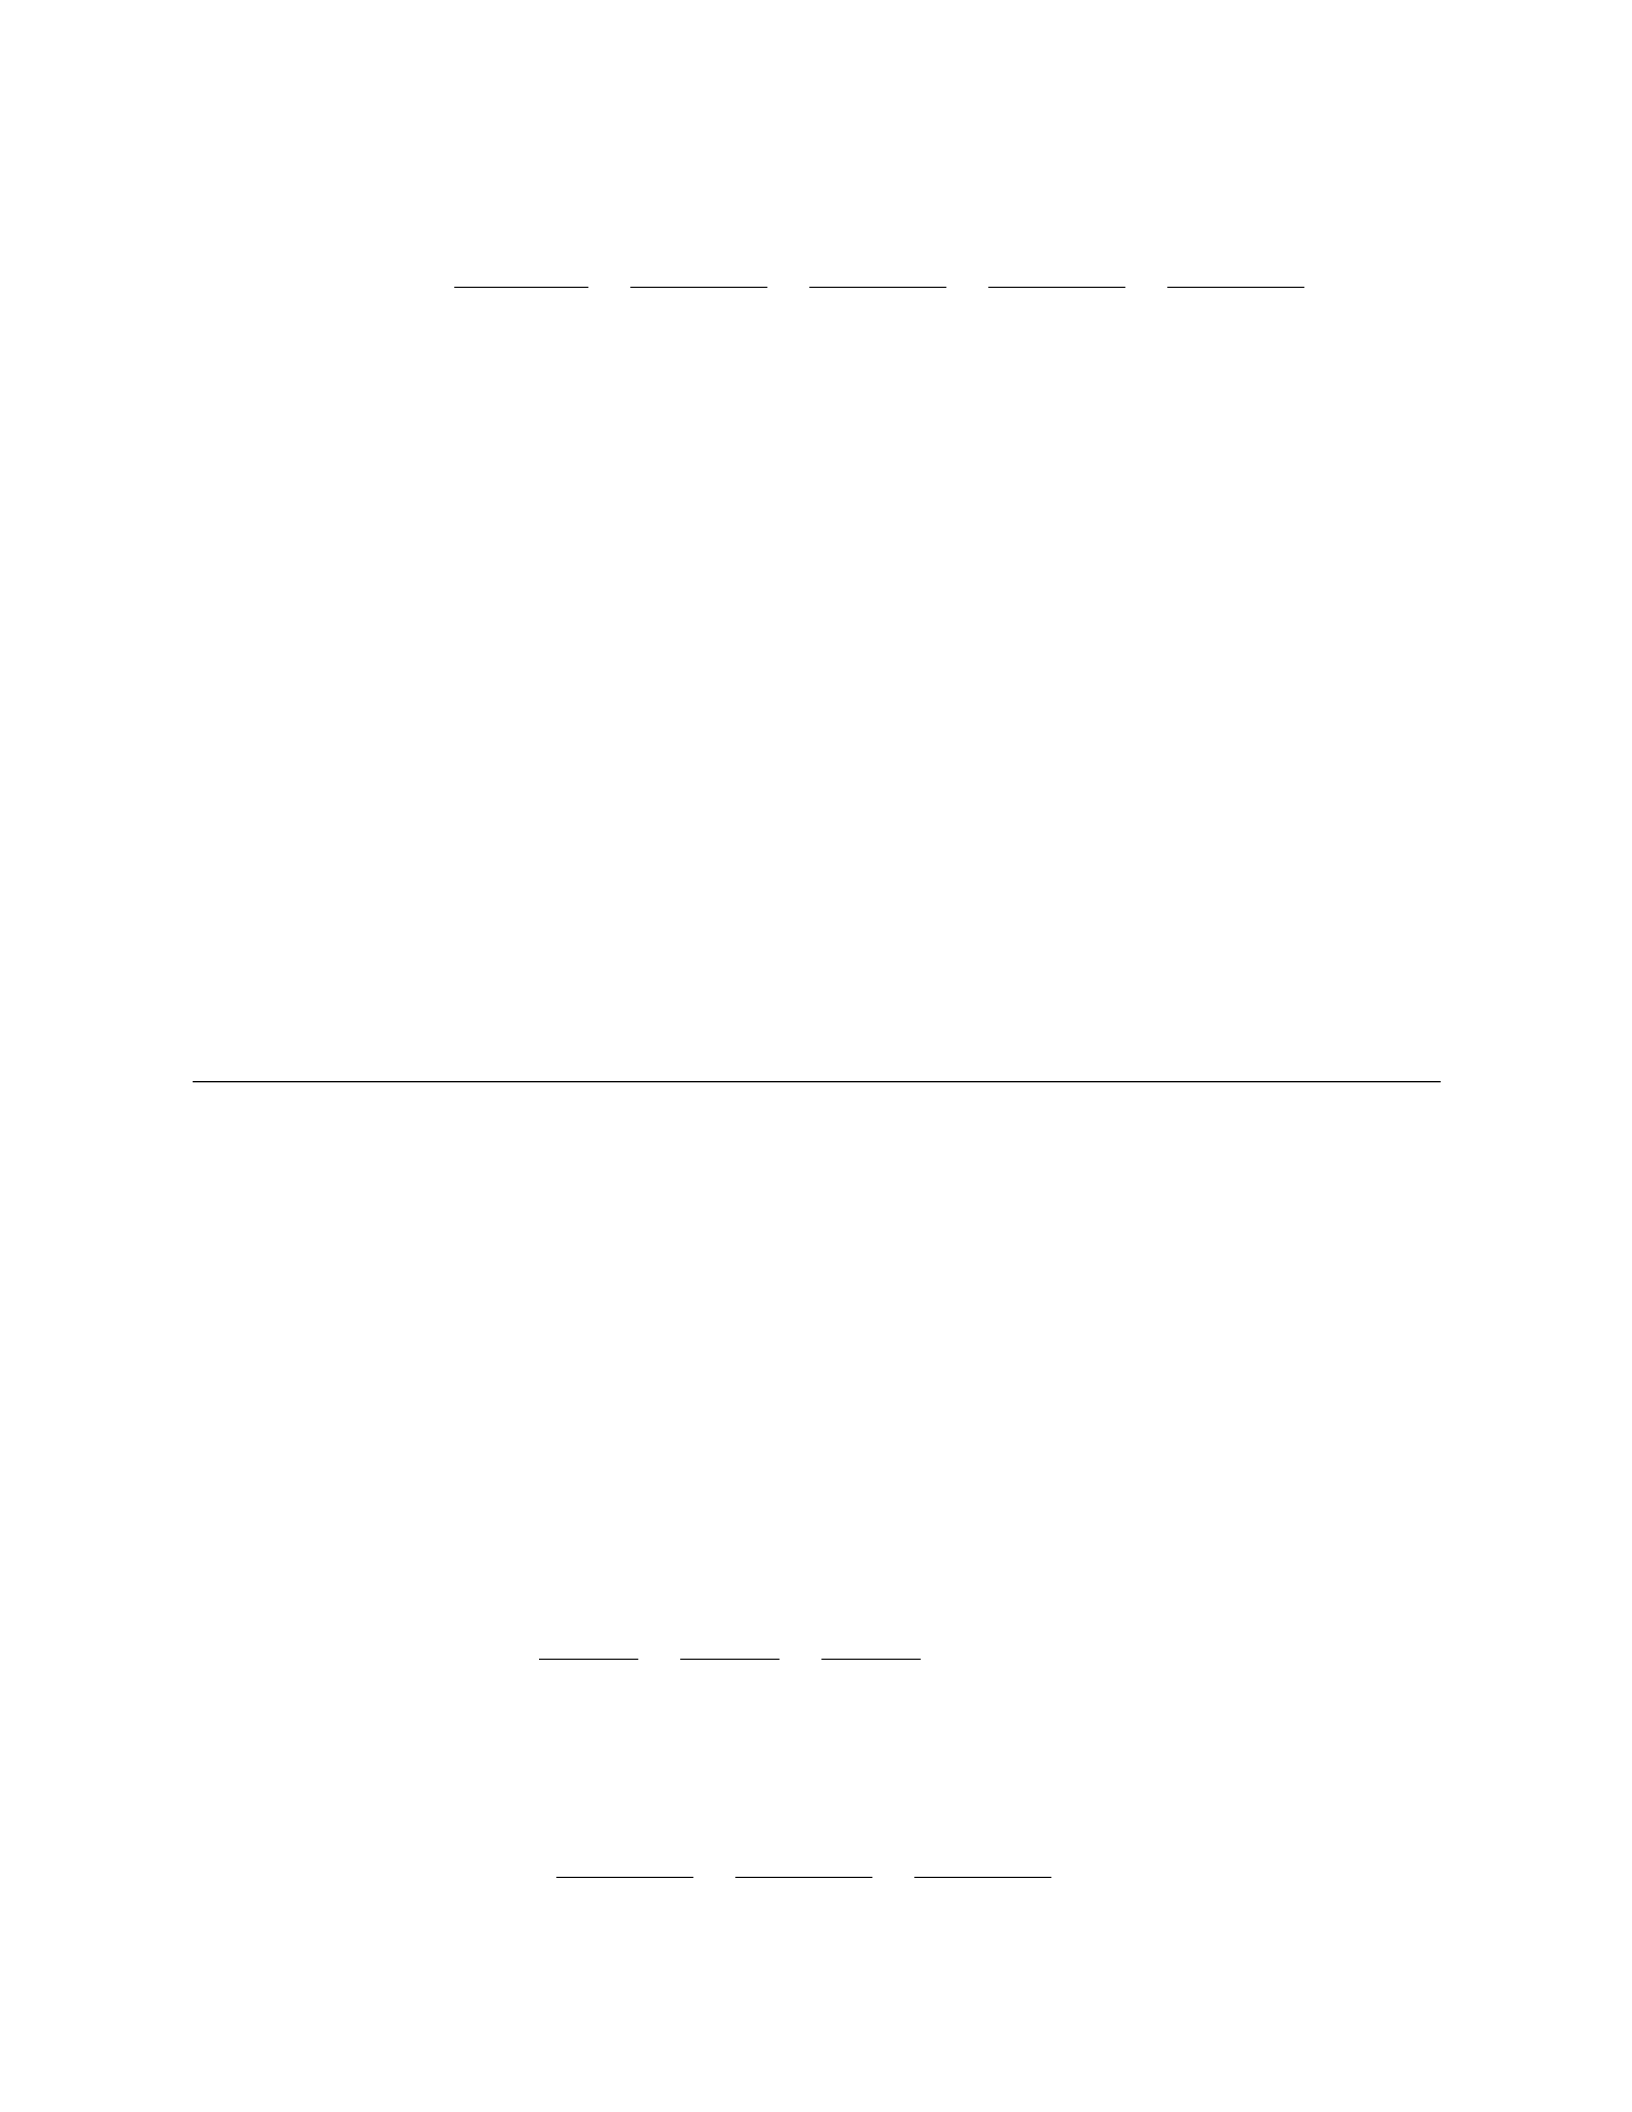
P V (Cash Flows) = $20 million
1+0.04 +$20 million
(1 + 0.04)2+$20 million
(1 + 0.04)3+$20 million
(1 + 0.04)4+$20 million
(1 + 0.04)5
= $18.68 million + $17.98 million + $17.30 million + $16.65 million + $16.03 million
= $86.64 million
The value of the real option is the difference between the expected value of the acquired firm
and the present value of the cash flows:
Real Option Value = $60 million −$86.64 million
=−$26.64 million
Therefore, the value of the real option to acquire the competitor is -$26.64 million.
b) To determine the optimal timing to exercise the real option, we need to compare the value of
waiting to the option to the value of immediate exercise. The value of waiting is the expected value
of the acquired firm minus the exercise price (market value of the competitor), which is $60 million
- $50 million = $10 million.
The option to acquire has negative value (-$26.64 million) which implies that it should not be
exercised. Therefore, the optimal timing is to never exercise the option to acquire the competitor.
16 17. REAL OPTIONS IN PROJECT FINANCE
Problem 17. A company is considering investing in a new project that has the following char-
acteristics:
- Initial investment cost: $500,000 - Expected cash inflows in the first year: $300,000 - Expected
cash inflows in the second year: $400,000 - Expected cash inflows in the third year: $600,000 -
Discount rate: 10% - Risk-free rate: 5% - Volatility of cash flows: 20% - Time to maturity for the real
option: 3 years - Exercise price for the real option: $100,000
The company can abandon the project after the first year of operation if the cash flows are not
as expected.
a) Calculate the Net Present Value (NPV) of the project without considering the real option.
b) Determine the value of the real option embedded in the project.
c) Should the company invest in the project based on the real option analysis?
Solution 17.
a) The Net Present Value (NPV) of the project without considering the real option can be cal-
culated using the formula:
NP V =CF1
(1 + r)1+CF2
(1 + r)2+CF3
(1 + r)3−Initial Investment
where ris the discount rate, CFiis the cash flow in year i, and the Initial Investment is the initial
cost of the project.
Substitute the given values into the formula:
NP V =300,000
(1 + 0.10)1+400,000
(1 + 0.10)2+600,000
(1 + 0.10)3−500,000
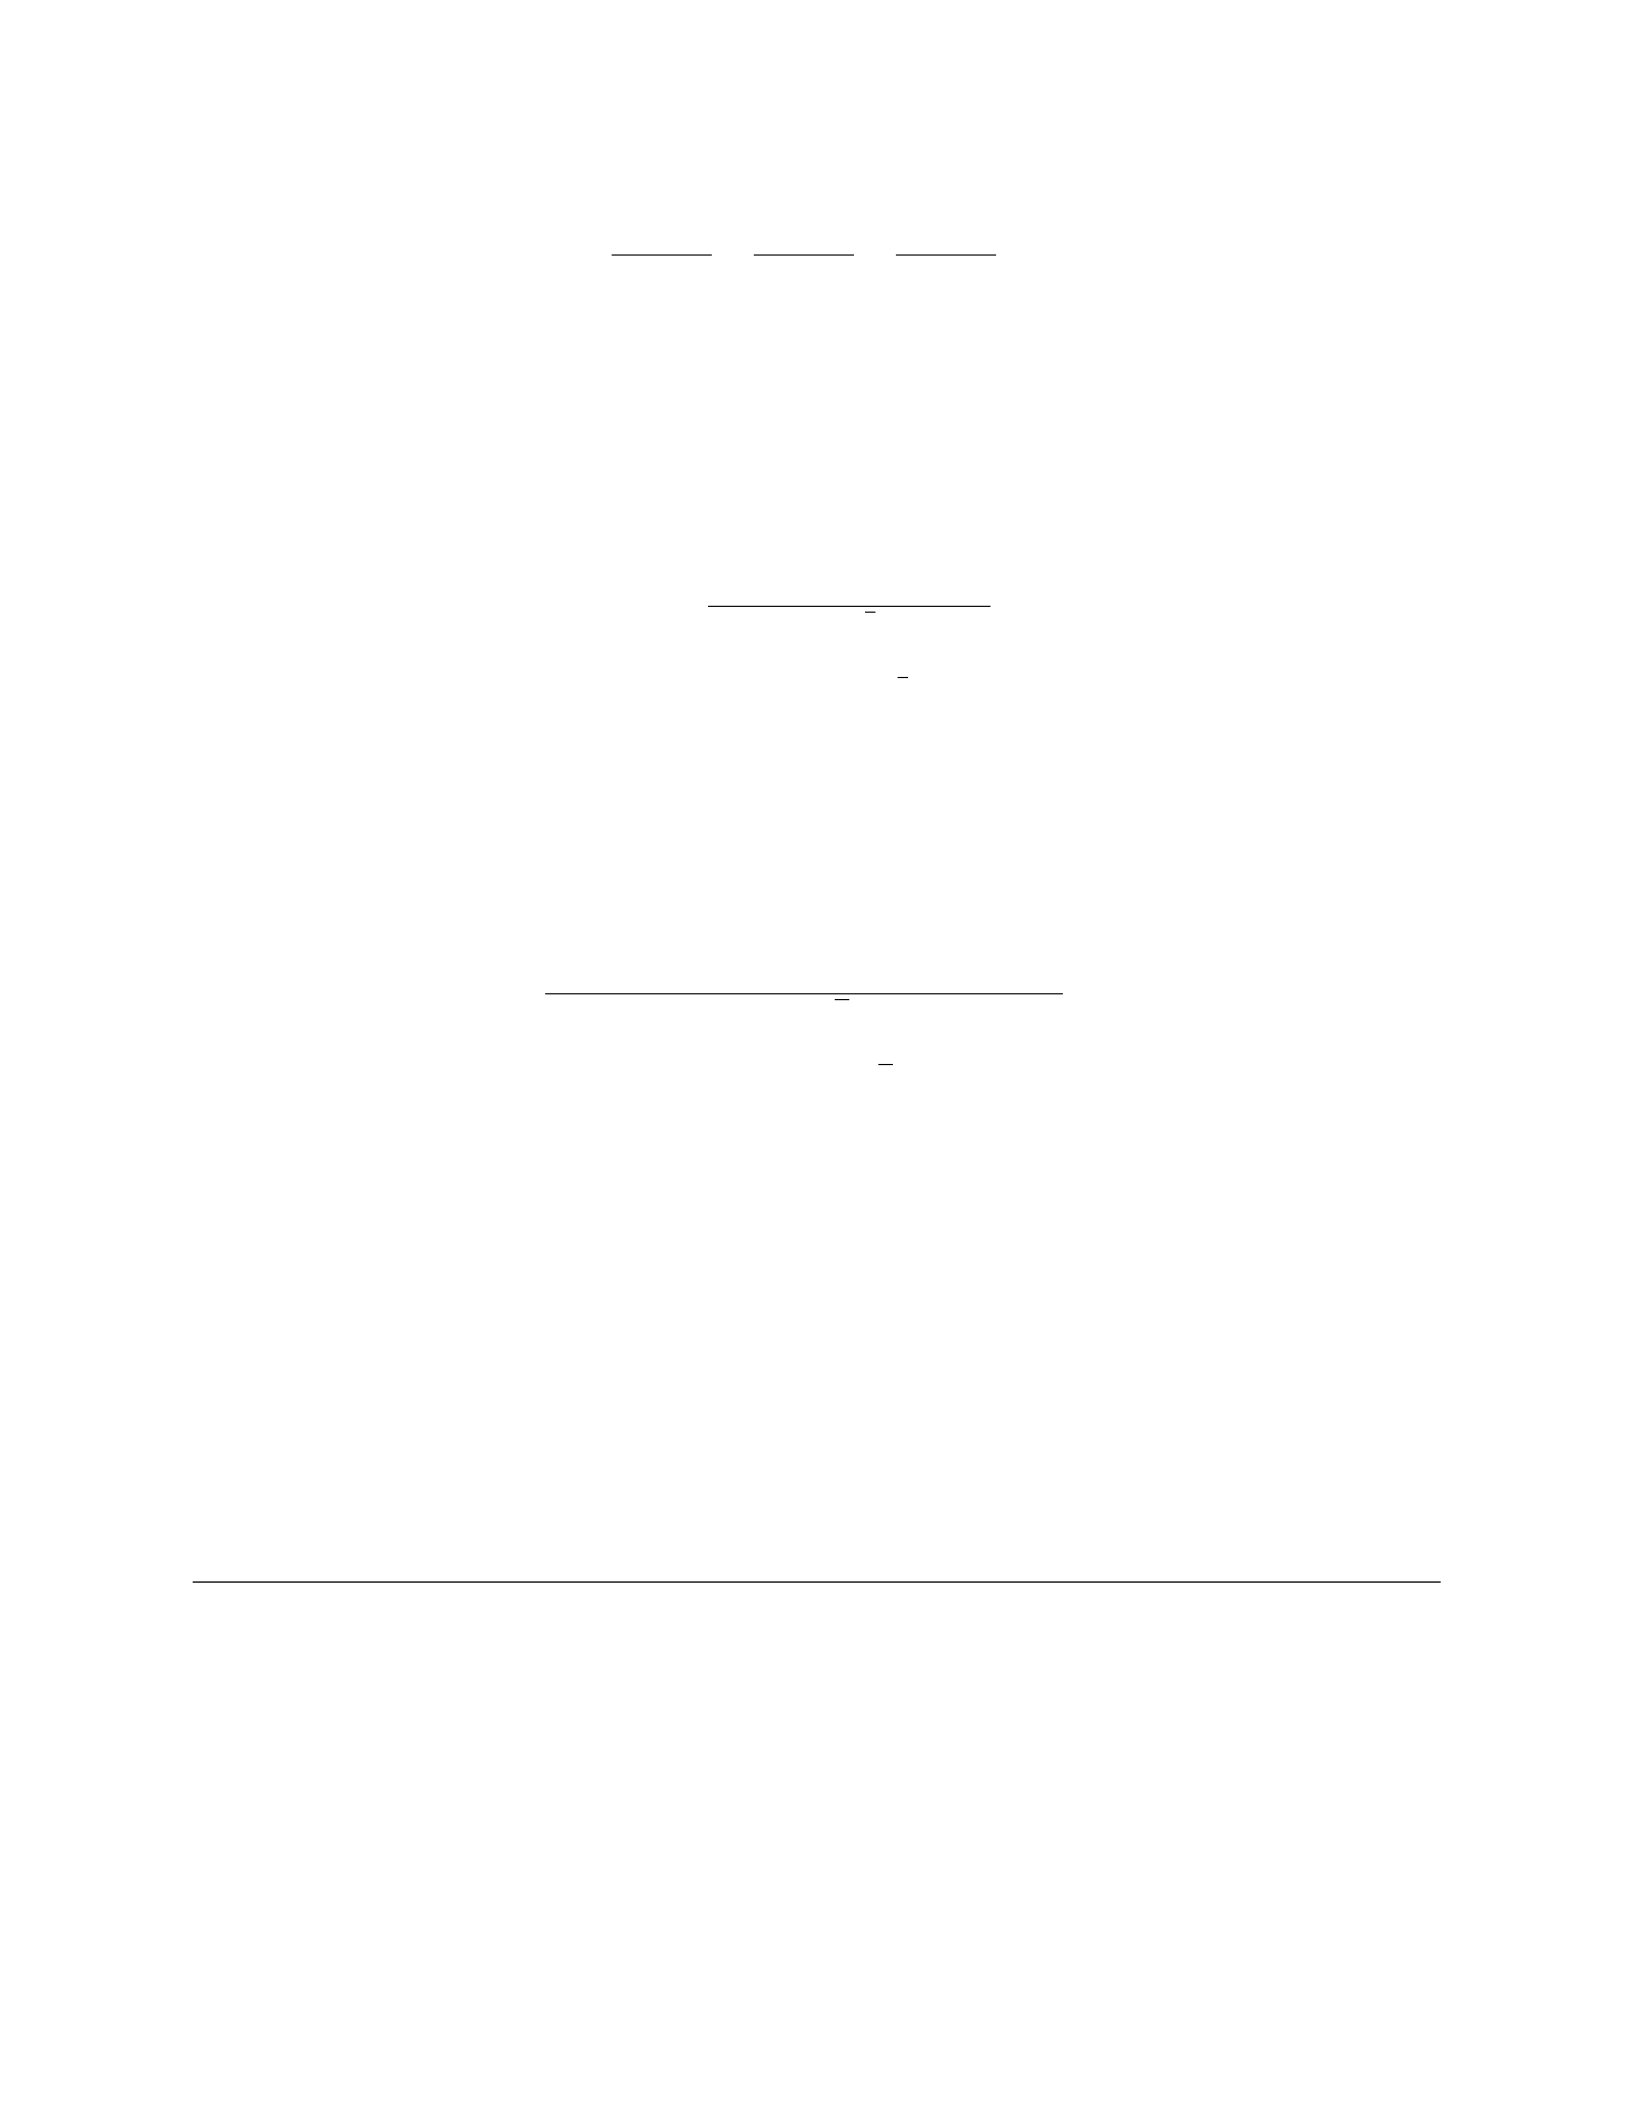
NP V =300,000
1.10 +400,000
1.102+600,000
1.103−500,000
NP V = 272,727.27 + 330,578.51 + 401,324.62 −500,000
NP V = 504,630.40
Therefore, the NPV of the project without considering the real option is $504,630.40.
b) The value of the real option can be calculated using the Black-Scholes Option Pricing Model.
d1=ln(S/E)+(r+σ2/2)t
σ√t
d2=d1−σ√t
Option V alue =SΦ(d1)−Ee−rtΦ(d2)
where: - S= current stock price (value of project) - E= exercise price - r= risk-free rate - t=
time to maturity - σ= volatility
Substitute the given values into the formula:
d1=ln(300,000/100,000) + (0.05 + 0.202/2)3
0.20√3= 1.85
d2= 1.85 −0.20√3=1.35
Option V alue = 300,000Φ(1.85) −100,000e−0.05∗3Φ(1.35) = 148,385.16
Therefore, the value of the real option embedded in the project is $148,385.16.
c) The total value of the project considering the real option is:
T otal V alue =NP V +Option V alue = 504,630.40 + 148,385.16 = 653,015.56
As the total value of the project exceeds the initial investment cost and considering the real
option, the company should invest in the project based on the real option analysis.
17 18. REAL OPTIONS IN R&D INVESTMENTS
Problem 18. A company is considering investing in a research and development (R&D) project.
The initial investment required is $500,000. The project is expected to generate cash flows of
$200,000 in the first year, $300,000 in the second year, and $400,000 in the third year. The risk-
free rate is 5% and the company’s cost of capital is 10%.
a) Calculate the Net Present Value (NPV) of the project without considering the real options.
b) Determine the value of the Real Option to Abandon.
c) Calculate the Real Options Value of Waiting to Invest if the company can decide at the end
of each year whether to continue the project or not.
Solution 18.
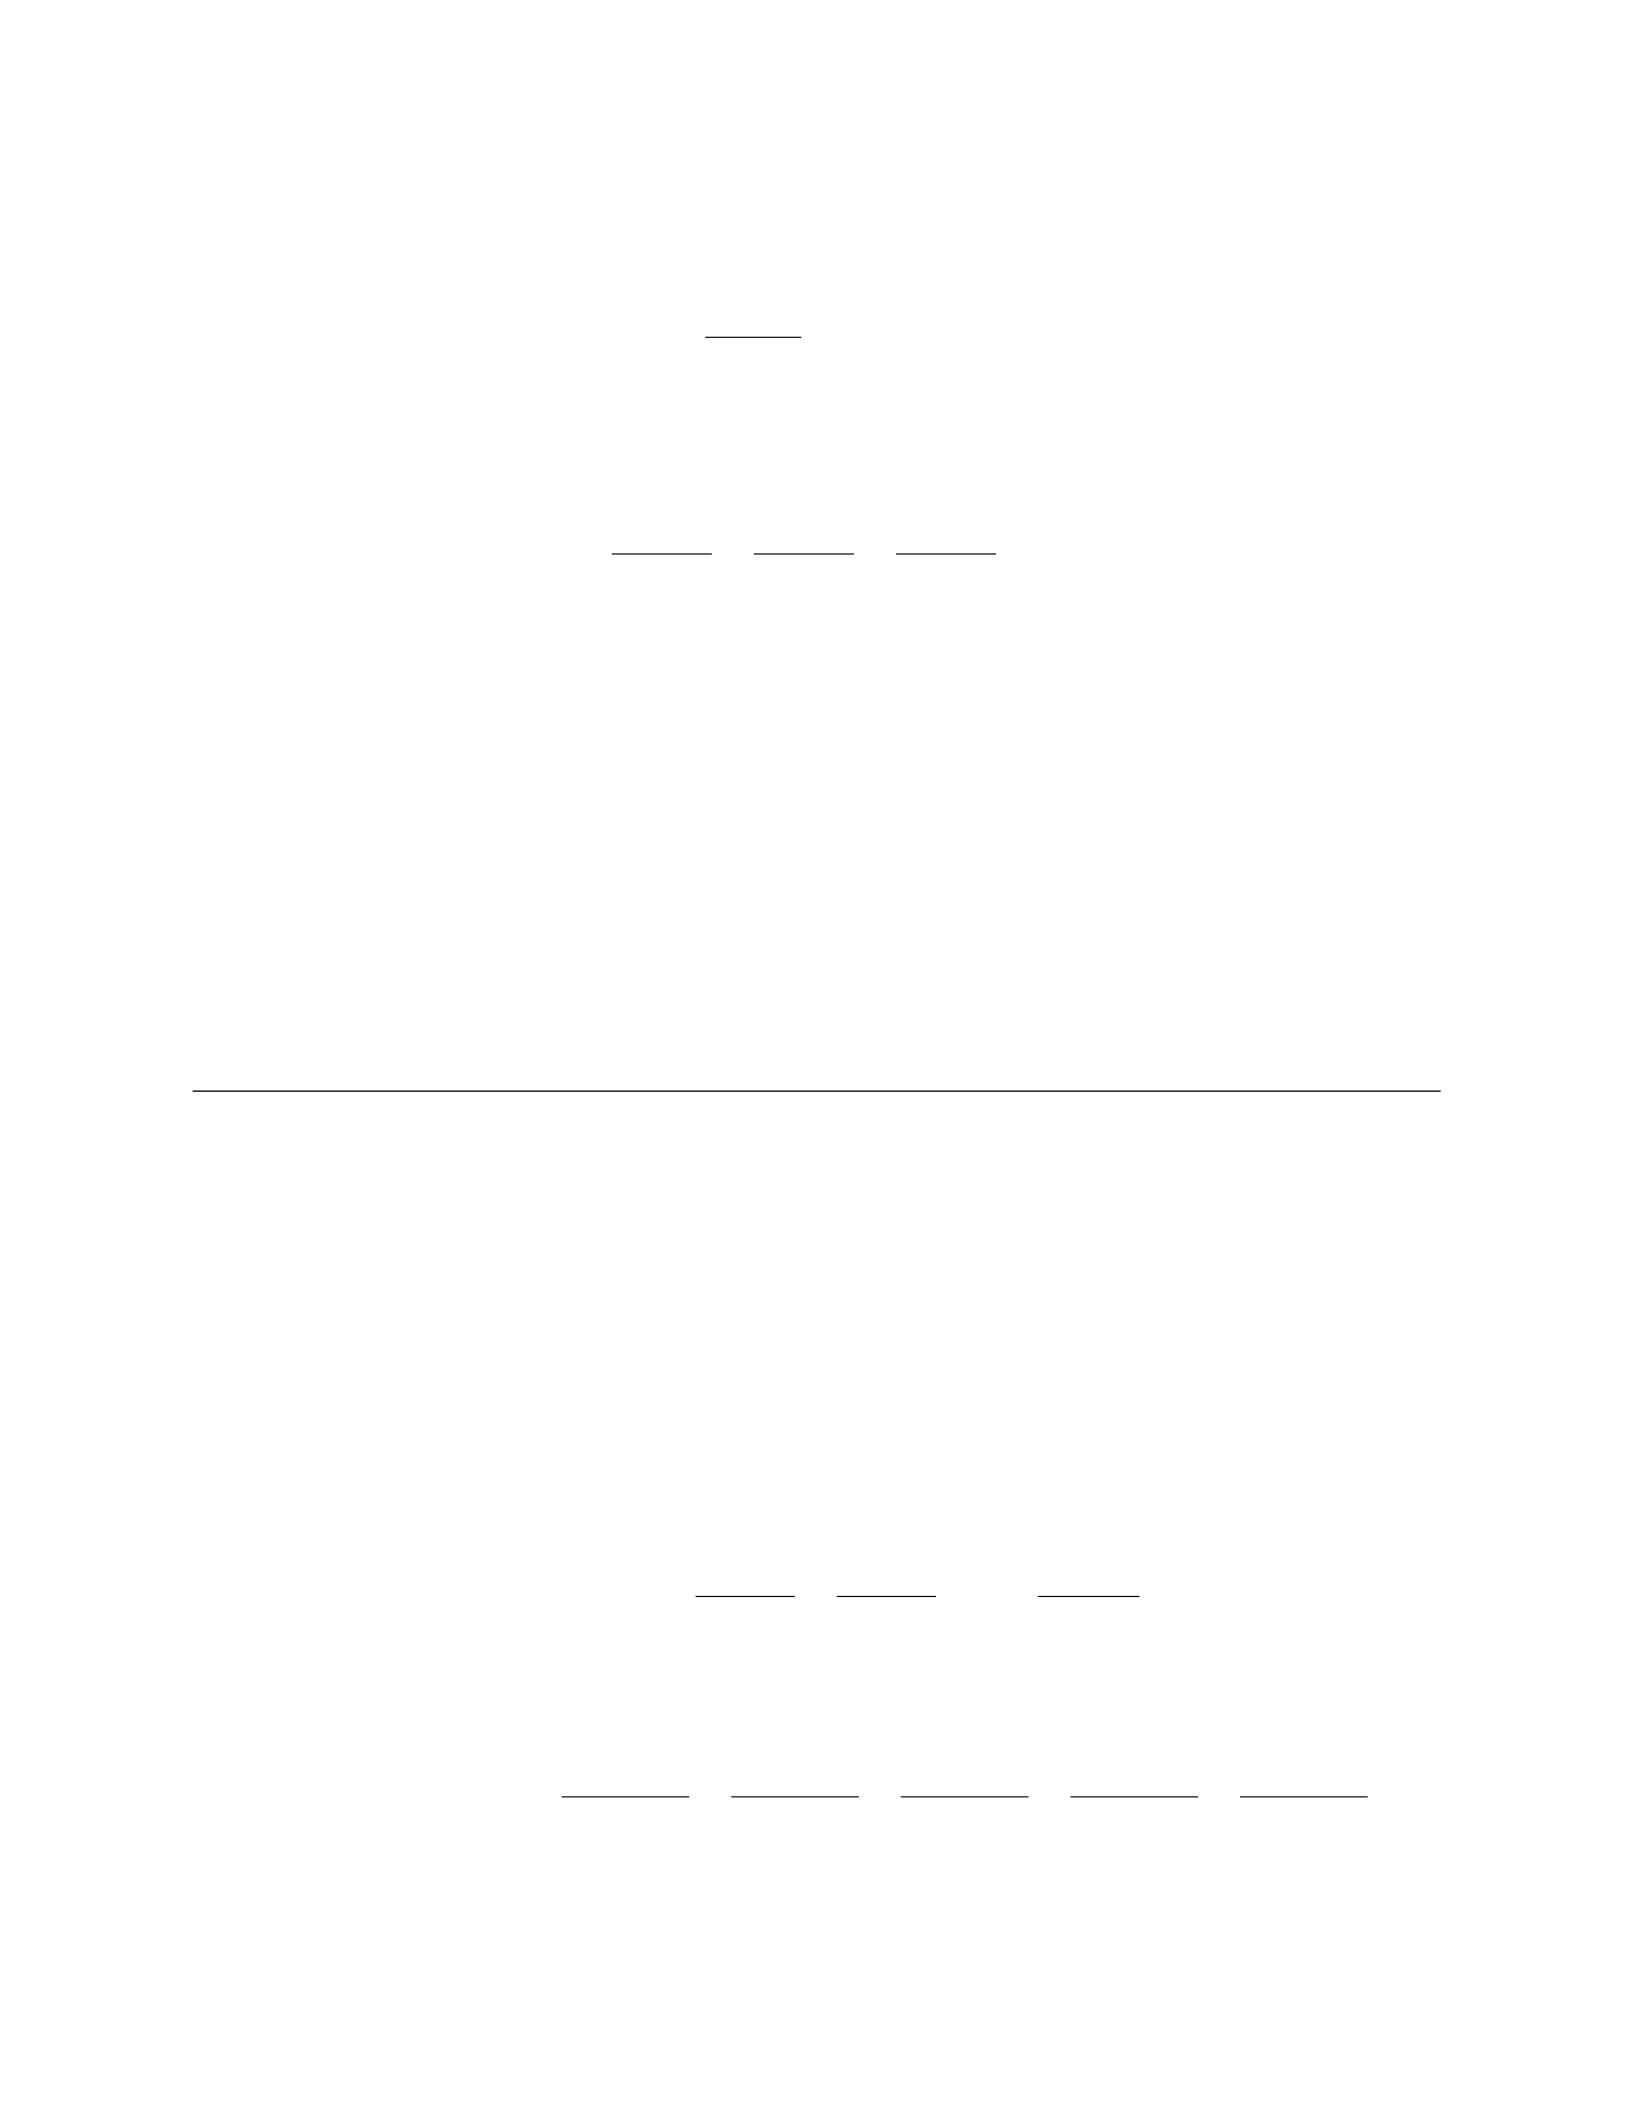
a) The NPV of the project without considering the real options can be calculated by discounting
the cash flows at the cost of capital. The formula for NPV is:
NP V =
n
X
t=1
CFt
(1 + r)t−Initial Investment
Where: - CFt= Cash flow in year t-r= Company’s cost of capital - Initial Investment =
$500,000
Plugging in the values:
NP V =200,000
1.10 +300,000
1.102+400,000
1.103−500,000
NP V = 181,818.18 + 247,933.88 + 300,043.71 −500,000
NP V = 229,795.77
Therefore, the NPV of the project without considering the real options is $229,795.77.
b) The Real Option to Abandon allows the company to abandon the project at the end of the
second year if it is no longer profitable. The value of this option can be calculated using the Binomial
option pricing model or decision tree analysis.
c) The Real Options Value of Waiting to Invest allows the company to assess whether to invest
at the end of each year based on the project’s performance. The decision to wait can be valued
using the Black-Scholes model or other numerical methods.
18 19. REAL OPTIONS IN INTERNATIONAL INVESTMENTS
Problem 19. A multinational corporation is considering investing in a project in a foreign coun-
try. The project has an initial investment cost of $5 million and is expected to generate cash flows of
$3 million per year for the next 5 years. The corporation has the option to expand the project after
2 years at an additional cost of $2 million. The risk-free rate is 5% and the corporation’s required
rate of return is 10%.
a) Calculate the Net Present Value (NPV) of the project without considering the option to ex-
pand.
b) Determine the value of the option to expand the project after 2 years.
c) Should the corporation proceed with the initial investment in the project?
Solution 19.
a) To calculate the NPV of the project without considering the option to expand, we use the
formula:
NP V =−C0+CF1
(1 + r)1+CF2
(1 + r)2+... +CFn
(1 + r)n
Where: C0= $5,000,000 CFt= $3,000,000 for t= 1,2,3,4,5r= 10%
Plugging in the values, we get:
NP V =−5,000,000 + 3,000,000
1.1+3,000,000
1.12+3,000,000
1.13+3,000,000
1.14+3,000,000
1.15
NP V =−5,000,000 + 2,727,273 + 2,479,338 + 2,254,853 + 2,049,866 + 1,861,696
NP V = $2,373,050
The NPV of the project without considering the option to expand is $2,373,050.
b) The value of the option to expand the project after 2 years can be calculated using the Black-
Scholes model. The formula for the value of the option is:
V=S0N(d1)−Xe−rtN(d2)
Where: S0= $3,000,000 (Value of the expanded project) X= $2,000,000 (Cost of expansion)
r= 5% (Risk-free rate) t= 2 years
Calculating d1and d2using the Black-Scholes formula, we find d1= 0.4407 and d2= 0.1841.
Plugging in these values, we get:
V= 3,000,000N(0.4407) −2,000,000e−0.05∗2N(0.1841)
V= 3,000,000 ×0.6703 −2,000,000 ×e−0.1×0.5749
V= 2,010,894 −1,273,239
V= $737,655
The value of the option to expand the project after 2 years is $737,655.
c) As the NPV of the project without considering the option to expand is positive ($2,373,050)
and the value of the option to expand is also positive ($737,655), the corporation should proceed
with the initial investment in the project.
19 20. REAL OPTIONS IN NEW PRODUCT DEVELOPMENT
Problem 20. A company is considering developing a new product. The initial investment re-
quired is $500,000. The expected cash flows from the product over the next 3 years are estimated
as follows: Year 1: $200,000, Year 2: $300,000, Year 3: $400,000. The company has the option
to abandon the project at the end of each year with the following abandonment values: Year 1:
$50,000, Year 2: $100,000, Year 3: $200,000. The risk-free rate is 5%.
a) Calculate the net present value (NPV) of the project without considering any abandonment
options.
b) Determine the net present value (NPV) of the project if the company has the flexibility to
abandon the project at the end of each year.
c) Discuss whether incorporating the abandonment options increases the value of the project.
Solution 20.
a) To calculate the NPV of the project without considering any abandonment options, we need
to discount the cash flows at the risk-free rate of 5%.
Using the formula for NPV:
NP V =CF0
(1 + r)0+CF1
(1 + r)1+CF2
(1 + r)2+CF3
(1 + r)3−Initial Investment
where r= 0.05 and the cash flows are 200,000,300,000, and 400,000f oryears1,2, and3respectively.
NP V =−500,000
(1 + 0.05)0+200,000
(1 + 0.05)1+300,000
(1 + 0.05)2+400,000
(1 + 0.05)3
NP V =−500,000 + 190,476.2 + 272,108.8 + 342,317.5 = 304,902.5
Therefore, the NPV of the project without considering any abandonment options is $304,902.5.
b) To calculate the NPV of the project with abandonment options, we need to consider the option
to abandon at the end of each year by comparing the continuation value with the abandonment
value.
In Year 1, the continuation value is $190,476.2 (the present value of cash flows from Year 2
and Year 3). If the abandonment value ($50,000) is greater, then the project would be abandoned,
resulting in an NPV of -$50,000. In this case, the NPV of Year 1 is -$50,000.
In Year 2, the continuation value is $272,108.8 (the present value of cash flow from Year 3). If
the abandonment value ($100,000) is greater, then the project would be abandoned, resulting in
an NPV of -$100,000. In this case, the NPV of Year 2 is -$100,000.
In Year 3, the project will not be abandoned as the cash flow of $400,000 is greater than the
abandonment value of $200,000. Therefore, the NPV of Year 3 is $357,142.9 (the present value
of the cash flow in Year 3).
The total NPV of the project with abandonment options is the sum of the NPVs of each year:
NP V =−50,000 −100,000 + 357,142.9 = 207,142.9
Therefore, the NPV of the project with abandonment options is $207,142.9.
c) Incorporating abandonment options increases the value of the project, as the NPV with aban-
donment options ($207,142.9) is higher than the NPV without considering any abandonment op-
tions ($304,902.5). Abandonment options provide flexibility in decision-making and can increase
the overall value of a project.
Solution 2.
a) The value of the real option to abandon the project can be calculated using the binomial
option pricing model. The option to abandon is equivalent to a put option. Using the risk-neutral
valuation approach, the value of the option can be found by working backwards from the final year.
Let’s denote: - S0= $50 (price of oil at time t= 0) - X= $200,000 (cash flow if oil prices remain
low) - R= 1.04 (risk-free rate) - T= 3 years (time to expiration)
The value of the option to abandon is:
V3=1
1.04 0.5×Vu
4+Vd
4
1.04 + 0.5×X
where Vu
4= 0 since if the price of oil increases, the company will not abandon the project.
Therefore:
V3=1
1.04 0.5×0 + Vd
4
1.04 + 0.5×200,000
Given that Vd
4= 0, we can calculate:
V3=1
1.04 0.5×0
1.04+ 0.5×200,000=1
1.04 ×0.5×192,307.69 = $92,746.91
Therefore, the value of the real option to abandon the project is $92,746.91.
b) The NPV of the project without the real option is calculated as the present value of the
expected cash flows minus the initial investment:
NP V =200,000
1.04 +250,000
(1.04)2+300,000
(1.04)3−1,000,000 = 535,725.89
c) The NPV of the project with the real option included is the sum of the NPV without the option
and the value of the option:
NP V = 535,725.89 + 92,746.91 = 628,472.80
3 3. TIMING OF INVESTMENTS
Problem 3. A company is considering investing in a new project. The initial investment cost
is $500,000. The project is expected to generate cash flows of $200,000 per year for the next 5
years. The company’s cost of capital is 10%. If the company decides to delay the investment by
one year, the initial investment cost will decrease to $450,000, but the annual cash flows will also
decrease to $180,000 per year for the next 5 years. Should the company invest now or delay the
investment for one year?
Solution 3. Let’s first calculate the net present value (NPV) of the project if the company invests
now and if it delays the investment by one year.
a) NPV of investing now: The NPV of investing now can be calculated as follows:
NP Vnow =−500,000 + 200,000
1.10 +200,000
(1.10)2+200,000
(1.10)3+200,000
(1.10)4+200,000
(1.10)5
NP Vnow =−500,000 + 200,000
1.10 +200,000
(1.10)2+200,000
(1.10)3+200,000
(1.10)4+200,000
(1.10)5
NP Vnow =−500,000 + 181,818.18 + 165,289.26 + 150,263.87 + 136,603.52 + 124,184.11
NP Vnow = $157,158.94
b) NPV of delaying the investment by one year: The NPV of delaying the investment by one
year can be calculated as follows:
NP Vdelayed =−450,000 + 180,000
1.10 +180,000
(1.10)2+180,000
(1.10)3+180,000
(1.10)4+180,000
(1.10)5
NP Vdelayed =−450,000 + 163,636.36 + 148,760.33 + 135,236.66 + 122,942.42 + 111,766.74
NP Vdelayed = $131,342.11
c) Conclusion: Comparing the two options, investing now yields an NPV of $157,158.94, while
delaying the investment by one year yields an NPV of $131,342.11. Therefore, the company should
invest in the project now as it provides a higher NPV.
4 4. FLEXIBILITY IN PROJECT DEVELOPMENT
Problem 4. A company is considering investing in a new project that has the following cash
flows for the next 3 years:
•Year 1: −1,000 (investment cost)
•Year 2: 500
•Year 3: 800
The company has the option to abandon the project after year 1 with a salvage value of 300.
The risk-free rate is 5%.
a) Calculate the net present value (NPV) of the project without the abandonment option.
b) Calculate the NPV of the project with the abandonment option.
c) Determine whether the company should exercise the abandonment option or not.
Solution 4.
a) The NPV of the project without the abandonment option is calculated by discounting the cash
flows at the risk-free rate:
NP V =−1,000 + 500
1.05 +800
1.052=−1,000 + 476.19 + 756.14 = 232.33
Therefore, the NPV of the project without the abandonment option is 232.33.
b) To calculate the NPV of the project with the abandonment option, we need to consider the
salvage value if the project is abandoned after year 1. The NPV with the abandonment option is:
NP V =−1,000 + 300 + 500
1.05 +800
1.052=−1,000 + 300 + 476.19 + 756.14 = 532.33
So, the NPV of the project with the abandonment option is 532.33.
c) Comparing the NPVs, we see that the NPV with the abandonment option is greater than the
NPV without the abandonment option. Therefore, the company should exercise the abandonment
option if the project’s cash flows are as predicted.
5 5. UNCERTAINTY IN PROJECT OUTCOMES
Problem 5. A company is considering investing in a new project that has two possible out-
comes: success or failure. The probabilities of success and failure are estimated to be 0.6 and
0.4, respectively. If the project is successful, the company expects to earn $500,000, but if it fails,
they will lose $200,000. The initial investment required for the project is $100,000. Calculate the
expected net present value (NPV) of the project.
Solution 5. The expected NPV of the project is calculated as the sum of the expected cash
flows discounted to the present value at the appropriate rate.
a) Expected Cash Flows: The expected cash flow from a successful project is $500,000 and
from a failed project is -$200,000.
Expected cash flow = (Probability of success * Cash flow from success) + (Probability of failure
* Cash flow from failure) Expected cash flow = (0.6 * $500,000) + (0.4 * -$200,000) Expected cash
flow = $300,000 - $80,000 Expected cash flow = $220,000
b) NPV Calculation: NPV = Expected cash flow / (1 + r)twhere, r =discountrate, t =timeperiod, inthiscase, t =
0
Given that the initial investment is $100,000 and the expected cash flow is $220,000, the NPV
can be calculated as:
NPV = (Expected cash flow - Initial investment) / (1 + r)tNP V = ($220,000 −$100,000)/(1 +
r)0NP V = $120,000
Therefore, the expected net present value (NPV) of the project is $120,000.
6 6. INVESTMENT DECISION UNDER COMPETITION
Problem 6. A company is considering expanding its production capacity to meet the increasing
demand for its product. There are two options available: Option A involves investing $400,000 to
increase capacity by 10,000 units annually for the next 5 years. Option B requires an investment
of $600,000 for a capacity increase of 15,000 units annually for the next 5 years.
The company’s estimated revenue per unit is $50, and the variable cost per unit is $20. The
discount rate is 10%. The company operates in a competitive market where the demand is uncer-
tain. Based on the current information, the company forecasts the demand for the next 5 years to
have the following probabilities:
Demand Level Probability
Low 0.2
Medium 0.5
High 0.3
a) Calculate the NPV for each option.
b) Determine the value of the real options present in this investment decision.
Solution 6.
a) The Net Present Value (NPV) for each option is calculated as follows: Let’s denote: - R= $50
(revenue per unit) - C= $20 (variable cost per unit) - IA= $400,000 (investment for Option A) -
IB= $600,000 (investment for Option B) - d= 10% (discount rate)
For Option A:
NP VA=
5
X
t=1
[(R−C)×Demandt×10,000] −IA
NP VA= [(50 −20) ×10,000 ×0.2 + (50 −20) ×10,000 ×0.5 + (50 −20) ×10,000 ×0.3]−400,000
NP VA= (30 ×10,000 ×0.2 + 30 ×10,000 ×0.5 + 30 ×10,000 ×0.3) −400,000
NP VA= (60,000 + 150,000 + 90,000) −400,000 = 300,000 −400,000 = −100,000
For Option B:
NP VB=
5
X
t=1
[(R−C)×Demandt×15,000] −IB
NP VB= [(50 −20) ×15,000 ×0.2 + (50 −20) ×15,000 ×0.5 + (50 −20) ×15,000 ×0.3]−600,000
NP VB= (30 ×15,000 ×0.2 + 30 ×15,000 ×0.5 + 30 ×15,000 ×0.3) −600,000
NP VB= (90,000 + 225,000 + 135,000) −600,000 = 450,000 −600,000 = −150,000
Therefore, the NPV for Option A is -$100,000 and for Option B is -$150,000.
b) To determine the value of the real options present in this investment decision, we would
need to consider the flexibility in the decision-making over the 5-year period based on the market
conditions. Real options analysis would allow the company to make optimal decisions in response
to the changing market conditions, such as the ability to expand further, contract, or delay expan-
sion. The value of the real options in this case would be the additional value generated by having
flexibility in decision-making compared to a static investment analysis.
It is important to note that the value of real options can be complex to quantify and may require
more detailed analysis based on specific scenarios and assumptions.
7 7. OPTIMAL INVESTMENT STRATEGIES
Problem 7. ABC Corporation is considering investing in a new project that will require an initial
investment of $500,000. The project is expected to generate cash flows of $150,000 in the first
year, $200,000 in the second year, and $300,000 in the third year. The risk-free rate is 4%. The
firm’s cost of capital is 12% and the project’s beta is 1.5. The current stock price is $50. Calculate
the Net Present Value (NPV) and the Real Options Value (ROV) of the project.
Solution 7. a) Calculate the Net Present Value (NPV):
The NPV calculation involves discounting the cash flows of the project at the firm’s cost of
capital. The formula for NPV is:
NP V =
3
X
t=1
CFt
(1 + r)t−Initial Investment
Where:
CFt:Cash flow in year t
r:Cost of capital
Substitute the given values into the formula:
NP V =150,000
(1 + 0.12)1+200,000
(1 + 0.12)2+300,000
(1 + 0.12)3−500,000
= 150,000/1.12 + 200,000/1.2544 + 300,000/1.4049 −500,000
= 133,928.57 + 159,544.29 + 213,143.16 −500,000
= $6,616.02
Therefore, the Net Present Value (NPV) of the project is $6,616.02.
b) Calculate the Real Options Value (ROV):
The Real Options Value (ROV) incorporates the value of managerial flexibility in decision mak-
ing. The formula for ROV is:
ROV =NP V + (Stock P rice ×β×NP V )
Where:
Stock P rice :Current stock price
β:Beta of the project
NP V :Net Present Value
Substitute the given values into the formula:
ROV = 6,616.02 + (50 ×1.5×6,616.02)
= 6,616.02 + 4,974.015
= $11,590.03
Therefore, the Real Options Value (ROV) of the project is $11,590.03.
8 8. REAL OPTIONS AND RISK MANAGEMENT
Problem 8. A company is considering investing in a project that has an initial cost of $1,000,000.
The project is expected to generate $400,000 in revenue in the first year, with a 30
a) Calculate the expected present value (EPV) of the project.
b) Determine the real option value (ROV) of the project.
Solution 8.
a) The EPV of the project can be calculated using the expected cash flow and discounting it
back to present value.
For the successful scenario (30
P V =400,000
1+0.03 =400,000
1.03 ≈$388,349.51
For the unsuccessful scenario (70The present value is zero as there is no revenue.
P V = 0
Therefore, the EPV of the project is:
EP V = 0.3×$388,349.51 + 0.7×$0 = $116,504.85
b) To determine the real option value (ROV) of the project, we need to calculate the value of the
option to continue the project given that it is successful.
The cash flow for each year in the successful scenario is given by:
CFt= 400,000 ×(1.05)t
The present value of the cash flows can be calculated using the risk-free rate of 3
P Vt=400,000 ×(1.05)t
(1 + 0.03)t=400,000 ×(1.05)t
1.03t
For simplicity, let’s consider a perpetuity formula to find the present value of expected cash
flows after year 1:
P V∞=400,000 ×(1.05)
0.03 −0.05 =400,000 ×1.05
−0.02 ≈ −$21,000,000.00
Therefore, the ROV of the project is positive (since the project should be continued) and is
approximately $21,000,000.00.
9 9. REAL OPTIONS IN TECHNOLOGY INVESTMENTS
Problem 9. A technology company is considering investing in a new project that will cost
$500,000 upfront. The project is expected to generate cash flows of $200,000 in one year with a
60% chance, and $100,000 with a 40% chance. The risk-free rate is 5%, and the company uses a
discount rate of 10% for risky projects. The company has the option to abandon the project in one
year if the cash flows are not satisfactory.
a) Calculate the present value of the project without the option to abandon it.
b) Calculate the project’s value if the company has the option to abandon it in one year.
c) Determine the value of the abandonment option.
Solution 9.
a) The present value of the project without the option to abandon it can be calculated by dis-
counting the expected cash flows at the discount rate of 10%:
P V =200,000 ×0.6
1.10 +100,000 ×0.4
1.10 = $145,454.55 + $36,363.64 = $181,818.19
Therefore, the present value of the project without the option to abandon it is $181,818.19.
b) To calculate the project’s value with the option to abandon it, we need to consider the option
to abandon the project in one year if the cash flows are not satisfactory. We use the risk-neutral
probabilities to estimate the expected cash flow and discount it back at the risk-free rate:
E(CF ) = 200,000 ×0.6 + 100,000 ×0.4 = $160,000
P V =160,000
1.05 = $152,380.95
Therefore, the project’s value with the option to abandon it in one year is $152,380.95.
c) The value of the abandonment option is the difference between the present value of the
project without the option to abandon it and the project’s value with the option to abandon it:
Abandonment Option = $181,818.19 −$152,380.95 = $29,437.24
Therefore, the value of the abandonment option is $29,437.24.
10 10. REAL OPTIONS IN NATURAL RESOURCE EXPLORATION
Problem 10. A mining company is considering opening a new mine in a mineral-rich region.
The company has the option to delay the opening of the mine for two years to allow for more
exploration and better market conditions. The initial investment cost for opening the mine now is
$10 million. If the company delays the opening, it would incur exploration costs of $2 million per
year for the two-year period. The present value factor for each year is 0.909.
a) Calculate the net present value (NPV) of opening the mine now.
b) Calculate the net present value (NPV) of delaying the opening for two years and incorporating
the exploration costs.
c) Discuss whether it is financially advantageous for the company to delay the mine opening
based on the NPV calculations.
Solution 10.
a) The NPV of opening the mine now can be calculated using the formula:
NP V =−InitialInvestment +XN etCashF lowt
(1 + r)t
Given that the initial investment is $10 million, the annual net cash flow from the mine operation
is expected to be $5 million, and the discount rate is 10
NP V =−10 + 5(0.909) + 5(0.909)2
NP V =−10 + 4.545 + 4.132 = −10 + 8.677 = −1.323
Therefore, the NPV of opening the mine now is -$1.323 million.
b) The NPV of delaying the mine opening can be calculated by considering the exploration costs
for two years:
NP V =−InitialInvestment +XExplorationCostst
(1 + r)t
The exploration costs for year 1 and year 2 are $2 million each. So, the NPV of delaying the
opening for two years is:
NP V =−2(0.909) −2(0.909)2=−1.818 −1.818 = −3.636
Therefore, the NPV of delaying the mine opening is -$3.636 million.
c) Comparing the NPVs, we see that delaying the mine opening results in a higher negative
NPV (-$3.636 million) compared to opening the mine now (-$1.323 million). Therefore, from a
financial perspective, it is not advantageous for the company to delay the mine opening.
11 11. CAPITAL BUDGETING WITH REAL OPTIONS
Problem 11. ABC Corporation is considering an investment in a new project. The initial cost
of the project is $500,000. The project is expected to generate cash flows of $150,000 per year for
the next 5 years. The risk-free rate is 4% and the project’s beta is 1.2. The strike price for the real
option to abandon the project is $400,000. Calculate the Net Present Value (NPV) of the project
with and without the real option to abandon.
Solution 11.
a) First, let’s calculate the NPV of the project without the real option to abandon:
The NPV formula is:
NP V =−C0+
n
X
t=1
CFt
(1 + r)t
Where: - C0= $500,000 (initial cost of project) - CFt= $150,000 for all years 1 to 5 - r= 4%
(risk-free rate)
Substitute these values into the formula:
NP V =−$500,000 + $150,000
1.04 +$150,000
(1.04)2+$150,000
(1.04)3+$150,000
(1.04)4+$150,000
(1.04)5
Calculating the above expression gives:
NP V =−$500,000 + $144,230.77 + $138,888.89 + $133,951.10 + $129,404.77 + $125,229.48
NP V =−$500,000 + $671,705.01
NP V = $171,705.01
Therefore, the NPV of the project without the real option to abandon is $171,705.01.
b) Now, let’s calculate the NPV of the project with the real option to abandon:
The real option to abandon adds an extra Pto cash flow in year 2. The value of this real option
can be calculated as:
P=Max(0, K −V2)
Where: - K= $400,000 (strike price to abandon) - V2= $500,000 + $150,000
1.04 = $630,769.23 (value
of the project in year 2)
P=Max(0,$400,000 −$630,769.23)
P=Max(0,−$230,769.23) = $0
Therefore, there is no value in exercising the real option to abandon the project in year 2. The
NPV remains $171,705.01.
Thus, the NPV of the project with and without the real option to abandon remains the same at
$171,705.01.
12 12. REAL OPTIONS IN REAL ESTATE INVESTMENTS
Problem 12.
A real estate developer is considering the purchase of a parcel of land for $500,000. The
developer has the option to build either residential units or commercial units on the land. The
expected cash flows associated with each type of development are as follows:
•Residential units: $300,000 in the first year, $200,000 in the second year, and $100,000 in
the third year.
•Commercial units: $400,000 in the first year, $250,000 in the second year, and $150,000 in
the third year.
The developer has the right to delay the development decision by one year. If the developer
chooses to wait, the cost of the land will remain the same and the expected cash flows will also
remain the same. The risk-free rate is 5%.
a) Determine the net present value (NPV) of developing residential units immediately.
b) Determine the net present value (NPV) of developing commercial units immediately.
c) Calculate the value of the option to delay the development decision by one year.
Solution 12.
a) To find the NPV of developing residential units immediately, we need to discount the expected
cash flows back to present value. The NPV can be calculated using the formula:
NP V =
3
X
t=1
CFt
(1 + r)t−Initial Cost
Where CFtis the cash flow in year t,ris the risk-free rate, and the initial cost is $500,000.
Plugging in the values for residential units:
NP V =300,000
(1 + 0.05)1+200,000
(1 + 0.05)2+100,000
(1 + 0.05)3−500,000
NP V = 285,714.29 + 181,405.90 + 83,305.95 −500,000
NP V = $50,426.14
Therefore, the NPV of developing residential units immediately is $50,426.14.
b) Similarly, the NPV of developing commercial units immediately can be calculated as:
NP V =400,000
(1 + 0.05)1+250,000
(1 + 0.05)2+150,000
(1 + 0.05)3−500,000
NP V = 380,952.38 + 235,449.74 + 131,724.89 −500,000
NP V = $248,127.01
Therefore, the NPV of developing commercial units immediately is $248,127.01.
c) To calculate the value of the option to delay, we need to find the NPV of waiting for one year
and compare it to the NPV of immediate development.
The NPV of waiting for one year is the same as the NPV of immediate development because
the land cost and cash flows remain the same.
Therefore, the value of the option to delay the development decision by one year is $0.
13 13. REAL OPTIONS IN PHARMACEUTICAL INVESTMENTS
Problem 13. A pharmaceutical company is considering investing in the development of a new
drug. The initial investment is $5 million, and the expected cash flows from the drug over the next
5 years are as follows (in millions of dollars):
Year Expected Cash Flow
1 2
2 3
3 4
4 4
5 5
The company has the option to abandon the project at the end of year 2. The risk-free rate is
5% and the company’s cost of capital is 10%.
a) Calculate the Net Present Value (NPV) of the project without the option to abandon.
b) Calculate the NPV of the project with the option to abandon after year 2.
Solution 13.
a) The NPV of the project without the option to abandon can be calculated using the formula:
NP V =−5 + 2
(1 + 0.05) +3
(1 + 0.05)2+4
(1 + 0.05)3+4
(1 + 0.05)4+5
(1 + 0.05)5
NP V =−5 + 2
1.05 +3
(1.05)2+4
(1.05)3+4
(1.05)4+5
(1.05)5
Calculating this gives:
NP V =−5+1.9048 + 2.7232 + 3.7891 + 3.4185 + 3.2164 = 9.0519 million
Therefore, the NPV of the project without the option to abandon is $9.05 million.
b) The NPV of the project with the option to abandon after year 2 can be calculated by comparing
the NPV of continuing the project with the NPV of abandoning it after year 2.
At the end of year 2, the expected cash flows from the project are $4 million and $5 million in
years 3 and 4 respectively.
To calculate the NPV of the project if abandoned after year 2:
NP Vabandon =−5 + 2
(1 + 0.05) +3
(1 + 0.05)2+4
(1 + 0.05)3= 7.7232 million
If the project is continued after year 2, the cash flows in years 3 and 4 would be $4 million and
$4 million respectively. Calculating the NPV in this case:
NP Vcontinue =−5 + 2
(1 + 0.05) +3
(1 + 0.05)2+4
(1 + 0.05)3+4
(1 + 0.05)4= 8.7891 million
Comparing the two options, the NPV of continuing the project after year 2 is higher, so the
company should continue with the project.
14 14. REAL OPTIONS IN RENEWABLE ENERGY PROJECTS
Problem 14. You are evaluating an investment in a renewable energy project with the following
parameters:
- Initial investment cost: 200,000 −Expectedannualcashflowsforthenext5years :50,000 - Dis-
count rate: 10- Estimated salvage value at the end of year 5: 20,000
The project also has a real option to expand its capacity in year 3 by investing an additional
100,000.T heexpandedprojectisexpectedtogenerateadditionalannualcashf lowsof30,000 for the re-
maining 3 years.
a) Calculate the NPV of the initial investment without considering the expansion option.
b) Determine the NPV of the expanded project considering the expansion option.
Solution 14.
a) To calculate the NPV of the initial investment without considering the expansion option, we
need to discount the expected cash flows over the next 5 years and subtract the initial investment
cost:
NP V =−200,000 + 50,000
1.10 +50,000
(1.10)2+50,000
(1.10)3+50,000
(1.10)4+50,000 + 20,000
(1.10)5
NP V =−200,000 + 50,000
1.10 +50,000
(1.10)2+50,000
(1.10)3+50,000
(1.10)4+70,000
(1.10)5
Calculating the NPV, we get:
NP V =−200,000 + 45,454.55 + 41,322.31 + 37,565.74 + 34,150.67 + 40,772.27
NP V = $ −4383.46
Therefore, the NPV of the initial investment without considering the expansion option is −4383.46.
b) To determine the NPV of the expanded project, we need to consider the additional cash flows
from year 3 onwards as well as the expansion cost. The expanded project’s cash flows will be:
NP V =−200,000+50,000
1.10 +50,000
(1.10)2+(30,000−100,000)×1
(1.10)2+(30,000−100,000)×1
(1.10)3+(30,000−100,000)×1
(1.10)4+50,000 + 20,000
(1.10)5
NP V =−200,000 + 45,454.55 + 41,322.31 + 21,818.18 + 18,926.53 + 16,296.85 + 40,772.27
NP V = $15,409.48
Therefore, the NPV of the expanded project considering the expansion option is −15,409.48.
I. Real Options and Investment Analysis
Problem 1. A company is considering investing in a new project with an initial cost of $1,000,000.
The project is expected to generate cash flows of $400,000 in the first year, $500,000 in the second
year, and $600,000 in the third year. The company has the option to abandon the project after the
first year. The risk-free rate is 5%. Should the company invest in this project?
Solution 1. Given: Initial investment (C): $1,000,000 Cash flows: year 1 = $400,000, year 2 =
$500,000, year 3 = $600,000 Risk-free rate (r): 5
The Net Present Value (NPV) of the project can be calculated as follows: NPV = -C + PCFt
(1+r)t
NPV = -$1,000,000 + $400,000/(1+0.05)1+ $500,000/(1 + 0.05)2+ $600,000/(1 + 0.05)3
NPV = -$1,000,000 + $380,952 + $454,851 + $497,618.85 NPV = $333,421.85
The NPV of the project is positive, which indicates that the project is expected to generate a
return greater than the required rate of return. Therefore, the company should invest in this project.
Problem 2. A company is evaluating an investment in a project that requires an initial outlay
of $800,000. The cash flows from the project are expected to be $300,000 in year 1, $400,000 in
year 2, and $500,000 in year 3. The company has the option to expand the project at the end of
year 1 at an additional cost of $200,000. If the expansion is undertaken, the expected cash flows
in year 4 would be $600,000. Should the company invest in the project and expand in year 1 if the
opportunity arises? Assume a discount rate of 8
Solution 2. Given: Initial investment (C): $800,000 Cash flows: year 1 = $300,000, year 2 =
$400,000, year 3 = $500,000, year 4 (if expanded) = $600,000 Expansion cost: $200,000 Discount
rate (r): 8
Calculate the NPV if the project is undertaken without expansion: NPV = -$800,000 + $300,000/(1+0.08)1+
$400,000/(1 + 0.08)2+ $500,000/(1 + 0.08)3NP V =−$800,000 + $277,777.78 + $308,641.98 +
$340,136.66NP V = $126,556.42
Calculate the NPV if the project is expanded in year 1: NPV = -$800,000 + $300,000/(1+0.08)1+
$400,000/(1+0.08)2+$500,000/(1+0.08)3+$600,000/(1+0.08)4−$200,000NP V =−$800,000+
$277,777.78 + $308,641.98 + $340,136.66 + $387,096.77 −$200,000NP V = $513,652.21
Comparing the two NPVs, it is more beneficial for the company to invest in the project and
expand in year 1 if the opportunity arises, as it yields a higher NPV.
15 Real Options and Investment Analysis
Problem:
A company is considering acquiring a competitor in the same industry. The current market
value of the competitor is $50 million. The company believes that if it acquires the competitor, it
can implement a growth strategy that has a 60% chance of increasing the value of the acquired
firm to $80 million and a 40% chance of decreasing the value to $30 million. If the growth strategy
is successful, the company can generate additional cash flows of $20 million per year for the next
5 years. The risk-free rate is 4%.
a) Calculate the value of the real option to acquire the competitor.
b) Determine the optimal timing to exercise the real option if the company can only exercise it
once.
Solution:
a) Let’s first calculate the expected value of the acquired firm:
E[V]=0.6×$80 million + 0.4×$30 million
= $48 million + $12 million
= $60 million
The present value of the expected cash flows from the growth strategy can be calculated as:
P V (Cash Flows) = $20 million
1+0.04 +$20 million
(1 + 0.04)2+$20 million
(1 + 0.04)3+$20 million
(1 + 0.04)4+$20 million
(1 + 0.04)5
= $18.68 million + $17.98 million + $17.30 million + $16.65 million + $16.03 million
= $86.64 million
The value of the real option is the difference between the expected value of the acquired firm
and the present value of the cash flows:
Real Option Value = $60 million −$86.64 million
=−$26.64 million
Therefore, the value of the real option to acquire the competitor is -$26.64 million.
b) To determine the optimal timing to exercise the real option, we need to compare the value of
waiting to the option to the value of immediate exercise. The value of waiting is the expected value
of the acquired firm minus the exercise price (market value of the competitor), which is $60 million
- $50 million = $10 million.
The option to acquire has negative value (-$26.64 million) which implies that it should not be
exercised. Therefore, the optimal timing is to never exercise the option to acquire the competitor.
16 17. REAL OPTIONS IN PROJECT FINANCE
Problem 17. A company is considering investing in a new project that has the following char-
acteristics:
- Initial investment cost: $500,000 - Expected cash inflows in the first year: $300,000 - Expected
cash inflows in the second year: $400,000 - Expected cash inflows in the third year: $600,000 -
Discount rate: 10% - Risk-free rate: 5% - Volatility of cash flows: 20% - Time to maturity for the real
option: 3 years - Exercise price for the real option: $100,000
The company can abandon the project after the first year of operation if the cash flows are not
as expected.
a) Calculate the Net Present Value (NPV) of the project without considering the real option.
b) Determine the value of the real option embedded in the project.
c) Should the company invest in the project based on the real option analysis?
Solution 17.
a) The Net Present Value (NPV) of the project without considering the real option can be cal-
culated using the formula:
NP V =CF1
(1 + r)1+CF2
(1 + r)2+CF3
(1 + r)3−Initial Investment
where ris the discount rate, CFiis the cash flow in year i, and the Initial Investment is the initial
cost of the project.
Substitute the given values into the formula:
NP V =300,000
(1 + 0.10)1+400,000
(1 + 0.10)2+600,000
(1 + 0.10)3−500,000
NP V =300,000
1.10 +400,000
1.102+600,000
1.103−500,000
NP V = 272,727.27 + 330,578.51 + 401,324.62 −500,000
NP V = 504,630.40
Therefore, the NPV of the project without considering the real option is $504,630.40.
b) The value of the real option can be calculated using the Black-Scholes Option Pricing Model.
d1=ln(S/E)+(r+σ2/2)t
σ√t
d2=d1−σ√t
Option V alue =SΦ(d1)−Ee−rtΦ(d2)
where: - S= current stock price (value of project) - E= exercise price - r= risk-free rate - t=
time to maturity - σ= volatility
Substitute the given values into the formula:
d1=ln(300,000/100,000) + (0.05 + 0.202/2)3
0.20√3= 1.85
d2= 1.85 −0.20√3=1.35
Option V alue = 300,000Φ(1.85) −100,000e−0.05∗3Φ(1.35) = 148,385.16
Therefore, the value of the real option embedded in the project is $148,385.16.
c) The total value of the project considering the real option is:
T otal V alue =NP V +Option V alue = 504,630.40 + 148,385.16 = 653,015.56
As the total value of the project exceeds the initial investment cost and considering the real
option, the company should invest in the project based on the real option analysis.
17 18. REAL OPTIONS IN R&D INVESTMENTS
Problem 18. A company is considering investing in a research and development (R&D) project.
The initial investment required is $500,000. The project is expected to generate cash flows of
$200,000 in the first year, $300,000 in the second year, and $400,000 in the third year. The risk-
free rate is 5% and the company’s cost of capital is 10%.
a) Calculate the Net Present Value (NPV) of the project without considering the real options.
b) Determine the value of the Real Option to Abandon.
c) Calculate the Real Options Value of Waiting to Invest if the company can decide at the end
of each year whether to continue the project or not.
Solution 18.
a) The NPV of the project without considering the real options can be calculated by discounting
the cash flows at the cost of capital. The formula for NPV is:
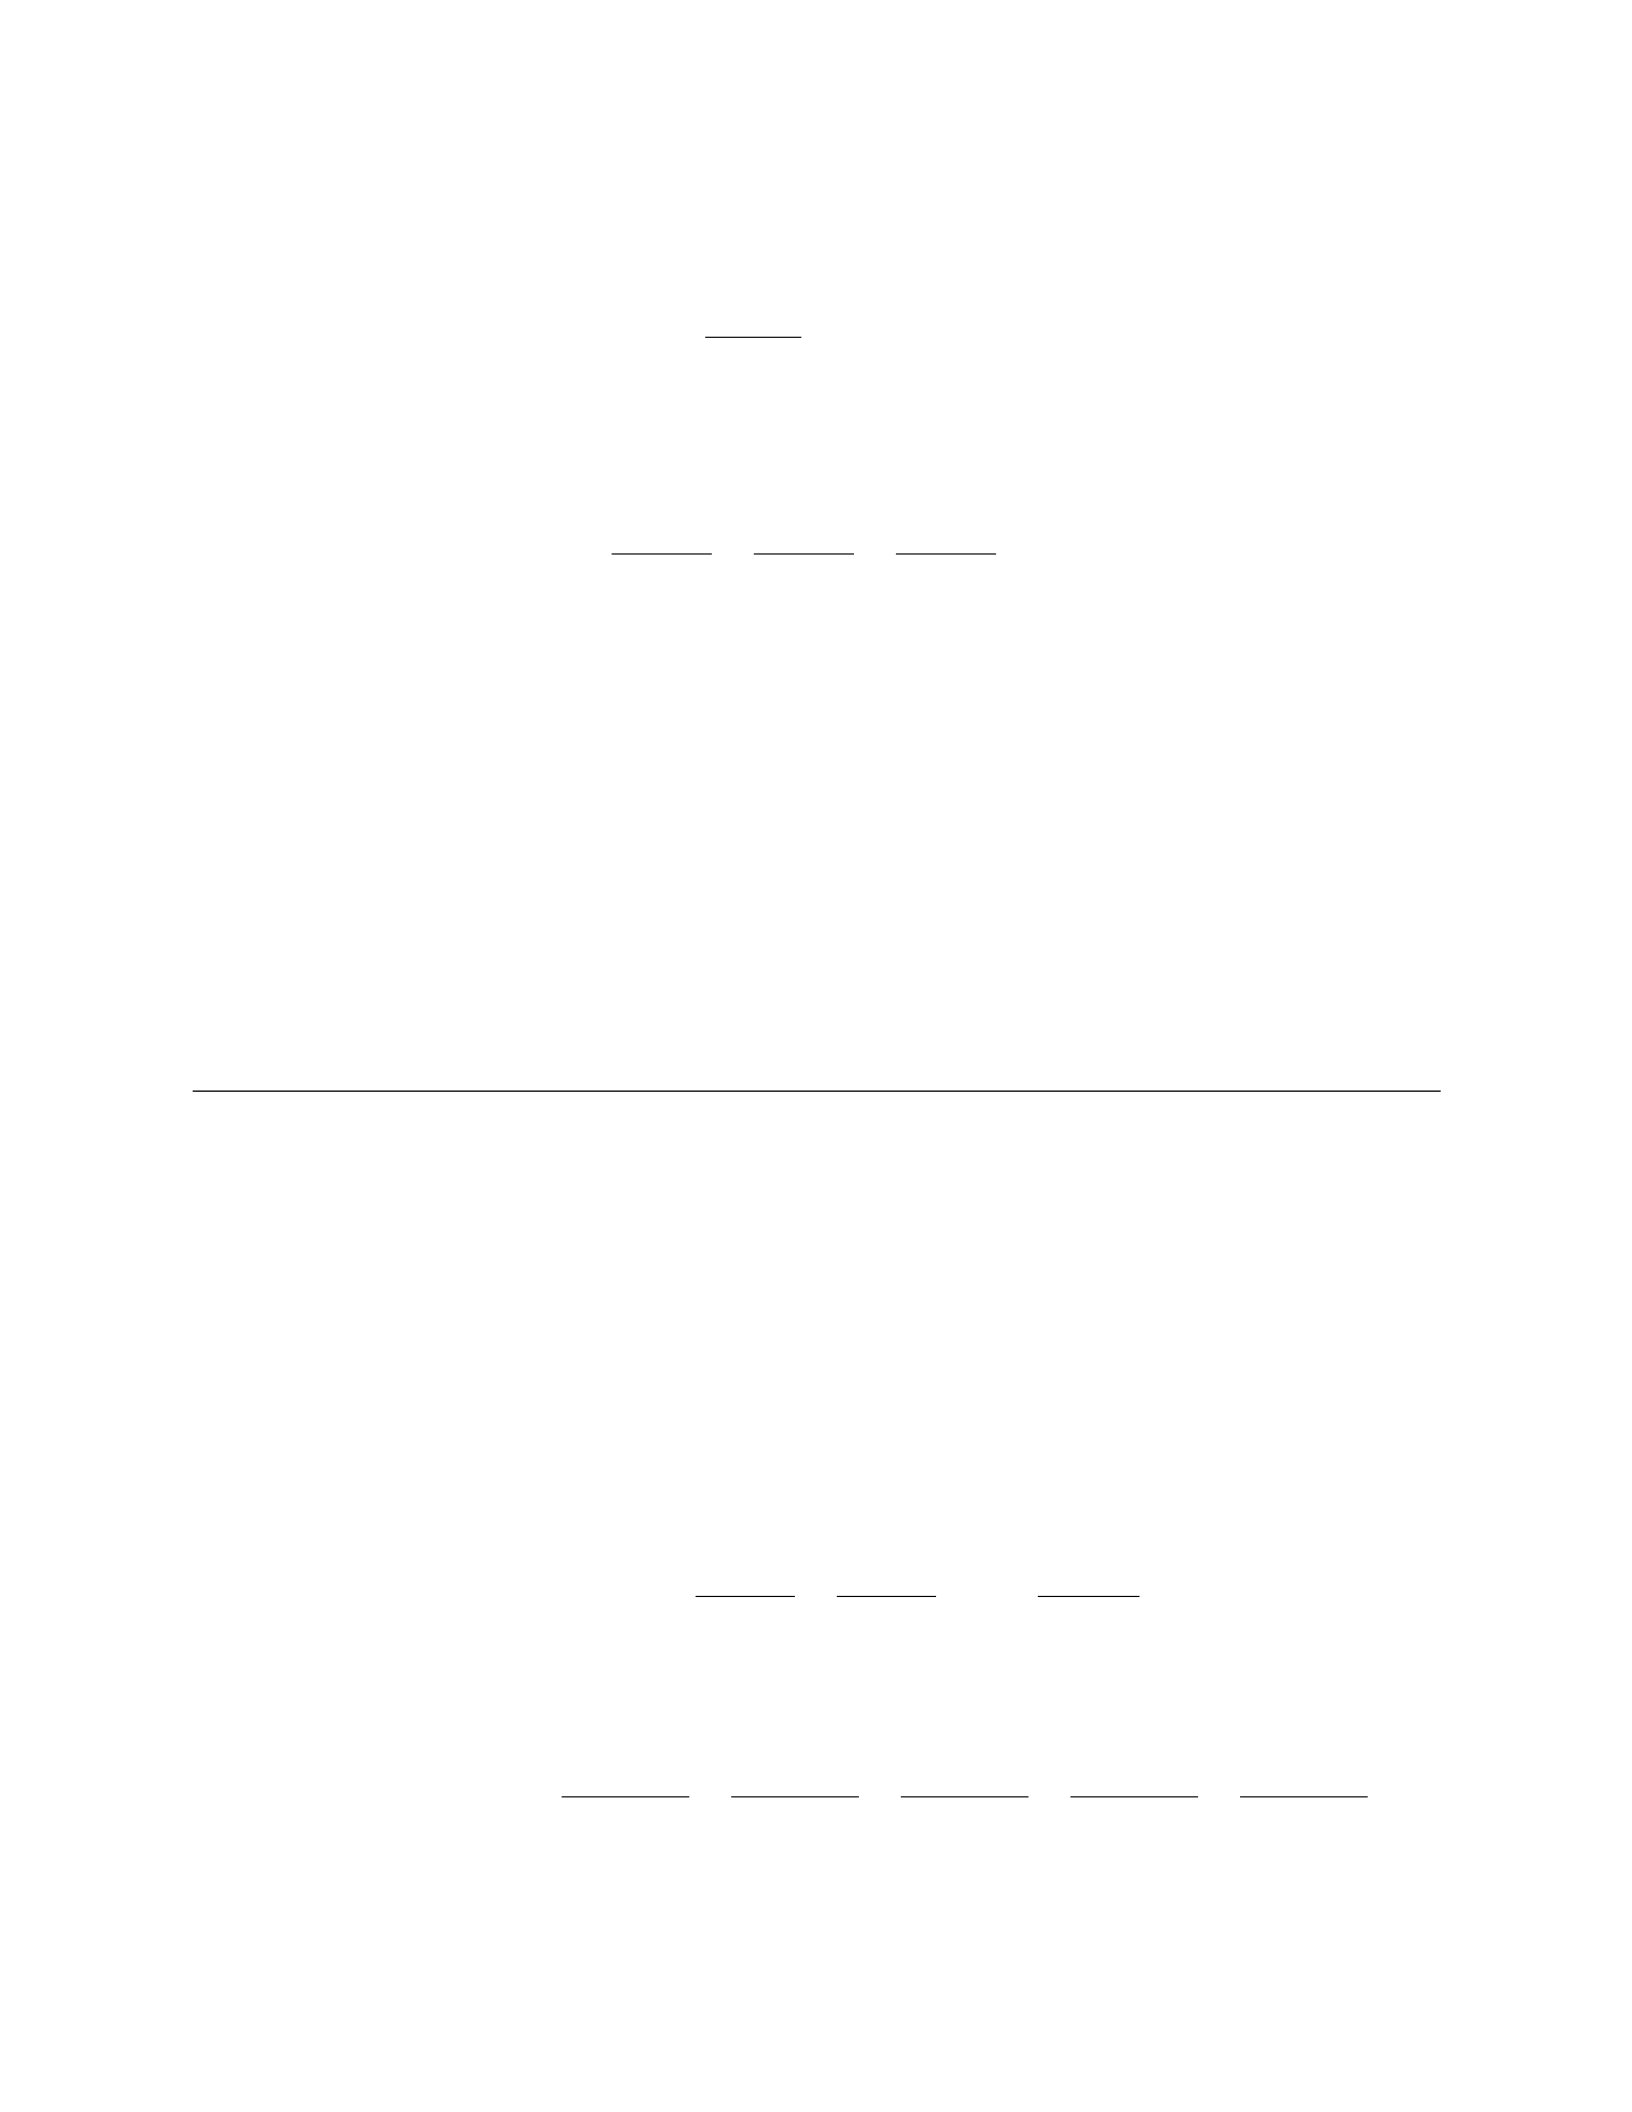
NP V =
n
X
t=1
CFt
(1 + r)t−Initial Investment
Where: - CFt= Cash flow in year t-r= Company’s cost of capital - Initial Investment =
$500,000
Plugging in the values:
NP V =200,000
1.10 +300,000
1.102+400,000
1.103−500,000
NP V = 181,818.18 + 247,933.88 + 300,043.71 −500,000
NP V = 229,795.77
Therefore, the NPV of the project without considering the real options is $229,795.77.
b) The Real Option to Abandon allows the company to abandon the project at the end of the
second year if it is no longer profitable. The value of this option can be calculated using the Binomial
option pricing model or decision tree analysis.
c) The Real Options Value of Waiting to Invest allows the company to assess whether to invest
at the end of each year based on the project’s performance. The decision to wait can be valued
using the Black-Scholes model or other numerical methods.
18 19. REAL OPTIONS IN INTERNATIONAL INVESTMENTS
Problem 19. A multinational corporation is considering investing in a project in a foreign coun-
try. The project has an initial investment cost of $5 million and is expected to generate cash flows of
$3 million per year for the next 5 years. The corporation has the option to expand the project after
2 years at an additional cost of $2 million. The risk-free rate is 5% and the corporation’s required
rate of return is 10%.
a) Calculate the Net Present Value (NPV) of the project without considering the option to ex-
pand.
b) Determine the value of the option to expand the project after 2 years.
c) Should the corporation proceed with the initial investment in the project?
Solution 19.
a) To calculate the NPV of the project without considering the option to expand, we use the
formula:
NP V =−C0+CF1
(1 + r)1+CF2
(1 + r)2+... +CFn
(1 + r)n
Where: C0= $5,000,000 CFt= $3,000,000 for t= 1,2,3,4,5r= 10%
Plugging in the values, we get:
NP V =−5,000,000 + 3,000,000
1.1+3,000,000
1.12+3,000,000
1.13+3,000,000
1.14+3,000,000
1.15
NP V =−5,000,000 + 2,727,273 + 2,479,338 + 2,254,853 + 2,049,866 + 1,861,696
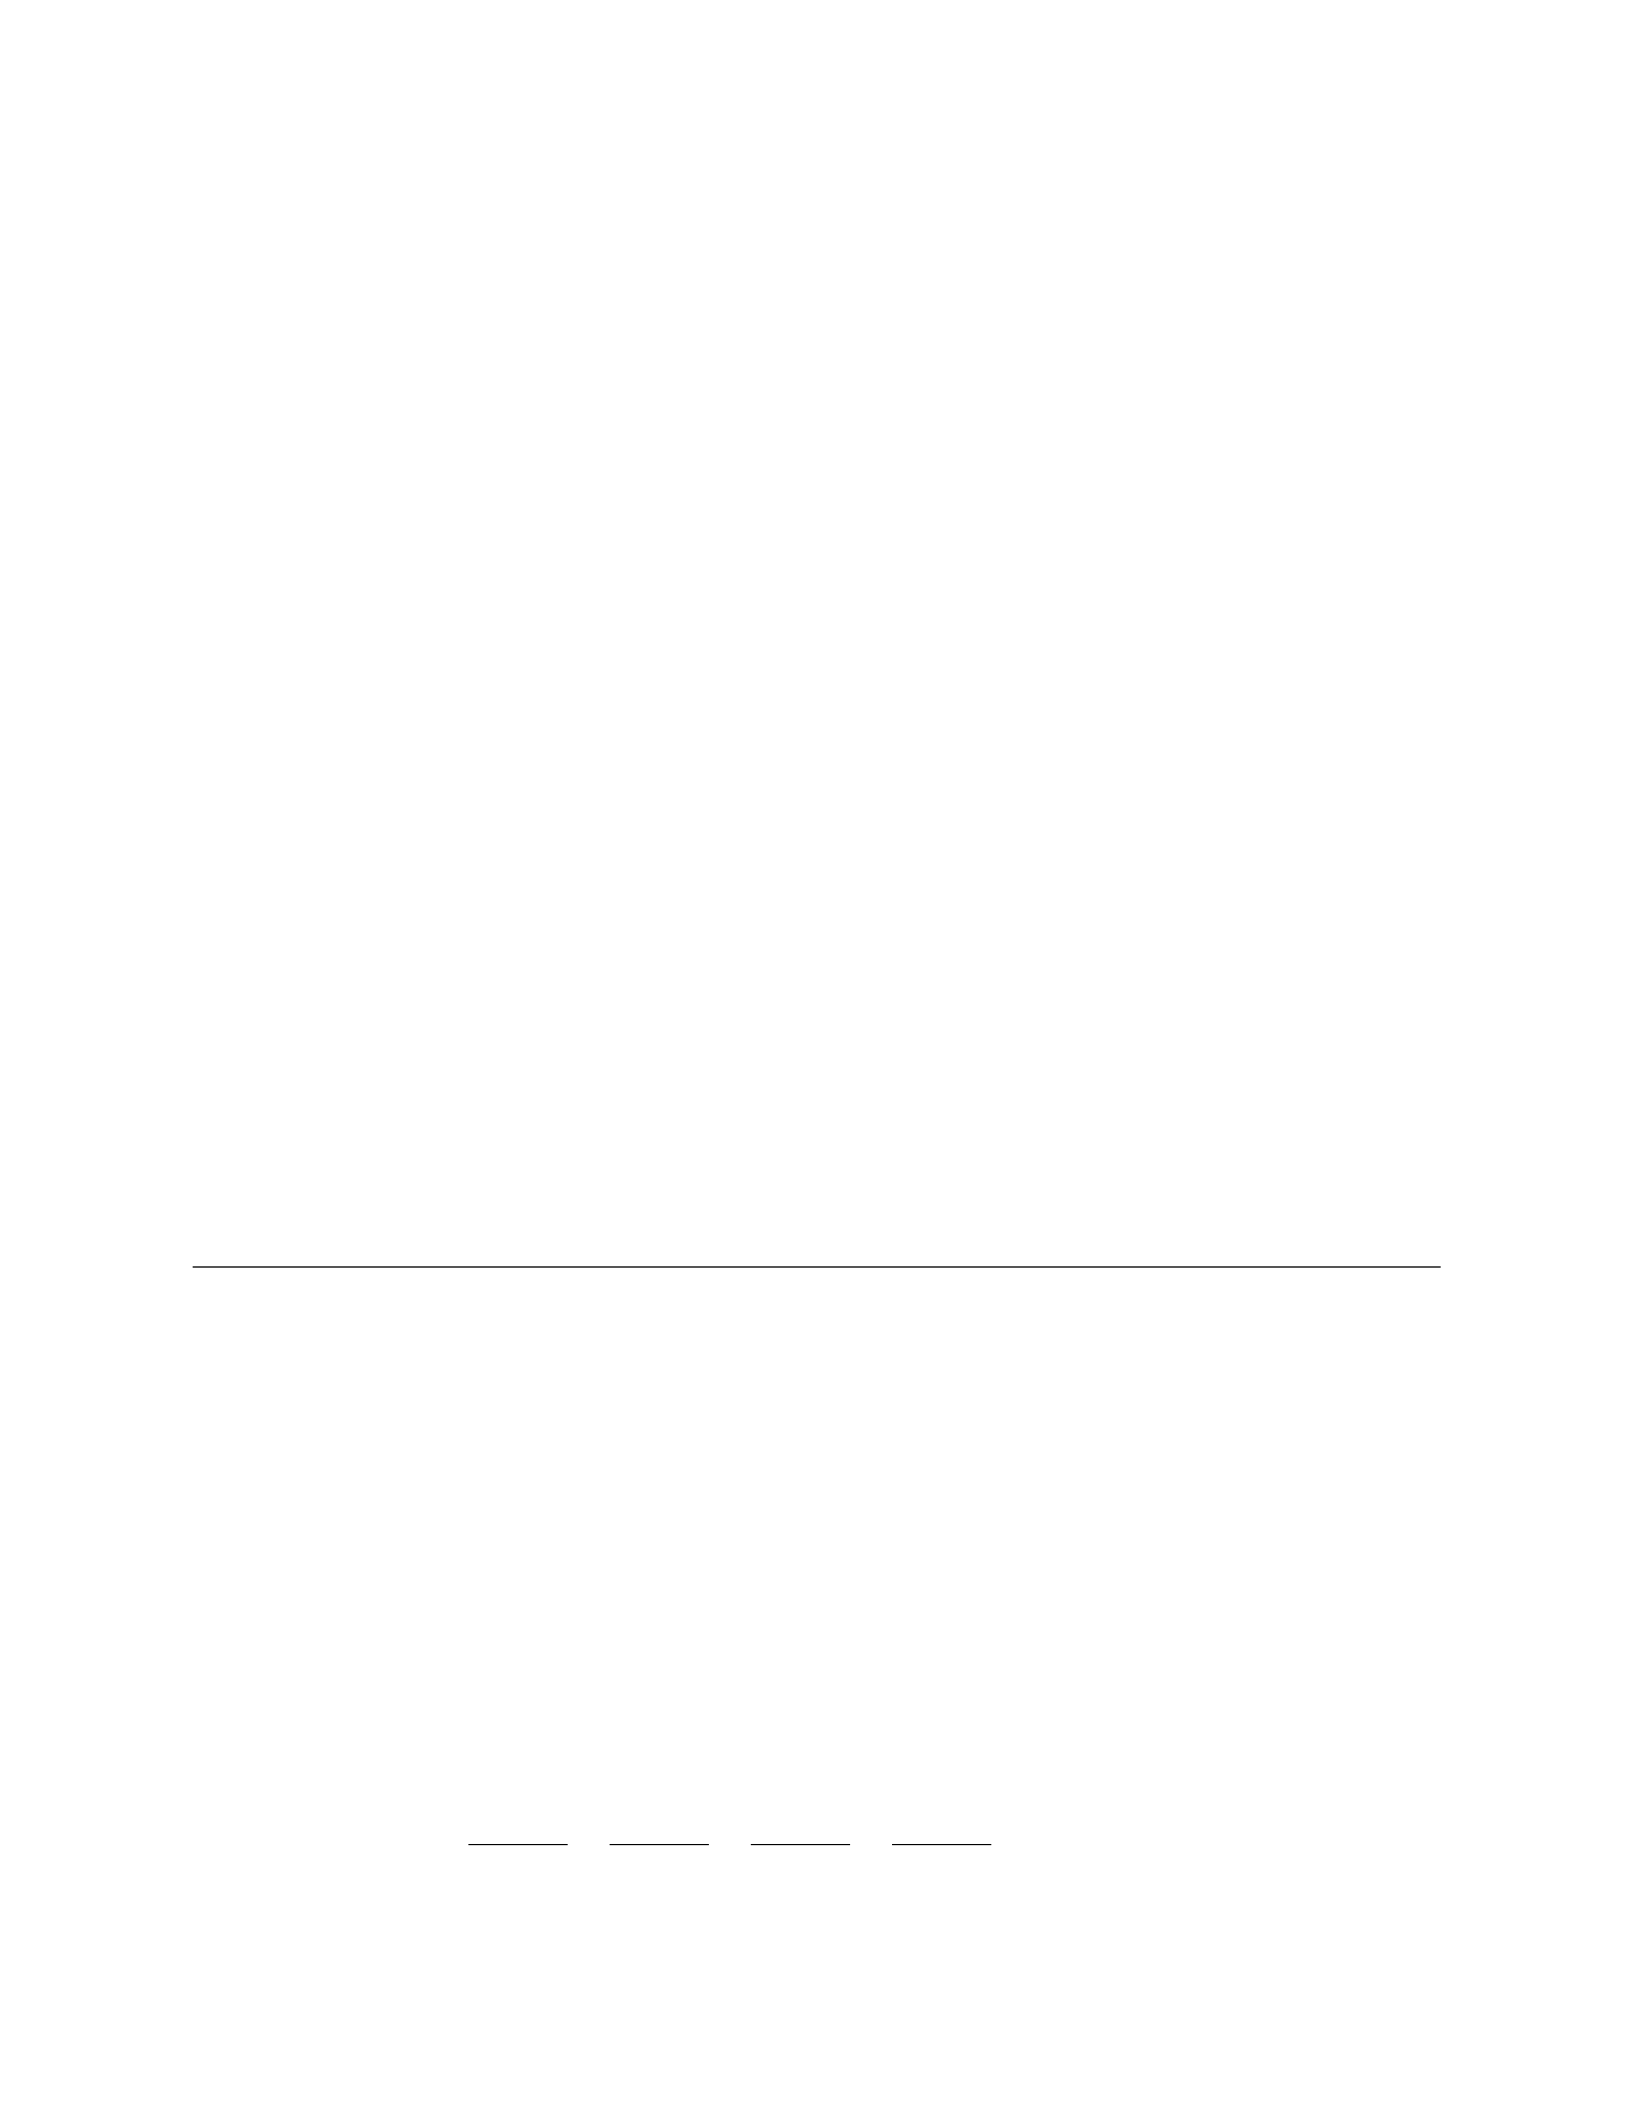
NP V = $2,373,050
The NPV of the project without considering the option to expand is $2,373,050.
b) The value of the option to expand the project after 2 years can be calculated using the Black-
Scholes model. The formula for the value of the option is:
V=S0N(d1)−Xe−rtN(d2)
Where: S0= $3,000,000 (Value of the expanded project) X= $2,000,000 (Cost of expansion)
r= 5% (Risk-free rate) t= 2 years
Calculating d1and d2using the Black-Scholes formula, we find d1= 0.4407 and d2= 0.1841.
Plugging in these values, we get:
V= 3,000,000N(0.4407) −2,000,000e−0.05∗2N(0.1841)
V= 3,000,000 ×0.6703 −2,000,000 ×e−0.1×0.5749
V= 2,010,894 −1,273,239
V= $737,655
The value of the option to expand the project after 2 years is $737,655.
c) As the NPV of the project without considering the option to expand is positive ($2,373,050)
and the value of the option to expand is also positive ($737,655), the corporation should proceed
with the initial investment in the project.
19 20. REAL OPTIONS IN NEW PRODUCT DEVELOPMENT
Problem 20. A company is considering developing a new product. The initial investment re-
quired is $500,000. The expected cash flows from the product over the next 3 years are estimated
as follows: Year 1: $200,000, Year 2: $300,000, Year 3: $400,000. The company has the option
to abandon the project at the end of each year with the following abandonment values: Year 1:
$50,000, Year 2: $100,000, Year 3: $200,000. The risk-free rate is 5%.
a) Calculate the net present value (NPV) of the project without considering any abandonment
options.
b) Determine the net present value (NPV) of the project if the company has the flexibility to
abandon the project at the end of each year.
c) Discuss whether incorporating the abandonment options increases the value of the project.
Solution 20.
a) To calculate the NPV of the project without considering any abandonment options, we need
to discount the cash flows at the risk-free rate of 5%.
Using the formula for NPV:
NP V =CF0
(1 + r)0+CF1
(1 + r)1+CF2
(1 + r)2+CF3
(1 + r)3−Initial Investment
where r= 0.05 and the cash flows are 200,000,300,000, and 400,000f oryears1,2, and3respectively.
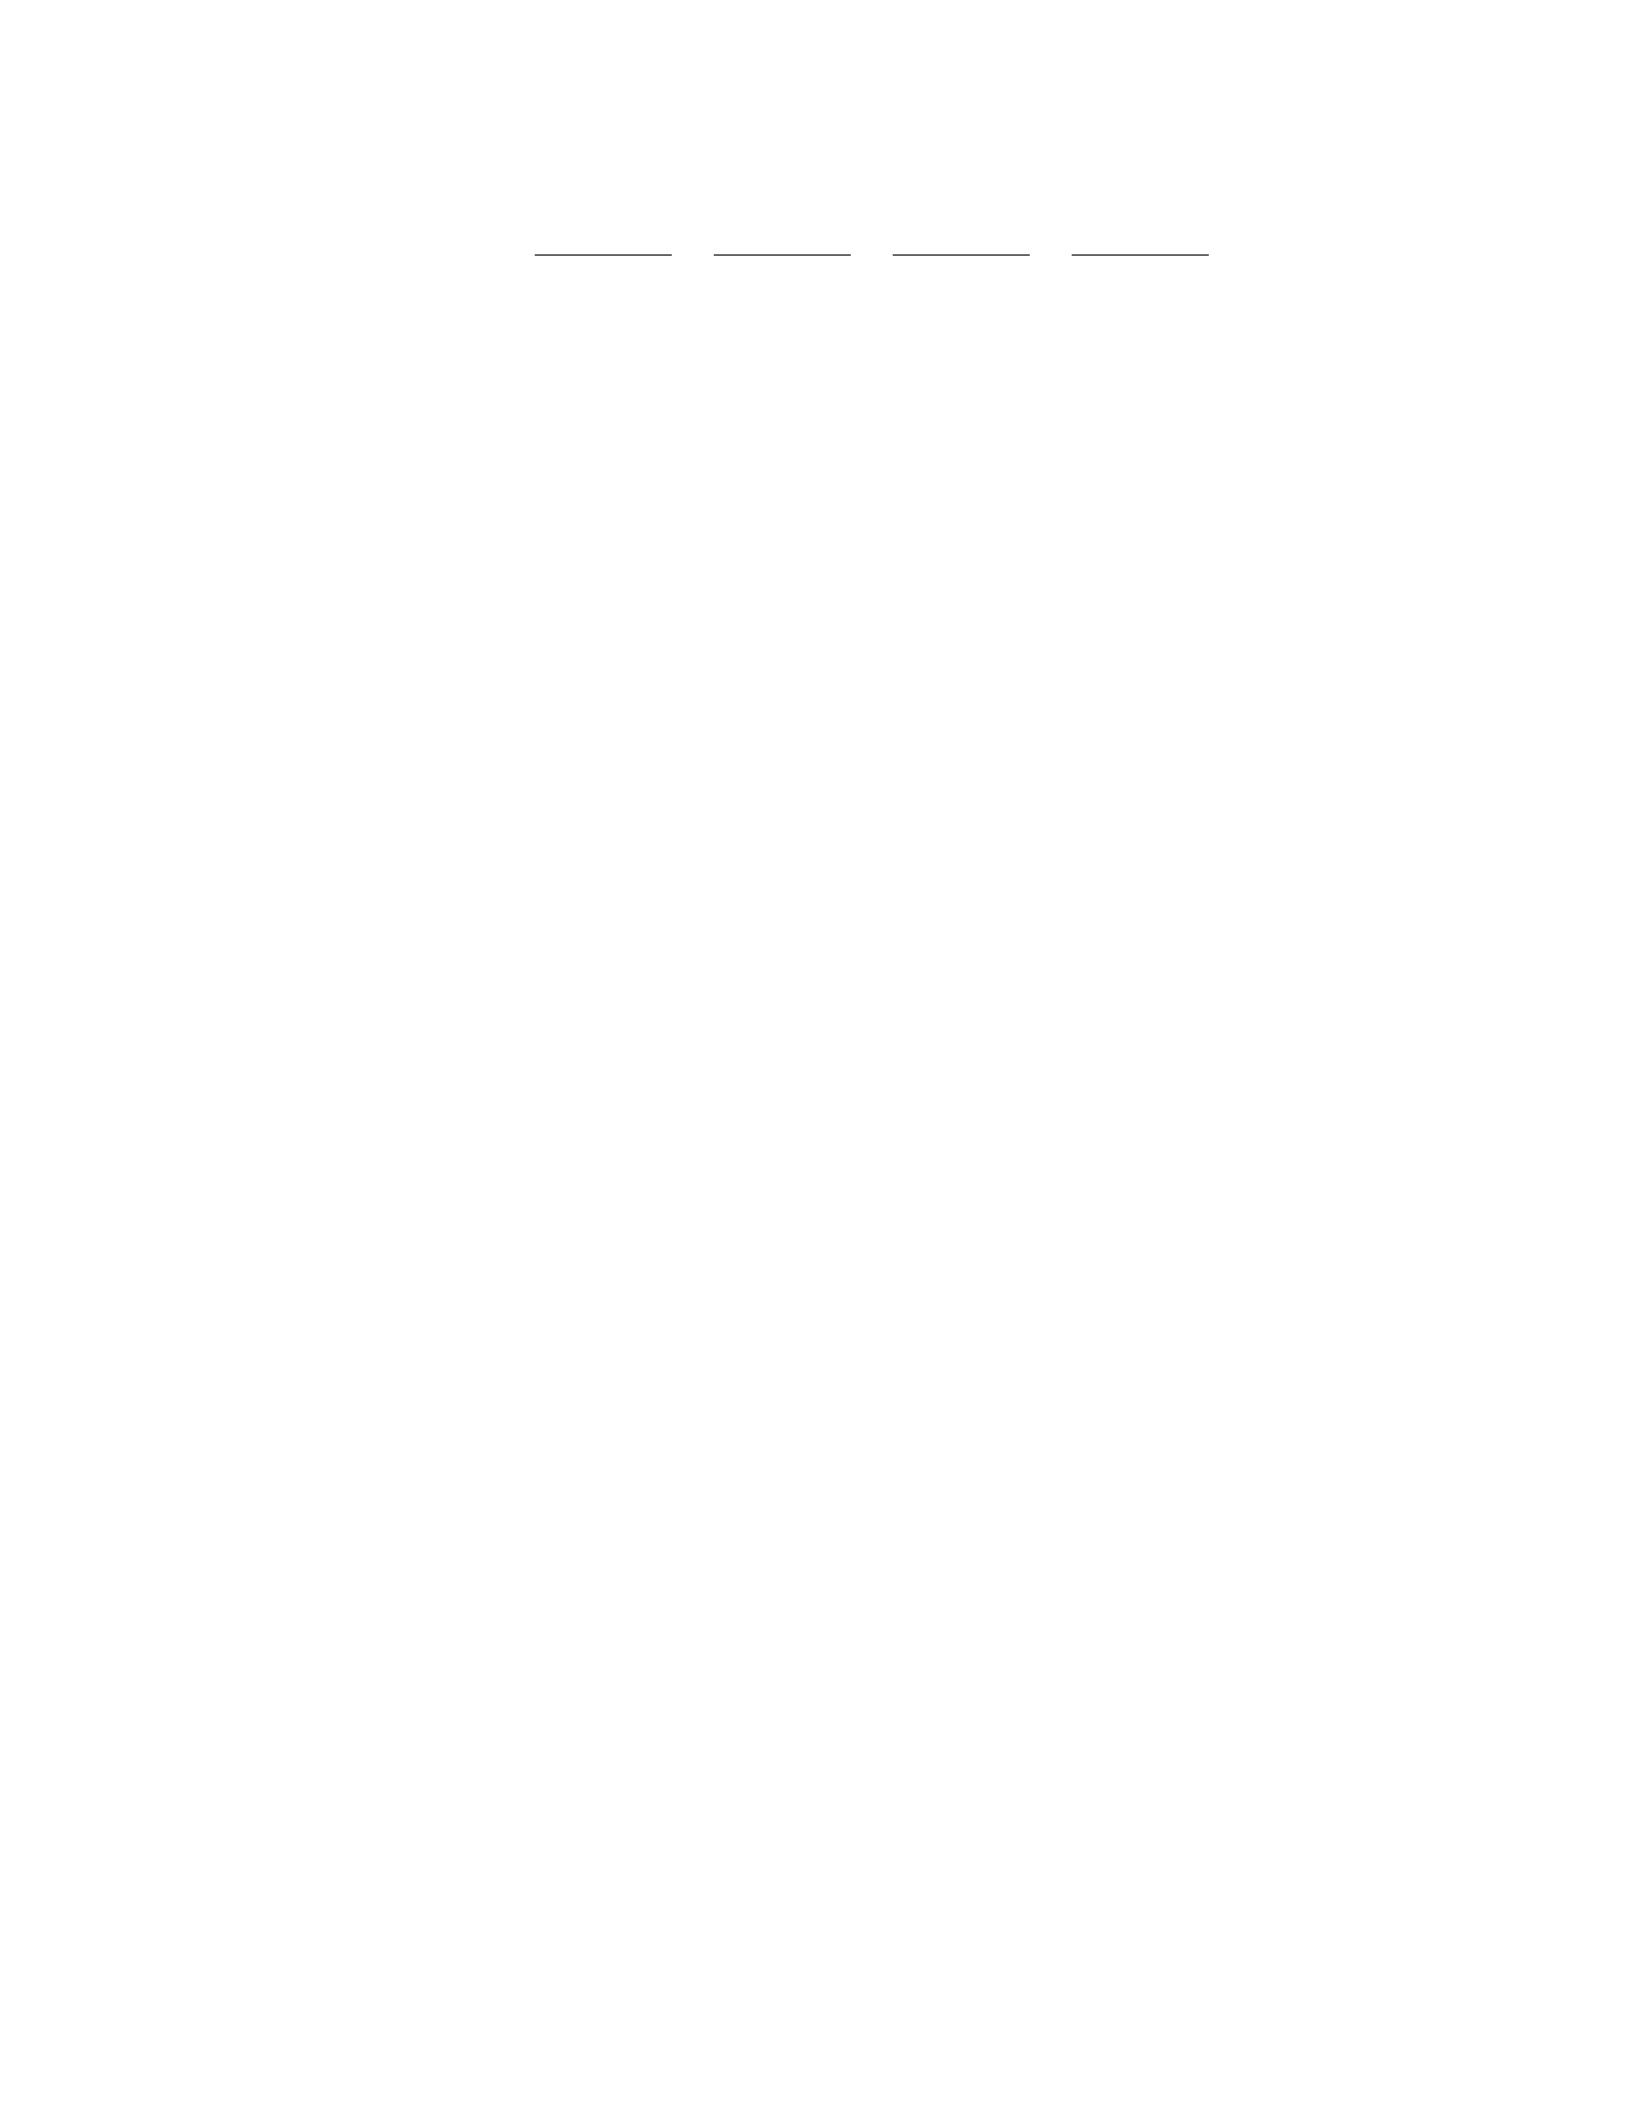
NP V =−500,000
(1 + 0.05)0+200,000
(1 + 0.05)1+300,000
(1 + 0.05)2+400,000
(1 + 0.05)3
NP V =−500,000 + 190,476.2 + 272,108.8 + 342,317.5 = 304,902.5
Therefore, the NPV of the project without considering any abandonment options is $304,902.5.
b) To calculate the NPV of the project with abandonment options, we need to consider the option
to abandon at the end of each year by comparing the continuation value with the abandonment
value.
In Year 1, the continuation value is $190,476.2 (the present value of cash flows from Year 2
and Year 3). If the abandonment value ($50,000) is greater, then the project would be abandoned,
resulting in an NPV of -$50,000. In this case, the NPV of Year 1 is -$50,000.
In Year 2, the continuation value is $272,108.8 (the present value of cash flow from Year 3). If
the abandonment value ($100,000) is greater, then the project would be abandoned, resulting in
an NPV of -$100,000. In this case, the NPV of Year 2 is -$100,000.
In Year 3, the project will not be abandoned as the cash flow of $400,000 is greater than the
abandonment value of $200,000. Therefore, the NPV of Year 3 is $357,142.9 (the present value
of the cash flow in Year 3).
The total NPV of the project with abandonment options is the sum of the NPVs of each year:
NP V =−50,000 −100,000 + 357,142.9 = 207,142.9
Therefore, the NPV of the project with abandonment options is $207,142.9.
c) Incorporating abandonment options increases the value of the project, as the NPV with aban-
donment options ($207,142.9) is higher than the NPV without considering any abandonment op-
tions ($304,902.5). Abandonment options provide flexibility in decision-making and can increase
the overall value of a project.
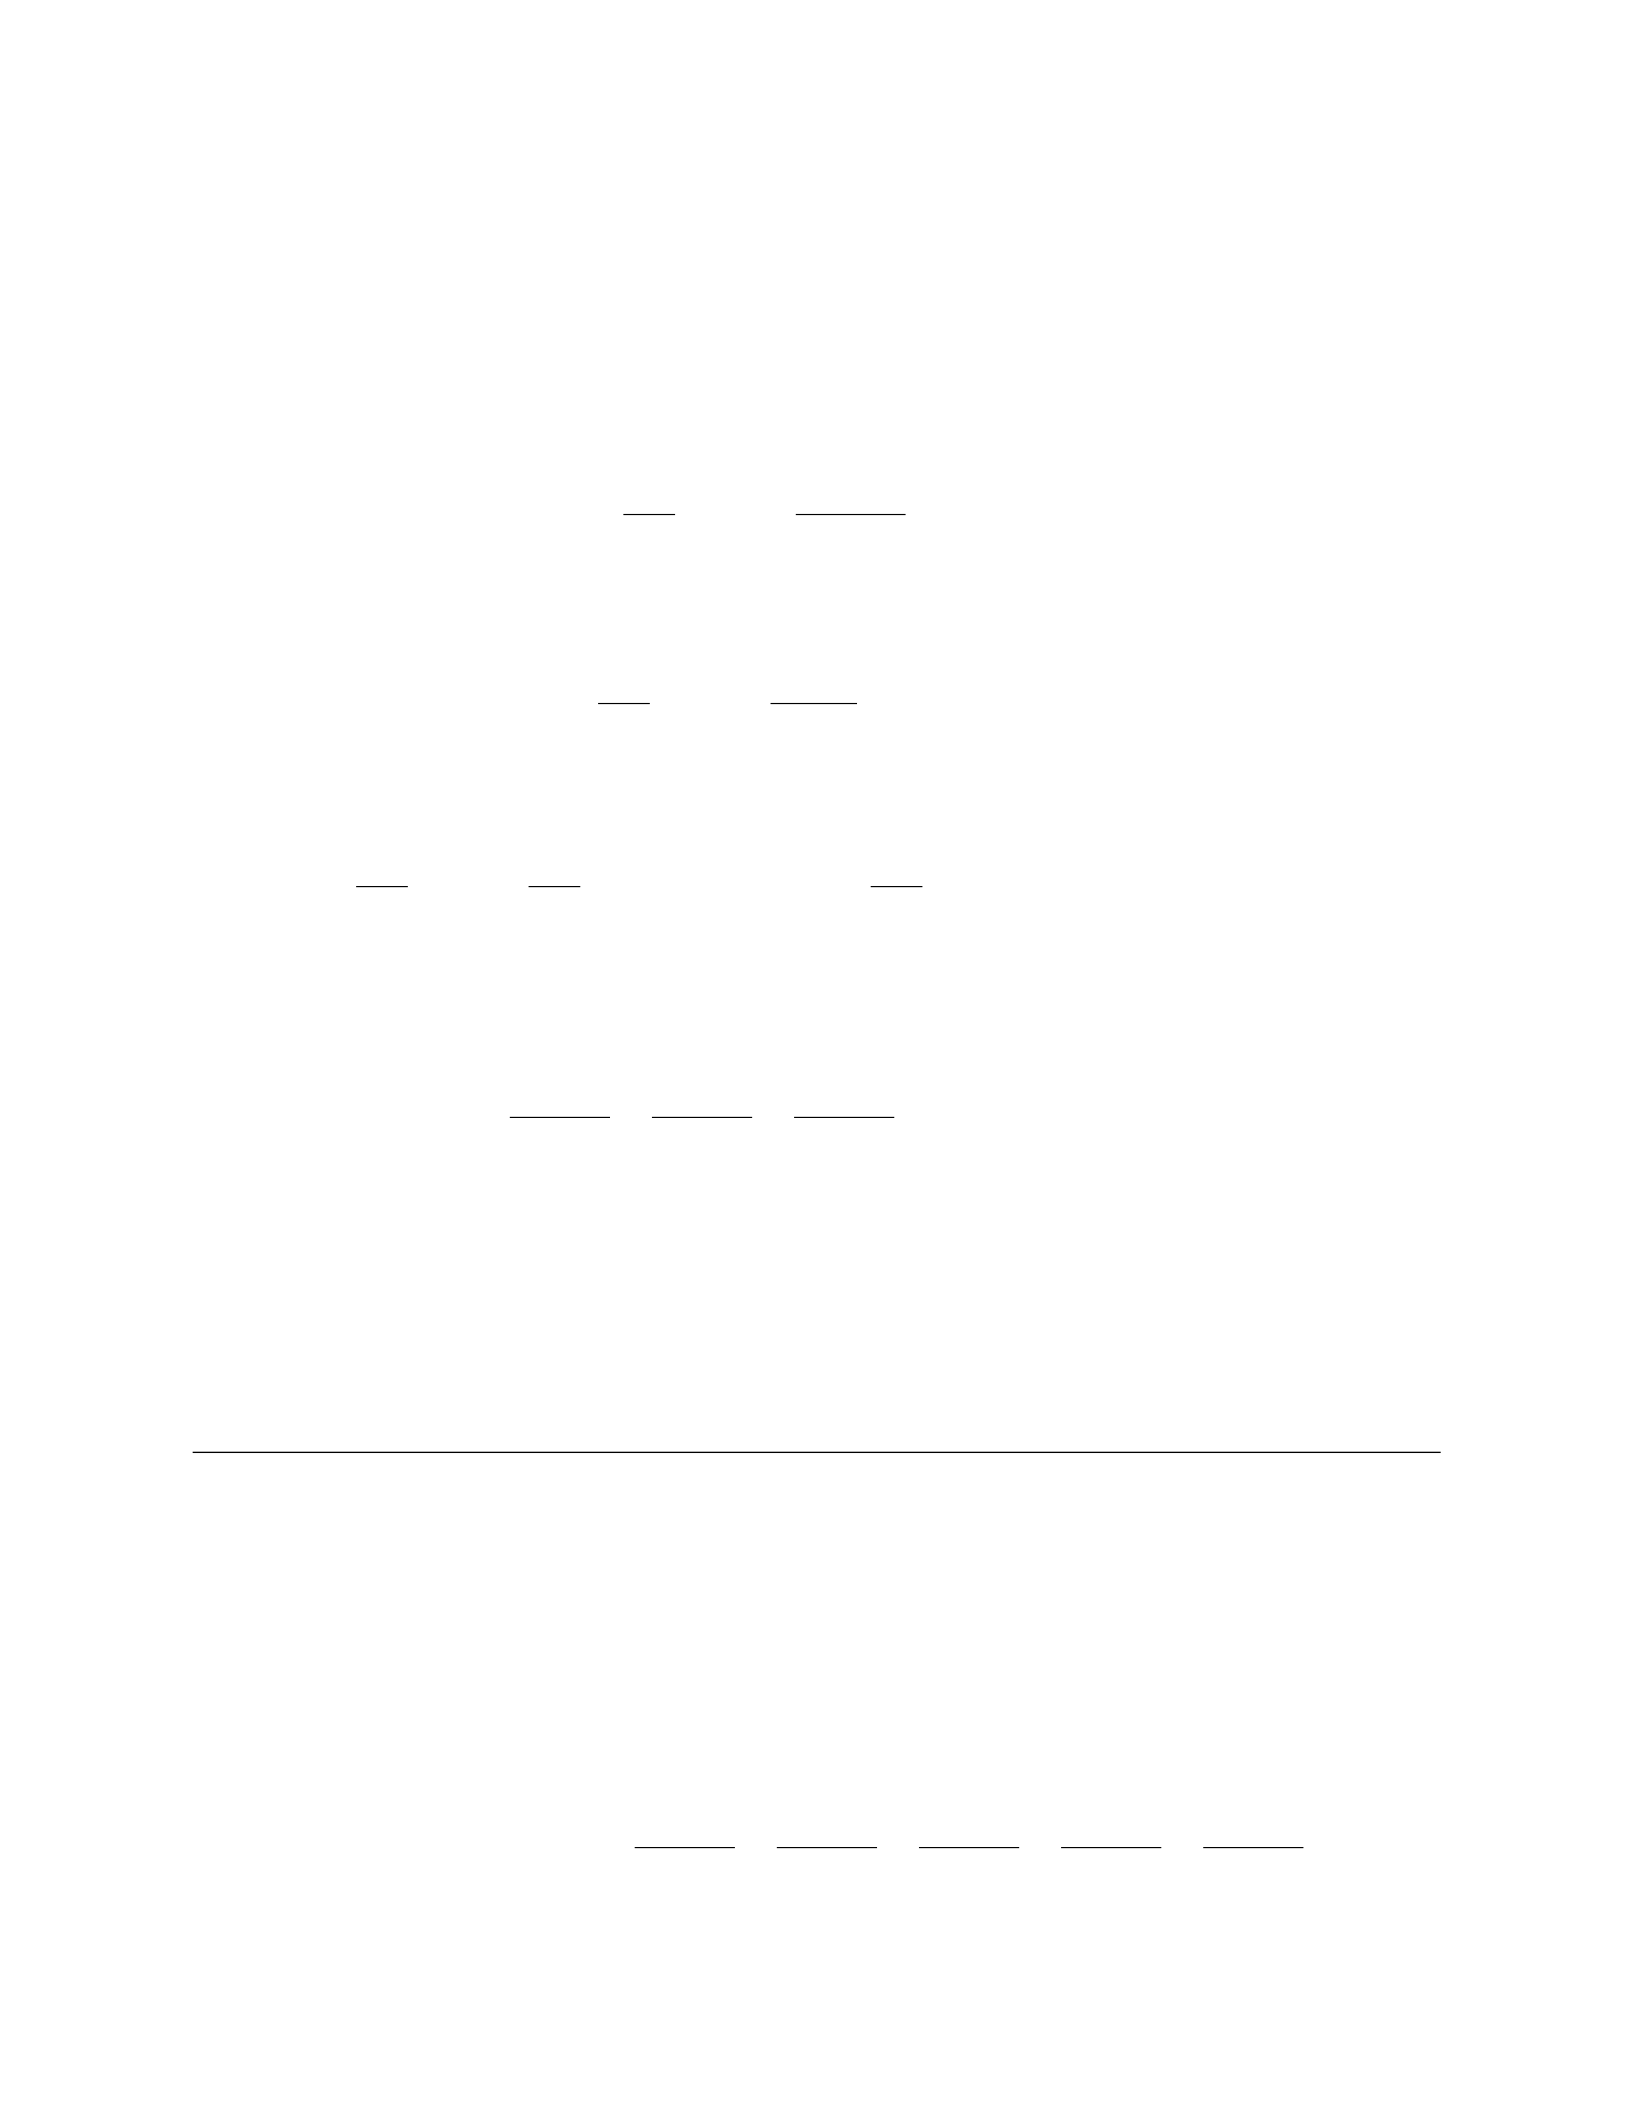
Solution 2.
a) The value of the real option to abandon the project can be calculated using the binomial
option pricing model. The option to abandon is equivalent to a put option. Using the risk-neutral
valuation approach, the value of the option can be found by working backwards from the final year.
Let’s denote: - S0= $50 (price of oil at time t= 0) - X= $200,000 (cash flow if oil prices remain
low) - R= 1.04 (risk-free rate) - T= 3 years (time to expiration)
The value of the option to abandon is:
V3=1
1.04 0.5×Vu
4+Vd
4
1.04 + 0.5×X
where Vu
4= 0 since if the price of oil increases, the company will not abandon the project.
Therefore:
V3=1
1.04 0.5×0 + Vd
4
1.04 + 0.5×200,000
Given that Vd
4= 0, we can calculate:
V3=1
1.04 0.5×0
1.04+ 0.5×200,000=1
1.04 ×0.5×192,307.69 = $92,746.91
Therefore, the value of the real option to abandon the project is $92,746.91.
b) The NPV of the project without the real option is calculated as the present value of the
expected cash flows minus the initial investment:
NP V =200,000
1.04 +250,000
(1.04)2+300,000
(1.04)3−1,000,000 = 535,725.89
c) The NPV of the project with the real option included is the sum of the NPV without the option
and the value of the option:
NP V = 535,725.89 + 92,746.91 = 628,472.80
3 3. TIMING OF INVESTMENTS
Problem 3. A company is considering investing in a new project. The initial investment cost
is $500,000. The project is expected to generate cash flows of $200,000 per year for the next 5
years. The company’s cost of capital is 10%. If the company decides to delay the investment by
one year, the initial investment cost will decrease to $450,000, but the annual cash flows will also
decrease to $180,000 per year for the next 5 years. Should the company invest now or delay the
investment for one year?
Solution 3. Let’s first calculate the net present value (NPV) of the project if the company invests
now and if it delays the investment by one year.
a) NPV of investing now: The NPV of investing now can be calculated as follows:
NP Vnow =−500,000 + 200,000
1.10 +200,000
(1.10)2+200,000
(1.10)3+200,000
(1.10)4+200,000
(1.10)5
NP Vnow =−500,000 + 200,000
1.10 +200,000
(1.10)2+200,000
(1.10)3+200,000
(1.10)4+200,000
(1.10)5
NP Vnow =−500,000 + 181,818.18 + 165,289.26 + 150,263.87 + 136,603.52 + 124,184.11
NP Vnow = $157,158.94
b) NPV of delaying the investment by one year: The NPV of delaying the investment by one
year can be calculated as follows:
NP Vdelayed =−450,000 + 180,000
1.10 +180,000
(1.10)2+180,000
(1.10)3+180,000
(1.10)4+180,000
(1.10)5
NP Vdelayed =−450,000 + 163,636.36 + 148,760.33 + 135,236.66 + 122,942.42 + 111,766.74
NP Vdelayed = $131,342.11
c) Conclusion: Comparing the two options, investing now yields an NPV of $157,158.94, while
delaying the investment by one year yields an NPV of $131,342.11. Therefore, the company should
invest in the project now as it provides a higher NPV.
4 4. FLEXIBILITY IN PROJECT DEVELOPMENT
Problem 4. A company is considering investing in a new project that has the following cash
flows for the next 3 years:
•Year 1: −1,000 (investment cost)
•Year 2: 500
•Year 3: 800
The company has the option to abandon the project after year 1 with a salvage value of 300.
The risk-free rate is 5%.
a) Calculate the net present value (NPV) of the project without the abandonment option.
b) Calculate the NPV of the project with the abandonment option.
c) Determine whether the company should exercise the abandonment option or not.
Solution 4.
a) The NPV of the project without the abandonment option is calculated by discounting the cash
flows at the risk-free rate:
NP V =−1,000 + 500
1.05 +800
1.052=−1,000 + 476.19 + 756.14 = 232.33
Therefore, the NPV of the project without the abandonment option is 232.33.
b) To calculate the NPV of the project with the abandonment option, we need to consider the
salvage value if the project is abandoned after year 1. The NPV with the abandonment option is:
NP V =−1,000 + 300 + 500
1.05 +800
1.052=−1,000 + 300 + 476.19 + 756.14 = 532.33
So, the NPV of the project with the abandonment option is 532.33.
c) Comparing the NPVs, we see that the NPV with the abandonment option is greater than the
NPV without the abandonment option. Therefore, the company should exercise the abandonment
option if the project’s cash flows are as predicted.
5 5. UNCERTAINTY IN PROJECT OUTCOMES
Problem 5. A company is considering investing in a new project that has two possible out-
comes: success or failure. The probabilities of success and failure are estimated to be 0.6 and
0.4, respectively. If the project is successful, the company expects to earn $500,000, but if it fails,
they will lose $200,000. The initial investment required for the project is $100,000. Calculate the
expected net present value (NPV) of the project.
Solution 5. The expected NPV of the project is calculated as the sum of the expected cash
flows discounted to the present value at the appropriate rate.
a) Expected Cash Flows: The expected cash flow from a successful project is $500,000 and
from a failed project is -$200,000.
Expected cash flow = (Probability of success * Cash flow from success) + (Probability of failure
* Cash flow from failure) Expected cash flow = (0.6 * $500,000) + (0.4 * -$200,000) Expected cash
flow = $300,000 - $80,000 Expected cash flow = $220,000
b) NPV Calculation: NPV = Expected cash flow / (1 + r)twhere, r =discountrate, t =timeperiod, inthiscase, t =
0
Given that the initial investment is $100,000 and the expected cash flow is $220,000, the NPV
can be calculated as:
NPV = (Expected cash flow - Initial investment) / (1 + r)tNP V = ($220,000 −$100,000)/(1 +
r)0NP V = $120,000
Therefore, the expected net present value (NPV) of the project is $120,000.
6 6. INVESTMENT DECISION UNDER COMPETITION
Problem 6. A company is considering expanding its production capacity to meet the increasing
demand for its product. There are two options available: Option A involves investing $400,000 to
increase capacity by 10,000 units annually for the next 5 years. Option B requires an investment
of $600,000 for a capacity increase of 15,000 units annually for the next 5 years.
The company’s estimated revenue per unit is $50, and the variable cost per unit is $20. The
discount rate is 10%. The company operates in a competitive market where the demand is uncer-
tain. Based on the current information, the company forecasts the demand for the next 5 years to
have the following probabilities:
Demand Level Probability
Low 0.2
Medium 0.5
High 0.3
a) Calculate the NPV for each option.
b) Determine the value of the real options present in this investment decision.
Solution 6.
a) The Net Present Value (NPV) for each option is calculated as follows: Let’s denote: - R= $50
(revenue per unit) - C= $20 (variable cost per unit) - IA= $400,000 (investment for Option A) -
IB= $600,000 (investment for Option B) - d= 10% (discount rate)
For Option A:
NP VA=
5
X
t=1
[(R−C)×Demandt×10,000] −IA
NP VA= [(50 −20) ×10,000 ×0.2 + (50 −20) ×10,000 ×0.5 + (50 −20) ×10,000 ×0.3]−400,000
NP VA= (30 ×10,000 ×0.2 + 30 ×10,000 ×0.5 + 30 ×10,000 ×0.3) −400,000
NP VA= (60,000 + 150,000 + 90,000) −400,000 = 300,000 −400,000 = −100,000
For Option B:
NP VB=
5
X
t=1
[(R−C)×Demandt×15,000] −IB
NP VB= [(50 −20) ×15,000 ×0.2 + (50 −20) ×15,000 ×0.5 + (50 −20) ×15,000 ×0.3]−600,000
NP VB= (30 ×15,000 ×0.2 + 30 ×15,000 ×0.5 + 30 ×15,000 ×0.3) −600,000
NP VB= (90,000 + 225,000 + 135,000) −600,000 = 450,000 −600,000 = −150,000
Therefore, the NPV for Option A is -$100,000 and for Option B is -$150,000.
b) To determine the value of the real options present in this investment decision, we would
need to consider the flexibility in the decision-making over the 5-year period based on the market
conditions. Real options analysis would allow the company to make optimal decisions in response
to the changing market conditions, such as the ability to expand further, contract, or delay expan-
sion. The value of the real options in this case would be the additional value generated by having
flexibility in decision-making compared to a static investment analysis.
It is important to note that the value of real options can be complex to quantify and may require
more detailed analysis based on specific scenarios and assumptions.
7 7. OPTIMAL INVESTMENT STRATEGIES
Problem 7. ABC Corporation is considering investing in a new project that will require an initial
investment of $500,000. The project is expected to generate cash flows of $150,000 in the first
year, $200,000 in the second year, and $300,000 in the third year. The risk-free rate is 4%. The
firm’s cost of capital is 12% and the project’s beta is 1.5. The current stock price is $50. Calculate
the Net Present Value (NPV) and the Real Options Value (ROV) of the project.
Solution 7. a) Calculate the Net Present Value (NPV):
The NPV calculation involves discounting the cash flows of the project at the firm’s cost of
capital. The formula for NPV is:
NP V =
3
X
t=1
CFt
(1 + r)t−Initial Investment
Where:
CFt:Cash flow in year t
r:Cost of capital
Substitute the given values into the formula:
NP V =150,000
(1 + 0.12)1+200,000
(1 + 0.12)2+300,000
(1 + 0.12)3−500,000
= 150,000/1.12 + 200,000/1.2544 + 300,000/1.4049 −500,000
= 133,928.57 + 159,544.29 + 213,143.16 −500,000
= $6,616.02
Therefore, the Net Present Value (NPV) of the project is $6,616.02.
b) Calculate the Real Options Value (ROV):
The Real Options Value (ROV) incorporates the value of managerial flexibility in decision mak-
ing. The formula for ROV is:
ROV =NP V + (Stock P rice ×β×NP V )
Where:
Stock P rice :Current stock price
β:Beta of the project
NP V :Net Present Value
Substitute the given values into the formula:
ROV = 6,616.02 + (50 ×1.5×6,616.02)
= 6,616.02 + 4,974.015
= $11,590.03
Therefore, the Real Options Value (ROV) of the project is $11,590.03.
8 8. REAL OPTIONS AND RISK MANAGEMENT
Problem 8. A company is considering investing in a project that has an initial cost of $1,000,000.
The project is expected to generate $400,000 in revenue in the first year, with a 30
a) Calculate the expected present value (EPV) of the project.
b) Determine the real option value (ROV) of the project.
Solution 8.
a) The EPV of the project can be calculated using the expected cash flow and discounting it
back to present value.
For the successful scenario (30
P V =400,000
1+0.03 =400,000
1.03 ≈$388,349.51
For the unsuccessful scenario (70The present value is zero as there is no revenue.
P V = 0
Therefore, the EPV of the project is:
EP V = 0.3×$388,349.51 + 0.7×$0 = $116,504.85
b) To determine the real option value (ROV) of the project, we need to calculate the value of the
option to continue the project given that it is successful.
The cash flow for each year in the successful scenario is given by:
CFt= 400,000 ×(1.05)t
The present value of the cash flows can be calculated using the risk-free rate of 3
P Vt=400,000 ×(1.05)t
(1 + 0.03)t=400,000 ×(1.05)t
1.03t
For simplicity, let’s consider a perpetuity formula to find the present value of expected cash
flows after year 1:
P V∞=400,000 ×(1.05)
0.03 −0.05 =400,000 ×1.05
−0.02 ≈ −$21,000,000.00
Therefore, the ROV of the project is positive (since the project should be continued) and is
approximately $21,000,000.00.
9 9. REAL OPTIONS IN TECHNOLOGY INVESTMENTS
Problem 9. A technology company is considering investing in a new project that will cost
$500,000 upfront. The project is expected to generate cash flows of $200,000 in one year with a
60% chance, and $100,000 with a 40% chance. The risk-free rate is 5%, and the company uses a
discount rate of 10% for risky projects. The company has the option to abandon the project in one
year if the cash flows are not satisfactory.
a) Calculate the present value of the project without the option to abandon it.
b) Calculate the project’s value if the company has the option to abandon it in one year.
c) Determine the value of the abandonment option.
Solution 9.
a) The present value of the project without the option to abandon it can be calculated by dis-
counting the expected cash flows at the discount rate of 10%:
P V =200,000 ×0.6
1.10 +100,000 ×0.4
1.10 = $145,454.55 + $36,363.64 = $181,818.19
Therefore, the present value of the project without the option to abandon it is $181,818.19.
b) To calculate the project’s value with the option to abandon it, we need to consider the option
to abandon the project in one year if the cash flows are not satisfactory. We use the risk-neutral
probabilities to estimate the expected cash flow and discount it back at the risk-free rate:
E(CF ) = 200,000 ×0.6 + 100,000 ×0.4 = $160,000
P V =160,000
1.05 = $152,380.95
Therefore, the project’s value with the option to abandon it in one year is $152,380.95.
c) The value of the abandonment option is the difference between the present value of the
project without the option to abandon it and the project’s value with the option to abandon it:
Abandonment Option = $181,818.19 −$152,380.95 = $29,437.24
Therefore, the value of the abandonment option is $29,437.24.
10 10. REAL OPTIONS IN NATURAL RESOURCE EXPLORATION
Problem 10. A mining company is considering opening a new mine in a mineral-rich region.
The company has the option to delay the opening of the mine for two years to allow for more
exploration and better market conditions. The initial investment cost for opening the mine now is
$10 million. If the company delays the opening, it would incur exploration costs of $2 million per
year for the two-year period. The present value factor for each year is 0.909.
a) Calculate the net present value (NPV) of opening the mine now.
b) Calculate the net present value (NPV) of delaying the opening for two years and incorporating
the exploration costs.
c) Discuss whether it is financially advantageous for the company to delay the mine opening
based on the NPV calculations.
Solution 10.
a) The NPV of opening the mine now can be calculated using the formula:
NP V =−InitialInvestment +XN etCashF lowt
(1 + r)t
Given that the initial investment is $10 million, the annual net cash flow from the mine operation
is expected to be $5 million, and the discount rate is 10
NP V =−10 + 5(0.909) + 5(0.909)2
NP V =−10 + 4.545 + 4.132 = −10 + 8.677 = −1.323
Therefore, the NPV of opening the mine now is -$1.323 million.
b) The NPV of delaying the mine opening can be calculated by considering the exploration costs
for two years:
NP V =−InitialInvestment +XExplorationCostst
(1 + r)t
The exploration costs for year 1 and year 2 are $2 million each. So, the NPV of delaying the
opening for two years is:
NP V =−2(0.909) −2(0.909)2=−1.818 −1.818 = −3.636
Therefore, the NPV of delaying the mine opening is -$3.636 million.
c) Comparing the NPVs, we see that delaying the mine opening results in a higher negative
NPV (-$3.636 million) compared to opening the mine now (-$1.323 million). Therefore, from a
financial perspective, it is not advantageous for the company to delay the mine opening.
11 11. CAPITAL BUDGETING WITH REAL OPTIONS
Problem 11. ABC Corporation is considering an investment in a new project. The initial cost
of the project is $500,000. The project is expected to generate cash flows of $150,000 per year for
the next 5 years. The risk-free rate is 4% and the project’s beta is 1.2. The strike price for the real
option to abandon the project is $400,000. Calculate the Net Present Value (NPV) of the project
with and without the real option to abandon.
Solution 11.
a) First, let’s calculate the NPV of the project without the real option to abandon:
The NPV formula is:
NP V =−C0+
n
X
t=1
CFt
(1 + r)t
Where: - C0= $500,000 (initial cost of project) - CFt= $150,000 for all years 1 to 5 - r= 4%
(risk-free rate)
Substitute these values into the formula:
NP V =−$500,000 + $150,000
1.04 +$150,000
(1.04)2+$150,000
(1.04)3+$150,000
(1.04)4+$150,000
(1.04)5
Calculating the above expression gives:
NP V =−$500,000 + $144,230.77 + $138,888.89 + $133,951.10 + $129,404.77 + $125,229.48
NP V =−$500,000 + $671,705.01
NP V = $171,705.01
Therefore, the NPV of the project without the real option to abandon is $171,705.01.
b) Now, let’s calculate the NPV of the project with the real option to abandon:
The real option to abandon adds an extra Pto cash flow in year 2. The value of this real option
can be calculated as:
P=Max(0, K −V2)
Where: - K= $400,000 (strike price to abandon) - V2= $500,000 + $150,000
1.04 = $630,769.23 (value
of the project in year 2)
P=Max(0,$400,000 −$630,769.23)
P=Max(0,−$230,769.23) = $0
Therefore, there is no value in exercising the real option to abandon the project in year 2. The
NPV remains $171,705.01.
Thus, the NPV of the project with and without the real option to abandon remains the same at
$171,705.01.
12 12. REAL OPTIONS IN REAL ESTATE INVESTMENTS
Problem 12.
A real estate developer is considering the purchase of a parcel of land for $500,000. The
developer has the option to build either residential units or commercial units on the land. The
expected cash flows associated with each type of development are as follows:
•Residential units: $300,000 in the first year, $200,000 in the second year, and $100,000 in
the third year.
•Commercial units: $400,000 in the first year, $250,000 in the second year, and $150,000 in
the third year.
The developer has the right to delay the development decision by one year. If the developer
chooses to wait, the cost of the land will remain the same and the expected cash flows will also
remain the same. The risk-free rate is 5%.
a) Determine the net present value (NPV) of developing residential units immediately.
b) Determine the net present value (NPV) of developing commercial units immediately.
c) Calculate the value of the option to delay the development decision by one year.
Solution 12.
a) To find the NPV of developing residential units immediately, we need to discount the expected
cash flows back to present value. The NPV can be calculated using the formula:
NP V =
3
X
t=1
CFt
(1 + r)t−Initial Cost
Where CFtis the cash flow in year t,ris the risk-free rate, and the initial cost is $500,000.
Plugging in the values for residential units:
NP V =300,000
(1 + 0.05)1+200,000
(1 + 0.05)2+100,000
(1 + 0.05)3−500,000
NP V = 285,714.29 + 181,405.90 + 83,305.95 −500,000
NP V = $50,426.14
Therefore, the NPV of developing residential units immediately is $50,426.14.
b) Similarly, the NPV of developing commercial units immediately can be calculated as:
NP V =400,000
(1 + 0.05)1+250,000
(1 + 0.05)2+150,000
(1 + 0.05)3−500,000
NP V = 380,952.38 + 235,449.74 + 131,724.89 −500,000
NP V = $248,127.01
Therefore, the NPV of developing commercial units immediately is $248,127.01.
c) To calculate the value of the option to delay, we need to find the NPV of waiting for one year
and compare it to the NPV of immediate development.
The NPV of waiting for one year is the same as the NPV of immediate development because
the land cost and cash flows remain the same.
Therefore, the value of the option to delay the development decision by one year is $0.
13 13. REAL OPTIONS IN PHARMACEUTICAL INVESTMENTS
Problem 13. A pharmaceutical company is considering investing in the development of a new
drug. The initial investment is $5 million, and the expected cash flows from the drug over the next
5 years are as follows (in millions of dollars):
Year Expected Cash Flow
1 2
2 3
3 4
4 4
5 5
The company has the option to abandon the project at the end of year 2. The risk-free rate is
5% and the company’s cost of capital is 10%.
a) Calculate the Net Present Value (NPV) of the project without the option to abandon.
b) Calculate the NPV of the project with the option to abandon after year 2.
Solution 13.
a) The NPV of the project without the option to abandon can be calculated using the formula:
NP V =−5 + 2
(1 + 0.05) +3
(1 + 0.05)2+4
(1 + 0.05)3+4
(1 + 0.05)4+5
(1 + 0.05)5
NP V =−5 + 2
1.05 +3
(1.05)2+4
(1.05)3+4
(1.05)4+5
(1.05)5
Calculating this gives:
NP V =−5+1.9048 + 2.7232 + 3.7891 + 3.4185 + 3.2164 = 9.0519 million
Therefore, the NPV of the project without the option to abandon is $9.05 million.
b) The NPV of the project with the option to abandon after year 2 can be calculated by comparing
the NPV of continuing the project with the NPV of abandoning it after year 2.
At the end of year 2, the expected cash flows from the project are $4 million and $5 million in
years 3 and 4 respectively.
To calculate the NPV of the project if abandoned after year 2:
NP Vabandon =−5 + 2
(1 + 0.05) +3
(1 + 0.05)2+4
(1 + 0.05)3= 7.7232 million
If the project is continued after year 2, the cash flows in years 3 and 4 would be $4 million and
$4 million respectively. Calculating the NPV in this case:
NP Vcontinue =−5 + 2
(1 + 0.05) +3
(1 + 0.05)2+4
(1 + 0.05)3+4
(1 + 0.05)4= 8.7891 million
Comparing the two options, the NPV of continuing the project after year 2 is higher, so the
company should continue with the project.
14 14. REAL OPTIONS IN RENEWABLE ENERGY PROJECTS
Problem 14. You are evaluating an investment in a renewable energy project with the following
parameters:
- Initial investment cost: 200,000 −Expectedannualcashflowsforthenext5years :50,000 - Dis-
count rate: 10- Estimated salvage value at the end of year 5: 20,000
The project also has a real option to expand its capacity in year 3 by investing an additional
100,000.T heexpandedprojectisexpectedtogenerateadditionalannualcashf lowsof30,000 for the re-
maining 3 years.
a) Calculate the NPV of the initial investment without considering the expansion option.
b) Determine the NPV of the expanded project considering the expansion option.
Solution 14.
a) To calculate the NPV of the initial investment without considering the expansion option, we
need to discount the expected cash flows over the next 5 years and subtract the initial investment
cost:
NP V =−200,000 + 50,000
1.10 +50,000
(1.10)2+50,000
(1.10)3+50,000
(1.10)4+50,000 + 20,000
(1.10)5
NP V =−200,000 + 50,000
1.10 +50,000
(1.10)2+50,000
(1.10)3+50,000
(1.10)4+70,000
(1.10)5
Calculating the NPV, we get:
NP V =−200,000 + 45,454.55 + 41,322.31 + 37,565.74 + 34,150.67 + 40,772.27
NP V = $ −4383.46
Therefore, the NPV of the initial investment without considering the expansion option is −4383.46.
b) To determine the NPV of the expanded project, we need to consider the additional cash flows
from year 3 onwards as well as the expansion cost. The expanded project’s cash flows will be:
NP V =−200,000+50,000
1.10 +50,000
(1.10)2+(30,000−100,000)×1
(1.10)2+(30,000−100,000)×1
(1.10)3+(30,000−100,000)×1
(1.10)4+50,000 + 20,000
(1.10)5
NP V =−200,000 + 45,454.55 + 41,322.31 + 21,818.18 + 18,926.53 + 16,296.85 + 40,772.27
NP V = $15,409.48
Therefore, the NPV of the expanded project considering the expansion option is −15,409.48.
I. Real Options and Investment Analysis
Problem 1. A company is considering investing in a new project with an initial cost of $1,000,000.
The project is expected to generate cash flows of $400,000 in the first year, $500,000 in the second
year, and $600,000 in the third year. The company has the option to abandon the project after the
first year. The risk-free rate is 5%. Should the company invest in this project?
Solution 1. Given: Initial investment (C): $1,000,000 Cash flows: year 1 = $400,000, year 2 =
$500,000, year 3 = $600,000 Risk-free rate (r): 5
The Net Present Value (NPV) of the project can be calculated as follows: NPV = -C + PCFt
(1+r)t
NPV = -$1,000,000 + $400,000/(1+0.05)1+ $500,000/(1 + 0.05)2+ $600,000/(1 + 0.05)3
NPV = -$1,000,000 + $380,952 + $454,851 + $497,618.85 NPV = $333,421.85
The NPV of the project is positive, which indicates that the project is expected to generate a
return greater than the required rate of return. Therefore, the company should invest in this project.
Problem 2. A company is evaluating an investment in a project that requires an initial outlay
of $800,000. The cash flows from the project are expected to be $300,000 in year 1, $400,000 in
year 2, and $500,000 in year 3. The company has the option to expand the project at the end of
year 1 at an additional cost of $200,000. If the expansion is undertaken, the expected cash flows
in year 4 would be $600,000. Should the company invest in the project and expand in year 1 if the
opportunity arises? Assume a discount rate of 8
Solution 2. Given: Initial investment (C): $800,000 Cash flows: year 1 = $300,000, year 2 =
$400,000, year 3 = $500,000, year 4 (if expanded) = $600,000 Expansion cost: $200,000 Discount
rate (r): 8
Calculate the NPV if the project is undertaken without expansion: NPV = -$800,000 + $300,000/(1+0.08)1+
$400,000/(1 + 0.08)2+ $500,000/(1 + 0.08)3NP V =−$800,000 + $277,777.78 + $308,641.98 +
$340,136.66NP V = $126,556.42
Calculate the NPV if the project is expanded in year 1: NPV = -$800,000 + $300,000/(1+0.08)1+
$400,000/(1+0.08)2+$500,000/(1+0.08)3+$600,000/(1+0.08)4−$200,000NP V =−$800,000+
$277,777.78 + $308,641.98 + $340,136.66 + $387,096.77 −$200,000NP V = $513,652.21
Comparing the two NPVs, it is more beneficial for the company to invest in the project and
expand in year 1 if the opportunity arises, as it yields a higher NPV.
15 Real Options and Investment Analysis
Problem:
A company is considering acquiring a competitor in the same industry. The current market
value of the competitor is $50 million. The company believes that if it acquires the competitor, it
can implement a growth strategy that has a 60% chance of increasing the value of the acquired
firm to $80 million and a 40% chance of decreasing the value to $30 million. If the growth strategy
is successful, the company can generate additional cash flows of $20 million per year for the next
5 years. The risk-free rate is 4%.
a) Calculate the value of the real option to acquire the competitor.
b) Determine the optimal timing to exercise the real option if the company can only exercise it
once.
Solution:
a) Let’s first calculate the expected value of the acquired firm:
E[V]=0.6×$80 million + 0.4×$30 million
= $48 million + $12 million
= $60 million
The present value of the expected cash flows from the growth strategy can be calculated as:
P V (Cash Flows) = $20 million
1+0.04 +$20 million
(1 + 0.04)2+$20 million
(1 + 0.04)3+$20 million
(1 + 0.04)4+$20 million
(1 + 0.04)5
= $18.68 million + $17.98 million + $17.30 million + $16.65 million + $16.03 million
= $86.64 million
The value of the real option is the difference between the expected value of the acquired firm
and the present value of the cash flows:
Real Option Value = $60 million −$86.64 million
=−$26.64 million
Therefore, the value of the real option to acquire the competitor is -$26.64 million.
b) To determine the optimal timing to exercise the real option, we need to compare the value of
waiting to the option to the value of immediate exercise. The value of waiting is the expected value
of the acquired firm minus the exercise price (market value of the competitor), which is $60 million
- $50 million = $10 million.
The option to acquire has negative value (-$26.64 million) which implies that it should not be
exercised. Therefore, the optimal timing is to never exercise the option to acquire the competitor.
16 17. REAL OPTIONS IN PROJECT FINANCE
Problem 17. A company is considering investing in a new project that has the following char-
acteristics:
- Initial investment cost: $500,000 - Expected cash inflows in the first year: $300,000 - Expected
cash inflows in the second year: $400,000 - Expected cash inflows in the third year: $600,000 -
Discount rate: 10% - Risk-free rate: 5% - Volatility of cash flows: 20% - Time to maturity for the real
option: 3 years - Exercise price for the real option: $100,000
The company can abandon the project after the first year of operation if the cash flows are not
as expected.
a) Calculate the Net Present Value (NPV) of the project without considering the real option.
b) Determine the value of the real option embedded in the project.
c) Should the company invest in the project based on the real option analysis?
Solution 17.
a) The Net Present Value (NPV) of the project without considering the real option can be cal-
culated using the formula:
NP V =CF1
(1 + r)1+CF2
(1 + r)2+CF3
(1 + r)3−Initial Investment
where ris the discount rate, CFiis the cash flow in year i, and the Initial Investment is the initial
cost of the project.
Substitute the given values into the formula:
NP V =300,000
(1 + 0.10)1+400,000
(1 + 0.10)2+600,000
(1 + 0.10)3−500,000
NP V =300,000
1.10 +400,000
1.102+600,000
1.103−500,000
NP V = 272,727.27 + 330,578.51 + 401,324.62 −500,000
NP V = 504,630.40
Therefore, the NPV of the project without considering the real option is $504,630.40.
b) The value of the real option can be calculated using the Black-Scholes Option Pricing Model.
d1=ln(S/E)+(r+σ2/2)t
σ√t
d2=d1−σ√t
Option V alue =SΦ(d1)−Ee−rtΦ(d2)
where: - S= current stock price (value of project) - E= exercise price - r= risk-free rate - t=
time to maturity - σ= volatility
Substitute the given values into the formula:
d1=ln(300,000/100,000) + (0.05 + 0.202/2)3
0.20√3= 1.85
d2= 1.85 −0.20√3=1.35
Option V alue = 300,000Φ(1.85) −100,000e−0.05∗3Φ(1.35) = 148,385.16
Therefore, the value of the real option embedded in the project is $148,385.16.
c) The total value of the project considering the real option is:
T otal V alue =NP V +Option V alue = 504,630.40 + 148,385.16 = 653,015.56
As the total value of the project exceeds the initial investment cost and considering the real
option, the company should invest in the project based on the real option analysis.
17 18. REAL OPTIONS IN R&D INVESTMENTS
Problem 18. A company is considering investing in a research and development (R&D) project.
The initial investment required is $500,000. The project is expected to generate cash flows of
$200,000 in the first year, $300,000 in the second year, and $400,000 in the third year. The risk-
free rate is 5% and the company’s cost of capital is 10%.
a) Calculate the Net Present Value (NPV) of the project without considering the real options.
b) Determine the value of the Real Option to Abandon.
c) Calculate the Real Options Value of Waiting to Invest if the company can decide at the end
of each year whether to continue the project or not.
Solution 18.
a) The NPV of the project without considering the real options can be calculated by discounting
the cash flows at the cost of capital. The formula for NPV is:
NP V =
n
X
t=1
CFt
(1 + r)t−Initial Investment
Where: - CFt= Cash flow in year t-r= Company’s cost of capital - Initial Investment =
$500,000
Plugging in the values:
NP V =200,000
1.10 +300,000
1.102+400,000
1.103−500,000
NP V = 181,818.18 + 247,933.88 + 300,043.71 −500,000
NP V = 229,795.77
Therefore, the NPV of the project without considering the real options is $229,795.77.
b) The Real Option to Abandon allows the company to abandon the project at the end of the
second year if it is no longer profitable. The value of this option can be calculated using the Binomial
option pricing model or decision tree analysis.
c) The Real Options Value of Waiting to Invest allows the company to assess whether to invest
at the end of each year based on the project’s performance. The decision to wait can be valued
using the Black-Scholes model or other numerical methods.
18 19. REAL OPTIONS IN INTERNATIONAL INVESTMENTS
Problem 19. A multinational corporation is considering investing in a project in a foreign coun-
try. The project has an initial investment cost of $5 million and is expected to generate cash flows of
$3 million per year for the next 5 years. The corporation has the option to expand the project after
2 years at an additional cost of $2 million. The risk-free rate is 5% and the corporation’s required
rate of return is 10%.
a) Calculate the Net Present Value (NPV) of the project without considering the option to ex-
pand.
b) Determine the value of the option to expand the project after 2 years.
c) Should the corporation proceed with the initial investment in the project?
Solution 19.
a) To calculate the NPV of the project without considering the option to expand, we use the
formula:
NP V =−C0+CF1
(1 + r)1+CF2
(1 + r)2+... +CFn
(1 + r)n
Where: C0= $5,000,000 CFt= $3,000,000 for t= 1,2,3,4,5r= 10%
Plugging in the values, we get:
NP V =−5,000,000 + 3,000,000
1.1+3,000,000
1.12+3,000,000
1.13+3,000,000
1.14+3,000,000
1.15
NP V =−5,000,000 + 2,727,273 + 2,479,338 + 2,254,853 + 2,049,866 + 1,861,696
NP V = $2,373,050
The NPV of the project without considering the option to expand is $2,373,050.
b) The value of the option to expand the project after 2 years can be calculated using the Black-
Scholes model. The formula for the value of the option is:
V=S0N(d1)−Xe−rtN(d2)
Where: S0= $3,000,000 (Value of the expanded project) X= $2,000,000 (Cost of expansion)
r= 5% (Risk-free rate) t= 2 years
Calculating d1and d2using the Black-Scholes formula, we find d1= 0.4407 and d2= 0.1841.
Plugging in these values, we get:
V= 3,000,000N(0.4407) −2,000,000e−0.05∗2N(0.1841)
V= 3,000,000 ×0.6703 −2,000,000 ×e−0.1×0.5749
V= 2,010,894 −1,273,239
V= $737,655
The value of the option to expand the project after 2 years is $737,655.
c) As the NPV of the project without considering the option to expand is positive ($2,373,050)
and the value of the option to expand is also positive ($737,655), the corporation should proceed
with the initial investment in the project.
19 20. REAL OPTIONS IN NEW PRODUCT DEVELOPMENT
Problem 20. A company is considering developing a new product. The initial investment re-
quired is $500,000. The expected cash flows from the product over the next 3 years are estimated
as follows: Year 1: $200,000, Year 2: $300,000, Year 3: $400,000. The company has the option
to abandon the project at the end of each year with the following abandonment values: Year 1:
$50,000, Year 2: $100,000, Year 3: $200,000. The risk-free rate is 5%.
a) Calculate the net present value (NPV) of the project without considering any abandonment
options.
b) Determine the net present value (NPV) of the project if the company has the flexibility to
abandon the project at the end of each year.
c) Discuss whether incorporating the abandonment options increases the value of the project.
Solution 20.
a) To calculate the NPV of the project without considering any abandonment options, we need
to discount the cash flows at the risk-free rate of 5%.
Using the formula for NPV:
NP V =CF0
(1 + r)0+CF1
(1 + r)1+CF2
(1 + r)2+CF3
(1 + r)3−Initial Investment
where r= 0.05 and the cash flows are 200,000,300,000, and 400,000f oryears1,2, and3respectively.
NP V =−500,000
(1 + 0.05)0+200,000
(1 + 0.05)1+300,000
(1 + 0.05)2+400,000
(1 + 0.05)3
NP V =−500,000 + 190,476.2 + 272,108.8 + 342,317.5 = 304,902.5
Therefore, the NPV of the project without considering any abandonment options is $304,902.5.
b) To calculate the NPV of the project with abandonment options, we need to consider the option
to abandon at the end of each year by comparing the continuation value with the abandonment
value.
In Year 1, the continuation value is $190,476.2 (the present value of cash flows from Year 2
and Year 3). If the abandonment value ($50,000) is greater, then the project would be abandoned,
resulting in an NPV of -$50,000. In this case, the NPV of Year 1 is -$50,000.
In Year 2, the continuation value is $272,108.8 (the present value of cash flow from Year 3). If
the abandonment value ($100,000) is greater, then the project would be abandoned, resulting in
an NPV of -$100,000. In this case, the NPV of Year 2 is -$100,000.
In Year 3, the project will not be abandoned as the cash flow of $400,000 is greater than the
abandonment value of $200,000. Therefore, the NPV of Year 3 is $357,142.9 (the present value
of the cash flow in Year 3).
The total NPV of the project with abandonment options is the sum of the NPVs of each year:
NP V =−50,000 −100,000 + 357,142.9 = 207,142.9
Therefore, the NPV of the project with abandonment options is $207,142.9.
c) Incorporating abandonment options increases the value of the project, as the NPV with aban-
donment options ($207,142.9) is higher than the NPV without considering any abandonment op-
tions ($304,902.5). Abandonment options provide flexibility in decision-making and can increase
the overall value of a project.
Solution 2.
a) The value of the real option to abandon the project can be calculated using the binomial
option pricing model. The option to abandon is equivalent to a put option. Using the risk-neutral
valuation approach, the value of the option can be found by working backwards from the final year.
Let’s denote: - S0= $50 (price of oil at time t= 0) - X= $200,000 (cash flow if oil prices remain
low) - R= 1.04 (risk-free rate) - T= 3 years (time to expiration)
The value of the option to abandon is:
V3=1
1.04 0.5×Vu
4+Vd
4
1.04 + 0.5×X
where Vu
4= 0 since if the price of oil increases, the company will not abandon the project.
Therefore:
V3=1
1.04 0.5×0 + Vd
4
1.04 + 0.5×200,000
Given that Vd
4= 0, we can calculate:
V3=1
1.04 0.5×0
1.04+ 0.5×200,000=1
1.04 ×0.5×192,307.69 = $92,746.91
Therefore, the value of the real option to abandon the project is $92,746.91.
b) The NPV of the project without the real option is calculated as the present value of the
expected cash flows minus the initial investment:
NP V =200,000
1.04 +250,000
(1.04)2+300,000
(1.04)3−1,000,000 = 535,725.89
c) The NPV of the project with the real option included is the sum of the NPV without the option
and the value of the option:
NP V = 535,725.89 + 92,746.91 = 628,472.80
3 3. TIMING OF INVESTMENTS
Problem 3. A company is considering investing in a new project. The initial investment cost
is $500,000. The project is expected to generate cash flows of $200,000 per year for the next 5
years. The company’s cost of capital is 10%. If the company decides to delay the investment by
one year, the initial investment cost will decrease to $450,000, but the annual cash flows will also
decrease to $180,000 per year for the next 5 years. Should the company invest now or delay the
investment for one year?
Solution 3. Let’s first calculate the net present value (NPV) of the project if the company invests
now and if it delays the investment by one year.
a) NPV of investing now: The NPV of investing now can be calculated as follows:
NP Vnow =−500,000 + 200,000
1.10 +200,000
(1.10)2+200,000
(1.10)3+200,000
(1.10)4+200,000
(1.10)5
NP Vnow =−500,000 + 200,000
1.10 +200,000
(1.10)2+200,000
(1.10)3+200,000
(1.10)4+200,000
(1.10)5
NP Vnow =−500,000 + 181,818.18 + 165,289.26 + 150,263.87 + 136,603.52 + 124,184.11
NP Vnow = $157,158.94
b) NPV of delaying the investment by one year: The NPV of delaying the investment by one
year can be calculated as follows:
NP Vdelayed =−450,000 + 180,000
1.10 +180,000
(1.10)2+180,000
(1.10)3+180,000
(1.10)4+180,000
(1.10)5
NP Vdelayed =−450,000 + 163,636.36 + 148,760.33 + 135,236.66 + 122,942.42 + 111,766.74
NP Vdelayed = $131,342.11
c) Conclusion: Comparing the two options, investing now yields an NPV of $157,158.94, while
delaying the investment by one year yields an NPV of $131,342.11. Therefore, the company should
invest in the project now as it provides a higher NPV.
4 4. FLEXIBILITY IN PROJECT DEVELOPMENT
Problem 4. A company is considering investing in a new project that has the following cash
flows for the next 3 years:
•Year 1: −1,000 (investment cost)
•Year 2: 500
•Year 3: 800
The company has the option to abandon the project after year 1 with a salvage value of 300.
The risk-free rate is 5%.
a) Calculate the net present value (NPV) of the project without the abandonment option.
b) Calculate the NPV of the project with the abandonment option.
c) Determine whether the company should exercise the abandonment option or not.
Solution 4.
a) The NPV of the project without the abandonment option is calculated by discounting the cash
flows at the risk-free rate:
NP V =−1,000 + 500
1.05 +800
1.052=−1,000 + 476.19 + 756.14 = 232.33
Therefore, the NPV of the project without the abandonment option is 232.33.
b) To calculate the NPV of the project with the abandonment option, we need to consider the
salvage value if the project is abandoned after year 1. The NPV with the abandonment option is:
NP V =−1,000 + 300 + 500
1.05 +800
1.052=−1,000 + 300 + 476.19 + 756.14 = 532.33
So, the NPV of the project with the abandonment option is 532.33.
c) Comparing the NPVs, we see that the NPV with the abandonment option is greater than the
NPV without the abandonment option. Therefore, the company should exercise the abandonment
option if the project’s cash flows are as predicted.
5 5. UNCERTAINTY IN PROJECT OUTCOMES
Problem 5. A company is considering investing in a new project that has two possible out-
comes: success or failure. The probabilities of success and failure are estimated to be 0.6 and
0.4, respectively. If the project is successful, the company expects to earn $500,000, but if it fails,
they will lose $200,000. The initial investment required for the project is $100,000. Calculate the
expected net present value (NPV) of the project.
Solution 5. The expected NPV of the project is calculated as the sum of the expected cash
flows discounted to the present value at the appropriate rate.
a) Expected Cash Flows: The expected cash flow from a successful project is $500,000 and
from a failed project is -$200,000.
Expected cash flow = (Probability of success * Cash flow from success) + (Probability of failure
* Cash flow from failure) Expected cash flow = (0.6 * $500,000) + (0.4 * -$200,000) Expected cash
flow = $300,000 - $80,000 Expected cash flow = $220,000
b) NPV Calculation: NPV = Expected cash flow / (1 + r)twhere, r =discountrate, t =timeperiod, inthiscase, t =
0
Given that the initial investment is $100,000 and the expected cash flow is $220,000, the NPV
can be calculated as:
NPV = (Expected cash flow - Initial investment) / (1 + r)tNP V = ($220,000 −$100,000)/(1 +
r)0NP V = $120,000
Therefore, the expected net present value (NPV) of the project is $120,000.
6 6. INVESTMENT DECISION UNDER COMPETITION
Problem 6. A company is considering expanding its production capacity to meet the increasing
demand for its product. There are two options available: Option A involves investing $400,000 to
increase capacity by 10,000 units annually for the next 5 years. Option B requires an investment
of $600,000 for a capacity increase of 15,000 units annually for the next 5 years.
The company’s estimated revenue per unit is $50, and the variable cost per unit is $20. The
discount rate is 10%. The company operates in a competitive market where the demand is uncer-
tain. Based on the current information, the company forecasts the demand for the next 5 years to
have the following probabilities:
Demand Level Probability
Low 0.2
Medium 0.5
High 0.3
a) Calculate the NPV for each option.
b) Determine the value of the real options present in this investment decision.
Solution 6.
a) The Net Present Value (NPV) for each option is calculated as follows: Let’s denote: - R= $50
(revenue per unit) - C= $20 (variable cost per unit) - IA= $400,000 (investment for Option A) -
IB= $600,000 (investment for Option B) - d= 10% (discount rate)
For Option A:
NP VA=
5
X
t=1
[(R−C)×Demandt×10,000] −IA
NP VA= [(50 −20) ×10,000 ×0.2 + (50 −20) ×10,000 ×0.5 + (50 −20) ×10,000 ×0.3]−400,000
NP VA= (30 ×10,000 ×0.2 + 30 ×10,000 ×0.5 + 30 ×10,000 ×0.3) −400,000
NP VA= (60,000 + 150,000 + 90,000) −400,000 = 300,000 −400,000 = −100,000
For Option B:
NP VB=
5
X
t=1
[(R−C)×Demandt×15,000] −IB
NP VB= [(50 −20) ×15,000 ×0.2 + (50 −20) ×15,000 ×0.5 + (50 −20) ×15,000 ×0.3]−600,000
NP VB= (30 ×15,000 ×0.2 + 30 ×15,000 ×0.5 + 30 ×15,000 ×0.3) −600,000
NP VB= (90,000 + 225,000 + 135,000) −600,000 = 450,000 −600,000 = −150,000
Therefore, the NPV for Option A is -$100,000 and for Option B is -$150,000.
b) To determine the value of the real options present in this investment decision, we would
need to consider the flexibility in the decision-making over the 5-year period based on the market
conditions. Real options analysis would allow the company to make optimal decisions in response
to the changing market conditions, such as the ability to expand further, contract, or delay expan-
sion. The value of the real options in this case would be the additional value generated by having
flexibility in decision-making compared to a static investment analysis.
It is important to note that the value of real options can be complex to quantify and may require
more detailed analysis based on specific scenarios and assumptions.
7 7. OPTIMAL INVESTMENT STRATEGIES
Problem 7. ABC Corporation is considering investing in a new project that will require an initial
investment of $500,000. The project is expected to generate cash flows of $150,000 in the first
year, $200,000 in the second year, and $300,000 in the third year. The risk-free rate is 4%. The
firm’s cost of capital is 12% and the project’s beta is 1.5. The current stock price is $50. Calculate
the Net Present Value (NPV) and the Real Options Value (ROV) of the project.
Solution 7. a) Calculate the Net Present Value (NPV):
The NPV calculation involves discounting the cash flows of the project at the firm’s cost of
capital. The formula for NPV is:
NP V =
3
X
t=1
CFt
(1 + r)t−Initial Investment
Where:
CFt:Cash flow in year t
r:Cost of capital
Substitute the given values into the formula:
NP V =150,000
(1 + 0.12)1+200,000
(1 + 0.12)2+300,000
(1 + 0.12)3−500,000
= 150,000/1.12 + 200,000/1.2544 + 300,000/1.4049 −500,000
= 133,928.57 + 159,544.29 + 213,143.16 −500,000
= $6,616.02
Therefore, the Net Present Value (NPV) of the project is $6,616.02.
b) Calculate the Real Options Value (ROV):
The Real Options Value (ROV) incorporates the value of managerial flexibility in decision mak-
ing. The formula for ROV is:
ROV =NP V + (Stock P rice ×β×NP V )
Where:
Stock P rice :Current stock price
β:Beta of the project
NP V :Net Present Value
Substitute the given values into the formula:
ROV = 6,616.02 + (50 ×1.5×6,616.02)
= 6,616.02 + 4,974.015
= $11,590.03
Therefore, the Real Options Value (ROV) of the project is $11,590.03.
8 8. REAL OPTIONS AND RISK MANAGEMENT
Problem 8. A company is considering investing in a project that has an initial cost of $1,000,000.
The project is expected to generate $400,000 in revenue in the first year, with a 30
a) Calculate the expected present value (EPV) of the project.
b) Determine the real option value (ROV) of the project.
Solution 8.
a) The EPV of the project can be calculated using the expected cash flow and discounting it
back to present value.
For the successful scenario (30
P V =400,000
1+0.03 =400,000
1.03 ≈$388,349.51
For the unsuccessful scenario (70The present value is zero as there is no revenue.
P V = 0
Therefore, the EPV of the project is:
EP V = 0.3×$388,349.51 + 0.7×$0 = $116,504.85
b) To determine the real option value (ROV) of the project, we need to calculate the value of the
option to continue the project given that it is successful.
The cash flow for each year in the successful scenario is given by:
CFt= 400,000 ×(1.05)t
The present value of the cash flows can be calculated using the risk-free rate of 3
P Vt=400,000 ×(1.05)t
(1 + 0.03)t=400,000 ×(1.05)t
1.03t
For simplicity, let’s consider a perpetuity formula to find the present value of expected cash
flows after year 1:
P V∞=400,000 ×(1.05)
0.03 −0.05 =400,000 ×1.05
−0.02 ≈ −$21,000,000.00
Therefore, the ROV of the project is positive (since the project should be continued) and is
approximately $21,000,000.00.
9 9. REAL OPTIONS IN TECHNOLOGY INVESTMENTS
Problem 9. A technology company is considering investing in a new project that will cost
$500,000 upfront. The project is expected to generate cash flows of $200,000 in one year with a
60% chance, and $100,000 with a 40% chance. The risk-free rate is 5%, and the company uses a
discount rate of 10% for risky projects. The company has the option to abandon the project in one
year if the cash flows are not satisfactory.
a) Calculate the present value of the project without the option to abandon it.
b) Calculate the project’s value if the company has the option to abandon it in one year.
c) Determine the value of the abandonment option.
Solution 9.
a) The present value of the project without the option to abandon it can be calculated by dis-
counting the expected cash flows at the discount rate of 10%:
P V =200,000 ×0.6
1.10 +100,000 ×0.4
1.10 = $145,454.55 + $36,363.64 = $181,818.19
Therefore, the present value of the project without the option to abandon it is $181,818.19.
b) To calculate the project’s value with the option to abandon it, we need to consider the option
to abandon the project in one year if the cash flows are not satisfactory. We use the risk-neutral
probabilities to estimate the expected cash flow and discount it back at the risk-free rate:
E(CF ) = 200,000 ×0.6 + 100,000 ×0.4 = $160,000
P V =160,000
1.05 = $152,380.95
Therefore, the project’s value with the option to abandon it in one year is $152,380.95.
c) The value of the abandonment option is the difference between the present value of the
project without the option to abandon it and the project’s value with the option to abandon it:
Abandonment Option = $181,818.19 −$152,380.95 = $29,437.24
Therefore, the value of the abandonment option is $29,437.24.
10 10. REAL OPTIONS IN NATURAL RESOURCE EXPLORATION
Problem 10. A mining company is considering opening a new mine in a mineral-rich region.
The company has the option to delay the opening of the mine for two years to allow for more
exploration and better market conditions. The initial investment cost for opening the mine now is
$10 million. If the company delays the opening, it would incur exploration costs of $2 million per
year for the two-year period. The present value factor for each year is 0.909.
a) Calculate the net present value (NPV) of opening the mine now.
b) Calculate the net present value (NPV) of delaying the opening for two years and incorporating
the exploration costs.
c) Discuss whether it is financially advantageous for the company to delay the mine opening
based on the NPV calculations.
Solution 10.
a) The NPV of opening the mine now can be calculated using the formula:
NP V =−InitialInvestment +XN etCashF lowt
(1 + r)t
Given that the initial investment is $10 million, the annual net cash flow from the mine operation
is expected to be $5 million, and the discount rate is 10
NP V =−10 + 5(0.909) + 5(0.909)2
NP V =−10 + 4.545 + 4.132 = −10 + 8.677 = −1.323
Therefore, the NPV of opening the mine now is -$1.323 million.
b) The NPV of delaying the mine opening can be calculated by considering the exploration costs
for two years:
NP V =−InitialInvestment +XExplorationCostst
(1 + r)t
The exploration costs for year 1 and year 2 are $2 million each. So, the NPV of delaying the
opening for two years is:
NP V =−2(0.909) −2(0.909)2=−1.818 −1.818 = −3.636
Therefore, the NPV of delaying the mine opening is -$3.636 million.
c) Comparing the NPVs, we see that delaying the mine opening results in a higher negative
NPV (-$3.636 million) compared to opening the mine now (-$1.323 million). Therefore, from a
financial perspective, it is not advantageous for the company to delay the mine opening.
11 11. CAPITAL BUDGETING WITH REAL OPTIONS
Problem 11. ABC Corporation is considering an investment in a new project. The initial cost
of the project is $500,000. The project is expected to generate cash flows of $150,000 per year for
the next 5 years. The risk-free rate is 4% and the project’s beta is 1.2. The strike price for the real
option to abandon the project is $400,000. Calculate the Net Present Value (NPV) of the project
with and without the real option to abandon.
Solution 11.
a) First, let’s calculate the NPV of the project without the real option to abandon:
The NPV formula is:
NP V =−C0+
n
X
t=1
CFt
(1 + r)t
Where: - C0= $500,000 (initial cost of project) - CFt= $150,000 for all years 1 to 5 - r= 4%
(risk-free rate)
Substitute these values into the formula:
NP V =−$500,000 + $150,000
1.04 +$150,000
(1.04)2+$150,000
(1.04)3+$150,000
(1.04)4+$150,000
(1.04)5
Calculating the above expression gives:
NP V =−$500,000 + $144,230.77 + $138,888.89 + $133,951.10 + $129,404.77 + $125,229.48
NP V =−$500,000 + $671,705.01
NP V = $171,705.01
Therefore, the NPV of the project without the real option to abandon is $171,705.01.
b) Now, let’s calculate the NPV of the project with the real option to abandon:
The real option to abandon adds an extra Pto cash flow in year 2. The value of this real option
can be calculated as:
P=Max(0, K −V2)
Where: - K= $400,000 (strike price to abandon) - V2= $500,000 + $150,000
1.04 = $630,769.23 (value
of the project in year 2)
P=Max(0,$400,000 −$630,769.23)
P=Max(0,−$230,769.23) = $0
Therefore, there is no value in exercising the real option to abandon the project in year 2. The
NPV remains $171,705.01.
Thus, the NPV of the project with and without the real option to abandon remains the same at
$171,705.01.
12 12. REAL OPTIONS IN REAL ESTATE INVESTMENTS
Problem 12.
A real estate developer is considering the purchase of a parcel of land for $500,000. The
developer has the option to build either residential units or commercial units on the land. The
expected cash flows associated with each type of development are as follows:
•Residential units: $300,000 in the first year, $200,000 in the second year, and $100,000 in
the third year.
•Commercial units: $400,000 in the first year, $250,000 in the second year, and $150,000 in
the third year.
The developer has the right to delay the development decision by one year. If the developer
chooses to wait, the cost of the land will remain the same and the expected cash flows will also
remain the same. The risk-free rate is 5%.
a) Determine the net present value (NPV) of developing residential units immediately.
b) Determine the net present value (NPV) of developing commercial units immediately.
c) Calculate the value of the option to delay the development decision by one year.
Solution 12.
a) To find the NPV of developing residential units immediately, we need to discount the expected
cash flows back to present value. The NPV can be calculated using the formula:
NP V =
3
X
t=1
CFt
(1 + r)t−Initial Cost
Where CFtis the cash flow in year t,ris the risk-free rate, and the initial cost is $500,000.
Plugging in the values for residential units:
NP V =300,000
(1 + 0.05)1+200,000
(1 + 0.05)2+100,000
(1 + 0.05)3−500,000
NP V = 285,714.29 + 181,405.90 + 83,305.95 −500,000
NP V = $50,426.14
Therefore, the NPV of developing residential units immediately is $50,426.14.
b) Similarly, the NPV of developing commercial units immediately can be calculated as:
NP V =400,000
(1 + 0.05)1+250,000
(1 + 0.05)2+150,000
(1 + 0.05)3−500,000
NP V = 380,952.38 + 235,449.74 + 131,724.89 −500,000
NP V = $248,127.01
Therefore, the NPV of developing commercial units immediately is $248,127.01.
c) To calculate the value of the option to delay, we need to find the NPV of waiting for one year
and compare it to the NPV of immediate development.
The NPV of waiting for one year is the same as the NPV of immediate development because
the land cost and cash flows remain the same.
Therefore, the value of the option to delay the development decision by one year is $0.
13 13. REAL OPTIONS IN PHARMACEUTICAL INVESTMENTS
Problem 13. A pharmaceutical company is considering investing in the development of a new
drug. The initial investment is $5 million, and the expected cash flows from the drug over the next
5 years are as follows (in millions of dollars):
Year Expected Cash Flow
1 2
2 3
3 4
4 4
5 5
The company has the option to abandon the project at the end of year 2. The risk-free rate is
5% and the company’s cost of capital is 10%.
a) Calculate the Net Present Value (NPV) of the project without the option to abandon.
b) Calculate the NPV of the project with the option to abandon after year 2.
Solution 13.
a) The NPV of the project without the option to abandon can be calculated using the formula:
NP V =−5 + 2
(1 + 0.05) +3
(1 + 0.05)2+4
(1 + 0.05)3+4
(1 + 0.05)4+5
(1 + 0.05)5
NP V =−5 + 2
1.05 +3
(1.05)2+4
(1.05)3+4
(1.05)4+5
(1.05)5
Calculating this gives:
NP V =−5+1.9048 + 2.7232 + 3.7891 + 3.4185 + 3.2164 = 9.0519 million
Therefore, the NPV of the project without the option to abandon is $9.05 million.
b) The NPV of the project with the option to abandon after year 2 can be calculated by comparing
the NPV of continuing the project with the NPV of abandoning it after year 2.
At the end of year 2, the expected cash flows from the project are $4 million and $5 million in
years 3 and 4 respectively.
To calculate the NPV of the project if abandoned after year 2:
NP Vabandon =−5 + 2
(1 + 0.05) +3
(1 + 0.05)2+4
(1 + 0.05)3= 7.7232 million
If the project is continued after year 2, the cash flows in years 3 and 4 would be $4 million and
$4 million respectively. Calculating the NPV in this case:
NP Vcontinue =−5 + 2
(1 + 0.05) +3
(1 + 0.05)2+4
(1 + 0.05)3+4
(1 + 0.05)4= 8.7891 million
Comparing the two options, the NPV of continuing the project after year 2 is higher, so the
company should continue with the project.
14 14. REAL OPTIONS IN RENEWABLE ENERGY PROJECTS
Problem 14. You are evaluating an investment in a renewable energy project with the following
parameters:
- Initial investment cost: 200,000 −Expectedannualcashflowsforthenext5years :50,000 - Dis-
count rate: 10- Estimated salvage value at the end of year 5: 20,000
The project also has a real option to expand its capacity in year 3 by investing an additional
100,000.T heexpandedprojectisexpectedtogenerateadditionalannualcashf lowsof30,000 for the re-
maining 3 years.
a) Calculate the NPV of the initial investment without considering the expansion option.
b) Determine the NPV of the expanded project considering the expansion option.
Solution 14.
a) To calculate the NPV of the initial investment without considering the expansion option, we
need to discount the expected cash flows over the next 5 years and subtract the initial investment
cost:
NP V =−200,000 + 50,000
1.10 +50,000
(1.10)2+50,000
(1.10)3+50,000
(1.10)4+50,000 + 20,000
(1.10)5
NP V =−200,000 + 50,000
1.10 +50,000
(1.10)2+50,000
(1.10)3+50,000
(1.10)4+70,000
(1.10)5
Calculating the NPV, we get:
NP V =−200,000 + 45,454.55 + 41,322.31 + 37,565.74 + 34,150.67 + 40,772.27
NP V = $ −4383.46
Therefore, the NPV of the initial investment without considering the expansion option is −4383.46.
b) To determine the NPV of the expanded project, we need to consider the additional cash flows
from year 3 onwards as well as the expansion cost. The expanded project’s cash flows will be:
NP V =−200,000+50,000
1.10 +50,000
(1.10)2+(30,000−100,000)×1
(1.10)2+(30,000−100,000)×1
(1.10)3+(30,000−100,000)×1
(1.10)4+50,000 + 20,000
(1.10)5
NP V =−200,000 + 45,454.55 + 41,322.31 + 21,818.18 + 18,926.53 + 16,296.85 + 40,772.27
NP V = $15,409.48
Therefore, the NPV of the expanded project considering the expansion option is −15,409.48.
I. Real Options and Investment Analysis
Problem 1. A company is considering investing in a new project with an initial cost of $1,000,000.
The project is expected to generate cash flows of $400,000 in the first year, $500,000 in the second
year, and $600,000 in the third year. The company has the option to abandon the project after the
first year. The risk-free rate is 5%. Should the company invest in this project?
Solution 1. Given: Initial investment (C): $1,000,000 Cash flows: year 1 = $400,000, year 2 =
$500,000, year 3 = $600,000 Risk-free rate (r): 5
The Net Present Value (NPV) of the project can be calculated as follows: NPV = -C + PCFt
(1+r)t
NPV = -$1,000,000 + $400,000/(1+0.05)1+ $500,000/(1 + 0.05)2+ $600,000/(1 + 0.05)3
NPV = -$1,000,000 + $380,952 + $454,851 + $497,618.85 NPV = $333,421.85
The NPV of the project is positive, which indicates that the project is expected to generate a
return greater than the required rate of return. Therefore, the company should invest in this project.
Problem 2. A company is evaluating an investment in a project that requires an initial outlay
of $800,000. The cash flows from the project are expected to be $300,000 in year 1, $400,000 in
year 2, and $500,000 in year 3. The company has the option to expand the project at the end of
year 1 at an additional cost of $200,000. If the expansion is undertaken, the expected cash flows
in year 4 would be $600,000. Should the company invest in the project and expand in year 1 if the
opportunity arises? Assume a discount rate of 8
Solution 2. Given: Initial investment (C): $800,000 Cash flows: year 1 = $300,000, year 2 =
$400,000, year 3 = $500,000, year 4 (if expanded) = $600,000 Expansion cost: $200,000 Discount
rate (r): 8
Calculate the NPV if the project is undertaken without expansion: NPV = -$800,000 + $300,000/(1+0.08)1+
$400,000/(1 + 0.08)2+ $500,000/(1 + 0.08)3NP V =−$800,000 + $277,777.78 + $308,641.98 +
$340,136.66NP V = $126,556.42
Calculate the NPV if the project is expanded in year 1: NPV = -$800,000 + $300,000/(1+0.08)1+
$400,000/(1+0.08)2+$500,000/(1+0.08)3+$600,000/(1+0.08)4−$200,000NP V =−$800,000+
$277,777.78 + $308,641.98 + $340,136.66 + $387,096.77 −$200,000NP V = $513,652.21
Comparing the two NPVs, it is more beneficial for the company to invest in the project and
expand in year 1 if the opportunity arises, as it yields a higher NPV.
15 Real Options and Investment Analysis
Problem:
A company is considering acquiring a competitor in the same industry. The current market
value of the competitor is $50 million. The company believes that if it acquires the competitor, it
can implement a growth strategy that has a 60% chance of increasing the value of the acquired
firm to $80 million and a 40% chance of decreasing the value to $30 million. If the growth strategy
is successful, the company can generate additional cash flows of $20 million per year for the next
5 years. The risk-free rate is 4%.
a) Calculate the value of the real option to acquire the competitor.
b) Determine the optimal timing to exercise the real option if the company can only exercise it
once.
Solution:
a) Let’s first calculate the expected value of the acquired firm:
E[V]=0.6×$80 million + 0.4×$30 million
= $48 million + $12 million
= $60 million
The present value of the expected cash flows from the growth strategy can be calculated as:
P V (Cash Flows) = $20 million
1+0.04 +$20 million
(1 + 0.04)2+$20 million
(1 + 0.04)3+$20 million
(1 + 0.04)4+$20 million
(1 + 0.04)5
= $18.68 million + $17.98 million + $17.30 million + $16.65 million + $16.03 million
= $86.64 million
The value of the real option is the difference between the expected value of the acquired firm
and the present value of the cash flows:
Real Option Value = $60 million −$86.64 million
=−$26.64 million
Therefore, the value of the real option to acquire the competitor is -$26.64 million.
b) To determine the optimal timing to exercise the real option, we need to compare the value of
waiting to the option to the value of immediate exercise. The value of waiting is the expected value
of the acquired firm minus the exercise price (market value of the competitor), which is $60 million
- $50 million = $10 million.
The option to acquire has negative value (-$26.64 million) which implies that it should not be
exercised. Therefore, the optimal timing is to never exercise the option to acquire the competitor.
16 17. REAL OPTIONS IN PROJECT FINANCE
Problem 17. A company is considering investing in a new project that has the following char-
acteristics:
- Initial investment cost: $500,000 - Expected cash inflows in the first year: $300,000 - Expected
cash inflows in the second year: $400,000 - Expected cash inflows in the third year: $600,000 -
Discount rate: 10% - Risk-free rate: 5% - Volatility of cash flows: 20% - Time to maturity for the real
option: 3 years - Exercise price for the real option: $100,000
The company can abandon the project after the first year of operation if the cash flows are not
as expected.
a) Calculate the Net Present Value (NPV) of the project without considering the real option.
b) Determine the value of the real option embedded in the project.
c) Should the company invest in the project based on the real option analysis?
Solution 17.
a) The Net Present Value (NPV) of the project without considering the real option can be cal-
culated using the formula:
NP V =CF1
(1 + r)1+CF2
(1 + r)2+CF3
(1 + r)3−Initial Investment
where ris the discount rate, CFiis the cash flow in year i, and the Initial Investment is the initial
cost of the project.
Substitute the given values into the formula:
NP V =300,000
(1 + 0.10)1+400,000
(1 + 0.10)2+600,000
(1 + 0.10)3−500,000
NP V =300,000
1.10 +400,000
1.102+600,000
1.103−500,000
NP V = 272,727.27 + 330,578.51 + 401,324.62 −500,000
NP V = 504,630.40
Therefore, the NPV of the project without considering the real option is $504,630.40.
b) The value of the real option can be calculated using the Black-Scholes Option Pricing Model.
d1=ln(S/E)+(r+σ2/2)t
σ√t
d2=d1−σ√t
Option V alue =SΦ(d1)−Ee−rtΦ(d2)
where: - S= current stock price (value of project) - E= exercise price - r= risk-free rate - t=
time to maturity - σ= volatility
Substitute the given values into the formula:
d1=ln(300,000/100,000) + (0.05 + 0.202/2)3
0.20√3= 1.85
d2= 1.85 −0.20√3=1.35
Option V alue = 300,000Φ(1.85) −100,000e−0.05∗3Φ(1.35) = 148,385.16
Therefore, the value of the real option embedded in the project is $148,385.16.
c) The total value of the project considering the real option is:
T otal V alue =NP V +Option V alue = 504,630.40 + 148,385.16 = 653,015.56
As the total value of the project exceeds the initial investment cost and considering the real
option, the company should invest in the project based on the real option analysis.
17 18. REAL OPTIONS IN R&D INVESTMENTS
Problem 18. A company is considering investing in a research and development (R&D) project.
The initial investment required is $500,000. The project is expected to generate cash flows of
$200,000 in the first year, $300,000 in the second year, and $400,000 in the third year. The risk-
free rate is 5% and the company’s cost of capital is 10%.
a) Calculate the Net Present Value (NPV) of the project without considering the real options.
b) Determine the value of the Real Option to Abandon.
c) Calculate the Real Options Value of Waiting to Invest if the company can decide at the end
of each year whether to continue the project or not.
Solution 18.
a) The NPV of the project without considering the real options can be calculated by discounting
the cash flows at the cost of capital. The formula for NPV is:
NP V =
n
X
t=1
CFt
(1 + r)t−Initial Investment
Where: - CFt= Cash flow in year t-r= Company’s cost of capital - Initial Investment =
$500,000
Plugging in the values:
NP V =200,000
1.10 +300,000
1.102+400,000
1.103−500,000
NP V = 181,818.18 + 247,933.88 + 300,043.71 −500,000
NP V = 229,795.77
Therefore, the NPV of the project without considering the real options is $229,795.77.
b) The Real Option to Abandon allows the company to abandon the project at the end of the
second year if it is no longer profitable. The value of this option can be calculated using the Binomial
option pricing model or decision tree analysis.
c) The Real Options Value of Waiting to Invest allows the company to assess whether to invest
at the end of each year based on the project’s performance. The decision to wait can be valued
using the Black-Scholes model or other numerical methods.
18 19. REAL OPTIONS IN INTERNATIONAL INVESTMENTS
Problem 19. A multinational corporation is considering investing in a project in a foreign coun-
try. The project has an initial investment cost of $5 million and is expected to generate cash flows of
$3 million per year for the next 5 years. The corporation has the option to expand the project after
2 years at an additional cost of $2 million. The risk-free rate is 5% and the corporation’s required
rate of return is 10%.
a) Calculate the Net Present Value (NPV) of the project without considering the option to ex-
pand.
b) Determine the value of the option to expand the project after 2 years.
c) Should the corporation proceed with the initial investment in the project?
Solution 19.
a) To calculate the NPV of the project without considering the option to expand, we use the
formula:
NP V =−C0+CF1
(1 + r)1+CF2
(1 + r)2+... +CFn
(1 + r)n
Where: C0= $5,000,000 CFt= $3,000,000 for t= 1,2,3,4,5r= 10%
Plugging in the values, we get:
NP V =−5,000,000 + 3,000,000
1.1+3,000,000
1.12+3,000,000
1.13+3,000,000
1.14+3,000,000
1.15
NP V =−5,000,000 + 2,727,273 + 2,479,338 + 2,254,853 + 2,049,866 + 1,861,696
NP V = $2,373,050
The NPV of the project without considering the option to expand is $2,373,050.
b) The value of the option to expand the project after 2 years can be calculated using the Black-
Scholes model. The formula for the value of the option is:
V=S0N(d1)−Xe−rtN(d2)
Where: S0= $3,000,000 (Value of the expanded project) X= $2,000,000 (Cost of expansion)
r= 5% (Risk-free rate) t= 2 years
Calculating d1and d2using the Black-Scholes formula, we find d1= 0.4407 and d2= 0.1841.
Plugging in these values, we get:
V= 3,000,000N(0.4407) −2,000,000e−0.05∗2N(0.1841)
V= 3,000,000 ×0.6703 −2,000,000 ×e−0.1×0.5749
V= 2,010,894 −1,273,239
V= $737,655
The value of the option to expand the project after 2 years is $737,655.
c) As the NPV of the project without considering the option to expand is positive ($2,373,050)
and the value of the option to expand is also positive ($737,655), the corporation should proceed
with the initial investment in the project.
19 20. REAL OPTIONS IN NEW PRODUCT DEVELOPMENT
Problem 20. A company is considering developing a new product. The initial investment re-
quired is $500,000. The expected cash flows from the product over the next 3 years are estimated
as follows: Year 1: $200,000, Year 2: $300,000, Year 3: $400,000. The company has the option
to abandon the project at the end of each year with the following abandonment values: Year 1:
$50,000, Year 2: $100,000, Year 3: $200,000. The risk-free rate is 5%.
a) Calculate the net present value (NPV) of the project without considering any abandonment
options.
b) Determine the net present value (NPV) of the project if the company has the flexibility to
abandon the project at the end of each year.
c) Discuss whether incorporating the abandonment options increases the value of the project.
Solution 20.
a) To calculate the NPV of the project without considering any abandonment options, we need
to discount the cash flows at the risk-free rate of 5%.
Using the formula for NPV:
NP V =CF0
(1 + r)0+CF1
(1 + r)1+CF2
(1 + r)2+CF3
(1 + r)3−Initial Investment
where r= 0.05 and the cash flows are 200,000,300,000, and 400,000f oryears1,2, and3respectively.
NP V =−500,000
(1 + 0.05)0+200,000
(1 + 0.05)1+300,000
(1 + 0.05)2+400,000
(1 + 0.05)3
NP V =−500,000 + 190,476.2 + 272,108.8 + 342,317.5 = 304,902.5
Therefore, the NPV of the project without considering any abandonment options is $304,902.5.
b) To calculate the NPV of the project with abandonment options, we need to consider the option
to abandon at the end of each year by comparing the continuation value with the abandonment
value.
In Year 1, the continuation value is $190,476.2 (the present value of cash flows from Year 2
and Year 3). If the abandonment value ($50,000) is greater, then the project would be abandoned,
resulting in an NPV of -$50,000. In this case, the NPV of Year 1 is -$50,000.
In Year 2, the continuation value is $272,108.8 (the present value of cash flow from Year 3). If
the abandonment value ($100,000) is greater, then the project would be abandoned, resulting in
an NPV of -$100,000. In this case, the NPV of Year 2 is -$100,000.
In Year 3, the project will not be abandoned as the cash flow of $400,000 is greater than the
abandonment value of $200,000. Therefore, the NPV of Year 3 is $357,142.9 (the present value
of the cash flow in Year 3).
The total NPV of the project with abandonment options is the sum of the NPVs of each year:
NP V =−50,000 −100,000 + 357,142.9 = 207,142.9
Therefore, the NPV of the project with abandonment options is $207,142.9.
c) Incorporating abandonment options increases the value of the project, as the NPV with aban-
donment options ($207,142.9) is higher than the NPV without considering any abandonment op-
tions ($304,902.5). Abandonment options provide flexibility in decision-making and can increase
the overall value of a project.
Solution 2.
a) The value of the real option to abandon the project can be calculated using the binomial
option pricing model. The option to abandon is equivalent to a put option. Using the risk-neutral
valuation approach, the value of the option can be found by working backwards from the final year.
Let’s denote: - S0= $50 (price of oil at time t= 0) - X= $200,000 (cash flow if oil prices remain
low) - R= 1.04 (risk-free rate) - T= 3 years (time to expiration)
The value of the option to abandon is:
V3=1
1.04 0.5×Vu
4+Vd
4
1.04 + 0.5×X
where Vu
4= 0 since if the price of oil increases, the company will not abandon the project.
Therefore:
V3=1
1.04 0.5×0 + Vd
4
1.04 + 0.5×200,000
Given that Vd
4= 0, we can calculate:
V3=1
1.04 0.5×0
1.04+ 0.5×200,000=1
1.04 ×0.5×192,307.69 = $92,746.91
Therefore, the value of the real option to abandon the project is $92,746.91.
b) The NPV of the project without the real option is calculated as the present value of the
expected cash flows minus the initial investment:
NP V =200,000
1.04 +250,000
(1.04)2+300,000
(1.04)3−1,000,000 = 535,725.89
c) The NPV of the project with the real option included is the sum of the NPV without the option
and the value of the option:
NP V = 535,725.89 + 92,746.91 = 628,472.80
3 3. TIMING OF INVESTMENTS
Problem 3. A company is considering investing in a new project. The initial investment cost
is $500,000. The project is expected to generate cash flows of $200,000 per year for the next 5
years. The company’s cost of capital is 10%. If the company decides to delay the investment by
one year, the initial investment cost will decrease to $450,000, but the annual cash flows will also
decrease to $180,000 per year for the next 5 years. Should the company invest now or delay the
investment for one year?
Solution 3. Let’s first calculate the net present value (NPV) of the project if the company invests
now and if it delays the investment by one year.
a) NPV of investing now: The NPV of investing now can be calculated as follows:
NP Vnow =−500,000 + 200,000
1.10 +200,000
(1.10)2+200,000
(1.10)3+200,000
(1.10)4+200,000
(1.10)5
NP Vnow =−500,000 + 200,000
1.10 +200,000
(1.10)2+200,000
(1.10)3+200,000
(1.10)4+200,000
(1.10)5
NP Vnow =−500,000 + 181,818.18 + 165,289.26 + 150,263.87 + 136,603.52 + 124,184.11
NP Vnow = $157,158.94
b) NPV of delaying the investment by one year: The NPV of delaying the investment by one
year can be calculated as follows:
NP Vdelayed =−450,000 + 180,000
1.10 +180,000
(1.10)2+180,000
(1.10)3+180,000
(1.10)4+180,000
(1.10)5
NP Vdelayed =−450,000 + 163,636.36 + 148,760.33 + 135,236.66 + 122,942.42 + 111,766.74
NP Vdelayed = $131,342.11
c) Conclusion: Comparing the two options, investing now yields an NPV of $157,158.94, while
delaying the investment by one year yields an NPV of $131,342.11. Therefore, the company should
invest in the project now as it provides a higher NPV.
4 4. FLEXIBILITY IN PROJECT DEVELOPMENT
Problem 4. A company is considering investing in a new project that has the following cash
flows for the next 3 years:
•Year 1: −1,000 (investment cost)
•Year 2: 500
•Year 3: 800
The company has the option to abandon the project after year 1 with a salvage value of 300.
The risk-free rate is 5%.
a) Calculate the net present value (NPV) of the project without the abandonment option.
b) Calculate the NPV of the project with the abandonment option.
c) Determine whether the company should exercise the abandonment option or not.
Solution 4.
a) The NPV of the project without the abandonment option is calculated by discounting the cash
flows at the risk-free rate:
NP V =−1,000 + 500
1.05 +800
1.052=−1,000 + 476.19 + 756.14 = 232.33
Therefore, the NPV of the project without the abandonment option is 232.33.
b) To calculate the NPV of the project with the abandonment option, we need to consider the
salvage value if the project is abandoned after year 1. The NPV with the abandonment option is:
NP V =−1,000 + 300 + 500
1.05 +800
1.052=−1,000 + 300 + 476.19 + 756.14 = 532.33
So, the NPV of the project with the abandonment option is 532.33.
c) Comparing the NPVs, we see that the NPV with the abandonment option is greater than the
NPV without the abandonment option. Therefore, the company should exercise the abandonment
option if the project’s cash flows are as predicted.
5 5. UNCERTAINTY IN PROJECT OUTCOMES
Problem 5. A company is considering investing in a new project that has two possible out-
comes: success or failure. The probabilities of success and failure are estimated to be 0.6 and
0.4, respectively. If the project is successful, the company expects to earn $500,000, but if it fails,
they will lose $200,000. The initial investment required for the project is $100,000. Calculate the
expected net present value (NPV) of the project.
Solution 5. The expected NPV of the project is calculated as the sum of the expected cash
flows discounted to the present value at the appropriate rate.
a) Expected Cash Flows: The expected cash flow from a successful project is $500,000 and
from a failed project is -$200,000.
Expected cash flow = (Probability of success * Cash flow from success) + (Probability of failure
* Cash flow from failure) Expected cash flow = (0.6 * $500,000) + (0.4 * -$200,000) Expected cash
flow = $300,000 - $80,000 Expected cash flow = $220,000
b) NPV Calculation: NPV = Expected cash flow / (1 + r)twhere, r =discountrate, t =timeperiod, inthiscase, t =
0
Given that the initial investment is $100,000 and the expected cash flow is $220,000, the NPV
can be calculated as:
NPV = (Expected cash flow - Initial investment) / (1 + r)tNP V = ($220,000 −$100,000)/(1 +
r)0NP V = $120,000
Therefore, the expected net present value (NPV) of the project is $120,000.
6 6. INVESTMENT DECISION UNDER COMPETITION
Problem 6. A company is considering expanding its production capacity to meet the increasing
demand for its product. There are two options available: Option A involves investing $400,000 to
increase capacity by 10,000 units annually for the next 5 years. Option B requires an investment
of $600,000 for a capacity increase of 15,000 units annually for the next 5 years.
The company’s estimated revenue per unit is $50, and the variable cost per unit is $20. The
discount rate is 10%. The company operates in a competitive market where the demand is uncer-
tain. Based on the current information, the company forecasts the demand for the next 5 years to
have the following probabilities:
Demand Level Probability
Low 0.2
Medium 0.5
High 0.3
a) Calculate the NPV for each option.
b) Determine the value of the real options present in this investment decision.
Solution 6.
a) The Net Present Value (NPV) for each option is calculated as follows: Let’s denote: - R= $50
(revenue per unit) - C= $20 (variable cost per unit) - IA= $400,000 (investment for Option A) -
IB= $600,000 (investment for Option B) - d= 10% (discount rate)
For Option A:
NP VA=
5
X
t=1
[(R−C)×Demandt×10,000] −IA
NP VA= [(50 −20) ×10,000 ×0.2 + (50 −20) ×10,000 ×0.5 + (50 −20) ×10,000 ×0.3]−400,000
NP VA= (30 ×10,000 ×0.2 + 30 ×10,000 ×0.5 + 30 ×10,000 ×0.3) −400,000
NP VA= (60,000 + 150,000 + 90,000) −400,000 = 300,000 −400,000 = −100,000
For Option B:
NP VB=
5
X
t=1
[(R−C)×Demandt×15,000] −IB
NP VB= [(50 −20) ×15,000 ×0.2 + (50 −20) ×15,000 ×0.5 + (50 −20) ×15,000 ×0.3]−600,000
NP VB= (30 ×15,000 ×0.2 + 30 ×15,000 ×0.5 + 30 ×15,000 ×0.3) −600,000
NP VB= (90,000 + 225,000 + 135,000) −600,000 = 450,000 −600,000 = −150,000
Therefore, the NPV for Option A is -$100,000 and for Option B is -$150,000.
b) To determine the value of the real options present in this investment decision, we would
need to consider the flexibility in the decision-making over the 5-year period based on the market
conditions. Real options analysis would allow the company to make optimal decisions in response
to the changing market conditions, such as the ability to expand further, contract, or delay expan-
sion. The value of the real options in this case would be the additional value generated by having
flexibility in decision-making compared to a static investment analysis.
It is important to note that the value of real options can be complex to quantify and may require
more detailed analysis based on specific scenarios and assumptions.
7 7. OPTIMAL INVESTMENT STRATEGIES
Problem 7. ABC Corporation is considering investing in a new project that will require an initial
investment of $500,000. The project is expected to generate cash flows of $150,000 in the first
year, $200,000 in the second year, and $300,000 in the third year. The risk-free rate is 4%. The
firm’s cost of capital is 12% and the project’s beta is 1.5. The current stock price is $50. Calculate
the Net Present Value (NPV) and the Real Options Value (ROV) of the project.
Solution 7. a) Calculate the Net Present Value (NPV):
The NPV calculation involves discounting the cash flows of the project at the firm’s cost of
capital. The formula for NPV is:
NP V =
3
X
t=1
CFt
(1 + r)t−Initial Investment
Where:
CFt:Cash flow in year t
r:Cost of capital
Substitute the given values into the formula:
NP V =150,000
(1 + 0.12)1+200,000
(1 + 0.12)2+300,000
(1 + 0.12)3−500,000
= 150,000/1.12 + 200,000/1.2544 + 300,000/1.4049 −500,000
= 133,928.57 + 159,544.29 + 213,143.16 −500,000
= $6,616.02
Therefore, the Net Present Value (NPV) of the project is $6,616.02.
b) Calculate the Real Options Value (ROV):
The Real Options Value (ROV) incorporates the value of managerial flexibility in decision mak-
ing. The formula for ROV is:
ROV =NP V + (Stock P rice ×β×NP V )
Where:
Stock P rice :Current stock price
β:Beta of the project
NP V :Net Present Value
Substitute the given values into the formula:
ROV = 6,616.02 + (50 ×1.5×6,616.02)
= 6,616.02 + 4,974.015
= $11,590.03
Therefore, the Real Options Value (ROV) of the project is $11,590.03.
8 8. REAL OPTIONS AND RISK MANAGEMENT
Problem 8. A company is considering investing in a project that has an initial cost of $1,000,000.
The project is expected to generate $400,000 in revenue in the first year, with a 30
a) Calculate the expected present value (EPV) of the project.
b) Determine the real option value (ROV) of the project.
Solution 8.
a) The EPV of the project can be calculated using the expected cash flow and discounting it
back to present value.
For the successful scenario (30
P V =400,000
1+0.03 =400,000
1.03 ≈$388,349.51
For the unsuccessful scenario (70The present value is zero as there is no revenue.
P V = 0
Therefore, the EPV of the project is:
EP V = 0.3×$388,349.51 + 0.7×$0 = $116,504.85
b) To determine the real option value (ROV) of the project, we need to calculate the value of the
option to continue the project given that it is successful.
The cash flow for each year in the successful scenario is given by:
CFt= 400,000 ×(1.05)t
The present value of the cash flows can be calculated using the risk-free rate of 3
P Vt=400,000 ×(1.05)t
(1 + 0.03)t=400,000 ×(1.05)t
1.03t
For simplicity, let’s consider a perpetuity formula to find the present value of expected cash
flows after year 1:
P V∞=400,000 ×(1.05)
0.03 −0.05 =400,000 ×1.05
−0.02 ≈ −$21,000,000.00
Therefore, the ROV of the project is positive (since the project should be continued) and is
approximately $21,000,000.00.
9 9. REAL OPTIONS IN TECHNOLOGY INVESTMENTS
Problem 9. A technology company is considering investing in a new project that will cost
$500,000 upfront. The project is expected to generate cash flows of $200,000 in one year with a
60% chance, and $100,000 with a 40% chance. The risk-free rate is 5%, and the company uses a
discount rate of 10% for risky projects. The company has the option to abandon the project in one
year if the cash flows are not satisfactory.
a) Calculate the present value of the project without the option to abandon it.
b) Calculate the project’s value if the company has the option to abandon it in one year.
c) Determine the value of the abandonment option.
Solution 9.
a) The present value of the project without the option to abandon it can be calculated by dis-
counting the expected cash flows at the discount rate of 10%:
P V =200,000 ×0.6
1.10 +100,000 ×0.4
1.10 = $145,454.55 + $36,363.64 = $181,818.19
Therefore, the present value of the project without the option to abandon it is $181,818.19.
b) To calculate the project’s value with the option to abandon it, we need to consider the option
to abandon the project in one year if the cash flows are not satisfactory. We use the risk-neutral
probabilities to estimate the expected cash flow and discount it back at the risk-free rate:
E(CF ) = 200,000 ×0.6 + 100,000 ×0.4 = $160,000
P V =160,000
1.05 = $152,380.95
Therefore, the project’s value with the option to abandon it in one year is $152,380.95.
c) The value of the abandonment option is the difference between the present value of the
project without the option to abandon it and the project’s value with the option to abandon it:
Abandonment Option = $181,818.19 −$152,380.95 = $29,437.24
Therefore, the value of the abandonment option is $29,437.24.
10 10. REAL OPTIONS IN NATURAL RESOURCE EXPLORATION
Problem 10. A mining company is considering opening a new mine in a mineral-rich region.
The company has the option to delay the opening of the mine for two years to allow for more
exploration and better market conditions. The initial investment cost for opening the mine now is
$10 million. If the company delays the opening, it would incur exploration costs of $2 million per
year for the two-year period. The present value factor for each year is 0.909.
a) Calculate the net present value (NPV) of opening the mine now.
b) Calculate the net present value (NPV) of delaying the opening for two years and incorporating
the exploration costs.
c) Discuss whether it is financially advantageous for the company to delay the mine opening
based on the NPV calculations.
Solution 10.
a) The NPV of opening the mine now can be calculated using the formula:
NP V =−InitialInvestment +XN etCashF lowt
(1 + r)t
Given that the initial investment is $10 million, the annual net cash flow from the mine operation
is expected to be $5 million, and the discount rate is 10
NP V =−10 + 5(0.909) + 5(0.909)2
NP V =−10 + 4.545 + 4.132 = −10 + 8.677 = −1.323
Therefore, the NPV of opening the mine now is -$1.323 million.
b) The NPV of delaying the mine opening can be calculated by considering the exploration costs
for two years:
NP V =−InitialInvestment +XExplorationCostst
(1 + r)t
The exploration costs for year 1 and year 2 are $2 million each. So, the NPV of delaying the
opening for two years is:
NP V =−2(0.909) −2(0.909)2=−1.818 −1.818 = −3.636
Therefore, the NPV of delaying the mine opening is -$3.636 million.
c) Comparing the NPVs, we see that delaying the mine opening results in a higher negative
NPV (-$3.636 million) compared to opening the mine now (-$1.323 million). Therefore, from a
financial perspective, it is not advantageous for the company to delay the mine opening.
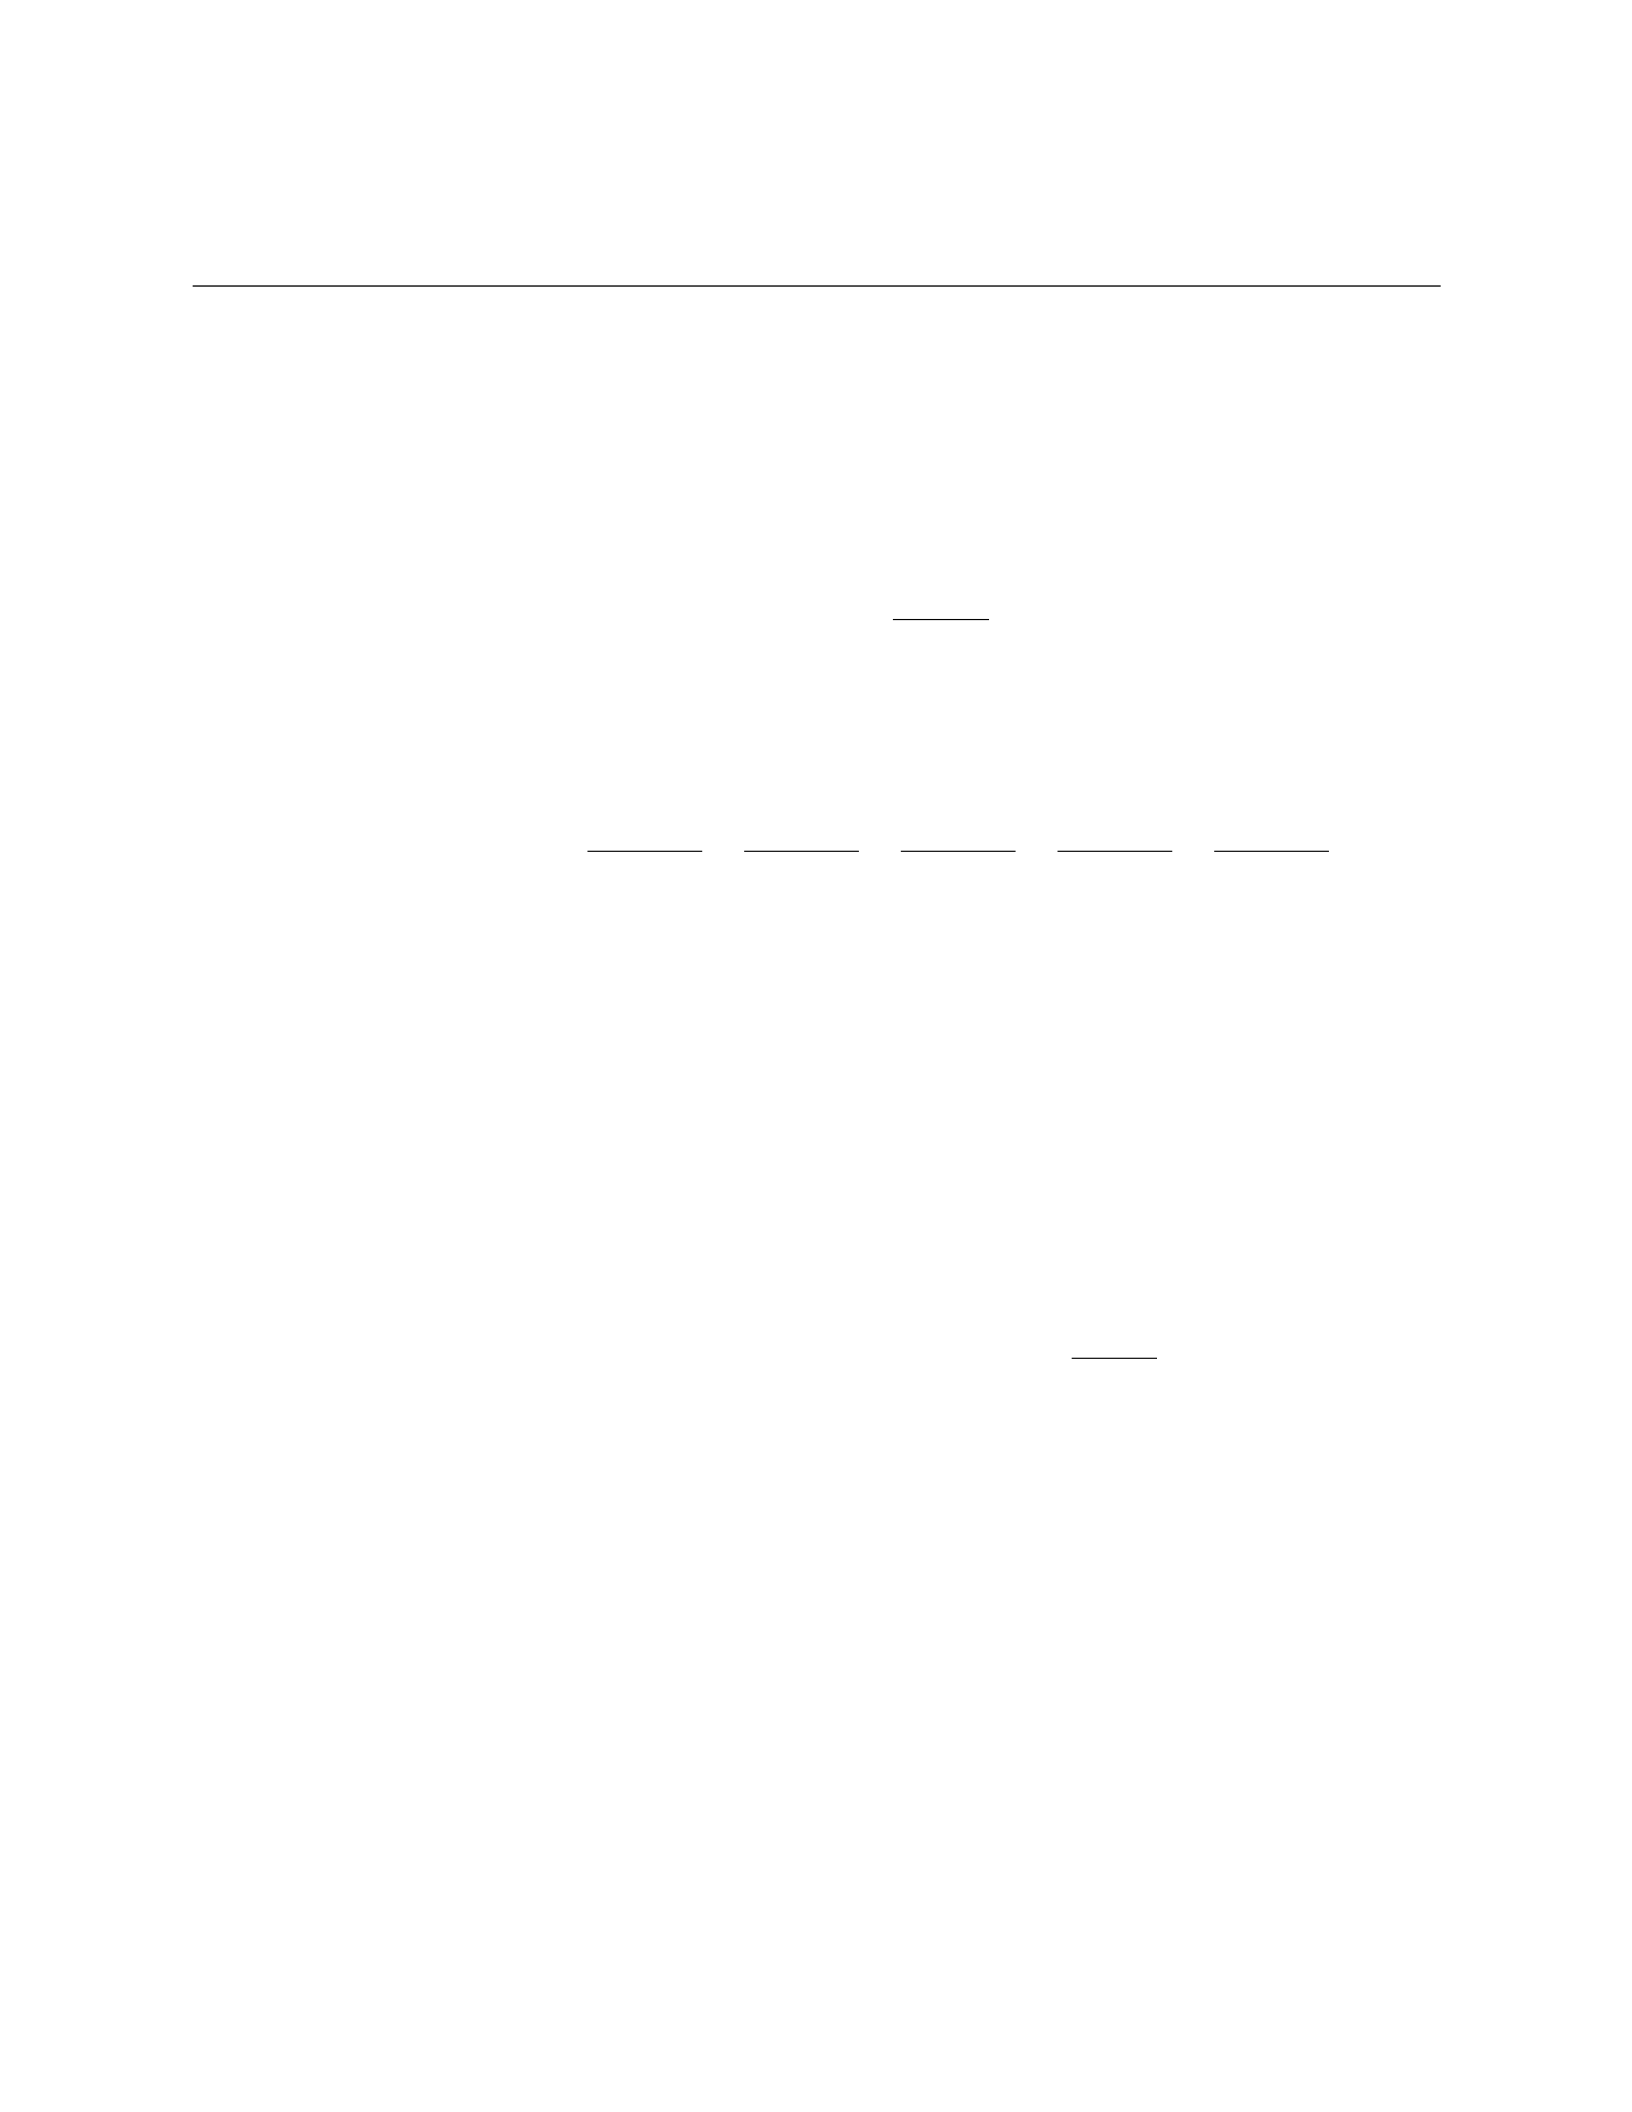
11 11. CAPITAL BUDGETING WITH REAL OPTIONS
Problem 11. ABC Corporation is considering an investment in a new project. The initial cost
of the project is $500,000. The project is expected to generate cash flows of $150,000 per year for
the next 5 years. The risk-free rate is 4% and the project’s beta is 1.2. The strike price for the real
option to abandon the project is $400,000. Calculate the Net Present Value (NPV) of the project
with and without the real option to abandon.
Solution 11.
a) First, let’s calculate the NPV of the project without the real option to abandon:
The NPV formula is:
NP V =−C0+
n
X
t=1
CFt
(1 + r)t
Where: - C0= $500,000 (initial cost of project) - CFt= $150,000 for all years 1 to 5 - r= 4%
(risk-free rate)
Substitute these values into the formula:
NP V =−$500,000 + $150,000
1.04 +$150,000
(1.04)2+$150,000
(1.04)3+$150,000
(1.04)4+$150,000
(1.04)5
Calculating the above expression gives:
NP V =−$500,000 + $144,230.77 + $138,888.89 + $133,951.10 + $129,404.77 + $125,229.48
NP V =−$500,000 + $671,705.01
NP V = $171,705.01
Therefore, the NPV of the project without the real option to abandon is $171,705.01.
b) Now, let’s calculate the NPV of the project with the real option to abandon:
The real option to abandon adds an extra Pto cash flow in year 2. The value of this real option
can be calculated as:
P=Max(0, K −V2)
Where: - K= $400,000 (strike price to abandon) - V2= $500,000 + $150,000
1.04 = $630,769.23 (value
of the project in year 2)
P=Max(0,$400,000 −$630,769.23)
P=Max(0,−$230,769.23) = $0
Therefore, there is no value in exercising the real option to abandon the project in year 2. The
NPV remains $171,705.01.
Thus, the NPV of the project with and without the real option to abandon remains the same at
$171,705.01.
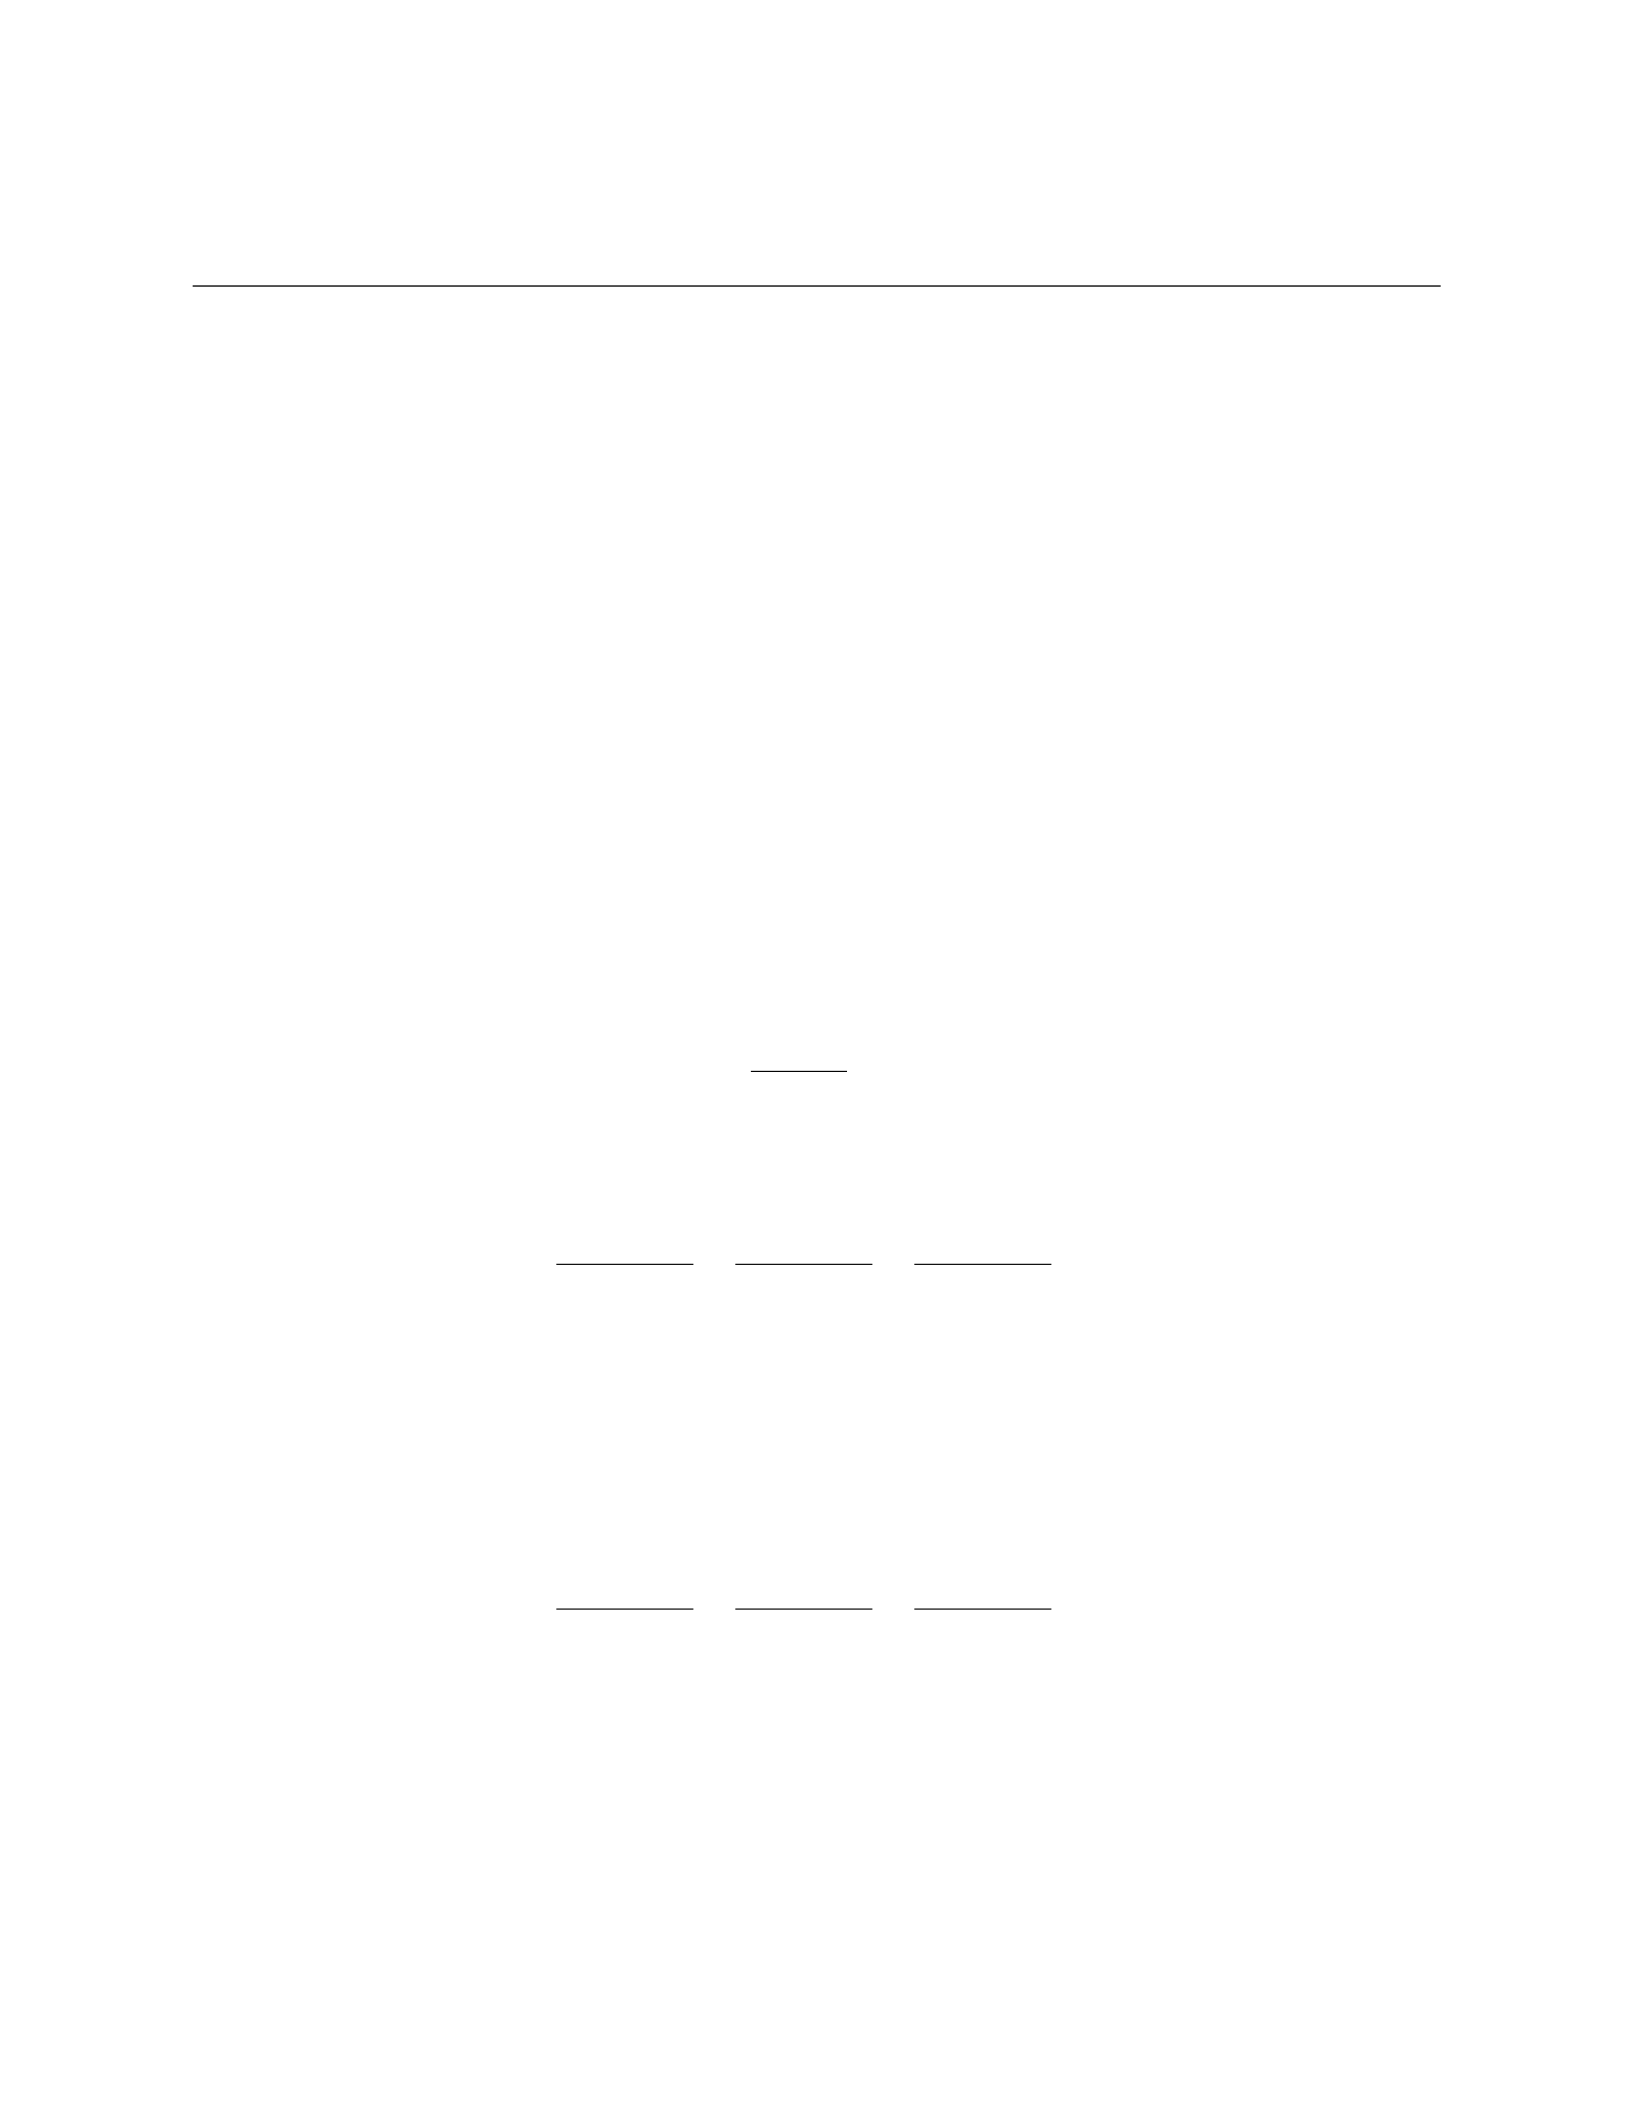
12 12. REAL OPTIONS IN REAL ESTATE INVESTMENTS
Problem 12.
A real estate developer is considering the purchase of a parcel of land for $500,000. The
developer has the option to build either residential units or commercial units on the land. The
expected cash flows associated with each type of development are as follows:
•Residential units: $300,000 in the first year, $200,000 in the second year, and $100,000 in
the third year.
•Commercial units: $400,000 in the first year, $250,000 in the second year, and $150,000 in
the third year.
The developer has the right to delay the development decision by one year. If the developer
chooses to wait, the cost of the land will remain the same and the expected cash flows will also
remain the same. The risk-free rate is 5%.
a) Determine the net present value (NPV) of developing residential units immediately.
b) Determine the net present value (NPV) of developing commercial units immediately.
c) Calculate the value of the option to delay the development decision by one year.
Solution 12.
a) To find the NPV of developing residential units immediately, we need to discount the expected
cash flows back to present value. The NPV can be calculated using the formula:
NP V =
3
X
t=1
CFt
(1 + r)t−Initial Cost
Where CFtis the cash flow in year t,ris the risk-free rate, and the initial cost is $500,000.
Plugging in the values for residential units:
NP V =300,000
(1 + 0.05)1+200,000
(1 + 0.05)2+100,000
(1 + 0.05)3−500,000
NP V = 285,714.29 + 181,405.90 + 83,305.95 −500,000
NP V = $50,426.14
Therefore, the NPV of developing residential units immediately is $50,426.14.
b) Similarly, the NPV of developing commercial units immediately can be calculated as:
NP V =400,000
(1 + 0.05)1+250,000
(1 + 0.05)2+150,000
(1 + 0.05)3−500,000
NP V = 380,952.38 + 235,449.74 + 131,724.89 −500,000
NP V = $248,127.01
Therefore, the NPV of developing commercial units immediately is $248,127.01.
c) To calculate the value of the option to delay, we need to find the NPV of waiting for one year
and compare it to the NPV of immediate development.
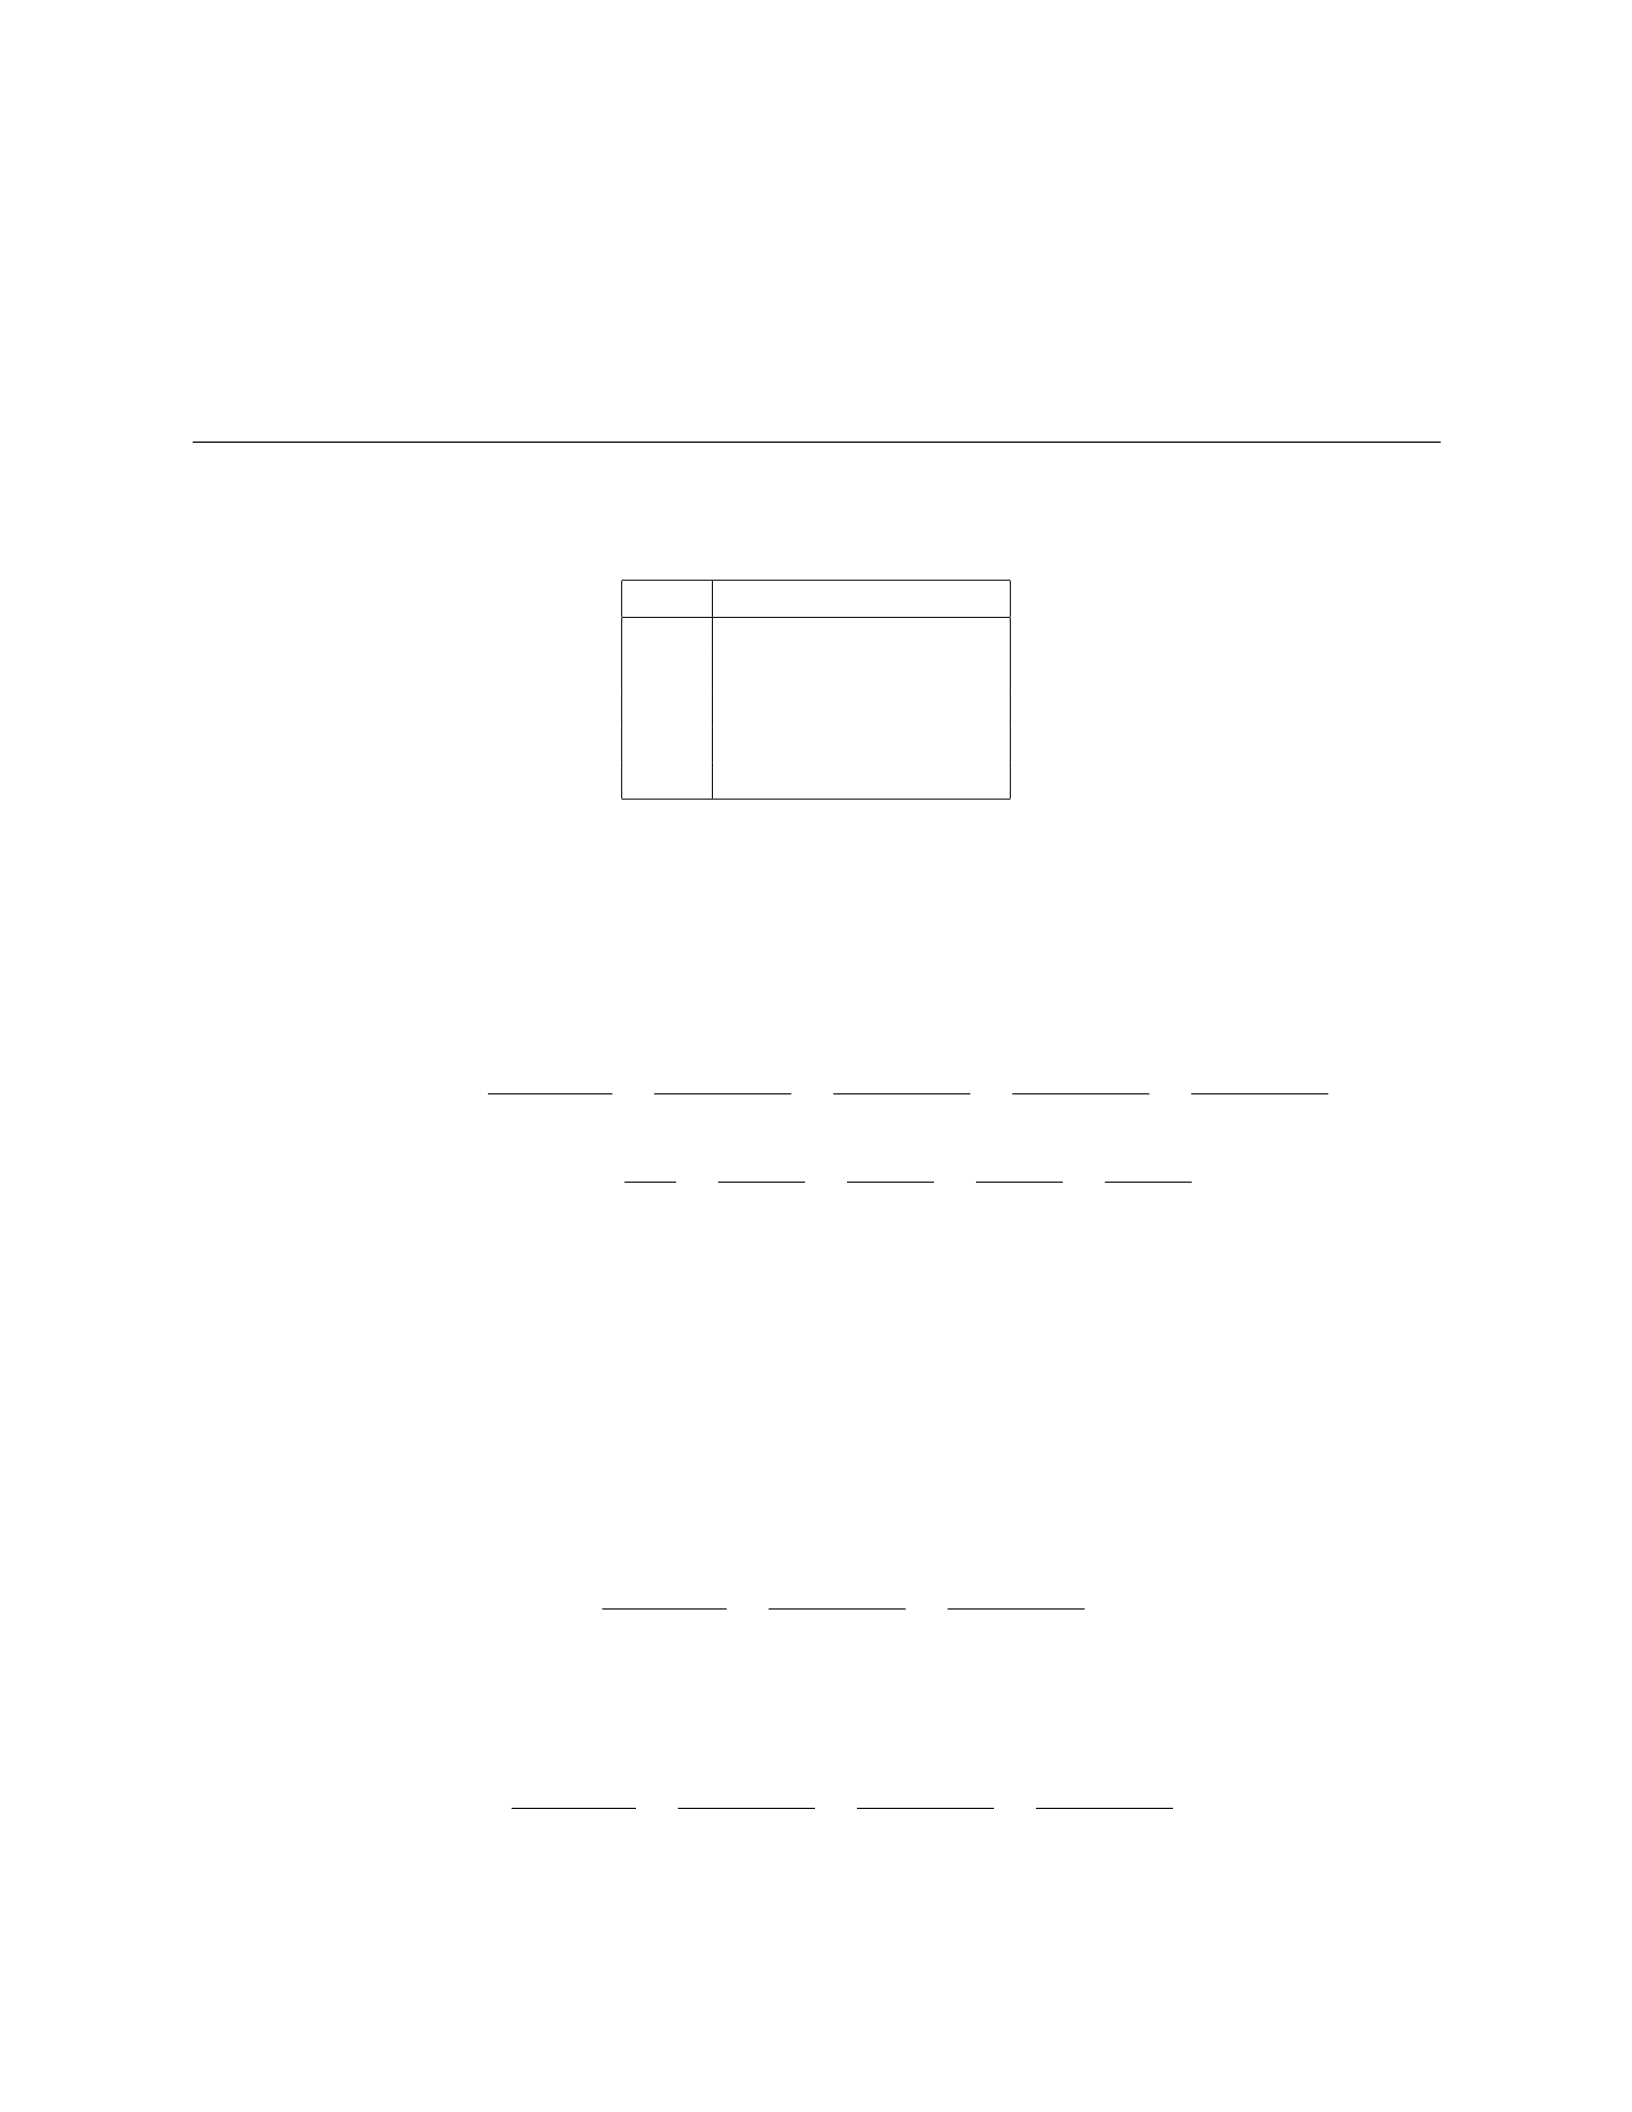
The NPV of waiting for one year is the same as the NPV of immediate development because
the land cost and cash flows remain the same.
Therefore, the value of the option to delay the development decision by one year is $0.
13 13. REAL OPTIONS IN PHARMACEUTICAL INVESTMENTS
Problem 13. A pharmaceutical company is considering investing in the development of a new
drug. The initial investment is $5 million, and the expected cash flows from the drug over the next
5 years are as follows (in millions of dollars):
Year Expected Cash Flow
1 2
2 3
3 4
4 4
5 5
The company has the option to abandon the project at the end of year 2. The risk-free rate is
5% and the company’s cost of capital is 10%.
a) Calculate the Net Present Value (NPV) of the project without the option to abandon.
b) Calculate the NPV of the project with the option to abandon after year 2.
Solution 13.
a) The NPV of the project without the option to abandon can be calculated using the formula:
NP V =−5 + 2
(1 + 0.05) +3
(1 + 0.05)2+4
(1 + 0.05)3+4
(1 + 0.05)4+5
(1 + 0.05)5
NP V =−5 + 2
1.05 +3
(1.05)2+4
(1.05)3+4
(1.05)4+5
(1.05)5
Calculating this gives:
NP V =−5+1.9048 + 2.7232 + 3.7891 + 3.4185 + 3.2164 = 9.0519 million
Therefore, the NPV of the project without the option to abandon is $9.05 million.
b) The NPV of the project with the option to abandon after year 2 can be calculated by comparing
the NPV of continuing the project with the NPV of abandoning it after year 2.
At the end of year 2, the expected cash flows from the project are $4 million and $5 million in
years 3 and 4 respectively.
To calculate the NPV of the project if abandoned after year 2:
NP Vabandon =−5 + 2
(1 + 0.05) +3
(1 + 0.05)2+4
(1 + 0.05)3= 7.7232 million
If the project is continued after year 2, the cash flows in years 3 and 4 would be $4 million and
$4 million respectively. Calculating the NPV in this case:
NP Vcontinue =−5 + 2
(1 + 0.05) +3
(1 + 0.05)2+4
(1 + 0.05)3+4
(1 + 0.05)4= 8.7891 million
Comparing the two options, the NPV of continuing the project after year 2 is higher, so the
company should continue with the project.
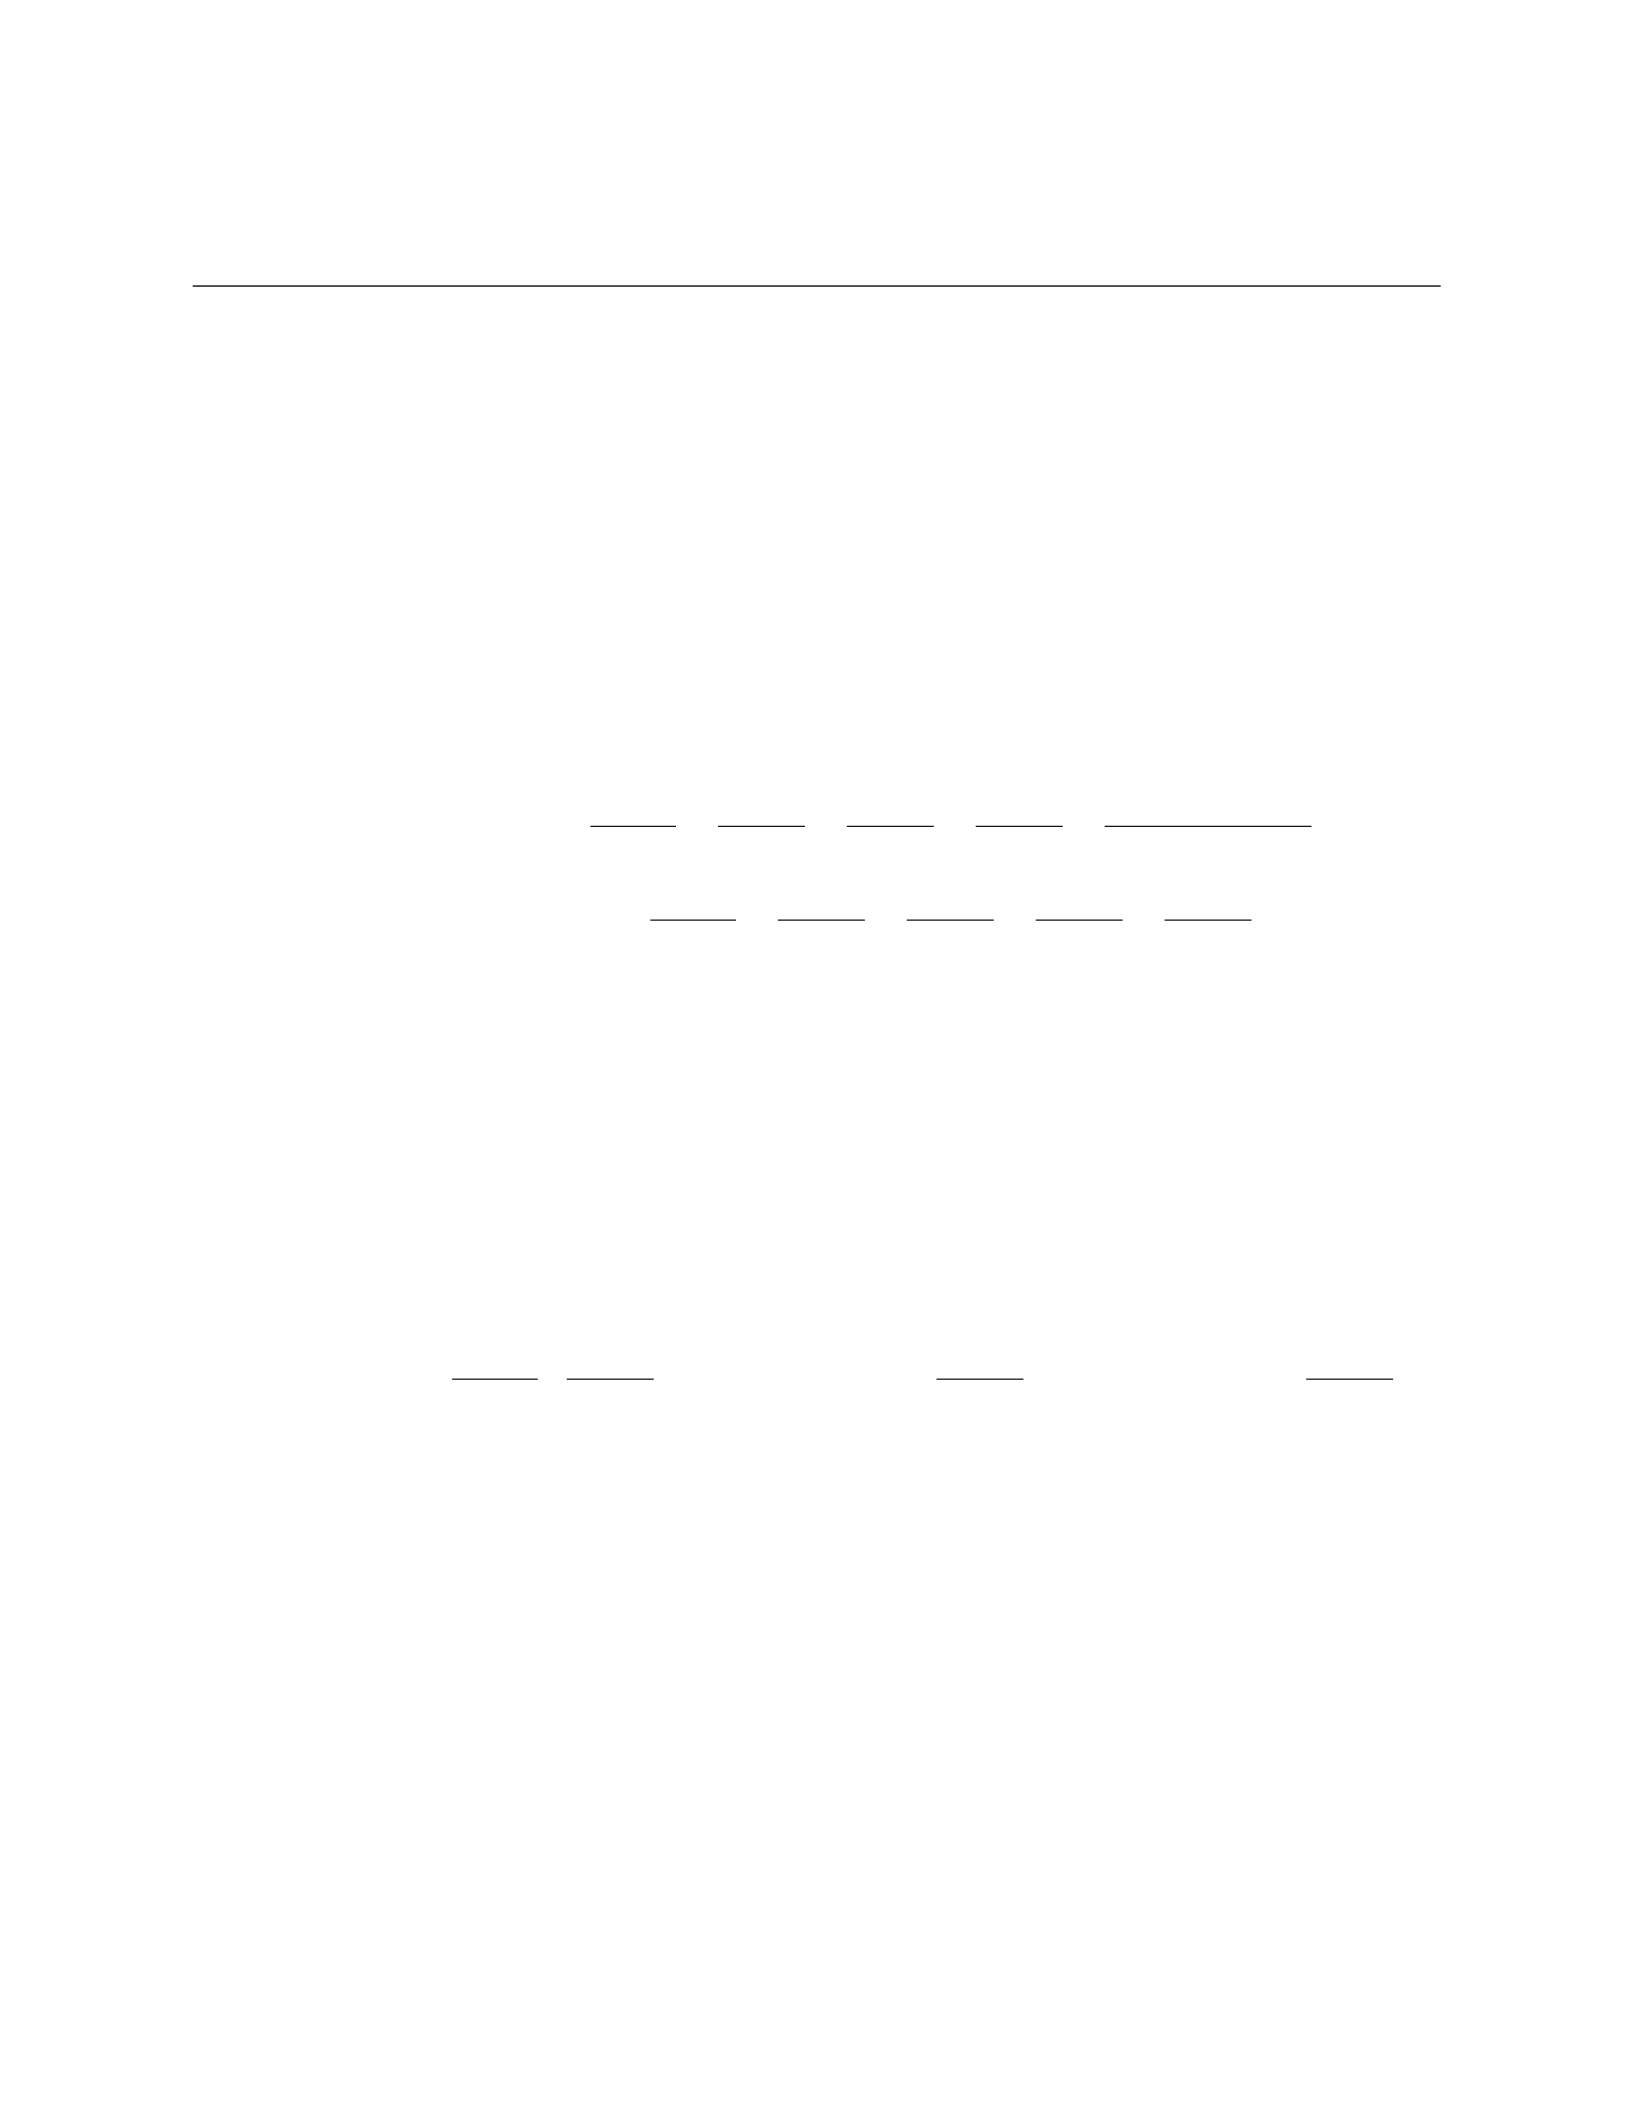
14 14. REAL OPTIONS IN RENEWABLE ENERGY PROJECTS
Problem 14. You are evaluating an investment in a renewable energy project with the following
parameters:
- Initial investment cost: 200,000 −Expectedannualcashflowsforthenext5years :50,000 - Dis-
count rate: 10- Estimated salvage value at the end of year 5: 20,000
The project also has a real option to expand its capacity in year 3 by investing an additional
100,000.T heexpandedprojectisexpectedtogenerateadditionalannualcashf lowsof30,000 for the re-
maining 3 years.
a) Calculate the NPV of the initial investment without considering the expansion option.
b) Determine the NPV of the expanded project considering the expansion option.
Solution 14.
a) To calculate the NPV of the initial investment without considering the expansion option, we
need to discount the expected cash flows over the next 5 years and subtract the initial investment
cost:
NP V =−200,000 + 50,000
1.10 +50,000
(1.10)2+50,000
(1.10)3+50,000
(1.10)4+50,000 + 20,000
(1.10)5
NP V =−200,000 + 50,000
1.10 +50,000
(1.10)2+50,000
(1.10)3+50,000
(1.10)4+70,000
(1.10)5
Calculating the NPV, we get:
NP V =−200,000 + 45,454.55 + 41,322.31 + 37,565.74 + 34,150.67 + 40,772.27
NP V = $ −4383.46
Therefore, the NPV of the initial investment without considering the expansion option is −4383.46.
b) To determine the NPV of the expanded project, we need to consider the additional cash flows
from year 3 onwards as well as the expansion cost. The expanded project’s cash flows will be:
NP V =−200,000+50,000
1.10 +50,000
(1.10)2+(30,000−100,000)×1
(1.10)2+(30,000−100,000)×1
(1.10)3+(30,000−100,000)×1
(1.10)4+50,000 + 20,000
(1.10)5
NP V =−200,000 + 45,454.55 + 41,322.31 + 21,818.18 + 18,926.53 + 16,296.85 + 40,772.27
NP V = $15,409.48
Therefore, the NPV of the expanded project considering the expansion option is −15,409.48.
I. Real Options and Investment Analysis
Problem 1. A company is considering investing in a new project with an initial cost of $1,000,000.
The project is expected to generate cash flows of $400,000 in the first year, $500,000 in the second
year, and $600,000 in the third year. The company has the option to abandon the project after the
first year. The risk-free rate is 5%. Should the company invest in this project?
Solution 1. Given: Initial investment (C): $1,000,000 Cash flows: year 1 = $400,000, year 2 =
$500,000, year 3 = $600,000 Risk-free rate (r): 5
The Net Present Value (NPV) of the project can be calculated as follows: NPV = -C + PCFt
(1+r)t
NPV = -$1,000,000 + $400,000/(1+0.05)1+ $500,000/(1 + 0.05)2+ $600,000/(1 + 0.05)3
NPV = -$1,000,000 + $380,952 + $454,851 + $497,618.85 NPV = $333,421.85
The NPV of the project is positive, which indicates that the project is expected to generate a
return greater than the required rate of return. Therefore, the company should invest in this project.
Problem 2. A company is evaluating an investment in a project that requires an initial outlay
of $800,000. The cash flows from the project are expected to be $300,000 in year 1, $400,000 in
year 2, and $500,000 in year 3. The company has the option to expand the project at the end of
year 1 at an additional cost of $200,000. If the expansion is undertaken, the expected cash flows
in year 4 would be $600,000. Should the company invest in the project and expand in year 1 if the
opportunity arises? Assume a discount rate of 8
Solution 2. Given: Initial investment (C): $800,000 Cash flows: year 1 = $300,000, year 2 =
$400,000, year 3 = $500,000, year 4 (if expanded) = $600,000 Expansion cost: $200,000 Discount
rate (r): 8
Calculate the NPV if the project is undertaken without expansion: NPV = -$800,000 + $300,000/(1+0.08)1+
$400,000/(1 + 0.08)2+ $500,000/(1 + 0.08)3NP V =−$800,000 + $277,777.78 + $308,641.98 +
$340,136.66NP V = $126,556.42
Calculate the NPV if the project is expanded in year 1: NPV = -$800,000 + $300,000/(1+0.08)1+
$400,000/(1+0.08)2+$500,000/(1+0.08)3+$600,000/(1+0.08)4−$200,000NP V =−$800,000+
$277,777.78 + $308,641.98 + $340,136.66 + $387,096.77 −$200,000NP V = $513,652.21
Comparing the two NPVs, it is more beneficial for the company to invest in the project and
expand in year 1 if the opportunity arises, as it yields a higher NPV.
15 Real Options and Investment Analysis
Problem:
A company is considering acquiring a competitor in the same industry. The current market
value of the competitor is $50 million. The company believes that if it acquires the competitor, it
can implement a growth strategy that has a 60% chance of increasing the value of the acquired
firm to $80 million and a 40% chance of decreasing the value to $30 million. If the growth strategy
is successful, the company can generate additional cash flows of $20 million per year for the next
5 years. The risk-free rate is 4%.
a) Calculate the value of the real option to acquire the competitor.
b) Determine the optimal timing to exercise the real option if the company can only exercise it
once.
Solution:
a) Let’s first calculate the expected value of the acquired firm:
E[V]=0.6×$80 million + 0.4×$30 million
= $48 million + $12 million
= $60 million
The present value of the expected cash flows from the growth strategy can be calculated as:
P V (Cash Flows) = $20 million
1+0.04 +$20 million
(1 + 0.04)2+$20 million
(1 + 0.04)3+$20 million
(1 + 0.04)4+$20 million
(1 + 0.04)5
= $18.68 million + $17.98 million + $17.30 million + $16.65 million + $16.03 million
= $86.64 million
The value of the real option is the difference between the expected value of the acquired firm
and the present value of the cash flows:
Real Option Value = $60 million −$86.64 million
=−$26.64 million
Therefore, the value of the real option to acquire the competitor is -$26.64 million.
b) To determine the optimal timing to exercise the real option, we need to compare the value of
waiting to the option to the value of immediate exercise. The value of waiting is the expected value
of the acquired firm minus the exercise price (market value of the competitor), which is $60 million
- $50 million = $10 million.
The option to acquire has negative value (-$26.64 million) which implies that it should not be
exercised. Therefore, the optimal timing is to never exercise the option to acquire the competitor.
16 17. REAL OPTIONS IN PROJECT FINANCE
Problem 17. A company is considering investing in a new project that has the following char-
acteristics:
- Initial investment cost: $500,000 - Expected cash inflows in the first year: $300,000 - Expected
cash inflows in the second year: $400,000 - Expected cash inflows in the third year: $600,000 -
Discount rate: 10% - Risk-free rate: 5% - Volatility of cash flows: 20% - Time to maturity for the real
option: 3 years - Exercise price for the real option: $100,000
The company can abandon the project after the first year of operation if the cash flows are not
as expected.
a) Calculate the Net Present Value (NPV) of the project without considering the real option.
b) Determine the value of the real option embedded in the project.
c) Should the company invest in the project based on the real option analysis?
Solution 17.
a) The Net Present Value (NPV) of the project without considering the real option can be cal-
culated using the formula:
NP V =CF1
(1 + r)1+CF2
(1 + r)2+CF3
(1 + r)3−Initial Investment
where ris the discount rate, CFiis the cash flow in year i, and the Initial Investment is the initial
cost of the project.
Substitute the given values into the formula:
NP V =300,000
(1 + 0.10)1+400,000
(1 + 0.10)2+600,000
(1 + 0.10)3−500,000
NP V =300,000
1.10 +400,000
1.102+600,000
1.103−500,000
NP V = 272,727.27 + 330,578.51 + 401,324.62 −500,000
NP V = 504,630.40
Therefore, the NPV of the project without considering the real option is $504,630.40.
b) The value of the real option can be calculated using the Black-Scholes Option Pricing Model.
d1=ln(S/E)+(r+σ2/2)t
σ√t
d2=d1−σ√t
Option V alue =SΦ(d1)−Ee−rtΦ(d2)
where: - S= current stock price (value of project) - E= exercise price - r= risk-free rate - t=
time to maturity - σ= volatility
Substitute the given values into the formula:
d1=ln(300,000/100,000) + (0.05 + 0.202/2)3
0.20√3= 1.85
d2= 1.85 −0.20√3=1.35
Option V alue = 300,000Φ(1.85) −100,000e−0.05∗3Φ(1.35) = 148,385.16
Therefore, the value of the real option embedded in the project is $148,385.16.
c) The total value of the project considering the real option is:
T otal V alue =NP V +Option V alue = 504,630.40 + 148,385.16 = 653,015.56
As the total value of the project exceeds the initial investment cost and considering the real
option, the company should invest in the project based on the real option analysis.
17 18. REAL OPTIONS IN R&D INVESTMENTS
Problem 18. A company is considering investing in a research and development (R&D) project.
The initial investment required is $500,000. The project is expected to generate cash flows of
$200,000 in the first year, $300,000 in the second year, and $400,000 in the third year. The risk-
free rate is 5% and the company’s cost of capital is 10%.
a) Calculate the Net Present Value (NPV) of the project without considering the real options.
b) Determine the value of the Real Option to Abandon.
c) Calculate the Real Options Value of Waiting to Invest if the company can decide at the end
of each year whether to continue the project or not.
Solution 18.
a) The NPV of the project without considering the real options can be calculated by discounting
the cash flows at the cost of capital. The formula for NPV is:
NP V =
n
X
t=1
CFt
(1 + r)t−Initial Investment
Where: - CFt= Cash flow in year t-r= Company’s cost of capital - Initial Investment =
$500,000
Plugging in the values:
NP V =200,000
1.10 +300,000
1.102+400,000
1.103−500,000
NP V = 181,818.18 + 247,933.88 + 300,043.71 −500,000
NP V = 229,795.77
Therefore, the NPV of the project without considering the real options is $229,795.77.
b) The Real Option to Abandon allows the company to abandon the project at the end of the
second year if it is no longer profitable. The value of this option can be calculated using the Binomial
option pricing model or decision tree analysis.
c) The Real Options Value of Waiting to Invest allows the company to assess whether to invest
at the end of each year based on the project’s performance. The decision to wait can be valued
using the Black-Scholes model or other numerical methods.
18 19. REAL OPTIONS IN INTERNATIONAL INVESTMENTS
Problem 19. A multinational corporation is considering investing in a project in a foreign coun-
try. The project has an initial investment cost of $5 million and is expected to generate cash flows of
$3 million per year for the next 5 years. The corporation has the option to expand the project after
2 years at an additional cost of $2 million. The risk-free rate is 5% and the corporation’s required
rate of return is 10%.
a) Calculate the Net Present Value (NPV) of the project without considering the option to ex-
pand.
b) Determine the value of the option to expand the project after 2 years.
c) Should the corporation proceed with the initial investment in the project?
Solution 19.
a) To calculate the NPV of the project without considering the option to expand, we use the
formula:
NP V =−C0+CF1
(1 + r)1+CF2
(1 + r)2+... +CFn
(1 + r)n
Where: C0= $5,000,000 CFt= $3,000,000 for t= 1,2,3,4,5r= 10%
Plugging in the values, we get:
NP V =−5,000,000 + 3,000,000
1.1+3,000,000
1.12+3,000,000
1.13+3,000,000
1.14+3,000,000
1.15
NP V =−5,000,000 + 2,727,273 + 2,479,338 + 2,254,853 + 2,049,866 + 1,861,696
NP V = $2,373,050
The NPV of the project without considering the option to expand is $2,373,050.
b) The value of the option to expand the project after 2 years can be calculated using the Black-
Scholes model. The formula for the value of the option is:
V=S0N(d1)−Xe−rtN(d2)
Where: S0= $3,000,000 (Value of the expanded project) X= $2,000,000 (Cost of expansion)
r= 5% (Risk-free rate) t= 2 years
Calculating d1and d2using the Black-Scholes formula, we find d1= 0.4407 and d2= 0.1841.
Plugging in these values, we get:
V= 3,000,000N(0.4407) −2,000,000e−0.05∗2N(0.1841)
V= 3,000,000 ×0.6703 −2,000,000 ×e−0.1×0.5749
V= 2,010,894 −1,273,239
V= $737,655
The value of the option to expand the project after 2 years is $737,655.
c) As the NPV of the project without considering the option to expand is positive ($2,373,050)
and the value of the option to expand is also positive ($737,655), the corporation should proceed
with the initial investment in the project.
19 20. REAL OPTIONS IN NEW PRODUCT DEVELOPMENT
Problem 20. A company is considering developing a new product. The initial investment re-
quired is $500,000. The expected cash flows from the product over the next 3 years are estimated
as follows: Year 1: $200,000, Year 2: $300,000, Year 3: $400,000. The company has the option
to abandon the project at the end of each year with the following abandonment values: Year 1:
$50,000, Year 2: $100,000, Year 3: $200,000. The risk-free rate is 5%.
a) Calculate the net present value (NPV) of the project without considering any abandonment
options.
b) Determine the net present value (NPV) of the project if the company has the flexibility to
abandon the project at the end of each year.
c) Discuss whether incorporating the abandonment options increases the value of the project.
Solution 20.
a) To calculate the NPV of the project without considering any abandonment options, we need
to discount the cash flows at the risk-free rate of 5%.
Using the formula for NPV:
NP V =CF0
(1 + r)0+CF1
(1 + r)1+CF2
(1 + r)2+CF3
(1 + r)3−Initial Investment
where r= 0.05 and the cash flows are 200,000,300,000, and 400,000f oryears1,2, and3respectively.
NP V =−500,000
(1 + 0.05)0+200,000
(1 + 0.05)1+300,000
(1 + 0.05)2+400,000
(1 + 0.05)3
NP V =−500,000 + 190,476.2 + 272,108.8 + 342,317.5 = 304,902.5
Therefore, the NPV of the project without considering any abandonment options is $304,902.5.
b) To calculate the NPV of the project with abandonment options, we need to consider the option
to abandon at the end of each year by comparing the continuation value with the abandonment
value.
In Year 1, the continuation value is $190,476.2 (the present value of cash flows from Year 2
and Year 3). If the abandonment value ($50,000) is greater, then the project would be abandoned,
resulting in an NPV of -$50,000. In this case, the NPV of Year 1 is -$50,000.
In Year 2, the continuation value is $272,108.8 (the present value of cash flow from Year 3). If
the abandonment value ($100,000) is greater, then the project would be abandoned, resulting in
an NPV of -$100,000. In this case, the NPV of Year 2 is -$100,000.
In Year 3, the project will not be abandoned as the cash flow of $400,000 is greater than the
abandonment value of $200,000. Therefore, the NPV of Year 3 is $357,142.9 (the present value
of the cash flow in Year 3).
The total NPV of the project with abandonment options is the sum of the NPVs of each year:
NP V =−50,000 −100,000 + 357,142.9 = 207,142.9
Therefore, the NPV of the project with abandonment options is $207,142.9.
c) Incorporating abandonment options increases the value of the project, as the NPV with aban-
donment options ($207,142.9) is higher than the NPV without considering any abandonment op-
tions ($304,902.5). Abandonment options provide flexibility in decision-making and can increase
the overall value of a project.
Solution 2.
a) The value of the real option to abandon the project can be calculated using the binomial
option pricing model. The option to abandon is equivalent to a put option. Using the risk-neutral
valuation approach, the value of the option can be found by working backwards from the final year.
Let’s denote: - S0= $50 (price of oil at time t= 0) - X= $200,000 (cash flow if oil prices remain
low) - R= 1.04 (risk-free rate) - T= 3 years (time to expiration)
The value of the option to abandon is:
V3=1
1.04 0.5×Vu
4+Vd
4
1.04 + 0.5×X
where Vu
4= 0 since if the price of oil increases, the company will not abandon the project.
Therefore:
V3=1
1.04 0.5×0 + Vd
4
1.04 + 0.5×200,000
Given that Vd
4= 0, we can calculate:
V3=1
1.04 0.5×0
1.04+ 0.5×200,000=1
1.04 ×0.5×192,307.69 = $92,746.91
Therefore, the value of the real option to abandon the project is $92,746.91.
b) The NPV of the project without the real option is calculated as the present value of the
expected cash flows minus the initial investment:
NP V =200,000
1.04 +250,000
(1.04)2+300,000
(1.04)3−1,000,000 = 535,725.89
c) The NPV of the project with the real option included is the sum of the NPV without the option
and the value of the option:
NP V = 535,725.89 + 92,746.91 = 628,472.80
3 3. TIMING OF INVESTMENTS
Problem 3. A company is considering investing in a new project. The initial investment cost
is $500,000. The project is expected to generate cash flows of $200,000 per year for the next 5
years. The company’s cost of capital is 10%. If the company decides to delay the investment by
one year, the initial investment cost will decrease to $450,000, but the annual cash flows will also
decrease to $180,000 per year for the next 5 years. Should the company invest now or delay the
investment for one year?
Solution 3. Let’s first calculate the net present value (NPV) of the project if the company invests
now and if it delays the investment by one year.
a) NPV of investing now: The NPV of investing now can be calculated as follows:
NP Vnow =−500,000 + 200,000
1.10 +200,000
(1.10)2+200,000
(1.10)3+200,000
(1.10)4+200,000
(1.10)5
NP Vnow =−500,000 + 200,000
1.10 +200,000
(1.10)2+200,000
(1.10)3+200,000
(1.10)4+200,000
(1.10)5
NP Vnow =−500,000 + 181,818.18 + 165,289.26 + 150,263.87 + 136,603.52 + 124,184.11
NP Vnow = $157,158.94
b) NPV of delaying the investment by one year: The NPV of delaying the investment by one
year can be calculated as follows:
NP Vdelayed =−450,000 + 180,000
1.10 +180,000
(1.10)2+180,000
(1.10)3+180,000
(1.10)4+180,000
(1.10)5
NP Vdelayed =−450,000 + 163,636.36 + 148,760.33 + 135,236.66 + 122,942.42 + 111,766.74
NP Vdelayed = $131,342.11
c) Conclusion: Comparing the two options, investing now yields an NPV of $157,158.94, while
delaying the investment by one year yields an NPV of $131,342.11. Therefore, the company should
invest in the project now as it provides a higher NPV.
4 4. FLEXIBILITY IN PROJECT DEVELOPMENT
Problem 4. A company is considering investing in a new project that has the following cash
flows for the next 3 years:
•Year 1: −1,000 (investment cost)
•Year 2: 500
•Year 3: 800
The company has the option to abandon the project after year 1 with a salvage value of 300.
The risk-free rate is 5%.
a) Calculate the net present value (NPV) of the project without the abandonment option.
b) Calculate the NPV of the project with the abandonment option.
c) Determine whether the company should exercise the abandonment option or not.
Solution 4.
a) The NPV of the project without the abandonment option is calculated by discounting the cash
flows at the risk-free rate:
NP V =−1,000 + 500
1.05 +800
1.052=−1,000 + 476.19 + 756.14 = 232.33
Therefore, the NPV of the project without the abandonment option is 232.33.
b) To calculate the NPV of the project with the abandonment option, we need to consider the
salvage value if the project is abandoned after year 1. The NPV with the abandonment option is:
NP V =−1,000 + 300 + 500
1.05 +800
1.052=−1,000 + 300 + 476.19 + 756.14 = 532.33
So, the NPV of the project with the abandonment option is 532.33.
c) Comparing the NPVs, we see that the NPV with the abandonment option is greater than the
NPV without the abandonment option. Therefore, the company should exercise the abandonment
option if the project’s cash flows are as predicted.
5 5. UNCERTAINTY IN PROJECT OUTCOMES
Problem 5. A company is considering investing in a new project that has two possible out-
comes: success or failure. The probabilities of success and failure are estimated to be 0.6 and
0.4, respectively. If the project is successful, the company expects to earn $500,000, but if it fails,
they will lose $200,000. The initial investment required for the project is $100,000. Calculate the
expected net present value (NPV) of the project.
Solution 5. The expected NPV of the project is calculated as the sum of the expected cash
flows discounted to the present value at the appropriate rate.
a) Expected Cash Flows: The expected cash flow from a successful project is $500,000 and
from a failed project is -$200,000.
Expected cash flow = (Probability of success * Cash flow from success) + (Probability of failure
* Cash flow from failure) Expected cash flow = (0.6 * $500,000) + (0.4 * -$200,000) Expected cash
flow = $300,000 - $80,000 Expected cash flow = $220,000
b) NPV Calculation: NPV = Expected cash flow / (1 + r)twhere, r =discountrate, t =timeperiod, inthiscase, t =
0
Given that the initial investment is $100,000 and the expected cash flow is $220,000, the NPV
can be calculated as:
NPV = (Expected cash flow - Initial investment) / (1 + r)tNP V = ($220,000 −$100,000)/(1 +
r)0NP V = $120,000
Therefore, the expected net present value (NPV) of the project is $120,000.
6 6. INVESTMENT DECISION UNDER COMPETITION
Problem 6. A company is considering expanding its production capacity to meet the increasing
demand for its product. There are two options available: Option A involves investing $400,000 to
increase capacity by 10,000 units annually for the next 5 years. Option B requires an investment
of $600,000 for a capacity increase of 15,000 units annually for the next 5 years.
The company’s estimated revenue per unit is $50, and the variable cost per unit is $20. The
discount rate is 10%. The company operates in a competitive market where the demand is uncer-
tain. Based on the current information, the company forecasts the demand for the next 5 years to
have the following probabilities:
Demand Level Probability
Low 0.2
Medium 0.5
High 0.3
a) Calculate the NPV for each option.
b) Determine the value of the real options present in this investment decision.
Solution 6.
a) The Net Present Value (NPV) for each option is calculated as follows: Let’s denote: - R= $50
(revenue per unit) - C= $20 (variable cost per unit) - IA= $400,000 (investment for Option A) -
IB= $600,000 (investment for Option B) - d= 10% (discount rate)
For Option A:
NP VA=
5
X
t=1
[(R−C)×Demandt×10,000] −IA
NP VA= [(50 −20) ×10,000 ×0.2 + (50 −20) ×10,000 ×0.5 + (50 −20) ×10,000 ×0.3]−400,000
NP VA= (30 ×10,000 ×0.2 + 30 ×10,000 ×0.5 + 30 ×10,000 ×0.3) −400,000
NP VA= (60,000 + 150,000 + 90,000) −400,000 = 300,000 −400,000 = −100,000
For Option B:
NP VB=
5
X
t=1
[(R−C)×Demandt×15,000] −IB
NP VB= [(50 −20) ×15,000 ×0.2 + (50 −20) ×15,000 ×0.5 + (50 −20) ×15,000 ×0.3]−600,000
NP VB= (30 ×15,000 ×0.2 + 30 ×15,000 ×0.5 + 30 ×15,000 ×0.3) −600,000
NP VB= (90,000 + 225,000 + 135,000) −600,000 = 450,000 −600,000 = −150,000
Therefore, the NPV for Option A is -$100,000 and for Option B is -$150,000.
b) To determine the value of the real options present in this investment decision, we would
need to consider the flexibility in the decision-making over the 5-year period based on the market
conditions. Real options analysis would allow the company to make optimal decisions in response
to the changing market conditions, such as the ability to expand further, contract, or delay expan-
sion. The value of the real options in this case would be the additional value generated by having
flexibility in decision-making compared to a static investment analysis.
It is important to note that the value of real options can be complex to quantify and may require
more detailed analysis based on specific scenarios and assumptions.
7 7. OPTIMAL INVESTMENT STRATEGIES
Problem 7. ABC Corporation is considering investing in a new project that will require an initial
investment of $500,000. The project is expected to generate cash flows of $150,000 in the first
year, $200,000 in the second year, and $300,000 in the third year. The risk-free rate is 4%. The
firm’s cost of capital is 12% and the project’s beta is 1.5. The current stock price is $50. Calculate
the Net Present Value (NPV) and the Real Options Value (ROV) of the project.
Solution 7. a) Calculate the Net Present Value (NPV):
The NPV calculation involves discounting the cash flows of the project at the firm’s cost of
capital. The formula for NPV is:
NP V =
3
X
t=1
CFt
(1 + r)t−Initial Investment
Where:
CFt:Cash flow in year t
r:Cost of capital
Substitute the given values into the formula:
NP V =150,000
(1 + 0.12)1+200,000
(1 + 0.12)2+300,000
(1 + 0.12)3−500,000
= 150,000/1.12 + 200,000/1.2544 + 300,000/1.4049 −500,000
= 133,928.57 + 159,544.29 + 213,143.16 −500,000
= $6,616.02
Therefore, the Net Present Value (NPV) of the project is $6,616.02.
b) Calculate the Real Options Value (ROV):
The Real Options Value (ROV) incorporates the value of managerial flexibility in decision mak-
ing. The formula for ROV is:
ROV =NP V + (Stock P rice ×β×NP V )
Where:
Stock P rice :Current stock price
β:Beta of the project
NP V :Net Present Value
Substitute the given values into the formula:
ROV = 6,616.02 + (50 ×1.5×6,616.02)
= 6,616.02 + 4,974.015
= $11,590.03
Therefore, the Real Options Value (ROV) of the project is $11,590.03.
8 8. REAL OPTIONS AND RISK MANAGEMENT
Problem 8. A company is considering investing in a project that has an initial cost of $1,000,000.
The project is expected to generate $400,000 in revenue in the first year, with a 30
a) Calculate the expected present value (EPV) of the project.
b) Determine the real option value (ROV) of the project.
Solution 8.
a) The EPV of the project can be calculated using the expected cash flow and discounting it
back to present value.
For the successful scenario (30
P V =400,000
1+0.03 =400,000
1.03 ≈$388,349.51
For the unsuccessful scenario (70The present value is zero as there is no revenue.
P V = 0
Therefore, the EPV of the project is:
EP V = 0.3×$388,349.51 + 0.7×$0 = $116,504.85
b) To determine the real option value (ROV) of the project, we need to calculate the value of the
option to continue the project given that it is successful.
The cash flow for each year in the successful scenario is given by:
CFt= 400,000 ×(1.05)t
The present value of the cash flows can be calculated using the risk-free rate of 3
P Vt=400,000 ×(1.05)t
(1 + 0.03)t=400,000 ×(1.05)t
1.03t
For simplicity, let’s consider a perpetuity formula to find the present value of expected cash
flows after year 1:
P V∞=400,000 ×(1.05)
0.03 −0.05 =400,000 ×1.05
−0.02 ≈ −$21,000,000.00
Therefore, the ROV of the project is positive (since the project should be continued) and is
approximately $21,000,000.00.
9 9. REAL OPTIONS IN TECHNOLOGY INVESTMENTS
Problem 9. A technology company is considering investing in a new project that will cost
$500,000 upfront. The project is expected to generate cash flows of $200,000 in one year with a
60% chance, and $100,000 with a 40% chance. The risk-free rate is 5%, and the company uses a
discount rate of 10% for risky projects. The company has the option to abandon the project in one
year if the cash flows are not satisfactory.
a) Calculate the present value of the project without the option to abandon it.
b) Calculate the project’s value if the company has the option to abandon it in one year.
c) Determine the value of the abandonment option.
Solution 9.
a) The present value of the project without the option to abandon it can be calculated by dis-
counting the expected cash flows at the discount rate of 10%:
P V =200,000 ×0.6
1.10 +100,000 ×0.4
1.10 = $145,454.55 + $36,363.64 = $181,818.19
Therefore, the present value of the project without the option to abandon it is $181,818.19.
b) To calculate the project’s value with the option to abandon it, we need to consider the option
to abandon the project in one year if the cash flows are not satisfactory. We use the risk-neutral
probabilities to estimate the expected cash flow and discount it back at the risk-free rate:
E(CF ) = 200,000 ×0.6 + 100,000 ×0.4 = $160,000
P V =160,000
1.05 = $152,380.95
Therefore, the project’s value with the option to abandon it in one year is $152,380.95.
c) The value of the abandonment option is the difference between the present value of the
project without the option to abandon it and the project’s value with the option to abandon it:
Abandonment Option = $181,818.19 −$152,380.95 = $29,437.24
Therefore, the value of the abandonment option is $29,437.24.
10 10. REAL OPTIONS IN NATURAL RESOURCE EXPLORATION
Problem 10. A mining company is considering opening a new mine in a mineral-rich region.
The company has the option to delay the opening of the mine for two years to allow for more
exploration and better market conditions. The initial investment cost for opening the mine now is
$10 million. If the company delays the opening, it would incur exploration costs of $2 million per
year for the two-year period. The present value factor for each year is 0.909.
a) Calculate the net present value (NPV) of opening the mine now.
b) Calculate the net present value (NPV) of delaying the opening for two years and incorporating
the exploration costs.
c) Discuss whether it is financially advantageous for the company to delay the mine opening
based on the NPV calculations.
Solution 10.
a) The NPV of opening the mine now can be calculated using the formula:
NP V =−InitialInvestment +XN etCashF lowt
(1 + r)t
Given that the initial investment is $10 million, the annual net cash flow from the mine operation
is expected to be $5 million, and the discount rate is 10
NP V =−10 + 5(0.909) + 5(0.909)2
NP V =−10 + 4.545 + 4.132 = −10 + 8.677 = −1.323
Therefore, the NPV of opening the mine now is -$1.323 million.
b) The NPV of delaying the mine opening can be calculated by considering the exploration costs
for two years:
NP V =−InitialInvestment +XExplorationCostst
(1 + r)t
The exploration costs for year 1 and year 2 are $2 million each. So, the NPV of delaying the
opening for two years is:
NP V =−2(0.909) −2(0.909)2=−1.818 −1.818 = −3.636
Therefore, the NPV of delaying the mine opening is -$3.636 million.
c) Comparing the NPVs, we see that delaying the mine opening results in a higher negative
NPV (-$3.636 million) compared to opening the mine now (-$1.323 million). Therefore, from a
financial perspective, it is not advantageous for the company to delay the mine opening.
11 11. CAPITAL BUDGETING WITH REAL OPTIONS
Problem 11. ABC Corporation is considering an investment in a new project. The initial cost
of the project is $500,000. The project is expected to generate cash flows of $150,000 per year for
the next 5 years. The risk-free rate is 4% and the project’s beta is 1.2. The strike price for the real
option to abandon the project is $400,000. Calculate the Net Present Value (NPV) of the project
with and without the real option to abandon.
Solution 11.
a) First, let’s calculate the NPV of the project without the real option to abandon:
The NPV formula is:
NP V =−C0+
n
X
t=1
CFt
(1 + r)t
Where: - C0= $500,000 (initial cost of project) - CFt= $150,000 for all years 1 to 5 - r= 4%
(risk-free rate)
Substitute these values into the formula:
NP V =−$500,000 + $150,000
1.04 +$150,000
(1.04)2+$150,000
(1.04)3+$150,000
(1.04)4+$150,000
(1.04)5
Calculating the above expression gives:
NP V =−$500,000 + $144,230.77 + $138,888.89 + $133,951.10 + $129,404.77 + $125,229.48
NP V =−$500,000 + $671,705.01
NP V = $171,705.01
Therefore, the NPV of the project without the real option to abandon is $171,705.01.
b) Now, let’s calculate the NPV of the project with the real option to abandon:
The real option to abandon adds an extra Pto cash flow in year 2. The value of this real option
can be calculated as:
P=Max(0, K −V2)
Where: - K= $400,000 (strike price to abandon) - V2= $500,000 + $150,000
1.04 = $630,769.23 (value
of the project in year 2)
P=Max(0,$400,000 −$630,769.23)
P=Max(0,−$230,769.23) = $0
Therefore, there is no value in exercising the real option to abandon the project in year 2. The
NPV remains $171,705.01.
Thus, the NPV of the project with and without the real option to abandon remains the same at
$171,705.01.
12 12. REAL OPTIONS IN REAL ESTATE INVESTMENTS
Problem 12.
A real estate developer is considering the purchase of a parcel of land for $500,000. The
developer has the option to build either residential units or commercial units on the land. The
expected cash flows associated with each type of development are as follows:
•Residential units: $300,000 in the first year, $200,000 in the second year, and $100,000 in
the third year.
•Commercial units: $400,000 in the first year, $250,000 in the second year, and $150,000 in
the third year.
The developer has the right to delay the development decision by one year. If the developer
chooses to wait, the cost of the land will remain the same and the expected cash flows will also
remain the same. The risk-free rate is 5%.
a) Determine the net present value (NPV) of developing residential units immediately.
b) Determine the net present value (NPV) of developing commercial units immediately.
c) Calculate the value of the option to delay the development decision by one year.
Solution 12.
a) To find the NPV of developing residential units immediately, we need to discount the expected
cash flows back to present value. The NPV can be calculated using the formula:
NP V =
3
X
t=1
CFt
(1 + r)t−Initial Cost
Where CFtis the cash flow in year t,ris the risk-free rate, and the initial cost is $500,000.
Plugging in the values for residential units:
NP V =300,000
(1 + 0.05)1+200,000
(1 + 0.05)2+100,000
(1 + 0.05)3−500,000
NP V = 285,714.29 + 181,405.90 + 83,305.95 −500,000
NP V = $50,426.14
Therefore, the NPV of developing residential units immediately is $50,426.14.
b) Similarly, the NPV of developing commercial units immediately can be calculated as:
NP V =400,000
(1 + 0.05)1+250,000
(1 + 0.05)2+150,000
(1 + 0.05)3−500,000
NP V = 380,952.38 + 235,449.74 + 131,724.89 −500,000
NP V = $248,127.01
Therefore, the NPV of developing commercial units immediately is $248,127.01.
c) To calculate the value of the option to delay, we need to find the NPV of waiting for one year
and compare it to the NPV of immediate development.
The NPV of waiting for one year is the same as the NPV of immediate development because
the land cost and cash flows remain the same.
Therefore, the value of the option to delay the development decision by one year is $0.
13 13. REAL OPTIONS IN PHARMACEUTICAL INVESTMENTS
Problem 13. A pharmaceutical company is considering investing in the development of a new
drug. The initial investment is $5 million, and the expected cash flows from the drug over the next
5 years are as follows (in millions of dollars):
Year Expected Cash Flow
1 2
2 3
3 4
4 4
5 5
The company has the option to abandon the project at the end of year 2. The risk-free rate is
5% and the company’s cost of capital is 10%.
a) Calculate the Net Present Value (NPV) of the project without the option to abandon.
b) Calculate the NPV of the project with the option to abandon after year 2.
Solution 13.
a) The NPV of the project without the option to abandon can be calculated using the formula:
NP V =−5 + 2
(1 + 0.05) +3
(1 + 0.05)2+4
(1 + 0.05)3+4
(1 + 0.05)4+5
(1 + 0.05)5
NP V =−5 + 2
1.05 +3
(1.05)2+4
(1.05)3+4
(1.05)4+5
(1.05)5
Calculating this gives:
NP V =−5+1.9048 + 2.7232 + 3.7891 + 3.4185 + 3.2164 = 9.0519 million
Therefore, the NPV of the project without the option to abandon is $9.05 million.
b) The NPV of the project with the option to abandon after year 2 can be calculated by comparing
the NPV of continuing the project with the NPV of abandoning it after year 2.
At the end of year 2, the expected cash flows from the project are $4 million and $5 million in
years 3 and 4 respectively.
To calculate the NPV of the project if abandoned after year 2:
NP Vabandon =−5 + 2
(1 + 0.05) +3
(1 + 0.05)2+4
(1 + 0.05)3= 7.7232 million
If the project is continued after year 2, the cash flows in years 3 and 4 would be $4 million and
$4 million respectively. Calculating the NPV in this case:
NP Vcontinue =−5 + 2
(1 + 0.05) +3
(1 + 0.05)2+4
(1 + 0.05)3+4
(1 + 0.05)4= 8.7891 million
Comparing the two options, the NPV of continuing the project after year 2 is higher, so the
company should continue with the project.
14 14. REAL OPTIONS IN RENEWABLE ENERGY PROJECTS
Problem 14. You are evaluating an investment in a renewable energy project with the following
parameters:
- Initial investment cost: 200,000 −Expectedannualcashflowsforthenext5years :50,000 - Dis-
count rate: 10- Estimated salvage value at the end of year 5: 20,000
The project also has a real option to expand its capacity in year 3 by investing an additional
100,000.T heexpandedprojectisexpectedtogenerateadditionalannualcashf lowsof30,000 for the re-
maining 3 years.
a) Calculate the NPV of the initial investment without considering the expansion option.
b) Determine the NPV of the expanded project considering the expansion option.
Solution 14.
a) To calculate the NPV of the initial investment without considering the expansion option, we
need to discount the expected cash flows over the next 5 years and subtract the initial investment
cost:
NP V =−200,000 + 50,000
1.10 +50,000
(1.10)2+50,000
(1.10)3+50,000
(1.10)4+50,000 + 20,000
(1.10)5
NP V =−200,000 + 50,000
1.10 +50,000
(1.10)2+50,000
(1.10)3+50,000
(1.10)4+70,000
(1.10)5
Calculating the NPV, we get:
NP V =−200,000 + 45,454.55 + 41,322.31 + 37,565.74 + 34,150.67 + 40,772.27
NP V = $ −4383.46
Therefore, the NPV of the initial investment without considering the expansion option is −4383.46.
b) To determine the NPV of the expanded project, we need to consider the additional cash flows
from year 3 onwards as well as the expansion cost. The expanded project’s cash flows will be:
NP V =−200,000+50,000
1.10 +50,000
(1.10)2+(30,000−100,000)×1
(1.10)2+(30,000−100,000)×1
(1.10)3+(30,000−100,000)×1
(1.10)4+50,000 + 20,000
(1.10)5
NP V =−200,000 + 45,454.55 + 41,322.31 + 21,818.18 + 18,926.53 + 16,296.85 + 40,772.27
NP V = $15,409.48
Therefore, the NPV of the expanded project considering the expansion option is −15,409.48.
I. Real Options and Investment Analysis
Problem 1. A company is considering investing in a new project with an initial cost of $1,000,000.
The project is expected to generate cash flows of $400,000 in the first year, $500,000 in the second
year, and $600,000 in the third year. The company has the option to abandon the project after the
first year. The risk-free rate is 5%. Should the company invest in this project?
Solution 1. Given: Initial investment (C): $1,000,000 Cash flows: year 1 = $400,000, year 2 =
$500,000, year 3 = $600,000 Risk-free rate (r): 5
The Net Present Value (NPV) of the project can be calculated as follows: NPV = -C + PCFt
(1+r)t
NPV = -$1,000,000 + $400,000/(1+0.05)1+ $500,000/(1 + 0.05)2+ $600,000/(1 + 0.05)3
NPV = -$1,000,000 + $380,952 + $454,851 + $497,618.85 NPV = $333,421.85
The NPV of the project is positive, which indicates that the project is expected to generate a
return greater than the required rate of return. Therefore, the company should invest in this project.
Problem 2. A company is evaluating an investment in a project that requires an initial outlay
of $800,000. The cash flows from the project are expected to be $300,000 in year 1, $400,000 in
year 2, and $500,000 in year 3. The company has the option to expand the project at the end of
year 1 at an additional cost of $200,000. If the expansion is undertaken, the expected cash flows
in year 4 would be $600,000. Should the company invest in the project and expand in year 1 if the
opportunity arises? Assume a discount rate of 8
Solution 2. Given: Initial investment (C): $800,000 Cash flows: year 1 = $300,000, year 2 =
$400,000, year 3 = $500,000, year 4 (if expanded) = $600,000 Expansion cost: $200,000 Discount
rate (r): 8
Calculate the NPV if the project is undertaken without expansion: NPV = -$800,000 + $300,000/(1+0.08)1+
$400,000/(1 + 0.08)2+ $500,000/(1 + 0.08)3NP V =−$800,000 + $277,777.78 + $308,641.98 +
$340,136.66NP V = $126,556.42
Calculate the NPV if the project is expanded in year 1: NPV = -$800,000 + $300,000/(1+0.08)1+
$400,000/(1+0.08)2+$500,000/(1+0.08)3+$600,000/(1+0.08)4−$200,000NP V =−$800,000+
$277,777.78 + $308,641.98 + $340,136.66 + $387,096.77 −$200,000NP V = $513,652.21
Comparing the two NPVs, it is more beneficial for the company to invest in the project and
expand in year 1 if the opportunity arises, as it yields a higher NPV.
15 Real Options and Investment Analysis
Problem:
A company is considering acquiring a competitor in the same industry. The current market
value of the competitor is $50 million. The company believes that if it acquires the competitor, it
can implement a growth strategy that has a 60% chance of increasing the value of the acquired
firm to $80 million and a 40% chance of decreasing the value to $30 million. If the growth strategy
is successful, the company can generate additional cash flows of $20 million per year for the next
5 years. The risk-free rate is 4%.
a) Calculate the value of the real option to acquire the competitor.
b) Determine the optimal timing to exercise the real option if the company can only exercise it
once.
Solution:
a) Let’s first calculate the expected value of the acquired firm:
E[V]=0.6×$80 million + 0.4×$30 million
= $48 million + $12 million
= $60 million
The present value of the expected cash flows from the growth strategy can be calculated as:
P V (Cash Flows) = $20 million
1+0.04 +$20 million
(1 + 0.04)2+$20 million
(1 + 0.04)3+$20 million
(1 + 0.04)4+$20 million
(1 + 0.04)5
= $18.68 million + $17.98 million + $17.30 million + $16.65 million + $16.03 million
= $86.64 million
The value of the real option is the difference between the expected value of the acquired firm
and the present value of the cash flows:
Real Option Value = $60 million −$86.64 million
=−$26.64 million
Therefore, the value of the real option to acquire the competitor is -$26.64 million.
b) To determine the optimal timing to exercise the real option, we need to compare the value of
waiting to the option to the value of immediate exercise. The value of waiting is the expected value
of the acquired firm minus the exercise price (market value of the competitor), which is $60 million
- $50 million = $10 million.
The option to acquire has negative value (-$26.64 million) which implies that it should not be
exercised. Therefore, the optimal timing is to never exercise the option to acquire the competitor.
16 17. REAL OPTIONS IN PROJECT FINANCE
Problem 17. A company is considering investing in a new project that has the following char-
acteristics:
- Initial investment cost: $500,000 - Expected cash inflows in the first year: $300,000 - Expected
cash inflows in the second year: $400,000 - Expected cash inflows in the third year: $600,000 -
Discount rate: 10% - Risk-free rate: 5% - Volatility of cash flows: 20% - Time to maturity for the real
option: 3 years - Exercise price for the real option: $100,000
The company can abandon the project after the first year of operation if the cash flows are not
as expected.
a) Calculate the Net Present Value (NPV) of the project without considering the real option.
b) Determine the value of the real option embedded in the project.
c) Should the company invest in the project based on the real option analysis?
Solution 17.
a) The Net Present Value (NPV) of the project without considering the real option can be cal-
culated using the formula:
NP V =CF1
(1 + r)1+CF2
(1 + r)2+CF3
(1 + r)3−Initial Investment
where ris the discount rate, CFiis the cash flow in year i, and the Initial Investment is the initial
cost of the project.
Substitute the given values into the formula:
NP V =300,000
(1 + 0.10)1+400,000
(1 + 0.10)2+600,000
(1 + 0.10)3−500,000
NP V =300,000
1.10 +400,000
1.102+600,000
1.103−500,000
NP V = 272,727.27 + 330,578.51 + 401,324.62 −500,000
NP V = 504,630.40
Therefore, the NPV of the project without considering the real option is $504,630.40.
b) The value of the real option can be calculated using the Black-Scholes Option Pricing Model.
d1=ln(S/E)+(r+σ2/2)t
σ√t
d2=d1−σ√t
Option V alue =SΦ(d1)−Ee−rtΦ(d2)
where: - S= current stock price (value of project) - E= exercise price - r= risk-free rate - t=
time to maturity - σ= volatility
Substitute the given values into the formula:
d1=ln(300,000/100,000) + (0.05 + 0.202/2)3
0.20√3= 1.85
d2= 1.85 −0.20√3=1.35
Option V alue = 300,000Φ(1.85) −100,000e−0.05∗3Φ(1.35) = 148,385.16
Therefore, the value of the real option embedded in the project is $148,385.16.
c) The total value of the project considering the real option is:
T otal V alue =NP V +Option V alue = 504,630.40 + 148,385.16 = 653,015.56
As the total value of the project exceeds the initial investment cost and considering the real
option, the company should invest in the project based on the real option analysis.
17 18. REAL OPTIONS IN R&D INVESTMENTS
Problem 18. A company is considering investing in a research and development (R&D) project.
The initial investment required is $500,000. The project is expected to generate cash flows of
$200,000 in the first year, $300,000 in the second year, and $400,000 in the third year. The risk-
free rate is 5% and the company’s cost of capital is 10%.
a) Calculate the Net Present Value (NPV) of the project without considering the real options.
b) Determine the value of the Real Option to Abandon.
c) Calculate the Real Options Value of Waiting to Invest if the company can decide at the end
of each year whether to continue the project or not.
Solution 18.
a) The NPV of the project without considering the real options can be calculated by discounting
the cash flows at the cost of capital. The formula for NPV is:
NP V =
n
X
t=1
CFt
(1 + r)t−Initial Investment
Where: - CFt= Cash flow in year t-r= Company’s cost of capital - Initial Investment =
$500,000
Plugging in the values:
NP V =200,000
1.10 +300,000
1.102+400,000
1.103−500,000
NP V = 181,818.18 + 247,933.88 + 300,043.71 −500,000
NP V = 229,795.77
Therefore, the NPV of the project without considering the real options is $229,795.77.
b) The Real Option to Abandon allows the company to abandon the project at the end of the
second year if it is no longer profitable. The value of this option can be calculated using the Binomial
option pricing model or decision tree analysis.
c) The Real Options Value of Waiting to Invest allows the company to assess whether to invest
at the end of each year based on the project’s performance. The decision to wait can be valued
using the Black-Scholes model or other numerical methods.
18 19. REAL OPTIONS IN INTERNATIONAL INVESTMENTS
Problem 19. A multinational corporation is considering investing in a project in a foreign coun-
try. The project has an initial investment cost of $5 million and is expected to generate cash flows of
$3 million per year for the next 5 years. The corporation has the option to expand the project after
2 years at an additional cost of $2 million. The risk-free rate is 5% and the corporation’s required
rate of return is 10%.
a) Calculate the Net Present Value (NPV) of the project without considering the option to ex-
pand.
b) Determine the value of the option to expand the project after 2 years.
c) Should the corporation proceed with the initial investment in the project?
Solution 19.
a) To calculate the NPV of the project without considering the option to expand, we use the
formula:
NP V =−C0+CF1
(1 + r)1+CF2
(1 + r)2+... +CFn
(1 + r)n
Where: C0= $5,000,000 CFt= $3,000,000 for t= 1,2,3,4,5r= 10%
Plugging in the values, we get:
NP V =−5,000,000 + 3,000,000
1.1+3,000,000
1.12+3,000,000
1.13+3,000,000
1.14+3,000,000
1.15
NP V =−5,000,000 + 2,727,273 + 2,479,338 + 2,254,853 + 2,049,866 + 1,861,696
NP V = $2,373,050
The NPV of the project without considering the option to expand is $2,373,050.
b) The value of the option to expand the project after 2 years can be calculated using the Black-
Scholes model. The formula for the value of the option is:
V=S0N(d1)−Xe−rtN(d2)
Where: S0= $3,000,000 (Value of the expanded project) X= $2,000,000 (Cost of expansion)
r= 5% (Risk-free rate) t= 2 years
Calculating d1and d2using the Black-Scholes formula, we find d1= 0.4407 and d2= 0.1841.
Plugging in these values, we get:
V= 3,000,000N(0.4407) −2,000,000e−0.05∗2N(0.1841)
V= 3,000,000 ×0.6703 −2,000,000 ×e−0.1×0.5749
V= 2,010,894 −1,273,239
V= $737,655
The value of the option to expand the project after 2 years is $737,655.
c) As the NPV of the project without considering the option to expand is positive ($2,373,050)
and the value of the option to expand is also positive ($737,655), the corporation should proceed
with the initial investment in the project.
19 20. REAL OPTIONS IN NEW PRODUCT DEVELOPMENT
Problem 20. A company is considering developing a new product. The initial investment re-
quired is $500,000. The expected cash flows from the product over the next 3 years are estimated
as follows: Year 1: $200,000, Year 2: $300,000, Year 3: $400,000. The company has the option
to abandon the project at the end of each year with the following abandonment values: Year 1:
$50,000, Year 2: $100,000, Year 3: $200,000. The risk-free rate is 5%.
a) Calculate the net present value (NPV) of the project without considering any abandonment
options.
b) Determine the net present value (NPV) of the project if the company has the flexibility to
abandon the project at the end of each year.
c) Discuss whether incorporating the abandonment options increases the value of the project.
Solution 20.
a) To calculate the NPV of the project without considering any abandonment options, we need
to discount the cash flows at the risk-free rate of 5%.
Using the formula for NPV:
NP V =CF0
(1 + r)0+CF1
(1 + r)1+CF2
(1 + r)2+CF3
(1 + r)3−Initial Investment
where r= 0.05 and the cash flows are 200,000,300,000, and 400,000f oryears1,2, and3respectively.
NP V =−500,000
(1 + 0.05)0+200,000
(1 + 0.05)1+300,000
(1 + 0.05)2+400,000
(1 + 0.05)3
NP V =−500,000 + 190,476.2 + 272,108.8 + 342,317.5 = 304,902.5
Therefore, the NPV of the project without considering any abandonment options is $304,902.5.
b) To calculate the NPV of the project with abandonment options, we need to consider the option
to abandon at the end of each year by comparing the continuation value with the abandonment
value.
In Year 1, the continuation value is $190,476.2 (the present value of cash flows from Year 2
and Year 3). If the abandonment value ($50,000) is greater, then the project would be abandoned,
resulting in an NPV of -$50,000. In this case, the NPV of Year 1 is -$50,000.
In Year 2, the continuation value is $272,108.8 (the present value of cash flow from Year 3). If
the abandonment value ($100,000) is greater, then the project would be abandoned, resulting in
an NPV of -$100,000. In this case, the NPV of Year 2 is -$100,000.
In Year 3, the project will not be abandoned as the cash flow of $400,000 is greater than the
abandonment value of $200,000. Therefore, the NPV of Year 3 is $357,142.9 (the present value
of the cash flow in Year 3).
The total NPV of the project with abandonment options is the sum of the NPVs of each year:
NP V =−50,000 −100,000 + 357,142.9 = 207,142.9
Therefore, the NPV of the project with abandonment options is $207,142.9.
c) Incorporating abandonment options increases the value of the project, as the NPV with aban-
donment options ($207,142.9) is higher than the NPV without considering any abandonment op-
tions ($304,902.5). Abandonment options provide flexibility in decision-making and can increase
the overall value of a project.

