


PORTFOLIO THEORY AND ASSET ALLOCATION
1 1. OVERCONCENTRATION RISK IN A PORTFOLIO
Problem 1. You have a portfolio consisting of three assets: Stock A, Stock B, and Stock C.
The current weights of these assets in the portfolio are as follows: Stock A - 40%, Stock B - 30%,
Stock C - 30%. The expected returns of these assets are: Stock A - 8%, Stock B - 12%, Stock C -
10%. The standard deviations of these assets are: Stock A - 12%, Stock B - 18%, Stock C - 15%.
a) Calculate the expected return of the portfolio.
b) Calculate the standard deviation of the portfolio.
c) Determine the overconcentration risk in the portfolio.
Solution 1.
a) The expected return of a portfolio can be calculated as the weighted average of the expected
returns of the individual assets:
Expected return of the portfolio = (Weight of Stock A * Expected return of Stock A) + (Weight of
Stock B * Expected return of Stock B) + (Weight of Stock C * Expected return of Stock C)
Expected return of the portfolio = (0.40 * 0.08) + (0.30 * 0.12) + (0.30 * 0.10) = 0.032 + 0.036 +
0.03 = 0.098 or 9.8%
b) The formula to calculate the standard deviation of a portfolio with three assets is as follows:
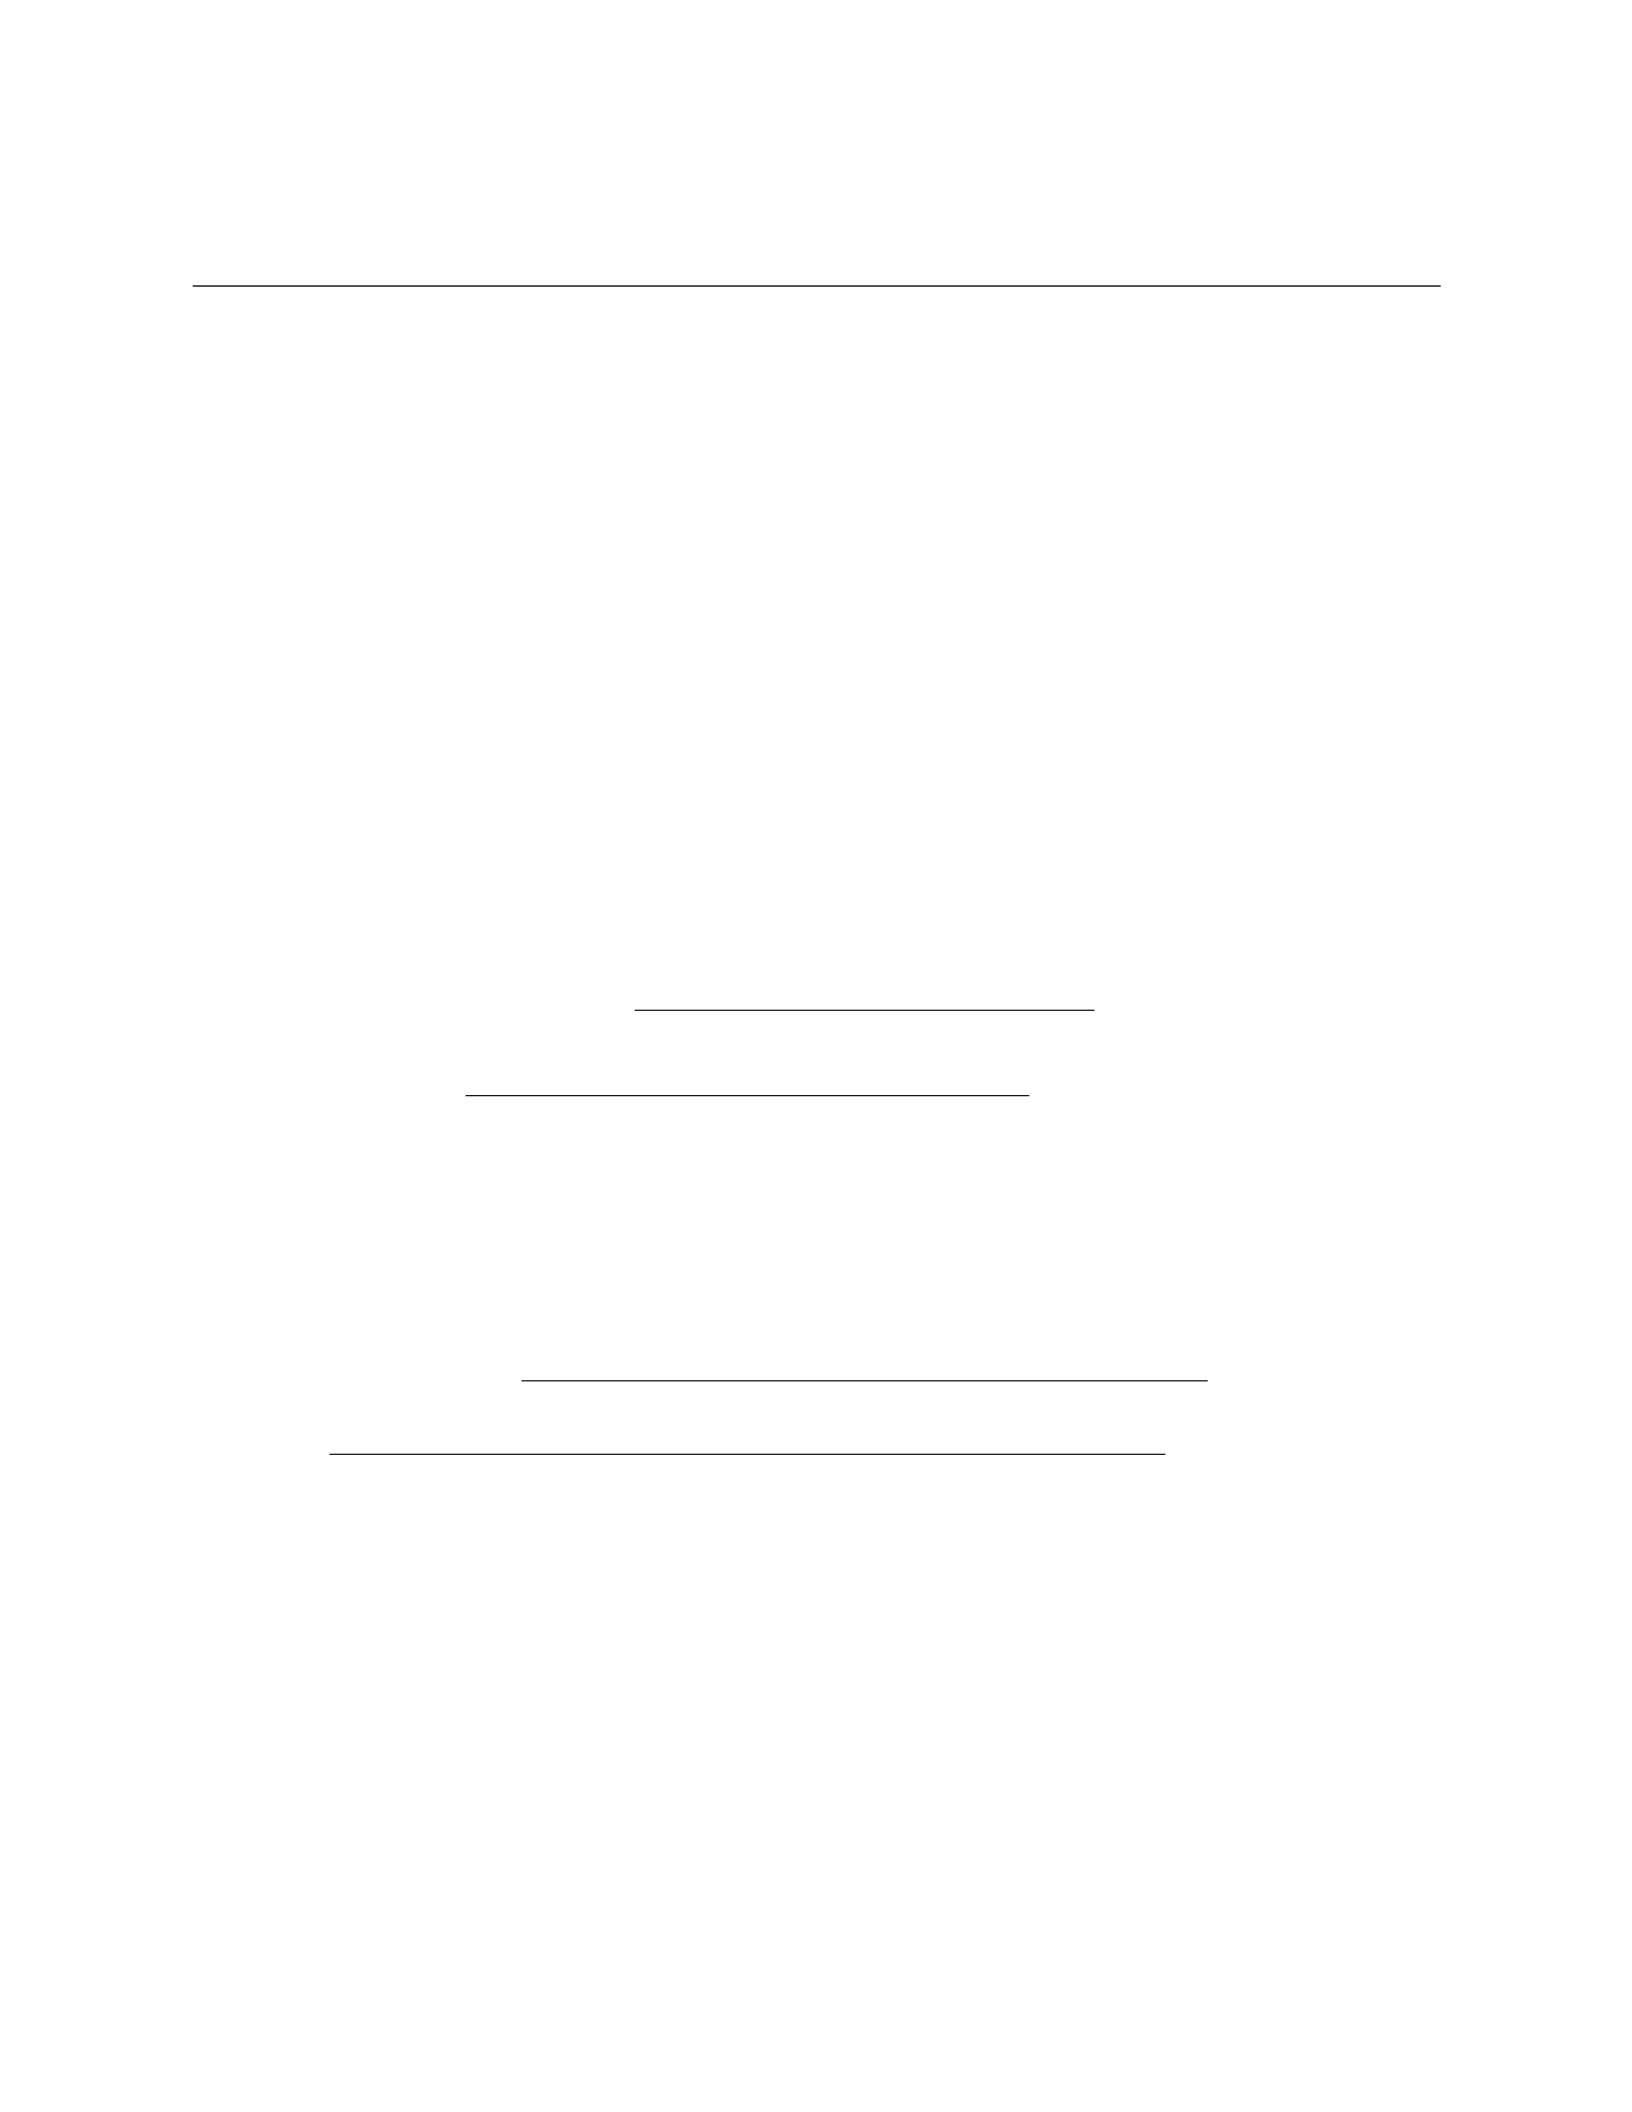
σp=q(w2
Aσ2
A)+(w2
Bσ2
B)+(w2
Cσ2
C)+2wAwBσAσBρAB + 2wAwCσAσCρAC + 2wBwCσBσCρBC
Where: - σpis the standard deviation of the portfolio - wA, wB, wCare the weights of Stocks A,
B, and C respectively - σA, σB, σCare the standard deviations of Stocks A, B, and C respectively -
ρAB, ρAC , ρBC are the correlations between Stocks A and B, A and C, B and C respectively
Given the values: wA= 0.40, wB= 0.30, wC= 0.30 σA= 0.12, σB= 0.18, σC= 0.15 ρAB =
0.6, ρAC = 0.4, ρBC = 0.7
Plugging in these values into the formula, we get:
σp=p(0.402∗0.122) + (0.302∗0.182) + (0.302∗0.152)+2∗0.40 ∗0.30 ∗0.12 ∗0.18 ∗0.6+2∗0.40 ∗0.30 ∗0.12 ∗0.15 ∗0.4+2∗0.30 ∗0.30 ∗0.18 ∗0.15 ∗0.7
σp=p(0.16 ∗0.0144) + (0.09 ∗0.0324) + (0.09 ∗0.0225) + 2 ∗0.04 ∗0.108 ∗0.6+2∗0.04 ∗0.09 ∗0.12 + 2 ∗0.09 ∗0.135 ∗0.7
σp=√0.002304 + 0.002916 + 0.002025 + 0.05184 + 0.00864 + 0.17
σp=√0.067845
σp≈0.2601
Therefore, the standard deviation of the portfolio is approximately 26.01%.
c) The overconcentration risk in a portfolio can be calculated by examining the weight of the
most heavily weighted asset. In this case, the most heavily weighted asset is Stock A with 40%.
We can say that the overconcentration risk in
2 2. LACK OF DIVERSIFICATION IN ASSET CLASSES
Problem 2. Suppose an investor has a portfolio with 60% invested in stocks, 30% invested in
bonds, and 10% invested in real estate. The annual returns for each asset class are as follows:
- Stocks: 12% - Bonds: 6% - Real estate: 8%
Calculate the overall annual return of the investor’s portfolio.
Solution 2.
The overall annual return of the investor’s portfolio can be calculated by weighting the returns
of each asset class according to their respective percentages in the portfolio.
a) Calculating the weighted returns of each asset class:
- Weighted return of stocks: 0.60×0.12 = 0.072 (or 7.2- Weighted return of bonds: 0.30 ×0.06 =
0.018 (or 1.8- Weighted return of real estate: 0.10 ×0.08 = 0.008 (or 0.8
b) Calculating the overall annual return of the portfolio by summing up the weighted returns of
each asset class:
0.072 + 0.018 + 0.008 = 0.098
Therefore, the overall annual return of the investor’s portfolio is 9.8
3 3. SHORT-TERM VOLATILITY IMPACTING PORTFOLIO RETURNS
Problem 3.
You are managing a portfolio with two assets: Asset A and Asset B. Asset A has an annual
expected return of 12
a) Calculate the expected return and the standard deviation of a portfolio that is equally weighted
in Asset A and Asset B.
b) Determine the correlation of the portfolio returns with the returns of each asset.
c) If you increase the weight of Asset A to 60
Solution 3.
a) The expected return of a portfolio, E(rP), that is equally weighted in two assets A and B can
be calculated as:
E(rP) = wA·E(rA) + wB·E(rB)
E(rP)=0.5×0.12 + 0.5×0.08 = 0.10 or 10%
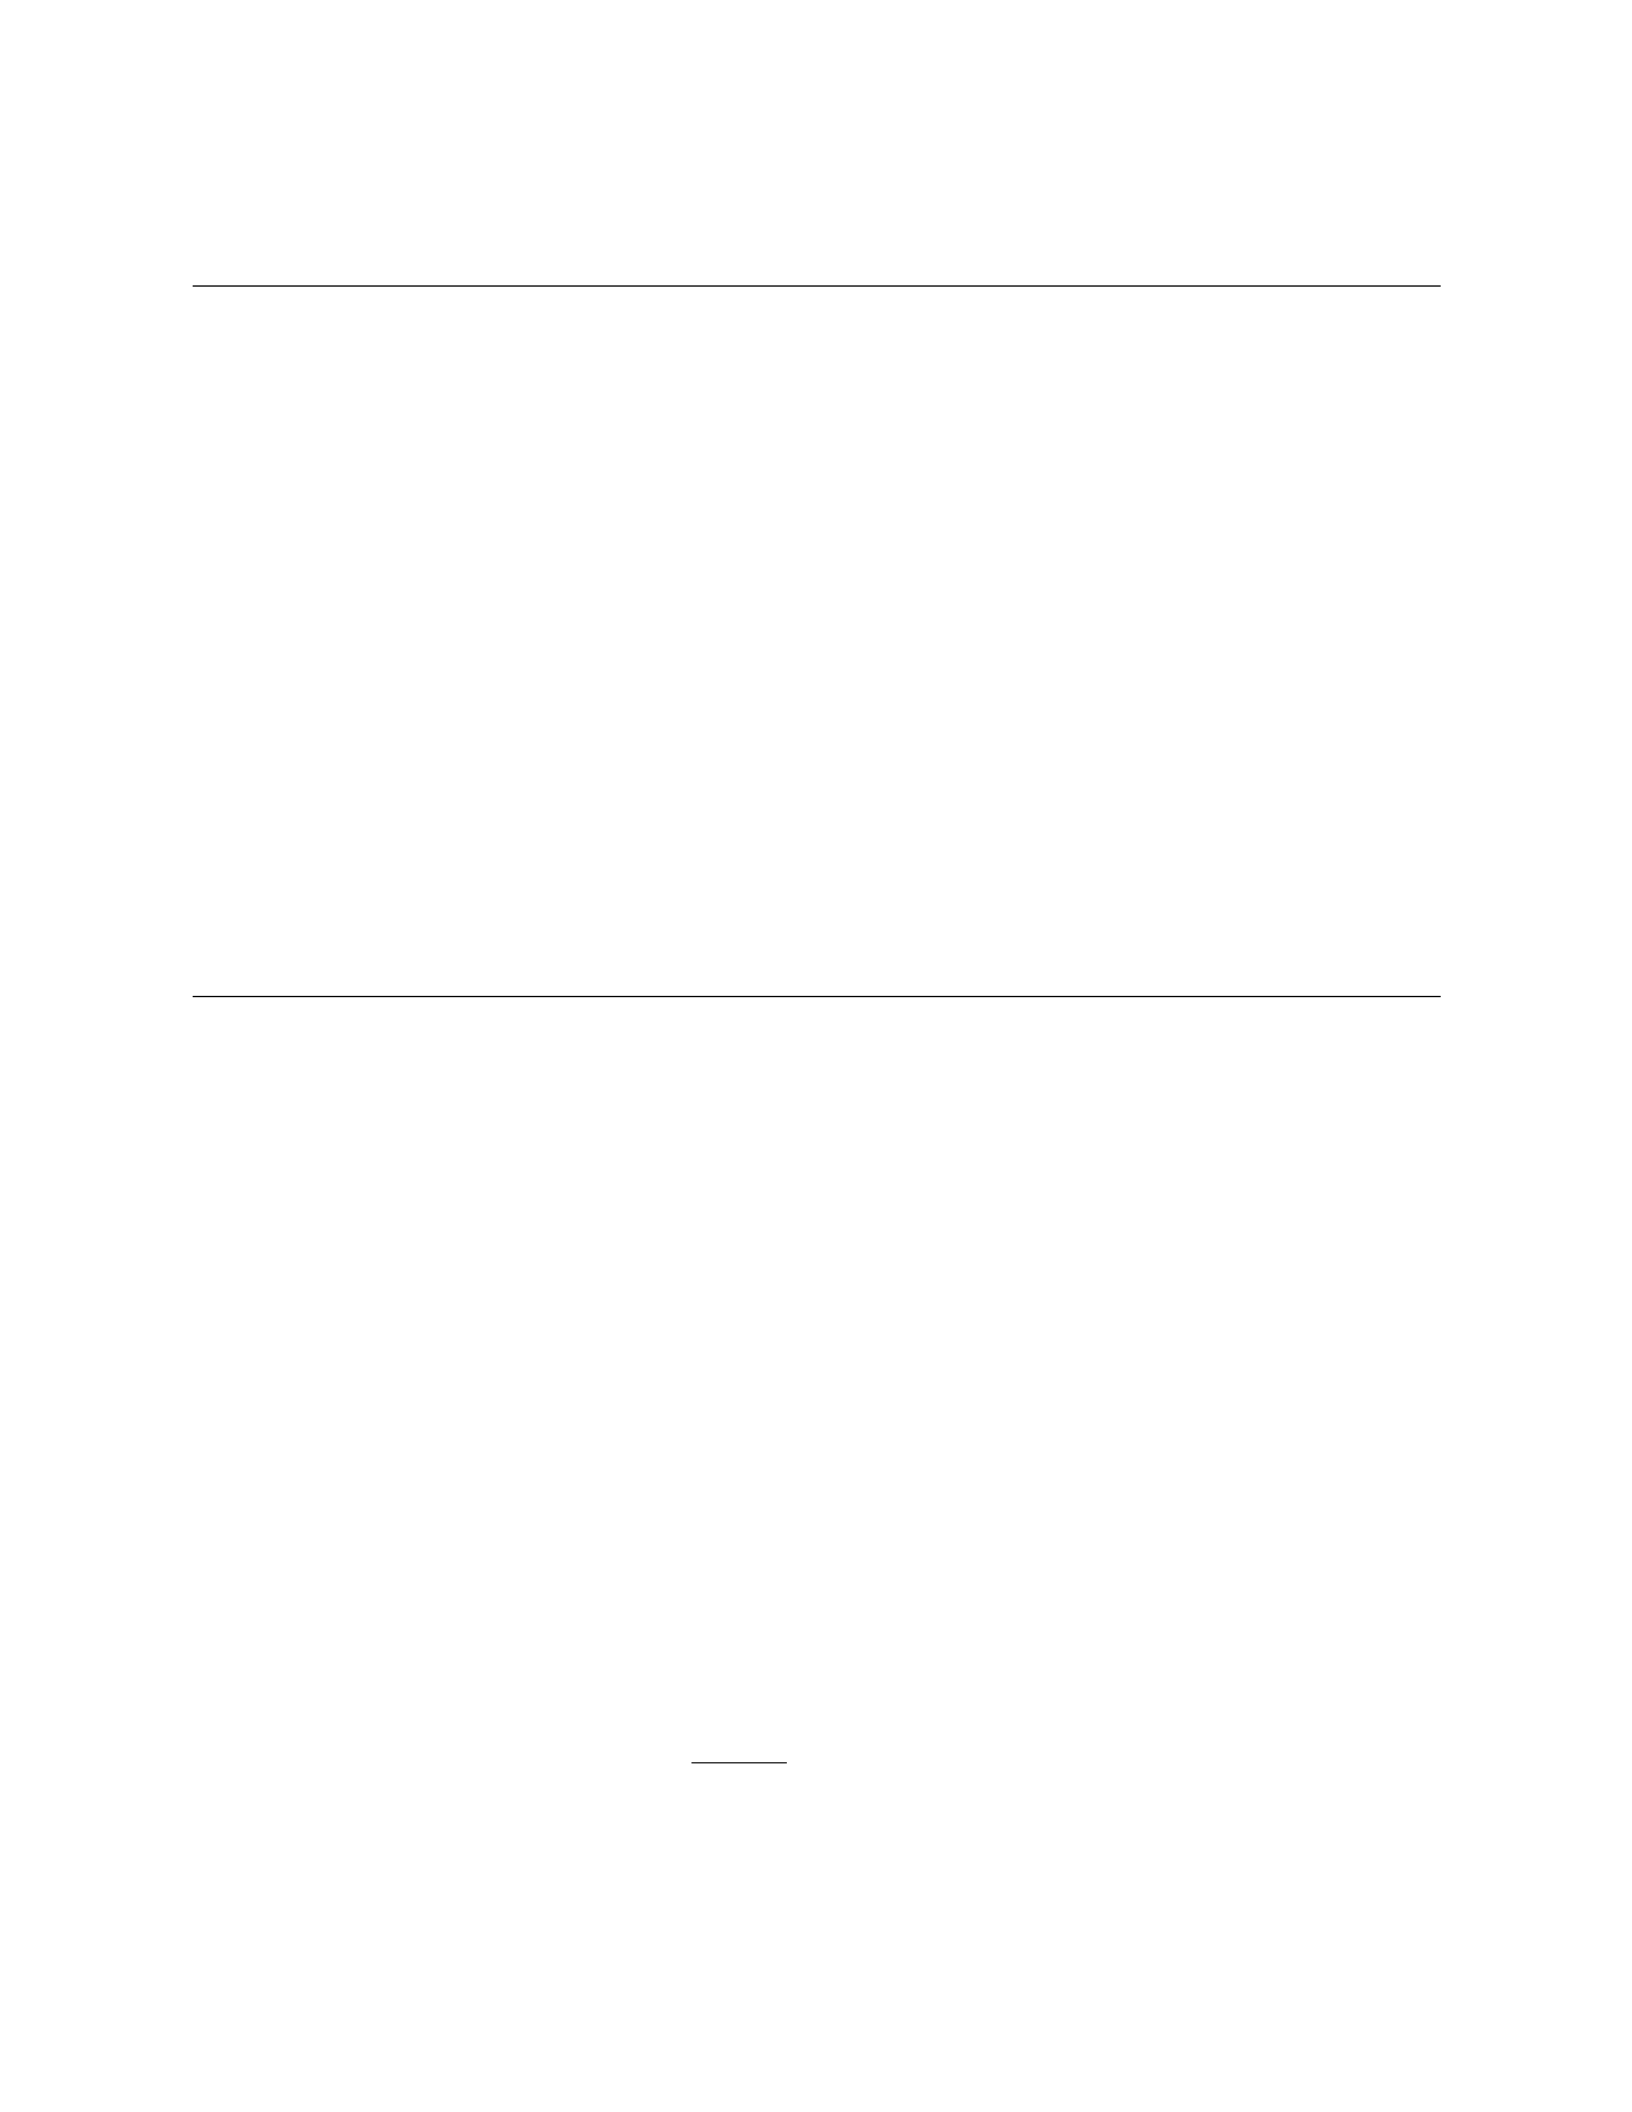
The variance of the portfolio, σ2
P, can be calculated as:
σ2
P=w2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·σA·σB·ρAB
σ2
P= 0.52×0.182+0.52×0.152+2×0.5×0.5×0.18×0.15×0.6 = 0.0288+0.01125+0.0081 = 0.04815
The standard deviation of the portfolio is the square root of the variance:
σP=√0.04815 ≈0.2196 or 21.96%
b) The correlation of the portfolio returns with the returns of each asset can be calculated using
the formula:
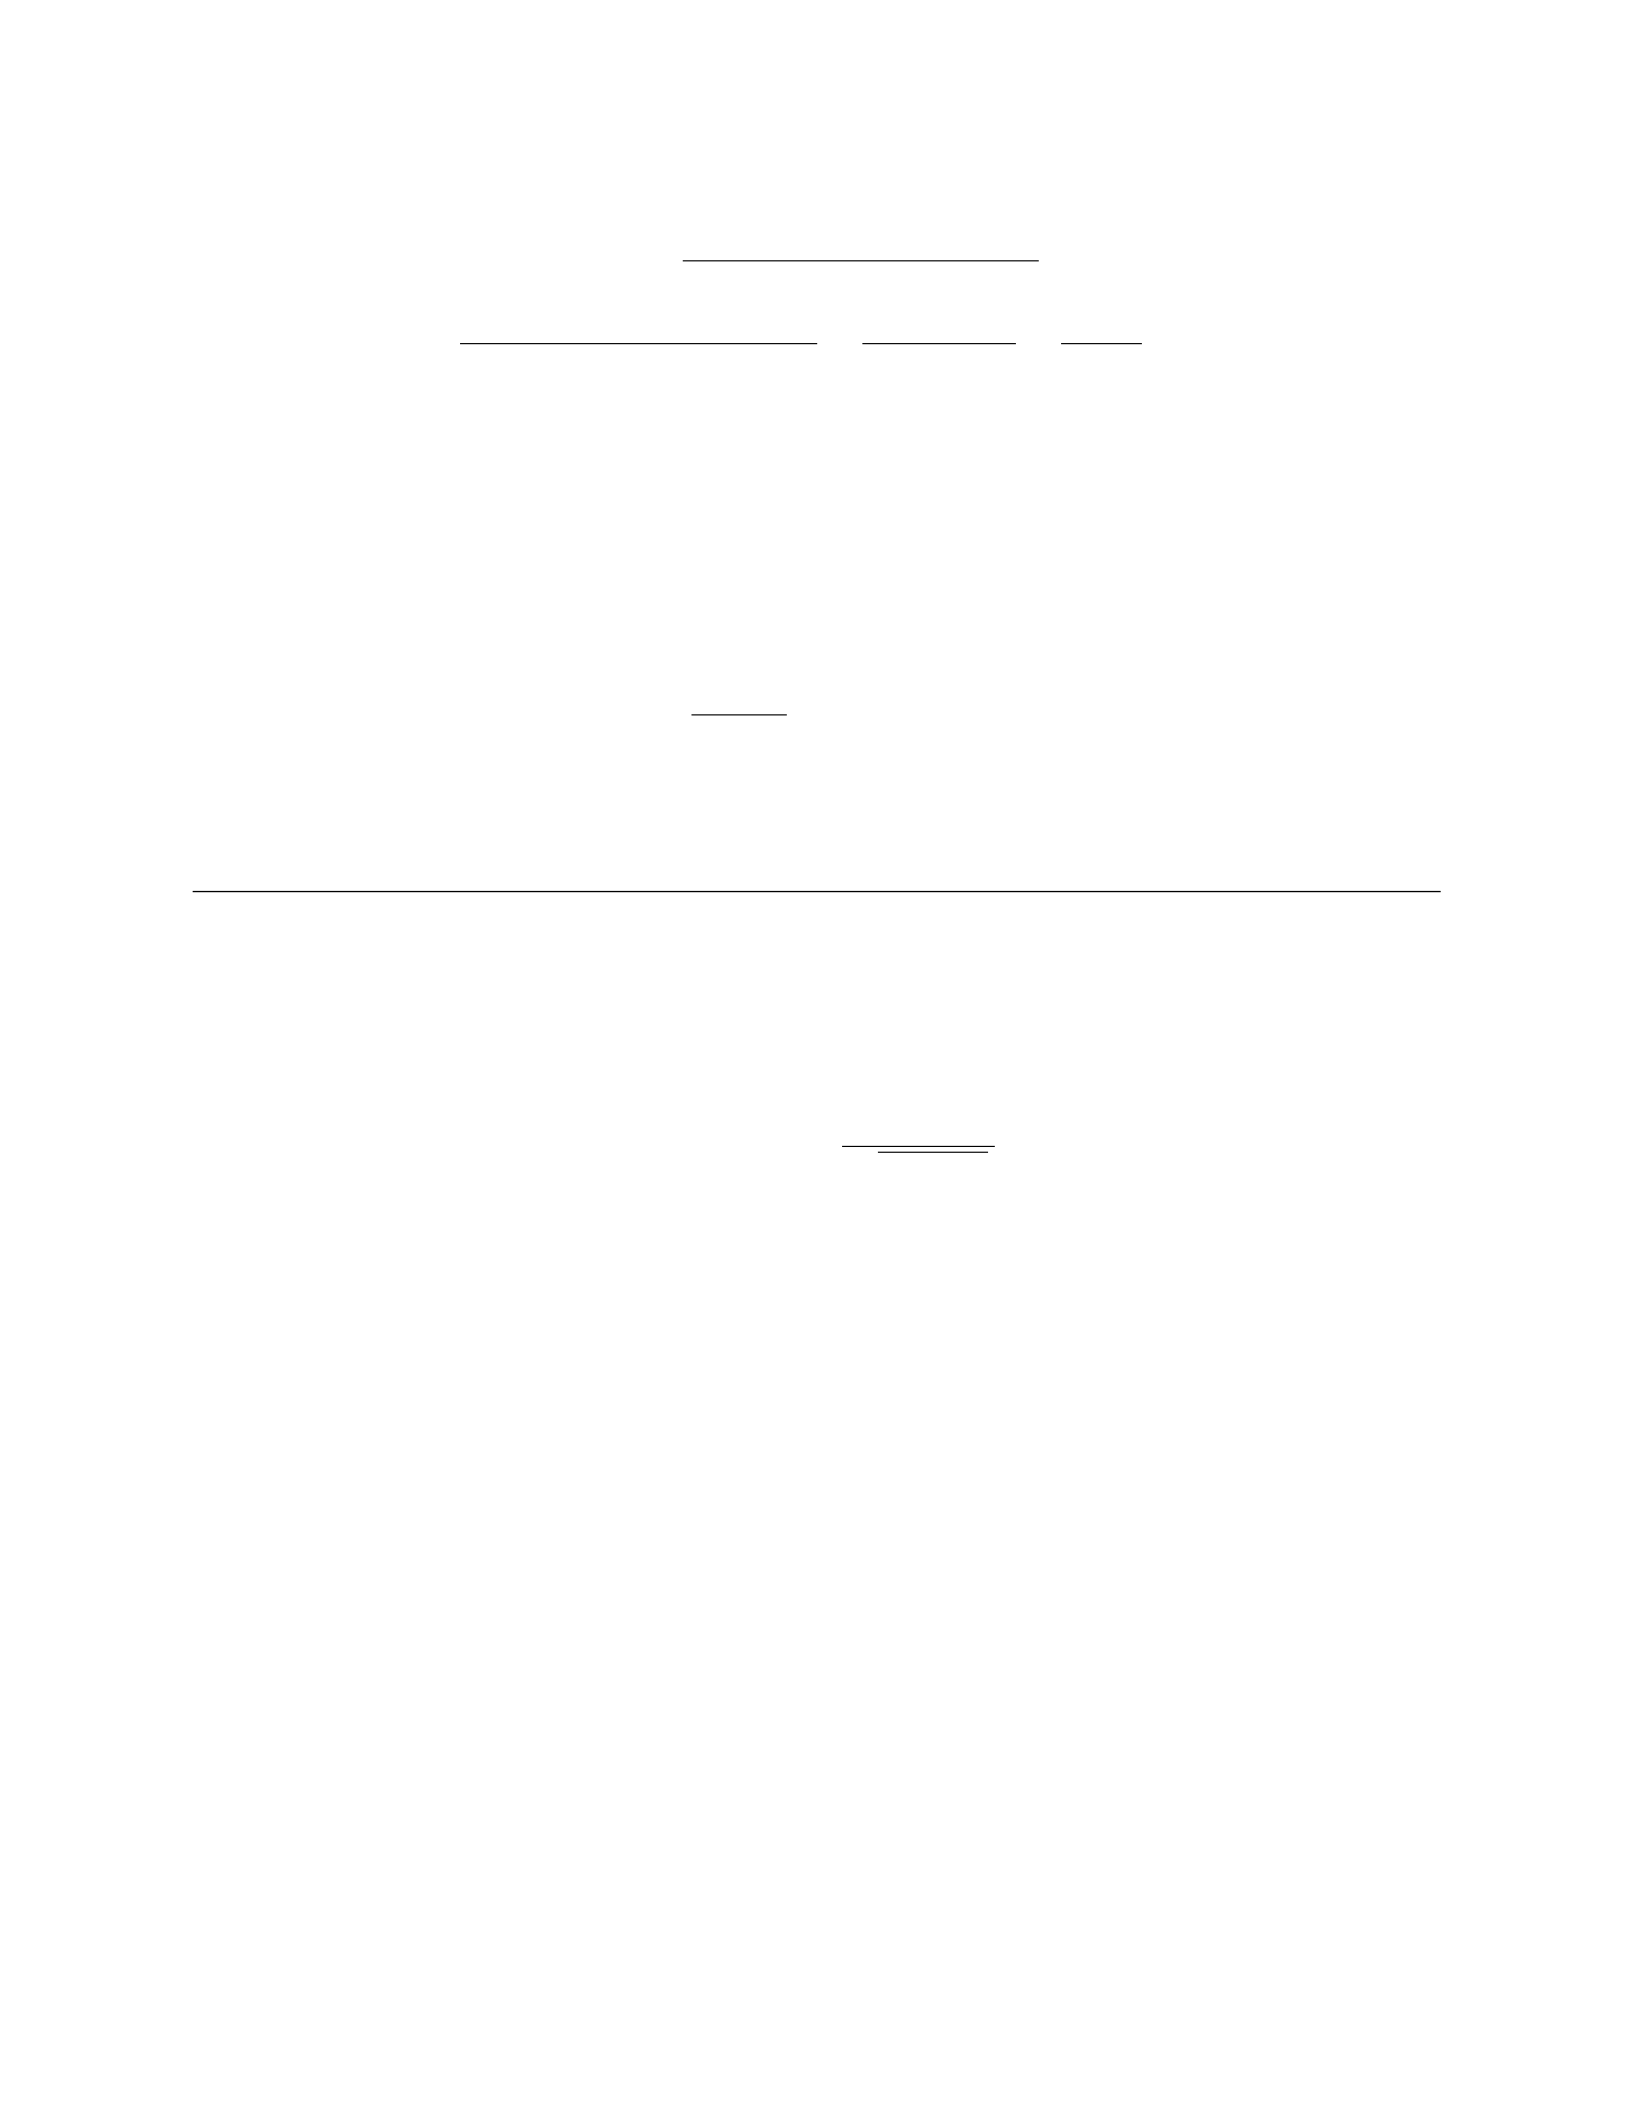
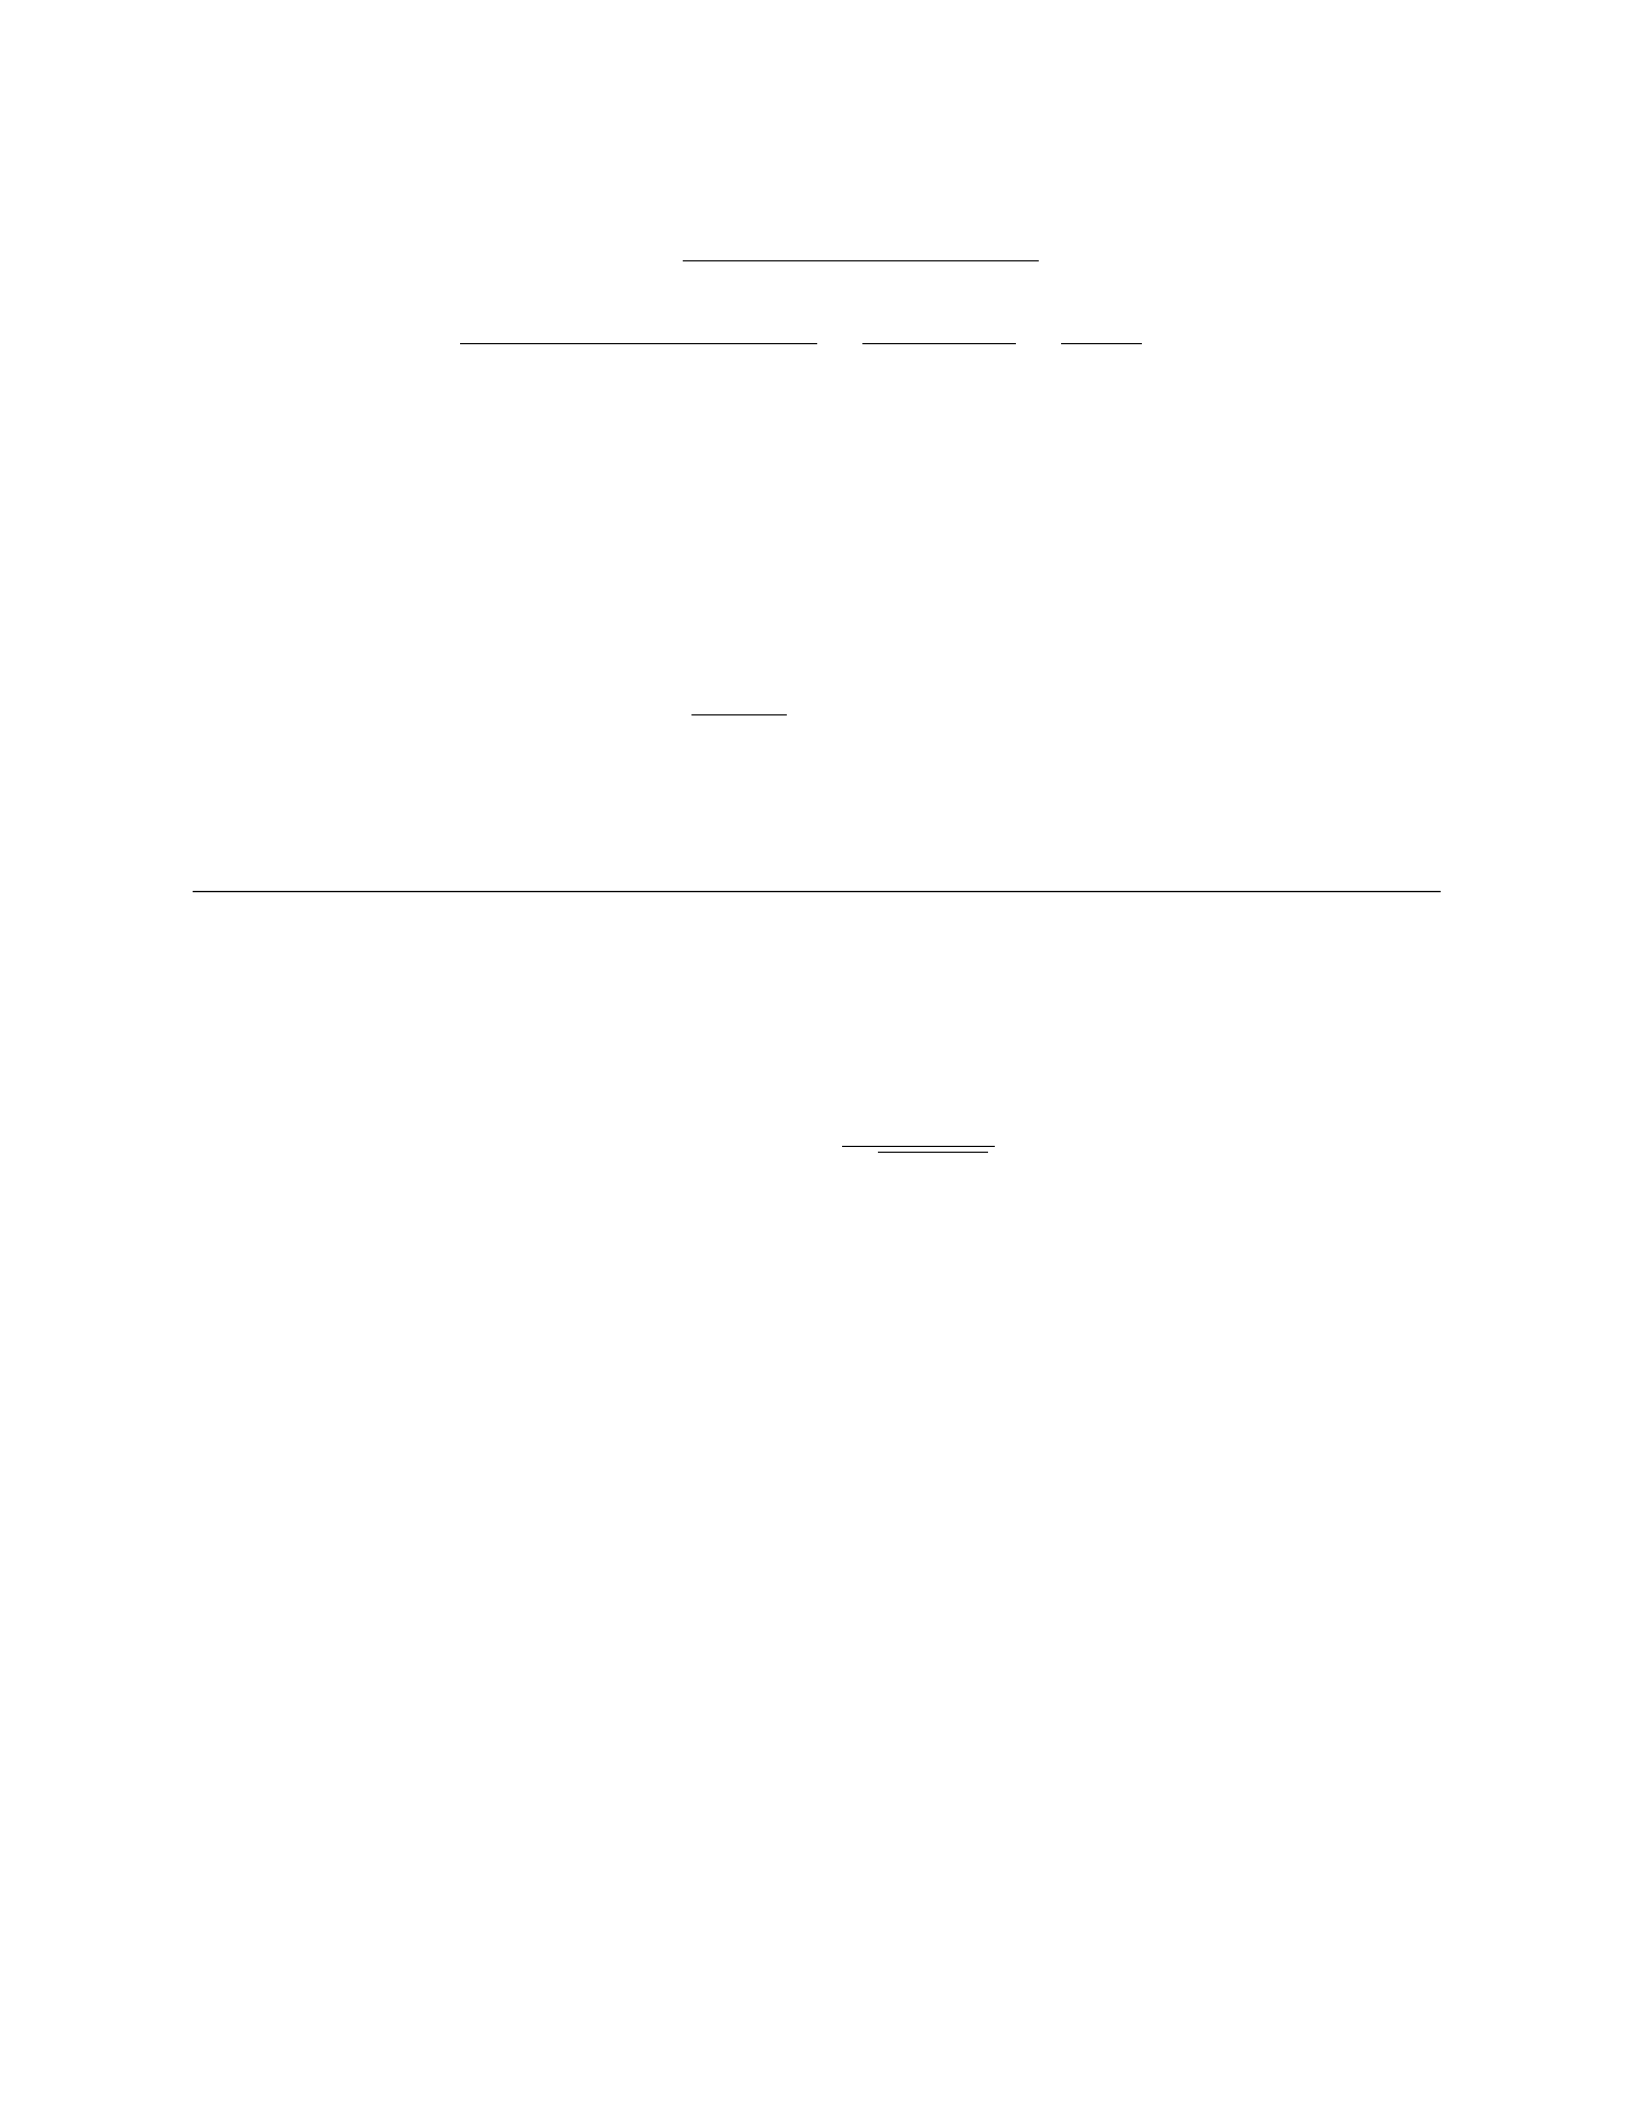
ρAP =wA·σ2
A+wB·σA·σB·ρAB
σP
ρAP =0.5×0.18 + 0.5×0.15 ×0.6
0.2196 ≈0.09 + 0.045
0.2196 ≈0.135
0.2196 ≈0.6148
Similarly, the correlation of the portfolio with Asset B, ρBP , can be calculated.
c) When the weights are changed to 60
E(rP)=0.6×0.12 + 0.4×0.08 = 0.104 or 10.4%
σ2
P= 0.62×0.182+0.42×0.152+2×0.6×0.4×0.18×0.15×0.6 = 0.03888+0.009+0.0162 = 0.06408
σP=√0.06408 ≈0.2531 or 25.31%
4 4. INEFFICIENT USE OF RISK BUDGET IN ASSET ALLOCATION
Problem 4.
An investor has a risk budget of $100,000 to invest in two assets: Asset A and Asset B. The
expected returns for Asset A and Asset B are 8
Solution 4.
The Sharpe ratio is given by:
SharpeRatio =E(Rp)−Rf
pV ar(Rp)
where:
•E(Rp)is the expected return of the portfolio,
•Rfis the risk-free rate (assumed to be zero in this case),
•V ar(Rp)is the variance of the portfolio return.
The expected return of the portfolio can be calculated using the weights assigned to Asset A
and Asset B:
E(Rp) = wAE(RA) + wBE(RB)
The variance of the portfolio return can be calculated as:
V ar(Rp) = w2
Aσ2
A+w2
Bσ2
B+ 2wAwBσAσBρA,B
Now, to maximize the Sharpe ratio, we need to find the weights (wAand wB) that maximize the
Sharpe ratio. Let xbe the weight of Asset A in the portfolio:
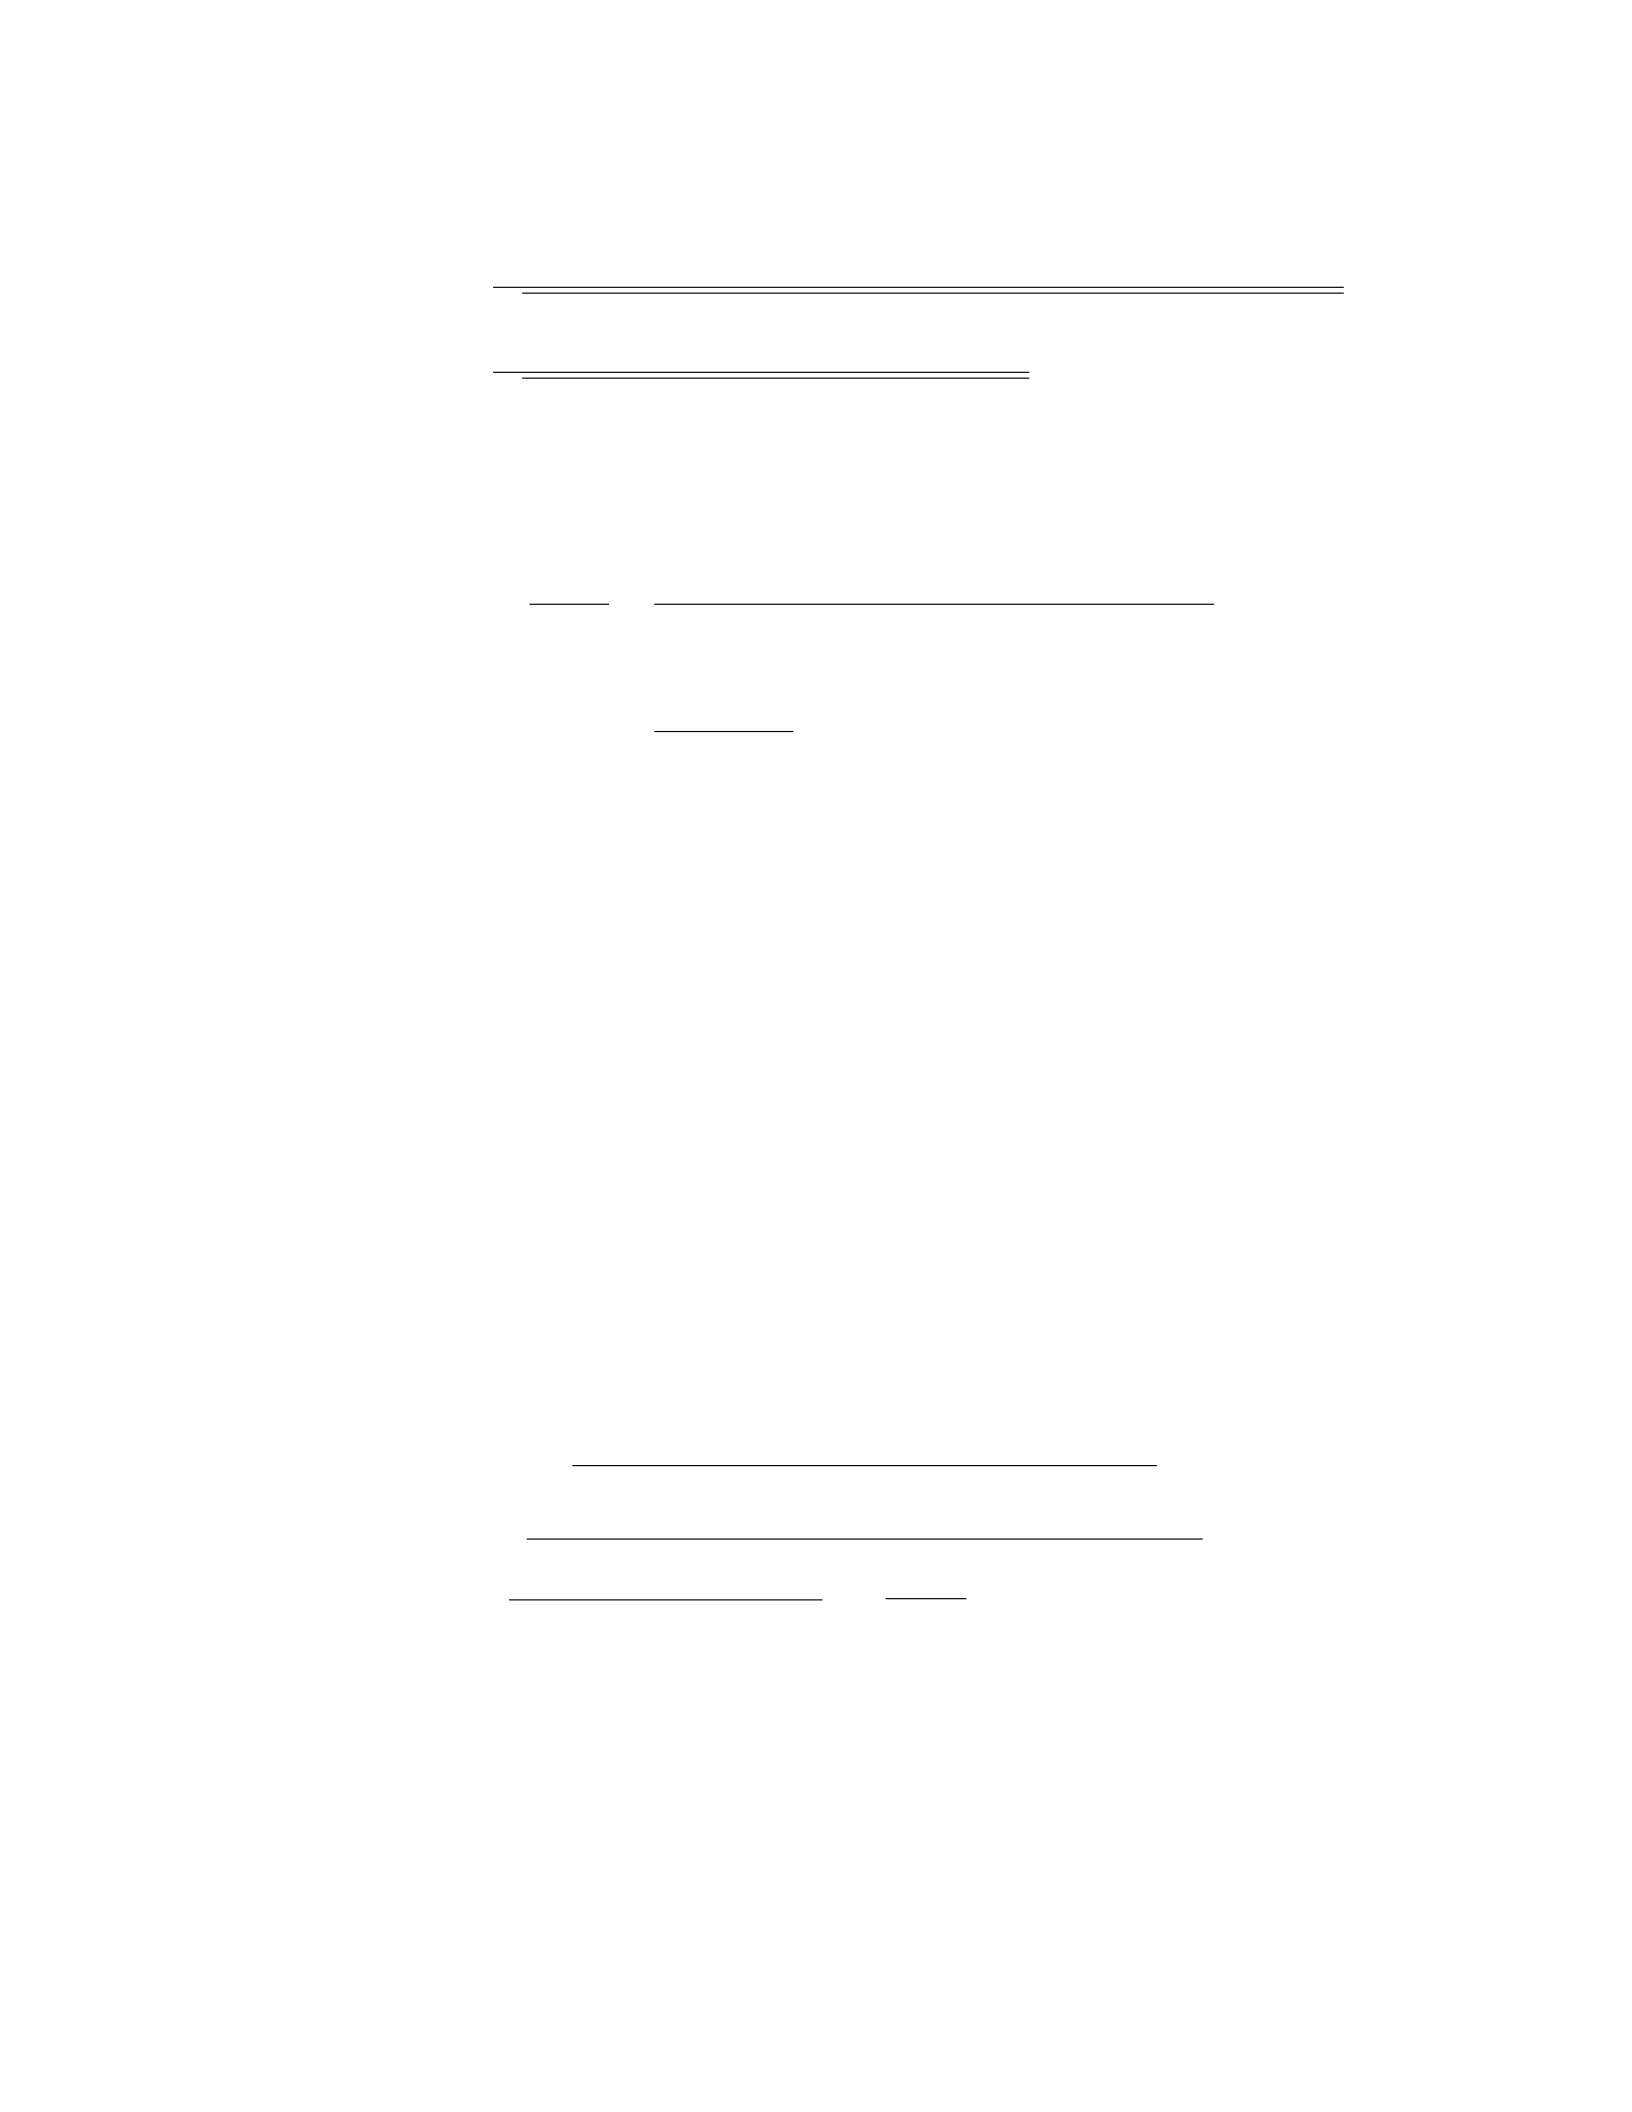
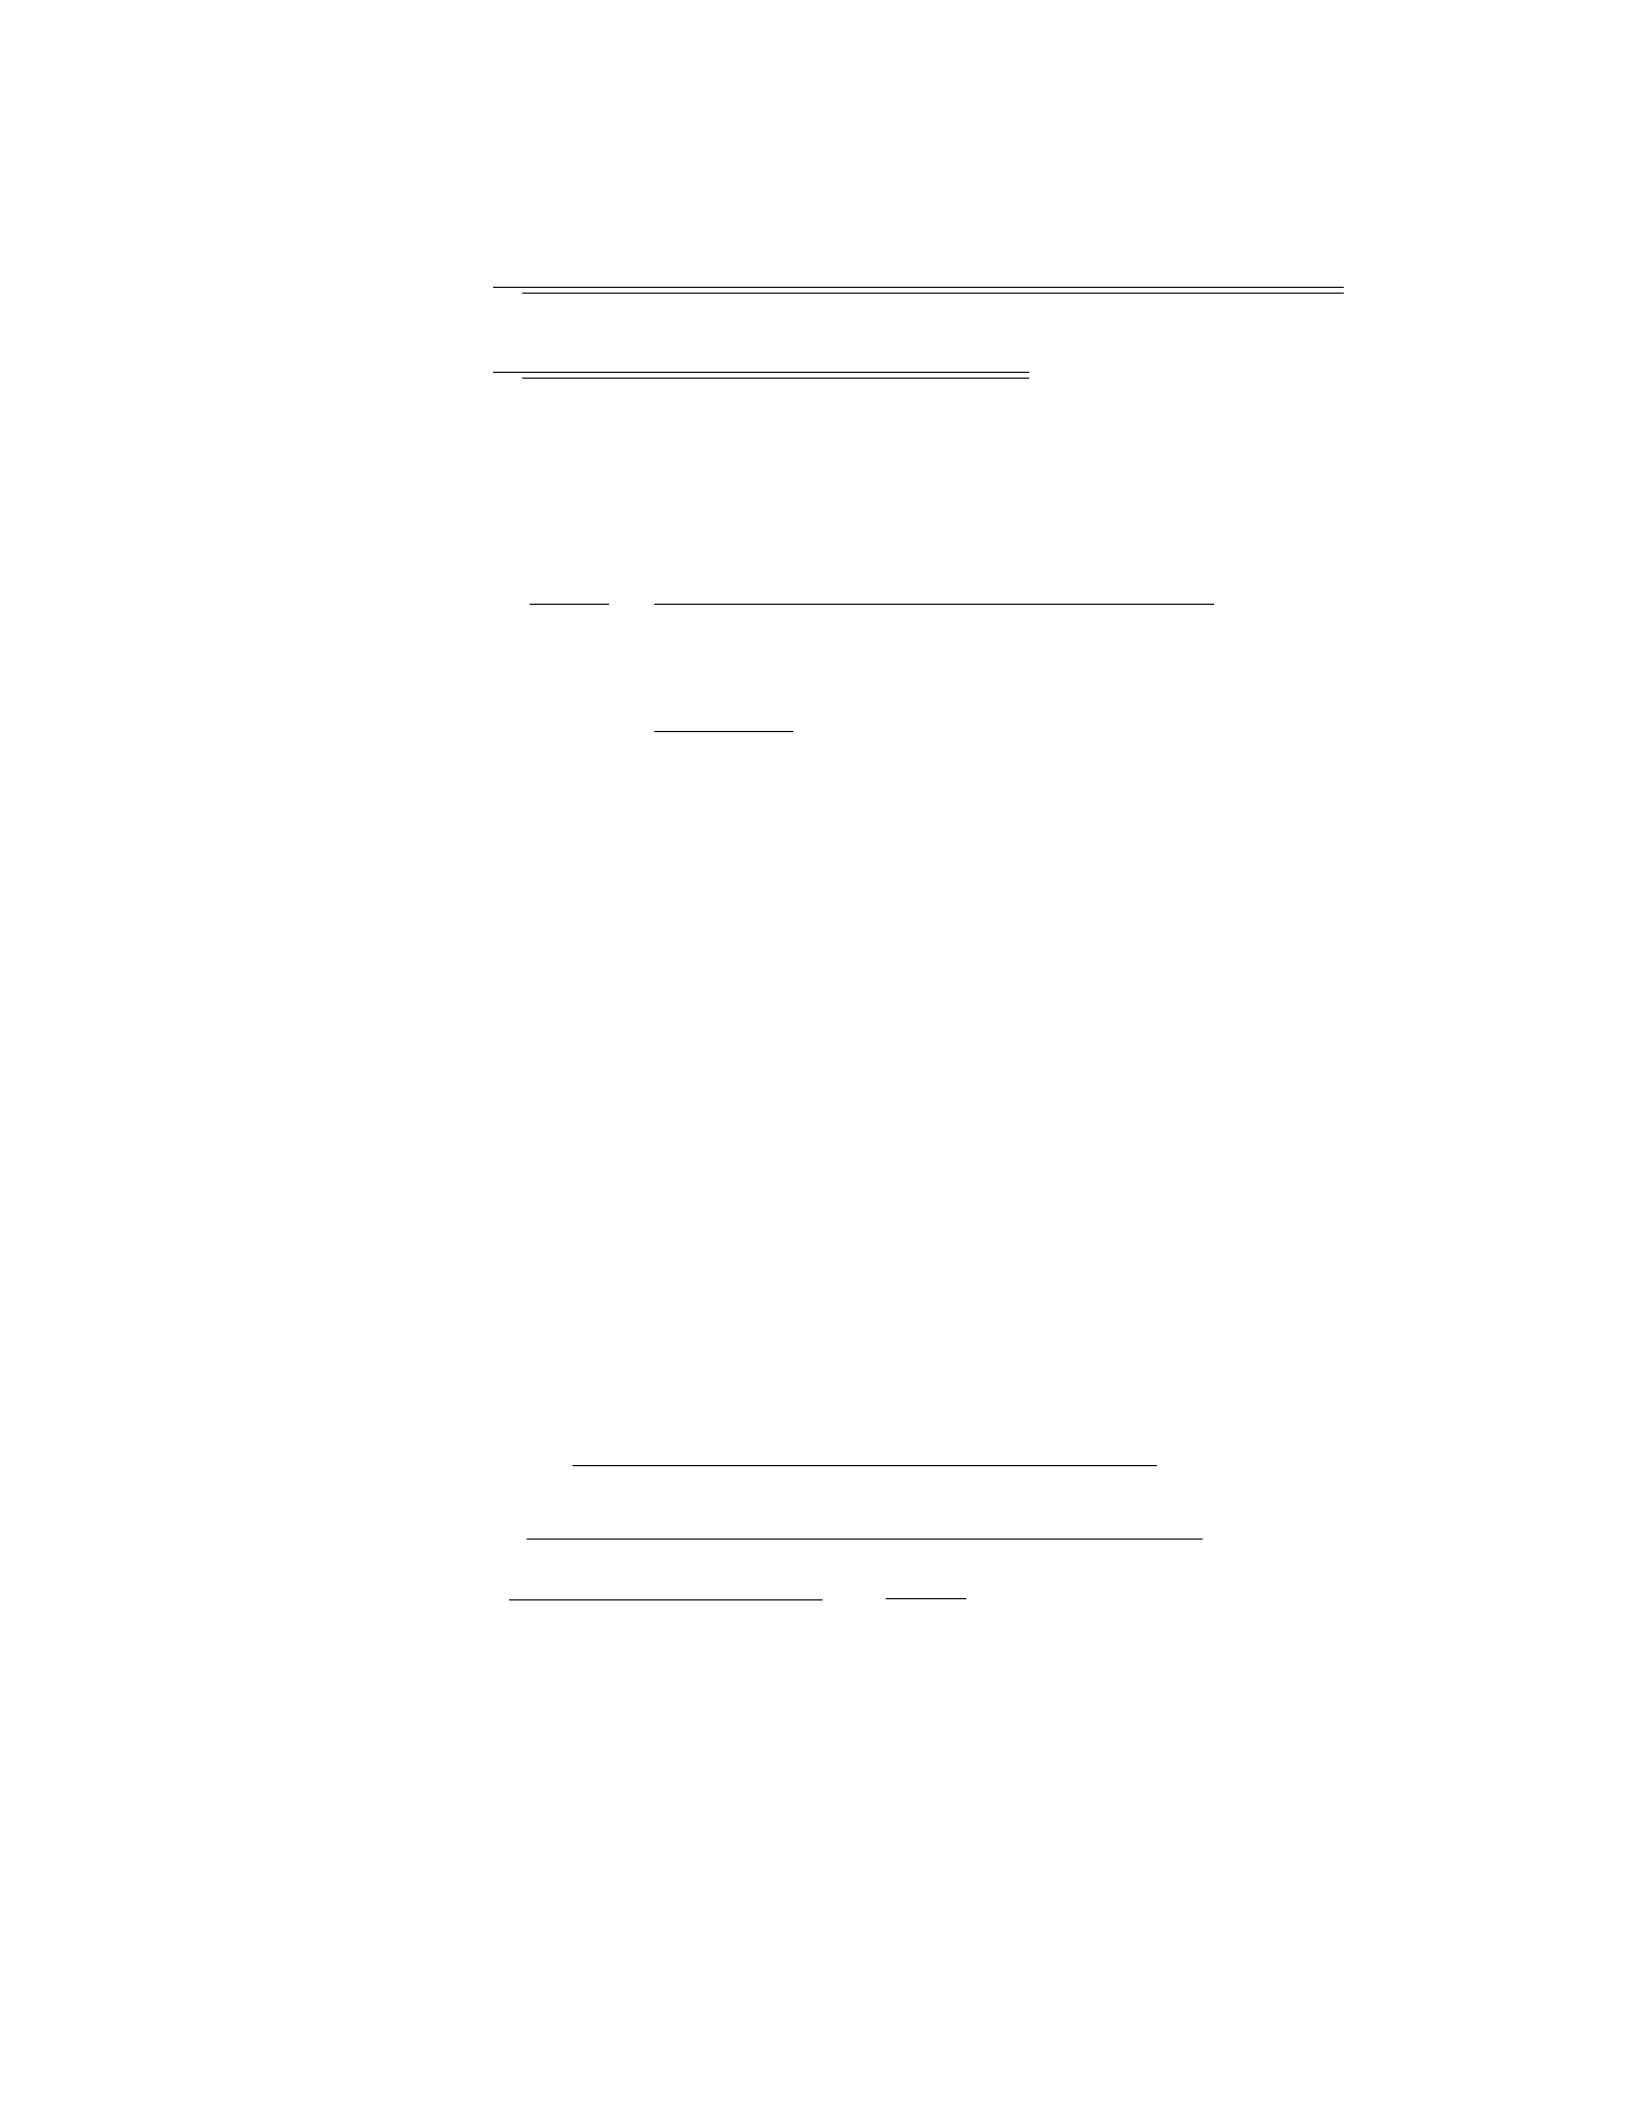
SharpeRatio =x×8% + (1 −x)×12%
px2×(15%)2+ (1 −x)2×(20%)2+ 2x(1 −x)×15% ×20% ×0.6
=0.08x+ 0.12(1 −x)
p0.0225x2+ 0.04(1 −x)2+ 0.018x(1 −x)
To maximize the Sharpe ratio, we need to differentiate it with respect to xand set the derivative
equal to zero:
d(SR)
dx =0.08 −0.12 −2.1x+ 1.68
(0.0225x2+ 0.04(1 −x)2+ 0.018x(1 −x))1.5= 0
−0.04 −2.1x+ 1.68 = 0
x=1.68 −0.04
2.1= 0.8
Therefore, the optimal allocation of the risk budget is 80% in Asset A and 20% in Asset B to
maximize the Sharpe ratio.
I. Problem: Portfolio Diversification
A portfolio manager is considering investing in two assets: Asset A and Asset B. The expected
returns and standard deviations of the two assets are given as follows:
- Asset A: Expected Return = 12- Asset B: Expected Return = 15
The correlation coefficient between the returns of Asset A and Asset B is 0.5. The manager
wants to create a portfolio with 60
a) Calculate the expected return and standard deviation of the portfolio. b) Determine the cor-
relation coefficient between the portfolio and the individual assets.
Solution:
a) Let wA= 0.6and wB= 0.4be the weights of Asset A and Asset B in the portfolio, respectively.
i) Expected Return of the Portfolio:
E(Rp) = wA·E(RA) + wB·E(RB)
E(Rp)=0.6×0.12 + 0.4×0.15 = 0.072 + 0.06 = 0.132 = 13.2%
ii) Standard Deviation of the Portfolio:
σp=qw2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·ρAB ·σA·σB
σp=p0.62·0.082+ 0.42·0.122+ 2 ·0.6·0.4·0.5·0.08 ·0.12
σp≈√0.0288 + 0.0192 + 0.0576 ≈√0.1056 ≈0.3251 = 32.51%
Therefore, the expected return of the portfolio is 13.2
b) Correlation coefficient between the portfolio and Asset A:
ρpA =wA·1 + wB·ρAB
ρpA = 0.6×1+0.4×0.5=0.6+0.2=0.8
Correlation coefficient between the portfolio and Asset B:
ρpB =wA·ρAB +wB·1
ρpB = 0.6×0.5+0.4×1=0.3+0.4=0.7
Therefore, the correlation coefficient between the portfolio and Asset A is 0.8, and with Asset
B is 0.7.
5 6. IGNORING LIQUIDITY RISK IN PORTFOLIO CONSTRUCTION
Problem 6. You are considering investing in two assets, Stock A and Stock B. The expected
returns of these assets are 8% and 12%, respectively. The standard deviation of Stock A is 10%
and the standard deviation of Stock B is 15%. The correlation between the returns of Stock A and
Stock B is 0.6. You have $50,000 to invest and want to allocate your portfolio to maximize the
Sharpe ratio. Assuming you are ignoring liquidity risk in portfolio construction, calculate:
a) The weights of Stock A and Stock B that maximize the Sharpe ratio.
b) The expected return and volatility of the optimal portfolio.
c) The maximum Sharpe ratio for the optimal portfolio.
Solution 6.
a) To find the weights that maximize the Sharpe ratio, we need to calculate the Sharpe ratio for
different weight combinations of Stock A and Stock B. The Sharpe ratio is given by:
Sharpe =E[rp]−rf
σp
where: - E[rp]is the expected return of the portfolio, - rfis the risk-free rate (we will assume 0
for simplicity), - σpis the standard deviation of the portfolio return.
Let wbe the weight of Stock A and 1−wbe the weight of Stock B. Therefore, wis the weight
we allocate to Stock A in our portfolio.
The expected return of the portfolio is given by:
E[rp] = w×E[rA] + (1 −w)×E[rB]E[rp] = w×0.08 + (1 −w)×0.12
The variance of the portfolio is given by:
σ2
p=w2×σ2
A+ (1 −w)2×σ2
B+ 2w(1 −w)×ρAB ×σA×σBσ2
p=w2×0.12+ (1 −w)2×0.152+
2w(1 −w)×0.6×0.1×0.15
Now we can calculate the Sharpe ratio for different weight combinations and choose the weights
that maximize the Sharpe ratio.
b) Once we find the optimal weights, we can calculate the expected return and volatility of the
optimal portfolio using the formulas for E[rp]and σ2
pderived in part (a).
c) The maximum Sharpe ratio for the optimal portfolio is simply the Sharpe ratio calculated
using the optimal weights from part (a).
I. Problem:
You are considering investing in two assets, Asset A and Asset B, with the following character-
istics:
Asset A has an expected return of 8% and a standard deviation of 4%. Asset B has an expected
return of 12% and a standard deviation of 6%.
The correlation between the returns of Asset A and Asset B is 0.5.
a) Calculate the expected return of a portfolio that consists of 40% Asset A and 60% Asset B.
b) Calculate the standard deviation of the portfolio in part (a).
c) Determine the optimal portfolio weights that minimize the standard deviation of the portfolio.
II. Solution:
a) Let E[A]and E[B]be the expected returns of Asset A and Asset B respectively. We want to
find the expected return of the portfolio:
Expected return of the portfolio = 0.4×E[A]+0.6×E[B]
= 0.4×8% + 0.6×12%
= 3.2% + 7.2%
= 10.4%
b) The formula for calculating the standard deviation of a portfolio consisting of two assets is
given by:
σp=qw2
Aσ2
A+w2
Bσ2
B+ 2wAwBρABσAσB
where: σp= standard deviation of the portfolio, wAand wB= weights of Asset A and Asset B in
the portfolio, σAand σB= standard deviations of Asset A and Asset B, ρAB = correlation coefficient
between the returns of Asset A and Asset B.
Substitute the known values into the formula:
σp=√0.42×0.042+ 0.62×0.062+ 2 ×0.4×0.6×0.5×0.04 ×0.06
σp=√0.0016 + 0.0036 + 0.00288
σp=√0.00808
σp≈0.09 or 9%
c) The optimal portfolio weights can be found by minimizing the standard deviation of the port-
folio using the formula for minimum variance portfolio weights, which is given by:
wA=σ2
B−σAB σBσA
σ2
A+σ2
B−2σAB σAσB
wB= 1 −wA
Substitute the given values into the formulas to find the optimal weights for Asset A and Asset
B.
6 8. BEHAVIORAL BIASES AFFECTING ASSET ALLOCATION DECISIONS
Problem 8. Mr. Smith is considering reallocating his investment portfolio to achieve a target
asset allocation. However, he is prone to anchoring bias, fixating on the historical performance of
certain assets. His current portfolio consists of $50,000 invested in Stocks, $30,000 in Bonds, and
$20,000 in Cash. His target allocation is 50% Stocks, 30% Bonds, and 20% Cash. Calculate the
amount Mr. Smith needs to reallocate to each asset to reach his target allocation.
Solution 8. a) Let Xbe the amount to be reallocated to Stocks, Yto Bonds, and Zto Cash.
The total amount of his current portfolio is $50,000 + $30,000 + $20,000 = $100,000.
So, the target amounts are: - Stocks: 50% of $100,000 = $50,000 - Bonds: 30% of $100,000
= $30,000 - Cash: 20% of $100,000 = $20,000
Therefore, we have the following system of equations:
X+ 50,000 = 50,000
Y+ 30,000 = 30,000
Z+ 20,000 = 20,000
Solving these equations, we get:
X= 0
Y= 0
Z= 0
Therefore, Mr. Smith does not need to reallocate any funds to reach his target asset allocation.
The anchoring bias in this case caused Mr. Smith to ignore his current allocation and blindly
stick to his past investments, even though he was already at his target allocation.
This example demonstrates the role of behavioral biases in asset allocation decisions.
7 9. INCONSISTENT RISK TOLERANCE ASSESSMENT AMONG INVESTORS
Problem 9. Assume two investors, Alice and Bob, have different assessments of their risk
tolerance. Alice has a risk tolerance level of 0.6, while Bob’s risk tolerance level is 0.4. They are
considering investing in two assets, Asset X and Asset Y, with the following characteristics:
Asset X: Expected return = 8%, Standard Deviation = 12%
Asset Y: Expected return = 12%, Standard Deviation = 18%
a) Calculate the expected return and standard deviation of a portfolio consisting of 60
b) Determine which investor should choose this portfolio based on their risk tolerance assess-
ment.
c) Discuss the implications of having inconsistent risk tolerance assessments among investors
in the context of portfolio construction.
Solution 9.
a) To calculate the expected return and standard deviation of the portfolio consisting of 60
Expected return of the portfolio = Weight of Asset X * Expected return of Asset X + Weight of
Asset Y * Expected return of Asset Y
Standard deviation of the portfolio = sqrt[ (Weight of Asset X)2∗(StandardDeviationofAssetX)2+
(W eightofAssetY )2∗(StandardDeviationofAssetY )2+2∗W eightofAssetX ∗W eightof AssetY ∗
Covariance(X, Y )]
For the given data:
Expected return of the portfolio = 0.6 * 8% + 0.4 * 12% = 4.8% + 4.8% = 9.6%
Standard deviation of the portfolio = sqrt[ (0.62)∗(122) + (0.42)∗(182) + 2 ∗0.6∗0.4∗(12) ∗(18)]
= sqrt[ (0.36) * (144) + (0.16) * (324) + 2 * 0.6 * 0.4 * 216 ]
= sqrt[ 51.84 + 51.84 + 51.84 ]
= sqrt[ 155.52 ]
12.476%
Therefore, for both Alice and Bob, the expected return of the portfolio is 9.6% and the standard
deviation is approximately 12.476%.
b) Based on their risk tolerance assessments, Alice (with a risk tolerance level of 0.6) should
choose this portfolio, as the portfolio’s risk tolerance matches her preferences (higher risk toler-
ance), whereas Bob’s risk tolerance level of 0.4 indicates he would prefer a lower risk portfolio.
c) Inconsistent risk tolerance assessments among investors can lead to conflicts in portfolio
construction decisions. It may result in suboptimal portfolio choices if the portfolio’s risk-return char-
acteristics do not align with the individual investors’ risk preferences. This highlights the importance
of understanding and incorporating different risk tolerance levels when constructing portfolios for
multiple investors.
8 10. LACK OF CLARITY IN INVESTMENT OBJECTIVES DRIVING POOR ASSET ALLOCA-
TION
Problem 10.
An investor is considering investing in two assets - Stock A and Stock B. The investor’s utility
function is given by U(W) = W0.5, where Wis the wealth at the end of the investment period. The
investor has a total of $100,000 to invest. Stock A has an expected return of 8% and a standard
deviation of 12%, while Stock B has an expected return of 6% and a standard deviation of 8%. The
correlation coefficient between the returns of Stocks A and B is 0.4.
a) Calculate the expected return and standard deviation of a portfolio that is 60% invested in
Stock A and 40% invested in Stock B.
b) Determine the optimal risky portfolio for this investor considering the given utility function.
Solution 10.
a) The expected return of a portfolio, denoted by E(Rp), is given by the weighted average of the
expected returns of individual assets in the portfolio. The standard deviation of a portfolio, denoted
by σp, is calculated using the formula for the portfolio variance.
a) To calculate the expected return and standard deviation of the portfolio with 60% invested in
Stock A and 40% in Stock B:
Expected return of the portfolio:
E(Rp)=0.6×0.08 + 0.4×0.06 = 0.048 + 0.024 = 0.072 = 7.2%
Standard deviation of the portfolio:
σp=p0.62×0.122+ 0.42×0.082+ 2 ×0.6×0.4×0.12 ×0.08 ×0.4 = √0.0144 + 0.0128 + 0.02304 ≈0.076 = 7.6%
Therefore, the expected return of the portfolio is 7.2% and the standard deviation is 7.6%.
b) To determine the optimal risky portfolio for the investor, we need to find the portfolio that
maximizes the investor’s utility function. This is achieved by locating the point of tangency between
the investor’s indifference curve and the efficient frontier.
Given the utility function U(W) = W0.5, the optimal risky portfolio allocation is given by the
formula:
w∗=E(RA)−rf
γ2σ2
A+σ2
B−2γσAσB
=0.08 −0.02
0.0006 = 100
So, the optimal risky portfolio for this investor is 100% Stock A and 0% Stock B.
I.
9 Problem on Portfolio Theory and Asset Allocation
Problem:
Suppose an investor has a portfolio consisting of two assets, Asset A and Asset B. Asset A has
a weight of 60% in the portfolio with an expected return of 8% and a standard deviation of 15%.
Asset B has a weight of 40% with an expected return of 12% and a standard deviation of 20%. The
correlation coefficient between the returns of Asset A and Asset B is 0.6. Calculate the expected
return and standard deviation of the portfolio.
Solution:
Let rAbe the return of Asset A, rBbe the return of Asset B, and wAand wBbe the weights of
Asset A and Asset B respectively.
a) The expected return of the portfolio (rp) is given by:
rp=wA×rA+wB×rB
rp= 0.60 ×0.08 + 0.40 ×0.12
rp= 0.048 + 0.048
rp= 0.096 or 9.6%
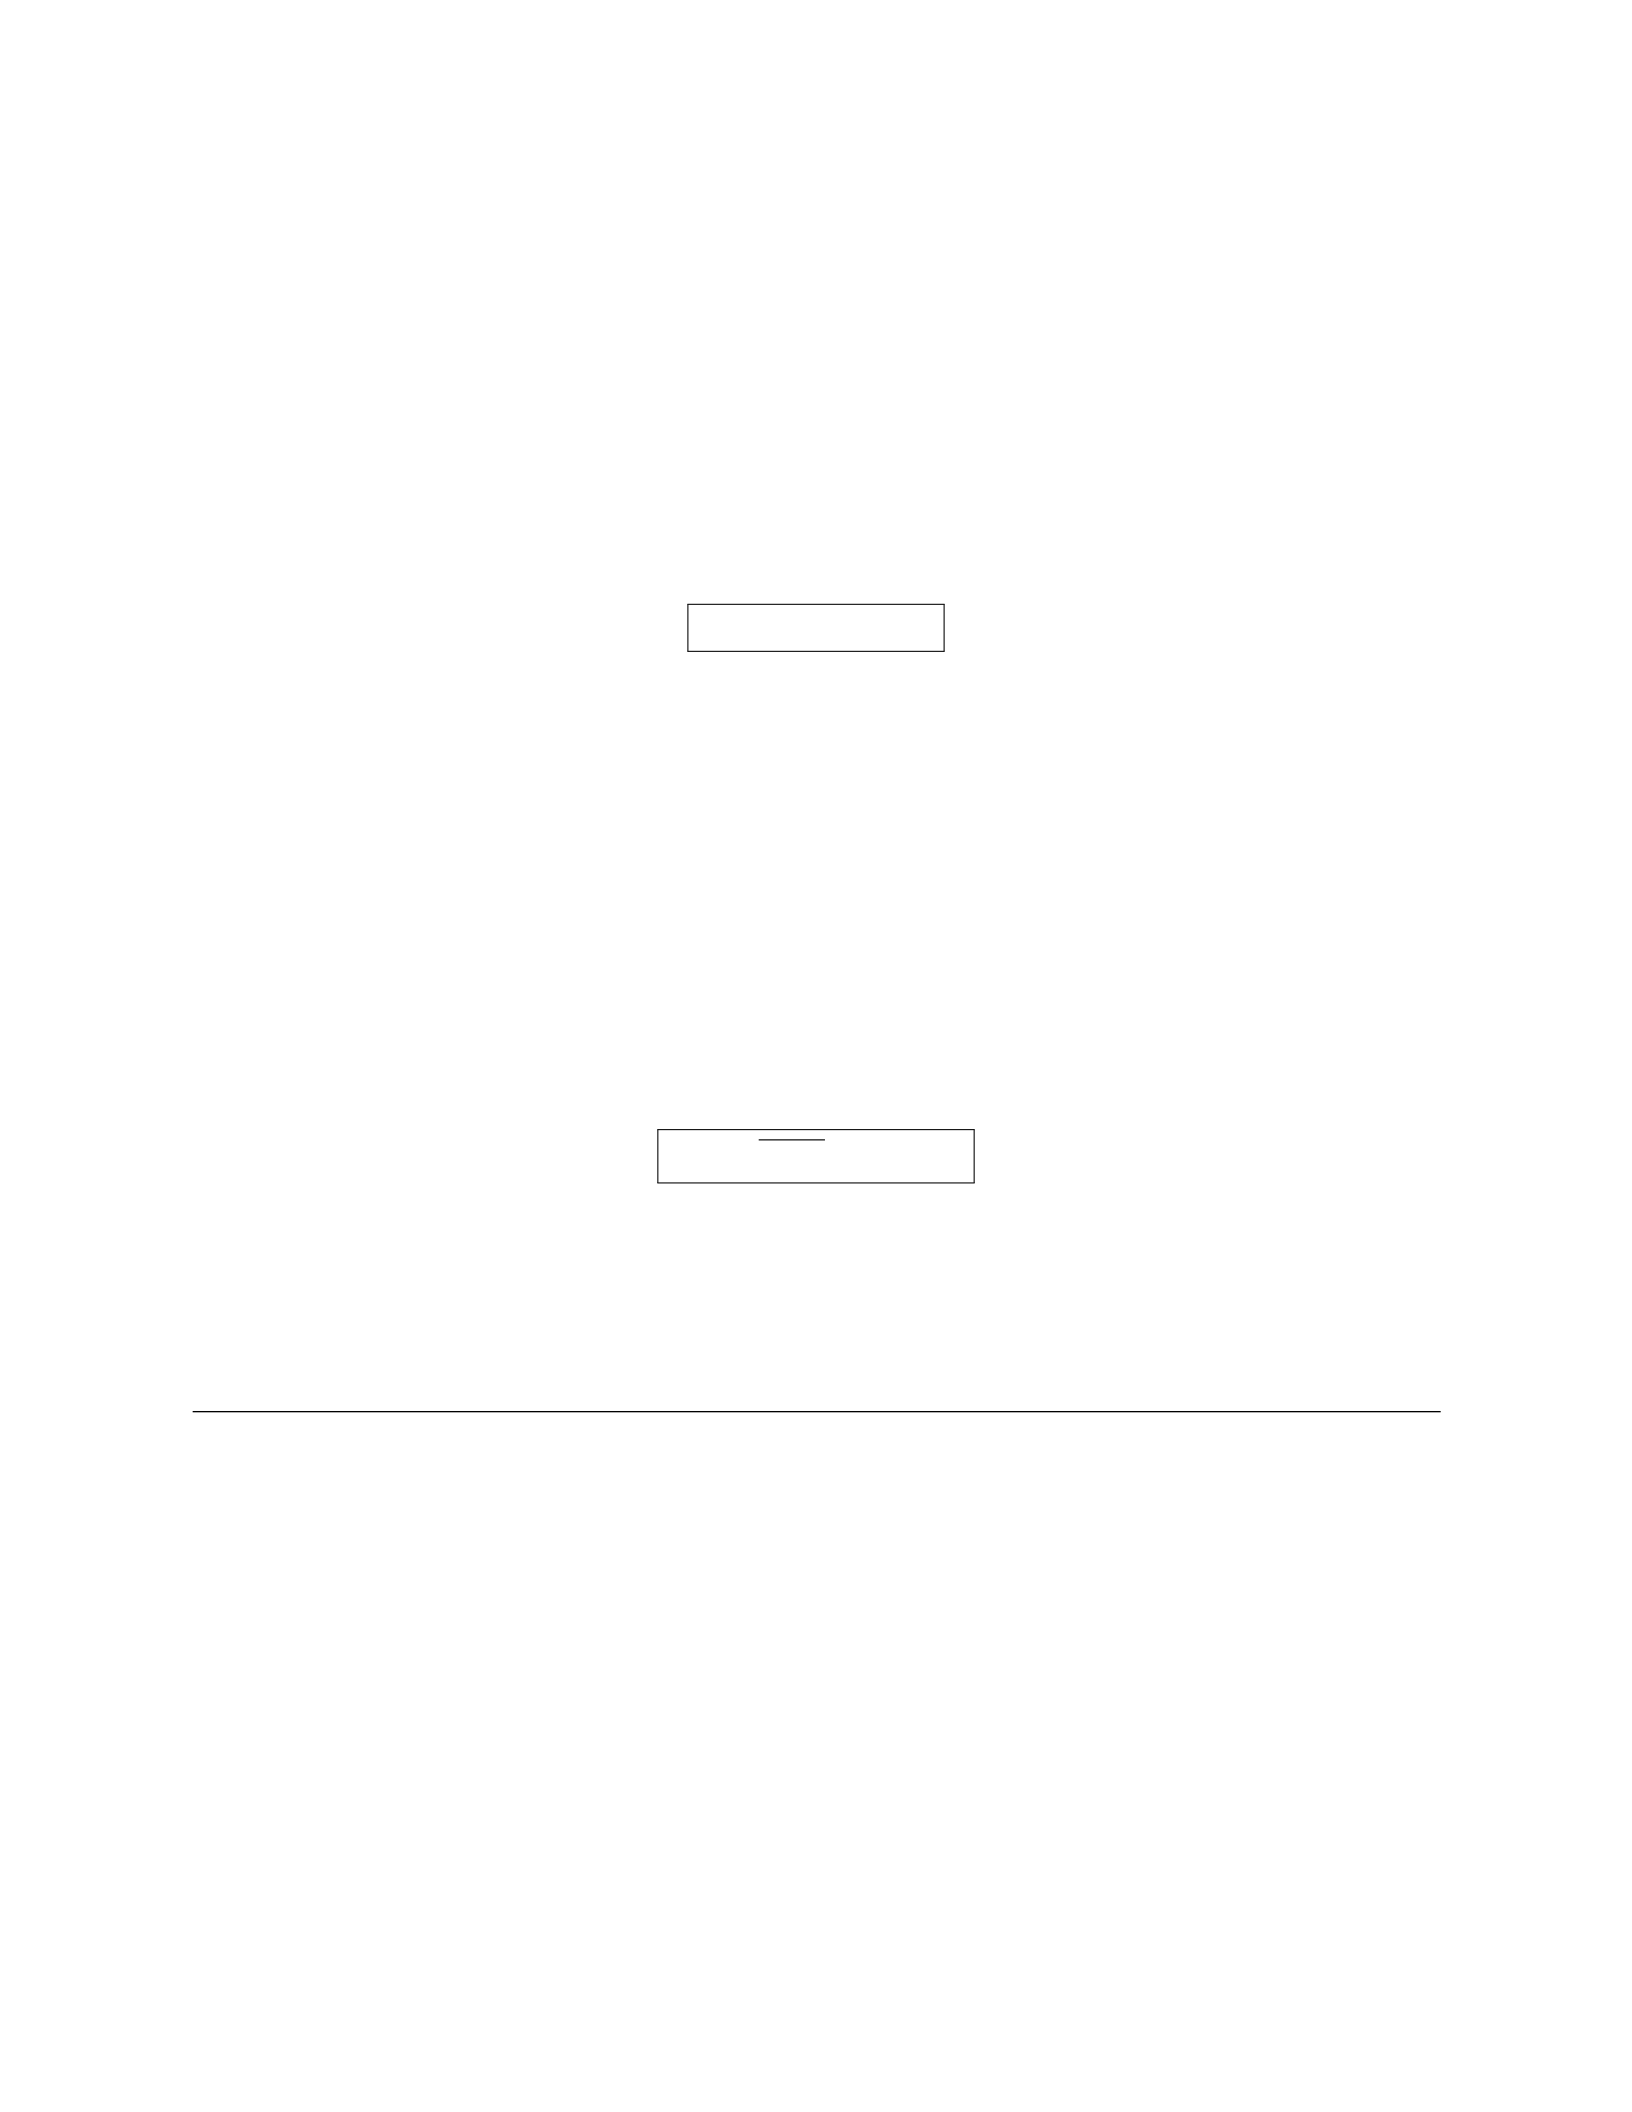
b) The variance of the portfolio (σ2
p) is given by:
σ2
p=w2
A×σ2
A+w2
B×σ2
B+ 2 ×wA×wB×Corr(A, B)×σA×σB
Plugging in the values:
σ2
p= 0.602×0.152+ 0.402×0.202+ 2 ×0.60 ×0.40 ×0.6×0.15 ×0.20
σ2
p= 0.09 + 0.16 + 0.144
σ2
p= 0.394
σp=√0.394 or 19.85%
Therefore, the expected return of the portfolio is 9.6% and the standard deviation of the portfolio
is 19.85%.
10 12. INEFFICIENT REBALANCING STRATEGIES IMPACTING PORTFOLIO PERFORMANCE
Problem 12.
You have a portfolio consisting of two assets, Stock A and Stock B, with the following charac-
teristics:
•Stock A has a weight of 40% in the portfolio and has an expected return of 8% with a standard
deviation of 12%.
•Stock B has a weight of 60% in the portfolio and has an expected return of 12% with a standard
deviation of 18%.
•The correlation coefficient between Stock A and Stock B is 0.6.
a) Calculate the expected return and standard deviation of the portfolio.
b) If you decide to rebalance the portfolio to 50% Stock A and 50% Stock B, calculate the new
expected return and standard deviation of the portfolio.
c) Evaluate the impact of the rebalancing on the portfolio performance.
Solution 12.
a) The expected return and standard deviation of the portfolio can be calculated using the
following formulas:
Expected Return of Portfolio =wA×Expected Return of Stock A+wB×Expected Return of Stock B
Standard Deviation of Portfolio =qw2
A×Variance of Stock A +w2
B×Variance of Stock B + 2 ×wA×wB×Standard Deviation of Stock A ×Standard Deviation of Stock B ×Correlation
Substitute the given values:
Expected Return of Portfolio = 0.4×8% + 0.6×12% = 0.04 + 0.072 = 0.112 = 11.2%
Standard Deviation of Portfolio =p0.42×(0.12)2+ 0.62×(0.18)2+ 2 ×0.4×0.6×0.12 ×0.18 ×0.6=0.1173 = 11.73%
a) Therefore, the expected return of the portfolio is 11.2% and the standard deviation of the
portfolio is 11.73%.
b) If we rebalance the portfolio to 50% Stock A and 50% Stock B, the new expected return and
standard deviation of the portfolio can be calculated in a similar way:
Expected Return of Portfolio = 0.5×8% + 0.5×12% = 0.04 + 0.06 = 0.1 = 10%
Standard Deviation of Portfolio =p0.52×(0.12)2+ 0.52×(0.18)2+ 2 ×0.5×0.5×0.12 ×0.18 ×0.6=0.1289 = 12.89%
b) Therefore, the new expected return of the portfolio is 10% and the new standard deviation
of the portfolio is 12.89%.
c) The rebalancing strategy has slightly reduced the expected return of the portfolio from 11.2%
to 10%, but it has also slightly increased the standard deviation from 11.73% to 12.89%. This
tradeoff between return and risk should be carefully considered based on the investor’s risk appetite
and investment objectives.
11 13. LACK OF CONSIDERATION FOR TAX IMPLICATIONS IN ASSET ALLOCATION
Problem 13. An investor has two investment options:
Option A: A stock that pays a dividend yield of 4% annually and has a capital gain of 10% at
the end of the year. The investor’s tax rate on dividends is 20% and on capital gains is 15%.
Option B: A tax-exempt municipal bond that pays a yield of 3.5% annually.
If the investor’s initial investment is 10,000, determinewhichoptionwouldprovidehigherafter −
taxreturnsaf teroneyear.
Solution 13.
To compare the after-tax returns of the two investment options, we calculate the after-tax returns
for options A and B separately:
a) Option A:
For Option A, the after-tax return is the sum of after-tax dividend and after-tax capital gain:
After-tax dividend = Dividend yield * (1 - Tax rate on dividends) = 0.04 * (1 - 0.2) = 0.04 * 0.8 =
0.032 = 3.2%
After-tax capital gain = Capital gain * (1 - Tax rate on capital gains) = 0.10 * (1 - 0.15) = 0.10 *
0.85 = 0.085 = 8.5%
Total after-tax return for Option A = After-tax dividend + After-tax capital gain = 3.2% + 8.5% =
11.7%
b) Option B:
For Option B, the after-tax return of the tax-exempt municipal bond is simply the yield of 3.5%.
c) Comparison:
Since Option A has a total after-tax return of 11.7%, which is higher than the 3.5% after-tax
return of Option B, the investor would achieve higher after-tax returns by investing in Option A.
12 Portfolio Theory and Asset Allocation
Problem 1.
You are considering investing in a portfolio that consists of two assets: Stock A and Stock B.
The expected return and standard deviation of each asset are as follows:
Stock A: Expected Return = 12%, Standard Deviation = 15%
Stock B: Expected Return = 8%, Standard Deviation = 10%
The correlation coefficient between the returns of Stock A and Stock B is 0.5. You are planning
to allocate 60% of your investment to Stock A and 40% to Stock B.
a) Calculate the expected return of the portfolio.
b) Calculate the standard deviation of the portfolio.
Solution 1.
a) The expected return of the portfolio can be calculated using the weighted sum of the individual
expected returns:
E(Rp) = wA×E(RA) + wB×E(RB)
Given that wA= 0.6,E(RA) = 0.12,wB= 0.4, and E(RB)=0.08, we have:
E(Rp)=0.6×0.12 + 0.4×0.08 = 0.072 + 0.032 = 0.104 = 10.4%
Therefore, the expected return of the portfolio is 10.4%.
b) The standard deviation of the portfolio can be calculated using the formula:
σp=qw2
A×σ2
A+w2
B×σ2
B+ 2 ×wA×wB×σA×σB×ρA,B
where σA= 0.15,σB= 0.10, and ρA,B = 0.5.
Plugging in the values, we get:
σp=p(0.6)2×(0.15)2+ (0.4)2×(0.10)2+ 2 ×0.6×0.4×0.15 ×0.10 ×0.5
=√0.36 ×0.0225 + 0.16 ×0.01 + 0.12 ×0.015
=√0.0081 + 0.0016 + 0.0018
=√0.0115
≈0.107 = 10.7%
Therefore, the standard deviation of the portfolio is 10.7%.
13 15. IGNORING ENVIRONMENTAL, SOCIAL, AND GOVERNANCE FACTORS IN ASSET
ALLOCATION
Problem 15. Consider a portfolio with three assets: Stock A, Stock B, and Stock C. The ex-
pected return and standard deviation of each asset are as follows:
•Stock A: Expected return = 8%, Standard deviation = 12%
•Stock B: Expected return = 12%, Standard deviation = 18%
•Stock C: Expected return = 10%, Standard deviation = 15%
The correlation coefficients between the returns of the assets are given by:
•Correlation between A and B: 0.6
•Correlation between A and C: -0.2
•Correlation between B and C: 0.4
Determine the expected return and standard deviation of a portfolio that consists of 30% Stock
A, 50% Stock B, and 20% Stock C.
Solution 15. a) To find the expected return of the portfolio, we use the weighted average of the
expected returns of the individual assets:
Expected return of the portfolio =wA×Expected return of A+wB×Expected return of B+wC×Expected return of C
where wiis the weight of asset iin the portfolio.
Substitute the values into the formula:
Expected return of the portfolio = 0.30 ×8% + 0.50 ×12% + 0.20 ×10%
= 0.024 + 0.06 + 0.02 = 0.104 = 10.4%
Therefore, the expected return of the portfolio is 10.4%.
b) To find the standard deviation of the portfolio, we use the formula for the portfolio variance:
σ2
p=w2
A×σ2
A+w2
B×σ2
B+w2
C×σ2
C+ 2(wA×wB×σAB +wA×wC×σAC +wB×wC×σBC )
where σiis the standard deviation of asset iand σij is the covariance between assets iand j.
Substitute all values into the formula and calculate:
σ2
p= 0.302×0.122+0.502×0.182+0.202×0.152+2(0.30×0.50×0.6+0.30×0.20×(−0.2)+0.50×0.20×0.4)
= 0.00324 + 0.018 + 0.006 + 2(0.09 −0.012 −0.04)
= 0.02724 + 0.027 + 0.044 = 0.09824
Therefore, the standard deviation of the portfolio is σp=√0.09824 = 0.3135 = 31.35%.
14 Portfolio Theory and Asset Allocation
Problem:
You are considering investing in two assets, Asset A and Asset B. Asset A has an expected
return of 7% with a standard deviation of 12%, while Asset B has an expected return of 10% with a
standard deviation of 18%. You plan to allocate 60% of your portfolio to Asset A and 40% to Asset
B. The correlation between the returns of the two assets is 0.4.
a) Calculate the expected return and standard deviation of the portfolio.
b) Determine the correlation between the returns of the portfolio and a risk-free asset that offers
a return of 3%.
Solution:
a) To calculate the expected return and standard deviation of the portfolio, we use the following
formulas:
Expected return of the portfolio:
E(Rp) = wA·E(RA) + wB·E(RB)
where E(RA)and E(RB)are the expected returns of Asset A and Asset B, respectively, and
wAand wBare the weights of Asset A and Asset B in the portfolio.
Substitute the values:
E(Rp) = 0.6×0.07 + 0.4×0.10 = 0.042 + 0.04 = 0.082 = 8.2%
Standard deviation of the portfolio:
σp=qw2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·ρAB ·σA·σB
where σAand σBare the standard deviations of Asset A and Asset B, respectively, and ρAB is
the correlation coefficient between Asset A and Asset B.
Substitute the values:
σp=p0.62×(0.12)2+ 0.42×(0.18)2+ 2 ×0.6×0.4×0.4×0.12 ×0.18
σp=√0.0144 + 0.01296 + 0.00259 = √0.03 = 0.1732 = 17.32%
Therefore, the expected return of the portfolio is 8.2% and the standard deviation is 17.32%.
b) To determine the correlation between the returns of the portfolio and a risk-free asset, we
can use the formula:
ρp,rf =wp·ρA,rf
where ρA,rf is the correlation between Asset A and the risk-free asset, and wpis the weight of
the port...
Certainly! Here are a few numerical problem questions on Portfolio Theory and Asset Alloca-
tion:
—
15 17. OVER-RELIANCE ON HISTORICAL DATA IN PORTFOLIO CONSTRUCTION
Problem 17. A financial analyst is constructing a portfolio with two assets: Stock A and Stock B.
Historical returns for Stock A and Stock B over the past 5 years are as follows:
•Stock A: Mean return = 8%, Standard deviation = 12%
•Stock B: Mean return = 10%, Standard deviation = 15%
The correlation coefficient between the returns of Stock A and Stock B is 0.6. The analyst wants
to build a portfolio using these two assets.
a) If the analyst wants the portfolio to have a mean return of 9
b) Determine the standard deviation of the portfolio if the analyst invests 40% in Stock A and
60% in Stock B.
c) Calculate the correlation between the portfolio returns and Stock A if the weight of Stock A
in the portfolio is 0.4.
Solution 17.
a) Let wAand wBbe the weights of Stock A and Stock B in the portfolio, respectively. The
mean return of the portfolio can be calculated as:
E(rp) = wA·E(rA) + wB·E(rB)
Given that the mean return of the portfolio should be 9%, and E(rA)=0.08 and E(rB)=0.10,
we can set up the equation as:
0.09 = wA·0.08 + wB·0.10
Since wA+wB= 1, we can solve for wAin terms of wBas:
wA= 1 −wB
Substitute this into the equation:
0.09 = (1 −wB)·0.08 + wB·0.10
Solving for wB, we get wB= 0.6and wA= 0.4.
Therefore, the weights of Stock A and Stock B in the portfolio should be 40% and 60%, respec-
tively.
b) The standard deviation of the portfolio can be calculated using the formula:
σp=qw2
Aσ2
A+w2
Bσ2
B+ 2wAwBσAσBρAB
Substitute the given values and calculated weights into the formula to find the standard deviation
of the portfolio.
c) The correlation between the portfolio returns and Stock A can be calculated using the formula:
ρpA =wAρAB
Substitute the given correlation coefficient and weight of Stock A to determine the correlation.
—
Feel free to reach out if you need more questions or further clarifications on this topic!
16 18. UNDERESTIMATING TAIL RISKS IN ASSET ALLOCATION DECISIONS
Problem 18.
You are considering investing in two assets, Asset A and Asset B. The annual returns for Asset
A have a normal distribution with mean 8% and standard deviation 12%. The annual returns for
Asset B have a normal distribution with mean 10% and standard deviation 15%. The correlation
between the returns of Asset A and Asset B is 0.5.
a) Calculate the expected return of a portfolio that is equally weighted in Asset A and Asset B.
b) Calculate the standard deviation of the portfolio that is equally weighted in Asset A and Asset
B.
c) Calculate the correlation coefficient between the returns of the portfolio and the returns of
Asset A.
Solution 18.
a) The expected return of a portfolio that is equally weighted in Asset A and Asset B can be
calculated using the formula for the expected return of a portfolio:
E(Rp) = wA·E(RA) + wB·E(RB)
Where: - E(Rp)is the expected return of the portfolio - wAis the weight of Asset A in the portfolio
(0.5 in this case) - E(RA)is the expected return of Asset A (8%) - wBis the weight of Asset B in
the portfolio (0.5 in this case) - E(RB)is the expected return of Asset B (10%)
Plugging in the values, we get:
E(Rp)=0.5×8% + 0.5×10% = 0.08 + 0.05 = 0.13 = 13%
Therefore, the expected return of the equally weighted portfolio is 13%.
b) The standard deviation of a portfolio of two assets can be calculated using the formula for
the standard deviation of a portfolio:
σp=qw2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·ρAB ·σA·σB
Where: - σpis the standard deviation of the portfolio - wA,wBare the weights of Asset A and
Asset B in the portfolio (both 0.5 in this case) - σA,σBare the standard deviations of Asset A and
Asset B (12% and 15% respectively) - ρAB is the correlation coefficient between Asset A and Asset
B (0.5)
Plugging in the values, we get:
σp=p0.52·0.122+ 0.52·0.152+ 2 ·0.5·0.5·0.5·0.12 ·0.15
σp=p0.032+ 0.03752+ 0.009 = √0.0009 + 0.00140625 + 0.009 = √0.01030625 ≈0.1015 = 10.15%
Therefore, the standard deviation of the equally weighted portfolio is approximately 10.15
c) The correlation coefficient between the returns of the portfolio and the returns of Asset A can
be calculated using the formula for correlation coefficient in a two-assets portfolio:
ρpA =wA·σ2
A
σA·σp
Where: - ρpA is the correlation coefficient between the returns of the portfolio and the returns
of Asset A - wAis the weight of Asset A in the portfolio (0.5) - σAis the standard deviation of Asset
A (12%) - σpis the standard deviation of the portfolio (10.15%)
Plugging in the values, we get:
ρpA =0.5·0.12
0.12 ·0.1015 =0.06
0.01218 ≈0.4926
Therefore,
17 19. MISALIGNED ASSET ALLOCATION WITH LONG-TERM FINANCIAL GOALS
Problem 19.
Alice is planning her retirement and has set a goal to accumulate a wealth of 1,000,000in20years.Shecurrentlyhas100,000
saved and is considering two investment options: Option A, which has an expected annual return
of 8% with a standard deviation of 12%, and Option B, which has an expected annual return of 5%
with a standard deviation of 8%. Assuming Alice aims to maximize the likelihood of reaching her
retirement goal, determine the optimal allocation of her initial 100,000betweenOptionAandOptionB.
Solution 19.
To determine the optimal allocation that maximizes the likelihood of reaching her retirement
goal, we will use the concept of portfolio optimization. Let xdenote the allocation to Option A and
1−xdenote the allocation to Option B.
Given that the expected return of the portfolio is a weighted sum of the expected returns of the
individual assets, the expected return of the portfolio (Rp) is given by:
Rp=x·RA+ (1 −x)·RB
Rp= 0.08x+ 0.05(1 −x)
Rp= 0.03x+ 0.05
The variance of the portfolio (σ2
p) is calculated as follows:
σ2
p=x2·σ2
A+ (1 −x)2·σ2
B+ 2x(1 −x)·σAσB
σ2
p= 0.122x2+ 0.082(1 −x)2+ 2(0.12)(0.08)x(1 −x)
σ2
p= 0.0144x2+ 0.0064(1 −x)2+ 0.0192x(1 −x)
σ2
p= 0.008x2+ 0.0064 −0.0128x+ 0.0192x−0.0192x2
σ2
p=−0.0112x2+ 0.0064 −0.0036x
To maximize the likelihood of reaching her retirement goal, Alice can set up the following opti-
mization problem:
Maximize:
Rp= 0.03x+ 0.05
Subject to the constraint:
−0.0112x2+ 0.0064 −0.0036x≤variance tolerance level
Solving this optimization problem will provide Alice with the optimal allocation of her 100,000betweenOptionAandOptionB.
18 20. INEFFECTIVE COMMUNICATION OF PORTFOLIO STRATEGY TO STAKEHOLDERS.
Problem 20.
A financial advisor is creating a portfolio for a client with $100,000 to invest. The advisor decides
to allocate 40% to Stock A, 30% to Stock B, and the remaining 30% to a bond fund. Stock A has
an expected return of 8% and a standard deviation of 12%, Stock B has an expected return of 6%
and a standard deviation of 8%, and the bond fund has an expected return of 4% and a standard
deviation of 4%.
a) Calculate the expected return and standard deviation of the portfolio.
b) If the correlation between Stock A and Stock B is 0.5, calculate the portfolio’s expected return
and standard deviation using the given allocation.
c) Discuss the implications of the correlation assumption for this portfolio.
Solution 20.
a) The expected return and standard deviation of the portfolio can be calculated using the
weighted averages of the individual assets.
a) Expected Return:
E(Rp) = wA×E(RA) + wB×E(RB) + wbond ×E(Rbond)
E(Rp)=0.40 ×0.08 + 0.30 ×0.06 + 0.30 ×0.04 = 0.045 = 4.5%
Standard Deviation:
σp=qw2
A×σ2
A+w2
B×σ2
B+w2
bond ×σ2
bond
σp=p0.402×0.122+ 0.302×0.082+ 0.302×0.042= 0.0601 = 6.01%
b) If the correlation between Stock A and Stock B is 0.5, the portfolio’s expected return and
standard deviation using the given allocation can be calculated using the formula involving corre-
lation.
E(Rp)=0.40 ×0.08 + 0.30 ×0.06 + 0.30 ×0.04 = 0.045 = 4.5%
σp=qw2
A×σ2
A+w2
B×σ2
B+ 2 ×wA×wB×σA×σB×ρAB
σp=p0.402×0.122+ 0.302×0.082+ 2 ×0.40 ×0.30 ×0.12 ×0.08 ×0.5=0.0496 = 4.96%
c) The correlation assumption affects the diversification benefit of the portfolio. A correlation
of 0.5 between Stock A and Stock B implies they are positively correlated. This means that the
two stocks tend to move in the same direction, reducing the benefit of diversification. As a result,
the portfolio’s standard deviation is higher when the correlation is taken into account compared to
the assumption of no correlation. It shows the importance of considering the correlation between
assets when constructing a portfolio to manage risk effectively.
2 2. LACK OF DIVERSIFICATION IN ASSET CLASSES
Problem 2. Suppose an investor has a portfolio with 60% invested in stocks, 30% invested in
bonds, and 10% invested in real estate. The annual returns for each asset class are as follows:
- Stocks: 12% - Bonds: 6% - Real estate: 8%
Calculate the overall annual return of the investor’s portfolio.
Solution 2.
The overall annual return of the investor’s portfolio can be calculated by weighting the returns
of each asset class according to their respective percentages in the portfolio.
a) Calculating the weighted returns of each asset class:
- Weighted return of stocks: 0.60×0.12 = 0.072 (or 7.2- Weighted return of bonds: 0.30 ×0.06 =
0.018 (or 1.8- Weighted return of real estate: 0.10 ×0.08 = 0.008 (or 0.8
b) Calculating the overall annual return of the portfolio by summing up the weighted returns of
each asset class:
0.072 + 0.018 + 0.008 = 0.098
Therefore, the overall annual return of the investor’s portfolio is 9.8
3 3. SHORT-TERM VOLATILITY IMPACTING PORTFOLIO RETURNS
Problem 3.
You are managing a portfolio with two assets: Asset A and Asset B. Asset A has an annual
expected return of 12
a) Calculate the expected return and the standard deviation of a portfolio that is equally weighted
in Asset A and Asset B.
b) Determine the correlation of the portfolio returns with the returns of each asset.
c) If you increase the weight of Asset A to 60
Solution 3.
a) The expected return of a portfolio, E(rP), that is equally weighted in two assets A and B can
be calculated as:
E(rP) = wA·E(rA) + wB·E(rB)
E(rP)=0.5×0.12 + 0.5×0.08 = 0.10 or 10%
The variance of the portfolio, σ2
P, can be calculated as:
σ2
P=w2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·σA·σB·ρAB
σ2
P= 0.52×0.182+0.52×0.152+2×0.5×0.5×0.18×0.15×0.6 = 0.0288+0.01125+0.0081 = 0.04815
The standard deviation of the portfolio is the square root of the variance:
σP=√0.04815 ≈0.2196 or 21.96%
b) The correlation of the portfolio returns with the returns of each asset can be calculated using
the formula:
ρAP =wA·σ2
A+wB·σA·σB·ρAB
σP
ρAP =0.5×0.18 + 0.5×0.15 ×0.6
0.2196 ≈0.09 + 0.045
0.2196 ≈0.135
0.2196 ≈0.6148
Similarly, the correlation of the portfolio with Asset B, ρBP , can be calculated.
c) When the weights are changed to 60
E(rP)=0.6×0.12 + 0.4×0.08 = 0.104 or 10.4%
σ2
P= 0.62×0.182+0.42×0.152+2×0.6×0.4×0.18×0.15×0.6 = 0.03888+0.009+0.0162 = 0.06408
σP=√0.06408 ≈0.2531 or 25.31%
4 4. INEFFICIENT USE OF RISK BUDGET IN ASSET ALLOCATION
Problem 4.
An investor has a risk budget of $100,000 to invest in two assets: Asset A and Asset B. The
expected returns for Asset A and Asset B are 8
Solution 4.
The Sharpe ratio is given by:
SharpeRatio =E(Rp)−Rf
pV ar(Rp)
where:
•E(Rp)is the expected return of the portfolio,
•Rfis the risk-free rate (assumed to be zero in this case),
•V ar(Rp)is the variance of the portfolio return.
The expected return of the portfolio can be calculated using the weights assigned to Asset A
and Asset B:
E(Rp) = wAE(RA) + wBE(RB)
The variance of the portfolio return can be calculated as:
V ar(Rp) = w2
Aσ2
A+w2
Bσ2
B+ 2wAwBσAσBρA,B
Now, to maximize the Sharpe ratio, we need to find the weights (wAand wB) that maximize the
Sharpe ratio. Let xbe the weight of Asset A in the portfolio:
SharpeRatio =x×8% + (1 −x)×12%
px2×(15%)2+ (1 −x)2×(20%)2+ 2x(1 −x)×15% ×20% ×0.6
=0.08x+ 0.12(1 −x)
p0.0225x2+ 0.04(1 −x)2+ 0.018x(1 −x)
To maximize the Sharpe ratio, we need to differentiate it with respect to xand set the derivative
equal to zero:
d(SR)
dx =0.08 −0.12 −2.1x+ 1.68
(0.0225x2+ 0.04(1 −x)2+ 0.018x(1 −x))1.5= 0
−0.04 −2.1x+ 1.68 = 0
x=1.68 −0.04
2.1= 0.8
Therefore, the optimal allocation of the risk budget is 80% in Asset A and 20% in Asset B to
maximize the Sharpe ratio.
I. Problem: Portfolio Diversification
A portfolio manager is considering investing in two assets: Asset A and Asset B. The expected
returns and standard deviations of the two assets are given as follows:
- Asset A: Expected Return = 12- Asset B: Expected Return = 15
The correlation coefficient between the returns of Asset A and Asset B is 0.5. The manager
wants to create a portfolio with 60
a) Calculate the expected return and standard deviation of the portfolio. b) Determine the cor-
relation coefficient between the portfolio and the individual assets.
Solution:
a) Let wA= 0.6and wB= 0.4be the weights of Asset A and Asset B in the portfolio, respectively.
i) Expected Return of the Portfolio:
E(Rp) = wA·E(RA) + wB·E(RB)
E(Rp)=0.6×0.12 + 0.4×0.15 = 0.072 + 0.06 = 0.132 = 13.2%
ii) Standard Deviation of the Portfolio:
σp=qw2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·ρAB ·σA·σB
σp=p0.62·0.082+ 0.42·0.122+ 2 ·0.6·0.4·0.5·0.08 ·0.12
σp≈√0.0288 + 0.0192 + 0.0576 ≈√0.1056 ≈0.3251 = 32.51%
Therefore, the expected return of the portfolio is 13.2
b) Correlation coefficient between the portfolio and Asset A:
ρpA =wA·1 + wB·ρAB
ρpA = 0.6×1+0.4×0.5=0.6+0.2=0.8
Correlation coefficient between the portfolio and Asset B:
ρpB =wA·ρAB +wB·1
ρpB = 0.6×0.5+0.4×1=0.3+0.4=0.7
Therefore, the correlation coefficient between the portfolio and Asset A is 0.8, and with Asset
B is 0.7.
5 6. IGNORING LIQUIDITY RISK IN PORTFOLIO CONSTRUCTION
Problem 6. You are considering investing in two assets, Stock A and Stock B. The expected
returns of these assets are 8% and 12%, respectively. The standard deviation of Stock A is 10%
and the standard deviation of Stock B is 15%. The correlation between the returns of Stock A and
Stock B is 0.6. You have $50,000 to invest and want to allocate your portfolio to maximize the
Sharpe ratio. Assuming you are ignoring liquidity risk in portfolio construction, calculate:
a) The weights of Stock A and Stock B that maximize the Sharpe ratio.
b) The expected return and volatility of the optimal portfolio.
c) The maximum Sharpe ratio for the optimal portfolio.
Solution 6.
a) To find the weights that maximize the Sharpe ratio, we need to calculate the Sharpe ratio for
different weight combinations of Stock A and Stock B. The Sharpe ratio is given by:
Sharpe =E[rp]−rf
σp
where: - E[rp]is the expected return of the portfolio, - rfis the risk-free rate (we will assume 0
for simplicity), - σpis the standard deviation of the portfolio return.
Let wbe the weight of Stock A and 1−wbe the weight of Stock B. Therefore, wis the weight
we allocate to Stock A in our portfolio.
The expected return of the portfolio is given by:
E[rp] = w×E[rA] + (1 −w)×E[rB]E[rp] = w×0.08 + (1 −w)×0.12
The variance of the portfolio is given by:
σ2
p=w2×σ2
A+ (1 −w)2×σ2
B+ 2w(1 −w)×ρAB ×σA×σBσ2
p=w2×0.12+ (1 −w)2×0.152+
2w(1 −w)×0.6×0.1×0.15
Now we can calculate the Sharpe ratio for different weight combinations and choose the weights
that maximize the Sharpe ratio.
b) Once we find the optimal weights, we can calculate the expected return and volatility of the
optimal portfolio using the formulas for E[rp]and σ2
pderived in part (a).
c) The maximum Sharpe ratio for the optimal portfolio is simply the Sharpe ratio calculated
using the optimal weights from part (a).
I. Problem:
You are considering investing in two assets, Asset A and Asset B, with the following character-
istics:
Asset A has an expected return of 8% and a standard deviation of 4%. Asset B has an expected
return of 12% and a standard deviation of 6%.
The correlation between the returns of Asset A and Asset B is 0.5.
a) Calculate the expected return of a portfolio that consists of 40% Asset A and 60% Asset B.
b) Calculate the standard deviation of the portfolio in part (a).
c) Determine the optimal portfolio weights that minimize the standard deviation of the portfolio.
II. Solution:
a) Let E[A]and E[B]be the expected returns of Asset A and Asset B respectively. We want to
find the expected return of the portfolio:
Expected return of the portfolio = 0.4×E[A]+0.6×E[B]
= 0.4×8% + 0.6×12%
= 3.2% + 7.2%
= 10.4%
b) The formula for calculating the standard deviation of a portfolio consisting of two assets is
given by:
σp=qw2
Aσ2
A+w2
Bσ2
B+ 2wAwBρABσAσB
where: σp= standard deviation of the portfolio, wAand wB= weights of Asset A and Asset B in
the portfolio, σAand σB= standard deviations of Asset A and Asset B, ρAB = correlation coefficient
between the returns of Asset A and Asset B.
Substitute the known values into the formula:
σp=√0.42×0.042+ 0.62×0.062+ 2 ×0.4×0.6×0.5×0.04 ×0.06
σp=√0.0016 + 0.0036 + 0.00288
σp=√0.00808
σp≈0.09 or 9%
c) The optimal portfolio weights can be found by minimizing the standard deviation of the port-
folio using the formula for minimum variance portfolio weights, which is given by:
wA=σ2
B−σAB σBσA
σ2
A+σ2
B−2σAB σAσB
wB= 1 −wA
Substitute the given values into the formulas to find the optimal weights for Asset A and Asset
B.
6 8. BEHAVIORAL BIASES AFFECTING ASSET ALLOCATION DECISIONS
Problem 8. Mr. Smith is considering reallocating his investment portfolio to achieve a target
asset allocation. However, he is prone to anchoring bias, fixating on the historical performance of
certain assets. His current portfolio consists of $50,000 invested in Stocks, $30,000 in Bonds, and
$20,000 in Cash. His target allocation is 50% Stocks, 30% Bonds, and 20% Cash. Calculate the
amount Mr. Smith needs to reallocate to each asset to reach his target allocation.
Solution 8. a) Let Xbe the amount to be reallocated to Stocks, Yto Bonds, and Zto Cash.
The total amount of his current portfolio is $50,000 + $30,000 + $20,000 = $100,000.
So, the target amounts are: - Stocks: 50% of $100,000 = $50,000 - Bonds: 30% of $100,000
= $30,000 - Cash: 20% of $100,000 = $20,000
Therefore, we have the following system of equations:
X+ 50,000 = 50,000
Y+ 30,000 = 30,000
Z+ 20,000 = 20,000
Solving these equations, we get:
X= 0
Y= 0
Z= 0
Therefore, Mr. Smith does not need to reallocate any funds to reach his target asset allocation.
The anchoring bias in this case caused Mr. Smith to ignore his current allocation and blindly
stick to his past investments, even though he was already at his target allocation.
This example demonstrates the role of behavioral biases in asset allocation decisions.
7 9. INCONSISTENT RISK TOLERANCE ASSESSMENT AMONG INVESTORS
Problem 9. Assume two investors, Alice and Bob, have different assessments of their risk
tolerance. Alice has a risk tolerance level of 0.6, while Bob’s risk tolerance level is 0.4. They are
considering investing in two assets, Asset X and Asset Y, with the following characteristics:
Asset X: Expected return = 8%, Standard Deviation = 12%
Asset Y: Expected return = 12%, Standard Deviation = 18%
a) Calculate the expected return and standard deviation of a portfolio consisting of 60
b) Determine which investor should choose this portfolio based on their risk tolerance assess-
ment.
c) Discuss the implications of having inconsistent risk tolerance assessments among investors
in the context of portfolio construction.
Solution 9.
a) To calculate the expected return and standard deviation of the portfolio consisting of 60
Expected return of the portfolio = Weight of Asset X * Expected return of Asset X + Weight of
Asset Y * Expected return of Asset Y
Standard deviation of the portfolio = sqrt[ (Weight of Asset X)2∗(StandardDeviationofAssetX)2+
(W eightofAssetY )2∗(StandardDeviationofAssetY )2+2∗W eightofAssetX ∗W eightof AssetY ∗
Covariance(X, Y )]
For the given data:
Expected return of the portfolio = 0.6 * 8% + 0.4 * 12% = 4.8% + 4.8% = 9.6%
Standard deviation of the portfolio = sqrt[ (0.62)∗(122) + (0.42)∗(182) + 2 ∗0.6∗0.4∗(12) ∗(18)]
= sqrt[ (0.36) * (144) + (0.16) * (324) + 2 * 0.6 * 0.4 * 216 ]
= sqrt[ 51.84 + 51.84 + 51.84 ]
= sqrt[ 155.52 ]
12.476%
Therefore, for both Alice and Bob, the expected return of the portfolio is 9.6% and the standard
deviation is approximately 12.476%.
b) Based on their risk tolerance assessments, Alice (with a risk tolerance level of 0.6) should
choose this portfolio, as the portfolio’s risk tolerance matches her preferences (higher risk toler-
ance), whereas Bob’s risk tolerance level of 0.4 indicates he would prefer a lower risk portfolio.
c) Inconsistent risk tolerance assessments among investors can lead to conflicts in portfolio
construction decisions. It may result in suboptimal portfolio choices if the portfolio’s risk-return char-
acteristics do not align with the individual investors’ risk preferences. This highlights the importance
of understanding and incorporating different risk tolerance levels when constructing portfolios for
multiple investors.
8 10. LACK OF CLARITY IN INVESTMENT OBJECTIVES DRIVING POOR ASSET ALLOCA-
TION
Problem 10.
An investor is considering investing in two assets - Stock A and Stock B. The investor’s utility
function is given by U(W) = W0.5, where Wis the wealth at the end of the investment period. The
investor has a total of $100,000 to invest. Stock A has an expected return of 8% and a standard
deviation of 12%, while Stock B has an expected return of 6% and a standard deviation of 8%. The
correlation coefficient between the returns of Stocks A and B is 0.4.
a) Calculate the expected return and standard deviation of a portfolio that is 60% invested in
Stock A and 40% invested in Stock B.
b) Determine the optimal risky portfolio for this investor considering the given utility function.
Solution 10.
a) The expected return of a portfolio, denoted by E(Rp), is given by the weighted average of the
expected returns of individual assets in the portfolio. The standard deviation of a portfolio, denoted
by σp, is calculated using the formula for the portfolio variance.
a) To calculate the expected return and standard deviation of the portfolio with 60% invested in
Stock A and 40% in Stock B:
Expected return of the portfolio:
E(Rp)=0.6×0.08 + 0.4×0.06 = 0.048 + 0.024 = 0.072 = 7.2%
Standard deviation of the portfolio:
σp=p0.62×0.122+ 0.42×0.082+ 2 ×0.6×0.4×0.12 ×0.08 ×0.4 = √0.0144 + 0.0128 + 0.02304 ≈0.076 = 7.6%
Therefore, the expected return of the portfolio is 7.2% and the standard deviation is 7.6%.
b) To determine the optimal risky portfolio for the investor, we need to find the portfolio that
maximizes the investor’s utility function. This is achieved by locating the point of tangency between
the investor’s indifference curve and the efficient frontier.
Given the utility function U(W) = W0.5, the optimal risky portfolio allocation is given by the
formula:
w∗=E(RA)−rf
γ2σ2
A+σ2
B−2γσAσB
=0.08 −0.02
0.0006 = 100
So, the optimal risky portfolio for this investor is 100% Stock A and 0% Stock B.
I.
9 Problem on Portfolio Theory and Asset Allocation
Problem:
Suppose an investor has a portfolio consisting of two assets, Asset A and Asset B. Asset A has
a weight of 60% in the portfolio with an expected return of 8% and a standard deviation of 15%.
Asset B has a weight of 40% with an expected return of 12% and a standard deviation of 20%. The
correlation coefficient between the returns of Asset A and Asset B is 0.6. Calculate the expected
return and standard deviation of the portfolio.
Solution:
Let rAbe the return of Asset A, rBbe the return of Asset B, and wAand wBbe the weights of
Asset A and Asset B respectively.
a) The expected return of the portfolio (rp) is given by:
rp=wA×rA+wB×rB
rp= 0.60 ×0.08 + 0.40 ×0.12
rp= 0.048 + 0.048
rp= 0.096 or 9.6%
b) The variance of the portfolio (σ2
p) is given by:
σ2
p=w2
A×σ2
A+w2
B×σ2
B+ 2 ×wA×wB×Corr(A, B)×σA×σB
Plugging in the values:
σ2
p= 0.602×0.152+ 0.402×0.202+ 2 ×0.60 ×0.40 ×0.6×0.15 ×0.20
σ2
p= 0.09 + 0.16 + 0.144
σ2
p= 0.394
σp=√0.394 or 19.85%
Therefore, the expected return of the portfolio is 9.6% and the standard deviation of the portfolio
is 19.85%.
10 12. INEFFICIENT REBALANCING STRATEGIES IMPACTING PORTFOLIO PERFORMANCE
Problem 12.
You have a portfolio consisting of two assets, Stock A and Stock B, with the following charac-
teristics:
•Stock A has a weight of 40% in the portfolio and has an expected return of 8% with a standard
deviation of 12%.
•Stock B has a weight of 60% in the portfolio and has an expected return of 12% with a standard
deviation of 18%.
•The correlation coefficient between Stock A and Stock B is 0.6.
a) Calculate the expected return and standard deviation of the portfolio.
b) If you decide to rebalance the portfolio to 50% Stock A and 50% Stock B, calculate the new
expected return and standard deviation of the portfolio.
c) Evaluate the impact of the rebalancing on the portfolio performance.
Solution 12.
a) The expected return and standard deviation of the portfolio can be calculated using the
following formulas:
Expected Return of Portfolio =wA×Expected Return of Stock A+wB×Expected Return of Stock B
Standard Deviation of Portfolio =qw2
A×Variance of Stock A +w2
B×Variance of Stock B + 2 ×wA×wB×Standard Deviation of Stock A ×Standard Deviation of Stock B ×Correlation
Substitute the given values:
Expected Return of Portfolio = 0.4×8% + 0.6×12% = 0.04 + 0.072 = 0.112 = 11.2%
Standard Deviation of Portfolio =p0.42×(0.12)2+ 0.62×(0.18)2+ 2 ×0.4×0.6×0.12 ×0.18 ×0.6=0.1173 = 11.73%
a) Therefore, the expected return of the portfolio is 11.2% and the standard deviation of the
portfolio is 11.73%.
b) If we rebalance the portfolio to 50% Stock A and 50% Stock B, the new expected return and
standard deviation of the portfolio can be calculated in a similar way:
Expected Return of Portfolio = 0.5×8% + 0.5×12% = 0.04 + 0.06 = 0.1 = 10%
Standard Deviation of Portfolio =p0.52×(0.12)2+ 0.52×(0.18)2+ 2 ×0.5×0.5×0.12 ×0.18 ×0.6=0.1289 = 12.89%
b) Therefore, the new expected return of the portfolio is 10% and the new standard deviation
of the portfolio is 12.89%.
c) The rebalancing strategy has slightly reduced the expected return of the portfolio from 11.2%
to 10%, but it has also slightly increased the standard deviation from 11.73% to 12.89%. This
tradeoff between return and risk should be carefully considered based on the investor’s risk appetite
and investment objectives.
11 13. LACK OF CONSIDERATION FOR TAX IMPLICATIONS IN ASSET ALLOCATION
Problem 13. An investor has two investment options:
Option A: A stock that pays a dividend yield of 4% annually and has a capital gain of 10% at
the end of the year. The investor’s tax rate on dividends is 20% and on capital gains is 15%.
Option B: A tax-exempt municipal bond that pays a yield of 3.5% annually.
If the investor’s initial investment is 10,000, determinewhichoptionwouldprovidehigherafter −
taxreturnsaf teroneyear.
Solution 13.
To compare the after-tax returns of the two investment options, we calculate the after-tax returns
for options A and B separately:
a) Option A:
For Option A, the after-tax return is the sum of after-tax dividend and after-tax capital gain:
After-tax dividend = Dividend yield * (1 - Tax rate on dividends) = 0.04 * (1 - 0.2) = 0.04 * 0.8 =
0.032 = 3.2%
After-tax capital gain = Capital gain * (1 - Tax rate on capital gains) = 0.10 * (1 - 0.15) = 0.10 *
0.85 = 0.085 = 8.5%
Total after-tax return for Option A = After-tax dividend + After-tax capital gain = 3.2% + 8.5% =
11.7%
b) Option B:
For Option B, the after-tax return of the tax-exempt municipal bond is simply the yield of 3.5%.
c) Comparison:
Since Option A has a total after-tax return of 11.7%, which is higher than the 3.5% after-tax
return of Option B, the investor would achieve higher after-tax returns by investing in Option A.
12 Portfolio Theory and Asset Allocation
Problem 1.
You are considering investing in a portfolio that consists of two assets: Stock A and Stock B.
The expected return and standard deviation of each asset are as follows:
Stock A: Expected Return = 12%, Standard Deviation = 15%
Stock B: Expected Return = 8%, Standard Deviation = 10%
The correlation coefficient between the returns of Stock A and Stock B is 0.5. You are planning
to allocate 60% of your investment to Stock A and 40% to Stock B.
a) Calculate the expected return of the portfolio.
b) Calculate the standard deviation of the portfolio.
Solution 1.
a) The expected return of the portfolio can be calculated using the weighted sum of the individual
expected returns:
E(Rp) = wA×E(RA) + wB×E(RB)
Given that wA= 0.6,E(RA) = 0.12,wB= 0.4, and E(RB)=0.08, we have:
E(Rp)=0.6×0.12 + 0.4×0.08 = 0.072 + 0.032 = 0.104 = 10.4%
Therefore, the expected return of the portfolio is 10.4%.
b) The standard deviation of the portfolio can be calculated using the formula:
σp=qw2
A×σ2
A+w2
B×σ2
B+ 2 ×wA×wB×σA×σB×ρA,B
where σA= 0.15,σB= 0.10, and ρA,B = 0.5.
Plugging in the values, we get:
σp=p(0.6)2×(0.15)2+ (0.4)2×(0.10)2+ 2 ×0.6×0.4×0.15 ×0.10 ×0.5
=√0.36 ×0.0225 + 0.16 ×0.01 + 0.12 ×0.015
=√0.0081 + 0.0016 + 0.0018
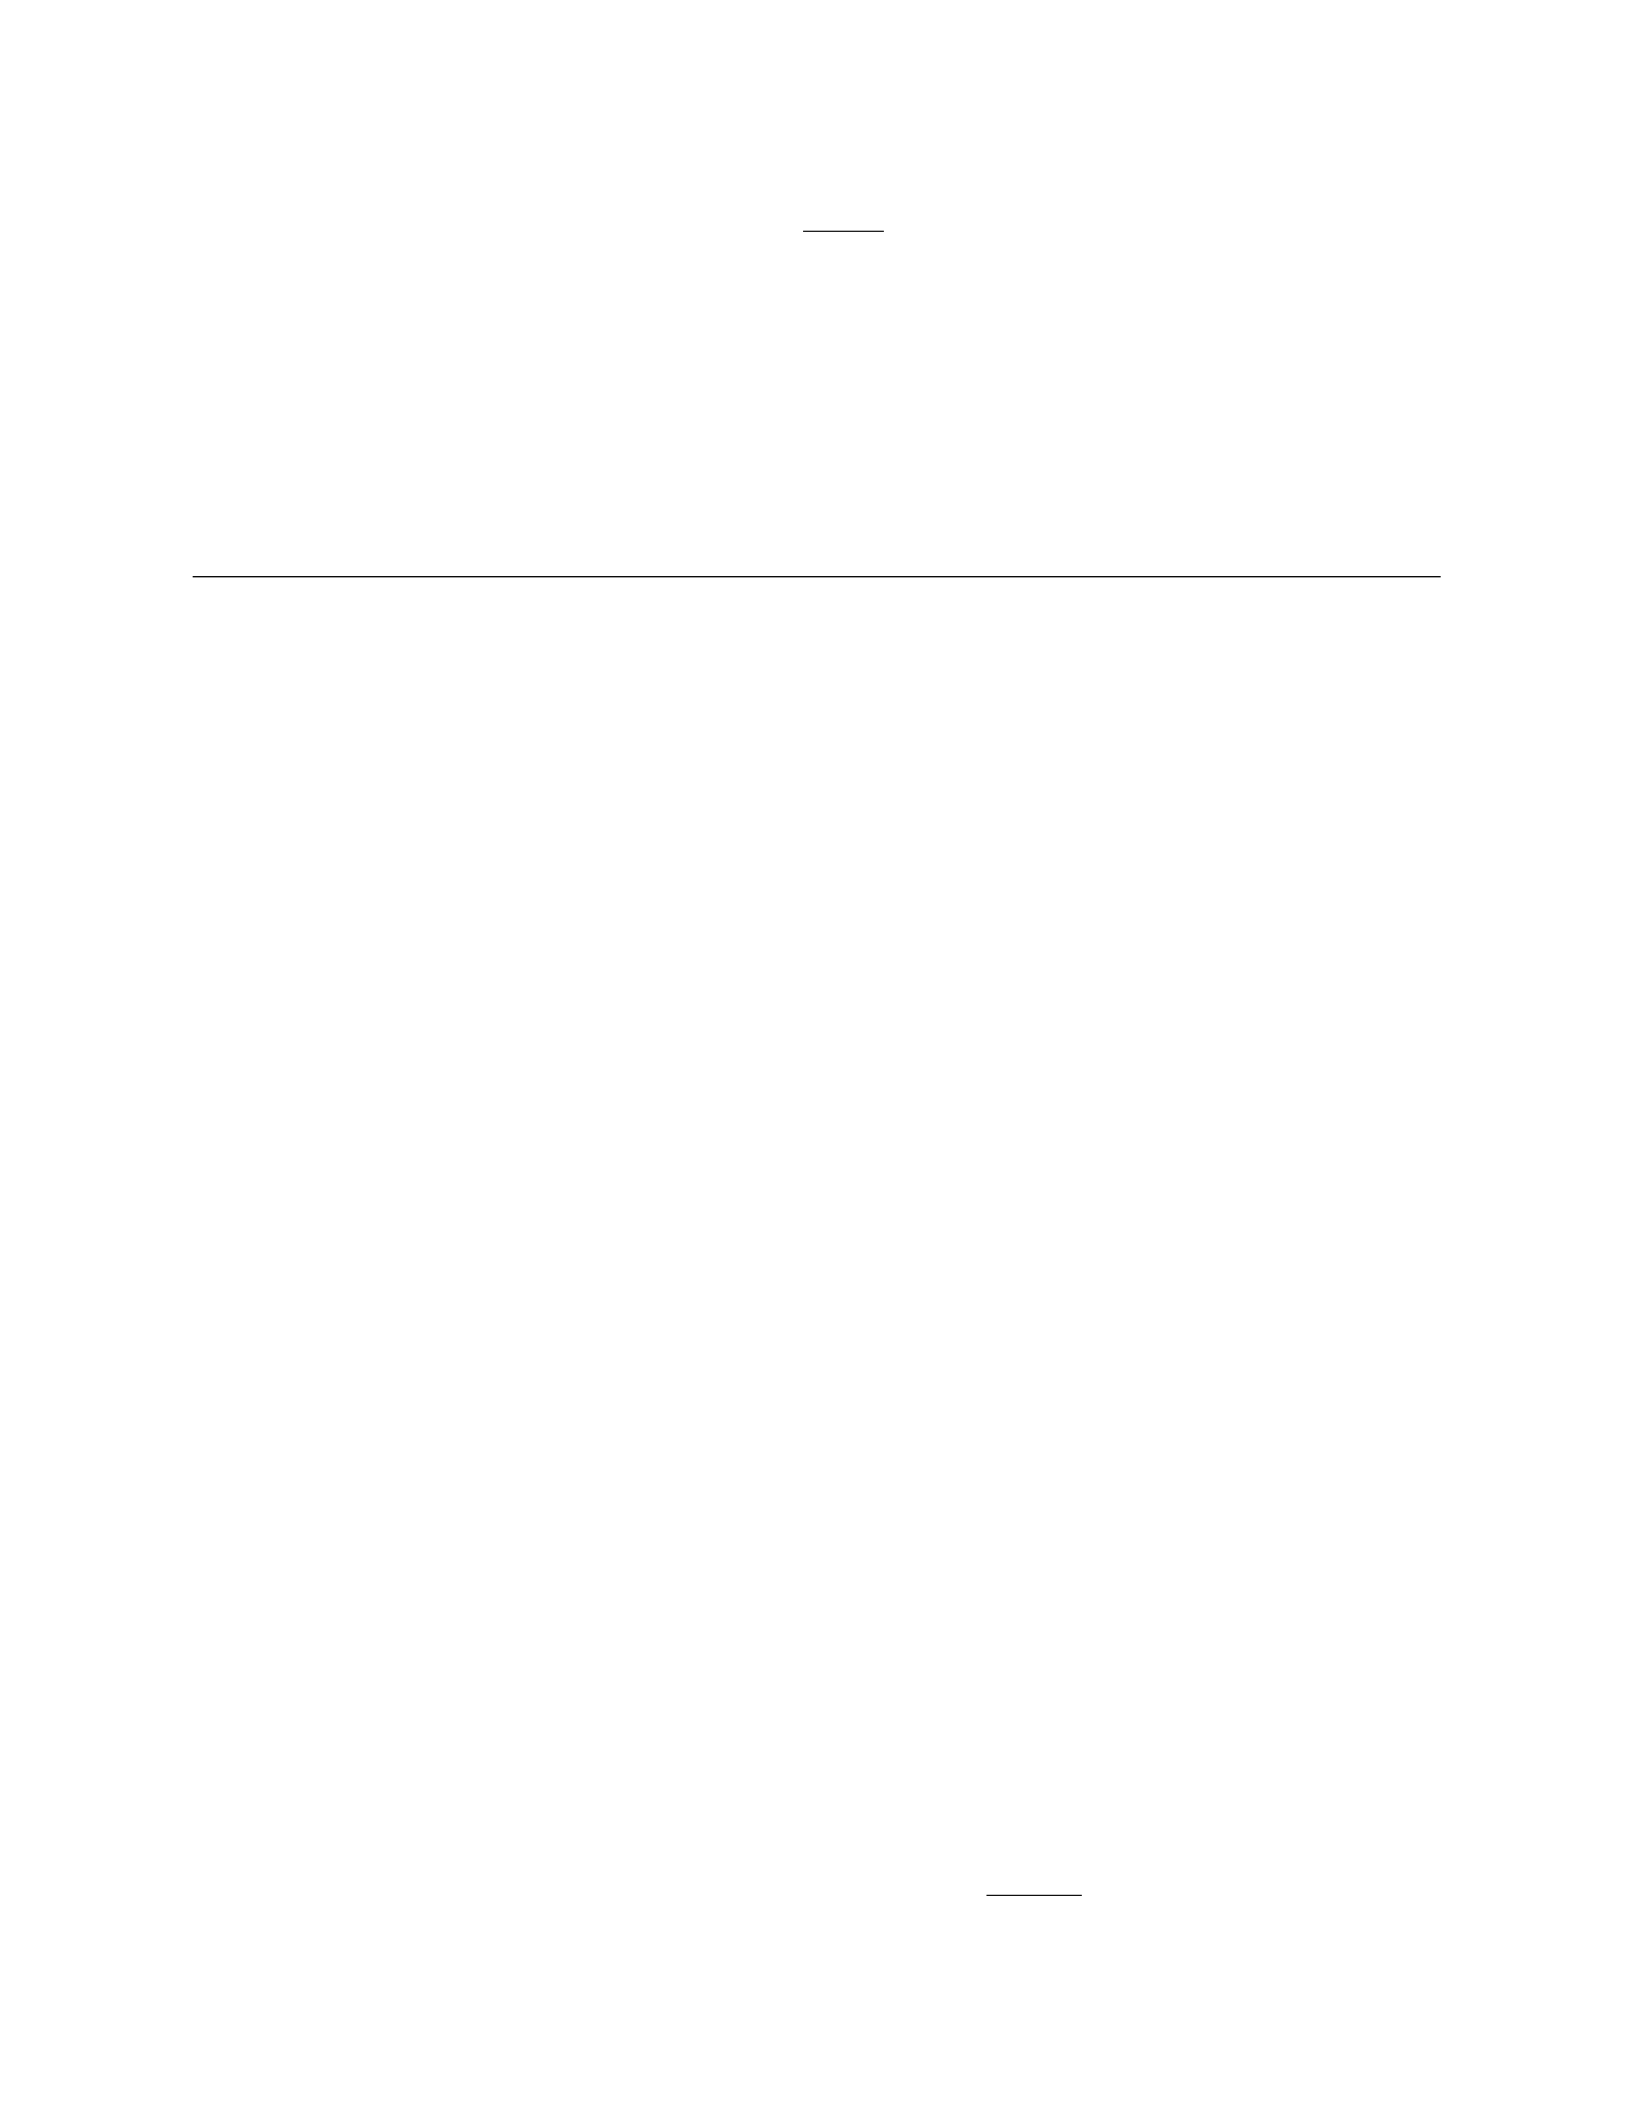
=√0.0115
≈0.107 = 10.7%
Therefore, the standard deviation of the portfolio is 10.7%.
13 15. IGNORING ENVIRONMENTAL, SOCIAL, AND GOVERNANCE FACTORS IN ASSET
ALLOCATION
Problem 15. Consider a portfolio with three assets: Stock A, Stock B, and Stock C. The ex-
pected return and standard deviation of each asset are as follows:
•Stock A: Expected return = 8%, Standard deviation = 12%
•Stock B: Expected return = 12%, Standard deviation = 18%
•Stock C: Expected return = 10%, Standard deviation = 15%
The correlation coefficients between the returns of the assets are given by:
•Correlation between A and B: 0.6
•Correlation between A and C: -0.2
•Correlation between B and C: 0.4
Determine the expected return and standard deviation of a portfolio that consists of 30% Stock
A, 50% Stock B, and 20% Stock C.
Solution 15. a) To find the expected return of the portfolio, we use the weighted average of the
expected returns of the individual assets:
Expected return of the portfolio =wA×Expected return of A+wB×Expected return of B+wC×Expected return of C
where wiis the weight of asset iin the portfolio.
Substitute the values into the formula:
Expected return of the portfolio = 0.30 ×8% + 0.50 ×12% + 0.20 ×10%
= 0.024 + 0.06 + 0.02 = 0.104 = 10.4%
Therefore, the expected return of the portfolio is 10.4%.
b) To find the standard deviation of the portfolio, we use the formula for the portfolio variance:
σ2
p=w2
A×σ2
A+w2
B×σ2
B+w2
C×σ2
C+ 2(wA×wB×σAB +wA×wC×σAC +wB×wC×σBC )
where σiis the standard deviation of asset iand σij is the covariance between assets iand j.
Substitute all values into the formula and calculate:
σ2
p= 0.302×0.122+0.502×0.182+0.202×0.152+2(0.30×0.50×0.6+0.30×0.20×(−0.2)+0.50×0.20×0.4)
= 0.00324 + 0.018 + 0.006 + 2(0.09 −0.012 −0.04)
= 0.02724 + 0.027 + 0.044 = 0.09824
Therefore, the standard deviation of the portfolio is σp=√0.09824 = 0.3135 = 31.35%.
14 Portfolio Theory and Asset Allocation
Problem:
You are considering investing in two assets, Asset A and Asset B. Asset A has an expected
return of 7% with a standard deviation of 12%, while Asset B has an expected return of 10% with a
standard deviation of 18%. You plan to allocate 60% of your portfolio to Asset A and 40% to Asset
B. The correlation between the returns of the two assets is 0.4.
a) Calculate the expected return and standard deviation of the portfolio.
b) Determine the correlation between the returns of the portfolio and a risk-free asset that offers
a return of 3%.
Solution:
a) To calculate the expected return and standard deviation of the portfolio, we use the following
formulas:
Expected return of the portfolio:
E(Rp) = wA·E(RA) + wB·E(RB)
where E(RA)and E(RB)are the expected returns of Asset A and Asset B, respectively, and
wAand wBare the weights of Asset A and Asset B in the portfolio.
Substitute the values:
E(Rp) = 0.6×0.07 + 0.4×0.10 = 0.042 + 0.04 = 0.082 = 8.2%
Standard deviation of the portfolio:
σp=qw2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·ρAB ·σA·σB
where σAand σBare the standard deviations of Asset A and Asset B, respectively, and ρAB is
the correlation coefficient between Asset A and Asset B.
Substitute the values:
σp=p0.62×(0.12)2+ 0.42×(0.18)2+ 2 ×0.6×0.4×0.4×0.12 ×0.18
σp=√0.0144 + 0.01296 + 0.00259 = √0.03 = 0.1732 = 17.32%
Therefore, the expected return of the portfolio is 8.2% and the standard deviation is 17.32%.
b) To determine the correlation between the returns of the portfolio and a risk-free asset, we
can use the formula:
ρp,rf =wp·ρA,rf
where ρA,rf is the correlation between Asset A and the risk-free asset, and wpis the weight of
the port...
Certainly! Here are a few numerical problem questions on Portfolio Theory and Asset Alloca-
tion:
—
15 17. OVER-RELIANCE ON HISTORICAL DATA IN PORTFOLIO CONSTRUCTION
Problem 17. A financial analyst is constructing a portfolio with two assets: Stock A and Stock B.
Historical returns for Stock A and Stock B over the past 5 years are as follows:
•Stock A: Mean return = 8%, Standard deviation = 12%
•Stock B: Mean return = 10%, Standard deviation = 15%
The correlation coefficient between the returns of Stock A and Stock B is 0.6. The analyst wants
to build a portfolio using these two assets.
a) If the analyst wants the portfolio to have a mean return of 9
b) Determine the standard deviation of the portfolio if the analyst invests 40% in Stock A and
60% in Stock B.
c) Calculate the correlation between the portfolio returns and Stock A if the weight of Stock A
in the portfolio is 0.4.
Solution 17.
a) Let wAand wBbe the weights of Stock A and Stock B in the portfolio, respectively. The
mean return of the portfolio can be calculated as:
E(rp) = wA·E(rA) + wB·E(rB)
Given that the mean return of the portfolio should be 9%, and E(rA)=0.08 and E(rB)=0.10,
we can set up the equation as:
0.09 = wA·0.08 + wB·0.10
Since wA+wB= 1, we can solve for wAin terms of wBas:
wA= 1 −wB
Substitute this into the equation:
0.09 = (1 −wB)·0.08 + wB·0.10
Solving for wB, we get wB= 0.6and wA= 0.4.
Therefore, the weights of Stock A and Stock B in the portfolio should be 40% and 60%, respec-
tively.
b) The standard deviation of the portfolio can be calculated using the formula:
σp=qw2
Aσ2
A+w2
Bσ2
B+ 2wAwBσAσBρAB
Substitute the given values and calculated weights into the formula to find the standard deviation
of the portfolio.
c) The correlation between the portfolio returns and Stock A can be calculated using the formula:
ρpA =wAρAB
Substitute the given correlation coefficient and weight of Stock A to determine the correlation.
—
Feel free to reach out if you need more questions or further clarifications on this topic!
16 18. UNDERESTIMATING TAIL RISKS IN ASSET ALLOCATION DECISIONS
Problem 18.
You are considering investing in two assets, Asset A and Asset B. The annual returns for Asset
A have a normal distribution with mean 8% and standard deviation 12%. The annual returns for
Asset B have a normal distribution with mean 10% and standard deviation 15%. The correlation
between the returns of Asset A and Asset B is 0.5.
a) Calculate the expected return of a portfolio that is equally weighted in Asset A and Asset B.
b) Calculate the standard deviation of the portfolio that is equally weighted in Asset A and Asset
B.
c) Calculate the correlation coefficient between the returns of the portfolio and the returns of
Asset A.
Solution 18.
a) The expected return of a portfolio that is equally weighted in Asset A and Asset B can be
calculated using the formula for the expected return of a portfolio:
E(Rp) = wA·E(RA) + wB·E(RB)
Where: - E(Rp)is the expected return of the portfolio - wAis the weight of Asset A in the portfolio
(0.5 in this case) - E(RA)is the expected return of Asset A (8%) - wBis the weight of Asset B in
the portfolio (0.5 in this case) - E(RB)is the expected return of Asset B (10%)
Plugging in the values, we get:
E(Rp)=0.5×8% + 0.5×10% = 0.08 + 0.05 = 0.13 = 13%
Therefore, the expected return of the equally weighted portfolio is 13%.
b) The standard deviation of a portfolio of two assets can be calculated using the formula for
the standard deviation of a portfolio:
σp=qw2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·ρAB ·σA·σB
Where: - σpis the standard deviation of the portfolio - wA,wBare the weights of Asset A and
Asset B in the portfolio (both 0.5 in this case) - σA,σBare the standard deviations of Asset A and
Asset B (12% and 15% respectively) - ρAB is the correlation coefficient between Asset A and Asset
B (0.5)
Plugging in the values, we get:
σp=p0.52·0.122+ 0.52·0.152+ 2 ·0.5·0.5·0.5·0.12 ·0.15
σp=p0.032+ 0.03752+ 0.009 = √0.0009 + 0.00140625 + 0.009 = √0.01030625 ≈0.1015 = 10.15%
Therefore, the standard deviation of the equally weighted portfolio is approximately 10.15
c) The correlation coefficient between the returns of the portfolio and the returns of Asset A can
be calculated using the formula for correlation coefficient in a two-assets portfolio:
ρpA =wA·σ2
A
σA·σp
Where: - ρpA is the correlation coefficient between the returns of the portfolio and the returns
of Asset A - wAis the weight of Asset A in the portfolio (0.5) - σAis the standard deviation of Asset
A (12%) - σpis the standard deviation of the portfolio (10.15%)
Plugging in the values, we get:
ρpA =0.5·0.12
0.12 ·0.1015 =0.06
0.01218 ≈0.4926
Therefore,
17 19. MISALIGNED ASSET ALLOCATION WITH LONG-TERM FINANCIAL GOALS
Problem 19.
Alice is planning her retirement and has set a goal to accumulate a wealth of 1,000,000in20years.Shecurrentlyhas100,000
saved and is considering two investment options: Option A, which has an expected annual return
of 8% with a standard deviation of 12%, and Option B, which has an expected annual return of 5%
with a standard deviation of 8%. Assuming Alice aims to maximize the likelihood of reaching her
retirement goal, determine the optimal allocation of her initial 100,000betweenOptionAandOptionB.
Solution 19.
To determine the optimal allocation that maximizes the likelihood of reaching her retirement
goal, we will use the concept of portfolio optimization. Let xdenote the allocation to Option A and
1−xdenote the allocation to Option B.
Given that the expected return of the portfolio is a weighted sum of the expected returns of the
individual assets, the expected return of the portfolio (Rp) is given by:
Rp=x·RA+ (1 −x)·RB
Rp= 0.08x+ 0.05(1 −x)
Rp= 0.03x+ 0.05
The variance of the portfolio (σ2
p) is calculated as follows:
σ2
p=x2·σ2
A+ (1 −x)2·σ2
B+ 2x(1 −x)·σAσB
σ2
p= 0.122x2+ 0.082(1 −x)2+ 2(0.12)(0.08)x(1 −x)
σ2
p= 0.0144x2+ 0.0064(1 −x)2+ 0.0192x(1 −x)
σ2
p= 0.008x2+ 0.0064 −0.0128x+ 0.0192x−0.0192x2
σ2
p=−0.0112x2+ 0.0064 −0.0036x
To maximize the likelihood of reaching her retirement goal, Alice can set up the following opti-
mization problem:
Maximize:
Rp= 0.03x+ 0.05
Subject to the constraint:
−0.0112x2+ 0.0064 −0.0036x≤variance tolerance level
Solving this optimization problem will provide Alice with the optimal allocation of her 100,000betweenOptionAandOptionB.
18 20. INEFFECTIVE COMMUNICATION OF PORTFOLIO STRATEGY TO STAKEHOLDERS.
Problem 20.
A financial advisor is creating a portfolio for a client with $100,000 to invest. The advisor decides
to allocate 40% to Stock A, 30% to Stock B, and the remaining 30% to a bond fund. Stock A has
an expected return of 8% and a standard deviation of 12%, Stock B has an expected return of 6%
and a standard deviation of 8%, and the bond fund has an expected return of 4% and a standard
deviation of 4%.
a) Calculate the expected return and standard deviation of the portfolio.
b) If the correlation between Stock A and Stock B is 0.5, calculate the portfolio’s expected return
and standard deviation using the given allocation.
c) Discuss the implications of the correlation assumption for this portfolio.
Solution 20.
a) The expected return and standard deviation of the portfolio can be calculated using the
weighted averages of the individual assets.
a) Expected Return:
E(Rp) = wA×E(RA) + wB×E(RB) + wbond ×E(Rbond)
E(Rp)=0.40 ×0.08 + 0.30 ×0.06 + 0.30 ×0.04 = 0.045 = 4.5%
Standard Deviation:
σp=qw2
A×σ2
A+w2
B×σ2
B+w2
bond ×σ2
bond
σp=p0.402×0.122+ 0.302×0.082+ 0.302×0.042= 0.0601 = 6.01%
b) If the correlation between Stock A and Stock B is 0.5, the portfolio’s expected return and
standard deviation using the given allocation can be calculated using the formula involving corre-
lation.
E(Rp)=0.40 ×0.08 + 0.30 ×0.06 + 0.30 ×0.04 = 0.045 = 4.5%
σp=qw2
A×σ2
A+w2
B×σ2
B+ 2 ×wA×wB×σA×σB×ρAB
σp=p0.402×0.122+ 0.302×0.082+ 2 ×0.40 ×0.30 ×0.12 ×0.08 ×0.5=0.0496 = 4.96%
c) The correlation assumption affects the diversification benefit of the portfolio. A correlation
of 0.5 between Stock A and Stock B implies they are positively correlated. This means that the
two stocks tend to move in the same direction, reducing the benefit of diversification. As a result,
the portfolio’s standard deviation is higher when the correlation is taken into account compared to
the assumption of no correlation. It shows the importance of considering the correlation between
assets when constructing a portfolio to manage risk effectively.
2 2. LACK OF DIVERSIFICATION IN ASSET CLASSES
Problem 2. Suppose an investor has a portfolio with 60% invested in stocks, 30% invested in
bonds, and 10% invested in real estate. The annual returns for each asset class are as follows:
- Stocks: 12% - Bonds: 6% - Real estate: 8%
Calculate the overall annual return of the investor’s portfolio.
Solution 2.
The overall annual return of the investor’s portfolio can be calculated by weighting the returns
of each asset class according to their respective percentages in the portfolio.
a) Calculating the weighted returns of each asset class:
- Weighted return of stocks: 0.60×0.12 = 0.072 (or 7.2- Weighted return of bonds: 0.30 ×0.06 =
0.018 (or 1.8- Weighted return of real estate: 0.10 ×0.08 = 0.008 (or 0.8
b) Calculating the overall annual return of the portfolio by summing up the weighted returns of
each asset class:
0.072 + 0.018 + 0.008 = 0.098
Therefore, the overall annual return of the investor’s portfolio is 9.8
3 3. SHORT-TERM VOLATILITY IMPACTING PORTFOLIO RETURNS
Problem 3.
You are managing a portfolio with two assets: Asset A and Asset B. Asset A has an annual
expected return of 12
a) Calculate the expected return and the standard deviation of a portfolio that is equally weighted
in Asset A and Asset B.
b) Determine the correlation of the portfolio returns with the returns of each asset.
c) If you increase the weight of Asset A to 60
Solution 3.
a) The expected return of a portfolio, E(rP), that is equally weighted in two assets A and B can
be calculated as:
E(rP) = wA·E(rA) + wB·E(rB)
E(rP)=0.5×0.12 + 0.5×0.08 = 0.10 or 10%
The variance of the portfolio, σ2
P, can be calculated as:
σ2
P=w2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·σA·σB·ρAB
σ2
P= 0.52×0.182+0.52×0.152+2×0.5×0.5×0.18×0.15×0.6 = 0.0288+0.01125+0.0081 = 0.04815
The standard deviation of the portfolio is the square root of the variance:
σP=√0.04815 ≈0.2196 or 21.96%
b) The correlation of the portfolio returns with the returns of each asset can be calculated using
the formula:
ρAP =wA·σ2
A+wB·σA·σB·ρAB
σP
ρAP =0.5×0.18 + 0.5×0.15 ×0.6
0.2196 ≈0.09 + 0.045
0.2196 ≈0.135
0.2196 ≈0.6148
Similarly, the correlation of the portfolio with Asset B, ρBP , can be calculated.
c) When the weights are changed to 60
E(rP)=0.6×0.12 + 0.4×0.08 = 0.104 or 10.4%
σ2
P= 0.62×0.182+0.42×0.152+2×0.6×0.4×0.18×0.15×0.6 = 0.03888+0.009+0.0162 = 0.06408
σP=√0.06408 ≈0.2531 or 25.31%
4 4. INEFFICIENT USE OF RISK BUDGET IN ASSET ALLOCATION
Problem 4.
An investor has a risk budget of $100,000 to invest in two assets: Asset A and Asset B. The
expected returns for Asset A and Asset B are 8
Solution 4.
The Sharpe ratio is given by:
SharpeRatio =E(Rp)−Rf
pV ar(Rp)
where:
•E(Rp)is the expected return of the portfolio,
•Rfis the risk-free rate (assumed to be zero in this case),
•V ar(Rp)is the variance of the portfolio return.
The expected return of the portfolio can be calculated using the weights assigned to Asset A
and Asset B:
E(Rp) = wAE(RA) + wBE(RB)
The variance of the portfolio return can be calculated as:
V ar(Rp) = w2
Aσ2
A+w2
Bσ2
B+ 2wAwBσAσBρA,B
Now, to maximize the Sharpe ratio, we need to find the weights (wAand wB) that maximize the
Sharpe ratio. Let xbe the weight of Asset A in the portfolio:
SharpeRatio =x×8% + (1 −x)×12%
px2×(15%)2+ (1 −x)2×(20%)2+ 2x(1 −x)×15% ×20% ×0.6
=0.08x+ 0.12(1 −x)
p0.0225x2+ 0.04(1 −x)2+ 0.018x(1 −x)
To maximize the Sharpe ratio, we need to differentiate it with respect to xand set the derivative
equal to zero:
d(SR)
dx =0.08 −0.12 −2.1x+ 1.68
(0.0225x2+ 0.04(1 −x)2+ 0.018x(1 −x))1.5= 0
−0.04 −2.1x+ 1.68 = 0
x=1.68 −0.04
2.1= 0.8
Therefore, the optimal allocation of the risk budget is 80% in Asset A and 20% in Asset B to
maximize the Sharpe ratio.
I. Problem: Portfolio Diversification
A portfolio manager is considering investing in two assets: Asset A and Asset B. The expected
returns and standard deviations of the two assets are given as follows:
- Asset A: Expected Return = 12- Asset B: Expected Return = 15
The correlation coefficient between the returns of Asset A and Asset B is 0.5. The manager
wants to create a portfolio with 60
a) Calculate the expected return and standard deviation of the portfolio. b) Determine the cor-
relation coefficient between the portfolio and the individual assets.
Solution:
a) Let wA= 0.6and wB= 0.4be the weights of Asset A and Asset B in the portfolio, respectively.
i) Expected Return of the Portfolio:
E(Rp) = wA·E(RA) + wB·E(RB)
E(Rp)=0.6×0.12 + 0.4×0.15 = 0.072 + 0.06 = 0.132 = 13.2%
ii) Standard Deviation of the Portfolio:
σp=qw2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·ρAB ·σA·σB
σp=p0.62·0.082+ 0.42·0.122+ 2 ·0.6·0.4·0.5·0.08 ·0.12
σp≈√0.0288 + 0.0192 + 0.0576 ≈√0.1056 ≈0.3251 = 32.51%
Therefore, the expected return of the portfolio is 13.2
b) Correlation coefficient between the portfolio and Asset A:
ρpA =wA·1 + wB·ρAB
ρpA = 0.6×1+0.4×0.5=0.6+0.2=0.8
Correlation coefficient between the portfolio and Asset B:
ρpB =wA·ρAB +wB·1
ρpB = 0.6×0.5+0.4×1=0.3+0.4=0.7
Therefore, the correlation coefficient between the portfolio and Asset A is 0.8, and with Asset
B is 0.7.
5 6. IGNORING LIQUIDITY RISK IN PORTFOLIO CONSTRUCTION
Problem 6. You are considering investing in two assets, Stock A and Stock B. The expected
returns of these assets are 8% and 12%, respectively. The standard deviation of Stock A is 10%
and the standard deviation of Stock B is 15%. The correlation between the returns of Stock A and
Stock B is 0.6. You have $50,000 to invest and want to allocate your portfolio to maximize the
Sharpe ratio. Assuming you are ignoring liquidity risk in portfolio construction, calculate:
a) The weights of Stock A and Stock B that maximize the Sharpe ratio.
b) The expected return and volatility of the optimal portfolio.
c) The maximum Sharpe ratio for the optimal portfolio.
Solution 6.
a) To find the weights that maximize the Sharpe ratio, we need to calculate the Sharpe ratio for
different weight combinations of Stock A and Stock B. The Sharpe ratio is given by:
Sharpe =E[rp]−rf
σp
where: - E[rp]is the expected return of the portfolio, - rfis the risk-free rate (we will assume 0
for simplicity), - σpis the standard deviation of the portfolio return.
Let wbe the weight of Stock A and 1−wbe the weight of Stock B. Therefore, wis the weight
we allocate to Stock A in our portfolio.
The expected return of the portfolio is given by:
E[rp] = w×E[rA] + (1 −w)×E[rB]E[rp] = w×0.08 + (1 −w)×0.12
The variance of the portfolio is given by:
σ2
p=w2×σ2
A+ (1 −w)2×σ2
B+ 2w(1 −w)×ρAB ×σA×σBσ2
p=w2×0.12+ (1 −w)2×0.152+
2w(1 −w)×0.6×0.1×0.15
Now we can calculate the Sharpe ratio for different weight combinations and choose the weights
that maximize the Sharpe ratio.
b) Once we find the optimal weights, we can calculate the expected return and volatility of the
optimal portfolio using the formulas for E[rp]and σ2
pderived in part (a).
c) The maximum Sharpe ratio for the optimal portfolio is simply the Sharpe ratio calculated
using the optimal weights from part (a).
I. Problem:
You are considering investing in two assets, Asset A and Asset B, with the following character-
istics:
Asset A has an expected return of 8% and a standard deviation of 4%. Asset B has an expected
return of 12% and a standard deviation of 6%.
The correlation between the returns of Asset A and Asset B is 0.5.
a) Calculate the expected return of a portfolio that consists of 40% Asset A and 60% Asset B.
b) Calculate the standard deviation of the portfolio in part (a).
c) Determine the optimal portfolio weights that minimize the standard deviation of the portfolio.
II. Solution:
a) Let E[A]and E[B]be the expected returns of Asset A and Asset B respectively. We want to
find the expected return of the portfolio:
Expected return of the portfolio = 0.4×E[A]+0.6×E[B]
= 0.4×8% + 0.6×12%
= 3.2% + 7.2%
= 10.4%
b) The formula for calculating the standard deviation of a portfolio consisting of two assets is
given by:
σp=qw2
Aσ2
A+w2
Bσ2
B+ 2wAwBρABσAσB
where: σp= standard deviation of the portfolio, wAand wB= weights of Asset A and Asset B in
the portfolio, σAand σB= standard deviations of Asset A and Asset B, ρAB = correlation coefficient
between the returns of Asset A and Asset B.
Substitute the known values into the formula:
σp=√0.42×0.042+ 0.62×0.062+ 2 ×0.4×0.6×0.5×0.04 ×0.06
σp=√0.0016 + 0.0036 + 0.00288
σp=√0.00808
σp≈0.09 or 9%
c) The optimal portfolio weights can be found by minimizing the standard deviation of the port-
folio using the formula for minimum variance portfolio weights, which is given by:
wA=σ2
B−σAB σBσA
σ2
A+σ2
B−2σAB σAσB
wB= 1 −wA
Substitute the given values into the formulas to find the optimal weights for Asset A and Asset
B.
6 8. BEHAVIORAL BIASES AFFECTING ASSET ALLOCATION DECISIONS
Problem 8. Mr. Smith is considering reallocating his investment portfolio to achieve a target
asset allocation. However, he is prone to anchoring bias, fixating on the historical performance of
certain assets. His current portfolio consists of $50,000 invested in Stocks, $30,000 in Bonds, and
$20,000 in Cash. His target allocation is 50% Stocks, 30% Bonds, and 20% Cash. Calculate the
amount Mr. Smith needs to reallocate to each asset to reach his target allocation.
Solution 8. a) Let Xbe the amount to be reallocated to Stocks, Yto Bonds, and Zto Cash.
The total amount of his current portfolio is $50,000 + $30,000 + $20,000 = $100,000.
So, the target amounts are: - Stocks: 50% of $100,000 = $50,000 - Bonds: 30% of $100,000
= $30,000 - Cash: 20% of $100,000 = $20,000
Therefore, we have the following system of equations:
X+ 50,000 = 50,000
Y+ 30,000 = 30,000
Z+ 20,000 = 20,000
Solving these equations, we get:
X= 0
Y= 0
Z= 0
Therefore, Mr. Smith does not need to reallocate any funds to reach his target asset allocation.
The anchoring bias in this case caused Mr. Smith to ignore his current allocation and blindly
stick to his past investments, even though he was already at his target allocation.
This example demonstrates the role of behavioral biases in asset allocation decisions.
7 9. INCONSISTENT RISK TOLERANCE ASSESSMENT AMONG INVESTORS
Problem 9. Assume two investors, Alice and Bob, have different assessments of their risk
tolerance. Alice has a risk tolerance level of 0.6, while Bob’s risk tolerance level is 0.4. They are
considering investing in two assets, Asset X and Asset Y, with the following characteristics:
Asset X: Expected return = 8%, Standard Deviation = 12%
Asset Y: Expected return = 12%, Standard Deviation = 18%
a) Calculate the expected return and standard deviation of a portfolio consisting of 60
b) Determine which investor should choose this portfolio based on their risk tolerance assess-
ment.
c) Discuss the implications of having inconsistent risk tolerance assessments among investors
in the context of portfolio construction.
Solution 9.
a) To calculate the expected return and standard deviation of the portfolio consisting of 60
Expected return of the portfolio = Weight of Asset X * Expected return of Asset X + Weight of
Asset Y * Expected return of Asset Y
Standard deviation of the portfolio = sqrt[ (Weight of Asset X)2∗(StandardDeviationofAssetX)2+
(W eightofAssetY )2∗(StandardDeviationofAssetY )2+2∗W eightofAssetX ∗W eightof AssetY ∗
Covariance(X, Y )]
For the given data:
Expected return of the portfolio = 0.6 * 8% + 0.4 * 12% = 4.8% + 4.8% = 9.6%
Standard deviation of the portfolio = sqrt[ (0.62)∗(122) + (0.42)∗(182) + 2 ∗0.6∗0.4∗(12) ∗(18)]
= sqrt[ (0.36) * (144) + (0.16) * (324) + 2 * 0.6 * 0.4 * 216 ]
= sqrt[ 51.84 + 51.84 + 51.84 ]
= sqrt[ 155.52 ]
12.476%
Therefore, for both Alice and Bob, the expected return of the portfolio is 9.6% and the standard
deviation is approximately 12.476%.
b) Based on their risk tolerance assessments, Alice (with a risk tolerance level of 0.6) should
choose this portfolio, as the portfolio’s risk tolerance matches her preferences (higher risk toler-
ance), whereas Bob’s risk tolerance level of 0.4 indicates he would prefer a lower risk portfolio.
c) Inconsistent risk tolerance assessments among investors can lead to conflicts in portfolio
construction decisions. It may result in suboptimal portfolio choices if the portfolio’s risk-return char-
acteristics do not align with the individual investors’ risk preferences. This highlights the importance
of understanding and incorporating different risk tolerance levels when constructing portfolios for
multiple investors.
8 10. LACK OF CLARITY IN INVESTMENT OBJECTIVES DRIVING POOR ASSET ALLOCA-
TION
Problem 10.
An investor is considering investing in two assets - Stock A and Stock B. The investor’s utility
function is given by U(W) = W0.5, where Wis the wealth at the end of the investment period. The
investor has a total of $100,000 to invest. Stock A has an expected return of 8% and a standard
deviation of 12%, while Stock B has an expected return of 6% and a standard deviation of 8%. The
correlation coefficient between the returns of Stocks A and B is 0.4.
a) Calculate the expected return and standard deviation of a portfolio that is 60% invested in
Stock A and 40% invested in Stock B.
b) Determine the optimal risky portfolio for this investor considering the given utility function.
Solution 10.
a) The expected return of a portfolio, denoted by E(Rp), is given by the weighted average of the
expected returns of individual assets in the portfolio. The standard deviation of a portfolio, denoted
by σp, is calculated using the formula for the portfolio variance.
a) To calculate the expected return and standard deviation of the portfolio with 60% invested in
Stock A and 40% in Stock B:
Expected return of the portfolio:
E(Rp)=0.6×0.08 + 0.4×0.06 = 0.048 + 0.024 = 0.072 = 7.2%
Standard deviation of the portfolio:
σp=p0.62×0.122+ 0.42×0.082+ 2 ×0.6×0.4×0.12 ×0.08 ×0.4 = √0.0144 + 0.0128 + 0.02304 ≈0.076 = 7.6%
Therefore, the expected return of the portfolio is 7.2% and the standard deviation is 7.6%.
b) To determine the optimal risky portfolio for the investor, we need to find the portfolio that
maximizes the investor’s utility function. This is achieved by locating the point of tangency between
the investor’s indifference curve and the efficient frontier.
Given the utility function U(W) = W0.5, the optimal risky portfolio allocation is given by the
formula:
w∗=E(RA)−rf
γ2σ2
A+σ2
B−2γσAσB
=0.08 −0.02
0.0006 = 100
So, the optimal risky portfolio for this investor is 100% Stock A and 0% Stock B.
I.
9 Problem on Portfolio Theory and Asset Allocation
Problem:
Suppose an investor has a portfolio consisting of two assets, Asset A and Asset B. Asset A has
a weight of 60% in the portfolio with an expected return of 8% and a standard deviation of 15%.
Asset B has a weight of 40% with an expected return of 12% and a standard deviation of 20%. The
correlation coefficient between the returns of Asset A and Asset B is 0.6. Calculate the expected
return and standard deviation of the portfolio.
Solution:
Let rAbe the return of Asset A, rBbe the return of Asset B, and wAand wBbe the weights of
Asset A and Asset B respectively.
a) The expected return of the portfolio (rp) is given by:
rp=wA×rA+wB×rB
rp= 0.60 ×0.08 + 0.40 ×0.12
rp= 0.048 + 0.048
rp= 0.096 or 9.6%
b) The variance of the portfolio (σ2
p) is given by:
σ2
p=w2
A×σ2
A+w2
B×σ2
B+ 2 ×wA×wB×Corr(A, B)×σA×σB
Plugging in the values:
σ2
p= 0.602×0.152+ 0.402×0.202+ 2 ×0.60 ×0.40 ×0.6×0.15 ×0.20
σ2
p= 0.09 + 0.16 + 0.144
σ2
p= 0.394
σp=√0.394 or 19.85%
Therefore, the expected return of the portfolio is 9.6% and the standard deviation of the portfolio
is 19.85%.
10 12. INEFFICIENT REBALANCING STRATEGIES IMPACTING PORTFOLIO PERFORMANCE
Problem 12.
You have a portfolio consisting of two assets, Stock A and Stock B, with the following charac-
teristics:
•Stock A has a weight of 40% in the portfolio and has an expected return of 8% with a standard
deviation of 12%.
•Stock B has a weight of 60% in the portfolio and has an expected return of 12% with a standard
deviation of 18%.
•The correlation coefficient between Stock A and Stock B is 0.6.
a) Calculate the expected return and standard deviation of the portfolio.
b) If you decide to rebalance the portfolio to 50% Stock A and 50% Stock B, calculate the new
expected return and standard deviation of the portfolio.
c) Evaluate the impact of the rebalancing on the portfolio performance.
Solution 12.
a) The expected return and standard deviation of the portfolio can be calculated using the
following formulas:
Expected Return of Portfolio =wA×Expected Return of Stock A+wB×Expected Return of Stock B
Standard Deviation of Portfolio =qw2
A×Variance of Stock A +w2
B×Variance of Stock B + 2 ×wA×wB×Standard Deviation of Stock A ×Standard Deviation of Stock B ×Correlation
Substitute the given values:
Expected Return of Portfolio = 0.4×8% + 0.6×12% = 0.04 + 0.072 = 0.112 = 11.2%
Standard Deviation of Portfolio =p0.42×(0.12)2+ 0.62×(0.18)2+ 2 ×0.4×0.6×0.12 ×0.18 ×0.6=0.1173 = 11.73%
a) Therefore, the expected return of the portfolio is 11.2% and the standard deviation of the
portfolio is 11.73%.
b) If we rebalance the portfolio to 50% Stock A and 50% Stock B, the new expected return and
standard deviation of the portfolio can be calculated in a similar way:
Expected Return of Portfolio = 0.5×8% + 0.5×12% = 0.04 + 0.06 = 0.1 = 10%
Standard Deviation of Portfolio =p0.52×(0.12)2+ 0.52×(0.18)2+ 2 ×0.5×0.5×0.12 ×0.18 ×0.6=0.1289 = 12.89%
b) Therefore, the new expected return of the portfolio is 10% and the new standard deviation
of the portfolio is 12.89%.
c) The rebalancing strategy has slightly reduced the expected return of the portfolio from 11.2%
to 10%, but it has also slightly increased the standard deviation from 11.73% to 12.89%. This
tradeoff between return and risk should be carefully considered based on the investor’s risk appetite
and investment objectives.
11 13. LACK OF CONSIDERATION FOR TAX IMPLICATIONS IN ASSET ALLOCATION
Problem 13. An investor has two investment options:
Option A: A stock that pays a dividend yield of 4% annually and has a capital gain of 10% at
the end of the year. The investor’s tax rate on dividends is 20% and on capital gains is 15%.
Option B: A tax-exempt municipal bond that pays a yield of 3.5% annually.
If the investor’s initial investment is 10,000, determinewhichoptionwouldprovidehigherafter −
taxreturnsaf teroneyear.
Solution 13.
To compare the after-tax returns of the two investment options, we calculate the after-tax returns
for options A and B separately:
a) Option A:
For Option A, the after-tax return is the sum of after-tax dividend and after-tax capital gain:
After-tax dividend = Dividend yield * (1 - Tax rate on dividends) = 0.04 * (1 - 0.2) = 0.04 * 0.8 =
0.032 = 3.2%
After-tax capital gain = Capital gain * (1 - Tax rate on capital gains) = 0.10 * (1 - 0.15) = 0.10 *
0.85 = 0.085 = 8.5%
Total after-tax return for Option A = After-tax dividend + After-tax capital gain = 3.2% + 8.5% =
11.7%
b) Option B:
For Option B, the after-tax return of the tax-exempt municipal bond is simply the yield of 3.5%.
c) Comparison:
Since Option A has a total after-tax return of 11.7%, which is higher than the 3.5% after-tax
return of Option B, the investor would achieve higher after-tax returns by investing in Option A.
12 Portfolio Theory and Asset Allocation
Problem 1.
You are considering investing in a portfolio that consists of two assets: Stock A and Stock B.
The expected return and standard deviation of each asset are as follows:
Stock A: Expected Return = 12%, Standard Deviation = 15%
Stock B: Expected Return = 8%, Standard Deviation = 10%
The correlation coefficient between the returns of Stock A and Stock B is 0.5. You are planning
to allocate 60% of your investment to Stock A and 40% to Stock B.
a) Calculate the expected return of the portfolio.
b) Calculate the standard deviation of the portfolio.
Solution 1.
a) The expected return of the portfolio can be calculated using the weighted sum of the individual
expected returns:
E(Rp) = wA×E(RA) + wB×E(RB)
Given that wA= 0.6,E(RA) = 0.12,wB= 0.4, and E(RB)=0.08, we have:
E(Rp)=0.6×0.12 + 0.4×0.08 = 0.072 + 0.032 = 0.104 = 10.4%
Therefore, the expected return of the portfolio is 10.4%.
b) The standard deviation of the portfolio can be calculated using the formula:
σp=qw2
A×σ2
A+w2
B×σ2
B+ 2 ×wA×wB×σA×σB×ρA,B
where σA= 0.15,σB= 0.10, and ρA,B = 0.5.
Plugging in the values, we get:
σp=p(0.6)2×(0.15)2+ (0.4)2×(0.10)2+ 2 ×0.6×0.4×0.15 ×0.10 ×0.5
=√0.36 ×0.0225 + 0.16 ×0.01 + 0.12 ×0.015
=√0.0081 + 0.0016 + 0.0018
=√0.0115
≈0.107 = 10.7%
Therefore, the standard deviation of the portfolio is 10.7%.
13 15. IGNORING ENVIRONMENTAL, SOCIAL, AND GOVERNANCE FACTORS IN ASSET
ALLOCATION
Problem 15. Consider a portfolio with three assets: Stock A, Stock B, and Stock C. The ex-
pected return and standard deviation of each asset are as follows:
•Stock A: Expected return = 8%, Standard deviation = 12%
•Stock B: Expected return = 12%, Standard deviation = 18%
•Stock C: Expected return = 10%, Standard deviation = 15%
The correlation coefficients between the returns of the assets are given by:
•Correlation between A and B: 0.6
•Correlation between A and C: -0.2
•Correlation between B and C: 0.4
Determine the expected return and standard deviation of a portfolio that consists of 30% Stock
A, 50% Stock B, and 20% Stock C.
Solution 15. a) To find the expected return of the portfolio, we use the weighted average of the
expected returns of the individual assets:
Expected return of the portfolio =wA×Expected return of A+wB×Expected return of B+wC×Expected return of C
where wiis the weight of asset iin the portfolio.
Substitute the values into the formula:
Expected return of the portfolio = 0.30 ×8% + 0.50 ×12% + 0.20 ×10%
= 0.024 + 0.06 + 0.02 = 0.104 = 10.4%
Therefore, the expected return of the portfolio is 10.4%.
b) To find the standard deviation of the portfolio, we use the formula for the portfolio variance:
σ2
p=w2
A×σ2
A+w2
B×σ2
B+w2
C×σ2
C+ 2(wA×wB×σAB +wA×wC×σAC +wB×wC×σBC )
where σiis the standard deviation of asset iand σij is the covariance between assets iand j.
Substitute all values into the formula and calculate:
σ2
p= 0.302×0.122+0.502×0.182+0.202×0.152+2(0.30×0.50×0.6+0.30×0.20×(−0.2)+0.50×0.20×0.4)
= 0.00324 + 0.018 + 0.006 + 2(0.09 −0.012 −0.04)
= 0.02724 + 0.027 + 0.044 = 0.09824
Therefore, the standard deviation of the portfolio is σp=√0.09824 = 0.3135 = 31.35%.
14 Portfolio Theory and Asset Allocation
Problem:
You are considering investing in two assets, Asset A and Asset B. Asset A has an expected
return of 7% with a standard deviation of 12%, while Asset B has an expected return of 10% with a
standard deviation of 18%. You plan to allocate 60% of your portfolio to Asset A and 40% to Asset
B. The correlation between the returns of the two assets is 0.4.
a) Calculate the expected return and standard deviation of the portfolio.
b) Determine the correlation between the returns of the portfolio and a risk-free asset that offers
a return of 3%.
Solution:
a) To calculate the expected return and standard deviation of the portfolio, we use the following
formulas:
Expected return of the portfolio:
E(Rp) = wA·E(RA) + wB·E(RB)
where E(RA)and E(RB)are the expected returns of Asset A and Asset B, respectively, and
wAand wBare the weights of Asset A and Asset B in the portfolio.
Substitute the values:
E(Rp) = 0.6×0.07 + 0.4×0.10 = 0.042 + 0.04 = 0.082 = 8.2%
Standard deviation of the portfolio:
σp=qw2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·ρAB ·σA·σB
where σAand σBare the standard deviations of Asset A and Asset B, respectively, and ρAB is
the correlation coefficient between Asset A and Asset B.
Substitute the values:
σp=p0.62×(0.12)2+ 0.42×(0.18)2+ 2 ×0.6×0.4×0.4×0.12 ×0.18
σp=√0.0144 + 0.01296 + 0.00259 = √0.03 = 0.1732 = 17.32%
Therefore, the expected return of the portfolio is 8.2% and the standard deviation is 17.32%.
b) To determine the correlation between the returns of the portfolio and a risk-free asset, we
can use the formula:
ρp,rf =wp·ρA,rf
where ρA,rf is the correlation between Asset A and the risk-free asset, and wpis the weight of
the port...
Certainly! Here are a few numerical problem questions on Portfolio Theory and Asset Alloca-
tion:
—
15 17. OVER-RELIANCE ON HISTORICAL DATA IN PORTFOLIO CONSTRUCTION
Problem 17. A financial analyst is constructing a portfolio with two assets: Stock A and Stock B.
Historical returns for Stock A and Stock B over the past 5 years are as follows:
•Stock A: Mean return = 8%, Standard deviation = 12%
•Stock B: Mean return = 10%, Standard deviation = 15%
The correlation coefficient between the returns of Stock A and Stock B is 0.6. The analyst wants
to build a portfolio using these two assets.
a) If the analyst wants the portfolio to have a mean return of 9
b) Determine the standard deviation of the portfolio if the analyst invests 40% in Stock A and
60% in Stock B.
c) Calculate the correlation between the portfolio returns and Stock A if the weight of Stock A
in the portfolio is 0.4.
Solution 17.
a) Let wAand wBbe the weights of Stock A and Stock B in the portfolio, respectively. The
mean return of the portfolio can be calculated as:
E(rp) = wA·E(rA) + wB·E(rB)
Given that the mean return of the portfolio should be 9%, and E(rA)=0.08 and E(rB)=0.10,
we can set up the equation as:
0.09 = wA·0.08 + wB·0.10
Since wA+wB= 1, we can solve for wAin terms of wBas:
wA= 1 −wB
Substitute this into the equation:
0.09 = (1 −wB)·0.08 + wB·0.10
Solving for wB, we get wB= 0.6and wA= 0.4.
Therefore, the weights of Stock A and Stock B in the portfolio should be 40% and 60%, respec-
tively.
b) The standard deviation of the portfolio can be calculated using the formula:
σp=qw2
Aσ2
A+w2
Bσ2
B+ 2wAwBσAσBρAB
Substitute the given values and calculated weights into the formula to find the standard deviation
of the portfolio.
c) The correlation between the portfolio returns and Stock A can be calculated using the formula:
ρpA =wAρAB
Substitute the given correlation coefficient and weight of Stock A to determine the correlation.
—
Feel free to reach out if you need more questions or further clarifications on this topic!
16 18. UNDERESTIMATING TAIL RISKS IN ASSET ALLOCATION DECISIONS
Problem 18.
You are considering investing in two assets, Asset A and Asset B. The annual returns for Asset
A have a normal distribution with mean 8% and standard deviation 12%. The annual returns for
Asset B have a normal distribution with mean 10% and standard deviation 15%. The correlation
between the returns of Asset A and Asset B is 0.5.
a) Calculate the expected return of a portfolio that is equally weighted in Asset A and Asset B.
b) Calculate the standard deviation of the portfolio that is equally weighted in Asset A and Asset
B.
c) Calculate the correlation coefficient between the returns of the portfolio and the returns of
Asset A.
Solution 18.
a) The expected return of a portfolio that is equally weighted in Asset A and Asset B can be
calculated using the formula for the expected return of a portfolio:
E(Rp) = wA·E(RA) + wB·E(RB)
Where: - E(Rp)is the expected return of the portfolio - wAis the weight of Asset A in the portfolio
(0.5 in this case) - E(RA)is the expected return of Asset A (8%) - wBis the weight of Asset B in
the portfolio (0.5 in this case) - E(RB)is the expected return of Asset B (10%)
Plugging in the values, we get:
E(Rp)=0.5×8% + 0.5×10% = 0.08 + 0.05 = 0.13 = 13%
Therefore, the expected return of the equally weighted portfolio is 13%.
b) The standard deviation of a portfolio of two assets can be calculated using the formula for
the standard deviation of a portfolio:
σp=qw2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·ρAB ·σA·σB
Where: - σpis the standard deviation of the portfolio - wA,wBare the weights of Asset A and
Asset B in the portfolio (both 0.5 in this case) - σA,σBare the standard deviations of Asset A and
Asset B (12% and 15% respectively) - ρAB is the correlation coefficient between Asset A and Asset
B (0.5)
Plugging in the values, we get:
σp=p0.52·0.122+ 0.52·0.152+ 2 ·0.5·0.5·0.5·0.12 ·0.15
σp=p0.032+ 0.03752+ 0.009 = √0.0009 + 0.00140625 + 0.009 = √0.01030625 ≈0.1015 = 10.15%
Therefore, the standard deviation of the equally weighted portfolio is approximately 10.15
c) The correlation coefficient between the returns of the portfolio and the returns of Asset A can
be calculated using the formula for correlation coefficient in a two-assets portfolio:
ρpA =wA·σ2
A
σA·σp
Where: - ρpA is the correlation coefficient between the returns of the portfolio and the returns
of Asset A - wAis the weight of Asset A in the portfolio (0.5) - σAis the standard deviation of Asset
A (12%) - σpis the standard deviation of the portfolio (10.15%)
Plugging in the values, we get:
ρpA =0.5·0.12
0.12 ·0.1015 =0.06
0.01218 ≈0.4926
Therefore,
17 19. MISALIGNED ASSET ALLOCATION WITH LONG-TERM FINANCIAL GOALS
Problem 19.
Alice is planning her retirement and has set a goal to accumulate a wealth of 1,000,000in20years.Shecurrentlyhas100,000
saved and is considering two investment options: Option A, which has an expected annual return
of 8% with a standard deviation of 12%, and Option B, which has an expected annual return of 5%
with a standard deviation of 8%. Assuming Alice aims to maximize the likelihood of reaching her
retirement goal, determine the optimal allocation of her initial 100,000betweenOptionAandOptionB.
Solution 19.
To determine the optimal allocation that maximizes the likelihood of reaching her retirement
goal, we will use the concept of portfolio optimization. Let xdenote the allocation to Option A and
1−xdenote the allocation to Option B.
Given that the expected return of the portfolio is a weighted sum of the expected returns of the
individual assets, the expected return of the portfolio (Rp) is given by:
Rp=x·RA+ (1 −x)·RB
Rp= 0.08x+ 0.05(1 −x)
Rp= 0.03x+ 0.05
The variance of the portfolio (σ2
p) is calculated as follows:
σ2
p=x2·σ2
A+ (1 −x)2·σ2
B+ 2x(1 −x)·σAσB
σ2
p= 0.122x2+ 0.082(1 −x)2+ 2(0.12)(0.08)x(1 −x)
σ2
p= 0.0144x2+ 0.0064(1 −x)2+ 0.0192x(1 −x)
σ2
p= 0.008x2+ 0.0064 −0.0128x+ 0.0192x−0.0192x2
σ2
p=−0.0112x2+ 0.0064 −0.0036x
To maximize the likelihood of reaching her retirement goal, Alice can set up the following opti-
mization problem:
Maximize:
Rp= 0.03x+ 0.05
Subject to the constraint:
−0.0112x2+ 0.0064 −0.0036x≤variance tolerance level
Solving this optimization problem will provide Alice with the optimal allocation of her 100,000betweenOptionAandOptionB.
18 20. INEFFECTIVE COMMUNICATION OF PORTFOLIO STRATEGY TO STAKEHOLDERS.
Problem 20.
A financial advisor is creating a portfolio for a client with $100,000 to invest. The advisor decides
to allocate 40% to Stock A, 30% to Stock B, and the remaining 30% to a bond fund. Stock A has
an expected return of 8% and a standard deviation of 12%, Stock B has an expected return of 6%
and a standard deviation of 8%, and the bond fund has an expected return of 4% and a standard
deviation of 4%.
a) Calculate the expected return and standard deviation of the portfolio.
b) If the correlation between Stock A and Stock B is 0.5, calculate the portfolio’s expected return
and standard deviation using the given allocation.
c) Discuss the implications of the correlation assumption for this portfolio.
Solution 20.
a) The expected return and standard deviation of the portfolio can be calculated using the
weighted averages of the individual assets.
a) Expected Return:
E(Rp) = wA×E(RA) + wB×E(RB) + wbond ×E(Rbond)
E(Rp)=0.40 ×0.08 + 0.30 ×0.06 + 0.30 ×0.04 = 0.045 = 4.5%
Standard Deviation:
σp=qw2
A×σ2
A+w2
B×σ2
B+w2
bond ×σ2
bond
σp=p0.402×0.122+ 0.302×0.082+ 0.302×0.042= 0.0601 = 6.01%
b) If the correlation between Stock A and Stock B is 0.5, the portfolio’s expected return and
standard deviation using the given allocation can be calculated using the formula involving corre-
lation.
E(Rp)=0.40 ×0.08 + 0.30 ×0.06 + 0.30 ×0.04 = 0.045 = 4.5%
σp=qw2
A×σ2
A+w2
B×σ2
B+ 2 ×wA×wB×σA×σB×ρAB
σp=p0.402×0.122+ 0.302×0.082+ 2 ×0.40 ×0.30 ×0.12 ×0.08 ×0.5=0.0496 = 4.96%
c) The correlation assumption affects the diversification benefit of the portfolio. A correlation
of 0.5 between Stock A and Stock B implies they are positively correlated. This means that the
two stocks tend to move in the same direction, reducing the benefit of diversification. As a result,
the portfolio’s standard deviation is higher when the correlation is taken into account compared to
the assumption of no correlation. It shows the importance of considering the correlation between
assets when constructing a portfolio to manage risk effectively.
2 2. LACK OF DIVERSIFICATION IN ASSET CLASSES
Problem 2. Suppose an investor has a portfolio with 60% invested in stocks, 30% invested in
bonds, and 10% invested in real estate. The annual returns for each asset class are as follows:
- Stocks: 12% - Bonds: 6% - Real estate: 8%
Calculate the overall annual return of the investor’s portfolio.
Solution 2.
The overall annual return of the investor’s portfolio can be calculated by weighting the returns
of each asset class according to their respective percentages in the portfolio.
a) Calculating the weighted returns of each asset class:
- Weighted return of stocks: 0.60×0.12 = 0.072 (or 7.2- Weighted return of bonds: 0.30 ×0.06 =
0.018 (or 1.8- Weighted return of real estate: 0.10 ×0.08 = 0.008 (or 0.8
b) Calculating the overall annual return of the portfolio by summing up the weighted returns of
each asset class:
0.072 + 0.018 + 0.008 = 0.098
Therefore, the overall annual return of the investor’s portfolio is 9.8
3 3. SHORT-TERM VOLATILITY IMPACTING PORTFOLIO RETURNS
Problem 3.
You are managing a portfolio with two assets: Asset A and Asset B. Asset A has an annual
expected return of 12
a) Calculate the expected return and the standard deviation of a portfolio that is equally weighted
in Asset A and Asset B.
b) Determine the correlation of the portfolio returns with the returns of each asset.
c) If you increase the weight of Asset A to 60
Solution 3.
a) The expected return of a portfolio, E(rP), that is equally weighted in two assets A and B can
be calculated as:
E(rP) = wA·E(rA) + wB·E(rB)
E(rP)=0.5×0.12 + 0.5×0.08 = 0.10 or 10%
The variance of the portfolio, σ2
P, can be calculated as:
σ2
P=w2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·σA·σB·ρAB
σ2
P= 0.52×0.182+0.52×0.152+2×0.5×0.5×0.18×0.15×0.6 = 0.0288+0.01125+0.0081 = 0.04815
The standard deviation of the portfolio is the square root of the variance:
σP=√0.04815 ≈0.2196 or 21.96%
b) The correlation of the portfolio returns with the returns of each asset can be calculated using
the formula:
ρAP =wA·σ2
A+wB·σA·σB·ρAB
σP
ρAP =0.5×0.18 + 0.5×0.15 ×0.6
0.2196 ≈0.09 + 0.045
0.2196 ≈0.135
0.2196 ≈0.6148
Similarly, the correlation of the portfolio with Asset B, ρBP , can be calculated.
c) When the weights are changed to 60
E(rP)=0.6×0.12 + 0.4×0.08 = 0.104 or 10.4%
σ2
P= 0.62×0.182+0.42×0.152+2×0.6×0.4×0.18×0.15×0.6 = 0.03888+0.009+0.0162 = 0.06408
σP=√0.06408 ≈0.2531 or 25.31%
4 4. INEFFICIENT USE OF RISK BUDGET IN ASSET ALLOCATION
Problem 4.
An investor has a risk budget of $100,000 to invest in two assets: Asset A and Asset B. The
expected returns for Asset A and Asset B are 8
Solution 4.
The Sharpe ratio is given by:
SharpeRatio =E(Rp)−Rf
pV ar(Rp)
where:
•E(Rp)is the expected return of the portfolio,
•Rfis the risk-free rate (assumed to be zero in this case),
•V ar(Rp)is the variance of the portfolio return.
The expected return of the portfolio can be calculated using the weights assigned to Asset A
and Asset B:
E(Rp) = wAE(RA) + wBE(RB)
The variance of the portfolio return can be calculated as:
V ar(Rp) = w2
Aσ2
A+w2
Bσ2
B+ 2wAwBσAσBρA,B
Now, to maximize the Sharpe ratio, we need to find the weights (wAand wB) that maximize the
Sharpe ratio. Let xbe the weight of Asset A in the portfolio:
SharpeRatio =x×8% + (1 −x)×12%
px2×(15%)2+ (1 −x)2×(20%)2+ 2x(1 −x)×15% ×20% ×0.6
=0.08x+ 0.12(1 −x)
p0.0225x2+ 0.04(1 −x)2+ 0.018x(1 −x)
To maximize the Sharpe ratio, we need to differentiate it with respect to xand set the derivative
equal to zero:
d(SR)
dx =0.08 −0.12 −2.1x+ 1.68
(0.0225x2+ 0.04(1 −x)2+ 0.018x(1 −x))1.5= 0
−0.04 −2.1x+ 1.68 = 0
x=1.68 −0.04
2.1= 0.8
Therefore, the optimal allocation of the risk budget is 80% in Asset A and 20% in Asset B to
maximize the Sharpe ratio.
I. Problem: Portfolio Diversification
A portfolio manager is considering investing in two assets: Asset A and Asset B. The expected
returns and standard deviations of the two assets are given as follows:
- Asset A: Expected Return = 12- Asset B: Expected Return = 15
The correlation coefficient between the returns of Asset A and Asset B is 0.5. The manager
wants to create a portfolio with 60
a) Calculate the expected return and standard deviation of the portfolio. b) Determine the cor-
relation coefficient between the portfolio and the individual assets.
Solution:
a) Let wA= 0.6and wB= 0.4be the weights of Asset A and Asset B in the portfolio, respectively.
i) Expected Return of the Portfolio:
E(Rp) = wA·E(RA) + wB·E(RB)
E(Rp)=0.6×0.12 + 0.4×0.15 = 0.072 + 0.06 = 0.132 = 13.2%
ii) Standard Deviation of the Portfolio:
σp=qw2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·ρAB ·σA·σB
σp=p0.62·0.082+ 0.42·0.122+ 2 ·0.6·0.4·0.5·0.08 ·0.12
σp≈√0.0288 + 0.0192 + 0.0576 ≈√0.1056 ≈0.3251 = 32.51%
Therefore, the expected return of the portfolio is 13.2
b) Correlation coefficient between the portfolio and Asset A:
ρpA =wA·1 + wB·ρAB
ρpA = 0.6×1+0.4×0.5=0.6+0.2=0.8
Correlation coefficient between the portfolio and Asset B:
ρpB =wA·ρAB +wB·1
ρpB = 0.6×0.5+0.4×1=0.3+0.4=0.7
Therefore, the correlation coefficient between the portfolio and Asset A is 0.8, and with Asset
B is 0.7.
5 6. IGNORING LIQUIDITY RISK IN PORTFOLIO CONSTRUCTION
Problem 6. You are considering investing in two assets, Stock A and Stock B. The expected
returns of these assets are 8% and 12%, respectively. The standard deviation of Stock A is 10%
and the standard deviation of Stock B is 15%. The correlation between the returns of Stock A and
Stock B is 0.6. You have $50,000 to invest and want to allocate your portfolio to maximize the
Sharpe ratio. Assuming you are ignoring liquidity risk in portfolio construction, calculate:
a) The weights of Stock A and Stock B that maximize the Sharpe ratio.
b) The expected return and volatility of the optimal portfolio.
c) The maximum Sharpe ratio for the optimal portfolio.
Solution 6.
a) To find the weights that maximize the Sharpe ratio, we need to calculate the Sharpe ratio for
different weight combinations of Stock A and Stock B. The Sharpe ratio is given by:
Sharpe =E[rp]−rf
σp
where: - E[rp]is the expected return of the portfolio, - rfis the risk-free rate (we will assume 0
for simplicity), - σpis the standard deviation of the portfolio return.
Let wbe the weight of Stock A and 1−wbe the weight of Stock B. Therefore, wis the weight
we allocate to Stock A in our portfolio.
The expected return of the portfolio is given by:
E[rp] = w×E[rA] + (1 −w)×E[rB]E[rp] = w×0.08 + (1 −w)×0.12
The variance of the portfolio is given by:
σ2
p=w2×σ2
A+ (1 −w)2×σ2
B+ 2w(1 −w)×ρAB ×σA×σBσ2
p=w2×0.12+ (1 −w)2×0.152+
2w(1 −w)×0.6×0.1×0.15
Now we can calculate the Sharpe ratio for different weight combinations and choose the weights
that maximize the Sharpe ratio.
b) Once we find the optimal weights, we can calculate the expected return and volatility of the
optimal portfolio using the formulas for E[rp]and σ2
pderived in part (a).
c) The maximum Sharpe ratio for the optimal portfolio is simply the Sharpe ratio calculated
using the optimal weights from part (a).
I. Problem:
You are considering investing in two assets, Asset A and Asset B, with the following character-
istics:
Asset A has an expected return of 8% and a standard deviation of 4%. Asset B has an expected
return of 12% and a standard deviation of 6%.
The correlation between the returns of Asset A and Asset B is 0.5.
a) Calculate the expected return of a portfolio that consists of 40% Asset A and 60% Asset B.
b) Calculate the standard deviation of the portfolio in part (a).
c) Determine the optimal portfolio weights that minimize the standard deviation of the portfolio.
II. Solution:
a) Let E[A]and E[B]be the expected returns of Asset A and Asset B respectively. We want to
find the expected return of the portfolio:
Expected return of the portfolio = 0.4×E[A]+0.6×E[B]
= 0.4×8% + 0.6×12%
= 3.2% + 7.2%
= 10.4%
b) The formula for calculating the standard deviation of a portfolio consisting of two assets is
given by:
σp=qw2
Aσ2
A+w2
Bσ2
B+ 2wAwBρABσAσB
where: σp= standard deviation of the portfolio, wAand wB= weights of Asset A and Asset B in
the portfolio, σAand σB= standard deviations of Asset A and Asset B, ρAB = correlation coefficient
between the returns of Asset A and Asset B.
Substitute the known values into the formula:
σp=√0.42×0.042+ 0.62×0.062+ 2 ×0.4×0.6×0.5×0.04 ×0.06
σp=√0.0016 + 0.0036 + 0.00288
σp=√0.00808
σp≈0.09 or 9%
c) The optimal portfolio weights can be found by minimizing the standard deviation of the port-
folio using the formula for minimum variance portfolio weights, which is given by:
wA=σ2
B−σAB σBσA
σ2
A+σ2
B−2σAB σAσB
wB= 1 −wA
Substitute the given values into the formulas to find the optimal weights for Asset A and Asset
B.
6 8. BEHAVIORAL BIASES AFFECTING ASSET ALLOCATION DECISIONS
Problem 8. Mr. Smith is considering reallocating his investment portfolio to achieve a target
asset allocation. However, he is prone to anchoring bias, fixating on the historical performance of
certain assets. His current portfolio consists of $50,000 invested in Stocks, $30,000 in Bonds, and
$20,000 in Cash. His target allocation is 50% Stocks, 30% Bonds, and 20% Cash. Calculate the
amount Mr. Smith needs to reallocate to each asset to reach his target allocation.
Solution 8. a) Let Xbe the amount to be reallocated to Stocks, Yto Bonds, and Zto Cash.
The total amount of his current portfolio is $50,000 + $30,000 + $20,000 = $100,000.
So, the target amounts are: - Stocks: 50% of $100,000 = $50,000 - Bonds: 30% of $100,000
= $30,000 - Cash: 20% of $100,000 = $20,000
Therefore, we have the following system of equations:
X+ 50,000 = 50,000
Y+ 30,000 = 30,000
Z+ 20,000 = 20,000
Solving these equations, we get:
X= 0
Y= 0
Z= 0
Therefore, Mr. Smith does not need to reallocate any funds to reach his target asset allocation.
The anchoring bias in this case caused Mr. Smith to ignore his current allocation and blindly
stick to his past investments, even though he was already at his target allocation.
This example demonstrates the role of behavioral biases in asset allocation decisions.
7 9. INCONSISTENT RISK TOLERANCE ASSESSMENT AMONG INVESTORS
Problem 9. Assume two investors, Alice and Bob, have different assessments of their risk
tolerance. Alice has a risk tolerance level of 0.6, while Bob’s risk tolerance level is 0.4. They are
considering investing in two assets, Asset X and Asset Y, with the following characteristics:
Asset X: Expected return = 8%, Standard Deviation = 12%
Asset Y: Expected return = 12%, Standard Deviation = 18%
a) Calculate the expected return and standard deviation of a portfolio consisting of 60
b) Determine which investor should choose this portfolio based on their risk tolerance assess-
ment.
c) Discuss the implications of having inconsistent risk tolerance assessments among investors
in the context of portfolio construction.
Solution 9.
a) To calculate the expected return and standard deviation of the portfolio consisting of 60
Expected return of the portfolio = Weight of Asset X * Expected return of Asset X + Weight of
Asset Y * Expected return of Asset Y
Standard deviation of the portfolio = sqrt[ (Weight of Asset X)2∗(StandardDeviationofAssetX)2+
(W eightofAssetY )2∗(StandardDeviationofAssetY )2+2∗W eightofAssetX ∗W eightof AssetY ∗
Covariance(X, Y )]
For the given data:
Expected return of the portfolio = 0.6 * 8% + 0.4 * 12% = 4.8% + 4.8% = 9.6%
Standard deviation of the portfolio = sqrt[ (0.62)∗(122) + (0.42)∗(182) + 2 ∗0.6∗0.4∗(12) ∗(18)]
= sqrt[ (0.36) * (144) + (0.16) * (324) + 2 * 0.6 * 0.4 * 216 ]
= sqrt[ 51.84 + 51.84 + 51.84 ]
= sqrt[ 155.52 ]
12.476%
Therefore, for both Alice and Bob, the expected return of the portfolio is 9.6% and the standard
deviation is approximately 12.476%.
b) Based on their risk tolerance assessments, Alice (with a risk tolerance level of 0.6) should
choose this portfolio, as the portfolio’s risk tolerance matches her preferences (higher risk toler-
ance), whereas Bob’s risk tolerance level of 0.4 indicates he would prefer a lower risk portfolio.
c) Inconsistent risk tolerance assessments among investors can lead to conflicts in portfolio
construction decisions. It may result in suboptimal portfolio choices if the portfolio’s risk-return char-
acteristics do not align with the individual investors’ risk preferences. This highlights the importance
of understanding and incorporating different risk tolerance levels when constructing portfolios for
multiple investors.
8 10. LACK OF CLARITY IN INVESTMENT OBJECTIVES DRIVING POOR ASSET ALLOCA-
TION
Problem 10.
An investor is considering investing in two assets - Stock A and Stock B. The investor’s utility
function is given by U(W) = W0.5, where Wis the wealth at the end of the investment period. The
investor has a total of $100,000 to invest. Stock A has an expected return of 8% and a standard
deviation of 12%, while Stock B has an expected return of 6% and a standard deviation of 8%. The
correlation coefficient between the returns of Stocks A and B is 0.4.
a) Calculate the expected return and standard deviation of a portfolio that is 60% invested in
Stock A and 40% invested in Stock B.
b) Determine the optimal risky portfolio for this investor considering the given utility function.
Solution 10.
a) The expected return of a portfolio, denoted by E(Rp), is given by the weighted average of the
expected returns of individual assets in the portfolio. The standard deviation of a portfolio, denoted
by σp, is calculated using the formula for the portfolio variance.
a) To calculate the expected return and standard deviation of the portfolio with 60% invested in
Stock A and 40% in Stock B:
Expected return of the portfolio:
E(Rp)=0.6×0.08 + 0.4×0.06 = 0.048 + 0.024 = 0.072 = 7.2%
Standard deviation of the portfolio:
σp=p0.62×0.122+ 0.42×0.082+ 2 ×0.6×0.4×0.12 ×0.08 ×0.4 = √0.0144 + 0.0128 + 0.02304 ≈0.076 = 7.6%
Therefore, the expected return of the portfolio is 7.2% and the standard deviation is 7.6%.
b) To determine the optimal risky portfolio for the investor, we need to find the portfolio that
maximizes the investor’s utility function. This is achieved by locating the point of tangency between
the investor’s indifference curve and the efficient frontier.
Given the utility function U(W) = W0.5, the optimal risky portfolio allocation is given by the
formula:
w∗=E(RA)−rf
γ2σ2
A+σ2
B−2γσAσB
=0.08 −0.02
0.0006 = 100
So, the optimal risky portfolio for this investor is 100% Stock A and 0% Stock B.
I.
9 Problem on Portfolio Theory and Asset Allocation
Problem:
Suppose an investor has a portfolio consisting of two assets, Asset A and Asset B. Asset A has
a weight of 60% in the portfolio with an expected return of 8% and a standard deviation of 15%.
Asset B has a weight of 40% with an expected return of 12% and a standard deviation of 20%. The
correlation coefficient between the returns of Asset A and Asset B is 0.6. Calculate the expected
return and standard deviation of the portfolio.
Solution:
Let rAbe the return of Asset A, rBbe the return of Asset B, and wAand wBbe the weights of
Asset A and Asset B respectively.
a) The expected return of the portfolio (rp) is given by:
rp=wA×rA+wB×rB
rp= 0.60 ×0.08 + 0.40 ×0.12
rp= 0.048 + 0.048
rp= 0.096 or 9.6%
b) The variance of the portfolio (σ2
p) is given by:
σ2
p=w2
A×σ2
A+w2
B×σ2
B+ 2 ×wA×wB×Corr(A, B)×σA×σB
Plugging in the values:
σ2
p= 0.602×0.152+ 0.402×0.202+ 2 ×0.60 ×0.40 ×0.6×0.15 ×0.20
σ2
p= 0.09 + 0.16 + 0.144
σ2
p= 0.394
σp=√0.394 or 19.85%
Therefore, the expected return of the portfolio is 9.6% and the standard deviation of the portfolio
is 19.85%.
10 12. INEFFICIENT REBALANCING STRATEGIES IMPACTING PORTFOLIO PERFORMANCE
Problem 12.
You have a portfolio consisting of two assets, Stock A and Stock B, with the following charac-
teristics:
•Stock A has a weight of 40% in the portfolio and has an expected return of 8% with a standard
deviation of 12%.
•Stock B has a weight of 60% in the portfolio and has an expected return of 12% with a standard
deviation of 18%.
•The correlation coefficient between Stock A and Stock B is 0.6.
a) Calculate the expected return and standard deviation of the portfolio.
b) If you decide to rebalance the portfolio to 50% Stock A and 50% Stock B, calculate the new
expected return and standard deviation of the portfolio.
c) Evaluate the impact of the rebalancing on the portfolio performance.
Solution 12.
a) The expected return and standard deviation of the portfolio can be calculated using the
following formulas:
Expected Return of Portfolio =wA×Expected Return of Stock A+wB×Expected Return of Stock B
Standard Deviation of Portfolio =qw2
A×Variance of Stock A +w2
B×Variance of Stock B + 2 ×wA×wB×Standard Deviation of Stock A ×Standard Deviation of Stock B ×Correlation
Substitute the given values:
Expected Return of Portfolio = 0.4×8% + 0.6×12% = 0.04 + 0.072 = 0.112 = 11.2%
Standard Deviation of Portfolio =p0.42×(0.12)2+ 0.62×(0.18)2+ 2 ×0.4×0.6×0.12 ×0.18 ×0.6=0.1173 = 11.73%
a) Therefore, the expected return of the portfolio is 11.2% and the standard deviation of the
portfolio is 11.73%.
b) If we rebalance the portfolio to 50% Stock A and 50% Stock B, the new expected return and
standard deviation of the portfolio can be calculated in a similar way:
Expected Return of Portfolio = 0.5×8% + 0.5×12% = 0.04 + 0.06 = 0.1 = 10%
Standard Deviation of Portfolio =p0.52×(0.12)2+ 0.52×(0.18)2+ 2 ×0.5×0.5×0.12 ×0.18 ×0.6=0.1289 = 12.89%
b) Therefore, the new expected return of the portfolio is 10% and the new standard deviation
of the portfolio is 12.89%.
c) The rebalancing strategy has slightly reduced the expected return of the portfolio from 11.2%
to 10%, but it has also slightly increased the standard deviation from 11.73% to 12.89%. This
tradeoff between return and risk should be carefully considered based on the investor’s risk appetite
and investment objectives.
11 13. LACK OF CONSIDERATION FOR TAX IMPLICATIONS IN ASSET ALLOCATION
Problem 13. An investor has two investment options:
Option A: A stock that pays a dividend yield of 4% annually and has a capital gain of 10% at
the end of the year. The investor’s tax rate on dividends is 20% and on capital gains is 15%.
Option B: A tax-exempt municipal bond that pays a yield of 3.5% annually.
If the investor’s initial investment is 10,000, determinewhichoptionwouldprovidehigherafter −
taxreturnsaf teroneyear.
Solution 13.
To compare the after-tax returns of the two investment options, we calculate the after-tax returns
for options A and B separately:
a) Option A:
For Option A, the after-tax return is the sum of after-tax dividend and after-tax capital gain:
After-tax dividend = Dividend yield * (1 - Tax rate on dividends) = 0.04 * (1 - 0.2) = 0.04 * 0.8 =
0.032 = 3.2%
After-tax capital gain = Capital gain * (1 - Tax rate on capital gains) = 0.10 * (1 - 0.15) = 0.10 *
0.85 = 0.085 = 8.5%
Total after-tax return for Option A = After-tax dividend + After-tax capital gain = 3.2% + 8.5% =
11.7%
b) Option B:
For Option B, the after-tax return of the tax-exempt municipal bond is simply the yield of 3.5%.
c) Comparison:
Since Option A has a total after-tax return of 11.7%, which is higher than the 3.5% after-tax
return of Option B, the investor would achieve higher after-tax returns by investing in Option A.
12 Portfolio Theory and Asset Allocation
Problem 1.
You are considering investing in a portfolio that consists of two assets: Stock A and Stock B.
The expected return and standard deviation of each asset are as follows:
Stock A: Expected Return = 12%, Standard Deviation = 15%
Stock B: Expected Return = 8%, Standard Deviation = 10%
The correlation coefficient between the returns of Stock A and Stock B is 0.5. You are planning
to allocate 60% of your investment to Stock A and 40% to Stock B.
a) Calculate the expected return of the portfolio.
b) Calculate the standard deviation of the portfolio.
Solution 1.
a) The expected return of the portfolio can be calculated using the weighted sum of the individual
expected returns:
E(Rp) = wA×E(RA) + wB×E(RB)
Given that wA= 0.6,E(RA) = 0.12,wB= 0.4, and E(RB)=0.08, we have:
E(Rp)=0.6×0.12 + 0.4×0.08 = 0.072 + 0.032 = 0.104 = 10.4%
Therefore, the expected return of the portfolio is 10.4%.
b) The standard deviation of the portfolio can be calculated using the formula:
σp=qw2
A×σ2
A+w2
B×σ2
B+ 2 ×wA×wB×σA×σB×ρA,B
where σA= 0.15,σB= 0.10, and ρA,B = 0.5.
Plugging in the values, we get:
σp=p(0.6)2×(0.15)2+ (0.4)2×(0.10)2+ 2 ×0.6×0.4×0.15 ×0.10 ×0.5
=√0.36 ×0.0225 + 0.16 ×0.01 + 0.12 ×0.015
=√0.0081 + 0.0016 + 0.0018
=√0.0115
≈0.107 = 10.7%
Therefore, the standard deviation of the portfolio is 10.7%.
13 15. IGNORING ENVIRONMENTAL, SOCIAL, AND GOVERNANCE FACTORS IN ASSET
ALLOCATION
Problem 15. Consider a portfolio with three assets: Stock A, Stock B, and Stock C. The ex-
pected return and standard deviation of each asset are as follows:
•Stock A: Expected return = 8%, Standard deviation = 12%
•Stock B: Expected return = 12%, Standard deviation = 18%
•Stock C: Expected return = 10%, Standard deviation = 15%
The correlation coefficients between the returns of the assets are given by:
•Correlation between A and B: 0.6
•Correlation between A and C: -0.2
•Correlation between B and C: 0.4
Determine the expected return and standard deviation of a portfolio that consists of 30% Stock
A, 50% Stock B, and 20% Stock C.
Solution 15. a) To find the expected return of the portfolio, we use the weighted average of the
expected returns of the individual assets:
Expected return of the portfolio =wA×Expected return of A+wB×Expected return of B+wC×Expected return of C
where wiis the weight of asset iin the portfolio.
Substitute the values into the formula:
Expected return of the portfolio = 0.30 ×8% + 0.50 ×12% + 0.20 ×10%
= 0.024 + 0.06 + 0.02 = 0.104 = 10.4%
Therefore, the expected return of the portfolio is 10.4%.
b) To find the standard deviation of the portfolio, we use the formula for the portfolio variance:
σ2
p=w2
A×σ2
A+w2
B×σ2
B+w2
C×σ2
C+ 2(wA×wB×σAB +wA×wC×σAC +wB×wC×σBC )
where σiis the standard deviation of asset iand σij is the covariance between assets iand j.
Substitute all values into the formula and calculate:
σ2
p= 0.302×0.122+0.502×0.182+0.202×0.152+2(0.30×0.50×0.6+0.30×0.20×(−0.2)+0.50×0.20×0.4)
= 0.00324 + 0.018 + 0.006 + 2(0.09 −0.012 −0.04)
= 0.02724 + 0.027 + 0.044 = 0.09824
Therefore, the standard deviation of the portfolio is σp=√0.09824 = 0.3135 = 31.35%.
14 Portfolio Theory and Asset Allocation
Problem:
You are considering investing in two assets, Asset A and Asset B. Asset A has an expected
return of 7% with a standard deviation of 12%, while Asset B has an expected return of 10% with a
standard deviation of 18%. You plan to allocate 60% of your portfolio to Asset A and 40% to Asset
B. The correlation between the returns of the two assets is 0.4.
a) Calculate the expected return and standard deviation of the portfolio.
b) Determine the correlation between the returns of the portfolio and a risk-free asset that offers
a return of 3%.
Solution:
a) To calculate the expected return and standard deviation of the portfolio, we use the following
formulas:
Expected return of the portfolio:
E(Rp) = wA·E(RA) + wB·E(RB)
where E(RA)and E(RB)are the expected returns of Asset A and Asset B, respectively, and
wAand wBare the weights of Asset A and Asset B in the portfolio.
Substitute the values:
E(Rp) = 0.6×0.07 + 0.4×0.10 = 0.042 + 0.04 = 0.082 = 8.2%
Standard deviation of the portfolio:
σp=qw2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·ρAB ·σA·σB
where σAand σBare the standard deviations of Asset A and Asset B, respectively, and ρAB is
the correlation coefficient between Asset A and Asset B.
Substitute the values:
σp=p0.62×(0.12)2+ 0.42×(0.18)2+ 2 ×0.6×0.4×0.4×0.12 ×0.18
σp=√0.0144 + 0.01296 + 0.00259 = √0.03 = 0.1732 = 17.32%
Therefore, the expected return of the portfolio is 8.2% and the standard deviation is 17.32%.
b) To determine the correlation between the returns of the portfolio and a risk-free asset, we
can use the formula:
ρp,rf =wp·ρA,rf
where ρA,rf is the correlation between Asset A and the risk-free asset, and wpis the weight of
the port...
Certainly! Here are a few numerical problem questions on Portfolio Theory and Asset Alloca-
tion:
—
15 17. OVER-RELIANCE ON HISTORICAL DATA IN PORTFOLIO CONSTRUCTION
Problem 17. A financial analyst is constructing a portfolio with two assets: Stock A and Stock B.
Historical returns for Stock A and Stock B over the past 5 years are as follows:
•Stock A: Mean return = 8%, Standard deviation = 12%
•Stock B: Mean return = 10%, Standard deviation = 15%
The correlation coefficient between the returns of Stock A and Stock B is 0.6. The analyst wants
to build a portfolio using these two assets.
a) If the analyst wants the portfolio to have a mean return of 9
b) Determine the standard deviation of the portfolio if the analyst invests 40% in Stock A and
60% in Stock B.
c) Calculate the correlation between the portfolio returns and Stock A if the weight of Stock A
in the portfolio is 0.4.
Solution 17.
a) Let wAand wBbe the weights of Stock A and Stock B in the portfolio, respectively. The
mean return of the portfolio can be calculated as:
E(rp) = wA·E(rA) + wB·E(rB)
Given that the mean return of the portfolio should be 9%, and E(rA)=0.08 and E(rB)=0.10,
we can set up the equation as:
0.09 = wA·0.08 + wB·0.10
Since wA+wB= 1, we can solve for wAin terms of wBas:
wA= 1 −wB
Substitute this into the equation:
0.09 = (1 −wB)·0.08 + wB·0.10
Solving for wB, we get wB= 0.6and wA= 0.4.
Therefore, the weights of Stock A and Stock B in the portfolio should be 40% and 60%, respec-
tively.
b) The standard deviation of the portfolio can be calculated using the formula:
σp=qw2
Aσ2
A+w2
Bσ2
B+ 2wAwBσAσBρAB
Substitute the given values and calculated weights into the formula to find the standard deviation
of the portfolio.
c) The correlation between the portfolio returns and Stock A can be calculated using the formula:
ρpA =wAρAB
Substitute the given correlation coefficient and weight of Stock A to determine the correlation.
—
Feel free to reach out if you need more questions or further clarifications on this topic!
16 18. UNDERESTIMATING TAIL RISKS IN ASSET ALLOCATION DECISIONS
Problem 18.
You are considering investing in two assets, Asset A and Asset B. The annual returns for Asset
A have a normal distribution with mean 8% and standard deviation 12%. The annual returns for
Asset B have a normal distribution with mean 10% and standard deviation 15%. The correlation
between the returns of Asset A and Asset B is 0.5.
a) Calculate the expected return of a portfolio that is equally weighted in Asset A and Asset B.
b) Calculate the standard deviation of the portfolio that is equally weighted in Asset A and Asset
B.
c) Calculate the correlation coefficient between the returns of the portfolio and the returns of
Asset A.
Solution 18.
a) The expected return of a portfolio that is equally weighted in Asset A and Asset B can be
calculated using the formula for the expected return of a portfolio:
E(Rp) = wA·E(RA) + wB·E(RB)
Where: - E(Rp)is the expected return of the portfolio - wAis the weight of Asset A in the portfolio
(0.5 in this case) - E(RA)is the expected return of Asset A (8%) - wBis the weight of Asset B in
the portfolio (0.5 in this case) - E(RB)is the expected return of Asset B (10%)
Plugging in the values, we get:
E(Rp)=0.5×8% + 0.5×10% = 0.08 + 0.05 = 0.13 = 13%
Therefore, the expected return of the equally weighted portfolio is 13%.
b) The standard deviation of a portfolio of two assets can be calculated using the formula for
the standard deviation of a portfolio:
σp=qw2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·ρAB ·σA·σB
Where: - σpis the standard deviation of the portfolio - wA,wBare the weights of Asset A and
Asset B in the portfolio (both 0.5 in this case) - σA,σBare the standard deviations of Asset A and
Asset B (12% and 15% respectively) - ρAB is the correlation coefficient between Asset A and Asset
B (0.5)
Plugging in the values, we get:
σp=p0.52·0.122+ 0.52·0.152+ 2 ·0.5·0.5·0.5·0.12 ·0.15
σp=p0.032+ 0.03752+ 0.009 = √0.0009 + 0.00140625 + 0.009 = √0.01030625 ≈0.1015 = 10.15%
Therefore, the standard deviation of the equally weighted portfolio is approximately 10.15
c) The correlation coefficient between the returns of the portfolio and the returns of Asset A can
be calculated using the formula for correlation coefficient in a two-assets portfolio:
ρpA =wA·σ2
A
σA·σp
Where: - ρpA is the correlation coefficient between the returns of the portfolio and the returns
of Asset A - wAis the weight of Asset A in the portfolio (0.5) - σAis the standard deviation of Asset
A (12%) - σpis the standard deviation of the portfolio (10.15%)
Plugging in the values, we get:
ρpA =0.5·0.12
0.12 ·0.1015 =0.06
0.01218 ≈0.4926
Therefore,
17 19. MISALIGNED ASSET ALLOCATION WITH LONG-TERM FINANCIAL GOALS
Problem 19.
Alice is planning her retirement and has set a goal to accumulate a wealth of 1,000,000in20years.Shecurrentlyhas100,000
saved and is considering two investment options: Option A, which has an expected annual return
of 8% with a standard deviation of 12%, and Option B, which has an expected annual return of 5%
with a standard deviation of 8%. Assuming Alice aims to maximize the likelihood of reaching her
retirement goal, determine the optimal allocation of her initial 100,000betweenOptionAandOptionB.
Solution 19.
To determine the optimal allocation that maximizes the likelihood of reaching her retirement
goal, we will use the concept of portfolio optimization. Let xdenote the allocation to Option A and
1−xdenote the allocation to Option B.
Given that the expected return of the portfolio is a weighted sum of the expected returns of the
individual assets, the expected return of the portfolio (Rp) is given by:
Rp=x·RA+ (1 −x)·RB
Rp= 0.08x+ 0.05(1 −x)
Rp= 0.03x+ 0.05
The variance of the portfolio (σ2
p) is calculated as follows:
σ2
p=x2·σ2
A+ (1 −x)2·σ2
B+ 2x(1 −x)·σAσB
σ2
p= 0.122x2+ 0.082(1 −x)2+ 2(0.12)(0.08)x(1 −x)
σ2
p= 0.0144x2+ 0.0064(1 −x)2+ 0.0192x(1 −x)
σ2
p= 0.008x2+ 0.0064 −0.0128x+ 0.0192x−0.0192x2
σ2
p=−0.0112x2+ 0.0064 −0.0036x
To maximize the likelihood of reaching her retirement goal, Alice can set up the following opti-
mization problem:
Maximize:
Rp= 0.03x+ 0.05
Subject to the constraint:
−0.0112x2+ 0.0064 −0.0036x≤variance tolerance level
Solving this optimization problem will provide Alice with the optimal allocation of her 100,000betweenOptionAandOptionB.
18 20. INEFFECTIVE COMMUNICATION OF PORTFOLIO STRATEGY TO STAKEHOLDERS.
Problem 20.
A financial advisor is creating a portfolio for a client with $100,000 to invest. The advisor decides
to allocate 40% to Stock A, 30% to Stock B, and the remaining 30% to a bond fund. Stock A has
an expected return of 8% and a standard deviation of 12%, Stock B has an expected return of 6%
and a standard deviation of 8%, and the bond fund has an expected return of 4% and a standard
deviation of 4%.
a) Calculate the expected return and standard deviation of the portfolio.
b) If the correlation between Stock A and Stock B is 0.5, calculate the portfolio’s expected return
and standard deviation using the given allocation.
c) Discuss the implications of the correlation assumption for this portfolio.
Solution 20.
a) The expected return and standard deviation of the portfolio can be calculated using the
weighted averages of the individual assets.
a) Expected Return:
E(Rp) = wA×E(RA) + wB×E(RB) + wbond ×E(Rbond)
E(Rp)=0.40 ×0.08 + 0.30 ×0.06 + 0.30 ×0.04 = 0.045 = 4.5%
Standard Deviation:
σp=qw2
A×σ2
A+w2
B×σ2
B+w2
bond ×σ2
bond
σp=p0.402×0.122+ 0.302×0.082+ 0.302×0.042= 0.0601 = 6.01%
b) If the correlation between Stock A and Stock B is 0.5, the portfolio’s expected return and
standard deviation using the given allocation can be calculated using the formula involving corre-
lation.
E(Rp)=0.40 ×0.08 + 0.30 ×0.06 + 0.30 ×0.04 = 0.045 = 4.5%
σp=qw2
A×σ2
A+w2
B×σ2
B+ 2 ×wA×wB×σA×σB×ρAB
σp=p0.402×0.122+ 0.302×0.082+ 2 ×0.40 ×0.30 ×0.12 ×0.08 ×0.5=0.0496 = 4.96%
c) The correlation assumption affects the diversification benefit of the portfolio. A correlation
of 0.5 between Stock A and Stock B implies they are positively correlated. This means that the
two stocks tend to move in the same direction, reducing the benefit of diversification. As a result,
the portfolio’s standard deviation is higher when the correlation is taken into account compared to
the assumption of no correlation. It shows the importance of considering the correlation between
assets when constructing a portfolio to manage risk effectively.
2 2. LACK OF DIVERSIFICATION IN ASSET CLASSES
Problem 2. Suppose an investor has a portfolio with 60% invested in stocks, 30% invested in
bonds, and 10% invested in real estate. The annual returns for each asset class are as follows:
- Stocks: 12% - Bonds: 6% - Real estate: 8%
Calculate the overall annual return of the investor’s portfolio.
Solution 2.
The overall annual return of the investor’s portfolio can be calculated by weighting the returns
of each asset class according to their respective percentages in the portfolio.
a) Calculating the weighted returns of each asset class:
- Weighted return of stocks: 0.60×0.12 = 0.072 (or 7.2- Weighted return of bonds: 0.30 ×0.06 =
0.018 (or 1.8- Weighted return of real estate: 0.10 ×0.08 = 0.008 (or 0.8
b) Calculating the overall annual return of the portfolio by summing up the weighted returns of
each asset class:
0.072 + 0.018 + 0.008 = 0.098
Therefore, the overall annual return of the investor’s portfolio is 9.8
3 3. SHORT-TERM VOLATILITY IMPACTING PORTFOLIO RETURNS
Problem 3.
You are managing a portfolio with two assets: Asset A and Asset B. Asset A has an annual
expected return of 12
a) Calculate the expected return and the standard deviation of a portfolio that is equally weighted
in Asset A and Asset B.
b) Determine the correlation of the portfolio returns with the returns of each asset.
c) If you increase the weight of Asset A to 60
Solution 3.
a) The expected return of a portfolio, E(rP), that is equally weighted in two assets A and B can
be calculated as:
E(rP) = wA·E(rA) + wB·E(rB)
E(rP)=0.5×0.12 + 0.5×0.08 = 0.10 or 10%
The variance of the portfolio, σ2
P, can be calculated as:
σ2
P=w2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·σA·σB·ρAB
σ2
P= 0.52×0.182+0.52×0.152+2×0.5×0.5×0.18×0.15×0.6 = 0.0288+0.01125+0.0081 = 0.04815
The standard deviation of the portfolio is the square root of the variance:
σP=√0.04815 ≈0.2196 or 21.96%
b) The correlation of the portfolio returns with the returns of each asset can be calculated using
the formula:
ρAP =wA·σ2
A+wB·σA·σB·ρAB
σP
ρAP =0.5×0.18 + 0.5×0.15 ×0.6
0.2196 ≈0.09 + 0.045
0.2196 ≈0.135
0.2196 ≈0.6148
Similarly, the correlation of the portfolio with Asset B, ρBP , can be calculated.
c) When the weights are changed to 60
E(rP)=0.6×0.12 + 0.4×0.08 = 0.104 or 10.4%
σ2
P= 0.62×0.182+0.42×0.152+2×0.6×0.4×0.18×0.15×0.6 = 0.03888+0.009+0.0162 = 0.06408
σP=√0.06408 ≈0.2531 or 25.31%
4 4. INEFFICIENT USE OF RISK BUDGET IN ASSET ALLOCATION
Problem 4.
An investor has a risk budget of $100,000 to invest in two assets: Asset A and Asset B. The
expected returns for Asset A and Asset B are 8
Solution 4.
The Sharpe ratio is given by:
SharpeRatio =E(Rp)−Rf
pV ar(Rp)
where:
•E(Rp)is the expected return of the portfolio,
•Rfis the risk-free rate (assumed to be zero in this case),
•V ar(Rp)is the variance of the portfolio return.
The expected return of the portfolio can be calculated using the weights assigned to Asset A
and Asset B:
E(Rp) = wAE(RA) + wBE(RB)
The variance of the portfolio return can be calculated as:
V ar(Rp) = w2
Aσ2
A+w2
Bσ2
B+ 2wAwBσAσBρA,B
Now, to maximize the Sharpe ratio, we need to find the weights (wAand wB) that maximize the
Sharpe ratio. Let xbe the weight of Asset A in the portfolio:
SharpeRatio =x×8% + (1 −x)×12%
px2×(15%)2+ (1 −x)2×(20%)2+ 2x(1 −x)×15% ×20% ×0.6
=0.08x+ 0.12(1 −x)
p0.0225x2+ 0.04(1 −x)2+ 0.018x(1 −x)
To maximize the Sharpe ratio, we need to differentiate it with respect to xand set the derivative
equal to zero:
d(SR)
dx =0.08 −0.12 −2.1x+ 1.68
(0.0225x2+ 0.04(1 −x)2+ 0.018x(1 −x))1.5= 0
−0.04 −2.1x+ 1.68 = 0
x=1.68 −0.04
2.1= 0.8
Therefore, the optimal allocation of the risk budget is 80% in Asset A and 20% in Asset B to
maximize the Sharpe ratio.
I. Problem: Portfolio Diversification
A portfolio manager is considering investing in two assets: Asset A and Asset B. The expected
returns and standard deviations of the two assets are given as follows:
- Asset A: Expected Return = 12- Asset B: Expected Return = 15
The correlation coefficient between the returns of Asset A and Asset B is 0.5. The manager
wants to create a portfolio with 60
a) Calculate the expected return and standard deviation of the portfolio. b) Determine the cor-
relation coefficient between the portfolio and the individual assets.
Solution:
a) Let wA= 0.6and wB= 0.4be the weights of Asset A and Asset B in the portfolio, respectively.
i) Expected Return of the Portfolio:
E(Rp) = wA·E(RA) + wB·E(RB)
E(Rp)=0.6×0.12 + 0.4×0.15 = 0.072 + 0.06 = 0.132 = 13.2%
ii) Standard Deviation of the Portfolio:
σp=qw2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·ρAB ·σA·σB
σp=p0.62·0.082+ 0.42·0.122+ 2 ·0.6·0.4·0.5·0.08 ·0.12
σp≈√0.0288 + 0.0192 + 0.0576 ≈√0.1056 ≈0.3251 = 32.51%
Therefore, the expected return of the portfolio is 13.2
b) Correlation coefficient between the portfolio and Asset A:
ρpA =wA·1 + wB·ρAB
ρpA = 0.6×1+0.4×0.5=0.6+0.2=0.8
Correlation coefficient between the portfolio and Asset B:
ρpB =wA·ρAB +wB·1
ρpB = 0.6×0.5+0.4×1=0.3+0.4=0.7
Therefore, the correlation coefficient between the portfolio and Asset A is 0.8, and with Asset
B is 0.7.
5 6. IGNORING LIQUIDITY RISK IN PORTFOLIO CONSTRUCTION
Problem 6. You are considering investing in two assets, Stock A and Stock B. The expected
returns of these assets are 8% and 12%, respectively. The standard deviation of Stock A is 10%
and the standard deviation of Stock B is 15%. The correlation between the returns of Stock A and
Stock B is 0.6. You have $50,000 to invest and want to allocate your portfolio to maximize the
Sharpe ratio. Assuming you are ignoring liquidity risk in portfolio construction, calculate:
a) The weights of Stock A and Stock B that maximize the Sharpe ratio.
b) The expected return and volatility of the optimal portfolio.
c) The maximum Sharpe ratio for the optimal portfolio.
Solution 6.
a) To find the weights that maximize the Sharpe ratio, we need to calculate the Sharpe ratio for
different weight combinations of Stock A and Stock B. The Sharpe ratio is given by:
Sharpe =E[rp]−rf
σp
where: - E[rp]is the expected return of the portfolio, - rfis the risk-free rate (we will assume 0
for simplicity), - σpis the standard deviation of the portfolio return.
Let wbe the weight of Stock A and 1−wbe the weight of Stock B. Therefore, wis the weight
we allocate to Stock A in our portfolio.
The expected return of the portfolio is given by:
E[rp] = w×E[rA] + (1 −w)×E[rB]E[rp] = w×0.08 + (1 −w)×0.12
The variance of the portfolio is given by:
σ2
p=w2×σ2
A+ (1 −w)2×σ2
B+ 2w(1 −w)×ρAB ×σA×σBσ2
p=w2×0.12+ (1 −w)2×0.152+
2w(1 −w)×0.6×0.1×0.15
Now we can calculate the Sharpe ratio for different weight combinations and choose the weights
that maximize the Sharpe ratio.
b) Once we find the optimal weights, we can calculate the expected return and volatility of the
optimal portfolio using the formulas for E[rp]and σ2
pderived in part (a).
c) The maximum Sharpe ratio for the optimal portfolio is simply the Sharpe ratio calculated
using the optimal weights from part (a).
I. Problem:
You are considering investing in two assets, Asset A and Asset B, with the following character-
istics:
Asset A has an expected return of 8% and a standard deviation of 4%. Asset B has an expected
return of 12% and a standard deviation of 6%.
The correlation between the returns of Asset A and Asset B is 0.5.
a) Calculate the expected return of a portfolio that consists of 40% Asset A and 60% Asset B.
b) Calculate the standard deviation of the portfolio in part (a).
c) Determine the optimal portfolio weights that minimize the standard deviation of the portfolio.
II. Solution:
a) Let E[A]and E[B]be the expected returns of Asset A and Asset B respectively. We want to
find the expected return of the portfolio:
Expected return of the portfolio = 0.4×E[A]+0.6×E[B]
= 0.4×8% + 0.6×12%
= 3.2% + 7.2%
= 10.4%
b) The formula for calculating the standard deviation of a portfolio consisting of two assets is
given by:
σp=qw2
Aσ2
A+w2
Bσ2
B+ 2wAwBρABσAσB
where: σp= standard deviation of the portfolio, wAand wB= weights of Asset A and Asset B in
the portfolio, σAand σB= standard deviations of Asset A and Asset B, ρAB = correlation coefficient
between the returns of Asset A and Asset B.
Substitute the known values into the formula:
σp=√0.42×0.042+ 0.62×0.062+ 2 ×0.4×0.6×0.5×0.04 ×0.06
σp=√0.0016 + 0.0036 + 0.00288
σp=√0.00808
σp≈0.09 or 9%
c) The optimal portfolio weights can be found by minimizing the standard deviation of the port-
folio using the formula for minimum variance portfolio weights, which is given by:
wA=σ2
B−σAB σBσA
σ2
A+σ2
B−2σAB σAσB
wB= 1 −wA
Substitute the given values into the formulas to find the optimal weights for Asset A and Asset
B.
6 8. BEHAVIORAL BIASES AFFECTING ASSET ALLOCATION DECISIONS
Problem 8. Mr. Smith is considering reallocating his investment portfolio to achieve a target
asset allocation. However, he is prone to anchoring bias, fixating on the historical performance of
certain assets. His current portfolio consists of $50,000 invested in Stocks, $30,000 in Bonds, and
$20,000 in Cash. His target allocation is 50% Stocks, 30% Bonds, and 20% Cash. Calculate the
amount Mr. Smith needs to reallocate to each asset to reach his target allocation.
Solution 8. a) Let Xbe the amount to be reallocated to Stocks, Yto Bonds, and Zto Cash.
The total amount of his current portfolio is $50,000 + $30,000 + $20,000 = $100,000.
So, the target amounts are: - Stocks: 50% of $100,000 = $50,000 - Bonds: 30% of $100,000
= $30,000 - Cash: 20% of $100,000 = $20,000
Therefore, we have the following system of equations:
X+ 50,000 = 50,000
Y+ 30,000 = 30,000
Z+ 20,000 = 20,000
Solving these equations, we get:
X= 0
Y= 0
Z= 0
Therefore, Mr. Smith does not need to reallocate any funds to reach his target asset allocation.
The anchoring bias in this case caused Mr. Smith to ignore his current allocation and blindly
stick to his past investments, even though he was already at his target allocation.
This example demonstrates the role of behavioral biases in asset allocation decisions.
7 9. INCONSISTENT RISK TOLERANCE ASSESSMENT AMONG INVESTORS
Problem 9. Assume two investors, Alice and Bob, have different assessments of their risk
tolerance. Alice has a risk tolerance level of 0.6, while Bob’s risk tolerance level is 0.4. They are
considering investing in two assets, Asset X and Asset Y, with the following characteristics:
Asset X: Expected return = 8%, Standard Deviation = 12%
Asset Y: Expected return = 12%, Standard Deviation = 18%
a) Calculate the expected return and standard deviation of a portfolio consisting of 60
b) Determine which investor should choose this portfolio based on their risk tolerance assess-
ment.
c) Discuss the implications of having inconsistent risk tolerance assessments among investors
in the context of portfolio construction.
Solution 9.
a) To calculate the expected return and standard deviation of the portfolio consisting of 60
Expected return of the portfolio = Weight of Asset X * Expected return of Asset X + Weight of
Asset Y * Expected return of Asset Y
Standard deviation of the portfolio = sqrt[ (Weight of Asset X)2∗(StandardDeviationofAssetX)2+
(W eightofAssetY )2∗(StandardDeviationofAssetY )2+2∗W eightofAssetX ∗W eightof AssetY ∗
Covariance(X, Y )]
For the given data:
Expected return of the portfolio = 0.6 * 8% + 0.4 * 12% = 4.8% + 4.8% = 9.6%
Standard deviation of the portfolio = sqrt[ (0.62)∗(122) + (0.42)∗(182) + 2 ∗0.6∗0.4∗(12) ∗(18)]
= sqrt[ (0.36) * (144) + (0.16) * (324) + 2 * 0.6 * 0.4 * 216 ]
= sqrt[ 51.84 + 51.84 + 51.84 ]
= sqrt[ 155.52 ]
12.476%
Therefore, for both Alice and Bob, the expected return of the portfolio is 9.6% and the standard
deviation is approximately 12.476%.
b) Based on their risk tolerance assessments, Alice (with a risk tolerance level of 0.6) should
choose this portfolio, as the portfolio’s risk tolerance matches her preferences (higher risk toler-
ance), whereas Bob’s risk tolerance level of 0.4 indicates he would prefer a lower risk portfolio.
c) Inconsistent risk tolerance assessments among investors can lead to conflicts in portfolio
construction decisions. It may result in suboptimal portfolio choices if the portfolio’s risk-return char-
acteristics do not align with the individual investors’ risk preferences. This highlights the importance
of understanding and incorporating different risk tolerance levels when constructing portfolios for
multiple investors.
8 10. LACK OF CLARITY IN INVESTMENT OBJECTIVES DRIVING POOR ASSET ALLOCA-
TION
Problem 10.
An investor is considering investing in two assets - Stock A and Stock B. The investor’s utility
function is given by U(W) = W0.5, where Wis the wealth at the end of the investment period. The
investor has a total of $100,000 to invest. Stock A has an expected return of 8% and a standard
deviation of 12%, while Stock B has an expected return of 6% and a standard deviation of 8%. The
correlation coefficient between the returns of Stocks A and B is 0.4.
a) Calculate the expected return and standard deviation of a portfolio that is 60% invested in
Stock A and 40% invested in Stock B.
b) Determine the optimal risky portfolio for this investor considering the given utility function.
Solution 10.
a) The expected return of a portfolio, denoted by E(Rp), is given by the weighted average of the
expected returns of individual assets in the portfolio. The standard deviation of a portfolio, denoted
by σp, is calculated using the formula for the portfolio variance.
a) To calculate the expected return and standard deviation of the portfolio with 60% invested in
Stock A and 40% in Stock B:
Expected return of the portfolio:
E(Rp)=0.6×0.08 + 0.4×0.06 = 0.048 + 0.024 = 0.072 = 7.2%
Standard deviation of the portfolio:
σp=p0.62×0.122+ 0.42×0.082+ 2 ×0.6×0.4×0.12 ×0.08 ×0.4 = √0.0144 + 0.0128 + 0.02304 ≈0.076 = 7.6%
Therefore, the expected return of the portfolio is 7.2% and the standard deviation is 7.6%.
b) To determine the optimal risky portfolio for the investor, we need to find the portfolio that
maximizes the investor’s utility function. This is achieved by locating the point of tangency between
the investor’s indifference curve and the efficient frontier.
Given the utility function U(W) = W0.5, the optimal risky portfolio allocation is given by the
formula:
w∗=E(RA)−rf
γ2σ2
A+σ2
B−2γσAσB
=0.08 −0.02
0.0006 = 100
So, the optimal risky portfolio for this investor is 100% Stock A and 0% Stock B.
I.
9 Problem on Portfolio Theory and Asset Allocation
Problem:
Suppose an investor has a portfolio consisting of two assets, Asset A and Asset B. Asset A has
a weight of 60% in the portfolio with an expected return of 8% and a standard deviation of 15%.
Asset B has a weight of 40% with an expected return of 12% and a standard deviation of 20%. The
correlation coefficient between the returns of Asset A and Asset B is 0.6. Calculate the expected
return and standard deviation of the portfolio.
Solution:
Let rAbe the return of Asset A, rBbe the return of Asset B, and wAand wBbe the weights of
Asset A and Asset B respectively.
a) The expected return of the portfolio (rp) is given by:
rp=wA×rA+wB×rB
rp= 0.60 ×0.08 + 0.40 ×0.12
rp= 0.048 + 0.048
rp= 0.096 or 9.6%
b) The variance of the portfolio (σ2
p) is given by:
σ2
p=w2
A×σ2
A+w2
B×σ2
B+ 2 ×wA×wB×Corr(A, B)×σA×σB
Plugging in the values:
σ2
p= 0.602×0.152+ 0.402×0.202+ 2 ×0.60 ×0.40 ×0.6×0.15 ×0.20
σ2
p= 0.09 + 0.16 + 0.144
σ2
p= 0.394
σp=√0.394 or 19.85%
Therefore, the expected return of the portfolio is 9.6% and the standard deviation of the portfolio
is 19.85%.
10 12. INEFFICIENT REBALANCING STRATEGIES IMPACTING PORTFOLIO PERFORMANCE
Problem 12.
You have a portfolio consisting of two assets, Stock A and Stock B, with the following charac-
teristics:
•Stock A has a weight of 40% in the portfolio and has an expected return of 8% with a standard
deviation of 12%.
•Stock B has a weight of 60% in the portfolio and has an expected return of 12% with a standard
deviation of 18%.
•The correlation coefficient between Stock A and Stock B is 0.6.
a) Calculate the expected return and standard deviation of the portfolio.
b) If you decide to rebalance the portfolio to 50% Stock A and 50% Stock B, calculate the new
expected return and standard deviation of the portfolio.
c) Evaluate the impact of the rebalancing on the portfolio performance.
Solution 12.
a) The expected return and standard deviation of the portfolio can be calculated using the
following formulas:
Expected Return of Portfolio =wA×Expected Return of Stock A+wB×Expected Return of Stock B
Standard Deviation of Portfolio =qw2
A×Variance of Stock A +w2
B×Variance of Stock B + 2 ×wA×wB×Standard Deviation of Stock A ×Standard Deviation of Stock B ×Correlation
Substitute the given values:
Expected Return of Portfolio = 0.4×8% + 0.6×12% = 0.04 + 0.072 = 0.112 = 11.2%
Standard Deviation of Portfolio =p0.42×(0.12)2+ 0.62×(0.18)2+ 2 ×0.4×0.6×0.12 ×0.18 ×0.6=0.1173 = 11.73%
a) Therefore, the expected return of the portfolio is 11.2% and the standard deviation of the
portfolio is 11.73%.
b) If we rebalance the portfolio to 50% Stock A and 50% Stock B, the new expected return and
standard deviation of the portfolio can be calculated in a similar way:
Expected Return of Portfolio = 0.5×8% + 0.5×12% = 0.04 + 0.06 = 0.1 = 10%
Standard Deviation of Portfolio =p0.52×(0.12)2+ 0.52×(0.18)2+ 2 ×0.5×0.5×0.12 ×0.18 ×0.6=0.1289 = 12.89%
b) Therefore, the new expected return of the portfolio is 10% and the new standard deviation
of the portfolio is 12.89%.
c) The rebalancing strategy has slightly reduced the expected return of the portfolio from 11.2%
to 10%, but it has also slightly increased the standard deviation from 11.73% to 12.89%. This
tradeoff between return and risk should be carefully considered based on the investor’s risk appetite
and investment objectives.
11 13. LACK OF CONSIDERATION FOR TAX IMPLICATIONS IN ASSET ALLOCATION
Problem 13. An investor has two investment options:
Option A: A stock that pays a dividend yield of 4% annually and has a capital gain of 10% at
the end of the year. The investor’s tax rate on dividends is 20% and on capital gains is 15%.
Option B: A tax-exempt municipal bond that pays a yield of 3.5% annually.
If the investor’s initial investment is 10,000, determinewhichoptionwouldprovidehigherafter −
taxreturnsaf teroneyear.
Solution 13.
To compare the after-tax returns of the two investment options, we calculate the after-tax returns
for options A and B separately:
a) Option A:
For Option A, the after-tax return is the sum of after-tax dividend and after-tax capital gain:
After-tax dividend = Dividend yield * (1 - Tax rate on dividends) = 0.04 * (1 - 0.2) = 0.04 * 0.8 =
0.032 = 3.2%
After-tax capital gain = Capital gain * (1 - Tax rate on capital gains) = 0.10 * (1 - 0.15) = 0.10 *
0.85 = 0.085 = 8.5%
Total after-tax return for Option A = After-tax dividend + After-tax capital gain = 3.2% + 8.5% =
11.7%
b) Option B:
For Option B, the after-tax return of the tax-exempt municipal bond is simply the yield of 3.5%.
c) Comparison:
Since Option A has a total after-tax return of 11.7%, which is higher than the 3.5% after-tax
return of Option B, the investor would achieve higher after-tax returns by investing in Option A.
12 Portfolio Theory and Asset Allocation
Problem 1.
You are considering investing in a portfolio that consists of two assets: Stock A and Stock B.
The expected return and standard deviation of each asset are as follows:
Stock A: Expected Return = 12%, Standard Deviation = 15%
Stock B: Expected Return = 8%, Standard Deviation = 10%
The correlation coefficient between the returns of Stock A and Stock B is 0.5. You are planning
to allocate 60% of your investment to Stock A and 40% to Stock B.
a) Calculate the expected return of the portfolio.
b) Calculate the standard deviation of the portfolio.
Solution 1.
a) The expected return of the portfolio can be calculated using the weighted sum of the individual
expected returns:
E(Rp) = wA×E(RA) + wB×E(RB)
Given that wA= 0.6,E(RA) = 0.12,wB= 0.4, and E(RB)=0.08, we have:
E(Rp)=0.6×0.12 + 0.4×0.08 = 0.072 + 0.032 = 0.104 = 10.4%
Therefore, the expected return of the portfolio is 10.4%.
b) The standard deviation of the portfolio can be calculated using the formula:
σp=qw2
A×σ2
A+w2
B×σ2
B+ 2 ×wA×wB×σA×σB×ρA,B
where σA= 0.15,σB= 0.10, and ρA,B = 0.5.
Plugging in the values, we get:
σp=p(0.6)2×(0.15)2+ (0.4)2×(0.10)2+ 2 ×0.6×0.4×0.15 ×0.10 ×0.5
=√0.36 ×0.0225 + 0.16 ×0.01 + 0.12 ×0.015
=√0.0081 + 0.0016 + 0.0018
=√0.0115
≈0.107 = 10.7%
Therefore, the standard deviation of the portfolio is 10.7%.
13 15. IGNORING ENVIRONMENTAL, SOCIAL, AND GOVERNANCE FACTORS IN ASSET
ALLOCATION
Problem 15. Consider a portfolio with three assets: Stock A, Stock B, and Stock C. The ex-
pected return and standard deviation of each asset are as follows:
•Stock A: Expected return = 8%, Standard deviation = 12%
•Stock B: Expected return = 12%, Standard deviation = 18%
•Stock C: Expected return = 10%, Standard deviation = 15%
The correlation coefficients between the returns of the assets are given by:
•Correlation between A and B: 0.6
•Correlation between A and C: -0.2
•Correlation between B and C: 0.4
Determine the expected return and standard deviation of a portfolio that consists of 30% Stock
A, 50% Stock B, and 20% Stock C.
Solution 15. a) To find the expected return of the portfolio, we use the weighted average of the
expected returns of the individual assets:
Expected return of the portfolio =wA×Expected return of A+wB×Expected return of B+wC×Expected return of C
where wiis the weight of asset iin the portfolio.
Substitute the values into the formula:
Expected return of the portfolio = 0.30 ×8% + 0.50 ×12% + 0.20 ×10%
= 0.024 + 0.06 + 0.02 = 0.104 = 10.4%
Therefore, the expected return of the portfolio is 10.4%.
b) To find the standard deviation of the portfolio, we use the formula for the portfolio variance:
σ2
p=w2
A×σ2
A+w2
B×σ2
B+w2
C×σ2
C+ 2(wA×wB×σAB +wA×wC×σAC +wB×wC×σBC )
where σiis the standard deviation of asset iand σij is the covariance between assets iand j.
Substitute all values into the formula and calculate:
σ2
p= 0.302×0.122+0.502×0.182+0.202×0.152+2(0.30×0.50×0.6+0.30×0.20×(−0.2)+0.50×0.20×0.4)
= 0.00324 + 0.018 + 0.006 + 2(0.09 −0.012 −0.04)
= 0.02724 + 0.027 + 0.044 = 0.09824
Therefore, the standard deviation of the portfolio is σp=√0.09824 = 0.3135 = 31.35%.
14 Portfolio Theory and Asset Allocation
Problem:
You are considering investing in two assets, Asset A and Asset B. Asset A has an expected
return of 7% with a standard deviation of 12%, while Asset B has an expected return of 10% with a
standard deviation of 18%. You plan to allocate 60% of your portfolio to Asset A and 40% to Asset
B. The correlation between the returns of the two assets is 0.4.
a) Calculate the expected return and standard deviation of the portfolio.
b) Determine the correlation between the returns of the portfolio and a risk-free asset that offers
a return of 3%.
Solution:
a) To calculate the expected return and standard deviation of the portfolio, we use the following
formulas:
Expected return of the portfolio:
E(Rp) = wA·E(RA) + wB·E(RB)
where E(RA)and E(RB)are the expected returns of Asset A and Asset B, respectively, and
wAand wBare the weights of Asset A and Asset B in the portfolio.
Substitute the values:
E(Rp) = 0.6×0.07 + 0.4×0.10 = 0.042 + 0.04 = 0.082 = 8.2%
Standard deviation of the portfolio:
σp=qw2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·ρAB ·σA·σB
where σAand σBare the standard deviations of Asset A and Asset B, respectively, and ρAB is
the correlation coefficient between Asset A and Asset B.
Substitute the values:
σp=p0.62×(0.12)2+ 0.42×(0.18)2+ 2 ×0.6×0.4×0.4×0.12 ×0.18
σp=√0.0144 + 0.01296 + 0.00259 = √0.03 = 0.1732 = 17.32%
Therefore, the expected return of the portfolio is 8.2% and the standard deviation is 17.32%.
b) To determine the correlation between the returns of the portfolio and a risk-free asset, we
can use the formula:
ρp,rf =wp·ρA,rf
where ρA,rf is the correlation between Asset A and the risk-free asset, and wpis the weight of
the port...
Certainly! Here are a few numerical problem questions on Portfolio Theory and Asset Alloca-
tion:
—
15 17. OVER-RELIANCE ON HISTORICAL DATA IN PORTFOLIO CONSTRUCTION
Problem 17. A financial analyst is constructing a portfolio with two assets: Stock A and Stock B.
Historical returns for Stock A and Stock B over the past 5 years are as follows:
•Stock A: Mean return = 8%, Standard deviation = 12%
•Stock B: Mean return = 10%, Standard deviation = 15%
The correlation coefficient between the returns of Stock A and Stock B is 0.6. The analyst wants
to build a portfolio using these two assets.
a) If the analyst wants the portfolio to have a mean return of 9
b) Determine the standard deviation of the portfolio if the analyst invests 40% in Stock A and
60% in Stock B.
c) Calculate the correlation between the portfolio returns and Stock A if the weight of Stock A
in the portfolio is 0.4.
Solution 17.
a) Let wAand wBbe the weights of Stock A and Stock B in the portfolio, respectively. The
mean return of the portfolio can be calculated as:
E(rp) = wA·E(rA) + wB·E(rB)
Given that the mean return of the portfolio should be 9%, and E(rA)=0.08 and E(rB)=0.10,
we can set up the equation as:
0.09 = wA·0.08 + wB·0.10
Since wA+wB= 1, we can solve for wAin terms of wBas:
wA= 1 −wB
Substitute this into the equation:
0.09 = (1 −wB)·0.08 + wB·0.10
Solving for wB, we get wB= 0.6and wA= 0.4.
Therefore, the weights of Stock A and Stock B in the portfolio should be 40% and 60%, respec-
tively.
b) The standard deviation of the portfolio can be calculated using the formula:
σp=qw2
Aσ2
A+w2
Bσ2
B+ 2wAwBσAσBρAB
Substitute the given values and calculated weights into the formula to find the standard deviation
of the portfolio.
c) The correlation between the portfolio returns and Stock A can be calculated using the formula:
ρpA =wAρAB
Substitute the given correlation coefficient and weight of Stock A to determine the correlation.
—
Feel free to reach out if you need more questions or further clarifications on this topic!
16 18. UNDERESTIMATING TAIL RISKS IN ASSET ALLOCATION DECISIONS
Problem 18.
You are considering investing in two assets, Asset A and Asset B. The annual returns for Asset
A have a normal distribution with mean 8% and standard deviation 12%. The annual returns for
Asset B have a normal distribution with mean 10% and standard deviation 15%. The correlation
between the returns of Asset A and Asset B is 0.5.
a) Calculate the expected return of a portfolio that is equally weighted in Asset A and Asset B.
b) Calculate the standard deviation of the portfolio that is equally weighted in Asset A and Asset
B.
c) Calculate the correlation coefficient between the returns of the portfolio and the returns of
Asset A.
Solution 18.
a) The expected return of a portfolio that is equally weighted in Asset A and Asset B can be
calculated using the formula for the expected return of a portfolio:
E(Rp) = wA·E(RA) + wB·E(RB)
Where: - E(Rp)is the expected return of the portfolio - wAis the weight of Asset A in the portfolio
(0.5 in this case) - E(RA)is the expected return of Asset A (8%) - wBis the weight of Asset B in
the portfolio (0.5 in this case) - E(RB)is the expected return of Asset B (10%)
Plugging in the values, we get:
E(Rp)=0.5×8% + 0.5×10% = 0.08 + 0.05 = 0.13 = 13%
Therefore, the expected return of the equally weighted portfolio is 13%.
b) The standard deviation of a portfolio of two assets can be calculated using the formula for
the standard deviation of a portfolio:
σp=qw2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·ρAB ·σA·σB
Where: - σpis the standard deviation of the portfolio - wA,wBare the weights of Asset A and
Asset B in the portfolio (both 0.5 in this case) - σA,σBare the standard deviations of Asset A and
Asset B (12% and 15% respectively) - ρAB is the correlation coefficient between Asset A and Asset
B (0.5)
Plugging in the values, we get:
σp=p0.52·0.122+ 0.52·0.152+ 2 ·0.5·0.5·0.5·0.12 ·0.15
σp=p0.032+ 0.03752+ 0.009 = √0.0009 + 0.00140625 + 0.009 = √0.01030625 ≈0.1015 = 10.15%
Therefore, the standard deviation of the equally weighted portfolio is approximately 10.15
c) The correlation coefficient between the returns of the portfolio and the returns of Asset A can
be calculated using the formula for correlation coefficient in a two-assets portfolio:
ρpA =wA·σ2
A
σA·σp
Where: - ρpA is the correlation coefficient between the returns of the portfolio and the returns
of Asset A - wAis the weight of Asset A in the portfolio (0.5) - σAis the standard deviation of Asset
A (12%) - σpis the standard deviation of the portfolio (10.15%)
Plugging in the values, we get:
ρpA =0.5·0.12
0.12 ·0.1015 =0.06
0.01218 ≈0.4926
Therefore,
17 19. MISALIGNED ASSET ALLOCATION WITH LONG-TERM FINANCIAL GOALS
Problem 19.
Alice is planning her retirement and has set a goal to accumulate a wealth of 1,000,000in20years.Shecurrentlyhas100,000
saved and is considering two investment options: Option A, which has an expected annual return
of 8% with a standard deviation of 12%, and Option B, which has an expected annual return of 5%
with a standard deviation of 8%. Assuming Alice aims to maximize the likelihood of reaching her
retirement goal, determine the optimal allocation of her initial 100,000betweenOptionAandOptionB.
Solution 19.
To determine the optimal allocation that maximizes the likelihood of reaching her retirement
goal, we will use the concept of portfolio optimization. Let xdenote the allocation to Option A and
1−xdenote the allocation to Option B.
Given that the expected return of the portfolio is a weighted sum of the expected returns of the
individual assets, the expected return of the portfolio (Rp) is given by:
Rp=x·RA+ (1 −x)·RB
Rp= 0.08x+ 0.05(1 −x)
Rp= 0.03x+ 0.05
The variance of the portfolio (σ2
p) is calculated as follows:
σ2
p=x2·σ2
A+ (1 −x)2·σ2
B+ 2x(1 −x)·σAσB
σ2
p= 0.122x2+ 0.082(1 −x)2+ 2(0.12)(0.08)x(1 −x)
σ2
p= 0.0144x2+ 0.0064(1 −x)2+ 0.0192x(1 −x)
σ2
p= 0.008x2+ 0.0064 −0.0128x+ 0.0192x−0.0192x2
σ2
p=−0.0112x2+ 0.0064 −0.0036x
To maximize the likelihood of reaching her retirement goal, Alice can set up the following opti-
mization problem:
Maximize:
Rp= 0.03x+ 0.05
Subject to the constraint:
−0.0112x2+ 0.0064 −0.0036x≤variance tolerance level
Solving this optimization problem will provide Alice with the optimal allocation of her 100,000betweenOptionAandOptionB.
18 20. INEFFECTIVE COMMUNICATION OF PORTFOLIO STRATEGY TO STAKEHOLDERS.
Problem 20.
A financial advisor is creating a portfolio for a client with $100,000 to invest. The advisor decides
to allocate 40% to Stock A, 30% to Stock B, and the remaining 30% to a bond fund. Stock A has
an expected return of 8% and a standard deviation of 12%, Stock B has an expected return of 6%
and a standard deviation of 8%, and the bond fund has an expected return of 4% and a standard
deviation of 4%.
a) Calculate the expected return and standard deviation of the portfolio.
b) If the correlation between Stock A and Stock B is 0.5, calculate the portfolio’s expected return
and standard deviation using the given allocation.
c) Discuss the implications of the correlation assumption for this portfolio.
Solution 20.
a) The expected return and standard deviation of the portfolio can be calculated using the
weighted averages of the individual assets.
a) Expected Return:
E(Rp) = wA×E(RA) + wB×E(RB) + wbond ×E(Rbond)
E(Rp)=0.40 ×0.08 + 0.30 ×0.06 + 0.30 ×0.04 = 0.045 = 4.5%
Standard Deviation:
σp=qw2
A×σ2
A+w2
B×σ2
B+w2
bond ×σ2
bond
σp=p0.402×0.122+ 0.302×0.082+ 0.302×0.042= 0.0601 = 6.01%
b) If the correlation between Stock A and Stock B is 0.5, the portfolio’s expected return and
standard deviation using the given allocation can be calculated using the formula involving corre-
lation.
E(Rp)=0.40 ×0.08 + 0.30 ×0.06 + 0.30 ×0.04 = 0.045 = 4.5%
σp=qw2
A×σ2
A+w2
B×σ2
B+ 2 ×wA×wB×σA×σB×ρAB
σp=p0.402×0.122+ 0.302×0.082+ 2 ×0.40 ×0.30 ×0.12 ×0.08 ×0.5=0.0496 = 4.96%
c) The correlation assumption affects the diversification benefit of the portfolio. A correlation
of 0.5 between Stock A and Stock B implies they are positively correlated. This means that the
two stocks tend to move in the same direction, reducing the benefit of diversification. As a result,
the portfolio’s standard deviation is higher when the correlation is taken into account compared to
the assumption of no correlation. It shows the importance of considering the correlation between
assets when constructing a portfolio to manage risk effectively.
2 2. LACK OF DIVERSIFICATION IN ASSET CLASSES
Problem 2. Suppose an investor has a portfolio with 60% invested in stocks, 30% invested in
bonds, and 10% invested in real estate. The annual returns for each asset class are as follows:
- Stocks: 12% - Bonds: 6% - Real estate: 8%
Calculate the overall annual return of the investor’s portfolio.
Solution 2.
The overall annual return of the investor’s portfolio can be calculated by weighting the returns
of each asset class according to their respective percentages in the portfolio.
a) Calculating the weighted returns of each asset class:
- Weighted return of stocks: 0.60×0.12 = 0.072 (or 7.2- Weighted return of bonds: 0.30 ×0.06 =
0.018 (or 1.8- Weighted return of real estate: 0.10 ×0.08 = 0.008 (or 0.8
b) Calculating the overall annual return of the portfolio by summing up the weighted returns of
each asset class:
0.072 + 0.018 + 0.008 = 0.098
Therefore, the overall annual return of the investor’s portfolio is 9.8
3 3. SHORT-TERM VOLATILITY IMPACTING PORTFOLIO RETURNS
Problem 3.
You are managing a portfolio with two assets: Asset A and Asset B. Asset A has an annual
expected return of 12
a) Calculate the expected return and the standard deviation of a portfolio that is equally weighted
in Asset A and Asset B.
b) Determine the correlation of the portfolio returns with the returns of each asset.
c) If you increase the weight of Asset A to 60
Solution 3.
a) The expected return of a portfolio, E(rP), that is equally weighted in two assets A and B can
be calculated as:
E(rP) = wA·E(rA) + wB·E(rB)
E(rP)=0.5×0.12 + 0.5×0.08 = 0.10 or 10%
The variance of the portfolio, σ2
P, can be calculated as:
σ2
P=w2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·σA·σB·ρAB
σ2
P= 0.52×0.182+0.52×0.152+2×0.5×0.5×0.18×0.15×0.6 = 0.0288+0.01125+0.0081 = 0.04815
The standard deviation of the portfolio is the square root of the variance:
σP=√0.04815 ≈0.2196 or 21.96%
b) The correlation of the portfolio returns with the returns of each asset can be calculated using
the formula:
ρAP =wA·σ2
A+wB·σA·σB·ρAB
σP
ρAP =0.5×0.18 + 0.5×0.15 ×0.6
0.2196 ≈0.09 + 0.045
0.2196 ≈0.135
0.2196 ≈0.6148
Similarly, the correlation of the portfolio with Asset B, ρBP , can be calculated.
c) When the weights are changed to 60
E(rP)=0.6×0.12 + 0.4×0.08 = 0.104 or 10.4%
σ2
P= 0.62×0.182+0.42×0.152+2×0.6×0.4×0.18×0.15×0.6 = 0.03888+0.009+0.0162 = 0.06408
σP=√0.06408 ≈0.2531 or 25.31%
4 4. INEFFICIENT USE OF RISK BUDGET IN ASSET ALLOCATION
Problem 4.
An investor has a risk budget of $100,000 to invest in two assets: Asset A and Asset B. The
expected returns for Asset A and Asset B are 8
Solution 4.
The Sharpe ratio is given by:
SharpeRatio =E(Rp)−Rf
pV ar(Rp)
where:
•E(Rp)is the expected return of the portfolio,
•Rfis the risk-free rate (assumed to be zero in this case),
•V ar(Rp)is the variance of the portfolio return.
The expected return of the portfolio can be calculated using the weights assigned to Asset A
and Asset B:
E(Rp) = wAE(RA) + wBE(RB)
The variance of the portfolio return can be calculated as:
V ar(Rp) = w2
Aσ2
A+w2
Bσ2
B+ 2wAwBσAσBρA,B
Now, to maximize the Sharpe ratio, we need to find the weights (wAand wB) that maximize the
Sharpe ratio. Let xbe the weight of Asset A in the portfolio:
SharpeRatio =x×8% + (1 −x)×12%
px2×(15%)2+ (1 −x)2×(20%)2+ 2x(1 −x)×15% ×20% ×0.6
=0.08x+ 0.12(1 −x)
p0.0225x2+ 0.04(1 −x)2+ 0.018x(1 −x)
To maximize the Sharpe ratio, we need to differentiate it with respect to xand set the derivative
equal to zero:
d(SR)
dx =0.08 −0.12 −2.1x+ 1.68
(0.0225x2+ 0.04(1 −x)2+ 0.018x(1 −x))1.5= 0
−0.04 −2.1x+ 1.68 = 0
x=1.68 −0.04
2.1= 0.8
Therefore, the optimal allocation of the risk budget is 80% in Asset A and 20% in Asset B to
maximize the Sharpe ratio.
I. Problem: Portfolio Diversification
A portfolio manager is considering investing in two assets: Asset A and Asset B. The expected
returns and standard deviations of the two assets are given as follows:
- Asset A: Expected Return = 12- Asset B: Expected Return = 15
The correlation coefficient between the returns of Asset A and Asset B is 0.5. The manager
wants to create a portfolio with 60
a) Calculate the expected return and standard deviation of the portfolio. b) Determine the cor-
relation coefficient between the portfolio and the individual assets.
Solution:
a) Let wA= 0.6and wB= 0.4be the weights of Asset A and Asset B in the portfolio, respectively.
i) Expected Return of the Portfolio:
E(Rp) = wA·E(RA) + wB·E(RB)
E(Rp)=0.6×0.12 + 0.4×0.15 = 0.072 + 0.06 = 0.132 = 13.2%
ii) Standard Deviation of the Portfolio:
σp=qw2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·ρAB ·σA·σB
σp=p0.62·0.082+ 0.42·0.122+ 2 ·0.6·0.4·0.5·0.08 ·0.12
σp≈√0.0288 + 0.0192 + 0.0576 ≈√0.1056 ≈0.3251 = 32.51%
Therefore, the expected return of the portfolio is 13.2
b) Correlation coefficient between the portfolio and Asset A:
ρpA =wA·1 + wB·ρAB
ρpA = 0.6×1+0.4×0.5=0.6+0.2=0.8
Correlation coefficient between the portfolio and Asset B:
ρpB =wA·ρAB +wB·1
ρpB = 0.6×0.5+0.4×1=0.3+0.4=0.7
Therefore, the correlation coefficient between the portfolio and Asset A is 0.8, and with Asset
B is 0.7.
5 6. IGNORING LIQUIDITY RISK IN PORTFOLIO CONSTRUCTION
Problem 6. You are considering investing in two assets, Stock A and Stock B. The expected
returns of these assets are 8% and 12%, respectively. The standard deviation of Stock A is 10%
and the standard deviation of Stock B is 15%. The correlation between the returns of Stock A and
Stock B is 0.6. You have $50,000 to invest and want to allocate your portfolio to maximize the
Sharpe ratio. Assuming you are ignoring liquidity risk in portfolio construction, calculate:
a) The weights of Stock A and Stock B that maximize the Sharpe ratio.
b) The expected return and volatility of the optimal portfolio.
c) The maximum Sharpe ratio for the optimal portfolio.
Solution 6.
a) To find the weights that maximize the Sharpe ratio, we need to calculate the Sharpe ratio for
different weight combinations of Stock A and Stock B. The Sharpe ratio is given by:
Sharpe =E[rp]−rf
σp
where: - E[rp]is the expected return of the portfolio, - rfis the risk-free rate (we will assume 0
for simplicity), - σpis the standard deviation of the portfolio return.
Let wbe the weight of Stock A and 1−wbe the weight of Stock B. Therefore, wis the weight
we allocate to Stock A in our portfolio.
The expected return of the portfolio is given by:
E[rp] = w×E[rA] + (1 −w)×E[rB]E[rp] = w×0.08 + (1 −w)×0.12
The variance of the portfolio is given by:
σ2
p=w2×σ2
A+ (1 −w)2×σ2
B+ 2w(1 −w)×ρAB ×σA×σBσ2
p=w2×0.12+ (1 −w)2×0.152+
2w(1 −w)×0.6×0.1×0.15
Now we can calculate the Sharpe ratio for different weight combinations and choose the weights
that maximize the Sharpe ratio.
b) Once we find the optimal weights, we can calculate the expected return and volatility of the
optimal portfolio using the formulas for E[rp]and σ2
pderived in part (a).
c) The maximum Sharpe ratio for the optimal portfolio is simply the Sharpe ratio calculated
using the optimal weights from part (a).
I. Problem:
You are considering investing in two assets, Asset A and Asset B, with the following character-
istics:
Asset A has an expected return of 8% and a standard deviation of 4%. Asset B has an expected
return of 12% and a standard deviation of 6%.
The correlation between the returns of Asset A and Asset B is 0.5.
a) Calculate the expected return of a portfolio that consists of 40% Asset A and 60% Asset B.
b) Calculate the standard deviation of the portfolio in part (a).
c) Determine the optimal portfolio weights that minimize the standard deviation of the portfolio.
II. Solution:
a) Let E[A]and E[B]be the expected returns of Asset A and Asset B respectively. We want to
find the expected return of the portfolio:
Expected return of the portfolio = 0.4×E[A]+0.6×E[B]
= 0.4×8% + 0.6×12%
= 3.2% + 7.2%
= 10.4%
b) The formula for calculating the standard deviation of a portfolio consisting of two assets is
given by:
σp=qw2
Aσ2
A+w2
Bσ2
B+ 2wAwBρABσAσB
where: σp= standard deviation of the portfolio, wAand wB= weights of Asset A and Asset B in
the portfolio, σAand σB= standard deviations of Asset A and Asset B, ρAB = correlation coefficient
between the returns of Asset A and Asset B.
Substitute the known values into the formula:
σp=√0.42×0.042+ 0.62×0.062+ 2 ×0.4×0.6×0.5×0.04 ×0.06
σp=√0.0016 + 0.0036 + 0.00288
σp=√0.00808
σp≈0.09 or 9%
c) The optimal portfolio weights can be found by minimizing the standard deviation of the port-
folio using the formula for minimum variance portfolio weights, which is given by:
wA=σ2
B−σAB σBσA
σ2
A+σ2
B−2σAB σAσB
wB= 1 −wA
Substitute the given values into the formulas to find the optimal weights for Asset A and Asset
B.
6 8. BEHAVIORAL BIASES AFFECTING ASSET ALLOCATION DECISIONS
Problem 8. Mr. Smith is considering reallocating his investment portfolio to achieve a target
asset allocation. However, he is prone to anchoring bias, fixating on the historical performance of
certain assets. His current portfolio consists of $50,000 invested in Stocks, $30,000 in Bonds, and
$20,000 in Cash. His target allocation is 50% Stocks, 30% Bonds, and 20% Cash. Calculate the
amount Mr. Smith needs to reallocate to each asset to reach his target allocation.
Solution 8. a) Let Xbe the amount to be reallocated to Stocks, Yto Bonds, and Zto Cash.
The total amount of his current portfolio is $50,000 + $30,000 + $20,000 = $100,000.
So, the target amounts are: - Stocks: 50% of $100,000 = $50,000 - Bonds: 30% of $100,000
= $30,000 - Cash: 20% of $100,000 = $20,000
Therefore, we have the following system of equations:
X+ 50,000 = 50,000
Y+ 30,000 = 30,000
Z+ 20,000 = 20,000
Solving these equations, we get:
X= 0
Y= 0
Z= 0
Therefore, Mr. Smith does not need to reallocate any funds to reach his target asset allocation.
The anchoring bias in this case caused Mr. Smith to ignore his current allocation and blindly
stick to his past investments, even though he was already at his target allocation.
This example demonstrates the role of behavioral biases in asset allocation decisions.
7 9. INCONSISTENT RISK TOLERANCE ASSESSMENT AMONG INVESTORS
Problem 9. Assume two investors, Alice and Bob, have different assessments of their risk
tolerance. Alice has a risk tolerance level of 0.6, while Bob’s risk tolerance level is 0.4. They are
considering investing in two assets, Asset X and Asset Y, with the following characteristics:
Asset X: Expected return = 8%, Standard Deviation = 12%
Asset Y: Expected return = 12%, Standard Deviation = 18%
a) Calculate the expected return and standard deviation of a portfolio consisting of 60
b) Determine which investor should choose this portfolio based on their risk tolerance assess-
ment.
c) Discuss the implications of having inconsistent risk tolerance assessments among investors
in the context of portfolio construction.
Solution 9.
a) To calculate the expected return and standard deviation of the portfolio consisting of 60
Expected return of the portfolio = Weight of Asset X * Expected return of Asset X + Weight of
Asset Y * Expected return of Asset Y
Standard deviation of the portfolio = sqrt[ (Weight of Asset X)2∗(StandardDeviationofAssetX)2+
(W eightofAssetY )2∗(StandardDeviationofAssetY )2+2∗W eightofAssetX ∗W eightof AssetY ∗
Covariance(X, Y )]
For the given data:
Expected return of the portfolio = 0.6 * 8% + 0.4 * 12% = 4.8% + 4.8% = 9.6%
Standard deviation of the portfolio = sqrt[ (0.62)∗(122) + (0.42)∗(182) + 2 ∗0.6∗0.4∗(12) ∗(18)]
= sqrt[ (0.36) * (144) + (0.16) * (324) + 2 * 0.6 * 0.4 * 216 ]
= sqrt[ 51.84 + 51.84 + 51.84 ]
= sqrt[ 155.52 ]
12.476%
Therefore, for both Alice and Bob, the expected return of the portfolio is 9.6% and the standard
deviation is approximately 12.476%.
b) Based on their risk tolerance assessments, Alice (with a risk tolerance level of 0.6) should
choose this portfolio, as the portfolio’s risk tolerance matches her preferences (higher risk toler-
ance), whereas Bob’s risk tolerance level of 0.4 indicates he would prefer a lower risk portfolio.
c) Inconsistent risk tolerance assessments among investors can lead to conflicts in portfolio
construction decisions. It may result in suboptimal portfolio choices if the portfolio’s risk-return char-
acteristics do not align with the individual investors’ risk preferences. This highlights the importance
of understanding and incorporating different risk tolerance levels when constructing portfolios for
multiple investors.
8 10. LACK OF CLARITY IN INVESTMENT OBJECTIVES DRIVING POOR ASSET ALLOCA-
TION
Problem 10.
An investor is considering investing in two assets - Stock A and Stock B. The investor’s utility
function is given by U(W) = W0.5, where Wis the wealth at the end of the investment period. The
investor has a total of $100,000 to invest. Stock A has an expected return of 8% and a standard
deviation of 12%, while Stock B has an expected return of 6% and a standard deviation of 8%. The
correlation coefficient between the returns of Stocks A and B is 0.4.
a) Calculate the expected return and standard deviation of a portfolio that is 60% invested in
Stock A and 40% invested in Stock B.
b) Determine the optimal risky portfolio for this investor considering the given utility function.
Solution 10.
a) The expected return of a portfolio, denoted by E(Rp), is given by the weighted average of the
expected returns of individual assets in the portfolio. The standard deviation of a portfolio, denoted
by σp, is calculated using the formula for the portfolio variance.
a) To calculate the expected return and standard deviation of the portfolio with 60% invested in
Stock A and 40% in Stock B:
Expected return of the portfolio:
E(Rp)=0.6×0.08 + 0.4×0.06 = 0.048 + 0.024 = 0.072 = 7.2%
Standard deviation of the portfolio:
σp=p0.62×0.122+ 0.42×0.082+ 2 ×0.6×0.4×0.12 ×0.08 ×0.4 = √0.0144 + 0.0128 + 0.02304 ≈0.076 = 7.6%
Therefore, the expected return of the portfolio is 7.2% and the standard deviation is 7.6%.
b) To determine the optimal risky portfolio for the investor, we need to find the portfolio that
maximizes the investor’s utility function. This is achieved by locating the point of tangency between
the investor’s indifference curve and the efficient frontier.
Given the utility function U(W) = W0.5, the optimal risky portfolio allocation is given by the
formula:
w∗=E(RA)−rf
γ2σ2
A+σ2
B−2γσAσB
=0.08 −0.02
0.0006 = 100
So, the optimal risky portfolio for this investor is 100% Stock A and 0% Stock B.
I.
9 Problem on Portfolio Theory and Asset Allocation
Problem:
Suppose an investor has a portfolio consisting of two assets, Asset A and Asset B. Asset A has
a weight of 60% in the portfolio with an expected return of 8% and a standard deviation of 15%.
Asset B has a weight of 40% with an expected return of 12% and a standard deviation of 20%. The
correlation coefficient between the returns of Asset A and Asset B is 0.6. Calculate the expected
return and standard deviation of the portfolio.
Solution:
Let rAbe the return of Asset A, rBbe the return of Asset B, and wAand wBbe the weights of
Asset A and Asset B respectively.
a) The expected return of the portfolio (rp) is given by:
rp=wA×rA+wB×rB
rp= 0.60 ×0.08 + 0.40 ×0.12
rp= 0.048 + 0.048
rp= 0.096 or 9.6%
b) The variance of the portfolio (σ2
p) is given by:
σ2
p=w2
A×σ2
A+w2
B×σ2
B+ 2 ×wA×wB×Corr(A, B)×σA×σB
Plugging in the values:
σ2
p= 0.602×0.152+ 0.402×0.202+ 2 ×0.60 ×0.40 ×0.6×0.15 ×0.20
σ2
p= 0.09 + 0.16 + 0.144
σ2
p= 0.394
σp=√0.394 or 19.85%
Therefore, the expected return of the portfolio is 9.6% and the standard deviation of the portfolio
is 19.85%.
10 12. INEFFICIENT REBALANCING STRATEGIES IMPACTING PORTFOLIO PERFORMANCE
Problem 12.
You have a portfolio consisting of two assets, Stock A and Stock B, with the following charac-
teristics:
•Stock A has a weight of 40% in the portfolio and has an expected return of 8% with a standard
deviation of 12%.
•Stock B has a weight of 60% in the portfolio and has an expected return of 12% with a standard
deviation of 18%.
•The correlation coefficient between Stock A and Stock B is 0.6.
a) Calculate the expected return and standard deviation of the portfolio.
b) If you decide to rebalance the portfolio to 50% Stock A and 50% Stock B, calculate the new
expected return and standard deviation of the portfolio.
c) Evaluate the impact of the rebalancing on the portfolio performance.
Solution 12.
a) The expected return and standard deviation of the portfolio can be calculated using the
following formulas:
Expected Return of Portfolio =wA×Expected Return of Stock A+wB×Expected Return of Stock B
Standard Deviation of Portfolio =qw2
A×Variance of Stock A +w2
B×Variance of Stock B + 2 ×wA×wB×Standard Deviation of Stock A ×Standard Deviation of Stock B ×Correlation
Substitute the given values:
Expected Return of Portfolio = 0.4×8% + 0.6×12% = 0.04 + 0.072 = 0.112 = 11.2%
Standard Deviation of Portfolio =p0.42×(0.12)2+ 0.62×(0.18)2+ 2 ×0.4×0.6×0.12 ×0.18 ×0.6=0.1173 = 11.73%
a) Therefore, the expected return of the portfolio is 11.2% and the standard deviation of the
portfolio is 11.73%.
b) If we rebalance the portfolio to 50% Stock A and 50% Stock B, the new expected return and
standard deviation of the portfolio can be calculated in a similar way:
Expected Return of Portfolio = 0.5×8% + 0.5×12% = 0.04 + 0.06 = 0.1 = 10%
Standard Deviation of Portfolio =p0.52×(0.12)2+ 0.52×(0.18)2+ 2 ×0.5×0.5×0.12 ×0.18 ×0.6=0.1289 = 12.89%
b) Therefore, the new expected return of the portfolio is 10% and the new standard deviation
of the portfolio is 12.89%.
c) The rebalancing strategy has slightly reduced the expected return of the portfolio from 11.2%
to 10%, but it has also slightly increased the standard deviation from 11.73% to 12.89%. This
tradeoff between return and risk should be carefully considered based on the investor’s risk appetite
and investment objectives.
11 13. LACK OF CONSIDERATION FOR TAX IMPLICATIONS IN ASSET ALLOCATION
Problem 13. An investor has two investment options:
Option A: A stock that pays a dividend yield of 4% annually and has a capital gain of 10% at
the end of the year. The investor’s tax rate on dividends is 20% and on capital gains is 15%.
Option B: A tax-exempt municipal bond that pays a yield of 3.5% annually.
If the investor’s initial investment is 10,000, determinewhichoptionwouldprovidehigherafter −
taxreturnsaf teroneyear.
Solution 13.
To compare the after-tax returns of the two investment options, we calculate the after-tax returns
for options A and B separately:
a) Option A:
For Option A, the after-tax return is the sum of after-tax dividend and after-tax capital gain:
After-tax dividend = Dividend yield * (1 - Tax rate on dividends) = 0.04 * (1 - 0.2) = 0.04 * 0.8 =
0.032 = 3.2%
After-tax capital gain = Capital gain * (1 - Tax rate on capital gains) = 0.10 * (1 - 0.15) = 0.10 *
0.85 = 0.085 = 8.5%
Total after-tax return for Option A = After-tax dividend + After-tax capital gain = 3.2% + 8.5% =
11.7%
b) Option B:
For Option B, the after-tax return of the tax-exempt municipal bond is simply the yield of 3.5%.
c) Comparison:
Since Option A has a total after-tax return of 11.7%, which is higher than the 3.5% after-tax
return of Option B, the investor would achieve higher after-tax returns by investing in Option A.
12 Portfolio Theory and Asset Allocation
Problem 1.
You are considering investing in a portfolio that consists of two assets: Stock A and Stock B.
The expected return and standard deviation of each asset are as follows:
Stock A: Expected Return = 12%, Standard Deviation = 15%
Stock B: Expected Return = 8%, Standard Deviation = 10%
The correlation coefficient between the returns of Stock A and Stock B is 0.5. You are planning
to allocate 60% of your investment to Stock A and 40% to Stock B.
a) Calculate the expected return of the portfolio.
b) Calculate the standard deviation of the portfolio.
Solution 1.
a) The expected return of the portfolio can be calculated using the weighted sum of the individual
expected returns:
E(Rp) = wA×E(RA) + wB×E(RB)
Given that wA= 0.6,E(RA) = 0.12,wB= 0.4, and E(RB)=0.08, we have:
E(Rp)=0.6×0.12 + 0.4×0.08 = 0.072 + 0.032 = 0.104 = 10.4%
Therefore, the expected return of the portfolio is 10.4%.
b) The standard deviation of the portfolio can be calculated using the formula:
σp=qw2
A×σ2
A+w2
B×σ2
B+ 2 ×wA×wB×σA×σB×ρA,B
where σA= 0.15,σB= 0.10, and ρA,B = 0.5.
Plugging in the values, we get:
σp=p(0.6)2×(0.15)2+ (0.4)2×(0.10)2+ 2 ×0.6×0.4×0.15 ×0.10 ×0.5
=√0.36 ×0.0225 + 0.16 ×0.01 + 0.12 ×0.015
=√0.0081 + 0.0016 + 0.0018
=√0.0115
≈0.107 = 10.7%
Therefore, the standard deviation of the portfolio is 10.7%.
13 15. IGNORING ENVIRONMENTAL, SOCIAL, AND GOVERNANCE FACTORS IN ASSET
ALLOCATION
Problem 15. Consider a portfolio with three assets: Stock A, Stock B, and Stock C. The ex-
pected return and standard deviation of each asset are as follows:
•Stock A: Expected return = 8%, Standard deviation = 12%
•Stock B: Expected return = 12%, Standard deviation = 18%
•Stock C: Expected return = 10%, Standard deviation = 15%
The correlation coefficients between the returns of the assets are given by:
•Correlation between A and B: 0.6
•Correlation between A and C: -0.2
•Correlation between B and C: 0.4
Determine the expected return and standard deviation of a portfolio that consists of 30% Stock
A, 50% Stock B, and 20% Stock C.
Solution 15. a) To find the expected return of the portfolio, we use the weighted average of the
expected returns of the individual assets:
Expected return of the portfolio =wA×Expected return of A+wB×Expected return of B+wC×Expected return of C
where wiis the weight of asset iin the portfolio.
Substitute the values into the formula:
Expected return of the portfolio = 0.30 ×8% + 0.50 ×12% + 0.20 ×10%
= 0.024 + 0.06 + 0.02 = 0.104 = 10.4%
Therefore, the expected return of the portfolio is 10.4%.
b) To find the standard deviation of the portfolio, we use the formula for the portfolio variance:
σ2
p=w2
A×σ2
A+w2
B×σ2
B+w2
C×σ2
C+ 2(wA×wB×σAB +wA×wC×σAC +wB×wC×σBC )
where σiis the standard deviation of asset iand σij is the covariance between assets iand j.
Substitute all values into the formula and calculate:
σ2
p= 0.302×0.122+0.502×0.182+0.202×0.152+2(0.30×0.50×0.6+0.30×0.20×(−0.2)+0.50×0.20×0.4)
= 0.00324 + 0.018 + 0.006 + 2(0.09 −0.012 −0.04)
= 0.02724 + 0.027 + 0.044 = 0.09824
Therefore, the standard deviation of the portfolio is σp=√0.09824 = 0.3135 = 31.35%.
14 Portfolio Theory and Asset Allocation
Problem:
You are considering investing in two assets, Asset A and Asset B. Asset A has an expected
return of 7% with a standard deviation of 12%, while Asset B has an expected return of 10% with a
standard deviation of 18%. You plan to allocate 60% of your portfolio to Asset A and 40% to Asset
B. The correlation between the returns of the two assets is 0.4.
a) Calculate the expected return and standard deviation of the portfolio.
b) Determine the correlation between the returns of the portfolio and a risk-free asset that offers
a return of 3%.
Solution:
a) To calculate the expected return and standard deviation of the portfolio, we use the following
formulas:
Expected return of the portfolio:
E(Rp) = wA·E(RA) + wB·E(RB)
where E(RA)and E(RB)are the expected returns of Asset A and Asset B, respectively, and
wAand wBare the weights of Asset A and Asset B in the portfolio.
Substitute the values:
E(Rp) = 0.6×0.07 + 0.4×0.10 = 0.042 + 0.04 = 0.082 = 8.2%
Standard deviation of the portfolio:
σp=qw2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·ρAB ·σA·σB
where σAand σBare the standard deviations of Asset A and Asset B, respectively, and ρAB is
the correlation coefficient between Asset A and Asset B.
Substitute the values:
σp=p0.62×(0.12)2+ 0.42×(0.18)2+ 2 ×0.6×0.4×0.4×0.12 ×0.18
σp=√0.0144 + 0.01296 + 0.00259 = √0.03 = 0.1732 = 17.32%
Therefore, the expected return of the portfolio is 8.2% and the standard deviation is 17.32%.
b) To determine the correlation between the returns of the portfolio and a risk-free asset, we
can use the formula:
ρp,rf =wp·ρA,rf
where ρA,rf is the correlation between Asset A and the risk-free asset, and wpis the weight of
the port...
Certainly! Here are a few numerical problem questions on Portfolio Theory and Asset Alloca-
tion:
—
15 17. OVER-RELIANCE ON HISTORICAL DATA IN PORTFOLIO CONSTRUCTION
Problem 17. A financial analyst is constructing a portfolio with two assets: Stock A and Stock B.
Historical returns for Stock A and Stock B over the past 5 years are as follows:
•Stock A: Mean return = 8%, Standard deviation = 12%
•Stock B: Mean return = 10%, Standard deviation = 15%
The correlation coefficient between the returns of Stock A and Stock B is 0.6. The analyst wants
to build a portfolio using these two assets.
a) If the analyst wants the portfolio to have a mean return of 9
b) Determine the standard deviation of the portfolio if the analyst invests 40% in Stock A and
60% in Stock B.
c) Calculate the correlation between the portfolio returns and Stock A if the weight of Stock A
in the portfolio is 0.4.
Solution 17.
a) Let wAand wBbe the weights of Stock A and Stock B in the portfolio, respectively. The
mean return of the portfolio can be calculated as:
E(rp) = wA·E(rA) + wB·E(rB)
Given that the mean return of the portfolio should be 9%, and E(rA)=0.08 and E(rB)=0.10,
we can set up the equation as:
0.09 = wA·0.08 + wB·0.10
Since wA+wB= 1, we can solve for wAin terms of wBas:
wA= 1 −wB
Substitute this into the equation:
0.09 = (1 −wB)·0.08 + wB·0.10
Solving for wB, we get wB= 0.6and wA= 0.4.
Therefore, the weights of Stock A and Stock B in the portfolio should be 40% and 60%, respec-
tively.
b) The standard deviation of the portfolio can be calculated using the formula:
σp=qw2
Aσ2
A+w2
Bσ2
B+ 2wAwBσAσBρAB
Substitute the given values and calculated weights into the formula to find the standard deviation
of the portfolio.
c) The correlation between the portfolio returns and Stock A can be calculated using the formula:
ρpA =wAρAB
Substitute the given correlation coefficient and weight of Stock A to determine the correlation.
—
Feel free to reach out if you need more questions or further clarifications on this topic!
16 18. UNDERESTIMATING TAIL RISKS IN ASSET ALLOCATION DECISIONS
Problem 18.
You are considering investing in two assets, Asset A and Asset B. The annual returns for Asset
A have a normal distribution with mean 8% and standard deviation 12%. The annual returns for
Asset B have a normal distribution with mean 10% and standard deviation 15%. The correlation
between the returns of Asset A and Asset B is 0.5.
a) Calculate the expected return of a portfolio that is equally weighted in Asset A and Asset B.
b) Calculate the standard deviation of the portfolio that is equally weighted in Asset A and Asset
B.
c) Calculate the correlation coefficient between the returns of the portfolio and the returns of
Asset A.
Solution 18.
a) The expected return of a portfolio that is equally weighted in Asset A and Asset B can be
calculated using the formula for the expected return of a portfolio:
E(Rp) = wA·E(RA) + wB·E(RB)
Where: - E(Rp)is the expected return of the portfolio - wAis the weight of Asset A in the portfolio
(0.5 in this case) - E(RA)is the expected return of Asset A (8%) - wBis the weight of Asset B in
the portfolio (0.5 in this case) - E(RB)is the expected return of Asset B (10%)
Plugging in the values, we get:
E(Rp)=0.5×8% + 0.5×10% = 0.08 + 0.05 = 0.13 = 13%
Therefore, the expected return of the equally weighted portfolio is 13%.
b) The standard deviation of a portfolio of two assets can be calculated using the formula for
the standard deviation of a portfolio:
σp=qw2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·ρAB ·σA·σB
Where: - σpis the standard deviation of the portfolio - wA,wBare the weights of Asset A and
Asset B in the portfolio (both 0.5 in this case) - σA,σBare the standard deviations of Asset A and
Asset B (12% and 15% respectively) - ρAB is the correlation coefficient between Asset A and Asset
B (0.5)
Plugging in the values, we get:
σp=p0.52·0.122+ 0.52·0.152+ 2 ·0.5·0.5·0.5·0.12 ·0.15
σp=p0.032+ 0.03752+ 0.009 = √0.0009 + 0.00140625 + 0.009 = √0.01030625 ≈0.1015 = 10.15%
Therefore, the standard deviation of the equally weighted portfolio is approximately 10.15
c) The correlation coefficient between the returns of the portfolio and the returns of Asset A can
be calculated using the formula for correlation coefficient in a two-assets portfolio:
ρpA =wA·σ2
A
σA·σp
Where: - ρpA is the correlation coefficient between the returns of the portfolio and the returns
of Asset A - wAis the weight of Asset A in the portfolio (0.5) - σAis the standard deviation of Asset
A (12%) - σpis the standard deviation of the portfolio (10.15%)
Plugging in the values, we get:
ρpA =0.5·0.12
0.12 ·0.1015 =0.06
0.01218 ≈0.4926
Therefore,
17 19. MISALIGNED ASSET ALLOCATION WITH LONG-TERM FINANCIAL GOALS
Problem 19.
Alice is planning her retirement and has set a goal to accumulate a wealth of 1,000,000in20years.Shecurrentlyhas100,000
saved and is considering two investment options: Option A, which has an expected annual return
of 8% with a standard deviation of 12%, and Option B, which has an expected annual return of 5%
with a standard deviation of 8%. Assuming Alice aims to maximize the likelihood of reaching her
retirement goal, determine the optimal allocation of her initial 100,000betweenOptionAandOptionB.
Solution 19.
To determine the optimal allocation that maximizes the likelihood of reaching her retirement
goal, we will use the concept of portfolio optimization. Let xdenote the allocation to Option A and
1−xdenote the allocation to Option B.
Given that the expected return of the portfolio is a weighted sum of the expected returns of the
individual assets, the expected return of the portfolio (Rp) is given by:
Rp=x·RA+ (1 −x)·RB
Rp= 0.08x+ 0.05(1 −x)
Rp= 0.03x+ 0.05
The variance of the portfolio (σ2
p) is calculated as follows:
σ2
p=x2·σ2
A+ (1 −x)2·σ2
B+ 2x(1 −x)·σAσB
σ2
p= 0.122x2+ 0.082(1 −x)2+ 2(0.12)(0.08)x(1 −x)
σ2
p= 0.0144x2+ 0.0064(1 −x)2+ 0.0192x(1 −x)
σ2
p= 0.008x2+ 0.0064 −0.0128x+ 0.0192x−0.0192x2
σ2
p=−0.0112x2+ 0.0064 −0.0036x
To maximize the likelihood of reaching her retirement goal, Alice can set up the following opti-
mization problem:
Maximize:
Rp= 0.03x+ 0.05
Subject to the constraint:
−0.0112x2+ 0.0064 −0.0036x≤variance tolerance level
Solving this optimization problem will provide Alice with the optimal allocation of her 100,000betweenOptionAandOptionB.
18 20. INEFFECTIVE COMMUNICATION OF PORTFOLIO STRATEGY TO STAKEHOLDERS.
Problem 20.
A financial advisor is creating a portfolio for a client with $100,000 to invest. The advisor decides
to allocate 40% to Stock A, 30% to Stock B, and the remaining 30% to a bond fund. Stock A has
an expected return of 8% and a standard deviation of 12%, Stock B has an expected return of 6%
and a standard deviation of 8%, and the bond fund has an expected return of 4% and a standard
deviation of 4%.
a) Calculate the expected return and standard deviation of the portfolio.
b) If the correlation between Stock A and Stock B is 0.5, calculate the portfolio’s expected return
and standard deviation using the given allocation.
c) Discuss the implications of the correlation assumption for this portfolio.
Solution 20.
a) The expected return and standard deviation of the portfolio can be calculated using the
weighted averages of the individual assets.
a) Expected Return:
E(Rp) = wA×E(RA) + wB×E(RB) + wbond ×E(Rbond)
E(Rp)=0.40 ×0.08 + 0.30 ×0.06 + 0.30 ×0.04 = 0.045 = 4.5%
Standard Deviation:
σp=qw2
A×σ2
A+w2
B×σ2
B+w2
bond ×σ2
bond
σp=p0.402×0.122+ 0.302×0.082+ 0.302×0.042= 0.0601 = 6.01%
b) If the correlation between Stock A and Stock B is 0.5, the portfolio’s expected return and
standard deviation using the given allocation can be calculated using the formula involving corre-
lation.
E(Rp)=0.40 ×0.08 + 0.30 ×0.06 + 0.30 ×0.04 = 0.045 = 4.5%
σp=qw2
A×σ2
A+w2
B×σ2
B+ 2 ×wA×wB×σA×σB×ρAB
σp=p0.402×0.122+ 0.302×0.082+ 2 ×0.40 ×0.30 ×0.12 ×0.08 ×0.5=0.0496 = 4.96%
c) The correlation assumption affects the diversification benefit of the portfolio. A correlation
of 0.5 between Stock A and Stock B implies they are positively correlated. This means that the
two stocks tend to move in the same direction, reducing the benefit of diversification. As a result,
the portfolio’s standard deviation is higher when the correlation is taken into account compared to
the assumption of no correlation. It shows the importance of considering the correlation between
assets when constructing a portfolio to manage risk effectively.
2 2. LACK OF DIVERSIFICATION IN ASSET CLASSES
Problem 2. Suppose an investor has a portfolio with 60% invested in stocks, 30% invested in
bonds, and 10% invested in real estate. The annual returns for each asset class are as follows:
- Stocks: 12% - Bonds: 6% - Real estate: 8%
Calculate the overall annual return of the investor’s portfolio.
Solution 2.
The overall annual return of the investor’s portfolio can be calculated by weighting the returns
of each asset class according to their respective percentages in the portfolio.
a) Calculating the weighted returns of each asset class:
- Weighted return of stocks: 0.60×0.12 = 0.072 (or 7.2- Weighted return of bonds: 0.30 ×0.06 =
0.018 (or 1.8- Weighted return of real estate: 0.10 ×0.08 = 0.008 (or 0.8
b) Calculating the overall annual return of the portfolio by summing up the weighted returns of
each asset class:
0.072 + 0.018 + 0.008 = 0.098
Therefore, the overall annual return of the investor’s portfolio is 9.8
3 3. SHORT-TERM VOLATILITY IMPACTING PORTFOLIO RETURNS
Problem 3.
You are managing a portfolio with two assets: Asset A and Asset B. Asset A has an annual
expected return of 12
a) Calculate the expected return and the standard deviation of a portfolio that is equally weighted
in Asset A and Asset B.
b) Determine the correlation of the portfolio returns with the returns of each asset.
c) If you increase the weight of Asset A to 60
Solution 3.
a) The expected return of a portfolio, E(rP), that is equally weighted in two assets A and B can
be calculated as:
E(rP) = wA·E(rA) + wB·E(rB)
E(rP)=0.5×0.12 + 0.5×0.08 = 0.10 or 10%
The variance of the portfolio, σ2
P, can be calculated as:
σ2
P=w2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·σA·σB·ρAB
σ2
P= 0.52×0.182+0.52×0.152+2×0.5×0.5×0.18×0.15×0.6 = 0.0288+0.01125+0.0081 = 0.04815
The standard deviation of the portfolio is the square root of the variance:
σP=√0.04815 ≈0.2196 or 21.96%
b) The correlation of the portfolio returns with the returns of each asset can be calculated using
the formula:
ρAP =wA·σ2
A+wB·σA·σB·ρAB
σP
ρAP =0.5×0.18 + 0.5×0.15 ×0.6
0.2196 ≈0.09 + 0.045
0.2196 ≈0.135
0.2196 ≈0.6148
Similarly, the correlation of the portfolio with Asset B, ρBP , can be calculated.
c) When the weights are changed to 60
E(rP)=0.6×0.12 + 0.4×0.08 = 0.104 or 10.4%
σ2
P= 0.62×0.182+0.42×0.152+2×0.6×0.4×0.18×0.15×0.6 = 0.03888+0.009+0.0162 = 0.06408
σP=√0.06408 ≈0.2531 or 25.31%
4 4. INEFFICIENT USE OF RISK BUDGET IN ASSET ALLOCATION
Problem 4.
An investor has a risk budget of $100,000 to invest in two assets: Asset A and Asset B. The
expected returns for Asset A and Asset B are 8
Solution 4.
The Sharpe ratio is given by:
SharpeRatio =E(Rp)−Rf
pV ar(Rp)
where:
•E(Rp)is the expected return of the portfolio,
•Rfis the risk-free rate (assumed to be zero in this case),
•V ar(Rp)is the variance of the portfolio return.
The expected return of the portfolio can be calculated using the weights assigned to Asset A
and Asset B:
E(Rp) = wAE(RA) + wBE(RB)
The variance of the portfolio return can be calculated as:
V ar(Rp) = w2
Aσ2
A+w2
Bσ2
B+ 2wAwBσAσBρA,B
Now, to maximize the Sharpe ratio, we need to find the weights (wAand wB) that maximize the
Sharpe ratio. Let xbe the weight of Asset A in the portfolio:
SharpeRatio =x×8% + (1 −x)×12%
px2×(15%)2+ (1 −x)2×(20%)2+ 2x(1 −x)×15% ×20% ×0.6
=0.08x+ 0.12(1 −x)
p0.0225x2+ 0.04(1 −x)2+ 0.018x(1 −x)
To maximize the Sharpe ratio, we need to differentiate it with respect to xand set the derivative
equal to zero:
d(SR)
dx =0.08 −0.12 −2.1x+ 1.68
(0.0225x2+ 0.04(1 −x)2+ 0.018x(1 −x))1.5= 0
−0.04 −2.1x+ 1.68 = 0
x=1.68 −0.04
2.1= 0.8
Therefore, the optimal allocation of the risk budget is 80% in Asset A and 20% in Asset B to
maximize the Sharpe ratio.
I. Problem: Portfolio Diversification
A portfolio manager is considering investing in two assets: Asset A and Asset B. The expected
returns and standard deviations of the two assets are given as follows:
- Asset A: Expected Return = 12- Asset B: Expected Return = 15
The correlation coefficient between the returns of Asset A and Asset B is 0.5. The manager
wants to create a portfolio with 60
a) Calculate the expected return and standard deviation of the portfolio. b) Determine the cor-
relation coefficient between the portfolio and the individual assets.
Solution:
a) Let wA= 0.6and wB= 0.4be the weights of Asset A and Asset B in the portfolio, respectively.
i) Expected Return of the Portfolio:
E(Rp) = wA·E(RA) + wB·E(RB)
E(Rp)=0.6×0.12 + 0.4×0.15 = 0.072 + 0.06 = 0.132 = 13.2%
ii) Standard Deviation of the Portfolio:
σp=qw2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·ρAB ·σA·σB
σp=p0.62·0.082+ 0.42·0.122+ 2 ·0.6·0.4·0.5·0.08 ·0.12
σp≈√0.0288 + 0.0192 + 0.0576 ≈√0.1056 ≈0.3251 = 32.51%
Therefore, the expected return of the portfolio is 13.2
b) Correlation coefficient between the portfolio and Asset A:
ρpA =wA·1 + wB·ρAB
ρpA = 0.6×1+0.4×0.5=0.6+0.2=0.8
Correlation coefficient between the portfolio and Asset B:
ρpB =wA·ρAB +wB·1
ρpB = 0.6×0.5+0.4×1=0.3+0.4=0.7
Therefore, the correlation coefficient between the portfolio and Asset A is 0.8, and with Asset
B is 0.7.
5 6. IGNORING LIQUIDITY RISK IN PORTFOLIO CONSTRUCTION
Problem 6. You are considering investing in two assets, Stock A and Stock B. The expected
returns of these assets are 8% and 12%, respectively. The standard deviation of Stock A is 10%
and the standard deviation of Stock B is 15%. The correlation between the returns of Stock A and
Stock B is 0.6. You have $50,000 to invest and want to allocate your portfolio to maximize the
Sharpe ratio. Assuming you are ignoring liquidity risk in portfolio construction, calculate:
a) The weights of Stock A and Stock B that maximize the Sharpe ratio.
b) The expected return and volatility of the optimal portfolio.
c) The maximum Sharpe ratio for the optimal portfolio.
Solution 6.
a) To find the weights that maximize the Sharpe ratio, we need to calculate the Sharpe ratio for
different weight combinations of Stock A and Stock B. The Sharpe ratio is given by:
Sharpe =E[rp]−rf
σp
where: - E[rp]is the expected return of the portfolio, - rfis the risk-free rate (we will assume 0
for simplicity), - σpis the standard deviation of the portfolio return.
Let wbe the weight of Stock A and 1−wbe the weight of Stock B. Therefore, wis the weight
we allocate to Stock A in our portfolio.
The expected return of the portfolio is given by:
E[rp] = w×E[rA] + (1 −w)×E[rB]E[rp] = w×0.08 + (1 −w)×0.12
The variance of the portfolio is given by:
σ2
p=w2×σ2
A+ (1 −w)2×σ2
B+ 2w(1 −w)×ρAB ×σA×σBσ2
p=w2×0.12+ (1 −w)2×0.152+
2w(1 −w)×0.6×0.1×0.15
Now we can calculate the Sharpe ratio for different weight combinations and choose the weights
that maximize the Sharpe ratio.
b) Once we find the optimal weights, we can calculate the expected return and volatility of the
optimal portfolio using the formulas for E[rp]and σ2
pderived in part (a).
c) The maximum Sharpe ratio for the optimal portfolio is simply the Sharpe ratio calculated
using the optimal weights from part (a).
I. Problem:
You are considering investing in two assets, Asset A and Asset B, with the following character-
istics:
Asset A has an expected return of 8% and a standard deviation of 4%. Asset B has an expected
return of 12% and a standard deviation of 6%.
The correlation between the returns of Asset A and Asset B is 0.5.
a) Calculate the expected return of a portfolio that consists of 40% Asset A and 60% Asset B.
b) Calculate the standard deviation of the portfolio in part (a).
c) Determine the optimal portfolio weights that minimize the standard deviation of the portfolio.
II. Solution:
a) Let E[A]and E[B]be the expected returns of Asset A and Asset B respectively. We want to
find the expected return of the portfolio:
Expected return of the portfolio = 0.4×E[A]+0.6×E[B]
= 0.4×8% + 0.6×12%
= 3.2% + 7.2%
= 10.4%
b) The formula for calculating the standard deviation of a portfolio consisting of two assets is
given by:
σp=qw2
Aσ2
A+w2
Bσ2
B+ 2wAwBρABσAσB
where: σp= standard deviation of the portfolio, wAand wB= weights of Asset A and Asset B in
the portfolio, σAand σB= standard deviations of Asset A and Asset B, ρAB = correlation coefficient
between the returns of Asset A and Asset B.
Substitute the known values into the formula:
σp=√0.42×0.042+ 0.62×0.062+ 2 ×0.4×0.6×0.5×0.04 ×0.06
σp=√0.0016 + 0.0036 + 0.00288
σp=√0.00808
σp≈0.09 or 9%
c) The optimal portfolio weights can be found by minimizing the standard deviation of the port-
folio using the formula for minimum variance portfolio weights, which is given by:
wA=σ2
B−σAB σBσA
σ2
A+σ2
B−2σAB σAσB
wB= 1 −wA
Substitute the given values into the formulas to find the optimal weights for Asset A and Asset
B.
6 8. BEHAVIORAL BIASES AFFECTING ASSET ALLOCATION DECISIONS
Problem 8. Mr. Smith is considering reallocating his investment portfolio to achieve a target
asset allocation. However, he is prone to anchoring bias, fixating on the historical performance of
certain assets. His current portfolio consists of $50,000 invested in Stocks, $30,000 in Bonds, and
$20,000 in Cash. His target allocation is 50% Stocks, 30% Bonds, and 20% Cash. Calculate the
amount Mr. Smith needs to reallocate to each asset to reach his target allocation.
Solution 8. a) Let Xbe the amount to be reallocated to Stocks, Yto Bonds, and Zto Cash.
The total amount of his current portfolio is $50,000 + $30,000 + $20,000 = $100,000.
So, the target amounts are: - Stocks: 50% of $100,000 = $50,000 - Bonds: 30% of $100,000
= $30,000 - Cash: 20% of $100,000 = $20,000
Therefore, we have the following system of equations:
X+ 50,000 = 50,000
Y+ 30,000 = 30,000
Z+ 20,000 = 20,000
Solving these equations, we get:
X= 0
Y= 0
Z= 0
Therefore, Mr. Smith does not need to reallocate any funds to reach his target asset allocation.
The anchoring bias in this case caused Mr. Smith to ignore his current allocation and blindly
stick to his past investments, even though he was already at his target allocation.
This example demonstrates the role of behavioral biases in asset allocation decisions.
7 9. INCONSISTENT RISK TOLERANCE ASSESSMENT AMONG INVESTORS
Problem 9. Assume two investors, Alice and Bob, have different assessments of their risk
tolerance. Alice has a risk tolerance level of 0.6, while Bob’s risk tolerance level is 0.4. They are
considering investing in two assets, Asset X and Asset Y, with the following characteristics:
Asset X: Expected return = 8%, Standard Deviation = 12%
Asset Y: Expected return = 12%, Standard Deviation = 18%
a) Calculate the expected return and standard deviation of a portfolio consisting of 60
b) Determine which investor should choose this portfolio based on their risk tolerance assess-
ment.
c) Discuss the implications of having inconsistent risk tolerance assessments among investors
in the context of portfolio construction.
Solution 9.
a) To calculate the expected return and standard deviation of the portfolio consisting of 60
Expected return of the portfolio = Weight of Asset X * Expected return of Asset X + Weight of
Asset Y * Expected return of Asset Y
Standard deviation of the portfolio = sqrt[ (Weight of Asset X)2∗(StandardDeviationofAssetX)2+
(W eightofAssetY )2∗(StandardDeviationofAssetY )2+2∗W eightofAssetX ∗W eightof AssetY ∗
Covariance(X, Y )]
For the given data:
Expected return of the portfolio = 0.6 * 8% + 0.4 * 12% = 4.8% + 4.8% = 9.6%
Standard deviation of the portfolio = sqrt[ (0.62)∗(122) + (0.42)∗(182) + 2 ∗0.6∗0.4∗(12) ∗(18)]
= sqrt[ (0.36) * (144) + (0.16) * (324) + 2 * 0.6 * 0.4 * 216 ]
= sqrt[ 51.84 + 51.84 + 51.84 ]
= sqrt[ 155.52 ]
12.476%
Therefore, for both Alice and Bob, the expected return of the portfolio is 9.6% and the standard
deviation is approximately 12.476%.
b) Based on their risk tolerance assessments, Alice (with a risk tolerance level of 0.6) should
choose this portfolio, as the portfolio’s risk tolerance matches her preferences (higher risk toler-
ance), whereas Bob’s risk tolerance level of 0.4 indicates he would prefer a lower risk portfolio.
c) Inconsistent risk tolerance assessments among investors can lead to conflicts in portfolio
construction decisions. It may result in suboptimal portfolio choices if the portfolio’s risk-return char-
acteristics do not align with the individual investors’ risk preferences. This highlights the importance
of understanding and incorporating different risk tolerance levels when constructing portfolios for
multiple investors.
8 10. LACK OF CLARITY IN INVESTMENT OBJECTIVES DRIVING POOR ASSET ALLOCA-
TION
Problem 10.
An investor is considering investing in two assets - Stock A and Stock B. The investor’s utility
function is given by U(W) = W0.5, where Wis the wealth at the end of the investment period. The
investor has a total of $100,000 to invest. Stock A has an expected return of 8% and a standard
deviation of 12%, while Stock B has an expected return of 6% and a standard deviation of 8%. The
correlation coefficient between the returns of Stocks A and B is 0.4.
a) Calculate the expected return and standard deviation of a portfolio that is 60% invested in
Stock A and 40% invested in Stock B.
b) Determine the optimal risky portfolio for this investor considering the given utility function.
Solution 10.
a) The expected return of a portfolio, denoted by E(Rp), is given by the weighted average of the
expected returns of individual assets in the portfolio. The standard deviation of a portfolio, denoted
by σp, is calculated using the formula for the portfolio variance.
a) To calculate the expected return and standard deviation of the portfolio with 60% invested in
Stock A and 40% in Stock B:
Expected return of the portfolio:
E(Rp)=0.6×0.08 + 0.4×0.06 = 0.048 + 0.024 = 0.072 = 7.2%
Standard deviation of the portfolio:
σp=p0.62×0.122+ 0.42×0.082+ 2 ×0.6×0.4×0.12 ×0.08 ×0.4 = √0.0144 + 0.0128 + 0.02304 ≈0.076 = 7.6%
Therefore, the expected return of the portfolio is 7.2% and the standard deviation is 7.6%.
b) To determine the optimal risky portfolio for the investor, we need to find the portfolio that
maximizes the investor’s utility function. This is achieved by locating the point of tangency between
the investor’s indifference curve and the efficient frontier.
Given the utility function U(W) = W0.5, the optimal risky portfolio allocation is given by the
formula:
w∗=E(RA)−rf
γ2σ2
A+σ2
B−2γσAσB
=0.08 −0.02
0.0006 = 100
So, the optimal risky portfolio for this investor is 100% Stock A and 0% Stock B.
I.
9 Problem on Portfolio Theory and Asset Allocation
Problem:
Suppose an investor has a portfolio consisting of two assets, Asset A and Asset B. Asset A has
a weight of 60% in the portfolio with an expected return of 8% and a standard deviation of 15%.
Asset B has a weight of 40% with an expected return of 12% and a standard deviation of 20%. The
correlation coefficient between the returns of Asset A and Asset B is 0.6. Calculate the expected
return and standard deviation of the portfolio.
Solution:
Let rAbe the return of Asset A, rBbe the return of Asset B, and wAand wBbe the weights of
Asset A and Asset B respectively.
a) The expected return of the portfolio (rp) is given by:
rp=wA×rA+wB×rB
rp= 0.60 ×0.08 + 0.40 ×0.12
rp= 0.048 + 0.048
rp= 0.096 or 9.6%
b) The variance of the portfolio (σ2
p) is given by:
σ2
p=w2
A×σ2
A+w2
B×σ2
B+ 2 ×wA×wB×Corr(A, B)×σA×σB
Plugging in the values:
σ2
p= 0.602×0.152+ 0.402×0.202+ 2 ×0.60 ×0.40 ×0.6×0.15 ×0.20
σ2
p= 0.09 + 0.16 + 0.144
σ2
p= 0.394
σp=√0.394 or 19.85%
Therefore, the expected return of the portfolio is 9.6% and the standard deviation of the portfolio
is 19.85%.
10 12. INEFFICIENT REBALANCING STRATEGIES IMPACTING PORTFOLIO PERFORMANCE
Problem 12.
You have a portfolio consisting of two assets, Stock A and Stock B, with the following charac-
teristics:
•Stock A has a weight of 40% in the portfolio and has an expected return of 8% with a standard
deviation of 12%.
•Stock B has a weight of 60% in the portfolio and has an expected return of 12% with a standard
deviation of 18%.
•The correlation coefficient between Stock A and Stock B is 0.6.
a) Calculate the expected return and standard deviation of the portfolio.
b) If you decide to rebalance the portfolio to 50% Stock A and 50% Stock B, calculate the new
expected return and standard deviation of the portfolio.
c) Evaluate the impact of the rebalancing on the portfolio performance.
Solution 12.
a) The expected return and standard deviation of the portfolio can be calculated using the
following formulas:
Expected Return of Portfolio =wA×Expected Return of Stock A+wB×Expected Return of Stock B
Standard Deviation of Portfolio =qw2
A×Variance of Stock A +w2
B×Variance of Stock B + 2 ×wA×wB×Standard Deviation of Stock A ×Standard Deviation of Stock B ×Correlation
Substitute the given values:
Expected Return of Portfolio = 0.4×8% + 0.6×12% = 0.04 + 0.072 = 0.112 = 11.2%
Standard Deviation of Portfolio =p0.42×(0.12)2+ 0.62×(0.18)2+ 2 ×0.4×0.6×0.12 ×0.18 ×0.6=0.1173 = 11.73%
a) Therefore, the expected return of the portfolio is 11.2% and the standard deviation of the
portfolio is 11.73%.
b) If we rebalance the portfolio to 50% Stock A and 50% Stock B, the new expected return and
standard deviation of the portfolio can be calculated in a similar way:
Expected Return of Portfolio = 0.5×8% + 0.5×12% = 0.04 + 0.06 = 0.1 = 10%
Standard Deviation of Portfolio =p0.52×(0.12)2+ 0.52×(0.18)2+ 2 ×0.5×0.5×0.12 ×0.18 ×0.6=0.1289 = 12.89%
b) Therefore, the new expected return of the portfolio is 10% and the new standard deviation
of the portfolio is 12.89%.
c) The rebalancing strategy has slightly reduced the expected return of the portfolio from 11.2%
to 10%, but it has also slightly increased the standard deviation from 11.73% to 12.89%. This
tradeoff between return and risk should be carefully considered based on the investor’s risk appetite
and investment objectives.
11 13. LACK OF CONSIDERATION FOR TAX IMPLICATIONS IN ASSET ALLOCATION
Problem 13. An investor has two investment options:
Option A: A stock that pays a dividend yield of 4% annually and has a capital gain of 10% at
the end of the year. The investor’s tax rate on dividends is 20% and on capital gains is 15%.
Option B: A tax-exempt municipal bond that pays a yield of 3.5% annually.
If the investor’s initial investment is 10,000, determinewhichoptionwouldprovidehigherafter −
taxreturnsaf teroneyear.
Solution 13.
To compare the after-tax returns of the two investment options, we calculate the after-tax returns
for options A and B separately:
a) Option A:
For Option A, the after-tax return is the sum of after-tax dividend and after-tax capital gain:
After-tax dividend = Dividend yield * (1 - Tax rate on dividends) = 0.04 * (1 - 0.2) = 0.04 * 0.8 =
0.032 = 3.2%
After-tax capital gain = Capital gain * (1 - Tax rate on capital gains) = 0.10 * (1 - 0.15) = 0.10 *
0.85 = 0.085 = 8.5%
Total after-tax return for Option A = After-tax dividend + After-tax capital gain = 3.2% + 8.5% =
11.7%
b) Option B:
For Option B, the after-tax return of the tax-exempt municipal bond is simply the yield of 3.5%.
c) Comparison:
Since Option A has a total after-tax return of 11.7%, which is higher than the 3.5% after-tax
return of Option B, the investor would achieve higher after-tax returns by investing in Option A.
12 Portfolio Theory and Asset Allocation
Problem 1.
You are considering investing in a portfolio that consists of two assets: Stock A and Stock B.
The expected return and standard deviation of each asset are as follows:
Stock A: Expected Return = 12%, Standard Deviation = 15%
Stock B: Expected Return = 8%, Standard Deviation = 10%
The correlation coefficient between the returns of Stock A and Stock B is 0.5. You are planning
to allocate 60% of your investment to Stock A and 40% to Stock B.
a) Calculate the expected return of the portfolio.
b) Calculate the standard deviation of the portfolio.
Solution 1.
a) The expected return of the portfolio can be calculated using the weighted sum of the individual
expected returns:
E(Rp) = wA×E(RA) + wB×E(RB)
Given that wA= 0.6,E(RA) = 0.12,wB= 0.4, and E(RB)=0.08, we have:
E(Rp)=0.6×0.12 + 0.4×0.08 = 0.072 + 0.032 = 0.104 = 10.4%
Therefore, the expected return of the portfolio is 10.4%.
b) The standard deviation of the portfolio can be calculated using the formula:
σp=qw2
A×σ2
A+w2
B×σ2
B+ 2 ×wA×wB×σA×σB×ρA,B
where σA= 0.15,σB= 0.10, and ρA,B = 0.5.
Plugging in the values, we get:
σp=p(0.6)2×(0.15)2+ (0.4)2×(0.10)2+ 2 ×0.6×0.4×0.15 ×0.10 ×0.5
=√0.36 ×0.0225 + 0.16 ×0.01 + 0.12 ×0.015
=√0.0081 + 0.0016 + 0.0018
=√0.0115
≈0.107 = 10.7%
Therefore, the standard deviation of the portfolio is 10.7%.
13 15. IGNORING ENVIRONMENTAL, SOCIAL, AND GOVERNANCE FACTORS IN ASSET
ALLOCATION
Problem 15. Consider a portfolio with three assets: Stock A, Stock B, and Stock C. The ex-
pected return and standard deviation of each asset are as follows:
•Stock A: Expected return = 8%, Standard deviation = 12%
•Stock B: Expected return = 12%, Standard deviation = 18%
•Stock C: Expected return = 10%, Standard deviation = 15%
The correlation coefficients between the returns of the assets are given by:
•Correlation between A and B: 0.6
•Correlation between A and C: -0.2
•Correlation between B and C: 0.4
Determine the expected return and standard deviation of a portfolio that consists of 30% Stock
A, 50% Stock B, and 20% Stock C.
Solution 15. a) To find the expected return of the portfolio, we use the weighted average of the
expected returns of the individual assets:
Expected return of the portfolio =wA×Expected return of A+wB×Expected return of B+wC×Expected return of C
where wiis the weight of asset iin the portfolio.
Substitute the values into the formula:
Expected return of the portfolio = 0.30 ×8% + 0.50 ×12% + 0.20 ×10%
= 0.024 + 0.06 + 0.02 = 0.104 = 10.4%
Therefore, the expected return of the portfolio is 10.4%.
b) To find the standard deviation of the portfolio, we use the formula for the portfolio variance:
σ2
p=w2
A×σ2
A+w2
B×σ2
B+w2
C×σ2
C+ 2(wA×wB×σAB +wA×wC×σAC +wB×wC×σBC )
where σiis the standard deviation of asset iand σij is the covariance between assets iand j.
Substitute all values into the formula and calculate:
σ2
p= 0.302×0.122+0.502×0.182+0.202×0.152+2(0.30×0.50×0.6+0.30×0.20×(−0.2)+0.50×0.20×0.4)
= 0.00324 + 0.018 + 0.006 + 2(0.09 −0.012 −0.04)
= 0.02724 + 0.027 + 0.044 = 0.09824
Therefore, the standard deviation of the portfolio is σp=√0.09824 = 0.3135 = 31.35%.
14 Portfolio Theory and Asset Allocation
Problem:
You are considering investing in two assets, Asset A and Asset B. Asset A has an expected
return of 7% with a standard deviation of 12%, while Asset B has an expected return of 10% with a
standard deviation of 18%. You plan to allocate 60% of your portfolio to Asset A and 40% to Asset
B. The correlation between the returns of the two assets is 0.4.
a) Calculate the expected return and standard deviation of the portfolio.
b) Determine the correlation between the returns of the portfolio and a risk-free asset that offers
a return of 3%.
Solution:
a) To calculate the expected return and standard deviation of the portfolio, we use the following
formulas:
Expected return of the portfolio:
E(Rp) = wA·E(RA) + wB·E(RB)
where E(RA)and E(RB)are the expected returns of Asset A and Asset B, respectively, and
wAand wBare the weights of Asset A and Asset B in the portfolio.
Substitute the values:
E(Rp) = 0.6×0.07 + 0.4×0.10 = 0.042 + 0.04 = 0.082 = 8.2%
Standard deviation of the portfolio:
σp=qw2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·ρAB ·σA·σB
where σAand σBare the standard deviations of Asset A and Asset B, respectively, and ρAB is
the correlation coefficient between Asset A and Asset B.
Substitute the values:
σp=p0.62×(0.12)2+ 0.42×(0.18)2+ 2 ×0.6×0.4×0.4×0.12 ×0.18
σp=√0.0144 + 0.01296 + 0.00259 = √0.03 = 0.1732 = 17.32%
Therefore, the expected return of the portfolio is 8.2% and the standard deviation is 17.32%.
b) To determine the correlation between the returns of the portfolio and a risk-free asset, we
can use the formula:
ρp,rf =wp·ρA,rf
where ρA,rf is the correlation between Asset A and the risk-free asset, and wpis the weight of
the port...
Certainly! Here are a few numerical problem questions on Portfolio Theory and Asset Alloca-
tion:
—
15 17. OVER-RELIANCE ON HISTORICAL DATA IN PORTFOLIO CONSTRUCTION
Problem 17. A financial analyst is constructing a portfolio with two assets: Stock A and Stock B.
Historical returns for Stock A and Stock B over the past 5 years are as follows:
•Stock A: Mean return = 8%, Standard deviation = 12%
•Stock B: Mean return = 10%, Standard deviation = 15%
The correlation coefficient between the returns of Stock A and Stock B is 0.6. The analyst wants
to build a portfolio using these two assets.
a) If the analyst wants the portfolio to have a mean return of 9
b) Determine the standard deviation of the portfolio if the analyst invests 40% in Stock A and
60% in Stock B.
c) Calculate the correlation between the portfolio returns and Stock A if the weight of Stock A
in the portfolio is 0.4.
Solution 17.
a) Let wAand wBbe the weights of Stock A and Stock B in the portfolio, respectively. The
mean return of the portfolio can be calculated as:
E(rp) = wA·E(rA) + wB·E(rB)
Given that the mean return of the portfolio should be 9%, and E(rA)=0.08 and E(rB)=0.10,
we can set up the equation as:
0.09 = wA·0.08 + wB·0.10
Since wA+wB= 1, we can solve for wAin terms of wBas:
wA= 1 −wB
Substitute this into the equation:
0.09 = (1 −wB)·0.08 + wB·0.10
Solving for wB, we get wB= 0.6and wA= 0.4.
Therefore, the weights of Stock A and Stock B in the portfolio should be 40% and 60%, respec-
tively.
b) The standard deviation of the portfolio can be calculated using the formula:
σp=qw2
Aσ2
A+w2
Bσ2
B+ 2wAwBσAσBρAB
Substitute the given values and calculated weights into the formula to find the standard deviation
of the portfolio.
c) The correlation between the portfolio returns and Stock A can be calculated using the formula:
ρpA =wAρAB
Substitute the given correlation coefficient and weight of Stock A to determine the correlation.
—
Feel free to reach out if you need more questions or further clarifications on this topic!
16 18. UNDERESTIMATING TAIL RISKS IN ASSET ALLOCATION DECISIONS
Problem 18.
You are considering investing in two assets, Asset A and Asset B. The annual returns for Asset
A have a normal distribution with mean 8% and standard deviation 12%. The annual returns for
Asset B have a normal distribution with mean 10% and standard deviation 15%. The correlation
between the returns of Asset A and Asset B is 0.5.
a) Calculate the expected return of a portfolio that is equally weighted in Asset A and Asset B.
b) Calculate the standard deviation of the portfolio that is equally weighted in Asset A and Asset
B.
c) Calculate the correlation coefficient between the returns of the portfolio and the returns of
Asset A.
Solution 18.
a) The expected return of a portfolio that is equally weighted in Asset A and Asset B can be
calculated using the formula for the expected return of a portfolio:
E(Rp) = wA·E(RA) + wB·E(RB)
Where: - E(Rp)is the expected return of the portfolio - wAis the weight of Asset A in the portfolio
(0.5 in this case) - E(RA)is the expected return of Asset A (8%) - wBis the weight of Asset B in
the portfolio (0.5 in this case) - E(RB)is the expected return of Asset B (10%)
Plugging in the values, we get:
E(Rp)=0.5×8% + 0.5×10% = 0.08 + 0.05 = 0.13 = 13%
Therefore, the expected return of the equally weighted portfolio is 13%.
b) The standard deviation of a portfolio of two assets can be calculated using the formula for
the standard deviation of a portfolio:
σp=qw2
A·σ2
A+w2
B·σ2
B+ 2 ·wA·wB·ρAB ·σA·σB
Where: - σpis the standard deviation of the portfolio - wA,wBare the weights of Asset A and
Asset B in the portfolio (both 0.5 in this case) - σA,σBare the standard deviations of Asset A and
Asset B (12% and 15% respectively) - ρAB is the correlation coefficient between Asset A and Asset
B (0.5)
Plugging in the values, we get:
σp=p0.52·0.122+ 0.52·0.152+ 2 ·0.5·0.5·0.5·0.12 ·0.15
σp=p0.032+ 0.03752+ 0.009 = √0.0009 + 0.00140625 + 0.009 = √0.01030625 ≈0.1015 = 10.15%
Therefore, the standard deviation of the equally weighted portfolio is approximately 10.15
c) The correlation coefficient between the returns of the portfolio and the returns of Asset A can
be calculated using the formula for correlation coefficient in a two-assets portfolio:
ρpA =wA·σ2
A
σA·σp
Where: - ρpA is the correlation coefficient between the returns of the portfolio and the returns
of Asset A - wAis the weight of Asset A in the portfolio (0.5) - σAis the standard deviation of Asset
A (12%) - σpis the standard deviation of the portfolio (10.15%)
Plugging in the values, we get:
ρpA =0.5·0.12
0.12 ·0.1015 =0.06
0.01218 ≈0.4926
Therefore,
17 19. MISALIGNED ASSET ALLOCATION WITH LONG-TERM FINANCIAL GOALS
Problem 19.
Alice is planning her retirement and has set a goal to accumulate a wealth of 1,000,000in20years.Shecurrentlyhas100,000
saved and is considering two investment options: Option A, which has an expected annual return
of 8% with a standard deviation of 12%, and Option B, which has an expected annual return of 5%
with a standard deviation of 8%. Assuming Alice aims to maximize the likelihood of reaching her
retirement goal, determine the optimal allocation of her initial 100,000betweenOptionAandOptionB.
Solution 19.
To determine the optimal allocation that maximizes the likelihood of reaching her retirement
goal, we will use the concept of portfolio optimization. Let xdenote the allocation to Option A and
1−xdenote the allocation to Option B.
Given that the expected return of the portfolio is a weighted sum of the expected returns of the
individual assets, the expected return of the portfolio (Rp) is given by:
Rp=x·RA+ (1 −x)·RB
Rp= 0.08x+ 0.05(1 −x)
Rp= 0.03x+ 0.05
The variance of the portfolio (σ2
p) is calculated as follows:
σ2
p=x2·σ2
A+ (1 −x)2·σ2
B+ 2x(1 −x)·σAσB
σ2
p= 0.122x2+ 0.082(1 −x)2+ 2(0.12)(0.08)x(1 −x)
σ2
p= 0.0144x2+ 0.0064(1 −x)2+ 0.0192x(1 −x)
σ2
p= 0.008x2+ 0.0064 −0.0128x+ 0.0192x−0.0192x2
σ2
p=−0.0112x2+ 0.0064 −0.0036x
To maximize the likelihood of reaching her retirement goal, Alice can set up the following opti-
mization problem:
Maximize:
Rp= 0.03x+ 0.05
Subject to the constraint:
−0.0112x2+ 0.0064 −0.0036x≤variance tolerance level
Solving this optimization problem will provide Alice with the optimal allocation of her 100,000betweenOptionAandOptionB.

18 20. INEFFECTIVE COMMUNICATION OF PORTFOLIO STRATEGY TO STAKEHOLDERS.
Problem 20.
A financial advisor is creating a portfolio for a client with $100,000 to invest. The advisor decides
to allocate 40% to Stock A, 30% to Stock B, and the remaining 30% to a bond fund. Stock A has
an expected return of 8% and a standard deviation of 12%, Stock B has an expected return of 6%
and a standard deviation of 8%, and the bond fund has an expected return of 4% and a standard
deviation of 4%.
a) Calculate the expected return and standard deviation of the portfolio.
b) If the correlation between Stock A and Stock B is 0.5, calculate the portfolio’s expected return
and standard deviation using the given allocation.
c) Discuss the implications of the correlation assumption for this portfolio.
Solution 20.
a) The expected return and standard deviation of the portfolio can be calculated using the
weighted averages of the individual assets.
a) Expected Return:
E(Rp) = wA×E(RA) + wB×E(RB) + wbond ×E(Rbond)
E(Rp)=0.40 ×0.08 + 0.30 ×0.06 + 0.30 ×0.04 = 0.045 = 4.5%
Standard Deviation:
σp=qw2
A×σ2
A+w2
B×σ2
B+w2
bond ×σ2
bond
σp=p0.402×0.122+ 0.302×0.082+ 0.302×0.042= 0.0601 = 6.01%
b) If the correlation between Stock A and Stock B is 0.5, the portfolio’s expected return and
standard deviation using the given allocation can be calculated using the formula involving corre-
lation.
E(Rp)=0.40 ×0.08 + 0.30 ×0.06 + 0.30 ×0.04 = 0.045 = 4.5%
σp=qw2
A×σ2
A+w2
B×σ2
B+ 2 ×wA×wB×σA×σB×ρAB
σp=p0.402×0.122+ 0.302×0.082+ 2 ×0.40 ×0.30 ×0.12 ×0.08 ×0.5=0.0496 = 4.96%
c) The correlation assumption affects the diversification benefit of the portfolio. A correlation
of 0.5 between Stock A and Stock B implies they are positively correlated. This means that the
two stocks tend to move in the same direction, reducing the benefit of diversification. As a result,
the portfolio’s standard deviation is higher when the correlation is taken into account compared to
the assumption of no correlation. It shows the importance of considering the correlation between
assets when constructing a portfolio to manage risk effectively.

