


BUSI 223 -COMPLEX DERIVATIVE SCENARIOS
COMPLEX DERIVATIVE SCENARIOS
1. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
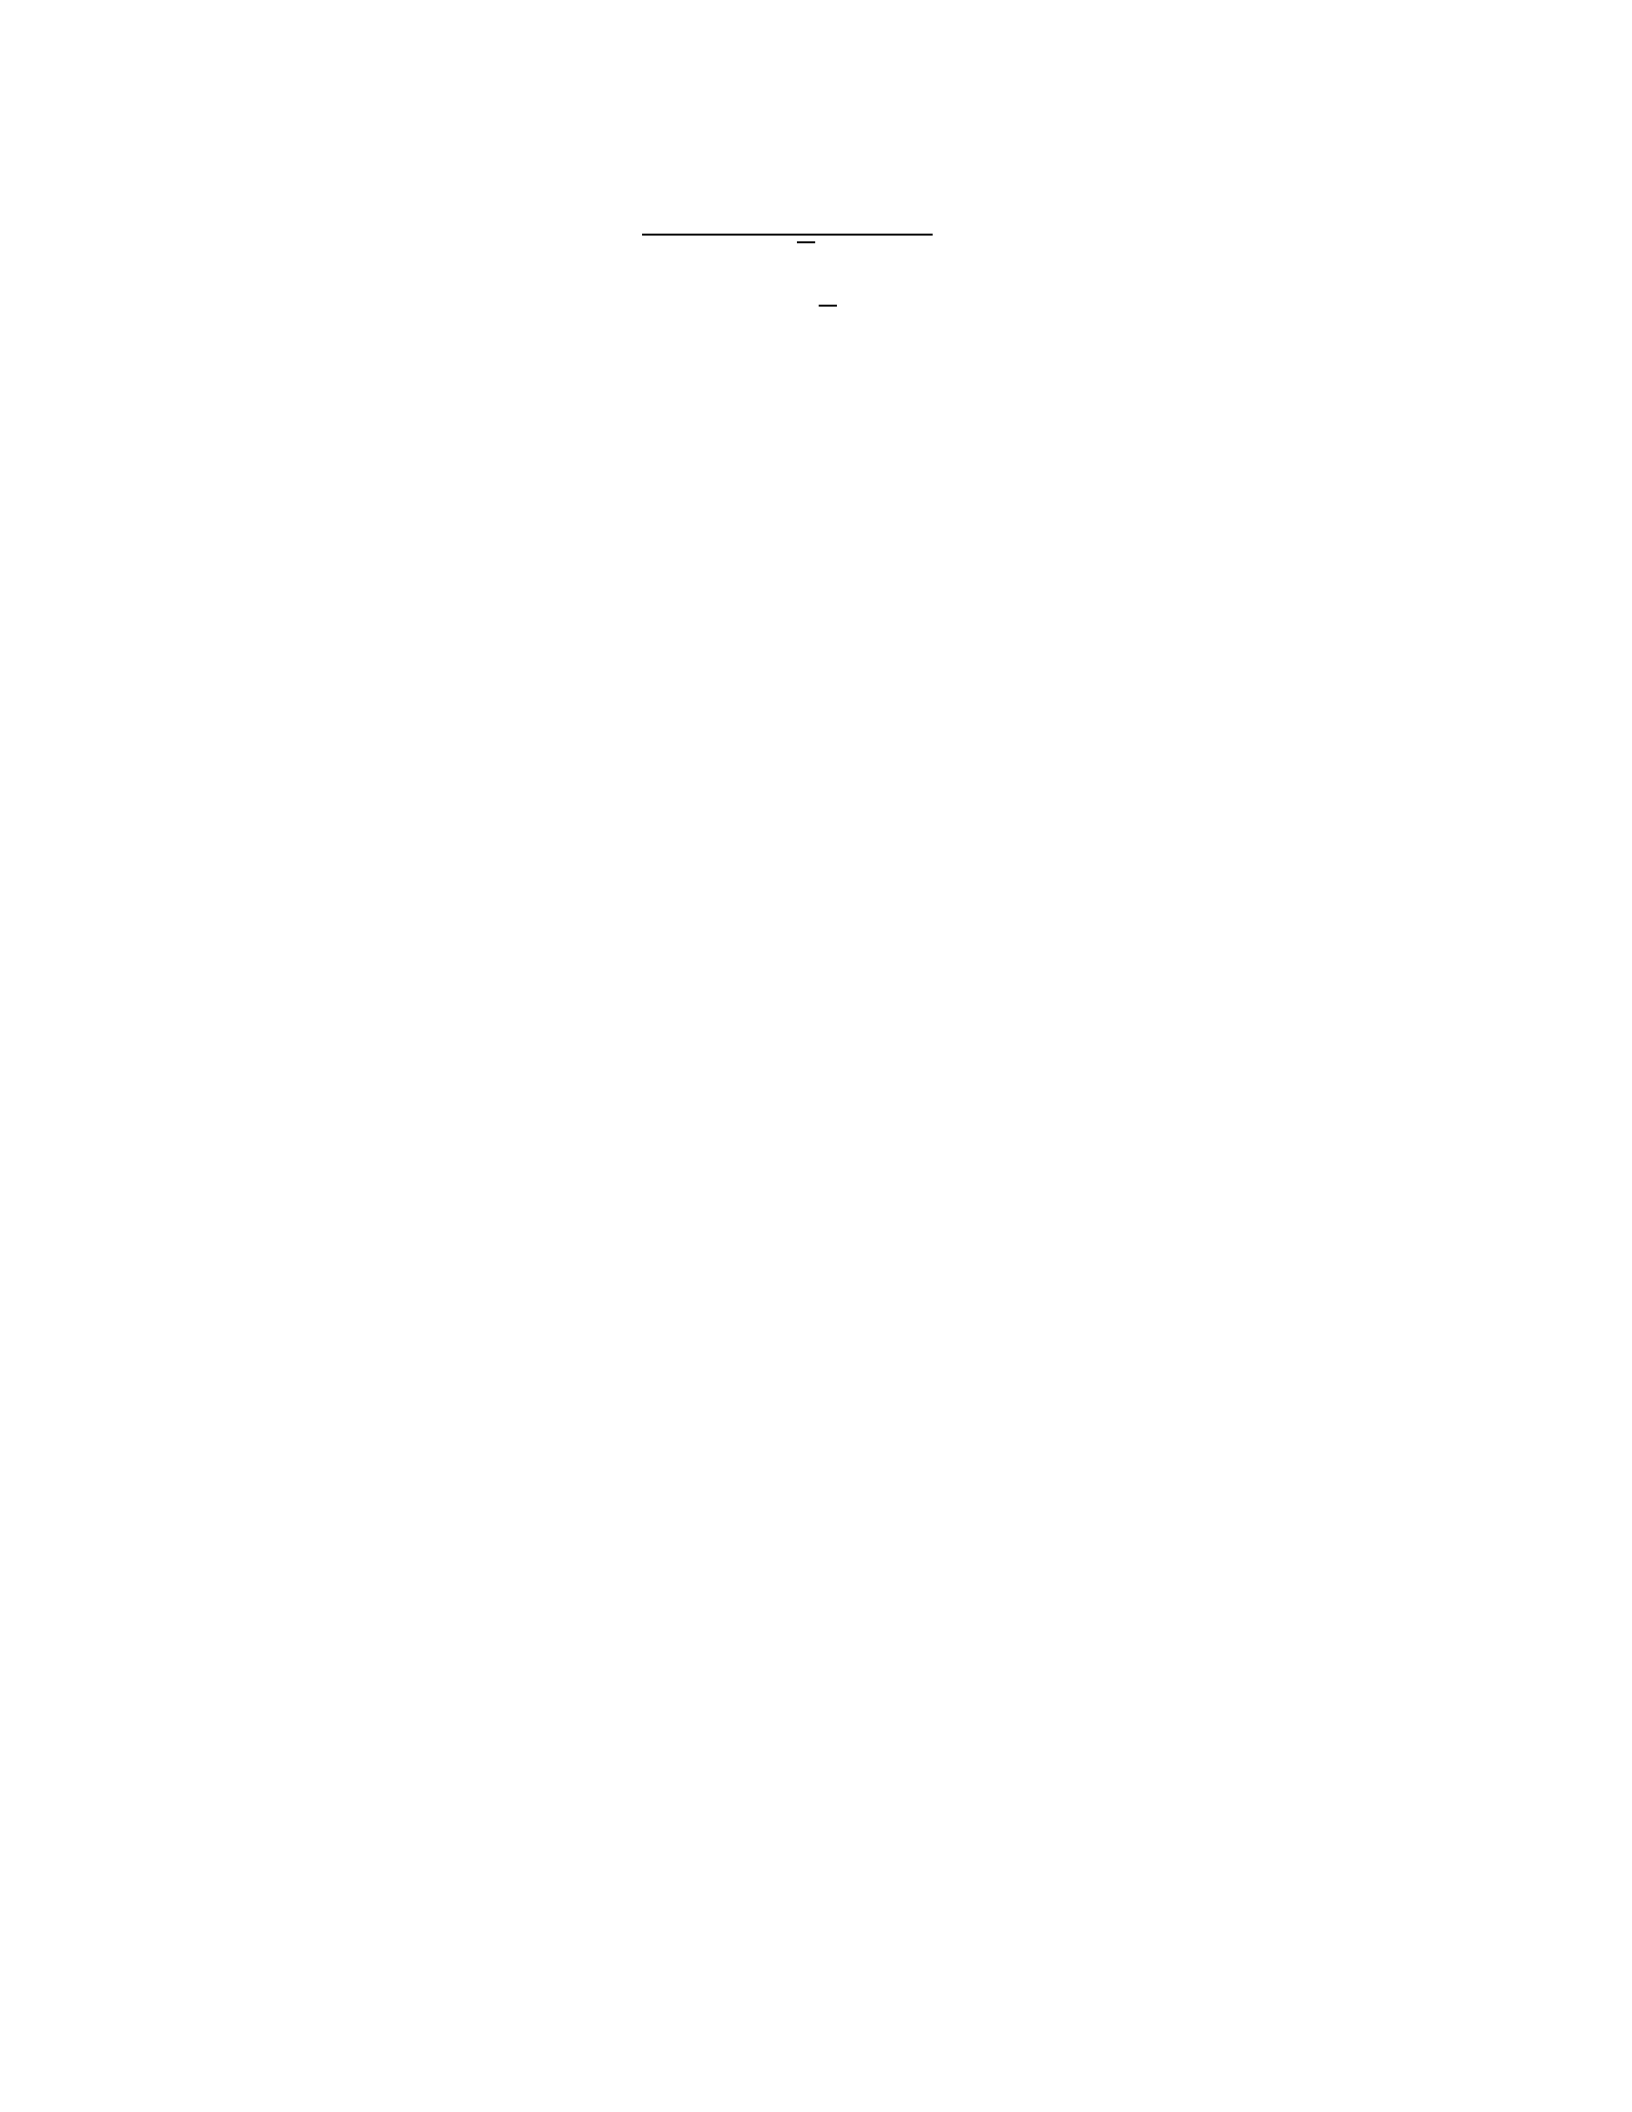
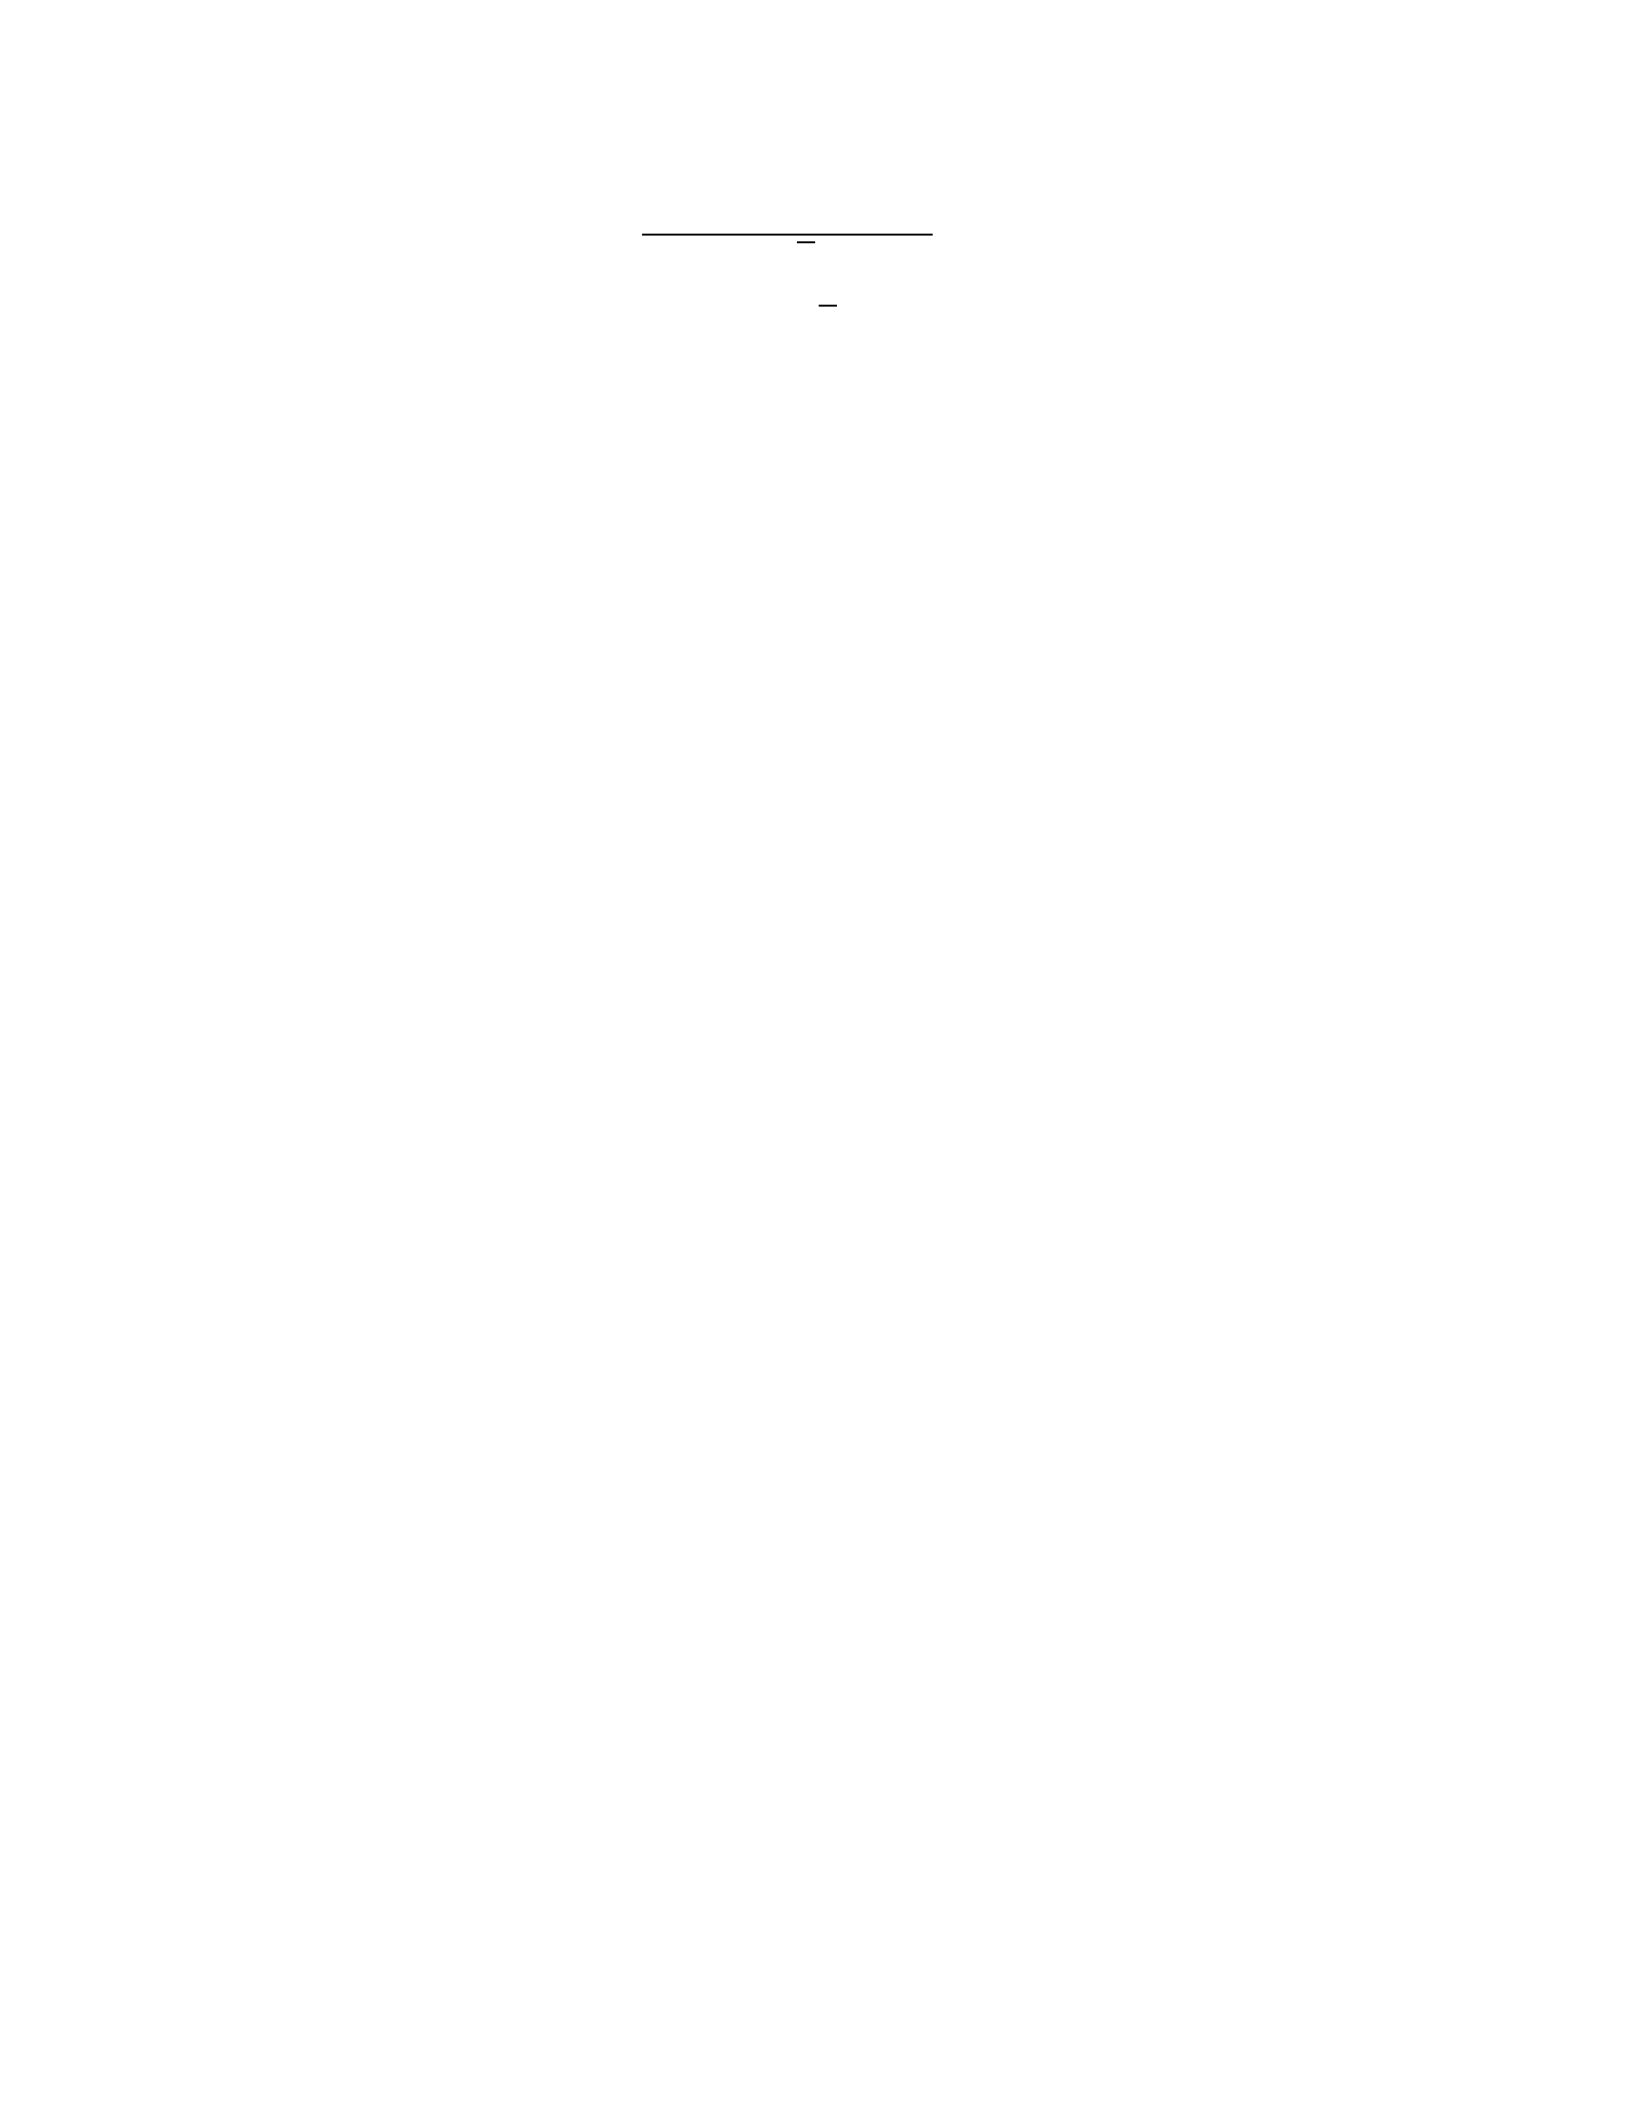
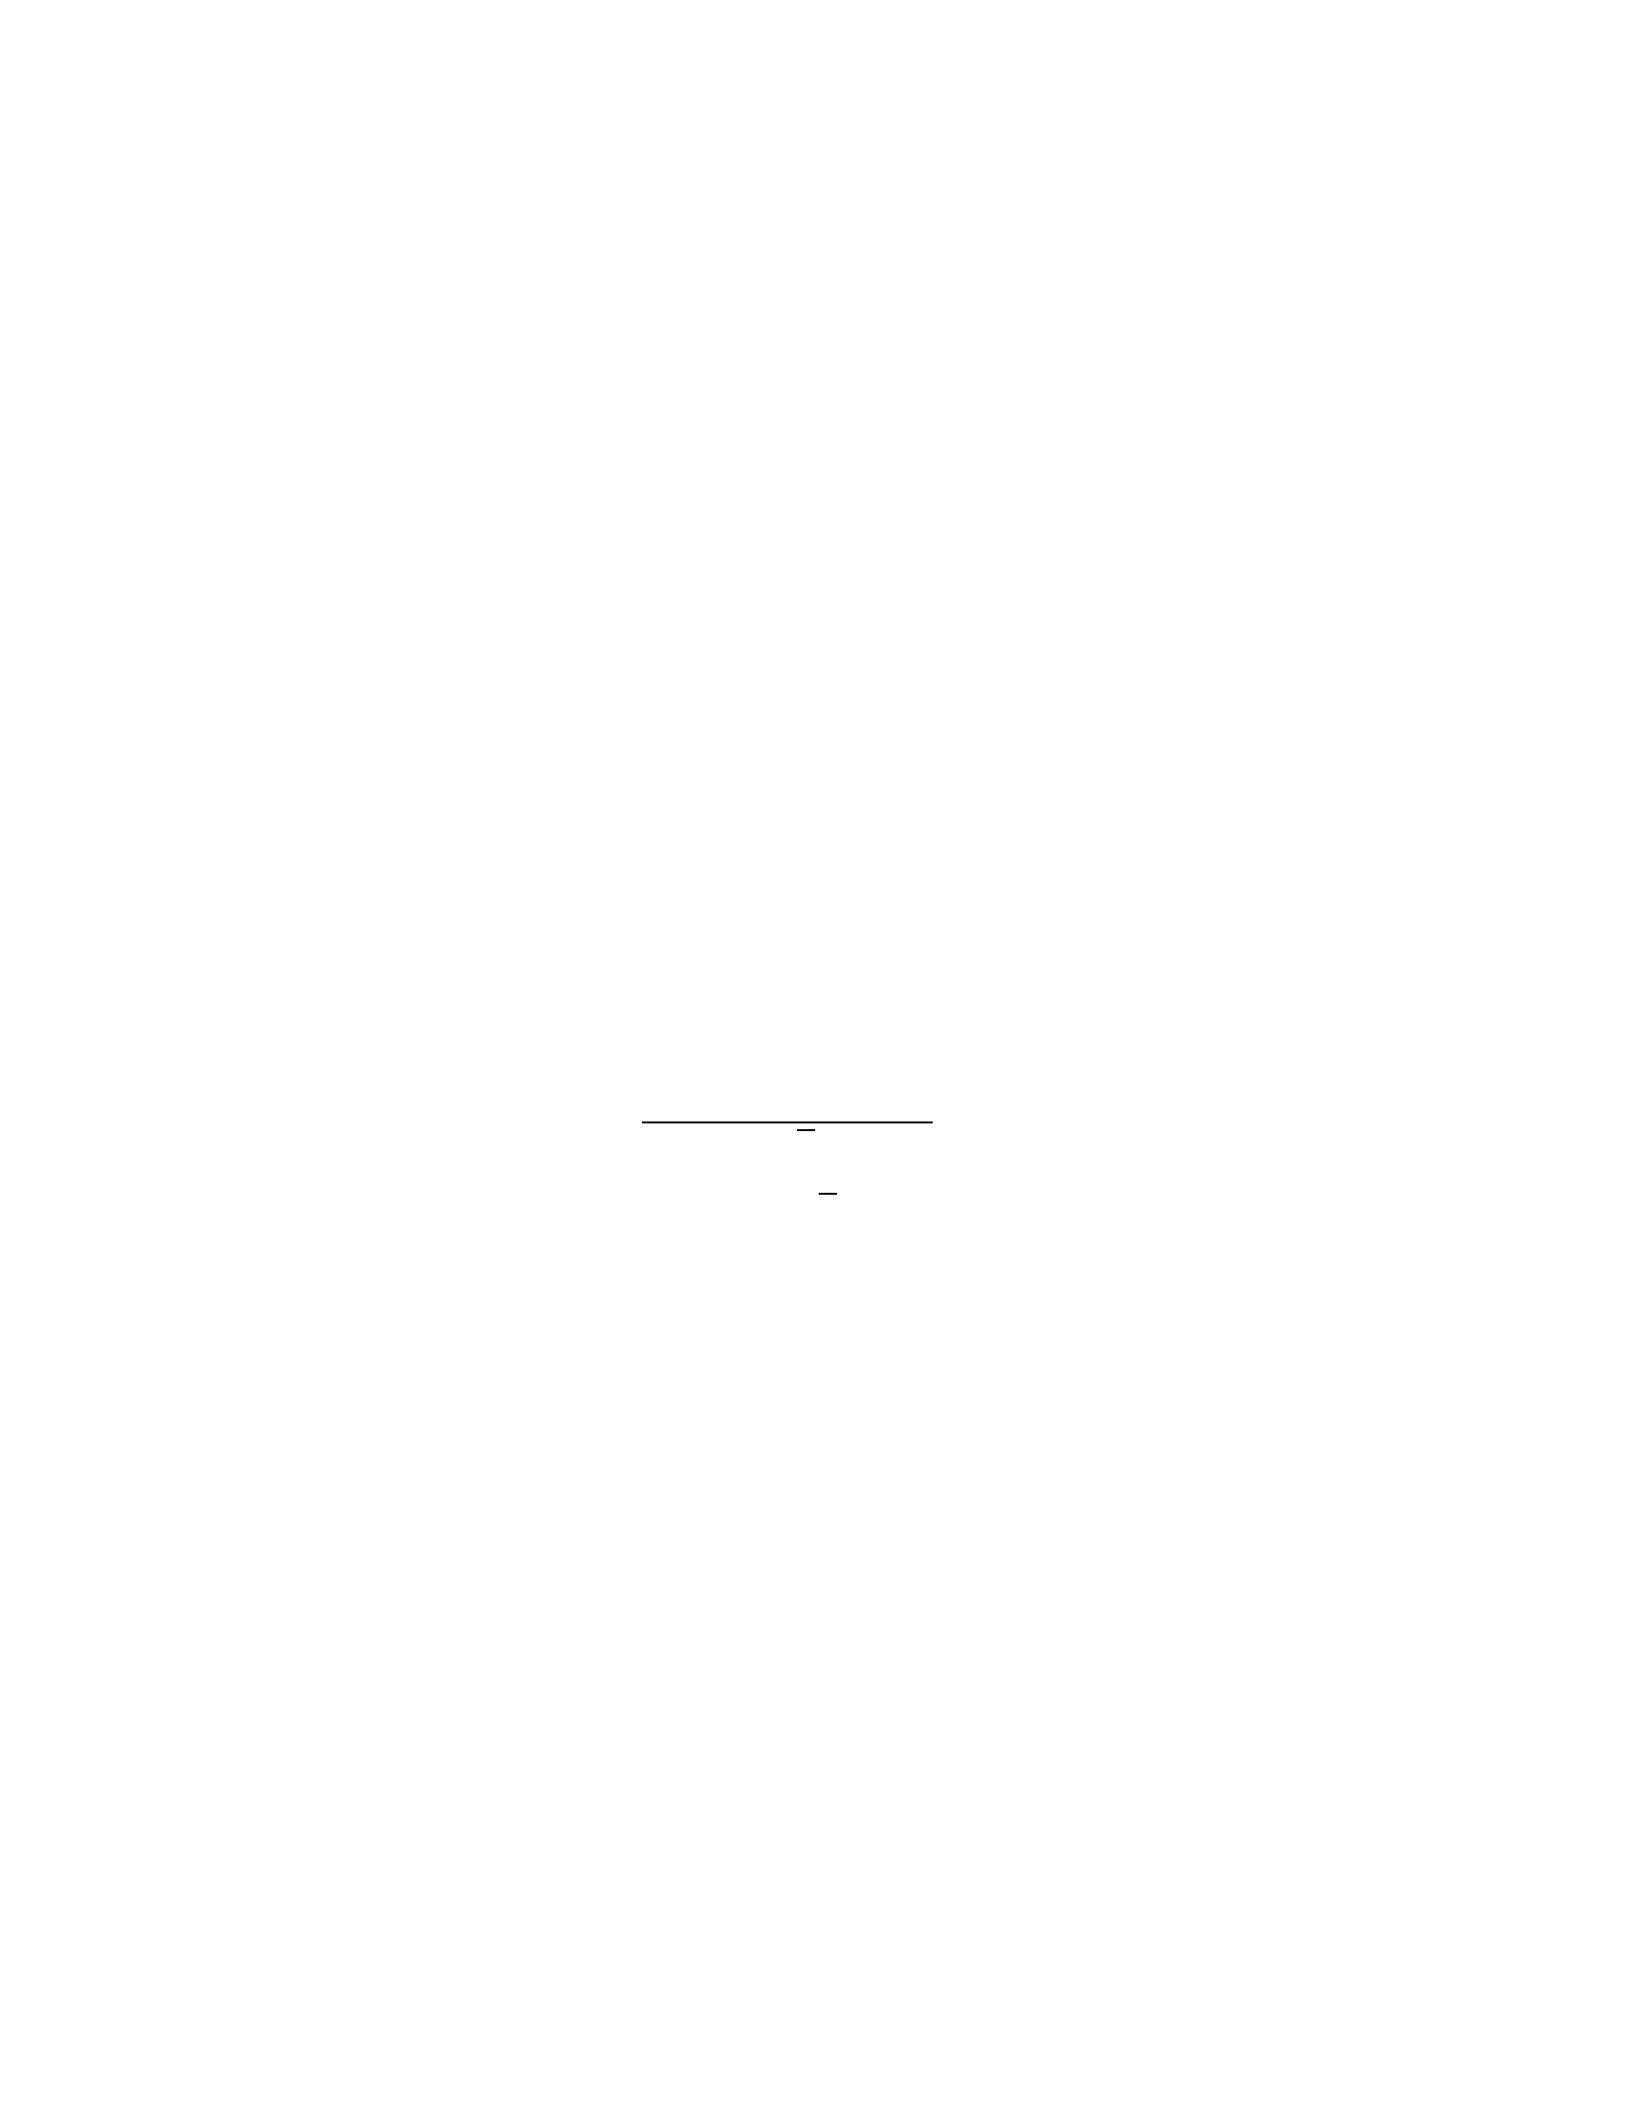
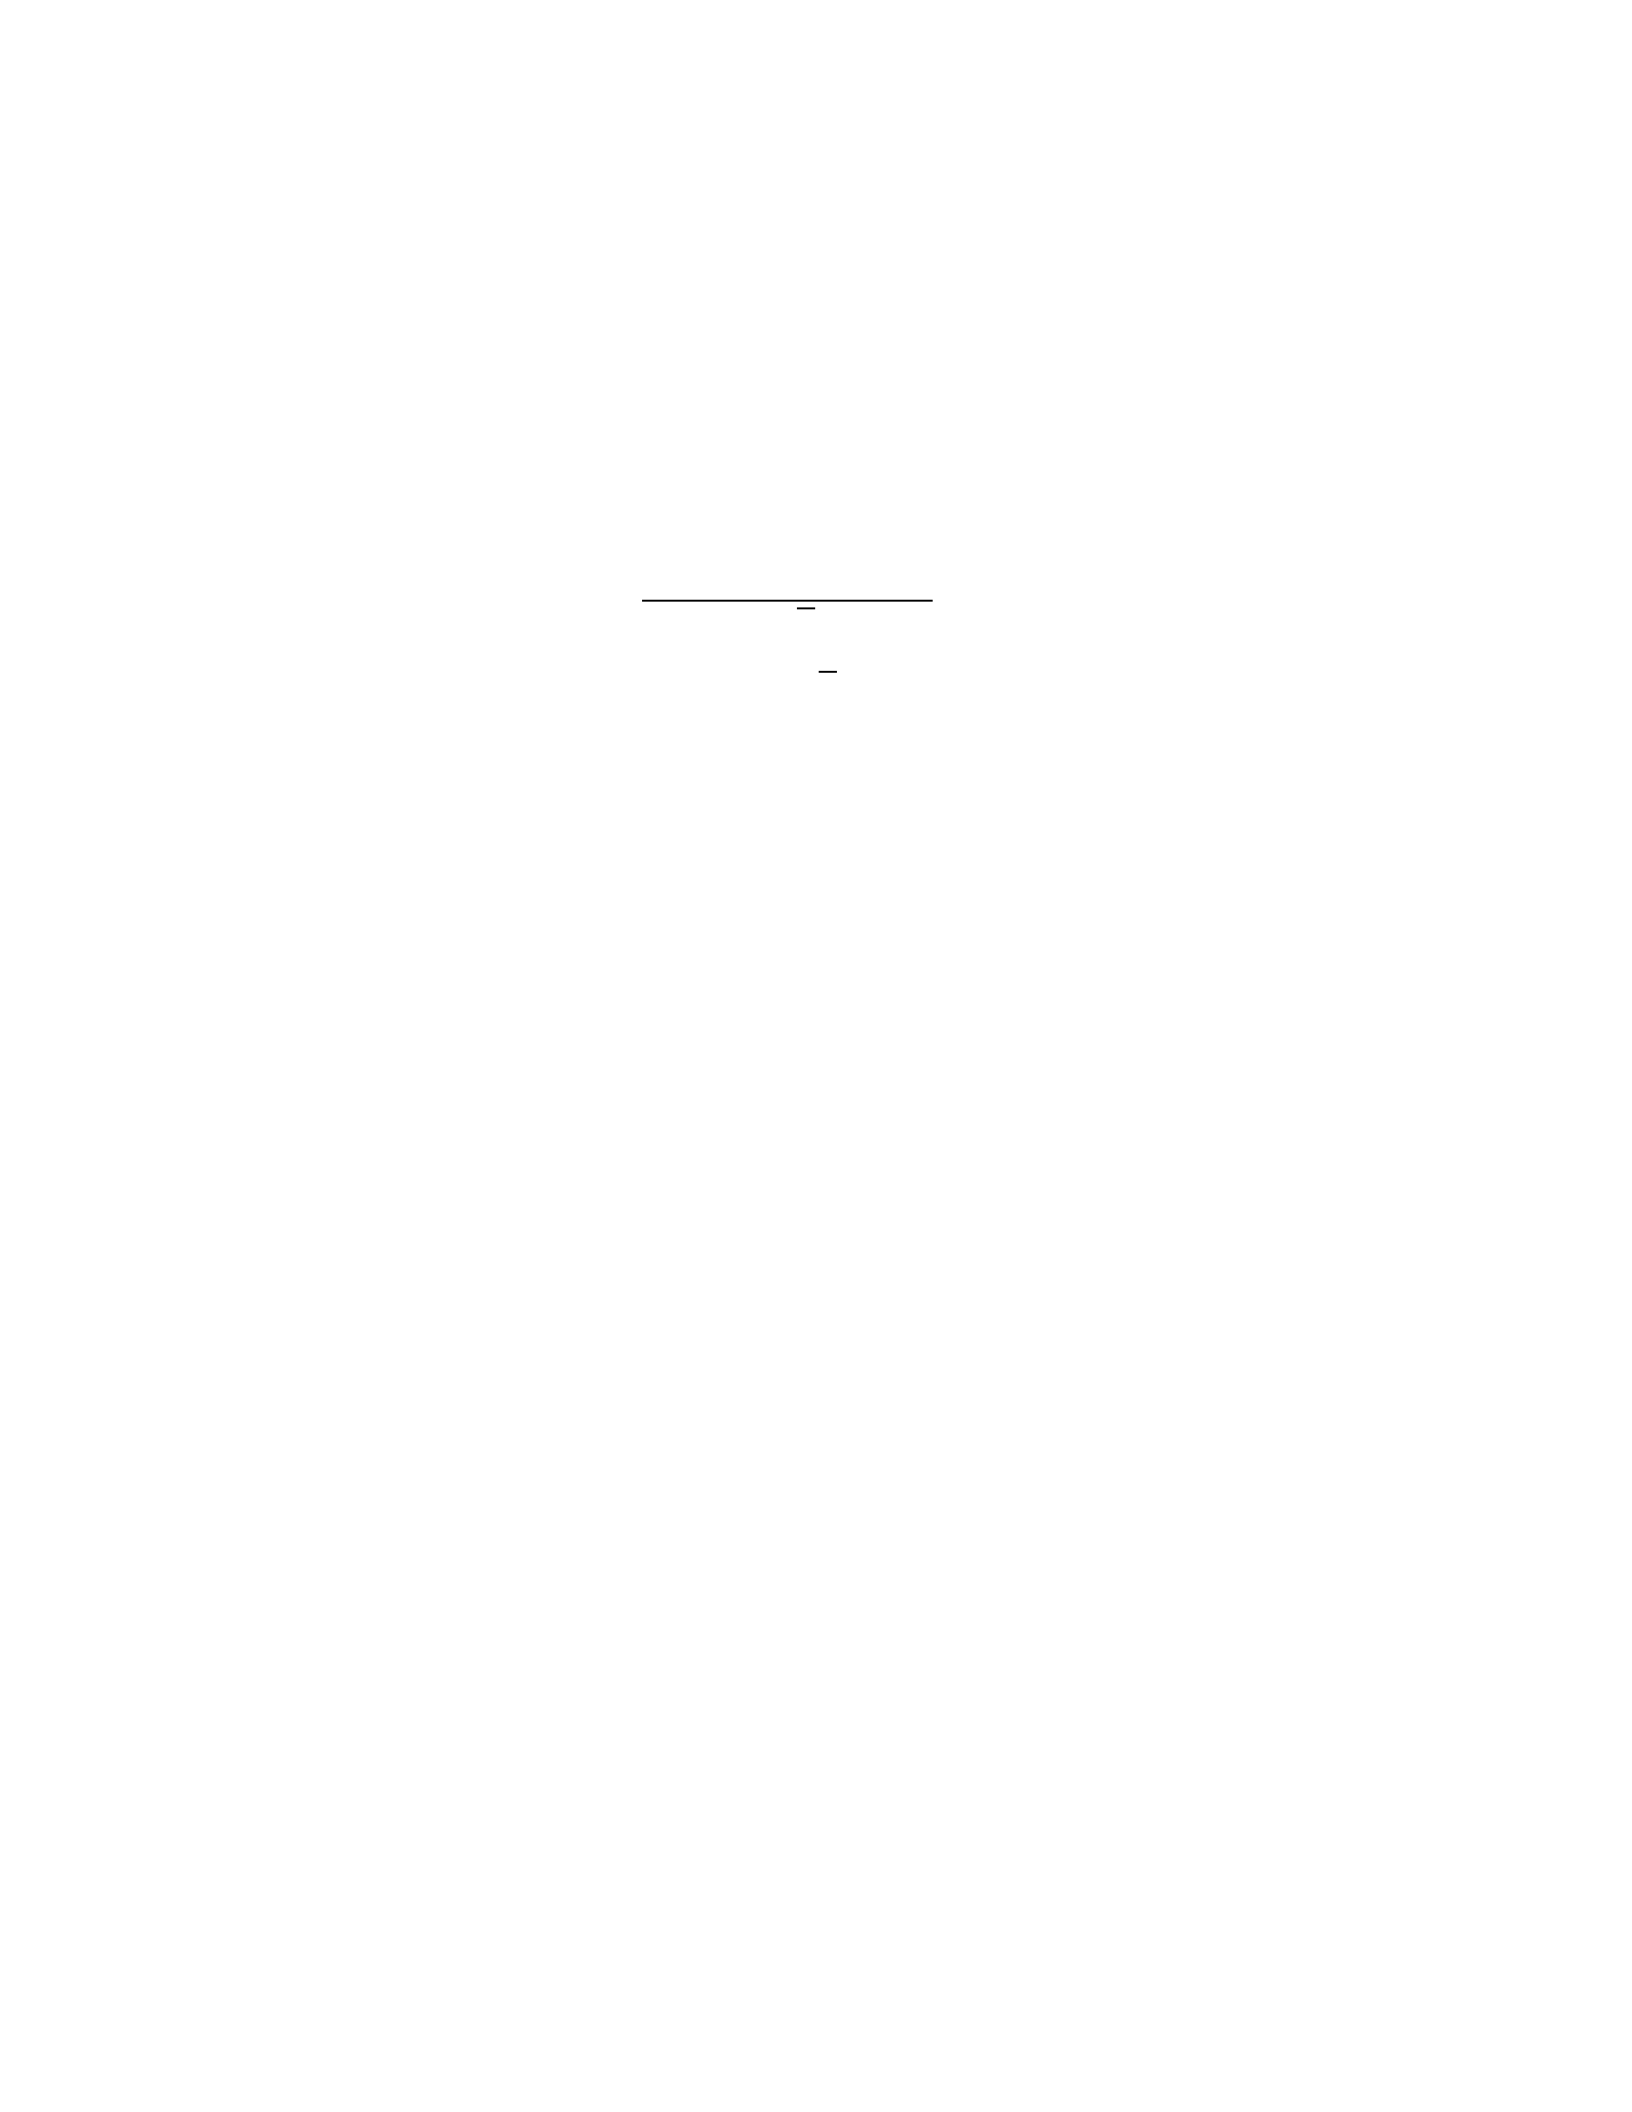
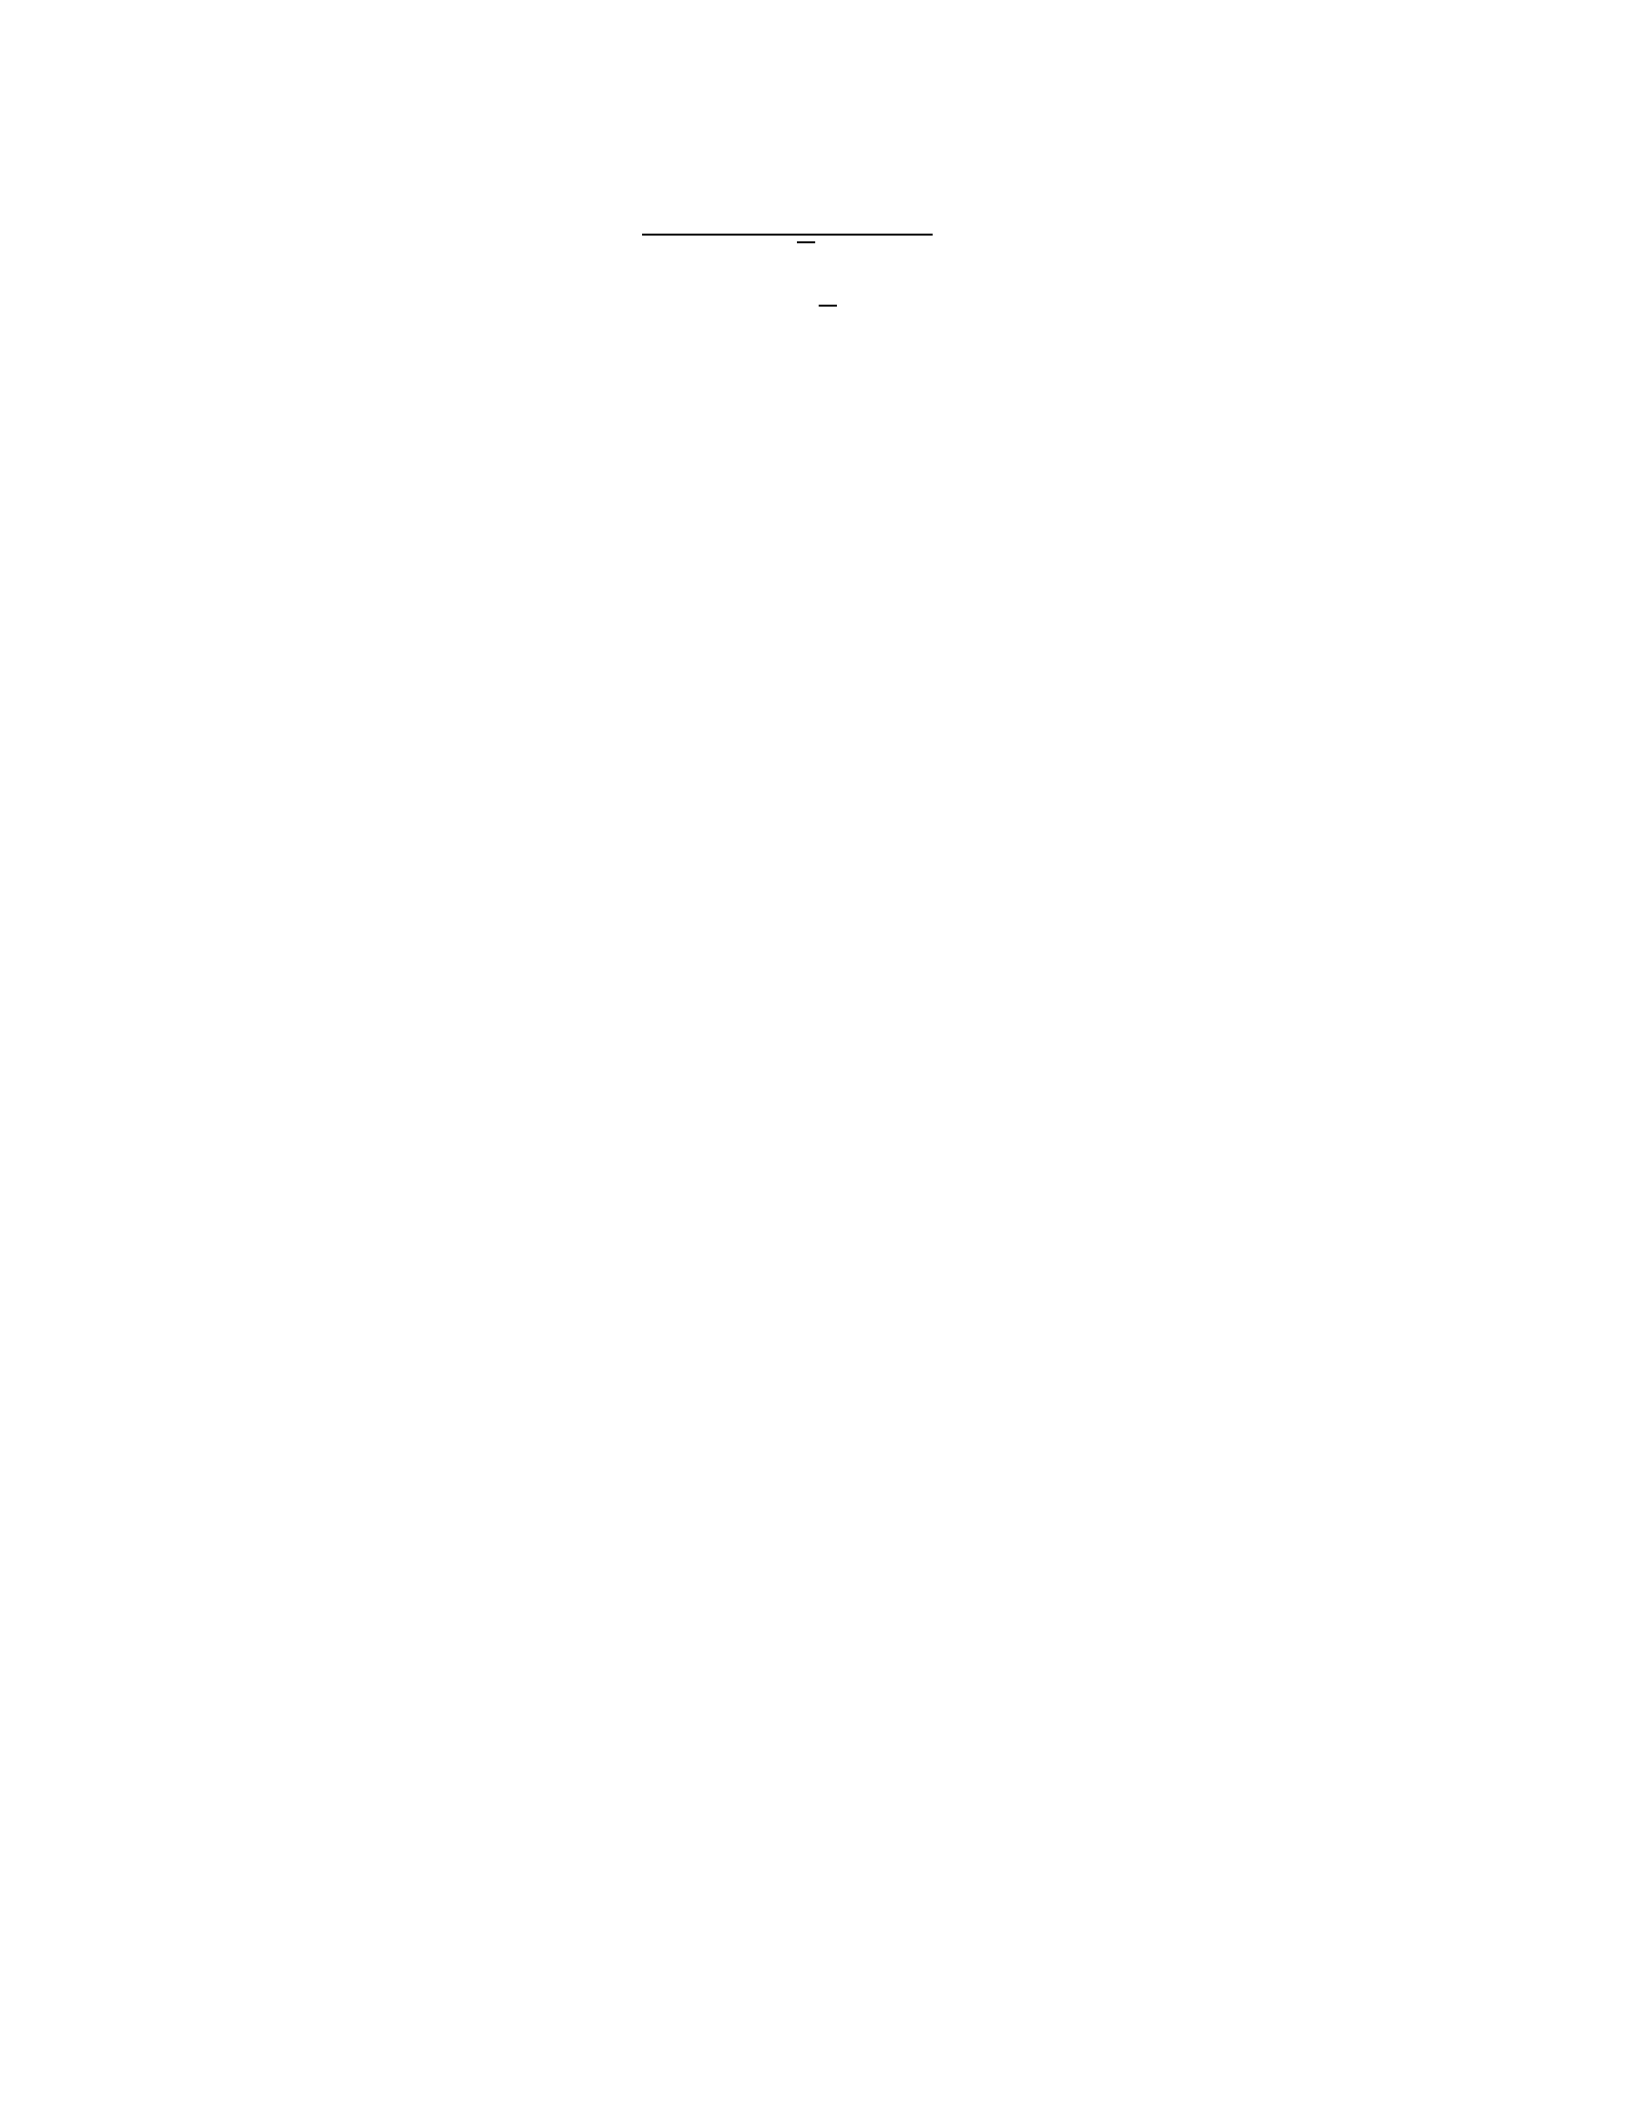
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
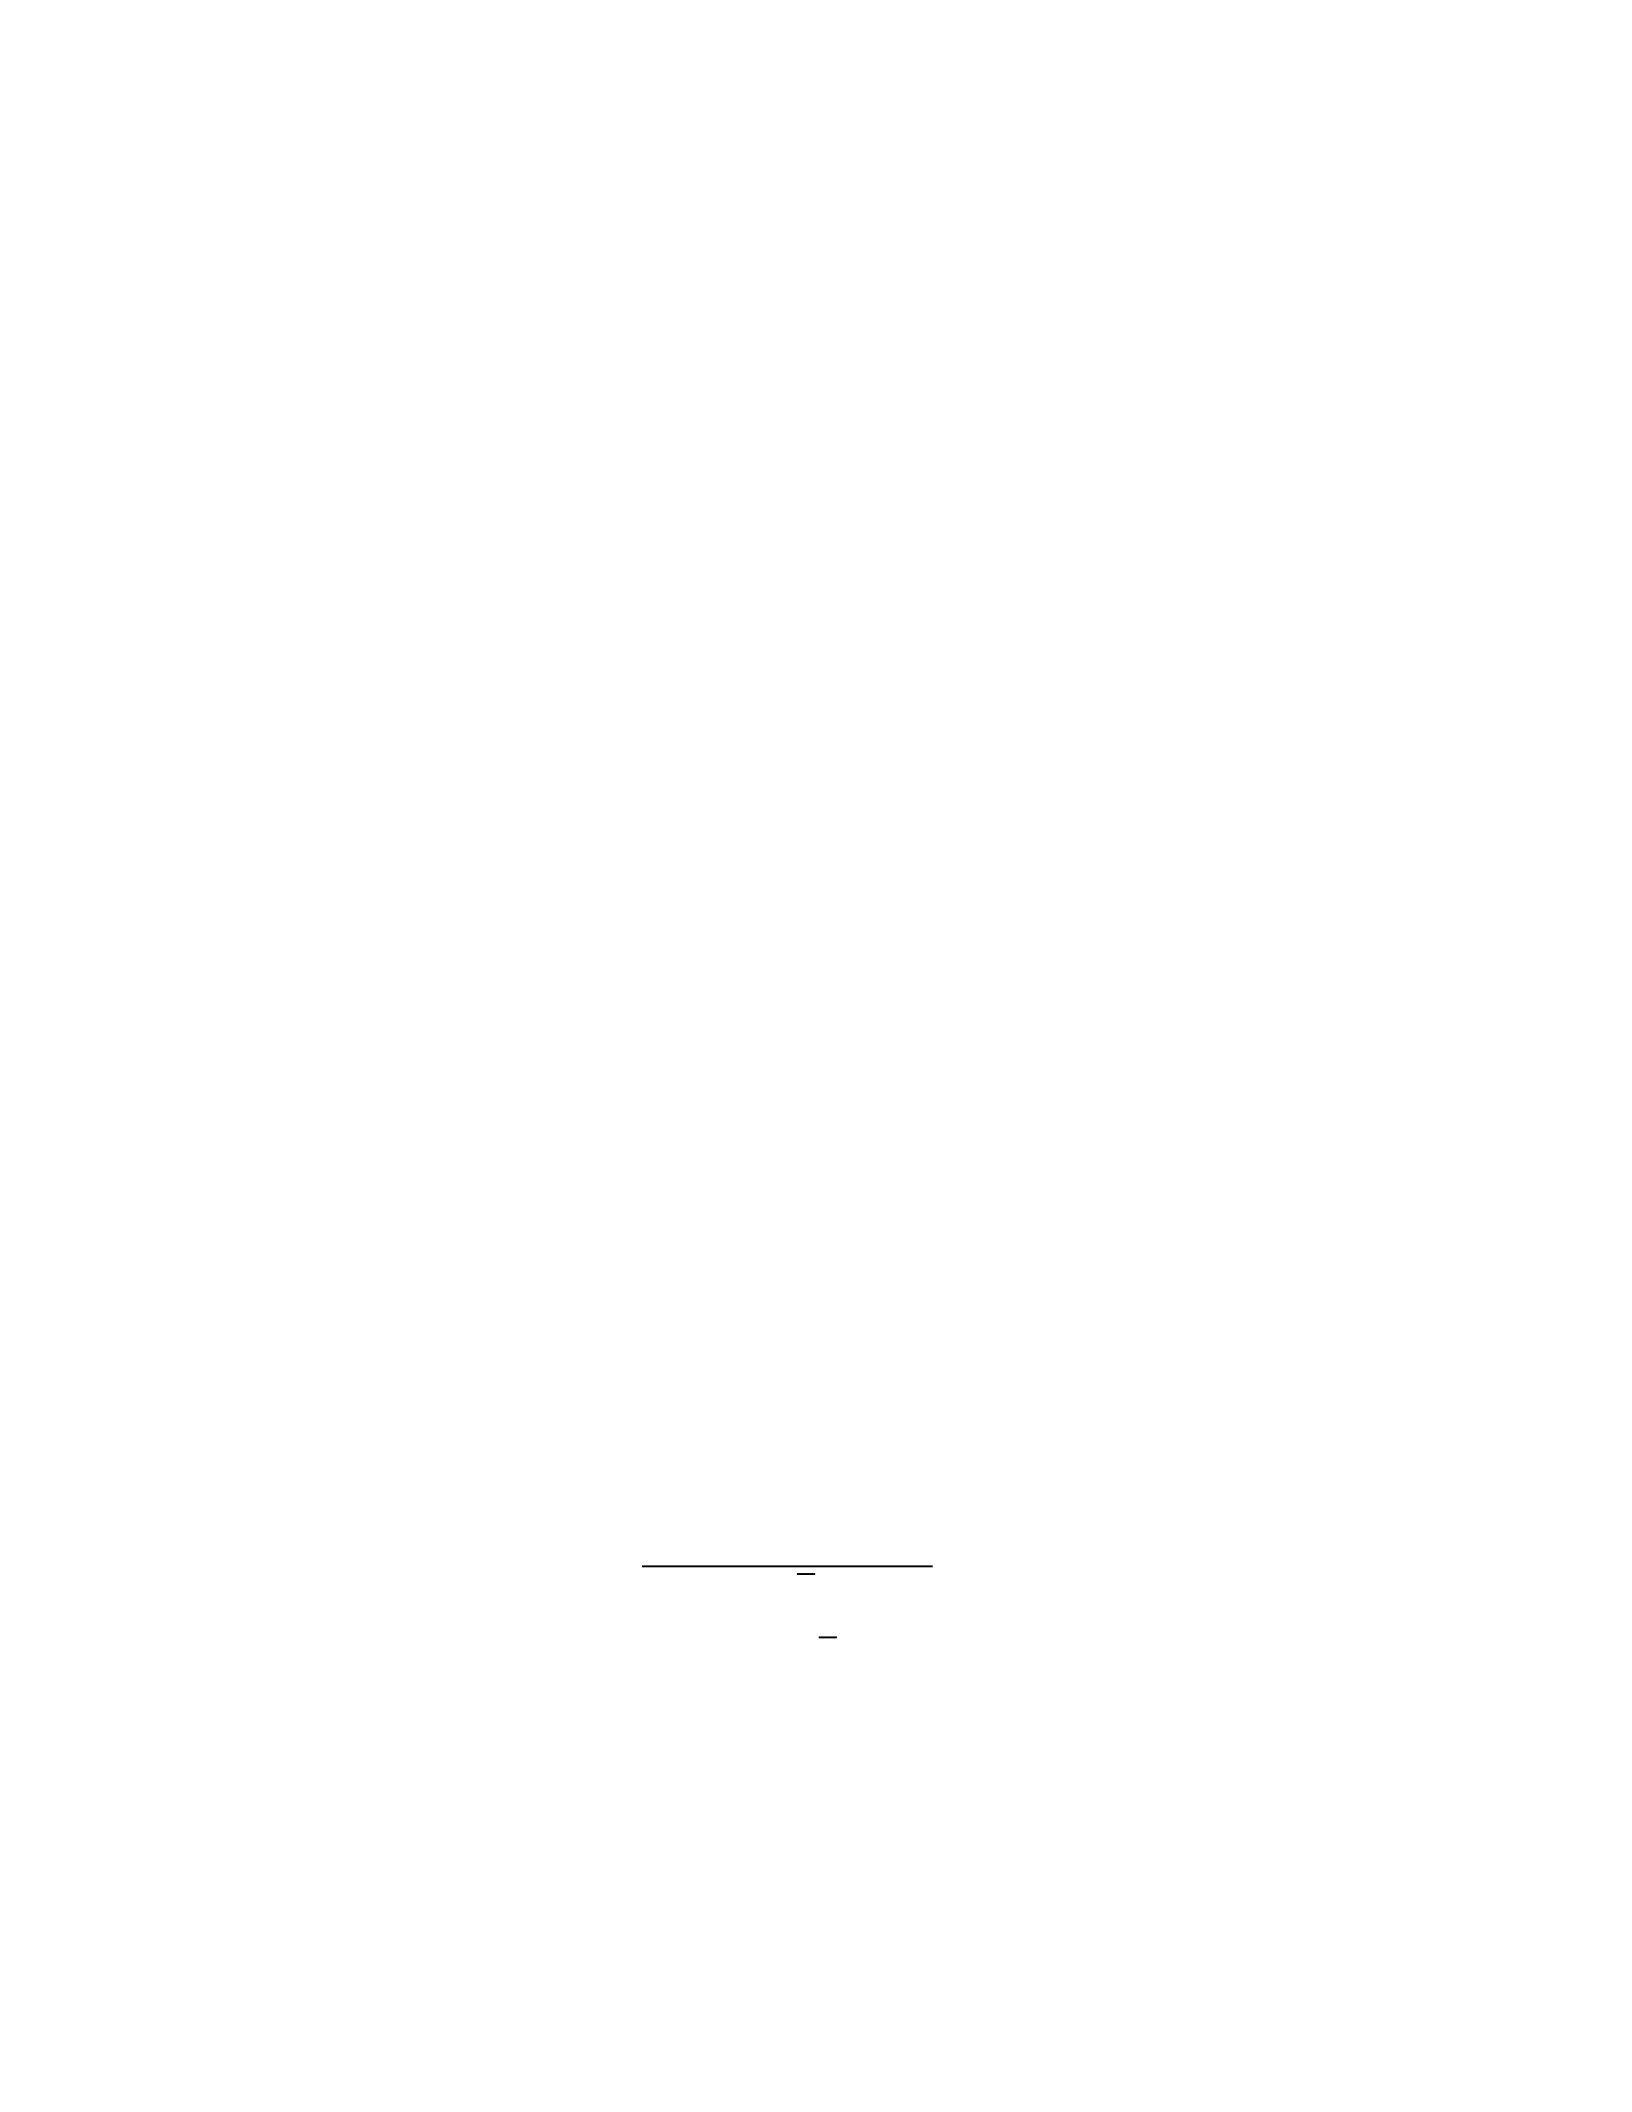
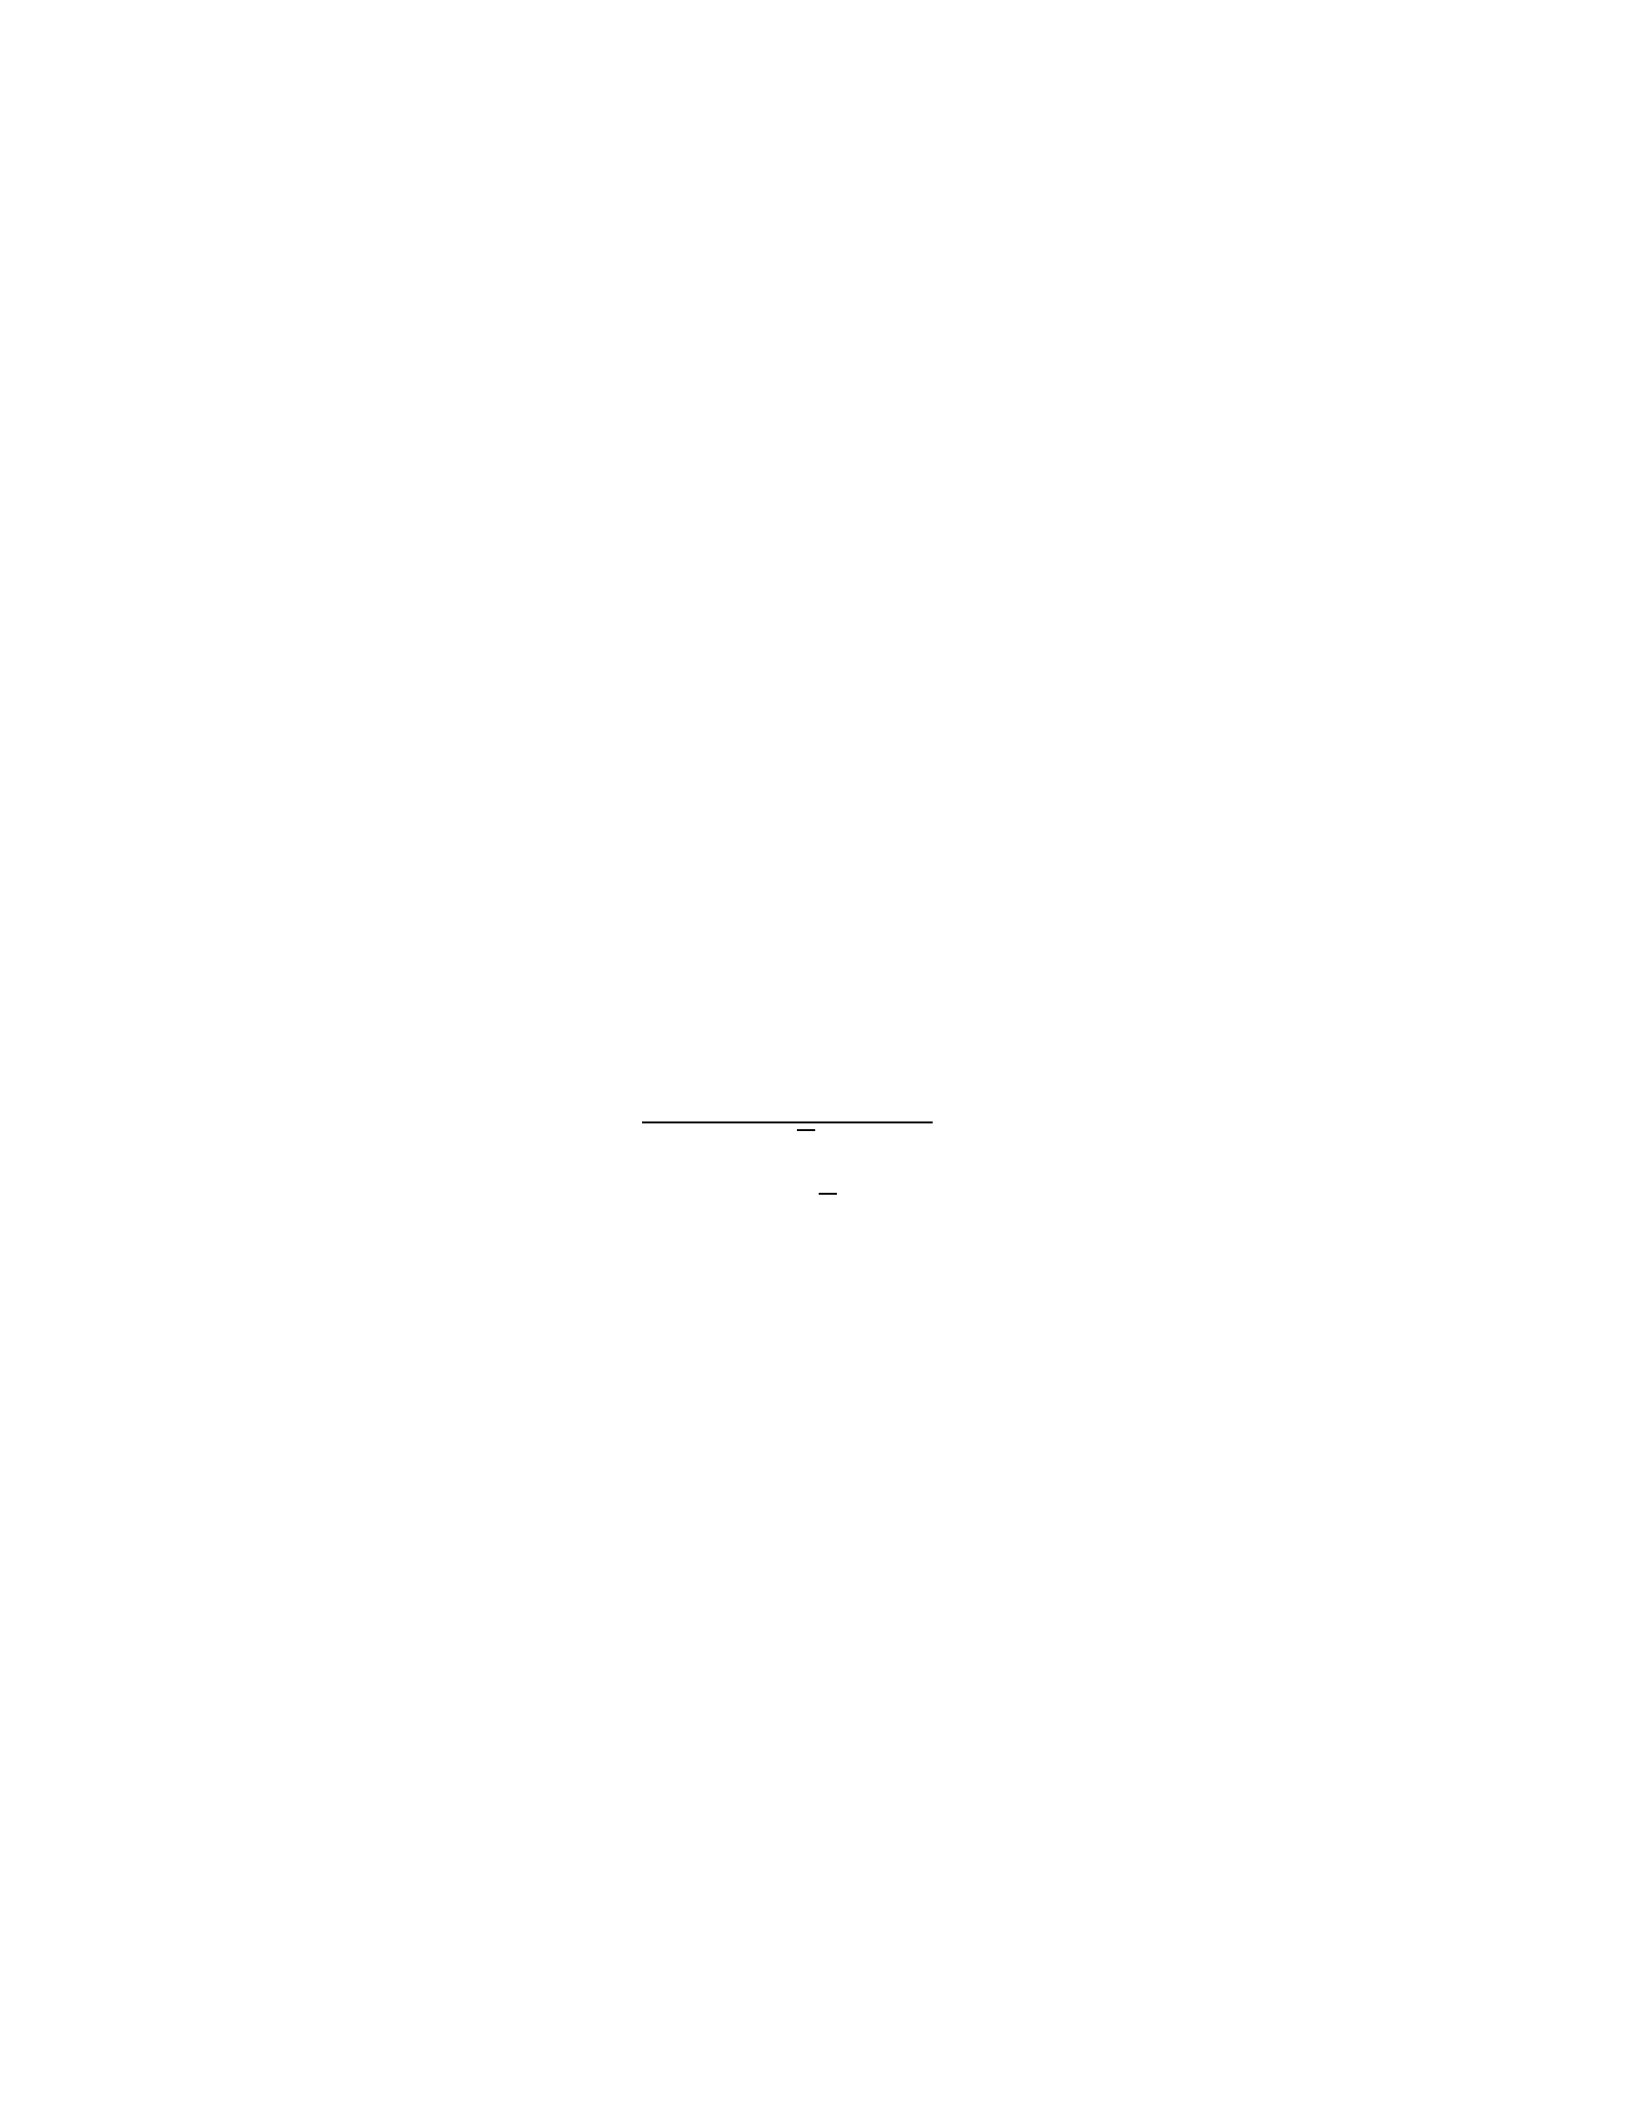
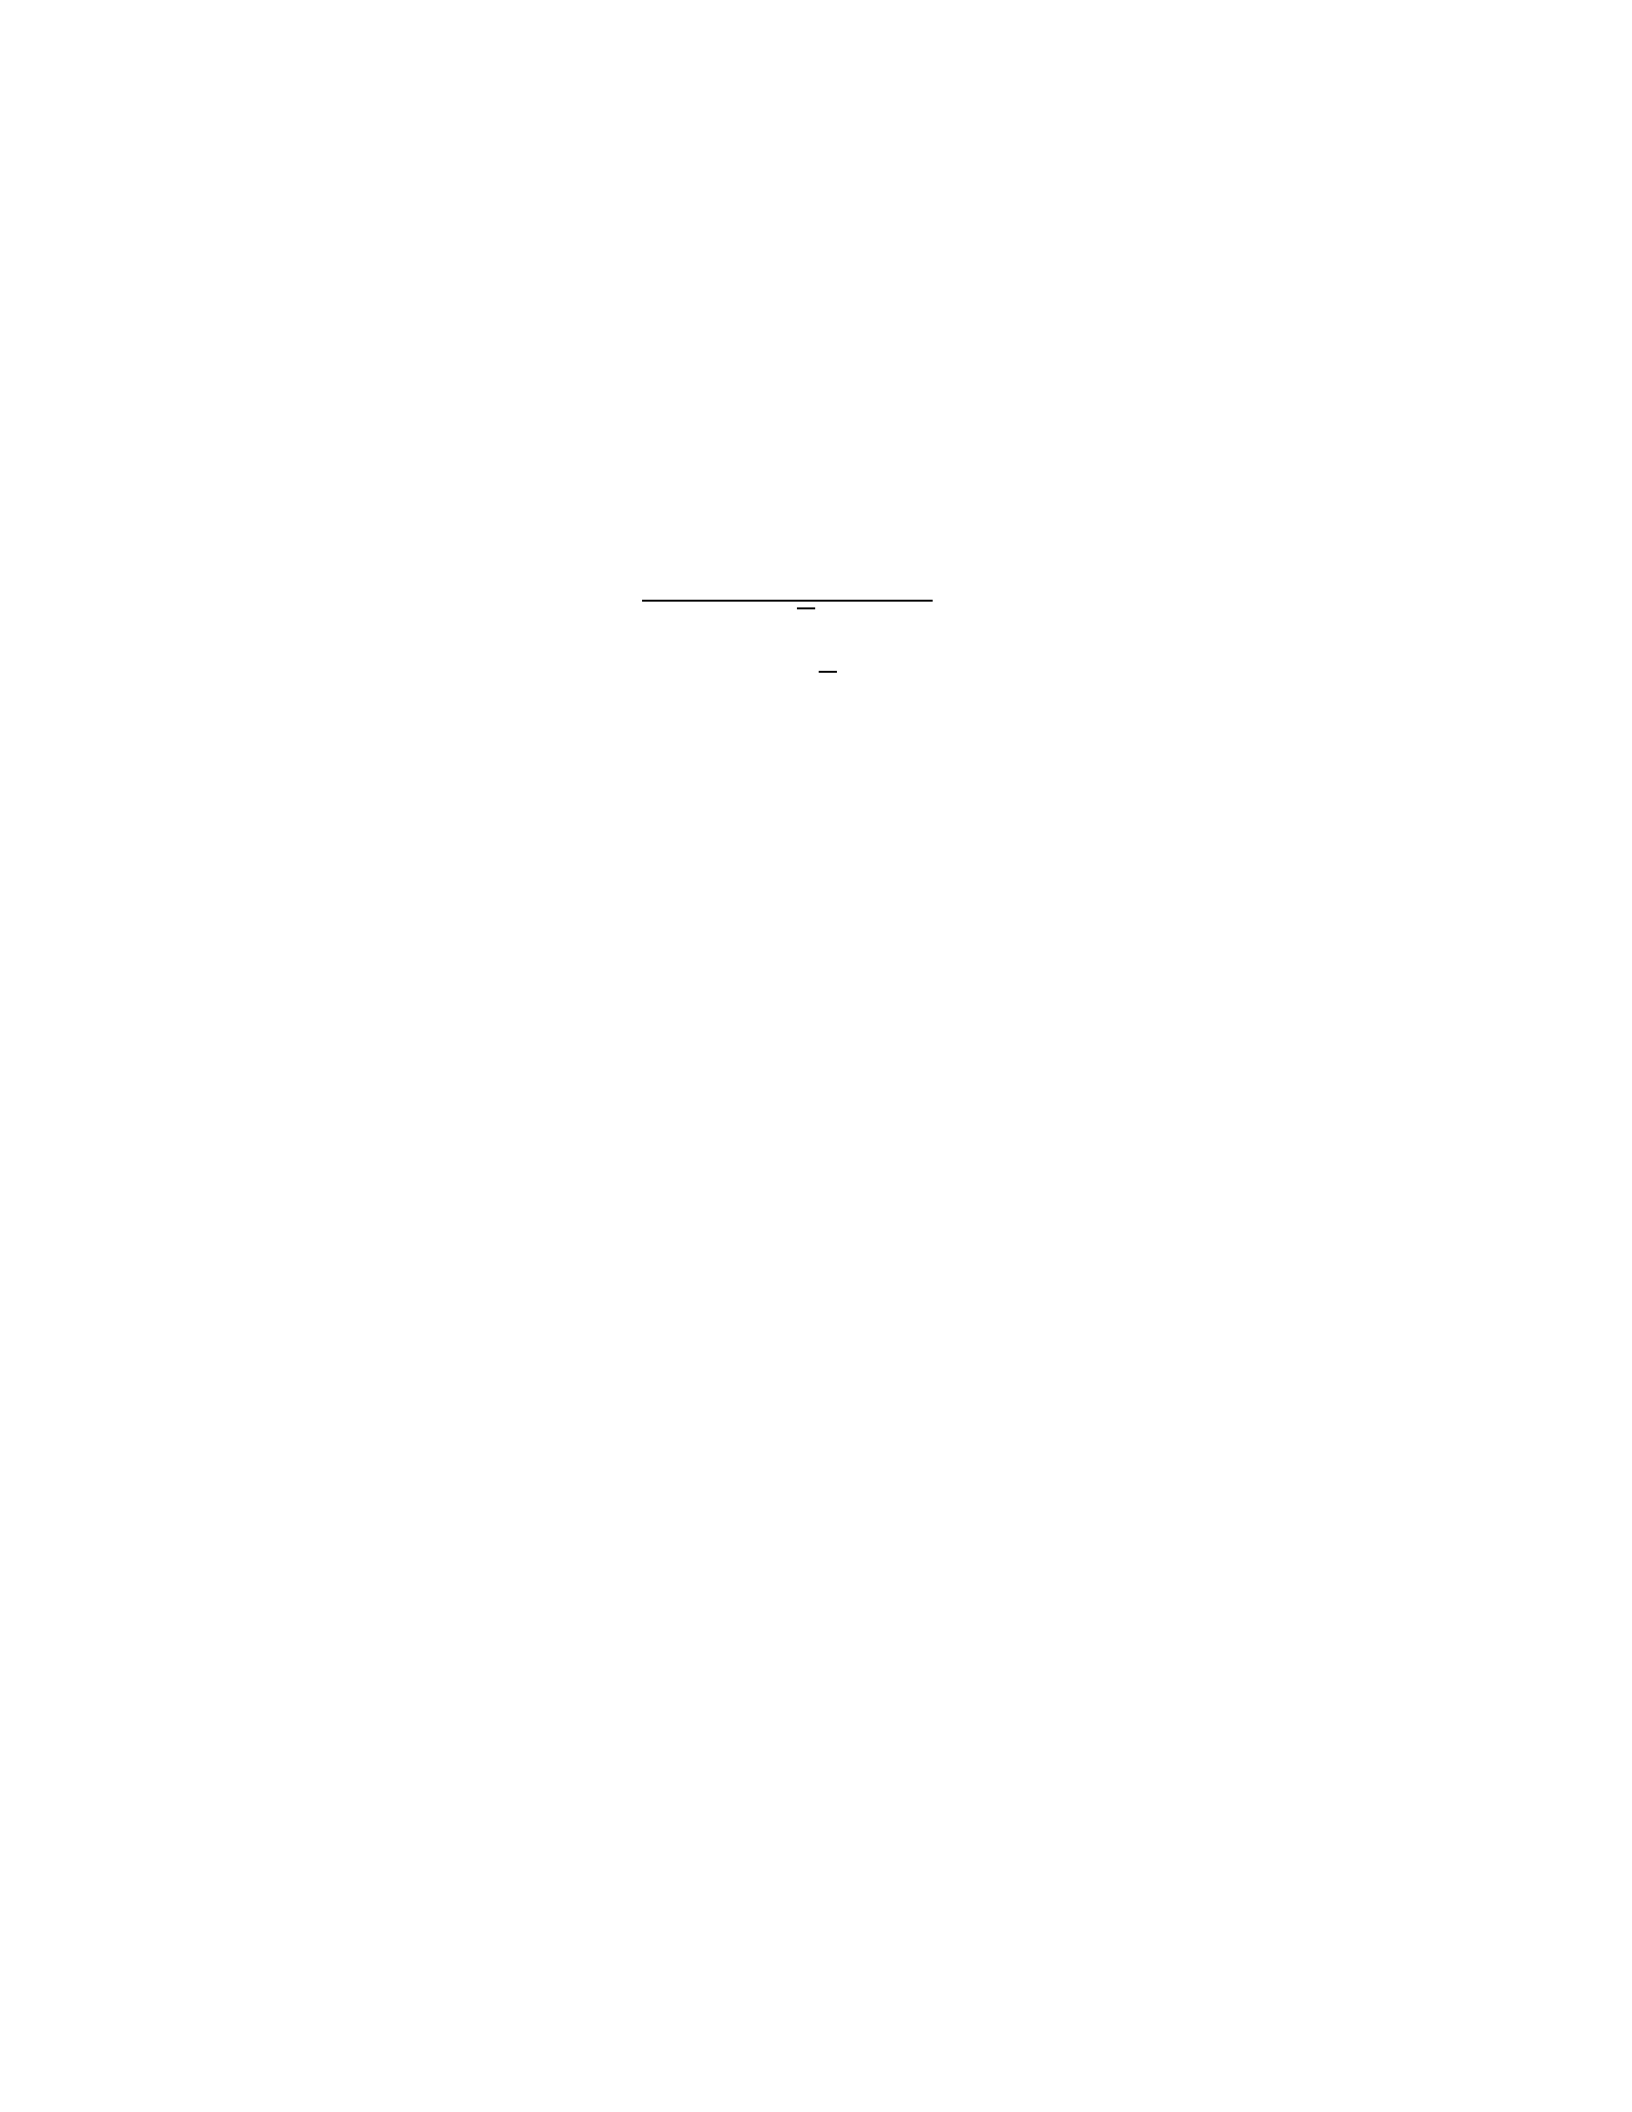
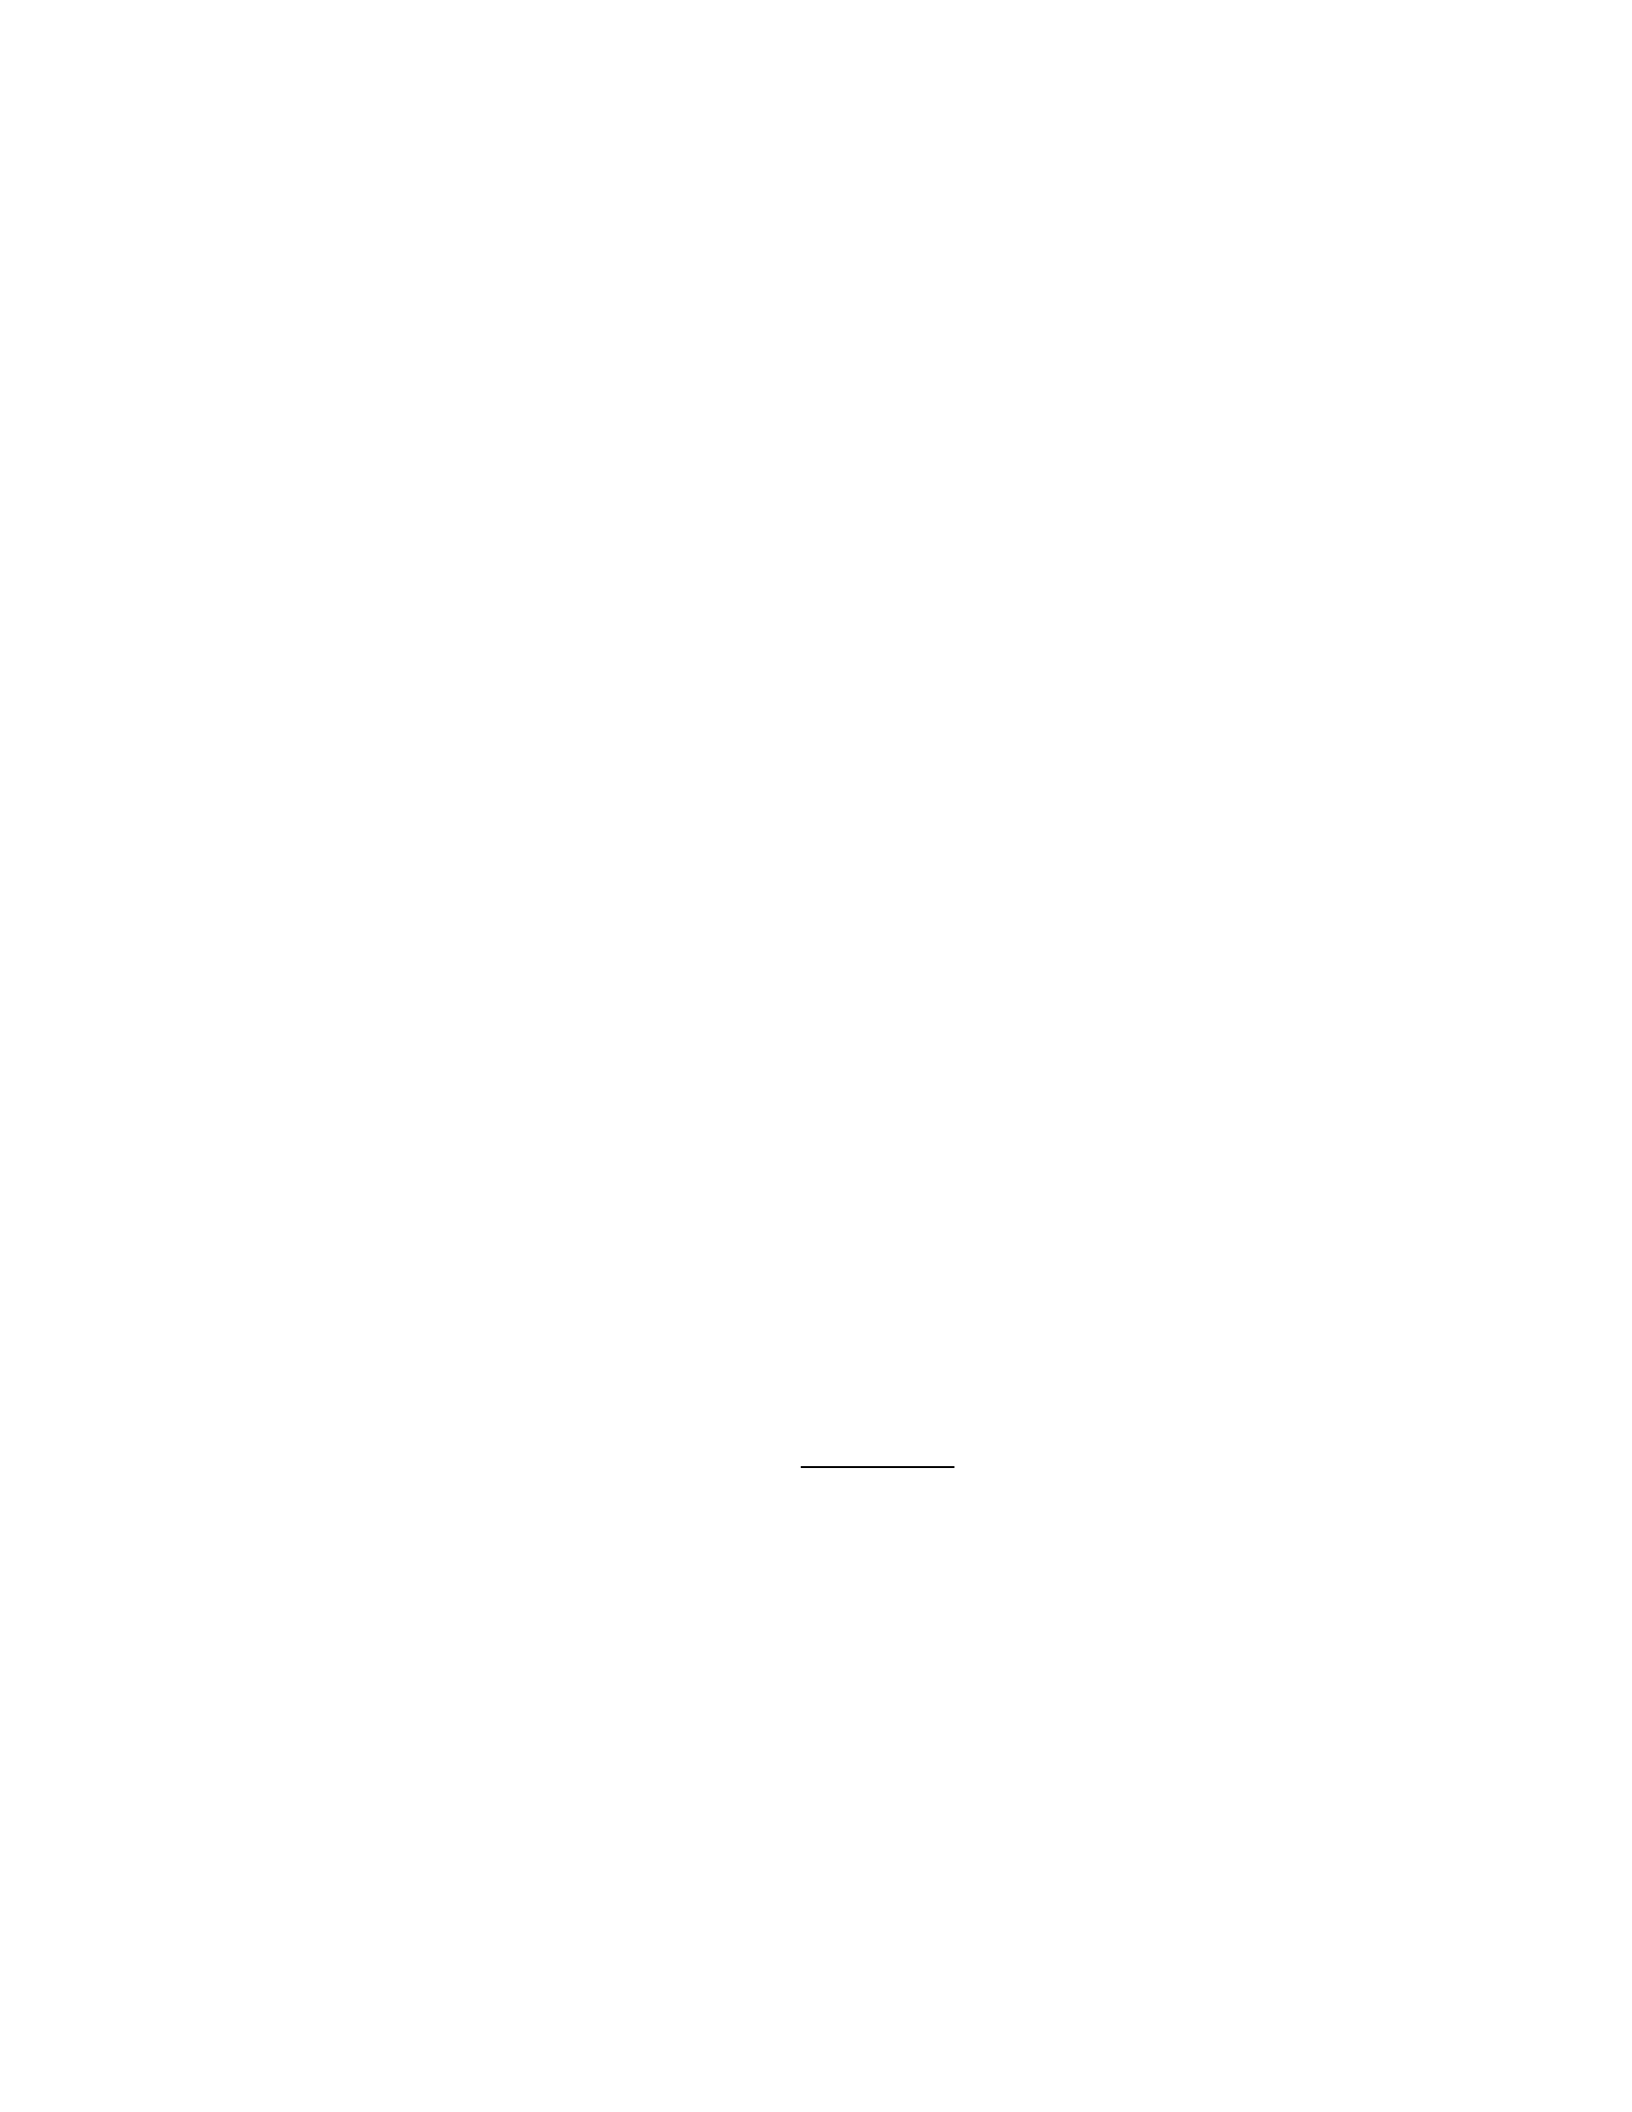
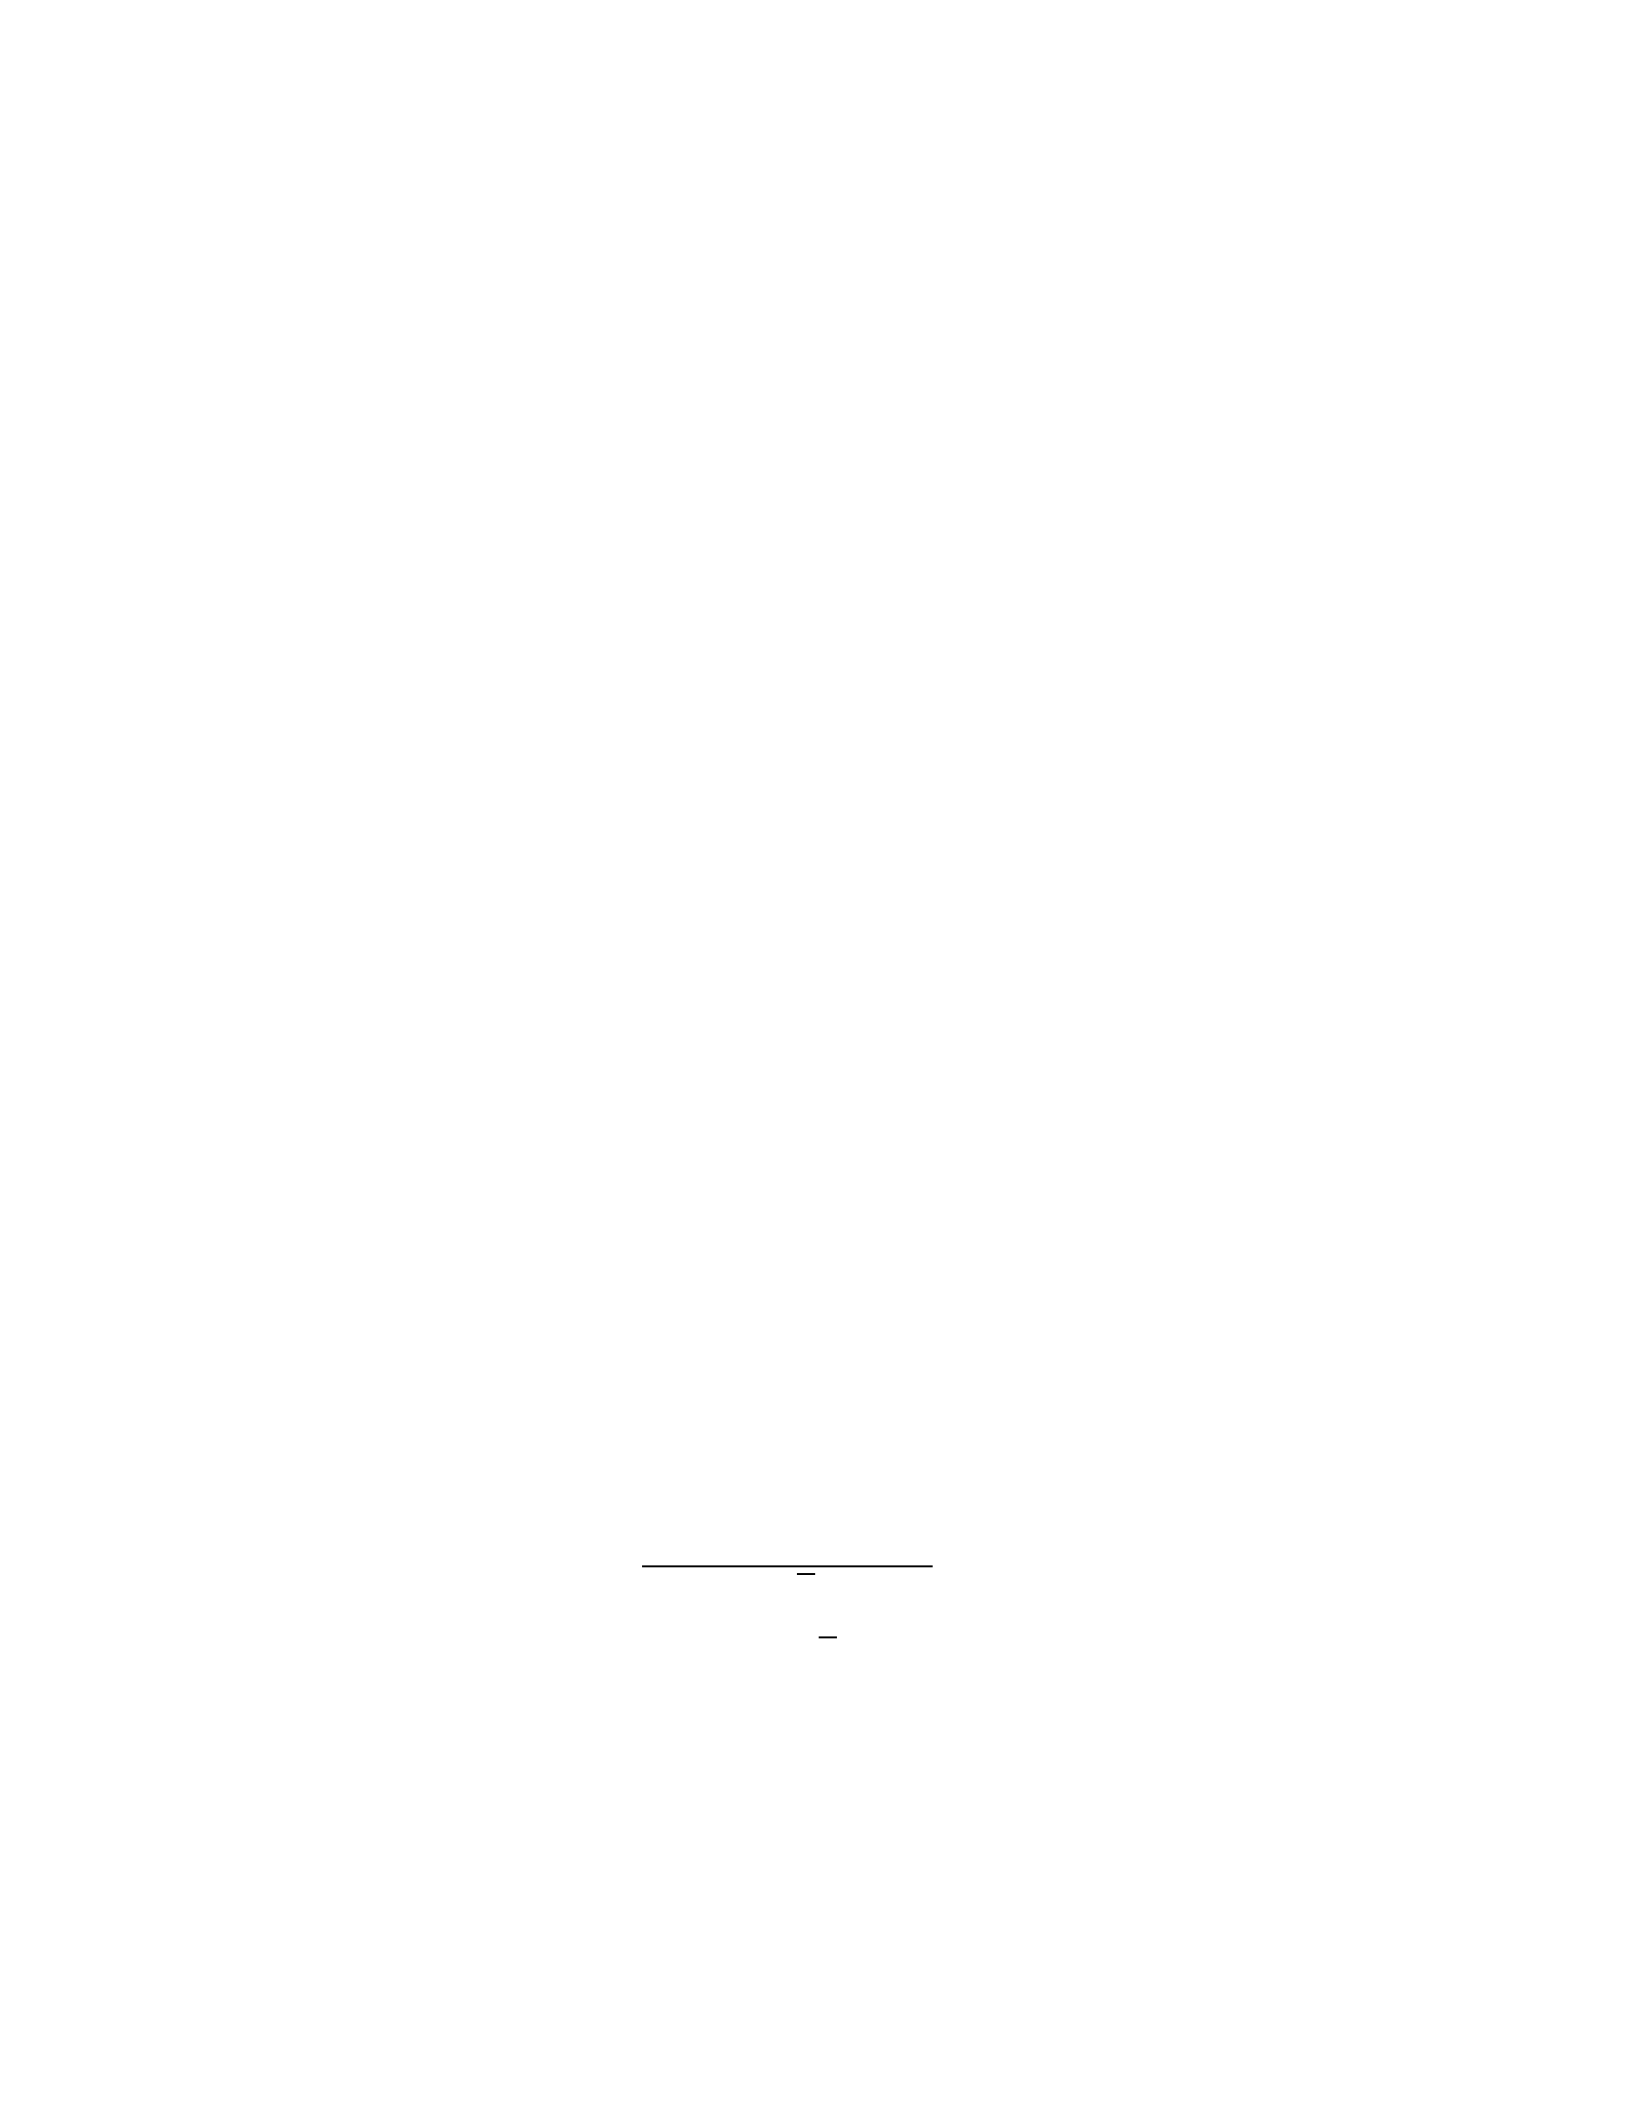
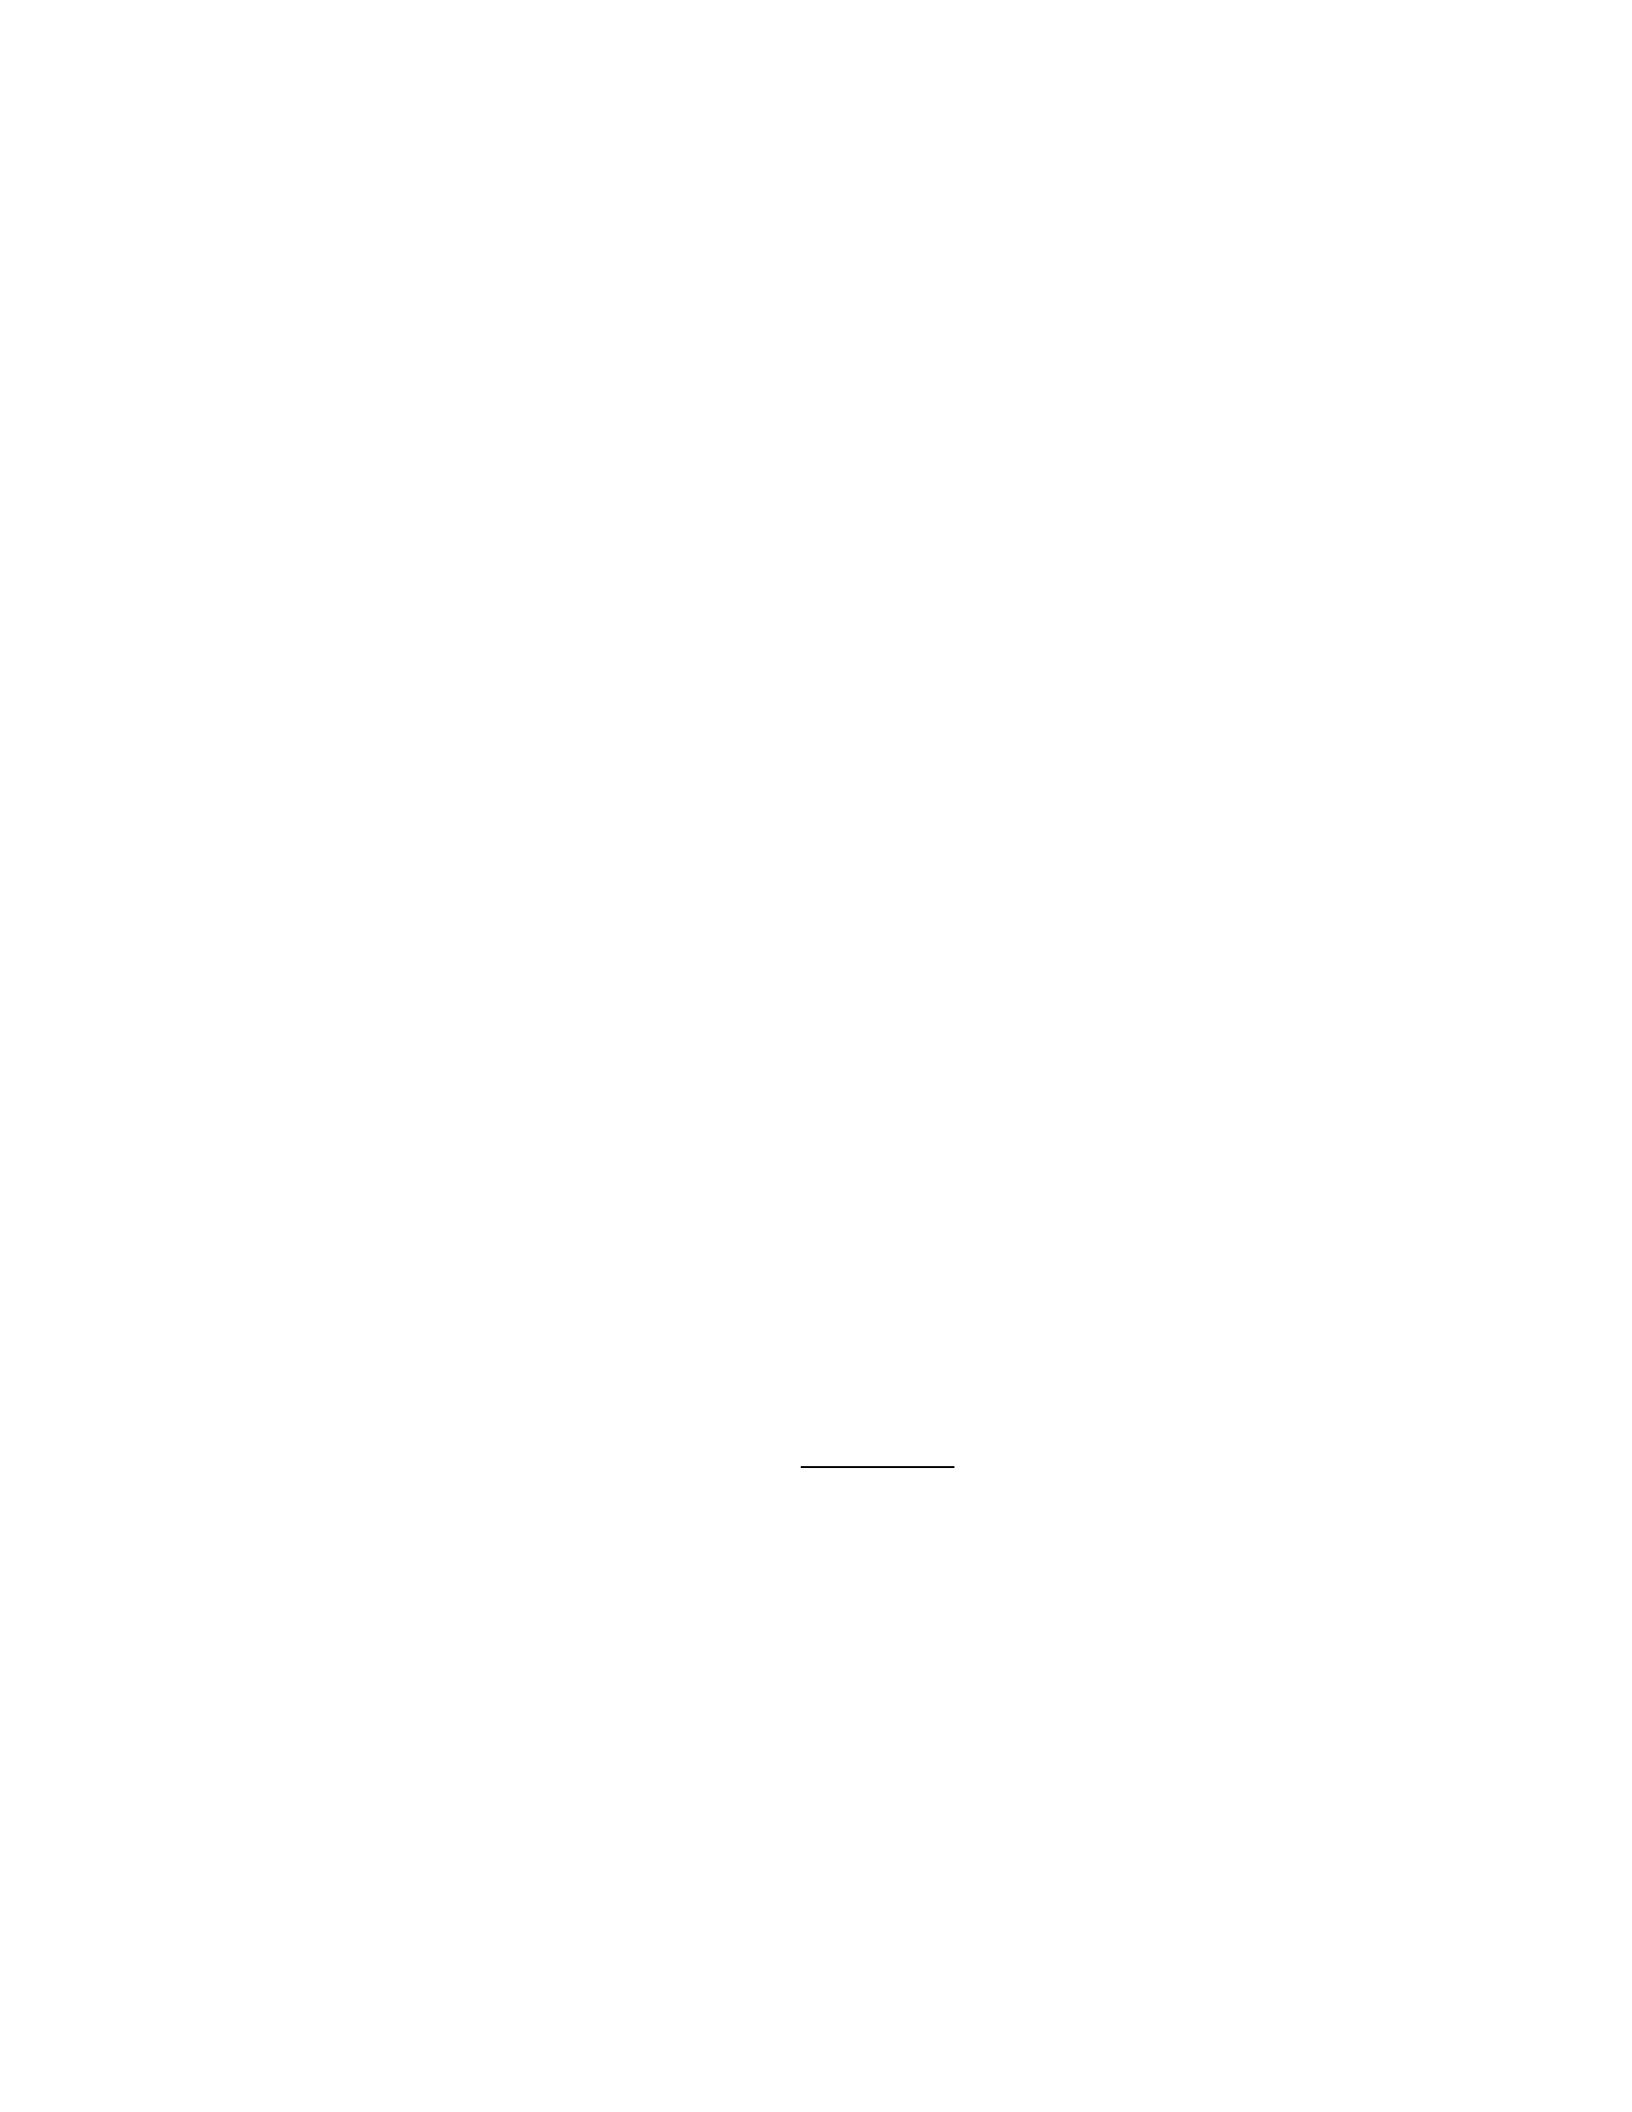
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
2. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:

a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
3. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
4. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit

from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
5. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
6. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options

and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
7. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
8. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
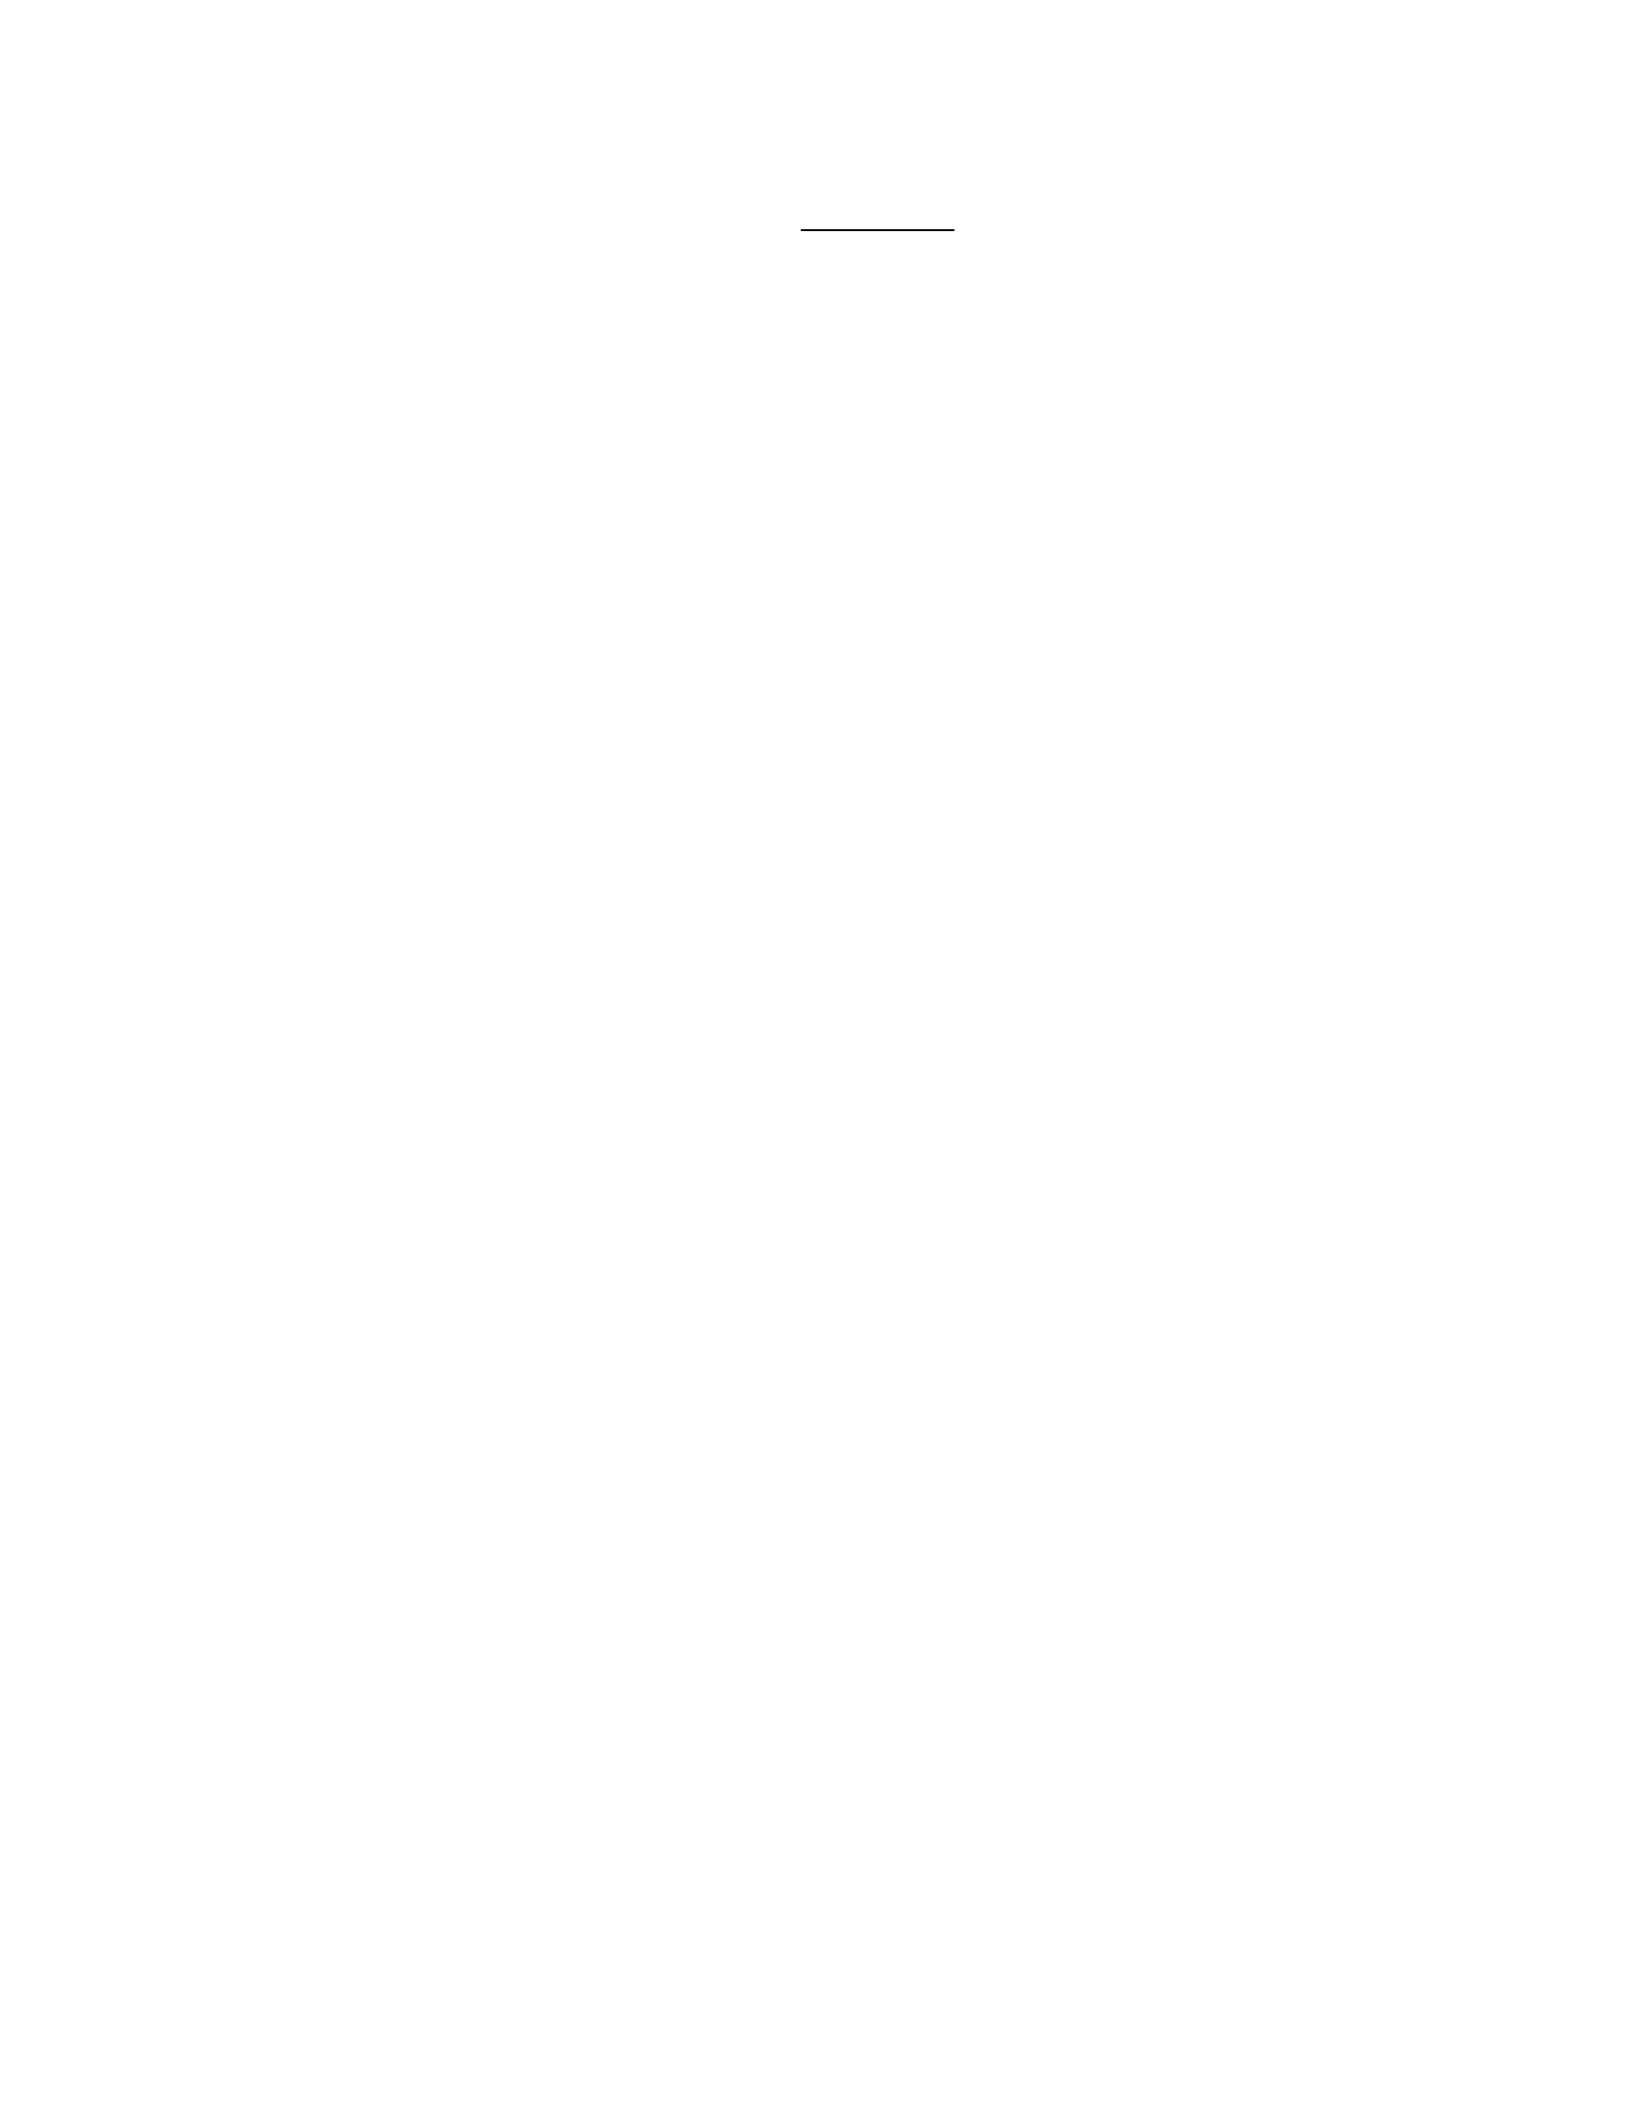
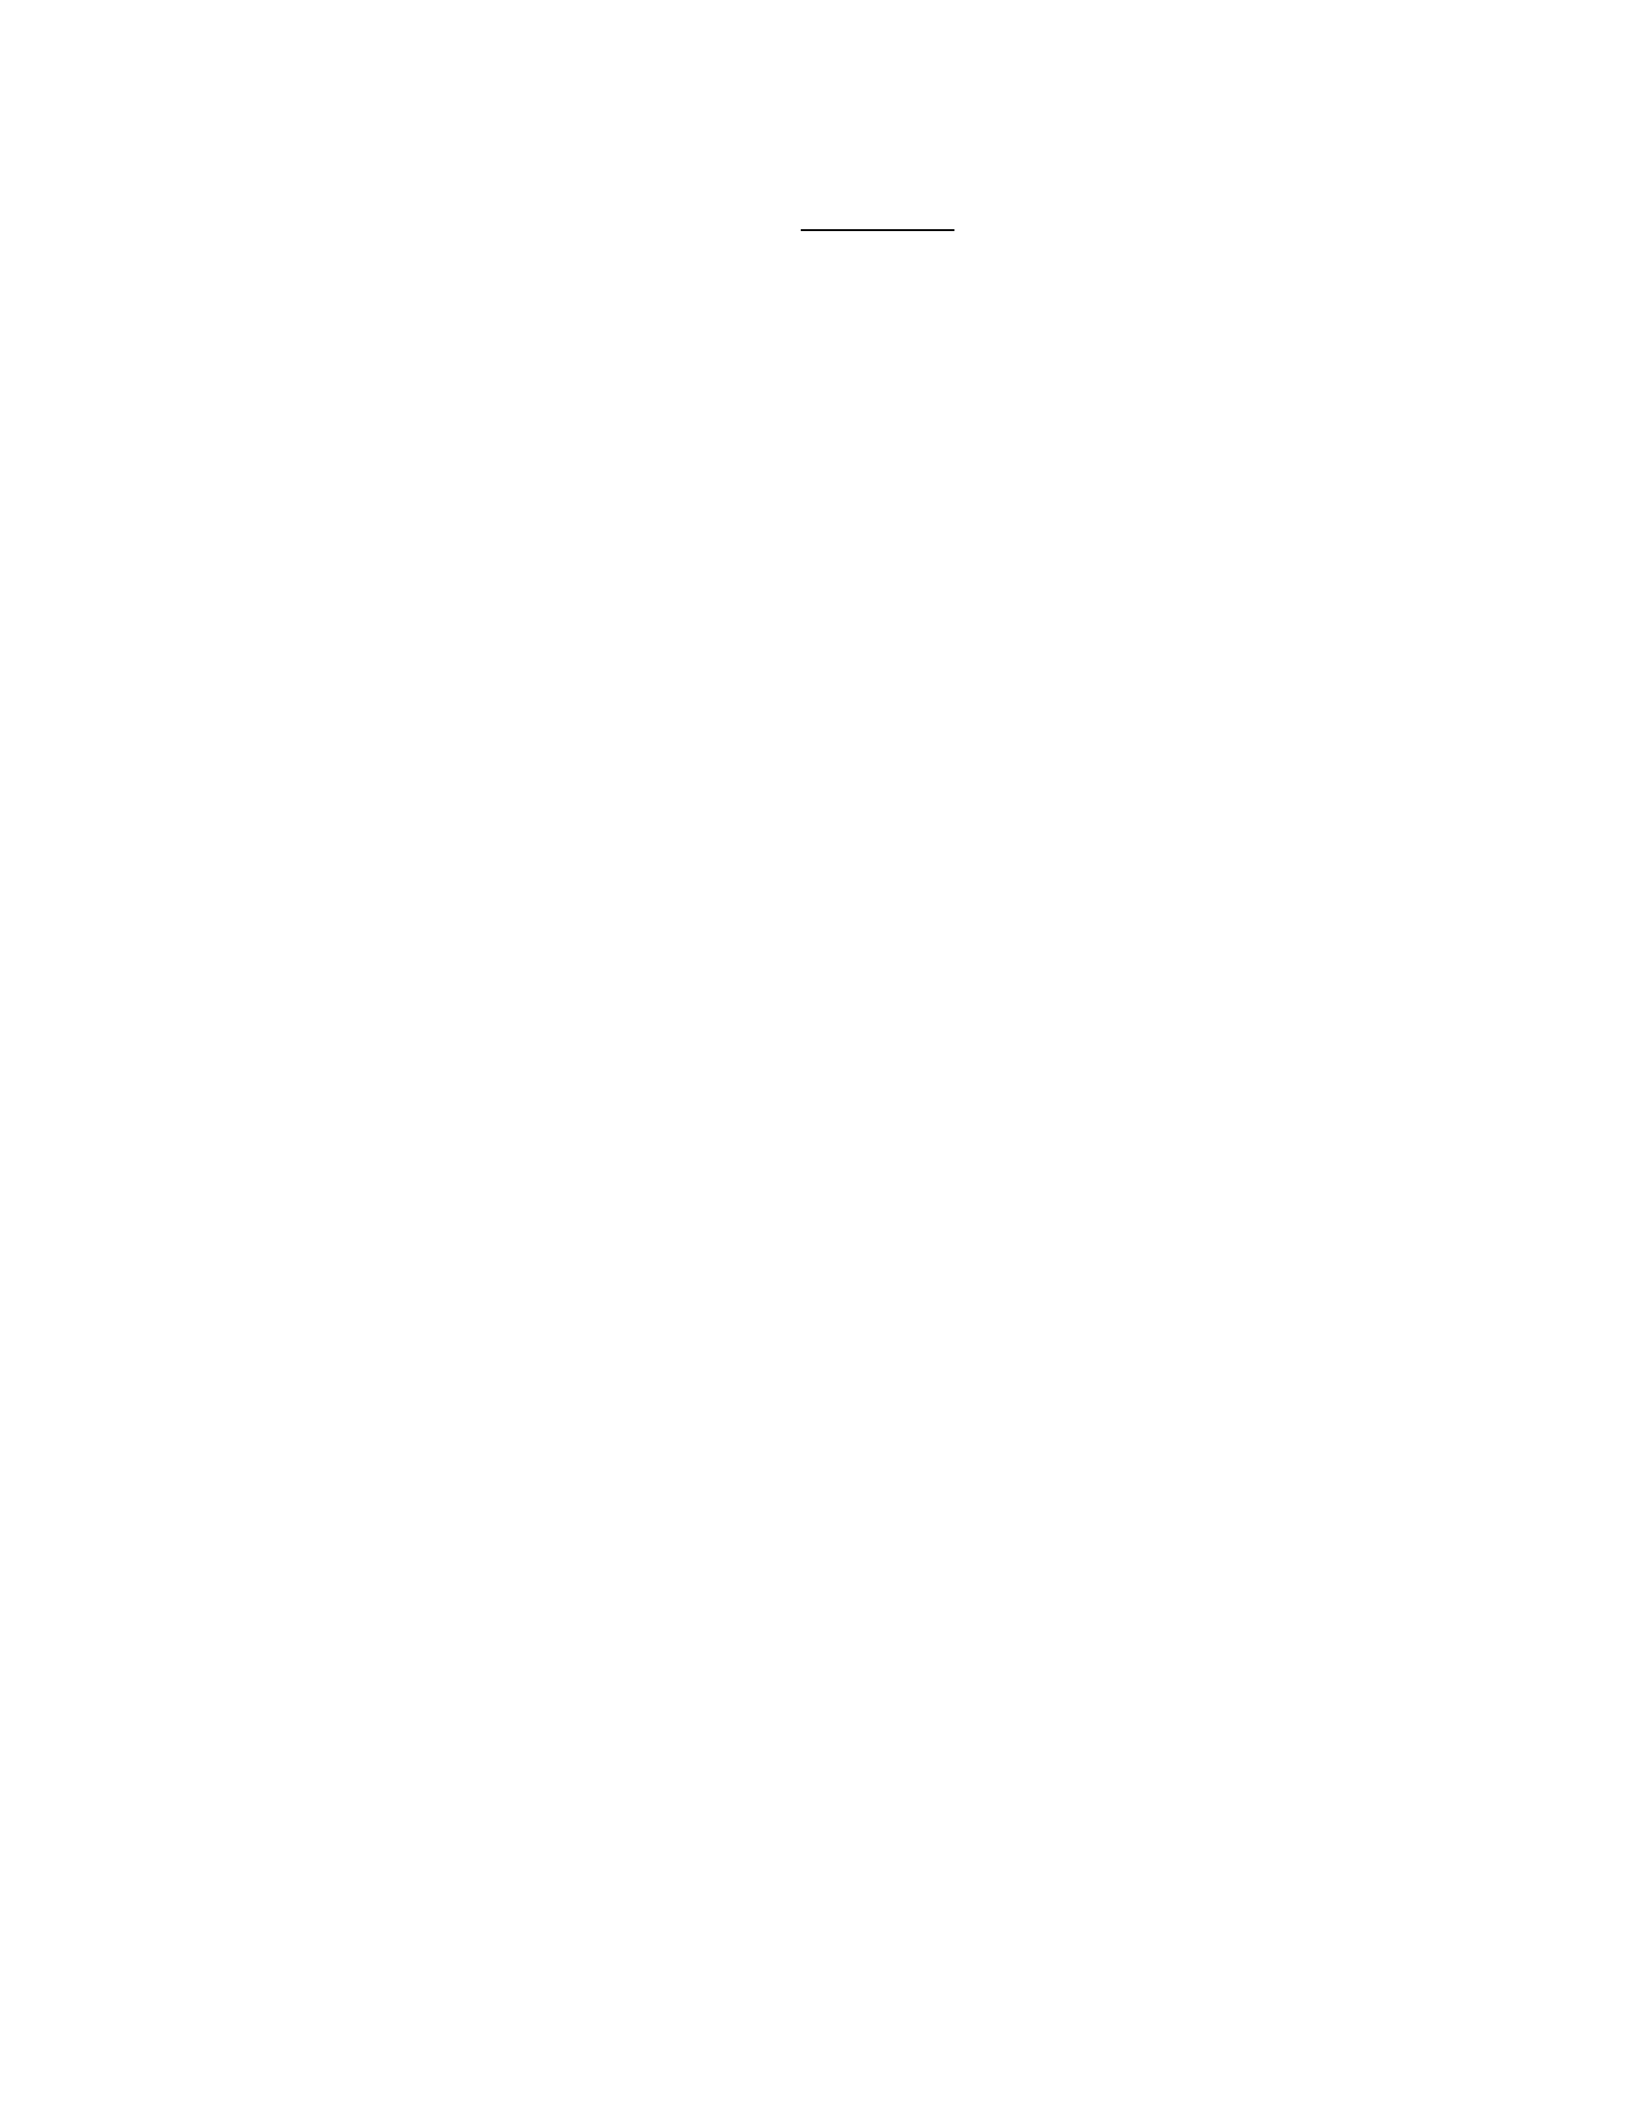
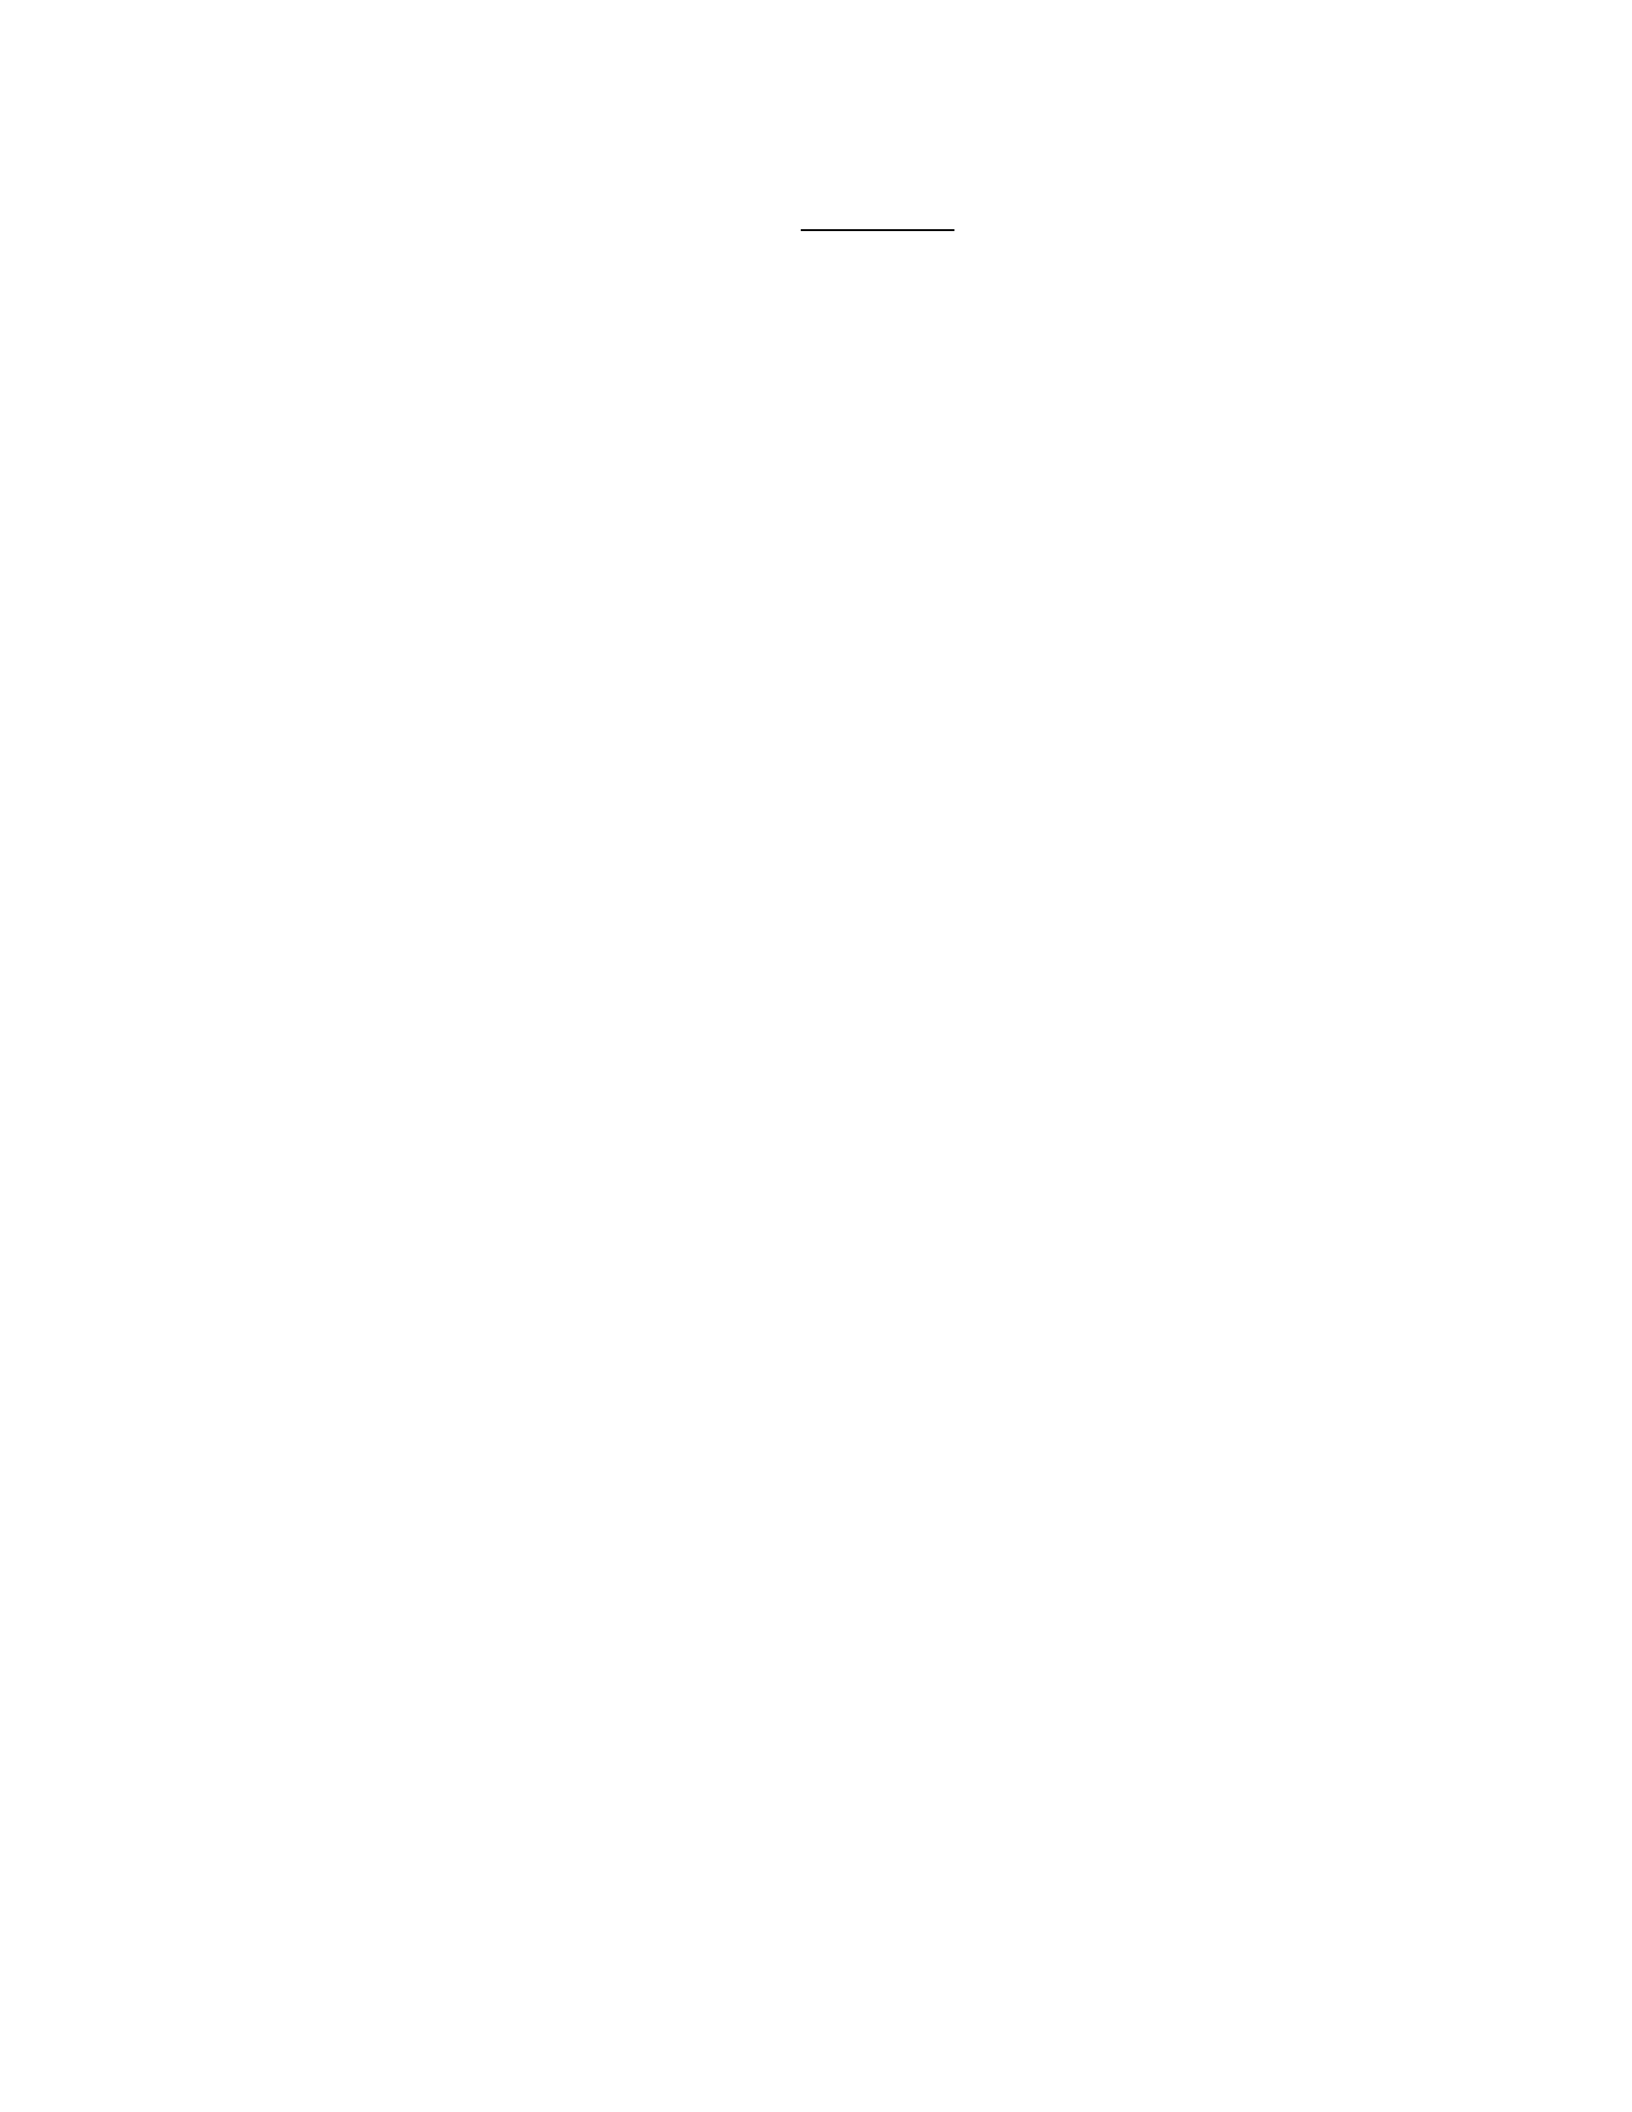
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
9. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
10. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
11. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
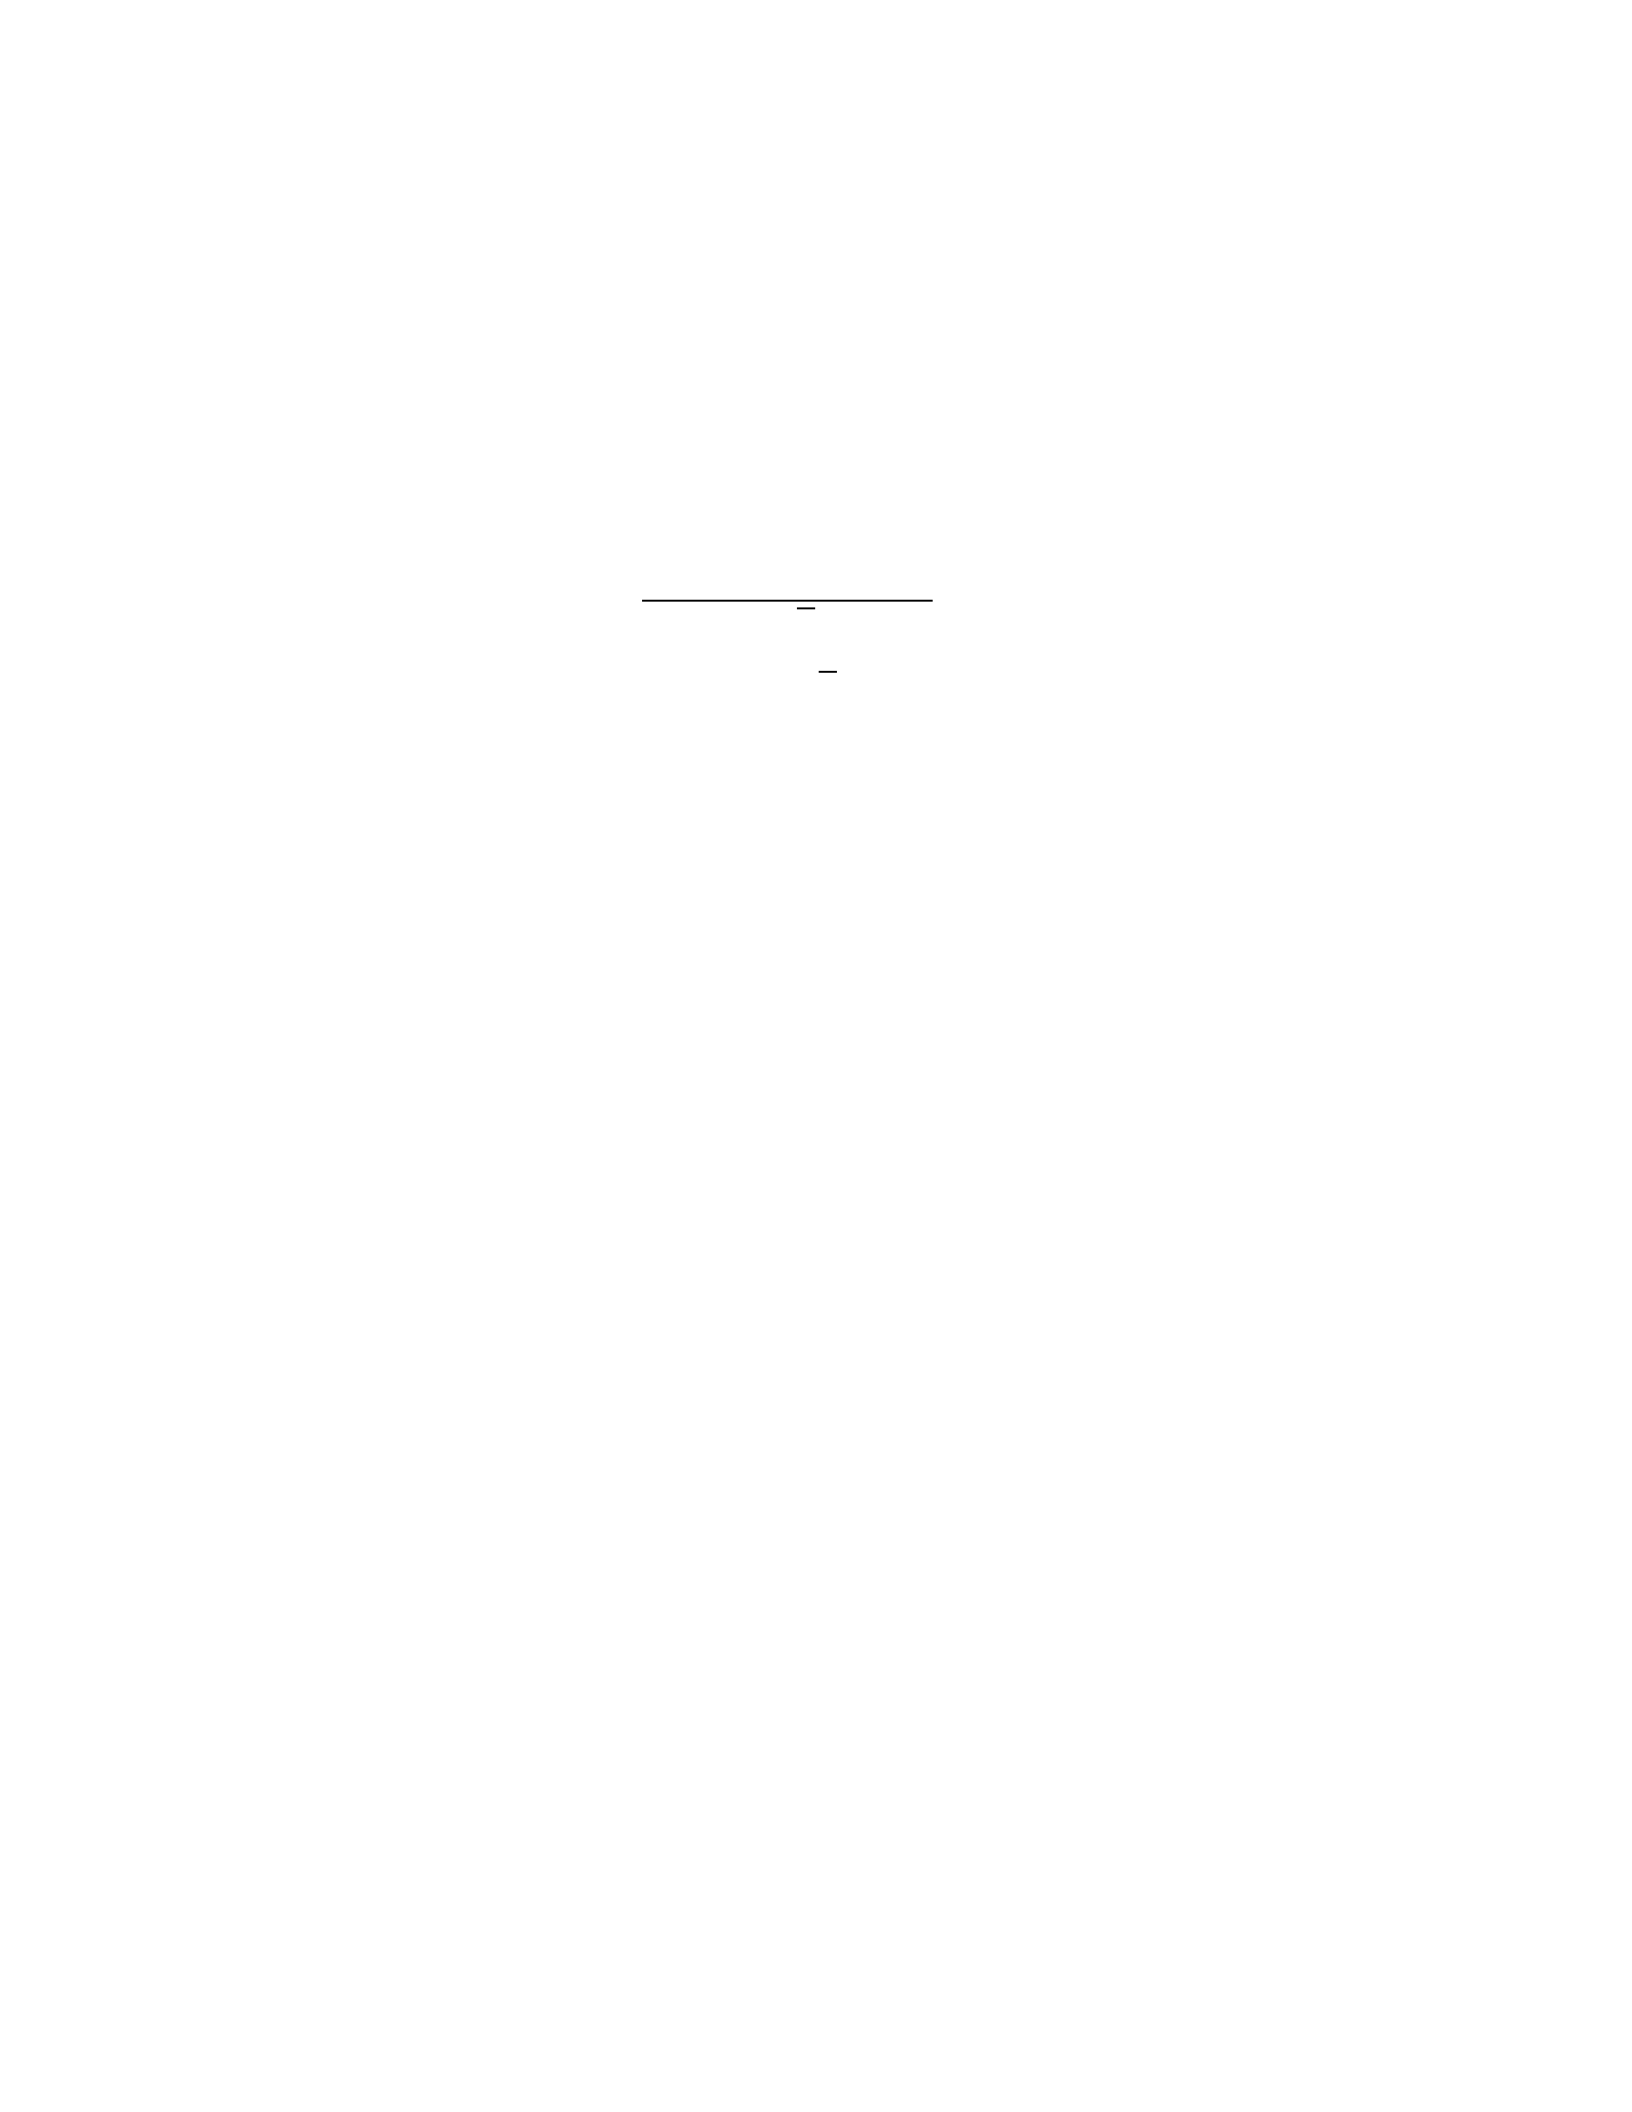
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
12. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500

• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
13. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
14. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:

• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
15. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
16. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
17. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
18. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
19. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%

– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
20. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
21. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
22. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
23. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:

a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
24. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10

– Breakeven points: $90 and $110
25. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
26. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
27. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
28. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
29. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
30. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
31. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula

𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
32. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
33. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711

• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
34. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
35. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:

– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
36. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
37. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
38. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
39. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
40. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
41. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
42. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:

a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
43. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
44. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit

from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
45. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
46. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options

and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
47. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
48. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
49. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
50. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
51. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
52. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500

• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
53. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
54. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:

• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
55. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
56. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
57. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
58. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
59. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%

– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
60. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
61. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
62. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
63. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:

a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
64. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10

– Breakeven points: $90 and $110
65. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
66. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
67. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
68. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
69. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
70. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
71. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula

𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
72. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
73. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711

• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
74. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
75. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:

– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
76. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
77. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
78. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
79. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
80. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
81. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
82. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:

a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
83. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
84. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit

from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
85. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
86. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options

and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
87. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
88. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
89. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
90. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
91. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
92. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500

• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
93. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
94. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:

• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
95. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
96. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
97. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
98. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
99. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%

– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
100. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
101. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
102. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
103. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:

a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
104. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10

– Breakeven points: $90 and $110
105. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
106. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
107. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
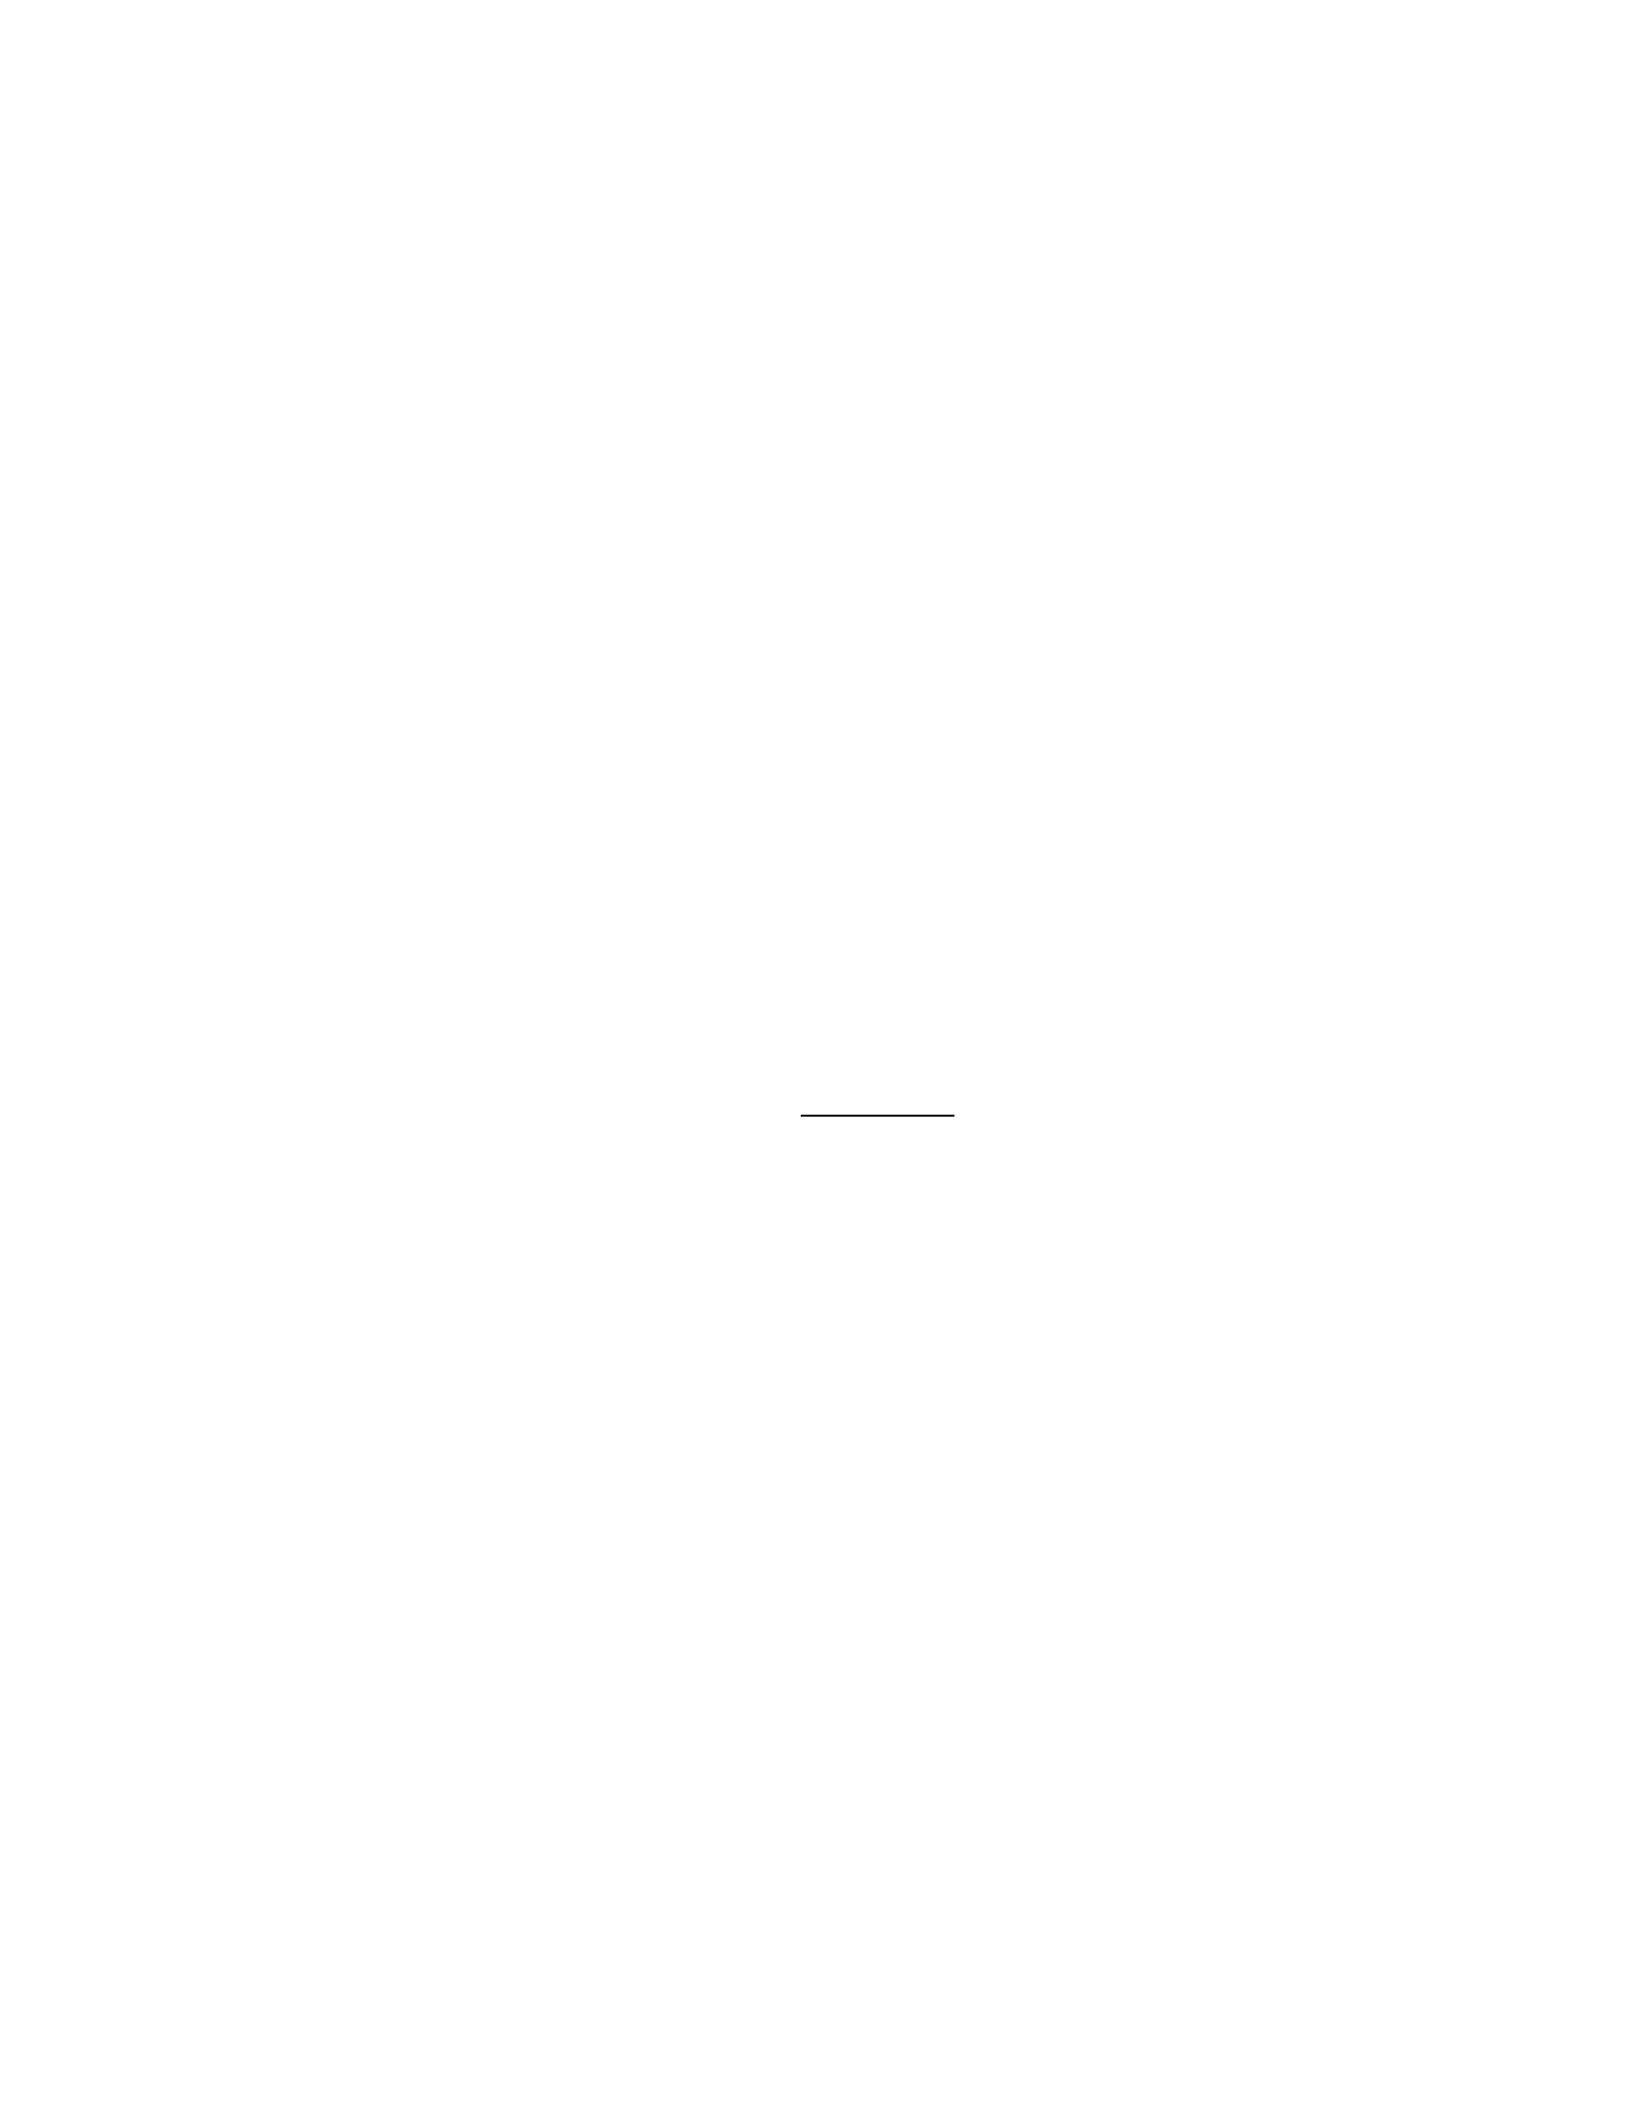
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
108. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
109. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
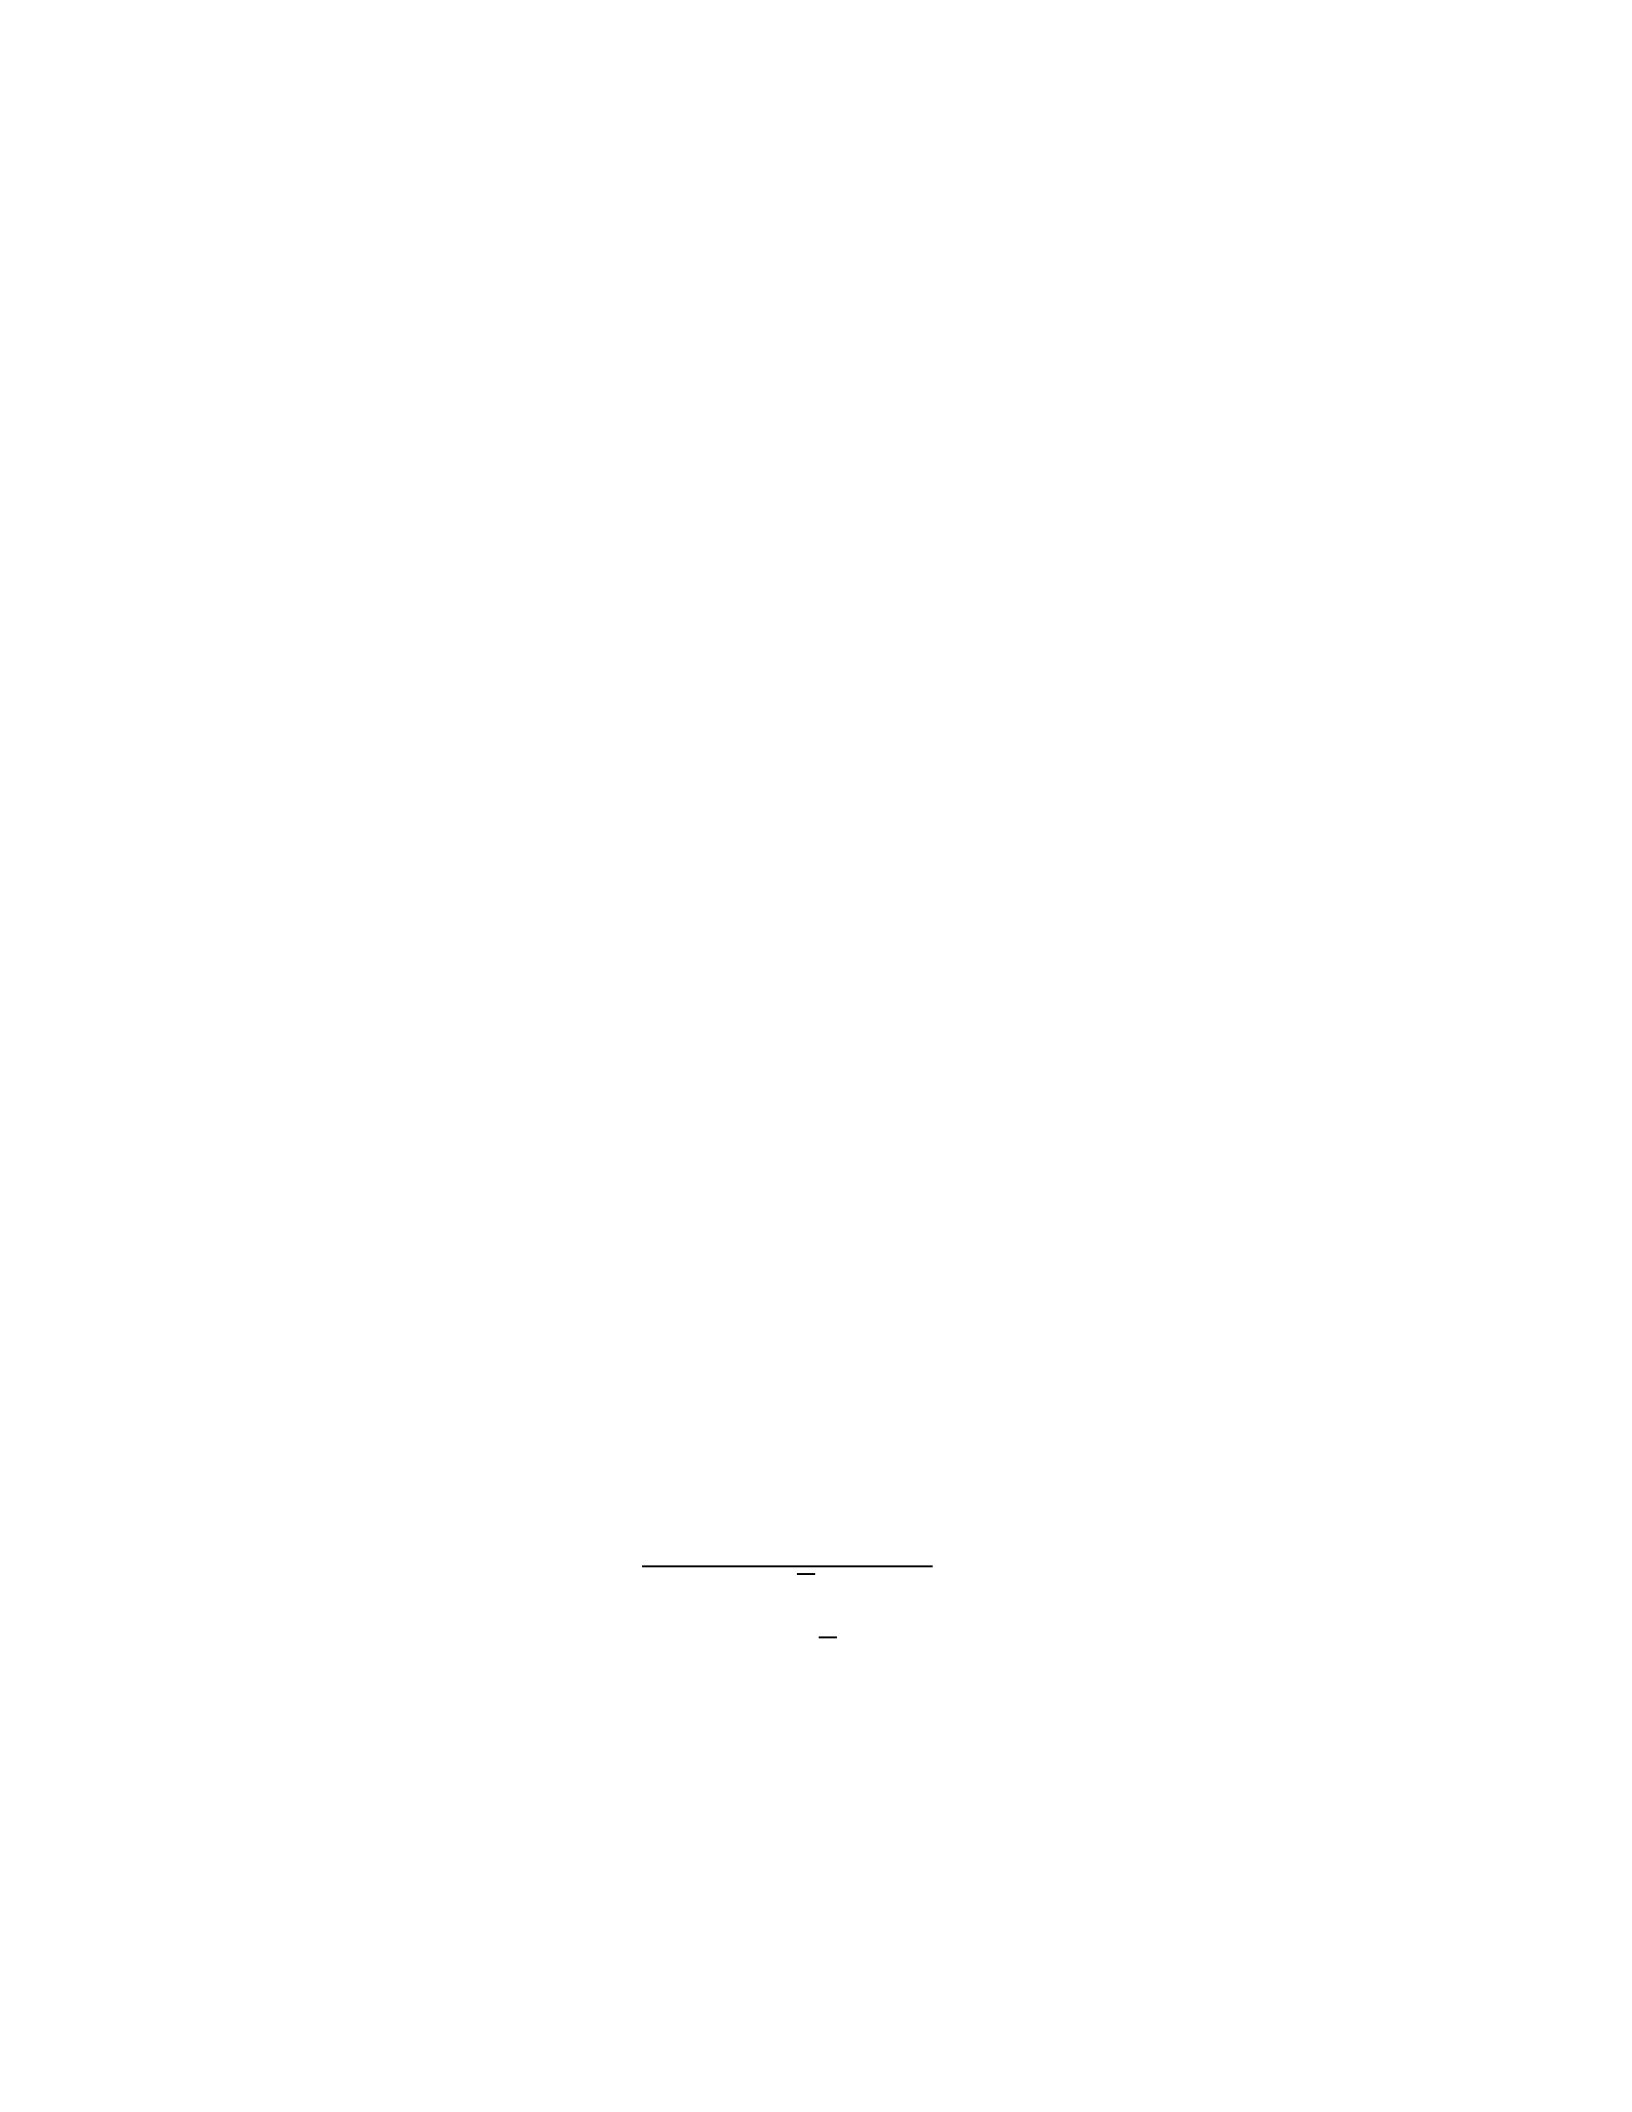
110. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
111. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula

𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
112. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
113. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711

• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
114. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
115. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:

– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
116. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
117. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
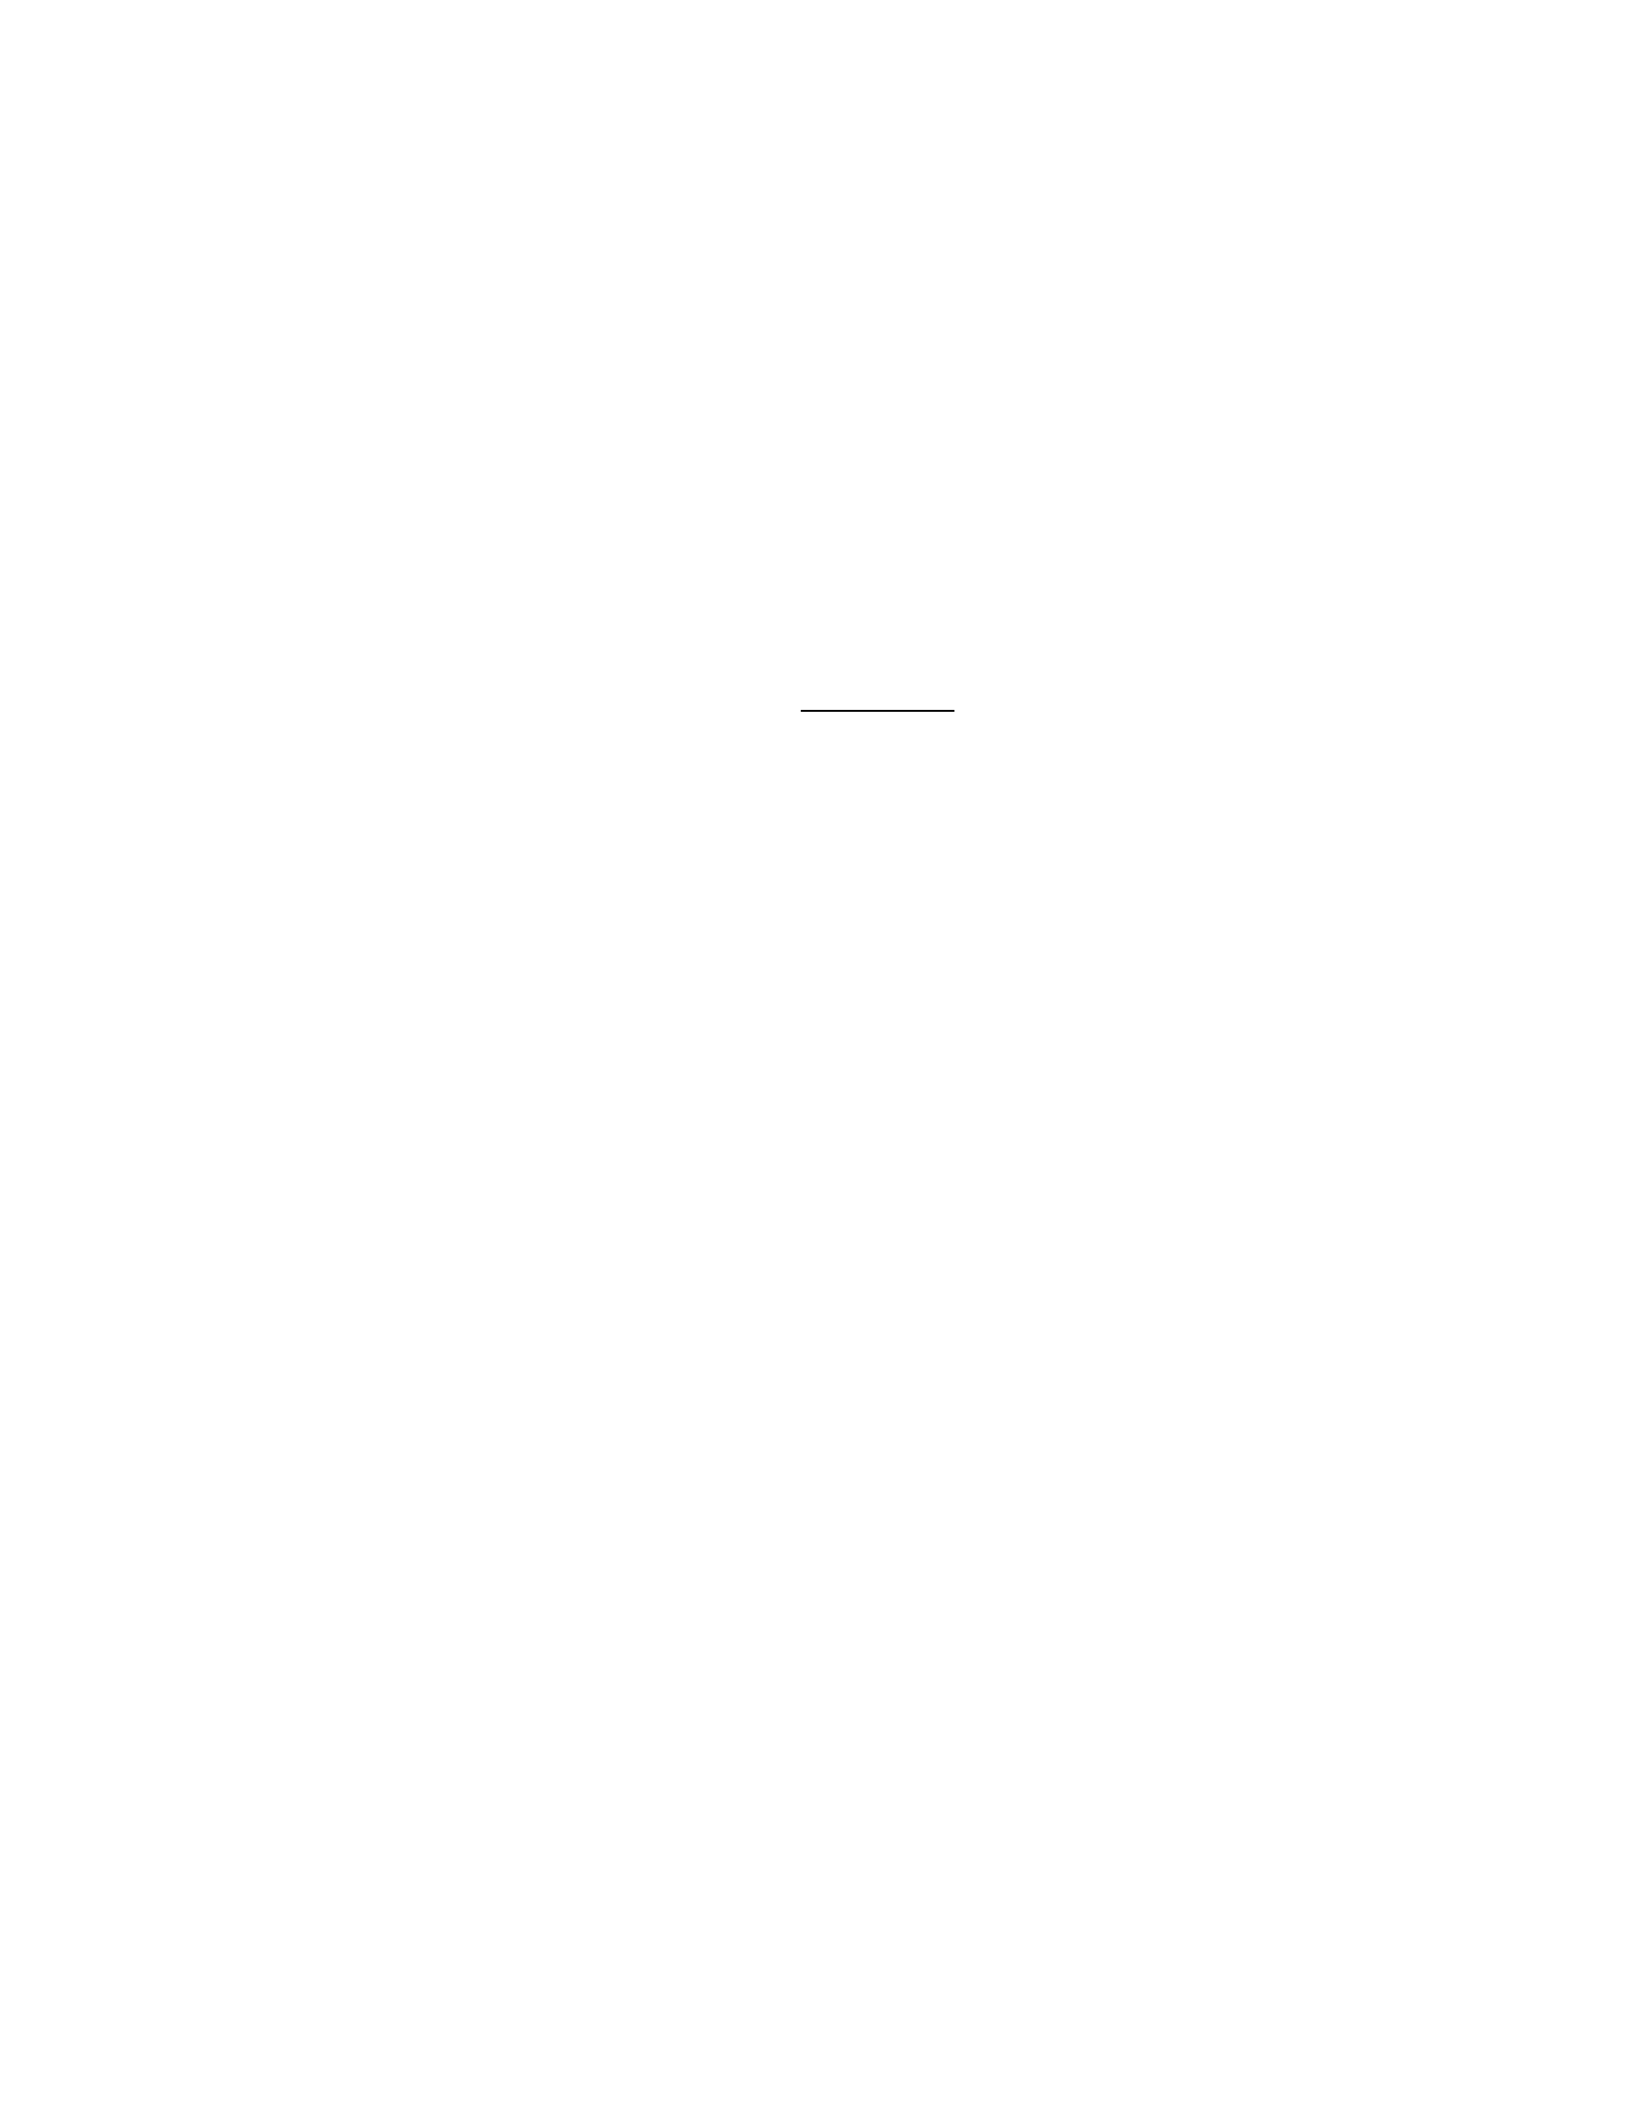
118. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
119. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
120. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
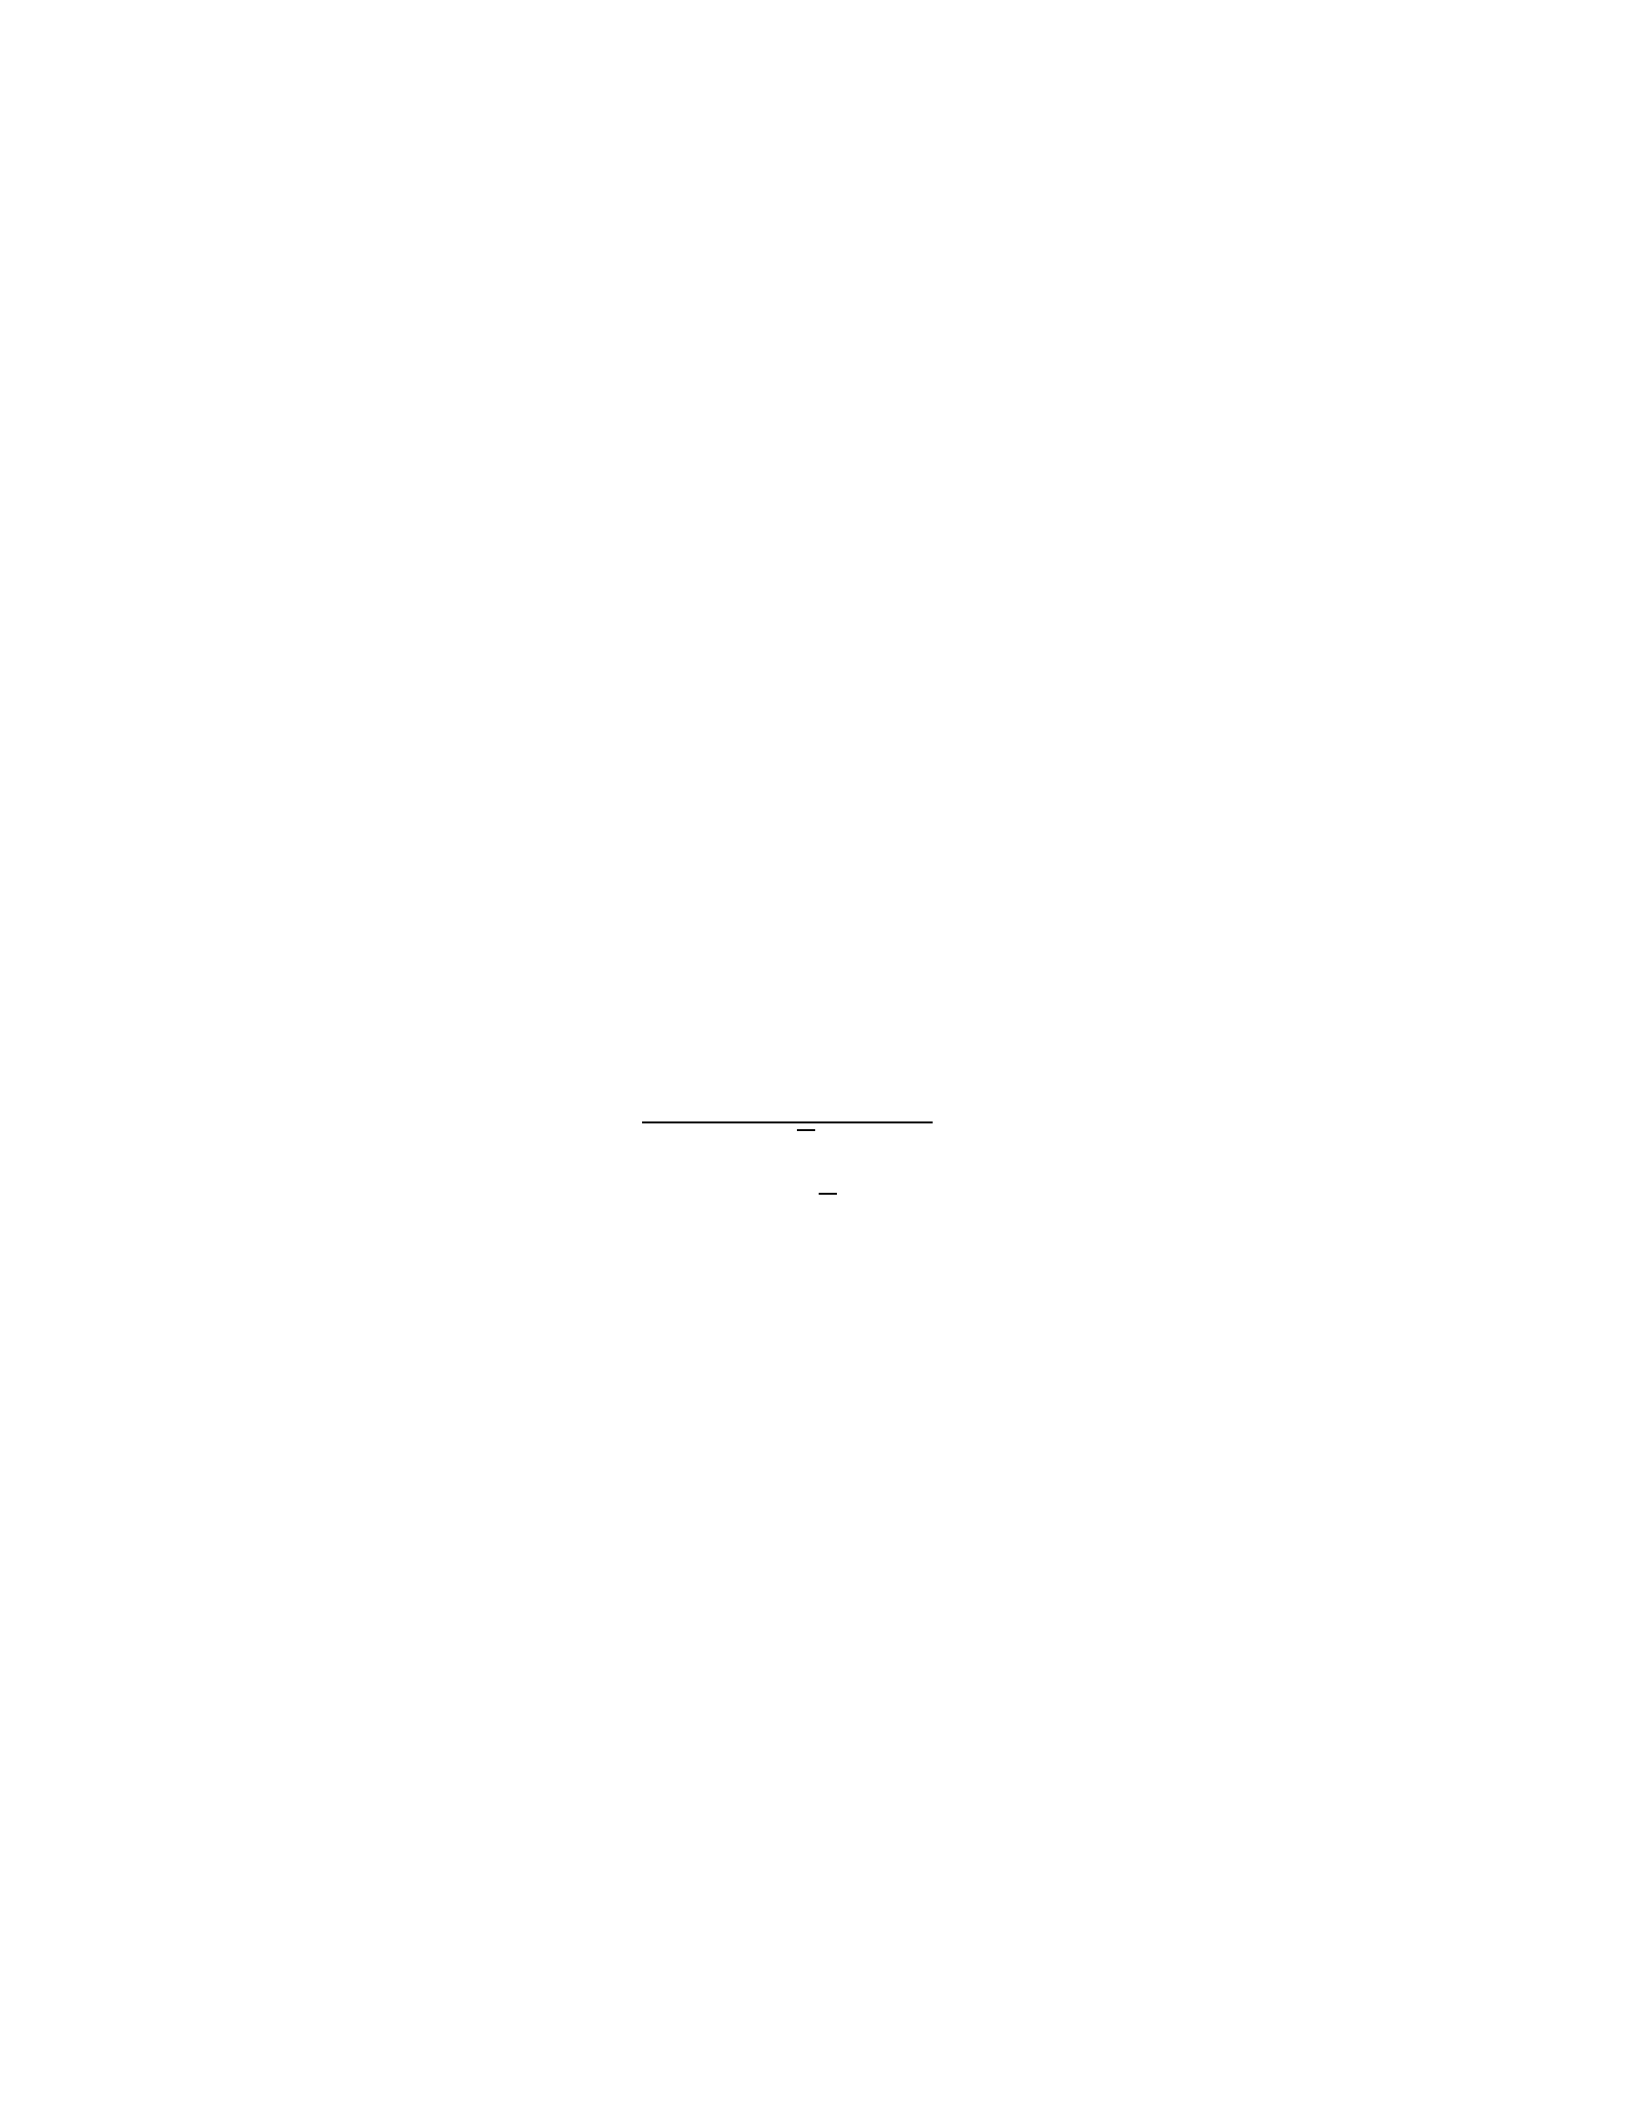
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
121. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
122. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:

a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
123. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
124. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit

from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
125. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
126. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options

and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
127. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
128. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
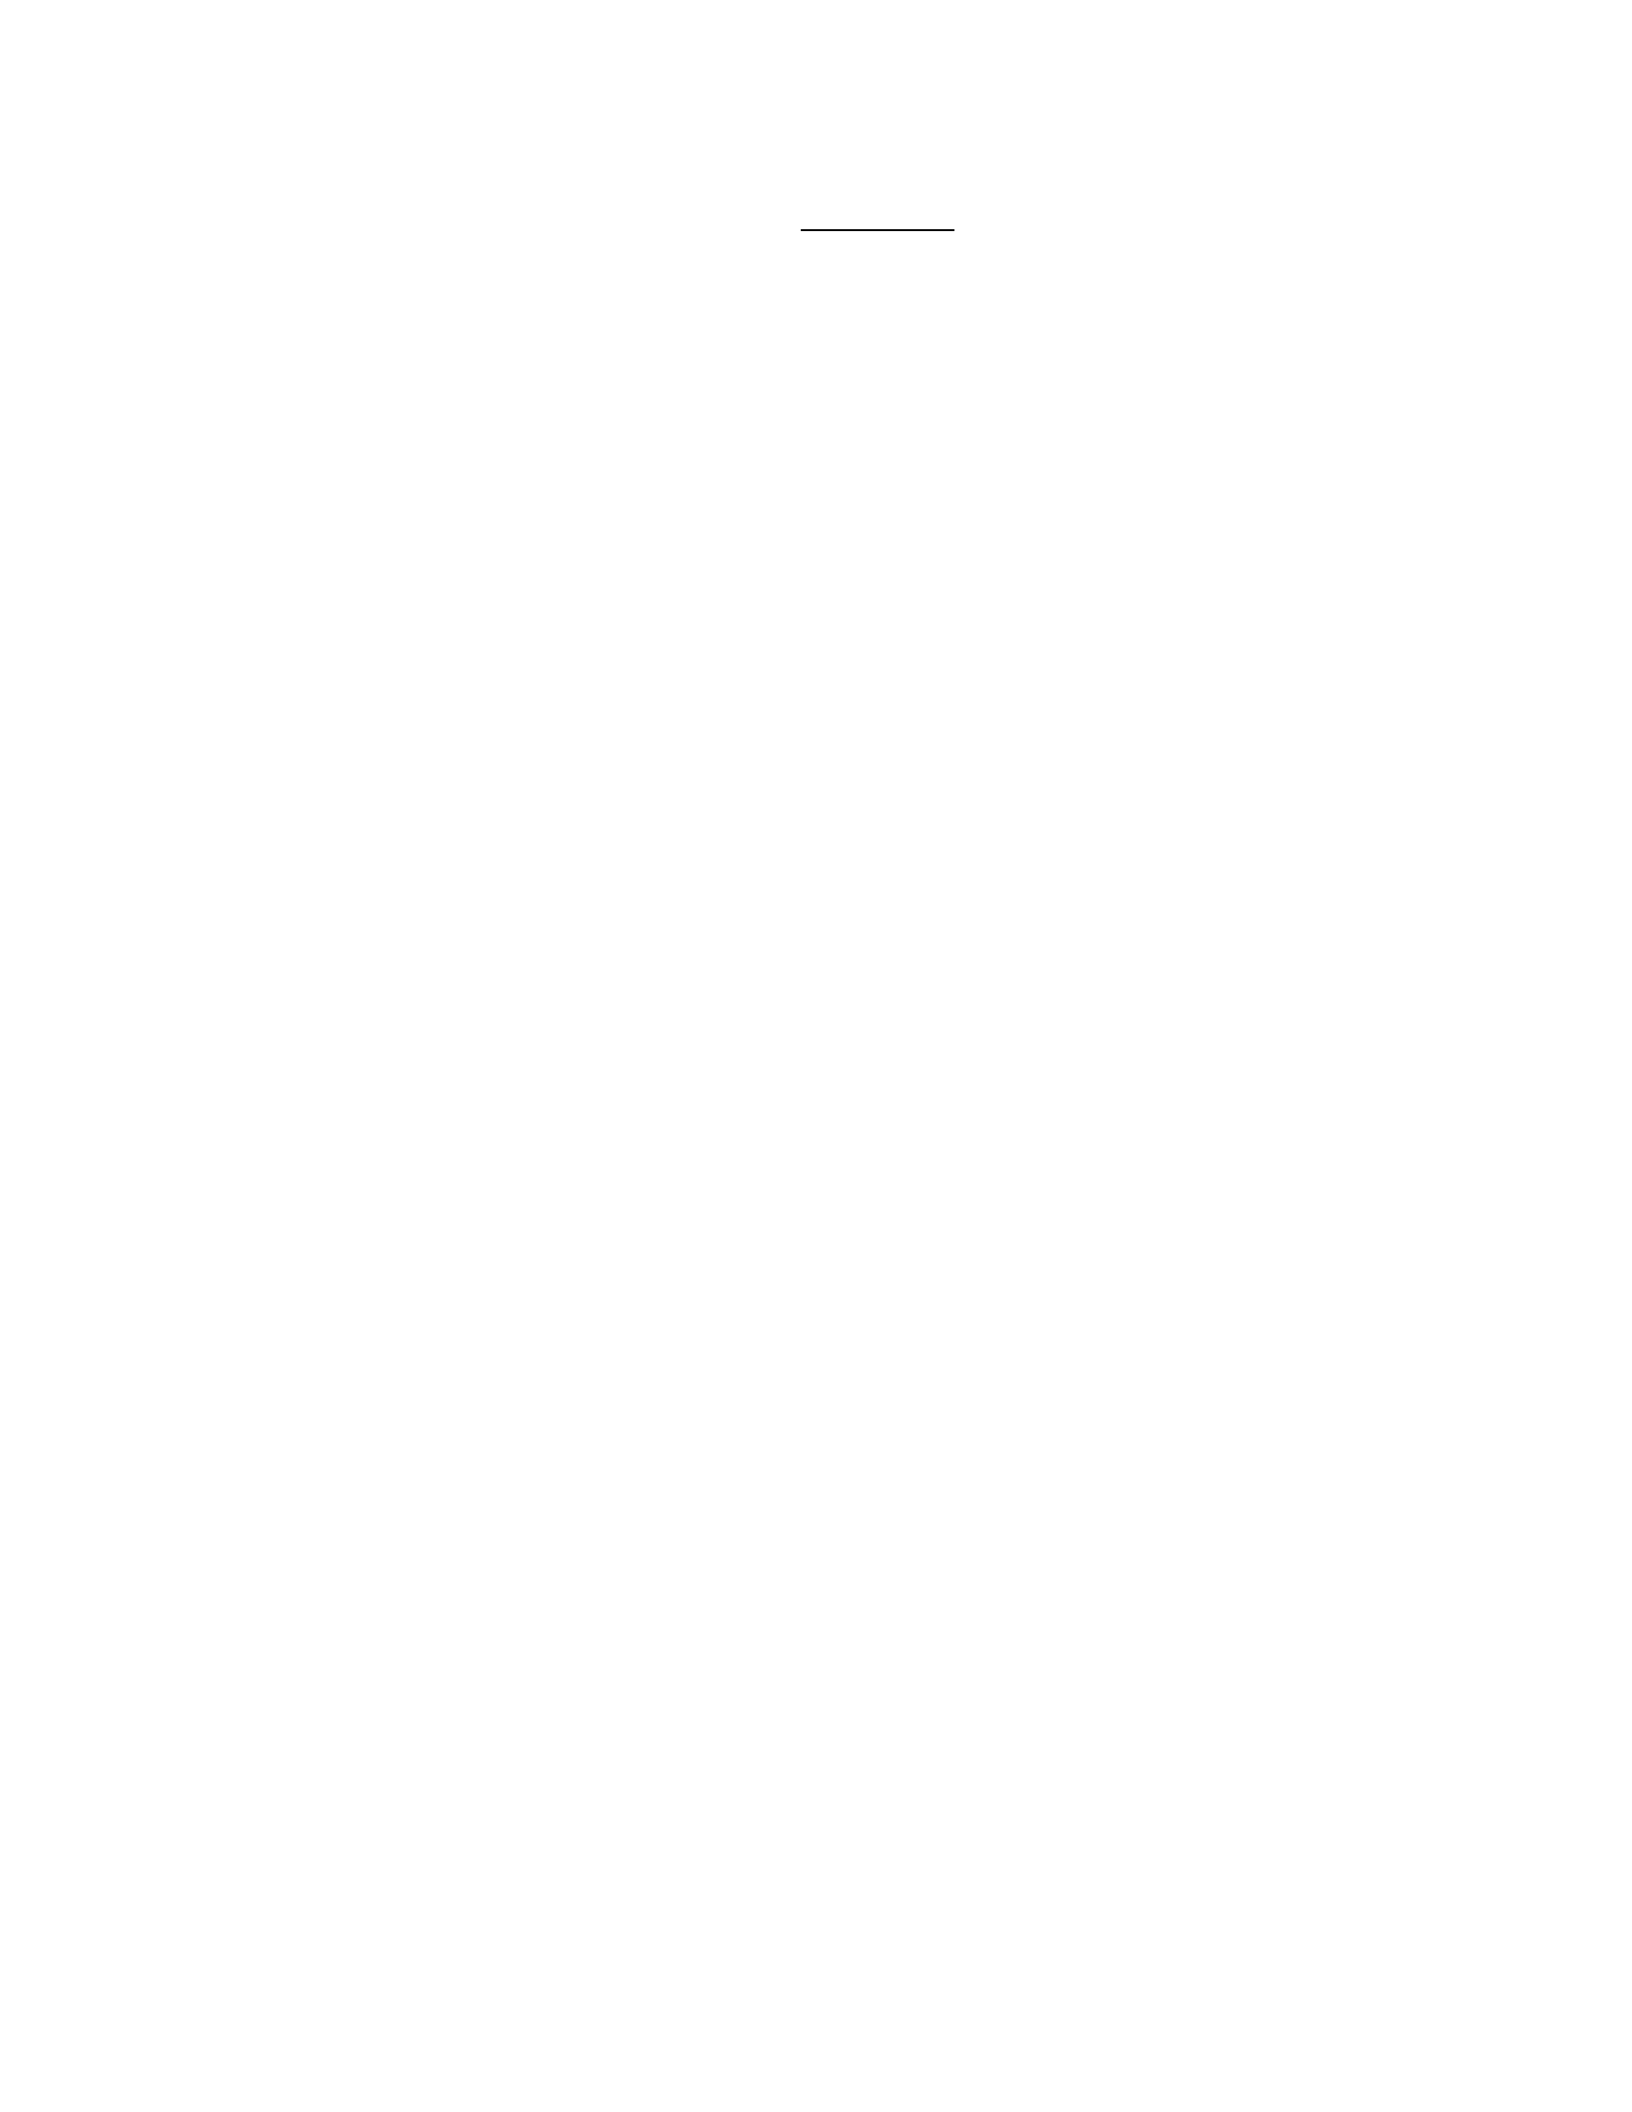
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
129. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
130. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
131. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
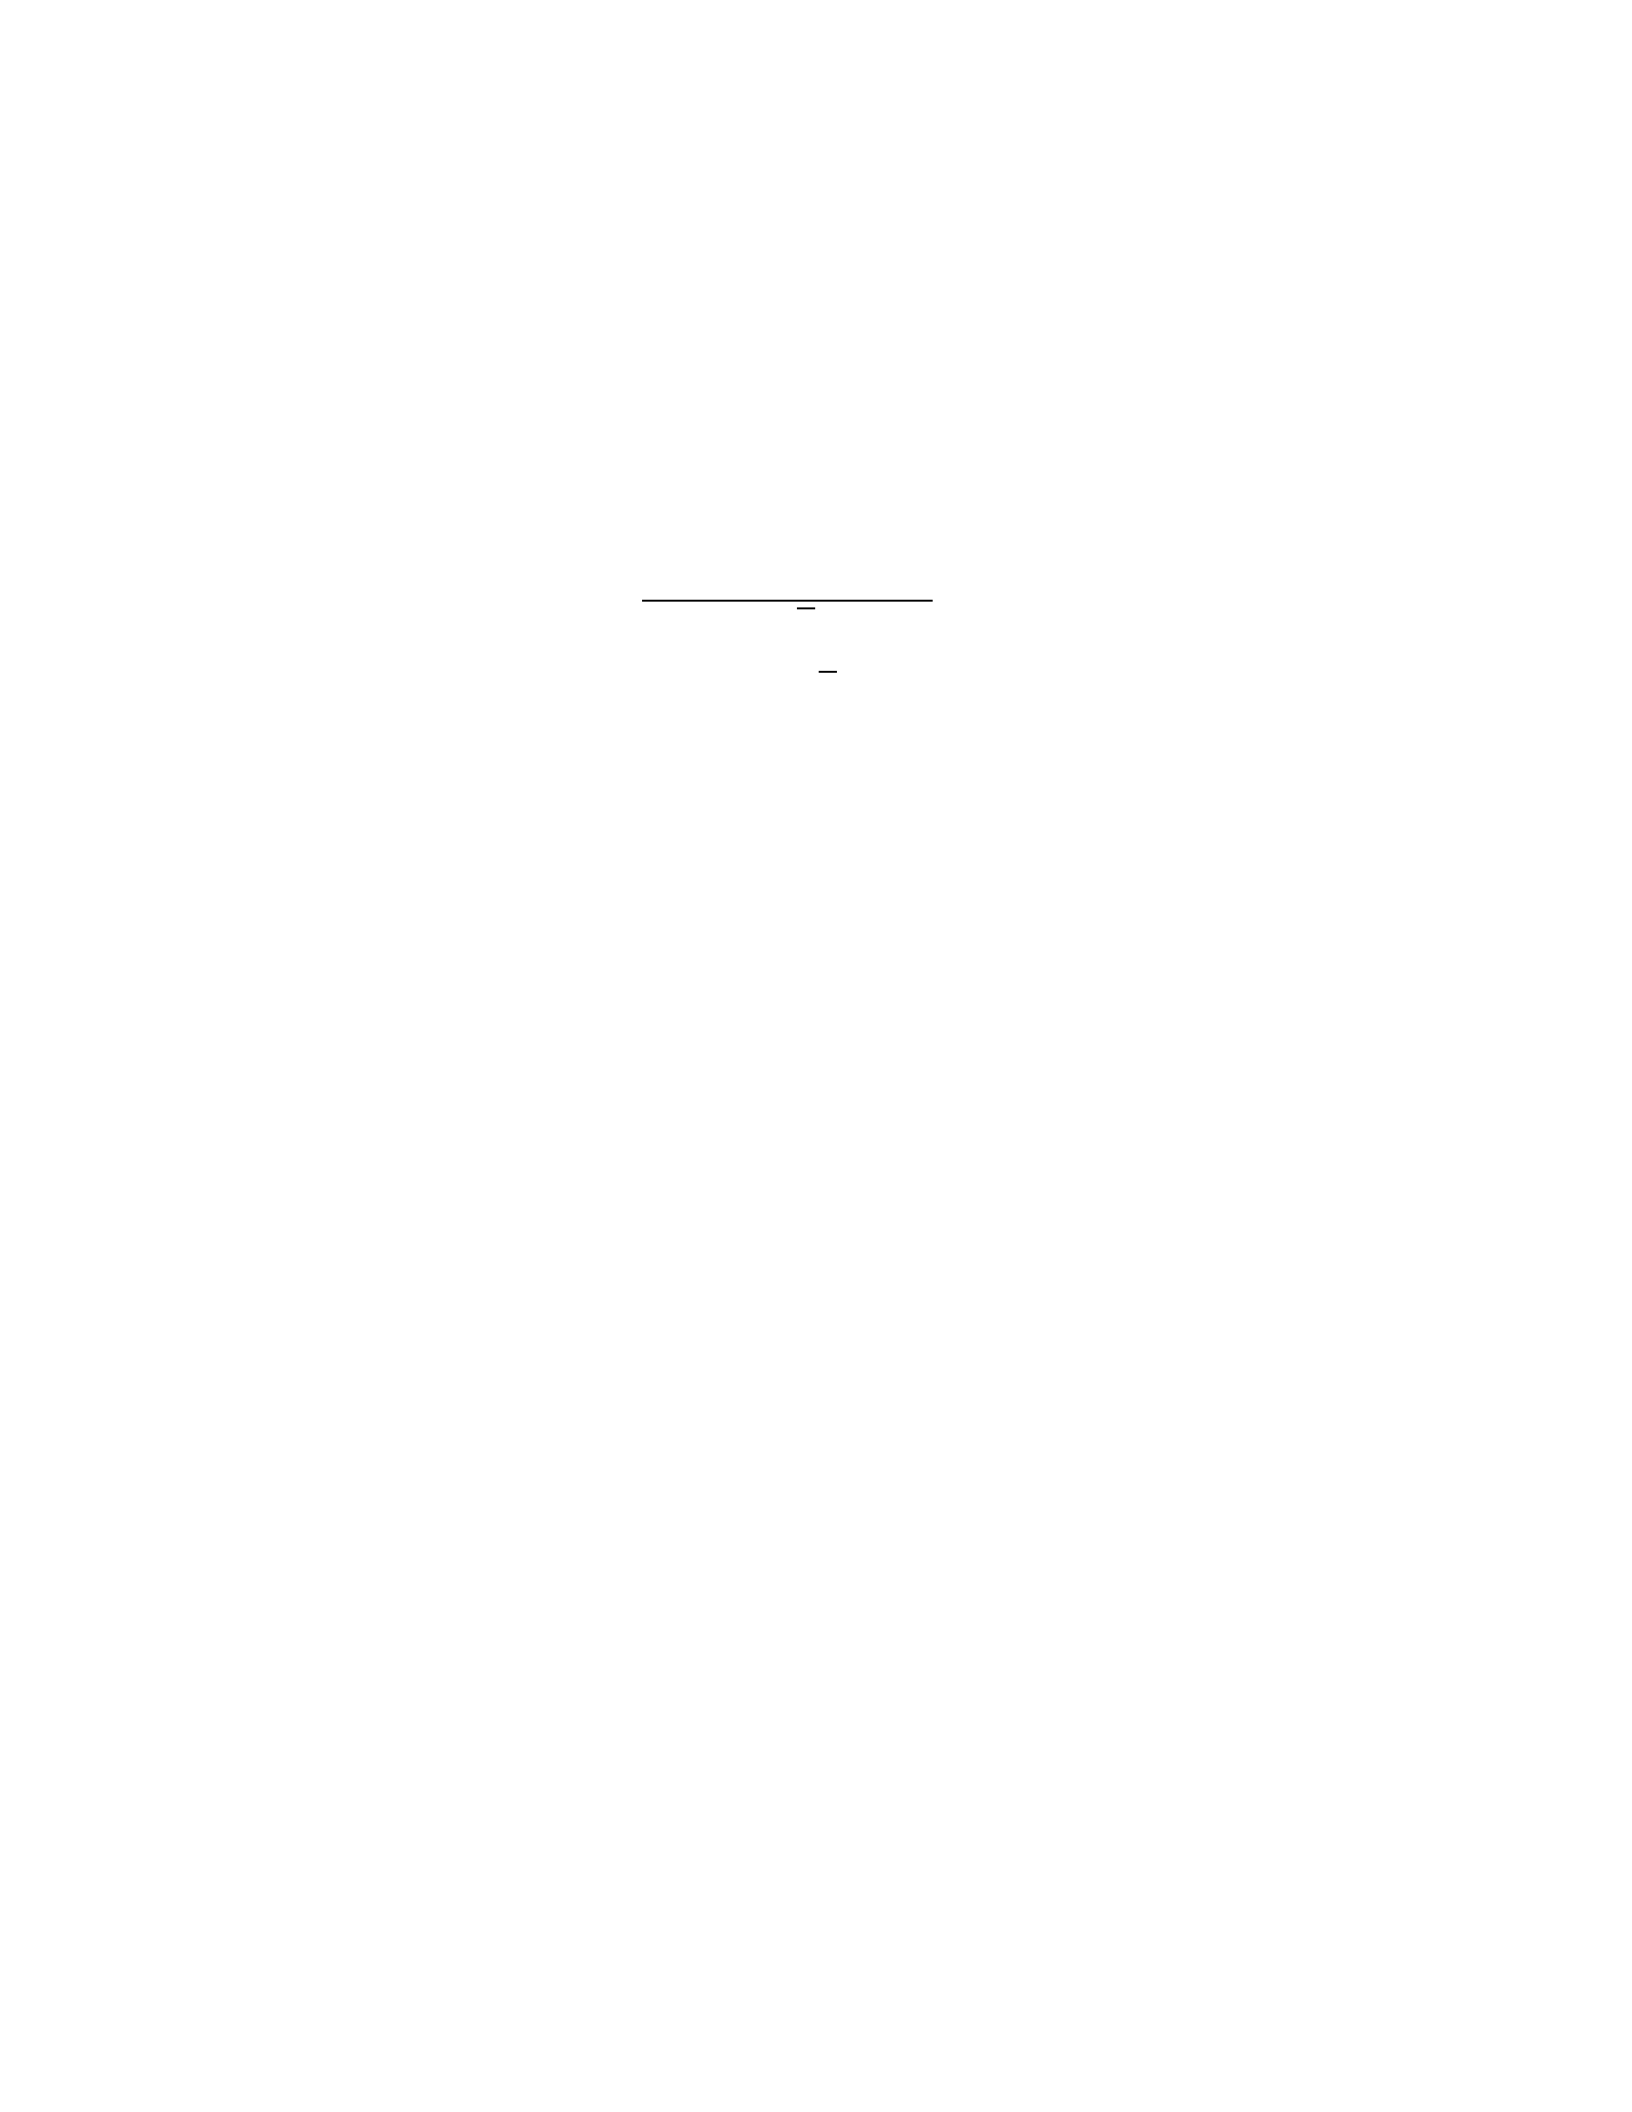
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
132. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500

• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
133. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
134. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:

• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
135. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
136. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
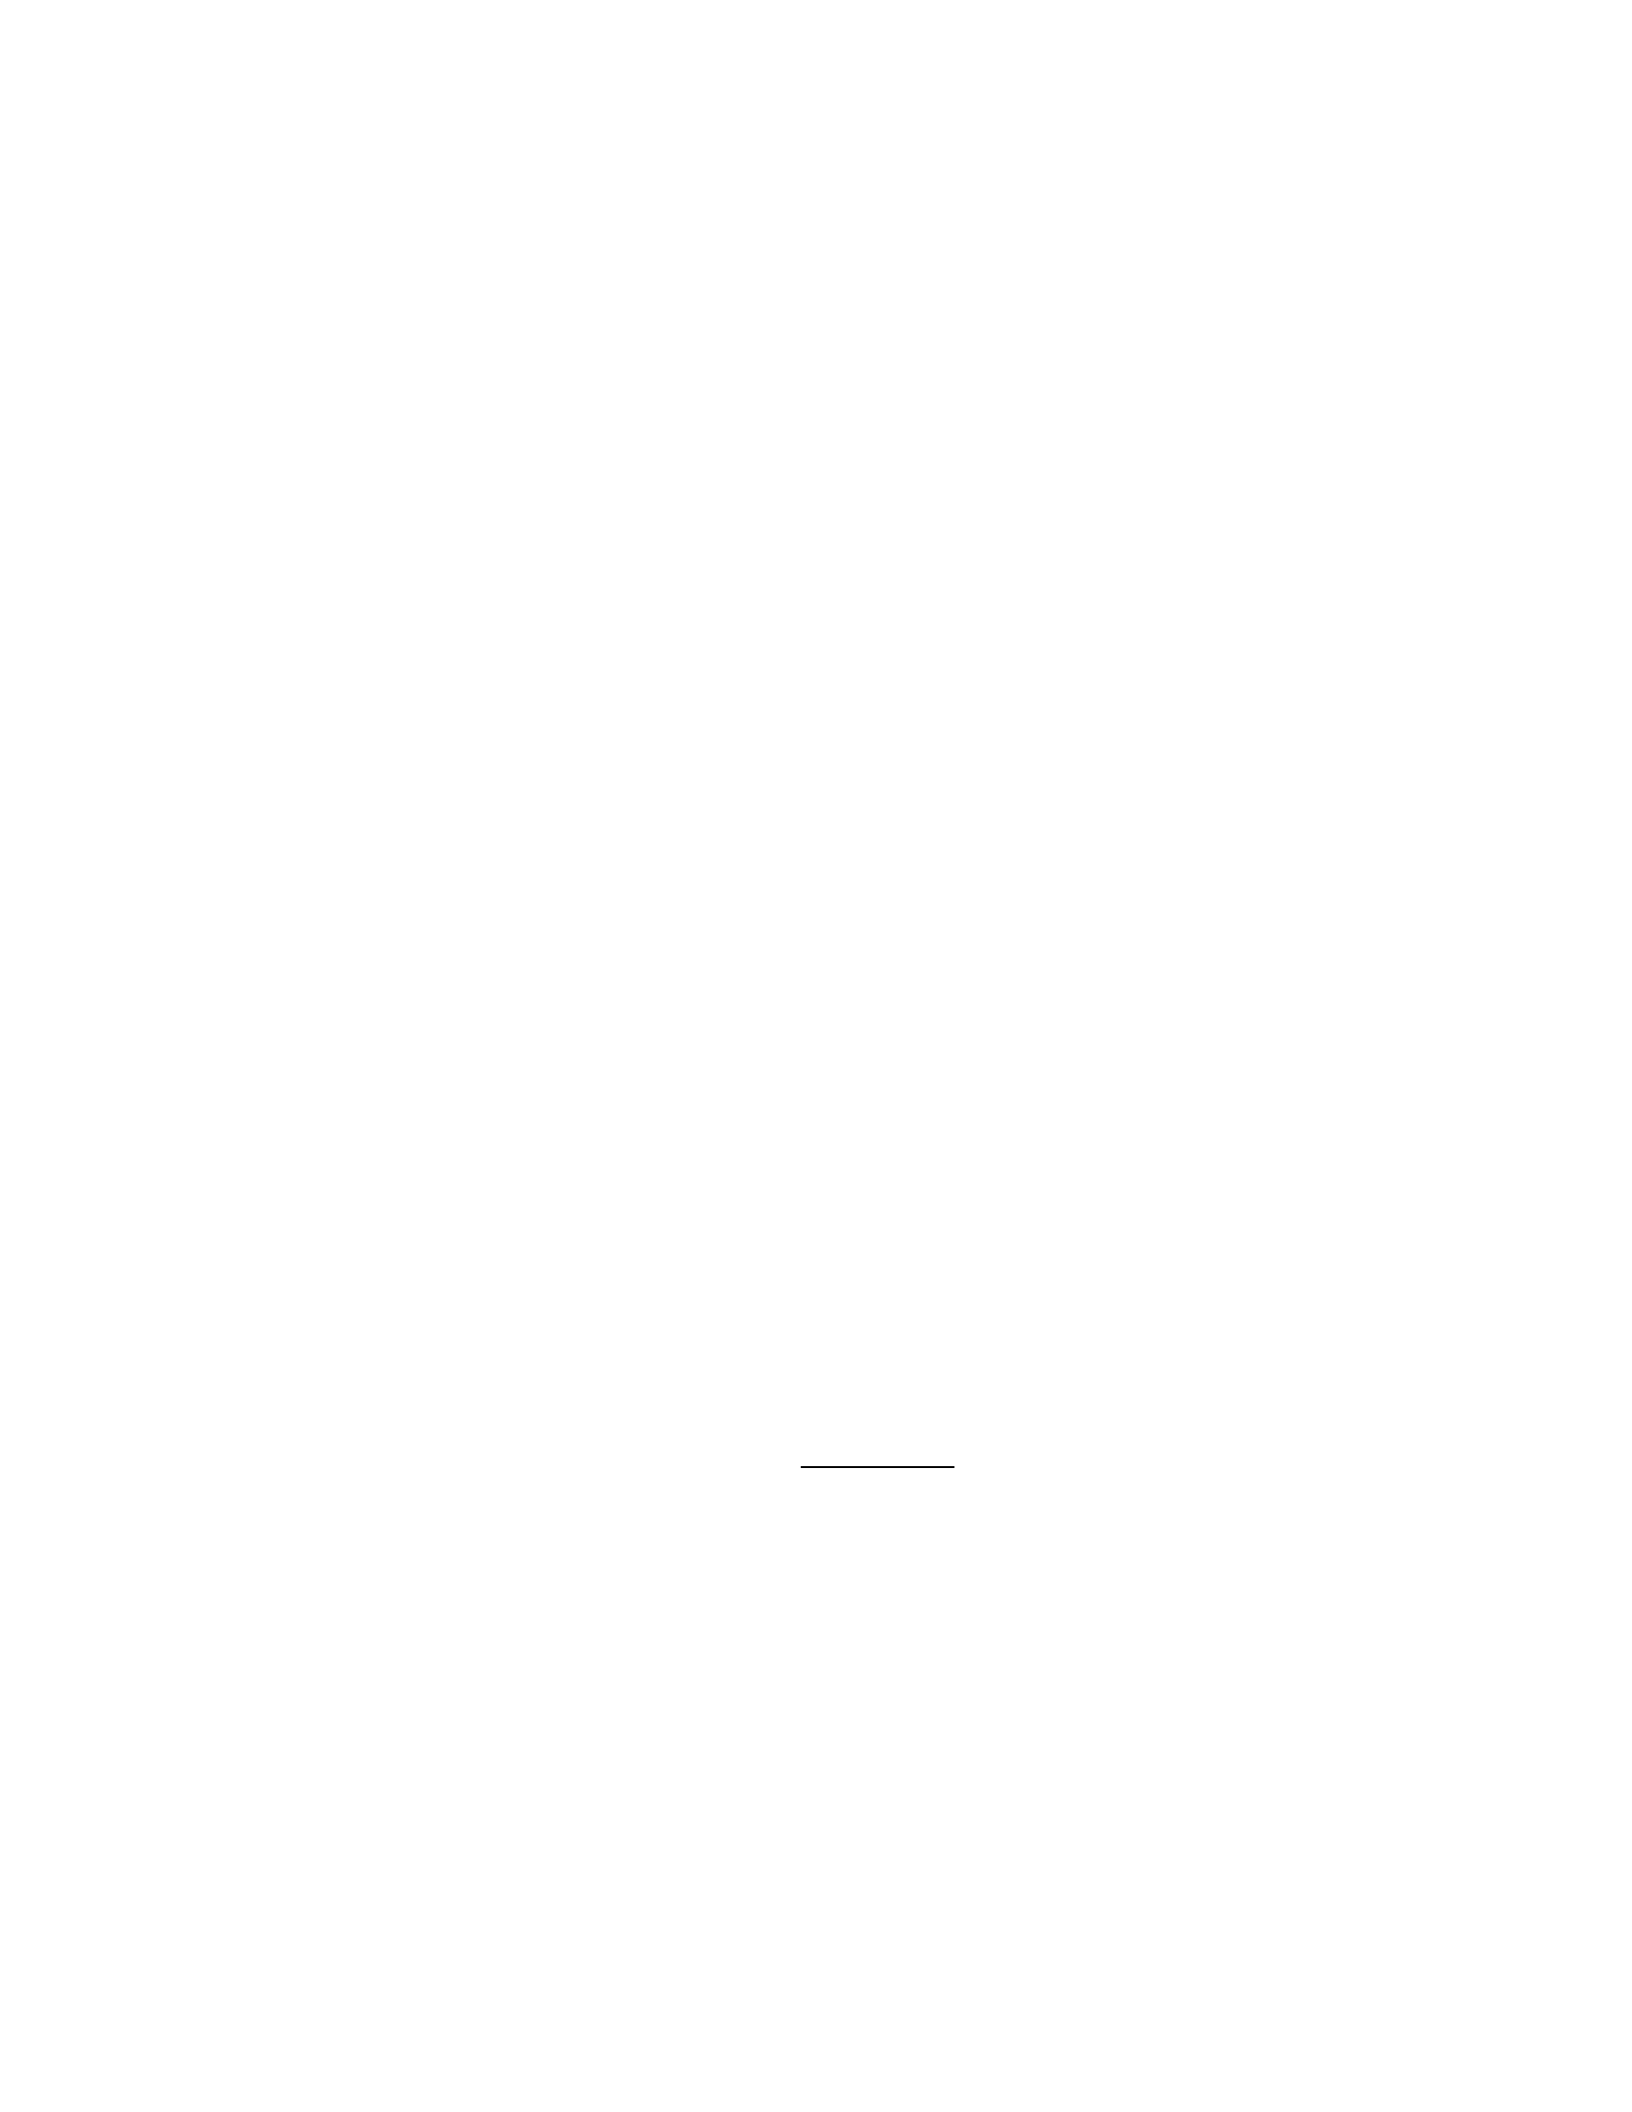
– Net cost = 0
137. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
138. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
139. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%

– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
140. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
141. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
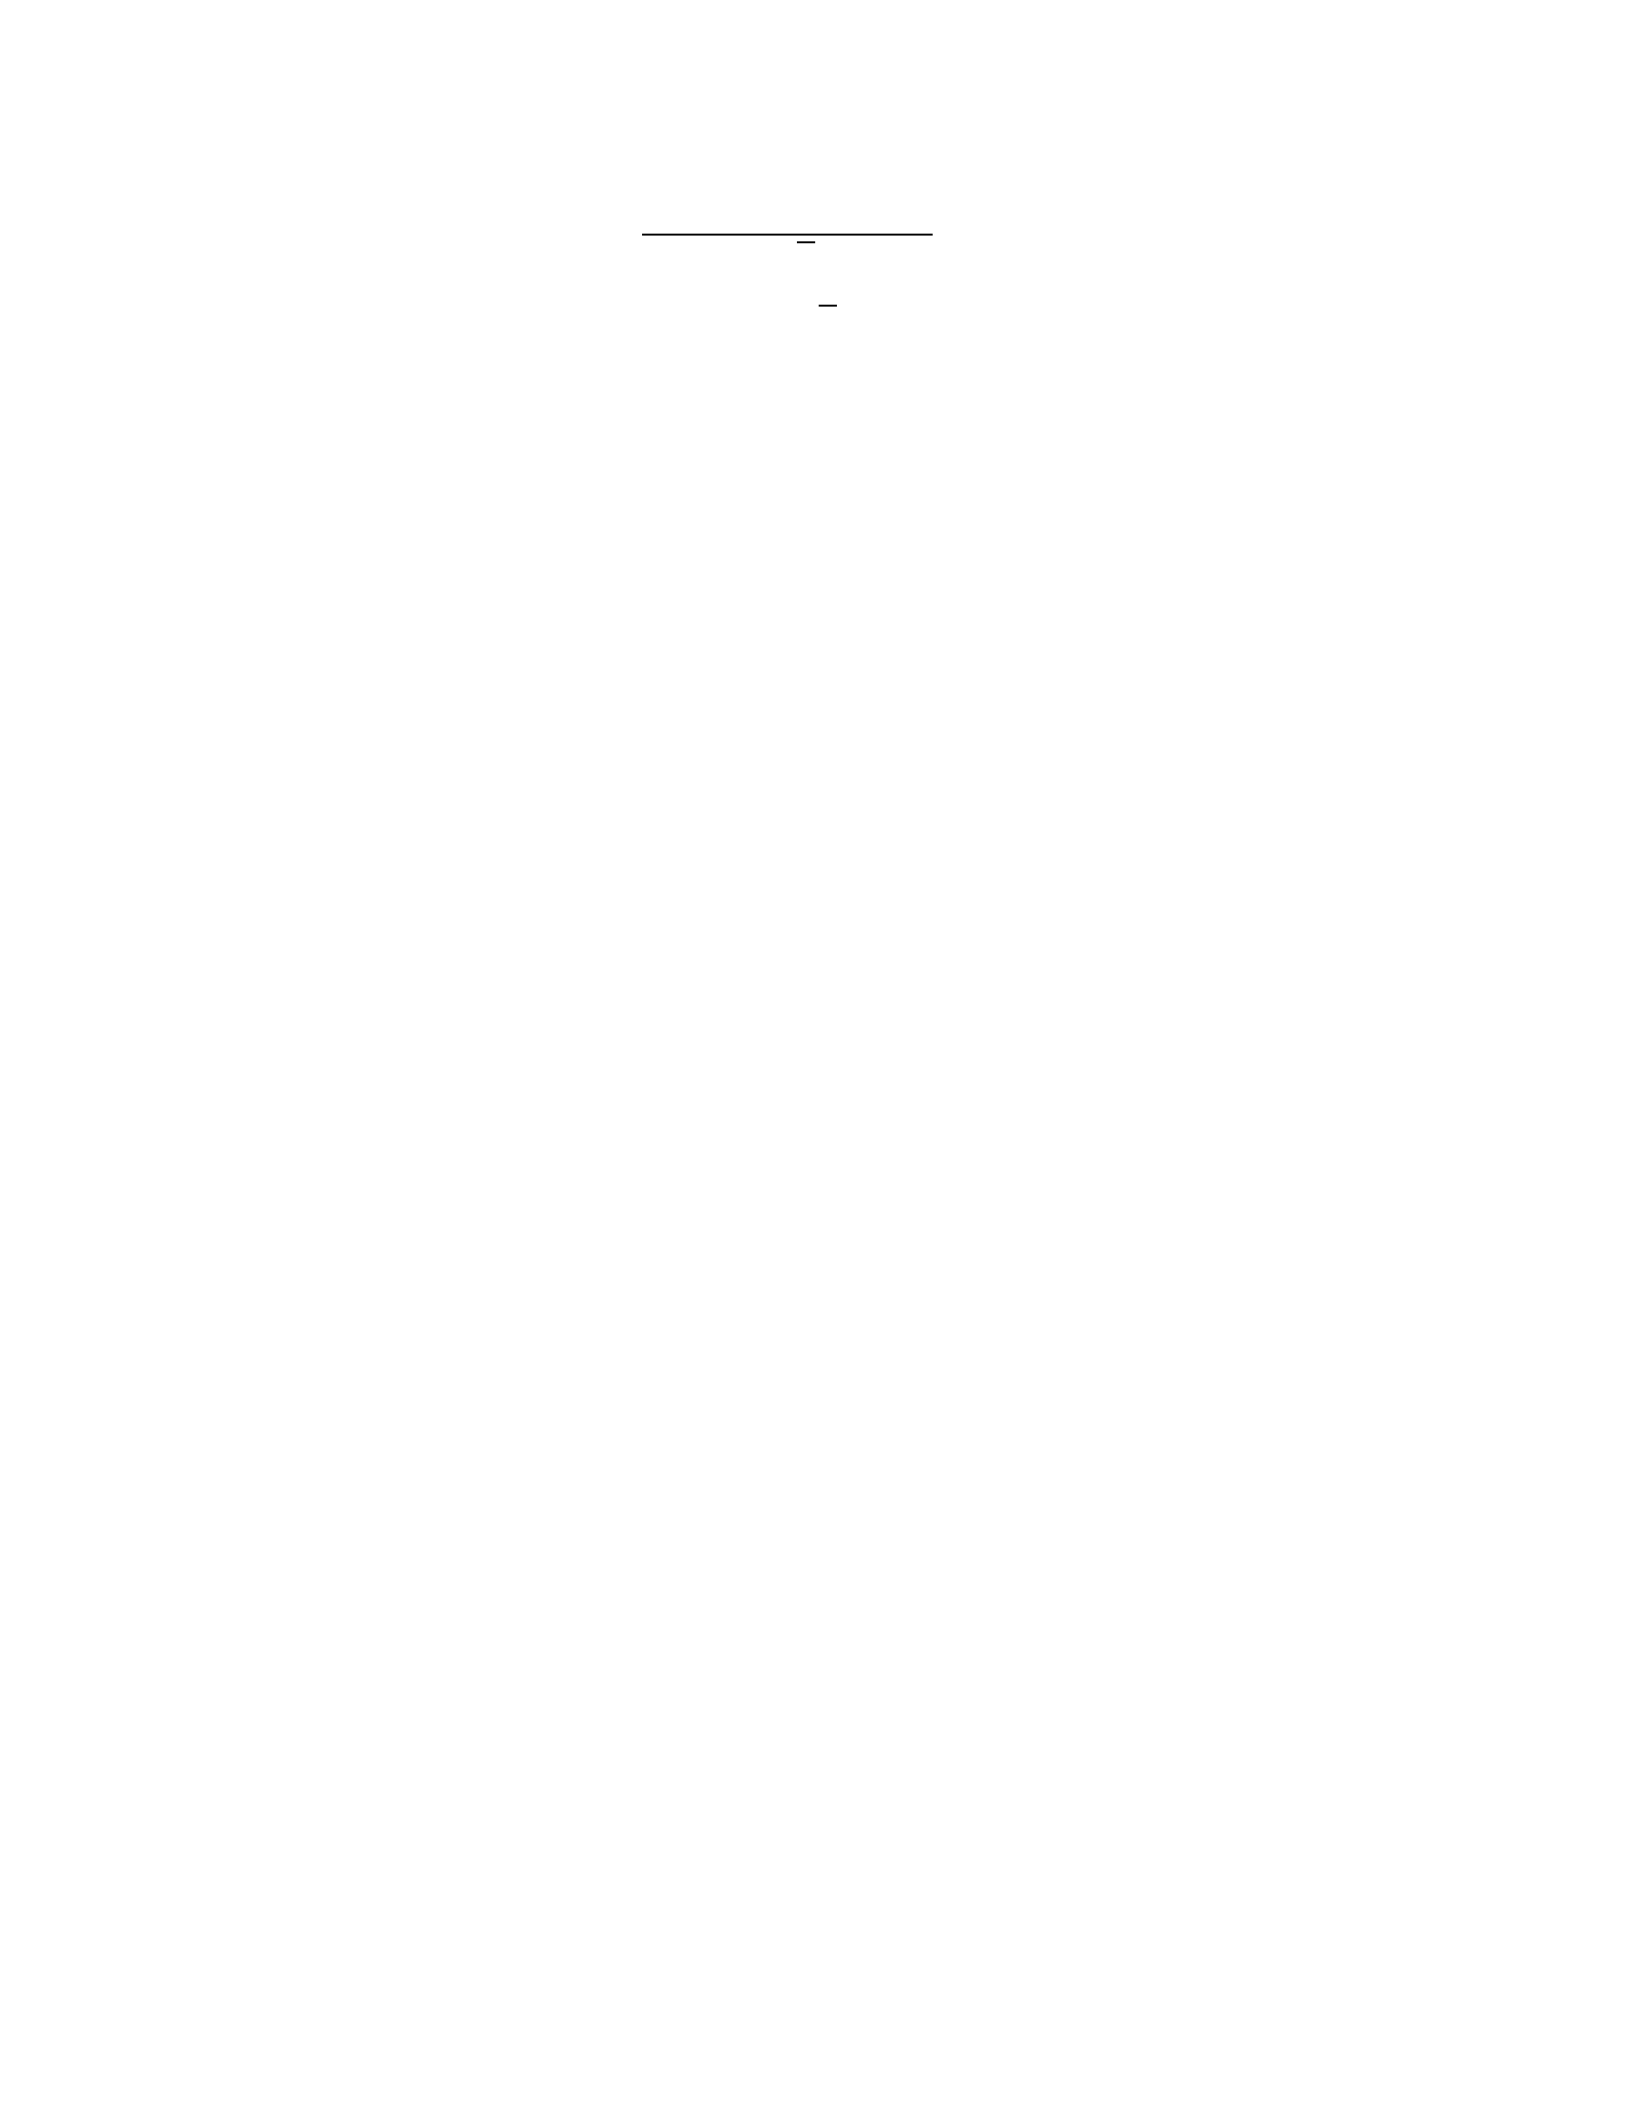
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
142. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
143. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:

a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
144. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10

– Breakeven points: $90 and $110
145. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
146. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
147. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
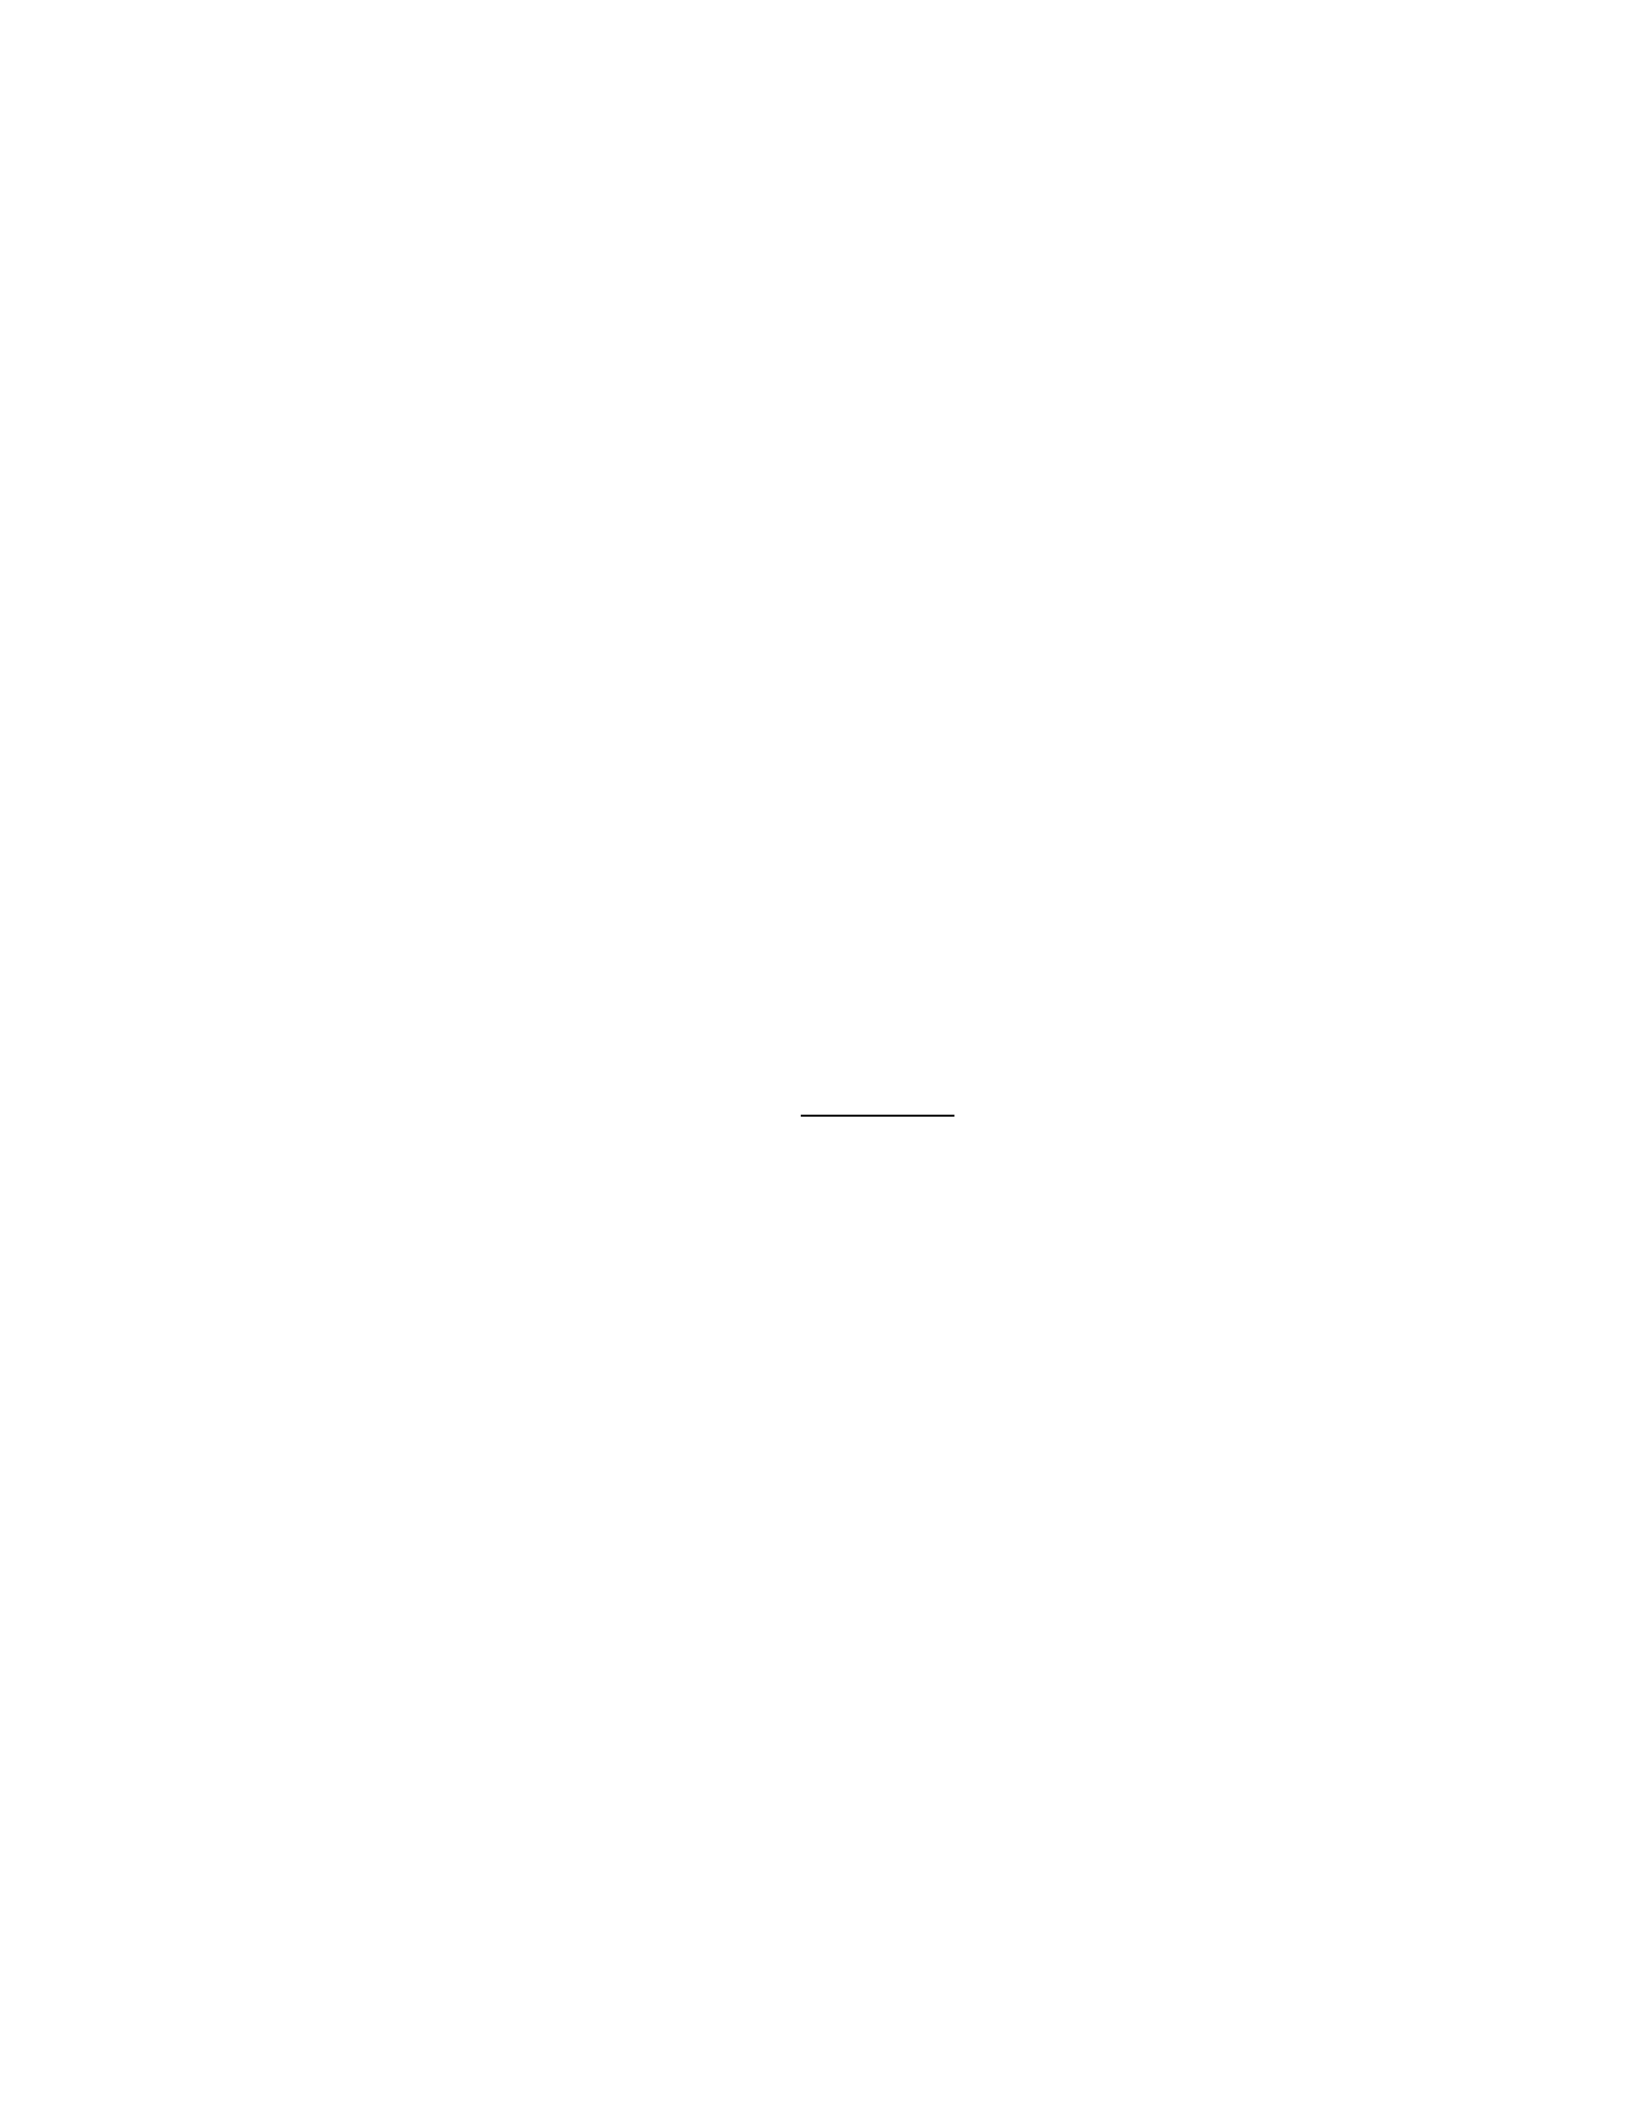
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
148. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
149. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
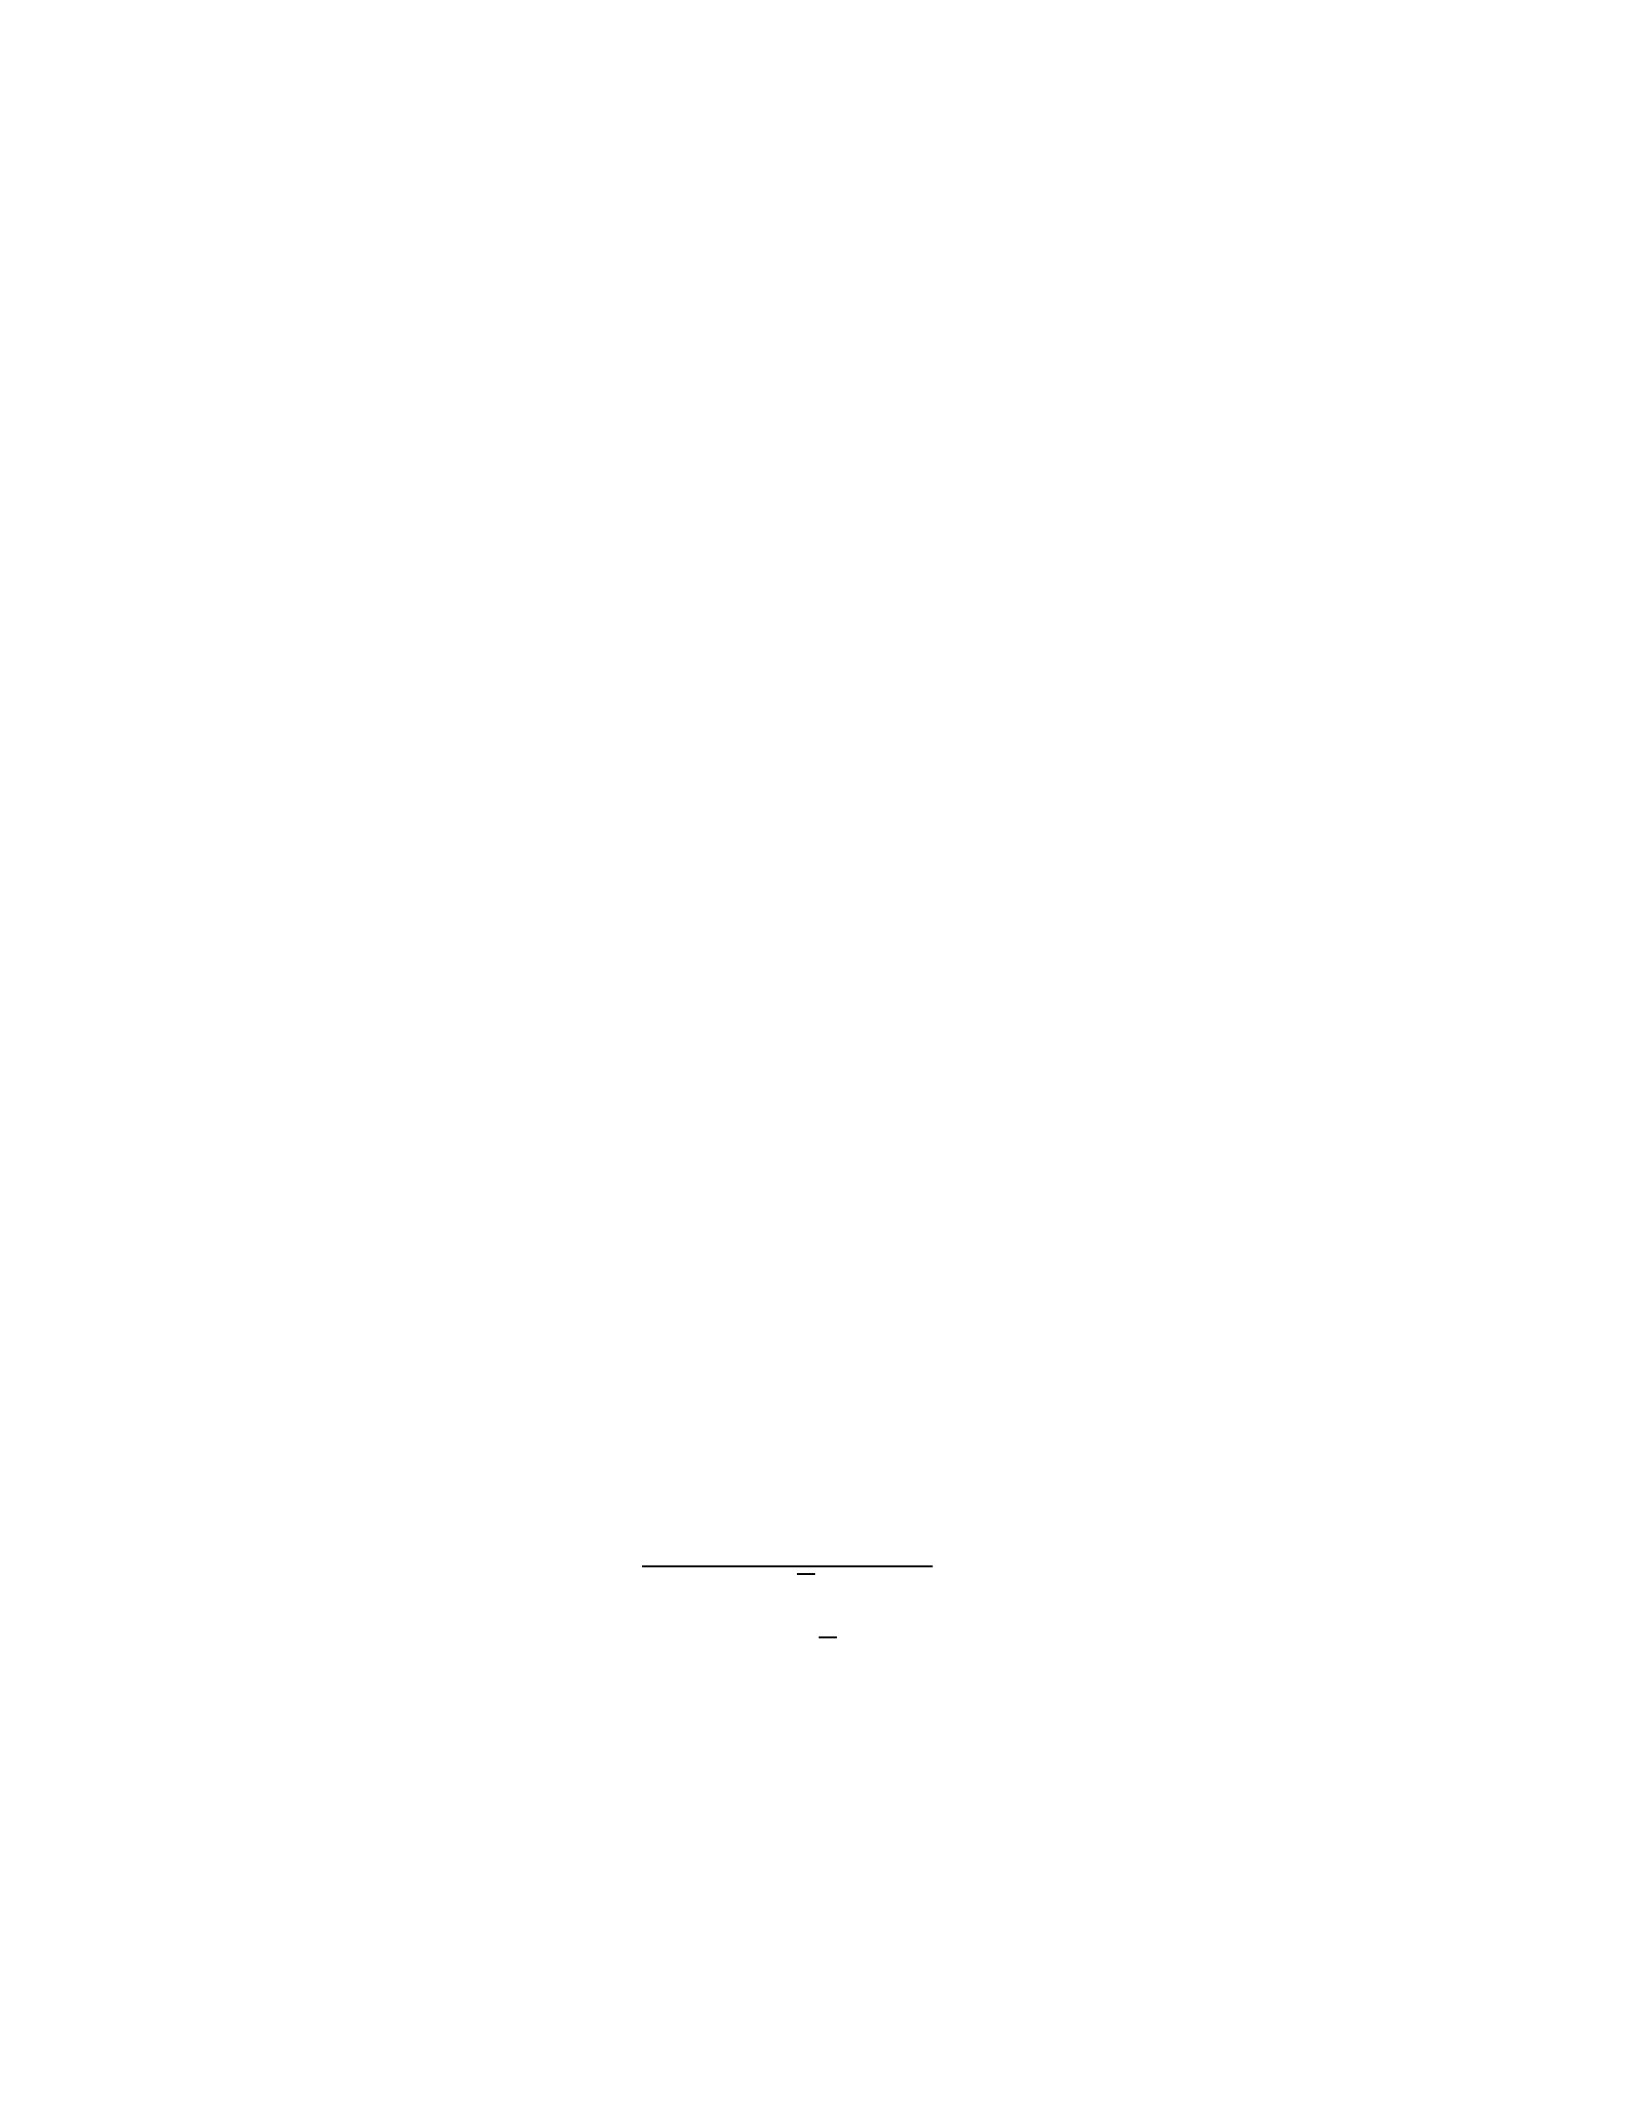
150. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
151. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula

𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
152. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
153. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711

• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
154. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
155. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:

– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
156. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
157. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
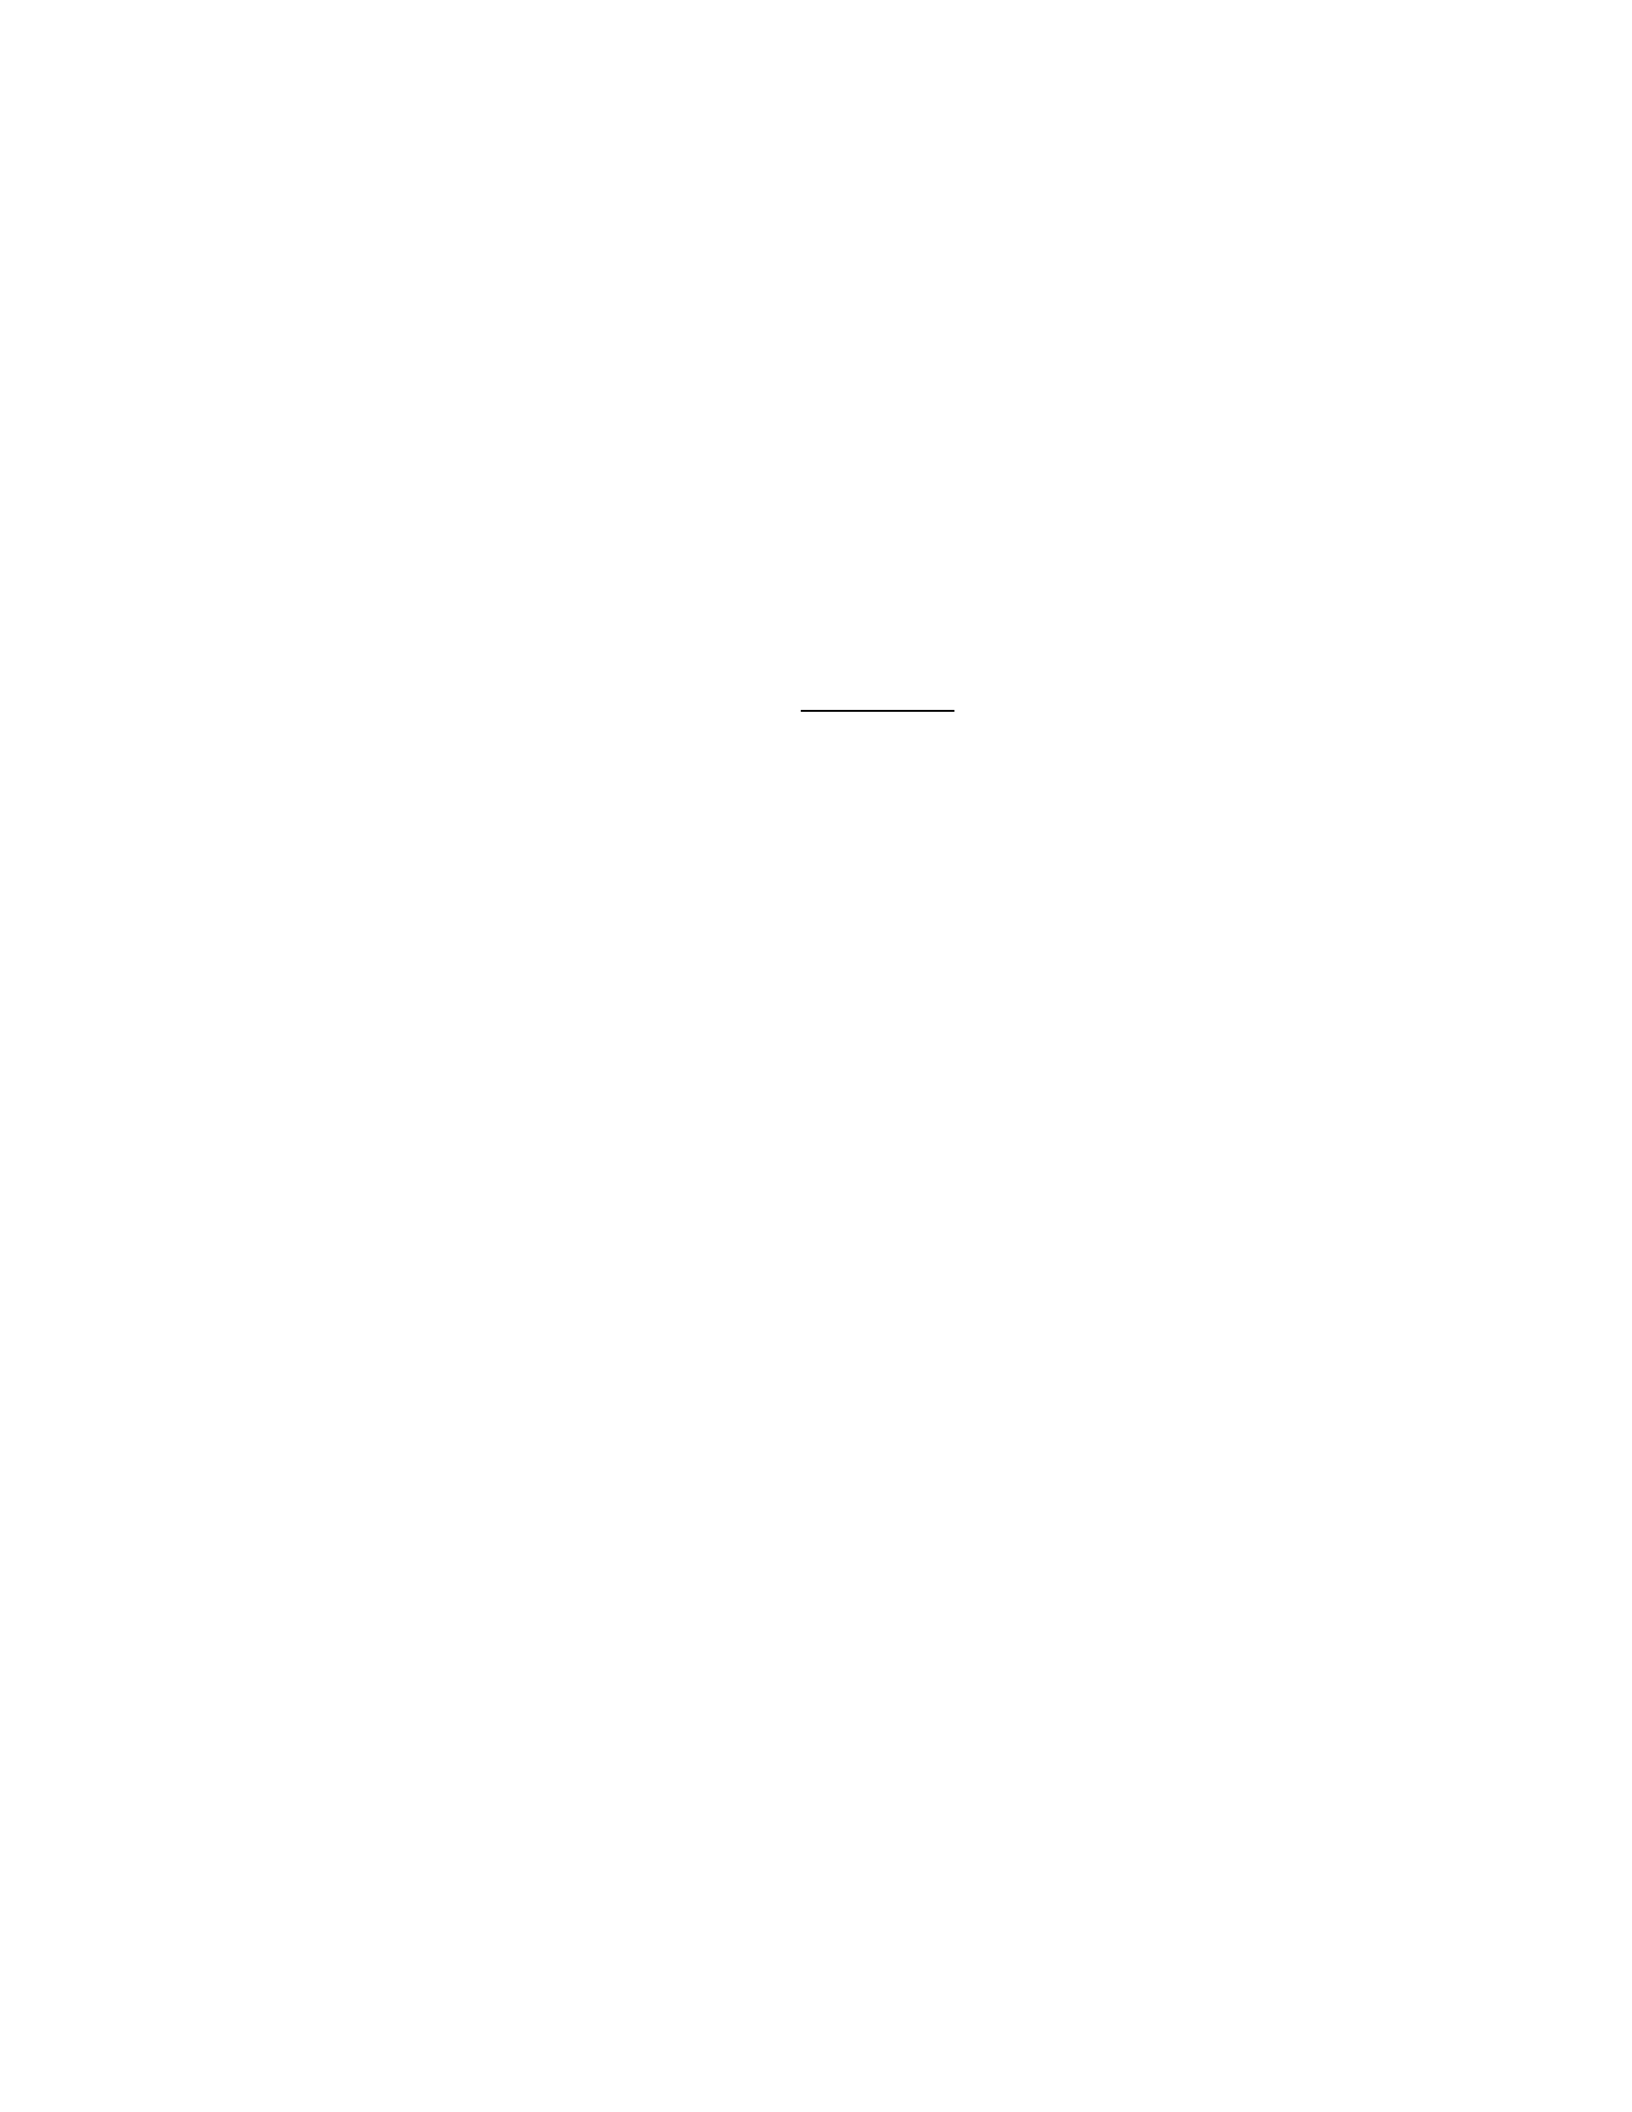
158. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
159. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
160. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
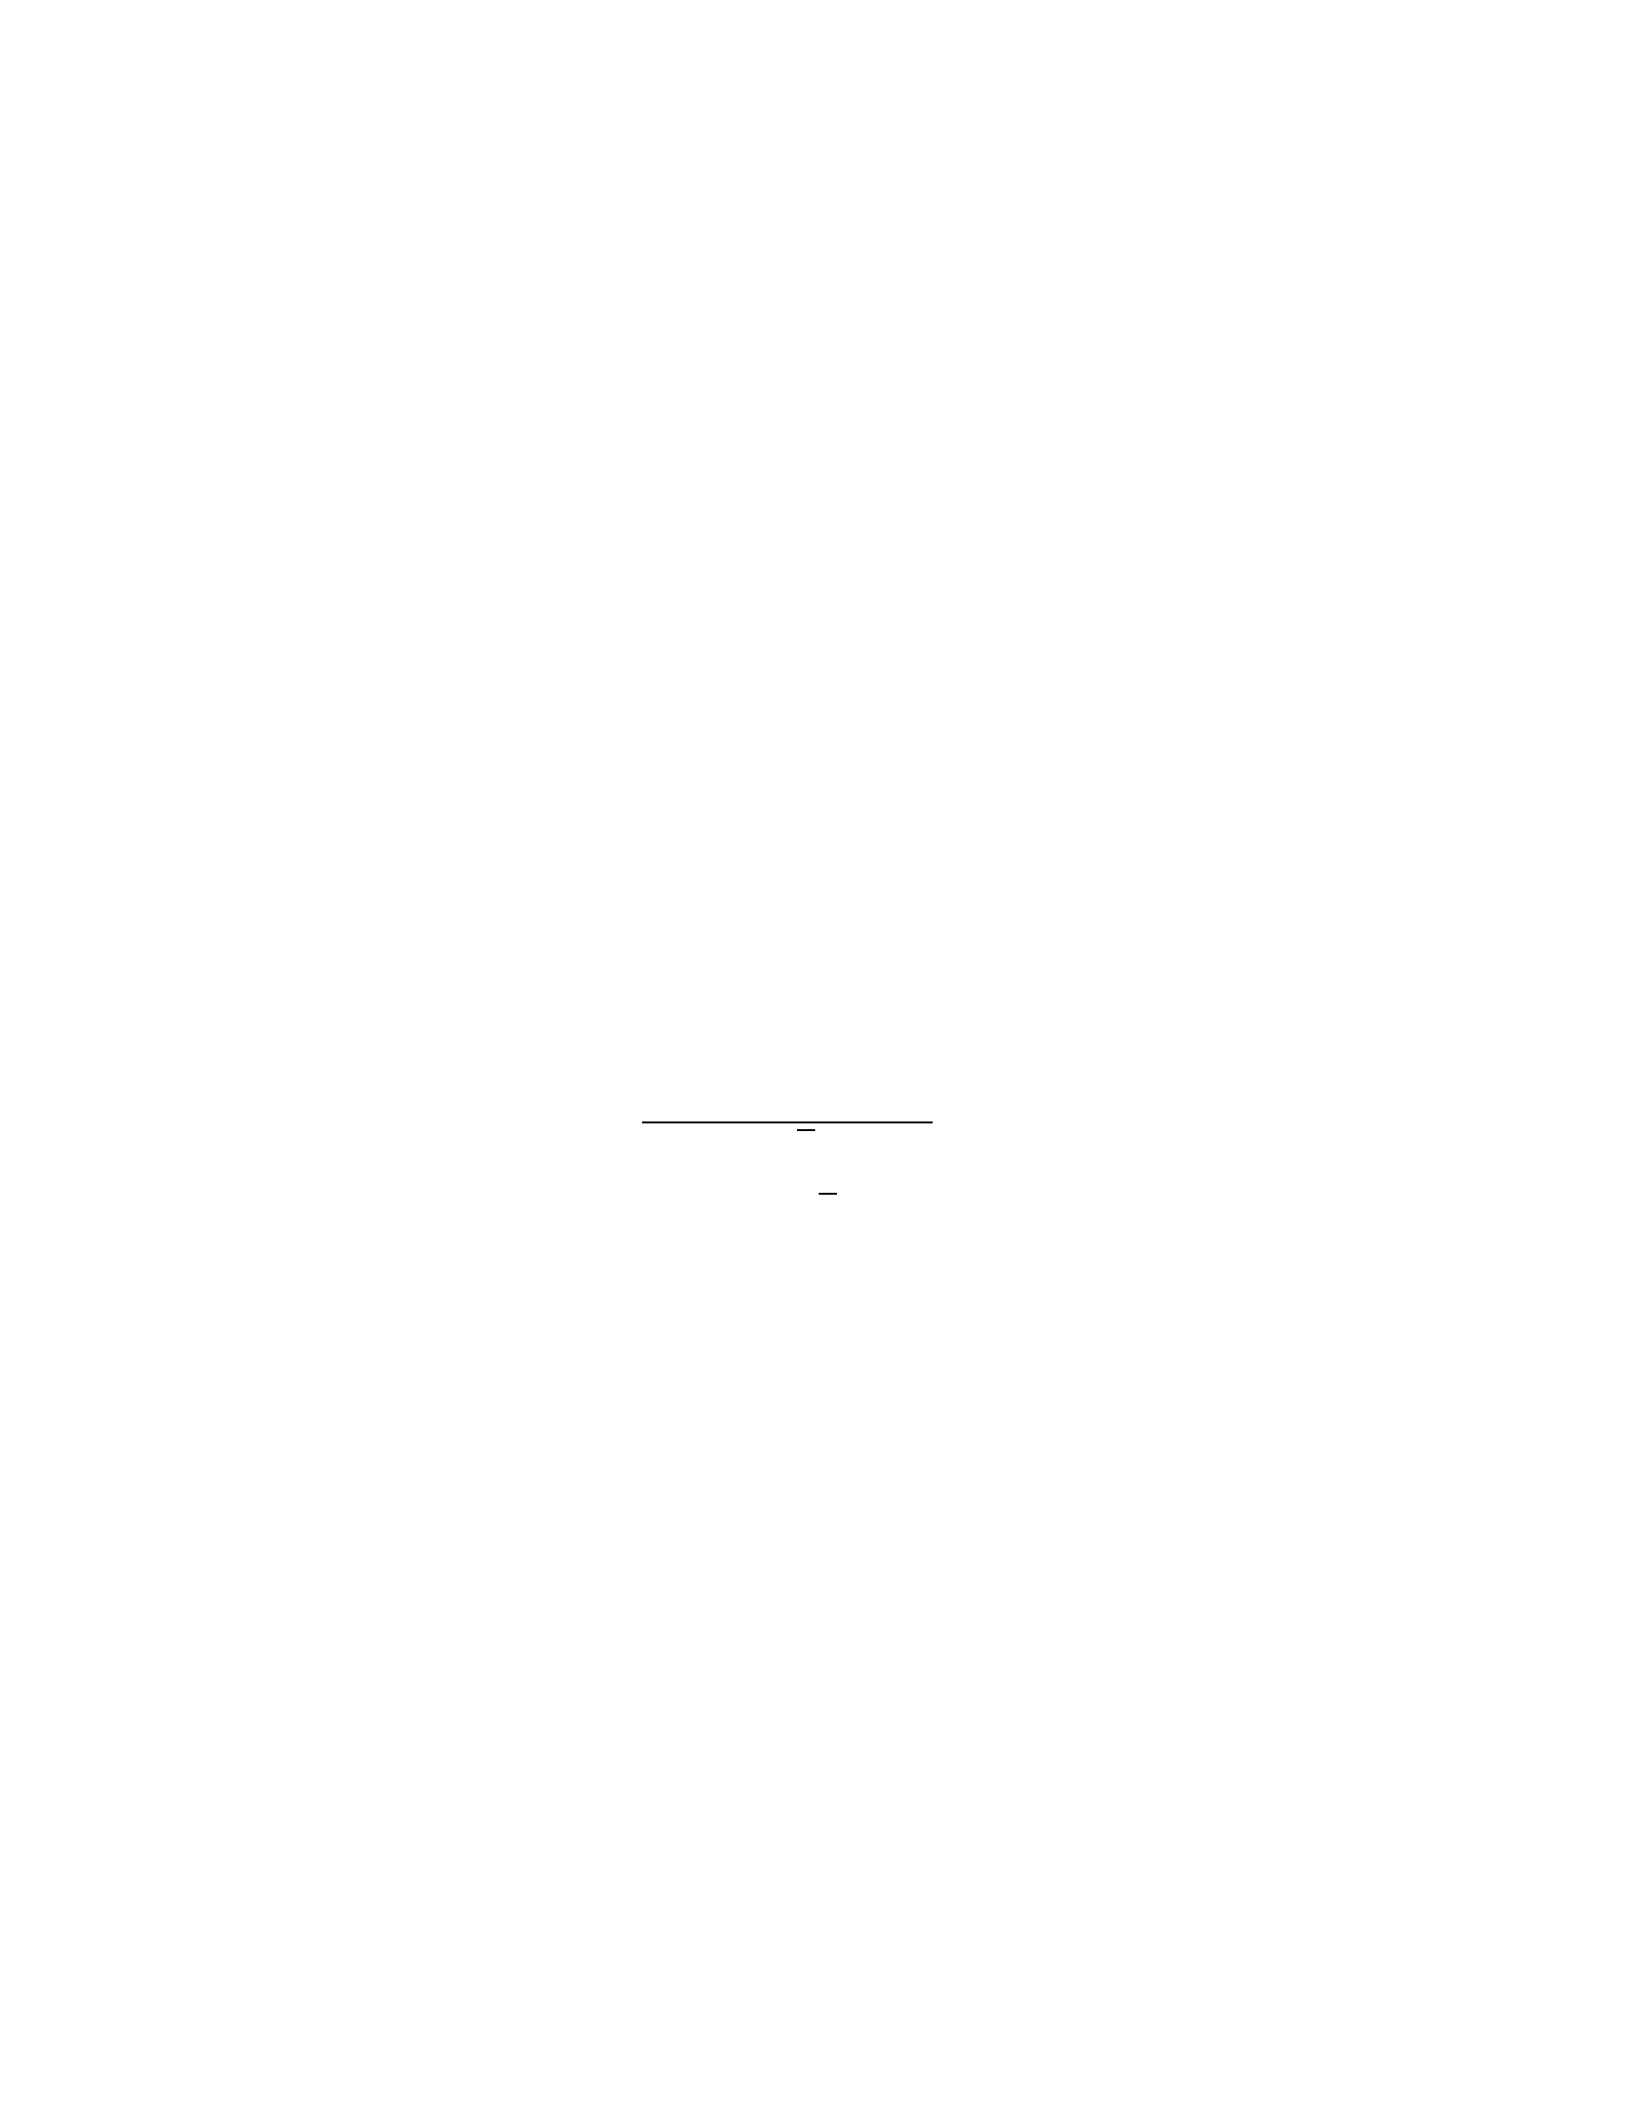
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
161. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
162. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:

a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
163. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
164. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit

from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
165. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
166. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options

and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
167. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
168. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
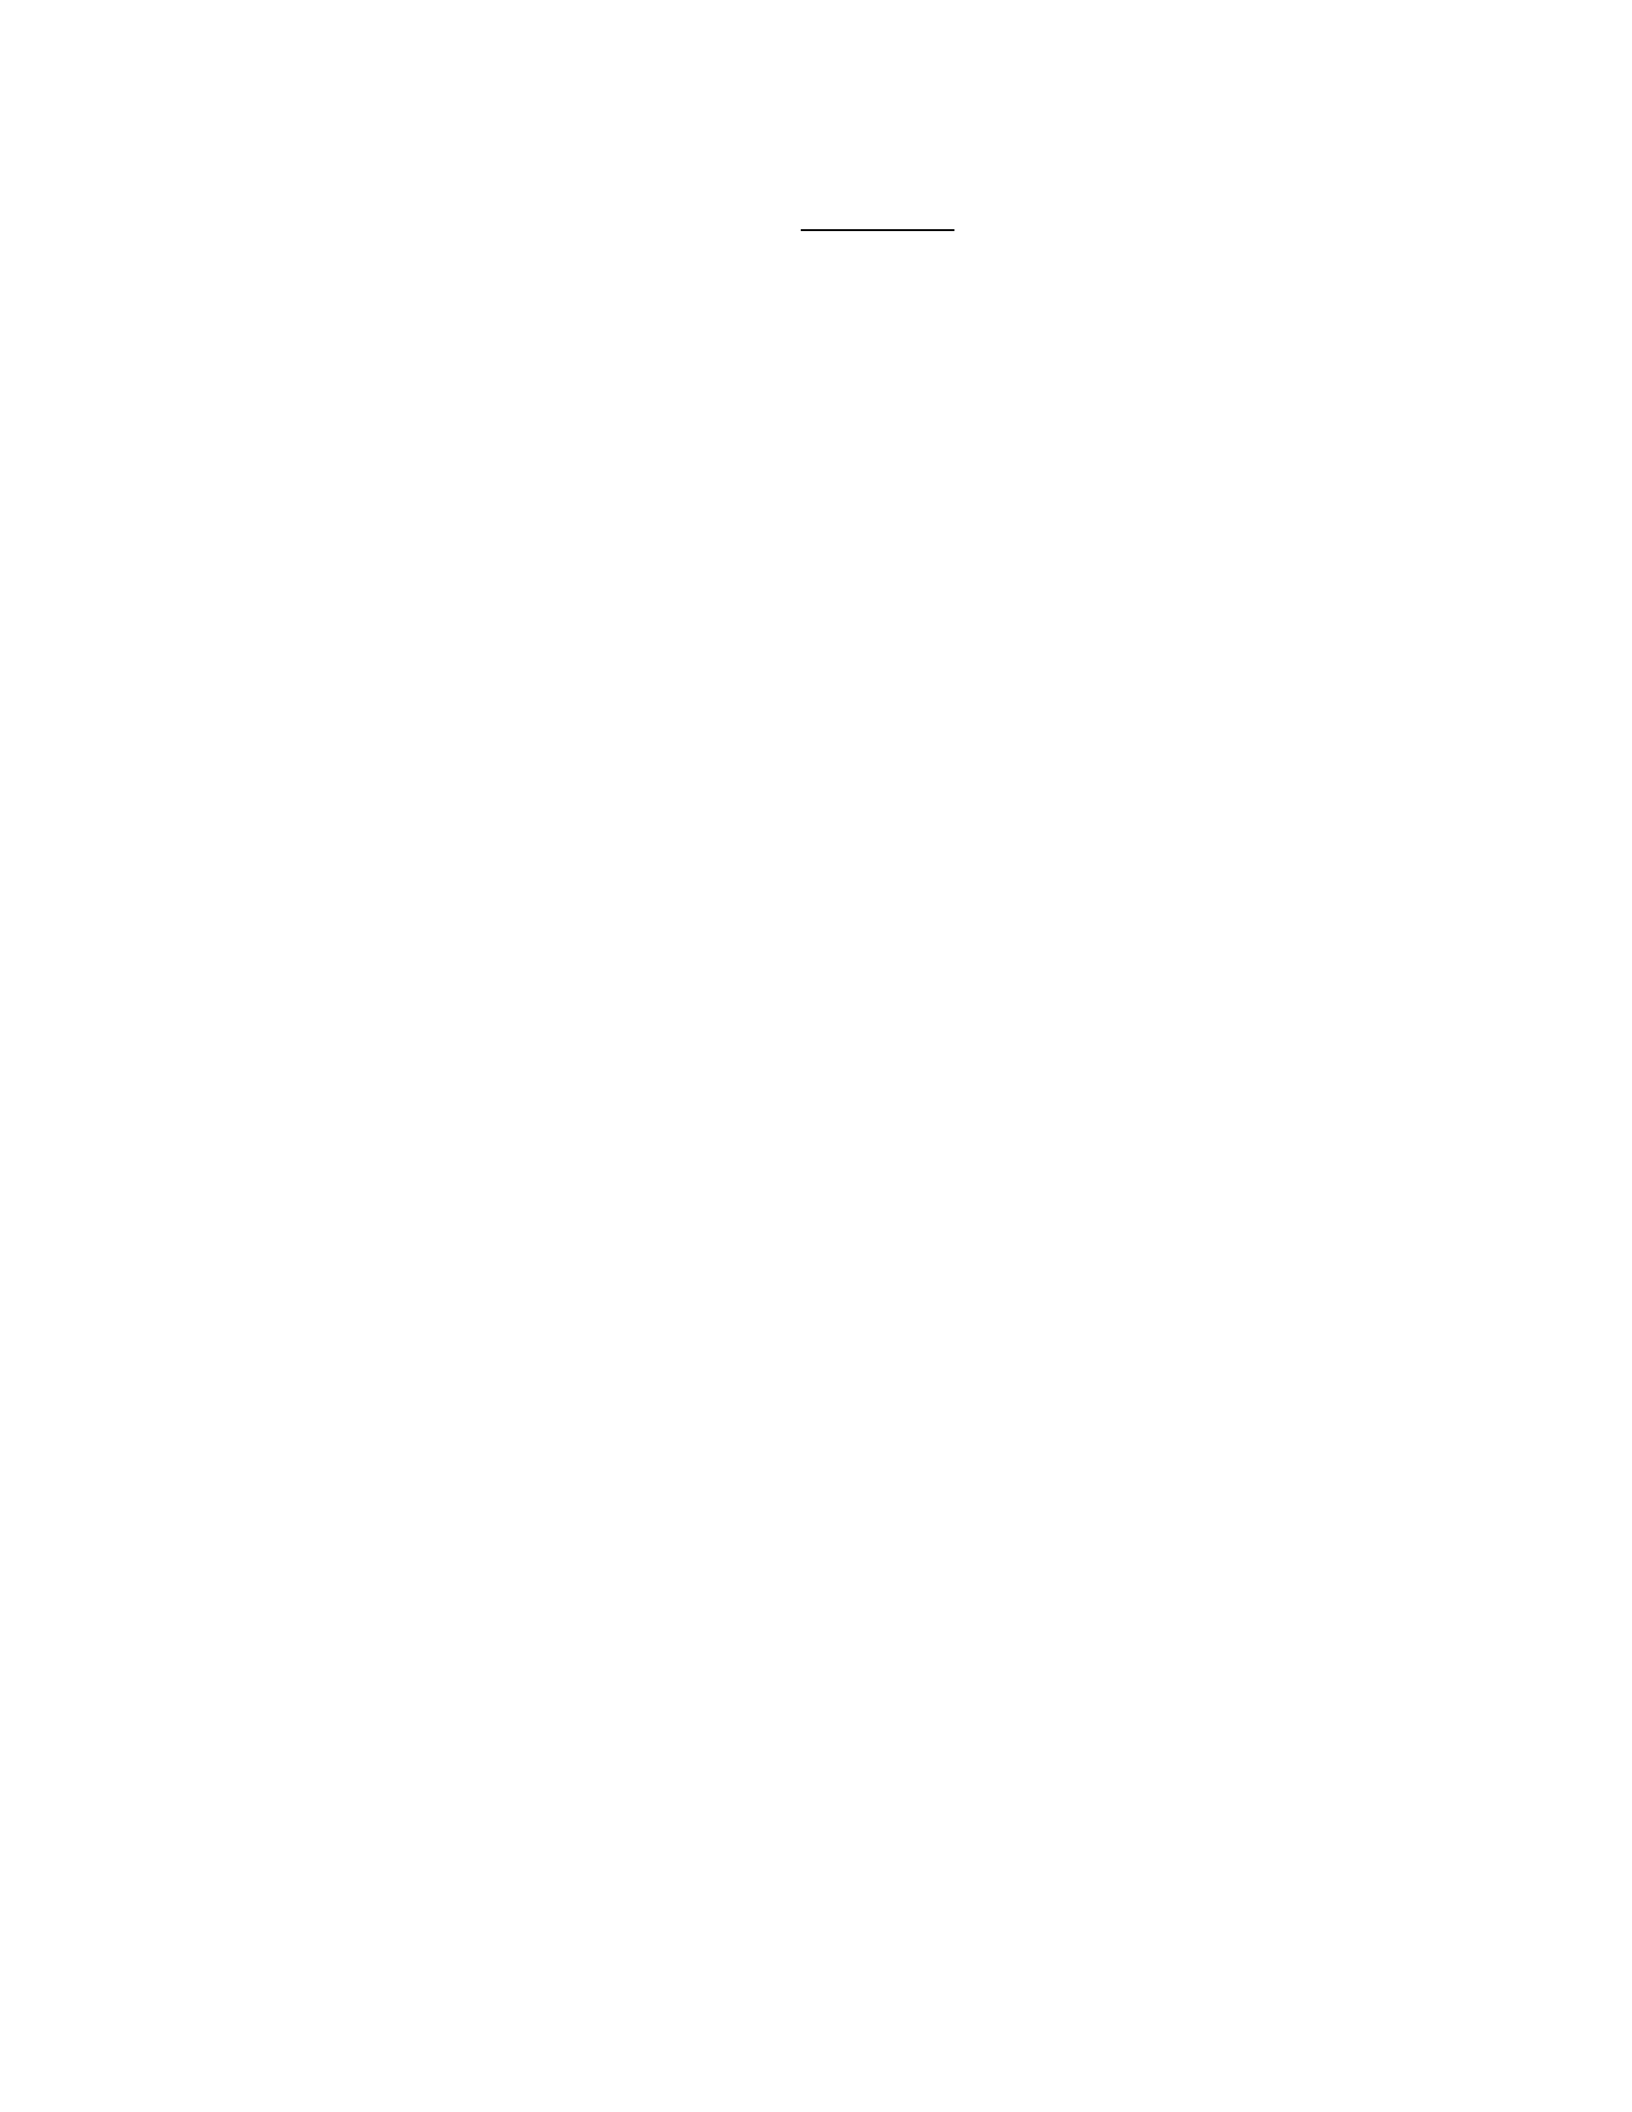
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
169. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
170. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
171. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
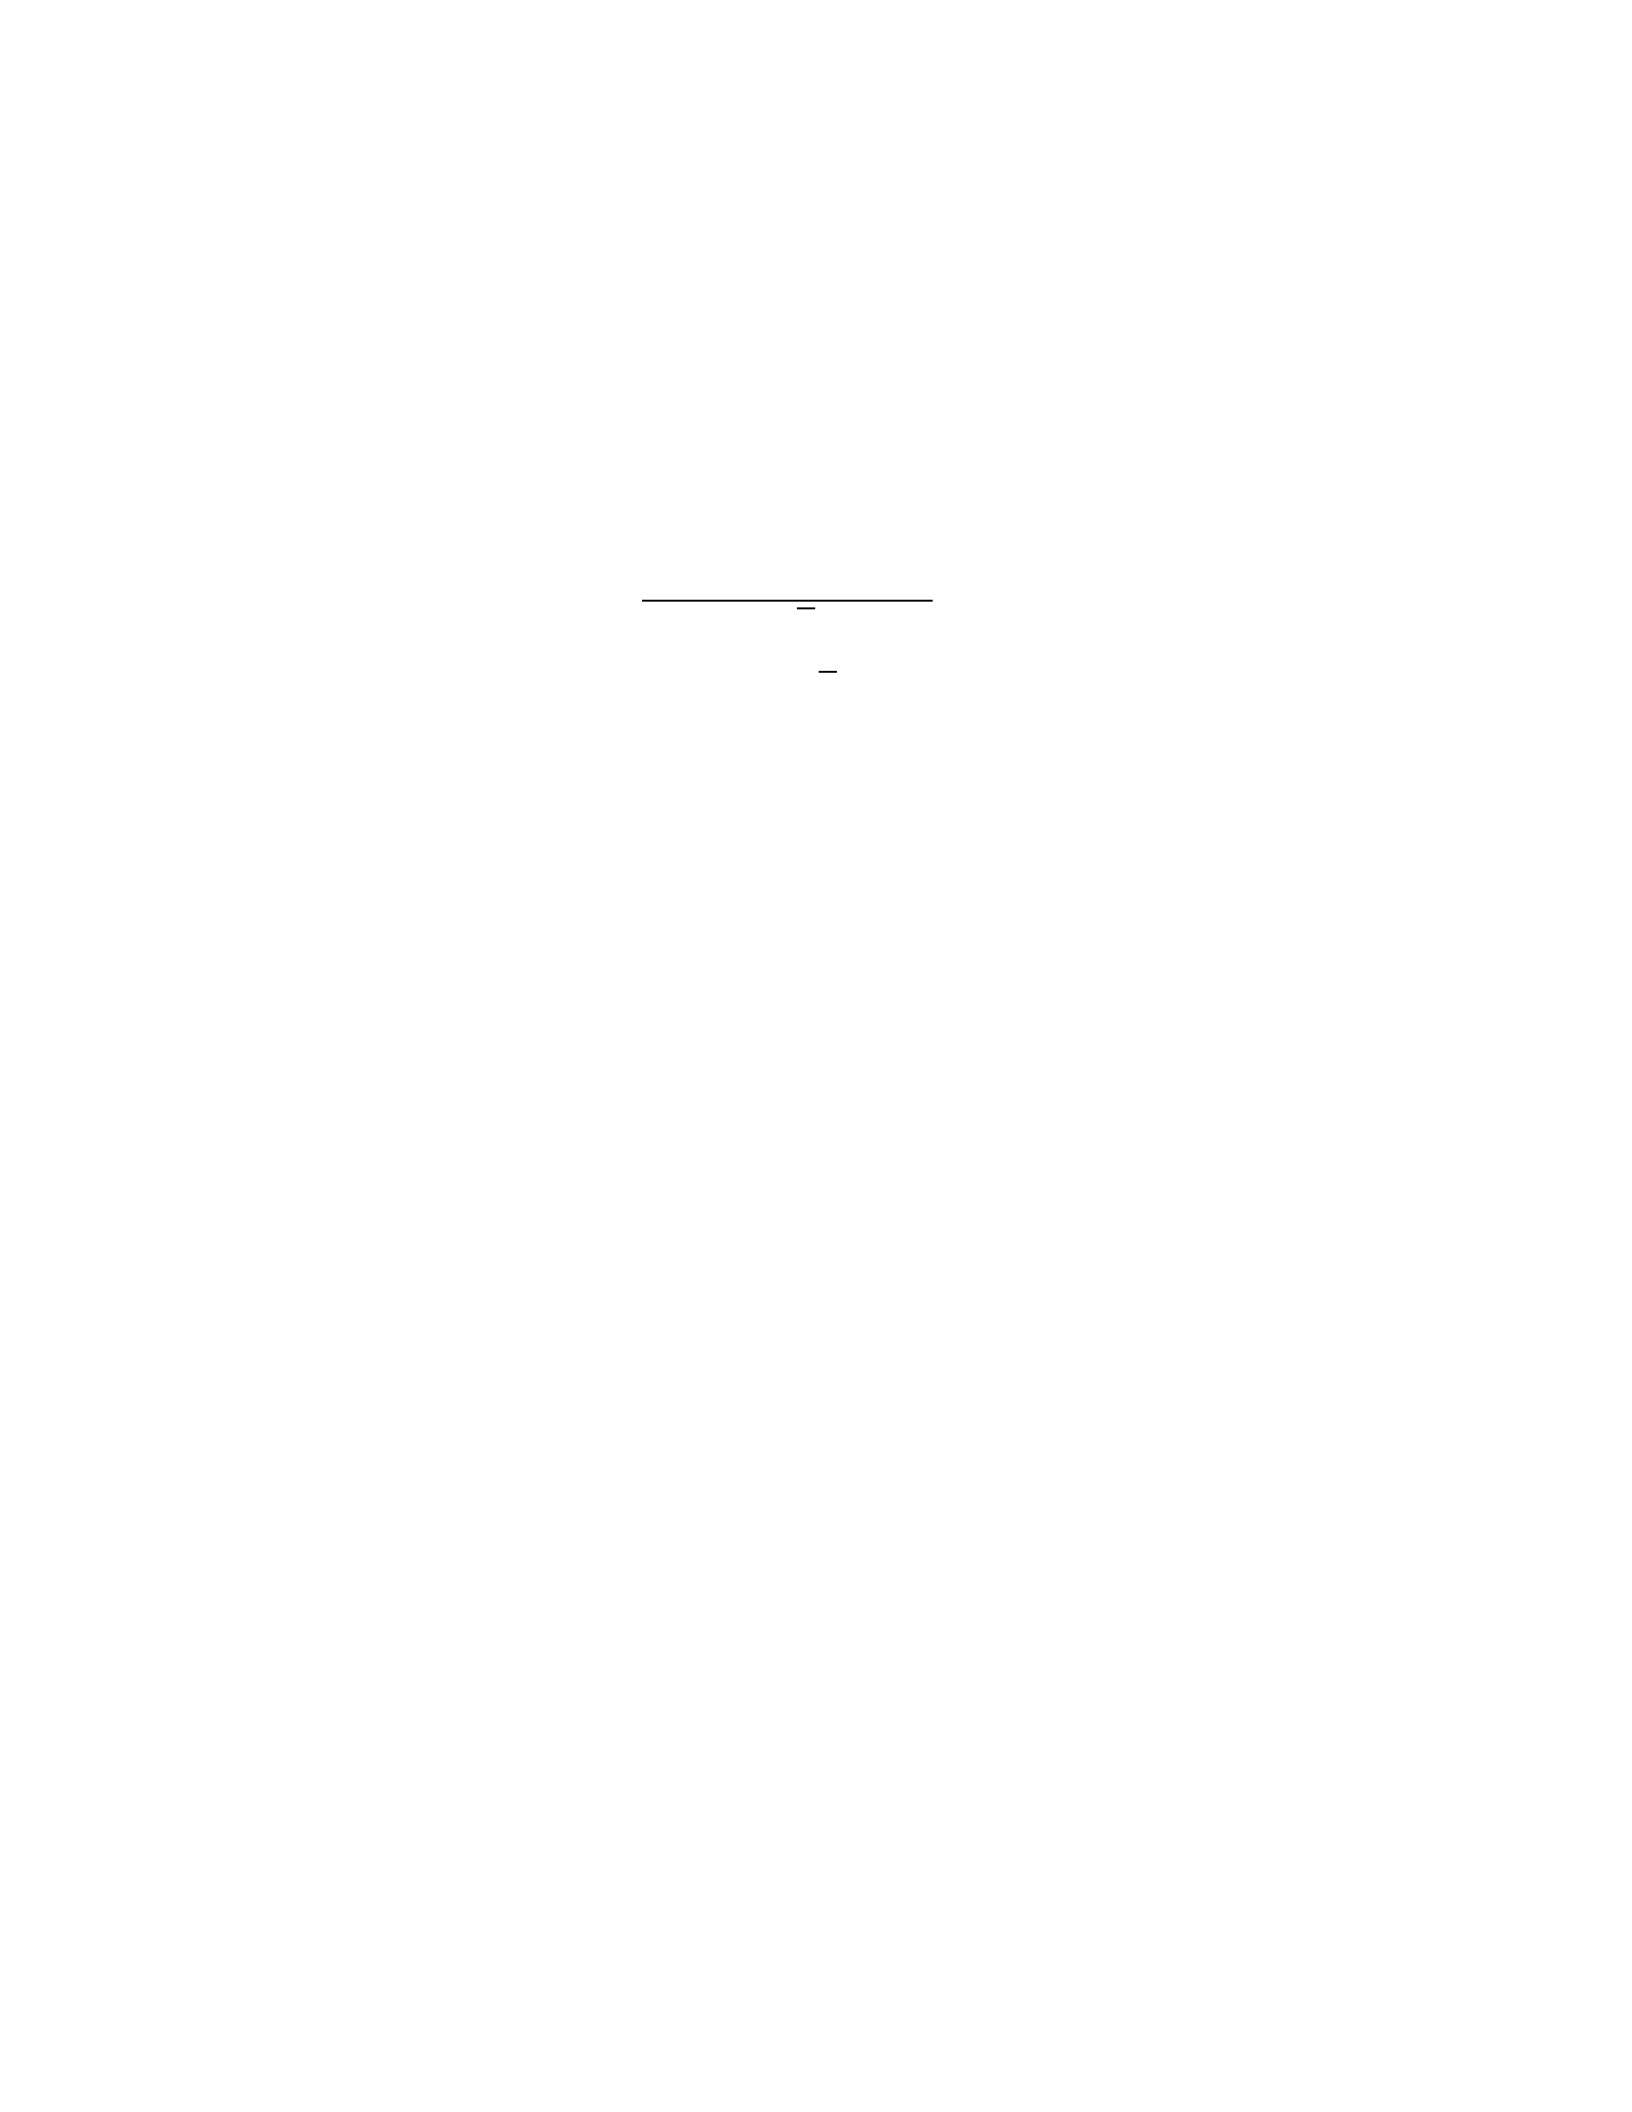
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
172. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500

• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
173. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
174. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:

• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
175. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
176. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
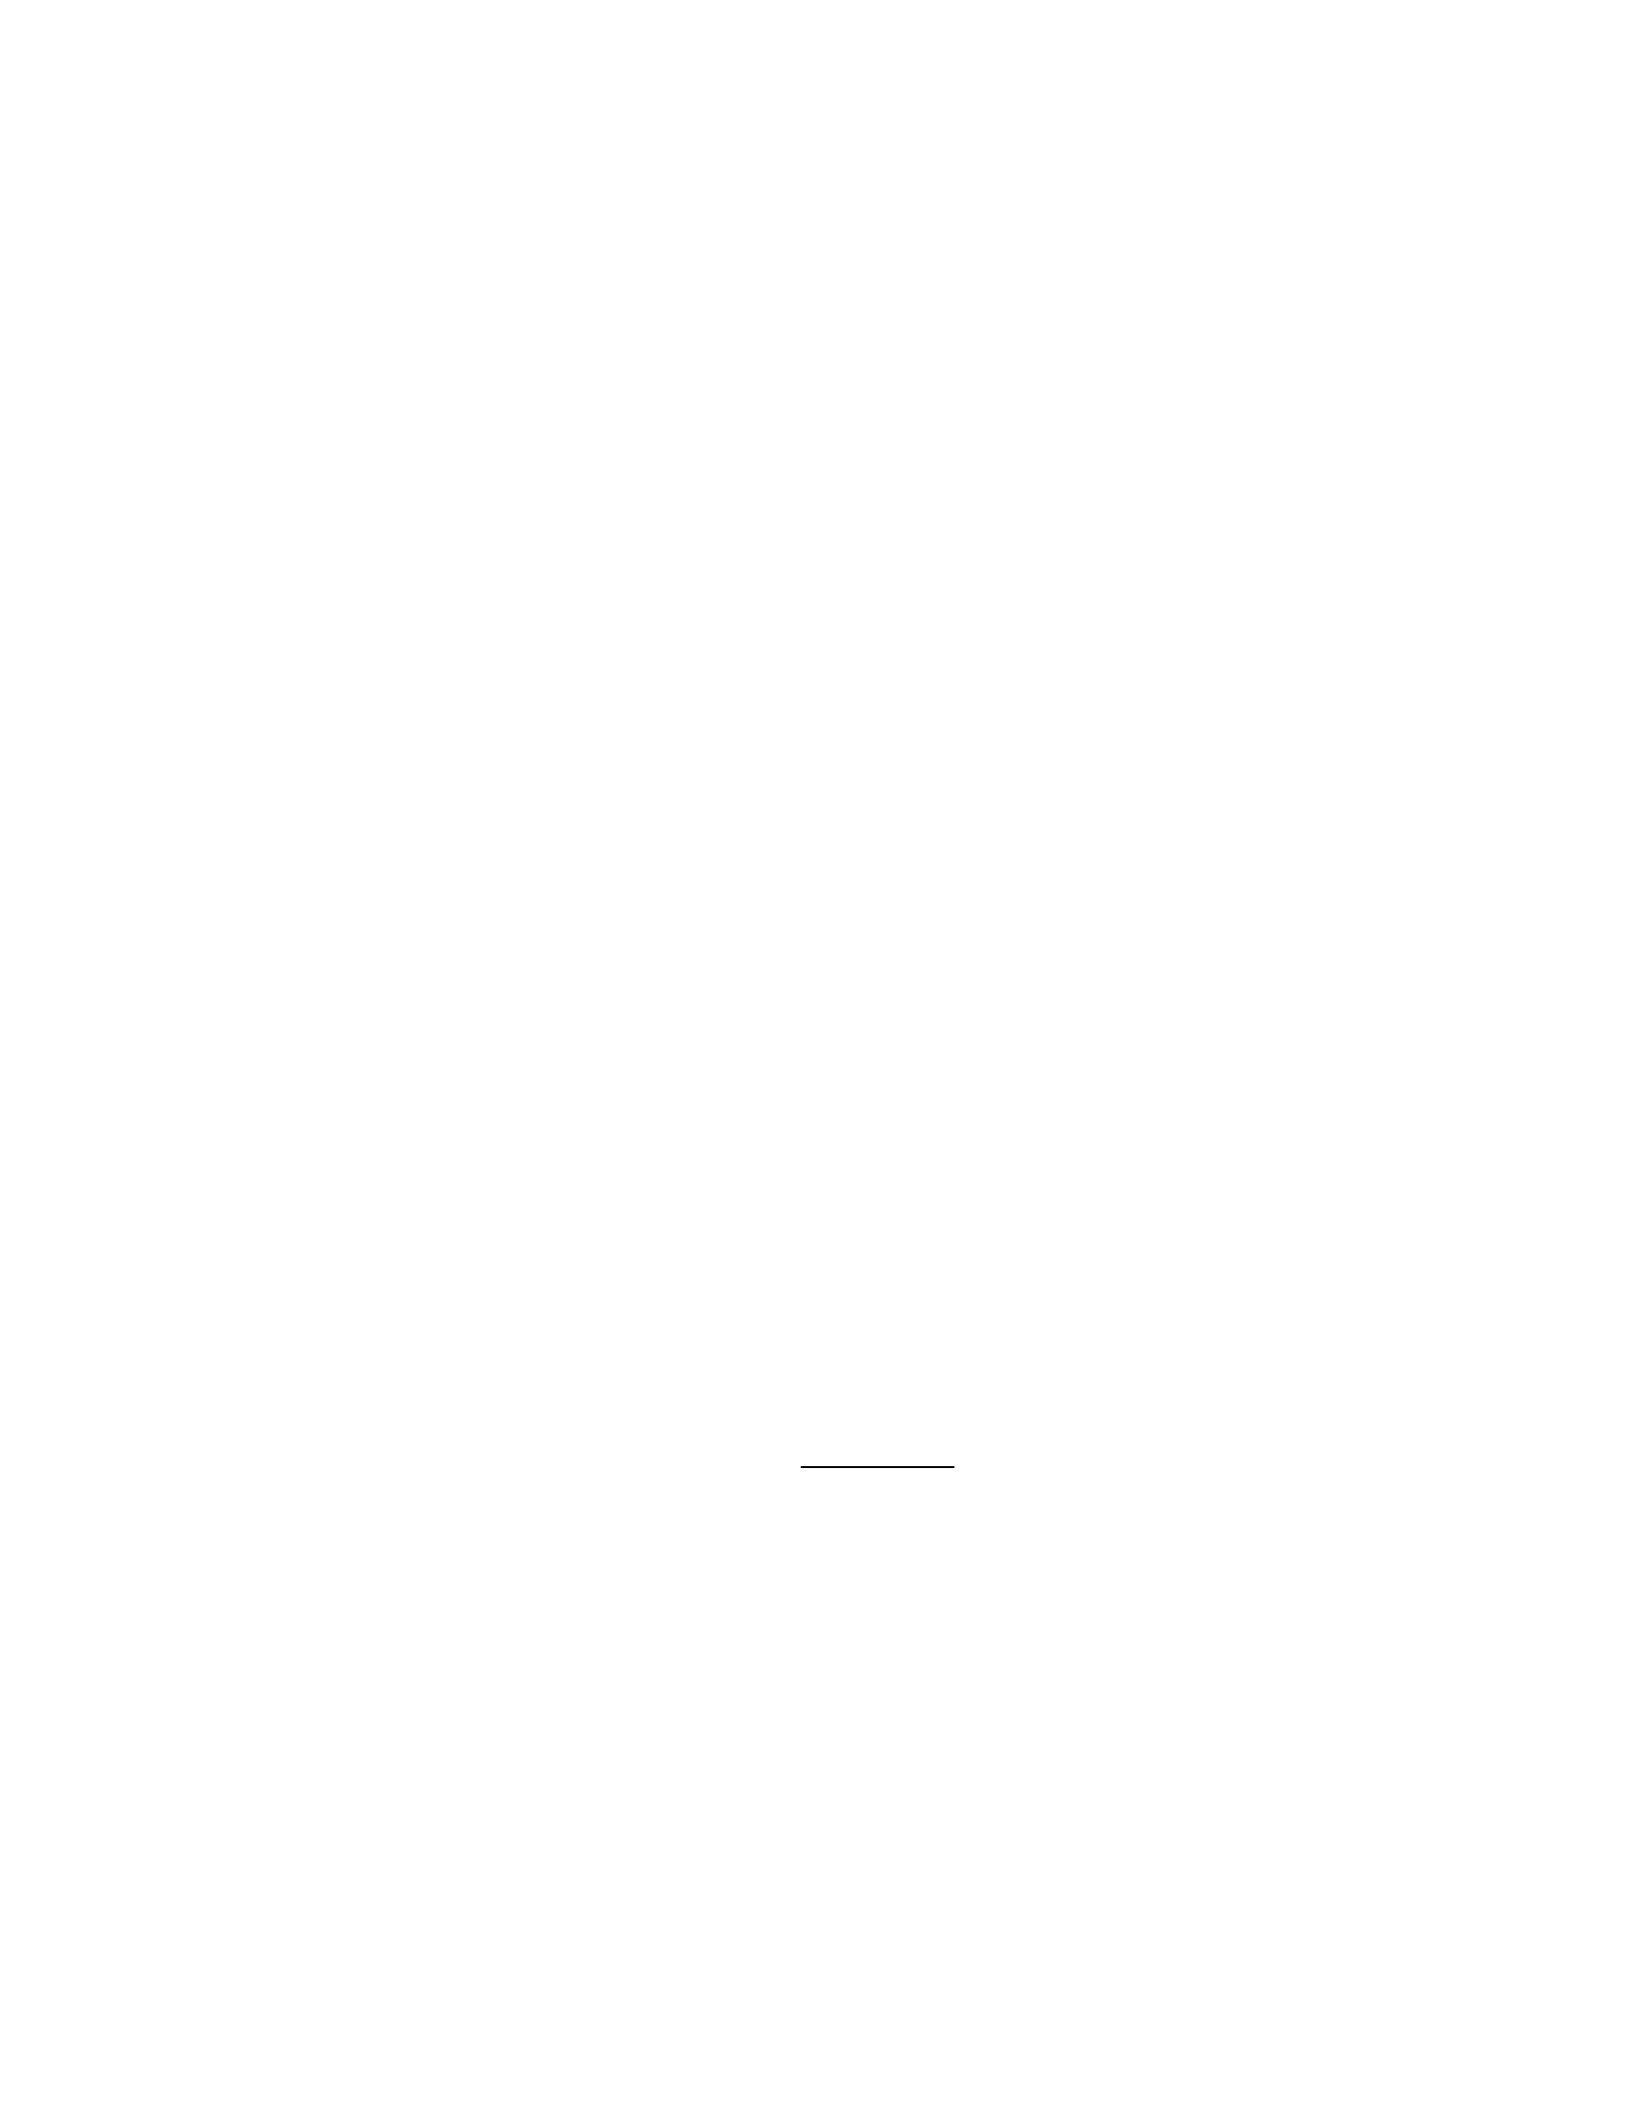
– Net cost = 0
177. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
178. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
179. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%

– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
180. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
181. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
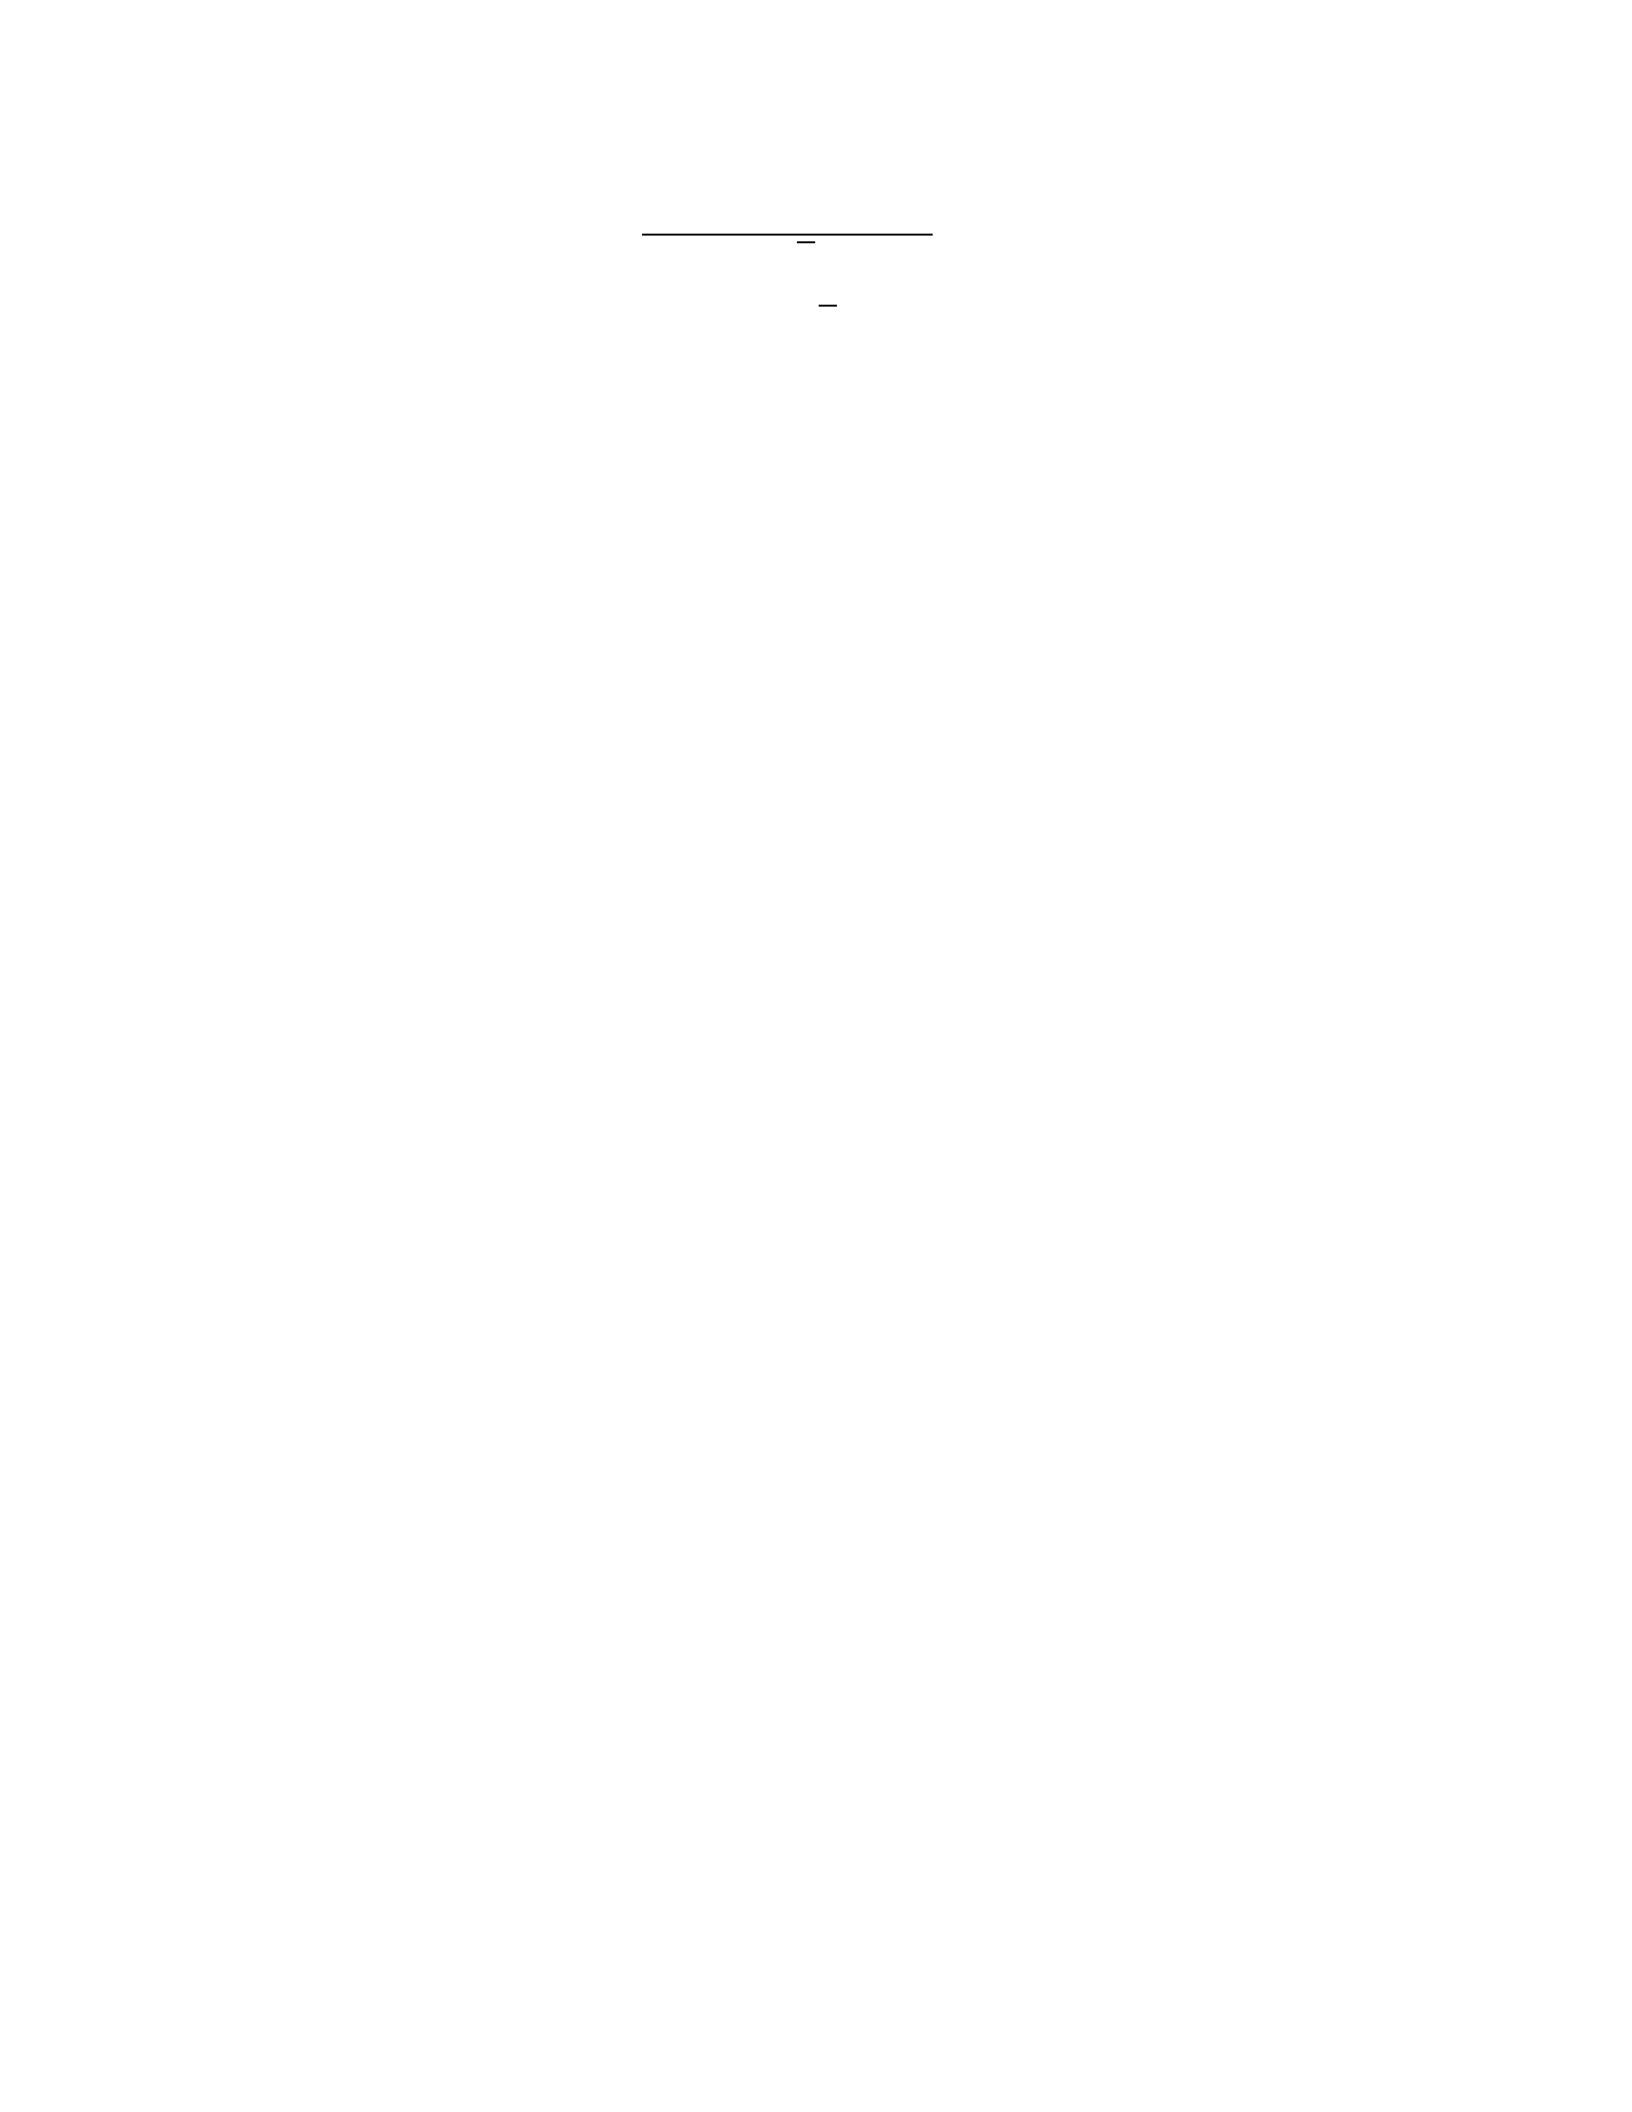
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
182. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
183. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:

a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
184. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10

– Breakeven points: $90 and $110
185. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
186. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
187. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
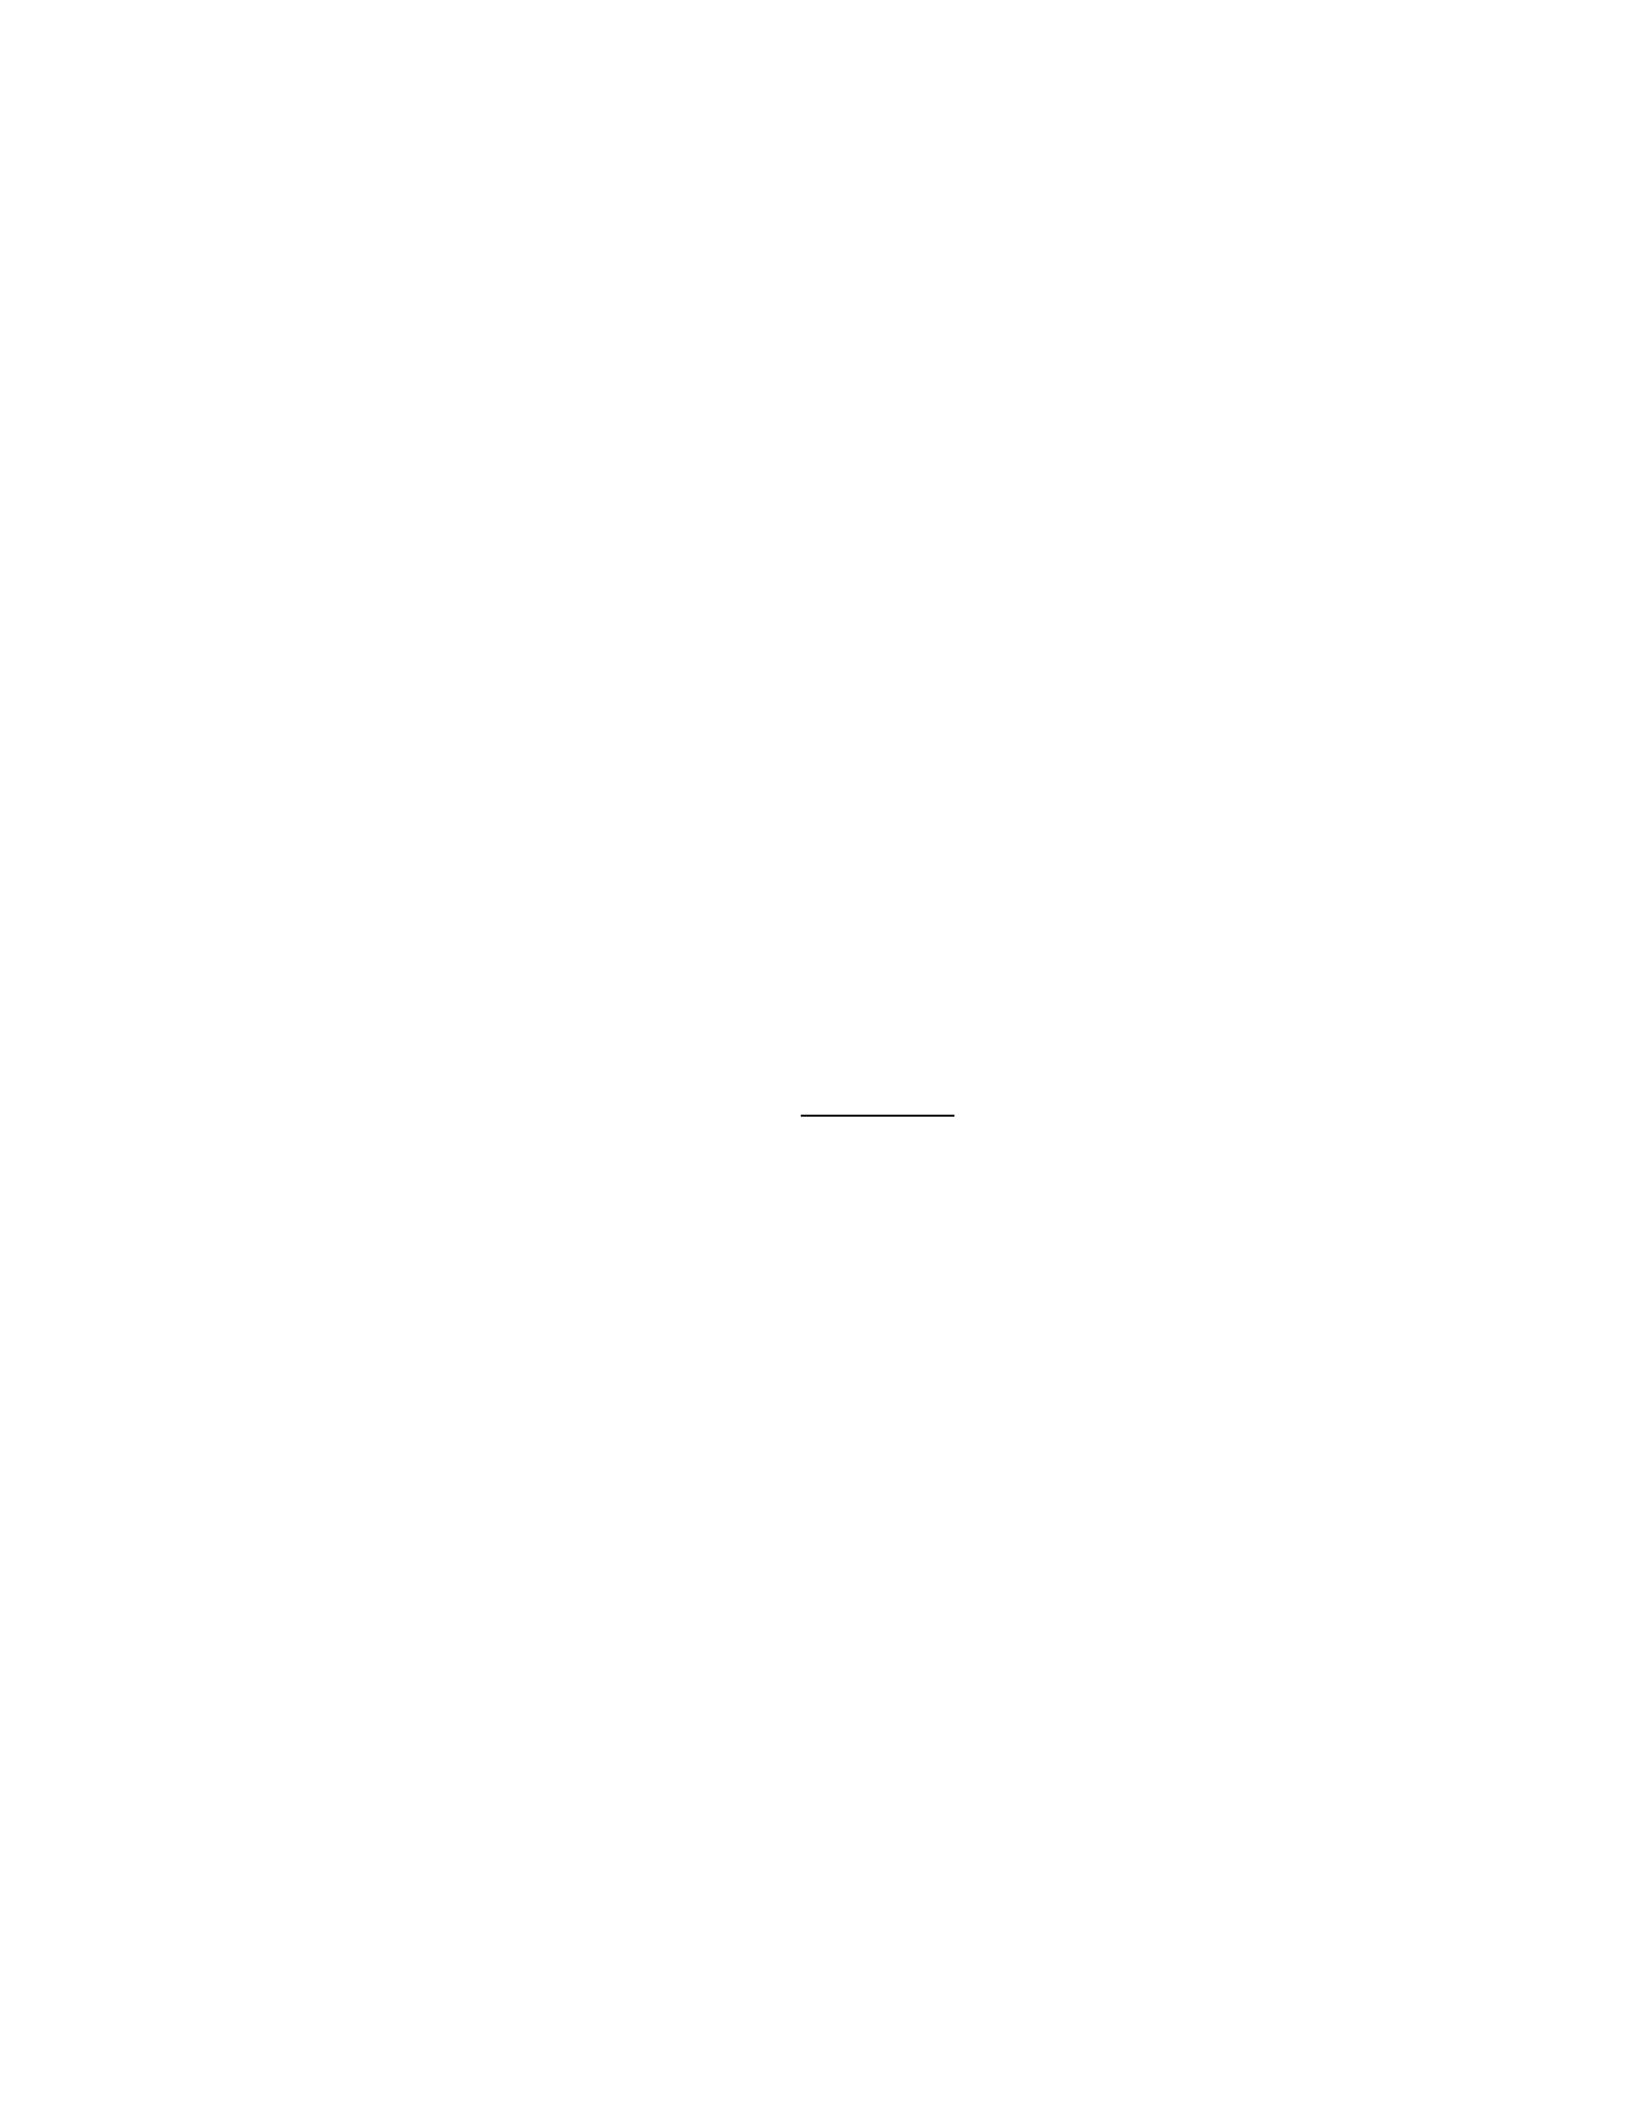
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
188. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
189. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
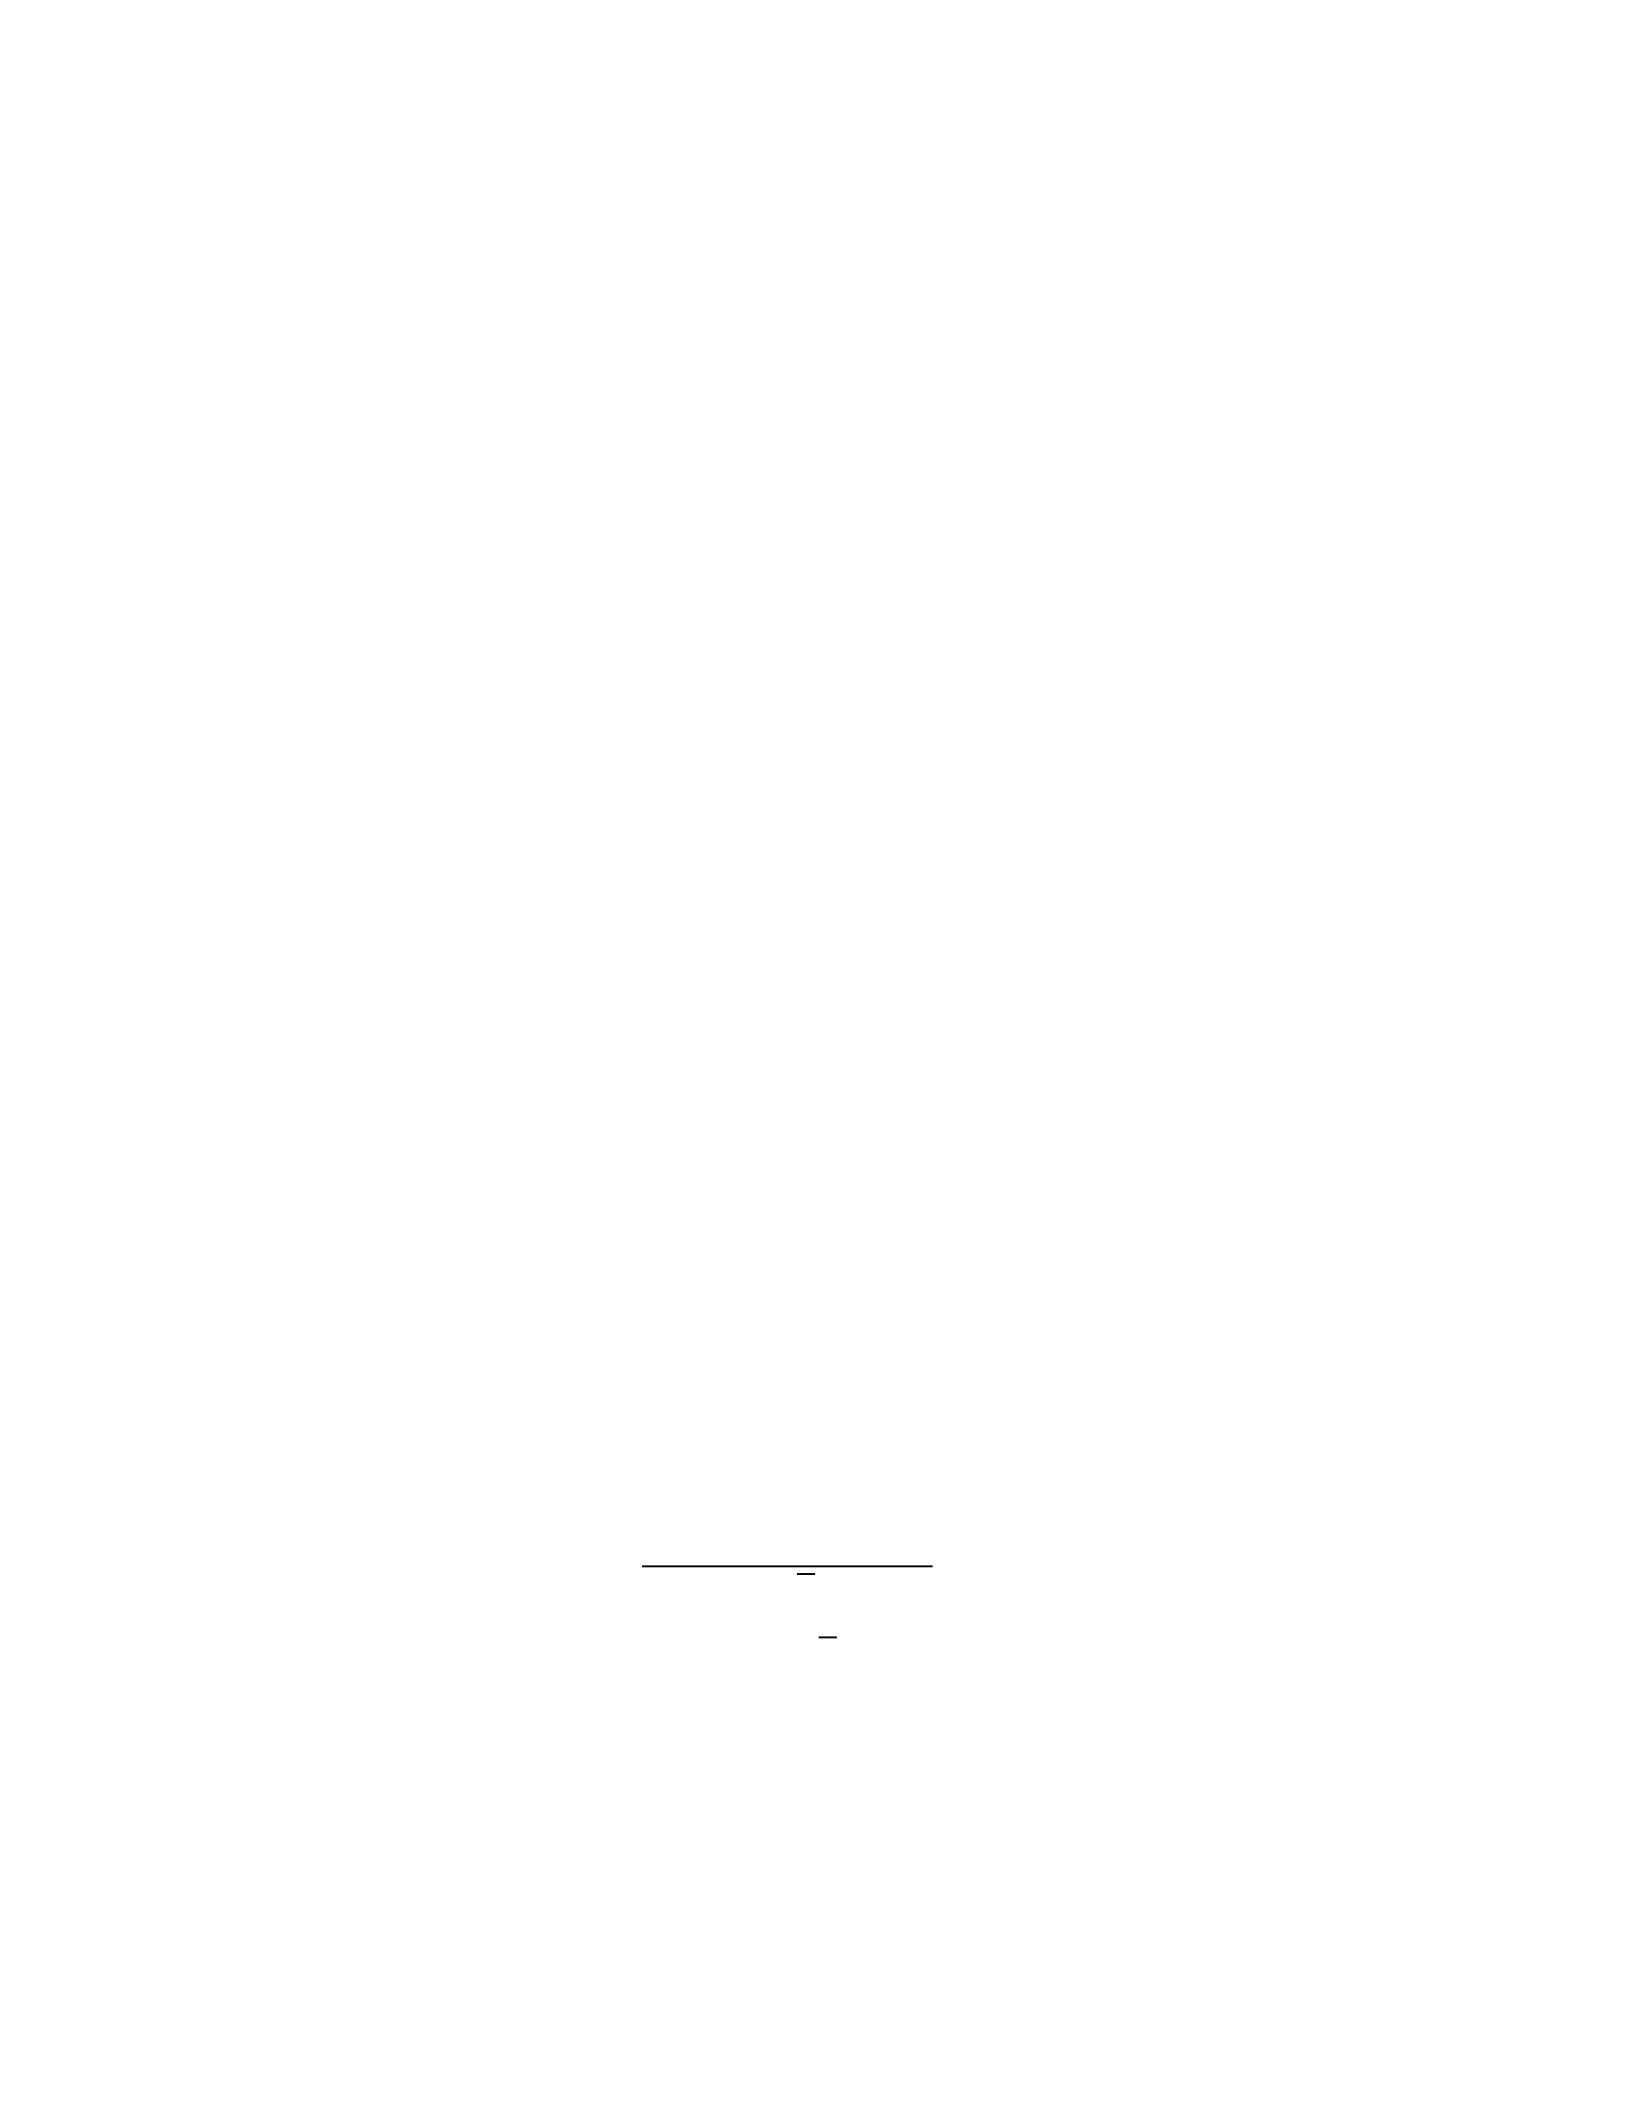
190. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
191. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula

𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
192. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
193. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711

• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
194. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
195. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:

– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
196. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
197. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
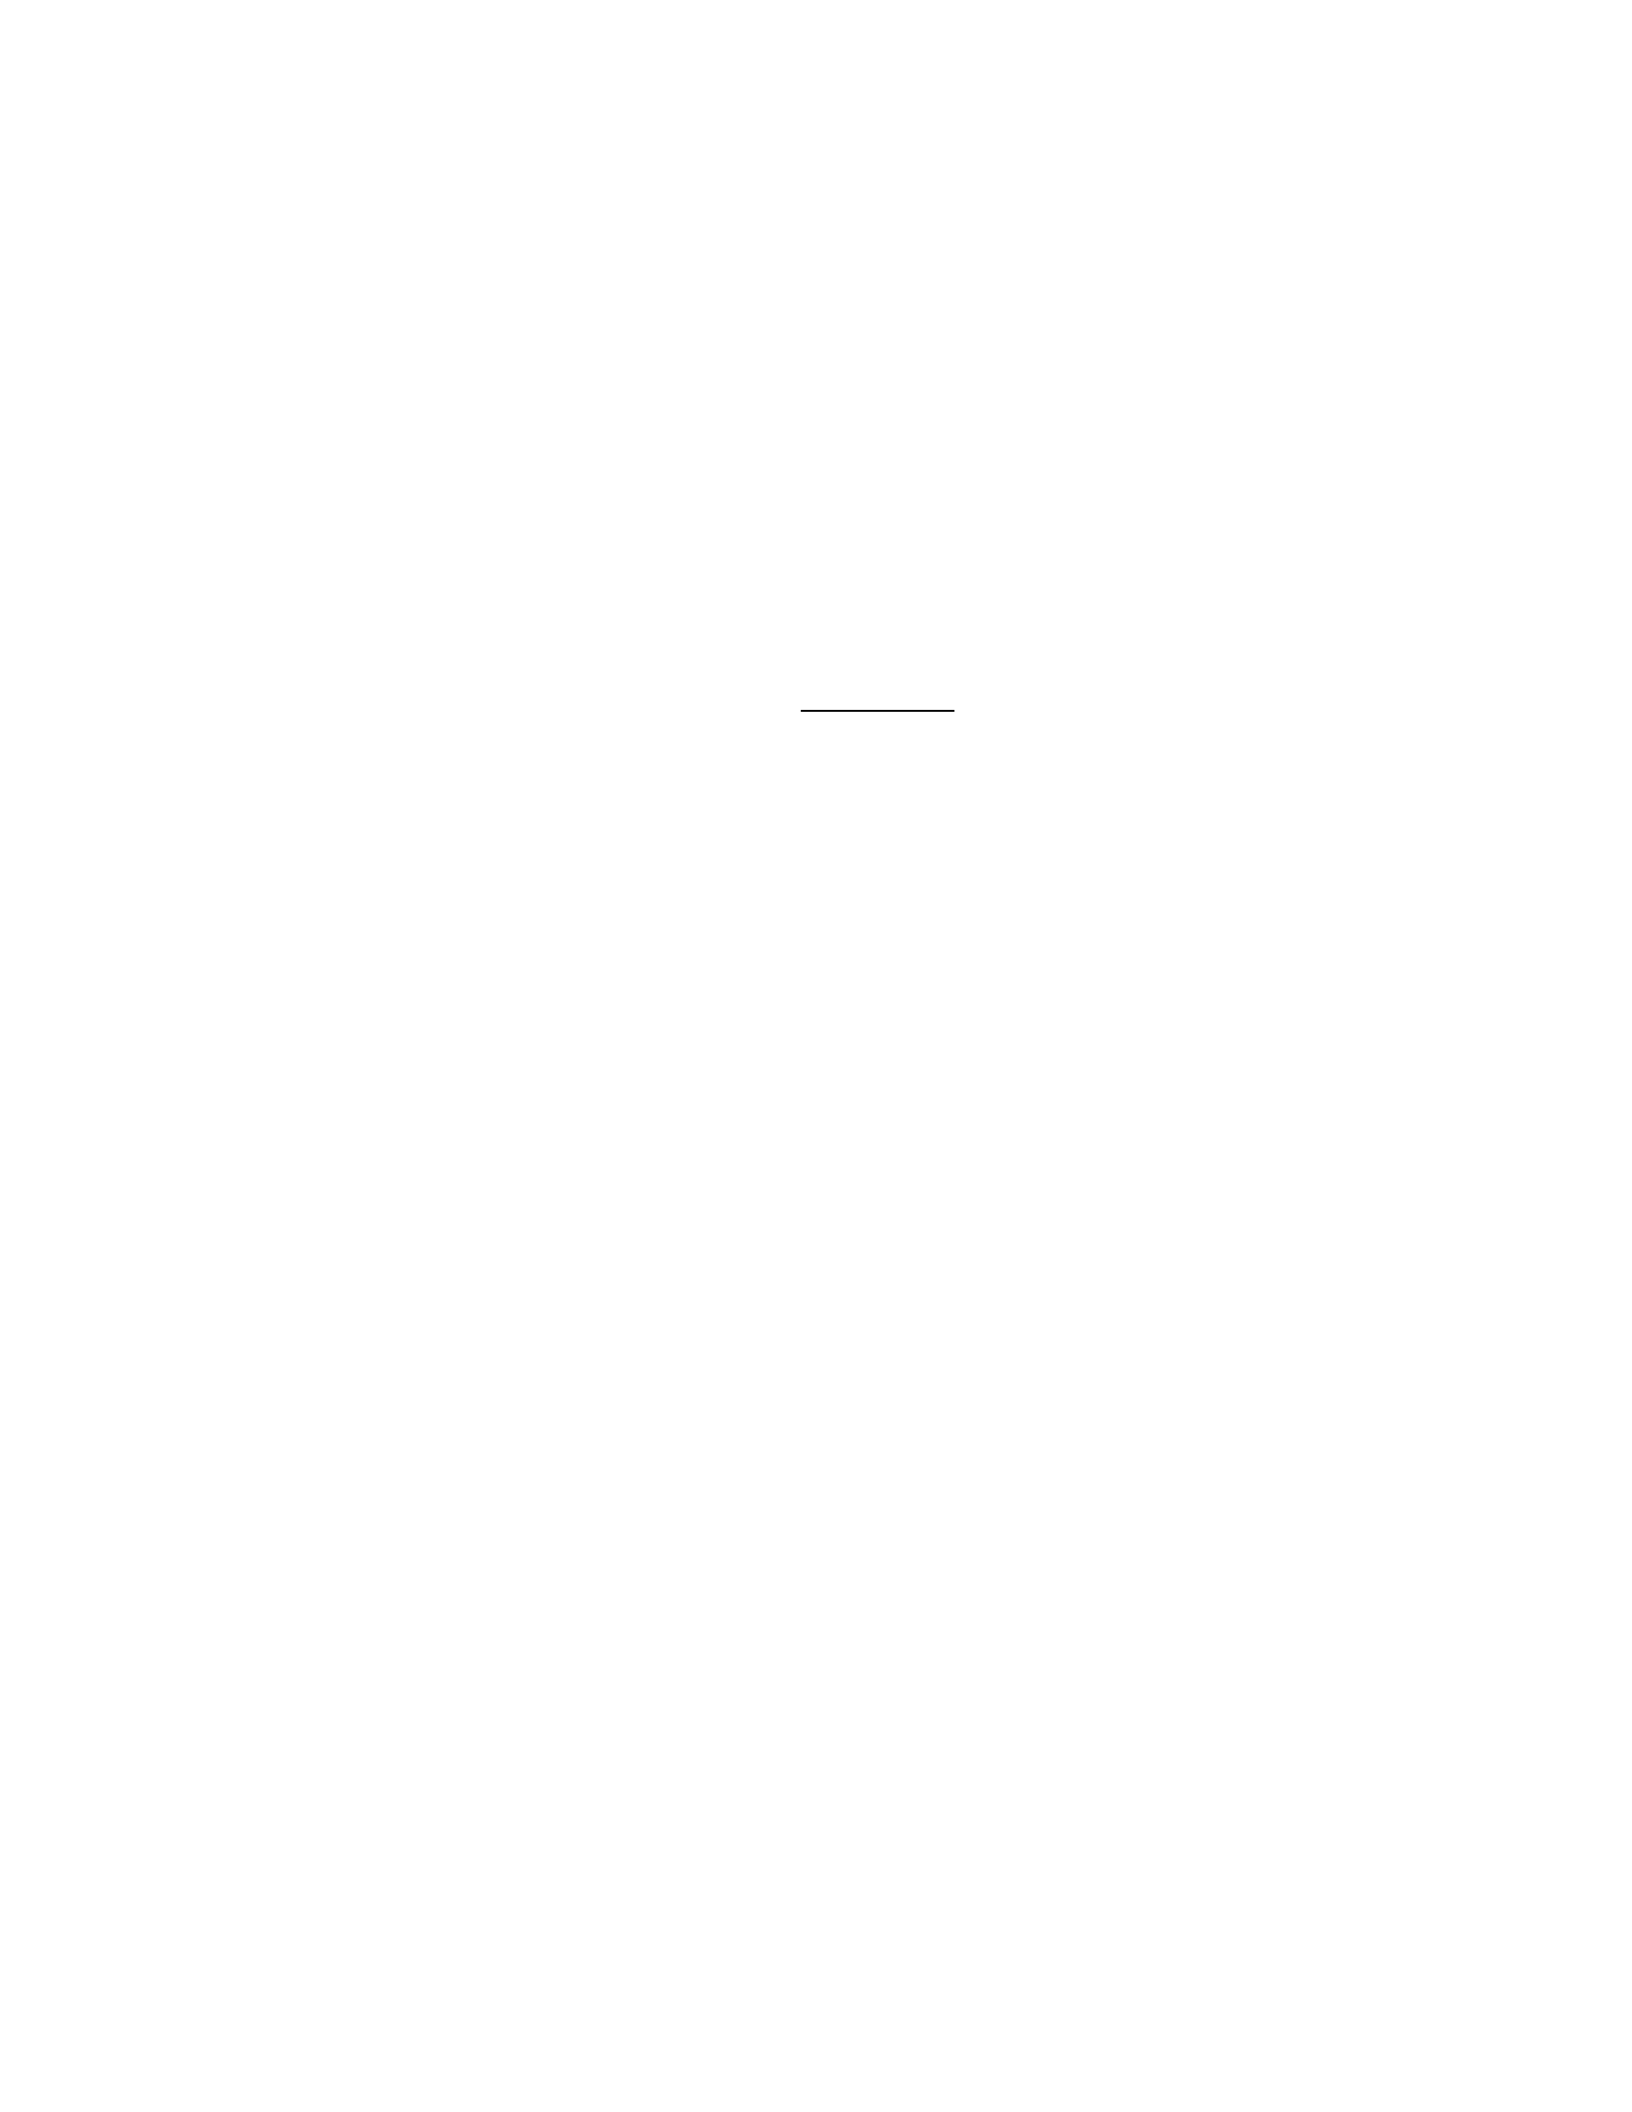
198. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
199. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
200. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
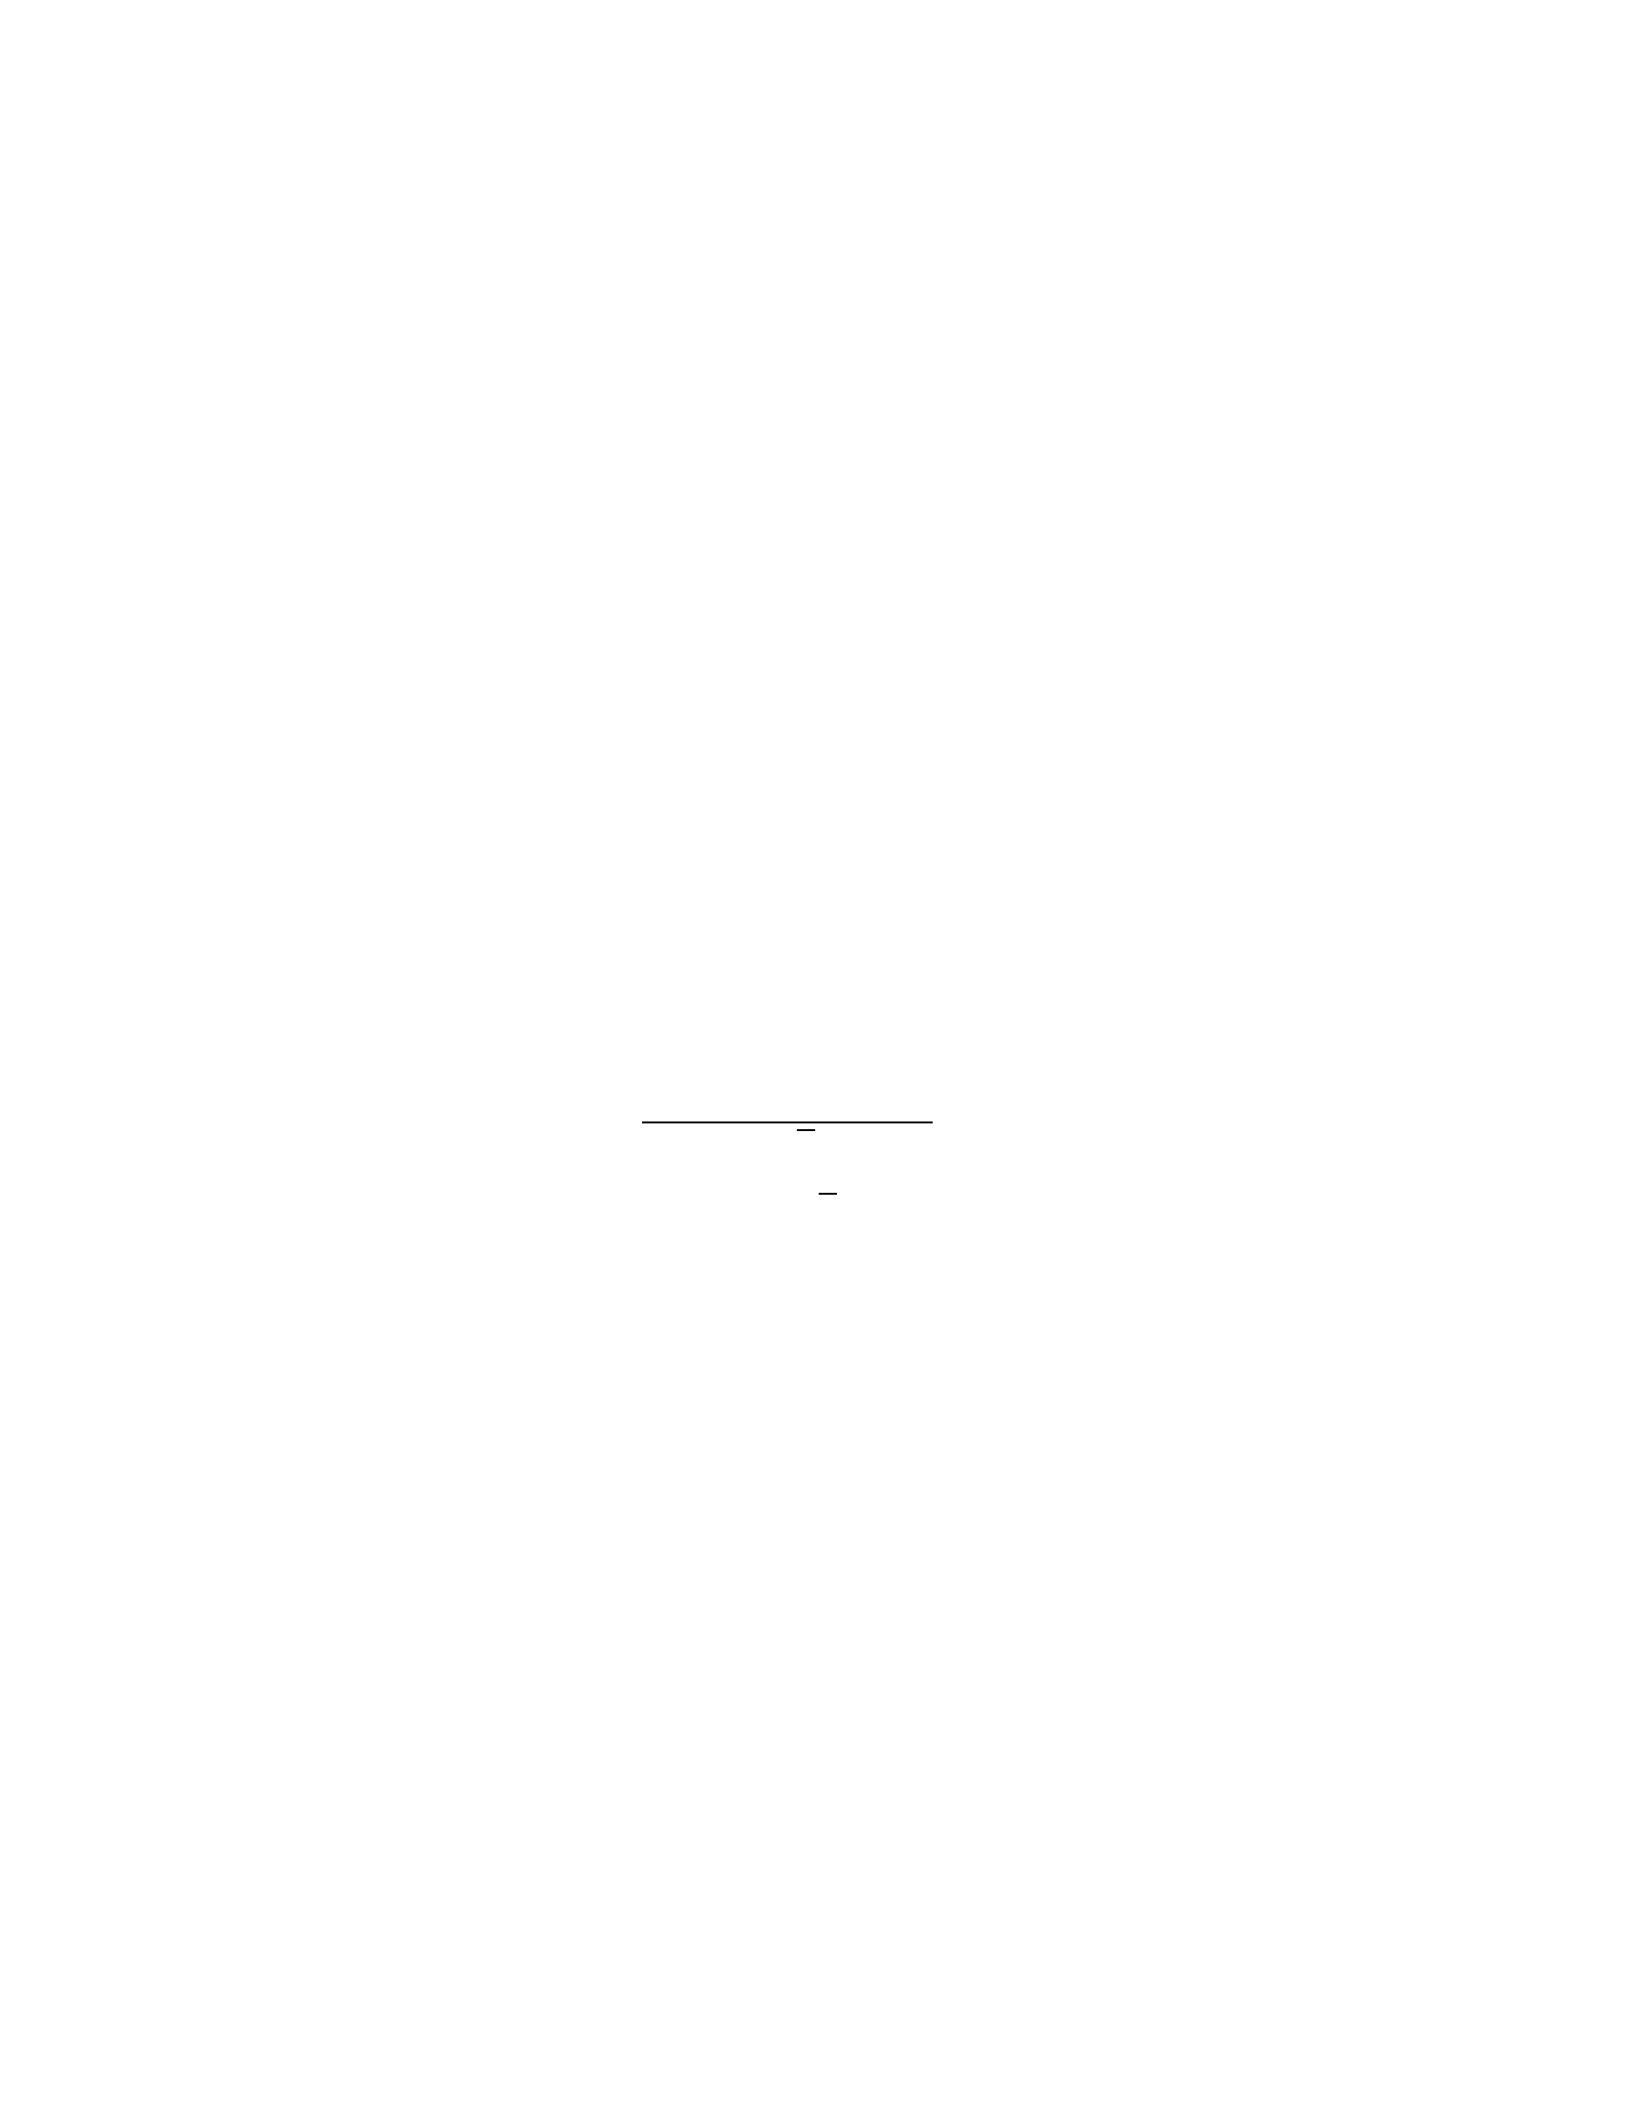
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
201. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
202. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:

a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
203. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
204. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit

from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
205. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
206. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options

and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
207. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
208. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
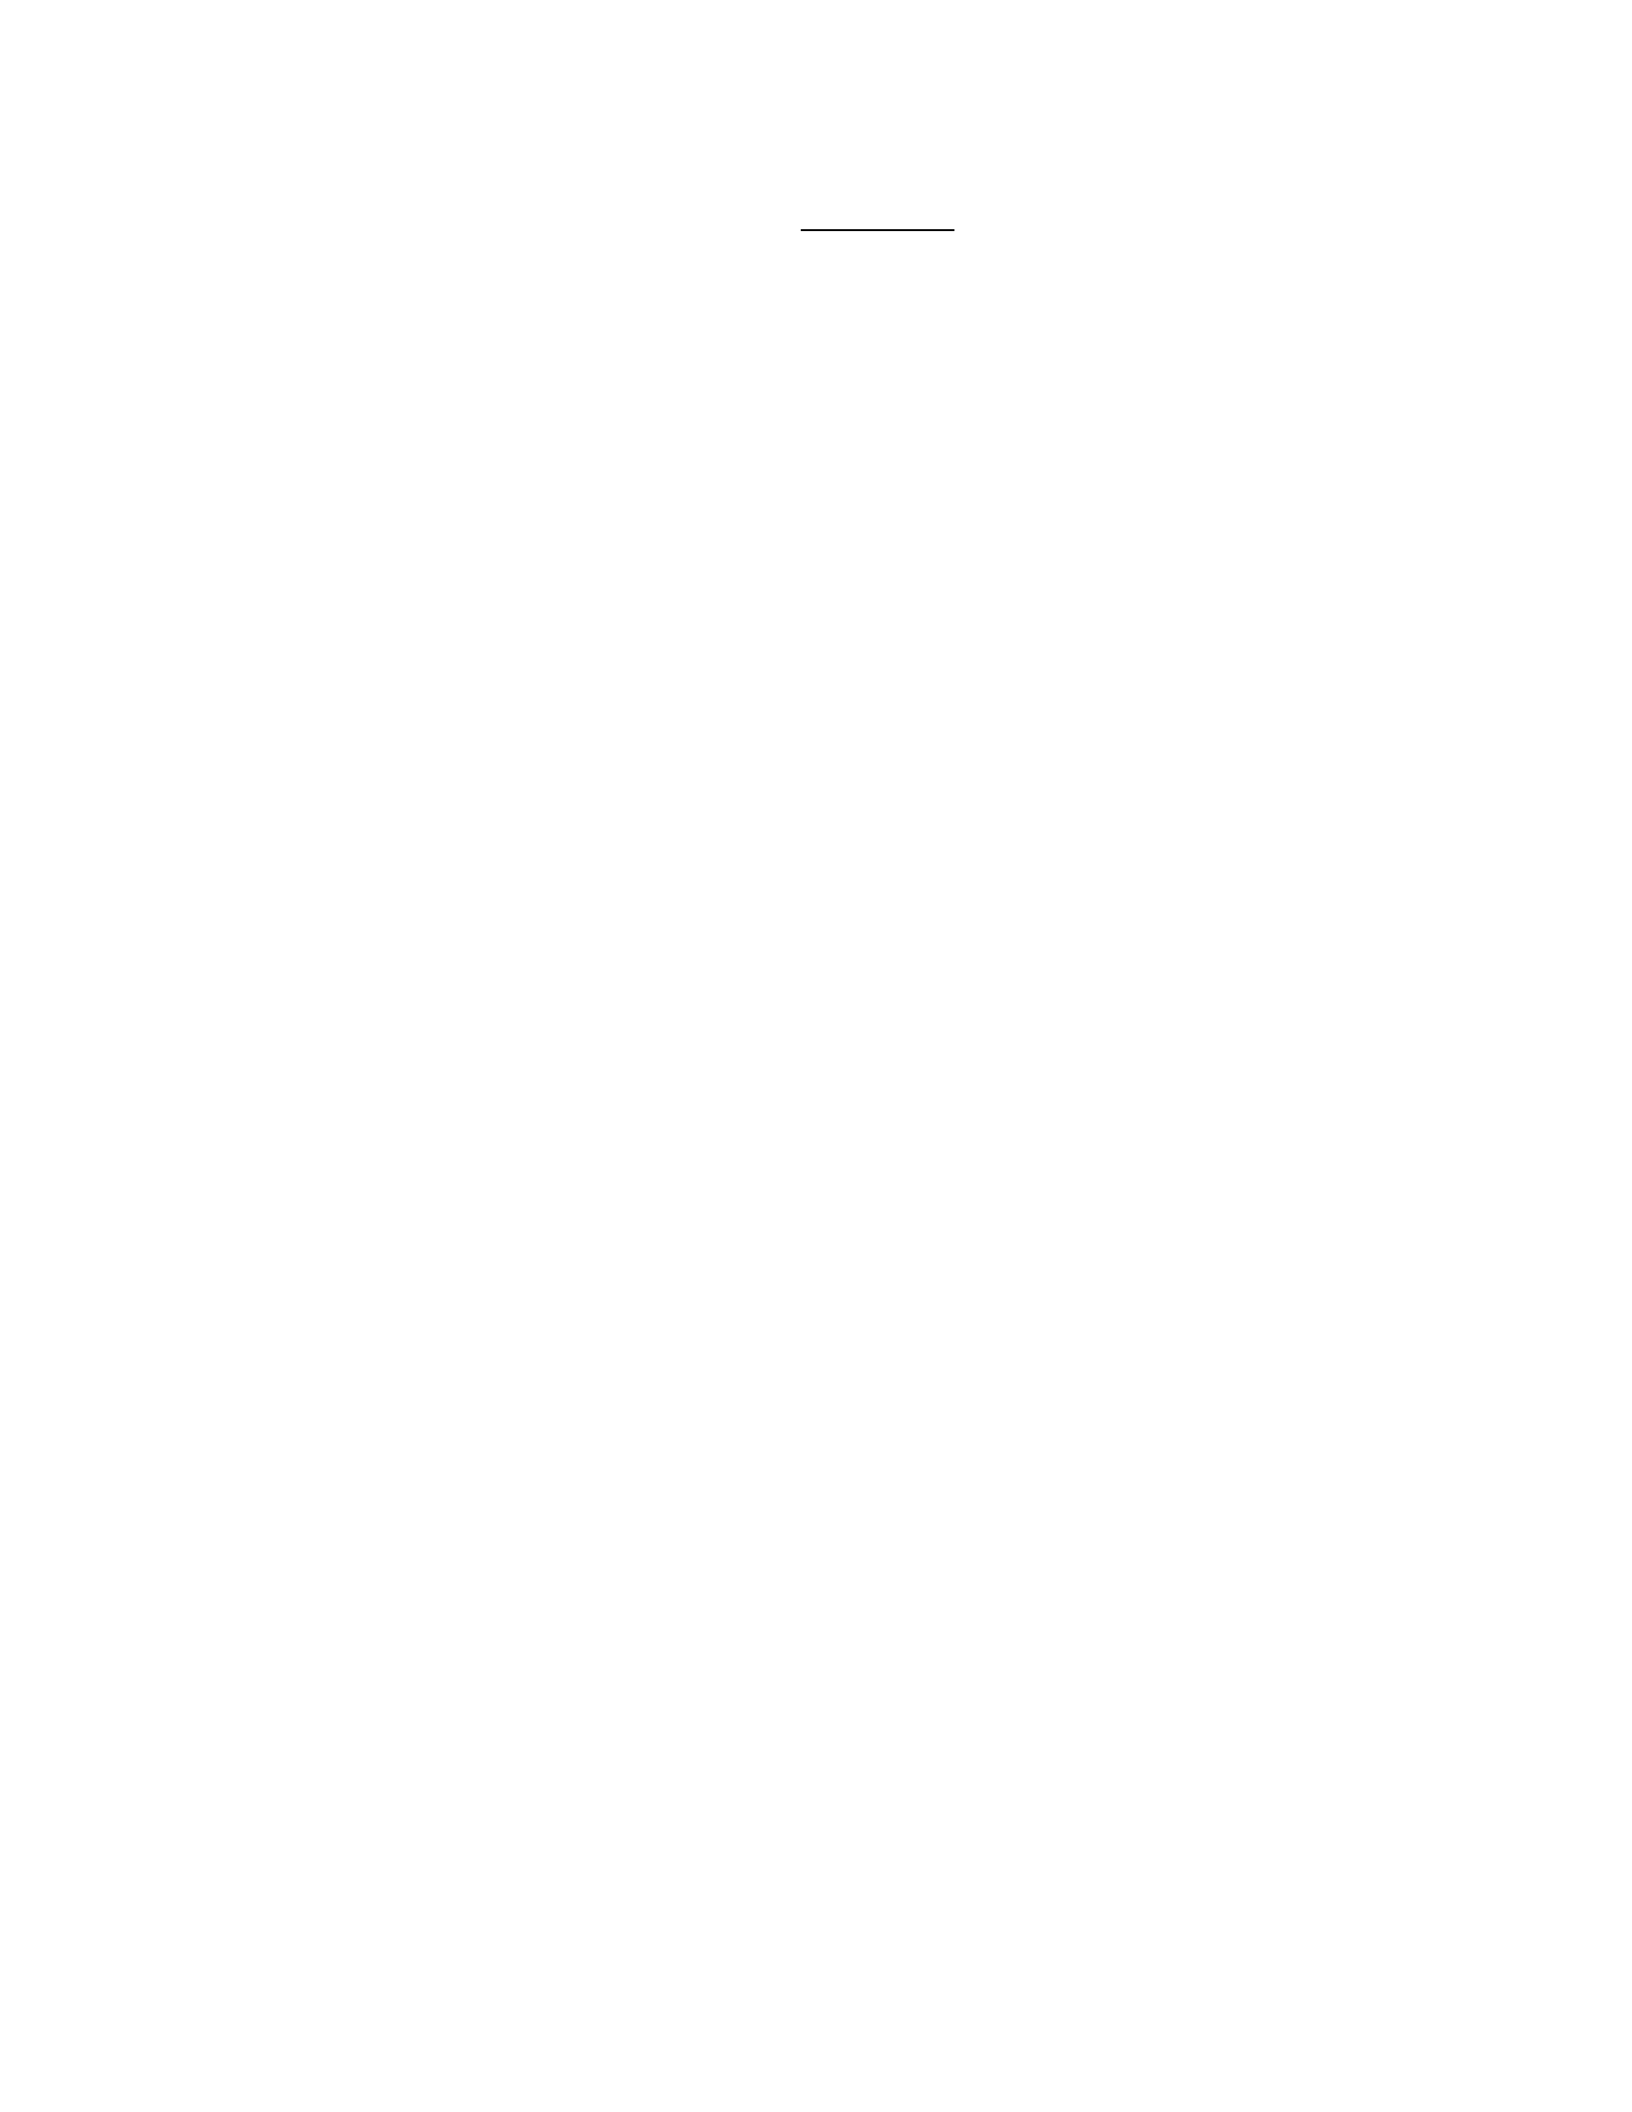
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
209. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
210. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
211. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
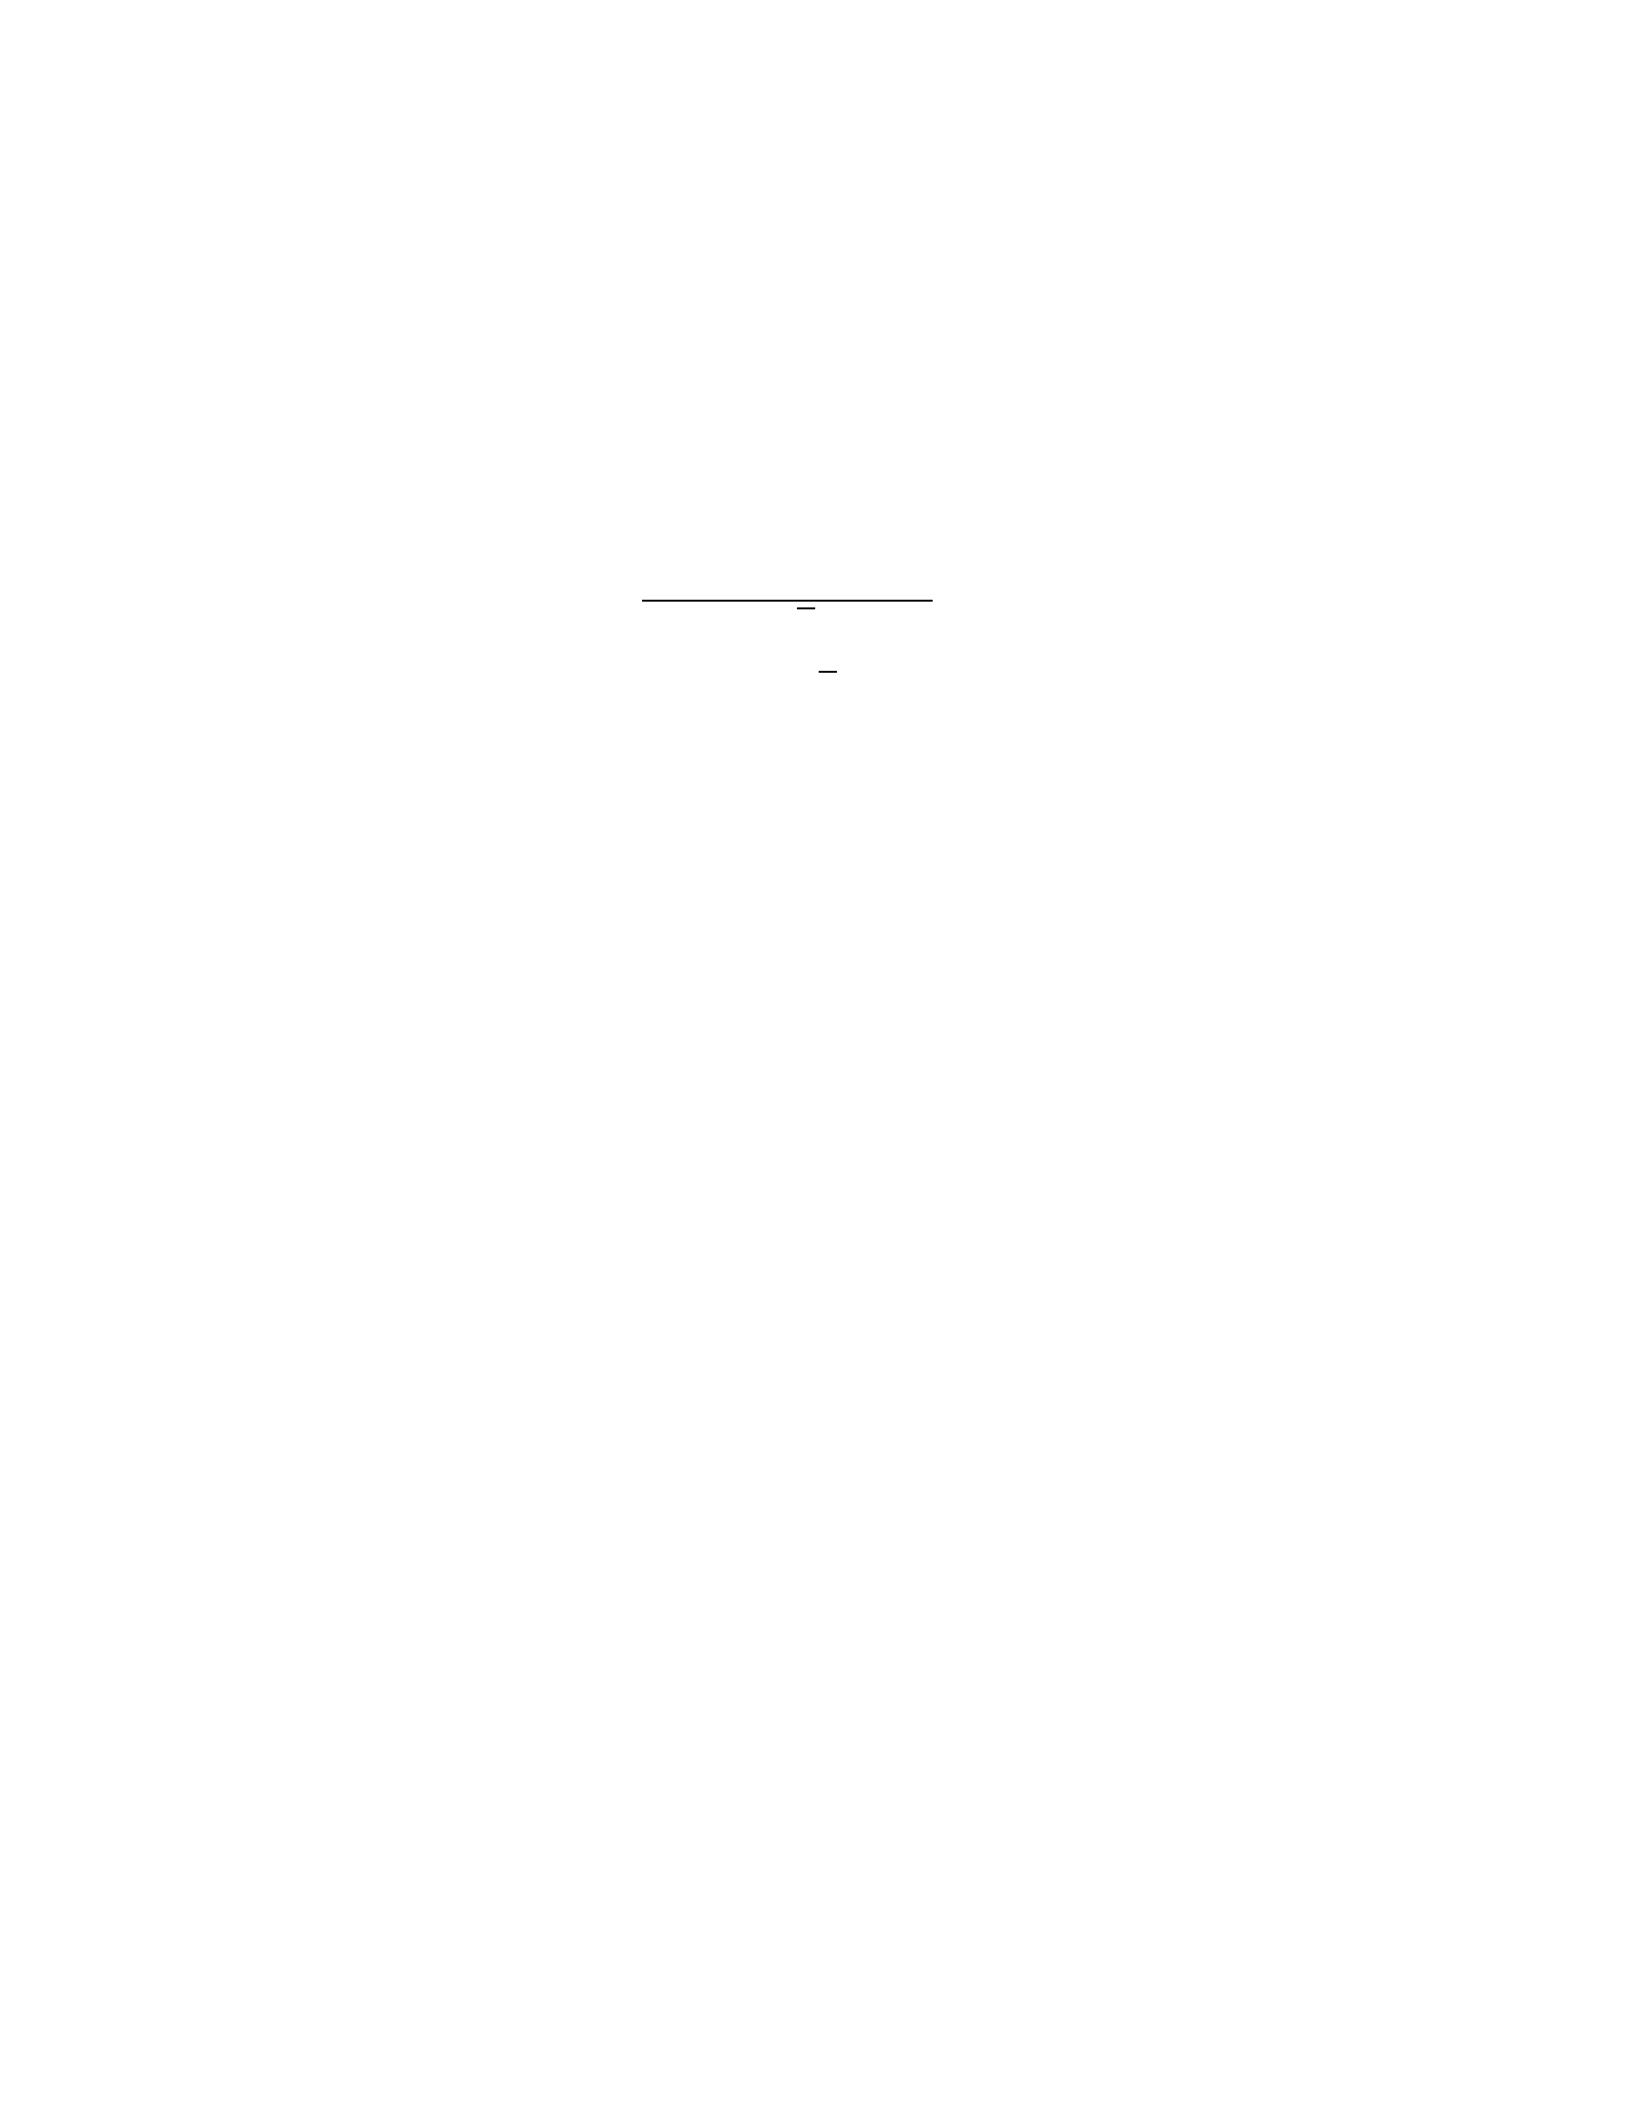
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
212. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500

• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
213. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
214. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:

• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
215. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
216. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
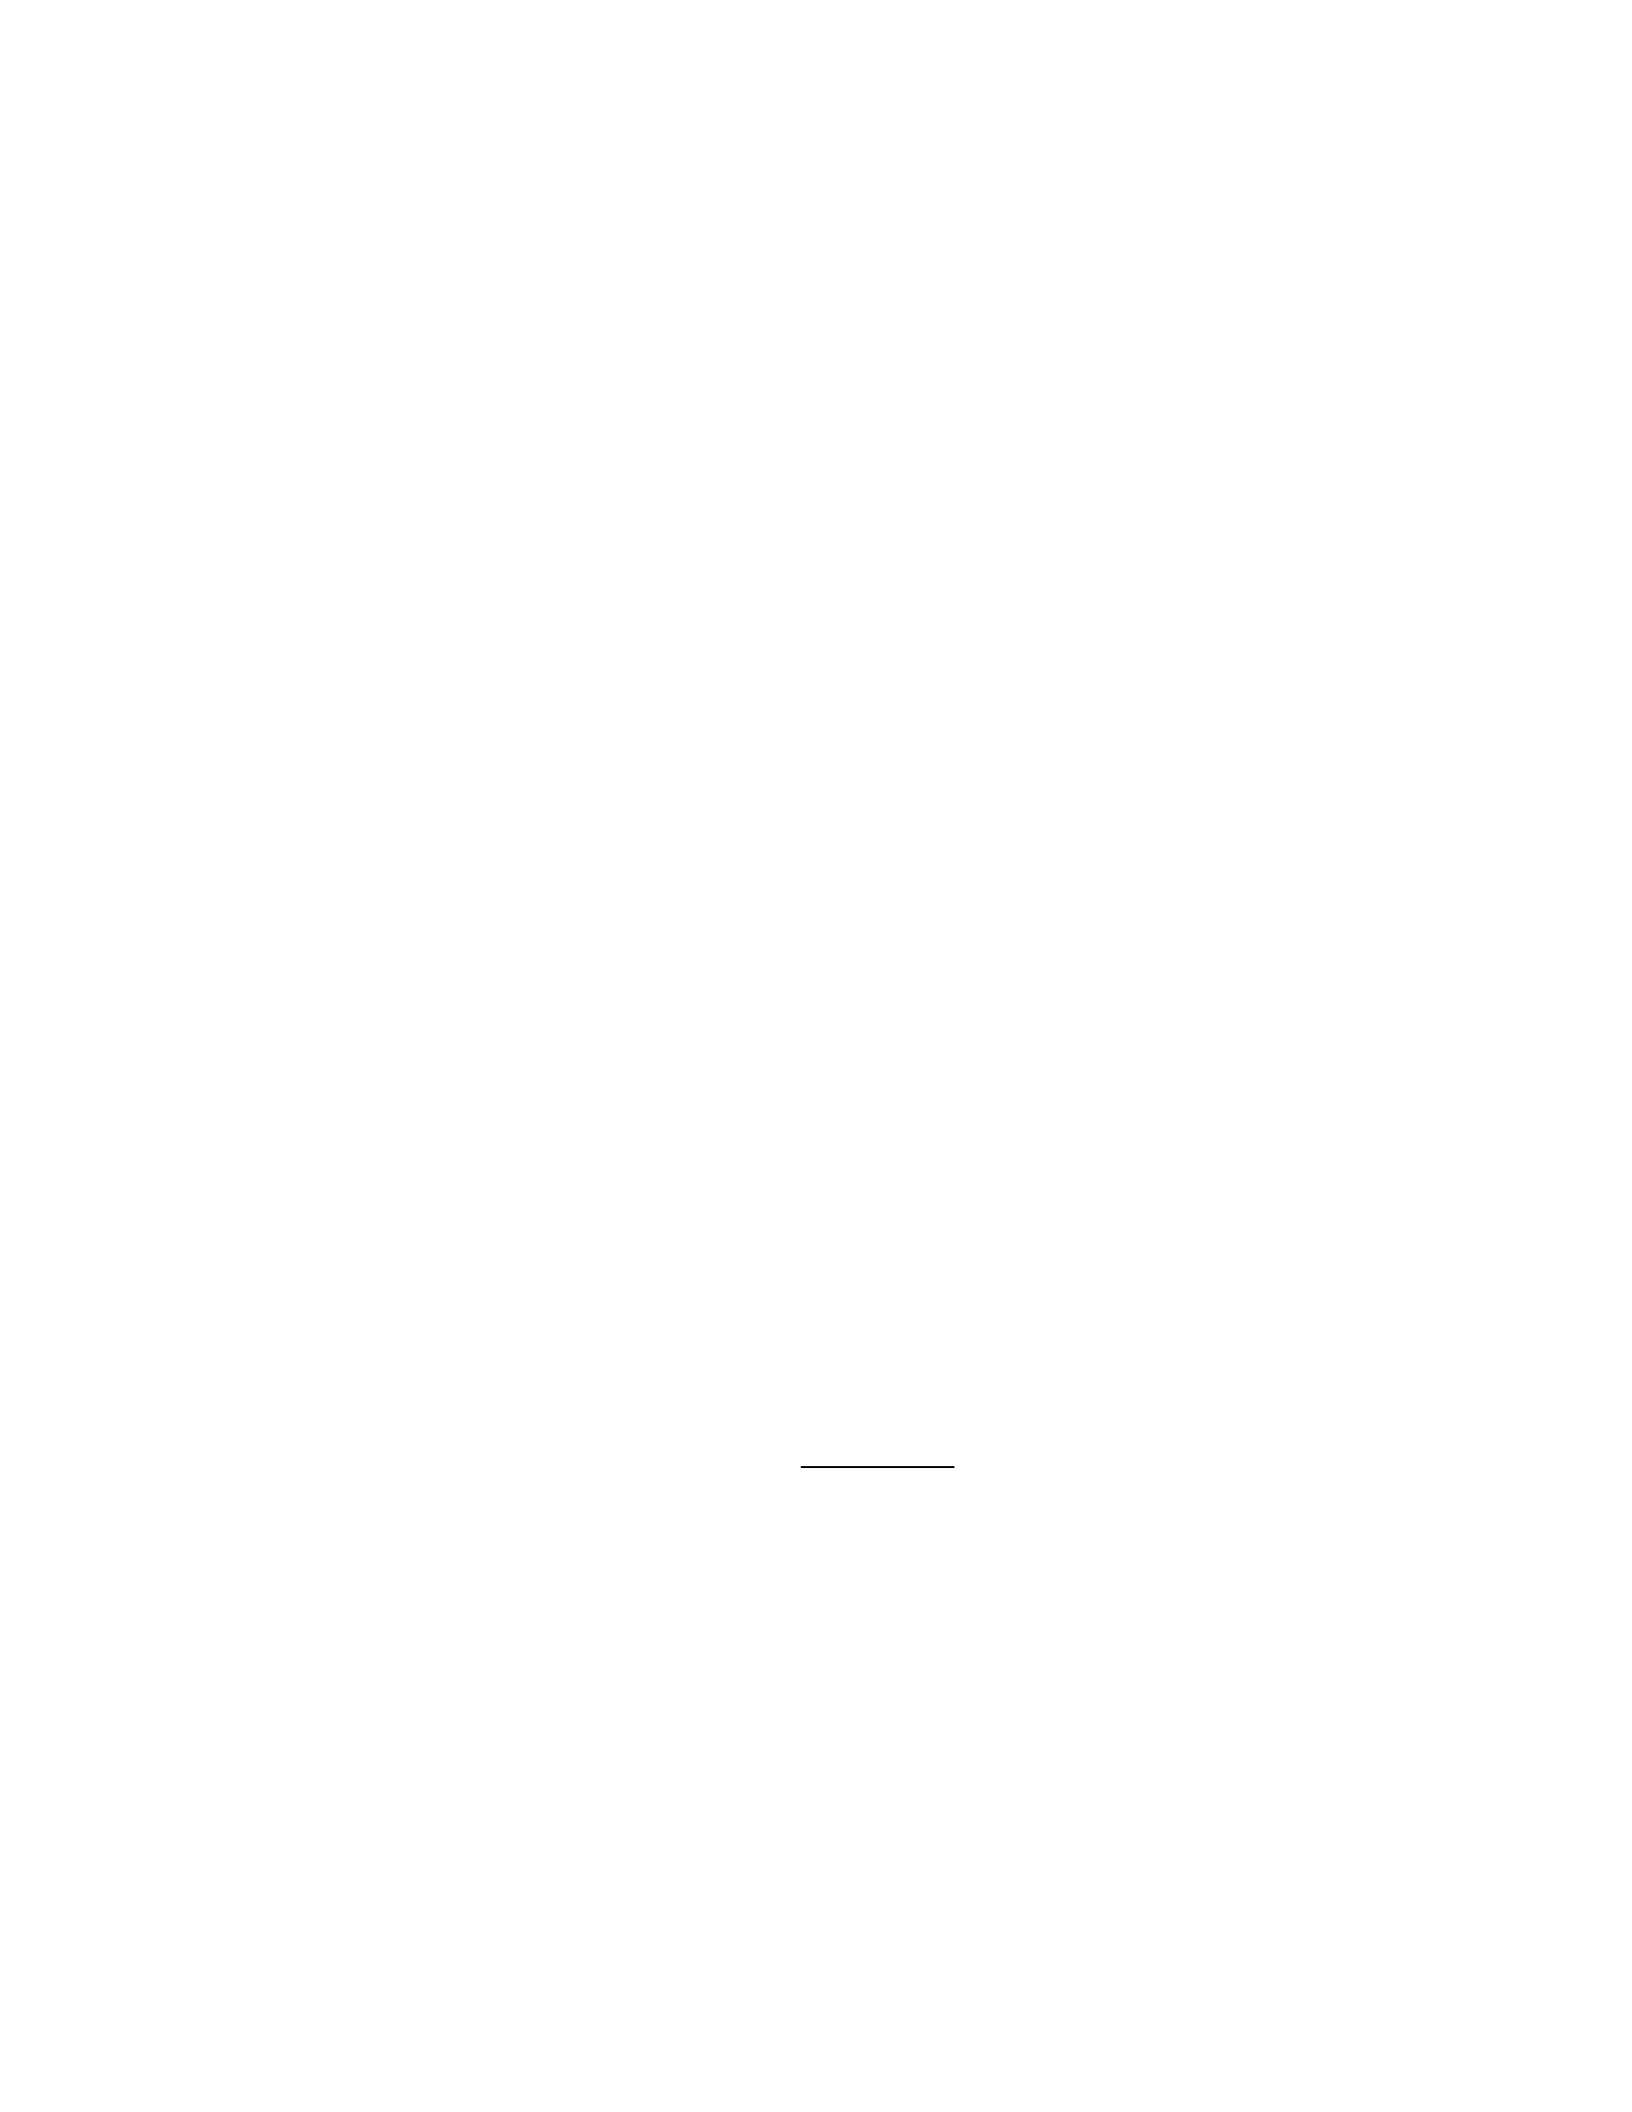
– Net cost = 0
217. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
218. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
219. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%

– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
220. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
221. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
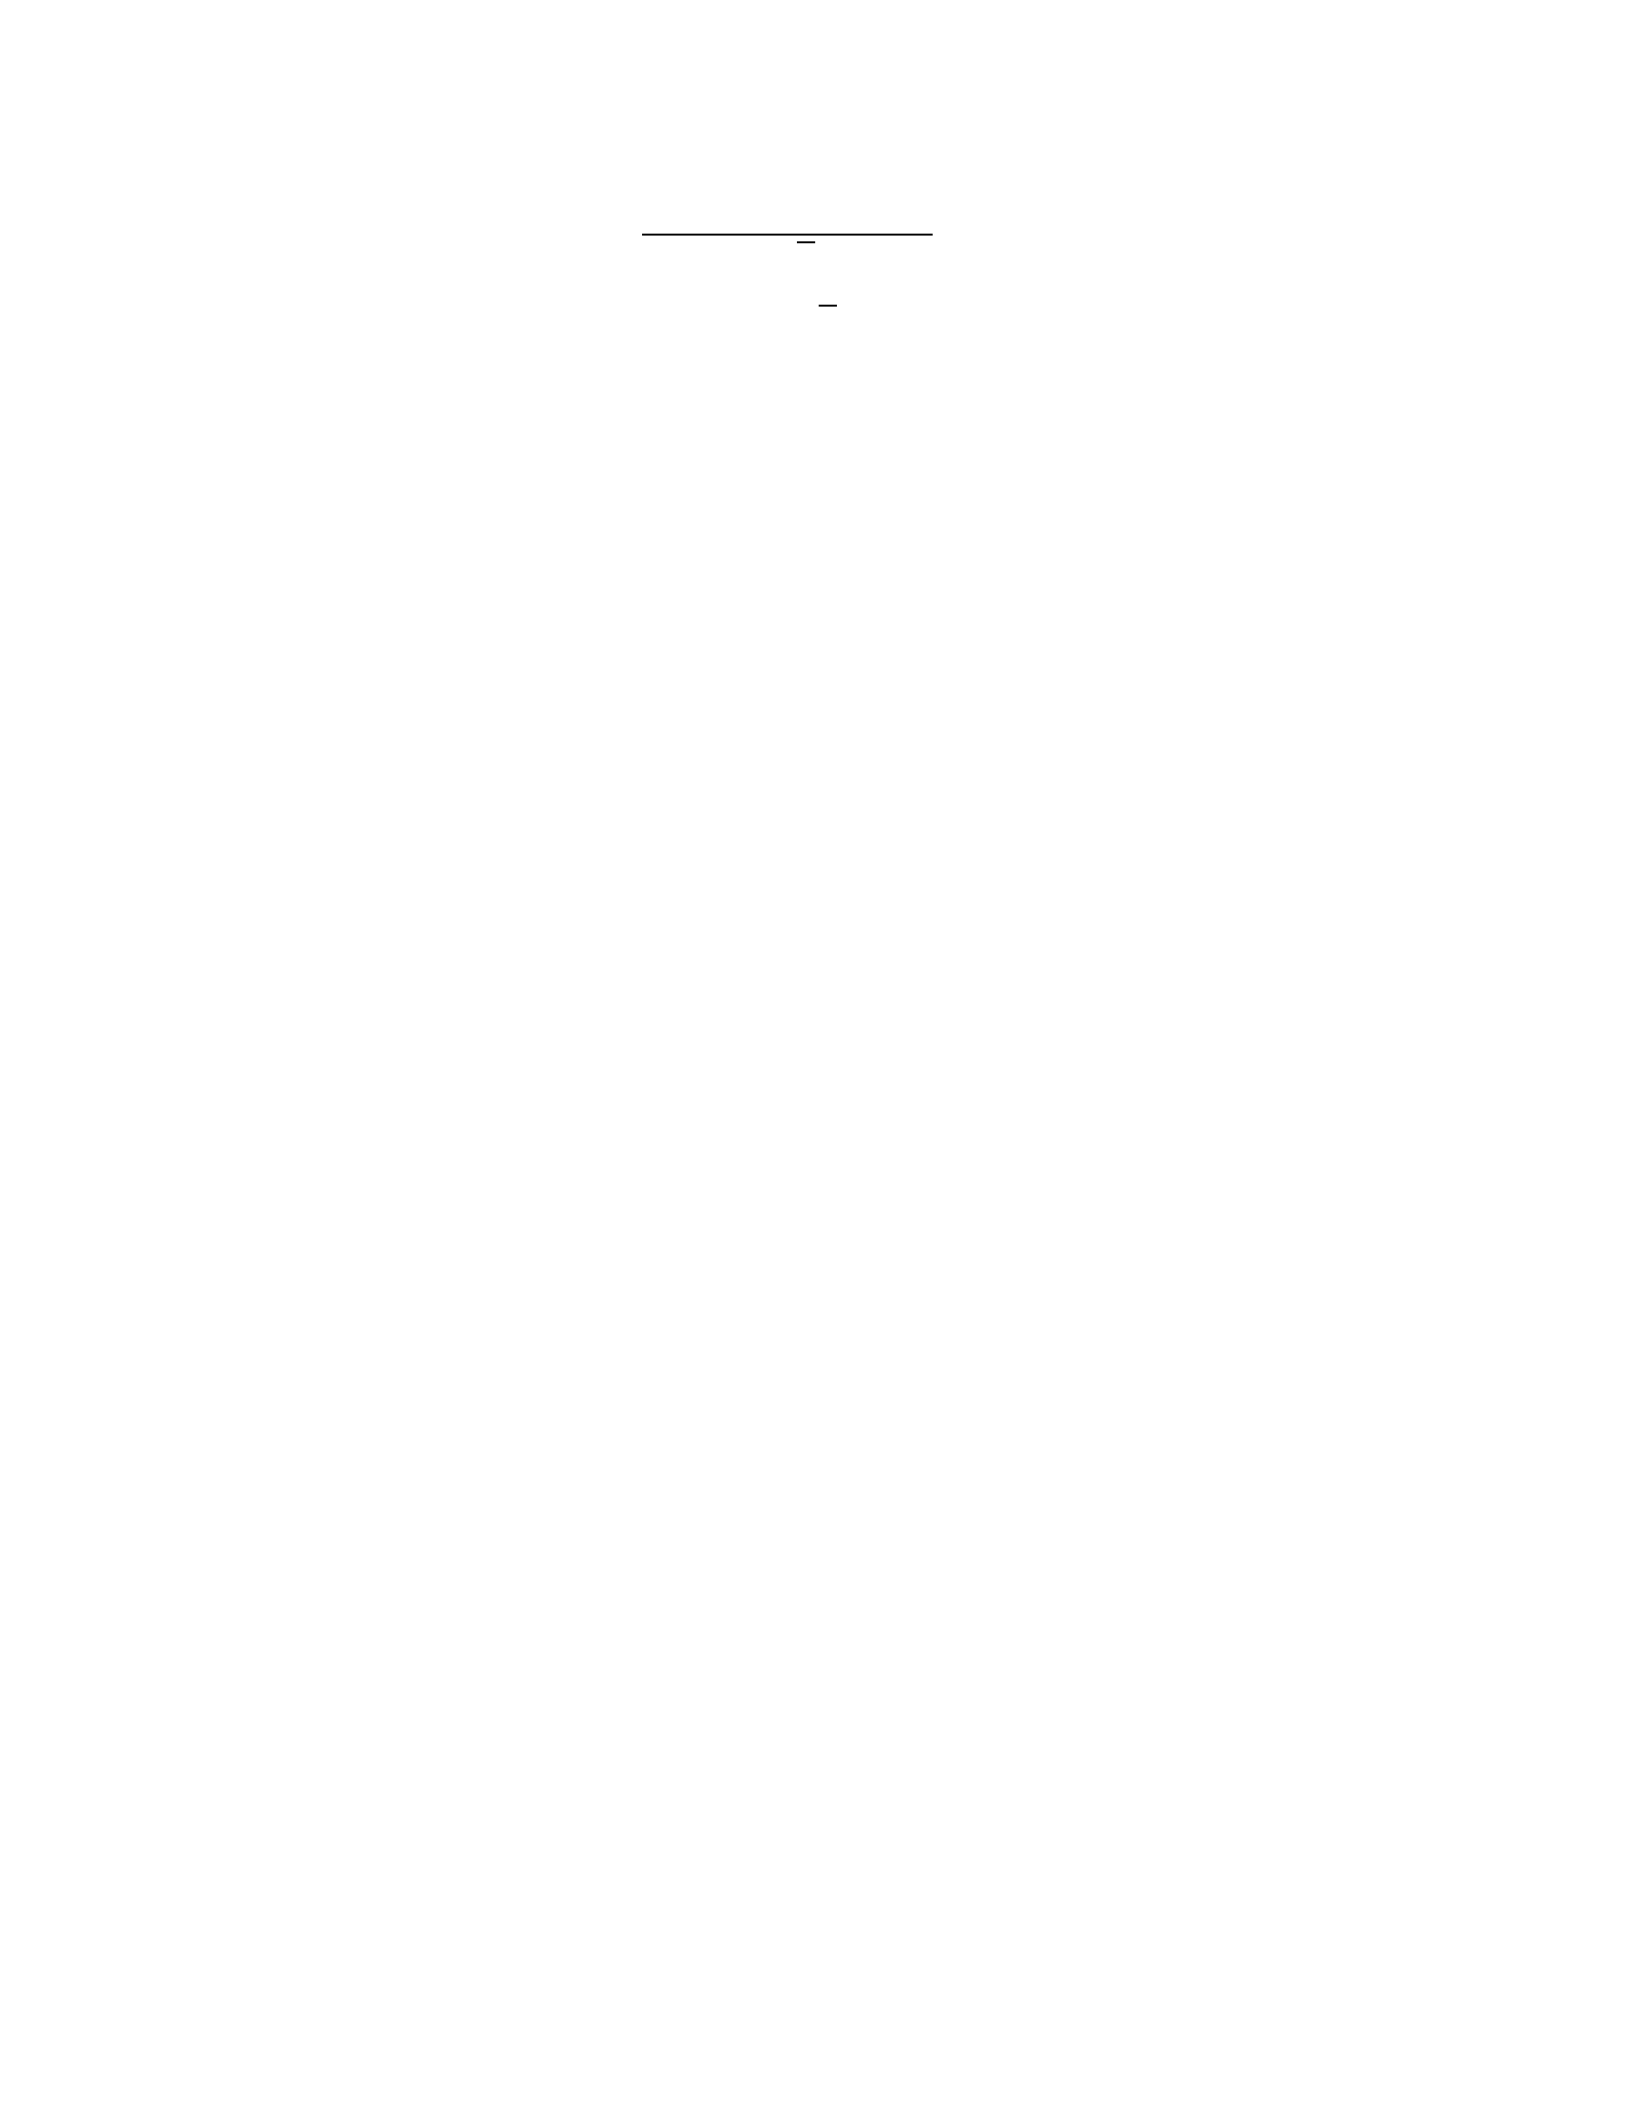
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
222. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
223. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:

a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
224. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10

– Breakeven points: $90 and $110
225. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
226. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
227. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
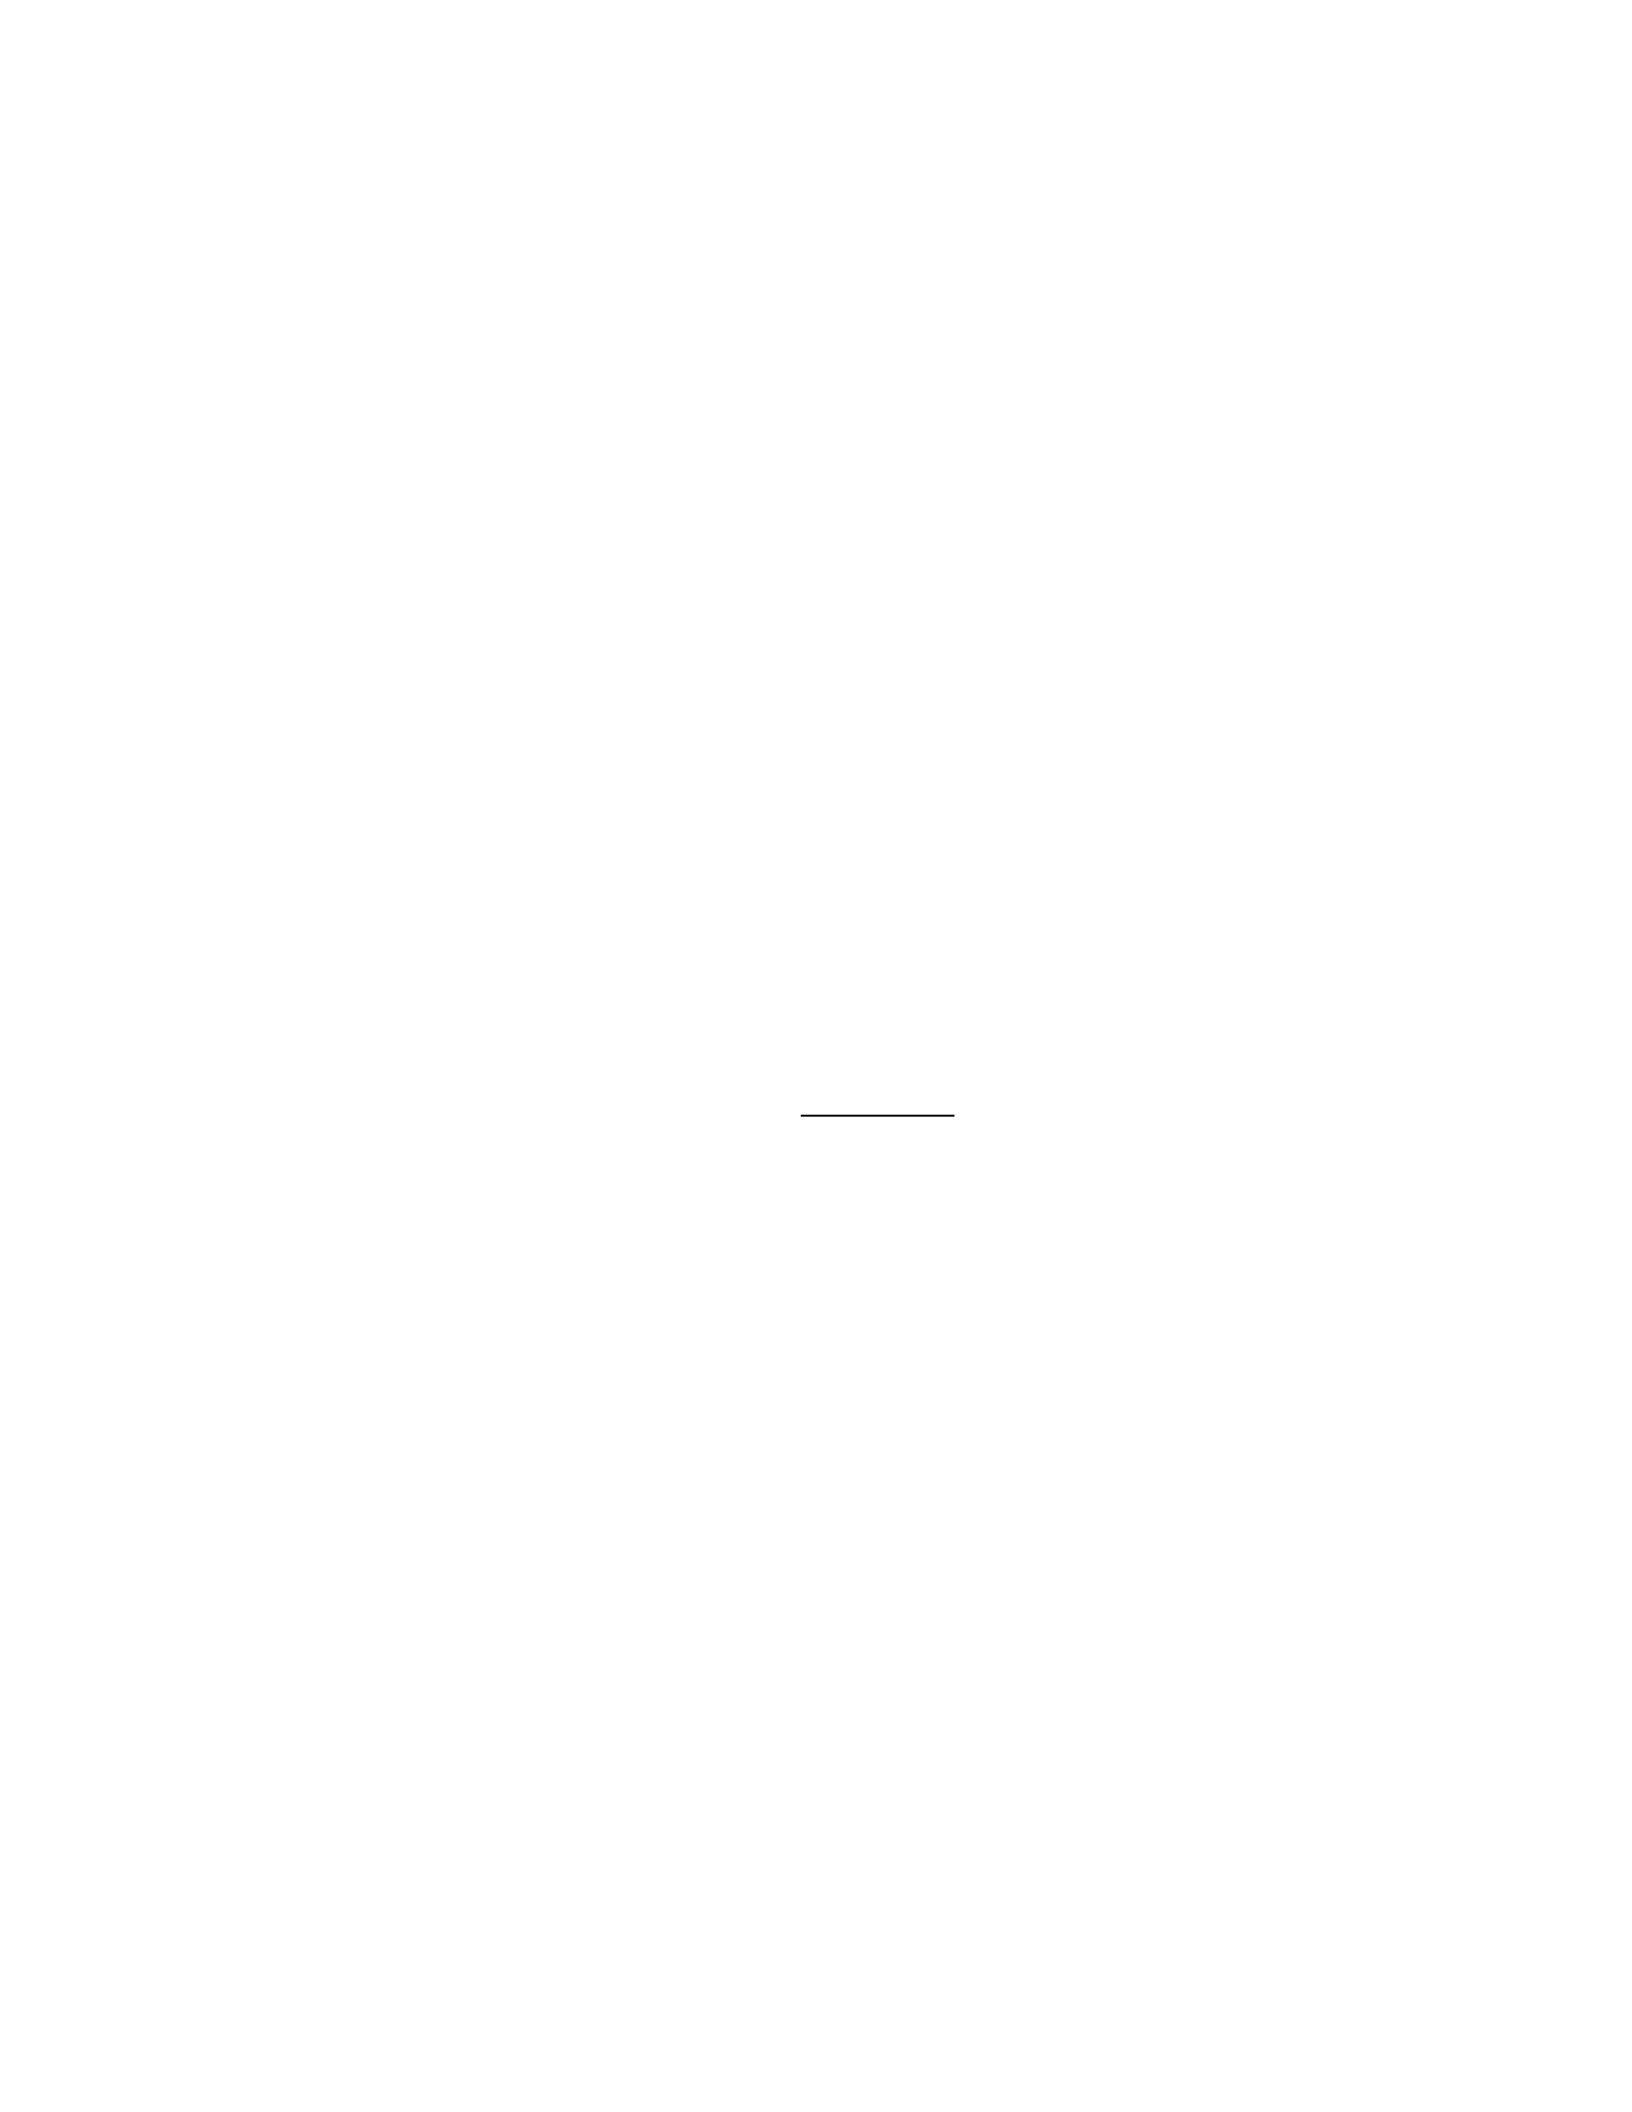
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
228. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
229. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
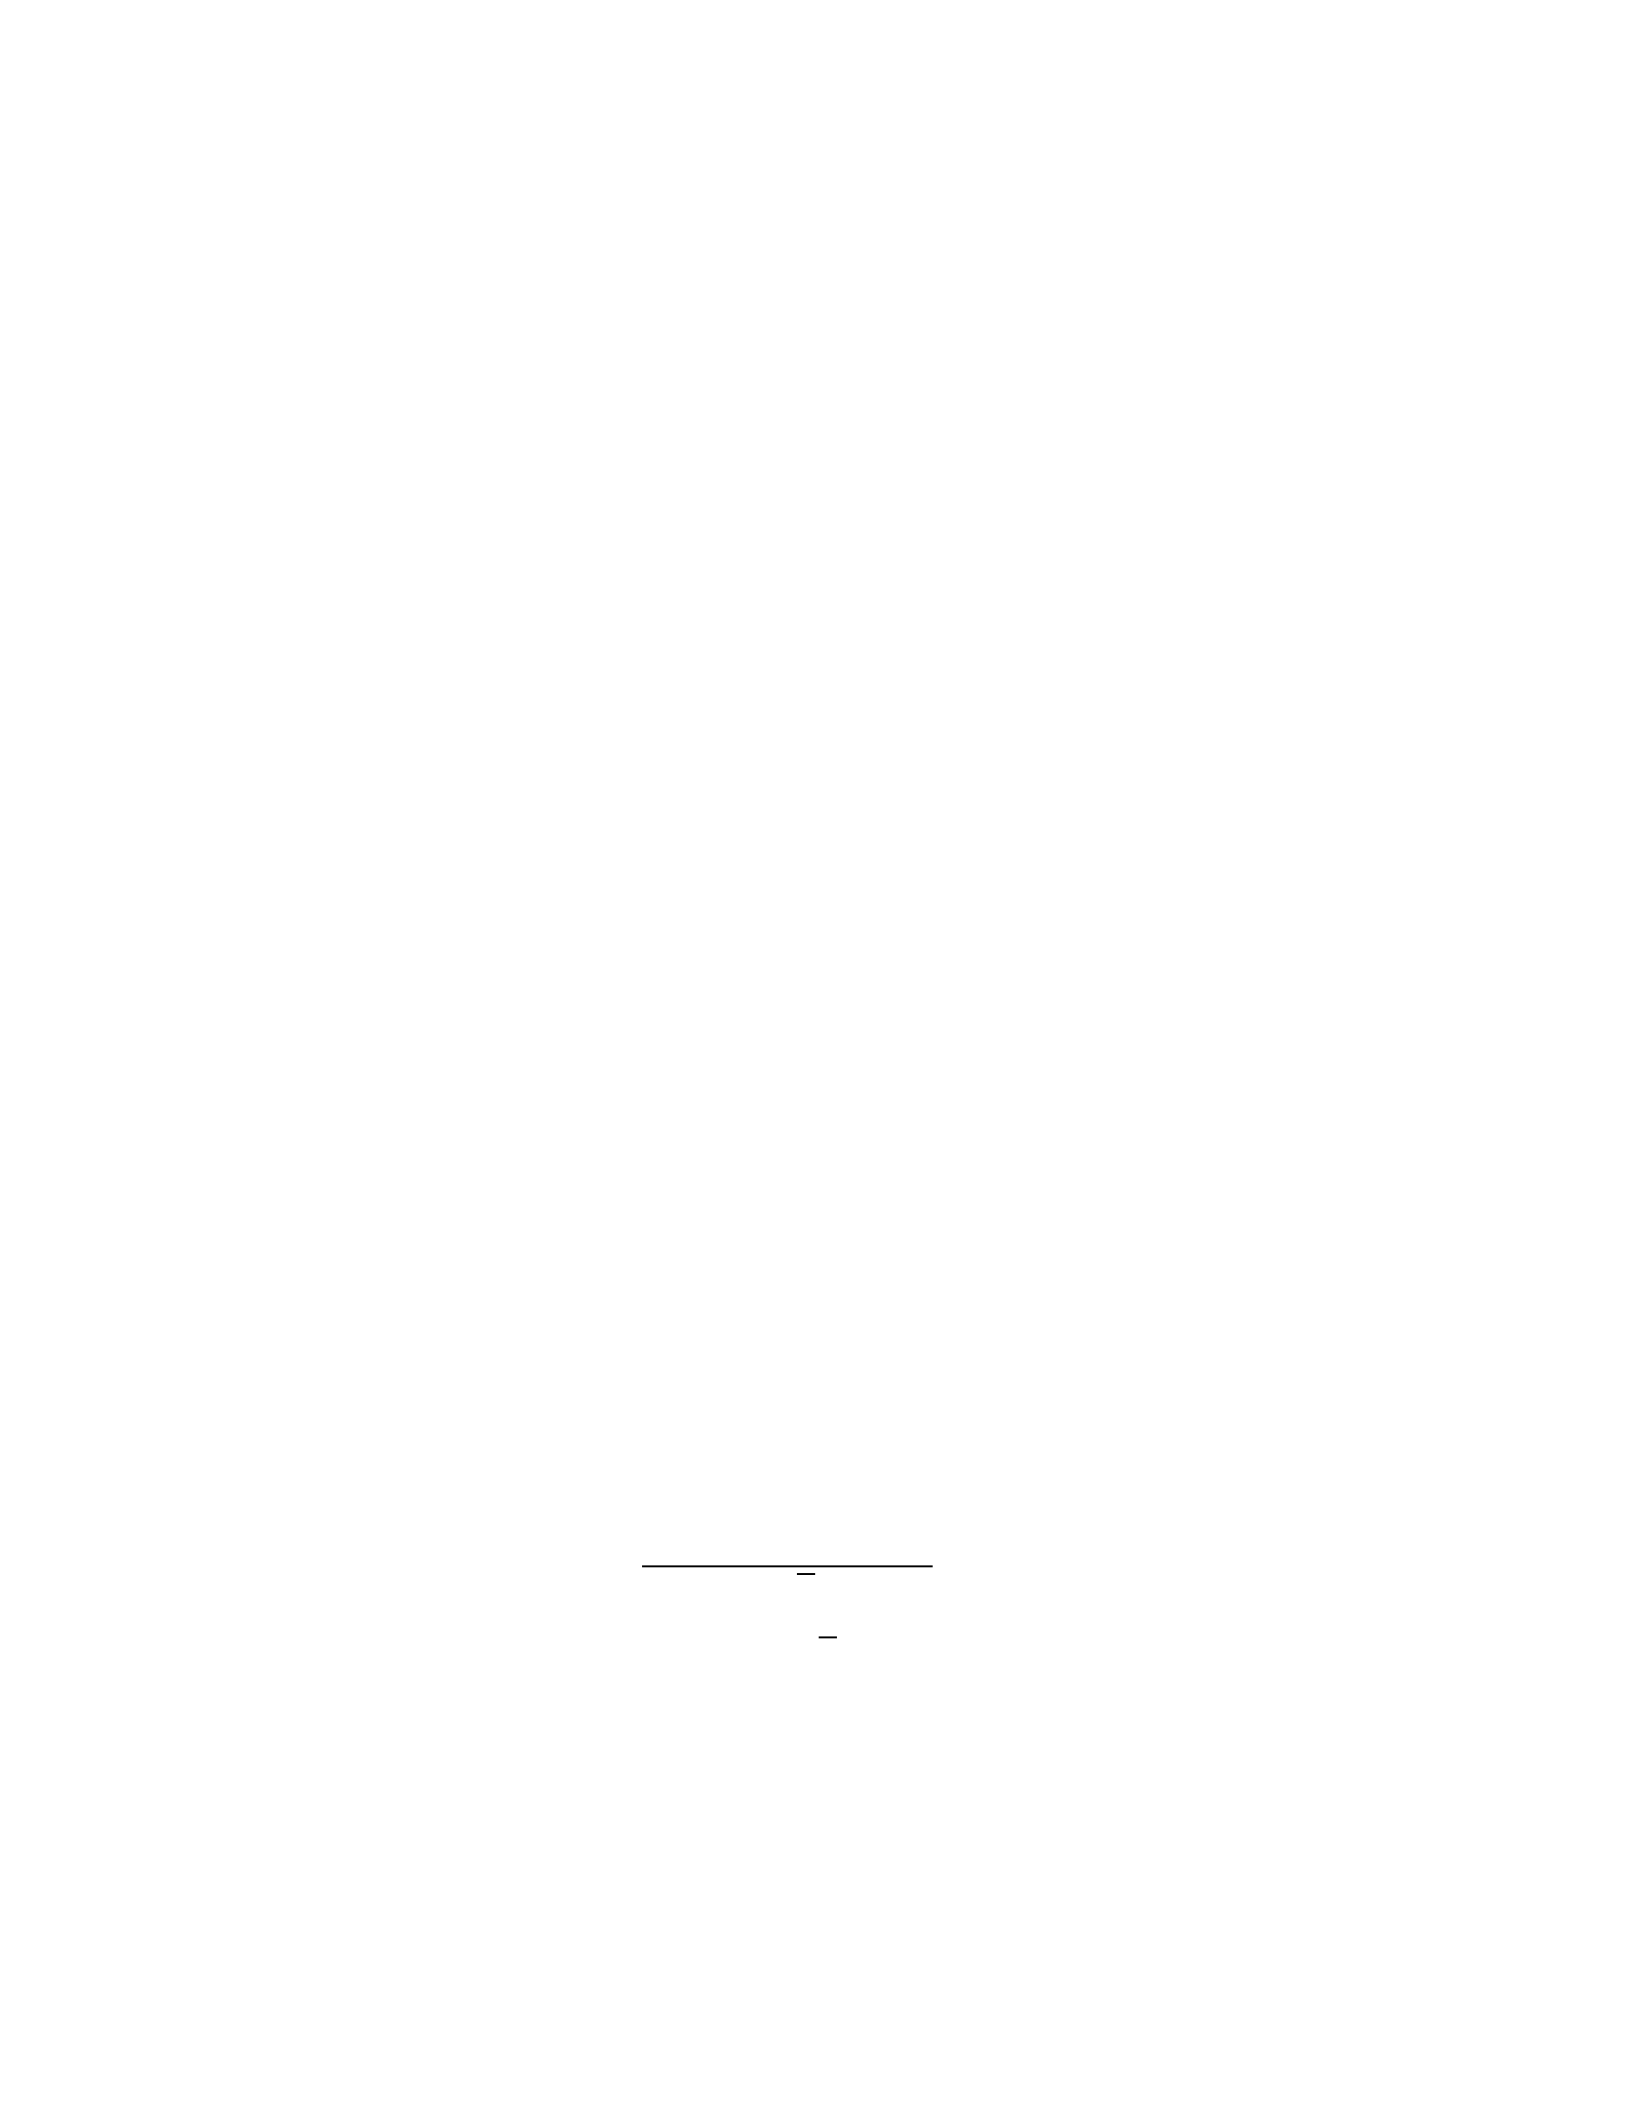
230. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
231. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula

𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
232. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
233. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711

• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
234. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
235. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:

– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
236. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
237. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
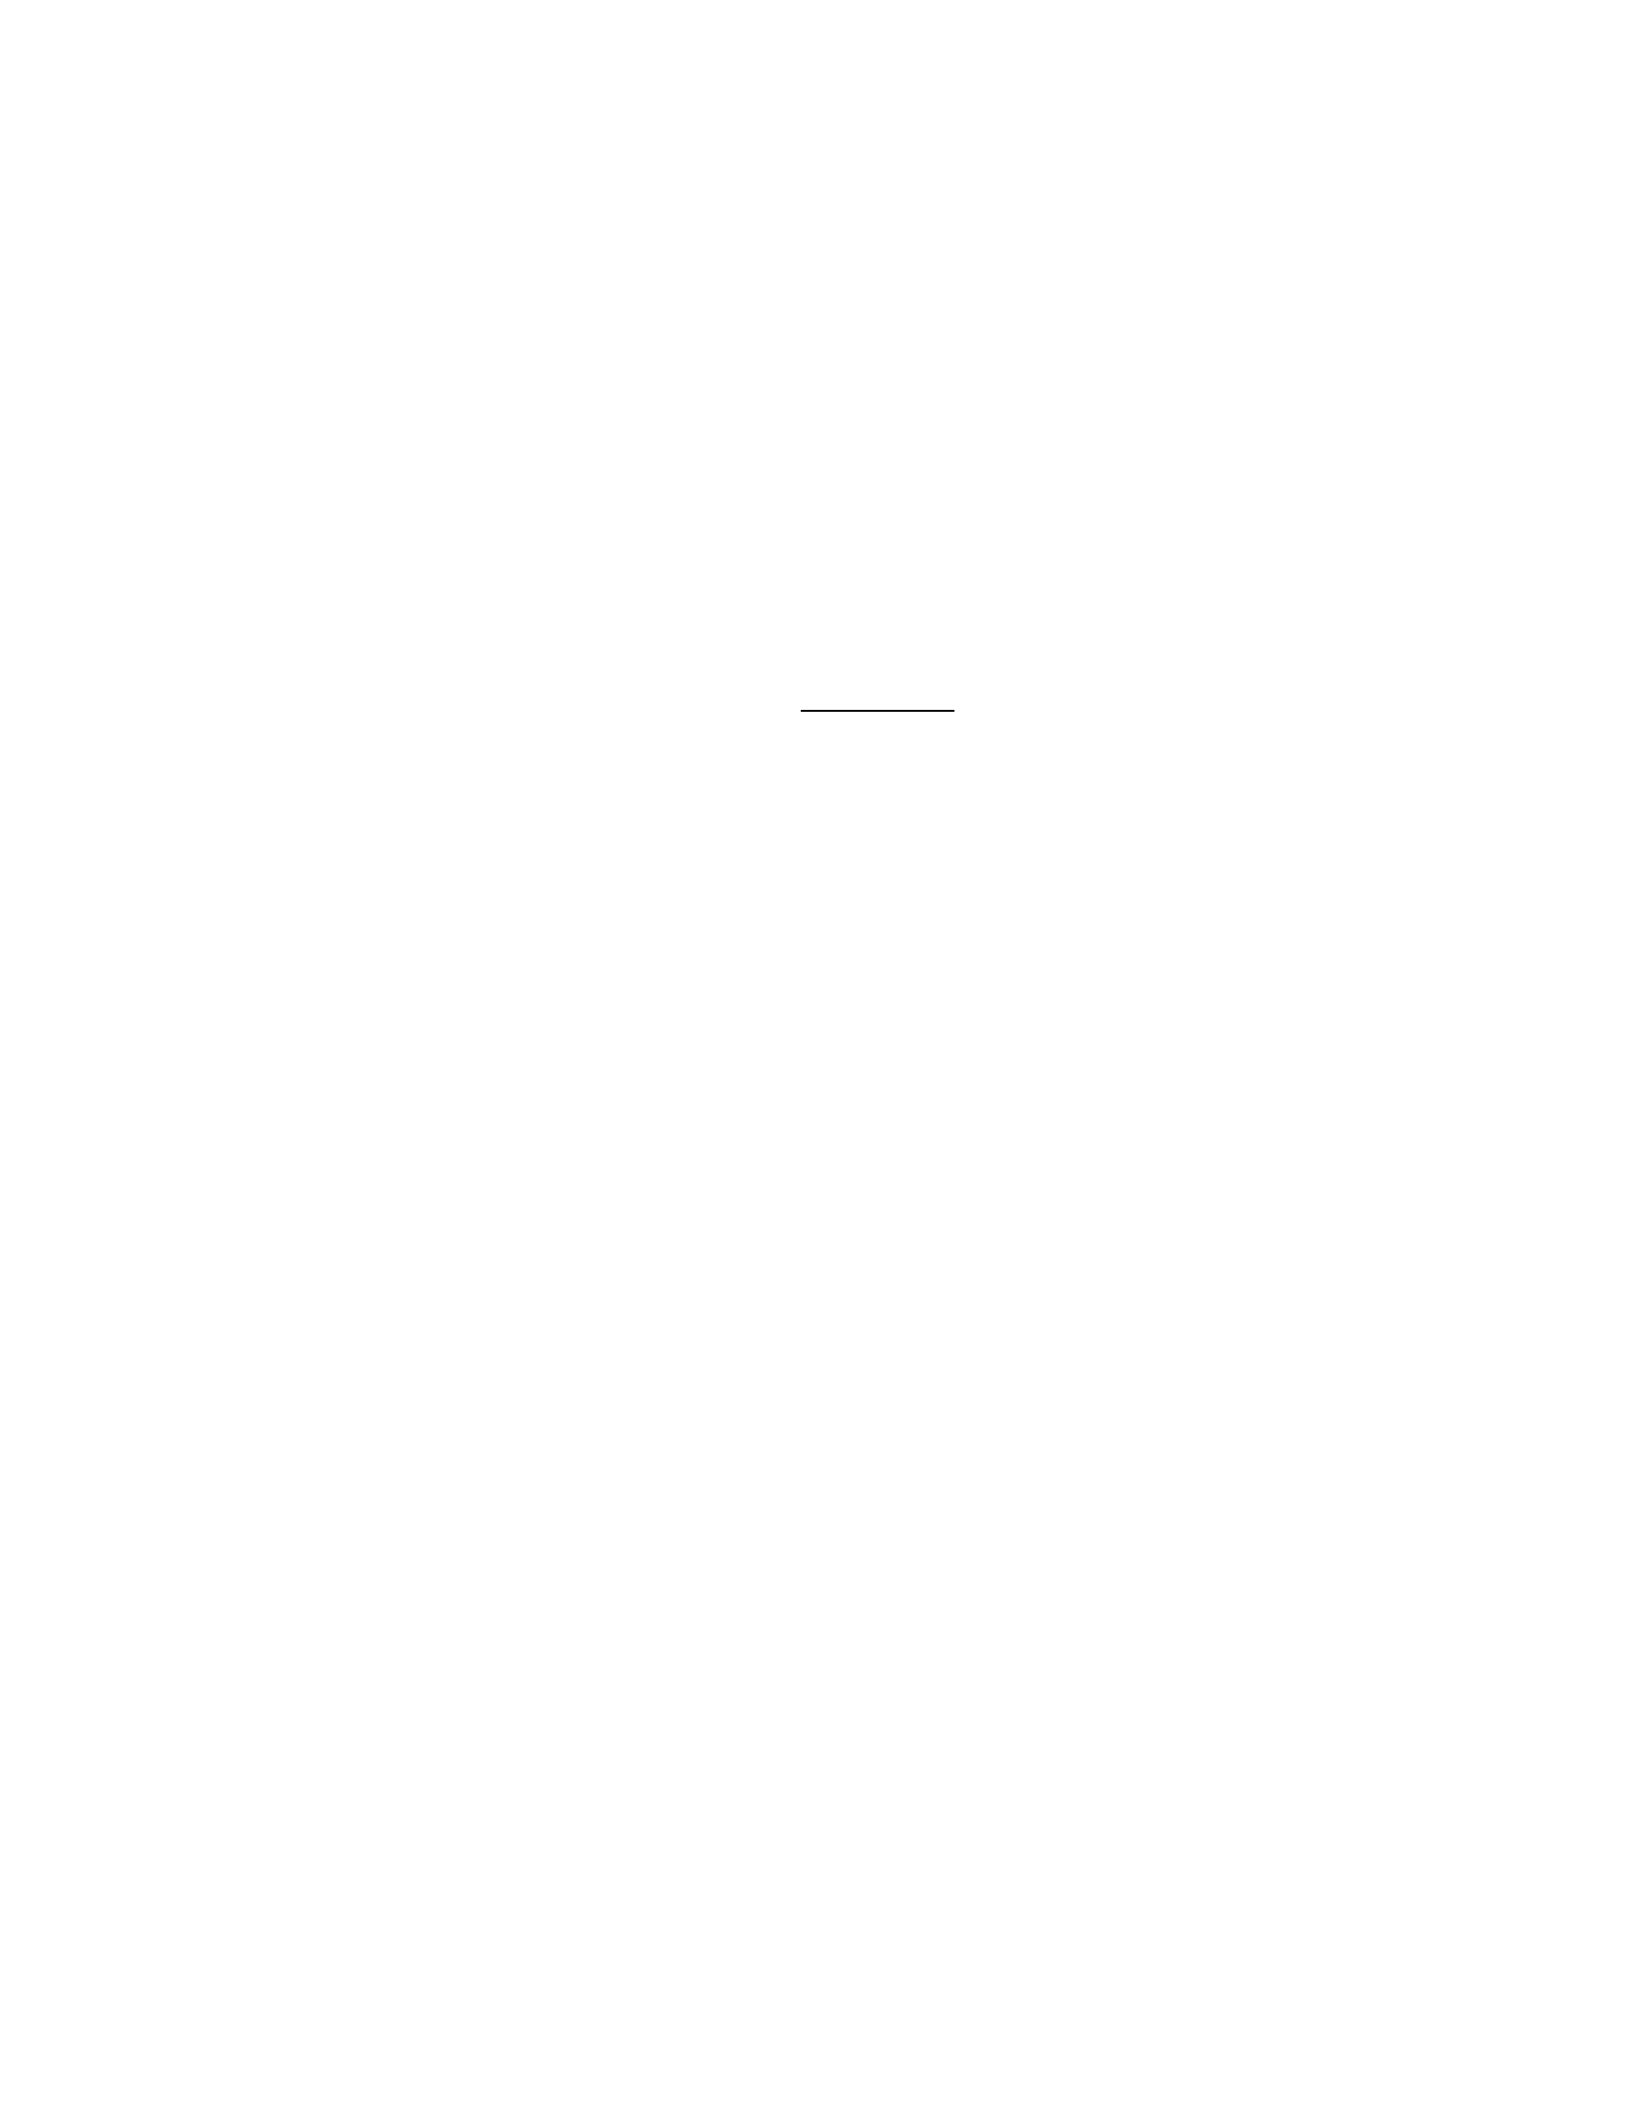
238. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
239. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
240. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
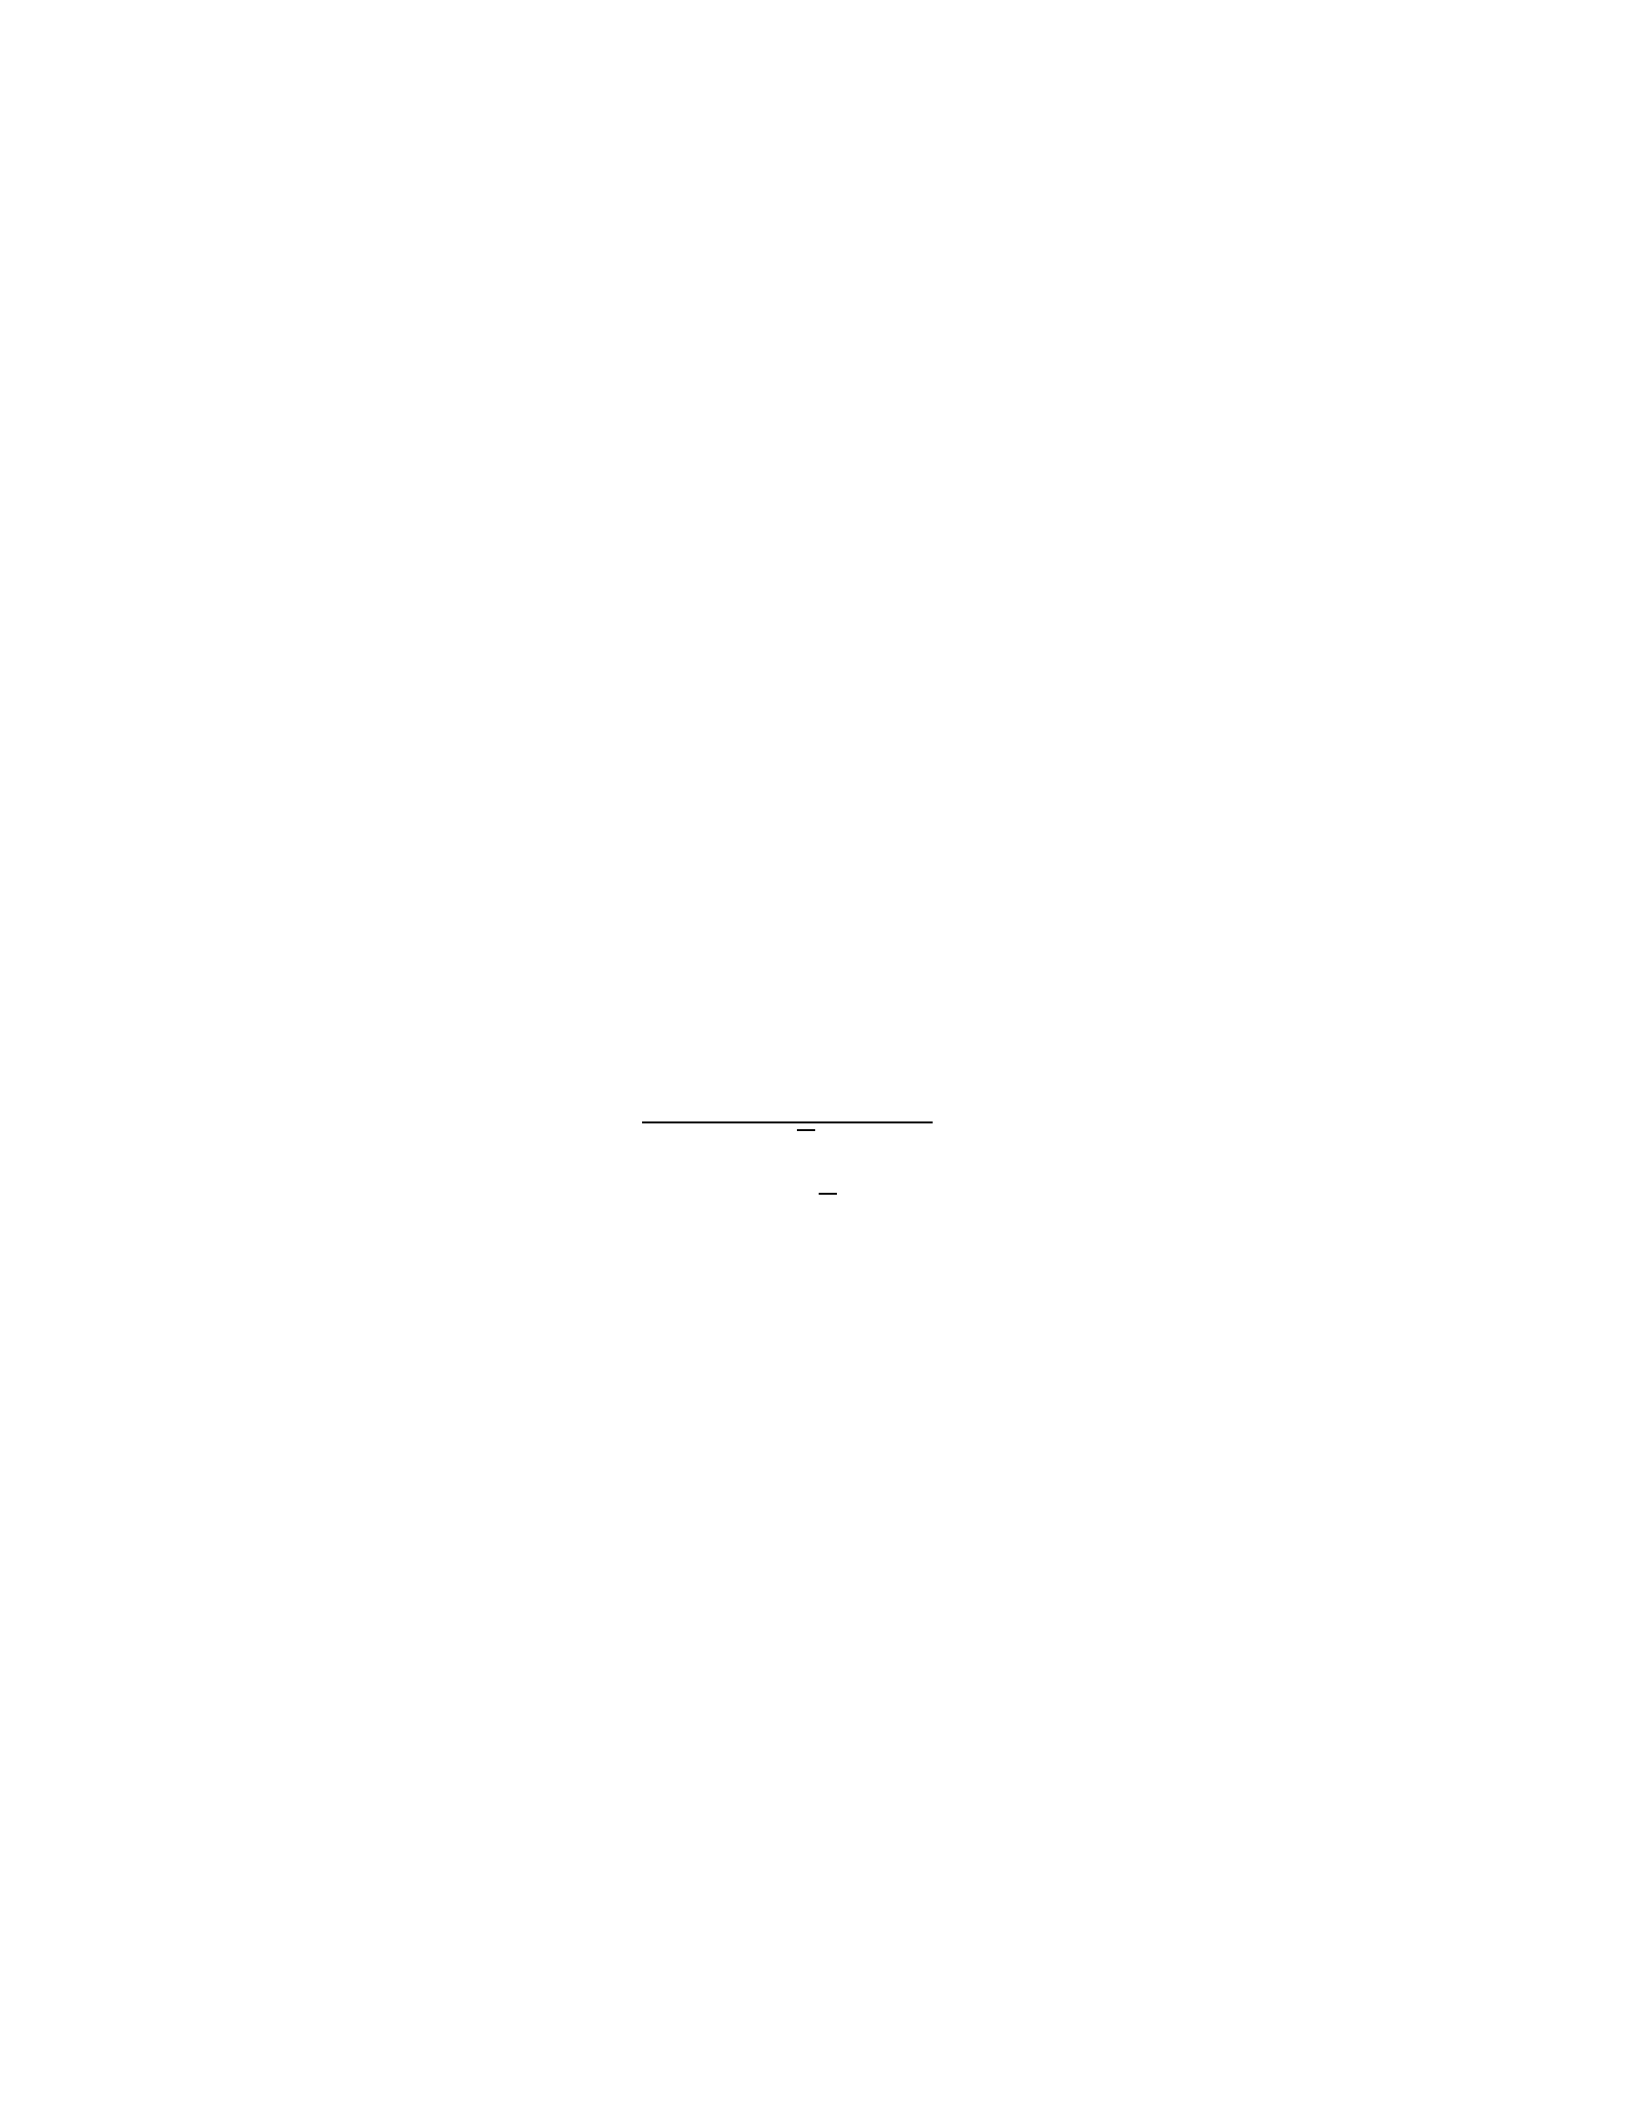
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
241. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
242. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:

a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
243. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
244. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit

from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
245. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
246. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options

and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
247. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
248. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
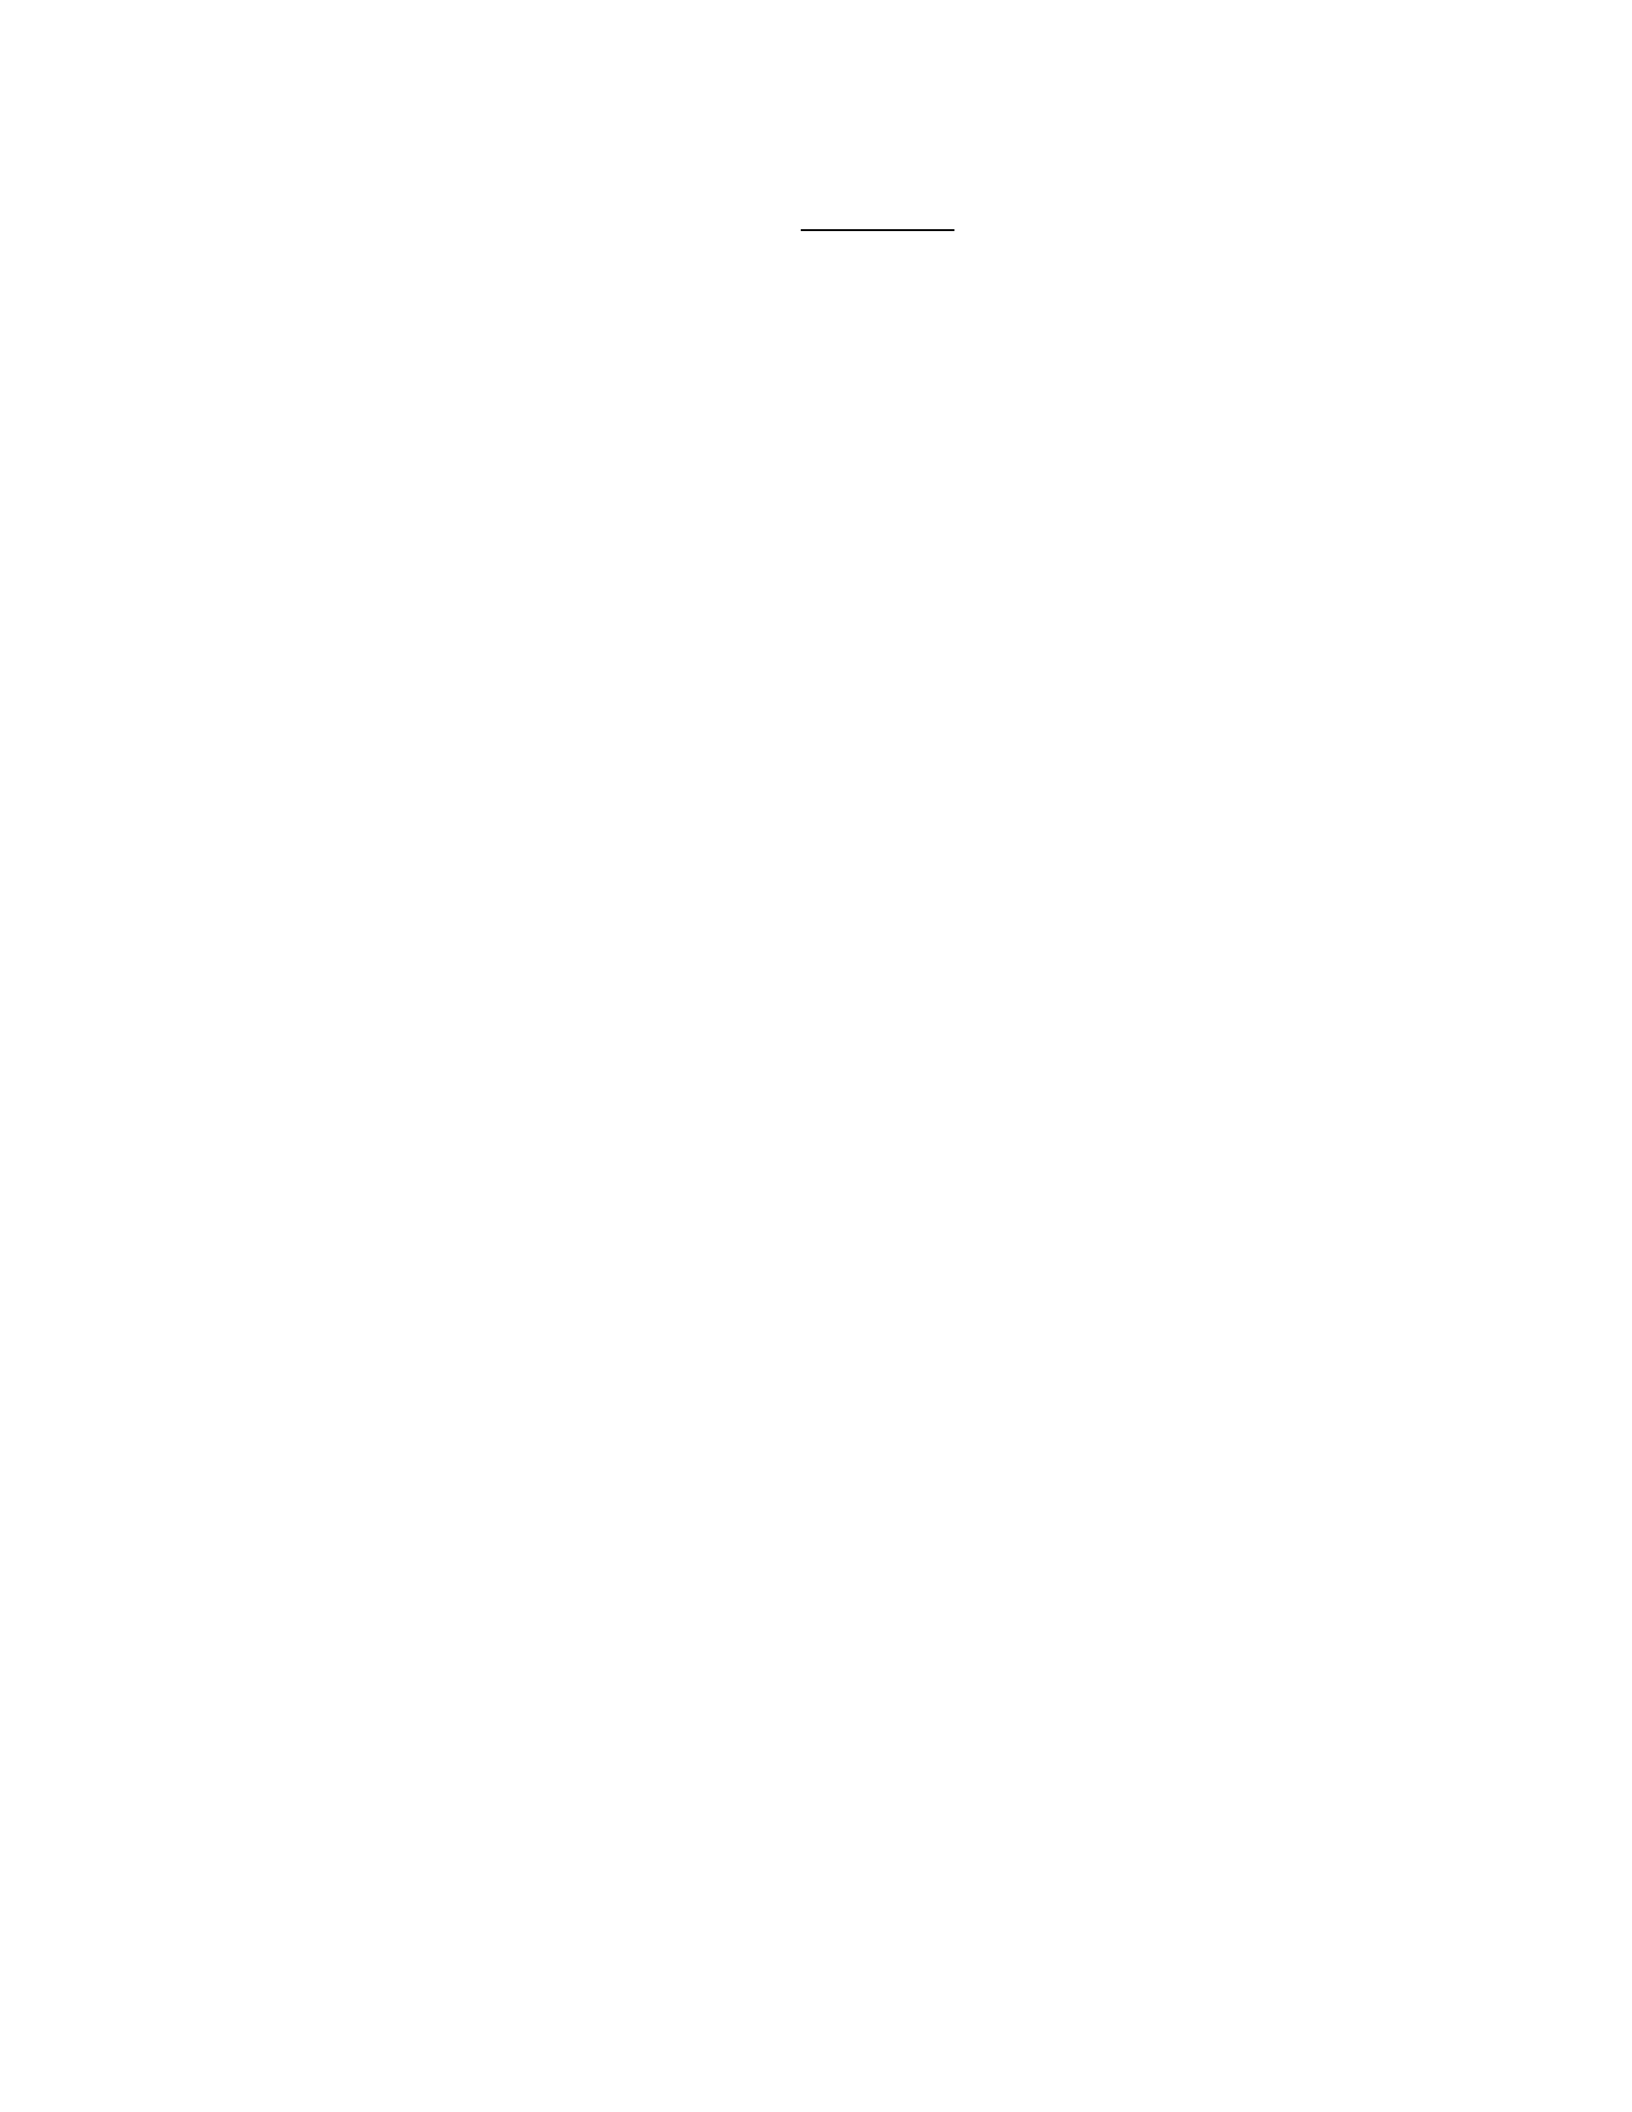
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
249. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
250. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
251. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
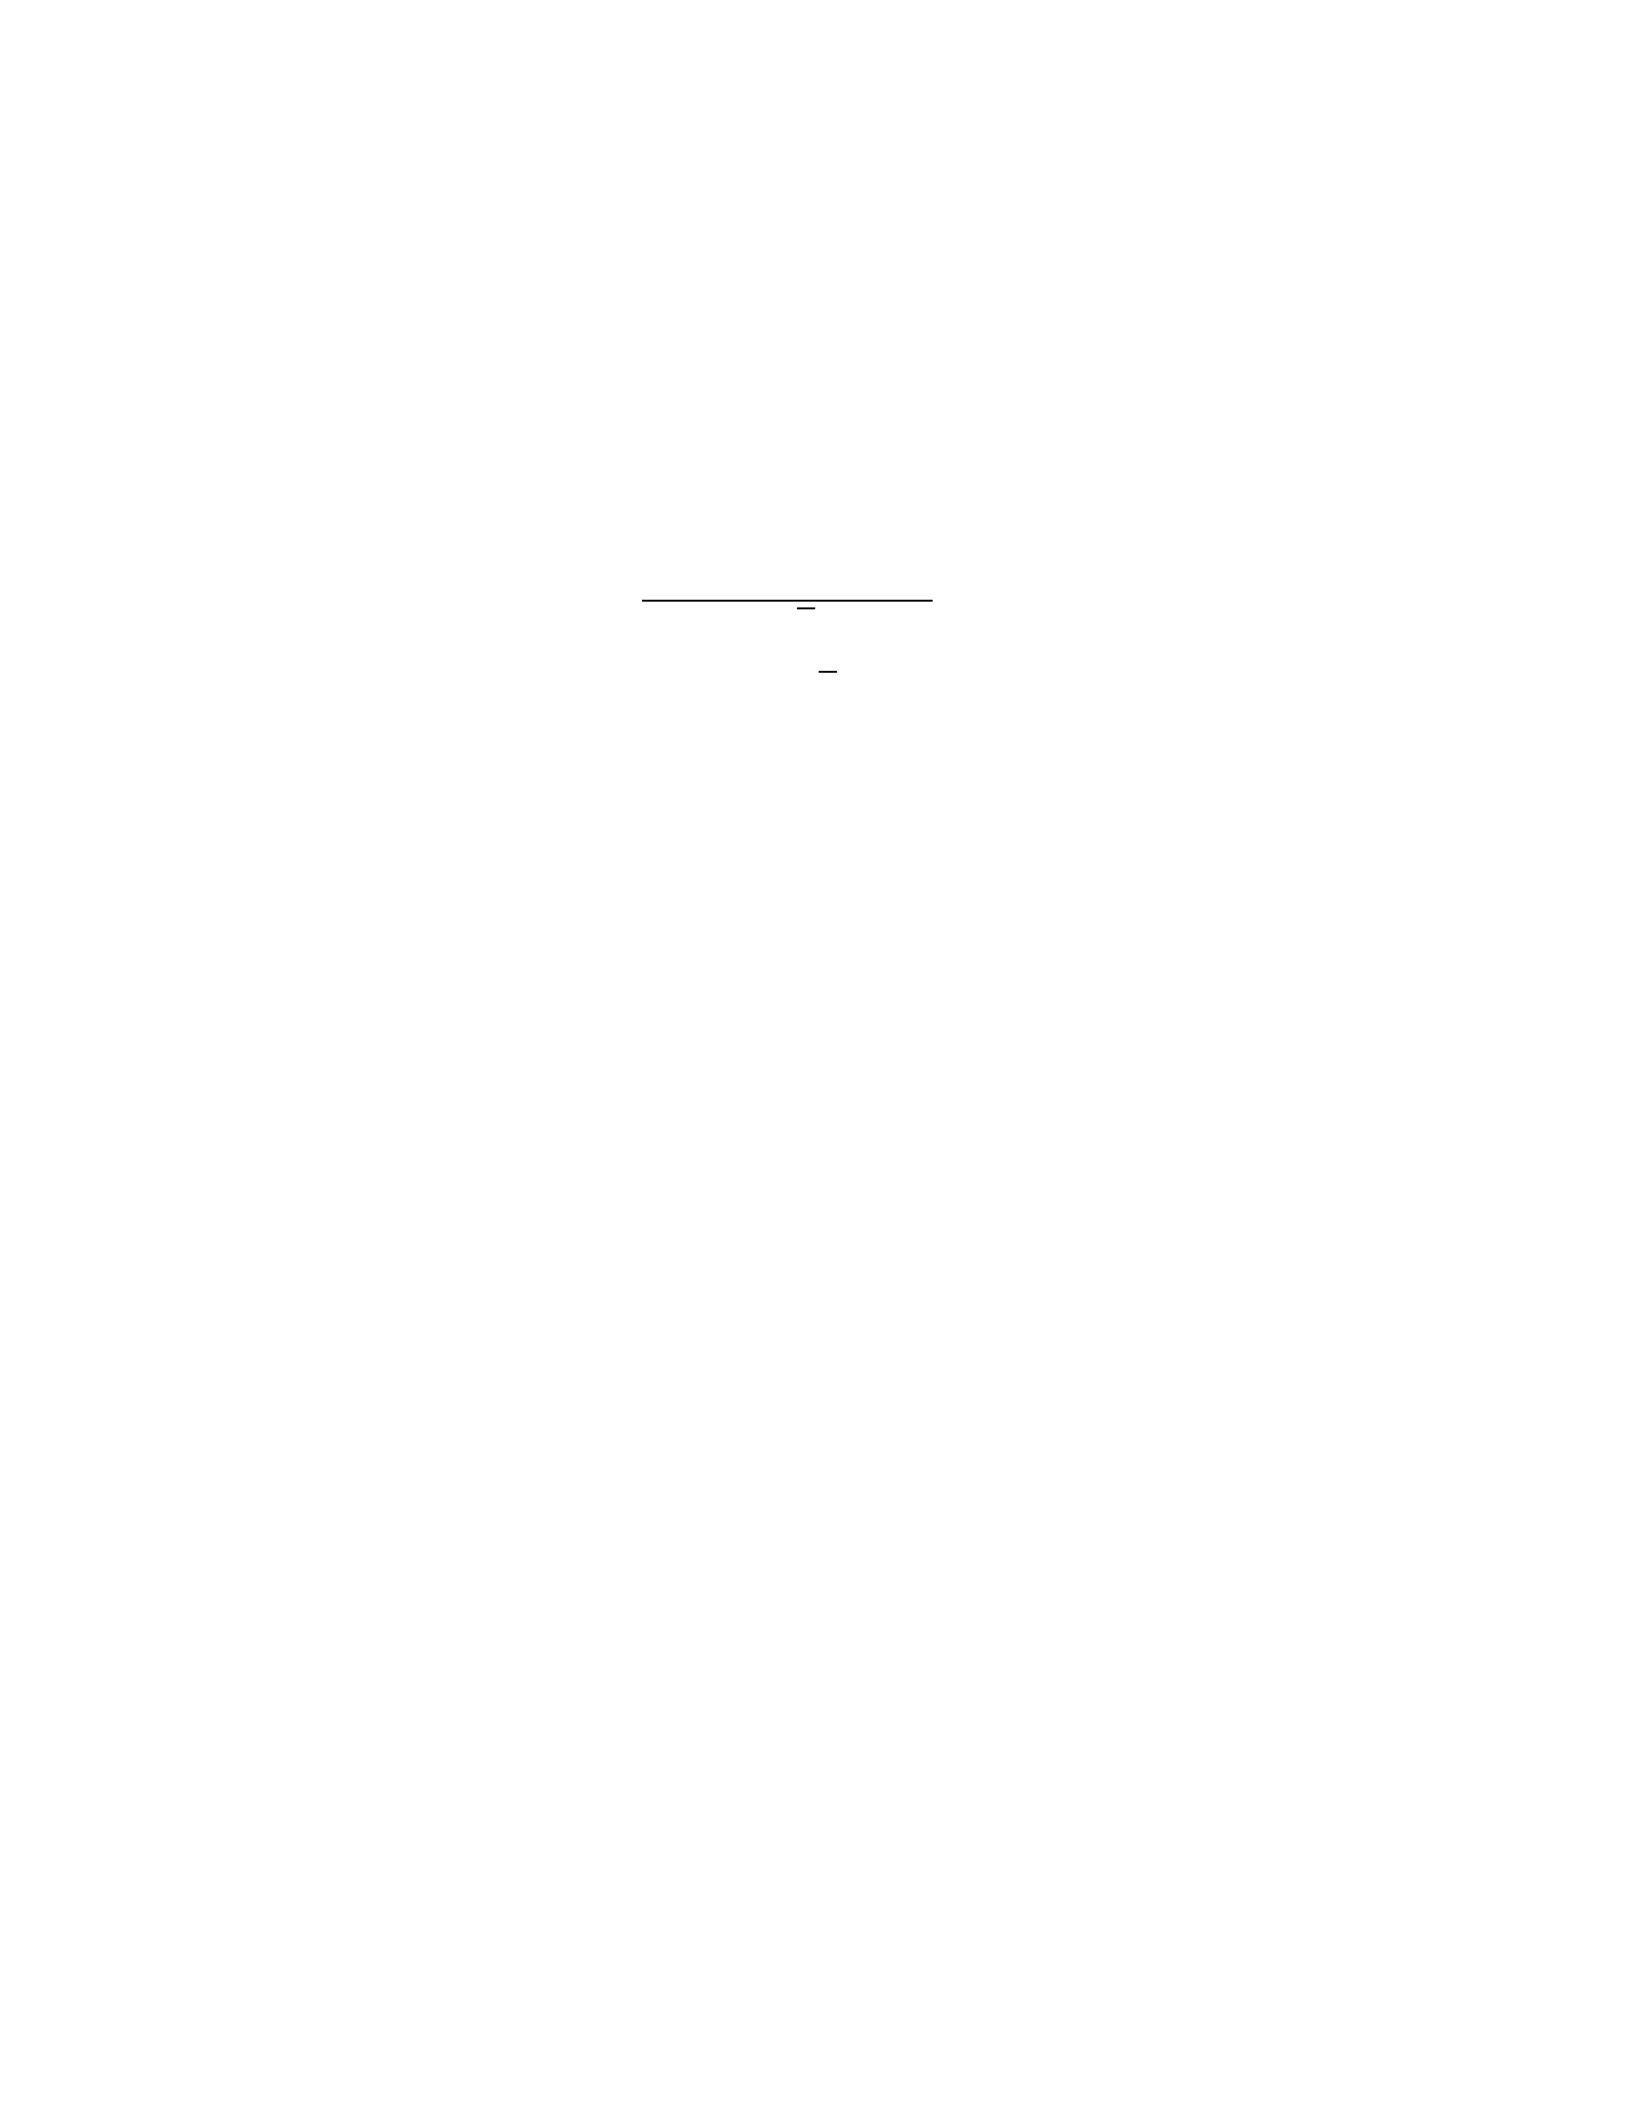
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
252. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500

• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
253. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
254. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:

• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
255. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
256. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
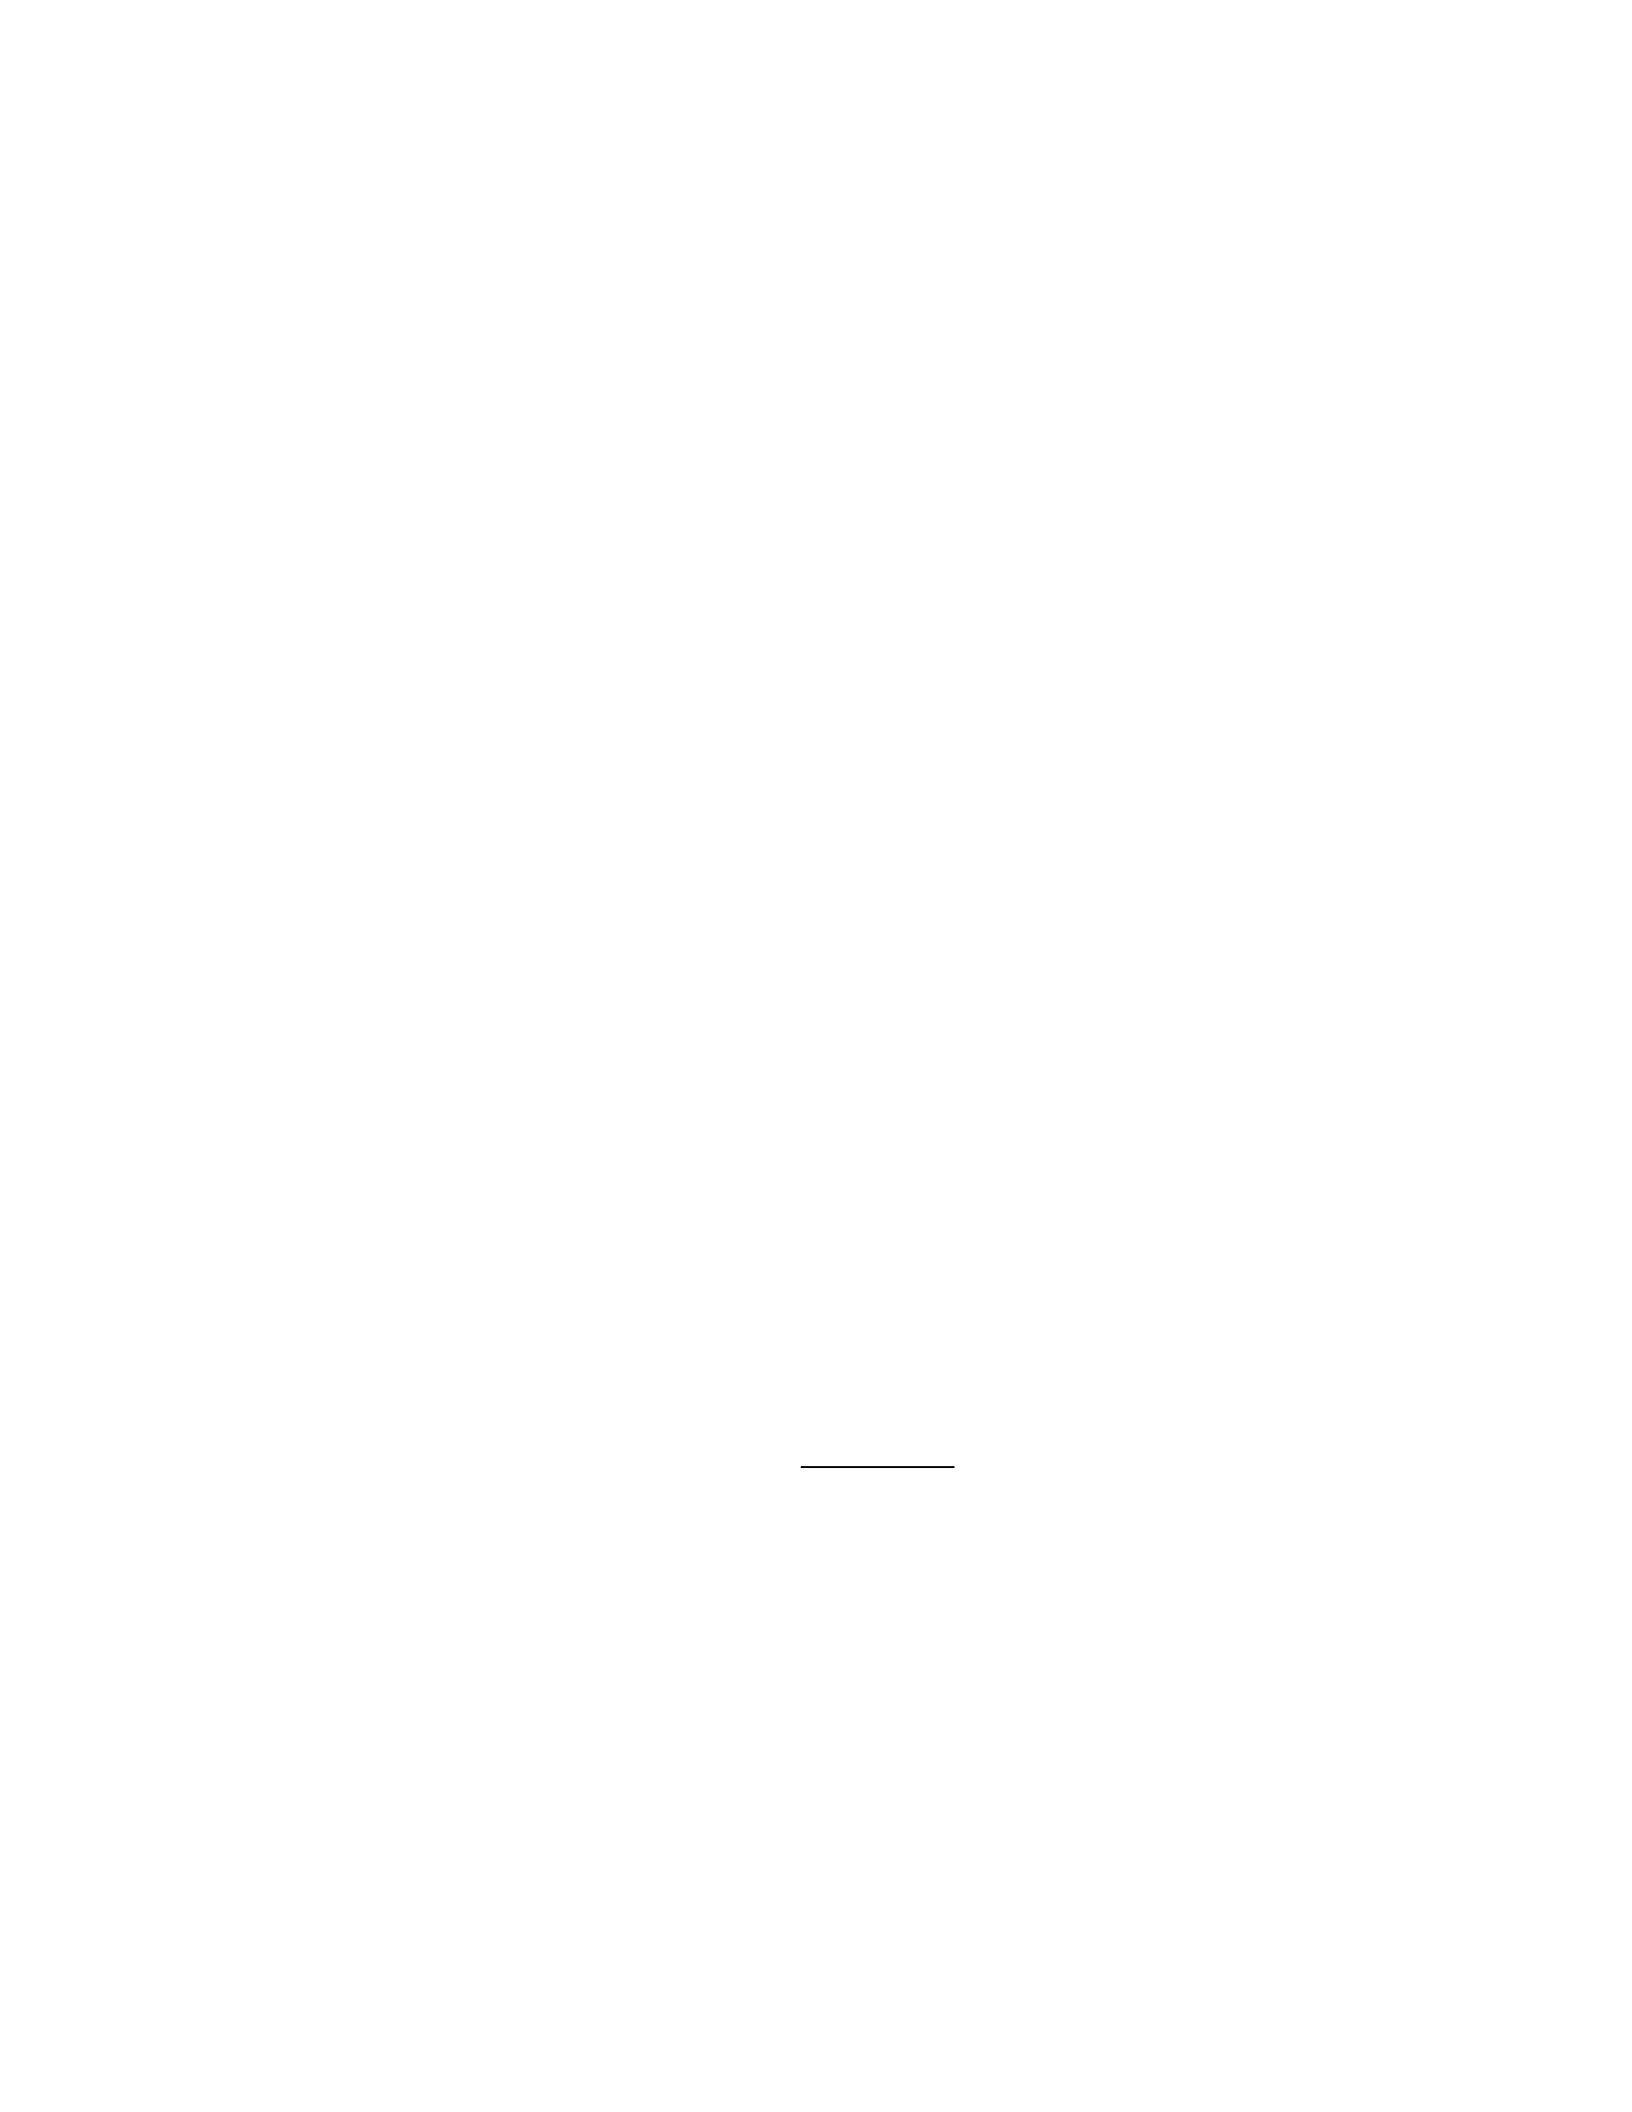
– Net cost = 0
257. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
258. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
259. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%

– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
260. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
261. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
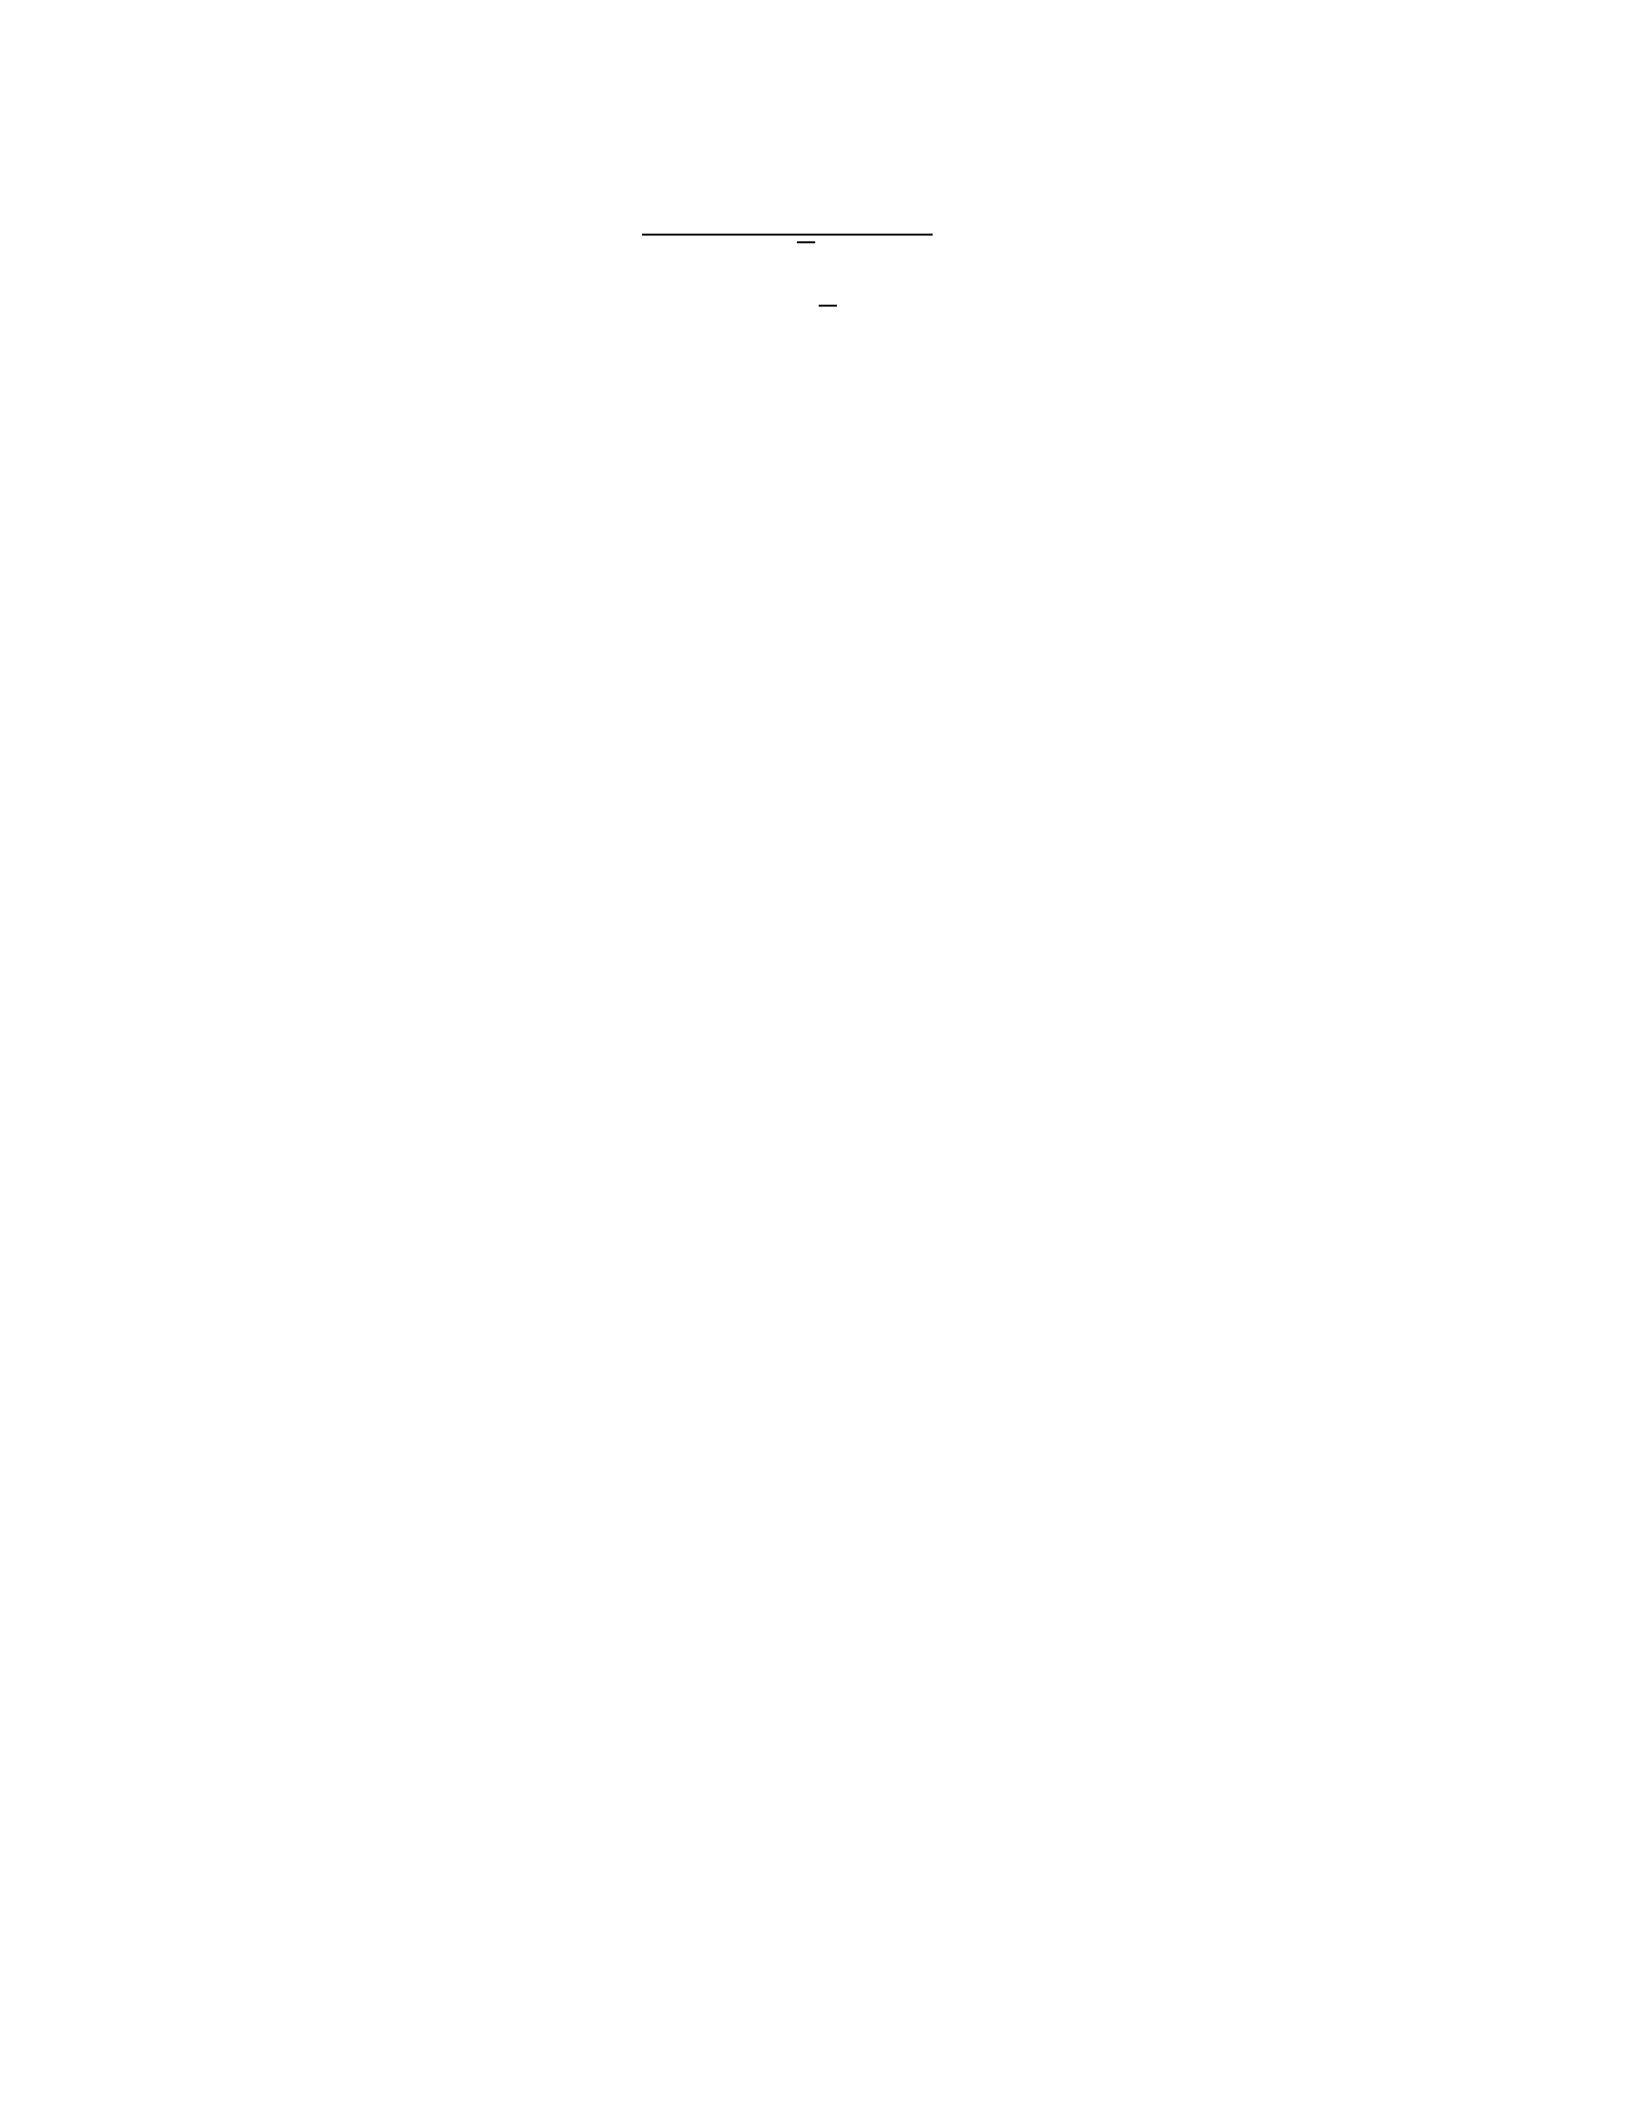
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
262. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
263. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:

a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
264. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10

– Breakeven points: $90 and $110
265. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
266. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
267. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
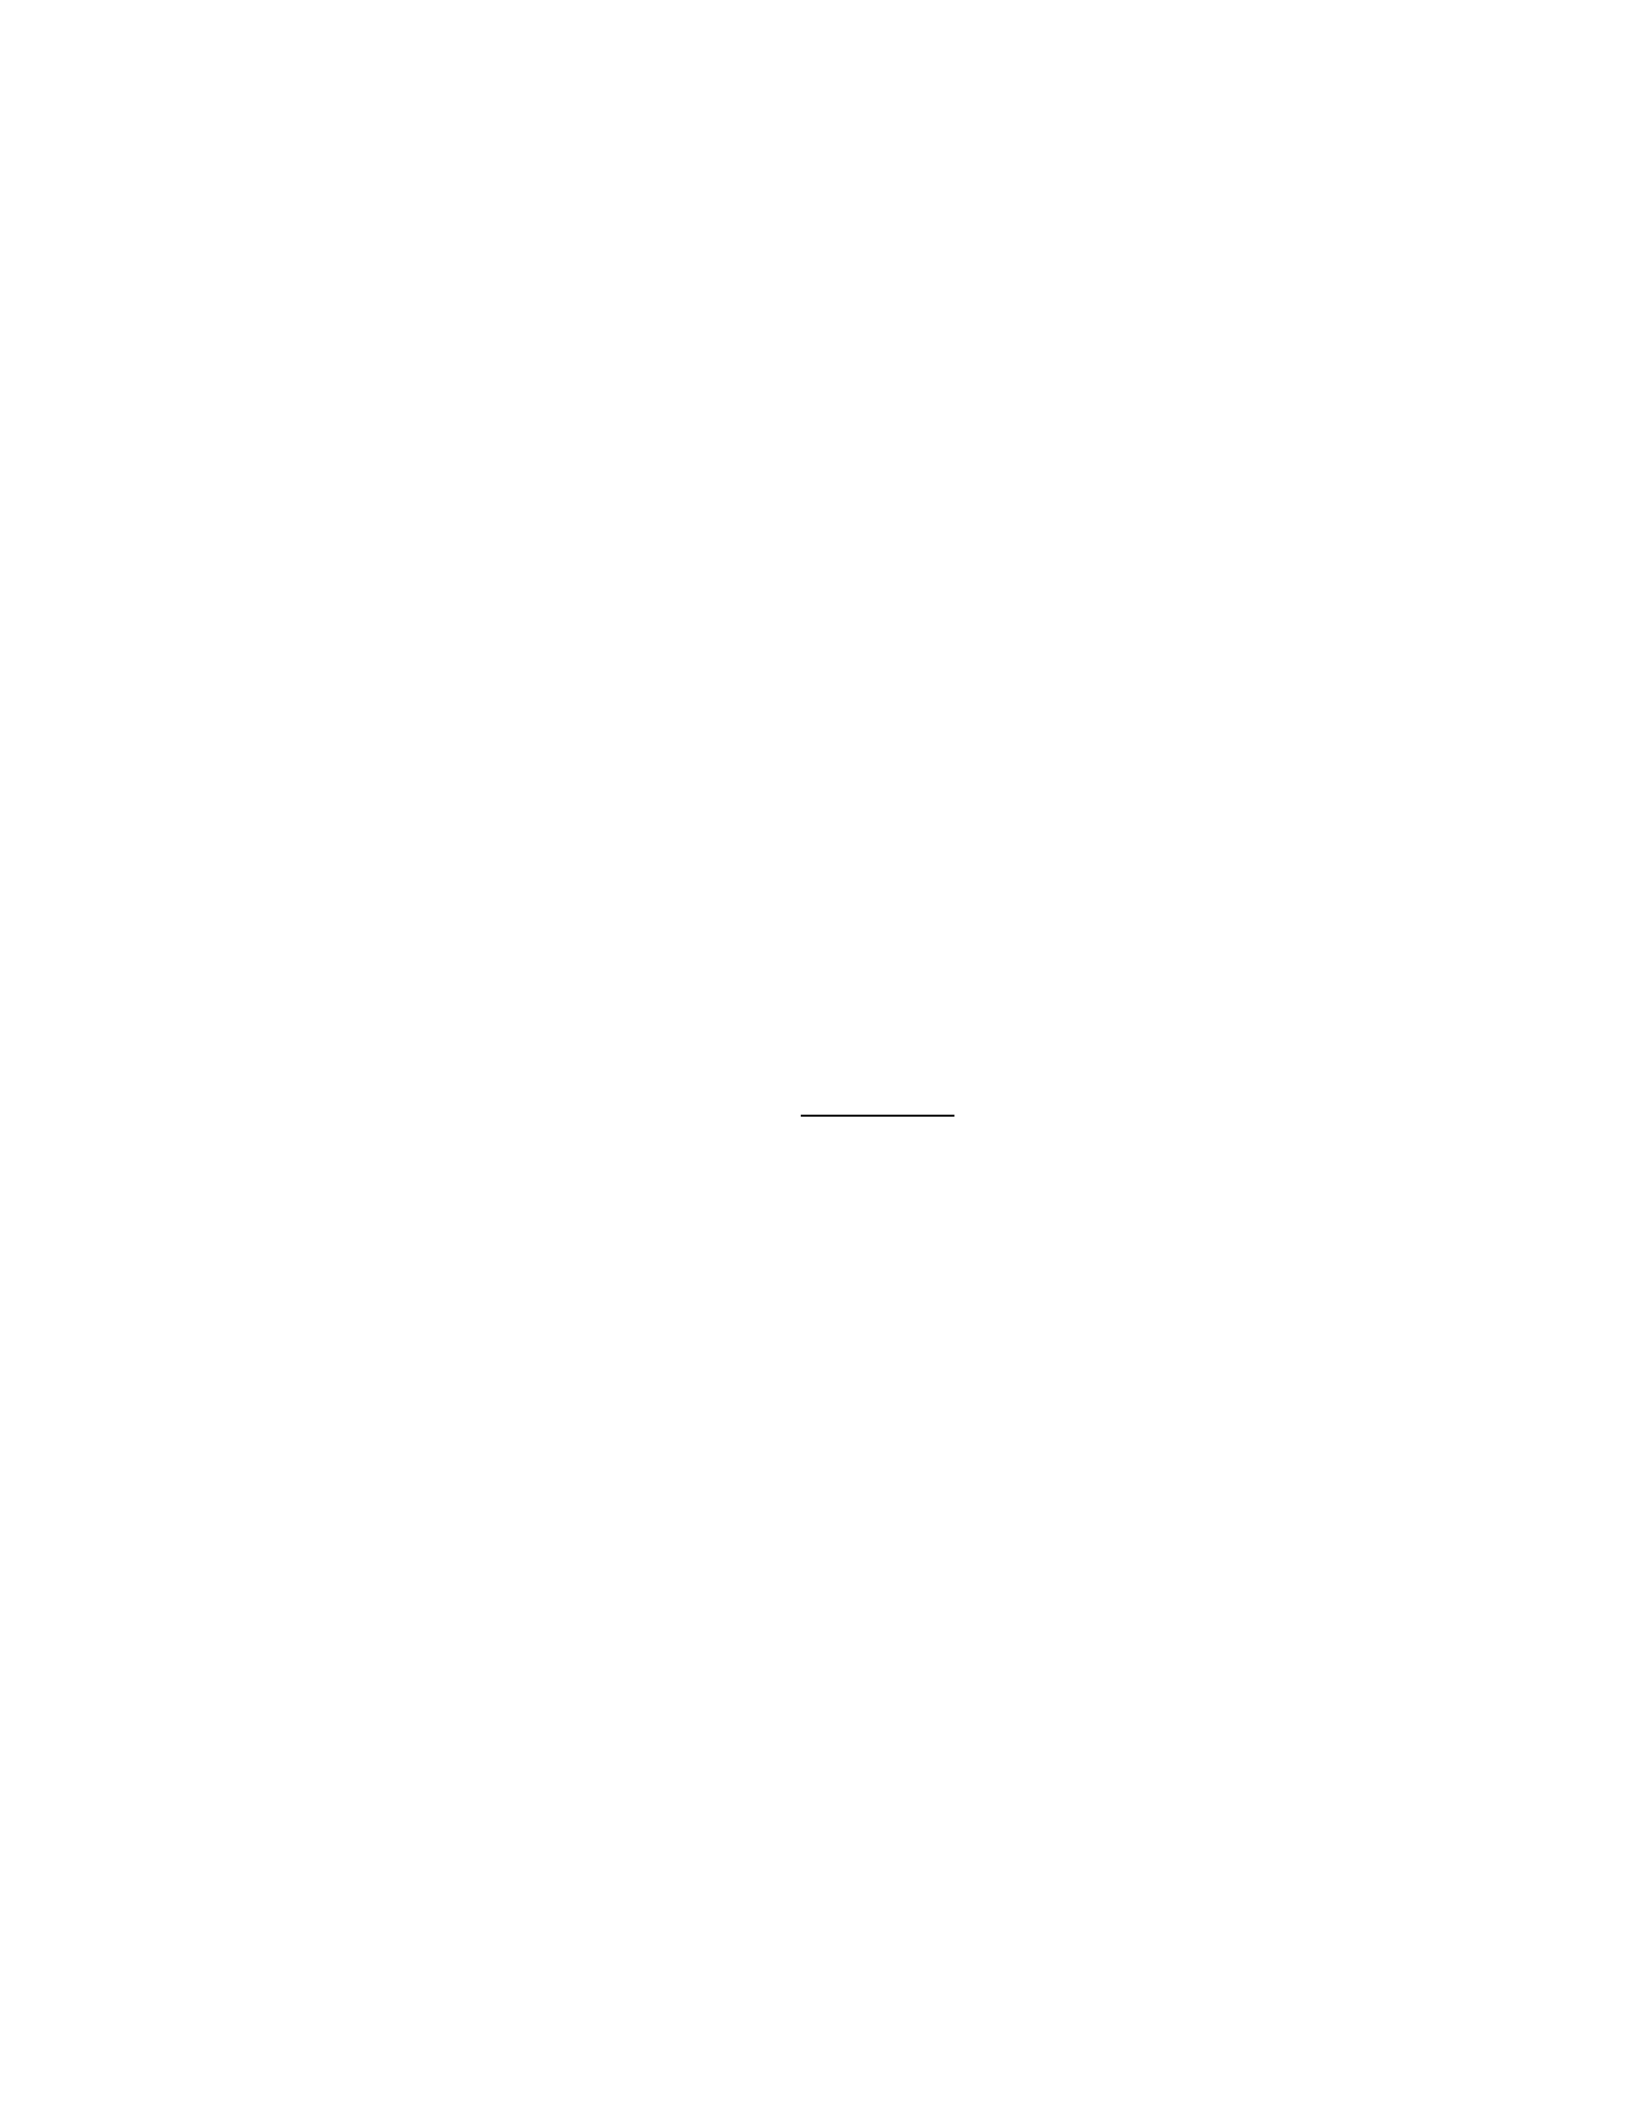
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
268. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
269. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
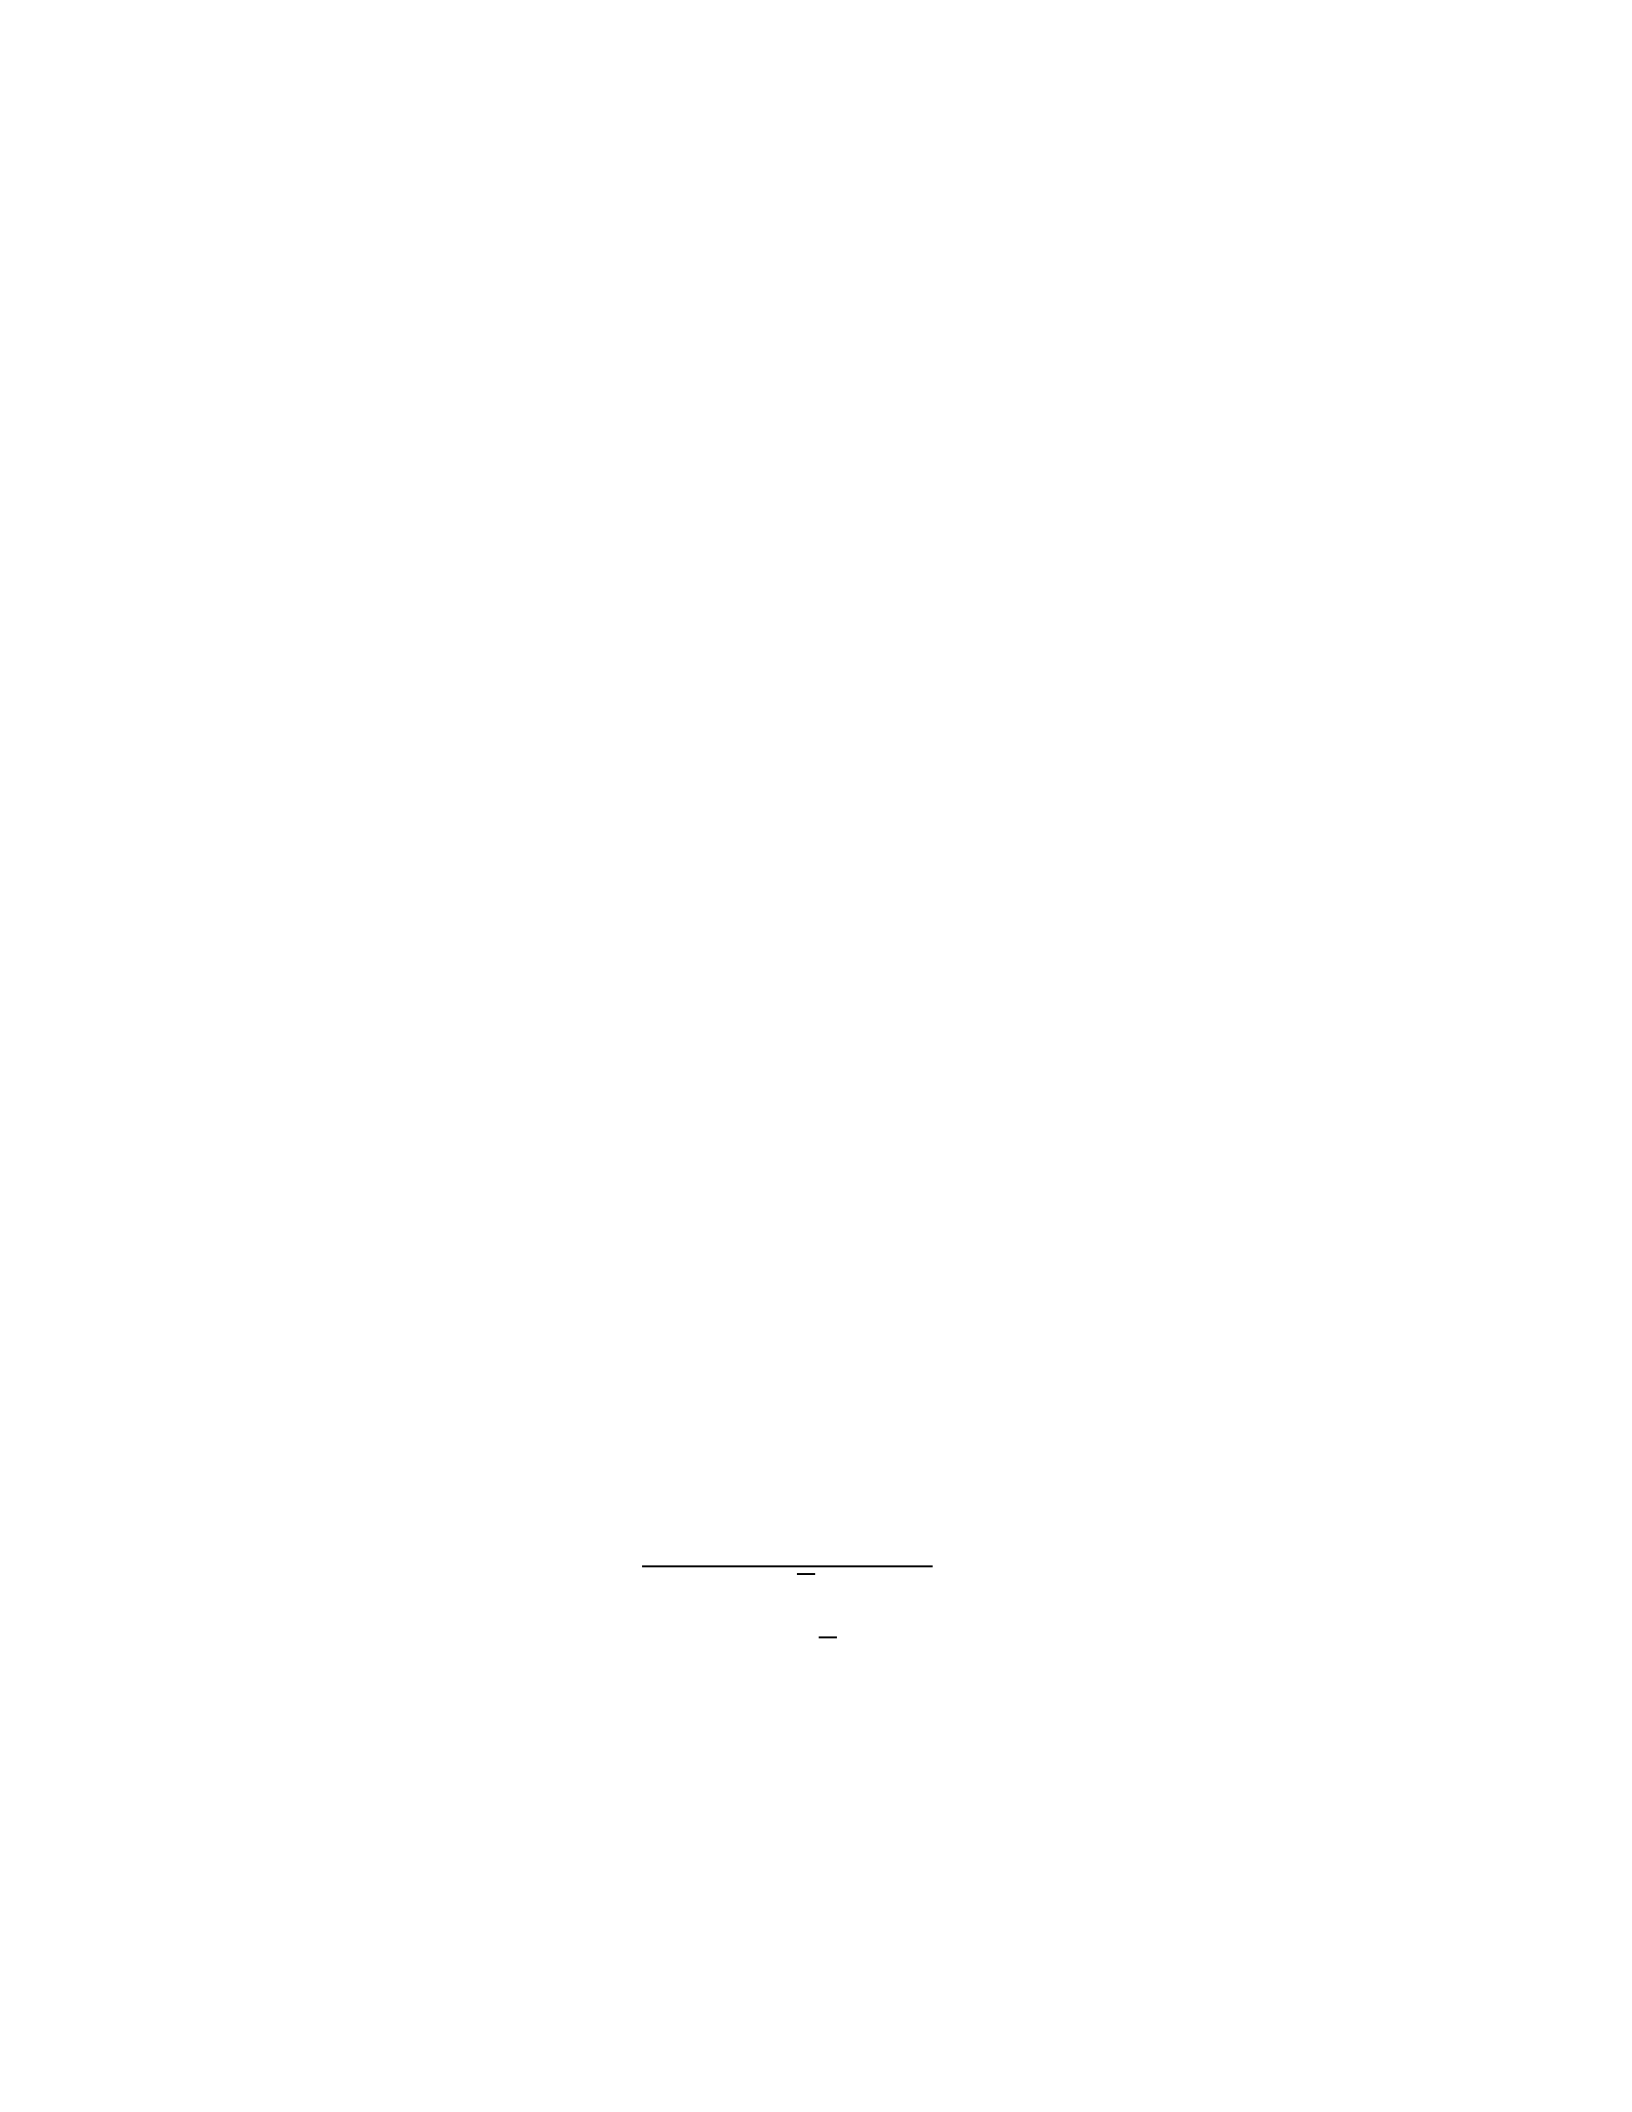
270. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
271. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula

𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
272. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
273. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711

• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
274. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
275. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:

– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
276. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
277. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
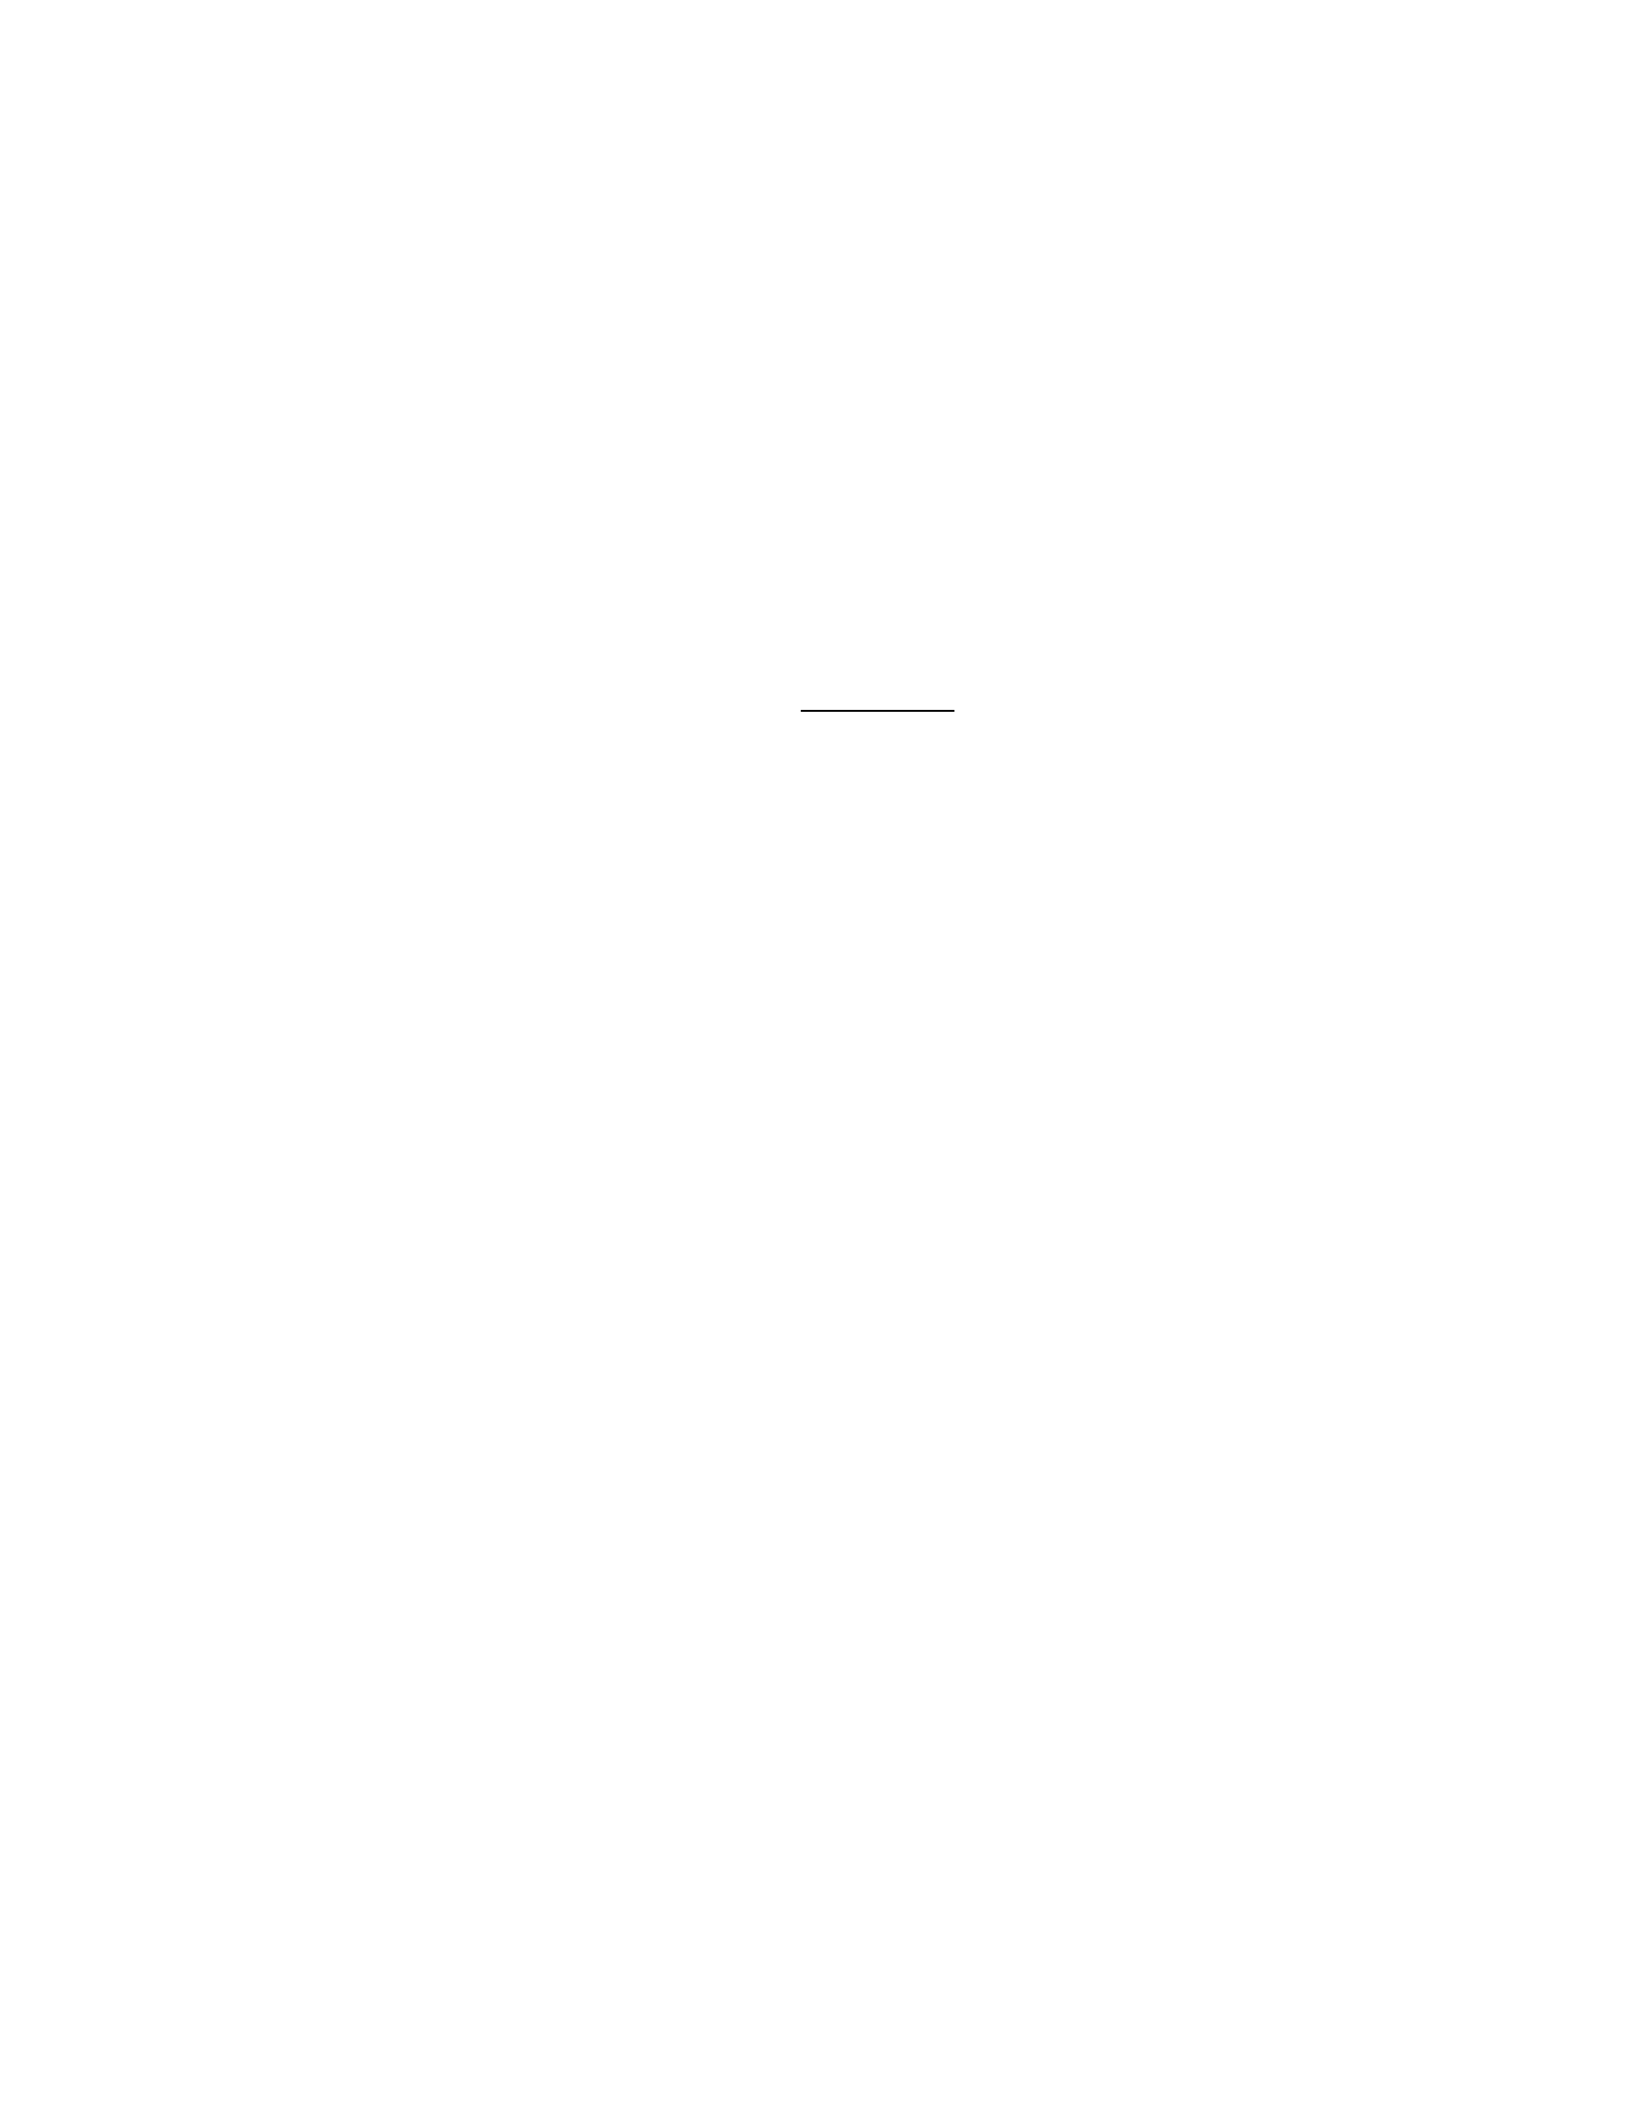
278. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
279. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
280. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
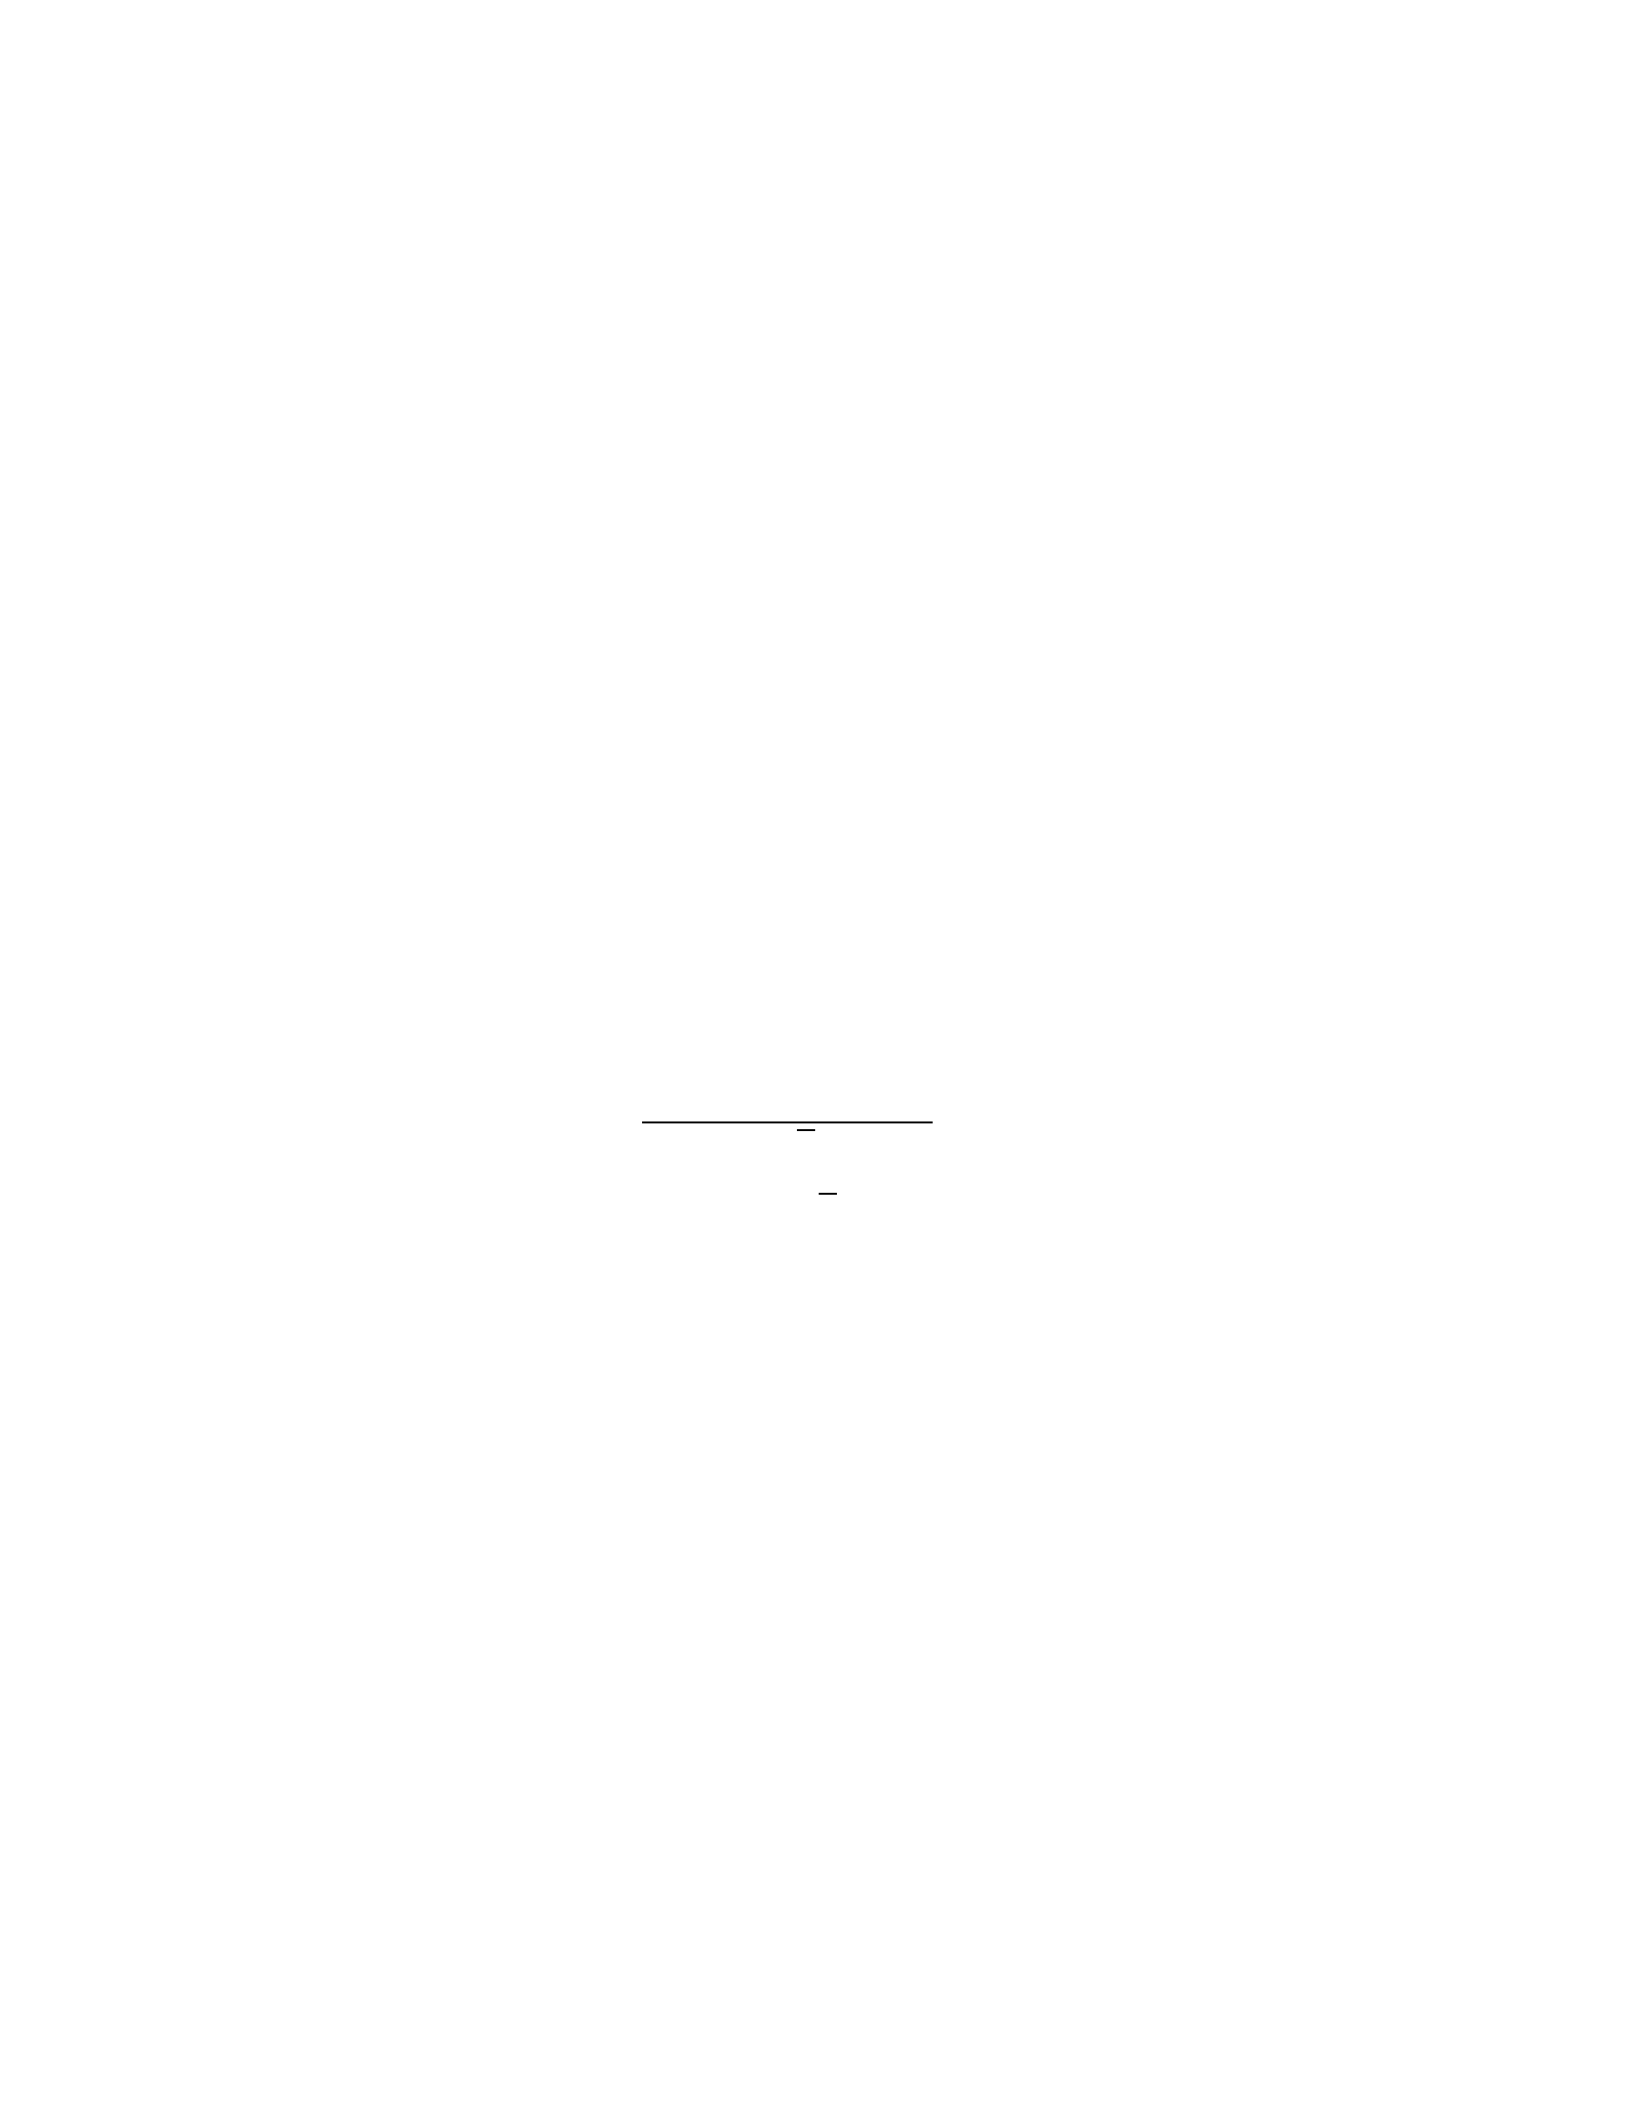
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
281. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
282. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:

a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
283. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
284. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit

from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
285. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
286. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options

and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
287. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
288. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
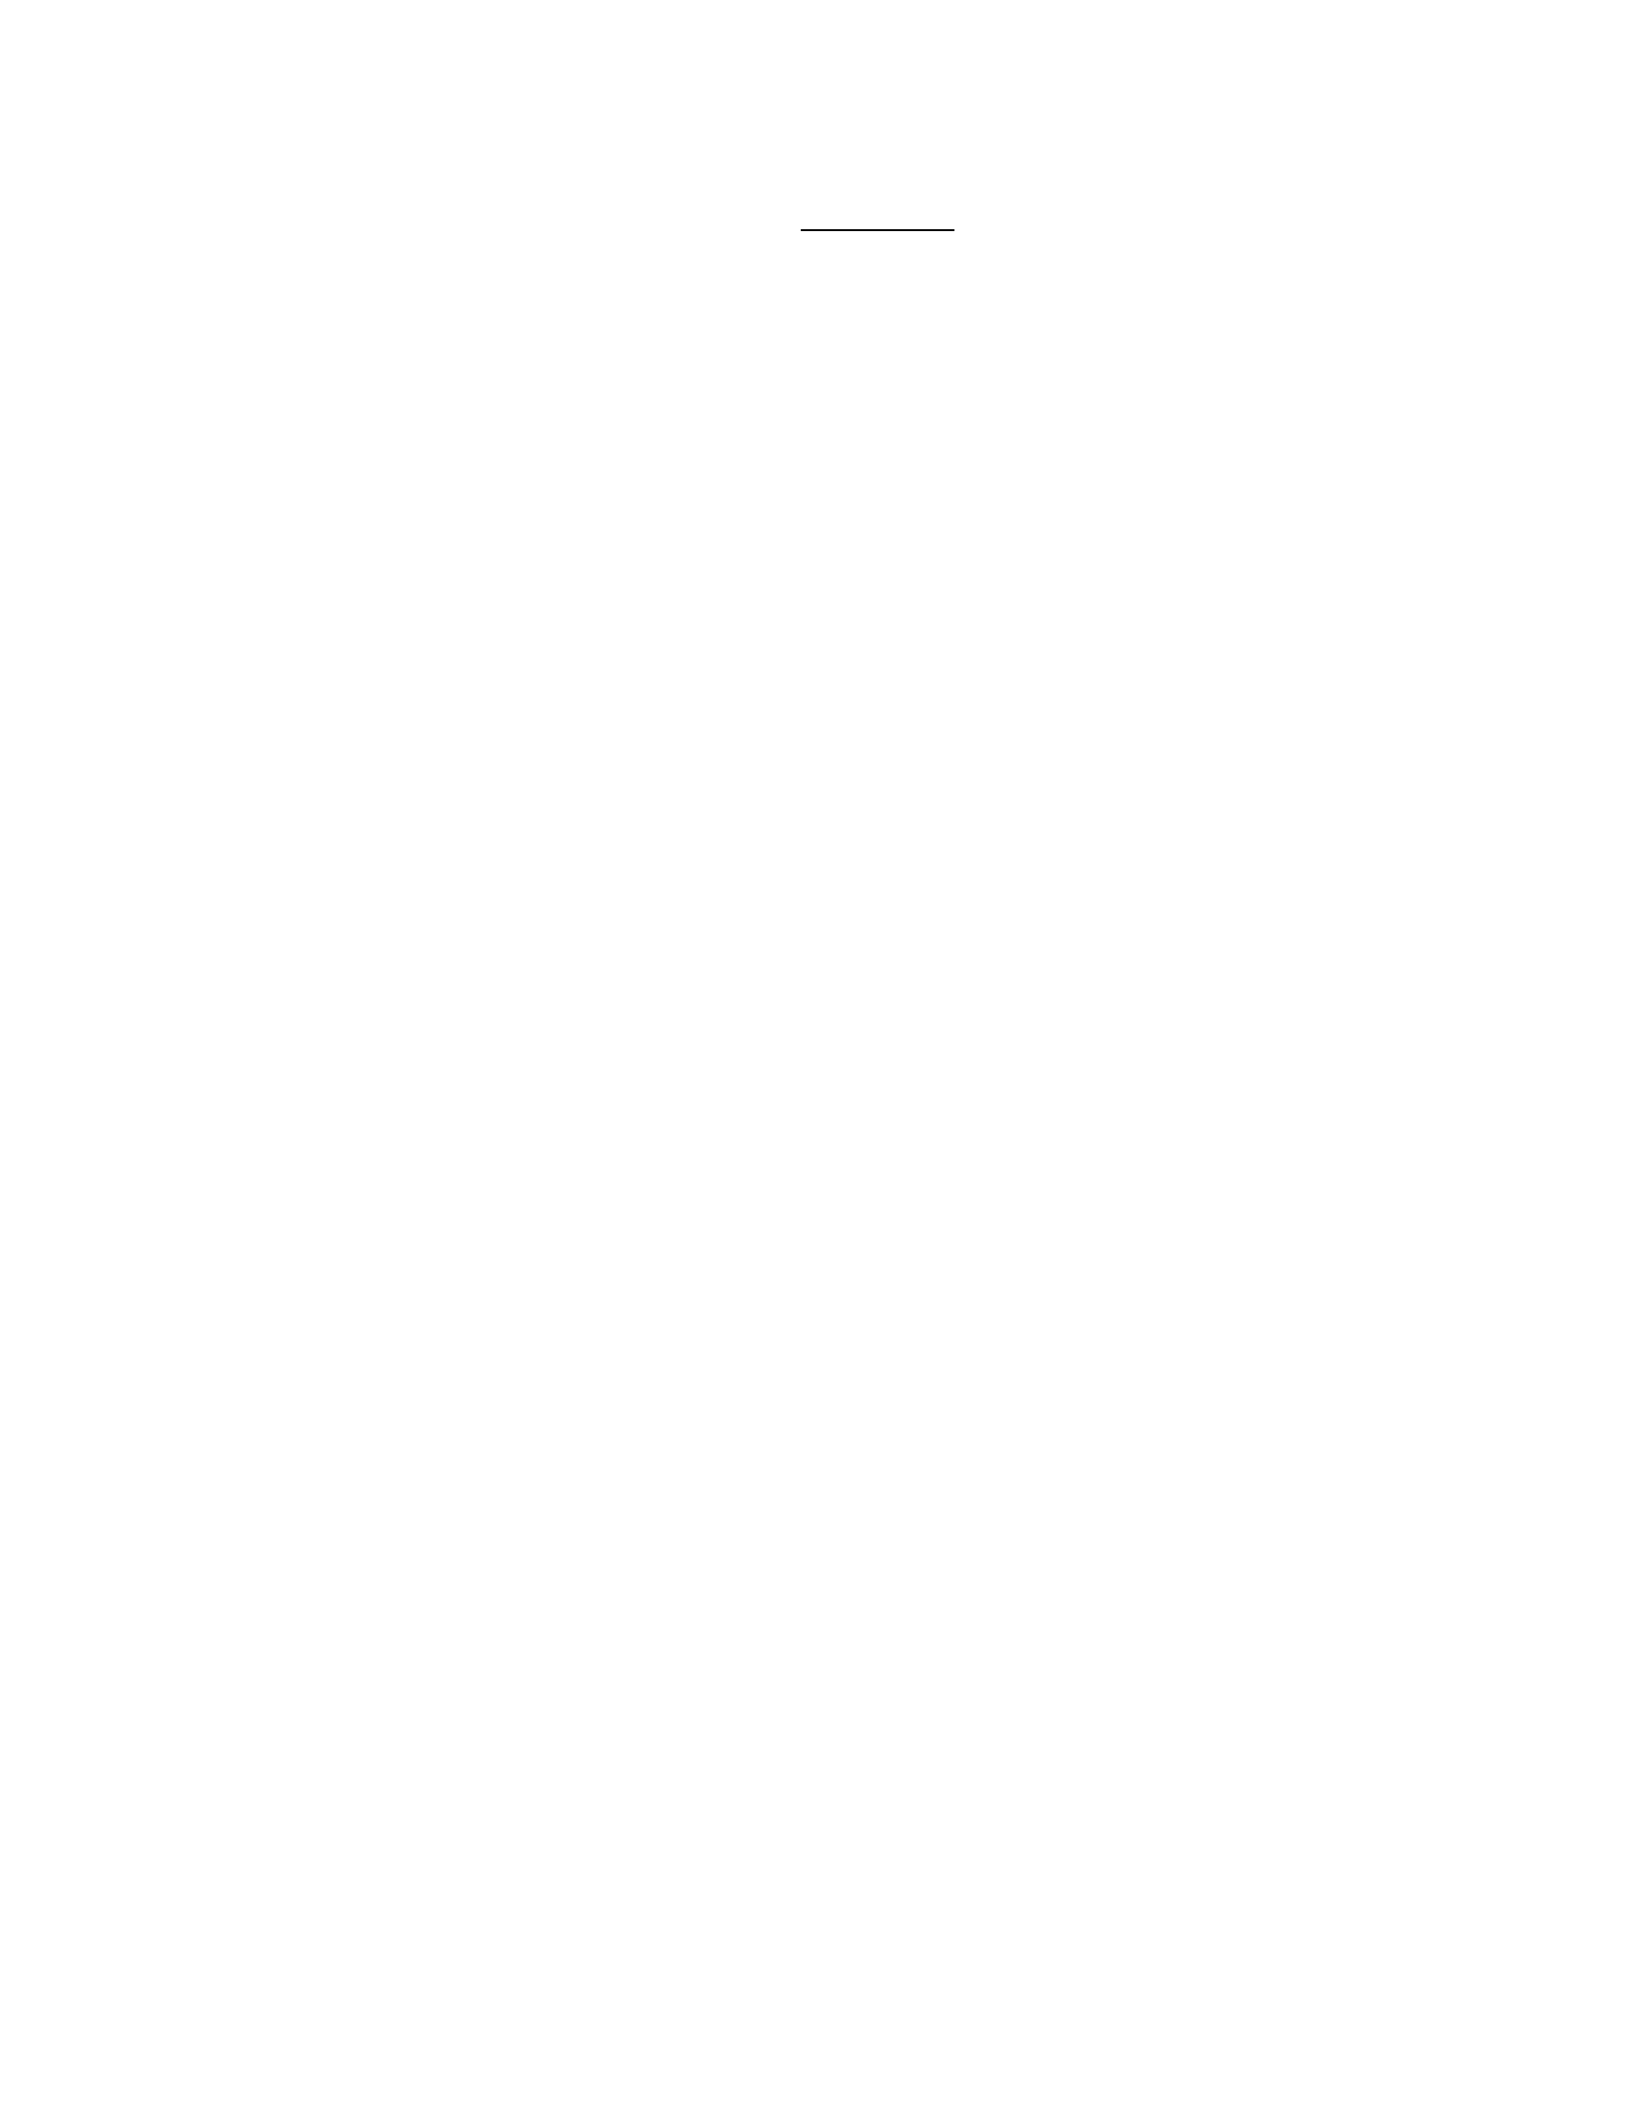
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
289. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
290. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
291. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
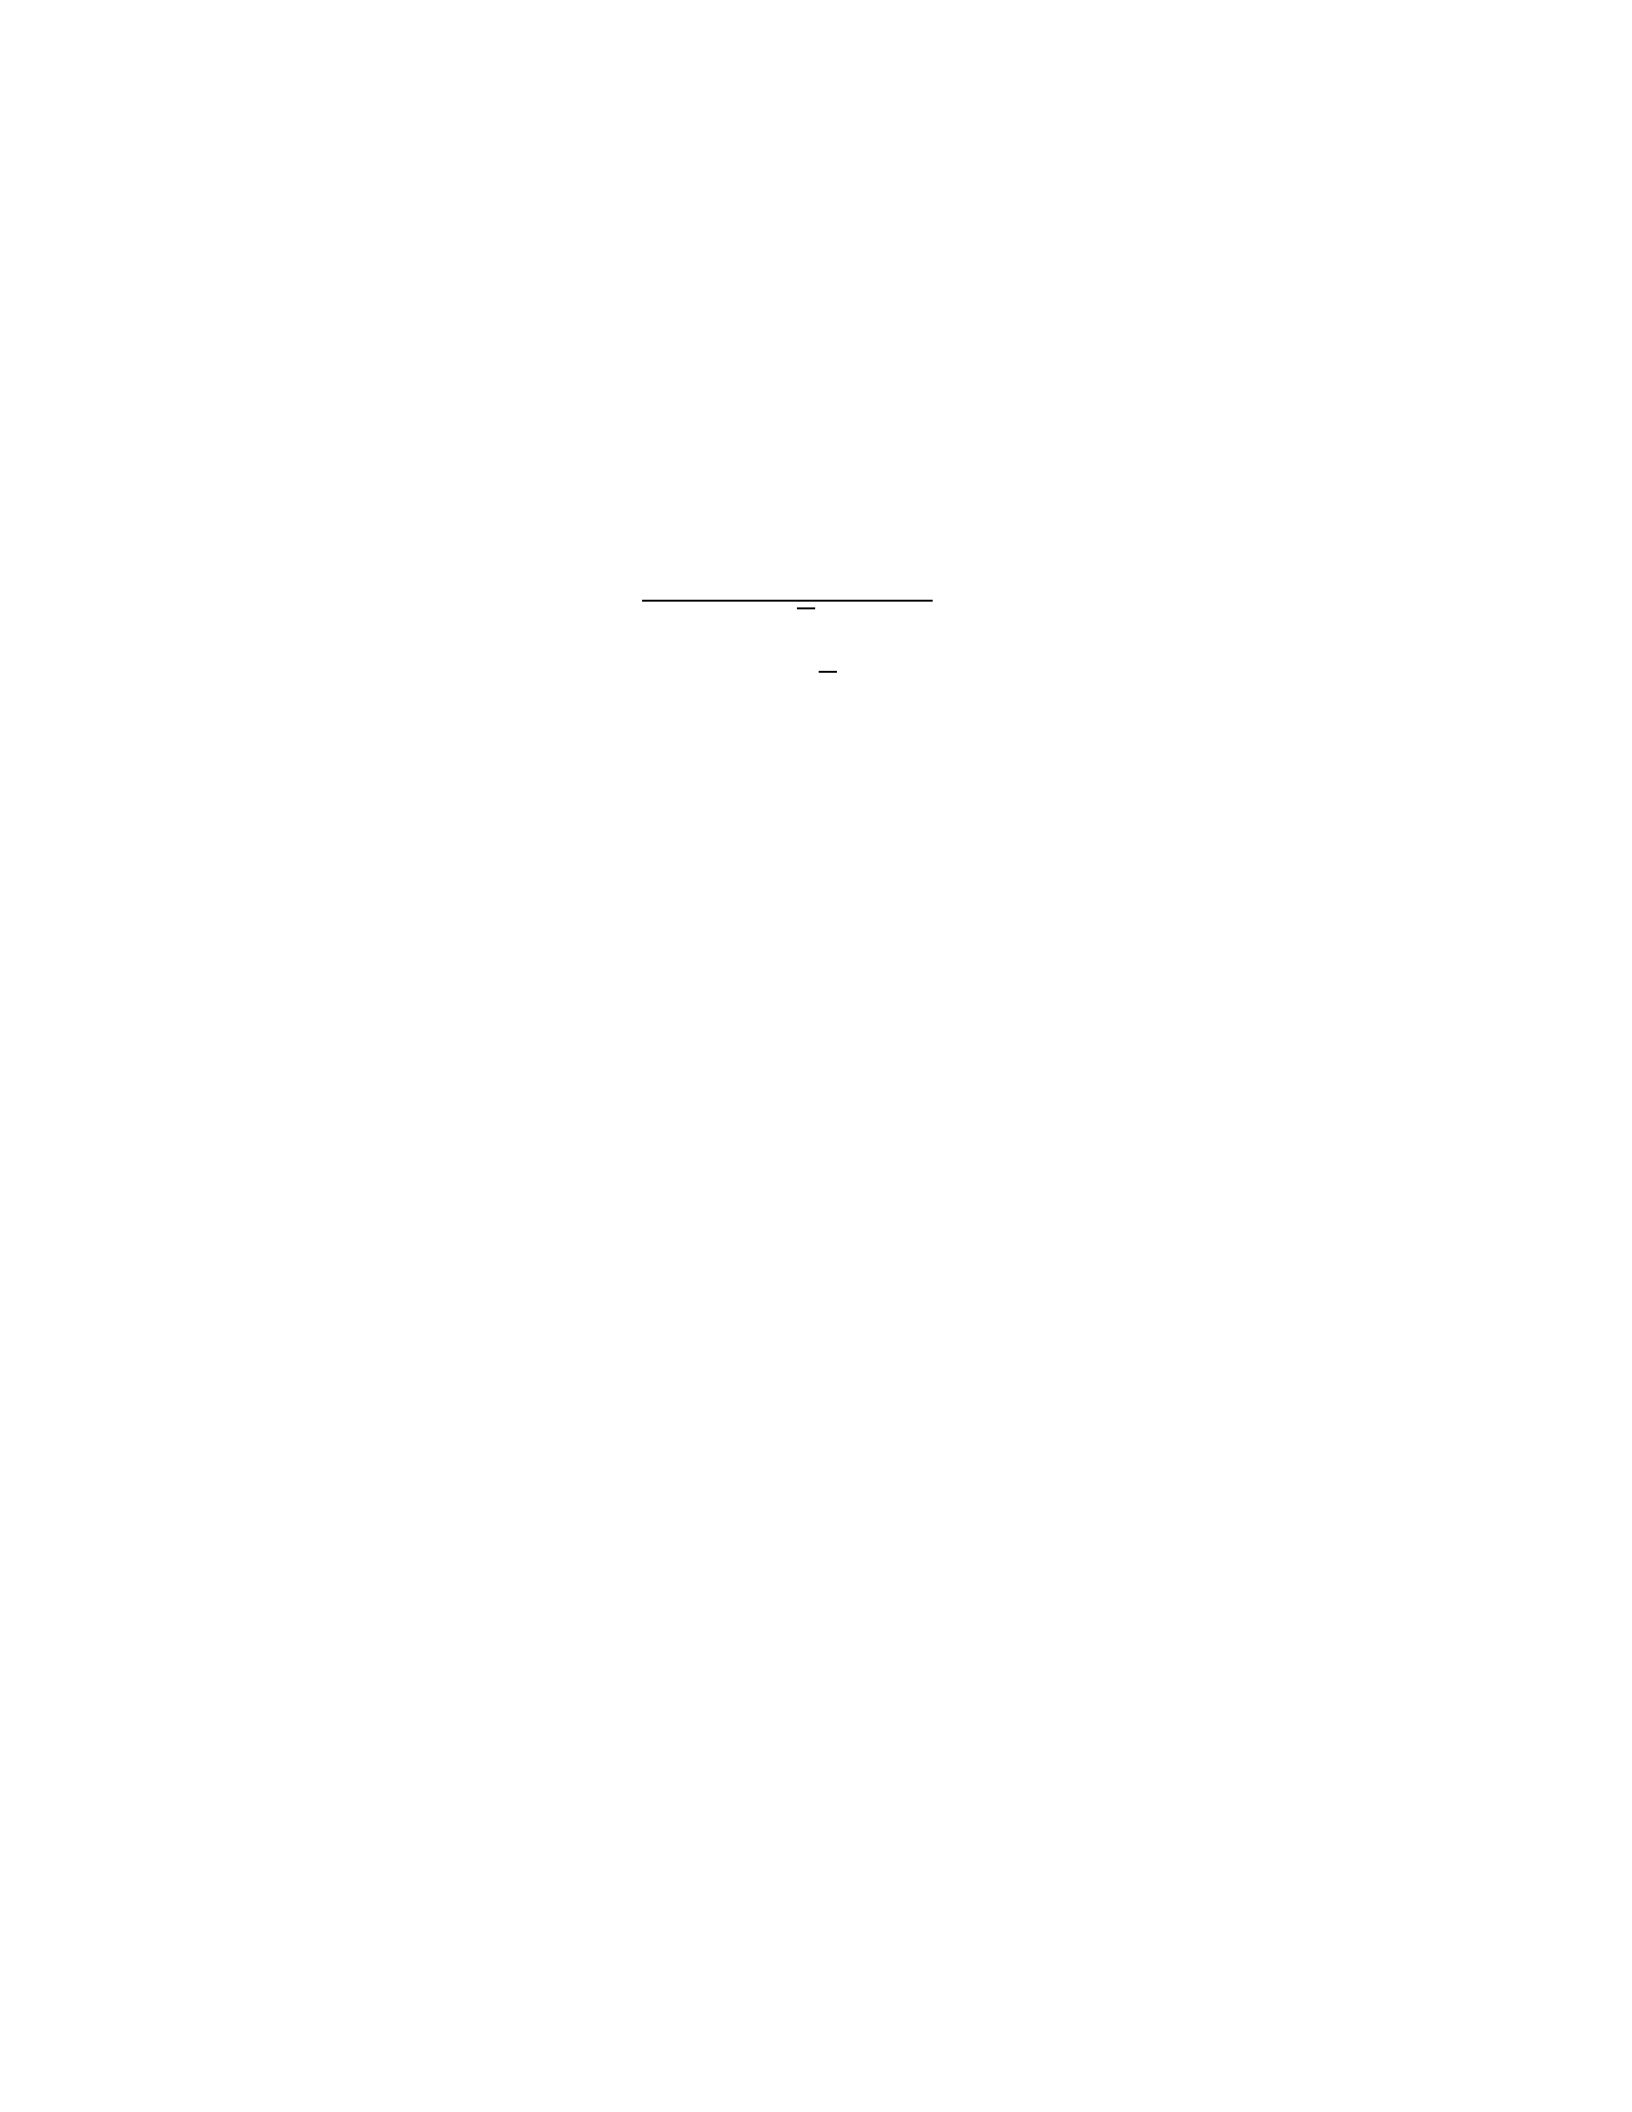
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
292. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500

• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
293. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
294. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:

• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
295. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
296. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
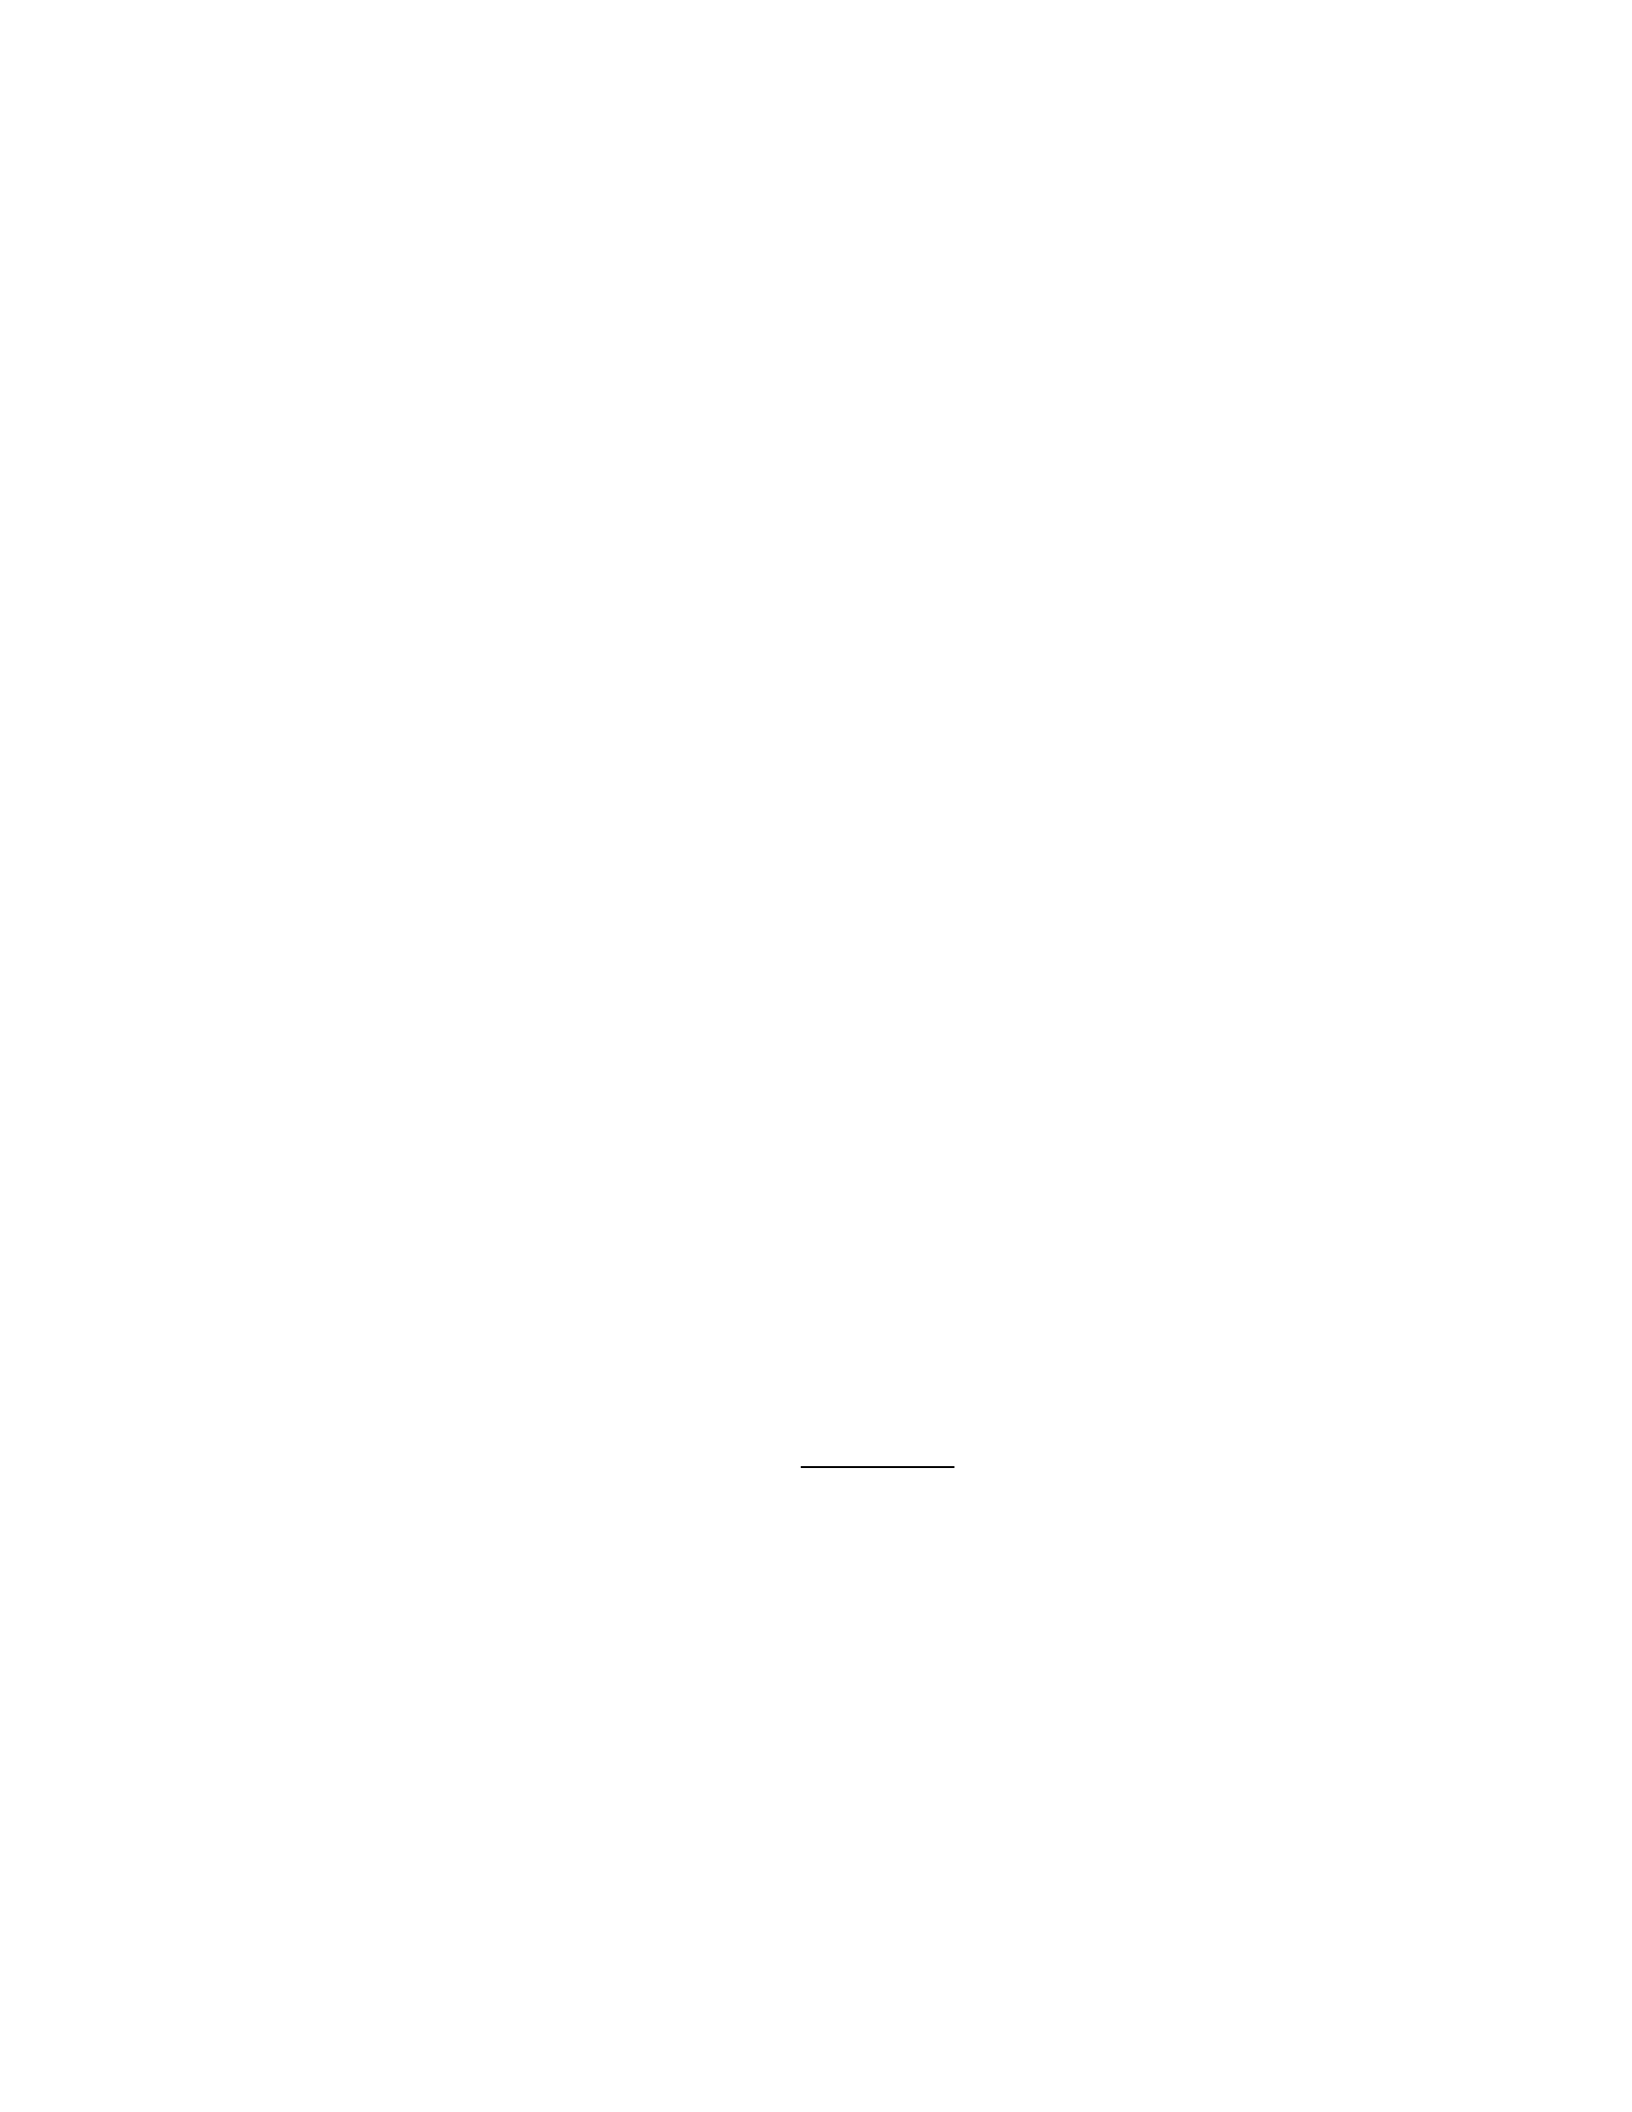
– Net cost = 0
297. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
298. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
299. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%

– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
300. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
301. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
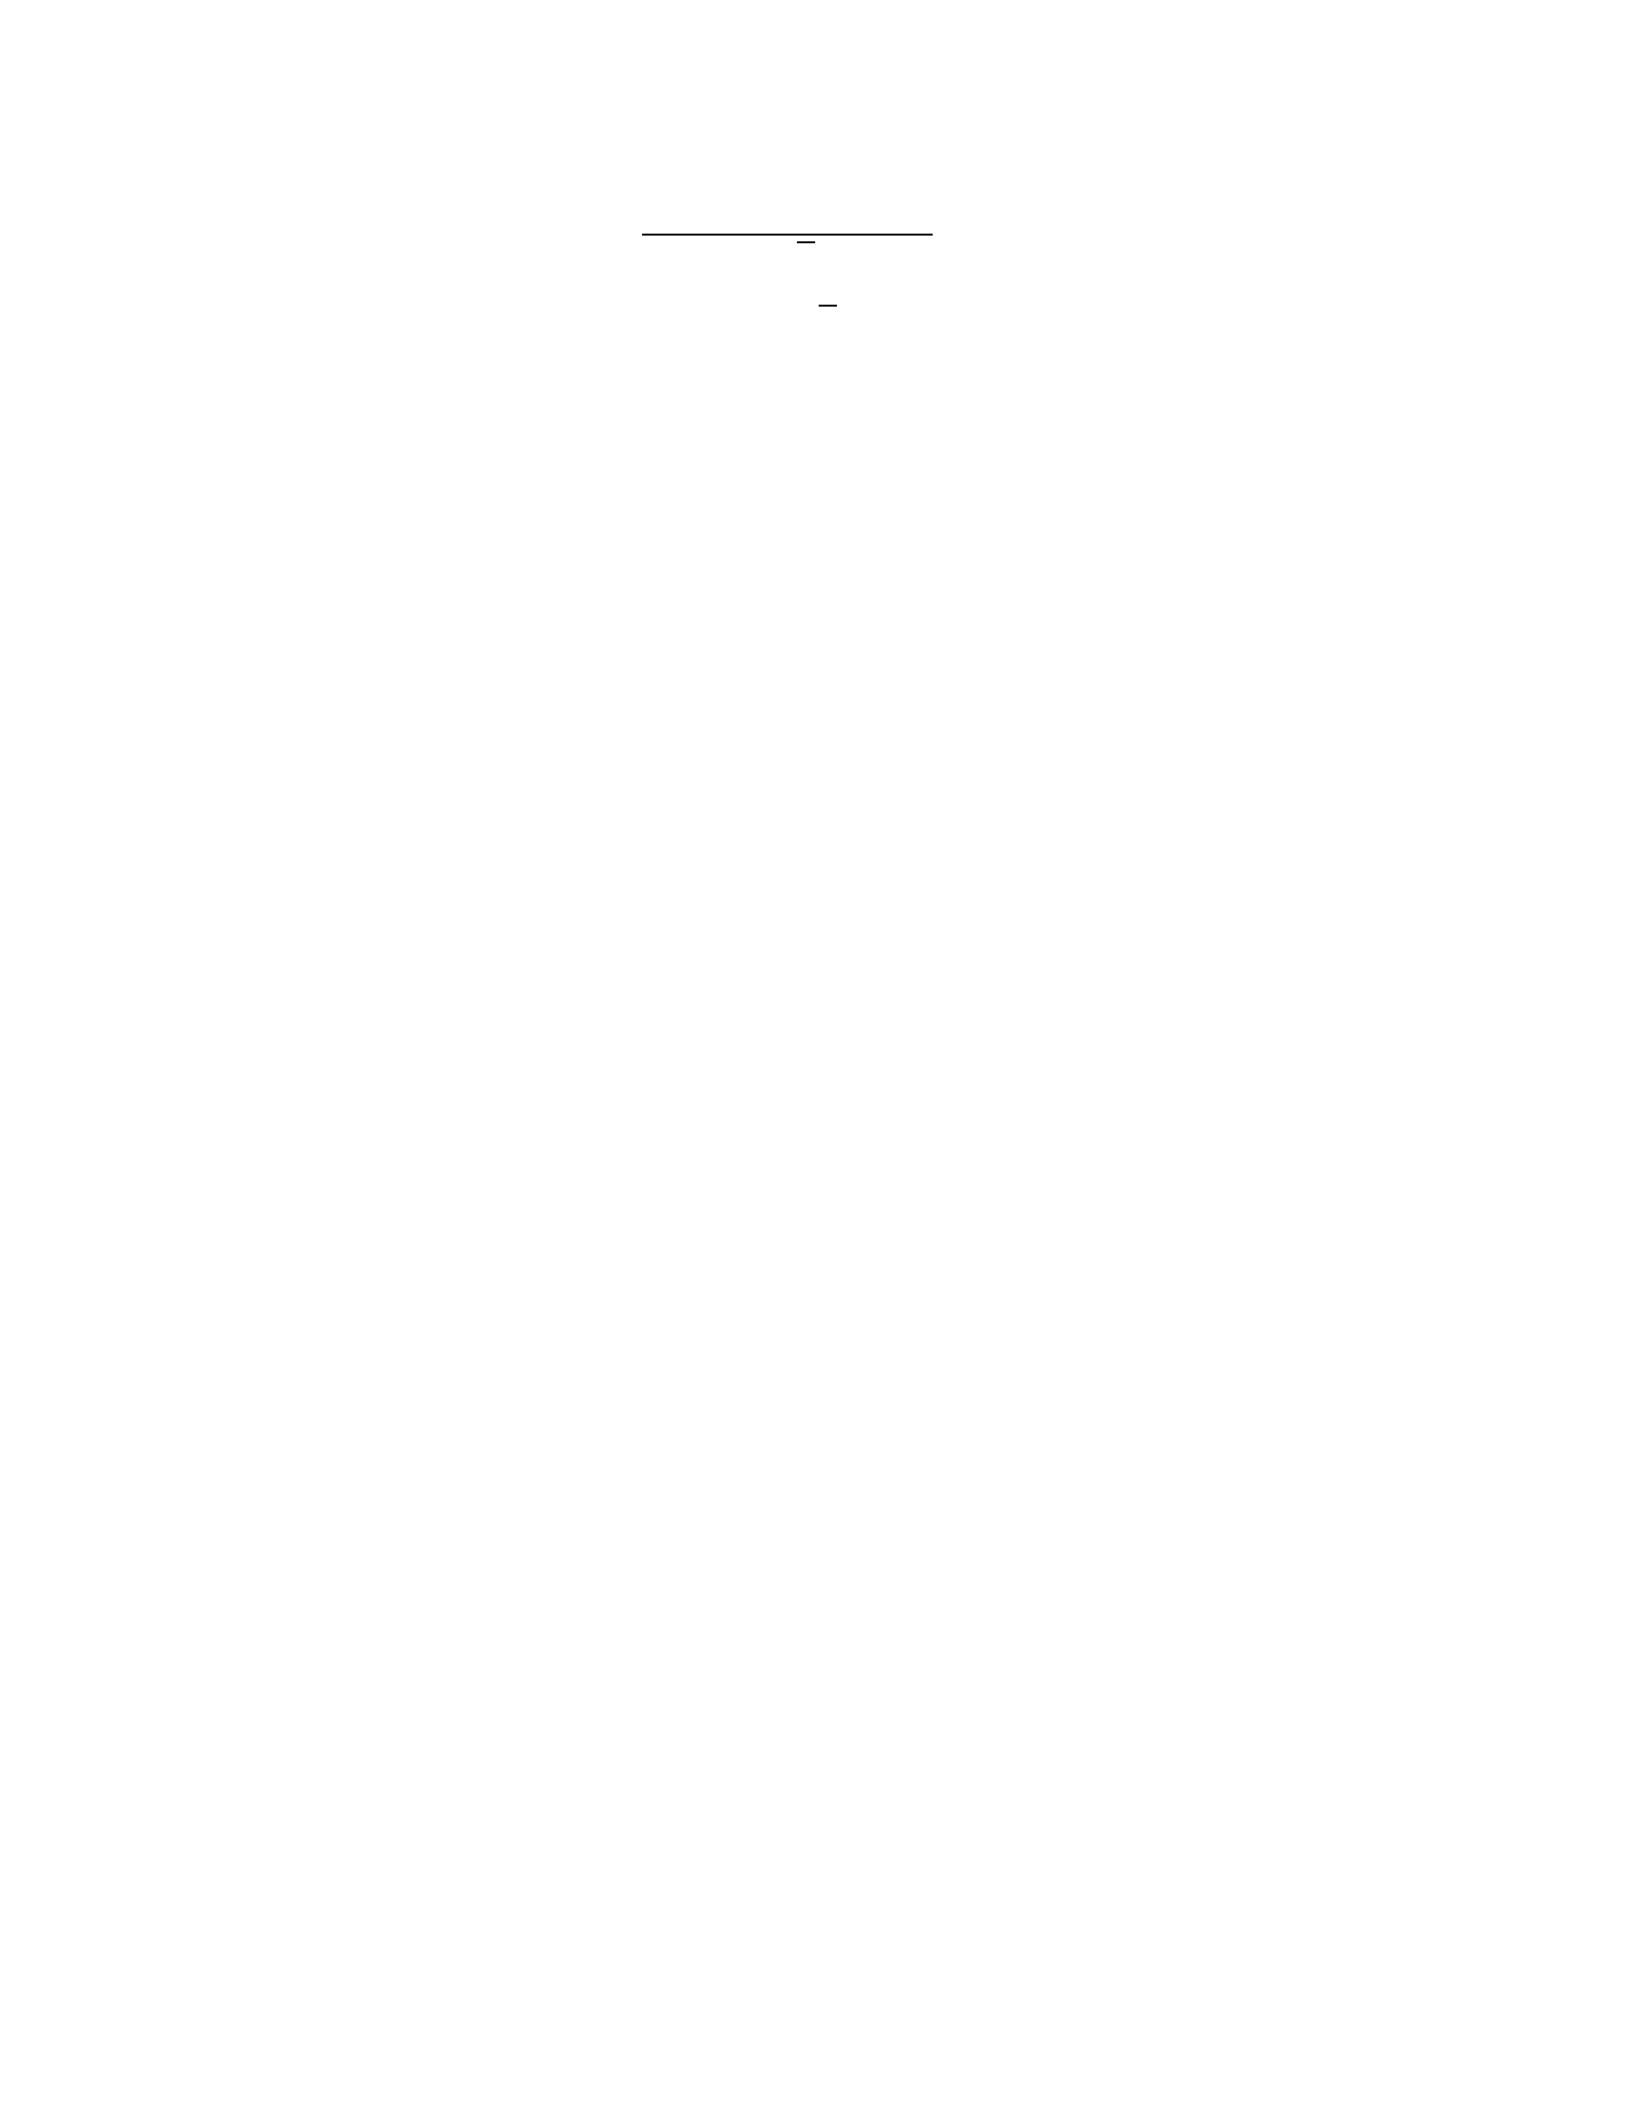
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
302. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
303. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:

a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
304. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10

– Breakeven points: $90 and $110
305. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
306. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
307. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
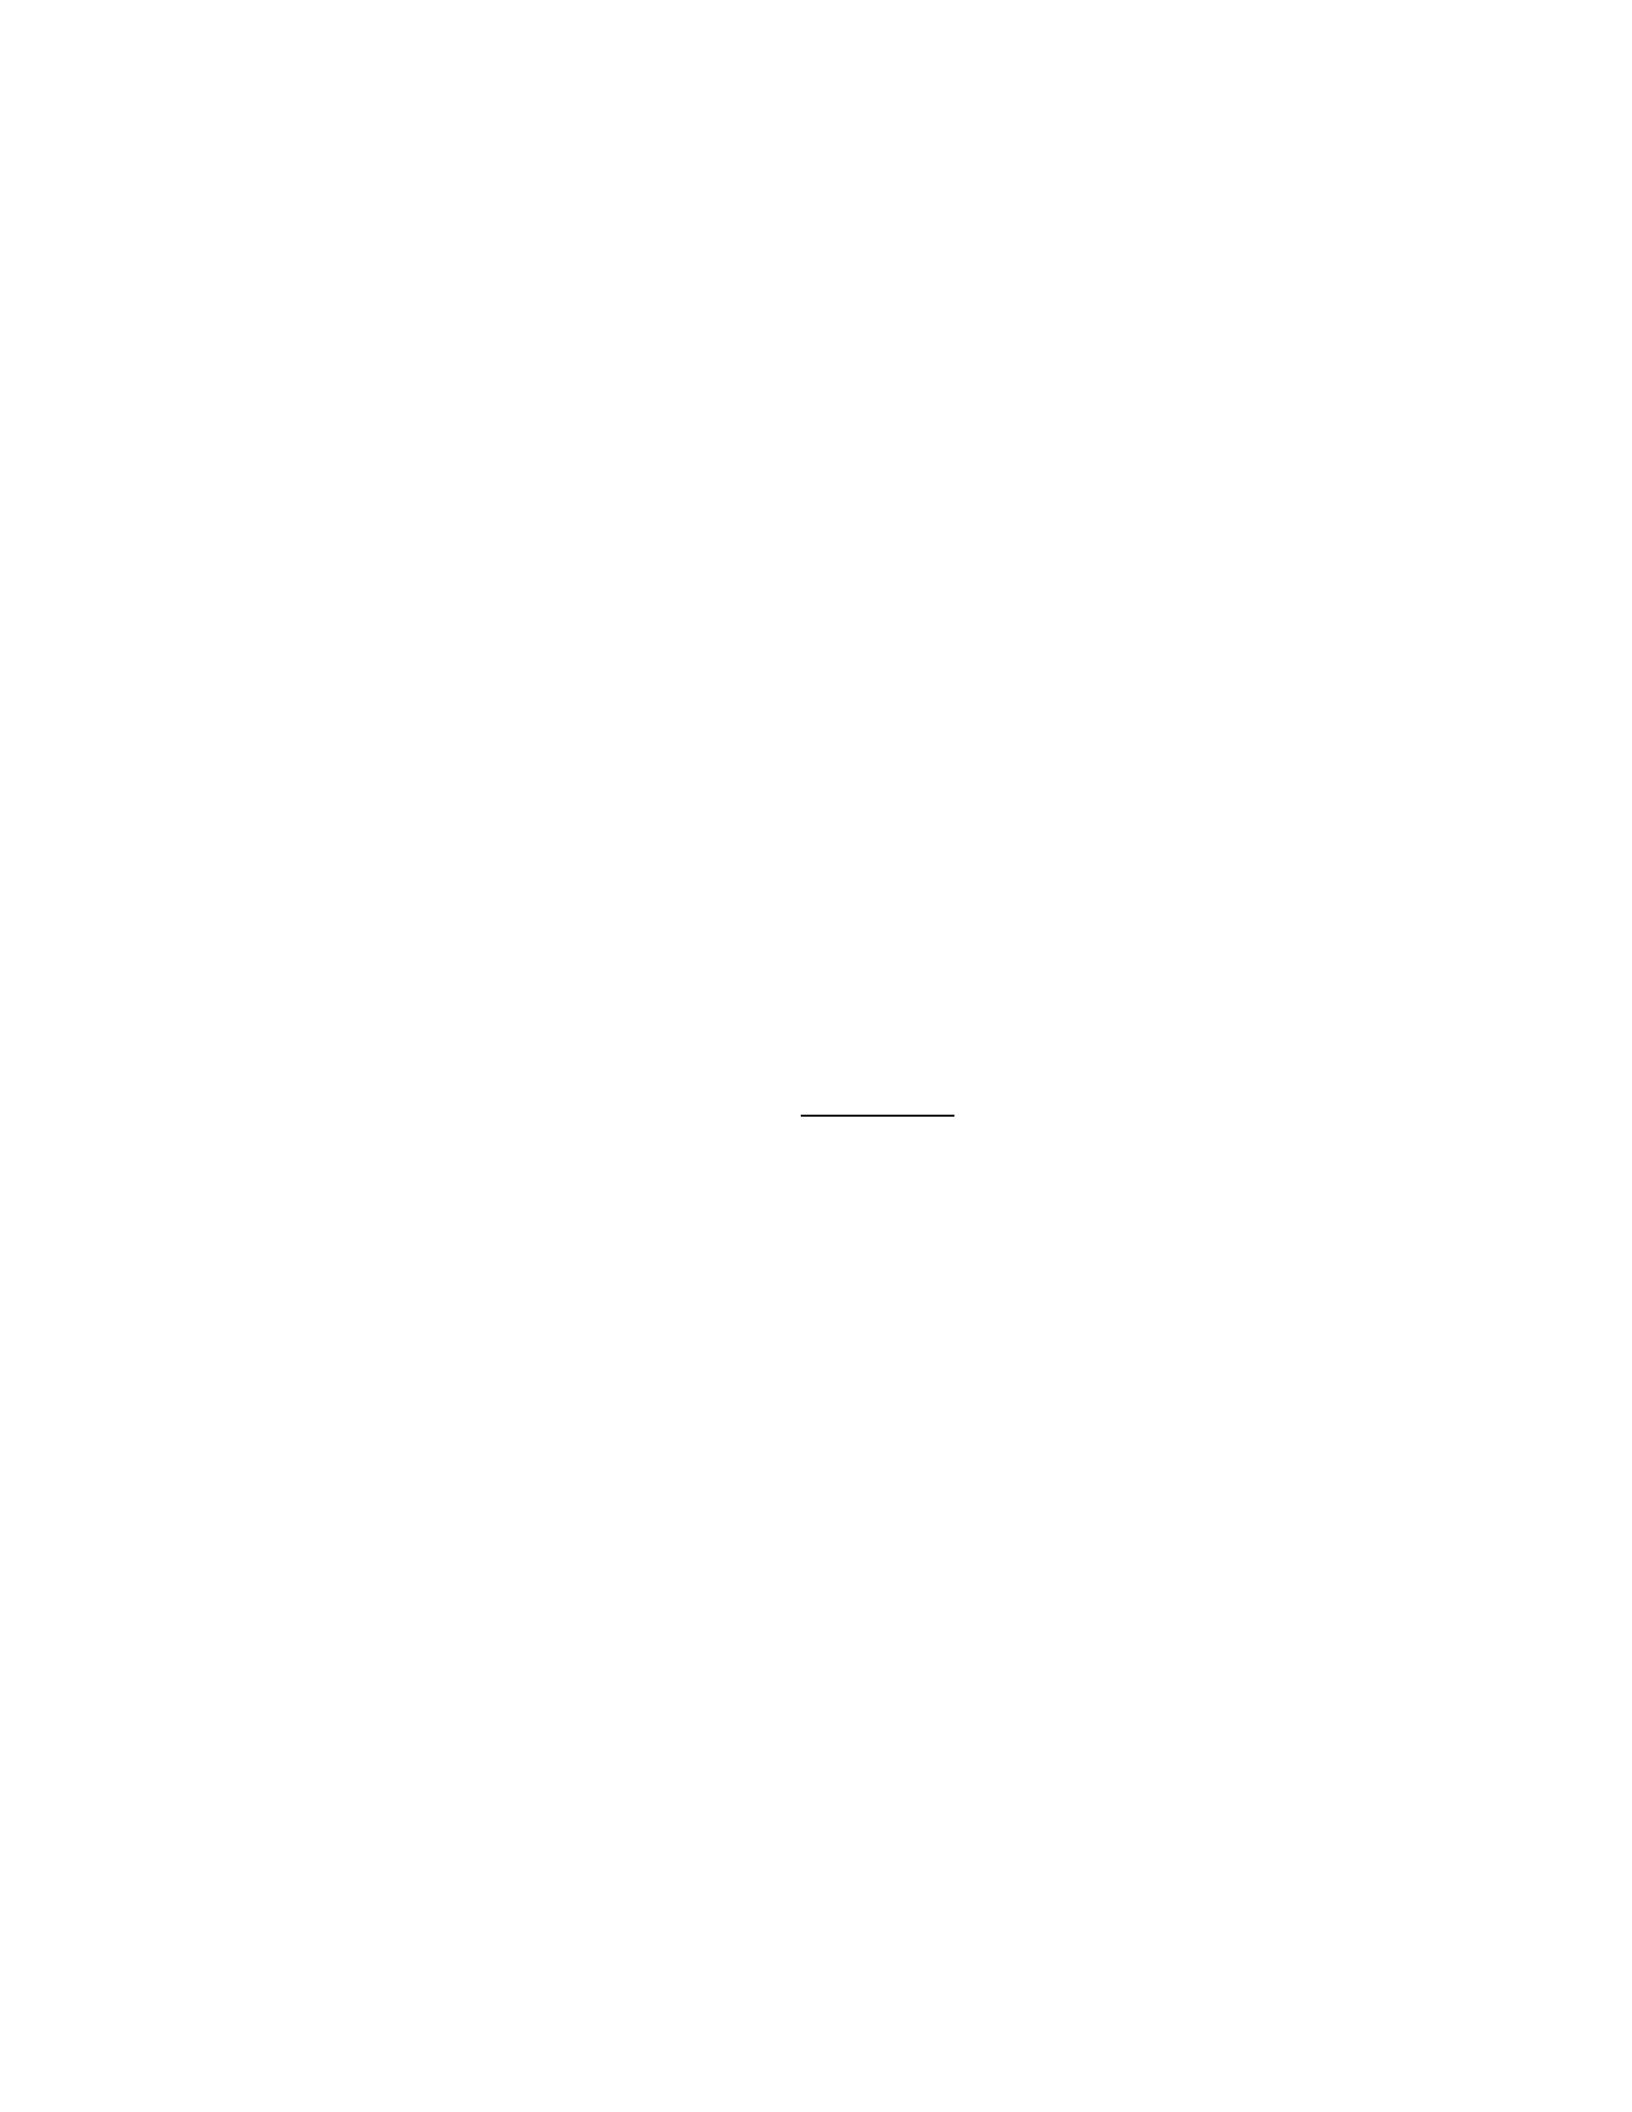
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
308. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
309. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
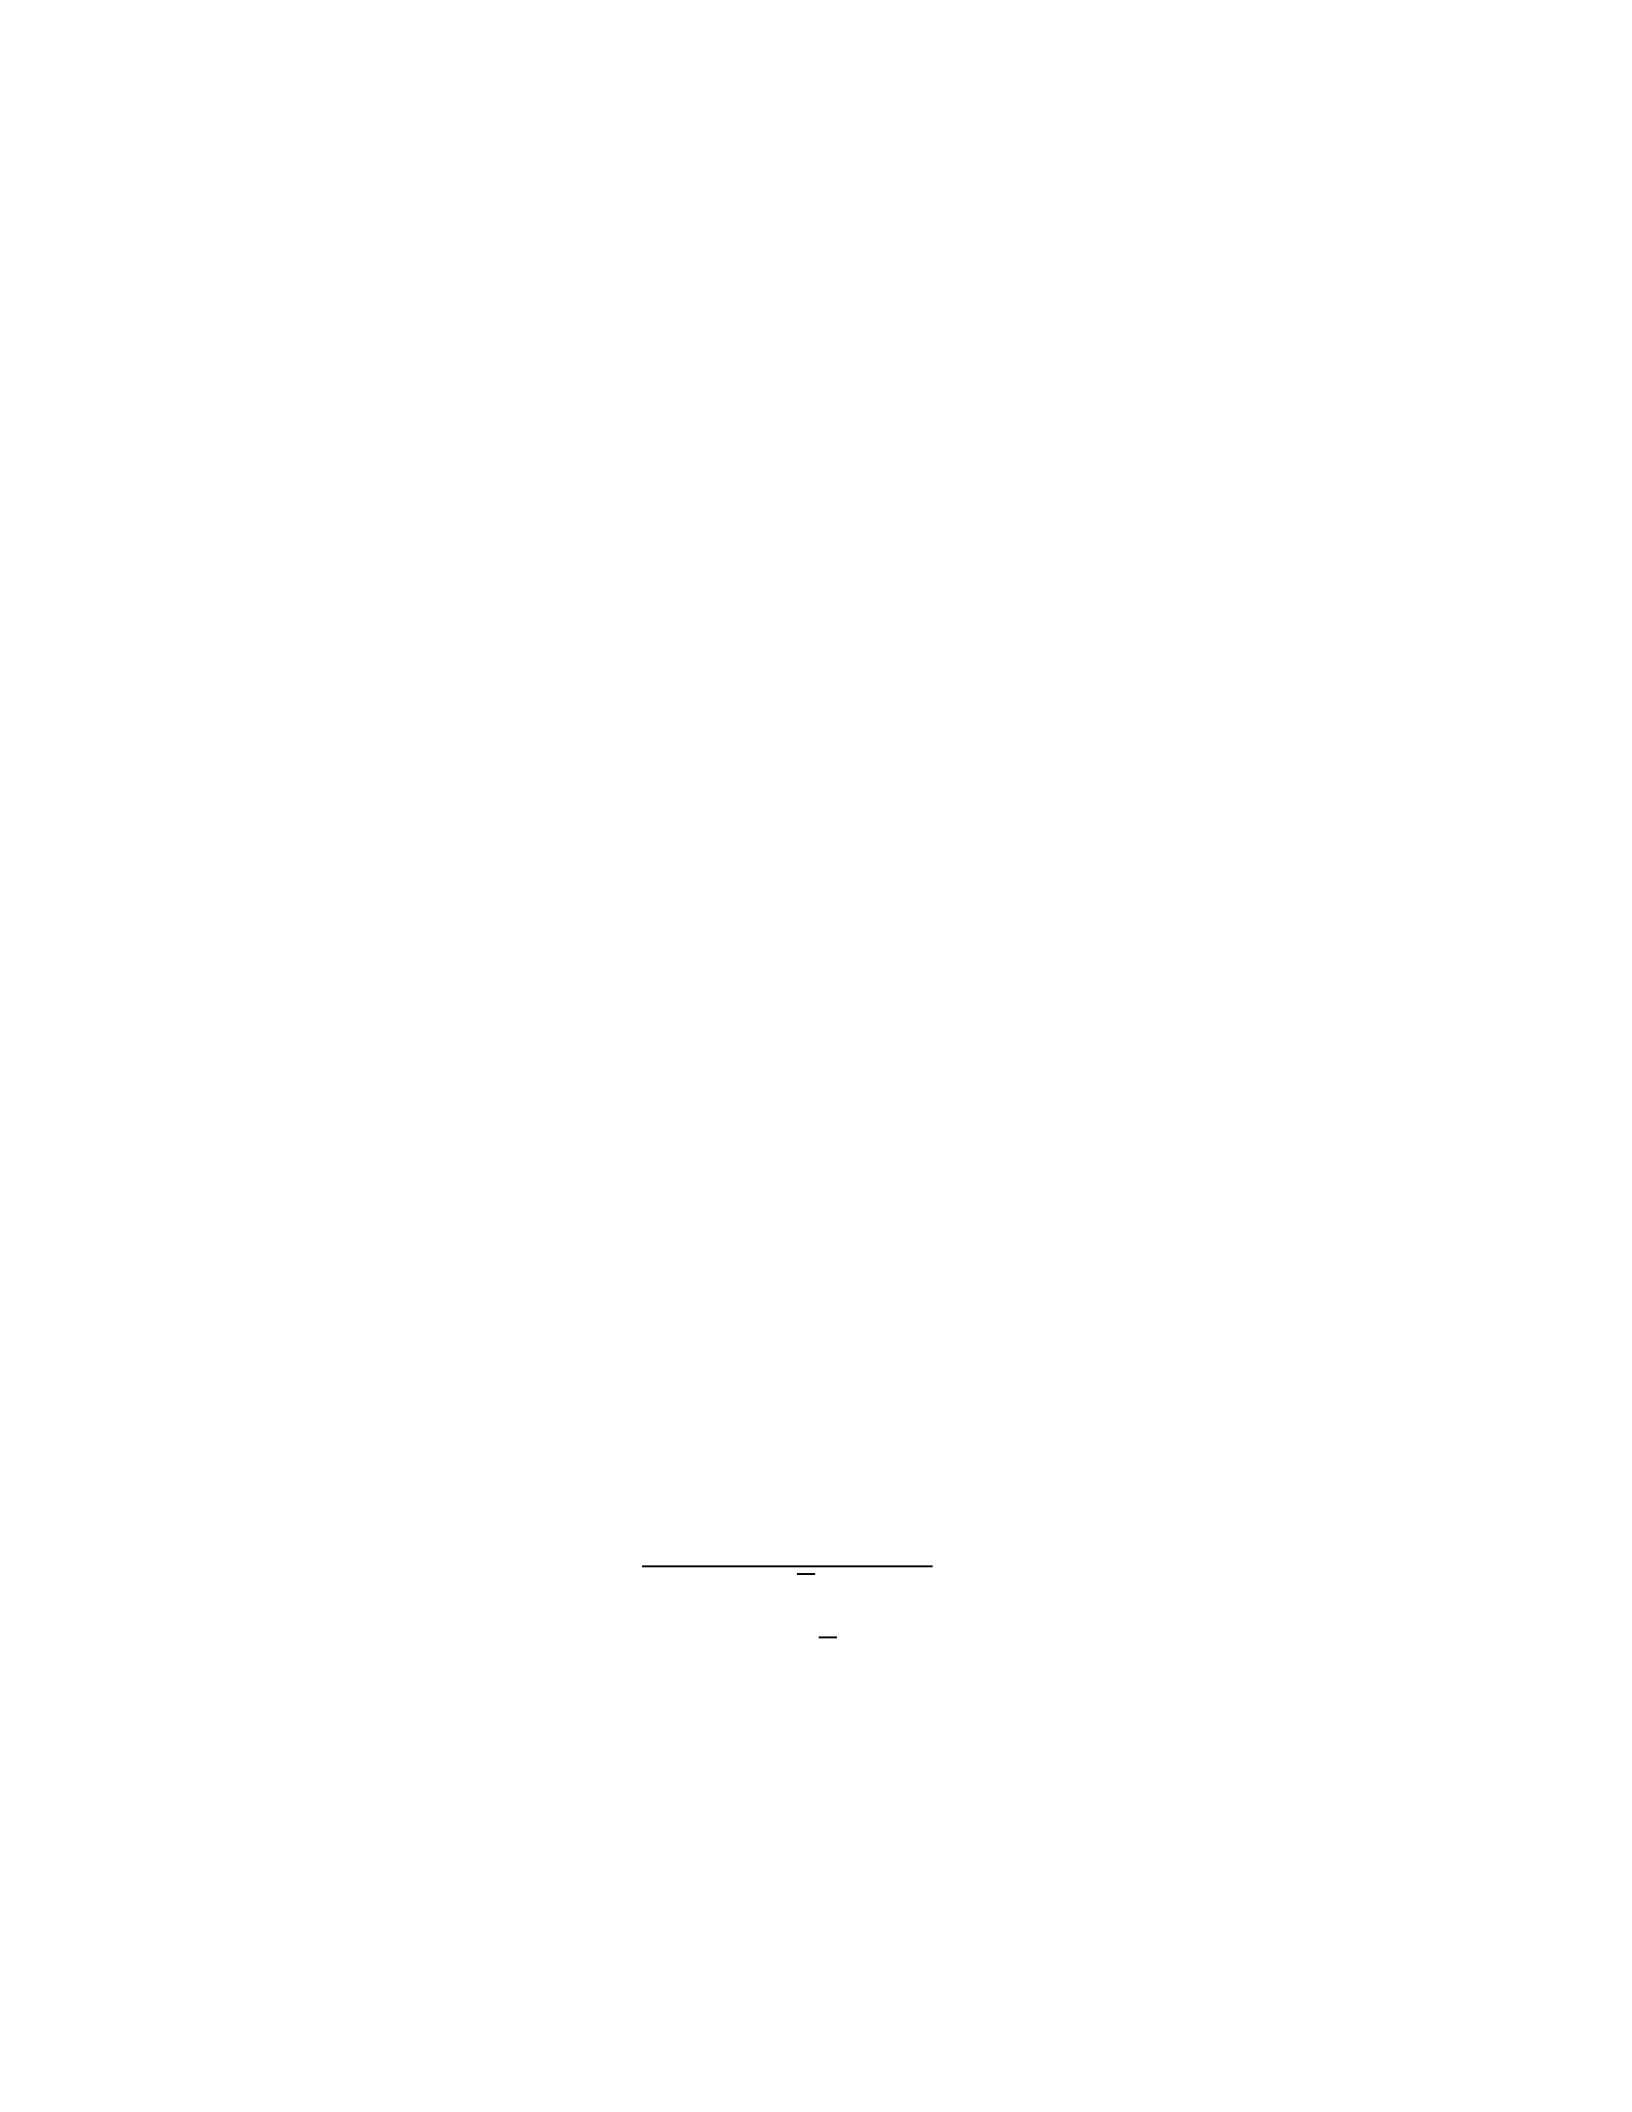
310. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
311. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula

𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
312. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
313. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711

• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
314. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
315. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:

– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
316. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
317. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
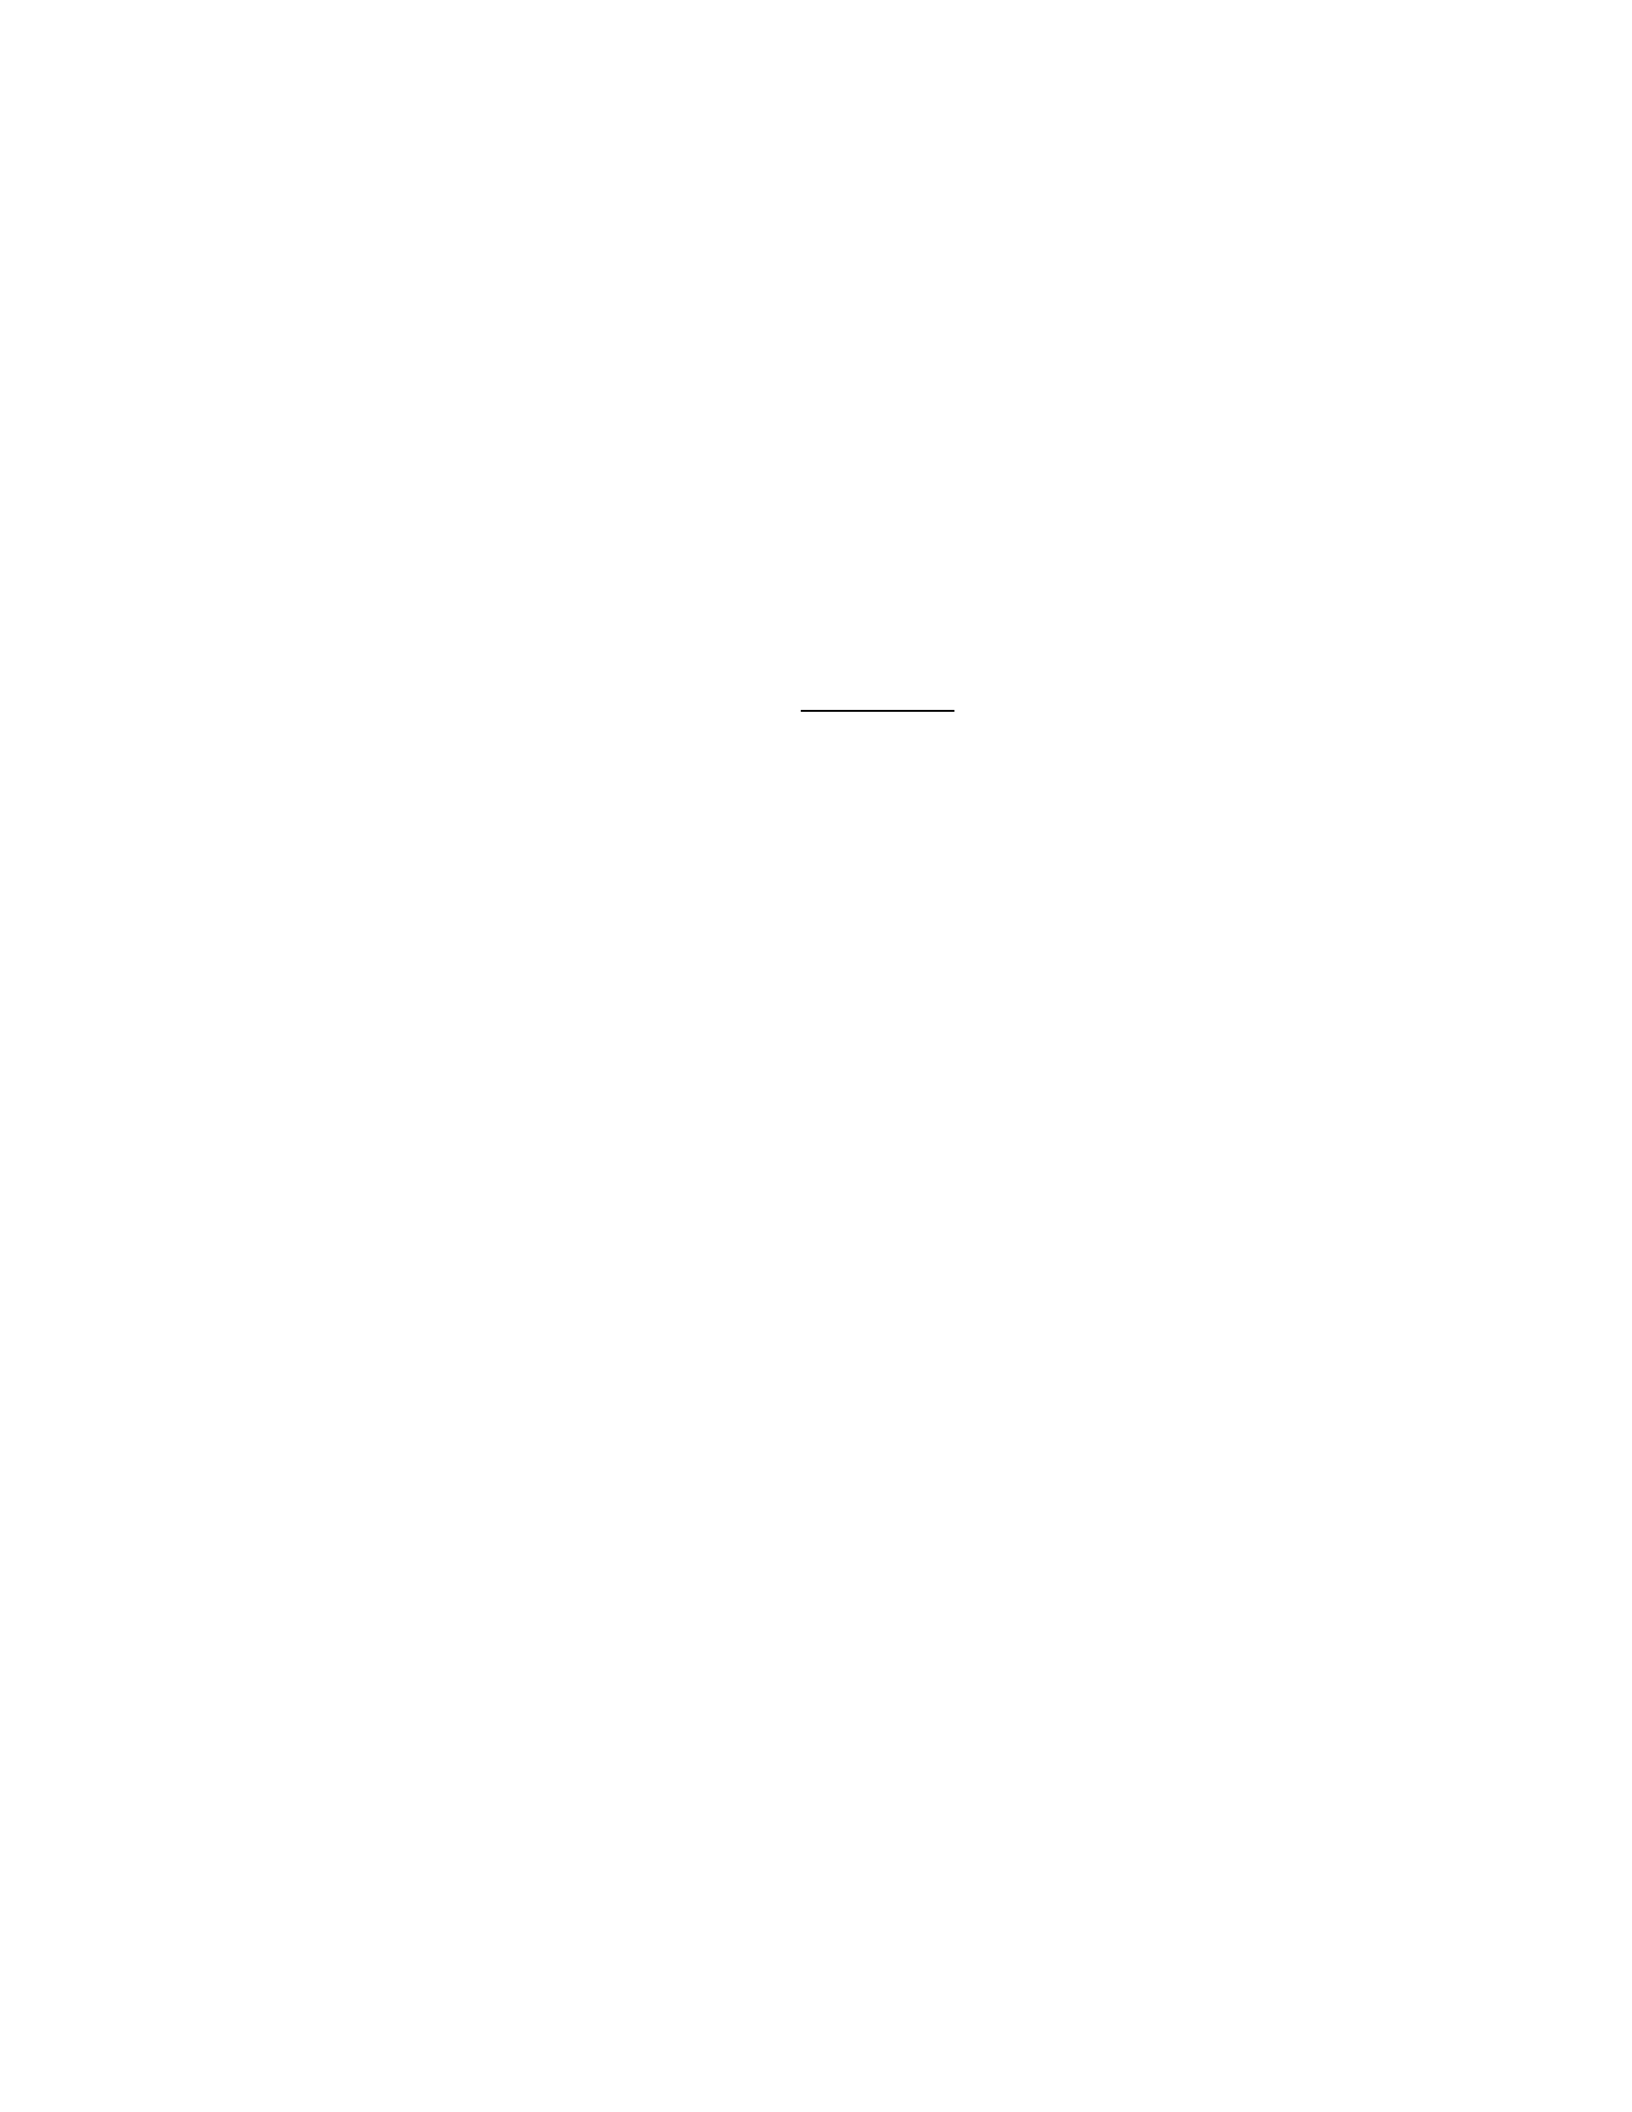
318. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
319. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
320. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
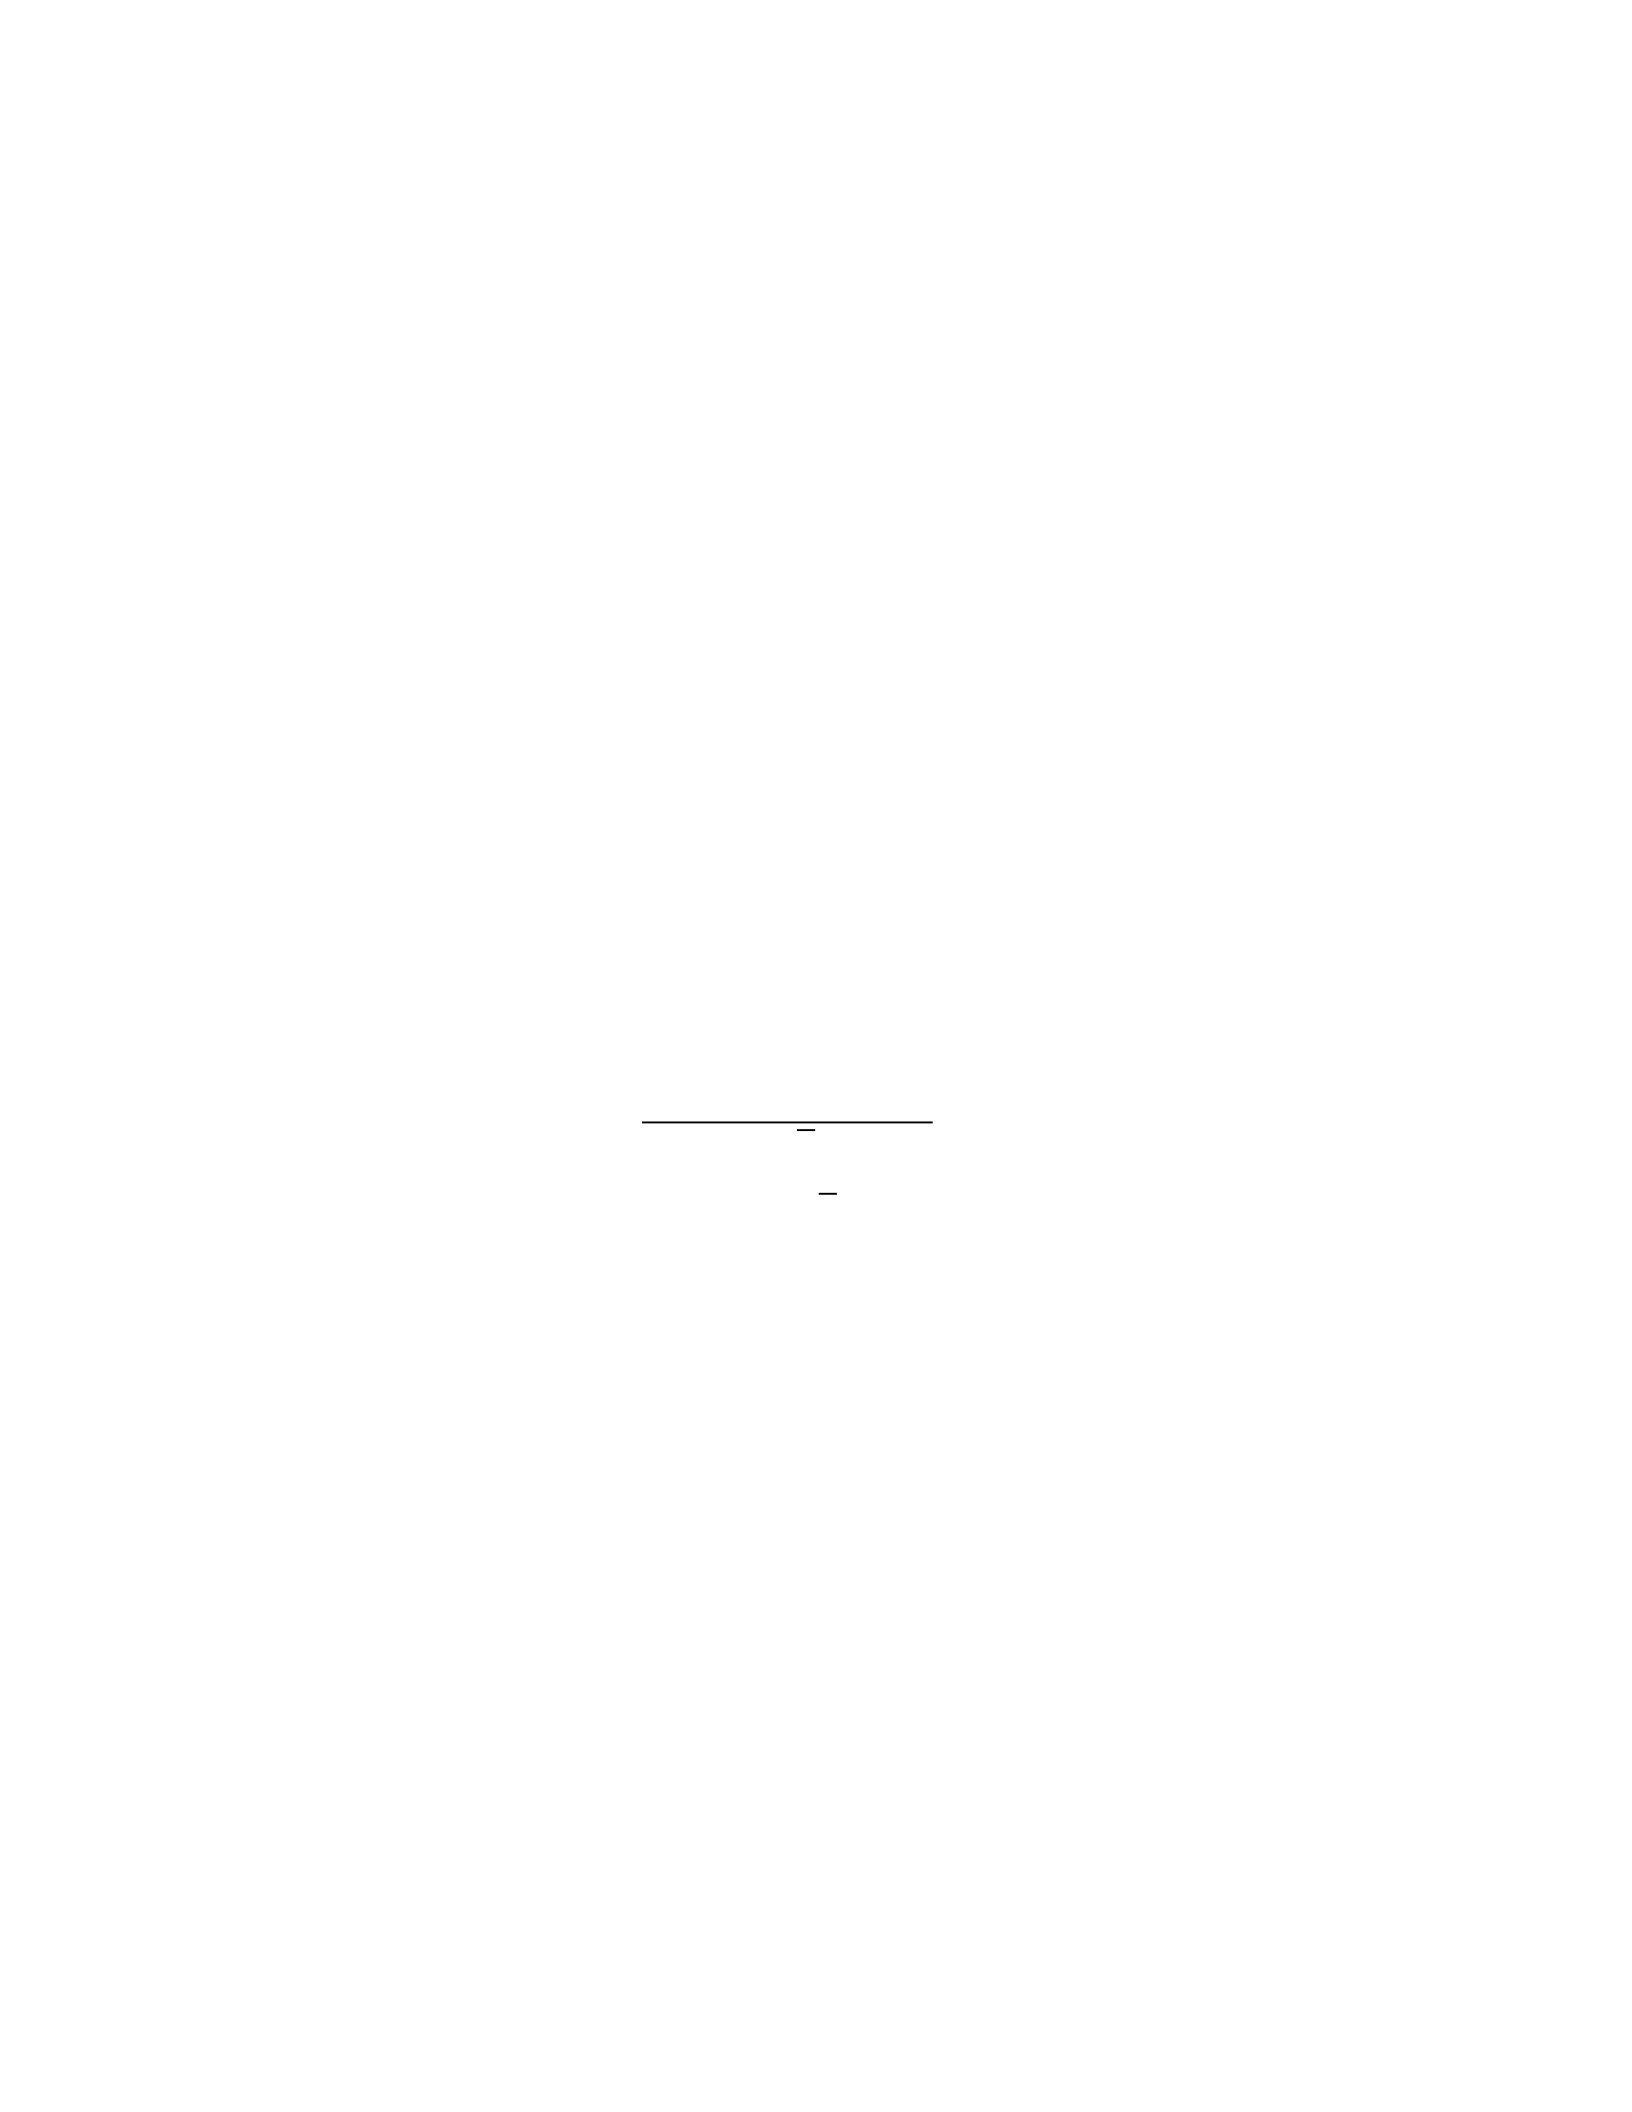
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
321. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
322. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:

a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
323. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
324. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit

from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
325. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
326. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options

and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
327. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
328. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
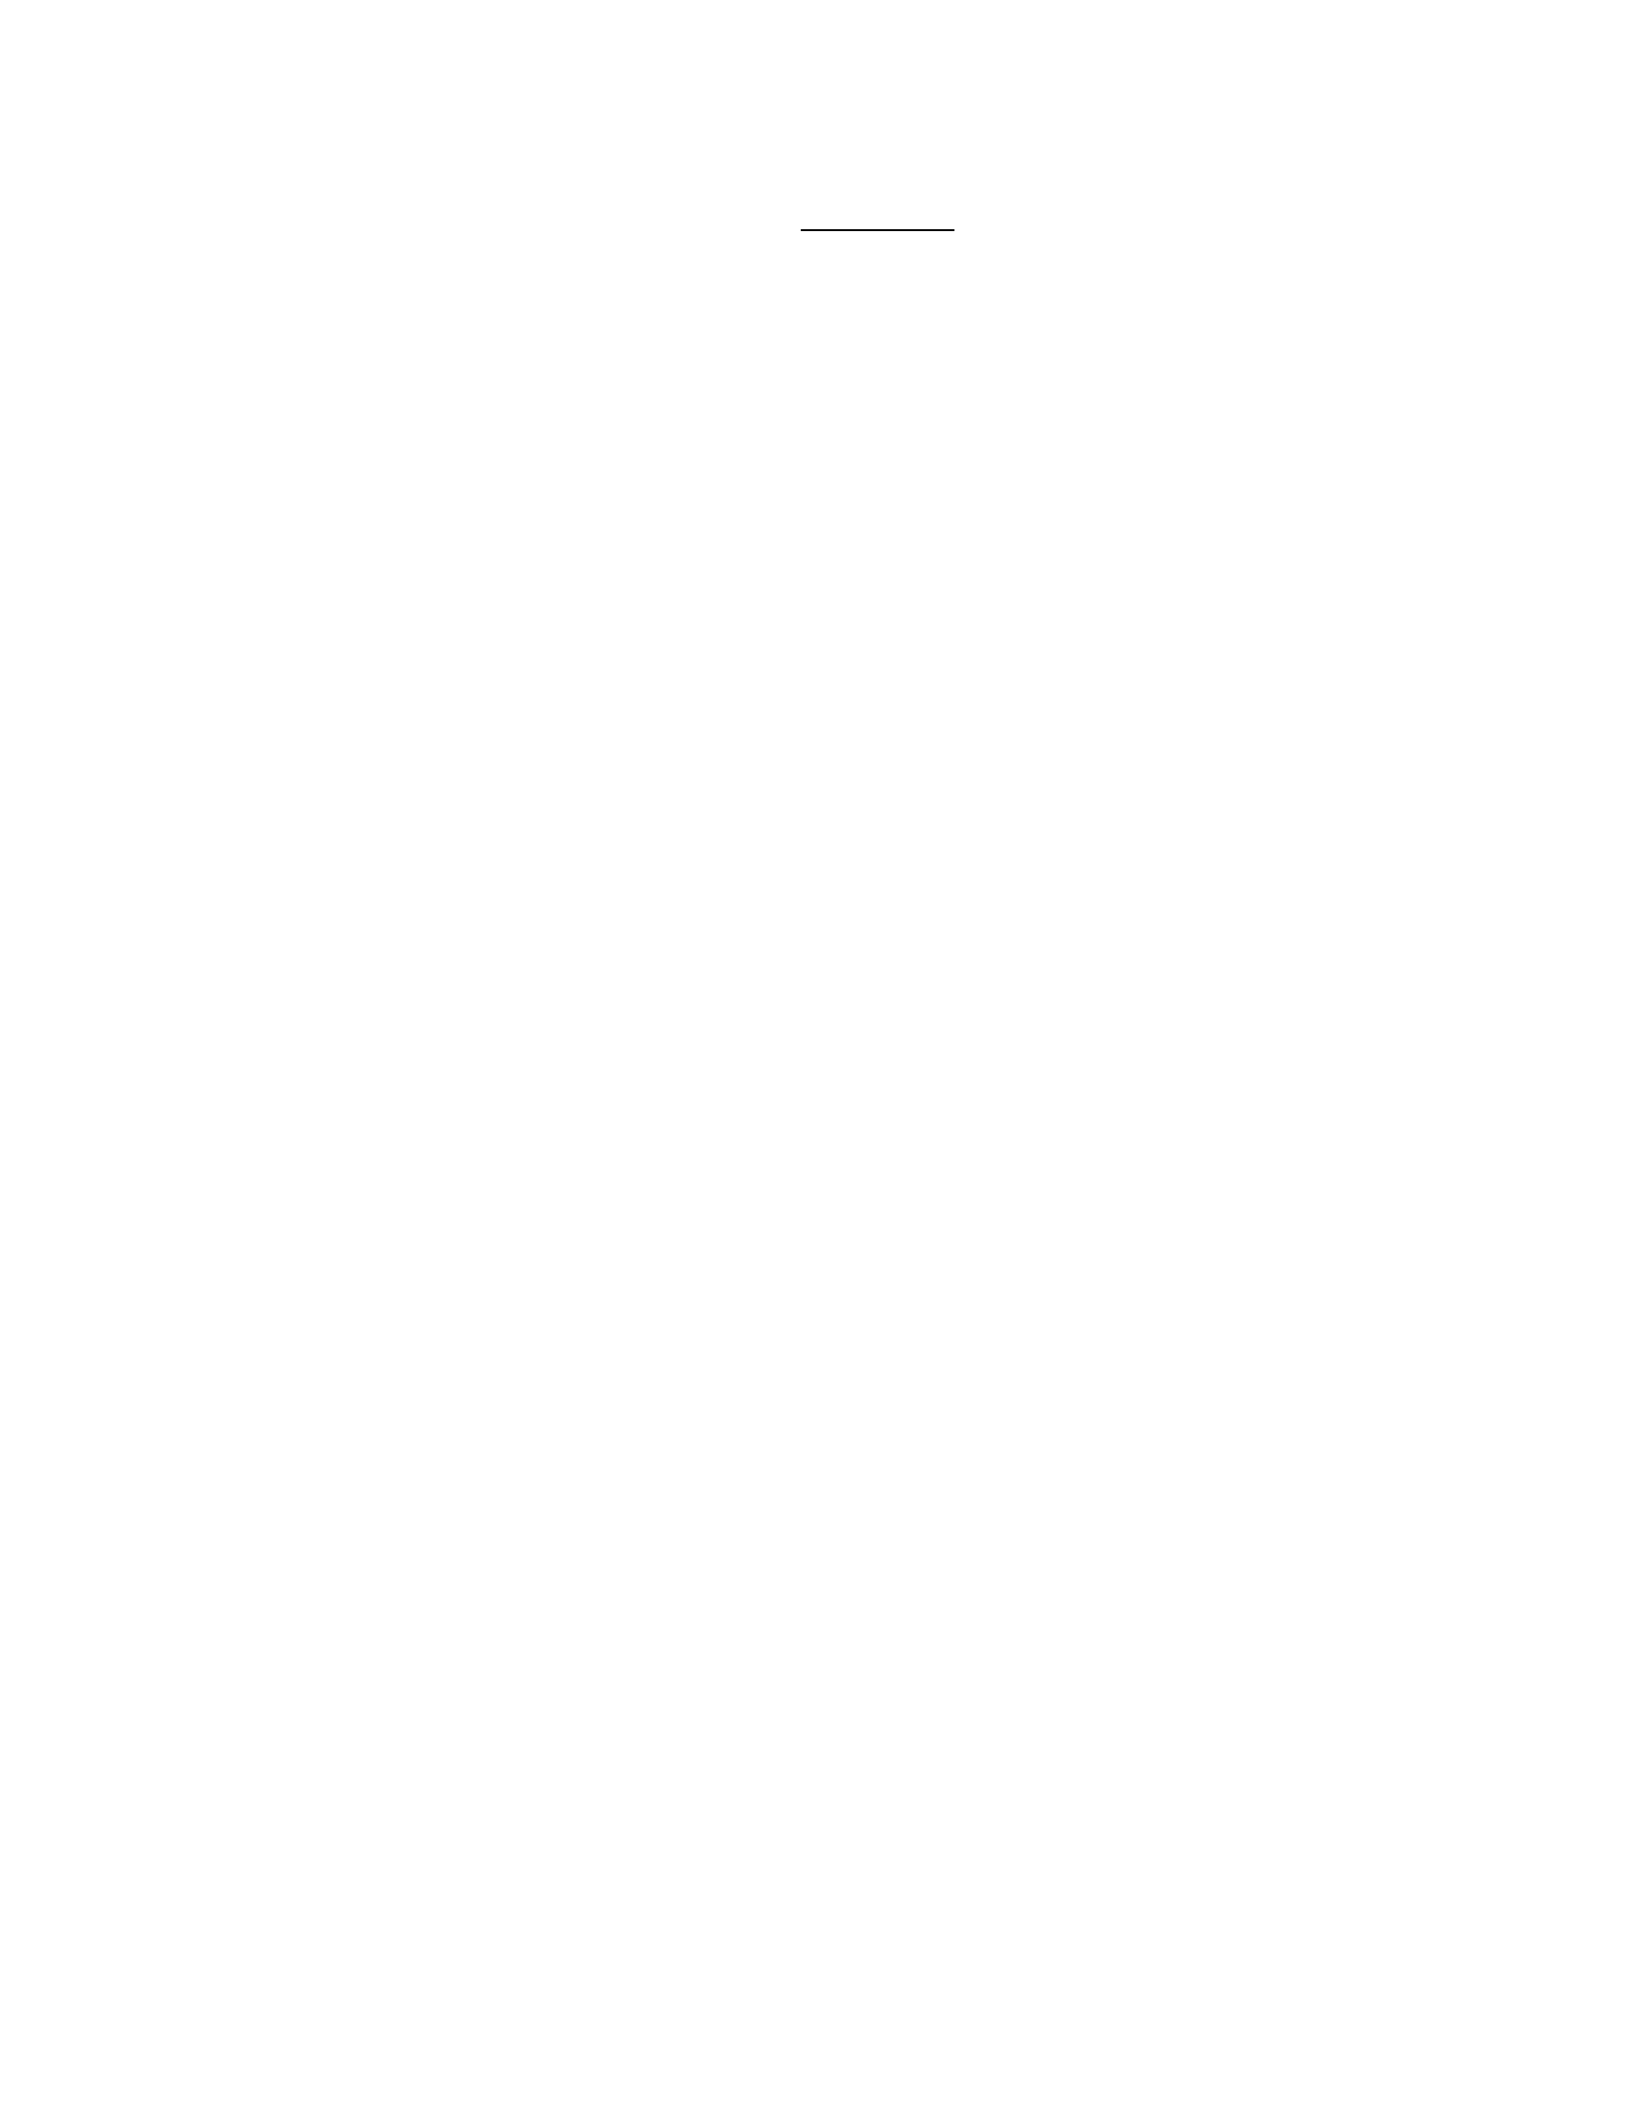
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
329. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
330. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
331. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
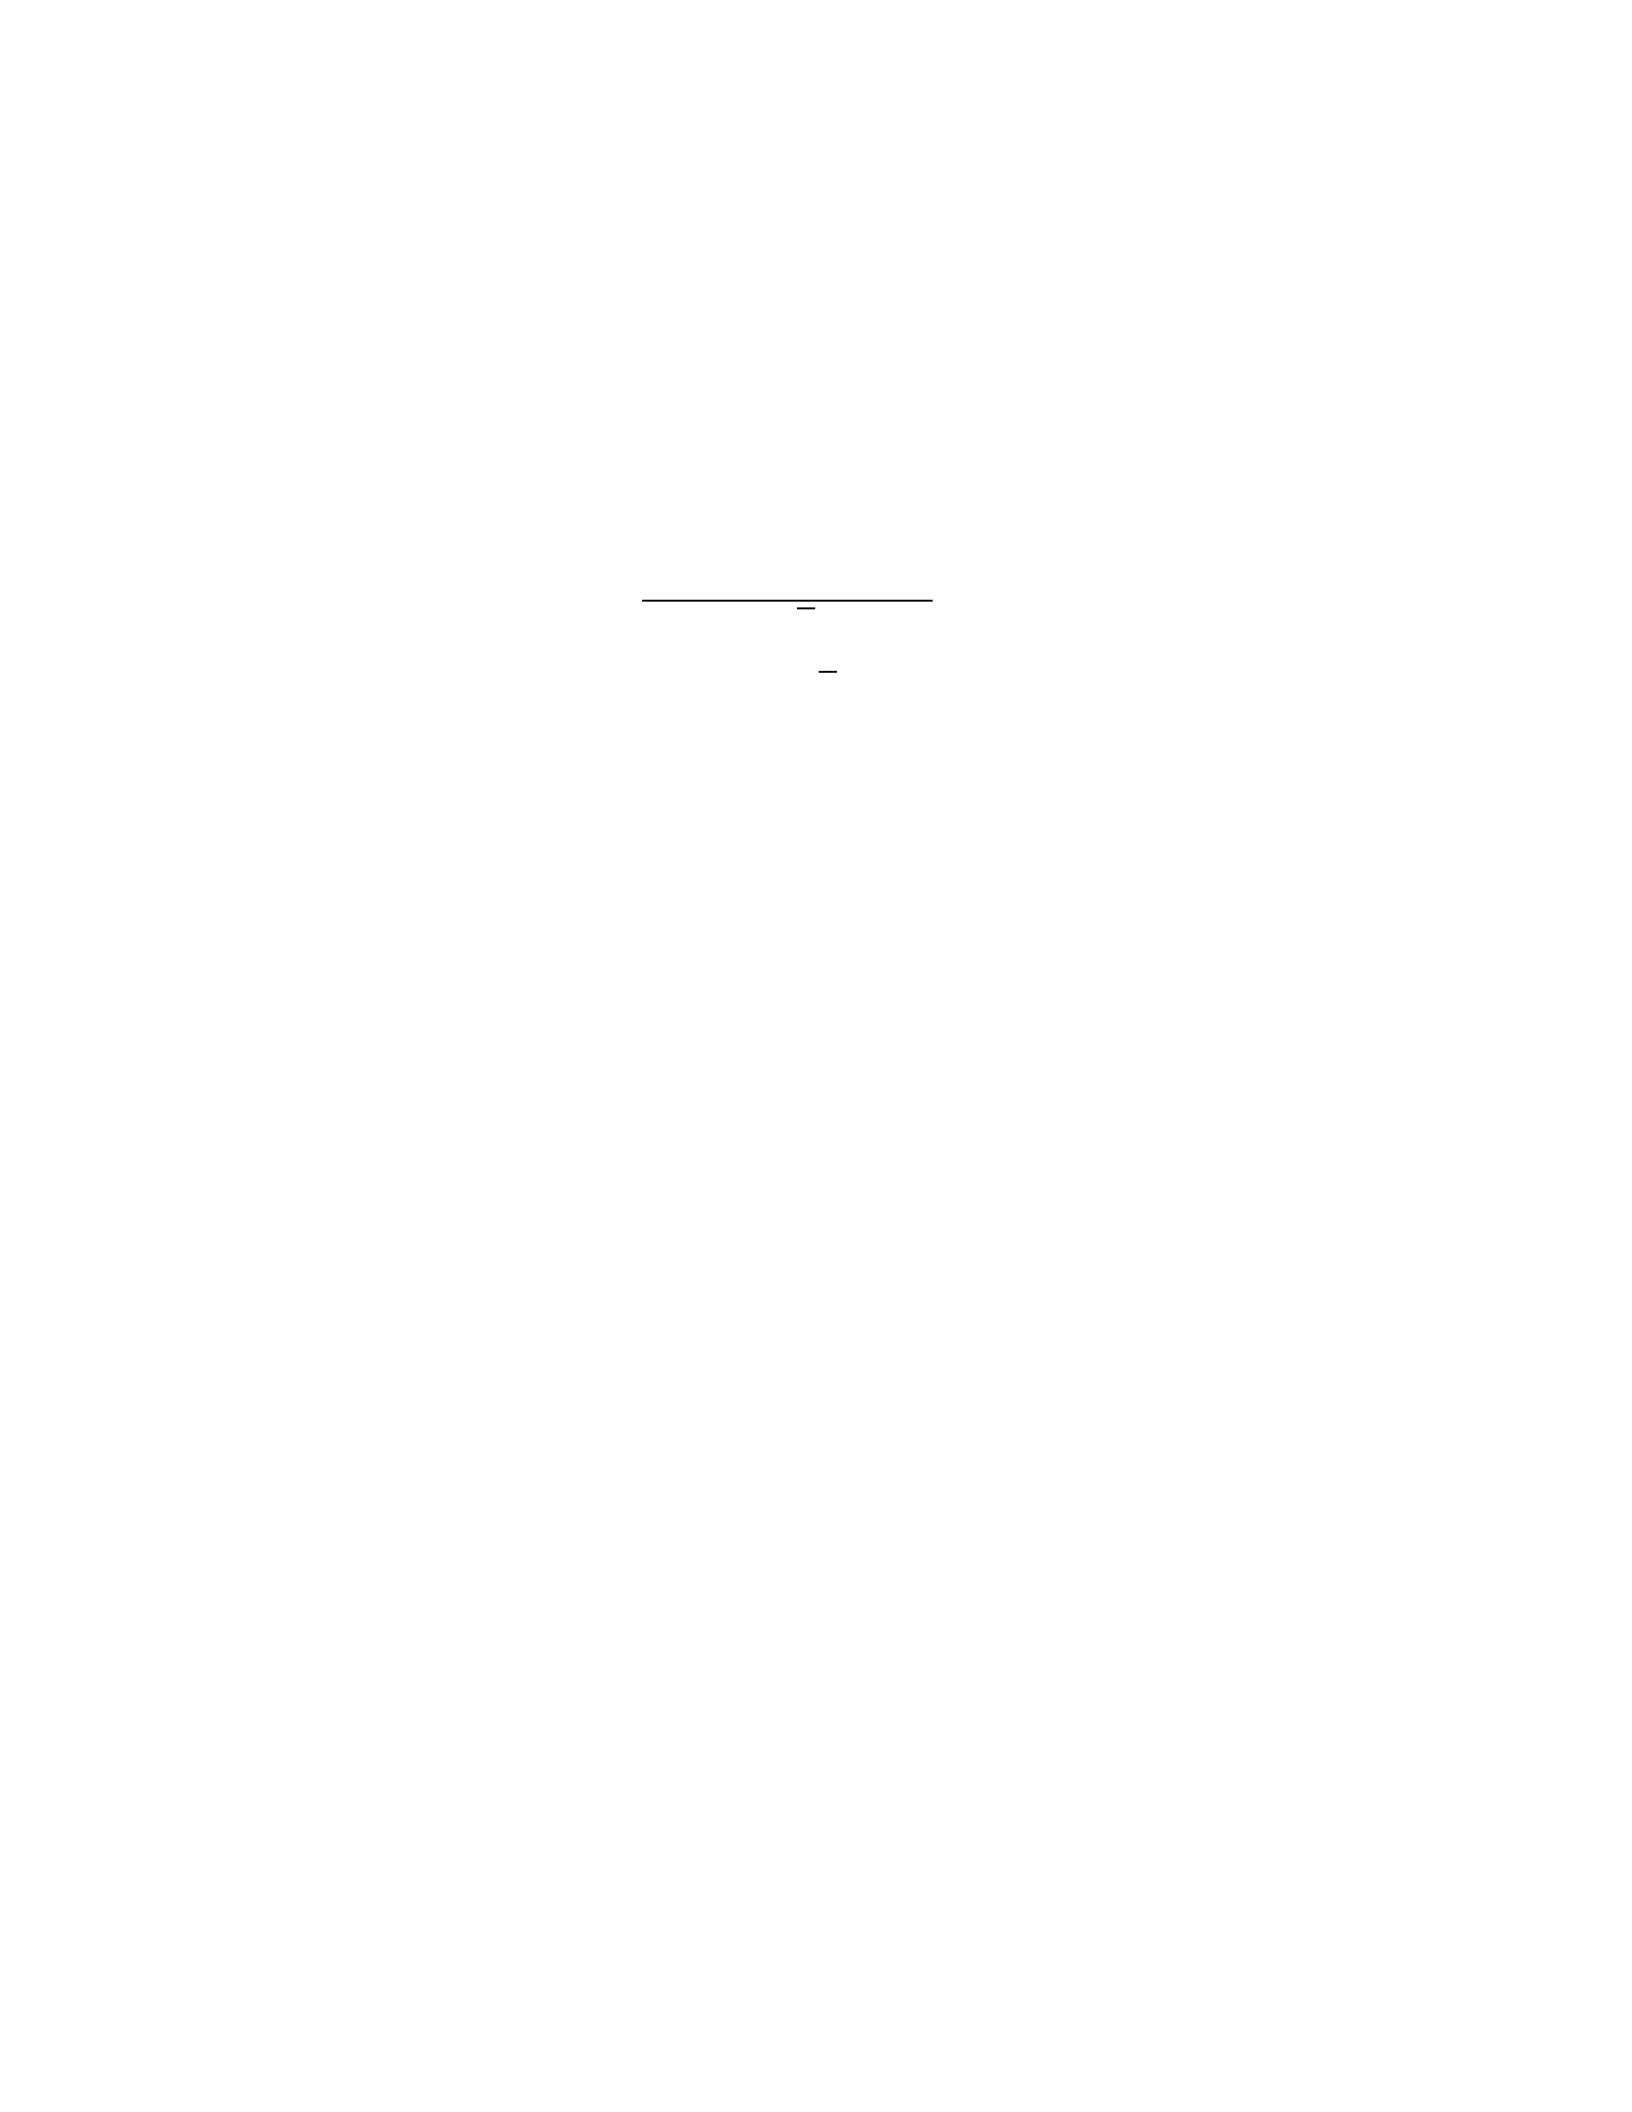
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
332. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500

• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
333. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
334. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:

• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
335. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
336. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
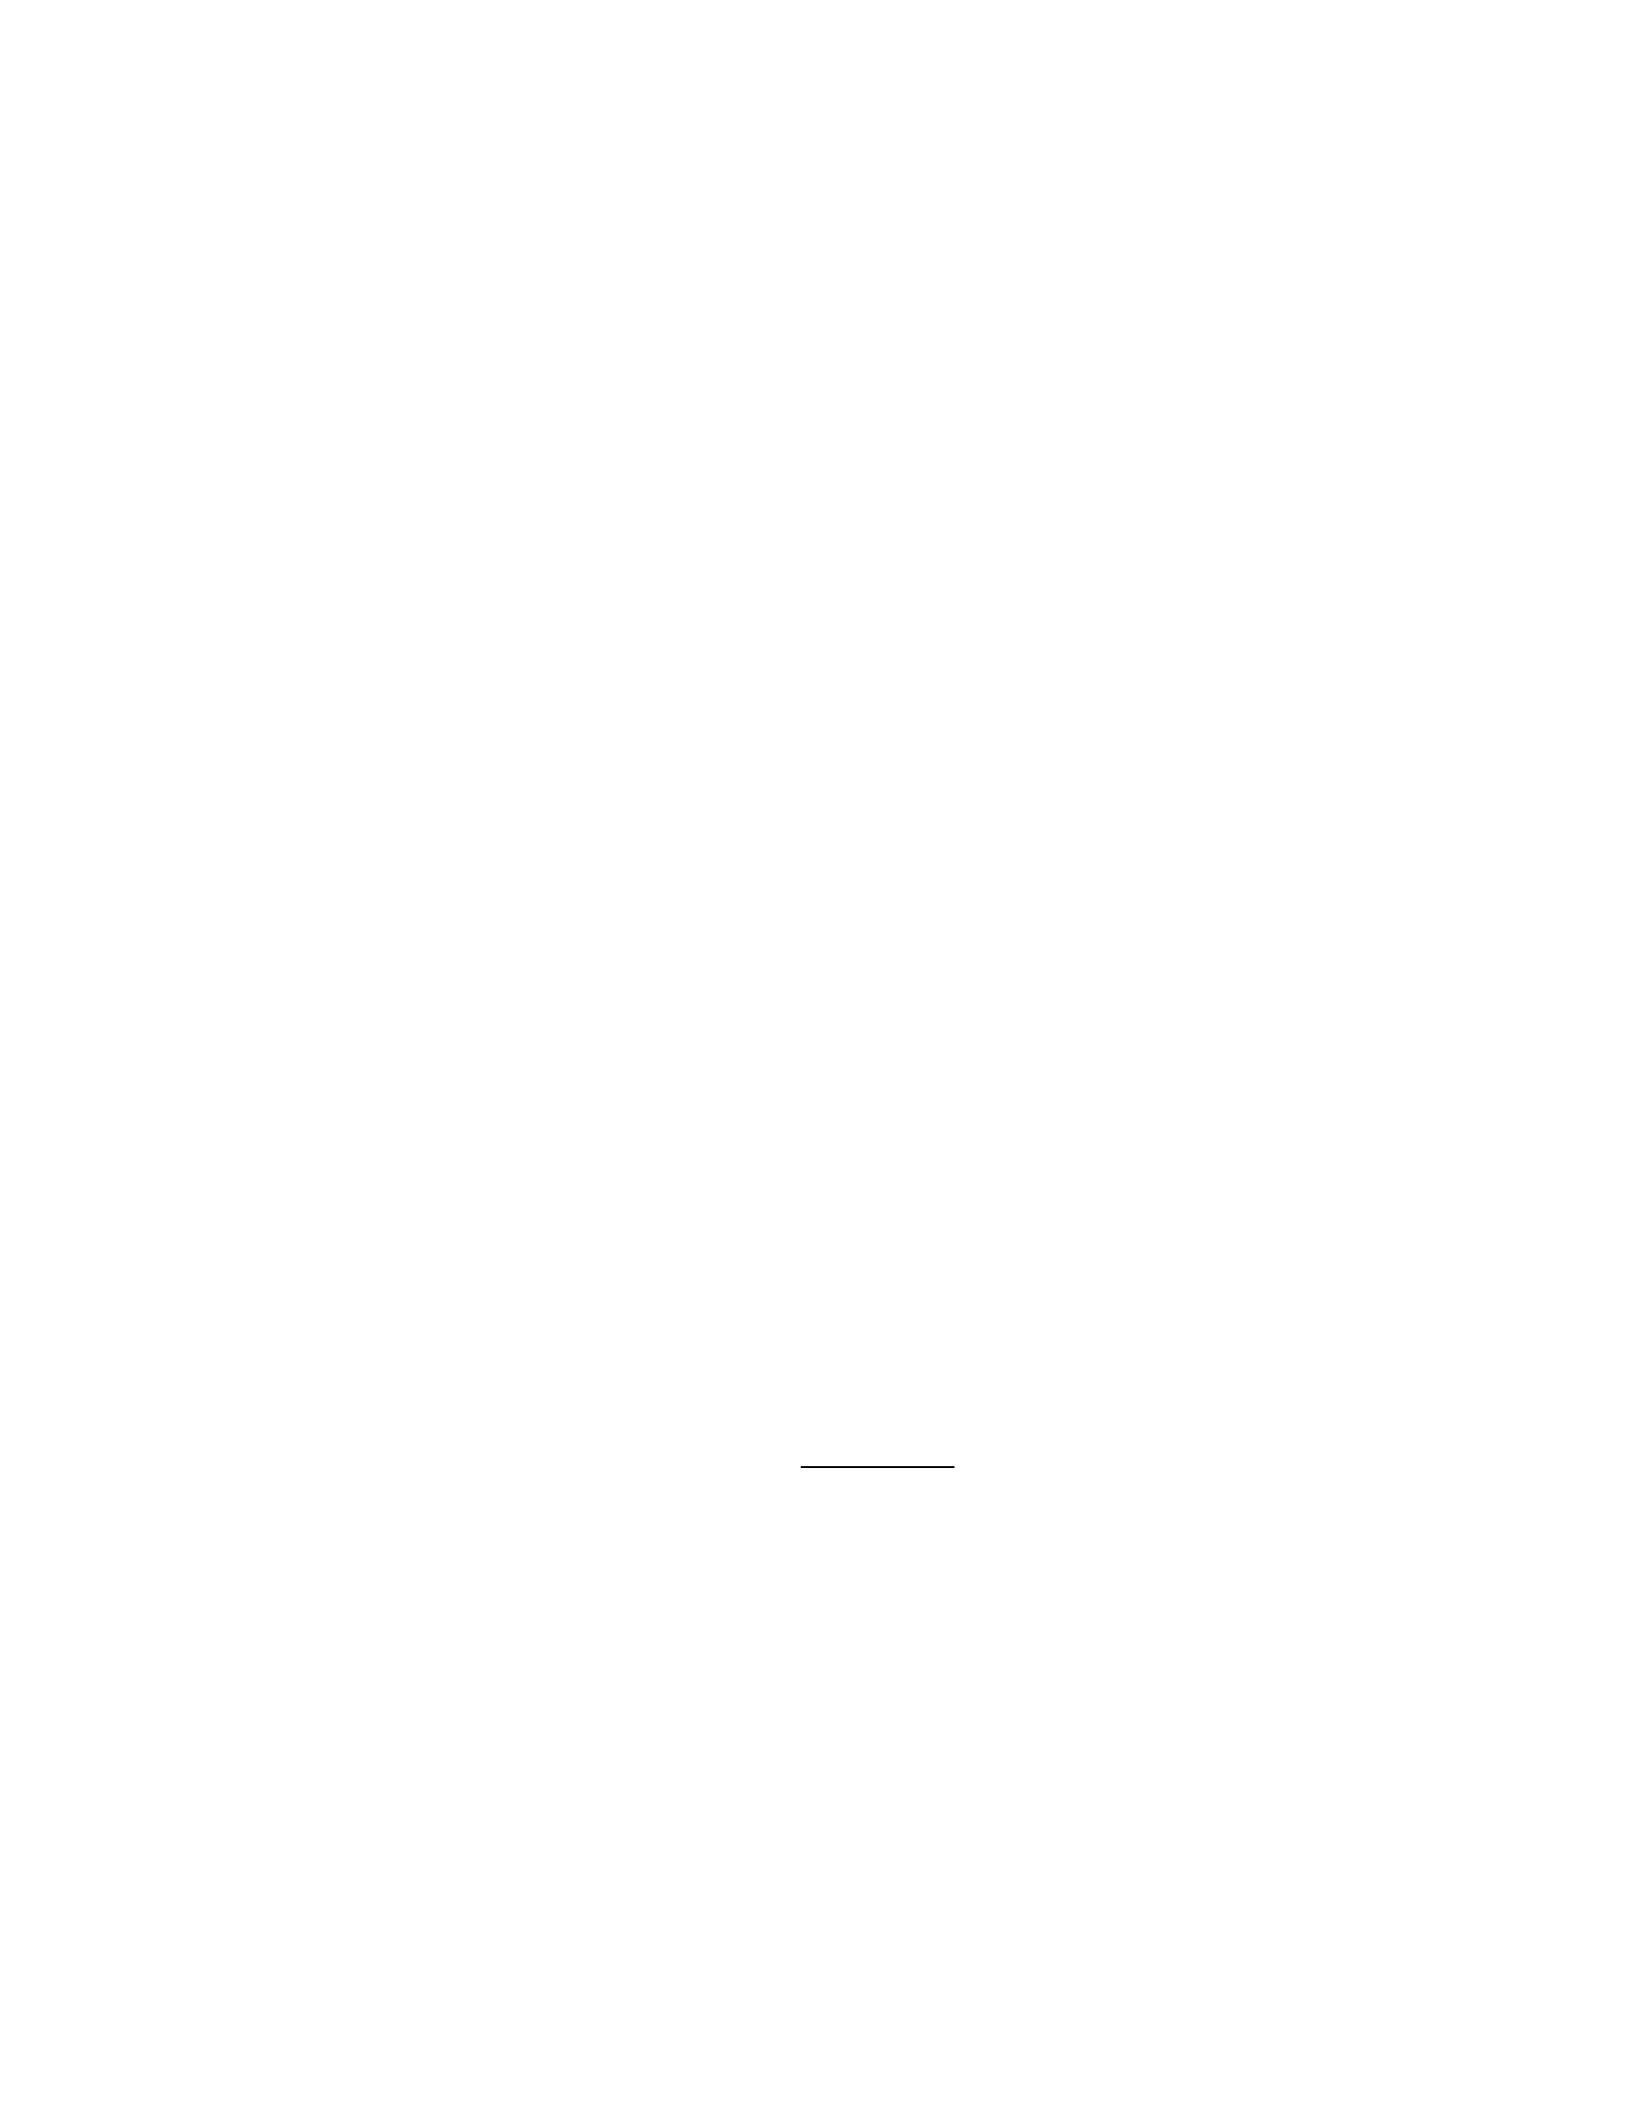
– Net cost = 0
337. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
338. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
339. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%

– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
340. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
341. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
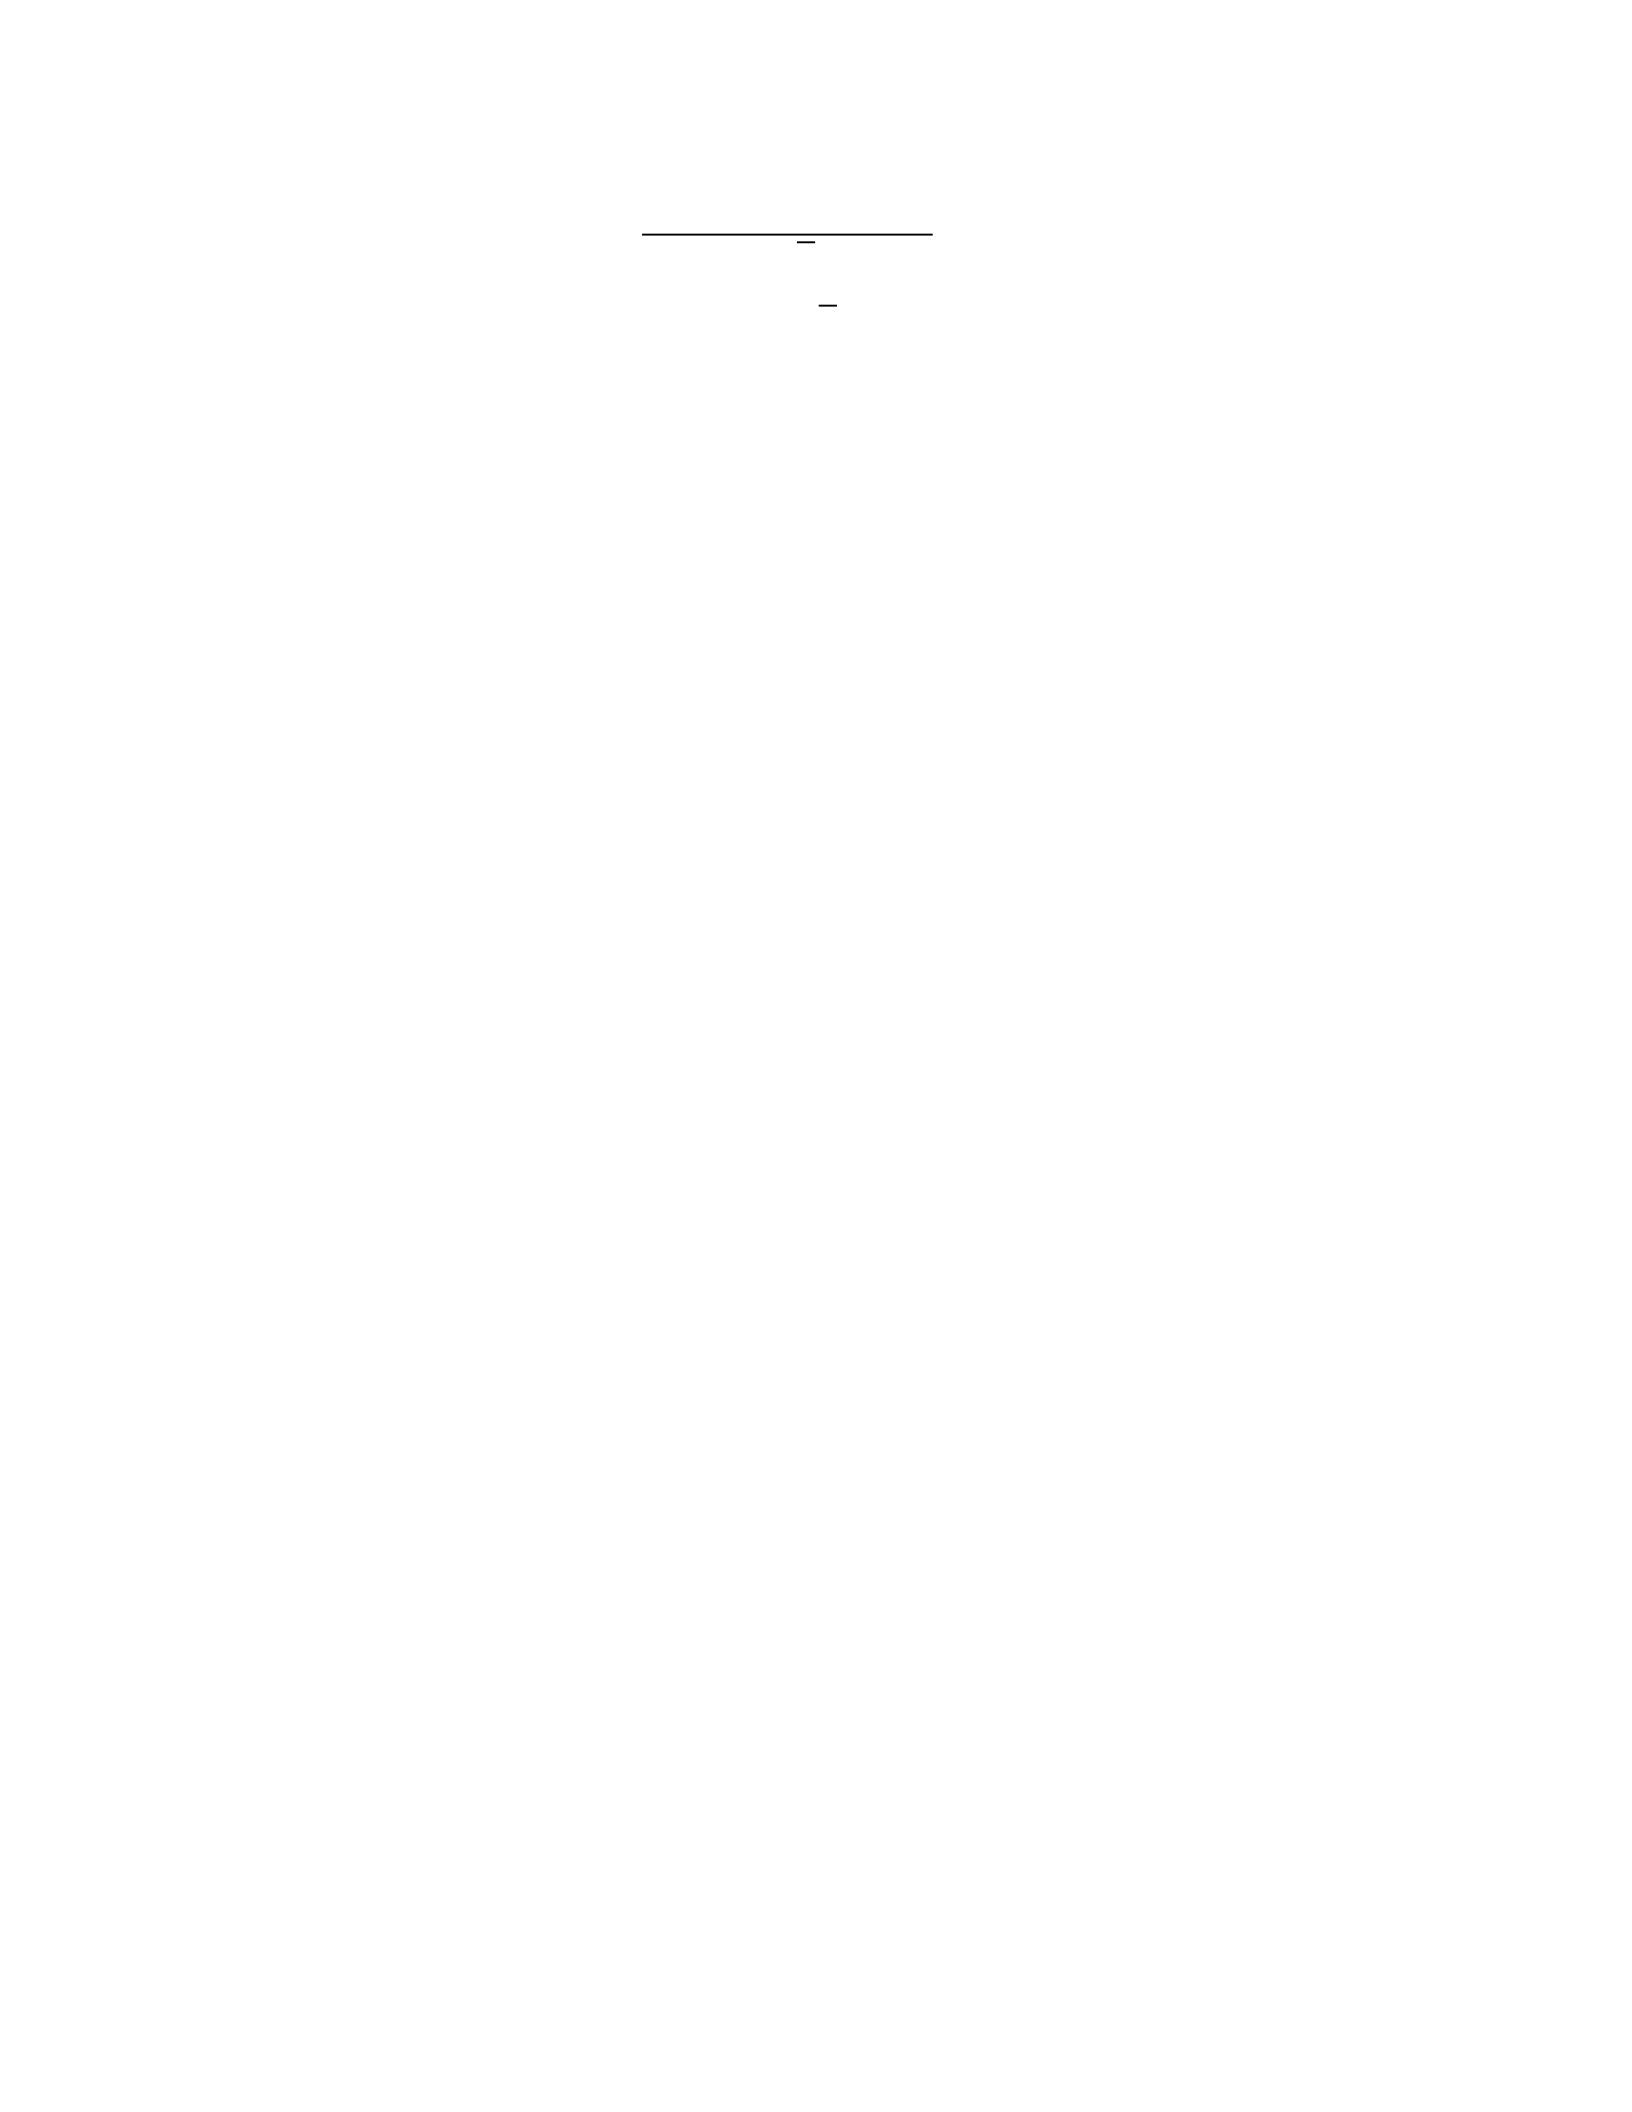
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
342. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
343. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:

a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
344. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10

– Breakeven points: $90 and $110
345. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
346. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
347. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
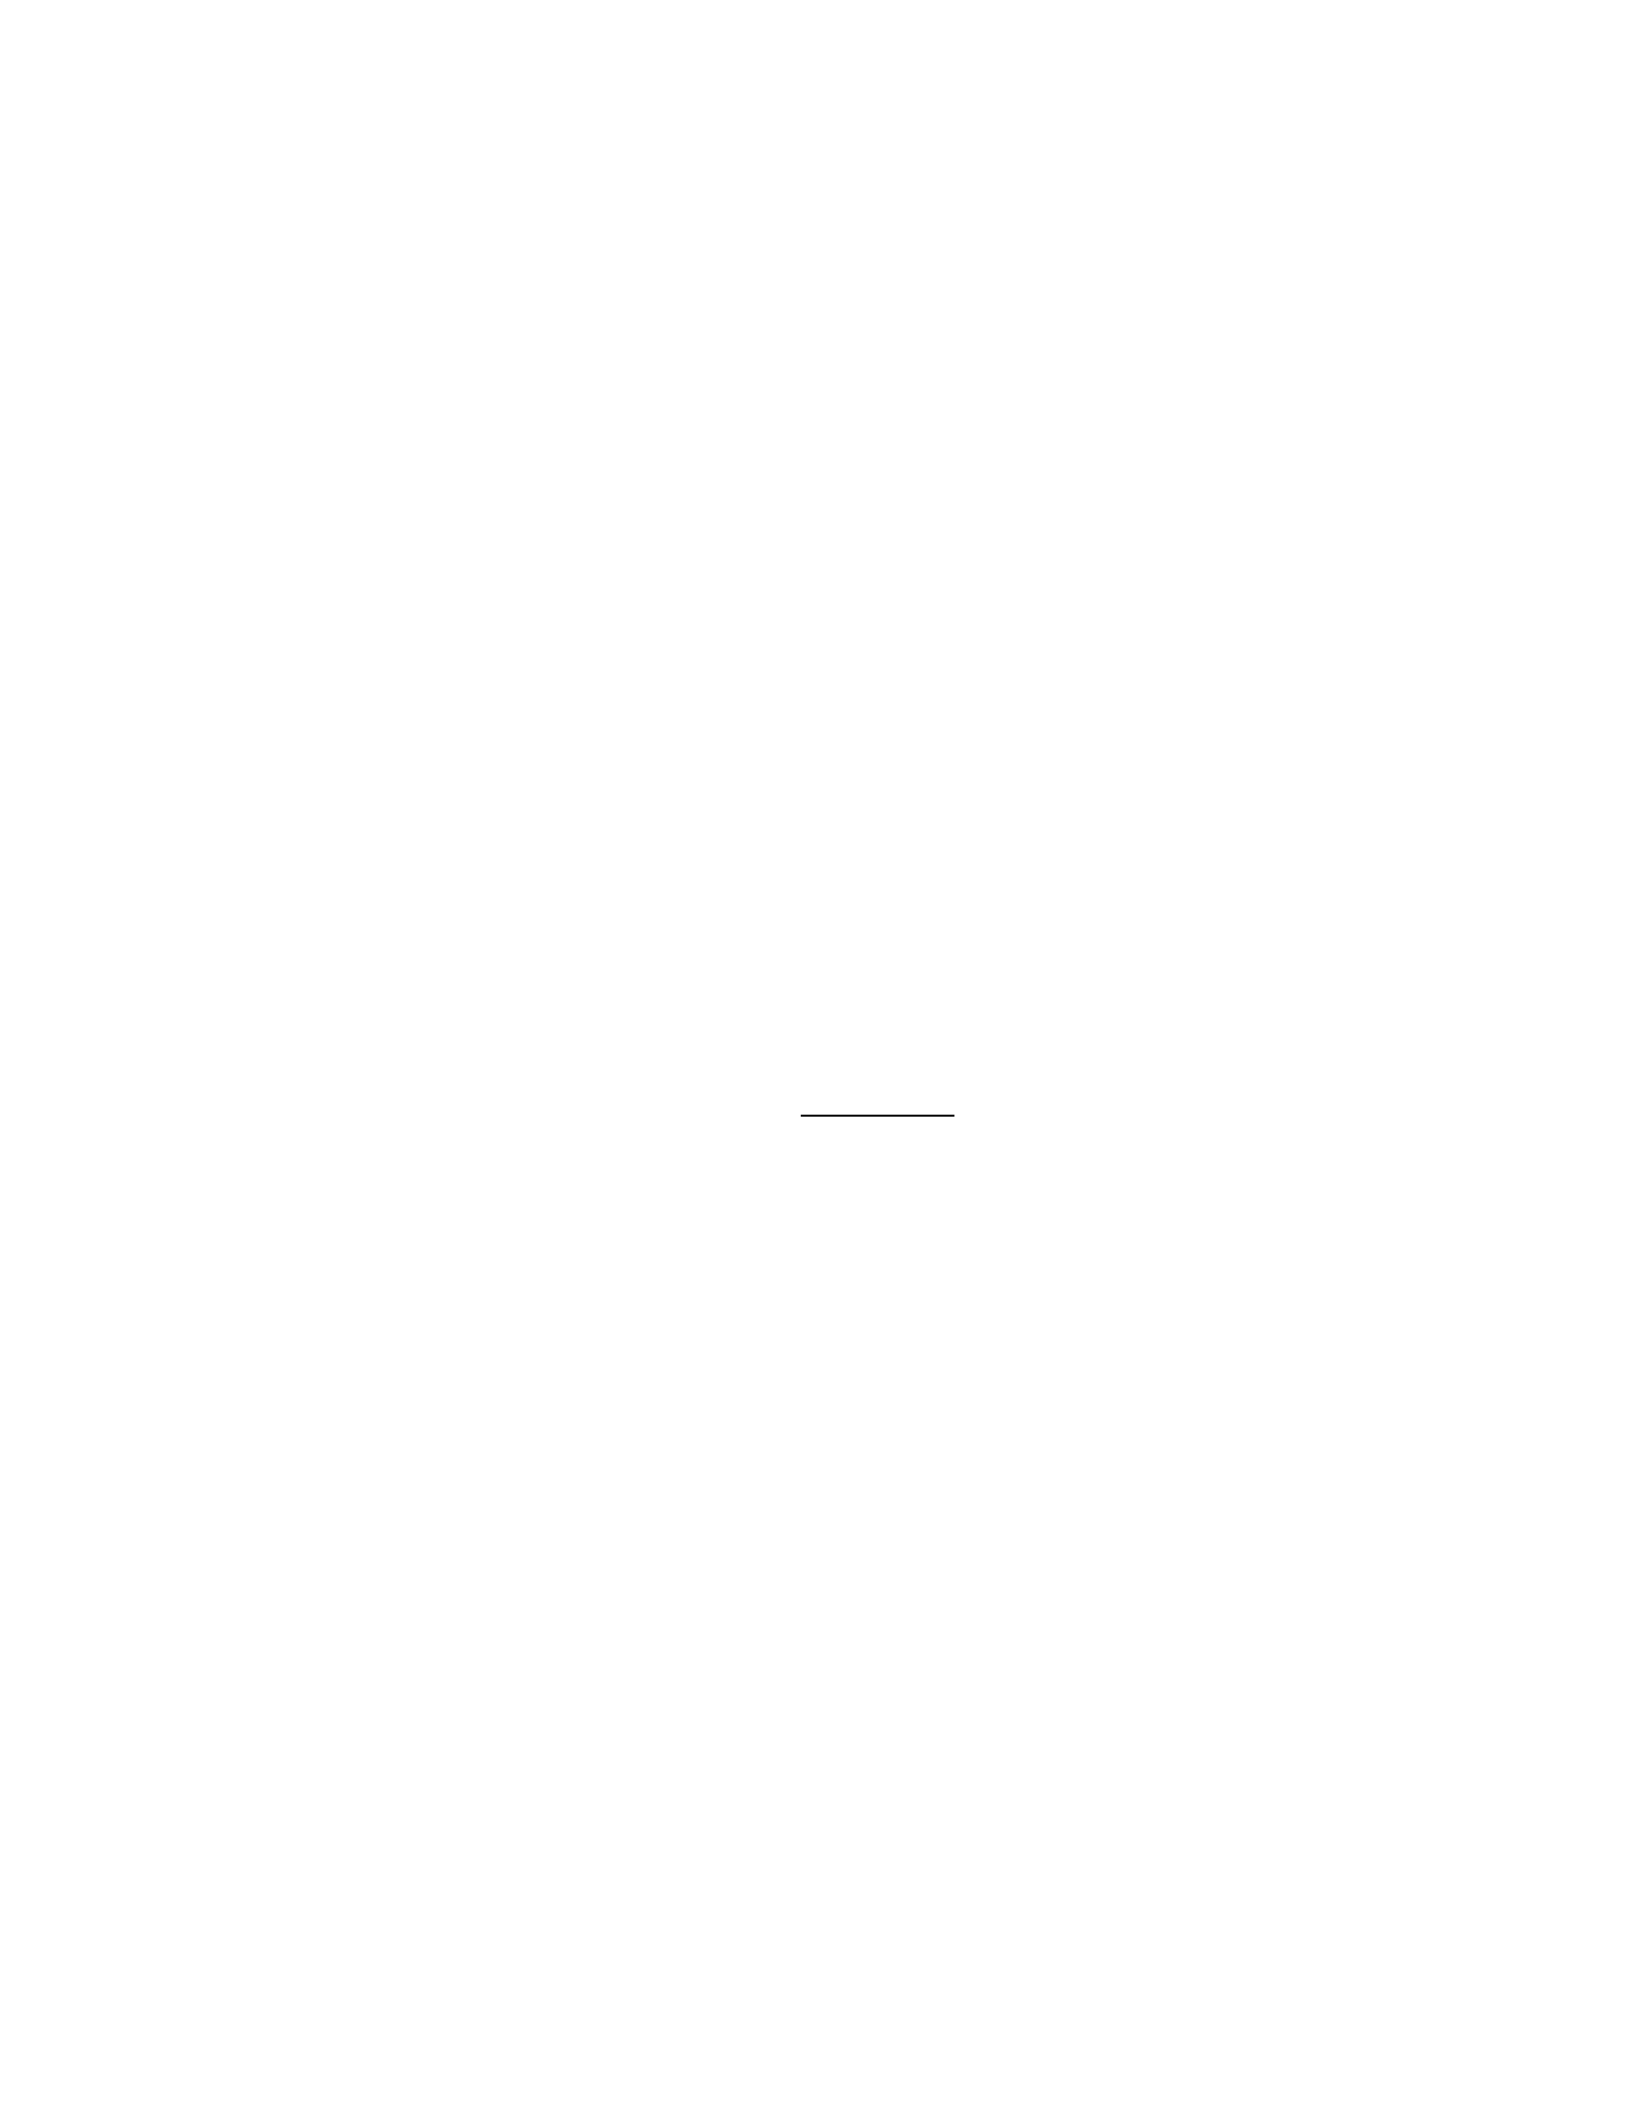
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
348. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
349. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
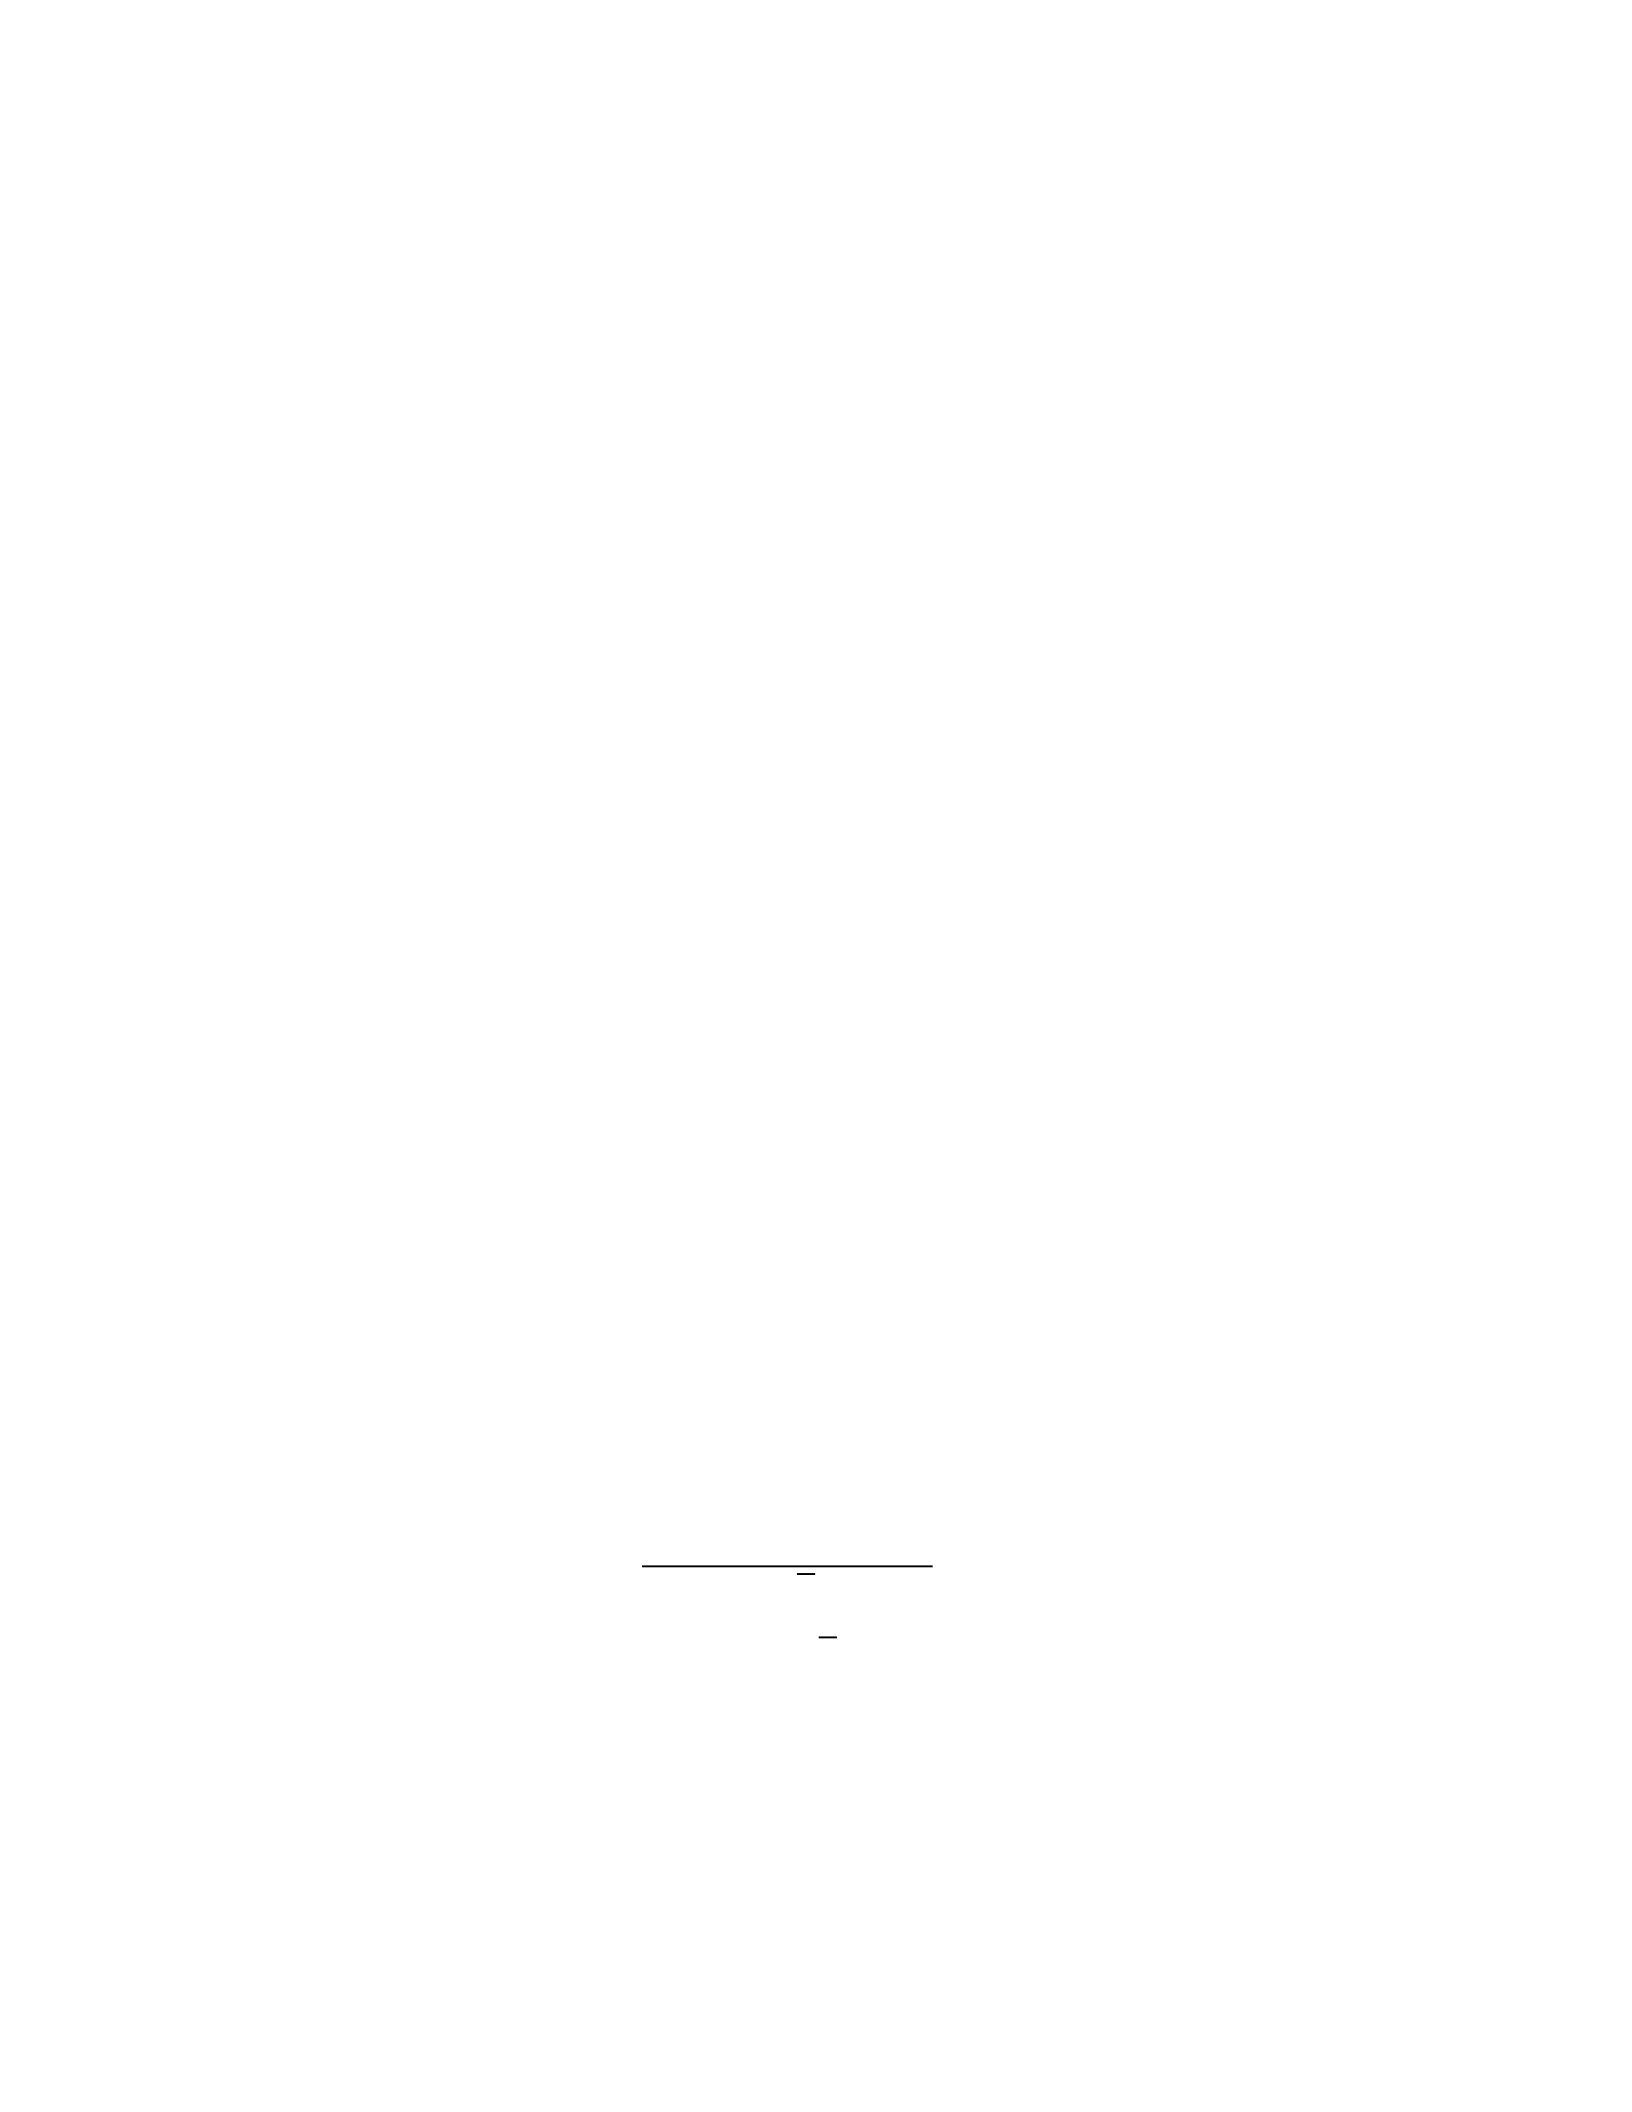
350. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
351. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula

𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
352. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
353. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711

• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
354. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
355. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:

– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
356. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
357. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
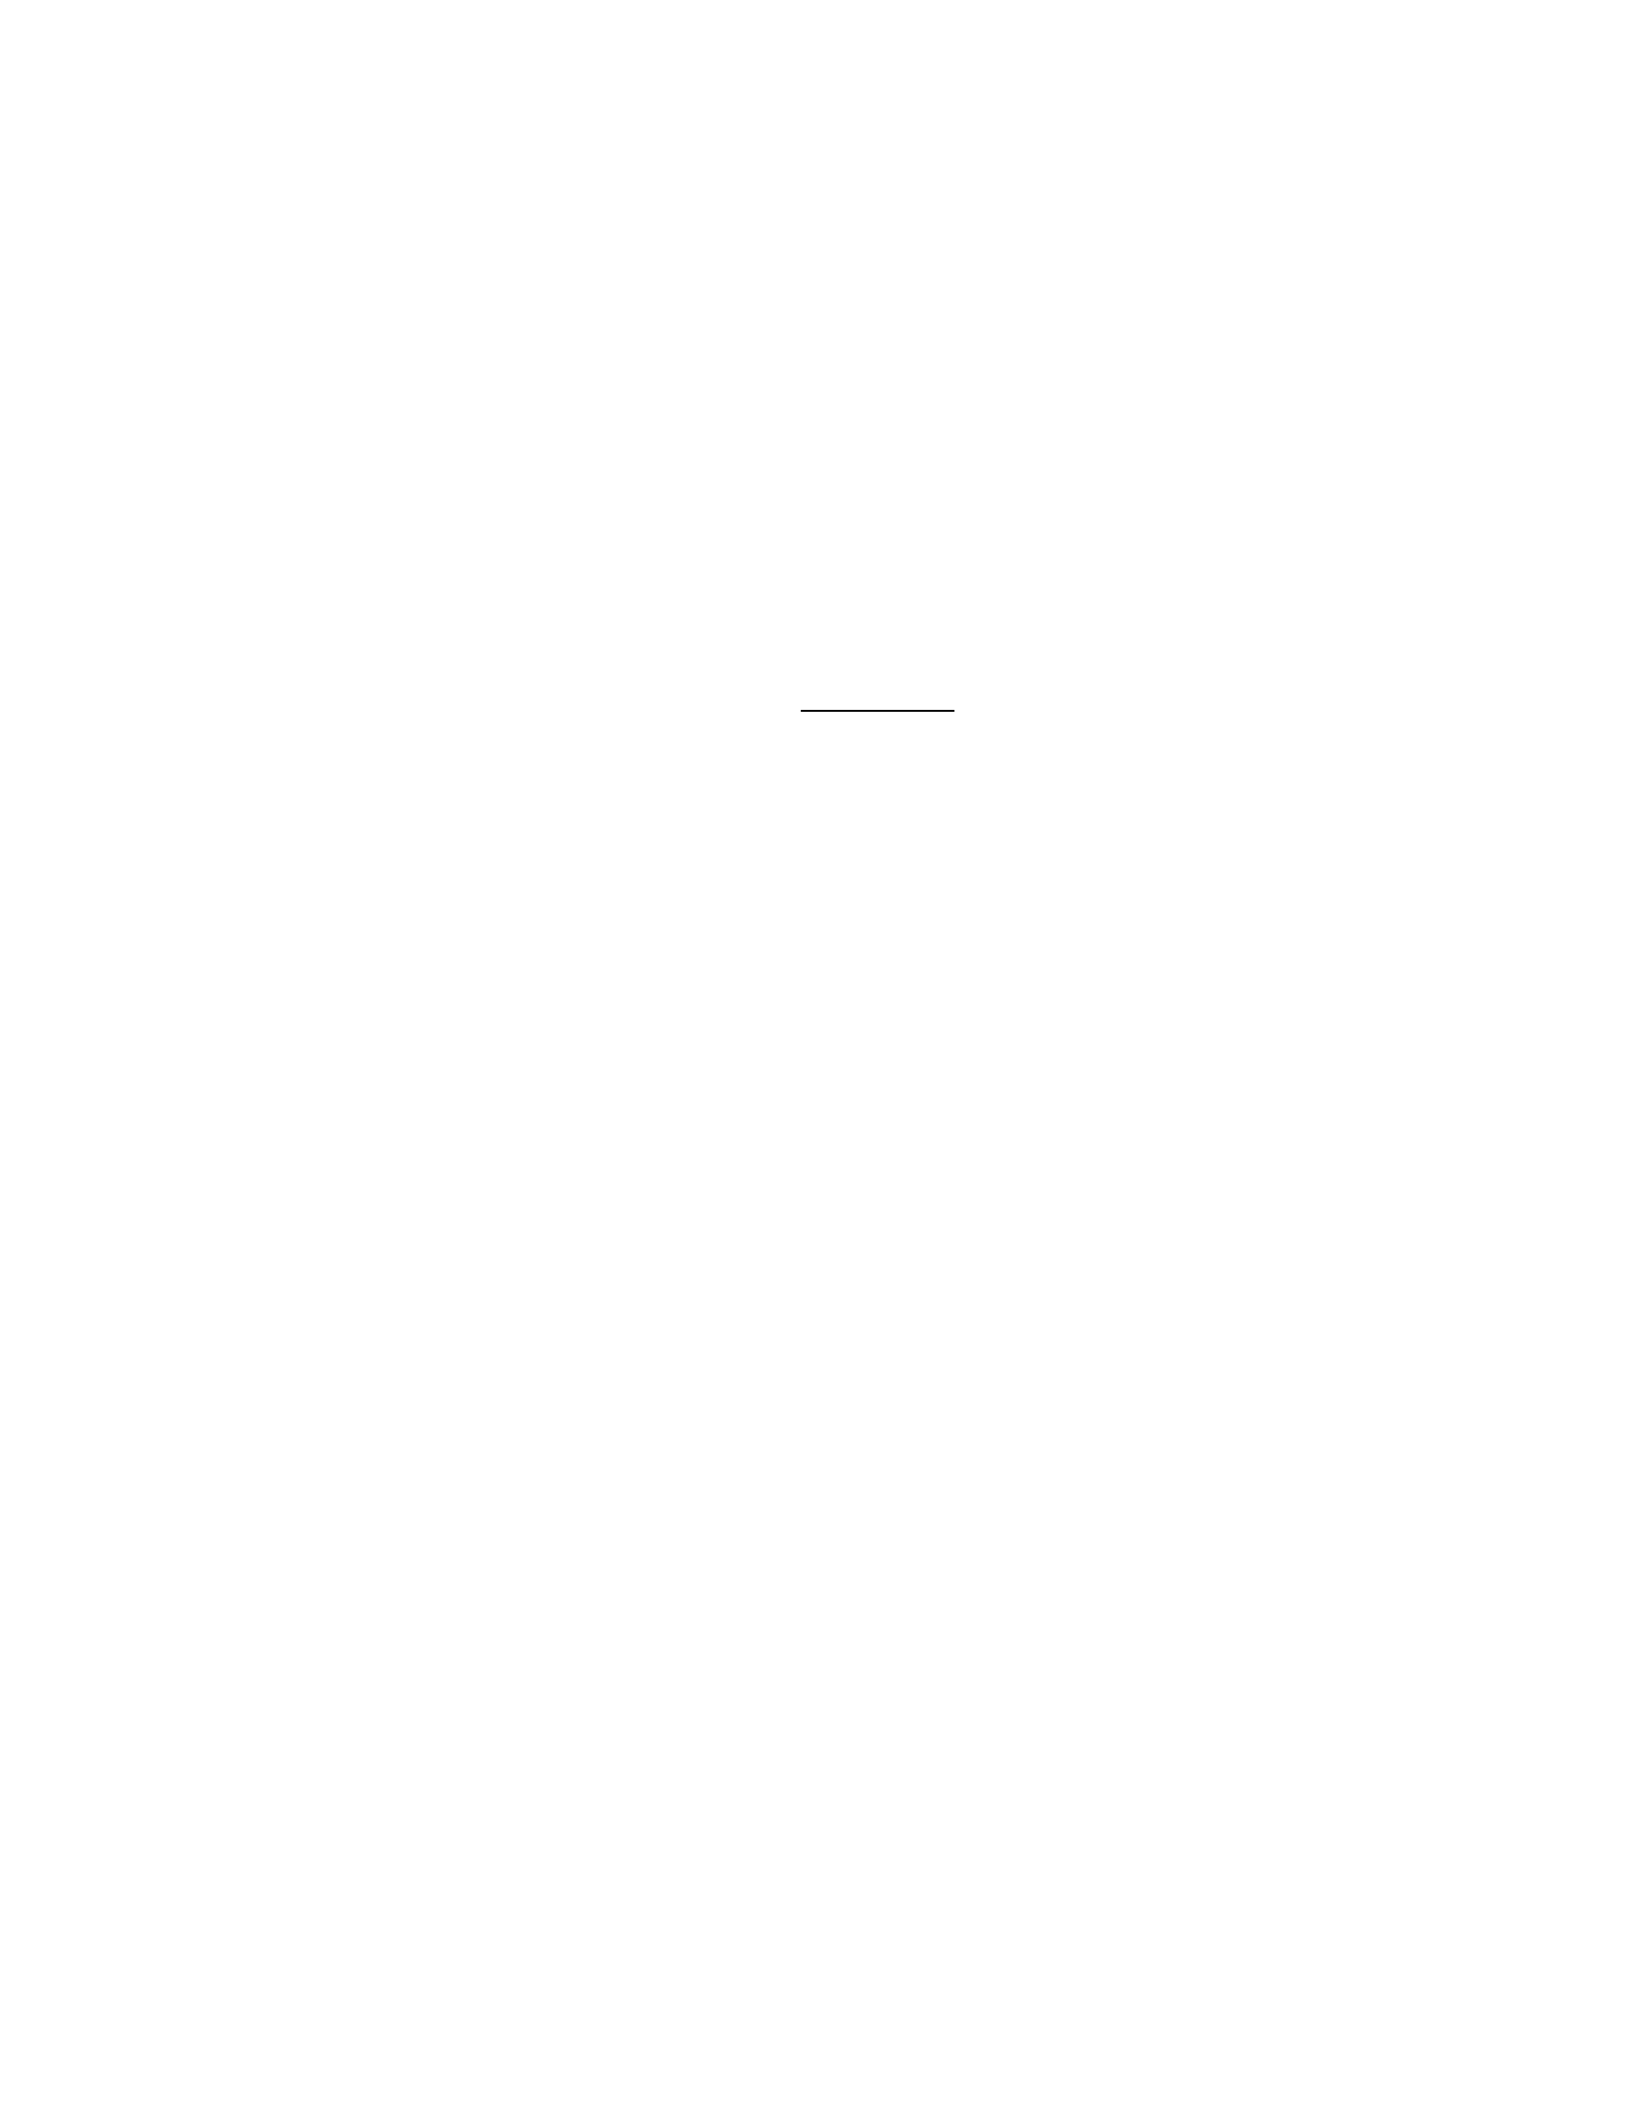
358. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
359. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
360. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
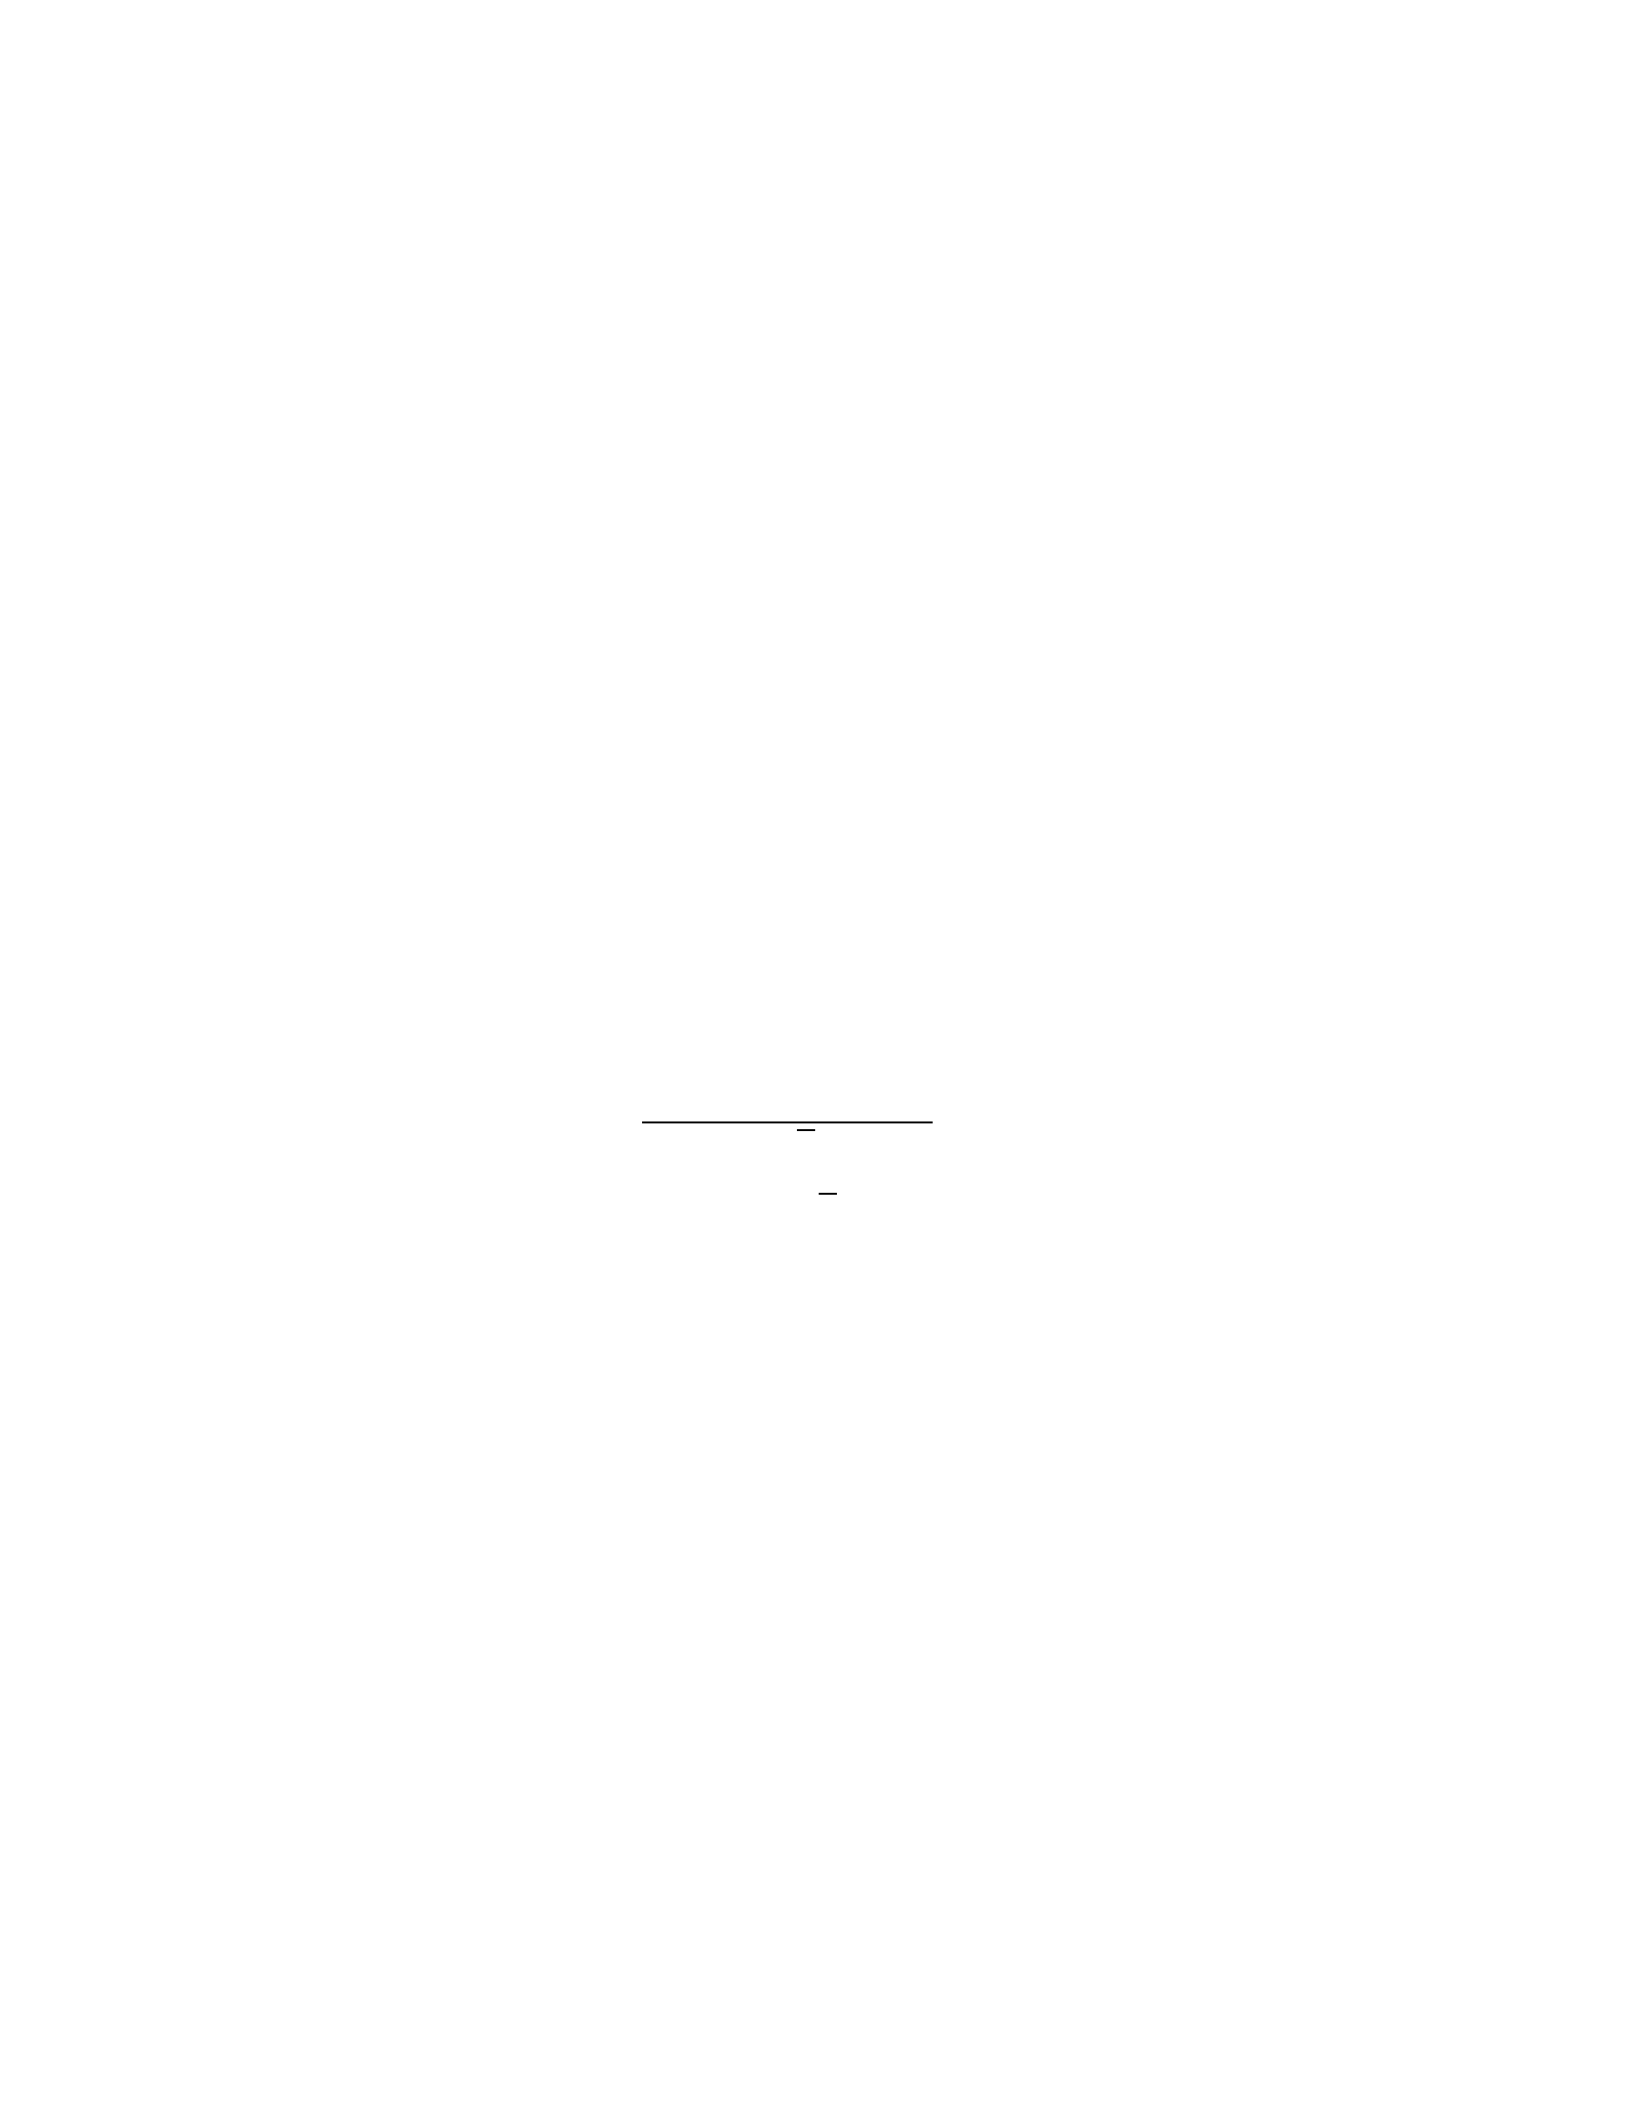
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
361. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
362. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:

a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500
• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
363. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
364. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit

from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:
• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
365. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
366. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options

and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
– Net cost = 0
367. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
368. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
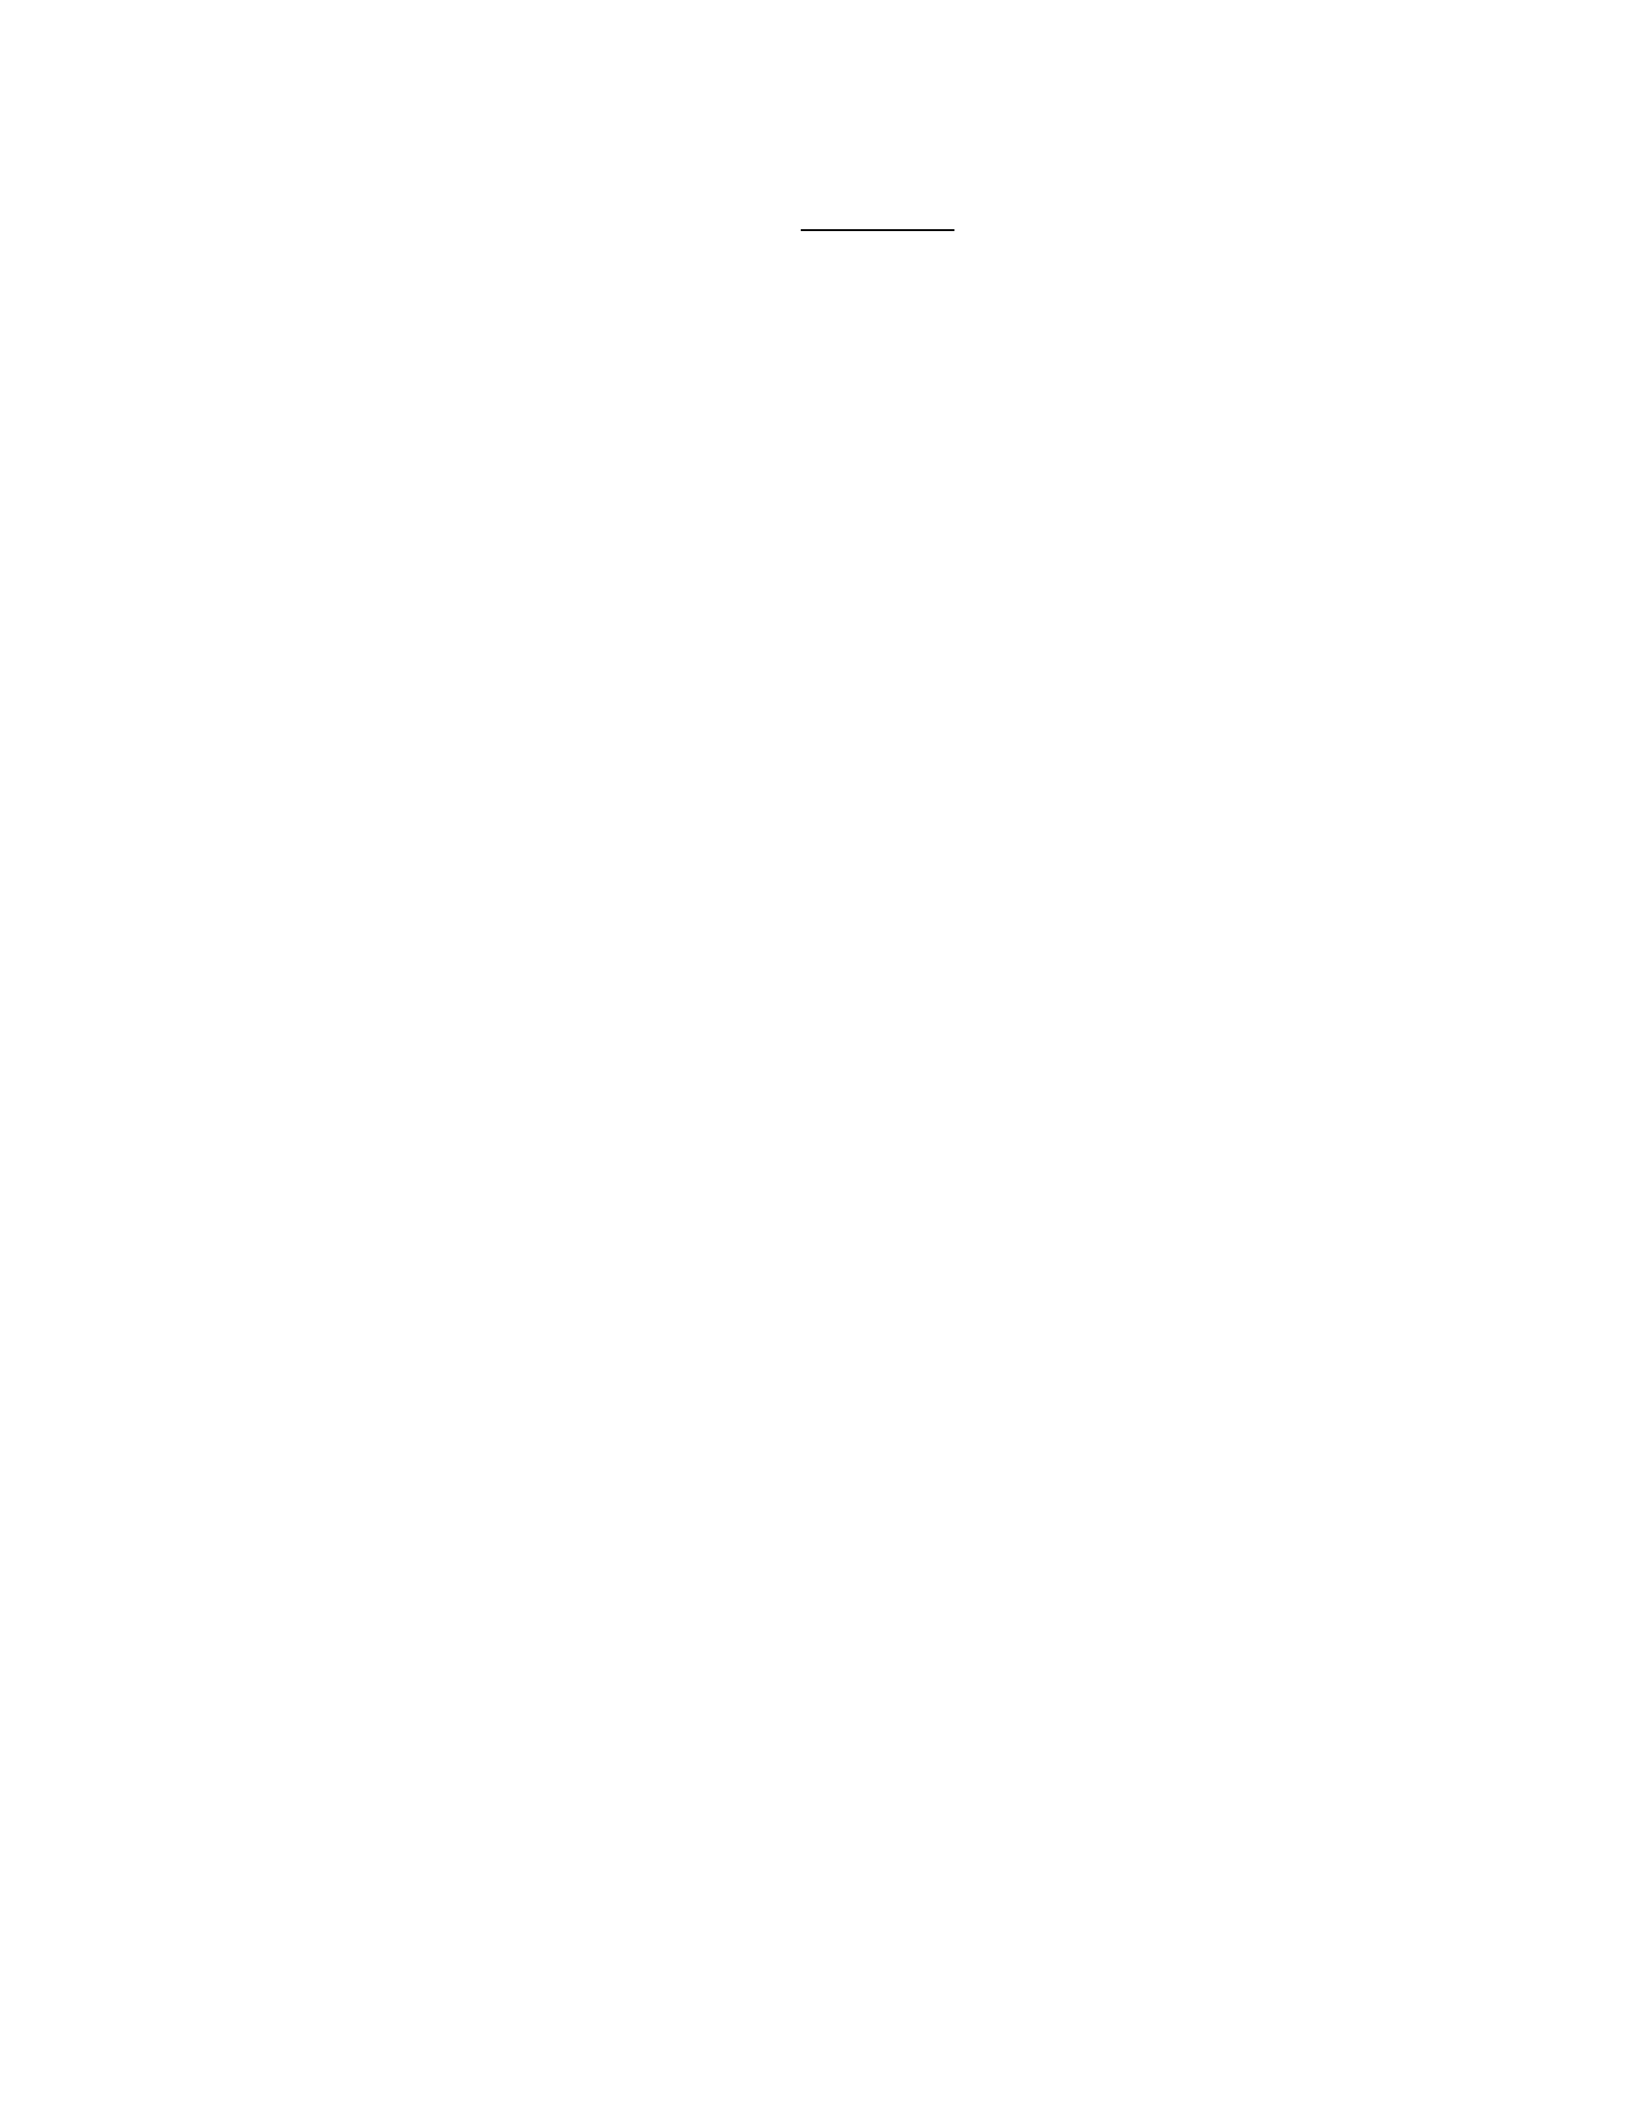
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
369. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%
– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
370. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.
371. Consider a European call option on a stock with the following parameters:
– Current stock price (S) = $50
– Strike price (K) = $52
– Time to expiration (T) = 6 months
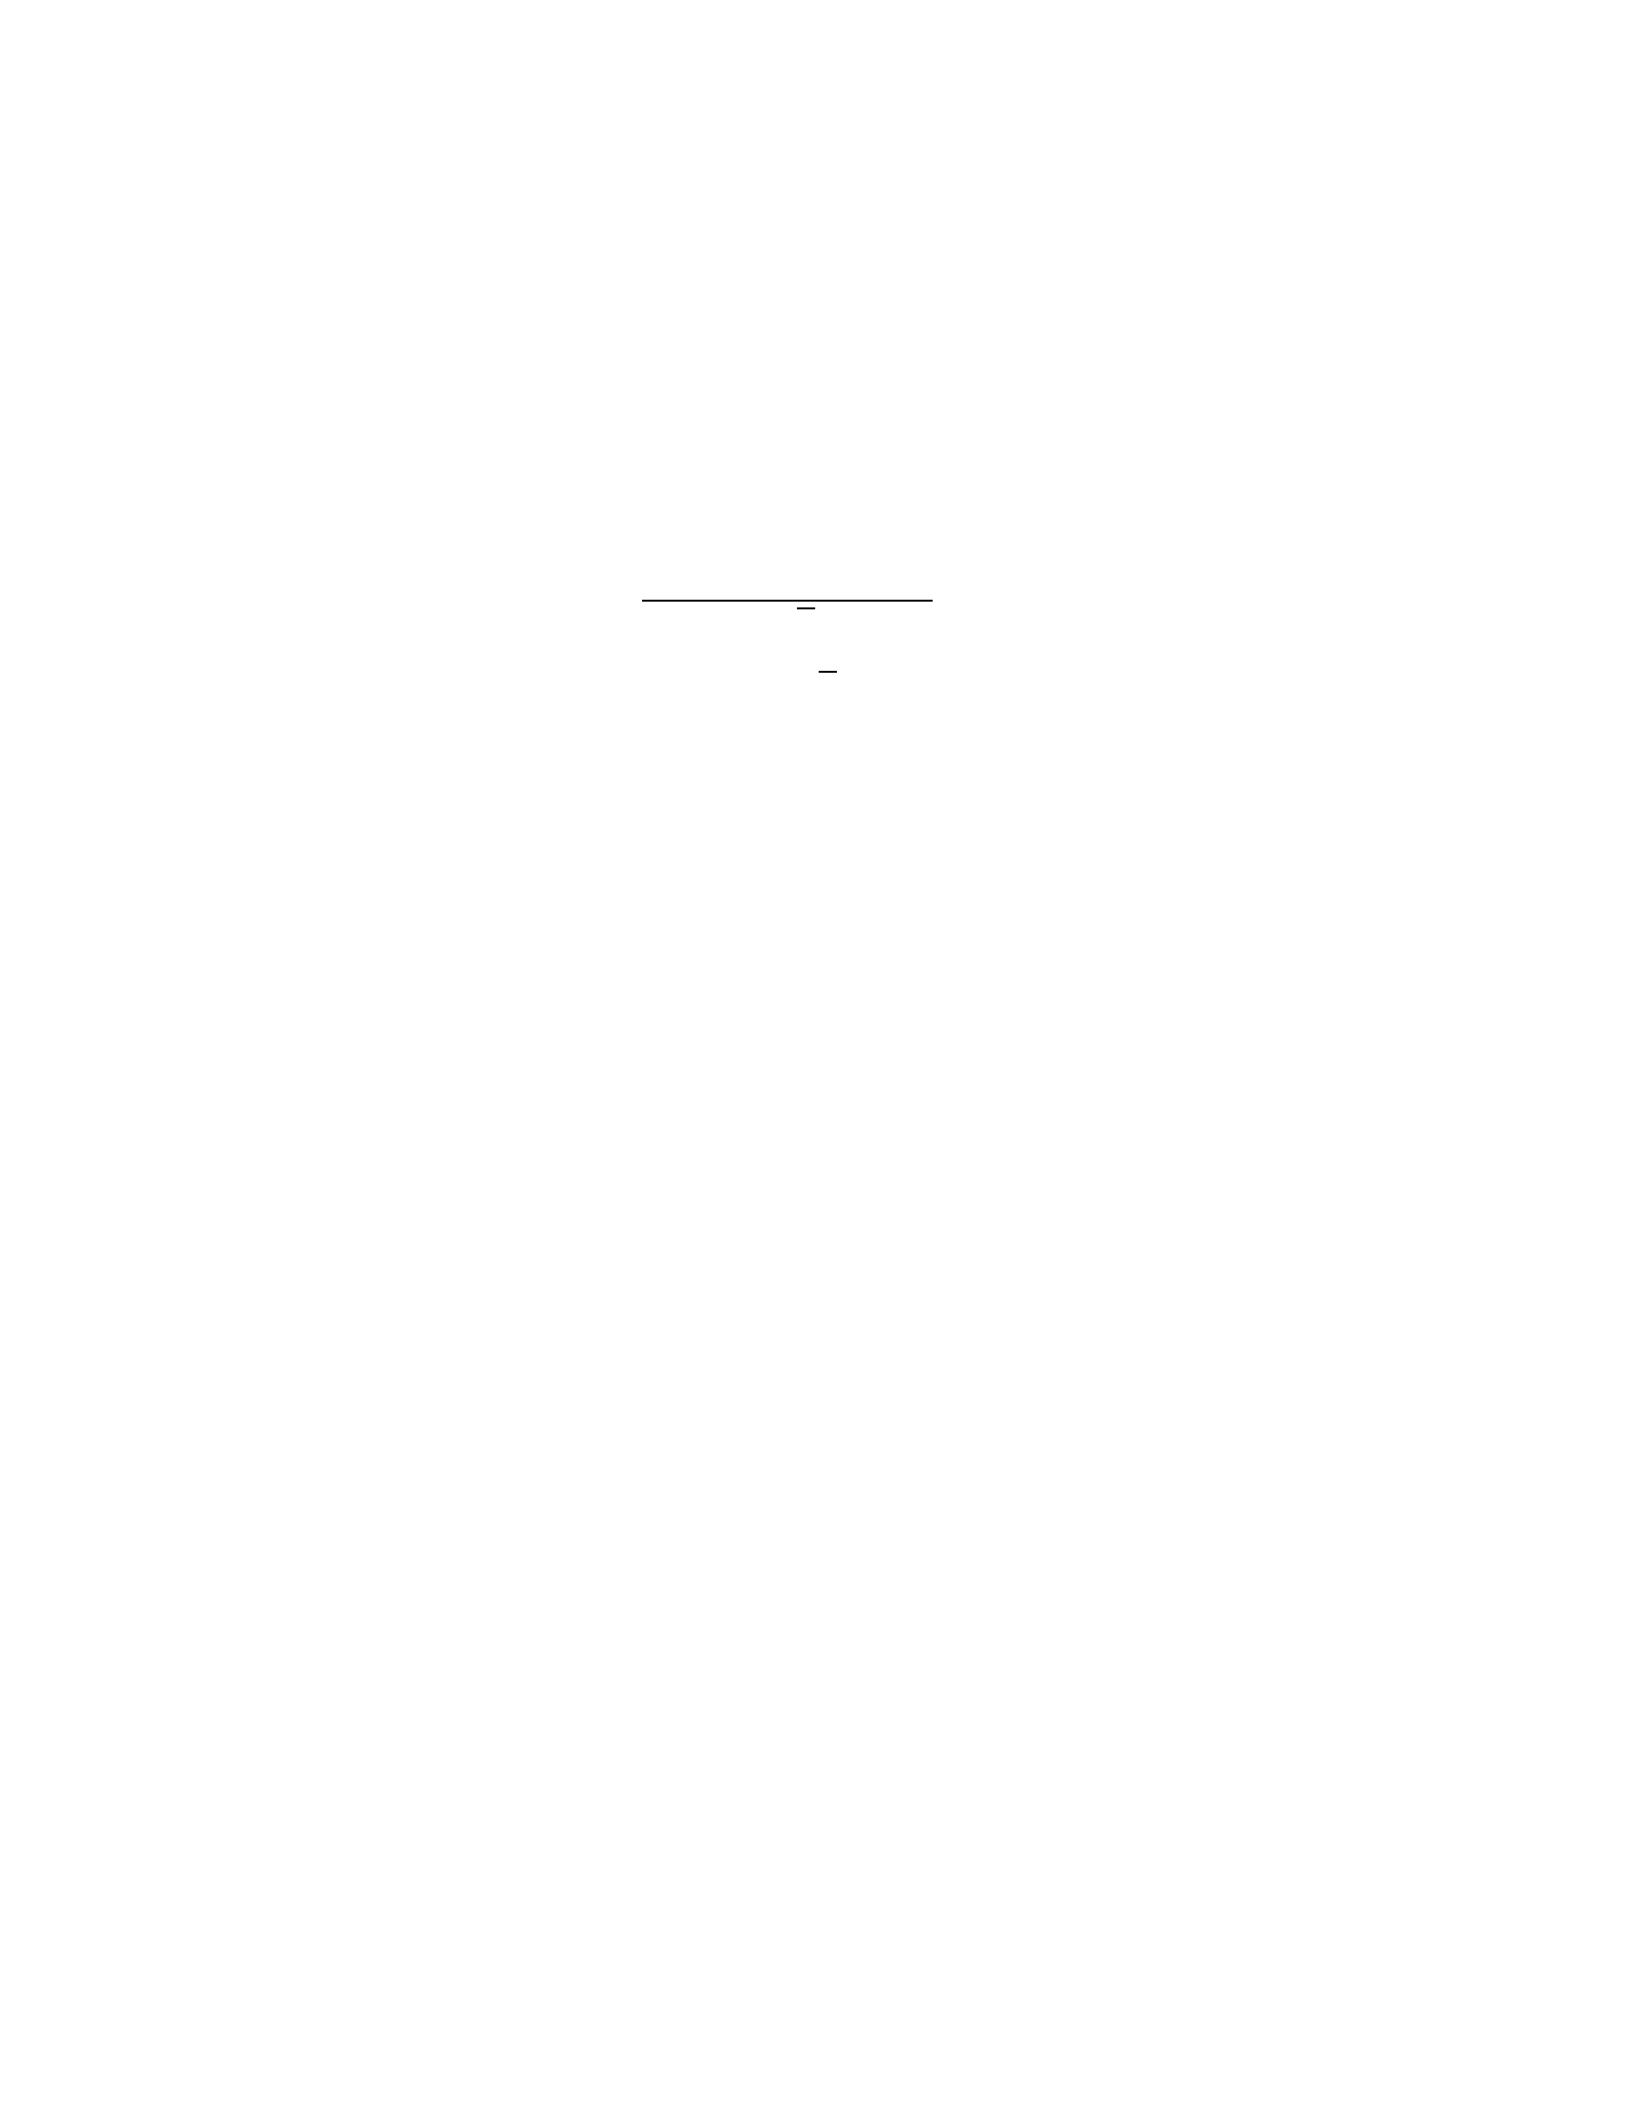
– Risk-free rate (r) = 4% per annum
– Stock volatility (σ) = 30% per annum
Calculate the option price using the Black-Scholes model and determine its delta,
gamma, and vega.
Solution:
– Step 1: Calculate d1 and d2
𝑑1=ln(𝑆/𝐾)+(𝑟 + 𝜎2/2)𝑇
𝜎√𝑇= 0.0391
𝑑2= 𝑑1− 𝜎√𝑇 = −0.1730
– Step 2: Calculate N(d1) and N(d2)
𝑁(𝑑1)= 0.5156, 𝑁(𝑑2)= 0.4313
– Step 3: Apply Black-Scholes formula
𝐶 = 𝑆𝑁(𝑑1)− 𝐾𝑒−𝑟𝑇𝑁(𝑑2)=50(0.5156)−52𝑒−0.04(0.5)(0.4313)= $3.79
– Step 4: Calculate Greeks
• Delta = N(d1) = 0.5156
• Gamma = = 0.0639
• Vega = SN’(d_1) = 11.9631
372. An investor holds a long position in a futures contract on gold. The current futures price
is $1,500 per ounce, and each contract represents 100 ounces. If the margin
requirement is 10% and the maintenance margin is 7%, calculate:
a. The initial margin deposit
b. The price at which a margin call would be issued
c. The investor’s profit or loss if the futures price increases to $1,550
Solution:
– (a) Initial margin deposit = $1,500 × 100 × 10% = $15,000
– (b) Margin call price:
• Maintenance margin = $1,500 × 100 × 7% = $10,500

• Price decrease to reach maintenance margin = ($15,000 - $10,500) / 100
= $45
• Margin call price = $1,500 - $45 = $1,455 per ounce
– (c) Profit = ($1,550 - $1,500) × 100 = $5,000
373. A company wants to hedge its foreign exchange risk for a payment of €10 million due in
6 months. The current spot rate is 1.20 USD/EUR, the 6-month forward rate is 1.22
USD/EUR, and the 6-month EUR and USD interest rates are 2% and 3% respectively.
Compare the hedging costs of:
a. A forward contract
b. A money market hedge
Solution:
– (a) Forward contract cost = €10,000,000 × 1.22 = $12,200,000
– (b) Money market hedge:
• Amount to borrow in USD: $12,000,000 / (1 + 0.03/2) = $11,823,711
• Convert to EUR: $11,823,711 / 1.20 = €9,853,093
• Invest in EUR: €9,853,093 × (1 + 0.02/2) = €9,951,624
• Additional amount needed: €10,000,000 - €9,951,624 = €48,376
• Cost of money market hedge: $11,823,711 + (€48,376 × 1.20) =
$11,881,862
The forward contract is more expensive in this case.
374. An investor believes that a stock currently trading at $100 will be highly volatile in the
near future but is unsure of the direction. Design an options strategy that would profit
from high volatility regardless of the direction of the stock price movement. Calculate the
maximum profit and loss for this strategy if the stock price moves to $80 or $120 at
expiration.
Solution: A long straddle strategy would be appropriate:
– Buy a call option with K = $100, premium = $5
– Buy a put option with K = $100, premium = $5
– Total premium paid = $5 + $5 = $10
– If stock price = $80:

• Call expires worthless, put payoff = $20
• Profit = $20 - $10 = $10
– If stock price = $120:
• Put expires worthless, call payoff = $20
• Profit = $20 - $10 = $10
– Maximum loss (if stock price remains at $100) = $10
– Breakeven points: $90 and $110
375. A 6-month European put option on a non-dividend-paying stock has a delta of -0.3 and a
gamma of 0.04. The current stock price is $50, and the risk-free rate is 5% per annum.
a. Estimate the new delta if the stock price increases to $51.
b. Using put-call parity, calculate the price of a corresponding call option if the put
price is $2.50 and the strike price is $52.
Solution:
– (a) New delta ≈ -0.3 + 0.04 × (51 - 50) = -0.26
– (b) Put-call parity: c + Ke^-rT = p + S
• Ke^-rT = 52e^-0.05(0.5) = 51.29
• c + 51.29 = 2.50 + 50
• c = 1.21
376. An oil producer wants to protect against a fall in oil prices below $60 per barrel for
1,000,000 barrels over the next year. The current spot price is $65, the one-year futures
price is $63, and the annual risk-free rate is 3%. Design a collar strategy using options
and calculate its cost. Assume the put option with K = $60 has a premium of $2, and
determine the appropriate strike price for the call option to make the collar costless.
Solution:
– Buy 1,000,000 put options with K = $60, total cost = $2,000,000
– To make the collar costless, sell call options with a premium of $2
– Using the Black-Scholes model, we can find that the call option with K ≈ $66.50
has a premium of $2
– Collar strategy: Buy 1,000,000 puts (K = $60) and sell 1,000,000 calls (K =
$66.50)
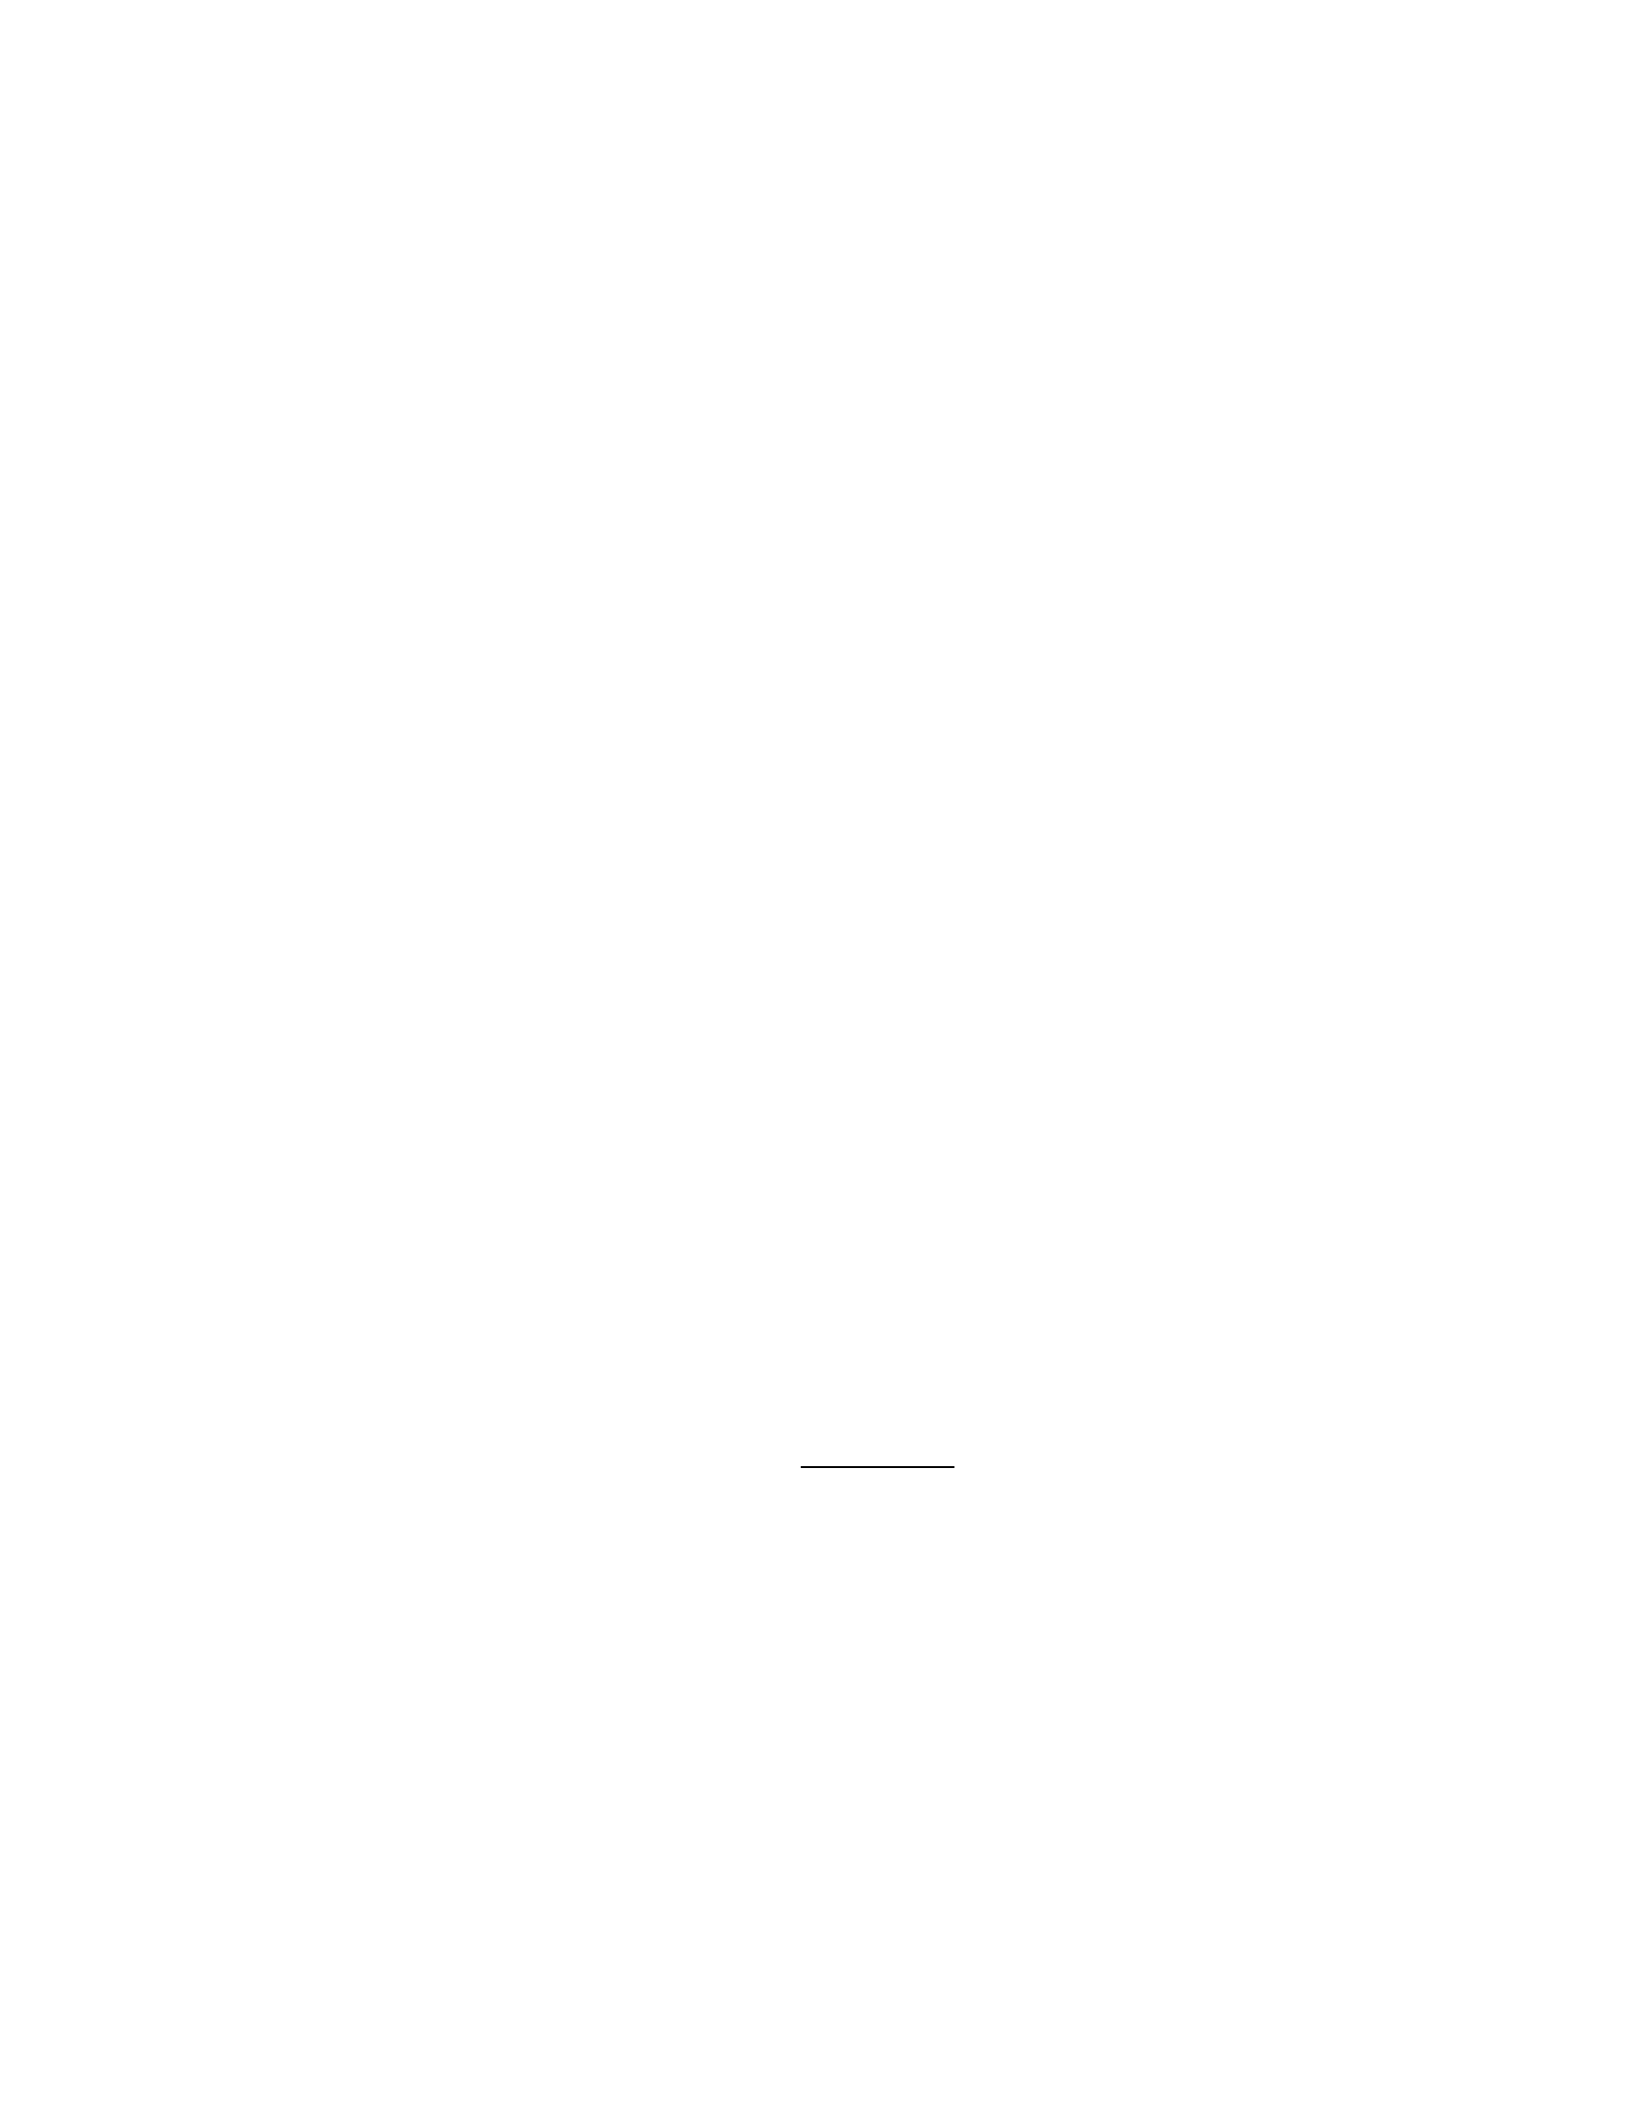
– Net cost = 0
377. A convertible bond has a face value of $1,000, coupon rate of 5% paid annually, and
matures in 5 years. It can be converted into 20 shares of the company’s stock at any
time. The stock currently trades at $40 and has a volatility of 30%. The risk-free rate is
4%. Using a binomial tree model with 5 steps, price this convertible bond.
Solution: This problem requires a detailed binomial tree calculation, which is too
extensive to show here. The main steps are:
– Calculate u and d factors for the stock price tree
– Build the stock price tree
– Calculate the bond value at each node, considering both the straight bond value
and the conversion value
– Work backwards through the tree, taking the maximum of the bond value and
conversion value at each node
– The value at the root of the tree is the convertible bond price
378. An investor holds a portfolio of stocks worth $10 million with a beta of 1.2. They want to
reduce the portfolio beta to 0.8 using index futures. The index is currently at 2,000, and
each futures contract is on $250 times the index. How many futures contracts should the
investor short? Assume the risk-free rate is 3% and the dividend yield on the index is
2%.
Solution:
– Step 1: Calculate the value of futures to be shorted
𝑉𝑎𝑙𝑢𝑒𝑡𝑜ℎ𝑒𝑑𝑔𝑒 = $10,000,000 × (1.2 − 0.8)= $4,000,000
– Step 2: Calculate the number of contracts
𝑁𝑢𝑚𝑏𝑒𝑟𝑜𝑓𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠 = 4,000,000
250 × 2,000 = 8𝑐𝑜𝑛𝑡𝑟𝑎𝑐𝑡𝑠
379. A company issues a 5-year zero-coupon bond with a face value of $1,000 and a yield to
maturity of 5
a. 4% on average over the 5 years
b. 5% on average over the 5 years
Solution:
– Bond yield = 5%

– Swap: Pay LIBOR, receive 4.5%
– (a) If LIBOR = 4%:
• Net cost = 5% + 4% - 4.5% = 4.5%
– (b) If LIBOR = 5%:
• Net cost = 5% + 5% - 4.5% = 5.5%
380. A bank has issued a 3-year USD floating rate note paying LIBOR + 50 bps annually. It
then enters into a 3-year cross-currency swap where it receives USD LIBOR and pays
EUR fixed rate of 3% on a notional principal of €10 million. The current exchange rate is
1.20 USD/EUR. Calculate the bank’s all-in Euro borrowing cost.
Solution:
– Step 1: Original USD borrowing cost = LIBOR + 50 bps
– Step 2: Swap effect
• Receive: USD LIBOR
• Pay: 3% EUR fixed
– Step 3: Net borrowing cost in EUR
3% + 50𝑏𝑝𝑠 = 3.50%
The bank’s all-in Euro borrowing cost is 3.50%.

