


Judgement Case 8-1 Riding the Merry-Go-Round
Real World Financials
Merry-Go-Round Enterprises, the clothing retailer for dedicated followers of young men’s and
women’s fashion, was looking natty as a company. It was March 1993, and the Joppa, Maryland-
based outfit had just announced the acquisition of Chess King, a rival clothing chain, a move that
would give it the biggest share of the young men’s clothing market. Merry-Go-Round told
brokerage firm analysts that the purchase would add $13 million, or 15 cents a share, to profits
for the year. So, some Wall Street analysts raised their earnings estimates for Merry-Go-Round.
The company’s stock rose $2.25, or 15%, to $17 on the day of the Chess King news. Merry-Go-
Round was hot - $100 of its stock in January 1988 was worth $804 five years later. In 1993, the
chain owned 1,460 stores in 44 states, mostly under the Cignal, Chess King, and Merry-Go-
Round names.
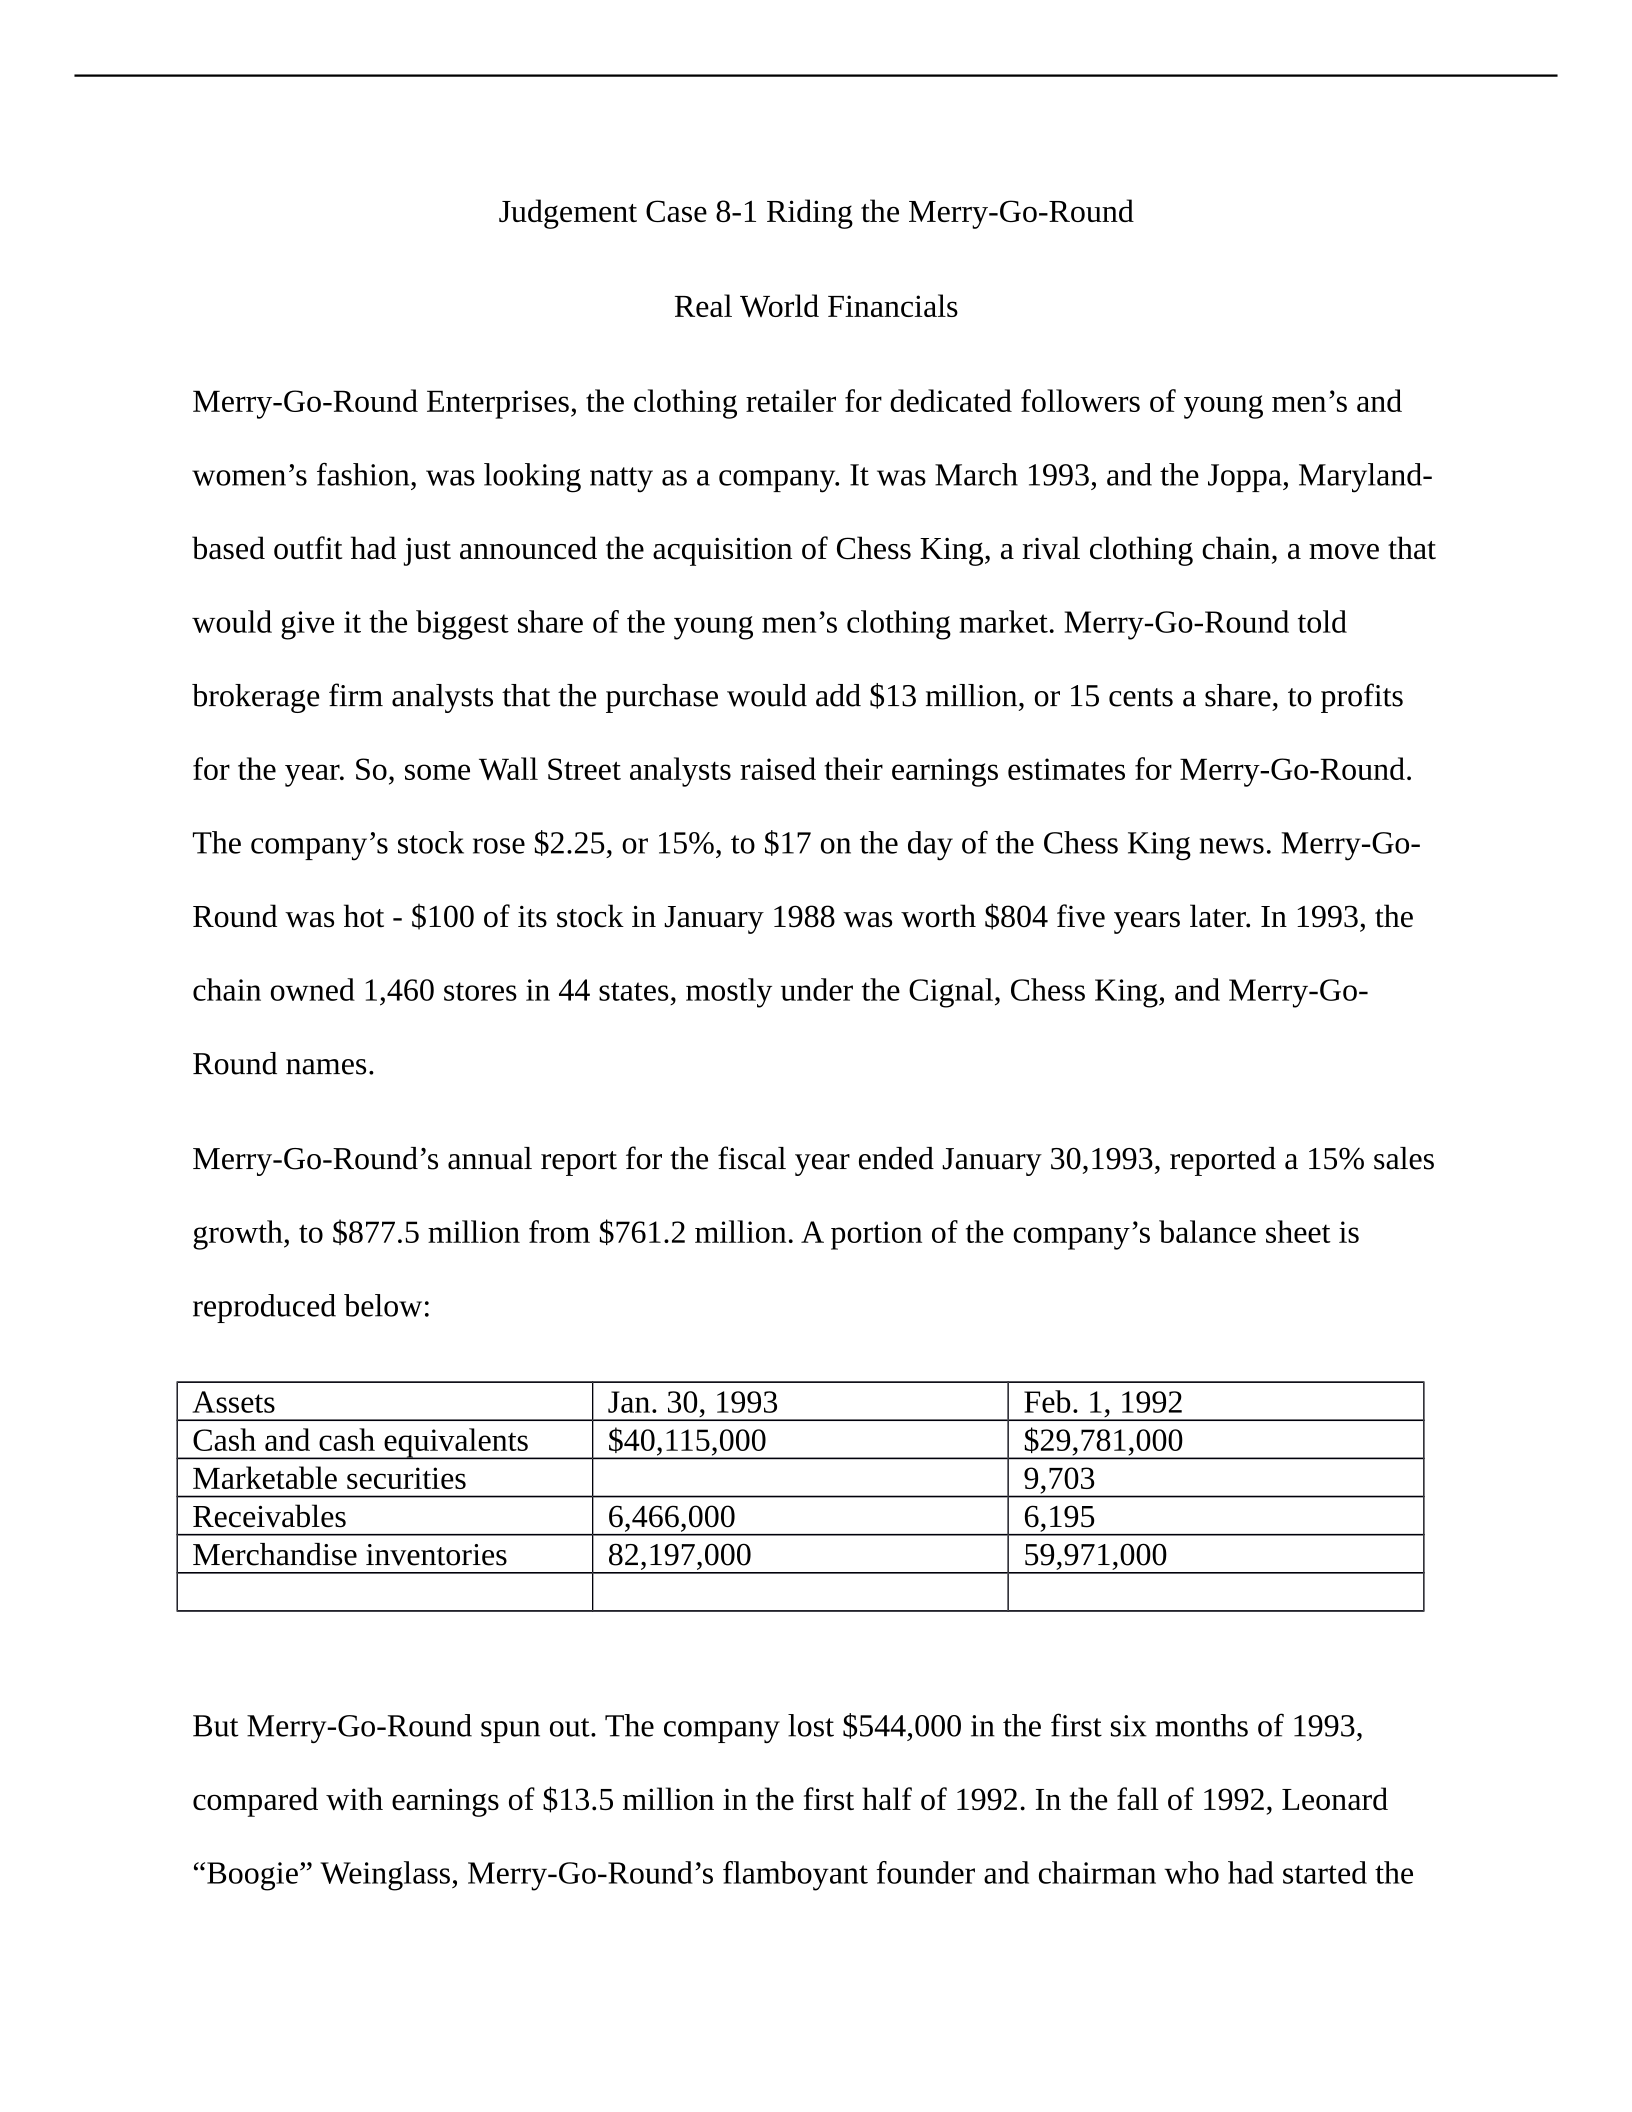
Merry-Go-Round’s annual report for the fiscal year ended January 30,1993, reported a 15% sales
growth, to $877.5 million from $761.2 million. A portion of the company’s balance sheet is
reproduced below:
Assets Jan. 30, 1993 Feb. 1, 1992
Cash and cash equivalents $40,115,000 $29,781,000
Marketable securities 9,703
Receivables 6,466,000 6,195
Merchandise inventories 82,197,000 59,971,000
But Merry-Go-Round spun out. The company lost $544,000 in the first six months of 1993,
compared with earnings of $13.5 million in the first half of 1992. In the fall of 1992, Leonard
“Boogie” Weinglass, Merry-Go-Round’s flamboyant founder and chairman who had started the
company in 1968, boarded up his Merry-Go-Ranch in Aspen, Colorado, and returned to
management after a 12-year hiatus. But the pony-tailed, shirtsleeved entrepreneur- the inspiration
for the character Boogie in the movie Diner-couldn’t save his protection in Baltimore. Shares
crumbled below $3.
Required:
In retrospect, can you identify any advance warning at the date of the financial statements of the
company’s impeding bankruptcy?
[Adapted from Jonathan Burton, “Due Diligence,” Worth, June 1994, pp 89-96]
Judgment Case 8-1 Riding the Merry-Go-Round
Inventory management is one of the differentiating factors in the Merry-Go-Round firm's
success and is seen as an essential business activity (Wild, 2018). To make inventory
management function effective, the firm must lower the unnecessary inventory management and
all associated costs in saving the capital of business and ensuring that customers are managed by
providing adequate stock inventory maintenance.
In our case, an essential company for clothes called Merry-Go-Round Enterprises existed
in the 1990s, a clothing company dedicated to young women and men followers of fashion. After
a close check of the balance sheet of MGR company for the year ending 30th January 1993, the
firm made losses for $544,000 in the first six months of 1993 compared to $13.5 million earnings
in the 1992 first half. The warning was seen in the company's financial statements that were
impending bankruptcy (Spiceland, Nelson, & Thomas, 2020). However, the MGR firm thought
they could bring resolution by acquiring Chess King, a rival chain in clothing, giving it the most
significant share of the market of the young man clothes it had already established.
The merchandise stock is growing fast, and income increases after a close check in the
balance sheet numbers. Bulging inventories may arise if there is faster growth in the inventories
number than in sales. The debtor’s turnover ratio indicates that the firm is very efficient in
gathering cash from its customers (Spiceland, Nelson, & Thomas, 2020). Close monitoring of the
turnover ratio of debtors and the average period of the collection over time may offer important
information on the prospect of the firm (Spiceland, Nelson, & Thomas, 2020). The turnover ratio
has slowed, as the case can tell.
In Case 6-7, the inventory turnover ratio measures the efficiency in investment in
inventory management. It is usually designed in the evaluation of the effectiveness of the firm in
investment management in inventory. Inventory turnover ratio shows the number of recurrent
and accurate times the balance or remainder of average stock is disposed of or sold in the
reporting period. If a business can sell or turn over its sales more frequently, less investment in
stock should give for a given sales level. Potential problems can be highlighted by monitoring
the inventory turnover ratio (Spiceland, Nelson, & Thomas, 2018). A declining inventory
turnover ratio could be caused by poor sales and marketing efforts, slow-moving products, or the
presence of obsolete materials and products.
The annual report of Merry-Go-Round Company for the financial year ending 30th
January 1993 reported growth in inventory from $59,971,000 to $82,197,000 from 1st February
1992 to 30th January 1993 respectively. There was another growth is sales of 15%, sales went
from $761.2 million to $877.5 million from 1st February 1992 to 30th January 1993, respectively
(Spiceland, Nelson, & Thomas, 2020). This has meant that the rate of inventory growth is higher
than the rate of growth in sales. The fast-growing stock and the lower sales growth could have
been a concern in the company because there was a significant rise in debtors from a figure of
$6,195 to a figure of $6,466,000. The warning was seen in the company financial statements that
were impending bankruptcy which is in the balance sheet. For this situation, effective control
standards must be formulated and implemented in Merry-Go-Round Company to prevent
bankruptcy.
References
Spiceland, J. D., Nelson, M., & Thomas, W. (2020). Intermediate accounting. Tenth
edition.: McGraw-Hill Education.
Spiceland, J. D., Nelson, M., & Thomas, W. (2018). Intermediate accounting. Ninth
edition.: McGraw-Hill Education.
Wild, T. (2018). Best Practice in Inventory Management. London: Routledge.
Powered by TCPDF (www.tcpdf.org)

