


Exploring Small Business Strategies to Comply
With the Foreign Corrupt Practices Act
Section 1: Foundation of the Study
Compliance with the Foreign Corrupt Practices Act (FCPA) is a significant
business issue in the United States (Cleveland, Favo, Frecka, & Owens, 2010). The U.S.
Congress enacted the FCPA in 1977 to criminalize corruption and to enhance the
corporate image of U.S. corporations in global markets (Feld, 2013). The intent of the
FCPA is to eliminate illegal foreign business transactions, but the leaders of small U.S.
companies conducting business with a foreign government continue to have questions
related to obtaining or retaining business with a foreign government (Yockey, 2013).
Leaders at U.S. companies encounter vague areas in the FCPA provisions; this vagueness
results in misinterpretations of FCPA rules, FCPA violations, and significant penalties
(Alemu, 2013; Jennings, 2013; Yockey, 2013). Without proper oversight by the U.S.
government, business transactions between U.S. companies and international
governments can also lead to noncompliance with FCPA provisions (Nadipuram, 2013;
Wedeman, 2013).
Background of the Problem
In 2007, U.S. industries increased global product transactions by more than $1.4
trillion (Das, 2010). Global product sales expose U.S. companies to business activities
with people from various cultures and with different values, norms, and regulations
(Baughn, Bodie, Buchanan, & Bixby, 2010). Fierce competition to provide global
products has led the leaders of multinational corporations to bribery on a large scale, with

global business bribery estimated at $1 trillion a year in 2002 (Eigen, 2013; Graycar &
Sidebottom, 2012; Hess, 2009). Based on the most recent U.S. international contracts
loses information available, from 1994 to 2001, U.S. companies lost an estimated $200
billion in international business contracts to foreign competitors that allegedly paid bribes
to win contracts (Darrough, 2010).
Bribery and corruption have significant consequences: Global business bribery
negatively affects the economic growth of businesses, and corruption leads to an
anticompetitive environment (Smith, Gruben, Johnson, & Smith, 2013). World Bank
analysts estimated the cost of corruption at $2.6 trillion annually, which is more than 5%
of global gross domestic product (GDP; Cleveland et al., 2010). The objective of
international antibribery laws and organizations such as the FCPA, the United Nations
Convention Against Corruption (UNCAC), and the Organization for Economic
Cooperation and Development (OECD) is to eliminate global corruption (Cleveland et
al., 2010). U.S. Congress enacted the FCPA in 1977 in response to the U.S. companies
including Lockheed and General Electric allegedly bribing foreign government officials,
politicians, and political parties to gain government contracts (Cascini, DelFavero, &
Mililli, 2012). Since the FCPA entered into effect, U.S. companies must comply with the
FCPA requirements and not use bribery to obtain international business contracts
(Cascini et al., 2012). However, noncompliance issues remain; for example, a recent
FCPA violation resulted in a $1.6 billion penalty to Siemens (Fox, 2010). Some U.S.
small business organizations have indicated that they lack strategies to ensure FCPA
compliance (Yockey, 2013).

Problem Statement
Estimates of international bribery are $1 trillion per year, and estimates of the
costs of global corruption range as high as 20% of the value of world business
transactions (Nadipuram, 2013). In 2009, U.S. companies lost more than $25 billion in
international contracts due to foreign competitors using bribery and corrupt practices
(Nickerson, 2011). The general business problem is that U.S. aerospace companies must
operate competitively in the global market and comply with the FCPA, but enforcement
of the FCPA by the U.S. Department of Justice does not occur in international settings for
non-U.S. companies. The specific business problem is that some U.S. aerospace small
business leaders lack strategies to comply with the FCPA.
Purpose Statement
The purpose of the qualitative single case study was to identify the strategies U.S.
aerospace small business leaders use to comply with the FCPA. The study population
consisted of leaders of a small U.S. aerospace company in California operating in the
international market that had an absence of penalties, a good international business record
of accomplishment, and successful compliance with the FCPA at the time of the study.
The selected population was appropriate because these leaders were part of California’s
aerospace industry, which represents 47% of the aerospace industry engineering and
product development in the United States (U.S. Department of Labor, 2012). The findings
of this study showed successful small business strategies for FCPA compliance. Reducing
crime in business transactions results in an improvement in the safety of people and
organizations, reduces the cost of conducting business, and improves the quality of life

for individuals and communities (Lestrange & Tolstikov-Mast, 2013; Lord, 2013). This
suggests that applying these findings will lead to reductions in the cost of conducting
global business and may lead to an increase in the number of U.S. aerospace jobs while
also demonstrating social integrity.
Nature of the Study
I used a qualitative case study design for this study. Qualitative research was
suitable for the study because the goal of the study was to identify strategies participants
used to comply with the FCPA. A qualitative researcher studies a phenomenon in the
related context of an experience (Sharma & Aniket, 2014; Yap & Webber, 2015). A
quantitative methodology was not suitable for the study because this research did not
involve comparing or analyzing variables. A quantitative methodology is suitable for
analyzing a relationship between variables (Gelei & Dobos, 2014; Macur, 2013). A
mixed methods methodology was not suitable for the study because the quantitative
aspect was not designed to address participants’ experiences with FCPA compliance
strategies, and did not require hypothesis testing.
Three qualitative research design options were evaluated: phenomenology,
ethnography, and case study design. For this study, I decided that the case study design
was the appropriate choice because the research consisted of studying individuals’ FCPA
compliance strategies through semistructured interviews. Researchers use a case study
design to explore a program, event, or person in depth for a particular amount of time to
determine real-life experiences regarding a specific phenomenon (Leedy & Ormrod,

2013). The ethnography design was not suitable for the study because this research did
not include lengthy observations of participants. The ethnography design encompasses
extended fieldwork involving observation and cultural interactions within members of a
group (Wagar, 2012). The phenomenological design was not suitable because
participants’ perspective and views of the FCPA were not part of this research.
Researchers use the phenomenological model to understand participants’ perspective and
opinions of a phenomenon (Leedy & Ormrod, 2013).
Research Question
The research question for the study was as follows: What strategies do U.S.
aerospace small business leaders use to comply with the FCPA?
Interview Questions
The qualitative single case study included the following open-ended interview
questions to collect data:
1. What strategies do you use to comply with the FCPA?
2. What recent changes have you made in your company policies to improve
compliance with the FCPA?
3. What does leadership consider essential for FCPA compliance?
4. What action plan considerations would ensure continued success with FCPA
compliance?
5. What other pertinent information do you see that we have not covered in this
interview?

Conceptual Framework
The conceptual framework for this study was based on the regulatory compliance
theoretical model (Sutinen & Kuperan, 1999) and the corruption conceptual model
(Becker & Stigler, 1974). The regulatory compliance and the corruption conceptual
models served as a conceptual reference and lens to identify the FCPA adherence
strategies needed by U.S. aerospace small business leaders. The regulatory compliance
conceptual model served as a theoretical lens for understanding strategies used by
executives to comply with the FCPA. The corruption conceptual model provided a
theoretical underpinning to gain deeper insight into how indicated strategies address the
FCPA requirements.
The key tenets of the regulatory compliance conceptual model are: (a) costs and
the revenues from illegal behavior, (b) the moral obligation of behavior, and (c) social
influence associated with criminal behavior (Sutinen & Kuperan, 1999). The key
constructs underlying the corruption model are (a) government structure influence, (b)
cultural influence, (c) corporate profits, (d) government officials’ self-interests, and (e)
strategies for FCPA compliance (Becker & Stigler, 1974). As applied to this study, the
propositions advanced by the regulatory compliance conceptual model and corruption
model established the framework needed for me as the research to use it as the theoretical
foundation for interpretation and analysis of participants’ experiences with strategies for
FCPA compliance.
Operational Definitions

Foreign Corrupt Practices Act (FCPA): A U.S. antibribery law passed by U.S.
Congress in 1977, prohibiting U.S. citizens and organizations from providing payments to
foreign government officials to obtain or retain business contracts (Cascini et al., 2012;
Feld, 2013).
Foreign Corrupt Practices Act (FCPA) compliance: Abstaining from bribing
government officials in foreign countries to gain business opportunities, in compliance
with the FCPA (Virginia & Maurer, 2013). FCPA strategies: Corporate, organization, or
small business plans created by executives and leaders to comply with the FCPA
(Lestrange & Tolstikov-Mast, 2013; Yockey, 2013).
Small aerospace company: In the context of this study, a U.S. aerospace company
with 500 employees or less (U.S. Small Business Administration, 2014).
Assumptions, Limitations, and Delimitations
Assumptions
The assumptions of a study usually relate to the research techniques employed in
the research and are the sentiments of what the researcher believes to be true for the
study, but are not verified (Leedy & Ormrod, 2013). The first assumption was that the
qualitative single case study is a useful design to explore the FCPA strategies used in
U.S. aerospace small businesses. The second assumption was that data saturation would
occur during interviews with the management of one small aerospace company in
California. The third assumption was that executives participating in the interview
process would accurately convey their strategies for FCPA compliance. The fourth

assumption was that the interview participants would represent an appropriate
crosssection of the U.S. small-business aerospace industry population.
Limitations
The limitations of a study include the research approaches used in the study
(Leedy & Ormrod, 2013). Limitations are potential research weaknesses over which a
researcher has no control (Bouzon, Augusto, & Manuel, 2014; Marshall & Rossman,
2011). The potential bias namely due to the desire to protect confidential company
information of participants during the interview, as well as the possible lack of
recollection of experiences with the FCPA, may have been a limitation of the study. The
mitigation of this limitation consisted of asking follow-up questions to clarify and to help
participants’ recollection of FCPA compliance experiences.
Participants’ potential concerns about a connection between personal identity and
the information disclosed during the interview might have represented a limitation of the
study. To mitigate this limitation, participants received a signed consent form before the
interview that listed the steps being taken to ensure participant anonymity (see Appendix
A).
Another limitation was been the small sample from a small aerospace company.
To mitigate this limitation, the corporation selected for gathering data was a successful
aerospace company in the United States operating in international markets.
Delimitations
Delimitations refer to the boundaries established by a researcher (Leedy &

Ormrod, 2013). Marshall and Rossman (2011) described study delimitations as the design
parameters that researchers control, such as the location and scope of a study. The first
delimitation of the study was geographical: Due to the limited time and financial
resources available, only U.S. aerospace companies located in California comprised the
population for this study. The second study delimitation was the research scope: The
number of participants in the interviews consisted of five to seven executives in a small
aerospace business experienced with FCPA compliance. The third delimitation of the
study was the restriction of the study to the U.S. aerospace industry: The FCPA
compliance strategies used in other industries were not part of the study. The fourth
delimitation of the study was the curtailing of the research to a small company size: The
study included an examination of only one small U.S. aerospace company with
international trade experience and has 500 or fewer employees.
Significance of the Study
This study was designed to generate information of interest to small business
leaders wanting to obtain and maintain international business contracts. The FCPA
compliance strategies identified, if followed, are expected to lead to a reduction of FCPA
violations during the pursuit and fulfillment of international contracts. The analysis of
gathered data included identified strategies for FCPA compliance that may result in the
reduction of law ambiguities. Reducing ambiguities in FCPA compliance may influence
the legality and positive social presence of small business operations in the global
markets.

Contribution to Business Practice
Compliance with the FCPA helps to reduce costs of operation, improve profits,
equalize competition, and enhance the competitive nature of conducting international
business (Lestrange & Tolstikov-Mast, 2013; Lord, 2013). Adapting strategies for FCPA
compliance is expected to increase profits and decrease costs for U.S. aerospace
corporations. Violations of the FCPA, however, cost corporations and shareholders more
than the benefits gained from bribery, including decreased profits, increased costs of
doing business, and wasted business opportunities (Choudhary, 2013). The findings from
this study are expected to contribute to knowledge on avoiding bribery and corruption in
international markets. The identified strategies from this study, if implemented, are
expected to decrease the business challenges faced in adhering to the FCPA. Using the
strategies discovered during this study is supposed to reduce the cost of conducting
international trade.
Contribution to Social Change
The results from this study are expected to lead to improvements in corporate
ethical standards in international trade practices by reducing contract corruption and
increasing compliance with the FCPA. Decreasing contract corruption is expected to
result in reduced corporate operational costs. Reduced operational costs are expected to
lead to additional jobs in the industry, which possibly improve the local economy.
Complying with FCPA mandates reduces business corruption. A decrease in corruption
frees small business funds. The freed additional funds and a corporate culture that
emphasizes compliance with laws are expected to positively affect small businesses and

affect quality of life in the local business community. Lestrange and Tolstikov-Mast
(2013) and Lord (2013) indicated reducing business transactional crime through FCPA
compliance creates a safe environment for conducting business, reduces costs, and creates
jobs, which results in a positive social change.
Review of the Professional and Academic Literature
Writing a comprehensive review of a research topic by examining related
literature involves developing a plan, obtaining the proper business orientation, and
emphasizing relatedness to the research (Leedy & Ormrod, 2013). Literature reviews start
with an exhaustive review of published papers on the research topic to provide new
perspectives on the themes of the study (Ergazakis, Metaxiotis, & Askounis, 2013;
Wolfswinkel, Furtmueller, & Wilderom, 2013). The literature review in this study
involved a comprehensive evaluation of the Walden Library databases to find articles and
seminal works related to FCPA compliance topics and subtopics. Of the 313 references
used, 307 were peer-reviewed articles (i.e., 98% of the cited references are peer-reviewed
articles) and 272 had a publication date of 2012 or later. Therefore, 87% of the cited
references were peer-reviewed articles published within 5 years old of the anticipated
graduation date, meeting university standards for recent research.
The literature review consisted of two parts. The first part of the literature review
discussion includes the databases and indexes searched using FCPA compliance, bribery,
and corruption terms. The first part also includes a resources table of the exhaustive
literature search and a figure of the main topics and subtopics of the literature review.

The second part of the literature review includes the synthesized analysis of peerreviewed
articles and seminal work related to identified topics and subtopics in the figure.
Literature Search Strategy
The literature search strategy used in this study started with keyword searches and
then subject term searches. The keyword and subject term searches included (a) foreign,
(b) foreign corruption, (c) Foreign Corrupt Practices Act, (d) corruption, (e) international
business, (f) FCPA compliance strategies, (g) bribery, (h) fraud, (i) anticorruption laws,
(j) fraudulent, (k) U.S. aerospace industry, and (l) California aerospace industry.
Keyword and subject term searches using the Walden Library online databases helped in
obtaining peer-reviewed articles and scholarly materials relevant to the concepts of the
study. The Walden Library databases searched included ProQuest, Academic Search
Complete, ABI/INFORM Global, PsycINFO, Education Research Complete, ERIC,
ScienceDirect, Emerald Management Journals, SAGE Premier, and Business Source
Complete.
The first searches of the databases using keywords generated 5,105 articles,
dissertations, books, and other materials related to the topic area and research process.
Narrowing the search to only peer-reviewed articles focused on the FCPA and articles
focused on aerospace industry compliance with FCPA issues reduced the number of
relevant articles to 304 items. Consequently, the second subject term searches yielded
98% of the peer-reviewed article, with 86% of the peer-reviewed articles published in
2012 or later. Table 1 includes the number of resources reviewed, including peerreviewed
journal articles, dissertations, books, reports, newspapers, websites, and corporate
information related to strategies for complying with the FCPA.
Table 1
Details of Literature Reviewed by Year of Publication
The purpose of this study was to explore the strategies used by U.S. aerospace
small business leaders to comply with the FCPA. The following section includes a
description of the literature related to the regulatory compliance theoretical model and the
corruption model. The following section also includes the literature review structure and
synthesis of reviewed articles related to the research question.
Regulatory Compliance Theoretical Model
Sutinen and Kuperan (1999) first developed the model of regulatory compliance
to account for the costs and the revenues from illegal behavior, as well as the moral
obligation and social influence associated with criminal behavior. Malik’s (2014)
regulatory compliance model showed that selective forgiveness of noncompliance is
optimal when the firm exerts a high level of compliance efforts. Yockey (2013) noted the
1961-2011 2012 2013 2014-2016
Literature Type
Peer-reviewed journal articles 139 169 287
Dissertations 60 50 100
Websites 30 50 175
Books and reports 25 68 113
Newspapers and editorials 80 105 280

FCPA is vague and often confusing about what qualifies as legal and illegal international
business transactions under the FCPA.
Hamilton (2012) maintained the regulatory compliance model functions because
people comply with the regulations and do the right thing. Hamilton indicated regulatory
compliance systems rely on the auditor’s review priorities and the appropriate penalties
imposed for noncompliance. Méndez (2014) maintained that individual desires for unjust
enrichment are the main factors that undermine regulatory compliance.
Joseph, Ngoboka, Mutebi, and Sitenda (2012) based regulatory compliance
successes on social values such as individual judgment, decision-making, and moral
calculus. The socioeconomic context of a country affects regulatory compliance
(Blackman, 2012). Governments of developing countries encourage industrial growth
over compliance; the intent is to remedy noncompliance with global industry regulations
(Blackman, 2012). Regulatory oversight influences regulatory compliance through the
rigorous government monitoring, enforcement, and prosecution of violators of
government compliance standards (Mande, Ishak, & Idris, 2014).
Corruption Model
Becker (1968) first discussed the corruption model in an essay on the economy of
crime and punishment and used economic analysis to develop governmental policies for
law enforcement officers to combat illegal behavior. Becker and Stigler (1974) presented
the concept of the corruption model by showing that corruption occurs due to poor law
enforcement. Becker and Stigler also indicated the violation of a law is a partial failure of
the law. Bowles and Garoupa (1997) complimented Becker and Stigler’s idea by

illustrating how the effectiveness of the government enforcement system diminishes
when the amount paid in bribes for a crime is less than the punishment for the offense.
Bowles and Garoupa extended the economic model of crime to include the process of
bribing a police officer for not disclosing the identity of a criminal.
Tullock (1996) based the corruption model on the premise that paying bribe fees
is usually less than paying required tax charges. Additionally, Tullock indicated the
complexity and ambiguity of the antibribery laws invite noncompliance with
anticorruption rules. The majority of people object to bribery on moral grounds without
considering that practical efforts such as corporate rent seeking, and complex
governmental laws could lead to corporate bribery to bypass local antibribery statutes
(Tullock, 1996). Furthermore, Tullock noted corporate funds received by a government
official as compensation for performing a task for the corporation are appropriate fees;
however, there is no differentiation between rent-seeking payments and bribes. Pillay and
Kluvers (2014) implied a country’s economic perspective, regulative structures,
government efficiencies, culture, and organization structures influence the levels of
corruption in that country.
Pillay and Kluvers (2014) used the institutional model to describe the influence of
organizational structure on corrupt actions. Eigen (2013) and Waldman (1974) defined
corruption as officials’ public misuse of the position to violate existing legal norms in the
country for personal gain. Waldman also indicated that business leaders participating in
corruption in a foreign country fall into four social categories: immoral, antagonist,
revisionist, or pragmatic.

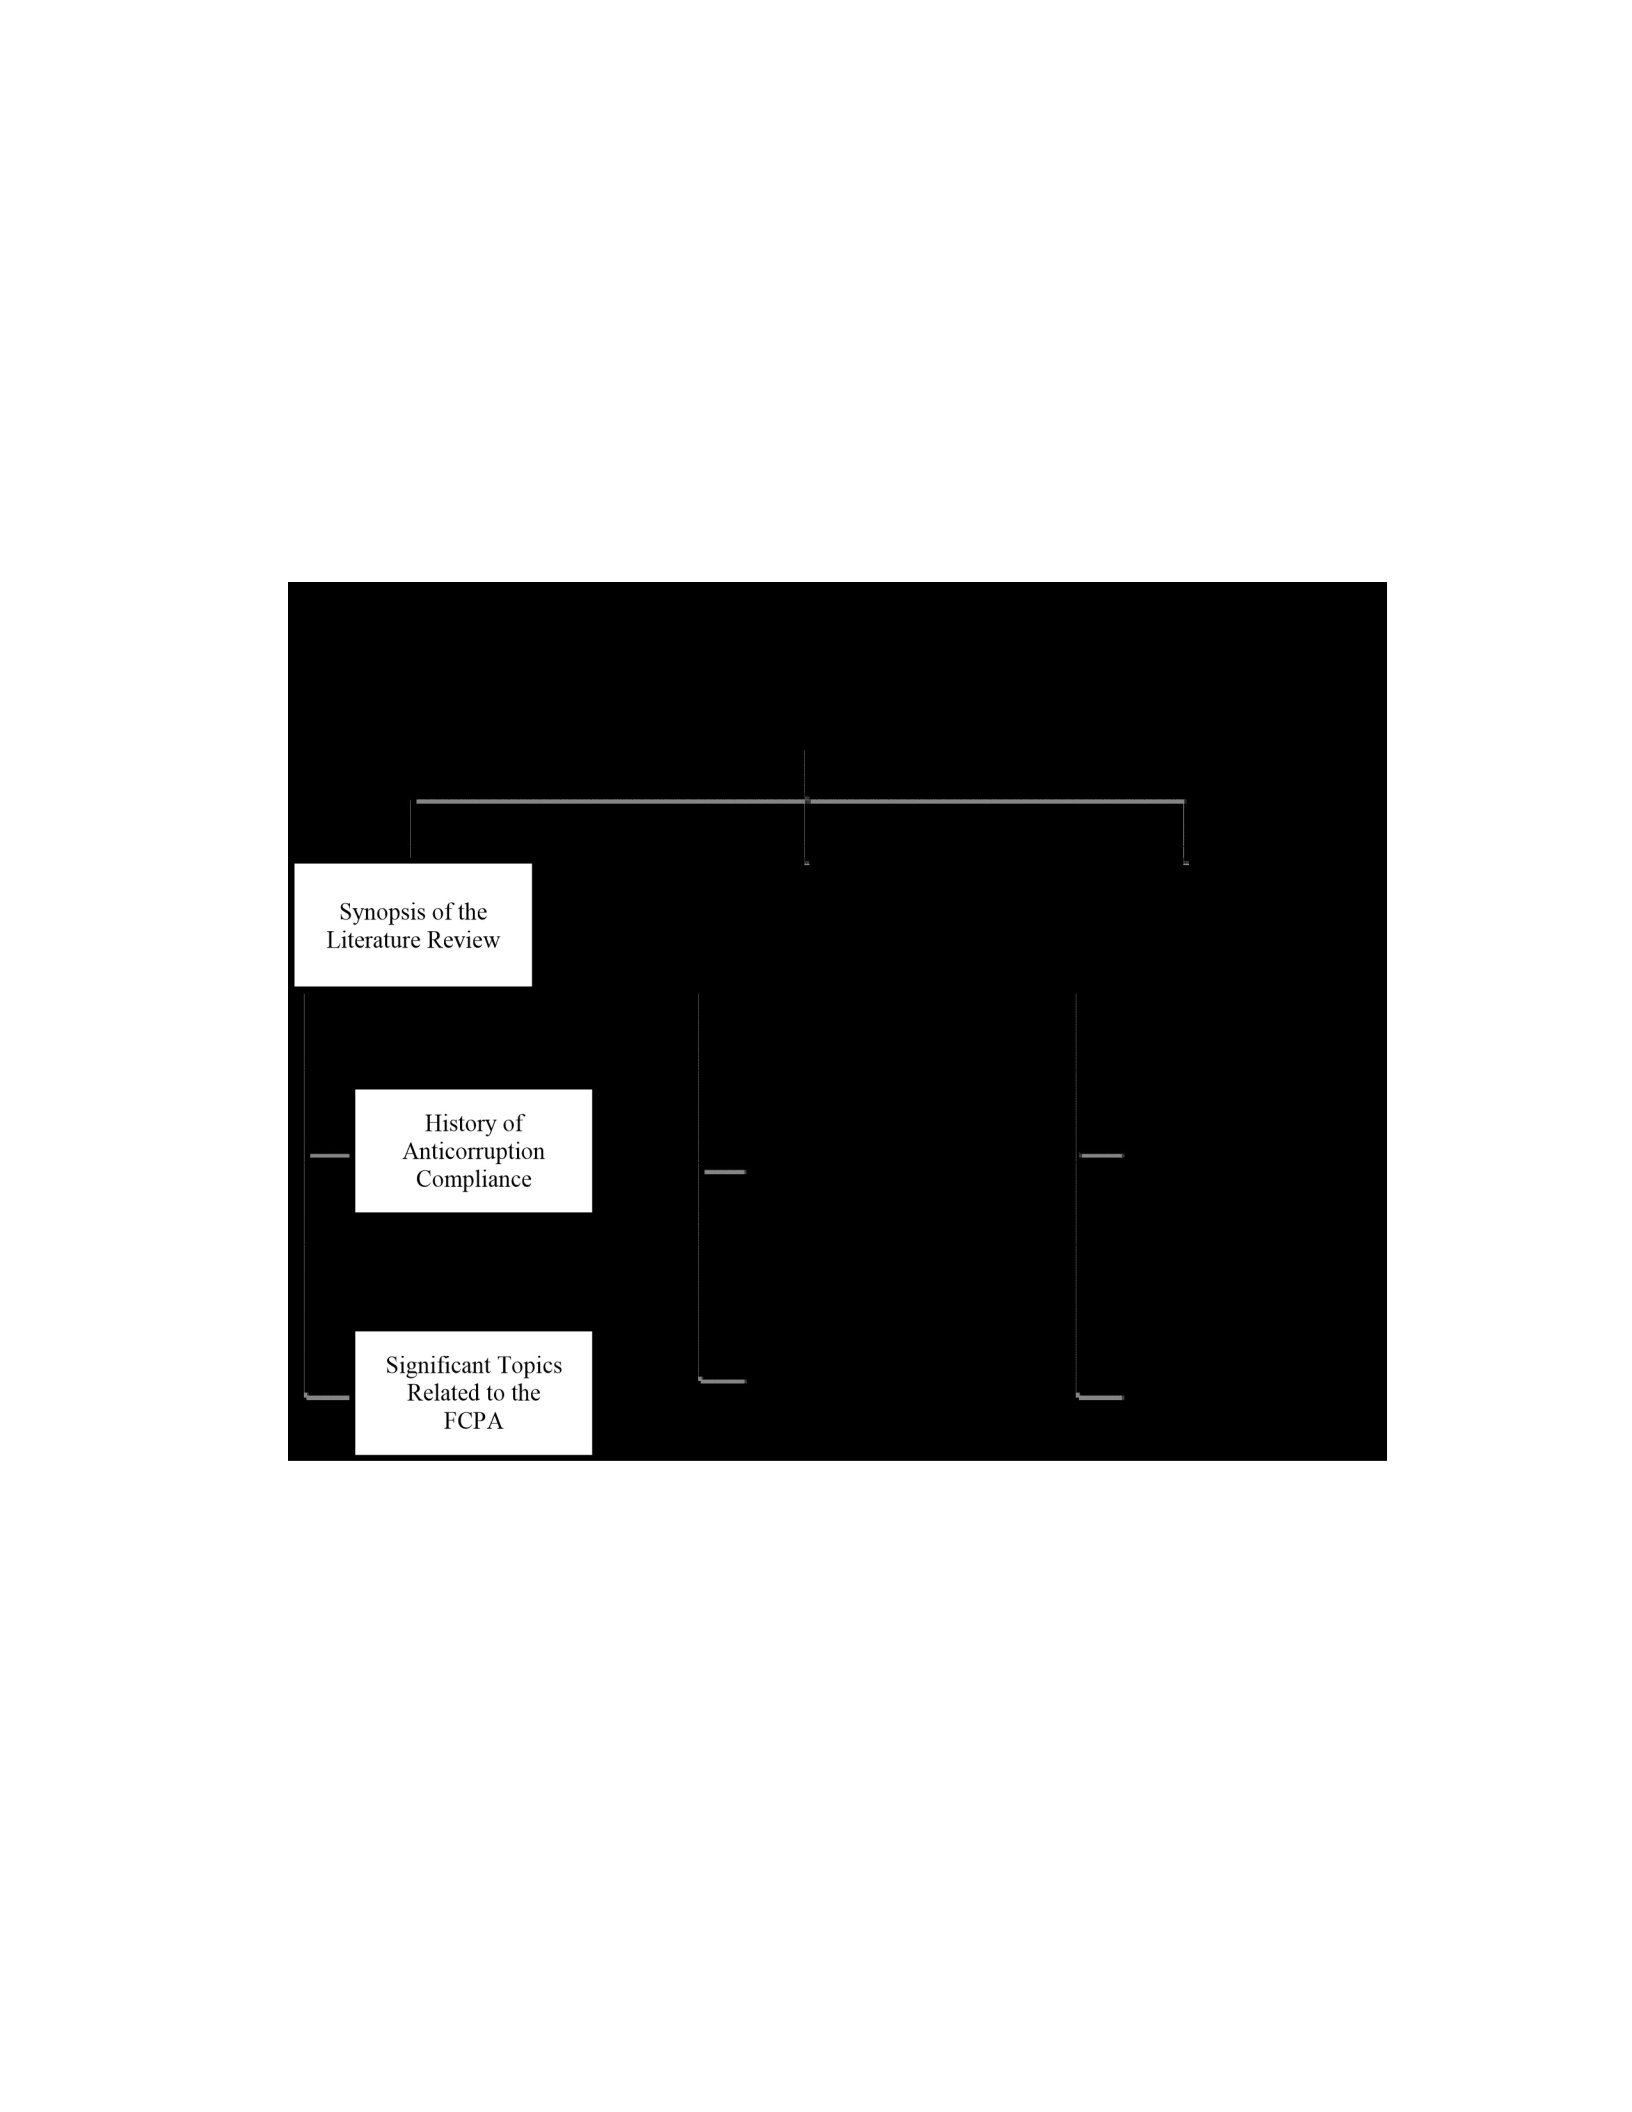
The main topics of the literature review are FCPA compliance strategies, a
synopsis of the literature, culture and corruption, self-regulation and corruption, and
anticorruption laws and local governments. The literature review includes other
subtopics, such as corporate FCPA internal compliance processes and self-regulation. The
subtopics of corruption history and significant topics related to the FCPA study explain
the development of strategic compliance with the FCPA. Other topics presented are the
crime and culture subtopics, including a country’s culture and corruption, company
culture and corruption, and the relationship between wealth and corruption.
Methodologies
To identify the suitable research methodology, an evaluation of the quantitative,
mixed, and qualitative methods was necessary. Based on the problem statement and the
literature reviews of similar studies, the qualitative methodology was the appropriate
method for this study. Yeoh (2012) applied the qualitative research methodology to
analyze the bribery act implications and compliance expectation from regulated firms in
the United Kingdom and the U.K. Bribery law expansion on FCPA expectations.
Karhunen and Kosonen (2013) applied a qualitative methodology approach in a study of
the strategic responses of foreign subsidiaries to host-country compliance with
anticorruption laws. Dhaher (2013) used the qualitative research methodology to study
the Palestinian Authority telecommunications regulation compliance with international
anticorruption laws. Dhaher, Karhunen and Kosonen, and Yeoh implemented the
qualitative research methodology in similar studies, which supported the selection of the
research approach for this study.
Literature Review Structure
The literature review structure for this study consisted of topics and subtopics
related to FCPA compliance strategies. Critical analysis and synthesis of peer-reviewed
articles related to the FCPA compliance strategies presented in the following paragraphs.
Figure 1 indicates the structure of the literature review.
Figure 1. A flowchart showing the structure of the literature review.
FCPA Compliance Strategies Used in the U.S. Aerospace Industry
The present FCPA and related amendments include general ambiguities, and
international governments do not adequately enforce the FCPA laws (Barker, Pacini, &
Sinason, 2012; Darrough, 2010). U.S. aerospace industry exports comprise 6% of total

U.S. exports (U.S. Census Bureau, 2012). The FCPA regulations significantly affect U.S.
exports, which amounted to $2.20 trillion in exports in 2012 (U.S. Department of
Commerce, 2013). Recent penalties imposed on the U.S. aerospace companies for
violating the FCPA prompted a need to examine the complexity of compliance
instructions for the FCPA (Cascini et al., 2012; Fox, 2010). U.S. industry leaders have
debated the need to make changes to the FCPA (Barker et al., 2012; Fraser, 2012;
Yockey, 2013). The following synopsis of the literature review includes a list of key areas
examined to ensure a clear understanding of the factors that influence global business
bribery and identify strategies used to comply with the FCPA.
Synopsis of the literature review. After a thorough review of more than 220
peer-reviewed articles related to the problem statement at the Walden University Library,
the following researchers emerged as establishing the literature underpinnings of this
study. Cascini et al. (2012), Klinkhammer (2013), Sanyal and Samanta (2011), and
Vanasco (1999) discussed the origination of the FCPA and the penalties related to
violations. Lord (2013) and Nell (2009) identified the relationship between governments’
types and fighting noncompliance with anticorruption laws. Weismann, Buscaglia, and
Peterson (2014) established that corporate leaders using the self-regulatory model of
corporate governance failed to comply with FCPA and to eliminate corruption in related
organizations.
Huang and Rice (2012) and Wedeman (2013) discussed the difficulties of
identifying international business bribery committed by multinational companies and the
lack of clear guidelines for management on how to deal with noncompliance with FCPA.

The literature review in this study encompassed an analysis of the lack of effectiveness of
the FCPA in reducing or eliminating international business corruption, using severe
penalties imposed on U.S. companies for FCPA violations. The literature review also
included a review of articles related to global governments’ involvement in fighting
crime, corporate self-regulations of corruption, and difficulties identifying international
noncompliance with the FCPA.
To ensure the completeness of the literature review, an extensive review of related
studies and relevant literature to the research topic is necessary (Moustakas, 1994). The
literature review included an extensive research of the Walden University Library
databases, including ProQuest, Academic Search Complete, ABI/INFORM Global, and
PsycINFO. Furthermore, the literature review included an exhaustive study of Walden
University Education Research Complete, ERIC, ScienceDirect, Emerald Management
Journals, SAGE Premier, and Business Source Complete databases. Other databases
searched included Google Scholar and local library databases on international business
corruption. A literature review involves examining books, websites, and peer-reviewed
studies related to the research question (Leedy & Ormrod, 2013). The literature review
included major topics related to complying with the FCPA and international business
corruption and includes support an annotated bibliography of related peer-reviewed
reference articles.
This study involved reviewing interpretations of FCPA compliance factors applied
in the U.S. aerospace industry and more specifically in the small-business aerospace
industry in California. This research involved identifying a set of interpretations of the

FCPA factors directly related to the small-business aerospace industry for fair
international market share. Akbar and Vujic (2014), Bierstaker (2009), and Eisenbeib and
Brodbeck (2014) explored the relationship between cultures, corruption, and different
attitudes toward compliance with antibribery laws. Results of such studies showed
corruption and noncompliance with the FCPA are more culturally acceptable in Eastern
countries than in Western countries, and Asian company executives are likely to engage
in bribes when managers encounter significant market competition.
The U.S. aerospace companies compete with Asian companies within Asian
markets. U.S. Companies are required to comply with the FCPA law when pursuing
international business. However, the FCPA law has limited reach to foreign companies
that are not listed on the U.S. Stock Exchange. The FCPA and related amendments bound
U.S. companies, but not Asian based companies that are not registered on the U.S. Stock
Exchange (Feld, 2013). Other areas of consideration are good government and the effects
of local laws on the enforcement of global anticorruption laws in corresponding countries
(Koike, 2013; Nathanson, 2013). International countries’ local laws lack the power
needed to enforce global anticorruption laws (Cuervo-Cazurra, 2008; Gao, 2011; Koike,
2013; Sanyal & Samanta, 2011). The form of government significantly affects the
enforcement of local antibribery laws (Bryane & Mendes, 2012; Ntayi, Ngoboka, &
Kakooza, 2013; Weismann et al., 2014).
Multiple studies have shown positive correlation relationships between a
country’s wealth, compliance with anticorruption laws, and corruption (Abdulai, 2009;
Mujtaba, Williamson, Cavico, & McClelland, 2013; Schofield, 2009). For example,

bribes are higher in developing countries than in developed countries (Abdulai, 2009).
Bierstaker (2009), Hess (2009), and D. Watson and Watson (2013) established a
relationship between corporate culture and corruption, where corporate behavior in
developing countries is a major factor that influences corporate crimes. Abdulai (2009),
Akbar and Vujic (2014), and Hess (2009) illustrated the relationship between
organizational culture, local laws, country wealth, and country culture. Koike (2013),
Schofield (2009), and Varottil (2013) discussed culture influence on the interpretation
and compliance with FCPA and the acceptance or elimination of corruption in a country.
The established relationships between corporate culture, local laws, country
wealth, and country culture influence the construct of the type of FCPA changes. The
FCPA changes are necessary to ensure the success of the California aerospace industry in
international markets. The literature review process involves focusing on the review and
evaluation of research conducted by others on the topic under study (Leedy & Ormrod,
2013). The focus of the literature review in this study was the examination of articles
related to the research question on the FCPA modifications needed by U.S. aerospace
companies in California.
History of anticorruption compliance. Corruptions, noncompliance with
anticorruption laws, and misuse of position power have occurred throughout history
(Singh & Singh, 2012). Corruption has existed since the development of a structured,
institutionalized society with leader–follower relationships (Singh & Singh, 2012).
Corruption also existed in the Egyptian Paranoiac era in 3000 B.C. and came through the
people’s offerings to the rulers (Warner & Scott, 2011). Greek philosophers such as

Aristotle and Plato referred to corruption in the Greek Classical era (Singh & Singh,
2012).
Corruption was documented in 30 B.C. in the Roman Empire, which occurred
through increased taxation on peasant farmers, by the ruling class (DeLorme, Isom, &
Kamerschen, 2005). The Roman governments changed from a democratic form of
government to increased misconduct through the rent-seeking behavior of the emperor
with virtually no compliance to anticorruption laws (Warner & Scott, 2011). The
corruption of the ruling class in the Roman Empire and the lack of a strategy to create and
comply with anticorruption laws were some of the factors that attributed to Roman
Empire’s failure in 476 A.D. (Warner & Scott, 2011). The Byzantine Empire also had
significant corruption and virtually no compliance with anticorruption laws, which
resulted in the loss of purpose and direction during the period between 1042 through1050
when Zoe and Constantine IX ruled Constantinople (Haldon, 2011).
Anticorruption laws and anticorruption strategies continued to be lacking in the
Byzantine Empire until period they lost power to the Ottoman Empire in 1453 (Haldon,
2011). In the late part of the 15th century and in the 16th century, corruption and
noncompliance with anticorruption laws continued in the Ottoman Empire with
documented evidence in court cases and imperial orders (Demirci, 2003). Evidence of
17th-century corruption and the lack of strategies to comply with anticorruption laws
appear in documented corrupt business practices during the relationship between the
English monarchy and the East India Company (Parkinson & Chew, 2013).

In the 18th century, corruption occurred in the Dutch tax-collecting process,
which prompted public discontent and resulted in tax riots (Kerkhoff, 2011). The tax riots
forced a radical alteration of the Dutch tax-collecting process, such as ending farm tax
collection by private tax collectors and starting institutional public tax collection in 1748
(Kerkhoff, 2011). In the 19th century, corruption existed in the United States, and
corruption continued to be visible in the building and operation of the U.S.
transcontinental railroads (Bogart, 2013). Railroad corruption occurred through bribes
given by railroad builders to government officials to ensure the continuous flow of
government funds to the projects (Bogart, 2013).
In the 20th century, the lack of compliance with anticorruption laws was present
and visible during the prohibition of the manufacture, sale, and transportation of alcohol
in the United States (Gaytan, 2014). In the 20th century, alcohol supplies came to the
United States from Mexico and Canada, which earned the smugglers millions of dollars
(Gaytan, 2014). The high demand for alcohol during the prohibition period by Mexicans
and the working class in the United States attributed to corruption in this market sector
(Gaytan, 2014).
Early in the 20th century, U.S. workers established labor unions to combat
corruption (Green & Isaacson, 2012). However, late in the 20th century, labor unions in
the United States experienced corruption, and leaders failed to comply with
anticorruption laws (Jacobs, 2013). The labor unions in this period controlled significant
financial resources, which allowed union leaders to bribe government officials and avoid
complying with anticorruption laws (Krinsky, 2013).

Buchheit and Reisner (1998) reported that Justice Holms in 1909 predicted that
the U.S. Department of Justice judges would struggle in how to extend U.S. laws
overseas, which may cause friction with other countries. U.S. Congress passed a law
known as the Helms-Burton Act in 1959 that extend the reach of U.S. laws outside of
U.S. territory (Buchheit & Reisner, 1998). The Helms-Burton Act was a federal law
created on behalf of U.S. citizens when the Cuban government confiscated U.S.-owned
property in Cuba (Buchheit & Reisner, 1998). The passage of the Helm-Burton Act led to
protests from other countries; however, an earlier proposed FCPA by Justice
HelmsBurton gained acceptance by the same countries that dissented against the Helms-
Burton Act (Buchheit & Reisner, 1998).
During the U.S. Watergate scandal in the early 1970s, researchers in the U.S.
Department of Justice uncovered questionable payments by global companies to
international government officials (Harris, 2011). The U.S. public was outraged at the
controversial payments, and the need to improve the international image of the U.S.
government led to the creation and introduction of the FCPA (Harris, 2011). As expected
with legislation, some people in Congress agreed with the FCPA and others disagreed
(Harris, 2011). Those who agreed believed that it was immoral and unethical for U.S.
companies to pay government officials in other countries (Harris, 2011). Those who
disagreed indicated compliance with the FCPA would hinder the competitiveness of U.S.
businesses overseas (Harris, 2011).
The FCPA passed in 1977 because of President Nixon and the Watergate scandal

(Feld, 2013). President Carter signed the FCPA into law in late 1977 (Cascini et al., 2012;
Feld, 2013). In the Watergate period, U.S. government officials discovered U.S.
aerospace and oil corporations allegedly bribed officials in other governments to gain
contracts (Cascini et al., 2012). The Trade and Competitive Act of 1988, as well as the
FCPA and related amendments, raised awareness of the need for additional internal
company anticorruption controls and strategies to comply with the FCPA (Vanasco,
1999). Company corruption allegedly occurred when foreign government officials
received bribes to gain contracts (Vanasco, 1999).
In the 21st century, lack of compliance with the FCPA is still present, and
employees of U.S. aerospace companies allegedly bribe international government
officials to gain contracts (Darrough, 2010). The FCPA, which is one of the significant
business corruption deterrents, applies to U.S. companies, U.S. company personnel, and
foreign firms trading on the U.S. Stock Exchange in U.S. territories (Feld, 2013). The
implementation of adequate controls to increase compliance with the FCPA in the 21st
century is helping to curb corruption (Sanyal & Samanta, 2011).
Researchers at the U.S. Department of Justice and the U.S. Securities and
Exchange Commission recorded only 72 cases of noncompliance with the FCPA by U.S.
industry in 2010 (Feld, 2013). Other countries such as Great Britain reduced corruption
by adopting the United Kingdom Bribery Act, in which 103 United Kingdom contractors
faced fines of 180.7 million pounds for corruption practices (Donohoe, 2011).
Developing countries created local anticorruption agencies to fight corruption (Doig &
Norris, 2012). The U.S. Department of Justice imposed a $2 billion penalty on Siemens

for an FCPA violation shows the vigorous enforcement of anticorruption laws in the
United States (Sanyal & Samanta, 2011). The Sarbanes-Oxley Act, passed by members of
U.S. Congress in 2002, holds executives personally liable for fraudulent acts committed
by corresponding corporations (Cascini et al., 2012).
Recent increases in FCPA enforcement in the United States led to debates
regarding the need for reforms to the act (Yockey, 2013). The ambiguity of the FCPA and
uncertainty among U.S. corporations and international business communities in how to
comply with the law led to the recent amendments to the FCPA (Vanasco, 1999). The
extensive literature review resulted in identifying international business compliance with
the FCPA and business corruption studies cited in this section. The annotated studies
include significant topics related to compliance with the FCPA that address the factors
influencing corruption in global business. The focus of this study was to identify the
FCPA compliance strategies used by U.S. aerospace small business leaders in California.
Significant topics related to the FCPA. Significant topics emerged from an
exhaustive literature review related to the research question. One of the topics that
emerged was the effect of countries’ culture on the development of corporate strategies
for compliance with FCPA (Baughn et al., 2010). Another topic was the influence of a
country’s wealth on compliance with anticorruption laws (Abdulai, 2009). Another topic
was the influence of corporate culture on the development of strategies to comply with
anticorruption laws (Bierstaker, 2009). Other topics included the failure of corporate
selfregulation to influence compliance with the FCPA (Yockey, 2013), as well as the
relationship between international and local anticorruption laws (Gao, 2011).

The relationships between a country’s culture, wealth, and compliance with FCPA
are significant for U.S. aerospace industry competitiveness in international markets
because such relationships clarify the contract governmental fees and influence pricing
strategies. The following subsections include discussions on the relationship between
culture and compliance with antibribery laws, self-regulation and corruption, and
enforcement of international and local antibribery laws. Also included in the following
subsections are discussions on the effect of the form of government, corporate culture,
local antibribery laws, and countries’ wealth on corporate compliance strategies for the
FCPA.
Culture and anticorruption compliance. National culture significantly
influences a country’s levels of corruption, where people in countries with high
masculinity and high levels of uncertainty avoidance are less compliant with
anticorruption laws than in countries with low masculinity and low levels of uncertainty
avoidance (Akbar & Vujic, 2014). Executives of multinational corporations need to assist
countries corruption and establish strategies on how to comply with the FCPA while
conducting business in such countries (Cleveland et al., 2010). Askari, Rehman, and
Arfaa (2012) indicated corruption occurs when public officials use of the public office for
unlawful private gains. Pacini (2012) defined bribery as the act of giving an item of value
to a public official in the hope of obtaining influence or benefits from the official during
the execution of official duties. National cultures shape the cultures of corruption at
different organizations and ultimately affect the strategies for complying with
anticorruption laws in organizations (Zaloznaya, 2012).

Different cultures use different interpretations of corruption and tolerate different
levels of corruption. Kumar (2013) discussed Indian corporate culture tolerance toward
corruption and the need for reforms to maintain the flow of international investments in
India. Gong and Wang (2013) explained the low tolerance levels of people in Hong Kong
toward corruption. In contrast, Bardhan (2014) showed the high tolerance levels of Indian
and Chinese populations toward corruption. Therefore, international business managers
need to understand the cultural tolerance and interpretations of corruption in their
assigned countries.
Some of the driving factors creating the cultural differences toward the
interpretation of corruption include level of power distance, level of uncertainty
avoidance, and the masculinity (Baughn et al., 2010). Power distance refers to the
relationship between executives and subordinates, and in high-power-distance cultures,
managers adapt paternalistic relationships toward subordinates, whereas in low-
powerdistance cultures, subordinates frequently question management decisions
(Winkler, Busch, Clasen, & Vowinkel, 2014). Researchers typically associate masculinity
with the level of aggression and assertiveness in a society, and corporations from high
masculinity societies tend to commit bribery to achieve corporate objectives (Baughn et
al., 2010; Schlaegel, He, & Engle, 2013). Uncertainty avoidance refers to society's
attitude toward the future and the population’s ability to deal with the inherent
complexities and ambiguities (Schlaegel et al., 2013). Corporations from low-uncertainty-
avoidance societies have the tendency to commit bribery to achieve corporate objectives
(Baughn et al., 2010). Understanding cultural differences, helps predict the severity of
domestic corruption and noncompliance with FCPA (Baughn et al., 2010). Cultural and
religious environments where firms conduct business influence behavior toward
corruption (Lee, 2012; Mensah, 2014; Pena Lopez & Sánchez Santos, 2014).
Quah (2013) and Smith et al. (2013) examined countries’ Corruption Perceptions
Index (CPI) scores and the numbers relationship to the levels of foreign investment in
such countries. Countries with low CPI scores had high corruption levels and were less
desirable for outside investors to invest in such countries’ projects. The FCPA laws forbid
employees of U.S. companies from bribing officials of foreign governments to obtain or
maintain business. The basis of complying with the FCPA is the theory of a self-
regulation process where leaders of a firm ensure compliance with the FCPA (Virginia &
Maurer, 2013; Weismann et al., 2014). However, in numerous cases, selfregulation was
not sufficient, and corporate governance failed to comply with the FCPA (Weismann et
al., 2014).
United Nations anticorruption laws failed to achieve intended goals because of the
lack of global enforcement power of such laws (Anechiarico, 2010). In the absence of an
international anticorruption-enforcing body, countries must rely on local anticorruption
agencies with little enforcement powers (Anechiarico, 2010). Anechiarico (2010)
contended that even though countries enacted local anticorruption laws, such local laws
often fail to enforce international anticorruption laws, including the FCPA. Strategies to
comply with FCPA by U.S. corporations need to include the FCPA international
enforcement limitations for countries where local laws have limited enforcement powers
(Virginia & Maurer, 2013).

Ethical issues, legal factors, and business growth challenges faced by international
firms when conducting business in the People’s Republic of China have deep roots in the
Eastern culture (Wen, 2013). O’Neill (2014) and Wen (2013) showed the effect of
foreign direct investment (FDI) into China on Chinese business strategies for compliance
with international anticorruption laws. Wen (2013) described the problems leaders of
foreign firms faced when conducting business in China, including low levels of
accountability, lack of transparency to the rule of law, and economic inefficiencies.
Highpower-distance cultures where managers adapt paternalistic relationships toward
subordinates harbor corruption more than low-power-distance cultures where
subordinates question management decisions and offer personal opinions (Yeganeh,
2014). O’Neill (2014) and Wen (2013) showed how noncompliance with anticorruption
laws affects competitiveness and profitability, cultural and ethical values, human rights,
civil liberties, protection of workers, and the destruction of the natural environment
related to sustainable development.
Wedeman (2013) and Zheng et al. (2013) indicated business bribery could be
difficult to identify in different cultures, and a company employee can hide bribes under
entertainment and travel expenses. In contrast, Mujtaba, Williamson, Cavico, and
McClelland (2013) contended the corruption levels in target countries determine a
country’s success in international business. Mujtaba et al. examined 10 Asian members of
the OECD that have similar laws regarding foreign corrupt practices.
Huang and Rice (2012) blamed corruption on the lack of corporate directives
written for global business leaders to follow in bribery situations and the lack of corporate

strategies to comply with international antibribery laws, including FCPA. Akbar and
Vujic (2014) and Grimes (2013) attributed business corruption to the different
interpretations of corruption in rules-based Western cultures versus relationship-based
Eastern cultures. Galang (2012) showed an organization’s characteristics and operating
environment significantly influence the levels of corruption, including the government’s
structure. Zhou, Han, and Wang (2013) noted Asian business leaders are more likely to
use bribery when facing market competition, corrupt local court systems, inefficient local
government, and high local taxes. Huang and Rice showed the significance of expatriate
executives in the corruption process and related cultural dilemmas when confronting
corruption in a host country. Expatriate managers encounter cultural difficulties with
corruption when differences exist between the host country’s culture and a corporate
culture’s interpretation of corruption (Huang & Rice, 2012).
Fighting corruption and compliance with FCPA across cultures is difficult due to
the different cultural perspectives and attitudes toward crime (Bierstaker, 2009). The
differences in attitudes by executives and employees toward FCPA compliance result in
varying interpretations of the corruption legislation (Bierstaker, 2009). Howson (2012)
and Sung (2012) examined the influence of gender on corruption in different cultures and
showed major differences toward crime between men and women, where they found that
women comment less business fraud than men do.
Akbar and Vujic (2014) and Bierstaker (2009) analyzed the differences between
cultures and corresponding tolerances to FCPA noncompliance. Corruption could be a
regular part of conducting business in a particular culture and an unacceptable act in

another culture; which makes compliance with FCPA more complicated (Akbar & Vujic,
2014; Bierstaker, 2009). Leaders of multinational corporations can reduce corruption
through global corporate directives sensitive to cultures that when their international
managers follow this instruction can achieve a reduction in business crimes and comply
with FCPA (Bierstaker, 2009; Huang & Rice, 2012).
Baughn et al. (2010), Anechiarico (2010), Akbar and Vujic (2014), and Eisenbeib
and Brodbeck (2014) used bribery, nepotism, and malpractice as examples of corruption
and related effect on the development of corporate strategies to comply with FCPA in
such countries. Huang and Rice (2012) analyzed the effects of consumer resource
availability in importing countries, the physical distance between importing and exporting
countries, and the cultural differences between importing and exporting countries.
O’Neill (2014) and Wen (2013) analyzed relationship influences versus information-
oriented influences on bribery and the effects of corruption on corporate success. The
identified cultural aspects are major elements to consider when addressing needed FCPA
modifications related to the U.S. aerospace industry in California.
Countries’ wealth and anticorruption compliance. The wealth of a country plays
a significant role in a nation’s approach to corruption. Wealthy countries in particular
instances contribute to the exportation of corruption. Studies of bribery showed one third
of the employees in European companies believe leaders would use bribery to gain new
business (Valentine, Godkin, & Vitton, 2012). At the 2009 OECD Forum on Fighting
Corruption, Schofield (2009) reported the magnitude of global bribery is reaching
trillions of dollars yearly.

In 2009, members of the OECD met to emphasize the need for additional controls
to reduce global business corruption (Schofield, 2009). G. Wilson and Wilson (2014)
maintained the world financial crisis occurred due to the failure of governments and the
laws used to predict and punish companies for employees’ financial misconduct. Graeff
and Svendsen (2013) showed a strong relationship between wealth and corruption in 25
European countries. Abdulai (2009) related poverty to the level of corruption and
supported the argument using GDP per capita, where lower GDP correlates with higher
corruption. However, Abdulia’s small sample size was not conclusive.
Abdulai (2009) and Graeff and Svendsen (2013) noted wealthy countries foster
less corruption than developing countries. However, Schofield (2009) and G. Wilson and
Wilson (2014) indicated the political will to fight corruption in developing countries
influences the levels of corruption. The desire to maintain an industrial base in wealthy
countries requires wealthy country policy makers to engage in protectionism (G. Wilson
& Wilson, 2014). The aspiration of organizational leaders in rich countries to gain global
market share creates a condition that invites noncompliance with anticorruption laws (G.
Wilson & Wilson, 2014).
According to Mujtaba et al. (2013), there is a significant linear relationship
between the wealth generation of a country and the country’s level of noncompliance
with FCPA through corruption. Understanding a country’s wealth effect on corruption is
essential for identifying possible FCPA compliance strategies related to the aerospace
industry in California. Understanding the relationship between state wealth and

corruption could help corporations in the formulation of FCPA compliance policies.
Knowledge of a country’s wealth relationship to crime influences the development of the
FCPA compliance strategies used by the aerospace industry in California.
Corporate culture and anticorruption compliance. Corporate culture
significantly affects the development and execution of FCPA compliance strategies
(Bierstaker, 2009). Clear guidelines regarding proper ethical behavior when conducting
business in the international markets affect corporate culture (Bierstaker, 2009). Global
corporate citizenship requires compliance with antibribery laws by small, medium, and
large enterprises (Galpin, 2013; Inyang, 2013). Small and medium enterprises account for
90% of worldwide business (Galpin, 2013; Inyang, 2013), and small and medium
enterprise leaders need to establish an anticorruption policy and create an FCPA
compliance program to ensure international business leaders avoid bribery situations
(Jorge & Basch, 2013).
Adeyeye (2014) maintained that corruption consists of a demand and a supply
side, as in every economic situation. Adeyeye also showed that leaders of corporations
needed to address the two sides of the crime simultaneously to effectively curb corruption
and achieve FCPA compliance. Leaders of organizations play a significant role in
eliminating corruption in international business by complying with FCPA (Adeyeye,
2014; Bierstaker, 2009). Furthermore, Adeyeye and Bierstaker indicated a favorable
investment climate does not necessarily reduce crime. In contrast, Alexeev and
Habodaszova (2012) and Dechenaux, Lowen, and Samuel (2014) revealed time pressure,

urgency to increase revenues, and the size of bribes are situational factors influencing
leaders’ decisions regarding corruption.
Chinese business leaders’ personal philosophies and ethical views play a
significant role in the interpretation and participation in unethical business activities
(Feldman, 2014; Lu, Ling, Wu, & Liu, 2012). Hess (2009) indicated a lack of corporate
commitment to combating corruption and the expansion of the definition of crime in
criminal law have a significant role in curbing corruption and FCPA compliance.
National culture influences corporate culture regarding how corporate leaders view
bribery and the potential of employees to engage in bribery when conducting business
overseas (Choudhary, 2013; Klinkhammer, 2013).
Ethical and unethical forms of networking facilitate corruption (Bhatt & Bhatt,
2013). Companies and individuals can benefit from belonging to a social network system
because of mutual understanding (Bhatt & Bhatt, 2013). Knowledge networking, which
includes utilitarian networking, emotional networking, and virtuous networking, is a
human activity with an ethical dimension (Huang & Rice, 2012). Acting within the moral
dimension of a network contributes to the creation of trust and harmony within the
network (Bhatt & Bhatt, 2013). Corruption occurs when an undeserving candidate
receives government benefits because an intermediary agent bribed government officials.
The result is noncompliance with anticorruption laws (Sabie, 2012; White, 2013).
Numerous factors can influence the corporate anticorruption culture, and
anticorruption organizations can be successful in adverse environmental conditions
(Vaccaro, 2012). A close inspection of the relationship between a culture of

noncompliance with anticorruption laws and developing culture is necessary (Akbar &
Vujic, 2014; Pena López & Sánchez Santos, 2014). Corruption and noncompliance with
anticorruption laws are acceptable in numerous cultures including Chinese, Vietnamese,
and Burmese cultures, where using an intermediary to facilitate corporate transactions
through bribes between government officials and the corporation is the norm (Feldman,
2014).
Compliance with local government anticorruption laws influences corporate
culture, corporate liquidity, and control of corporate corruption (Bryane & Mendes,
2012). Company leaders need to be proactive to ensure compliance with the FCPA.
Company leaders should also maintain procedures in place to ensure corporate
compliance with the FCPA (Fox, 2010). Companies should have global standards and an
ongoing auditing program to ensure proper governance and accountability (Badamasiuy
& Bello, 2013; Wanyama, Burton, & Helliar, 2013). Corruption negatively affects the
development of developing countries, and governments must demand strict compliance
with anticorruption laws (Abdulai, 2009). Abdulai (2009) concluded fighting corruption
in a sustainable manner requires a genuine and strong commitment from the top political
elite within a country.
Corrupt organization leaders create organizational cultures and establish work
structures where employees facilitate corruption on a daily basis without being aware that
something illegal is occurring (Campbell & Goritz, 2014). Corporate culture, including
management behavior toward corruption as well as corporate procedures, affects
employees’ behaviors toward bribery (Braje & Galetic, 2014; Tilley, Fredricks, &

Hornett, 2012). An analysis of the relationship between corruption and gender in
corporate cultures revealed no relationship exists between gender and corruption
(Howson, 2012; Sung, 2012).
The relationship between networking and openness in companies increases the
tendency toward greater bribery, noncompliance with anticorruption laws, and corruption
(Huang & Rice, 2012). Cascini et al. (2012) analyzed the inclusion of FCPA compliance
in the corporate code of ethics and employee training and the ways compliance with the
FCPA can lead to an antibribery corporate culture. One of the limitations of Cascini et
al.’s study was the author's focus on big business’ compliance with FCPA. Current trends
in FCPA enforcement are ineffective, and the integration of the FCPA into corporate
culture through value-based management strategies could improve FCPA compliance at
both small and large companies (Lestrange & Tolstikov-Mast, 2013).
Self-regulation and anticorruption compliance. Based on Weismann et al.
(2014), the self-regulation approach in U.S. industries has been unreliable and has failed
to enforce compliance with FCPA due to the concentration of power at U.S. major
institutions. Self-regulation has also been ineffective because corporate stakeholders have
failed to control the ethical business behavior of organization members. In contrast,
Yockey (2013) and Sethi and Schepers (2014) attributed self-regulation failure to a lack
of governmental regulatory resources, which forced authorities to rely on voluntary
corporate self-disclosure. Adegbite (2012) noted the corporate governance failures of
self-regulation in Nigeria increased corruption, and good corporate governance is
necessary to curb corruption in the country. Weismann et al. identified U.S. corporate

leaders as the primary reason for self-regulatory failure in enforcing FCPA compliance
due to leaders’ engagement in questionable financial schemes and the way leaders
continually shifted risks to innocent parties.
The failure of the corporate FCPA self-regulatory model to control corruption has
deep roots in the theory of self-regulation (Virginia & Maurer, 2013; Weismann et al.,
2014). Burger (2012) noted neither self-regulation nor government oversight leads to a
dramatic reduction in FCPA compliance, although the combined efforts of the two
systems could result in a needed reduction in corruption. In contrast, Blackburn (2012)
attributed corruption to the misuse of government-delegated power, as seen in the
relationship between the differing powers given by the government through the
delegation of authority to bureaucrats. Blackburn further showed the delegation of
government authority to bureaucrats gives government officials the administrative
discretion to collect bribes from the public and invites noncompliance with anticorruption
laws. Blackburn indicated there is evidence of the negative effect of bribes on economic
growth because corruption diverts money from a country’s economic growth activities
into power-seeking activities.
Ionescu (2013) contended technological improvements introduced through
egovernment databases significantly affected the reduction in corruption. Weismann et al.
(2014) revealed self-regulation is not sufficient to reduce bribery or increase FCPA
compliance, and it is essential to maintain oversight and good governance to promote and
maintain economic growth. Blackburn (2012) indicated the delegation of government

powers to public officials can create opportunities for corruption, and monitoring systems
are necessary to ensure corruption is not present.
Technology such as e-government would be effective in increasing compliance
with antibribery laws, lowering the levels of corruption, and potentially increasing
specific types of bribery in the public sector (Ionescu, 2013; Ojha & Palvia, 2012).
Blackburn (2012), Weismann et al. (2014), and Yockey (2013) indicated self-regulation
is not sufficient in fighting corruption and increasing FCPA compliance. Government
oversight is necessary to ensure compliance with anticorruption laws. Ionescu (2013) and
Weismann et al. (2014) discussed the role of technology in monitoring compliance with
antibribery laws and limiting corruption. Effective corporate self-regulations and
government oversight of FCPA compliance using technology-monitoring processes
reduces FCPA violations by U.S. corporations (Weismann et al., 2014; Yockey, 2013).
International and local anticorruption compliance laws. International
antibribery laws remain unenforced and conflict with local country laws (CuervoCazurra,
2008; Darrough, 2010). The Chinese government’s intervention in the cause of bribery on
behalf of the bribing company influences the company’s bribing behavior (Gao, 2011). In
contrast, Nell (2009) contended the government should intervene and treat contracts as
valid to avoid additional costs and legal complexity. China antibribery laws possess
severe penalties; however, enforcing the laws is difficult. In contrast, the enforcement of
Canada’s Corruption of Foreign Public Officials Act was successful and reached the $10
million range in enforcement penalties (Keith, 2014). Good governance in Singapore

reduced corruption, increased compliance with anticorruption laws, and led to
Singapore’s success in attracting international business (Jon, 2013).
Adeyeye (2014) discussed the effect of creating a governmental mechanism for
combating bribery in Singapore, such as the Prevention of Corruption Act and related
limited successes in fighting corruption. Cuervo-Cazurra (2008) showed noncompliance
with anticorruption laws had no effect on the flow of FDI funds to corrupt countries.
Antibribery international laws need global coordination to ensure effective compliance
and a level playing field for participants (Cuervo-Cazurra, 2008). Saleh (2014) showed a
lack of focus on internal compliance audits of antibribery laws, government oversight,
and appropriate justice procedures are factors in the corruption problems in Iraq.
Gao (2011) revealed government leniency toward bribing firms might send the
wrong message to such firms that reduce compliance with antibribery laws. In
comparison, Nell (2009) asserted that governments occasionally might need to intervene
and accept contracts obtained through bribery as valid contracts to avoid costly legal fees
and legal complexity. Sanyal and Samanta (2011) indicated the enactment of national
antibribery laws, coupled with vigorous transnational enforcement of compliance with
international antibribery laws, influenced the levels of bribery with no effect on FDI
funds. In contrast, Quazi, Vemuri, and Soliman (2014) maintained corruption and
noncompliance with antibribery laws in the short term positively affect FDI, but
ultimately negatively affects a country’s economic growth. Moreover, Quazi et al.
indicated market size, government effectiveness, infrastructure, and economic freedom
affect FDI significantly.

Gao (2011), Nell (2009), and Cuervo-Cazurra (2008) discussed government
enforcement of compliance with international and local anticorruption policies and the
need for transnational enforcement of international antibribery laws. Adeyeye (2014) and
Darrough (2010) discussed the lack of compliance with current international antibribery
laws due to conflicts with local laws intended to enforce the international laws. However,
Jura, Aninat, and Mefford (2014) indicated an increase in transnational lawsuits by U.S.
courts related to compliance with FCPA, even when the originating country is not a
signatory of international anticorruption laws.
Government from, local laws, and anticorruption compliance. This section
includes an examination of the immoral and unethical aspects of bribery discussed in the
principal provisions of the antibribery compliance legislation, including the FCPA,
OECD, United Nations Convention Against Corruption, and laws of participant countries.
The World Bank analysts estimated international bribery at $1 trillion per year and
corruption at $2.5 trillion per year, which amounts to 5% of global GDP (Cleveland et al.,
2010). Cleveland et al. (2010) showed the effects of the FCPA and the FCPA’s
antibribery compliance provisions, the OECD organization, and local antibribery laws
and policies as evidence of progress in fighting international bribery.
The large fines paid in 2010, including the Siemens company payment of $1.6
billion for FCPA violations, showed active observation and compliance with the
antibribery law (Fox, 2010; Turk, 2013). However, legal complications deeply rooted in
antibribery noncompliance cases are concerns in countries such as the United Kingdom
because of the law’s effectiveness (Virginia & Maurer, 2013). Schmidt and Gualmini

(2013) illustrated how the form of government and government leadership in Italy
influenced corruption in Italy, which reduced the domestic wealth of the country.
Henning (2009) focused on financial crimes in Roman-Dutch law and showed how
Roman laws had a greater effect than the current fraud laws, which would be more
efficient in combating financial corruption in the 21st century. Lash and Batavia (2013)
indicated property rights are the biggest sources of corruption, and reforms of antibribery
laws are necessary for diverse legal systems. Mitchell, Merrington, and Bell (2014)
showed 117 studied countries had local anticorruption laws in place, but 50% of the
countries had low CPI scores, which indicated the need for more oversight.
Cleveland et al. (2010) suggested conducting additional studies to monitor and
examine progress in fighting the battle against noncompliance with anticorruption laws
and transnational bribery, including human rights and environmental protection
dimensions. In contrast, Bryane and Mendes (2012) contended the form of government
and local laws significantly affect noncompliance with antibribery laws and corruption in
a country where bureaucrats demanded bribes as a condition for project approval. Two of
the weaknesses of Bryane and Mendes’s study were the geographical and theoretical
limitations in the scope of the study.
Ntayi et al. (2013) indicated economic changes and the form of government used
in the procurement of public infrastructure projects are critical factors that contribute to
corruption in Ghana. In comparison, Goel and Nelson (2011) contended in the United
States, the levels of FCPA noncompliance and corruption related inversely to the wealth
and level of education of state populations. Goel and Nelson derived conclusions from

empirical models of individual state convictions of corrupt public officials measured over
a 5-year period. Goel and Nelson also derived conclusions over a longer period of crime
across states.
Religion in the United States has shown no effect on FCPA compliance or
corruption levels; however, an association exists between greater prosperity and lower
corruption (Goel & Nelson, 2011). Gjinovci (2013) showed the informal economy in
transition countries fosters corruption due to the lack of public understanding and
willingness to participate in the enforcement of anticorruption laws. Feldman (2014)
revealed other methods used in business corruption monitoring such as using
intermediation between corrupt government officials and recipient candidates for
government services. Noncompliance with antibribery laws and corruption occurs when
an undeserving candidate receives government benefits by using an intermediation agent
bribing of government officials (Feldman, 2014). Corrupt officials can offer services to
individuals not entitled to government services for a price (Sabie, 2012; White, 2013).
One area not investigated was the effect of potential collusion between officials and
intermediaries.
Lawyers at the U.S. Department of Justice frequently used criminal and civil
actions as an instrument to reduce corruption and increase FCPA compliance in global
markets (Jennings, 2013; Virginia & Maurer, 2013). The increase in civil actions is not
necessarily due to a failing criminal system, but is a result of suitable recovery
alternatives. Civil actions against corruption occur when company leaders need to take
decisive and immediate action for rehabilitation and compensation. Tas (2012) showed

local laws in Iraq need amendments to allow Iraq’s legislation to address money
laundering and financial institutions’ noncompliance with anticorruption laws. Another
form of noncompliance with antibribery laws is corporate tax evasion, where the practice
of bribing government officials results in corporate tax avoidance (Alexeev &
Habodaszova, 2012; Fakile & Adegbie, 2012).
This section included a review of Cleveland et al. (2010), Fox (2010), and
Virginia and Maurer’s (2013) research on governments’ role in enforcing FCPA
compliance. The section included a discussion of government influences controlling
corruption and the enforcement of compliance with local and international anticorruption
laws. Bryane and Mendes (2012) and Goel and Nelson (2011) indicated key public
contracts are more vulnerable to corruption as well as tax evasion because of government
officials’ roles in fostering corruption. Because of government-related corruption, an
examination of local and international anticorruption law enforcement is necessary for the
context of FCPA compliance strategies needed in the California aerospace industry.
In summary, the reviewed literature showed the effects of cultural, wealth,
corporate self-regulation, and forms of government in fighting business corruption and
the need for effective corporate compliance strategies to comply with antibribery laws.
Bryane and Mendes (2012), Cleveland et al. (2010), Fox (2010), Goel and Nelson (2011),
Ntayi et al. (2013), and Virginia and Maurer (2013) indicated compliance with FCPA in
global business depends on (a) the form of government, (b) corporate self-regulation, (c)
local enforcement of international anticorruption laws, (d) a country’s wealth, and (e)
organizational culture. The literature review provided the context for explaining and

understanding the elements of the improved business practice of the study on exploring
aerospace business changes in the FCPA.
Transition and Summary
This section included a discussion of global corruption in business, bribery’s
historical background, and corruption growth in the international market. This section
also included organizational bribery, FCPA compliance, and other international
antibribery laws. The section encompassed the history of FCPA compliance strategy
problems, the problem statement, the nature of the study, the objective, the research
question, and the significations of the study to the aerospace industry. Furthermore, this
section included a description of the theoretical framework, the transformational
leadership theory, the corruption model, and the regulatory compliance model, including
the models’ suitability for this case study. This section included the assumptions,
limitations, delimitations, and anticipated social change, as well as a review and synthesis
of the academic literature related to culture and compliance with antibribery laws,
selfregulation of bribery, enforcement of international laws, and enforcement of local
antibribery statutes.
Additionally, this section included a discussion of a country’s wealth and a
country’s effect on bribery, FCPA compliance, and corporate culture and related effect on
corruption. Section 2 includes the role of the researcher, participants, sampling, data
collection, data analysis, research method and design, data validity, and data reliability.
Section 3 includes a discussion on the application of the findings to professional practice
and recommendations for further research. Furthermore, Section 3 includes an overview

of the study, a presentation of the data, the findings, applications of the results to global
management professional practice, and social change implications.
Section 2: The Project
Aerospace companies in California are losing international business due to
briberies by foreign competitors. From 1994 to 2001, U.S. companies, including the
aerospace industry, lost $200 billion of foreign trade contracts to competitors allegedly
bribing government officials to win new contracts (Darrough, 2010). Corruption in the
aerospace industry is an international business problem in which government officials
around the world use position and power for illegal financial gains through bribes
(Blackburn, 2010).
To combat international corruption, U.S. Congress approved the FCPA in 1977 to
preclude a particular class of persons and entities namely U.S. companies, U.S.
individuals, and foreign companies listed on the U.S. Stock Exchange from bribing
government officials to obtain or retain business (Vanasco, 1999). Dissenters against the
FCPA in the U.S. Congress contended that compliance with FCPA would negatively
affect U.S. business (Harris, 2011). The U.S. Fortune 500 companies’ annual
international business losses to competitors due to competitors’ noncompliance with the
FCPA are over $36 billion of potential new business (Thompson & Medina, 2012). The
primary focus of this research study was to identify the FCPA compliance successful
strategies used by leaders in a small California aerospace company.
Purpose Statement
The purpose of the qualitative single case study was to identify the strategies U.S.

aerospace small business leaders use to comply with the FCPA. The study population
consisted of business leaders at a small U.S. aerospace company in California that was
operating in the international market, had not received any FCPA penalties, had a good
international business record of accomplishment, and was successfully complying with
the FCPA. The selected population was appropriate because the population is part of
California’s aerospace industry, which represents 47% of the aerospace industry’s
engineering and product development in the United States (U.S. Department of Labor,
2012). The findings of this study showed successful small business strategies for FCPA
compliance are expected to reduce the cost of conducting global business and lead to an
increase in the number of U.S. aerospace jobs while demonstrating social integrity. This
is important because Lestrange and Tolstikov-Mast (2013) and Lord (2013) indicated that
reducing crime in business transactions results in positive social changes such as
improving the safety of people and organizations, reducing the cost of conducting
business, and improving the quality of life for individuals and communities.
Role of the Researcher
I was the primary data collection instrument in this qualitative single case study.
The role of the researcher is to ensure the data collected are valid and reliable (Leedy &
Ormrod, 2013). Networking, collaborating, managing the analysis, performing the
research, and collecting data are part of the researcher role (Kyvik, 2013). Researchers
must ensure safety and confidentiality while paying close attention to researcher behavior
during the interviews to avoid harming the participants (Gibson, Benson, & Brand, 2013).

My work as a researcher was informed by my having held a senior executive
position in the aerospace industry for over 28 years, including significant exposure to
international business development and contract negotiations. This aerospace experience
was helpful in contacting participants and asking members to participate in the study. The
basic ethical principles applied throughout the research process involved informing the
participants of the right to have a safe environment for the interview, receiving an
informed consent form (see Appendix A), and explaining a participant’s right to
terminate the interview without giving a reason for ending the interview.
Participants signed consent forms collection process occurred before the
interviews begin. I took steps to maintain the highest level of ethics and to comply with
the Belmont Report protocol by focusing on the well-being of the research participants.
The authors of the Belmont Report principles primarily focused on the well-being of
study subjects, including specifying steps to protect participants’ anonymity, safety,
vulnerability, and right to terminate the interview without giving an explanation, as well
as the data protection process (Bromley, Mikesell, Jones, & Khodyakov, 2015). Rogers
and Lange (2013) indicated the Belmont Report protocol protects vulnerable research
populations from potential exploitation. Strause (2013) described the three principles of
the Belmont Report protocol as autonomy, beneficence, and justice for study participants.
Researchers should ensure no harm comes to participants due to participation in a
study (DuBois et al., 2012; McKee, Schlehofer, & Thew, 2013). Further safeguards
during the data collection process must prevent risks to participants because of joint
involvement in the study (Durham, Brolan, & Mukandi, 2014; McInnes et al., 2012).

Researchers should ensure the data collection is nonintrusive, and participants can stop
the interview without giving a reason for the decision (Hassali, Siang, Saleem, &
Aljadhey, 2013; Yuan, Bartgis, & Demers, 2014).
Biases can occur due to preexisting knowledge and experience with the topic
under study; I therefore took steps to use a nonpersonal lens to view the collected data to
help mitigate potential biases. A plan existed to ensure personal biases do not affect the
performance of this study through careful note taking, performing data triangulation,
category coding, and using open-ended questions during the interviews. Additionally, I
focused solely on the answers to the interview questions as presented by participants, a
review of company policies, and personal reflective journal. Kache and Seuring (2014)
and Lituchy, Ford, and Punnett (2013) indicated open-ended questions, content analysis
supplemented by contingency analysis, and individual category coding reduce researcher
bias in a study. Researchers can minimize personal biases, but eliminating individual
biases is often difficult (Kache & Seuring, 2014; Ülle, 2014). I therefore also practiced
triangulation after collecting the data to reduce researcher bias, as recommended by
Kauppinen-Räisänen et al. (2014) and Lin, Wu, and Hua-Ling (2013).
The semistructured interview protocol (see Appendix B) used in this study to gain
insight on participants’ strategies for FCPA compliance served to encourage members to
discuss personal experiences with FCPA compliance and provided an opportunity for
follow-up questions. Using a semistructured interview protocol creates an open,
nonthreatening environment for the participants (Burgess & Wake, 2013; Rodrigue,
Riopelle, Bernat, & Racine, 2013). Researchers use semistructured interview protocols to
encourage participants to discuss individual experiences with a phenomenon (Hohl,

Gonzalez, Carosso, Ibarra, & Thompson, 2014). Using the semistructured interview
protocol provided insights into the strategies corporate leaders use for FCPA compliance
and an opportunity to ask follow-up questions (Burgess & Wake, 2013; Fox, 2010).
Participants
The participant eligibility criteria for this study were that participants must be
executives at a small U.S. aerospace company in California and have at least 1 year of
experience addressing FCPA compliance. Experiences with the research phenomenon
forms the basis of a study’s participant selection criteria (Minis et al., 2014; Moustakas,
1994). My selection of participant criteria aligned with DeFeo (2013) and Shaw,
Robinson, Starks, Burke, and Dillard’s (2013) reports that researchers choose participants
based on members ability to meet described research objectives. Bhakta Bhandari (2014)
and Dennett, Cameron, Bamford, and Jenkins (2014) also indicated that researchers select
participants based on individual knowledge and experience with the studied phenomenon.
The strategy for gaining access to the study participants involved advanced
coordination with one small aerospace organization at which the participants presently
work. The goal was to gain access to the participants through the recommendations of the
public relations executive at the small aerospace company. The intent was to contact
identified members to describe the value of the study and to request participation in the
study. After IRB approval, I contacted candidates via email and sent them the consent
information (see Appendix A). I followed-up with the candidates via email and by phone
and checked on their decision to participate in the study, coordinated their availability,
and collected the signed consent forms from the candidates that were willing to take part

in the study. The step that followed receipt of the participants’ agreement and the consent
forms consisted of coordinating members’ availability for a semistructured interview.
Arendt et al. (2012) and Leedy and Ormrod (2013) explained researchers must go through
a gatekeeper at an organization to gain access to participants. Chikweche and Fletcher
(2012) and Pollack (2015) illustrated that gaining access to corporate gatekeepers is
challenging due to a general mistrust of an outsider and the unwillingness to discuss
sensitive and proprietary data with a stranger. Frich, Røthing, and Berge (2014) and
Nightingale, Sinha, and Swallow (2014) indicated researchers gain access to participants
by ensuring participants’ clear understanding of the purpose of the study and securing
participants’ approval to participate in the study.
Establishing a working relationship with the participants, started by sending the
consent form (see Appendix A) to the participants with detailed information on the
interview process, the objective of the study, and member potential role as a study
participant for approval. A follow up with participants after receiving approval to
participate by signing the consent form took place. After gaining participants’ consent
(see Appendix A) to take part in this study, the objective was to establish a working
relationship with members by reviewing candidates public profiles through professional
networking databases, including LinkedIn and Google search engines. Knowing a
participant’s public profile assisted in identifying common areas of interest, which helped
in the development of working relationships with participants. Researchers conducting
qualitative research must establish a relationship with participants to conduct a successful
study (Turpin, McWilliam, & Ward-Griffin, 2012). Interdependency between partners

must exist for a relationship to exist between such partners (Fournier, 1998; Hughes,
Allen, Doheny, Petsoulas, & Vincent-Jones, 2013). Trust plays a critical role in the
development of a relationship when people experience difficulty assessing the others'
potential for goodwill or harm toward the group (Aamir & Buckley, 2013; Miltgen &
Peyrat-Guillard, 2014).
To accomplish the alignment of the participants with the overarching research
question, participants must meet the eligibility criteria. Participants’ ability to answer the
research questions plays a primary role in candidates selection process (Yin, 2014).
Researchers use the participant selection process to evaluate individuals’ capacity to
understand the phenomenon under investigation (Leedy & Ormrod, 2013). Participant
must be qualified in the field related to the research question and be able to provide
needed information to answer the research question (Maxwell, 2013).
Research Method and Design
Researchers use a methodology in research to understand participants’
experiences with a particular phenomenon (Leedy & Ormrod, 2013; Moustakas, 1994).
Research methodology and design are techniques used to define the research question and
methodology for gathering relevant data to answer a research question (Bowyer & Davis,
2012; Marais, 2012; Yin, 2014). The research methodology and design included
techniques to establish a process for collecting and analyzing data (Cao & Nymeyer,
2013; Leedy & Ormrod, 2013).

Research Method
The qualitative research method was the research method used in the study
because the goal was to understand participant’s perceptions, experiences, perspectives,
and understandings of a particular situation. Stacke (2010) explained researchers use the
qualitative methodology to understand individuals’ perception, personal experience,
perspective, and understanding of a particular situation. Leedy and Ormrod (2013)
indicated researchers use the qualitative methodology when focusing on a phenomenon in
a natural setting. Heffernan, E. Heffernan, and Pan (2014) and Montero-Marin et al.
(2013) noted a researcher uses a qualitative research methodology to understand
participants’ perceptions and experiences with a phenomenon through data and theory.
Researchers use the qualitative method to tell the story of participants’ experience
through careful preparation and execution of a research plan (Bansal & Corley, 2012;
Rowley, 2012).
Doig (2010) conducted a qualitative study to analyze business corruption in
Turkey and considerations for admitting Turkey into the European Union. In the study,
Doig noted the slow reform in revising corruption laws and the continuing presence of
governmental corruption in Turkey. Luiz and Stewart (2014) performed a qualitative
study of African public responses to public service corruption when policymakers
adopted a public service anticorruption strategy in South Africa in 2002. Agbiboa (2012)
conducted a qualitative study to investigate the relationship between corruption and a
country’s development. Zuofa and Ochieng (2014) used the qualitative methodology to
study project failure and concluded that a direct link exists between project failures and

corruption in Nigeria. Doig (2010), Luiz and Stewart (2014), and Agbiboa (2012)
employed a qualitative methodology to analyze participants’ perception of the meaning of
a situation or an event. The qualitative studies performed by Doig, by Luiz and Stewart
(2014), and by Agbiboa (2012) had the same context as the study. Therefore, the
qualitative research method was deemed suitable for this study.
The quantitative methodology was not appropriate for this study because the
approach would not address the lived experience of the FCPA participants, nor the
examination of relationship between variables required in this study. Researchers use
quantitative research to measure the relationship between variables numerically (Leedy &
Ormrod, 2013). Researchers use the quantitative methodology when seeking to analyze a
hypothesis or to examine one or more variables of interest (Gelei & Dobos, 2014; Macur,
2013). Caruth (2013) indicated qualitative researchers often claimed that quantitative
researchers use simple descriptions and immaterial hypotheses. Allwood (2012) reported
the distinction between quantitative and qualitative methods is problematic when
attempting to separate methods by using the data collection process, studied phenomena,
and the philosophy of the research.
The mixed methods methodology was not suitable because the goal was to
understand the participants’ perceptions of FCPA compliance. Researchers conduct
mixed methods research when a combination of elements from a qualitative and a
quantitative approach is necessary to provide a picture of a particular phenomenon
(Leedy & Ormrod, 2013). Caruth (2013) explained the mixed methods methodology
evolved to address the limitations of the individual qualitative and quantitative methods.

Venkatesh, Brown, and Bala (2013) indicated researchers use mixed method design to
complete, expand, confirm, and obtain opposing views of the same experience. Through
the interviews conducted during this study, the goal was to gain sufficient information to
determine the participants’ FCPA compliance strategies and experiences.
Research Design
Given the selection of a qualitative methodology, using a single case study design
for this research was appropriate because the objective of this study was to identify the
FCPA compliance strategies used by executives at one small U.S. aerospace company in
California. Researchers use a research design and methodology to establish the
techniques for collecting and analyzing data (Leedy & Ormrod, 2013). Case studies
consist of in-depth data gathering about programs, companies, events, or individuals to
learn about poorly described or poorly understood phenomena (Leedy & Ormrod, 2013).
Chambers et al. (2013) noted researchers use a case study when the goal is to get beneath
the surface of policy implementation, challenge current thinking, and reconstruct
understanding. Jones (2012) indicated researchers use a single case study when the
primary research data consist of concepts used by study participants in the field where the
researcher wants to know the participants’ level of understanding. The identification of
FCPA compliance strategies involved collecting data using in-depth interviews with
employees of one California aerospace company. For this study, ethnography,
phenomenology, and case study design options received consideration.
The ethnography design was not suitable because the plan for this study was to
identify strategies and not observe participant interactions. Ethnography involves lengthy

planning, early engagements, fieldwork trips for group observations, exploring the
settings, and multiple cultural interactions (Simpson, Slutskaya, Hughes, & Simpson,
2014). Marshall and Rossman (2016) indicated ethnography researchers study groups in a
natural environment for long periods, although due to advancements in technology,
Internet ethnography and multimodal inquiries are possible. Ethnography is a style of
research used to understand the activities of people in a given setting, and ethnography
enables fuller social experiences (Simpson et al., 2014).
The phenomenological design was not suitable for this study because the focus of
the design was not to understand aerospace executives’ perceptions of the meaning of a
particular phenomenon, but documenting aerospace executives’ understanding of FCPA
compliance. Phenomenological design involves lengthy interviews and a focus on
understanding participants’ perception and perspective and the meaning of a particular
event (Leedy & Ormrod, 2013). Researchers use a phenomenological research method
when studying the essence of participants’ experience (Moustakas, 1994). Tomkins and
Eatough (2013) defined the phenomenological design as the process a researcher uses to
understand participants’ experiences with a particular phenomenon.
Data saturation in this study took place through the interviews with leaders across
an organization and by asking participants follow-up questions during the interview to
ensure the gathering of sufficient data on the research topic. Coenen, Stamm, Stucki, and
Cieza (2012) defined data saturation as the point during data gathering that indicates two
similar ideas from two consecutive individual interviews, but reveals no additional new
information from previous interviews. Goffin, Raja, Claes, Szwejczewski, and Martinez

(2012) indicated researchers reach saturation when no new categories or groupings are
surfacing during participant interviews. Keyvanara, Karimi, Khorasani, and Jazi (2014)
and Guzys, Dickson-Swift, Kenny, and Threlkeld (2015) asserted researchers reach data
saturation when no new categories, new coding, or new information occurs, and if a study
replication takes place, the results will be the same.
Population and Sampling
The study population consisted of leaders of small U.S. aerospace company in
California operating in the international market. The population was representative of the
aerospace industry in California, which handled over one third of the $95.5 billion
aerospace exports from the United States in 2012 (Aerospace Industry Association, 2012;
Kyser Center for Economic Research, 2012). Manerikar and S. Manerikar (2013) defined
population as the total group of people, things, or events a researcher desires to
investigate.
The purposeful sampling method was the procedure used for the study. The plan
was to select five to seven executives purposefully from one company for members’
aerospace experience, international business experience, industry knowledge, and
realworld experience with FCPA compliance. Researchers use purposeful sampling to
understand an experience from the participants’ point of view (Leedy & Ormrod, 2013).
Purposeful sampling involved selecting a sample to access research participants using the
criteria guided by the research purpose and conducting an in-depth exploration of rich
sources of information (O. Asst & Asst, 2014; Zeldenryk, Gray, Gordon, Speare, &

Hossain, 2014). Hanson, Stephens, Pangaro, and Gimbel (2012) indicated researchers use
the purposeful sampling method to maximize diversity in a study.
Participants in the study were seven executives responsible for FCPA compliance
in one small aerospace company in California. The research problem, research purpose,
and eligibility criteria for such participants strongly influence researchers’ selection of the
participants (Leedy & Ormrod, 2013). Petit (2011) had one participant in a case study of
police corruption in New York. Kramer’s (2009) case study of eliminating fraud
consisted of one participant. Choudrie and Culkin (2013) conducted eight face-to-face
interviews in a qualitative case study of innovation diffusion. Zuofa and Ochieng’s
(2014) analysis of the failure of Nigerian infrastructure projects had eight participants.
Aloysius (2013) used five international students to study the perception of empowerment
among international students at Putra University in Malaysia. The average number of
participants identified in the five studies was five. Based on the five examples having the
same context as the study, five to seven small business executives with FCPA
responsibilities at an aerospace company in California were suitable for the study.
I achieved saturation in the study by gathering sufficient data from participants
using open-ended questions and follow-up questions. A sample size in qualitative studies
can be much smaller than in a quantitative study and still achieve saturation (Marshall et
al., 2013). Data saturation occurs at the point at which the gathered data and analysis
from two consecutive individual interviews reveal no additional information to the same
question (Coenen et al., 2012). In qualitative research data, saturation occurs when no
new information or categories emerge in the responses to interview questions (Horter et

al., 2014). Data saturation occurs when participants provide similar answers to the same
interview questions (Goffin et al., 2012).
The basis for the selection criteria for the seven study participants was the
participants must be executives at a U.S. aerospace company in California and must have
established a successful compliance strategy for the FCPA. The seven interviews took
place in a conference room setting to ensure the comfort, safety, and privacy of
participants. The selection standard was appropriate because participants’ direct
involvement with the FCPA provides members the ability to answer the research question
and give insights on members’ strategies to comply with the FCPA. Researchers select
interview locations to provide a quiet area with minimal distraction that is comfortable,
safe, and a relaxed environment (Kitchen, 2013). Hanssen (2012) reported a link in
qualitative studies between the interview setting and question limitations concerning the
need for data comparison, interview findings, and the reluctance of expressing contrary
opinions to strangers. Nwagwu and Igwe (2015) indicated researchers select interview
locations based on ease of access to participants, the safety of participants, and
availability of resources needed for the interview.
Ethical Research
The informed consent process consisted of sending participants the consent form
(see Appendix A) for review and signature before interviews began. Getz (2014)
emphasized the consent form must be simple, be easily understandable, and address the
demographics of participants. The consent form should include (a) the reason for the
study, (b) the involvement of participates, (c) how long the participant will be in the

study, (d) the risks of the research, (e) the benefits of taking part, (f) other options, (g)
confidentiality, (h) the costs involved, and (i) the rights of the participant (Wright, 2012).
Participants should receive the informed consent form after accepting an invitation to a
study and sign the form before beginning the interview (Leedy & Ormrod, 2013). The
process of collecting the signed consent form occurred before the interview begins.
Participants can withdraw from the study or interview without reason through
email, phone, mail, or other communication methods (Tam et al., 2015). Researchers
should inform participants of the option to withdraw from the research (Rasmussen &
Berntsen, 2014). Participants can withdraw from a study without penalty or the need to
give a reason for withdrawal (Abdelhamid et al., 2012). The participants did not receive
an incentive or payment for participating.
Measures to provide adequate ethical protection for the participants throughout the
study include (a) obtaining from participants a signed informed consent to participate, (b)
ensuring data do not include personal information, and (c) not modifying participants’
responses to give better results. The intent was to ensure no harm comes to participants
because of candidate participation in the research. Durham et al. (2014) and Rothstein
(2013) indicated the protection from harm for study participants includes respect for
participants, autonomy, and protection of defenseless populations, beneficence, and
justice. Researchers must ensure no physical or psychological harm comes to participants
because of members’ participation in a study (Leedy & Ormrod, 2013). Boutin-Foster et
al. (2013) indicated researchers extend ethical considerations to participants, including

safety, respect for autonomy, facility space, and sufficient time for conducting the
research.
One of the objectives for the consent form was to protect the anonymity of the
source of the information obtained during the interviews before the interview begins (see
Appendix A). The purpose of the consent form was to ensure no harm would reach
participants because of members’ involvement in the study. Individuals receiving the
consent form understood the study risks and expectations before deciding whether to take
part in the study, and the structure included background information on the FCPA and
compliance. The consent form included information on the procedures, invitation to
participate, the voluntary nature of the study, payments, privacy, contact information, and
the statement of consent.
Agreement documents included an invitation for cooperation (see Appendix C).
The letter of cooperation consisted of an overview of the study and the permission
process from the approving executive at one U.S. aerospace company to use employees
from the company for the study. After the approving manager at the U.S. aerospace
company gave permission to use the company for this study by signing the permission
letter (see Appendix D), the process of scheduling the interviews with the participants
took place. The participant consent form (see Appendix A) contained the background
information on the study, an invitation to participate, interview procedures, risks,
benefits, and consent to participate in the study.
Collected data will remain in a secured file cabinet at the home office for 5 years
to protect participants’ confidentiality. Full control over the collected data included

maintaining the gathered data in a locked cabinet at the home office. The plan was to
safeguard the names of the participants and the organization participating in the study by
the assigned seven different letters to the seven members and a numeric code for the
company.
Data Collection Instruments
In the study, I was the primary research instrument and collected data by
conducting semistructured interviews with seven aerospace participants at a single
aerospace company in California. Data included participants’ data collected through
interviews, the company’s FCPA compliance strategy directives, and personal journaling
data. Thompson et al. (2013) claimed that Internet technology reduced data collection
costs, but also reduced the reliability of responses, so I did not use Internet-based data
collection. Using simplicity, flexibility, data quality, timeliness, and acceptability might
help researchers to improve a study’s data collection process (Heidebrecht et al., 2014).
Researchers can improve the data collection process by clearly communicating the
purpose of the data collection to the participants (Iqbal et al., 2012); therefore, the
informed consent form included a description of the study purpose and data collection
process.
Semistructured interviews using open-ended questions (see Appendix E) were the
primary data collection technique. As the researcher, I was the instrument in this
qualitative study, and the bulk of the data collection was dependent on my level of
involvement, as noted by Leedy and Ormrod (2013). Data collection involves informal
interactive discussions with open-ended questions and comments (Moustakas, 1994).

Data collection included interviews of participants, which is a method frequently
employed to collect data for qualitative studies (Anyan, 2013). Carcone, Tokarz, and
Ruocco (2015) and Knudsen et al. (2012) indicated researchers use semistructured
interviews to improve the validity and reliability of the research results. The data
collection process in qualitative research consists of collecting data from a limited
number of participants that provide information on the phenomenon under study (Leedy
& Ormrod, 2013).
I reviewed company directives related to the FCPA compliance process,
maintained a paper journal to document the research activities, and took related notes
during the study. The journal included the notes taken during the interviews. During the
interviews, the process of capturing data included the planned use of two audio tape
recorders and handwritten notes. A planned expert review of the set of open-ended
semistructured questions served to validate the interview questions. The collected data
consisted of responses to the interview questions (see Appendix E) developed to answer
the research question.
I enhanced the reliability and validity of collected data by conducting an expert
review of the interview questions, member checking, and triangulation of data.
Researchers often use triangulation to enhance the reliability of gathered data and
improve the validity of the study (Houghton, Casey, Shaw, & Murphy, 2013; Mysen,
2012). Using a qualitative case study enhances validity by controlling study factors,
including scenario settings that are difficult to control in other research approaches

(Hodge, Oppewal, & Terawatanavong, 2013). Data collection reliability refers to the
consistency of the results when the measured entity remains the same (Leedy & Ormrod,
2013).
The study included an expert’s review of the interview questions to enhance the
reliability and validity of the data collection instrument. Reliability includes the
validation of the study conclusion and the trustworthiness, relevance, conformability, and
credibility of study results (Otieno-Odawa, 2014). Researchers perform reliable and valid
research when investigators conduct expert’s reviews (Moustakas, 1994). The validity of
research refers to the accuracy, meaningfulness, and credibility of the results (Leedy &
Ormrod, 2013). Aust, Diedenhofen, Ullrich, and Musch (2013) showed that a significant
number of participants increase validity in a study, and increasing rigorous checks
improve validity. Martirosyan, Markhorst, Denig, Haaijer-Ruskamp, and Braspenning
(2012) reported an expert’s review identifies quality indicators used to develop questions
for a larger group of participants. Frolic et al. (2013) used an expert’s review to identify
trends, themes, and organizational challenges and to assist in an efficient rollout of the
survey to more participants. The expert review began after the study received Institutional
Review Board (IRB) approval, after which I adjusted the interview questions.
Conducting member checking enhances the reliability and validity of the data
collection process. After reviewing the interview data, I sent the individual interpretations
of the interviews to the participants to ensure the accuracy of the descriptions, as
suggested by Awad (2014) and in alignment with Li et al. (2013) and Goldman et al.
(2014).

The interview protocol (see Appendix B) describes the steps taken with the
individual participants during the face-to-face interviews. The use of an interview
protocol aligned with instructions by Briggs and Murphy (2011), Brown et al. (2013), and
De Ceunynck et al. (2013). Briggs and Murphy (2011) maintained that an interview
protocol should include a collaboration process to discover and evaluate research goals.
De Ceunynck et al. (2013) indicated the interview protocol structure includes a
consideration of respondents’ decision-making processes when answering interview
questions and includes measures for risk and bias of interviewer interpretations of the
responses given by participants. Brown et al. (2013) reported interview protocols
emphasize the elicitation of as much information as possible during the interview to
establish rapport with participants and provide clear guidelines for the interview.
Data Collection Technique
The research question for this study was as follows: What are the strategies that
U.S. aerospace small business leaders use to comply with the FCPA? The primary data
collection technique selected to answer the research question was semistructured
interviews, which was combined with research on the company’s FCPA compliance
strategy directives and personal journaling data. Using semistructured interviews does not
bias participants’ responses to open or closed-ended questions (Covell, Sidani, & Ritchie,
2012). Semistructured interviews provide reliable data, and researchers using
semistructuresd interviews acquire a deep understanding of participants’ experiences
(Marshall & Rossman, 2011). Irvine, Drew, and Sainsbury (2013) suggested using
semistructured interviews to encourage interviewees to elaborate on what members said.

I interviewed seven participants that handle international business in one small
aerospace company in California. During the meetings, the plan was to ask participants
the open-ended interview questions and potential follow-up questions during the
semistructured interviews. Irvine et al. (2013) showed interviewees in semistructured
interviews could ask answers during the interviews. At the end of the interviews, the data
collected included recorded data, corporate documents, informed consent documents, and
personal journal notes. Alfonso, Nickelson, and Cohen (2012) used brief interview
questions in a case study on farmers’ markets in rural communities. Researchers
frequently conduct case studies in social science research to answer how and why
questions regarding situations over which researchers have limited control over the
outcomes (Ranjbarfard, Aghdasi, Albadvi, & Hassanzadeh, 2013). Colombini, Mayhew,
Ali, Shuib, and Watts (2013) and Sylvain and Lamothe (2012) noted researchers using a
case study method should employ interview questions and follow-up questions to explore
constructs, patterns, and interrelationships of the collected data.
Phone and email were the communication methods used to confirm the
executive’s intent to participate in the study and to coordinate the executive’s availability.
Participants received my contact information, including a phone number and email
address, at the beginning of the study. Communications with participants via email and
phone calls continued until the completion of the study.
I reserved the meeting room by coordinating with the sponsoring executive one
week before the interview date. Some participants elected to have the meeting take place

at the candidate’s office, and no room reservation was required. The process of securing a
hotel near the interview location took place after confirming the interview date.
I arrived in California one day ahead of the interview date and check into a hotel
near the interviews location. The next day, one hour before the first scheduled meeting,
the preparation of the conference room started by locating the power outlets and setting
up the two tape recorders and the laptop computer. Conference room table clearing
occurred except the consent forms that still needed signatures.
Greeted the participant upon arriving at the interview location and initiated a
general conversation that helped to make the participant comfortable. After greeting the
participant, I provided members with an overview of the interview process and collected
the signed consent forms. At this point, I turned on the two tape recorders and the
interview began by asking the first question. After the participant answered the first
question, additional clarification questions took place.
After the participant provided an answer to the first question and related followup
questions, the second interview question occurred. The process continued until the
participant responded to the interview questions. At this point, I informed the participant
that the interview was over. A repeat of the interview process took place with the seven
participants. Gathering the tape recorders, laptop computer, and notes taken during the
interviews completes the seven interviews. Documents collected during the data
collection process include interview audio tapes, company’s FCPA compliance strategy
directives, and personal journaling data. The review process included the three collected
documents data during the study. The advantage of the onsite interview technique

included costs borne by the researcher, timesavings with little interruption of participant
work schedules, elimination of travel time for participants, and opportunities to ask
follow-up questions. The disadvantages of the onsite interview technique included a limit
on the number of participants and the possible increase of participant stress levels.
Participants’ limited recollection of FCPA experiences meant participants needed to
prepare for the interview beforehand. Researchers can tape record onsite interviews,
which results in more accurate accounts of the phenomenon under study (Fullerton,
McGettigan, & Stephens, 2010; Kotlarsky, Scarbrough, & Oshri, 2014). Transcribing
interviews enabled the removal of superfluous information such as repetitions (Kotlarsky
et al., 2014). Researchers conducting face-to-face interviews have the opportunity to
record the interviews, observe participants’ physical expressions, and take field notes, but
this process may increase participants’ tensions (Schäffler et al., 2014). Researchers
conducting onsite interviews control the shift of power and record and transcribe
interview data; however, onsite interviews limited the number of participants (Laukner,
Paterson, & Krupa, 2012).
The advantage of obtaining and reviewing the company directive related to FCPA
compliance served as a comparison tool to validate the answers to the interview questions
and the credibility of the responses. The disadvantages may be discrepancies between the
participant’s responses and the corporate directive that would require additional
interviews and therefore lengthen the time needed for the research. Company regulations
include the company’s anticorruption FCPA compliance process that executives must
follow when conducting international business (Jorge & Basch, 2013). Leaders of

corporations develop self-regulation and anticorruption strategic directives to ensure
compliance with the FCPA and to use as a defense against any major bribery legislations
(Lord, 2013). Corporate FCPA compliance guidelines provided a coherent description for
employees that served as the code of conduct staffers needed to follow within the country
in which organization members operated (Klinkhammer, 2013).
The advantage of using a personal journaling technique includes improving the
recollection of events, filling the gaps in the literature, reducing discrepancies, reducing
the author’s potential misinterpretations of the responses gathered during the interview,
and achieving data triangulation. The disadvantages of writing a personal journal
included possible distractions during the meetings and the additional time needed to write
the personal journal. A researcher uses personal notes, including personal experience, to
fill the gaps in the literature and to clarify ideas of different elements in the research
process (Lamb, 2013). Researchers use personal diaries and reflexive journals to disclose
personal experiences, including seeing, understanding, and interpreting events (Aguilar
Delgado & Barin Cruz, 2014). Researchers use a personal journal to stimulate the
reflection and awareness of personal experiences during the research process (Starr-
Glass, 2014).
I enhanced the reliability and validity of the data collection process by conducting
an expert review after receiving IRB approval. The outcomes of the expert review
assisted in improving the validity, reliability, and level of understanding of the interview
questions. The expert review helped to ensure the answers to the open-ended questions
provided valid and reliable data (Leedy & Ormrod, 2013). Researchers conducting expert

review can tailor interview questions to improve the efficient use of interview time and
validate interview questions (Frolic et al., 2013). Clyne et al. (2013) conducted expert
review of eight participants to validate the process of prescribing medication to older
patients.
The expert review involved surveying four aerospace participants experienced in
international markets. The four participants had 20 or more years of experience as
aerospace contractors leading international business activities. Identified participants had
a postgraduate credential and had experience in interpersonal communications. The
expert review consisted of the following steps: (a) obtained IRB approval, (b) contacted
four aerospace participants via email and telephone to explain the expert review process
and expectations, (c) sent the expert review questions to the four aerospace participants,
(d) followed up via email or phone and answer questions the expert review participants
present, (e) collected executive’s suggested changes and comments for improving the
interview questions, and (f) updated the interview questions based on the expert review
results.
Member checking occurred after completing the seven semistructured interviews.
Member checking is a quality control process researchers use to verify the accuracy of
collected data during or after the interview (Harper & Cole, 2012). Member checking was
the process of checking researchers’ interpretations of interviews with participants for
accuracy (Harper & Cole, 2012). Awad (2014) and Andrasik et al. (2014) described
member checking as the process used by researchers to confirm with participants the
researchers’ interpretation of the data provided during interviews.

Davidson et al. (2012) concluded member checking involves coordinating a
researcher’s interpretations of interview results with participants to validate the
researcher’s interpretations. Li, Westbrook, Callen, and Georgiou (2012) noted member
checking is the process of clarifying interview interpretations with participants. Reilly
(2013) illustrated member checks help to ensure credibility by providing participants the
opportunities to challenge data interpretation and to correct errors. Kim, Kim, Han, and
Chin (2015) reported researchers use the member-checking process to ensure the quality
and interpretations of collected data are in agreement with understandings of the
participants.
Data Organization Technique
Data organization involved using an electronic data filing system to organize
study data for ease of retrieval and data analysis. The data support documents filed
electronically included (a) consent form, (b) invitation for cooperation, (c) permission
letter, (d) interview protocol, (e) interview questions, (f) interviews transcripts and
analysis, (g) corporate directives related to FCPA compliance, (h) copy of all cited
articles, and (i) reflective journal. A removable data storage device with password
protection ensures data security. The data remains in a locked file cabinet located in the
home office for 5 years after the completion of the study. After the 5th year, I will
remove the collected data from the storage device and delete the data permanently to
protect participants’ confidentiality.
Basurto and Speer (2012) explained researchers’ efficient organization and
analysis of collected data helps to answer research questions. Vernon-Dotson (2013)

asserted that during a qualitative case study, researchers perform numerous data
organization and analysis techniques to improve the quality of the research. Lawrence
and Tar (2013) illustrated researchers use the coding method in data organization to
group similar concept into categories and subcategories to facilitate answering the
research question.
Data Analysis
Data analysis in a qualitative study starts with organizing the collected
information, followed by data perusal, classification, and synthesis (Leedy & Ormrod,
2013). Mugarura, Slobogean, and Bouchard (2014) indicated the data analysis process
involves the emergence of overarching themes from participants’ interview transcripts
and other collected data from the study. Haanstra et al. (2013) indicated data analysis
includes category development and coding recurring themes. Analyzing qualitative data
involves organizing, perusing, and identifying general themes and integrating and
summarizing the data to the reader (Leedy & Ormrod, 2013). The data analysis process
used thematic analysis, including methodological triangulation, to identify key themes
was used to examine data in the study.
Using thematic analysis including methodological triangulation of key concepts
from three data sources contributed to the quality of conclusions by verifying the findings
through the concurrence of data collected from three resources. Through triangulation, I
identified categories and themes using multiple resources. This process aided in
interpreting the research evidence and supported the study conclusions. Torrance (2012)
indicated the four essential forms of triangulation are data triangulation, investigator

triangulation, theoretical triangulation, and methodological triangulation. Triangulation is
a data analysis technique used in qualitative case studies to compare data from different
sources to ensure the accuracy of research results while supporting data validity and
reliability (Othman & Rahman, 2014; Street & Ward, 2012). Triangulation was the
process of using multiple data sources and applying multiple perspectives to the
phenomenon under study (Homburg, Klarmann, Reimann, & Schilke, 2012; Lin et al.,
2013).
Two audio recordings captured the interview data and recorded information
transcriptions in Microsoft Word documents after the seven interviews were completed.
Study data included coded transcripts, detailed notes, the journal, and corporate
documents. The member checking process commenced after data collection using the
interpretation of the interview data. After member checking was complete, the thematic
analysis including methodological triangulation of key concepts from three data sources
began, which involved triangulating the interview data, corporate directives, and the
journal themes. Additionally, I identified and documented the common strategies used in
small aerospace companies to comply with the FCPA.
This study included the analysis of compiled data from seven participants’
interviews using NVivo software tools to organize the research data and establish a data
traceability matrix. General coding, theme identification, data relationships, annotations,
and linked data sets of the study’s evidence accomplished by using the NVivo software
thematic analysis including methodological triangulation. Basurto and Speer (2012)
maintained coding would help data reliability because the researcher can organize coded

data in an efficient and useful manner. After sorting and categorizing the data, I used
NVivo to identify common themes, analyze the themes, and establish the strategies to
answer the research question.
Coding and classifying qualitative data increases validity and facilitates the
analysis of collected data (Habib, Etesam, Ghoddusifar, & Mohajeri, 2012). Lawrence
and Tar (2013) indicated coding is the process of naming and categorizing phenomena
through a close examination of collected data. Sánchez-Algarra and Anguera (2013)
emphasized coding provides coherence to the flow of events or phenomenon behavior.
Line-by-line coding of the answers obtained from study participants’ responses to the
interview questions served to establish categories and themes (Klassen et al., 2012).
Habib et al. (2012) noted using NVivo software in qualitative data analysis increases the
reliability and validity of study results. One of the tasks was to triangulate the themes
generated by the NVivo software.
Using the themes identified through NVivo data analysis, triangulation of the data,
and additional literature search data enhanced the focus on the central topics and the
conceptual framework of the study. I concentrated on the main categories and compared
identified groups with the literature review, journal notes, and corporate documents
before sending the interview analysis results to the participants. The study included
changes received from the participants that resulted from the member checking process.
Andrasik et al. (2014) asserted researchers conduct member checking to improve the
accuracy of collected data, resolve misinterpretations of gathered information, resolve
disagreements in codes, and identify new themes. Goldblatt, Karnieli-Miller, and

Neumann (2011) referred to member checking as the process of participants verifying the
research findings to improve the data accuracy and credibility of the study results. Li et
al. (2013) reported member checking involves analyzing the transcribed responses to the
interview questions and coordinating the researcher’s interpretations of the results with
participants to ensure data accuracy.
Reliability and Validity
Reliability relates to the ability of a measuring instrument to yield consistent
results when the measured entity stays the same, and validity refers to the accuracy of the
research findings (Leedy & Ormrod, 2013). Reliability refers to the extent of the
consistency of the measurements by an instrument (T. J. Hess, McNab, & Basoglu,
2014). Validity consists of the internal validity of the outcome and the external validity of
the results of an experiment (Jackson, 2012).
Reliability
Reliability is the consistency with which researchers measure the results of an
instrument when the entity measured is constant and with additional changes (Leedy &
Ormrod, 2013). Triangulation improves the reliability of collected data through a
comparison of interpretations and facts from different sources converging on the same
event (Street & Ward, 2012). The reliability of the collected data obtained by asking
precise open-ended questions increases the integrity of the investigation and the
applicability of the findings (Cook, 2012; Leedy & Ormrod, 2013; Street & Ward, 2012).
I addressed dependability in the study through member checking, triangulation,
and an expert review. To ensure the data collection process, instrument, and study were

dependable and reliable, the procedures followed involved (a) ensuring the focus of
interview questions and follow-up clarification questions answered the research question;
(b) ensuring interview questions were accurate, simple, and clear; (c) using an expert
reviewer to validate clarity, understanding, and desired outcomes; (d) comparing the
interview data to the interview questions; (e) conducting multiple reviews of data
including cross checking journal notes and interview data; and (f) using NVivo software
for data analysis. Researchers achieve dependability of collected data by using NVivo
software to provide clarity on repeated themes of researcher inquiries (Lancaster et al.,
2013). Using NVivo query tools to audit findings guards against rare discoveries that
happen to suit a researcher’s potential preferred argument, and maintaining a reflective
diary enhances study dependability (Houghton et al., 2013). Elo et al. (2014) referred to
dependability as the stability of collected data over time and under different situations.
Söderholm and Norrbin (2014) described dependability as the ability to perform the task
as needed and when needed.
Validity
Validity refers to the accuracy, credibility, and meaningfulness of a research study
(Leedy & Ormrod, 2013). Achieving validity involves establishing sufficient controls to
ensure collected data will support the study conclusions and the study results generalized
beyond the research context (Leedy & Ormrod, 2013; Morgan-Thomas, 2012). Validity
entails the internal validity and external validity (Jackson, 2012; Yin, 2013).
Researchers ensure the credibility of collected data by reaching saturation,
demonstrated through evidence of recurring themes throughout the developmental

process (Ashworth, 2012). Nordhagen et al. (2014) illustrated three forms of credibility:
professional credibility, public credibility, and personal credibility. Henry (2012)
indicated the credibility of a case study increases by triangulating data from multiple
sources. In this study, I focused on professional credibility, which included academic and
nonacademic research credibility.
To improve the credibility of the study, I triangulated the data collected from
participants’ interviews, against the company’s directives, and the personal journal
developed during the study. Triangulation involves comparing data from different sources
to ensure the accuracy of research results and contributes to the reliability, credibility, and
validity of collected data (Othman & Rahman, 2014). Triangulation is the process of
using multiple data sources and multiple perspectives for a phenomenon under study to
arrive at conclusions to a research question (Leedy & Ormrod, 2013; Lin et al., 2013).
Kapoulas and Mitic (2012) indicated researchers use data triangulation to increase the
credibility, validity, and quality of the research.
To attain transferability, the FCPA compliance strategies identified must apply to
other companies. As the FCPA affects all U.S. individuals and corporations, part of the
identified FCPA compliance strategies could be transferable to other organizations or
industries. Järvensivu and Törnroos (2010) defined transferability as the process of
transferring the study results to other situations. Järvensivu and Törnroos also indicated
transferability can be partial and requires testing the resulting framework application in
another context to explore the potential for transferability. Due to time limitations, I did
not anticipate the need for transferability testing in the study. Detailed results of interview

transcripts and a literature search enhance the transferability of study results (Houghton et
al., 2013). The integrative review of literature related to a topic and that draws similar
conclusions from different studies improves the transferability of research results (Leon,
Lewin, & Mathews, 2013; Moustakas, 1994). Knies et al. (2012), Perrier et al. (2014),
and Malterud (2001) described transferability as the extent of study findings’ applications
beyond the scope of the study. In this study, the transferability of identifying FCPA
strategies used by aerospace executives to all U.S. industries left to the reader and future
researcher to determine.
Establishing confirmability in the study involved tape recording the interviews,
taking notes during the meetings, and obtaining participants’ feedback regarding the
accuracy of the interpretation of the collected data. Researchers can ensure confirmability
throughout a study by taping the conversation, taking notes, and asking participants to
examine the accuracy of collected data transcripts (T. R. Wilson, Birks, & Alexander,
2013). The confirmability of a study refers to the accuracy of collected data and neutrality
of the researcher during the collection and analysis of collected data (Houghton et al.,
2013). The confirmability process secured the neutrality of the researcher and the
accuracy of the data (Marshall & Rossman, 2011; T. R. Wilson et al., 2013).
I ensured that saturation occurs before concluding the participant interviews by
looking for the point at which no new themes or new data are surfacing in participants’
answers to interview questions. Data saturation occurs at the point in which data collected
from two consecutive interviews reveal no additional information on the same issue
(Coenen et al., 2012). Anyan (2013) explained that during data collection, power between

the interviewers and interviewees shifts; however, interviewers must learn how to control
this power shift to reach data saturation during the interview. Guzys et al. (2015) and
Ruijs et al. (2012) asserted data saturation occurs when no new categories, new coding, or
new information emerges. Data saturation occurred during data collection when all the
participants’ answers to the same question are comparable (Coenen et al., 2012).
Marshall and Rossman (2011) indicated that to reach saturation, researchers must
conduct additional interviews with participants. Researchers achieve data saturation when
new data reveal less than 5% new categories (Mueller, Schuster, Strobl, & Grill, 2012). In
qualitative research, saturation occurs when no new information or a limited number of
categories emerge from case study interview responses (Goffin et al., 2012).
Transition and Summary
Section 1 included the study purpose, my role regarding designing the research
interview process, interview questions, and participant selection. This section included
information about obtaining permission from a company executive to perform the study,
obtaining consent from participants for the interview, setting up interviews, and
informing participants of the participant’s rights. Section 1 also included a discussion of
the critical issue of preventing harm from coming to participants due to participating in
the study and validating research data.
Section 2 included a description of the research design and the research method
selection, as well as the rationale for selecting the method. The section also included a
description of the research population and participant selection criteria. Other topics
included data collection techniques, data organization, data security, data analysis

methods, dependability, credibility, transferability, confirmability, data saturation,
validity, and the final presentation format.
Section 3 included the application of study results to professional practice and
implications for social change. Section 3 includes an overview of the study, the
presentation of data, findings, applications of the results of global management
professional practice, and social change implications. Finally, Section 3 includes a
recommendation for action, recommendation for further study, reflections on personal
experiences during the study, a summary, and research conclusions.
Section 3: Application to Professional Practice and Implications for Change
Introduction
This section presents the findings of the study. The problem that I addressed in
this study is that U.S. aerospace companies must operate competitively in the global
market and comply with the FCPA, but enforcement of the FCPA by the U.S.
Department of Justice does not occur in international settings for non-U.S. companies.
The specific business problem is that some U.S. aerospace small business leaders lack
strategies to comply with the FCPA.
This section includes the results of the data collected from seven small aerospace
executives experienced with the FCPA compliance in California. The section also
includes the themes that surfaced from semistructured interviews conducted with the
seven participants described, and I illustrate how these ideas apply to the aerospace
industry professional practice and the implications for social change. In addition, I
suggest recommendations for future studies that would complement these research

findings. Finally, I reflect on my experience as a researcher, indicate how this process
influences my way of thinking, and describe potential bias that may have influenced the
study.
The purpose of this qualitative, single case study was to explore the strategies that
U.S. aerospace small business leaders use to comply with the FCPA. The population of
this study was seven executives at a small aerospace company in California. The
overarching question guiding this study was: What strategies do U.S. aerospace small
business leaders use to comply with the FCPA? By interviewing the seven company
executives from the small aerospace company, I was able to identify and gain in-depth
understanding of successful strategies that small aerospace companies use to comply with
the FCPA.
The research data were primarily captured during semistructured interviews that I
conducted with seven executives at a small U.S. aerospace company based in California.
These interviews showed that the participants were experienced in international business
and with the FCPA compliance. The seven executives responded to both open-ended
questions (see Appendix E) and follow-up clarification questions. I used two tape
recorders to capture the executives’ answers and took additional notes during these
meetings.
I used thematic analysis including methodological triangulation of key concepts
from all collected data, including interview data, interview notes, a personal journal, and
corporate directives. Four themes emerged from the research: (a) the importance of
continuous FCPA compliance training; (b) interactive management; (c) compliance with

cultural norms, policy, and FCPA; and (d) qualifying for FCPA compliance. Through this
study, I offer insights on how to establish effective FCPA compliance strategies that
account for the cultural norms and maintain compliance with local laws. These findings
are intended to positively influence social change by reducing the costs of doing
international business, potentially creating new jobs and improving the quality of life for
individuals and communities.
Presentation of the Preliminary Findings
In this section, I present the data collected related to the semistructured interviews
with participants presented, interview questions tested through expert reviews that
resulted in no recommended changes, and semistructured interviews conducted and
openended questions asked during the semistructured interviews. I coded the obtained
data from all resources using NVivo software. The following paragraphs include the
findings of the data analysis.
The data collection processed included collecting answers to the open-ended
questions that I asked in the seven interviews, personal notes I took during the meetings
and samples of corporate directives collected during the interview. The data collection
also included member-checking inputs and my personal journal data collected throughout
the study. The study involved extensive research on literature related to compliance with
the FCPA, identification of Candidate Company for analysis, conducting interviews with
participants, and analyzing all collected data to explain successful strategies used by a
small aerospace company to comply with the FCPA.

I used findings from semistructured interviews to identify successful strategies a
small aerospace company uses, which provide the basis for compliance with the FCPA.
After semistructured interviews, data collected during these interviews was electronically
transcribed using TranscribeMe through NVivo. Uploaded transcribed interview data into
NVivo led to developing nodes or themes. I input these topics into NVivo by reviewing
transcribed interview data, assigning a theme for each appropriate answer or sentence
related to the research question. The result was a complete list of all themes created by
the NVivo software, as well as consolidation of similar ideas into four main general
themes.
I uploaded other collected into NVivo including company policy for FCPA
compliance and data from my personal journal. Data triangulation of gathered data from
the seven interviews, company policy for FCPA, and my personal journal validated the
four main themes. NVivo software facilitated the organization of collected data and
themes, and it allowed me to explore and analyze collected data.
The interview questions developed for this research were suitable for exploring
and eliciting data consistent with the FCPA compliance strategies used by small
aerospace companies to achieve satisfactory compliance with the FCPA. Each interview
lasted approximately 25 to 35 minutes. Participants responded to each of the seven
interview questions and any additional follow-up questions. The analysis of participants’
responses to each question follows.
Interview Question 1
Interview Question 1 was: What strategies do you use to comply with the FCPA?
The objective of this question was to determine participants’ familiarity with the overall
FCPA compliance process and what strategies the leadership uses to ensure employees,
customers, and representative comply with the FCPA. As shown in Table 2, all
participants (100%) were fully knowledgeable of the full range of FCPA compliance
strategy initiatives occurring in the organization.
Table 2
Strategies Used to Comply with FCPA
Code n %
Continuous FCPA training
Interactive management
Internet search for periodic updates to the FCPA
7
5
5
100
71
71
RM06 stated that continuous training on FCPA compliance process including
timely email notifications of any changes of the FCPA as they occur are an essential part
of the company strategy for FCPA compliance process. Participants’ responses to this
question indicate that the organization leaders are promoting sustainable FCPA
compliance training initiatives throughout the organization. The results in Table 2 show
that seven study participants (100%) were aware of the full range of sustainable FCPA
compliance training initiatives. The general business problem is that U.S. aerospace
companies must operate competitively in the global market and comply with the FCPA,
but enforcement of the FCPA by the U.S. Department of Justice does not occur in
international settings for non-U.S. companies. These results partially supported the
study’s general business problem.
Interview Question 2
Interview Question 2 was: What recent changes have you made in your company
policies to improve compliance with the FCPA? The objective of this question was to
determine participants’ familiarity with the company policy for FCPA compliance and
the process that corporate leadership uses to ensure employees, customers, and
representative are aware of policy changes. Participants’ responses to the interview
questions provided varying results, as shown in Table 3.
Table 3
Company Policy Changes: Aware or Unaware of Policy Changes
Code n %
Quarterly reviews and yearly FCPA re-certification
Use of CRM tools for FCPA updates
7
2
100
28
The results in Tables 3 show that seven participants (100%) indicated that they
were aware of the policy change that mandates a quarterly FCPA compliance review
including a yearly certification of compliance with the FCPA for all employees and
customers. LT08 stated that improving compliance with the FCPA throughout the
organization, and within the international customer’s organization quarterly was the goal
for making these changes. RM08 indicated that maintaining currency on the FCPA
changes requires timely updates to all employees and clients through a corporate
automatic alerts system, providing all stakeholders with the latest FCPA changes.
The results of Table 3 also show that two participants (29%) were not aware of the
recent changes made to the corporate policy that required using customer relationship
management (CRM) tools to provide timely information regarding the FCPA changes to
all stakeholders. EW08 and SM08, who were among the more senior organizational
leaders participating in the study, indicated that some of the changes to the FCPA
compliance policy were designed to meet the organization’s FCPA goals. LT08 and
RM08 added that senior leadership made these changes to ensure that all employees
pursuing international business and their customers are fully compliant with the latest
FCPA requirements.
Interview Question 3
Interview Question 3 was: What does leadership consider essential for FCPA
compliance? The objective of this question was to determine key strategic items
considered critical for a small aerospace company to comply with the FCPA.
Participants’ responses to Interview Question 3 varied significantly. This variation of the
responses prompted me to capture their responses in Table 4 and Table 5.
Table 4
Compliance with Cultural Norms and Corporate Policy
Code n %
Comply with cultural norms governed by the FCPA
Follow corporate FCPA compliance policies
6
7
86
100
Initial FCPA training and certification 6 86
Table 5
License Fees and Informing Customer of Conflict with the FCPA
Code n %
Explain to customers potential conflicts with the FCPA
Pay fees that are compliant with the FCPA
7
6
100
86
As the results in Table 4 show, six study participants (86%) indicated that
management considers initial training and certification essential for FCPA compliance.
RM12 noted that new employee’s initial training and certification are essential for
ensuring that employees are aware of the FCPA compliance requirements and that there
are severe penalties imposed by the government on employees and management for any
violations of the FCPA law. RM14 and EW12 indicated that they complied with cultural
norms as long as they were compliant with the FCPA and, in some cases, had to decline
gifts from customers to maintain compliance with the FCPA.
Table 5 shows the additional information study participants provided in response
to Interview Question 3. Seven study participants (100%) indicated that they explained to
the customers any potential conflicts with the FCPA during the initial business pursuit
process. SM18 explained that each culture has its own business rules and that
management complies with cultural rules as long as they do not violate the FCPA law.
KL26 and RM16 stated that some customers required a significant fee and even these
payments are compliant with the FCPA. Paying or not paying these charges becomes part
of a strategic business decision because these costs increase the overall value of the
contract.
Interview Question 4
Interview Question 4 was: What action plan considerations would ensure
continued success with FCPA compliance? The objective of this question was to
determine participants’ familiarity with the company action plan for FCPA compliance
and the effect of the cultural situation on being compliant with the FCPA. The results in
Table 6 show that seven interview participants (100%) were aware of the corporate action
plan that ensures continued success with the FCPA compliance.
Table 6
Compliance Action Plan with FCPA
Code n %
Aware of FCPA compliance action plan
Cultural effect on FCPA compliance action plan
7
6
100
85
KL30 and RM20 stated that FCPA compliance action plans include responding to
any updates to the FCPA. Both employees and customers have access to these plans
before any contract engagements. SM15 and LT22 indicated that FCPA compliance
action plans are customer specific and include regular certification, field visits, and
mutually agreed upon rules of business engagements.
Interview Question 5
Interview Question 5 was: What other pertinent information do you see that we
have not covered in this interview? The objective of this question was to determine
participants’ familiarity with FCPA compliance and the process that company leadership
uses to address encountered cultural conflicts with the FCPA. As Table 7 shows, four
study participants (57%) provided additional information regarding FCPA compliance.
Table 7
Recommendations for FCPA Currency and Addressing Noncompliances
Code n %
Noncompliance with the FCPA
Maintaining up-to-date FCPA compliance database
4
4
57
57
KL34’s remarks provided useful insight into the company’s commitment to
maintaining full compliance with the FCPA. These actions included maintaining the upto-
date database of FCPA requirements, regularly revising the corporate FCPA directive,
and using CRM tools to provide email notifications of FCPA to all employees. RM24
stated that company management must examine each opportunity for FCPA compliance
and try to avoid the engagements with business situations that may violate the FCPA at
any point during the execution of the project.
Triangulation of the interviews data, FCPA compliance corporate policy, and my
personal notes improved the validity of the collected data. I compared the interpretation
of the data gathered from the open-ended question during the semistructured interviews,
corporate policy for FCPA compliance, and my personal notes. I used NVivo as part of
the audit process: the triangulation results validated my interpretations of the collected
data.

Overarching Research Question
The overarching research question for the study was “What strategies do U.S.
aerospace small business leaders use to comply with the FCPA?” I answered this question
through posing five open-ended interview questions to participants (see Appendix E).
Multiple themes have emerged from the study: I used NVivo to tabulate and consolidated
the developed nodes into four main themes:
•Continuous FCPA compliance training,
•Interactive management,
•Compliance with cultural norms and corporate policy, and
•Qualifying for FCPA compliance.
Through this study, I identified insights on how to establish effective FCPA compliance
strategies that take into account the cultural norms and maintain compliance with local
laws. These findings are intended to positively influence social change by reducing the
costs of doing international business, which creates jobs, and improves the quality of life
for individuals and communities.
Findings in Relation to the Themes
The problem concentrated in this study was that small U.S. aerospace company
business leaders lack strategies to comply with the FCPA, which they need to do to
compete effectively in international markets. I specifically investigated these using
semistructured interviews with business leaders who had at least one year of experience
addressing FCPA compliance at a small U.S. aerospace company in California.
There are several different perspectives on the importance, application, and
implications of adopting a corporate FCPA compliance strategy due to the complexities
associated with the U.S. aerospace industry. I categorized, organized, coded, and
uploaded participant answers to NVivo for qualitative data analysis. The main themes
that emerged from this research as listed in Table 8 along with significant relevant
statements from interview participants.
Table 8
Themes Supported by Significant Statements From Interview Participants
Continuous FCPA compliance
training
RM04: We do online training to the greatest extent
possible. We look on the FCPA website for periodic
updates, and we join in industry associations who
sometimes alert us to what's going on internationally.
Therefore, we have a variety of sources of which we try
to keep as current as possible on the latest FCPA
requirements.
EW10: We all need ongoing training and timely
updated on any FCPA changes. If there are any
changes that I may have missed that the boss knows
about, he makes sure that I am aware of it. Then we
flow all these FCPA changes down to the
subcontractors.
Active management RM06: From an employee standpoint wherever they
are - we have people in multiple locations - and we try
to ensure on a regular basis - once a quarter - that they
are up to date on the FCPA requirements. We send out
website alerts; we send out email alerts, we connect
employees and customers up to the latest government
site.
LT22: Just keep all your employees up-to-date and
make sure that you always have a feedback loop so that
management in the U.S. are always aware of what is
going on in the field with your employees.
Compliance with cultural
norms and corporate policy
RM22: Sometimes you have to be very careful in
reminding our people that we are doing business with
Themes Participants’ Statements
international corporation that have to meet U.S.
government regulations. Some of the countries that we
do business with, sometimes they have no rules
whatsoever. We have to remind them that we are
representatives of the US government and must comply
with the U.S. laws. Therefore, we are diligent about
reminding our potential suppliers with the FCPA
compliance.
EW12: We follow the normal cultural practices. If it is
a European customer, they may have different rules
than we do. We try to follow the laws of the other
country without violating the FCPA.
Qualifying for FCPA KL02: About the FCPA, most of our customers we vet compliance
for compliance with the FCPA. We do not work for people who are noncompliant with
the FCPA. We do vet our customers in that we do not work for people that we would
mistrust, noncompliant with the FCPA or find as a demanding customer.
EW18: We try to understand the customers' cultural
issues, address these issues and considerations while
maintaining compliance with the FCPA and local laws
Findings Related to Body of Literature
Prior literature on FCPA compliance strategies has focused on identifying
corruption, courts’ role in controlling bribery, the dangerousness of business crimes, and
how much money companies need to spend to effectively comply with the FCPA
(Virginia & Maurer, 2013). Case studies regarding strategies for compliance with the
FCPA have linked reducing business transactional crimes to reducing business costs, and
creating jobs, creating positive social change (Lestrange & Tolstikov-Mast, 2013, and
Lord, 2013). Operational literature on this topic has documented the relationships
between culture, corporate policies, local laws, the wealth of the country, penalties for
corruption, and FCPA compliance strategies. Theoretical writings have examined
corruption from a cultural, ethical, moral, ambiguity of governmental laws or corporate

structures point of view (Lestrange & Tolstikov-Mast, 2013, and Lord, 2013). These
theoretical articles examined corruption from cultural, ethical, moral, ambiguity of
governmental laws, and corporate structures point of view (Kluvers, 2014; Rullock,
1996). Liu (2015) noted that current literature on FCPA compliance provides different
and contradictory views.
In this section, I relate the research findings to the existing body of literature on
FCPA compliance strategies. These study findings are based upon extensive knowledge
on the topics discussed in the literature review including new studies that were published
since I wrote the proposal for this study.
Theme 1: Continuous FCPA Compliance Training
The research findings showed a direct links to the larger body of literature related
to the FCPA compliance. Elements from the literature on FCPA compliance strategies
were used to code, organize, and categorize the information collected from each of the
interviews. Continuous FCPA compliance training emerged as a significant finding. Jorge
and Basch (2013) contributed significantly to the literature on continuing education as an
element of FCPA compliance strategies. Jorge and Basch considered continuous
corporate training as essential for achieving the ultimate goal of FCPA compliance
program where employees internalize the FCPA compliance code of conduct into their
daily routines. Cascini et al. (2012) recommended the inclusion of FCPA compliance in
the corporate code of ethics and implanting strong and transparent anticorruption
employee training programs.
The findings from this study supported Jorge and Basch’s (2013) assertion that
continuous FCPA compliance training is essential for employee’s internalization of

compliance with the FCPA in their daily business dealings. In particular, study
participants referenced using CRM tools to notify employees via email of any FCPA
updates by the DOE or the SEC. The timely notification process of the FCPA changes
ensures that employees have current knowledge of FCPA changes and protects
companies from potentially significant penalties due to violations of the FCPA.
Theme 2: Active Management
Active management was a significant study finding. As an element of strategic
compliance with anticorruption laws, management uses initial orientation, and a regular
training process that serves for screening employees that already have ethical values
concurrent with those of the corporation and involve employees in commitment to follow
moral norms (Braje & Galetic, 2014). Company leaders should also maintain procedures
in place to ensure corporate compliance with the FCPA (Fox, 2010). Executives of
multinational corporations need to assess countries’ corruption and establish strategies on
how to comply with the FCPA while conducting business in these countries (Cleveland et
al., 2010). Huang and Rice (2012) blamed corruption on the lack of corporate
management directives written for global business leaders to follow in bribery situations
and the lack of corporate strategies to comply with international antibribery laws,
including FCPA. Active corporate management must include having a clear FCPA
compliance directive, interactive monitoring of FCPA compliance, and monitoring of
travel expenses and gift giving to a foreign official to ensure compliance with the FCPA
safeguard corporations against major DOJ and SEC penalties (Jordan, 2016).

The findings from this study support Jordan’s (2016) assertion that active
management through monitoring of business entertainment of government official and
travel expenses helps in improving corporate compliance with the FCPA. For example,
R30’s reference to monitoring the entertainment and gift giving to government officials
to avoid the perception of corruption in the business dealings supported Jordan’s
assertion. Fox (2010) asserted that active management in maintaining corporate
anticorruption policy current ensures compliance with the FCPA, an assertion that was
supported by SM06’s reference to corporate policy updates to stay compliant with the
FCPA supported Fox’s assertion.
Theme 3: Compliance with Cultural Norms and Corporate Policy
The theme of compliance with cultural norms and corporate policy while
addressing the FCPA compliance was a significant finding from analyzing the research
data. FCPA compliance improved in companies that have a clear corporate policy that
addresses both FCPA compliance and how to navigate through cultural expectations.
National culture significantly influences countries’ level of corruption, especially in
countries with high masculinity and elevated levels of uncertainty avoidance, which tend
to be less compliant with anticorruption laws than in countries with low masculinity and
low levels of risk avoidance (Akbar & Vujic, 2014).
National cultures shape the cultures of corruption at different organizations and
ultimately affect the strategies for complying with anticorruption laws in organizations
(Zaloznaya, 2012). Executives of multinational corporations need to assess countries
corruption and establish strategies on how to comply with the FCPA and the cultural
norms while conducting business in such countries (Cleveland et al., 2010). This was

supported by RM22’s reference to complying with cultural expectation when they are
compliant with corporate FCPA compliance policy, and diplomatically rejecting any
actions to comply with cultural expectations that violate the FCPA.
Theme 4: Qualifying for FCPA Compliance
Another emergent theme was the importance of screening business opportunities,
customers, and employees for FCPA compliance. Jorge and Basch (2013) stated that
enterprise leaders need to establish an anticorruption policy and create an FCPA
compliance program that is easily audited and verified, so as to ensure employees,
intermediaries, consultants, distributors, and subcontractors are compliant with the
FCPA. This aligned with EW04’s recommendation of FCPA compliance programs with
online training and yearly certifications.
Cascini et al. (2012) analyzed the inclusion of FCPA compliance in the corporate
code of ethics and employee training and the ways compliance with the FCPA can lead to
an antibribery corporate culture. Tadajewski’s (2015) statement that international
managers must screen customers for honesty and trust during their business transactions
to comply with antibribery laws. Tadajewski’s statement was supported by KL02’s
reference to vetting customers for FCPA compliance and declining business from people
that are suspicious of potential corruption.
Findings Related to the Conceptual Framework
The conceptual framework for this study was based on Sutinen and Kuperan’s
(1999) regulatory compliance model and Becker and Stigler’s (1974) conceptual model
of corruption. These models described multifaceted processes that are continuously

evolving. Sutinen and Kuperan (1999) developed the model of regulatory compliance to
account for the costs and the revenues from illegal behavior popularized the regulatory
compliance theory. Becker and Stigler (1974) published the concept of the corruption
model, which popularized corruption theoretical model. I specifically employed these
models as a conceptual reference and lens to identify the FCPA adherence strategies
needed by U.S. aerospace small business leaders, following Méndez’s (2014) statement
that regulatory compliance is always less present in a corrupt environment.
Continuous FCPA Compliance Training
Training on the FCPA compliance is an essential part of the corporate strategy
that ensures compliance with the FCPA. Cascini et al. (2012) asserted that the inclusion
of FCPA compliance in the business code of ethics and employee training could lead to
an antibribery corporate culture. Similarly, AR11 described companies' concept of
continuous training to ensure compliance with the FCPA by both employees and
international customers, in alignment with Sutinen and Kuperan (1999).
Active Management
The importance of active management emerged was also a significant finding.
Jordan (2016) asserted that leaders of companies that have international operations need
to be actively managing FCPA compliance, create proper compliance policies, and
develop robust internal controls to combat corruption. RM12’s comments indicated that
management is active in the creation of the FCPA policy and the enforcement of this
policy, in alignment with Jordan (2016).

Compliance with Cultural Norms and Corporate Policy
Compliance with cultural norms and corporate policy addressing the FCPA
compliance emerged as a significant finding. Conceptually, designing corporate policies
that reduce corporate liability, compliant with cultural norms without improper benefits
being realized by foreign government officials, serves to achieve compliance with the
FCPA (Jorge & Basch, 2013). The study findings included a variation on this concept.
MR16’s comments indicate that the target company’s leadership focus on the creation of
a corporate policy that provides instructions to employees on how to address cultural
norms deviates from Jarge and Basch’s (2013) conceptual framework that provides for a
more holistic approach to the compliance with cultural norms, policy, and the FCPA.
Qualifying for FCPA Compliance
Qualifying for FCPA compliance emerged as a significant finding. Jordan (2016)
posited that integrity, honesty, good record keeping and full disclosure of business
transaction financials are emerging as integral elements of a business successful strategy
for compliance with the FCPA. KL02 commented that integrity is essential in all business
dealings and company management qualifies clients for integrity through their
compliance with the FCPA. The study findings concurred with Jordan’s
conceptualization that honesty and compliance with the FCPA are elements of long-term
business success.
Tie Findings or Disputes Findings to Existing Literature on Effective Business

Practice
In the 21st century, lack of compliance with the FCPA is still present, and
employees of U.S. aerospace companies allegedly bribe international government
officials to gain contracts (Darrough, 2010). The FCPA, which is one of the significant
business corruption deterrents, applies to U.S. companies, U.S. company personnel, and
foreign firms trading on the U.S. Stock Exchange in U.S. territories (Feld, 2013). The
implementation of adequate controls to increase compliance with the FCPA in the 21st
century is helping to curb corruption (Sanyal & Samanta, 2011). In this section, I
addressed the research findings as they relate to strategies for compliance with the FCPA.
In addition, I identified the successful business plan for compliance with the FCPA that
improves corporate competitiveness, reduces costs for doing business, and leads to
economic profits.
Continuous FCPA Compliance Training
Continuous employee training on the FCPA compliance methods can lead to an
antibribery corporate culture (Cascini et al., 2012). Given the continued risks of
noncompliance with FCPA, companies must have adequate compliance policies, internal
controls, and plans to detect and prevent bribery including an ongoing training program
for corporate employees engaged in international business pursuits (Jordan, 2016).
Ethical training does not necessarily provide a stronger ethical culture. However, data
suggest that an ethical training program in an organization can prevent and deter criminal
conduct (Stucke, 2014).

Development and training of multinational companies’ management on corporate
FCPA compliance guidelines and how to management addresses noncompliance
situations, identify and avoid international business corruption is important (Weeman,
2013). The findings from the research confirmed Weeman's observation that effective
training on corporate FCPA directives assists in identifying and preventing fraud. In
addition, LT10’s comments regarding yearly training and timely updates to corporate
employees of FCPA amendments as they occur concurred with the assertions of Jordan
(2016).
Active Management
High-power-distance cultures where managers adapt paternalistic relationships
toward subordinates harbor corruption more than low-power-distance cultures where
subordinates question management decisions and offer personal opinions (Yeganeh,
2014). Current trends in FCPA enforcement are ineffective, and the integration of the
FCPA into corporate culture through value-based management strategies could improve
FCPA compliance at both small and large companies (Lestrange & Tolstikov-Mast,
2013). Leaders of organizations play a significant role in eliminating corruption in
international business by actively participating in the compliance process with FCPA
(Adeyeye, 2014; Bierstaker, 2009).
Stucke (2014) noted that to reduce the potential of corruption in international
business, management must actively promote ethical behaviors at all levels of the
organization and monitor compliance with FCPA. The findings from the research
confirmed Stucke observation that active management reduces corruption within the

organization. RM06 commented that web-based notifications sent to all employees
notifying them of any FCPA changes to keep employees informed of the FCPA
requirements concurred with Stucke with Stucke (2014). In addition, AR24’s comment
regarding periodic reviews of the FCPA requirements implementation and actively
reaching to employees and customers with updates as they occur concurred with Adeyeye
(2014) and Bierstaker (2009).
Compliance with Cultural Norms and Corporate Policy
Small and medium enterprise leaders need to establish an anticorruption policy
and create an FCPA compliance program to ensure international business leaders avoid
bribery situations (Jorge & Basch, 2013). A close inspection of the relationship between a
culture of noncompliance with anticorruption laws and developing culture is necessary
(Akbar & Vujic, 2014; Pena López & Sánchez Santos, 2014). Vietnamese and Burmese
cultures, where using an intermediary to facilitate corporate transactions through bribes
between government officials and the corporation is the norm (Feldman, 2014).
In the literature, Choudhary (2013) and Klinkhammer (2013) provided that
national culture influences corporate culture regarding how corporate leaders view
bribery and the potential of employees to engage in corruption when conducting business
overseas. The finding from the study provided a variation on the existing literature
presented by Choudhary and Klinkhammer. In addition, MR02’s comment relating to
providing employees with the latest changes in FCPA through clear corporate directives
concurred with Jorge and Basch (2013).

Qualifying for FCPA Compliance
Corrupt organization leaders create organizational cultures and establish work
structures where employees facilitate corruption on a daily basis without being aware that
something illegal is occurring (Campbell & Goritz, 2014). In the literature, Sanyal and
Samanta (2011) noted that companies implementation of adequate controls to increase
compliance with the FCPA in the 21st century is helping to curb corruption. Executives
of multinational corporations need to assist countries with corruption and establish
strategies on how to comply with the FCPA while conducting business in such countries
(Cleveland et al., 2010).
Cascini et al. (2012) asserted that the inclusion of FCPA compliance in the
corporate code of ethics and employee training and the ways compliance with the FCPA
could lead to an antibribery corporate culture. RM12 concurred with Cascini et al.’s
assertion. Furthermore, LT06’s comment relating to verifying customers compliance
standards with the FCPA concurred with Sanyal and Samanta (2011).
Applications to Professional Practice
This research applies to the professional practice of pursuing international
business. The purpose of the study was to explore the strategies used by U.S. aerospace
small business leaders to comply with the FCPA. I expect this research to benefit
primarily U.S. small aerospace and defense businesses in complying with the FCPA
while pursuing international trade. Second, I expect this research to help those designing
corporate compliance strategy and developing FCPA corporate compliance directives.

Continuous FCPA Compliance Training
This research may benefit U.S. small aerospace business executives who are
seeking international trade. The findings covered within this theme may help U.S. small
aerospace business executives in designing and maintaining FCPA compliance training
programs that may save money by avoiding potential FCPA violation penalties and
improve profits. Cascini et al. (2012) showed that employees training on the FCPA
compliance process leads to an antibribery corporate culture. Huang and Rice (2012)
indicated the need for developing clear corporate guidelines for a manager on how to deal
with noncompliance with the FCPA.
The findings of this theme may help U.S. small aerospace business executives to
establish a robust FCPA compliance program that reduces international trade risks. The
analysis of the participants’ responses revealed U.S. small aerospace companies should
develop an FCPA program that has
•Initial FCPA compliance certification,
•Continuous training,
•Timely online notification of changes, and
•Periodic auditing.
These findings are relevant to U.S. small aerospace business that are not only trying to
comply with the FCPA but also are focusing on the creation of an ethical corporate
culture.

Active Management
The findings in this study may help management to be proactive in the creation of
FCPA compliance policies and monitor compliance with these policies. These results
apply to a U.S. small aerospace business that is seeking international trade. Throughout
this case study, I showed the importance of active management in the compliance with
FCPA. With these findings, I indicate that U.S. small aerospace business executives
should be involved and take ownership of the FCPA compliance program to protect the
corporation, employees, and management from potential FCPA violations.
Compliance with Cultural Norms and Corporate Policy
The study findings are intended to help U.S. small business executives develop
FCPA compliance policies that address cultural norms and remain compliant with FCPA.
Baughn et al. (2010) asserted that countries’ culture has a significant effect on the
compliance with anticorruption laws and countries’ cultural environment need
consideration during the development of corporate strategies for compliance with FCPA.
Baughn et al. (2010) concluded that understanding cultural differences helps predict the
severity of domestic corruption and noncompliance with FCPA. Mensah (2014) asserted
that cultural and religious environments influence business behavior toward corruption.
The finding encompassed within this theme concurred with Mensah’s assertion and may
help the U.S. small aerospace business manager in the establishment of corporate
strategies that address cultural norms while complying with the FCPA. In addition, the
findings revealed that company executives must ensure that all international contracts
have an FCPA clause that requires the participant to comply fully with the FCPA.

Qualifying for FCPA Compliance
This research may benefit U.S. small aerospace businesses with limited resources
that are expanding in the international markets with qualifying opportunities. The analysis
of the participants’ responses revealed U.S. small aerospace company executives should
vet international opportunities for (a) integrity of the customers, and (b) customers
compliance with the FCPA. Findings also revealed that management, in some cases,
declines to participate in international opportunities that appear noncompliant with the
FCPA.
Implications for Social Change
The results presented in this study may have positive implications for social
change. The results from this study are expected to improvements in corporate ethical
standards in international trade practices by reducing contract corruption and increasing
compliance with the FCPA. Decreasing contract corruption may result in reduced
corporate operational costs. Reduced operational costs are expected to lead to additional
jobs in the industry, which improve the local economy leading to a positive social change.
Lestrange and Tolstikov-Mast (2013) and Lord (2013) asserted that reducing
transactional business crime through FCPA compliance creates a safe environment for
conducting business, reduces costs, and creates jobs, which results in a positive social
change. Global business bribery negatively affects corporations’ economic and corruption
leads to an anticompetitive environment (Smith, Gruben, Johnson, & Smith, 2013). The
findings in this study may have positive implications in increasing the competitive
markets where products and services evaluation usually based on their value and merit
resulting in economic efficiency within the country, which is a positive social change.

Recommendations for Action
By examining participant responses, company policy, my personal journal,
collected data triangulation, and material on FCPA compliance strategies, I identified
multiple themes that address how U.S. small aerospace business might use FCPA
compliance to improve their international business. These themes included that the design
and implementation of FCPA compliance strategy requires cultural knowledge, economic
knowledge, global markets knowledge, understanding of local laws, and FCPA
requirements knowledge. Based on the study findings, a successful FCPA compliance
policy should include full compliance with the FCPA and comprehensive compliance
monitoring program.
The first recommendation is that U.S. aerospace business leaders should establish
a comprehensive FCPA compliance program that includes
•Ongoing training,
•Active management,
•Cultural norms compliance guidelines, and
•Qualifying business opportunities for compliance with the FCPA. The
established FCPA compliance program must provide employees with clear instructions
on how to comply with the FCPA. In addition, FCPA ongoing training should include an
electronic notification of any updates and amendments to the FCPA to the employees and
customers.
The second recommendation in those U.S. small aerospace business leaders
should actively participate in the FCPA compliance process. Leaders’ participation can

come in a form of regular audits, periodic interactive seminars, or periodic requests of
FCPA compliance feedback from their managers involved in international business
pursuits. In addition, leaders should set an example for all employees, be transparent, and
not tolerate any violations of the FCPA by any member of the corporation. Leaders also
should not penalize employees for rejecting business opportunities that prove
noncompliant with the FCPA.
I plan to disseminate the study findings through a variety of channels. This topic is
relevant to current international business transactions issues. These include the significant
penalties levied on corporation due to violations of the FCPA, the sheer volume of world
transactions conducted on a daily basis, and the need to protect corporate, management,
and employees for personal liability due to violations of the FCPA. Initially, I expect to
share these findings with the leaders of U.S. small aerospace companies that they are in
the process of expanding their business in the international markets. I hope that
organizations presently developing FCPA compliance strategies will find this information
helpful to create guidelines that they follow during their policy formulations stage.
Recommendations for Further Research
The observations and findings in this study show the need for additional research
in several different areas. In this study, I explored the strategies used by U.S. aerospace
small business leaders to comply with the FCPA. The participants in this study gave their
view on how their aerospace companies were successful in complying with the FCPA.
This study was limited geographically to California and addresses only small aerospace
businesses in that region. I recommend further research on the FCPA compliance

strategies used by all U.S. aerospace companies engaged in international trade pursuits.
Other recommended study can be a study focused on the transferability of the research
findings to other U.S. industries that are involved in international business. Another
recommended area for study is the close inspection of existing FCPA and amendments to
identify areas that may require a change to improve the competitive edge of U.S.
companies in the international arena.
Reflections
This study gave me a deeper understanding of the value of the case study in a
qualitative research and its contribution to the academic body of knowledge. Through this
process, I believe that I have transformed from being a practitioner to a
scholarpractitioner, capable of contributing to our understanding of global business
issues. When I began this journey, I naively thought that it would be solving all business
corruption problems and helping the U.S. industry gain international trade by evening the
competitive field. I have quickly realized that these efforts may need many studies and a
significant amount of time to perform these studies. Some of the faculty members helped
me narrow this study to exploring small aerospace companies’ strategies to comply with
the FCPA.
This research was enhanced by my prior knowledge and experience. My
experience in the aerospace and defense industry helped me in identifying the population
for this study and in conducting the interviews with the participants. Having experience
with international pursuits, international contracts, and international business
development for the aerospace and defense also gave me first-hand knowledge of the

compliance with the FCPA. I have tried to ensure that my personal biases did not
influence the study results; I believe that I was successful in achieving this goal.
I found the process of performing the literature search, conducting the interviews,
member checking, coding, and triangulation of data to be invigorating. Synthesizing the
themes to answer the research question helped me in formulating the questions for the
interviews and in the conduct of these meetings. This process has increased my
confidence as a researcher, and I am looking forward to completing more research in the
international business field.
Conclusion
Compliance with the FCPA is critical to the success of U.S. small aerospace
companies pursuing international business. I conducted this study to identify successful
strategies used by U.S. small aerospace companies to comply with the FCPA. Based on
the findings in this study, there are four themes that successful U.S. small aerospace
companies are engaged in that make these companies successful in the compliance with
the FCPA. Managers seeking international business need to consider these themes during
the formulation of a corporate strategy for FCPA compliance. The four themes that
emerged from this study were
•Continuous FCPA compliance training,
•Active management,
•Compliance with cultural norms and corporate policy, and
•Qualifying business opportunities for FCPA compliance.

These findings are intended to be used by small aerospace company leaders may use the
findings of this study to create successful corporate strategies for complying with the
FCPA while also pursuing international business opportunities, reducing the cost of
making the international trade, avoiding significant penalties, and establishing a good
corporate global image.
This research promotes positive social change by facilitating adherence to
strategic FCPA compliance policy developed by company leaders, including
improvements in corporate international trade practices by reducing corruption. Reducing
business crime reduces overall corporate operational costs, which expected to lead to
hiring more people. Hiring more people improves local economies leading to a positive
social change.

