


1
Chapter 1: Introduction to the Study
Turmoil, apprehension, and overreaction may be the new normal in financial
markets (Black et al., 2017). The problem is that investor uncertainty results in
suboptimal resource allocation in capital markets, which inhibits economic growth,
innovation potential, and investor returns. Black et al. (2017) found that heightened
uncertainty levels increase corporate takeover activity based on inside information, which
is a violation of federal law and contributes to market failure. Connolly et al. (2005)
found that investors have a stronger tendency to eschew stocks in favor of safer
investments like Treasury bonds when faced with market uncertainty. Romeo (2015)
found a similar correlation between stocks and property assets.
Scholars have criticized initial coin offerings (ICOs) as inherently inefficient
bubbles and have warned investors away from them (Quiggin, 2013), yet others have
argued that ICO markets can exhibit efficiency and do perform critical functions where
traditional capital markets tend to fail (Littlewood, 2018), thus providing democracy and
opportunity to innovative and often marginalized entrepreneurs. Crowdfunded equity
markets share many central features of ICOs, including a reliance on crowd funding
techniques and support from nonaccredited investors. Critics have raised similar concerns
regarding crowdfunded equity markets (Ibrahim, 2015), but crowdfunded equity markets
have shown a level of efficiency (Gruner & Siemroth, 2019) and opportunity (Gale,
2018). A study assessing ICO market efficiency compared to crowdfunded equity market
efficiency was needed to reduce uncertainty in ICO markets by informing investors of the
dynamics in markets, thus reducing turmoil within them and improving capital allocation.

2
In Chapter 1, I outline the background, problem statement, purpose, research questions,
theoretical foundation, nature, definitions, assumptions, scope and delimitations,
limitations, and significance of the study.
Background of the Study
The damaging effects of uncertainty in markets, particularly capital markets, is
well documented in the literature. Black et al. (2017) documented the effect of
uncertainty in markets to increase not only inefficiency but also even criminal activity.
Connolly et al. (2005) discussed how uncertainty also results in capital allocation away
from innovative assets in favor of safe, low yield alternatives. Romeo (2015) found
similar results concerning stocks and real estate.
Researchers have also found similar outcomes regarding the effect of uncertainty
on ICOs and other emerging capital market types. Neuman (2018) highlighted many
uncertainty risks pertaining to ICO and cryptocurrency markets via a discussion of the
many risks inherent to those offerings and assets. Lichfield (2018) provided a similar
discussion during an interview with digital currency researcher Robleh Ali who discussed
the general lack of transparency in ICO markets, including a dearth of reporting
information regarding most ICOs when compared to the reporting standards of initial
public offerings (IPOs). Quiggin (2013) argued that crypto markets are inherently
inefficient, that the rise of crypto markets in recent years represents a financial bubble in
truest form, and that this bubble provides proof in refuting the efficiency of markets
overall. Zetzsche et al. (2019) offered a similar argument by asserting that the rise of
ICOs represents a market bubble that cannot offer investors enough material information

3
to afford rational engagement in crypto markets or efficiency of those markets. The
authors argued, however, that one reason for the rapid rise of ICOs has been the failure of
traditional capital markets to provide support for innovative yet socioeconomically
marginalized entrepreneurs and investors, which is also a consistent narrative among
those who argue in favor of ICOs and other emergent capital market types.
The rise of crowdfunded equity offerings parallels ascension of ICOs in recent
years. Gale (2018) argued in favor of crowdfunded equity as a means of providing
democracy currently missing in traditional capital markets, while Ibrahim (2015) argued
that crowdfunded equity endangers investors via undue risk due to lack of transparency,
reporting, and certainty compared to traditional capital market types.
But other scholars have shown crowdfunded equity markets to exhibit efficiency,
thus bolstering their arguments that they provide an alternative to traditional capital
markets, along with opportunities to entrepreneurs and investors traditionally shut out
from markets. Gruner and Siemroth (2019) found that crowdfunded equity can efficiently
allocate capital. Ahlers (2015) discovered that crowdfunded equity markets often respond
to signaling to attract investor support, most particularly by providing information about
retained equity and risk. Mamonov and Malaga (2017) examined success factors
affecting crowdfunded equity markets and found that key information affects the success
of equity crowdfunding. These combined findings suggest a level of efficiency in
crowdfunded equity markets, despite their many criticisms and concerns to the contrary.
Both ICOs and crowdfunded equity offerings emerged as alternative financing
options for entrepreneurs within the last few decades due to recent advances in

4
technology, social understanding, and legal/regulatory evolution (Brown et al., 2018;
Dudgeon & Malna, 2018). Additionally, ICOs and crowdfunded equity markets have
been simultaneously lauded as harbingers of improved opportunity and democracy in
capital markets (Gruner & Siemroth, 2019; Littlewood, 2018). However, both ICOs and
crowdfunded equity markets have also been criticized as dangerous, corrupt, and unstable
(Beloussov, 2016; Ibrahim, 2015; Zetzsche, 2019).
Lee (2017) offered a macro-level assessment of the ICO market and warned of
parallels with the Dot.com bubble. Lichfield (2018) also addressed systemic concerns of
the ICO market by noting the danger that noninstitutional investors pose to the ICO
market compared to the assumed safety of IPO markets. Debler (2018) discussed the
regulatory environment surrounding ICOs pertaining to the Securities and Exchange
Commission. Adhami et al. (2018) conducted research on the success factors of ICOs
from a capital acquisition standpoint. Brown et al. (2018) investigated characteristics of
entrepreneurs who pursued crowdfunded equity in the UK. Signori and Vismara (2018)
also researched success factors that allowed crowdfunded equity-reliant firms to acquire
additional capital post initial offering. Wonglimpiyarat (2018) and Fisch (2019) studied
similar factors among startups relying on ICOs for initial capital infusion. However, few
researchers have attempted to compare success outcomes between ICOs and
crowdfunded equity offerings.
My study contributes to the literature by comparing ICOs and crowdfunded equity
market dynamics to investigate efficiency characteristics like those previously found in
crowdfunded equity markets. The literature has lacked comparisons, thus representing a

5
material knowledge gap pertinent to the rise and subsequent debates concerning ICOs and
crowdfunded equity. My study comparing each market type may reduce uncertainty and
increased efficiency in both markets.
Problem Statement
The social problem in my study was that uncertainty in markets increases the
likelihood of market failure due to volatility and suboptimal functioning. This social
problem pertains also to capital markets, including emergent types like ICOs and
crowdfunded equity offerings. Whereas both ICOs and crowdfunded equity exhibit
similar structure, dynamics, promises, and criticism, prior studies have shown
crowdfunded equity markets exhibit some degree of market efficiency (Gruner &
Siemroth, 2019). However, the literature prior to my study has not compared ICOs to
crowdfunded offerings through this perspective.
This gap has deprived marginalized entrepreneurs and nonaccredited investors of
critical information that would otherwise guide their decisions to enter emergent capital
markets. The consequence of this knowledge gap is that market participants have to either
choose blindly between the ICOs or crowdfunded equity markets, thus exposing
themselves to otherwise preventable risks, or they have to opt out of emergent capital
markets altogether, thus depriving themselves of the many opportunities that capital
markets may provide them. The combined result of this knowledge gap was loss of
macroeconomic innovation, perpetuated socioeconomic inequality, reduced capital
market functionality, and increased volatility and risk in the entrepreneurial and investor
communities. For example, Sunil (2021) documented a crash of the crypto markets that

6
wiped out $600 billion in a single week. For many investors, particularly nonaccredited
investors, these losses can be devastating.
The research problem was lack of knowledge and understanding pertaining the
relative efficiency and behavior of ICO markets compared to crowdfunded equity
markets, which perpetuates the uncertainty associated with crowdfunded asset types and
thwarts the various communities they are intended to serve. My study compared the
primary market outcomes of ICOs compared to those of crowdfunded equity offerings,
along with the factors that may have influenced those outcomes and may have informed
burgeoning and otherwise marginalized startups and investors in which market, if either,
would best match their individual needs. My study may also inform investors and broader
market stakeholders in the actual functioning of emergent capital markets, which may
guide future legal and regulatory evolutions. Information stemming from my study may
contribute to positive social change by reducing uncertainty, risk, and market volatility
while also increasing opportunity and innovation, particularly among marginalized
entrepreneurs and nonaccredited investors.
Purpose of the Study
The purpose of this quantitative study was to compare a group of ICOs versus a
group of crowdfunded equity offerings with the intent of identifying predictive factors of
those funding outcomes. Using analysis of variance (ANOVA), my study had one
primary binary control factor that denoted whether the offerings relied on either ICOs or
crowdfunded equity offerings as a form of capital acquisition. My study had one
continuous, numerical dependent variable that denoted the dollars raised by the

7
participants in the two different market types. I also assessed the influence of eight
secondary control factors, each related respectively to access to historical financial data,
pro forma financial projections, detailed product descriptions, video of product
demonstrations, company website, company history, company leadership, and company
investors. All of the secondary control factors were binary (Yes or No) denoting whether
the startups provided access to this information during their offerings.
Research Question(s) and Hypotheses
Research Question: How does capital offering type predict the amount of funds
raised while controlling for access to the offering companies’ historical financial data,
pro forma financial projections, detailed product descriptions, video of product
demonstrations, company website, company history, company leadership, and company
investors?
For each of the nine control factors (one primary and eight secondary), the
following were the hypotheses that were tested to address the RQ:
Hj0: There is no difference in mean funds raised due to control factor j.
μj1 = μj2 where μj1 is the mean funds raised with control factor j at Level 1,
and where μj2 is the mean funds raised with control factor j at Level 2; and j = 1, 2…9.
HjA: Mean funds with control factor j at Level 1 is not equal to mean funds raised
with control factor j at Level 2.
μj1 ≠ μj2.
For each pair of control factors, j and k, the following are the hypotheses related
to the two-factor interaction (2FI) equal to j*k.

8
Hf0: The interaction of factors j and k is equal to zero.
j*k = 0.
HfA: The interaction of factors j and k is not equal to zero.
j*k ≠ 0.
Theoretical Foundation
The theoretical foundation grounding this study was the efficient market
hypothesis (EMH; Leković, 2018). According to EMH, well-functioning markets should
incorporate all historical, public, and inside information into current asset prices;
therefore, it is very difficult (if not impossible) to consistently find arbitrage opportunities
via deliberate analysis (Fama, 1970). Were ICO and/or crowdfunded equity markets to
function efficiently, the central tenets of EMH would also hold true, and their aggregate
outcomes would roughly match those of traditional equity markets when controlling for
risk premiums. Given this result, the investment community would utilize these markets
in an efficient manner, based on the central tenets of EMH (Fama, 1970). However, if
this were not the case, then arbitrage opportunities would exist in the ICO or
crowdfunded equity markets, and investors should either boost investment or increase
divestment, accordingly. Were performance differentials found, then EMH would suggest
the existence of inefficiencies in the ICO and crowdfunded equity markets, thus
supporting the need for market reform appropriate to the findings (Zetzsche et al., 2019).
A key difference between traditional IPOs and emergent capital markets (ICOs
and crowdfunded equity) pertains to regulations requiring financial reporting disclosures
prior to launching a public offering. A widely accepted body of regulatory law pertaining

9
to traditional capital markets requires businesses seeking capital injection via IPOs to
provide significant financial reporting to the public prior to any offering, coupled with
illustrating proof of feasibility via a documented track record of organizational success
(Lichfield, 2018). Traditional capital offerings typically also require partnership with an
institutional underwriter, usually an investment bank, to guide processes and proofs along
in preparation for the eventual launch. These long-held market expectations generally
allow the accredited investors who participate in traditional capital markets to find and
incorporate public and historical data into their pre-offering valuation assessments
(Lichfield, 2018).
Conversely, ICOs and crowdfunded equity offerings adhere to far less stringent
financial disclosure regulations when compared to traditional IPOs (Zetzsche et al.,
2019). Moreover, both ICOs and crowdfunded equity offerings typically occur prior to
establishing any viable proof of work to support project feasibility, as most offerings
occur at the very beginning of the organizational life cycle and often prior to rigorous
testing of the product/service prototype with a mainstream consumer base (Lichfield,
2018). Information deficiencies make it difficult for investors to incorporate public and
historical data into their pre-offering valuations when considering investment in
crowdfunded equity offerings and especially ICOs. Some scholars have argued that these
issues render ICOs inherently inefficient (Quiggin, 2013). Additionally, because ICOs
and crowdfunded equity offerings do not rely solely on the support of accredited
investors, their capital networks not only often lack the sophistication expected from an
exclusively accredited support base, but the nonaccredited investors who often participate

10
in emergent capital offerings are often friends, family, or some other interested parties of
the entrepreneur (Lichfield, 2018). Dynamics seemingly present a challenge to the
efficient workings of marketplaces, along with a heightened propensity toward behavioral
characteristics among participating investors. Still, scholars have also argued in favor of
ICOs as potentially performing needed functions that traditional capital markets have
historically failed to meet, like offering opportunities to high-innovation entrepreneurs
when ICO markets behave efficiently (Zetzsche et al., 2019). To adequately examine
EMH in the ICO and crowdfunded equity markets, it was necessary to incorporate
innovative efficiency indicators into the analysis, supported by a nuanced theoretical
foundation integrated with EMH.
One avenue toward testing efficiency in ICO markets was to actively compare
them to crowdfunded equity markets. Both emergent capital market types rely on
crowdfunding as a central function, along with nonaccredited investor bases, early in the
startup lifecycle. Whereas crowdfunded equity markets have been criticized
nontransparent and volatile (Ibrahim, 2015), scholars have also found crowdfunded
equity to exhibit efficient characteristics (Gruner & Siemroth, 2019) like signaling
material information to the investment community (Ahlers et al., 2015), which scholars
have found to influence positive outcomes during the offering process (Mamonov &
Malaga, 2017).
My study compared ICOs and crowdfunded equity offerings according to
transparency and outcomes, and it thus provides insights into whether ICOs share the
efficiency characteristics previously identified in crowdfunded equity markets. My

11
approach theorized that if both markets share efficiency characteristics, then access to
material information should have predicted funding outcomes regardless of offering type
chosen by the individual startups. I further theorized, if one or both markets lack
efficiency, then access to material information should not predict funding outcomes. I
elaborate further on this approach in Chapter 2.
Nature of the Study
In this quantitative study, I used ANOVA to compare the amounts of money
raised by a group of startups that recently completed ICO offerings, versus a group of
startups that recently completed crowdfunded equity offerings. The primary control
factor denoted whether each startup in the study relied on an ICO or a crowdfunded
equity offering, and this primary control factor was therefore binary. The dependent
variable was a continuous numerical variable measuring the amount of money that each
startup in my study raised, whether via ICOs or crowdfunded equity. I also examined the
influence of eight secondary binary control factors, expressed as Yes or No, that signified
whether each startup in the sample provided investors with the following:
• Historical financial data
• Pro forma financial projections
• Detailed product descriptions
• Video of product demonstrations
• Company website
• Company history
• Company leadership

12
• Company investors
I relied on publicly available secondary data from emergent capital market
websites. Post-ICO data were found on the ICO crowdfunding website, icodrops.com
(2022), which facilitates ICOs and stores historical market information. Post-
crowdfunded equity offering data were initially to be found on the startengine.com
(2022) website, which facilitates crowdfunded equity offerings and stores historical
information on these offerings. But I ultimately relied on the sites localstake.com (2022),
mainvest.com (2022), and fundable.com (2022), which provide similar data to
startengine.com.
The intent of my study was to explore the efficiency of the ICO market compared
to the crowdfunded equity market. The objective for my study design was to assess
whether offering type (ICOs or crowdfunded equity) predicted funding outcomes
(amount of money raised) of the startups in my study when controlling for access to the
offering companies’ historical financial data, pro forma financial projections, detailed
product descriptions, video of product demonstrations, company website, company
history, company leadership, and company investors.
The study design and variables related directly to the research questions,
hypotheses, and theoretical foundation. The intent of the research was to fill the gap in
the research related to the social problem. As previously discussed, prior research has
indicated that crowdfunded equity offerings exhibit efficiency characteristics. However,
little was known about whether the ICO market functions as efficiently as the
crowdfunded equity market. By comparing two groups of startups using ANOVA, I

13
sought to discover how the two markets compared regarding efficiency by comparing the
amount of funding raised by each group; and if other factors influenced those outcomes.
Definitions
Amount of funds raised: The single dependent variable. It was a continuous,
numerical variable and denoted the amount of money that a startup raised via their public
offerings, either via ICOs or crowdfunded equity.
Capital offering type: The primary control factor. It was a binary control factor
that appeared as one of two possible outcomes: ICO offering organization or
crowdfunded equity offering organization. The former denoted startups that sought
capital via ICO offerings, and the latter denoted startups that sought capital via
crowdfunded equity.
Company history: A secondary binary control factor that denoted whether the
capital seeking organization provided a company history prior to the offering launch. The
range of possible values was either Yes or No.
Company investors: A secondary binary control factor that denoted whether the
capital seeking organization provided a list of investors in the company prior to the
offering launch. The range of possible values was either Yes or No.
Company leadership: A secondary binary control factor that denoted whether the
capital seeking organization provided a company leadership detail prior to the offering
launch. The range of possible values was either Yes or No.

14
Company website: A secondary binary control factor that denoted whether the
capital seeking organization provided a company website prior to the offering launch.
The range of possible values was either Yes or No.
Detailed product descriptions: A secondary binary control factor that denoted
whether the capital seeking organization provided a detailed product description prior to
the offering launch. The range of possible values was either Yes or No.
Historical financial data: A secondary binary control factor that denoted whether
the capital seeking organization provided historical financial data prior to the offering
launch. The range of possible values was either Yes or No.
Pro forma financial data: A secondary binary control factor that denoted whether
the capital seeking organization provided pro forma financial data prior to the offering
launch. The range of possible values was either Yes or No.
Video of product demonstrations: A secondary binary control factor that denoted
whether the capital seeking organization provided a video of product demonstrations
prior to the offering launch. The range of possible values was either Yes or No.
Assumptions
An underlying assumption in my study was that rational, self-interested investors
would respond, as a general tendency, more favorably to fundraising startups that provide
material information to the investment community prior to making a public offering, as
compared to those startups that offered relatively less material information to the
investment community prior to an offering. A follow up assumption was that this
assumed tendency of investors represented an efficient behavior within primary capital

15
markets. I based this assumption on the central assertion of EMH, which holds that
investors naturally price all available material information into asset prices in an efficient
marketplace (Fama, 1970). According to EMH then, investors in an efficient marketplace
naturally seek out information material to asset prices. I relied on this rationale in my
assumption that investors should show a greater propensity to invest in startups that
provide greater transparency relative to other startups, and that this propensity to invest
toward greater transparency is a sign of an efficient market.
Scope and Delimitations
The social problem was that investor uncertainty results in suboptimal resource
allocation in capital markets, which inhibits economic growth, innovation potential, and
investor returns. The research problem was lack of knowledge and understanding among
investors and financial professionals pertaining to the efficiency of ICOs versus
crowdfunded equity offerings, which perpetuates the uncertainty associated with
emergent markets and thwarts the various communities they are intended to serve.
The specific aspect of the social problem that I sought to focus on was the
knowledge gap regarding the differences between outcomes in the ICO market and those
in the crowdfunded equity market when accounting for market transparency. I chose this
focus based on the complete or near complete dearth of research that has actively
compared the outcomes and dynamics of the two markets of interest.
The population in the study consisted of firms that sought startup capital via ICO
offerings and those that sought startup capital from crowdfunded equity offerings. The
target population derived from publicly available data for these firms provided by four

16
popular websites that serve those populations. The target population did not include
startups listed on other websites or those that were not accessible to the general public.
The website ICOdrops.com (2022) maintains both ongoing and completed ICO offerings
and their associated funding results, including a listing of 1,305 completed ICOs that
have run on the site between July 2014 to January 2022. The website startengine.com
(2022) maintains both ongoing and completed crowdfunded equity offerings and their
associated results, including a listing of 583 companies that have completed
crowdfunding campaigns on the website. However, startengine.com ceased offering this
information during the course of my research, so I found similar data from the
crowdfunded equity sites localstake.com (2022), mainvest.com (2022), and fundable.com
(2022). My study relied on a sampling of the target population.
The primary theory that provided a framework to the study was EMH as seen in
the primary capital markets. The study did not cover EMH from a secondary market
perspective, nor did the study account for behavior finance theory, although future
researchers may further close the knowledge gap by doing so. The focus of the study also
did not account for other seminal theoretical families in financial thought, like modern
portfolio theory, nor did it account for the effects of business cycles on the markets of
interest.
Limitations
One limitation was that other influences may have also affected the investment
community’s propensity to engage in emergent capital markets, some based on efficiency
and rationality, and others based on inefficient or behavioral factors. Examples of rational

17
or efficient factors not considered in my study that may influence emergent capital
market outcomes include privy investment information available to key investors but not
the public, the respective strength of individual entrepreneurs’ funding networks, etc. An
example of nonefficient or behavioral factors that may influence capital market outcomes
may include personal investor relations/affinities to the entrepreneurs and secondary
capital market behavior. These other factors were beyond the scope of my research.
The study was also limited in that it only pertained to primary emergent capital
market outcomes, rather than also incorporating secondary capital market outcomes.
Secondary market information lacks transparency, but future researchers may wish to
seek this information if conditions allow.
An additional limitation to the study was that it relied solely on a quantitative
design to assess market efficiency and outcomes via publicly available secondary data.
Future researchers may also choose to incorporate direct feedback from market
participants via surveys or qualitative approaches such as interviews or focus groups.
Future inquiry may inform the behavioral side of emergent capital market dynamics,
along with further informing rational behavior within the realms of market efficiency.
Significance of the Study
This study was significant according to its potential to advance financial theory
into emergent ICO and crowdfunded equity markets, improve the practical functioning of
those burgeoning capital market types, and create positive social change by reducing
uncertainty in those markets along with mitigating the turmoil associated with
uncertainty. I elaborate on each of the areas of significance in the following subsections.

18
Significance to Theory
While much has been written and studied pertaining to the efficiency and
transparency of capital markets, the current body of literature is almost exclusively
focused on traditional capital market structures, like primary and secondary equity, bond,
options, and commodities markets that are highly regulated and have long histories of
study and commentary (Leković, 2018). The vast majority of research surrounding EMH
and its related body of theory has focused on established marketplaces, and even
emergent bodies of financial thought that somewhat counter EMH, like those ideas
prevalent in behavioral finance, are almost exclusively dedicated to those traditional
capital and securities markets, as well.
The sudden explosion of ICOs and crowdfunded equity offerings has grown those
emergent markets into a force in the field of finance faster than the ability of researchers
in the discipline to keep pace with their development and acceptance. These emergent
markets are some of the most dynamic, promising, and evolving sectors of capital
finance, yet their opacity and theoretical mystery make them also some of the riskiest,
most volatile, and least understood markets in the capital sector.
Even those few theorists who have researched the workings and efficiencies of
ICOs and crowdfunded equity markets have not compared outcomes between the two in
comprehensive and meaningful ways. My study may make a significant contribution to
theory by providing cross-market research likely for the first time. The results and
conclusions of my study may subsequently guide the work of future theorists who may

19
choose to build upon my work, thus encouraging and empowering the next generation of
scholars to usher EMH and its broader theoretical family into this new age of finance.
Significance to Practice
ICOs and crowdfunded equity offerings have developed rapidly in recent years,
even now making inroads into mainstream practice. Many entrepreneurs and investors
have entered these emergent arenas in pursuit of the vast opportunities that others have
enjoyed while participating in them, yet they ultimately do so at their peril given the
dearth of comprehensive research pertinent to crowdfunded markets. Opacity further
prevents entrepreneurs and investors from fully knowing if they are choosing the best
option in emergent finance, particularly when considering the many similarities and
differences between ICOs and crowdfunded equity offerings.
Many startups may benefit from seeking capital via either ICOs or crowdfunded
equity offerings, but the gap in research that meaningfully compares the two forces
entrepreneurs to intuitively choose one or the other, as opposed to relying on informed
and educated knowledge when selecting a capital market type. A similar problem exists
for investors who wish to participate in emergent capital markets but who also lack
access to the requisite knowledge to know whether ICOs or crowdfunded equity offerings
represent the best markets for them.
My study may help to close this gap of practicable knowledge by offering
entrepreneurs and investors useful knowledge that may guide their entrance into either
emergent capital market, based on their own individual aptitudes for risk and reward.
This added professional insight may even reduce the tendency by market participants to

20
react to behavioral factors, like herd behavior, in favor of transparency and efficiency
factors. These outcomes may also reduce risk and volatility in both the ICO and
crowdfunded equity markets on a practical basis. The study may contribute to greater
efficiency, less risk, and improved stakeholder outcomes in both emergent capital market
types.
Significance to Social Change
Advocates for both ICOs (Littlewood, 2018) and crowdfunded equity markets
(Gale, 2018) have argued that traditional capital markets behave unfairly by favoring
accredited and institutional investors while simultaneously blocking out and
marginalizing small and individual investors who lack access to institutional wealth, thus
creating misbalanced feedback loops in traditional capital markets that trend toward
increased inequality. Similar arguments exist regarding the unfair nature of traditional
capital markets toward favoring established companies over fledgling startups, thus
creating noncompetitive business landscapes. Proponents of ICOs and crowdfunded
equity offerings argue that they operate more equitably than traditional capital markets
and even represent the democratization of capital offerings, thus empowering
entrepreneurs, bettering marginalized communities, and enriching nonaccredited
investors while contributing to a more vibrant, dynamic, and innovative economy.
Critics of ICOs (e.g., Quiggin, 2013) and crowdfunded equity offerings (e.g.,
Ibrahim, 2015) have argued that crypto marketplaces suffer higher risks for volatility,
corruption, fraud, crime, and systemic failure, while also exhibiting the overall behavior
of a market bubble that must inevitably correct itself. These dueling and seemingly

21
mutually exclusive narratives inhibit market stakeholders from safely and knowledgably
engaging with emergent capital markets while also causing these marketplaces to grow
with asymmetry and instability, thus harming stakeholders and causing risk and lost
opportunity to the broader economy.
My study may create positive social change by empowering stakeholders to
engage in ICO and crowdfunded equity markets, along with better knowing which of
those markets may be right for them. This may in turn result in improved efficiency,
transparency, and stability of emergent capital markets while also bettering marginalized
entrepreneurs, investors, and communities, alongside strengthening the broader economy.
Summary and Transition
In this chapter, I outlined the recent research related to my social problem,
problem statement, purpose, research questions, theoretical foundation, nature of the
study, definitions, assumptions, scope and delimitations, limitations, and significance of
the study. I assessed the mean primary market outcomes of startups seeking ICO funding
versus startups seeking crowdfunded equity funding, along with assessing the influence
of other factors that may affect those outcomes.
Both emergent capital market types have exploded in recent years due to
breakthroughs and reforms in technology and regulations, respectively. Their market
growth has developed faster than scholars have been able to study them, resulting in
significant knowledge gaps pertaining to those markets. The knowledge gap concerning
differences in outcomes between the two markets and factors that may influence those
outcomes has created much uncertainty among stakeholders in those markets. This

22
uncertainty inhibits optimal market performance and leads to reduced outcomes for
investors, entrepreneurs, communities, and the broader economy.
The theoretical foundation of my study, study design, and research questions were
designed to fill this knowledge gap via a quantitative assessment comparing those
specific market types. The study may contribute to positive social change by optimizing
the outcomes for participants of those markets, along with the communities and
economies that rely on them. In the next chapter, I outline the search strategy I relied on
to conduct the literature review, the theoretical and conceptual lens I interpreted it
through, and my conclusions drawn from it.

23
Chapter 2: Literature Review
The social problem of my study was that investor uncertainty results in
suboptimal resource allocation in capital markets, which inhibits economic growth,
innovation potential, and investor returns. As such, the research problem was lack of
knowledge and understanding among investors and financial professionals regarding
ICOs and crowdfunded equity offerings, which is perpetuating the uncertainty associated
with these asset types and thwarts the various communities they are intended to serve.
The purpose of this quantitative study was to compare a group of ICOs versus a group of
crowdfunded equity offerings with the intent of identifying predictive factors of those
funding outcomes.
The current literature surrounding ICOs and crowdfunded equity is expansive and
quickly evolving, but also lacking in critical areas. The majority of past researchers have
examined the technology, laws, potentials, risks, and other fundamental and systemic
factors that influence these emergent capital markets. A small but arguably growing
number of scholars have researched factors that affect primary market outcomes for ICOs
and crowdfunded equity offerings. However, few if any scholars have attempted to
directly compare outcomes and influencing factors of the two emergent primary markets.
In this chapter, I provide my literature search strategy, my theoretical foundation, my
literature review, and my summary and conclusions.
Literature Search Strategy
The primary sources of information that I relied on while conducting my literature
review are found through the Walden University Library portal, which subsequently

24
connects to numerous databases and search engines. The database I relied on most
heavily was Business Source Complete followed by Academic Search Complete. My key
search terms included: Initial Coin Offerings, ICOs, Crowd Funded Equity, Block chain,
Distributed Ledger Systems, Crypto Currency, Emergent Finance, and Crypto Tokens. I
also included secondary search terms for technologies that may currently or in the future
interface with the block chain platforms that ICOs run on, including Artificial
Intelligence, AI, Internet of Things, IoT, and Quantum Computing.
Most of the literature that I included in my search came from a window between
2015 to present, with the majority of sources originating in the years 2017 to 2022. The
exceptions to this date range pertained to the seminal works that I relied on to formulate
my theoretical foundation, particularly those pertaining to EMH and the functioning of
traditional capital markets. I have included a wide range of sources and literature types
including peer-reviewed works like scholarly papers. I also included many works from
industry and professional publications due to the nature of the constantly evolving ICO
and crowdfunded equity spaces. While many of those works have not been peer-
reviewed, they contain commentary and reporting that have and continue to influence
prevailing opinion among professionals, industry practitioners, and future researchers, so
I included those works because of their influence on scholarly thought.
Theoretical Foundation
EMH is a prevailing body of theoretical thought and was first formalized by
Harry Roberts in 1967 (Sewell, 2011). Existing within mainstream financial thought,
EMH is widely adhered to among both financial scholars and also practitioners (Leković,

25
2018). The central tenets of the theoretical foundation rest on the assertion that financial
markets (or any markets broadly) are fundamentally efficient in that they efficiently
incorporate all pertinent information from historical, public, and (arguably) private
sources, and that this information informs and guides the investment community in
setting asset prices in open places of commerce (Fama, 1970). EMH holds that it is very
difficult if not impossible to find arbitrage opportunities within efficient markets, as
traders and analysists in any transparent and functioning market would very quickly find
pricing aberrations and subsequently trade them away via opportunistic buying and
selling reactions (Leković, 2018). While proponents of EMH agree that market failures,
bubbles, and imbalances are both possible and common, they argue that this volatility
stems more from lack of material information to properly guide markets, rather than
market participants failing to incorporate this information in their collective decisions.
The prevailing assumptions of EMH are that asset prices within any reasonably
transparent and functioning market reflect the best estimates of those market participants
at any given time, and those participants may rationally assume that the prices within
those markets at any time have been efficiently priced at those levels (Fama, 1970).
The foundational concepts for EMH have existed in the realms of financial
thought and practice for centuries and have evolved over time through the seminal and
iterative contributions of many scholars before Roberts formalized the concept in 1967
(Sewell, 2011). EMH has fallen in and out of favor with mainstream thought throughout
the decades, and the hypothesis was considered largely heterodox until the mid- to late-
20th century (Sewell, 2011). One of the most influential contributions to EMH came from

26
Fama (1970) whose work entitled “Efficient Capital Markets: A Review of Theory and
Empirical Work” influenced generations of subsequent EMH theorists, thus contributing
to the adoption of EMH into mainstream financial thought. EMH prevailed as a widely
accepted body of theory throughout the 1980s, 90s, and early 2000s and was often cited
as justification for the deregulation of financial markets (Sewell, 2011). Many contrarian
theorists criticized EMH following the 2008 financial crisis (see for example O’Sullivan
[2018] and Yusuf [2015]). They pointed to the crisis as proof that EMH did not hold true,
even blaming EMH as encouraging and justifying the many market misbehaviors that
created the crisis (Sewell, 2011). Behavioral finance theorists have put forward
psychological theories to explain how markets may behave irrationally and thus
inefficiently. Decades of scholarly research have resulted in mixed conclusions across
many industries, markets, and countries concerning the validity of EMH in its different
forms (Sewell, 2011).
The rise of Bitcoin and other crypto assets into major markets has spurred some
critics of digital currencies to further argue that EMH does not hold true. Quiggin (2013)
argued that the rapid adoption and growth of Bitcoin markets, which the author asserted
lacks true value and represent an impending market bubble, proves that the central tenets
of EMH are false. They asserted that if EMH were true that the investment community
would never have priced Bitcoin at the heights of value that the emergent currency has
attained (Quiggin, 2013), both since the writing of their article and especially in years
subsequent.

27
The question of EMH validity as applied to the burgeoning ICO and crowdfunded
equity markets is of great importance regarding the assumed risks and opportunities
found within those rapidly expanding markets. If Quiggin (2013) was correct in their
assertions, then investors and entrepreneurs assume great peril when choosing to
participate in those forums. Other scholars have also seconded this assessment. Lichfield
(2018) discussed the information asymmetries inherent to ICOs compared to traditional
equity markets, which would signify market inefficiencies and their associated risks.
Neuman (2018) also discussed many similar risks inherent to cryptocurrencies. Zetzsche
et al. (2019) discovered an overall dearth of material information after examining more
than 1,000 ICO whitepapers. All these observations and findings would suggest a high
degree of inefficiency in ICO markets; however, Zetzsche et al. (2019) also argued that
ICOs arose in large part due to the failure of traditional capital markets to meet the needs
of highly innovative startups and that ICOs may provide solutions to these shortcomings
were they able to function efficiently.
An avenue toward discovering the true level of efficiency in ICO markets may
come through actively comparing them to crowdfunded equity offerings. Like ICOs,
crowdfunded equity relies on a non-accredited investor base and emergent crowdfunding
technology. Also, like ICOs, crowdfunded equity has been criticized as being inefficient
(Ibrahim, 2015).
Other scholars, however, have argued that crowdfunded equity markets do exhibit
efficiency. For example, Gruner and Siemroth (2019) along with Ahlers et al. (2015)
found that entrepreneurs communicate with investors via signaling. Mamonov and

28
Malaga (2017) found that investors responded to material information provided by
startups during the crowdfunded equity process. These findings suggest a level of
efficiency in crowdfunded equity markets not accounted for by other scholars.
My research directly compared outcomes between ICOs and crowdfunded equity
offerings, along with the influence of market transparency on those outcomes and
illustrated whether ICOs exhibit similar efficiencies that scholars have previously found
in crowdfunded equity markets. These observations may reduce the uncertainty
surrounding ICOs, along with reducing the market volatility surrounding them. Sunil
(2021) discussed a recent drop in secondary crypto markets that wiped out $600 billion in
a single week. Assessing the true level of efficiency in the ICO markets may smooth
volatility, thus better informing and protecting vulnerable stakeholders from losses and
contributing to positive social change.
Literature Review
Initial Coin Offerings (ICOs) are a crowdfunding method that firms, often startup
ventures, rely on to raise capital by offering cryptocurrencies to investors who conversely
seek shares of ownership in those ventures or access to their goods and services (Gale,
2018). ICOs have risen in popularity with the rise of blockchain based networks, which
provide the technological foundation that allow for cryptocurrencies like Bitcoin to exist.
ICOs have also grown in scope and scale alongside crowdfunded equity offerings.
Similar to ICOs, crowdfunded equity offerings also seek funding from investors who
provide capital via crowdfunding platforms. Crowdfunded equity offerings differ from
ICOs insofar as they provide ownership of traditional stocks instead of cryptocurrencies.

29
ICOs and crowdfunded equity’s exponential market growth stem from recent
technological advances, coupled with contemporary loosening of regulations that allow
for them to operate under certain conditions. Numerous uncertainties, bottlenecks,
opportunities and speculations concerning technology, regulation, and investor sentiment
pertinent to ICOs and crowdfunded equity offerings have motivated numerous authors,
scholars, practitioners, and investigators to study, conjecture, and argue concerning the
trajectory of crowdfunded markets. For this literature review, I present a comprehensive
summary and critical comparison of the existential literature pertinent to ICOs,
crowdfunded equity, blockchain networks, and associated technologies. I conclude my
review and synthesis by identifying the gap within the literature. To ease in
comprehension and analysis, I present my review according to broad topics within the
literature, starting with regulation and policy.
Regulation and Policy
Due to legal uncertainties surrounding ICOs specifically and distributed ledger
systems generally, a significant share of the existential literature focuses on current and
likely regulations in the US. Price (2017) discussed issuer obligations when issuing ICOs.
As the commissioner of the Australian Securities and Investments Commission (ASIC),
Price sought to provide clear guidance to readers as to under what conditions an ICO
would be subject to the Corporations Act, which is the primary regulatory body of
securities in Australia. As in the United States and other nations, Australia considers
ICO-issued tokens to be securities if ownership of them entails ownership or dividend
rights. If an ICO necessitates operation of a financial market (in that the tokens can be

30
subsequently bought, sold, or issued on a standing exchange) then they are also subject to
additional oversight via proper licensing requirements. However, ICOs may be required
to merely abide by the general laws pertinent to sellers of goods and services, like basic
consumer protection and rudimentary transparency. Price also made a point to
differentiate ICOs from crowdfunded equity markets, the latter pertaining to the actual
issuance of equity stocks, and the other to cryptocurrency. While this article was limited
in that it did not provide original insights consistent with primary research, the work was
useful in that it offered yet another contrast between international efforts to regulate
ICOs. Future research could center on better understanding investor and entrepreneur
response to policy differences, as in nations where capital has flowed, and where
investors and customers have been most protected.
Lee (2018) postulated emergent ICO standards via new wealth management
technology. The author completed a case study on an entrepreneurial venture known as
Tend. Operating on a blockchain based distributed ledger system, the fledgling company
(as of the time of writing) was seeking funding from investors via an ICO. The business
model sought to mimic popular timeshare structures whereby millionaire investors would
gain partial ownership and access to extremely expensive assets (i.e., vineyards, art, and
autos) from billionaire divestors who are seeking to add liquidity to fallow assets. The
intention was to provide investors not only access to assets but also capital appreciation
(like capital gains and dividends) from them. The company was seeking to capitalize on
emerging psychological needs whereby experience supersedes outright ownership, thus
partially democratizing and liquidating asset allocation across the emerging economy.

31
The author wrote the work as a profile piece, so the author’s assertions should be viewed
as if written with bias, and the findings are not fully generalizable. The work is valuable
in that it provides a personalized expression of an emerging trend in ICO-funded markets:
the tendency of investors to prefer access to assets on demand, rather than full-time
access rights afforded to outright ownership. The author’s article provided an
international perspective to digital token use and ICOs insofar as the company founder is
applying experience from Swiss banking and pursuing funding from investors in
emerging markets East Asia, Latin America, and the Emirates.
Conversely, other scholars have focused on the regulatory and policy environment
surrounding ICO markets. Tashea (2018) described legal uncertainties surrounding ICOs.
The author discussed how different standards exist in different legal jurisdictions
regarding disparate fintech vehicles among various agencies. Many regulators fail to
agree on whether ICO-issued tokens are commodities or securities, thus affecting their
legal requirements. According to the author, many entrepreneurs and investors find this
ambiguity concerning, therefore likely stifling growth in the industry and funneling funds
into legal jurisdictions with relatively lax sentiments. The author did not conduct original
research, instead relying on in-person interviews and summarized concepts based on
previous studies. The article is valuable in providing an intriguing view into the disparate
legal opinions on the issue.
Whereas Tashea (2018) focused on the legal landscape surrounding ICOs, Pooley
and Lee (2018) covered the legal landscape for blockchain economies, along with the
ways that technology may even change the legal industry itself. The authors wrote the

32
piece to better inform their readership who are attorneys and other legal professionals on
the issues surrounding the burgeoning field that they should be aware of. The authors
provided a description of what Bitcoin and other cryptocurrencies are and the legal
environment pertaining to digital assets. The authors discussed blockchain distributed
ledger systems with a particular emphasis on how public databases may provide
innovation opportunities across multiple industries, many of which are not even related to
cryptocurrency markets. Examples include real estate transactions, remittance markets,
and the wholesale decentralization of the information economy, all of which do and will
carry significant implications for the legal profession and the client base it serves. The
authors have provided a valuable contribution to the literature, particularly regarding how
law and technology interface. Future researchers could benefit from this starting point by
focusing on how future cases will set precedents around cryptocurrencies and blockchain
technology, coupled with how innovations in those technologies may affect legal issues
at a later date.
Not all scholars shared the concerns expressed by Tashea (2018) regarding ICO
regulatory uncertainty, instead arguing that regulators and blockchain developers should
coordinate efforts. For example, Werbach (2018) argued the legal needs for blockchain
success. Because of the inherently transparent and immutable nature of blockchain
networks, the author conjectured that blockchain technology may represent the most
important technological breakthrough since the internet insofar as it fulfills this most
basic human need. Werbach argued that trust verification efforts via blockchain may be
counterproductive if lacking a sound regulatory environment and legal landscape.

33
Werbach deviated from typical discussion on the topic by asserting that practitioners,
regulators, lawmakers, and jurists should not concentrate on how to regulate blockchain
so much as how blockchain regulates itself. The author suggested that stakeholders
should look at process rather than procedure. Werbach stated that blockchain may act as a
partner in legal enforcement rather than as a problem requiring regulating. The author
argued that blockchain developers and regulators should work together to create mutually
desirable solutions. This article was valuable insofar as it framed blockchain technology
from a legal perspective, similar to the work of DiNizo (2018) and Fenwick et al. (2017).
Werbach’s (2018) recommendations seemed sanguine compared to del Castillo’s
(2018) writings about SEC actions against Ethereum-based ICOs. del Castillo reported on
the punitive actions of the Securities and Exchange Commission against two firms
financed via initial coin offerings. These firms where Carrier EQ and Paragon, which had
raised funds to provide mobile banking to emerging markets and sales legally sanctioned
medical marijuana, respectively. These dual enforcements came just after the SEC
leveraged punitive action against the restaurant rating firm Munchee. The firms raised
startup funds via initial coin offering under the assumption that the cryptocurrencies that
they were raising were commodities rather than securities, the latter requiring greater
regulatory oversight than the former according to the Securities Exchange Act of 1934.
These increasingly aggressive actions by the SEC toward interpretation and enforcement
of cryptocurrency markets coincided with extreme market duress affecting digital asset
exchanges, following the onset of a broad-based market correction of blockchain based
assets.

34
A frequent topic of interest in blockchain and ICO research and commentary is
concerned with the inherent risks of emergent technologies and practices. For example,
Mckendry (2018) addressed the need for new legislation to prevent hate groups from
leveraging crypto groups for gain. Mckendry reported on the efforts of Rep. Emanuel
Clever and other lawmakers to restrict digital currency flows from supporting hate
groups. According to the author, the House Financial Services Committee identified
instances where groups associated with the Unite the Right rally in Charlottesville, VA.
Lawmakers have voiced concern that the anonymity factor underlying blockchain based
cryptocurrencies allow hate groups and other prohibited parties from transferring funds to
one another, along with potentially raising funds via digital crowdfunding platforms.
Rather than seeking legislation to curtail these activities from Congress, however, Clever
sought out responses from heads of the Digital Chamber of Commerce and the Bitcoin
Foundation seeking clarification on how the private sector seeks to provide remedy to
these concerns in the absence of regulatory response. Mckendry provided a valuable
contribution to the existential literature by highlighting the potential threats that exist via
the emergence of fintech solutions like digital crowdfunding and cryptocurrencies.
Similarly, the literature reflects broad concerns regarding the financial and
macroeconomic risks of crypto markets. Specifically, Nelson (2018) discussed monetary
policy and financial stability concerns surrounding crypto currencies. Nelson conducted
an analysis regarding the potential macro risks to financial and monetary systems owing
to the rise of digital currencies. The author was interested in two primary threats to
existing fiat currency markets. The degree of leverage in digital currency markets may

35
theoretically pose a systemic risk to traditional monetary markets if investors have
borrowed heavily from the latter to finance their speculations in the former. The elevated
volatility in digital currency markets could result in a bubble that rippled into traditional
money markets pending high macro leveraging between the two. The author asserted that
leverage remains low, given the reluctance of accredited investors to speculate in
cryptocurrency markets. The systemic risk of digital token market shock to established
money markets remains small. Nelson also investigated the likelihood of crypto currency
markets eventually undermining or replacing established national monetary markets. The
author also asserted that this outcome is unlikely. Digital currency markets pose low risk
to macro monetary markets on both accounts, according to the author.
Similar to Nelson’s (2018) concerns, Rahman (2018) postulated on monetary
policy given fiat and crypto currency competition. Rahman analyzed how the rise of
digital currency markets may affect optimal monetary policy under conditions of
competition between fiat and digital currencies. The author relied on the Friedman rule,
which advocates deflationary monetary policy as optimal, according to a Fernández-
Villaverde and Sanches framework and devoid of friction. The author found that
monetary equilibrium in a completely private digital currency landscape would be
suboptimal, given the profit motive of markets to expand. The author also found that,
given the presence of governmental intervention to curb profit maximization of miners to
constantly grow the digital money supply, crowdfunded markets could achieve optimal
monetary policy under key conditions. Rahman asserted that direct competition between
digital and traditional monetary systems is suboptimal according to the Friedman rule,

36
and only fiat monetary regimes are capable of socially desirable policy according to the
Friedman rule. This article is an interesting companion piece to the work of Nelson
(2018) mentioned previously. The practical importance of Rahman’s findings is limited
insofar as the author relied on the Friedman rule as a representation of optimal monetary
policy, despite the reluctance of central banks to apply it in real life.
In contrast to the regulatory and policy research and commentary discussed
previously, Truby (2018) focused instead on ways that policy and regulation might
improve blockchain functioning itself. Specifically, Truby addressed legal and policy
options that may result in reduced blockchain and crypto energy needs. Truby evaluated
the intensive use of energy and other finite, carbon-based resources to support digital
currency transactions and all other blockchain based activities. While energy usage,
mostly expended by miners who are needed to prevent the double-spending problem of
crypto assets, does allow for increased trust, security, and transactional outcomes in these
markets, the author asserted that the environmental strain that these operations entail
grossly overshadows these advantages, particularly during a critical time in ecological
history when global climate change threatens continued human existence. Caldwell
(2018) discussed anticompetitive outcomes in crypto mining networks. Caldwell
provided an expose on emergent cyber attacks in which nefarious actors have been
infiltrating both private and, increasingly, organizational IT systems to hijack their
electronic infrastructure to conduct digital currency mining operations on their behalf.
Because crypto mining is the method in which market participants may create and,
therefore, possess new digital monies, there is a direct incentive for hackers to conduct

37
these operations. Because mining is highly expensive and capital intensive, however,
malicious actors also have an incentive to trick others to conduct these activities on their
behalf. Targets will not realize that their assets are running mining operations, therefore
draining energy and productivity to enrich the hackers. These operations can occur on
enterprise infrastructure or personal devices on a wide network. While hackers are not
necessarily trying to damage their targets through malware or spyware, their infiltrations
do enable increased vulnerabilities to the target for follow up attacks.
Whereas many of the authors discussed previously focused on domestic
blockchain concerns, lack of consensus between governments and the patchwork legal
approach that globally exists has caused many scholars to focus on international
regulations of ICOs and associated block chains. Debler (2018) examined the
implications of foreign-based ICO-issuers that make offerings in the US, thus falling
under Securities and Exchange Commission (SEC) jurisdiction. Debler started out by
offering a background on basic concepts like cryptocurrencies, ICOs, how startups
leverage ICOs and their inherent risks, and how regulators are increasing their scrutiny of
cross-border ICOs. The author launched a nuanced legal argument affirming that the SEC
does have authority to regulate the majority of ICOs, as they meet the primary
requirements of securities according to salient, precedent-setting cases. Debler argued
that the SEC also possesses sweeping authority to regulate international ICOs, which the
author supported via reference and analysis of existential agency law and landmark court
cases. Debler argued that the SEC also possesses sweeping authority to regulate
international ICOs, which the author supported via reference and analysis of existential

38
agency law and landmark court cases. Overall, the author contributed a valuable addition
to the literature pertaining to ICOs. This is especially true because, unlike many other
authors on the topic who rely on opinion and conjecture, Debler synthesized a compelling
argument via analysis of the legal system and case law. The topic of ICO regulation from
a securities perspective is one of great interest to many researchers, lawmakers, investors,
and entrepreneurs, and Debler offered a niche perspective by focusing on international
ICOs.
Many scholars have researched and discussed the need and types of regulations
best pertaining to blockchain, cryptocurrencies, and ICOs. Bellavitis et al. (2022)
discussed entrepreneurship, ICOs, and regulation; whereas Yeung and Galindo (2019)
assessed internal governance mechanisms for blockchain, as did Jayasuriya
Daluwathumullagamage and Sims (2020) regarding blockchain governance and
regulation. Zhang and Zhang (2021) explored policy uncertainty and its effects on ICO
markets while Truby (2020) evaluated sandbox regulation proposals. O’Dair and Owen
(2019) examined blockchain financing, opportunity, and policy; meanwhile, Matei and
Baks (2019) analyzed bitcoin regulation and challenges. These challenges often stem
from the rapid rise of ICO and crypto markets (Vega, 2021). The conversation of ICO
and crypto trends and regulations remains a major topic among industry insiders with
Hajric (2020) reporting on a crypto exchange’s CEO remarks.
A major driver of the debate around crypto regulation is regarding whether crypto
currencies constitute securities or not, as discussed by Lambert et al. (2022) and
Maughan (2019), the latter evaluating whether security tokens could potentially convert

39
to non-security tokens. Amid this activity and discussion, the Securities and Exchange
Commission (SEC) has played a central role. Kharif (2021) discussed cryptocurrencies
and increased SEC oversight. Perhaps as an example, Robinson and Kharif (2019)
reported the SEC’s halt on Telegram token sales after the company’s $1.7 Billion ICO.
Conversely, SEC alleged that a cryptocurrency analyst was paid $5 million to push ICO
(Dolmetsch, 2022). Simultaneously, Meyerowitz (2022) reported on the Justice
Department’s launch of a national cryptocurrency enforcement team. In one example of
state response, Massachusetts formed a fintech panel following a crypto crackdown
(Hernandez, 2019).
Another major issue pertaining to crypto regulation has been the content of ICO
white papers, particularly legal content (Kasatkin, 2022). Thewissen et al. (2022) studied
ICO white papers via a topic modeling approach, along with the role of linguistic errors
and investment decisions pertaining to ICO white papers.
Outside of formal regulation, many scholars have attempted innovative
approaches to regulating the sector, including through machine learning (Yin et al.,
2019), and through the controversial use of future token agreements (Strassman, 2019).
Conversely, Collomb et al. (2019) discussed a risk-run approach to blockchain regulation.
Efforts by organizations and industries to self-regulate are a mainstay in the literature.
International Regulation
Similar to the landscape in the U.S., many other national governments are
choosing their own regulatory paths (Pavlidis, 2020). Bacina (2019) discussed token

40
offering regulation in Austria while (Vandezande, 2020) evaluated the EU’s framework,
and Kondova and Simonella (2019) assessed blockchain financing in Switzerland.
In contrast to Debler’s (2018) work, which focused on attempts by American
regulators to enact policy on foreign based entities, others have focused on the attempts
of foreign governments themselves to regulate their own ICO and crypto markets. For
example, Nordrum (2017) provided an interesting article focusing on potential ICO and
blockchain application in the public sector. Because of the improved functionality that
distributed ledger systems offer regarding transparency, speed of transaction, and
security, many public organizations like local, state, and national governments are
exploring the idea of replacing their central, relational databases with DLT. Nordrum
conducted a case study research project wherein two public sector DTL projects were
highlighted. The first cast focused on Dubai, the most economically prosperous city in
the Emirates, which is the current blockchain epicenter of the Middle East. According to
the author, the city was planning to launch a shared platform next year that several
governments projects will be able to utilize next year to host their individual projects in
blockchain technology. The Emirates were pursuing a share asset approach. The state of
Illinois was encouraging various departments to utilize blockchain networks to manage
their various projects, but it was allowing each department partaking in the initiative to
select its own blockchain network for their separate projects. While Dubai was seeking
synergy gains with a common network, Illinois was attempting to find optimal
functionality via customization. This was a very interesting article in that it highlighted
how public sector entities are embracing blockchain technology, which thus far has been

41
positioned as an alternative to governments. The author showcased two very different
methods of adopting and applying blockchain technology, which is very pertinent toward
any attempt to leverage these networks in a real-world setting.
Conversely, Reutter et al. (2017) provided an overview of the how initial coin
offerings are regulated under Swiss law. Beginning with an explanation of what ICOs are
and how they operate, they categorized cryptocurrency tokens according to five distinct
yet potentially overlapping groups: usage tokens that allow the owner to utilize a
platform, good or service, work tokens that allow a holder to procure their work to the
issuer, profit tokens that allow the owner to claim rights to net gains from the issuer from
dividends, voting tokens that provide the right to voter on management issues of the
company, and native cryptocurrency tokens that allow the holder to own, hold, and then
trade those assets. Depending on which class any given token falls under, they may be
subject to certain regulations under Swiss law but not to others. The authors provided an
overview on what conditions would require the ICO issuer to provide merely a white
paper versus a full prospectus, the former generally pertaining to goods and services
provision, the latter to issuance of securities. The authors discussed differing allocation
schemes by issues to investors. They expressed their aversion to first-come-first-served
arrangements in favors of others like the pro rata cut back basis. The article was a useful
companion piece to that provided by Lai (2018) and Price (2017), which covered ICO
issuance regulations in East Asia and Australia, respectively. Generally, the Swiss system
is more permissive of these arrangements, as has been its cultural long-term trend in

42
many financial matters. Future research could center on how investors, entrepreneurs, and
consumers respond to national and local regulatory differences.
Asian markets are also a primary source of discussion including a primer on ICO
regulation across the continent. Lai (2018) offered an overview of the regulatory
environment of initial coin offerings in the leading economies of Asia. The author began
by providing a concise explanation as to when ICOs would be regulated according to
existing securities laws that govern initial public offerings of stocks. Generally speaking,
cryptocurrency offerings that provide ownership, voting, dividend, and other rights often
associated with stocks are subject to national and local security regulations. Tokens that
merely provide usage rights of the network under construction are not subject to scrutiny.
The regulatory landscape in many countries is confused in the sense that many ICOs offer
mixed benefits to investors, and it is often difficult to decipher where a commodity
offering ends and a securities offering begins. Lai offered a brief explanation of how
ambiguity is being regulated in five major East Asian economies: China, South Korea,
Hong Kong, Singapore, and Japan. Overall, China has adopted the most stringent stance
with a ban on all ICOs; meanwhile, South Korea has issued a partial ban. Hong Kong,
Singapore, and Japan have offered a much more welcoming environment to ICOs insofar
as they provide only limited regulations in select cases. This article was useful as a
survey work, but it did not provide an original contribution regarding empirical findings.
The work was useful in that it did compare and contrast differing approaches among
neighboring economies on the issue. Further research could focus on the outcomes of
differing strategies utilizing empirical and original research. This work is similar to many

43
I have read on the topic in its emphasis on regulatory stances regarding initial coin
offerings among national governments, especially in East Asia.
Similar to Lai (2018), Kim (2018) presented an overview of the South Korean
landscape regarding blockchain technology, cryptocurrencies, and initial coin offerings.
According to the author, South Korea is an international epicenter in the emergent field,
only eclipsed in size by the United States and Japan. The country hosts the home of the
Ether exchange, one of the largest cryptocurrencies in the world currently. While the field
in South Korea is highly populated with small-cap investors and entrepreneurs, many
large-scale corporations in the country are also involving themselves in the arena with
significant investments in the field. These companies include well known names like
Samsung. South Korea is establishing itself as a leader in the emerging field. South
Korean authorities are seeking to tighten regulations in the field, even banning the use of
ICOs as means of raising startup capital. Following similar actions by China, this step
clearly demarcates South Korea from cryptocurrency friendly Asian centers like Hong
Kong and Singapore. The author sought to explain why South Korean regulators made
this decision, given its likely outcome of alienating international capital and reducing
financial competitiveness. The author noted that, while the desire to reduce corruption
and scams contributed to the decision, South Korean regulators are also very wary of
North Korean cyber attacks, which have been frequent in recent years. Further research
could benefit from focusing on the financial ramifications of this decision over the next
few years.

44
In some cases, Asian governments themselves have articulated their regulatory
stances. For instance, Lan (2017) presented a quasi official statement from on behalf of
the Chinese government regarding its recent decision to tighten regulations on
cryptocurrencies, including a wholesale ban on initial coin offerings. While the author
noted the exponential growth rates that cryptocurrency markets had enjoyed, they framed
this rapid development as unsustainable and rife with corruption. They noted several
cases of fraud. They positioned cryptocurrencies and associated exchanges as a
dangerous alternative to the established currency and securities markets in China, which
they argued offered a much safer, better regulated, and more efficient space for investors.
They refuted the legality of cryptocurrencies in China altogether, as many investors and
entrepreneurs alleged that the ICO violated. They argued that Chinese law only
accounted for the renminbi as the official national currency, and all others represented
unsanctioned and illegal units of exchange, including cryptocurrencies. The article is
limited in that the author is acting as a representative of the Chinese government on the
issue, and they therefore harbor a bias on the issue. The article does represent a valuable
resource as a quasi-official statement from the government to the business community on
the issue. Likewise, the work compliments the work of Kim (2018) who wrote about the
South Korean government’s decision to pursue similar regulations.
Seeking to focus on another crypto power center in both Europe and Asia,
Zharova and Lloyd (2018) offered a focused discussion on the status of cryptocurrencies
specifically in Russia. The authors began by launching into a philosophical evaluation of
the nature of money from an economic standpoint, along with the notion of legal tenders,

45
starting from the 18th century onward. The authors then honed their discussion on the rise
of cryptocurrencies and their ongoing place in the Russian monetary system. The
tendency from the Kremlin has been one of caution and suspicion. The Putin led
government has (while voicing concern for the emerging assets) slowly enacted measures
to rein it in to the broader monetary system, particularly through the use of sandbox
systems whereby entrepreneurs and regulators work together during the asset
development process to identify and head off risks before they become manifest.
Littlewood (2018) elaborated on the regulatory policy that Singapore has adopted
in response to blockchain and other distributed ledger technologies. According to the
author, Singapore is emerging as an international epicenter for the emerging industry,
largely because of the public/private partnership that has arisen there whereby the
government is actively collaborating with for-profit ventures in the development of
innovative tech solutions. As a companion piece to the article, Global Finance also
offered a sidebar that discussed how bitcoin is gaining acceptance among Islamic Finance
scholars, one of whom offered a qualified yet positive opinion of the cryptocurrency.
Littlewood’s contribution provided an interesting contrast to that of Tashea (2018) who
outlined other governments that are moving to ban blockchain technology (notably China
and South Korea internationally and New York state domestically) versus those who are
embracing it (i.e., Switzerland, Cayman Islands, Hong Kong, Israel, Singapore, and the
Emirates). The work was limited in that its conclusions were based on surface-level
interviews and generalized assumptions. Future research could benefit from an in-depth
exploration of blockchain regulation, coupled with an exhaustive attempt to better

46
understand the outcomes (either intended or otherwise) of regulatory attempts.
Littlewood’s contribution was valuable in deepening the overall mosaic of national policy
regarding the rapid, expansive, and transformative nature of distributed ledger
technologies like blockchain. The article also outlined new diversification schemes
around the topic like 108 Token that represents an aggregate basket index of 108
blockchain based investment vehicles specifically made for buy-and-hold investors who
are interested in but not deeply informed on crowdfunded markets.
Many national governments have enacted strict regulations on blockchain
technologies, cryptocurrencies, and especially ICOs. The Chinese government has
adopted a strict regulatory environment concerning cryptocurrencies, along banning ICOs
despite their large and growing market presence. South Korea has implemented similar
regulations albeit with much laxer measures. Nations and autonomous municipalities
with a history of permissive financial regulations like Singapore, Switzerland, and many
Caribbean Island nations have positioned themselves as safe havens for crypto storage,
trading, and innovation. Many Western governments have sought to balance market
dynamics and regulatory stability via the sandbox model, whereby crypto markets may
exist and innovate provided certain conditions. The overall emphasis within the literature
concerning international regulations of ICO and crypto markets tends to focus on the
current or future implications on affected markets and the likely impact of those
implications on investment communities.

47
Industry and Market Concerns
A large section of the literature is dedicated to industry and market risks regarding
the new technology and associated practices. Lee (2017) offered a critical analysis of
initial coin offerings specifically and cryptocurrencies generally. The author began with
an explanation of what ICOs are, followed by an overview on the exponential growth
rates of crypto markets. Lee was skeptical of the trend and predicted that a bubble similar
to the Dot Com Bubble is forming in the cryptocurrency arena, fueled largely by investor
desire to capitalize on the early phase of a next generation in fintech. Lee did not conduct
original research on the topic, relying instead on available public data and interviews to
construct a commentary. The work was limited in its depth and findings, coupled with its
openly opinionated stance, which was negative overall. The work is also useful and
insightful, particularly in its observation that ICOs differ from IPOs not only in the nature
of their offerings (i.e., cryptocurrencies versus equity stocks) but also in their likely stage
in the entrepreneurial lifecycle. IPOs by regulation must occur later in the lifecycle after
the company has established a revenue stream and possibly even profitability. The often
cash-free nature of ICOs favors startups that do not have adequate funds to compensate
investors with dividends, have not established revenue streams, and are initially seeking
to build out operational infrastructure prior to the beginning of business activity with the
public. It is not appropriate to apply equal expectations from ICOs with IPOs. The author
offered a valuable contribution and provided a pessimistic perspective on the subject.
Not all authors shared Lee’s (2017) cautionary narrative. Specifically, Shin
(2017) wrote about the exponential growth rates of initial coin offerings, coupled with

48
examples from specific companies that have utilized the procedure to raise startup
capital. The author discussed how many entrepreneurs are harnessing Etherium, which
provides additional services through smart contracts for holders of its currency ether, thus
allowing many startups to write functional code based on the foundational platform. The
author speculated that this new phase in blockchain technology is opening up possibilities
that exist well beyond the speculation and trading that dominates investments in bitcoin
and earlier cryptocurrencies. Ether and similar technologies provide the ability for
startups to not only fund projects but also manage their operations. While acknowledging
the opportunities for quality ideas to evolve into established companies, the author also
noted several ways that investors may suffer fraud and speculative losses, which are akin
in structure to the Dot Com bubble of the 1990s. This article was valuable in framing the
opportunities and threats of the ICO arena, while also placing it in context of the
regulatory environment, which is ill-suited to manage it. It should be read in conjunction
with those previously discussed previously.
Shin’s (2017) comparison of the financial bubble of the 1990s to cryptos today is
a common theme in the literature. Steele (2018) compared the rise of bitcoin investing
and its inherently volatile nature to the beanie baby bubble of the 1990s. They noted
similarities in marketing between both assets, including overblown TV personalities,
unrealistic expectations, profile pieces on highly successful and youthful investors, and
tragic stories of those who lost nearly everything in those respective arenas. Steele took
care to differentiate between blockchain technology and cryptocurrencies generally from
their critique, instead focusing on the unscrupulous marketing tactics employed by TV

49
personalities and advertisers who prey on the ignorance, desperation, and aspirations of
uninformed investors, most of whom are in precarious financial straights from the
beginning. Their argument was similar in a broad sense to that of Lichfield (2018).
Steele’s conceptual worldview was valuable in formulating a research framework,
particularly among qualitative researchers.
Similar to the beanie babies comparison, Mentzer and Gough (2018) analyzed the
effect that the advent and application of the ether-based digital game Cryptokitties has
had on the Ethereum blockchain network. Debuting in late November of 2017, the online
game crypto kitties enjoyed exponential adoption rates which propelled the ether
cryptocurrency within digital asset marketplaces, second only to Bitcoin. The authors
started to ascertain whether rapid adoption rates of the game resulted in slower
processing times within the Ethereum network. Two primary considerations that the
authors examined were in weather the games adoption rate allowed the Ethereum
network to onboard new participants and whether the game could be used as in as an
educational platform to educate students about crypto currencies. The authors provided a
valuable addition to the literature, insofar as they utilized network analysis as a basis for
their primary research.
Choosing to focus on an individual company and its relation to market risks,
McDowell (2018) reported on speculative financial troubles concerning blockchain based
firm R3. McDowell conveys a rebuttal by R3 CEO David Rutter who attested those
recent assertions by their former employees regarding the organization’s financial
position were false. The former employees alleged that R3 could face insolvency as early

50
as 2019, despite receiving recent and substantial support from its external partners.
According to Rutter, these statements were not true, and he seconded that the firm had
just received $120 million from some 45 partners while also enjoying $20 million of
annual revenue. McDowell further explained the nature of R3, which is a consortium
created in 2014 by nine large banks with a stated mission of integrating blockchain
technology into capital markets. The consortium has been controversial, as many of its
founding firms have opted out of the alliance while other market players have signed on.
In relation to many of the polarized opinions discussed previously, Lichfield
(2018) provided a nuanced discussion about the rise of initial coin offerings, focusing
largely on their negative aspects coupled with improved alternatives for the future. The
author did not assert that ICOs are inherently harmful or dangerous. Lichfield did argue
that ICOs could be beneficial if they are marketed to accredited investors (i.e., those
whose aggregate wealth allow for safety via high-risk ventures) while incorporating
contracts between investors and entrepreneurs. The author argued that many ICOs do not
employ safety precautions, instead often relying on capital from small-cap investors who
cannot suffer high risk ventures but who engage in this activity based on unrealistic
expectations and already desperate financial positions. The author proposed that ICOs
could under ideal circumstances be reformed and renamed into IPOs with a similar
structure that IPOs had in the 19th and early 20th centuries whereby small regional
businesses could seek capital influx from prospective shareholders who harbored realistic
interests in those businesses. They harkened back to the early days of the NYSE before
entrance into the exchange was limited only to well-established, large cap firms. They

51
also called for the removal of token or coin as definitions, instead arguing that ICOs
should provide ownership in the venture by investors, rather than merely access to the
prospective network. The article was valuable as effectively a Q&A opinion piece by a
resident expert in the field, but it was limited insofar as the concepts presented were
basically the educated opinions of a subject matter expert. While not scientific in the
strict sense, future researchers could incorporate the article into their future investigative
pursuits.
The consensus among scholars is that ICOs specifically and blockchain based
crypto markets pose heightened volatility risks. Many argued that the explosive growth of
crypto markets derives not from true economic value but, rather, primarily through
speculation and market mania. A common theme in the literature has been comparisons
to the Dot.com bubble of the early 2000s in relation to crypto markets today. Most
scholars aligning to this school of thought have asserted the need for greater regulatory
scrutiny within crypto markets, while simultaneously warning investors to avoid crypto
marketplaces. A major concern among industries and markets is the use, ease, and
acceptance of blockchain transactions, which Grover et al. (2019) addressed.
In contrast to McDowell’s (2018) focus on an individual company, Yacik (2017)
took an industry approach and highlighted recent warnings by the Office of the
Comptroller of the Currency toward perils associated with onboarding of fintech by
banks. Because of the exponential growth of financial technology, many banks are either
onboarding solutions internally or partnering with external fintech providers to remain
competitive. The Comptroller issued its concerns that doing so could increase banking

52
sector volatility. The author also highlighted recent fintech trends in the banking industry
including use of biometric data from fingerprints and eyeballs for customer recognition,
corporate credit cards to cover employee reimbursable expenses, and digital currencies
like those raised via ICOs. The author discussed how regulators are requiring disclosure
of banking culture to assure corporate risk reduction. Although somewhat disjointed in
format, the article provided a useful overview of fintech and regulation trends in the
banking industry.
Crime and Corruption Concerns
Other authors have focused on crime and corruption risks associated with ICOs
and blockchains. Weaver (2018) presented in this article a very scathing critique of
cryptocurrencies based on four primary criteria. The author addressed the market from a
technological standpoint, followed secondly by economic risks. Third, the author
cautioned against the risks inherent to the cryptocurrency ecosystem. Finally, Weaver
discussed societal risks. The article was limited in that it lacked balance, only focusing on
negative factors. Many of the points that author made were intuitive and worth future
investigation. Weaver did not conduct any original research in this piece, instead relying
on educated conjecture, as has been a very common pattern in the literature regarding this
subject. The piece is valuable, but it should be paired with other sources to provide a
more balanced perspective on the overall market.
Similar to Weaver (2018), Higbee (2018) provided an analysis of three primary
cybercrime threats that are both on the rise and rely on cryptocurrencies to function.
Higbee addressed mining application attacks, just as Caldwell (2018) did. The author

53
mentioned the common utilization of the Coinhive application to carry out these attacks.
Because both writers are colleagues as the same publication, this similar dialogue is
aligned with the mission and focus of their journal. Higbee also discussed ransomware
attacks. Hackers will beguile targets to infect their IT systems or personal devices with
infectious viruses that will halt or inhibit their operational capabilities. The hackers will
engage the targets into negotiations to free their electronic assets in exchange for
cryptocurrencies, which may be transferred and traded anonymously. Due to the volatile
nature of digital tokens, the hackers often must directly negotiate to ensure they are
reaping sufficient rewards to justify the effort of their attacks. The author addressed
phishing attacks. These resembled the former discussion in which hackers force targets to
unwittingly engage in mining operations on their behalf, typically mining for Monero
tokens (which can be mined on basic computer systems) utilizing Coinhive. The hackers
rely on phishing schemes to capture target login information so they can hijack their IT
assets.
Rotundu (2022) discussed the benefits, risks, and threats of blockchain, while
Benedetti et al. (2021) evaluated blockchain and corporate fraud. Teichmann and Falker
(2021) assessed cryptocurrencies and financial crime, and Dumchikov (2022) explored
digital currency and economic crime. Tarabay (2021) reported that Google sued two
Russians for an alleged crime scheme, while Meyerowitz (2021) reported that three North
Koreans were charged in an alleged scheme to commit cyberattacks and financial crimes
across the globe. In this context, Ramanan and Gebraeel (2022) evaluated blockchain
based decentralized replay attack detection for large scale power systems, and Grech et

54
al. (2020) provided critical analysis of smart contracts. Despite efforts by law
enforcement, Kim (2022) asserted that crypto crimes have hit record highs, and Redmond
et al. (2022) discussed the rise of crypto private investigations.
Sigler (2018) likewise provided an expose on cyber attacks that rely on
cryptocurrency. The content in their article was very similar to that of both Higbee (2018)
and Caldwell (2018), particularly given the fact that Sigler also focused on attacks that
force targets to mine on behalf of hackers. Sigler did provide original content by
explaining in detail how hackers achieve their objectives through infection of either
malware or, as is increasingly popular, Java Script into web site code. Web sites mine as
long as their browsers are open. Hackers can maximize their profits by employing
watering hole attacks against influential web sites that stream content for long periods of
time to large networks of users, thus infecting the entire information web. Sigler then
concluded by explaining how these attacks are harmful to targets and ways that
individual and organizations may mitigate the dangers. Sigler’s, Weaver’s (2018), and
Higbee’s (2018) alarmist views regarding crypto markets are not the only perspectives in
the literature, which also includes sanguine views.
Benefits and Opportunities
The literature also includes work focused on the benefits and opportunities of
ICOs and crypto networks, along with potentials for blockchain technology in general.
For example, Gale (2018) provided a profile piece regarding a new entrant into the initial
coin offering sector. Named Equi after the Ethereum-based digital assets that the firm
will issue, Equi combines characteristics of equity crowdfunding markets and venture

55
capital firms. The firm’s advisory council will select between 10 to 15 startups to receive
capital injection. Successful applicants, according to the firm’s founders, should exhibit
high growth potential and hail from the technology sectors. The firm differs from other
private equity firms in that it will accept capital injection not only from accredited
investors but, also, from small cap investors. It combines a venture capital governance
structure with a crowdfunding capital base. Gale provided a useful contribution to the
literature here by highlighting a novel approach in the initial coin offering realm, which
hybridizes traditional and emergent forms of capital markets.
Casey and Vigna (2018) provided a compelling argument toward the likely future
benefits of blockchain technology, particularly regarding its ability to revolutionize the
financial sector. While acknowledging that a bubble is almost surely forming similar to
the Dot Com Bubble, the authors countered that the unsustainable exuberance that cause
so much disruption in the late 1990s allowed for the creation of an information
infrastructure that has fueled economic growth and development throughout the 2000s.
While that infrastructure was largely based on physical technology like coils and servers,
the authors argued that the blockchain bubble is creating a societal infrastructure based
on open-source knowledge creation. The authors presented a summary of dual-entry
ledger history, which began in the 14th century and contributed to the Renaissance and
later the Industrial Revolution. Casey and Vigna affirmed that the ongoing development
of distributed ledger systems may replace the dual-entry ledger system and allow for the
emergence of a new wave of innovation across several industries, particularly in the
financial arena. Their central point was that ledger systems, although banal and often

56
overlooked, are key drivers of human innovation and progress. While the authors did
make interesting assertions and observations, they did not support their arguments with
original research, which has been a common pattern in many blockchain-related
resources. Likewise, the piece was somewhat limited insofar as the comments were very
general. Future research could benefit by conducting original research focused on a
specific industry, time, place, etc. Casey and Vigna have provided a valuable contribution
to the literature.
Lewis et al. (2017) also provided a useful overview regarding blockchain
application in the financial sector. The authors began with an explanation of distributed
ledger systems, which they supplemented with explanatory graphics. They compared and
contrasted how distributed ledgers offer improvements compared to traditional relational
databases. They also provided an explanation regarding the similarities and differences of
permissionless distributed ledgers versus networks that do require permission to utilize,
and they discussed under what conditions one version may be preferable to another. They
then offered a discussion on the potential applications and benefits of blockchain
technology in the financial area, followed by their drawbacks or challenges. Applications
and benefits included how blockchain technology allows for the digitalization of assets,
digital record keeping, smart contracts, reduction in post trade settlement time, and faster
payments. Regarding challenges, the authors divided them up into two groups:
technological/business and regulatory. The first group included difficulties in achieving
consensus, standardization, interoperability, scalability, efficiency, immutability, legal
uncertainty, security, liquidity, privacy and intellectual property. Regarding regulations,

57
the authors asserted challenges related to uncertainty and currency control. In many
cases, the listed challenges were also benefits that posed additional considerations. The
paper relied less on original research and more on the educated opinions of the authors.
Much of the existential literature is limited in that regard. Future research could benefit
by seeking to discover or reject scientific validity of the previously mentioned ideas.
Whereas Casey and Vigna (2018) historical viewpoint, Orcutt (2017) wrote
specifically about a new initiative in Finland that utilizes blockchain technology to
manage the ongoing refugee crisis. Because most refugees lack identifiable documents
like IDs or passports, it is very difficult if not impossible for them to open traditional
checking or savings accounts, let alone qualify for credit lines. Orcutt discussed a
financial vehicle that is very similar to a MasterCard in look and functionality, but it
relies on a distributed ledger network to run operations. The users do not need to furbish
identifiable information to gain access to the asset, as the card links to the user via a
unique identifier number. According to the author, this would allow refugees to start over
in Finland, as they would be able to establish a financial background in their new home.
This article was very interesting from a developmental finance perspective in that is
showcased how blockchain technology may be harnessed to address global demographic
challenges while also extending opportunities to disadvantaged persons. The article was
limited in that it was describing new technology that had not yet been tested; thus, future
research should focus on the real-world applicability and results of the program.
Similar to the emphasis that Orcutt (2017) placed on potential refugee benefits
from blockchains, Guillermo (2017) conducted research into the behaviors and

58
characteristics of unbanked persons with the intent to identify pertinent factors that
blockchain developers may utilize when creating technology solution to serve that
population. The author relied on fuzzy-set qualitative comparative analysis to find five
sensitivities of the unbanked population, it now estimated at 2 billion persons worldwide.
The author postulated that blockchain does pose a positive potential in providing
financial services to marginalized people due to the major roles of nonmonetary factors
and informal financial practices on the lives of the financially excluded. Guillermo
argued that the decentralized and anonymous nature of blockchain distributed ledger
systems may better serve these populations, as centralized bureaucracies and identifiable
prerequisites in formal banking institutions likely bar excluded persons from participating
in them. The author provided a valuable contribution to the literature, particularly
regarding this issue, which is a much anticipated and discussed potential benefit of
distributed ledger systems and the global poor.
The potential for blockchain and crypto technologies to benefit people vulnerable
to climate change and natural disasters is also a theme in the literature. del Castillo (2018)
described the emergence of an ether based insurance market forming during the prelude
of Hurricane Florence. The author began by explaining the current structure of traditional
insurance markets, which rely on overlapping and often redundant layers of
intermediaries whose collective functions are to verify and re-verify the authenticity of
claimant information prior to a potential payout. Because these processes are slow and
costly, an emergent industry has formed that relies on Ethereum supported smart
contracts and the universally verifiable nature of blockchain transactions. Claims are

59
subject immediate recording and timely verification based on trusted third-party
information provision, like satellite maps and publicly available weather conditions in
affected areas. Hence, the author explained a concrete example of how blockchain and
cryptocurrencies may revamp traditional industries for the better.
In contrast to Casey and Vigna (2018) historical viewpoint, Harnett (2018)
provided an argument for why firms in the financial services sector should embrace next-
gen learning platforms in anticipation of industry disruptions by emergent fintech. The
author began with a historical example of how ATMs disrupted retail banking, even as
the number of tellers increased via the demand for new skills that ATMs could not
provide. The author pivoted to the contemporary landscape and alluded to the myriad
emergent fintech innovations widely assumed to disrupt the industry, including AI,
blockchain, and others. Harnett argued that financial services employees can stay
competitive in the industry via next-gen learning platforms that provide multimedia tools,
video, and adaptive learning paths, which are often available via multiple channels via
mobile technology. Harnett asserted that organizations could recruit, develop, and retain
talent, thus staying competitive despite ongoing industry disruption by adopting these
platforms, along with implementing innovative onboarding techniques like preboarding
to train recruits prior to their arrival.
The predominant theme among scholars focuses on the anticipated capacity of
ICOs and crypto markets to provide capital and liquidity to marginalized communities.
Many have argued that ICOs may provide a better avenue for minority-owned startups
and financially oppressed entrepreneurs toward acquiring needed capital injections to

60
form and launch innovative ventures. Scholars have put forward similar arguments
regarding crowdfunded equity markets, including those that rely on fiat currencies as well
as cryptocurrencies. Others focused on the ability of blockchain networks to host
decentralized cryptocurrency markets, which may be more accessible for unbanked
persons than traditional financial institutions.
Pandey (2020) asserted why blockchain is needed, while Bollaert et al. (2021)
discussed fintech’s potential to expand access to finance. Barreto et al. (2019) postulated
the opportunities for cryptocurrencies and blockchain in tourism as a strategy to reduce
poverty. Boulianne and Fortin (2020) balanced the risks and benefits of ICOs.
Emerging Trends
Because of their rapidly evolving nature, ICOs and associated blockchains and
cryptocurrencies are a frequent topic of emergent trends across industry and the
economy. Obukhova (2020) discussed ICO financing for high tech projects, while Chow
and Zorthian (2021) assessed NFTs and the rise of crypto art. Kshetri (2019) evaluated
the evolution of formal ICO institutions, and Yu et al. (2022) assessed blockchain based
control on design of secure and real-time techniques. Li et al. (2019) explored a
blockchain based decentralized framework for crowdsourcing, and Yeh et al. (2020)
discussed a privacy preserving DDoS data exchange service over SOC consortium
blockchain.
Alvarez and Tashea (2018) showcased the 2018 ABA Techshow and its emphasis
on technology implications in the legal profession. The authors wrote about the recent
contents of the ABA Techshow of 2018, which is an annual expo hosted by the American

61
Board Association. According to the authors, the agenda of the event showcased
emerging technology trends and how they will likely affect practitioners in the legal
industry, which was a departure from traditional areas of interest in prior events. Alvarez
and Tashea noted that the primary focus in 2018 was on blockchain technology, the
Internet of things (IoT), artificial intelligence, and virtual reality. While each area of
technology is expected to bring change to the legal sector, the authors’ observations were
important in that they also noted the potential confluence of technologies to work
together as a transformative force. This is a primary theme among other authors discussed
in this paper, particularly those who note that the decentralized nature and complimentary
characteristics of these technologies will likely allow for considerable synergy moving
forward. The article was somewhat limited in its depth, as the authors covered the event
from a reporting standpoint, often relying on direct quotes and paraphrasing of
participants, rather than on direct research findings. This is a common theme among
blockchain-related resources, as the emerging nature of the technology is often evolving
faster than researchers can anticipate and respond to, thus forcing surface-level coverage
of salient industry issues, often relying on conjecture and intuition rather than empirical
findings. Future researchers can provide a significant contribution in the field by devising
a study design that is both timely and focused on original findings via research.
Pãnescu and Manta (2018) examined smart contracts pertinent to research data
rights management regarding Ethereum blockchain networks. Pãnescu and Manta
constructed an interesting analysis regarding the potential for smart contracts, a key
component of blockchain technology, regarding their application and enforcement of

62
reuse rights of research data. Data derived from primary inquiry is of value, both
monetary and otherwise, and many authors and institutions limit access to data via the
use of subscriptions and other means. Pãnescu and Manta analyzed the potential for smart
contracts to verify and enforce agreements via the Ethereum blockchain network.
Blockchain networks and smart contracts provide added efficiency in these agreements
based on their ability to create a permanent and transparent record of transactions, which
is more granular than alternative methods. The authors then honed their inquiry by
focusing on the Solidity smart contract language, which runs on the Ethereum network.
Pãnescu and Manta offered a valuable contribution to the literature by assessing a
specific and salient set of concerns, which have heretofore not been analyzed.
Sun (2018) focused on crypto currency innovation in China. Sun discussed the
unexpected ramifications of the recent ban on initial coin offerings by the Chinese
government. The article is a valuable follow up piece to that of Lan (2018). Rather than
resulting in a wholesales halt of cryptocurrency trading in the country, Sun described how
entrepreneurs have leveraged various creative responses to circumvent the ban, thus
arguably strengthening the market and mitigating the problems in ICO markets those
Chinese officials had cited as justifications for the ban. Many entrepreneurs have utilized
open-source technology and multilateral frameworks to work around the national
regulatory framework, thus increasing transparency, system robustness, and asset fluidity.
Sun highlighted how the ban actually hurt many Chinese investors who were forced to
sell their cryptocurrency assets at greatly reduced prices following the ban, or even lost
their portfolios entirely after it. The author provided a valuable follow up and balancing

63
perspective to the prior on the topic. Future researchers and policy makers in the West
could benefit by incorporating these insights prior to recommending or implementing any
similar policies, respectively.
Similar to Alvarez and Tashea (2018) industry specific focus, Crosman (2018)
explored technology disruption implication in the banking sector. Crosman, a leading
technology writer in the fintech arena, offered an expose on the potential benefits to the
financial sector of three emergent solutions: quantum computing, blockchain, and
artificial intelligence. Regarding quantum computing, the author provided a brief
explanation of the technology dynamics and potentials, followed by a discussion on
potential applications. From a fintech standpoint, these mostly focused on how banks and
wealth management firms may optimize portfolio returns and risk/reward assessments
like Monte Carlo analysis. Regarding blockchain, Crosman highlighted the heightened
security potential provided by an immutable, verifiable, and instantaneous network. The
author touted the benefits of AI from a wealth management perspective, as it can
potentially allow portfolio managers to customize communications to their clients despite
the seemingly overwhelming nature of big data. The author’s primary point was that
emergent fintech could assist the banking and wealth management community, rather
than threaten its existence as others have postulated.
Crosman (2018) also wrote about the emergent partnership between banks and
fintech companies providing quantum computing solutions. JPMorgan Chase and
Barclay’s have signed on to the IBM Q network, which allows them to test quantum
applications in their own industries. The primary quantum solutions that banks are

64
interested in focus on portfolio optimization and scenario simulation like Monte Carlo
analysis, given the massive amount of data and computation power that institutional
investors and bankers require in these regards. Quantum computing could be partnered
with AI, blockchain, and other emergent technology solutions. The interest of banks in
quantum computing is similar to the role they played in blockchain development insofar
as they are legitimizing functions, funding research, guiding inquiry, and encouraging
infrastructure rollout. This article is similar to others in that the author highlighted how
emergent technologies (mainly blockchain, IoT, artificial intelligence, quantum
computing, and augmented reality) may interface with each other, especially as they are
accepted by mainstream firms.
Essen (2017) looked beyond banking and focused to focus on the broader
economy and conducted a Delpli study on potential blockchain applications in business
and management. Essen asserted the disruptive nature of blockchain innovations to a host
of industries, along with affirming that a knowledge gap exists regarding blockchain
techniques, and this frustrates both academic inquiry and managerial application.
According to the author, this hingers managers from both recognizing looming
disruptions and performance improvement opportunities. The author employed a two-
round Delphi study methodology to assess the expert opinions of business management
scholars and expert practitioners in the ways they expected blockchain technology to
change the future of business. They found high scores from both rounds regarding the
effects that blockchain technology will have on the transfer of bonds, deeds, and stocks,
particularly those currently relying on physical currency. The participants analyzed

65
myriad industries and forecasted material implications for many. The author provided a
valuable contribution to the literature on the disruptive nature of blockchain and other
emergent technologies, particularly via the addition of much-needed primary research on
the topic. The authors acknowledged that the study was limited in its emphasis on
managerial disciplines. The response rates of the participants were low, thus limiting the
sample size. They speculated that lack of understanding of blockchain technology may
have reduced response rates and even insights from those who did respond. They
recommended that future studies should include participants from both the business
management sphere and also the computer sciences realm, the latter assumedly
possessing a greater understanding of the topic than the former, on average.
Conversely, Dibrova (2016) focused even more broadly than Essen (2017) and
assessed the impacts of virtual currency in monetary development. Dibrova conducted a
survey and discussion on the rise of cryptocurrencies from the vantage point of the larger
monetary system. The author initiated with an historical analysis on money as an
economic concept, which has grown and evolved since its modern emergence and
theoretical underpinnings beginning in the 18th century. The author addressed the radical
nature of crypto currencies, which differ from traditional monies in many ways, including
lack of a central authority and a completely new technological infrastructure relying on
distributed ledger systems. The author conducted a survey of general regulations across
numerous countries, mostly focusing on China, Western Europe, and Eastern Europe.
Hence, the author found that Russia was most strict among the survey countries, whereas
China had targeted restrictions in place, and most other European countries had no

66
regulations or prohibitions. The author also tabulated prevailing Bitcoin prices between
January 2013 and October 2015 to find significant volatility and overall exponential
growth. The author found that cryptocurrencies pose both opportunities and dangers, and
they possess long term survivability and potential. The author cautioned that governments
should move to regulate them first.
Technological and Scholarly Analysis
Many authors have focused on in-depth technical analysis of ICOs and blockchain
technology. For example, Kugler (2018) discussed the problematic energy needs of
cryptocurrencies. Kugler provided a concise explanation for the energy expenditure
problems that cryptocurrencies suffer, coupled with a few alternatives to reduce
consumption rates. According to the author, the proof of work mining activities that
allow cryptocurrency generation are inherently unsustainable from an environmental
standpoint, their aggregate operations expending more energy in 1 year than the nation of
Serbia. This is because the number of bitcoins is fixed to expand by one unit every 10
seconds, but the number of miners increases as the price of the currency appreciates due
to profit-seeking behavior. The numeric puzzles needed to prove work become harder,
therefore mitigating the industry influx but then also requiring more computing power to
sustain operations. This pattern is compounded because other cryptocurrencies also
utilize proof of work requirements to support monetary supply expansion and transaction
verification. The problem represents a reinforcing feedback loop that may worsen
exponentially over time. Some cryptocurrency providers have chosen more sustainable
technologies. For example, Ethereum miners utilize GPU units unlike the ASIC units

67
used to mine bitcoin. Ripple and others have chosen not to require proof of work
altogether, instead choosing more centralized designs like proof of stake. The author
acknowledged that no true solution exists to solving the energy exhaustion issue without
fundamentally altering the key characteristics of cryptocurrencies and, therefore,
undermining their support. This article is useful insofar as it provided a good explanation
to the energy problem, which is often referenced in related sources. The work is limited
in its scope, the authors having wrote the piece to be brief and understandable to a lay
audience. Future researchers could focus on either the technical aspects of the mining-
related energy consumption process or finding possible solutions toward reducing energy
consumption.
Like the emphasis that Kugler (2018) placed on blockchain energy needs, Liang
and Zeng (2018) provided an empirical study regarding cryptocurrency transaction
networks. Drawing on network theory, the authors studied the changing characteristics of
three large blockchains over time: Bitcoin, Ethereum, and Namecoin. Despite patterns of
other networks, the three prior mentioned did not increase in density over time, and they
all exhibited constant changes with low node and edge repetition. They found that the
power-law distribution as not effective in predicting network evolution behavior. The
authors designed their study to utilize network construction analysis on a monthly basis.
The authors found that the three networks exhibited high evolutionary tendencies and
competitive power, and they asserted the need for future research in the field. This article
is valuable insofar as its content provides an often-mentioned issue in blockchain
technology sources, namely that they rely most heavily on conjecture and educated

68
opinion rather than primary research. The authors have provided a true research study
utilizing a design, method, methodology, and framework appropriate for emergent
technology. Future researchers could harness this starting point and continue
investigating the topic, perhaps expanding on this initial inquiry.
Focusing on a very technical and scholarly viewpoint, Phillips and Gorse (2018)
reassessed wavelet coherence analysis as a cryptocurrency price driver. The authors
sought to identify any potential relationship between cryptocurrency price volatility and
social media content. Seeking to understand the very volatile nature of cryptocurrency
pricing markets, which often exhibit market bubbles, the author attempted to identify
whether social media attention to markets via social media postings were correlated to
market swings. The author conducted original research utilizing wavelet coherence
measures to assess any potential medium-term positive correlations between the two
factors. Philips ascertained that a relationship does exist, but it is moderated by market
regime conditions, which necessitate the propensity for speculative bubbles in the
cryptocurrency markets. The author also found short term correlations based on salient
issues of the times, like largescale and publicized cyber security breaches. This article is
valuable in that the author conducted new and informative primary research in a field that
is currently lacking these findings.
Dos Santos (2017) also focused on scholarly theory and crypto markets. They
examined whether bitcoin and blockchain technology could be considered a chaotic and
complex system. The author framed this discussion via an ontological perspective
evaluated blockchain technology and related markets from a comprehensive perspective,

69
considering its primary stakeholders and processes. The author evaluated the Information
Theory of Complex Systems under the backdrop of blockchain technology. Dos Santos’
work was valuable from at least two perspectives. The literature currently suffers a dearth
of literature when considering blockchain technology from a purely theoretical or
ontological perspective, as most authors choose to focus on purely practical applications
or legal/regulatory considerations. The author contributed to the science and research of
the field. The author also focused on the very salient concern that, if blockchain
represents a complex and chaotic system, the networks may suffer from a 2010 Flash
Crash style of crisis. The author conducted original research utilizing the Crutchfield’s
Statistical Complexity measure, therefore assessing that blockchain networks are
sufficiently algorithmically complicated, but not complex and therefore not susceptible to
the prior mentioned phenomenon.
Xing et al. (2018) explored internet number resource authority and BGP security
solutions. Xing et al. discussed the inherent security flaws associated with Border
Gateway Protocol (BGP). BGP is vulnerable to prefix and sub prefix hijacks and similar
hacks, particularly when attacks originate from a central authority. The authors
recommended utilization of an Ethereum-based smart contract system that would be
inherently resistant to attacks based on the immutable and transparent nature of its design.
The authors proposed the design and utilization of the so-called BGPcoin. They tested
this early-stage digital asset via auditing procedures via extensive experimentation. This
article is useful insofar as the authors focused their inquiry on BGP, which had not been
the topic of much interest in the blockchain debate. The authors relied on experimentation

70
and synthesis, therefore, rendering a more-scientific perspective on the topic than had
previously existed.
Woodside et al. (2017) studied technology adoption statuses and strategies for
blockchain technologies. The authors conducted a primary research study on blockchain
technology across a myriad of industries. Starting with a comprehensive literature
analysis and background section, the authors expounded the specific nature, history, and
mathematical theory behind distributed ledger technology. They assessed how this
technology may disrupt numerous industries and in what potential ways. The authors
conducted original research utilizing a mixed methods study that harnessed a
triangulation method that included secondary data environmental, text, and financial
analysis. The authors concluded that blockchain technology is currently positioned on the
innovation stage of the innovation curve, but it is poised to move toward the diffusion
and innovation phases. The technology is akin to the internet in the 1990s. The authors
presented a deep, comprehensive, and rigorous study worthy of further review in while I
conduct my own studies on the topic.
Dwyer (2015) examined the economics of private digital currencies. Dwyer
provided an evaluation regarding the development of digital currencies like Bitcoin. The
author began by explaining how recent breakthroughs utilizing distributed ledger
technology and currency miners combine to prevent the double spending problem, which
has long prevented tokens from retaining a positive value without the presence of a
central banking system. The author then conducted an analysis of 24/7 computerized
trading markets dealing in cryptocurrencies devoid of brokers or other similar trading

71
agents. Dwyer researched volatility rates in computerized digital token markets to find
that they are on average higher than other relatively volatile commodity markets like gold
or foreign currencies. That said, the author also found that the lowest monthly bitcoin
volatility rates were lower than the highest gold and foreign currency market volatility
rates. Dwyer’s observations are valuable in the literature generally; specifically, findings
were especially valuable for my own research.
Finally, Lo and Medda (2020) conducted an empirical study of Tokenomics,
while Kher et al. (2021) assessed review and research on blockchain, bitcoins, and ICOs.
Xu et al. (2019) provided a systemic review of blockchain.
Industry Impacts
Several scholars investigated the anticipated industry impacts of cryptocurrencies
and blockchains. Zalatimo (2018) focused on the innovation and disruption of blockchain
on publishing. Zalatimo began by providing historical examples of entrepreneurs who
disrupted established industries because they embedded inefficiencies in widely adopted
processes, and they created inventions that not only solved these problems but unseated
the entire industrial order. These inventors included the creators of the printing press, the
steam engine, the photograph, the computer, and the internet. The author then reported on
a recent exposition that assembled a group of 50 executives and stakeholders from the
publishing industry to hear from three entrepreneurs seeking to disrupt the industry.
These startups included: Po.et, which focuses on content attribution, permission, and
discovery; Amino Pay, a venture seeking to improve digital advertising supply chains;
and Unlock, a new firm attempting to disrupt current paywalls and subscription

72
verification processes. The author did provide a valuable contribution to the literature, but
the article did not include many details about the event itself (i.e., time, place,
participants) nor did it contain much information about the actual discussion highlights.
In contrast to Zalatimo (2018) who focused on the publishing industry, Chavali et
al. (2018) discussed blockchain effects on biotechnology, pharmacy, and life sciences.
The authors explored the potential of integrating blockchain technology with life
science/pharmaceutical applications. The authors discussed blockchain technology as a
primary factor in the 4th industrial revolution, which is expected to fundamentally
interface previously disparate realms like digital, physical, and biological processes. The
authors discussed the opportunities and threats associated with multi sphere integration.
They focused much attention on the possibilities of storing medical/pharmaceutical
information on distributed ledger technology. The authors concluded that such an
arrangement would create improvements in the affected industries. The article was
valuable insofar as the authors explored yet another potential application of blockchain
technology beyond merely hosting cryptocurrencies. The authors identified another
sphere where initial coin offerings could be utilized and harnessed.
Conversely, Dupont (2017) explored the technology pertinent to notational
services. Dupont explored the concept of blockchain technology as a notational
technology. Stated otherwise, notation allows for the storage and verification of
information that can be mutually referenced and agreed upon by multiple entities.
Information is easily recorded, replicated, and verified by each block on the chain and
stored on the node computational devices that support the network. The author argued

73
that blockchain technology represents an ideal candidate. The emphasis of this paper was
to focus on the potential for blockchain networks to support abstract identities through
the process of notation. This article was valuable within the existential literature because
it highlighted how blockchain technology may enhance a given sector of information
management.
Focusing more broadly than the industry analyses discussed previously, Fowler
(2018) conjectured blockchain as a solution for benefit corporation certification. Fowler
explored the potential of blockchain technology to assist in verification of company
claims to the greater good. The author focused on public benefit corporations (PBC),
which, while structured as for-profit entities, purport to promote positive social outcomes
as part of their business operations and missions. PBCs have faced scrutiny from
skeptical consumer and investor groups as being merely a label to attract business and
capital while lacking any objective method to prove benevolent outcomes. Fowler
proposed the utilization of blockchain networks as a verification methodology. Because
blockchain bear the ability to store information in a transparent and immutable fashion,
the author argued that PBCs could harness these networks as a justifiable verification
system to their stakeholders regarding their ability to fulfill the altruistic objectives of
their publicly espoused missions. Like the other articles discussed in this paper, the
author created a valuable contribution by exploring how blockchain technology may be
valuable outside of its currently used functions.
Pop et al. (2018) offered a specific conversation regarding impact on smart energy
grids. The authors sought to ascertain it the value of blockchain networks utilizing smart

74
contracts to enforce regulations within smart energy grids. Within agreements,
participants concur on energy usage production and consumption levels, which result in
corresponding rewards and punishments. Those participants, whether firms or
households, suffer financial fees if their pre-agreed consumption rates exceed those
rations afforded to them; those participants who expend less energy enjoy financial
benefits. Similar arrangements have often suffered due to lack of regulatory enforcement
mechanisms, but the authors speculated that smart contracts running on blockchain
technology could provide a needed regulatory arbiter, which could render smart energy
grid agreements applicable. The authors provided the valuable contribution to the
literature, particularly regarding the potential application of blockchain technology
toward environmental processes.
DiNizo (2018) explored blockchain patent eligibility in a post CLS bank world.
DiNizo explored whether blockchain technology is patent eligible under the current U.S.
legal system. The author began by placing the importance of blockchain technology from
a financial perspective insofar as the topic dominated the most recent World Economic
Forum discussions while the blockchain industry has attracted billions of dollars even in
its embryonic state. The intense interest in this this situation, according to the author,
justifies a desire to protect blockchain related ideas via intellectual property law. The
author began by discussing the intellectual property landscape via the landmark Supreme
Court case Alice v. CLS Bank. DiNizo then discussed patent eligibility requirements as
they pertain to software and business processes. The author considered the specific nature
of blockchain technology from this perspective. DiNizo concluded that blockchain

75
technology should be eligible for protection under patent law, and the author discussed
how attorneys should structure their arguments. This work was valuable insofar as it
provides a lucid argument on a salient legal topic in blockchain technology. Future
researchers should focus on how courts rule on this topic in the near term in relation to
the arguments previously discussed.
Fenwick et al. (2017) examined blockchain impact in legal education. The authors
assessed how emergent technology is disrupting the legal profession, particularly from a
consulting standpoint. According to the authors, the legal profession is one of the most
disrupted industries owing to the emergence of artificial intelligence and machine
learning, coupled with big data. Their focus was mostly on blockchain, which they
asserted as being the most significant disruptor to the practice. They justified this
argument by considering how the sharing economy will nullify many of the fundamental
assumptions embedded within legal thought, and they attested those legal practitioners
must change their worldview to accommodate shifts. They suggested a change to the
legal education system. This article was useful insofar as it complimented many of the
other studies based around blockchain and its influence on the legal profession like the
work of DiNizo (2018).
del Castillo (2018) discussed implications of Ethereum in commodities futures
markets. This work compiled a collective commentary by a group of subject matter
experts on the topic. These included those by Securities and Exchange Commission
director William Hinman and the president of the Chicago Board of Exchange Chris
Concannon. Both discussed the somewhat murky and mercurial regulatory commercial

76
and regulatory environment surrounding futures speculation of ether specifically and
cryptocurrency generally. Future investigators could follow up on this work by
conducting primary research on the futures markets surrounding ether and other
cryptocurrencies to verify if the positions and expectations presented in this and the
previous article were accurate.
Many scholars pointed to the decentralized nature of blockchain networks as a
means of industry stakeholders to participate more freely, thus expanding collaboration
opportunities in many industries and markets. Others posited that the transparency and
immutability characteristics purported in distributed network systems may allow for
improved authentication processes across multiple industries, along with improved
crowdsources capacities across the economy. Still others focused more on the security
characteristics of blockchain networks, often exploring how security could be improved
following the introduction of these technologies as solutions to current industry
vulnerabilities.
Despite the pervasive concerns pertaining to cryptocurrencies and associated
blockchains, their potential to transform law enforcement is also a topic in the literature.
Skelton (2022) discussed a possible overhaul of police tech, and Li et al. (2021) explored
blockchain based lawful evidence management scheme for digital forensics. Kumar et al.
(2021) provided a blockchain based digital forensics framework for IoT applications.
Wang et al. (2020) described a blockchain based anonymous reporting scheme with
anonymous rewarding. del Castillo (2019) reported on a search engine and law firm for
Bitcoin crime.

77
The transformative potential of blockchain is a topic of discussion broadly. Li et
al. (2019) postulated blockchain based fair and anonymous ad dissemination in vehicular
networks, and Sharma et al. (2020) discussed a design of blockchain based precision
healthcare using soft systems methodology. Aujla et al. (2020) assessed blockchain
service for software defined networking in smart city applications.
Broad Topics of Interest
Other authors focused on general information specific to the technologies.
Cennamo (2020) balanced decentralized versus proprietary blockchains on digital
currency performance. Engle (2018) provided a contrarian opinion on blockchain
technology, cryptocurrency, and bitcoins regarding their applicability to the financial
sector. They argued that their continued challenges preclude any likely adoption by
mainstream consumers and investors. According to Engle, a central problem of
cryptocurrencies is that they must be mined to verify the validity of every transaction.
Engle went further to attest that this prerequisite makes crypto currency inherently
susceptible to criminal intentions. They noted that currency creation occurs at a rapid
pace with very little oversight, which makes them attractive to drug dealers, money
launderers, tax evaders, and even terrorists. They also countered blockchain proponents
by asserting that built-in control mechanisms like public verifiability via hash coding can
be overwritten by malware, which can result in identity theft. They also argued that
governments are likely to continue eschewing cryptocurrency in favor of money that they
can directly issue, control, and tax. The paper was limited insofar as its content relies
mostly on the educated opinions of the author, rather than extensive research, either

78
primary or secondary. Future researchers could test Engle’s assumptions via scientific
inquiry. Indeed, doing so may assist in finding solutions to the many problems that the
author underscored, thus contributing to positive social change.
Similar to Engle (2018), Beloussov (2016) attempted to mediate between the
ongoing debate surrounding blockchain technology and its application potential.
Blockchain proponents assert that these networks may be harnessed in an innumerable
number of ways across seemingly endless industries, thus providing a viable solution to a
great array of the earth’s problems. Blockchain detractors systemically deny these claims
with counter arguments. Currently, the technology is still too new for a definitive
resolution, as it has not been applied to most cases. The author attempted to arbitrate the
conflict via a moderated and nuanced discussion. Beloussov affirmed that many
blockchain proponents are overly optimistic in their claims, which they largely fail to
verify via empirical proof. The author also asserted that the central characteristics of
blockchain technology position it as the currently best solution to many of the world’s
most pressing issues. The author did not see blockchain technology as a panacea for the
world’s many woes but, however, a potential paradigm shift in mitigating many of them.
Wilson (2016) also focused on blockchain application potential and provided
background information regarding blockchain. Wilson provided a critical analysis of
blockchain’s application potential beyond Bitcoin and other cryptocurrencies. The
author’s primary skepticism rested on three overarching premises. Blockchain proponents
have posited the technology to solve all manner of problems across myriad industries and
applications. They have often only supported their assertions with hypotheticals rather

79
than proof of case examples. The author attributed this tendency to the same irrational
exuberance that has accompanied many tech booms. The author asserted that, while
blockchain applications can occur separate from bitcoin (or some other cryptocurrency)
those same functions often require a digital monetary unit to support operations. Third, if
organizations are to successfully adopt blockchain technology as part of their enterprise
infrastructure, they would necessarily integrate them with centralized features.
Permissioned networks are a primary example of this trend. The author asserted that
centralized changes fundamentally undermine the decentralized foundations of
blockchain technologies, thus rendering them meaningless. The author did provide
legitimate challenges to blockchain viability. Those objections are not necessarily
insurmountable or universal, as other sources have addressed and mitigated these claims.
It is also possible that the article, written in 2016, was timely when written, but the rapid
pace of development in the arena has already mollified these concerns in whole or in part.
Dudgeon and Malna (2018) provided an in-depth question-and-answer format
surrounding distributed ledger technology. Their discussion began with very general
remarks on what distributed ledgers are, how they may be both akin to or different from
blockchains, how blockchains operate (including their use of hashes), how blockchains
support bitcoins and other digital assets or infrastructures, the potential future uses of
blockchain technology to include initial coin offerings (ICOs), corresponding challenges,
what ICOs are and why they are gaining in popularity, how ICOs are (or are currently
not) regulated, and the likely future of both ICOs specifically and blockchain generally.
Dudgeon and Malna did not conduct original research in this paper. They listed a series

80
of common questions on the topic and provided concise yet informed answers to them,
given the previous contributions of cited sources. Unlike Chen, the authors focused on
both positive and negative aspects of their chosen topics, although their overall
assessment was still generally optimistic. While somewhat elementary in depth, their
commentary was very useful insofar as it provided valuable definitions to common yet
often misunderstood terms. Their work was limited in that it only provides a survey-style
understanding of a very complex and dynamic realm. The authors have also created a
valuable contribution to the existing literature, particularly for scholars who are novices
on the subject and who need a firm starting point prior to moving further in their
investigations. Future areas of study could expand on the main issues addressed in this
article to gain a deeper understanding of them individually, especially through the use of
original research.
Unlike Dudgeon and Malna (2018) focus on the present, Extance (2015) explored
the future of cryptocurrencies. Extance provided an overview of bitcoin specifically, and
blockchain generally. The author focused on cryptocurrencies, particularly both bitcoin
and ether. The emphasis of the piece was on discussing both the positive innovations and
the ongoing challenges inherent to the technology. Extance dedicated the core of the
article to explaining the mining process, which is crucial in verification of transactions,
creation of new cryptocurrencies, and the prevention of the double-spending problem.
The author credited cryptocurrencies with the creation of a monetary platform that is both
anonymous, immutable, adaptive, and decentralized. The author focused on security,
consolidation of power by mining pools, mining energy uses, criminal activity, etc. The

81
author also provided examples of potential solutions to address these issues. Extance
offered a valuable contribution to the literature. The content was informative, particularly
regarding issues that are not often covered in other resources.
Vigna (2016) discussed a controversial Ethereum update. Vigna reported and
commented on a major action on the Ethereum network that occurred in 2016. Shortly
before Vigna wrote the piece, practitioners created the Decentralized Autonomous
Organization (DAO), which served as an Ethereum-based venture fund for startups,
which peaked at an aggregate value of $155 million dollars just prior. Although the fund
was designed to convene funds for entrepreneurial ventures, a bug in the code allowed for
a copy-cat hacker to steal $60 million from the fund. The fund managers orchestrated a
hard fork, therefore reversing all transactions during the timeframe of the heist and
returning the fund to its previously unaltered state. Fund stakeholders were given a choice
whether to accept the changes or not, and the vast majority did, therefore resulting in a
retroactive state adoption. While this emergency maneuver allowed the fund managers to
prevent the theft and return the imperiled capital to its rightful owners, many critics
alleged that this action inherently violated the core principles of blockchain technology
by allowing for a centralized authority to alter a P2P system that was supposedly
immutable. This article was interesting insofar as it discussed a material event in
blockchain history while also highlighting a primary set of concerns among its users,
most notably the need for security versus transparency and decentralization.
Nott (2018) reported on the recent launch of a startup incubator in Melbourne,
which will be the first in its state. Designed to onboard five ventures per year, program

82
participants will partake in regular workshops intended to help them understand their
respective industries, potential needs, and ways that the technology may be able to meet
them. On completion of the program, the startups will be offered the chance to pitch
before investors in hopes of acquiring seed capital. Through brief and structured akin to a
news article, Nott provides a valuable contribution to the literature in a few ways. First,
the authored showed how adoption of the technology is taking place internationally, and
in what ways various cities are seeking to insource market participants. From the
perspective of initial coin offerings, the emergence of workshops may also affect the
standard processes whereby entrepreneurs gain access to digital capital.
Similar to Nott’s (2018) interest in a single entity, Reosti (2016) explored a
collaboration between a crypto crowd funder and a bank. Reosti offered an expose on a
new partnership between traditional banking and emergent crowdfunded equity markets.
The author wrote about an arrangement between Fresno First Bank and Breakaway
Funding. In this burgeoning arrangement, startups will seek crowdfunded support via
Breakaway, as is an emergent practice among startups that lack a financial performance
history. The innovation involved is that Fresno First will factor crowdfunded support into
loan applications from startups as proof of viability. The bank is offering more flexible
loan requirements than traditional banks, which normally seek at least 3 years of revenue
and profits to prove credit eligibility, according to representatives from Fresno. This
arrangement does not represent loosening of its overall requirements, which they tout as
being very stringent. The new model is intended to allow the bank access to potentially
lucrative investments before they would otherwise be available via traditional credit

83
rating means. Similar to the work of Brown et al. (2018), this contribution from Reosti
highlighted new arrangements between traditional and emergent finance.
Many authors providing general information have approached the topic from
either a broad or specific perspective. Authors focusing on a broad vantage point tended
to provide background information on blockchain networks, which appear intended for
readers without a cursory understanding of these technologies or their associated primary
and secondary crypto markets. The authors contribute to the literature by satisfying
increasing demand from readers without extensive exposure to these markets and
technologies who simultaneously have an interest or need to better understand them.
Other scholars focusing on specific background interests tended to study and report on
timely occurrences in blockchain based markets following recent breakthroughs,
innovations, and discoveries. The scholars appeared interested in providing salient
information to readers dependent on remaining informed of material occurrences within
these markets, i.e., market participants.
Essaghoolian (2019) provided a comprehensive review of the many facets of
Bitcoin, block chain, and ICOs. They divided the document into three parts, which
respectively covered the following three components: an overview of what block chain
technology is, the history and current status of cryptocurrency from a legal perspective,
and a proposed framework to regulate ICOs. Chapter one covered block chain technology
and its relation to Bitcoin, smart contracts and their relation to Ethereum, and what ICOs
are and how they function. Chapter two covered several topics, including: cryptocurrency
crimes and regulations; regulatory positions of the IRS, SEC, and FinCEN; and the

84
regulatory positions of foreign nations including China, South Korea, Russia, and
Switzerland. The author also included in chapter two a discussion of the Howey Test, to
include investment of money, horizontal commonality, vertical commonality, expectation
of profits, and the effects of efforts from third parties. The author closed the second
chapter by discussing the Simple Agreement for Future Tokens (SAFT), along with
SAFT’s many limitations. They finally closed the document by putting forward a
proposed regulatory framework intended to improve upon the many limits to current ICO
regulations that discussed structure, digital utility token exemption (DUTE), pre-ICO
disclosures, post-ICO disclosures, and enforcement and penalties.
Similar to Essaghoolian (2019), Casarella and Manfrè (2019) created a concise
but comprehensive document surveying several key concepts pertinent to ICOs. They
began by dissecting the tradition capital raising methods of either conducting a private
placement (whereby accredited investors inject money into the enterprise in a non-public
and largely non-regulated environment) or via a public offering like an IPO on an
exchange like the NYSE or NASDAQ. Public offerings are highly regulated with the
Securities and Exchange Commission (SEC) because of their potential to affect retail or
non-accredited investors. The authors finished the first section of the document by
discussing the recent legalization of Regulation A+ offerings, which allow ventures to
raise effectively crowdfund capital of up to $20 million in a Tier 1 offering or $50 million
in a Tier II offering during a 12-month public solicitation period. Organizations seeking
capital via Regulation A+ offerings may choose to have their outstanding share prices
listed on a public exchange, thus resulting in the term mini-IPO. The authors then

85
transitioned into a background discussion of block chain, cryptocurrencies, and tokens
including an overview of how distributed ledger systems, digital currencies and tokens
exist and are traded, current and potential business applications of block chain, and
current regulations. The authors closed the document by examining ICOs as an extension
of Regulation A+ offerings that seek crowdfunded capital specifically by raising
cryptocurrencies or digital tokens from investors, typically non-accredited. They covered
regulatory and reporting requirements, which is typically little more than publishing a
white paper. The authors also discussed the shift away from public ICO offerings in favor
of private offerings, as the former is constrained by regulations limiting capital seeking
firms to aggregate funds raised of only $1,070,000 per 12 months. The authors dissected
the ICO advantage of not diluting equity as an IPO would, along with access to difficult
to gain funds for technology and market intelligence including customer tastes for
proposed goods or services. They also highlighted an advantage of ICOs over private
equity placements due to increased access to liquidity in secondary markets, which also
allow investors insights into startup progress via the fluctuation of tradable token prices.
The authors then closed with a discussion on ICO regulatory considerations, specifically
focusing on the difficulty in distinguishing security tokens versus utility tokens, the
former requiring additional regulatory oversight than the latter. The authors provided a
valuable contribution in the literature by affording a novel and critical regulatory and
market linkage pertaining to ICOs as a specialized sub-market of Regulation A+
offerings, under which crowdfunded equity IPOs also apply. In the absence of a formal

86
regulatory framework, efforts at self-regulation through innovation have grown within
the IPO sector and the literature, alike.
Integration with other Emergent Technologies
Many scholars have explored blockchain integration with other emergent
technology, particularly Internet of thing (IoT), like Krichen et al. (2022) who surveyed
blockchain applications, Amin et al. (2022) who explored next generation IoT, and Khan
et al. (2022) who surveyed blockchain consensus algorithms for resource constrained IoT
systems.
A major portion of the literature includes analysis on the potential for blockchain
and IoT to transform healthcare like Mohammed and Hussein (2022), Said (2022),
Lakhan et al. (2022), Sadhu et al. (2022), Kumar and Tripathi (2021), Veeramakali et al.
(2021), and Srivastava et al. (2022). Other scholars have focused on blockchain and IoT
integration for improved security functions, including Ibrahim et al. (2022), Na and Park
(2022), and Sabrina and Sohail (2022). Lv et al. (2022) explored blockchain spoofing
detection via fuzzy AHP in IoT systems, as did Roy et al. (2022) regarding IoT security
on a multi-robot system for cloud-based rescue operations. Others focused on blockchain
and IoT authentication like Liu et al. (2021), Liu et al. (2021), Hameed et al. (2021), and
Umoren et al. (2022).
The nexus of blockchain and IoT in market operations is also a source of interest.
Yujie and Qiuxia (2022) discussed IoT and blockchain integration into e-commerce, and
Baig et al. (2022) explored open-source peer-to-peer energy trading system for a remote
community using the IoT, Blockchain, and Hypertext Transfer Protocol. Both Baig et al.

87
(2022) and Rizwan et al. (2022) investigated blockchain and IoT integration into supply
chain management.
Other scholars chose to explore blockchain and IoT integration in various
industries and sectors. Yang et al. (2022) and Igboanusi et al. (2022) both focused on the
transformative potential of the technologies in industry, as did Vangipuram et al. (2022)
in agriculture, Li et al. (2022) in finance, Freire et al. (2022) in maritime monitoring,
Trček (2022) regarding cultural heritage preservation, Ahamed Ahanger et al. (2022) for
unmanned aerial vehicles, Lavaur et al. (2022) for Zk-Rollups, Honar Pajooh at al. (2022)
for scalable distributed Hyperledger fabric for an IoT testbed, Li and Lin (2022) in
vocational education, Antwi at al. (2022) on network optimization, and Chen et al. (2021)
regarding blockchain based group key agreement protocol for IoT.
Like IoT, integration of blockchain and AI, along with federated and machine
learning, is a major interest. Javed et al. (2022) surveyed integration of blockchain
technology and federated learning in vehicular IoT networks, as did Ogundokun et al.
(2022), Chen et al. (2021), and Chang et al. (2021) pertaining to federated and/or
machine learning.
Many others have shared broad-based interests regarding blockchain integration.
Zhang and Zhu (2022) explored environmental accounting based on AI, blockchain,
embedded sensors. Zahoor et al. (2022) surveyed blockchain applications for Covid-19.
Liu et al. (2022) discussed rural live broadcasting via blockchain and AI. Ding et al.
(2022) investigated blockchain and cyber threats to smart grids. Ma (2022) conducted
feasibility analysis of intelligent piano teaching, and Sousa et al. (2022) explored AI and

88
blockchain in education. Manoharan et al. (2022) examined blockchain and AI industrial
applications.
Blockchain integration with quantum computing is also a topic of interest.
Edwards et al. (2020) reviewed quantum and hybrid quantum blockchain protocols.
Wang et al. (2022) evaluated quantum blockchain integration based on asymmetric
quantum encryption. Sun et al. (2019) explored quantum-secured permissioned
blockchain. Gao et al. (2020 expounded a novel quantum blockchain scheme based on
quantum entanglement. Mosteanu and Faccia (2021) discussed fintech, quantum
computing, fractals, and blockchain. Dai (2019) evaluated quantum-computing with AI
and blockchain, as did Benkoczi et al. (2022) regarding quantum Bitcoin mining and Sun
et al. (2019) regarding voting protocol on quantum blockchain.
Crosman (2018) wrote about Barclays’ testing of quantum computing. The author
wrote about the emergent partnership between banks and fintech companies providing
quantum computing solutions. JPMorgan Chase and Barclay’s have signed on to the IBM
Q network, which allows them to test quantum applications in their own industries.
Currently, the primary quantum solutions that banks are interested in focus around
portfolio optimization and scenario simulation like Monte Carlo analysis, given the
massive amount of data and computation power that institutional investors and bankers
require in these regards. Quantum computing could be partnered with AI, blockchain, and
other emergent technology solutions. The interest of banks in quantum computing is
similar to the role they played in blockchain development insofar as they are legitimizing
these functions, funding research, guiding inquiry, and encouraging infrastructure rollout.

89
Panarello et al. (2018) conducted a systemic survey of blockchain and IoT integration.
The authors conducted a survey on the current research trends in IoT and blockchain
technology integration. The authors of this work focused on understanding research and
application on the topic from prior investigators and practitioners with an emphasis on
different application domains, device manipulation and data management, and
development levels of presented solutions. The authors began by dividing the literature
into categories based on those three criteria before beginning their survey on the topic.
Like Crosman, Chao et al. (2018) examined the same integration in smart homes
using a hypergraph-based blockchain model. The authors presented an analysis of a
potential interface between smart homes and blockchain technology. Smart homes allow
for the exchange of information between homes and any number of other IoT devices,
including other homes, mobile units, etc. While this arrangement may provide an added
level of convenience for the smart home dwellers via added intel and services, the
solution also raises privacy issues, as personal information could easily be taken from the
home by external sources and used in malicious or opportunistic ways. The authors
presented the concept of pairing smart homes with blockchain networks to increase
transparency and security of personal information. They also addressed the limited
storage and battery life of IoT technology, which is problematic when paired with the
energy and data heavy needs of blockchain technology. The authors presented a solution
utilizing hypergraphs and hyperedge for node storage.
Park et al. (2018) explored smart contracts as a review system for IoT
marketplaces. The authors suggested integrating smart contracts running on blockchain

90
technology as a natural verification method. These applications and networks also rely on
P2P systems, but their inherently immutable and transparent nature also act to mitigate
the prior mentioned shortcomings of alternative networks. The authors argued that
integration of blockchain technology into IoT-bases systems could allow for value added
outcomes. This line of inquiry is increasingly popular among industry analysts, so the
authors have contributed a useful contribution in this case.
Harper (2017) examined both a tri-combination of artificial intelligence (AI),
blockchain, and IoT. Harper (2017) offered an overview on three emerging technology
forces anticipated to fundamentally alter big data collection, analysis, and application in
the next few years. The author showcased artificial intelligence, IoT and blockchain
technology. According to Harper, the distributed nature of these technologies will result
in an increasingly decentralized structure in big data moving forward. IoT technology
will continue to grow as a data-generating force, as these devices will only expand in
terms of sophistication and social adoption. Personal data collected by mobile devices
and other personalized smart technology will result in mass aggregations of big data
stored in numerous and disparate cloud structures. AI will be needed to analyze and apply
data aggregates via advanced and self-learning operations and outputs like algorithms and
neural networks. This will allow users to make sense of information derived from the big
data caches. The non-secured nature of most IoT devices creates a situation where data
collected at the network peripheries (the majority of data in these networks) will be both
isolated from central depositories and prone to compromise and attack. Harper argued
that blockchain technology will allow for secure storage and practical retrieval of data.

91
This is due to the decentralized yet inherently secure, immutable, instantaneous, and
verifiable nature of blockchain networks, which are well-suited to complement and
augment both AI and IoT technologies. Harper offered a compelling argument for the
future influence and coupling of these technologies. Harper (2018) separately studied
distributed automation. The focus in this particular article centered on distributed
automation, and Harper utilized a deeper analysis than in the 2017 article to explore the
following areas of interest: AI, IoT, and singular blockchain networks. The author
committed some effort to explaining the role of enterprise knowledge graphs, enterprise
data fabrics, and comprehensive platforms, along with the singular trajectory of the prior
mentioned technologies in a shared confluence and direction.
Hernandez (2016) covered the expansion of Microsoft’s Azure blockchain service
ecosystem. Hernandez provided an article explaining how Microsoft if entering into the
blockchain market via it cloud-based Azure, which will provide customers with a
blockchain-as-a-service offering. The author further noted that several other tech
solutions are joining in on the effort including C++ Ethereum Stack and Bitpay. This
article provided an important insight into the direction of mainstream technology
provision, given the size and reach of the Microsoft brand coupled with its potential to
enter and expand the blockchain sector. The author noted that other tech giants are also
moving in this direction including the Linux Foundation, Accenture, Cisco, IBM, Intel,
and J.P. Morgan.
Like Harper (2017), Imran et al. (2019) discussed challenges of and solutions to
blockchain and IoT integration. The authors conducted a systemic investigation into the

92
specific needs of IoT devices, with a particular emphasis on security and performance
issues, within the larger perspective of potential partnerships between IoT devices and
blockchain based distributed ledgers. The authors identified gaps between performance
and security benefits of paired blockchain-IoT solutions when viewed in relation to IoT
performance requirements. The authors discovered and discussed the practicality of
paring distributed ledger systems with IoT devices in reality. Having identified
operational gaps and application issues, the authors then formulated their proposed
approach to solving those prior mentioned considerations, which they argued would
resolve what they consider as currently significant challenges toward the real-time
integration of blockchain based information platforms and IoT device ecosystems.
Conversely to the work of Imran et al., Minoli and Occhiogrosso (2018) asserted
blockchain as a possible security apparatus for IoT. Minoli and Occhiogrosso analyzed
the significant security challenges that IoT solutions face on deployment. Because
technology ecosystems rely on widely distributed networks of disparate and unique
devices, individual units face increased security threats given their large attack surface
that they host and the numerous vulnerabilities that devices suffer, particularly when
operating on the network fringes, when relying on limited or outdated firewalls, or when
falling into the hands of bad actors. Because IoT networks are all integrated, however,
corruption of individual IoT units or weakening of their connection to one another can
compromise entire IoT ecosystems. According to the authors, this problem is most
pressing for mission-critical predicaments regarding transportation, health care
surveillance, etc.; meanwhile, the authors also affirmed the need for reliability and

93
security among downstream IoT networks, as well. The authors analyzed blockchain
technology as a potential solution to IoT security challenges, owing largely to the
transparent, decentralized, and immutable nature of distributed ledger databases, which
IoT network designers utilize in a defense-in-depth or Castle defense strategy. The
authors acknowledged that blockchains should only be viewed as a piece of an emergent
IoT security mosaic approach. Reyna et al. (2018) further discussed blockchain
integration with IoT. The authors affirmed their expectation that blockchain will
revolutionize IoT utilization; however, they cautioned against integration before gaining
a full understanding of downside risks and improvement opportunity. The authors argued
that formulation of consistent regulation of technology will speed their development,
along with creation and application of consensus. The authors also predicted a dualism of
opposing forces when onboarding both blockchain security solutions versus new and
large waves of IoT devices into tech ecosystems. The authors predicted that the
partnership between blockchain and IoT networks will cause cryptocurrencies to grow in
scale to rival that of current fiduciary monetary systems. Wang et al. (2019) conducted a
survey on the same topic. The authors here presented an extensive analysis of the
potential integration of blockchain based networks to improve IoT ecosystems. The
authors noted the challenges inherent among IoT devices and associated networks that
will challenge these efforts, including the overwhelming and ever-increasing number of
IoT devices, differences in structure between IoT networks, and the limited bandwidth,
battery-power, erroneous radio linkages, and computational efficacy of IoT devices. The
authors affirmed their prediction that the anticipated integration of blockchain and IoT

94
will address the challenges. The authors conducted and presented a comprehensive
analysis of blockchain technology to date, particularly concerning its partnership with
IoT. The authors concluded by suggesting future research to improve capacity, security,
and scalability of blockchain based distributed ledger systems. Du et al. (2018)
investigated blockchain integration into Fin Tech. The authors acknowledged that, given
the very new and changing nature of distributed ledger technology, most discourse on this
topic has focused on broad application ideation rather than specific organizational
integration. The authors focused on the latter perspective by utilizing an affordance-
actualization (A-A) framework that firms could utilize when integrating blockchain based
fintech solutions. From this A-A theoretical foundation, the authors then developed a
process model by adding an experimental phase whereby organizational leaders may
identify, develop, and trial solutions. The authors noted that their case-study research
should only be generalized following future research. The authors noted that their case
study focused on a large and established organization, rather than among startups, which
tend to operate differently. The authors specified that their case-study participant operates
in an emerging economy; thus, future researchers should attempt to follow up on their
findings in industrial and post-industrial landscape. Scholars focused on the potential
compatibility between blockchain and IoT technologies tend to identify the purported
decentralization, transparency, security, and immutability of blockchain networks as
viable options for storage and retrieval of mass data captured via IoT devises. Those
investigating potential AI integration have conjectured the potential of AI to analyze big
data stored on distributed ledger systems, including big data gathered via aggregate IoT

95
device information integration. Scholars interested in integration of quantum computing
into blockchain networks tend to focus on potential compatibility solutions between the
divergent technologies, often seeking to reconcile the decentralized posture of
blockchains with the centralized architecture of emergent quantum computers. Scholars
focusing on emergent technology integration broadly agree that innumerable industries
and economies will likely experience seismic shifts following widespread amalgamation
of these technologies.
Investing Strategies
Many authors have focused on investing strategies for cryptocurrencies and
blockchain. Speed (2016) discussed optimal crypto spending habits. The author provided
advice in a series of numbered paragraphs, each focusing on one area of interest. These
included the need to understand the following risks: technological, business and
economic, financial, and legal. Additionally, the author counselled that most projects
would fail, and those investors should only engage in crypto currencies if they are
financially capable and comfortable doing so and they only wager what they can afford.
Finally, the author strongly suggested conducting sound research prior to investing, study
of the crypto economics, and adoption of a long term buy-and-hold strategy rather than
focusing on short term fluctuations and reactions.
Kauflin and Baldwin (2018) showcased the investing tips of a China-based crypto
trader. The authors highlighted the trading practices of Shuoji Vincent Zhou and this
cryptocurrency investment firm he started named FBG Capital. Originating in China, the
firm has gone international and enjoys some of the highest reported returns in the ICO

96
investment market. According to the authors, the firm’s investment strategies rely on
rapid volume trading driven by market inefficiencies, insider relationships, and market
hype. Initially, the founders focused on arbitrage exploitation by buying and trading
tokens across platforms that offered differential prices for the same assets. As these
markets became more efficient, however, the firm shifted its strategy to a relationship
business whereby FBG has formed close connections to media outlets, token exchanges,
and crypto startups. In this model, the firm conducts close research on entrepreneurs to
identify viable investment targets. Then, they infuse firms with capital; afterwards, the
firm pays media influencers like prominent bloggers to hype the venture while also
convincing exchanges to list them. This causes the venture’s value to bloat rapidly, and
FBG then quickly divests before the market corrects itself. In addition to this pump and
dump model, the firm also follows industry news such as regulatory changes to anticipate
how these occurrences will affect crypto market prices. Moynihan and Syracuse (2018)
explored obstacles toward creating crypto and blockchain mutual funds. The authors
focused on the past, present, and future of cryptocurrencies in the mutual fund industry.
Moynihan and Syracuse began by presenting an overview on blockchain platforms and
digital tokens, including initial coin offerings. The authors then provided an industry
overview of how many major financial sector participants are seeking to integrate the
embryonic technology into their own operations. They discussed barriers to blockchain
and cryptocurrency utilization by mutual funds, much of which stems from both
uncertainties in the regulatory code and shortcomings of existential technology to meet
mandatory legal requirement intended to safeguard mutual fund investors. The authors

97
lauded the rapid growth of the blockchain industry while also cautioning against
unrealistic expectations, and they speculated that the greatest adoption of blockchain in
the mutual fund industry may be more geared toward harnessing blockchain
infrastructure for processing client information rather than as a portfolio asset option.
Despite Kauflin and Baldwin (2018)’ cautionary narrative, Daly (2016) focused
on an expected blockchain bull market. The author noted opinions from industry experts
who attested that widespread adoption of blockchain technology is actually years away,
despite optimistic reporting of advances in the field. While Daly noted that periodicals
and industry reports show rapid adoption rates and lucrative potentials, particularly in the
realm of asset clearance processes that are currently slow and require third party
verification, other factors are slowing firms from practically applying distributed ledger
systems. While mentioning several concerns, Daly noted two primary concerns:
regulation and partnership uncertainty. Regarding the first, the author did not elaborate,
but this is a much-discussed topic in other articles on the issue. Regarding the issue of
partnership uncertainty, Daly noted that large organizations must choose between many
tech firms to form strategic partnerships, and it is often difficult to differentiate the best
coupling. The author cited a source that affirmed interoperability among numerous
system options as a good decision rubric.
Lee and Yong (2018) highlighted Fintech ecosystems and business models, along
with investment decisions and challenges. Lee and Yong discussed the emergence of
financial technology, widely known as fintech, in the financial services sector, which
they described as a paradigm shift. The authors posited fintech as the integration of

98
information technology into financial markets, which then upend traditional methods,
protocols, and practices. Lee and Yong first provided a historical perspective on fintech
and the formation of its own ecosystem. The authors also considered the various business
models within that ecosystem, along with different investment types and decisions related
to their growth and development. Lee and Yong finally investigated the numerous kinds
of challenges that business may face in creating fintech solutions. The authors created a
consideration matrix that delved into these challenges from technology and managerial
standpoints, opposite challenges from startup versus established organization
perspectives. Del Castillo (2018) wrote of the launch of a regulated Ethereum futures
trading platform. The author described the most recent launch of Ethereum futures.
Funded by Akuna Capital, the project will allow traders to take long or short positions on
future Ethereum cryptocurrency prices. This represents an additional step toward
cryptocurrency integration into traditional currency markets, as speculations will be
hosted by mainstream institutions like the Chicago Mercantile Exchange and the Chicago
Board of Exchange. This development for Ethereum occurred just recently, whereas
futures trading of Bitcoin and XRP have existed since 2015 and 2016, respectively. The
author provided commentary on the regulatory environment surrounding Ethereum
futures, which must abide by those mandated for the wider derivatives markets.
Manta and Pop (2017) discussed current trends in digital finance pertinent to
cryptocurrencies and blockchain. The authors positioned the currently climate as one
where contemporary monetary ecosystems are being rapidly upended and updated based
on the widespread development and adoption of digital tokens, then numbering greater

99
than 850 coin types in Europe at the time of writing. The authors noted an overall
sentiment of caution among national, European, and international regulators regarding
utilization of digital currencies in their myriad and often unregulated forms. In particular,
the authors noted concern from governing authorities that the decentralized and
anonymous nature of crypto tokens can be easily misused to fund money laundering and
terrorist activities. The authors specifically analyzed Directives 2015/849 and
2009/101/EC of the European Union. The authors tended to provide a myriad of
perspectives regarding crypto investment. The inherent uncertainty surrounding
investment strategies, particularly concerning speculative markets, necessitates numerous
and often divergent opinions regarding best practices for individual investors, specific
market occurrences, and industry developments.
A subset of scholars has investigated ICOs and their fundraising outcome factors,
along with crowdfunded equity offering outcomes. Wonglimpiyarat (2018) relied on an
innovation system approach toward assessing challenges and dynamics of FinTech
crowdfunding. The author conducted a review of the myriad challenges that face full
development and implementation of FinTech crowdfunding mechanisms like
crowdfunded equity offerings. The author focused on the dynamics and challenges of
emergent capital markets in the United States, Asia, and Europe. The author conducted a
case study on the Thai innovation environment currently dubbed Thailand 4.0. The author
found that the Thai entrepreneurial sector suffers from barriers to innovation both
regarding the nation’s regulatory system and its operational capabilities. The author
concluded that their findings are valuable to improved innovation in the FinTech

100
crowdfunding arenas globally, with particular emphasis on developing economies like
those in Southeast Asia.
Fisch (2019) examined ICOs as a capitalization method for startups. The author
conducted a primary investigation into the determinants of initial coin offerings to better
predict amount of capital raised and other success factors. Fisch relied on signaling to
identify how information signals put out by capital seeking startups might incentivize
investors to provide seed funding. The author conducted an empirical study of 423 initial
coin offerings between 2016 and 2018. The author found that certain startup signals do
indeed affect amount of capital raised. Capital seeking firms that issued white papers with
technological language and high-quality source code raised more money on average than
firms that did not. Firms that patented their technology did not enjoy elevated capital
returns during the issuance process. The author conducted research into firm-specific
results to find that some initial coin offering outcomes resembled those found broadly in
prior entrepreneurial finance literature; however, these observations did not hold
universally. Given the lack of research on initial coin offerings, the author’s contribution
to the literature here is significant, and the study conclusions validate similar findings on
the topic.
Adhami et al. (2018) conducted an empirical analysis regarding the reasons why
new ventures choose crypto based funding. The authors in this study provided both a
comprehensive description of ICOs as a capital fundraising phenomenon, along with an
empirical study into the success factors of ICOs. Their research methodology consisted of
a sample of 253 ICO campaigns; therefore, the authors found that ICOs enjoy an elevated

101
rate of success given the presence of three variables: source code availability, presale
organization, and service availability or profit sharing for campaign participants. The
authors in this study have provided a valuable contribution to the literature, particularly
through their explanation of the ICO process and their primary research study, which was
original to the topic.
Huang et al. (2020) conducted a quantitative study regarding the numbers and
successes of ICOs across the world. They then compared results to identify success
factors that influence ICO prevalence and outcomes, along with listing which countries
have had relative success in their domestic ICO markets. The authors acknowledged the
difficulty in conducting a study of this nature, as no global ICO register currently exists.
They gathered their sample by exhaustively cross-referencing ICO lists across hundreds
of nations. According to their initial hypotheses, ICOs are a function of well functioning
capital markets and infrastructure. They selected degree of development in financial
systems, debt markets, public equity markets, and private equity markets. The authors
then cross-referenced all ICOs listed on ICObench with all numerous other public
information sites. They identified 915 ICOs that finished from January 1, 2017, to March
31, 2018. Each ICO listed had to be identifiable by country of origin, with the full sample
ranging from a group of 73 originating countries. Their dependent variable was the
number of ICOs completed in each country during the study timeframe. Their
explanatory variables were composite index ratings for each listed country according to
the Financial Development Index, Banking Index, Equity Market Index, VC Index, ICT
market development, ICO regulation, and availability of crowd funding platforms. The

102
authors found that a nation’s market development represents a positive and significant
coefficient on ICT market development. Sufficient and transparent regulatory
frameworks were also a significant factor. They found no relationship between ICOs and
venture capital or private equity funds. The authors found their hypotheses proven with
some limitations. The US performed highest in terms of number of ICOs during the study
period. Most of the other high performing nations ascribed to a commonly Western
model of financial, regulatory, political, and socioeconomic design, which matches
closely with the authors’ study design assumptions. The primary exemption was Russia,
which scored second highest on the list of overall completed originating ICOs during the
study timeframe, despite scoring low on most independent variables. The authors noted
that Russia did score high on population and mathematical capacity, and the authors
concluded that ICOs may also be significantly influenced by mathematical or technical
population expertise. They suggested that future researchers look into their findings.
Masiak et al. (2020) conducted a quantitative auto-regression study to assess
whether market cycles affect ICO generation, along with the relationship between ICOs
and cryptocurrencies bitcoin and ether. The authors started with a brief introduction into
distributed ledger technology and the rise of ICOs as a capital seeking vehicle. They also
enunciated their intended views for their study, which they suggested could benefit
startups considering launching ICOs by better informing market participants in the
macro-level forces affecting these markets. The authors then afforded a background
section providing context in the ICO process including the pre-, main-, and post-ICO
phases. They also conducted a literature review. Their unique study comprised 104

103
weekly ICO observations between January 1, 2017, and December 30, 2018. They also
included three variables: total amounts raised in the ICO campaigns, the price of bitcoin,
and the prices of ether. The authors also relied on two primary data sources for their
study. CoinSchedule collects key information about many ICOs like amount raised, date
offered, and links to the offering startups’ web sites. CoinMarketCap offers information
about daily bitcoin and ether prices. Their econometric test results showed a pattern of
bullish (bearish) tendencies in ICO markets persisting an average of 4 weeks. They also
found that innovations in bitcoin and ether affected ICO markets for an 8-week window.
They attributed both cycles to the effects of market hype. The authors were not able to
show a significant relationship between ICO growth rates and cryptocurrency returns, nor
a relation between ICO volumes and cryptocurrency volatility. The authors suggested that
startups may want to postpone ICO offerings until market conditions were favorable or, if
that is not possible, focus on quality of crowdfunding tactics and product/service
strengths. The authors did note limitations insofar as not considering exogenous
variables, crowdfunding methods, macro trends in ICOs markets, discrepancies between
ICO tracking sites, and post offering returns or volatility.
Hsieh and Opperman (2021) conducted a study of ICOs and their initial returns
following issuance of cryptocurrencies/tokens. The authors based their study on the
theory of initial returns, which asserts that IPOs generally exhibit underpricing due to
information asymmetry at the time of offering. Information imbalances benefit investors
with inside information while punishing those without it. The issuing venture also tends
to enjoy potential value based on underpricing. Inside investors are able to leverage privy

104
knowledge to best select share issuances that are initially underprices, which they
subsequently hold until market forces correct their prices upward. This results in the
winner’s curse whereby outside investors suffered from crowded out capital markets that
generally only offer them investment opportunities with suboptimal return outcomes.
This crowding out is only partial because uninformed investors stay in the market,
suggesting at least some residual return opportunities. The authors postulated that similar
dynamics from the IPO market also exist in the ICO market. The authors expressed the
initial return equation as equaling price of issued share after first day less the price of
share set by the ICO, divided by price of share set by the ICO. The authors gathered their
sample and variables from CoinDesk.com, which provides ICO data and prices indices.
They then cross-referenced ICOs listed between January 2014 and August 2018 against
Coinmarketcap.com to compare crypto price changes from issuance. They also gathered
additional information to support variable analysis from several other sources including
white papers. They chose a final sample of 502 ICOs. They set the dependent variable as
the initial return for each ICO. The authors segmented for time of issuance to control for
aggregate changes in the cryptocurrency markets. They also established regulatory
frameworks, gold, and stock markets as independent variables. The authors found that
underpricing predominates in ICO markets even more so than in IPO markets, suggesting
significant information asymmetry and market inefficiency in ICO markets generally.
They also found that these characteristics can be moderated by presales and lengthy white
papers. Shorter issuance durations, native coinage use, and independent block chain
platform usage have a positive relationship on initial returns. The authors also found that

105
industry, regulation, and the larger cryptocurrency market movements significantly
influence initial returns. They also found that the movements of traditional stock and gold
investment markets have a positive correlation with ICO initial returns.
Benedetti and Nikbakht (2021) assessed returns and network growth of cross-
listed tokens. Boreiko and Risteski (2021) discussed serial and large investor involvement
in ICOs. Fisch et al. (2021) evaluated motives and profiles of ICO investors. Le Moign
(2019) postulated ICOs as a new mode of finance in France. Demarco (2019) analyzed
blockchains in capital markets. Cappa and Pinelli (2021) investigated ICOs and
determinants of returns. Zhang and Gregoriou (2021) weighed return and liquidity
tradeoff of including crypto assets in portfolio after China’s crypto ban. Lambert et al.
(2022) discussed security token offerings, and Campino et al. (2022) explored reasons for
ICO success. Bogusz et al. (2020) studied crowdfunding and cryptos from social media.
Crowdfunded Equity Investing
Similar to Fisch’s (2019) focus on ICO success factors, Mamonov and Malaga
(2017) discovered success factors for startups seeking initial equity offerings via
crowdfunding in the US. The authors investigated the success factors of crowdfunded
equity launches. Owing to the lack of research in this emerging field, the authors
specifically researched participants in Title III markets in the United States that, by
regulation, allow non-accredited investors to gain ownership in capital seeking startups.
They relied on a data set taken from 16 equity crowdfunding platforms. They identified
133 startups that collectively raised $11 million from crowdfunded equity markets. The
authors assessed three risk variables: agency, execution, and market risks. Mamonov and

106
Malaga found that all three risk variables played a material role in the success factors of
their participant firms. They also found that involvement of accredited investors in Title
III public offerings (although not required by law) represented a critical component of
early-stage success in these markets.
In contrast to Adhami et al.’s (2018) focus on reasons that startups choose to
launch ICOs, Brown et al. (2018) discussed equity crowdfunding among startups. The
authors conducted a study of 42 startups in the United Kingdom that relied on equity
crowdfunding to finance their ventures. Their research method relied on a qualitative
interview approach to gather and analyze feedback from the study participants on why
they chose to rely on equity crowdfunding. They found significant disillusionment among
the participants regarding traditional funding sources like banks or venture funds, which
generally are not accessible to startups. The authors discovered additional benefits to
entrepreneurial ventures from equity crowdfunding that exceed those merely attainable
by capital injection. Given the behavioral tendencies of the study participants, the authors
proposed utilization of an entrepreneurial bricolage as an appropriate theoretical lens
from which to understand their behavior. The overall interest among scholars has been to
assess factors that may affect offering outcomes. The predominant focus, then, has been
in assessing what actions, advantages, and precursors may result in an offering that reaps
large shares of capital compared to other firms seeking ICO-derived capital or
crowdfunded equity. Some authors have also examined factors post-offering that may
facilitate future access to capital, whether through subsequent offerings or access to angel
investors.

107
Many of the topics of discussion pertaining to equity crowdfunding span a broad
range of topics. Elder and Hayes (2021) provided a guide to equity crowdfunding.
Colombo and Shafi (2021) discussed receiving internal equity following successful
crowdfunded tech projects, while Troise et al. (2020) evaluated the role of intellectual
capital in the growth of equity crowdfunded companies. Cabarle (2021) explored future
tax benefits planning for regulation crowdfunding, and Coakley et al. (2022) assessed
seasoned crowdfunded equity offerings. Cumming et al. (2021) provided an integrative
model and research agenda toward equity crowdfunding and governance. Buttice et al.
(2020) explored deal structure and attraction of venture capital investors to crowdfunded
equity. Sanders (2020) reported that the SEC announced temporary rules for certain
regulation crowdfunding offerings, and Gong et al. (2022) analyzed the influence of
auditor attestation in Securities Based Crowdfunding for startups. dos Santos Felipe and
Franca Ferreira (2020) assessed the determinants of the success of equity crowdfunding
campaigns.
Some issues are regional in nature. For example, Woolard and Steigner (2020)
leveraging social networks for offline crowdfunding in rural communities. Conversely,
many of the issues pertaining to equity crowdfunding are of an international nature. Li
(2022) analyzed regulation of equity crowdfunding in the US including remaining
concerns and lessons from the UK. Cicchiello (2020) discussed the needs, challenges,
and risks to harmonizing crowdfunding regulation in Europe while Battisti et al. (2020)
covered equity crowdfunding and regulation implications for the real estate sector in

108
Italy. Balta and Greece (2021) postulated EU crowdfunding regulation as an investment
model across the EU.
Certainly, one of, if not the, earliest examples of comparison between ICOs and
crowdfunded equity markets was through the work of Block et al. (2021) who contrasted
the two capital market types in detail. The authors placed a public call for research
submissions pertaining to each market, and they highlighted findings in their publication,
which weaved those investigations together into a cohesive narrative. The authors also
tabulated comparison charts that matched and contrasted the similarities and differences
between ICOs and crowdfunded equity campaigns. However, the authors did not conduct
empirical research that directly compared the functioning of ICOs and crowdfunded
equity campaigns via a single sample, nor did they analyze those sample results to draw
combined quantitative findings. At the end of their work, the authors acknowledged that
several unknowns currently exist between ICOs and crowdfunded equity, and they
provided future researchers with several areas where research could be of great benefit.
The authors have provided a valuable contribution to the literature, and I hope that my
own research has been able to further those efforts.
Summary and Conclusions
Many scholars have studied both ICO and crowdfunded equity markets. Their
collective attention focused on many areas of those markets like technology, regulation,
opportunity and risk. A small but growing number of scholars have also investigated the
factors that influence outcomes in those emergent primary markets, though these works
are still small in relative scope and depth compared to other areas of interest.

109
Few if any scholars have compared direct outcomes between ICOs and
crowdfunded equity via qualitative analysis in a single sample. This gap in the literature
is problematic insofar as a dearth in cross-market comparison data inhibits the efficient
operation of capital markets by depriving investors and entrepreneurs of critical historical
information to help guide the complex decision-making processes involved with going
public. These conditions force capital market participants to avoid ICOs and other
emergent capital markets entirely or to enter upon their own risk. This outcome is a
specific example of my previously identified social problem, which was that uncertainty
in markets increases the likelihood of market failure due to volatility and suboptimal
functioning.
I sought to close the current gap in the literature outlined previously by directly
comparing ICO and crowdfunded equity markets via their outcomes, by testing the
relationship of those outcomes to factors that may influence them, and to draw
conclusions from those discoveries to assess the relative efficiency of the emergent
capital market types. In Chapter 3, I outline the specifics of my research by describing its
design, methodology, data analytics, and validity.

110
Chapter 3: Research Method
The purpose of this quantitative study was to compare a group of ICOs versus a
group of crowdfunded equity offerings with the intent of identifying predictive factors on
those funding outcomes. In this chapter, I outline the major components of my study. I
describe my research design and rationale, including my population, sampling and
sampling procedures, participant recruitment, data collection, archival data, and data
analysis. I also explore potential threats to internal validity, external validity, and
construct validity, along with ethical factors. I then close the chapter with a summary
section.
Research Design and Rationale
My focus was on one primary binary control factor, which denoted whether the
individual startups included in my sample chose to conduct an ICOs or a crowdfunded
equity offering. The values for this control factor were either ICO offering organization
or crowdfunded equity offering organization.
I had a single continuous, numerical dependent variable, which represented the
amount of money that each startup in my sample was able to raise as part of their
respective public offerings. The values for this response variable were denoted in whole
dollars and cents.
I also evaluated eight secondary binary control variables which denoted whether
the individual startups in my study provided different forms of material information to
the investment community as part of their respective offerings: historical financial
information, pro forma financial forecasts, detailed product descriptions, video of product

111
demonstrations, company website, company history, company leadership, and company
investors. Each of these factors had a value that was either Yes or No depending on
whether the startup made the information available to the investment community as part
of their respective offering.
My research design and choice of variables connected directly to my research
question: How does capital offering type predict the amount of funds raised while
controlling for access to the offering companies’ historical financial data, pro forma
financial projections, detailed product descriptions, video of product demonstrations,
company website, company history, company leadership, and company investors? As
such, I used univariate ANOVA (single dependent variable) with multiple control factors
to assess if offering type (the primary control factor) predicted amount of funds raised
(the single dependent variable) when controlling for investor access to historical financial
information, pro forma financial forecasts, detailed product descriptions, video of product
demonstrations, company website, company history, company leadership, and company
investors (eight secondary control factors).
I evaluated a sample of publicly available archival data, collected from the
inception of my data archives to present. This design choice was consistent with the
objective to determine if a difference existed in funding obtained using two primary
capital market types. This is an issue that many scholars and practitioners have fiercely
debated using subjective arguments while largely lacking objective data findings to
support their assertions.

112
Methodology
In this section I outline the overall methodology of my study, including my
population, sampling, data collection, archival data, and data analysis.
Population
The population consisted of startups that received initial capital funding via ICOs
and those that received funding through crowdfunded equity offerings. The target
population comprised the completed funding campaigns listed on the websites
ICOdrops.com (2022), localstake.com, mainvest.com, and fundable.com (2022). The first
site hosts and records ICO offerings, and the latter three hosts and records crowdfunded
equity offerings. These websites provided a target population of 1,800+ completed
campaigns.
Sampling and Sampling Procedures
My study relied on publicly available archival data of both ICOs and
crowdfunded equity campaigns. Selection criteria for those data required that all
campaigns chosen for the study had been fully completed, were not listed according to
any outcome bias, and provided sufficient information about each selected campaign that
meaningful conclusions could be drawn according to a cross market perspective.
Data were available from four primary sources. The website icodrops.com (2022)
is one of the largest hosting sites for ICOs globally, allowing an online forum for startups
and investors to meet, learn about one another, and decide to partner via capital injection
into the respective crypto ventures. The site also maintains historical data, including
material information about past ICO offerings that have occurred through the website.

113
Selecting Ended ICOs on the upper right corner of the homepage yielded a listing of all
finished campaigns. As of January 24, 2022, this site has produced a listing of 1,305
completed ICOs that have run on the site since July 2014. This listing included important
information about each offering including the name of the startup, its site rating,
industry/category, total amount raised, fundraising goal, and the campaigns closing date.
Site users can also click through the listed company names in the listing to access a
profile page for each of the startups, which offers more detailed information about each
venture, coupled with additional links to their respective webpages.
The websites fundable.com (2002), mainvest.com (2002), and localstake.com
(2022) are online platforms for ventures seeking crowdfunded equity for capital injection.
The sites offer selection criteria that allows the user to edit the listing of startups they are
interested in exploring, including several hundred completed campaigns. Clicking
through the listed firm names allows the site users to access much material information
about the listed firms and their respective offerings, along with links to their individual
websites.
These individual listings on each website represented my target population.
Because I had access to the entire target population, I initially intended to conduct a full
census of the sites, but later chose to sample from them for time and viability concerns. I
used G*Power (Faul et al., 2007) to compute the statistical power for this census, based
on a target population size of N = 1888, level of significance of α = .05, numerator df = 1
(factor levels [2] – 1), number of groups = 9 control factors x 2 levels each = 18, and

114
small effect size f = 0.10. A post hoc computation of statistical power (1 – β) was .991
(less than a 1% probability of failing to detect a true effect among the control factors).
Procedures for Recruitment, Participation, and Data Collection (Primary Data)
All data collection occurred via the four websites. Because the startups listed on
those sites have chosen to list their offering results publicly, I did not plan any direct
communications with the sample startups, nor did I release information about specific
startups or their respective offerings. I instead relied only on the information that those
entrepreneurs and the website hosts had already provided for public use, so there was not
a need for the individual startups to provide informed consent for this specific study, nor
was there a need for formalized exiting procedures like debriefings or post-study follow
up.
All data collection occurred via tabulation of the offering results listed on the four
websites, coupled with material information about those offerings like company-specific
details needed to adequately address my research question. These company-specific data
included company close of campaign date, and binary outputs denoting the availability of
material information that investors would need to make informed decisions pertaining to
those individual offerings including access to historical financial documents, pro forma
financial forecasts, and other information like product descriptions, company websites,
company leadership, and key investors.
Data were input to an Excel spreadsheet where all information is be available for
future analysis. I conducted quantitative analysis using SPSS, and the data contained in
the spreadsheets were easily importable into the analytic tool.

115
Data Analysis Plan
Data structure captured from the websites was identical and included the
following:
• company name
• campaign closing date
• amount raised
• historical financial data
• pro forma financial forecasts
• product descriptions
• company website
• product video/pictures
• company history
• leadership
• current investors
My research question was, how does capital offering type predict the amount of
funds raised while controlling for access to the offering companies’ historical financial
data, pro forma financial projections, detailed product descriptions, video of product
demonstrations, company website, company history, company leadership, and company
investors?
For each of the nine control factors (one primary and eight secondary), the
following were the hypotheses that were tested to address the RQ:
Hj0: There is no difference in mean funds raised due to control factor j.

116
μj1 = μj2 where μj1 is the mean funds raised with control factor j at Level 1,
and where μj2 is the mean funds raised with control factor j at Level 2; and j = 1, 2…9.
HjA: Mean funds with control factor j at Level 1 is not equal to mean funds raised
with control factor j at Level 2.
μj1 ≠ μj2.
For each pair of control factors, j and k, the following are the hypotheses related
to the two-factor interaction (2FI) equal to j*k.
Hf0: The interaction of factors j and k is equal to zero.
j*k = 0.
HfA: The interaction of factors j and k is not equal to zero.
j*k ≠ 0.
I used univariate ANOVA to assess if offering type (primary binary control
factor) predicted amount of funds raised (continuous, numerical dependent variable)
when controlling for investor access to historical financial information, pro forma
financial forecasts, detailed product descriptions, video of product demonstrations,
company website, company history, company leadership, and company investors (eight
secondary, binary control factors). These secondary control factors had values of Yes or
No outputs denoting whether the information was provided as part of the offering.
ANOVA was the statistical technique used to identify relationships between
categorical (nominal) control factors, or independent variables, and a single continuous
(numerical) dependent variable (Warner, 2020). The technique is used to assess
differences in dependent variable means among different groups defined by control

117
factors and their values, along with possible interactive effects between the control
factors. The benefit of this technique is that relationships identified may be used to
predict dependent variable outcomes based on actual control factor values. This ties back
to my study methodology, which utilizes ANOVA to identify the relationship between
the study’s control factors (offering type and access to material information) and
dependent variable (funding outcomes).
Threats to Validity
External Validity
Threats to external validity existed regarding actual amounts raised and actual
availability to material information by investors. An assumption of the data analysis plan
was that access to material investor information could be verified via a search of internet
resources found on the ICO and crowdfunded equity websites, along with that
information found on the company-specific websites associated with each offering. This
assumption held true pertaining to a weak EMH, which affirms that efficient market
valuations incorporate all historical data. This assumption also held true pertaining to a
semi-strong EMH, which affirms that efficient market valuations incorporate all
historical and public information material to investment decisions.
The assumptions outlined in my data analysis plan did not hold true for a strong
EMH, however, which affirms that efficient market valuations incorporate all historical,
public, and private information material to investor decisions. My study design was not
able to assess availability to private information to the investment community by the
market participants in my sample. It is possible that the entrepreneurs who have launched

118
offerings on the host sites may have held private relationships with their investor bases,
and it is equally possible that the individual startups may have shared private information
(i.e., financial data or other material information) to the investors who have chosen to
take a stake of ownership in those ventures without making that information also
available to the wider public. Given this threat to external validity, any outcomes of my
research should be interpreted as pertinent to a weak or semi-strong EMH but not
necessarily to a strong EMH.
Internal Validity
Threats to internal validity existed in relation to possible differences between the
target population and the global population, although the actual existence and level of
threats are difficult to determine. The websites listed previously are online investing
platforms for crowdfunded equity and ICOs, respectively. Those sites host initial
offerings across a wide array of industries. I also pursued a purposeful strategy of
including a sample of completed campaigns listed on the sites, regardless of funding
outcomes to avoid any preference or bias toward those campaigns that have performed
well. It is therefore a reasonable assumption that results rendered from the target
population should correspond to the aggregate outcomes of the global population. This
assumption is difficult to prove, however, as many other factors may cause target
population behavior to differ from global population behavior. It is difficult to know what
may cause startups to choose alternative sites to host their initial offerings and if those
factors are merely arbitrary or rooted in rational causes. Causes may include access to the

119
sampling sites in remote areas or perhaps preference for other sites based on industry,
country, regulations, or some other factors entirely.
To mitigate internal threats, any conclusions drawn from the study should be
noted as probably but not necessarily representative of the vast, diverse, and extremely
complex global ecosystems surrounding ICOs and crowdfunded equity offerings, and
future researchers should be encouraged to test findings on other sites, as well.
Construct Validity
A potential threat to construct validity exists through potential for reader
misinterpretation of the outcomes of the study. A critical limitation is the fact that
ANOVA may be extremely useful in identifying factors that predict the dependent
variable, but readers should take care not to interpret my findings as representing any
form of causality between the primary and secondary control factors and the dependent
variable, as predictive factors may not represent causality. It is very possible that the
research may identify differences in funding outcomes based on access to material
information available to the investment community, and my findings may suggest overall
market efficiency based on transparency. It may be incorrect to assume, however, that
investor behavior is directly affected by transparency, as it is equally feasible that those
startups that provide access to this information are simply more efficient and organized
than those that do not, and that the former tend to run better and more organized
crowdfunding campaigns in general. My findings would merely show a relationship
rather than a cause of those outcomes. Perhaps the best method to mitigate a threat to
construct validity was to directly point out these limitations here and in the conclusion of

120
my study and to encourage future researchers to explore ways of testing for causality, if
possible.
Ethical Procedures
Because my study relied on secondary data that is available to the public, ethical
considerations, and agreements to gain access to data were very real but also minimal. I
was able to gather data for analysis without written approval from the website
owners/managers. This was also the case regarding the owners of the startups listed on
those websites, as I did not make any direct contact with them nor do I plan on publishing
any individual outcomes from their respective launches, although this information is
already publicly transparent and available to interested parties. I did not rely on
recruitment materials, nor did anyone participate in the study directly.
I plan to keep the data anonymous and secured on my personal computer, which
will not be available to view without formal request from Walden officials. After
publication of the study, I plan to transfer the data onto a backup device, which will be
secured.
There were no conflicts of interest, as I was in no way associated with the
websites, nor any of the startups listed on them. I was also neither personally,
professionally, financially, or in any other way invested in any stakeholders of those
organizations.
Summary
My population comprised companies that used the global ICO and crowdfunded
equity markets, and my target population consisted of those companies listed on the

121
websites listed previously. My sampling method relied on publicly available secondary
data found on those sites that represent completed primary capital market offerings and
their associated outcomes. I compared those data first by capturing their respective
information in an Excel spreadsheet, which I then exported into SPSS for statistical
analysis. I used univariate ANOVA to assess if offering type (ICO or crowdfunded
equity) predicted funding outcomes, while controlling for access to material investor
information. These outputs enabled the detection of relative efficiency in the markets of
interest. Threats to external validity related to the inability of my study to gauge access to
privy information by investors in those markets. Threats to internal validity existed
concerning the generalization of the target population to the global population, and
results were incapable of proving causation due to the need for construct validity. Ethical
concerns were minimal because the research relied on publicly available secondary data.
I kept all data secured, private, and aggregated. In Chapter 4, I present my results.

122
Chapter 4: Results
The purpose of this quantitative study was to compare a group of ICOs versus a
group of crowdfunded equity offerings with the intent of identifying predictive factors of
those funding outcomes. My research question was as follows:
How does capital offering type predict the amount of funds raised while
controlling for access to the offering companies’ historical financial data, pro forma
financial projections, detailed product descriptions, video of product demonstrations,
company website, company history, company leadership, and company investors?
For each of the nine control factors (one primary and eight secondary), the
following were the hypotheses that were tested to address the RQ:
Hj0: There is no difference in mean funds raised due to control factor j.
μj1 = μj2 where μj1 is the mean funds raised with control factor j at Level 1,
and where μj2 is the mean funds raised with control factor j at Level 2; and j = 1, 2…9.
HjA: mean funds with control factor j at Level 1 is not equal to mean funds raised
with control factor j at Level 2.
μj1 ≠ μj2.
For each pair of control factors, j and k, the following were the hypotheses related
to the two-factor interaction (2FI) equal to j*k.
Hf0: The interaction of factors j and k is equal to zero.
j*k = 0.
HfA: The interaction of factors j and k is not equal to zero.
j*k ≠ 0.

123
In this chapter, I provide my data collection effort, study results, and a summary
and transition into Chapter 5.
Data Collection
The timeframe for data collection began on June 11, 2022, when I received
Walden’s Institutional Review Board’s (IRB) approval to move forward with my final
study (06-10-22-0617361). Data collection ended on September 14, 2022, which was the
date that I completed gathering all of my publicly available data from the websites
icodrops.com (2022), localstake.com (2022), fundable.com (2022), and mainvest.com
(2022). Because my study’s data derived solely from publicly available sources,
recruitment and response rates were not a consideration in the study.
In Chapter 3, I identified two publicly available data sources for my study. The
website icodrops.com provides historical data from completed ICOs that the site has
hosted since its inception. The website startengine.com (2022) provided similar historical
data for crowdfunded equity campaigns that it hosted. However, startengine.com recently
stopped providing post-offering information, which caused me to identify and rely upon
three other sites instead: localstake.com (2022), fundable.com (2022), and mainvest.com
(2022). Each of these sites provides historical information on crowdfunded equity
campaigns, just as startengine.com did. This allowed me to move forward with my
research with few alterations. An added benefit of integrating the three replacement sites
into the study was that they collectively provided arguably more diversified data than
those provided previously by startengine.com, which helped to strengthen the study’s
validity to the macro crowdfunded equity ecosystem.

124
The baseline descriptive and demographic characteristics of the four websites are
as follows. The site icodrops.com is one of the world’s largest ICO website hosts, with
historical listings from July 2014 to present. The site offers historical information on the
more than 1,530 ICOs (as of August 14, 2022) it has hosted since inception. The ICOs
listed fall along a myriad of industries, which icodrops.com categorizes into broad
groupings like platform, predictions, blockchain service, protocol, network, gaming,
finance, marketplace, and so on. Given this wide array of ICO venture types, a full
survey of icodrops.com rendered a broadly representative depiction of the global ICO
ecosystem.
The crowdfunded equity site, localstake.com, as of mid-2022 listed 43 completed
campaigns on its website. The site helps U.S. based entrepreneurial startups with a strong
local connection or mission from an array of several industries to connect with accredited
investors who may contribute capital in exchange for one of four arrangements: revenue
share loans, preferred equity, convertible debt, and traditional loans. The site
fundable.com hosts crowdfunded equity campaigns from a variety of U.S. based startups
across several industries. Entrepreneurial campaigns listed on the website may connect
with accredited investors, and, as of early July 2022, the site hosted historical campaign
results for 119 ventures. For a minimum amount of $1,000, investors have the option of
providing capital in exchange for either rewards (meaning a startup-specific incentive) or
equity, convertible equity, and debt, depending on the offering specifics. The site
mainvest.com provides historical information on roughly 200 (as of mid 2022)
crowdfunded equity campaigns. The site primarily helps small, brick-and-mortar

125
businesses based in the United States to connect with accredited and nonaccredited
investors alike to raise capital via equity and debt offerings. Minimum investment
amounts are set by each startup and average about $100. In combination, a full survey of
the three sites, localstake.com, fundable.com, and mainvest.com, rendered a broadly
representative sample of the U.S.-based crowdfunded equity ecosystem.
My original data collection plan was to conduct a full census of the websites. Due
to time and feasibility considerations, I altered the data collection plan to create a
randomized sample of those sites, instead. My sampling plan is described in the
following sections, including my study population, target population, and sample.
The population in my study was the global crowdfunding market, which was
estimated at $13.5 billion in 2021 and is projected to grow to $28.2 billion by 2028,
exhibiting a compound annual growth rate of roughly 11.8 percent (GlobeNewswire,
2022). That population includes several sub populations, including the respective ICO
and crowdfunded equity markets.
Conceived in 2012, the first ICO launched in 2013 and the market grew
exponentially year to year, eventually reaching a peak in 2018 of $7.8 billion raised by
1,253 ICOs (Zerocap, 2022). The website Coin Insider (2022) recorded 3,336 ICOs as of
April 26, 2022, and the website CoinMarketCap.com (2022) logged 20,562
cryptocurrencies issued from these launches. The market for equity crowdfunding
became legalized in the United States in 2017, which catapulted the fledgling
marketplace from $74 million in 2018 to $211 million in 2020 (Arora, 2021).
Secondary data on the four websites were available to inform my study’s

126
variables, covering roughly 5 years (2017 to 2022) for those records listed on
icodrops.com. There were 1,861 records in the target population. The website
icodrops.com provided publicly available secondary data from 1,499 completed ICOs,
and the sites localstake.com, fundable.com, and mainvest.com provided similar data for
362 completed crowdfunded equity campaigns. There were issues with recent changes to
website access, and assembling the data for each record (i.e., informing the control
factors and dependent variable) was tedious and time consuming. For efficiency, I
decided to randomly sample from the original data set, using the Excel random number
generator. An a priori sample size was calculated using G*Power v. 3.1.9.7 (Faul et al.,
2009), with the following parameters and excerpt from G*Power:
• Parameters: F tests; ANOVA: Fixed effects, special, main effects, and
interactions
• Effect size (Cohen, 1988) = f = 0.25 (medium)
• α = .05, Power = 1 – β = .80, numerator df = 1, number of groups = 18
total sample size = n = 128
Those inputs rendered the following graphical outputs in SPSS, as depicted via Figure 1.
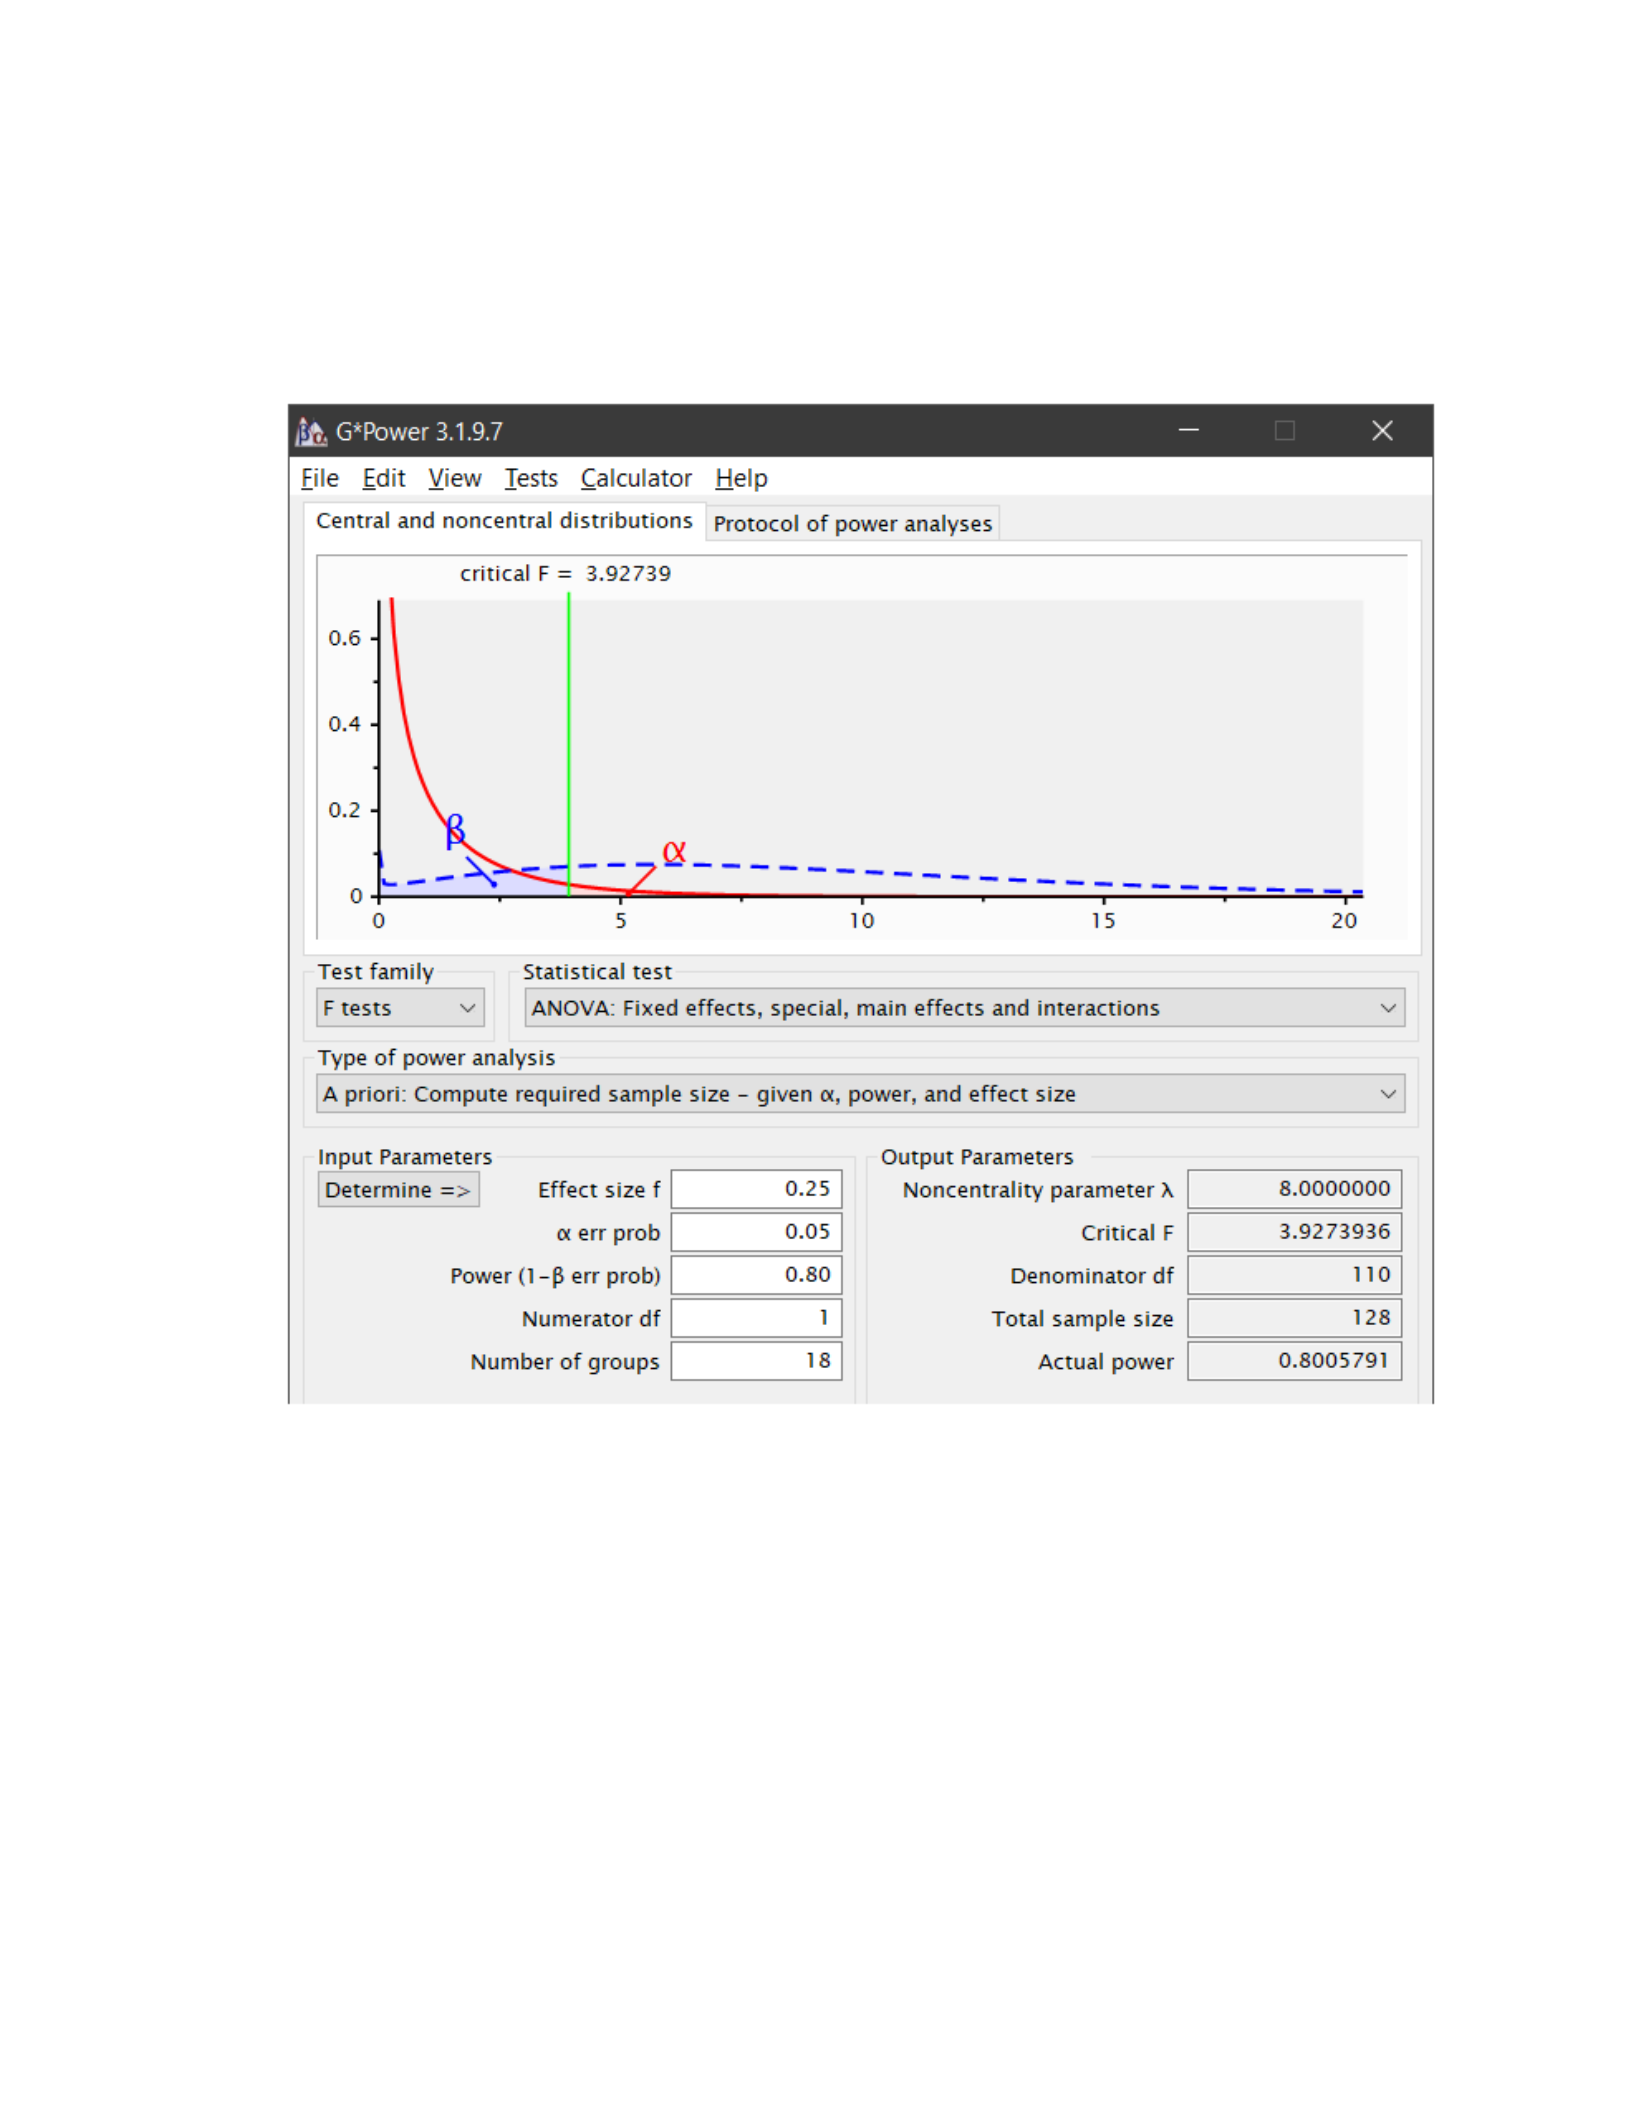
127
Figure 1
A Priori Sample Size Calculated Using G*Power v. 3.1.9.7
An initial sample of n = 148 was selected from the original data set using a
random number generator. The sample was intended to account for the likelihood that
some of the sampled records may have needed to be discarded for different reasons, like
broken links, missing information, or violations of ANOVA assumptions, and still meet
the minimum sample size. Of those 148 records, 10 lacked complete information and I
removed them for a trimmed preliminary sample of 138 records.

128
Data were cleansed to address a number of issues. Data were re-coded to be
compatible with SPSS, so that a yes value = A = 1; and a no value = B = 0. In that way,
the reference response (value of 0) was the no response. Of the control factors, product
descriptions (PDS) had all yes values, historical financial data (HFD) had all but one no
values; and pro forma financial projections (PFP) had all no values. For that reason, these
three control factors were eliminated. Another check of the data revealed the presence of
outliers in the dependent variable. Consistent with conventional criteria (Levine et al.,
2011), an outlier was defined as a value = sample mean 3 standard deviations. An
initial scrub eliminated four records. A subsequent scrub, with a re-defined outlier value
after the first scrub, eliminated 19 more records.
The final data set had n = 115 records with no missing or corrupt data, with no
outliers, and with viable control factors. A post hoc power analysis, with the same
parameters as the a priori sample size calculation, yielded a power = 1 – β = .76 or the
ability to detect an effect = .26 with the original statistical power (.80) and confidence (1
– = .05). This was considered acceptable risk and the analysis proceeded.
Study Results
There was one dependent variable in this analysis, and therefore a single
analytical, multi-stage effort. The dataset was provided, and then prepared for analysis,
using Excel. The dependent variable (funds raised, or FNDS) was a continuous,
numerical variable expressed as integers (whole dollar amounts) ranging from $7,500 to
$125.640 million, with a mean = $10.377 million and standard deviation = $19.863
million. The eight original control factors were categorical with two levels each. The

129
primary control factor of interest was type of fund source (TYPE) with two values:
crowdfunded equity (CFE) and initial coin offerings (ICO). The other control factors
were either yes or no, pertaining to whether the startup company provided various forms
of information. Because the control factors were categorical, and the dependent variable
was numerical, univariate analysis of variance (ANOVA) was chosen as the statistical
methodology.
To perform a preliminary test of assumptions, I ran an initial ANOVA with the
full set of control factors, using the SPSS General Linear Model > Univariate method
(one dependent variable). I selected the numerical dependent variable (FNDS) and the
categorical control factors as fixed factors. Because the design was not balanced (varying
sample size per group), I chose to build the model terms, and chose Type III sum of
squares. I selected post hoc homogeneity tests (Levene’s test), and I saved unstandardized
residuals. These are the assumptions of ANOVA that I assessed:
• The dependent variable was a continuous, numerical variable.
• Each control factor consisted of two or more categorical and independent
groups (levels or values).
• Independence of observations
• No time-related relationship between observations (randomized data
collection, checked with scatterplot of the dependent variable over time which revealed
no visible pattern)
• No significant outliers (as already discussed)

130
Experimental errors (residuals) were checked in the beginning, and again post
hoc, and were approximately normally distributed (a histogram of residuals and a normal
Q-Q plot revealed no significant departures from normality and is presented in Figure 3).
Homogeneity of variance for each combination of groups/levels/values (Levene’s test of
equality of error variances) was checked with the original data set, and after each scrub of
the data to remove outliers and control factors. Levene’s test evaluates the null hypothesis
that the variance in the residuals is equal for all groups, as shown in Table 1. In the test,
the null hypothesis was rejected, resulting in the conclusion that there was evidence that
the variance was not equal. A scatterplot of residuals versus the main control factor,
TYPE, corroborated the results from Levene’s test and is presented in Figure 4. To
address this violation in the assumption of homoscedasticity, the first remedy was to
remove outliers. A second remedy was to use another statistical test, a t test of means for
different groups, to assess the difference in dependent variable means for the two groups
defined by the main control factor, TYPE. Finally, a review of the data set revealed that
there was a significant imbalance in samples from the two groups defined by TYPE: 84
for ICO and 31 for CFE. In addition, the values for the dependent variable, FNDS,
revealed that far more of the high values were associated with ICO, thereby exacerbating
the imbalance in the data. This imbalance is depicted in Figure 2. In retrospect, it would
have been beneficial to perform a stratified sample, based on the stratum, TYPE.
However, some of the imbalance in the data were due to eliminating variables and
records, and so the extent of the imbalance was not known before data collection.
Secondly, due to the challenge of creating the data set, obtaining more was impractical.
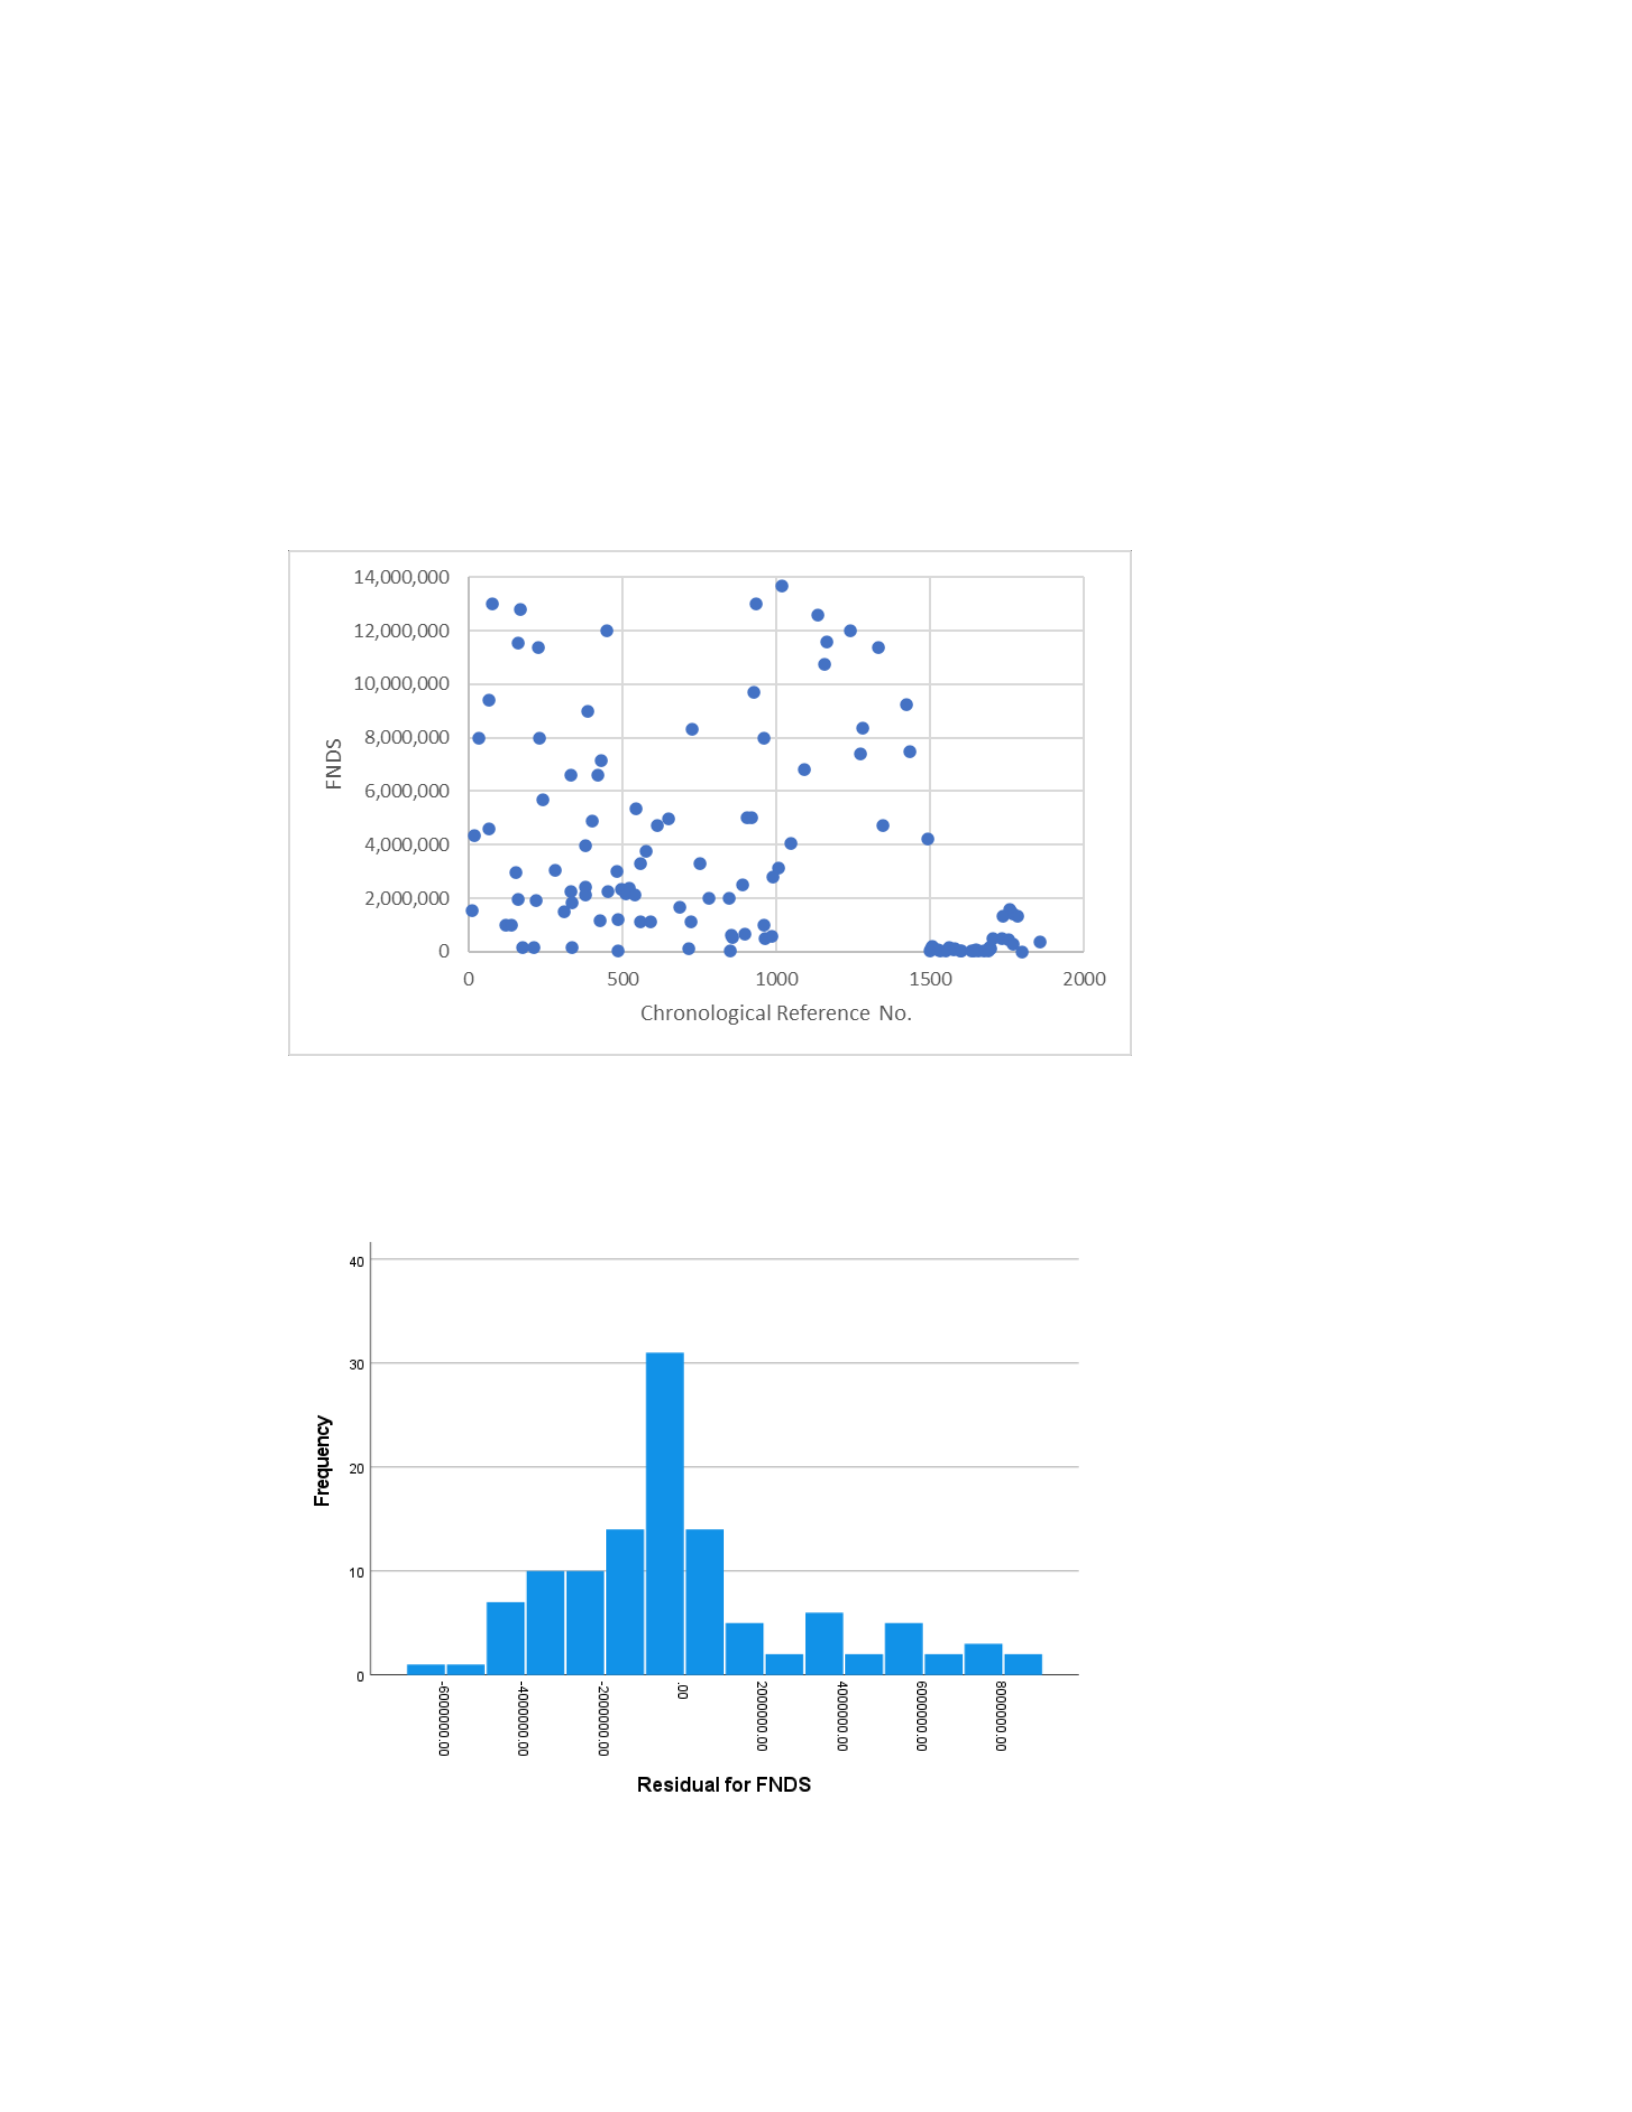
131
Therefore, the decision was to proceed with the analysis, and offer prudent cautions about
the reliability of the ANOVA results and conclusions.
Figure 2
Funds Raised by Chronological Reference Number
Figure 3
Residual for Funds Raised by Frequency Across Sample
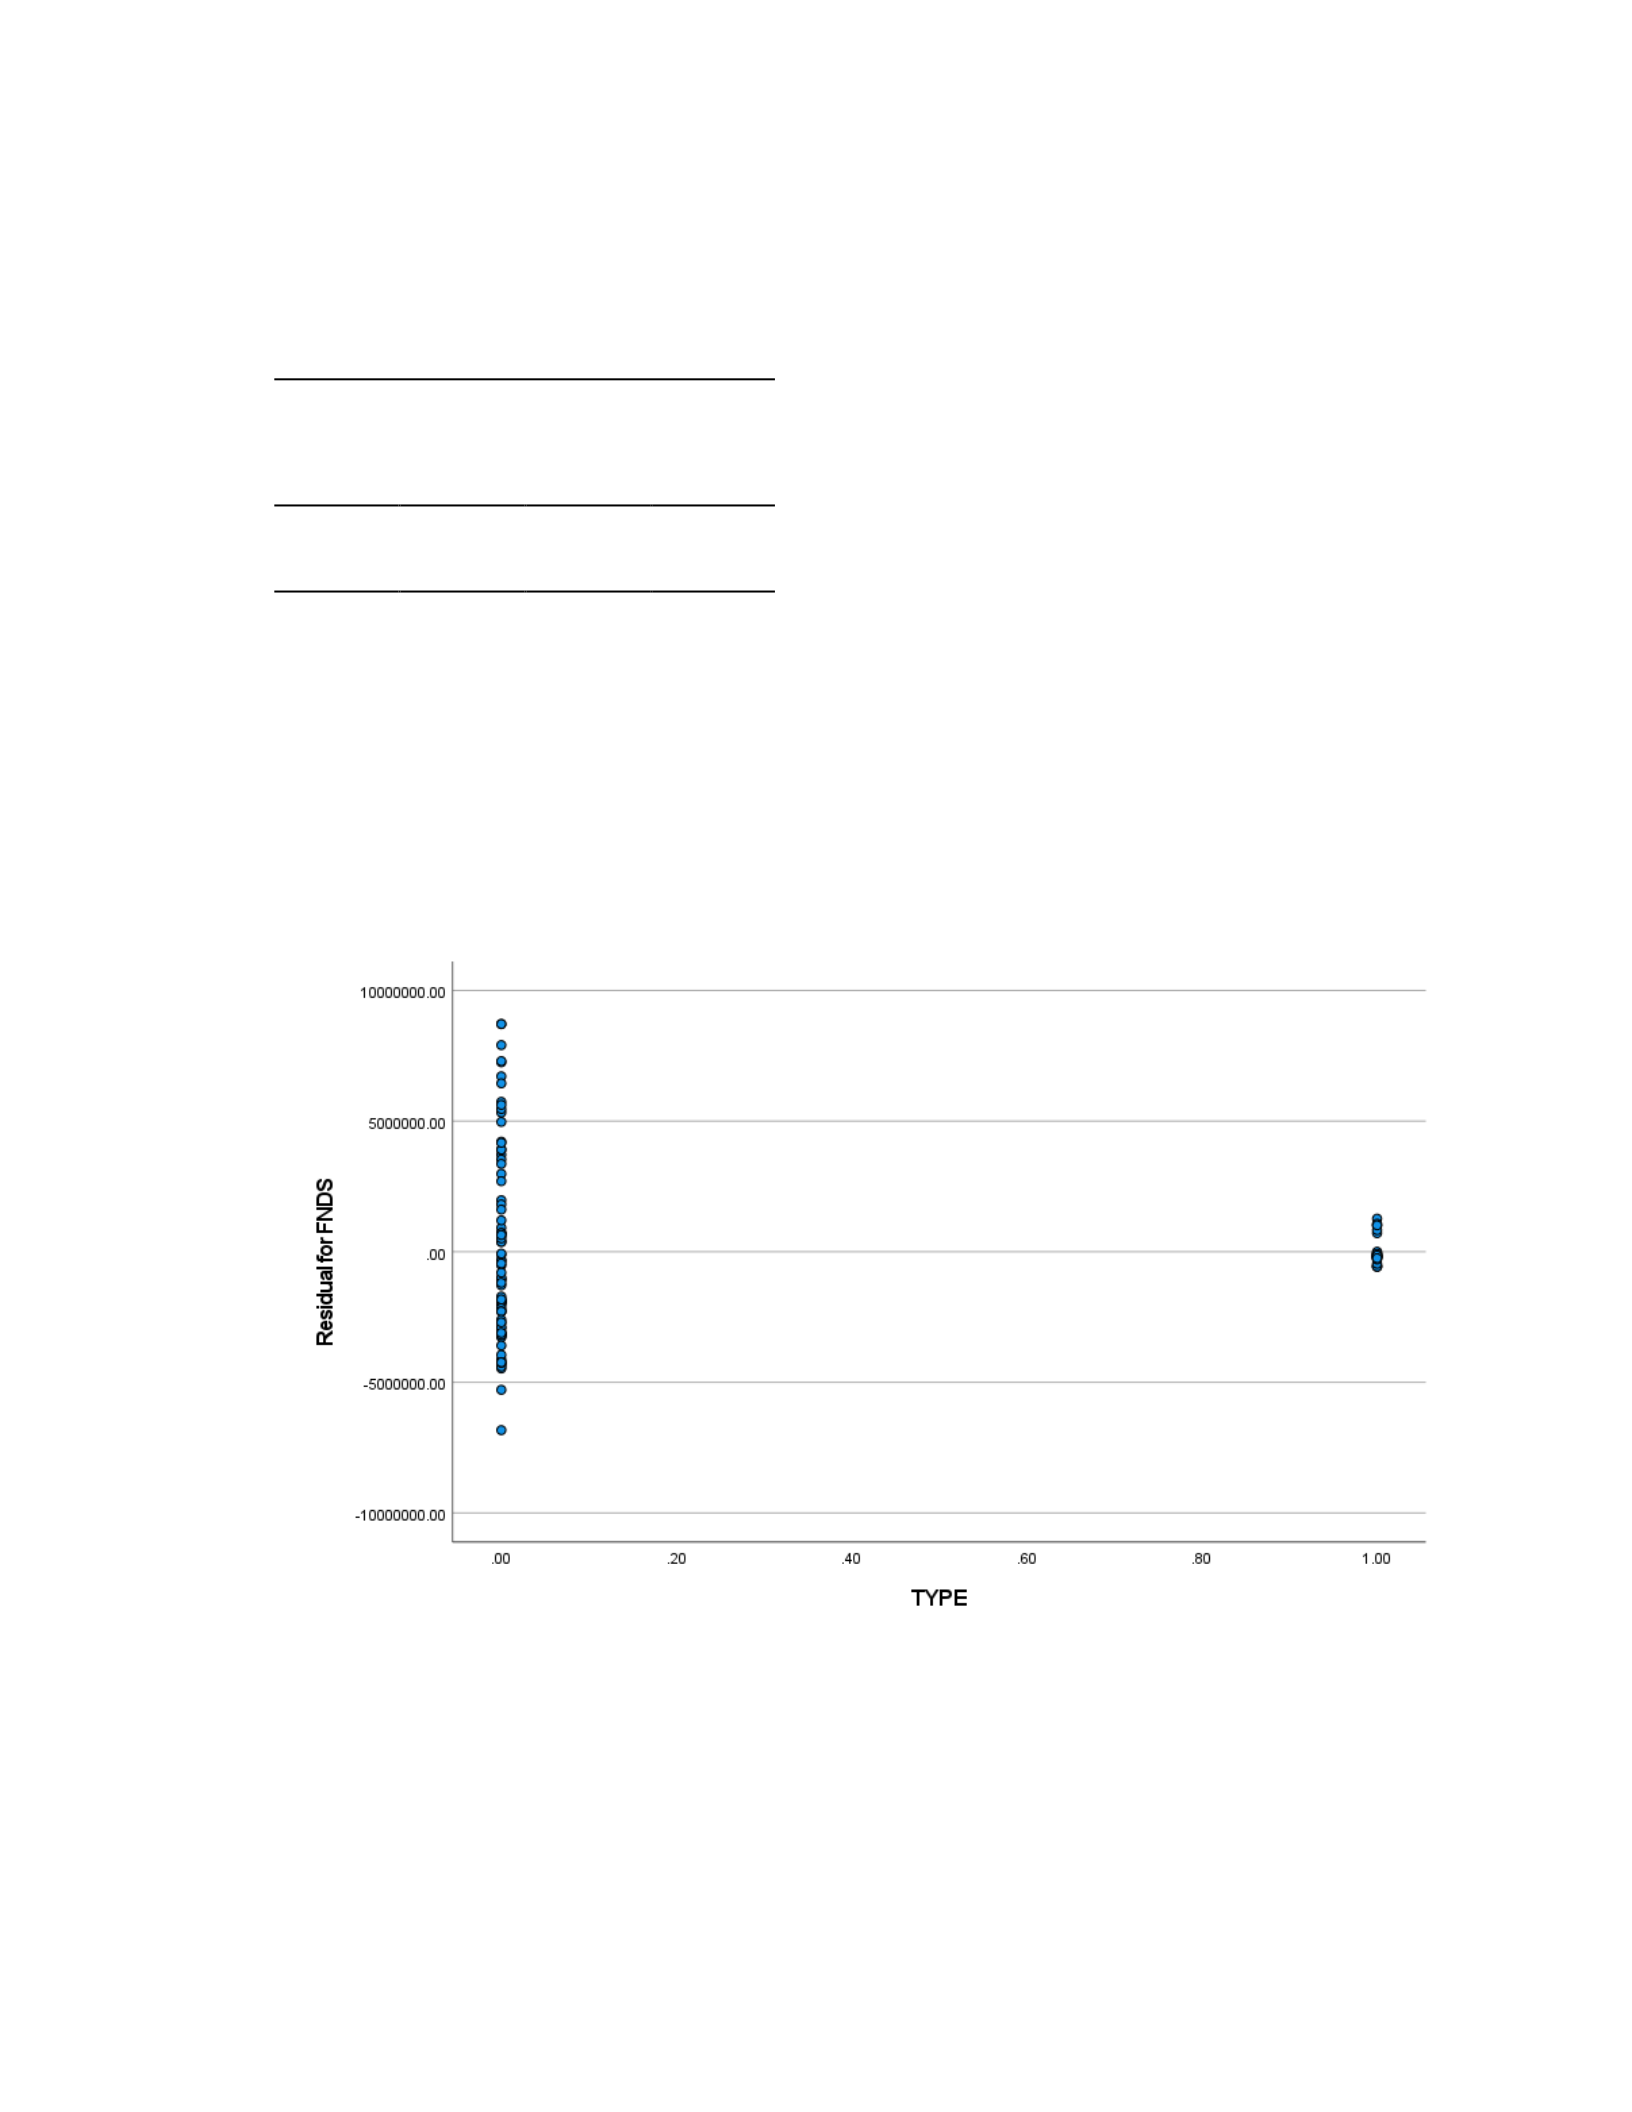
132
Table 1
Test of Dependent Variable Error Variance
Dependent Variable: FNDS
F
df1
df2
Sig.
5
11
103
0
Tests the null hypothesis that the
error variance of the dependent
variable is equal across groups.
Figure 4
Residual for Funds Raised by Offering Type (ICO or CFE)
ANOVA Model-Building
I employed the SPSS General Linear Model > Univariate method with one
dependent variable (FNDS) and the five categorical control factors as fixed factors with

133
Type III sum of squares. My intent was to use purposeful sequential model building
employing a series of ANOVAs on various combinations of control factors to find the
best predictive model. Because there were only five control factors, I began my analysis
with all of the control factors and the 10 two-factor interactions (2FIs). Recent research
(see, for example, Heinze & Dunkler, 2017) has argued for avoiding missing variable
bias in predictive model-building. This occurs when an arbitrary and overly stringent
variable selection criterion is used, like .05. While a level of significance = α = .05 is
appropriate for testing the hypothesis of the significance of the overall model, it is overly
restrictive in model specification. To combat the potential for missing variable bias,
Heinze and Dunkler (2017) suggested a more liberal variable selection criterion and a
focus on the contribution of each variable to the model’s goodness of fit (adjusted R2).
I evaluated each successive model, considering the influence of each predictor (p
value compared to the variable selection criterion; and partial η2) and a measure of
goodness-of-fit (adjusted R2), to decide which control factors to add or eliminate after
each run. To avoid missing variable bias, I used .20 as the variable selection criterion
(Heinze & Dunkler, 2017). The process progressed incrementally, run to run, with
iteration and various combinations of control factors until the best model was found
(highest adjusted R2, and all terms [control factors and 2FIs] significant [p < variable
selection criterion]).
Of note is that the only 2FI remaining at the end of the model building analysis
consisted of two original control factors that were not found by themselves to be
statistically significant influences on the dependent variable, FNDS. Instead, the
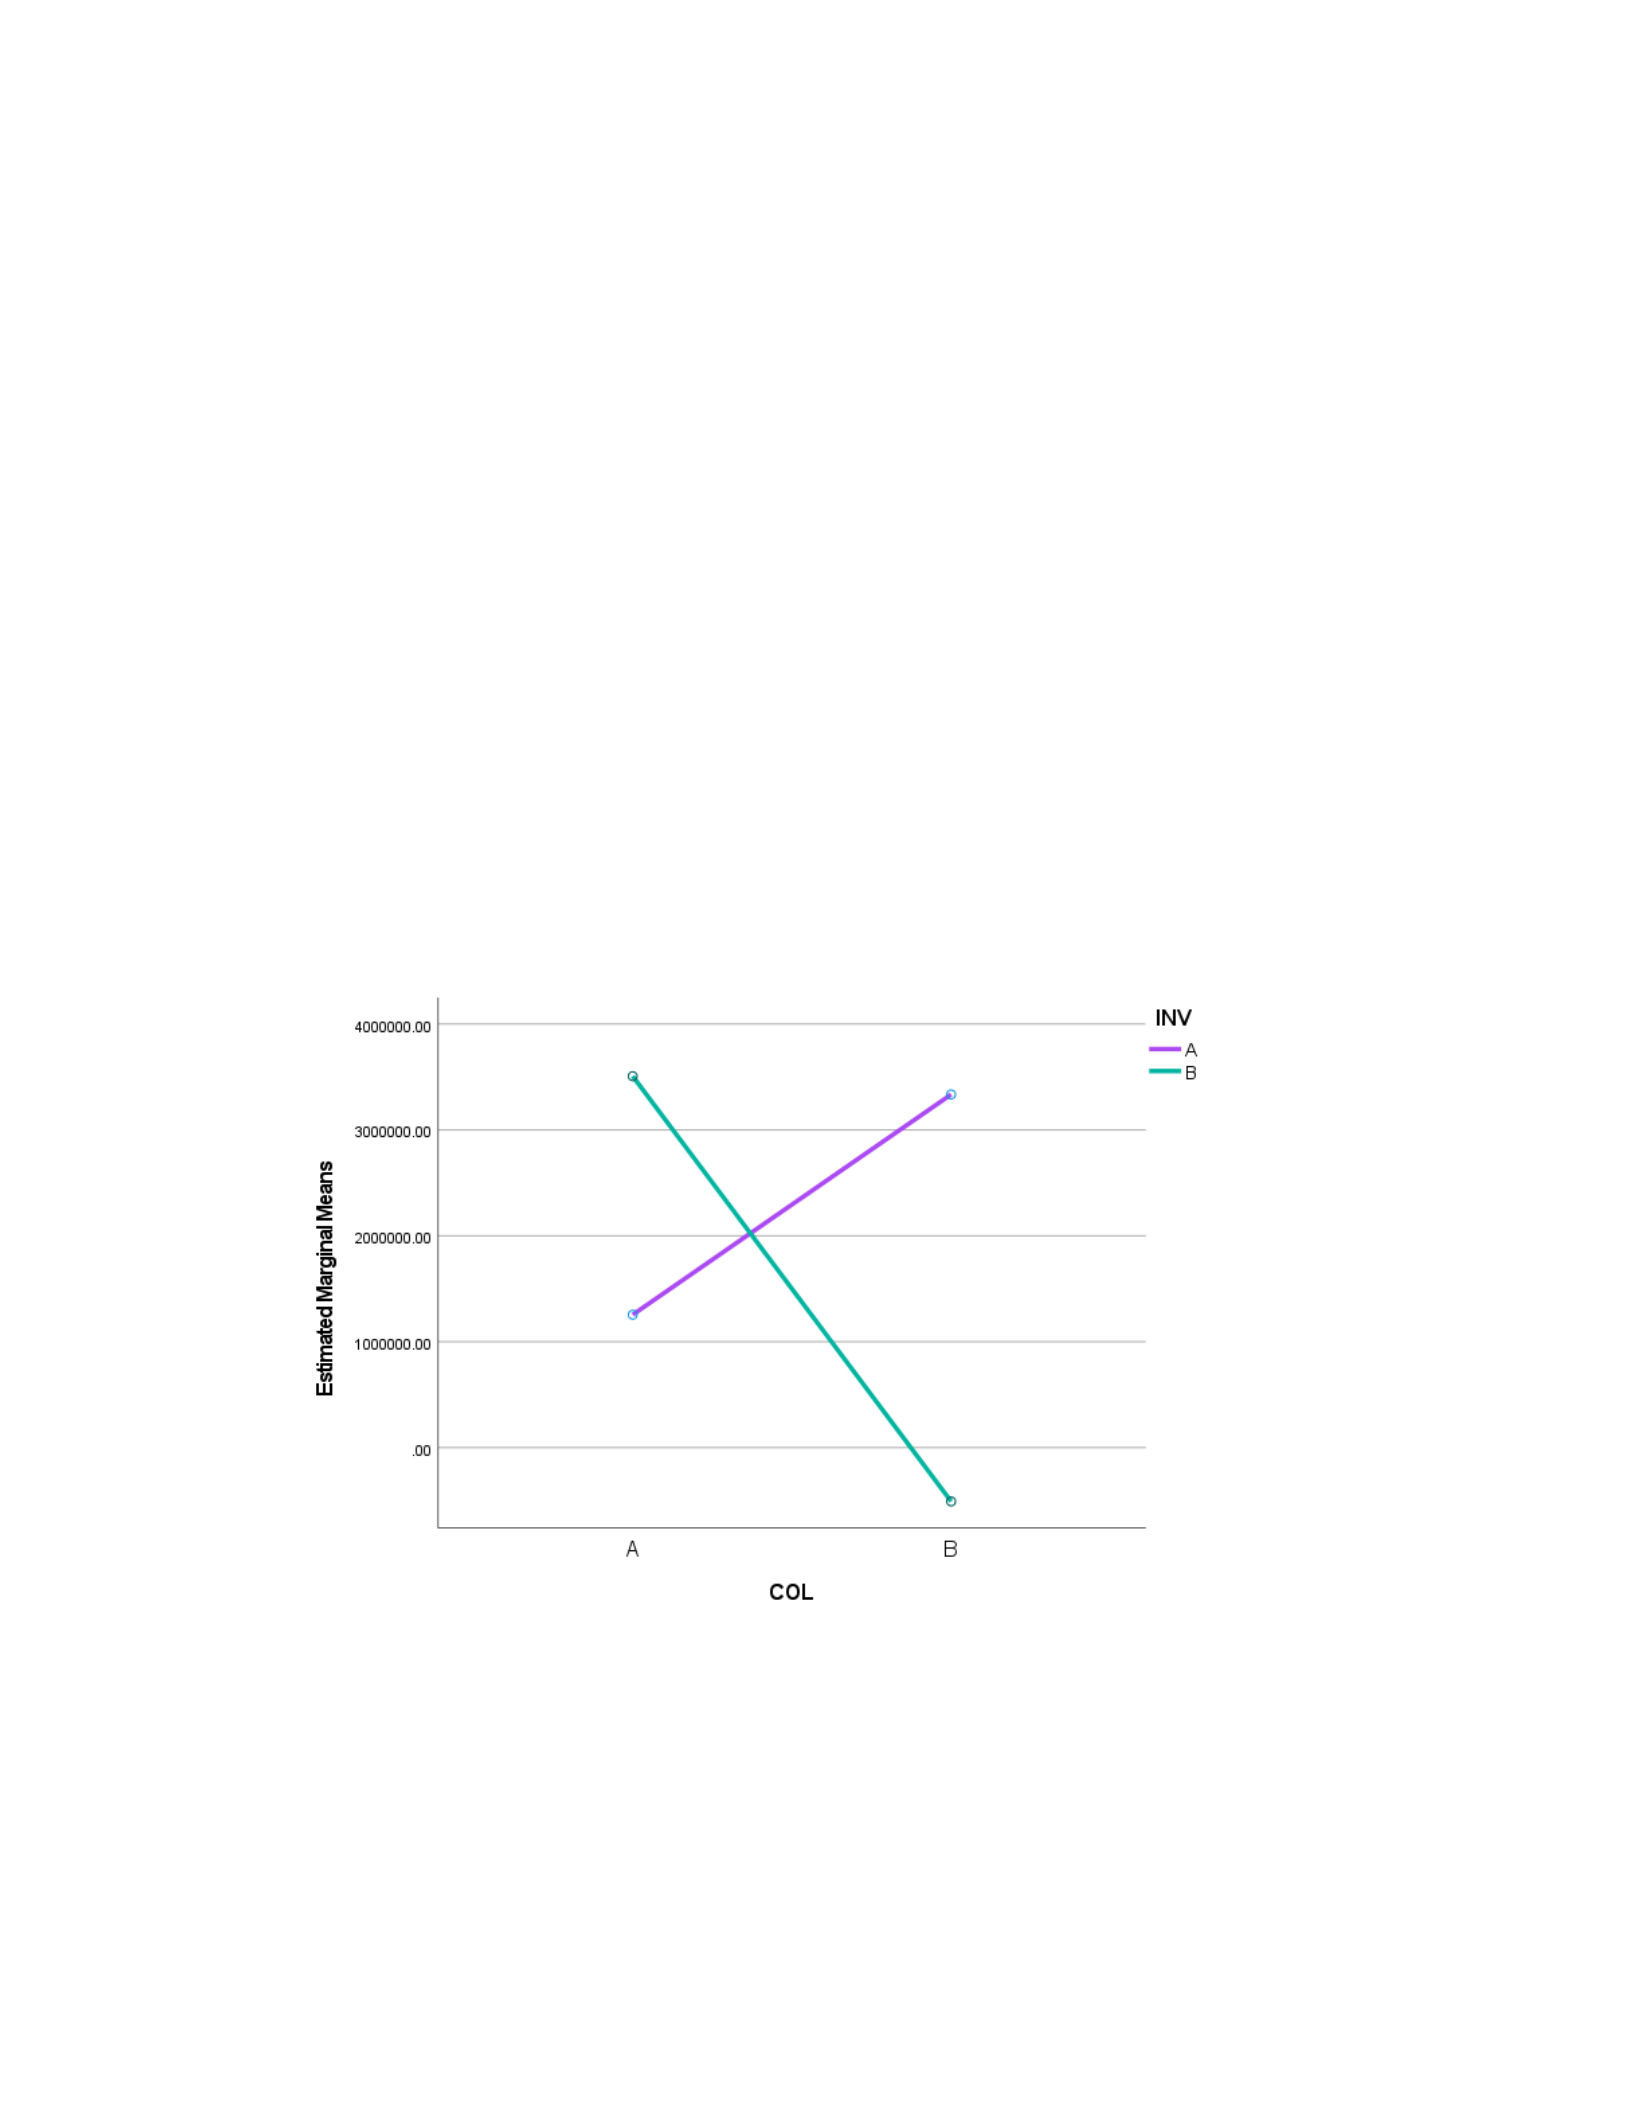
134
combination of these two control factors was found to be an influential predictor. In other
words, the combination of these two control factors (their cross product: COL INV)
acted as a distinct predictor of the dependent variable. Their relationship is shown in
Figures 5 and 6 showing non-parallel lines and corroborating the presence of the 2FI. The
2FI indicated that various combinations of COL and INV predicted distinctly different
levels of funding. For example, when both were yes, there was an average level of
funding. When either COL or INV were yes, but not both, there was a relatively high
amount of funding. When COL and INV were both no, there was minimal funding.
Figure 5
Estimated Marginal Means by Company Leadership and Investors
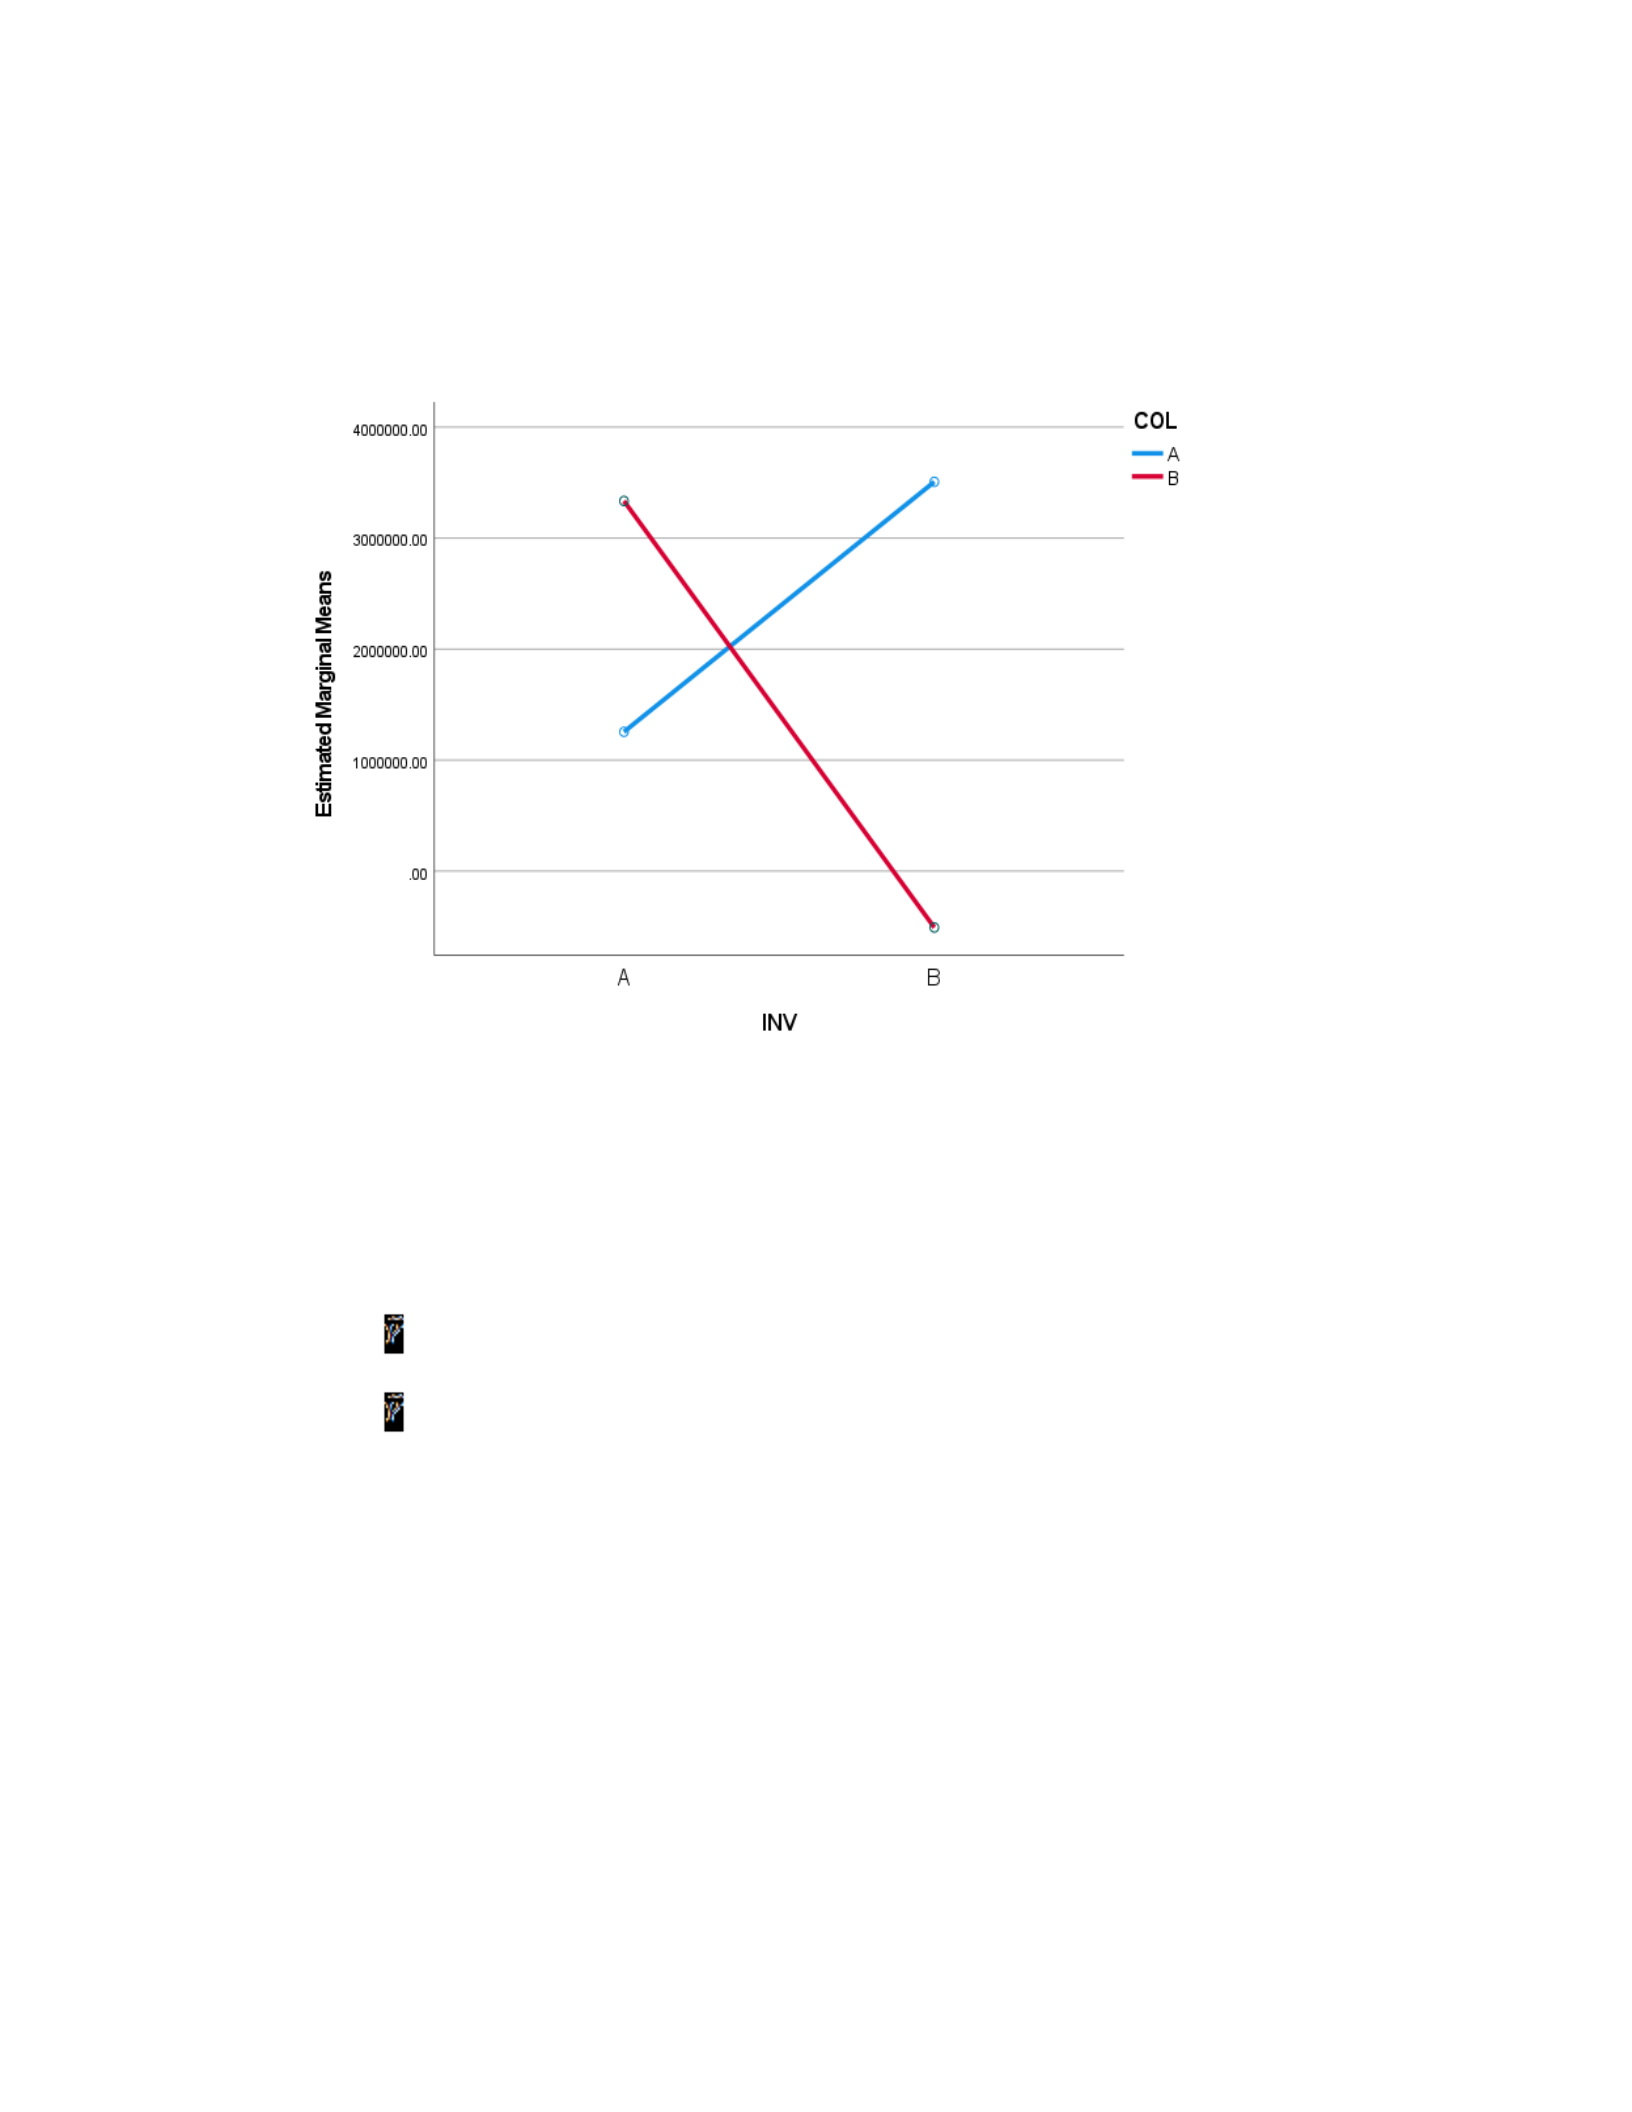
135
Figure 6
Estimated Marginal Means by Transparency of Investors and Leadership
Selecting and Expressing a Final Predictive Model
The final predictive model from ANOVA can be expressed as a mathematical
equation for all factors (control factors) in the model:
ijk = μY + αi + βγij ⋯ where
ijk = the predicted value of the dependent variable (FNDS) for record k within the
group that corresponds to level i of factor A (TYPE) and level j for the 2FI, B*C
(COL*INV)
μY = the population grand mean of Y values
αi = the effect of the ith level of factor A (TYPE)
βγij = the interaction effect for the i, j cell (interaction between factors B and C, or
COL*INV)
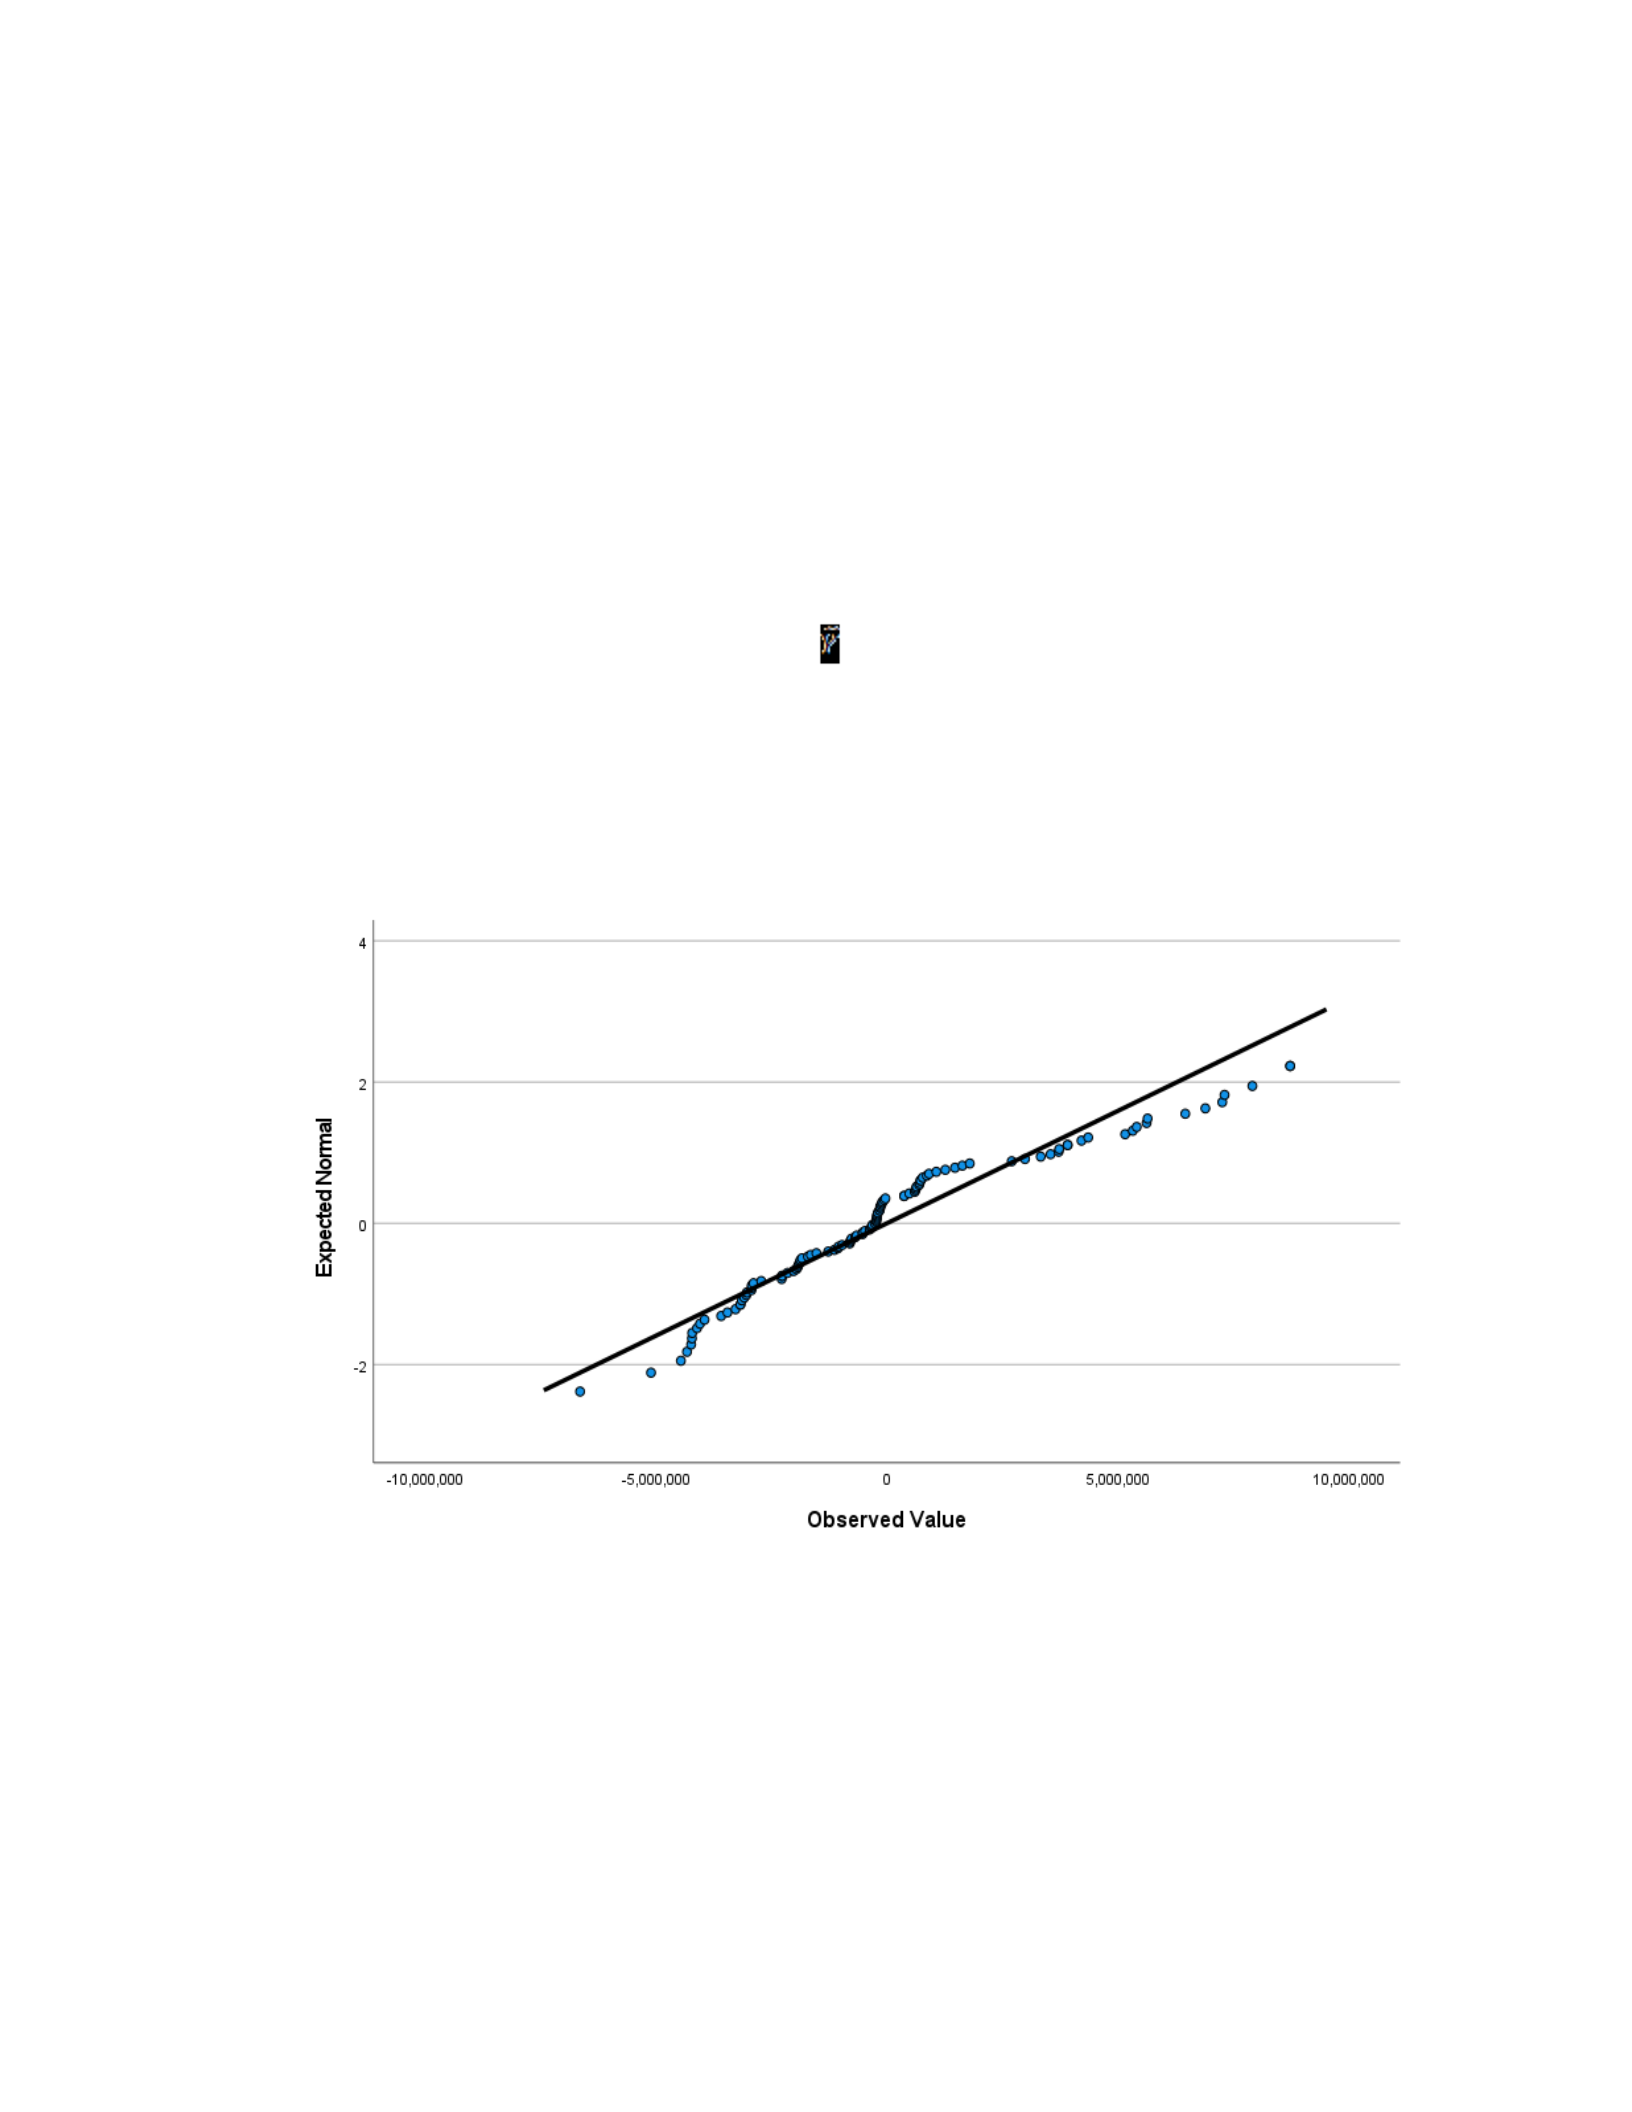
136
The equation indicates, the value of FNDS for any record (case, combination of
values for the control factors) is predicted to be the sum of the grand mean; the effects of
factor A (TYPE); and the interaction between factors B and C (COL*INV). The
coefficients in the predictive equation represent the estimated effects in the ANOVA
model (ai, the effect of the ith value of TYPE). The difference between the actual value of
Yijk and the estimated or predicted value ( ijk,) is the error term, or the residual, for the kth
record, and is presented in Figure 7.
Figure 7
Expected Value by Observed Normal
137
The effect for each significant predictor in the final model for this analysis can be
derived from the parameter estimates in Table 2:
Table 2
Significance of Funds Raised by Control Factors
Dependent Variable: FNDS
Parameter
B
Std.
Error
t
Sig
95% Confidence Int.
Partial
Eta
Sq.
Lower
Bound
Upper
Bound
Intercept
2452150
979782
3
0
510452
4393848
0
[TYPE=CFE]
-5919648
926960
-6
0
-7756665
-4082630
0
[TYPE=ICO]
0a
[COL=A] *
[INV=A]
1763288
1088505
2
0
-393873
3920450
0
[COL=A] *
[INV=B]
4015775
1203774
3
0
1630177
6401373
0
[COL=B] *
[INV=A]
3843235
1329003
3
0
1209463
6477007
0
[COL=B] *
[INV=B]
0a
ANOVA Hypotheses
There are multiple hypothesis tests to perform in ANOVA. When evaluating more

138
than two control factors, the number of hypotheses increases accordingly. This is the
proper form of ANOVA hypotheses for two control factors (factors):
• The hypothesis of no difference in the dependent variable due to factor A:
H0: 1 = 2 = ⋯ = i ⋯ = m (means for all m levels of A are equal)
where the number of levels of factor A = m
against the alternative:
H1: not all i are equal.
• The hypothesis of no difference in the dependent variable due to factor B
(which, as an example, has two levels):
H0: 1 = 2 (means for both levels of B are equal)
where the number of levels of factor B = 2
against the alternative:
H1: 1 ≠ 2 (general form: not all i are equal).
• The hypothesis of no interaction between factors A and B:
H0: the interaction of A and B is equal to zero.
against the alternative:
H1: the interaction of A and B is not equal to zero
In this analysis, hypotheses were tested using the F test (and its p value). The F
test assesses whether a factor predicts the dependent variable (i.e., the dependent variable
means are different for various treatments). The hypothesis test results are in the Tests of
Between-Subjects Effects table (Table 3).
139
Table 3
Tests of Between-Subjects Effects
Dependent Variable: FNDS
Source
Type III
Sum of
Squares
df
Mean
Square
F
Sig.
Partial
Eta Sq.
Corrected
Model
6E+14
4
2E+14
14
0
0
Intercept
2E+14
1
2E+14
16
0
0
TYPE
4E+14
1
4E+14
41
0
0
COL *
INV
2E+14
3
5E+13
5
0
0
Error
1E+15
110
1E+13
Total
3E+15
115
Corrected
Total
2E+15
114
Note. a. R Squared = .344 (Adjusted R Squared = .320)
The results of the ANOVA hypothesis tests are as follows:
• The individual control factors were analyzed considering the F test,
associated p value (Sig.), and model selection criterion (.20). For each of the five control
factors other than TYPE, the null hypothesis was not rejected. There was insufficient
evidence to conclude that the alternate hypothesis was true, that there was a difference in
mean FNDS due to each of these control factors.
• For the control factor, TYPE, the null hypothesis was rejected. There was
sufficient evidence to conclude that the alternate hypothesis was true, that there was a
difference in mean FNDS due to TYPE.
• Likewise, for each of the 10 2FIs that were analyzed other than one,

140
considering the F test, associated p value (Sig.), and model selection criterion, the null
hypothesis was not rejected. There was insufficient evidence to conclude that the
alternate hypothesis was true, that there was a difference in mean FNDS due to each of
these 2FIs.
• For the 2FI, COL*INV, the null hypothesis was rejected. There was
sufficient evidence to conclude that the alternate hypothesis was true, that there was a
difference in mean FNDS due to COL*INV.
• Factor interactions were also evaluated graphically, and only COL*INV
was evident.
Interpreting, Testing, and Using the Final Model
Various statistical outputs of SPSS can be used to interpret the results:
• Based on the results depicted in the SPSS Tests of Between-Subjects
Effects in Table 3, the final predictive model was a statistically significant predictor of
the dependent variable, FNDS (F = 14.414, p < .001 < = .05).
• Based on adjusted R2 = .311 from the same table, the predictive model
accounted for approximately 31% of the variation in FNDS for the data set. While this
might be considered a strong outcome, it does indicate that approximately 69% of the
variation in FNDS was attributed to noise (statistical variation) or other explanatory
factors.
Because the control factor, TYPE, was included in the final, significant model,
there was evidence that FNDS was influenced by the type of fundraising. Since there was
a need to be cautious of this conclusion due to the violation of homoscedasticity, I
141
conducted a t test of means using the Two Sample Assuming Unequal Variances routine
in Excel, as shown in Table 4:
Table 4
Two Sample Assuming Unequal Variances
CFE
ICO
Mean
346075
4756464
Standard Deviation
506085
3971506
Observations
31
84
Hypothesized Mean
Diff.
0
df
90
t Stat
-10
p (T ≤ t) one-tail
0
t Critical one-tail
2
p (T ≤ t) two-tail
0
t Critical two-tail
2
The null hypothesis was that the difference in means = 0. Based on the t test, its p
value (one-tail or two-tail), and a level of significance = α = .05, the null hypothesis was
rejected. There was sufficient evidence to conclude that there is a difference in mean
142
FNDS between CFE and ICO (in this sample, $346,075 compared to $4,756,464,
respectively). This is corroborated in the Mean Values Funds Raised for Various
Combinations of Control Factors table from SPSS. Table 5 shows the mean values of FNDS
for various combinations of the control factors:
Table 5
Mean Values Funds Raised for Various Combinations of Control Factors
Dependent Variable: FNDS
TYPE COL INV
Mean
Std.
Deviation
N
CFE
A
A
7500.00
1
B
366097.41
517508.20
29
Total
354144.17
512704.74
30
B
B
104000.00
1
Total
104000.00
1
Total
A
7500.00
1
B
357360.83
510753.94
30
Total
346075.00
506085.37
31
ICO
A
A
4177400.00
3715575.34
45
B
6798125.00
4491326.78
16
Total
4864803.28
4064253.77
61
B
A
6295384.62
3530617.55
13
B
2095000.00
2710827.06
10
Total
4469130.43
3786597.07
23
Total
A
4652120.69
3751655.61
58
B
4989230.77
4493714.65
26
Total
4756464.29
3971506.01
84
Total
A
A
4086750.00
3725145.99
46
B
2653040.56
4091731.73
45
Total
3377772.80
3955122.39
91
B
A
6295384.62
3530617.55
13
B
1914000.00
2640851.38
11
Total
4287250.00
3809047.66
24
Total
A
4573398.31
3768008.01
59
B
2507871.88
3840522.28
56
Total
3567576.74
3926162.17
115
143
The final model can be used to predict a value for the dependent variable (FNDS)
based on the values of the predictors in the final model, using the parameter estimates
shown in Table 6 from SPSS. Predicted values of the dependent variable can be
compared to actual values from the data set as a method of validating the predictive,
mathematical model.
Table 6
Parameter Estimates
Dependent Variable: FNDS
Parameter
B
Std.
Error
t
Sig
95% Confidence Int.
Partial
Eta
Sq.
Lower
Bound
Upper
Bound
Intercept
2452150
979782
3
0
510452
4393848
0
[TYPE=CFE]
-5919648
926960
-6
0
-7756665
-4082630
0
[TYPE=ICO]
0a
[COL=A] *
[INV=A]
1763288
1088505
2
0
-393873
3920450
0
[COL=A] *
[INV=B]
4015775
1203774
3
0
1630177
6401373
0
[COL=B] *
[INV=A]
3843235
1329003
3
0
1209463
6477007
0
[COL=B] *
[INV=B]
0a

144
Note that for each of the categorical control factors, SPSS coded their values for
the purpose of executing the least squares approach to the general linear model.
Therefore, for each control factor, there was a baseline value whose coefficient was zero.
All other coefficients reflected the difference in mean value of FNDS compared to the
baseline case.
As an example, FNDS can be predicted for the case when TYPE = CFE, COL =
yes = A, and INV = no = B. The predicted value of the dependent variable was computed
as follows (rounded to the nearest whole dollar):
Predicted FNDS = 2,452,150 + (-5,919,648) + (4,015,775) = $548,277.
Because of the lack of homoscedasticity, caution should be used in making
predictions of FNDS based on the data set, and extrapolating conclusions regarding the
relationship (influence, predictability) of the control factors with the dependent variable.
One control factor was a statistically significant predictor (TYPE), meaning the difference
in mean FNDS due to a different fundraising method was statistically significant. A
combination of two original control factors (COL and INV) was found to be a significant
influence on FNDS, even though neither was a significant predictor by itself.
It is possible that other factors may be found to explain the variation in FNDS.
While exploring every possible predictor for FNDS was outside the scope of this analysis,
it does represent a possible future research topic.
Summary
My research question was as follows: How does capital offering type predict the
amount of funds raised while controlling for access to the offering companies’ historical

145
financial data, pro forma financial projections, detailed product descriptions, video of
product demonstrations, company website, company history, company leadership, and
company investors?
Analyzing my study results provided answers to my research question. My first
result was that ICO offerings raised greater mean funds than crowdfunded equity
offerings. Additionally, I found no significant influence on amount of funds raised due to
access to the offering companies’ historical financial data, pro forma financial
projections, detailed product descriptions, video of product demonstrations, company
website, company history, company leadership, and company investors, respectively.
Finally, my results showed that there is a statistically significant influence on amount of
funds raised due to access to the offering companies’ leadership and/or investors when
considering these factors in combination with one another. I found that companies
seeking crowdfunded capital injection enjoyed greater mean capital injection if they
provided public access to either their company leadership or their investors. However,
companies providing public access to both their leadership and investors suffered reduced
mean funds raised.
These research results yielded three key findings. The first key finding was that
offering type matters in crowdfunded capital markets, with investors favoring crypto
crowdfunding over equity crowdfunding. The second key finding was that crowdfunded
capital investors exhibited information disinterest to company information that is
traditionally considered material within capital markets, as reflected in my secondary
control factors. My third key finding was that investors in crowdfunded capital markets

146
prefer selective company information, shunning those that offer too little or too much. In
Chapter 5, I interpret my findings in light of current scholarly research, along with
discussing limitations of my study and recommendations for future research.

147
Chapter 5: Discussion, Conclusions, and Recommendations
The purpose of this quantitative study was to compare a group of ICOs versus a
group of crowdfunded equity offerings with the intent of identifying predictive factors of
those funding outcomes. In this quantitative study, I used ANOVA to compare the
amounts of money raised by a group of startups that recently completed ICO offerings,
versus a group of startups that recently completed crowdfunded equity offerings. The
primary control factor denoted whether each startup in the study relied on an ICO or a
crowdfunded equity offering, and this primary control factor was therefore binary. The
dependent variable was a continuous numerical variable measuring the amount of money
that each startup in my study raised, whether via ICOs or crowdfunded equity. I also
examined the influence of secondary binary control factors, expressed as Yes or No, that
signified whether each startup in the sample provided investors with video of product
demonstrations, company history, company leadership, and company investors. By
conducting these tests, I sought to discover whether participants in ICO and crowdfunded
equity markets behaved efficiently.
Regarding my results, only the primary control factor, type of fund source
(TYPE), was a significant predictor of the dependent variable, funds raised (FNDS). The
two-factor interaction between access to information on company leadership (COL) and
information on company investors (INV) indicated that various combinations predicted
distinctly different levels of funding. No secondary control factors exhibited significant
influence in funds raised.

148
There were three key findings of my research. First, investors in crowdfunded
capital markets preferred crypto offerings over equity offerings and, therefore, considered
offering type materially important. Second, those same investors did not consider broad
access to company information, as captured by my secondary control factors, to be
materially important. However, this information is generally considered critical in
traditional capital markets. Third, the investors preferred, as shown through greater
propensity to invest, companies that provided limited and selected information about their
leadership or their past investors. However, companies that offered either both or neither
information suffered suboptimal fundraising results. These findings provide important
insights into the professional and practical aspects of crowdfunded capital market
dynamics, while simultaneously challenging and enriching the broader scholarly
literature pertaining to the topic.
Interpretation of Findings
From a professional perspective, my study’s key findings lead to important
practical interpretations. Regarding the disparity in funding outcomes between the ICOs
and crowdfunded equity campaigns in my sample, the critical lesson for market
participants is that investors consider type of offering to be important, with a much larger
share of their capital being directed toward crypto offerings as opposed to crowdfunded
equity offerings. The underlying reasons for investor preference are still unclear, possibly
relating to a greater public interest in cryptocurrencies compared to traditional equities,
the different mix of industries and human capital within those respective markets, or
differences in the makeup of each market’s respective stakeholders. While those

149
underlying causes are of valid interest to future researchers, the important lesson to
practitioners today, whether they be investors, entrepreneurs, regulators, or any other
stakeholders, is that capital flows seem to favor ICOs, and ICO offerings on average will
likely raise more than crowdfunded equity offerings.
That crowdfunded capital market investors exhibited indifference to company
information bears important interpretations and implications for those market
participants. Many have affirmed the assertion that providing investors with information
and transparency will likely optimize fundraising outcomes, like Adhami et al. (2018),
Fisch (2019), Ahlers et al. (2015), Gruner and Siemroth (2019), and Mamonov and
Malaga (2017). However, my findings suggest otherwise, owing to the insignificant
influence of the individual secondary control factors in my study. Investors in
crowdfunded capital markets (the majority in my sample being ICO investors) seemingly
consider this information to be materially irrelevant when making investment decisions in
those spaces. The only exception to this broad information indifference pertained to the
investor preference to see either company leadership or prior investors, rather than
neither or both. One possible explanation is that capital market investors reward limited
information but punish both full opacity and greater disclosure, reflecting an investor
preference for information minimalism. These findings bear important implications for
any parties interested in optimizing fundraising results in professional practice.
My research findings broadly challenge the prevailing consensus in the literature
toward signaling, which holds that investors in crowdfunded capital markets are
motivated by signaling factors. Researchers have investigated the existence of signaling

150
factors in crowdfunded capital markets. For example, Adhami et al. (2018) found that
ICOs enjoy an elevated rate of success given the presence of three variables: source code
availability, presale organization, and service availability or profit sharing for campaign
participants. Fisch (2019) discovered that ICOs that issued white papers with
technological language and high-quality source code raised more money on average than
firms that did not. One may reasonably infer from my findings that ICO markets
therefore function according to some level of efficiency, as investors seemingly weigh
public information like those listed previously when deciding if and/or how to participate
in crypto offerings.
Other scholars have argued that crowdfunded equity markets exhibit similar
efficiencies. Gruner and Siemroth (2019) along with Ahlers et al. (2015) found that
entrepreneurs communicate with investors via signaling in these markets. Mamonov and
Malaga (2017) found that investors responded to material information provided by
startups during the crowdfunded equity process. Similar to the studies on ICOs
previously, this research suggests that investors participating in crowdfunded equity
offerings base their decisions, at least in part, on the presence, and possibly quality, of
publicly available information. These findings align with the general definition of market
efficiency according to Fama (1970) and other EMH theorists who define the term
according to the ability and propensity of market participants to absorb and analyze
relevant information when making rational and self-interested market decisions.
My results, however, challenge these past findings. In fact, companies offering
greater transparency did not enjoy greater fundraising success than those that did not

151
offer transparency. Moreover, none of the individual information sources were influential
on fundraising outcomes.
Market behavioralists and crowdfunded capital critics like Lichfield (2018),
Quiggin (2013), and Ibrahim (2015) have broadly challenged the assumptions of EMH.
My findings strengthen their case that recent and exponential growth in crowdfunded
capital markets, particularly regarding ICOs, is driven more by herd mentality and other
irrational factors, rather than by efficiency. My findings show a lack of influence on
funds raised as a function of the company information provided. This is noteworthy
particularly given the basic and fundamental inclination to inform the public of the
offering companies’ journey and makeup.
The underlying reasons behind capital market investors’ disinterest in traditional
startup information may stem from any number of sources. One possible reason may be
that investors suffer from general information aversion due to factors like stress,
information overload, low financial literacy, etc. This may also explain why investors in
my study sought only limited information in the form of either company leadership or
company past investors while simultaneously turning from those who offered both forms
of info, which may have been too much for their prospective investors to ingest and
analyze. Conversely, those same investors may have rationally opted not to invest in
startups with higher relative transparency because the information they provided may
have exposed underlying weaknesses in those startups and possibly in the market, overall.
It is also possible that, perhaps due to the fundamental differences in function and form

152
between traditional and crowdfunded markets, that participants in the latter seek out non-
traditional information not captured in this study.
A compelling question following my findings is to consider whether investors
who choose to participate in crowdfunded capital markets are driven largely by herd
behavior, or whether they are actually weighing salient data and information in a rational
manner. My findings suggest that information matters regarding crowdfunded capital
outcomes, but what information actually matters to investors, why it matters, and whether
its perceived importance is actually rational remain unsettled questions. The discovery
that investors much preferred funding ICOs rather than crowdfunded equity campaigns
may be due to herd behavior and supported by the work of Bogusz et al. (2020) who
found that online interest around crypto dominated social media discussions pertaining to
crowdfunding topics broadly. It is also possible that investor preference for information
related only to company leadership or past investors is a sign of herd mentality, as those
investors may be seeking first-mover advantage by selecting startups that have yet to
fully develop, or at least announce, either their leadership teams or their investor bases.
Conversely, it is possible that investors were rationally drawn more to ICOs than
crowdfunded equity campaigns due to perceived greater opportunity for ROI in the
former owing to industry differences compared to the latter.
The question of herd influence in crowdfunded capital markets, therefore, remains
unanswered. Given the ongoing implosion of crypto markets worldwide, and in the wake
of major crypto failures like FTX (Forbes, 2022) these questions seem even more

153
pressing, especially considering the much larger share of capital flowing into ICO
markets compared to crowdfunded equity, as revealed by my findings.
Amid the polarized debate concerning the perceived merits, opportunities,
dangers, and shortcomings of crowdfunded capital markets, my findings offer nuanced
and complex insights that may inform the ongoing discussions around ICOs and
crowdfunded equity offerings. My findings suggest that some level of efficiency exists in
crowdfunded capital markets. The influence of the interaction between access to an
offering company’s leaders and/or investors on the amount of funds raised suggests that
participants in crowdfunded capital markets do, indeed, consume and analyze public
information when making investing decisions in those spaces. Investors also seem more
attracted to ICOs than crowdfunded equity offerings, which means that preferences exist
among investors regarding different types of crowdfunded capital markets. However, the
discovery that investors responded positively to access to either a company’s leadership
or their investors but negatively to access to both (or neither) is a surprising and thought-
compelling insight, which may both bolster and challenge the assumptions of
crowdfunded capital adherents and detractors, alike.
Rather than settling the debate, my findings enrich the discussion by providing
important insights into future research. Future research, however, must remain informed
of the limitations to my current study, along with the recommendations that it suggests
for future investigators.

154
Limitations of the Study
A primary limitation of my study was that it investigated correlation not
causation. I discovered intriguing relationships between my dependent variables, the
primary control factor, and the secondary control factors; however, it is not possible to
draw valid assumptions about the causes of those relationships, which could be many.
One possible influence not captured in my study, albeit a possible cause of my results, is
the influence of insider or privy information on funds raised. If investors seemingly do
not consider access to a company’s video of product demonstrations, company history,
company leadership, and company investors to represent materially important investing
information, then it is possible that those investors already possess this information via
private channels, possibly due to direct contact with the leadership of those capital
seeking companies. A limitation in the secondary data I collected was that most of the
sites did not offer a breakdown of how many investors each offering enjoyed, nor how
much each investor contributed. This information may have informed whether companies
enjoying significant success benefited from one or a few privy investors. Although
controlling for outliers in my study may have eliminated a few cases of insider
knowledge, the issue still remains a limitation.
Conversely, the results are also limited in their ability to discern rational versus
behavioral decisions among the study’s investors. Although my results may suggest a
large degree of irrational psychology, like potential herd behavior, regarding the lack of
significant influence of access to company information on funds raised, it is not possible
to draw firm conclusions simply from correlations alone.

155
A related limitation is that my study relied entirely on publicly available
secondary data, so I did not have direct access to input from market participants to know
why they made the decisions that they did. A similar limitation exists in that my study
was entirely quantitative, versus qualitative or mixed methods, which may have rendered
direct contact with crowdfunded capital market participants.
My results captured mean funding differences between ICOs and crowdfunded
equity offerings. The reasons for those rather large differences are still a matter of debate,
given the reasons discussed previously. The small size of my sample also makes
discerning relationships in funding outcomes between the two offering types and my
secondary control factors difficult. A larger sample may mitigate this limitation.
Recommendations
Regarding my study’s limitations in identifying the influence of privy information
or behavioral psychology on my sample’s funding results, I recommend that future
researchers investigate the influence of direct communications with crowdfunded capital
market participants. The use of qualitative surveys among company leadership and
investors in crowdfunded capital markets may render valuable insights and discoveries
into why and how they make the decisions that they do. Qualitative interviews and focus
groups with key stakeholders, like company leaders and investors, may also render
valuable insights that remain beyond the scope of my work in this study. Qualitative
methods may also assist future researchers in identifying the possible influence of privy
information on investment decisions in crowdfunded capital markets, which was a
limitation in my study. If future researchers investigate the similarities and differences of

156
ICOs versus crowdfunded equity offerings, I recommend a larger sample that more
closely balances the two types of offerings. Researchers interested in determining
causality may also consider sampling through controlled experiments that are more
capable of these discoveries. These efforts may help to determine the actual drivers of
crowdfunded capital outcomes, whether they are based primarily on behavioral
influences, access to insider information, or some other reasons entirely.
A key finding from my study was the large difference in mean funds raised
between ICOs versus crowdfunded equity campaigns, with the former enjoying a
considerable funding advantage over the latter. However, identifying the reasons was
beyond the scope of my research. Any number of reasons may account for larger amounts
of capital flowing toward ICOs compared to crowdfunded equity, including differences in
types of firms that respectively gravitate toward those different markets, along with
divergent public attitudes toward the directions of long term economic growth and
innovation. Future researchers should investigate these results and work to identify their
causes.
A second key finding from my research was that none of my secondary control
factors had a significant influence on funds raised, including investor access to assumedly
important information like video of product demonstrations, company history, company
leadership, and company investors. However, the specific reasons behind this information
indifference are still unclear. I urge future researchers to investigate why investors may
not consider access to this information important, and whether prevailing attitudes are
rational or not. Crowdfunded equity markets remain promising in a variety of ways,

157
including their potential to transform and improve the world’s socio-economy, but they
also harbor many risks. Future researchers could strengthen the promise and mitigate the
peril by investigating my findings further.
A third key finding from my research was the discovery that the interaction
between access to company leadership and company investors was a significant influence
on funds raised; however, investors gravitated toward companies that only provided
access to one or the other and shunned those that offered both or neither. Future research
into this phenomenon utilizing surveys, focus groups, interview, and controlled
experiments may help to explain the reasons for this unexpected outcome.
Implications
My study promises many opportunities for positive social change. Many
individuals and families have entered into the crowdfunded capital space, including both
the ICO and crowdfunded equity markets. These market stakeholders include those who
are seeking capital for startups and entrepreneurial endeavors but who lack access to
traditional capital markets. This lack of access may stem from entrepreneurs’ inability to
make connections and contacts with accredited investors, which are needed to participate
in traditional capital markets like IPOs. Many entrepreneurs from economically
marginalized backgrounds and experiences may suffer from these restrictions, thus
making it more difficult to thrive and succeed. Many entrepreneurs and startups also lack
the proof of success needed to meet and adhere to many traditional underwriting
requirements prior to launching an IPO or from seeking capital via some other traditional
means. My findings may inform startups and innovators in terms of what kinds of

158
ventures investors, whether accredited or not, may be interested in supporting withing the
crowdfunded capital sector. For example, my results show that a strong propensity among
the investment community exists to participate in crowdfunded capital markets, most
especially in the ICO markets. Individuals and organizations may also benefit from my
findings by understanding what information investors seek when launching crowdfunded
offerings, along with what information they are not seeking. These insights may improve
success outcomes for entrepreneurs who need starting capital.
Similar opportunities for positive social change also apply to the investment
community. Both accredited and nonaccredited investors alike have chosen to participate
in crowdfunded capital markets, especially the ICO sectors. My findings may help other
investors to know what information fellow investors are interested in seeing, thus
improving the odds that they select to support enterprises that enjoy viability among the
larger investment community.
My findings should also inform investors of the potential perils and challenges of
entering into crowdfunded capital markets, as well. As my results show, crowdfunded
capital markets function in ways that are difficult to explain compared to traditional
equity markets, and it is often difficult to know what ventures will likely receive funding
aside from one’s own, or which ones will likely survive long term, simply from perusing
the information and data that are typically considered fundamental in traditional equity
markets. My study should inform investors who wish to participate in ICO and
crowdfunded equity markets that they enter with a large degree of peril to their own
fortunes, albeit perils that also come with many opportunities. Until crowdfunded capital

159
markets are better understood within the literature, a large amount of risk and mystical
thinking will always exist around them, and my findings may underscore this point for all
who wish to participate in them.
My study may benefit the larger crowdfunded capital markets, along with the
broader stakeholder communities that they serve. Though crowdfunded capital markets
harbor much risk and uncertainty, they also promise much opportunity and
transformation potential. The better entrepreneurs, investors, employees, regulators,
scholars, and the general public understand the dynamics of these markets, the more
likely it will be that those exchanges and technologies may provide tangible benefit to our
collective lives. Though my results have not answered all questions surrounding the
myriad uncertainties of crowdfunded capital, my findings do add to a share of the
existing knowledge, which may inform others moving forward.
Conclusions
With the torrid and tumultuous rise of crowdfunded capital markets, the public
and academic narrative surrounding ICOs and crowdfunded equity offerings continues to
unfold along often sharply disagreeable, even divisive, lines. Despite much criticism and
skepticism regarding the safety, sustainability, and viability of crowdfunded capital
markets, innumerable investors, entrepreneurs, and stakeholders have and continue to
participate in those spaces, often with little or no guidance regarding best practices or
reasonable expectations. My study provides a valuable contribution to the scholarly
literature, research, and body of knowledge by providing new discoveries and novel
insights into the often-mysterious functioning of crowdfunded capital offerings. Scholars

160
and practitioners alike may glean useful knowledge from my research, particularly when
attempting to understand or navigate different kinds of crowdfunded capital markets (i.e.,
ICOs versus crowdfunded equity). Through this knowledge, those participants may
achieve greater results, enjoy better outcomes, and accomplish optimal innovation in
these emergent, enigmatic, perilous, and promising marketplaces.
161
References
Adhami, S., Giudici, G., & Martinazzi, S. (2018). Why do businesses go crypto? An
empirical analysis of initial coin offerings. Journal of Economics & Business,
100, 64-75. https://doi.org/10.1016/j.jeconbus.2018.04.001
Ahamed Ahanger, T., Aldaej, A., Atiquzzaman, M., Ullah, I., & Yousufudin, M. (2022).
Distributed blockchain-based platform for unmanned aerial
vehicles. Computational Intelligence & Neuroscience, 1–16.
https://doi.org/10.1155/2022/4723124
Ahlers, G. K. C., Cumming, D., Günther, C., & Schweizer, D. (2015). Signaling in equity
crowdfunding. Entrepreneurship: Theory & Practice, 39(4), 955–980.
https://doi.org/10.1111/etap.12157
Alvarez, G. & Tashea, J. (2018). Looking ahead: ABA Techshow 2018 examined where
the legal profession is heading - with a heavy focus on new and emerging
technology. ABA Journal, 104(6), 33-34.
Amin, F., Abbasi, R., Mateen, A., Ali Abid, M., & Khan, S. (2022). A step toward next-
generation advancements in the internet of things technologies. Sensors, 22(20),
8072. https://doi.org/10.3390/s22208072
Antwi, R., Gadze, J. D., Tchao, E. T., Sikora, A., Nunoo-Mensah, H., Agbemenu, A. S.,
Obour Agyekum, K. O.-B., Agyemang, J. O., Welte, D., & Keelson, E. (2022). A
survey on network optimization techniques for blockchain
systems. Algorithms, 15(6), 193. https://doi.org/10.3390/a15060193
162
Arora, K. (2021, December 20). The meteoric rise of equity crowdfunding. Forbes.
https://www.forbes.com/sites/forbesagencycouncil/2021/12/20/the-meteoric-rise-
of-equity-crowdfunding/?sh=18fbef9e4d41
Aujla, G. S., Singh, M., Bose, A., Kumar, N., Han, G., & Buyya, R. (2020). BlockSDN:
Blockchain-as-a-service for software defined networking in smart city
applications. IEEE Network, 34(2), 83–91.
https://doi.org/10.1109/MNET.001.1900151
Bacina, M. (2019). Regulating STOs and token offerings: Australian treasury seeks
submissions. Banking & Financial Services Policy Report, 38(2), 5–6.
Baig, M. A., Ali Sunny, D., Alqahtani, A., Alsubai, S., Binbusayyis, A., & Muzammal,
M. (2022). A Study on the adoption of blockchain for IoT devices in supply
chain. Computational Intelligence & Neuroscience, 1–25.
https://doi.org/10.1155/2022/9228982
Baig, M. J. A., Iqbal, M. T., Jamil, M., & Khan, J. (2022). A low-cost, open-source peer-
to-peer energy trading system for a remote community using the internet-of-
things, blockchain, and hypertext transfer protocol. Energies, 15(13), 4862.
https://doi.org/10.3390/en15134862
Balta, A., & Greece, E. (2021). EU crowdfunding regulation: An investment model
across the EU. International Tax Review.
Barreto, I. B., Maggia, J. A. U., & Acevedo, S. I. (2019). Cryptocurrencies and
blockchain in tourism as a strategy to reduce poverty. Retos, Revista de Ciencias
163
Administrativas y Económicas, 9(18), 275–290.
https://doi.org/10.17163/ret.n18.2019.07
Battisti, E., Creta, F., & Miglietta, N. (2020). Equity crowdfunding and regulation:
implications for the real estate sector in Italy. Journal of Financial Regulation &
Compliance, 28(3), 353–368. https://doi.org/10.1108/JFRC-08-2018-0109
Bellavitis, C., Cumming, D., & Vanacker, T. (2022). Ban, boom, and echo!
Entrepreneurship and initial coin offerings. Entrepreneurship: Theory &
Practice, 46(5), 1136–1169. https://doi.org/10.1177/1042258720940114
Beloussov, S. (2016). Blockchain: Panacea or hype or a little of both? CIO, 1.
Benedetti, H., & Nikbakht, E. (2021). Returns and network growth of digital tokens after
cross-listings. Journal of Corporate Finance, 66, 101853.
https://doi.org/10.1016/j.jcorpfin.2020.101853
Benedetti, H., Nikbakht, E., Sarkar, S., & Spieler, A. C. (2021). Blockchain and corporate
fraud. Journal of Financial Crime, 28(3), 702–721. https://doi.org/10.1108/JFC-
09-2020-0187
Benkoczi, R., Gaur, D., Nagy, N., Nagy, M., & Hossain, S. (2022). Quantum bitcoin
mining. Entropy, 24(3), 323. https://doi.org/10.3390/e24030323
Black, E. L., Jie, G., Nan H., & Vagenas-Nanos, E. (2017). Uncertainty triggers
overreaction: Evidence from corporate takeovers. European Journal of Finance,
23(14), 1362-1389. https://doi.org/10.1080/1351847X.2016.1202296
164
Block, J. H., Groh, A., Hornuf, L., Vanacker, T., & Vismara, S. (2021). The
entrepreneurial finance markets of the future: A comparison of crowdfunding and
initial coin offerings. Small Business Economics, 57(2), 865–882.
https://doi.org/10.1007/s11187-020-00330-2
Bogusz, C. I., Laurell, C., & Sandstrom, C. (2020). Tracking the digital evolution of
entrepreneurial finance: The interplay between crowdfunding, blockchain
technologies, cryptocurrencies, and initial coin offerings. IEEE Transactions on
Engineering Management, 67(4), 1099–1108.
https://doi.org/10.1109/TEM.2020.2984032
Bollaert, H., Lopez-de-Silanes, F., & Schwienbacher, A. (2021). Fintech and access to
finance. Journal of Corporate Finance, 68, N.PAG.
https://doi.org/10.1016/j.jcorpfin.2021.101941
Boreiko, D., & Risteski, D. (2021). Serial and large investors in initial coin
offerings. Small Business Economics, 57(2), 1053–1071.
https://doi.org/10.1007/s11187-020-00338-8
Boulianne, E., & Fortin, M. (2020). Risks and benefits of initial coin offerings: Evidence
from impak finance, a regulated ICO*. Accounting Perspectives, 19(4), 413–437.
https://doi.org/10.1111/1911-3838.12243
Brown, R., Mawson, S., Rowe, A., & Mason, C. (2018). Working the crowd:
Improvisational entrepreneurship and equity crowdfunding in nascent
entrepreneurial ventures. International Small Business Journal: Researching
Entrepreneurship, 36(2), 169-193. https://doi.org/10.1177/0266242617729743
165
Buttice, V., Di Pietro, F., & Tenca, F. (2020). Is equity crowdfunding always good? Deal
structure and the attraction of venture capital investors. Academy of Management
Annual Meeting Proceedings, 2020(1), 1.
https://doi.org/10.5465/AMBPP.2020.13802abstract
Cabarle, C. (2021). Planning for future tax benefits of investing in regulation
crowdfunding securities. Journal of Taxation of Investments, 38(3), 21–41.
Caldwell, T. (2018). The miners strike - addressing the crypto-currency threat to
enterprise networks. Computer Fraud & Security, 5, 8-14.
Campino, J., Brochado, A., & Rosa, Á. (2022). Initial coin offerings (ICOs): Why do
they succeed? Financial Innovation, 8(1), 1–35. https://doi.org/10.1186/s40854-
021-00317-2
Cappa, F., & Pinelli, M. (2021). Collecting money through blockchain technologies: First
insights on the determinants of the return on initial coin offerings. Information
Technology for Development, 27(3), 561–578.
https://doi.org/10.1080/02681102.2020.1801564
Casarella, P., & Manfrè, C. (2019). Capital raises, initial coin offerings, and token sales.
Graziadio Business Review, 22(1), 1-9.
Casey, M. J., & Vigna, P. (2018). In blockchain we trust. MIT Technology Review,
121(3), 10-16.
Cennamo, C., Marchesi, C., & Meyer, T. (2020). Two sides of the same coin?
Decentralized versus proprietary blockchains and the performance of digital
166
currencies. Academy of Management Discoveries, 6(3), 382–405.
https://doi.org/10.5465/amd.2019.0044
Chang, Y., Fang, C., & Sun, W. (2021). A blockchain-based federated learning method
for smart healthcare. Computational Intelligence & Neuroscience, 1–12.
https://doi.org/10.1155/2021/4376418
Chao, Q., Ming T., & Ruifen, Y. (2018). A hypergraph-based blockchain model and
application in internet of things-enabled smart homes. Sensors, 18(9), 2784.
https://doi.org/10.3390/s18092784
Chavali L. N., Prashanti, N. L., Sujatha, K., Rajasheker, G., Kishor, P.B., & Kavi (2018).
The emergence of blockchain technology and its impact in biotechnology,
pharmacy, and life sciences. Current Trends in Biotechnology & Pharmacy,
12(3), 304-310.
Chen, C. M., Deng, X., Gan, W., Chen, J., & Islam, S. K. H. (2021). A secure
blockchain-based group key agreement protocol for IoT. Journal of
Supercomputing, 77(8), 9046–9068. https://doi.org/10.1007/s11227-020-03561-y
Chen, F., Wan, H., Cai, H., & Cheng, G. (2021). Machine learning in/for blockchain:
Future and challenges. Canadian Journal of Statistics, 49(4), 1364–1382.
https://doi.org/10.1002/cjs.11623
Chow, A. R., & Zorthian, J. (2021). NFTs and the crypto art revolution. Time
International (South Pacific Edition), 197(11/12), 36.
167
Cicchiello, A. F. (2020). Harmonizing the crowdfunding regulation in Europe: Need,
challenges, and risks. Journal of Small Business & Entrepreneurship, 32(6), 585–
606. https://doi.org/10.1080/08276331.2019.1603945
Coakley, J., Lazos, A., & Liñares-Zegarra, J. M. (2022). Seasoned equity crowdfunded
offerings. Journal of Corporate Finance, 77, N.PAG.
https://doi.org/10.1016/j.jcorpfin.2020.101880
Cohen, J. (1988). Statistical power analysis for the behavioral sciences. Hillsdale, New
Jersey: Lawrence Erlbaum Associates.
Coin Insider. (2022). 3336 ICOs with ratings. https://www.coininsider.com/ico/
CoinMarketCap. (2022). Global cryptocurrency charts.
https://coinmarketcap.com/charts/
Collomb, A., De Filippi, P., & Sok, K. (2019). Blockchain technology and financial
regulation: A risk-based approach to the regulation of ICOs. European Journal of
Risk Regulation, 10(2), 263–314. https://doi.org/10.1017/err.2019.41
Colombo, M. G., & Shafi, K. (2021). Receiving external equity following successfully
crowdfunded technological projects: An informational mechanism. Small
Business Economics, 56(4), 1507–1529. https://doi.org/10.1007/s11187-019-
00259-1
Connolly, R., Stivers, C., & Sun, L. C. (2005). Stock market uncertainty and the stock-
bond return relation. Journal of Financial & Quantitative Analysis, 40(1), 161-
194.
168
Crosman, P. (2018). Quantum leap: How banks can get the most from cutting-edge tech.
American Banker, 183(133), 1.
Crosman, P. (2018). Why banks like Barclays are testing quantum computing. American
Banker, 183(136), 1.
Cumming, D. J., Vanacker, T., & Zahra, S. A. (2021). Equity crowdfunding and
governance: Toward an integrative model and research agenda. Academy of
Management Perspectives, 35(1), 69–95. https://doi.org/10.5465/amp.2017.0208
Dai, W. (2019). Quantum-computing with AI and blockchain: Modelling, fault tolerance
and capacity scheduling. Mathematical & Computer Modelling of Dynamical
Systems, 25(6), 523–559. https://doi.org/10.1080/13873954.2019.1677725
Daly, R. (2016). Waiting for blockchain to spark. Traders Magazine, 28(384), 7.
Debler, J. (2018). Foreign initial coin offering issuers beware: The Securities and
Exchange Commission is watching. Cornell International Law Journal, 51(1),
245-272.
del Castillo, M. (2018). An Ethereum futures future? U.S. commodities giants lie in wait
after SEC surprise. Forbes.com, 1.
del Castillo, M. (2018). Cryptocurrency trading platform launches first regulated
Ethereum futures. Forbes.com, 1.
del Castillo, M. (2018). Ethereum gets introspective. Forbes.com, 1.
del Castillo, M. (2018). Hurricane victims edge closer to automated insurance payouts
with Ethereum. Forbes.com, 10.
169
del Castillo, M. (2018). SEC escalates measures against shady Ethereum ICOs with pair
of charges. Forbes.com, 10.
del Castillo, M. (2019). Bitcoin crime search engine paves way for a new kind of law
firm. Forbes.Com, N.PAG.
Demarco, A. E. (2019). Analysing blockchain/distributed ledger technology in capital
markets and know your customer process. Journal of Securities Operations &
Custody, 12(1), 58–71.
Dibrova, A. (2016). Virtual currency: New step in monetary development. Procedia -
Social and Behavioral Sciences, 229(19), 42-49.
https://doi.org/10.1016/j.sbspro.2016.07.112
Ding, J., Qammar, A., Zhang, Z., Karim, A., & Ning, H. (2022). Cyber threats to smart
grids: Review, taxonomy, potential solutions, and future directions. Energies
(19961073), 15(18), 6799. https://doi.org/10.3390/en15186799
DiNizo Jr., A. M. (2018). From Alice to Bob: The patent eligibility of blockchain in a
post-CLS bank world. Journal of Law, Technology & the internet, 9(1), 1-28.
Dolmetsch, C. (2022). Cryptocurrency analyst was paid $5 million to push ICO, SEC
says. Bloomberg.Com, N.PAG.
dos Santos Felipe, I. J., & Franca Ferreira, B. C. (2020). Determinants of the success of
equity crowdfunding campaigns. Revista Contabilidade & Finanças -
USP, 31(84), 560–573.
170
Dos Santos, R. P. (2017). On the philosophy of bitcoin/blockchain technology: Is it a
chaotic, complex system? Metaphilosophy, 48(5), 620-633.
https://doi.org/10.1111/meta.12266
Du, W., Pan, S. L., Leidner, D. E., & Ying, W. (November 2018). Affordances,
experimentation and actualization of FinTech: A blockchain implementation
study. Journal of Information Systems, 28(1), 50-65.
https://doi.org/10.1016/j.jsis.2018.10.002
Dudgeon, N. & Malna, G. (2018). Distributed ledger technology: From blockchain to
ICOs. Banking & Financial Services Policy Report, 38(2), 4-9.
Dumchikov, M., Horobets, N., Honcharuk, V., & Dehtiar, R. (2022). Digital currency as
a subject of economic criminal offenses. Revista de Direito, Estado e
Telecomunicações, 14(1), 20–30. https://doi.org/10.26512/lstr.v14i1.38676
Dupont, Q. (2017). Blockchain identities: Notational technologies for control and
management of abstract entities. Metaphilosophy. 48(5), 634-653.
https://doi.org/10.1111/meta.12267
Dwyer, G. (2015). The economics of Bitcoin and similar private digital currencies.
Journal of Financial Stability, 17, 81-91.
Edwards, M., Mashatan, A., & Ghose, S. (2020). A review of quantum and hybrid
quantum/classical blockchain protocols. Quantum Information Processing, 19(6),
1–22. https://doi.org/10.1007/s11128-020-02672-y
Elder, B., & Hayes, S. K. (2021). Gather your crowd: A guide to equity
crowdfunding. Journal of Financial Service Professionals, 75(2), 70–80.

