


1
Section 1: Foundation of the Study
The success of the low-income housing tax credit (LIHTC) program has been
demonstrated in the creation of nearly 2.9 million housing units since its inception in
1986 (Novogradac, 2016). The LIHTC program has become the primary vehicle to
finance affordable rental housing in the United States (Hammett, 2015), with nearly 8
billion tax credits awarded (Kalugina, 2016). Emerging from concerns that the existing
system of subsidized housing was ineffective, the LIHTC program was launched as a
housing system that was financially sustainable and politically popular, with the infusion
of tax credit allocations to commercial enterprises (Johnson, 2014). One of the driving
forces for implementing the LIHTC program was to end tax shelters (Stanhope, 2016).
The problem facing tax credit developers, however, is of a growing reliance on the
housing choice voucher (HCV) program and other means to sustain profit margins. The
HCV program represents subsidized rental income (SRI). In addition to SRI, tax credit
developers seek nonrental income (NRI) means to support profitable operations. With
continued Congressional budget cuts of the HCV program, the profit margins of tax credit
developments are often at risk. The purpose of this quantitative correlational study was to
examine the relationship between the independent variables SRI and NRI and the
dependent variable of the profitability of tax credit development companies. Quantitative
designs are used by researchers to examine the relationship between independent and
dependent variables (Al-Thani & Semmar, 2017; Guo, 2015; Onen, 2016), which was the
aim of this study.

2
Background of the Problem
LIHTC developments are made affordable because commercial enterprises use
federal subsidies to pay a significant portion of the construction costs, thereby
minimizing debt service payments. Tax credit developers create commercial enterprises
and must agree to set aside a certain percentage of units at reduced rates for low- and
moderate-income tenants (Johnson, 2014). Subsidy infusion is exchanged for affordable
units within the tax credit developments (Schwartz, 2015). The exchange forms the basis
for the public-private partnership between the government and tax credit real estate
developers (Novogradac, 2014).
Low-income housing tax credits represent a supply-side program, which means
that the federal subsidy is delivered directly to construct or rehabilitate buildings and is
not distributed to households (Schwartz, 2015). The HCV program, however, is a
demand-side program in which federal assistance is provided directly to tenants in the
form of vouchers to find available housing (Hsu, 2015). Public and private funds are used
to construct and operate tax credit developments. The financing mechanism was designed
so that the developments can sustain favorable profit margins (Johnson, 2014). In
addition to housing tenants that meet LIHTC criteria of 60% or below median income,
the program can also house persons who receive federal assistance from the HCV
program (Novogradac, 2014), which is the demand-side program. An overreliance on
voucher holders by tax credit developers poses a risk to profitable operations as the HCV
program is subject to Congressional budget cuts (Affordablehousing, 2017).
Hsu (2015) found that there has been a heavy reliance on the HCV program to fill
LIHTC developments. Researchers have recently discovered that the LIHTC program

3
may be considered more of a hybrid of supply-side and demand-side programs, with
voucher holder participation estimated between 16% and 40% (Hsu, 2015). Many tenants
use housing choice vouchers to rent from tax credit developments (Kingsley, 2017). Tax
credit developers tend to target HCV households for two reasons. First, voucher holders
are sought in areas where the tax credit rents are competitive with fair market rents.
Second, surplus income is derived from housing voucher holders, which is not the case
with housing nonvoucher holders. Tenant voucher holders pay above maximum rents
because their payment standards are higher than LIHTC rents, creating a windfall for the
developers of tax credit units.
Problem Statement
Many tax credit development companies that build affordable housing fail to
operate profitably as commercial enterprises without assistance from government
subsidies (Hsu, 2015). Nearly 35% of tax credit development companies were operating
below break-even (Hammett, 2015), and have required additional streams of income to
sustain operations. The general business problem was that some tax credit housing
developers fail to understand the negative impact of dwindling income sources on
profitable operations. The specific business problem was that some tax credit developers
do not know the relationship among SRI, NRI, and profitability.
Purpose Statement
The purpose of this quantitative correlational study was to examine the
relationship between SRI, NRI, and profitability as this pertains to tax credit housing
developers. The independent variables were SRI and NRI, and the dependent variable
was profitability. The targeted population consisted of tax credit housing developments

4
with 200 or more units in the state of Florida, from which a random sample was drawn.
The implications for positive social change from the study findings may lie in the
possible contribution to knowledge, which could advance the ability to offer affordable
housing to the economically disadvantaged in society. The study findings may provide tax
credit housing developers with an improved understanding of the association between
SRI, NRI, and profitability, and may thereby benefit low-income tenants. With an
improved understanding of the relationship between SRI, NRI, and profitability, the
potential for positive social change could include the development of more affordable
housing by developers to meet the needs of low-income tenants.
Nature of the Study
The three types of research methods include quantitative, qualitative, and mixed
methods (Yin, 2017). For this study, a quantitative method was chosen to examine the
relationships between variables (see Lach, 2014). The purpose of the quantitative method
was to examine the relationship between SRI, NRI, and profitability. Qualitative methods
are used by researchers who seek to understand a phenomenon by seeking answers to how
and why questions rather than using statistical results (Yin, 2017); the latter was the aim
of the current study. The need for results based on statistical testing rendered the
qualitative method inappropriate for the study. Mixed methods, a combination of
quantitative and qualitative approaches, is advantageous when addressing research
questions that require both types of data in a single study (Zhang & Watanabe-Galloway,
2014). The mixed-methods approach was not chosen for this study because there was no
need to combine objective measurements with a subjective inquiry. The mixed-methods

5
approach is often cumbersome and may require additional time in executing the research
(McKim, 2015).
Nonexperimental, experimental, and quasi-experimental designs were reviewed to
determine the appropriate design for this study. Based on the objective of the study, which
was to examine the relationship between SRI, NRI, and profitability within the tax credit
housing industry, a nonexperimental correlational design was appropriate. A correlational
design is used to determine the degree and strength of the relationship between the
independent and dependent variables from data generated using appropriate correlational
techniques and analyzed using appropriate statistical techniques (Arkkelin, 2014). The
purpose of the correlational design was to examine the relationship between two
independent variables (SRI and NRI) and the dependent variable (profitability).
Experimental and quasi-experimental designs involve controlled environments, which
may entail the manipulation of variables and interventions as the aim is to examine
causeand-effect relationships (Walter, Dunsmuir, & Westbrook, 2015). The aim of the
current study was to examine the correlational relationship between variables, not cause
and effect; therefore, quasi-experimental and experimental designs were inappropriate.
Research Question
The research question was the following: What is the relationship between
subsidized rental income, nonrental income, and profitability?
Hypotheses
H0: There is no relationship between subsidized rental income, nonrental income,
and profitability.

6
H1: There is a relationship between subsidized rental income, nonrental income,
and profitability.
Theoretical Framework
The supply-side theory (Laffer, 1983) and the demand-side theory (Keynes, 1936)
underpinned the study and constituted the theoretical framework. The aim was to
understand how tax credit housing developers apply SRI and NRI to profitability. The
two categories of federal housing programs, supply-side and demand-side, aligned with
the economic theories chosen to underpin the study. Canto, Joines, and Laffer (1982)
argued that reduced taxes spur economic growth. Economic growth is driven by the
supply of goods and services (Laffer, 1983). The constructs underlying the supply-side
theory include reduced taxes, increased private sector investments, and increased capital
production, pertain to the tax credit housing program. The supply-side theory was
relevant to this study because the federal government created a supply of goods and
services through the LITHC program, which includes tenants who provide SRI and NRI
to support the profitability of tax credit housing companies. SRI and NRI are sources that
may negatively affect profitability.
Keynes (1936) developed the demand-side economic theory. Keynesian theorists
have argued that economic growth is driven by the demand for goods and services
(Prizio, 2015). One of the constructs underlying the demand-side theory is the infusion of
spending to create consumer demand (Keynes, 1936). The demand-side theory was
relevant to this study because the federal government has created a demand for goods and
services through the HCV program. Tenant voucher holders provide income streams to
tax credit developments that include SRI and NRI to sustain profitability (Hsu, 2015).

7
Operational Definitions
The following operational definitions provide clarity regarding the meaning of
terms as they were used in this study:
Affordable housing: Rental dwellings within reach of individuals and families
who pay no more than 30% of annual income for rent and utilities (Hammett, 2015).
Area median income: The midpoint household income from a metropolitan area or
a nonmetropolitan county used in determining eligibility for housing programs (U.S.
Department of Housing and Urban Development [HUD], 2015b).
Developers: Professionals involved in the production of LIHTC multifamily
housing, including syndicators, bankers, builders, managers, and investors (Hammett,
2015).
Gross operating profit: The difference between the cost of goods sold and total
sales divided by total assets minus financial assets (Ukaegbu, 2014).
Low-income households: Households with incomes between 50.1% and 80% area
median income (HUD, 2015b).
Low income housing tax credits (LIHTC): The largest subsidy that provides tax
credits as an incentive for private investors participating in low-income housing
production (Schwartz, 2015).
Public-private partnership: Partnerships between governments and the private
sector that spur the development of affordable housing by adding resources (Johnson,
2014).

8
Qualified allocation plan (QAP): A federally required annual planning tool used
by state housing finance agencies to explain how tax credits were allocated (HUD,
2015b).
Return on assets (ROA): The earnings before interest, taxes, depreciation, and
amortization divided by the total assets (Kara, Erdur, & Karabiyik, 2015).Assumptions,
Limitations, and Delimitations
Assumptions, limitations, and delimitations provide critical information about the
methodology, findings, and scope of a study (Leedy & Ormrod, 2015). Assumptions are
assertions not confirmed in the study (Marshall & Rossman, 2016). Limitations are
potential weaknesses of a study (Leedy & Ormrod, 2015), while the scope and
delimitations indicate the boundaries of a study (Leedy & Ormrod, 2015).
Assumptions
Assumptions in a study are assertions that the researcher takes to be true in the
absence of confirmation (Marshall & Rossman, 2016). The first assumption was that I
would be able to locate tax credit developers who rely on households receiving federal
rent assistance to bolster favorable profit margins of the company. The second assumption
was that I would be able to retrieve archival financial data from the Florida State Housing
Corporation and public housing authorities to gather information for the independent and
dependent variables. The last assumption was that there would be an alignment between
the study and the quantitative correlational design. The purpose of the study was to
examine the relationship between the independent variables (SRI and NRO) and the
dependent variable (profitability).

9
Limitations
Limitations are potential weaknesses that represent important components of a
study (Leedy & Ormrod, 2015). First, there was a lack of data to identify the percentage
of HCV households who occupy tax credit developments. Second, there appeared to be a
dearth of research as to how tax credit developers apply surplus income from voucher
households to their developments. Finally, the findings from the study may not be
generalizable to all tax credit housing developments in the United States because different
locations can affect rents and profitability.
Delimitations
Delimitations indicate boundaries regarding what the researcher will cover in the
study (Leedy & Ormrod, 2015). The first delimitation was that only the strength and
direction of the association were examined in the study, not the cause-and-effect
relationship between SRI, NRI, and profitability. The second delimitation was that the
focus of the study was on developments that contain 200 or more units and excluded
smaller properties. The last delimitation was that the study was restricted to the state of
Florida.
Significance of the Study
The findings from this study may provide tax credit housing developers and
affordable housing researchers with a better understanding of the possible risks and
opportunities to profitable operations from the use of different income streams. The study
may also fill a gap in the literature regarding the impact of SRI on the tax credit housing
development industry. The study may also contribute to the improvement of business

10
practices in the tax credit housing industry and to the advancement of positive social
change.
Contribution to Business Practice
The findings from the study may contribute to business practice by providing new
knowledge on the for-profit concept of maximization of profits and minimization of risks.
Hammett (2015) posited that the goal of commercial businesses is to maximize profits
and reduce risks. The findings may also lead to a better understanding of the effect of SRI
and NRI on the profitability of tax credit developments. Tax credit housing developers
may use the findings to improve their understanding of the connection between SRI, NRI,
and profitability within operations (see Bratt & Lew, 2016). Second, the results could
help tax credit developers avoid possible risks to profitable operations (see Hammett,
2015). Third, the findings may help public policy officials implement regulations
designed to increase the population of eligible tax credit tenants. Finally, public policy
officials may use the findings to fund additional solutions to the affordable housing
dilemma (see Hsu, 2015).
Implications for Social Change
The findings from this study may contribute to positive social change by
increasing the understanding of developers with respect to the association between SRI,
NRI, and profitability. The findings of the study may contribute to existing knowledge in
this domain and may be used to increase affordable housing for the economically
underserved. Tax credit developers and public housing officials may be informed of ways
to decrease rent burdens (see Bratt & Lew, 2016), which could benefit low-income

11
tenants and communities that address homelessness (see Hsu, 2015).. Society may benefit
as additional renters move from substandard living conditions to affordable housing (see
Hsu, 2015).
A Review of the Professional and Academic Literature
Researchers often seek to gain an intimate understanding of themes related to the
objectives of a study through an exhaustive review of articles, books, and other literature.
With a thorough understanding of themes, researchers can convey the intent of the study.
The purpose of this quantitative correlational study was to examine the relationship
between the dependent variable of profitability and the independent variables of SRI and
NRI in LIHTC developments. The following research question guided this study: What is
the relationship between SRI, NRI, and profitability? The hypotheses for this study were
the following:
H0: There is no relationship between SRI, NRI, and profitability.
H1: There is a relationship between SRI, NRI, and profitability.
The supply-side theory (Laffer, 1983) and the demand-side theory (Keynes, 1936)
underpinned the study. The theoretical framework was used to guide the examination of
the research variables. Information in this section includes supply-side theory,
demandside theory, and profitability as the main topics of review. The constructs
underlying the supply-side theory include reduced taxes, increased private sector
investments, and increased capital production, pertain to the tax credit housing program.
A major construct underlying the demand-side theory is government intervention to
promote consumer spending. The demand-side theory was relevant to this study because
the federal government created a demand for goods and services through the HCV

12
program from which tax credit housing developers receive SRI, which is relied on for
profitable operations. The two economic theories contain opposing perspectives regarding
affordable housing, which may be relevant when examining profitability within the tax
credit housing arena.
Strategy for Sourcing Literature
Dissertations, industry websites, journal articles, and scholarly texts were primary
sources for the literature review for this study. The Walden University online library was
the primary source for finding and selecting pertinent peer-reviewed and other journal
articles. Access to online library databases was based on enrollment status at Walden
University. The academic journal repositories proved beneficial for relevant searches.
Keywords were used in the following databases: Thoreau, Academic Search Complete,
ProQuest Central, SAGE Premier, and Google Scholar. Keywords and phrases queried in
the databases included LIHTC, supply-side theory, demand-side theory, affordable
housing, quantitative correlation, qualified action plan, profitability measures, Housing
Choice Vouchers, public-private partnerships, and subsidized housing.
Table 1 provides a summary of the references used in this doctoral study. Queries
from databases resulted in 130 research items. The appropriateness for retrieval of
scholarly and practitioner literature was determined by reviews of the abstracts,
introductions, and conclusions. The literature review for this study included 130
references, and 112 were published between 2015 and 2018. Over 85% of the references
in this study were peer-reviewed and published on or after 2015. The literature review
contains 82 in-text citations with 70 from peer-reviewed references. The results reflect
compliance with the 85% guide.
13
Table 1
Detailed List of References
Description
Value
Total number of references used in this doctoral study
130
Total number of references within the last 5 years
112
Percentage of references within the last 5 years
86%
Total number of peer-reviewed references
111
Percentage of peer-reviewed references
85%
Total number of references used in the literature review
82
Number of literature review references within the last 5 years
71
Percentage of literature review references within the last 5 years
87%
Five topics are covered in the literature review. The first and second topics include
a review of studies on the theoretical frameworks: the supply-side economic theory and
the demand-side economic theory. Review of the literature addressing the SRI
independent variable is covered under the demand-side housing topic. The NRI
independent variable is addressed under the supply-side housing topic. The third topic is
the dependent variable (profitability). Construct measurements and profitability
methodologies are covered in the last two topics. The section concludes with a summary
and transition.
Supply-Side Housing
The LIHTC program is an $8 billion industry that was created by Congress to
build affordable housing for low-income families (Gramlich, 2016; Sullivan & Anderson,
2017). Supply-side theorists have argued that economic growth is driven by the supply of

14
goods and services (Prizio, 2015). The constructs underlying the supply-side theory
include lower taxes, increased private sector investments, and increased capital
production. The supply-side theory was relevant to this study because the LIHTC
program is a supply-side government subsidy derived from tax credits. Shaw (2015)
posited that tax credit subsidies are the only way affordable housing can be built
effectively. One of the weaknesses identified in the LIHTC program was sensitivity to
shifts in the economy (Schwartz, 2015). The market for tax credits showed that as the
economy slows, the demand for tax credits may also decline (Schwartz, 2015).
Supply-side theorists are often at odds with demand-side theorists who support the
Keynesian economic theory (Phelps, 2016). Keynesian theorists have argued that
economic growth is based on the demand for goods and services (Prizio, 2015).
Incorporated in both theories is the reliance on government intervention. Demand-side
economists argue that placing money in the hands of lower- and middle-income renters
increases aggregate demand and thereby increases economic activity (Prizio, 2015).
Within the demand-side housing program, vouchers are placed in the hands of lowincome
persons who use them to rent from private landlords or tax credit companies (Hsu, 2015).
Within the supply-side housing program, subsidies are provided to private real estate
companies to build and rehabilitate affordable housing (Shaw, 2015).
The U.S. government categorizes housing subsidies into supply-side or
demandside programs. The categories align with the supply-side and demand-side
economic theories. A subsidy for affordable housing tenants delivered indirectly for the
construction or rehabilitation of buildings is characterized as supply-side and has
produced 2.6 million units of affordable housing (Hsu, 2016). The tax credit program has

15
been criticized for higher costs and lower numbers of units produced in the past 20 years
(Sullivan & Anderson, 2017). Sullivan and Anderson (2017) found that tax credits cost
66% more during that period, with industry officials citing increased construction costs,
lower grant revenue, and increased targeting of low-income renters as the reasons.
Federal government officials adopted the belief that all citizens should be
provided access to decent, safe, and affordable housing (Johnson, 2014). Housing needs
fall into Maslow’s (1943) theory Layer 2: hierarchy of needs. Maslow (as cited in
Henwood, Derejko, Couture, & Padgett, 2015) described safety needs as a primary
motivation for behavior if they go unmet. Maslow noted that housing is one of the
measures for an individual or family to feel secure. Within Maslow’s levels of
progression to an individual’s self-actualization, the need for housing must be met after
the basic needs are met. Criticism of Maslow’s theory and hierarchy has arisen from
many scholars (Bouzenita & Boulanouar, 2016). According to Harrigan and Commons
(2015), Maslow did not explain elements of behavior that cause individuals to move from
one stage to another. With the application of Maslow’s theory of the hierarchy of needs to
explain renter motivations, it may be evident from the literature review that when people
are provided affordable housing, a level of behavioral motivation may have been
experienced for them to become productive citizens. Henwood et al. (2015) posited that
the identification of self-actualization goals is associated with the lack of having basic
needs met instead of the fulfillment of basic needs.
The housing goal, along with the demand for increased accountability from the
government in resource distribution, became the basis for resolving housing issues and
led to the implementation of the LIHTC program (Johnson, 2014). Greater accountability

16
of government resources was one of the reasons for creating the tax credit housing
program. However, in recent years public accounting of the program costs among
government officials and regulators responsible for monitoring has been insufficient, with
some calling for changes (Sullivan & Andersons, 2017). Sullivan and Anderson (2017)
also found insignificant data pertaining to the oversight and monitoring efforts of the tax
credit housing program, with the possible implication that the IRS is not properly
performing its oversight responsibilities. Advocates have argued that the tax credit
housing program has an effective built-in self-monitoring mechanism (Di & Murdoch,
2013). Bratt and Lew (2016) noted that monitoring is performed by the developer and
owner who require exemplary management for the development to remain in compliance.
The LIHTC program aligns with the supply-side economic theory. Supply-side
theorists have supported the use of tax cuts to spur private investment in the production of
capital projects (Prizio, 2015). Although broad support for the LIHTC program has been
expressed, skepticism has arisen about the ability of the program to have a significant
national impact on affordable housing needs (Johnson, 2014). The tax credit housing
program gained widespread popularity with developers who saw the benefits of building
housing complexes in which a significant portion of the construction was funded by the
government (Schwartz, 2015).
The LIHTC program was initially criticized because of the assertion that
underwriting was unnecessarily burdensome (Hammett, 2015). The program has also
been criticized because of complex rules and inefficiency (Sullivan & Anderson, 2017).
Critics have complained about high transaction costs and inefficiency within the LIHTC
(Edwards & Calder, 2017). Hammett (2015) highlighted the efficiency with which tax

17
credit dollars have been applied to construction development rather than administrative
costs. Tax credit housing efficiency production has declined in recent years with the
production of fewer units and the use of more housing tax credits (Sullivan & Anderson,
2017).
Ihlanfeldt and Mayock (2017) advocated for the need to locate affordable housing
near high-quality schools as a means of improving academic achievement for students of
low-income households. Perceptions of deterioration in the quality of schools and
neighborhoods loom as barriers to establishing tax credit housing developments. Tax
credit developers, as well as other affordable housing developers, must address the notin-
my-backyard perception of residents when planning housing developments (Scally &
Tighe, 2015). Dillman, Horn, and Verrilli (2017) noted that the production of LIHTC
housing in economically distressed communities has a positive impact on surrounding
neighborhoods in terms of modest increases in property values and enhanced safety.
Higher opportunity neighborhoods that receive LIHTC housing experience modest
property value reductions and no effect on crime (Dillman et al., 2017).
Additional operating income is often required for tax credit developments to
operate profitably (Hsu, 2015). Thayer (2018) described subsidy layering as a
gapfinancing mechanism that has been used for over 30 years. Tax credit projects are
complicated due to the layering of grants, tax credits, bonds, and municipal assistance.
Funding mechanisms from states and local governments are sought by developers. Bratt
(2016) suggested that tenant incomes and the ability to pay should drive the affordability
of rental apartments, but such a mechanism requires additional subsidies beyond the
LIHTC funding. Weisbach (2006) argued that the LIHTC program should be replaced

18
with vouchers because the voucher program is less expensive. Although less expensive,
the voucher program is subject to annual funding cuts from Congress, which is not the
case with the LIHTC program. Housing advocates promoted the view that the LIHTC
program was more geared toward benefiting wealthy investors than low-income
households (Johnson, 2014) because upper-income investors and big corporations
benefited from poor households. Novogradac (2016) noted that more than 13.3 million
Americans have benefited from the LIHTC program over a 30-year period. Freedman and
McGavock (2015) argued that LIHTC crowds out private development, and that nearly
half of existing tax credit housing units would have been constructed without a subsidy.
Overall, the tax credit program has been viewed as a win-win process because the
benefits accrue to all parties within the affordable housing arena. An affordability
problem exists among a growing number of renter households in the United States
(Johnson, 2014). An important housing policy question to ask would be the following:
Are LIHTC developers doing a disservice to eligible nonvoucher holders by limiting
available units when they rent to voucher holders? Demand subsidies in the form of
vouchers can harm nonvoucher holders who seek housing in tax credit developments.
Supply-side operations include the application process, compliance, tax credit developers,
and public-private partnerships.
Application process. The profitability of tax credit housing developments is
affected by the application process, which includes the developer identifying levels of
rents and the location of the development. The application process is a competitive
mechanism that is geared toward ensuring the best housing is produced, and the process
begins with a project owner submitting a competitive application to the state housing

19
agency (Hsu, 2015). The intense competition for tax credits has come under scrutiny as
the process hampers development and serves to frustrate developers who would rather
spend the time working additional tax credit applications (Bratt, 2016).
Federal law requires that states give preference to developments serving the
lowest income renters and within poverty areas (HUD, 2015a). However, market forces
govern income levels and profit margins of tax credit developments, as with other real
estate markets (Johnson, 2014). Developers have targeted the higher income group at or
below 60% of area median income for 88% of tax-credit projects placed in service
between 1987 and 2014 (Lew, 2015).
The application process includes developers’ attentiveness to the Qualified
Allocation Plan, which is used by states to award the tax credits to developers (Skuzinski
et al., 2016). Section 42 of the Internal Revenue Code requires that states create an annual
QAP, which sets the criteria for how tax credit projects are to be selected. Preferences are
set for projects serving the lowest income tenants (Ellen, Horn, Kuai, Pazuniak, &
Williams, 2015). The building locations used for affordable housing development are often
less than ideal for market-rate developers, who seek the best sites (Davis, 2016).
Affordable housing developers choose to maximize the amount of LIHTCs
received by targeting neighborhoods designated as Difficult Development Areas or
Qualified Census Tracts, which are frequently characterized as poverty areas (Eriksen,
2017; Niver, 2016). Awarding of tax credits by state agencies is a process of chasing
points by developers. To ensure that LIHTC developments are built in high-opportunity
areas, Spotts (2016) argued that housing finance agencies (HFA) should adopt
locationsensitive cost evaluations.

20
High-opportunity areas are described as geographic locations that are served by
high-quality schools and have such amenities as access to quality transportation, jobs,
superior health care, and public services (Neville, 2017). Higher opportunity
neighborhoods that are occupied by LIHTCs experience modest property value reductions
with little to no effect on crime (Dillman et al., 2017). Although additional points are
awarded based on the location of developments in high poverty areas, the negative effect
on profit margins could cause developers to seek rental assistance from the HCV program
as well as other streams of income.
Currently, developers are reluctant to target high-opportunity areas because QAPs
contains threshold requirements such as land and per unit development costs that are not
conducive to high opportunity areas (Spotts, 2016). Progress to deconcentrate poverty has
been made within the LIHTC program (Niver, 2016). Affordable housing is more
regionally distributed within the LIHTC, providing low-income households with greater
access to high-opportunity neighborhoods. Tax credit developers locate more than
onethird of units in the suburbs (Niver, 2016). Profitability is ultimately at risk when
developers chase points by locating their developments in high poverty areas, leading to
the need for greater rental assistance in the form of SRI.
Compliance. The Internal Revenue Service (IRS) mandates compliance with rent
structures and unit restrictions that affect the profit margins of tax credit housing
developments as specific percentages of rents and units must be maintained during a
15year period (Schwartz, 2015). Compliance monitoring for a subsequent 15-year period
is provided by state housing agencies (Bratt, 2016). The monitoring efforts by the IRS
have been criticized in recent years, as Sullivan and Anderson (2017) noted that only

21
seven audits had been performed of the 58 housing agencies assigned by the IRS to
monitor the program since its inception in 1986. Lipschultz (2016) noted the Internal
Revenue Service (IRS) has generally found that program requirements are met by
developers of LIHTC properties.
The quality of the LIHTC project is maintained by private for-profit investors who
provide oversight and discipline (Bratt, 2016). The LIHTC program is an IRS
responsibility, included in the 1986 Tax Reform Act; however, enforcement and
assessment rest with the Department of Housing and Urban Development (Schwartz,
2015). The oversight for the first fifteen years of a LIHTC project is provided by the
federal government, which includes the threat that tax credits could be rescinded if the
project fails to comply with the proper level of income and units (Bratt, 2016).
Proponents have argued that less than 1% foreclosure rate occurs within the LIHTC
program (Johnson, 2014). Compliance with reduced rents and a target number of units set
aside for low-income use means that the developer has agreed to forego maximum rents,
resulting in the need for additional income streams such as the HCV program. Developers
seek rental assistance from the HCV program to bolster their profit margins (Hsu, 2015).
Affordable housing advocates have expressed concern that the affordability
component would cease after the compliance period ended (Sullivan and Anderson,
2017). The shortage of affordable housing fuels the concerns when considering which
direction tax credit developments will move after the compliance period. Weiss (2016)
predicted by 2043, two million apartments in the U.S. will have lost the affordability
component attached to federal restrictions. Researchers, however, found that only 6% of
projects whose compliance period ended reverted to market-rate housing, with the

22
remainder of the projects either having their tax credits renewed or remaining affordable
without tax credits (Schwartz, 2015). Affordability of developments in the absence of tax
credits places an additional strain on profit margins and a greater reliance on voucher
holder income to fill the financial gap.
Tax credit developers. Tax credit developers exchange the opportunity to charge
market-rate rents for the subsidy provided through the tax credit program (Johnson,
2014). The process effectively lowers the debt service costs for the development
(Schwartz, 2015). Maximization of profits and minimization of risks are established goals
within real estate development (Hammett, 2015). However, maximization of profits is not
realized for developers within the LIHTC industry as rental income is sometimes reduced
for the sake of affordability. With nearly one-fourth of all tax credit developments
operating below breakeven, as found in several publications, the implications may be that
the tax credit subsidy is not enough to sustain profitable operations. Invariably,
developers turn to SRI and other means to sustain profitable operations.
Tax credit developments receive higher rent payments from voucher holders than
from eligible non-voucher holders. HUD provides a higher payment standard for voucher
holders than the 60% LIHTC payments (Novogradac, 2014). Novogradac further posited
that researchers have recently discovered that the LIHTC program may be considered a
hybrid of supply-side and demand-side programs as development managers use HCV
households to fill their apartment complexes. However, the risk is posed to tax credit
developers by overly relying on income from the HCV program as it is subject to annual
Congressional budgetary cuts (Hammett, 2015).

23
Tax credit housing developers have grown dependent on the voucher program to
fill units and to gain incremental income to sustain operations and profit margins (Hsu,
2015). The HCV program is subject to annual Congressional review and budget
reductions. Unlike the HCV program, the LIHTC program is not subject to annual review
for spending authorization because the program has been established by the 1986 Tax
Reform Act within the IRS tax code and is therefore not subject to annual funding cuts
(Hammett, 2015).
Developers use tax credit subsidies to pay a significant portion of construction
costs for erecting affordable developments, with the intent of reducing debt service costs
and creating sustainable operations (Schwartz, 2015). Sustainable operations within the
tax credit development industry have been realized through additional funding sources
(Hsu, 2015). Although SRI increases the profit margins of tax credit developments,
shrinking federal dollars within the HCV program should serve to motivate tax credit
developers to more aggressively market the vast pool of non-voucher renters who meet
the 60 percent AMI eligibility.
Many of the extremely-low-income renters experience rent burdens while housed
in tax credit housing programs (HUD, 2015a). JCHS (2015) reported a shortage of
affordable housing in the U.S., which results in cost burdens to renter households. HUD
defines extremely-low-income households as earning 30% or less of the area median
income compared to 60% or less for the LIHTC program (HUD, 2015b). Housing
extremely low-income renters negatively affect the profitability of tax credit
developments. Bratt (2016) observed that tenant income and the ability to pay should

24
drive the affordability of rental apartments, but such a mechanism requires additional
subsidies beyond the LIHTC funding.
Developers who are committed to serving extremely low-income households tend
to employ creative strategies in mixed-income complexes (Johnson, 2014). Some tax
credit developers use incremental income to assist extremely-low-income households
through a strategy termed cross-subsidization (Hsu, 2015). Hsu also noted that the
crosssubsidization strategy implemented by some development firms in utilizing income
from higher-earning households might help offset lower rents to meet the overall
operating costs of the development.
Most of the criticism of the tax credit program was based on earlier observations
such as cumbersomeness of the paperwork and syndication costs (Hammett, 2015). A
reduction in syndication costs has occurred as well as a willingness on the part of
investors to accept lower returns (Niver, 2016). Throughout the years, the tax credit
housing program has been demonstrated to be a stable investment that attracts developers
and investors (Schwartz, 2015). The program is described as beneficial to all parties:
lowincome families receive modern, well-built, affordable dwellings; and developers,
syndicators, and investors profit from their roles.
Investments in LIHTC developments are viewed as low risk because of the high
demand and low foreclosure rates associated with the program. Sullivan and Anderson
(2017) noted that tax credit housing is perceived by investors as a safe investment
because the developments are often filled with tenants and long waiting lists. Incentives
within the tax credit housing industry are crucial for attracting private sector investment.

25
Schwartz (2015) suggested that the tax credit housing program was vulnerable to
economic shifts as there was a reticence on the part of developers to purchase tax credits
during the great recession. The susceptibility of the LIHTC market to shifts in investor
demand was evidenced during the financial crisis when revenues were reduced across the
United States, slashing the demand for tax credits.
Surplus income from voucher holders is used by tax credit housing developers in
the operations of the developments (Hsu, 2015). Other developers fill the gap in operating
tax credit developments by applying traditional financial housing mechanisms (Johnson,
2014). A gap in literature may exist regarding how tax credit developers use the
incremental income from voucher holders, which could serve as an additional stream of
income to sustain operations. HUD does not mandate how the surplus income derived
from voucher holders should be used by tax credit developers (Hammet, 2015). An
important question is raised based on developers receiving incremental income from
voucher holders: Should all developers use the surplus to cross-subsidize, reduce rents for
other extremely low-income households as some developers are doing? Additional
research may be needed to determine how tax credit developers use surplus funds from
SRI within the housing developments.
Public-private partnerships within tax credits. The low-income housing tax
credit (LIHTC) is a public–private partnership that has become an integral part of
affordable housing. A public-private partnership is often described as a mutually
beneficial relationship between the public and private sectors (Du, Wu, & Zhu, 2018;
Wang, Cui, Liu, 2018). The entrance of private sector developers into affordable housing
production has proven to be a successful strategy (Woo, Joh, & Van Zandt, 2016; Woo & Yu, 2017).

26
The LIHTC program represents an evolution from government conventional
lowincome housing programs, to a gradual shift in responsibility to private landlords,
developers, investors, and public-private partnerships (Johnson, 2014). Banks have
recently become the largest investors in LIHTCs. The bankers are statutorily motivated
by the Community Reinvestment Act, which was enacted in 1977 to meet the credit needs
within a community. Investors are incentivized to partner with developers to build
affordable housing apartments by providing a portion of the capital for construction and
in turn receiving tax credits for a 10-year period.
The federal government has become dependent on for-profit and non-profit
organizations to deliver affordable housing, which has brought about decentralization of
the affordable housing program (Bratt & Lew, 2016). Concerns have been raised
regarding the seemingly over-reliance on private actors by the federal government (Niver,
2015). The question of accountability was raised with government dependence on
private-sector production of affordable housing. The profitability of tax credit
developments can be attributed to the private sector partnerships as developers seek
various financial means, including the HCV program, to sustain operations.
Shifting the responsibility of affordable housing production to the private sector,
the federal government additionally devolved its responsibility for affordable housing to
regional, state, and local government for creating greater productivity and efficiency
(Bratt & Lew, 2016). Some criticism has arisen concerning the degree that the
government relies on the private sector to perform functions formerly handled by the
government (Sullivan & Anderson, 2017). The role of the private sector in performing
public functions has been valued at a trillion dollars annually (Niver, 2015).

27
The tax credit program was designed as a catalyst for private investment in
affordable housing (Schwartz, 2015). A paradigm shift occurred within the federal
housing policy that moved the responsibility of resolving housing issues from the federal
level to public-private partnerships. Efficiency and profitability drivers of private
business coupled with governmental goals account for the astounding production of
affordable housing. Public-private partnerships have been widely used in the operations
and responsibilities of public service (Liu et al., 2017). Although the public-private
partnership has been instrumental in the success of affordable housing production within
the LIHTC program, goal congruence has become a concern as the two entities
collaborate to address housing needs (Bratt & Lew, 2016). Higgins and Huque (2015)
found differences in how the two sectors measured accountability, with the public partner
requiring greater visibility of its investment than the private partner.
Within the affordable housing realm, the goal of the public sector is to meet the
demands of public policy in providing affordable housing for its citizenry (Johnson,
2014). Tax incentives were the motivation for private developers to take on the role of
affordable housing production (Schwartz, 2015). However, the goal of commercial
businesses is to maximize profits and reduce risks (Hammett, 2015). The goals of public
and private sector representatives may not always intersect perfectly because of their
respective motives. However, despite ambiguity, conflicts, and complexities, public and
private sectors have been extremely successful in merging to produce nearly 2.9 million
affordable housing units (Novogradac, 2016). Inherent within goal congruence are issues
such as goal ambiguity, goal conflicts, and goal complexity.

28
One of the chief goals of the tax credit program was to encourage private sector
support of affordable housing (Johnson, 2014). Nearly $8 billion tax credits are awarded
on an annual basis within the tax credit program (Hammett, 2015). The exchange of
subsidy for affordable housing units forged the relationship upon which the publicprivate-
partnership has been based between the federal government and residential real estate
developers (Johnson, 2014). As private sector investors benefit from the cost reduction of
government subsidy, they must balance the need to sustain profitability by providing the
required number of affordable units for low-income tenants (Shaw, 2015).
The opportunity to claim a federal tax credit is the main economic incentive
derived from tax credit investment by the private sector (Hsu, 2015). Equity for the
development is generated from private investors who then use tax credits to offset their
tax liability. Schwartz (2015) noted that private investment in affordable housing was
spurred by the tax credit program. Corporations and individuals are provided incentives
to invest in the construction or rehabilitation of affordable rental housing (Johnson,
2014). Although the investment component is largely responsible for attracting investors
into the affordable housing market, public officials are incentivized by the creation of
affordable housing (Schwartz, 2015).
Public-private partnership agreements abound in communities across the United
States. The city of Buffalo, NY, represents an example of a private-partnership agreement in which
city officials demonstrated partnership cooperation by offering 17 acres to developers for the
purpose of building affordable housing (Popiolkowski, 2015). Success stories abound where
partnerships have formed between public and private sectors to achieve affordable housing.
Municipalities have demonstrated a willingness to donate or sell land at a low cost. Additionally,

29
local governments, through their Community Redevelopment Agency entities, have demonstrated
a willingness to fund infrastructure for LIHTC projects that benefit the housing community (Hsu,
2015). Although public officials are influenced to merge with private developers in providing
affordable housing, private developers are generally influenced by economic reasons (Fyall, 2014).
Additional funding is commonly required for profitable operations of tax credit
developments (Hsu, 2015). Tax credit housing developments generally require multiple
layers of funding sources, in addition to the tax credit housing subsidy (Bratt, 2016). The
need for additional funding is indicative of the higher cost of the tax credit program
compared to the voucher program. Replacement of the tax credit housing program with
the voucher program was advocated by Weisbach (2006) because the voucher program
has been deemed to be less expensive and complicated.
Demand-Side Housing
The demand-side housing program aligns with the theory developed by economist
Keynes (1936), which is termed Keynesian economics or demand-side economics.
Keynesian economics is based on the premise that economic activity is driven by the
demand for goods and services (Backhouse, 2015). Demand-side economics is often at
odds with the supply-side theory, which is based on the presumption that the supply of
goods and services is the main driver of economic growth (Prizio, 2015). Government
intervention is a common theme in demand-side and supply-side housing. Vouchers
provided to low-income persons to find available housing is an example of government
intervention in demand-side economics. Money allocated to businesses through tax
credits to build affordable housing is an example of government intervention in
supplyside economics (Laffer, 1983).

30
Governmental interaction to boost consumer spending is a key construct of the
demand-side theory (Keynes, 1936). The HCV program, implemented in 1998 with the
Quality Housing and Work Responsibility Act, is a demand-side housing program (Niver,
2016). The HCV program was designed to pay the rent of eligible households with
government vouchers. The program provides affordable housing for renters who earn
60% or less of the area median income (Johnson, 2014). Tenant-based vouchers are
currently held by approximately two million families. Renters who have vouchers are
provided the option to rent from private landlords and tax credit developments (Hsu,
2015). Private landlords have the option of accepting or rejecting voucher holders, but tax
credit developers are prohibited from rejecting voucher holders (Schwartz, 2015).
Hsu (2015) found that there has been a growing dependence on the HCV program
by tax credit developers. Researchers have discovered that the LIHTC program may be
considered more of a hybrid of supply-side and demand-side programs as tax credit
developers use voucher holders to fill their complexes (Novogradac, 2014: Edwards and
Calder, 2017). Based on studies by HUD and others that demand-side programs are more
cost-effective than the supply-side programs, Weisbach (2006) argued that the LIHTC
should have been replaced by demand-side rent vouchers. Shaw (2015) posited that tax
credit subsidies are the only way affordable housing can be built effectively.
The HCV program is a demand-side mechanism in which federal assistance is
provided directly to tenants in the form of vouchers to find available housing
(Novogradac, 2014). Quite frequently, developers of tax credit apartments seek out
voucher holders to increase their profit margins (Hsu, 2015). Hsu noted that SRI from the
demand-side program is known to be present in some of the tax credit developments, but

31
there is a lack of academic literature on the number of voucher holders who comprise the
developments. Congressional budget cuts within the HCV program are threats to
sustained profitability of tax credit developments. The funding for housing assistance in
2016 was 4.6% or $2.1 billion below the level for 2010 adjusted for inflation (Rice,
2016).
Johnson (2014) observed that the LIHTC program was launched as a housing
system that would be both financially sustainable and politically popular. However, the
problem facing tax credit developers is a growing reliance on demand-side subsidy from
voucher holders to sustain profit margins. Many tax credit development companies that
develop affordable housing do not operate profitably without government subsidies (Hsu,
2015). The HCV program continues to shrink with Congressional cuts
(Affordablehousing, 2017). The aim of the study is to determine to what extent, if any,
developers rely on these demand-side subsidies to increase profitability. A gap in
knowledge exists about the financial impact of the incremental income derived from
vouchers on tax credit developments. Further research is needed to generate answers in
these areas. The proposed cuts to demand-side housing programs are indicative of the
risks to profitability faced by tax credit developers who may rely on SRI. To avoid the
risk to profitability, tax credit developers should apply greater efforts to attract eligible
non-voucher holders within supply-side housing because LIHTC funding is not subject to
annual budget cuts (Affordablehousing, 2017).
Residents of LIHTC-funded units often receive other forms of housing support.
The exchange of reduced debt for low-income units was intended to improve the cash
flow of tax credit developments (Hsu, 2015). Indicated within the review of literature is

32
that the tax credit subsidy does not provide adequate funding to support operating
expenses. Quite often, developers seek additional subsidies, including SRI from HCV
holders. In addition to voucher holder income, state and local governments provide
income to fill the financial gap in operating costs (Johnson, 2014). The need for
additional subsidy is demonstrated as nearly 35% of tax credit properties operated below
the break-even point (Hammett, 2015).
The findings from several researchers indicated that all production subsidy
programs are more expensive than vouchers when considering both government and
tenant costs (Niver, 2017). Although more expensive, the tax credit program is not subject
to annual Congressional cuts faced by the HCV program (Affordablehousing, 2017). As
the demand-side subsidies undergo Congressional cuts, tax credit developers will need to
operate with greater efficiency and less reliance on voucher holders. Greater marketing
efforts should be applied by tax credit developers to rent their units to a greater number of
tax credit eligible tenants and rent less to voucher holders to break what could be an
increasing dependency on the declining voucher program. With the recently proposed
funding cuts to the HCV program, the argument that Weisbach (2006) raised for replacing
the tax credit housing program with the voucher program could prove questionable.
Revealed in a recent analysis of the LIHTC database was that developers targeted
the higher income group more frequently over the past twenty years (Lew, 2016).
Sustained profitability within tax credit housing requires a delicate balance between
housing low-income tenants and generating adequate income. Bratt (2016) posited that
the affordability of rental units should be driven by tenant incomes and the ability to pay.
Johnson (2014) argued that rent levels are essential for maintaining the affordability of

33
housing. The affordability component within the LIHTC program caused a strain on the
profit margins of tax credit developments, resulting in the possible reliance on the
voucher program and other additional funding streams in order to sustain profit margins
(Hsu, 2015).
Profitability
Profitability is a measure of performance, which includes a level of financial
knowledge. Financial performance has long been an indicator of a firm’s success
(Edgeman, Eskildsen, & Neely, 2015). Secondary data was used to examine firm
profitability. Arguably however, calculations using financial ratios cannot address
nonfinancial issues. Ahmad and Zabri (2016) used nonfinancial performance measures to
investigate 102 Malaysian manufacturing firms. Edgeman et al. (2015) explained that the
occurrence of nonfinancial issues is commonly due to organizational failure to implement
appropriate policies. Weaknesses due to nonfinancial issues should be addressed with
organizational policies. Profitability is the dependent variable in this study and was
measured by the ROA and gross operating profits financial ratios. Tan (2016) used ROA
as a profitability indicator to successfully study 41 Chinese banks over a period of 8
years.
A non-experimental design was used in the study to examine profitability from
secondary data as the dependent variable. With the use of a non-experimental design as a
theoretical framework, profitability was used as a dependent variable by Temtime (2016)
to examine the working capital of small and medium-sized enterprises. Multiple measures
of profitability are needed to effectively gage firm performance (Abu-Shanab,
AbuShanab, & Khairallah, 2015; Mas’adeh, Tayeh, Al-Jarrah, & Tarhini, 2015; Wang,

34
Feng, & Lawton, 2016). The researchers noted that a more comprehensive perspective of
firm performance is gained through the application of a multi-dimensional measurement
approach versus the use of a single measurement. Multiple measures of profitability have
been advocated to convey the diversity of stakeholder’s interests (Falavi & Abdoli, 2015;
Feng, Morgan, & Rego, 2015). Firm performance includes business financial and
operational performance.
Edgeman et al. (2015) argued the traditional use of financial measures to
determine firm success. Firm performance is also determined by means other than
financial measures. Lazăr (2016) found that sales growth and value-added resulted in a
positive effect on firm performance. Bhatia and Srivastava (2016) advocated the use of
market-based measures in addition to accounting measures to gauge firm performance.
SRI and NRI are the independent variables in the study. These variables were examined
to determine the degree of relationship between profitability, the dependent variable. SRI
and non-rental income were also examined to determine whether the use of these
indicators can predict profitability.
Construct Measurement
Measurement accuracy is often achieved with quantitative research, using
statistical and mathematical approaches to develop and project experimental research
findings (Campbell & Stanley, 2015; Gorard, 2015; McCusker & Gunyadin, 2015). The
confidence in quality may be built in the discerning reader through the execution of a
quality and rigorous study. The objective for researchers using qualitative research is to
probe for why and how answers pertaining to the phenomenon (Yin, 2017). Measurement
and discernment of quality in quantitative research is often evident and achieved rigorous

35
construct measurement. The next section covers the review of the measurement variables
for the constructs of SRI, NRI, and profitability.
Measures of subsidized rental income. SRI is a demand-side subsidy directly
provided in the HCV program to low-income renters (Novogradac, 2014). The LIHTC is
a supply-side subsidy that is indirectly provided for eligible renters for tax credit units
(Hammett, 2015). Renters must meet 60% or below area median income (AMI) to qualify
for the LIHTC program (Schwartz (2015).
For the study, SRI is rental assistance received by tax credit developers who house
voucher holders. The rental assistance is provided in the form of HCV payments to the
tax credit companies from local housing authorities. The income from voucher holders is
targeted by developers because higher payments are received from voucher holders and
have the effect of increasing profitability (Hsu, 2015). When voucher holders are re-
directed from the private market to tax credit housing, the effect could be that fewer
LIHTC units are available for non-voucher holders. A primary focus of the study was to
determine the degree of the financial impact that the HCV program (SRI) has on the
LIHTC program.
The value for SRI is mined from 1099-Misc documents, secondary financial data
sources. The reliability of secondary data sources was argued by Johnston (2014), who
posited that researchers could collect data in a less obtrusive manner. Dunn et al. (2015)
posited that secondary data was an efficient and effective approach in research. Tasic and
Feruh (2012) noted that secondary data might not be appropriate to address a research
question under study because the purpose of the original data collection may be different.
The secondary data sources in this study aligned with the intended purpose. SRI was

36
calculated as a percentage of total income, to potentially determine the degree of the
financial impact that the voucher program has on the tax credit housing program.
Measures of nonrental income. Although rent restrictions lower development
income, subsidy mechanisms have been put in place to support facility operations and
debt service (Schwartz, 2015). NRI represents non-rental income that is generated by the
tax credit development entity and is an independent variable. Nearly one-fourth of
LIHTC developments operate below the break-even point (Hammett, 2015). The
construct was calculated as a percentage of total revenue, and that percentage was
converted as a value. The NRI variable was mined from the income section of the
independently audited financial statements. Rents and subsidies are frequently
supplemented with NRI to sustain tax credit housing operations. Rent levels are essential
for maintaining the affordability of housing (Johnson, 2014). NRI represents additional
services and means on the part of tax credit developments to generate supplemental
income with the intent of bolstering profitability.
Measures of profitability. The accounting measures of profitability in the study
include ROA and GOP. These proxies were used to determine the degree of profitability
for tax credit development companies (Kara et al., 2015), and posited that profitability
could be measured from the accounting ratio and measure of ROA. Temtime (2015)
argued the use of GOP as an effective accounting measure. The ROA is an accounting
financial performance measurement (Kara et al., 2015). The ROA is a familiar
measurement of profitability within accounting (Faello, 2015; Kara et al., 2015; Masadeh,
2015).

37
Wang et al. (2016) and Margaretha and Supartika (2016) argued that a more
comprehensive perspective of firm performance is gained through the application of a
multi-dimensional measurement approach versus the use of a single measurement. Falavi
and Abdoli (2015) supported the use of multiple measures of profitability in conveying
the diversity of stakeholder’s interests. For the study, ratio analyses for the ROA and the
GOP were applied to measure the profitability of low-income housing tax credit
developments.
The ROA and GOP ratios are standard measures of profitability used in
accounting. The ratios are used in this study to answer the research question: What is the
relationship between SRI, NRI, and profitability of the tax credit development industry?
Both U.S. companies and non-U.S. companies use ROA as a measure of profitability.
ROA is often used as a measure of profitability by non-U.S. firms (Enqvist, Graham, &
Nikkinen, 2014). The fact that the ROA was not affected by various degrees of financial
leverage was pointed out as a weakness (Enqvist et al., 2014).
Within this study, gross operating profit (GOP) was also used as a proxy for
profitability. The degree of profitability for tax credit development companies was
determined by the GOP ratio. Temtime (2016) used GOP as a proxy for profitability to
examine the working capital of small and medium-sized enterprises. The ratio of GOP is
derived from the formula of sales minus costs of goods sold to total assets minus financial
assets, where financial assets are characterized as non-physical in nature (Enqvist et al.,
2014). The GOP reflects the measure of a firm’s operating efficiency to physical assets.

38
Reliability and validity properties of measurements. Reliability and validity
are concepts of measurement and affect the rigor of research instruments and the
trustworthiness of findings within a study (Sing, 2017). Researchers in economics and
finance have experienced a proliferation of governmental and private databases, which
has spurred the use of archival data. A decline in the use of laboratory studies and surveys
has occurred while an increase has occurred in the use of archival data (Boyd, Bergh,
Ireland, & Ketchen, 2013). Archival data for the independent variables of SRI and NRI
and the dependent variable of profitability were used in this study to answer the research
question: What is the relationship between SRI, NRI, and Profitability in the low-income
housing tax credit industry?
The use of secondary archival data sources has increased because of the expansion
of electronic databases in the fields of finance and economics (Tasic & Feruh,
2012). Researchers used fewer surveys and laboratory studies from the 1980s to the
2000s, during which an increase occurred in the use of archival data (Boyd et al., 2012).
The limitations in research design and methodology were experienced by Cotteleer and
Wan (2016) in the use of archival data to examine a phenomenon. The reliability and
validity of archival data must be ensured as greater reliance is placed on these sources. A
detailed account of reliability and validity is provided in the following section.
Reliability is characterized by dependability and consistency in the measurement
of variables (Du & Zhou, 2012). Researchers have a variety of ways to test reliability.
The test-retest reliability is used to demonstrate the stability of a test in different sessions
(Bolarinwa, 2015). Inter-rater reliability is used to evaluate different observers scoring an
event using the same instrument (Bolarinwa, 2015). The split-half reliability analysis is a

39
process of dividing question items into two groups in which scores are computed for each
half and then examining their correlation (Du & Zhou, 2012). Other conventional
reliability methods include the Cronbach’s alpha coefficient and Confirmatory Factor
Analysis (Sing, 2017). No objective statistical tests exist to evaluate the reliability and
validity of archival data sources (Du & Zhou, 2012).
Measurement validity is described as the accuracy of the instrument to perform
the intended measurements (Singh, 2017). Internal validity analysis is based on the
premise that variations in the dependent variable result from changes in the independent
variables and refer to the accuracy of measurement obtained from the research
(Bolarinwa, 2015). Internal validity is supported by analysis procedures that are credible.
Construct validity refers to the extent to which an instrument measures the constructs that
are intended to be measured (Aravamudhan, & Krishnaveni, 2016). A lower degree of
measurement credibility is ascribed to an analysis that may indicate a lower construct
validity (Tasic & Feruh, 2012).
Researchers use convergent and discriminant validity to demonstrate the
correlation of scores on one measure with other measures of the same construct
(Bolarinwa, 2015). Indicated within discriminant validity is the degree to which the test
assesses the construct to be examined (Singh, 2017). Demonstrated within convergent
validity is the extent to which a construct measure and other measures of the same
construct are consistent (Duppong Hurley, Lambert, Epstein, & Stevens, 2015).
External validity may reflect how well the results of the research can be applied to
groups and environments outside of the study (Bolarinwa, 2015). External validity often

40
depicts a broader application of the results of the study. The reliability of secondary data
sources is gauged from the credibility ascribed to the reports (Tasic & Feruh, 2012).
Financial reports, as secondary data sources, were considered reliable by Du and Zhou
(2012). Independent auditing firms verify and attest to the credibility of the financial
statements. Quality indicators for financial statements include the process of independent
auditing, attesting, and verification (Boyd et al., 2013). Although audited financial reports
are reliable sources, the reliability of the reports can be affected by computational errors,
sample errors, and missing data (Du & Zhou, 2012).
Potential errors can occur with the use of secondary data. The occurrence of
sampling error means that an equal chance of selection is not afforded to each element of
the population (Tasic & Feruh, 2012). The purpose of the original data could have been
reorganized to meet a purpose that is different from the current study (Johnston, 2017).
Threats from secondary data sources can be mitigated when researchers use a random
sampling technique and by confirming that the same measurements and units of analysis
were used in the archival data sources (Tasic & Feruh, 2012).
Boyd et al. (2013) posited that the selection of secondary data proxies should be
based on clear theoretical specifications of the constructs and variables. Boyd et al.
further stated that the literature review should contain an explanation of the fit between
the secondary data proxies and the theoretical constructs. The occurrence of missing data
is less likely as it would be with survey and observation approaches because of the
subjectivity of participants in the survey and observation techniques (Eisenhardt,
Graebner, & Sonenshein, 2016; Slater, Joksimović, Kovanovic, Baker, & Gasevic, 2017).
Encounters with missing data should result in the removal of the entire data record from

41
consideration within the study and replacing the missing record with a new complete data
record (Xu, Baldea, Edgar, Wojsznis, Blevins, & Nixon, 2015).
The use of secondary data sources, such as financial statements, has been
questioned by some scholars (Du & Zhou, 2012). Financial reports were shown as
reliable and dependable sources through literature review. Miller (2016) and Temtime
(2016) used archival financial data to conduct their doctoral studies. Johnston (2017)
noted that the reliability of financial reports is often based on that external and
independent entities have already audited, verified, and attested to the accuracy of the
financial data.
Profitability Study Methodologies
Creditors, investors, and financial analysts make decisions based on the reliability
of audited financial reports (Johnston, 2017). Researchers use a variety of methods to
measure firm performance. Profitability has been commonly examined through the lens
of quantitative research. However, few researchers appear to have used qualitative
research to explore profitability. Qualitative research was used by Gandy (2015) to
explore the strategies small business owners used to achieve profitability by the end of
the first 5 years from business establishment. However, based on an extensive review of
literature, the standard in the study of profitability generally favored by researchers
included quantitative research. Temtime (2016) used a quantitative correlation design to
examine the relationship between working capital management, policies, and profitability.
Researchers, therefore, predominantly used quantitative research, invariably using a non-
experimental design to examine profitability.

42
Transition
Section 1 reflects descriptions of the general and specific business problems, as
well as the purpose, nature, and significance of the study to provide a foundational basis
for the research. The review of prior study models may show that a quantitative research
method, correlation design, and archival data available through public entities are
appropriate to examine the relationship between SRI, NRI, and profitability. Also
included in Section 1 was a review of academic and professional literature on the topic of
inquiry and the theoretical framework, study constructs and variables, research
measurements, and methods and designs. Assumptions, limitations, and delimitations
related to the study were also discussed in Section 1.
Section 2 includes discussions regarding the role of the researcher, the rationale
and justification of research data source mining, and the research method and design
selection. Section 2 also includes a restatement of the purpose statement, specific details
on population and sampling, ethical research instrumentation, data collection, and
analysis techniques, and the validity of the study. Section 3 includes the results and
findings of the research, the application to professional practice and the implication for
social change from the possible contribution of knowledge that the study may hold for the
community of renters and the providers of low-cost housing.
Section 2: The Project
The purpose of this quantitative correlational study was to examine the
relationship between SRI, NRI, and profitability of the tax credit development industry.
In Section I, I provided an explanation of the general business problem and the specific
business problem. Section 2 includes details on conducting the study: (a) the role of the

43
researcher, (b) qualifications of participants, (c) methodology, (d) tools used in data
collection, and (e) study validity.
Purpose Statement
The purpose of this quantitative correlational study was to examine the
relationship between the independent variables of SRI and NRI and the dependent
variable of profitability as it pertained to tax credit housing developers. The targeted
population consisted of tax credit housing companies in the state of Florida. The
implications for positive social change include the contribution to knowledge, which
could advance the ability to offer affordable housing to the economically disadvantaged
in society. The study findings may also provide tax credit housing developers with an
improved understanding of the association between SRI, NRI, and profitability, which
may benefit low-income tenants. With an improved understanding of the relationship
between SRI, NRI, and profitability, the potential for positive social change could include
the development of more affordable housing by developers to meet the needs of
lowincome tenants.
Role of the Researcher
This quantitative correlational study was undertaken by analyzing archival data
from financial statements and 1099 documents. The financial statements of tax credit
documents were requested from the Florida Housing Finance Corporation, which
administers tax credit developments within the state of Florida. The 1099 documents,
which reflect annual payments to these entities, were requested from public housing
authorities in the state of Florida. These agencies are required by law to honor a public

44
records request; therefore, data collection for this study did not pose difficulties. Email
was used to request and receive financial documents.
Multiple regression analysis was used to examine the data and determine the
degree and extent of any correlations between SRI, NRI, and profitability. I (a) collected
the data for the variables, (b) organized the data on an Excel spreadsheet for the year
2014, (c) and imported the data into Statistical Package for the Social Sciences (SPSS)
quantitative analytical software. The data collection efforts involved retrieving secondary
data for the independent variables of SRI and NRI, and the dependent variable of
profitability for the 31 tax credit developments that constituted the sample population.
I participated in all facets of the study, which included (a) ensuring appropriate
storage of data, (b) ensuring data integrity, and (c) assuring confidentiality. I reviewed the
Belmont Report protocol and completed the Protecting Human Research Participants
training by the National Institutes of Health Office of Extramural Research. Statistical
analysis results were used to assess the significance of the correlation between the
dependent and independent variables (see McCusker & Gunyadin, 2015). Analysis of the
relationships was based on the degree of covariance found between the correlated
independent variables.
Researcher bias can occur in any stage of the data collection process and may
cause a misrepresentation of the study findings (Tasic & Feruh, 2012). My role as a
researcher aligned with standardized academic protocols established by Walden
University and its Institutional Review Board (IRB). The method, analysis, and
conclusions of a study are ensured with the alignment of established IRB protocols.
Implementing measures to ensure the validity and reliability in this study helped ensure

45
that data analysis was robust and rigorous. The intent of the study was to examine the
degree and extent of any positive, negative, or lack of correlation between SRI, NRI, and
profitability of tax credit developments.
Data were entered from the census population into SPSS. The research question
and hypotheses were addressed based on an analysis of the data from the correlation
testing. To avoid bias, I maintained the confidentiality of participating tax credit
companies and avoided subjectivity throughout the data analysis process (see Tasic &
Feruh, 2012).
Participants
This study did not involve the recruitment of individuals as study participants
because the aim was to collect and analyze secondary data from a sample of tax credit
developments that had a minimum of 200 units and operated in the state of Florida for the
year 2015. The eligibility criteria for the tax credit developments to merit inclusion in the
study were the following: (a) active status within the low-income housing tax credit
program in 2015 and (b) financial documents containing income statements, balance
sheets, and 1099 Misc. forms for 2015.
The strategy to access the data included requests via email to the Florida Housing
Finance Corporation and officials of public housing agencies. The clerk for the Florida
Housing Finance Corporation was contacted for a listing of low-income housing tax
credit companies. After selecting the sample firms, I requested financial statements from
the Florida Housing Finance Corporation. Public housing authority officials of the sample
firms were contacted for 1099 Misc. documents. The requested documentation from these
agencies was received either by email or regular mail. As noted by Johnson (2014),

46
Miller (2016), and Temtime (2016), archival financial reports can be used to test
hypotheses and answer research questions.
Research Method and Design
I chose a quantitative correlational design to examine the relationship between
SRI, NRI, and profitability of tax credit developments. Researchers may choose from
quantitative, qualitative, and mixed methodologies to conduct research (McKim, 2015).
Quantitative and qualitative methodologies are the two primary research methods, and
mixed-method is a combination of the two (Fetters & Molina-Azorin, 2017).
Research Method
I used a positivist philosophy and a quantitative method instead of qualitative and
mixed methods to conduct the study. Researchers who have a positivist worldview are
often inclined to use quantitative methodology in the social or natural sciences (Yin,
2017). Quantitative methodology is favored when researchers seek to examine
relationships between variables, which may include making predictions (Babones, 2016;
Onen, 2016).
The use of the quantitative methodology was justified in support of the need to
test a relationship between SRI, NRI, and profitability within the tax credit development
industry. Statistical testing may provide answers regarding the strength and degree of
positive or negative relationships, or a lack thereof, between the independent and
dependent variables. The objective for researchers using qualitative methods is to probe
for answers to why and how questions pertaining to the phenomenon, rather than
providing conclusive results from statistical or mathematical testing (Ott & Longnecker,
2015; Rahn, 2016; Yin, 2017).

47
The need for conclusive results based on experimental testing rendered the
qualitative method inappropriate for the study. Within quantitative methodology, a
hypothesis or theory is tested to explain relationships between dependent and independent
variables (Babones, 2016; Simpson & Lord, 2015). The selection of a research method is
based on the research question as well as external and internal conditions of validity
(Fetters & Molina-Azorin, 2017).
Researchers may choose to use the mixed-methods approach when ambiguity
exists within the statistical data (Fetters & Molina-Azorin, 2017). The intent of
researchers using a mixed-methods approach is to gain a better understanding of the
phenomenon by including both qualitative and quantitative methods of research
(Humphreys & Jacobs, 2015; Schoonenboom, 2017; Stockman, 2015; Venkatesh, Brown
& Sullivan, 2016). Requirements in terms of additional time and integration of skills for
the different methods rendered the mixed-methods approach inappropriate for this study
(see Mckim, 2015). Because only numerical analysis was used for this study, a
mixedmethods approach was not appropriate.
Experimental and nonexperimental are two types of quantitative designs used to
test the validity of a hypothesis (McCusker & Gunyadin, 2015). Correlational research is
included in nonexperimental designs and often involves an examination of relationships
between two or more nonmanipulated variables (Fetters & Molina-Azorin, 2017).
The research question for this study addressed the possible correlational
relationships between SRI, NRO, and profitability. A numerical interpretation of a
specified relationship is established in quantitative studies rather than an attempt to
provide an explanation of the data (McCusker & Gunyadin, 2015). Quantitative research

48
provides results from statistical or mathematical testing (Yin, 2017). The quantitative
method with a correlational design was appropriate for this study. Researchers use
quantitative methods with a correlational design to measure variables and to test
hypotheses while addressing research questions (Fetters & Molina-Azorin, 2017).
Research Design
Experimental and nonexperimental quantitative research designs were considered
for this study. The selection was guided by the purpose of the study. Experimental designs
are used to establish a cause-and-effect relationship and include random sampling and
manipulated data (McCusker & Gunyadin, 2015). The study was nonexperimental with
no (a) manipulation of variables, (b) random sampling, or (c) data to determine a cause-
and-effect relationship. The nonexperimental design was the appropriate choice for the
study because it aligned with the purpose of the study, which entailed hypothesis testing
to examine the correlation between variables.
A correlational design for testing hypotheses was useful to determine the degree
and extent of any positive or negative, or a lack thereof, the correlation between the
independent variables of SRI and NRI and the dependent variable of profitability of tax
credit developments. A correlational design is categorized as a nonexperimental design,
which also includes causal-comparative and descriptive (McCusker & Gunyadin, 2015;
Park & Park, 2016; Reio, 2016). Based on the need to examine relationships between
variables, a correlational design was appropriate for this study (see Wagner, 2017). With
the application of an appropriate research design, suitable research methods can be
applied to hypotheses in a study (Fetters & Molina-Azorin, 2017). The current focus was

49
on the research question addressing the correlation between SRI, NRI, and profitability of
tax credit developments.
Population and Sampling
The population for this study was LIHTC developments in the state of Florida for
the year 2015. Listings of LIHTC developments in the state of Florida are available
through the Florida Housing Finance Corporation. Records of financial statements and
1099 Misc. documents from Florida Housing Finance Corporation and public housing
agencies for the year 2015 were used to examine the relationship between SRI, NRI, and
profitability. Archival data were mined from the financial records of the sample
population to answer the research question. The population was appropriate for this study
because LIHTC companies use SRI and NRI as components of profitability (Johnson,
2014: Hsu, 2015). The data needed to answer the research question and test the
hypotheses were publicly available.
The sample for the study consisted of financial data for 31 tax credit housing
developments in the state of Florida for 2015. Samples must be large enough for
correlations to be established between variables, must be aligned with techniques for data
analysis, and must be representative of the population (Wagner, 2017). Random
probability sampling was used because selection bias and skewed results were minimized,
and because of the potential for high internal and external validity (see McCusker &
Gunyadin, 2015). I examined financial records drawn from the population of 1,050
records, and I used a sample of 31 tax credit developments with 200 or more units within
the state of Florida.

50
The data for SRI, NRI, and profitability were mined from income statements,
balance sheets, and 1099 Misc. forms. Researchers use effect size and value for small,
medium, and large to determine the sample size for a population (Tabachnick & Fidell,
2013). I used a power test analysis to calculate the minimum sample size required for the
study, as suggested by Greenland et al. (2016). The sample size generated by G*Power
3.10 software for conducting a one-tailed test (see Faul et al., 2009) in which α = .05,
power = .80, and effect size = .42 (large) was 31 (see Figure 1).
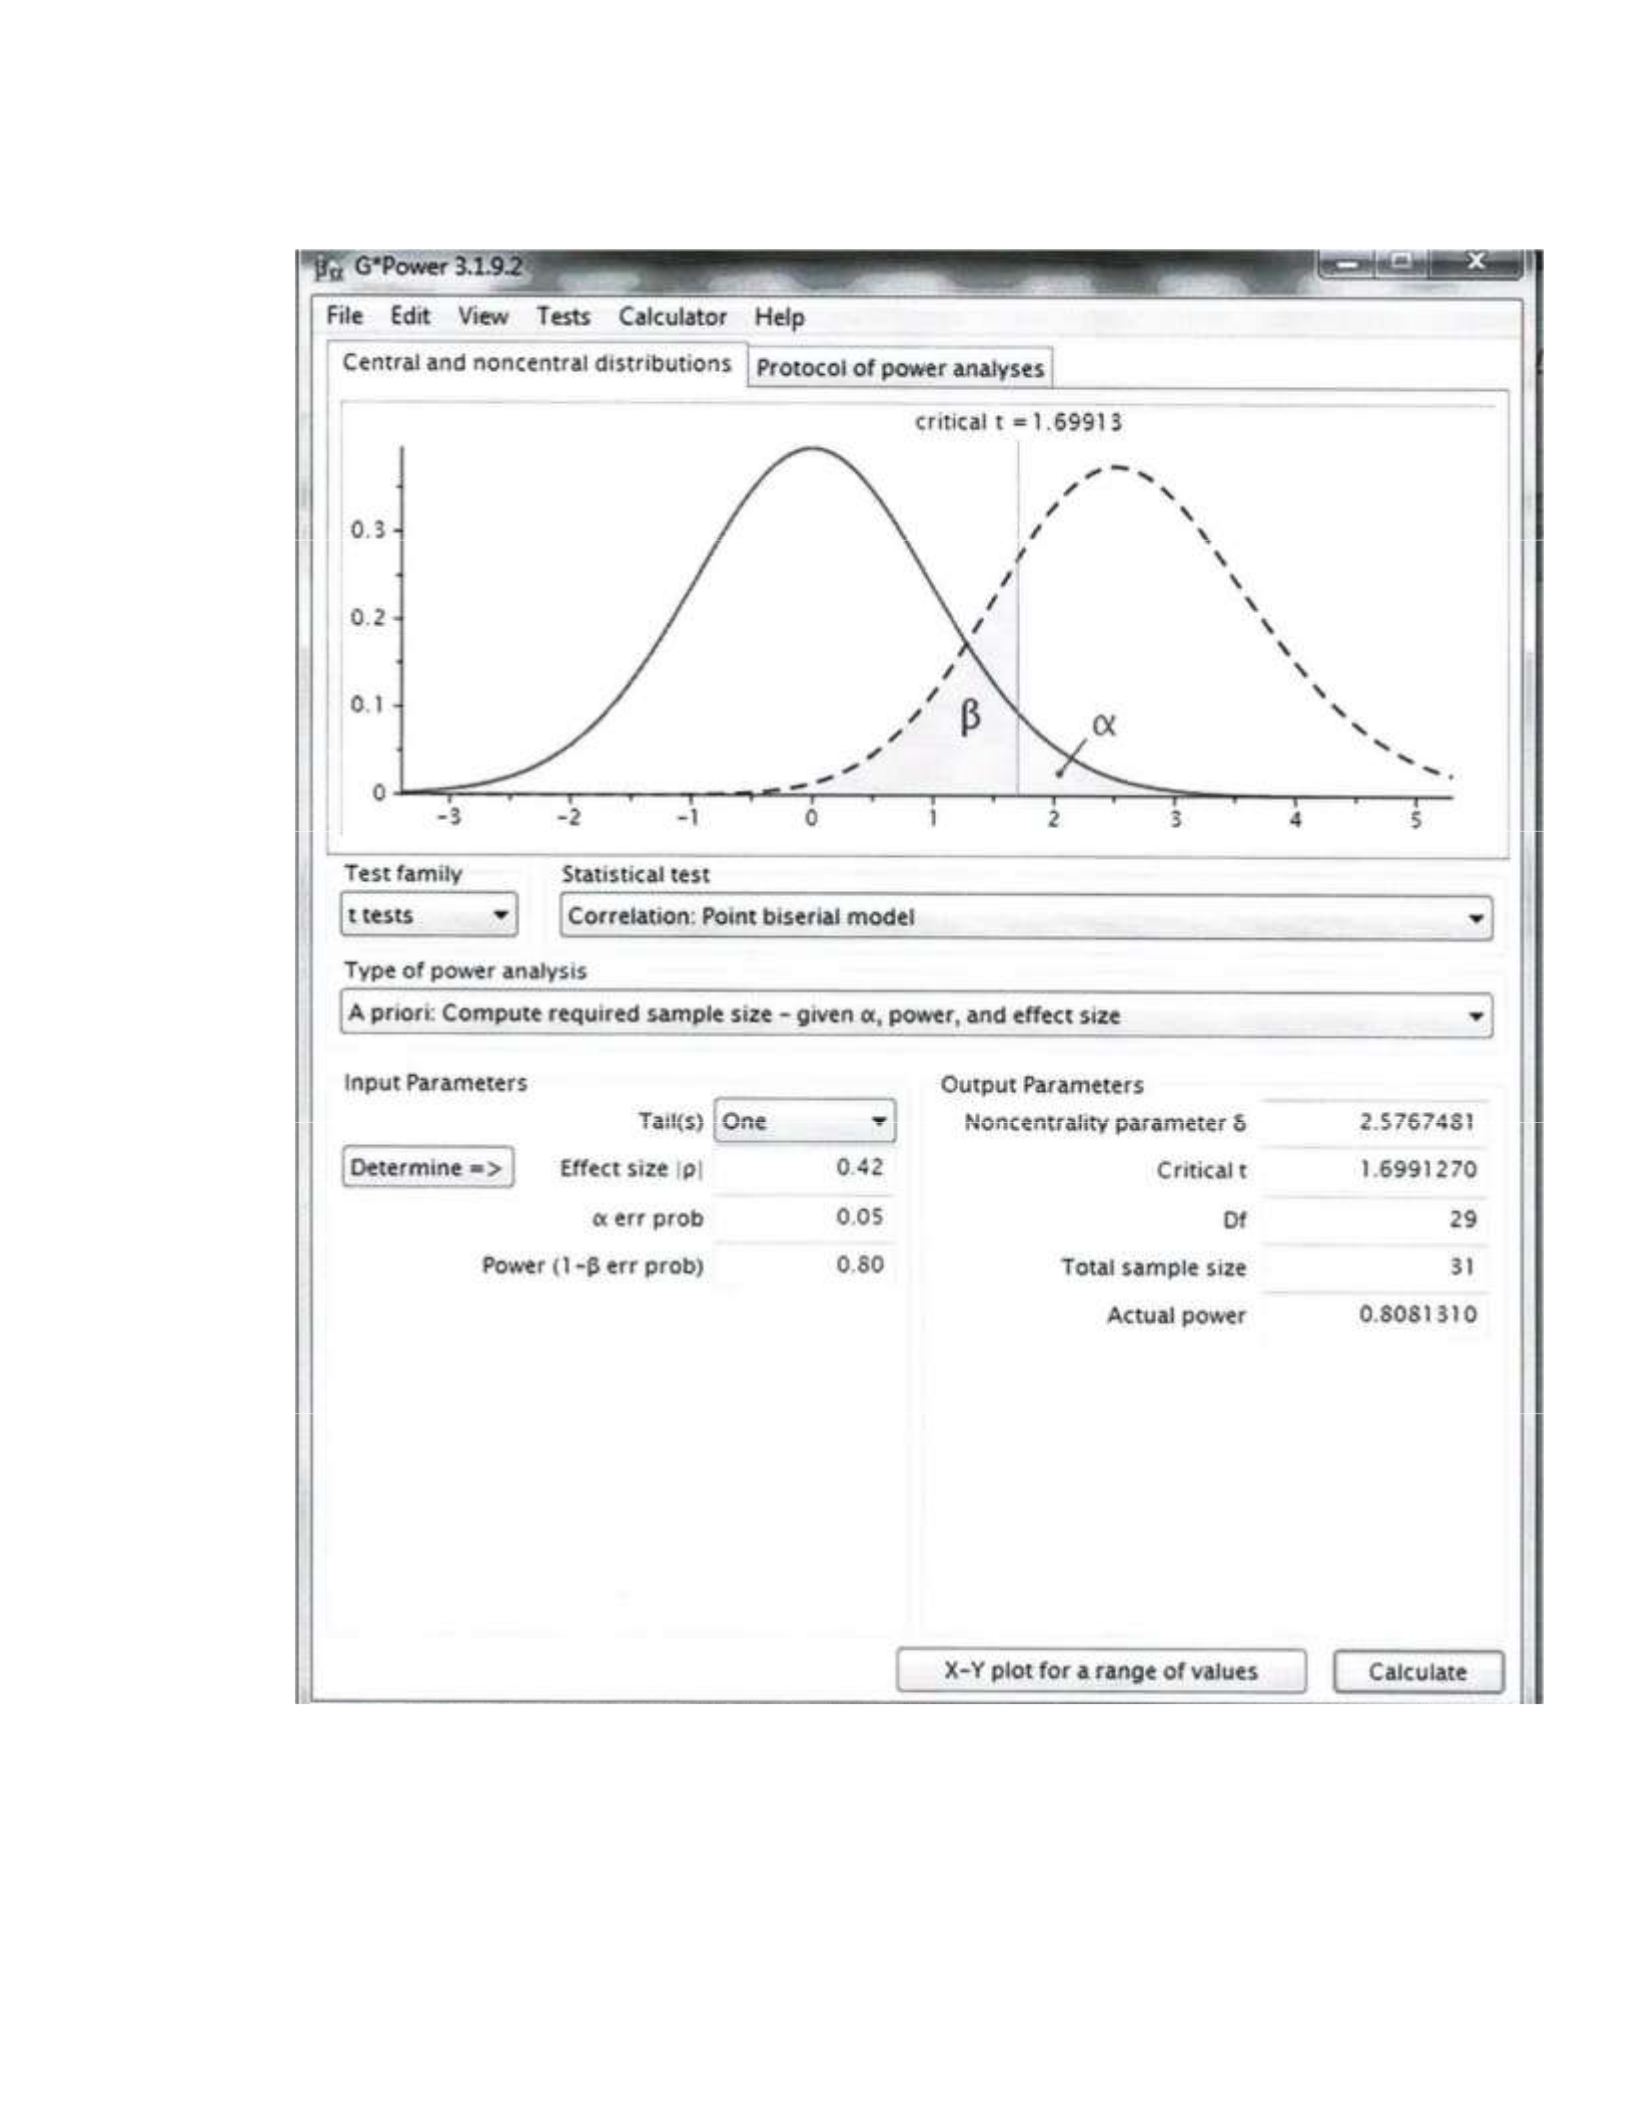
51
Figure 1. A priori sample size (N =31) generated by using the free G*Power 3.1 software
by Faul et al. (2009).

52
Ethical Research
Respect, beneficence, and justice are terms described in the Belmont
Report
(USDHH, 2015) as the essential guidelines for ethical research. Wallace and Sheldon
(2015) noted that some elements for ethical research include (a) voluntary participation,
(b) confidentiality, (c) informed consent, (d) protection of vulnerable populations, and (e)
harm protection. Voluntary participation, informed consent, and freedom to withdraw
from participation align with the imperative of ensuring respect to participants (Wallace
& Sheldon, 2015). Protection of vulnerable populations, avoidance of harm, and
confidentiality fall under the category of beneficence; informed consent and voluntary
participation refer to Justice (Wallace & Sheldon, 2015). The elements did not apply to
the study because the data were mined from secondary sources. Protection and
confidentiality of mined data was maintained through the coding of participating tax
credit companies during and after the stages of data analysis
There was no need for an agreement with representatives of tax credit
developments because all the information needed for the study consisted of publicly
available secondary data. Johnston (2017) noted that ethical considerations are minimal
with research using secondary data. Because no human subjects were directly involved in
the research, there should be minimal potential for ethical threats. However, ethical
concerns can be raised by biases in collecting and analyzing data (Tasic & Feruh, 2012).
The data were sanitized by the removal of all identifiers as all names of companies on the
tables were replaced with numerical codes. Access to all data was in the sole control of
the researcher. I saved the data on a USB drive, and it will be secured in a locked safe for

53
five years from the official completion date of the study. After this date, all text data will
be shredded, and electronic files destroyed by program deletion using the Active@
KillDisk. The IRB must approve research studies as mandated by the governing board of
Walden University to ensure compliance in accordance with the requirements of the
rubric (Walden University, 2016). Walden University’s approval number for this study
was 10-30-19-0544500. I have reviewed the Belmont Report protocol, and as required,
completed Protecting Human Research Participants training by the National Institutes of
Health Office of Extramural Research.
Data Collection Instruments
No formal instrument was used in the study as data were extracted, mined, and
analyzed from existing financial records, audited financial statements, and 1099-Misc
forms of tax credit developments from the state of Florida. Income statements and
balance sheets were used to determine ROA and GOP, proxies for the dependent variable
profitability. SRI and NRI are the two independent variables. SRI is reflected in the 1099
Misc. Forms as payments on behalf of residents from public housing agencies to tax
credit developments. NRI includes receipts for laundry, vending, and other activities
reported on the income statement. The mining of secondary data sources could uncover
new insights that may have been passed over and not examined by other researchers and
analysts. Raw data were available from the researcher upon request.
Instrumentation
Data for this study were collected from two secondary sources used in the operations of
tax credit developments: audited financial statements and 1099 forms of the sample 31
tax credit developments. Clear theoretical specifications of the constructs and variables

54
should be the basis for selecting secondary data proxies (Boyd et al., 2012). SRI, an
independent variable, is embedded within the income of audited financial statements.
Because it is not a separate income line item, the data must be mined from the 1099-
Misc forms. The form reflects the aggregate dollar value of rental assistance paid to the
tax credit developments by public housing agencies on behalf of low-income tenants.
Audited financial statements and 1099-Misc forms are accessible by the public,
and available upon request. The IRS requires each tax credit development company to
prepare and file annual financial reports that follow the Generally Accepted Accounting
Principles (GAAP) and laws governing financial and accounting reports. An independent
auditing firm verifies and attests to the credibility of the financial statements, as was true
of the records from the 31 sample tax credit housing companies.
The financial reports were appropriate sources of information to measure the
constructs of SRI, NRI, and profitability for several reasons. First, audited financial
statements and the 1099-Misc forms contain all the relevant information to operationalize
the constructs to be studied, contain answers to the research question, and can be used to
test the hypotheses. Second, from a historical standpoint, researchers are provided the
capability to examine the study within the context of events that have already occurred
(Johnston, 2017). Third, when the organization is used as a unit for analytical purposes,
financial reports provide reliable measures. Fourth, financial metrics are necessary tools
for performance evaluation. Last, creditors, investors, and financial analysts make
decisions based on the reliability of audited financial reports (Johnston, 2017).
55
Subsidized Rent Measure
SRI represents federally provided funds to households whose incomes range
between 80% and below area median income (HUD, 2015b). Tenants are provided a
payment standard based on household size from HUD with which to rent housing from
tax credit developers and private landlords. For this study, the payment to tax credit
developers on behalf of voucher holders was termed SRI. SRI is an independent variable
and was calculated as a percentage of total revenue earned by tax credit companies. The
percentage was converted to a value to test the hypotheses. Some tax credit developments
may reflect SRI, while others may not. A higher ratio would likely indicate a greater
reliance on SRI to support the operations of the tax credit development, and conversely, a
lower ratio would indicate a lesser dependence on the variable. The following ratio was
used in computing SRI:
=
Nonrental Income Measures
NRI, an independent variable, represents income that is not derived from rents
generated by the tax credit development entity such as laundry and vending. The amount
was calculated as a percentage of total revenue, and that percentage was converted to a
value. The NRI variable was mined from the income section of the independently audited
financial statement. The existence of NRI data was revealed through the examination of
income statements from the 31-sample tax credit housing companies. A higher ratio
would indicate a greater reliance on NRI to support the tax credit development, and
56
conversely, a lower ratio would indicate a lesser dependence on the variable. The
following ratio was used in computing Non-income rental value:
−
− =
Profitability Measures
The interests of stakeholders are reflected by profitability (Margeretha
&
Supartika, 2016). Multiple measures of profitability have been advocated by Falavi and
Abdoli (2015) and Feng et al. (2015) to convey the diversity of stakeholder interests. A
more comprehensive perspective of firm performance is gained through the application of
a multi-dimensional measurement approach versus the use of a single measurement
(Wang et al., 2016). Multiple calculations of measures of profitability were used in this
study to reflect the interests of stakeholders of tax credit development companies. The
ROA and GOP were used as independent variables to measure the construct of
profitability. ROA is a ratio that reflects net income to total assets (Faello, 2015), as
denoted by the following formula, to be used in this study.
( ) =
The ratio of GOP is derived from the application of sales minus costs of goods
sold to total assets minus financial assets (Enqvist et al., 2014). Financial assets are
characterized as non-physical in nature. A higher GOP reflects a better return (Ukaegbu,
2014). Because tax credit development companies fall within the service industry, gross
57
income or total revenue was used as the numerator, which is equivalent to sales minus
cost of goods sold within the industry, as reflected in the following formula:
− #
! , ! =
Table 2
Research Constructs, Variables, and Measures
Income
Non-rental Income Non-rental Income (NRI) ℎ
!
Profitability Return on Asset (ROA)
Gross Operating Profits #
Financial statements are invariably independently audited, verified, and attested as
reliable sources (Boyd et al., 2013). Research quality is indicated by the reliability and
validity of measurement instruments (Singh, 2017). Researchers are admonished to
provide controls for potential sources of error and can convey the reliability and validity
properties of the measurements (Tasic & Feruh, 2012). Reliability is characterized by
dependability and consistency in the measurement of variables (Du & Zhou, 2012).
(
−
$
)

58
Although audited financial reports are reliable sources, their reliability can be
affected by computational errors, sample errors, and missing data (Du & Zhou, 2012).
The occurrence of sampling error means that an equal chance of selection is not afforded
to each element of the population (Tasic & Feruh, 2012). To address possible sampling
errors in this study, I (a) used random sampling, (b) ensured that no changes had occurred
from the original financial statements to the date and time of retrieval and access, and (c)
personally checked for incorrect and missing entries. Missing and incomplete data were
replaced. The inclusion of all the data for a given period ensures there is no chance of
selection bias.
Measurement validity refers to the functionality of an instrument based on its
design (Tasic & Feruh, 2012). Du and Zhou (2012) postulated that there are usually no
objective statistical tests to evaluate the reliability and validity of archival data sources.
However, I (a) used prior studies to guide and follow a rigorous process to select the
secondary data proxies, (b) ensured that the theoretical specifications of the study
variables were precise, and (c) ensured that the measurement variables aligned with the
theoretical constructs.
Data Collection Technique
The aim of this correlation study was to examine the potential relationships
between the independent variables of SRI, NRI, and the dependent variable of
profitability within the tax credit housing development industry. Upon obtaining IRB
approval, I collected data through email requests for audited financial statements and
1099 forms of the 31 sample tax credit developments from the Florida Housing Finance
Corporation and from public housing authorities. The population from which the sample

59
was drawn consists of 1,050 tax credit developments within the state of Florida. A power
test analysis should be used to calculate sample size in quantitative research (Greenland
et al., 2016). The sample size generated by G*Power 3.10 software for conducting a
1tailed test in this research (Faul et al., 2009) where α = .05, power = .80, and effect size
= .42 (large) was 31 (see Figure 1, page 49).
The examination of financial documents to evaluate company performance is akin
to the data collection technique that financial analysts and investors use to analyze the
performance of publicly traded firms (Johnston, 2017). The use of secondary data
sources, such as financial statements, has been questioned by some scholars. However,
financial reports were shown as reliable and dependable sources through extensive
endorsements found in reviewing pertinent literature. Financial reports were considered
reliable data sources by Miller (2016) and Temtime (2016). Archival financial data were
used by Brown (2018) and Tannous (2018) to conduct their doctoral studies. These
researchers have considered archival data sources as reliable and dependable.
The sample of 31 tax credit companies containing 200 or more units was drawn
from a population of 1,050 developments within the state of Florida. The sample size
generated by G*Power 3.10 software for conducting a 1-tailed test in this research (Faul
et al., 2009) where α = .05, power = .80, and effect size = .42 (large) was 31 (see Figure
1). The Florida Housing Finance Corporation, a public entity charged with administering
the low-income housing tax credit program, is a repository of financial data for tax credit
developments. The initial step in collecting secondary data must be to ensure that the data
is relevant and can be used to answer the research question (Tasic & Feruh, 2012). The
second step in secondary data collection included (a) assembling and populating mined
60
data from financial documents into a Microsoft Excel Spreadsheet, (b) calculating the
measures for SRI, NRI, ROA, and GOP variables for the calendar year 2015, and (c)
importing the values of the independent and dependent variables to SPSS for analysis.
Tasic and Feruh (2012) posited that rigorous analysis is achieved when
researchers have comparable and consistent financial data across companies. Johnston
(2017) provided several arguments supporting the use of secondary data sources: (a)
secondary data are economical as researchers could bypass data collection and instrument
creation by mining data from existing sources, (b) secondary sources are reliable because
the data can be collected in a less obtrusive manner, (c) secondary data proxies are more
advantageous in minimizing biases than informant-sampling approaches, and (d)
secondary data sources are used by researchers to overcome the barriers of accessing the
research setting. Johnston (2017) argued that the use of secondary data in the absence of
human subjects minimizes biases. Identifiers were removed from documents. No
information was presented in the study that would compromise the confidentiality and
identity of the entities analyzed.
Table 3 shows an example of raw data from financial documents.
Table 3
Example of Raw Data Imported From Audited Financial Statements and 1099-Misc
Forms for Company 010
Company Code 010
2013
Variables
Values
Units
Subsidized Rental Income
$6,528
SRI
0.00
320
Non-rental Income
$306,814
NRI
0.08
61
Total Assets
$38,879,041
ROA
-0.03
Total Revenue
$3,684,939
GOP
0.10
Total Financial Assets
$2,642,728
Net Income / Loss
($1,250,331)
Data usage from archival documents will likely be beneficial in reducing the cost
of data collection, reducing the time required for data collection, and improving data
reliability (Johnston, 2017). The authors further argued that conceptual-substantive
reasons are used to justify secondary data as the information may be the only data
available for the study of a problem. For this study, the preferable method for collecting
data was to use existing data sources. The study data are secured in a locked safe for a
period of 5 years from the date of publishing this doctoral study. Table 4 shows an
example of the relevant variables.
Table 4
Example of Measures of Research Variables
Code
SRI
NRI
ROA
GOP
# of units
1
0.02
0.04
0.01
0.13
Units 336
2
0.01
0.06
(0.06)
0.15
Units 246
3
0.01
0.06
(0.05)
0.13
Units 212
4
0.01
0.06
0.02
0.18
Units 292
5
0.00
0.08
(0.03)
0.1
Units 320
6
0.01
0.08
(0.02)
0.08
Units 264
7
0.03
0.07
(0.01)
0.19
Units 300
8
0.12
0.06
(0.02)
0.09
Units 234
62
9
0.14
0.07
(0.40)
0.24
Units 360
10
0.35
0.06
0.00
0.04
Units 340
11
0.02
0.00
(0.03)
0.25
Units 376
Note. SRI = Subsidized Rental Income, NRI = Non-rental Income, ROA = Return on Asset, GOP
= Gross Operating Profit.
Table 5
Example of Calculation of Research Variables
Mined Raw Data
Values
Variables
Calculated Data
SRI
$27,905
SRI
$0.01
NRI
$237,059
NRI
$0.07
Total Revenue
$3,195,654
ROA
-$0.00
Total Assets
$21,384,996
GOP
$0.16
Total Financial
Assets
$1,572,425
Total Assets Less
Financial
$19,812,571
Net Income / Loss
-$92,351
Note. SRI = Subsidized Rental Income, NRI = Non-rental Income, ROA = Return on
Asset, GOP = Gross Operating Profit.
Data Analysis
This study was designed to answer the research question: What is the relationship
between SRI, NRI, and profitability? The central hypothesis of the study was: There is no
significant relationship between SRI, NRI, and profitability in the low-income housing
tax credit development industry. The independent variables were SRI and NRI; the
dependent variable is profitability.

63
Data quality of financial statements was confirmed through the process of
independent auditing, attesting, and verification. Independent auditors are required to
certify the reliability of financial statements (Du & Zhou, 2012). In addition to the
importance of descriptive, correlation, and regression analysis to answer the research
question and test the null hypothesis, Xu et al. (2015) noted that data editing and cleaning
are also necessary steps to confirm the quality of data.
Tabachnick and Fidell (2013) emphasized that the selection of a statistical analysis
technique is based on the type of research question, the number of variables in the
research, and the measurement scale. Data editing and cleaning are quality measures used
to verify the completeness, consistency, and accuracy of data (Xu et al., 2015).
Different approaches to data collection require different techniques for data screening
(DeSimone, Harms, & DeSimone, 2015; Lin, Shen, Chen, & Sehldon, 2017; Sleeper et
al., 2017).
The process of data cleaning included checking for inaccurate or missing
information within the dataset, such as duplicate entries, and applying corrective actions.
Any encounters with missing data resulted in the removal of the entire data record from
consideration within the study and replacing the missing record with a new complete data
record, an approach suggested by (Xu et al., 2015). Replacement or removal of outliers is
another aspect of data cleaning (Tabachnick & Fidell, 2013).
Descriptive analyses were calculated to examine raw data in a form that is easier
to understand and interpret. Descriptive statistics were used to show the mean and
standard deviation for SRI, NRI, and profitability of the sample 31 tax credit housing
developments. Data interpretation is generally facilitated using descriptive analyses

64
(Tabachnick & Fidell, 2013). Detection of data abnormalities and understanding of data
characteristics are achieved using descriptive analyses. Graphical illustrations were used
in the study. Tabachnick and Fidell (2013) advocated the use of graphical displays such as
charts, frequency tables, and scatter plots as necessary tools for visual checking of
normality. The use of the Shapiro-Wilk test is recommended to evaluate the normality
assumption (Tabachnick & Fidell, 2013).
Correlation analysis is important to determine the strength and direction of the
relationship between SRI and NRI to profitability. The ratio Return on Assets was used as
a proxy for profitability to examine the correlations between SRI and NRI. Gross
operating profit was used as the other proxy for profitability to examine the correlations
between SRI and NRI. A correlation coefficient is used to measure and establish a linear
relationship between SRI, NRI, and profitability. The correlation coefficient is presented
as values from -1 to +1 (Greenland et al., 2016). A correlation coefficient close to -1
indicates a strong negative relationship, a correlation coefficient close to +1 indicates a
strong positive relationship, and a correlation coefficient of zero indicates that no
relationship exists between the variables (Greenland et al., 2016).
Correlation analysis was also used to help test the assumptions of linearity,
normality, multicollinearity, autocorrelation, and homoscedasticity. Multicollinearity was
evaluated by examining the correlation coefficients collinearity coefficients. The bivariate
correlation between SRI and NRI was examined. An acceptable level (1,000), which
would indicate no violation of the assumption of multicollinearity. An evaluation was
completed of the normality, linearity, homoscedasticity, and independence of residuals by
examining the normal probability plot (P-P) of the regression standardized residuals and

65
the scatterplot of standardized residuals for both proxies of the independent variable. A
visual inspection of the normal probability plot was undertaken to determine whether or
not the normality assumption for ROA and GOP are violated. When the residuals are in a
somewhat straight-line pattern, the indication is assumed of the absence of serious
violations to the assumptions of normality. The scatterplot of the dependent residuals was
examined to determine the presence of a dispersed data set with limited or no visible
pattern, which would indicate no gross assumptions violation.
Features in SPSS, such as the normal probability plot (P-P) and the scatterplot, are
useful tools to examine linearity, homoscedasticity, and normality. Violations of statistical
assumptions can be addressed with the application of bootstrapping and a series of other
measures. Multicollinearity is described as a condition in which the independent variables
are highly correlated with values of .80 or higher, and singularity is described as
conditions in which the predictor variables reflect perfect correlation (Vatcheva, Lee,
McCormick, & Rahbar, 2016). SPSS output on the correlation matrix is used by
researchers to observe the correlation coefficients among the independent variables in
their examination of multicollinearity and singularity (Boyd et al., 2013). The assumption
of multicollinearity is also tested by researchers in the use of variance inflation factors
(VIF) and tolerance indices (Yu et al., 2015), and were likewise in this study as well.
The results of the study contained computations and reporting of all Variance
Inflation Factors and tolerances of variables, which measures violation of the assumption
of multicollinearity. SRI and NRI may affect profitability simultaneously, and therefore,
independently measuring the effect of each variable on profitability through only
correlation analysis would yield an incorrect result. Multiple regression analysis is a

66
statistical procedure used to test the hypothesized simultaneous relationship between the
study variables (Harrell, 2015; Montgomery, Peck, & Vining, 2015). Analysis of variance
(ANOVA) and Chi-square tests are inappropriate for the research. ANOVA and Chisquare
tests are geared toward evaluating the effects of different interventions and group
differences on the dependent variable (Wagner, 2017). The predictor variables in a study
are continuous and not categorical (Greenland et al., 2016). Lastly, the purpose of the
research was not to analyze variances among different groups, but rather to determine
whether a relationship existed between the independent and dependent variables. The
regression coefficient, R2, indicates the power of the independent variables in explaining
the variances in the dependent variable (Tabachnick & Fidell, 2013). The percentage of
variance in the data is demonstrated by the coefficient of determination within the
regression model (Harrell, 2015).
The size of the beta coefficients for the independent variables and their R2 values
were examined and statistically analyzed by using F tests to see whether they contribute
to improving the predictive efficiency of the equation. If the test shows a statistical
significance level greater than 0.05, it would indicate a lack of significant relationships
(Greenland et al., 2016). The coefficient of determination can have values ranging from 1,
which indicates a perfect negative correlation between variables to +1, which indicates a
perfect positive correlation between variables and a correlation coefficient of zero which
reflects that the variables have no relationship (Greenland et al., 2016). In this study, I
used IBM SPSS version 21 to complete the statistical analysis. The analysis and
interpretation were reflected in the study. SPSS is a commonly used statistical software in

67
academic research (Boyd, 2013; Wagner, 2017). The data were secured on a flash drive,
and a summary of findings is provided in the manuscript of this research
Study Validity
Validity related to quantitative research includes three general types:
measurement validity, design validity, and inferential validity (Singh, 2017).
Measurement validity refers to the quality of the instrument and how well the instrument
performs its intended function. There are no instruments in the current study; therefore,
measurement validity was not applicable. Data were mined from the income statements,
balance sheets, and 1099 Misc. documents of tax credit housing companies for the year
2015. Total revenue, net income, and NRI were mined from the income statements; total
assets and nonfinancial assets were derived from the balance sheet, and SRI were drawn
from the 1099 Misc. documents. The data were used to calculate and examine the
independent variables, SRI and non-rental income, and the ratios ROA and GOP, proxies
for the dependent variable profitability. Internal and external validity are included in
design validity; both are applicable to the study, as well as statistical validity.
External validity refers to how well the results of the research can be generalized
to similar groups and environments outside of the study (Mckibben & Silvia (2016).
Mckibben and Silvia (2016) described external validity as the accurate interpretation of
outcomes to reflect the truth in the objective world. The application of a random
probabilistic sampling strategy would indicate a strong external validity. The focus of
external validity is a broader application of the results of the study. Bolarinwa (2015)
posited that researchers obtain a representative sample of the target population as an
effective strategy to mitigate threats to external validity. As proposed by Mckibben and

68
Silvia (2016), potential threats to external validity should be addressed, and the results of
research should be validated. I employed a sample (N = 31) of tax credit housing
companies, which is adequate to generalize the results to a broader population.
The internal validity is applicable for quantitative and quasi-experimental designs
because it refers to approximate truth about causal relationship interferences. Internal
validity is only relevant in experimental and quasi-experimental studies in which a causal
relationship is sought (McCusker & Gunyadin, 2015). Threats to internal validity were
not applicable because the research was a nonexperimental correlation study. However,
threats to statistical conclusion validity were identified.
Inferential validity or statistical conclusion validity refers to how legitimate the
correlation is between the dependent and independent variables (Gözü, Anandarajan, &
Simmers, 2015). Threats to statistical conclusion validity are described as low reliability
of the measure, sample size, and assumptions derived from the data (Call-Cummings,
2017). Descriptive, correlation, and multiple regression are analysis tools frequently used
to mitigate the threats to validity (McCusker & Gunyadin, 2015). Type I error is defined
as the probability of incorrectly rejecting the null hypothesis, and Type II error is defined
as falsely accepting the null hypothesis (Johnston et al., 2017). Threats to statistical
conclusion validity are minimized by quantitative researchers selecting the appropriate
value of significance (p-value) for the study (Gözü et al., 2015).
Prior to conducting the statistical tests, relevant assumptions of the study were
addressed. Assumptions relevant to multiple regression tests were identified by Lopez,
Valenzuela, Nussbaum, and Tsa (2015) as (a) variables are normally distributed, (b) a
linear relationship between the dependent variable and the independent variables, (c) the

69
residual is homoscedastic, indicating the independent variables have equal variance of
errors and (d) reliability of the measurement. With the violation of any of the
assumptions, the threat to a statistical conclusion would increase. An appropriate level of
significance is helpful in minimizing the risk of a Type I error. Typically, business
researchers apply an α-value of .05 and represent what I used in the study (Greenland et
al., 2016; Sing, 2017).
Transition and Summary
Section 2 includes the purpose of the study, the role of the researcher, and the
research method and design selection. Section 2 also includes details of the population
and sampling, ethical research, instrumentation, data collection and analysis techniques,
and the validity of the study. The rationale for selecting a quantitative research method,
correlation design, and archival data to examine the relationship between SRI, NRI, and
profitability was also addressed in Section 2. Section 3 includes a discussion of the results
and findings of the research and the application to professional practice. The implications
for positive social change and recommendations for action are also included in Section 3.
Section 3: Application to Professional Practice and Implications for Change
Introduction
The purpose of this quantitative correlational study was to examine the
relationship between SRI, NRI, and profitability among LIHTC companies in the state of
Florida for the year 2015. I collected financial data from the Florida Housing Finance
Corporation and from public housing authorities regarding the relationship between SRI,
NRI, and profitability. The research question for this study was the following: What is the

70
relationship between SRI, NRI, and profitability? The hypotheses for the study were as
follows:
H0: There is no relationship between SRI, NRI, and profitability.
H1: There is a relationship between SRI, NRI, and profitability.
The independent variables were SRI and NRI. The dependent variable of profitability was
measured by ROA and GOP.
Two measures of profitability were used within the regression model
computations. Based on the regression results, I failed to reject the null hypothesis, which
indicated that a significant relationship did not exist between SRI, NRI, and profitability.
Tax credit developers may gain knowledge in the identification of appropriate income
streams that maximize profitability from the results of this study. Included in this section
are (a) the presentation of findings, (b) application to professional practice, (c) positive
social change implications, (d) recommendations for action and additional study, (e)
reflection of my research experience, and (f) conclusion of the study.
Tests of Assumptions
The assumptions necessary to run multiple linear regression include
nonmulticollinearity, normality, linearity, homoscedasticity, and independence of
residuals. The results of the tests of assumptions are presented in this section.
Multicollinearity
Vatcheva et al. (2016) described multicollinearity as a condition in which the
independent variables are highly correlated. The independent variables of SRI and NRI
were examined with collinearity statistics to determine the correlation coefficients and the
variance inflation factor. Researchers use correlation coefficients among independent
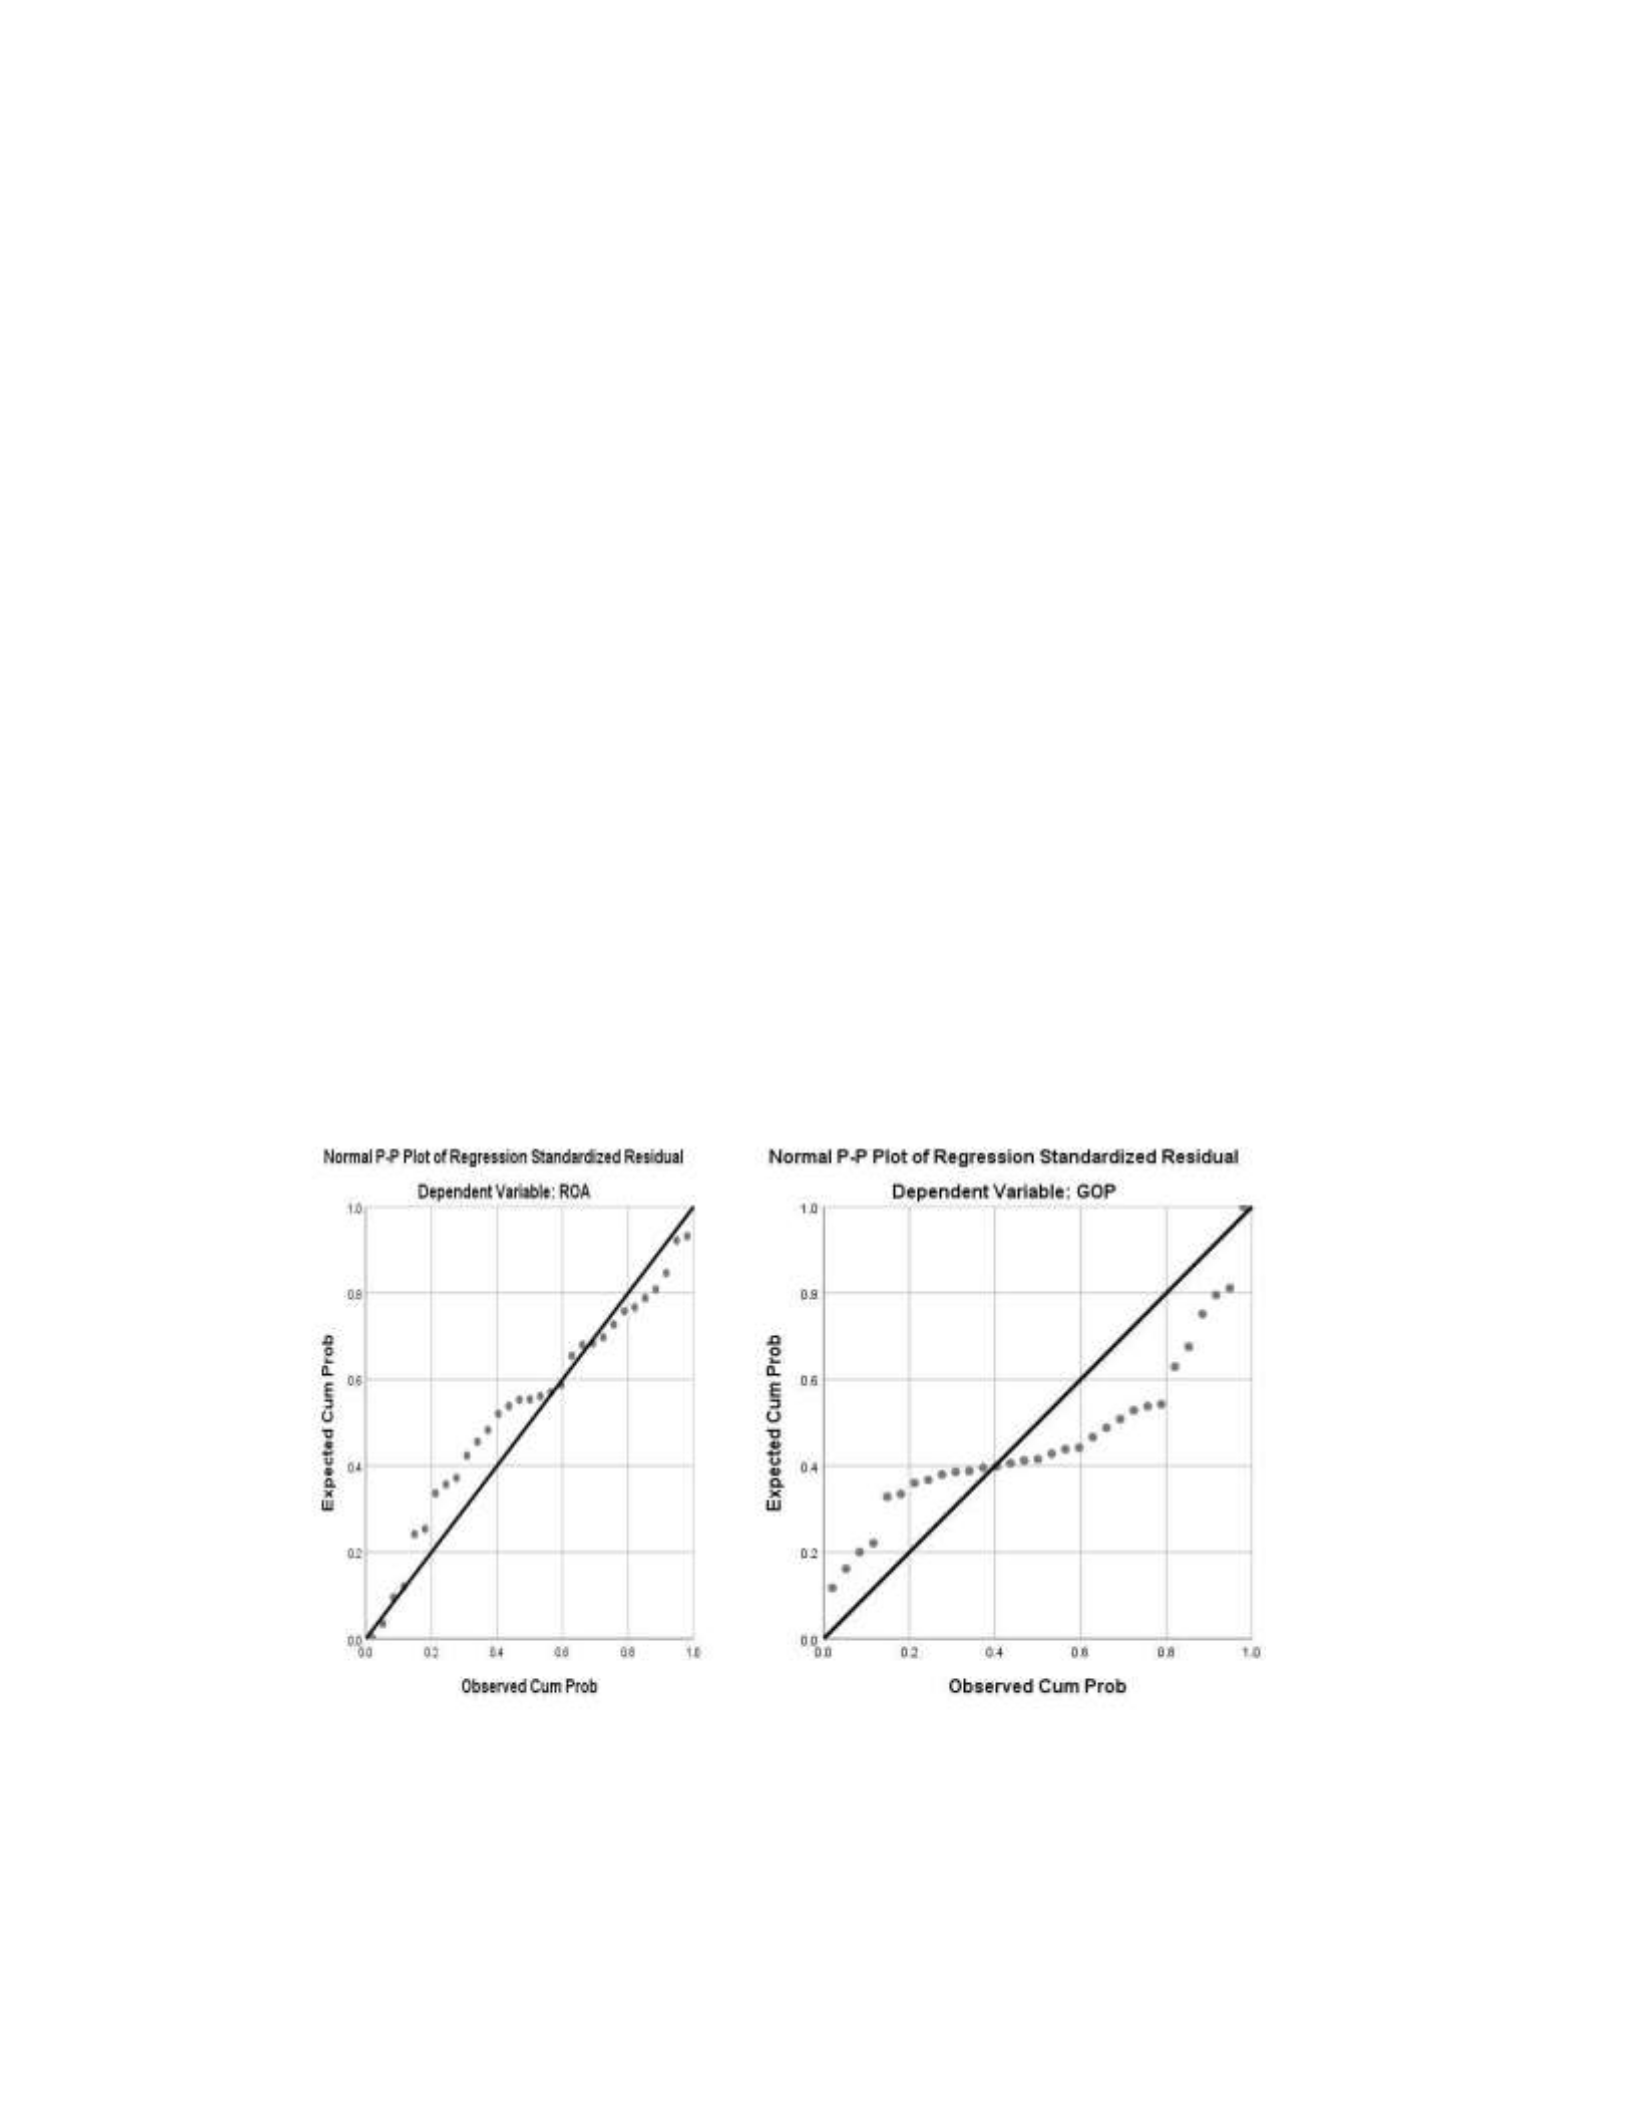
71
variables to examine multicollinearity (Boyd et al., 2013). The assumption of
nonmulticollinearity is also tested using variance inflation factors and tolerance indices
(Yu et al., 2015). Multicollinearity was evaluated by examining the correlation coefficient
collinearity statistics. The bivariate correlation between SRI and NRI was acceptable
(1.000), indicating no violation of the assumption of multicollinearity. The variables also
reflected a tolerance value of 1.000 and a variance inflation factor value of
1.000.
Normality, Linearity, Homoscedasticity, and Independence of Residuals
An evaluation was completed for the normality, linearity, homoscedasticity, and
independence of residuals by examining the normal probability plot (P-P) of the
regression standardized residuals and the scatterplot of the standardized residuals for both
proxies for the dependent variable, as shown in Figure 2.
Figure 2. Normality P-P plot for variables predicting ROA and GOP.
A visual inspection of the normal probability plot in Figure 2 indicated the
normality assumptions for ROA and GOP were not violated, which meant the multiple
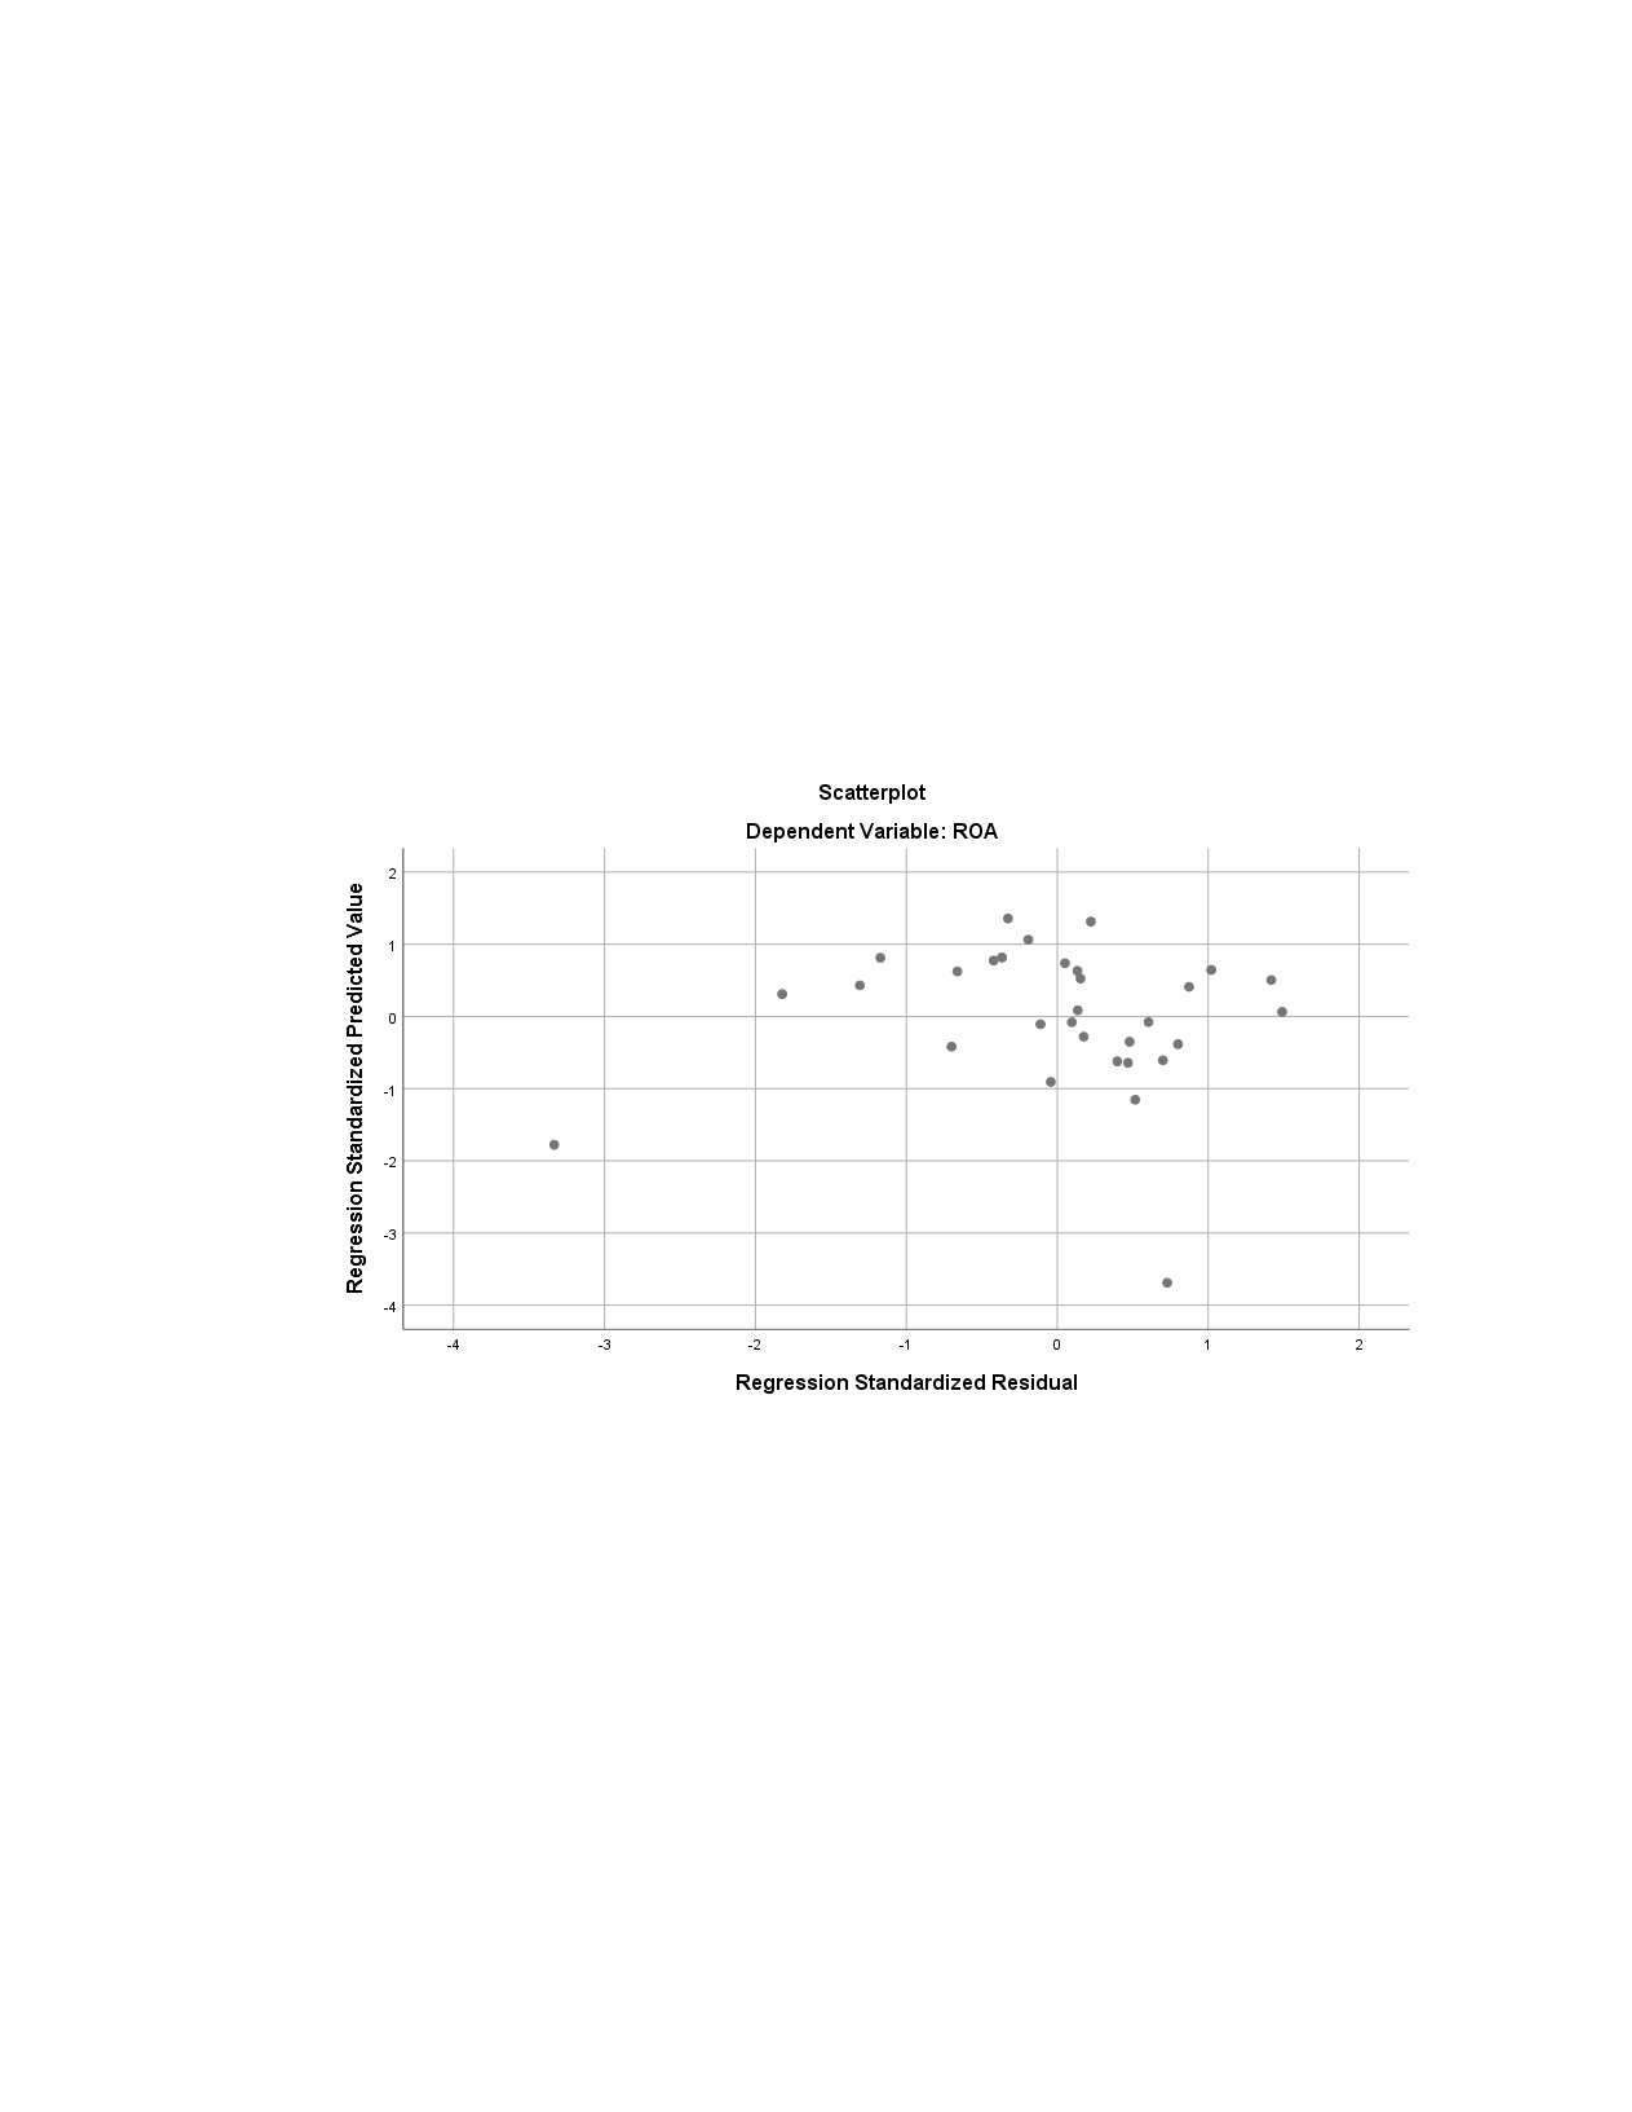
72
linear regression fit test was appropriate for the study. The figures show that the residuals
followed a somewhat straight line, indicating no serious violations of the assumptions of
normality. The scatterplot of the standardized residuals was also evaluated. A review of
the scatterplot of the dependent residuals revealed a dispersed data set with limited or no
visible pattern, which meant the linear regression model was appropriate for the data. No
gross assumption violations were detected because there was a lack of clear patterns in
the scatterplot of standardized residuals (see Figures 3, 4, and 5).
Figure 3. Scatterplot of regression residuals for ROA (homoscedasticity test).
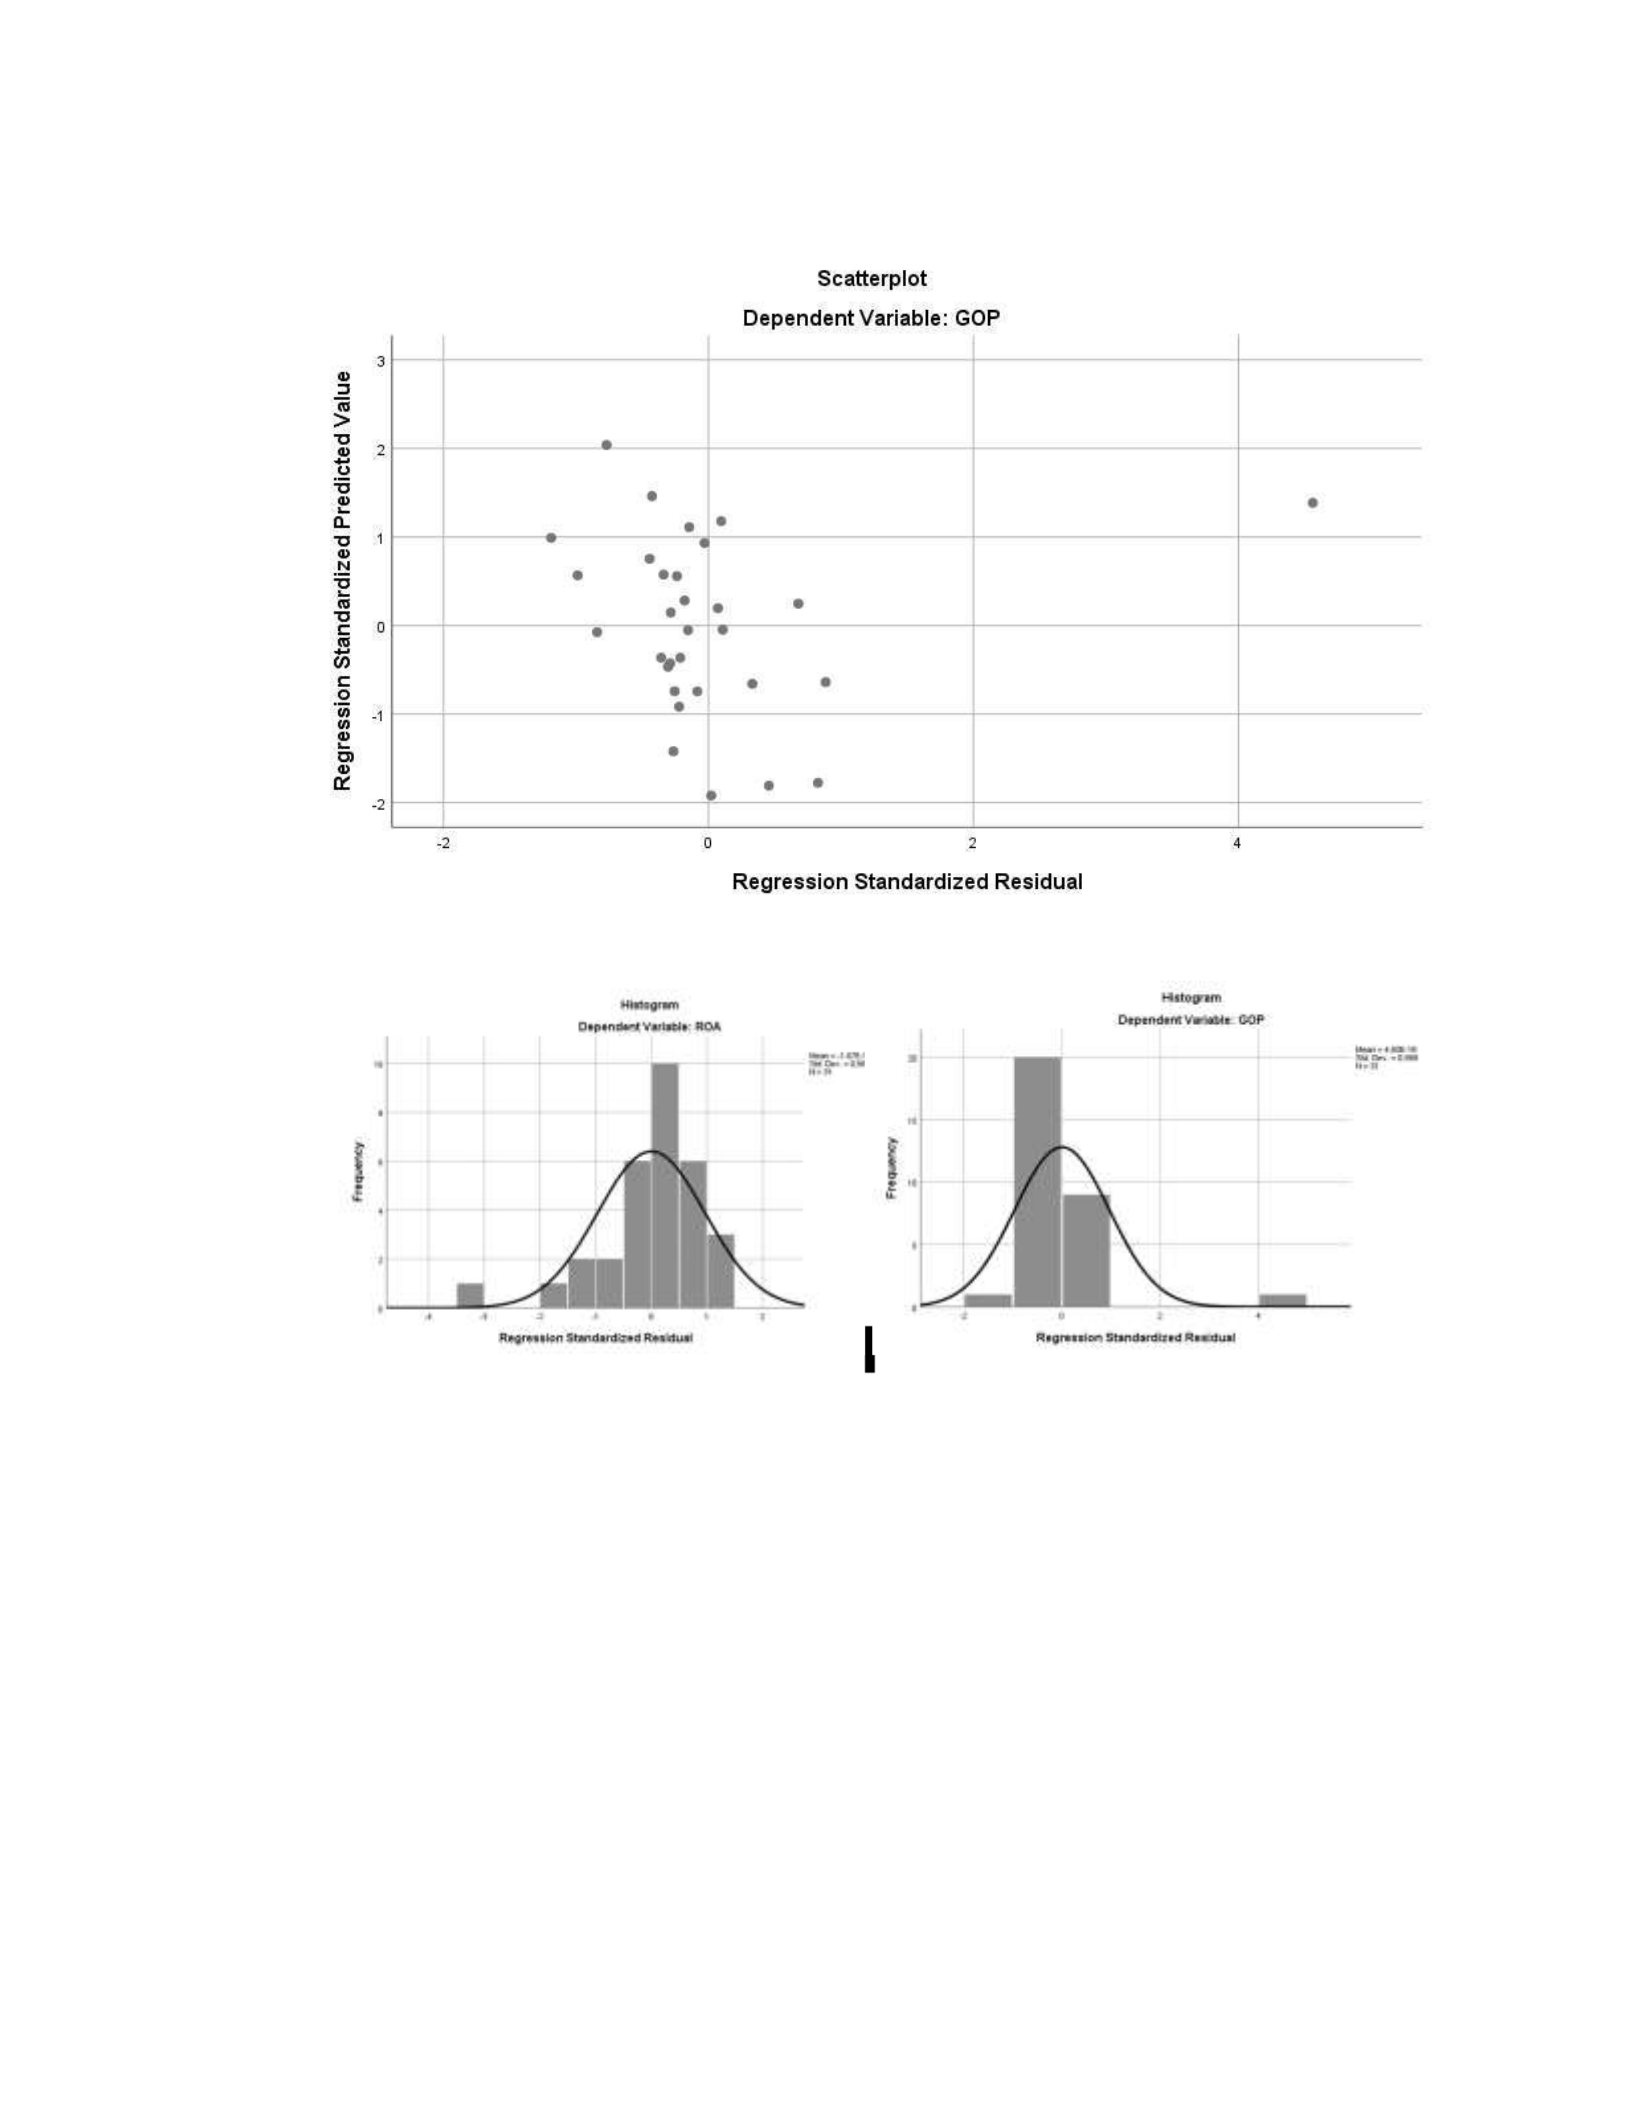
73
Figure 4. Scatterplot of regression residuals for GOP (homoscedasticity test).
Figure 5. Histogram (test of normally distributed residuals).
Presentation of the Findings
Pearson correlation and linear regression were the statistical tests applied for data
analysis. The independent variables were SRI and NRI. The dependent variable was
profitability, as measured by ROA and GOP. The first correlation test addressed whether
there was a significant relationship between SRI and ROA. The second correlation test
addressed whether there was a significant relationship between NRI and ROA. The third
74
correlation test addressed whether there was a significant relationship between SRI and
GOP. The fourth correlation test addressed whether there was a significant relationship
between NRI and GOP.
The alternative hypothesis stated that there was a relationship between SRI, NRI,
and profitability. The null hypothesis stated that there was no relationship between SRI,
NRI, and profitability. Descriptive statistics and correlation analysis were applied to
assess the data before testing the hypothesis with multiple regression analysis. The
descriptive statistics for the independent variables (SRI and NRI) and the proxies for the
dependent variable profitability (ROA & GOP) are presented in Table 6. Figure 3 and
Figure 4 scatterplots depict the linearity between each independent variable and the
dependent variable.
Descriptive Data of Independent and Dependent Variables
Descriptive analyses are used to facilitate data interpretation (Rovai et al., 2013).
Descriptive statistics in Table 6 shows the mean (M) and the standard deviation (SD) for
all 31 tax credit housing development companies.
Table 6
Descriptive Statistics for the Independent and Dependent Variables
Variable
N
M
SD
Variance
SRI
31
.06
.07
.004
NRI
31
.06
.03
.001
ROA
31
-.02
.04
.002
GOP
31
.18
.10
.011
75
The ROA and the GOP models, proxies for profitability, were used to test the
hypotheses. Two correlations were tested to examine the ROA model. There was a weak
negative correlation between SRI and ROA, r(30) = -.368, that was not statistically
significant, p = .042. The results indicated that the null hypothesis could not be rejected,
and that support was not found for the alternative hypothesis; therefore, results indicated
no significant relationship between SRI and ROA.
The correlation between NRI and ROA was -0.119, indicating a weak negative
correlation that was not statistically significant, p = .525. The results indicated that the
null hypothesis could not be rejected, and grounds were not found for the alternative
hypothesis; therefore, results indicated no significant relationship between NRI and ROA.
The multiple linear regression model was performed to test whether ROA (dependent
variable) could be predicted from SRI and NRI (independent variables). NRI and SRI
account for approximately 14.8% of the variability in ROA (see Table 7), but the
regression model was not significant, F(2,28) = 2.426, p = .107 (see Table 8). Therefore,
support for the alternative hypothesis was not found, and the null hypothesis could not be
rejected. NRI and SRI were not significant predictors of profitability as measured by
ROA. SRI (independent variable) was not significant in the estimated model coefficients
.045 > .0125; NRI (independent variable) was not significant .525 > .0125 (see Table 9),
indicating no need to conduct a separate regression to determine whether one or both
could better predict ROA.
Table 7
Regression Model for Return on Assets
Model R R2 Adj R2 Std Err
76
ROA/NRI,SRI .384 .148 .087 .037
Table 8
ANOVA Analysis of Regression Model for Return on Assets
Model
SS
df MS
F
p
ROA/NRI,SRI Regression
.007
2 .003
2.426
..107
Residual
.040
28 .001
Total
.047
30
Note. Dependent variable: ROA, Predictors: NRI, SRI.
Table 9
Regression Test Analysis of Return on Assets (N = 31)
Variable
B
SErr
Beta
t
p
Constant
.002
.016
0.151
.881
SRI
-.219
.104
-0.366
-2.095
.045
NRI
-.134
.210
-0.111
-0.638
.529
Note. Dependent Variable ROA.
Two correlations were tested to examine the GOP model. The results indicated
that the correlation was neutral to negative between SRI and GOP, r(30) = -.061, p =
.738). The correlation between NRI and GOP was moderately positive, r(30) = .401, and
not statistically significant, .025 > .0125. The results indicated that the null hypothesis
could not be rejected, and support was not found for the alternate hypothesis; therefore,
results indicated no significant relationship between NRI and GOP. The multiple linear
regression model was performed to test whether GOP (dependent variable) could be
predicted from SRI and NRI (independent variables). NRI and SRI account for
77
approximately 16.4% of the variability in GOP (see Table 10), but the regression model
was not significant, F(2,28) = 2.747, p = .081 (see Table 11). Therefore, support to accept
the alternative hypothesis was not found, and the null hypothesis could not be rejected.
NRI and SRI were not significant predictors of profitability as measured by GOP, as
shown in Table 12.
Table 10
Regression Model for Gross Operating Profits
Model R R2 Adj R2 Std Err
GOP/NRI,SRI .405 .164 .104 .100
Table 11
ANOVA Analysis of Regression Model for Gross Operating Profits
Model
SS
df MS
F
p
GOP/NRI,SRI Regression
.055
2 .028
2.747
.081
Residual
.282
28 .010
Total
.338
30
Note. Dependent variable: ROA, Predictors: NRI, SRI.
Table 12
Regression Test Analysis for Gross Operating Profits (N = 31)
Variable
B
SErr Beta
t
p
Constant
0.093
.044
2.140
.041
SRI
0.088
.277
.055
.317
.754
NRI
1.290
.557
.400
2.316
.028
Note. Dependent variable GOP.

78
The results of the correlation tests and regression models are statistically
presented to answer the research question pertaining to supply-side and demand-side
economic theories. However, the results verified that there was no relationship between
SRI, NRI, and profitability within the tax credit housing industry. Therefore, SRI, NRI
(independent variables) cannot predict profitability (dependent variable), and the null
hypotheses failed to be rejected.
The purpose of this study was to examine the influence of demand-side and
supply-side practices on profitability within tax credit housing developments in the State
of Florida. The supply-side and demand-side programs, as the theoretical framework of
this study, are used to explain how SRI and NRI affect profitability. The central concept
in the framework is that tax credit housing developers achieve profitability through
effective management of SRI and NRI. The application of the supply-side and
demandside economic theories to this study yielded a deeper understanding of the
interrelationships between SRI, NRI, and profitability.
The concept held within the supply-side theory, in which economic activity is
spurred by tax reduction to the supplier, is that profitable operations will be derived from
the governmental infusion of cash in the form of tax credits to affordable housing
developers. The subsidy, which finances a significant portion of building costs, reduces
debt service, and effectively increases income and profitability. However, reduced income
because of rent restrictions, which make the developments affordable, may negatively
affect profitability. The NRI from vending, laundry, and other activities have the effect of
increasing net income, and ultimately, profitability. The demand-side theory proponents
have held that profitability is gained through a governmental infusion of cash in the form

79
of vouchers to renters of affordable housing. The increase in rental income increases net
income, and effectively increases profitability.
The regression results showed that the SRI, independent variable, is not a
significant predictor of ROA, a proxy of profitability, the dependent variable. The lack of
a significant relationship between the SRI and ROA means that the HCV program is not a
major determinant of profitable operations within the tax credit housing program. Instead,
tax credit subsidy and LIHTC program rents are used to sustain profitable operations that
are based on the extant literature (Johnson, 2014; Shaw, 2015; Sullivan & Anderson,
2017).
NRI is also not a significant predictor of ROA. The lack of a significant
relationship between NRI and ROA means that ancillary income from vending, laundry,
and other activities associated with development operations is not a major determinant of
profitable operations within tax credit housing operations. This means that the tax credit
subsidy and program rents are used to sustain profitable operations, which aligns with the
extant literature (Johnson, 2014; Shaw, 2015; Sullivan & Anderson, 2017). The literature
review reflects that IHTC subsidy and rents support profitable operations of tax credit
developments.
The regression also indicated that the SRI and NRI combined are not significant
predictors of GOP. The lack of a significant relationship between SRI and GOP means
that the HCV program is not a major contributor to profitability as measured by the GOP.
The tax credit subsidy and program rents sustain tax credit operations, which aligns with
the extant literature (Johnson, 2014; Shaw, 2015; Sullivan & Anderson, 2017).

80
The ROA is represented as a percentage of net income divided by total assets. A
significant portion of buildings was paid from supply-side tax credits, net income, and
profitability increase because of reduced debt service costs (Prizio, 2015). The GOP ratio,
as a proxy for profitability, is represented as a percentage of total revenue divided by total
physical assets of the tax credit development. The GOP aligns with supply-side theory
because it reflects the measure of a firm’s operating efficiency to physical assets (Enqvist et
al., 2014). SRI and NRI are components of total revenue, yet the results of findings
indicate that the independent variables are not significant predictors of profitability
measured by GOP.
Applications to Professional Practice
Based on the findings of this study, it appeared that SRI has no effect on
profitability as no significant relationship between SRI and profitability were observed
from the analysis. Tax credit developers use the supply-side program of the tax credit
subsidy and program rents to sustain profitable operations (Johnson, 2014; Shaw, 2015;
Sullivan & Anderson, 2017). Various layers of income streams are used to support the
supply-side program of LIHTC, including the demand-side program of HCVs (HSU,
2015; Johnson, 2014; Novogradac, 2014). SRI is known to be present in many tax credit
developments, providing additional income for operations (Novogradac, 2014).
Further, NRI was found to have no effect on profitability because there was no
significant relationship between NRI and profitability. In examining the regression
analysis, there were no significant relationships between NRI and the two proxies for
profitability, ROA and GOP. NRI could not be used as a predictor of profitability. As a
component of the supply-side program, which includes ancillary services such as laundry

81
and vending, NRI contributed more to the profitability of tax credit operations than SRI,
based on the findings of the study. SRI derived from the HCV program was found to be a
dwindling income stream because of Congressional budget cuts (Affordablehousing,
2017).
As a result, tax credit developers could improve the stability of their income
streams by targeting program eligible tenants because low-income housing tax credits are
not subject to annual Congressional budget cuts (Hammett, 2015). NRI, as part of
supplyside operations, is ancillary to program rental income. Tenants who live in the
LIHTC units who are not recipients of SRI are likely to continue using laundry and
vending services because they are not affected by subsidy cuts. The identification of
alternative streams of income for tax credit development operations should serve to
encourage researchers in their work.
Implications for Social Change
The implications for positive social change include the potential for tax credit
developers to provide jobs, benefits, and training to workers. Communities may benefit
from increased economic activity and capital improvements through the construction of
new and rehabilitated housing developments. Society may benefit from this study as
lowincome renters move from sub-standard living conditions to better affordable housing
opportunities
Another implication for positive social change from this study is the potential for
tax credit developers to use incremental income in ways that benefit the poor. The
incremental income component is found within the hybrid relationship between LIHTC
and the HCV program (HSU, 2015; Novogradac, 2014). The rate for rental income

82
derived from eligible LIHTC tenants is less than the HCV program (Novogradac, 2014).
Tax credit developers and public housing officials may be informed of ways to decrease
rent burdens, in which tenants pay more than 30% of monthly income in rent and utilities
(Bratt, 2016; HUD, 2015b; JCHS 2015).
Recommendations for Action
Tax credit developers may benefit from this study by identifying sustainable
income streams that support profitability. Many tax credit developers have considered
income from Section 8 vouchers as a preferred source of income and have targeted
renters from this demand-side program to fill their complexes (Hsu, 2015; Novogradac,
2014). However, rental income from eligible supply-side tenants was designed to sustain
profitable operations (Johnson, 2014; Shaw, 2015; Sullivan & Anderson, 2017).
Tax credit developers can benefit by identifying which income streams have the
greatest sustainable effect on profitability. I recommend that steps are taken by tax credit
housing developers to identify sources of income that offer sustainable profitability. It is
also important to identify which streams of income may pose the greatest risk to
profitability in the long run. Based on the findings of the study, SRI and NRI are not
significant predictors of profitability as measured by ROA and GOP.
I further recommend that tax credit developers focus their marketing efforts on
attracting traditional tax credit eligible tenants. Section 8, tenant income, as represented
by SRI, was present in 87% of the tax credit developments within the study. As indicated
by the regression analysis, however, no significant relationship existed between the
income generated from the HCV program and profitability, nor could the independent
variable be used as a predictor of profitability. From the regression analysis, NRI, which

83
includes income from vending, laundry, and other ancillary activities, held no significant
relationship between ROA and GOP, nor could it be used as a predictor of profitability.
Recommendations for Further Research
Future researchers who examine affordable housing data and practices may
benefit from the findings of this study by gaining an understanding of the relationship
between SRI, NRI, and profitability. Examination of potential income sources may
initially appear beneficial for profitable operations but could pose a risk depending on the
stability of the funding sources. Funding sources that are subject to annual reductions or
termination should be viewed as a risk to sustainable operations.
I also recommend further research from the perspective of a qualitative study. A
qualitative study would be required to explore how and why developers use incremental
income in their operations. Exploring income streams may lead to further insights into the
operational interplay between demand-side and supply-side programs.
Reflections
After learning the difference between research methods, my decision to use a
quantitative approach rather than a qualitative approach became quite clear. The purpose
of examining the effect of different income streams on profitability within tax credit
housing required a quantitative method. The process of acquiring data from various
public housing agencies posed the greatest challenge. A surprising discovery within my
research was that the ROA ratio, one of the proxies for profitability, yielded an
overwhelming majority of negative results because net income was negative. The lesson
learned is that data are not always what is expected by the researcher. Although the GOP
ratio, the other proxy for profitability, was positive, I was surprised that the results were

84
different from what I had anticipated. Profitability was not significantly affected by the
two independent variables of SRI and NRI. From a business standpoint, tax credit
developers use various layers of income, including SRI and NRI, to sustain operations.
The tax credit housing industry is comprised of public-private partnerships in which a
variety of funding sources is often required.
I found that gaining a working knowledge of the SPSS statistical software was
both interesting and challenging. The application of a quantitative methodology requires
the use of various statistical tests that include correlation and regression. A degree of
intense study was personally needed for me to understand the tests and then to properly
write the interpretation. Confidence was gained from using the SPSS software and
generating reports. In the beginning, my journey seemed endless and appeared enormous,
but through persistence and perseverance, milestones were reached, and the goal was
accomplished.
Conclusion
The purpose of this study was to examine relationships between SRI, NRI, and
profitability. The effect of SRI and NRI, independent variables, to predict ROA and GOP,
proxies for profitability, were examined within the research. This study was comprised of
a sample of 31 tax credit housing developments within the state of Florida for the year
2015. Within Section 3, the results of descriptive correlation and regression analysis on
the relationship between SRI, NRI, and profitability were provided. The findings
confirmed that SRI and NRI are not significant predictors of firm profitability. Tax credit

85
housing developers should consider the results of this test in assessing the viability of
different income streams.

86
References
Abu-Shanab, E., Abu-Shanab, R., & Khairallah, M. (2015). Critical success factors for
ERP implementation: The case of Jordan. International Arab Journal of
eTechnology, 4(1), 1-7. Retrieved from
https://pdfs.semanticscholar.org/ee4b/cf23b9c6b0300c4a0eb2be1c74a35642298a.
pdf
Affordablehousing Online. (2017). Trump-Carson housing budget cut estimator.
Retrieved from https://affordablehousingonline.com/FY18-HUD-Budget-Cuts
Ahmad, K., & Zabri, S. M. (2016). The application of non-financial performance
measurement in Malaysian manufacturing firms. Procedia Economics and
Finance, 35, 476-484. https://doi.org/10.1016/S2212-5671(16)00059-9
Al-Thani, T., & Semmar, Y. (2017). An exploratory study of teachers’ perceptions of
prosocial behaviors in preschool children. International Journal of Educational
Development, 53, 145-150. https://doi.org/10.1016/j.ijedudev.2017.01.005
Aravamudhan, N. R., & Krishnaveni, R. (2016). Establishing content validity for new
performance management capacity building scale. IUP Journal of Management
65 Research, 15(3), 20-43. Retrieved from http://www.iupindia.in
Arkkelin, D. (2014). Using SPSS to understand research and data analysis. Valparaiso,
IN: Psychology Curricular Materials.
Babones, S. (2016). Interpretive quantitative methods for the social sciences. Sociology,
50, 453-469. https://doi.org/10.1177/0038038515583637
Backhouse, R. E. (2015). Samuelson, Keynes, and the search for a general theory of
economics. Italian Economic Journal,1, 139-153.

87
https://doi.org/10.1007/s40797-015-0009-4
Bhatia, S., & Srivastava, A. (2016). Working capital management and firm performance
in emerging economies: Evidence from India. Management and Labor Studies,
41(2), 71-87. https://doi.org/10.1177/0258042X16658733
Bolarinwa, O. A. (2015). Principles and methods of validity and reliability testing
questionnaires used in social and health science researches. Niger Postgrad Med J
[serial online] 2015. Retrieved from
http://www.npmj.org/text.asp?2015/22/4/195/173959
Bouzenita, A. I., & Boulanouar, A. W. (2016). Maslow’s hierarchy of needs: An Islamic
critique. Intellectual Discourse, 24(1), 59-81. Retrieved from
https://www.researchgate.net/publication/305552656_Maslow's_hierarchy_of_ne
eds_An_Islamic_critique
Boyd, B. K., Bergh, D. D., Ireland, R. D., & Ketchen, D. J. (2013). Constructs in strategic
management. Organizational Research Methods, 16, 3-14.
https://doi.org/10.1177/1094428112471298
Bratt, R., & Lew, I. (2016). Affordable rental housing development in the for-profit
sector: A review of the literature. Cityscape, 18, 229-262. Retrieved from
https://www.jstor.org/stable/26328285
Brown, L. R. (2018). Relationship between federal compliance complexity and internal
control infraction (Doctoral dissertation, Walden University). Retrieved from the
ProQuest Theses and Dissertations Database. (UMI No. 10749406)
Call-Cummings, M. (2017). Establishing communicative validity: Discovering theory
through practice. Qualitative Inquiry, 23, 192-200.

88
https://doi.org/10.1177/1077800416657101
Campbell, D. T., & Stanley, J. C. (2015). Experimental and quasi-experimental designs
for research. Chicago, IL: Ravenio Books.
Canto, V., Joines, D., & Laffer, A. (1982). Foundations of supply-side economics—
Theory and evidence. New York, NY: Academic Press.
Cotteleer, M. J., & Wan, X. (2016). Does the starting point matter? The literature-driven
and phenomenon-driven approaches of using corporate archival data in academic
research. Journal of Business Logistics, 37, 26-33.
https://doi.org/10.1111/jbl.12114
Davis, S. (2016, June 27). The housing affordability crisis: Can it be solved? [blog] The
Berkley Blog. Retrieved from https://blogs.berkeley.edu/2016/06/27/the-
housingaffordability-crisis-can-it-be-solved/
DeSimone, J. A., Harms, P. D., & DeSimone, A. J. (2015). Best practice
recommendations for data screening. Journal of Organizational Behavior, 36,
171-181. https://doi.org/10.1002/job.1962
Di, W., & Murdoch, J. C. (2013). The impact of the low income housing tax credit
program on local schools. Journal of Housing Economics, 22(4), 308-320.
https://doi.org/10.1016/j.jhe.2013.10.002
Dillman, K., Horn, K. & Verrilli, A. (2017). The what, where, and when of place-based
housing policy’s neighborhood effects paper. Taylor & Francis in Housing Police
Debate. http://dx.doi.org/10.1080/10511482.2016.1172103
Du, J., & Zhou, L. (2012). Improving financial data quality using ontologies. Decision
Support Systems, 54, 76-86. https://doi.org/10.1016/j.dss.2012.04.016

89
Du, J., Wu, H., & Zhu, L. (2018). Influencing factors on profit distribution of public
private partnership projects: Private sector’s perspective. Advances in Civil
Engineering, 2018, 1-10. Retrieved from https://doi.org/10.1155/2018/2143173
Dunn, S. L., Arslanian-Engoren, C., DeKoekkoek, T., Jadack, R., & Scott, L. D. (2015).
Secondary data analysis as an efficient and effective approach to nursing research.
Western Journal of Nursing Research, 37, 1295-1307.
https://doi.org/10.1177/0193945915570042
Duppong Hurley, K., Lambert, M., Epstein, M., & Stevens, A. (2015). Convergent
validity of the strength-based behavioral and emotional rating scale with youth in
a residential setting. Journal of Behavioral Health Services & Research, 42, 346-
354. https://doi.org/10.1007/s11414-013-9389
Edgeman, R., Eskildsen, J., & Neely, A. (2015). Translating triple top line strategy into
triple bottom line performance. Measuring Business Excellence, 19.
https://doi.org/10.1108/mbe-12-2014-0054
Edwards, C., & Calder, V. (2017). Low-income housing tax credit costly, complex, and
corruption-prone. Tax & Budget Bulletin Cato Institute, 79. Retrieved from
https://www.cato.org/publications/tax-budget-bulletin/low-income-housing-
taxcredit-costly-complex-corruption-prone#full
Ellen, I. G., Horn, K., Kuai, Y., Pazuniak, R., & Williams, M. D. (2015). Effect of QAP
incentives on the location of LIHTC properties. Washington, DC: U.S.
Department of Housing and Urban Development.
Enqvist, J., Graham, M., & Nikkinen, J. (2014). The impact of working capital
management on firm profitability in different business cycles: Evidence from

90
Finland. Research in International Business and Finance, 32, 36-49.
https://doi.org/10.1016/j.ribaf.2014.03.005
Faello, J. (2015). Understanding the limitations of financial ratios. Academy of
Accounting & Financial Studies Journal, 19(3), 75-85. Retrieved from
https://www.semanticscholar.org/paper/Understanding-the-Limitations-of-
Financial-Ratios-Faello/f4bfe3da94a62e67ab94498f9364df76db195e59
Falavi, M., & Abdoli, M. R. (2015). The efficiency of data mining models in determining
the effect of working capital management on corporate performance. 122
International Journal of Academic Research, 7, 339-343.
https://doi.org/10.7813/2075-4124.2015/7-1/B.57
Faul, F., Erdfelder, E., Buchner, A., & Lang, A.-G. (2009). Statistical power analyses
using G*Power 3.1: Tests for correlation and regression analyses. Behavior
Research Methods, 41, 1149-1160. http://dx.doi.org/10.3758/brm.41.4.1149
Feng, H., Morgan, N. A., & Rego, L.L. (2015). Marketing department power and firm
performance. Journal of Marketing, 79(5), 1-20.
https://doi.org/10.1509/jm.13.0522
Eisenhardt, K. M., Graebner, M. E., & Sonenshein, S. (2016). Grand challenges and
inductive methods: Rigor without rigor mortis. Academy of Management Journal,
59, 1113-1123. https://doi.org/10.5465/amj.2016.4004
Eriksen, M. D. (2017). Difficult development areas and the supply of subsidized housing.
Regional Science and Urban Economics, 64, 68-80.
https://doi.org/10.1016/j.regsciurbeco.2017.02.004

91
Freedman, M., & McGavock, T. (2015). Low-income housing development, poverty
concentration, and neighborhood inequality. Association for Public Policy
Analysis and Management. https://doi.org/10.1002/pam.21856
Gandy, D. L. (2015). Small business strategies for company profitability and
sustainability (Doctoral dissertation, Northcentral University). Retrieved from
https://pdfs.semanticscholar.org/331f/7bdcc27a981750fae8885eeaf12d8691499b.
pdf
Gorard, S. (2015). Rethinking ‘quantitative’ methods and the development of new
researchers. Review of Education, 3(1), 72-96. https://doi.org/10.1002/rev3.3041
Gramlich, E. (2016). Low-income housing tax credits. Retrieved from the National
LowIncome Housing Coalition web site: Retrieved from
http://nlihc.org/sites/default/files/2016AG_Chapter_5-9.pdf
Greenland, S., Senn, S. J., Rothman, K. J., Carlin, J. B., Poole, C., Goodman, S. N., &
Altman, D. G. (2016). Statistical tests, P values, confidence intervals, and power:
A guide to misinterpretations. European Journal of Epidemiology, 31, 337-350.
https://doi.org/10.1007/s10654-016-0149-3
Gözü, C., Anandarajan, M., & Simmers, C. A. (2015). Work–family role integration and
personal well-being: The moderating effect of attitudes towards personal web
usage. Computers in Human Behavior, 52, 159-167.
https://doi.org/10.1016/j.chb.2015.05.017
Guo, S. (2015). Shaping social work science: What should quantitative researchers do?
Research on Social Work Practice, 25, 370-381.
https://doi.org/10.1177/1049731514527517

92
Hammett, V. (2015). Risk analysis and disaster recovery: A Florida LIHTC case study
(Doctoral dissertation, Clemson University). Retrieved from
https://pdfs.semanticscholar.org/358c/54b6f8fbfe8fd81353da5eaa6bdc8c695f5c.p
df
Harrell, F. (2015). Regression modeling strategies (2nd ed). Amsterdam, The
Netherlands: Springer International.
Harrigan, W. J., & Commons, M. L. (2015). Replacing Maslow’s needs hierarchy with an
account based on stage and value. Behavioral Development Bulletin, 20, 24-31.
https://doi.org/10.1037/H0101036
Henwood, B. F., Derejko, K.-S., Couture, J., & Padgett, D. K. (2015). Maslow and mental
health recovery: A comparative study of homeless programs for adults with
serious mental illness. Administration and Policy in Mental Health, 42, 220-
228. https://doi.org/10.1007/s10488-014-0542-8
Higgins, C. D., & Huque, A. S. (2015). Public money and Mickey Mouse: Evaluating
performance and accountability in the Hong Kong Disneyland joint venture
public-private partnership. Public Management Review, 17, 1103-1123.
https://doi.org/10.1080/14719037.2014.881533
Hsu, J. (2015). NLIHC releases report on federal low-income housing programs and
housing need. Journal of Housing and Community Development, 72(1), 15.
Retrieved from https://www.journalofhousing.org/about-journal-
housingcommunity-development
Humphreys, M., & Jacobs, A. M. (2015). Mixing methods: A Bayesian approach. The
American Political Science Review, 109, 653-673.

93
https://doi.org/10.1017/S0003055415000453
Ihlanfeldt, K. & Mayock, T. (2017). Affordable housing and the socio-economic
integration of elementary schools. SSRN Online. Retrieved from
http://dx.doi.org/10.2139/ssrn.2838401
Johnson, M. (2014). Poverty deconcentration priorities in low-income housing policy: A
content analysis of low-income housing tax credit (LIHTC) qualified allocation
plans (Doctoral dissertation). Retrieved from the ProQuest Dissertations & Theses
database. (UMI No. 3620695)
Johnston, M. P. (2017). Secondary data analysis: A method of which the time has come.
Qualitative and quantitative methods in libraries, 3, 619-626. Retrieved from
http://www.qqml.net/papers/September_2014_Issue
Kalugina, A. (2016). Affordable housing policies: An overview. Cornell Real Estate
Review, 14, 76-83. Retrieved from
http://scholarship.sha.cornell.edu/crer/vol14/iss1/10
Kara, E., Erdur, D. A., & Karabiyik, L. (2015). Effects of corporate governance level on
the financial performance of companies: A research on BIST corporate 379
governance index (XKURY). Ege Academic Review, 15, 265-274. Retrieved from
http://www.econpapers.repec.org/article/egejournl/v_3a15_3ay_3a2015
Keynes, J. (1936). The general theory of employment, interest, and money. London, UK:
Macmillan.
Kingsley, T. (2017). Trends in housing problems and federal housing assistance.
Washington, DC: Urban Institute.

94
Lach, D. (2014). Challenges of interdisciplinary research: Reconciling qualitative and
quantitative methods for understanding human-landscape systems. Environmental
Management, 53, 88-93. https://doi.org/10.1007/s00267-013-0115-8
Lazăr, S. (2016). Determinants of firm performance: Evidence from Romanian listed
companies. Review of Economic and Business Studies, 9(1), 53-69.
https://doi.org/10.1515/rebs-2016-0025
Leedy, P. D., & Ormrod, J. E. (2015) Practical research planning and design (11th ed.).
Upper Saddle River, NJ: Pearson Education.
Lew, I. (2015). Analysis of data from the Low-Income Housing Tax Credit database, U.S.
Department of Housing and Urban Development (unpublished). Cambridge, MA:
Joint Center for Housing Studies.
Lin, C., Shen, Z., Chen, Q., & Sehldon, F. T. (2017). A data integrity verification scheme
in mobile cloud computing. Journal of Network and Computer Applications, 77,
146-151. https://doi.org/10.1016/j.jnca.2016.08.017
Lipschultz, M. (2016). Merging the public and private: The LIHTC program and formula
for more affordable housing. Retrieved from
https://www.bu.edu/rbfl/files/2017/03/07_Lipschultz.pdf
Lopez, X., Valenzuela, J., Nussbaum, M., & Tsai, C. C. (2015). Some recommendations
for the reporting of quantitative studies. Computers & Education, 91, 106-110.
https://doi.org/10.1016/j.compedu.2015.09.010
Margaretha, F. & Supartika, N. (2016). Factors affecting profitability of small-medium
enterprises (SMEs) listed in Indonesia Stock Exchange. Journal of Economics,

95
Business, and Management, 4, 131-137.
https://doi.org/10.7763/joebm.2016.V4.379
Marshall, C., & Rossman, G. B. (2016). Designing qualitative research (6th ed.).
Thousand Oaks, CA: Sage.
Mas’adeh, R., Tayeh, M., Al-Jarrah, I. M., & Tarhini, A. (2015). Accounting vs.
marketbased measures of firm performance related to information technology
investments. International Review of Social Sciences and Humanities, 9, 129-145.
Retrieved from
http://eacademic.ju.edu.jo/m.tayeh/Lists/Published%20Research/Attachments/5/A
ccounting%20Mesures%202015.pdf
Maslow, A. H. (1943). A theory of human motivation. Psychological Review, 50, 370-
396. https://doi.org/10.1037/h0054346
McCusker, K., & Gunyadin, S. (2015). Quantitative research designs function through the
use of statistics and mathematics to convey conclusive experimental results.
Perfusion, 30, 537-542. https://doi.org/10.1177/0267659114559116
Mckibben, W. B., & Silvia, P. J. (2016). Inattentive and socially desirable responding:
Addressing subtle threats to validity in quantitative counseling research.
Counseling Outcome Research and Evaluation, 7, 53-64.
https://doi.org/10.1177/2150137815613135
McKim, C. A. (2015). The value of mixed methods research: A mixed-methods study.
Journal of Mixed Methods Research, 1-21.
https://doi.org/10.1177/1558689815607096

96
Miller, D. P. (2016). The relationship between corporate social performance and financial
performance (Doctoral dissertation). Retrieved from the ProQuest
Dissertations and Theses database. (UMI No. 10131738)
Montgomery, D. C., Peck, E. A., & Vining, G. G. (2015). Introduction to linear
regression analysis. New York, NY: John Wiley & Sons.
Neville, B. (2017). Affordable housing in high opportunity areas: An examination of
effective Qualified Allocation Plans. Muncie IN: Ball State University Press.
Niver, K. (2016). Changing the face of urban America: Assessing the low-income housing
tax credit. Virginia Law Review, 102(48). Retrieved from
http://www.virginialawreview.org/volumes/content/changing-face-urban-
americaassessing-low-income-housing-tax-credit
Novogradac, M. (2014). Better by design: Tax credits’ structure provides superior results.
Journal of Tax Credits. Retrieved from
https://www.novoco.com/periodicals/articles/washington-wire-better-design-
taxcredits-structure-provides-superior-results
Novogradac, M. (2016). LIHTC celebrates three decades of bipartisan support, success.
Novogradac & Company Certified Public Accountants. Retrieved from
https://www.novoco.com/notes-from-novogradac/lihtc-celebrates- three-
decadesbipartisansupport-success
Onen, D. (2016). Appropriate conceptualisation: The foundation of any solid quantitative
research. Electronic Journal of Business Research Methods, 14, 28-38. Retrieved
from http://ewww.ejbrm.com

97
Ott, R. L., & Longnecker, M. T. (2015). An introduction to statistical methods and data
analysis. Belmont, CA: Cengage Learning.
Park, J., & d, M. (2016). Qualitative versus quantitative research methods: Discovery or
justification? Journal of Marketing Thought, 3(1), 1-7.
https://doi.org/10.15577/jmt.2016.03.01.1
Phelps, E. S. (2016, May 19). Supply-side, demand side, or innovation side? Project
Syndicate Retrieved from https://jordantimes.com/opinion/edmund-
sphelps/supply-side-demand-side-or-innovation-side
Popiolkowski, J. (2015, August 19). Third developer interested in city land. Buffalo News
Retrieved from https://.pressreader.com/usa/the-buffalo-
news/20150819/textview&usg=AOvVaw1yBchMrmzlebICEM5KsSEP
Prizio, D. P. (2015). Jack Kemp: Champion of the American idea (Doctoral dissertation).
Retrieved from ProQuest Dissertations & Theses database. (UMI No. 3717971)
Rahn, M. (2016). The analysis factor: Making statistics make sense. Retrieved from
http://www.theanalysisfactor.com/factor-analysis-1-introduction/
Reio, T. G. (2016). Nonexperimental research: Strengths, weaknesses, and issues of
precision. European Journal of Training and Development, 40, 676-690.
https://doi.org/10.1108/ejtd-07-2015-0058
Rice, R (2016). Chart book: Cuts in federal assistance have exacerbated families’
struggles to afford housing. Center on Budget and Policy Priorities. Retrieved
from https://www.cbpp.org/research/housing/chart-book-cuts-in-federalassistance-
have- exacerbated-families-struggles-to-afford

98
Rovai, A. P., Baker, J. D., & Ponton, M. K. (2013). Social science research design and
statistics: A practitioner’s guide to research methods and SPSS analysis (1st ed.).
Chesapeake, VA: Watertree Press.
Scally, C. & Tighe, J. (2015). Democracy in action?: NIMBY as impediment to equitable,
affordable housing siting. Housing Studies, 30, 749-769.
https://doi.org/10.1080/02673037.2015.1013093
Schoonenboom, J., & Johnson, R. B. (2017). How to construct a mixed methods research
design. KZfSS Kölner Zeitschrift für Soziologie und Sozialpsychologie, 69, 107-
131. https://doi.org/10.1007/s11577-017-0454-1
Schwartz, A. (2015). Housing policy in the United States. New York, NY: Routledge
Shaw, B. (2015, June 6). This is why low-income housing is so costly in the twin cities.
Saint Paul Pioneer Press. Retrieved from
https://www.twincities.com/2015/06/06/this-is-why-low-income-housing-is-
socostly-in-the-twin-cities/
Simpson, G., & Lord, B. (2015). Enhancing the reporting of quantitative research
methods in Australian social work. Australian Social Work, 68, 375-383.
https://doi.org/10.1080/0312407X.2015.1035662
Singh, A. (2017). Common procedures for development, validity, and reliability of a
questionnaire. International Journal of Economics, Commerce and Management
United Kingdom, 5. Retrieved from
http://ijecm.co.uk/wpcontent/uploads/2017/05/5549.pdf
Skuzinski, T., Jones, M., Zhang, Y., & McCoy, A. (2016). Do Qualified Allocation Plans
influence developers’ LIHTC siting decisions: The case of access to

99
highperforming schools (Master’s thesis, Virginia Institute of Technology).
Retrieved from https://vtechworks.lib.vt.edu/handle/10919/9291
Slater, S., Joksimović, S., Kovanovic, V., Baker, R. S., & Gasevic, D. (2017). Tools for
educational data mining: A review. Journal of Educational and Behavioral
Statistics, 42, 85-106. https://doi.org/10.3102/1076998616666808
Sleeper, J. D., LeBlanc, L. A., Mueller, J., Valentino, A. L., Fazzio, D., & Raetz, P. B.
(2017). The effects of electronic data collection on the percentage of current
clinician graphs and organizational return on investment. Journal of
Organizational Behavior Management, 37, 83-95.
https://doi.org/10.1080/01608061.2016.1267065
Spotts, M. (2016). Giving due credit: Balancing priorities in state Low-Income Housing
Tax Credit allocation policies. Enterprise communities. Retrieved from
https://www.enterprisecommunity.org/download?fid=546&nid=3814
Stanhope, B. (2016). Tax shelters, floor fights, deals, negative reactions: Remembering
the dawn of the LIHTC. Novogradac Journal of Tax Credits, 7(10). Retrieved
from https://www.novoco.com/ periodicals/articles/tax-shelters-floor-fights-deals-
negative-reactions-remembering-dawn-lihtc
Stockman, C. (2015). Achieving a doctorate through mixed methods research. Electronic
Journal of Business Research Methods, 13, 74-84. Retrieved from
http://www.ejbrm.com/issue/download.html/idArticle=401&usg=AOvVaw1NX7
Ues3SmGGEGx4ADJlAh
Sullivan, R., & Anderson, M. (2017, May 9). Affordable housing program costs more,
shelters fewer. NPR. Retrieved from

100
https://www.npr.org/2017/05/09/527046451/affordable-housing-program-
costsmore-shelters-less
Tabachnick, B., & Fidell, L. (2013). Using multivariate statistics (6th ed.). Boston, MA:
Pearson Education.
Tannous, K. A. (2018). Impact of mortgage characteristics on retail mortgage transaction
completion time (Doctoral dissertation). Retrieved from the ProQuest
Dissertations and Theses database. (UMI No. 10824435)
Tan, Y. (2016). The impacts of risk and competition on bank profitability in China.
Journal of International Financial Markets, Institutions and Money 40, 85-110.
https://doi.org/10.1016/j.intfin.2015.09.003
Tasic, S., & Feruh, M. B. (2012). Errors and issues in secondary data used in marketing
research. The Scientific Journal for Theory and Practice of Socioeconomic
Development, 1, 326-335. Retrieved from
https://pdfs.semanticscholar.org/9c7b/2024f73127680508b398b5715114dfb6f56d
.pdf
Temtime, Z. T. (2016). Relationship between working capital management, policies, and
profitability of small manufacturing firms (Doctoral dissertation). Retrieved from
the ProQuest Dissertations and Theses database. (UMI No. 10017861)
Thayer, C. (2018). Contesting conventional wisdom: The link between subsidy layering
and legal expenses in the LIHTC program. Retrieved from
https://smartech.gatech.edu/handle/1853/38252
Ukaegbu, B. (2014). The significance of working capital management in determining
firm profitability: Evidence from developing economies in Africa. Research in

101
International Business and Finance, 31,1-16.
https://doi.org/10.1016/j.ribaf.2013.11.005
U.S. Department of Housing and Urban Development. (2015a, April 7). Effect of QAP
incentives on the location of LIHTC properties. Retrieved from
https://www.huduser.gov/publications/pdf/QAP_incentive_mdrt.pdf
U.S. Department of Housing and Urban Development. (2015b). Glossary. Retrieved from
https://www.huduser.gov/portal/glossary/glossary_all.html
U.S. Department of Health and Human Service (2015c), Office for Human Research
protections. The Belmont Report. Retrieved from
http://www.hhs.gov/ohrp/humansubjects/guidance/belmont.html
Vatcheva, K. P., Lee, M., McCormick, J. B., & Rahbar, M. H. (2016). Multicollinearity in
regression analyses conducted in Epidemiologic Studies. Epidemiology
(Sunnyvale, Calif.), 6(2), 227. https://doi.org/10.4172/2161-
1165.1000227
Venkatesh, V., Brown, S. A., & Sullivan, Y. W. (2016). Guidelines for conducting mixed-
methods research: An extension and illustration. Journal of the Association for
Information Systems, 17, 435. Retrieved from
http://aisel.aisnet.org/jais/vol17/iss7/2/
Wagner, W. (2017). Using IBM SPSS statistics for research methods and social science
statistics (6th ed.). Thousand Oaks, CA: Sage.
Walden University. (2016). Doctor of business administration study rubric and research
handbook [Pamphlet]. Baltimore, MD: Author.
Walter, S. R., Dunsmuir, W. T. M., & Westbrook, J. I. (2015). Studying interruptions and
multitasking in situ: The untapped potential of quantitative observational studies.

102
International Journal of Human-Computer Studies, 79, 118-125.
https://doi.org/10.1016/j.ijhcs.2015.01.008
Wang, Y., Cui, P., & Liu, J. (2018). Analysis of the risk-sharing ratio in PPP projects
based on government minimum revenue guarantees. International Journal of
Project Management, 36, 899-909.
https://doi.org/10.1016/j.ijproman.2018.01.007
Wang, F., Feng, T., & Lawton, A. (2016). Linking ethical leadership with firm
performance: A multi-dimensional perspective. Journal of business ethics, 1, 1-
12. https://doi.org/10.1007/s10551-015-2905-9
Weisbach, D. (2006). Tax expenditures, principal agent problems, and redundancy.
Washington University Law Review, 84,1823-1860.
https://doi.org/10.2139/ssrn.912735
Weiss, B. (2016). Residual value capture in subsidized housing. Retrieved from
https://heinonline.org/HOL/LandingPage?handle=hein.journals/harlpolrv10&div=
24&id=&page
Woo, A., Joh, K., & Van Zandt, S. (2016). Impacts of the low-income housing tax credit
program on neighborhood housing turnover. Urban Affairs Review, 52, 247-279.
https://doi.org/10.1177/1078087414561824
Woo, A., & Yu, C. (2017). Beyond affordable shelters: Subsidized housing and
surrounding environments for pedestrian safety. Applied Geography, 83, 37-45.
https://doi.org/10.1016/j.apgeog.2017.03.014
Xu, S., Baldea, M., Edgar, T. F., Wojsznis, W., Blevins, T., & Nixon, M. (2015). An
improved methodology for outlier detection in dynamic datasets. AIChE Journal,

103
61, 419-433. https://doi.org/10.1002/aic.14631
Yin, R. (2014). Case study research: Design and methods (5th ed.). Thousand Oaks, CA.
Yin, R. (2017). Case study research: Design and methods (6th ed.). Thousand Oaks, CA.
Yu, H., Jiang, S., & Land, K. C. (2015). Multicollinearity in hierarchical linear models.
Social Science Research, 53, 118-136.
https://doi.org/10.1016/j.ssresearch.2015.04.008
Zhang, W., & Watanabe-Galloway, S. (2014). Using mixed methods effectively in
prevention science: Designs, procedures, and examples. Prevention Science, 15,
654-662. https://doi.org/10.1007/s11121-013-0415-5
Appendix A: Certificate of Completion of the Student Researcher’s Course

