


1
Section 1: Foundation of the Study
As a result of the 2007-2009 financial crisis, lenders and financial regulators
implemented several changes to mortgage lending in an effort to mitigate a similar future
crisis (Scanlon & Elsinga, 2014). Sullivan and Bernstein (2013) stated that although 20%
of the 315 million Americans reside in multifamily rental properties (U.S. Census Bureau,
2012), little information is available regarding their funding options. There are many
publications on the five Cs of credit and different lending criteria (Carl-Christian &
Hemlin, 2012). However, little information exists on the average ranking of mortgage
lending criteria among different categories of lenders (Agyapong, Agyapong, & Darfor,
2011). While lending criteria are important in the underwriting process, some criteria may
have more importance or weight among the different categories of lenders.
The objective of this study was to examine the average ranking of mortgage
outcome measures among different categories of lenders for multifamily rental properties
in Ontario, Canada. Identifying the average ranking of mortgage outcome measures will
prepare borrowers when applying for multifamily rental property mortgages. Further,
identifying the ranking or weighting of the different mortgage underwriting criteria could
contribute to an effective credit management system (Ferreira, Santos, Marques, &
Ferreira, 2014). Mortgage agents and brokers could benefit from an effective credit
management system as mortgage application processing time decreases (Glascock & Lu-
Andrews, 2014).

2
Background of the Problem
The 2007-2009 financial crisis was caused by ineffective banking, financial
regulation, and poor financial governance (Tatom, 2013). Kiani (2017) stated that over
speculation in the real estate market was a contributing factor to the financial crisis. Low
credit score, high loan-to-value (LTV) ratio, adjustable rate mortgages, and high debt
service coverage ratio (DSCR) were some factors that fostered foreclosures (Roulac,
2014).
Hoelle, Pireddu, and Villanacci (2016) stated that pre-recession lenders lowered
their credit standards and overlooked credit scores, employment confirmation, and down
payment requirements. The financial crisis forced regulators to revise lending standards
and implement stricter lending criteria (Scanlon & Elsinga, 2014). Mortgage lenders and
regulators implemented several changes to the mortgage lending process and monetary
policy to mitigate the probability of another sub-prime mortgage disaster (Peicuti, 2014).
Lenders now conduct detailed scrutiny of mortgage applications and borrowers’
profiles, to determine their ability to repay or maintain their debt obligation
(CarlChristian & Hemlin, 2012). Prospective borrowers continue to experience
challenges and barriers when seeking mortgages for multifamily rental properties because
of increased scrutiny and regulations (Liu & Quan, 2013). Given the 2007-2009 financial
crisis and changes in the financing sector, understanding the knowledge gap with
multifamily rental property financing and types of mortgages that facilitate multifamily

3
rental property ownership is critical for providing affordable housing (Sullivan &
Bernstein, 2013).
Problem Statement
The 2007-2009 recession negatively impacted the global economy, especially the
real estate industry (McDaniel, 2014). Nichols, Hendrickson, and Griffith (2011) stated
that because of the recession, obtaining credit became difficult, real estate lost 41%
equity, 223 commercial banks failed, and 3.2 million homes were in foreclosure. The
financial crisis forced regulators to implement stricter lending criteria (Scanlon &
Elsinga, 2014). In the future, over $1 trillion in commercial mortgages will come due,
and a significant number of borrowers have concerns with not being able to renew their
mortgages (Downs, 2011). The general business problem is the credit challenges real
estate investors experience when seeking commercial real estate financing. The specific
business problem is that some real estate investors do not know the impact of lender type
on the average rankings of mortgage underwriting outcome measures.
Purpose Statement
The purpose of this quantitative causal comparative study was to examine impact
of lender type on the average rankings of mortgage underwriting outcome measures. The
independent variable was lender category, with three levels (Category A, B, and C). The
dependent variables were average rankings for gross debt service (GDS) ratio, Total Debt
Service (TDS) ratio, DSCR, LTV ratio, property appraisal, and borrowers’ credit score,
industry experience, and length of employment. The target population was mortgage

4
agents and brokers with an Accredited Mortgage Professional (AMP) designation who
facilitate mortgages for multifamily rental property in Ontario, Canada. In Ontario,
mortgage agents and brokers are independent professionals who liaise between lenders
and borrowers; and have knowledge and understanding of the lending environment and
lender requirements. The findings could be advantageous to real estate investors by
providing the average ranking of mortgage underwriting criteria that could ensure their
success in securing financing. Limited financing could adversely affect the supply of
affordable housing because of higher interest rates and borrowing costs (Sullivan &
Bernstein, 2013). Therefore, sufficient financing may ensure an adequate supply of
affordable housing while improving the standard of living (Ferreira et al., 2014).
Nature of the Study
Given that the objective of this study was to identify the average ranking of eight
dependent variables, a quantitative research method was more appropriate than a
qualitative method. Because data for this study was structured and numerical in nature, a
quantitative research method was more appropriate (Slife & Melling, 2012). A
quantitative research method presents unbiased findings when identifying relationships,
measuring differences between variables, and testing hypotheses (Ragas & Laskin, 2014).
In contrast, the qualitative research method seeks to understand phenomena and explore
issues to identify underlying causes (Slife & Melling, 2012). Additionally, in a qualitative
study, the researcher usually collects data directly from participants by conducting
observation, interviews, and reviewing audio, video, and documents (Smith, 2014). A

5
qualitative research method involves gathering data and forming opinions on the topic
based on the researcher’s subject matter knowledge and experience (Slife & Melling,
2012). Therefore, a qualitative research method could cause skewed or biased opinions
and findings (Slife & Melling, 2012).
Given that the objective of this study was to identify the average ranking of
mortgage outcome measures among different categories of lenders, a causal comparative
research design was more appropriate than the descriptive, experimental, and causation
research designs. Both causation and causal comparative research designs explore
variable relationships. Guo, Cai, and Zhang (2016) identified causation research design as
a cause-effect relationship. Causal comparative research design only includes
identification of patterns and trends but does not identify cause-effect relationships
(Leedy & Ormrod, 2010). Causation research design does not involve manipulating
variables but the identification of the effect of the dependent variable on the independent
variable. Experimental research design does involve manipulating the control variable to
identify the effect on the dependent variable (Wester, Borders, Boul, & Horton, 2013). In
most cases, experimental research design involves a laboratory setting or environment
(Parolini, 2015). Descriptive research design, which assists in describing or reporting the
current situation of a variable and the development of hypothesis, usually occurs only
after data are gathered (Leedy & Ormrod, 2010).
A causal comparative research design meets the needs of a study when gathering
data in a natural setting rather than a laboratory or other experimental setting (Wester et

6
al., 2013). Data for this study originated from a natural setting and was derived by
surveying mortgage agents and brokers. Additionally, the manipulation of variables or
identification of cause-effect relationships is not necessary. Therefore, a causal
comparative research design was appropriate for this study.
Research Question
The following research question assisted to identify the average ranking of mortgage
outcome measures among different categories of lenders for multifamily rental property
in Ontario, Canada. The dependent variables were GDS ratio, TDS ratio, DSCR,
LTV ratio, property appraisal, and borrower’s profile (credit score, industry experience,
and length of employment). The independent variables were Category A, B, and C
lenders for multifamily rental property in Ontario, Canada.
The research question was: What is the impact of lender type on GDS ratio, TDS
ratio, DSCR, LTV ratio, property appraisal, borrower’s credit score, borrower’s industry
experience, and borrower’s length of employment?
Hypotheses
The following null and alternative hypotheses assisted in identifying the average
ranking of mortgage outcome measures among categories A, B, and C lenders for
multifamily rental property in Ontario, Canada. The hypotheses relate to mortgage
underwriting criteria and types of lenders. Statistical tests and analysis were performed to
either accept or reject the hypotheses.

7
H10: There is no statistical significant difference in ranking of GDS ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
H1A: There is a statistical significant difference in ranking of GDS ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
H20: There is no statistical significant difference in ranking of TDS ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
H2A: There is a statistical significant difference in ranking of TDS ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
H30: There is no statistical significant difference in ranking of DSCR for
categories A, B, and C lenders when seeking multifamily rental property financing.
H3A: There is a statistical significant difference in ranking of DSCR for categories
A, B, and C lenders when seeking multifamily rental property financing.
H40: There is no statistical significant difference in ranking of LTV ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
H4A: There is a statistical significant difference in ranking of LTV ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
H50: There is no statistical significant difference in ranking of property appraisal
for categories A, B, and C lenders when seeking multifamily rental property financing.
H5A: There is a statistical significant difference in ranking of property appraisal
for categories A, B, and C lenders when seeking multifamily rental property financing.

8
H60: There is no statistical significant difference in ranking of credit score for
categories A, B, and C lenders when seeking multifamily rental property financing.
H6A: There is a statistical significant difference in ranking of credit score for
categories A, B, and C lenders when seeking multifamily rental property financing.
H70: There is no statistical significant difference in ranking of industry experience
for categories A, B, and C lenders when seeking multifamily rental property financing.
H7A: There is a statistical significant difference in ranking of industry experience
for categories A, B, and C lenders when seeking multifamily rental property financing.
H80: There is no statistical significant difference in ranking of employment
history for categories A, B, and C lenders when seeking multifamily rental property
financing.
H8A: There is a statistical significant difference in ranking of employment history
for categories A, B, and C lenders when seeking multifamily rental property financing.
Theoretical Framework
Systems theory served as the theoretical framework for this study. von Bertalanffy
(1968) first introduced the general system theory in the 1940s. von Bertalanffy
emphasized how systems interact with their environments, and acquire new properties
through emergence, resulting in continual evolution. von Bertalanffy mentioned that
system theory extends beyond manufacturing industry and are also present in financial,
social, and political environments. Laszlo and Kripper (1998) stated that a system is a
combination of several elements that bond together to accomplish a common goal and

9
could encompass both natural phenomena and process. Therefore, any challenges among
the components within a system could significantly influence the outcome or objective of
that system.
The mortgage market operates as a complex system with several interacting and
relational components, which could influence the expansion or contraction of an
economy (Teye, Teye, & Asiedu, 2015). Moreover, mortgage lending criteria form part of
a micro system within the mortgage lending environment (Teye et al., 2015). The
macroeconomic system is influential and is also impacted by the mortgage market and the
lending criteria (Teye et al., 2015). Lending criteria enable mortgage underwriters and
lenders to analyze, approve, or reject mortgage applications (Teye et al., 2015).
Challenges or barriers among mortgage underwriting criteria could affect the lending
process, which could negatively affect the outcome of mortgage applications.
Additionally, barriers with mortgage lending could negatively influence the housing
industry, which could eventually affect both the local and global economy (Ferreira et al.,
2014).
Operational Definitions
Adjustable rate mortgage: An adjustable rate mortgage is a mortgage with an
interest rate that adjusts based on economic and market conditions (Chiang & Sa-aadu,
2014).
Credit score: A credit score is a numeric presentation that represents an
individual’s credit history and trends (Citron & Pasquale, 2014).

10
Debt-service coverage ratio (DSCR): The DSCR indicate a business or
individual’s ability to service debts based on their current net income (Mason & Jayadev,
2014). The result from dividing annual net operating income by annual debt obligation is
the DSCR.
Gross debt service (GDS) ratio: The GDS ratio indicates the debt level of a
potential borrower (Heylen & Haffner, 2013). The result from dividing annual mortgage
payments plus property taxes by gross family income is the GDS ratio.
Loan-to-value (LTV) ratio: The LTV ratio shows the amount of financial
commitment by the buyer (Scanlon & Elsinga, 2014). The result from dividing the
amount of down payment by the cost of the asset is the LTV ratio.
Mortgage broker and agent: A mortgage broker and agent is an individual or
corporation that acts as intermediary between borrower and lender facilitating the
brokering of mortgage loans (Peicuti, 2014).
Mortgage fraud: A mortgage fraud occurs when there is willful material
misrepresentation, misstatements, or omissions that underwriters relied on when deciding
on funding applications or loan insurance (McDonald, 2016).
Property appraisal: A property appraisal is the process of assigning a fair value of
a property by assessing the current market value based on comparables, income, or
replacement cost (Cummings & Epley, 2013).
Total debt service (TDS) ratio: The TDS ratio indicates the debt level of a
potential borrower and how much of the borrower’s total income covers outstanding

11
debts (Akoto & Awunyo-Vitor, 2014). The result from dividing annual mortgage
payments plus property taxes plus other recurring debt payments by gross family income
is the TDS ratio.
Underwriters: A mortgage underwriter is an individual who is primarily
responsible for approving a mortgage application. The underwriter reviews
documentation, debt ratios, and income verification. Additionally, underwriters align
mortgage application to lenders criteria (Sanderford, Overstreet, Beling, & Rajaratnam,
2015).
Assumptions, Limitations, and Delimitations
This study was not without boundaries and had limitations and delimitations.
Additionally, there were assumptions made about participants’ experience and responses.
The following discussion includes identification of assumptions, limitations, and
delimitations of this study.
Assumptions
Assumptions occur by accepting theory as fact even if no evidence exists to
support the theory (Schoenung & Dikova, 2016). Assumptions relate to instances where
theoretical boundaries exist within the research (Scherdin & Zander, 2014). An
assumption of this study was that the intended participants would personally complete the
survey and responses are accurate and free from personal bias. Another assumption was
responses that apply to mortgage underwriting criteria that could hinder real estate
investors and landlords from obtaining financing for multifamily rental properties and not
obtaining mortgages for owner-occupied residential or vacation homes.

12
Limitations
Limitations are components within a research study with potential weaknesses
that are outside of the researcher’s control (Simon, 2011). A limitation of this study was
obtaining responses from a sample that generalized the target population. The sample size
could be a limitation; an inefficient sample size could present difficulty determining
statistical significance (Lintukangas, Anni-Kaisa, & Veli, 2013). I sent surveys to the
target population; however, if responses are only from certain demographics then the data
only represented the experience and opinion from that particular demographic. Another
limitation of this study was the use of a ranking system to identify potential weighting of
mortgage underwriting criteria. The survey only allowed participants to assign one rank
for each criterion; no two criteria had the same rank. Consequently, survey responses
could result in skewed findings because some participants may want to assign the same
weighting to more than one underwriting criterion.
Delimitations
Delimitations relate to research boundaries, limiting the scope of the study
(Simon, 2011). Mortgage agents and brokers with an AMP designation who facilitate
mortgage applications for multifamily rental properties in Ontario, Canada served as the
primary data collection source for this study. Therefore, mortgage agents and brokers
without the AMP designation were not part of the target population. The AMP
designation denotes a certain level of education and experience in the mortgage industry.
Consequently, data from mortgage agents and brokers without the AMP designation could

13
potentially skew the findings given their lack of industry experience and education.
Further, given that this study focused on multifamily rental property financing, mortgage
agents and brokers who did not facilitate mortgage applications for multifamily rental
properties were not part of the target population. The financing process and requirement
for multifamily rental properties could be different from owner occupied or vacation
properties. Therefore, data from mortgage agents and brokers with limited or no
experience processing multifamily rental property mortgages could potentially skew the
findings of this study.
Significance of the Study
Identifying the average ranking of mortgage outcome measures among different
categories of lenders for multifamily rental property in Ontario, Canada could be
beneficial to both businesses and social welfare. An understanding of financing and
funding barriers could assist business leaders to identify ways and methods to reduce
funding barriers and increase funding. The following discussion expands on the benefits
for business practice and potential social change.
Contribution to Business Practice
The findings from this study could be beneficial and useful to financial regulators,
municipal and federal governments, real estate investors and developers, mortgage
lenders, investment advisors, and other stakeholders. Sullivan and Bernstein (2013) found
that although one-in-five American families live in a multifamily rental property, there is
little information on the financing options or assessments for these properties.

14
Identifying the average ranking of mortgage outcome measures among different
categories of lenders could assist regulators to identify financing barriers and bottlenecks
within the lending process. Understanding the ranking of mortgage underwriting criteria
could assist real estate investors to determine the importance of each mortgage
underwriting criterion and be better prepared when seeking multifamily rental property
mortgages, therefore reducing processing times and repetition of duties among mortgage
agents and brokers. The identification of mortgage underwriting criteria that contribute to
mortgage application rejections could enable regulators to analyze the effectiveness of the
current guideline and enact more effective guidelines (Sullivan & Bernstein, 2013).
Determining potential mortgage financing barriers that real estate investors experience
when seeking mortgages for multifamily rental properties in Ontario, Canada could assist
banking and lending representatives to identify financing patterns and trends. Banking
and financial regulators could utilize the findings to develop appropriate credit products
for qualified borrowers. An increase in credit products could facilitate the buying, selling,
and development of multifamily rental properties.
An effective credit management system could assist in reducing predatory
lending, which usually means higher interest rate loans (Nembhard, 2013). As a result of
dealing with predatory lenders, the cost of borrowing is high because of the higher
interest rate (Nembhard, 2013). Higher borrowing costs impact financial performance,
which could lead to a reduction in spending. Mortgage financing could contribute to

15
employment growth, increase the standard of living, and foster local and global economic
growth (Ferreira et al., 2014).
Implications for Social Change
Limitation of mortgage financing for multifamily rental properties could motivate
black market and underground financing and increase mortgage fraud. Limited financing
could result in an increase in fraudulent and criminal activities that could ultimately
hinder public safety. To secure a mortgage, applicants that do not satisfy the criteria are
more likely to falsify information on their mortgage application (Carrillo, 2013).
Mortgage applicants may seek financing from loan sharks and lenders involved in
criminal activities interested in converting money from illegal activities into the legal
monetary system.
Limited mortgage products could cause interest rate and borrowing costs to
increase, eventually causing rents to increase. Lack of mortgage funding could affect both
local and global economies, as spending and investment drop. Lack of spending forces
governments to reduce expenses and cut vital emergency and law enforcement personnel;
this action leads to an increase in crimes and fraudulent activities (Islam, 2014).
Limitation on financing could impede multifamily rental property development, which
could limit the supply of quality and affordable rental units (Sullivan & Bernstein, 2013).
A Review of the Professional and Academic Literature
The purpose of this study was to identify the average ranking of
mortgage underwriting criteria among Categories A, B, and C lenders for

16
multifamily rental properties in Ontario, Canada. The null and alternative
hypotheses were:
H10: There is no statistical significant difference in ranking of GDS ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
H1A: There is a statistical significant difference in ranking of GDS ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
H20: There is no statistical significant difference in ranking of TDS ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
H2A: There is a statistical significant difference in ranking of TDS ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
H30: There is no statistical significant difference in ranking of DSCR for
categories A, B, and C lenders when seeking multifamily rental property financing.
H3A: There is a statistical significant difference in ranking of DSCR for categories
A, B, and C lenders when seeking multifamily rental property financing.
H40: There is no statistical significant difference in ranking of LTV ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
H4A: There is a statistical significant difference in ranking of LTV ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
H50: There is no statistical significant difference in ranking of property appraisal
for categories A, B, and C lenders when seeking multifamily rental property financing.
17
H5A: There is a statistical significant difference in ranking of property appraisal
for categories A, B, and C lenders when seeking multifamily rental property financing.
H60: There is no statistical significant difference in ranking of credit score for
categories A, B, and C lenders when seeking multifamily rental property financing.
H6A: There is a statistical significant difference in ranking of credit score for
categories A, B, and C lenders when seeking multifamily rental property financing.
H70: There is no statistical significant difference in ranking of industry experience
for categories A, B, and C lenders when seeking multifamily rental property financing.
H7A: There is a statistical significant difference in ranking of industry experience
for categories A, B, and C lenders when seeking multifamily rental property financing.
H80: There is no statistical significant difference in ranking of employment
history for categories A, B, and C lenders when seeking multifamily rental property
financing.
H8A: There is a statistical significant difference in ranking of employment history
for Categories A, B, and C lenders when seeking multifamily rental property financing.
Table 1 highlights some articles reviewed when compiling data for this literature
review. The table is organized by author, publication year, journal, purpose of study,
research method, and key findings. While 144 articles were reviewed for this study, five
key resources are shown in Table 1.
Table 1
Highlighting Some Materials Adapted in this Study
Author/year Journal Purpose Methods

18
Galster,
Tatian,
Wilson,
(1999)
Ferreira et al.
(2014)
Gan, Li,
Wang, and
Kao (2012)
Jones and
Richardson
(2014)
Laszlo and
Krippner
(1998)
Housing
Policy
Debate
Management
Decision
International
Journal of
Housing
Markets and
Analysis
International
Journal of
Housing
Markets and
Analysis
J.S. Jordan
(Ed.)
To determine the
financial condition
of multifamily
housing stock.
To propose a
methodological
framework to
evaluate mortgage
lending decision
process. To
investigate the
determinants of
mortgage defaults.
To examine how
the shock of the
recent financial
crisis impact USA
and UK housing
markets
Discussion of
System Theory
Quantitative
research method
utilizing Pearsonian
correlation and
Spearman rank-order
statistical analysis.
Data derived from the
Residential Finance
Survey (RFS);
administered by the
U.S Bureau of
Census. Quantitative
research method
utilizing the
MACBETH
approach.
Quantitative research
study employing the
credit scoring model.
Qualitative research
approach.
Qualitative research
paper presenting key
characteristics of
system theory.
Key findings
Rent-to-Value ratio
and Net Operating
Income to Value ratio
are highly correlated
and Loan-to-Value
ratio and Debt
Coverage ratio are two
of the most used
indicators.
The authors provided a
framework to guide
lenders when
assessing lending
risks.
The findings indicated
that mortgage rate and
duration, and borrower
rating are related to
default rate. The
authors concluded that
subprime lending in
the USA resulted in
the global financial
crisis. Further, the
relaxation of lending
criteria and subprime
lending led to housing
market downturn.
Provide insights on
systems theory and the
evolution of systems
theory.
In this literature review section, 95% of the articles were peer-reviewed and 87%
published in 2013 or later. I reviewed articles from the Walden University Library that
related to the 2007-2009 recession, mortgage lending criteria, mortgage characteristics,
multifamily rental properties, and types of mortgage lenders. Articles reviewed related to
systems theory, research methodologies, and statistical analysis. This literature review
began with a discussion of the 2007-2009 recession, followed by mortgage characteristics,

19
and the different categories of lenders. The conclusion included a discussion on systems
theory as related to mortgage financing and a detailed discussion on different mortgage
underwriting criteria applicable to multifamily rental properties.
2007-2009 Recession
The 2007-2009 financial crisis contributed to more than one trillion dollars in
losses in the United States and resulted in one of the largest global recessions since World
War II (Jordà, Schularick, & Taylor, 2016). The recession adversely impacted households,
businesses, and governments’ revenue and spending (Ewalt & Jennings, 2014). The 2007-
2009 recession fostered economic fear, panic, and uncertainty within the global economy
and impacted both local and global financial markets (Dufwenberg, 2015). Tatom (2013)
mentioned that the 2007-2009 financial crisis occurred because of poor government
regulations and increased homeownership with unrealistic expectations. To encourage
homeownership, the U.S. government introduced several homeownership programs
including subprime borrowing to encourage lenders to extend mortgages to families with
substandard credit (Murty, Kiran, & Gupta, 2013). Steinbuks and
Elliehausen (2014) stated that financial deregulation and lower lending standards of
financial institutions in the United States and other developed nations encouraged lending
to mortgagees with poor credit histories.
The U.S. government encouraged home ownership by introducing tax treatment
options for homeowners to deduct mortgage interest as a tax liability (Fetter, 2013). The
objective of these programs was to assist borrowers with poor credit history, unstable
household income, and little down payment to enter homeownership and build equity

20
(Schwarcz, 2013). As the demand for homes increased, prices also increased, fostering an
increase in homeowner equity (Murty et al., 2013). Murty et al. (2013) said that as equity
increased, homeowners took out equity through refinancing, second mortgages, or home
equity lines of credit, resulting in an increase in household debts relative to household
income. To account for inflation, the increased demand for real estate triggered an
increase in interest rates (Chen, Gan, Hu, & Cohen, 2013). Increased interest rates
eventually led to increased household expenses, forcing borrowers with limited or lower
household income to default on their mortgages (Tatom, 2013). As mortgage default
increases, it triggered an increase in foreclosure rate, which eventually increased the
supply of homes available for sale (Murty et al., 2013). The increased supply of homes
available for sale outpaced the demand for homes and eventually forced prices to decline
(Murty et al., 2013). As prices declined, many homeowners evaluated their financial
position. Some homeowners with negative equity strategically or voluntarily defaulted on
their mortgage obligation (Seiler & Walden, 2015). A rapid decline in house price,
increase in house supply, and increase in foreclose rate triggered a national panic and
economic contraction (Seiler & Walden, 2015).
Bloom (2014) stated that because of economic fear, panic, and uncertainty caused
by the 2007-2009 recession, mortgage lenders are fearful of similar future financial
collapse. Given the U.S. subprime crisis, the global financial market has changed
significantly and is still changing (Bryant, 2012). To prevent a future financial crisis
similar to the 2007-2009 recession, government representatives and lenders tightened and
reinforced mortgage underwriting criteria for all types of mortgages (Ferreira et al., 2014).

21
Consequently, mortgage lenders implemented new lending regulations and criteria for
LTV ratio, income requirement, TDS ratio, GDS ratio, and credit score (Fabozzi,
McBride, & Clancy, 2015). New mortgage underwriting regulations limiting the number
of financed properties a borrower could have before extending more credit could
negatively impact real estate investors and landlords (Dumitriu, 2015). Additionally, some
lenders only recognize 50% of rental income in the calculation of GDS and TDS (Canada
Mortgage and Housing Corporation, 2015). DSCR, industry experience, and property
appraisals are other underwriting criteria mortgage underwriters scrutinize
(Mason & Jayadev, 2014).
Increased scrutiny of mortgage applications is causing limitations with mortgage
financing, especially among landlords and real estate investors (Roulac, 2014). The
changes to mortgage lending regulations and criteria have significantly affected financing
of multifamily rental properties in Ontario, Canada (DiPasquale & Cummings, 1992).
Sullivan and Bernstein (2013) stated a lack of knowledge exists on how multifamily rental
properties achieve financing and the type of mortgages available for investors of
multifamily rental properties.
Mortgage Financing
Mortgage financing dates back to the 1100s, and the word mortgage, derived from
Latin, means a dead pledge. A mortgage is a loan, secured by real property and structured
in a manner where the borrower is required to pay interest based on the principal amount
(Lydon & McCarthy, 2013). Ferreira et al. (2014) mentioned that mortgages are the most
common and probably easiest form of financing to enable homeownership. Quercia, Ding,

22
and Reid (2012) stated that homeownership is the foundation for long-term asset building;
therefore, the availability of mortgages is critical. Mortgage lending is critical for
satisfying basic housing needs while fostering both local and global economic growth
(Ferreira et al., 2014). There are different mortgages based on the type of property,
residential, commercial, and industrial (Ghosh, 2016). Industrial mortgages are mainly for
manufacturing and distributing properties (Cortes, Marcondes, & Diaz, 2014).
Commercial mortgages are usually for hotels, office buildings, and retail stores (An,
Deng, Nichols, & Sanders, 2013). Residential mortgages are comprised mainly of
owneroccupied and residential rental properties (Harrison & Seiler, 2015).
Residential mortgages for owner-occupied properties are primarily for single
detached homes, semi-detached homes, townhomes, and condominium units. The
mortgage application and process for owner-occupied properties are more straightforward
than those for multifamily rental properties. During a period of financial constraint, a
mortgagee for owner-occupied properties is less likely to default on their mortgage
obligations (Teo, 2004). Ghosh (2016) found that banks associated with residential
mortgages for owner-occupied homes are less likely to fail than banks that deal with
multifamily rental property mortgages. Concerns underwriters and lenders have for
owner-occupied property include borrowers’ income, GDS, TDS, and LTV ratio (Teo,
2004). Their objective is to ensure that borrowers have enough disposable income to cover
the projected expenses of operating and maintaining their home and other debt obligations
(Teo, 2004).

23
Rental property mortgages are mainly for apartment buildings and other
multifamily rental properties (Galster, Tatian, & Wilson, 1999). Zietz (2003) stated that a
multifamily rental property is any building with two or more units under one roof. These
types of mortgage applications are more complex than owner-occupied mortgages and
require extensive analysis of the borrower, the property, and regulatory compliance.
DiPasquale and Cummings (1992) mentioned that mortgages for multifamily rental
properties are less standardized than mortgages for owner-occupied properties. There is no
specific mechanism or structure when accessing mortgage applications for multifamily
rental properties (DiPasquale & Cummings, 1992). DiPasquale and Cummings (1992)
stated that because of past financial crises, multifamily rental properties are experiencing
a limitation of funding. Teo (2004) found that during periods of financial constraint, the
mortgagee for investment properties is more likely to default on their mortgage obligation
because their venture is profit driven.
Underwriters analyze borrowers’ experience or education with managing rental
property, employment income and consistency, GDS ratio, TDS ratio, LTV ratio, and
credit score (Galster et al., 1999). Additionally, underwriters analyze the subject property
appraised value, DSCR, and any potential environmental or regulatory compliance
requirement (An et al., 2013). An underwriter objective is to ensure that borrowers have
the ability to manage their rental property (Archer & Smith, 2013). An underwriter
assesses the subject property environment and earning potential to determine operation
sustainability (Archer & Smith, 2013). Further, an underwriter ensures that the subject
property complies with regulations and has no outstanding deficiencies.

24
Categories of Lenders
While there are several different types of mortgage products, there are also
different types of mortgage lenders. Regardless of the type of mortgage products or type
of lenders, the mechanics and principles are the same. A lender lends money to a borrower
and expects repayment of principal plus interest, amortized over an agreed period (Nesiba,
Sorenson, & Sturm, 2012). If the borrower fails to pay the agreed installment, the creditor
or lender could foreclose and sell the property to cover the outstanding mortgage balance
and any accrued interest (Nesiba et al., 2012).
The different types of lenders are banks, credit unions, insurance companies,
monoline lenders, and private lenders (Nembhard, 2013). These lenders fall into three
categories. Category A includes banks, credit unions, and other depository institutions
(Downs & Shi, 2015). Zietz (2003) found that thrift institutions positioned as the primary
funding source for multifamily rental properties have declined. Commercial banks,
government sponsored agencies, and private lenders have now become the primary
funding source for multifamily rental properties (Zietz, 2003). Conversely, Eisenbeis and
Kaufman (2016) stated that prior to the 2007-2009 recession, commercial banks were the
premiere source for business financing; however, post-recession, commercial banks
position as the premier funding source declined. Category B includes insurance
companies, monoline lenders (lenders that only deal with mortgage agents and brokers
and only deal with mortgages products), and other non-depository institutions (Eisenbeis
& Herring, 2015). Mason and Jayadev (2014) found that loans originated from insurance

25
companies have less probability of delinquency. Category C includes private lenders
(Downs & Shi 2015).
In general, Category A lenders offer lower interest rates on mortgages with
excellent prepayment privileges. However, Category A lenders conduct detailed analysis
and follow stricter lending criteria than Category B and C lenders. Agyapong, Agyapong,
and Darfor (2011) found that banks seek to maximize profits and their lending activities
account for 80% of their overall profit. Therefore, to reduce loan default risk, they adhere
to strict lending practice and assessment of prospective borrower creditworthiness
(Zeidan, Boechat, & Fleury, 2015). Category B lenders follow less strict criteria than
Category A lenders; however, they usually have higher interest rates and strict prepayment
privileges. Category C lenders are private lenders and have few criteria (Downs & Shi,
2015). Category C lenders will usually accept applicants with low credit scores and
minimal documentation. Further, Category C lenders assess applications on a case-by-case
basis and approve or reject applications based on their capacity and expected value of the
subject property. Category C lenders usually have higher interest rates, higher prepayment
penalties, and more upfront processing fees than Categories A and B lenders.
Mortgage lenders employ mortgage underwriters to perform and conduct detailed
analyses of mortgage applications. Mortgage underwriters process mortgage applications
and assess the information on a mortgage application to determine borrowers’ ability to
service or repay the mortgage debt (Sanderford et al., 2015). Further, mortgage
underwriters assess the five Cs of credit to determine potential credit default risk,
prepayment, and repayment risk (Bryant, 2012).

26
Mortgage lenders and underwriters are usually concerned with interest rate risk,
default or credit risk, and prepayment risk (Archer & Smith, 2013). Interest rate risk
relates to uncertain future interest rates and the effect on asset market value (Martin,
2013). Interest rate risk could affect both bonds and stocks but usually affect bonds more
than stocks (Martin, 2013). Usually, when interest rates increase bond prices decrease and
vice versa. Some lenders sell their mortgage portfolio on the secondary mortgage market,
so bond interest rates are important. Default risk is the probability that borrowers will not
be able to repay or service the mortgage obligation (Ofonyelu & Alimi, 2013). To account
for default or credit risk, lenders will charge interest rates based on the level of perceived
risks. Sanderford et al. (2015) mentioned that credit risk is important to the lender and
helps assess house price, interest rate, and LTV ratio. Prepayment risk occurs when
borrowers make early repayment of mortgage principal (Theiakos, Tas, Van, & Kandhai,
2015). Lenders are concerned when borrowers repay full or part of their mortgage
principal early or unscheduled because of losing future interest payments (DiPasquale &
Cummings, 1992). Usually, lenders implement prepayment penalties to reduce or mitigate
prepayment risks (DiPasquale & Cummings, 1992). However, Quercia et al. (2012)
mentioned that high prepayment penalties could trigger mortgage defaults and
foreclosures. To ensure transparency and highlight mortgage details, lenders prepare a
mortgage disclosure statement, which contains important information pertaining to the
mortgage agreement (Shiller, 2014).
A mortgage disclosure statement highlights key details of the mortgage, interest
rates, amortization, mortgage terms, prepayment penalty, and authorized prepayment

27
amount (Stephen, Kasozi, Nalukenge, & Tauringana, 2014). Additionally, some lenders
may require semiannual and annual reporting. Mortgages could be structured in a manner
where borrowers pay an incremental amount every week, biweekly, or monthly. Based on
the type of mortgage, the incremental payment could comprise of principal and interest or
interest only (Archer & Smith 2013). The amount of the incremental payment depends on
the interest rate, principal, amortization, and type of mortgage (fixed or variable term)
(Desai, Elliehausen, & Steinbuks, 2013). A fixed rate mortgage means that the interest rate
remains constant for an agreed period, usually 6 months, 1 year, 2 years, 3 years, 4 years,
5 years, 7 years, or 10 years (Shiller, 2014). A variable rate mortgage means the rate of the
mortgage depends on prime rate and could fluctuate during the term of the mortgage
(Shiller, 2014).
To assist in mitigating potential credit risks, lenders may adopt and implement
different guidelines, analyses, and investigations of mortgage applicants’ profile,
documentation, and application details (Ofonyelu & Alimi, 2013). Ofonyelu and Alimi
(2013) stated that mortgage underwriters perform detailed analyses of borrowers’ financial
position and scrutinize supporting documentation to ensure accuracy and the ability to
service both current and future debt obligations. Further, Quercia et al. (2012) stated that
no documentation mortgages have a higher probability of default risk. Regardless of the
type of property that requires financing, mortgage underwriters approve or reject
mortgage applications based on preset lending criteria (Mahadkar, 2013). In Ontario,
mortgage underwriters who deal with multifamily rental properties conduct calculations
and analyses of borrowers TDS, GDS, LTV, and DSCR ratios. Additionally, mortgage

28
lenders and underwriters review and confirm borrowers’ employment history, experiences
owning and managing residential rental properties, credit scores, and the subject property
appraised value (DiPasquale & Cummings, 1992). Based on borrower credit history and
income, some lenders may require additional collateral as security.
Mortgage Underwriting Criteria
Mortgage underwriting criteria are parameters or guidelines that lenders set and
use to assist when deciding whether to approve or reject a mortgage application (Ferreira
et al., 2014). Mortgage underwriting criteria enable lenders to assess various risks
associated with the borrower or the subject property (Ferreira et al., 2014). To reduce
default risk mortgage underwriters, there is a need to effectively assess and scrutinize
borrowers’ character and application details (Ofonyelu & Alimi, 2013). Therefore,
mortgage underwriters are usually concerned with the five Cs of credit: collateral,
condition, capacity, capital, and character (Wilson, 2016).
The Five Cs of Credit
The five Cs of credit, collateral, character, capacity, condition, and capital are
aspects of a borrower profile that mortgage underwriters scrutinize to determine credit risk
exposure (Wilson, 2016). Components of the five Cs are critical to the lending process
and a decision is therefore equally important (Carl-Christian & Hemlin, 2012). Challenges
with any of the five Cs could increase application processing time and even lead to
rejection. Therefore, the five Cs operate as a micro system, where the components need to
operate efficiently to be effective and contribute to economic growth.

29
The assessment of a borrower character encompasses the borrower credit history
(Carl-Christian & Hemlin, 2012). In Ontario, the credit assessment displays on a report,
analyzes several criteria and assign a numerical score, referred to as a credit score. A
credit assessment highlights a borrower payment history, credit utilization, and credit
inquiries (Chan, Sharygin, Been, & Haughwout, 2014). Character also relates to
borrowers’ stability and overall trustworthiness, the length of employment, industry
experience, and years lived at current address is a key indicator of a borrower character
(Bryant, 2012). Agyapong et al. (2011) found that some lenders base their assessment on
the relationship with the borrower and therefore adapt relationship lending practices.
Collateral assessment involves the revision and confirmation of borrowers’ assets
and liability to determine net equity and possibility of takeover in the event that the
borrower defaults on their debt obligation (Agyapong et al., 2011). A collateral assessment
also includes the subject property appraised value relative to the intended loan amount
(Bryant, 2012). Further, a collateral assessment could also include co-signers net assets
and securities (Bryant, 2012).
Capital is the amount of financial commitment a borrower is willing to invest in a
subject property (Bryant, 2012). Loan-to-value ratio represents the capital invested, which
could indicate borrowers’ ability to service monthly debt obligation (Sanderford et al.,
2015). The higher the down payment, the more security lenders have in the event that
borrowers’ fail to maintain debt obligations (Sanderford et al., 2015).
When reviewing the capacity component, an underwriter will evaluate borrowers’
existing debts to determine their ability to take on more debts and maintain current debt

30
obligation (Bryant, 2012). The TDS, GDS, and DSCR are ratios that assist in determining
borrowers’ existing debts and ability to service future mortgage obligation (Agyapong et
al., 2011). House hold income is an element of TDS and GDS calculations and operating
income is an element of DSCR calculation.
The condition component of the five Cs involves the assessment of the purpose of
the mortgage. Mortgage underwriters will assess the micro and macro-economic
environment to determine if there are factors that could affect the borrower financial
position (Carl-Christian & Hemlin, 2012). Mortgage underwriters will also assess
borrowers’ employment or business condition to determine income stability and
sustainability (Bryant, 2012).
Ofonyelu and Alimi (2013) found that failing to assess the five Cs could expose
the lender to potential default or credit risks. Carl-Christian and Hemlin (2012) mentioned
that while the five Cs should assist mortgage underwriters in making objective lending
decision, because of decision-making bias mortgage underwriters sometimes overlook key
details.
Underwriting Criteria Assessed
The eight underwriting criteria assessed in this study are TDS, GDS, LTV, DSCR,
appraisal, borrower credit score, in industry experience, and length of employment
(Wilson, 2016). While some lenders or underwriters may not place the same weight on
each of the criteria, a general understanding of the impact of the criteria in the lending
process could be beneficial. Mortgage application for multifamily rental property
undergoes different scrutiny than owner-occupied residential property and other types of
31
mortgage products (DiPasquale & Cummings, 1992). Underwriters and lenders for owner-
occupied residential properties review credit score, LTV, GDS, TDS, and income
(Mahadkar, 2013). In contrast, for multifamily rental properties, there are more criteria in
addition to the criteria for owner-occupied properties such as DSCR, detailed property
appraisal, and borrowers’ industry experience (Galster et al., 1999).
Gross debt service (GDS) ratio is a calculation that mortgage underwriters perform
to determine the percentage of a borrower gross household income that relates to their
household expenses (Hossain & Hossain, 2015). Household income and interest are
significant components in the calculation of GDS. Quercia et al. (2012) stated that both
household income and interest rates could influence default rates. The higher the GDS
ratio, the less likely potential borrower will be able to service new debt obligation (Heylen
& Haffner, 2013). Therefore, a high GDS is an indication that a potential borrower may
have too much household debt relative to gross household income and could potentially
be in a situation where servicing both the new debts and existing debts becomes
overwhelming. In Ontario, a GDS ratio less than 32% is acceptable (Canada Mortgage
and Housing Corporation, 2015). Household debts include mortgage payments, property
taxes, heating expenses, and condominium fees. The formula to calculate GDS ratio is as
follows,
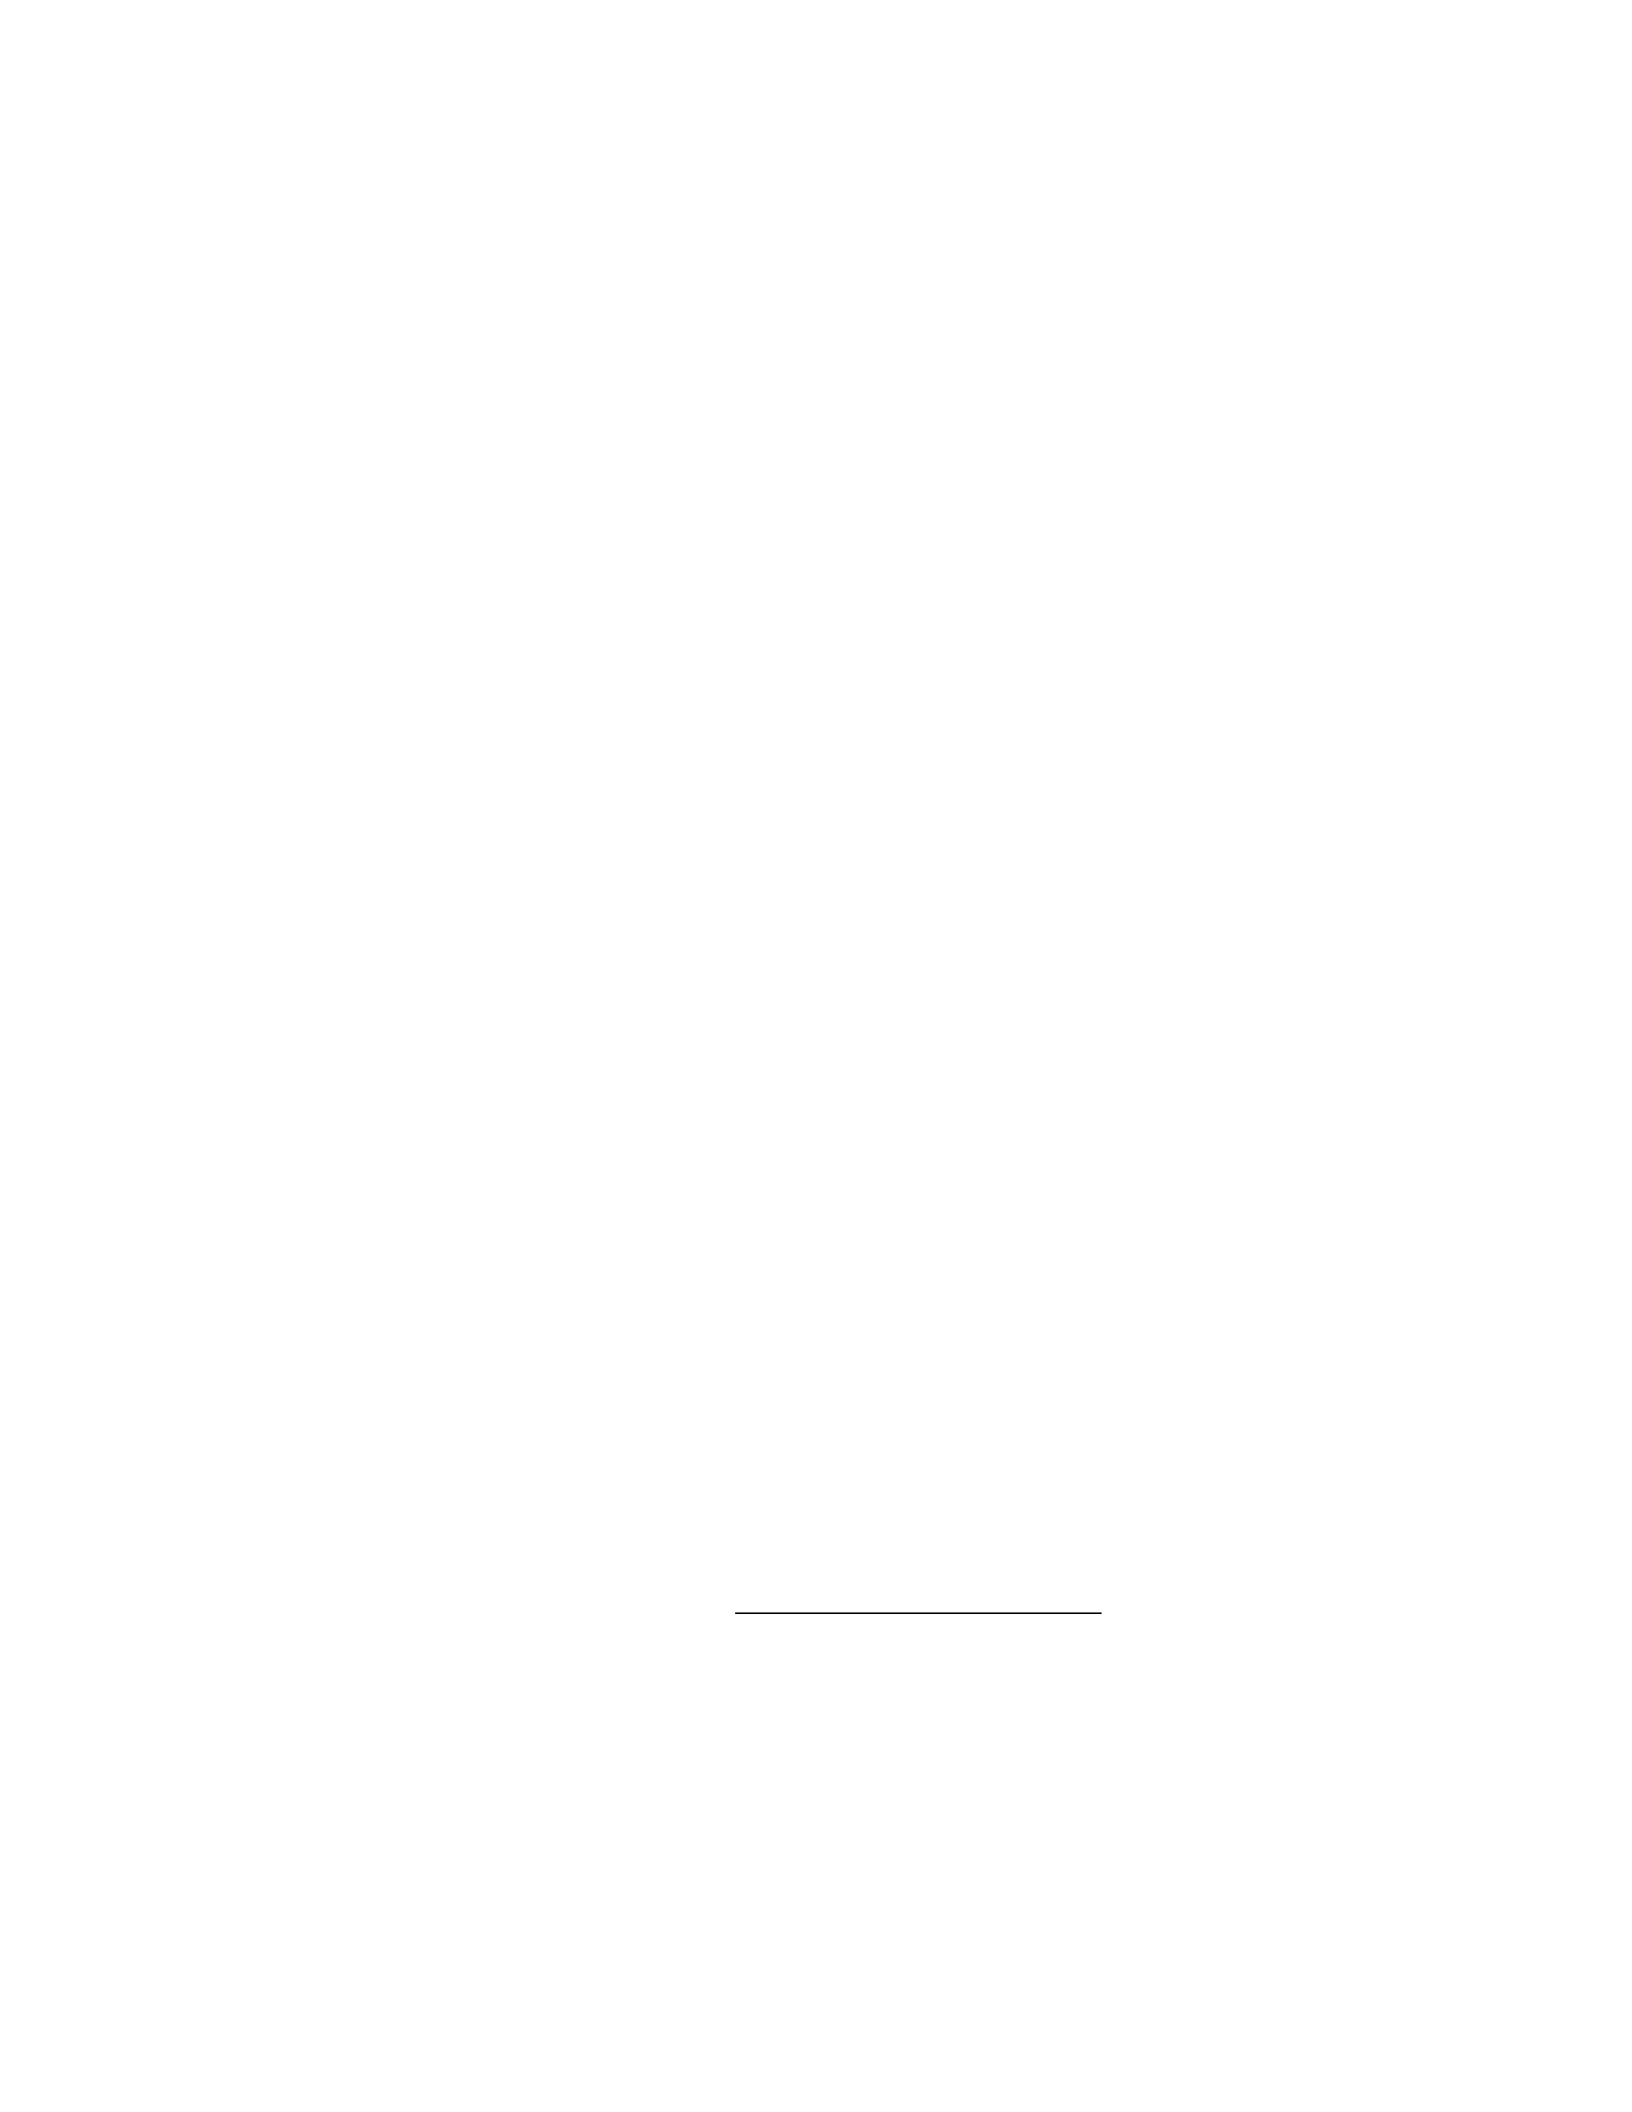
GDS = (MP + PT + HC) + CF (50%)
AHI
Where:
MP = mortgage payments
PT = property taxes
32
HC = heating costs
CF = condo fees
AHI = annual household income
Total debt service (TDS) ratio is a calculation that mortgage underwriters perform
to determine the percentage of a borrower gross household income that relates to their
housing-related expenses and other debt obligations (Akoto & Awunyo-Vitor, 2014).
Household income and interest rate are important factors in the calculation of TDS and
could influence foreclosure and default rates (Quercia, Ding, & Reid, 2012). A high TDS
ratio indicates that a potential borrower may have too much household debt relative to
gross household income. In Ontario, a TDS ratio less than 40% is acceptable (Canada
Mortgage and Housing Corporation, 2015). Therefore, monthly household debts plus
other debt obligations should be less than 40% of gross household income. Monthly debts
include housing costs plus all other debt obligations (car loans or leases monthly
obligation, credit card required payments, line of credit required payments, and other
debts with required monthly payments). The formula for TDS ratio is as follows,
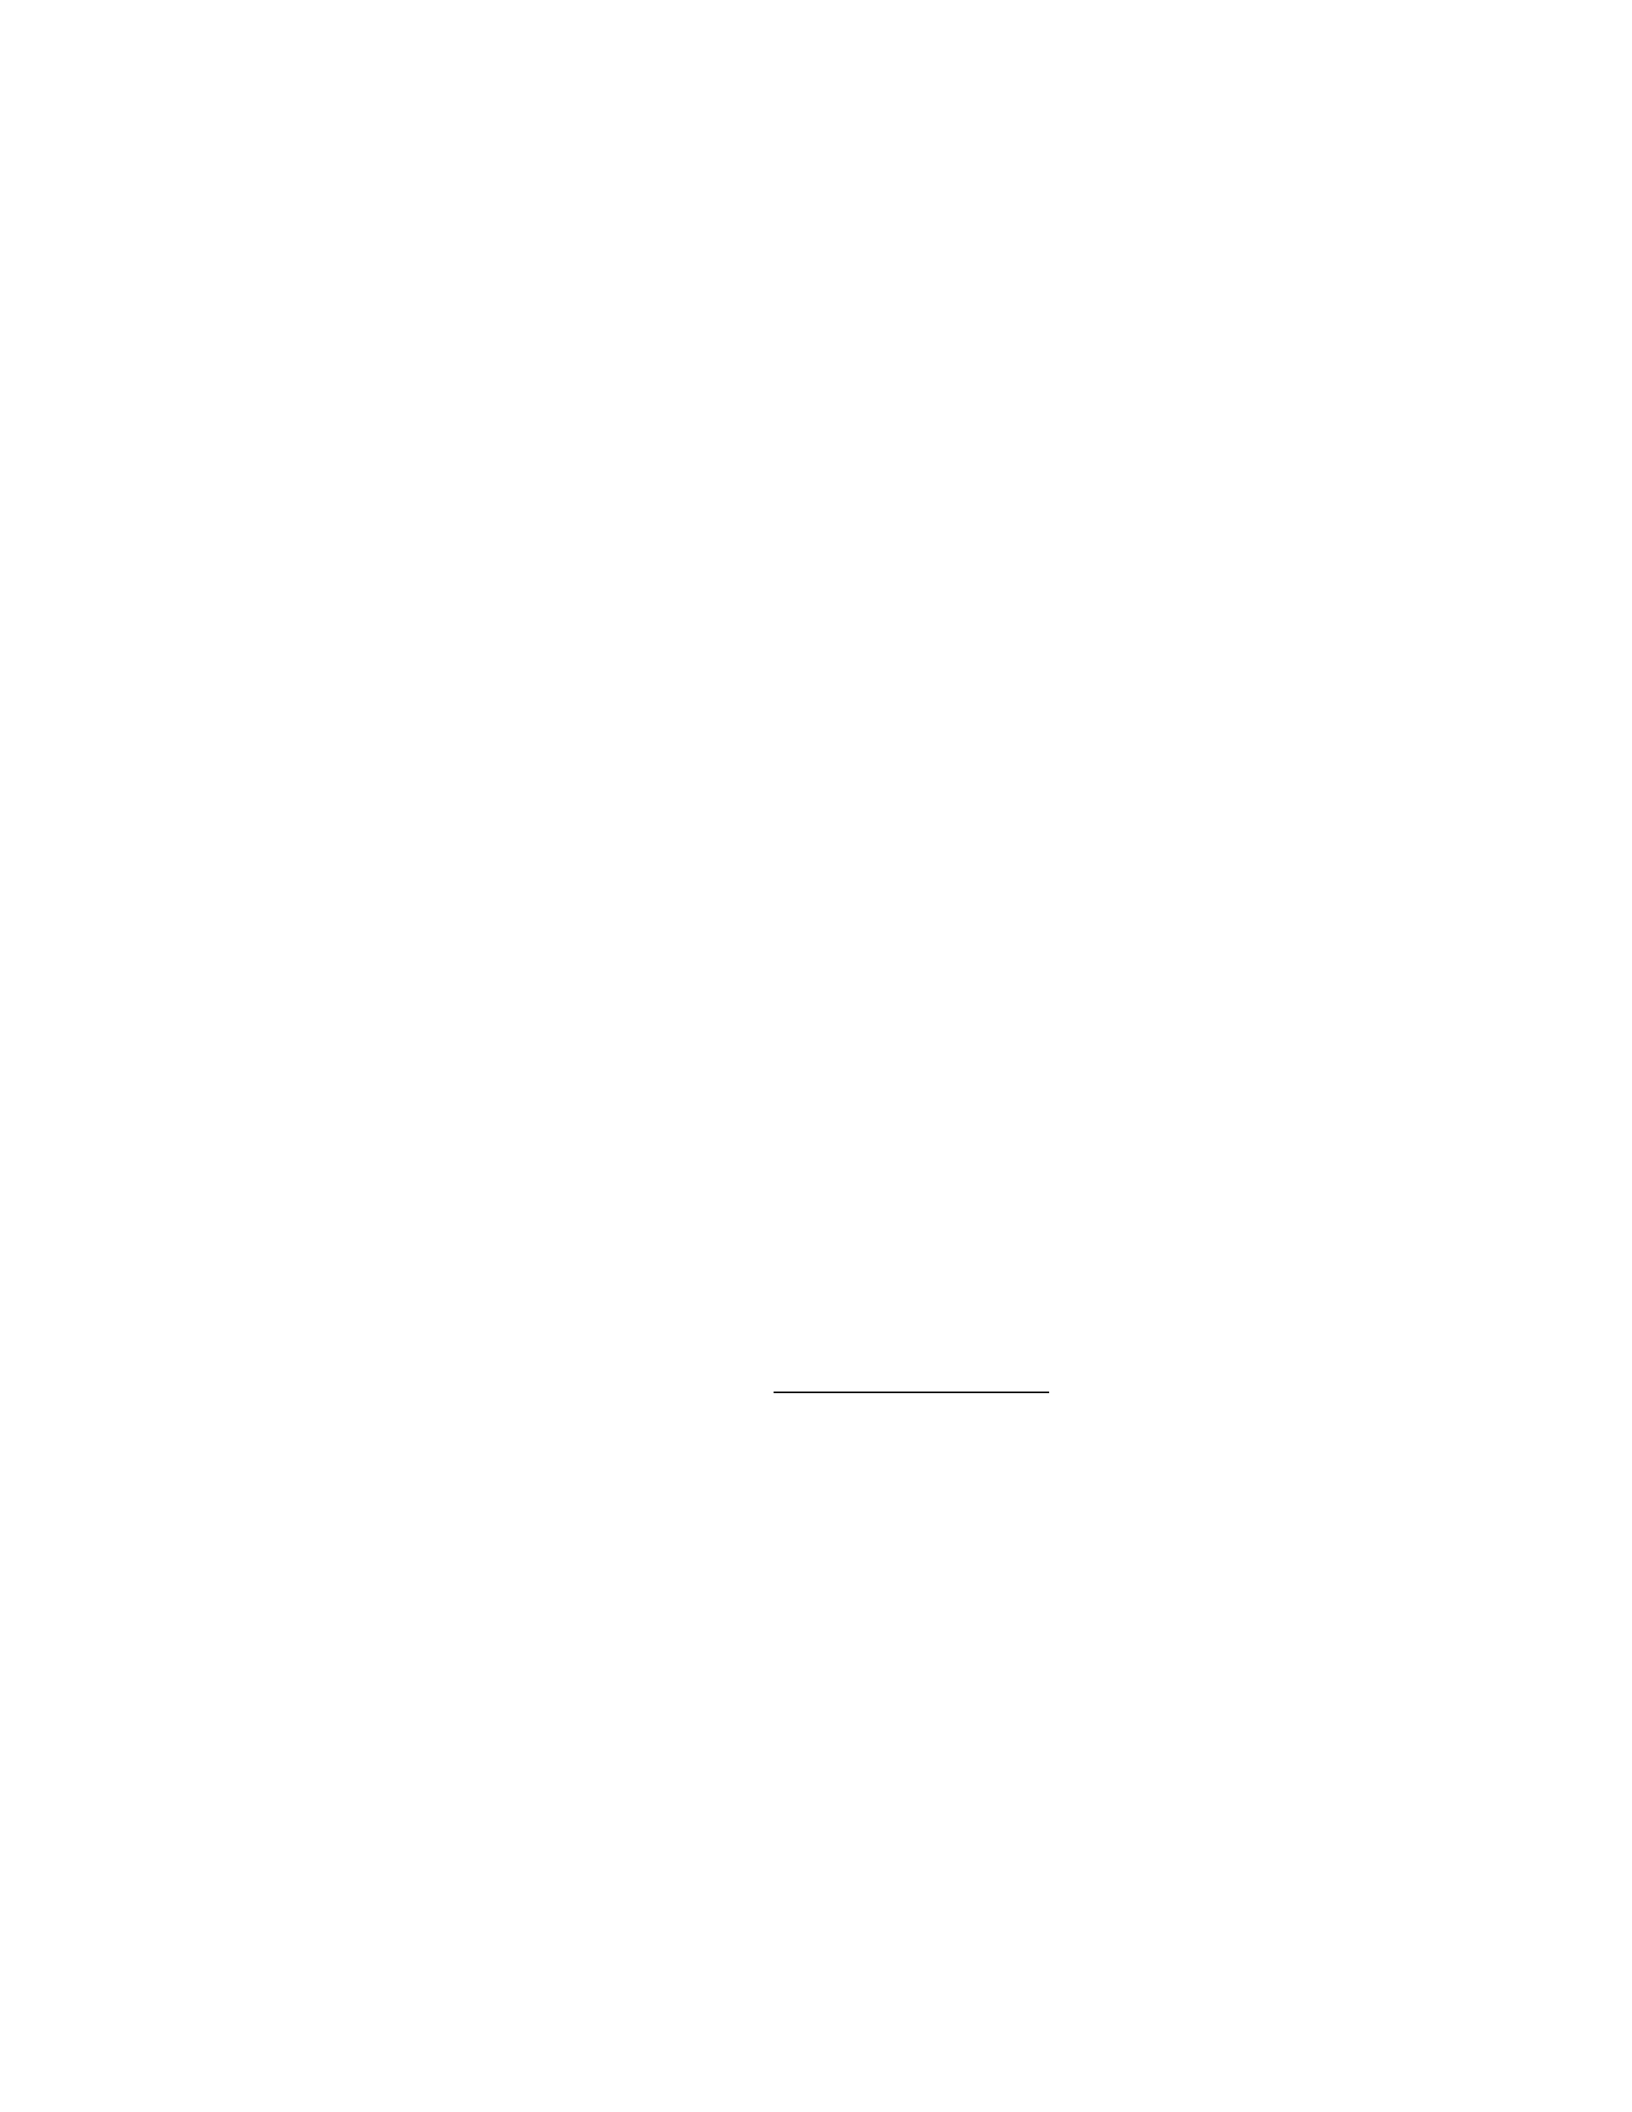
TDS = HE + CP + LE + CCI
AHI
Where:
HE = housing expenses
CP = car payments
LE = loan expenses
CCI = credit card interest
AHI = annual household income
33
Loan-to-value (LTV) ratio is the percentage of down payment a borrower will
commit relative to the appraised value of the subject property (Scanlon & Elsinga, 2014).
A higher LTV ratio indicates a riskier transaction because the borrower has little invested
which will result in more interest payments (Scanlon & Elsinga, 2014). Ferreira et al.
(2014) mentioned that LTV ratio is a commonly used criterion to determine mortgage
lending risks. During an economic crisis where house price falls, borrowers with higher
LTV ratio could be in a negative equity position (Quercia et al., 2012). Consequently, the
probability of default is higher for borrowers to foreclose either voluntarily or
strategically. Lin (2014) found that LTV ratio could serve as an indicator to determine the
probability of a borrower default potential. Lower LTV ratio indicates a lower credit risk
for the lender (Sanderford et al., 2015). Conversely, Glascock and Lu-Andrews (2014)
argued that there is no relation between mortgage default and LTV. However, in cases
where secondary financing is present, there is a positive relationship between mortgage
default and mortgage duration (Gan, Li, Wang, & Kao, 2012). Quercia et al. (2012)
argued that high LTV alone does not trigger default, other factors such as unemployment,
high-interest rates, prepayment penalties, and balloon payments could facilitate
foreclosures. The formula to calculate LTV ratio is as follows,
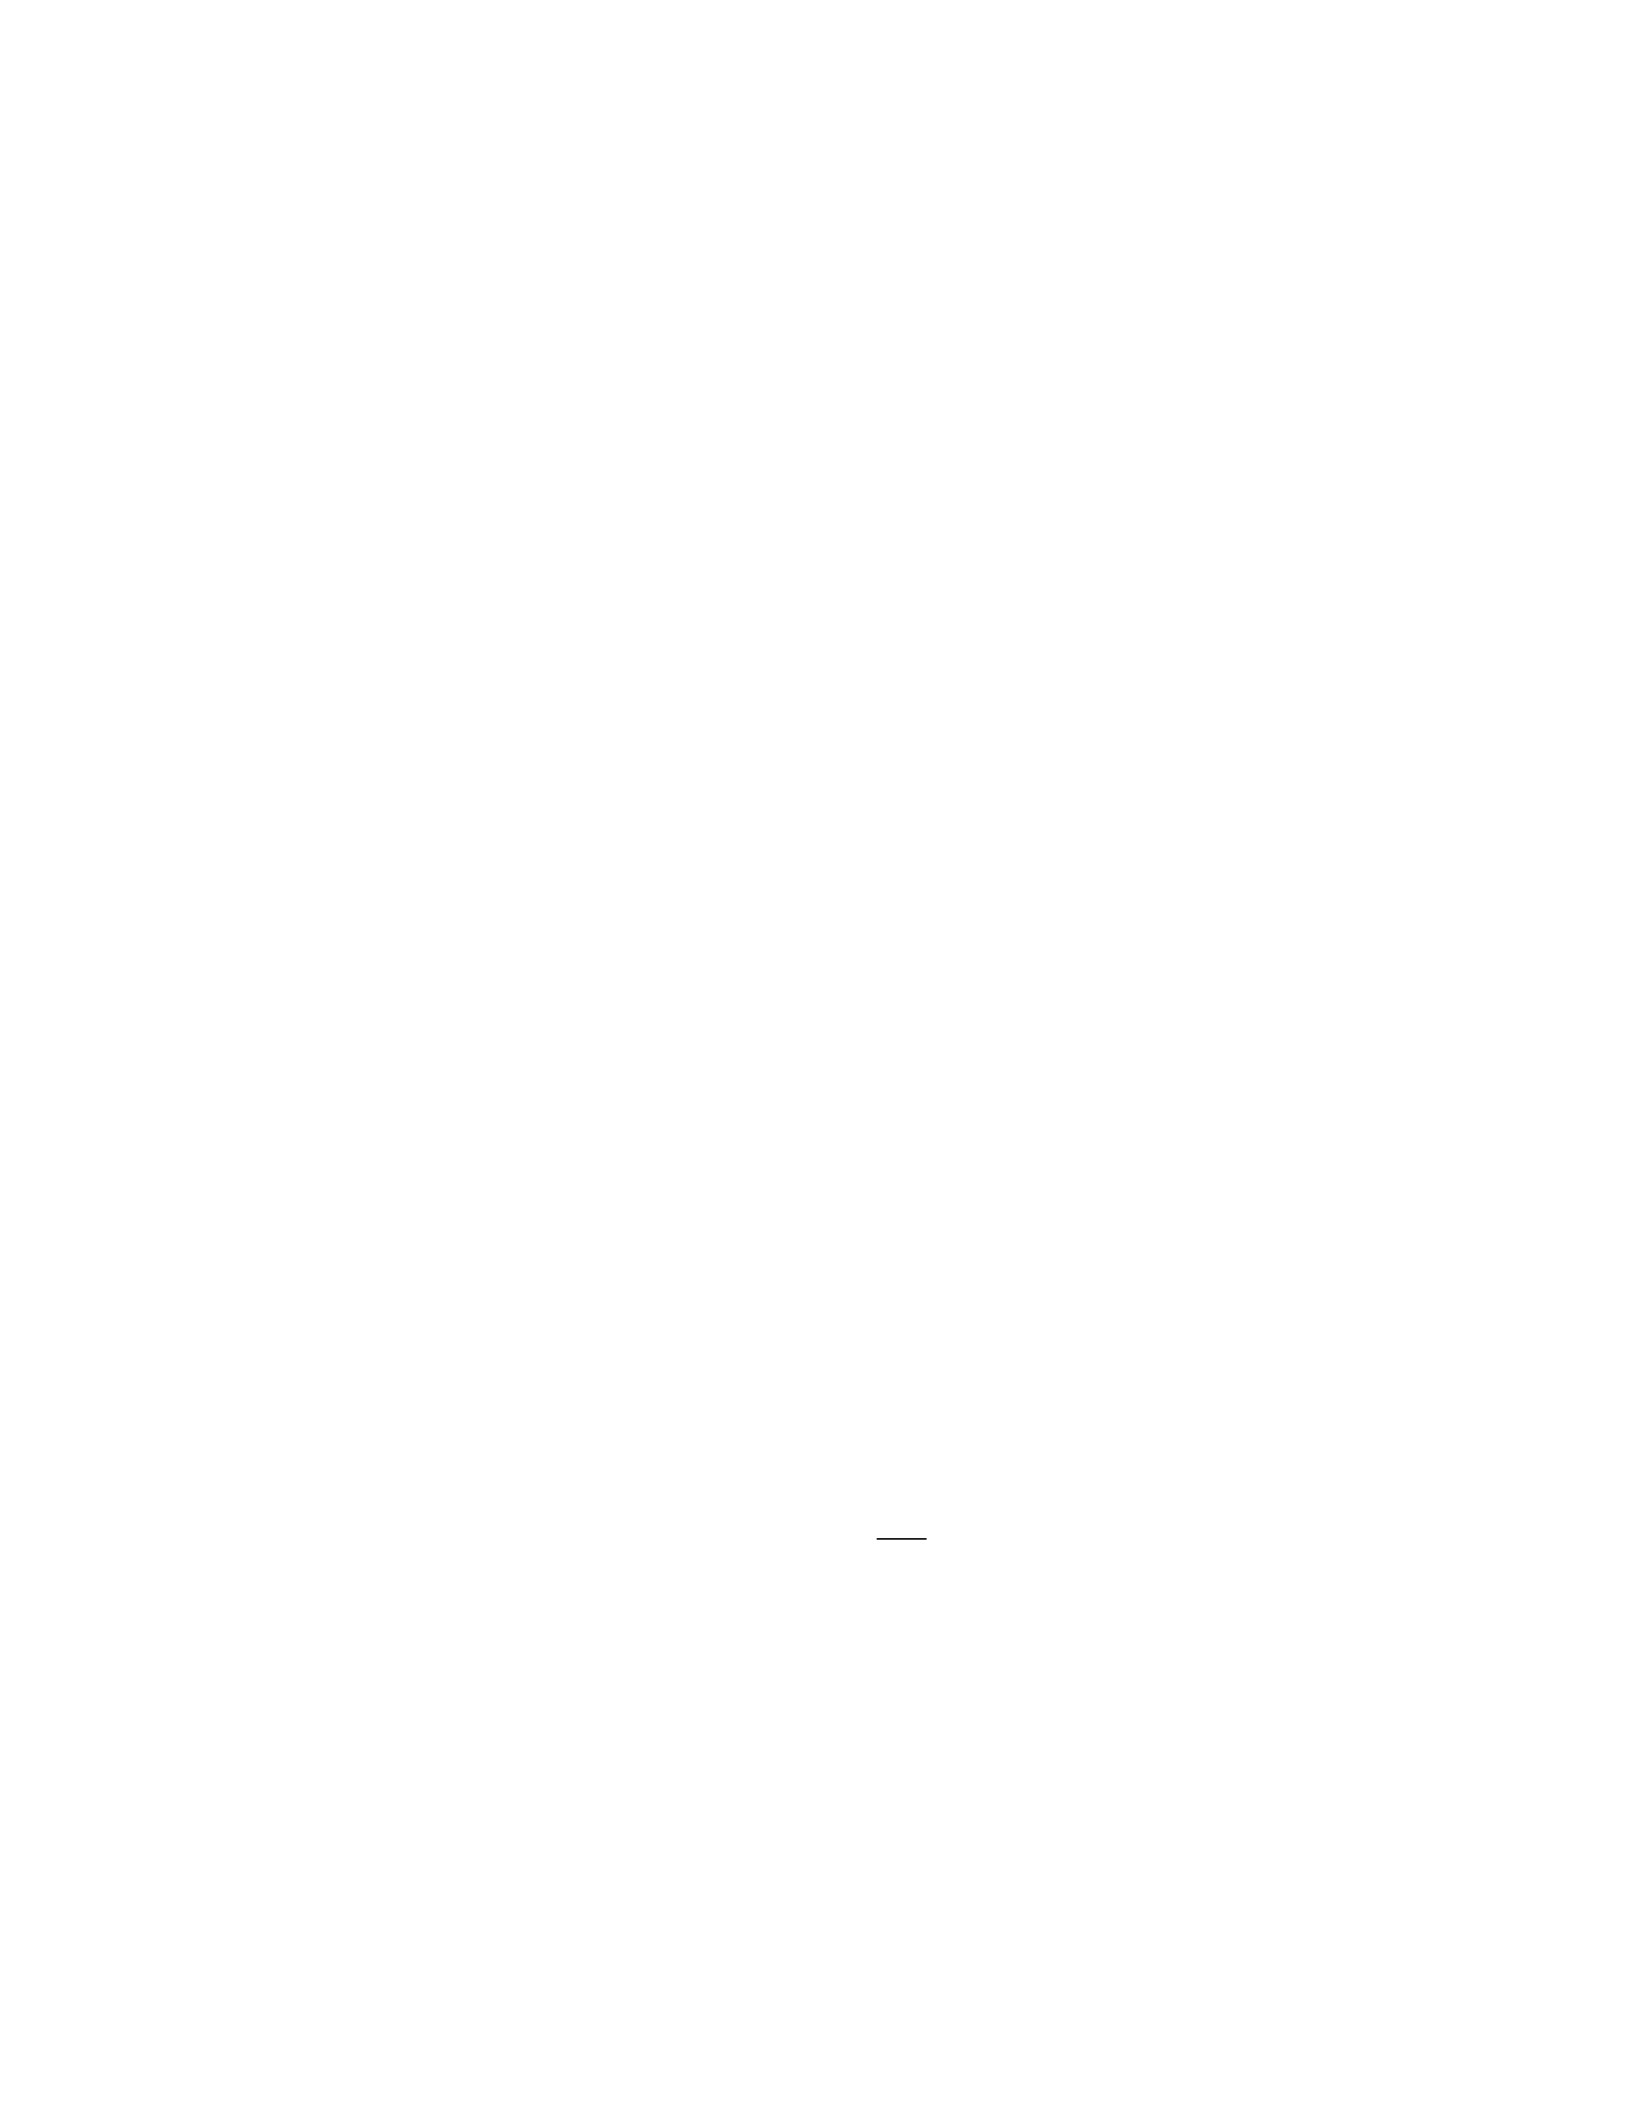
LTV = MA
APV
Where:
MA = mortgage amount
APV = appraised property value
34
Debt-Service-Coverage-Ratio (DSCR) enables underwriter and lenders to
determine how much of the annual rental income covers the annual principal and interest
payments (Galster et al., 1999). Additionally, DSCR enables landlords and mortgage
underwriters to measures the rental property ability to service the current debts obligation
by comparing net operating income with total debt obligations (Ofonyelu & Alimi, 2013).
Consequently, DSCR enables the comparison of a rental property available cash flow with
the current interest, principal, and sinking fund obligations (Galster et al., 1999). Given
that DSCR measures rental property ability to maintain debt obligations, lenders value
this ratio (Galster et al., 1999). DiPasquale and Cummings (1992) found that lenders and
underwriters of multifamily rental property, value DSCR as more important in ranking
than LTV ratio. The formula to calculate DSCR is as follows,
DSCR = NOI
TDS
Where:
NOI = net operating income
TDS = total debt service
A credit score can range from 300 to 900 and represent the probability of
borrowers’ ability to service current or future debts (Ferreira et al., 2014). Sharpe and
Sherlund (2016) stated that the purpose of credit scoring is to classify borrowers in either
a good credit or bad credit group. To mitigate financial risks and uphold high underwriting
standards, underwriters have improved the credit scoring systems (Ferreira et al., 2014).
Pennington-Cross (2012) mentioned that higher credit score could result in higher quality
loans. A higher credit score indicates that the borrower is less likely to default on
35
payments (Ferreira et al., 2014). Therefore, borrowers with lower credit score have a
higher probability of mortgage application rejection, higher interest rates, or may require a
co-signor (Sharpe & Sherlund, 2016). Conversely, Quercia et al. (2012) stated that the
calculation of credit scores is less transparent and needs updating. Wahyudin, Djatna, and
Kusuma (2016) mentioned that there is a leakage between the credit scoring system and
the borrower financial quality. A credit score derives based on several input variables of a
borrower characteristic, reported on the borrower credit report (Sharpe & Sherlund, 2016).
A credit report records a borrower payment history, outstanding balance or utilization,
length of credit history, types of credit used, and frequency of new credit application (My
Money Coach, 2015).
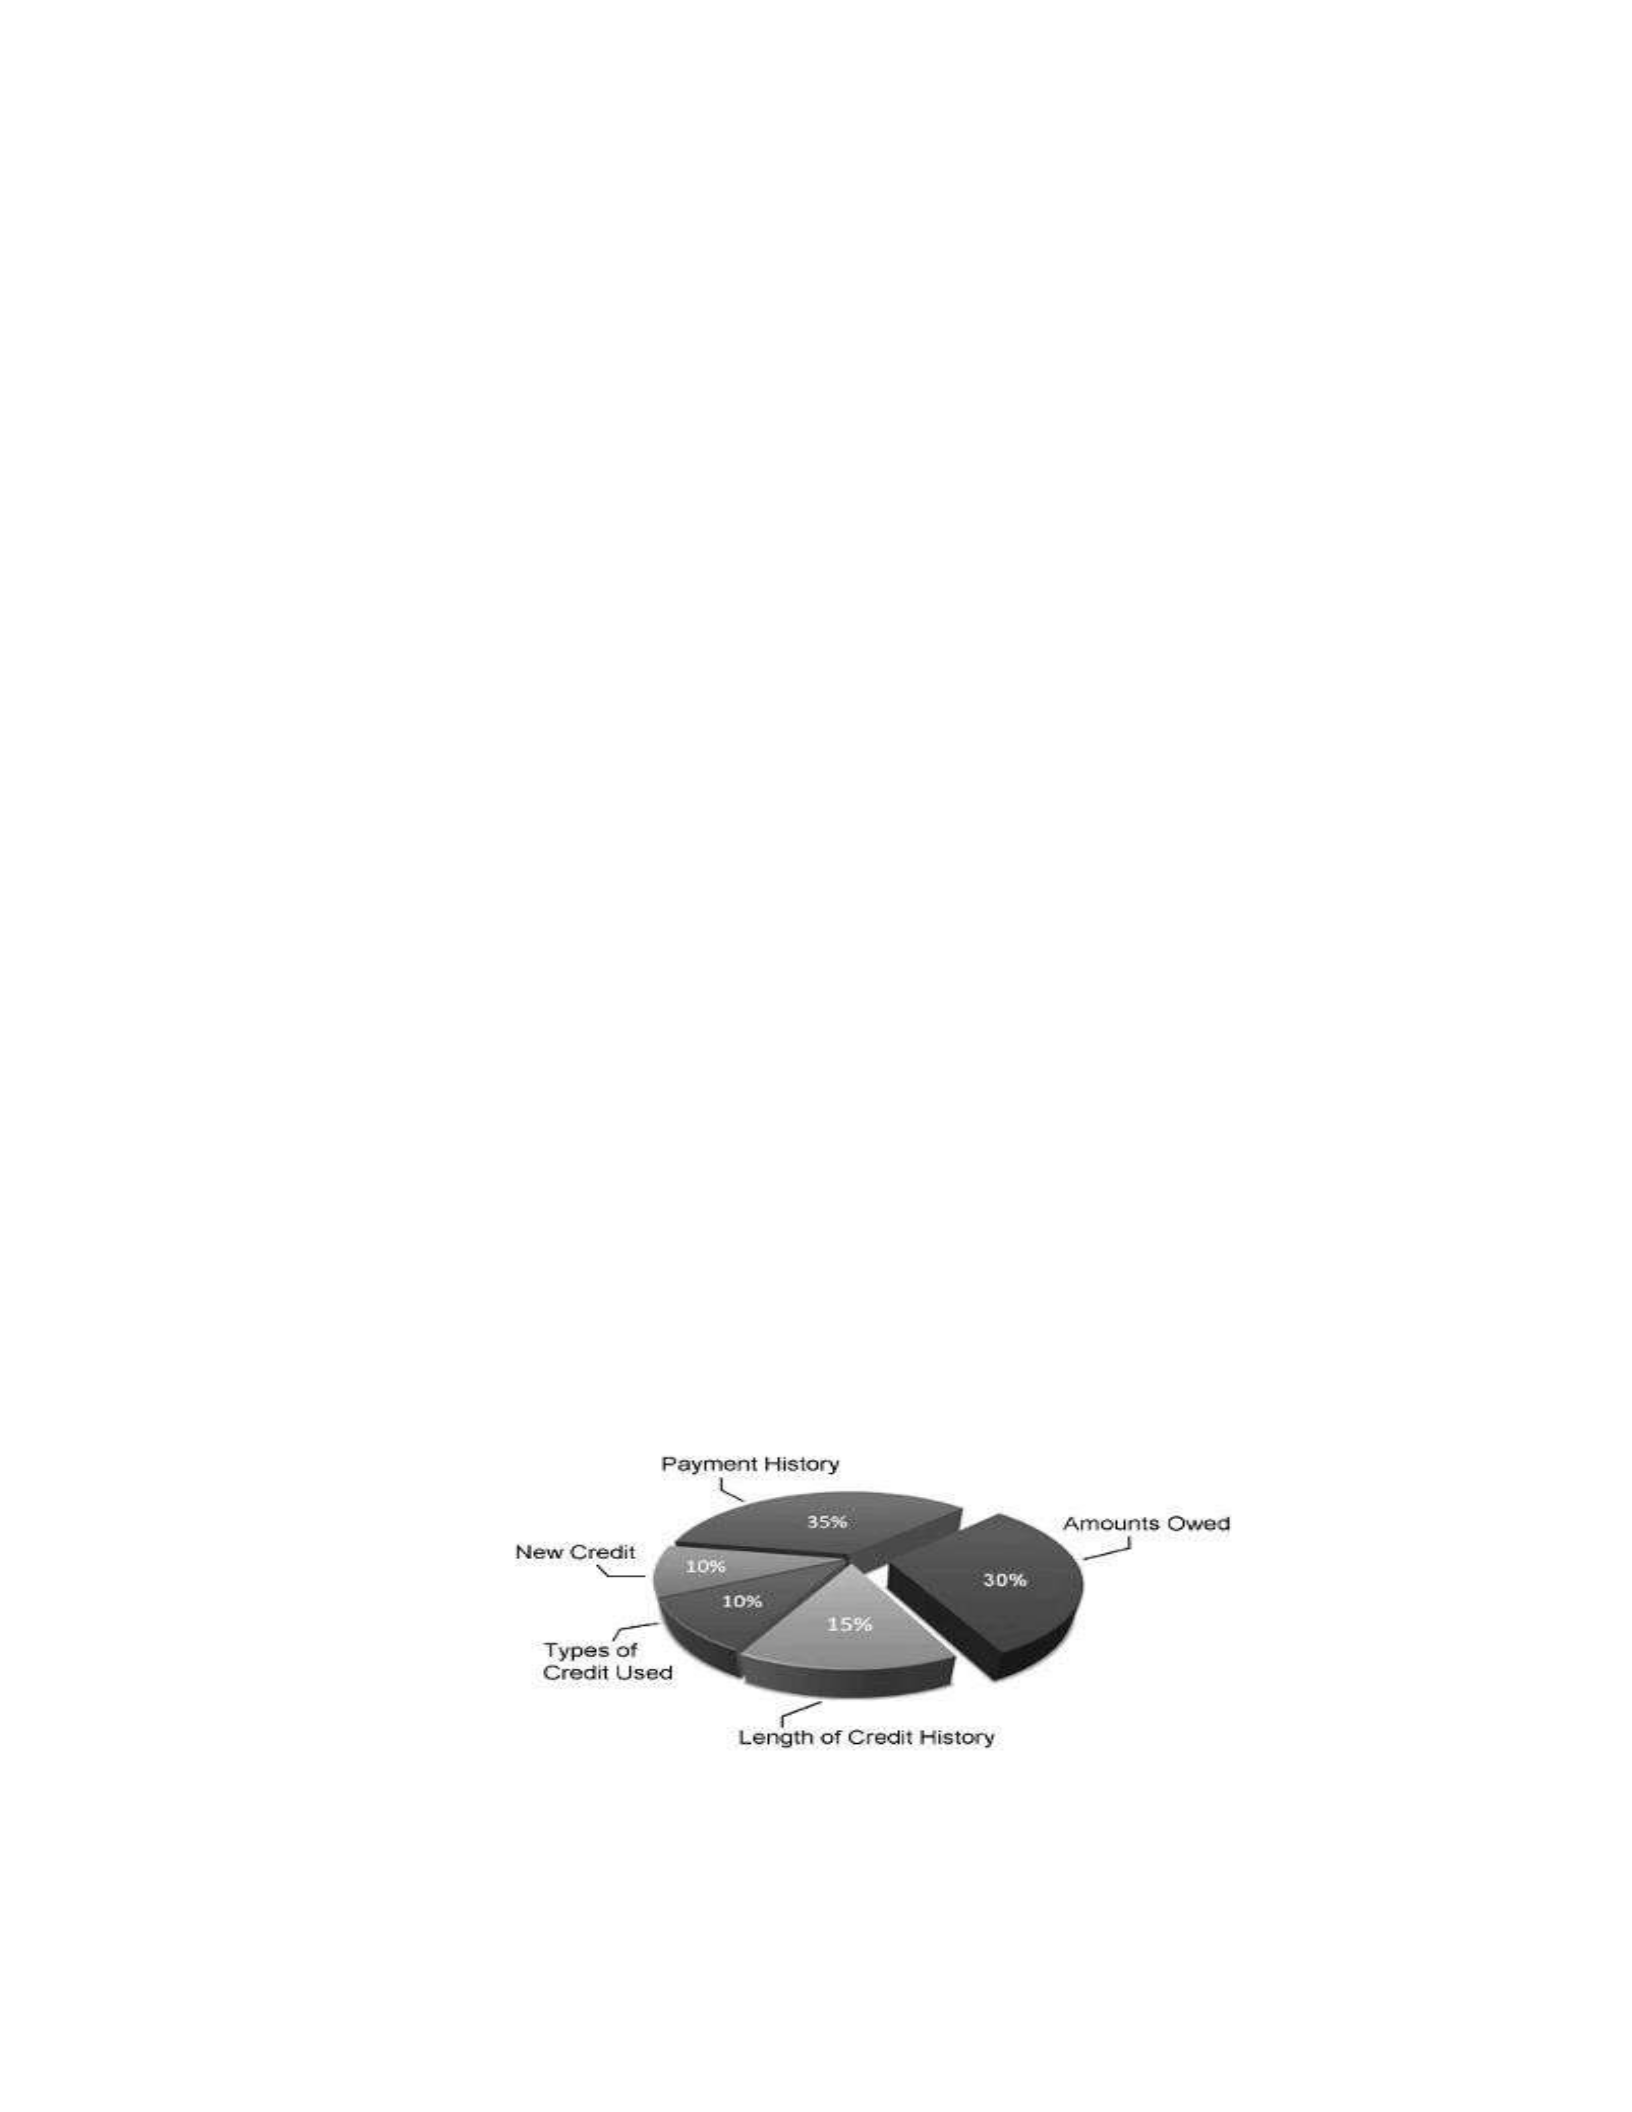
Five factors that affect credit score are payment history, balance outstanding, new
credit inquiries and applications, types of credit, and length of credit history (Volpone,
Tonidandel, Avery, & Castel, 2015). Payments history accounts for 35% of the credit
score, balance outstanding or credit utilization accounts for 30%, length of credit history
accounts for 15%, and both credit inquiries and types of credit accounts for 10%
respectively (My Money Coach, 2015) (see Figure 1).

36
Figure 1. Five key factors in calculating and determining your credit score. Copyright
2015 by My Money Coach. (2015). What is a credit score & how is a credit score
calculated in Canada. Retrieved from http://www.mymoneycoach.ca/credit/check-
creditrating-report-score/what-is-a-credit-score
Payment history is a reflection of payments made to creditors and accounts for
35% of the credit score (Sah, 2015).). Payment history highlights payments made within
30 days, 60 days, and 90 days or sent to collections. Additionally, payment history shows
bankruptcy information if the debtor claimed bankruptcy in the past. Further, credit
reports also present creditors and credit utilization information separately for each
creditor. Creditors of credit cards, lines of credit, car loans, personal loans,
telecommunication, mortgages, and other debts regularly send payment details to the
credit-reporting agency. At that point, the credit-reporting agency tabulates and report the
debtor credit score for the period (My Money Coach, 2015).
Credit utilization is another aspect of a borrower credit history that accounts for
30% of the credit scores (My Money Coach, 2015). Credit utilization is how much of the
available credit a borrower used (Citron & Pasquale, 2014). The amount outstanding
relative to the available credit limit could represent the borrower financial situation.
Utilization of 75% or more of the available credit limit could rank the borrower in a higher
risk category and negatively influence the credit score (My Money Coach, 2015).
The length of credit history is the third largest component that influences the credit score
and accounts for 15% of the credit score (My Money Coach, 2015). The length of credit
history shows the history of each payment categorized by individual creditors (Steinbuks,

37
& Elliehausen, 2014). The length of credit history enables an underwriter to review a
borrower credit history over a longer period and determine the probability of default (My
Money Coach, 2015).
A credit report highlights the number of times borrowers apply for new credit or
the number of credit inquiries performed on the borrower (Carl-Christian & Hemlin,
2012). Additionally, a credit report highlights the number of new accounts recently
opened. New applications and inquiries account for 10% of a borrower credit score,
therefore, more inquiries and new accounts could lead to a lower credit score (My Money
Coach, 2015). Additionally, a higher number of new accounts and credit inquiries indicate
to lenders that the borrower could be riskier.
The final component of the credit report highlights the type of credit used by the
borrower. This component accounts for 10% of the borrower credit score and could
indicate how a borrower manages their finances (My Money Coach, 2015). Payment
plans, consumer proposal, and debt consolidation are some types of credit that could
indicate that the borrower is having difficulties servicing current debt obligations
(CarlChristian & Hemlin, 2012).
The property appraised value is a critical aspect of the underwriting process.
Arsenault, Clayton, and Peng (2013) stated that the value of the property assists in
determining collateral or equity which is taken into consideration when assessing credit
risk. Additionally, lenders and underwriters rely on property appraisals as a confirmation
of value and security (Guo, Xu, & Bi, 2014). Appraisers conduct evaluation of the real
property to determine fair market value and collateral (Austin, 2013). Three appraisal

38
approaches are sales comparison, income capitalization, replacement cost approach (Guo
et al., 2014). DiPasquale and Cummings (1992) found that lenders may require that the
subject property is appraised based on either one of the three valuation models, market
comparison, cost replacement, and capitalization. The property appraised value will assist
in determining the equity position of the property, especially in recessionary periods
(Quercia et al., 2012). Zietz (2003) mentioned that the value of a rental property is
dependent on the property proximity to major cities, economic activity in the
neighborhood, age, and rental income. A lender uses the value of the property as collateral
in the event that the borrower default or are unable to service their debt obligation
(Austin, 2013). If a borrower cannot service their debt obligation, the lender will foreclose
and sell the subject property to recoup mortgage principal and accrued interest (Liu &
Quan, 2013). Consequently, it is paramount that the appraised value is accurate and free
from bias to ensure that there is minimal risk exposure for lenders.
A borrower industry experience and education are important factors during the
underwriting process for multifamily rental property. Gan et al. (2012) found that
borrowers with a formal education are less likely to default on their debt obligation.
Lenders and underwriters view multifamily rental property as risky because rental
property management could become cumbersome (DiPasquale & Cummings, 1992). A
lender or underwriter may feel more secure that the borrower experienced dealing with
tenants and is aware of the real estate industry laws and regulations. Borrowers with little
or no experience managing rental property have a higher probability of making decisions
that might not be cost effective, resulting in lower return on investment (Kabir, 2015).

39
Therefore, the more property management or rental property ownership experience a
borrower has, the better the chance of getting approved for a new mortgage.
A borrower employment history and consistency shows stability and is a positive
indication of the borrower creditworthiness (Hoelle, Pireddu, & Villanacci, 2016).
Quercia et al. (2012) found that income has a direct relation to foreclosure and mortgage
default as it impacts the borrower ability to service mortgage obligation. Employment
income is a confirmation that the borrower has a stable income to support the rental
property in the event that collecting rent from tenants becomes challenging. Additionally,
employment income could be beneficial if there is a requirement for significant capital
expenditure. Lenders and underwriters perceived borrower with longer employment
history as presenting less probability of default or late payments. Therefore, higher
household income indicates that a borrower is less likely to default (Gan et al., 2012).
Pennington-Cross (2012) stated that higher quality loans are possible for borrowers with
high credit score and verified income. Gan et al. (2012) found that occupation has a direct
relation to income level; stable employment and professional occupation are less likely to
default on debt obligations.
Lending criteria are indicators that underwriters analyze when making lending
decisions (Quercia et al., 2012). Underwriters’ objective when conducting analysis of
lending criteria is to reduce the probability of lending to borrowers who could not service
the mortgage debt obligation (Sanderford et al., 2015). Pennington-Cross (2012)
mentioned that while mortgage regulations alone cannot prevent a financial crisis, it could
reduce the effect of a crisis. Quercia et al. (2012) stated that while stricter mortgage

40
underwriting criteria could assist in reducing default, it could also limit access to credit.
Galster, Tatian, and Wilson (1999) found that single dimensional lending criterion are not
isolated and further investigation is needed to identify which multifamily rental property
lending criteria have higher probability of default. Although, not all criteria have the same
weighting and different types of lenders may view the importance differently, each
criterion assists to identify potential strengths or weaknesses of a mortgage applicant
character and application (Wilson, 2016). Therefore, lending criteria works within a micro
system and any challenges within the system could hinder or affect the application and
distribution of multifamily rental property mortgages.
Mortgage Financing Relation to Systems Theory
Biologist Ludwig von Bertalanffy introduced systems theory in the 1940s (von
Bertalanffy, 1968). Laszlo and Kripper (1998) mentioned a system consists of natural
phenomena and a process to accomplish a common goal. Systems are in sciences,
economics, nature, and information systems (Cudworth & Hobden, 2013). Mangal (2013)
stated that a system is a group of components strategically organized and interact,
functioning as a single unit. Chan (2014) stated that a system comprised of several
interacting elements working together in a dynamic environment. Systems theory focuses
on the arrangement and relationship between the components that connect them as a
whole (Sayin, 2016). Systems theory originally focused on physics, biology, and
engineering but further evolved into other fields, such as sociology, economics,
management, philosophy, and organizational theory (Bunn, 2014). Tuan and Shaw (2016)
mentioned that social systems have similar characteristics as supra-individual entities.

41
Mangal (2013) stated that an effective and efficient system should incorporate
selforganization, resilience, and hierarchy.
Therefore, components within the mortgage lending process operate as a system.
Further, mortgage financing could also be one component within a macro system. To be
effective and efficient, lending criteria self-organization and robustness are critical.
Mortgage underwriters decide to approve or reject a mortgage application based on the
lending guidelines and criteria assessment (Neidermeyer, Boyd, & Neidermeyer, 2014).
Mortgage underwriters and the mortgage process interaction represent a hierarchical
function. Any challenges within the underwriting process or criteria that do not meet the
required benchmark could result in more processing time or application rejection by the
mortgage underwriter. Further, misunderstanding or misinterpretation of mortgage lending
criteria could hinder transparency and increase mortgage application processing time.
Therefore, testing the resilience of a mortgage lending system by incorporating feedback
and achieve a common goal. Awareness of the ranking of mortgage underwriting criteria
among different categories of lenders could assist borrowers when seeking mortgages for
multifamily rental properties. Consequently, mortgage agents and brokers could become
more efficient, as they will spend less time processing mortgage applications and
achieving higher approval rate.
Ferreira et al. (2014) found that the relationship between the economy and
mortgage lending is mutual. Ofonyelu and Alimi (2013) stated that a successfully banking
system relates to the performance of businesses and the economy. Further, Jones and
Richardson (2014) stated a direct relationship exists between real estate prices and the
42
macro economy. Therefore, mortgage financing is a micro system that is also a critical
function within a macro environment.
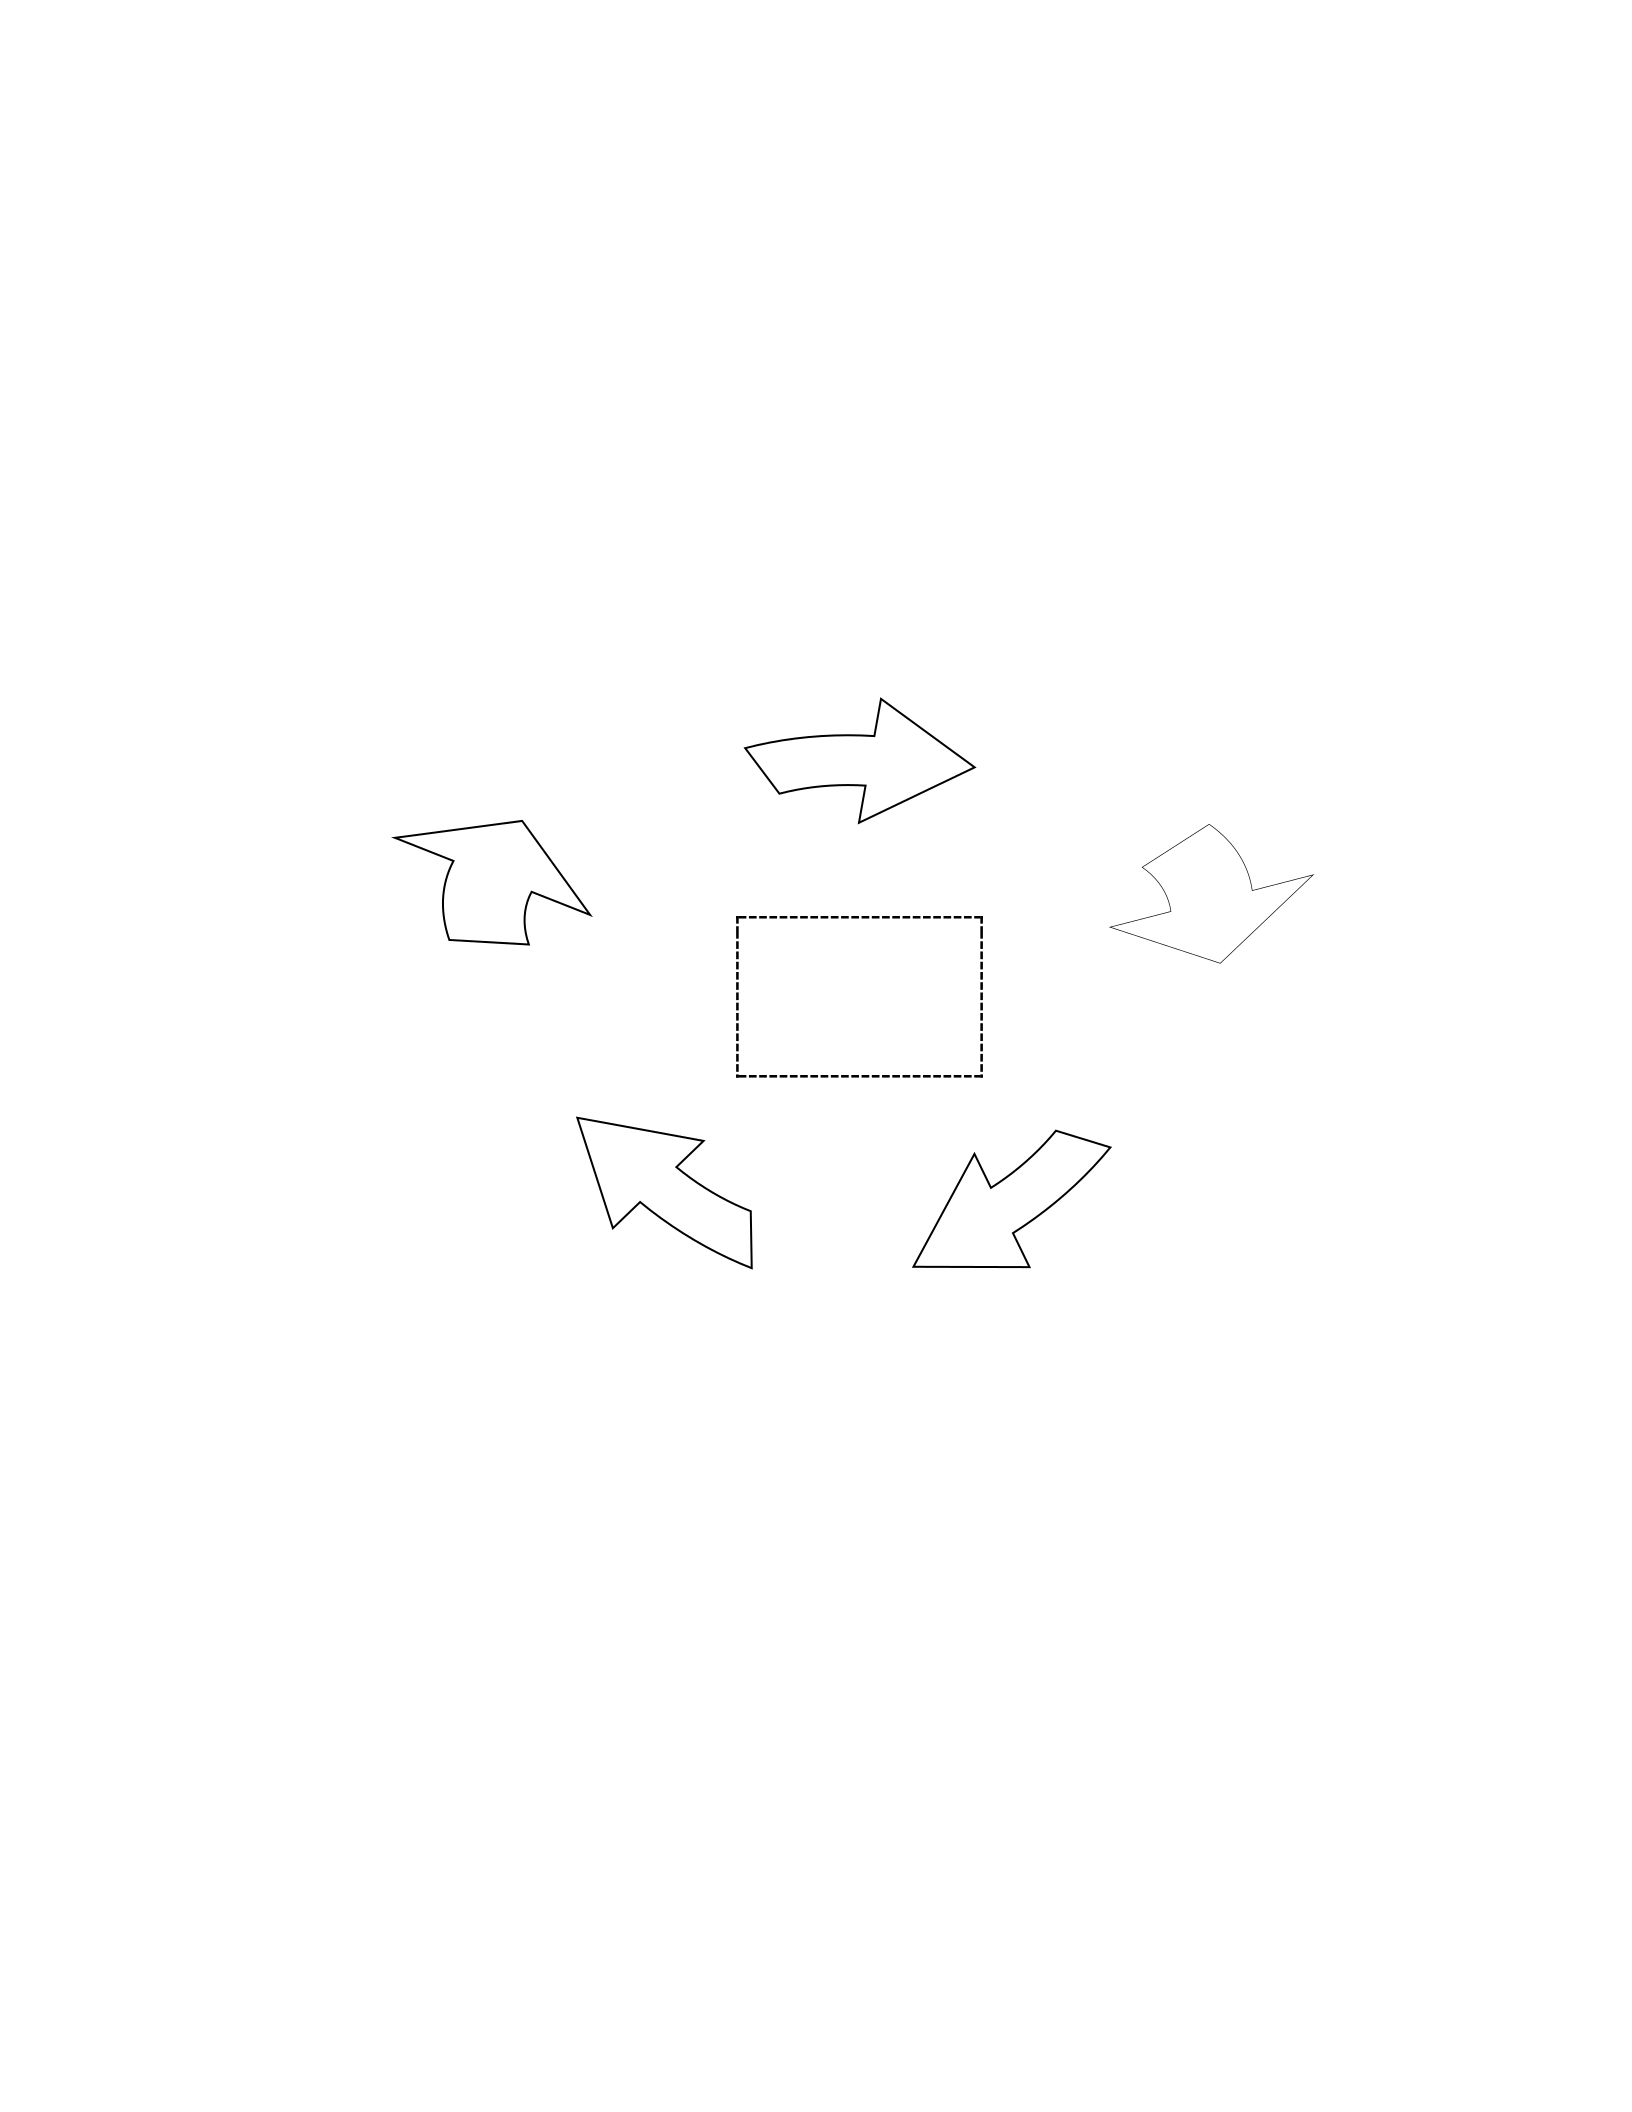
Figure 2 displays how financing, business spending, employment, government
revenue, and government spending contributes to macro-economic growth. Any
challenges with one or more of the components of this macro system could directly or
indirectly impact components within the system. Consequently, impacting macroeconomic
growth.
Government
Employment Revenue
Business Government
Spending Spending
Financing
Figure 2. Factors that impact macro-economic growth
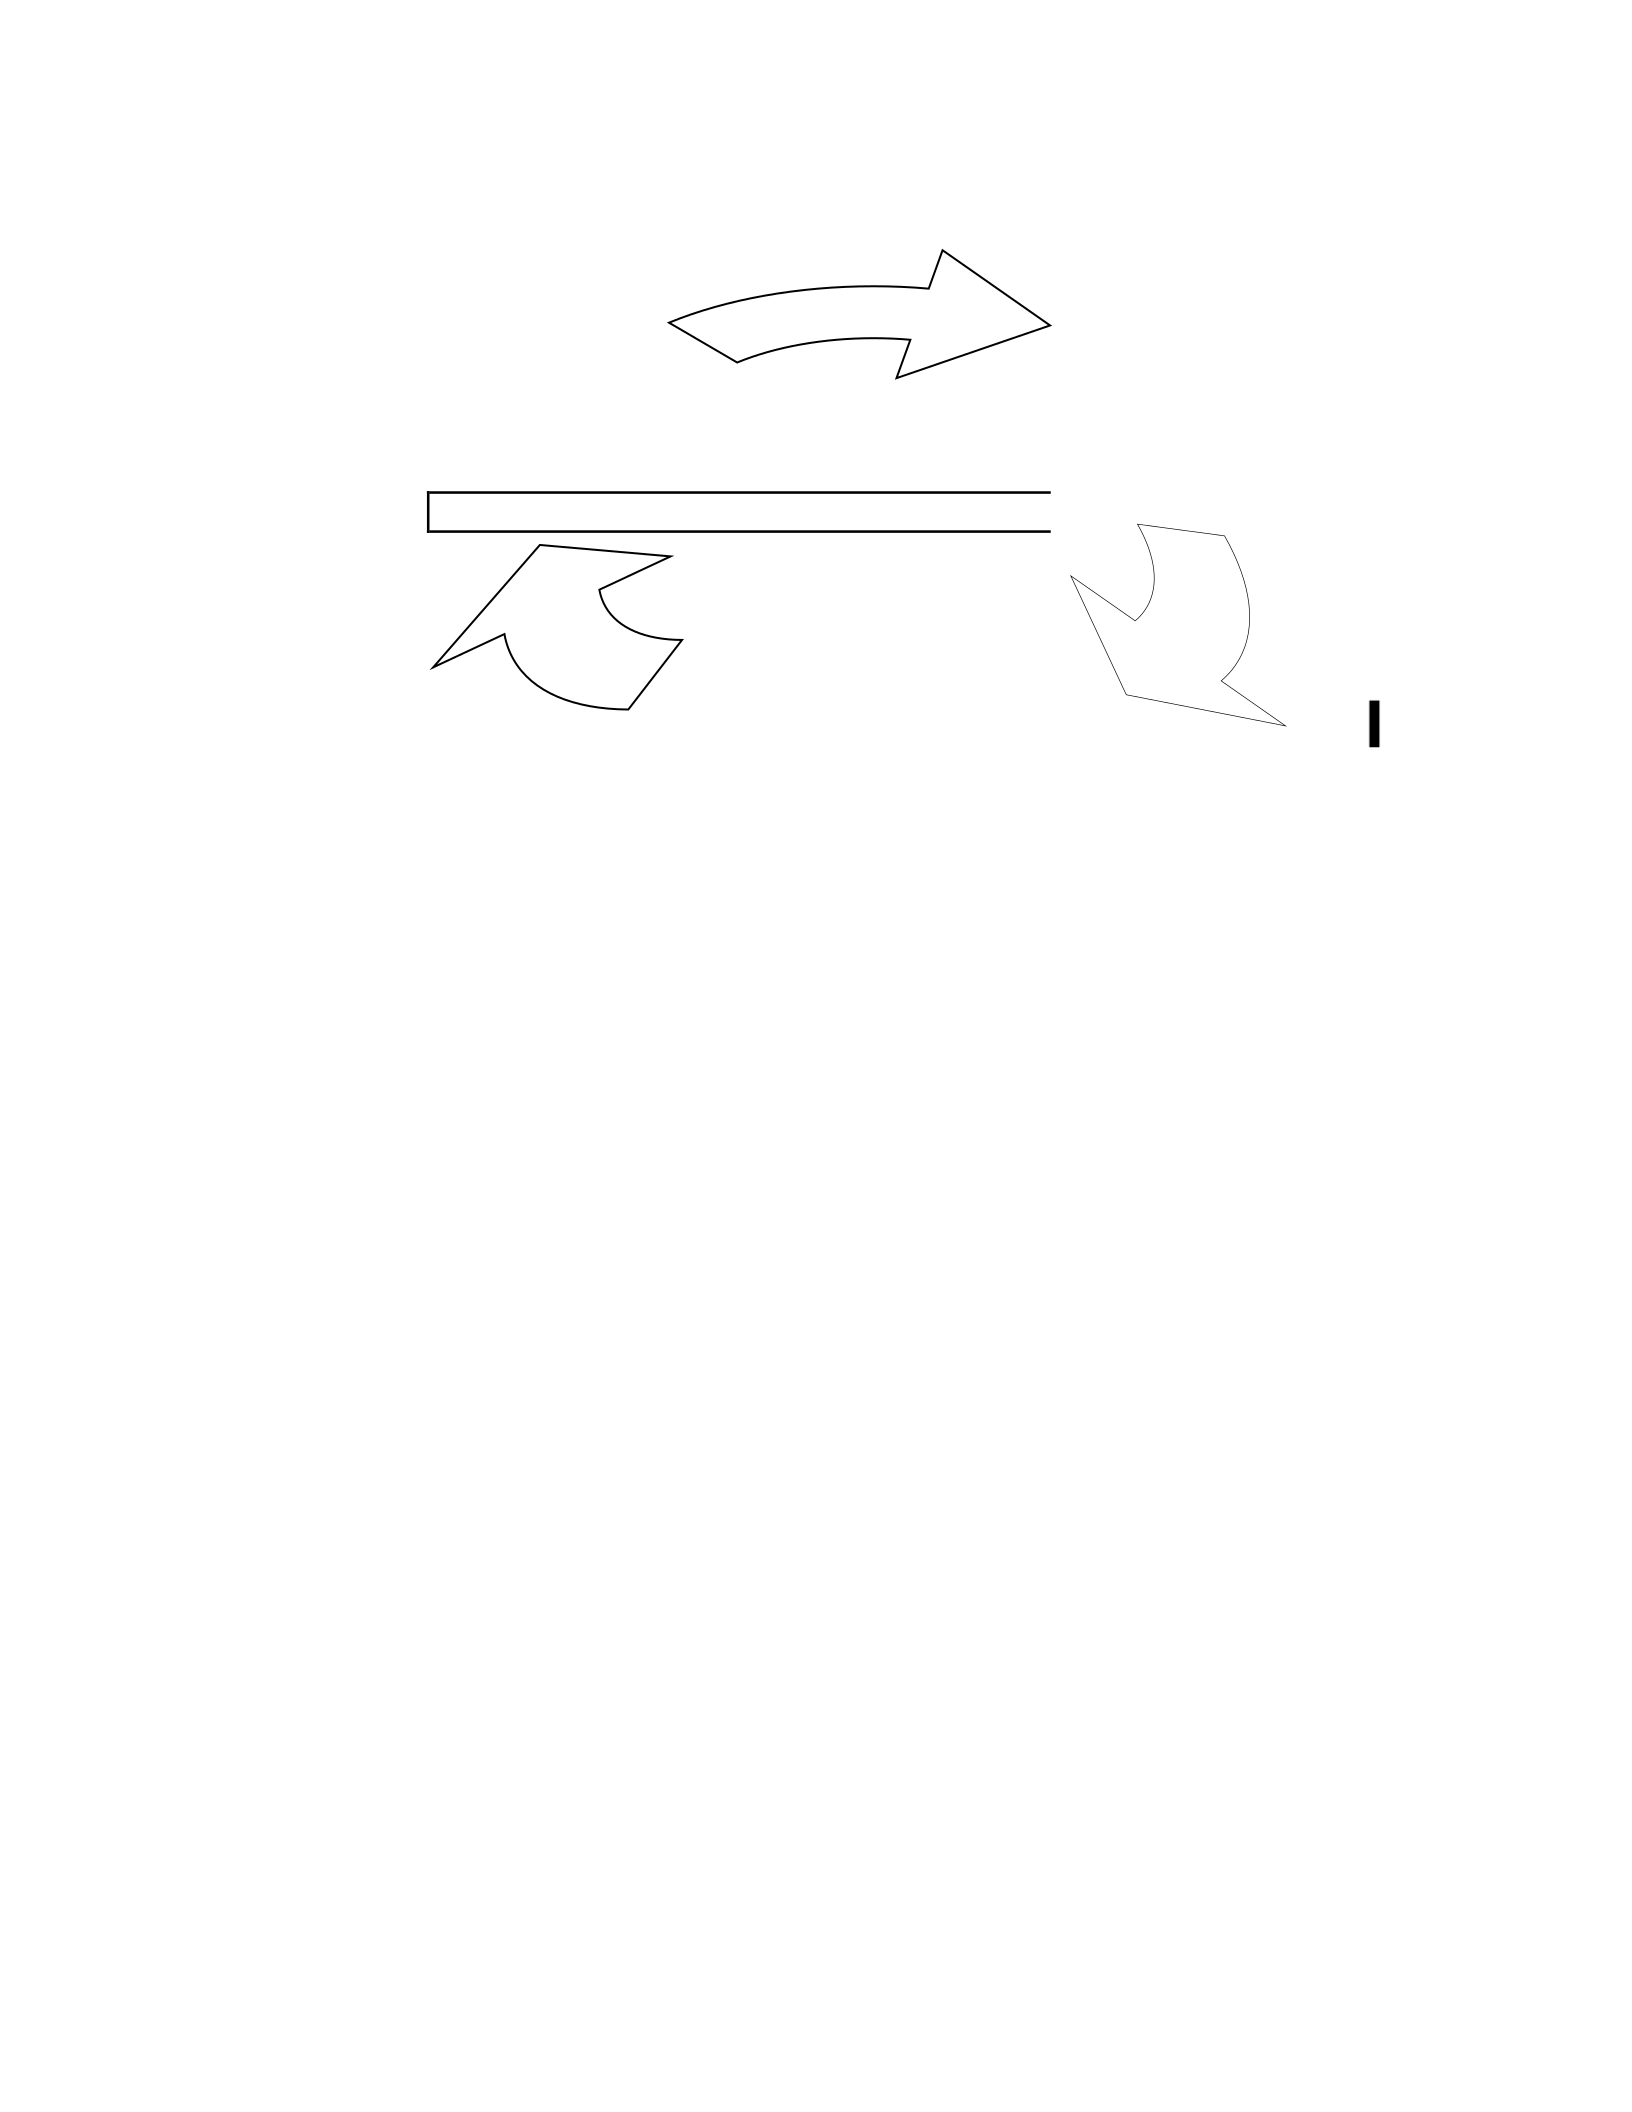
Figure 3 displays how mortgage underwriting criteria could assist in determining
whether to approve or reject a mortgage application. Mortgage lending criteria operate
within a micro system that forms part of the financing component in a macro system.
Further, a barrier within the macro system could impact the micro system and barrier
within the micro system could impact the macro system.
MacroEconomic
Growth
43
Mortgage
Criteria Mortgage Satisfied Funded
Micro
Financing Growth
Mortgage
Application
Figure 3. Lending criteria and micro financing growth
Mortgage financing as a whole is one component within a macro system. Any
challenges that hinder mortgage financing could eventually affect the macroeconomic
system. Mortgage financing is critical in assisting potential homeowners to acquire real
property without having the full amount of the purchase price to fund the transaction
(Ferreira et al., 2014). Ferreira et al. (2014) stated that mortgage financing fosters
homeownership and encourage builders to build more homes, which eventually lead to job
creation and increased employment. Therefore, mortgage financing could promote local
and global economic growth (Ferreira et al., 2014). The aspect of mortgage financing acts
as a system and could impact both local and global economies and an economy gross
domestic product (GDP) (Ferreira et al., 2014). Limited mortgage financing could lead to
higher interest rates, increased mortgage fraud, reduced building and construction, and
increased unemployment. Consequently, limited financing could trigger local and global
economic contraction (Darvas, 2014). During or after a recessionary period mortgage
financing become limited because lenders are more hesitant to lend during periods of
uncertainty (Ofonyelu & Alimi, 2013). Lenders usually increase scrutiny of mortgage

44
applications and adapt more mortgage underwriting criteria during recessionary periods
(Ferreira et al., 2014).
The 2007-2009 recession negatively impacted households, businesses, and
governments causing a global economic crisis. After careful analysis and investigation of
the recession, financial experts identified that several practices in the housing industry
contributed to the recession. Lower underwriting standards and tax incentives triggered an
increased demand for homeownership. The increased demand for houses outweighs the
supply of houses and caused an upward pressure on prices. As house prices increased and
with low or sub-standard lending practices, homeowners took out equity in the form of
second mortgages or line of credits. The effect of current market value and interest rate
encouraged equity takeout. To combat inflation, financial regulators implemented small
incremental interest rates increases. The interest rate increases caused an increase in
household debts, which eventually triggered some mortgage defaults and foreclosures.
As foreclosures increased, the supply of houses increases. This economic
phenomenon caused an oversupply of houses, which eventually put downward pressure on
house prices and value. As house value decreased, market panic in the housing market
triggered a mass contraction. Some homeowners overleveraged the value in their homes
and could not afford to maintain their debt obligation resulting in voluntary or involuntary
foreclosure. The rapid increase in foreclosures propelled the economic contraction which
then caused a ripple effect and triggered a global recession.
Financial experts argued that the sub-standard underwriting standards caused
lenders to overlook or ignore lending criteria. Lending criteria assist underwriters to

45
identify borrowers’ payment history and current financial situation to predict future
payment patterns. In general, mortgage underwriters assess the five Cs of credit, which are
collateral, character, capacity, condition, and capital. The five Cs of credit become part of
the lending criteria. Mortgage underwriters conduct several analysis and statistical testing
on the potential borrower collateral, character, capacity, condition, and capital to
determine default probability.
A negative impact in the housing market caused a ripple effect and impacted the
global economy. The housing market contraction triggered a loss in equity and cashflow.
Resulting in a reduction in economic activities; spending and profits. Concurrently, the
financial market collapsed because mortgage-backed securities lost significant value. The
interrelationship of mortgage lending and the different components of the global
economic environment could relate as a macro system. Therefore, mortgage lending as a
single component within a macro system could form part of a micro system. If one the
lending criteria or components of the five Cs of lending fails, then it creates a limitation
on mortgage lending and loan approvals. Therefore, if one component within the macro
system fails, then the entire system could fail. If one component within the micro system
fails, then a single component within the macro system could fail and could trigger the
macro system also to fail (Teye et al., 2015). This theory holds true based on the recent
2007-2009 recession.
Transition
As a result of the 2007-2009 recession, mortgage lenders and financial regulators
have implemented transactional changes to mortgage lending and the financial industry as

46
a whole. In addition to owner-occupied dwellings, real estate investors are facing
mortgage financing challenges and barriers. This study included examination of the
impact of lender type on the average rankings of mortgage underwriting outcome
measures. Changes to mortgage regulations affected real estate investors seeking
mortgage for their rental property. Limited financing could hinder the quality and number
of residential rental units available for rent. Therefore, the availability of multifamily
rental property mortgages could increase the number of affordable housing, standard of
living, and overall community morale.
In the following sections, I discussed the role of the researcher, participants,
population and sampling, scope, research methodology, ethical implication, data
collection instruments and technique, data collection organization, data analysis,
reliability, and validity of this study. This section also includes a presentation of the
findings, align findings to professional practice, identify potential social change aspect,
reflection, and provide recommendation for possible future studies.

47
Section 2: The Project
The objective of this study was to identify the average ranking of mortgage
outcome measures: GDS ratio, TDS ratio, DSCR, LTV ratio, property appraisal, and
borrowers’ profile (credit score, industry experience, and length of employment) for
multifamily rental property financing in Ontario, Canada. In this section, I discussed the
research method and design, population and sampling, role of the researcher, participants,
data collections instruments and techniques, data analysis, validity, and ethical
implications of this study.
Purpose Statement
The purpose of this quantitative causal comparative study was to examine impact
of lender type on the average rankings of mortgage underwriting outcome measures. The
independent variable was lender category, with three levels (Category A, B, and C). The
dependent variables were average rankings for GDS ratio, TDS ratio, DSCR, LTV ratio,
property appraisal, and borrowers’ credit score, industry experience, and length of
employment. The target population was mortgage agents and brokers with an AMP
designation who facilitate mortgages for multifamily rental properties in Ontario, Canada.
In Ontario, mortgage agents and brokers are independent professionals who liaise between
lenders and borrowers and have knowledge and understanding of the lending environment
and lender requirements. The findings could be advantageous to real estate investors by
providing the ranking of mortgage underwriting criteria that could ensure their success in
securing financing. Limited financing could adversely affect the supply of affordable
housing because of higher interest rates and borrowing costs (Sullivan & Bernstein, 2013).

48
Therefore, sufficient financing may ensure an adequate supply of affordable housing
while improving the standard of living (Ferreira et al., 2014).
Role of the Researcher
The selection of this proposed research topic draws from my experience,
contribution, and current dealings in the real estate industry. Mortgage financing peaked
my interest because of my passion for real estate and keen interest in economic growth.
The success of a research study depends on the author’s experience, contribution, and
commitment (Simon, 2011).
I am a real estate investor with 15 years of experience as a founder of a private real
estate investment company and property management company in Ontario, Canada. Given
my extensive experience and participation in the multifamily rental market in Ontario, I
established business relationships with real estate investors, real estate sale professionals,
mortgage lenders and brokers, and municipal government representatives. I also
developed business relationships with other stakeholders in the residential rental industry
such as service contractors, utility providers, and building material distributors.
Randomly selecting participants from a public database that met the eligibility
criteria reduced researcher bias. The survey instrument was adapted from another
researcher where the questions were developed to meet the research purpose. The purpose
of this study relates to the five Cs of credit and the questions in the survey pertain to
aspects of the five Cs of credit. The data for analysis were anonymous, and the analysis
followed a structural statistical process.

49
The Belmont Report protocol highlights basic ethical principles and guidelines
when conducting research that involves human subjects (see Bromley, Mikesell, Jones, &
Khodyakov, 2015). Bromley et al. (2015) mentioned that three of the primary ethical
principles identified on the Belmont Report are respect for participants, beneficence, and
justice. Researchers should ensure participants remain autonomous and participation is
voluntary, mitigate any potential harm that can affect participants, and ensure that the
potential societal benefit of the findings does not burden the participants (Bromley et al.,
2015).
Data collection began after Walden University Institutional Review Board (IRB)
approved the proposed study and after prospective participants acknowledged, and agreed
to participate in this study. I disclosed the nature of the proposed study with prospective
participants and highlighted that participating in this study is voluntary, and participants
can withdraw from the study any time before data analysis and publishing of the findings.
In order to ensure the protection of participants’ responses and identity, surveys did not
have any identification information. Ensuring participants’ autonomy will assist in
preventing any potential harm to participants by either beneficence or justice, as
mentioned in the Belmont Report protocol.
I adopted SurveyMonkey tools to develop and deliver surveys electronically to
prospective participants. SurveyMonkey is an online survey development and delivery
website that is cost effective and timesaving (Woodward & Harris, 2013).
SurveyMonkey’s privacy policy assures the protection of participants’ identity. To
maintain privacy and confidentiality, surveys did not contain any personal identifiers.

50
Each survey invitation highlighted the consent and withdrawal process and options.
Survey instructions highlighted how participants could complete and return the survey or
withdraw. Submitted surveys were reviewed to determine completeness and qualification
for the study. After the analysis of surveys, the statistical package for social sciences
(SPSS) tools enabled sorting, coding, analyzing, and presentation of findings (Bhunia,
2013). Bhunia (2013) mentioned that SPSS v.22.0 is a computer application that interprets
and analyzes data from surveys and present findings in various formats. I will securely
store raw data for 5 years after completion of the study and then destroy it through
shredding and electronic erasure.
Participants
The objective of this study was to identify the average ranking of mortgage
outcome measures among different categories of lenders for multifamily rental properties
in Ontario, Canada. The findings could be beneficial to real estate investors, banking
representatives, mortgage brokers, financial regulators, and municipal government
representatives. Determining financing barriers is critical to banks, real estate investors,
mortgage agents and brokers, and other stakeholders’ success. Consequently, the findings
could assist mortgage institutions and lending representatives to identify potential areas of
improvement that could strategically position their institution at a competitive advantage
and maximize profitability. Therefore, mortgage agents and brokers have a vested interest
to participate in this study.
The primary data collection source was mortgage agents and brokers who are

51
AMP designated and facilitate mortgage financing for multifamily rental properties in
Ontario, Canada. Mortgage agents and brokers’ contact information was obtained from the
AMP member page on the Mortgage Professionals Canada (formerly Canadian
Association of Accredited Mortgage Professionals) website and from prospective
participants’ websites. I searched the AMP member directory on the Mortgage
Professionals Canada website to identify and obtain contact information of accredited
members who operate in Ontario. Numerical labels were assigned to prospective
participants and required SPSS v.22.0 to generate a randomized list of prospective
participants. The target population included participants who facilitate mortgage
applications for multifamily rental properties in Ontario, attained the AMP designation,
and also deals with Category A, B, and C lenders.
Simple random sampling is a common and easy way to analyze gathered data
(Abdulai & Shafiwu, 2014). McLeod (2014) found that although probabilistic sampling
could be time-consuming and require more financial resources if done correctly,
probabilistic sampling allows for generalization based on the sample population. After
randomly selecting participants, an invitation email was sent to each prospective
participant, introducing myself, explaining the purpose of the study and the importance of
their participation. In the invitation email, the consent form was attached, which contained
the survey link, allowing participants to click and complete the survey. A reminder email
was sent to all prospective participants 7 days before the survey period closed.
SurveyMonkey was applied to develop and distribute surveys to prospective participants.

52
SurveyMonkey is an online assessment platform that enables surveyors to develop,
deliver, and receive responses from participants (Gupta & Tiwari, 2016).
Research Method and Design
Wester, Borders, Boul, and Horton (2013) stated that research quality relies on the
literature reviewed, research design, research question, data analysis, and presentation of
findings. To ensure research quality, the selection of an appropriate research question,
sampling, analysis, research design, and sample size is critical (Wester et al., 2013). While
there are different research methods and designs, selecting the appropriate research
method and design is critical for ensuring higher research quality.
The objective of this study was to identify the average ranking of borrower profile
(credit score, industry experience, and length of employment), GDS, TDS, DSCR, LTV,
and property appraisal. There were eight dependent variables and three independent
variables in this study. The quantitative causal comparative research method assisted in
ranking the eight dependent variables. The primary data collection tool to gather relevant
and appropriate data was a survey including close-ended questions. SPSS v.22.0 software
assisted to conduct statistical analysis and interpretation of gathered data by organizing,
coding, and analyzing raw data (Bhunia, 2013). Further, SPSS software assisted to present
findings in tables (Ueng, 2016).
Research Method
The quantitative research method was more relevant for this study as it analyzes
and interprets numerical and statistical data (Slife & Melling, 2012). Statistical tools and
procedures facilitate the interpretation of raw data for quantitative research (Smith, 2014).

53
A quantitative research method follows a structured layout, testing theories and
hypotheses (Ragas & Laskin, 2014). Consequently, a quantitative research method could
eliminate the probability of research bias or skewed findings based on gathered data. A
quantitative research method was appropriate when attempting to identify relationships
among variables, sample testing, and null and alternative hypothesis testing (Ragas &
Laskin, 2014). Therefore, a quantitative research method was appropriate to identify the
average ranking of borrowers’ profile (credit score, industry experience, and length of
employment), GDS, TDS, DSCR, LTV, and property appraisal based on the different types
of lenders underwriting criteria. Surveys comprising of close-ended questions served as
the primary data collection tools for this quantitative study.
Alternatively, the qualitative research method focuses on exploring a general
problem and understanding views or opinions of individuals (Slife & Melling, 2012). A
qualitative study analyzes textual data and is more suitable for exploratory studies (Smith,
2014). Qualitative studies seek to understand or explore opinions and motives and gather
data from multiple sources (Slife & Melling, 2012). The final write-up of a qualitative
research study follows a flexible structure building upon a general theme (Garcia &
Gluesing, 2013). Qualitative researchers gather data and form an opinion on the topic
based on the researchers’ knowledge or experience on the topic (Ragas & Laskin, 2014).
Subsequently, there could be research bias or skewed opinions and findings (Slife &
Melling, 2012). A qualitative research method enables researchers to collect raw data
directly from participants and usually within the participant’s natural setting (Garcia &

54
Gluesing, 2013). Further, a qualitative research method enables the researcher to conduct
observation during the initial interview (Ragas & Laskin, 2014).
Garcia and Gluesing (2013) stated that a qualitative research method involves gathering
data by observation, narratives, interviews, audio and video, and documents.
The mixed methods research approach employs a pragmatic worldview through
sequential, transformative, and concurrent strategies of inquiry (Romm, 2015). Mixed
methods use both quantitative and qualitative research approaches by adapting a
combination of quantitative and qualitative data gathering procedures, analysis, and
presentation techniques within the study (Ragas & Laskin, 2014). Aldebert and Rouzies
(2014) stated that mixed methods research could enrich the research question or finding,
or both. The mixed methods research approach capitalizes on both the qualitative and
quantitative research strengths. However, the mixed methods could be time-consuming
and require more financial resources; therefore, it is not preferential for this proposed
study (Dumbili, 2014). In addition, Romm (2015) found that an inherent issue with mixed
methods research is the reporting and integration of findings given the different data
collection methods and analysis.
While all the different research methods are effective and seek to identify trends
and patterns, a researcher should select the appropriate method based on the nature of the
study (Slife & Melling, 2012). Given that the objective of this study was to identify the
average ranking of mortgage outcome measures among Categories A, B, and C lenders for
multifamily rental property financing, there are several variables and hypotheses to test.
This study followed a structured write-up and used statistical procedures to analyze,

55
interpret, and present findings (Miles, Gordon, & Storlie, 2013). Consequently, a
quantitative research method was more favorable than a qualitative or mixed methods
research approach.
Research Design
A quantitative causal comparative research design formed the basis for conducting
this study. This non-experimental design fit the purpose of the study more than an
experimental design as it followed a structured research approach and procedure (Leedy &
Ormrod, 2010). A causal comparative research design does not have the same internal and
external validity threats as an experimental research design (Vollmer & Seyr, 2013). While
the experimental design focuses on identifying causes and effects, the nonexperimental
design focuses on descriptive details of trends, opinions, or attitudes of a sample
population (Leedy & Ormrod, 2010). Therefore, a quantitative causal comparative
research design was appropriate when identifying the average ranking of borrowers’
profile (credit score, industry experience, and length of employment), GDS, TDS, DSCR,
LTV, and property appraisal when seeking multifamily rental property financing in
Ontario, Canada.
Raw data for this study derived from mortgage brokers and agents that operate in
Ontario, Canada. A survey with close-ended questions assisted me to gather data from
mortgage agents and brokers. Wester et al. (2013) stated that the causal comparative
research design is suitable when gathering data in a natural setting rather than a laboratory
or other experimental setting. Therefore, the causal comparative research approach fit the
purpose of the study.

56
Population and Sampling
The primary data collection source were mortgage agents and brokers who were
AMP designated, operate in Ontario, Canada, and facilitate multifamily rental property
mortgages. SurveyMonkey served as the instrument development and delivery method to
gather raw data from mortgage agents and brokers. SPSS software served as the
application to conduct random sampling and statistical tests.
I used the probabilistic sampling method with the simple random sampling
approach. McLeod (2014) found that probability sampling ensures that every member of
the target population has an equal opportunity to be selected. Therefore, if conducted
correctly, results from the sampled population could represent the target population.
Probability sampling could become time-consuming and expensive if extensive data
collection is necessary to generalized results (McLeod, 2014). There are sub-categories of
sampling methods, such as systematic, stratified, cluster, and multi-stage (Raina, 2014). I
employed the simple random sampling approach for this study. The simple random
sampling approach is common, straight forward, and easy to analyze collected data
(Abdulai & Shafiwu, 2014). If conducted correctly, simple random sampling could reduce
the potential of systematic and sampling bias (Nahorniak, Larsen, Volk, & Jordan, 2015).
The simple random sampling approach ensures that each member of the target population
has an equal opportunity to be part for the sample (Asgari, Ahmadi, Shamlou, Farokhi, &
Farzin, 2014). The disadvantage of the simple random sampling approach is it does not
ensure the information of the target population is current and easily accessible
(Singh & Solanki, 2013). Additionally, simple random sampling could be time-

57
consuming and expensive if more sampling is needed to ensure that adequate proportion
of the sample population participates in the study (McLeod, 2014).
The target population for this study was 1025 designated Accredited Mortgage
Professional (AMPs) that operates in Ontario. To ensure appropriate information
gathering, verification was conducted to confirm that AMP designated mortgage agents
and brokers deals with all categories of lenders, and facilitate multifamily rental property
mortgages. To determine and confirm participants’ qualification, area of operation, and
types of lenders and mortgage dealings, I reviewed the AMP members’ directory on the
Mortgage Professionals Canada website and individual AMP members’ website.
After identification of AMPs that deal with rental property mortgages in Ontario
and deals with all categories of lenders, SPSS v.22.0 application was used to randomly
select prospective participants. A numerical label was assigned to each potential
participant, input the numerical label in SPSS v.22.0 application, and used the random
sampling function to randomly select the required sample of 159 participants out of the
total population. Bhunia (2013) mentioned that SPSS v.22.0 application serves as a
statistical tool to assist researcher with statistical tests, data collection and organization,
and presentation of findings.
After randomly selecting prospective participants, I sent an email to prospective
participants introducing myself, explaining the purpose of the study, the importance of
their participation, and providing a link to the survey. A reminder email was sent 7 days
before the survey close, as a reminder to prospective participants of the survey. Figure 4
displays the data collection and analysis process.
58
Using G*Power version 3.1.7 to conduct an a priori power analysis and determine
the minimum sample size required to find significance with a desired level of power set at
.80, an α-level at .05, and a moderate effect size of .50(f) (see Appendix A) (Erdfelder,
Faul, & Buchner, 1996). Based on the one-way ANOVA, a minimum of 42 participants
will ensure adequate power. However, a minimum sample size of 159 participants is
required to ensure adequate power for the preliminary analyses (one-way ANOVA and
ttests). Figure 4 highlights the data collection and analysis process.
Figure 4. Data collection and analysis process.
Ethical Research
The purpose of this study was to examine the average ranking of mortgage
outcome measures among different categories of lenders for multifamily rental properties
in Ontario, Canada. Data for this study derived by surveying mortgage brokers and agents
who facilitate mortgages for multifamily rental properties in Ontario. The survey gathered
information pertaining to the weighting or ranking of individual mortgage underwriting
criteria for multifamily rental properties. Further, the survey draws from mortgage brokers
Qualify
prospective
AMP
participants
Random
sampling
Invitation
and
consent
sent
Assess
completed
surveys to
confirm
usability
Descriptive
statistics
One
-
way
ANOVA
t
-
tests

59
and agents’ professional experience and industry knowledge. As a result, no part of the
survey requested participants’ identification or personal information.
Surveys did not contain discriminatory language that reference gender, race, disability,
age, sexual orientation, or social connection. SurveyMonkey application facilitated the
development and delivery of surveys to prospective participants. Employing
SurveyMonkey for survey development and delivery assisted in protecting participants’
identity (O'Brien & McGaha, 2014).
Ensuring that none of the participants were at risk by ethical oversight, I obtained
Walden University Institutional Review Board (IRB) approval (number 01-17-
170383044) and permission before commencing data gathering. Walden University IRB
reviewed the research design and methodology to ensure that the proposed study did not
affect participants from an ethical standpoint. McShane, Davey, Rouse, Usher, and
Sullivan (2015) stated that ensuring the protection of participants by ethical factors or
oversight is critical and necessary for the successful completion of a research study.
After selecting prospective participants and receiving approvals from Walden
University IRB, data collection commenced. An introductory letter and consent form was
sent to prospective participants, highlighting my background and contact information,
research purpose, the significance of the research and findings, and participants’
confidentiality. Further, I disclosed in the introductory letter the potential publishing of
findings. The consent letter stated that participation is voluntary and participants
acknowledge their intention to participate in the research by responding to the survey.

60
Each introductory letter had a unique identifier number to protect participants’
identity and enable for an effective withdrawal process if necessary. Participants’
identification and survey responses will remain classified and kept for 5 years in a locked
safe located at my residence. Additionally, participants’ unique identifier code will remain
in a locked safe at my residence for 5 years.
There was no incentive for participants to participate in this study. There was no
authority or control over any of the participants that could influence their response to the
survey. Participation was voluntary, and participants had the option to withdraw from the
study any time during the research stages without any challenges. If participants wanted to
withdraw from the research and communicated their intention to withdraw, the
participants’ unique identifier code would have assisted in retrieving and shredding the
appropriate participants’ survey response. The unique code also ensures accuracy and
reduces the probability of name confusion.
Data Collection Instruments
A survey designed by Charles Kwame Addo in 2006 and used in a doctoral study
titled Predicting Powers of Potential Income Versus Credit History for Loan Repayment
served as the data-gathering instrument for this study. Charles Kwame Addo granted
permission to use, modify, and adapt the full or part of the original survey (see Appendix
B). After Charles Kwame Addo granted permission to use and modify the survey as
necessary to meet this research objective (see Appendix C). Addo (2006) designed the
original survey to access how lenders evaluate the five Cs of credit when making lending
decisions. This study also focused on the five Cs of credit and accessed which of the five

61
Cs are critical among the different types of lenders. The modification of the instrument
was cosmetic with the layout and did not distract from the validity of the instrument. The
modified survey assisted in ranking credit score, LTV, GDS, TDS, experience,
employment history, DSC, and property appraisal to identify importance when issuing
mortgages for multifamily rental property in, Ontario, Canada. Further, the survey
measured participants’ credibility, industry experience, and area of operation.
The survey designed by Charles Kwame Addo (2006) was effective, pertained to
loan criteria, and proved successful for the purpose of the study. Addo (2006) used the
original instrument to determine loan officers’ likelihood of granting credit to potential
borrower based on credit history, income, and probability of repayment (Addo, 2006).
Addo (2006) used a Likert scale instrument to survey experienced loan officers. Addo
(2006) stated that surveying experienced loan officers increases the probability of
gathering reliable and valid data. Given that this study was similar in nature to Charles
Kwame Addo (2006) study because the target population comprised of participants that
operate in the same industry, and the survey design are both Likert-type scale format, this
increased the probability of achieving similar reliability and validity of this survey
instrument.
Addo (2006) stated that validity is reliant on reliability and better captured in a
comparative situation. The primary concept of validity is the instrument measurement
truthfulness, and the primary concept of reliability is the instrument measurement
consistency (Addo, 2006). While survey validity focuses on instrument measurement
clarity and accuracy, reliability focuses on consistency or repeatability (Grimes & Schulz,

62
2002). Addo (2006) adapted the bathroom scale analogy to confirm reliability and validity
of the survey instrument. The bathroom scale analogy comprises of three scenarios; If the
scale always records accurately, then it is considered both reliable and valid; If the scale
consistently over or under weighs by the same weight, then the scale is considered reliable
but not valid; and If the scale is unpredictable, then it is not reliable nor valid (Addo,
2006). Grimes and Schulz (2002) stated that a scale that consistently measures five
pounds heavier than the actual weight can be reliable but may not be valid. Given that
Addo (2006) and Grimes and Schulz (2002) experienced similar illustration of reliability
and validity through the bathroom scale analogy, this study should obtain the same
application of comparative situation.
Chow, Kwan, Morrow, Cooper, and Leask (2013) stated that survey instruments
could ensure high quality of content validity and hypothesis testing. The survey comprised
of two sections. The first part of the survey provided data pertaining to participants’
licensure, the category of lender participation, and area of operation. The second part of
the survey provided underwriting criteria data that enabled for descriptive analysis.
Akhavan, Elahi, and Jafari (2014) stated that Likert-type scales are reliable, simple, and
efficient. Therefore, the second part of the survey used as a Likert-type scale and required
participants to rank the eight dependent variables from 1 to 8 with one being the least
important and eight being the most important. The eight dependent variables were
borrowers’ profile (credit score, industry experience, and length of employment),
GDS, TDS, DSCR, LTV, and property appraisal. The three independent variables were
Category A, B, and C mortgage lenders for multifamily rental property in Ontario,

63
Canada.
SurveyMonkey served as the development and delivery application for the survey
instrument. As participants complete the survey, the completed surveys are accessible by
the senders via SurveyMonkey electronic portal. Independent samples t tests (effect size =
Cohen’s d) and Analysis of variance (ANOVA; effect size = partial eta squared (pη2)
assessed the relationships between one categorical variable and one continuous variable.
The results indicated that credit score ranks significantly different between the
groups; comparison between Category A and B lender indicated (p = 0.006), Category A
and C lender indicated (p < 0.001), and Category B and C lender show (p < 0.001). The
results for LTV showed a significant difference between Category A and B lenders with (p
= 0.017) and also Category A and C lenders with (p < 0.001), but the difference between
Category B and C lenders was not statistically significant with (p = 0.063).
The findings highlighted the average ranking of mortgage outcome measures from
mortgage agents and brokers perspective. Additionally, the findings highlighted the
average ranking of mortgage underwriting outcome measures among three categories of
lenders, A, B, and C. Raw data will remain in a locked safe for 5 years.
Data Collection Technique
A survey with closed-ended questions served as the primary data-gathering tool for
this study. Kwatra, Pandey, and Sharma (2014) mentioned that surveys with closedended
questions enable respondents to answer questions appropriately. Shorter effective surveys
could reduce respondents fatigue and therefore have a positive effect on the validity of
respondents’ scores (Wiklund et al., 2014). Rowley (2014) stated that concise and

64
effective questionnaire could improve response rate and reduce coding and analysis time.
The survey comprised of two sections with six questions in total. In Section 1, participants
selected the most appropriate answer based on preselected answers. In
Section 2, participants ranked eight dependent variables.
Tella, (2015) mentioned that online data collection is increasing; researcher can
benefit both financially and reaching a larger population than traditional data collection
method. Online environment enables expedited data collection since there is no delay
because of transportation or postal error. Conversely, the disadvantage of online data
collection or survey is the reliance on participants who may not be technologically
advanced. Some participants may not want to participate or complete online survey
because of online security or privacy concerns. Computer glitches or compatibility issues
may hinder survey delivery or completion. Additionally, some participants may fear that
completing online survey will expose their computer to virus.
SurveyMonkey is an online survey development and delivery tool, which enables
surveyors to develop, deliver, and receive surveys online (Gupta & Tiwari, 2016).
Therefore, SurveyMonkey served as the method for developing, distributing, and
receiving completed surveys for this study. Participants received an invitation via email,
allowing them to complete and return survey electronically. Post-delivery could result in
significant cost, get lost, and require participants to complete and return via postal service,
which could be inconvenient (Woodward & Harris, 2013). SurveyMonkey online delivery
is easy, convenient for data analysis and less probability of getting lost (Woodward &

65
Harris, 2013). SurveyMonkey parameters ensure questions are complete before
proceeding to the next question, ensuring completeness of survey once returned.
This study is similar in scope to the study which the original survey instrument
was developed and applied. An approval of the original study by Walden University Chief
Academic Officer was an indication that the survey instrument suitability, question
format, validity, and scales were tested and valid for the intended purpose. Therefore,
adapting the survey instrument for this study seemed necessary and relevant.
After Walden University IRB granted permission, review of the AMP members
section on the Mortgage Professionals Canada website and individual AMPs website
indicated qualified prospective participants and contact information. Statistical Package
for Social Sciences (SPSS) v.22.0 application generated a randomized list of prospective
participants with prospective participants assigned numerical labels. After selecting
prospective participant, consent and invitation letters via email. When prospective
participant received invitation and consent form, they could have decided if they want to
proceed with the survey or not. If participants decided to participate, they clicked on the
SurveyMonkey link embedded in the invitation and completed the survey. Once finished,
participants clicked on the “return button” to return the completed survey. If they did not
want to proceed with the study, they simply could have deleted or ignored the invitation
email. After confirmation of completed surveys, I imported raw data in the statistical
package for social sciences (SPSS) software and conducted analysis and tests.

66
Data Analysis
The objective of this study was to examine the impact of lender type on the
average rankings of mortgage underwriting outcome measures. The dependent variables
were borrowers’ profile (credit score, industry experience, and length of employment),
GDS, TDS, DSCR, LTV, and property appraisal. The independent variable was the types
of mortgage lenders for multifamily rental property. The research question was; what is
the impact of lender type on GDS ratio, TDS ratio, DSCR, LTV ratio, property appraisal,
borrowers’ credit score, borrowers’ industry experience, and borrowers’ length of
employment? The null and alternative hypotheses were the following,
H10: There is no statistical significant difference in ranking of GDS ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
H1A: There is a statistical significant difference in ranking of GDS ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
H20: There is no statistical significant difference in ranking of TDS ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
H2A: There is a statistical significant difference in ranking of TDS ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
H30: There is no statistical significant difference in ranking of DSCR for
categories A, B, and C lenders when seeking multifamily rental property financing.
H3A: There is a statistical significant difference in ranking of DSCR for categories
A, B, and C lenders when seeking multifamily rental property financing.

67
H40: There is no statistical significant difference in ranking of LTV ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
H4A: There is a statistical significant difference in ranking of LTV ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
H50: There is no statistical significant difference in ranking of property appraisal
for categories A, B, and C lenders when seeking multifamily rental property financing.
H5A: There is a statistical significant difference in ranking of property appraisal for
categories A, B, and C lenders when seeking multifamily rental property financing.
H60: There is no statistical significant difference in ranking of credit score for
categories A, B, and C lenders when seeking multifamily rental property financing.
H6A: There is a statistical significant difference in ranking of credit score for
categories A, B, and C lenders when seeking multifamily rental property financing.
H70: There is no statistical significant difference in ranking of industry experience
for categories A, B, and C lenders when seeking multifamily rental property financing.
H7A: There is a statistical significant difference in ranking of industry experience
for categories A, B, and C lenders when seeking multifamily rental property financing.
H80: There is no statistical significant difference in ranking of employment
history for categories A, B, and C lenders when seeking multifamily rental property
financing.
H8A: There is a statistical significant difference in ranking of employment history
for categories A, B, and C lenders when seeking multifamily rental property financing.

68
Statistical package for social sciences (SPSS) v.22.0 application served as the tool
to sort, analyze raw data, and present findings in graphical and tabular format (Bhunia,
2013). I conducted descriptive statistics for all variables and calculated means, standard
deviations, and the minimum and maximum for continuous variables and frequencies and
percentages for all categorical demographic variables. After examining of distributions of
the continuous variables to determine if normality assumptions and parametric testing
were adequate and appropriate, I investigated extreme outliers for technical or clerical
errors.
Independent samples t tests (effect size = Cohen’s d) and Analysis of variance
(ANOVA; effect size = partial eta squared (pη2) was conducted to assess the relationships
between one categorical variable and one continuous variable. After conducting the one-
way ANOVA analysis to identify statistical significance among the 3 categories of lenders
for 8 mortgage outcome measures. There was a statistical significant difference, I
conducted pair two sample t tests to identify significant difference between Category A
and B lenders, Category A and C lenders, and Category B and C lenders.
The results indicated that credit score ranks significantly different between the
groups; comparison between Category A and B lender indicated (p = 0.006), Category A
and C lender indicated (p < 0.001), and Category B and C lender show (p < 0.001). The
results for LTV showed a significant difference between Category A and B lenders with (p
= 0.017) and also Category A and C lenders with (p < 0.001), but the difference between
Category B and C lenders was not statistically significant with (p = 0.063).

69
Using G*Power version 3.1.7 to conduct an a priori power analysis and determine
the minimum sample size required to find significance with a desired level of power set at
.80, an α-level at .05, and a moderate effect size of .50 (f). Based on the one-way ANOVA,
a minimum of 42 participants ensured adequate power. However, a minimum sample size
of 159 participants ensured adequate power for the preliminary analyses
(one-way ANOVA and t-tests).
Friedman and Mann-Whitney U tests are appropriate for ranking variables and
testing paired sample data (Taheri & Hesamian, 2013). I did not select the Friedman and
Mann-Whitney U tests for this study because of the paired sample data testing aspect.
Portmann and Mlambo (2013) tested and rank paired sample data by employing both
Friedman and Mann-Whitney U tests to rank four variables among two different types of
firms.
The first assumption was participants are familiar with the ranking of underwriting
criteria based on their experience. The second assumption was participants understood and
responded appropriately. Use of a scatter plot diagram to test and assess participants’
responses identified knowledge on the subject matter and possible extreme outliers. The
third assumption was raw data would be appropriate or adequate to perform statistical
analysis for this study. Based on the G*Power analysis (see Appendix A), 42 complete
responses were required to ensure adequate power. However, a minimum of
159 participants was required to ensure adequate power for one-way ANOVA and t-tests.
SurveyMonkey served as the tool to develop, distribute, and receive the surveys
(Gupta & Tiwari, 2016). SurveyMonkey parameters ensured that participants complete
each question before proceeding to the next question on the survey. SurveyMonkey

70
parameters assisted in ensuring that surveys are fully complete before returned. Based on
the survey (see Appendix C), questions 1 to 4 confirmed participants profile (area of
operation, qualification, and category of lenders participation). Question five assisted in
ranking mortgage underwriting criteria among different categories of lenders. Question
six gave participants the opportunity to add more information pertinent to mortgage
underwriting criteria.
Study Validity
During a research process, several factors could occur and render the findings
skewed or incomplete. These factors are threats to validity and divided into two
categories, internal and external (Henderson, Kimmelman, Fergusson, Grimshaw, &
Hackam, 2013). Internal validity threats are experimental in nature, maturation,
regression, selection, history, mortality, diffusion of treatment, testing, instrumentation,
compensatory rivalry, and compensation demoralization (Afzali, Gray, & Karnon, 2013).
Henderson et al. (2013) stated that internal validity threat could derive from researcher
expectation, which could lead to bias findings. Given that this study was a
nonexperimental, causal comparative study, there were no threats to internal validity.
Threats to statistical conclusion validity applied in this study. There were three
potential threats to statistical conclusion validity, data assumptions, sample size, and
modified instrument reliability. Statistical conclusion validity relates to effective
sampling, reliability measurements, and effective statistical testing. The instrument
developer adapted the bathroom scale analogy to confirm reliability and validity of the
instrument. The bathroom scale analogy includes three scenarios; if the scale always

71
records accurately, then the scale is considered reliable and valid; if the scale consistently
over or under weighs, then the scale is considered reliable but not valid; and if the scale is
unpredictable, then the scale is not reliable nor valid (Addo, 2006). Grimes and Schulz
(2002) stated that a scale that consistently measures five pounds heavier than the actual
weight is reliable but not valid. Since both Addo (2006) and Grimes and Schulz (2002)
presented similar illustration of reliability and validity through the bathroom scale
analogy, this study should obtain the same application as modified to fit the purpose of
this specific study purpose.
The study used the G*Power software to determine the appropriate number of
sample size for this study (Erdfelder et al., 1996) (see Appendix A). The final statistical
conclusion validity is that participants would accurately rank mortgage underwriting
criteria for the three categories of lenders. To test this assumption, I performed a scatter
plot diagram to identify cluster and abnormal variance among the different individual
criteria and categories of lenders. Any criteria within the same category of lender that is
not close to the cluster could be an indication that the participant may have misinterpreted
the question and inaccurately answered the question.
Transition and Summary
This quantitative causal comparative study assisted in examining the average
ranking of mortgage outcome measures among different categories of lenders for
multifamily rental property in Ontario, Canada. Surveys comprised of closed-ended
questions served as the primary data collection tool. SurveyMonkey was used to develop,
gather, and transmit raw data via email transmission. Data gathered and developed during

72
the process of this study will remain in a locked cabinet for 5-years after completion of the
study and then destroyed by shredding and electronic erasure. Section 3 presents the
findings from the study and recommendations.
Section 3: Application to Professional Practice and Implications for Change
Introduction
The purpose of this quantitative causal comparative study was to examine the
average ranking of mortgage outcome measures among different categories of lenders of
multifamily rental properties in Ontario, Canada. The dependent variables were GDS
ratio, TDS ratio, DSCR, LTV ratio, property appraisal, and borrowers’ profile (credit
score, industry experience, and length of employment). The independent variable was the
type of lenders (A, B, or C) for rental property.
Based on the findings there is no statistical difference in the average ranking of the
following mortgage underwriting criteria; GDS ratio, TDS ratio, DSCR, property
appraisal, industry experience, and length of employment among the three different
categories of lenders. However, there are statistical differences for LTV ratio and credit
score.
The results indicated that credit score ranks for each category of lenders are
significantly different from each other. Comparison between Category A (banks and
depository institutions) and B (insurance companies and non-depository institutions)
lenders show (p = 0.006), Category A and C (private) lenders show (p < 0.001), and
Category B and C lenders show (p < 0.001). The result for LTV ratio shows a significant
difference between Category A and B lenders with (p = 0.017) and Category A and C
73
lenders with (p < 0.001), but the difference between Category B and C lenders is not
statistically significant with (p = 0.063).
Presentation of the Findings
While most of the overall ranking is not significantly different between the three
categories of lenders, the ranking of LTV ratio and credit score are different among the
three categories of lenders. The post hoc test determined where the differences occurred
between different categories of lenders. The results indicated that credit score ranks
significantly different between the groups; comparison between Category A (banks and
depository institutions) and B (insurance companies and non-depository institutions)
lenders indicated a statistical difference with (p = 0.006), Category A and C (private)
lenders indicated a statistical difference with (p < 0.001), and Category B and C lenders
indicated a statistical difference with (p < 0.001). The results for LTV indicated a
significant difference between Category A and B lenders with (p = 0.017) and also
Category A and C lenders with (p < 0.001), but the difference between Category B and C
lenders is not statistically significant with (p = 0.063) (see Table 2).
Table 2
Descriptive Statistics - Mean and Standard Deviation of Ranking for Different Lenders
Items
Category A
Category B
Category C
p-value
M
SD
M
SD
M
SD
Borrower employment history
5.59
1.20
5.70
1.15
5.48
1.48
0.646
Borrower industry experience
7.48
0.55
7.45
0.66
7.30
0.85
0.604
Credit score
1.93
0.99
2.55
0.87
3.61
1.08
<0.001
**
74
Debt service coverage ratio
7.11
0.92
6.93
1.04
6.95
0.96
0.625
Gross debt service ratio
5.23
0.94
5.45
1.02
5.41
1.08
0.347
Loan-to-value ratio
2.11
0.87
1.75
0.78
1.45
0.62
<0.001
**
Property appraised value
2.11
0.84
1.89
0.92
1.70
0.63
0.074
Total debt service ratio
4.34
0.94
4.27
0.87
4.09
1.23
0.093
** significance at 0.01 level
The research question was: What is the impact of lender type on GDS ratio, TDS
ratio, DSCR, LTV ratio, property appraisal, borrower’s credit score, borrower’s industry
experience, and borrower’s length of employment?
The dependent variables were GDS ratio, TDS ratio, DSCR, LTV ratio, property
appraisal, and borrower’s profile (credit score, industry experience, and length of
employment). Independent variables were Category A, B, and C lenders for multifamily
rental property. To answer the research question, eight hypotheses were tested.
H10: There is no statistical significant difference in ranking of GDS ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
H1A: There is a statistical significant difference in ranking of GDS ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
H20: There is no statistical significant difference in ranking of TDS ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
H2A: There is a statistical significant difference in ranking of TDS ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
H30: There is no statistical significant difference in ranking of DSCR for
categories A, B, and C lenders when seeking multifamily rental property financing.

75
H3A: There is a statistical significant difference in ranking of DSCR for categories
A, B, and C lenders when seeking multifamily rental property financing.
H40: There is no statistical significant difference in ranking of LTV ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
H4A: There is a statistical significant difference in ranking of LTV ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
H50: There is no statistical significant difference in ranking of property appraisal
for categories A, B, and C lenders when seeking multifamily rental property financing.
H5A: There is a statistical significant difference in ranking of property appraisal for
categories A, B, and C lenders when seeking multifamily rental property financing.
H60: There is no statistical significant difference in ranking of credit score for
categories A, B, and C lenders when seeking multifamily rental property financing.
H6A: There is a statistical significant difference in ranking of credit score for
categories A, B, and C lenders when seeking multifamily rental property financing.
H70: There is no statistical significant difference in ranking of industry experience
for categories A, B, and C lenders when seeking multifamily rental property financing.
H7A: There is a statistical significant difference in ranking of industry experience
for categories A, B, and C lenders when seeking multifamily rental property financing.
H80: There is no statistical significant difference in ranking of employment history
for categories A, B, and C lenders when seeking multifamily rental property financing.
H8A: There is a statistical significant difference in ranking of employment history
for categories A, B, and C lenders when seeking multifamily rental property financing.

76
Null Hypothesis 1
H10: There is no statistical significant difference in ranking of GDS ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
According to a one-way ANOVA test with (p = 0.542), there is not enough support
to reject the null hypothesis. Consequently, the ranking of GDS ratio for the three
categories of lenders is similar (see Table 2). Therefore, there is no requirement to conduct
independent samples t tests.
Null Hypothesis 2
H20: There is no statistical significant difference in ranking of TDS ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
According to a one-way ANOVA test with (p = 0.501), there is not enough support
to reject the null hypothesis. Consequently, the ranking for TDS ratio for the three
categories of lenders is similar (see Table 2). Therefore, there is no requirement to conduct
independent samples t tests.
Null Hypothesis 3
H30: There is no statistical significant difference in ranking of DSCR for
categories A, B, and C lenders when seeking multifamily rental property financing.
According to a one-way ANOVA test with (p = 0.637), there is not enough support
to reject the null hypothesis. Consequently, the ranking for DSCR for the three categories
of lenders is similar (see Table 2). Therefore, there is no requirement to conduct
independent samples t tests.
77
Null Hypothesis 4
H40: There is no statistical significant difference in ranking of LTV ratio for
categories A, B, and C lenders when seeking multifamily rental property financing.
A one-way ANOVA test with (p < 0.001) supports rejecting the null hypothesis.
Consequently, the LTV rank is significantly different between the three groups of lenders.
Table 3 displays how LTV ratio ranked among A, B, and C lenders. The (p <
0.001) indicated that there was a significant difference among the lenders.
Table 4 displays how LTV ratio ranked among Category A and Category B lenders.
The (p = 0.0165) indicated that there was a significant difference between Category A and
Category B lenders for LTV ratio. Table 5 displays how LTV ratio ranked among Category
A and Category C lenders. The (p < 0.001) indicated that there was a significant difference
between Category A and Category C lender for LTV ratio.
Table 6 displays how LTV ratio ranked between Category B and Category C lenders. The
(p = 0.0625), indicated that there was no significant difference between Category B and
Category C lender for LTV ratio.
Table 3
One-way ANOVA – Loan-To-Value Ratio Among Lenders
Summary
Groups Count Sum Average Variance
Category A lender
44
93
2.113636364
0.75422833
Category B lender
44
77
1.75
0.610465116
78
Category C lender
ANOVA
44
64
1.454545455
0.393234672
Source of variation
SS
df
MS
F
Pvalue
F crit
Between groups
9.590909091
2
4.795454545
8.183704149
0.000
3.066391037
Within groups
75.59090909
129
0.585976039
Total
85.18181818
131
Table 4
Paired Two Sample t-test – Category A and Category B Lenders
Mean
2.113636364
1.75
Variance
0.75422833
0.610465116
Observations
44
44
Pearson Correlation
0.317023481
Hypothesized Mean Difference
0
df
43
t Stat
2.495244346
P(T<=t) one-tail
0.008252322
t Critical one-tail
1.681070703
P(T<=t) two-tail
0.0165
t Critical two-tail
2.016692199
Table 5
Paired Two Sample t-test – Category A and Category C Lenders
Category A Lender
Category C
Lender
Mean
2.113636364
1.454545455
Variance
0.75422833
0.393234672
Category A
Lender
Category B
Lender
79
Observations
44
44
Pearson Correlation
-0.139753933
Hypothesized Mean Difference
0
df
43
t Stat
3.834890443
P(T<=t) one-tail
0.000202759
t Critical one-tail
1.681070703
P(T<=t) two-tail
0.0004
t Critical two-tail
2.016692199
Table 6
Paired Two Sample t-test – Category B and Category C Lenders
Mean
1.75
1.454545455
Variance
0.610465116
0.393234672
Observations
44
44
Pearson Correlation
-0.047465189
Hypothesized Mean Difference
0
df
43
t Stat
1.91239961
P(T<=t) one-tail
0.031250627
t Critical one-tail
1.681070703
P(T<=t) two-tail
0.0625
t Critical two-tail
2.016692199
Null Hypothesis 5
H50: There is no statistical significant difference in ranking of property appraisal
for categories A, B, and C lenders when seeking multifamily rental property financing.
Category B
Lender
Category C
Lender
80
According to a one-way ANOVA test with (p = 0.062), there is not enough support
to reject the null hypothesis. Consequently, the ranking of property appraisal for all three
categories of lenders is similar (see Table 2). Therefore, there is no requirement to conduct
independent samples t tests.
Null Hypothesis 6
H60: There is no statistical significant difference in ranking of credit score for
categories A, B, and C lenders when seeking multifamily rental property financing.
A one-way ANOVA test with (p < 0.001) supports rejecting the null hypothesis.
Consequently, credit score is significantly different between the three categories of
lenders. Table 7 indicated how credit score ranked among A, B, and C lenders. The (p <
0.001) indicated that there was a significant difference between the lenders.
Table 8 highlights how credit score ranked between Category A and Category B
lenders. The (p = 0.006) indicated that there is a significant difference between Category
A and Category B lenders for credit score. Table 9 indicated a statistical significant
difference with (p < 0.001) between Category A and Category C lenders for the credit
score. Table 10 indicated a statistical significant difference with (p < 0.001) between
Category B and Category C lenders for the credit score.
Table 7
One-way ANOVA – Credit Score Among Lenders
Summary
Groups Count Sum Average Variance
81
Category A lender
44
85
1.931818182
0.995243129
Category B lender
44
112
2.545454545
0.765327696
Category C lender
ANOVA
44
159
3.613636364
1.172832981
Source of Variation
SS
df
MS
F
Pvalue
F crit
Between groups
63.74242424
2
31.87121212
32.59477477
0.000
3.066391037
Within groups
126.1363636
129
0.977801268
Total
189.8787879
131
Table 8
Paired Two Sample t-test – Category A and Category B Lenders
Mean
1.931818182
2.545454545
Variance
0.995243129
0.765327696
Observations
44
44
Pearson correlation
-0.116276456
Hypothesized mean difference
0
df
43
t Stat
-2.904815698
P(T<=t) one-tail
0.002891268
t Critical one-tail
1.681070703
P(T<=t) two-tail
0.0058
t Critical two-tail
2.016692199
Table 9
Paired Two Sample t-test – Category A and Category C Lenders
Category A Lender
Category C
Lender
Category A
Lender
Category B
Lender
82
Mean
1.931818182
3.613636364
Variance
0.995243129
1.172832981
Observations
44
44
Pearson correlation
0.018100806
Hypothesized mean difference
0
df
43
t Stat
-7.645769774
P(T<=t) one-tail
0.0000
t Critical one-tail
1.681070703
P(T<=t) two-tail
0.0000
t Critical two-tail
2.016692199
Table 10
Paired Two Sample t-test – Category B and Category C Lenders
Mean
2.545454545
3.613636364
Variance
0.765327696
1.172832981
Observations
44
44
Pearson correlation
0.252159598
Hypothesized mean difference
0
df
43
t Stat
-5.863293621
P(T<=t) one-tail
0.0000
t Critical one-tail
1.681070703
P(T<=t) two-tail
0.0000
t Critical two-tail
2.016692199
Null Hypothesis 7
H70: There is no statistical significant difference in ranking of industry experience
for categories A, B, and C lenders when seeking multifamily rental property financing.
Category B
Lender
Category C
Lender

83
According to a one-way ANOVA test with (p = 0.416), there is not enough support
to reject the null hypothesis. Consequently, the ranking of industry experience for all three
categories of lender is similar (see Table 2). Therefore, there is no requirement to conduct
independent samples t tests.
Null Hypothesis 8
H80: There is no statistical significant difference in ranking of employment history
for categories A, B, and C lenders when seeking multifamily rental property financing.
According to a one-way ANOVA test with (p = 0.712), there is not enough support
to reject the null hypothesis. Consequently, the ranking of employment history for all
three categories of lender is similar (see Table 2). Therefore, there is no requirement to
conduct independent samples t tests.
Applications to Professional Practice
Mortgage criteria are factors that assist mortgage lenders when making lending
decisions. The assessed criteria in this study were GDS ratio, TDS ratio, DSCR, LTV
ratio, property appraisal, and borrower’s profile (credit score, industry experience, and
length of employment). The objective of assessing the criteria was to evaluate borrowers’
financial strength and probability of default (Krainer & Laderman, 2014). While a
mortgage application is between a borrower and lender, the impact of mortgage lending
for multifamily rental properties impacts many stakeholders. Other parties impacted by
multifamily rental property mortgages were real estate sales professionals, mortgage
brokers, financial regulators, tenants, social housing representatives, and the economy as a

84
whole. Asabere, McGowan, and Lee (2016) mentioned a positive correlation between the
mortgage industry and positive economic growth.
While all mortgage lending criteria are important in the lending process, some
lenders rank the criteria differently. Based on the findings of the study, Category C
(private) lenders rank LTV ratio higher than Category A (banks and depository
institutions) and B (insurance companies and non-depository institutions) lenders. The
results for LTV shows a significant difference between Category A and B lenders with (p
= 0.017) and Category A and C lenders with (p < 0.001), but the difference between
Category B and C lenders is not statistically significant with (p = 0.063). The results
indicated that credit score ranked significantly different between Category A and C lender
with (p < 0.001), and Category B and C lender with (p < 0.001). There is a significant
difference between Category A and B lender with (p = 0.006).
An understanding and awareness of the ranking of the different lending criteria
could be beneficial to all stakeholders in the mortgage and multifamily rental
environment. Understanding how the different categories of lenders value and rank the
different underwriting criteria will enable borrowers to be better prepared when seeking
mortgage financing. Mortgage borrowers will be able to determine which category of
lenders to pursue based on their strengths and weaknesses or suitability of the lender. As a
result, mortgage borrowers could become more efficient and save time and financial
resources. A borrower with a low LTV ratio should focus on Category A and B lenders
because based on the findings Category C lenders rank LTV as a high requirement.

85
Moreover, a borrower with a low credit score should focus their application towards
Category C lenders.
Knowledgeable borrowers who understand their funding requirements could
identify potential lenders that offer better mortgage options which could result in
significant financial savings. Identifying which lender is suitable in the early stages of the
mortgage application could enable the borrower to save significant time and utilize
economies of scale on other projects. Further, borrowers could save on appraisal,
environmental assessment, broker, and other fees related to the mortgage application
process (Ding, 2014). In the multifamily rental property renewal or new mortgage
application process, the lender sometimes requires environmental assessment and
appraisal complete before releasing funds (Pu, Fan, & Deng, 2014). Additionally, some
lenders require a mortgage application fee. Consequently, if a borrower could determine
which lender is more suitable for their application and profile, then the borrower could
only incur fees that are required by that specific lender. As a result of lower financing cost,
borrowers could become more profitable. As landlords become more profitable, they will
eventually reinvest in the community; buying more properties, redeveloping older
properties and/or building new properties. Stimulating and fueling other sectors growth
and eventually positively impact both the local and global economic growth.
An understanding as to what other lenders value when issuing mortgage financing
could enlighten other lenders on possible liability exposure or areas of improvement.
Lenders could use the results of this study and compare or revise their criteria
requirements to mitigate mortgage default. Since the primary objective of all lenders is to

86
reduce default risk, understanding and identifying strength and weaknesses based on other
lenders could enable revision of processes and checks. Consequently, the findings of this
study could enable lenders to save both time and money with mitigating mortgage
defaults and foreclosure process.
Both lenders and borrowers could save time and financial resources by using the
findings of this study. Additionally, other stakeholders in the multifamily rental property
mortgage application process could benefit from the results of this study. The ripple effect
of savings and job creation from lenders, borrowers, and other stakeholders could
stimulate economic growth and redevelopment. Further, enhanced profitability and
productivity could reduce the probability of recession or economic contraction and
enhance growth (Christopoulos & León-Ledesma, 2014).
The process of mortgage lending for multifamily rental property is a micro system.
There are several factors and steps involved in the lending process. These factors and
steps need to cohesively work together to ensure a successful mortgage application and
funding (Teye et al., 2015). The probability of mortgage application approval increases as
criteria fulfill. Further, multifamily mortgage lending as a micro system forms part of a
macro system which relates to local, global, and international economic growth (Driver &
Matthews, 2016). Enhanced productivity and profitability for all stakeholders in the
multifamily rental property mortgage process could enable a balanced economy and
improve the standard of living (Kofner, 2014).

87
Implications for Social Change
The findings of this study could create awareness of the impact of lender type on
the average rankings of mortgage underwriting outcome measures. The findings could
assist financial regulators and mortgage lenders when enacting and implementing lending
regulations and process. Additionally, an understanding of the ranking of the mortgage
underwriting criteria could assist borrowers when seeking and completing mortgage
applications. An understanding of the ranking of mortgage underwriting criteria could
improve efficiency and productivity among the different stakeholders within the mortgage
lending sector. The improved efficiency could enable stakeholders to enhance productivity
and profitability. Properties with lower financing cost or where the landlord has a better
probability of obtaining financing are more likely to experience more frequent capital
improvements and maintenance (Downs & Xu, 2015). As a result, tenants that reside in
properties with lower financing cost could benefit from improvements and a home that is
in a safe livable condition. Further, a landlord that is profitable or has less barriers with
financing is less likely to raise rent or overcharge tenants. The result of a better living
condition and competitive rent payments will improve tenants living standard which will
positively impact society and the economy.
The community, society, and culture is also impacted with improved profitability.
As profitability and spending increases, job creation and employment will increase
(Alhassan, Tetteh, & Brobbey, 2016). With better standard of living, increased spending,
and overall better community morale the community appearance and presentation will
improve.

88
Recommendations for Action
The results of this study could be beneficial to mortgage lenders, financial
regulators, mortgage brokers, and borrowers. It is critical that borrowers are aware of the
different weighting or ranking of mortgage underwriting criteria among the different types
of lenders. An awareness as to how different lenders value mortgage criteria will enable
financial regulators to enact effective policies and remedies.
Financial regulators should be aware that different lenders value LTV ratio and
credit scores differently. Table 3 indicated a statistical difference between the different
categories of lenders for LTV ratio. Table 4 indicated a statistical difference for categories
A and B lenders for LTV ratio. Table 5 indicated a statistical difference for categories A
and C lenders for LTV ratio. Table 6 indicated no statistical difference for categories B
and C lenders for LTV ratio. Table 7 indicated a statistical difference between the different
categories of lenders for credit score. Table 8 indicated a statistical difference for
categories A and B lenders for credit score. Table 9 indicated a statistical difference for
categories A and C lenders for credit score. Table 10 indicated a statistical difference for
categories B and C lenders for credit score.
Colleges and universities that facilitate real estate and mortgage programs could
adapt and implement aspects of this study within the curriculum. Real estate sales
professionals, investors, and other mortgage stakeholders could use the findings as
additional resource for their clients. Additionally, publishing the findings online could
make it available to the general public.

89
Recommendations for Further Research
The findings from the study indicated that Category C lenders rank LTV ratio
higher than Category A and B lenders. The study also indicated that Category A and B
lenders rank credit score higher than Category C lenders. The following opportunities
exist for future research:
• What motivates Category C lenders to value LTV ratio when underwriting a
mortgage application? The objective is to identify why Category C lenders
rank LTV as the most important.
• What motivates Category A and B lenders to value credit score when
underwriting a mortgage application? The objective is to identify why
Category A and B lenders rank credit score as the most important.
• What is the mortgage default rate between Category A, B, and C lenders? The
objective is to compare default rates between the different categories of
lenders to identify potential strengths and weaknesses among the lenders.
• What category of lenders do landlords prefer to deal with? The objective of
this study is to identify if there is a specific category of lender that landlords
prefer to deal with and why, and
• What factors influence landlords to spend on capital improvements? The
objective is to identify what factors encourages landlords to conduct capital
improvements.

90
To address limitations mentioned in Section 1 of this study; such as efficient and
appropriate sample size, responses from only a specific demographic, and closed-ended
questions, the following studies could assist in mitigating these limitations:
• A qualitative study to identify relative ranking of mortgage underwriting
criteria to enable the researcher to ask open-ended questions and participants
would provide responses that are not limited to pre-selected answer options.
• Separate studies focusing on the different regions of Ontario; such as Eastern,
Northern, Southern, Central, and Western to identify if respondents in different
demographic regions value the criteria differently, and
• A study focusing on all of Canada. The findings could be used to identify
mortgage criteria benchmark among different regions of Canada.
Reflections
Before embarking on this doctoral study journey, my expectation was to commit
research time for quality completion of the study, but the approaches and requirements for
doctoral study research was different than my previous research experiences. Time
management skills, self-starter attitude, perseverance, and optimism are some attributes I
developed to succeed in this journey.
In relation to this study, I was under the impression that credit score was the single
most important criteria that all lenders value when issuing mortgage financing and did not
expect how important the five Cs of credit is in the mortgage lending industry. I expected
the importance of GDS ratio, TDS ratio, credit score, LTV ratio, and property appraisal
but did not expect that lenders value the borrower industry experience and length of

91
employment or that DSCR was reviewed based on how the rental portfolio was structured.
From conducting scholarly doctoral research, my outlook on the application of factual
data along with personal opinions and experiences can provide objective analysis for
decision making.
Conclusions
Mortgage lending for multifamily rental properties may seem to be an isolated
issue that only concerns landlord and mortgage lenders. On the contrary, mortgage lending
for multifamily rental properties extends beyond just the landlords and lenders and could
impact the economy and society. Other stakeholders that could be impacted by
multifamily rental mortgage lending are mortgage regulators, tenants, social housing
representatives, and real estate sales professionals. It is advisable that all stakeholders
continue to research, understand, forecast, and implement effective regulations to mitigate
financial crises; such as the 2007-2009 recession. It is also important to continue
researching the topic to improve efficiency and enhance profitability. Fueling economic
growth and improving the standard of living, could positively impact social change.
References
Abdulai, I. A., & Shafiwu, A. B. (2014). Participatory decision making and employee
productivity: A case study of community banks in the upper east region of Ghana.
Business and Economics Journal, 5(3), 1-10. doi:10.4172/2151-6219.100099
Addo, C. K. (2006). Predicting powers of potential income versus credit history for loan
repayment (Doctoral dissertation). Retrieved from ProQuest Dissertations and
Theses database. (Order No. 3237579).

92
Afzali, H. H. A., Gray, J., & Karnon, J. (2013). Model performance evaluation
(validation and calibration) in model-based studies of therapeutic interventions for
cardiovascular diseases: A review and suggested reporting framework. Applied
Health Economics and Health Policy, 11, 85-93. doi:10.1007/s40258-013-0012-6
Agyapong, D., Agyapong, G. K. Q., & Darfor, K. N. (2011). Criteria for assessing small
and medium enterprises' borrowers in Ghana. International Business Research, 4,
132-138. doi:10.5539/ibr.v4n4p132
Akhavan, P., Elahi, B., & Jafari, M. (2014). A new integrated knowledge model in
supplier selection. Education, Business and Society: Contemporary Middle
Eastern Issues, 7, 333-368. doi:10.1108/EBS-07-2014-0035
Akoto, R. K., & Awunyo-Vitor, D. (2014). What determines the debt policy of listed
manufacturing firms in Ghana? International Business Research, 7, 42-48.
doi:10.5539/ibr.v7n1p42
Aldebert, B., & Rouzies, A. (2014). Quelle place pour les méthodes mixtes dans la
recherche francophone en management ?/What role for mixed methods in French
management research? Management International, 19, 43-60. Retrieved from
http://www.managementinternational.ca/catalog/
Alhassan, A. L., Tetteh, M. L., & Brobbey, F. O. (2016). Market power, efficiency and
bank profitability: Evidence from Ghana. Economic Change and
Restructuring, 49, 71-93. doi:10.1007/s10644-015-9174-6
An, X., Deng, Y., Nichols, J. B., & Sanders, A. B. (2013). Local traits and securitized
commercial mortgage default. Journal of Real Estate Finance and Economics, 47,

93
787-813. doi:10.1007/s11146-013-9431-2
Archer, W. R., & Smith, B. C. (2013). Residential mortgage default: The roles of house
price volatility, euphoria and the borrower's put option. Journal of Real Estate
Finance and Economics, 46, 355-378. doi:10.1007/s11146-011-9335-y
Arsenault, M., Clayton, J., & Peng, L. (2013). Mortgage fund flows, capital appreciation,
and real estate cycles. Journal of Real Estate Finance and Economics, 47, 243-
265. doi:10.1007/s11146-012-9361-4
Asabere, P. K., McGowan Jr., C.,B., & Lee, S. M. (2016). A study into the links between
mortgage financing and economic development in africa. International Journal of
Housing Markets and Analysis, 9(1), 2-19. doi:10.1108/IJHMA-05-2014-0014
Asgari, N., Ahmadi, M. H., Shamlou, M., Farokhi, A. R., & Farzin, M. (2014). Studying
the impact of E-service quality on E-loyalty of customers in the area of E-banking
services. Journal of Management and Sustainability, 4, 126-133.
doi:10.5539/jms.v4n2p126
Austin, C. (2013). Appraisal institute releases guide note 13: Performing evaluations of
real property collateral for lenders. The Appraisal Journal, 81, 173-179. Retrieved
from http://www.appraisalinstitute.org/appraisal-institute-helps-appraisersperform-
evaluations-for-lenders/
Bhunia, A. (2013). Statistical methods for practice and research (A guide to data analysis
using SPSS). South Asian Journal of Management, 20, 154-157. Retrieved from
http://sajm-amdisa.org/
Bloom, N. (2014). Fluctuations in uncertainty. The Journal of Economic
Perspectives, 28, 153-176. doi:10.1257/jep.28.2.153

94
Bromley, E., Mikesell, L., Jones, F., & Khodyakov, D. (2015). From subject to
participant: Ethics and the evolving role of community in health research.
American Journal of Public Health, 105, 900-908.
doi:10.2105/AJPH.2014.302403
Bryant, L. (2012). An assessment of development funding for new housing post gfc in
Queensland, Australia. International Journal of Housing Markets and Analysis, 5,
118-133. doi:10.1108/17538271211225887
Bunn, J. (2014). Questioning autonomy: An alternative perspective on the principles
which govern archival description. Archival Science, 14(1), 3-15.
doi:10.1007/s10502-013-9200-2
Canada Mortgage and Housing Corporation. (2015). CMHC income property. Retrieved
from http://www.cmhc-schl.gc.ca/en/hoficlincl/moloin/hopr/hopr_007.cfm
Carrillo, P. E. (2013). Testing for fraud in the residential mortgage market: How much did
early-payment-defaults overpay for housing? Journal of Real Estate Finance and
Economics, 47, 36-64. doi:10.1007/s11146-011-9343-y
Chan, S. F. X. (2014). What's the law got to do with corruption in Indonesia A case study
for systems theory. Global Jurist, 14, 67-99. doi:10.1515/gj-2013-0013
Chan, S., Sharygin, C., Been, V., & Haughwout, A. (2014). Pathways after default: What
happens to distressed mortgage borrowers and their homes? Journal of Real
Estate Finance and Economics, 48, 342-379. doi:10.1007/s11146-012-9400-1
Chen, R. D., Gan, C., Hu, B., & Cohen, D. A. (2013). An empirical analysis of house
price bubble: A case study of Beijing housing market. Research in Applied

95
Economics, 5, 77-97. doi:10.5296/rae.v5i1.3433
Chiang, Y., & Sa-aadu, J. (2014). Optimal mortgage contract choice decision in the
presence of pay option adjustable rate mortgage and the balloon mortgage.
Journal of Real Estate Finance and Economics, 48, 709-753.
doi:10.1007/s11146-012-9397-5
Chow, M. Y., Kwan, Morrow, A. M., Cooper Robbins, S. C., & Leask, J. (2013).
Condition-specific quality of life questionnaires for caregivers of children with
pediatric conditions: A systematic review. Quality of Life Research, 22, 2183-200.
doi:10.1007/s11136-012-0343-z
Christopoulos, D., & León-Ledesma, M.,A. (2014). Efficiency and production frontiers in
the aftermath of recessions: International evidence. Macroeconomic
Dynamics, 18, 1326-1350. doi:10.1017/S1365100512000983
Citron, D. K., & Pasquale, F. (2014). The scored society: Due process for automated
predictions. Washington Law Review, 89(1), 1-33. Retrieved from
https://www.law.uw.edu/wlr/
Cortes, G. S., Marcondes, R. L., & Diaz, M. D. M. (2014). Mortgages for machinery:
Credit and industrial investment in pre-world war I Brazil. Financial History
Review, 21(2), 191-212. doi:10.1017/S0968565014000110
Cudworth, E., & Hobden, S. (2013). Complexity, ecologism, and posthuman politics.
Review of International Studies, 39, 643-664.
doi:10.1017/S0260210512000290

96
Cummings, J. R., & Epley, D. R. (2013). A national profile of the real estate industry and
the appraisal profession. The Appraisal Journal, 81, 129-142. Retrieved from
http://www.appraisalinstitute.org/
Darvas, Z. (2014). Can Europe recover without credit? Society and Economy, 36, 129-
149. doi:10.1556/SocEc.36.2014.2.1
Desai, C. A., Elliehausen, G., & Steinbuks, J. (2013). Effects of bankruptcy exemptions
and foreclosure laws on mortgage default and foreclosure rates. Journal of Real
Estate Finance and Economics, 47, 391-415. doi:10.1007/s11146-012-9366-z
Ding, L. (2014). Information externalities and residential mortgage lending in the hardest
hit housing market: The case of Detroit. Cityscape, 16, 233-252. Retrieved from
https://www.huduser.gov/portal/periodicals/cityscape.html
DiPasquale, D., & Cummings, J.L. (1992). Financing multifamily rental housing: The
changing role of lenders and investors. Housing Policy Debate, 3, 77-116.
Retrieved from http://www.tandfonline.com/toc/rhpd20/current
Downs, A. (2011). The outlook for recovery in U.S. real estate markets. Real Estate
Issues, 35(3), 8-11. Retrieved from https://www.cre.org/
Downs, D. H., & Shi, L. (2015). The impact of reversing regulatory arbitrage on loan
originations: Evidence from bank holding companies. Journal of Real Estate
Finance and Economics, 50, 307-338. doi:10.1007/s11146-014-9468-x
Downs, D. H., & Xu, P. (. (2015). Commercial real estate, distress and financial
resolution: Portfolio lending versus securitization. Journal of Real Estate Finance
and Economics, 51, 254-287. doi:10.1007/s11146-014-9471-2

97
Driver, R., & Matthews, W. (2016). The global financial crisis and US housing policy.
Journal of Business and Retail Management Research, 7, 157-161.
Retrieved from http://www.jbrmr.com/
Dufwenberg, M. (2015). Banking on experiments? Journal of Economic Studies, 42,
943-971. doi:10.1108/JES-08-2015-0145
Dumbili, E. W. (2014). Use of mixed methods designs in substance research: A
methodological necessity in Nigeria. Quality and Quantity, 48, 2841-2857.
doi:10.1007/s11135-013-9928-z
Dumitriu, D. (2015). The impact of financial diplomacy and the effects of financial crisis
on Norwegian firms' capital. Management Dynamics in the Knowledge Economy,
3, 171-186. Retrieved from
http://www.managementdynamics.ro/index.php/journal/index
Eisenbeis, R. A., & Herring, R. J. (2015). Playing for time: The fed's attempt to manage
the crisis as a liquidity problem. Journal of Financial Economic Policy, 7, 68-88.
doi:10.1108/JFEP-11-2014-0074
Eisenbeis, R. A., & Kaufman, G. G. (2016). Not all financial crises are alike! Atlantic
Economic Journal, 44(1), 1-31. doi:10.1007/s11293-016-9483-9
Erdfelder, E., Faul, F., & Buchner, A. (1996). Gpower: A general power analysis program.
Behavior Research Methods, Instruments, & Computers, 28(1), 1-11.
doi:10.3758/BF03203630
Ewalt, J. A. G., & Jennings, E. T., J. (2014). The great recession and social welfare
spending in the American states. International Review of Public

98
Administration, 19, 308-323. doi:10.1080/12294659.2014.966887
Fabozzi, F. J., McBride, J., & Clancy, M. (2015). The post-crisis CMBS market: Will
regulations prevent another market meltdown? Journal of Portfolio
Management, 41, 118-125. doi:10.3905/jpm.2015.41.6.118
Fetter, D. K. (2013). How do mortgage subsidies affect home ownership? evidence from
the mid-century GI bills. American Economic Journal:Economic Policy, 5, 111-
147. doi:10.1257/pol.5.2.111
Ferreira, F. A. F., Santos, S., Carla S. E. Marques, & Ferreira, J. (2014). Assessing credit
risk of mortgage lending using MACBETH: A methodological framework.
Management Decision, 52, 182-206. doi:10.1108/MD-01-2013-0021
Galster, G., Tatian, P., & Wilson, C. (1999). Alternative measures for the financial
condition of the multifamily housing stock. Housing Policy Debate, 10, 59-73.
doi:10.1.1.199.5081
Gan, C., Li, Z., Wang, W., & Kao, B. (2012). Credit scoring in mortgage lending:
Evidence from China. International Journal of Housing Markets and Analysis, 5,
334-350. doi:10.1108/17538271211268457
Garcia, D., & Gluesing, J. C. (2013). Qualitative research methods in international
organizational change research. Journal of Organizational Change Management,
26, 423-444. doi:10.1108/09534811311328416
Ghosh, A. (2016). Do real estate loans reflect regional banking and economic conditions?
Journal of Financial Economic Policy, 8, 37-63. doi:10.1108/JFEP-
09-2015-0050

99
Glascock, J., & Lu-andrews, R. (2014). An examination of macroeconomic effects on the
liquidity of REITs. Journal of Real Estate Finance and Economics, 49, 23-46.
doi:10.1007/s11146-013-9406-3
Grimes, D. A., & Schulz, K. F. (2002). Uses and abuses of screening tests. The Lancet,
359, 881-884. doi:10.1016/S0140-6736(02)07948-5
Guo, R., Cai, L., & Zhang, W. (2016). Effectuation and causation in new internet venture
growth. Internet Research, 26, 460-483. doi:10.1108/IntR-01-2015-0003
Guo, J., Xu, S., & Bi, Z. (2014). An integrated cost-based approach for real estate
appraisals. Information Technology and Management, 15, 131-139.
doi:10.1007/s10799-012-0152-7
Gupta, A., & Tiwari, P. (2016). Investment risk scoring model for commercial properties
in India. Journal of Property Investment & Finance, 34, 156-171.
doi:10.1108/JPIF-05-2015-0031
Harrison, D. M., & Seiler, M. J. (2015). The paradox of judicial foreclosure: Collateral
value uncertainty and mortgage rates. Journal of Real Estate Finance and
Economics, 50, 377-411. doi:10.1007/s11146-014-9467-y
Henderson, V. C., Kimmelman, J., Fergusson, D., Grimshaw, J. M., & Hackam, D. G.
(2013). Threats to validity in the design and conduct of preclinical efficacy studies:
A systematic review of guidelines for in vivo animal experiments. PLoS
Medicine, 10, e1001489. doi:10.1371/journal.pmed.1001489
Heylen, K., & Haffner, M. (2013). A ratio or budget benchmark for comparing
affordability across countries? Journal of Housing and the Built Environment, 28,
547-565. doi:10.1007/s10901-012-9325-2

100
Hoelle, M., Pireddu, M., & Villanacci, A. (2016). Incomplete financial markets with real
assets and wealth-dependent credit limits. Journal of Economics, 117(1), 1-36.
doi:10.1007/s00712-015-0438-4
Hossain, M. I., & Hossain, M. A. (2015). Determinants of capital structure and testing of
theories: A study on the listed manufacturing companies in Bangladesh.
International Journal of Economics and Finance, 7, 176-190.
doi:10.5539/ijef.v7n4p176
Islam, A. (2014). Economic growth and crime against small and medium sized enterprises
in developing economies. Small Business Economics, 43, 677-695.
doi:10.1007/s11187-014-9548-6
Jordà, Ò., Schularick, M., & Taylor, A. M. (2016). The great mortgaging: Housing
finance, crises and business cycles. Economic Policy, 31, 107-152.
doi:10.1093/epolic/eiv017
Jones, C., & Richardson, H. W. (2014). Housing markets and policy in the UK and the
USA. International Journal of Housing Markets and Analysis, 7, 129-144.
doi:10.1108/IJHMA-10-2012-0052
Kabir, R. (2015). Does sme loan repayment influenced by specific attributes of borrowers
– A study on selected banks. Indian Journal of Commerce and Management
Studies, 6, 45-50. Retrieved from http://scholarshub.net/ijcms/
Kiani, K. M. (2017). Financial factors and financial crises: Evidence from financial
statements of mainland Chinese firms. Chinese Economy, 50, 78-93.
doi:10.1080/10971475.2016.1211907
Kofner, S. (2014). The German housing system: Fundamentally resilient? Journal of

101
Housing and the Built Environment, 29, 255-275. doi:10.1007/s10901-013-9383-
0
Krainer, J., & Laderman, E. (2014). Mortgage loan securitization and relative loan
performance. Journal of Financial Services Research, 45, 39-66.
doi:10.1007/s10693-013-0161-7
Kwatra, S., Pandey, S., & Sharma, S. (2014). Understanding public knowledge and
awareness on e-waste in an urban setting in India. Management of Environmental
Quality, 25, 752. doi:10.1108/MEQ-12-2013-0139
Laszlo, A., & Krippner, S. (1998). Systems theories: Their origins, foundations, and
development. In J.S. Jordan (Ed.). Systems Theories and A Priori Aspects of
Perception (Ch.3, pp.47-74). Amsterdam: Elsevier Science.
Leedy, P. D., & Ormrod, J. E. (2010). Practical research: Planning and design (9th ed.).
Boston, MA: Pearson.
Lin, L. (2014). Optimal loan-to-value ratio and the efficiency gains of default. Annals of
Finance, 10, 47-69. doi:10.1007/s10436-013-0232-7
Lintukangas, K., Anni-Kaisa Kähkönen, & Veli, M. V. (2013). The antecedents of supply
strategy. European Business Review, 25, 396-410. doi:10.1108/EBR-08-2012-
0046
Liu, P., & Quan, D. (2013). Foreclosure of securitized commercial mortgages--A model
of the special servicer. Journal of Real Estate Finance and Economics, 46, 321-
338. doi:10.1007/s11146-011-9337-9

102
Lydon, R., & McCarthy, Y. (2013). What lies beneath? understanding recent trends in
Irish mortgage arrears. The Economic and Social Review, 44, 117-150. Retrieved
from http://www.esr.ie
Mahadkar, V. M. (2013). Defending skin-in-the-game: How regulators should structure
the final credit risk retention rules for the residential mortgage market. Fordham
Journal of Corporate & Financial Law, 18, 405-449. Retrieved from
http://ir.lawnet.fordham.edu/jcfl/
Mangal, V. (2013). Systems theory and social networking: Investigation of systems
theory principles in web 2.0 social network systems. International Journal of
Business and Commerce, 3, 117-133. Retrieved from www.ijbcnet.com/
Martin, M. (2013). Assessing the model risk with respect to the interest rate term
structure under solvency II. The Journal of Risk Finance, 14, 200-233.
doi:10.1108/JRF-11-2012-0083
Mason, J. W., & Jayadev, A. (2014). "Fisher dynamics" in US household debt, 1929-
2011. American Economic Journal:Macroeconomics, 6, 214-234.
doi:10.1257/mac.6.3.214
McDaniel, B. A. (2014). A schumpeterian view of the U.S. housing crisis. Journal of
Management Policy and Practice, 15, 25-29. Retrieved from http://jmppnet.com/
McDonald, O. A. (2016). Holding banks to account for the financial crisis? Journal of
Financial Crime, 23, 45-69. doi:10.1108/JFC-08-2015-0041
McLeod, S. A. (2014). Sampling Methods. Retrieved from
http://www.simplypsychology.org/sampling.html

103
McShane, K. E., Davey, C. J., Rouse, J., Usher, A. M., & Sullivan, S. (2015). Beyond
ethical obligation to research dissemination: Conceptualizing debriefing as a form
of knowledge transfer. Canadian Psychology, 56, 80-87. doi:10.1037/a0035473
Miles, S., Gordon, J., & Storlie, C. (2013). Job satisfaction, perceived career plateau, and
the perception of promotability: A correlational study. Journal of International
Management Studies, 8(1), 1-9. Retrieved from http://www.jimsjournal.org
My Money Coach. (2015). What is a credit score & how is a credit score calculated in
Canada. Retrieved from http://www.mymoneycoach.ca/credit/check-credit-
rating-report-score/whatis-a-credit-score
Murty, A. V. N., Kiran, T., & Gupta, R. (2013). Sub prime crises: It’s impact on global
and Indian economy. International Journal of Trade & Global Business
Perspectives, 2, 641-645. Retrieved from http://pezzottaitejournals.net
Nahorniak, M., Larsen, D. P., Volk, C., & Jordan, C. E. (2015). Using inverse probability
bootstrap sampling to eliminate sample induced bias in model based analysis of
unequal probability samples. PLoS One, 10, e0131765.
doi:10.1371/journal.pone.0131765
Neidermeyer, A., Boyd, N. E., & Neidermeyer, P. (2014). PMI: Mortgage backstop from
the alger report to dodd-frank. Journal of Financial Regulation and
Compliance, 22, 43-48. doi:10.1108/JFRC-02-2013-0003
Nembhard, J. G. (2013). Community development credit unions: Securing and protecting
assets in black communities. Review of Black Political Economy, 40,
459-490. doi:10.1007/s12114-013-9166-6

104
Nesiba, R. F., Sorenson, D. J., & Sturm, K. (2012). Who is foreclosing on whom? home
mortgage lending and foreclosures in Sioux Falls, South Dakota, 2004-2010.
Journal of Economic Issues, 46, 323-331. doi:10.2753/JEI0021-3624460207
Nichols, M. W., Hendrickson, J. M., & Griffith, K. (2011). Was the financial crisis the
result of ineffective policy and too much regulation? An empirical investigation.
Journal of Banking Regulation, 12, 236-251. doi:10.1057/jbr.2011.3
O'Brien, V.,H., & McGaha, J. L. (2014). Current practice patterns in conservative thumb
cmc joint care: Survey results. Journal of Hand Therapy, 27(1), 14-22.
doi:10.1016/j.jht.2013.09.001
Ofonyelu, C. C., & Alimi, R. S. (2013). Perceived loan risk and ex post default outcome:
Are the banks' loan screening criteria efficient? Asian Economic and Financial
Review, 3, 991. Retrieved from http://www.aessweb.com
Parolini, G. (2015). The emergence of modern statistics in agricultural science: Analysis
of variance, experimental design and the reshaping of research at rothamsted
experimental station, 1919-1933. Journal of the History of Biology, 48, 301-335.
doi:10.1007/s10739-014-9394-z
Peicuti, C. (2014). The great depression and the great recession: A comparative analysis
of their analogies. The European Journal of Comparative Economics, 11, 55-78.
Retrieved from http://www.eaces.eu/
Pennington-cross, A. (2012). Mortgage finance markets: Lessons from the past and keys
to the future. Atlantic Economic Journal, 40, 225-227. doi:10.1007/s11293-012-
9324-4

105
Portmann, D., & Mlambo, C. (2013). Private equity and venture capital in South Africa:
A comparison of project financing decisions. South African Journal of Economic
and Management Sciences, 16, 258. Retrieved from
http://www.sajems.org/index.php/sajems/
Pu, M., Fan, G., & Deng, Y. (2014). Breakeven determination of loan limits for reverse
mortgages under information asymmetry. Journal of Real Estate Finance and
Economics, 48, 492-521. doi:10.1007/s11146-013-9415-2
Quercia, R. G., Ding, L., & Reid, C. (2012). Balancing risk and access: Underwriting
standards for qualified residential mortgages. Rochester: Social Science Research
Network. doi:10.2139/ssrn.1991262
Ragas, M. W., & Laskin, A. V. (2014). Mixed-methods: Measurement and evaluation
among investor relations officers. Corporate Communications, 19, 166-181.
doi:10.1108/CCIJ-10-2012-0071
Raina, S. (2014). Performing multi stage random sampling in community based surveys.
Journal of Postgraduate Medicine, 60, 221-222. doi:10.4103/0022-3859.132385
Romm, N. R., & A. (2015). Reviewing the transformative paradigm: A critical systemic
and relational (indigenous) lens. Systemic Practice and Action Research, 28, 411-
427. doi:10.1007/s11213-015-9344-5
Roulac, S.,E. (2014). Commercial mortgages - money is available if you are willing to
pay the price. Journal of Property Investment & Finance, 32, 589-609.
doi:10.1108/JPIF-06-2014-0042
Rowley, J. (2014). Designing and using research questionnaires. Management Research
Review, 37, 308-330. doi:10.1108/MRR-02-2013-0027

106
Sah, R. (2015). Loan recovery monitoring mechanism. International Journal of Trade,
Economics and Finance, 6, 62-66. doi:10.7763/IJTEF.2015.V6.444
Sanderford, A. R., Overstreet, G. A., Beling, P. A., & Rajaratnam, K. (2015). Energy-
efficient homes and mortgage risk: Crossing the chasm at last? Environment
Systems & Decisions, 35, 157-168. doi:10.1007/s10669-015-9535-8
Sayin, U. (2016). A short introduction to system theory: Indispensible postulate systems
and basic structures of the systems in quantum physics, biology and neuroscience.
NeuroQuantology, 14, 126-142. doi:10.14704/nq.2016.14.1.855
Scanlon, K., & Elsinga, M. (2014). Policy changes affecting housing and mortgage
markets: How governments in the UK and the Netherlands responded to the
GFC. Journal of Housing and the Built Environment, 29, 335-360.
doi:10.1007/s10901-013-9390-1
Scherdin, M., & Zander, I. (2014). On the role and importance of core assumptions in the
field of entrepreneurship research. International Journal of Entrepreneurial
Behaviour & Research, 20, 216-236. doi:10.1108/IJEBR-01-2012-0015
Schoenung, B., & Dikova, D. (2016). Reflections on organizational team diversity
research. Equality, diversity and inclusion: An International Journal, 35, 221-231.
doi:10.1108/EDI-11-2015-0095
Schwarcz, S. L. (2013). Securitization, structured finance, and covered Bonds. Journal of
Corporation Law, 39, 129-154. Retrieved from https://jcl.law.uiowa.edu
Seiler, M. J., & Walden, E. (2015). A neurological explanation of strategic mortgage
default. Journal of Real Estate Finance and Economics, 51, 215-230.
doi:10.1007/s11146-014-9479-7

107
Sharpe, S. A., & Sherlund, S. M. (2016). Crowding out effects of refinancing on new
purchase mortgages. Review of Industrial Organization, 48, 209-239.
doi:10.1007/s11151-016-9500-9
Shiller, R. J. (2014). Why is housing finance still stuck in such a primitive stage? The
American Economic Review, 104, 73-76. doi:10.1257/aer.104.5.73
Simon, M.K. (2011). Assumptions, limitations and delimitations. From Dissertation and
scholarly research: Recipes for success. Seattle, WA: Dissertation Success, LLC.
Singh, H. P., & Solanki, R. S. (2013). A new procedure for variance estimation in simple
random sampling using auxiliary information. Statistical Papers, 54, 479-497.
doi:10.1007/s00362-012-0445-2
Slife, B. D., & Melling, B. S. (2012). Method decisions: Quantitative and qualitative
inquiry in the study of religious phenomena. Pastoral Psychology, 61, 721-734.
doi:10.1007/s11089-011-0366-3
Smith, T. A. (2014). Testing theory and related factors for influencing proficiency in
quantitative research. Academy of Educational Leadership Journal, 18, 117-128.
Retrieved from http://www.alliedacademies.org/academy-of-
educationalleadership-journal/
Steinbuks, J., & Elliehausen, G. (2014). The economic effects of legal restrictions on
high-cost mortgages. Journal of Real Estate Finance and Economics, 49, 47-72.
doi:10.1007/s11146-013-9413-4
Stephen, K. N., Kasozi, D., Nalukenge, I., & Tauringana, V. (2014). Lending terms,
financial literacy and formal credit accessibility. International Journal of Social

108
Economics, 41, 342-361. doi:10.1108/IJSE-03-2013-0075
Sullivan, B., & Bernstein, R. (2013). Hub and census bureau release new survey on
characteristics of nations’s multi-family rental properties. Retrieved from
http://portal.hud.gov/hudportal/HUD?src=/press/press_releases_media_advisories
/2013/HUDNo.13-035
Taheri, S. M., & Hesamian, G. (2013). A generalization of the Friedman signed-rank test
and its applications. Statistical Papers, 54, 457-470. doi:10.1007/s00362-012-
0443-4
Tatom, J. A. (2013). Crises and the great recession. Business Economics, 48, 175-181.
doi:10.1057/be.2013.20
Tella, A. (2015). Electronic and paper based data collection methods in library and
information science research. New Library World, 116, 588. doi:10.1108/NLW-
12-2014-0138
Teo, A. H. L. (2004). Delinquency risk in residential ARMs: A hazard function approach.
Journal of Real Estate Portfolio Management, 10, 243-258.
doi:10.5555/repm.10.3.c454h7q82w401258
Teye, J. K., Teye, I., & Asiedu, M. O. (2015). Financing housing in Ghana: Challenges to
the development of formal mortgage system. Journal of Housing and the Built
Environment, 30(1), 1-16. doi:10.1007/s10901-013-9376-z
Theiakos, A., Tas, J. M. C., van, d. L., & Kandhai, D. (2015). Ultra-fast scenario analysis
of mortgage prepayment risk. The Journal of Risk, 17(3), 19-33.
doi:10.21314/JOR.2015.323

109
Trönnberg, C-C., & Hemlin, S. (2012). Banker's lending decision making: A
psychological approach. Managerial Finance, 38(11), 1032-1047.
doi:10.1108/03074351211266775
Tuan, N., & Shaw, C. (2016). Consideration of ethics in systemic thinking. Systemic
Practice and Action Research, 29, 51-60. doi:10.1007/s11213-015-9352-5
Ueng, C. J. (2016). The analysis of corporate governance policy and corporate financial
performance. Journal of Economics and Finance, 40, 514-523.
doi:10.1007/s12197-015-9316-8
U.S. Census Bureau. (2012). Census Bureau Projects U.S. Population of 315.1 Million on
New Year's Day. Retrieved from
https://www.census.gov/newsroom/releases/archives/population/cb12-255.html
Vollmer, A., & Seyr, S. (2013). Constructive controversy research in the business
organizational context. International Journal of Conflict Management, 24, 399-
420. doi:10.1108/IJCMA-07-2011-0055
Volpone, S. D., Tonidandel, S., Avery, D. R., & Castel, S. (2015). Exploring the use of
credit scores in selection processes: Beware of adverse impact. Journal of
Business and Psychology, 30, 357-372. doi:10.1007/s10869-014-9366-5 von
Bertalanffy, L. (1968). General systems theory. New York, NY: Braziller
Wahyudin, I., Djatna, T., & Kusuma, W. A. (2016). Cluster analysis for SME risk analysis
documents based on Pillar K-Means. Telkomnika, 14, 674-683.
doi:10.12928/TELKOMNIKA.v14i1.2385
Wester, K. L., Borders, L. D., Boul, S., & Horton, E. (2013). Research quality: Critique of
quantitative articles in the journal of counseling & development. Journal of

110
Counseling and Development: JCD, 91, 280-290. doi:10-1002/j.1556-
6676.2013.00096x
Wiklund, I., Raluy-callado, M., Chen, W., Muenzer, J., Fang, J., & Whiteman, D. (2014).
The hunter syndrome-functional outcomes for clinical understanding scale (HS-
FOCUS) questionnaire: Item reduction and further validation. Quality of Life
Research, 23, 2457-62. doi:10.1007/s11136-014-0703-y
Woodward, A. L., & Harris, Z. L. (2013). Employment of a needs assessment survey to
shape a novel web-based pediatric rheumatology curriculum for primary care providers.
Pediatric Rheumatology, 11, 26. doi:10.1186/1546-0096-11-26
Wester, K. L., Borders, L. D., Boul, S., & Horton, E. (2013). Research quality: Critique of
quantitative articles in the journal of counseling & development. Journal of
Counseling and Development: JCD, 91, 280-290. doi:10.1002/j.1556-
6676.2013.00096x
Wilson, F. F. (2016). Making loan decisions in banks: Straight from the gut?. Journal of
Business Ethics, 137, 53-63. doi:10.1007/s10551-014-2515-y
Zeidan, R. R., Boechat, C., & Fleury, A. (2015). Developing a sustainability credit score
system. Journal of Business Ethics, 127, 283-296. doi:10.1007/s10551-013-2034-
2
Zietz, E. N. (2003). Multifamily housing: A review of theory and evidence. The Journal of
Real Estate Research, 25(2), 185-244. Retrieved from
http://aresjournals.org/loi/rees?code=ares-site

