


1
Section 1: Foundation of the Study
In the mortgage profession, managers identify procedural problems to make
educated decisions to improve business processes (Agarwal, Ben-David, & Yao, 2017;
Bapat, 2015). Managerial decision-making, whether positive or negative, may influence a
firm’s profitability (Persson & Ryals, 2014). The goal of this study was to examine a
potential impact of mortgage loan purpose (MLP), mortgage loan type (MLT), and subject
property type (SPT) on average turnaround time (ATT) to complete a retail mortgage
transaction (RMT) from origination to funding.
Background of the Problem
The mortgage trade is a vast, sophisticated group of financial transactions that
deliver intangible services with a possibility of financial risk at every link of the value
chain (Muthusamy & Dass, 2014; Zhang & Tang, 2014). Mortgage loan originators (LOs)
provide consumers with retail mortgage products in the primary market, while private and
public investors supply capital to the finance and housing industries in the secondary
market (Ametefe, Devaney, & Marcato, 2016; Petersen, Waal, MukuddemPetersen, &
Mulaudzi, 2014; Roulac, 2014). Eckstein (2015) noted that understanding complex
mortgage investments requires a sophisticated knowledge of the extensive guidelines and
complicated regulations of the primary and secondary mortgage sectors. Hall (2015)
found that an LOs inefficient processes with complex mortgage procedures increase ATT
to complete an RMT. A better understanding of the impact of MLP, MLT, and SPT on ATT
may help managers to perfect the retail mortgage lending process.

2
The formation of the Consumer Financial Protection Bureau (CFPB) spurred
consumer expertise in mortgage products and guidelines while adding to the competitive
nature of the business for service quality and efficiency (Ambrose & Conklin, 2014;
Eckstein, 2015). Hall (2015) stated that a firm’s leaders would need quantifiable data and
research to refine a business or process. Eckstein (2015) also mentioned that stricter
mortgage regulations and credit standards cause competitors to rethink consumer
acquisition strategies and to revise mortgage-processing techniques. Examination of the
impact of MLP, MLT, and SPT on ATT may offer mortgage managers insight for retail
mortgage process improvements to reduce ATT, thus increasing efficiency. Furthermore,
these results may offer managers ways to reduce transaction costs, improve organizational
reputation, and hence increase profitability and intrinsic value.
The consolidation and loss of financial institutions, which resulted from the 2008-
2009 financial crisis, caused customer acquisition costs to increase (Harrison & Seiler,
2015). Abosag, Yen, and Barnes (2016) showed that LOs develop mortgage business
through proven marketing strategies to attract consumers to purchase or refinance
residential real estate. Carswell and Babiarz (2016) noted that the increase in overall
transaction costs and process turnaround times should alert managers to consider
functional relationships between consumers and employees. Customer acquisition
happens through networking with realtors and builders, and through direct consumer
advertising.

3
Problem Statement
Above-industry ATT to complete an RMT from origination to funding results in
revenue losses (Hall, 2015). On average, only 20% of mortgage applicants continue to
closing; however, mortgage origination costs represent 33% of the total closing costs of an
RMT (Ambrose & Conklin, 2014; Carswell & Babiarz, 2016). The general business
problem is that retail mortgage institutions incur escalating transaction costs as ATT
increases to complete an RMT (Bakare, 2016). The specific business problem is that some
mortgage managers do not know the impact of MLP, MLT, and SPT on ATT to complete
an RMT from origination to funding.
Purpose Statement
The purpose of this quantitative, causal-comparative study was to examine the
impact of MLP, MLT, and SPT on ATT. The independent variables were MLP, MLT, and
SPT. The dependent variable was ATT to complete an RMT from origination to funding.
The archival population data included a selected mortgage institution’s retail originations
data from the state of Florida. Mortgage managers may increase the firm’s intrinsic value
through more efficient ways to minimize ATT by reducing transaction costs and lessening
risks to complete an RMT. Therefore, the social change implication of this doctoral study
includes the potential increase in the firm’s intrinsic value for organizational stakeholders.
Nature of the Study
Dobbin and Ionan (2015) mentioned that a quantitative method, as I used in this
study, is valid when a researcher collects numerical data for hypotheses testing. A
quantitative method was suitable for this doctoral study because I collected numerical data

4
and tested the study hypotheses. Marshall and Rossman (2015) stated that a qualitative
research method is appropriate when a scholar seeks to explore a phenomenon through
participant interviews. The qualitative method would not have been conducive to my
research goals because I did not conduct interviews to explore a phenomenon. Finally,
researchers use the mixed method to explore phenomena and examine numerical data,
concurrently, through interviews and surveys (Stockman, 2015). Again, the mixedmethod
approach was not appropriate because I did not conduct interviews to research a
phenomenon.
Explicitly, the use of a causal-comparative design can indicate statistical
relationships between three categorical independent variables and one continuous
dependent variable (Huck, 2012). Dobbin and Ionan (2015) mentioned that other
quantitative designs indicate correlations between research variables. The objective of this
doctoral study was not to show a correlation but to examine a potential impact between
the independent variables on a dependent variable. Koskey and Stewart (2014) offered
that an exact experimental design requires four elements that include manipulation,
control, random assignment, and random selection. In this doctoral study, I did not show
any experimental manipulation, control, nor selection. Therefore, an appropriate design
for this doctoral research is a causal-comparative design.
Research Question and Hypotheses
Research Question: What is the impact of MLP, MLT, and SPT on ATT to
complete an RMT from origination to funding?

5
H0: MLP, MLT, and SPT do not have an impact on ATT to complete an RMT from
origination to funding.
H1: MLP, MLT, and SPT do have an impact on ATT to complete an RMT from
origination to funding.
Theoretical Framework
Previous scholars have used theoretical propositions as lenses to view a business
problem or phenomenon (Krahmer & Strausz, 2015; Lahav & Zimand-Sheiner, 2016). I
developed a proposition regarding a possible theoretical explanation for the impact of
MLP, MLT, and SPT on ATT in an RMT, which I justified using findings in extant
literature. Al-Bahrani and Su (2015) demonstrated that MLP is a significant variable to
determine mortgage pricing. Park (2016) proved that MLT is an influential variable to
assess risk performance between insured and uninsured MLTs in RMTs. Gallagher
(2016) verified SPT as a significant indicator of tax revenues in local governments. Feng,
Fan, and Yoon (2015) measured loan popularity and proved ATT is a critical variable in
the assessment of peer-to-peer (P2P) lending strategies for borrowers and lenders. The
review of concurrent and previous studies assisted me in evaluating potential impacts of
the developed research variables.
In this doctoral study, the independent variables may indicate an impact on the
dependent variable based on previous scholars’ research. Bhutta, Ringo, and Kelliher
(2016) examined MLP and MLT data retrieved from the Home Mortgage Disclosure Act
(HMDA aka Humda) database and reported that an increase in MLP and MLT data
indicated industry growth. McCormick and Calahan (2013) used SPT as the foundation

6
for a unique loan identifier in an RMT to track performance throughout primary and
secondary market transactions. Li and Goodman (2015) also mentioned that many indices
include MLP, MLT, and SPT as factors to investigate critical mortgage problems.
Therefore, drawing on existing literature, I proposed that a linear combination of MLP,
MLT, and SPT may predict ATT when using a selected institution’s RMT data.
Operational Definitions
Average turnaround time: The average time, in days, to complete the RMT process
from mortgage origination to funding (Gupta, Yadav, & Goyal, 2017).
Closing: Closing is the finalizing stage for an approved RMT in the process
(Barrutia & Espinosa, 2014).
Funding: Funding is the disbursement of funds that consummates an RMT (Papin
& Turinici, 2014).
Mortgage loan purpose: Consumers us a mortgage loan to purchase or refinance
real estate (Mason, Imerman, & Lee, 2014).
Mortgage loan type: Mortgage loan type is the type of insured or securitized loan
provided by retail mortgage companies (Rose, 2016). For the proposed study, loan types
include government-insured loans, such as Federal Housing Administration (FHA) and
Veterans Administration (VA) mortgages, and conventional loans, securitized by private
investors.
Mortgage process: LOs workflow for transaction processing retail mortgages
(Hall, 2015). For the proposed study, the mortgage process includes origination,
processing, underwriting, closing, and funding.

7
Origination: The consumer or LO initiate the mortgage process by completing a
mortgage application with the intent to proceed (Ambrose & Conklin, 2014).
Processing: The accumulation of all stipulated borrower, LO, title, insurance,
home association, taxes, inspection, and appraisal documents to support underwriter
approval (Hall, 2015).
Subject property type: Mortgage applications indicate the subject property, or the
type of real estate collateral, in an RMT (Thode & Levine, 2017). The SPT for the
proposed study is owner-occupied and non-owner-occupied property types.
Underwriting: The overall assessment of borrower and lender risks associated with
the approval or denial of an RMT (Bakare, 2016).
Assumptions, Limitations, and Delimitations
Scholars acquire knowledge and information from research to
help with developing expectations, boundaries, and omissions in a study (Marshall &
Rossman, 2015). A scholar demonstrates the range of intensity of the research by
identifying assumptions, limitations, and delimitations (Baumeister, 2013; Riffe,
Lacy, & Fico,
2014). In the following literature, I outline my assumptions and the study’s limitations and
omissions to provide an opening for future scholars to fill any research gaps.
Assumptions
An assumption is a non-testable claim that a researcher takes as true without
knowing if the statement is factual (Riffe et al., 2014). My first assumption was that the
independent variables reflected an accurate representation of loan characteristics within an

8
RMT. The second assumption was that the dependent variable was an appropriate measure
of efficiency in all mortgage institutions. The third assumption was that the selected data
was indicative of all mortgage company data compliant with HMDA and respective state
statutes. My final assumption was that there was consistency in the selected data across
the mortgage industry.
Limitations
Stockman (2015) mentioned that the shortcomings in research design and
methodology indicate the potential boundaries of a study. Specifically, in this study, the
limitations were the ex post facto study design and archival data. Koskey and Stewart
(2014) stated that a study might be limited owing to the researcher’s inability to generalize
the research findings and establish study validity. Reio (2016) identified a limitation to the
causal-comparative research design noting that it lacks randomization and control and
increases the chance of researcher bias. Cotteleer and Wan (2016) experienced limitations
in research design and methodology when using archival data to analyze and interpret a
phenomenon or to ascertain potential relationships between industry and research. Turiano
(2014) stated that the main limitation to archival data is the lack of reciprocity among
previous research studies for present scholars to use. In this doctoral study, I sought to
define the boundaries and minimize limitations by developing constraints such as
controlling data sets and limiting the range of the selected data.
Delimitations
Delimitations are the constraints or controls in research (Atencia, 2014; Wang J,
2015). In this doctoral study, I did not include retail mortgage data from outside the

9
United States. Similarly, I did not include retail mortgage data outside of Florida in the
procured study sample. Furthermore, I did not include retail home improvement mortgage
data. Amadi-Echendu and Pellissier (2014) indicated that personal employee data, such as
marital status and age, have minimal significance on turnaround times.
Therefore, I omitted personal employee data from this examination.
Significance of the Study
Findings from this study may extend mortgage knowledge in scholarly literature
and be used to improve retail mortgage processes. Mortgage managers may gain
additional perspectives for procedural improvements to increase efficiency, decrease
transaction costs, and diminish moral hazard. Bakare (2016) determined that significance
in scholarly research depends on the application of the research to a real-time business
environment. For bank owners, mortgage lenders, and managers, understanding the value,
contribution, and social change factors in this study may lead them to develop vital
procedural improvements in RMTs (Adeleye, 2015; Barrutia & Espinosa, 2014).
Mortgage managers may choose to apply the findings, whether significant or not, to
improve or modify overall loan processes while seeking to improve efficiency, reduce
transaction costs, and curb moral hazard.
Contribution to Business Practice
This study has four identifiable contributions to mortgage business practices to
help mortgage leaders and managers improve RMT processes and profits. Mortgage
managers who can pinpoint and attract applicants with the lowest acquisition costs tend to
profit the most (Van Rensselaer, Blackstone, Crabb, & Gordon, 2014). Adeleye

10
(2015), Bapat (2015), and Ertürk (2014) showed that theoretical research applied in
business practices has included significant findings, which have provided managers with
applicable results to contribute knowledge and innovate business practices. Hence, the
first benefit of this study’s findings is the reduction of RMT costs. A second benefit from
my findings is the potential for a more efficient mortgage process. A third benefit is that
mortgage managers may use the findings to better understand the impact relationships of
RMT characteristics have on ATT to achieve organizational goals. A final benefit of this
study is that it provides significant data and results to mortgage managers seeking to help
increase their firms’ intrinsic value. Therefore, my evaluation of MLP, MLT, SPT, and
ATT in this study may help mortgage leaders and managers reduce transaction costs,
improve RMT efficiencies, and increase their firms’ intrinsic value for stakeholders.
Implications for Social Change
This study’s positive social change implications include the potential to assist
mortgage stakeholders (customers, employees, managers, government agencies,
shareholders, and third-party vendors) with process improvements to boost industry
reputation. Since 2008, real estate, mortgage, and finance professionals have experienced
an increased level of consumer animosity while completing an RMT (Abosag et al., 2016;
Hall, 2015). Hall (2015) further stated that the mortgage process needs an overhaul to
improve industry reputation to decrease moral hazard and consumer animosity.
Understanding among mortgage leaders and managers regarding consumer and employee
experiences is vital to achieving a firm’s social objectives in the mortgage industry
(Bordo, 2014; Pelser, 2014). Markovitch and Willmott (2014) also mentioned that

11
improving the mortgage process may mitigate the moral hazard felt by consumers during
the 2008-2009 financial crisis. My analysis of the impact of MLP, MLT, and SPT on ATT
may assist managers in simplifying the loan process to curb consumer animosity and
moral hazard and improve industry reputation while increasing the firm’s intrinsic value.
A Review of the Professional and Academic Literature
A review of the academic and professional literature shows the various sources a
researcher utilized in a study, including peer-reviewed journal articles, government
sources, and seminal books (Baumeister, 2013). Cotteleer and Wan (2016) suggested that
literature reviews should adopt a phenomenon-driven approach as an alternative approach
to literature-driven reviews. Irrespective of the literature review approach, the content
analysis must be succinct and show synthesis between professional application, academic
research, and results (Larsen & How Bong, 2016). In the literature review, I offer a critical
analysis of the extant sources associated with the developed independent variables
supporting the refined theoretical proposition while including a critical analysis of the
extant sources related to the dependent variable.
Analyzing the literature and synthesizing the research indicated the following
topics, (a) theoretical framework; and (b) supportive theoretical reviews, complete with a
transitory synopsis of the literature. The following tables represent the frequencies of
peer-reviewed and non-peer-reviewed sources organized by year, percentages, and
sections. Table 1 represents the number and frequency of peer-reviewed and non-
peerreviewed sources by year. Table 2 indicates the number and frequency of literature
review sources by variables. Table 3 displays the number and frequency of unique sources
12
by literature review section. Table 4 shows the reference type by peer-reviewed and non-
peer-reviewed frequencies.
Table 1
Number and Frequency of Peer-Reviewed and Non-Peer-Reviewed Sources by Year
Source year
No. of sources
% of total
PR
Non-PR
<2014
9
5.03%
5
4
2014
29
16.20%
26
3
2015
44
24.58%
44
0
2016
48
26.82%
46
2
2017
42
23.46%
42
0
2018
7
3.91%
7
0
Total sources
179
100.00%
170
9
Table 2
Number and Frequency of Literature Review Sources by Variable
Research variables
No. of sources
% of total
PR
Non-PR
13
MLP - Independent variable 1
25
32.89%
23
2
MLT - Independent variable 2
20
26.32%
18
2
SPT - Independent variable 3
19
25.00%
18
1
ATT - Dependent variable
12
15.79%
8
1
Totals
76
100%
67
6
Table 3
Number and Frequency of Unique Sources by Literature Review Section
Literature review section
No. of sources
% of total
PR
Non-PR
Search database & terms
3
3.61%
3
0
Theoretical framework
70
84.34%
66
4
Supportive theories
10
12.05%
9
1
Totals
83
100%
78
5
Table 4
14
Number and Frequency of Reference Type by Peer-Reviewed and Non-Peer-Reviewed
Reference type
Peer-reviewed
Non-PR
Totals
% of total
Book
2
2
1.12%
Conference
1
1
0.56%
Government
3
3
6
3.35%
Journal article
164
2
166
92.74%
Report
3
3
1.68%
Website
1
1
0.56%
Totals
170
9
179
100.00%
Search Databases and Terms
I used Google Scholar, EBSCO Host, ProQuest, Emerald Insight, SAGE Journals,
and Science Direct databases to gather materials for this literature review. The search
strategy included using multiple search windows, copy and pasting search terms into
different databases, using keyboard shortcuts, and brainstorming. An additional strategy
involved combining search terms and quoted phrases to narrow down sources. The
following were the significant terms and combined quoted phrases I used in searches:
mortgage operations, mortgage turnaround, average turnaround time, mortgage loan
types, mortgage loan purposes, subject property types, and theoretical propositions.
Additional search terms and quoted phrases included: loan originator, home loan,
mortgage process, mortgage originations, owner occupied, non-owner occupied, 1-4

15
units, multifamily, purchase, refinance, FHA, VA, and conventional mortgages. Other
search terms and quoted phrases included: theory of constraints, thinking process,
qualitative, quantitative, mixed methods, turnover, and experience.
Theoretical Framework
In this research, my goal was to show that MLP, MLT, and SPT have a significant
impact on the ATT to complete an RMT from origination to funding. Scholars have used
MLP, MLT, and SPT as independent or predictor variables in different studies that
determined significance on corresponding dependent variables (Al-Bahrani & Su, 2015;
Feng et al., 2015; Gallagher, 2016; Park K. A., 2016). Al-Bahrani and Su (2015) applied
ordinary least squares (OLS) in a quantile regression (N = 5,013) to predict the
significance of purchase MLPs on mortgage pricing. The regression results were
significant, (OLS = .1174; df = 33; p < .05). Park (2016) examined the risk performance of
insured MLTs relative to uninsured MLTs. Park used a propensity score matching
technique on observed credit risk scenarios (N = 2,325,945) that yielded notable results
that showed MLT as a significant predictor in the model, (t = 1.607; p = .01). Gallagher
(2016) examined municipalities and school district data (N = 5,280) from 1980 to 2010 to
correlate SPT and property taxes as a funding source for local governments. First-stage
regression results were significant for multifamily SPTs in suburban municipalities,
(F[3,388] = -.876; p ≤ .01; R2 = .42), meaning multifamily SPTs indirectly related to
funding for suburban municipalities. Feng et al. (2015) examined loan characteristics,
such as rate, amount, and period correlated to predict loan popularity, measured by
funding success rates, the number of bids, and funding times, among potential P2P

16
investors. Feng et al. observed transactions (N = 1,057) and verified, with statistical
significance, that loan period had an impact on funding time as a predictor in the model,
(t[3] = .866; p < .01). The research findings for the independent variables, MLP, MLT, and
SPT, may show mortgage managers a potential impact on the dependent variable, ATT. I
will further discuss the independent variables along with the dependent variable in the
remaining portion of the theoretical framework.
Mortgage Loan Purposes
A consumer uses a retail mortgage to purchase or refinance residential real estate
(Mason et al., 2014). There are similarities and differences in time-based procedures
between the two loan purposes, although completion times are almost identical (Bhutta et
al., 2016). A purchase MLP requires additional inspectors whereas a refinance MLP may
not require an appraiser (Wilcox, 2015). Comparing and contrasting MLP characteristics
may offer mortgage managers viable solutions to improve processes to reduce ATT. An in-
depth examination of MLP attributes’ may provide managers with the data regarding RMT
outcomes; however, it will help me to provide a succinct and critical analysis for the
inclusion of MLP as a study variable.
Purchase. The purpose of a primary loan is to facilitate a consumer’s procurement
of residential real estate (Agarwal, Chomsisengphet, & Zhang, 2017).
Quantitative and qualitative researchers have found significant relationships between
MLP characteristics and the impacts on RMT outcomes (Berg, 2015; Neuhauser, 2015;
Serrano-Cinca, Gutiérrez-Nieto, & López-Palacios, 2015). Berg’s (2015) regression
discontinuity analysis of MLP originations (N = 4,013) showed a 50% reduction in default

17
rates because of the involvement of a risk manager in an RMT approval process. The
regression results were significant, (OR = .313; p = .01; R2 = .08). Serrano-Cinca et al.
(2015) analyzed P2P lending applications (N = 24,449) with 14 loan purposes and found,
with statistical significance (p < .001), that the P2P borrower lending grade is an accurate
variable for default prediction for 10 of the 14 loan purposes. More interestingly and
specifically, a borrower’s home purchase did not have any significant impact on P2P
lending grades or mortgage defaults in the sampled data. Conversely, in a qualitative
review of post-2008 recession articles on financial crisis, Neuhauser (2015) observed that
the relaxed rating agency guidelines on MLP, particularly with subprime mortgage loans,
increased default rates in securitized RMTs. Collectively, previous research has shown
that MLP is an important and required research variable to assess default risk and loan
performance. A mortgage manager’s analysis of MLP characteristic impacts in an RMT
may lead to improved processes to reduce ATT and minimize transaction costs.
Scholars have found that purchase MLPs have a substantial role in estimating risk
and capacity metrics to improve efficiencies and reduce costs (Li & Goodman, 2015;
Serrano-Cinca et al., 2015; Sharpe & Sherlund, 2015). Li and Goodman (2015) stated and
measured probability factors of borrower default, and calculated credit accessibility and
risk, simultaneously. Li and Goodman’s risk index showed that government-insured
purchase MLPs increased by 48% after the 2008 housing crisis. Serrano-Cinca et al.
(2015) stated that loan purpose is a risk assessment factor associated with the probability
of loan defaults among all P2P lending grades, A through G. For the highest P2P lending
grade (A), chi-square test results were statistically significant, (χ2[6, N = 7,901] =

18
342.041; p = .01), whereas the chi-square test results for the lowest grade (G) were also
statistically significant (χ2[6, N = 55] = 42.218; p = .01). Sharpe and Sherlund (2015)
completed a regression analysis of HMDA data applications and originations between
2003 and 2014, to determine if mortgage employees, credit scores, and MLPs predicted
capacity utilization. Purchase MLPs (N = 4) per mortgage employee was a significant
predictor in the model, (t = .196; p < .001). An LOs efficient ATT, or capacity utilization,
of RMTs, is critical to delivering an intangible product in consumer lending; therefore,
managers’ capabilities to utilize the metrics to make decisions may assist them in meeting
company goals to optimize capacity, thus reducing ATT and RMT costs.
Process optimization to manage capacity is an organizational goal for mortgage
managers to increase mortgage-backed securities (MBSs) investments influencing market
activity (Downs & Shi, 2015; Teye, Teye, & Asiedu, 2015). Downs and Shi (2015)
conducted a difference-in-differences estimate of HMDA data between 2003 and 2010 to
compare pre-2008 and post-2008 securitization regulations on RMT denial rates between
various lender types. RMT denial rates influenced purchase MLP capacities in subprime
lending within bank holding companies (BHCs) and respective affiliates, unaffiliates, and
independent mortgage companies. Downs and Shi assessed the association, with statistical
significance, between lender type and MLP denial rates, where lender type, MBSs of
BHCs showed above average purchase MLP denial rates that resulted in chisquare test
results, (χ2[3, N = 6,364,421] = .48; p = .01). In the rural housing sector of
Ireland, Teye et al. (2015) surveyed two housing communities (N = 380) to explore the
systematic relationship between new housing finance and supply and demand capacities

19
in the Ghanaian mortgage market. The chi-square test results showed with statistical
significance, (χ2[4, N = 196] = .148; p = .05), that the relationship between purchase
MLPs and housing supply capacities signals strength in industry activities. A successful
mortgage manager’s ability to manage RMT capacity through purchase MLPs will require
minimization of ATT to maximize profitability on the sale of MBSs in the secondary
mortgage market. The significance between purchase MLPs and capacity management in
various mortgage systems has stalled efficient operations in multiple real estate sectors;
therefore, is a justified reason for me to include MLP as a study variable to predict a
potential impact on ATT in completed RMTs.
Researchers have presented additional justification for the inclusion of MLP as a
research variable and have shown various relationships and phenomena between purchase
MLPs and market activity (Bhutta et al., 2016; Curtis, 2014; Zou, 2016). Bhutta et al.
(2016) examined 2012 HMDA RMT data (N = 18,691,550) to analyze market activity by
lending institution segmented by MLP. The scholars calculated a 10% increase in
purchase MLPs from 2011 to 2012, which resulted in a 26% increase in total RMT
activity for the same period. This statistic is important as it indicated the first increase in
purchase MLPs since 2004. Curtis (2014) observed mortgage transactions (N = 31,971)
and created a state-specific index that showed which state foreclosure laws favored
lenders, and that predicted the impact of the laws to mortgage origination activity in prime
and subprime markets. Lender-favored state foreclosure law contained mixed results of
prime purchase MLP activity as a predictor variable being insignificant, (t[12]

20
= .48; p > .10; R2 = .361), whereas the scholar’s results also exhibited with statistical
significance, (t[12] = 1.90; p < .10; R2 = .431), subprime purchase MLP activity as a
predictor variable influenced LOs to originate in states with lender-favored foreclosure
laws. In contrast, Zou (2016) analyzed the challenges and changes that arose from the
evolution of Chinese housing operations through a combination of financial liberalization
regulations to increase affordable housing. Zou found that a location-specific mix of
financial liberalization regulations assisted borrowers with alternative purchase MLPs,
which contributed to a 10% increase in location-specific economic development.
Mortgage managers who can optimize purchase MLP activity may produce an increase in
overall market activity as indicated in the research above; therefore, improving ATT to
meet demand validates the inclusion of MLP as a study variable.
Financiers, private and public, moderate investing behaviors by evaluating market
activity, examining borrower creditworthiness, and utilizing available information (Kim,
Tunas, & Green, 2016; Prystav, 2016; Zhang & Tang, 2014). Zhang and Tang (2014)
showed government-sponsored enterprises (GSEs) investor performance through 15
different credit standards segmented by MLP among RMTs (N = 18,700,000) and
calculated the modification rates between 2000 and 2010. The GSE, Federal Home
Mortgage Loan Corporation (FHMLC aka Freddie Mac) had higher modification rates
eight out of 10 years compared to GSE, Federal National Mortgage Association (FNMA
aka Fannie Mae). Kim et al. (2016) stated that MLP is the second most significant factor
to predict loan delinquency but did not provide statistical findings to support the claim.
Prystav (2016) experimented with German business students (N = 432) to evaluate the

21
relationship between loan purpose, information availability, investor behaviors, and loan
project investment amount. The loan purpose results of the one-way ANOVA were
significant, (F[3,235.653] = 3.789; p < .01). The challenge is for investors to moderate
financing behaviors through market analysis, creditworthiness, and information
availability; therefore, analyzing MLPs to determine an impact on ATT in an RMT may
also provide mortgage investors with additional, yet critical information to moderate
investing behaviors.
Refinance. An alternative loan purpose for consumers in an RMT is to refinance
real estate to receive cash or reduce interest rates and maturity terms (Mason et al., 2014).
Researchers showed that refinance MLPs had a significant impact on origination capacity
(Bhutta et al., 2016; Downs & Shi, 2015; Sharpe & Sherlund, 2015). Sharpe and Sherlund
(2015) found an inverse relationship between refinance MLPs and interest rate
adjustments controlled by the LOs to manage refinancing demand. Downs and Shi (2015)
proved those capacity limitations were significant between 2003 and 2010 as the research
indicated LOs originated 11% less refinance MLPs. Bhutta et al. (2016) confirmed
Downs and Shi’s research through the analysis of purchase and refinanced MLPs of
HMDA data between 2004 and 2015, which indicated that LOs originated 14% less
refinance MLPs. An LOs ability to control refinance MLP capacity with interest rate
adjustments is more reason for the inclusion of MLP as a study variable to examine the
impact on ATT in an RMT.
Scholars also examined significant relationships between risk, default,
prepayment, and refinance MLPs, respectively (Bylander & Hamilton, 2015; Caplin,

22
Cororaton, & Tracy, 2015; Gibilaro & Mattarocci, 2016). Gibilaro and Mattarocci (2016)
completed a regression analysis of property market trends and bank risk exposure (N =
2,798) while controlling for type of bank and loan purpose. Loan purpose was a
significant predictor in the model, (t = .16; p = .05), as mortgage managers determined
default risk in an RMT. In the Cambodian microfinance industry, Bylander and Hamilton
(2015) examined socio-economic relationships (N = 11,662) between credit risk and
migration and used loan purpose as a control variable. The logistic regression results were
significant for 2 of 3 loan purposes, (OR = 1.39; p < .01) and (OR = 1.38; p < .01),
investment and consumption loan purposes, respectively. Among borrowers with Federal
Housing Administration (FHA) mortgages, Caplin et al. (2015) defined sustainable
homeownership as paying off a current loan by refinancing or held to maturity by default.
The prepayment (N = 188,789) and default (N = 191,393) results indicated statistical
significance for cash-out and no cash-out refinance MLPs. The scholars found statistically
significant findings for cash-out refinance MLPs was, (F[1,3] = 1.30; p = .01;
R2 = .024), whereas no cash-out refinance MLPs was, (F[1,3] = 1.44; p = .01; R2 = .023).
The prepayment result for cash-out refinance MLPs was (F[1,3] = 1.38; p = .01; R2 =
.019), whereas no cash-out refinance MLPs was (F[1,3] = .78; p = .01; R2 = .012).
Migration, sustainable homeownership, and capital necessities for different borrowers
proved that loan purpose, whether in retail banking or microfinance, significantly impacts
socio-economic consequences as well as transaction outcomes. Therefore, previous
researchers justified my decision for the inclusion of MLP as an independent study
variable.

23
Additional justification for the inclusion of the MLP variable was because of the
various relationships between decision-making, costs, competition, and refinance MLPs.
Ambrose and Conklin (2014) used the refinance MLP characteristic, cash-out loans (N =
269,573), as a predictor in an OLS regression to examine the relationship between
mortgage broker competition and costs. The scholars found MLP predictor variable results
statistically significant, (OLS = 443.00; df = 18; p = .01). Al-Bahrani and Su (2015) also
used OLS, although in a quantile regression to indicate the significance in refinance
MLPs, specifically cash-out loans (N = 5,013), on mortgage pricing. The results were
significant, (OLS = .3011; df = 33; p < .01). Agarwal, Ben-David et al. (2017) assessed
borrower decision-making and measured the net present value (NPV) of investing in one
percentage point to reduce the note rate and exiting a mortgage within a specified time.
Agarwal, Ben-David et al. used the Cox model hazard regression and yielded results, with
statistical significance, for refinance MLP types (N = 17,204,751), rate-term and cash-out,
(t[-46.84] = -.027; p = .01) and (t[-78.92] = -.045; p = .01), respectively. Refinance MLPs,
specifically cash-out, had a significant impact on mortgage pricing, costs, and
competition; therefore, may offer mortgage managers additional data in decision-making
processes and provides further justification for the inclusion of MLP as a variable in this
study.
Mortgage Loan Types
LOs sell bundles of RMTs by MLT to secure private or government-insured
investors in the secondary market to replenish primary market capital (Cao & Liu, 2016).

24
In this study, MLT characteristics in RMTs included conventional and government
purchase and refinance mortgages (Rose, 2016). Conventional, FHA, and VA mortgages
differ in lending institutions, guidelines, costs, and turnaround times (Harrison & Seiler,
2015). In this study, assessing similarities and differences between MLT characteristics in
RMTs may offer significant data for industry stakeholders to make effective decisions to
reduce costs, minimize turnaround and achieve socio-economic goals.
Conventional. A conventional mortgage is a residential, non-government real
estate loan provided by LOs to borrowers with a specific risk profile (Cao & Liu, 2016).
Previous quantitative and qualitative researchers analyzed primary and secondary data and
found various relationships between borrower decisions, MLT characteristics and RMT
purposes (Lang & Hurst, 2014; Park K. A., 2016; Rose, 2016). Park (2016) analyzed a
scenario after borrowers decided to default on conventional and government loans. Park’s
results indicated statistical significance for borrowers (N = 6,625) that decided to default
on conventional loans, (t[10] = 1.607; p = .01) compared to government loans. Rose
(2016) showed that MLT guidance regarding debt structure and utilization choices for
people with homeownership as an objective. Rose advised homeownership-seeking
decision-makers that effective debt management and utilization strategies will lead to
lower cost mortgages, such as conventional MLTs. Lang and Hurst (2014) assessed the
decision-making of state grant recipients (N = 35,161) through observation of MLT
selection in RMTs. Lang and Hurst proved with statistical significance, (t[16] = .096; p <
.01), (t[16] = .217, p < .01), (t[16] = .123; p < .01), for 2007, 2008, and 2009, respectively,
state grant recipients made correct decisions to choose conventional MLTs over

25
government MLTs as related to loan size and down payment options in RMTs. Mortgage
borrowers’ individual decisions influenced MLT choice in a purchase RMT; therefore,
including MLT as a variable to examine the impact on ATT may offer mortgage managers
significant data for profitability and efficiency metrics to make effective decisions to meet
organizational goals.
Prior researchers used MLT data to calculate industry performance metrics, such
as changes in the federal funds rate (FFR), regulation, and foreclosure rates (Bhutta et al.,
2016; Orzechowski, 2017; Shindelar, 2015). Bhutta et al. (2016) analyzed HMDA data
and showed that conventional MLT originations decreased by 14% between 2009 and
2015 because of the increased role of government in consumer lending. Orzechowski
(2017) estimated loan growth rates by MLTs as grouped into high and low capitalintensive
banks to determine significant changes in the FFR. The generalized least square (GLS)
regression of MLT to predict the changes in the FFR indicated with statistical significance
in both high (N = 1,008) and low (N = 1,440) capital intensive banks, (t = .095; p < .001)
and (t = -.102; p < .001), respectively. Shindelar (2015) showed that there was no
significance in the foreclosure rates among prime, conventional MLTs (4%) measured
against sub-prime conventional (15%) and FHA (4%) government loans. MLT as a
variable to explore industry performance metrics provided mortgage managers with
quantified performance data to make valuable decisions to minimize foreclosure rates,
improve regulations, and capitalize on FFR changes.
Mortgage consumers use credit availability, risk, and financial literacy
fundamentals as crucial decision variables for MLT choice in mortgage markets (Cox,

26
Brounen, & Neuteboom, 2015; Li & Goodman, 2015; Lucas, 2016). In the Dutch
mortgage market, loan types are amortizing, deferred amortization, and interest-only
loans. Cox et al. (2015) found that risk aversion and financial literacy decision variables
were only statistically significant in relationship, both indirect and direct, to interest-only
loan types, (t = -2.33; p = .05) and (t = 2.11; p = .05), respectively. In the U.S. market, Li
and Goodman (2015) measured the expected GSEs default risk versus origination quarter
between 1998 and 2013 that yielded a credit availability trend. The scholars used the trend
line to show that the GSEs parallel industry credit trends, reducing conventional MLT
credit accessibility during the 2008 financial crisis. Lucas (2016) grouped loan type data
between 1998 and 2010 and stated that by 2010, GSEs financed 63% of new home
purchase MLPs with conventional MLTs. Credit, risk, and financial literacy are essential
variables in borrowers’ decisions to choose loan type; therefore, verified the inclusion of
MLT as an independent variable to determine an impact on ATT to complete RMTs from
origination to funding.
Government. Government MLTs, for the purposes this study, included
FHAinsured and VA-guaranteed mortgages (Reiss, 2016). In previous quantitative and
qualitative research studies, scholars examined different relationships between
decisionmaking, sustainability, and government MLTs (Aksoy, Keiningham, Buoye, &
Ball,
2016; Caplin et al., 2015; Reiss, 2016). Reiss (2016) assessed the sustainability of the
FHA and the impact in the secondary mortgage market during the Great Recession. Reiss
stated that it benefits the FHA to ensure sustainable mortgages to limit default risk, which

27
leads to increased transaction costs. Conversely, Caplin et al. (2015) defined and analyzed
homeownership sustainability through FHA MLTs paid in full or refinanced to non-FHA
mortgages. Caplin et al. found that prepayment risk of FHA MLTs (N = 159,169) at a
loan-to-value (LTV) level of 80-84%, (t = .96; p = .05), are twice as likely than LTV level
of 100-104%, (t = .64; p = .01), to pay off FHA mortgages. Aksoy et al.
(2016) surveyed credit union members (N = 642) and applied the wallet allocation rule
(WAR) to members’ decisions to use a credit union or bank for a purchase MLP controlled
by seven loan types. Aksoy et al. revealed that most credit union members surveyed
(70%), used the WAR to choose a bank over a credit union regarding competition in value
and loan type offerings and yielded a 55% bank application rate. Borrowers that sought
funds obtained competitive government MLT offerings compared to conventional MLT
offerings in down payment and RMT costs. Therefore, my assertion is correct to include
MLT as an independent variable in this study to examine the impact on ATT in RMTs
between origination and funding.
Scholars further analyzed the lending decisions in primary and secondary markets
to determine MLT characteristics impact on credit supply and borrower decision-making
to attain company goals (Dettling & Hsu, 2017; Ivanov & Wang, 2017; Metawa, Hassan,
& Elhoseny, 2017). In the primary market at the state level, Dettling and Hsu (2017)
stated loan types (N = 3,555,612) are credit cards, auto loans, unsecured loans, and
mortgages and examined consumer offers received by census tract income. Dettling and
Hsu’s results, (t[3] = -.0349; p = .01), proved, with statistical significance, that changes in
the minimum wage rate influenced loan type decisions as income levels increased. Ivanov

28
and Wang (2017) defined loan types as revolving or term loans (N = 6,190) and found
with statistical significance, in an OLS regression, results, (OLS = .4016; p < .01), as
lender credit ratings declined, borrowers loan type options to access credit also declined.
Metawa et al. (2017) defined mortgage, personal, and auto loans as loan types. Metawa et
al. provided a genetic algorithm (GA) assisting mortgage managers to make effective
decisions based on loan types during periods of illiquidity as compared to other
algorithms, such as two-level partitioning (TLP) algorithm and the multi-objective
evolutionary algorithm (MODE-GL). The scholars’ results indicated that MLT was a
significant variable (M = .43, SD = .011) in GA lending decisions as compared to lending
decisions based on TLP and MODE-GL algorithms. The impact of MLT characteristics on
credit supply and borrower decision-making is noteworthy because mortgage managers
used MLT attributes that derived the information to make effective decisions to achieve
company objectives.
Further justification for MLT inclusion as a variable in this study is because in
prior studies scholars assessed MLT attributes and various RMT metrics (Akins, Li, Ng, &
Rusticus, 2016; Dodson, 2014; Ellie Mae, Inc, 2016). Akins et al. (2016) examined the
relationships (N = 21,454,463) between competition and loan application rejection,
controlling for MLT among other predictors. Akins et al. proved that MLT is a significant
predictor in the model, (t[17] = -.83; p =.01), where competition decreases, and rejections
increase. Dodson (2014) performed tests (N = 370) that assessed the comparative
advantages between large and small banks government MLT offerings in competition for
fixed-asset lending in rural areas. Borrower MLT selection and property equity were

29
significant indicators for large banks to lend in rural areas for fixed assets. The scholar’s
results were statistically significant, (t[13] = -.88; p = .10) and (t[13] = -.0375; p = .10),
respectively. In 2016, Ellie Mae analysts assessed the time to close mortgage loans in
days, segmented by MLT. The analysts found as of December 2016, the FHA averaged
one business day better than conventional lenders, and three days better than VA lenders.
The results indicated the FHA time to close was 49 days, 50 days for conventional, and 52
days for VA mortgages. The scholars above showed that MLT was a significant indicator
for RMT metrics; therefore, qualifying my decision to include MLT as an independent
variable to examine the impact on ATT in RMTs.
Subject Property Types
In RMTs, the SPT refers to housing units that are single family residences (SFRs),
both detached and attached, condominiums, and multifamily properties (DeLisle, 2015).
LOs classify owner-occupied SFRs and condominiums as one detached to four attached
residential housing units whereas non-owner occupied multifamily properties, such as
apartments, are greater than five units (McCormick & Calahan, 2013). Private and public
investors use specific guidelines, procedures, and valuation models for SPT attributes
(Bellotti, 2017). Mortgage managers’ assessments of SPT characteristics may help to
decide on process improvements to reduce ATT and increase intrinsic value for
stakeholders.
Owner-occupied. Much of residential real estate includes owner-occupied
properties appraised as detached SFRs to attached SFRs, such as a townhome or a
quadplex, and condominium (Thode & Levine, 2017). Quantitative and qualitative

30
researchers used SPT characteristics to examine various industry metrics, such as
liquidity, homeownership rates, and market shifts (Blau, Nguyen, & Whitby, 2015;
Glascock & Lu-Andrews, 2015; Grover & Grover, 2014). Glascock and Lu-Andrews
(2015) showed that size and liquidity have a significant impact on real estate investment
trusts (REITs) stock price behaviors in extreme stock market declines. The scholars
measured REITs size by market capitalization and REITs liquidity by turnover and bidask
spread. Glascock and Lu-Andrews controlled for SPTs and examined beta statistics of
REIT stocks (N = 5,652) before an extreme stock market decline to predict stock pricing
behaviors that affected abnormal returns. The scholars’ findings were statistically
significant. Glascock and Lu-Andrews found that liquid REITs holding residential SPTs
were an influential predictor in the pricing behavior model, (t[10] = 1.04; p = .01) and
(t[10] = -.6215; p = .01), turnover and bid-ask spread, respectively, to maximize abnormal
returns during extreme market declines. Blau et al. (2015) performed a multivariate
analysis that observed (N = 8,848) effects of the distribution of market liquidity between
REITs and non-REITs, which used seven SPTs as indicator variables of the REITs bid-ask
spread. The scholars’ results for residential SPTs as a predictor in the model showed
statistical significance on REITs liquidity distribution, (t[7] = -4.36; p = .01). In the
European Union (EU), Grover and Grover (2014) explored the phenomena of residential
property prices indices (RPPI) on integrated financial systems to develop an aggregation
of EU financial systems into a single index. Grover and Grover did not provide statistics
but stated that Central and Eastern EU members have higher owner occupancy rates
although a low mortgage usage rate, which indicated less cohesion among EU financial

31
systems that contributed to market declines. Although Grover and Grover showed that the
EU members had substantial homeownership rates, instability remained in respective
financial systems whereas Glascock and Lu-Andrews and Blau et al. indicated that REITs
with high liquidity, holding specific rather than diverse SPTs, capitalized on financial
instabilities during extreme market declines, maximizing abnormal returns. Maintaining
liquidity in the primary mortgage market from the secondary market allows for LOs to
take additional risks on SPTs to maximize homeownership rates and minimize default
rates.
Additional researchers showed that market declines accounted for defaulted
mortgages and assessed loan performance metrics controlling for SPT attributes
(Adelino, Gerardi, & Hartman-Glaser, 2016; Agarwal, Chomsisengphet, et al., 2017;
Brueckner, Calem, & Nakamura, 2016). Adelino et al. (2016) examined mortgages (N =
5,313,951) from Lender Processing Services (LPS) and Core Logic (CL) and assessed the
relationship between default and the time to sell mortgages to private investors,
controlling for SPT. The scholars’ results showed SPT as an indicator variable that did not
have any statistical significance on defaulted loans, (t[32] = -.0012; p = .01). Conversely,
Brueckner et al. (2016) used SPT attributes and created a model to predict default among
private (N = 401,017), public (N = 1,100,972), and portfolio (N = 151,058) investors in
securitized mortgages originated with alternative mortgage products (AMPs). Brueckner
et al. conducted a proportional hazard regression and verified, with statistical significance,
that owner-occupied residences defaulted on AMPs regardless of investor types, (t[44] =
.158; p = .001), (t[44] = .253; p = .001), (t[44] = .255; p = .001), respectively. Agarwal,

32
Chomsisengphet et al. (2017) examined delinquency rates among professionals in the
finance industry, controlling for SPT. Agarwal, Chomsisengphet et
al. found with statistical significance, (OR = .84; p = .01), that SPT was a noteworthy
indicator in the model that determined delinquency rates among financial professionals
that owned and resided at their primary residence. Even though Adelino et al. did not find
any significance in the results, Agarwal, Chomsisengphet et al. and Brueckner et al.
proved that SPT characteristics are significant predictors for default. Therefore, mortgage
managers may use SPT characteristics to determine an impact on ATT in an RMT, as
considered for this study.
Prior scholars showed that information and feedback influenced profitability and
value, respectively, among private and public investors (Freybote, Ziobrowski, &
Gallimore, 2014; Gokkaya, Highfield, Roskelley, & Steele, 2015; Ribeiro-Ferreira, 2016).
Ribeiro-Ferreira (2016) stated that the Australian government put profits before people
during the financial reform that led to exclusionary policies for potential homeowners. To
determine the association between profitability and SPT attributes, Gokkaya et al. (2015)
examined REITs with single and multiple property types (N = 126) between 1993 and
2007 and correlated information asymmetry impacting IPO returns between specific REIT
holdings. Gokkaya et al. found, with statistical significance, that IPO returns for REITs
holding a particular property type realized fewer returns than REITs holding multiple
property types at IPO. The ANOVA results were significant for single and multiple SPTs,
(F[2, 90] = 2.701; p = .01) and (F[2, 36] = 11.491; p = .01), respectively. Freybote et al.
(2014) created a controlled experiment of residential appraisers (N = 30) that determined a

33
relationship between feedback and appraisers’ SPT value judgments since Dodd-Frank
required LOs to use appraisal management companies (AMCs). Freybote et al. results,
(t[3] = .668; p = .05), proved that feedback had not influenced appraisers’ SPT value
judgments since the start of AMCs. Although RibeiroFerreira did not show any
significance with SPT valuations, which could have been from the small sample, Gokkaya
et al. and Freybote et al. provided noteworthy evidence of the relationships and
associations between SPT attributes and RMT metrics, such as valuations and
profitability. Therefore, the decision to include SPT as an independent research variable is
correct.
Non-owner occupied. Many homeowners purchase additional real estate in
various locations for use as a second home or an investment property (McCormick &
Calahan, 2013). Qualitative and quantitative scholars explored phenomenon and examined
stock prices to determine effects and impacts on the mortgage and real estate industries
(Bokhari & Geltner, 2016; Glascock & Lu-Andrews, 2015; Ribeiro-Ferreira,
2016). With a qualitative lens, Ribeiro-Ferreira (2016) analyzed the change in the
Australian residential real estate market through the evolution of the mortgage industry.
The scholar found that the evolution of the mortgage industry caused a decline in
owneroccupied properties and a corresponding rise in non-owner-occupied properties.
Glascock and Lu-Andrews (2015) created a model, controlling for REIT SPTs. Glascock
and LuAndrews examined beta metrics of REIT stocks before an extreme stock market
decline to predict stock pricing behaviors impacting abnormal returns on the day of (Day

34
0), the day after (Day 1), and up to three days (Days 1-3) after an extreme stock market
decline.
The scholars’ results indicated with statistical significance, (t[10] = -.8479; p = .01),
(t[10] = .9058; p = .01), and (t[10] = .4936; p = .01), respectively, that industrial/office
SPT is another influential predictor in the pricing behavior model. Bokhari and Geltner
(2016) used SPT characteristics and predicted the nature and magnitude of depreciation in
multifamily and commercial properties (N = 107,805) and the impact on valuations over
time, from an investment perspective. The scholars OLS regression predicted, with
statistical significance, (OLS = 50.46; p < .01) and (OLS = 52.99; p < .01), office and
retail SPTs, respectively, depreciated at a faster rate than industrial SPTs, (OLS = 73.75; p
< .01). Bokhari and Geltner’s results proved that office and retail SPTs required
redevelopment at least 21 years earlier, impacting depreciation values over time. Property
valuations affected by defaults impacted corporate profits; therefore, a review of default,
trends, and profitability associated with SPTs may assist managers to limit default,
minimize ATT, and reduce transaction costs.
In previous research, scholars used SPT characteristics as predictors to determine
default and profitability; and indicators to explore trends in laws and regulations (Aznar,
Sayeras, Rocafort, & Galiana, 2017; Griffin & Maturana, 2016; Sklar & Edwards, 2017).
Griffin and Maturana (2016) examined MBS loan data from 2002 to 2007 that determined
the effects of occupancy misreporting predicted delinquencies that resulted in MBS loan
losses. In a logit regression, the researchers evidenced, with statistical significance,
occupancy misreporting influenced delinquencies, (OR = 1.08; p < .01). In

35
Barcelona, Spain, Aznar et al. (2017) found that new non-owner-occupied property types
(N = 43), such as properties listed on Airbnb, impacted the profitability of area hotels. At
the p = .05 significance level, the scholars’ results exhibited ten hotels with negative
profitability, ten hotels showed positive profitability levels less than a 5% return, and 12
hotels stated profitability above a 10% return, an indication of variability of profitability
among hotels within one kilometer of an Airbnb. Conversely, Sklar and Edwards (2017)
explored Florida community deeds, covenants, and restrictions regarding non-residential
use of residential properties, such as Airbnb and vacation rentals by owner (VRBO). Sklar
and Edwards stated that local, state, and federal governments ruled for the community
association laws that disallow the use of residential properties for Airbnb and VRBO
businesses. The SPTs as indicators and predictors may help to assist mortgage managers
in making decisions on SPTs impact on ATT in an RMT; therefore, further justified for
inclusion as an independent variable in this study.
Average Turnaround Time
Mortgage managers use ATT as a critical industry metric to monitor the efficiency
of sales and operations employees who execute the retail mortgage process
(Markovitch & Willmott, 2014). The time begins with the borrower’s signature on the
intent to proceed document and ends with the disbursement of funds, typically measured
in days (McCormick & Calahan, 2013). The industry ATT is 50 days from mortgage
origination to funding (Bhutta et al., 2016). Analysis of the ATT metric in various
industries may offer mortgage managers meaningful results to maximize process

36
efficiencies, thus reducing costs, and increasing profitability and intrinsic value for
stakeholders.
Most of the previous research about ATT was outside the mortgage industry,
although scholars found that consumer preferences indicated that process efficiencies, or
efficient ATT, increases intrinsic value (Amadi-Echendu & Pellissier, 2014; Coletti,
Gosselin, & MacDonald, 2016; Lanzarini, Monte, Bariviera, & Santana, 2017).
Conducting interviews and distributing questionnaires, Amadi-Echendu and Pellissier
(2014) analyzed conveyancing transactions in South Africa and found that because of the
number of role players and regulations, buyers and sellers had similar research results that
concerned process impediments that hindered ATT in transactions. Amadi-Echendu and
Pellissier did not provide statistical data but provided a framework to reduce delays and
improve ATT in conveyancing transactions in South Africa. Coletti et al. (2016) discussed
the benefits of non-depository mortgage finance companies (MFCs) in the Canadian
mortgage market that delayed ATT. Coletti et al. stated that the benefits of technological
enhancements improved efficiency, which reduced ATT in Canadian mortgage processes
but did not provide statistical data for verification. In Ecuador, Lanzarini et al. (2017)
created a decision tree model and examined credit records to analyze time-consuming
processes in credit scoring applications, or ATT, and two previous models, C4.5 and
PART, that showed the same metrics with different attributes. Lanzarini et al. compared
the research credit model to two previous models, individually, and found that alpha
levels for the two previous models were lower than the research model method by α = .03
as well as model precision 2% more accurate. Technology, process optimization, and

37
improved credit assessment techniques improved credit granting processes thus reducing
ATT and increasing the firm’s intrinsic value for stakeholders.
Previous researchers examined the maritime industry, focusing on industry metrics, such
as occupancy rates and turnaround time of seaports in various locations that influenced
competition (Omoke, Diugwu, Nwaogbe, Ibe, & Ekpe, 2015; Santos, Mendes, & Soares,
2016; Schepler, Balev, Michel, & Sanlaville, 2017). In Portugal, Santos et al. (2016)
created a marginal cost pricing model for European maritime seaport throughput
analysis. In the dynamic model, Santos et al. measured throughput as the number of
containers processed per unit of time, or the ATT of seaport employees handling
containers. The scholars model specified increases in marginal costs, which increased
capacity and occupancy rates, increased ATT, thus reducing seaport efficiency. Schepler
et al. (2017) created an optimization model for competing European seaports based on
the scheduling of trucks, trains, and ships on port terminals that determined ATT, or port
efficiencies. The unique optimization model from Schepler et al. provided multi-terminal
and multi-modal container ports optimal configurations to reduce ATT and improve port
services to increase profitability and market share among competitors for maritime ports.
Omoke et al. (2015) investigated privatization effects of the Nigerian transportation
industry, specifically maritime performance, which used average berth occupancy and
ATT data. The scholars used non-parametric tests, specifically Mann-Whitney U and
Wilcoxon W tests, and rejected the null in both scenarios, meaning that privatization had
a positive and significant impact on average berth occupancy, (MWU = 6; WW = 72; .02
< p < .05), and ATT, (MWU = 5; WW = 33; .001 < p < .05), in Nigerian ports.

38
In addition, prior researchers showed that scheduling algorithms influenced ATT in
automated and digital queuing processes (Gupta et al., 2017; Tani & El-Amrani, 2017;
Wang, Huang, & Wang, 2016). Wang et al. (2016) devised a scheduling framework that
divides processes into four phases to reduce ATT in workflow systems. Wang et al. found
that the developed scheduling framework improved performance, or ATT, by over 20%.
Tani and El-Amrani (2017) showed the importance of developing efficient scheduling
algorithms that dealt with big data and cloud computing efficiency to complete tasks. Tani
and El-Amrani examined five algorithms and proved that ATT decreases, significantly,
with higher-order algorithms that are more complex and advanced to accomplish tasks
with swiftness. Moreover, Gupta et al. (2017) assessed scheduling algorithms between
several queues by developing a unique model. The scholars’ models stated that a
combination of prior scheduling algorithms could improve ATT in multilevel queuing
processes. Scheduling algorithms can transpose into the mortgage industry by
streamlining departmental processes and wait times to reduce ATT, thus increasing
profitability and value. The previous scholars’ research provided excellent evidence and
support for utilizing ATT as the dependent research variable.
Supportive Theoretical Reviews
The highest level of scholarly research requires that the researcher provide an
opposing or supporting view of a phenomenon to substantiate a literature analysis
(Baumeister, 2013). Also, a scholar’s critical analysis of peer-reviewed literature increases
research synthesis and construct identity (Larsen & How Bong, 2016). Moreover, the
development of literature reviews through a different lens further shows breadth and depth

39
to scholarly research (Stockman, 2015). I confirmed that the theoretical propositions of
the causal-comparative relationships between MLP, MLT, SPT, and the corresponding
impact on ATT through a supportive lens with two theories, the theory of constraints and
the thinking process theory.
Theory of Constraints
The objective for any organization is the principle of continuous improvement
through lean operations (Goldratt & Cox, 1984; Golmohammadi & Mansouri, 2015;
Taylor & Mead, 2015). Goldratt and Cox (1984) defined the theory of constraints (TOC)
as the development of manufacturing processes around the point of congestion to improve
throughput or ATT. As defined previously in this study, the RMT process begins with
origination, continues through processing, underwriting, closing, and concludes with
funding. Golmohammadi and Mansouri (2015) stated that managers created production
strategies based on the TOC. The complexity of the retail mortgage process includes
production phases that may require improvement centered around TOC. Identifying
constraints is a challenging goal, although Taylor and Mead (2015) mentioned that
undesired effects, or constraints, arise during competitive times along the process.
Therefore, application of TOC in the mortgage process may assist mortgage managers
with identifying and eliminating constraints that delay ATT and reduce costs to increase
profitability and intrinsic value for stakeholders.
Thinking Process
Previous scholars identified theoretical concepts that offered managers analytical
data to determine process optimization and improvements in various industries (Santos,

40
2013; Taylor & Asthana, 2016; Taylor, Hailey, & Parajuli, 2015). Fulfilling mortgage
consumer demand requires lean operations to deliver intangible services. Taylor, Hailey et
al. (2015) used Goldratt’s thinking process theory, which is identifying what to change,
knowing what to change it to, and how to implement the change, to help eliminate
constraints and improve lending processes in the rural Nepalese microfinance industry.
The current mortgage process is factory-like from the perspective of process fulfillment.
Santos (2013) stated that process perfection was the product of identifying process
inadequacies to re-prioritize competencies in real time. Taylor and Asthana (2016)
examined the U.S. electrical industry and applied the TOC and the thinking process to
inventory control problems to minimize cost and to meet delivery dates. Although
managers implement TOC and thinking process concepts in manufacturing, the principles
of lean production may convey into the consumer lending industry. Therefore, coupling
the thinking process concept with TOC in this study may allow for constraint
identification and throughput improvements in the mortgage process to reduce costs,
ATT, and to maximize profitability and intrinsic value.
Literature Synopsis
The potential results of this study may provide mortgage managers with credible
data to make valuable decisions regarding process optimization, cost reduction, and value
maximization. The purpose of this study was to analyze the impact of MLP, MLT, and
SPT on ATT to reduce customer wait times and transaction costs in an RMT. Moreover,
another purpose of this study was to improve the retail mortgage process to increase

41
profitability and intrinsic value for organizational stakeholders. Furthermore, this study
may offer scholars additional data to fill knowledge gaps in future studies.
Transition
The background of this study showed the procedural problems with the
consumers, employees, and management’s inabilities to complete an RMT in an efficient
time. Identification of the general and specific business problems identified the purpose of
the study, which led to the articulation of research questions and hypotheses from the
extensive literature review. Additionally, the first section of the proposal indicated the
importance of justifying theoretical propositions as a lens to view the business problem.
The appropriate terminology of the established operational definitions justified the
assumptions, limitations, and delimitations. Furthermore, Section 1 indicated the
importance of the study, which benefits mortgage institutions through business
contributions and social change.
In Section 2, I discussed my role as the researcher, the reason for the lack of
participants along with the procured archival research data. This section also included the
research methods and design chosen for this study as well as the determination of the
population and sampling, which will show the appropriate sample size from a target
population for the evaluated archival data records. Also, in Section 2, I indicated that the
data instruments and techniques for this study included data analysis and research
validation. The concluding section, Section 3, showed the findings and an applicable
presentation of the completed study into mortgage practices. Moreover, Section 3 showed
that the findings applied to professional practice while creating social action in the

42
mortgage industry. Additionally, in Section 3, I offered recommendations for action and
future studies. Furthermore, I concluded this study with a reflection on the process and
experience.
Section 2: The Project
In applied research, identifying the purpose of the study, the researcher’s role, the
participants, and the research information may improve academics and businesses.
Scholarly research information includes a method, design, instrumentation, data
collection, analysis, and validity, which provides the academic and business communities
with numerical data to make effective decisions based on statistical evaluation and
interpretation. In the following section, I present the methodology I used for the study and
describe the significance of the research.
Purpose Statement
The purpose of this quantitative, causal-comparative study was to examine the
impact of MLP, MLT, and SPT on ATT. The independent variables were MLP, MLT, and
SPT. The dependent variable was ATT to complete an RMT from origination to funding.
The archival population data included a selected mortgage institution’s retail originations
data from the state of Florida. Mortgage managers may increase the firm’s intrinsic value
through more efficient ways to minimize ATT by reducing transaction costs and lessening
risks to complete an RMT. Therefore, the social change implication of this doctoral study
includes the potential increase in the firm’s intrinsic value for
organizational stakeholders.

43
Role of the Researcher
A researcher’s role in a scholarly study depends on the selected research
methodology and design (Call-Cummings, 2017; Metcalf, 2016; Stockman, 2015). My
role as the researcher was to contact a targeted retail mortgage company in order to
procure, analyze, and interpret the archival data; in doing so, I ensured ethical compliance
under the purview of the Belmont Report. The Belmont Report contains the guidelines
and ethical principles for the protection of human subjects during behavioral and
biomedical research (The National Commission for the Protection of Human Subjects of
Biomedical and Behavioral Research, 1979). The Belmont Report consists of three
primary principles that indicate (a) respect for persons, (b) beneficence, and (c) justice
(The National Commission for the Protection of Human Subjects of Biomedical and
Behavioral Research, 1979). In what follows, I discuss these principles in detail as they
applied to this study.
Respect for Persons
In this study, I did not use human participants, thus eliminating the need for any
biomedical or behavioral tests as indicated in the Belmont Report (Clayton, Supiano,
Wilson, Lassche, & Latendresse, 2017; Guillemin et al., 2017). I collected and
incorporated primary archival data records into this study from a selected mortgage
institution for analysis and interpretation. Acemoglu, Johnson, Kermani, Kwak, and
Mitton (2016) stated that personal connections are biased towards a given side of an issue,
which reduces beneficial outcomes. As I procured the archival data to complete this study,
I showed respect and professionalism towards my professional partners within the

44
selected mortgage institution. Obeying the Belmont Report guidelines required meticulous
attention to the line between academic research and professional practice. While not using
human participants, abiding by the guidelines, with beneficence and justice, exudes
respect for people in academic and professional research.
Beneficence
Beneficence is the act of doing good or providing a benefit in research, which
leads to favorable societal outcomes (Borgia, 2013; Hales, 2016; McCann & Sweet,
2014). Hales (2016) showed that research requires an objective perspective, which
benefits academic and professional research because a subjective view indicates
researcher bias. Bradley, Gokkaya, and Liu (2017) gathered 28 years of employment
history from the financial analyst industry that indicated increased knowledge and
expertise benefits personal and professional development among employees and leaders in
an organization. Ertürk (2014) proved that managers gained tacit knowledge from a
hands-on approach throughout organizational processes benefits further scholarly research
to improve business procedures. The breadth and depth of this study provided me the
appropriate materials to complete this study commensurate with my education and
experience and to benefit academic research and professional practice.
Moreover, ethical consideration is mandatory in scholarly research; it must be
upheld and continued by all researchers, academic and professional (Borgia, 2013;
Clayton et al., 2017; Hales, 2016). Borgia (2013) stated that ethical governance in banking
requires a social report to maintain the organization’s success at implementing and
assessing corporate social responsibility activities. Also, Hales (2016) showed that a

45
researcher’s uses of the appropriate tests for proposed research would reduce intentional
and unintentional personal biases in cultural research. Therefore, I approached this study
with objectivity to minimize any researcher bias and maximize research benefits.
Justice
The concept of justice in research is synonymous with respect for people regarding
their equality and rationality (Call-Cummings, 2017; Hales, 2016; Lahav & Zimand-
Sheiner, 2016). Ertürk (2014) mentioned that managerial rationality supports the ability to
innovate processes from experience whereas Bradley et al. (2017) showed that the
employee equality gained over time benefited the organization with rational
decisionmakers. Rational and equitable working relationships develop over an employee’s
tenure in any industry (Acemoglu et al., 2016; McCann & Sweet, 2014). Even though I
sustained a career in the mortgage industry for over 25 years, no professional relationship
existed between the mortgage institution, the employees, or myself. However, I do have a
relationship with the topic because of my career in the industry. In Florida, I am a licensed
real estate agent and mortgage loan originator, and I actively work in the industry. I
previously worked at many large banks and owned my own mortgage business during my
professional tenure. Sustaining the justice principle of the Belmont Report required me to
draw from previous working experiences to ensure equitable benefits for all vested
stakeholders.
Participants
In this study, I did not include any human participants because I used recent
archival data from a selected retail mortgage company. Previous researchers stated that

46
successful research includes and excludes specific data determined by eligibility criteria
(Bailey, 2014; LaBonte & Kilpatrick, 2017; Reio, 2016). My criteria for data included in
this study was that it was archival data from a selected retail mortgage company doing
business in the state of Florida for at least 5 years. Excluding archival data from outside
the state of Florida allowed me to generalize the findings to a national scale. Additionally,
I did not include home improvement data in the research. Moreover, the mortgage
characteristics of the archival data were specific to MLP, MLT, SPT, application dates, and
funding dates. Furthermore, I excluded employee demographic information because of the
lack of human participants.
Previous scholars have justified the use of archival data in research to analyze,
predict, and interpret observable facts in research (Barraclough, af Wahlberg, Freeman,
Watson, & Watson, 2016; Gligor, Esmark, & Holcomb, 2015; Szabó, Müllerová,
Suchánková, & Kotačka, 2015). Acemoglu et al. (2016) used a relationship network to
obtain archival data to analyze unusual returns from firms that have employees nominated
for high public office positions. Similarly, to procure the raw archival data I contacted
decision-making, mortgage professionals, via networking, phone, and email, whom
originated and funded retail mortgages in the state of Florida.
Creating and sustaining effective working relationships requires a scholar to use a
robust professional network within the targeted industry, which is important to further
reinforce academic and professional research applications (de Sivatte, Gordon, Rojo, &
Olmos, 2015; Houghton, 2016; Malone & Issa, 2013). My strategy was to reach out to
affiliates in my professional network to obtain contact information of decision-makers in

47
retail mortgage companies to procure archival RMT data for analysis and interpretation.
Moreover, I planned and organized virtual meetings that developed and maintained a
working relationship with mortgage professionals in various departments, such as IT,
sales, and operations to complete this study.
Research Method and Design
There are three research methodologies used in conducting social scientific
studies: qualitative, quantitative, and mixed methods (Koskey & Stewart, 2014; Park &
Park, 2016; Runfola, Perna, Baraldi, & Gregori, 2017). Specific research methodologies
parallel scholars’ philosophical assumptions of worldviews. My selection of a specific
method resulted from careful consideration of all three methodologies.
Research Method
Scholars’ worldviews are the set of principles that influence their actions in
research (Cairney & St Denny, 2015; Cap, 2017; Shahadan & Oliver, 2016). Worldviews
derive from scholars’ research disciplines, mentorships, and previous research experiences
(Guo, 2015; Kaplan, 2015; Neuman & Guterman, 2016). The three worldviews that
influence researchers when choosing a methodology are pragmatic, constructivist, and
post-positivist.
Pragmatic. Pragmatic researchers will apply all sensible and realistic research
methods to analyze variable relationships and explore phenomena (Cap, 2017; Ralph,
Birks, & Chapman, 2015; Snelgrove, 2017). Scholars with commonsensical worldviews
will complete mixed methods research, which is the combination of qualitative and
quantitative methods (Cairney & St Denny, 2015; Hales, 2016; Shahadan & Oliver, 2016).

48
Further, pragmatic researchers implement all research approaches to solve theoretical
problems with rational principles (Shahadan & Oliver, 2016; Snelgrove, 2017; Stockman,
2015). The pragmatic worldview offers scholars the most advantageous methods to
analyze and interpret data (Hales, 2016; Koskey & Stewart, 2014; Stockman, 2015).
Because the formulation of my research questions and hypotheses were quantitative, I
omitted qualitative research scenarios, and thus also omitted the use of a mixed-methods
approach. Even though I approached the research study with practical knowledge from
education and experience, there were not any immeasurable data characterizations
involved in this research. Although a pragmatic worldview is essential to complete a
mixed-method research approach, it was not suitable because of the lack of qualitative
research methods for the research study.
Constructivist. Scholars with a constructivist worldview use subjectivity to
explore and assess phenomena in a qualitative approach (Jakobsen, 2016; Neuman &
Guterman, 2016; Raza, Murad, & Zakar, 2016). Constructivist researchers analyze and
interpret study participants’ views with qualitative research methods (Neuman &
Guterman, 2016; Ralph et al., 2015; Snelgrove, 2017). Researchers with constructivist
philosophies also work to understand study participants’ backgrounds to gain cultural and
historical perspectives (Jakobsen, 2016; Raza et al., 2016; Snelgrove, 2017). Researchers
who use a qualitative methodology to describe the accounts of participants’ views or
observations of a phenomenon articulated a conceptual basis for a study (Bailey, 2014;
Cairney & St Denny, 2015; Runfola et al., 2017). Again, I simplified the research study by

49
using quantitative archival data, so a constructivist approach was not suitable for this
research.
Post-positivist. Post-positivist researchers analyze data through quantitative
methods to predict relationships between variables and then use the assessments to test
projections stemming from the theories (Guo, 2015; Kaplan, 2015; Snelgrove, 2017).
Post-positivist researchers employ a deterministic worldview to resolve possible outcomes
and effects of research studies (Guo, 2015; Hales, 2016; Kaplan, 2015). Scholars will be
more inclined to select a quantitative method with a post-positivist emphasis in research
studies with testable theories (Bailey, 2014; Hales, 2016; Snelgrove, 2017). Therefore, I
drew upon post-positivist philosophical assumptions to shape the research technique for
this study.
In quantitative research, scholars created a hypothetical framework for data
acquisition from primary and secondary data sources, which requires a statistical lens to
formulate an analysis of the findings (Onen, 2016; Park & Park, 2016; Reio, 2016). An
appropriate quantitative evaluation technique is a factorial analysis of variance (ANOVA)
F test to measure three categorical independent variables and one continuous dependent
variable (Dobbin & Ionan, 2015; Koskey & Stewart, 2014; Onen, 2016). After
consideration of all three methods, I determined that a quantitative approach would be the
most effective method for this current study. I analyzed an impact relationship between
independent and dependent variables that yielded numerical results for statistical analysis
and interpretation. For the reasons above, application of the quantitative research
methodology to the study is reasonable and justified.

50
Research Design
Three quantitative designs in scholarly research include correlation, experimental,
and quasi-experimental designs (Dobbin & Ionan, 2015; Hales, 2016; Park & Park, 2016).
Researchers use quantitative designs to analyze scientific theories by investigating
relationships between independent and dependent variables (Al-Thani & Semmar, 2017;
Cotteleer & Wan, 2016; Guo, 2015). Moreover, scholars use quantitative research designs
to answer research questions by evaluating hypotheses with statistical procedures, which
yields numerical results to interpret and generalize to a larger population. I used a causal-
comparative design to analyze the impact of MLP, MLT, and SPT on ATT to complete an
RMT from origination to funding.
Correlational. Quantitative researchers use correlational designs to examine a
relationship between continuous independent and continuous dependent variables (Bosco,
Aguinis, Singh, Field, & Pierce, 2015; Dobbin & Ionan, 2015; Kaplan, 2015). Although a
correlational design helps researchers to relate variables, researchers are unable to imply
causality by using this design (Dobbin & Ionan, 2015; Guo, 2015; McCarthy, Whittaker,
Boyle, & Eyal, 2017). Thus, scholars will use regression analyses to analyze and interpret
the results to the general population (Guo, 2015; McCarthy et al., 2017; Park & Park,
2016). The primary objective of this study was to determine an impact of categorical
independent variables on a continuous dependent variable; therefore, a correlational
design was not suitable.
Experimental. Quantitative researchers use experimental designs to analyze a
cause and effect association between categorical independent variables and categorical

51
dependent variables (Al-Thani & Semmar, 2017; Guo, 2015; Marshall & Rossman, 2015).
In an experimental design, researchers randomly assign variables for manipulation to
make causal inferences (Koskey & Stewart, 2014; Marshall & Rossman, 2015; Park &
Park, 2016). Scholars use an experimental design to test variances with statistical
procedures such as ANOVA, analysis of covariance (ANCOVA), and multivariate analysis
of variance (MANOVA) to interpret and generalize study results (Guo, 2015; McCarthy et
al., 2017; Runfola et al., 2017). In this study, I sought to examine a causalcomparative
impact of independent variables on a dependent variable; thus, a cause and effect
relationship was not sufficient. Instead, I used an ANOVA to examine the impact of three
categorical independent variables on a continuous dependent variable.
Quasi-experimental. Quantitative researchers also assess causal relationships in
quasi-experimental designs, although there is a lack of randomization for study variables
(Cotteleer & Wan, 2016; Park & Park, 2016; Reio, 2016). Scholars may also influence
independent variables but have a lessened ability to make causal inferences (Guo, 2015;
Koskey & Stewart, 2014; McCarthy et al., 2017). A causal-comparative design provides
future scholars a pre-established relationship of variables for future research (Al-Thani &
Semmar, 2017; Park & Park, 2016; Riffe et al., 2014). Although scholars will use
ANOVAs, ANCOVAs, and MANOVAs in quasi-experimental research, a
quasiexperimental design was not suitable for this study.
Population and Sampling
Scholarly research requires a targeted sample from a population to obtain
necessary data for statistical analysis and interpretation (Gibson, 2017; Koskey & Stewart,

52
2014; Onen, 2016). Researchers segment quantitative data collection by demographics
and psychographics in surveys whereas with the use of archival data; appropriate
sampling methods could be randomized (Aziz & Hassan, 2017; Ciabuschi, Forsgren, &
Martín, 2017; Sage, Blalock, & Carpenter, 2017). A selected mortgage institution
provided the population with archival data from which to retrieve the sample for this
study.
Population
I used lender-provided data to select a sample from the population of originated
and funded retail mortgage data in the state of Florida within the previous 12 months of
this study. The procured archival data contained in the population included mortgage
characteristics such as loan purpose, loan type, and property type. Moreover, the primary
archival data included loan application dates and loan funding dates for me to compute the
difference in days between the dates, or ATT. Furthermore, I derived the research sample
from the population for analysis and interpretation.
Sampling
Researchers group sampling in two categories, probabilistic and non-probabilistic
methods, which include specific methods for each sampling category (Aziz & Hassan,
2017; Ciabuschi et al., 2017; Sage et al., 2017). I used a probabilistic, simple random
sampling approach in this study. The reason I included the research variables stems from
literature investigation and professional experience. Prior scholars showed that the
propositioned independent variables, MLP, MLT, and SPT, influenced various mortgage
industry outcomes, respectively (Al-Bahrani & Su, 2015; Gallagher, 2016; Park K. A.,

53
2016); therefore, these were necessary for inclusion as research variables. Moreover, the
independent research variables are necessary mortgage application inputs to determine
underwriting approvals and successful disbursements of funds in RMTs.
A probabilistic technique involves a random sampling procedure, whereas
nonprobabilistic is a specific sampling method (Dobbin & Ionan, 2015; Koskey &
Stewart, 2014; Turiano, 2014). As in all research, there are advantages and disadvantages
to a proposed sampling approach and technique. The strengths of a simple random,
probabilistic approach are that the random selection of the sample data from the target
population creates an equal chance to minimize data variabilities along with an unbiased
selection process (Aziz & Hassan, 2017; Ciabuschi et al., 2017; Sage et al., 2017). The
weaknesses of a simple random, probabilistic technique are the increased chances of
sampling errors, wider dispersion of the sample, and heterogeneity for a scholar to
generalize research findings (Aziz & Hassan, 2017; Ciabuschi et al., 2017; Sage et al.,
2017).
There are four broad probabilistic sampling techniques used by scholars in
quantitative research, which are simple random, stratified, systematic, and cluster
sampling. I selected a simple random sampling procedure because the independent
research variables in this study are not mutually exclusive. Researchers must define the
sampling technique in the proposed study to assist with data collection, analyses,
interpretation, and generalization (Çankaya, 2016; Khan M, 2016; Scealy & Welsh, 2017).
Scholars design research around a simple random sampling technique, giving each
population data point and an equal chance for selection to limit uncertainty, decrease

54
variability and simulate patterns (Endo, Watanabe, & Yamamoto, 2015; McCormick,
Jackson, Carr, & Meyer, 2015; Xu & Yan, 2017). Scholars use stratified sampling to
organize the population into mutually exclusive groups, then apply simple random
procedures to reduce dispersal among a sample of predicted and observed trials
(Bensadoun, Monod, Makowski, & Messean, 2016; Hu et al., 2016; Lafontaine, Sawada,
& Kristjansson, 2017). A mortgage loan originator can have owner-occupied, government-
refinance transactions or non-owner occupied, conventional-purchase transactions. Also,
my use of a simple random sampling technique was because the developed independent
research variables are not subsequent variables of the other; thus, eliminating a systematic
sampling method. Systematic sampling has a multitude of variations dating back to 1948,
although researchers use a systematic sampling procedure when the population sizes, N,
are a multiple of sample sizes, n, and intervals, k (Çankaya, 2016; Khan M., 2016; Khan,
Shabbir, & Gupta, 2015). In research, where variables occur naturally, scholars use a
cluster sampling procedure to select a sample from the target population groups (Firoozi,
Kazemi, & Jokar, 2017; Momeni, Mohammadreza, & Amini, 2017; Scealy & Welsh,
2017). Moreover, the justification for my selection of a simple random sampling
technique was because the developed independent research variables do not occur in
natural groups.
Evaluating the sample size requires computer applications to assess mathematical
relationships. MS Excel 2016, G*Power version 3.1.9.2, and Statistical Package for Social
Sciences (SPSS) version 24 are software packages used to analyze statistical significance
of a potential impact of independent variables on a dependent variable (Faul, Erdfelder,
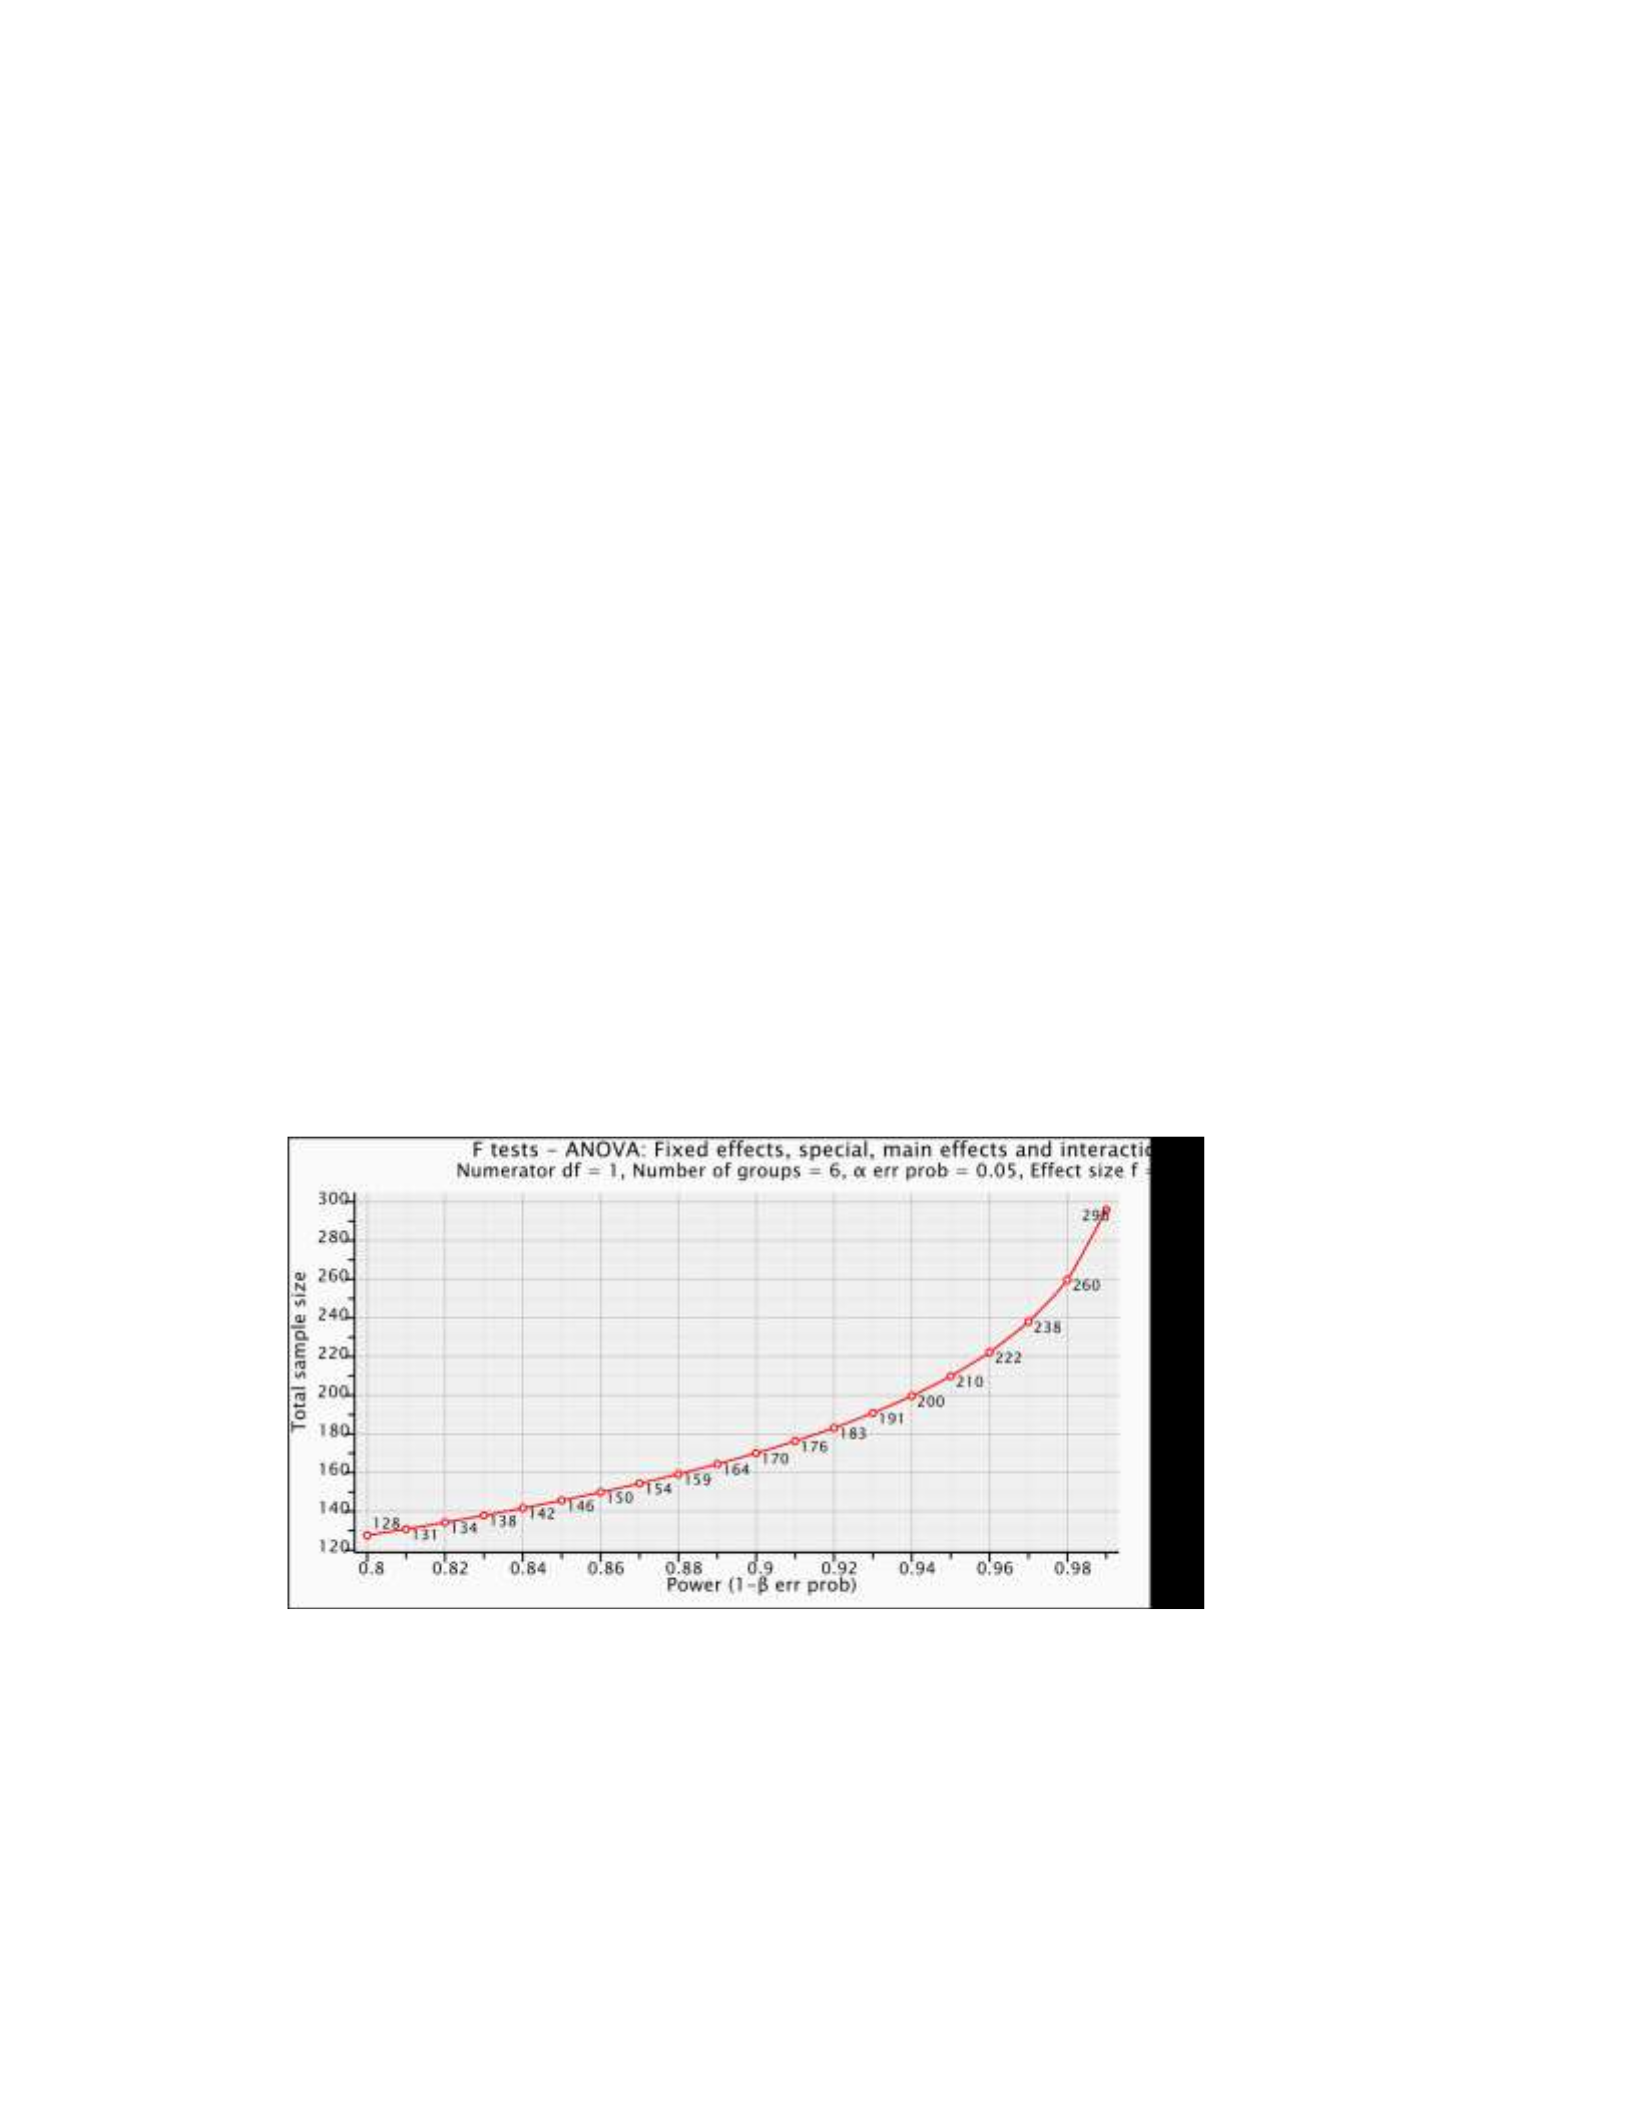
55
Buchner, & Lang, 2009). Effect sizes and power analyses are essential to empirical study
scholars who seek relationships between categorical and continuous variables using
statistical tests (Bosco et al., 2015). Additionally, effect sizes and power analyses indicate
the magnitude of a relationship in an empirical study (Bosco et al., 2015). Therefore,
conducting a priori power analyses will identify the sample size range for an empirical
study. In this study, I conducted a 2 x 2 x 2 factorial ANOVA, as shown in a G*Power F-
test selection, applying a medium effect size f = .25, α = .05, and df = 1, indicating a
minimum sample size of 128 archival data records required to achieve a power analysis of
.80. Increasing the sample size to 296 will increase the power level to .99. Further
increasing the sample size to 410 will increase the power level to .999. Therefore, an
appropriate sample size for the proposed study will be between 128 and 410 archival data
records graphed in Figures 1 and 2, respectively.
Figure 1. Total range of archival data records between .80 and .99 power analyses.
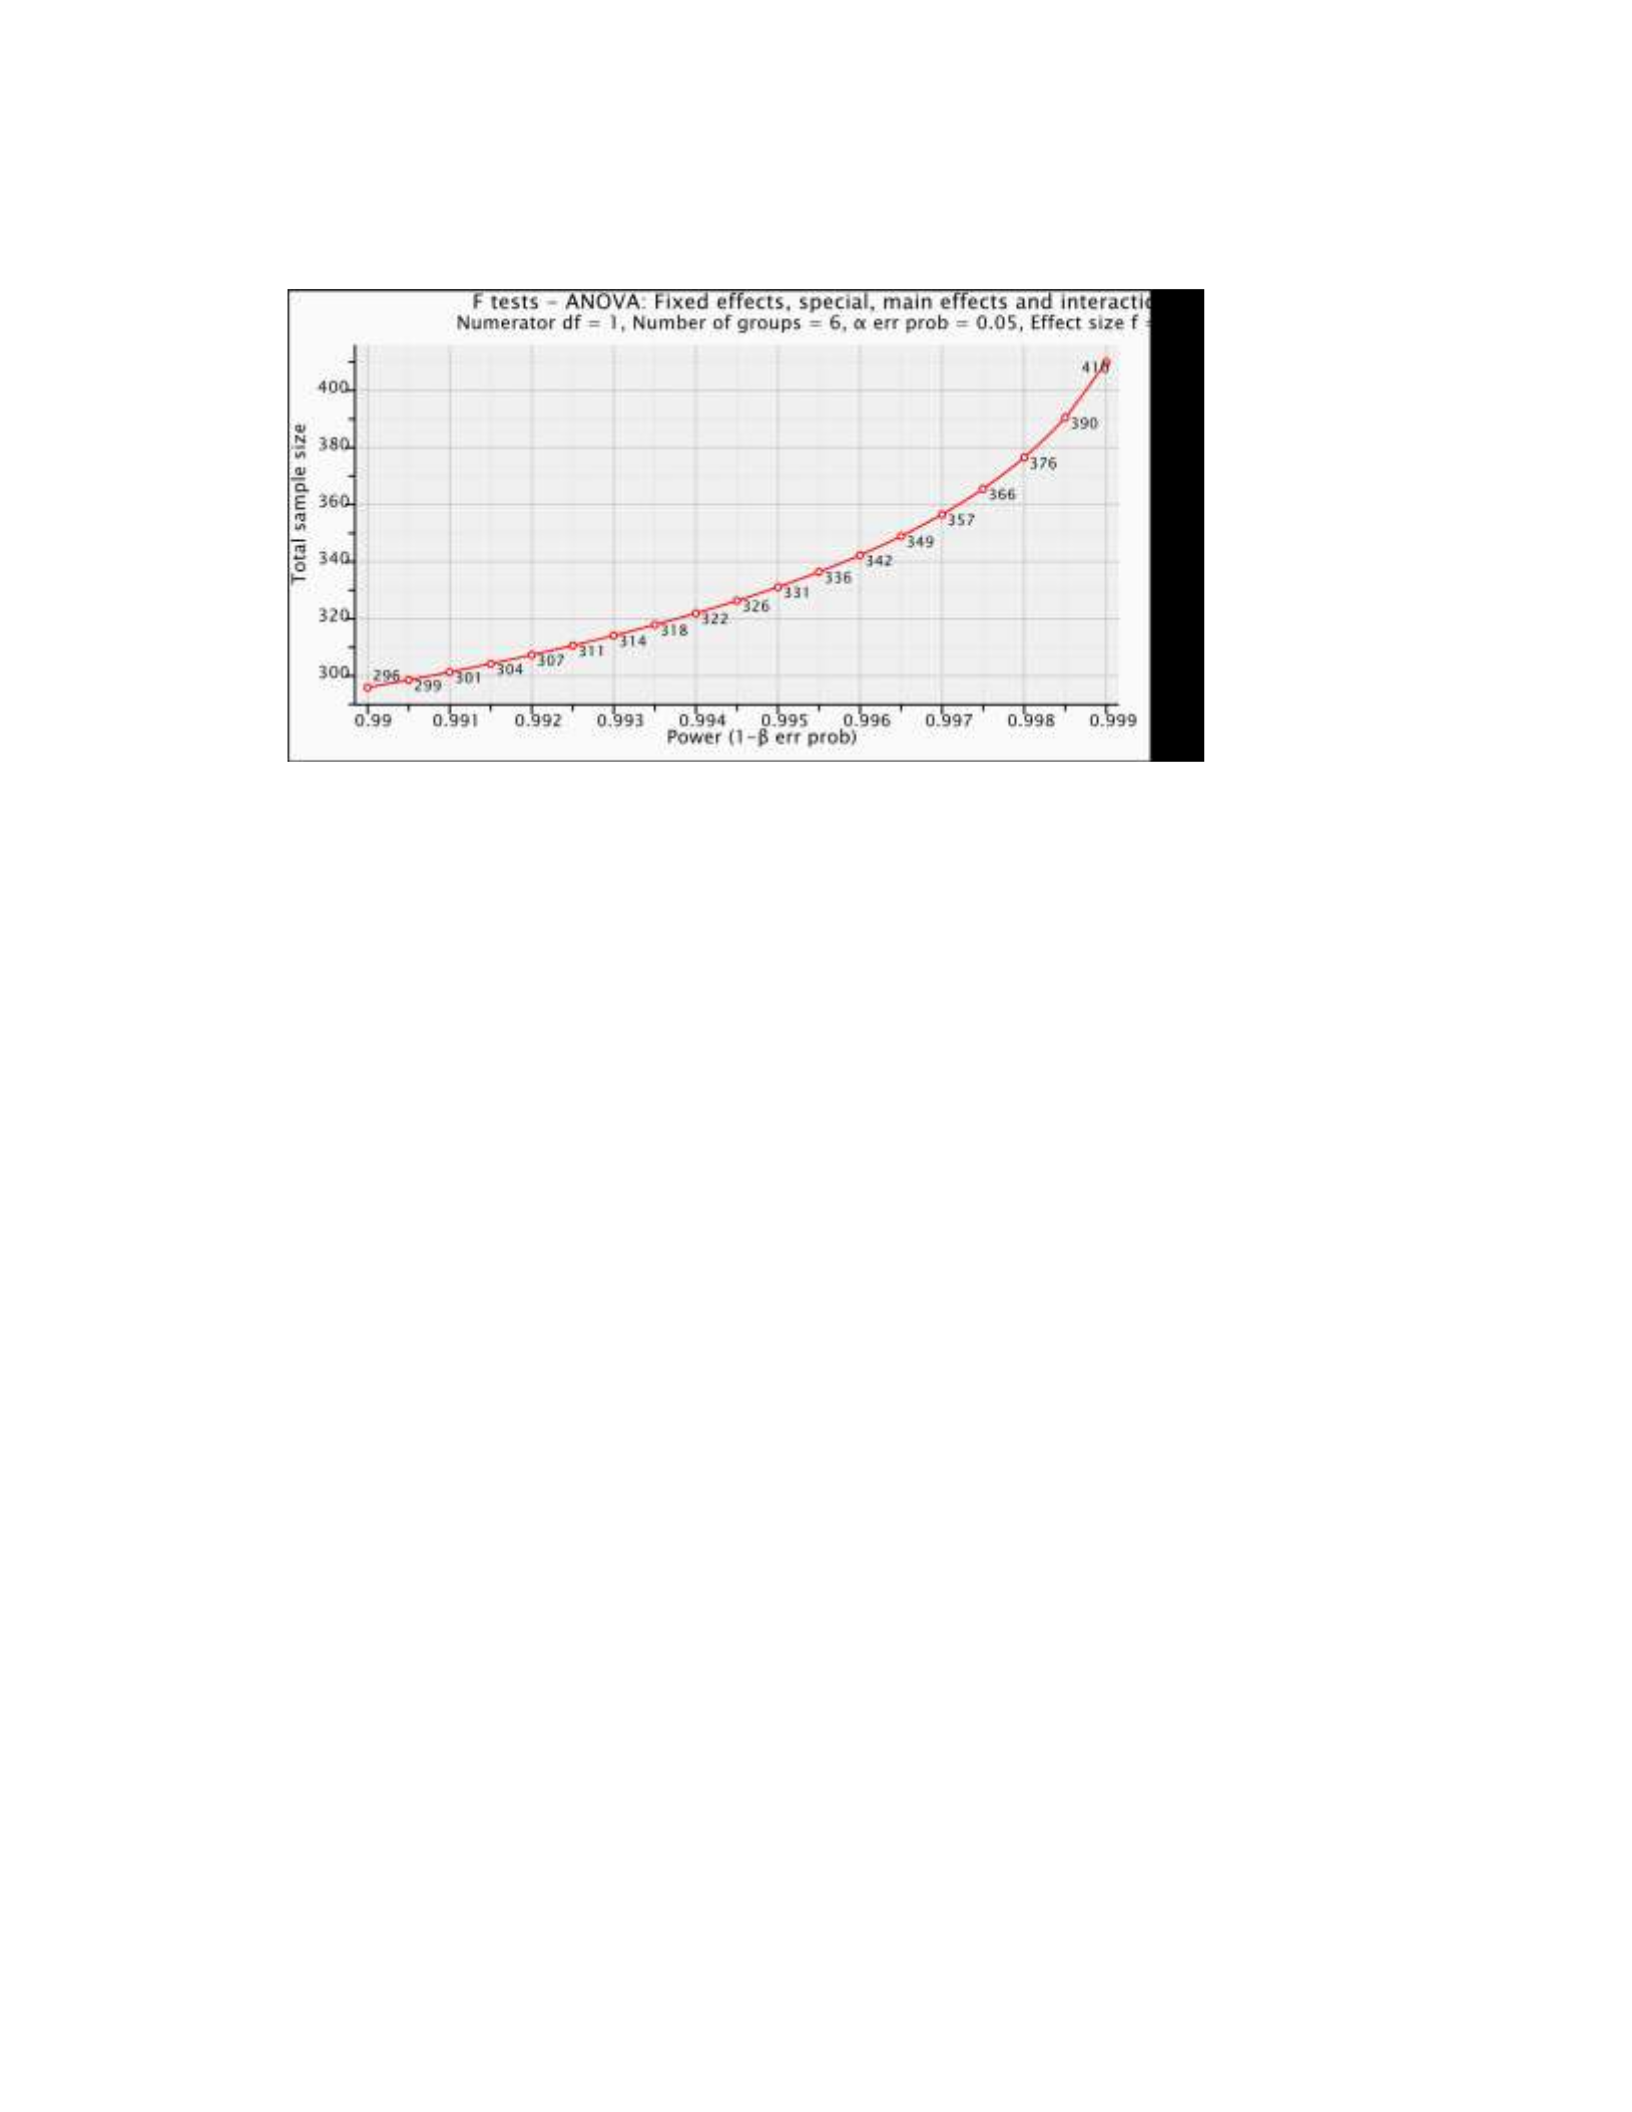
56
Figure 2. Total range of archival data records between .99 and .999 power analyses.
Ethical Research
I sampled non-identifiable, archival data records from a selected mortgage
institution for analysis and interpretation. To maintain ethical standards and
professionalism, the Walden University Institutional Review Board reviewed and
approved the request for collected data (approval number 11-13-17-0426588) for this
study. Also, I sent an initial request to participate in the study to the company
decisionmaker (see Appendix A). Also, I needed the company’s decision-maker to
authorize an official letter of cooperation to begin data collection of archival data within
the firm (see Appendix B). Moreover, both parties will agree to a mutual confidentiality
agreement limited to the proposed study (see Appendix C). Furthermore, both parties will

57
consent to a mutual limited dataset user agreement limited to the scope of the current
research (see
Appendix D).
The selected mortgage institution, nor the employees received any compensation
for participation in this research study. I did not receive any compensation, nor incentives
limited to the facilitation of the developed research. Also, if the decision-maker decided to
withdraw the selected mortgage institution from the study, there are no penalties for doing
so. The requirement for withdrawal from the study is a written correspondence from the
decision-maker explaining the reason(s) for withdrawal. Also, upon confirmed withdrawal
from the study, I would appropriately dispose of all raw data, following all federal, state,
and local electronic disposal laws.
An affirmative response showed that the decision-maker acquiesced to my
professional request and agreed to participate in this research study. I will store the
archival data in an encrypted and password-protected storage drive for at least five years
by all research compliance regulations. DeSimone, Harms, and DeSimone (2015) stated
that data screening and storage in scholarly research requires techniques to minimize
weak data points. Although I took precaution with encryption and password protective
security measures, screening the archival data confirmed that the data did not contain any
private identifying information specific to any borrower in any retail mortgage
transaction. Furthermore, the appendices contain specific details regarding all consent,
compliance, and confidentiality forms for this study.

58
Data Collection Instruments
Researchers gathered data to correlate the significance of various data collection
methods, including archival data, to provide an analysis of the findings and to generalize
to the population (Barraclough et al., 2016; Ma, Zhang, Lin, & Li, 2017; Reio, 2016).
Upon gathering the data, scholars begin to screen, analyze, and organize the data for
outliers, anomalies, and incomplete data points (LaBonte & Kilpatrick, 2017; Sleeper et
al., 2017; Zhang et al., 2017). I did not require the use of standardized data collection
instruments such as surveys because the population of data is archival; therefore, once I
received the archival data, I processed the data to ensure that the requested variable
information was correct in the electronic source document. The independent variables,
MLP, MLT, and SPT, reflect a nominal scale of measurement with two levels per
independent variable. The dependent variable, ATT, is continuous with a ratio scale of
measurement.
The archival data consisted of mortgage characteristics such as loan purpose, loan
type, and property type, which defines the independent variables, respectively. The first
independent variable, loan purpose or MLP, consisted of two levels, purchase and
refinance mortgage transactions. The second independent variable, loan type or MLT,
consisted of two levels, conventional and government mortgage transactions. The final
independent variable, property type or SPT, consisted of two levels, owner-occupied and
non-owner-occupied mortgage transactions. Also, the archival data contained continuous
dependent variable information, such as application and funding dates, to determine ATTs
to complete RMTs from the selected random sample.

59
Using SPSS, I measured the nominal independent variables in a 0/1 scoring
system. The MLP variable, 0 = purchase, 1 = refinance. The MLT variable, 0 =
conventional, 1 = government. The SPT variable, 0 = owner-occupied, 1 = non-
owneroccupied. Moreover, I measured the continuous dependent variable, ATT, through
calculating the difference between the funding date and the application date to derive the
turnaround time, or ATT, to complete an RMT from origination to funding. Furthermore,
the raw archival data records may be provided upon request.
In prior research, many scholars collected data through different methods and
means to produce raw data for analysis and interpretation (LaBonte & Kilpatrick, 2017;
Ma et al., 2017; Sleeper et al., 2017). Previous researchers used technology to improve
data collection methods to enhance data screening and project efficiencies (Huang &
Savkin, 2017; Read, LaPolla, Tolea, Galvin, & Surkis, 2017; Zhang et al., 2017). A variety
of researchers in different industries used electronic data capture methods to provide
accurate and precise data analysis for reliable data interpretation (Huang & Savkin, 2017;
LaBonte & Kilpatrick, 2017; Zhang et al., 2017). In this study, I was the primary source
for data collection; although, I did retrieve the data set from the selected mortgage
institution, electronically.
Data Collection Techniques
Researchers use various data collection techniques, such as surveys, archival
databases, and structured observations, to acquire data from reliable and valid collection
instruments (Eisenhardt, Graebner, & Sonenshein, 2016; George, Haas, & Pentland, 2014;
Gibson, 2017). For this study, the decision to select archival data required careful thought

60
and scrutiny, to ensure accurate and precise data records for results interpretation and
generalization (Gibson, 2017; Houghton, 2016; LaBonte & Kilpatrick, 2017). My
decision to procure the archival data was to utilize professional affiliations, which
provided a benefit for me with minimal travel costs, maximum data availability, and
convenience. Surveys and observations may require additional levels of cost, security, and
privacy factors exceeding the scope of this study. The deficiency in the professional
affiliation method was the time needed to contact decision-makers of the selected firm and
secure a time to speak about the research and set up appropriate security and privacy
credentials to obtain the archival dataset.
Data Analysis
Research Question
What is the impact of MLP, MLT, and SPT on ATT to complete an RMT from
origination to funding?
Hypotheses
Null Hypothesis (H0). MLP, MLT, and SPT do not have an impact on ATT to
complete an RMT from origination to funding.
Alternative Hypothesis (H1). MLP, MLT, and SPT do have an impact on ATT to
complete an RMT from origination to funding.
For the completion of this study, I analyzed and interpreted the archival data
records through a statistical ANOVA F-test. A correlation design requires that both,
independent and dependent variables use scale measurements whereas a chi-square design
requires independent and dependent variables in nominal measurements, or levels

61
(Dobbin & Ionan, 2015; Huck, 2012; Park & Park, 2016). Independent-samples t-tests
mandates for a single independent variable, which have two or more levels on a nominal
scale of measurement whereas an ANOVA F-test better fits the statistical analyses for the
research study because of the multiple, two level, categorical independent variables, and
the scale, continuous, dependent variable.
Different data collection methods require different data scrubbing and screening
techniques although all approaches require security measures to maintain data integrity
(DeSimone et al., 2015; Lin, Shen, Chen, & Sehldon, 2017; Sleeper et al., 2017). I
collected the archival data from a lone source, thus allowing me to screen and clean the
data efficiently. Even though there was not an issue with missing data, there was a
minimal opportunity for missing data from data retrieval and through electronic transfer.
However, missing data was not as likely as it would have been with survey and
observation techniques because of the subjective variability of participants in the survey
and observation approaches (Eisenhardt et al., 2016; George et al., 2014; Slater,
Joksimović, Kovanovic, Baker, & Gasevic, 2017). In the case of missing archival data, I
contacted the appropriate company liaison to retrieve the missing information to complete
this study.
Previous scholars stated that ordinary factorial ANOVA assumptions include
random sampling, an adequate sample size, appropriate scales of measurement, and
regular data distribution (McCarthy et al., 2017; Serbic & Pincus, 2017; Tacikowski,
Freiburghaus, & Ehrsson, 2017). Researchers test hypotheses by utilizing various
statistical measures such as ANOVA F-tests and independent samples t-tests (McCarthy et

62
al., 2017; Serbic & Pincus, 2017; Tacikowski et al., 2017). I tested and assessed
assumptions in the evaluated data research through factorial design ANOVA to interpret
the findings and make recommendations for future research. Although I am utilizing a
probabilistic, simple random sampling method, which is an assumption violation,
bootstrapping the archival data may offer an indication of a normal distribution of data
within the acceptable sample size range shown in Figures 1 and 2, respectively.
Scholars who conduct empirical studies must consider descriptive and inferential
statistics to analyze, interpret, and generalize significant findings (van Schaik & Weston,
2016). The Delphi Method is a statistical procedure that allows a researcher to infer
results that will help solve business problems (Ertürk, 2014; van Schaik & Weston, 2016).
Furthermore, inferring results from selected categorical and continuous variable
relationships to require the appropriate data analysis instruments, such as SPSS, to prove
strong numerical relationships for analysis and interpretation (Larsen & How Bong, 2016;
van Schaik & Weston, 2016). Interpretation of the statistical results will use effect sizes
and confidence intervals to determine a significant impact of the independent variables on
the dependent variable.
Study Validity
In this study, I used a probabilistic, simple random sampling method to ensure the
external validity of the research. Also, the selection, uniqueness, and timing of data can
threaten external validity (Call-Cummings, 2017; Gibson, 2017; van Duijn & Post, 2014).
External validity determines the scholar’s opportunity for generalizing the findings to the
population (Gibson, 2017; van Duijn & Post, 2014; Wacker, Hershauer, Walsh, & Sheu,

63
2014). Moreover, a correlation design would threaten the external validity of the study;
thus, further justifying my decision for a causal-comparative design.
Scholars threaten internal validity in research by the data selection to make
inferences, experimental data manipulation, and testing procedures such as data collection
instruments (Cotteleer & Wan, 2016; Ma et al., 2017; Onen, 2016). I used archival data in
this study; therefore, mitigating any internal validity threats. Scholars can lessen internal
validity threats by creating control groups, developing equality among data points, and
increased data randomization (Call-Cummings, 2017; Onen, 2016; van Duijn & Post,
2014). Thus, I integrated the present archival data records required to minimize any
internal validity threats and to examine, interpret, and generalize the findings to a larger
population.
Statistical conclusion validity ensures that the inferences made regarding the
research questions, and models are correct (Huck, 2012; van Duijn & Post, 2014; Wacker
et al., 2014). Also, construct validity ensures that the variables are appropriate for the
proposed measurements and analysis (Call-Cummings, 2017; van Duijn & Post, 2014;
Wacker et al., 2014). The threats to statistical conclusion validity consist of the reliability
of the instrument, the assumptions made from the data, and the sample size
(CallCummings, 2017; Gibson, 2017; Huck, 2012). These three validity threats magnify
the Type I error rate, which causes the rejection of the null hypothesis when, in fact, the
null hypothesis is correct.
Seeking an acceptable coefficient value higher than 0.7, I conducted an internal
consistency reliability check against the sample size that showed the relative association

64
through Cronbach’s alpha (Huck, 2012; Slater et al., 2017; van Duijn & Post, 2014).
Moreover, the appropriate sample size will improve the validity of a proposed study
whereas a sample size below the optimal study requirements may limit or nullify the
findings causing improper inferences (Dobbin & Ionan, 2015; Huck, 2012; van Duijn &
Post, 2014). Furthermore, ensuring the use of an appropriate sample size, by conducting a
power analysis through the G*Power tool sufficed as evidence of an appropriate sample
size.
Summary and Transition
Above-industry average turnaround time (ATT) to complete an RMT from
origination to funding results in revenue losses. I grounded this study based on the
hypothesis that MLP, MLT, and SPT could have a significant impact on ATT to complete
an RMT from origination to funding. To test this hypothesis, I implemented a 2 x 2 x 2
factorial ANOVA to examine the impact of the categorical independent variables on the
continuous dependent variable. My role as the researcher was to contact and acquire a
targeted retail mortgage company followed up with procuring, analyzing, and interpreting
the archival data, and in doing so, ensure the ethical compliance under the purview of the
Belmont Report. I did not include any human participants because the data comprised
archival data records for the last 12 months from a selected retail mortgage company
operating in the state of Florida. Based on a sample size calculation, I selected, randomly,
between 128 and 410 archival records to complete the statistical analysis.
In Section 3, I introduce the findings of the statistical analysis and any
professional applications related to the mortgage industry. Also, the next section included

65
implications for social change along with my recommendations for action and future
studies. Furthermore, I concluded with a reflection on my experiences with the doctoral
process and completed the study.
66
Section 3: Application to Professional Practice and Implications for Change
Research Study Overview
The purpose of this quantitative, causal-comparative study was to examine the
impact of MLP, MLT, and SPT on ATT. The independent variables were MLP, MLT, and
SPT. The dependent variable was ATT to complete an RMT from origination to funding.
The null hypothesis was that MLP, MLT, and SPT did not have an impact on ATT to
complete an RMT from origination to funding. The alternative hypothesis was that MLP,
MLT, and SPT did have an impact on ATT to complete an RMT from origination to
funding. The results of the 2 x 2 x 2 ANOVA indicated non-significant results; I found no
main or interaction effects. Therefore, I failed to reject the null hypothesis that MLP, MLT,
and SPT do not have an impact on ATT to complete an RMT from origination to funding.
Presentation of the Findings
Descriptive Statistics
The research analysis included 146 archival data records from a selected mortgage
institution in the state of Florida. The analysis comprised three nominal variables and one
ratio variable. Table 5 shows the descriptive statistics for the study nominal variables.
Table 6 depicts the descriptive statistics for the doctoral study scale variable.
Table 5
Frequencies (f) & Percentages (%) by Nominal Level
Independent variable
Nominal level
f
%
67
Mortgage loan purpose
Purchase
137
93.8%
Refinance
9
6.2%
Total
146
100.0%
Mortgage loan type
Conventional
64
43.8%
Government
82
56.2%
Total
146
100.0%
Subject property type
Owner-occupied
136
93.2%
Non-owner-occupied
10
6.8%
Total
146
100.0%
Table 6
ATT Mean (M) and Standard Deviation (SD) by Factor Nominal Level
Independent variable
Nominal level
M
SD
Mortgage loan purpose
Purchase
41.41
20.57
Refinance
45.78
20.64
68
Mortgage loan type
Conventional
39.28
17.99
Government
43.55
22.25
Subject property type
Owner-occupied
41.93
20.32
Non-owner-occupied
38.30
24.25
Assumptions Testing
The ANOVA assumptions tested normality and equality of variances; however, the
Levene’s test of equality of variances was not significant (F = .982; p = .43), showing the
assumption of equal variances was not in violation. The normality assumption as violated
is depicted in Figure 3.
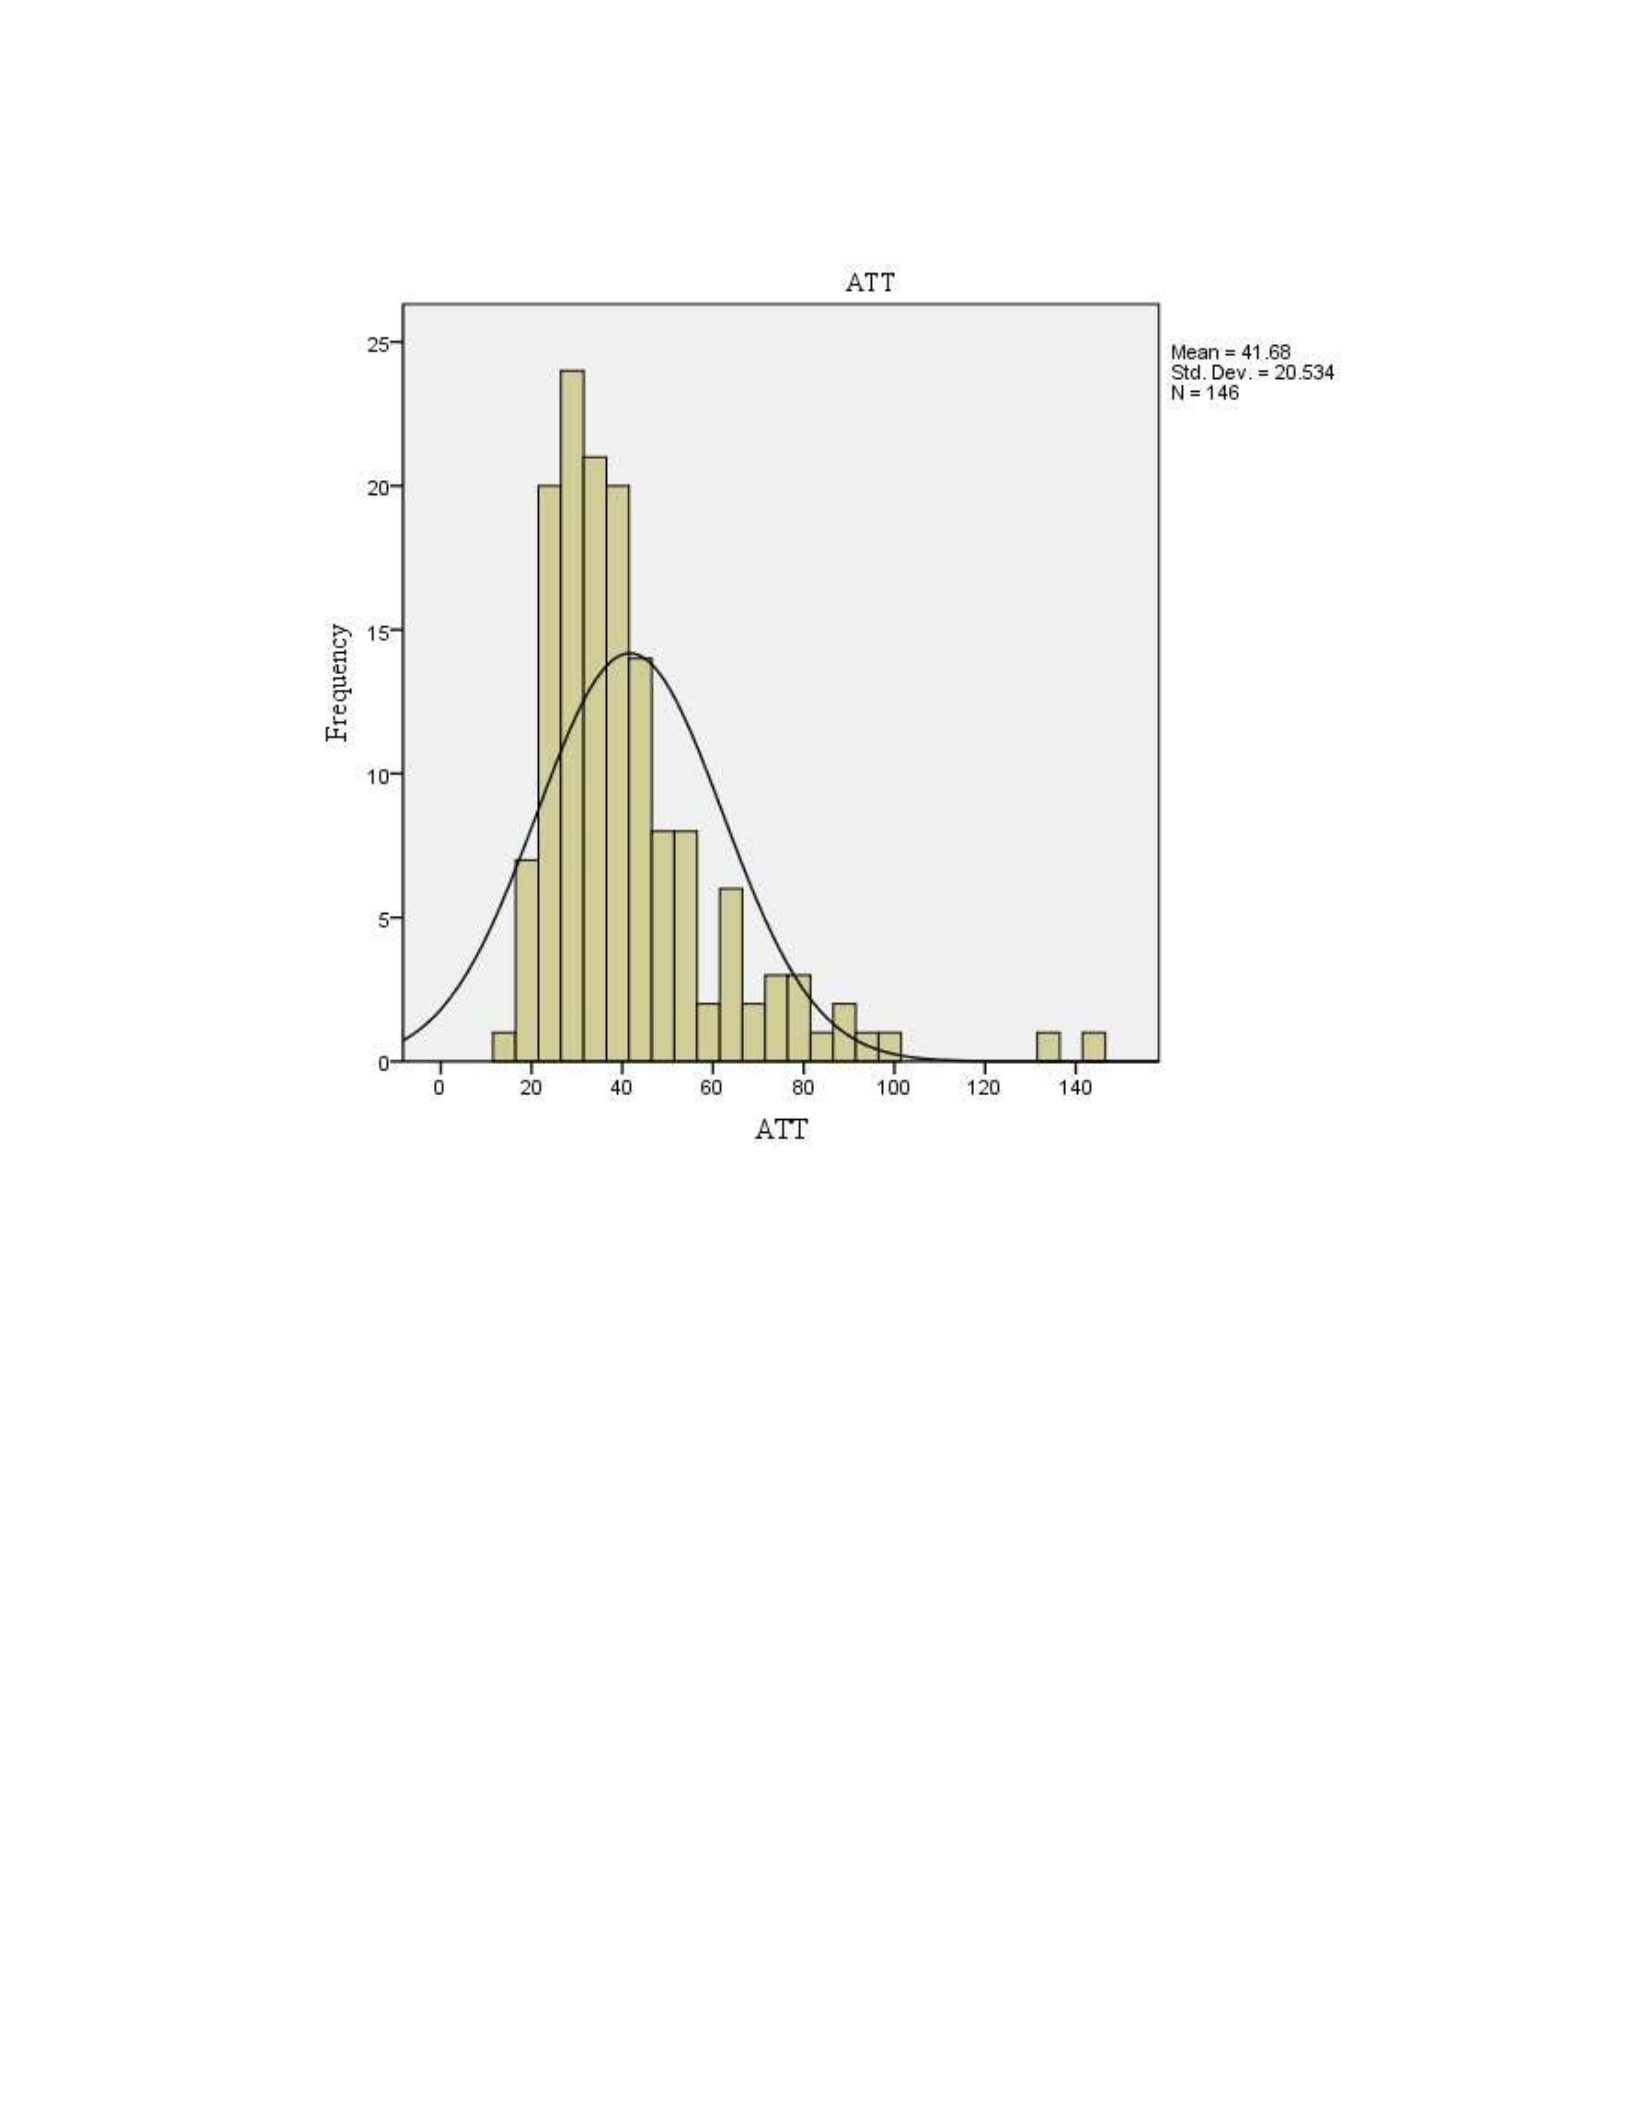
69
Figure 3. Histogram of average turnaround time frequency
Inferential Statistics
The results of the 2 x 2 x 2 ANOVA indicated that there was no significant main
effect (F[5,140] = 0.42; p = .83); MLP, MLT, and SPT did not significantly impact ATT to
complete an RMT. There were no significant interaction effects found either. Table 7
depicts the results of the 2 x 2 x 2 ANOVA.
Table 7
2 X 2 X 2 ANOVA Results (N = 146)
70
a
Values could not be computed due to small cell sample size
Analysis of Findings
The theoretical framework I used in
this study was a proposition supported with
theories such as TOC and thinking process to
determine if MLP, MLT, and SPT impacted ATT during the completion of an RMT from
origination to funding. The theoretical proposition required me to develop constructs I
could use to determine the significance of any impacts between MLP, MLT, SPT, and ATT
in an RMT. The first independent variable, MLP, was not significant in this study,
although other researchers have determined it to be significant in relation to mortgage
pricing, denial rates, and loan performance (Al-Bahrani & Su, 2015; Downs & Shi, 2015;
Li & Goodman, 2015). Also, previous scholars have identified statistical significance
between purchase MLPs and regulations, risk, and capacity (Neuhauser, 2015; Serrano-
Variable
df
F
η
p
MLP
1
.135
.001
.714
MLT
1
.837
.006
.362
SPT
1
.016
.000
.900
MLP*MLT
1
.257
.002
.613
MLP*SPT
1
.063
.000
.802
MLT*SPTa
0
MLP*MLT*SPTa
0

71
Cinca et al., 2015; Sharpe & Sherlund, 2015). However, in this study, purchase MLPs did
not indicate statistical significance as an interaction effect with the dependent variable,
ATT. Moreover, previous scholars found that MLP and market activity relationships were
statistically significant (Bhutta et al., 2016; Curtis, 2014; Zou, 2016). Although in this
study, purchase MLPs indicated greater market activity than refinance MLPs, there was no
statistical significance to market activity regarding ATT.
Analysis from earlier researchers also showed that significant statistical
relationships existed between MLP and origination activity, costs, and decision-making
(Agarwal, Ben-David, et al., 2017; Al-Bahrani & Su, 2015; Downs & Shi, 2015). Downs
and Shi (2015) found a significant difference between purchase and refinance MLPs,
favoring purchase MLPs. My findings confirmed this statistic in that the selected
mortgage organization data showed a significant difference in nominal MLP levels (see
Table 5). Al-Bahrani and Su (2015) found that MLP influenced mortgage pricing at the
refinance level, while Agarwal, Ben-David et al. (2017) assessed the NPV of costs. Both
prior studies resulted in statistically significant findings among the relationships.
Understanding the relationship between MLP and RMT outcomes may allow mortgage
managers additional data to make improved decisions regarding capacity, risk, and
regulation while working towards continuous process improvements.
Prior researchers have evaluated MLT (the second independent variable in this
study) and various RMT characteristics and have found statistical significance in their
respective findings (Lang & Hurst, 2014; Park K. A., 2016; Rose, 2016). The statistical
significance in the earlier scholars’ research showed that managers’ decisions pertaining to

72
loan type offered effective debt management strategies and lower costs when borrowers
chose conventional MLTs rather than government MLTs. This borrower decision increased
risk and pricing of government MLTs for down payments less than 20%. In this study,
MLT, on either nominal level, did not indicate any statistical significance in regard to
completing an RMT from origination to funding. However, the frequencies of MLT
nominal levels were the closest among the three independent variables with government
MLTs greater than conventional MLTs (see Table 5). My study data supports the MLT
frequency statistic because the higher percentage of government MLTs indicates the
inability of potential mortgage consumers to realize a 20% down payment as needed for
conventional MLTs.
Scholars also have examined MLT nominal levels in conjunction with industry
performance metrics, such as foreclosure rates and regulations (Bhutta et al., 2016;
Orzechowski, 2017; Shindelar, 2015). These scholars analyzed data between 2009 and
2015 and determined that increase in government MLTs had not influenced the rate of
foreclosures; however, the ability of MLT characteristics to predict regulatory changes,
such as the FFR, showed significance. In this study, MLT as an independent variable did
not indicate statistical significance in RMT performance.
The increase in mortgage costs is a concern for all parties involved in an RMT,
especially purchase customers who seek to limit cash outflows for physical real estate
investments (Aksoy et al., 2016; Caplin et al., 2015; Reiss, 2016). Prior scholars’ have
found that the greater the LTV of government MLTs, the greater the risk of default; hence,
the stringent decision-making necessary to maintain homeownership sustainability leading

73
to lower mortgage costs. Moreover, previous researchers showed how minimum wage
changes impacted MLT choice from mortgage customers (Dettling & Hsu, 2017).
Thus, I found that a borrower’s ability to afford a conventional MLT was limited and that
conventional MLTs are not as frequent as government MLTs (see Table 5).
Previous researchers indicated that there was a statistically significant relationship
between SPT nominal levels and various industry metrics, which included liquidity,
homeownership rates, and market shifts (Blau et al., 2015; Glascock & Lu-Andrews,
2015; Grover & Grover, 2014). These scholars found that liquidity, ownership rates, and
market changes determined specific investment behaviors of real estate investors.
However, SPT characteristics in my study did not indicate any statistical significance to
complete an RMT. In contrast to the analysis of Grover and Grover (2014), who indicated
that Eastern EU members had high homeownership rates, yet low financing rates, my data
analysis yielded a more significant percentage of owner-occupied SPT transactions (see
Table 5).
Many scholars have associated and evaluated real estate investment trends and the
impact on SPT characteristics. My findings indicated a higher percentage of
owneroccupied SPTs, whereas Ribeiro-Ferreira (2016) showed that, in the Australian real
estate market, non-owner-occupied property investments rose with the evolution of the
mortgage industry. Additionally, prior scholars found that specific non-owner-occupied
SPT characteristics predicted, with statistical significance, depreciation in the several
types of non-owner-occupied SPTs, such as office/retail, industrial, and multifamily
properties.

74
In this study, the findings that resulted for ATT indicated consistency in the
mortgage industry as related to prior research. In previous research, Bhutta et al. (2016)
yielded a 50-day turnaround time to complete an RMT. My findings showed improvement
of this metric, yielding a 42-day ATT. However, Bhutta et al. included a more substantial
amount of archival data records from the HMDA database. Also, previous scholars
indicated that automated scheduling and queueing algorithms helped to reduce ATT in
workflow processes (Tani & El-Amrani, 2017; Wang et al., 2016). Also, Gupta et al.
(2017) evaluated the scheduling algorithms between a multi-queue workflow system and
found that algorithms could improve ATT. Although the selected categorical, independent
variables did not yield results of statistical significance to ATT in an RMT, process
improvements should remain as priorities for organizations to meet consumer demand.
Applications to Professional Practice
Since the advent of mobile technology and as society progresses into the future,
consumers will demand more user-friendly technology for more efficient mortgage
transactions, continually, while LOs seek to mitigate financial risks (Asal, 2018;
Blackwell & Kohl, 2018; Li, Skouri, Teng, & Yang, 2018). In 2018, Blackwell and Kohl
studied the typology of housing financing systems. Blackwell and Kohl determined four
ideal systems that included person-to-person, state, deposit-based, and bond-based
financing systems. Also, in 2018, Li et al. analyzed various trade credit payment options
to mitigate default risks by the buyers and the impact on seller profitability. Li et al. found
a minimal profitability impact to demand from sellers who requested advanced payments
versus credit payments using trade credit financing. Moreover, in 2018, Asal analyzed

75
Swedish housing price data between the first quarter of 1986 and the last quarter of 2016,
controlled with affordability, demographics, and price effects. Asal found a direct
statistical relationship between a long-run indicator, housing prices, and a shortterm
dynamic metric, disposable income, affecting financing decisions. Thus, researching the
alternative mortgage characteristics that impact ATT while investing in innovative
technologies to improve customer relationships will provide LOs with more efficient
processes to reduce costs and to increase stakeholder value.
Mortgage managers can apply the findings of this study to make operational and
technological advancements to the current mortgage process, in respective organizations.
Based on the results of this study, I found that not all theoretical propositions accurately
gave an analysis of the impact on a specific outcome. The relevance of these study
findings as related to mortgage business practices offered a gap in knowledge between
research and practice. The association between research, such as TOC and thinking
process, and mortgage lending using MLP, MLT, and SPT to evaluate the impact on ATT
to complete an RMT from origination to funding offers managers applicable business and
research findings in areas of risk, capacity, efficiency, and value.
Additionally, alternative research characteristics such as communication between
borrower and lender will offer LOs increased knowledge of respective mortgage
consumers. Xu and Chau (2018) researched the impact of communications between
borrower and lender in successful peer-to-peer lending transactions. Xu and Chau found
an indirect relationship between lender comments and funding success while a direct

76
relationship between borrower responses to lender comments and funding success. Hence,
efficient communications between borrower and lender impact funding rates, or ATT.
The mortgage industry is evolving as technological tools expand organizational
reach to the market. A manager’s ability to minimize risk and maximize resources to
capitalize on technological advances may provide an increase in profitability and intrinsic
value. Understanding the relationship between various RMT characteristics may also
provide mortgage managers with data to make necessary changes at the right time as
previous research showed. Moreover, comprehending when and how to implement the
change is critical to successful and efficient operations. Therefore, making necessary
adjustments, knowing how to adjust, and implementing the adjustment to mortgage
operations may deliver improved results in RMT outcomes.
Implications for Social Change
Social change in the mortgage industry derives from geopolitical, socioeconomic,
and environmental factors in which lawmakers react via policy-making; and most often,
too slow to impede crises (Emin, 2018; Graff, 2018). In 2018, Graff examined and
measured the performance metrics of homeownership policies, namely Roosevelt-era
housing policies and Clinton-era housing policies. Graff defined two metrics being
government homeownership rates and mortgage market financial frictions. Furthermore,
in 2018, Emin researched the effects of crisis origin countries on global finance and trade.
Emin used statistical relationships between correlation data that found investors liquidate
holdings in crisis originated countries, which cause financial shocks in the investor’s
home country. The researchers showed that geopolitical, socioeconomic, and

77
environmental factors impact global financing; thus, impacting retail financing.
Mitigating crises risk and market frictions will offer LOs incentives to provide mortgage
customers with most effective technologies to complete RMTs more efficiently,
considering mortgage debt to be the most significant percentage of consumer investment
portfolios.
A real estate transaction is the most valuable asset an individual will have in their
respective investment portfolios, and the ability to transact real estate efficiently supports
socio-economic improvements. In 2018, Shichor investigated the social impacts of the
unethical and illegal activities and the lack of criminal sanctions against guilty parties.
Shichor found that judges and lawmakers imposed minimal penalties against guilty
parties. The propositions for positive social change included the possibility to provide
value to mortgage stakeholders, who include customers, employees, managers,
government agencies, shareholders, and third-party vendors, with process improvements
to enhance mortgage business attractiveness and reduce costs. Mortgage managers
application of effective processes may lead to improved industry reputation, technological
process advancements, reduced employee moral hazard, and increased intrinsic value.
Realistic and logical implications are that mortgage leaders can apply this study to obtain
a better understanding of ways to improve the overall retail mortgage transaction
processes from origination to funding.
Recommendations for Action
Continuous improvement is the most common goal in all production-based
organizations. The results from this study are relevant to mortgage lenders, and I

78
recommend that industry decision-makers research and implement technological process
improvements to the mortgage process that focuses on reducing ATT to complete an RMT
from origination to funding. The independent variables, MLP, MLT, and SPT, are
significant about decision-making, capacity constraints, and profitability while the
dependent variable is significant to improve efficiency and reduce costs.
The successful implementation of process advancements may help lending
managers to enhance employee-customer relationships. Mortgage institutional
decisionmakers should apply findings of this study to business processes to improve on
ATT to complete RMTs from origination to funding. The earlier research and current
findings support the need for industry leaders to consider technological advancements in
information processing and verification to complete RMTs more efficiently and
effectively to increase intrinsic value.
I will share my study results with other industry colleagues and professionals
through scholarly journal publications. Additionally, I will share the results through
training courses and seminars regarding technological RMT process enhancements. My
focus will be on assisting institutional leaders to reduce costs, improve ATT, and increase
intrinsic value for organizational stakeholders.
Recommendations for Further Research
I offer the following areas for future research on the topic of mortgage
characteristics impacting completion times. Recommendations for further research include
identifying additional mortgage characteristics, such as default rates, regulatory controls,
and secondary market investors, which will allow for other statistical analyses, such as

79
multivariate regression analysis. Moreover, a future scholar could use interest rates as an
independent variable or a control variable. Further recommendations include a more
extensive dataset and multiple organizations to analyze and interpret results more
significantly that limited the statistical findings of this study.
Also, future scholars should conduct further research to examine ATT and the
relationship to alternative mortgage metrics not covered in the scope of this study.
Performing future studies about ATT could help mortgage leaders with the data necessary
to make the proper adjustments to workflow processes. Moreover, considering this study
focused on a single mortgage institution in the state of Florida, future scholars should
acquire data outside the state to compare any relevance or statistical significances.
Reflections
The DBA Doctoral Study process was a motivating and humbling experience for
me. This DBA Doctoral Study process was a challenge for me to balance work, home, and
school while recovering from an economic disaster. Each procedure required of me to be
meticulous to ensure that I met and exceeded the Walden University requirements of a
rigorous process. Attention to detail is necessary to complete the various steps along the
process, including meeting the DBA rubric requirements from committee members, the
IRB process, and conforming to APA guidelines. Exceeding the requirements offered an
implication of higher academic recognition by writing and communicating with peers and
professionals.
Investing the time to complete a retail mortgage transaction from origination to
funding is a personal objective of mine, considering my employment history in the

80
mortgage business. As a licensed mortgage loan originator for over 25 years, this topic is
essential to determine expectations for your customers and improve efficiency metrics for
the organization. The results pertaining to the independent variables of this research study
were typical to my personal experiences in the industry as the majority of my clients were
owner-occupant borrowers seeking either conventional or government financing. The
findings for ATT were also better than average from my experiences in the mortgage
industry and examined research.
Conclusion
The explicit goal of this study was to determine if specific mortgage
characteristics, such as MLP, MLT, and SPT impacted ATT to complete an RMT from
origination to funding. The results of this study showed that I fail to reject the null
hypothesis because of the lack of significance between the independent, nominal variables
and the dependent, interval variable. Although, the data conformed to industry averages as
the frequencies of the independent variable confirmed the economic lending environment
in the state of Florida. Owner-occupant, government-insured, purchase mortgages are still
dominating the industry and maintaining market share since the 2008-
2009 financial crisis.
Moreover, the results of this study substantiate and reinforce the theoretical
framework and supportive theories of throughput (TOC) and process improvements
(Thinking Process). Even though the data yielded insignificance, the data results may lead
to further research to improve upon workflow completion times in the mortgage industry.

81
The general idea to improve ATT was to improve the overall intrinsic value of the
organization for all stakeholders.

82
References
Abosag, I., Yen, D. A., & Barnes, B. R. (2016). What is dark about the dark-side of
business relationships? Industrial Marketing Management, 55, 5-9.
doi:10.1016/j.indmarman.2016.02.008
Acemoglu, D., Johnson, S., Kermani, A., Kwak, J., & Mitton, T. (2016). The value of
connections in turbulent times: Evidence from the United States. Journal of
Financial Economics, 121, 368-391. doi:10.1016/j.jfineco.2015.10.001
Adeleye, I. (2015). Accelerating corporate transformation in emerging markets: The case
of FirstBank. South Asian Journal of Business and Management Cases, 4(2), 182-
191. doi:10.1177/2277977915596247
Adelino, M., Gerardi, K., & Hartman-Glaser, B. (2016). Are lemons sold first? Dynamic
signaling in the mortgage market (Working Paper 2016-8b). Retreived from
Federal Reserve Bank of Atlanta website: https://www.frbatlanta.org/research
/publications/wp/2016/08-are-lemons-sold-first-dynamic-signaling-in-
themortgage-market-2016-07-18
Agarwal, S., Ben-David, I., & Yao, V. (2017). Systematic mistakes in the mortgage market
and lack of financial sophistication. Journal of Financial Economics, 123,
42-58. doi:10.1016/j.jfineco.2016.01.028
Agarwal, S., Chomsisengphet, S., & Zhang, Y. (2017). How does working in finance
profession affect mortgage delinquency? Journal of Banking and Finance, 78, 1-
13. doi:10.1016/j.jbankfin.2017.01.019

83
Akins, B., Li, L., Ng, J., & Rusticus, T. O. (2016). Bank competition and financial
stability: Evidence from the financial crisis. Journal of Financial and
Quantitative Analysis, 51(1), 1-28. doi:10.1017/S0022109016000090
Aksoy, L., Keiningham, T. L., Buoye, A., & Ball, J. (2016). Relative value and customer
choice in loan decisions: An application of the wallet allocation rule. Journal of
Creating Value, 2(1), 92-108. doi:10.1177/2394964316630403
Al-Bahrani, A., & Su, Q. (2015). Determinants of mortgage pricing: A quantile regression.
Journal of Housing Economics, 30, 77-85.
doi:10.1016/j.jhe.2015.10.005
Al-Thani, T., & Semmar, Y. (2017). An exploratory study of teachers' perceptions of
prosocial behaviors in preschool children. International Journal of Educational
Development, 53, 145-150. doi:10.1016/j.ijedudev.2017.01.005
Amadi-Echendu, A. P., & Pellissier, R. (2014). Eliminating bottlenecks in the South
African conveyancing environment. Mediterranean Journal of Social Sciences,
5(14), 97-103. doi:10.5901/mjss.2014.v5n14p97
Ambrose, B. W., & Conklin, J. N. (2014). Mortgage brokers, origination fees, price
transparency and competition. Real Estate Economics, 42, 363-421.
doi:10.1111/1540-6229.12039
Ametefe, F., Devaney, S., & Marcato, G. (2016). Liquidity: A review of dimensions,
causes, measures, and empirical applications in real estate markets. Journal of
Real Estate Literature, 24, 3-29. doi:10.1007/s10901-014-9399-0
Asal, M. (2018). Long-run drivers and short-term dynamics of Swedish real house prices.
International Journal of Housing Markets and Analysis, 11, 45-72.

84
doi:10.1108/IJHMA-08-2017-0070
Atencia, I. (2014). A discrete-time system with service control and repairs. International
Journal of Applied Mathematics and Computer Science, 24, 471-484.
doi:10.2478/amcs-2014-0035
Aziz, Z., & Hassan, B. A. (2017). The effects of honey compared to silver sulfadiazine for
the treatment of burns: A systematic review of randomized controlled trials.
Burns, 43, 50-57. doi:10.1016/j.burns.2016.07.004
Aznar, J. P., Sayeras, J. M., Rocafort, A., & Galiana, J. (2017). The irruption of Airbnb
and its effects on hotel profitability: An analysis of Barcelona's hotel sector.
Intangible Capital, 13, 147-159. doi:10.3926/ic.921
Bailey, L. F. (2014). The origin and success of qualitative research. International Journal
of Market Research, 56, 167-184. doi:10.2501/IJMR-2014-013
Bakare, S. (2016). Banking, mortgage and the credit industry in the USA. Journal of
Internet Banking and Commerce, 21, 1-21. Retrieved from
http://www.icommercecentral.com/
Bapat, D. (2015). Union experience: Towards excellence in retail banking. Decision, 42,
335-345. doi:10.1007/s40622-015-0095-z
Barraclough, P., af Wahlberg, A., Freeman, J., Watson, B., & Watson, A. (2016).
Predicting crashes using traffic offences: A meta-analysis that examines potential
bias between self-report and archival data. PLoS ONE, 11(4), 1-32.
doi:10.1371/journal.pone.0153390

85
Barrutia, J. M., & Espinosa, M. P. (2014). Consumer expertise matters in price
negotiation: An empirical analysis of the determinants of mortgage loan prices in
Spain prior to the financial crisis. European Journal of Marketing, 48, 1962-1985.
doi:10.1108/EJM-04-2013-0208
Baumeister, R. F. (2013). Writing a literature review. In R. F. Baumeister, & M. J.
Prinstein (Ed.), The Portable Mentor: Expert guide to a successful career in
Psychology (2nd ed., pp. 119-132). New York, NY: Springer Science & Business
Media. doi:10.1007/978-1-4614-3994-3_8
Bellotti, A. (2017). Reliable region predictions for automated valuation models. Annals of
Mathematics and Artificial Intelligence. doi:10.1007/s10472-016-9534-6
Bensadoun, A., Monod, H., Makowski, D., & Messean, A. (2016). A Bayesian approach to
model dispersal for decision support. Environmental Modelling & Software, 78,
179-190. doi:10.1016/j.envsoft.2015.12.018
Berg, T. (2015). Playing the devil's advocate: The causal effect of risk management on
loan quality. Review of Financial Studies, 25, 3367-3406. doi:10.1093/rfs/hhv040
Bhutta, N., Ringo, D. R., & Kelliher, J. (2016). Residential mortgage lending from 2004
to 2015: Evidence from the Home Mortgage Disclosure Act data. Federal Reserve
Bulletin, 102(6), 1-26. Retrieved from
http://www.federalreserve.gov/pubs/bulletin/
Blackwell, T., & Kohl, S. (2018). The origins of national housing finance systems: A
comparative investigation into historical variations in mortgage finance regimes.
Review of International Political Economy, 25, 49-74.

86
doi:10.1080/09692290.2017.1403358
Blau, B. M., Nguyen, N., & Whitby, R. J. (2015). The distribution of REIT liquidity.
Journal of Real Estate Literature, 23, 233-252. doi:10.2139/ssrn.2274391
Bokhari, S., & Geltner, D. (2016). Characteristics of depreciation in commercial and
multi-family property: An investment perspective. Real Estate Economics, 1-57.
doi:10.1111/1540-6229.12156
Bordo, M. D. (2014). Rules for a lender of last resort: An historical perspective. Journal
of Economic Dynamics and Control, 49, 126-134. doi:10.1016/j.jedc.2014.09.023
Borgia, M. S. (2013). The social report as a tool of ethical governance in cooperative
banking. Megatrend Review, 10(3), 139-154. Retrieved from
http://megatrendreview.naisbitt.edu.rs/index.php/sr/
Bosco, F. A., Aguinis, H., Singh, K., Field, J. G., & Pierce, C. A. (2015). Correlational
effect size benchmarks. Journal of Applied Psychology, 100, 431-449.
doi:10.1037/a0038047
Bradley, D., Gokkaya, S., & Liu, X. (2017). Before an analyst becomes an analyst: Does
industry experience matter? The Journal of Finance, 72, 751-792.
doi:10.1111/jofi.12466
Brueckner, J. K., Calem, P. S., & Nakamura, L. I. (2016). House-price expectations,
alternative mortgage products, and default. Journal of Money, Credit & Banking,
48, 81-112. doi:10.1111/jmcb.12291

87
Bylander, M., & Hamilton, E. (2015). Loans and leaving: Migration and the expansion of
microcredit in Cambodia. Population Research & Policy Review, 34, 687-708.
doi:10.1007/s11113-015-9367-8
Cairney, P., & St Denny, E. (2015). Reviews of what is qualitative research and what is
qualitative interviewing. International Journal of Social Research Methodology:
Theory & Practice, 18, 117-125. doi:10.1080/13645579.2014.957434
Call-Cummings, M. (2017). Establishing communicative validity: Discovering theory
through practice. Qualitative Inquiry, 23, 192-200.
doi:10.1177/1077800416657101
Çankaya, M. N. (2016). Propositions for confidence interval in systematic sampling on
real line. Entropy, 18, 352-373. doi:10.3390/e18100352
Cao, Q., & Liu, S. (2016). The impact of state foreclosure and bankruptcy laws on higher-
risk lending: Evidence from FHA and subprime mortgage originations.
Journal of Real Estate Research, 38, 505-537. doi:10.2139/ssrn.2586873
Cap, P. (2017). Studying ideological worldviews in political discourse space:
Criticalcognitive advances in the analysis of conflict and coercion. Journal of
Pragmatics, 108, 17-27. doi:10.1016/j.pragma.2016.11.008
Caplin, A., Cororaton, A., & Tracy, J. (2015). Is the FHA creating sustainable
homeownership? Real Estate Economics, 43, 957-992. doi:10.1111/1540-
6229.12106
Carswell, A. T., & Babiarz, P. (2016). Benefit-cost analysis and optimization modeling for
a seller/builder buydown mortgage. Journal of Real Estate Practice and

88
Education, 19, 87-97. Retrieved from http://aresjournals.org/loi/repe
Ciabuschi, F., Forsgren, M., & Martín, O. M. (2017). Value creation at the subsidiary
level: Testing the MNC headquarters parenting advantage logic. Long Range
Planning, 50, 48-62. doi:10.1016/j.lrp.2016.03.004
Clayton, M. F., Supiano, K., Wilson, R., Lassche, M., & Latendresse, G. (2017). Using
simulation in nursing PhD education: Facilitating application of responsible
conduct of research principles. Journal of Professional Nursing, 33, 68-73.
doi:10.1016/j.profnurs.2016.05.010
Coletti, D., Gosselin, M.-A., & MacDonald, C. (2016). The rise of mortgage finance
companies in Canada: Benefits and vulnerabilities. Financial System
Review(December), 39-52. Retrieved from
http://www.bankofcanada.ca/publications/fsr/
Cotteleer, M. J., & Wan, X. (2016). Does the starting point matter? The literature-driven
and phenomenon-driven approaches of using corporate archival data in academic
research. Journal of Business Logistics, 37, 26-33. doi:10.1111/jbl.12114
Cox, R., Brounen, D., & Neuteboom, P. (2015). Financial literacy, risk aversion and
choice of mortgage type by households. Journal of Real Estate Finance &
Economics, 50, 74-112. doi:10.1007/s11146-013-9453-9
Curtis, Q. (2014). State foreclosure laws and mortgage origination in the subprime.
Journal of Real Estate Finance & Economics, 49, 303-328. doi:10.1007/s11146-

89
013-9437-9 de Sivatte, I., Gordon, J. R., Rojo, P., & Olmos, R. (2015). The
impact of work-life culture on organizational productivity. Personnel Review, 44,
883-905.
doi:10.1108/PR-12-2013-0226
DeLisle, J. R. (2015). Uncertain times with business as unusual. The Appraisal Journal,
83(4), 272-288. Retrieved from
http://www.myappraisalinstitute.org/taj/default.aspx
DeSimone, J. A., Harms, P. D., & DeSimone, A. J. (2015). Best practice recommendations
for data screening. Journal of Organizational Behavior, 36,
171-181. doi:10.1002/job.1962
Dettling, L. J., & Hsu, J. W. (2017). Minimum wages and consumer credit: Impacts on
access to credit and traditional and high-cost borrowing. U.S. Federal Reserve
Board's Finance & Economic Discussion Series, 1-40.
doi:10.17016/FEDS.2017.010
Dobbin, K. K., & Ionan, A. C. (2015). Sample size methods for constructing confidence
intervals for the intra-class correlation coefficient. Computational Statistics and
Data Analysis, 85, 67-83. doi:10.1016/j.csda.2014.11.010
Dodson, C. (2014). Bank size, lending paradigms, and usage of Farm Service Agency's
guaranteed loan programs. Agricultural Finance Review, 74, 133-152.
doi:10.1108/AFR-01-2013-0002
Downs, D. H., & Shi, L. (2015). The impact of reversing regulatory arbitrage on loan
originations: Evidence from bank holding companies. Journal of Real Estate

90
Finance & Economics, 50, 307-338. doi:10.1007/s11146-014-9468-x
Eckstein, A. (2015). Great expectations: The peril of an expectations gap in proxy
advisory firm regulation. Delaware Journal of Corporate Law, 40, 77-162.
doi:10.2139/ssrn.2469158
Eisenhardt, K. M., Graebner, M. E., & Sonenshein, S. (2016). Grand challenges and
inductive methods: Rigor without rigor mortis. Academy of Management Journal,
59, 1113-1123. doi:10.5465/amj.2016.4004
Ellie Mae, Inc. (2016). Origination Insight Report. Pleasanton, CA: Ellie Mae, Inc.
Retrieved from http://www.elliemae.com/resources/origination-insight-reports
Emin, D. (2018). A policymaker's dilemma: Real linkages or irrational behaviors?
Journal of Financial Economic Policy, 10, 185-200. doi:10.1108/JFEP-05-2017-
0037
Endo, T., Watanabe, T., & Yamamoto, A. (2015). Confidence interval estimation by
bootstrap method for uncertainty quantification using random sampling method.
Journal of Nuclear Science and Technology, 52, 993-999.
doi:10.1080/00223131.2015.1034216
Ertürk, M. (2014). Determinants and effects of innovation on the firm level: An empirical
investigation. International Journal of Research in Business and Social Science,
3, 118-129. Retrieved from http://www.ssbfnet.com/ojs/index.php/ijrbs
Faul, F., Erdfelder, E., Buchner, A., & Lang, A.-G. (2009). Statistical power analyses
using G*Power 3.1.9.2: Test for correlations and regression analyses. Behavior
Research Methods, 41, 1149-1160. Retrieved from
http://www.gpower.hhu.de/en.html

91
Feng, Y., Fan, X., & Yoon, Y. (2015). Lenders and borrowers' strategies in online peerto-
peer lending market: An empirical analysis of ppdai.com. Journal of Electronic
Commerce Research, 16, 242-260. Retrieved from http://www.jecr.org/
Firoozi, M. R., Kazemi, A., & Jokar, M. (2017). The role of socio-cognitive variables in
predicting learning satisfaction in smart schools. International Electronic Journal
of Elementary Education, 9, 613-626. Retrieved from www.iejee.com
Freybote, J., Ziobrowski, A. J., & Gallimore, P. (2014). Residential real estate appraisal
bias in the absence of client feedback. Journal of Housing Research, 23, 127-142.
doi:10.5555/jhor.23.2.t148613586rmpx64
Gallagher, R. M. (2016). The fiscal externality of multifamily housing and its impact on
the property tax: Evidence from cities and schools, 1980-2010. Regional Science
and Urban Economics, 60, 249-259. doi:10.1016/j.regsciurbeco.2016.07.012
George, G., Haas, M. R., & Pentland, A. (2014). Big data and management. Academy of
Management Journal, 57, 321-326. doi:10.5465/amj.2014.4002
Gibilaro, L., & Mattarocci, G. (2016). Are real estate banks more affected by real estate
market dynamics? International Real Estate Review, 19(2), 151-170. Retrieved
from http://www.umac.mo/fba/irer/
Gibson, C. B. (2017). Elaboration, generalization, triangulation, and interpretation: On
enhancing the value of mixed method research. Organizational Research
Methods, 20, 193-223. doi:10.1177/1094428116639133
Glascock, J. L., & Lu-Andrews, R. (2015). The price behavior of REITs surrounding
extreme market-related events. Journal of Real Estate Finance & Economics, 51,

92
441-479. doi:10.1007/s11146-015-9495-2
Gligor, D. M., Esmark, C. L., & Holcomb, M. C. (2015). Performance outcomes of supply
chain agility: When should you be agile? Journal of Operations
Management, 33-34, 71-82. doi:10.1016/j.jom.2014.10.008
Gokkaya, S., Highfield, M. J., Roskelley, K., & Steele, D. F. (2015). An examination of
primary and secondary market returns in equity REIT IPOs. Journal of Real
Estate Research, 37, 23-64. doi:10.2139/ssrn.2127880
Goldratt, E. M., & Cox, J. (1984). The Goal: A Process of Ongoing Improvement. Great
Barrington, MA: North River Press.
Golmohammadi, D., & Mansouri, S. A. (2015). Complexity and workload considerations
in product mix decisions under the theory of constraints. Naval Research
Logistics, 62, 357-369. doi:10.1002/nav.21632
Graff, R. A. (2018). Measuring performance of US homeownership policies past and
present. International Journal of Housing Markets and Analysis, 11, 173-203.
doi:10.1108/IJHMA-05-2017-0051
Griffin, J. M., & Maturana, G. (2016). Who facilitated misreporting in securitized loans?
Review of Financial Studies, 29, 384-419. doi:10.1093/rfs/hhv130
Grover, R., & Grover, C. (2014). The role of house price indices in managing the
integration of finance and housing markets in the European Union. Journal of
European Real Estate Research, 7, 270-294. doi:10.1108/JERER-02-2014-0013
Guillemin, M., McDougall, R., Martin, D., Hallowell, N., Brookes, A., & Gillam, L.
(2017). Primary care physicians' views about gatekeeping in clinical research
recruitment: A qualitative study. AJOB Empirical Bioethics, 8(2), 99-105.

93
doi:10.1080/23294515.2017.1305007
Guo, S. (2015). Shaping social work science: What should quantitative researchers do?
Research on Social Work Practice, 25, 370-381. doi:10.1177/1049731514527517
Gupta, A. K., Yadav, N. S., & Goyal, D. (2017). Design and performance evaluation of
smart job first multilevel feedback queue (SJFMLFQ) scheduling algorithm with
dynamic smart time quantum. International Journal of Multimedia Data
Engineering and Management, 8, 50-64. doi:10.4018/IJMDEM.2017040106
Hales, P. D. (2016). Changing perspectives: Validation framework review of examples of
mixed methods research into culturally relevant teaching. Multicultural Education
Review, 8, 195-210. doi:10.1080/2005615X.2016.1184020
Hall, P. (2015). Mortgage origination overhaul looms. ABA Banking Journal, 107(1), 38-
40. Retrieved from http://bankingjournal.aba.com/
Harrison, D. M., & Seiler, M. J. (2015). The paradox of judicial foreclosure: Collateral
value uncertainty and mortgage rates. Journal of Real Estate Finance &
Economics, 50, 377-411. doi:10.1007/s11146-014-9467-y
Houghton, T. (2016). Establishing effective working relationships. Nursing Standard,
30(26), 41-48. Retrieved from http://journals.rcni.com/journal/ns
Hu, Y., Schmeits, M. J., van Andel, S. J., Verkade, J. S., Xu, M., Solomatine, D. P., &
Liang, Z. (2016). A stratified sampling approach for improved sampling from a
calibrated ensemble forecast distribution. Journal of Hydrometeorology, 17,
2405-2417. doi:10.1175/JHM-D-15-0205.1
Huang, H., & Savkin, A. V. (2017). Aan energy efficient approach for data collection in
wireless sensor networks using public transportation vehicles. International

94
Journal of Electronics and Communications, 75, 108-118.
doi:10.1016/j.aeue.2017.03.012
Huck, S. (2012). Reading Statistics and Research. Boston, MA: Pearson Education, Inc.
Ivanov, I. T., & Wang, J. Z. (2017). The effect of supervisory loan ratings on syndicated
lending. Federal Reserve Board, 1-42. doi:10.2139/ssrn.2929670
Jakobsen, T. G. (2016). Environmental ethics: Anthropocentrism and
nonanthropocentrism revised in the light of critical realism. Journal of Critical
Realism, 16, 184-199. doi:10.1080/14767430.2016.1265878
Kaplan, A. (2015). Opinion: Paradigms, methods, and the (as yet) failed striving for
methodological diversity in educational psychology published research. Frontiers
in Psychology, 6(1370), 1-4. doi:10.3389/fpsyg.2015.01370
Khan, M. (2016). A generalized class of exponential type estimators for population mean
under systematic sampling using two auxiliary variables. Journal of Probability
and Statistics, 2016, 1-6. doi:10.1155/2016/2374837
Khan, Z., Shabbir, J., & Gupta, S. (2015). Generalized systematic sampling.
Communications in Statistics - Simulation and Computation, 44, 2240-2250.
doi:10.1080/03610918.2013.800209
Kim, B., Tunas, N., & Green, A. (2016). Analyzing risks for home loans during financial
crisis of 2008 using data mining. Issues in Information Systems , 17(1), 206-211.
Retrieved from http://www.iacis.org/index.php

95
Koskey, K. L., & Stewart, V. C. (2014). A concurrent mixed methods approach to
examining the quantitative and qualitative meaningfulness of absolute magnitude
estimation scales in survey research. Journal of Mixed Methods Research, 8, 180-
202. doi:10.1177/1558689813496905
Krahmer, D., & Strausz, R. (2015). Optimal sales contracts with withdrawal rights.
Review of Economic Studies, 82(2), 762-790. doi:10.1093/restud/rdv003
LaBonte, A. M., & Kilpatrick, H. J. (2017). A state and provincial survey of harvest
reporting and data collection methods. Human Dimensions of Wildlife, 22, 189-
195. doi:10.1080/10871209.2016.1272145
Lafontaine, S. J., Sawada, M., & Kristjansson, E. (2017). A direct observation method for
auditing large urban centers using stratified sampling, mobile GIS technology and
virtual environments. International Journal of Health Geographics, 16(6), 1-15.
doi:10.1186/s12942-017-0079-7
Lahav, T., & Zimand-Sheiner, D. (2016). Public relations and the practice of paid content:
Practical, theoretical propositions and ethical implications. Public
Relations Review, 42, 395-401. doi:10.1016/j.pubrev.2016.02.003
Lang, B., & Hurst, E. (2014). The effect of down payment assistance on mortgage choice.
Journal of Real Estate Finance & Economics, 49(3), 329-351.
doi:10.1007/s11146-013-9432-1
Lanzarini, L. C., Monte, A. V., Bariviera, A. F., & Santana, P. J. (2017). Simplifying credit
scoring rules using LVQ + PSO. Kybernetes, 46, 8-16. doi:10.1108/K-06-
2016-0158

96
Larsen, K. R., & How Bong, C. (2016). A tool for addressing construct identity in
literature reviews and meta-analyses. MIS Quarterly, 40, 529-A20. Retrieved from
http://misq.org/
Li, R., Skouri, K., Teng, J.-T., & Yang, W.-G. (2018). Seller's optimal replenishment
policy and payment term among advance, cash, and credit payments.
International Journal of Production Economics, 197, 35-42.
doi:10.1016/j.ijpe.2017.12.015
Li, W., & Goodman, L. S. (2015). A new mortgage credit availability index. Journal of
Structured Finance, 20(4), 67-83. Retrieved from
http://www.iijournals.com/toc/jsf/current
Lin, C., Shen, Z., Chen, Q., & Sehldon, F. T. (2017). A data integrity verification scheme
in mobile cloud computing. Journal of Network and Computer Applications, 77,
146-151. doi:10.1016/j.jnca.2016.08.017
Lucas, D. (2016). Credit policy as fiscal policy. Brookings Papers on Economic Activity,
1-57. Retrieved from https://www.brookings.edu/project/brookings-papers-
oneconomic-activity/
Ma, Y., Zhang, S., Lin, C., & Li, L. (2017). A data collection method based on the region
division in opportunistic networks. Applied Computational Electromagnetics
Society Journal, 32(1), 43-49. Retrieved from http://aces-society.org/
Malone, E. K., & Issa, R. R. (2013). Work-life balance and organizational commitment of
women in the U.S. construction industry. Journal of Professional Issues in
Engineering Education and Practice, 139(2), 87-98.

97
doi:10.1061/(ASCE)EI.1943-5541.0000140
Markovitch, S., & Willmott, P. (2014, May). Accelerating the digitization of business
processes. Retrieved from McKinsey&Company:
https://digitalstrategy.nl/wpcontent/uploads/2014-J-Accelerating-the-digitization-
of-business-processes.pdf
Marshall, C., & Rossman, G. B. (2015). Designing qualitative research (6th ed.).
Thousand Oaks, CA: Sage.
Mason, J. R., Imerman, M. B., & Lee, H. (2014). Self-reporting under SEC Reg AB and
transparency in securitization: Evidence from loan-level disclosure risk factors in
RMBS deals. The Journal of Risk Finance, 15, 334-384. doi:10.1108/JRF-05-
2014-0069
McCann, J., & Sweet, M. (2014). The perceptions of ethical and sustainable leadership.
Journal of Business Ethics, 121, 373-383. doi:10.1007/s10551-013-1704-4
McCarthy, C. J., Whittaker, T. A., Boyle, L. H., & Eyal, M. (2017). Quantitative
approaches to group research: Suggestions for best practices. The Journal for
Specialists in Group Work, 42, 3-16. doi:10.1080/01933922.2016.1264520
McCormick, J. L., Jackson, L. S., Carr, F. M., & Meyer, D. H. (2015). Evaluation of
probabilistic sampling designs for estimating abundance of multiple species of
migratory fish using video recordings at fishways. North American Journal of
Fisheries Management, 35, 818-826. doi:10.1080/02755947.2015.1040562
McCormick, M., & Calahan, L. (2013, December 5). Common ground: The need for a
universal mortgage loan identifier. Office of Finance Research, pp. 1-21.
Retrieved from https://www.financialresearch.gov/working-papers

98
Metawa, N., Hassan, M. K., & Elhoseny, M. (2017). Genetic algorithm based model for
optimizing bank lending decisions. Expert Systems with Applications, 80, 75-82.
doi:10.1016/j.eswa.2017.03.021
Metcalf, J. (2016). Big data analytics and revision of the common rule. Association for
Computing Machinery, 59(7), 31-33. doi:10.1145/2935882
Momeni, S., Mohammadreza, K., & Amini, R. (2017). The role of creative drama in
improving the creativity of 4-6 years old. Journal of History, Culture, and Art
Research, 6, 617-626. doi:10.7596/taksad.v6i1.765
Muthusamy, S., & Dass, P. (2014). Toward a smarter enterprise: Disaggregation and
dispersion for innovation and excellence. Competitiveness Review, 24, 211-239.
doi:10.1108/CR-12-2012-0031
Neuhauser, K. L. (2015). The global financial crisis: What have we learned so far?
International Journal of Managerial Finance, 11, 134-161. doi:10.1108/IJMF-02-
2015-0014
Neuman, A., & Guterman, O. (2016). The clash of two world views - a constructivist
analysis of home educating families' perceptions of education. Pedagogy, Culture
& Society, 24, 359-369. doi:10.1080/14681366.2016.1178664
Omoke, V., Diugwu, I. A., Nwaogbe, O. R., Ibe, C. C., & Ekpe, D. A. (2015).
Infrastructure financing and management: The impact of concession on the
operations and performance of Nigerian seaports. Journal of Behavioral
Economics, Finance, Entrepreneurship, Accounting and Transport, 3, 65-70.
doi:10.12691/jbe-3-2-1

99
Onen, D. (2016). Appropriate conceptualisation: The foundation of any solid quantitative
research. Electronic Journal of Business Research Methods, 14, 28-38. Retrieved
from www.ejbrm.com
Orzechowski, P. E. (2017). Bank capital, loan activity, and monetary policy: Evidence
from the FDIC's historical statistics on banking. Journal of Economics and
Finance, 41, 392-407. doi:10.1007/s12197-016-9359-5
Papin, T., & Turinici, G. (2014). Prepayment option of a perpetual corporate loan: The
impact of the funding costs. International Journal of Theoretical and Applied
Finance, 17(4), 1-32. doi:10.1142/S0219024914500289
Park, J., & Park, M. (2016). Qualitative versus quantitative research methods: Discovery
or justification? Journal of Marketing Thought, 3(1), 1-7.
doi:10.15577/jmt.2016.03.01.1
Park, K. A. (2016). FHA loan performance and adverse selection in mortgage insurance.
Journal of Housing Economics, 34, 82-97. doi:10.1016/j.jhe.2016.07.004
Pelser, T. G. (2014). Sustaining industry leadership through innovation strategy
archetypes. International Business & Economics Research Journal, 13, 697-714.
Retrieved from http://www.cluteinstitute.com/journals/international-
businesseconomics-research-journal-iber/
Persson, A., & Ryals, L. (2014). Making customer relationship decisions: Analytics v
rules of thumb. Journal of Business Research, 67, 1725-1732.
doi:10.1016/j.jbusres.2014.02.019

100
Petersen, M., Waal, B. D., Mukuddem-Petersen, J., & Mulaudzi, M. (2014). Subprime
mortgage funding and liquidity risk. Quantitative Finance, 14, 545-555.
doi:10.1080/14697688.2011.637076
Prystav, F. (2016). Personal information in peer-to-peer loan applications: Is less more?
Journal of Behavioral and Experimental Finance, 9, 6-19.
doi:10.1016/j.jbef.2015.11.005
Ralph, N., Birks, M., & Chapman, Y. (2015). The methodological dynamism of grounded
theory. International Journal of Quantitative Methods, 14(4), 1-6.
doi:10.1177/1609406915611576
Raza, A., Murad, H. S., & Zakar, M. Z. (2016). Contextualizing poverty and culture;
towards a social economy of community centered knowledge based development.
International Journal of Social Economics, 43, 486-501. doi:10.1108/IJSE-04-
2014-0072
Read, K. B., LaPolla, F. W., Tolea, M. I., Galvin, J. E., & Surkis, A. (2017). Improving
data collection, documentation, and workflow in a dementia screening study.
Journal of the Medical Library Association, 105, 160-166.
doi:10.5195/jmla.2017.221
Reio, T. G. (2016). Nonexperimental research: Strengths, weaknesses and issues of
precision. European Journal of Training and Development, 40, 676-690.
doi:10.1108/EJTD-07-2015-0058
Reiss, D. (2016). Underwriting sustainable homeownership: The Federal Housing
Administration and the low down payment loan. Georgia Law Review, 50, 1019-
1091. Retrieved from http://georgialawreview.org/

101
Ribeiro-Ferreira, R. (2016). Stepping stones to an exclusionary model of home ownership
in Australia. Journal of Australian Politcal Economy, 48, 79-109. Retrieved from
http://australianpe.wixsite.com/japehome
Riffe, D., Lacy, S., & Fico, F. (2014). Analyzing media messages: Using quantitative
content analysis in research (3rd ed.). New York, NY: Routledge.
Rose, C. C. (2016). Overcoming the obstacles student debt presents to the ability to buy a
home. Journal of Financial Services Professionals, 70, 72-80. Retrieved from
https://www.financialpro.org/
Roulac, S. E. (2014). Commercial mortgages: Money is available if you are willing to pay
the price. Journal of Property Investment & Finance, 32, 589-609.
doi:10.1108/JPIF-06-2014-0042
Runfola, A., Perna, A., Baraldi, E., & Gregori, G. L. (2017). The use of qualitative case
studies in top business and management journals: A quantitative analysis of recent
patterns. European Management Journal, 35, 116-127.
doi:10.1016/j.emj.2016.04.001
Sage, A., Blalock, S. J., & Carpenter, D. (2017). Extending FDA guidance to include
consumer medication information (CMI) delivery on mobile devices. Research in
Social and Administrative Pharmacy, 13, 209-213.
doi:10.1016/j.sapharm.2016.01.001
Santos, A. M., Mendes, J. P., & Soares, G. (2016). A dynamic model for marginal cost
pricing of port infrastructures. Maritime Policy & Management, 43, 812-829.
doi:10.1080/03088839.2016.1152404

102
Santos, H. (2013). Lean, Mean Mortgage Machine. Charlott, NC: Accenture Credit
Services.
Scealy, J., & Welsh, A. (2017). A directional mixed effects model for compositional
expenditure data. Journal of the American Statistical Association, 112, 24-36.
doi:10.1080/01621459.2016.1189336
Schepler, X., Balev, S., Michel, S., & Sanlaville, É. (2017). Global planning in
multiterminal and multi-modal maritime container port. Transportation Research
Part
E, 100, 38-62. doi:10.1016/j.tre.2016.12.002
Serbic, D., & Pincus, T. (2017). The relationship between pain, disability, guilt and
acceptance in low back pain: A mediation analysis. Journal of Behavioral
Medicine, 1-8. doi:10.1007/s10865-017-9826-2
Serrano-Cinca, C., Gutiérrez-Nieto, B., & López-Palacios, L. (2015). Determinants of
default in P2P lending. PLoS ONE, 10(10), 1-22.
doi:10.1371/journal.pone.0139427
Shahadan, A., & Oliver, R. (2016). Elementary school leaders' perceptions of their roles in
managing school curriculum: A case study. Educational Research and Reviews,
11, 1785-1789. doi:10.5897/ERR2015.2490
Sharpe, S. A., & Sherlund, S. M. (2015). Crowding out effects of refinancing on new
purchase mortgages. Washington: Board of Governors of the Federal Reserve
System. doi:10.17016/FEDS.2015.017

103
Shichor, D. (2018). Thinking about punishment (or the lack of it): The case of the
economic meltdown. Journal of Business Ethics, 147, 185-195.
doi:10.10007/s10551-015-2989-2
Shindelar, S. (2015). Federal Housing Administration's default mortgage insurance
program creates public value by increasing lending making affordable
homeownership possible. Housing Finance International, 22-33. Retrieved from
http://www.housingfinance.org/
Sklar, W. P., & Edwards, J. C. (2017). Florida community associations versus Airbnb and
VRBO in Florida. Florida Bar Journal, 91, 16-20. Retrieved from
https://floridabar.org/DIVCOM/JN/JNJournal01.nsf
Slater, S., Joksimović, S., Kovanovic, V., Baker, R. S., & Gasevic, D. (2017). Tools for
educational data mining: A review. Journal of Educational and Behavioral
Statistics, 42, 85-106. doi:10.3102/1076998616666808
Sleeper, J. D., LeBlanc, L. A., Mueller, J., Valentino, A. L., Fazzio, D., & Raetz, P. B.
(2017). The effects of electronic data collection on the percentage of current
clinician graphs and organizational return on investment. Journal of
Organizational Behavior Management, 37, 83-95.
doi:10.1080/01608061.2016.1267065
Snelgrove, R. (2017). Advancing paradigmatic consistency and distinction in leisure
studies: From epistemology to method. Annals of Leisure Research, 20, 131-136.
doi:10.1080/11745398.2017.1287579

104
Stockman, C. (2015). Achieving a doctorate through mixed methods research. Electronic
Journal of Business Research Methods, 13, 74-84. Retrieved from
http://www.ejbrm.com/main.html
Szabó, P., Müllerová, J., Suchánková, S., & Kotačka, M. (2015). Intensive woodland
management in the Middle Ages: Spatial modelling based on archival data.
Journal of Historical Geography, 48, 1-10. doi:10.1016/j.jhg.2015.01.005
Tacikowski, P., Freiburghaus, T., & Ehrsson, H. H. (2017). Goal-directed processing of
self-relevant information is associated with less cognitive interference than the
processing of information about other people. Journal of Experimental Social
Psychology, 68, 93-100. doi:10.1016/j.jesp.2016.05.007
Tani, H. G., & El-Amrani, C. (2017). Smarter round robin scheduling algorithm for cloud
computing and big data. Journal of Data Mining and Digital Humanities, 1-8.
Retrieved from http://jdmdh.episciences.org/
Taylor, L. J., & Asthana, R. (2016). Applying theory of constraints principles and
Goldratt's thinking process to the problems associated with inventory control.
Franklin Business & Law Journal, 2016, 83-104. Retrieved from
http://www.franklinpublishing.net/businesslaw.html
Taylor, L. J., & Mead, A. (2015). Goldratt's theory applied to the problems associated with
commercial underwriting in financial institutions. Global Education Journal,
2015, 20-41. Retrieved from http://franklinpublishing.net/globaleducation.html
Taylor, L. J., Hailey, K. W., & Parajuli, B. S. (2015). Goldratt's theory applied to the
problems associated with the distribution of microfinance services to the poor of

105
rural Nepal. Global Education Journal, 2015, 153-174. Retrieved from
http://franklinpublishing.net/globaleducation.html
Teye, J. K., Teye, I., & Asiedu, M. O. (2015). Financing housing in Ghana: Challenges to
the development of formal mortgage system. Journal of Housing and the Built
Environment, 30, 1-16. doi:10.1007/s10901-013-9376-z
The National Commission for the Protection of Human Subjects of Biomedical and
Behavioral Research. (1979, April 18). Human Subjects Research (45 CFR 46).
Retrieved from U.S. Department of Health & Human Services:
http://www.hhs.gov/ohrp/humansubjects/guidance/belmont.html
Thode, S. F., & Levine, M. L. (2017). On the valuation of real estate with public sector
subsidies: Issues for developers, lenders, appraisers, and assessors. Real Estate
Finance, 33, 142-152. Retrieved from http://www.aspenpublishers.com
Turiano, N. A. (2014). Archival data analysis introduction. The International Journal of
Aging and Human Development, 79, 323-325. doi:10.1177/0091415015574188
van Duijn, M. A., & Post, W. J. (2014). Teaching scientific integrity through statistics.
Proceedings of the Ninth International Conference on Teaching Statistics (pp. 1-
4). Voorburg: International Statistical Institute. Retrieved from
http://iaseweb.org/icots/9/proceedings/pdfs/ICOTS9_C237_VANDUIJN.pdf
Van Rensselaer, K. N., Blackstone, T. F., Crabb, J., & Gordon, B. L. (2014). Mortgage
pricing and gender: A study ofNew Century Financial Corporation. Academy of
Accounting and Financial Studies Journal, 18, 95-110. Retrieved from
http://www.alliedacademies.org/academy-of-accounting-and-financial-

106
studiesjournal/ van Schaik, P., & Weston, M. (2016). Magnitude-based inference
and its application in user research. International Journal of Human-Computer
Studies, 88, 38-50. doi:10.1016/j.ijhcs.2016.01.002
Wacker, J., Hershauer, J., Walsh, K. D., & Sheu, C. (2014). Estimating professional
service productivity: Theoretical model, empirical estimates and external validity.
International Journal of Production Research, 52, 482-495.
doi:10.1080/00207543.2013.836611
Wang, J. (2015). A stochastic comparison result about hazard rate ordering of two parallel
systems comprising of geometric components. Statistics and Probability
Letters, 106, 86-90. doi:10.1016/j.spl.2015.07.006
Wang, Y.-R., Huang, K.-C., & Wang, F.-J. (2016). Scheduling online mixed-parallel
workflows of rigid tasks in heterogeneous multi-cluster environments. Future
Generations Computer Systems, 60, 35-47. doi:10.1016/j.future.2016.01.013
Wilcox, J. A. (2015). The home purchase sentiment index: A new housing indicator.
Business Economics, 50, 178-190. doi:10.1057/be.2015.27
Xu, J., & Chau, M. (2018). Cheap talk? The impact of lender-borrower communication on
peer-to-peer lending outcomes. Journal of Management Information Systems,
35, 53-85. doi:10.1080/07421222.2018.1440776
Xu, X., & Yan, Z. (2017). Probabilistic load flow calculation with quasi-monte carlo and
multiple linear regression. Electrical Power and Energy Systems, 88, 1-12.
doi:10.1016/j.ijepes.2016.11.013

107
Zhang, J., & Tang, H. (2014). U.S. prime mortgage credit risk: Insight from the GSE loan
level credit data release. Real Estate Finance, 30, 77-106. Retrieved from
https://lrus.wolterskluwer.com/pdfs/SampleIssuesPDF/1064.pdf
Zhang, J., Sun, L., Liu, Y., Wang, H., Sun, N., & Zhang, P. (2017). Mobile device-based
electronic data capture system used in a clinical randomized controlled trial:
Advantages and challenges. Journal of Medical Internet Research, 19(3), 1-12.
doi:10.2196/jmir.6978
Zou, Y. (2016). The emergence of China's housing finance system: Challenge and change.
Open House International, 41(1), 14-26. Retrieved from http://www.openhouse-
int.com/

