


1
An Examination of the Differences in the Funding of Minority-Owned Businesses
(Small and Large) Compared to Non-Minority Businesses
Small and medium enterprises (SMEs) are crucial for the economic development
of a region and a country (Rahman & Kabir, 2019). However, access to capital is a major
challenge for minority-owned companies (Robb, 2020). Research utilizing the Small
Business Credit Survey (SBCS) indicated that minority-owned companies regularly rely
on personal funds and often have a weak relationship with banks, as demonstrated by a
low credit application rate (Banks, 2021). In fact, even when minority-owned business
leaders have good credit, they may not be approved for a loan. The denial of capital is due
to a lack of adequate information among minority-owned small business owners. Also,
financial institutions impose requirements (e.g., past performance, credit score, etc.) for
accessing capital that automatically excludes many small firms. In 2017, the value-added
contribution of minority business enterprises (MBEs) to the gross domestic product
(GDP) was 2.3%, or approximately $500 billion, compared to 15.5% for nonminority-
owned businesses.
The findings from this study may enable minority-owned leaders to have an
informed understanding of the challenges they face so they can adopt appropriate
measures promoting their financial performance and, therefore, business growth. On the
other hand, more excellent knowledge of the funding disproportion among
minorityowned businesses could encourage financial institutions and government
agencies to ease business loan procedures, policies, and regulations that are detrimental to
this group of companies. The goal of this research study was to examine the degree to

2
which minorityowned business status and size of business explain the funding received
by businesses may limit minority-owned businesses’ ability to contribute to the
development of local economies and, therefore, the nationwide economy.
Historical Background
Minority-owned businesses are essential to the United States' economic growth.
Winston (2021) estimated that by 2044, the U.S. would have a majority-minority
population, and minority workers and MBEs would have a significant impact on the GDP.
In 2018, approximately 18.5%, or one million, U.S. employers were minority business
owners, and most were contributors to their communities’ job creation and wealth growth
(Vilasquez, 2020). Over the last 10 years, among the two million small businesses
created, 50% were minority-owned and contributed to as many as 4.7 million jobs created
in the United States of America, according to the US Committee on Small Business and
Entrepreneurs. A recent change due to the COVID-19 pandemic impacted small
businesses.
The COVID-19 pandemic has disproportionately impacted small businesses.
African Americans have faced economic hardships with 41% of active businesses,
followed by 32% of Latinx-owned compared to 17% of White-owned in the second
quarter of 2020 (Fairlie & Fossen, 2022; Fairlie, 2020; Velasquez, 2020). The CARES
Act, which included the Paycheck Protection Program (PPP) and Economical Injuries
Disaster Loan (EIDL) program, was not beneficial for many minority-owned businesses
(Fairlie & Fossen, 2022). The majority of MBEs are not affiliated with the Small Business
Administration (SBA). Even among affiliated businesses, many did not receive early

3
information about the program needed to apply. Institutional discrimination and social
inequalities create challenges that prevent minority-owned businesses from accessing
capital (Berdejo, 2021; Robb, 2020; Wainwright, 2020). Minority-owned businesses often
have weak relationships with financial institutions, have bad experiences with credit
applications, and rely on self-financing, unlike their non-minority-owned business
counterparts (SBCS, 2021).
Research has found that access to capital remains a factor disproportionately
affecting minority-owned businesses (Robb & Niwot, 2018), which prevents expansion
and innovation. Financing minority firms remains the top priority challenge in the US for
job creation and economic growth. Research has provided evidence of racial
discrimination against Black-owned businesses by banks and commercial lenders during
the COVID-19 pandemic disruption (Atkins et al., 2022). The concern was that
Blackowned businesses received approximately 50% lower loans through the PPP than
Whiteowned. A survey of businesses has shown that 41% of Black-owned businesses who
applied for loans through PPP did not receive funds, and an additional 21% were not
informed about the program (Atkins et al., 2022). The advocacy organizations Unidos
U.S. and Color of Change published that only 12% of Black and Latino small business
owners received the exact amount of loan applied through PPP, while 26% got a portion
of the funds requested (Santellano, 2021).
Organizational Context
In this quantitative non-experimental causal-comparative study, I used ex post
facto data to examine the differences in the disbursed/shipped approved funding amount

4
based on the minority-owned status and size of the business. The data set used within this
study was the Working Capital Transactions Authorization data set from 01/01/2006 to
09/01/2022, administrated by the Export-Import Bank of the United States (EXIM Bank,
2020). The data were drawn from businesses and lenders across the United States. The
data set enabled the identification of minority-owned small business enterprises regularly
established in the United States of America and engaged in exporting goods and services
abroad and well-established financial institutions that have agreements with EXIM Bank
and specialize in lending funds to small businesses. For the data set, I searched the
Walden University library, SBA, data.gov, and Census Bureau research engines. The data
set describes the capital transactions that small and minority-owned businesses have
received or been denied for exports and imports from EXIM Bank.
EXIM Bank is an official Export Credit Agency (ECA) founded under the renewal
statutory charter (Act of 1945, as amended; 12 U.S.C. §§635 et Seq.), which respects
international rules on ECA financing, and is a member of the Organization for Economic
Cooperation for Development (OECD) (Akhtar, 2019 & 2022). OECD was established in
1978 to provide credit to exporters while doing business abroad and facing competitors.
With ECA financing, the terms and conditions of financing are determined, and an
agreement for the repayment period is also made. In the early 1970s, EXIM Bank created
the Private Export Funding Corporation (PEFCO) as a privately owned entity designed to
buy loans from private lenders. The EXIM bank guarantees the loans and reduces risk-
taking associated with borrowing from commercial banks on the market (De Rugy, 2020).
In addition to EXIM Bank, other U.S. Government agencies also finance exports. The

5
U.S. Department of Agriculture specializes in agricultural goods and services exports.
SBA promotes small businesses for exports with a guaranteed program. Under the World
Trade Organization rules, arrangement-compliant export credit practices are not subject to
export subsidy prohibition. The bank’s goal is to fill market gaps when the private sector
is reluctant or unable to finance U.S. exporting companies and or when U.S. exports
compete against ECA-backed foreign export companies (Shekhar & Jena, 2021).
EXIM Bank is led by a five-member board of directors appointed by the President
of the United States of America and confirmed by the Senate (Democrat and Republican)
(Akhtar, 2019 & 2022). The president and vice-president of the EXIM bank are,
respectively, the board chairman and vice-chairman. A quorum of three out of five board
members is sufficient to conduct business, which includes the approval of financing over
10 million dollars with at least a term of 7 years for repayment. The board of directors
makes decisions on the bank’s requirements and policies. In addition, advisors and other
committee members assist the board of directors.
The primary mission of EXIM Bank is to support U.S. exports of goods and
services and to sustain jobs (Akhtar, 2019). To do so, the bank developed four key
programs:
1. Direct loans to foreign buyers of U.S. exports with an interest rate in
accordance with international trade rules and above the rate of the U.S.
Treasury.
2. Loan guarantees to lenders to protect U.S. exports against no-payment from
foreign buyers. The lenders fix the loan rate.

6
3. Insurance to protect U.S. exporters or financial institutions against any
exportrelated risk.
4. Working capital guarantees short-term loans to U.S. exporters (Akhtar, 2019,
2022; Young, 2019).
EXIM Bank is required to ensure that U.S. private exporters are properly financed
and that the repayment conditions are well-defined. The bank may enter into competition
to protect U.S. exports with terms, rates, and conditions when the international ECA
landscape changes. Each year, EXIM Bank extends more than 30% of its financing
authority to support small business exports, with a minimum of five percent to renewable
energy, energy efficiency, and energy storage technology exports (Akhtar, 2022).
Additionally, the bank’s objectives include environmentally beneficial exports and
exports to sub-Saharan Africa. EXIM bank set its default rate up to 2%. Thus, the bank
monitors its credit and transaction risks every quarter and reports its default rate. The
bank sets up the credit underwriting and due diligence of potential transactions to mitigate
risks to ensure repayment.
The charter of EXIM Bank requires that 75% of its funding be granted to small
businesses. The bank defines a small business as a company with no more than 1500
employees (Young, 2019). EXIM Bank protects small businesses against risks and losses
with loan dispenses, working capital, and guarantees (de Rugy & Leventhal, 2019).
Considering the organizational context, within this quantitative study, I examined the
differences in the disbursed/shipped approved funding amount based on the
minorityowned status and size of the business.

7
Problem Statement
Access to capital is vital for small enterprises for job creation, innovation, and
economic growth in the United States (Robb & Niwot, 2018). Recently, the U.S. Treasury
Department invested more than $4 billion in 332 institutions, where $3.9 billion was
assigned to community banks and $104 million to community development loan funds
(CDLFs; Brock, 2018). Between 2018 and 2019, the business lending rate increased by
seven percent, while the growth rate of small business loans ($1 million or less) was
stagnant (SBA Advocacy Office, 2020). The general problem was that some minority-
owned business entrepreneurs (who often have small businesses) could not gain a similar
success level in accessing lender funding as non-minorities, resulting in the high failure
rates of their business operations. The specific problem was that some business leaders
did not know the differences in the disbursed/shipped approved funding amount based on
the minority-owned status and size of the business.
Purpose Statement
The purpose of this quantitative non-experimental causal-comparative study
utilizing ex post facto data was to examine the differences in the disbursed/shipped
approved funding amount based on the minority-owned status and size of the business.
The targeted population was small enterprises legally established in the U.S. for over 5
years and small business loan banks. The independent variables were minority-owned
businesses (minority-owned businesses and non-minority-owned) and small businesses
(small and large businesses). The dependent variable was the disbursed/shipped amount.

8
The social change implication for this research was to investigate whether differential
loan funding exists (i.e., access to distributed/shipped approved loan amounts). Leader
resources were essential for businesses to improve their profitability. Also, access to
resources enhanced organizations’ job creation, innovations, and overall economic
growth.
Target Audience
The key stakeholders in this portfolio are small business leaders with a specific
focus on minority-owned business leaders. The research findings could give small
business leaders, specifically small minority-owned business owners, an opportunity to
understand their challenges and strategies to promote their financial performance.
Additionally, the proposed study’s findings have the potential to inform financial
institutions, loan banks, and government agencies (federal and local) to ease policies,
procedures, and loan processes toward the minority-owned business organizations, which
are the backbone of the local economy.
Research Question
Research Question (RQ): Is there a significant difference in the disbursed/shipped
approved funding amount based on the minority-owned status and size of the business?
Hypotheses
Based on the research questions, the hypotheses are:
Null Hypothesis (Ho1): There is no difference in the disbursed/shipped approved
funding amount based on the minority-owned status of the business.

9
Alternative Hypothesis (HA1): There is a difference in the disbursed/shipped
approved funding amount based on the minority-owned status of the business
Null Hypothesis (Ho2): There is no difference in the disbursed/shipped approved
funding amount based on the size of the business.
Alternative Hypothesis (HA2): There is a difference in the disbursed/shipped
approved funding amount based on the size of the business.
Null Hypothesis (Ho3): There is no difference in the disbursed/shipped approved
funding amount among minority-owned businesses and non-minority-owned businesses
based on the size of the business.
Alternative Hypothesis (HA3): There is a difference in the disbursed/shipped
approved funding amount among minority-owned businesses and non-minority-owned
businesses based on the size of the business.
Significance
The contribution to business practice and the potential positive implications for
social change are considerable for this study. Robb and Niwot (2018) argued that
Minority Business Development Agencies and SBA provided evidence of continuing
disparities between minority and non-minority-owned businesses for accessing capital. In
this study, I examined the differences in the funding of minority-owned businesses (small
and large) compared to non-minority companies, the disbursed/shipped approved funding
amount, and the relationship between minority-businesses status and the
disbursed/shipped approved loan amount when controlling for business size. This study’s
findings have the potential to positively contribute to business practices within

10
minorityowned companies of any size. They could inform leaders within small businesses
by better understanding funding allocations.
Contribution to Business Practice
This research study's results, conclusions, and recommendations may benefit
financial institutions and small businesses. Small business refers to a privately owned
corporation, partnership, or sole proprietorship, having 500 employees or fewer
depending on the industry and generating an average annual income of 28.5 million U.S.
dollars (Robb, 2018; SBA, 2020; & U.S. Census, 2020). Small businesses are the basis of
economic growth in the U.S. Recently, the Department of Treasury approved more than $
4 billion for 332 small business lending institutions, of which $ 3.9 billion went to
community banks and $104 million to 51 CDLFs (Brock, 2018). While small businesses
have received funding from the federal government, minority-owned businesses
disproportionately received less funding than their non-minority counterparts (Robb &
Niwot, 2018)
Access to the distributed/shipped approved loan amount may be disproportionate
due to factors not considered by financial and small businesses. The study is vital for
business practice, given an investigation of whether funds are distributed equitably
between minority and non-minority-owned businesses may illuminate potential
disparities. Whether disparities are found or not, the study’s findings have the potential to
inform stakeholders within the government and business. Thus, the study’s findings have
the potential to reduce possible disparities and, as a result, improve the business
performance of minority-owned businesses.

11
Positive Social Change Implications
The positive social change implication of the proposed study was to investigate if
differential loan funding (i.e., access to disbursed/shipped approved loan amount) exists
so that leaders in business and financial sectors can be made aware of how funding
resources are distributed. Lender resources are essential for businesses to improve their
profitability. Also, additional funding resources have the potential to enhance job
creation, innovations, and overall economic growth. Small and medium enterprises
(SMEs) represent 95% of firms, participate in between 60% and 70% of global
employment, and contribute to the largest share of new jobs in the economies (Observer,
2000). Furthermore, SMEs contribute to the eradication of poverty and the improvement
in the living standards of vulnerable groups through the increase in income and
selfemployment (Naradda Gamage et al., 2020).
Theoretical Framework
The financial growth cycle (FGC) model for SMEs was introduced in 1988 by
Berger and Udell and later developed by Sanchez-Vital and Martin-Ugedo (2012) and
Huang et al. (2020). FGC offers an explanation for how small businesses progress
through the growth cycle stages with various financial characteristics. SMEs pass through
phases of financial growth and crisis. Borio et al. (2018) stressed that companies are
financed by angel finance, friends, family members, and others to encourage financial
growth. This growth was followed by a period of crisis due to the high credit interest rates
and the restrictions of financial institutions due to a lack of business information.
Hawkins and Kuang (2017) stated that it is vital to understand the drivers and dynamics

12
of lending behavior to understand the financial business cycle. The key tenants of the
FGC theoretical framework include SMEs, venture capital, financial institutions, angel
finance, public equity, lenders, and stakeholders.
The financial institutions, angel financers, and lenders perform transactions of the
disbursed/shipped approved loan amount based on the status and size of the business. The
FGC measures the cycle of financial growth for businesses in relation to the availability
of approved funding. This framework will be used as a lens within the proposed study to
provide a structure for understanding whether the growth of funding is equitably
disbursed based on minority status and the size of the business. Thus, the FGC theory
provides a framework for understanding the study’s focus on examining the differences
between minority-owned and non-minority-owned businesses (after controlling for
business minority status and size) in the funding received.
Operational Definitions
Angel finance is a term used to qualify personal or group funds invested in small
businesses with high risks and high returns on investment (Edelman et al., 2017).
Financial institutions are organizations that act as mobilizers and depositories of
savings and provide credit services and other financial services to the communities
(Bhole, 2004).
Public equity refers to large companies that raise capital publicly by issuing
shares, which enable investors to acquire the ownership interest in the company (Kumar
Rai & Shaikh, 2021; Meoli et al., 2018; Szkuta et al., 2021).
Small and medium enterprises (SMEs) represent 95% of firms, participate
between 60% and 70% of global employment, and contribute to the largest new jobs

13
share in the economies (Observer, 2000), are the most dynamic ventures in the global
economy and play a vital role in developing the human welfare of any country (Naradda
Gamage et al., 2020).
Venture capital is a mid-term equity investment or direct investment that promotes
the growth of SMEs to the stage of public equity with a clear exit strategy
(Nyagadza et al., 2019)
A Review of the Professional and Academic Literature
This literature review focuses on small businesses’ potential capital access status,
particularly the financial growth that challenges minority small business owners. The
literature review was conducted to examine research on topics surrounding the study’s
dependent variable, disbursed/shipped amount, and the independent variable,
minorityowned business status, when controlling for the size of the business. Within this
extant review of the literature, I critically analyzed and synthesized research describing
the theoretical framework, and prior studies focused on the funding of minority-owned
businesses’ status and size of business as they relate to funding received. The data
reviewed included peer-reviewed journal articles, books, and reports from governments'
and organizations’ websites. The vast majority of data reviewed were recently published
and no more than 5 years old.
The research literature I reviewed was retrieved from Walden Library, Business
and Management Academic databases with Business Source Complete, ABI/INFORM
Complete, Emerald Management, ProQuest Central, ScienceDirect, and Sage Premier.
Also, Data.gov, SBA, Census Bureau, Google, and Google Scholar engine search

14
contributed to my research. The literature review retrieved enabled me to identify
peerreviewed on the FGC model.
The Financial Growth Cycle (FGC) Model
Many researchers have established the business FGC models and theories. In this
business literature, I reviewed the business growth stages of development and the FGC in
the small business growth process. Penrose, in 1952 and 1959, originated the “Life Cycle
theory of the Firm” (LCTF) in the economics literature (Mac & Bhaird, 2010). The LCTF
is used to describe the growth phases of a firm from its creation to its maturity. The stage
of growth is set as follows: the traditional society, the precondition for take-off, the
takeoff, the drive to maturity, and the age of high mass consumption (Jacobs, 2022; Li &
Hung, 2013; Rostow, 1959).
The five growth stages, which are a sequential linear process, are inherent to any
country in the world. Traditional society has the characteristics of subsistence economics,
where all activities are at the rudimentary stage (Jacobs, 2022; Li & Hung, 2013; Rostow,
1959). Within this stage, the product from agriculture was sold for fiscality and not for
profit or gain (Hoffman, 2018). The population has no scientific perspective on the world
and technology. In the second stage, the precondition to take off, the production of
agriculture increases with trade activities which enable the creation of other business
services. The third is the stage of take-off, a period at the beginning of industrialization
characterized by economic growth and institutionalization of activities and workers. The
drive to maturity stage is the period where standardization of living increases with the use
of high technology, and it is characterized by the growth of the national economy and its

15
diversity. The last stage is high mass consumption; at this stage, the process of
industrialization is completed. The income of the workforce increases with the
establishment of labor unions. Even though these five stages of economic growth are
important, they are not necessary for today’s economic development of many countries
(Tsiang, 1964).
The number of stages of economic growth is not standard across all organizations.
Steinmetz (1969) proposed a growth model based on three stages, and Greiner, in 1972,
proposed a five-stage evolution-revolution model where each stage is separated by
revolution change (Mac and Bhaird, 2010). However, management succession is a crucial
factor contributing to changes in the organizational structure and small business progress.
Churchill and Lewis (1983) developed a five-stage model with eight prominent factors
for business succession (Manna, 2018). The five stages of business succession are
existence, survival, success, take-off, and resource maturity. These five stages are vital for
business management leaders, practitioners, and researchers to understand each step and
implement them according to business strategies and environment. The varied economic
growth models each provide an example of how companies move through the growth
stages.
In the sales-marketing cooperation strategy, researchers developed many stages of
growth for firm development. Manna (2018) established six stages for business growth as
follows:
x Bare land devoid of business is the area without any business. Some factors,
such as culture, tribal, and new business policy, naturally may influence the

16
business existence, or the business activities are relatively weak due to the
unfavorable environment.
x Establishment, at this stage, the businesses are set up with all opportunities to
succeed or disappear. The firm develops marketing and growth strategies to
conquer the market.
x Aggregation, the established business grows and creates extension branches. x
Competition and coaction, business leaders develop expansion strategies with the
local market as well as nationwide with specific products or services. In
competitive conditions, managers implement customer service as a key area of
innovation and invest in information technologies to achieve a high level of
customer satisfaction.
x Reaction is the stage at which the business leaders invest innovation and
information technologies to change the business market environment and
customer behavior.
x Stabilization, the stage where the firm becomes public. The period of the
standardization of living increases with the use of high technology and the
growth and diversity of the national economy (Jacobs, 2022; Li & Hung,
2013; Rostow, 1959).
However, this stage model does not apply in a biological analogy of organizations’
existence. Organizations are born, grow, and decline; and may also reawaken or disappear
(Mac & Bhaird, 2010).

17
The firm life cycle approach is a linear sequential process of firm growth, and it is
particularly applied in the literature on management and organizational studies. However,
the firm life cycle is not standardized. Atolia et al. (2018) explained that business cycles,
which are asymmetrical, are divided into two categories: steepness and deepness.
Steepness is marked by a sharp contraction followed by a long recovery period, and
deepness refers to the business cycle troughs which are often deeper than tall peaks.
Therefore, the business life cycle evolves at the same time with many economic activities
that are characterized by general recessions, contractions, and revivals (Tahir et al., 2020).
The cyclical period of businesses, such as duration, amplitude, and severity of economic
evolution, enables researchers to follow fluctuations in the economy and implement
strategies accordingly.
The business life cycle passes through at least three phases (startup, growth, and
crisis). The startup phase is the period of uncertainty characterized by Porter’s five forces
framework, introduced in 1979 to understand the market (Isabelle et al., 2020; Porter,
2021). The five forces framework are the threat of new entrants, the bargaining power of
buyers, the bargaining power of suppliers, the threat of substitute products or services,
and the rivalry existing among competitors. Challenges are high because the potential
partners, customers, and financial institutions do not have enough data and hesitate to
work with the company. The phase of growth is the period the company enters the
market, and, at this phase, the company may easily access capital. However, growth is
also considered as a period of stability. At that period, the company benefits and may
intend to invest in many sectors. The crisis phase is the period when the company faces

18
new challenges. The poor forecasting performance is due to the linear relationship
between the financial cycle and output fluctuations (Ng, 2011). The financial cycle boom
may end in crisis and weaken the company’s growth (Borio et al., 2018).
The life cycle theory of business is the foundation of economic progress that
allows businesses to mitigate risks through forecasting. Goodwin (1967) introduced the
growth cycle model based on Minorski’s (1962) classic predator-prey model for fish
population (Dessai et al., 2006). The growth cycle model was used to generate the growth
rate between capital and labor in the national revenue distribution (Sordi & Vercelli,
2014). The extension of the model in many directions has led to a framework that
combines growth and cycles that has been used by many researchers (Dessai et al., 2006).
The concept of growth is that investments have a determining effect on economic
dynamics and enfold two main directions (Sukharev & Voronchikhina, 2020). The
economic growth depends on the dynamic of the investments spending and investments
in the non-financial assets are crucial for future economic growth. Five channels of
financial development may influence economic growth (Levine, 2005; He et al., 2019).
Firstly, the improvement of investment formation and efficiency of capital distribution;
second, the level of enterprises management improved; third, the high-tech innovation
and the reduction of innovation risk create an excellent business environment for
enterprises; fourth, efficiently enhance investment savings; and lastly, promote trade in
goods and services.
The financial growth life cycle describes a business life cycle that passes through
three phases: the growth stage, maturity stage, and decline stage. The concept of a

19
financial cycle is the perceptions and attitudes of financial risk fluctuations observed over
time (Ng, 2011). It is self-reinforcing interactions between perceiving values and risk,
risk-taking, and financing constraints (Borio et al., 2018). Changes observed during
fluctuations are marked by swings in credit growth, asset prices, terms of access to
external funding, and other indicators of financial behavior (Borio et al., 2018; Ng, 2011).
The financial cycle is based on the forecast of public and private investors and the
behavior of the economy. A significant increase in financial investment, marked by an
economic boom or growth, can be ended with crises such as recessions (Borio et al.,
2018). Financial resources may affect non-financial aspects, mass spending, the behavior
of a whole economy, and even natural factors. Crises accompanied by recessions are the
characteristics of fallen asset prices, debts increase, and the reform of balance sheets,
which drag down growth. Overall, financial performance is measured through profit
behavior, earning behavior, dividend behavior, risk behavior, and cash flow behavior
(Dan Perbankan, 2021).
Through Goodwin’s growth cycle model, the financial growth model (FGC) for
SMEs was introduced in 1998 by Berger and Udell. The FGC is proper for every firm and
may be applied depending on internal factors (e.g., decision-making, policies,
organization, operations, etc.) and external factors (e.g., government business policies,
lenders, market orientation, etc.). A firm needs additional financing due to business
growth, financial performance, innovations, and to be competitive in the global market.
SMEs, including minority-owned small businesses, often only have access to funding
from family and friends, private equity, or debt markets where the interest rate is often

20
high. The information asymmetry problem (Butt et al., 2013; Sanchez-Vidal &
MartinUgedo, 2012) and the agency costs problem (Sanchez-Vidal & Martin-Ugedo,
2012) interact because the lender companies control the interest cost. As long as the
company grows, the leadership has the capacity to mitigate or alleviate information
asymmetry problems. The more the company grows (age and size), the manager controls
the financial cycle, becomes less risky, and gets confidence from external investors and
financial institutions. Sanchez-Vidal and Martin-Ugedo (2012) formulated five
hypotheses for testing the FGC essentially based on age and size. The study’s two
independent variables (age and size) are selected because they influence the information
asymmetry problem. Age and size may significantly contribute to the FGC.
A company, in the process of attaining a level of sustainability, develops growth
strategies for risks and overcomes uncertainties. Some researchers argued that resource
constraints, challenges, capabilities, structures, and strategies enable the company to grow
and reach sustainability (Huang et al., 2020). FGC is a cycle with consecutive positive
and negative changes in the business process (Paweta, 2018). It is considered a financial
cycle (Borio et al., 2018) encompassing the interactions between the value perceived and
risk, risk-taking, and financial constraints. An increase in the credit value implies an
increase in asset value, the price of assets. The financial constraints and risks prevent
small businesses from accessing loans and may provoke an economic crisis. The period
of random fluctuation, during which a company gathers financial information and
resources, develops networking through marketing, workshops, and exhibitions and is
followed by an expansion phase. Three stakeholder groups (business owners, workers,

21
and investors) are important to reduce the information asymmetry problem in the business
growth cycle (Atolia et al., 2018). The business owner (manager) elaborates the project
plan, mobilizes funds, and hires resources; the worker provides service for wages; and the
investor provides capital, equity, and liquidity assets against interest.
The capital debt and equity are vital for a company’s financial growth, especially
when intending to become a public company. As the company progresses, the capital
structure contributes to the benefits realization (Butt et al., 2013; Modigliani & Miller,
1958, 1963; Pandey, 2004; Shahar et al., 2015). The capital structure is a combination of
short-term and long-term financing with a mix of debt and equity capital that is
indispensable for a company to achieve its financial goals (Butt et al., 2013). Pecking
order theory and signaling theory are essential to understanding the relationship between
financing decisions and investments. Signaling theory and pecking order theory (Butt et
al., 2013; Huang et al., 2020; Pandey, 2004; Shahar et al., 2015) are vital in the capital
structure and FGC. According to the Pecking order theory (Myers & Majluf, 1984), a
company may finance a project with only its internal resources like reserves and benefits
(Ahmadimousaabad et al., 2013), and use less debt with high growth (Pandey, 2004).
Instead, the Signaling theory promotes the growth of a company during the recession risk
by contracting external debt (Butt et al., 2013). Huang et al. (2020) argued that at the
same time, pecking order and signaling theories are concerned with the relationship
between a firm’s cash flow and debt structure to growth; they individually contribute to
the company's growth at all levels of the company’s financial life cycle. Micro, small, and

22
medium enterprises, which are the pillars of economic growth, need support from
financial institutions and their stakeholders.
Micro, Small, and Medium Enterprises (MSMEs)
The development of the economy of any country often depends on micro, small,
and medium enterprises (MSMEs). MSMEs are the backbone of the world economy, and
their performance impacts social development and economic growth (Bashir et al., 2021;
Martins et al., 2022; Novikasari et al., 2021; Velasquez,2020). SMEs represent 95% of
firms, participate in between 60% to 70% of global employment, and contribute to the
largest new jobs share in the overall economy (Ridwan et al.,2020). More than 90% of
SMEs represent the total enterprises in a country, contribute up to 80% of employment in
the industry workforce, and about 40% to the national GDP (Albassami et al., 2019;
Bashir et al., 2021). SMEs are also the most dynamic ventures in the global economy and
play a vital role in developing the human welfare of any country (Naradda Gamage et al.,
2020). SMEs are critical for sustainable economic growth, and their integration in the
region considerably contributes to economic development. MSMEs/SMEs have been
regulated into many sectors of activity, such as industry, service, agriculture, restaurant,
and transport (Novikasari et al., 2021; SBA, 2020).
Small business refers to a privately owned corporation, partnership, or sole
proprietorship with 500 s or fewer employees, depending on the industry. Small
businesses generate an average annual income of 28.5 million U.S. dollars (Robb, 2018;
SBA, 2020; U.S. Census, 2020). The definition of SMEs varies by country and region.
This definition is based on each country's economic, cultural, and social habits, often on

23
the value of assets or the number of employees (Martins et al., 2022). The European
Commission (EC) considers SMEs as those companies with 250 employees or fewer and
that make no more than 50 million Euros and/or present an annual total balance sheet of
less than 43 million Euros (Bashir et al., 2021; Martins et al., 2022). The statistical data of
the Organization for Economic Cooperation and Development (OECD) explained that
99% of all businesses correspond to SMEs (Niewohner et al., 2019), contribute about
60% of employment, and make between 50 and 60% of GDP (Martins et al., 2022). The
contribution of SMEs is to alleviate poverty and sustain economic growth. SMEs are
involved in community development, specifically in rural economies. The importance of
small businesses in community development is to eradicate poverty, inequality, and
unemployment, support the local population to fulfill their basic needs, and help
marginalized groups (e.g., disabled, female heads of household, uneducated persons;
Naradda Gamge et al., 2020).
SMEs, which play an important role in the job creation, poverty and
unemployment reduction, and economic growth, have a very high failure rate. The failure
rate of SMEs is high in the short period from their inception because many of them face
challenges, including little or no investment, lack of knowledge of the market, lack of
formal planning and demand forecasting, lack of managerial and technical skills, and
limited access to economic resources (Caballero-Morales, 2021). The vulnerability of
SMEs is due to internal and external risks (Asgary et al., 2020; Caballero-Morales, 2021)
and is often beyond their capacity to control, influence, and manage. However, internal
risks can be controlled through risk management and treatment measures that managers

24
and business owners implement. This approach is not often set up in developing
countries. SMEs are vulnerable to external risks because these risks are beyond their
capacity to manage, control, or influence (Asgary et al., 2020).
The vulnerability of SMEs in developing and emerging countries is more
pronounced. Weak institutional support makes SMEs less prepared to manage the risks.
Also, they often do not have the expertise to manage risks and anticipate the risks
outbreak. Thus, to mitigate risks in emerging countries as well as developed countries, the
World Economic Forum (WEF) has created, assessed, and monitored 30 global risks
since 2005 (Asgary et al., 2020). According to the WEF, a global risk is an uncertain
event or condition that, if it occurs, may negatively impact SMEs for at least ten years.
SMEs represent more than 90% of all companies worldwide and are the backbone of the
world economy in formal and informal business sectors (Thorgren & Williams, 2020). In
Japan, over 99.8% of all companies are SMEs, which employ more than 70% of the
workforce and generate at least 50% of the GDP (Asgary et al., 2020). Ninety-eight
percent of all economic entities in Mexico are SMEs, and they contribute more than 50%
of the country’s GDP (Caballero-Morales, 2021).
In the global market, SMEs remain vital for global supply chain and international
transactions, contributing to global economic growth and alleviating poverty. The aim of
the International Labor Organization (ILO) is that SMEs contribute to creating productive
employment and decent work for all (ILO, 2022). SMEs are the key factor to a nation's
economic development and social well-being. Two in three jobs created in the world
come from SMEs, according to ILO. In developing countries, SMEs with less than 100

25
employees and from the private sector generate at least 50% of job creation, whereas in
developed economies, they contribute up to 55% to the GDP. Policymakers may focus
more on SMEs to enhance economic growth. The performance of SMEs is vital for
economic and social development, specifically in rural economies (Bashir et al., 2021).
Two factors are important for SMEs. The first factor is that SMEs stand to improve
antipoverty programs efficiently; second, SMEs' development is an ingredient for
innovation and sustainable growth. These factors are vital for SMEs’ performance and
sustainability and contribute to global economic growth.
Small businesses are the basis of economic growth in the U.S. Recently, the
Department of Treasury approved more than $4 billion for 332 small business lending
institutions, of which $ 3.9 billion went to community banks and $104 million to 51
CDLFs (Brock, 2018). According to the ILO, at least 62% of employment (Ridwan,
2020; Tambunan, 2018, 2019) created by SMEs are informal and often have difficult
working conditions (e.g., lack of social security, lower wages, poor occupational safety
and health conditions, and weaker industrial relations). Also, SMEs are flexible and have
the capacity to move from one product to another in an environment where the market
demand changes quickly; expansion is easy during economic growth (Tambunan, 2018,
2019). SMEs are social entrepreneurs working for community interests and processing
minimum profit distribution among their members (Ridwan et al., 2020). However, at the
same time, they can be used for any contract during an economic crisis, and their degree
of failure is very high.

26
One of the biggest challenges SMEs encounter in launching their operations is
accessing capital. Access to capital is a challenge, and the lack of adequate policies
beneficial for both lenders and borrowers prevents small startup businesses from
innovating, growing, and creating jobs (Robb & Niwot, 2018). Many researchers have
shared the factors specific to different countries that impede the growth and sustainability
of SMEs. In Bangladesh, scientists found that among SMEs, 50.53% have no access to
formal sources of finance, 13.68% have restricted access, and 35.79% have no restrictions
(Islam & Miajee, 2018). Although 59.6% of SMEs applied for working capital financing,
only half of them got loans from their banks. SMEs often have initial finance to startup,
but not sufficient for operations. Due to the lack of information from SMEs, traditional
banks' financial requirements can be extremely costly (Dong et al., 2019). The weak
growth of SMEs is due to the financial constraints, capital constraints, poor technologies,
and tight regulations faced by these businesses (Nkwabi & Mboya, 2019).
Many studies proved that the absence of the use of technologies and financial
resources prevents small businesses from innovating and, therefore, contributing to the
country’s economic growth. Information on SMEs’ financial health is opaque, so they do
not expose their financial statements to the public. Investing in innovation and technology
requires external finance from banks and financial institutions, the main source of
funding (Kijkasiwat & Phuensane, 2020). The fact that external investors do not have
enough data on SMEs, their level of credit trustworthiness is very low, and they have
difficulties accessing financial capital. Lenders hesitate to extend credit loans to small
businesses because they consider small business loaning an alluring and gainful endeavor

27
(Islam & Miajee, 2018). SMEs are viewed to be high-hazard borrowers due to their low
level of capitalization, deficient resources, and failure to conform to the lender’s security
requirements. Islam and Miajee (2018) identified seven reasons that make formal banks
to loan small businesses less probable:
x Lending small businesses is seen to be extremely hazardous. They are very
vulnerable, the rate of failure is very high, and the financial statements and
operation information are opaque, preventing lenders from being hesitant
(Kijkasiwat & Phuensane, 2020).
x Small business owners experience fear of gaining access to financial capital due
to the conditions of loaning and the high cost of processing before getting the
loan.
x Banks prefer loaning to large companies to protect their investment, and
shareholders often control these companies. The fact that large companies
have a long history with banks, they have an investment agreement that
facilitates the process of transactions. Also, shareholders influence banks’
policies and may restrict SMEs’ access to capital.
x The loan managerial expenses are very high, as is the interest rate, orienting
small businesses to other sources of financing.
x The absence of SMEs’ history (e.g., financial statements, records
bookkeeping) automatically excludes them from accessing financing. x

28
Borrowers do not have any means to guarantee the loan requested, even
though banks may be willing to support the project.
x Many small businesses are informal or do not register with legal institutions for
the benefit inherent to SMEs.
Overall, SMEs struggle due to many factors, with financing and access to credit being
among the most challenging, as reported by industry experts and researchers (Rao et al.,
2018). Policymakers, banks, financial institutions, and small business organizations must
come together to define rules and regulations that are beneficial for all and boost the
economy of nations.
The economic development of a country depends on its SMEs. SMEs play a vital
role in developed and developing countries and are the most dynamic in the present
global economy, contributing to human well-being (Naradda Gamge et al., 2020;
Albassami, 2019). Even though large companies influence SMEs, their collaboration is
significant in enhancing the global economy. Small businesses are the foundation for
large companies in many countries. They construct a local technological base, have the
capacity to use local resources such as raw materials, generate savings, encourage the
participation of vulnerable groups, and support local economies (Naradda Gamge et al.,
2020; Albassami, 2019). However, financial accessibility constraints negatively impact
SMEs’ performance. The financial constraints are a handicap to innovation and
technologies (Kijkasiwat & Phuensane, 2020). Large companies can use internal and
external finance from banks for innovation and technology and prevent risks. In contrast,
internal finance is the only source of investment for many SMEs. Due to financial

29
hardship, SMEs see their cash flow decline and are outperformed by larger companies.
U.S. SBA instituted many programs that contribute to enhancing small business activities
and the communities’ well-being. Recently SBA developed many programs to support
small businesses, including loan guaranty programs, small business development centers,
women development centers, Service Corps of retired executive, microloan Technical,
and others to enhance small business access to capital, and increase small business
opportunities in federal contracting, access to direct loans for businesses, and other
financial opportunities (Fairlie, 2021; CRS, 2021). Congressional interest in these
programs has increased for two reasons (SBA, 2021). The first is that small businesses
are the pillar of the U.S. economic growth and job creation. Second, since 2020, the
interest again increased to support small businesses negatively affected by the
coronavirus pandemic and, in turn, the nationwide economy. To respond to the crisis,
Congress passed on March 27th, 2020, the Coronavirus Aid, relief, and Economic
Security (CARES) Act, including $349 billion and later increased by $669 billion to fund
the PPP (CRS, 2021; Fairlie & Fossen, 2021; Humphries et al., 2020). This fund,
designed to support small business endeavors and provide economic relief, should be
reimbursed partially or forgiven once established conditions are met. The EIDL programs
(about 3.6 EIDL loans for $200 billion and about 5.8 million EIDL advances for $20
billion) were designed to support small businesses that were forced to close or lose their
activities due to the coronavirus (CRS, 2021; Fairlie & Fossen, 2021; Humphries et al.,
2020).

30
The event of high technologies and digitalization enable SMEs to enter the global
market and do business with any company. Globalization and rapid technological
improvements promoted international trade, which eased the SMEs to export products
and services (Safari & Saleh, 2019). The expansion of SMEs in the global market
significantly impacts job creation, innovation, and economic growth. Globalization and
technological improvements created opportunities and threats for SMEs in developed and
developing countries. SMEs have opportunities because they can enter the global market
and develop partnerships with any company. SMEs are completely integrated into their
community, and partnering with other businesses gives them a competitive advantage in
their products and services.
Entering the global market is a challenge for SMEs. Multinational corporations
(MNCs) and transnational corporations (TNCs) have occupied the global market,
impeding SMEs and threatening them with potential closures. The financial accessibility
constraints negatively impact SMEs’ performance. The financial constraints handicap
innovation and advancements in technologies (Kijkasiwat & Phuensane, 2020). Large
companies can use internal and external finance from banks for innovation and
technology advancement as well as to prevent risks. In contrast, for many SMEs, internal
finance is the only source of investment. Facing financial hardship, SMEs see their cash
flow decline and continue to be outperformed by larger companies.
With the rapid technological improvement, U.S. small business exporters have
easy access to the global market but face adversities. Recent changes to the global
economy (market and trade liberalization initiatives) and rapid improvement technologies

31
have contributed to SMEs’ growth through exporting products and services (Safari &
Saleh, 2019). To support SMEs that are specialized in exporting or importing products or
services and avoid the influence of foreign MNCs/TNCs, the SBA has created export
financing programs to ensure lenders with up to a 90% guarantee of export loans (SBA,
nd). In the same perspective, EXIM-Bank was created to support U.S. exporters of goods
and services and promote job creation and economic growth.
The fact that U.S. SMEs may have a cash flow shortage to fulfill an export order
and seek a capital working loan to finance, for instance, its purchase of materials or
supplies for the export order, the product of the good, or the collection of payment from
the foreign buyers, EXIM Bank put in place the working capital guarantee program which
guarantees up to 90% of the principal and interest on a loan made to participating lenders
for export-related inventory and accounts receivables (Akhtar, 2019; EXIM Bank, 2020).
Also, EXIM Bank has created the supply chain finance guarantee program to guarantee
up to 90% to approved lenders and exporters and increase liquidity for the fulfillment of
export orders. Each year, EXIM Bank extends more than 30% of its financing authority to
support small business exports, with a minimum of 5% to renewable energy, energy
efficiency, and energy storage technology exports (Akhtar,
2019; EXIM Bank, 2020). Despite SMEs' challenges to global market entry and rivalry,
the U.S. EXIM Bank strives to boost economic growth with small businesses' protection
abroad and promote job creation.
Going globally is a partnership and networking process based on each company's
specialization. Supply chain financial (SCF) is a key factor for small businesses to easily

32
operate in the global market and promote economic growth (Ali & Gongbing, 2018). The
SCF was introduced to reduce the working capital, cut transaction costs, and decrease
debt ratios through financial mechanisms (e.g., factoring, trade financing, and inventory
financing; Ali et al., 2018; Jia et al., 2020; Zhu et al., 2019). The SCF builds trust
between the buyer, supplier, and financial institutions. The fact that information is
asymmetric is a huge challenge for SMEs seeking to finance their business growth.
Financial institutions use SCF as a tool to fulfill financing requirements and accomplish
their growth in a timely manner (Ali et al., 2018). Supply chain finance is a critical tool
for SMEs’ growth because it contributes to the reduction of net operative capital,
increases profit, and strategic benefit (Zhu et al., 2019). In addition, SCF can mitigate
risks between supply and demand in the financial flow and create value-added for the
supply chain with capital constraints by integrating the financial institutions, SMEs, and
constraints capital firms’ members of the supply chain.
Supply chain finance promotes financial transactions based on confidence. The
importance of SCF for SMEs is that it contributes to minimizing debt costs, creating new
opportunities to obtain loans, and decreasing working capital, especially for weak supply
chain players (Ali et al., 2018). Information on the SCF, including transaction costs,
debts, management liabilities, and information on the market, politics, and technology
environment, contribute to reducing investment risks and capital costs of projects
financed within supply chains, enhance financial decisions, and optimize financing (Jia et
al., 2020) which are vital for SMEs financial performance and therefore the U.S.
economy. The SCF brings supply chain partners together to build trust commitment,

33
develop mutual benefit, and therefore benefit SMEs’ performance, which positively
impacts economic growth in the global market. SCF is an opportunity for policymakers,
experts, and business practitioners to lean on the researchers’ findings and implement
appropriate strategies that may contribute to SMEs’ financial performance, which,
therefore, positively affects the well-being of the community.
The growth of small businesses necessarily passes through the small business
owners' and managers' competencies and skills building. The government should promote
vocational training to empower small business owners or those willing to build businesses
in financial management and promote the best practices to access finance (Tambunan,
2018, 2019). Companies should comply with legal requirements specific to bookkeeping,
reporting gross income, and paying taxes to the government (Novikasari et al., 2021).
Knowledge, skills, and abilities are the three main areas that business owners, managers,
and personnel must possess to boost businesses and have access to any resources
(Sedyastuti et al., 2021). Thus, minority-owned small business enterprises involved in
local economic development to reduce poverty and inequality and protect vulnerable
persons are more concerned with getting skills, knowledge, competencies, etc., to
promote their companies.
Minority-Owned Small Business Enterprises (MBEs)
Minority small businesses, despite their statute second zone companies, contribute
to their community’s well-being and economic growth. Minority-owned small business
enterprises are the pillar of job creation and create jobs at a similar rate to newly created
non-minority businesses (Montout, 2019; Fairlie et al., 2010). Minority-owned small

34
businesses also play a vital role in community development and improve the population's
well-being in areas where poverty and unemployment are historically high (Berdejo,
2021). MBEs are composed of African Americans, Hispanics, women-owned small
businesses, veterans, and other ethnic groups. Over the last 10 years, among the two
million small businesses created, 50% were minority-owned and contributed to as many
as 4.7 million jobs created in the United States of America, according to the U.S.
Committee on Small Business and Entrepreneurs. Minorities are less represented in the
entrepreneurial marketplace. Even though they represent 38% of the U.S. population,
only 19% own small businesses (Berdejo, 2021). In the inner cities, this gap is more
pronounced, where 67% of the population are minorities, and 23% are minority-owned
businesses, according to census data (Berdejo, 2021).
The contribution of MBEs is significant to U.S. economic growth due to their
integration into community development and population welfare. Winston (2021)
estimated that by 2044, the United States would have a majority-minority population, and
minority workers and MBEs would have a significant impact on the GDP. According to
the data in 2017, MBEs with employees were 1.015 million and generated $1.401 trillion
in revenue with 8.923 million people employed (Winston, 2021). In 2018, approximately
18.5%, or one million U.S. employers, were minority business owners and most were
contributors to their communities’ job creation and wealth growth (Vilasquez, 2020). The
contribution of MBEs to GDP is 2.3% value-added or $500 million against 15.5% for
non-minority. By 2044, the minority population will constitute the majority of the
workforce. At that trend, the contribution of MBEs to GDP will be 5.5% value-added,

35
which is insufficient to catch up with the non-minority (Winston, 2021). To avoid
harming the United States’ human capital development and economic growth, researchers
recommended that policymakers, experts, business practitioners, and other stakeholders
consider the implications of the shifting marketplace.
Accessing capital and attracting opportunities remain a challenge for
minorityowned businesses due to the persistent disparities. A report from the Federal
Reserve in 2017 supported that the source of external credit to small businesses always
comes from banks. Carlisle (2019) argued that some small businesses lack expertise or
cannot support the costs related to the financing program; thus, lenders designed
intermediaries to assist low-income minority communities in accessing capital. The recent
works and federal officials underlined factors like the small size of business, low income,
weak credit histories, lack of loan information, or lack of clear title of agricultural land
prevent or dissuade minority farmers and ranchers, and women from accessing loans
(Clements, 2021). The disparities between minority-owned and non-minority-owned
firms regarding loan approval rates, credit lines, cash advances, etc., remain current.
Mayorga (2019) argued that the new securing funding rule that the administration
introduced made it hard for small businesses to access the capital for growth.
Any restrictive policy prevents minority-owned businesses from accessing credit
and contributes to their underperforming, preventing community members from taking
advantage of it and thus limiting local economic growth. Capital is vital for new and
existing businesses that need startup costs and growth financing. The research of Hwang
et al. (2019) found three vital sources of capital that small business owners may use for

36
startup and/or launch activities. The research studies showed that 64.4% of funds come
from personal/family savings, 16.5% are business loans from banks or financial
institutions, and 9.1% use personal credit cards.
The disparity between minority-owned businesses and non-minority-owned
businesses is current despite efforts made by governments and other organizations. The
difference in accessing financing across racial and ethnic groups has been noted by
researchers (Hwang et al., 2019). Barriers to accessing financing prevent many positive
trends and outcomes for minority entrepreneurs. Barriers often stop people in the process
of running their businesses. Barriers are one of the factors that slow business activities
and may contribute to failure. In the United States, many minority-owned small
businesses experience additional challenges from different barriers. At least 83% of
entrepreneurs do not access bank loans or venture capital at the time of startup, 65% rely
on personal and family savings for startup capital, and 10% carry balances on their
personal credit cards (Hwang et al., 2019). Some research shows that minority business
owners use their personal and family savings for startup capital (Robb & Niwot, 2018).
The data from the U.S. Census Bureau show that half of all Hispanic and half of all
African American households have less than $7,683 and $6,314, respectively, compared to
$110,500 for non-minority households. In 2021, the Federal Reserve System (FRS) data by race
and ethnicity indicated that 43% of Black adults and 40% of Hispanic adults had a family income
less than $25000, which is at least twice the rate among White and Asian adults (FRS, 2022). In
contrast, the family income of Whites and Asians was disproportionately over $100,000. The levels
of income of African American and Hispanic individuals and households are a challenge for saving

37
and often prevent minorities from investing directly in the business, using collateral to obtain a
business loan, and/or acquiring other businesses (Robb & Niwot, 2018). The fact that minorities
have the lowest income and do not have enough savings presents a challenge to running a business.
Although minorities are able to launch the business due to the barriers they face, the degree of
survival is very low.
Financial institutions and their shareholders contribute to the minority-owned
business’s success as well as their failure. Financial constraints are one of the factors
playing an important role in racial inequality (Kim et al., 2021). The problem of liquidity
negatively affects current consumption and reduces investment, mobility, and wealth
accumulation in the repetitive economic cycle. Universal employer data from the Census
Bureau shows that the racial financing gap is most pronounced at the startup and narrows
as the firm ages (Kim et al., 2021). Black-owned businesses are less likely to obtain bank
loans, more likely to refrain from applying because of expected denial, and more likely to
report that lack of finance reduces their profitability. Black and Hispanics are twice as
likely to start a business with less than $10,000 compared with White and Asian business
owners (Robb & Niwot, 2018). When minority business owners request a loan from a
bank, contrary to their White counterparts, Hispanic-owned businesses may not be
granted the full amount, while Black-owned businesses may see the requested amount cut
in half or the total amount rejected. Most of the time, Black-owned businesses refuse to
request business finance loans because they do not want to link their business profitability
to the bank rejection (Kim et al., 2021). Racial bias persists when it comes to financing
new businesses, influencing lenders' consideration toward minority-owned businesses'

38
success. Lenders charge minority business owners a high-interest rate on bank loans
compared to similar white business owners (Fairlie & Niwot, 2018; Hwang et al., 2019).
Although minority-owned businesses are marginalized, the population of this
ethnic group remains vital to the U.S. economic growth. With the growing minority
population in the U.S. (Robb & Niwot, 2018), Boston’s 200-year-old Eastern Bank
initiated an ambitious goal to fill the wealth gap and enhance economic inclusion
(Carlisle, 2019). In 2017, the bank, in partnership with Eastern Bank Charitable
Foundation, launched the Business Equity Initiative with a three-year commitment of $10
million to substantially reduce wealth inequality by bringing together minority-owned
businesses, supplier partnerships, and community development experts to address the
problem of income inequality in Massachusetts and southern New Hampshire. Federal,
state, and local governments have made direct investments, grants, and guarantees
through SBA loans, Small Business Innovation Grants, Small Business Transfer
Technology Program, regional venture capital funds, and other initiatives designed to
support SMEs (Hwang et al., 2019). In the same perspective, large-cap companies have
initiated programs to support Black-owned businesses with the intention to reduce the
racial wealth gap (Velasquez, 2020). The amount of funds that financial services pledged
was $1.15 billion which included $350 million in procurement spending on Black-owned
businesses. While the federal government is the largest procurer in the U.S., State
governments, municipalities, and public educational institutions contribute up to $1.5
trillion for procurements. In addition to these programs that the government reinforced,

39
the PPP was initiated for the resilience of small businesses due to the COVID-19
pandemic. The Coronavirus Aid, relief, and Economic Security (CARES) Act, included
$349 billion and later increased by $669 billion to fund the PPP (CRS, 2021; Fairlie &
Fossen, 2021; Humphries et al., 2020).
Many research studies underlined that in addition to financial discrimination,
minority-owned businesses are confronted by diverse types of discrimination, such as
loan application denial, discouraging borrowers, demanding a price premium, and
supplying lower quantities of credit. Discrimination is recurrent in the small business loan
lending marketplace (Fairlie et al., 2010; Montout, 2019). The racial differences in
financial hardships are due to racial differences in credit risk (Robb, 2020). Companies
specialized in determining credit scores are prohibited from using race, gender, and other
forms of discrimination as criteria for lending money (Montout, 2020; Robb & Robinson,
2018). Minority-owned businesses may face challenges to market access for the goods
and services they produce due to consumer discrimination by customers, other
companies, or redlining (Fairlie & Robb, 2010). The term redlining” was the way the
federal government and lenders would select or delimit a neighborhood with a red line
where they would not invest based on demographics alone (Burke et al., 2023). Redlining
is a discriminatory practice that prohibits a community based on racial and ethnicity
access to elementary services such as mortgage, insurance, loans, and other financial
services (Burke et al., 2023; Egede et al., 2023; Swape et al., 2022). About 38% of White-
owned businesses had not experienced financial hardship for 12 months, compared with
17% of Black-owned and 29% of Asian-owned and Hispanic-owned businesses. Over

40
decades, national and regional studies proved that limited capital, human and social
capital, and racial discrimination are the main sources of disparity in minority business
performance (Fairlie & Robb, 2010). Inequal access to financial capital remains the most
important factor that prevents minority-owned businesses from growing.
Minorities and women's businesses, which contribute to the families’ job creation
and promote the community’s development, always face discrimination challenges. Many
studies and reports support that minorities and women have been historically and
consistently disadvantaged by the effects of discrimination in business enterprises
(Wainwright, 2020). Although disparities between non-minority male-owned businesses
and minority-owned and women-owned businesses have been severe, the Disadvantaged
Business Enterprise Program has significantly reduced the gap. The Office of Minority
and Women Inclusion, established under the Dodd-Frank Wall Street Reform and
Consumer Protection Act section 342, which oversees Federal Deposit Insurance
Corporation’s (FDIC) Minority and the Women Outreach Program, strives to promote
minority- and women-owned businesses through the FDIC’s procurements for goods and
services (FDIC, 2022). The FDIC is an independent government corporation that
provides deposit insurance and performs bank supervision. The FDIC intends to maintain
stability and confidence within the bank system and protect against loss nationwide.
Nowadays, high-tech enterprises nourish the business world and promote economic
growth. However, compared to their counterparts, the representation of African
American-owned enterprises and innovation in the high-tech sector are quasi-inexistent
(London & Sheikh, 2020). Most of the White-owned Businesses or 68.5% created

41
businesses specialized in high-tech and innovation. African American-owned businesses
are underrepresented with 7.4% compared to the 14% overall private-sector African
Americans employment rate. According to London and Sheikh (2020), African Americans
only represent 2% of executives and 11% of technicians in the high-tech sector, which
highlights the lack of diversity in high-tech. High-tech innovation is a powerful tool in
today’s economic development. Winston (2021) estimated that by 2044, the United States
would have a majority-minority population, and minority workers and MBEs would have
a significant impact on the GDP. The exclusion of African Americanowned businesses has
a negative impact on this community, and therefore, the overall economic growth will be
negatively impacted.
In addition, MBEs challenge discrimination in the U.S. business development,
whatever their contribution to the U.S. economic growth. The performance of MBEs
depends on the measures that the shareholders of commercial banks undertake regarding
their orientations (Franquesa & Vera, 2021). The grant of credit to minority-owned small
business enterprises depends on the ethnicity/race of the owners, size, and the age of the
business. Nguyen and Pacheco (2021) supported that confidentiality in loan credit
agreements is vital for affiliated-bank mutual funds while investing in the firms that
borrow with the affiliated banks. The confidentiality strictness is a factor that impairs the
financial covenants, which may affect minority-owned businesses. The request for
proposal or request for quote procedures and policies are restrictive, preventing
minorityowned small businesses from being competitive because of limited access to the
funding source to satisfy the financial requirement (Offei et al., 2019).

42
Recent business development and economic growth changes challenge SMEs to
implement new proactive strategies to access finance. Environmental, social, and
governance are the measures SMEs need to introduce in the strategic planning for getting
finance and short and long-term sustainability (Păun (Zamfiroiu) et al., 2021). In addition,
Velasquez (2020) argued that minority small business owners, especially blackowned
businesses, the local employers contributing to their community's job creation, face
institutional discrimination and social inequalities, losing approximately a billion dollars
of revenue every year. The three persistent challenges, such as inadequate access to
capital, lack of mentorship, and non-proportionate business opportunities, prevent
minority business owners from prospering.
In the wake of COVID-19, minority-owned small businesses have experimented
with new ways to work with their employees safely, offer better income, and propose new
community services. Among 1,000 small businesses nationwide, more than 40% of
minority-owned-small businesses created new services to support their communities,
compared to 27% of businesses overall (Dua et al., 2020). During COVID-19, business
knowledge information is shared among small business owners and ethnic groups that
support their communities (Crick et al., 2021). The COVID-19 pandemic drastically
changed people's lifestyles (e.g., live, learn, work, and socialize) and small businesses
where socioeconomic and ethno-racial inequality were crucial (Ong et al., 2020). The
disruption of businesses which led to the closure of stores, factories, and businesses of all
sectors due to the COVID-19 pandemic, has disproportionately hit small businesses.

43
Among the businesses that COVID-19 negatively impacted, African Americans owned
41%, and 32% were Latinx compared to 17% whites owned (Atkins et al., 2022; Berdejo,
2021; Fairlie & Fossen, 2022; Fairlie, 2020; Ong et al., 2020; Velasquez, 2020).
The COVID-19 pandemic provoked a sudden disruption in economic behavior,
specifically with SMEs. The first quarter of 2020 started with the massive closing of
stores and other businesses, which negatively affected the U.S. economy and the
worldwide economy (Fairlie, 2020; Fairlie & Fozen, 2021). The mandatory closing due to
the COVID-19 outbreak plummeted the number of U.S. business owners from 15.0
million in February 2020 to 11.7 million in April 2020. The COVID-19 pandemic has
created unfavorable economic, social, and financial conditions similar to the crisis of
2000 (Kottika et al., 2020). In the first quarter of 2020, the U.S. GDP was reduced by
4.8% while the GDP of the Eurozone was reduced by 3.8%. In addition to the structural
challenge that minority-owned businesses face (Dua et al., 2020), COVID-19 negatively
impacted 41% African American-owned U.S. small businesses and 32% Latinx compared
to 17% White-owned (Atkins et al., 2022; Berdejo, 2021; Fairlie & Fossen, 2022; Fairlie,
2020; Ong et al., 2020; Velasquez, 2020). The COVID-19 pandemic outbreak challenges
small business leaders and researchers to develop appropriate strategies to prevent similar
events.
The coronavirus pandemic outbreak caused U.S. federal and state governments to
make drastic decisions to protect the population and businesses. The federal government
established the CARES Act, which offered support to businesses, including the PPP and
the EIDL program (Fairlie & Fossen, 2022) to support SMEs that were victims of the

44
COVID-19 pandemic. Priority was given to underserved markets and minority-owned
businesses. However, minority-owned small businesses face structural challenges due to
their economic fragility (Dua et al., 2020). While the federal government offered $349
billion through the PPP to address the COVID-19 crisis, many minority-owned small
businesses did not receive support because most were not members of the SBA (Hangen
& Swack, 2020). Forty-one percent of Black-owned small businesses did not benefit from
the PPP funds, and 21% did not get feedback from lenders (Atkins et al., 2022). It has
been noted that the first round of the PPP was not beneficial to Black-owned businesses
(e.g., the loan amounts that Black-owned businesses received were approximately 50%
lower compared to similar White-owned businesses). Overall, the smallest businesses
were unaware of the PPP and less likely to apply. In addition, those who applied later for
a loan saw the process take longer and somewhat did not get approved (Humphries et al.,
2020).
Summary and Transition
In this section, I presented the proposed study's background, problem, purpose,
and significance. The problem was that some business leaders did not know the
differences in the disbursed/shipped approved funding amount based on the
minorityowned status and size of the business. The research question that guides this
study is: Is there a difference in the disbursed/shipped approved funding amount based on
the minority-owned status and size of the business? I highlighted the target population,
the contribution to business practice, and the positive social change implications. Next, I
identified the FGC as the study’s theoretical framework and provided the key tenants of

45
the FGC. To assist readers’ comprehension of the study’s research and findings, I
provided operationalized definitions to elucidate the minority-owned businesses. Finally,
this section concludes with a summary of prior literature and highlights current gaps in
the research that this study intends to fill.

46
Section 2: Project Design and Process
Within this study, I examined the differences in the disbursed/shipped approved
funding amount based on the minority-owned status and size of the business. I utilized ex
post facto data collected from the Working Capital Transactions Authorization dataset
from 01/01/2006 to 09/01/2021, administrated by the Export-Import Bank of the United
States (EXIM Bank, 2020). Section 2 of this study includes a discussion of the study
method and design along with a description of how I collected and analyzed that data
within this study.
Method and Design
The purpose of this quantitative non-experimental causal-comparative study
utilizing ex post facto data was to examine the differences in the disbursed/shipped
approved funding amount based on the minority-owned status and size of the business.
Research Question (RQ): Is there a significant difference in the disbursed/shipped
approved funding amount based on the minority-owned status and size of the business?
Based on the research questions, the hypotheses are:
Null Hypothesis (Ho1): There is no difference in the disbursed/shipped approved
funding amount based on the minority-owned status of the business.
Alternative Hypothesis (HA1): There is a difference in the disbursed/shipped
approved funding amount based on the minority-owned status of the business
Null Hypothesis (Ho2): There is no difference in the disbursed/shipped approved
funding amount based on the size of the business.

47
Alternative Hypothesis (HA2): There is a difference in the disbursed/shipped
approved funding amount based on the size of the business.
Null Hypothesis (Ho3): There is no difference in the disbursed/shipped approved
funding amount among minority-owned businesses and non-minority-owned businesses
based on the size of the business.
Alternative Hypothesis (HA3): There is a difference in the disbursed/shipped
approved funding amount among minority-owned businesses and non-minority-owned
businesses based on the size of the business.
Research Method
In a quantitative study, a researcher uses quantitative methods to quantify and
analyze variables to get probate results (Apuke, 2017). A quantitative researcher
investigates the pertinent data to find the relationship between variables and provide
further recommendations. My research topic was an examination of the differences in the
funding of minority-owned businesses (small and large) compared to non-minority
businesses. The quantitative methodology was suitable for this study.
Research Design
The non-experimental design should be used since the groups examined are
neither randomly assigned nor should the independent variables be actively manipulated
within the proposed study. I analyzed secondary data to explain the interaction effect
between the independent and dependent variables. Using ex post facto data enabled me as
the researcher to identify the independent and dependent variables clearly and to what
extent these independent variables explain the dependent variable. My study focused on

48
ex post facto data with two existing independent variables (minority-owned businesses
and non-minority-owned) and a dependent variable (disbursed/shipped approved funding
amount). This study enabled me to examine the interaction effect of these two
independent variables on the dependent variable (Bougie & Sekaran, 2019).
Assumptions
Assumptions are notions or beliefs the researcher believes accurately guide the
study (Tocaven Gonsalez & Kastereen, 2021). The researcher conducts the study with the
operating assumptions. This study assumes that small businesses seek to acquire loans
from lenders (e.g., financial institutions). Another assumption is that the constructs that
fall under the secondary data (e.g., the Working Capital Transactions Authorization
dataset from 01/01/2006 to 09/01/2021) used for the study are valid and reliable sources.
Limitations
Limitations for any study are the potential weaknesses that the researcher cannot
control but are inherent to the research design, statistical model, and funding constraints
(Theofanidis & Fountouki, 2018). I used the data from the existing dataset; thus, the
variables available for examination are restricted to what is initially collected. Within the
authorizations dataset on the Import-Export Bank of the United States, the minority flag
was predetermined, preventing us from operationalizing minorities within the proposed
study.
Delimitations
Delimitations are the boundaries or limit the researcher sets within the study's
objectives (Theofanidis & Fountouki, 2018). With this study, I examined the differences

49
in the funding of minority-owned businesses (small and large) compared to non-minority
companies. My study was focused on small companies based in the United States from
2017 to 2022.
Data Collection
The Export-Import Bank of the United States approved the Working Capital
Transactions Authorization dataset from 01/01/2006 to 09/01/92022 (EXIM Bank, 2020).
The data were drawn from businesses and lenders across the United States. I used
Walden Library, ProQuest, ScienceDirect, Emerald, Sage, and Singer for my research.
Google Scholar and Google Search engine to find the Working Capital Transactions
Authorization data set from 01/01/2006 to 09/01/92021 (EXIM Bank, 2020). The data set
described the capital transactions that small and minority-owned businesses received for
exports and imports. The independent variables were minority-owned business status and
size of business. The dependent variable was the disbursed/shipped approved funding
amount. The scale of the measurement for the independent variable (minority-owned
business status) was nominal (minority = 1 and non-minority = 0), and the measurement
for the independent variable (business size) was nominal (small = 1 and not small = 0).
The measurement scale for the dependent variable was the ratio (disbursed/shipped
approved funding amount).
Data Analysis
Within this non-experimental causal-comparative study, I conducted a two-way
ANOVA. This enabled me to identify the main effect differences for each independent
variable on the dependent variable and the interaction of the independent variables within

50
the two-way ANOVA. Within this study, I examined the difference in the
disbursed/shipped approved funding amount based on the minority-owned status of the
business and the difference in the disbursed/shipped approved funding amount based on
the size of the business. Lastly, I examined the difference in the disbursed/shipped
approved funding amount among minority-owned and non-minority-owned businesses
based on the size of the business.
Ethics
Ethical research is the fundamental ethical principle that researchers must follow in
the process of dealing with participants (e.g., physical, institutional, and others). When
conducting research with human subjects, the U.S. government and institutions set up
regulations and ethical guidelines focusing on the participant’s rights and welfare
(Fernandez Lynch, 2020). In the context of this research, Walden University mandated
institutional review board (IRB) guidelines that I complied with to meet the university’s
ethical standards. Four steps were imperative to be completed: the researcher must
complete Form A, enabling IRB to provide tailored guidelines, submit the required
documents that meet the university’s ethical standards for approval, gain approval for the
proposal in accordance with the required documents, and finally I as the researcher
received a confirmation via email. I complied with the university’s ethical standards
before conducting my research.
This proposed research study used a quantitative research methodology using ex
post facto data the Working Capital Transactions Authorization dataset from 01/01/2006
to 09/01/2022. I explained my research work to all participants, including how I planned

51
to collect the data and protect the documentation, ensuring their privacy. The data will be
destroyed after 5 years in accordance with the university’s policy. I signed an agreement
with participants to ensure the research was conducted within the code of conduct.
According to Sim and Waterfield (2019), the consent has four components: disclosure, the
researcher gets adequate information needed; comprehensive, all participants properly
understand the information that the researcher collected; competence, the participants
have the capacity to accept or refuse the agreement; and voluntarily, any participant is not
under pressure to give his consent. The application of ethical principles was crucial to
protect and preserve participants’ dignity, rights, and personal identification information
during the designing, conducting, and reporting of research (Matandika et al., 2022).
The term “ethics” is a set of normative rules that define the behavior and actions
of a group living in an organization based on the norms and conducts (Pappa & Filos,
2019; Pappa et al., 2022). A code of ethics is a set of rules, principles, and practices that
all actors voluntarily adhere to for the performance of an organization. The code of ethics
requires continually implementing the best practices through training and communication
of an organization's ethics guidelines and policies (Pappa et al., 2022). The relationship
between methods and ethics is noticeable in the quantitative method because researchers
often claim that the quantitative methods are value-neutral or objective (Zyphur &
Pierids, 2019). An ethical climate is imperative for improving organizational performance
(Sabiu et al., 2019). The ethical climate defines policies, practices, and procedures on
ethical matters, which influences the participants’ attitudes and behavior toward the
performance of an organization (Ahmad et al., 2018). The decision-making and conduct

52
of people are based on the trust between the researcher and participants and what is
considered as wrong or right.
Transition and Summary
In Section 2, in addition to the purpose statement and the research
question/hypothesis I presented briefly, I explained the importance of the study’s research
method and design. After enumerating the assumptions, limitations, and delimitations, I
described how I collected and analyzed data and ended with a discussion of ethical
research. In Section 3, I work on deliverables. The contents of deliverables consists of an
executive summary, a presentation of quantitative data analysis, which includes graphs
and figures, results and conclusions of the analysis, recommendations for action,
communication plan, social change impact, and skills and competencies,

53
Section 3 The Deliverable
In this section, I provide an executive summary of the quantitative data analysis
results, including conclusions, recommendations for actions, a communication plan, and a
description of the impact of social change. I organized this section as follows: (a)
executive summary, (b) presentation of quantitative data analysis, (c) descriptive and
inferential results and conclusions of the analysis, (d) recommendations for action, (e)
communication plan, (f) social impact, and (g) skills and competencies.
Executive Summary
The purpose of this quantitative non-experimental causal-comparative study
utilizing ex post facto data is to examine the differences in the disbursed/shipped
approved funding amount based on the minority-owned business status and size of the
business. The data set used within this study is the Working Capital Transactions
Authorized data set, administered by the Export-Import Bank of the United States (EXIM
Bank, 2020) and drawn from businesses and lenders across the United States. The target
population examined within this study was small enterprises legally established in the
United States for more than 5 years and small business loan banks. A two-way ANOVA
analysis was used to determine if there was a statistically significant difference between
the disbursed/shipped approved funding amount for the two independent variables: size
of the business and minority-owned business status.
Purpose of the Project
Utilizing a quantitative methodology, I examined the differences in the funding of
minority-owned businesses (small and large) compared to non-minority businesses. A

54
non-experimental causal-comparative design was used since the groups examined were
neither randomly assigned nor were the independent variables actively manipulated
within the study. My study focused on ex post facto data with two independent variables:
minority-owned business status and size of business, and a dependent variable:
disbursed/shipped approved funding amount. My study was to examine the interaction
effect of the two non-numeric independent variables on the single numeric dependent
variable (Bougie & Sekaran, 2019).
The social change implications associated with this research are the potential
contribution of highlighting the iniquities in the disbursed/shipped approved funding
amount between minority and non-minority businesses, thereby reducing the inequalities
between minority and small businesses. Within this study, I present the study’s findings,
including the descriptive results, the tests for assumptions, and the results addressing the
research question. This section also includes a discussion of the applications for
professional practice and social change implications. Finally, this section ends with
recommendations for action and further research, a reflection based on this study, and a
conclusion of the study.
Overview of Findings
Within this study, I examined whether there was a significant difference in the
disbursed/shipped approved funding amount based on the minority-owned status and size
of the business. I used Statistical Package for Social Science (SPSS) statistical software to
conduct a two-way ANOVA for data analysis. I ued SPSS to examine the descriptive and
inferential results and provided my analysis and conclusions. The results of the findings

55
indicated that there was a statistically significant interaction between minorityowned
status and the size of the business on the disbursed/shipped approved funding amount F
(1, 48014) = 36.49, p < .001, Partial η2= .001. Thus, the null hypothesis (Ho3), that There
is no difference in the disbursed/sipped approved funding amount among minority-owned
and non-minority-owned businesses based on the business size, was rejected. Given that a
significant interaction was found, I analyzed the simple main effects of minority-owned
status and the size of the business. There was a statistically significant difference in
disbursed/shipped approved funding amount between small and non-small businesses
based on minority business status, F (1, 48014) = 95.932, p < .001,
Partial η2 = .001.
Recommendations
Within this quantitative ex-post facto study, I analyzed the difference in the
disbursed/shipped approved funding amount based on the minority-owned status and size
of the business. The independent variables were minority-owned business status and
small business size with two categorical value levels, respectively. The dependent
variable was the ranked disbursed/shipped approved amount. The findings of this study
might contribute to positive social change by highlighting iniquities between minority and
non-minority businesses, thereby reducing the inequalities between minority and small
businesses in the disbursed/shipped approved loan amount. Also, the results of the
findings could challenge lenders and decision-makers to create greater equity in funding
minority businesses. Results might enhance business strategies and financial performance
and improve nationwide economic growth.

56
Presentation of the Findings
In this section, I share the research study’s findings aligned with the research
question. I briefly discuss the techniques of data collection and data analysis. Then, I
present descriptive and inferential statistical results, discuss the tests of the assumptions,
and conclude with a concise summary. Descriptive statistics depict the sample using
central tendency (mean, median, and mode), range and standard deviation, and graphics
(Guetterman, 2019; Sullivan-Bolyai & Bova, 2014). Descriptive statistics are used to
describe in a few words the basic features of the data in a study, such as the mean and
standard deviation (SD) (Mishra et al., 2019), and provide a first view of the data
(MacFarland, 2011). Inferential statistics enable a researcher to analyze the data collected,
test hypotheses, answer research questions (Sullivan-Bolyai & Bova, 2014), and draw
conclusions from a sample to a population (Guetterman, 2019; Mishra et al., 2019). The
two-way ANOVA is the appropriate method used to examine whether the independent
variables have an interaction effect on the dependent variable. The SPSS is the software
that I used to conduct a two-way ANOVA to examine the difference in the fractional
ranked data of disbursed/shipped loan amount based on the minority-owned status of the
business and the difference in the fractional ranked data of disbursed/shipped loan
amount based on the size of the business. The two-way conducted utilizing SPSS enabled
me to test the data in accordance with the research question and hypotheses. The test of
between-subjects showed that there was a statistically significant interaction between
minority-owned status and the size of business on disbursed/shipped approved funding

57
amount, F (1, 48014) = 36.49, p < .001, Partial η2 = .001. The null hypothesis was
rejected because the interaction effect between variables was statistically significant
(p < .05).
Data Collection
The data set used in this research study, the Export-Import Bank of the United
States, Approved Working Capital Transactions Authorization dataset from 01/01/2006 to
12/31/2022, includes minority-owned small businesses in the United States of America
(EXIM Bank, 2020). I used Google Scholar and Google Search to find the Approved
Working Capital Transactions Authorization dataset drawn from businesses and lenders
across the United States. The Approved Working Capital Transactions Authorization
dataset described the capital transactions that small and minority-owned businesses
received for exports and imports. The independent variables used within this study were
minority-owned business status and size of business. The dependent variable was the
disbursed/shipped loan amount. The scale of the measurement for the independent
variable minority-owned business status is nominal (minority = 1 and non-minority = 0),
and the measurement for the independent variable the business size is nominal (small = 1
and not small = 0). The measurement scale for the dependent variable, the
disbursed/shipped approved funding amount, is a ratio. The dependent variable was
operationalized as a percentage of fractional ranked disbursed/shipped loan amount data.
The percentage of fractional ranked data of disbursed/shipped loan amount was created
using a transformation of the disbursed/shipped approved funding amount variable to
address the outliers within the data. I used Transform, the Rank Case, and Rank Types

58
(Fractional Rank as Percentage) within the analyses I conducted in SPSS to create the
percentage of fractional ranked data of disbursed/shipped loan amount for analysis.
Data Analysis
Within this non-experimental causal-comparative study, I conducted descriptive
statistics to depict the sample and inferential statistics, specifically a two-way ANOVA, to
examine the interaction between minority-owned status and the size of the business on
the disbursed/shipped approved funding amount. Descriptive statistics depicting the
sample's central tendency (i.e., mean and median), range, and standard deviation are
presented. The study’s analysis also included tests of the assumptions associated with the
two-way ANOVA. The application of the two-way ANOVA is necessary for the
interaction effects and to test the significance of the interaction term. A two-way ANOVA,
also known as a two-way factor, was used to determine whether there is a simultaneous
effect of at least two nominal independent variables (Assaad et al., 2015). A two-way
ANOVA was used to understand whether there was any interaction between the
independent and dependent variables (Mishra et al., 2019). The two-way ANOVA enabled
me to identify the effect differences for each independent variable on the dependent
variable and the interaction effect of the independent variables on the dependent variable.
Within this study, I examined the difference in the fractional ranked data of
disbursed/shipped loan amount based on the minority-owned status of the business and
the difference in the fractional ranked data of disbursed/shipped loan amount based on the
size of the business. Lastly, I examined the difference in the fractional ranked data of

59
disbursed/shipped loan amounts among minority-owned and non-minority-owned
businesses based on the size of the business.
Descriptive Statistics
I retrieved the data set from the U.S. EXIM Bank website. The data set described
the capital transactions that small and minority-owned businesses received for exports
and imports. I identified two independent variables: small business size, which was
categorized into two groups (small = 1 and non-small = 0), and minority-owned business,
which was split into two categories (minority = 1 and non-minority = 0). The
measurement scale for the dependent variable disbursed/shipped approved funding
amount is ratio. The dependent variable was a percentage of fractional ranked
disbursed/shipped loan amount data. I used Transform, Rank Case, and Rank Types
(Fractional Rank as Percentage) to calculate the percentage of fractionally ranked
disbursed/shipped approved funding amounts utilizing SPSS statistical software.
The data included 48,018 businesses within the Approved Working Capital
Transactions Authorization data set. The mean funding amount for small businesses was
$2,346,909 with a standard deviation (SD) = $27,100,000, while the mean for non-small
businesses was $4,304,617 with an SD = $33,300,000. Given the presence of outliers and
the large standard deviations, I transformed the dependent variable (disbursed/shipped
approved funding amount) to the percentage of fractional ranked data of
disbursed/shipped loan amount. I then calculated the descriptive statistics for the
percentage of fractional ranked data of disbursed/shipped approved funding amounts. The
mean percentage of fractional ranked data of disbursed/shipped loan amount for
60
nonminority-owned small businesses was M = 49.53 (SD = 27.59), while the mean for
minority-owned small businesses was M = 44.97 (SD = 27.49). The mean percentage of
fractional ranked data of disbursed/shipped approved funding amount for non-small
businesses was M = 56.45 (SD = 32.69). The mean percentage of fractional ranked data
of disbursed/shipped loan amount for minority-owned businesses was M = 63.00 (SD =
28.71) compared to non-minority was M = 56.21 (SD= 32.80). Minority-owned small
businesses had the smallest percentage (27.49) of fractional ranked data of
disbursed/shipped approved funding amount. No missing data were noticed. Table 1
depicts the descriptive statistics for the independent and dependent variables included in
the study.
Table 1
Means and Standard Deviations for Fractional Rank Percent of Disbursed Shipped
Amount
Small
Non-minority
49.5318
27.58647
34815
Minority
44.9744
27.48759
5994
Total
48.8624
27.61879
40809
Total
Non-minority
50.6451
28.62926
41776
Small business flag
Minority owned flag
Mean
Std. deviation
N
Non-small
Non-minority
56.2131
32.79896
6961
Minority
62.9964
28.71475
248
Total
56.4465
32.68856
7209
61
Minority
45.6904
27.75914
6242
Total
50.0010
28.56601
48018
Note: Dependent variable: Fractional Rank Percent of Disbursed Shipped Amount
Test of Assumptions
Assumptions testing is crucial for data analysis in any statistical model. When
tests of the assumptions are met for the test statistics (e.g., F, t), it indicates that the
results, including p-values and descriptive and inferential statistics (e.g., effect size,
confidence intervals, correlation coefficients), are accurate (Hu & Plonsky, 2021). The
analysis of variance F test is commonly used to test the null hypothesis to determine the
effect of the independent variable on the dependent variable (Sheng, 2008). Thus,
assumptions need to be met so that the F test may produce a valid statistical result. The
testable assumptions for the two-way ANOVA are no significant outliers, the dependent
variable (residuals) should be approximately normally distributed, and the homogeneity
of variance (i.e., the variance of your dependent variable [residuals] should be equal)
(Laerd Statistics, 2024). I conducted a two-way ANOVA to test the main and interaction
effects of the two independent variables (categorical) on the continuous dependent
variable (Bougie & Sekaran, 2019; Green & Salkind, 2019).
Outliers
An examination of the assumption of no significant outliers was generated from
an exploration of the descriptive statistics. The independent variables included in this
study were both dichotomous. The first independent variable, minority-owned business
status, is nominal (minority = 1 and non-minority = 0), and the second independent

62
variable, small business size, is also nominal (small = 1 and non-small = 0). Utilizing
SPSS Statistics software, I split the data files to explore the descriptive statistics and
evaluate outliers within the dependent variable, the percentage of fractional ranked data
of disbursed/shipped loan amount. The two-way ANOVA is concerned with the
investigation of the simultaneous effects of two nominal variables, which might take
different categorical values known as levels (Assaad et al., 2015). The manipulated test of
boxplots proved that there were no outliers as assessed by inspection of the boxplots. The
examination of the boxplots (see Figure 1) displaying the interaction between
independent variables small business size and minority-owned small business status on
the dependent variable ranked data of disbursed/shipped loan amount showed the normal
distribution of disbursed/shipped approved amount. Thus, the results proved no outliers,
as assessed by inspection of a boxplot.
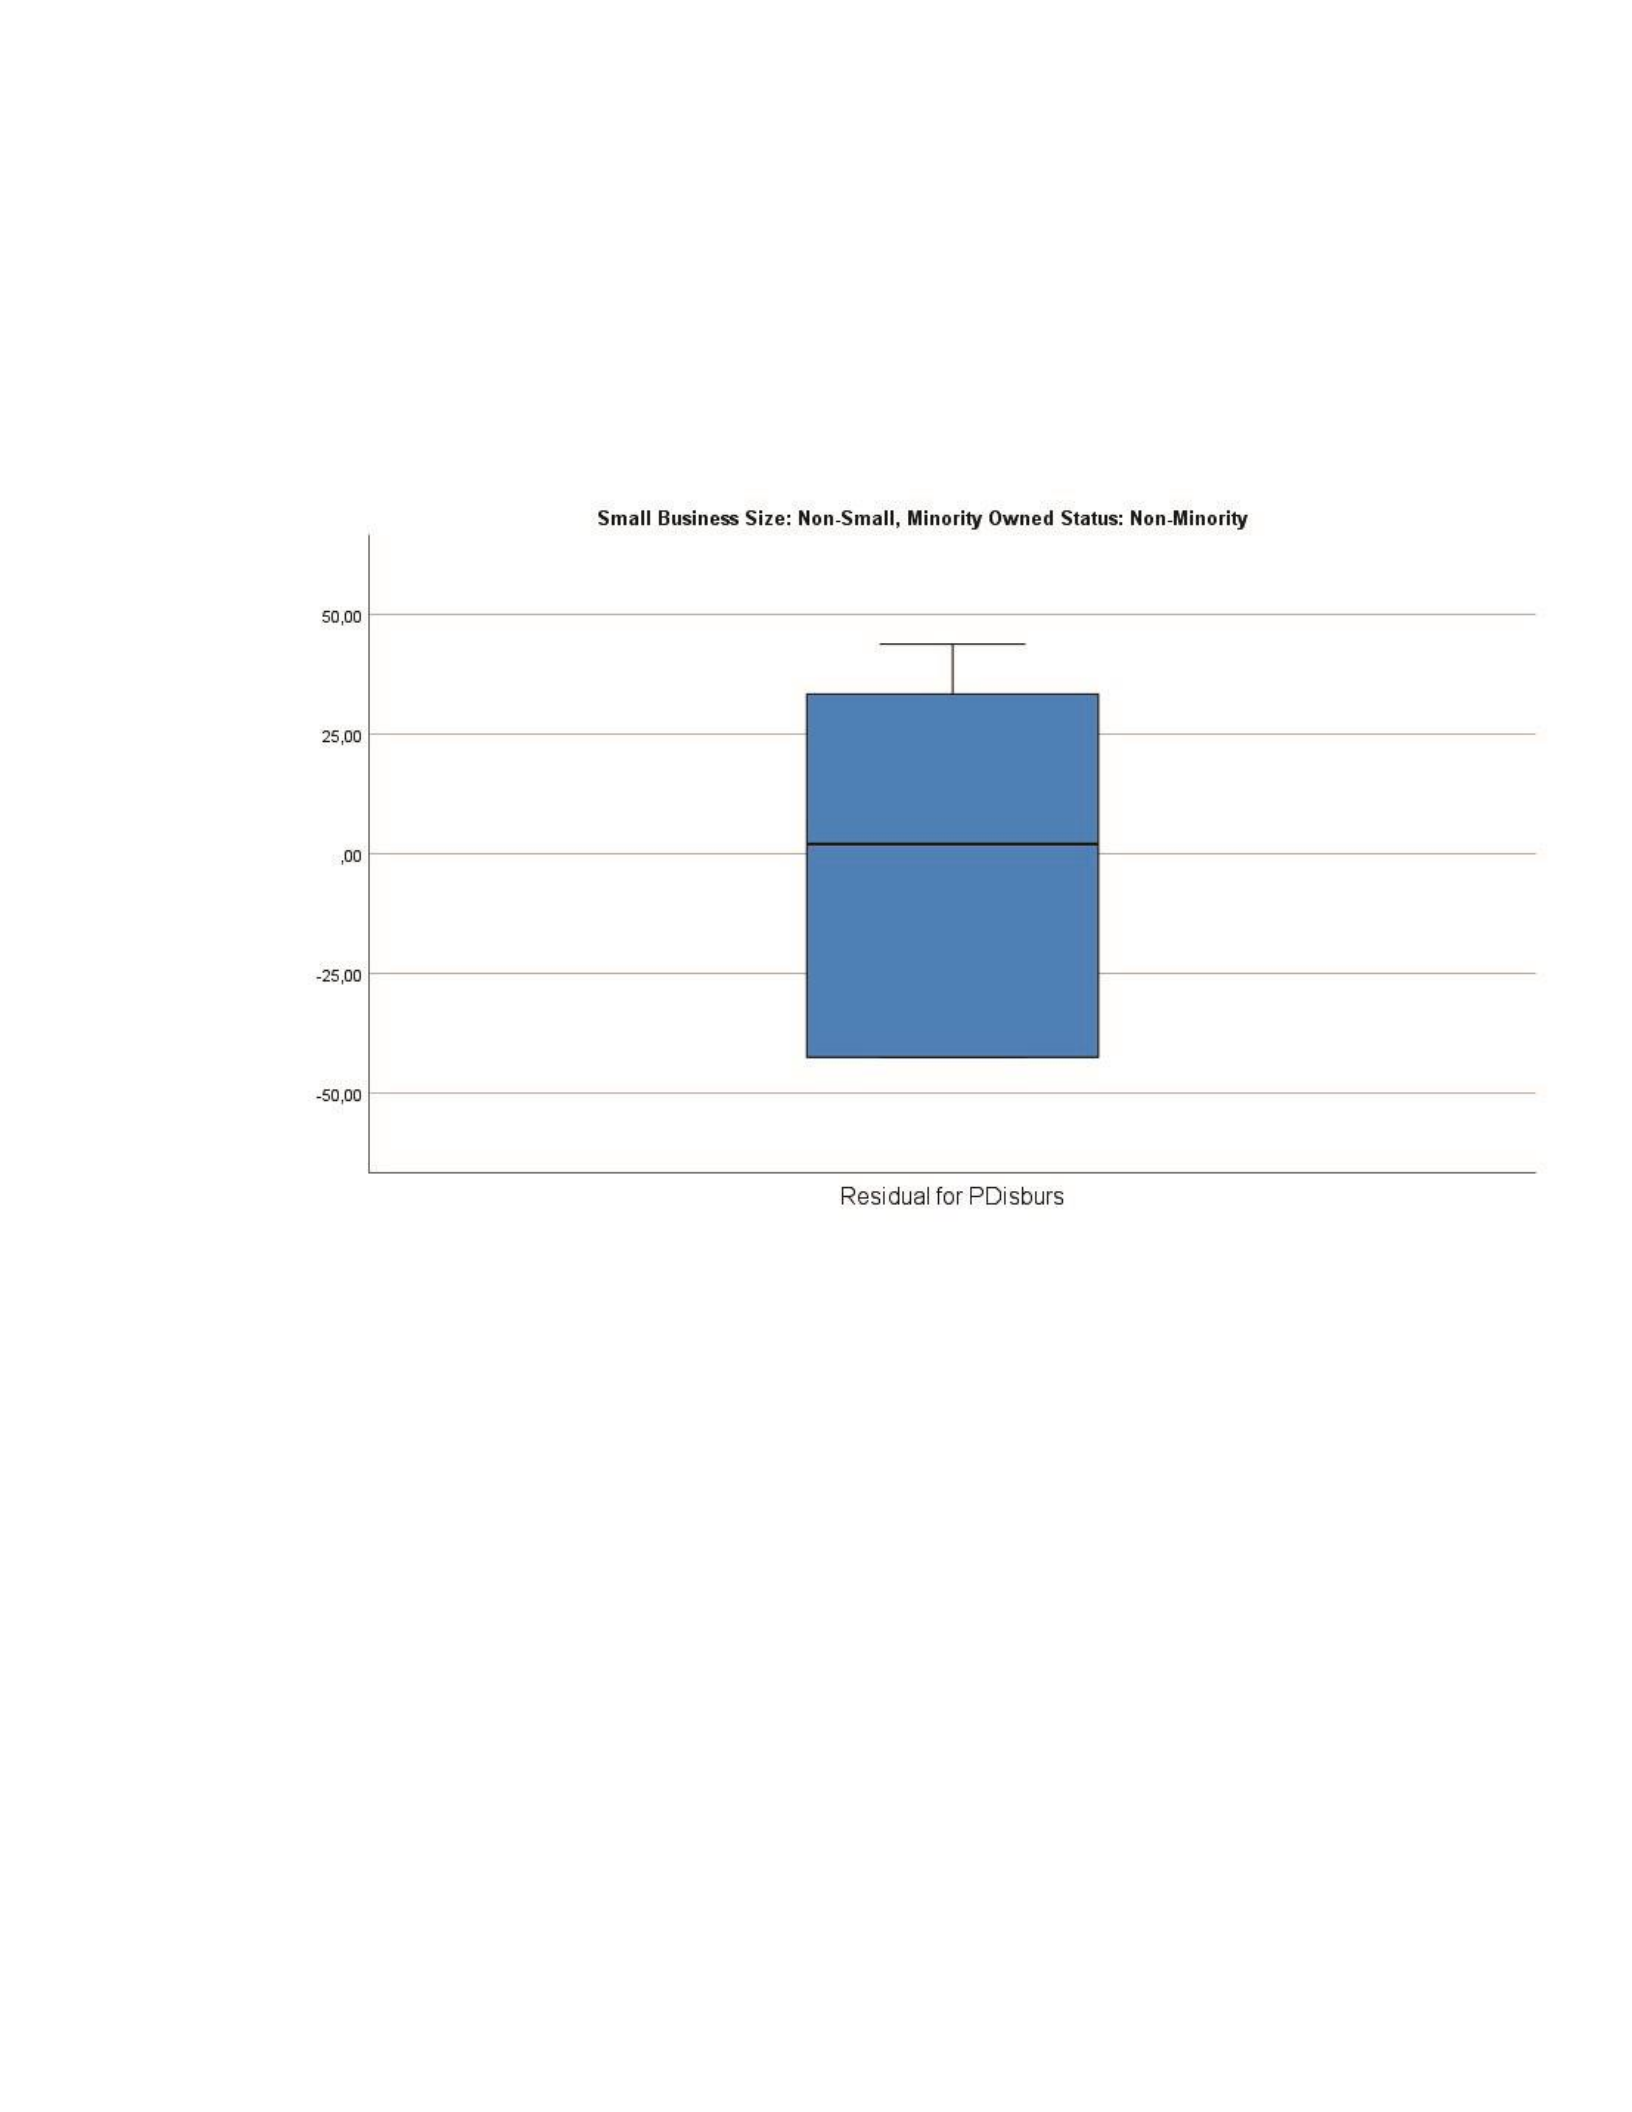
63
Figure 1
Outliers of Small Businesses and Minority-Owned Small Businesses
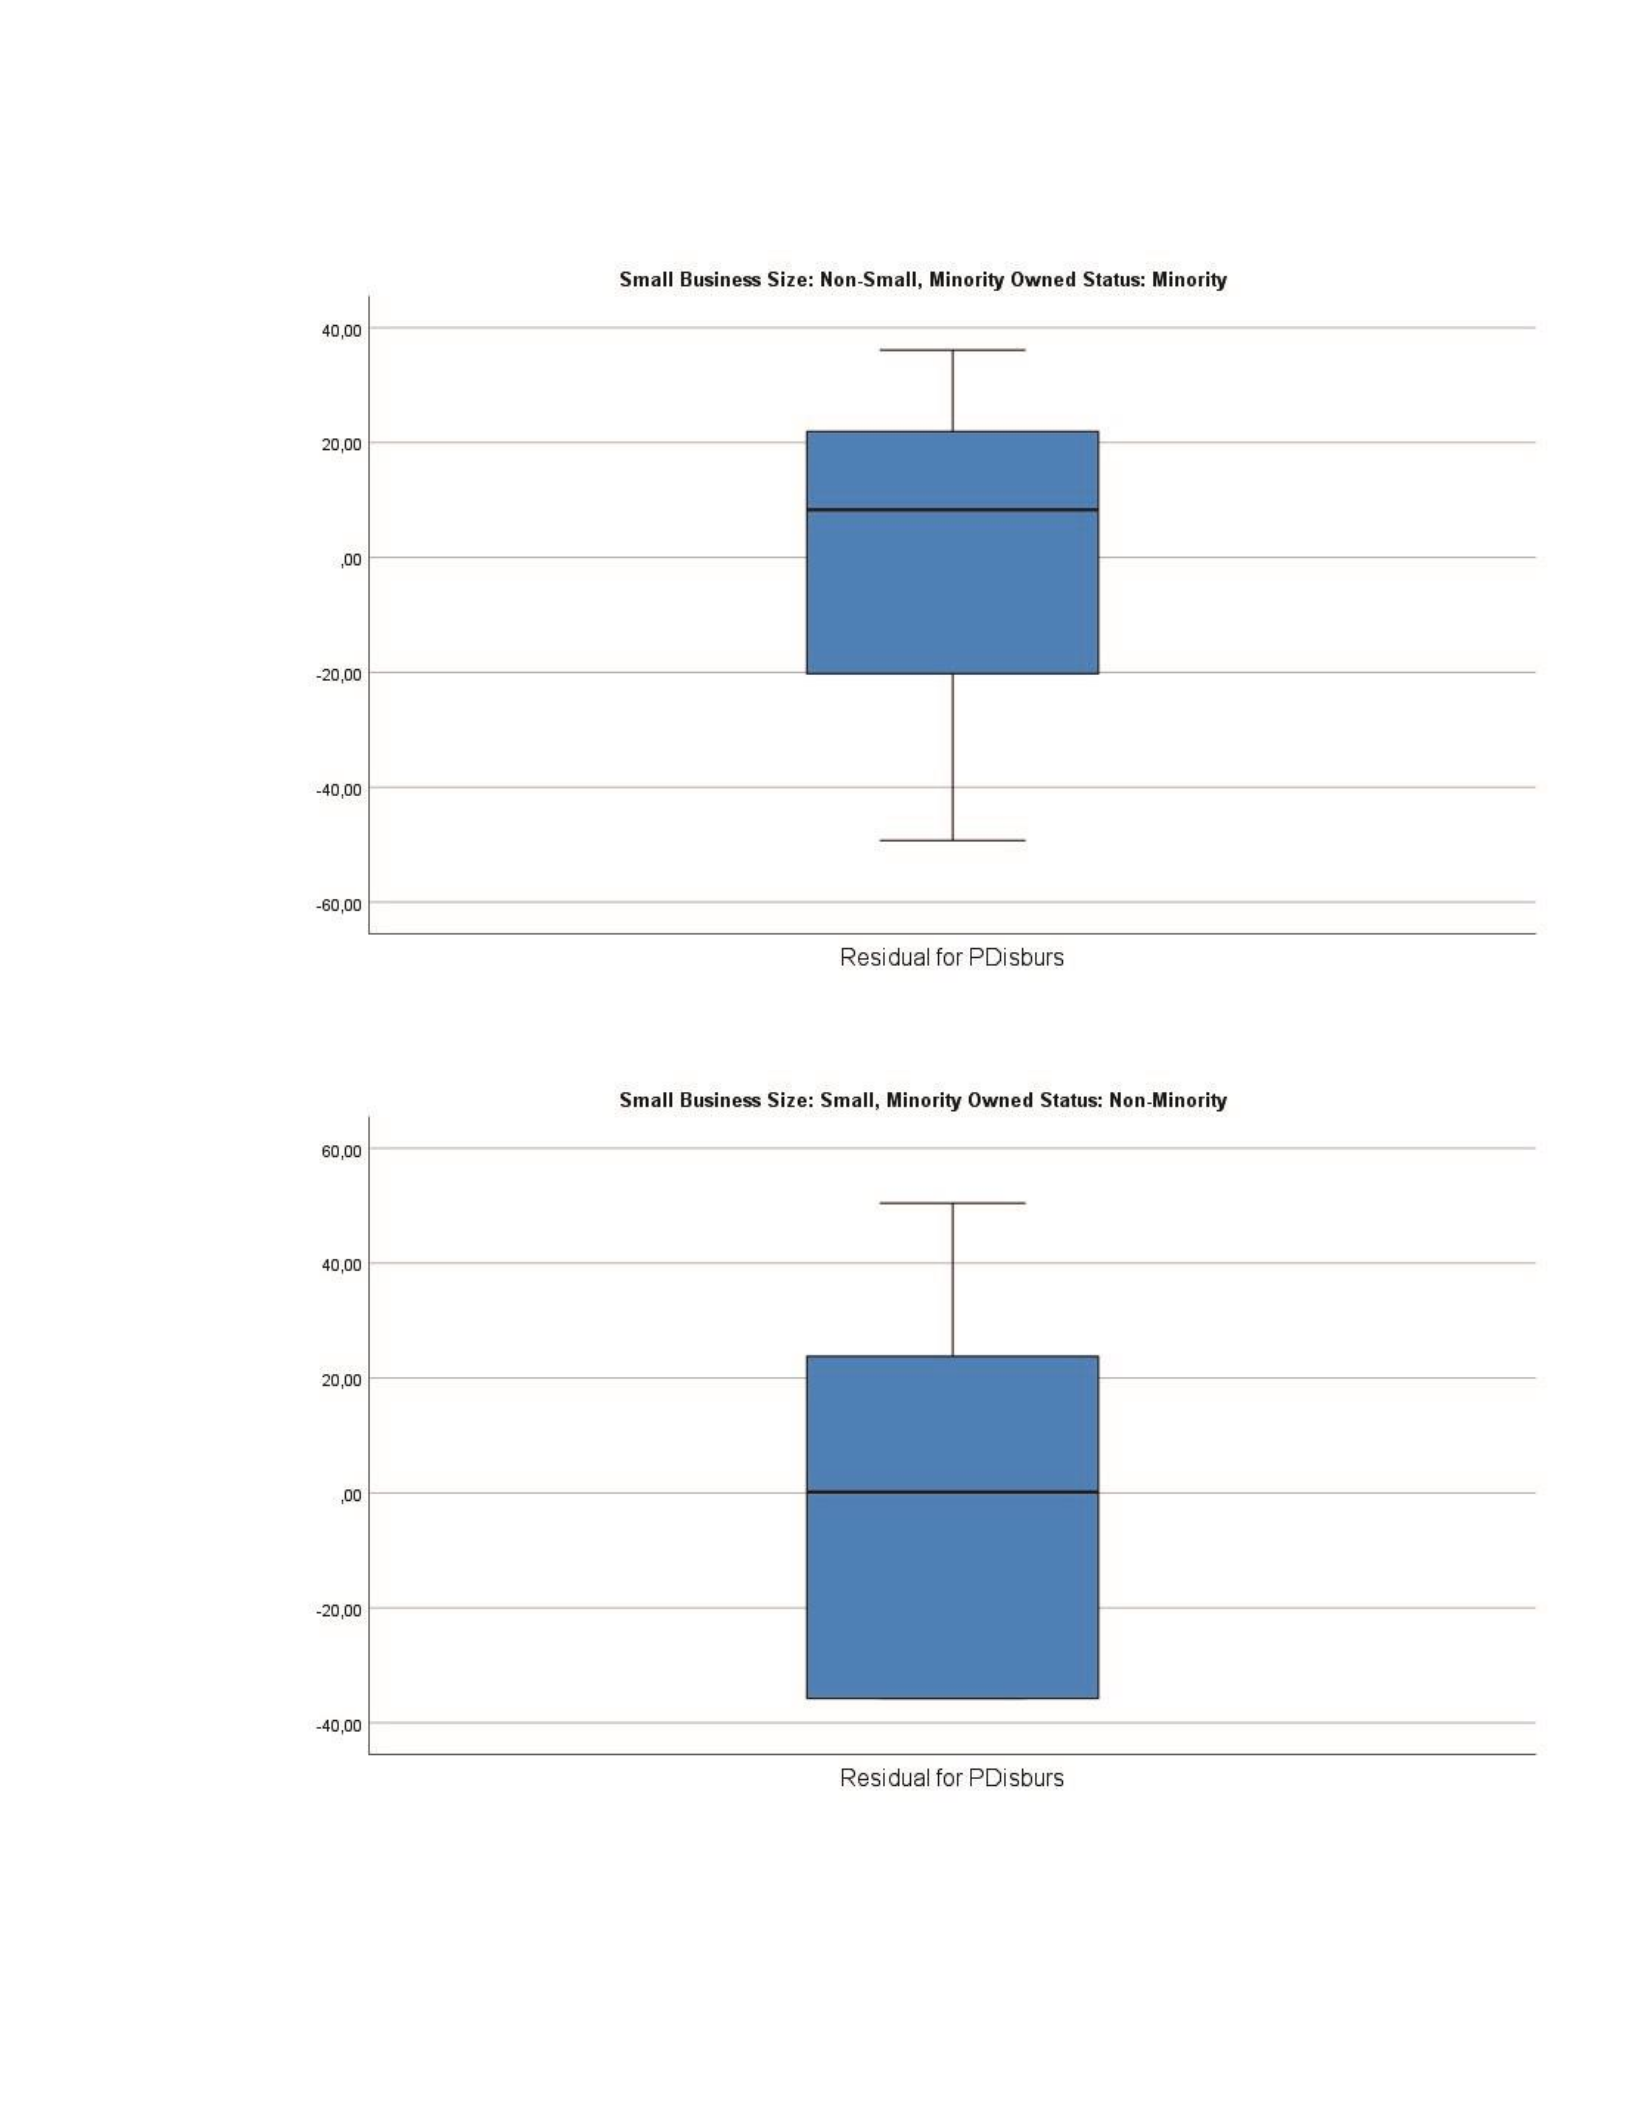
64
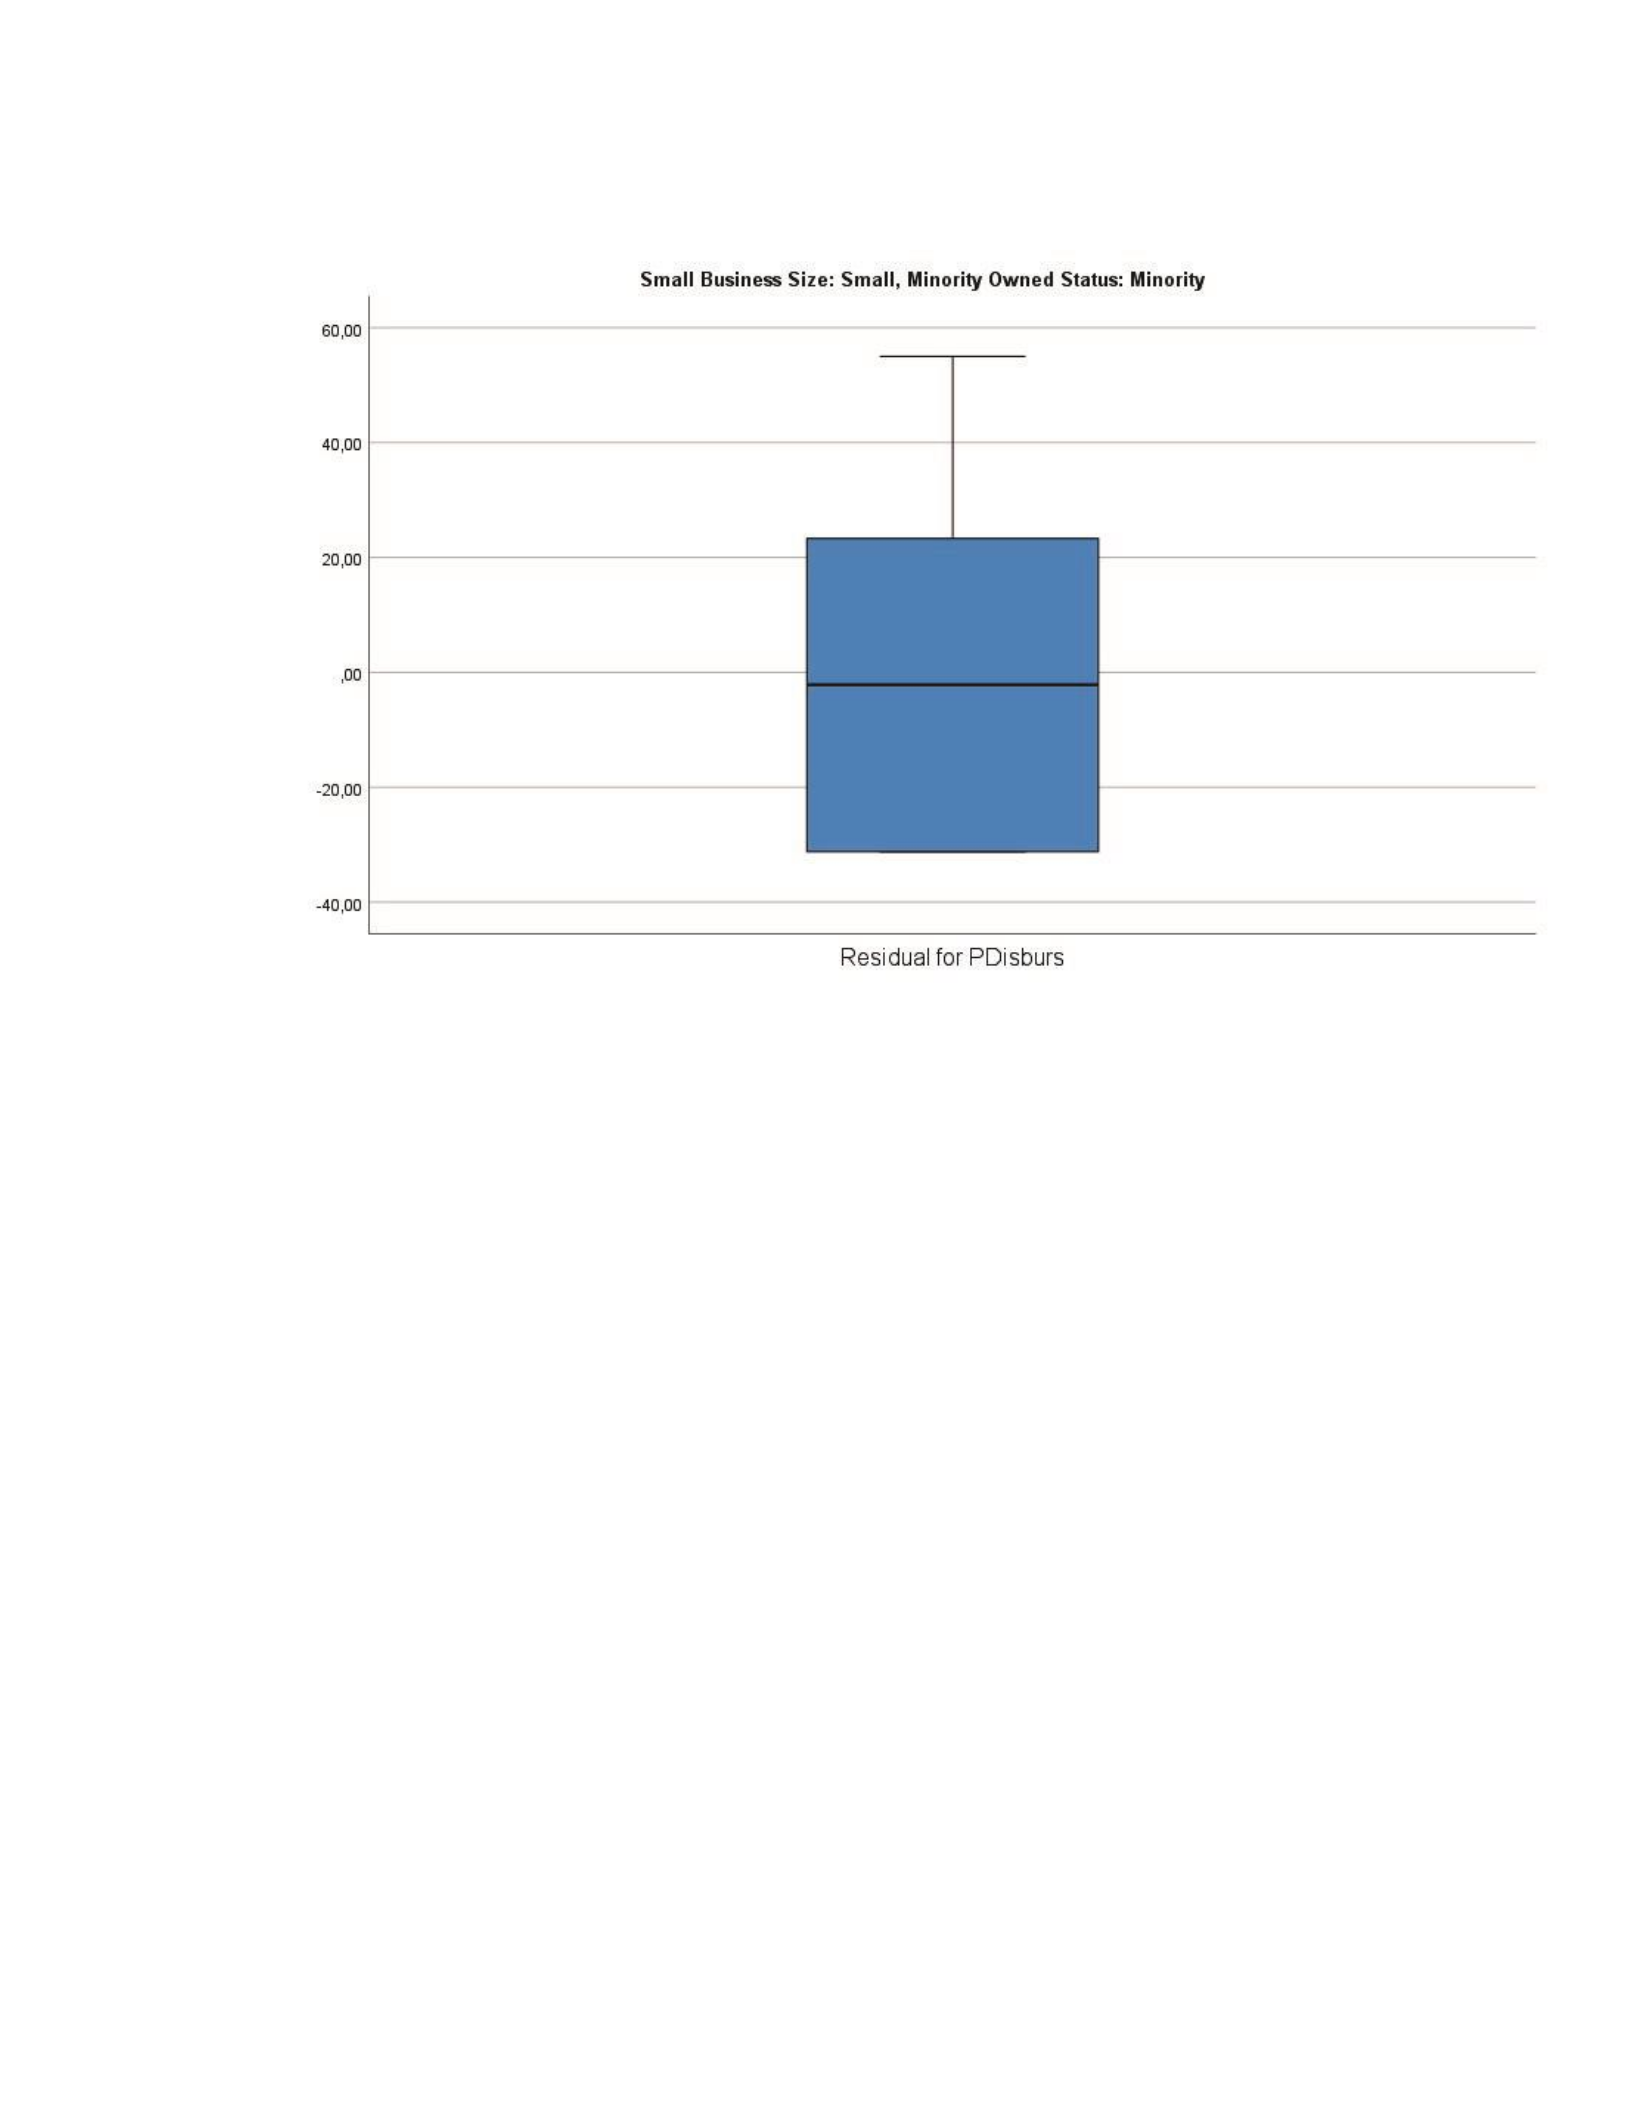
65
Normality
The assumption of normality is a test of the residuals rather than the raw data.
Therefore, an investigation of the residuals, Res_1, is required to determine if each cell of
the design is normally distributed (Laerd Statistics, 2024). The two-way ANOVA assumes
that the data/residuals of each cell are normally distributed. Thus, I conducted the
Kolmogorov-Smirnov normality test as a test of normality. The Kolmogorov-Smirnov
normality test was run to test each group's combination of the two independent variables
(Minority-Owned small business status and small business size). The p-value of the
Kolmogorov-Smirnov normality test was less than 0.001 (p < .001). The assumption of
normality has been violated, indicating that the Residual (Res_1) and dependent variable
(percentage of fractional ranked data of disbursed/shipped loan amount) have not been
normally distributed for each group combination of the two independent variables. Thus,
66
248
<.001
34815
.000
the data were not normally distributed as assessed by the Kolmogorov-Smirnov normality
test (p < .001). Table 2 depicts the assumption of normality for the variables within the
study.
Table 2
Assumption of Normality Test
Small Kolmogorov-Smirnova business flag Minority owned flag Statistic df
Sig.
Non-small Non-minority Residual for PDisburs .190 6961 .000
Minority Residual for PDisburs .134
Small Non-minority Residual for PDisburs .166
Minority Residual for PDisburs .201 5994 .000
Note: “a”; Lilliefors significance correction
The data set used in this study is large, and ANOVAs can be fairly robust to
deviations from normality, although no specific research has been conducted into a
twoway ANOVA. Given that two-way ANOVA could be robust to the violation of
normality, it may allow the researcher to make inferences without needing the assumption
of normality (Laerd Statistics, 2024). Also, at this time, SPSS statistics does not offer a
robust test for the two-way ANOVA.
The histogram enabled me to understand the way the data were distributed and
provided a visual inspection of the assumption of normality. The histogram examined the
displayed curve of the dependent variable ranked disbursed/shipped approved amount
(see Figure 2). The assumption of normality on the dependent variable ranked
disbursed/shipped approved amount was statistically significant. Thus, I failed to reject
the null hypothesis. A visual inspection of the histogram displaying the fractional ranked
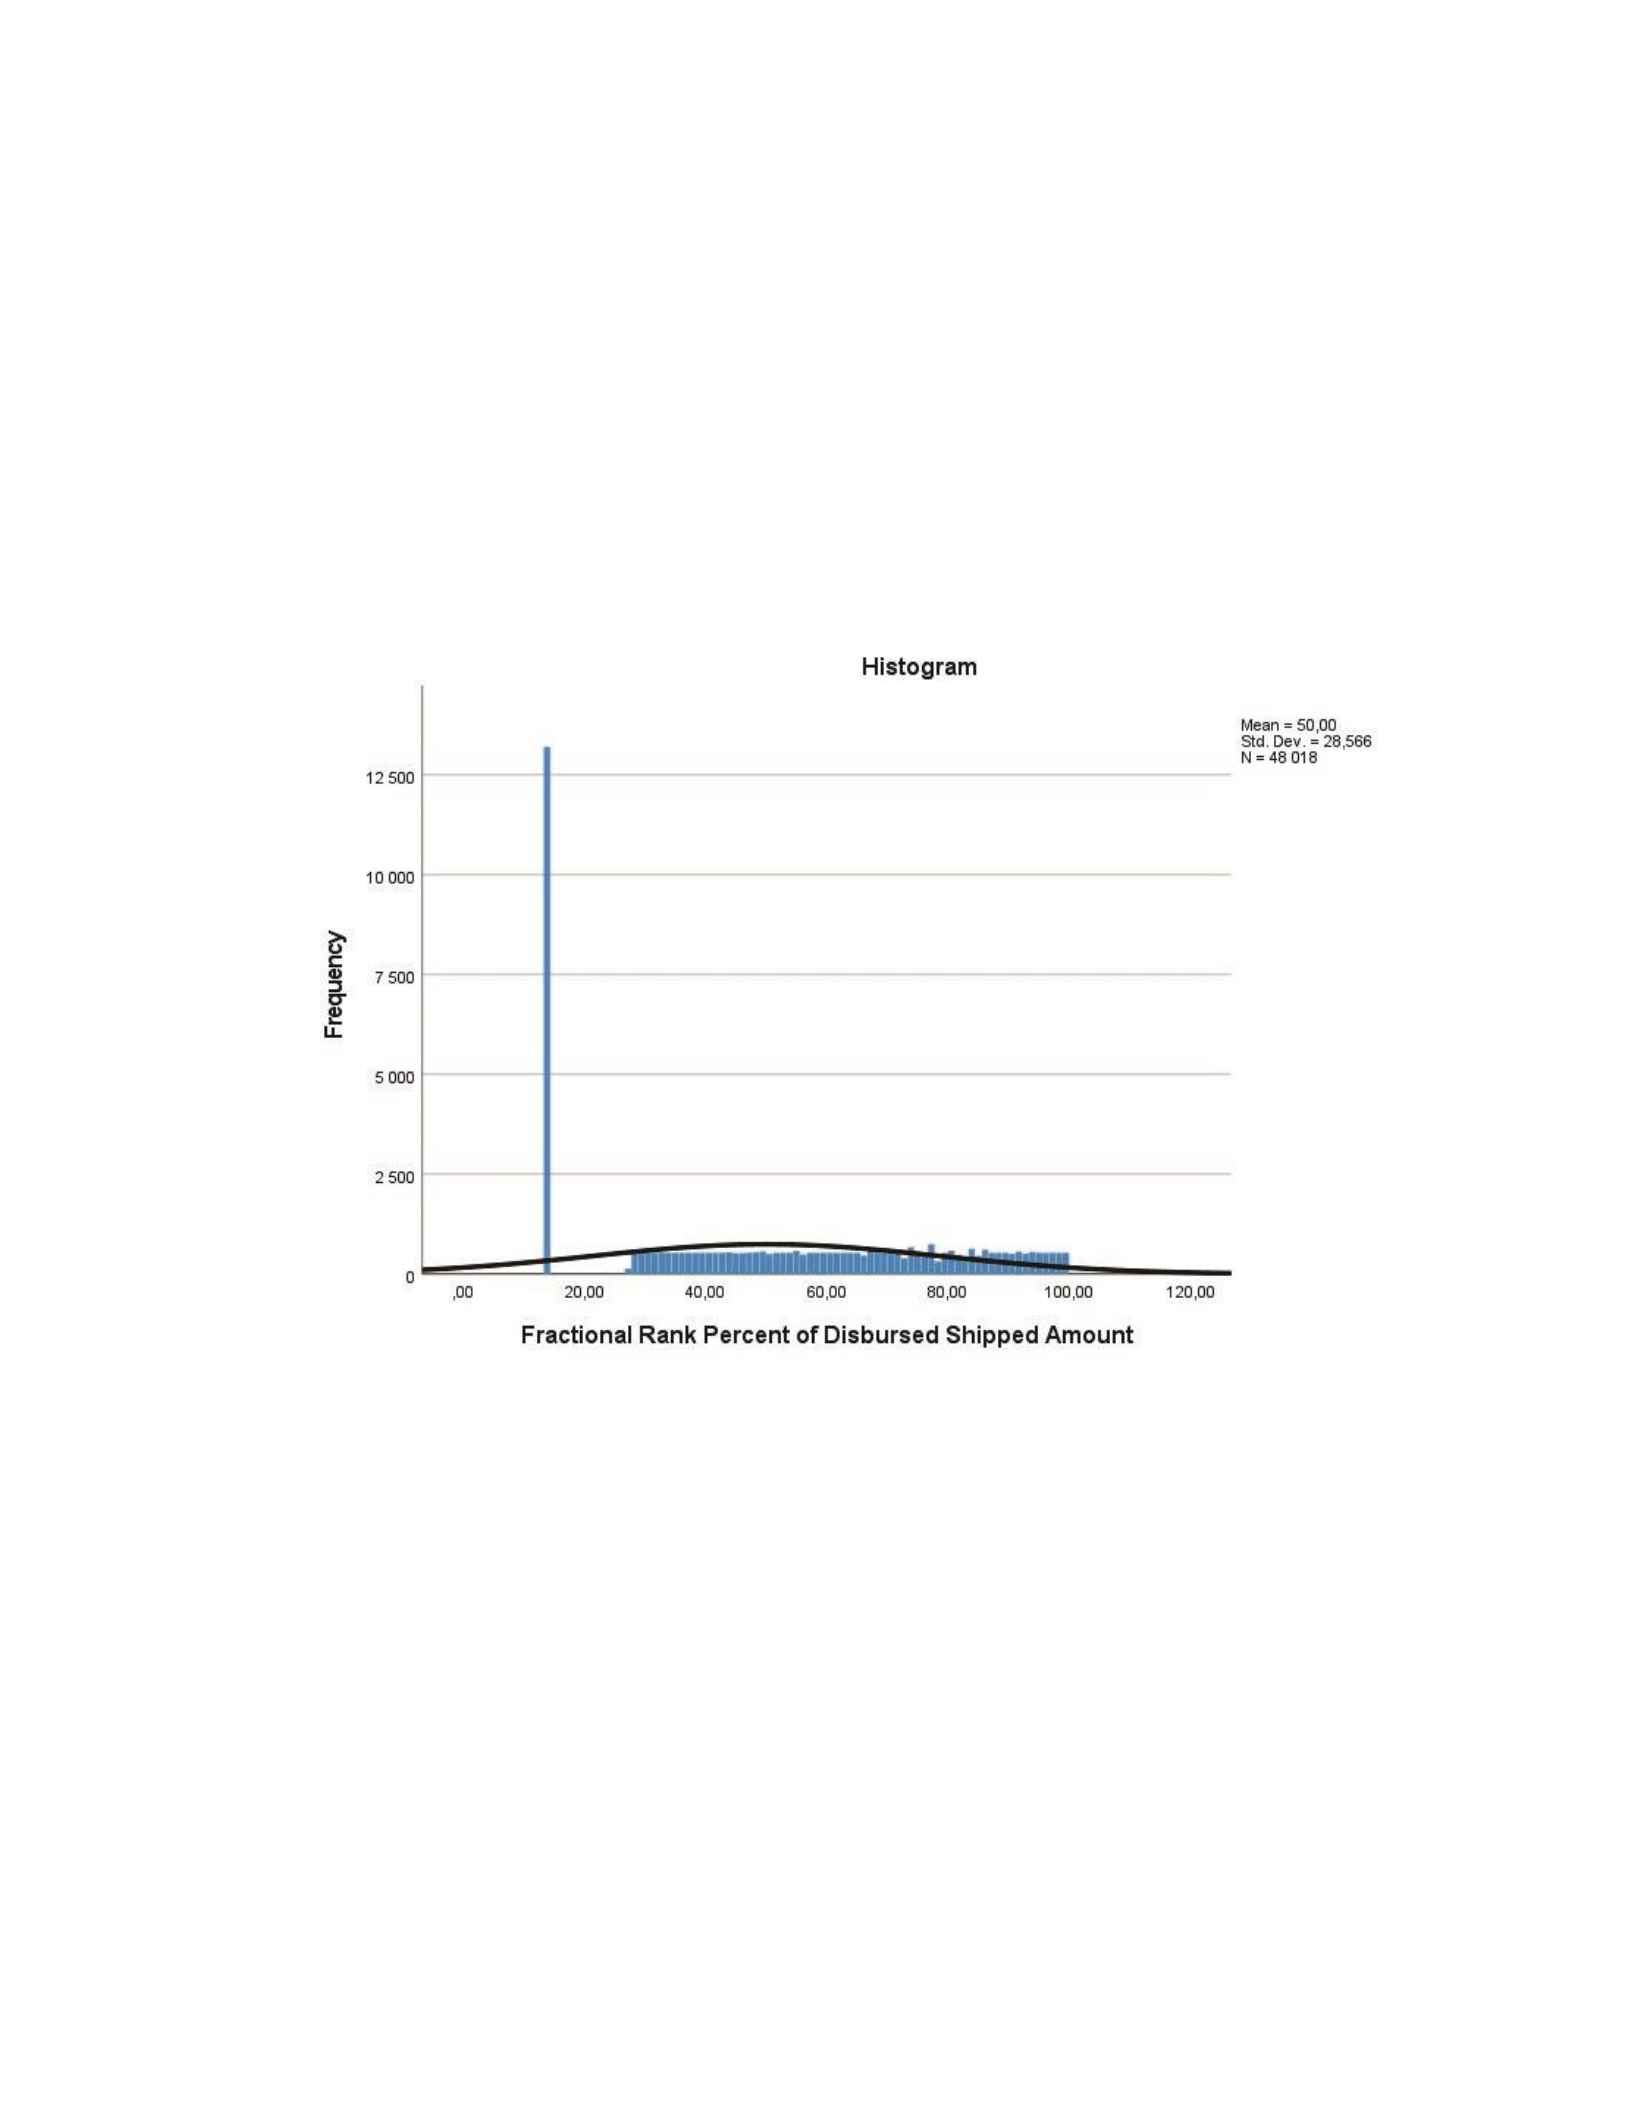
67
percentage of the disbursed/shipped approved amount indicated that the assumption of
normality was violated (see Figure 2).
Figure 2
Histogram of Fractional Rank Percent of Distributed Shipped Amount
Another method of assessing the normality of the residuals of the dependent
variable, the percentage of fractional ranked data of disbursed/shipped loan amount, was
through examining a Q-Q plot. The normal Q-Q plots were used to assess the assumption
of normality graphically. Based on an inspection of the residuals presented in the Q-Q
plots in Figure 3, the groups considered are all skewed in a similar manner; thus, the
violation of normality is not considered a serious violation of this assumption (Laerd
Statistics, 2024). It should be noted that if the distributions are all skewed in a similar
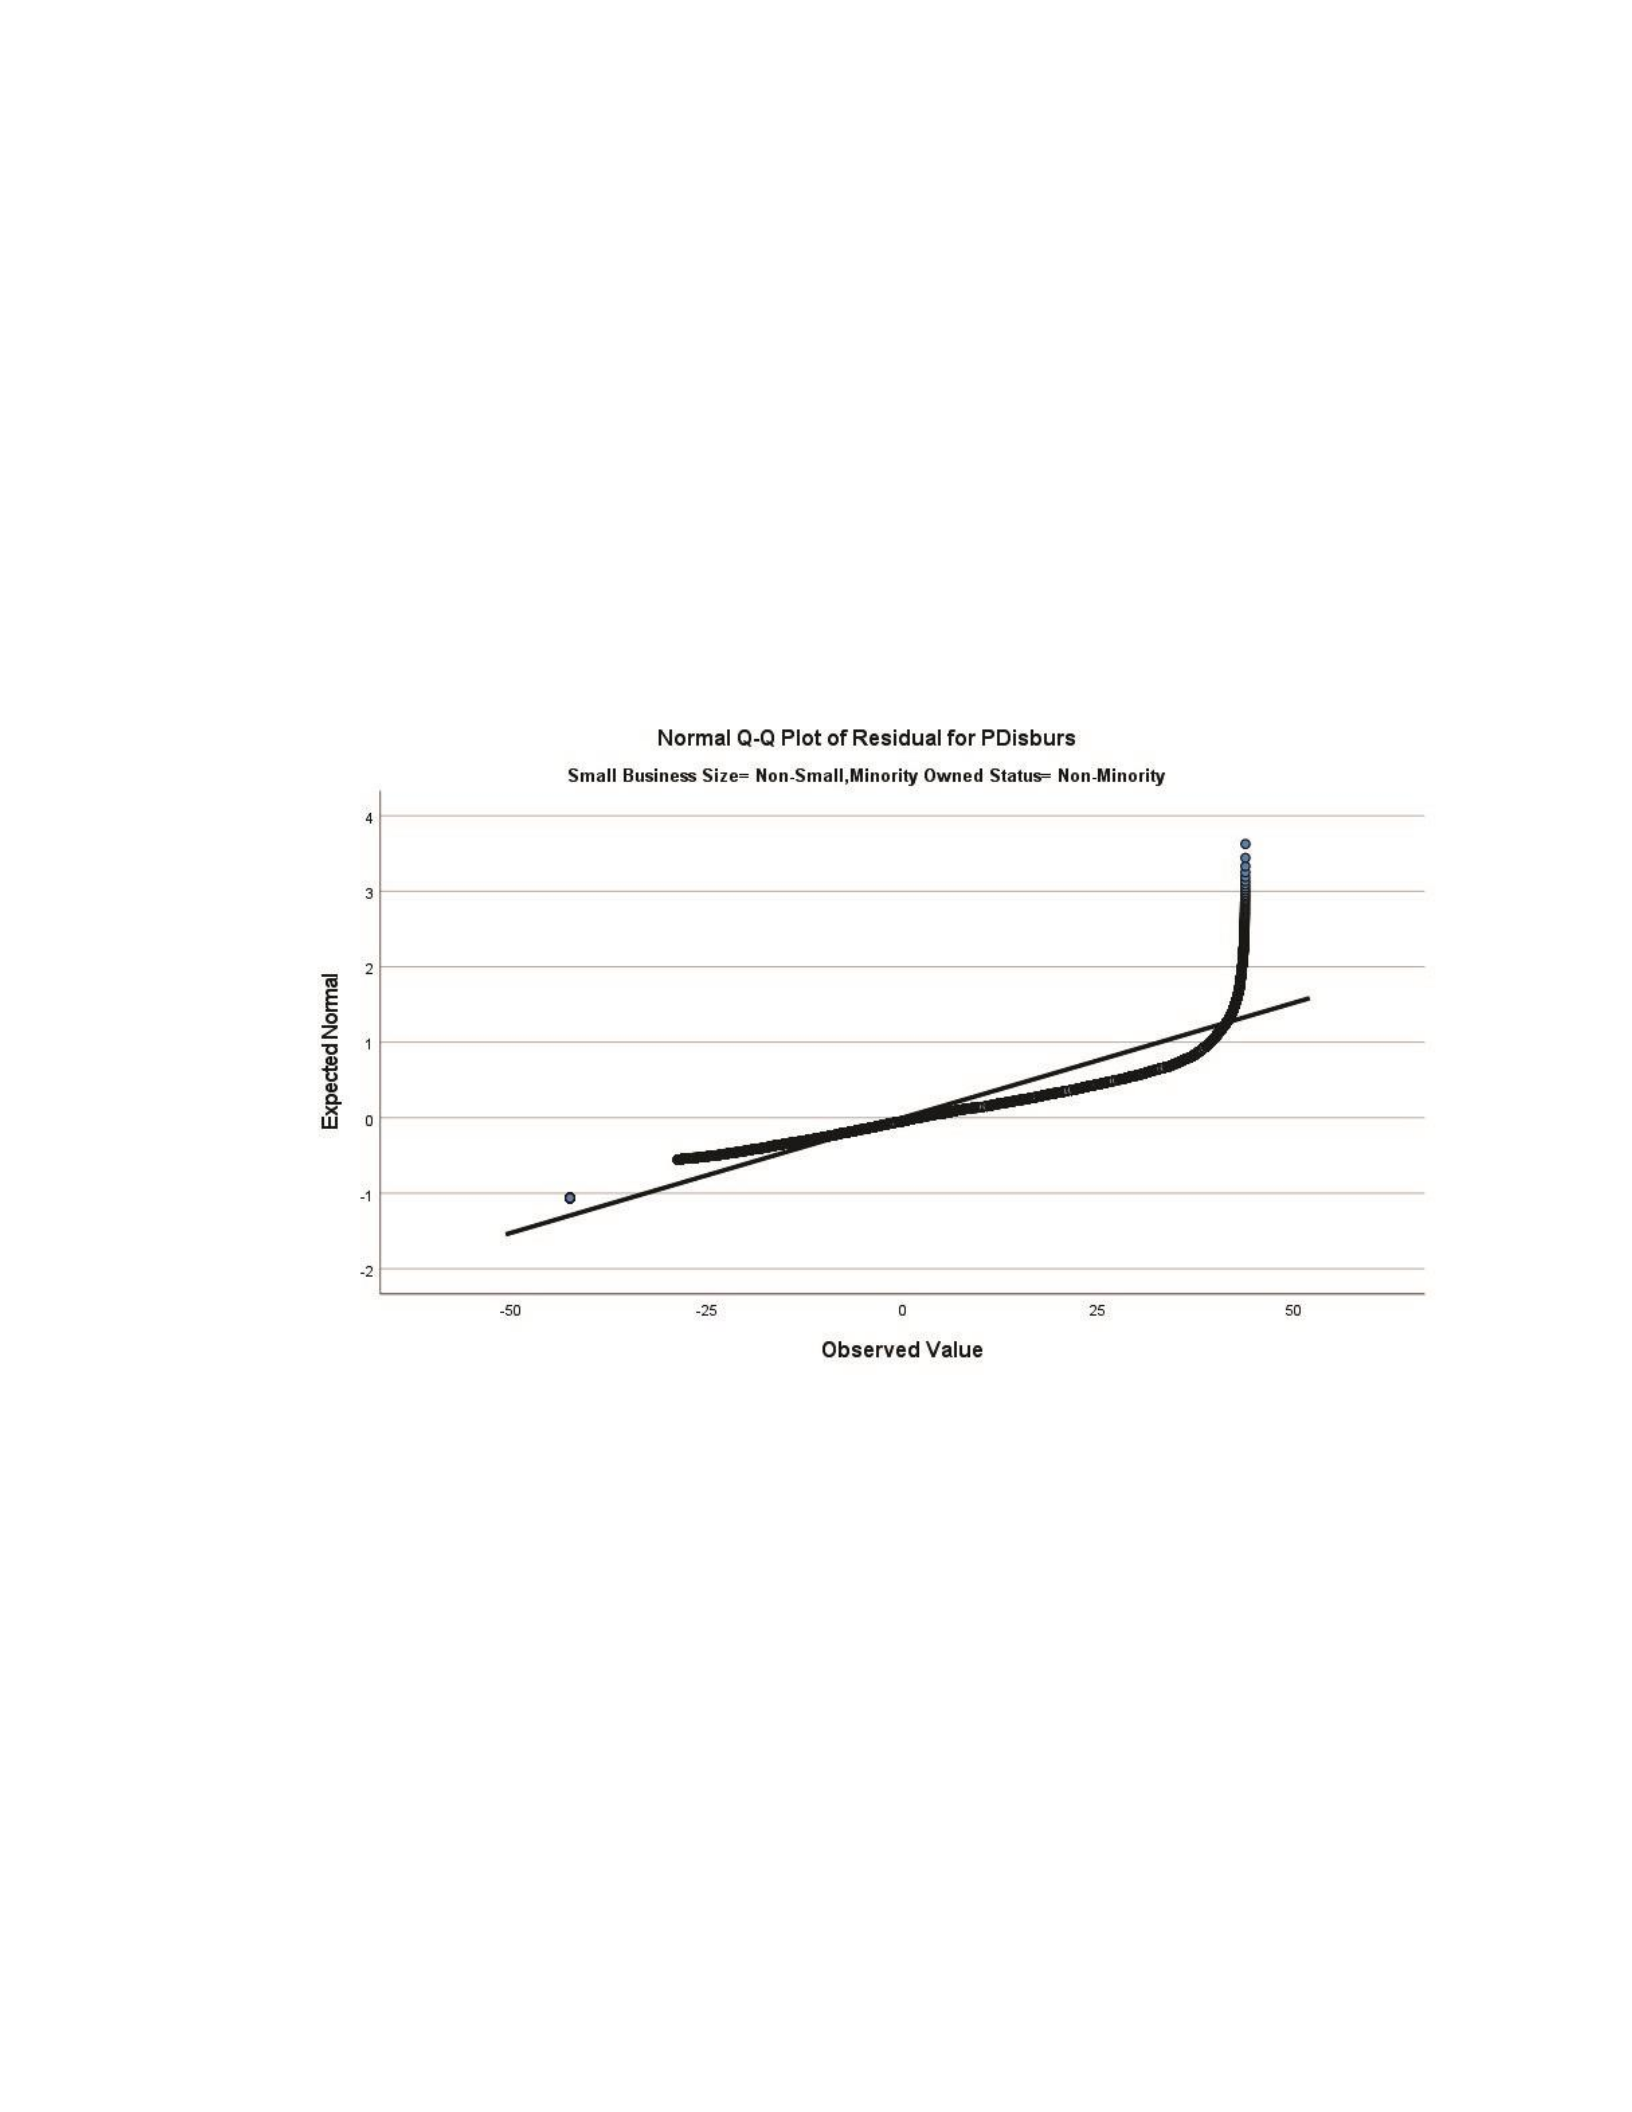
68
manner, this is not as troublesome when compared to the situation where you have groups
that have differently shaped distributions (e.g., each combination of groups has different
skews) (Laerd Statistics, 2024).
Figure 3
Normal Q-Q Plots of Residual for Percentage of Disbursed Shipped Amount
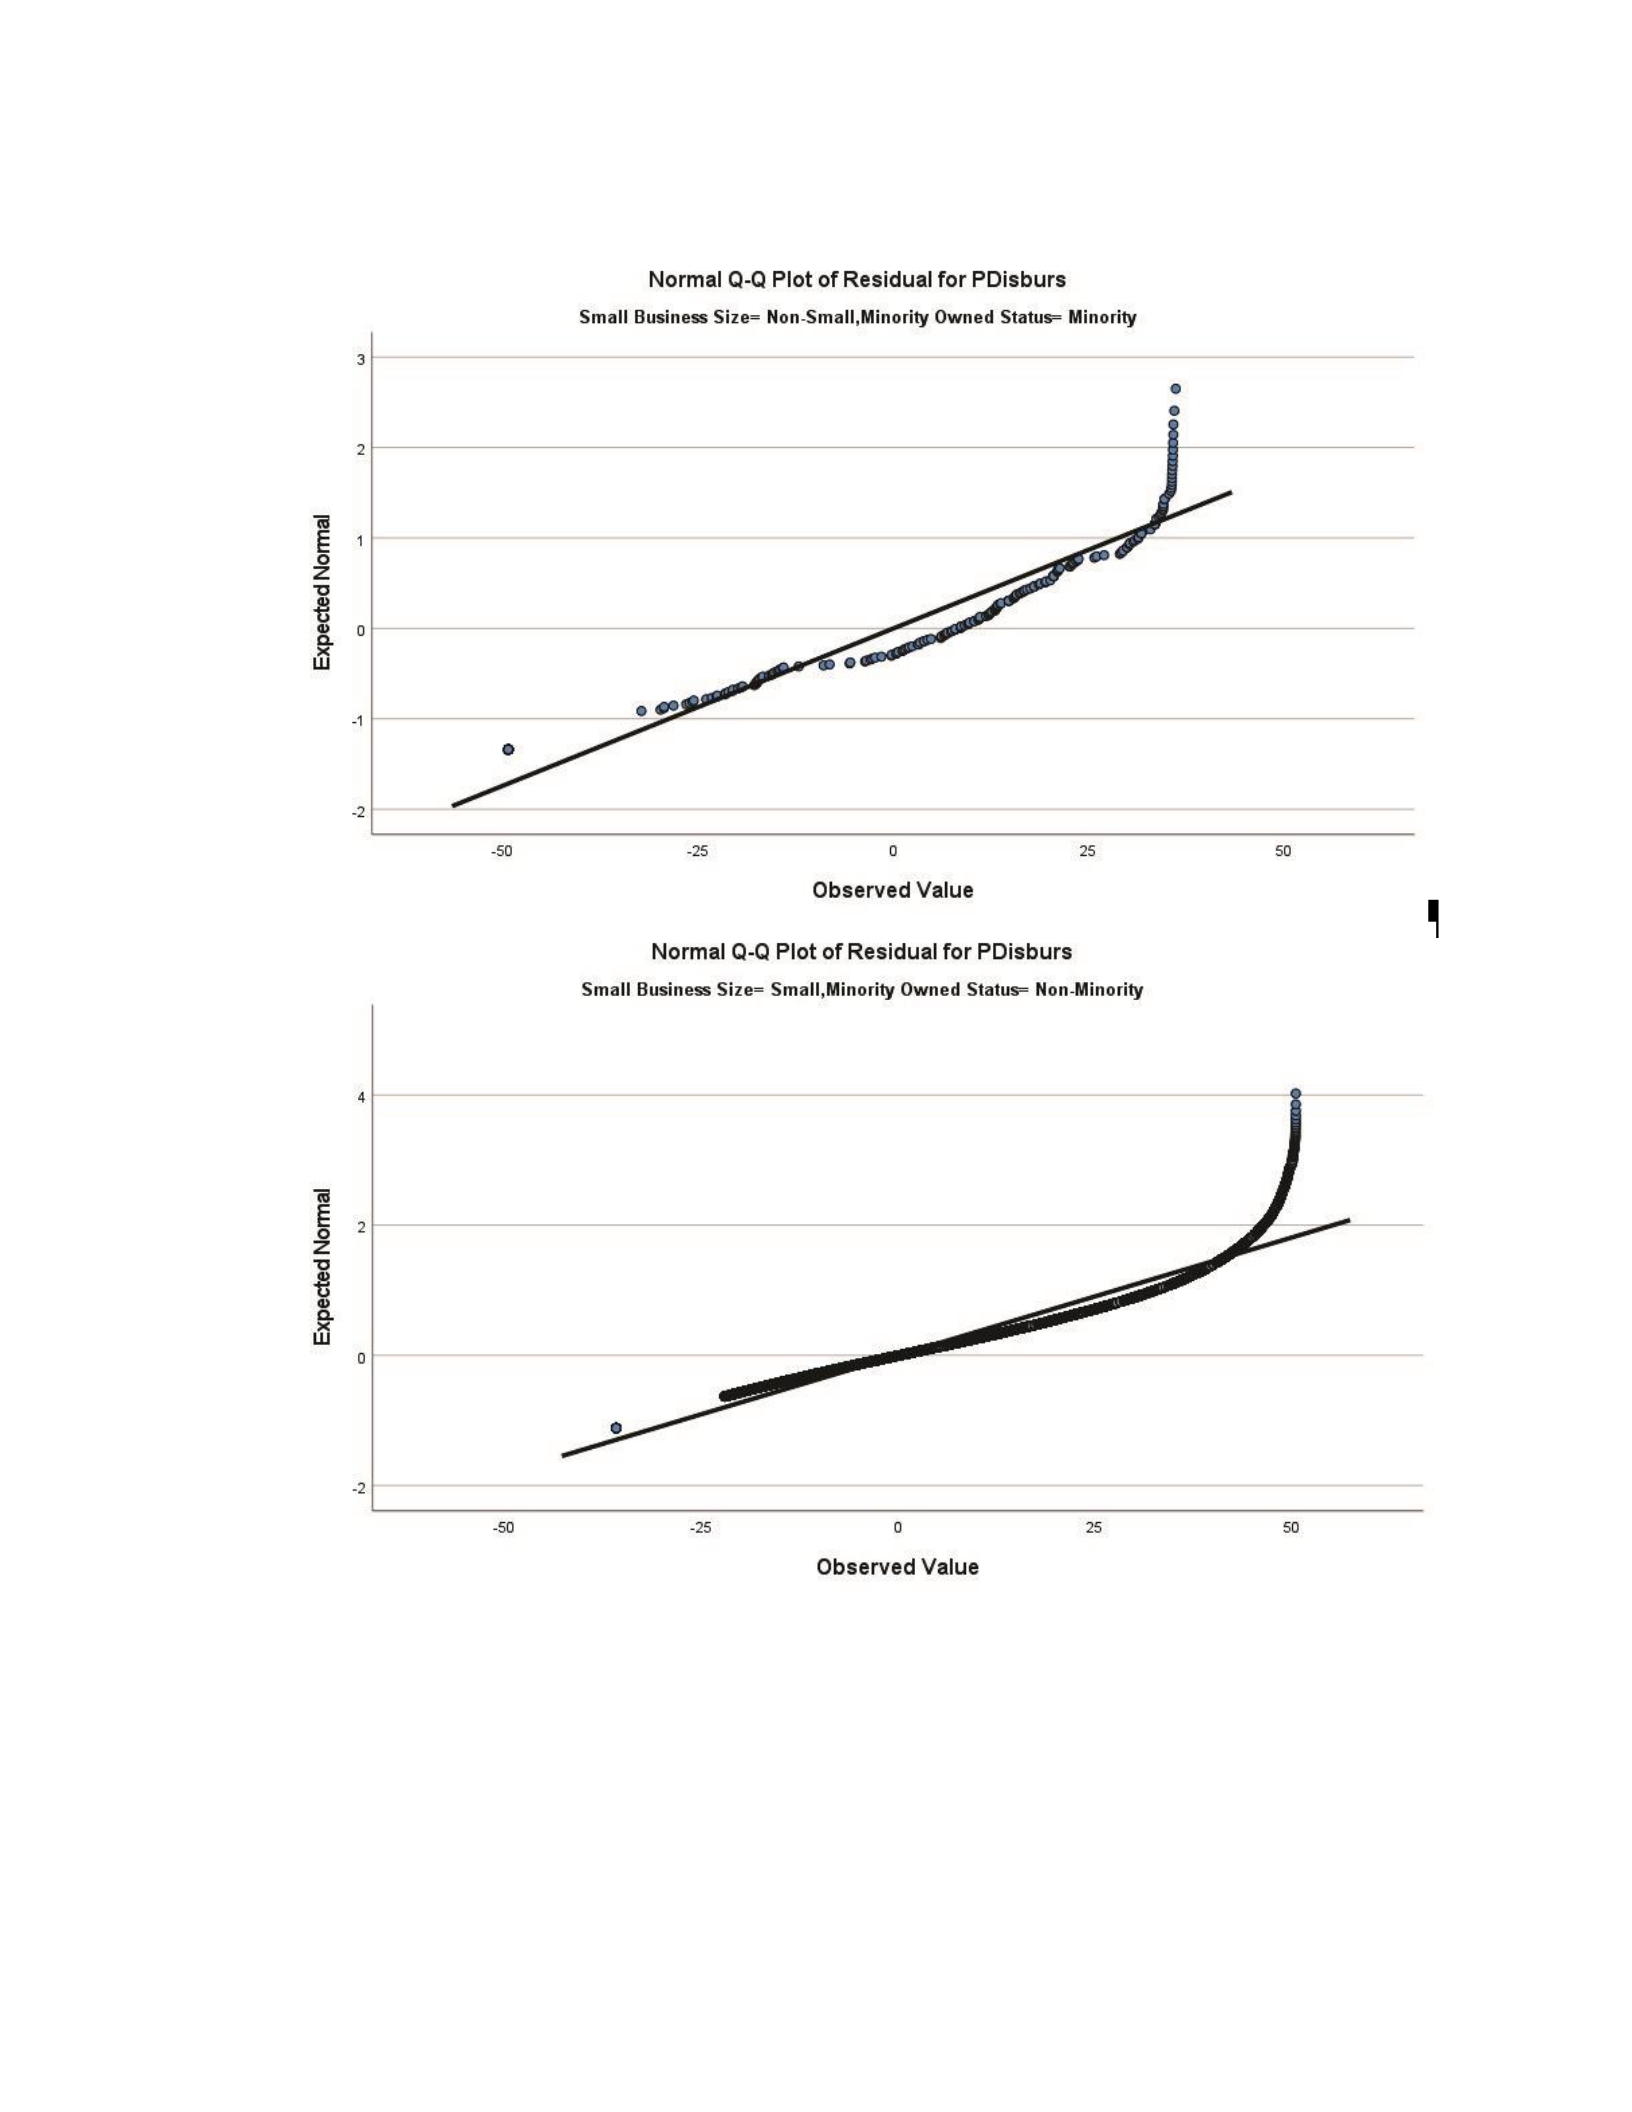
Expected
Normal
Expected
Normal
Normal
Q-Q
Plot
of
Residual
for
PDisburs
Small
Business
Size=
Non-Small,Minority
Owned
Status=
Minority
-50 -25 0
25 50
Observed
Value
Normal
Q-Q
Plot
of
Residual
for
PDisburs
Small
Business
Size=
Small,Minority
Owned
Status=
Non-Minority
-50
-25
0
25 50
Observed
Value
69
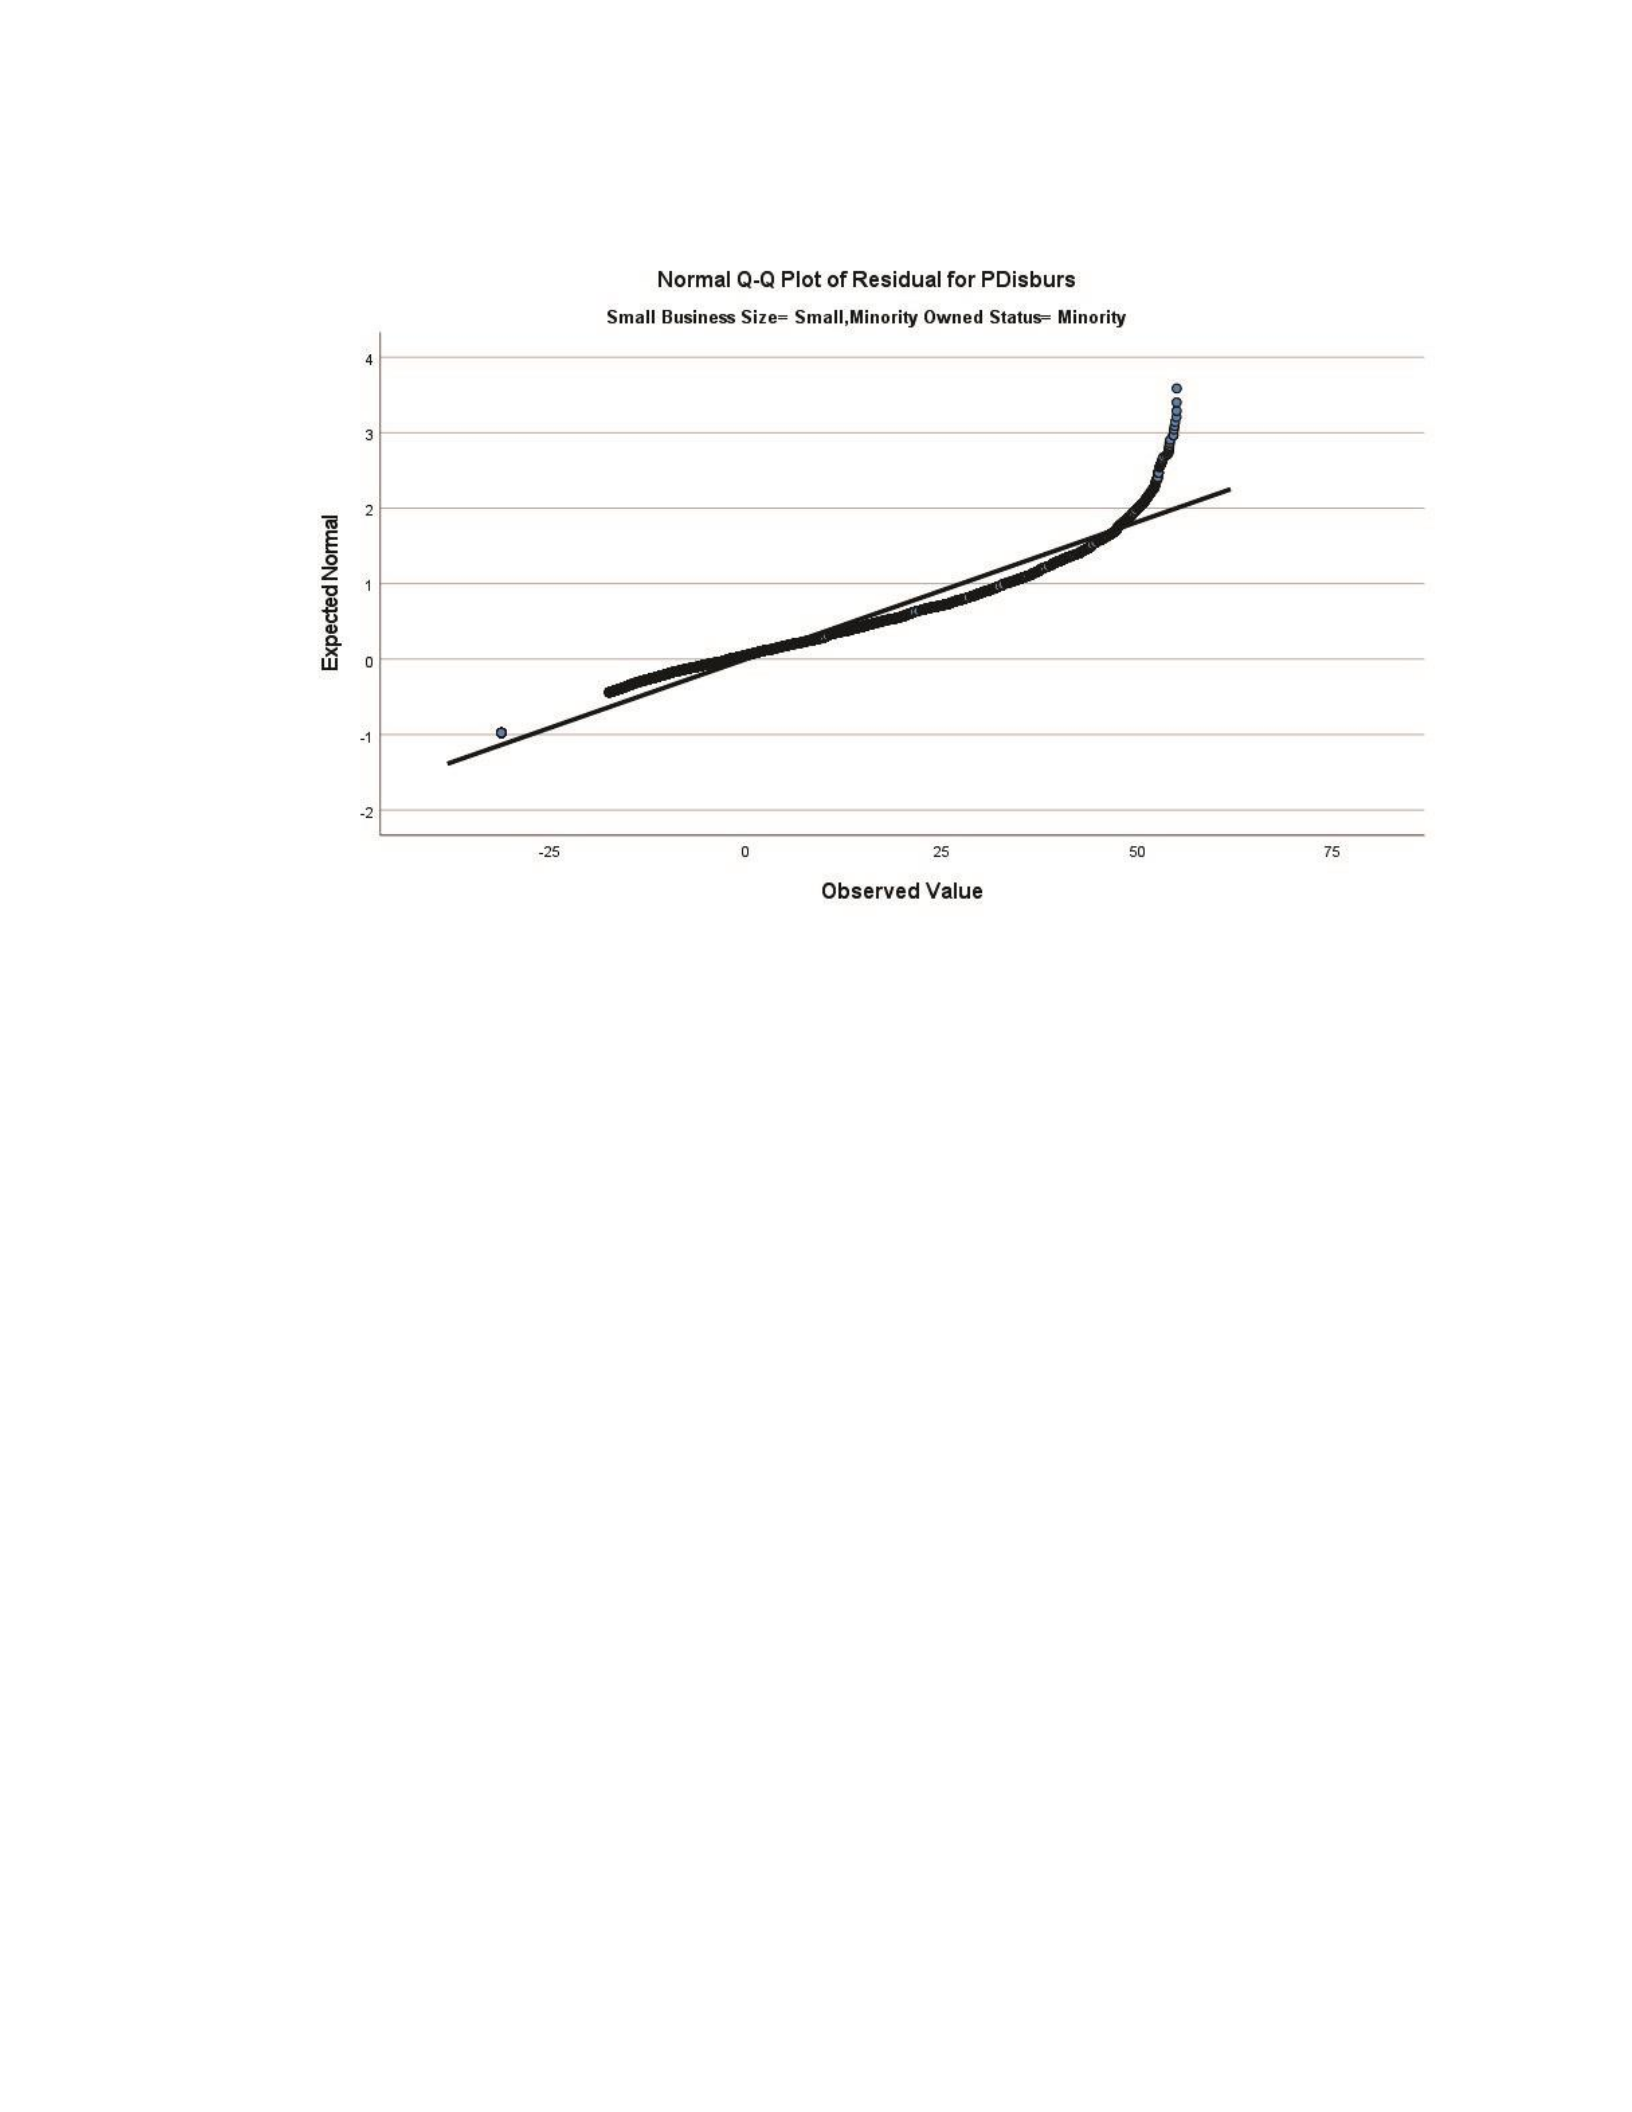
70
Homogeneity
The assumption of homogeneity of variance was tested with Levene’s test of
equality of variance. The importance of testing for the assumption of homogeneity was to
raise questions concerning the degree of precision (Forbes & Ingebo, 1975). The test of
homogeneity of variance was vital to verify the assumption of the homogeneity of
variance (i.e., variance of your dependent variable [residuals] should be equal) before
running the two-way ANOVA (Manshur & Husni, 2020). The null hypothesis for the
assumption of equal variance of the dependent variable (the ranked disbursed/shipped
approved amount) was equal across groups of the independent variables (i.e.,
minorityowned business status and small business size). The assumption of homogeneity
of variances was violated, as assessed by Levene’s test for equality of variances, p < .001.
71
Thus, I rejected the null hypothesis. Table 3 depicts the results of Levene’s Test of equality
of error variance.
Table 3
Levene’s Test of Equality of Error Variance
Levene
statistic
df1
df2
Sig.
Fractional rank percent of
disbursed/shipped
amount
Based on mean
Based on median
Based on median
and with adjusted df
304.771
298.579
298.579
3
3
3
48014
48014
47637.54
<.001
<.001
<.001
Based on trimmed
mean
304.325
3
48014
<.001
Inferential Results
A two–way ANOVA was conducted at p = .05 and 95% confidence interval to
evaluate whether there was a statistically significant difference in the ranked
disbursed/shipped approved amount based on the minority-owned status and size of the
small business. The independent variables were minority-owned business status and small
business size with two categorical value levels respectively. The dependent variable was
the ranked disbursed/shipped approved amount. The research question was: Is there a
significant difference in the disbursed/shipped approved funding amount based on the
minority-owned status and size of the business? The study’s hypotheses were:
Null Hypothesis (Ho1): There is no difference in the disbursed/shipped approved
funding amount based on the minority-owned status of the business.
Alternative Hypothesis (HA1): There is a difference in the disbursed/shipped
approved funding amount based on the minority-owned status of the business

72
Null Hypothesis (Ho2): There is no difference in the disbursed/shipped approved
funding amount based on the size of the business.
Alternative Hypothesis (HA2): There is a difference in the disbursed/shipped
approved funding amount based on the size of the business.
Null Hypothesis (Ho3): There is no difference in the disbursed/shipped approved
funding amount among minority-owned businesses and non-minority-owned businesses
based on the size of the business.
Alternative Hypothesis (HA3): There is a difference in the disbursed/shipped
approved funding amount among minority-owned businesses and non-minority-owned
businesses based on the size of the business.
The results of the two-way ANOVA conducted to examine the effects of minority-
owned business status and size of business on the distributed/shipped approved funding
amount allowed for an examination of the study’s three null hypotheses. The main effect
of minority-owned small business status on the distributed/shipped approved funding
amount was not statistically significant with F(1, 48014) = 1.41, p = .236; thus, I failed to
reject the null hypothesis (Ho1. The main effect of small business size was statistically
significant with F(1, 48014) = 173.14, p < .001; thus, the null hypothesis (Ho2) was
rejected. These tests were based on the linearity-independent pairwise comparisons
among the estimated marginal means. The results of the interaction between minority-
owned business status and size of the business on the distributed/shipped approved
funding amount were statistically significant with F (1, 48014) = 36.49, p <
.001, partial η2 = .001. Thus, I concluded that the null hypothesis (Ho3) was rejected.
73
Table 4 and profile plots (see Figure 4) show that the assessment of the interaction
between independent variables on the dependent was statistically significant.
Table 4
Tests of Between–Subjects Effects: Dependent Variable Fractional Rank Percent of
Disbursed/Shipped Amount
Source
Type III Sum of
Squares
df
Mean Square
F
Sig.
Partial
Eta
Squared
Corrected Model
469623.112a
3
156541.037
194.151
<.001
.012
Intercept
10448295.455
1
10448295.455
12958.5
33
.000
.213
SmallBusinessFlag
139599.412
1
139599.412
173.139
<.001
.004
MinorityOwnedFlag
1133.375
1
1133.375
1.406
.236
.000
SmallBusinessFlag *
MinorityOwnedFlag
29421.083
1
29421.083
36.490
<.001
.001
Error
38713059.011 48014
806.287
Total
159232682.17 48018
6
Corrected Total
39182682.124 48017
a. R Squared = .012 (Adjusted R Squared = .012)
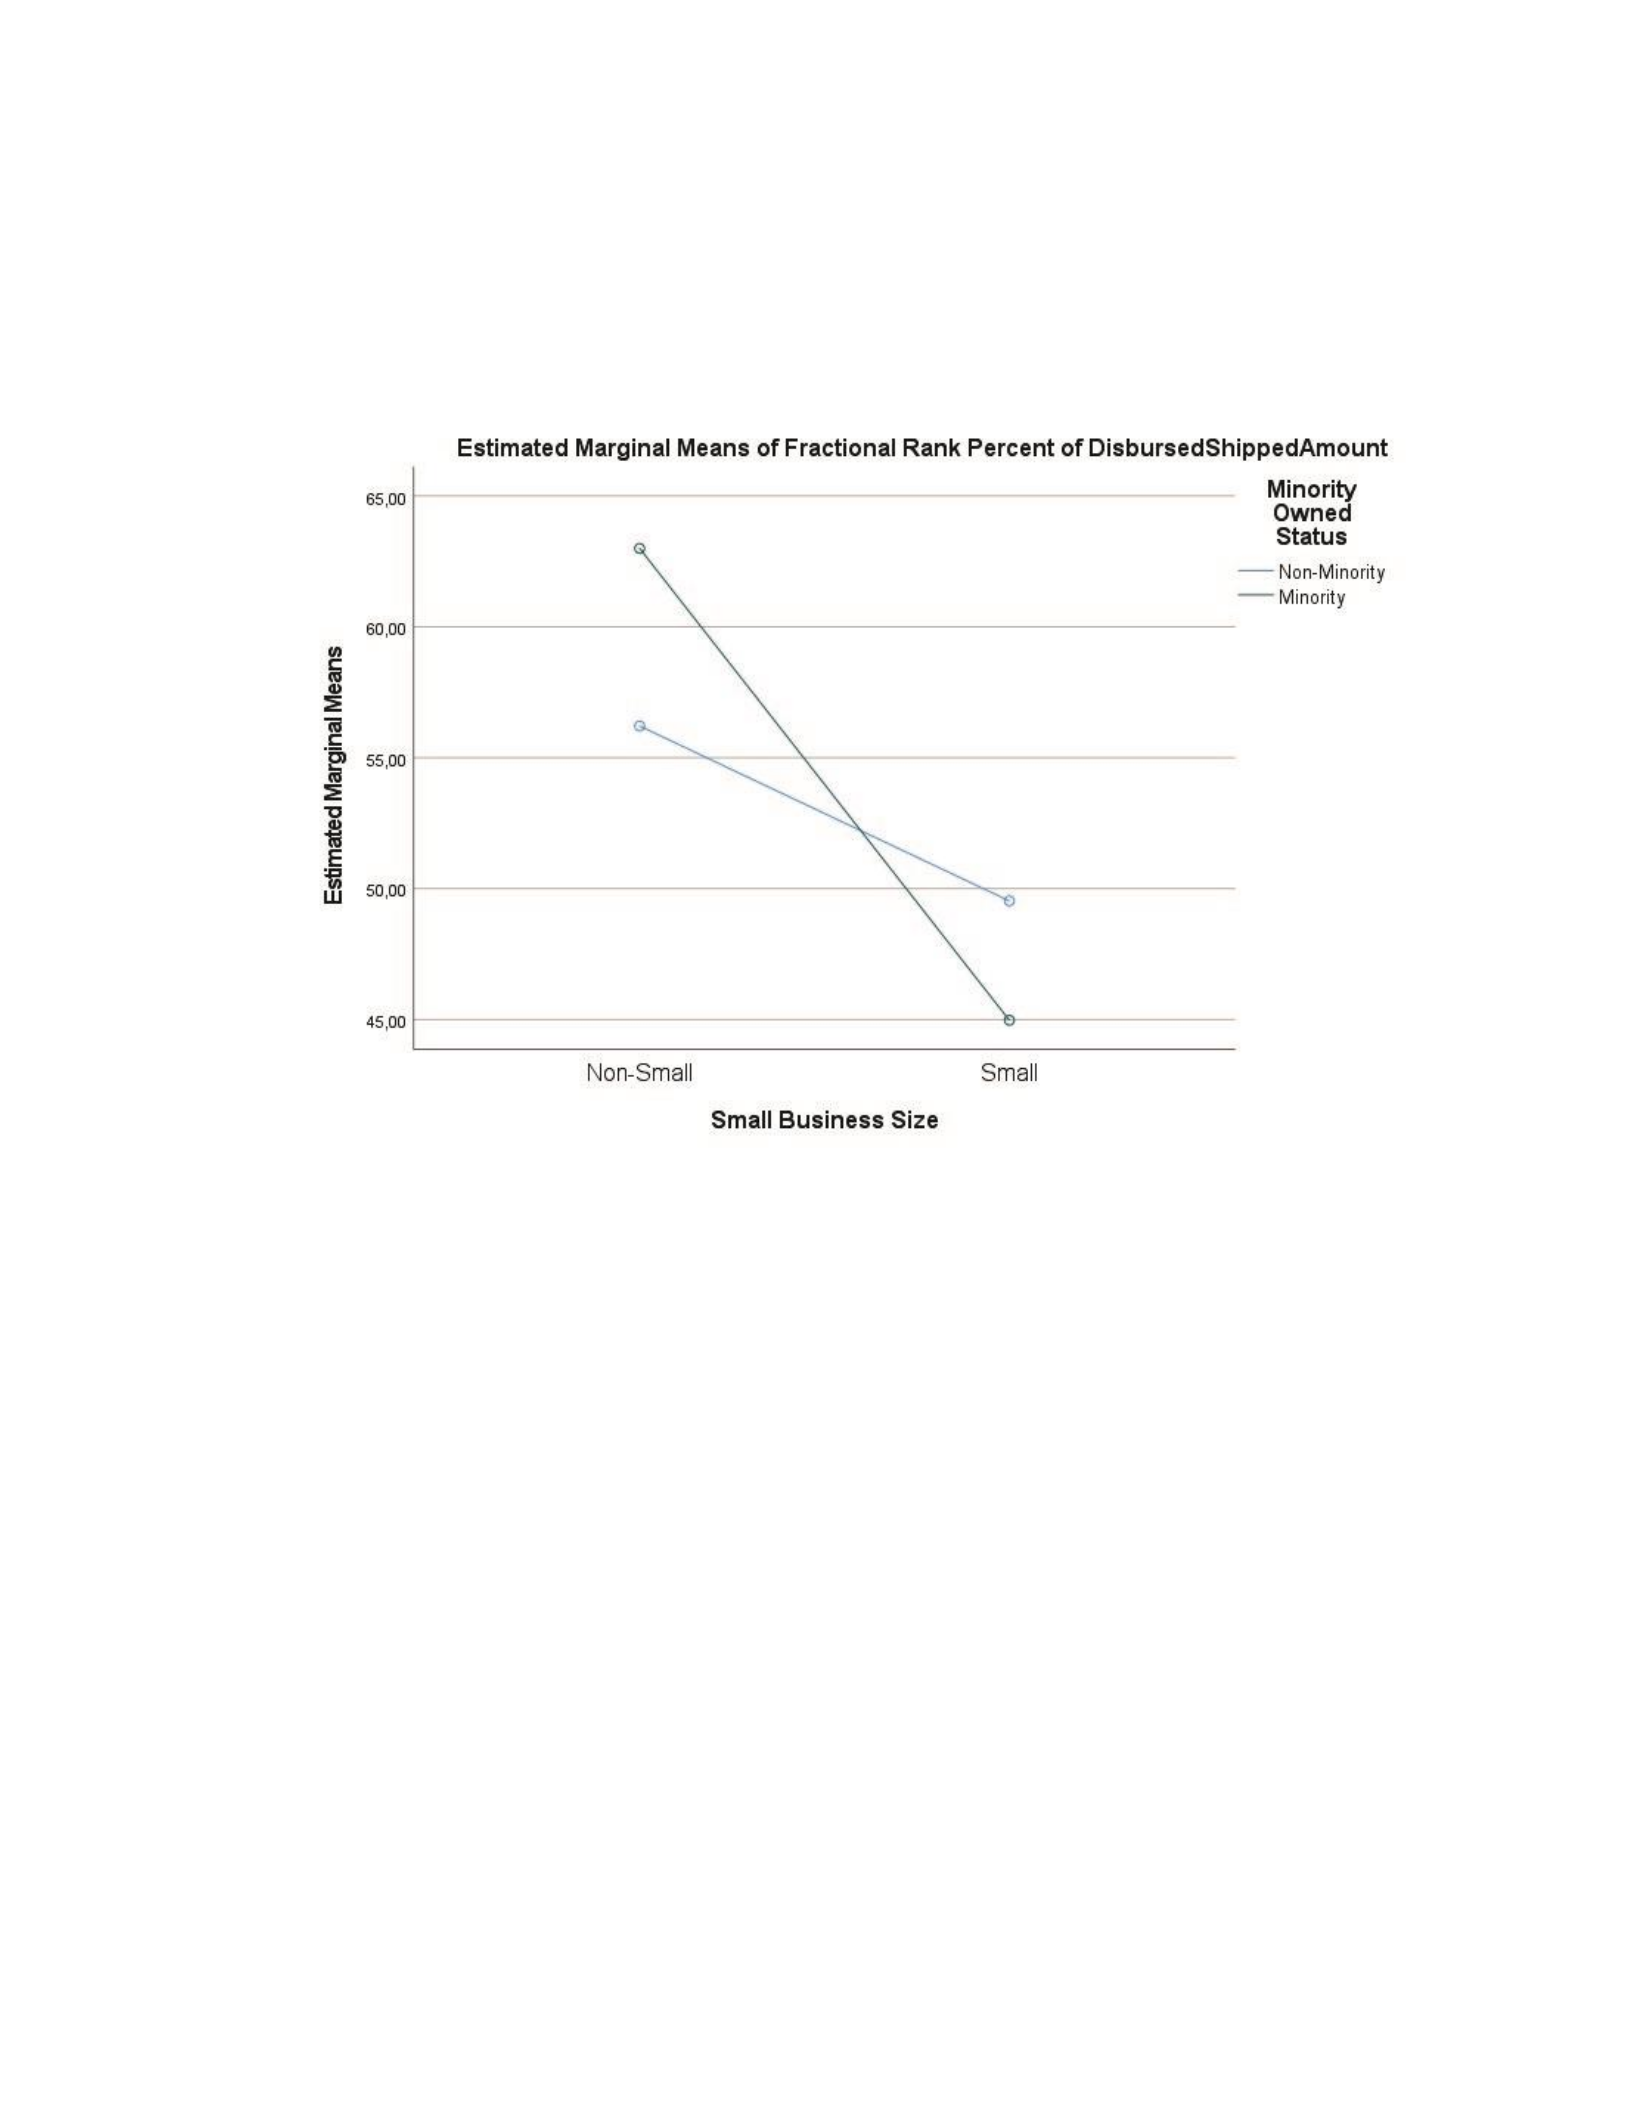
74
Figure 4
Profile Plots
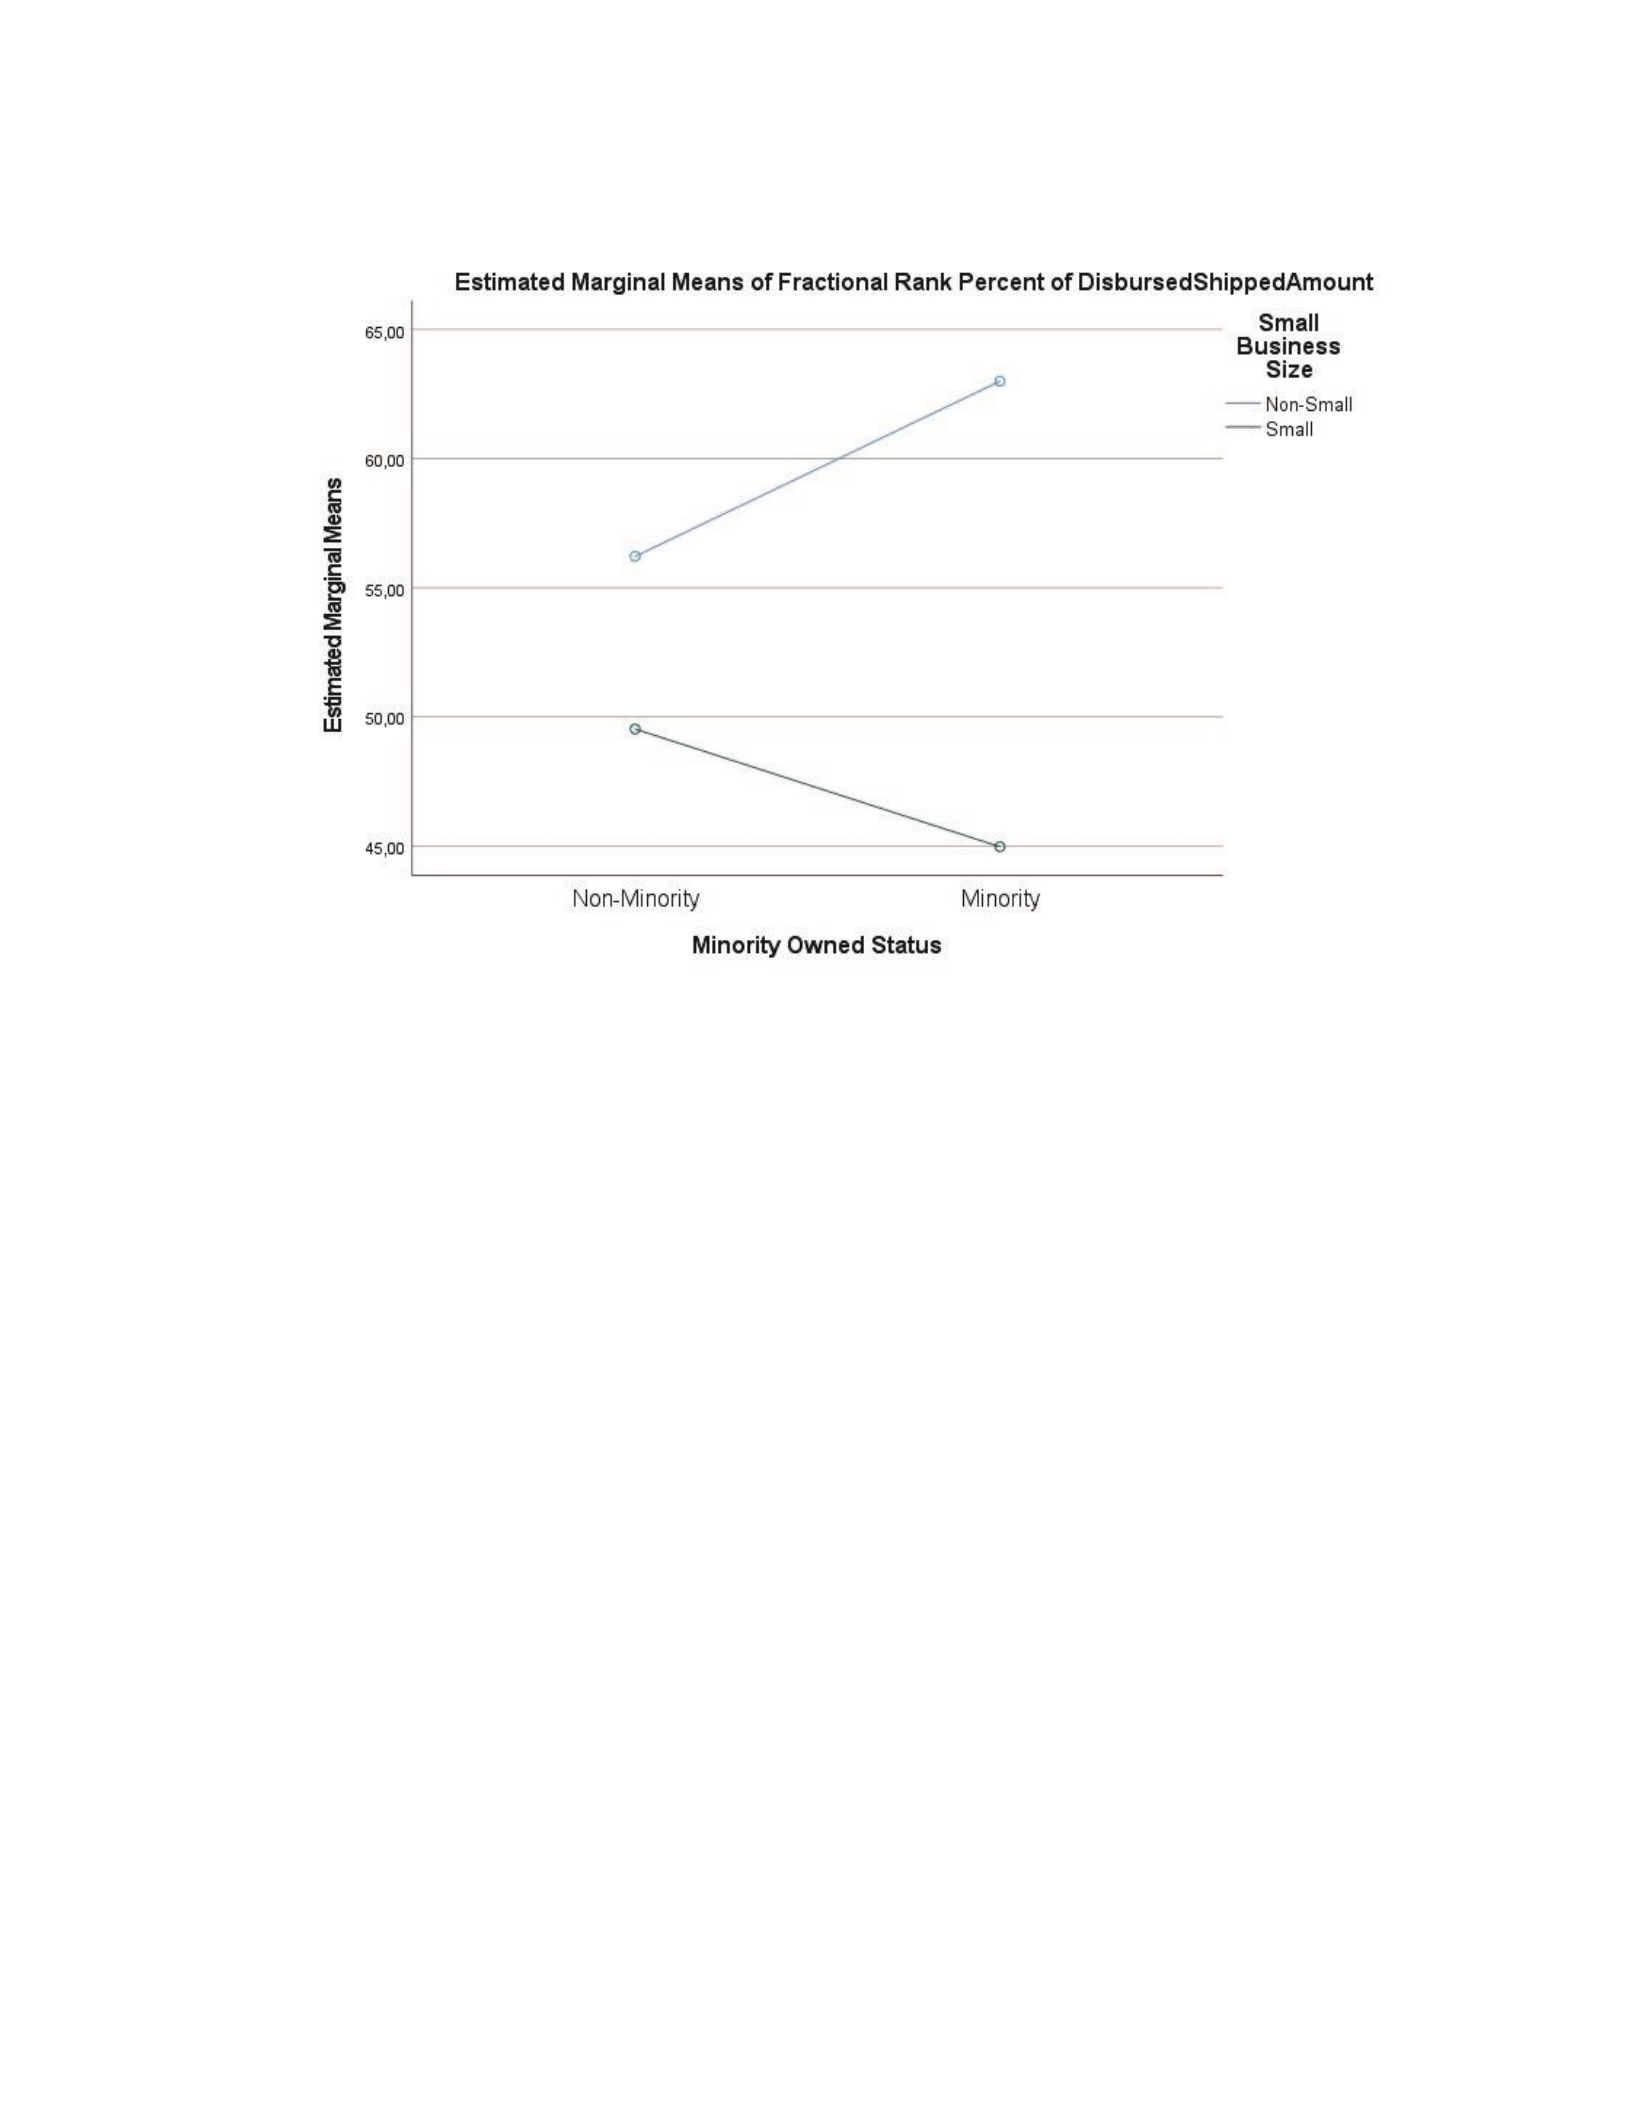
75
Analysis Summary
A two-way ANOVA was conducted to examine the effects of minority-owned
business status and small business size on the disbursed/shipped approved funding
amount. The assumptions of the two-way ANOVA were tested by residual analysis. The
assumption of no outliers was assessed by inspection of boxplots; the normality
assumption was assessed using Kolmogorov-Smirnov’s normality test for each cell of the
design and the homogeneity of variance assumption was assessed by Levene’s test. There
were no outliers; however, residuals were not normally distributed (p < .05) and there was
a violation of the homogeneity of the variances (p = .001). While the two-way ANOVA is
robust to the violation of normality of the residuals, the unequal variances may impact the
accuracy of the study’s findings; thus, the findings should be interpreted with caution.

76
There was a statistically significant interaction between minority-owned business
status and small business size on the disbursed/shipped approved funding amount, F (1,
48014) = 36.49, p < .001, partial η2 =.001. An analysis of the simple main effects for
small business size was performed with statistical significance receiving a Bonferroni
adjustment p < .001. There was a statistically significant difference in the mean of
disbursed/shipped approved funding amount between minority small businesses and
nonsmall businesses for minority–owned businesses, F (1, 48014) = 95.93, p < .001,
partial η2 = .002, and for non-minority-owned businesses F (1, 48014) = 321.17, p <
.001, partial η2 = .007. There also was a statistically significant difference in mean
disbursed/shipped approved funding amount scores between minority-owned businesses
and non-minority-owned businesses for small businesses, F (1, 48014) = 131.729, p <
.001, partial η2 = .003 and for non-small, F (1, 48014) = 13.666, p < .001, partial η2 =
.000.
All pairwise comparisons were conducted to examine each simple main effect
with reported 95% confidence intervals (CI) and p-values Bonferroni-adjusted within
each simple main effect. The mean “disbursed/shipped approved funding amount” for
minority and non-minority small businesses were 44.97 ± 27.49 and 49.53 ± 27.59,
respectively. Non-minority small businesses had a statistically significantly higher mean
“disbursed/shipped approved funding amount” than minority small businesses, 4.56 (95%
CI, 3.78 to 5.34), p <.001. Minority non-small businesses had a statistically significantly
higher mean disbursed/shipped approved funding amount than non-minority non-small
businesses 6.78 (95% CI, 3.19 to 10.38), p <.001.

77
The mean disbursed/shipped approved funding amount for minority and
nonminority non-small businesses were 63.00 ± 28.71 and 56.21 ± 32.80, respectively.
Nonsmall non-minority businesses had a statistically significantly higher mean
disbursed/shipped approved funding amount than small non-minority Businesses 6.68
(95% CI, 5.95 to 7.41), p <.001. Non-small minority businesses had a statistically
significantly higher mean disbursed/shipped approved funding amount than small
minority businesses, 18.02 (95% CI, 14.42 to 21.63), p <.001.
Recommendation for Action
This research study's results, conclusions, and recommendations might be
beneficial to financial institutions and small businesses. Small business refers to a
privately owned corporation, partnership, and sole proprietorship, having 500 employees
or fewer depending on the industry, and generating an average annual income of 28.5
million U.S. dollars (Robb, 2018; SBA, 2020). Small businesses are the basis of
economic growth in the United States. Recently, the Department of Treasury approved
more than $4 billion for 332 small business lending institutions in which $3.9 billion
went to community banks and $104 million to 51 CDLFs (Brock, 2018). While small
businesses have received funding from the federal government, minority-owned
businesses disproportionately received less funding than their non-minority counterparts
(Robb & Niwot, 2018)
Access to the distributed/shipped approved loan amount might be disproportionate
due to factors not considered by financial and small businesses. The proposed study was
vital for business practice, given that an investigation of whether funds were distributed

78
equitably between minority and non-minority-owned businesses might illuminate
potential disparities. The study’s findings have the potential to inform stakeholders within
the government and business. Examining the proportionality of the disbursed/shipped
approved funding amount provides evidence that can inform future decisions regarding
the distribution of funding. Thus, the study’s findings had the potential to reduce possible
disparities and, as a result, improve the business performance of minority-owned
businesses and the nationwide economy.
Recommendations for Further Research
This study was a quantitative ex post facto study and could not be conducted
without some limitations. Limitations for any study are the potential weaknesses that the
researcher cannot control but are inherent to the research design, statistical model, and
funding constraints (Theofanidis & Fountouki, 2018). In the secondary data analysis,
researchers are limited to the available data or cannot conduct follow-up surveys with
participants (Johnston, 2014; Kumara, 2022). In my research, I faced limitations
associated with secondary analysis specific to unbalanced data. The original dependent
variable, disbursed/shipped approved funding amount, failed the assumption of normality
for the two-way ANOVA. Although I used the transform procedure within SPSS to create
the percentage of fractional ranked data of disbursed/shipped approved funding amount
and Residual (Res-1), the assumption of normality was still violated.
In addition to limitations associated with the data, I faced other limitations during
the data analysis and examination of the findings. In the process of the dataset
manipulation, it was necessary for me to categorize the data into dichotomized variables

79
(i.e., small businesses versus non-small businesses and minority-owned businesses versus
non-minority-owned businesses). To deepen the analysis of the study topic future research
could categorize these data further. The primary researchers conducted the initial data
collection; thus, as the secondary researcher, I did not have full knowledge of the primary
data collection process (Johnston, 2014). Additional research should be conducted to
document further any disproportionality in the disbursed/shipped approved funding
amount. That may address businesses and other institutions concerned and boost
economic growth in general.
Communication Plan
Once the results of this study’s findings are published in ProQuest, the first step is
to share my research results with my peers, community, and Walden University social
media, which I am part of. Next, I will publish the study’s findings on Facebook,
LinkedIn, and other relevant social media. As an expert and consultant, I will organize
webinars to share results with small business owners, banks, and other stakeholders and
provide advice on the importance of the study’s results as assets for them to improve their
turnover and growth and, therefore, impact their communities. I will participate in
conferences, seminars, and workshops concerned with small business development.
Implications for Social Change
The results of the study’s findings underlined that the minority-owned small
businesses only represented 6,242 among the 48,014 businesses within the dataset
examined, with a mean of M = 45.69 (SD = 27.76) that had access to the
disbursed/shipped approved funding amount. Minority-owned small businesses play a

80
vital role in community development and improve the population's well-being in areas
where poverty and unemployment are historically high (Berdejo, 2021). It is estimated
that by 2044, the U.S. will have a majority-minority population, and minority workers
and MBEs will significantly impact the GDP (Winston, 2021). This study’s findings may
be used to challenge leaders in business and financial sectors to be aware of how funding
resources are distributed. Lender resources are essential for businesses to improve their
profitability. Also, additional funding resources have the potential to enhance job
creation, innovation, and overall economic growth. SMEs represent 95% of firms,
between 60% and 70% of global employment, and contribute to the largest new jobs
share in the economies (Observer, 2000). Positive social change implications for this
study enhanced the promotion of minority-owned small businesses. Furthermore, SMEs
contributed to the eradication of poverty and the improvement in the living standards of
vulnerable groups through the increase in income and self-employment (Narada Gamage
et al., 2020).
Skills and Competencies
Prior to starting this research study, I was facing many challenges, as a startup
business owner. With my work experience with many organizations and institutions, my
first challenge was to build my business database and professional networking. My first
idea was to approach small business agencies, especially the Veteran Business Outreach
Center, for assistance, seminars, and workshops. Next, I went to get financing from banks
and financial institutions for my business building and operations. Most of them refused
due to the lack of business history. Those who agreed to finance my business proposed a

81
credit line with high-interest rates. The last challenge was that I am Black and an
immigrant in the United States. I had to work hard to finance my business. Furthermore, I
observed that in my community, many small businesses had minority or immigrant
owners.
Small businesses, specifically minority-owned small businesses, although they are
the foundation of economic growth in the United States, often experience the highest rate
of failure. Growth is a challenge for SMEs due to the lack of financing and credit, as
reported by industry experts and researchers (Rao et al., 2019). The COVID-19 pandemic
disproportionately impacted small business owners: 41% among Back/African American
owners and, 34% for Latinx owners compared to 17% for White owners (Belitski et al.,
2022; Fairlie & Fossen, 2022). Despite governmental efforts (local or nationwide) to
promote small businesses, the discrimination against minority-owned small businesses
remains current. Minority-owned small business enterprises, which are often involved in
their local economic development to reduce poverty, and inequality and protect
vulnerable persons, are in need of support to strengthen their skills, knowledge, and
competencies to promote their companies and communities.

