


BITCOIN, ENERGY, AND DIGITAL ASSET PUBLIC POLICY
Introduction
The Byzantine General’s Problem is a game theory allegory in which hypothetical
military leaders besieging an enemy city from different locations must figure out how to
communicate with one another by messenger to coordinate a plan of attack with traitors
in their midst. To solve the problem, these leaders need an algorithm which guarantees all
loyal generals will adopt the same, “good” plan. This allegory serves as an analogy for
fault redundancy in computer systems and several researchers have proposed proofs and
algorithms to solve it for decades (Lamport et al. 1982). It is also critical to understanding
why cryptocurrencies were developed and how they work.
Satoshi Nakamoto’s stated intention with the invention of Bitcoin was the secure
transfer of value between two parties without the need for a trusted third-party
(Nakamoto 2008). They sought to solve the Byzantine General’s Problem and apply that
solution to value exchanges in the digital world rather than the exchange of information
in the physical world. To do so, they incorporated knowledge of academic theories from a
wide range of disciplines including economics, game theory mathematics, cryptography,
computer science, and electrical engineering. In a sense, the novelty of
Nakamoto’s invention is the unification and application of the novel ideas of others (see
Figure 1.3).
Any rush to answer public policy questions about what to do with cryptocurrency
without considering what ethos lies at the core of these new efforts to decentralize finance
is a missed opportunity to learn more about why people choose to opt-in to such
systems in the first place. As an asset, Bitcoin is a cryptocurrency, but its underlying
network functions as a decentralized autonomous organization (DAO). DAOs represent a
new method of organizing and operating the exchange of information and/or value within
a network where smart contracts and code eliminate the need for trust in third parties. The
goal is to replace hierarchical organization or chain of command with a robust, “flat”
network whose operations are executed according to embedded code.
This essay begins with a brief review of DAO origins and early definitions/views
of DAOs from various research perspectives (1.2). I contend that DAOs are best viewed
as networks with a new hybrid form of governance. The bulk of this paper grounds an
understanding of DAO governance in a multidisciplinary literature review of network
theory. Specifically, it distinguishes where DAO governance overlaps with – or is
distinctly different from – network governance in computer science, economics, and
public administration literature. Early computer science network theory (1960s) centered
on how to communicate in the presence of faults and offers a useful framework for
understanding how DAOs utilize network distribution and automated processes for
security (1.3). Communications networks become the subject of a new subfield of
economic research on network effects in the 1980s, and I consider how various network
effect mechanisms work within DAOs (1.4). Public administration scholars begin to give
serious consideration to governance by network outside the context of the firm during the
1990s as part of a broader exploration of decentralizing the provision of public goods
(1.5). Finally, I outline these DAO-specific network theory insights as they relate to
public policy (1.6) and show them at work in the Bitcoin network (1.7).
1.2 Origins and Early Research on Decentralized Autonomous Organizations
Five years after first offering his own formal definition for the term, Chohan
(2022) laments that DAOs still suffer from “definitional ambiguity” as the social sciences
struggle to define the “new socio-technological arrangement” (1) of organizations using
technological innovations to encode social structures. This section attempts to alleviate
this definitional ambiguity by reviewing the conceptual origins of the DAO (1.2.1) and
focusing on the role smart contracts play as a mechanism of governance (1.2.2). Finally,
gaps in the existing research on DAOs demonstrate the need for a unifying,
multidisciplinary framework for understanding how public policy relates to this novel
form of governance (1.2.3).
1.2.1 DAO Origins in Bitcoin
Nakamoto’s release of the Bitcoin white paper in 2008 triggered several online
discussion forum posts and e-mails between cryptography enthusiasts and Bitcoin’s core
software developers. In 2013, one such enthusiast named Daniel Larimer began using the
phrase ‘decentralized autonomous corporation’ (DAC) in blogposts to describe a new
form of “incorruptible” corporate governance in which bylaws were encoded in “open
source software distributed across the computers of their stakeholders” (Larimer 2013;
Hassan and DeFillipi 2021). Larimer and others effectively sought to generalize and
apply the governance structure at work in Bitcoin, namely blockchain and an open,
distributed network of users, to other organizations (Hsieh et al. 2018). They envisioned
DACs as corporations where shareholders own, run, and revenue share according to
published rules without hierarchical control or figureheads. Larimer (2013) saw
applications to banking, electronic courier, venture capital, and escrow services. Vitalik
Buterin, the eventual inventor of the Ethereum network, expanded on the DAC concept in
a 2013 article in Bitcoin Magazine and proposes the phrase ‘decentralized autonomous
organization’ a year later as a more general and inclusive term for the use of autonomous
code to decentralize organizational governance (Buterin 2013; 2014).
Early libertarian-minded crypto enthusiasts saw Bitcoin as the original, “model”
DAO (Larimer 2013; Buterin 2014; Hsieh et al. 2018). They envisioned DAOs with
virtually zero human control, immune to government regulation. In describing the “future
of DACs,” Larimer (2013) said “Like Bitcoin, DACs armed with a set of inviolable core
laws are far safer to deal with than corruptible human organizations… DACs don’t need
regulation, you don’t want to regulate them, and happily you can’t.” But DAOs are coded
and designed by humans. Human decision-making plays a role in choosing to join or
leave a DAO, and – even in Bitcoin – mechanisms exist for humans to modify core
software and change consensus rules. While governments may not be able to change on-
chain protocol and automated operations directly, they have several tools at their disposal
to exert pressure on human participation in DAOs. Governments are clearly interested in
regulating DAOs (OSTP 2022) and much of the nascent DAO-related
literature explores this DAO-government relationship. But a consensus definition for
what constitutes a DAO is needed to clarify the policy concerns at hand.

1.2.2 DAO Definitions
Bitcoin undoubtedly provided “a glimpse into the future of new organizational
forms,” (Lakhani 2018, 10) but academics and outside observers have struggled to pin
down what DAO governance means and often disagree on the limits of its applicability.
Hassan and DeFillipi (2021) define a DAO as “a blockchain-based system that enables
people to coordinate and govern themselves mediated by a set of self-executing rules
deployed on a public blockchain, and whose governance is decentralized” (2). Most
formal definitions for DAOs mention the use of smart contracts to assign roles and
responsibilities, allocate decision-making power and resources, or assign other
operational functions to user-members of the organization (Chohan 2022; Singh and Kim
2019; DeFilippi and Hassan 2018). Smart contracts are transaction protocol embedded in
code (Wright 2021) and changing this code requires some form of consensus among users
according to the consensus rules (Dwivedi et al. 2021).
Unlike corporations, DAOs like Bitcoin lack formal leadership and are not
registered to operate under any specific jurisdictional authority. A true DAO should have
a decentralized governance structure and run autonomously – owned and operated by no
one person or small group of persons – but the level of autonomy and decentralization
may vary (DeFillipi and Wright 2018). The use of smart contracts in organizational
processes does not necessarily constitute DAO governance. Smart contracts can simply
program functions to run when triggered by certain events or when certain conditions are
met. Krishnan (2020) described a potential use case where a user could make a payment
which triggers a software command to unlock a rental car’s doors. Here the use of a smart
contract does not mean we should consider the rental car company a DAO. Organizations
can use smart contracts to automate certain processes but maintain human, hierarchical
control of broader decision-making and operations.
However, smart contracts can also govern the allocation of resources and control.
This application is core to DAO governance. One of the most common use cases for
smart contracts in DAOs is for tokens which are transferable and tradeable (Krishnan
2020). Users can gain decision-making power or a share of ownership in the DAO by
exchanging capital or as a reward for work invested in achieving some organizational
goal. In DAOs, control of such smart contracts is not owned by any one or small group of
persons but by the members of the organization. Defillipi and Wright (2018) describe a
ride-sharing use case where a DAO could replace a company like Uber. Artificial
intelligence could aid in matching drivers to users, smart contracts would handle
automatic payments from customers to drivers for services rendered, and even collect
administrative fees required to keep the DAO online. While this is entirely automated,
code could also allow for a negotiation between the driver and customer, adding an
element of human control. Furthermore, the DAO could tokenize ownership in the
organization by awarding tokens to drivers per service or in exchange for capital. Here
smart contracts effectively govern both equity within the organization and the doing of
certain organizational processes without human assistance.
1.2.3 Existing Research on DAOs and Government
DAOs lack solid definition and treatment from a legal standpoint besides SEC
warnings that they can be used to offer unregistered securities illegally (Tse 2020; Pranata
and Tehrani 2022). Some DAO governance studies highlight the practical issues
associated with this legal ambiguity (Rodrigues 2018; Werbach 2018). DeFillipi and
Wright (2018) introduce the concept of lex cryptographia, or the idea that the only law
organizations like DAOs truly follow is that which is embedded in code. Combined with
a decentralized node structure spanning across geographic borders, DAOs effectively lack
a specific jurisdiction and any “personhood” status to grant legal rights to or hold
accountable (Bayern 2014).
Economists’ attitudes towards the potential of DAO governance in economics
range tremendously. Techno-optimists argue blockchains will usher in a “revolutionary
new institutional technology of governance” (Davidson et al. 2016, 2) and discuss the
possibility of an apolitical crypto-economy which rivals capitalism and becomes its own
formal academic discipline (Babitt and Dietz 2014; Pilkington 2015). Others see DAO
governance as best suited for smaller scale use cases like a new form of corporate
governance (Sims 2019; Kaal 2020). But skeptics see DAO governance as a solution in
search of a problem to solve, where security risks outweigh any benefits that the
democratization of finance might bring. TheDAO was one of the first decentralized
autonomous organizations founded in 2016 and ended in disaster (DuPont 2017;
Morrison et al. 2020; DeFillipi and Wright 2018). The idea was for TheDAO to use smart
contracts to govern decisions ranging from “distribution and management of its $150
million dollar fund, risk, residual claims, voting rights, and voting itself… achieved
through the consensus of the investing community” (Morrison et al. 2020, 1). But when
users and hackers found vulnerabilities in TheDAO code, nearly $50 million was
siphoned away from the organization (Price 2016).
Some early qualitative research explores how DAOs might change various
nationstate security dynamics. Leaderless or decentralized organizations have long been
topics of interest for those studying social resistance, civil disobedience, and terrorism
(Beckstrom and Brafman 2006; Sageman 2008; Michael 2012; McFate 2018). But
Krishnan (2020) argues that adding blockchain, digital autonomy (smart contracts), and
anonymity elements seen in DAOs add a new level of evasiveness for governments
contending with social resistance and/or terrorism. The internet provided the platform for
a new kind of illicit black market called “Silk Road,” but it also enabled the FBI’s
cybercrime team to track its users and servers to usher in its eventual downfall (Kushner
2014). Krishnan (2020) outlines how a Silk Road running on DAO governance would
make it harder to shut down. Conversely, it could provide citizens with workarounds to
censorship and suppression of civil rights in totalitarian states. In three case studies in
Africa, Gladstein (2021) finds Bitcoin’s DAO structure helps individuals protect their
identities in anonymous exchanges of value with nothing more than a phone and internet
data. He argues this enables families living under centralized governments which brutally
punish their citizens for owning precious metals or foreign currencies the opportunity to
shield themselves from rampant inflation.
Most public-oriented research on DAOs focuses on blockchain applications in
government or the delivery of public goods. In a systematic literature review of
blockchain governance in the public sector, Tan et al. (2022) find that leveraging
blockchain technology in public administration requires careful consideration of system
design characteristics based on contextual factors. At the micro level, governance
decisions seem highly technical (e.g., blockchain architecture, specific smart contracts)
but implementation at the macro level involves normative and subjective concerns (e.g.,
accountability, control of governance). This limits the DAO public sector use case.
Distributed ledger technology and blockchain was designed to increase trust, legitimacy,
and transparency between transactions within a system, but whether “the transaction rules
are fairly established” in the first place is “beyond the technical scope of blockchains”
(2). While citizens may feel blockchain-based government processes are more
decentralized and transparent, questions about who designs or changes the system create
a “governance paradox” where blockchain loses its value as the central party ends up in a
position of authority regardless (Werbach 2018). If public blockchains are designed to
mitigate concerns when trust is low (Meijer and Ubacht 2018), highly automated
(nonhuman controlled) DAOs only risk exacerbating that lack of trust by obscuring the
notion of accountability further (Tan et al. 2022). Removing the human aspect of
governance in favor of over-automation risks missing out on the “embedded public
values in public sector organizations” (8) in the pursuit of transparency and efficiency.
Public blockchains may execute primary rules and functions well but lack secondary
rules which capture the nuance of informal social dynamics and the flexibility required in
delivering most social/public goods (Hart 1961; Simpson 2014; Yeung and Galindo
2019).
1.3 DAOs: Hybrid Governance with Multidisciplinary Roots
DAOs possess both human and technical (i.e., coded, automated) elements –
policies aimed at thwarting, supporting, or regulating a DAO must consider both. Hsieh et
al. (2018) describe machine consensus as the process of enforcing smart contracts along
the blockchain through code. But “humans must first decide what protocol to run before
the machines can enforce it,” (Lopp 2016) requiring a social consensus among DAO
stakeholders. Janssen et al. (2020) suggest academia is replete with research focusing on
the technical aspects of blockchain but lacks insights concerning the
“complex socio-technical infrastructures… like culture, laws and regulations, contracts
which guide and coordinate the behavior of actors and the technology” (16) within these
new organizations. Pedagogically, DAOs lie at the nexus of computer science and several
social sciences. But scholars tend to study and define DAOs only within the context of
their respective academic disciplines.
Just as DAOs rely on hybrid governance (i.e., a mix of human and automated
control), a great deal of cross-disciplinary literature focuses on the formal and informal
forces at work in networks. ‘Network governance’ emerges as a new subfield for public
academic inquiry in the late 1990s, but pluricentric conceptualizations of public and/or
private governance have multidisciplinary roots throughout the mid-20th century
(Kersbergen and Waarden 2004). Early communications systems modeling provided a
foundation for algorithmic-based security measures in computer science and contributed
network typology definitions still used to describe organizational structures (1.3.1).
Studies of the underlying mechanisms powering network effects help explain DAO value
proposition in terms of the ‘cost of trust’ (1.4). Finally, network theories in public
administration illustrate the role trust plays in decentralized authority, shedding light on
the motivations behind the creation of Bitcoin and early DAO development (1.5).
1.3.1 Communications Network Theory: Centralization Typology and Automated

Security
Writing during the height of the Cold War, Paul Baran’s (1964) “Typology of
Networks” endures as a seminal work of network theory with interdisciplinary
applicability. While Baran focused primarily on communications network survivability,
the terminology for network typology he offered is still commonly used today. With the
backdrop of a potential looming nuclear threat, Baran felt the existing communications
apparatus in the United States was highly vulnerable to single points of failure and attack
(Yoo 2019; Hafner and Lyon 1996). Through his work at the RAND Corporation, he
proposed a new communications system based on a distributed configuration which
utilized redundancy to maximize survivability against attacks to the network.
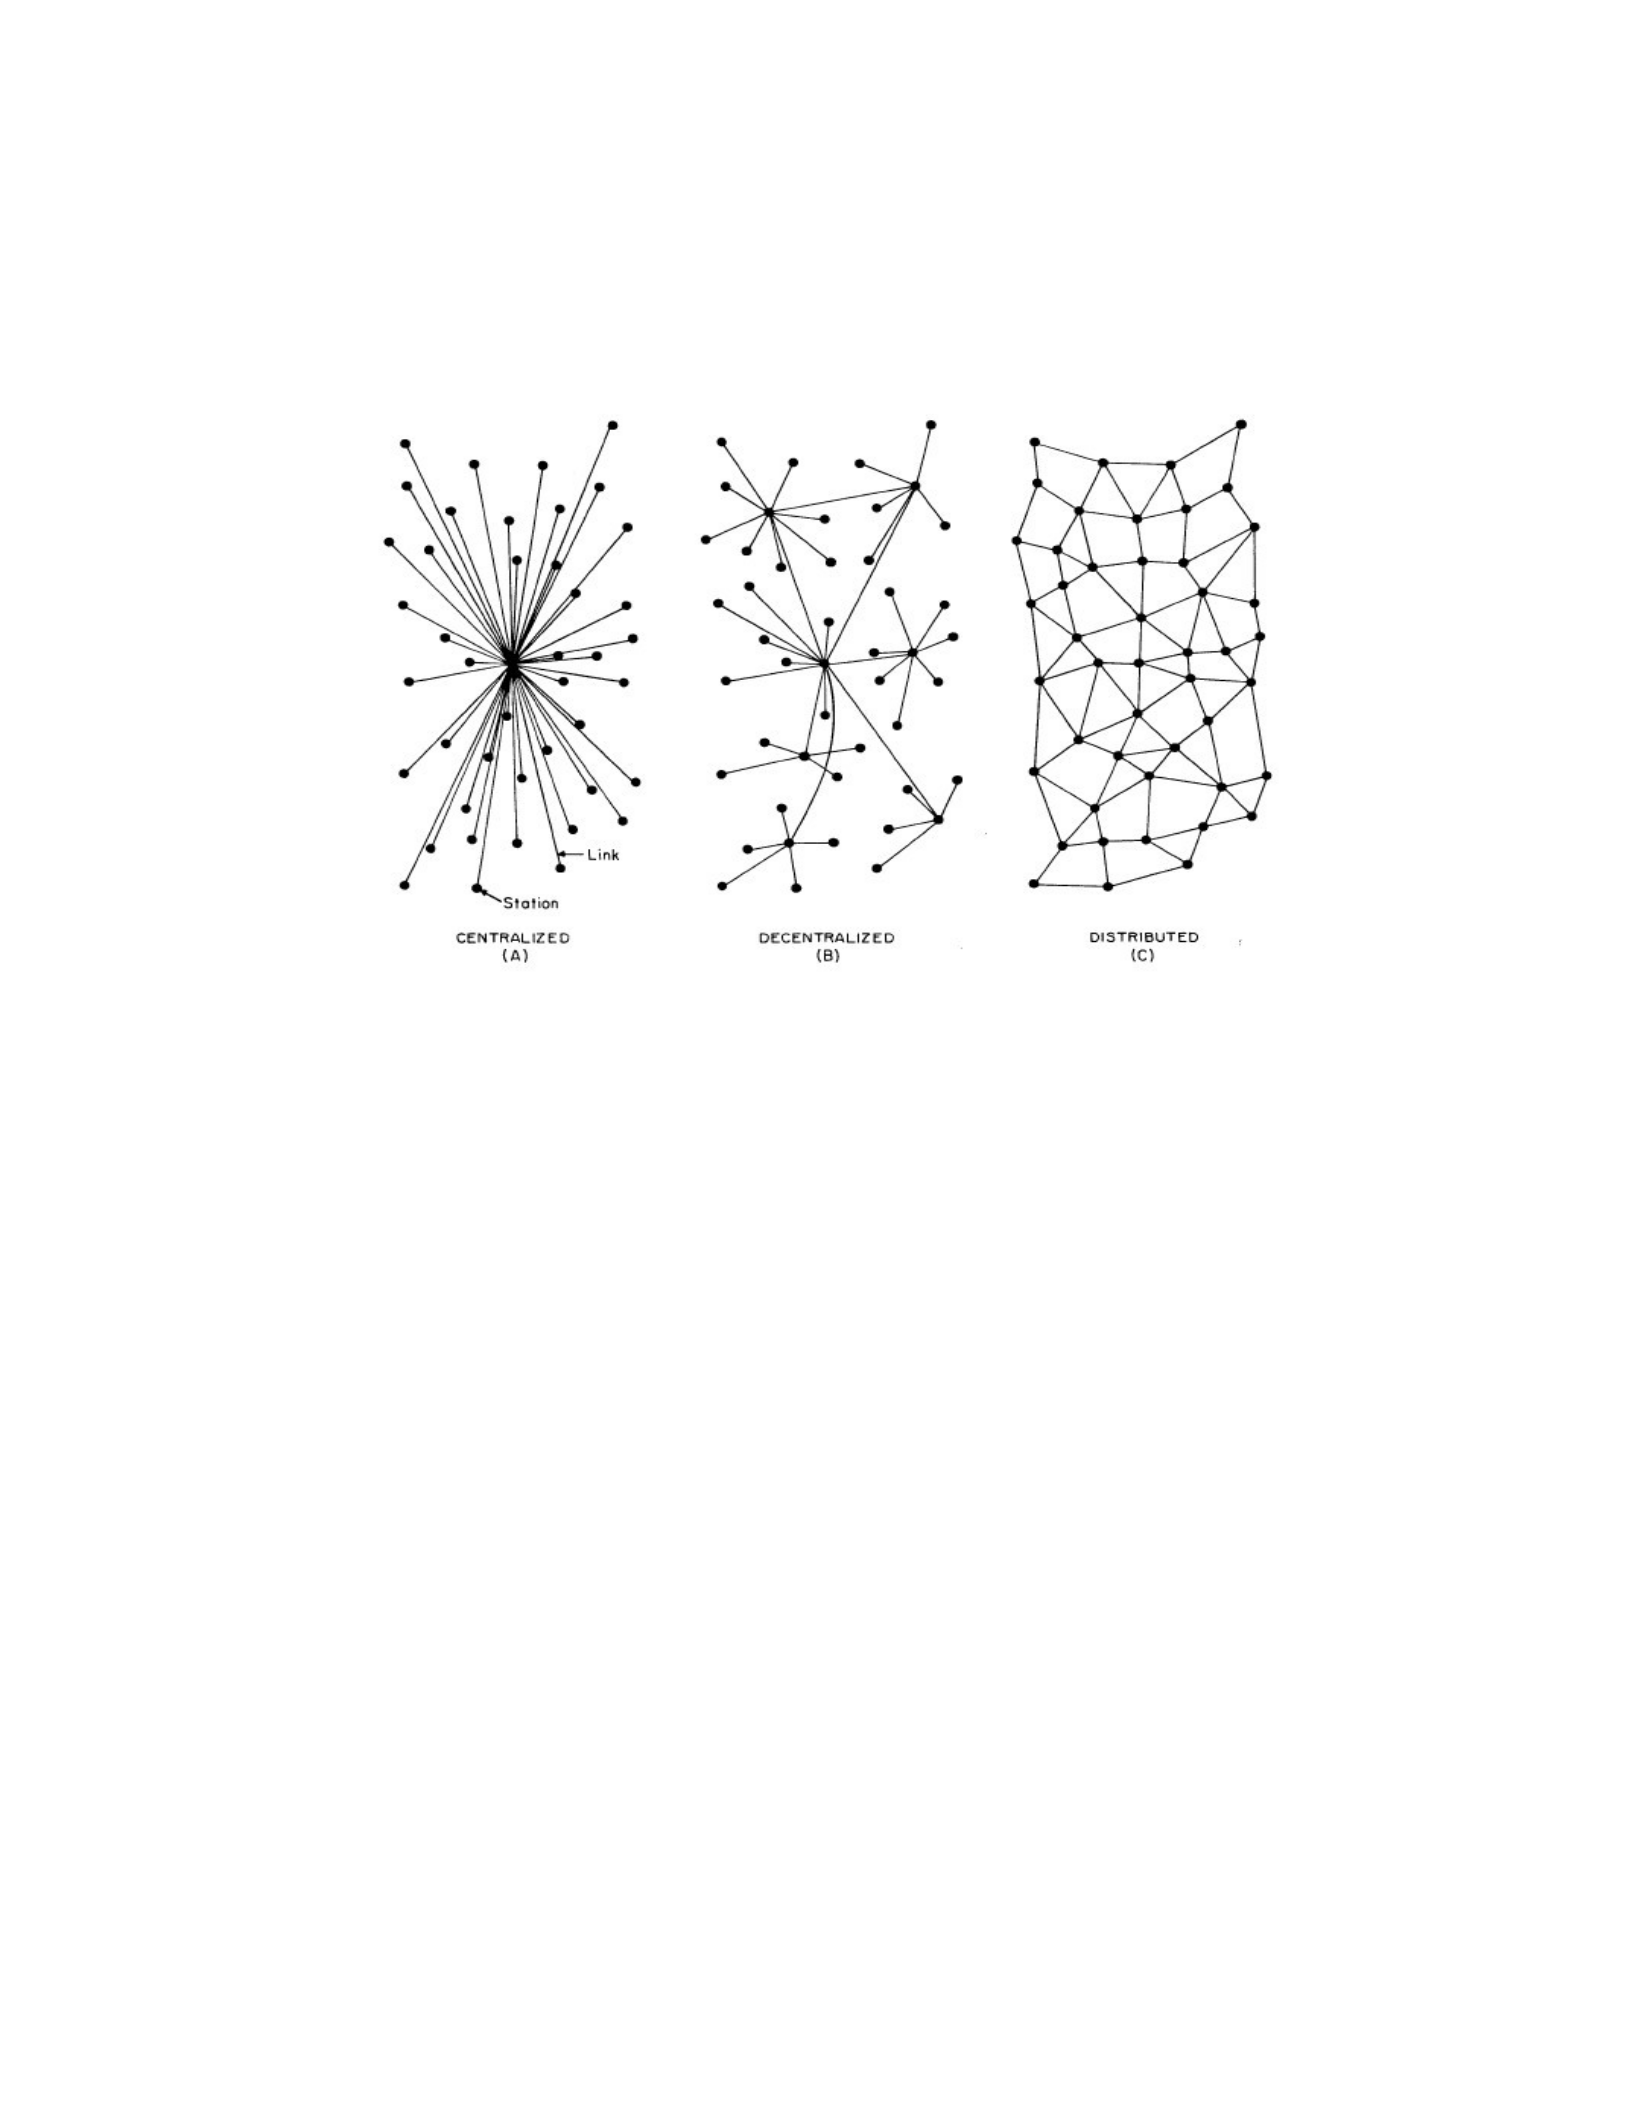
Baran made two early contributions along the path to DAO governance: 1) a
useful typology for classifying network decentralization (Figure 1.1); and 2) combining
distributed network structure with digitally automated processes (i.e., algorithms) as a
security measure. Baran described communications networks as the combination of
nodes, stations and links (Baran 1964, 1). A purely centralized network has a singular
node with a link to each station. Destruction of the central node effectively kills the
network by severing all links to communications stations. A decentralized network has
many nodes each with links to stations they own and links to other nodes. Reliance on a
single link/node is not required, but attacks on single links/nodes can offline several
stations. The distributed network has many nodes which double as stations with links to
other nodes with double as stations. The destruction of one link may have no effect on the
overall strength of the network beyond severing one of several links between
stationnodes. The destruction of one station-node has no effect on the remaining station-
nodes.
Baran said, “We will soon be living in an era in which we cannot guarantee survivability
of any single point. However, we can still design systems in which system destruction
requires the enemy to pay the price of destroying n of n stations” (16).
Figure 1.1 Communications Network Typology From Baran (1964, 2)
Trust is the driving motivator in network security research. The presence of bad
actors in a communications network is inevitable – this is the Byzantine General’s
“problem.” Baran’s paper was intended as an appeal to revamp defense communications
systems based on this distributed network model, posing centralization as the key
network vulnerability. But his novel contention that distributed system operation must be
necessarily digital proves remarkably prescient for modern network security research
(Baran 1964, 17). Redundancy only succeeds in making networks more resilient if nodes
are “able to make independent routing decisions and reroute traffic autonomously in the
face of partial network failure” (Yoo 2019, 166). Today’s basic personal computing
firewalls rely on automatic algorithms and distributed network setups for digital security
(Alfaro et al. 2006), but this was a revolutionary idea in 1964 – and incredibly difficult to
pull off. In fact, Baran’s idea was never adopted by the Air Force because the Defense
Communications Agency had so little experience in implementing digital technology in
communications systems and the proposal was ultimately scrapped (Abbate 1999, 21).
It is striking to see the parallels between Baran’s work, the democratization or
“flattening” of the internet (Abbate 1999; Yoo 2019), decentralized finance,
cryptocurrency, and DAOs. Bitcoin was designed to operate much like Baran’s
distributed network. In Bitcoin’s founding document, Satoshi Nakamoto (2008) outlines
how Bitcoin works and echoed both key features of Baran’s proposal: a distributed
network model and digital operation of the system embedded in code. Nakamoto
envisioned an immutable monetary policy encoded in consensus protocol and (perhaps
unwittingly) used several principles of Baran’s network typology to operate it and used
many of the same terms to describe its operation. On the very first page, Nakamoto
mentioned Bitcoin’s “distributed timestamp server” and “nodes [which] collectively
control more CPU power than any cooperating group of attacker nodes” (Nakamoto
2008, 1). While transactions are processed on a blockchain, its network is effectively
secured by independent operators who choose to run the code necessary to validate those
transactions. Note that these independent validators of Bitcoin’s network are commonly
referred to as “nodes,” (3) just as Baran described the operators of his communications
network.
1.3.2 Network Typology and Automated Security in DAO Governance Framework
We can use Baran’s (1964) typology as a sliding scale of decentralization for
various aspects of DAO governance. The words ‘decentralized’ and ‘distributed’ are often
used interchangeably, but Baran’s distinctions help clarify and distinguish key differences
between the two. The question determining the network’s classification is: what happens
when a node or station is compromised? Different aspects of a DAO’s network need not
share the same typology. Wang et al. (2019) argue an ideal DAO is organizationally
distributed but power is decentralized as opposed to traditional pyramidal organizations
with centralized power.
Network security (i.e., resistance to network attack) increases with its level of
decentralization, but decentralization alone cannot ensure network security without sound
cryptography and invulnerable code. Smart contract robustness must increase as DAO
network distribution increases as well. Hackers took advantage of flaws in the TheDAO’s
smart contract governance (Reijers et al. 2021). This is primarily an issue for the digital
element of DAO governance, but vulnerabilities within TheDAO’s voting protocols
helped enable the hack (Mark et al. 2016). TheDAO’s downfall had as much to do with
failing to account for bad faith actors within the network as flawed transaction
verification methodology did. Furthermore, its smart contracts lacked rules/methods for
dealing with such an instance (DuPont 2017). Core developers had no way of returning
funds or rectifying the situation immediately – proposed changes required approval by
token-holder vote.
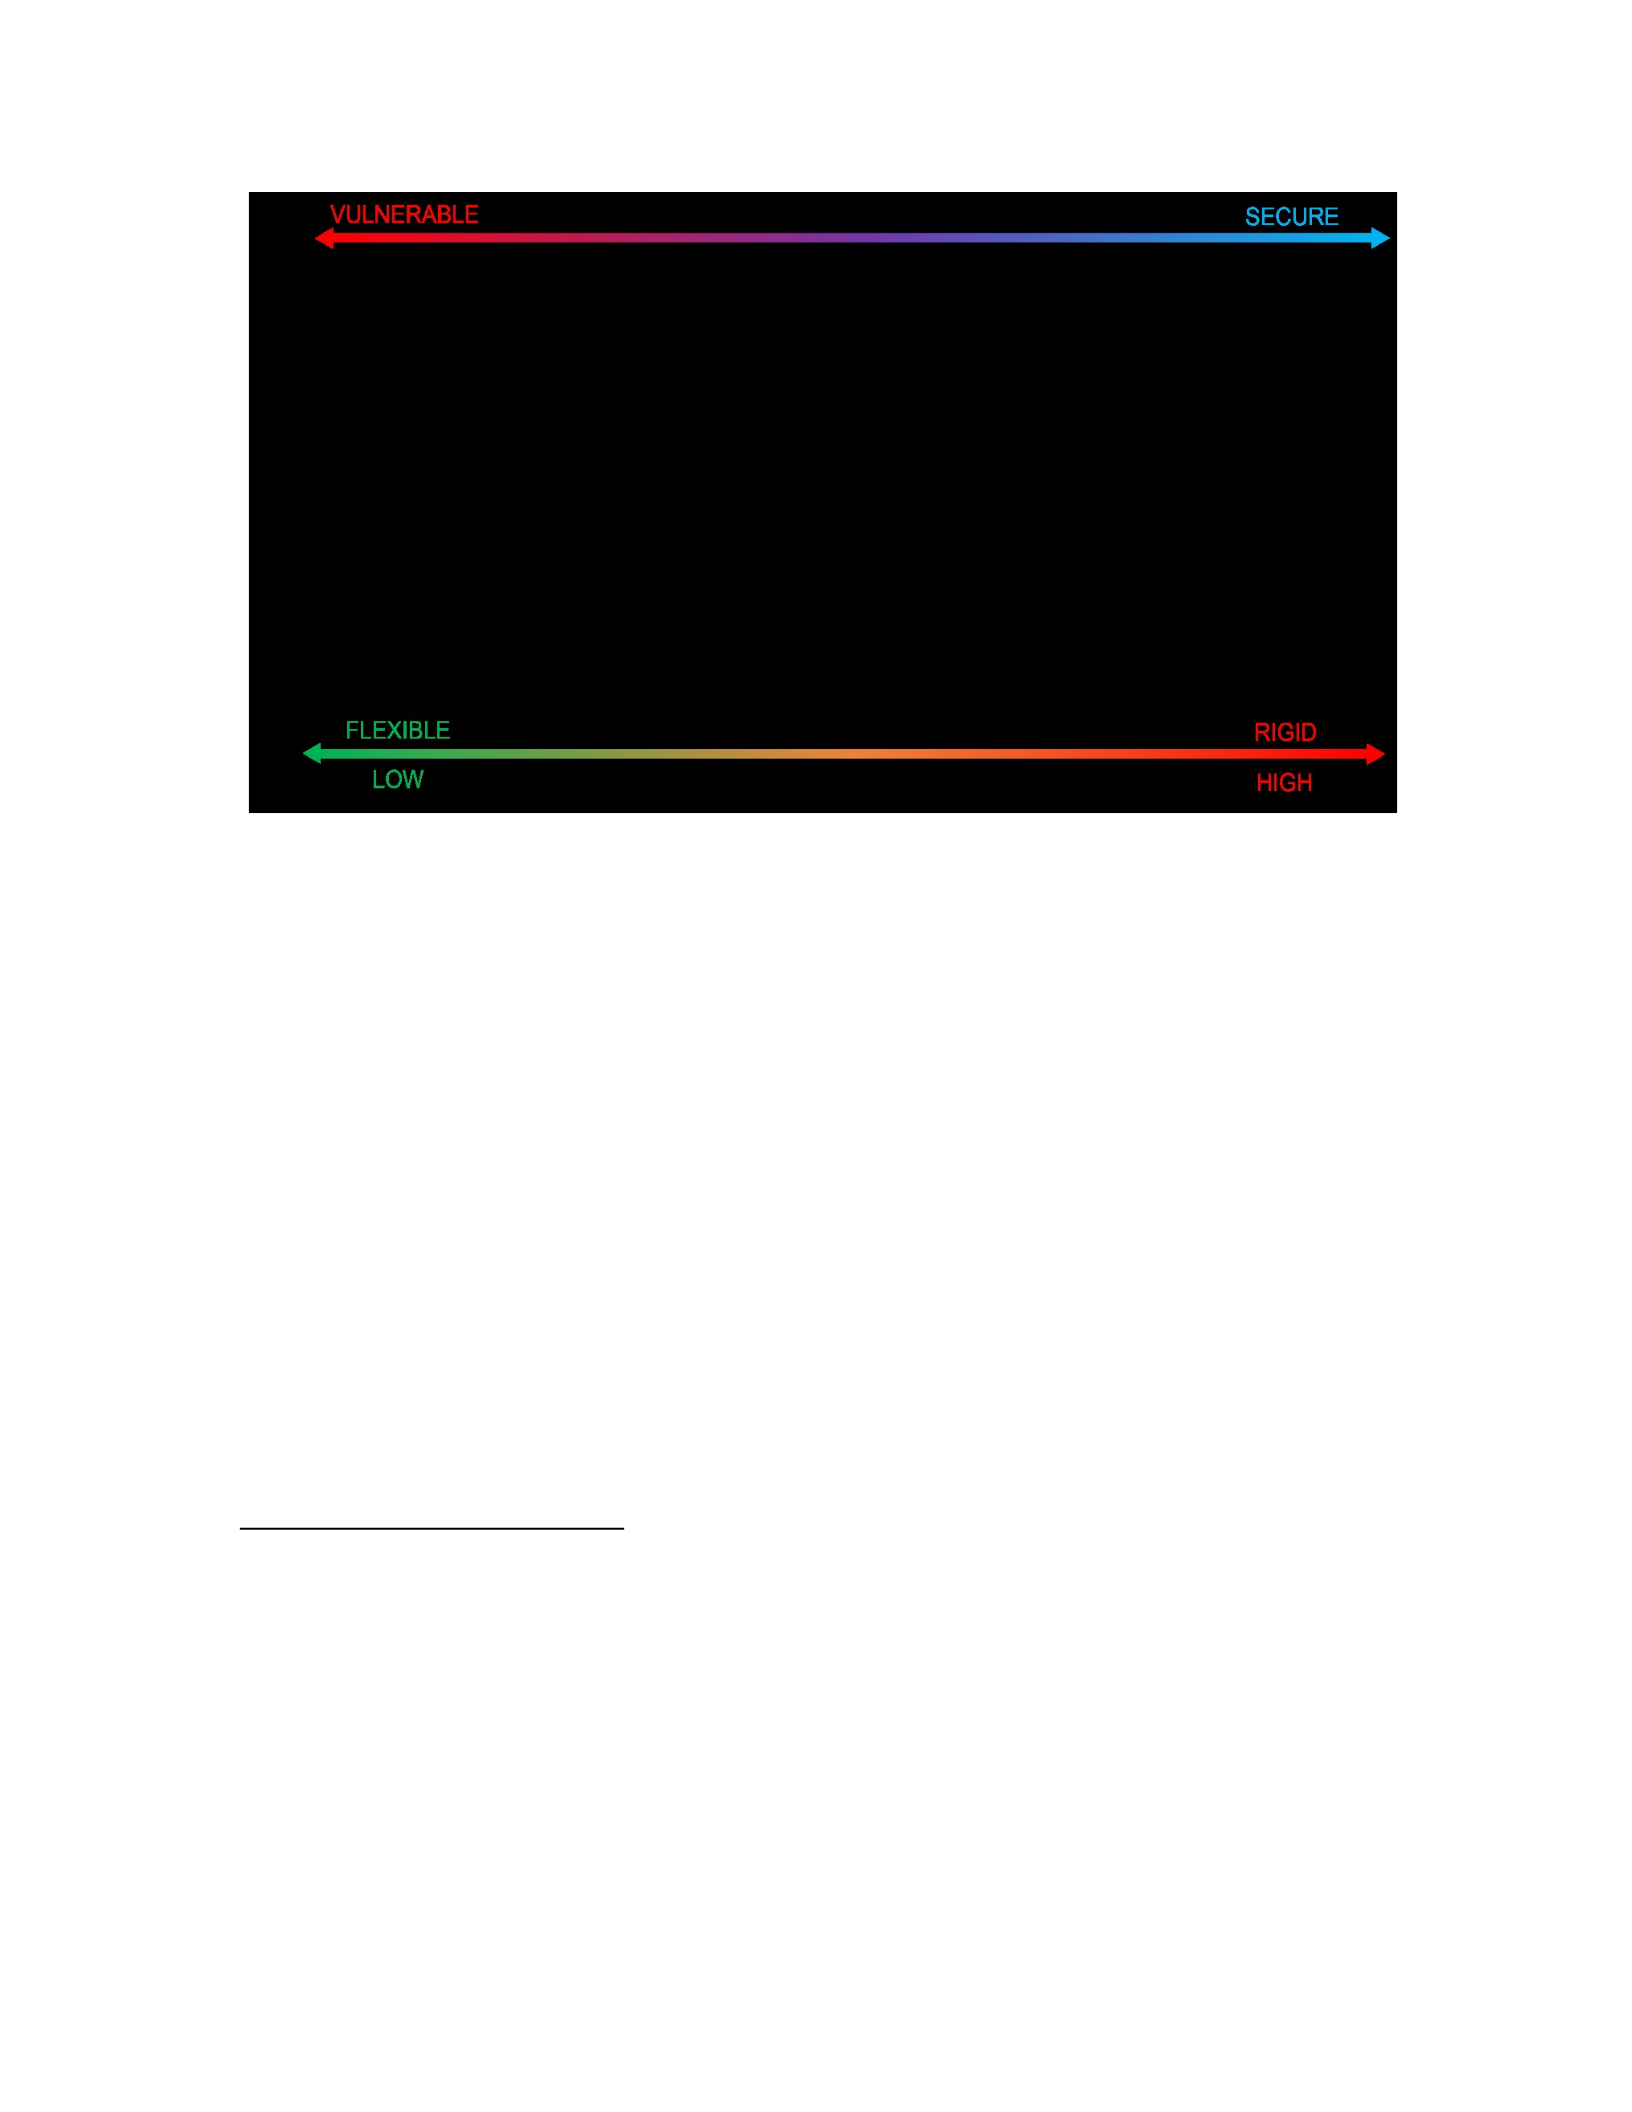
Figure 1.2 Network Typology and DAO Tradeoffs (author)
Fully centralized systems suffer from a single point of failure at the point of
central authority (Figure 1.2). In perfectly distributed systems, each member shares equal
authority. Partially decentralized systems may have members with varying degrees of
authority or particularly high barriers to entry for prospective new members.28 Truly
decentralized systems may have actors with more power than others, but still benefit from
less exposure to the possibility that 51% of the network could fall under the control of a
bad actor (or actors) to carry out invalid transactions or act against the best interests of
the network. This affords them significant security advantages over more centralized
networks. Aside from decentralization, there are few security techniques to provide
protection against 51% attacks because of how consensus protocols are designed to work
in DAO governance (Sayeed and Gisbert 2019).
The question determining the network’s adaptability is: what happens when a
change needs to be made? More centralized authority in the hands of fewer members of a
DAO allows them to adapt quickly to flaws in the core protocol (i.e., hacks, faults etc.).
More decentralized networks requiring democratic consensus mechanisms (e.g., voting)
to alter code are capable of instituting changes but are less agile in doing so. For this
reason, cryptographic processes and smart contract logic must be sound to protect the
integrity and security of their network since there are no elite players like a CEO to make
quick, unilateral decisions in the face of adversity. In open networks, the burden of
responsibility to evaluate the soundness of core software security protocols falls to the
user. Information asymmetries can arise when the threshold for truly understanding
coding language is too high for the average network participant.
From a public policy perspective, network typology speaks to how, where and to
what extent a DAO can be influenced. The digital element of a DAO network is governed
entirely by the smart contracts within the core software. Assuming no glaring security
vulnerabilities, effecting changes to digitally automated operations depends on the
consensus rules of the organization. Unless governments can gain enough control of
membership within the organization (e.g., acquiring voting rights), exerting pressure on
existing members may be the only way to modify core software. For example,
environmental concerns about energy use and the carbon footprint of cryptocurrencies
provide the public policy rationale for switching from proof-of-work (PoW) to a less
energy-intensive consensus mechanism known as proof-of-stake (PoS). But since these
consensus mechanisms are embedded in core software, programmers must develop new
software and network participants effectively “vote” by choosing to adopt it or not.
The divergent paths of Bitcoin and Ethereum’s consensus mechanism illustrate
this point. Though Ethereum recently switched from a PoW to PoS consensus
mechanism, Bitcoin remains on its original PoW system. Understanding where a network
is truly decentralized and automated helps delineate where the digital, hard to change
aspects of DAOs end and where human control, power, and influence begins. DAOs may
be non-hierarchical but many are not entirely leaderless. For example, the Ethereum
community recognizes seven kinds of stakeholders with varying roles and responsibilities
in the governance process (Ethereum 2022). The barriers of entry for each kind of
stakeholder vary drastically, as does the influence they hold over the network. Since
inception, Ethereum has had a clear set of “primary core developers” followed by
“primary non-development members” (Buterin 2014) who played a critical role in two
hard forks of the Ethereum blockchain and serve as the final authority on proposed
changes to the Ethereum protocol. “Protocol Developers have no way to force people to
adopt network upgrades” (Ethereum 2022) but those who do not upgrade risk being left
behind.
Table 1.1 Bitcoin and Ethereum Network Participant Types
DAO Network Network Participant Type Level of Individual
Influence
Bitcoin
Miners & *Mining Pool
Leadership
Users (wallet address holders)
Developers
Low & *Medium
Very Low
Medium
Node Operators (can also be
users) Low
Ethereum
Ether Holders
Application Users
Application/Tooling
Developers
Node Operators
Low
Low
Medium
Low-Medium
EIP Authors Medium
Miners/Validators Medium
Protocol Developers ("Core
Developers") High
Furthermore, Vitalik Buterin’s power and influence as the highly visible
leadercreator of Ethereum cannot be understated. He made both Time magazine’s “most
influential people” list and Forbes magazine’s “30 under 30” list. He spearheaded the
launch of, and all major subsequent changes to the Ethereum network since 2015 and
wrote a book promoting the merits of PoS-based blockchains (Buterin 2022). Bitcoin has
fewer individually influential network participants and no such recognizable human
leadership (Table 1.1). Bitcoin’s creator(s) released its white paper under a pseudonym,
worked to modify it for a few years, and then disappeared into obscurity (Champagne
2014). This makes it comparatively difficult to garner enough support to execute protocol
switches in Bitcoin. Environmental campaigns have struggled to convince Bitcoin
network participants they should adopt a less energy-intensive consensus mechanism like
PoS (Gkritsi 2022).
1.4.1 From Communications Research to Network Effects
In the early 1980s, economists began studying communications systems as
markets with demand externalities where “benefit to a subscriber depends upon how
many of his communication partners also subscribe” (Oren and Smith 1981, 467). With a
focus on practical use cases for networks in national defense, Baran (1964) saw each
additional node in a communications system as increased security. Economists saw a
“network effect” at work where each additional subscriber-user added to the value of the
network. Before reaching an equilibrium or “critical mass subscription level” (Oren and
Smith 1981, 484), each additional subscriber receives more benefits than the last. Due to
advances in microelectronics and reduced costs of manufacturing, telephones provided
the greatest example of such a product at the time (Coase 1987): if 100 people own
telephones, the value of owning their respective telephones increases when the 101st
telephone is purchased and added to the network. Critical mass points are a function of
various subscriber cost/pricing mechanisms (e.g., flat rate subscription or volume-based
charges) and whether the system suffers from the negative externalities of congestion at
some point (Katz and Shapiro 1985; Liebowitz and Margolis 1994).
Katz and Shapiro (1985) expanded this analysis beyond monopolistic
communications networks. Much like Oren and Smith (1981) they defined positive
consumption externalities as “products for which the utility that a user derives from
consumption of the good increases with the number of other agents consuming the good”
(Katz and Shapiro 1985, 424) and use telephone networks as the primary example. But
telephones were a bit too simplistic to capture all the dynamics at play. They felt that
network externalities could be found in other markets as technology advanced (e.g.,
machinery). For example, positive consumption externalities for computers go beyond
the benefit of simply adding another hardware computer to a network. Incentives lead to
the creation of new programs and software to run on computers and increase their
functionality further.
Economists dubbed this the “hardware-software paradigm” (Church and Gandal
1992). But unlike the monopolistic view of the telephone, firms compete in these other
markets, and Katz and Shapiro developed a model to capture the dynamics of competition
in markets with positive consumption externalities. They conclude public policy would
have to consider both protecting firms’ technological innovations while ensuring healthy
competition between firms. Societal pareto optimality must take both static efficiency
(improving existing products) and dynamic efficiency (developing new products) under
consideration (Ghemawat and Costa 1993). Similarly, policymakers needed to consider
“costs of compatibility” (439) and adaptability to protect the firm’s intellectual property
without stifling the benefits of positive network externalities for consumers.
Their work in this field expanded well beyond their initial model. Katz and
Shapiro led a symposium for studies of network effects, or the broader economics
surrounding systems where component parts are complementary and boost value when
combined. Scholars of network effects found market competition between such systems
was different than with individual products in three important ways (Katz and Shapiro
1994). First, expectations really matter; and studying expectations in the context of
network effects opens new opportunities to examine the consumer’s ability to make
rational decisions in the face of inadequate or asymmetric information. Consumers’
willingness to pay for a network effect product is not just based on its immediate utility,
but an expectation of what might develop around it (i.e., the hardware-software
paradigm) and who else may buy it in the future. Similarly, coordination matters. If the
internet is the software which makes the hardware of a computer more valuable, much of
that potential value is tied to expectations that others will collaborate, share ideas, and
boost collective human capital. Finally, compatibility is an issue where many scholars
expanded upon Katz and Shapiro’s (1985) earlier work summarized above. How do
consumers evaluate the cost of technology adoption, or choose between two rival
incompatible systems (Katz and Shapiro 1994)? They found that imperfect competition,
inadequate/asymmetric information, and issues with compatibility/coordination result in
some market inefficiencies where “it is theoretically possible for government intervention
to improve market performance” (112) as not all network effects are necessarily positive
network externalities. Incumbent firms benefit from network effects, naturally seek to
elements of smartphones has been contested in court for decades and several antitrust suits continue for the
country’s largest corporation.
box out potential rivals and also possess certain rights in protecting their intellectual
property.
1.4.2 Network Governance Roots in Economics
As the analysis of network effects expanded beyond communications systems,
economists considered the roles social dynamics play in firms. Though commonly
associated with public management today, ‘network governance’ originated as the study
of “network forms of organization” (Powell 1990, 295) among business economics
scholars in the 1990s. They sought to distinguish behavior within and between firms
(Ring and de Ven 1992; Larson 1992; Kreiner and Schultz 1993; Jones et al. 1997) from a
dichotomous view of ‘market’ and ‘hierarchical’ modes of organization which previously
dominated the field of economics (Richardson 1972). Coase (1937) and Simon (1962;
1985) provided early inspiration for economists to consider firms separate from their
component parts. Firms form to limit transaction costs independent persons would face in
the absence of cooperation (Coase 1937) and maximize different individual competencies
(Simon 1962). But Simon (1985) implored the field to expand studies of economic
cooperation by considering a “view of the nature of the human beings whose behavior we
are studying” as “fundamental in setting… and informing our research” (77). Such
studies in the 1980s and 90s were dubbed the interdisciplinary field of “new institutional
economics” (NIE) (Williamson 1979; 1998).
NIE birthed two concepts critical to understanding why firms work as a method of
organization: transaction cost economics (TCE) and embeddedness. Interfirm trust
dynamics play a role in each. The study of transaction costs was not new to the field, but
Oliver Williamson was the first to define (1979) and advocate for TCE as a method of
studying organizations with transaction costs as the basic unit of analysis (Williamson
1981; 1986). His theory expanded upon the Coase Theorem (1937) in suggesting that
firms possess advantages over markets in “harmonizing bilateral exchange” (Williamson
1981, 559) and the optimal organizational form should seek to minimize transaction
costs. By joining individuals together in pursuit of a common goal, firms may reduce
incentives for opportunism (Provan and Gassenheimer 1994) and try to replace it with
interfirm trust instead (Noteboom 1996). Williamson (1998, 2000) distinguishes between
kinds of transactions requiring different forms of governance in TCE literature. Basic
governance structures suffice for “ideal” transactions in law and economics (Williamson
1998). Ideal transactions utilize general purpose technologies and require no safeguards
between parties whose identities are irrelevant (Macneil 1978). As transactions utilizing
special purpose technology increase in their complexity, more safeguards are required.
Contractual safeguards leverage penalties built into contract language to deter contractual
breaches. Williamson refers to this as a “hybrid” form of organization. Other transactions
are so complex they require organization “under unified ownership within hierarchy,”
(Williamson 1998, 38) better known as firm organization.
TCE was widely considered the branch of NIE concerned with firm governance
and predictive behavior (Williamson 1998), but Jones et al. (1997) were among the first
to incorporate both TCE and social network theory into a framework for identifying when
and how network governance works (913). TCE logic informs when network governance
may emerge: when problems are complex, requiring adaptation, coordination, and
safeguarding exchanges more efficiently; and when other modes of organizing (market
and hierarchical) are at a competitive disadvantage (917). A network governance structure
can reduce the cost of trust in transactions by bringing transactions within the firm. Entire
industries revolve around profiting off a lack of trust between parties (e.g., contract law)
and reducing the cost of trust is a key component of TCE literature (Williamson 1975;
Chiles and McMackin 1996; McMackin et al. 2021).
Still, trust issues exist within firms as well (Mellinger 1956). Participative
management styles and democratic organizations were found to increase trust among firm
operatives in non-managerial positions (Savery 1982) and embeddedness emerged in the
1990s as the social mechanism by which intrafirm trust could be built. Embeddedness
stems from the idea that transactions have a human, relational component (Granovetter
1985) and that repeated positive exchanges generate trust (Buskens 1998). Jones et al.
(1997) saw embeddedness as the connective tissue between social network theory and
network governance. Unlike in one-on-one relationships, structural embeddedness is
defined by how many mutual contracts (“third” parties) are linked indirectly. The level of
structural embeddedness is a “function of how many participants interact with one
another, how likely future interactions are among participants, and how likely participants
are to talk about these interactions” (924). This incentivizes the diffusion of information
(potentially eliminating information asymmetries), enhances coordination and safeguards
exchanges within the network. Even something like “negative gossip” can serve as an
accountability check between members of a network. Embeddedness studies considered
interfirm patterns of social behavior and the economic outcomes that result
(Granovetter 1985; Williamson 1994).
Table 1.2. Economic Network Theory and DAO Concepts
Foundations Economic Concept DAO Concept Public Policy Implications
Network Effects:
Demand Externality (Positive)
Communications Network
(Oren and Smith 1981)
Theory:
Capacity Limits/congestion
(Negative)
Typology (Baran 1964)
(Katz and Shapiro 1985; Liebowitz
and
Externalities and Pricing (Squire
Margolis 1994)
1973; Littlechild 1975)
Positive Consumption Externalities
Value increase with new subscribers
(Katz and Shapiro 1985)
(Artle and Averous 1975) hardware-software paradgm (Church and
Gandal 1992)
Value co-creation (Yang 2021)
Digital platform governance
tradeoffs
(McIntyre 2017; Chen and Patel
2021)
Blockchain Trilemma
(Buterin 2017; Abadi and
Brunnermeier 2018)
Competition concerns; encourage
positive externalities vs. discourage
natural monopolistic tendency
intergenerational rivalry, compatibility
(Katz and Shapiro 1992; Farrell and
Saloner 1986)
users value shared responsibility and
ownership in decentralized ecosystems
(Yang
2021); public admin. implications
Transaction Cost Economics
Theory/Nature of the Firm
(Williamson 1975; 1981; 1998)
(Coase 1937)
Embeddedness
Complex hierarchical systems (Simon
(Granovetter 1985; 1992; Williamson
1994)
1962)
Embeddedness in Network Effects
Human psychology in economics (Uzzi 1996; 1997; Dnyawali and
Madhavan
(Simon 1985) 2001; Simsek et al. 2003)
Distributed Ledger Technology
(Swanson 2014; Davidson et al.
2019; Sims
2019)
Transparency; Information
Diffusion
(Nakamoto 2008)
Blockchain
(Haber and Stornetta 1991)
DAC/DAO "bootstrapping"
(Larimer 2013; Buterin 2013; 2014)
"cost of networking" (Catalini and
Gans 2016)
transaction transparency; public
blockchain transaction broadcasting
semantically-defined contract
advantage; smart contract inflexibility
may induce transaction costs; DAO use
case limitations
(Sklaroff 2017; Meunier and Zhao 2019;
Murray et al. 2021)
minimize cost of trust in traditional
finance (Chiles and Macklin 1996; Casey
et al. 2018) information asymmetries
for DAO participants
New Institutional Economics
(NIE): TCE, Embeddedness
Network Governance (Jones et al.
1997)
Macroculture (Camerer &
Verpsalainen
1988)
opportunism (Provan and
Gassenheimer
1994; Noteboom 1996)
smart contracts (Chohan 2017; 2022;
Singh and Kim 2019; DeFillipi and Hassan semantic gaps (Wang
et al. 2019)
2018; Wright 2021)
practical governance issues; lack of flexibility in
consensus rules (Dwivedi et al. 2021)
DAO gov. (Dupont 2017)
open source software collaboration
1.4.3 TCE, Structural Embeddedness and Network Effects in the DAO Framework
The previous section of this paper poses trust as a main factor in DAO network
design – increasing network decentralization/distribution decreases vulnerability to a

compromised central authority. In economics, the idea that individuals might seek their
own self-interest while obfuscating the truth is the assumption of opportunism
(Williamson 1993). The psychology of trust for economic agents (Ho 2021) and
determining the transaction costs of mitigating trust-related concerns (Pratten 1997) is
essential to economics. Public blockchain-based DAOs seek to mitigate this cost of trust
by relying on a new kind of transparent, distributed ledger to verify ownership and past
transactions without the need for the type of centralized authority which makes
communications networks vulnerable. This demonstrates a novel shift in the concept of
how ledgers have worked historically (Davidson et al. 2016).
In an op-ed on distributed ledgers and blockchain technology, a group of
prominent regulators and digital currency educators including Gary Gensler, Chair of the
Securities and Exchange Commission, said “We believe this technology could reduce the
ingrained ‘cost of trust’ that currently adds friction to commerce and enriches
trustintermediating gatekeepers across the economy” (Narula et al. 2018). But they
questioned the long-term fate and value proposition of decentralized systems. Catalini
and Gans (2016) contend the true economic innovation in blockchain technology, DAOs,
and cryptocurrency lies in the shift away from centralization. They showed how several
general-purpose technologies have enabled a consistent reduction in the “cost of
verification,” as embedding incentives and governance rules into protocol reduce the
“cost of networking,” or the launching, operating, and scaling an economic network
(Catalini and Gans 2016). Still, the field lacks empirical studies comparing the
transaction and administrative costs of DAOs to that of hierarchical organizations
performing the same functions. Permissionless networks without centralized control and

self-contained incentive systems do not operate without costs and fees. There is
tremendous value to be gained from exploring where human action and centralization
outperforms hard-wired autonomy in decentralized systems.
The substitution of code for the human element of organizational power and
process is the central difference between DAOs and firms relying on network governance.
In offering “A General Theory of Network Governance,” Jones et al. (1997) discussed
“coordination characterized by informal social systems rather than by bureaucratic
structures within firms and formal contractual relationships between them”
(911). Relationships are often informal and “based on implicit and open-ended contracts” (914)
and eventually lead to a “macroculture" of shared values and knowledge (Abrahamson &
Fombrun 1992). This macroculture “enhances coordination among autonomous parties” (Jones et
al. 1997, 930) who tacitly understand the unwritten rules which benefit the organization (Camerer
& Vepsalainen 1988; Williamson 1991).
Notably, in their definition of network governance, Jones et al. (1997) described
firms as “autonomous” and adaptable, just as DAOs strive to be. But the major difference
between DAO and network governance lies in that DAOs effectively try to formally
embed what is informal in network governance using smart contracts. When “code is
law” (lex cryptographia) and the code is vulnerable, DAO members protected by
anonymity and unmotivated by organizational goals take advantage with no social
repercussions, as seen in failure of TheDAO. In network governance, macroculture allows
members of a firm to respond with “appropriate actions under unspecified contingencies”
(Camerer & Verpsalainen 1988), but when “code is law,” the potential exists for

“semantic gaps” (Wang et al. 2019, 876) between the code written in smart contracts and
intended organizational rules. Here, DAO governance suffers from a lack of flexibility
(Wang et al. 2019) or “practical governance” (DuPont 2017) relative to network
governance.
This lack of flexibility plays into the transaction cost economics of DAOs. Recall
that TCE works along a continuum of contractual complexity (Williamson 1998). DAOs
smart contracts can govern both simple transactions (e.g., “A” send value to “B”) and
complex ones (e.g., ownership rights) using special purpose technology (e.g., blockchain,
distributed ledgers, cryptography). DAOs also utilize various incentive structures to deter
bad actors from violating consensus rules rather than relying on unified ownership. For
example, Bitcoin miners who attempt to add an invalid block to the chain risk receiving
no block reward for the work (energy) expended. Thus, the TCE at work in DAO
governance look like Williamson’s description of hybrid modes of organizing
transactions – distinct from market and firm modes of organization.
Just as economists contend firms can reduce opportunism through embeddedness,
DAOs attempt to do the same through the public transparency and cryptographic
enforcement of their distributed ledgers (Swanson 2015; Davidson et al. 2019; Sims
2019). In fact, Catalini and Gans (2016) claim DAOs provide lower authentication costs
and reduce opportunism relative to traditional conceptions of the firm (Williamson 1981).
But others argue that smart contract inflexibility creates transaction costs relative to
traditional, semantically-defined contracts (Sklaroff 2017; Murray et al. 2021). For this
reason, Meunier and Zhao-Meunier (2019) specify simple, natively digital transactions as
the best use case for DAOs seeking to avoid the need for a trusted third party in the
process.
Collaboration plays a role in strengthening DAO networks but is fundamentally
different than the embeddedness at work in traditional conceptions of the firm. Most
DAO transactions occur anonymously, so incorporating embeddedness into the TCE
framework (Jones et al. 1997) does not apply in the context of a DAO. Granovetter
(1992) referred to both relational and structural embeddedness. Relational embeddedness
is “the degree to which exchange parties consider one another’s needs and goals” (Jones
et al. 1997, 922) and the behaviors they exhibit as a result (e.g., information sharing)
(Uzzi 1996). Blockchain and distributed ledger technologies are based on information
diffusion through transaction transparency, but the impacts of what limited social
interactions occur between DAO participants is unknown. DAO message boards and
instant messaging social platforms (e.g., Discord, Reddit) certainly provide platforms for
the sharing of ideas and open-source software. However, consensus rules written into
core software (e.g., proof-of-work, proof-of-stake) are what tie DAO network
stakeholders together by disincentivizing any attempt to add invalid transactions to the
blockchain. Whether relational embeddedness intrinsically motivates participants to
promote DAO goals requires further examination.
Recall that structural embeddedness is the extent to which two parties have mutual
contacts – and share information about those mutual contacts. Structural embeddedness
can be difficult to operationalize and measure empirically in network governance (Moody
and White 2003), but information diffusion and transparency are core to the blockchain
and distributed ledger aspects of any DAO (Nakamoto 2008; Swanson 2014; Pilkington
2015; Davidson et al. 2019). In this sense, the digital aspect of DAO governance is quite
literally structurally embedded into its code while the human aspect is more akin to
whatever relational embeddedness results from discourse between network participants.
DAOs benefit from the same demand externalities seen in communications
networks (Oren and Smith 1981). Whether designed to exchange value (e.g.,
cryptocurrency), pool capital (e.g., The LAO) or support online gaming (e.g.,
GameDAO), DAOs get better as more users are added to the network until reaching some
theoretical critical mass. In a study of technology adoption where network externalities
are present, Katz and Shapiro (1992) raised the potential for issues of intergenerational
rivalry when “an older technology with an installed base competes against a newer
technology lacking such a base” (57). Policies involving licensing contracts and
intellectual property are designed to promote intergenerational compatibility, so the
market is not biased for or against certain products and technologies
(Farrell and Saloner 1986). Models exist for determining whether existing incentives “to
adopt a new technology are socially excessive or insufficient” (Katz and Shapiro 1992,
56) (Farrell and Saloner 1986), but no such models and studies exist specific to DAO
technology or cryptocurrencies. The highly technical nature of DAO digital governance
may result in significantly different rates of financial technological adoption across age
groups due to digital proficiency gaps.
Existing research touts the advantages decentralized governance enjoys over more
centralized platforms thanks to network effects. Chen et al. (2021) find sharing
responsibilities, rights and control with participants causes them to act in the interests of
the overall network and attracts more participants. Yang (2021) adopts a view of DAOs as
decentralized ecosystems with different layers and subsystems. Motivations for
participation in different layers or subsystems of the network may vary, but they each
engage in “value co-creation activities [which] generate network effects” (55)
nonetheless. Cryptocurrency miners, investors, and users, have different motivations
(short-term, long-term profits, and value exchange respectively) but each new miner,
investor, and user added serves to push the network towards the benefits of further
distribution.
Concerns about consumer expectations and information asymmetries (Katz and
Shapiro 1994) in DAOs abound. The degree to which regulators should try to protect
consumers from themselves – particularly when DAOs involve the exchange of fiat
currency for tokens – is up for debate. But what is clear is that few people possess the
requisite knowledge to read code and comprehend the smart contracts running these
organizations. Competition presents another public policy dilemma. Since further
decentralization/distribution benefits network security, new additions boost DAO value
proposition. Policymakers must decide whether to encourage positive externalities or
discourage the natural monopolistic position of the network. Lack of recognized legal
status and DAO ownership play a confounding role amidst antitrust concerns (DeFillippi
and Wright 2018). Developers create inherently open-source software in the public
domain – unlike in other markets, there is nothing proprietary about DAO code.
Conversely, this also allows for anyone to create competing DAOs at any time.
However, network effects have natural negative externalities which may mediate
such policy concerns as well. Capacity limits may result in crowding and congestion
within the network as additional participants are added (Katz and Shapiro 1985;
Liebowitz and Margolis 1994). There is considerable debate as to whether
blockchainbased systems must also reach a saturation point where additional user-
members reduce their value proposition.
The advent of blockchain-based systems leads to theoretical debates about a
“Blockchain Trilemma.” Buterin (2017) claims blockchains can possess only two of three
properties: decentralization, scalability, and security. Critics of cryptocurrencies point to
their scalability problem (Croman et al. 2016). Because cryptocurrencies operate on
decentralized networks and exchanges of value require high security, their efficiency in
transaction processing pales in comparison to more traditional digital payment methods
(i.e., credit cards). Assuming the trilemma holds, any secure DAO must also be limited in
scalability. Thus, DAOs processing high amounts of data should reach some capacity
where they suffer the same negative externalities (i.e., congestion) as seen in other
networks (Katz and Shapiro 1985; Liebowitz and Margolis 1994) unless they centralize
or make some security concessions.
1.5 The Push For Decentralized Governance in Public Administration
Since the Minnowbrook Conference in 1968, the field of public administration
has been engaged in a near-constant state of critical self-examination. One topic of debate
is whether practitioners and scholars of public administration are too far removed from
those whom government is meant to serve. So far, this paper has explored network
theories and their derivatives to describe how, why, and when DAOs work and the
resulting public policy implications therein. This section explores why people find
decentralized systems attractive in the context of evolving perceptions of trust and
legitimacy in public administration. I find motivations to opt-in to DAO participation
resemble desires for more participatory, representative, and decentralized provisions of
public services.
1.5.1 Polycentricity
With the help of Charles Tiebout, Vincent and Elinor Ostrom developed and
popularized the concept of polycentric governance in political economics from the 1960s
through the early 2000s. As economists developed theories of TCE, network effects, and
structural embeddedness from the perspective of firms competing in markets, early
political economy scholars developed governance theories through the lens of public
finance. Economists considered the merits of socialism (Mises 1922; Lange 1938) in the
wake of stark class divisions, economic depression, and a World War. Polanyi (1951) first
used the term ‘polycentricity’ to describe a system in which individuals possess some
autonomy in decision-making within a larger rules-based order, and their decisions
impact or “adjust” the decision-making calculus of other individuals (Carlisle and Gruby
2019). For Polanyi, socialists erred in thinking central planning could reach Pareto
efficiency in polycentric systems (Aligica and Tarko 2011).
The Ostroms theoretical development of polycentricity began with the observation
that metropolitan governments benefit from multiple independent (and often
uncoordinated) decision-making centers providing various goods and services (Ostrom et
al. 1961). Since metropolitan areas are home to a variety of stakeholders with different
needs, public goods are more efficiently produced and distributed “at different levels of
special aggregation” (Stephan et al. 2019, 21). These political units often compete with
one another and “enter into various contractual and cooperative undertakings or have

recourse to central mechanisms to resolve conflicts” (Ostrom et al. 1961, 831) that make
their patterns and behavior quite predictable. This theoretical work is supported by
empirical findings which show advantages of polycentric and self-governance systems in
metropolitan areas over more centralized local governments (Ishak 1972; Ostrom et al.
1973; Ostrom et al. 1973; Rogers and Lipsey 1974; Ostrom and Whitaker 1974; Ostrom
1976). Notably, in studies of police departments across 80 metropolitan areas, “large
centralized departments [never] outperformed smaller departments serving similar
neighborhoods” (Ostrom 2010, 644) and no evidence was found to support widely held
claims that polycentric policing approaches are less efficient.
In the Ostrom view, trust plays “the central role in coping with” and “overcoming
social dilemmas” (Ostrom 2010, 662) when perfectly rational individuals should expect
others to be self-interested (Rothstein 2005). Private citizens need not be trapped by
selfishness which precludes them from any ability to solve problems collectively without
a government presiding over the administration of maximum social welfare (Loomes and
Sugden 1986). Citing the failures of several highly centralized governments in preserving
common resources (e.g., climate, oceans), Dietz et al. (2003) touted the benefits of
“institutional variety,” (1910) or a mix of hierarchical, market, and community
selfgovernance approaches to avoid environmental degradation. Decentralizing control in
common-pool resource environments allows individuals to develop norms to specific
various ‘microsituational’ contexts (Crawford and Ostrom 2005). Boundedly rational
participants in these microsituations build trust that others will reciprocate and cooperate,
resulting in net benefits for all despite incomplete information regarding future events

(Poteete et al. 2010). Decentralized governance is complex, but not necessarily chaotic
(Andersson and Ostrom 2008) in the delivery of public goods and services. It serves as a
remedy for the otherwise helplessly trapped individual in the rational model (Ostrom
2010).
Technological changes and contemporary urban organization challenged
definitions and conceptions of polycentricity. The democratization of information and
ubiquity of internet access transformed communication, space, and time so that cities with
once easily defined borders now looked like functional metropolitan regions (Castells
1996). As a result, urban-geographic polycentricity research in the 2000s focused on the
flow of people and information between centers rather than municipal government or the
physical structures of where people reside (Parr 2005; 2007; Hall and Pain 2006; Hall
2009). Scholars questioned whether urban government was too narrow a lens through
which to view a phenomenon which could refer to any multimodal human activity
(Kloosterman and Musterd 2001). Others questioned the mechanisms by which
polycentricity worked, emphasizing the need for firm definitions for the functional
linkages between nodes and sub-centers (Green 2007; Vasansen 2012). For this subset of
researchers, trust is rarely mentioned as a mechanism for polycentric success. Like the
mechanisms at work in transaction cost minimization, increased connectivity and robust
transport infrastructure serve as remedies for the problems of geographic space and
incomplete information (Agarwal et al. 2012; Vasansen 2012).
1.5.2 Network Governance in Public Administration
Network governance studies captured the attention of a wide range of scholars
from various academic disciplines, particularly during the 1990s. Jones et al. (1997)
synthesized TCE and social networking theories (e.g., embeddedness) into an

economicspecific framework for network governance as sociologists declared the rise of
a new network society (Castells 1996; van Dijk 1999). Social networks used micro-
electronics to process information within the network, giving people access to a diverse
set of individualized networks (Wellman 2001) which would transform the diffusion of
information. O’Toole (1997) recognized the network concept taking hold in business,
nonprofit, and some governmental sectors and implored public administration to pursue
research focused on networks. He argued public administration needs to be a part of the
world it seeks to operate in and points out mismatches between the administrator and
networked world (e.g., conceptions of authority, outgroup influence, coordination
opportunities) (O’Toole 1997).
Provan and Milward (1995) were among the first to offer a theory of network
effectiveness in their comparative study of four community mental health delivery
systems. One primary finding is that “predominantly centralized” (25) networks
performed better than those which relied on stronger integration of decentralized
networks. However, in Provan’s most recent work on the topic of network stability, his
conclusions were modified slightly. Provan and Lemaire (2012) stated the limited
research conducted on network stability points to a “stability-flexibility” paradox where
“networks need to be relatively stable at their core, while maintaining flexibility,
especially at the periphery” (645).
Provan and Milward (2001) still viewed principal-agent theory as a useful lens
through which to examine network effectiveness. Whether someone is a principal, agent,
or client, the effectiveness of the network depends entirely upon the “level” of network
analysis (community, network, or organization/participant). Agranoff and McGuire

(2001) review relevant research about the intersection of network theory and the public
sector primarily conducted throughout the 1990s in pursuit of a better-defined subfield of
public network management and come to a different conclusion. The concept of network
management relies on trust between participants in achieving network success through
social capital (O’Toole 1995; Fountain 1998) and conceptions of accountability are often
ambiguous (O’Toole 1997). For Agranoff and McGuire, this diminishes the applicability
of principal-agent theory in network management:
… because in networks there is no obvious principal or agent, and no exigent
authority to steer the activities of the network in harmony with elected officials, the issue
of accountability is miscast. With no single authority, everyone is somewhat in charge,
thus everyone is somewhat responsible; all network participants appear to be
accountable, but none is absolutely accountable. (Agranoff and McGuire 2001, 310)
Similar to economic studies of network governance, Agranoff and McGuire
(2001) find social capital, shared learning, and negotiation are the ingredients which
made up the concept of groupware: the synergistic effects associated with group tasks
(Agranoff and McGuire 2001). Public administration scholars differ on the role trust
plays in building social capital and the power it holds in network governance. Clegg and
Hardy (1996) referred to a “façade of trust,” (679) where “power over” remains just as
powerful in policy networks as “power to.” Others argued trust is required in any public
network – even centralized ones – due to the nature and fundamental importance of the
problems public networks try to solve (Moynihan 2009). Provan and Kenis (2007)
framed trust in a more nuanced light with their discussion of ‘trust density,’ contrasting
dyadic trust with the kind of “dense web of trust-based ties” (238) which enables shared
governance within networks. They argued network governance can still be effective in

the presence of low-density trust provided participants believe collaboration to be
beneficial.
1.5.3 DAOs and Public Administration Network Theory
DAOs use polycentric systems to govern the distribution of community-pool
resources (Howell et al. 2019; Tan et al. 2022). Well-designed DAOs take the
motivations, roles, and responsibilities of various network actors and stakeholders into
account in their digital governance structure (Stephan et al. 2019). Hierarchical
governments appear less suited to solve the increasingly complex problems of a diverse
polity (Sorensen 2002; Goldsmith and Eggers 2004; Eggers and O’Leary 2009; Sorensen
and Torfing 2015). Just as technological advances changed how people and information
move across geographic space and created new functional metropolitan sub-regions
(Castells 1996), it now enables the borderless and permissionless transfer of information
and/or value in DAOs. Still, DAOs suffer constant failures in the trial and error of this
new form of organization just as Sorensen and Torfing (2015) saw “inherent risks and
frequent failures of public innovation projects” (146).
While decentralizing the provision of public goods may have benefits, public
administration literature is replete with cautions about removing government from
governance. Fung and Wright (2003) warned explicitly against radical “demands for
autonomous decentralization” (21) where simply empowering citizens to participate in
their government might alleviate the tensions between the governed and their
government. Sorensen and Torfing (2005) found network self-governance fails without
some form of regulating ‘meta-governance,’ but the push for inclusion in democratic
processes is natural and healthy. Like Crawford and Ostrom (2005), Sorensen and Torfing

(2005) posed meta-governance as setting the conditions (i.e., incentives, identity
development, shared values) for trust building and reinforcing norms. Pure self-regulating
governance networks like DAOs could “lead to the atomization and fragmentation of
societal governance” (224) but promoting meta-governance principles could provide
institutional structure for incorporating the best parts of network governance into a new
kind of democratic network governance.
For public administration scholars, the push for decentralized self-governance is
an indication of “a gradual problematization of the traditional focus on the sovereign
political institutions that allegedly govern society top-down” (Sorensen and Torfing 2005,
200). But decentralizing government is radically different than replacing its functions
entirely with automation. Early DAO enthusiasts sought to eliminate the need for
government and highly institutionalized organizations in the delivery of various services
(Larimer 2013). DAOs attempt to engrain all governance functions into a technical
system of peer-to-peer accountability. Meijer and Ubacht (2018) argue blockchain
technology “enables the technological institutionalization of values in environments that
are highly dependent on these values” (3). In the disintermediation of trust, blockchain
technology lowers the level of control any single actor or institution has over a DAO’s
processes. Trust lies in the fidelity of the transaction rather than in third parties or other
network participants (Meijer and Ubacht 2018).
Therefore, trust plays an important role in DAO formation, but in a radically
different sense than the way it is described in building social capital in network
governance (O’Toole 1995; Agranoff and McGuire 2001) or conceptions of
metagovernance (Sorensen and Torfing 2005). The aim of DAO governance is to use

technology to develop systems in which participants can be indifferent to intra-network
trust. “The DAO represents a new species of governance characterized by the alienation
of trust from the ownership and control of the organization” (Morrison et al. 2020, 12).
Where citizens crave top-down accountability from leadership in network governance
(Tummers and Knies, 2016), DAOs turn the democratic concept of ownership and
accountability on its head. DAO membership may constitute some level of equity in the
organization, but conceptions of accountability and ownership are nebulous by design.
DAOs, network governance, and the push for government decentralization share a
similar propensity for challenging traditional conceptions of trust and sovereignty in
public administration. Rhodes (1997) saw the rise of “self-organizing,” “autonomous”
networks as “a challenge to governability” with “important implications… for democratic
accountability” (667). Sorensen (2002) felt network governance presented specific
challenges to liberal democracy. She argued decentralizing political and administrative
authority away from the state towards local or self-governance could delegitimize the
internal sovereignty of the state. Network governance brings “a multi-layered system of
shared sovereignty” (696) and “highlights deficiencies in traditional theories of
democracy” (696). New questions emerge about the decision-making competence of “the
people” and how the sovereign citizen might engage in decision-making processes.
Sorensen’s questions about where sovereignty lies relative to “the people” echoes
a trend seen across public management and public administration scholarship at the turn
of the 21st century. Denhardt and Denhardt (2000) famously asked, “In our rush to steer,
are we forgetting who owns the boat?” (549) in reference to the analogy of how to best
row and steer government with a renewed focus on a more involved democratic polity.
McSwite (1997) re-examined the historical discourse around the Anti-Federalist spirit and
recasts the American origin story as one where colonists wanted a personal, heuristic
discourse about a government in which they were actively involved. Anti-Federalists
were fundamentally distrustful of centralized governance and opposed the creation of a
central bank. Bitcoin was born out of the Great Recession and a desire for a peer-to-peer
payment system without the need of third-party verification by a financial institution
(Nakamoto 2008). More faith is placed in “the people” or the member-nodes ability to
understand and take ownership of their own governance and responsibilities. As open
networks, DAOs only further complicate these questions of ownership, individual
sovereignty, and the role of the state in regulating peer-to-peer transactions.
Blockchain, DAO governance, and cryptocurrencies may foster financial
inclusion (Vincent and Evans 2019), censorship resistance and increased privacy (Catalini
and Gans 2019). But technological utopianism in American society historically lacks
practical solutions to social problems (Segal 1985). Atzori (2015) argued DAOs can
enable the very fragmentation Sorensen and Torfing (2005) warned about. Rather than
promoting trust and norm-building between participants in microsituational contexts
(Crawford and Ostrom 2005) over-decentralizing governance now risks having the
opposite effect. Society risks the “regression of human communities into a pre-political
condition” (Atzori 2015, 25) not unlike “Hobbesian deregulated landscapes” (Marden
2003, 90) with no concern for the public good.
1.6 Central Insights
A multidisciplinary review of network theory yields several insights regarding
DAO governance:

1) DAOs vary in design but possess both a human and digital element. Digital
decisionmaking is ruled by the base DAO core software. But this code is designed and
often changed by various human stakeholders. Understanding the hybrid nature of each
DAO – where digital control stops and human control and/or influence begins – is critical
to crafting effective policy. Unilateral policies mandating changes to core features of a
wellgeographically distributed DAO are likely to have a limited effect, as opposed to
influencing network stakeholder attitudes/opinions.
2) Networks use decentralization and automation to boost security against
untrustworthy participants to avoid single points of failure. DAOs often consist of
various kinds of stakeholders with varying degrees of power and influence over the
network. In this sense, there are varying degrees of decentralization between and within
DAOs. While increased network distribution among those with decision-making power
may provide better defense against bad actors, it requires broader consensus in changing
core software. As a result, we can conclude highly distributed networks may suffer from
a lack of adaptability (absent any automated adaptability built into base code).
Additionally, the ability to read and understand code and smart contract logic presents
information asymmetry issues.
3) Because increased distribution adds an element of security, DAOs benefit from
the positive externalities of network effects as seen in purely digital communications
networks. At some saturation point, we can expect capacity limits and congestion to cap
DAO scalability.
4) DAOs try to formally embed informal social systems found in network
governance using smart contracts (the ‘embeddedness’ concept literally embedded into
code).

Distributed ledgers and blockchain can reduce the cost of trust in TCE. But they may also
suffer from a lack of flexibility and are better suited for uncomplicated tasks and
processes.
5) Trust is a key concept in both DAO and network governance. Public
administration has been frustrated by the question of how to develop effective and
inclusive forms of governance for years to build trust with citizens. DAOs seek to form
systems in which trust is placed in some form of distributed network of validators –
placing faith in algorithms over bureaucratic structure, centralized authority and/or
human leadership.
DAO design choices can largely be seen as trust tradeoffs between human influence
(adaptability)/digital control and scalability/decentralization/security.
1.7 Applying Network Insights to Bitcoin
These insights can help analysts and policymakers better understand how DAOs
work in relation to nation-state governments. In this section, I apply the lessons drawn
from this review of network theory to Bitcoin to distill broad conclusions about DAO
governance into specific policy applications for the world’s original DAO and most
popular cryptocurrency. Nakamoto invented neither digital cash nor blockchain. In fact,
Bitcoin’s novelty comes from combining and applying several academic concepts listed
in Figure 1.3 to the transfer of value. Social science theories on decentralization and
network organization guide the incentive structure built into Bitcoin to keep various
human network participants honest, while blockchain technology, advances in
cryptography, and past attempts at creating non-state-controlled forms of electronic
money informed the creation of the digitally automated portion of Bitcoin’s hybrid
governance (1.7.1). Baran’s network typology can be applied to classify different aspects
of the Bitcoin network (1.7.2). I then demonstrate how network effects (1.7.3),
embeddedness and TCE (1.7.4) are at work in the Bitcoin network.
1.7.1 Hybrid Governance in the Bitcoin Network
The digital-automated portion of Bitcoin’s governance uses proof-of-work (PoW)
cryptography along a blockchain to prevent bad actors from counterfeiting transactions.
Nakamoto’s white paper (2008) references and applies Haber and Stornetta’s (1991;
1993; 1997) work on using linked digital timestamping for document certification to form
the basis for Bitcoin’s blockchain. The idea for requiring computer effort to validate
transactions came from Hashcash, an idea for combatting junk mail (Dwork and Naor
1993; Back 1997; 2002). A digital stamp in the header of an email requiring computing
time and effort to obtain prior to sending would signal that the sender was unlikely to be a
spammer. Bitcoin combines these two ideas so that transactions are recorded on
timestamped blocks and PoW is required to solve for a block’s nonce (an arbitrary
number used only once) and earn the block reward. Changing transactions within a block
would require attackers to commit more computer power to re-do the work, and each
block is deterministic from the last. This combination of ideas distinguished Bitcoin from
previous attempts at electronic money which failed to solve the double-spend problem
(Figure 1.3).
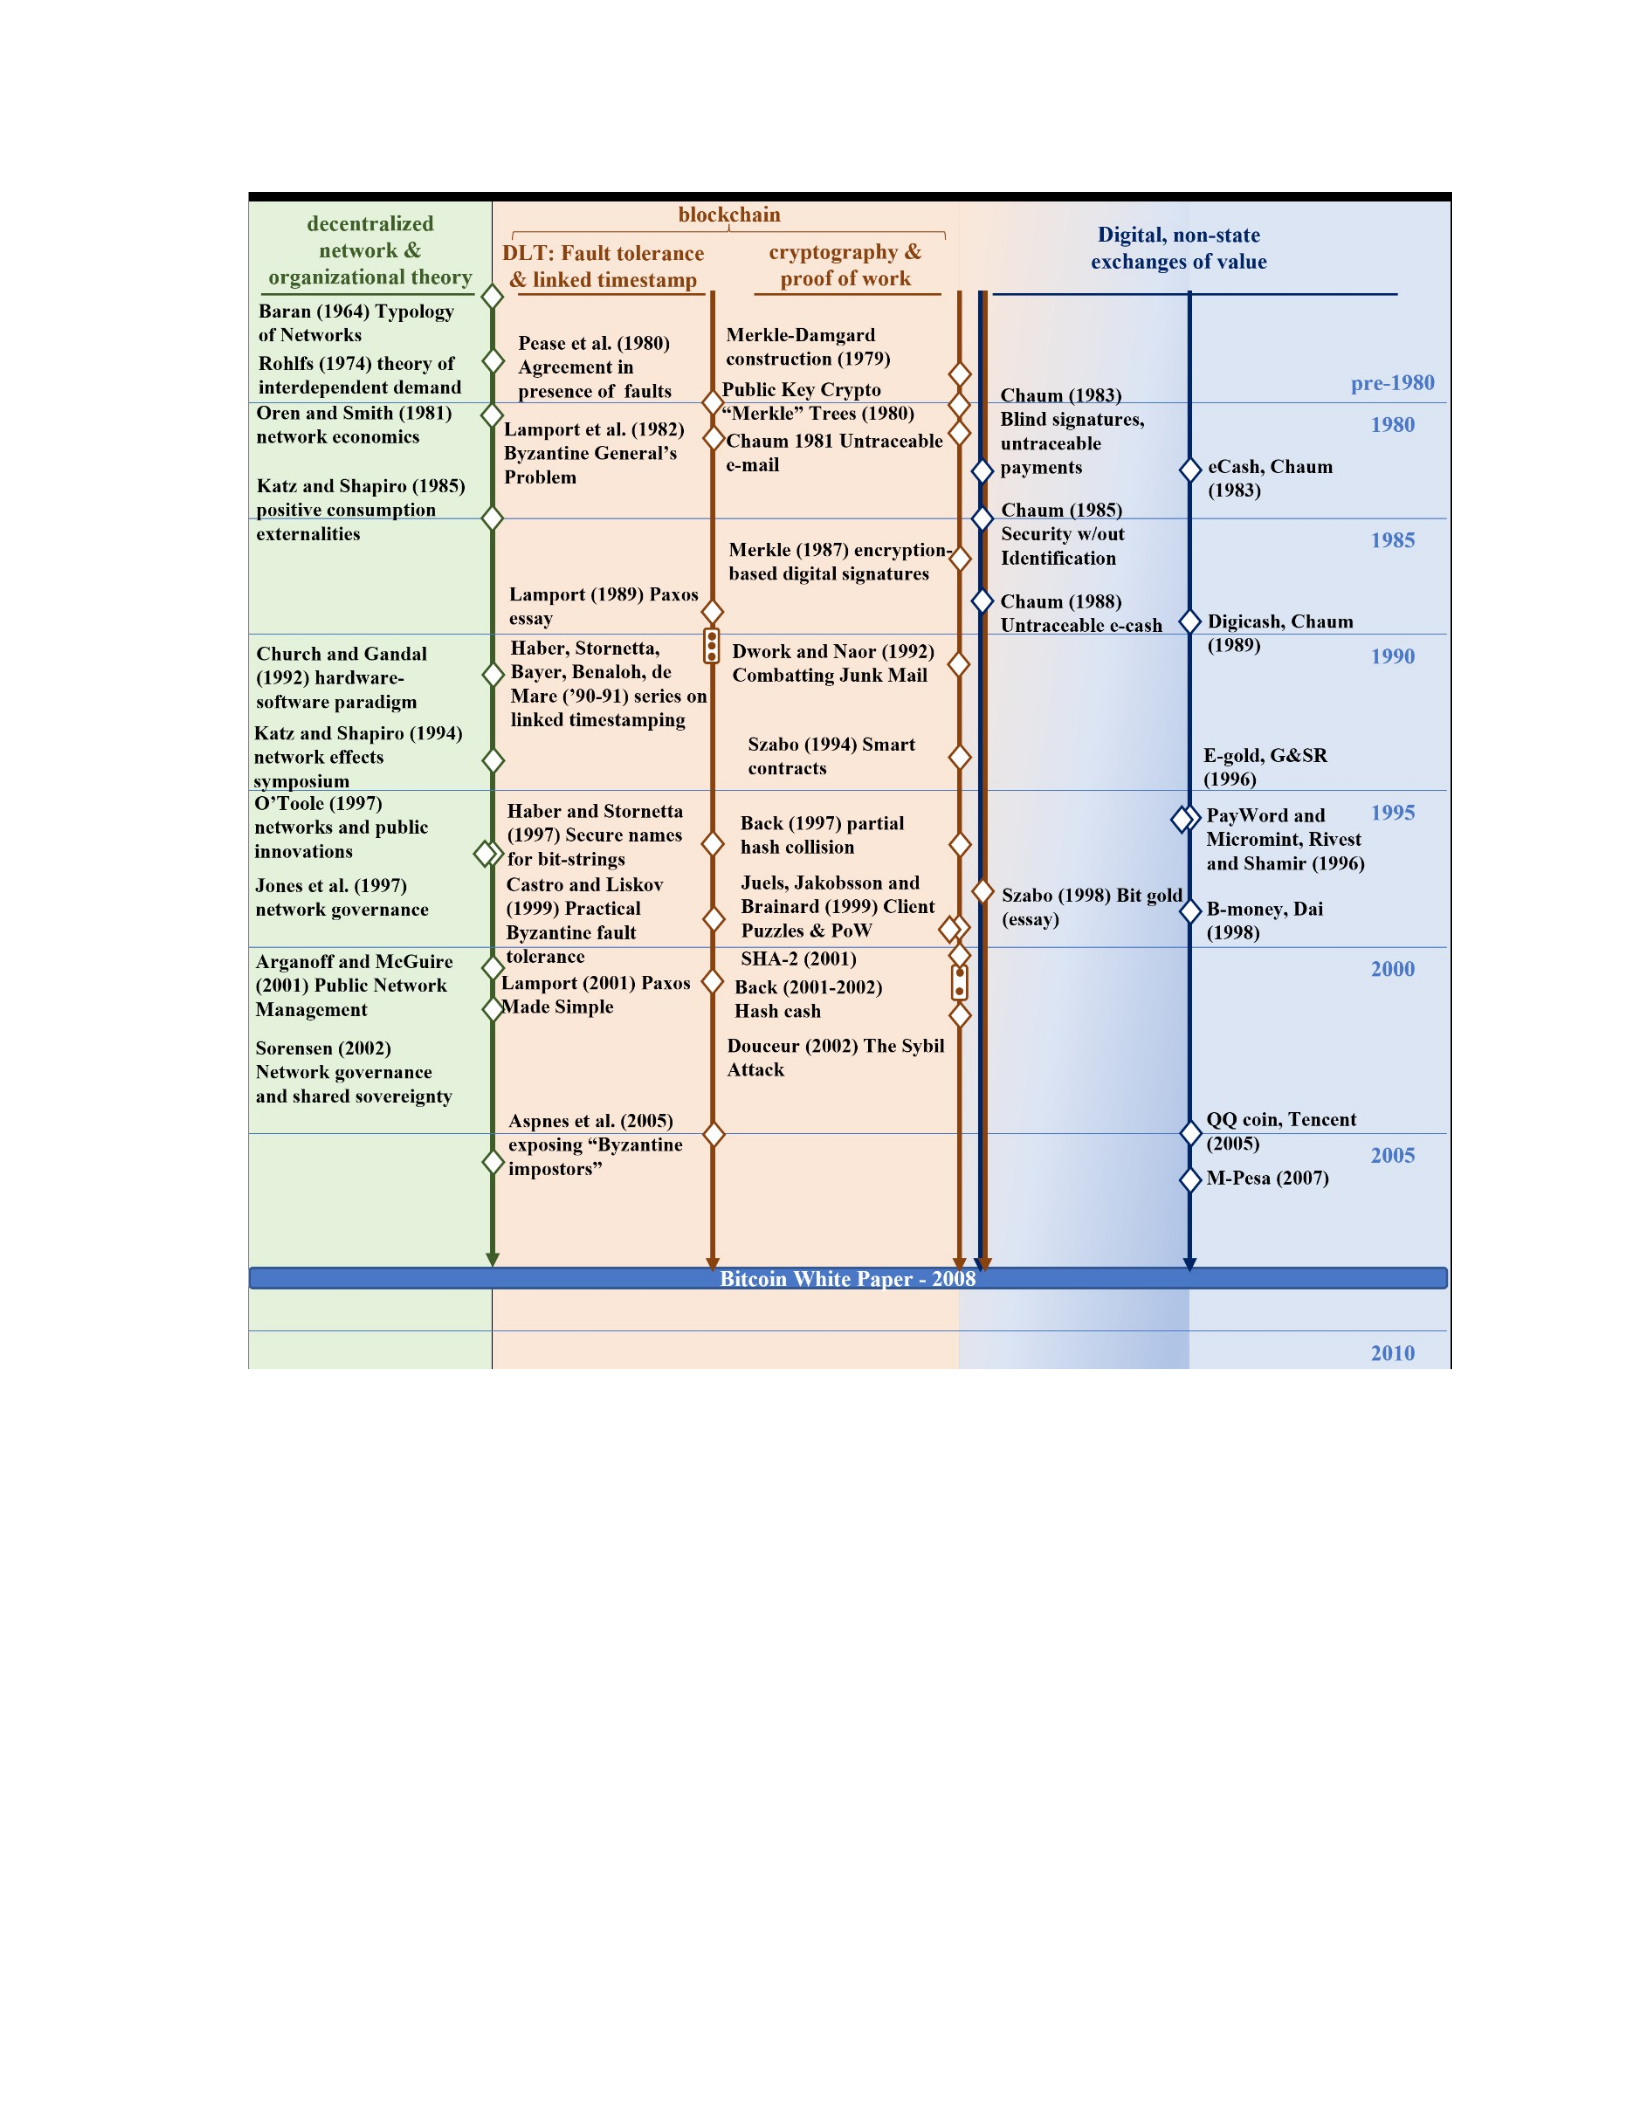
Figure 1.3 Academic and Technological Inspirations for Bitcoin (author)
There are several stakeholders within the human element of Bitcoin’s governance
(Table 1.1). Some individuals simply choose to hold Bitcoin as an investor or transact in
it. Miners conduct the PoW algorithm hashing to compete for block rewards and process
transactions in the process. Other network participants run independent nodes capable of
broadcasting and confirming the validity of other transactions. Each node holds the
distributed ledger’s history of transactions. They help secure the network by adhering to
the consensus rules; validating and blocks and transactions within blocks. rejecting
invalid transactions. Programmers can code and propose changes to the Bitcoin Core
software. These core developers submit bitcoin improvement protocols (BIPs) and review
the proposals of others. Miners signal support for BIPs by adding a certain digit visible in
blocks along the chain. An even smaller group operating on the software repository are
known as ‘maintainers’ with authorization authority to merge new code with Bitcoin
Core. Nodes then choose whether to update to new software depending on if they agree
with changes in the code as the final check on the system.
From a public policy perspective, Bitcoin’s popularity and the mining incentives
built into Bitcoin’s core protocol are lucrative enough to motivate thousands of miners to
expend massive amounts of energy to mint new coins. Approximately 105 TWh of
electricity was expended to mine Bitcoin in 2021 (CBECI 2022), equal to roughly 2.6%
of total electricity consumption in the United States for the year (EIA 2022). This energy
consumption is a top concern for the environmentally conscious. But the PoW aspect of
Bitcoin’s governance is embedded into the digital-automated element of the network. It
cannot be changed without consensus from various network stakeholders as illustrated
above.
Furthermore, history tells us it is unlikely to change anytime soon. Ethereum, the
second largest cryptocurrency by market cap, recently switched from PoW to a less
energy-intensive consensus mechanism known as proof-of-stake (i.e., the “Ethereum
merge”), but we should not expect a similar push in the Bitcoin network. In 2017,
concerns about Bitcoin’s scalability and processing speed caused some to call for an

increase in block size (Bier 2021). On one side of the debate, originalists felt Bitcoin
should emphasize a high degree of security with low barriers to entry for miners and node
operators to serve as the best store of value. On the other, supporters of what would
become “Bitcoin Cash” felt larger block sizes posed negligible risks to network security
compared to the benefits of boosting its practicality as a medium of exchange. After no
agreement could be reached, dissenters “hard forked” the blockchain into Bitcoin Cash
(Bier 2021).
Bitcoin Cash is still active today, though the original Bitcoin is far more relevant
in terms of active users and market cap. Originalists won the “block wars” – a clear
triumph for those who valued maximum competition among miners and decentralized
governance over scalability. Bitcoiners have similar concerns about moving away from
PoW. Some argue Ethereum’s new proof-of-stake model centralizes power in the hands of
the largest miners (Koss 2022). LeClair and Rule (2022) take issue with reliance on
“social governance” to deter bad actors rather than the “economic incentives and
realworld physical constraints” found in PoW. While the Ethereum merge proves there is
some appetite in the cryptocurrency community for environmentally friendly changes to
consensus protocols, environmentalist groups have been unsuccessful thus far in gaining
similar traction in the Bitcoin network (Gkritsi 2022).
1.7.2 Bitcoin’s Network Typology: Decentralized or Distributed?
Miners organize into pools and are compensated based on how much
computational power they have contributed to trying to solve cryptographic problems
using a secure hash algorithm. For this reason, blocks are typically won by pools, not
individual miners. Additionally, the barrier to entry to mining is quite high. Mining is
expensive in terms of hardware and electricity costs. So, while individual miners may
resemble a distributed network, the advent of pools makes the overall mining network
look decentralized with certain stations possessing more power than others.
Running a full node is relatively cheap and each node possesses equal power to
validate transactions.52 There are approximately 15,000 reachable nodes in the Bitcoin
network, with no more than 11% of nodes located in a single country (Bitnodes 2022).
Validating nodes mirror Baran’s (1964) depiction of a distributed network. While
programmers and core software maintainers represent are a much more centralized
network, the consensus required from a decentralized network of miners to signal support
for protocol changes followed by actual adoption of new protocol software by this highly
distributed network of nodes make effecting major changes to core code very difficult.
From an environmental perspective, a more fruitful policy approach might consider
discouraging certain mining practices and incentivizing others.
1.7.3 Bitcoin and Network Effects
1.7.3.1 Users
Historically, electronic money (e.g., e-cash, credit cards) product adoption
demonstrates positive demand externalities (i.e., network externalities) due to the utility
gains they enjoy from each user added to their networks (Van Hove 1999). The number of
Bitcoin users is hard to pin down since wallet addresses are anonymous and there is no
limit to how many addresses a single individual can have. But the number of wallet
addresses and changes in the wealth distribution of the asset across those addresses can
give us an indication of whether the Bitcoin network is truly benefitting from demand
externalities (Figure 1.4). Over the last ten years, the number of overall active Bitcoin
addresses has steadily risen along with the proportion of low balance holders (<1.0 BTC).
Transactions between addresses indicate whether holders are using Bitcoin as a medium
of exchange. As of January 2023, the network processes roughly six times as many
Bitcoin transactions per second as it did in January 2013.
1.7.3.2 Lightning Network
The usage of Bitcoin as a payment system on the base layer is still a long way
away from all-time highs in December 2017 (Figure 1.5), but it may have something to
do with the advent of Bitcoin’s ‘layer 2’ protocol, better known as the ‘Lightning
Network.’ The Lightning Network was invented to solve Bitcoin’s scalability problem
and break the Blockchain Trilemma by establishing a series of peer-to-peer
micropayment channels between users to facilitate payments and unburden the main
blockchain (Poon and Dryja 2016). Because these transactions occur off-chain, reliable
data on exactly how many transactions occur is hard to approximate. One study estimates
over 120,000 payment channels opened between January 2018 and July 2019 (Lin et al.
2020), which would help explain the drop in visible, on-chain transactions since 2018.
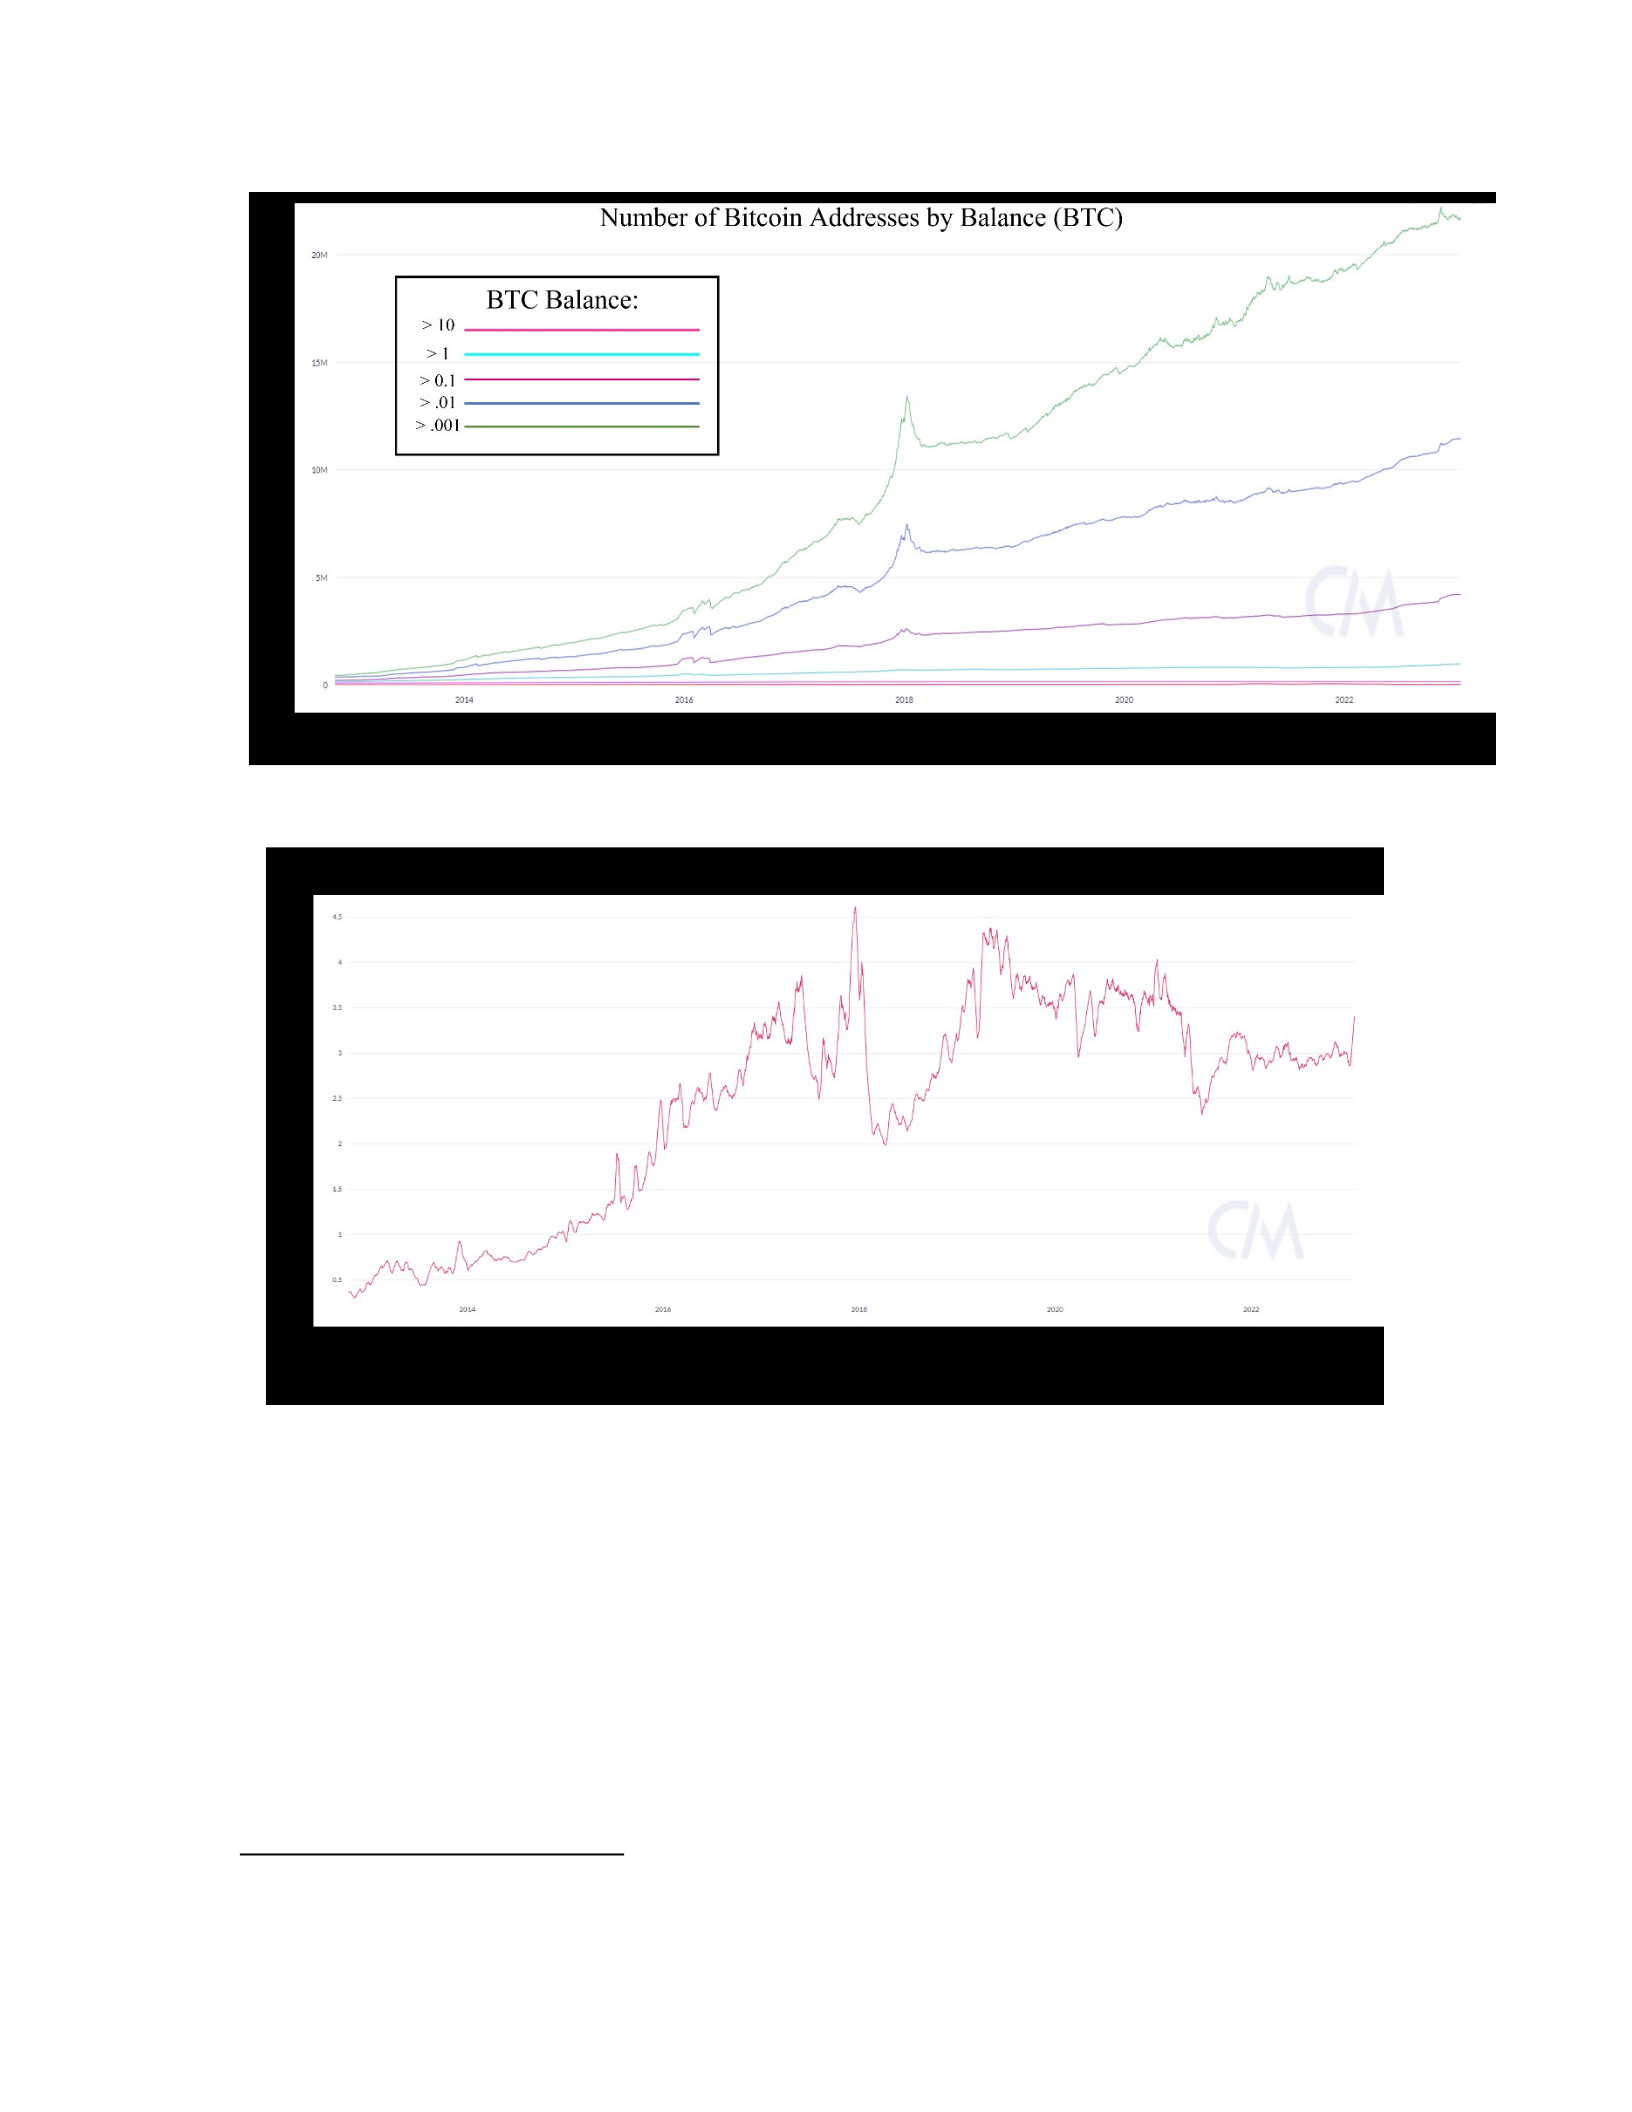
Figure 1.4 Bitcoin Addresses by Balance (author)
Figure 1.5 Bitcoin Transactions per Second (14-day moving average) (author)
1.7.3.3 Miners
Bitcoin’s network hashrate, or the amount of computing power dedicated to
mining/securing the network, has steadily increased despite major downward asset price
movement in recent years (Figure 1.6). This signals some degree of bullishness among
miners even in the face of lower profits. High hashrate makes executing an attack on the
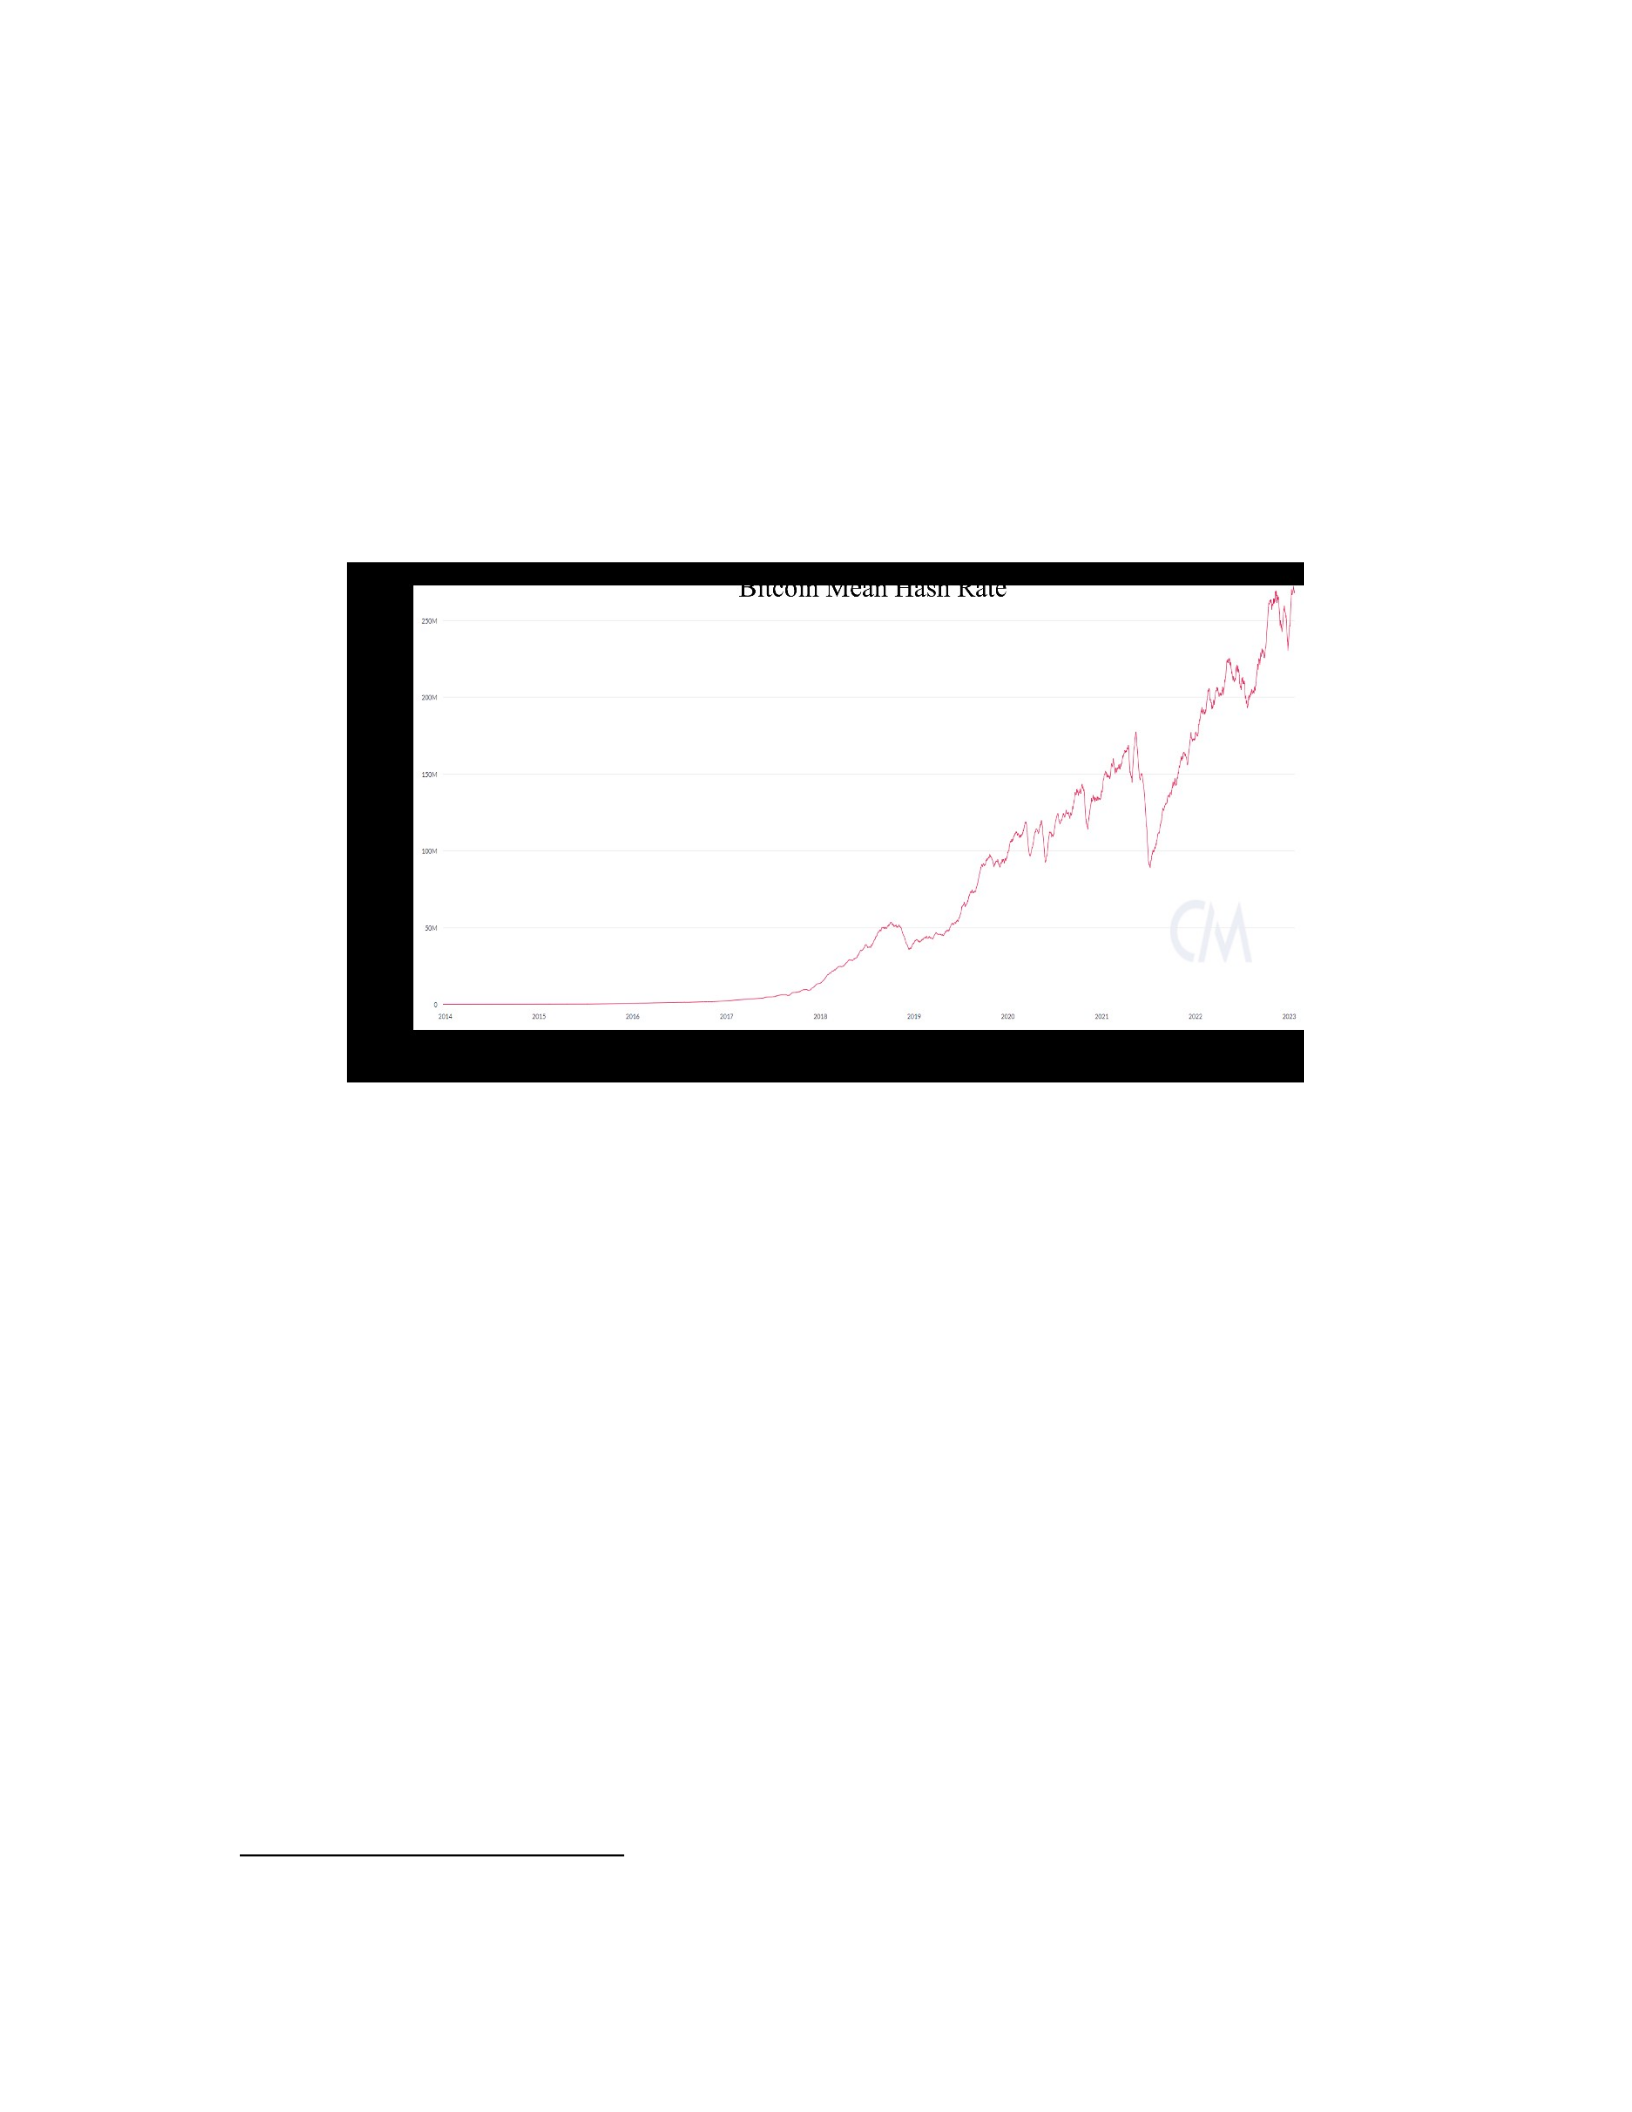
network very difficult and expensive to pull off, so additional mining power coming
online effectively adds network security and increases the asset’s fundamental value
proposition. Competition among miners drives innovation to develop the most efficient
hashing technology possible – a prime example of the “hardware-software paradigm”
(Church and Gandal 1992).
Figure 1.6 Bitcoin Hashrate (author)
1.7.3.4 Adoption
Studies show such electronic money products can be slowed by a lack of
compatibility with vendors and widespread adoption by institutional players (Van Hove
1999). Just as in communications products, e-money can reach a critical mass where the
effects of positive network externalities plateau (Economides and Himmelberg 1995).
2021 was a significant year for institutional Bitcoin adoption. 14 publicly traded
companies ended the year with over 1000 BTC on their balance sheet (Radmilac 2022),
including Microstrategy and Tesla. Liberty Mutual Insurance (NYDIG 2021) and Fidelity
Investments (Tellez 2021) invested in Bitcoin mining and technology companies. Visa
rolled out several cryptocurrency-related products and reported $2.5 billion in payments
by customers with “crypto-linked cards” in the first quarter of 2022 (Holland 2022).
Still, there is a big difference between customers using such cards to pay U.S.
dollars for products at a vendor to get cash back in Bitcoin and paying the vendor in
Bitcoin. More research is needed to show how the rate of institutional adoption of
Bitcoin-related products compares to the adoption rate of similar technologies and
electronic money products. From the standpoint of individual users and miners, Bitcoin’s
adoption rate appears to be growing despite a massive drop in market price. Despite
several hard forks, competing cryptocurrencies, and some policies aimed at curtailing
Bitcoin mining and adoption (e.g., China’s cryptocurrency ban), Bitcoin appears to be
benefitting from the positive externalities of network effects in several ways. Among
U.S. adults, major discrepancies for cryptocurrency adoption exist across age and gender
(Faverio and Massarat 2022). Assuming adoption continues at the same pace, social
inefficiencies (i.e., the differences between marginal social and private costs and benefits)
are sure to arise with Bitcoin and any PoW-based cryptocurrency due to the negative
externalities associated with energy-intensive mining.
1.7.4 Embeddedness and TCE Within the Bitcoin Network
As with any DAO, the cost of trust between parties in a Bitcoin transaction is not
related to embeddedness in the traditional social network theory sense. Bitcoiners and
other crypto enthusiasts are a very active subculture on online forums and social media
platforms. Empirically based research examining who typically uses and/or supports
Bitcoin is lacking, but one study finds higher rates of Bitcoin use in nation-states with
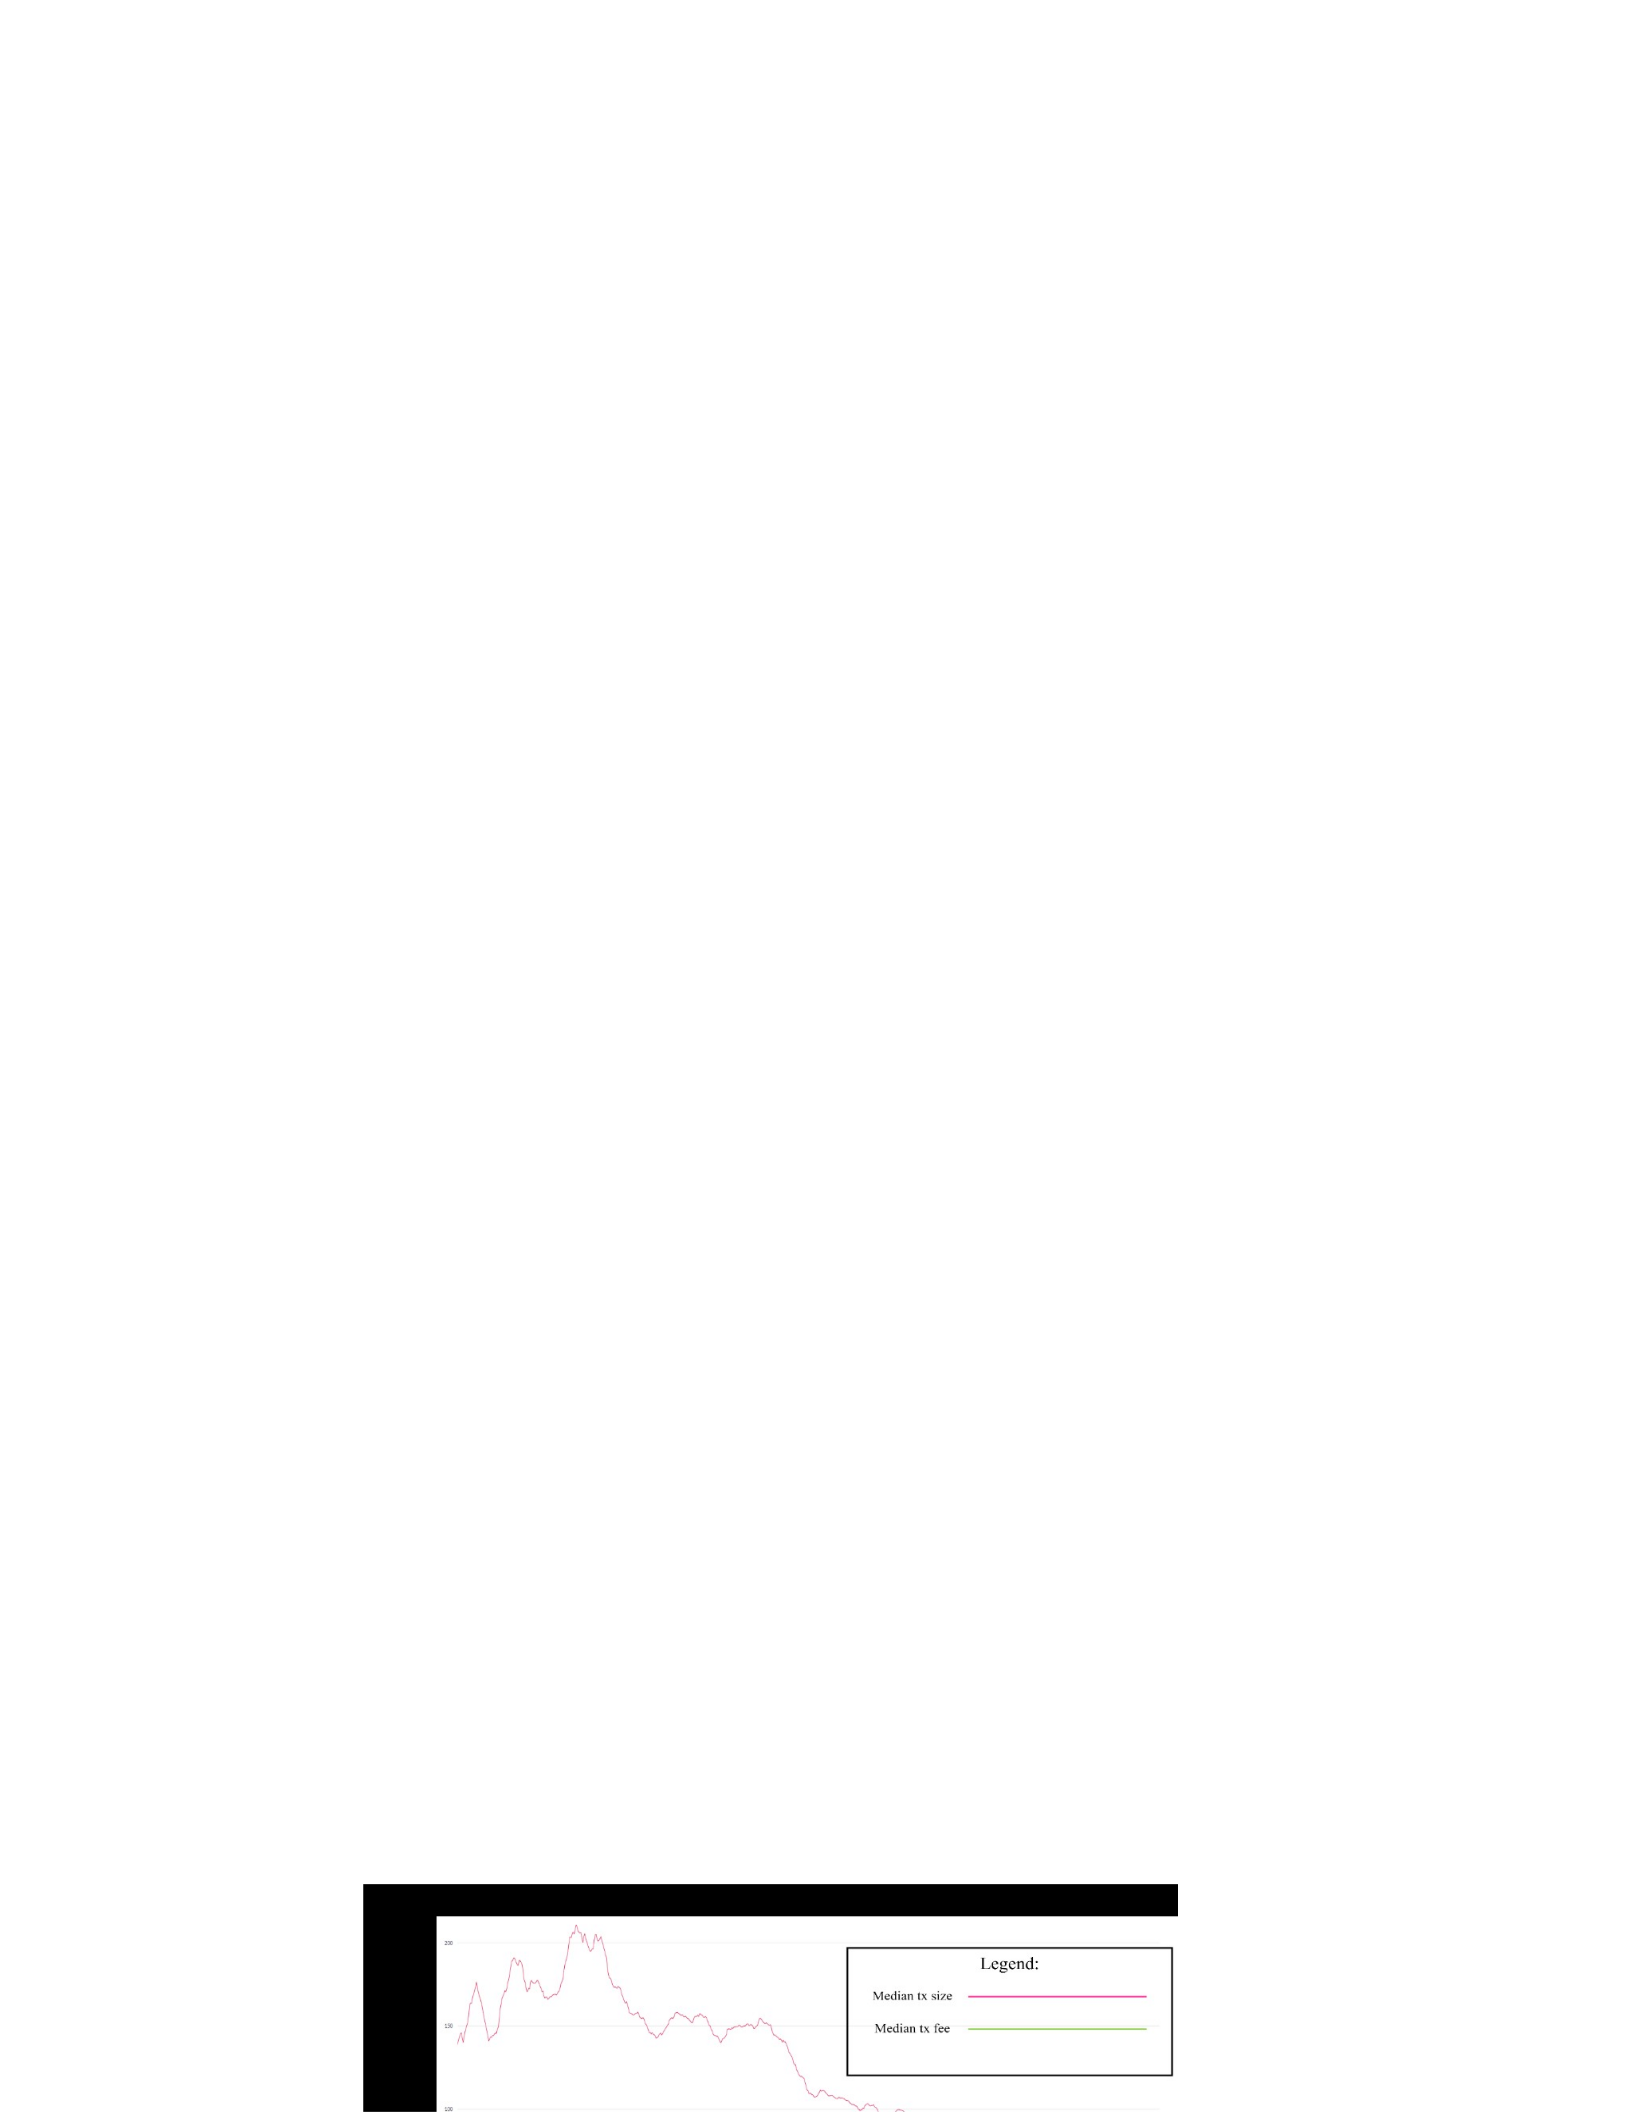
high “country individualism” scores (Foley et al. 2021). Bitcoin is assumed to be a
libertarian idea, and Nakamoto (2008) said “It’s very attractive to the libertarian
viewpoint.” But in the United States, Bitcoin has broad support and opposition across the
political aisle.58 Critics lament a culture of “Bitcoin maximalism” among many online
supporters embracing “aggression, hostility and toxicity” (Dylan-Ennis 2022) which
stems from the aforementioned “block wars.” But data supporting a definitive Bitcoin
cultural significance or a prototypical “Bitcoiner” beyond anecdotal evidence (Yelowitz
and Wilson 2015) are scarce.
The transaction cost economics of Bitcoin are based on the use of distributed
ledger technology (DLT) and blockchain to eliminate the trusted intermediary and reduce
transaction settlement costs. Blockchain serves as “a commonly agreed record of truth to
multiple, mutually distrusting participants in an economic system” (Casey et al. 2018, 9).
As long as transaction fees to network participants stay low, blockchain-based DAOs like
Bitcoin simply use transparency and automated processes to honestly record and
complete transactions.
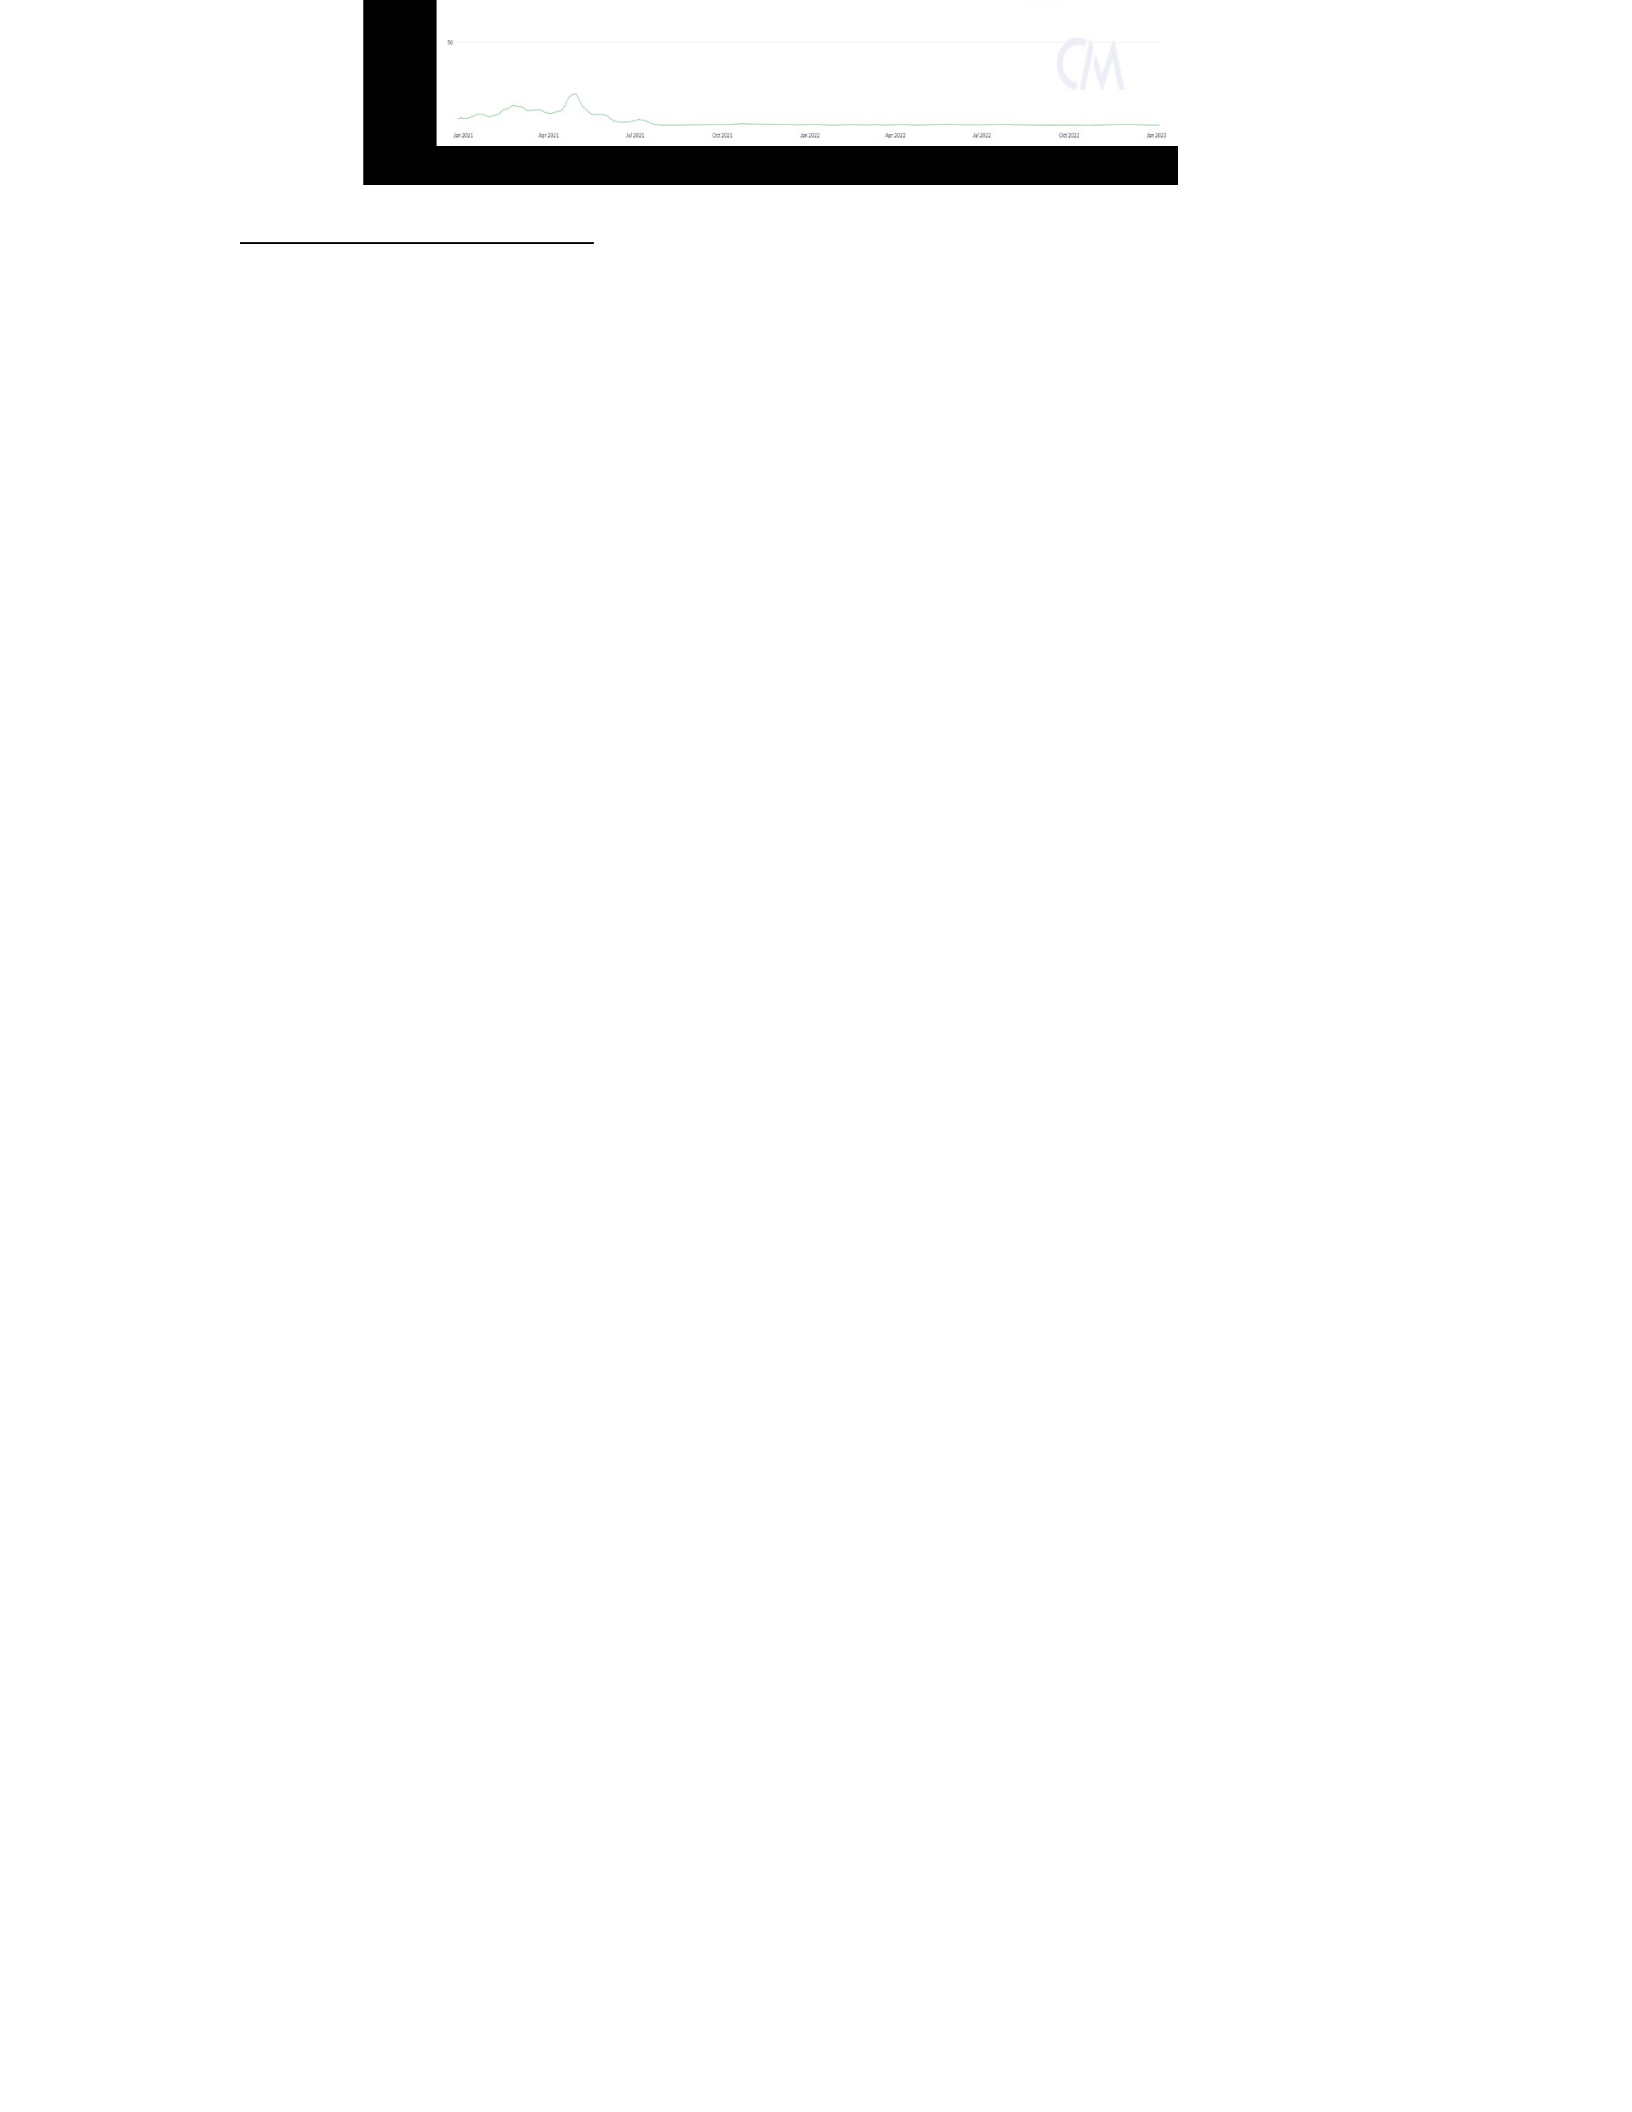
59
58 For example, the most comprehensive piece of cryptocurrency-related legislation to date (S.4356) is
cosponsored by Democrat Kirsten Gillibrand and Republican Cynthia Lummis.
59 Data sourced from CoinMetrics
Bitcoin’s base layer is particularly appealing for settling very large transactions
and the legacy payment system needs a 21st century upgrade. Since the Federal Reserve
started using telegraph wires to transfer funds between banks, automated clearinghouse
(ACH) services developed in the 1980s are the most significant, broadly applied
technological innovation in e-payment infrastructure (Powell 2021). Bitcoin proponents
point out how relatively cheap it is to transfer large sums of money on its blockchain
protocol (Figure 1.7). One analyst conducted an on-chain settlement efficiency analysis of
the 7-day moving average of volume of Bitcoin transacted fees charged on the protocol’s
base layer and found that an average transaction value of $95,142 and a median
transaction value of $751 was transferred for every $1 of fees in November 2021
(LeClair 2021). Domestic wire transfer fees within the U.S. average roughly
$20/transaction and international fees range from $40 and $65/transaction.
Bitcoin was the first financial tool to leverage this technology, but DLT and
blockchain are by no means exclusive to Bitcoin now. Policymakers must consider ways
to reduce the cost of trust by simply leveraging this technology in other forms. For major
financial institutions and large corporations, cryptocurrencies and central bank digital
currencies (CBDCs) offer tremendous promise for eliminating market inefficiencies in
large transactions/transfers, specifically for cross-border payments. Cross-border
payments face high costs, low speed, limited access, and insufficient transparency (FSB
2021). A Republican working group for the House Financial Services Committee cited
Figure 1.7 Bitcoin Median Tx Size vs. Tx Fees (14-day moving average) (author)
“addressing inefficiencies in the U.S. payment system” specifically among cross-border
payments as its first principle for CBDC development in the United States (Financial
Services Committee Republicans 2021). The private sector has a vested interest in
eliminating fees and slow speeds associated with large cross-border payments for
fiat/reserve currencies. In 2020, JP Morgan launched Onyx, “a blockchain network
enabling the exchange of value for various types of digital assets” (JP Morgan 2021) and
conducted a simulated experiment in June 2021, using a common multi-CBDC network
to facilitate cross-border payments between the Monetary Authority of Singapore
(denominated in Singapore Dollars CBDC) and Banque de France (denominated in Euro
CBDC). They found that completely different cloud infrastructures and systems could
become interoperable on the blockchain, increased visibility for both central banks could
be achieved, and “know your client” (KYC) burdens could be minimized (Onyx JP
Morgan 2021).
1.8 Conclusion: The Role of Trust in Bitcoin
With the creation of Bitcoin, Nakamoto combined principles of network theories
across several academic disciplines to create a new form of organizational governance
now known as the decentralized autonomous organization. DAOs use hybrid governance:
human stakeholders with various interests and motivations are bound together by smart
contracts written into core software governing several aspects of organizational control
and operation. These organizations are best viewed as a series of networks made up of
humans with varying levels of power and influence over changes to the digital
governance of the organization. Distribution of power and authority away from individual

human stakeholders in DAO networks is critical to their security but can cause a level of
organizational inflexibility which leads some researchers to advocate for a rather limited
DAO use case.
Writing in the wake of the Great Recession, Nakamoto’s (2008) white paper
specifically cites frustrations with how “the entire money system depends” on a “trusted
central authority” (2). They included a note in the first block of Bitcoin’s chain:
“Chancellor on brink of second bailout for banks,” a London Times headline about the
state of centralized economic planning in the wake of the Great Recession, and uploaded
the first source code for Bitcoin six days later (Champagne 2014). Trust is not just
operative in distributed computer system security or transaction cost economics – it is a
central motivator behind the very invention of Bitcoin. After Enron and Bernie Madoff, a
generation learns that “honesty comes at a price,” just as “the need for trust and
middlemen allows behemoths such as Google, Facebook, and Amazon to turn economies
of scale and network effects into de facto monopolies” (Casey and Vigna 2018). There are
several public policy implications associated with this unique form of DAO governance –
especially when applied to storing and exchanging value in the form of cryptocurrency.
But the push to use systems which disintermediate governments and institutions from the
exchange of information and value raises questions about legitimacy, individual
sovereignty, and trust in public administration.

Essay 2
China’s Crypto Ban: How Decentralized Networks React to Hostile Policy Interventions
Abstract:
Beginning in May 2021, the People’s Bank of China enacted a series of policies
rendering cryptocurrency transactions and mining illegal, citing their role in enabling
illicit finance and their impact on the environment (2.2). The ban was the largest
exogenous public policy shock to the Bitcoin network to date, setting up a natural
experiment (2.4). This essay examines the ban’s impact on the digital and human
elements of the Bitcoin network. It establishes several quantitative measures of
decentralized cryptocurrency network conditions and compares these metrics before and
after the intervention (2.5). It also considers the decision-making calculus of Bitcoin
miners displaced by the ban (2.6). I find little evidence of any long-term impacts to the
Bitcoin network after the ban (2.7). Additionally, much of the mining activity lost in
China relocated to Texas primarily because of the availability of cheap energy, but new
regulatory and policy considerations factored into miners’ decision-making processes as
well. Interestingly, new evidence suggests several miners are still operating in China
undetected. Bitcoin’s quick rebound calls into question the effectiveness of individual
nation-state bans on curbing cryptocurrency use and energy consumption. More broadly,
this case study demonstrates how well-designed decentralized autonomous organizations
adapt to hostile policy interventions.
2.1 Introduction
Bitcoin began in 2008 as the curious experiment of “cypherpunks” who sought to
develop a natively digital system of value exchange without the need for a trusted third
party. It became the catalyst for the birth of a broader movement towards systems of
decentralized finance (DeFi). Less than 14 years after the invention of Bitcoin, the global
cryptocurrency market capitalization eclipsed $2 trillion, up from $600 billion the year
prior. Cryptocurrencies like Bitcoin were designed to run as decentralized autonomous
organizations (DAOs) without government involvement or permission. But this does not
make DAOs fundamentally immune to nation-state intervention. The field of public
policy lacks studies examining the impacts of exogenous policy shocks to organizations
and/or assets which run on decentralized network consensus mechanisms (e.g., DAOs,
public blockchain-based cryptocurrencies). These organizations attempt to replace the
hierarchical, centralized structure of traditional institutions with an open network; using
smart contracts embedded into code to govern the allocation of resources, assign roles
and responsibilities, and automate processes.
This study asks, How did the Bitcoin network change after China’s cryptocurrency
mining ban? to fill that gap.63 After providing some background information (2.2), this
essay establishes, defines, and explains the significance of key metrics of cryptocurrency
asset viability (2.3). On-chain data from the Bitcoin blockchain, cryptocurrency exchange
pricing data, and IP address-based geolocational
data speak to network security and decentralization, perceptions of Bitcoin’s value as an
asset, and its utility as a medium of exchange (2.4). I then use statistical analyses to

compare those metrics before and after the policy intervention to describe the ex-ante and
ex-post states of the Bitcoin network and explore whether ex-post changes correlate with
the timing of China’s mining ban (2.5). The ban serves as an opportunity to see how the
digital-automated aspects of Bitcoin’s core software compensate and/or adapt to a sudden
loss of computational power. The actions of cryptocurrency miners displaced from China
provide insights into the decision-making calculus of the network’s human element
relative to host nation-state cryptocurrency policy disposition (2.6). Finally, I draw
lessons learned for other governments considering various policy approaches to
regulating cryptocurrency mining and use (2.7).
2.2 Background
The cryptocurrency-state relationship is a complex one. Many popular
cryptocurrencies use an energy-intensive process called ‘mining’ to process transactions
and mint new units of the cryptocurrency (i.e., tokens, coins) into circulation. Thus, a
very physical infrastructure of data centers and electricity generation underpins an
intangible, non-physical digital asset. The physical nature of these mining operations
yields environmental policy concerns about energy use and greenhouse gas emissions
(Benneton et al. 2021; Roeck and Drennen 2022). The digital assets themselves can help
facilitate illicit finance (Fletcher 2022) and present a host of questions about how they
should be treated (i.e., regulated) as financial instruments (Clayton 2017; Hacker and
Thomale 2018) when used legally. These policy implications led President Biden to call
for a review of digital assets among all federal agencies dealing in financial regulation to
develop a comprehensive, interagency approach to addressing DeFi (Exec. Order No.
14067, 2022). The order comes at a time when the United States is now the world leader
in energy-intensive Bitcoin mining by global share of network hashrate (CBECI 2022)
and several DeFi products and cryptocurrency exchanges are the subjects of
governmentled litigation.
Despite humble beginnings, several cryptocurrency proponents believe this new
technology can revolutionize financial transactions (Davidson et al. 2016) and create a
new form of apolitical international economics (Babitt and Dietz 2014; Zamfi 2015;
Pilkington 2016). The technological ideas and infrastructure they run on (e.g.,
blockchain) offer tremendous opportunities and use cases for traditional fiat currencies
like providing financial services to the unbanked (Schuetz and Venkatesh 2020) and
addressing inefficiencies in final settlement transfers and cross-border payments (Guo
and Liang 2016). Stablecoins, or “digital assets that are designed to maintain a stable
value relative to a national currency,” (President’s Working Group 2021, 1) use
cryptographic security to enable near-instantaneous transaction settlement across
international borders. The amount of US dollar (USD)-pegged stablecoins in circulation
increased over 500% from 2020 to 2021 (Liao and Carmichael 2022). But stablecoins
carry significant risks. One such risk is that stablecoin holdings are not FDIC-insured like
a bank account, nor are they subject to the kind of audits and stress tests eligible financial
institutions which hold digital USD reserves with the Federal Reserve are. There is
comparatively little transparency about how DeFi platforms are leveraged and how they
would meet a 1:1 exchange of stablecoins for USD in the event of a massive liquidity
crisis. Since stablecoins are used to trade cryptocurrencies and several traders do so with
leverage, some feel the growing size of the stablecoin market poses some threats to
overall macroeconomic and market stability (President’s Working Group on Financial
Markets 2021).
Central bank digital currencies (CBDCs) may offer the chance to bring some of
the same functionality and advantages of stablecoins and cryptocurrencies under the
purview of a central bank. The two kinds of existing central bank money are cash and
reserves held by eligible financial institutions. CBDC is “a generic term for a third
version of currency that could use an electronic record or digital token to represent the
digital form of a nation's currency. CBDC is issued and managed directly by the central
bank” (Board of Governors of the Federal Reserve 2021). For major financial institutions
and large corporations, CBDCs offer tremendous promise for eliminating market
inefficiencies in large transactions/transfers, specifically for cross-border payments.
Cross-border payments face high costs, low speed, limited access and insufficient
transparency (FSB 2021). A Republican working group for the House Financial Services
Committee cited “addressing inefficiencies in the U.S. payment system” specifically
among cross-border payments as its first principle for CBDC development (Financial
Services Committee Republicans 2021).
Another potential advantage of CBDCs is in banking the unbanked. According to
the Federal Reserve, 6% of Americans are unbanked (no bank account) and 16% are
underbanked (may have a bank account but rely on alternative financial service products).
This is an equity issue, as there are serious consequences for being underbanked and
these individuals are more likely to be minorities, poor, and less educated than the fully
banked population (Federal Reserve 2020). The Financial Health Network estimated that
underbanked and unbanked Americans spent $189 billion in fees and interest on financial
products in 2018 (Financial Health Network 2019). A CBDC would allow individuals to
essentially establish an account through a digital wallet directly with a central bank
providing some financial services rather than through a traditional bank account as an
intermediary. But CBDCs present concerns about individual privacy and autonomy since
their programmability and central control affords the government a high degree of
surveillance. Depending on CBDC design choices, CBDCs could infringe upon the very
financial privacy rights popular cryptocurrencies were designed to protect.
The nation-state challenge with blockchain and cryptocurrency is to strike the
right balance between fostering financial innovation, securing financial system integrity,
and protecting the public from bad actors (Ducas and Wilner 2017). Likewise, energy and
environmental considerations are chief concerns among nations like the United States
seeking to slow the impacts of climate change (OSTP 2022). Blockchains are
fundamentally disintermediated, transnational, and resilient; they enable anonymous
exchanges of value and data transfer, and they lack specific legal and policy frameworks
for addressing them comprehensively (DeFilippi and Wright 2018). Prasad (2021; 2022)
echoes the concerns of many economists (Bohme et al. 2015) in imploring U.S.
policymakers to consider whether this combination of stablecoins, cryptocurrencies, and
CBDCs could threaten monetary sovereignty and existing national currencies. The
“future of finance” may be filled with promise, but it is also murky – especially in the
absence of official policy statements indicating how the world’s leading economy might
approach various aspects of DeFi.
The Biden administration appears poised to address this ambiguity. Notably,
President Biden’s order on digital assets directs the Federal Reserve and other
agencies/departments to explore the development and implications of a United States

CBDC. As for non-state cryptocurrencies on public blockchains (e.g., Bitcoin), the order
focuses on the energy, climate, and pollution impacts of cryptocurrency mining. The
subsequent White House Office of Science and Technology Policy (OSTP 2022) report
on ‘crypto-assets,’ climate, and energy proposes no specific policy prescriptions but
recommends Congress and the Biden administration “might consider legislation to limit
or eliminate the use of high energy intensity consensus mechanisms for crypto-asset
mining” (7) should other methods of regulation (e.g., establishing environmental
evidence and performance-based standards for mining) prove ineffective.
2.2.1 The Cryptocurrency-State Relationship
A country-wide ban on cryptocurrency is not unique to China, but it is still an
extreme approach to cryptocurrency policy relative to the rest of the world. According to
a Thomson Reuters study (2022), cryptocurrency use is highly restricted or completely
illegal in just thirteen countries. As more countries and territories establish laws,
regulations, and policies specific to cryptocurrency, subsequent studies might analyze the
relationship between regime type and cryptocurrency restrictions. So far, authoritarian
regimes are more likely to restrict cryptocurrency use and legality. Of the 13 countries
where cryptocurrency is illegal or heavily restricted by law, only one is considered “free”
(Thomson-Reuters 2022; Freedom House 2022).
Despite similar environmental and regulatory concerns about cryptocurrency use,
the United States’ approach to cryptocurrency regulation stands in stark contrast to
China’s. As a starting point, the legal and regulatory frameworks and precedents
governing currency in the U.S. and China before the creation of cryptocurrency differ.
The U.S. Constitution and subsequent laws were designed to establish the government’s
sovereignty as the issuer of its own currency and have historically “been exclusively
applied to prosecute counterfeited dollar bills and coins” (Xie 2019, 467) and do not bar
the creation of virtual currencies. From there, the U.S. approach to regulation has
essentially been to apply existing frameworks to cryptocurrencies largely based on
whether virtual currencies and their derivatives meet the standard for treatment as a
commodity or a security (Henderson and Raskin 2019). People’s Bank of China
(PBOC) laws expressly forbid anyone outside the Chinese central bank from “printing or
issuing token tickets which could replace renminbi” (Xie 2019, 472).
China’s path to an all-out ban on cryptocurrency evolved over time. In 2013, the
PBOC declared Bitcoin was not a currency, but a “virtual asset or digital commodity”
(PBOC 2013) and barred “financial institutions and payment companies from engaging in
Bitcoin-related businesses” (Xie 2019, 474). However, the public was still allowed to
trade virtual assets and digital commodities like Bitcoin. In 2017, depreciation of the
renminbi (RMB) and large capital outflows led China’s State Administration of Foreign
Exchange (SAFE), to place a cap on the amount of foreign currency its citizens could
exchange, annually (PBOC 2017; Xie 2019). Due to SAFE’s limited ability to monitor
cryptocurrency transactions, the PBOC also expanded upon its 2013 announcement by
explicitly prohibiting financial institutions from acting as cryptocurrency exchanges
(PBOC 2017). The PBOC then launched investigations into large cryptocurrency trading
platforms and instituted a series of restrictions designed to keep exchanges from
converting RMB into cryptocurrency (Borri and Shakhnov 2019).71
In 2021, Bitcoin’s price and trading volume surged, prompting a joint statement
on May 18th from three Chinese financial regulatory bodies expanding and specifying
exactly what constituted “business related to virtual currency” which “financial
institutions, payment institutions, and other member units” (PBOC 2021) were disallowed
from participating in. Three days later, the Financial Stability and
Development Committee of the State Council convened a meeting and announced a
forthcoming “crack down on Bitcoin mining and trading behavior” (China Government
Network 2021). News reports indicate several provinces where Bitcoin mining was
prevalent (Sichuan, Qinghai, Xinjiang, and Inner Mongolia) shut down miners in early
May before the PBOC formally instituted its country-wide ban on mining in June (Feng
et al. 2021; Zhang 2022). Finally, all forms of cryptocurrency exchange were formally
banned in September 2021 (PBOC 2021). Between May and July, over 60% of the total
amount of computing power dedicated to mining Bitcoin across the entire network,
known as network hashrate, came offline – the largest such drop since Bitcoin began.
Literature on why nations like China and the U.S. might differ in their approach to
cryptocurrency regulation is scarce. Dion (2013) sees the U.S. following long-standing
precedent of recognizing other legal currencies or mediums of exchange. The dollar
remains as the country's legal tender, but the law does not require the exclusive use of
dollars in the exchange of goods and services. The Federal Reserve has regulations
designed to monitor and regulate banking and lending practices where the PBOC has a
wider scope for issuing laws and regulations designed to maintain tight control on capital.
Xie (2019) argues the Chinese approach is designed to “maintain existing regulatory
consistency and conserve institutional resources,” (491) and that the U.S. is more
comfortable with folding technological ambiguity into existing legal frameworks
wherever possible.
Another possibility is that China views blockchain technology as an opportunity
to seize a geopolitical monetary advantage with their own CBDC and views other
cryptocurrencies as competitors. In 2020, the People’s Bank of China (PBOC) launched
its CBDC pilot program in Shenzhen. Commonly referred to as the eCNY or “digital
yuan,” China became the world’s first major power to launch a fully functioning CBDC
(Deutsche Bank 2021). In July, the PBOC released a white paper about eCNY research
and development. The purpose of the white paper was to outline the objectives of the
eCNY system and “to seek public comments, as well as to deepen communication with
all those concerned and join hands with them in building an open, inclusive, interoperable
and innovative currency service system for the era of digital economy” (PBOC 2021, 1).
The brief, 15-page document does not address issues faced during the pilot’s rollout, says
very little about CBDC programmability, and has scant details of how user privacy might
be protected under the eCNY system. But the document makes one thing abundantly
clear: China intends to expand eCNY use well beyond its pilot program and will market
its use to financial service companies, commercial banks, and corporations outside its
borders.
2.2.2 Explaining the Focus on Bitcoin
DAOs and digital assets are broadly defined terms encompassing a wide range of
network/organizational structures and financialization. The set of relevant public policy
concerns necessarily differs for each type of asset. Even a focus on cryptocurrencies
alone is too broad in scope for meaningful empirical or theoretical research. Several
estimates suggest roughly 20,000 different cryptocurrencies exist today (Kharpal 2022;
Jones 2022).
This essay focuses on the impact of China’s cryptocurrency ban on Bitcoin
specifically for several reasons. First, it has the highest market capitalization of any
crypto-asset – over twice that of the next highest cryptocurrency by market cap,
Ethereum – and it has maintained this dominance since its inception for over a decade.
This speaks to its current significance despite the emergence of other cryptocurrencies
and its sustained popularity over time. Second, launched in 2009, Bitcoin is the original
and longest-tenured cryptocurrency. Most importantly, from a research perspective it is
the easiest to study due to its data availability. Transactions, wallet addresses, block
timing, and other information are all fully transparent and available on the blockchain.
Accurate market pricing data have been available since its inception, as well.
Bitcoin is recognized and singled out as different than other cryptocurrencies by several
financial regulatory institutions in the United States. Gary Gensler, Chairperson of the
U.S. Securities and Exchange Commission, has stated on record several times that he
considers Bitcoin to be the only cryptocurrency which qualifies as a commodity rather
than as a security (Gensler 2018). Gensler argues that all other cryptocurrencies are at
least somewhat controlled by a centralized entity which stands to profit more than other
stakeholders in the network. Commodities are typically raw materials like gold and are
often regulated less stringently than securities and their derivatives. Similarly, the
Commodity Futures Trading Commission declared Bitcoin a commodity in 2015..
From a public policy perspective, Bitcoin has perhaps never been more salient as
a topic of study and debate due to recent changes to Ethereum. In September 2022,
Ethereum switched from a proof-of-work (PoW) to a proof-of-stake (PoS) protocol to
reduce its energy consumption and assuage concerns about its carbon footprint and
environmental impact. Bitcoin now stands alone as the only major cryptocurrency relying
on PoW, and in many ways Ethereum 2.0 serves as a referendum on the viability of PoW
as a consensus mechanism in an environmentally conscious world.
2.2.3 A Brief Overview of Proof-of Work (PoW) Mining
The incentive structure built into Bitcoin mining is just one of several key aspects
of Bitcoin’s overall monetary design. A comprehensive explanation of Bitcoin’s full
monetary policy is outside the scope of this essay. But an abbreviated overview of
“proof-of-work” (PoW) mining is necessary to understand both how Bitcoin mining
works and why it is an energy intensive process.
For starters, we must return to the concept of lex cryptographia, or the processes
and operations of an organization occurring according to embedded code only. The rules
and smart contracts embedded within that code must prevent bad actors from taking
advantage of the system. Proof-of-work systems are designed to make it cost prohibitive
for bad actors to alter the blockchain or operate outside the consensus rules of the
protocol. For this reason, the Bitcoin core software is open-source code, all transactions
are broadcast transparently across the network, and the record of all historical
transactions on the blockchain are publicly available. Additionally, Bitcoin nodes capable
of verifying valid blocks and transactions serve as checks on the network by running the
Bitcoin core software. These nodes are relatively cheap to buy and are only as energy
intensive as an internet modem or wireless router.
In PoW, miners dedicate computing power to a process called hashing, or solving
cryptographic puzzles in hopes of earning the reward (denominated in the
cryptocurrency) associated with adding a new block to the chain. There is only one
reward per block, paid entirely to the miner who discovers the solution first. The data
contained in each block serve as a record of transactions between different addresses.
Once a miner solves the puzzle and “wins” a block, it must broadcast the solution for
verification by other miners and nodes. Invalid data can be immediately detected and
ignored. If this occurs, not only do bad actors not receive the block reward, but they get
nothing in return for the computational power (energy) expended.
For this reason, the more decentralized the network becomes (more honest nodes
and miners), the more secure it becomes. A group of miners would need to control more
than 50% of the hashrate to alter PoW blockhains with invalid data. Specifically, Bitcoin
is designed to adjust to the amount of hashing power dedicated to solving these
cryptographic puzzles and adding new blocks to the chain across the entire network.
These difficulty adjustments (how hard it is to solve the puzzle) occur automatically
every 2016 blocks based on how difficult it was to find the previous 2016 blocks.
Individual miners organize mining pools for several reasons. As overall network
hashrate increases, the probability of a single miner winning a block reward decreases
and it becomes nearly impossible for an individual miner to win a block without pooling
their hash with others. At current levels of network hashrate, it is highly improbable for
even the most well-capitalized individual miners to win blocks without collaboration.
Mining pools now win block rewards and split those rewards amongst the individual
miners in their pools according to how much hashrate they dedicated to solving that
block. Mining pools may also offer certain hosting, flexible payment, software, security,
and/or tax reporting services.
In the cost accounting analysis of a large-scale Bitcoin miner, energy is the most
significant variable/operating cost. Efficient mining requires application-specific
integrated circuits (ASICs); highly specialized machines designed specifically to solve
the Bitcoin hashing algorithm known as SHA-256. The Antminer S19 Pro is currently the
most profitable mining equipment available at an average cost of $3734 per ASIC
(Hashrate Index 2023), before power, cooling, and hosting costs. To remain competitive,
miners must generate enough revenue to cover the initial hardware costs of these ASICs,
any debt service associated with capital raises, their respective fixed costs (e.g., data
center hosting), plus the cost of running the machines designed to solve the hashing
algorithm. Overall network hashrate, the price of Bitcoin, and the price of energy are the
primary determinants of Bitcoin mining profitability. Since individual miners have
virtually zero impact on network hashrate and the price of Bitcoin, finding areas with
cheap energy at scale is the critical determinant in mining profitability.
Cambridge University’s Bitcoin Electricity Consumption Index (CBECI), began
collecting regional data on Bitcoin mining in September 2019, over 75% of the network
hashrate came from mainland China (Figure 2.1). Xinjiang province is abundant in cheap
wind and solar power generation and Sichuan province was once abundant in seasonal
hydropower (Xu and Stanway 2022). During the peak of China’s rainy season in
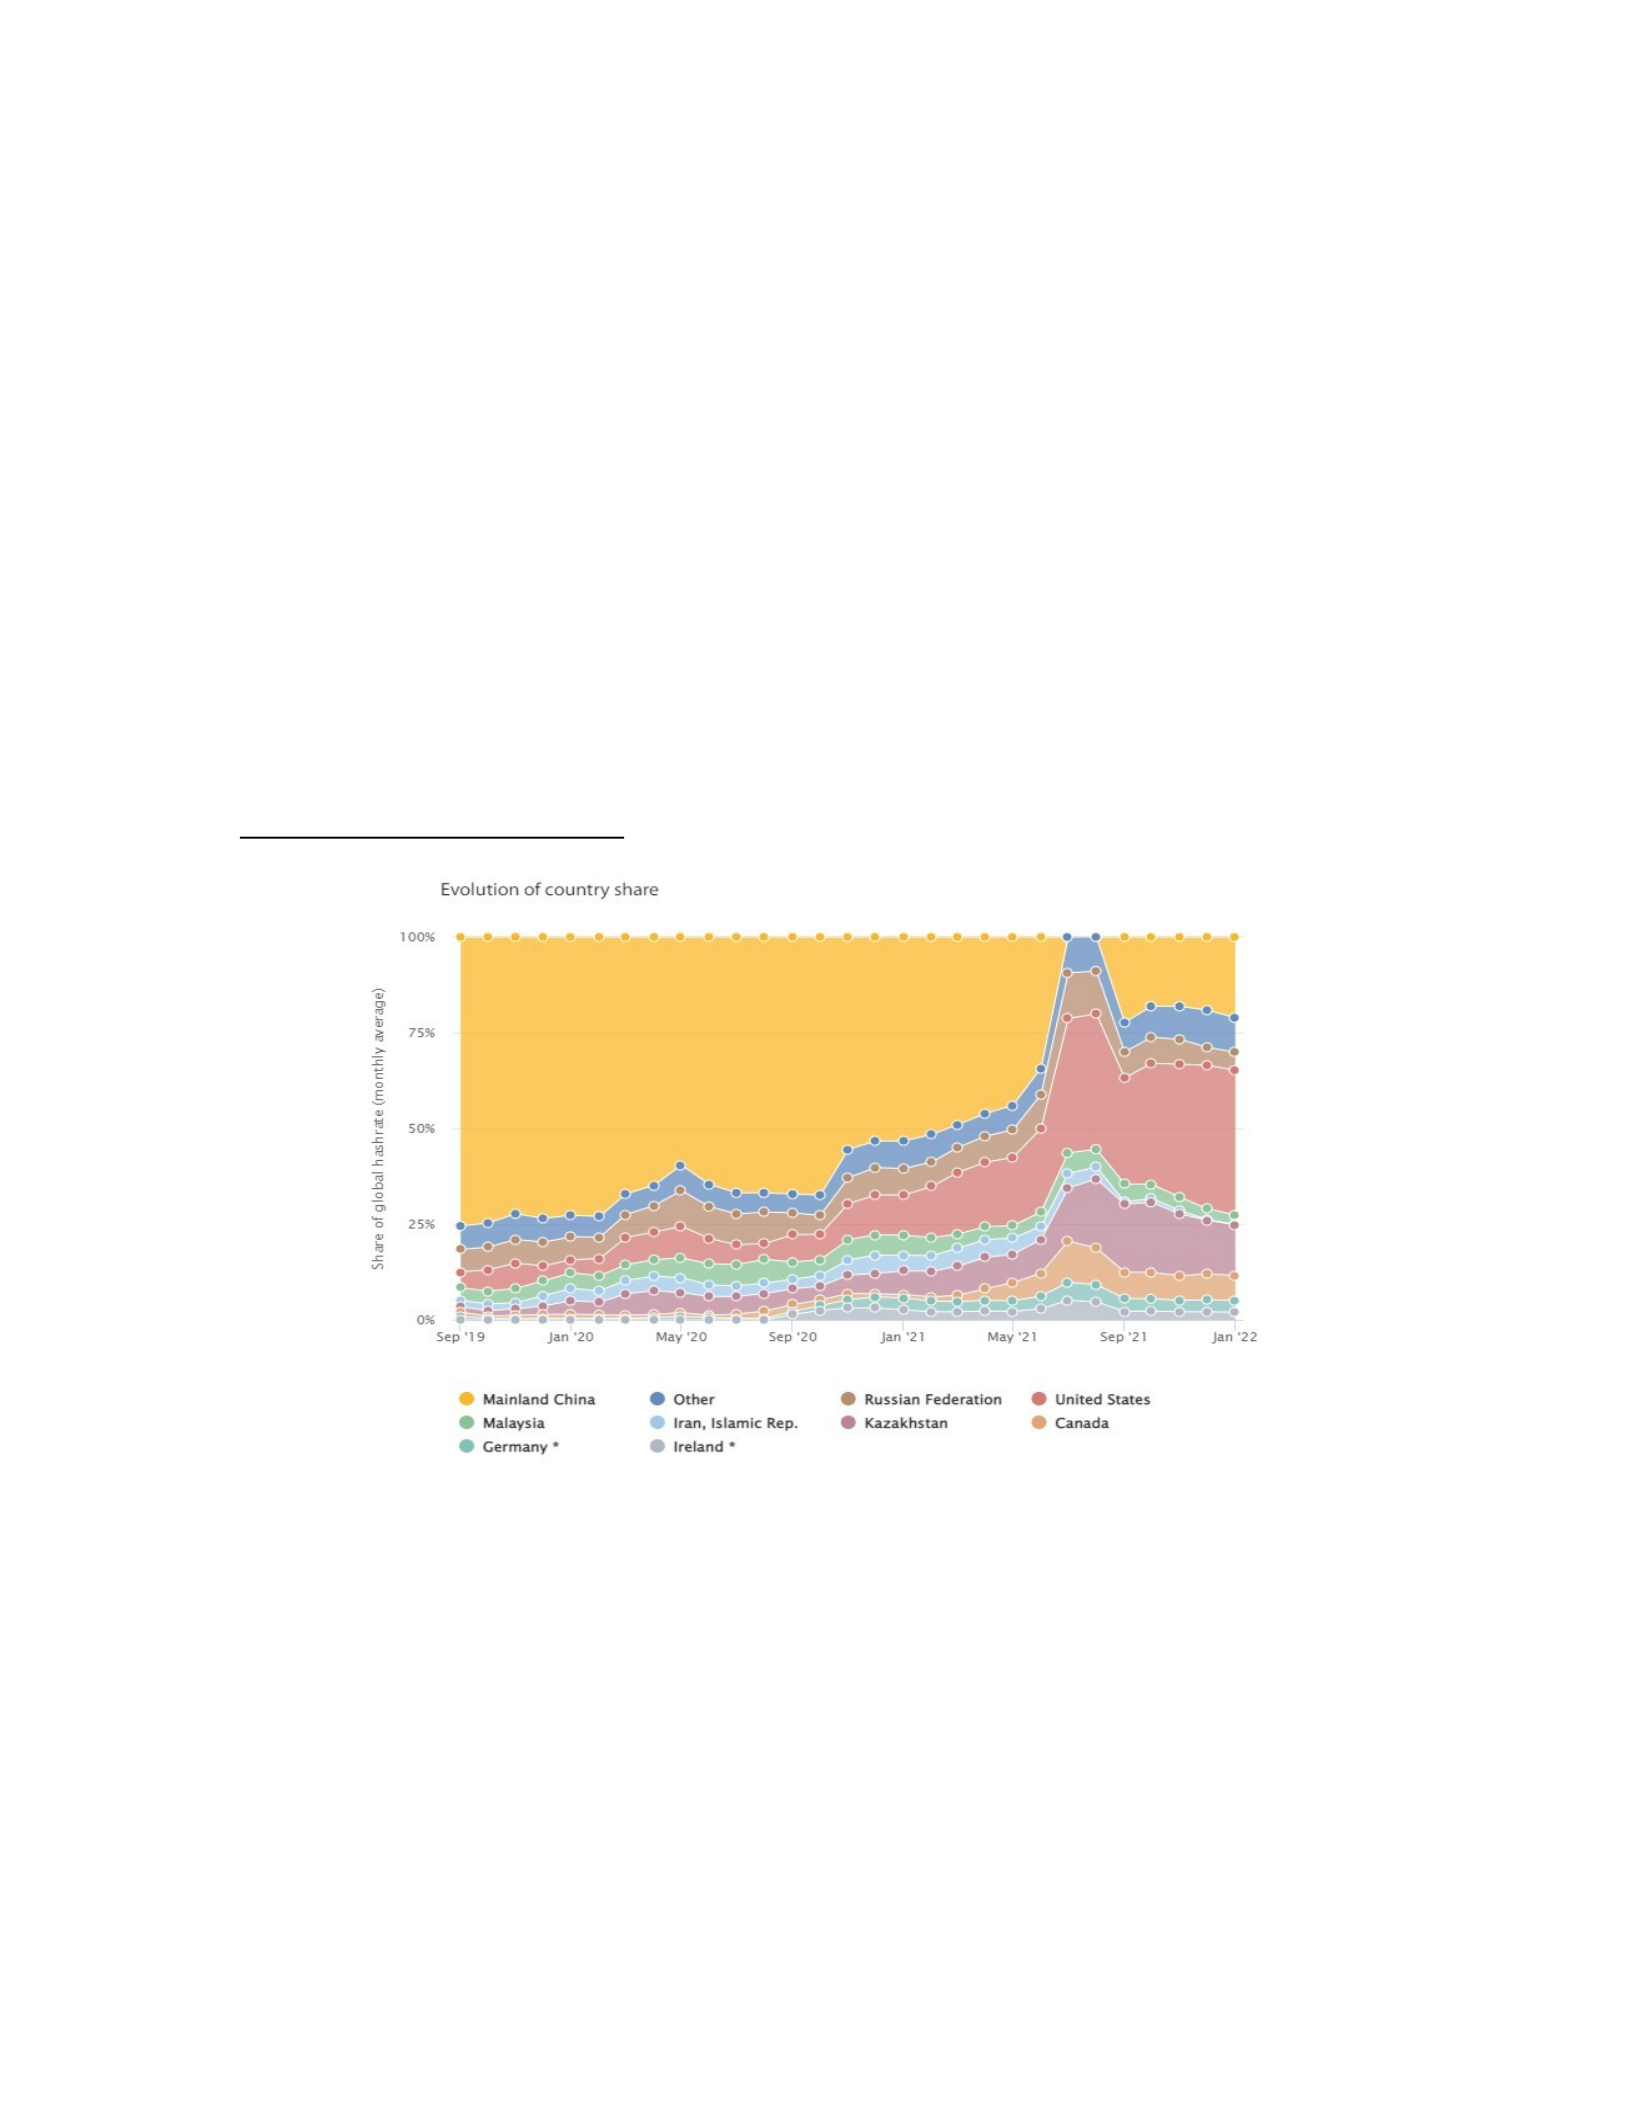
September 2020, Sichaun province accounted for over 50% of hashrate in China (Figure
2.2). Furthermore, China is more willing than other nations to fill energy gaps with cheap
coal despite its propensity for pollution and higher greenhouse gas emissions (Standaert
2021). Additionally, China’s industrial-level electrical infrastructure was robust enough
to support large-scale mining operations.
Figure 2.1 Share of Bitcoin Network Hashrate by Country (CBECI 2022)
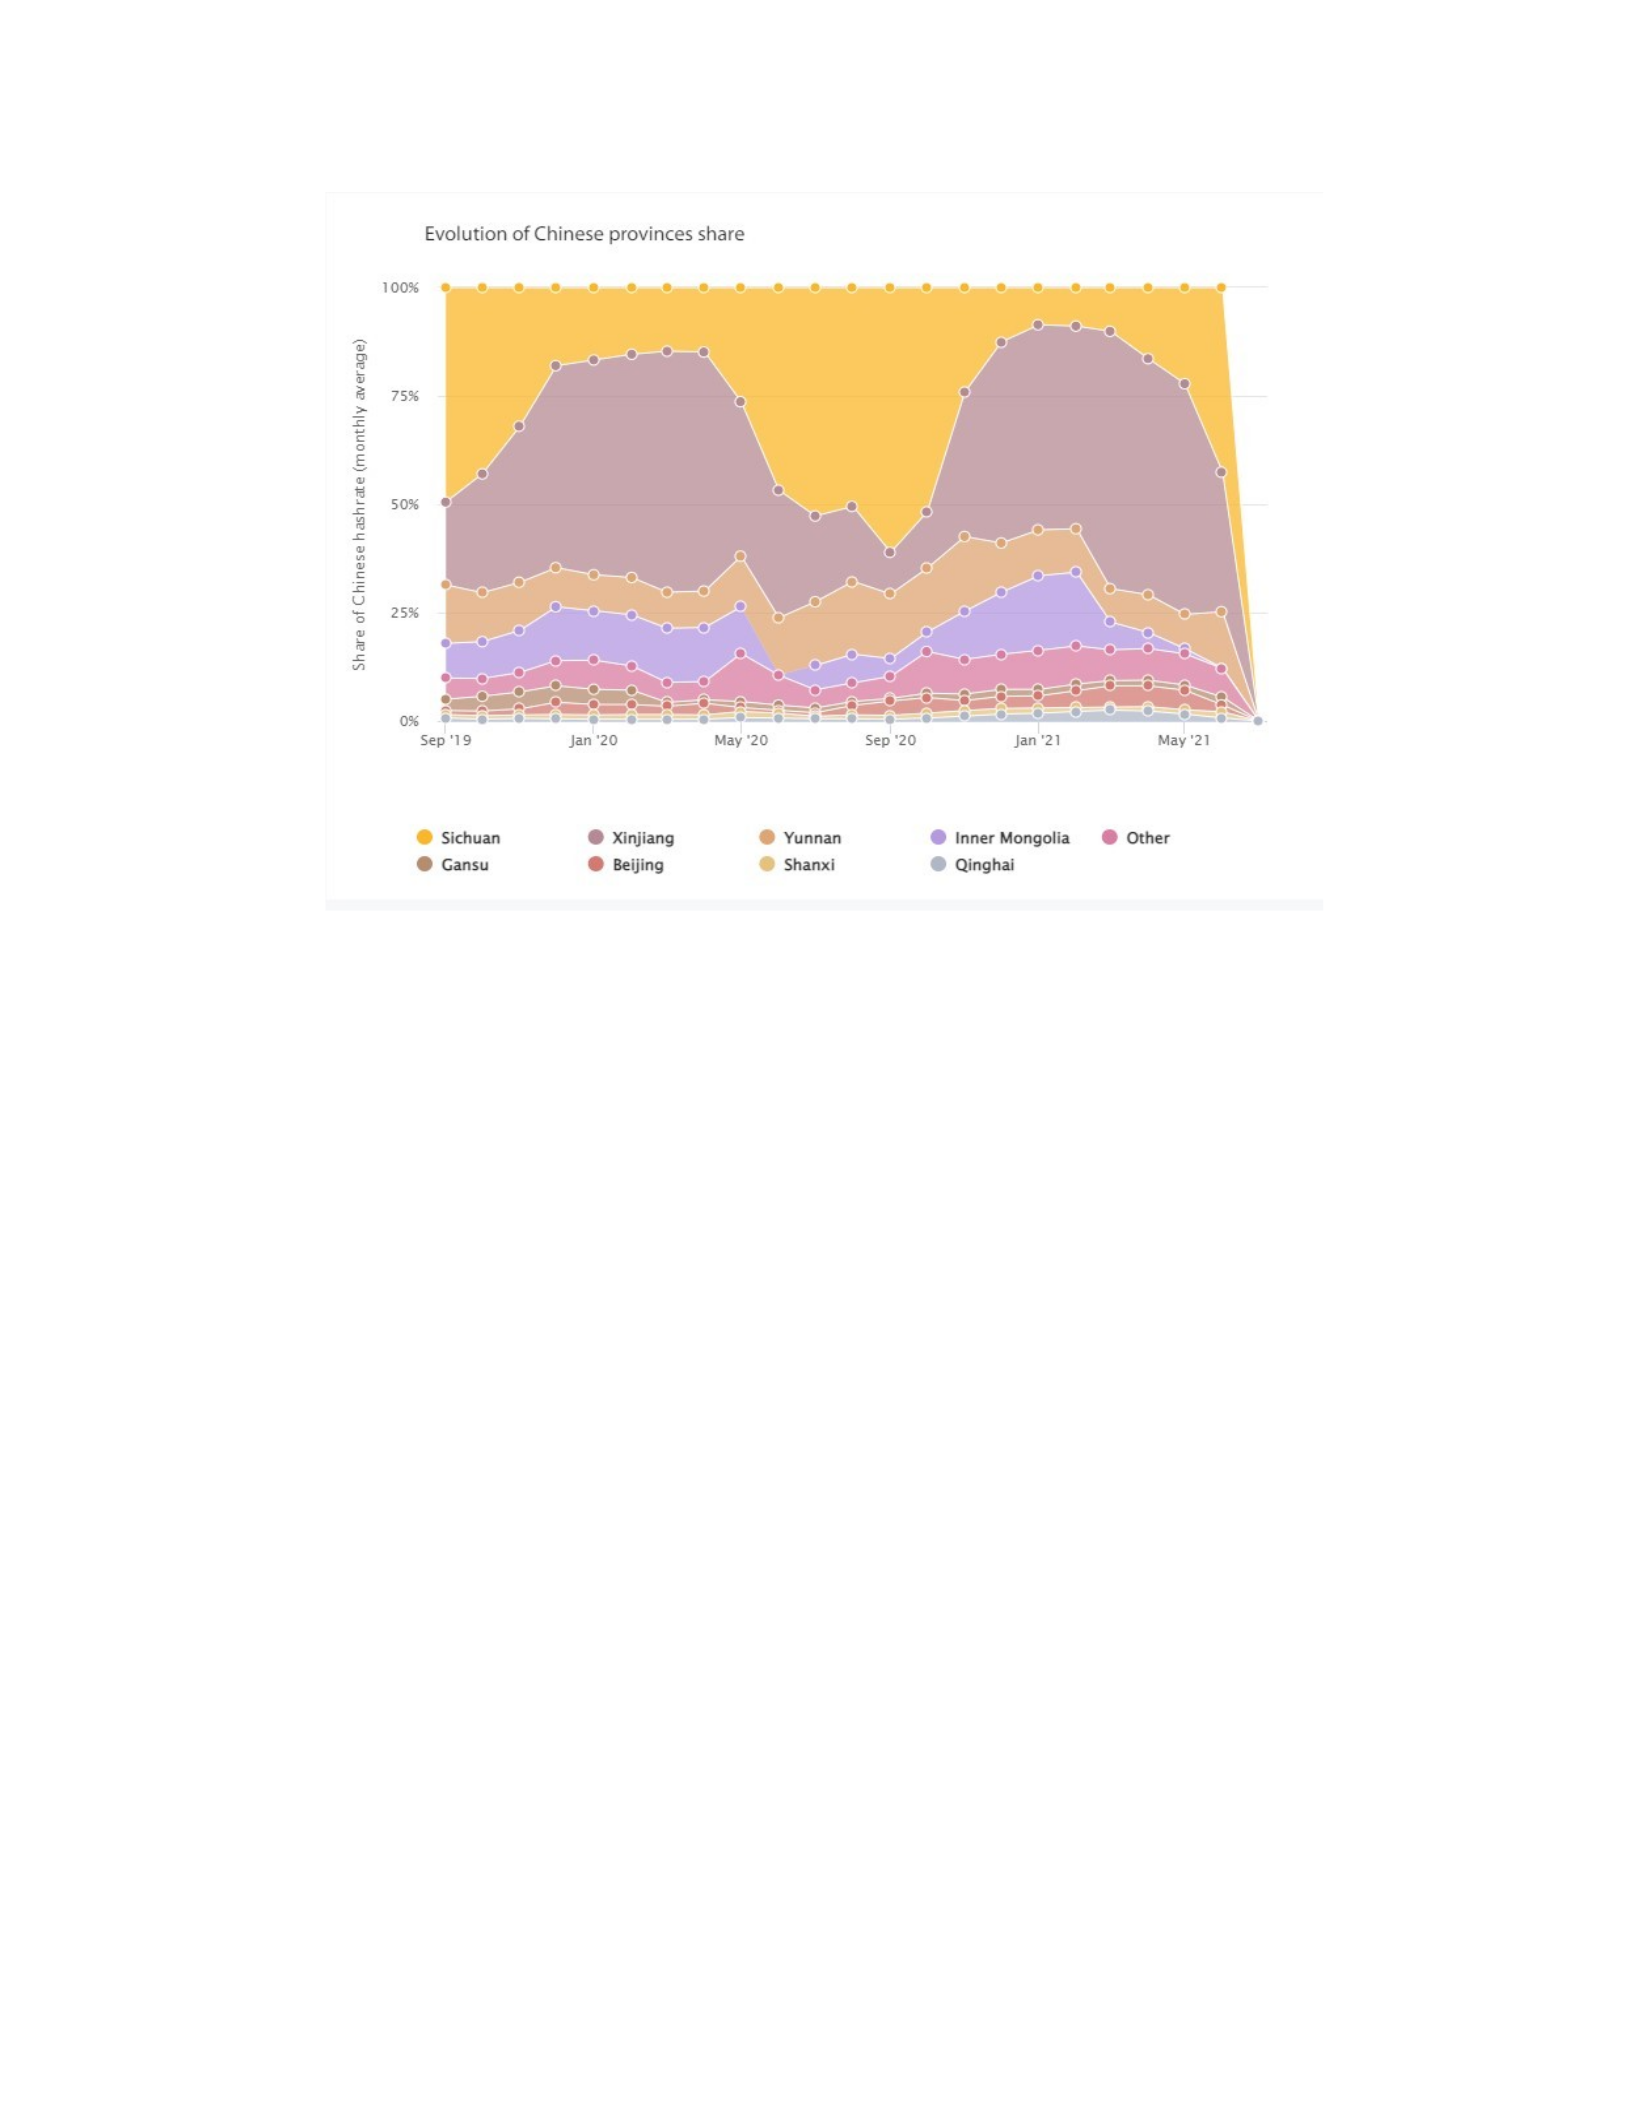
Figure 2.2 Seasonal Impact on Bitcoin hashrate by Chinese province (CBECI 2022)
CBECI partners with mining pools to aggregate a representative sample of
geolocational data on mining facilities across the globe and then extrapolates this data to
generate an estimate of the geographic distribution of Bitcoin’s hashrate over time. This
data is based on the IP addresses of miners connected to mining pool servers. Though
widely considered as the best estimator of geographic hashrate distribution (Harper 2019;
Carter 2021; OSTP 2022), CBECI recognizes that the assumption of IP address accuracy
is a significant one. The use of virtual private networks (VPNs) to spoof IP addresses and
obfuscate locational data across the Bitcoin network can introduce noise in CBECI
estimates. CBECI has some limited ways to recognize when the impacts of VPNs are
“particularly visible” in mining pool reporting and takes steps to proportionally adjust
hashrate estimations. They also encourage transparency among participating miners;
mining pool identities are encrypted and pseudonymized between the pool and the
application programming interface (API) from which CBECI pulls its data (CBECI
2022). Ultimately, CBECI concludes the VPNs “only moderately impact the validity of
the overall analysis” (2022) because VPNs increase network latency, reducing miner
revenues in the process. This puts miners using VPNs at a competitive disadvantage
relative to those who do not use such proxy services.
2.3 Measuring Cryptocurrency Asset Viability
Describing potential impacts of the Chinese ban on Bitcoin requires objective
metrics of its utility and viability as a digital asset. This necessitates some examination of
both Bitcoin’s original, expressed purpose (i.e., what was Bitcoin meant to do?) and its
most popular use case currently (i.e., how do people view/utilize cryptocurrencies
today?). It is widely accepted that money serves three purposes: 1) a store of value; 2) a
medium of exchange; and 3) a unit of account. The Bitcoin white paper (Nakamoto 2008)
focuses overwhelmingly on the mechanics of functioning as a medium of exchange.
Nakamoto set out to establish “an electronic payment system based on cryptographic
proof instead of trust, allowing any two willing parties to transact directly with each other
without the need for a trusted third party” (1). The white paper briefly explains the intent
of having an eventual hard cap on the number of coins in circulation to be “completely
inflation free” but otherwise mentions value only in the context of transactions or as it
pertains to incentivizing good behavior.
Nakamoto’s correspondence with cypherpunks via email and internet forums
lasted just two years after the release of the Bitcoin white paper (Champagne 2014).
During this time, most of their correspondence continued to center on how Bitcoin would
operate as an exchange of value. But some of this correspondence gives insight into what
they thought about Bitcoin’s potential as a store of value. First, Nakamoto felt Bitcoin’s
value derived from its immunity to government control and its decentralized network
structure. In releasing version 0.3 of Bitcoin’s core software, Nakamoto (2010) describes
Bitcoin as an escape from “the arbitrary inflation risk of centrally managed currencies!
Bitcoin’s total circulation is limited to 21 million coins.” They also explicitly addressed
concerns with Bitcoin’s propensity to consume energy. In a forum post, one concerned
observer argued that Bitcoin carried an unnecessary “thermodynamic burden” and that
mediums of exchange did not need to have value to be useful. But Nakamoto
(2008) believed mediums of exchange needed to have some value to work, and Bitcoin’s
value would be derived from its network of miners and honest validator nodes. They also
argued that Bitcoin and gold mining are similar in that the energy expended to mine gold
“is a waste, but that waste is far less than the utility of having gold available as a medium
of exchange” (Nakamoto 2010). Lastly, Nakamoto clearly felt Bitcoin’s value would
benefit from network effects, explicitly stating they expected value per coin to increase
with the number of users, triggering “a positive feedback loop” (Nakamoto 2009)
rewarding early holders of Bitcoin in the process.
Today, Bitcoin is clearly used as both a medium of exchange and a long-term store
of value. In 2022, the Bitcoin network processed between 200,000 and 300,000
transactions/day for most of the year on its base layer (Coinmetrics 2023). However,
hundreds of thousands of small payments between vendors and customers transacting in
Bitcoin now take place on the Lightning Network – a ‘layer 2’ protocol designed to
facilitate micropayments and free up traffic on Bitcoin’s base layer blockchain. But the
majority of Bitcoin in circulation remains in the hands of long-term holders, defined as
users who have bought and held their Bitcoin for at least six months. Since 2019, onchain
data shows 70% and 80% of all Bitcoin supply has been held by long-term holders
(Radmilac and Van Straten 2022). Despite several bear market periods in which the
market price of Bitcoin has dropped over 60% in a short period of time, long-term holders
rarely divest their Bitcoin holdings. Data shows the most committed holders typically
acquire more Bitcoin during periods of low prices (Radmilac and Van Straten
2022).
Table 2.1 is a summary of key metrics of Bitcoin’s viability as a financial
instrument: as a store of value and a medium of exchange. Blockchain-based
cryptocurrencies with DAO governance are different than other commodities in that their
value is so closely tied to the health of the network which processes transactions and runs
core software. If gold mining and bullion exchanges ceased to exist, gold would retain its
intrinsic value and individuals could still find ways to trade it, if needed.
Cryptocurrency miners effectively execute all base layer transactions. Exchanges provide
an interface for users to trade fiat currency for cryptocurrency in a nominal sense, but
exchanges effectively issue users the right to withdraw crypto coins/tokens from the
exchange’s holdings on the blockchain.94 Users do not truly “own” their cryptocurrency
until they withdraw it from the exchange and manage their own private keys. Exchanges
do not play a role in processing on-chain transactions. Token transfer on the blockchain
occurs between private key holders with miners processing transactions. For this reason,
several metrics in Table 2.1 have to do with the distribution and security of different
aspects of the Bitcoin network.
Table 2.1. Measures of Bitcoin Network Security, Health, and Distribution
Metric Units Data Source Description
Total Network Hashrate TH/s Blockchain Explorer
The amount of computing
power dedicated to mining
across the entire Bitcoin
network
Country Share of Hashrate % per country/month CBECI
The amount of computing
power dedicated to mining by
country
Mining Pool Hashrate
Distribution
% blocks/day blockchain.com % of blocks mined by each
pool
Market Price $USD Yahoo! Finance daily closing price of 1 BTC
denominated in USD
Transactions per second
transactions/sec (7-day
Coin Metrics
moving avg.)
average number of Bitcoin
transactions processed per
second per day
Block Time minutes BitInfo Charts daily average of time between
blocks added to the blockchain
Nodes Online* # nodes bitnodes.io number of reachable nodes
verifying transactions
Nodes by Country* % bitnodes.io % distribution of nodes by
country
*raw numerical data unavailabe. Graphic depictions only available through bitnodes.io
2.4 Design of the Natural Experiment
The nature of the treatment in this natural experiment – the Chinese
cryptocurrency ban – is multifaceted and requires clarification regarding the kind of
knowledge that can be gleaned from pre/post statistical analyses. The first aspect of
China’s ban was announced on May 18, 2021, targeting financial institutions participating
in “business related to virtual currency” (PBOC 2021). Three days later, a forthcoming
ban on cryptocurrency mining was announced, but not formally instituted across all of
China until June. The final aspect of the ban barring any form of cryptocurrency
exchange took effect in September.
The timing of the three different aspects of the ban, and gaps between
announcements and formal implementation complicates claims of causality and the

identification of causal mechanisms therein. For example, the first aspect of the ban was
the third of three such crackdowns (2013, 2017, 2021) specific to financial institutions.
Following the 2013 and 2017 announcements, the price of Bitcoin dropped over 30%
within the next 10 days. Price action following the announcement of the forthcoming
mining ban was likely impacted by the financial institution aspect of the ban and a host of
other potential contributing factors which are difficult to control for. Bitcoin’s price
tumbled 13% from $56,700 to $49,100/BTC in one day after electric-vehicle maker Tesla
announced it would no longer accept Bitcoin as a form of payment on May 12th. When
the PBOC’s expanded ban on financial institutions was announced six days later, (PBOC
2021) the price of Bitcoin was already down almost 15% from the previous day, closing
at roughly $37,000/BTC. For some metrics (e.g., total network hashrate, country share of
network hashrate), drawing a causal relationship between the ban and changes to that
metric are clearer than others (e.g., market price), but most of the analysis in this study is
necessarily descriptive and correlational.
This study focuses on the mining aspect of the ban and relies on statistical
analyses of several Bitcoin metrics to paint a picture of the Bitcoin network before and
after miners in China were ordered to shut down their operations. The mining aspect of
the ban represents the greatest departure from previous Chinese policy positions. Mining
is also critical to Bitcoin’s use as a medium of exchange. The crackdown specific to
crypto-related financial services is not insignificant, but Bitcoin was designed to facilitate
value exchange without the involvement of third-party intermediaries (i.e., financial
services industry). Furthermore, the financial services ban did not constitute a stark
change in China’s cryptocurrency policy disposition. The third and final aspect of the ban
clearly states all “virtual currency-related activities are illegal financial activities” (PBOC
2021) which represents some departure from previous policies which allowed private
Chinese citizens to continue trading cryptocurrencies. But China had already prohibited
the exchange of fiat currency for cryptocurrency and barred Chinese financial services
industries from facilitating such cryptocurrency trading in China four years prior (PBOC
2017). The only new specified “virtual currency-related [activity]” in the order which had
not been barred prior to September 2021 was the “[exchange] of one virtual currency for
another” (PBOC 2021).
The policy intervention is also designated as a period (May ’21 through June ’21)
rather than a single point in time. As previously mentioned, evidence suggests some
miners in certain provinces began shuttering operations as early as April 2021, but news
reports of the forthcoming ban broke in May before the formal ban was implemented in
June. Starting with the one-year period (May ’20 through April ’21) before PBOC’s
crypto ban allows us to build an ex-ante profile of the overall condition of the Bitcoin
network by each metric before the policy intervention. The period for ex-post analysis of
network conditions is designated as the one-year period (July ’21 through June ’22) when
dislocated miners found new hosting sites outside of China. Data for all metrics in Table
2.1 is available from May 2020 through June 2022 except for country share of hashrate
since CBECI locational mining data has only been published through January 2022.
The following sections analyze metric trends before and after the PBOC’s
cryptocurrency ban. Each section begins by offering a formal definition of each metric
followed by an explanation of each metric’s significance to Bitcoin as a digital asset
and/or the Bitcoin network. I then cover the data collection process and present a
statistical analysis of the pre and post periods to discern whether there are observable
treatment effects. Finally, each section concludes with a discussion of potential
confounders and/or barriers to causal analysis, as well as any useful information which
can be gleaned from correlational relationships.
2.5.1 Network Hashrate
The total amount of computing power dedicated to mining Bitcoin across the entire
network. Critical to network security, asset store of value, and asset functionality as a
medium of exchange.
In proof-of-work (PoW) based systems, aggregate hashrate is a critical indicator
of the network’s security in defending against attacks. As hashrate increases, attacking the
network effectively becomes more expensive. If attackers control over 50% of network
hashrate in PoW-based systems, they can create a new blockchain with a new transaction
history and double-spend cryptocurrency. Nakamoto (2008) proposed a timestamp server
and distributed ledger technology to account for the double-spend problem. The public
and transparent nature of broadcast transactions and the blockchain history provides all
nodes awareness of a single historical record of transactions. Hashrate is measured
in hashes per second. Bitcoin uses SHA-256 cryptography – a deterministic, one-way
hashing function. Hashrate can be thought of the amount of hashes mining equipment
work through over time as they order transactions and compete for block rewards. Basic
home computing equipment is capable of thousands of hashes per second, but mining
equipment specifically designed to solve the SHA-256 hash function are typically
measured in terahashes (trillions of hashes per second).
Figure 2.3 Bitcoin Network Hashrate (million TH/s) Around the Ban (author)
During the 12-month ex-ante period before China’s cryptocurrency ban, hashrate
generally increased by 154,000 TH/s per day. After approaching a new all-time high on
May 13th, 2021, China’s massive share of global hashrate (Figure 2.1) came offline in the
span of just two months. Network hashrate crashed from 186 million TH/s to just 58
million TH/s on June 27th (Figure 2.3). But Bitcoin’s mining difficulty – which adjusts
every 2016 blocks – dropped on July 3rd making it easier for miners based elsewhere.101
Older, less efficient mining equipment suddenly became profitable (Sigalos 2021). No
evidence exists that a serious 51% attack was attempted during the intervention period,
despite half the network hashrate coming offline. Hashrate recovered at a rate of 281,000
TH/s per day during the ex-post period, surpassing the previous all-time high by early
December 2021.
Table 2.2a. Paired two-sample t-test: Total Network Hashrate
ex-ante ex-post
Mean 134.648 172.058
Variance 445.272 1621.460 Observations 365 365
Degrees of Freedom 364
T Statistic -24.6614
P(T<=t) two-tail
t Critical two-tail 1.9665
Slope
Standard Error (slope)
R-squared
F-statistic
Residual sum of squares
Regression sum of squares
0.1541
0.0067
0.5936
530.2785
96215.3169
65863.8047
0.3473
0.0083
0.8281
1748.9064
488764.4937
101447.1165
Table 2.2 compares only the one-year ex-ante and ex-post periods using a paired
two-sample t-test of means and the ordinary least squares method of a linear best fit for
the data.102 The t-test yields a low p-value providing some support for claims that the
treatment effect had a significant impact on mean hashrate between the two periods. In
fact, mean hashrate increased during the year following the intervention period. Hashrate
increased at a faster rate after the ban, and OLS statistics indicate the regression model
provides a better explanation for the higher variance seen in the ex-post year than the year
prior.
Both CBECI data (Figure 2.1) and news reports indicate a disproportionately
large share of Bitcoin’s network hashrate was based in China prior to instituting a
complete ban on cryptocurrency mining.103 Quantitative evidence supports claims that the
mining ban played a significant role in the unprecedented drop in network hashrate
between May and July 2021 as China-based miners shutdown operations and began to
102 The two-month intervention period is excluded because it is likely to be driven by many idiosyncratic
factors that are of little interest to policymakers.
103 I expand on this in the next section regarding country share of network hashrate.
Table 2.2b. OLS Trend Statistics
ex-ante ex-post
1.1815E-79
relocate. However, the drop in network hashrate cannot be entirely explained by the loss
of China-based hashrate. Monthly network hashrate grew in absolute terms through May
2021 while China’s absolute hashrate began its decline in March. Total network hashrate
dropped by 41.1 EH/sec from May to June, while China’s absolute hashrate decreased
only 29.9 EH/sec over the same period (Table 2.3).
Table 2.3. China and Total Network Hashrate Around the Policy Intervention
March April May June July
Total Network Hashrate (monthly avg., EH/sec)
Change from previous month (EH/sec)
% Change from previous month
China monthly absolute hashrate
Change from previous month (EH/sec)
% Change from previous month
159.
6
78.3
157.
2
-2.4
-1%
72.4
-5.9
-8%
161.
2
4.0
3%
71.0
-1.4
-2%
120.1
-41.1
-26%
41.1
-29.9
-42%
10
0.4
-
19.
7
-
16
%
0
-
41.
1
-
100
%
Bitcoin’s sudden decline in market value during this period (see section 2.3.4)
likely contributed to network hashrate losses. While hashrate does not typically correlate
with Bitcoin’s market price, studies suggest there may be some unidirectional causal
relationship from Bitcoin price to hashrate, just as oil and gas revenues/losses drive the
purchase/shut down of rigs (Fantazzini and Kolodin 2020; Rehman and Kang 2021).
Miner revenues are tied to Bitcoin’s market value, so miners with less efficient ASICs can
often afford to keep their machines on when the price of Bitcoin is high. These miners
will keep less efficient ASICs running so long as the price of energy is below the
breakeven price at which they know their machines will be profitable. All else equal,
more efficient mining machines effectively raise this breakeven price of energy. As
Bitcoin prices drop, the rational, but less efficient miners will be forced to turn off their
machines while more efficient miners continue to be profitable.
2.5.2 Country Share of Network Hashrate
The amount of computing power dedicated to mining Bitcoin in each country – a
“geographic distribution of Bitcoin’s total hashrate over time” (CBECI 2023). Critical
measurement of network decentralization, susceptibility to individual nation-state policy,
and thus a contributor to asset value.
Country share of network hashrate lies at the center of this paper’s main research
question: what happens when a single country – which serves as a base for the majority
of a DAO-based cryptocurrency’s operations – adopts policies to eliminate that operation
(i.e., mining)? We know from the previous section that Bitcoin quickly bounced back
from the loss of hashrate, but changes in country share of network hashrate speak to how
the geographic distribution of the main engine of Bitcoin changed as a result of China’s
ban. As seen in the previous section, non-China hashrate grew significantly over time
before and after the policy intervention, so this section includes analysis of absolute
levels of country hashrate as well. Increased distribution makes the network less
susceptible to the policies of a single nation-state. Decreased distribution would suggest a
troubling tendency for a so-called “decentralized” autonomous
organization to concentrate its operations.
These data are sourced entirely from CBECI estimates. Estimates are based on IP
addresses of mining facility operators shared with CBECI through mining pools which
voluntarily participate in CBECI’s studies. Participating mining pools represent between
33%-38% of total network hashrate (CBECI 2022). This means use of VPNs to spoof
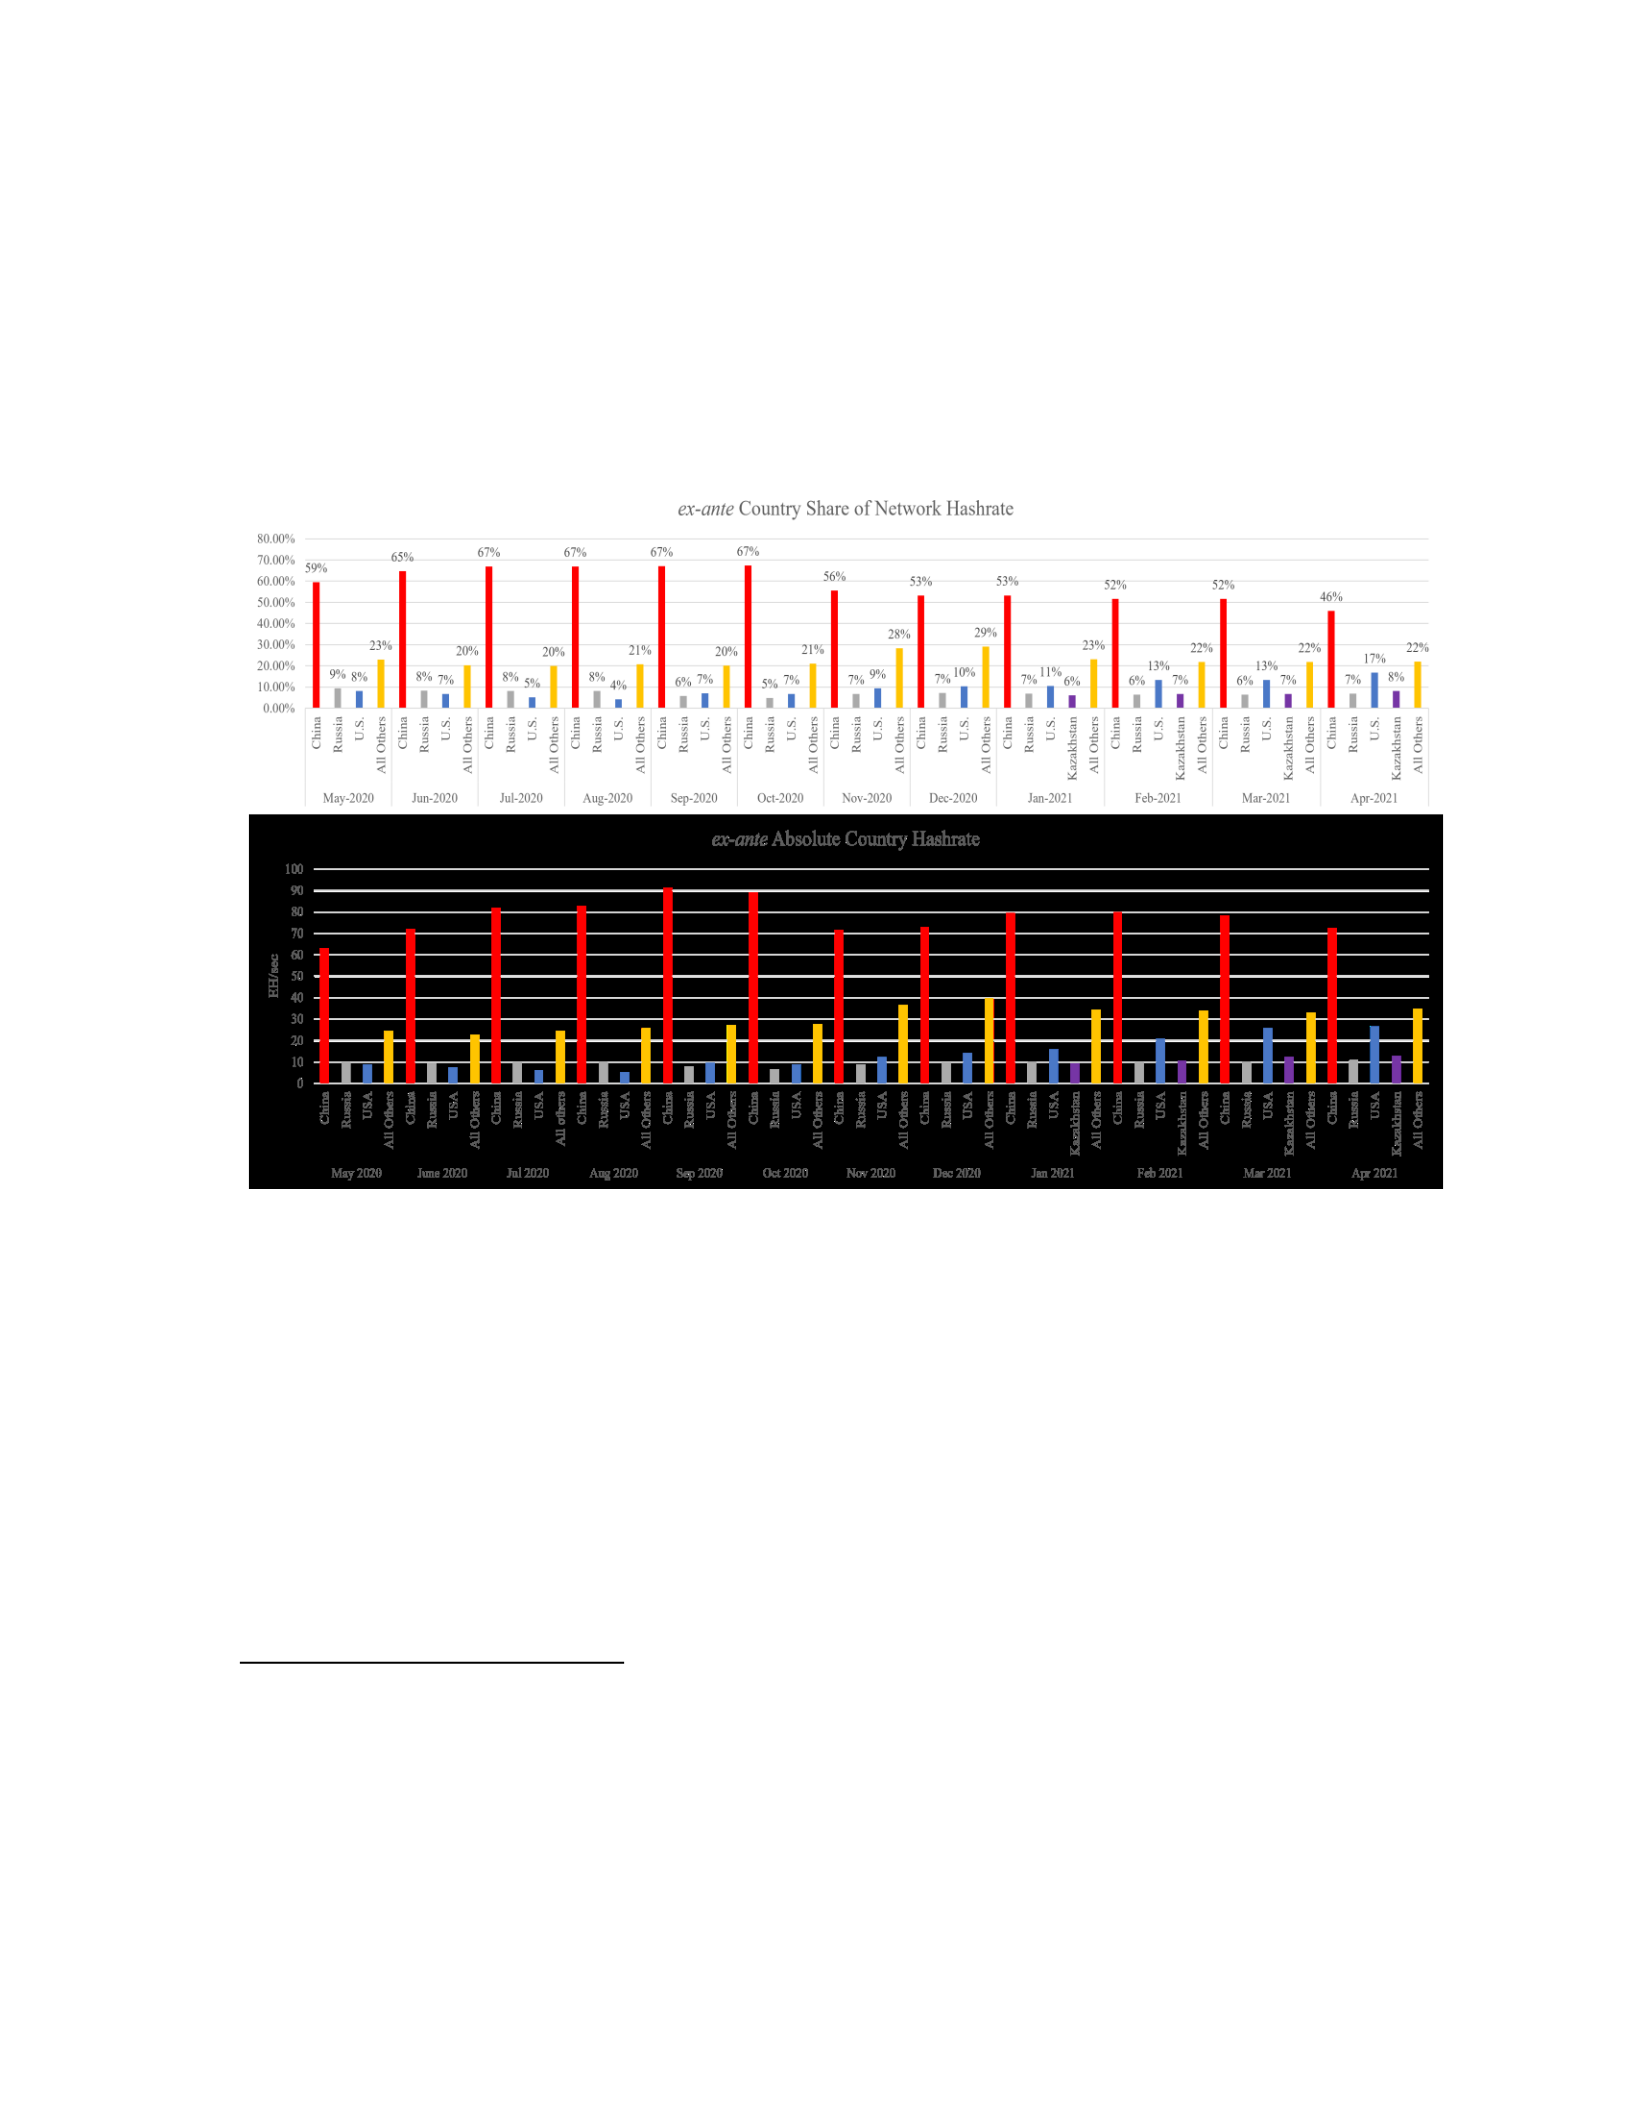
locations and representative sample size concerns are limitations to their methodology. It
seems unlikely that miners hashing illegally after the ban would voluntarily participate in
location disclosure. But CBECI takes several steps to protect miner identities, and
network latency associated with VPN use disincentivizes location spoofing.
Figure 2.4. ex-ante Country Share of Network Hashrate (top)
Figure 2.5. ex-ante Absolute Levels of Country Network Hashrate (bottom)
For most of the year preceding China’s cryptocurrency ban, the United States and
Russia were the only two countries which to consistently account for more than 5% of
global hashrate. China’s share of global hashrate began to decline in November 2020 as
more hashrate came online in neighboring Kazakhstan and in the United States.
Kazakhstan added a little over 1 exahash (EH)/sec per month between October 2020 and
April 2021 while monthly absolute hashrate tripled in the United States over the same
period. During the intervention period, China’s hashrate came offline completely by July
2021, leaving the United States as the new leader in global hashrate. U.S.-based hashrate
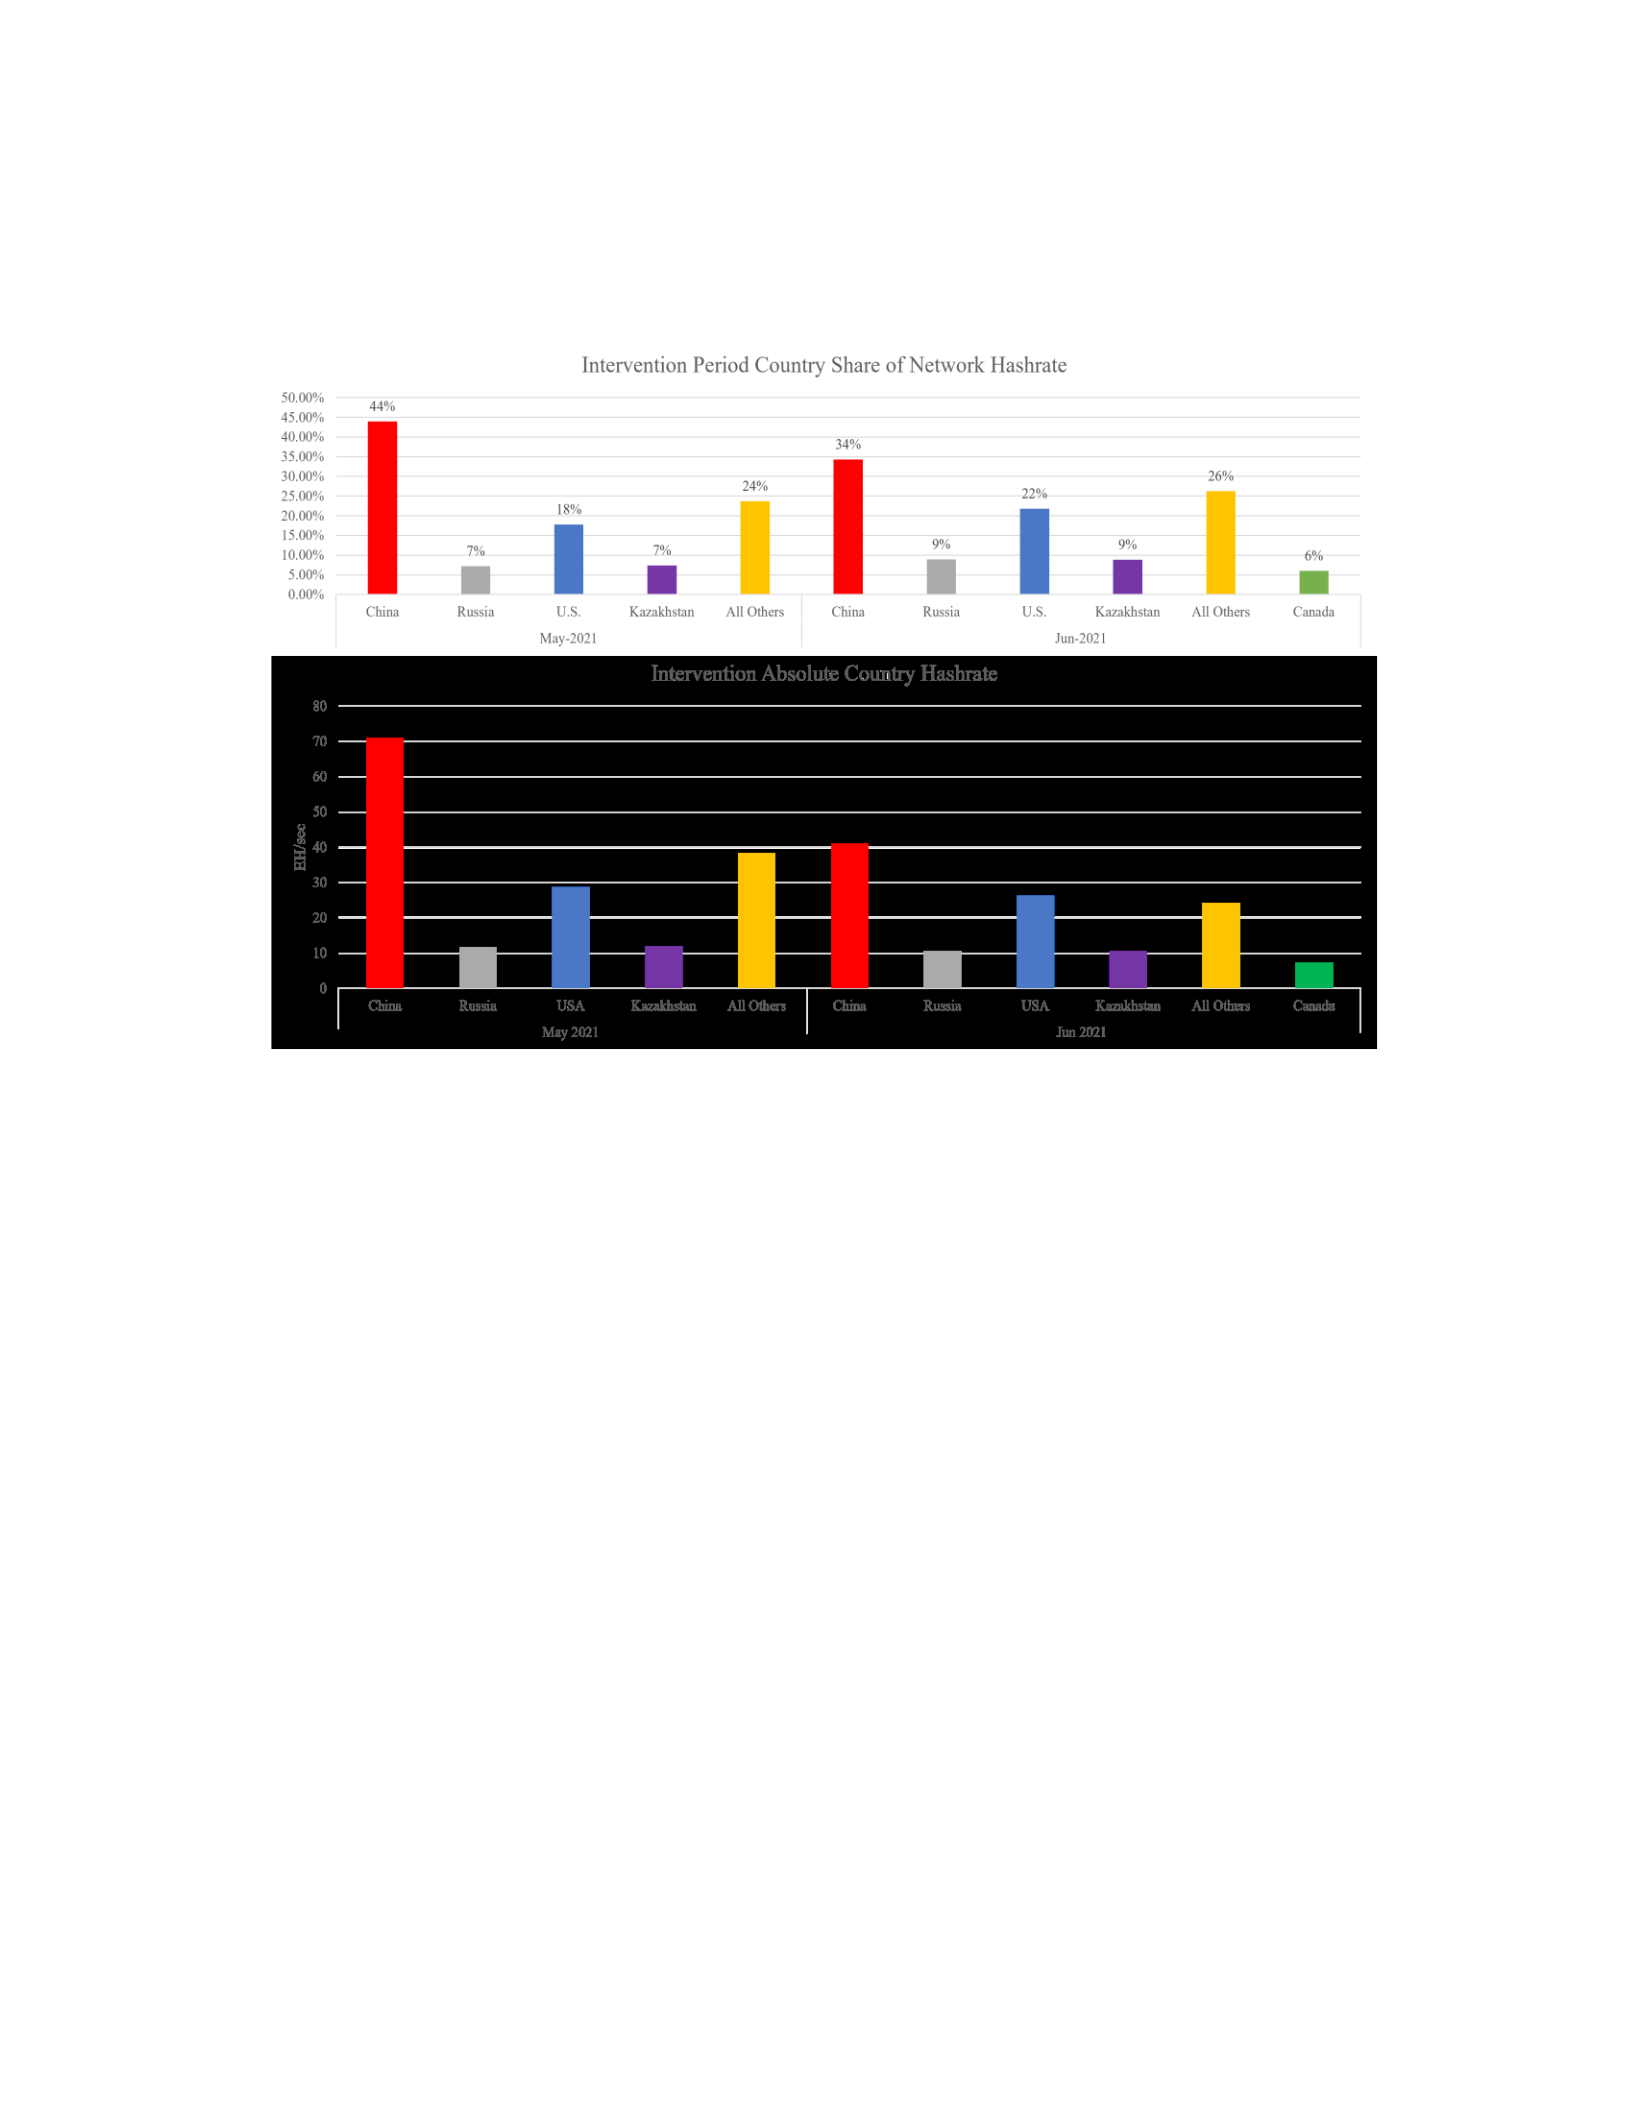
remained consistent in absolute terms between April and June 2021, but jumped
significantly beginning in July.
Figure 2.6 Intervention Country Share of Network Hashrate (top)
Figure 2.7 Intervention Absolute Levels of Country Network Hashrate (bottom)
The ex-post period brings about the most evenly distributed months of network
hashrate geographically since CBECI began tracking mining locational data. Canada’s
absolute monthly hashrate began increasing month-over-month in February 2021 and
accounts for a greater than 5% share of global hashrate by June 2021. China re-emerges
as a significant contributor of network hashrate in September 2021, but the U.S. remains
the new post-ban global leader. The U.S. share of hashrate never surpasses more than
38%, compared to China’s 65% share as the pre-ban leader.
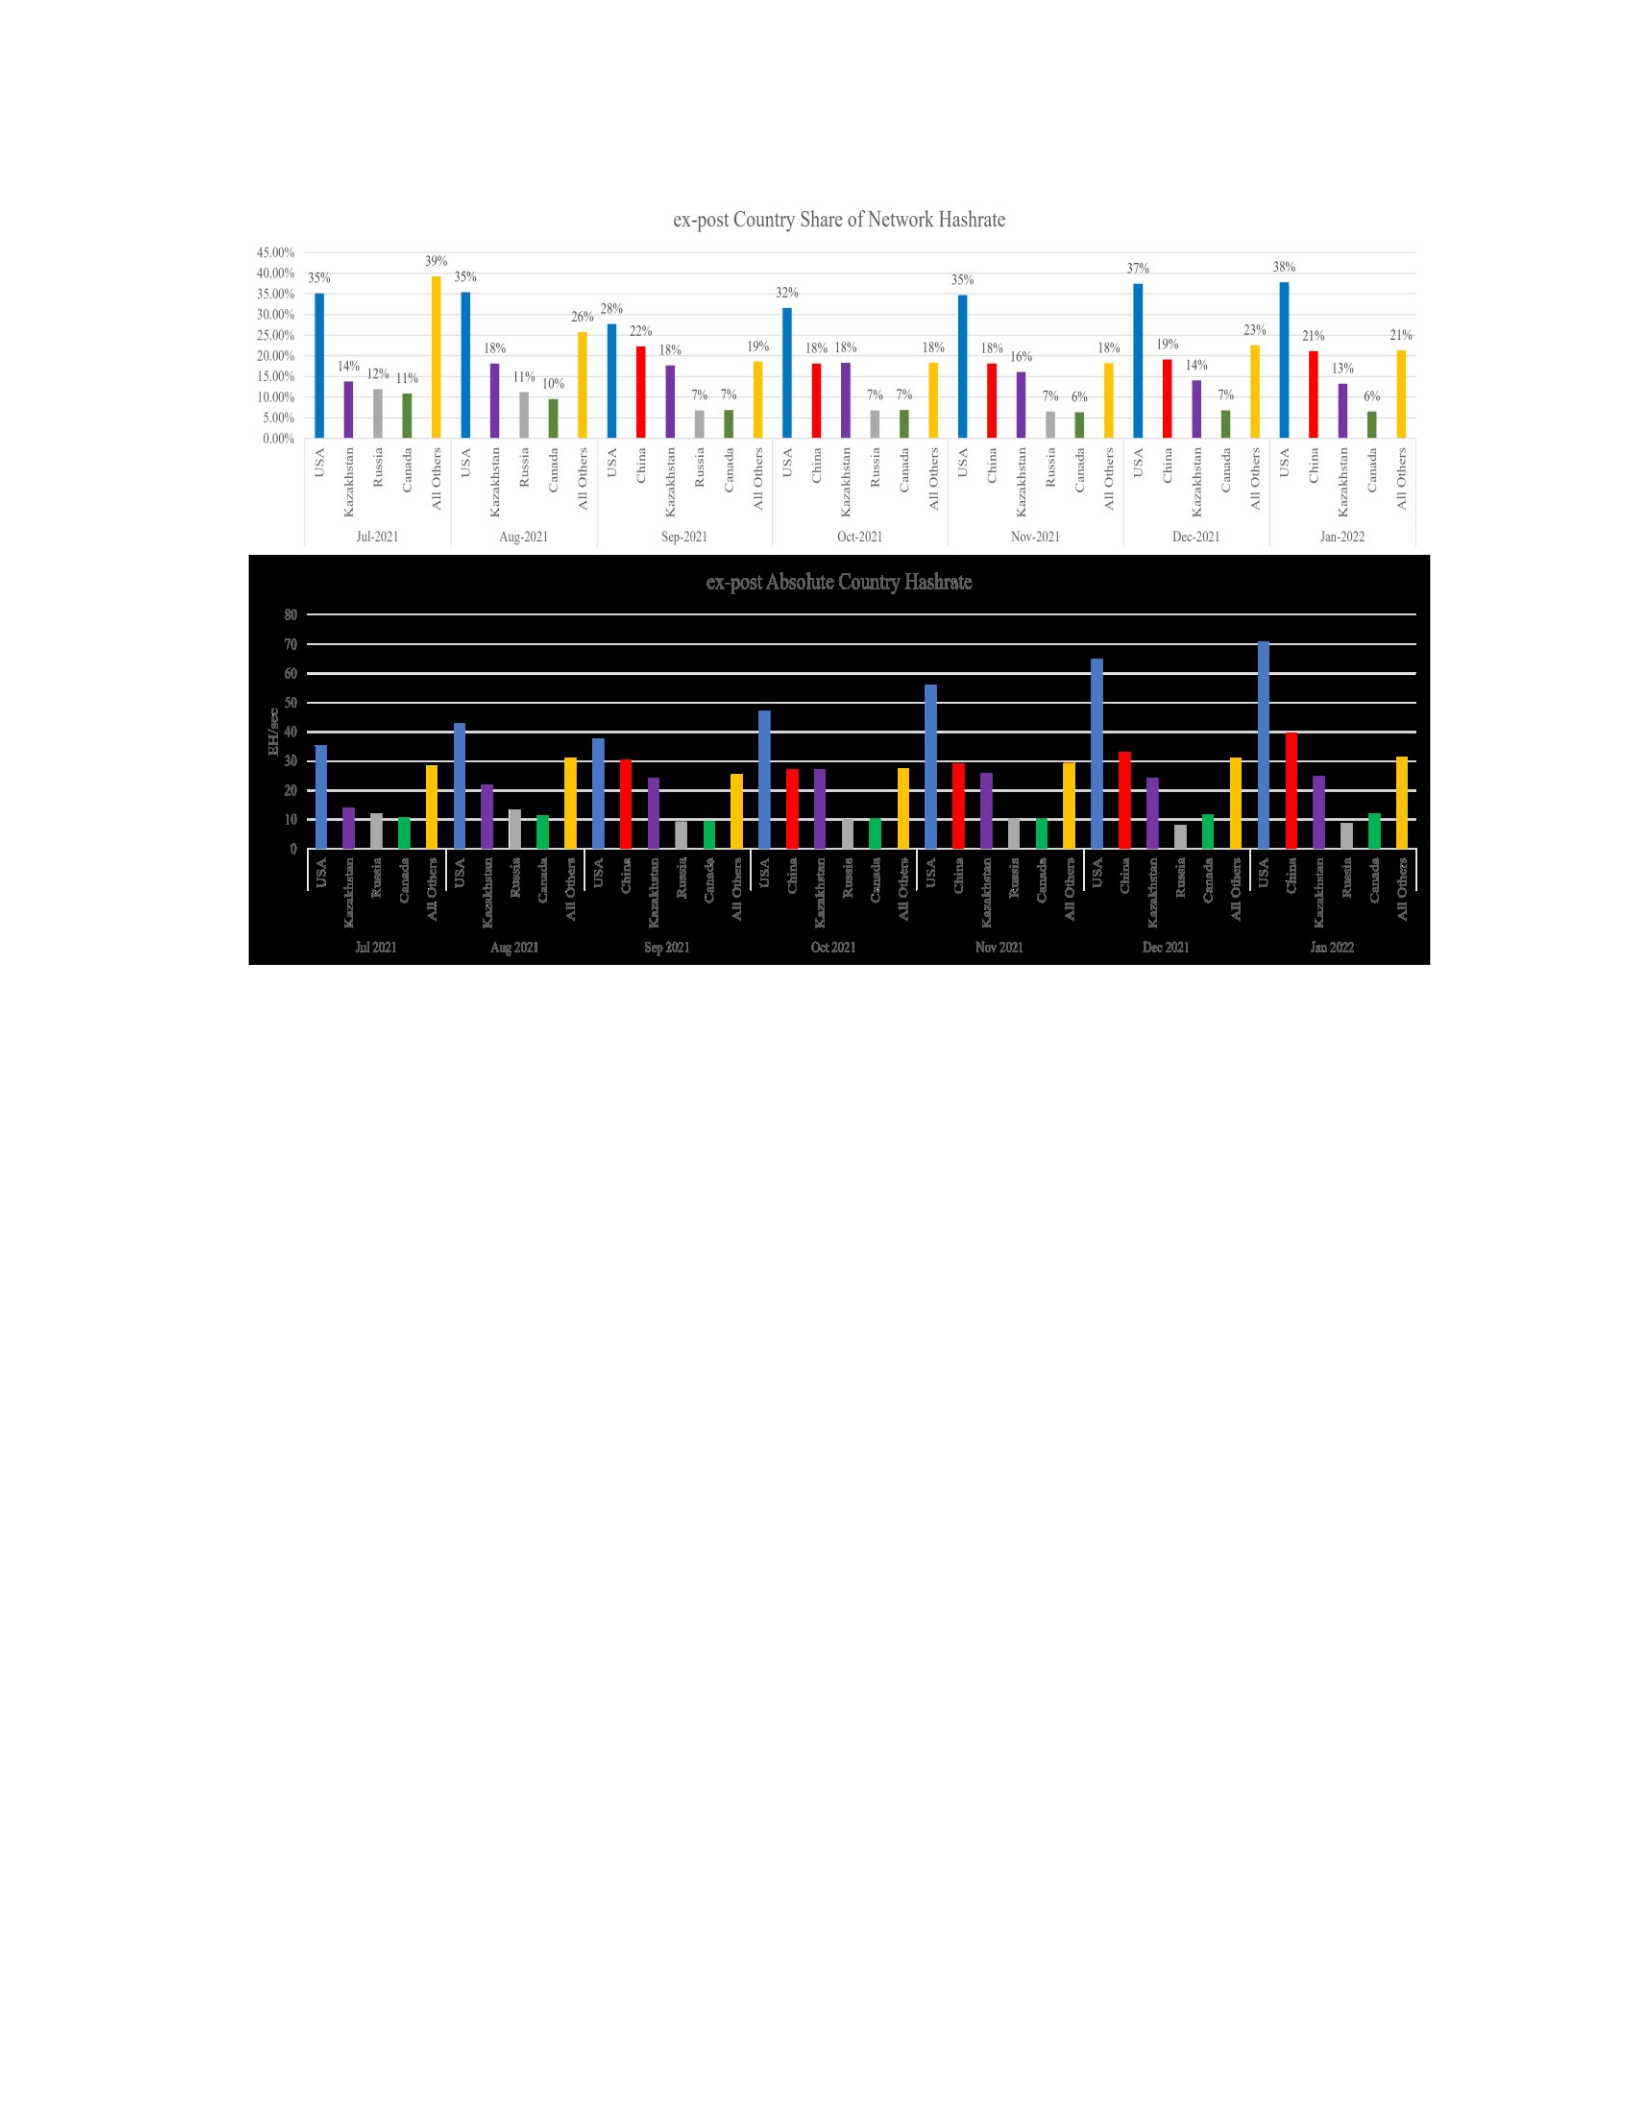
Figure 2.8 Ex-post Country Share of Network Hashrate (top)
Figure 2.9 Ex-post Country Share of Network Hashrate (bottom)
Absolute hashrate CBECI data suggests China-based mining was virtually
nonexistent in July and August 2021 and then 30 EH/sec suddenly came back online in
September 2021. The amount of power and physical infrastructure required to support
mining that much hashrate means the likelihood that those operations shutdown, moved,
and subsequently returned is highly improbable (Kaloudis 2022). The more likely
explanation is that CBECI’s data collection methods lead to useful estimations of
geolocational mining distribution but fall short of meeting a reliable enough standard to
justify robust empirical support for causal analysis. In fact, this jump in China-based
hashrate in CBECI data prompted the Cambridge Center for Alternative Finance (CCAF)
to publish an article discussing the methodological tradeoffs inherent in their CBECI
estimates. CCAF (2022) admits “a comeback of this magnitude within the period of one

month would seem unlikely given physical constraints… Instead, a more likely
explanation lies within our top-down research methodology” and its vulnerability to VPN
and proxy services.
Still, CCAF maintains IP address tracking limitations usually “only moderately
impact” the validity of their estimates unless “sudden shocks” (CCAF 2022) occur which
alter miner risk tolerance and expectations. They argue China’s ban represents such a
shock which prompted “a non-trivial share of Chinese miners” (CCAF 2022) to operate
covertly with foreign proxies (high in network latency) until determining local proxy
services (relatively lower in network latency) offered sufficient protection from Chinese
state enforcement. This theory is supported by anecdotal evidence from several news
reports (Kaloudis 2022; Feng 2022; Browne 2022). Regardless of how exactly miners
obfuscate their locations, quantitative and qualitative evidence show large-scale mining
operations still exist in China, calling the ban’s efficacy and/or China’s enforcement
mechanisms into question.
2.5.3 Mining Pool Hashrate Distribution
The percentage of blocks on the Bitcoin blockchain mined by each mining pool, daily. Or
a market share of the most popular bitcoin mining pools. The true level of
decentralization of hashrate control. Critical measure of network security.
Pools act as a centralizing force upon an aspect of the Bitcoin network which is
meant to be decentralized. In theory, if a single pool or miner controlled enough hashrate,
it could act independently to conduct a 51% attack on the network or execute false
transactions. Therefore, it is critical that no single pool amasses too much control over
network hashrate for distributed consensus to serve its true purpose. Bitcoin has never
suffered a 51% attack. At the end of 2021, no mining pool controlled more than 17% of
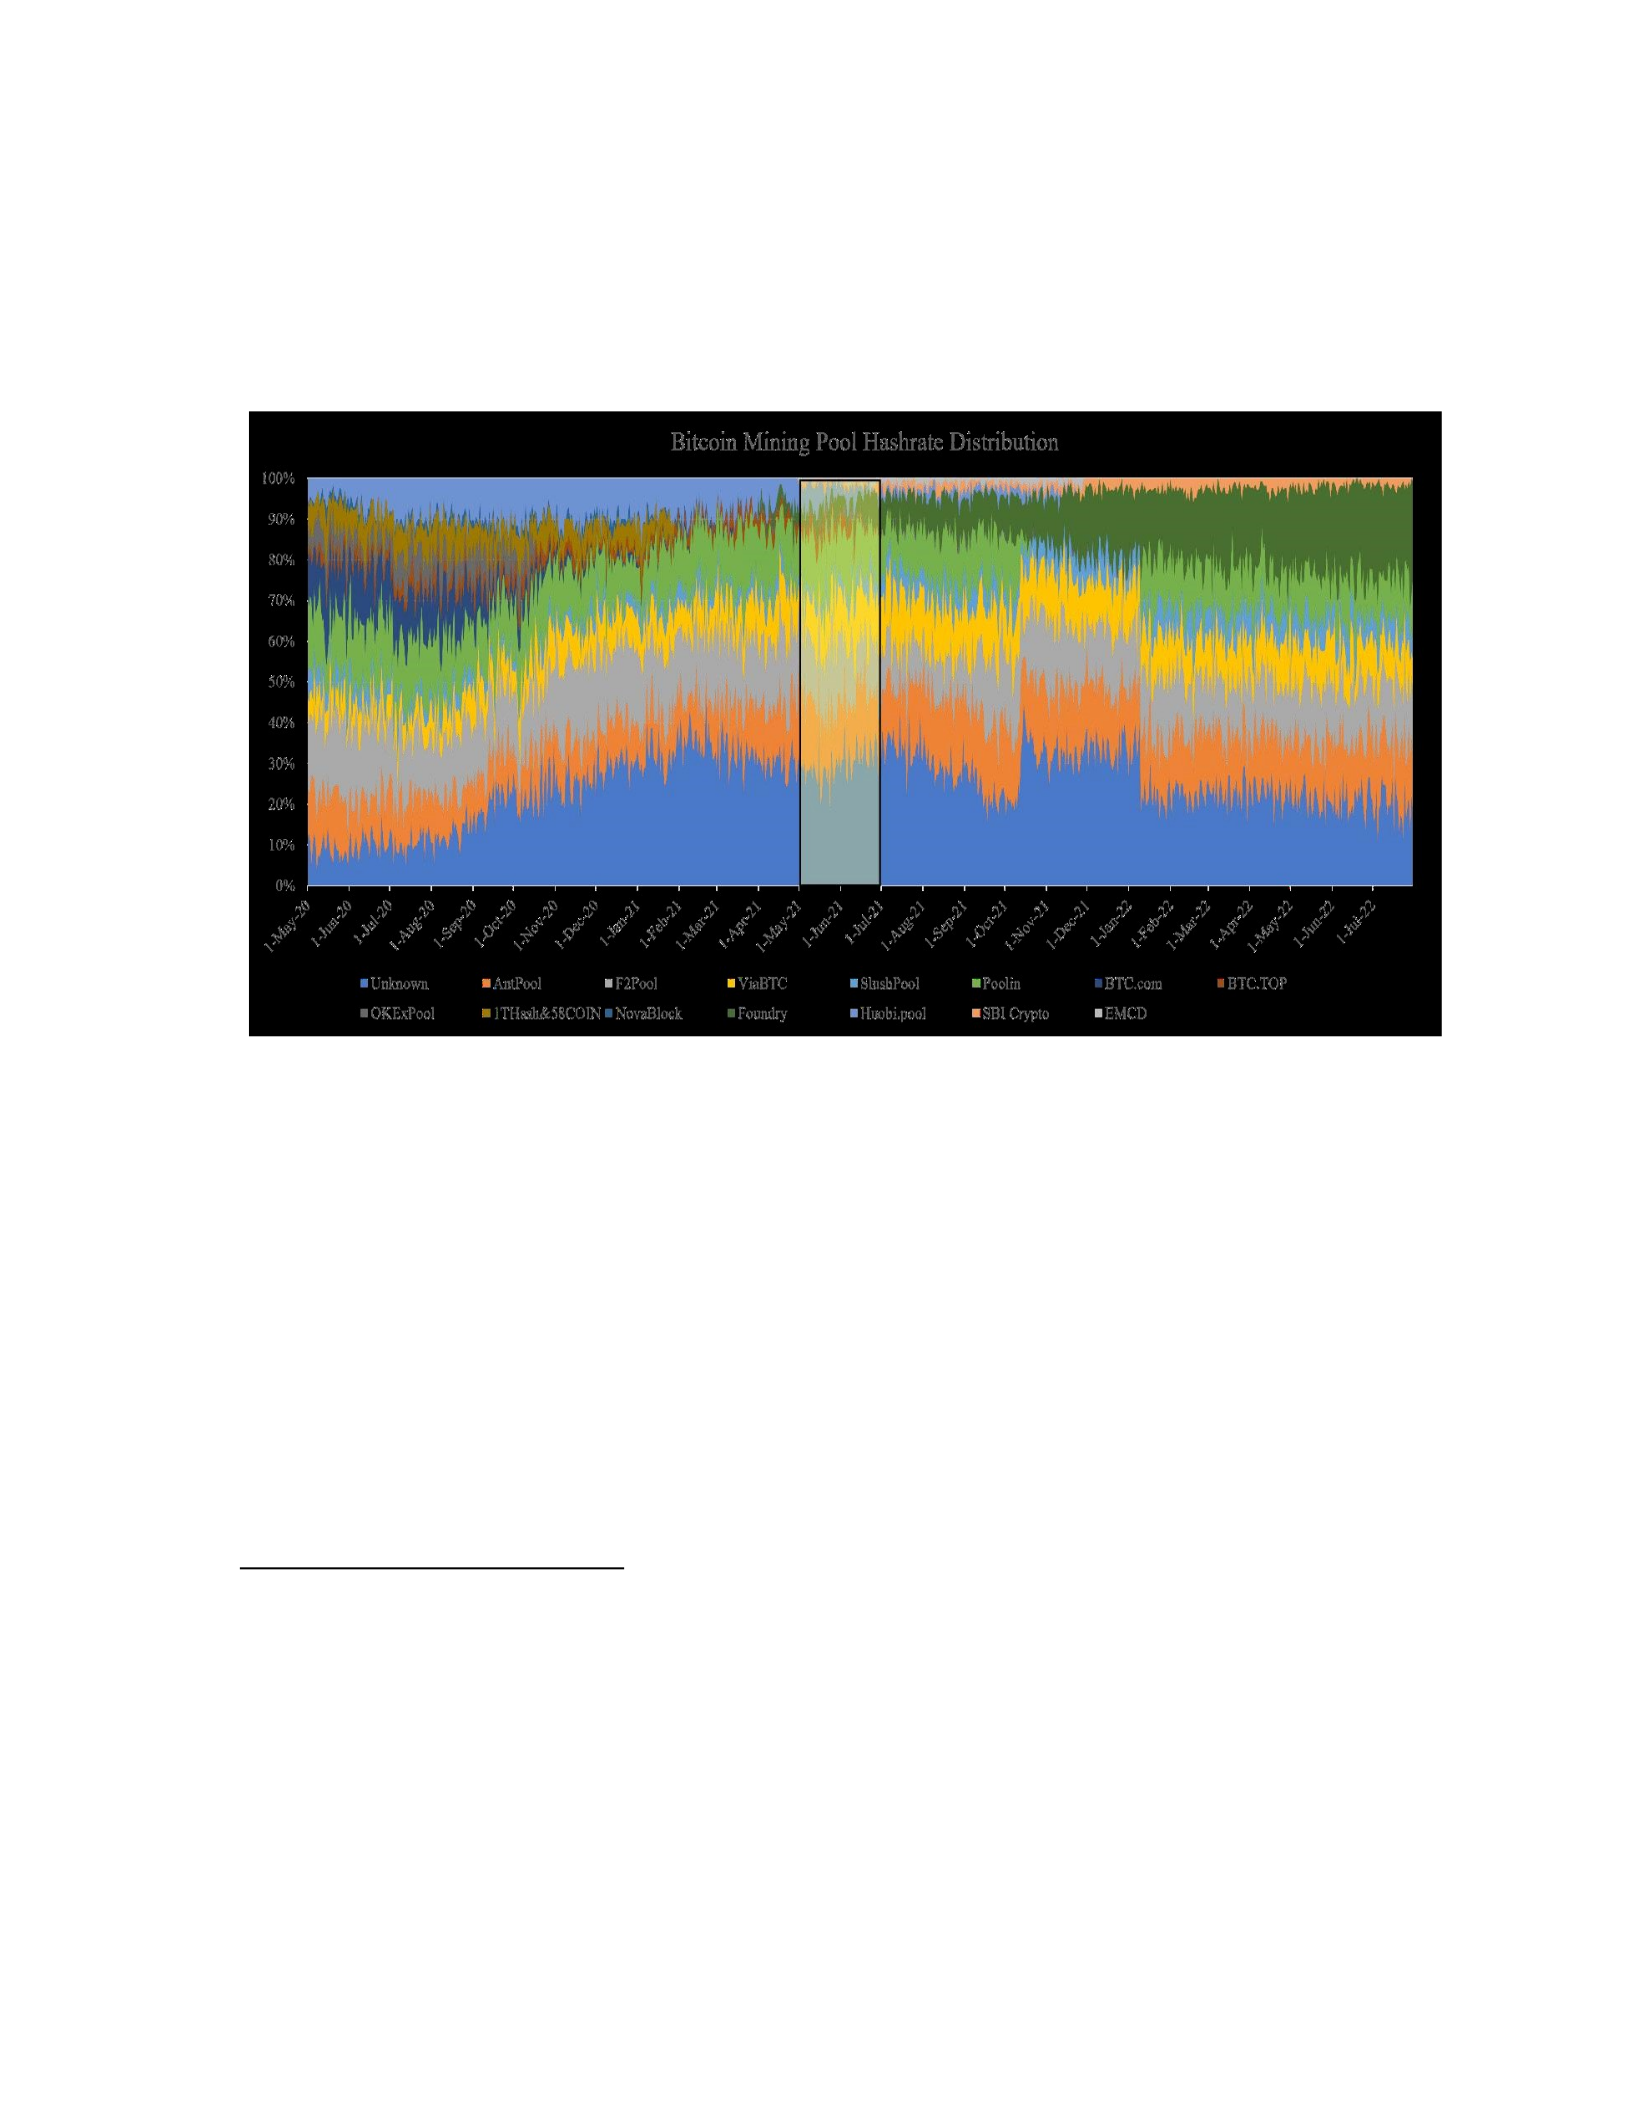
the overall network hashrate. When one mining pool eclipsed 42% in 2014, several
miners joined other pools to prevent the possibility of a 51% attack (Blockchain.info;
Hajdarbegovic 2014).
Figure 2.10 Percentage of Blocks Won Daily by Major Mining Pools (author)
Figure 2.10 shows the percentage of blocks won daily by major mining pools
from May 2020 through July 2022. While the share of blocks won by specific pools
certainly changes, the overall distribution remains consistent throughout the time around
China’s ban, with no single pool amassing more than 31.5% of network hashrate at any
time. Unless known mining pools announce and/or distribute their block rewards to
miners, there is no way of knowing who wins individual blocks by simply looking at
native block information along the blockchain. Known mining pools are now so big that
the winners of most blocks are known. However, unknown or “stealth” miners have
captured most blocks since Bitcoin’s inception (Redman 2022). There is no way to
identify who these unknown block winners are, but it is highly unlikely that they
represent a single stealth pool.
Table 2.4. Paired two-sample t-test: Non Top-4 Mining Pool Hashrate
ex-ante ex-post
Mean 50.13% 44.30%
Variance 0.0022 0.0037
Observations 365 365
Degrees of Freedom
T-Statistic
P(T<=t) two-
tail t Critical
two-tail
364
14.18048682
1.19925E-36
1.966502569
Table 2.4 compares the means of the daily percentage of blocks won by all miners
outside the top four most dominant pools during the ex-ante and ex-post periods. Though
no single mining pool approached the 50% threshold, the top four mining pools became
more dominant after the ban. Prior to the mining ban, miners outside the top four mining
pools were responsible for half the blocks won compared to 44% after the ban. If this
trend continues, independent miners and smaller mining pools are less likely to win block
rewards and pressure to join a dominant mining pool will increase. However, there is no
reason to suspect China’s mining ban is responsible for this trend. Three of the top four
dominant mining pools during both the ex-ante (AntPool, F2Pool, and Poolin) and expost
(AntPool, F2Pool, ViaBTC) periods are based in China. AntPool and F2Pool
remained in the top four during the ex-post period and Poolin continued to win a
significant number of daily blocks. ViaBTC, headquartered in Shenzen, China, was a top-
four miner during the ex-post period as well. So far, there is no indication that
China’s various cryptocurrency bans will force mining pool companies to relocate even as
these pools suspend services to IP addresses originating in China (Ashraf 2021).
2.5.4 Market Price
Daily closing price of 1 BTC, denominated in $USD. Store of value measurement.
In the early years after its inception, Bitcoin was mostly exchanged between early
miners, cypherpunks, and other cryptography enthusiasts. It was first listed on an online
exchange with a floating exchange rate in 2010 (Gemini 2022). Significant trading
volume and some mainstream curiosity led to Bitcoin’s first “bull market” run in 2011 as
price jumped from $1 to $30/BTC in just two months. In 2013, Bitcoin eclipsed
$1000/BTC in October after starting the year around $30/coin. There have been four bull
runs in Bitcoin’s history (2017, 2021 also), each characterized by parabolic rises in price,
followed by huge losses and volatility in price discovery. Still, even after pull backs,
Bitcoin has maintained higher prices than those prior to each bull run.
There are generally two schools of thought regarding Bitcoin’s market price
volatility around bull runs and crashes. The first has to do with Bitcoin’s built-in
limitation on supply inflation through the periodic halving (approximately every 4 years)
of block rewards, making it deflationary relative to fiat currencies and some other more
inflationary assets. Halving the reward also makes production more expensive, but lowers
the rate of new Bitcoin entering circulation, triggering higher demand and higher prices
and preserving mining incentives in the process. Meynkhard (2019) refers to this as a
“halving effect” resulting in “halving cycles” which result in sustained increases in
market value after price discovery. Under this halving cycle theory, bull runs begin a few
months after the effects of halving are felt by the network. Then, Bitcoin overshoots its
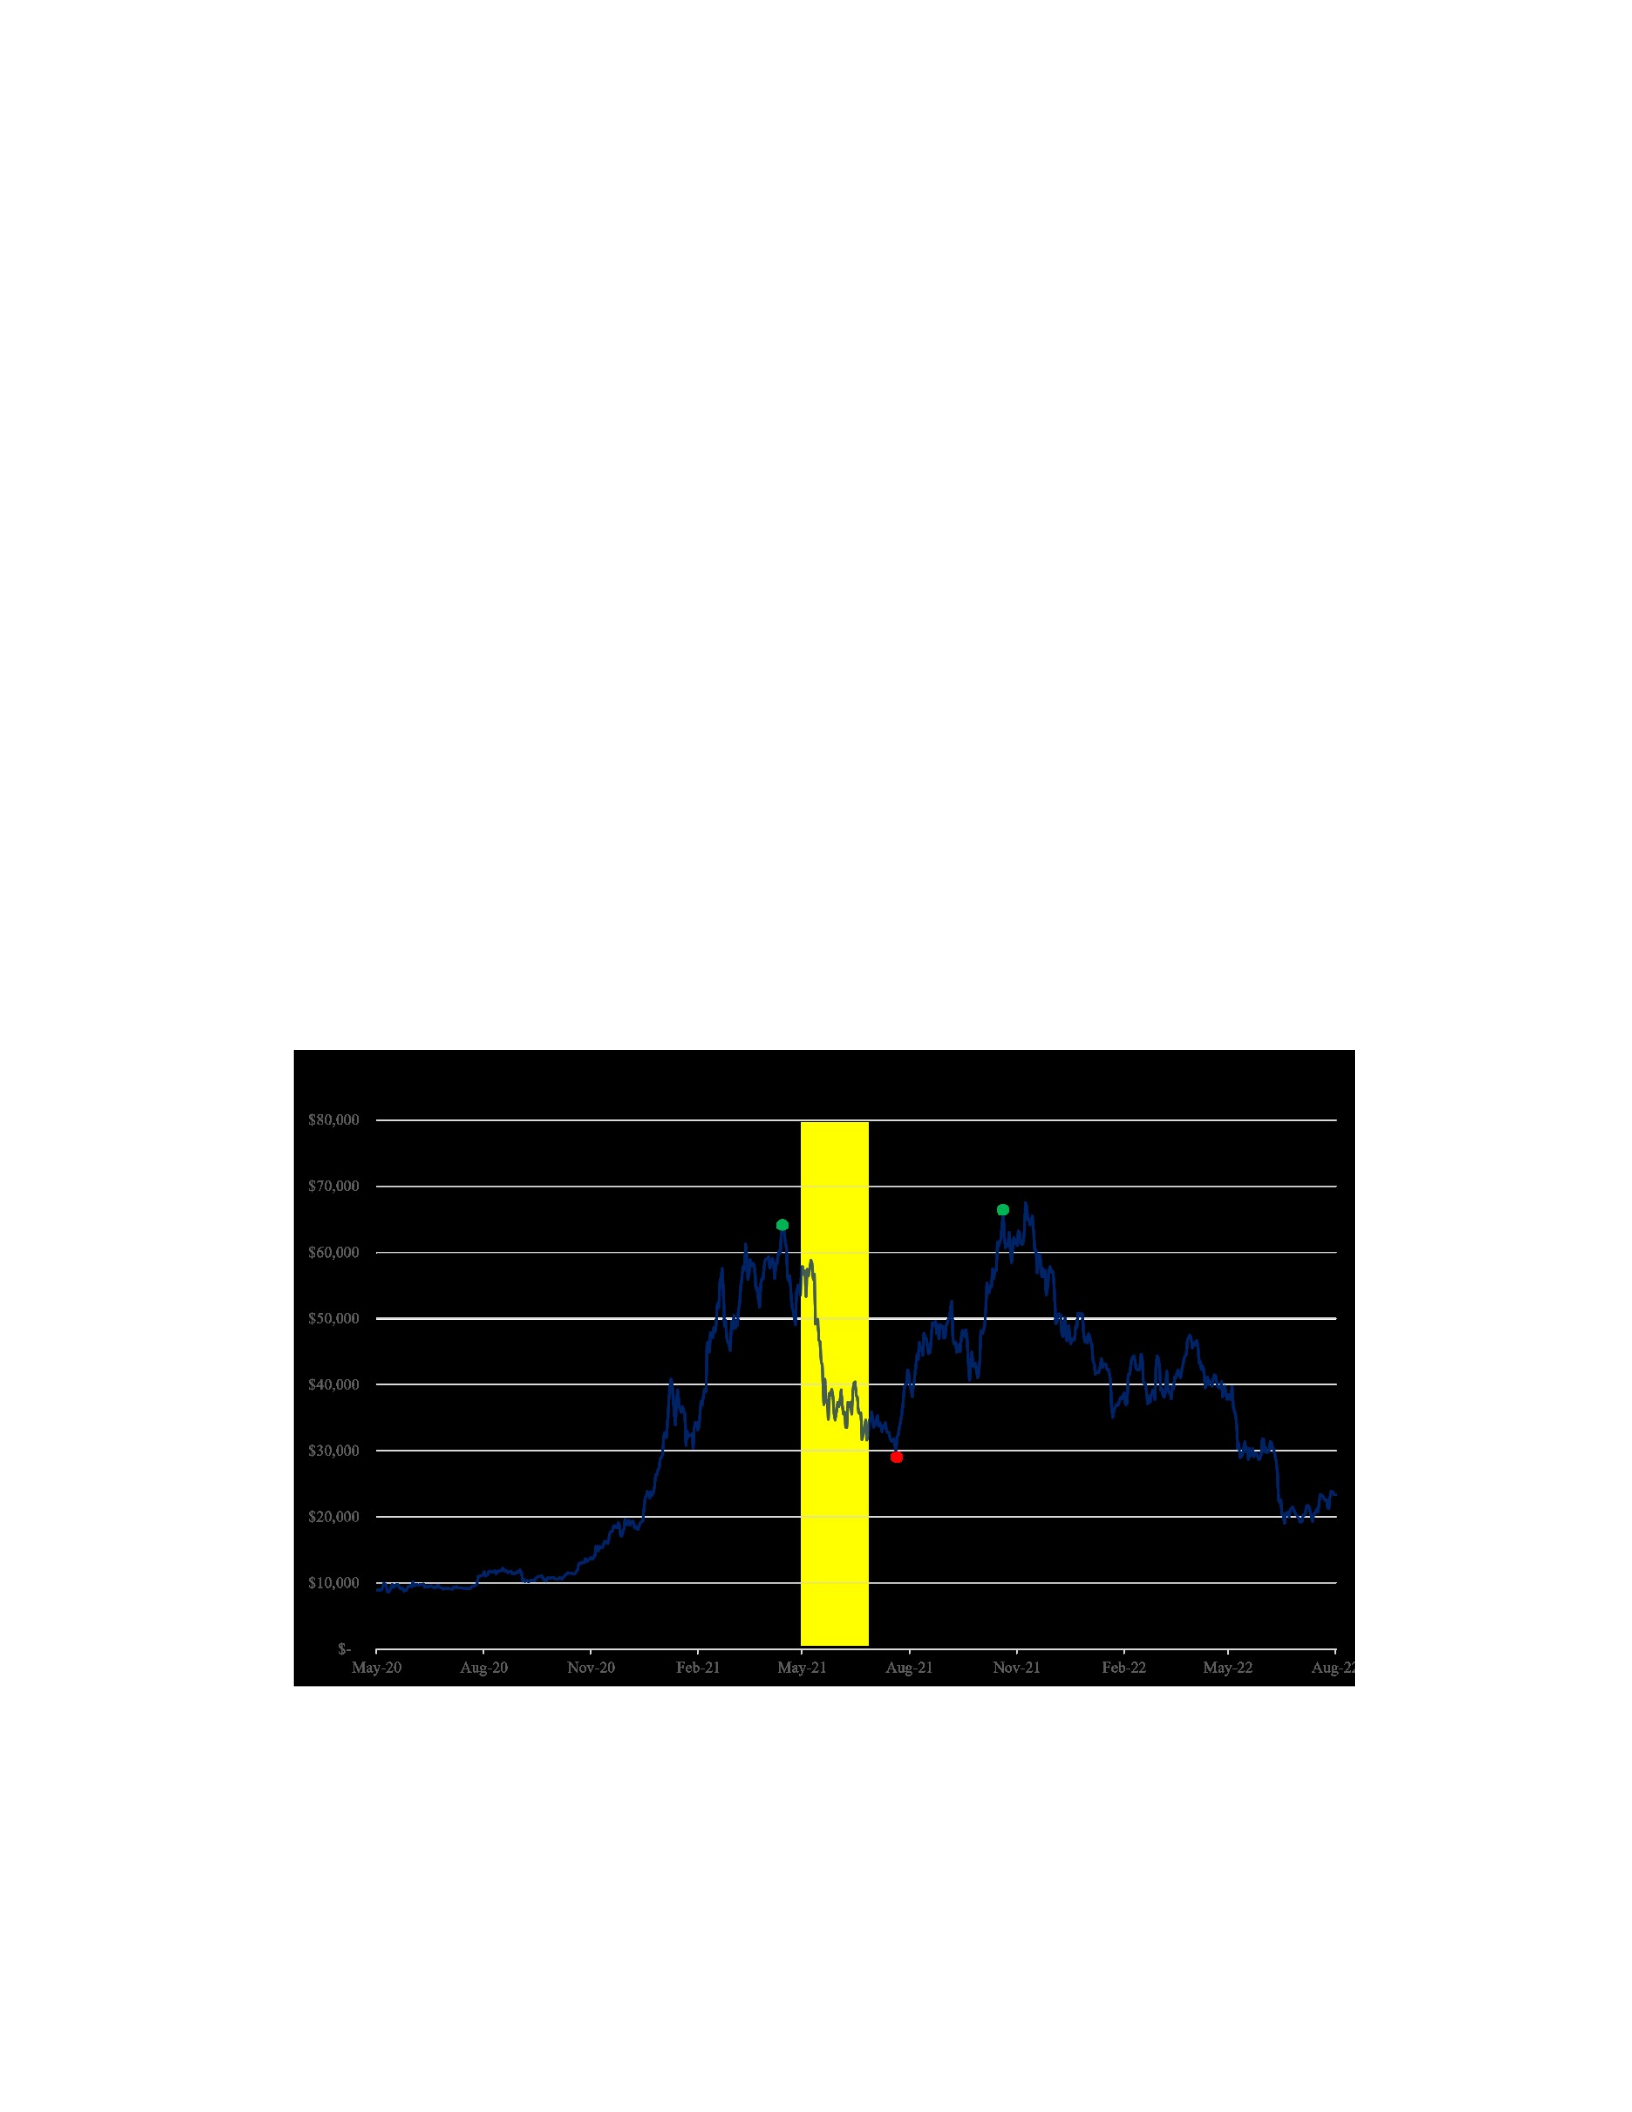
true market value (due to temporary overexuberance and massive increases in trading
volume/derivatives) before settling back to some pre-bull market higher floor value.
Halvings occurred prior to three of the four bull runs (2013, 2017, 2021), but others feel
basic international macroeconomic trends, state policy, and other “black swan” events are
more causal in affecting Bitcoin volatility (Dion 2013; Borri and
Shakhnov 2019; Xie 2019). In 2013, a popular Japan-based Bitcoin exchange named Mt.
Gox was hacked (Dion 2013) and the Chinese government announced new
cryptocurrency regulations with warnings about “speculative assets” (Xie 2019) resulting
in nearly 50% drops in price from earlier highs. Borri and Shakhnov (2019) present
quantitative empirical evidence showing correlation between the “China shock” – a series
of policy implementations and announcements by the PBOC in late 2016 and early 2017
– and drops in Bitcoin trading volume and price.
Figure 2.11 2021 Bitcoin bull run, China ban, and 2022 market price crash (author)
The 2020 halving, 2020-2021 bull run, China’s cryptocurrency ban, followed by a
Bitcoin price crash and recovery, and a final price crash in 2022 has elements of both
theories (Figure 2.11). A Bitcoin halving occurs on May 11, 2020, a bull run begins
somewhere between August and November before prices reach six times their prehalving
levels in February 2021. China’s cryptocurrency ban certainly corresponds with a roughly
50% drop in Bitcoin market value in just over two months. But Bitcoin’s immediate price
recovery to pre-ban levels just a few months after the ban takes effect calls into question
what long-term effects this state policy intervention really has.
Table 2.5a. Paired two-sample t-test: Bitcoin Price
ex-ante ex-post
Mean 24369.43 42954.46
Variance 326612577.57
107511232.74
Observations 365 365
Degrees of Freedom 364
T-Statistic -13.61034216
P(T<=t) two-tail t
Critical two-tail
2.179
4E-34
1.966
50256
9
Table 2.5b. OLS Trend Statistics e
x
-
p
o
s
t
-
9
1
2
8
0
Slope
Standard Error (slope)
R-squared
F-statistic
Residual sum of squares
Regression sum of
squares
ex
-
an
te
153
.61
065
46
3.9
773
538
95
0.80
427
112
8
149
1.60
630
1
232
696
141
96
956
173
640
38
3
1
2
1
2
High variance, residuals, and standard errors in the t-test and OLS trends results in
Table 2.5 point to a great deal of volatility in Bitcoin price, particularly during the expost
period. The mean ex-post Bitcoin price is nearly twice that of the ex-ante period, but ex-
post OLS statistics point to no meaningful trend. The price drop from all-time highs in
November 2021 could simply mirror the same downside volatility and price discovery
which follows each bull run, but it corresponds with several macroeconomic trends and
newsworthy developments which might better explain the asset’s decline. Bitcoin saw
wider institutional adoption in 2021, giving it much more exposure to broader market
sentiment. As mentioned in section 2.4, Tesla’s announcement suspending Bitcoin as
payment for its products corresponds with a precipitous decline in Bitcoin market value
over a week before the PBOC announced China’s forthcoming cryptocurrency mining
ban. Additionally, the federal funds rate increased dramatically in 2022. Retreats away
from risk-on assets towards cash and less volatile assets are typical in high and/or rising
interest rate macroeconomic environments (Litzenberger and Tuttle 1970). The techheavy
Nasdaq Composite Index also hit all-time highs in November 2021, followed by a 37%
decline in 2022.
Volatility and several confounders make drawing causal links between Bitcoin
price and China’s cryptocurrency ban difficult. It is possible that the combination of
negative news around China’s ban and Tesla’s announcement played a role in temporarily
halting Bitcoin’s bull run which resumed in August 2021. But the relationship between
China’s mining ban and Bitcoin’s price drop is at best correlational over the short-term.
2.5.5 Transactions per second
7-day moving average of average daily Bitcoin transactions per second. A dynamic
measure of transaction volume of native Bitcoin on the layer 1 blockchain – does not
include volume on various cryptocurrency exchanges or the layer 2 “Lightning” network.
A measure of Bitcoin’s use case as a medium of exchange.
Transaction volume speaks to Bitcoin’s viability as a medium of exchange.
Overall network hashrate dropped significantly following China’s ban on cryptocurrency
mining (Section 2.3.1). Because mining facilitates the execution of transactions, mining
bans might negatively impact the ability of the network to efficiently process
transactions. Also, the news of a major nation-state ban could lead to a loss of interest in
utilizing cryptocurrency as a medium of exchange. The drop in hashrate during the ban
corresponds with a significant decrease in transactions processed across the network.
Following the ban, transaction volume recovered significantly, but never reaching preban
levels (Figure 2.12).
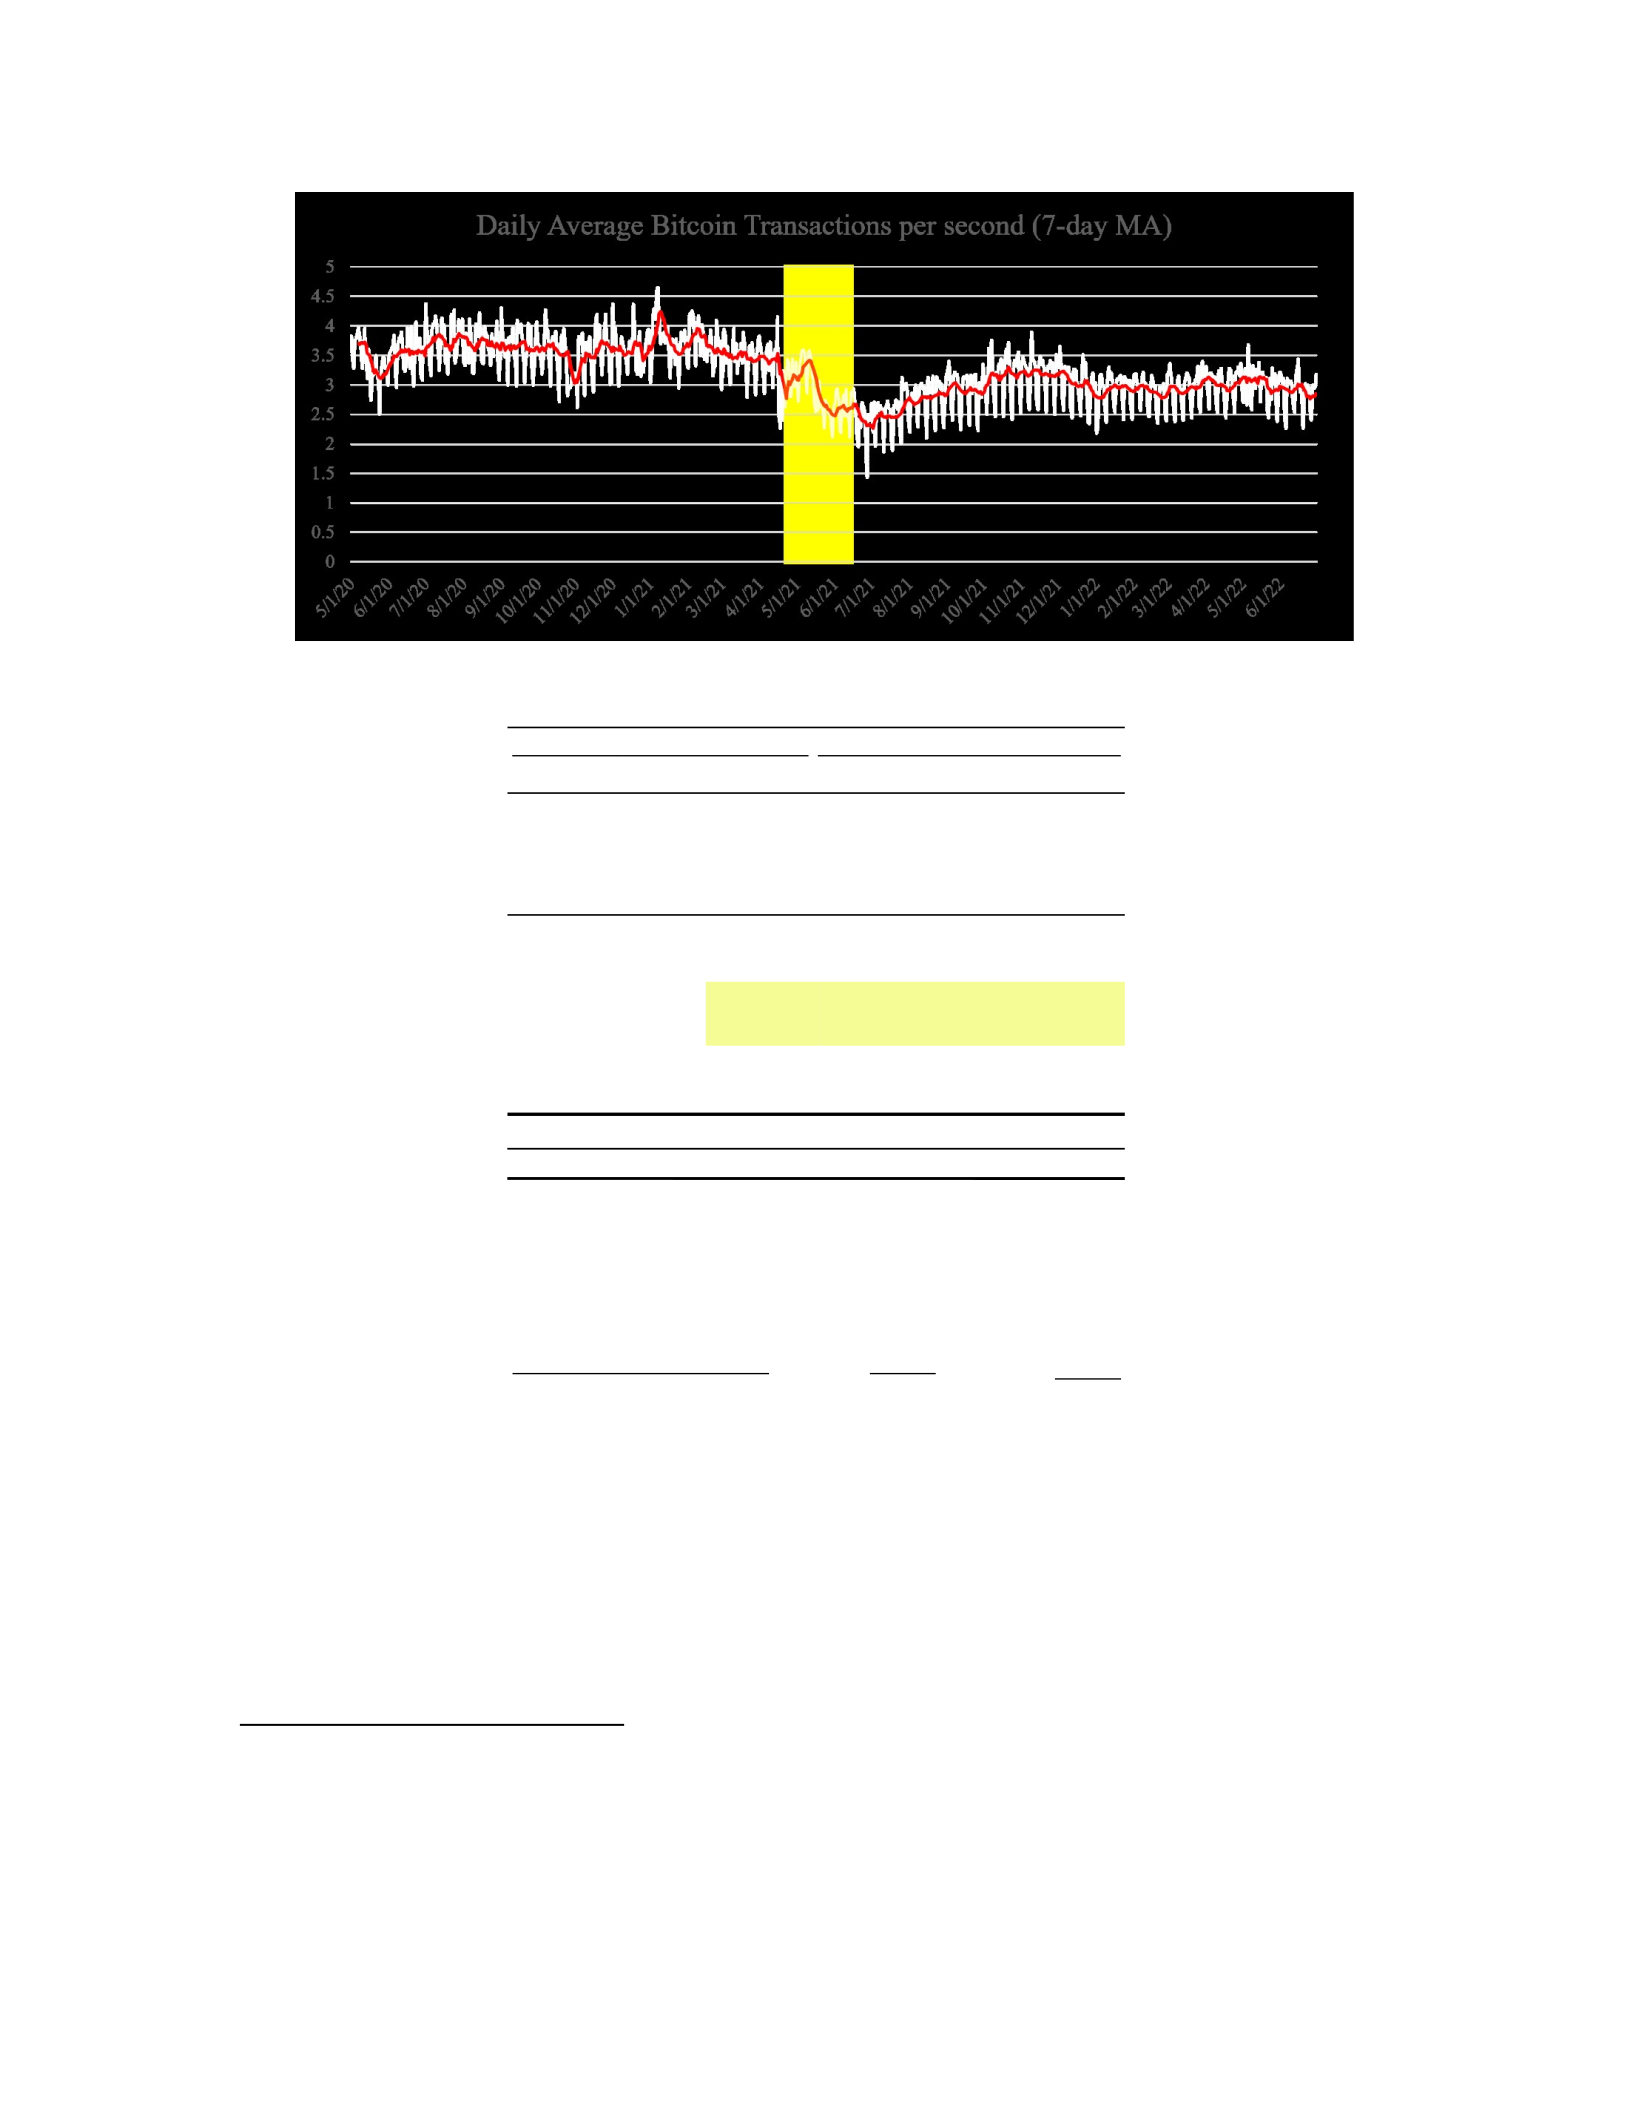
Figure 2.12 Average Daily Bitcoin transactions per second, 7-day moving average (author)
Table 2.6a Paired two-sample t-test: Transactions per second
ex-ante ex-post
Mean 3.570 2.943
Variance 0.147 0.128
Observations 365 365
Degrees of Freedom 364
T-Statistic 29.2410139
P(T<=t)
two-tail
t Critical
two-tail
1.45542E-97
1.966502569
Table 2.6b OLS Trend Statistics
Slope
Standard Error (slope)
R-squared
F-statistic
Residual sum of squares
Regression sum of squares
-0.0003
0.0002
0.0086
3.1612
53.1155
0.4626
0.0005
0.0002
0.0248
9.2128
45.6004
1.1573
Figure 2.12 shows the 7-day moving average of the daily average of Bitcoin
transactions per second to present a smoother depiction of the metric over time, but the
ttest and OLS trend statistics in Table 2,6 use the daily averages only. OLS modeling
accounts for little variation in daily averages (r-squared) when removing the moving
average component. However, the t-test of the means indicates a significant difference
ex-ante ex-post
between transactions per second before and after the ban. Before the ban, an average of
3.57 Bitcoin transactions were processed every second compared to just 2.94 during the
ex-post period (Table 2.6a).
The usage of Bitcoin as a payment system on the base layer is still a long way
away from all-time highs in December 2017, but it may have something to do with the
advent of Bitcoin’s ‘layer 2’ protocol, better known as the ‘Lightning Network.’ The
Lightning Network was invented to solve Bitcoin’s scalability problem and break the
Blockchain Trilemma by establishing a series of peer-to-peer micropayment channels
between users to facilitate payments and unburden the main blockchain (Poon and Dryja
2016). Because these transactions occur off-chain, reliable data on exactly how many
transactions occur is hard to approximate. One study estimates over 120,000 payment
channels opened between January 2018 and July 2019 (Lin et al. 2020), which would
help explain the drop in visible, on-chain transactions since 2018.
Several other factors could drive Bitcoin’s transaction volume. Transaction fees,
competing methods of value transfer (e.g., other cryptocurrencies), or even
macroeconomic factors might influence Bitcoin’s transaction volume. Still, there is at
least a very strong correlational relationship between China’s mining ban and a sustained
ex-post period of less transactions processed per second. If the relationship is causal,
reduced hashrate is unlikely to be the mechanism preventing more transactions.
Reductions in average daily hashrate during the intervention (~25%, see Section 2.3.1)
correlate with a similar reduction in average daily transactions processed per second
(~18%) over the same period. But if mining power acted as the limiting factor in
transaction processing efficiency, then the recovery in network hashrate to new all-time
highs would allow Bitcoin transactions per second to return to pre-ban levels. It is more
likely that some other factor – which may or may not have been triggered by something
related the ban – is driving less demand for using Bitcoin as a medium of exchange.
2.5.6 Block Time
Daily average of time (in minutes) between completed blocks added to the Bitcoin
blockchain. A measure of Bitcoin’s effectiveness and efficiency in processing transactions
(medium of exchange); a measure of Bitcoin core software’s adaptability to changes in
hashrate using difficulty adjustments.
Bitcoin transactions are organized into blocks by miners and then broadcast on its
distributed ledger for validation. Transactions are not finalized and settled until organized
into blocks and added to the chain. Bitcoin was designed to add a new block every 10
minutes. As hashrate changes, automated smart contract algorithms built into Bitcoin’s
core software protocol are designed to adjust the difficulty of mining a new block to try to
meet this 10-minute goal about every two weeks.
Table 2.7 Bitcoin Mining Difficulty Adjustments Around Intervention Period
Date Block # Difficulty % Change Average Block time (seconds) Average Hashrate
4/15/202
1
679392 2.36E+13 1.92 589 1.68792E+20
5/1/2021 681408 2.06E+13 -12.61 687 1.47416E+20
5/13/202
1
683424 2.50E+13 21.53 494 1.79249E+20
5/29/202
1
685440 2.10E+13 -15.97 715 1.5048E+20
6/13/202
1
687456 1.99E+13 -5.3 634 1.42678E+20
7/3/2021 689472 1.44E+13 -27.94 833 1.02781E+20
7/17/202
1
691488 1.37E+13 -4.81 630 9.78715E+19
7/31/202
1
693504 1.45E+13 6.03 566 1.03721E+20
8/13/202
1
695520 1.56E+13 7.31 559 1.11286E+20
China’s ban triggered an unprecedented drop in hashrate (Figure 2.3). Since 2010,
automated processes in Bitcoin’s core software have routinely adjusted to small changes
in block time quite well. But the ban served as the most significant test of the difficulty
adjustment algorithms’ ability to adapt to a sudden drop in computing power dedicated to
adding blocks to the chain. An ineffective adjustment which does not sufficiently
compensate for a hashrate decrease could lead to two additional weeks of long waits for
transaction settlement. Block time stayed above 10 minutes from June 9th through July 6th,
hitting an all-time high of 24.8 minutes between blocks on June 27th 2021 during the
intervention period, but the July 3rd difficulty adjustment (Table 2.7) succeeded in
returning block time to the 10-minute average rather quickly. July 6th saw an average
block time of 10.14 minutes, and a pre-ban pattern of average block time was restored
(Figure 2.13).
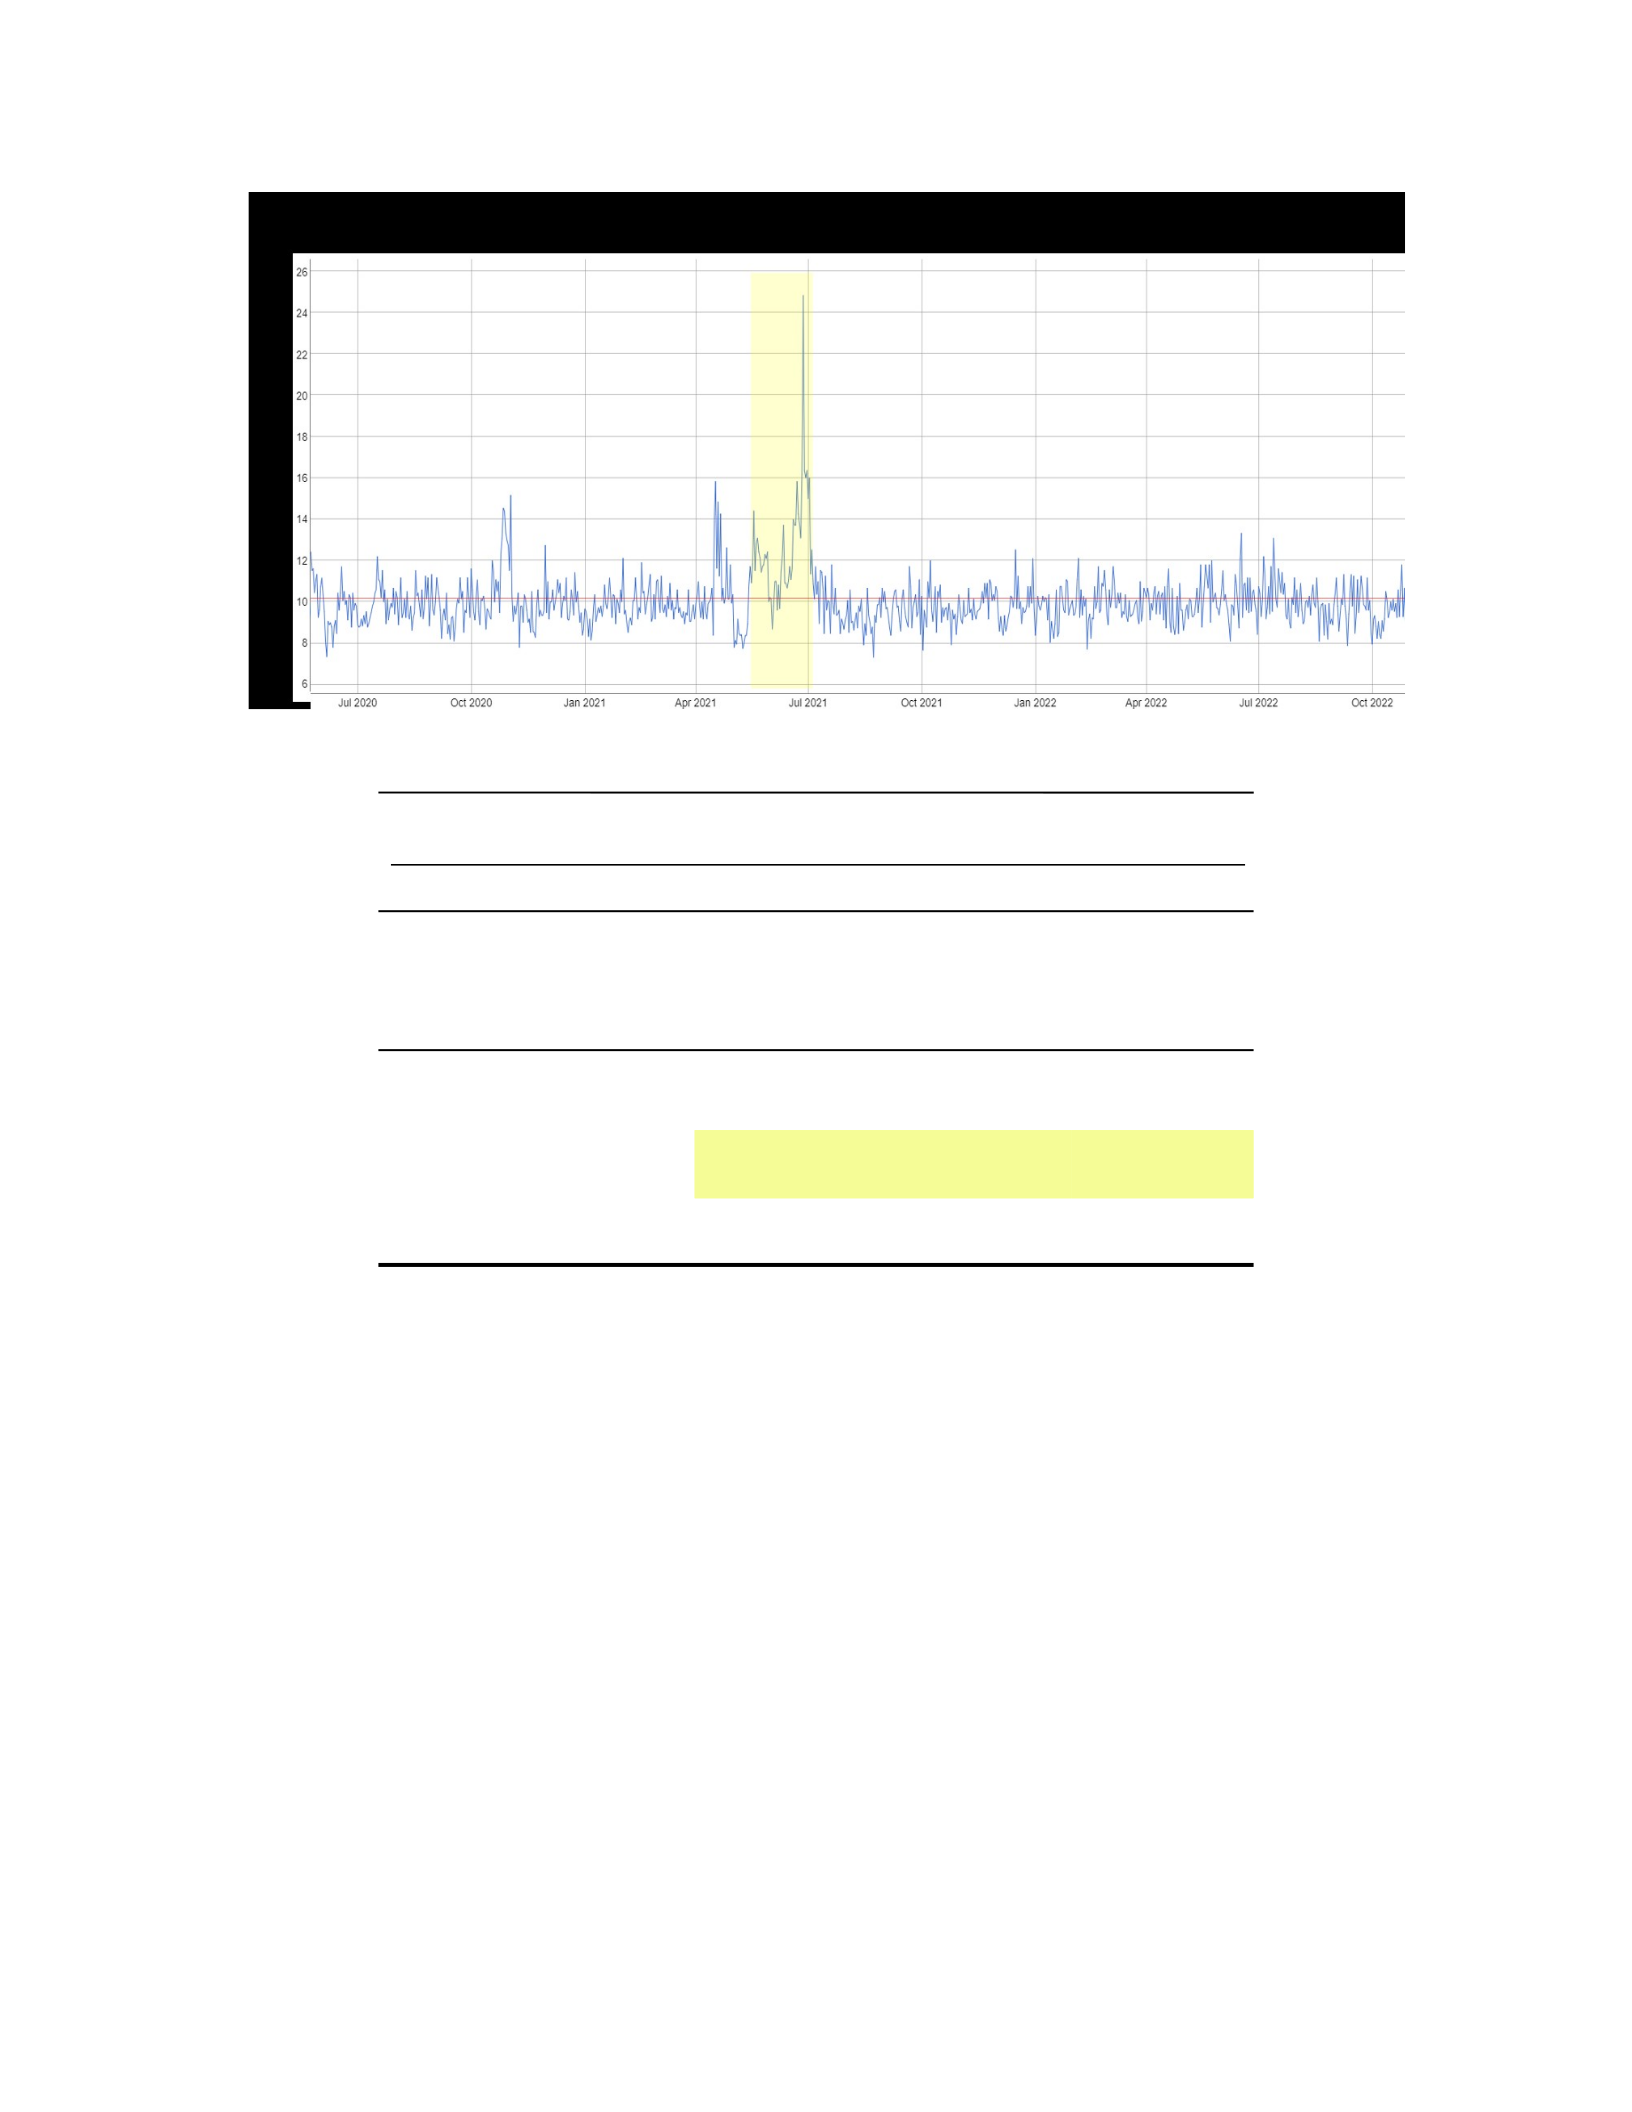
Figure 2.13 Daily Average Time Between Bitcoin Blocks (BitInfo Charts 2023)
Table 2.8 Paired two-sample t-test: Average Daily Block Time (minutes)
ex-ante ex-post
Mean 10.054 9.858
Variance 1.456 1.012
Observations 365 365
Degrees of Freedom
T-Statistic
P(T<=t) two-tail
t Critical two-tail
364
2.4675
0.0141
1.9665
While the p-value of the t-test comparing the two periods indicates a statistically
significant difference of the means (95% confidence level), average daily block time
decreased by just 11.4 seconds between the ex-ante and ex-post periods (Table 2.8).
China’s ban on cryptocurrency mining led to an increase in average daily block time for
the months of May (10.4 minutes) and June 2021 (12.8 minutes), but these results
indicate the mining difficulty adjustment successfully compensated for the loss of
hashrate during the intervention period over the long-term.
2.5.7 Nodes Online and Nodes by Country
Nodes online: Number of reachable nodes running Bitcoin Core software. Key measure of
decentralization and active interest in securing the Bitcoin network. Speaks to network
strength/security; asset value metric
Nodes by Country: Number of reachable nodes running Bitcoin Core software by country.
Measure of node geographic distribution; network susceptibility to nation-state policy
For both nodes online and nodes by country, raw numerical data is unavailable for
statistical analysis. Figures 2.14 and 2.15 are taken directly from the Bitnodes website.
Bitnodes is a privately developed software which interrogates any nodes connected to the
Bitcoin network using a protocol message which is a request for information from each
node. Bitnodes was developed and published online anonymously, and data on node
connections over time is not available for download. For this reason, analyses for these
sections are limited to visual inspections of the graphics posted on the bitnodes.io website
and are not included as evidence to support causal claims in this essay.
There are several stakeholders in Bitcoin’s governance. Miners conduct the PoW
algorithm hashing to compete for block rewards and process transactions while other
network participants run independent nodes capable of broadcasting and confirming the
validity of those transactions. Independently run nodes are critical to the trustless
consensus mechanisms which underpin value transfer without third party intermediation.
Node operators can facilitate the transfer of their own cryptocurrency to another address
and verify the transaction without the use of an exchange. They help secure the network
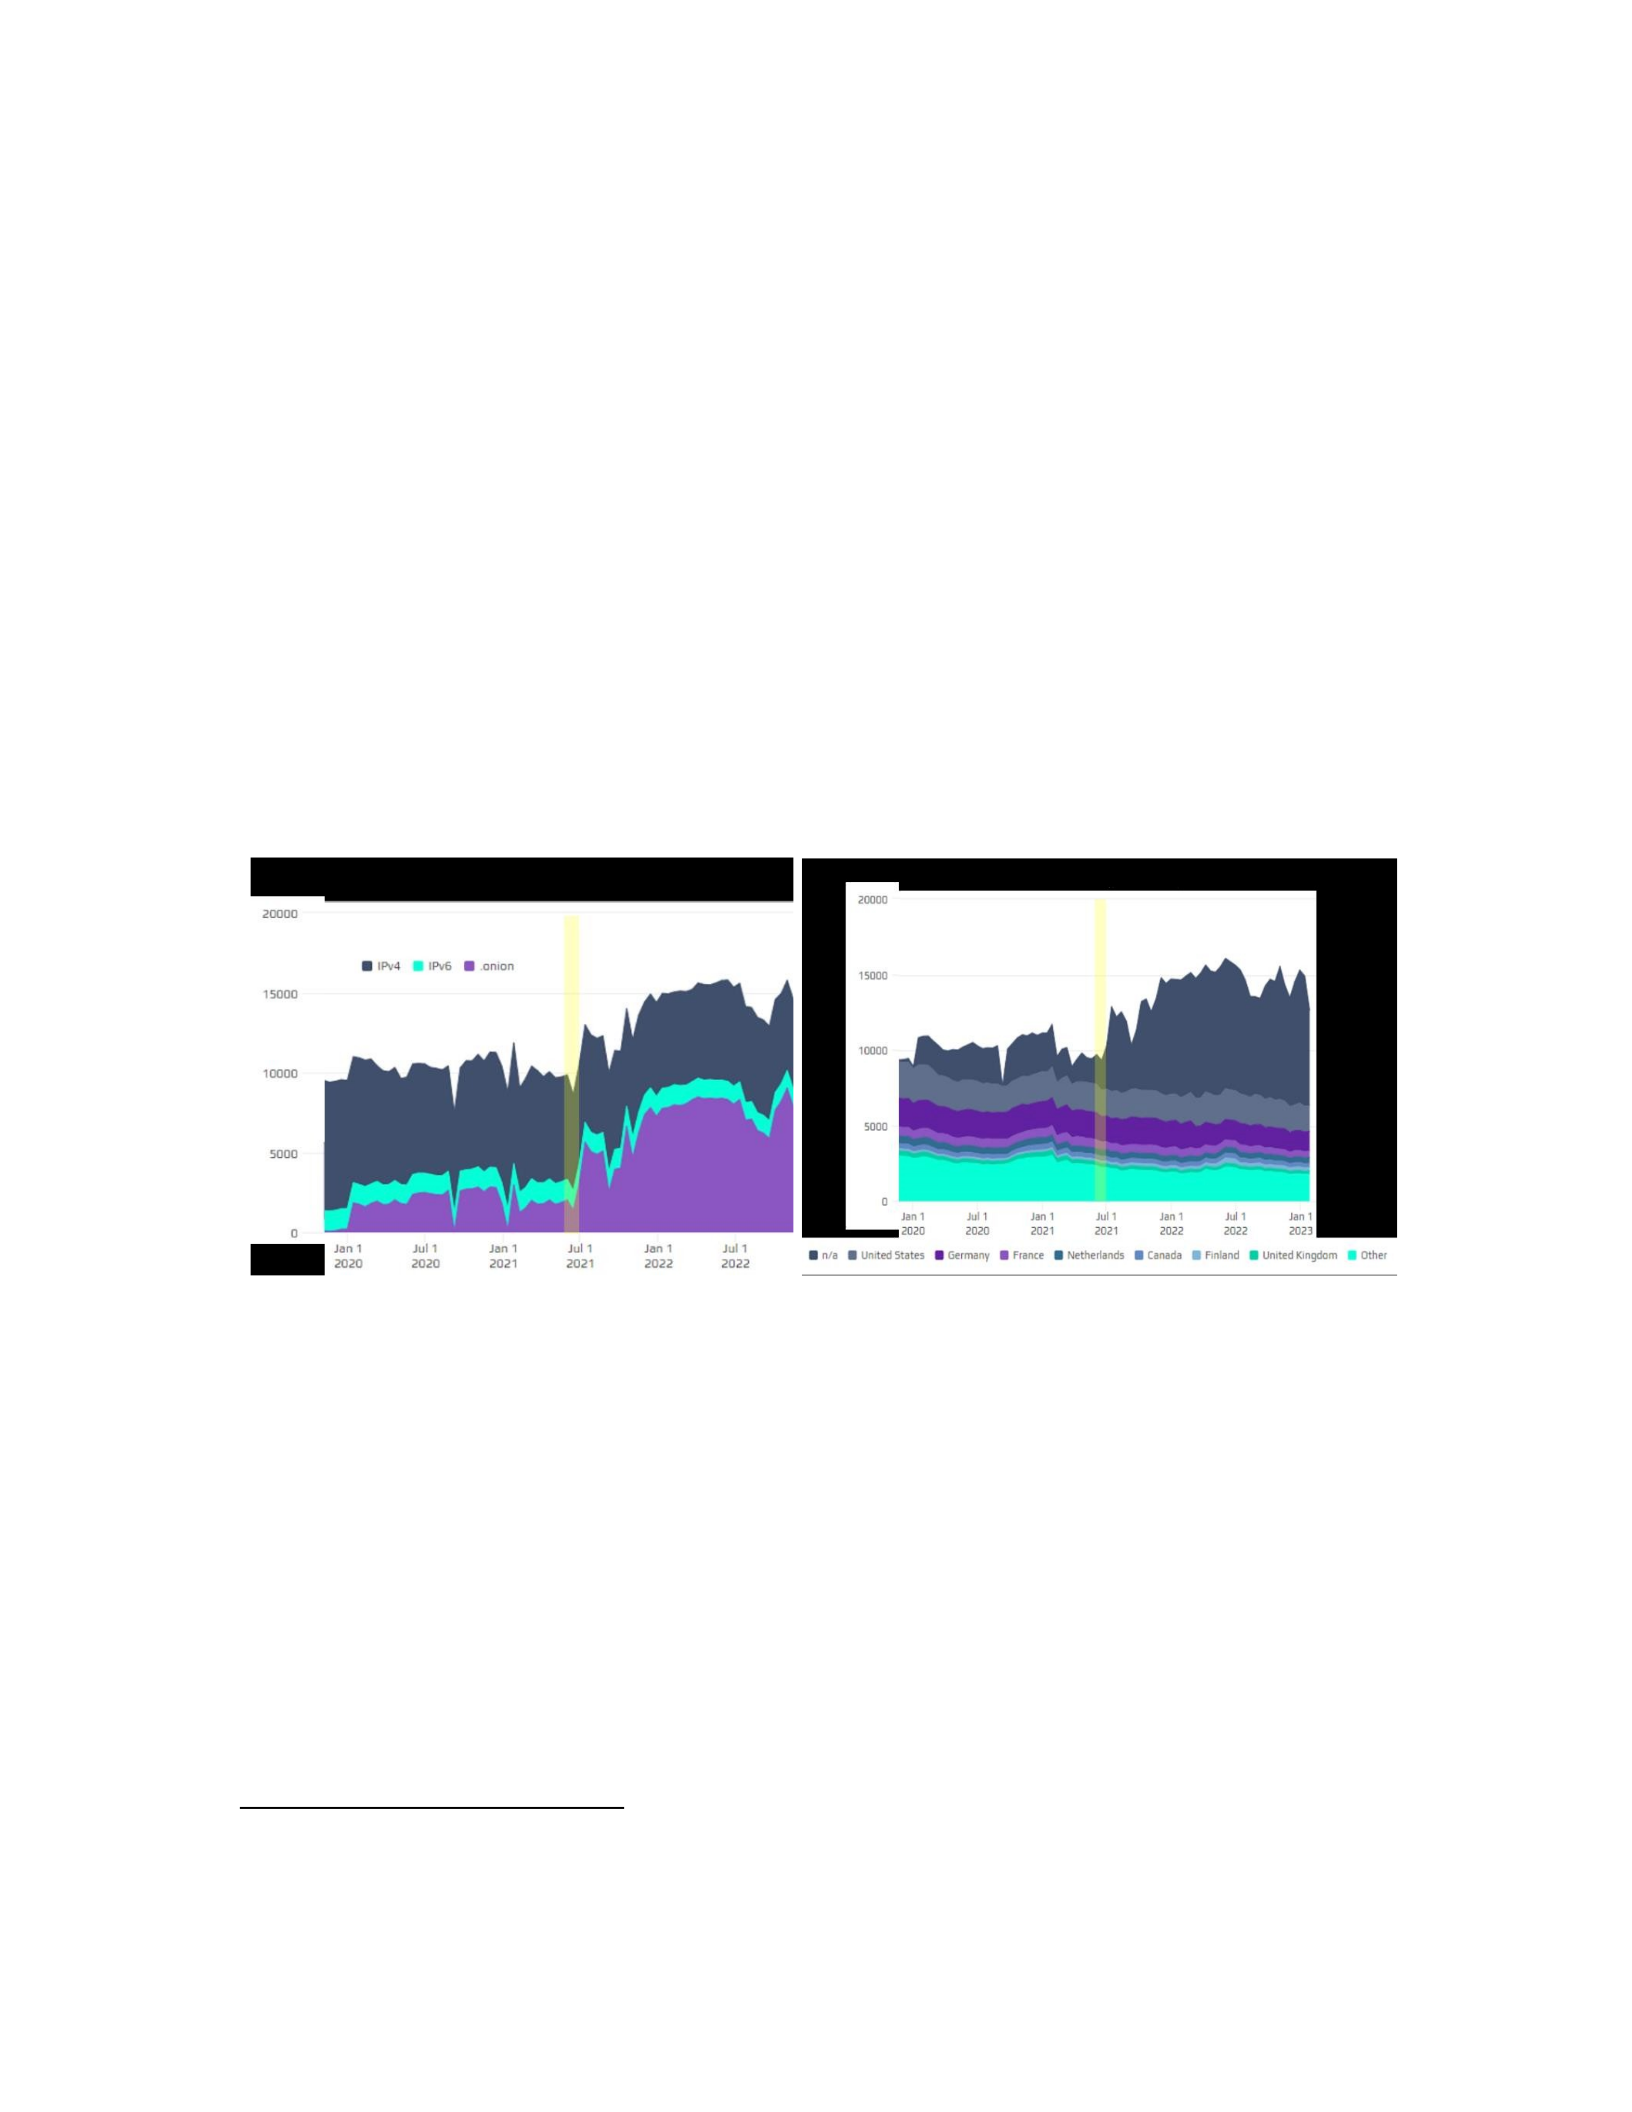
by adhering to the consensus rules; validating blocks and transactions within blocks and
rejecting invalid transactions. Running a full node is relatively cheap (~$300) and each
node possesses equal power to validate and/or initiate transactions. Each node holds the
distributed ledger’s history of transactions and runs the Bitcoin core software to be
counted in this metric. For this reason, nodes are a measure of support for the Bitcoin
network. The geographic distribution of nodes running Bitcoin core software is important
in determining whether transaction validation is a global or regional effort. Much like
hashrate distribution by country, it is an indicator of how susceptible the network is to the
policies of a single nation-state.
Figure 2.14 Reachable Nodes (left, Bitnodes 2023)
Figure 2.15 Bitcoin Nodes by Country (right, Bitnodes 2023)
A visual inspection of Figure 2.14 indicates reachable nodes validating
transactions increased after the intervention. There were roughly 10,000 reachable nodes
from January 2020 through June 2021, but the total reached 15,000 by January 2022.
Several potential explanations for this change exist. It is possible that displaced miners
dispersed into smaller operations. But media reports indicate it took several months for
many miners to find new homes (Ostroff and Yu 2021) and China-based IP addresses did
not account for a large proportion of known reachable nodes (Figure 2.15) before the ban
took effect. The expansion of cryptocurrency payment processors during this time may
also contribute to the rapid increase in online nodes. For example, BTCPay Server
provides a point-of-sale application for merchants to accept cryptocurrency payments
which Tesla briefly explored using to facilitate Bitcoin payments for their vehicles before
abandoning the idea in May 2021 (Harper 2021). The growing popularity of the
Lightning Network and other Bitcoin derivatives provides increased utility for the use of
nodes in facilitating micropayments.
While the overall distribution of nodes by country appears to be unaffected by the
ban, the number of “n/a” nodes increases dramatically after the ban. We now lack location
data on nearly half the nodes running Bitcoin core software. Howell et al. (2023) point
out a broader trend towards anonymization and privacy across several peer-to-peer
cryptocurrency networks with the increased use of “the onion router” (TOR) since 2021.
TOR is an open-source software for “executing programs as hidden services, shielding
the source IP address of the server running the application” (Howell et al. 2023, 5). Much
of the increase in online nodes in Figure 2.14 is from “onion” (TOR) coded nodes. In a
review of four different blockchain networks (including Bitcoin) Howell et al. (2023)
found that 54.3% of all nodes in 2021 utilized TOR. This makes node geolocational
analysis particularly difficult and offers further support for theories of increased
IPspoofing measures discussed in section 2.3.2.
Table 2.9 Summary of Bitcoin Network Metric Changes Around the
Ban
Metric pre/post intervention change Suspected causal or correlational
relationship
Total Network Hashrate robust recovery following intervention ban likely caused drop in network hashrate
during the intervention period
Country Share of Hashratemore distributed post-intervention
ban likely contributed to and accelerated
pre-ban trends of growing absolute
hashrate outside of China
Mining Pool Hashrate
Distribution
Market Price
no change
robust initial recovery after intervention,
followed by losses late in ex-post period
none
may have contributed to short-term losses;
no longterm impact
Transactions per second less transactions after intervention correlational
Block Time no change
causal impact over the short term before
difficulty adjustment; no long-term
impacts
Nodes Online* increase following intervention correlational
Nodes by Country* more distributed post-intervention correlational
*raw numerical data unavailabe. Graphic depictions only available through bitnodes.io
2.6 Miner Decision-making and Public Policy: Qualitative Analysis
Miners represent the most significant human decision-making element of
Bitcoin’s DAO governance. Like any DAO, the consensus rules governing most
Bitcoinrelated operations are embedded into automated code (digital governance). But
individual miners control where and when they turn on their equipment. Though mining
economics (i.e., the price of energy) is the primary driver for these decisions, evidence is
mounting that anticipated regulatory environment is a serious consideration in miner
decisionmaking calculus.
In a spatial analysis of Bitcoin mining across the globe over time, Sun et al.
(2022) detect Bitcoin mining in 139 countries, with the greatest concentrations of
hashrate coming from areas with abundant and cheap energy production. They describe a
system of dynamic mining where large-scale miners are more willing than small miners
to relocate when regional energy economics change. But both favorable regulatory
measures (e.g., subsidies and tax benefits) and regulator attitudes were found to

“dramatically influence” (Sun et al. 2022, 5) movement decisions of major miners while
adverse policies drive them away. In particular, China’s ban spurred a new flurry of
“spatial fluctuation and migration” (5) in which regulatory policy became more
influential in the miner decision-making process than before.
Several media reports indicate that dislocated miners from China packed up and
moved their operations across the globe to Texas (Feng 2021; Sigalos 2021; Rutwitch and
Feng 2022). Of course, the opportunity to capitalize on low energy prices is a primary
consideration. But in interviews, displaced miners also cite Texas policies favorable to
Bitcoin miners and a general positive disposition among prominent Texas politicians as
reasons for settling there. Texas has a deregulated energy market, low barriers to entry for
new businesses, and advantageous tax policies for industrial energy producers and
consumers.
Texas senators Ted Cruz and John Cornyn and Texas Governor Greg Abbott have
publicly expressed support for hosting Bitcoin mining in Texas, along with the CEO of
Texas’ energy grid manager, the Electric Reliability Council of Texas (ERCOT) (CNBC
2022). ERCOT runs a deregulated market where several market participants own power
plants and delivery energy through transmission lines they own as well. Contrast this with
markets in several states where utility companies have a monopoly on the generation and
distribution of electricity to end-users. These markets often feature variable energy
pricing based on demand dynamics, allowing miners to take advantage of extended
periods of low energy pricing (Hartley et al. 2019; Brown et al. 2020). Another prominent
feature of deregulated electricity markets is a robust, separate market for demand
response and ancillary services. Miners can be paid to provide a base load of energy
demand provided they are able to respond to grid operator instructions to curtail
or shut down their loads. This changes the mathematical modeling for Bitcoin mining
profitability by adding the possibility for revenue generation through participation in the
ancillary services market.
CBECI lacks quantitative data on hashrate share of individual states within the
Untied States over time – it has only an estimate of where things stood as of December
2022. But a slew of media reports across several outlets point to miner migration within
the United States away from states like New York towards Georgia and Texas (Lonnroth
2022; Saul 2022; Hutton 2022). The tone among New York state regulators and
politicians changed in 2021 as an environmental push for curbing emissions led to
legislative efforts to expel cryptocurrency miners out of certain areas. Despite low energy
prices and cool weather favorable to mining, major miners like Foundry USA cite
“political and regulatory ambiguity” and “the possibility of a moratorium” (Saul 2022) as
reasons for moving away from New York as a base of operations. Months after Texas
Governor Greg Abbott made it clear he wanted his state to be the world’s leading
cryptocurrency mining location (Abbott 2021), New York Governor Kathy Hochul signed
a two-year moratorium on new permits for power plants housing cryptocurrency mining
equipment (Hutton 2022).
2.7 Key Findings and Implications for Policymakers
Current approaches to cryptocurrency regulation across countries and jurisdictions
vary based on existing and precedent-setting regulatory frameworks, the domestic
cryptocurrency activity within each country, and each government’s general disposition
towards strict or flexible financial regulation (Blandin et al. 2019). Historically, the
United States and China have adopted different approaches towards currency and the role
of the state in regulating new forms of value exchange. We should not expect the United
States to mirror China’s approach to cryptocurrency regulation, but policy analysts should
objectively consider the merits of their aggressive approach. The specific research
questions of this study are aimed at determining what impacts China’s mining ban had on
Bitcoin. But the macro implications of this essay speak to whether the policies of a single
government can influence the behavior, actions, value of a highly decentralized
autonomous organization. These findings include both analysis specific to Bitcoin as it
relates to the China ban and what it might mean for cryptocurrency policy more broadly.
1. Nation-state policies may impact cryptocurrency values over the short-term, but
evidence suggests cryptocurrencies like Bitcoin recover and retain their value over time.
First, there is little to no evidence to suggest the ban impacted Bitcoin as a store of
value over the long term. Other studies suggest the announcement of adverse state
policies in the past negatively impacted Bitcoin’s market price over the short-term (Borri
and Shakhnov 2019; Xie 2019). While the price of Bitcoin dropped after the ban was
announced, it recovered to new all-time highs within four months. Perhaps China’s 2021
mining ban had the same effect as other past announcements of adverse state policy. But
major news specific to institutional adoption of Bitcoin (i.e., Tesla’s announcement),
broader macroeconomic dynamics, and Bitcoin’s history of sudden downside price
volatility make determining causal mechanisms difficult in this case.

Nakamoto touted Bitcoin as an innovation in monetary policy which could offer
people a hedge against “the arbitrary inflation risk of centrally managed currencies”
(Nakamoto 2010). But the volatility in Bitcoin’s price action has made it so that only
long-term holders willing to endure massive unrealized gains and losses could possibly
view it that way. Bitcoin has suffered price drops of 40% or more in a four-month span
seven times since 2011.132 Still, policymakers should not expect wild price swings to
threaten the long-term appeal of Bitcoin. Even if Bitcoin performs more like a speculative
stock than a true inflation hedge, its risk-adjusted rate of return over time has been strong
enough to keep long-term holders from selling their holdings (Radmilac and Van Straten
2022).133 Bitcoiners clearly see strong enough fundamentals to endure over 70% losses, so
market price cannot be the only metric of asset value, although it is the most obvious
place to start.
Hashrate is a key metric of network security in Bitcoin. Much of the asset’s value
is tied to whether Bitcoin works as intended. Aggregate network hashrate establishes a
threshold for mining control bad actors would need to add invalid blocks to the chain or
alter transactions. The distribution of both where that hashrate is based geographically
and how much individual mining pools control are matters of decentralization also critical
to network security. While multiple sources of quantitative and qualitative evidence point
to miners using proxy services to obfuscate their locations, China-based miners were
responsible for the majority of network hashrate throughout the pre-ban period and the
ban resulted in most of that hashrate coming offline for some time. Drops in aggregate
network hashrate occur during the intervention through some combination of the loss of
China’s hashrate (Table 2.3) and less efficient miners being forced offline due to
tightened profit margins as Bitcoin’s market value dropped. Top mining pools became
somewhat more powerful after the ban, but no single pool came close to controlling 51%
of total hashrate.
132 88%, 54%, 44%, 60%, 46%, 41%, 55% drops in 2011, 2014, 2015, 2018, 2021, and 2022 (twice) 133
Since 2014, Bitcoin has never lost value (in $USD terms) over a three-year span.
The rapid recovery of overall network hashrate during the ex-post period is the
most significant policy takeaway for consideration from this study. Increases in hashrate
based outside of China before the ban resumed during the ex-post period. Both CBECI
geolocational data and aggregate hashrate data show a robust and sustained recovery to
previous highs in just four months. Through some combination of rapid miner relocation
and increases in absolute hashrate already underway at the time of the ban, the broader
mining network supporting Bitcoin proved quite resilient.
This calls the limits of unilateral state action into question when it comes to
affecting geographically distributed DAOs. Bitcoin is far from immune to broader
negative economic market sentiments and further still from serving as a hedge against
inflation under a three-year time horizon. Macroeconomic trends, news regarding
institutional adoption, and/or nation-state policy still has a significant ability to damage
perceptions of Bitcoin’s value (i.e., market price), even as network fundamentals and
measures of its intrinsic value (i.e., network hashrate) remain solid. But impacting
network fundamentals like total hashrate would likely require coordinated action by
nation-states since the ability to locate nodes and mining operations which drive network
success anywhere help make DAOs resilient to geographically isolated policy.
Federalism presents special challenges to such coordinated action within the
United States. Policymaker attitudes towards cryptocurrency mining vary across states

and local governments (Section 2.6). We can expect states with deregulated energy
markets, relatively low energy prices, and crypto-friendly policy dispositions (e.g., Texas)
to continue attracting cryptocurrency mining companies. Resilience in the market value
of Bitcoin makes it economically rational for miners to operate at maximum capacity
most of the time. Absent some intervention, miners will continue to operate their
equipment so long as Bitcoin’s market value continues to facilitate high breakeven energy
prices. In such deregulated environments, economic incentives become the only real
governor of mining activity. Miners’ demonstrated willingness to relocate to
cryptofriendly regions means the current state-by-state, piecemeal approach to
cryptocurrency mining regulation in the United States may do little to affect country-wide
mining behavior over the long term. A White House Office of Science and Technology
Policy report on climate, energy, and crypto-assets recommended establishing “evidence-
based environmental performance standards” (OSTP 2022, 7) for cryptocurrency mining
across the country. Federal policymakers should move quickly to establish such clear
guidelines and consider disparate regional impacts as cryptomining becomes more
entrenched in certain states/localities than others.
2. Well-designed DAOs can embed adaptability measures (e.g., Bitcoin’s difficulty
adjustment) into their core software making them more resilient to adverse events (e.g.,
sudden loss of network hashrate).
Hashrate also plays a role in facilitating Bitcoin’s use as a medium of exchange.
Bitcoin’s ability to adapt to sudden, massive losses in hashrate is governed by the
algorithms in its core software. Difficulty adjustments occur every 2016 blocks, based on
the previous 2015 blocks, and difficulty “cannot be altered above [+300% change] or
below [-75% change] four times the current difficulty level” (Sergeenkov 2022). In
theory, a policy intended to devastate Bitcoin’s ability to add new blocks and complete
new transactions would have to remove a tremendous amount of hashrate early in a
2016block cycle with near immediacy across several regions where Bitcoin operates.
China’s mining ban (while not designed to destroy Bitcoin completely) called for
an “orderly phasing out” (Zhang 2022) of cryptocurrency mining in the country. Even
with roughly half of Bitcoin’s hashrate coming offline, it took almost seven weeks to do
so, and enough hashrate existed outside of China to keep adding blocks to the chain
during the intervention period, albeit slower. Transaction volume decreased somewhat
following the ban, indicating reduced use of Bitcoin’s Layer 1 blockchain for final
settlement, but block time returned to normal less than a month after the cryptocurrency
mining portion of the ban formally took effect. In total, the ban appears to have no
discernible long-term effects on Bitcoin’s functionality as a medium of exchange.
Researchers and policy analysts at the Federal Reserve, Department of the
Treasury, and the Office of the Comptroller of the Currency should consider why people
continue to choose decentralized blockchain protocols as a method of value exchange.
The technology underlying cryptocurrencies like Bitcoin may facilitate efficiencies in
final settlement and cross-border payments (Gensler 2018; Casey et al. 2018; Onyx JP
Morgan 2021). This same technology can be leveraged for fiat currencies in the form of
CBDCs (e.g., China’s eCNY) and/or stablecoins and policymakers must consider the
advantages and disadvantages of each. CBDCs already face opposition in the United
States primarily due to financial privacy concerns. Both CBDCs and stablecoins may also
threaten the stability of the fractional reserve banking system (Yanagawa and

Yamaoka 2019; Baer 2021). Rapid, widespread adoption of either CBDCs or stablecoins
could impact banknote deposit levels, reserve requirements, and lending costs
(President’s Working Group on Financial Markets 2021). But failure to provide a more
efficient settlement system for fiat currencies could lead to further adoption of
decentralized methods of value exchange outside the purview of state control.
3. The use of proxies and other technologies to obfuscate the locations of various
cryptocurrency network-related activities complicates geolocational data analysis and
presents a policy enforcement challenge.
CBECI’s data collection process suffers from some methodological limitations
and this study lacks fidelity on the sources of node activity reporting, but available data
indicates the Bitcoin network became more evenly geographically distributed in terms of
node and mining control (i.e., hashrate) after the ban. If this data is accurate, it indicates
the Bitcoin network is even less susceptible to the policies of individual nation-states
today. But there are several reasons to suspect geolocational data is unreliable, or
incomplete at the very least.
This study illuminates several potential cryptocurrency policy enforceability
problems caused by widespread use of privacy-enhancing technologies (i.e., VPNs and
TOR). CCAF protects miner anonymity at the CBECI application programming interface,
recognizes VPN activity in their data (and adjusts estimates accordingly), and relies on
the network latency associated with VPN use to discourage IP address spoofing. But the
sudden re-emergence of 30+ EH/sec China-based hashrate in September 2021 points to
the limits of these measures in accurately accounting for VPN use. CCAF should provide
more details about these limitations and a sensitivity analysis of the parameters involved
in determining their estimation if CBECI data is to be empirically useful to policymakers.

Policymakers should consider the use of VPNs and TOR to protect the locations of
miners (Section 2.3.2) and node operators (Howell et al. 2023) when crafting rules and
regulations. Any policy designed to limit or restrict mining and/or cryptocurrency
operations would require some degree of non-IP address-based tracking enforcement to
be effective.
Policymakers might also consider how to encourage honest and transparent
mining practices and data sharing. Use of TOR (Section 2.3.7; Howell et al. 2023) and
VPNs (Section 2.3.2) increased during the ex-post period, though this study lacks
evidence to support claims of a causal relationship between the ban and increased privacy
measures. The privacy of network participants was a chief concern for Nakamoto (2008)
and early cypherpunks working on Bitcoin (Champagne 2014). It is possible that adverse
public policy measures only further incentivize trends towards anonymity and discourage
data sharing transparency while putting cryptocurrency proponents on the defensive.
4. Despite the ability to obfuscate their locations, network participants still factor
the anticipated local regulatory environment into their decision-making calculus.
Though the results of this study suggest there is little correlation between China’s
cryptomining ban and long-lasting changes to the Bitcoin network, policy environment
clearly matters to many cryptominers. Evidence suggests some miners based in China
remained there after the ban; either shutting down operations temporarily and restarting,
or using proxy services to obfuscate their locations until they deemed it safe to return to
business as usual (CCAF 2022; Kaloudis 2022; Feng 2022; Brown 2022). But both
quantitative and qualitative evidence shows several major mining operations were
dislocated by the ban and specifically sought a more favorable regulatory environment.
The United States saw an influx of displaced miners from China (Feng 2021; Sigalos

2021; Rutwitch and Feng 2022) and a migration within the country away from states with
unfavorable cryptocurrency policy dispositions (Lonnroth 2022; Saul 2022; Hutton
2022), simultaneously. Despite the ability to obfuscate their locations, local regulations
and policies still factor into Bitcoin miner decision-making (Sun et al. 2022).
Policymakers should consider the merits of more accommodative cryptomining policies,
including deregulated energy markets and low barriers of market entry for cryptomining
businesses (e.g., Texas). Cryptomining companies can provide jobs, stimulate regional
economic growth, and expand the corporate tax base. But these benefits must be weighed
against the potential negative impacts of cryptomining.
Understanding how digital assets and DAOs function and how they differ from
traditional financial instruments and institutions is key to the development of effective
policy. The results of this study point to the challenges even large, influential nationstates
face when unilaterally implementing policies designed to affect digital assets governed by
well-distributed networks. But this study examines policy impacts from the perspective of
the DAO. While the Bitcoin network survived and may have even grown more resilient as
a result of China’s ban, it is entirely possible that the ban served its
purposes in the eyes of the PBOC and Chinese Communist Party. Another study might
consider the ban’s effectiveness from that perspective, including an analysis of the kind
of capital outflows and renminbi circulation China sought to control two years earlier
with its State Administration of Foreign Exchange policy without a ban in place. Finally,
this study is mostly quantitative and limited to statistical analyses of newly developed
metrics for understanding how these new organizations work. The human element of
DAOs (e.g., Bitcoin miners) requires a closer qualitative look (e.g., deliberate,

semistructured interviews) than the one included in this essay to unpack the relationship
between anticipated regulatory environment and decision-making considerations.
Essay 3
‘Green’ Bitcoin? Evaluating Proof-of-Work Mining as a Tool in the Energy Transition

Abstract:
Bitcoin’s high energy use and carbon footprint is a major part of the public
discourse around the world’s most popular cryptocurrency. In recent years, some Bitcoin
miners have made a concerted effort to align their operations with energy and
environmental policy goals. In Texas, several politicians at the local, state, and national
levels of government and Electric Reliability Council of Texas (ERCOT) leaders have
welcomed these miners, touting the benefits of incorporating flexible loads onto the
energy grid. Models and simulations suggest that flexible loads can provide grid stability
and incentivize the buildout of further renewable energy generation. But others caution
new loads may place undue burdens on a stressed energy grid. This study evaluates
several claims made about the potential benefits of proof-of-work cryptocurrency mining
using empirical data from the recent influx of Bitcoin mining on the Texas energy grid.
Results show most large Bitcoin mining data centers are in regions with high levels of
renewable power generation relative to the rest of the state while nearby wholesale energy
prices remain consistent with statewide trends. Additionally, evidence shows
Bitcoin miners are uniquely suited to participate in ERCOT’s “controllable load resource”
program – a demand response program requiring loads to cede a high degree of control to
grid operators. This essay provides policymakers with insights regarding grid expansion,
energy economics, and how to best incorporate flexible data centers into the renewable-
led energy transition, responsibly.
3.1 Introduction
In recent years, Bitcoin proponents have made a concerted effort to recast
proofof-work (PoW) cryptocurrency mining in a more positive and environmentally
friendly light. PoW mining effectively functions as a kind of highly flexible data center
which can be located anywhere. Renewable energy resources (e.g., wind and solar) are
intermittent, meaning their capacity to produce energy is mostly dependent on
environmental factors outside human control. Renewable generators often curtail output
when capable of producing more energy than the grid demands and/or can transmit.
Mining advocates argue these loads are uniquely positioned to address the increasing
curtailment and intermittency issues in electricity markets with high variable renewable
energy (VRE) penetration by acting as a consistent customer and consumer of cheap
energy for renewable power generators. This could improve renewable plant economics
and incentivize VRE growth (Carter and Connell 2021; Saylor et al. 2022). Furthermore,
several studies suggest adaptable data centers are particularly well-suited to participate in
demand response programs which can help provide grid operators with greater flexibility
and improve grid stability (Chen et al. 2014; Wierman et al. 2014; Hale et al. 2016;
Klinger and Szilvas 2020). Demand response programs are used by grid planners and
operators to provide financial incentives to energy producers and/or consumers to reduce,
increase, or shift their production or consumption.
The purpose of this study is to shed light on three questions regarding Bitcoin’s
long-term sustainability:
1. Does Bitcoin mining incentivize renewable growth?
2. How does Bitcoin mining impact energy prices?
3. Does Bitcoin mining provide flexibility to grid operators?
Crypto advocates and energy experts have discussed how Bitcoin mining can incentivize
renewable growth and increase grid stability in articles, podcasts, and blogposts while

presenting little evidence to demonstrate whether this is happening in practice at a
meaningful scale. If in fact the Bitcoin network can lower its carbon footprint and
conduct mining sustainably over the long-term, the field lacks empirically based
assessments of whether its network of miners is currently well-positioned to align with
energy policy goals.
This essay begins with an explanation of the various theoretical arguments and
models for how PoW mining data centers might play a role in the transition to a
renewable-based energy grid. Next, I take a critical look at the academic literature around
Bitcoin’s sustainability. I find most published literature focuses on the energy
consumption associated with PoW cryptocurrencies and their potential negative effects on
the environment (e.g., pollution, e-waste, carbon emissions) while far fewer
cryptocurrency mining studies even consider its potential benefits. Finally, I look at
Bitcoin mining in Texas using geolocational data, wholesale electricity pricing, and
demand response data from the Electric Reliability Council of Texas (ERCOT) to
determine whether miners are well-positioned to incentivize renewable growth, describe
wholesale energy pricing trends before/after mining data centers came online, and
examine miners’ participation in demand response programs.
This work sheds light on the three questions above regarding Bitcoin’s long-term
sustainability and the energy economics associated with using flexible data centers in the
transition to a more renewably based grid. Methodologically, it offers a replicable
template for using publicly available data to determine the local impact of high loads on
electricity pricing beyond synthetic grid simulations (Li et al. 2020; Menati et al. 2022).
From a public policy perspective, the analysis, results, and conclusions of this study could

be considered in determining optimal wholesale electricity market design (i.e., regulated
vs. de-regulated market structures) and PoW mining regulation and legislation.
3.2 Background and Theory
In April 2021, President Biden set an ambitious goal for the United States:
“achieve a 50-52 percent reduction from 2005 levels in economy-wide net greenhouse
gas (GHG) pollution in 2030” (Biden 2021) with the ultimate goal of a net-zero emission
(NZE) economy by 2050. Experts generally agree that both increased electrification
(electricity’s share of total energy consumption) and the decarbonization of that electricity
(the share of electricity sourced from high greenhouse gas emitters) are critical to making
meaningful progress toward NZE goals (Steinberg et al. 2017; Nadel and Ungar 2019;
Griffith 2022). In other words, power grids will need to be able to deliver much more
electricity to end users and utilize more renewable power generation to do it.
This section provides a background on the challenges associated with
incorporating more renewable power generation onto power grids in the United States.
The first two subsections focus on energy economics. Renewable growth is costly and
requires grid infrastructure expansion to avoid curtailment (3.2.1). I outline the theoretical
use case for how PoW mining can improve renewable economics during the energy
transition (3.2.2). Renewable intermittency and increased reliance on electricity also
present grid stability challenges (3.2.3). This section concludes with a brief review of
electrical engineering research on the role interruptible data centers could play in
alleviating this problem by providing grid flexibility (3.2.4).
3.2.1 Renewable Power Generation Economic Challenges
Achieving net-zero emissions (NZE) through electrification by 2050 is a massive
undertaking. In the Electric Power Research Institute’s (EPRI) analysis of what it would
take for the U.S. to meet 50% GHG reduction by 2030 goals, it found electrification of
end-use sectors (transport, buildings, and industry) would need to accelerate rapidly to
reduce emissions (by 23-33% compared to the current reduction of just 2% from 2005
levels) and capacity additions to wind and solar power would need to double or triple
currently projected additions for the 2020s (EPRI 2021, 3-4). Texas leads the United
States on this front, adding 7352 megawatts (MW) of new wind and solar capacity in
2021 – more than the next four highest states combined (American Clean Power
Association 2022).
But high levels of VRE penetration come with economic challenges. The costs of
producing wind and solar have decreased as technologies improve over time (Creutzig et
al. 2017; Victoria et al. 2021). However, the “energy and capacity revenue potential for
wind and solar generation in a wholesale market environment” (Millstein et al. 2021,
1750) declines as it becomes more abundant in a market due to its low marginal cost,
particularly during peak production times. With few exceptions, researchers found
regional transmission organizations (RTOs) and independent service operators (ISOs)
with higher levels of wind and solar penetration levels see the largest reductions in
marginal wind and solar energy value (Millstein et al. 2021). This well-documented
economic trend is called VRE value deflation. If falling costs of renewable production
fail to keep pace with the declining value of marginal renewable energy in high
penetration markets, wind and solar may reach saturation points due to simple
supply/demand economic infeasibility. As renewable energy penetration increases,
integration costs for new projects increase as well, passing costs on to customers and
discouraging generator investment (Imcharoenkul and Chaitusaney 2022).
Wholesale electricity prices vary geographically depending on load patterns,
generation capacities, and transmission limits at each location. Locational marginal
pricing (LMP) reflects this dynamic value of energy across different pricing nodes (ISO
NE 2022). Energy-rich areas with low levels of demand and limited transmission capacity
often experience negative wholesale energy pricing. Regions with high VRE penetration
see a higher frequency of negative LMPs relative to the rest of the United States (Seel et
al. 2021). In theory, negative energy prices should result in the cessation of energy
production – it seems nonsensical for producers to pay consumers to take energy it costs
them to generate. However, generators may continue production due to the physical
constraints or prohibitive costs associated with ramping down and subsequently
restarting production. Various tax credits and subsidies allow renewable producers to
remain profitable despite paying the grid to take their energy when LMPs turns negative.
As such, continued development of new VRE projects and the profitability of existing
VRE plants is largely dependent on non-permanent subsidies and tax credits.
Figure 3.1 Notional Example of Curtailment (author)
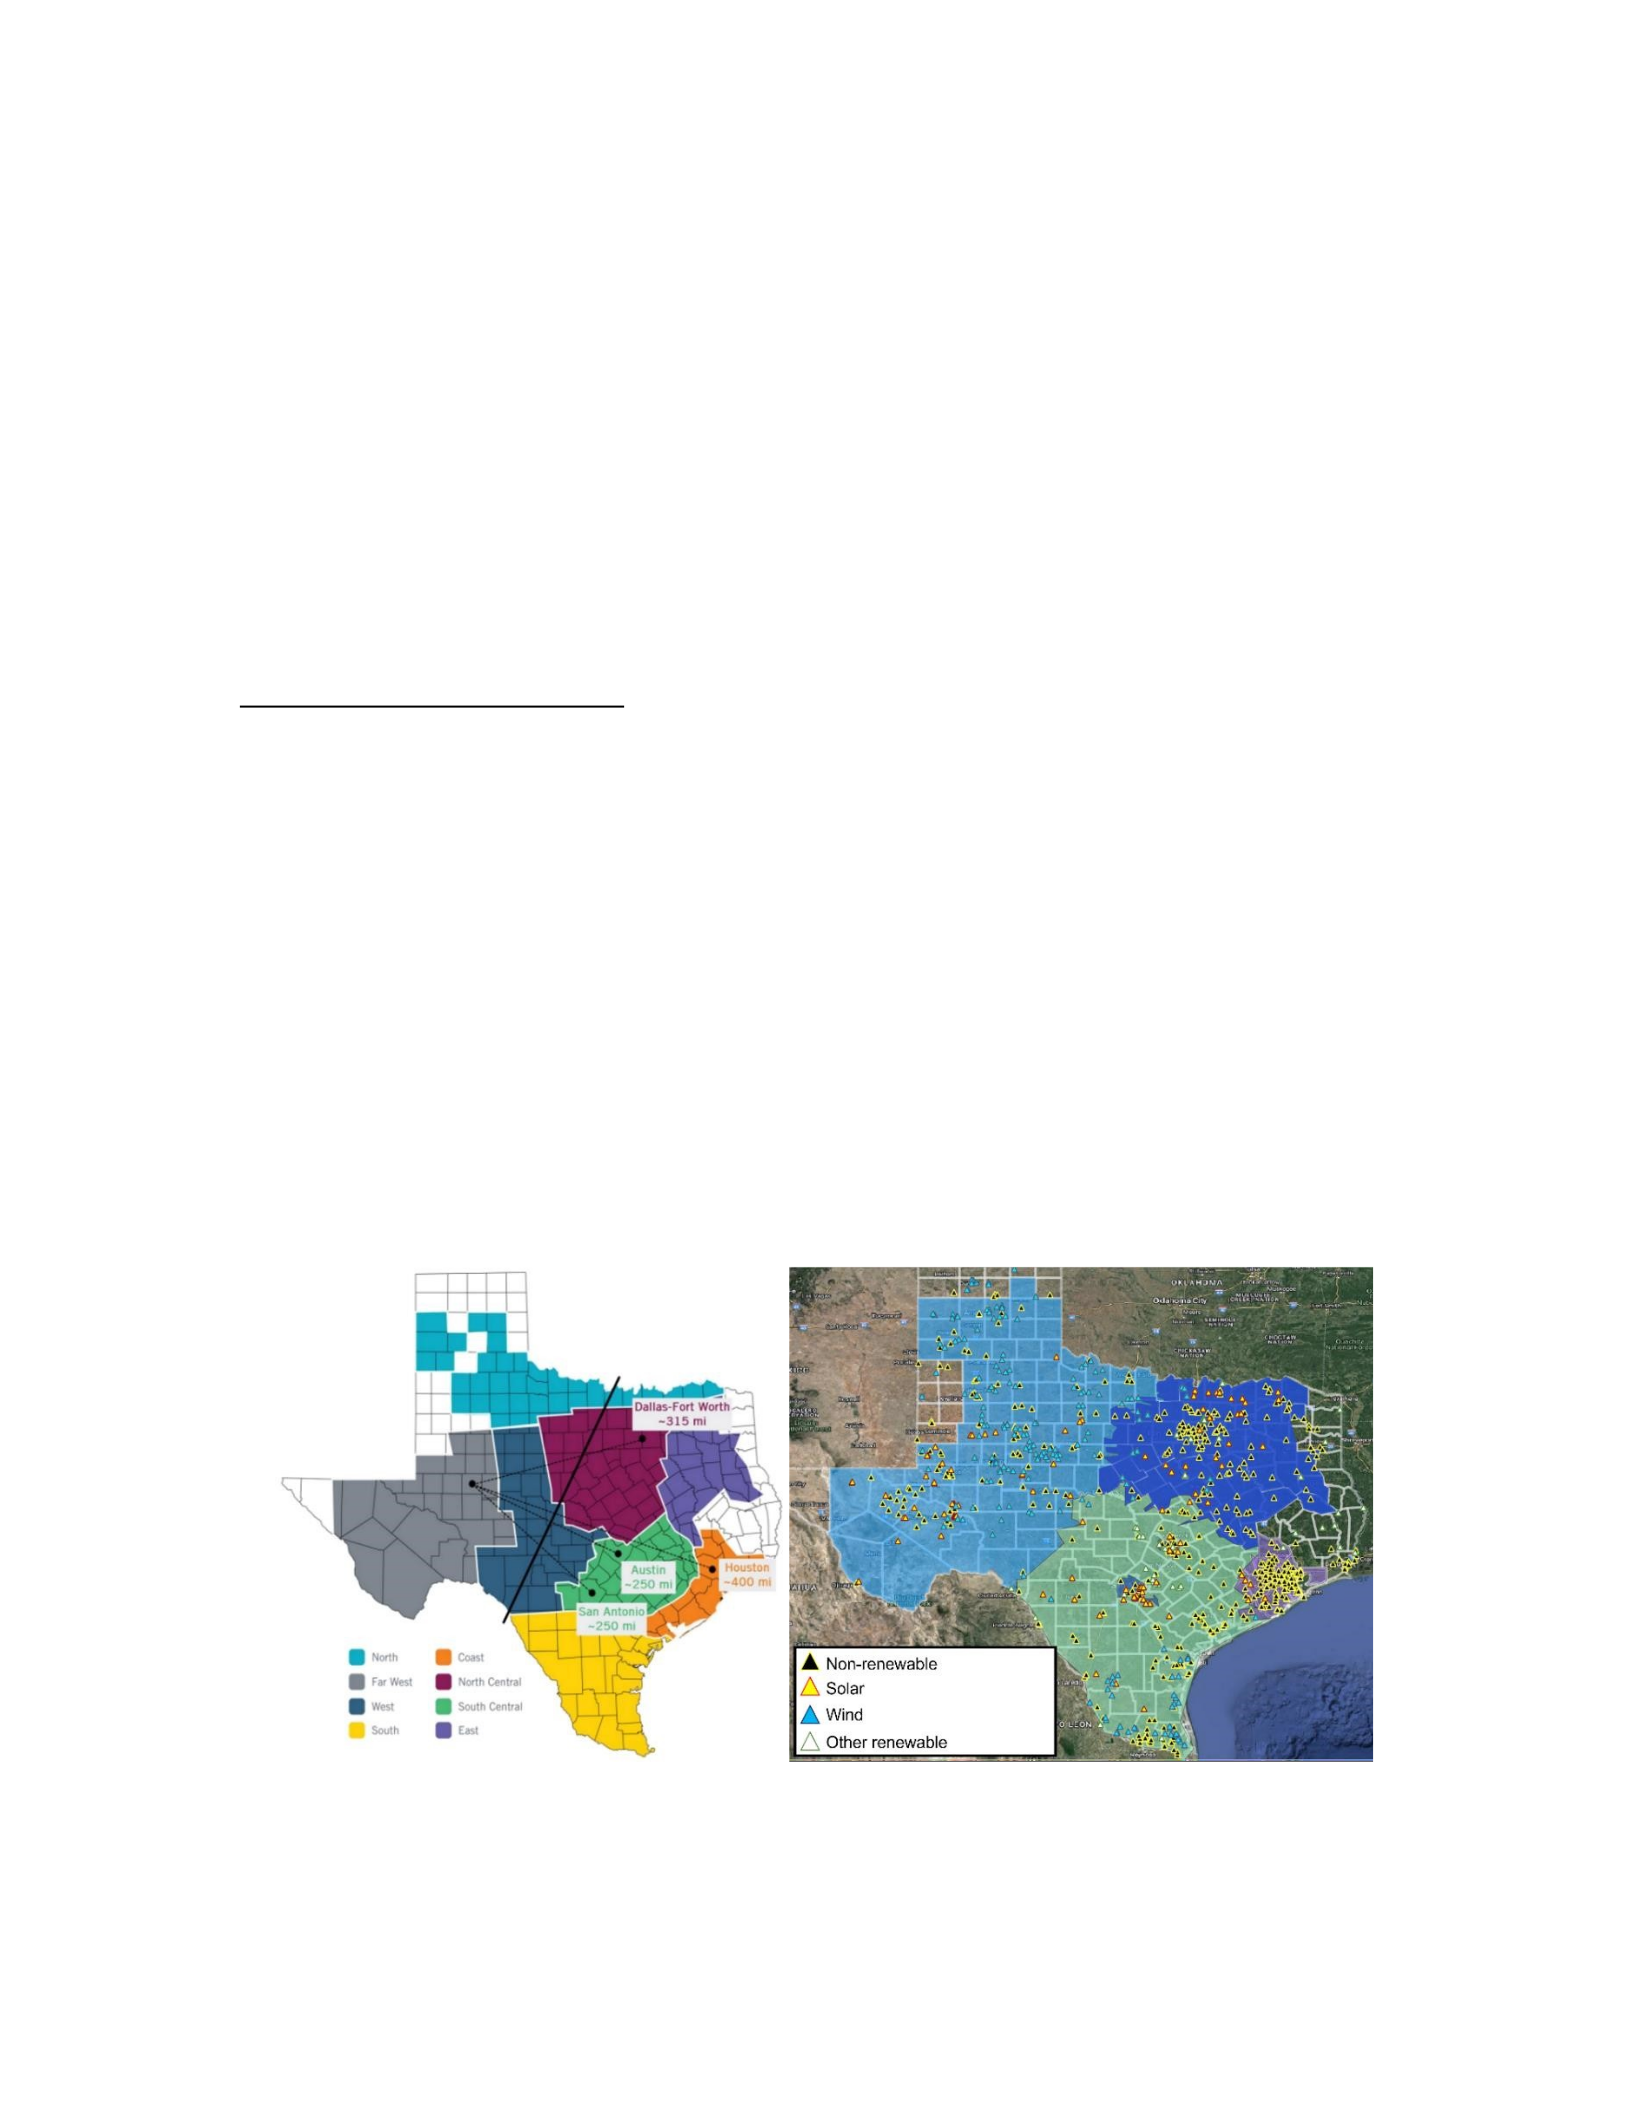
The grid in Texas was originally designed for a small number of centralized power
stations placed in optimal locations. Geographic mismatches between the point of
abundant renewable energy generation and high demand load centers can only be solved
by increasing transmission capacity and/or storing surplus energy in utility-scale batteries
or other storage technologies (e.g., pumped-storage hydropower) to be used later when
the wind is not blowing, or the sun is not shining, and transmission lines are no longer
congested. But building out high-capacity transmission infrastructure is very costly and
can take over a decade to complete, while renewable plants may take just 2-3 years to
construct (NREL 2016). Estimates vary depending on assumptions and various modeling
inputs but building battery infrastructure to support 12-hour electricity storage for an 80%
renewable system could cost around $2.5 trillion (Shaner et al. 2018; Temple 2018). In
the absence of more storage or transmission, this excess energy gets curtailed and local
wholesale energy prices drop (Figure 3.1).
Figure 3.2 (left). Distance Between West Texas VRE and Metro Areas (ERCOT 2022)
Figure 3.3 (right). Wind (blue) and Solar (yellow) Plants in Texas (author)146
West Texas is rich in wind and solar energy generation (Figure 3.3) but far from
the major electrical load demand centers in the east (Figure 3.2). Dallas, Austin, Houston,
and San Antonio all lie at least 250 miles away from where the vast majority of Texas’
renewable energy is generated (ERCOT 2022, 18). ISOs must set interconnection limits,
or a “maximum amount of power that a facility can inject into the grid,” (Kahrl et al.
2021, 14) for all generators; and VRE projects are often capable of providing more power
than the grid can accept. Additionally, transmission lines are limited by how much power
they can carry.
In Texas, insufficient transmission infrastructure constrains VRE growth and leads
to congestion and curtailment. Congestion occurs when transmission lines are overloaded
(i.e., trying to deliver more power than lines are designed to carry). When congestion
occurs, ERCOT must rely on higher-cost generators closer to load demand centers to
reduce power flows while lower-cost generation options are available. ERCOT defines
transmission congestion as “the differences in costs of delivering electricity to different
locations” and calculates these costs based on “the difference between the payments by
loads at their locations and the payments to generators at their locations” (Potomac
Economics 2021, 19). Real-time congestion costs reached $2.1 billion by the end of July
2022, matching total congestion costs for the entire year in 2021 (Potomac Economics
2022). Because of Texas’ high (and growing) level of solar and wind
energy penetration, ERCOT’s 2023 projection of 6,700 GWh of wind and solar
curtailment due to West Texas export limits is projected to increase tenfold to about
67,000 GWh of curtailment by 2030. Solar power curtailment was once practically
nonexistent, but Texas has set a new record for curtailment of both wind and solar
production each year since 2017.
Finally, the United States has a transmission/distribution problem paired with an
administrative bottleneck at the point of interconnection. A massive influx of planned
renewable power plants have led to long interconnection queues or wait times between
when a generator requests and is granted interconnection to the grid for commercial
operation. These wait times “increased from ~2.1 years for projects built in 2000-2010 to
~3.7 years for those built in 2011-2021” (Rand et al. 2022, 21). PJM Interconnection (the
nation’s largest grid operator) faces an interconnection backlog so large they called for a
two-year pause on reviewing new projects (Bruggers 2022). This extends the time
horizon for VRE projects to see returns on investment.
3.2.2 How Miners Hope to Improve Renewable Economics
Proof-of-work (PoW) mining involves the application of computing power to
solve the SHA-256 algorithm (i.e., cryptographic puzzles) in hopes of winning the
subsidy associated with completing a block of Bitcoin transactions and adding it to the
blockchain. Application-specific integrated circuits (ASICs) are the individual machines
used to work through secure hash algorithms and “mine” Bitcoin. Miners organize into
pools, where they are compensated according to how much algorithm they “hash” or
contribute to solving the puzzle. Mining profitability is mostly dependent on the price of
Bitcoin (the reward for solving a block), the price of energy (the cost of powering
computing equipment), the efficiency/performance level of the mining equipment, and
network hashrate (how many others are competing). Miners can do little to affect Bitcoin
price, ASIC efficiency, and hashrate, so they are highly incentivized to seek out the
cheapest energy possible.
Bitcoin miners and some energy experts argue mining operations can serve as a
near-constant buyer of cheap energy – helping renewable generators avoid curtailment
and setting an energy “price floor” when LMPs go negative. Mining data centers are
highly scalable, allowing miners to provide precisely as much demand capacity needed to
soak up excess power generation.153 This level of scalability plays a role in Bitcoin
mining’s “unconstrained location agnosticism” (Carter and Connel 2021). Since miners
only need to be able to broadcast and participate in the blockchain network via cellular
data or satellite internet, they can co-locate with any power generation source. Mining
data centers are commonly housed in the equivalent of a shipping container that has been
optimized for computational processing. In fact, some companies build highly modular
containers outfitted with ASICs and a self-contained airflow system.154 These containers
can be transported directly to and co-located with sources of power generation,
eliminating the need for costly transmission lines and their associated electricity losses.
3.2.3 Grid Stability Challenges
By several estimates, meeting President Biden’s goals for decarbonization could
require electricity’s share of end-use energy consumption in the United States to increase
from 20% currently to 60% by 2050 (Princeton 2021; U.S. Department of Energy 2022;
Walton 2022). This effectively triples the United States’ reliance on the power grid. The
grid is a complex mix of varying levels of demand at different geographic points,
connected to various sources of power generation by transmission lines with varying
capacities. ISOs manage this complexity constantly using projections, modeling, and
adjusting to real-time data. The grid must maintain a nominal frequency of 60 Hz to
remain operational and avoid blackouts. Sudden losses of generation or dramatic,
unanticipated changes in load can cause the grid frequency to deviate from this nominal
value and trigger cascading failures (i.e., “rolling blackouts”) if left uncorrected over
certain time durations (Folgueras et al. 2017). Grid operators often get commitments from
commercial loads (i.e., large energy consumers) to reduce their power demand when
electrical supply frequency drops below acceptable limits in exchange for some form of
financial compensation in various demand response programs.
The U.S. Energy Information Administration (EIA) projects the share of
renewable electricity generation in the United States will increase from 21% in 2021 to
44% by 2050, requiring more demand-side flexibility as VRE penetration increases (Pina
et al. 2012; Alizadeh et al. 2016; Olsen et al. 2020). In California where solar
photovoltaic (PV) penetration is high, grid managers keep a close eye on net load, or “the
difference between forecasted load and expected electricity production from variable
generation resources” (CAISO 2021, 1). Figure 3.4 depicts CAISO’s net load at each
hour of January 11th for years 2012 through 2020. The resulting net load curves show how
much controllable power generation CAISO must leverage to fill the gap between
variable generation resources and load demand across the system. These net load curves
grow increasingly steep each year as solar PV penetration increases. The “start” points on
the graph show when CAISO must begin dispatching flexible resources to meet demand
(i.e., net load curves ramp up). The “stop” points show when CAISO must reduce that
flexible generation. The lower the net load is in the early afternoon, the higher the risk of
overgeneration, so oversupply must be mitigated. As the curve ramps up in the late
afternoon, this signals a mismatch as electricity demand rapidly outpaces VRE
generation. As this happens, ISOs like CAISO require more flexible, controllable
resources on the demand side which can ramp up or down inexpensively to adapt to
changing grid conditions. (CAISO 2021).
157 Researchers projected the steepening curves would resemble a duck and coined the term “duck curve”
(Roberts 2016; 2018). Their projections were correct. In fact, net load fell even faster than predicted
(Breakthrough Institute 2021).
3.2.4 How Miners Hope to Stabilize the Grid
In theory, pairing renewable power generation with Bitcoin miners offers
tremendous economic benefits and potentially ensures Bitcoin is mined with clean power,
only. Miners can provide a source of revenue for projects stuck in interconnection queues
awaiting connection to the grid. But this implies a “behind the meter” Bitcoin mining
configuration, where miners draw power directly from renewable generators and not the
grid itself. In practice, most Bitcoin mining in the United States today is gridconnected.
Electricity from the grid can come from renewable or high carbon-emitting power
Figure 3.4 “Duck Curve”: CAISO’s Net L oad for Jan. 11, Y ears 2012-2020 (CAISO )157
sources. Like any new load, grid-connected miners increase energy demands and
contribute to higher prices.
But mining proponents argue their data centers are uniquely positioned to provide
the kind of flexible base loads grid managers need to ensure stability. During mining,
each successive hash is statistically independent of the last, so the mining process is
perfectly interruptible without negating any work previously done or affecting any future
work yet to be complete. Frequency response is just one of many ancillary services (AS)
or demand response (DR) programs ISOs engage in with commercial loads to keep the
grid operational. Demand response constitutes any agreement between grid managers and
consumers to shift or reduce electricity demand in power markets to provide flexibility
and help balance the grid (IEA 2022).
Electrical engineering research supports arguments for the usefulness of
interruptible data centers in providing flexible base loads in various demand response
programs (Wierman et al. 2014; Patki et al. 2016; Klinger and Szilvas 2020).
Interruptible loads were found to be highly competitive, cost-effective alternatives to both
storage as a compensation for renewable intermittency as grid capacity expands, and as a
planning reserve requirement reducing the need for natural gas during periods of peak
demand (Hale et al. 2016). A data center’s suitability to participate in demand response
programs correlates to the degree of flexibility and interruptibility it can tolerate,
suggesting fully interruptible Bitcoin miners could be more effective than typical data
centers in providing demand response. Researchers found potential profits and the
amount of control ceded to operators were positively correlated in the New York
Independent System Operator (NYISO) ancillary services market, while response time
requirements and potential profits were negatively correlated (Aikema et al. 2012). One
study found that more adaptable data centers capable of dynamic control can “decrease
their energy costs around 50%, while providing the ISOs and the society in general with
cost effective demand side reserves that render massive renewable generation adoption
affordable” (Chen et al. 2014, 105).
Using data centers as interruptible loads for grid stabilization is a novel idea
already underway in Singapore (Xia et al. 2015) and ERCOT has expressed the need for
similar controllable load resources (CLR) in Texas. Non-controllable load resources are
“blocky loads” that are triggered automatically by an underfrequency relay or manually
after an order from ERCOT to help with frequency response. ERCOT requires CLRs to
be capable of both base point following and primary frequency response (ERCOT 2022).
With primary frequency response, CLRs can drop load immediately and unilaterally to
bring frequency back into tolerance in the event of a generator failure and a massive drop
in frequency. But under base point following, grid operators tell resources how much load
to drop over a certain period. This type of load attenuation is more difficult to achieve
than basic emergency response.
3.2.5 Summary
It is true that several synergies exist between Bitcoin’s incentive structure and
policy goals in the energy transition. Miners seek out cheap energy and the levelized
costs of wind and solar energy have decreased relative to carbon-emitting sources over
time (Lazard 2021). Early investment incentives in wind and solar projects decrease as
VRE penetration increases. Bitcoin mining can certainly provide another source of
revenue when renewable power would otherwise be curtailed or sold at low/negative
prices. As battery and transmission infrastructure buildout lags VRE generation,
controllable base loads provide grid operators with much needed flexibility – particularly
as the grid becomes increasingly dependent on intermittent sources of energy.
But if Bitcoin mining is to play a role in the energy transition, a sober assessment
of the gap between where mining is today and where this ideal, sustainable Bitcoin
concept would like to be is needed. Additionally, the feasibility of any partnership
between VRE power generation and Bitcoin miners is dependent on sensitivity analyses
of the factors which play a role in mining profitability: Bitcoin price, energy price, miner
efficiency, and network hashrate. More efficient ASICs increase the breakeven price of
energy (under which it is profitable to mine), but since this equipment is more expensive
than older, less efficient equipment it also requires more uptime to ensure profitability.
Simply stating Bitcoin miners will only soak up cheap, clean, and stranded energy is not
an accurate statement without attaching several caveats. Additionally, Bitcoin’s history of
rapid downside price volatility can quickly shrink mining profit margins or make mining
unprofitable. This changes the math for VRE investors factoring mining revenues into
their planning assumptions. Lastly, flexible base load still increases aggregate energy
demand for any grid. This can add stress on the grid and increase energy prices, so the
minute details of how such loads work in demand response programs matter.
The literature review that follows aims to provide an assessment of where Bitcoin
mining currently sits along the path to sustainability. Determining Bitcoin’s energy
consumption and its carbon footprint should factor into weighing its costs against
potential future benefits. Studies specific to the feasibility of the Bitcoin-VRE partnership

include sensitivity analyses of factors critical to Bitcoin profitability outlined above and
shed some light on the pros and cons operators must consider when welcoming Bitcoin
miners onto their grid.
3.3 Bitcoin’s Energy Use and Impacts – A Critical Literature Review
PoW cryptocurrency mining has attracted a great deal of negative attention and
critical analysis in academic circles for its high energy use. Largely in response to this
criticism, new cryptocurrencies have emerged intending to be less energy-intensive by
design, and others have made changes to make their existing protocols more eco-friendly.
Ethereum, the world’s second-most popular cryptocurrency, switched from a proof-
ofwork (PoW) protocol to a proof-of stake (PoS) protocol with the expressed purpose of
making its network “less energy-intensive, and better for implementing new scaling
solutions” (Ethereum 2022) than its previous PoW system in September 2022. This
“Ethereum merge” left Bitcoin as the last major cryptocurrency to use the more
energyintensive PoW protocol for validating/processing transactions and creating new
coins
(i.e., mining). Bitcoin remains the world’s most popular cryptocurrency by market
capitalization and the amount of computing power dedicated to mining remains near
alltime highs historically despite major downside price volatility in 2022. Bitcoin’s
proponents insist that its energy-intensive protocol is critical to the security of its
network. Energy backs its value as an asset, and its use is a “feature, not a flaw”
(Bradford, Bloomberg 2022) in its design.
Still, Bitcoin mining’s long-term future in the United States depends in large part
on perceptions of its ability to minimize its carbon emissions; and the academic
community plays a significant role in shaping those perceptions. Several studies estimate
Bitcoin’s overall energy use (3.3.1) and its impacts on climate change (3.3.2). The White
House Office of Science and Technology Policy (OSTP) report on “Climate and Energy
Implications of Crypto-Assets in the United States” (2022) cites several of the studies
included in this literature review in its recommendations to policymakers. Evaluating the
quality of these studies (3.3.3) is of critical importance to formulating good policy. The
impacts Bitcoin mining may have on nearby communities are also relevant policy
considerations (3.3.4). Finally, I summarize the findings of other studies focused on the
economics of renewable-based Bitcoin mining (3.3.5) and its potential impacts on grid
stability (3.3.6).
3.3.1 Assessing and Projecting Bitcoin’s Overall Energy Use
Methods for estimating and/or projecting Bitcoin’s overall energy consumption
have evolved considerably over time. Early estimates suffered from a lack of precision.
Wide ranges were based on best available data, broad assumptions, and more
simulation/extrapolation than concrete empirical evidence. For example, O’Dwyer and
Malone (2014) published one of the earliest estimates of Bitcoin’s overall energy use
between 2009-2014 using historical data about Bitcoin’s mining difficulty and the
hashing efficiency of various mining hardware at the time. The range of energy
efficiencies for various hashing technologies yielded a wide estimate of possible overall
network power usage (0.1-10.0 GW per year).
McCook (2014) was the first to use aggregate data about large mining pools to
estimate how much hashrate specific models of application-specific integrated circuits
(ASICs) were responsible for across the network and included this mix in an estimation
of overall energy consumption. His sensitivity analysis included different hashing
efficiencies and electricity prices and came up with a range of estimates much lower than
O’Dwyer and Malone’s but comparable to Vranken’s (2017) work years later. Vranken
considered capital expenditures and new research (Magaki et al. 2016) about the use of
several ASICs in specialized data centers in his estimations. Vranken found the
upper bound of O’Dwyer and Malone’s (2014) estimate to be “completely unrealistic”
(Vranken 2017, 5) placing his upper bound 95% lower than O’Dwyer and Malone’s
(Table 3.1).
More assessments of Bitcoin’s power consumption based on network hashrate,
mining hardware efficiency, and estimated share of network hashrate per hardware model
were published in 2018 (Bevand 2018; Krause and Tolaymat 2018; deVries 2018) but
deVries added a new, economic-based method for projecting its expected electricity
consumption in the future. Based on Hayes’ (2017) cost production model for valuing
Bitcoin, deVries assumed miners would hash until marginal costs equaled marginal
revenue. Since “market forces drive the industry toward an equilibrium whereby firms
will earn zero economic profit” (deVries 2018, 803), deVries argued the electricity and
production costs at equilibrium could be used to determine where Bitcoin’s electricity
costs were headed based on lifetime electricity use assumptions and production costs
associated with various ASICs.
A similar methodology is used in Digiconomist’s Bitcoin Energy Consumption
Index. Digiconomist is a self-described platform “dedicated to exposing the unintended
consequences of digital trends, typically from an economic perspective” (Digiconomist
2022). Its index seeks to measure Bitcoin’s yearly energy consumption in TWh/year
dating back to July 2017. Its process begins by calculating miner revenues, estimating
what percent of revenues are spent on electricity “in equilibrium” and then converting
those costs to electricity consumption based on another per kWh estimate of their
respective electricity costs.
Cambridge University’s Bitcoin Electricity Consumption Index (CBECI) is now
widely accepted by academics and Bitcoin enthusiasts alike as one of the most accurate
estimators of the Bitcoin network’s power demand (Carter 2021). CBECI includes several
parameters in its model and uses actual empirical data from Bitcoin mining pools.
Cambridge is quite transparent about the limitations of its methodology, assumptions
made, and what factors into its sensitivity analysis. Table 3.1 compares yearly estimates
of Bitcoin’s electricity consumption to CBECI estimates and shows the number of
citations for each study on Google Scholar. CBECI estimates are much lower than that of
Digiconomist’s index, deVries’ 2018 estimates, and O’Dwyer and Malone’s 2014
estimates. Studies concluding with high and low estimates of Bitcoin’s electricity
consumption (relative to CBECI) are both widely cited.
Table 3.1 Estimates of the Yearly Electricity Consumption of the Bitcoin Network Over Time (TWh)
Author/Source
O'Dwyer and Malone
McCook
Krause and Tolaymat
Bevand
Vranken
Digiconomist
Krause and Tolaymat
Bevand
Stoll et al. deVries
Digiconomist
Digiconomist
Digiconomist
Jones et al
Digiconomist
Year Citations (Google) Lower bound Estimate Upper bound
87.6
1.708
10.93 4.38
27.47
78.139
CBECI
4.79 4.79
5.46
14.44
14.44
14.44
14.44
45.44
45.44
45.44
45.44
57.09
68.52
68.52
104.89
2014
2014
2016
2017
2017
2017
2017
2018
2018
2018
2018
2019
2020
2020
2021
37
26
19
26
268
511
19
19
19
8
19
0.876 0.911
5.61
0.876 5.03
14.19
22.338
43.67 39.87
46.97
28.85
26.28 1
2.479
7.15-8.27
13.66
8.304
18.4 48.2
67.189
71.12
69.79
59.32
75.4
134.76
3.3.2 Assessing and Projecting Bitcoin’s Impact on Climate Change A group of
climate researchers at the University of Hawaii set off a flurry of debate with their study
titled “Bitcoin Emissions Alone Could Push Global Warming Above 2°C” (Mora et al.
2018). First, Mora et al. (2018) assumed entire blocks were mined by a single model of
ASIC or mining hardware and randomly assigned each Bitcoin block mined in 2017 to
one of 62 types of Bitcoin computing hardware and its respective energy efficiency. Total
carbon emissions were aggregated using the energy mix of the host country (carbon
emissions required per unit electricity) for each company or mining pool winning a block
multiplied by the estimated electricity required to mine that block for all blocks in 2017.
From there, the authors projected future Bitcoin transactions based on the adoption rates
of 40 different technologies and calculated aggregate carbon emissions on a per-
transaction basis (based on their estimated CO2 emissions/Bitcoin transaction in 2017).
Their projections showed that assuming various rates of technological adoption, Bitcoin
alone could account for cumulative emissions
“likely to warm the planet by 2°C within only 16 years” (Mora et al. 2018, 1). Krause
and Tolaymat (2018) and Stoll et al. (2018) provided estimates of both the
Bitcoin network’s overall electricity consumption and its corresponding GHG emissions.
Much like CBECI methodology, Stoll et al. (2018) used known IP address locational data
to estimate the geographic distribution and subsequent energy mix of the network’s
hashrate. Krause and Tolymat (2018) provided a range of potential emissions based on
various energy mixes not necessarily based on known geographic distribution of network
hashrate. Jiang et al. (2021) found carbon emissions from China-based Bitcoin mining
alone exceeded the footprint of several small countries and encouraged policy
interventions to confine PoW mining operations to low carbon-emitting regions.
CBECI’s Digital Assets Project Lead Alexander Neumueller (2022) combined
Cambridge’s empirically based estimation of Bitcoin’s overall electricity consumption
with its geographical data regarding miner IP addresses and several studies estimating
regionally specific electricity mix profiles to estimate yearly Bitcoin GHG emissions
since 2011. They found 2022 emissions were set to decline year over year for the first
time in the digital asset’s history. Their “best-guess” figure of Bitcoin’s 2022 carbon
footprint represented roughly 0.10% of global GHG emissions, comparable to that of
countries like Nepal and the Central African Republic (Neumueller, CCAF 2022). Most
notably, Neumueller found that recent increases in mining hardware efficiency led to a
drop in the network’s annual electricity consumption while network hashrate continued to
increase, where prior to January 2021, hashrate and electricity consumption generally
moved in concert with one another.
Table 3.2 Estimates of Yearly GHG Emissions of the Bitcoin Network (MtCO2e)
Author/Source Year Citations (Google) Estimate
Mora et al. 2017 250 69
Neumueller*** 2017 0 7.65
Masanet et al. 2017 46 16
Calvo-Pardo et al. 2017 6 2.8
Foteinis 2018 49 43.9
Krause and Tolaymat** 2016-'18 218 3-13
Calvo-Pardo et al. 2018 6 16
Stoll et al. 2018 268 21.5-53.6
Jones et al. 2018 8 16.632
McCook 2018 37 0.6
Kohler and Pizzol 2019 58 17
Digiconomist 2018 19 33.5
Neumueller 2018 0 23.92
Houy 2019 29 15.5
Calvo-Pardo et al. 2019 6 15
Jones et al. 2019 8 24.567
Neumueller 2019 0 28.13
Jones et al. 2020 8 37.132
Neumueller 2020 0 34.37
Neumueller 2021 0 56.29
Jiang et al.* 2021 43 25
deVries et al. 2021 42 65
Jones et al. 2021 8 37.256
Jiang et al. 2022 43 52
Digiconomist 2022 19 64.86
Neumueller 2022 0 48.35
Jiang et al. 2023 43 106
Jiang et al. 2024 43 130
*Jiang et al. (2021) estimated Bitcoin GHG emissions for just China in the year
2021, and projected subsequent years through year 2024
**Krause and Tolymat estimate total emissions from Jan '16-Jun'18
***Neumueller's study was recently posted (at the time of this writing) as a part of
CCAF's broader efforts to track Bitcoin's usage and emissions with CBECI
Table 3.2 lists the wide range of estimates resulting from these studies. OSTP
(2022) cites and includes several of these estimates in their report on the climate
implications of crypto assets. If reducing or eliminating Bitcoin-related emissions is a
policy goal, this wide range of estimates makes framing the scope of the problem rather
difficult. One solution to this problem is to evaluate the merits of each study’s
methodological approach and the validity of their baseline assumptions (Section 3.3.3).
Policy analysts should consider establishing a standard for emissions estimation. The
OSTP (2022) report outlines the need for “evidence-based environmental performance
standards” (7) for mining issued by the Environmental Protection Agency and
Department of Energy, but establishing valid methods of measurement and estimation
should be the first steps in setting such standards. Calvo-Pardo et al. (2022) propose
comparing the merits of top-down and bottom-up approaches to estimation to establish a
standard for Bitcoin-emissions literature. Top-down approaches begin with network
aggregate measures of Bitcoin’s usage (e.g., total network hashrate) and then assign
weights for emissions input estimation (e.g., mining efficiencies, power usage
effectiveness, mining facility types) according to market share estimates. Bottom-up
approaches begin with determining the hashrate contributions of miners in each specific
location and then aggregating.
3.3.3 A Critical Look at Studies of Bitcoin’s Energy Consumption and Climate
Impact
Cambridge launched CBECI with data-driven estimates in mind – partnering with
Bitcoin miners in lieu of making assumptions and overreliance on simulation and
theoretical modeling. Neumueller (2022) lamented the abundance of “cherry-picked data
points” (1) and the dearth of objective, nuanced research regarding Bitcoin’s
environmental impact. He found two sides too obsessed with “vying for interpretive
authority to sway public opinion in their favour and persuade policymakers” to appreciate
and communicate the complexities involved with measuring Bitcoin’s environmental
footprint.
Neumueller arguably understates the lack of objectivity and intellectual
transparency in Bitcoin research. Hass McCook (2014) is a self-described “Bitcoin
evangelist” who vastly underestimated Bitcoin’s energy consumption. Methodologically,
O’Dwyer and Malone (2014) were not measuring “the energy consumption of Bitcoin
mining” so much as they were reporting how dependent any estimate was on assumptions
and/or data about the energy efficiencies of mining equipment. Presenting their findings
in Ireland, they claimed their study “shows that the power currently used for Bitcoin
mining is comparable to Ireland’s electricity consumption” (1) although their results
yielded a massive range of possible network electricity consumption (0.1-10GW).
Digiconomist was founded by Alex deVries. Digiconomist claims to provide “further
substantiation” of the methodology used in its Bitcoin Energy Consumption Index in
“peer-reviewed academic literature” hyperlinked to other articles written by DeVries in
which he cites Digiconomist data. DeVries’ studies (2018; 2022) are peer-reviewed and
published in online journals but cite data from an index he created which lacks detailed
explanation about its inputs, assumptions, and estimation methodology. As such, both
Digiconomist’s index and deVries consistently overestimate Bitcoin’s carbon footprint
and energy consumption relative to CBECI and other studies.
The alarming findings found by Mora et al. (2018) elicited several scathing
critiques. Houy (2019) took issue with the “inclusion of unprofitable mining rigs” (1) in
the very first step of the Mora et al. (2018) estimation methodology and found the
exclusion of this basic rational assumption of only mining when profitable led to an
overestimation by a factor of 4.5. Dittmar and Praktinknjo (2019) criticized the Mora et
al. (2018) “demand scenario” and the ignorance of “fundamental constraints imposed by
the transaction-processing capacity of the Bitcoin network” (1). Masanet et al. (2019)
replicated the Mora et al. study and found they made several mistakes in addition to using
a fundamentally flawed methodological design from the outset. Masanet et al. argued the
study’s demand scenarios lacked plausibility, credibility, failed to meet the standard of
“analytical rigour and transparency,” (1) and warned their results “should not be taken
seriously by the public, researchers or policymakers” (2).
Broad, unexplained assumptions and a lack of replicability in research on Bitcoin
and the environment are common. In “Bitcoin’s Growing e-Waste Problem,” DeVries and
Stoll (2021) offer no explanation for assuming a short lifecycle for ASIC mining
equipment despite evidence that old hardware models account for a significant portion of
network hashrate (Saylor et al. 2022). Jones et al. (2022) used “methods described in the
existing literature in this space” (6) citing Goodkind et al. (2020) and Krause and
Tolaymat (2018) in their estimates of the network’s overall electricity usage but offered
no elaboration regarding how they came up with the “average efficiency of BTC mining
rigs” (Jones et al. 2022, 6) used in their equation. Their supplementary data on emissions
factors, mining locations, and energy mix came directly from deVries (2022) with no
further elaboration.
This critique of existing literature estimating Bitcoin’s overall energy use and
emissions impact yields three takeaways for policymakers. First, more cooperation
between researchers and miners is needed to generate the most accurate possible
estimates. CBECI uses as application program interface (API) which allows mining pools
to report data anonymously (CBECI 2022). Incorporating empirical data into estimates is
not a panacea to estimation problems – CBECI’s locational data is susceptible to
IPaddress spoofing measures (e.g., virtual private networks) – but it helps limit the
number of assumptions and parameter estimates in the model. Second, academics should
be more explicit about the limits of their estimation methodologies and more transparent
about the precision of their results. Almost all the studies and indexes reviewed here fail
to include robust sensitivity analyses. Finally, knowledge of how the Bitcoin network
actually works in practice can help us identify which studies include nonsensical
assumptions and therefore yield estimates that should not be taken seriously. For
example, understanding the circumstances under which it is economically profitable for a

Bitcoin miner to operate informs which mining equipment should be feasibly included in
both top-down and bottom-up estimations.
3.3.4 Assessing Bitcoin Mining Impacts at the Local Level
One objective of this study is to determine wholesale energy pricing impacts as a
function of distance from major Bitcoin mining locations. While several studies have
estimated aggregate costs of cryptocurrency mining, less research has focused on its
localized impacts. Greenberg and Bugden (2019) conducted a case study of a
cryptocurrency “boomtown” dissecting qualitative data (e.g., newspapers, public
comments, public meeting records) to find common threads in the local debate around the
costs and benefits of hosting large-scale miners. They found citizens were concerned
about much more than potential increases in their electricity bills, suggesting that studies
like this one which focus solely on economic impacts may ignore critical elements of a
more comprehensive benefit-cost analysis. Taking a quantitative approach, Roeck and
Drennen (2022) conducted a life cycle inventory and analysis of a single natural gas
power plant dedicated to Bitcoin mining. Their focus on a single plant enabled them to
develop a clear and replicable research design, yielding precise results and conclusions
based on data-driven analysis. They found a fossil fuel generator solely dedicated to
Bitcoin mining was very profitable and a significant contributor to GHG emissions in a
state trying to meet difficult emissions reductions goals.
One criticism of overly restrictive mining regulation is that it can shut out
muchneeded jobs in struggling communities. Benetton et al. (2021) incorporated
employment among several other considerations into a broader benefit-cost analysis of
cryptomining penetration in upstate New York. They found that cryptominers caused high
electricity bills for residential households and small businesses, crowded out the local

economy, and created fewer new jobs relative to other similar industries. Points about
both relatively limited job creation and higher electricity bills are substantiated by other
research on the local impacts of PoW mining (Congressional Research Service 2019) and
basic energy economic theory – all else equal, a sudden increase in demand without new
supply should cause higher prices, particularly in deregulated retail electricity markets.
But their
“crowding out” conclusions were based on results that local fixed asset investments and
labor market wage levels declined due to cryptomining entrants by just 0.36% and 0.68%,
respectively (Benneton et al. 2021).
Benneton et al. (2021) is one of the most econometrically rigorous works on the
topic but still suffered from a flawed instrumental variable methodology and a lack of
understanding about the economics of PoW mining. Their stage 1 estimation tried to
capture “the elasticity of location-based marginal price to the price of Bitcoin" (15) with
the idea that large spikes in Bitcoin price cause an exogenous shock to electricity demand
due to cryptomining. They found each “10% increase in the price of Bitcoin is associated
to a 1.4% increase in the location-based marginal price” (16) suggesting increased mining
as the causal mechanism between the two. Assuming they behave as rational actors,
miners will run at full potential so long as they can operate below a certain breakeven
point based on Bitcoin price, network hashrate and price of electricity. Subsequent
increases in Bitcoin price (all else equal) will not cause such miners to suddenly turn on
more ASICs.180 Additionally, changes in wholesale locational marginal pricing do not
necessarily cause a corresponding change in retail electricity bills. Extensive literature
suggests that wholesale prices “pass-through” to retail prices at rates below 100% across
several energy markets (Mirza and Bergland 2012; Mulder and Willems 2019; Brown et
al. 2020).
3.3.5 Studies of Paired Bitcoin Mining with Renewable Energy Generation
This essay explores whether Bitcoin mining might incentivize renewable growth.
Academic interest in renewable-based cryptocurrency mining began internationally in
2019. An exploratory qualitative case study showed hydro, solar, wind, and geothermal
sources powered mining operations for three European-based companies (Govender
2019). Semi-structured interviews revealed these miners were certainly motivated to
protect the environment, but cheap renewable energy prices enabled profit maximization
and served as the primary driver of eco-innovative business models. DeVries (2019)
largely dismissed the possibility of sustainable Bitcoin mining using renewable energy
over the long term based solely on a brief analysis of hydro-based mining in southwest
China and aforementioned faulty assumptions about ASIC utility and lifecycle longevity.
Several studies have used quantitative models and simulations to consider the
possibility of improving renewable power generation economics by pairing solar and
wind plants with PoW mining rigs. Shan and Sun (2019) looked at Bitcoin mining as a
potential solution to increasing solar photovoltaic (PV) power curtailment in California.
They determined the optimum number of mining rigs needed to minimize curtailment at
solar PV generation sites across California and calculated potential mining profits using
curtailed energy based on the daily market price of Bitcoin. Two later studies took a more
generalized approach as business researchers in Rio de Janeiro paired notional Bitcoin
mines with wind projects (Bastian et al. 2021) and a group of engineers from the Institute
of Electrical and Electronics Engineers (IEEE) did the same for solar photovoltaic (PV)

projects (Eid et al. 2021). Both studies ran various simulations and found mining
enhanced project profitability and could bolster early investment incentives. Findings
from Eid et al. (2021) even suggested pairing solar PV projects with Bitcoin mines was
more profitable than battery storage due to relatively lower capital costs.
Like Shan and Sun (2019), Niaz et al. (2022) ran simulations for mining curtailed
energy within a specific regional independent system operator (ISO) but focused on
Texas. However, their study used empirical data regarding curtailments, Bitcoin price,
and network hashrate at an hourly level and considered optimal mining scenarios from
the perspective of the ISO (maximize use of curtailed renewable energy) and the investor
(maximize profits). Most importantly, their sensitivity analysis and Monte Carlo
simulations found a floor price of Bitcoin for which mining curtailed energy would still
be profitable due to Bitcoin’s history of massive and unpredictable downside price
volatility. Much like Eid et al. (2021), Niaz et al. (2022) also found Bitcoin mining was
more profitable than battery storage options due to their relative costs.
Finally, this study limits its scope to examining Bitcoin mining with solar and
wind power. Early evidence suggests mining cryptocurrency off flared gas may greatly
reduce GHG emissions (Vazquez and Crumbley 2022) and mining using carbon capture
technologies may also be profitable (Niaz et al. 2022).182 Opportunities exist to study the
economics of PoW mining using hydroelectric and Ocean Thermal Energy Conversion
(OTEC) power as well.
3.3.6 Studies of Bitcoin Mining Impacts on Grid Stability
The second major research question of this essay is whether Bitcoin mining
contributes to grid stability. The studies above assumed grid-independent Bitcoin mining
from the perspective of renewable-only generators. But most Bitcoin mining today is
done in “front of the meter,” meaning miners draw power from the grid. This limits the
usefulness and applicability of these studies beyond hypothetical consideration. Grid-
connected Bitcoin mining cannot guarantee the use of curtailed renewable energy only
and raises concerns about grid stability and higher prices during periods of high demand.
Fridgen et al. (2021) conducted net-present value evaluations of renewable plants
paired with two kinds of flexible data centers: one used for machine learning (Amazon
Web Services) and the other for Bitcoin mining. They found pairing both types of flexible
data centers with renewable plants boosted their net present values when compared to
their standalone applications, but they argued Bitcoin mining data centers were
particularly well-suited to provide demand-side flexibility, contribute to grid stability and
participate in demand response (DR) programs. This argument was based on other
scholarship about the relationship between data center flexibility and ability to participate
in DR (Santana-Viera et al. 2015; Bai et al. 2016; Thimmel et al. 2019). But like the
studies outlined above, the Fridgen et al. (2021) analysis focused primarily on the energy
economics of data centers and renewable plants. A great deal of scholarship explaining
how flexible data centers and interruptible loads offer solutions for renewable
intermittency exists as well (Wierman et al. 2014; Xia et al. 2015; Hale et al. 2016).
Energy experts and crypto enthusiasts have discussed potential synergies between DR and
cryptomining data centers, but few rigorous studies have focused specifically on
cryptocurrency uses in DR.

Advances in synthetic grid modeling make it possible to simulate the addition of
various types of loads and predict certain grid outcomes. Texas’ deregulated energy
market and standalone grid (separate from the Eastern and Western Interconnections)
makes it ideal for detailed synthetic grid development and DR analysis (Li et al. 2020).
Rhodes et al. (2021) used a capacity expansion model designed for high-renewable power
systems (Johnston et al. 2019) to model the optimal energy mix for the Texas grid under various
scenarios of increased data center demand throughout the state. Wind and solar capacities were
highest and natural-gas capacities were lowest in scenarios with more data center flexibility.185
They found additional inflexible data centers resulted in more carbon emissions than a base case
with no additional data centers while more flexible data centers could “result in a net-reduction of
carbon emissions from the base case” and
“increase the resiliency of the grid by reducing demand during high-stress times”
(Rhodes et al. 2021, 3).
Bruno et al. (2022) found that adding Bitcoin demand to a “long-run equilibrium
capacity investment” (2) model of the Texas grid increased renewable capacity and
carbon emissions as generation from natural gas plants would also have to increase along
with renewables to keep up with demand. However, another version of the simulation
allowing miners in the model to participate in demand response programs nearly
eliminated the additional carbon emissions. Menati et al. (2022) added new
cryptocurrency mining loads of varying sizes across several locations on a synthetic
Texas power grid and looked at outcomes in terms of locational marginal pricing (LMP)
and DR profits for cryptomining facilities. Adding new mining loads increased average
LMPs statewide and created large price fluctuations. However, LMP increases were
highly dependent on the location of the new notional mine, the amount of added capacity,
and were most pronounced during the warmest hours of the day during summer
months. Ultimately, the location of cryptocurrency mines had “decisive impact” (Menati
et al. 2022, 9) in determining costs and benefits to the Texas grid. However, they also
found integration into Texas’ price-driven DR markets incentivized cryptominers to
reduce their loads to maximize profits when electricity prices were high. In sum, their
findings emphasized the nuance involved with incorporating new high-capacity loads
onto electrical grids and the importance of future coordination between grid operators and
cryptominers to ensure the greatest societal benefits.
3.3.7 Summary
Using CBECI as the standard, most studies have overestimated the Bitcoin
network’s aggregate energy demand, historically. Bitcoin’s energy consumption in 2022
(107.6 TWh) was comparable to 2021 levels (104.9 TWh), marking the first time mining
did not consume vastly more electricity year-over-year in the asset’s history, despite
record high hashrate (CBECI 2022). Context and perspective matter in framing this
amount of power use. The Bitcoin network consumes more power in a year than at least a
dozen countries, but less than 10 individual U.S. states. Value judgments of what
constitutes a good use of energy are highly subjective. Those who feel cryptocurrency is a
worthless endeavor see its energy consumption as obviously wasteful, just as those who
do not celebrate might find Christmas lights wasteful.
To this end, the field could benefit from more comparative studies of the energy
costs associated with securing various economic networks.188 Bitcoin proponents argue
expending energy to derive value is the whole point of its existence – it serves as the very
forcing function the asset’s security depends upon. Digiconomist, DeVries (2019), and
even OSTP (2022) have used a per-transaction basis for comparing Bitcoin to other
methods of value exchange (e.g., credit card transactions) while completely ignoring the
existence of Bitcoin’s Layer 2 (“Lightning” Network) protocol where most smaller
Bitcoin transactions now occur. Future research might consider Bitcoin’s scalability
through the lens of the Lightning Network and compare its energy requirements to the
legacy banking system and other means of value exchange.
More qualitative assessments of Bitcoin mining impacts (Greenberg and Bugden
2019) are needed to ensure all costs, benefits, and positive/negative externalities not
captured in quantitative data are considered in crafting digital asset public policy. The
field also desperately needs more rigorous and objective assessments of Bitcoin’s carbon
footprint. Accounting for less than 0.5% of the world’s electricity consumption, the
suggestion that Bitcoin could be solely responsible for a 2°C rise in average global
temperature in just 16 years defies logic, yet the Mora et al. (2018) study is cited ad
nauseum in warnings about Bitcoin’s environmental impact. More studies of behind-
themeter mining (Roeck and Drennen 2022) and more precise analyses of energy mix
based on mining location can improve the precision of rigorous GHG estimates (CBECI
2022). Policymakers might also consider ways to compel miners to share their data to
increase transparency and improve these estimates.
In a systematic review of academic literature related to sustainable development
goals and cryptocurrencies, Mustafa et al. (2021) found most literature was

disproportionately focused on cryptocurrency energy requirements and its negative
environmental impacts. They identified a “clear gap in the literature that focuses on the
possibility” (1152) of various cryptocurrency use cases to help reach sustainable
development goals. The purpose of this study is to help fill that gap. Theoretically based
research, project simulations, and synthetic grid modeling are good tools for planning and
forecasting, but the field lacks rigorous empirical assessments of mining impacts.
3.4 Research Design
This study is designed to use empirical data to describe Bitcoin mining’s role in
renewable energy development and grid stability efforts. ERCOT’s market structure and
the recent influx of new Bitcoin mining make Texas a great location to study these
relationships and test my research questions (3.4.1). I then describe how available data
can be used to test each question, and how certain data limitations may impact the
strength of the results and conclusions of this study (3.4.2).
3.4.1 How Texas Tests the Questions
Following China’s cryptocurrency ban, many displaced miners chose to relocate
to Texas because of its low energy prices and friendly regulatory environment (Feng
2021; Sigalos 2021; Rutwitch and Feng 2022). The goal of this work is to provide
empirical assessments of grid-connected Bitcoin mining’s sustainability in renewablerich
Texas to explore potential impacts in practice as opposed to modeling them. Rhodes et al.
(2021) did not consider potential negative effects of increased data center load capacity. I
try to capture those negative effects by looking at wholesale energy price changes near
new Bitcoin mining data centers. Bruno et al. (2022) “abstracted away from the details of
the miners’ operational decisions” (15). Menati et al. (2022) admitted “it is rightfully
possible that mining facilities apply more sophisticated load control strategies” but
assumed mining facilities consumed “a fixed amount of loads for all time steps” (6) for
the sake of simplicity in the model. But we should expect miners to respond to realtime
(RT) and day-ahead market (DAM) price signals and adjust their loads accordingly to
maximize profits. Pulling actual LMP data captures miner behavior and responses to
dynamic pricing, in practice. Data on participation in AS and DR markets shows how
miners currently engage in grid stability efforts and what can be done to maximize
benefits of available programs.
Question 1: Are miners in Texas positioned to incentivize renewable growth?
Drawing a causal relationship between Bitcoin mining and renewable investment
incentives is difficult for several reasons. A number of factors influence investment
decisions that are hard to measure, there is a significant lag between the decision to build
a power plant and when that plant is registered in publicly available data, and
comprehensive data on power purchase agreements (PPAs) are limited. But the
regionally-skewed distribution of Texas’ renewable power capacity allows us to examine
whether Bitcoin miners are geographically positioned in regions with disproportionately
high amounts of renewable energy. Of course, when drawing power from the grid, there is
no guarantee of what type of energy is being consumed. However, west to east export
constraints due to insufficient transmission infrastructure in Texas are well-documented
(ERCOT 2022), and low LMPs capture the costs of congestion (Singh et al. 2010;
Ahmadi and Lesani 2014).
ERCOT lacks interconnection to other grids and effectively operates independent
of the eastern and western interconnections which bind the rest of the continental United
States together. It is unique in that it effectively functions as a self-contained, intrastate
only, deregulated energy market. Generators sell energy on the wholesale market while
retail electricity providers (REPs) compete to buy this energy, and then sell/deliver it to
end-users with the “power to choose” their electric providers (Brown et al. 2020). One
feature of this system is relatively high price caps and low price floors compared to other
RTOs/ISOs. This allows a wide range of high and negative wholesale energy prices to
exist simultaneously across different locations which can be flagged to signal congestion
constraints.
Question 2: What do energy prices look like before and after Bitcoin mining data centers
come online?
Suppose grid-connected Bitcoin mining does incentivize renewable growth. If it
also leads to substantially higher energy prices, miners and renewable producers stand to
gain as other local consumers pay more for their electricity. This question explores
whether grid-connected Bitcoin mining in renewable-rich areas is truly a win-win for
miners and producers, or if a win-win-lose dynamic is more at play when considering
local stakeholders.
Texas’ competitive retail pricing approach to energy markets is designed to
maximize efficiency leading to lower prices for most consumers relative to the U.S.
average (Stoft 2002; Hartley et al. 2019). Wholesale electricity price changes do not
“pass through” perfectly to retail and residential customers as REPs factor wholesale
price volatility into retail quotes by charging risk premiums (Brown et al. 2020). Still,
evidence suggests increased competition in Texas forces REPs to reflect wholesale
(marginal) costs in their prices (Hartley et al. 2019) and retail quotes decrease as
customer switching activity increases (Brown et al. 2020). For the purposes of this study,
this means immediate LMP changes are an imperfect proxy for the prices
retail/residential customers see. However, wholesale volatility does price into retail in
other ways, so a large sample of LMPs over longer periods of time should capture the
impacts of various exogenous shocks (i.e., increased base load due to Bitcoin mining).
Question 3: Does Bitcoin mining provide flexibility to grid operators?
West Texas sees a relatively high frequency of low and negative wholesale energy
prices, with limited periods of extremely high energy prices typically due to weather
events causing massive amounts of supply to come offline simultaneously. For example,
in 2021, average hourly prices in the West Load Zone (LZ) were single digit or negative
($/MWh) almost 20% of the time while prices over $50/MWh occurred less than 10% of
the time. Most of the extremely high pricing (>$100MWh) occurred during Winter Storm
Uri in February 2021.
Figure 3.5 Hourly Wholesale Energy Price Frequency in West Texas in 2021 (author)
This high frequency of tail-end pricing provides two methods of determining
whether Bitcoin miners help stabilize the grid: 1) DR participation rates; and 2)
examining miner activity during tail-end events (e.g., major winter storms). In demand
response programs, consumers are compensated for scaling back consumption when
electricity is scarce or providing a kind of insurance to grid operators as controllable base
load. ERCOT has a separate, robust DR market with large amounts of publicly available
data about its participants. If in fact Bitcoin miners are uniquely suited to provide grid
stability, we should see evidence of their participation in various DR programs, but
specifically in those requiring highly flexible and controllable loads. Also, regardless of
DR participation, we should expect to see miners voluntarily curtail their consumption
during high energy pricing events. If miners are rational economic actors and mining is
were as low as $27/MWh in January 2021 and as high as $41/MWh in July 2021 (Thomas 2021; Wood
Mackenzie 2021).
both highly interruptible and highly responsive to real-time price changes, miners should
shut down their ASICs when electricity costs rise above certain breakeven prices.
3.4.2 Data Collection
Bitcoin miners are not required to publicly disclose the precise location of their
operations. Cross referencing publicly available satellite imagery with returns from basic
internet keyword searches, YouTube videos, news articles, information from mining
company websites and quarterly earnings reports yielded 11 major mining sites across 8
different towns/cities (Table 3.3). Mining operations needed a capacity of at least 20MW
for inclusion in the sample. The level of fidelity on when each site is operating and at
what capacity varies depending on the amount of information available and the
responsiveness of each company to inquiries and requests for further information. The
conclusions which can be drawn regarding the impact(s) of each mining site vary to some
degree depending on that level of fidelity. What is/is not known about each location and
how it may affect these conclusions is explained in detail in Appendix B.
Table 3.3 Bitcoin Mines in Texas
Company Name Location Load ZoneLat Long Size
Riot Blockchain Whinstone Rockdale South 30.573 -97.078 450 MW
Bitdeer Alcoa Rockdale South 30.567 -97.069 300 MW
Lancium Fort Stockton Clean Campus Fort StocktWest 30.900 -102.926 25 MW
Lancium Abilene Clean Campus Abilene West 32.503-99.790 Unknown o
Argo Blockchain Helios Afton West 33.778 -100.876 200MW
Poolin/Bitmain Poolin Data Centers Pyote West 31.553 -103.119 Unknown
o
Layer1 Technologies Layer1 Pyote Pyote West 31.553 -103.119 Unknown
o
Genesis Digital Assets Genesis Pyote Pyote West 31.553 -103.119 150MW
Compute North Big Spring Data Center Big SpringWest 32.226 -101.516 25 MW
Compute North (Marathon Digital) Upton County McCameyWest 31.255 -102.244 40MW
Core Scientific DME Denton Energy Center Denton North 33.216 -97.210 22 MW
U.S. Energy Information Administration (EIA) Form 860 information is used to
determine regional energy mixes. EIA-860 collects details on power plants and
generators including, but not limited to, their locations (lat-long), nameplate capacity, and
generation type. Any existing and proposed power generators that are grid-connected
with the ability to draw/deliver power to the grid and a nameplate capacity of 1 MW or
greater are required to fill out EIA-860. Precise coordinates allow me to plot generator
locations on geographic information system (GIS) software to see where renewable
generators are relative to the locations of major Bitcoin mines. Nameplate capacities of
these generators show how much active power generation comes from renewable sources.
Recent LMP pricing data are publicly available on the ERCOT website and
ERCOT makes historical LMP data available to researchers by request. LMP data show
LMP name, time, and price, but ERCOT does not publish coordinates for their LMPs.
However, LMP names and locations are shown on ERCOT’s real-time market pricing
map. Exact coordinates can be determined and plotted on GIS since LMP settlement
points (SPs) are visible on publicly available satellite imagery. Finally, I create an
aggregate dataset of LMPs by settlement point name, location, and price organized into a
5-minute interval time series for years 2017-2022. Using GIS, I build regional wholesale
energy pricing profiles over time to determine whether proximity to a Bitcoin mining data
center impacts price.
To examine miner participation in grid stability efforts, my quantitative data are
limited to what miners were willing to share. ERCOT established controllable load
resource (CLR) qualification requirements in 2020 and Lancium shared a limited data
sample (July-August 2022) of how their software works with Bitcoin mining to meet
CLR standards. I use a model for determining the dynamic breakeven price for Bitcoin to
show when miners were likely economically motivated by market conditions to curtail or
shutdown operations. Finally, qualitative data from news articles, quarterly earnings
reports, and interviews shed light on the pros and cons of ERCOT’s current DR market
structure as it relates specifically to Bitcoin mining.
3.5 Results
This section first shows where large, grid-connected Bitcoin mines are located in
Texas relative to different types of power generators and regional energy mixes across the
state (3.5.1). It also covers how often settlement points near these major Bitcoin mines
experience negative LMPs. I then examine whether the presence of an active Bitcoin
mine correlates with higher nearby wholesale energy prices relative to the rest of the
region/state (3.5.2). Finally, this section concludes with a look at how one data center
(Fort Stockton) behaves as a controllable load resource in real time (3.5.3).
3.5.1 Geographic Positioning of Bitcoin Mining Relative to Incentivizing Renewable
Growth
For the year 2021, Texas had a total of 928 unique plants with 1737 generators.
Each individual plant has a unique location. A single plant can also host multiple
generators of varying types at the same location. EIA recognizes 18 forms of generator
technology that exist in Texas and most active generators (933) still use natural gas-based
technologies. 416 generators in Texas fit the EIA definition for renewable technology and
78% of these generators are wind (212) or solar (111). For decades the Permian Basin has
been a powerhouse for U.S. domestic oil and gas extraction and production, but it is now
one of the most popular locations for renewable projects. Of ERCOT’s six major load
zones (LZs) depicted in Figure 3.6, the West LZ has the highest percentage of renewable
plants by far (Figure 3.3, Table 3.4).
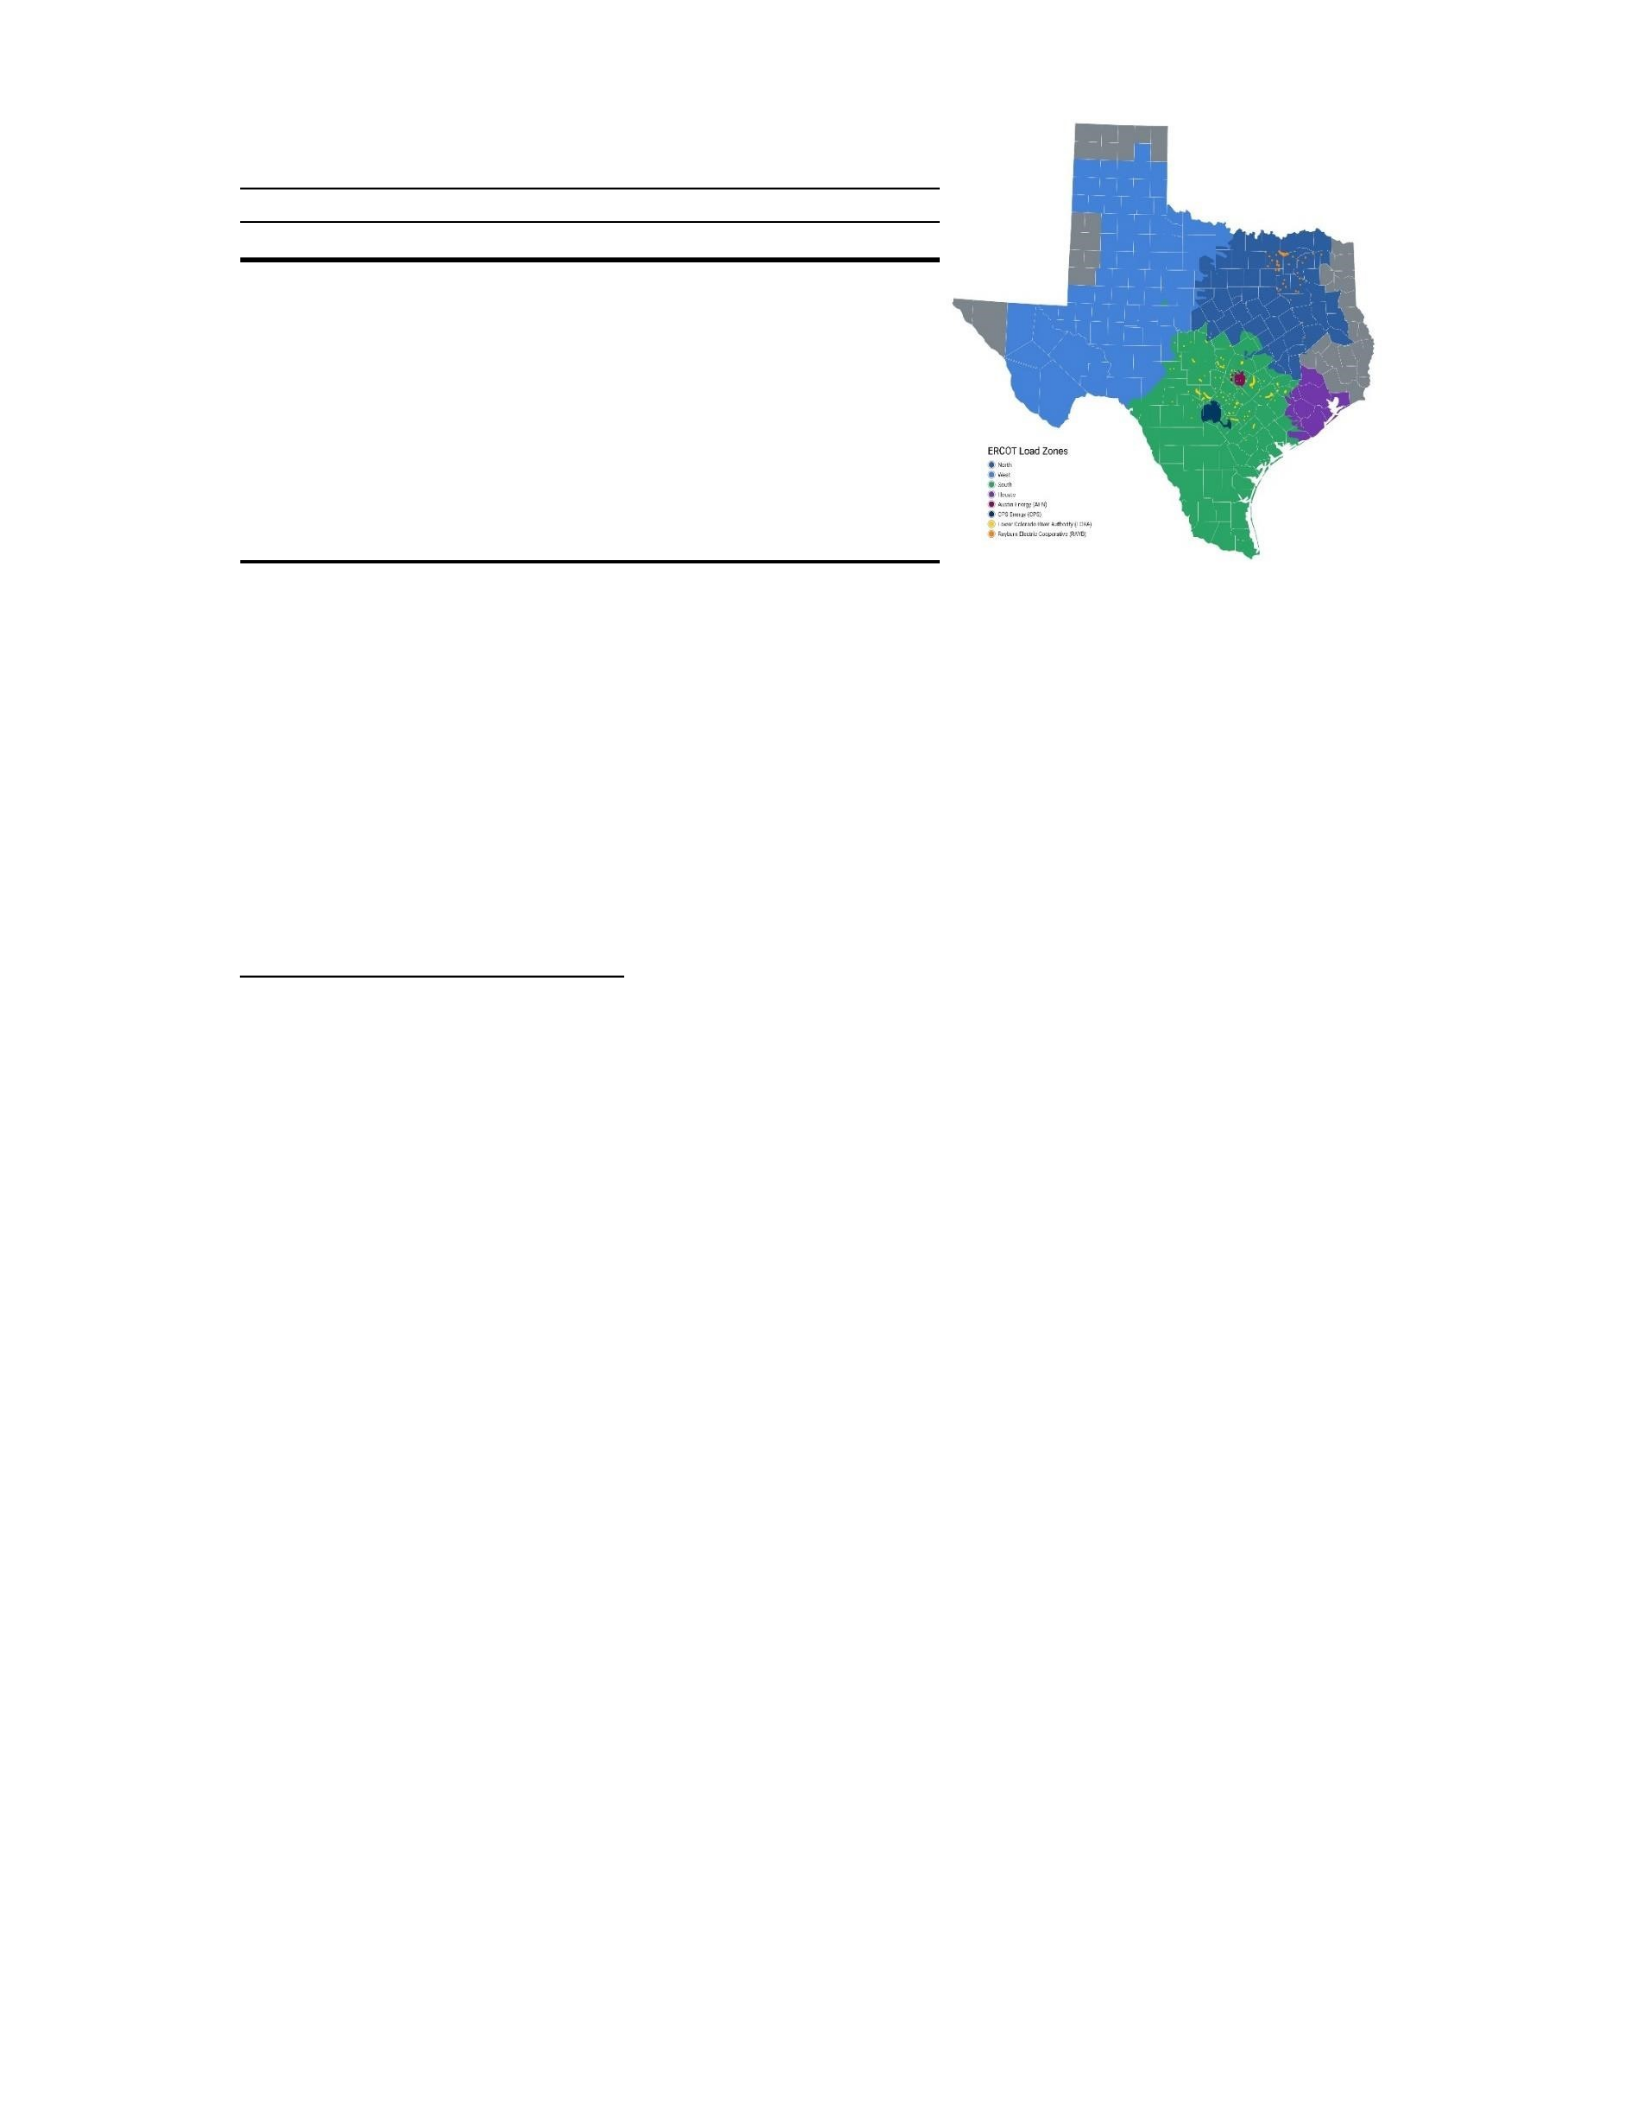
Table 3.4 Power Plants in Texas (2021)
All Plants Wind Solar Other Renew Total Renew
% Renew
*820 Plants under ERCOT Balancing Authority
Figure 3.6 (right) ERCOT Load Zones (ERCOT 2022)
Most major Bitcoin mining facilities (8/11) are in the West LZ near this abundant
and expanding bastion of renewable energy. The three concentric rings around each red
dot seen in Figure 3.7 capture the local energy mixes within 25km, 50km, and 100km of
each mining data center. Geographic proximity is only a proxy for the likely source of a
grid-connected data center’s power, so I consider both the quantity of nearby generators
by type (Table 3.5) and the local energy mix surrounding large mines (Table 3.6). Table
3.5 shows the number of generators within those rings by each power generation
technology type according to EIA data. EIA-860 also reports the precise nameplate
capacities (measured in MW) of each generator. Table 3.6 provides a breakdown by
capacity for a more accurate depiction of the renewable energy mix within each ring. It
shows the wide range of clean and carbon-based mining occurring in the state. For
example, Lancium aptly titles their data centers in Fort Stockton and Abilene as “clean
campus” facilities, sourcing almost all power from 100% renewable sources nearby.
However, the two Rockdale data centers demanding the highest power capacities of all
mining facilities in the state still pull from a disproportionately high non-renewable
Location
Texas* 928 168 107 41 316 34%
West Load Zone278 128 40 0 168 60%
North Load Zone 181 14 27 9 50 28%
South Load Zone 206 41 20 14 75 36%
Houston 152 0 3 1 4 3%
CPS 24 0 10 2 12 50%
Austin 14 0 1 2 3 21%
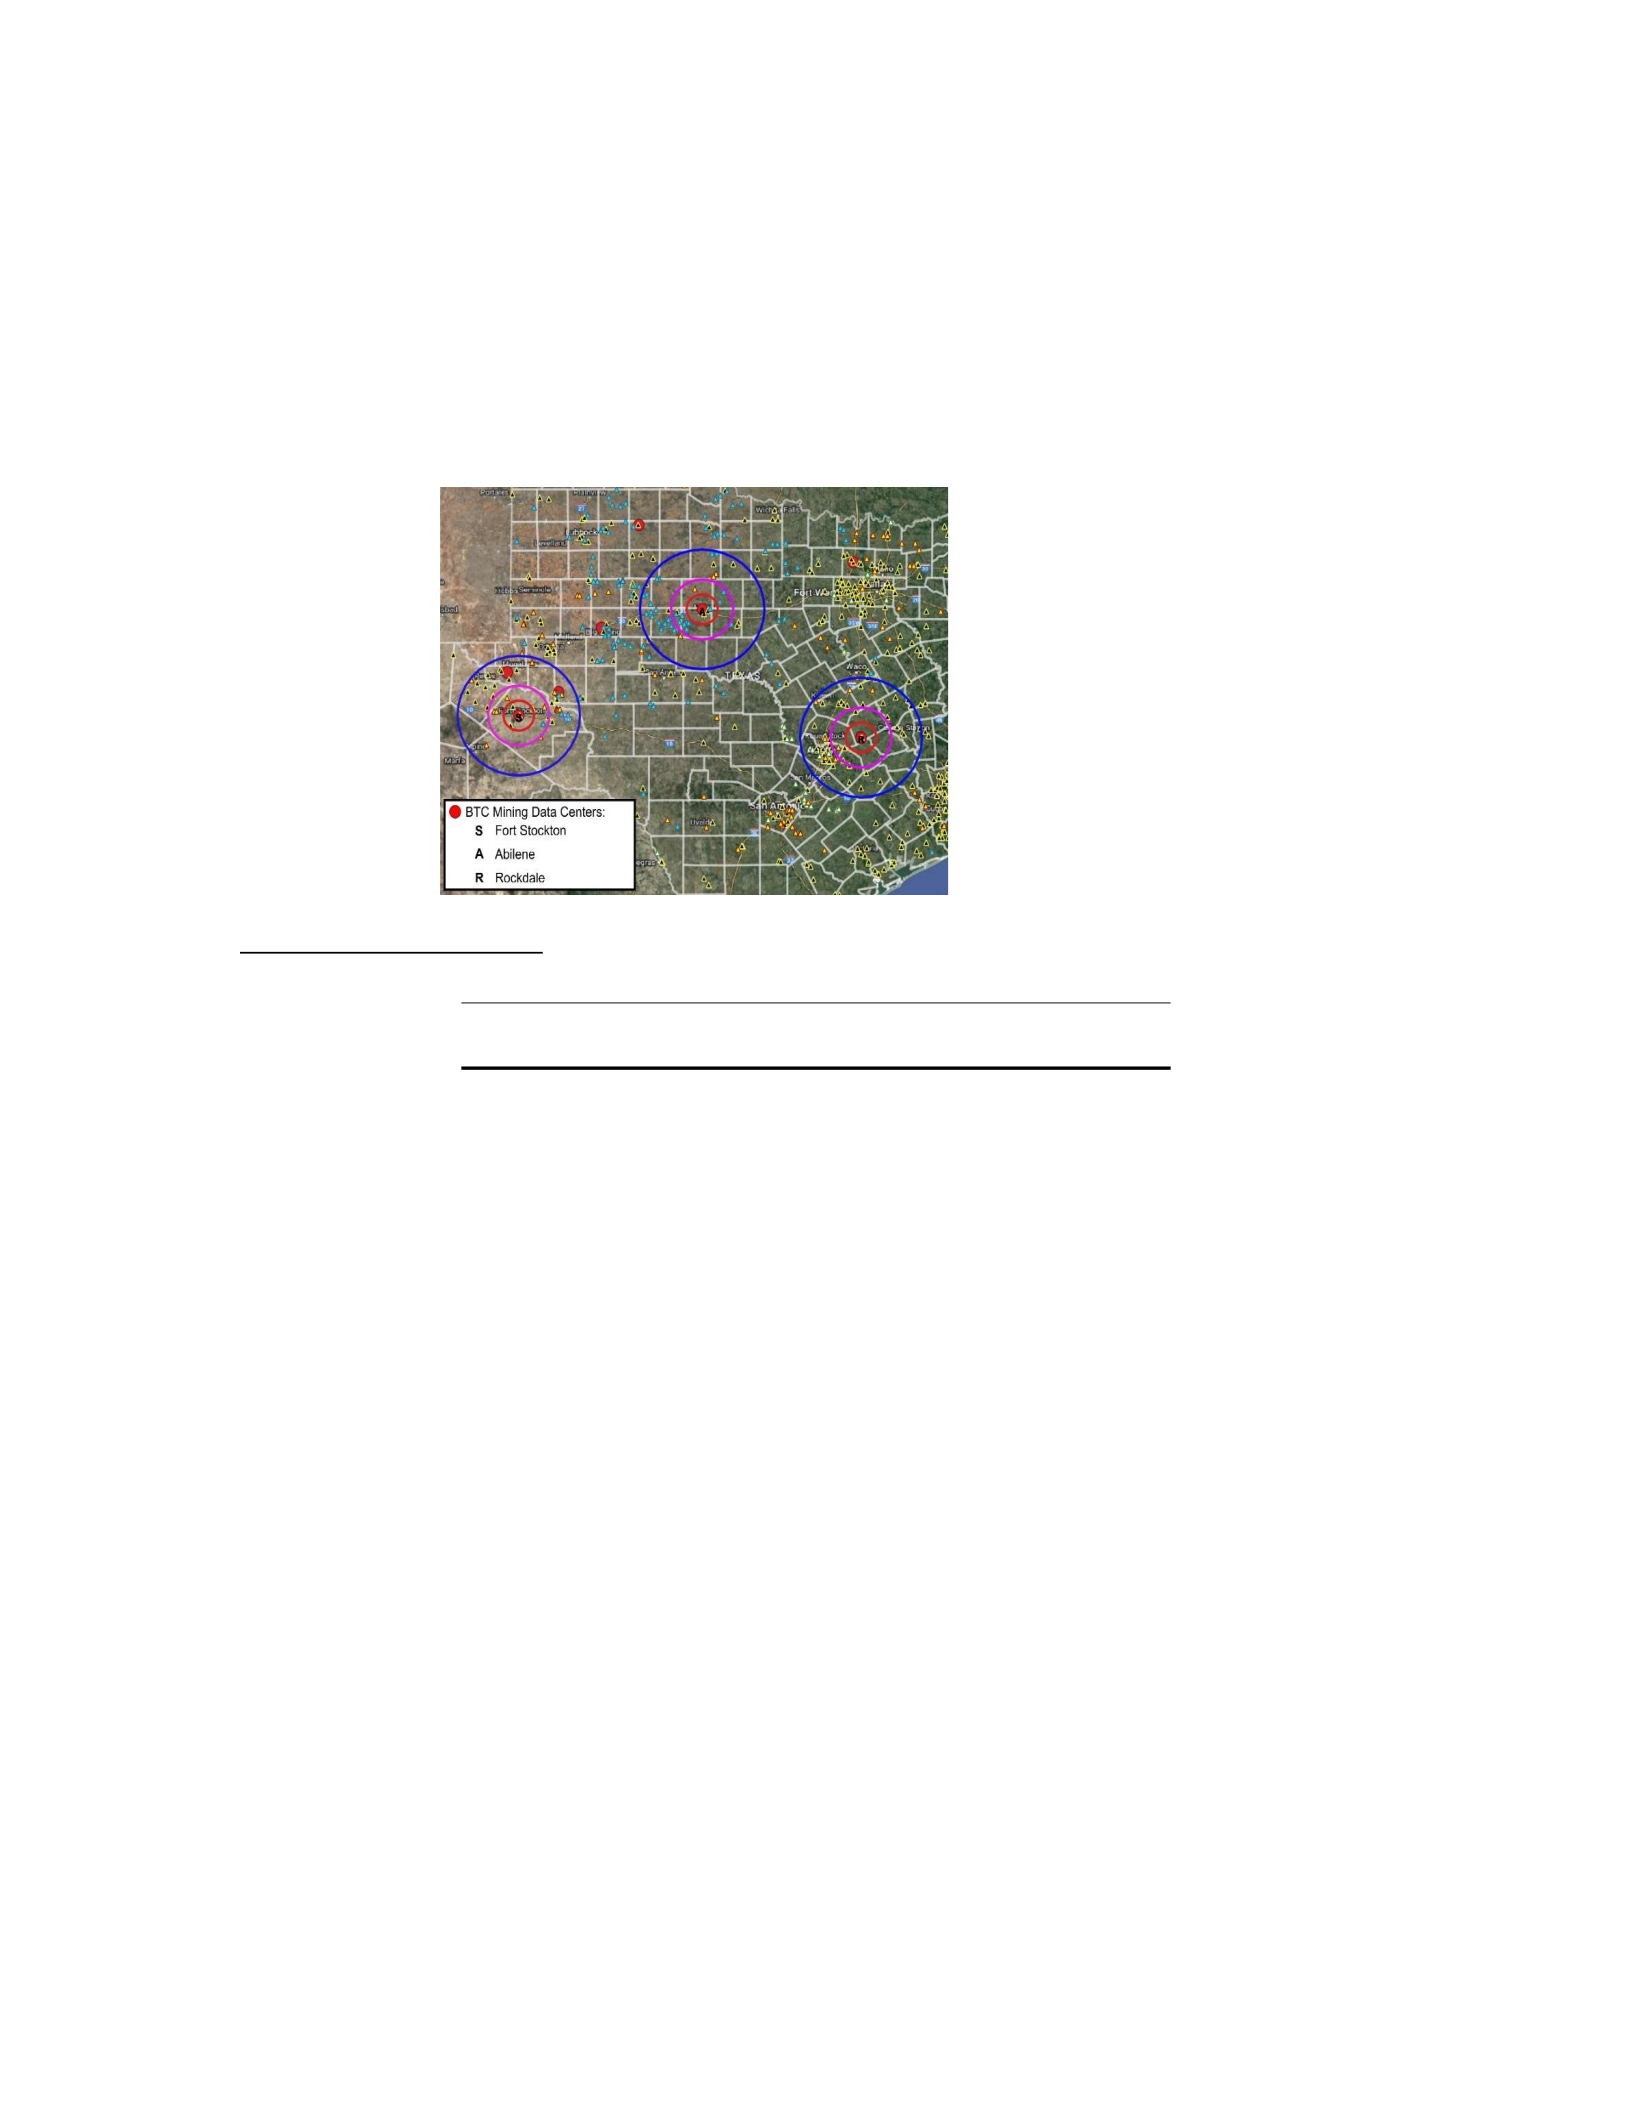
energy mix. Wind, solar and other renewable sources generated 31% of electricity
ERCOT-wide in 2022 (Irfan 2023). 8 of the 11 Bitcoin mining data centers in this study
are in regions where renewables accounts for at least 60% of power capacity within
100km Table 3.6).
Table 3.5 Number of Power Plants Near Bitcoin Mining Facilities by Energy Technology
Technology Type Wind Solar Other Renew Total Renew All % Renew
Location Distance within
Ft. Stockton 25km 0 0 0 0 4 0%
West LZ 50km 3 4 0 7 14 50%
100km 6 18 0 24 49 49%
Upton County 25km 1 4 0 5 8 63%
West LZ 50km 6 10 0 16 22 73%
100km 11 17 0 28 53 53%
Pyote* 25km 0 0 0 0 4 0%
West LZ 50km 0 4 0 4 14 29%
100km 5 16 0 21 56 38%
Big Spring 25km 5 0 0 5 7 71%
West LZ 50km 10 0 0 10 14 71%
100km 36 8 0 44 69 64%
Abilene 25km 1 0 0 1 3 33%
West LZ 50km 10 1 0 11 14 79%
100km 30 4 0 34 45 76%
Argo 25km 2 0 0 2 3 67%
West LZ 50km 6 0 0 6 9 67%
100km 19 1 0 20 36 56%
Denton 25km 0 1 0 1 7 14%
North LZ 50km 1 5 3 9 34 26%
Figure 3.7 Example of Select Data Centers with Energy Mix Concentric Rings (author)
100km 4 12 5 21 83 25%
Rockdale** 25km 0 0 0 0 2 0%
South LZ 50km 0 1 0 1 7 14%
100km 0 7 3 10 56 18%
*3 mining facilities in Pyote
**2 mining facilities in Rockdale
Table 3.6 Power Capacity Near Bitcoin Mining Facilities by Energy Technology (MW) Technology
Type Wind Solar Other Renew Total Renew Total All Types % Renew
Location Distance within
Ft. Stockton 25km 0 0 0 0 8.8 0%
West LZ 50km 292 700.2 0 992.2 1001 99%
100km 820.2 2779.6 0 3599.8 4236.5 85%
Upton County 25km 278 880 0 1158 1158 100%
West LZ 50km 1187.7 1840.5 0 3028.2 3028.2 100% 100km 2212.1 3156.3 0 5368.4 7934.2 68%
Pyote* 25km 0 0 0 0 456.9 0%
West LZ 50km 0 685 0 685 1171.6 58%
100km 787.2 3146.9 0 3934.1 6560 60%
Big Spring 25km 477.5 0 0 477.5 709.5 67%
West LZ 50km 1142.7 0 0 1142.7 1374.7 83%
100km 6533.7 1298.8 0 7832.5 10508.1 75%
Abilene 25km 200 0 0 200 202.4 99%
West LZ 50km 2191.6 200 0 2391.6 2394 100%
100km 5742.8 725 0 6467.8 6472 100%
Argo 25km 407.3 0 0 407.3 407.3
West LZ 50km 678.7 0 0 678.7 678.7
100km 3050.5 240 0 3290.5 5160.8
Denton
North LZ
25km
50km
0
180.1
2
75.1
0
118.4
2
373.6
227.6
623.6
1%
60%
100km 528.2 125.4 228.2 881.8 10179.7 9%
Rockdale** 25km 0 0 0 0 590.6 0%
South LZ 50km 0 144 0 144 734.6 20%
100km 0 208.7 131 339.7 10566.8 3%
*3 mining facilities in Pyote
**2 mining facilities in Rockdale
The most interesting finding relating to the geographic positioning of Bitcoin
mines has to do with their proximity to SPs with a high frequency of negative LMPs.
Negative LMPs are most frequent in the West LZ by a wide margin, consistent with
ERCOT concerns about regional congestion (Potomac Economics 2022). Negative
LMPs occurred an average of 6,394 times per SP (i.e., individual LMP location) across
Texas in 2021. Frequency of negative LMPs for SPs within 100km of Bitcoin mine
locations was much higher, indicating that most mining data centers are well-positioned
100%
100%
64%
to provide demand during periods of depressed pricing (Table 3.7). The probability of a
negative LMP from the miner sample (SPs within 100km of a Bitcoin data center) was
56.3% higher than the ERCOT-wide average. Four of the eight locations (Fort Stockton,
Upton County, Pyote, and Afton) saw negative wholesale energy prices at twice the
frequency of the statewide average.
Table 3.7 Frequency of ERCOT negative LMPs in 2021
Settlement Points Count Average Median Min Max
ERCOT ALL 783 6394 3516 10 27450
within 100km
of: Fort Stockton 15 13165 13206 11922 14507
Upton County 21 12910 12833 11630 14507
Pyote 14 12312 12076 11630 13850
Big Spring 33 11253 11209 9975 12714
Abilene 21 10290 10292 8814 11427
Afton 12 20556 24482 8780 27450
Denton 17 3820 2452 15 7061
Rockdale 18 2724 2928 2102 3043
Only two of eight data center locations, Rockdale (South LZ) and Denton (North
LZ) are in regions with a below-average frequency of negative pricing. Denton’s negative
LMP frequency is below the state SP average, but above the median. But SPs around
Rockdale certainly have negative pricing less often than the rest of the state. It is possible
that the combined power draw of the two large Bitcoin mining facilities in Rockdale has
reduced the frequency of negative LMPs. However, SPs around Rockdale have
historically had a lower frequency of negative LMPs relative to the rest of the state, even
before Riot Blockchain and Bitdeer built their mines. In 2018 well before either facility
was built, SPs within 100km of Rockdale saw negative LMPs an average of 422 times,
compared to the statewide average of 2449 occurrences.
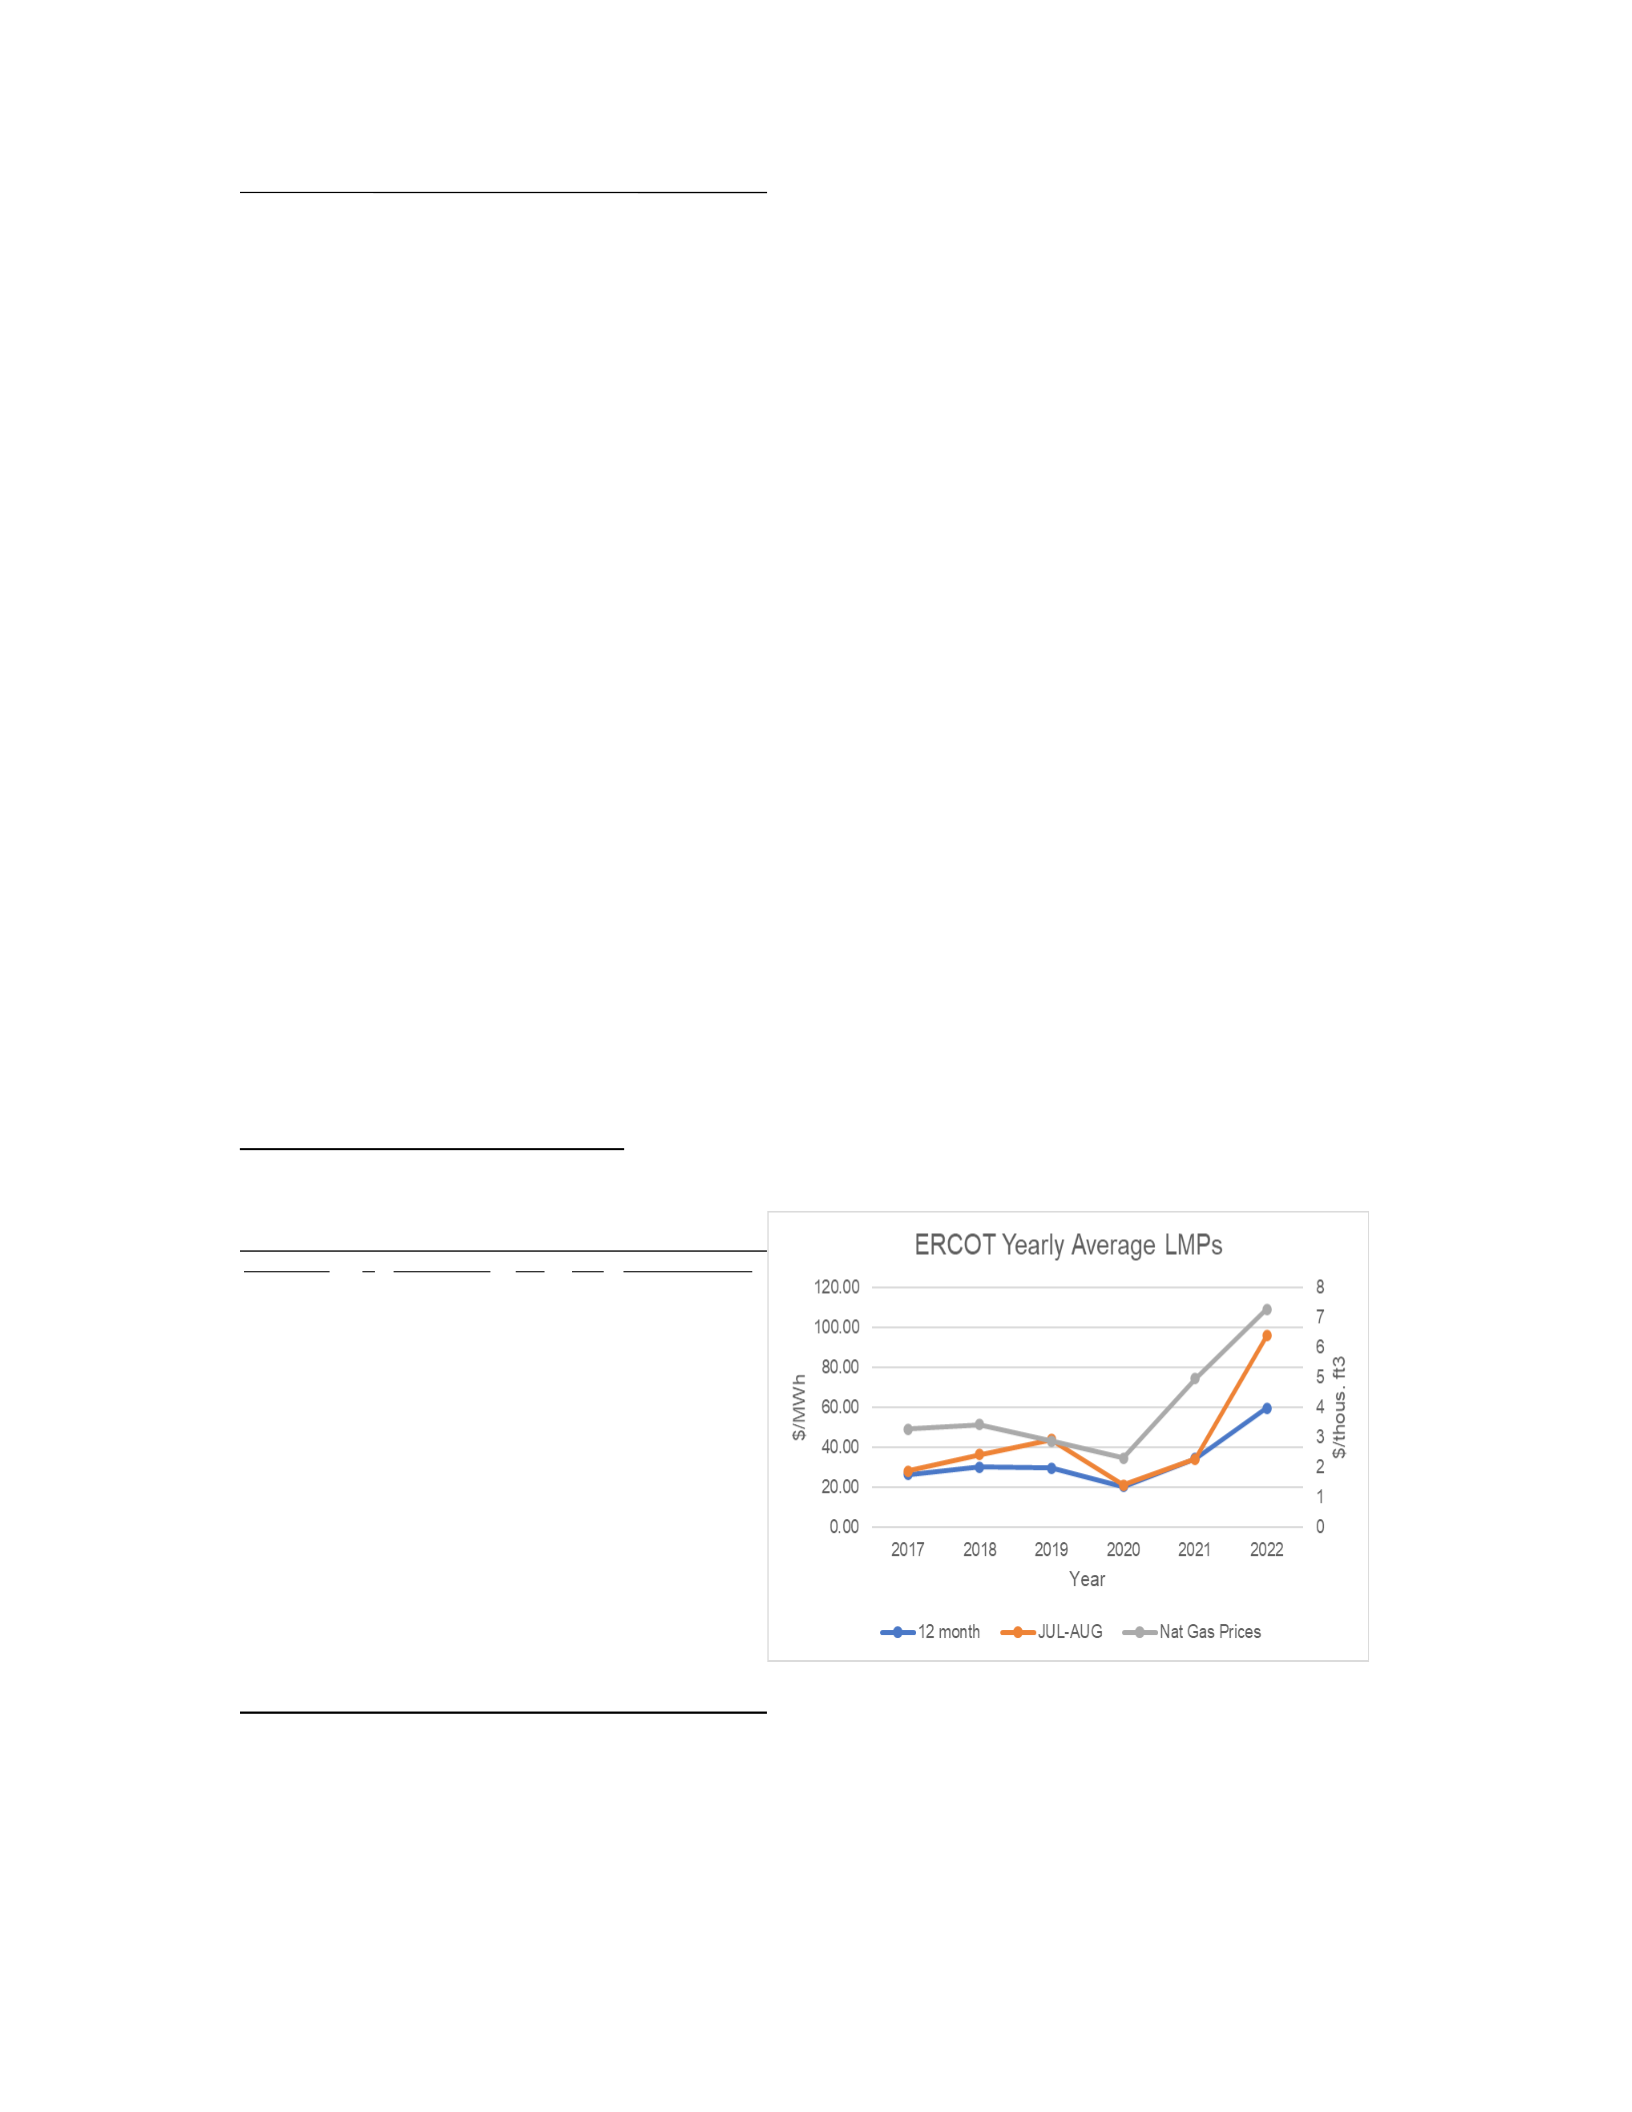
3.5.2 Bitcoin Mining Impacts on Wholesale Energy Prices
Average wholesale energy prices remained relatively consistent across Texas
between 2017 and 2020 (Table 3.8). A massive jump in mean wholesale energy prices in
2021 can be mostly attributed to Winter Storm Uri. Dropping LMP observations during
the storm decreases the average 2021 LMP by ~$34/MWh. Still, average wholesale prices
increased significantly from 2020 to 2021 even after correcting for both Winter Storm Uri
and hot summer months. While a great deal of new Bitcoin mining came online during
this period, a 66% jump in Texas natural gas industrial prices in Q4 2021 accounts for
this rise in wholesale energy prices (Webb 2022; EIA 2022). Persistent elevated natural
gas prices combined with increased demand during hot summer months led to a
continued increase in average wholesale energy prices in 2022 (Figure 3.8).
Table 3.8. ERCOT Average Locational Marginal Prices
Time Period N Mean Median Min Max Variance Std. Dev.
2017 646 26.45 25.52 16.37 47.40 30.54 5.53
Summer 638 28.05 27.57 20.03 38.27 3.24 1.80
2018 655 30.10 29.36 21.25 284.98 168.23 12.97
Summer 643 36.32 33.65 19.23 1167.41 2166.88 46.55
2019 677 29.56 28.82 -21.43 150.43 116.80 10.81
Summer 656 43.99 44.54 21.77 74.46 19.84 4.45
2020 715 20.55 20.34 7.95 132.11 69.88 8.36
Summer 686 21.12 20.48 14.35 113.94 38.47 6.20
2021* 783 34.32 35.34 16.33 50.45 20.13 4.49
(w/Uri) 783 78.31 83.37 16.33 133.34 261.54 16.17
Summer 753 34.18 34.88 23.48 47.82 4.76 2.18
2022* 808 59.59 59.22 15.43 96.28 93.07 9.65
Summer 802 95.67 100.42 51.70 119.26 150.46 12.27
Figure 3.8 (right) ERCOT Average LMP and Natural Gas Price Over Time (author)
Historically, the West LZ where most major Bitcoin mining is now located had
higher wholesale energy prices relative to other regions in the state, particularly during
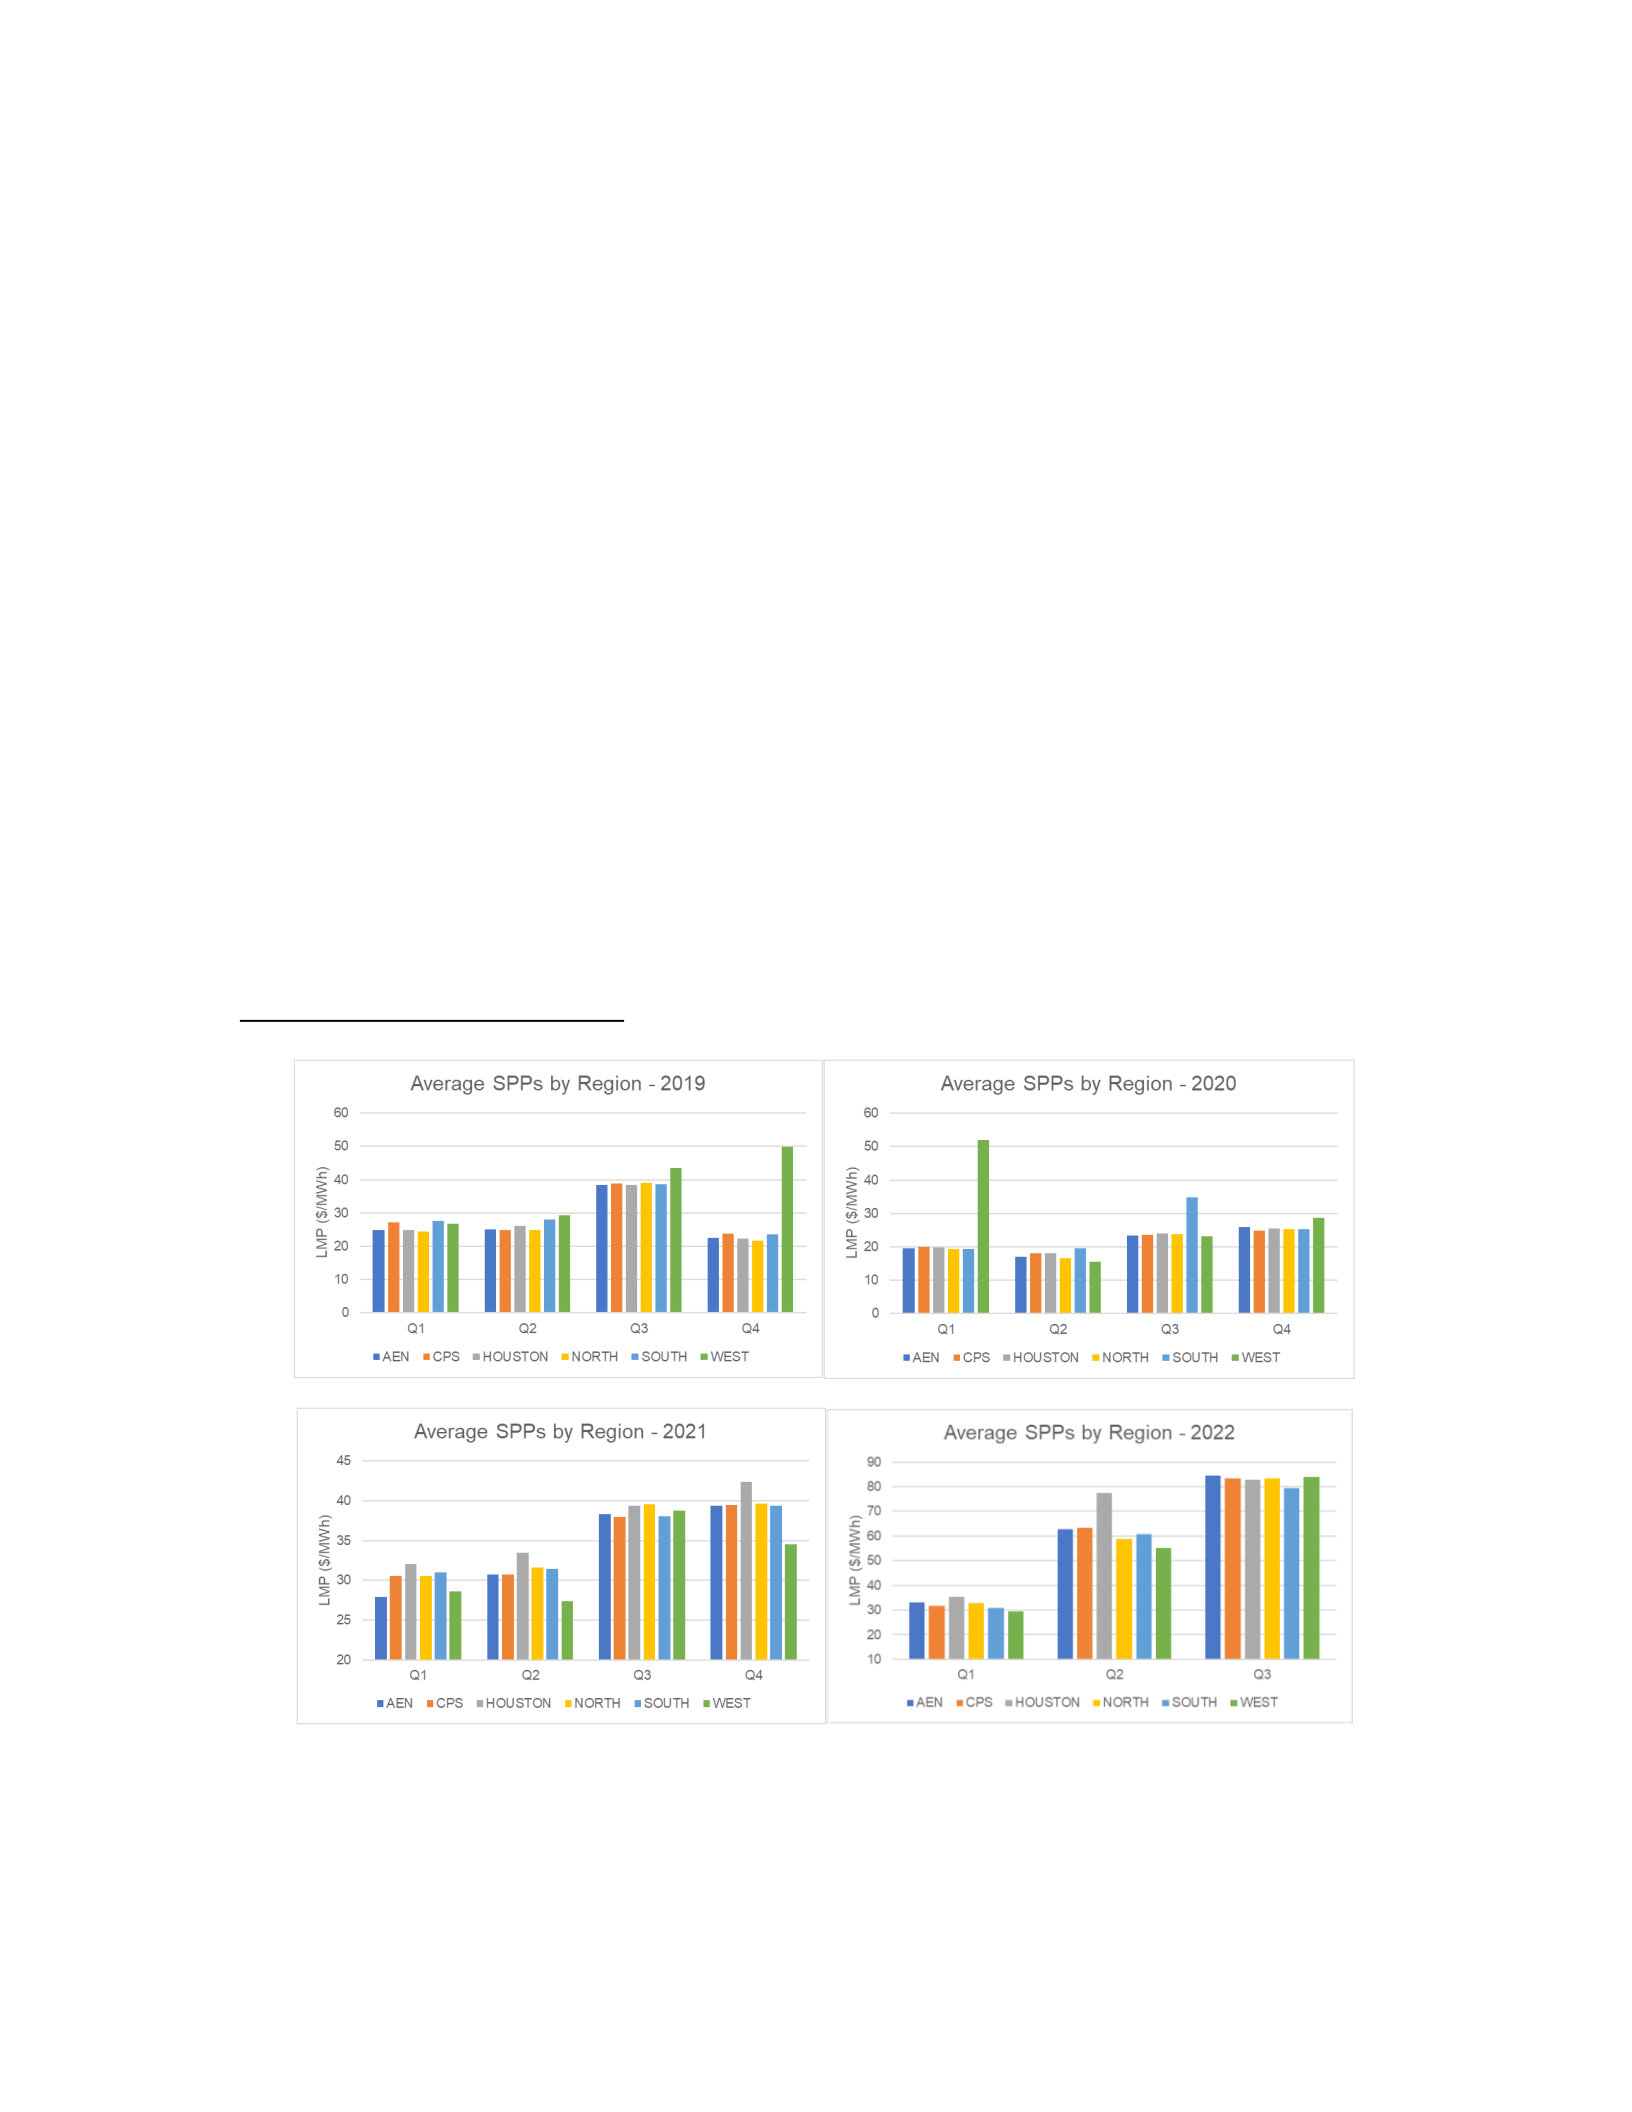
the winter months. Figures 3.9-3.12 compare ERCOT settlement point prices (SPP)
across load zones. Q4 2019 and Q1 2020 average SPPs in the West LZ were twice as
expensive as the other five major ERCOT load zones. More recently, this trend changed
significantly as VRE penetration has increased in the region. The West LZ had the lowest
average SPPs of all LZs in five of the last seven quarters (Q1 2021-Q3 2022). Still,
pricing differences between the West LZ and the rest of the state are small. The average
West LZ SPP was just $3/MWh and $4/MWh lower than the rest of the LZs for 2020 and
2022, respectively.
Figures 3.9-3.12 Average Settlement Point Prices by Load Zone, 2019-2022 (author)
To examine wholesale energy pricing near large-scale Bitcoin miners, I took the
yearly means of LMPs within 25km, 50km, and 100km of each data center location from
2017-2022. Figures in Appendix B show these average LMPs compared to the ERCOT
wide averages for the same time periods. Comparisons of LMPs at different distances
allows us to see whether proximity to high demand mining data centers affects average
wholesale energy prices. Information about when data centers come online allows for
before/after comparisons of energy pricing trends. If proximity impacts prices, we should
expect to see the 25km (red) and 50km (purple) trend lines to be higher than the 100km
(blue) on the charts after the point in time where mines become operational.
However, the level of fidelity regarding how much capacity is online and when
varies between the various locations. Mining companies are not required to report when
they are online and how much power they draw. For those loads coming online late in the
time series, it is harder to draw ex-post conclusions about their pricing impacts. However,
comparing ex-ante (pre-operational) LMP trend data to the ERCOT-wide average is still
useful in assessing whether regional wholesale energy pricing played a significant role in
choosing mining locations as opposed to regulatory concerns (i.e., partnerships with local
governments/municipal authorities).
A full breakdown of my findings based on each individual location is available in
Appendix B. Overall, I find that proximity to Bitcoin mining data centers has no
correlation to changes in wholesale energy prices. Including LMPs falling within 100km
of an active data center lowers average price more than $1/MWh compared to the 25km
& 50km proximities at just three of eight locations, while average prices actually increase
with distance from the data center at two locations. Additionally, only three data centers
were built in regions with historically low wholesale energy costs. In fact, four data
centers were built at locations with higher locational marginal prices relative to the
ERCOT average since 2017. In 2022, LMPs around all five “green” data centers (>60%
renewable energy mix, see Table 2.6) are lower than the ERCOT average, whereas LMPs
near carbon-based data centers are closer to the ERCOT average.
Still, yearly averages may not effectively capture pricing dynamics when system
demand is highest. In May 2022, ERCOT released a statement imploring customers to
conserve power “by setting their thermostats to 78-degrees or above and avoiding the
usage of large appliances (such as dishwashers, washers and dryers) during peak hours
between 3 p.m. and 8 p.m.” due to “unseasonably hot weather driving record demand
across Texas” (ERCOT 2022). Figure 3.13 shows average LMPs for all SPs within
100km of a Bitcoin mining facility during peak demand hours (3PM-8PM) from May
through August 2022. Five locations saw average LMPs at or below the ERCOT-wide
average, and seven locations averaged LMPs at or below the ERCOT-wide median
settlement point LMP. The breakeven price of energy for major high-efficiency miners
throughout most of this period was well below average wholesale energy prices across all
regions. The rational economic miner would turn off their equipment above this
breakeven price, but would still contribute to increased demand up until this price point.
Table 3.9 summarizes descriptive statistics and the results of a two-tail t-test comparison
between average LMPs for all ERCOT SPs and all SPs falling within 100km of a Bitcoin
mining data center during this same high demand period. The mean LMP for SPs near
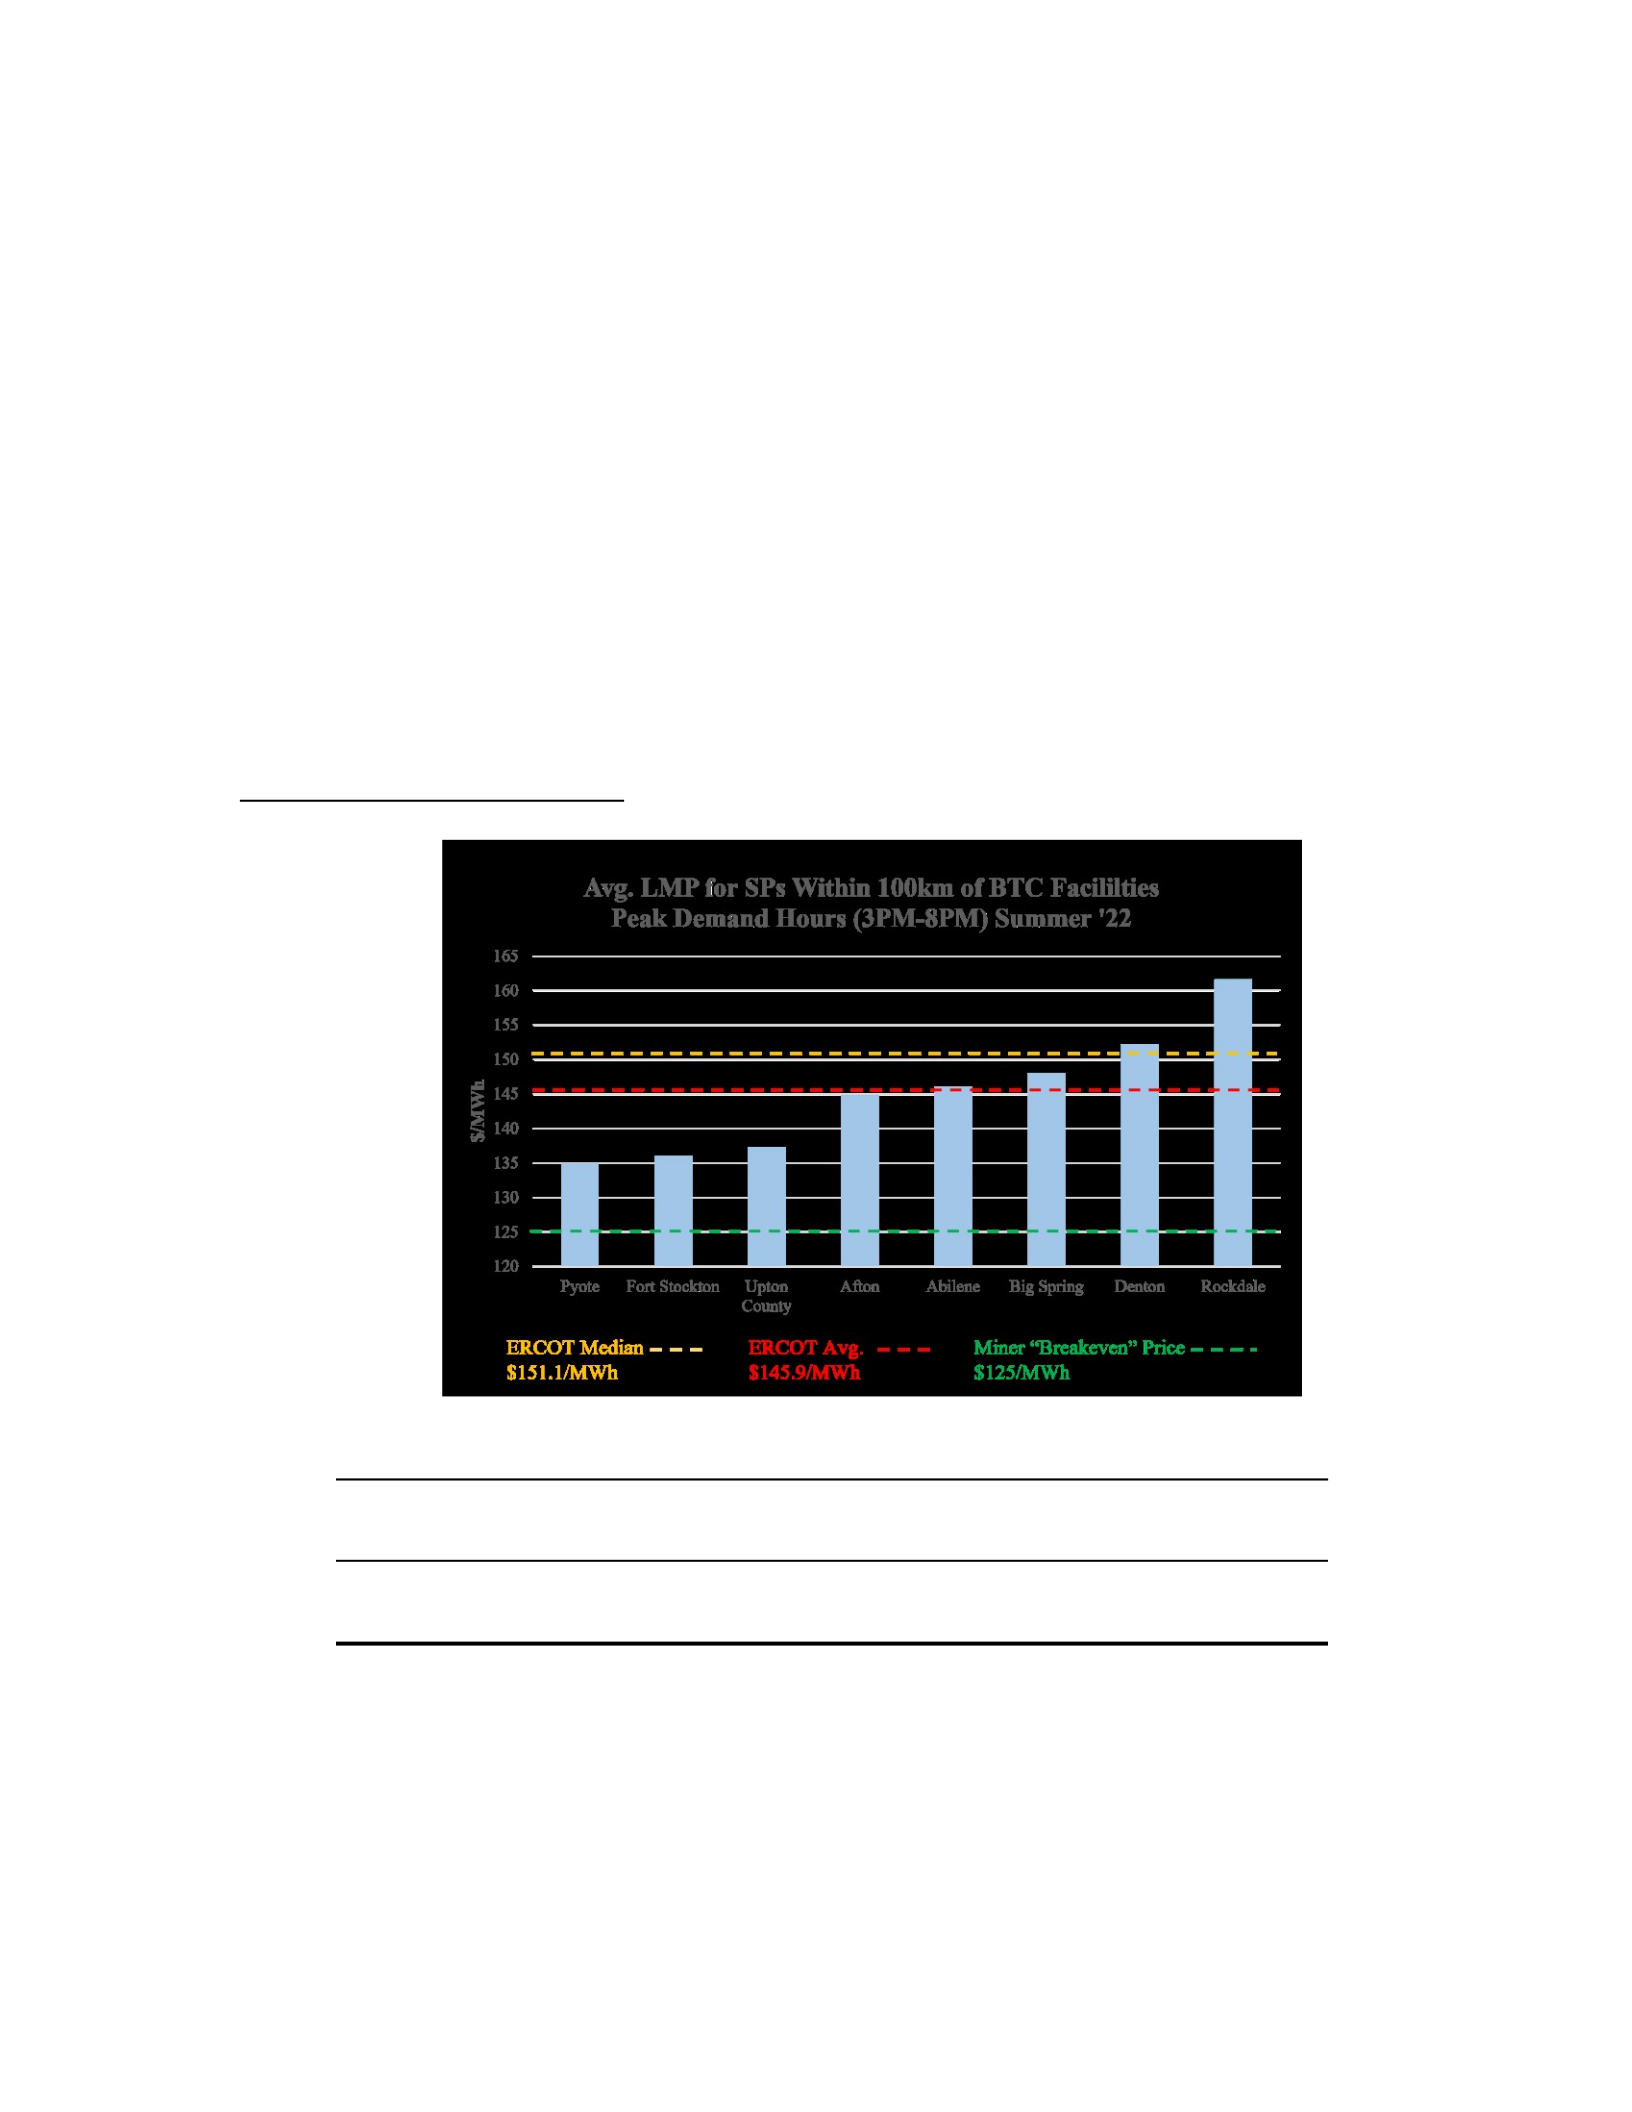
Bitcoin mining facilities was slightly higher (~$2/MWh) than the ERCOT-wide average.
However, the median LMP for SPs near these data centers was lower than the ERCOT
median and t-test results indicate there is no meaningful difference between the two
group means.
Figure 3.13 Average LMPs During High Demand Hours, May-August ’22 (author)
Table 3.9 Statistical Comparison of LMPs: High Demand Summer '22 ($/MWh)
ERCOT ALL SPs SPs w/in
100km BTC
Mean $145.93 $147.
90
Median $151.11 $146.
38
Minimum $30.00 $121.
32
Maximum $217.77 $178.
15
Variance $1,351.31 $103.
67
Observation
s
802 110
t Stat
P(T<
=t)
two-
tail t
Critic
al
two-
tail
-
1.2
2
0.2
2
1.9
6
It is possible that companies hosting new loads in the early stages of coming fully
online are too small to impact nearby electricity prices. But the most interesting finding
of this study is that proximity to massive mining loads has almost no correlation to higher
average wholesale energy prices over the course of an entire year. Riot Blockchain hosts
the largest cryptocurrency mine in North America less than a mile from Bitdeer’s 170MW
mine in Rockdale, Texas (Sigalos 2021). Both facilities were operational with a combined
capacity of at least 470MW when Bitcoin’s price hit all-time highs and all
Chinese-based hashrate fell offline in 2021, making it even easier and more profitable to
mine Bitcoin. Yet, LMPs within 25, 50, and 100km of Rockdale were just $1/MWh
higher than the ERCOT-wide average in 2021, continuing a trend for the region of LMPs
at or near ERCOT yearly averages. However, the average LMP for the 17 SPs within
100km of Rockdale were $15.69/MWh higher than the ERCOT-wide average during the
high demand hours (3PM-8PM) of Summer 2022 (Figure 3.13).
3.5.3 Bitcoin Mining Impacts on Grid Flexibility
Any Bitcoin facilities participating in wholesale or AS markets must be registered
under a qualified scheduling entity (QSE). QSEs must meet certain qualification
requirements to submit schedules and bids for their load resources to participate in
various demand response programs. QSEs are often separate entities which act as
qualified representatives of cryptocurrency miners, participating in these markets on their
behalf (Menati et al. 2022). ERCOT makes data available on demand response
participation on day-ahead market disclosure reports. But data are sorted by “load
resource name” and/or QSE name (depending on the report). Load resource names are
made up of alphanumeric characters, but neither the type of load nor who owns that load
is clear from the load resource name. ERCOT provides a list of QSEs, but it is not clear
which QSE might represent a Bitcoin mining data center and mining companies were
generally unwilling to share this information with me for this research. Without the
ability to match bitcoin facilities to QSE or load resource names, there is little useful
quantitative data from ERCOT beyond statewide trends in demand response program
participation rates, which say nothing about Bitcoin mining impacts on grid flexibility
efforts.
ERCOT sheds some light on the unique ability of data centers to qualify as
controllable load resources (CLRs). CLRs distinguish themselves from non-controllable
load resources (NCLRs) with the capability to precisely follow and respond to security
constrained economic dispatch (SCED) base point instructions over short intervals. This
involves adjusting power consumption up or down every few seconds commensurate
with real-time grid operator instructions. NCLRs and other demand response participants
merely shift blocky loads in response to economic incentives (ERCOT 2022). In year-end
reports on demand response for 2021 and 2022, Bitcoin mining data centers were the
“first substantial amount of conventional load to participate in the AS market as a
Controllable Load Resource” in 2020 (ERCOT 2021) and are still the only loads to meet
CLR requirements today (ERCOT 2022).
This kind of flexibility benefits both grid operators and cryptocurrency miners
adjusting to real-time changes. Ancillary services are sold in day ahead markets and
delivered in real time. For example, ERCOT maintains certain load resources as
responsive reserve services (RRS) to restore grid frequency “within the first few minutes
of an event that causes a significant deviation from the standard frequency” (ERCOT
2005). If an RRS-participant load sells a day-ahead ancillary, they must be online and
available if called upon by ERCOT. If a black swan event occurs with a large mismatch
between the AS clearance price and a much higher real-time price, these load resources
cannot “sell back” the ancillary services they bought in the day-ahead market; they must
consume energy at the real-time price to stay compliant with their ancillary sale (Helman
2021).
Lancium’s CLR software dynamically adjusts its power use to real time pricing
changes and/or grid operator instructions. This allows its Bitcoin mining data centers to
avoid high prices and turn down consumption during periods of high system-wide
demand. Figure 3.14 shows Lancium’s Fort Stockton active power consumption
compared to real-time energy prices in LZ West and Figure 3.15 shows the comparison to
ERCOT system-wide demand. Predictably, we see Fort Stockton drop electricity
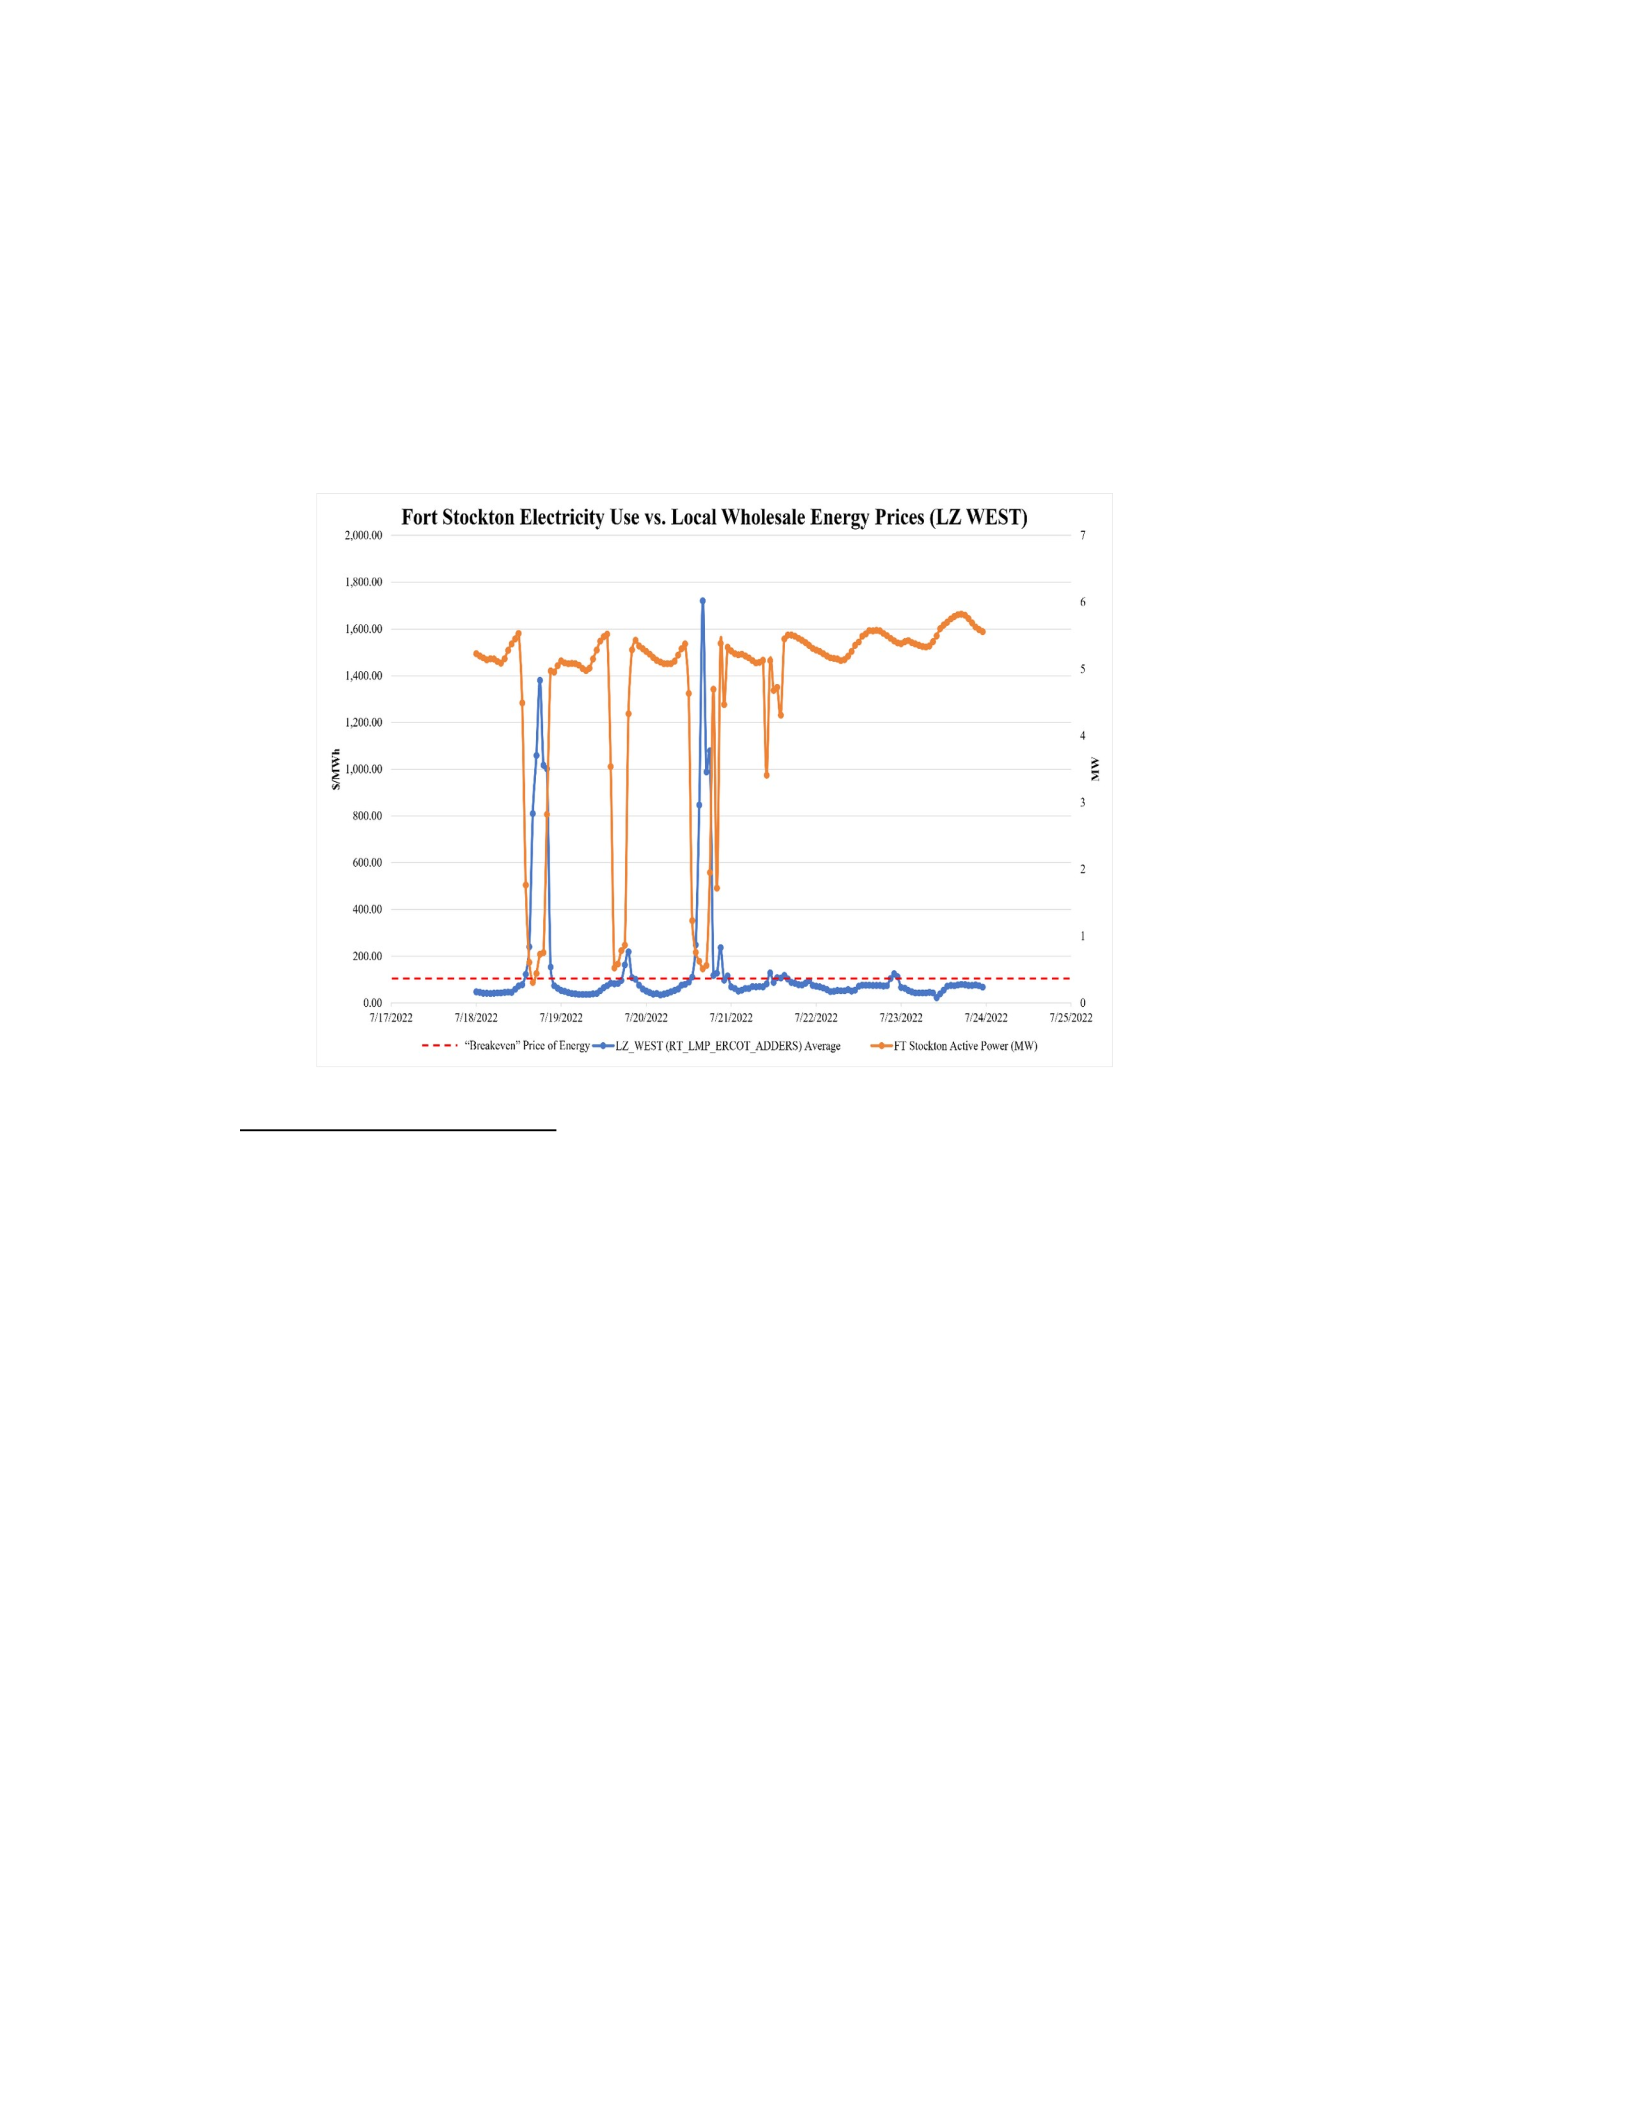
consumption dramatically during periods of high real time prices during a hot week in
mid-July. 222 These large drops in power consumption typically correspond to increases in
system-wide demand as well. Lancium’s software automatically curtailed mining when
the price of power was above Bitcoin’s breakeven price.
222 The breakeven price for Bitcoin mining profitability with a S19 Pro miner was around $125/MWh during
that week. This is based on a model for determining the breakeven price of energy depending on mining
equipment and Bitcoin market/network conditions (i.e., ASIC model, market price, total network
hashrate). I elaborate on this breakeven price model in Appendix A.
223 Figures 14 and 15 are author-generated from raw data provided directly to the author from Lancium.
Lancium provided their active power use during July and August 2022, only.
Figure 3.14 Fort Stockton Electricity Use vs. LZ West Energy Prices (author)
223
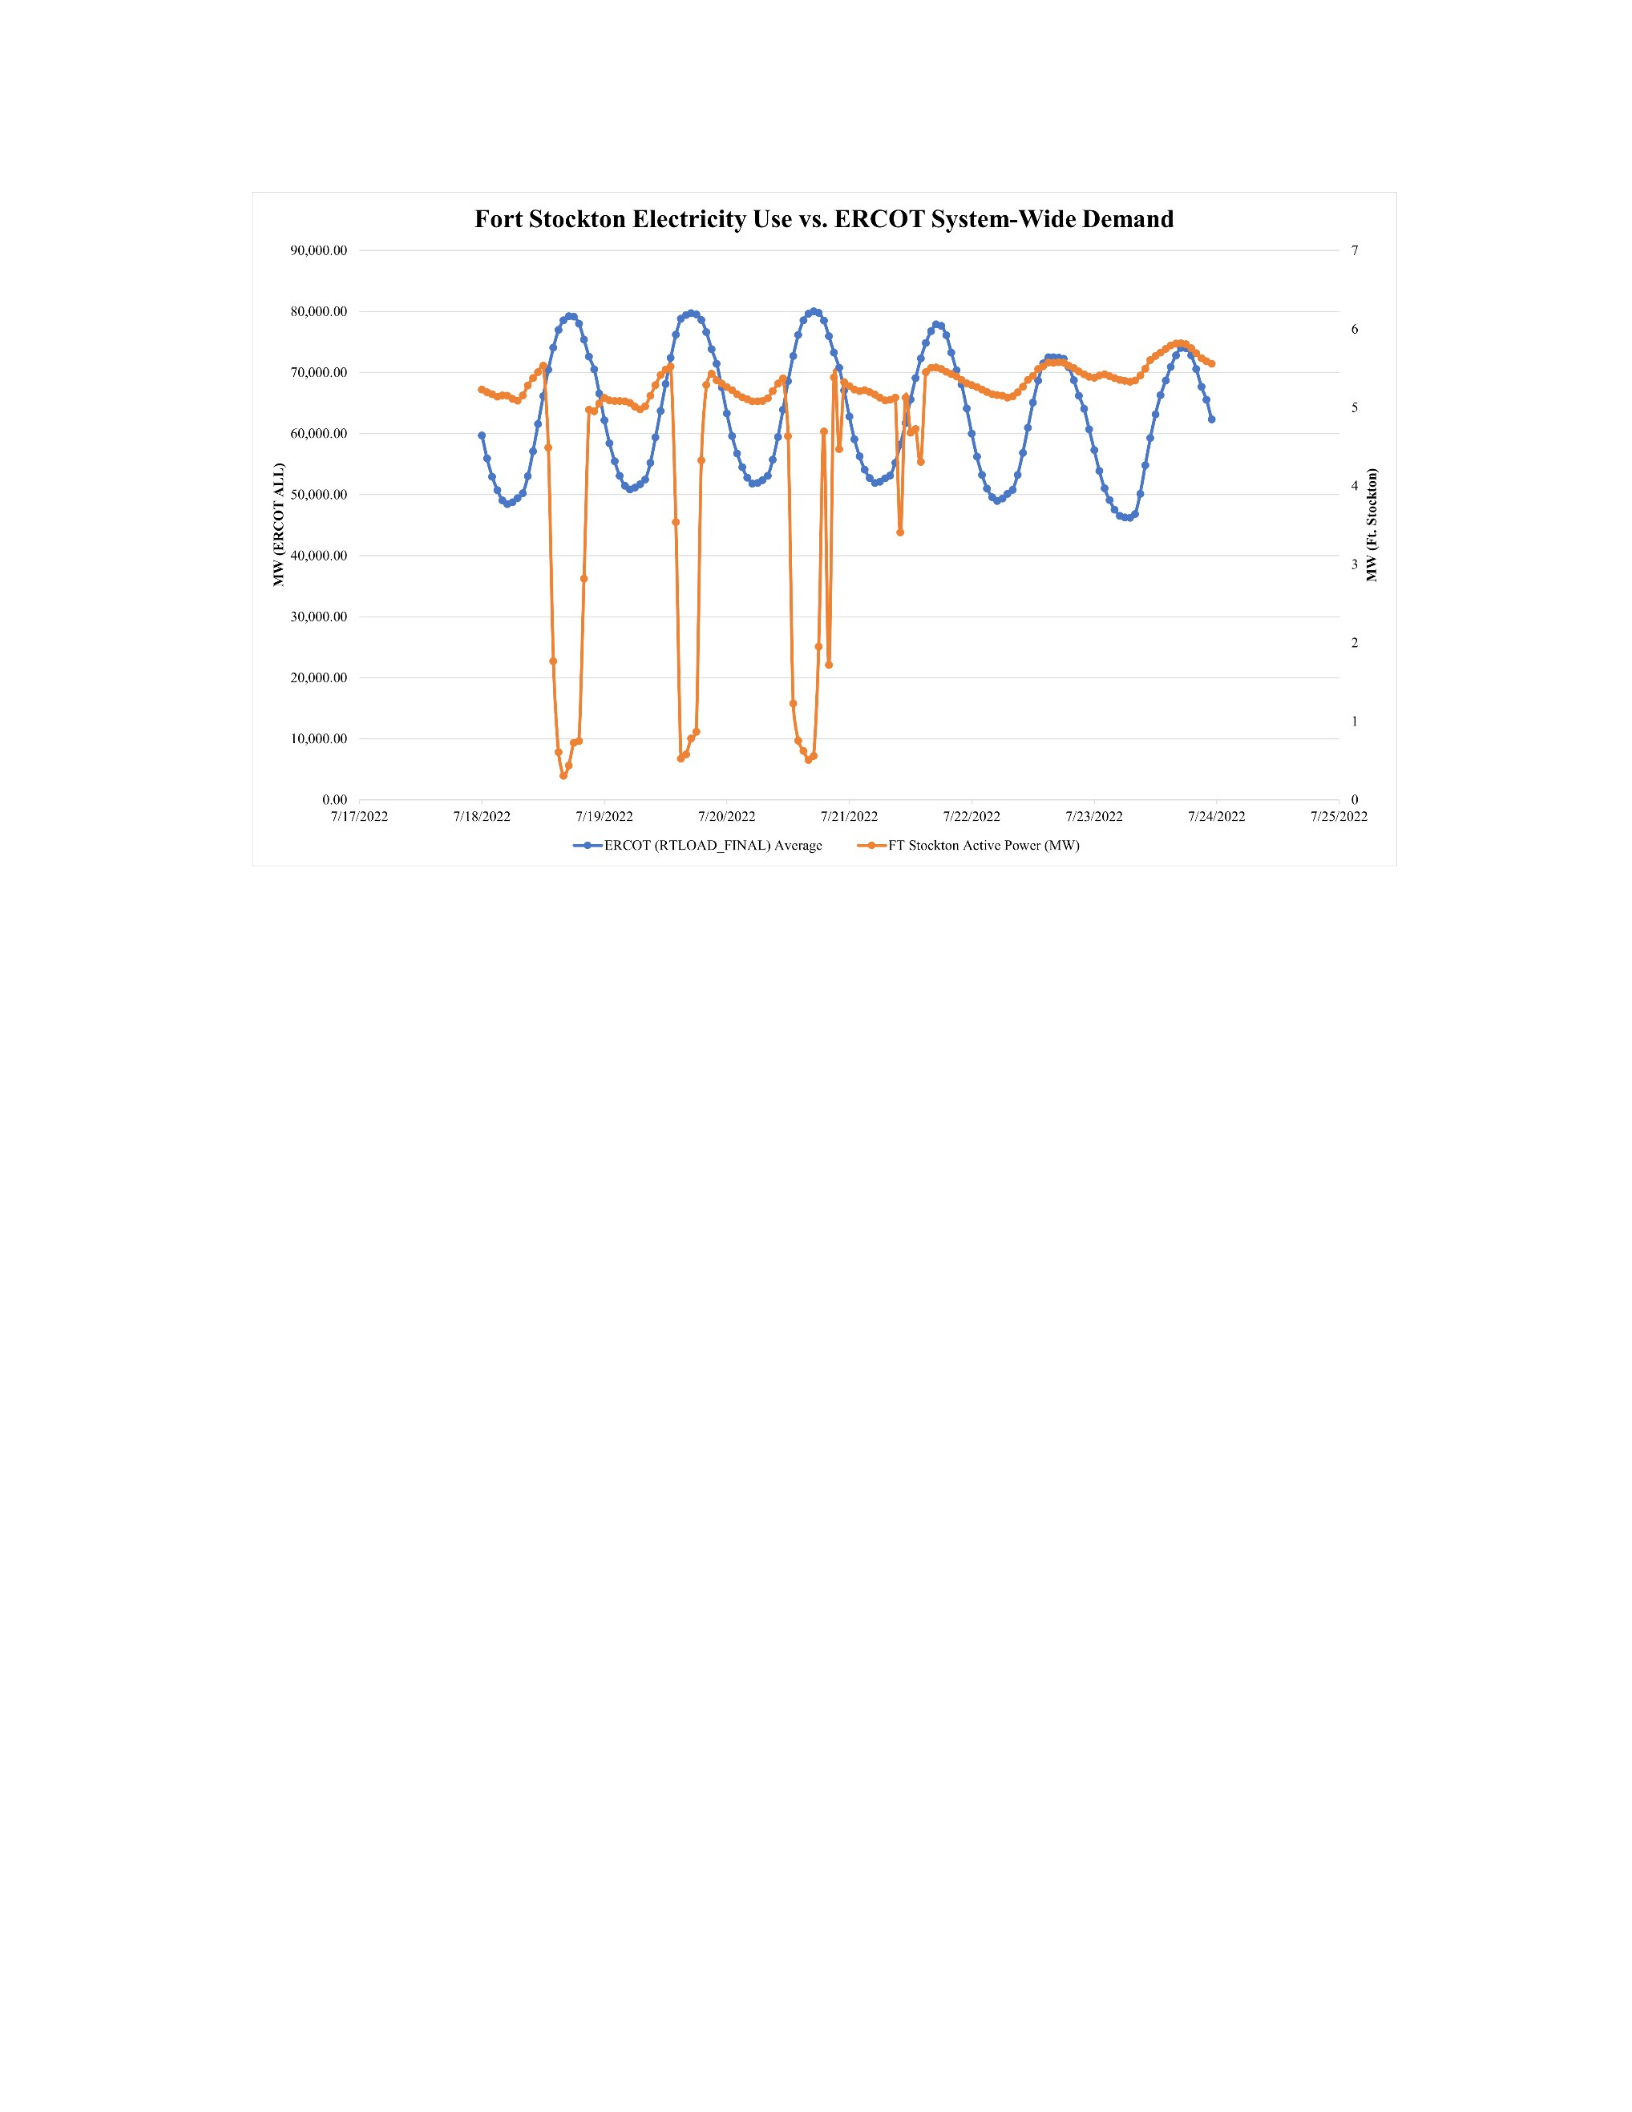
Figure 3.15 Fort Stockton Electricity Use vs. System Wide Demand
High degrees of flexibility and mining partnership with grid operators also enable
miners to rapidly offload power demand in response to certain grid conditions. Figure
3.16 shows how Fort Stockton miners dropped 50MW of power consumption within
seconds during an underfrequency event in January 2022. ERCOT CEO Brad Jones
touted the utility of Bitcoin mining in providing grid flexibility in March 2022 saying,
“cryptocurrency [mining] is very unique in that way in that all of the loads can come off.
Most other data centers, whether Microsoft or any other data center provider like
Amazon, they all have customers to serve every other day so they can’t just turn off – but
these cryptocurrencies can” (CNBC 2022). In February 2021, Winter Storm Uri led to
widespread power loss, several deaths, and economic losses exceeding $200 billion in
Texas (ASCE 2021). The following winter, virtually all industrial Bitcoin mining shut
down ahead of Winter Storm Landon to relieve pressure on the grid (Gkritsi 2022). The
Texas Blockchain Council (TBC) worked directly with ERCOT to ensure Bitcoin mining
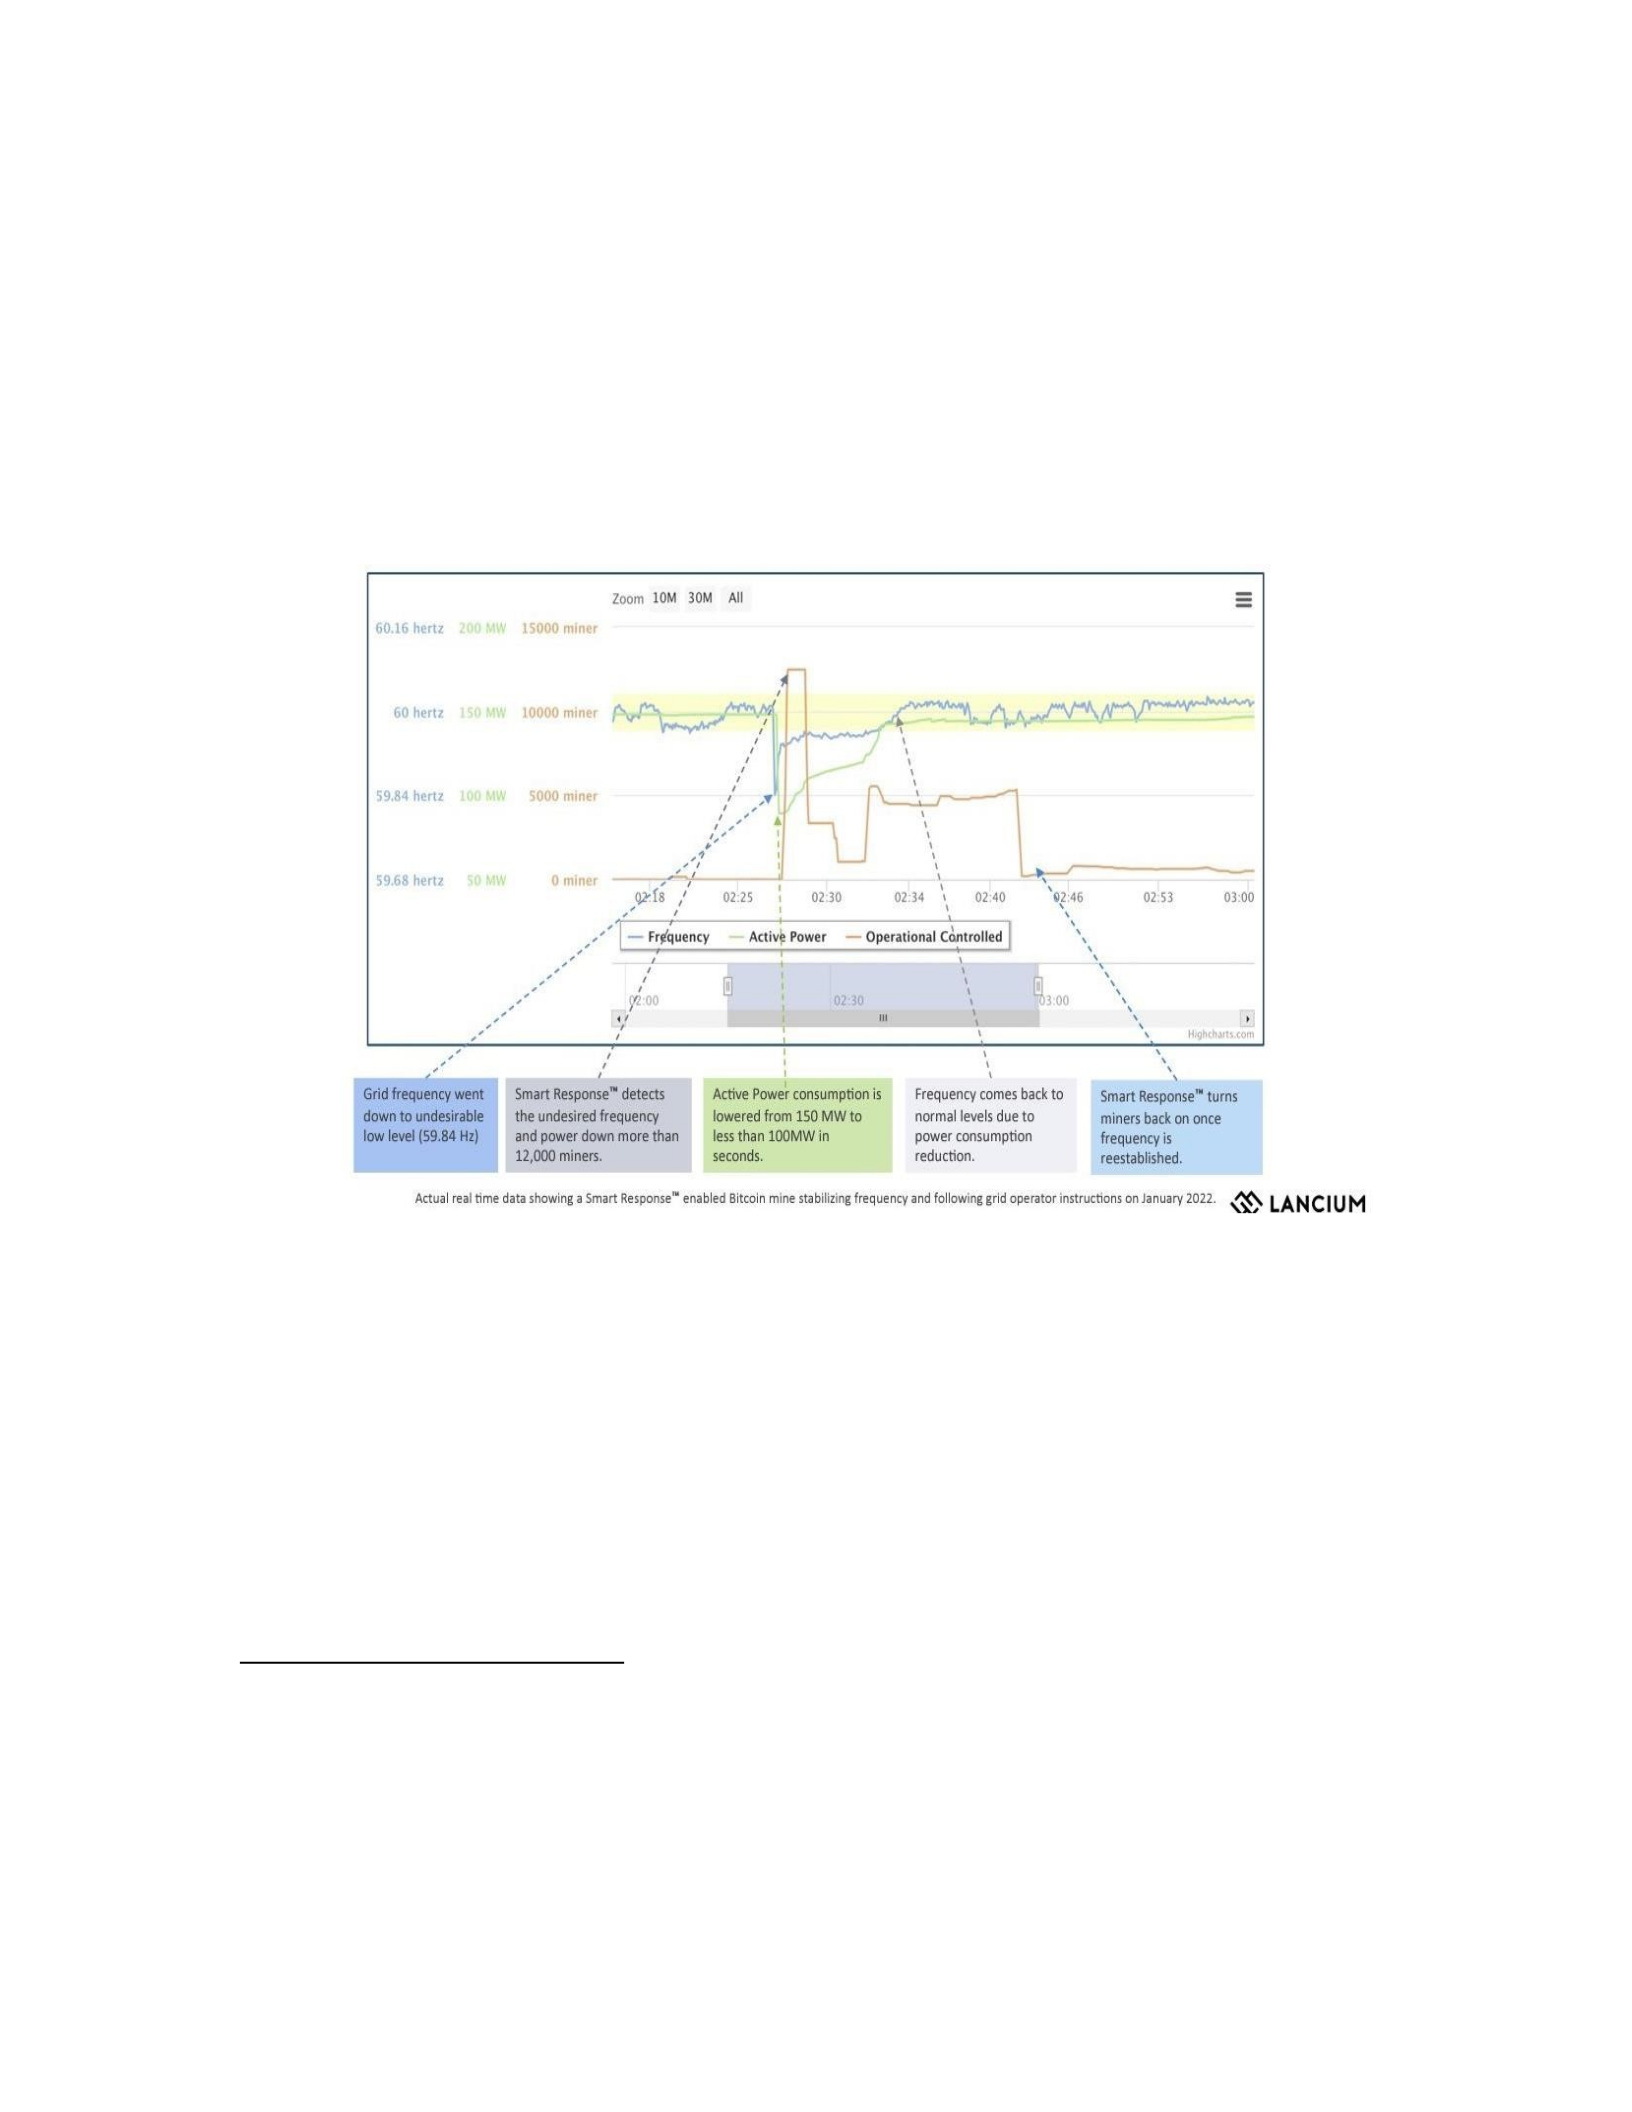
was part of the solution, and not a contributor to the problem in 2022. In a letter to Texas
Governor Gregg Abbot, TBC wrote “Just as important as the positive market signals we
send to generators is our unique ability to immediately shed load when ERCOT demands
it. This sort of demand response has and should continue to be a powerful tool in any grid
management strategy” (Wright 2022).
Figure 3.16 CLR Response to Underfrequency Event (Lancium 2022)
3.6 Discussion
Power grids are complex systems wherein supply, demand, and pricing vary over
time and space. The results of this study rely on quantitative empirical data to describe
the state of the ERCOT grid relative to the presence of large Bitcoin mining data centers.
Most of these data centers are positioned in regions with a relatively high proportion of
renewable energy and a high frequency of negative wholesale energy prices (3.5.1). But
whether this incentivizes further development of renewable generation requires causal
analysis (3.6.1). Time series data also indicate no correlation between these data centers

and wholesale energy prices, but policymakers should consider retail markets and other
factors impacting local communities (3.6.2). Lastly, some evidence from Fort Stockton,
Texas suggests Bitcoin mines are particularly well-suited to function as highly flexible
data centers. But more empirical data on widespread miner participation in demand
response programs is needed to conclude Bitcoin mining helps provide grid flexibility in
a meaningful way (3.6.3).
3.6.1 Does Bitcoin mining incentivize renewable growth?
The high concentration of renewable energy and saturation of transmission
infrastructure in West Texas pre-dates the inflow of most new Bitcoin mining hashrate in
the state. Nearly all the mining power analyzed in this study came online after 2020. It is
still too early to conclude that the arrival of new Bitcoin mining causes further growth of
new renewable projects that would not have been developed otherwise. Future EIA Form
860 data on both “proposed” and “operable” generators could allow for a quantitative
study (e.g., difference in difference) comparing renewable growth trends before and after
the arrival of new Bitcoin mining. Of course, such studies would require more concrete
data on precisely when these data centers came online (as well as how much power they
use) to draw a causal relationship. If data on power purchasing agreements (PPA)
between cryptocurrency miners and power plants were publicly available, hybrid project
research studies (Bolinger et al. 2021; 2022; Gorman et al. 2022) could be conducted as
well.
If anything, it is more likely that the causal link has run in the opposite direction:
saturation of renewables leads to congestion and a higher frequency of low and negative
wholesale energy pricing which entices Bitcoin miners to set up nearby. The results of
this study demonstrate that most Bitcoin miners in Texas choose areas with

disproportionately high levels of renewable energy relative to the rest of the state. It
stands to reason that the presence of flexible data centers in these regions provide a
consistent and reliable customer of excess renewable energy during low pricing events.
Former ERCOT CEO Brad Jones said, “crypto has found a way to come into our market
and take some of that excess wind in off-peak periods… we can use that cryptocurrency
to soak up the excess generation and really provide a home for more wind and solar to
come to our state” (CNBC 2022).
Still, the largest mining data centers by capacity are in Rockdale, Texas; a region
low on renewable energy capacity. Grid-connected power consumption draws from the
energy mix of the region (Table 2.6). If cryptocurrency mining incentivizes further energy
production in renewable-rich areas, it does the same in high carbon-emitting regions.
Evidence suggests Bitcoin mining provides a customer for carbon-emitting power plants
(Roeck and Drennen 2022; Millman 2022) and creates fewer new jobs than other
industrial energy consumers (Benetton et al. 2021).
Cryptocurrency mining’s utility to society writ large is a normative question. A
libertarian viewpoint might suggest that value-based judgments on who should be
allowed to consume carbon-emitting energy constitutes governmental overreach. An
environmentally conscious observer might deem any incentive for carbon-emitting
growth unacceptable. The results of this study suggest energy-intensive data centers can
improve the economics of renewable projects as curtailment and congestion continue to
grow in regions with high VRE penetration like West Texas. An “all or nothing” policy
approach to cryptocurrency mining fails to recognize either the costs or benefits of its
utility in facilitating the transition to a net-zero economy. A policy “middle ground” exists
where grid-connected mining in renewable-rich regions can be incentivized.

Policymakers can also encourage behind-the-meter cryptocurrency mining co-located
with renewable or low-carbon-emitting generators.
3.6.2 How does Bitcoin mining impact energy prices?
This study yields little evidence to support claims that Bitcoin mining
significantly impacts nearby wholesale energy prices most of the time. Results suggest
exceptionally large data centers like Rockdale may contribute to higher nearby energy
prices during periods of high system-wide demand (Figure 3.13). But convincing causal
claims to that end would require demand data from these large data centers at the hourly
time interval. If these miners were to provide such data, researchers could identify exactly
when they curtail energy consumption relative to the dynamic breakeven price of energy
for Bitcoin miners, nearby wholesale energy prices, and system wide demand as seen in
seen in the analysis of Lancium data in section 3.5.3 (Figures 3.15 and 3.16).
Surprisingly, high regional wholesale energy prices relative to the rest of the state
do not appear to factor into miner decision-making calculus on where to locate their data
centers. For example, Fort Stockton, Upton County, and Pyote, Texas are all within
100km of one another. Regional LMPs were higher than the ERCOT-wide average prior
to new Bitcoin mines becoming operational, but lower than the ERCOT average in 2022
when all data centers were online (see Appendix B).
However, these results do not speak to the retail customer experience. Subsequent
studies might look specifically at whether retail electricity pricing is similarly unaffected
by nearby mining data centers by analyzing REP data (Hartley et al. 2019). Like
Greenberg and Budgen’s (2019) case study of a cryptocurrency “boomtown,” other
studies should look at localized cryptomining impacts beyond energy prices. Finally,
while cryptocurrency adoption is growing, the number of U.S. adults who use it is still

small (Faverio and Massarat 2022). A full cost-benefit analysis must consider that
negative externalities of carbon-based mining (e.g., pollution, emissions) affect those
who have no interest in utilizing or investing in cryptocurrency.
3.6.3 Does Bitcoin mining provide flexibility to grid operators?
Evidence supporting the use of cryptocurrency mining in ERCOT’s demand
response programs and ancillary services markets is limited but supports theoretical
claims regarding highly flexible loads as demand-side grid stability solutions to
intermittency issues. Without transparency from cryptomining companies in sharing their
QSE and/or load resource names, researchers have no way of quantitatively and
empirically assessing DR/AS participation rates. Still, the fact that cryptomining data
centers in Texas are the only loads to qualify for CLR certification supports claims that
these interruptible loads are uniquely suited to partner with grid operators in efforts to
boost grid flexibility in real time. Data shared from Lancium (Figures 3.14-3.16)
demonstrate how quickly these loads can reduce power consumption and aid in frequency
response. More hourly electricity consumption data sharing from mining companies
could show skeptics how natural, built-in economic incentives (i.e., high energy prices)
are in fact causing these data centers to scale back operations during periods of peak
demand.
There is also the question of whether the ERCOT demand response programs
cryptominers participate in are too expensive, market-distorting, or pass on unnecessary
costs to Texans when that money could be used to develop more transmission or battery
storage to cope with renewable intermittency. A report by the Tech Transparency Project
(2022) found “Bitcoin miners may collect as much as $170 million a year from programs
that pay large energy consumers for their willingness to shut down” (3). However, this

claim (and others made throughout the report) was unsubstantiated by empirical data and
no explanation was given for how this total yearly figure was calculated. Still, it is clear
from SEC filings that miners like Riot Blockchain (Rockdale, TX Bitcoin mine owner)
participate in demand response programs where they “opportunistically sell electricity
back to ERCOT in exchange for cash payments, rather than providing the power to our
customers during these peak times” (Riot Blockchain Inc 2021, 11). This occurs when
cryptominers like Riot Blockchain enter into contracts which lock in electricity prices at
specific rates ahead of time to avoid tail-end event volatility. While it received no revenue
from demand response in 2019 and just $9 million in 2020, Riot Blockchain reported it
was entitled to receive $125.1 million for its power sales during Winter Storm Uri, alone
(Riot Blockchain Inc 2021).
A report on the costs and benefits pairing cryptocurrency mining with demand
response efforts finds a “win-win range of curtailed hours when both the utility and
crypto miner are better off than the status quo of no coordination and no demand
response” (Wright and Shaban 2022). This range depends on miner revenue factors like
cryptocurrency price, hashrate, and mining equipment efficiency, and grid conditions for
the utility (i.e., grid manager). Optimum hours of mining curtailment which maximize
utility wholesale value differ from that of the miner’s optimum level of curtailment hours
to maximize revenue, but a wide “win-win” range exists, nonetheless. Furthermore,
Wright and Shaban (2022) find wholesale energy prices correlate with grid emissions,
therefore emissions reductions are possible when grid managers issue “an emissions
intensity signal” to “modulate crypto load and contribute to reducing grid emissions.”
In sum, the results of this study suggest there is potential for Bitcoin and
cryptocurrency mining to provide flexibility to grid operators, though collaboration is

critical to mutual success. Limited data shared from Lancium demonstrates how miners
react to price signals in real time and assist grid managers during underfrequency events
within seconds. Grid managers like ERCOT should be transparent with their customers
about the costs and benefits of demand response programs, and those costs/benefits
should be considered alongside alternatives like increased transmission and utility-scale
battery storage to facilitate energy arbitrage. Additionally, policymakers should insist on
transparent data sharing practices regarding demand response participation rates.
3.7 Conclusion
…the more demand to the degree that its flexible – that it can turn down whenever we
need the power for other customers – is fantastic. We can use that cryptocurrency to soak
up the excess generation and really provide a home for more wind and solar to come to
our state. And at the same time, it reduces their consumption during periods where we get
tight and we need the power for other customers. Now what we have to do in Texas is
figure this thing out. Its new. The solar is new, the batteries are new, and this
cryptocurrency is new. We have to find a way to utilize it within our system most
advantageously… we have to figure out ways to make sure we’re putting them at the right
location and that we can build out our transmission grid to accommodate them.
- Former ERCOT CEO Brad Jones (CNBC 2022)
This essay set aside normative arguments for or against the utility of
cryptocurrencies in favor of an objective exploration of how the world’s largest and most
energy-intensive cryptocurrency might serve as a tool in the energy transition. The scope
of this study is narrowly focused on a single energy grid – isolated from the Western and
Eastern Interconnections. The Texas deregulated approach to electricity markets differs
from most states. Subsequent studies might consider how the specific structures of
ERCOT’s energy pricing, demand response programs, and ancillary services market work
in concert with PoW mining that may not be applicable to the rest of the United States.
Blanket statements from cryptocurrency enthusiasts touting PoW mining data
centers as a panacea for renewable energy development and grid stability fail to capture

the nuance of what is at stake for grid operators and the customers who rely on it.
Academic studies suggesting the elimination of Bitcoin mining might help prevent the
world from a climate catastrophe are similarly biased and wildly misleading. In Texas,
cryptocurrency miners have demonstrated the ability to provide a constant customer for
cheap or often-curtailed energy in areas of high VRE penetration without significantly
impacting wholesale energy prices. Limited empirical work suggests they are capable of
functioning as interruptible data centers grid operators can partner with to make energy
grids more flexible under the right circumstances. Both are needed to facilitate a
transition to the green grid of the future which will power the net-zero economy. Utility-
scale battery storage and transmission infrastructure are essential, longterm solutions to a
reliable energy grid. But they are also expensive (Desing and Widmer 2022), time-
consuming (Cohn and Jankovska 2020), and natural resource-intensive (Xu et al. 2020).
If managed properly, PoW- based cryptocurrency mining can serve as one of many
helpful solutions in the energy transition. Natural economic forces disincentivize miners
from using power when it is expensive and needed most. But a deregulated market
approach to electricity generation and delivery should not constitute an unregulated one.
Carbon-based cryptomining results in negative externalities leading to market failures
which regulators must compensate for. I propose three specific policy prescriptions to
ensure a “win-win” relationship between cryptominers and grid customers in deregulated
markets:
1. Mandate transparent sharing of cryptomining load and demand response
participation data
Researchers need access to data for analysis and grid operators must insist on
maximum transparency from and coordination with mining companies. Understanding
the relationship between the grid and cryptocurrency mining requires a high degree of
literacy in energy economics and the fundamentals of how proof-of-work consensus
mechanisms work in practice. With data transparency, researchers can produce more
studies that help citizens better understand the costs and benefits of incorporating more
cryptomining data centers along the power grid. Sharing detailed time series demand data
could allow studies like this one to include regressions drawing more causal relationships
between a data center’s load and nearby energy prices in real time.
2. Grid operators in deregulated energy markets like ERCOT should establish shut
off criteria for non-essential loads like cryptocurrency miners – particularly during
periods of high demand.
Relying on the free market to regulate cryptocurrency miner demand works when
the breakeven price of energy for mining profitability is low. Economically rational
miners will turn off their equipment when energy prices are too expensive relative to the
revenue potential of mined Bitcoin. But the price of Bitcoin can surge rapidly, raising the
breakeven price of energy and creating a revenue incentive for miners to keep ASICs
running despite high prices and a high level of overall system demand. Without
participation in demand response, such miners could add to the risk of grid failure and
rolling blackouts which threaten the wellbeing of millions.
Thus far, the Texas Blockchain Council has voluntarily worked with ERCOT
managers to ensure large-scale miners shed load and relieve pressure on the grid when
needed. But there is no requirement for cryptominers to join the TBC or follow ERCOT
instructions. Based on a risk assessment of projected grid conditions, ERCOT could
establish a ceiling price of energy or system demand above which cryptomining and other
non-essential uses of power are not permitted when economic conditions (i.e., the

breakeven price of energy for cryptomining) fail to provide natural disincentives to
operating mining equipment.
3. Incentivize mining in regions with a high proportion of renewable energy for
gridconnected miners.
While most large-scale miners in Texas are in regions with relatively high
percentages of nearby renewable power generation, the largest mining operations in the
state are in regions which rely heavily on carbon-emitting energy sources (Table 3.6).
Policymakers can incentivize renewable growth by encouraging (or requiring) miners to
place their load demand in regions rich in renewable generation. Conversely,
policymakers can impose disincentives for mining in heavy carbon-emitting regions in
the form of a carbon tax on companies running data centers in these regions.
Lastly, this study focuses on grid-connected Bitcoin mining in a deregulated
energy market that lacks connection to the Western and Eastern Interconnections. This
effectively creates a unique situation where Texas is the only state which does not have
the ability to draw significant amounts of power from other states (Oxner 2022). The
external validity of the findings of this study may be limited as energy regulation and the
structure of demand response/ancillary services markets vary by state and ISO/RTO.
Subsequent studies might examine energy pricing around PoW cryptocurrency mining in
different types of energy markets and policymakers should consider the costs and benefits
of energy deregulation. Studies focused on data centers co-located with renewable
generators sourcing power behind-the-meter could shed light on further opportunities for
mutually beneficial, sustainable cryptomining in the energy transition.

