


The Impact of Acquisitions on Entrepreneurial
Technical Organizations
Section 1: Foundation of the Study
Innovative technology has been the cornerstone of economic sustainability in the
United States since the mid-1800s; however, since the 2000s, emerging global economies
and domestic acquisition strategies have jeopardized innovation. Therefore, transcending
technologies that could have created new industries, making the U.S. economy stronger,
have been compromised. Lynn and Salzman (2007) noted that countries such as India,
China, Brazil, and Mexico have adapted to high-end technology development, and
U.S.based global organizations are now competing with new technology-based
companies from emerging economies. Increased competition from emerging global
economies, along with decreased innovation in the United States, jeopardizes economic
standards in the United States. Therefore, transcending technological innovation from
acquired smaller entrepreneurial technological organizations needs to mature to generate
increased economic sustainability for the United States, resulting in positive social
change.
Background of the Problem
Since its inception, the United States has been a nation of liberty, and most
Americans see themselves as democratic people dedicated to free enterprise, celebrate the
founding fathers‘ ideology, and understand that the business of America is business
(Hughes, 2004). The founding fathers displayed inventiveness as conceived by the

Declaration of Independence, and Americans following this tradition have built on this
foundation a boldness of comparable inventiveness in technological transcendence. No
other nation has displayed such innovation and developed such inventive sustainability as
the United States from 1870 to 1970 (Hughes, 2004).
Large technology firms with substantial cash reserves, such as Cisco, IBM, and
Hewlett-Packard, acquire smaller firms for diversification. In 2006, these three firms
acquired 28 organizations, with the combined deals exceeding $4.7 billion (Adavikolanu
& Korrapati, 2009). The intention of these acquisitions was to acquire complementary
and fringe technologies for a diversified portfolio to achieve sustainability. The decision
whether to acquire an organization or organically produce a technology is based on the
entrepreneurial innovative success the acquired or target organization has developed,
which, if integrated correctly, may produce favorable results. Within an acquisition
framework, where successful entrepreneurial firms started by individuals with either a
record of sustaining successful ventures or who have held senior positions in technology
firms have been able to acquire funding through venture capitalists, monetary ambition
outweighs innate principles (Umesh, Jessup, & Huynh, 2007). The dynamics of the
vision and demonstrable leadership might create an innovative culture unique to a
particular organization, and that frontier on the fringe technology sets innovative
technology companies apart from any competition. Leaders of larger technology firms
are encouraged to, and are often enticed to, target successful, smaller, innovative
technology organizations and focus on pure monetary gain (K. S. Christensen, 2006).

Problem Statement
Transcending innovation, entrepreneurship, and acquisitions in information
technology organizations was the focus of the current research study as a strategic
corporate growth initiative for presumed sustainability. The problem was that new
startup companies with innovative ideas do not mature when they are acquired by larger
companies and do not fully articulate potential industry-transcending innovation
(DiGuardo & Valentini, 2007). Adavikolanu and Korrapati (2009) completed a study on
234 acquisition deals valued at approximately $100 billion conducted by leading
technology firms over an 8-year period, which resulted in several hundred million dollars
of valuation loss due to inadequate integration of the acquired firm.
The quantitative quasi-experimental study involved examining control variables
before and after the acquisition of entrepreneurial innovative start-up organizations with
larger acquiring public organizations within the United States. Kapoor and Lim (2008)
noted that high-technology acquisitions tend to stall innovative fervor, meaning the
leaders of larger firms acquiring smaller firms tend not to anticipate the creative
leadership and engineering synergies of the organizations they purchase. Although
mergers and acquisitions have become the best-known business strategies for growth in
U.S. organizations, acquiring organizations tend to underestimate the complexity of
integrating all the acquired organization‘s resources, resulting in an unsuccessful
acquisition dismantling the innovation that was once thriving (Kongpichayanond, 2009).

Purpose Statement
The purpose of the quantitative quasi-experimental study was to test the theory
that transcending innovation is lost due to the acquisition strategies of larger public
technological organizations acquiring smaller start-up innovative entrepreneurial
organizations, controlling for patent generation, stock price trend, and stakeholder
retention. DiGuardo and Valentini (2007) noted that new start-up companies with
innovative ideas do not mature when they are acquired; therefore, the companies do not
fully articulate potential industry-transcending innovation. The independent variable,
large publicly traded technical organizations, included organizations that had made many
acquisitions and were either computer software or hardware manufacturers. The
dependent variable was disruptive technology firms that possessed innovative resources
typically funded by venture capital, with the controlling variables defined as the
comparison of the number of patents generated, stock price fluctuation, and retention of
the ownership and lead engineering talent of the acquired firm before and after the
acquisition.
Additional considerations of the study were to determine why acquisitions
between large technical organizations and smaller entrepreneurial innovative firms are
not successful and therefore to learn the potential transcending innovations that are lost
when smaller creative entities are integrated into larger, culturally different organizations.
An assumption was that the acquiring organization decreased value as a result of the
insufficient integration of the acquired company. The outcomes of decreased

organizational value have a negative impact on new technologies that could have
potentially created new industries, and therefore the United States could remain the
dominant economic power in the world (Adavikolanu, 2008).
Nature of the Study
The focus of the current study was primarily on large global enterprises such as
Apple, Cisco, Dell, Hewlett-Packard, EMC, Google, IBM, Intel, Microsoft, and other
leading technology organizations in the United States and their strategic acquisitions.
Acquisitions of smaller entrepreneurial start-up firms by these large global entities have a
negative impact on innovation and equity after an acquisition and therefore decrease
economic value for the United States. A quantitative, nonequivalent (pretest and
posttest), quasi-experimental research design was appropriate because the design helped
to determine conclusive evidence that innovation needs to mature for technological
revival to occur in the United States. Nonequivalent quasi-experimental methods are
appropriate for studies in which individuals are not randomly assigned, thus
acknowledging a strong base of criteria for determining technological relevance
(Creswell, 2009). The nonequivalent quasi-experimental design was more suitable for
this study than other research designs because of the statistical nature of the technology
industry and its need for large amounts of conclusive data from many research
perspectives. Clougherty and Moliterno (2010) determined that the quasi-experimental
design approach crosses the boundaries of many different disciplines; the approach is
appropriate for this context as organizational leaders are readily able to surmise the
impact of managers and their environments for relevance to organizations.

A sequential mixed research study was considered but not selected because of the
complexity of the procedure. Johnson, Onwuegbuzie, and Turner (2007) determined that
the mixed method approach is appropriate when the complexities between the connected
groups, in relation to a complex research question, indicate that mixed methods research
is likely to provide superior outcomes. Due to the nature of the problem of lost
innovation due to acquisitions, a statistical approach was necessary to ensure secured
outcomes. The quasi-experimental approach was appropriate for the current study
because it enables the research structure to be presented in comparative sections.
Magnusson (2009) determined that a quasi-experimental design is necessary for a
comprehensive determination of correlational significance among relevant dimensions for
reliability. The quasi-experimental design also made a clear and concise measure on how
a quantitative research method can impact a complex, technical business problem that has
implications for the economic stability of the United States.
Research Question
Large companies in the technology industry are investing billions of dollars in
acquisitions every year. The effects of these acquisitions on the value of the acquired
firm were not readily evident to determine if innovation continues after an acquisition.
To determine if innovation continues when smaller start-up firms have been acquired,
rigorous data collection and analysis on multiple scenarios was needed. Cisco Systems
estimated the failure rate for technology acquisitions was 90%, Graebner, Eisenhardt, and
Roundy (2010) noted that outlining the motivation for these deals and potential pitfalls

could undermine the intent to acquire. Acquisition pitfalls are subject to wealth
redistribution, which in its intent is strategically sound but in its execution delineates
macro global implications with potential transcending innovation. The central research
question for the study was as follows: How do start-up entrepreneurial technical firms
lose innovation when acquired by larger global public entities?
Hypotheses
Hypotheses 1: Patent Generation
Patent generation is a key determination of the innovative significance for a
startup entrepreneurial firm, for which creating intellectual property and protecting those
rights may be the basis of an organization‘s existence (Raghu, Woo, Mohan, & Rao,
2008). Building on patents becomes a measurement of an organization‘s innovation and
whether acquired patent generation may cease. Gittelman (2008) noted that patents play
a central role in empirical research on innovation, the results of which provide rich details
of technologies, enabling the analysis of a wealth of valuable and easily accessible
information.
H10: Patent generation rate of the target firm was greater before acquisition.
H1a: Patent generation rate of the surviving firm was greater after acquisition.
Hypotheses 2: Stakeholder Retention
Schlange (2009) noted that successful, sustainable, driven, entrepreneurial
organization stakeholders are derived from an internal network of individuals who
develop a framework considered the nature of the organization‘s success. After an

acquisition, the ability of the acquiring firm to acquire, transfer, and integrate the
acquired firm‘s knowledge base framework into its own enterprise creates a sustainable
competitive advantage (Cloodt, Hagedoorn, & Kranenburg, 2006). The social framework
that made the target organization innovative because of the nonretention of personnel
after an acquisition often leaves the surviving entity in jeopardy. Desyllas and Hughes
(2010) noted that if the full framework of innovators from the target firm no longer exists
in the surviving organization, the innovation that existed before acquisition might no
longer be applicable.
H20: Stakeholder acquisition decreased after acquisition.
H2a: Stakeholder acquisition increased after acquisition.
Hypotheses 3: Stock Price Trend
Ma, Pagan, and Chu (2009) noted that when an acquisition is made and the bidder
is a publicly traded organization, a 5-day window exists where stock price dictates if the
transaction is a favorable or unfavorable event. A method that compares the stock price
change of acquiring firms around the acquisition announcement date to a benchmark
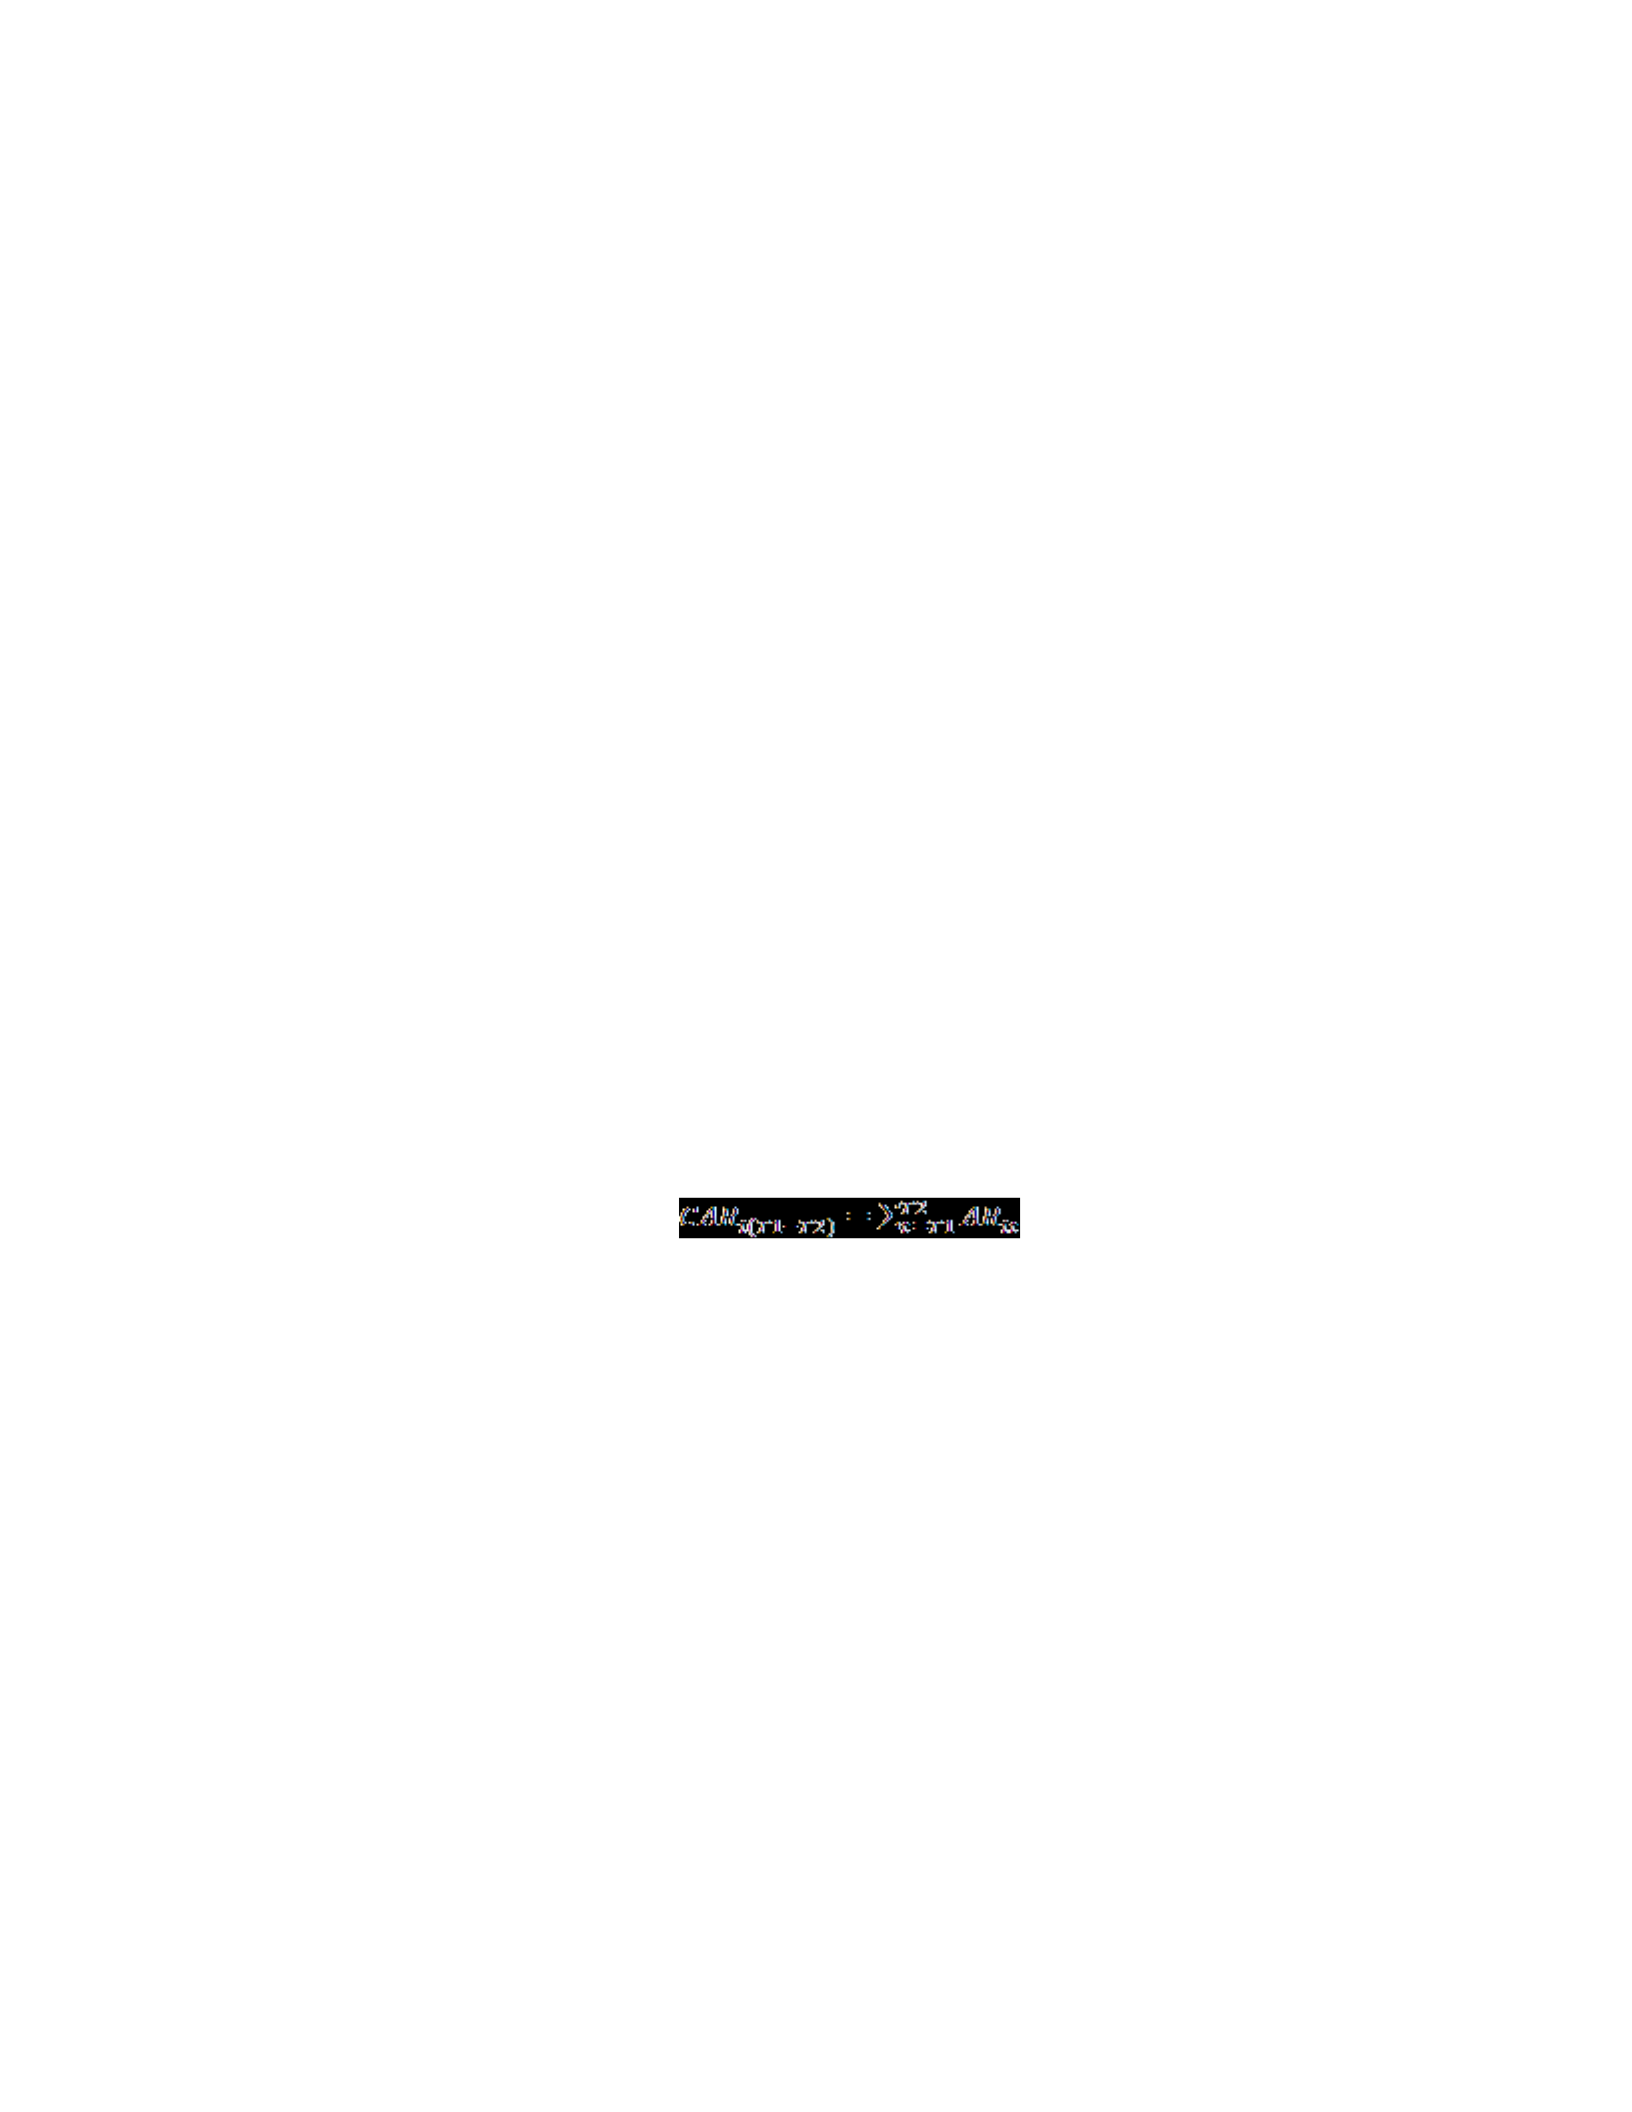
index to acquisition success is the cumulative abnormal return (CAR) value. S. Lee and
Connolly (2010) concluded that the CAR value results are systematically estimated and
statistically analyzed to determine the magnitude and direction of the effect of the event
on the firms‘ valuation. S. Lee and Connolly noted that the market model assumes the
linear relationship between the return of any security and the return of the market
portfolio, as noted in Equation (1):
Rit = αi + βiRmt + eit (1)
where Rit is returns of security i at time t; Rmt is returns of the market portfolio at time t;
and eit is error terms on security i at time t. According to Ma et al. (2009), Equation (1) is
estimated over a period of time beginning at -125 days and ending at -6 days from the
event day, depicting an event window of 5 days (-2, +2). With the estimates of αi and βi
from Equation (1), a normal return is predicted during the days covered by the event
window, where the prediction error commonly known as the abnormal return (AR) is
calculated from Equation (2):
ARit = Rit - αi – βiRmt (2)
where ARit is the AR for i on day t and Rit is actual return for firm i on day t (Ma et al.,
2009).
The daily ARs are summed over the event window to derive the CARs, as noted in
Equation (3):
(3)
H30: Stock price trend decreased after acquisition.
H3a: Stock price trend increased after acquisition.
Operational Definition of Variables
Independent Variable (X)
The independent variable was large publicly traded technical organizations,
defined as organizations that have made many acquisitions and were either computer
software or hardware manufacturers. Audretsch (2009) noted that entrepreneurship has

emerged as the engine of economic growth, creation, and competitiveness in global
markets. Markets of entrepreneurial innovation are the essence of continued economic
growth in the global continuum (Fontana & Nesta, 2009).
Dependent Variable (Y)
The dependent variable was disruptive technology firms that possess innovative
resources typically funded by self-funding, venture capital, or equity funding. The data
analysis process involved evaluating whether small, successful, innovative, technical
organizations continued to be innovative after being acquired. If innovation continues,
the United States will continue to be a dominant economic force in the global economy.
Bordoff, Deich, Kahane, and Orszag (2005) contended major policy priorities are
necessary to promote U.S. leadership in science and technology to spur economic growth
through innovation, where individuals, human talent, investment, research and
development, incentives, and effective government regulations all have sustainable
characteristics. The United States should renew this commitment for future generations
to enjoy economic prosperity, such as has occurred from past economic growth.
Control Variables
Control variables are the comparison of the number of patents generated, stock
price fluctuation, and retention of the ownership and lead engineering talent of the
acquired firm before and after an acquisition. The control variables determined the
statistical relevance for the study (Gittelman, 2008; Lee & Connolly, 2020; Schlange,
2009). The significance of the control variables dictated the outcome of the study.

Theoretical Framework
The theoretical framework for the study included the disruptive innovation theory
and the resource-based theory. C. M. Christensen (2003a) established the idea of
disruptive technologies, where organizations are subject to new innovative technologies
that if not adopted pose substantial risk to the survival of the organizations. This idea
over time became a theory to explain all kinds of disruptive innovation, where different
kinds of innovation have different competitive effects and produce different kinds of
markets (Markides, 2006). D. Yu and Hang (2009) noted that the disruptive innovation
theory is a powerful means of broadening and developing new markets that may in turn
disrupt existing market linkages. The resulting linkages are important to any study
because the need to bridge a theoretical concept and the research question demonstrates
the particulars of the study to illustrate the significance of the findings (Rocco &
Plakhotnik, 2009).
A secondary theoretical framework in the study was the resource-based theory.
The resource-based theory supports the disruptive innovation theory by identifying that
firms must develop distinct capabilities to enhance their ability to adapt to the changing
environments that disruptive innovation will challenge in order to compete in the
changing environments and improve their survival instincts (Esteve-Perez &
ManezCastillejo, 2008). The resource-based theory enables corporate leaders to
understand the capabilities of the organization in an innovative competitive marketplace.
Drawing from the resource-based theory is the resource-based view, in which choices of a
firm are based on the relation between the resource base of a firm and the resource

requirements of the market that is new to the firm (G. K. Lee & Lieberman, 2010). Both
the disruptive innovation theory and the resource-based theory supported the current
study and the ability to understand why large public organizations decide to acquire
smaller innovative start-up firms for competitive advantage and also helped to establish
why those acquisitions most likely will fail. Further discussion of these two theories
occurs in the literature review section.
Definition of Terms
The following terms and phrases are defined as used in this study.
Disruptive technology is an innovation that improves a product or service in ways
that the market does not expect and in turn accomplishes potential trendsetting innovation
(C. M. Christensen, 2003a).
Diversification means expanding a business or line of products by increasing the
variety of things produced or the number of operations undertaken in a given construct
(Harvard Business Essentials, 2003).
Emerging global economies are countries with relatively stable governments,
developing economies, and an increasing ability to spend money on consumer goods
(Tassey, 2008).
Entrepreneurial innovation is the use of tools to effect change and create better
products from a start-up organization (Sarkar, Echambadi, Agarwal, & Sen, 2006).
Inadequate integration is the inability to manage fully a newly acquired product
or service (Graebner et al., 2010).

Industry-transcending innovations are new products or services that disrupt
existing industries (C. M. Christensen, 2003a).
Innovative culture is a culture in which everyone in the business has a deep
understanding of the business in technically fierce market competition (C. M.
Christensen, 2003b).
Innovative fervor means continuing to provide new products or services in fierce
market competition that is characteristic of entrepreneurial start-ups (C. M. Christensen,
2003b).
Innovative technology is a new product or service that challenges existing
industries (C. M. Christensen, 2003a).
Organic research and development occurs when corporations invest in internal
research and development strategies rather than through acquiring the technology through
acquisitions (C. M. Christensen, 2003b).
Start-up is a business or an undertaking that has recently begun operation and
grew from a tiny organization to a multimillion-dollar corporation (Barringer & Ireland,
2010).
Technical organizations are companies that produce products or services that
focus on engineering or scientific solutions (Khallaf & Skantz, 2007).
Assumptions, Limitations, and Delimitations

Assumptions
Ownership and key technical officers are the reason for the success of smaller
innovative start-up technical organizations (Sarkar et al., 2006). The amount of energy
extended to start a technology firm requires an enormous amount of rigorous effort from
the ownership and the technologists who devise the technology and can be defined as the
stakeholders. These individuals‘ knowledge and passion are the essence of a particular
organization and are noted as the reason for their success or failure.
Tassey (2008) noted the rise of competition with innovative technology from
emerging economies is compromising the U.S. economy and suggested domestic
innovation is crucial. Foreign students educated in the United States who once stayed in
the United States for opportunity now move back to their homeland after receiving their
education because these emerging global economies provide greater prosperity. Less
technical ingenuity from foreign students, along with greater competition from emerging
economies, weakens the innovative spirit and threatens the U.S. economy.
Craig, Jackson, and Thomson (2007) noted that current economic conditions in
the United States require government policy for incentive programs for innovation. The
essence of the U.S. economic system has competed in free market entrepreneurial
competition for economic sustainability; however, to persevere in competitive markets
dominated by larger institutions, small businesses need assistance. Government programs
that enable small institutions to grow their business are very effective for innovation and
sustainability.

Limitations
The study had two limitations. First, the valuation of the acquirer‘s stock price
after an acquisition may have had external implications that may have indicated an
unfavorable result when in fact the acquisition was successful. External implications
may be defined as adverse market conditions, political unrest, or unforeseeable disasters
within the time frame of the acquisition. The introduction of supplementary asset
acquisitions may lessen potential volatility and therefore extend the scope of the
variations beyond short-term value creation (Adavikolanu, 2008). Additionally, the
global technology acquirers selected in this study may have had foreign revenue
investments that may have distorted the domestic stock valuation during the CAR value
analysis.
A second limitation was the data collected were limited to large public technical
organizations comprised of data-center technologies, described as organizations that
manufacture software and computing solutions and do not comprise innovation in all
businesses. The rationale for the hypotheses was that technological innovation,
disruptive technologies, and emerging markets were all compliant to the data set but did
not include all technological organizations in the United States that generate innovation.
The high-technology industry data set collected in the current study had a sufficient
representation of entrepreneurial start-up firms to determine if innovation is lost due to
acquisitions.

Delimitations
The scope of the research was to identify areas within the technology industry in
the United States that will be able to mature and innovate, transcending completely new
industries, which will generate sustainable employment and wealth for Americans. The
selected data set narrowed the population to a few highly publicized global technology
firms from the United States with robust acquisition strategies and determined if the
acquired firms would have generated transcending innovation if they had not been
acquired. The study did not include acquisitions held by private entities or investment
data held by private equity firms into technology start-up organizations, which would
have presented innovative tendencies for institutions that do not affect global trends.
Representation of the data included the innovation level of a particular targeted
acquisition before and after an acquisition.
Significance of the Study
The significance of the study is prevalent where unsuccessful integration after an
acquisition because of organizational, cultural, and policy differences will dismantle the
creative think tank of the stakeholders that enabled the acquired firm to succeed (Sarkar
et al., 2006). Innovation requires an entrepreneurial mind-set, and after that strategic
initiative changes through an acquisition, the stakeholders from the acquired firm will not
be as creative because of the integration into a more formal culture. This lost opportunity
is significant because the potential creation of the now-stalled ideas may have produced a
new transcending industry, as Apple Computer did with the creation of the Apple

Macintosh and the first graphical user interface (C. M. Christensen, 2003a). The
innovative creation has the ability to change the way business and daily lives are
conducted.
Tassey (2008) wrote that the economic dominance of the United States peaked in
the 1960s, and in the 2000s, in addition to weak recoveries, sluggish growth, and
competition from increasing global emerging economies, being competitive requires the
adoption of growth policies that are implemented with additional resources. To achieve
growth, innovative entrepreneurial organizations must be able to mature, thereby
generating greater opportunity for sustainable new technologies. The consequence of the
lack of successful integration therefore devalued stock, where an acquiring technology
organization would have retained its potential value loss by not acquiring; the shareholder
wealth would have increased due to positive cash flows through no cash layout during the
unsuccessful acquisition transaction. Innovative technology will enable future
generations to enjoy a better life, and letting entrepreneurial organizations grow will help
(Estrin, 2009).
Review of the Professional and Academic Literature
Decreasing innovation from U.S. corporations, along with increasing competition
from foreign emerging economies, has jeopardized the U.S. economy. Innovation in the
United States has been the cornerstone of its success based on free enterprise and
ingenuity that can transcend new technologies for competitive advantage (Hughes, 2004).
An example of transcendence through innovation is Apple, Inc., which in 2011 was the
second largest market capitalization company in the world behind Exxon Mobile

Corporation, and in 2010 became the largest technology company in the world, passing
Microsoft (Svensson, 2011). Technological innovation in corporations such as Apple,
Inc., takes many disciplines to be successful. In an interview with Neil Armstrong and
Steve Jobs, founder and former chief executive officer (CEO) of Apple, Inc., Jobs was
enamored with the enormous amounts of small and large innovations needed to put a man
on the moon and determined that innovation had become his blueprint to develop a plan
to put a computer in every person‘s hands for social change (Gallo, 2010). Innovation
ingenuity will drive technology transcendence.
The challenges society faces with decreased innovation in the U.S. economic
system can be attributed to flat investment in research and development by the U.S.
government and corporations over the past few decades. Altman, Greenstone, Rubin, and
Cannon (2010) noted that the future growth of the United States relies on appropriating
expenditures on innovation by investing in research investment, but over the past two
decades since the early 1990s research investment has comprised only 2.5% of gross
domestic product. Ultimately, leaders in the United States should begin to look at
longterm economic strategies for sustainability. Aghion, David, and Foray (2009) studied
the relevance of the systems theoretic approach for sustainability to progress in the
United States, where advances in research for innovation must be in U.S. political,
scientific, and corporate business policy. Long-term innovative policy to drive economic
conditions in the United States will have sustaining implications (Tassey, 2008).

The knowledge gap that U.S. corporate organizations‘ sustainable policy is to
acquire new start-up organizations instead of investing in organic research and
technology themes was addressed in the current study. The policy of acquisition within
the start-up entrepreneurial sector does not have transcending implications because
innovation will be lost due to acquisition payouts that are too high. An example is the
acquisition by Dell, Inc. of EqualLogic in 2007. Dell, a manufacturer of personal
computer and server products and a reseller of storage technology products, had an
acquisition ambition to enter the enterprise storage market. EqualLogic, a storage
technology start-up founded in 1999 with revenues of $100 million in 2007 and a
negative net income, was acquired by Dell for $1.4 billion (Kovar, 2007). In 2009, Dell
announced that the total revenue of EqualLogic accounted for only $400 million on an
acquisition of $1.4 billion just 2 years earlier (Mellor, 2009). Overpayment for
technology acquisitions does not uphold the acquirer‘s stakeholder and market
capitalization value; overpayment decreases the financial opportunity for corporations to
invest in organic research and development initiatives, which lends to decreasing
competitive advantage.
Another gap in the literature is the decrease of technological innovation due to
inadequate postmerger integration. Efforts to leverage the technology of the acquired
firm become mismanaged because of the disruption to the organizational process.
Puranam and Srikanth (2007) studied 99 acquisitions by 43 acquirers and determined that
44% of the acquisitions produced no patenting activity, whereas 40% were considered

integrated. Furthermore, inadequate integration can be linked to the nonretention of the
acquired stakeholders. The leaders of entrepreneurial start-up organizations tend to be
multi-task oriented, that is, involved in many layers of their business. Once acquired,
their duties change or, if payout is acceptable, they exit the firm and compromise
innovation (Graebner et al., 2010). The critical personnel elements that drive an
entrepreneurial organization to innovation may leave the organization when acquired
therefore are jeopardizing the continuation of innovation.
This literature review includes the most relevant contemporary and historical
information concerning innovative technology start-up firms acquired by larger, publicly
traded, global corporations. The intent of the literature review was to analyze the
methodologies used in research on the issues of mergers and acquisitions, corporate
business strategy, sustainability, entrepreneurship, innovation, technology disruption,
financial implications, patent generation, stock price fluctuation, and stakeholder
retention aspects of both start-up target firms and their acquiring public firms before and
after acquisition. Zhao (2009) revealed that large global strategies will continue to
overpay for start-up technology firms and will not receive the return on investment they
have calculated, resulting in diminished innovative and creative fervor in the acquired
company compared to before acquisition.
Literature Review Development Strategy
Information for the literature review was obtained by searching and examining
research works, dissertations, and peer-reviewed literature in journals. The information

was gathered through a range of portals that included electronic resources (ABI/INFORM
Complete, Business Source Complete, ScienceDirect, Emerald Management Journals,
Management & Organization Studies: A Sage Full-Text Collection, Google Scholar,
ProQuest, the Walden University library, and practitioner knowledge within the
technology innovation construct. The following keywords and phrases were used:
acquisitions, business strategy, entrepreneurship, financial, innovation, mergers,
research methodology, sustainability, and technology. Full-text scholarly articles found
in the Walden University database and other electronic resources, along with novels
yielded more than 175 relevant sources, with 125 used in the study. Most resources not
used in the study were not chosen because they were published before 2006, which is
outside the 5-year cutoff of resources allowed in the study. Some resources older than
2006 were relevant to the study and were used. The search was limited to articles and
resources specific to the high-technology industry, where the information used related to
technology organizations relevant to the computing and software industries. The articles
used from outside the high-technology industry pertained to the research methodology in
the study.
Methodological Review
The foundation of the technology industry was shaped through disruptive
technology that created innovation and new industries (C. M. Christensen, 2003b). The
disruptive innovation theory and resource-based theory are organizational theories that
focus on understanding how innovation is generated and how to manage the innovative

process through acquisitions. The following is a description on how both theories
supported the study.
Disruptive innovation theory. Disruptive innovation substantiated the study
because disruptive innovation alters industry boundaries by displacing established
technologies with newer aggressive innovation that could compromise an organization
(Adner & Zemsky, 2005). Due to disruptive technology, corporate business strategies are
acquiring innovative firms for competitive advantage, making it difficult for emerging
technologies to sustain their creative aspects (Dewald & Bowen, 2009). Because of an
era of diversification that led to the consolidation of the technology industry, large
established corporate firms try to acquire smaller innovative firms, exploiting the target
firms‘ qualities to foster their ingenuity for sustainability (Puranam, Singh, & Zollo,
2006). The side effect of consolidation is substantial—how an organization integrates an
acquired entity will dictate the survival of that acquired organization. Ribeiro (2010)
found that the survival of an acquired organization in mergers and acquisitions depends
on the value of that firm, but certain general factors apply. The technological frontier,
innovative capital, previous experience, age, and size are all important determinants for
the survival of an organization (Fontana & Nesta, 2009). Such disruptive qualities have
an effect on the outcome of the acquisition event because organizations located by the
technical frontier are more likely to be acquired.
The relationship dynamics on understanding different cultural attributes between
executives of both the acquired and the acquiring firms‘ stakeholder retention, and the

inability to bridge different organizational characteristics, will have an effect on how or
why acquisitions fail (Zhao, 2009). The competitive advantage in successful start-up
technology firms lies within the strategy process of managers that allows them to perfect
themselves in real time for future events. Dewald and Bowen (2009) wrote that a
cognitive perspective of a manager‘s responses to disruptive business models provides an
important understanding to how entrepreneurial innovative organizations pose a threat to
the management of the acquiring entity. The disruptive innovation theory exists if
managers in a larger organization do not research a potentially new transcending
technology and they risk a rapidly changing business environment or failure. C. M.
Christensen (2003a) described the disruptive innovation model as a paralyzing effect on
industry leaders. With resource allocation processes designed to support sustaining
innovations, the quicker entrepreneurial technological start-up firms can go to market, the
harder it is for established larger corporations to respond toward new technology
advancements (C. M. Christensen, 2003a). Based on the disruptive innovation theory, the
motivation of managers is the underlying reason why smaller innovative technology
organizations are acquired, but innovative fervor will ultimately be lost with the
unsuccessful integration of the acquired management.
Resource-based theory. The resource-based theory substantiates the current
study because the focus of the resource-based view is how firms acquire, adapt, and
integrate internal and external resource skills to capitalize on the changing environment
when acquisitions are consummated (Uhlenbruck, Hitt, & Semadeni, 2006).

Understanding that technology-innovative organizations are acquired by larger public
corporations for diversification in the larger corporations‘ strategic portfolios, the
resource-based theory provides a conceptual vantage point to explain the diversification
methodology in a manner that management can grasp and implement (Wan, Hoskisson,
Short, & Yiu, 2010). The resource-based theory is an important determinant of how an
organization can adapt and excel in an acquisition environment.
The resource-based theory supports disruptive innovation by defining the internal
resource capabilities toward the external competitive environment that exists in a firm.
As disruptive innovation will challenge a firm‘s ability to compete, the resource-based
theory provides an organization the ability to adapt to the changing competitive
environment (Esteve-Perez & Manez-Castillejo, 2008). A firm‘s internal resource view
will determine if the firm is capable of formulating the successful integration of an
acquired organization. The resource-based view is the outlook of an organization on its
ability to interpret its resource base and the resource requirements of the market of the
acquired firm (G. K. Lee & Lieberman, 2010). To achieve sustainable competitive
advantage through acquisition, the leaders of a firm need to exploit the full competitive
potential of the firm‘s resources, but too often, the resources are compromised by diverse
management practices. Yang and Konrad (2011) noted that after acquisition, diversity
management practices are compromised when corporate strategy and resource availability
are not aligned, signifying that integration of an acquired firm requires extreme due
diligence. The recourse-based theory may support a firm‘s ability to enhance its

competitive intent, but if not aligned with an innovative corporate strategy may derail a
company‘s initiative.
Acquiring Firms
During the late 19th and early 20th centuries, independent inventor entrepreneurs,
fueled by university and private funding, created one of the most innovative times in the
history of humankind (Hughes, 2004). Inventors such as Edison and Bell developed
transcending technological advancements that catapulted the United States to the
distinctive power that remains the largest national economic engine in the world (Hughes,
2004). Senge and Carstedt (2001) noted waves of technological advancement sparked
innovation during the 19th century, such as the steam engine, railroads, steel,
electrification, and telecommunications, as well as automotive and air transport, synthetic
fibers, and television in the first half of the 20th century. These technological advances
triggered ―disruptive innovation‖ (C. M. Christensen, 2003b, p. 43), where old industries
subsided and new ones were born.
The creation of the Apollo space program in 1961 triggered an innovative
renaissance that paved the way for technological innovation to transgress in the United
States. From 1961 to 1975, the ambitious Apollo program, although costly at $25 billion,
provided a technological economic boost that propelled American ingenuity during the
Vietnam War period toward technology transcendence (Gisler & Sornette, 2009). The
sprawling technological innovation from the Apollo program provided new ideas for
technology-based start-ups. Entrepreneurial start-up companies such as Apple, EMC,

Intel, Microsoft, and Oracle were born during this period as transcending innovative
thinking organizations, but in the 2000s these companies, along with Cisco, Dell,
Hewlett-Packard, and IBM, became global conglomerates due to aggressive acquisition
strategies.
The matured technology industry has consolidated into diversified global
enterprise organizations with large cash reserves that are able to purchase small start-up
technology firms and fold them into their offering. Since 1995, IBM has purchased more
than 100 companies to increase its portfolio with higher value offerings while reducing
lower margin commodity divisions (Bramante, Frank, & Dolin, 2010). From 1993 to
2005, Cisco Systems acquired 120 organizations and developed a scalable business model
to incorporate merger and acquisition formations (Li, 2009). The technology industry is a
challenging environment where change is the only constant, and organizational leaders
must constantly look at new and emerging technologies to survive. Kongpichayanond
(2009) acknowledged that mergers and acquisitions are the key management business
strategies to sustain growth. In 2006, U.S. firms conducted more than 8,000 acquisitions
with a total value of $1,371 billion, which was a value 30% higher than the previous year
(Adavikolanu & Korrapati, 2009). Acquisitions may be the business strategy target for
global technology corporations‘ sustainability measure, but if this strategy transcends
both the acquirer and the United States remains unknown.
Corporate business strategy. Time to market pressures in the technology
industry often compromise a corporation‘s internal research and development strategy as

too slow to compete against disruptive technologies. Organizations such as Cisco and
Microsoft augment their internal research and development with robust acquisition
strategies to fill gaps in product portfolios (Ransbotham & Mitra, 2010). When
organizations are purchased, generally they are evaluated by their balance sheet and cash
flows. This evaluation occurs in the technology industry with the inclusion of innovative
intangibles, which can derail an acquisition. The underlying value of complementary
technologies is how the acquisition of that technology can take place through the
retention of stakeholders (Desyllas & Hughes, 2008). Acquisition integration through
stakeholder retention due to the inevitable disruption of the acquired technology is most
important. The acquiring firm must retain the stakeholders of the sought-after
technology, whether they are the ownership, key engineer, or project management team,
and the acquisition strategy must incorporate these individuals for the surviving entity to
succeed (Paruchuri, Nerkar, & Hambrick, 2006). The shareholder framework in
entrepreneurial firms is to be the key element for sustainability in an acquisition where an
acquirer must identify the economically, socially, and ecologically driven stakeholders
for a sustainable result (see Figure 1; Schlange, 2009).
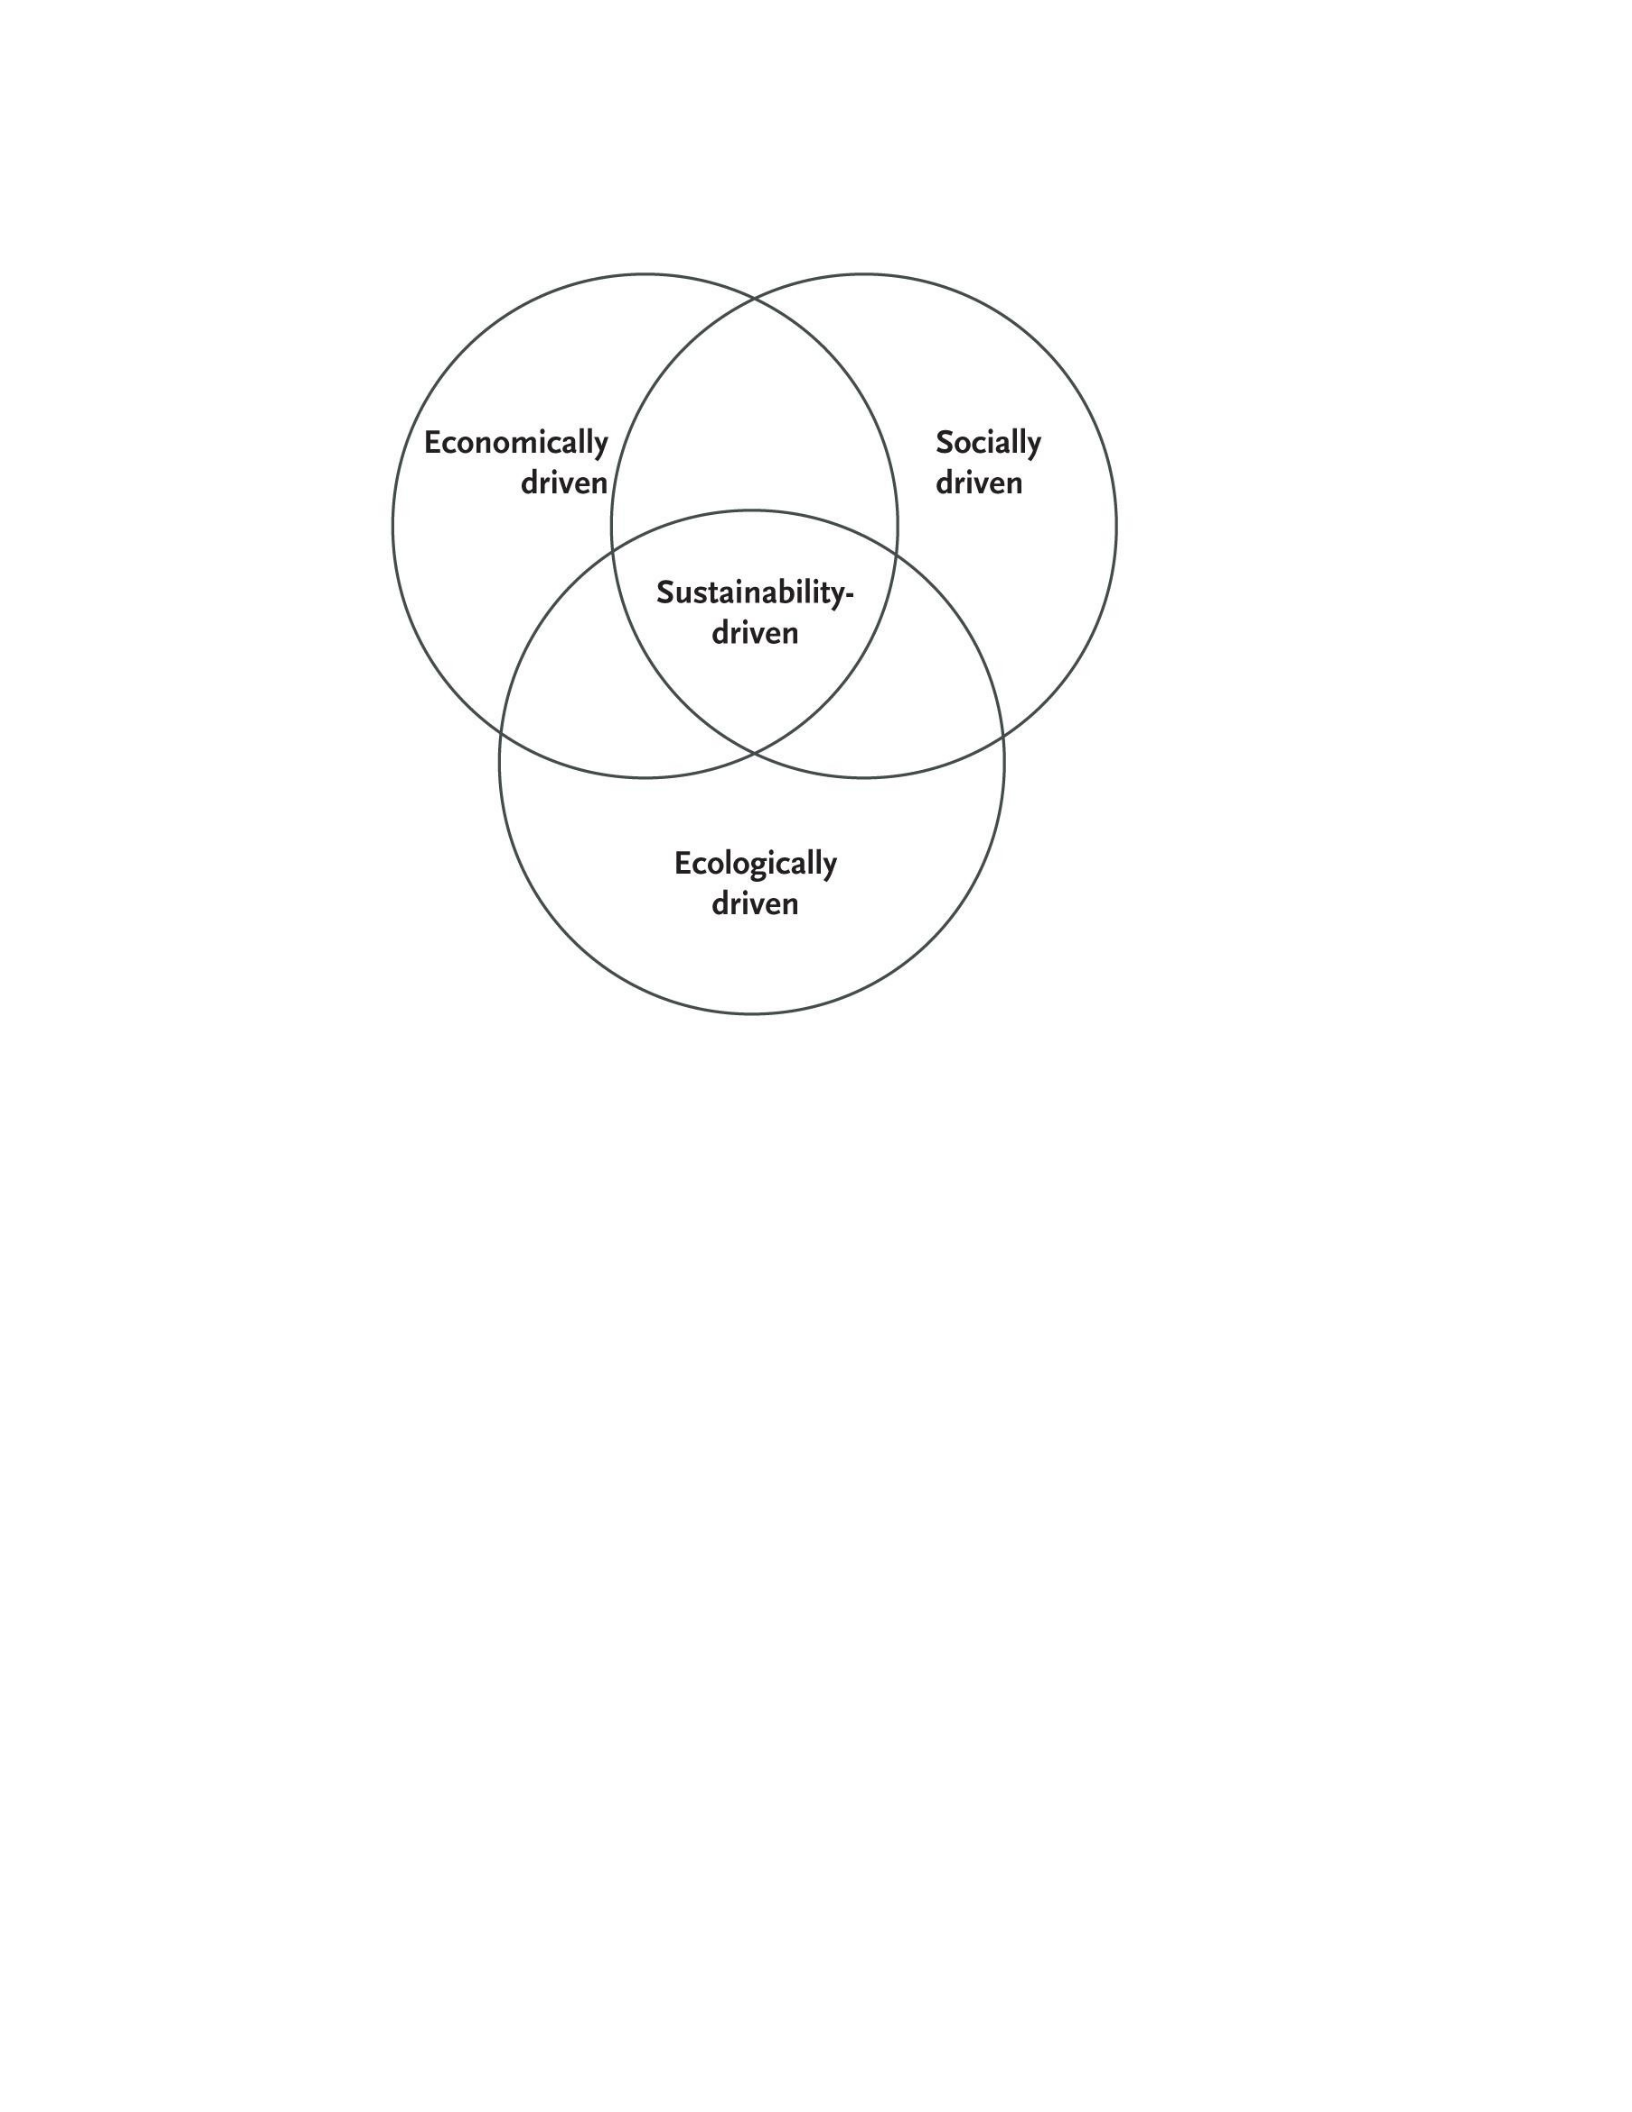
Figure 1. Sustainability-driven entrepreneurship as a concept of intersection. From
―Stakeholder Identification in Sustainability Entrepreneurship,‖ by L. E. Schlange, 2009,
Greener Management International, 55, p. 19. Copyright 2009 by L. E. Schlange.
Reprinted with permission (see Appendix A).
The technology industry moves at a very fast pace and the key to corporate
sustainability is innovation through competitive advantage, yet many companies lack a
well-communicated technology implementation strategy. Strategic roadmaps are an
effective way to initiate a technology strategy, yet only 27.6% of businesses develop a
technology roadmap (Cooper & Edgett, 2010). Integration of an acquired firm‘s
technology is paramount for sustainability, but this management discipline is not widely
used. Approximately 50% of technology implementation failures are due to internal

issues, and 27% are due to customer dissatisfaction (Chow, Goodman, Rooney, & Wyble,
2007). It is most important for organizations, especially because of the fast pace that is
the nature of the technology industry, to develop a technology innovation plan or face
unsustainability. Nortel Networks, once a thriving networking company, was never able
to recover from the dot-com crash of 2000 because the company lacked a clear corporate
direction and strategy; in 2010, Nortel filed for Chapter 11 bankruptcy and will be broken
up (Cooper & Edgett, 2010). The ability of corporate business structure to comprehend a
technology strategy that is true to its market is an important element when organizations
acquire other firms.
Sustainability. Global technology organizations must adopt sustainable measures
through acquisitions for competitive advantage. Sustainable development in an
organization has three goals most notable for sustainability in a business strategy in order
to be innovative: environmental, social, and economic (Placet, Anderson, & Fowler,
2005). The idea of sustainable development through innovation has transcending
implications. The economies of sustainability warrant a way to raise the standard of
living of a large number of individuals while reducing the negative impacts on
environmental economic activity (M. C. King, 2008). The implication of innovation in
technology organizations lends itself to positive sustainable measures and social change
in corporations.
Economic sustainability through acquisitions resulting in innovation and positive
social change must have successful integration. For the successful integration of a

transaction to occur between a buyer and a seller, a level of trust must be established due
to the asymmetric views of each party (Graebner, 2009). Graebner et al. (2010)
established that buyers and sellers have different viewpoints, by conducting a survey of
firms with less than 1,000 employees it was found that the sellers‘ top priority is to
relieve personal pressures to eliminate stress resulting in sellers exit postacquisition. A
top priority for successful integration is for the major stakeholders of the acquired
organization to stay intact to create innovative sustainability. Generally, smaller
entrepreneurial firms‘ stakeholders, based on aggressive fast-track energy with potential
life-altering monetary gain, decide not to stay on as an employee when acquired.
Schwienbacher (2008) noted that the entrepreneur‘s role, after venture capital invest in
their organizations, will change to decreased involvement and cash out or to
recapitalizing for increased venture capital ownership. In smaller firms, leadership is
likely to be involved in day-to-day operations, whereas larger firms have many resources
to provide resource advantage and the change can be difficult for an entrepreneur to bear
(Graebner, 2009). The disadvantage for sellers in a capacity where they do not control
their destiny after an acquisition dilutes the continuation and potential innovation loss.
Social and environmental sustainability in corporations are part of the overall
sustainability pie that has been emerging as an important consideration for global public
technology organizations. The United Nations Global Compact-Accenture CEO study in
2010 surveyed 788 CEOs from all over the globe and showed 93% of CEOs indicated
that sustainability is critical to the future success of their business (Leavoy & Phyper,

2010). The corporate sustainability model of an organization supports its sustainable
performance and financial performance. The corporate sustainability model claims that
the inputs, outputs, processes, and outcomes of a business need to be productive enough
to support a sustainable model (O‘Dwyer, 2009). Social, environmental, and economic
sustainability are all important strategies that are linked directly to financial performance
to which business leaders are directing their efforts, and if corporations do not consider
the parameters, they risk failure.
Mergers and acquisitions. Global technology organizations have been acquiring
private start-up entrepreneurial firms in the United States. Compared with 2009, the
number of technology merger and acquisition deals increased 41% in 2010 to 2,685 or
$119 billion, of which private equity deals accounted for $19.7 billion (Preston, 2011).
The history of acquisitions involving privately held entrepreneurial organizations
surpasses the history of publicly traded firms; in fact, between 60% and 75% of the firms
acquired in the United States between 2000 and 2004 were privately held, indicating a
business strategy of corporations acquiring start-up innovative firms (Capron & Shen,
2007). Ma et al. (2009) noted that mergers and acquisitions have expanded over the past
quarter century and are commonly used by corporations to achieve strategies and growth
initiatives, which indicates that public companies are acquiring smaller
technologyinnovative organizations to enhance or diversify their current solution
offering.
The technology industry has become one of the most cash-rich industries in the

United States because of consolidation and maturity. Cisco, Microsoft, and Google have
$105 billion at their disposal while Apple has amassed close to $50 billion in cash, which
suggests that Apple, a company that normally does not acquire for growth, will begin to
do so (Marino, 2011). The fact that Apple, an innovative transcendence organization,
will revert to acquisitions due to excessive cash flows, as did their competition, is
unsettling. An example of acquisition intoxication can be seen with the high-technology
storage industry‘s current acquisition strategy. Hewlett-Packard is careful about
acquisitions because of its size, which is a $120 billion market capitalization (Austin,
2010), but in 2010 acquired 3Par after outbidding Dell for $1.6 billion on 3Par revenues
of only $54 million (3Par, 2011). EMC followed suit with a $2.2 billion acquisition of
Isolon, which completed the jockeying of overpriced acquisition due to excessive cash
reserves (Marino, 2011). High-technology corporations are acquiring technology in a
reactionary mode to outpace their competition, but who wins remains unknown.
Investment in new technologies that enable high-technology companies to gain
competitive advantage over their competitors is not sustainable when the acquisition is
made outside the acquirer‘s competency. Using the evaluation methodology to
differentiate mergers and acquisitions with strategic fits from those without strategic fits,
the results indicated that mergers and acquisitions were more successful with firms that
had similar finances, management, and technology than with firms that did not (Hsieh &
Tsai, 2005). Furthermore, Flowers (2007) noted that mergers and acquisitions for closely
related organizations are easier to implement than for firms in unrelated industries, but

remain difficult to integrate. Technology acquisitions that have unrelated technologies
will tend to fail while similar technologies, if integrated properly, will tend to succeed.
Postmerger and acquisitions have an impact on technical performance. Through a
regression analysis study of a subset of 35 companies, Hagedoorn and Duysters (2002)
concluded that organizations must have a strategic technological similarity fit to succeed,
which underscores the importance of investors considering differences before acquisition
due to the potential failure in integrating the targeted technology. The consideration that
integration after an acquisition must drive the technical performance of both the acquired
and the acquirer for sustainability becomes a paramount conversation. The acquisition
effect on an acquirer‘s research and development intensity and productivity had a
significant decrease of 8% in productivity and a decrease of 12.9% in intensity generated
in a study of 2,624 acquisitions in high-technology U.S. corporations over a 3-year period
(Desyllas & Hughes, 2010).
Mergers and acquisitions have some impact on innovation. Positive mergers and
acquisitions have been associated with a firm‘s ability to integrate the acquired
knowledge and alter the existing routines of its research (Altman et al., 2010). Acquiring
organizations are motivated by the notion that the combination of two companies
provides sustainable measures, but organizational leaders should consider implementation
strategies. K. S. Christensen (2006) interviewed 120 employees after acquisitions and
noted that innovation perception among employees on how to integrate an acquisition
was mixed regarding the ability of the boards of directors or sponsors. The main

stakeholders in the acquiring organizations must identify the right acquisition, and their
integration strategy must be well thought out and executed properly.
Although technology-based organizations in the United States have adopted a
business strategy to acquire entrepreneurial start-up organizations with excessive cash
incentives, the dynamics of the innovative process within the fabric of the entrepreneurial
process is compromised. Value leakages from acquisition premiums in technology
mergers and acquisitions tend to reduce gains and increase costs, resulting in decreasing
shareholder value. Acquisition premiums are the price paid for an acquired firm that
exceeds its preacquisition market value, and over the past 20 years, the average premium
has been 40%–50% (Hitt et al., 2009). Technology acquisitions continue to overpay for
technology, resulting in shareholder devaluation.
Target Firms
The drive of technology invention has been the strategic cornerstone for
innovation in the United States. During the hundred years following 1870, Americans
created the modern technological nation with inventions such as incandescent light, the
radio, the airplane, gasoline-driven automobiles, and the computer (Hughes, 2004, p. 3).
These inventions were made by creative individuals through self-funding, government, or
institutional funding; thus, the entrepreneur was born and paved the way for the modern
technology entrepreneur. The modern technology entrepreneur was conceived through
the explosion of technological innovative transcendence during the Apollo space program
from 1963 to 1972, which enabled clusters of high-technology areas to flourish (Gisler &

Sornette, 2009). Clusters of high-technology industry incubators accounted for the
majority of technology start-up firms by fostering innovation through multiple layers of
entrepreneurialism, disruptive technology, and financial implications noted as the
entrepreneurial society. The entrepreneurial society refers to technological
knowledgebased start-up firms that are the driving force for economic growth,
employment creation, and competitiveness in the United States (Audretsch, 2009).
Entrepreneurial technological innovation continues to be the primary criterion for U.S.
economic transcendence.
Creative individuals continue to drive innovation in the United Sates by means of
personal ambition through technological talent and institutional funding. The United
States is the world leader in scientific education and venture investment, where
entrepreneurial start-ups are more likely to access knowledge through the combination of
existing business, academic, and capital resources to generate science-based
entrepreneurial firms (Colombo, Mustar, & Wright, 2010). Although the current
economic technological nurturing environment may have transcending implications, too
often the entrepreneurial stakeholders decide to be acquired before their technology can
mature and transcend.
Entrepreneurship. Entrepreneurial firms represent a large percentage of job
growth and innovation in the United States. In 2007, approximately 5.5 million firms
existed in the United States, of which about half a million were created by new start-up
innovation and generated approximately 40% of the new jobs in that year (Strangler,

2010). The dependence of the entrepreneur on economic growth is imperative for the
U.S. economy to transcend and to further the development of technological innovation
for American prosperity.
The dynamics of the lead entrepreneur nurtures the innovative capability of
startup entrepreneurial ventures. This capability was demonstrated in a study focusing on
112 entrepreneurs in the high-technology industry that showed a positive relationship
toward entrepreneurial leadership and new patent generation as the level of creativity of
entrepreneurial teams increased (M. H. Chen, 2007). Successful technology start-ups are
commanded by innovative thinkers who are surrounded by a strong technical staff that
works in unison. To be successful, the significant relationship between the competitive
position of a company and the cooperative behavior of its people must include a clear
strategy all participants understand (Shan, 1990). When a new start-up is acquired, the
unique dynamic of the management structure must be analyzed and integrated efficiently
for innovation to continue. In a study of 207 acquisitions of small technology firms by
larger corporations, only 27 maintained the acquired management structure to be
successful (Puranan et al., 2006). The philosophy of entrepreneurial leadership, which
has a practical hands-on approach and motivates the firm‘s strategy process, is elaborate
in the measure of the complexities that exist in innovativeness in new start-up technology
organizations. Campos, Aguirre, Parellada, and Nuno (2009) created a model that shows
that through the technology strategy process, new technology-based firms reaffirm the
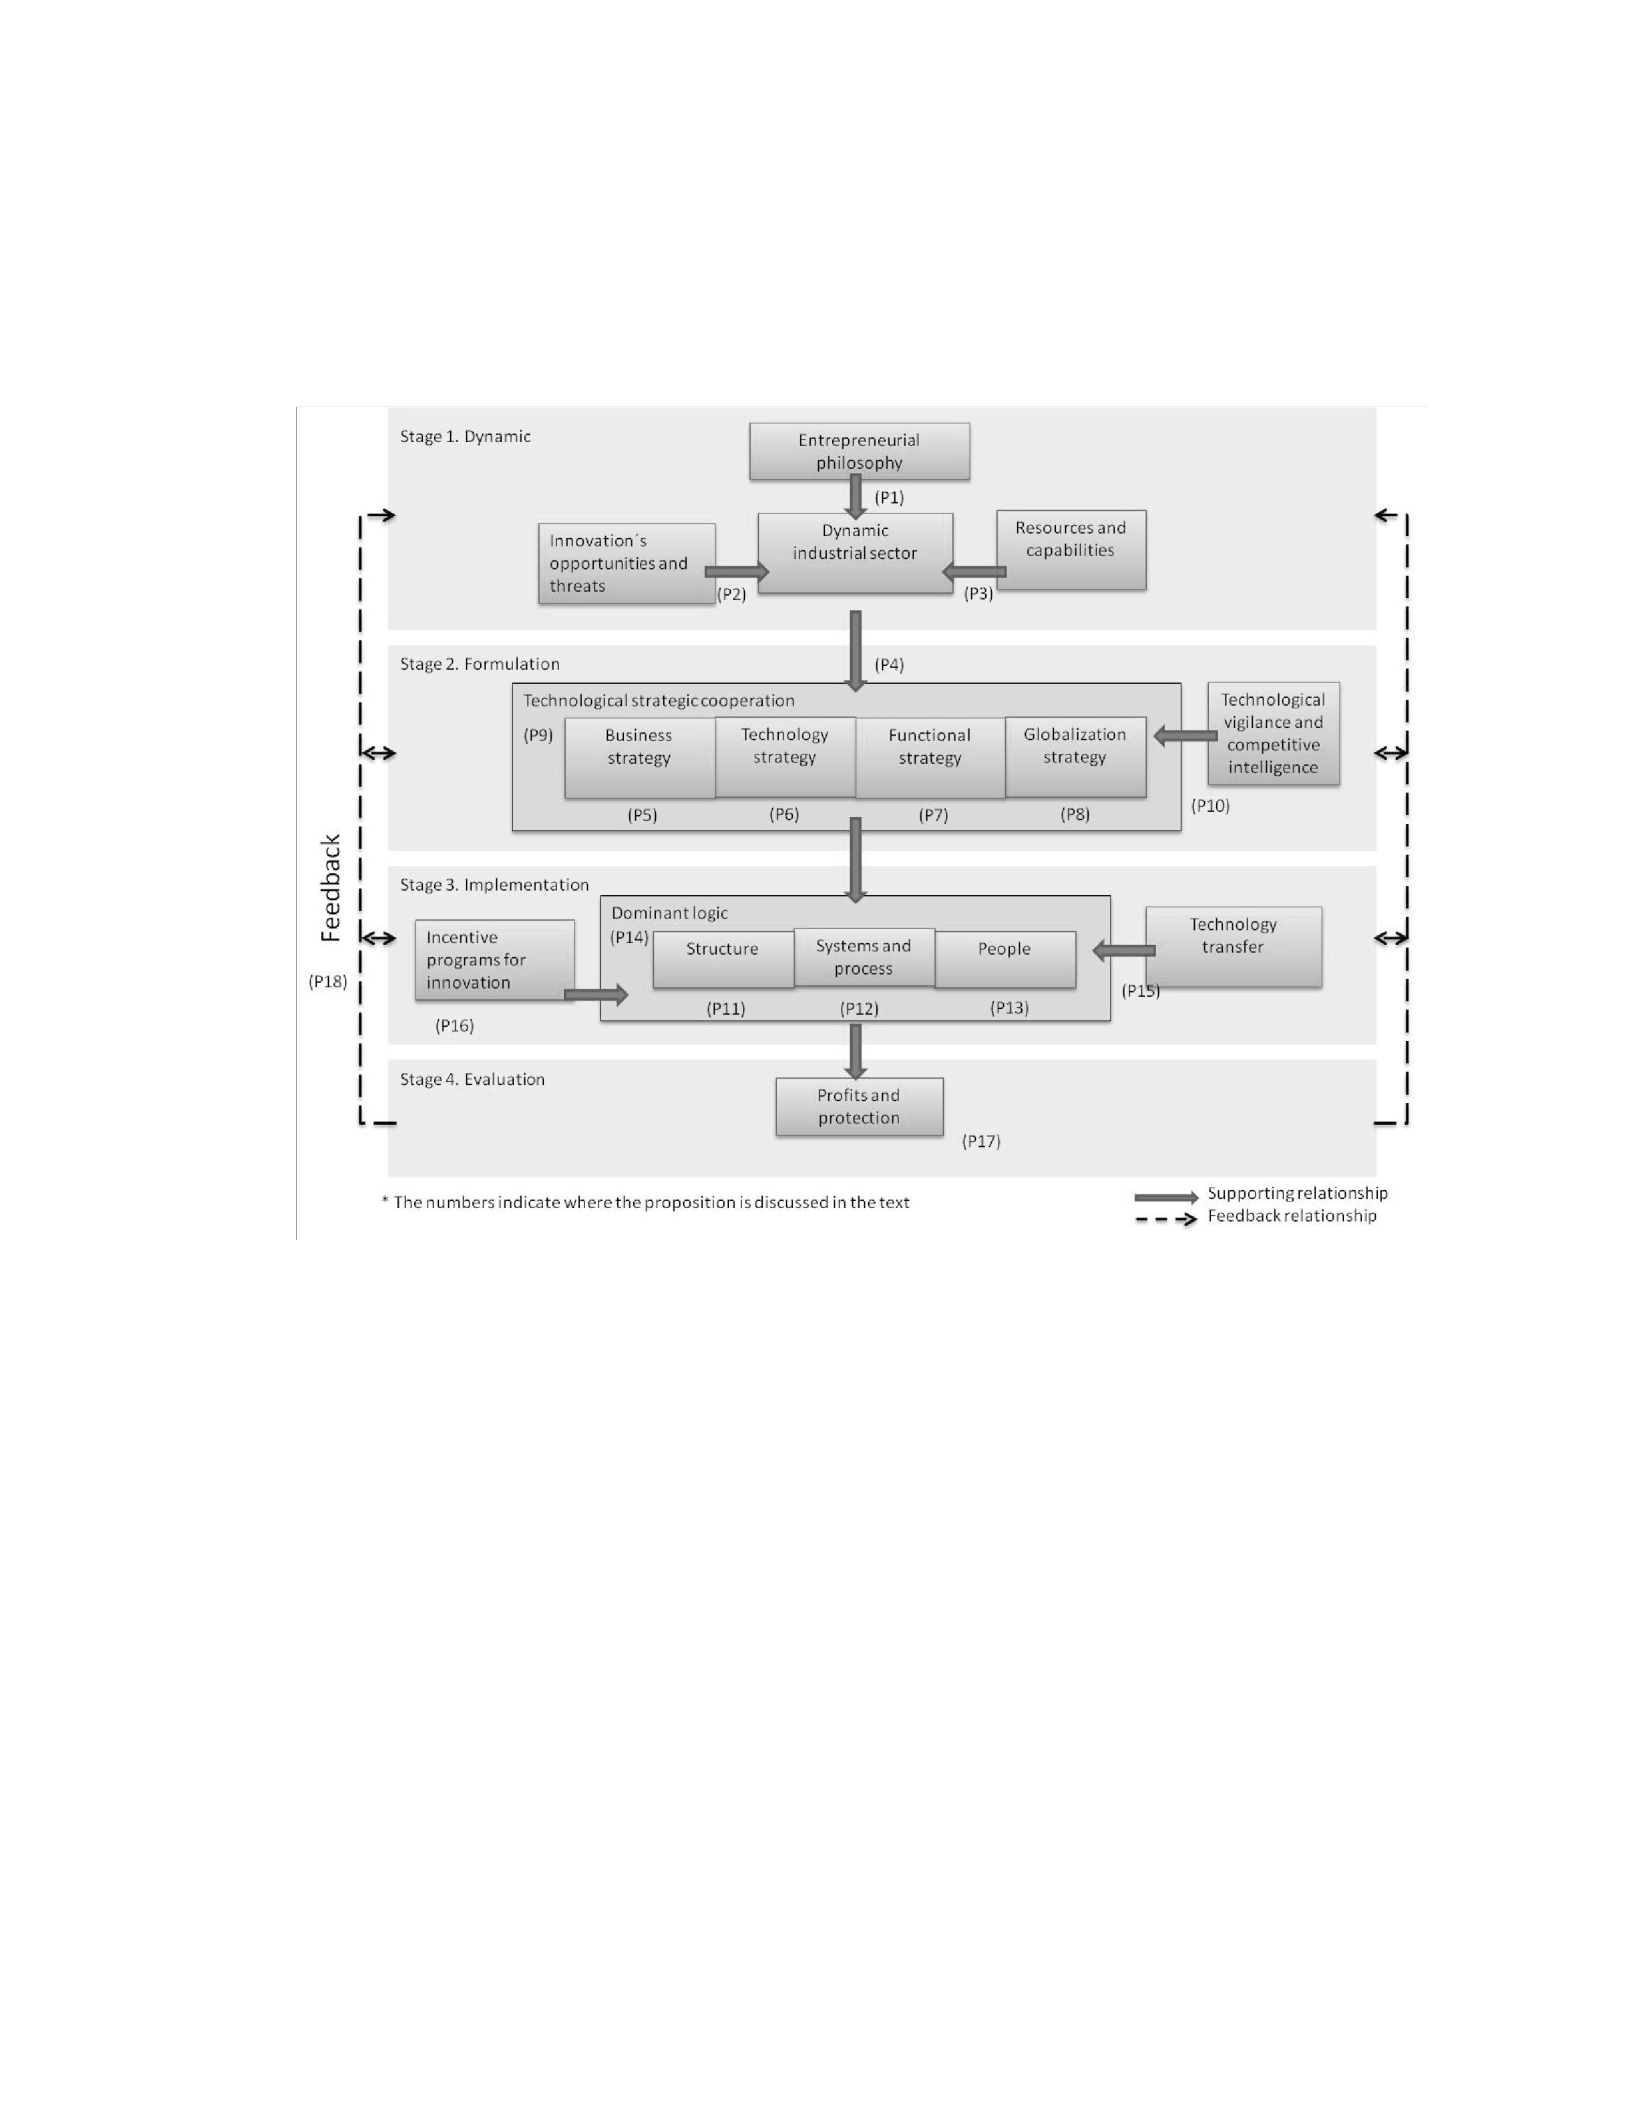
importance of the entrepreneurial philosophy to be the foundation of the firms‘ innovative
essence (see Figure 2).
Figure 2. The technology strategy process. From ―Technology Strategy and New
Technology Based Firms,‖ by H. M. Campos, I. P. Aguirre, F. S. Parellada, and J. P.
Nuno, 2009, Journal of Technology Management & Innovation, 4(4), p. 47. Copyright
2009 by H. M. Campos. Reprinted with permission (see Appendix A).
Technology entrepreneurs must overcome many obstacles to achieve transcending
technology. Having an exaggerated focus on core competencies at the early stages when
solutions have not been crafted hinders a company‘s market potential (Boccardelli &
Magnusson, 2006). Entrepreneurial managers must pay attention to the uncertainties that

exist in both resource and market dimensions to avoid missing the timing of market
potential. Timing an innovative market within the technology industry has many
restraints, but with a little luck, appropriate funding, and hard work the best ideas can
lead to transcending new industries (Umesh et al., 2007). Furthermore, timing
technological market potential may be limited to adoption by consumers, whereas the
technology may be infant but transcending. When visiting a Xerox think-tank campus
under nondisclosure with the permission of Xerox management, Steve Jobs stumbled on a
technology within the business model of Xerox that did not provide innovation, but under
Apple‘s later direction transcended the technology industry with the graphical user
interface (Gallo, 2010). The suggestion that under the right leadership direction and
economic conditions a creative technological idea can potentially generate transcending
innovative implications motivates the American dream.
The motivation of technology entrepreneurs is to develop disruptive technology,
but most importantly define the exit strategy. The majority of entrepreneurs initiate a
business without an exit strategy. Only 45% of the 2004 Inc. Magazine‘s 500 CEOs,
which were the 500 fastest growing privately held companies in the United States at that
time, reported that they started their companies with an exit strategy (DeTienne, 2010).
Believing that a technology start-up does not have a defined end game plan leads to
problematic dismantling circumstances, especially in the fast-paced technology industry.
Innovation. Technological innovation has been the driving determinant of
economic growth in the United States. Technology innovation is an important sector for

the United States, as more than 50% of the economic growth between 1945 and 2002 can
be attributed to innovations in the high-technology industry (Makri & Scandura, 2010).
Continued technological innovation to drive economic conditions is a necessity, but new
start-up businesses have many challenges. Eighty percent of new businesses fail;
therefore, to combat business failure, leaders of new start-ups must build better theories
(Tan, Fischer, Mitchell, & Phan, 2009). Building better theories for small business will
create better business models for sustainable innovation. Business models are
performances and encounters in which a presentation is to be displayed to an audience
and contributes to a better understanding of an entrepreneur‘s understanding of their
processes and functions (Doganova & Eyquem-Renault, 2009).
Innovation excels when different individuals group together for idea generation
and to enhance a common business issue, where cluster management involves having
multiple resources available due to the advantages of geography. An example is the
Boston Route 128 belt, where 1,065 of the 4,000 companies related to the Massachusetts
Institute of Technology with revenues of $230 billion or more are headquartered
(Wonglimpiyarat, 2006). In technology cluster advantage areas, venture capital
investment, integration of industries, university location, and government leading
programs are prevalent and yield innovative organizations (Wonglimpiyarat, 2006).
The climate for innovation in organizations before and after acquisition lies in
research and development, but when organizations are acquired with similar research and
development in related industries, innovation tends to decrease, while partners in
unrelated research lines increase after acquisition. In a data set comprised of 72

technology acquisitions with and categories, 84% of the research and development in
related organizations decreased while 22% of the research and development in unrelated
organizations increased (Ruckman, 2009). Although acquired organizations with the
same subset of technology as the acquirer may add to the structure, they do not have
innovative transcending sustainability. According to D. R. King, Slotegraaf, and Kesner
(2008), target acquisitions have a negative impact on a firm‘s research and development,
resulting in decreased innovation.
New firms must survive the first few turbulent years to generate creative
disruption for innovation. A 32% decrease in start-up company failure occurs when
organizations are aligned for innovation (Sarkar et al., 2006). Innovation is the function
of a set of elements: entrepreneurship through courage and vision; institutions in a social,
economic, and cultural frame; capabilities within a developed group of resources and
competences; and capital of financial resources (Zawislak, Borges, Wegner, Santos, &
Castro-Lucas, 2008). The set of elements must work together for a sustainable result;
hence, effort must be produced for the appropriate outcome.
Disruptive technology. Disruptive technological innovation is a technology that
supports start-up technology firms and if successful can transcend an industry. Some
examples of innovation that transcended the technology industry are the personal
computer, the router, Kodak‘s original camera, and Xerox‘s original photocopier (Eucher,
2011). Technology disruption is a major concern for established public companies, and
the level of not understanding the new technology effect on their business can potentially

be devastating. A classic example of disruption is Cisco‘s creation of the router, which
became disruptive to Lucent, but when a little-known company named Linksys created
the wireless router, the technology became disruptive to Cisco; Linksys was later
purchased by Cisco to mitigate the disruption (Eucher, 2011). Acquisition behavior is
generated when technology start-ups create a window of opportunity to dismantle an
established public firm‘s business strategy by producing disruptive technologies.
The leaders of new start-up firms must adopt and understand the complexities of
the disruptive technologies before embarking on such a difficult task. Klimis and Wallis
(2009) noted the disruptive role of new technologies could hinder or facilitate
entrepreneurship and innovation. Cloud computing is an example of a disruptive
technology on a potential innovation that has been adopted by U.S. corporations and
emerging economies. Katzan (2010) defined cloud computing as, ―an architecture for
providing computing service via the Internet‖ (p. 1). At the chief technology officer
roundtable at a cloud computing seminar with participation of the top chief technology
officers from companies such as Amazon, Google, and Sun Microsystems, Creeger
(2009) acknowledged that because of the disruptive cloud computing technologies, their
corporate activity is to acquire new start-up cloud organizations before they become
established and transcend. Although cloud technology can be considered an innovative
transcending technology identified by large global corporations, the technology may not
be mature enough to be sustainable to an acquiring organization. Hayes (2010)
acknowledged that the cloud is both ―a fuzzy marketing term‖ (p. 46) and a tangible

technology, where investment from corporations to acquire cloud organizations may
distract true investment. Global technology companies must take notice of new
technology, but disruption timing and the understanding of consumer appetite for the
potential disruptive technology are important considerations.
The timing of disruptive technologies is based on many elements such as funding,
market potential, and stakeholder endurance with many obstacles to fail, but if
orchestrated correctly disruption can develop incredible results. Founded in 1998,
Google was the idea of information utility, a Web-based concept developed in the 1970s;
in 2009, just 11 years later, the stock price was $600 per share and the company had a
market capitalization of around $200 billion (R. Chen, Kraemer, & Sharma, 2009). The
ability to develop such a large market capitalization in such a short time, creating
transcendence, dominates the American innovative process and creates a need to
understand a common theme for such an impact of the economic implications. The
disruptive innovation theory has had a significant impact on management practices,
where new entrants have an advantage compared to larger public technology
organizations because of their smaller size, shorter histories, and more limited
commitments to current structures (D. Yu & Hang, 2009). A timetable appears in Figure
3. New start-up firms must overcome a multitude of challenges to succeed in
understanding the complexities of developing a disruptive technology. Financial
implications, timing of the market, and stakeholder endurance all contribute to a shorter
go-to-market strategy.
1942, Schumpeter, 1990, 1992,1993,1996,1997,2003,
Creative
Destruction in
“Capitalism,
Socialism and
Henderson and
Clark,
Architectural
Christensen, The
Innovator’s
Challenge:
Understanding the
Influence of Market
Environment on
Process of
Technology
Development in the
Christensen, “The
Rigid Disk Drive
Industry: A
History of
Commercial and
Technological
Turbulence”
in Business
Bower and
Christensen,
Customer Power,
Strategic
Investment, and
the Failure of
Christensen,
Book, The
Innovator’s
Dilemma, and
Christensen
The
Innovator’s
Rigid Disk Drive History Review, Leading Firms 7 papers Solution
Industry. Dissertation 67(4), 531-589 (See Ref.) (See Ref.)
1986,1991,
McKinsey&Richard Foster, Geoffrey
Moore,
Technology S-curveCrossing the Chasm
and “Discontinuities” Marketing and
Innovation: The attacker’s Selling
advantage: Technology
NY: Summit Books Products to
Mainstream
Customers. NY:
Harper Business.
1992,
Christensen,
“Exploring the
Limits of the
Technology S-
Curve” in
Production
and
Operation
Management
,
1(4), 334-357
1995,
Bower and
Christensen
Disruptive
Technology:
Catching the
Wave
(See Ref.)
1996,
Jean-Marie Dru,
Disruption:
Overturning
Conventions
and
Shaking up the
Marketplace
John
Wiley&Sons
Inc.
2001,
Richard Foster
and
Sarah Kaplan,
Creative
Distruction:
Why Companies
That
Are Built to Last
Underperform
the
Market-and
How to
Successfully
Transform
Them.
NY: Doubleday
Figure 3. Timeline of the evolution of disruptive innovation theory. From ―A
Reflective
Review of Disruptive Innovation Theory,‖ by D. Yu and C. C. Hang, 2009, International
Journal of Management Reviews, 12, p. 2. Copyright 2009 by D. Yu. Reprinted with
permission (see Appendix A).
Democracy”
Harper&Brothers (See Ref.)
Innovation
(See Ref.)

The disruptive technological implications can be structured in two ways for
entrepreneurial start-ups to succeed: by developing a disruptive technology that can
transcend an industry and by understanding the incredible dynamics an entrepreneur must
orchestrate with the multitude of challenging factors to achieve success. Out of a
selection of 710 relevant entrepreneurial technology companies, only 121 of the analyzed
organizations used strategic modeling for innovation, and 79% of these were deemed
innovative with an effective innovative technology model suggesting that disruptive
technology and entrepreneurship overcame potential failure when organizations focused
on strategic modeling (Carlo, Lyytinen, & Rose, 2011). Disruptive technology is the
cornerstone of the transcendence of technological entrepreneurial start-ups in the
technology industry, and established public firms are targeting disruptive technology
organizations for acquisition on an excessive financial level, making the acquired
stakeholders financially sound. By making these stakeholders financially sound, their
early exits are compelling.
Financial implications. The financial implications for entrepreneurial start-ups
hinge on the ability of the entrepreneur to raise funding that enables an organization to
continue to operate for a time before revenues are compromised. The three areas to
consider in raising funds are self-funding (or bootstrapping), bank lending, and venture
capital (D. Smith, 2009). These three areas have varying levels of commitment that
entrepreneurs will have to consider regarding how much ownership and control on

management decisions they will give up, which can determine if an acquisition is
inevitable.
Self-funding, also termed bootstrapping, enables entrepreneurs to start up their
organization by not giving control to any outside resource. Bootstrapping involves
launching a new venture with limited personal funds without relying on long-term
external financing or using highly creative ways of acquiring resources without
borrowing from traditional resources (D. Smith, 2009). Bootstrapping has lower
liquidity, higher leverage, and lower profitability than other methods. Young
bootstrapping firms, firms between 5 and 15 years old, have significantly lower liquidity
and profitability than firms that are 15 years and older (Ebben, 2009). Young selffunding
entrepreneurs are most likely not positioned to be acquired.
Bank financing requires an organization to secure funding on the assets of the
organization and generally requires the entity to have a record of accomplishment of
revenues before the bank will lend finances, indicating the organization must be mature
enough for a substantial investment. Winton and Yerramilli (2008) surmised that bank
financing is a viable option if an organization is not a risky proposition and the lending is
proportionate to the organization‘s asset value, where bank monitoring on financial
activity is lessened. Bank or debt financing is not considered the most frequently chosen
method of innovative organizations. Only 12% of innovative entrepreneurial start-ups in
the planning stage have debt financing, whereas 19% have debt financing in the early
stage; innovative new ventures that cannot attract financial resources for new inventions

will fail (Audretsch, Bonte, & Mahagaonkar, 2009). Although bank financing has
transcending potential due to the ability to fund with less monitoring from external
resources, market timing for innovation due to the length of the venture may lend to
stagnation.
Venture capital is the most popular form of funding for innovative entrepreneurial
start-ups, but ownership control is then given up. Venture capital, the pure financial
advisor, in addition to providing monetary capital, human capital, and advice, in return
for their investment and guidance venture capital firms gain an ownership percentage of
the start-up (Fulghieri & Sevilir, 2009). From 1978 to 2004, venture funding increased
from $424 million to $21 billion (De Clercq, Fried, Lehtonen, & Sapienza, 2006).
Increased investments in venture capital firms are also the result of creative cluster
technology locations throughout the United States that provide a high level of
technological competence for universities. Venture-backed firms in Silicon Valley
absorb 20%–26% of the total venture capital investment in the United States and by 2000
housed more than 25,000 technology firms and provided 670,000 well-paying jobs
(Zhang, 2007). Venture capital investment in the high-technology cluster areas such as
Silicon Valley and the Route 128 belt in Massachusetts are the most influential areas for
public companies to be acquired. Ten universities, 180 venture capital companies, 392
recruitment companies, and 700 merchant banks devoted to the high-technology industry
exist in Silicon Valley, and in 2000, acquisitions by large public companies in this area
represented 25% of Silicon Valley technology start-ups (Ferrary & Granovetter, 2009).

Venture-capital-funded technological start-up firms are being acquired.
Of the three financial elements for entrepreneurship, venture-capital-backed
financing organizations have the most potential for being acquired and have the ability to
transcend due to the fast-track innovative process. In the first quarter of 2010, 81
innovative entrepreneurial start-ups with a total value of $2.3 billion and backed by
venture capital were acquired by cash-rich public organizations (Quinn, 2010).
Venturecapital-backed technological entrepreneur firms are on a fast track toward
innovation and acquisition. According to a VentureXpert data set conducted between
1980 and 2004, a sample of 3,756 entrepreneurial portfolio companies from an
information database of 67,505 concluded that 38% of the start-ups were acquired (Fitza,
Matusik, &
Mosakowski, 2008). Venture-capital-backed technological start-ups are being positioned
for acquisition by venture capitalists, and innovation becomes the conversation for
continuation.
Control Variables
The determination of whether innovation is lost due to acquisitions is comprised
of the measurement of patent generation, stock price fluctuation, and stakeholder
retention analysis before and after an acquisition of a smaller entrepreneurial start-up is
made by a public technology organization. Raghu et al. (2008) determined that patents
are important determinants of a firm‘s intellectual property, and Khallaf and Skantz
(2007) noted that stakeholder expertise in acquisition has an effect on the market value of

a firm. The control variables determined the essence of the current study by supporting
the endurance of the study‘s significance. By subjecting the data to rigorous analysis, the
control variable provided a subjective picture that innovation is lost when technology
organizations are acquired.
Patent generation. Patent generation in an entrepreneurial organization is the
means through which a firm can measure if innovation exists. In a sample of 1,194
international high-technology sector organizations, 85% were considered innovative due
to increased research and development expenditures resulting in increased patent counts
(Hagedoorn & Cloodt, 2003). A major indication if innovation continues postacquisition
is through continued patent generation. Patents within the technology industry increased
from 66,170 in 1980 to 157,717 in 2005 (Desyllas & Hughes, 2010). The increase
indicates that intellectual property and patent generation are important for an organization
to possess a competitive advantage, and infringement of a company‘s proprietary
information jeopardizes that institution (Raghu et al., 2008). Innovation can be defined
through patent generation.
Patent generations decrease after an acquisition and jeopardize the initial
innovation the acquired firm possessed before being acquired. In a dataset of 3,858
individual patents extracted from the U.S. Patent and Trademark Office, using the recent
patent indicator variable that was set to 1 if the target firm held one or more patents
during the 3 years prior to the acquisition and 0 otherwise, only 25% of targets had
patents 3 years after the acquisition (Ransbotham & Mitra, 2010). Patents can be

measured to find out if innovation decreases by the number of new patents produced after
an acquisition.
Stock price fluctuation. Conducting CARs by using stock price is a method of
measuring if an acquisition is successful or not. This widely used research technique
measures the abnormal effect of a firm‘s stock market value during a short period of time,
usually 2 days before and 2 days after an acquisition, which creates a 5-day window of
activity to understand the response of the stock market and the investment community to
the acquisition (S. Lee & Connolly, 2010). An example of a stock valuation trending
downward by using the CAR model is when acquisitions that decide not to reinvest in
research and development after the acquisition of a target firm will most likely decrease
the acquirer‘s stock market value. Although in many cases innovation may be lost due to
inadequate integration, in a study conducted using a sample of 129 mergers and
acquisitions in the United States, Hsu, Kin, and Song (2009) found that firms that
writeoff in-process research and development 2 days after a merger and acquisition have
a
2.73% decrease in stock valuation. The notion that the investment community gathered
knowledge of low investment in research and development created a downward trend,
indicating that reduced investments in this area decrease innovation. Kallunki, Pyykko,
and Laamanen (2009) noted in a study of 1,879 high-technology industry mergers and
acquisitions in the United States from 1993 to 2006, 75% of the firms that did not invest
in the research and development integration process had a decrease in stock price.

Negative stock price fluctuation is due to a low investment in research and development
after acquisition and can impede innovation.
Negative stock price fluctuation indicates that innovation and market
capitalization of the acquiring firm have decreased postacquisition, but additional factors
may also lead to a decrease in shareholder value. Leakage of shareholder value or market
capitalization can occur from the inadequate integration of the acquired entity due to a
preoccupation in empire building. Meyer (2008) noted that preacquisition acquirers
spend 80% of their organization‘s time on customer activity, whereas postacquisition they
spend the same amount of time on internal affairs. Management‘s commitment to
continue innovation after an acquisition is necessary, yet the cultural differences may lead
to inadequate integration. Integrating the acquired organizational resources and
knowledge base is a complicated process; because of inadequate integration in a recent
study, patent generation was reduced to less than 50% of what was attained before
acquisition, which decreased the market value of the surviving corporation (Graebner et
al., 2010). Inadequate integration of the acquired management resources has an adverse
effect on the stock price of the acquiring corporation.
Stakeholder retention. The retention of the stakeholders of the acquired
organization has significant value to the surviving innovative process after an acquisition,
but if not intact can have derailing tendencies. Executive vice president Paula Long, the
driving force behind the early success in research and development for EqualLogic,
resigned from Dell just 2 years after being acquired (Mellor, 2010), but revenues in 2007

were only $400 million on an acquisition of $1.4 billion (Mellor, 2009). Schlange (2009)
determined that stakeholder-driven entrepreneurs are the reason for organizations‘
success, and removing that recipe of teamwork and inventiveness can be catastrophic to a
firm‘s survival. For a technological entrepreneurial firm to continue innovation after
being acquired, the stakeholders must remain intact, meaning all individuals who
contributed to and continue to sustain the innovative process must remain for innovative
sustainability to continue (Graebner et al., 2010). The innovative management makeup of
the entrepreneurial technology start-up must remain intact after an acquisition for
innovation to continue, but stakeholders for many reasons do not remain in the surviving
acquirer‘s organization.
The motivation of entrepreneurial stakeholder exit strategies is an important
element to understand how to address an acquisition, but many entrepreneurs lack a
proper exit strategy when a firm was first incorporated. Only 45% of Inc. Magazine‘s
500 privately held, fastest growing companies‘ CEOs of 2004 reported they had an exit
plan, and although 65% of CEOs plan to leave their organization in 10 years, 43% have
done little or no planning (DeTienne, 2010). Little or no exit planning in a fast-paced
innovative environment may set the stage for venture capital investment.
Entrepreneurial start-up organizations that use venture capital do so as a means
for raising capital and using an experienced management team, yet some venture-
capitalbacked transactions have multiple owners. Venture-backed transactions contain
venture capitalists, angel investors, and individuals including the founders and key

employees, all investing for their share of the investment (Fitza et al., 2009). The
complexity of multiple owners with differencing agendas, where the stakeholders in the
current study were defined as the founders and key employees of the target firm who
were responsible for the innovative technology and knowledge transfer, may be
compromising when the start-up is acquired. Mergers and acquisitions that focused less
on the transfer of knowledge from the stakeholders and more on the financial
implications of the venture investment experienced a negative effect on innovative
performance (Cloodt et al., 2006), whereas acquiring firms that focused on organizations
with greater innovative potential paid premium prices (Schwienbacher, 2008).
Organizations that pay premium prices must focus on retaining the stakeholders for
innovation to continue.
Empirical Research Related to This Study
Empirical studies that focus on the merger and acquisition of technology
organizations and their apparent postacquisition results existed in the literature. The
examination of these empirical studies provided a better understanding of the relationship
that existed in previous research that supported the findings in the current research study.
The following analysis of the empirical research supports this study.
In an empirical study, Ransbotham (2008) examined abnormal stock value returns
during acquisition in the high-technology industry. Ransbotham searched the Wall Street
Journal, Business Wire, PR Newswire, and Dow Jones News Service, identified 238
acquisitions of technology firms in the telecommunications industry such as Cisco,

Nortel, and Lucent, and then used an event study methodology or CAR to estimate the
stock price using the market model and the market AR model. ―The Market Model
posits a linear relationship between the return on the stock and the return on the portfolio
over a given time period‖ (Ransbotham, 2008, p. 18). Using the ordinary least square
regression analysis on the data set over a period of 200 days ending 10 days prior to the
acquisition announcement, the acquisitions of younger companies had a positive effect
with stock price, whereas acquisitions of older public firms yielded a negative effect on
their stock price (Ransbotham, 2008). CAR values may be considered a viable
measurement tool for understanding stock market acceptance toward acquisitions.
In a second empirical study, Hagedoorn and Cloodt (2003) measured innovation
by using multiple indicators to determine the relationship between inventive,
technological, and innovative performance for indicator viability. In a study of 1,200
companies in four high-technology industries using the indicators of research and
development, patents, patent citation, and new product development, it was determined
that while the measurement of all the indicators combined was ambiguous, patent counts
and citations in computer and office machinery scored above a 95% variance for reliable
measurement (Hagedoorn & Cloodt, 2003). Patent counts and patent citations can be a
viable measurement tool in determining if innovation continues postacquisition. In a
third empirical study, Desyllas and Hughes (2010) determined whether acquisitions
become more innovative if the acquired knowledge base or stakeholders remained in the
surviving organization. In a study of 2,624 high-technology acquisitions from 1984 to

1998, Desyllas and Hughes (2010) determined that during the 3 years after an
acquisition, a negative 8% effect occurs on research and development when stakeholder
retention does not exist. Not retaining stakeholders may cause a decrease in research
and development and innovation.
A review of these empirical studies revealed discussions that if a high-technology
acquisition is not integrated properly and if the stakeholders of an acquired organization
are not retained postacquisition, a reduction in research and development and a decline in
innovation are likely. The social implications have economically driven consequences;
for example, if research and development declines and competitive advantage decreases,
jobs will be lost due to corporate downsizing. With nearly 75% of all households in the
United States having a family member, friend, or neighbor being laid off or touched in
one form or another because of merger and acquisition failure (DiGeorgio, 2003), the
current research study provides information for research practitioners and business
leaders who are contemplating merger and acquisition activity regarding the problems
they face.
Transition and Summary
The basis of the current study was transcending innovation and how technology
can generate sustaining economic value for the United States. With increased
competition from emerging economies and larger firms acquiring smaller innovative
organizations, the combination is having a compromising effect on the competitive
advantage of U.S. corporations. Statistical data have shown that corporate value

decreases when start-up entrepreneurial firms are acquired by public corporations before
they mature. Furthermore, without stakeholder retention and a compromising decrease in
patent generation after an acquisition, a once-promising transcending technology
dissipates. The disruptive innovation theory supported by the recourse-based theory
identifies a rational motive that if entrepreneurial organizations are left alone, they can
transcend into new technologies. The transcendence into new technologies by
encouraging entrepreneurial firms to mature will enable the United States to compete in a
competitive global economy, resulting in increased revenues and positive social change
for Americans.
Section 2 contains a detailed account of the methodology chosen for the study.
The section also contains an examination of the role of the researcher, of the study
participants, and the sampling technique. Finally, section 2 contains a discussion of the
data collection technique, data analysis process, instruments chosen to collect and analyze
the data, and the reliability and validity of those instruments. Section 3 contains the
results obtained from the data analysis.
Section 2: The Project
The project topic was to determine whether small start-up entrepreneurial
innovative firms, when acquired by larger technology organizations, lose innovation and,
in doing so, negatively affect the U.S. economy. Bordoff et al. (2006) contended that
innovation has long fueled economic growth, giving rise to new jobs and new industries,
and the economic growth throughout the world has been driven by science, engineering,

and technological innovation. Leaders of large global enterprise organizations with
excessive cash flows have embarked on a business strategy that involves acquiring startup
innovative firms that lose their innovation when acquired (K. S. Christensen, 2006).
The research study involved investigating acquisitions from the top technical
global organizations in the United States using quantitative analysis. Creswell (2009)
noted that within a quantitative study, researchers should specify the reasons for the
method approach and identify key elements of the design early. The current project
includes a discussion of the quantitative quasi-experimental research methodology,
population and sampling, data collection and analysis, reliability, and validity of whether
smaller start-up innovative organizations lose innovation when acquired. Section 2
includes (a) a restatement of the purpose statement; (b) a description of the role of the
researcher; (c) a description of the participants; (d) a description of the research and
design; (e) a description of the population and sampling; (f) a description of the data
collection instruments, data collection techniques, and data collection organization
techniques; (g) data analysis techniques; and (h) a discussion of the reliability of the
instruments to be used and their validity for the study.
Purpose Statement
The purpose of the quantitative quasi-experimental study was to determine
whether small start-up innovative firms lose innovation when they are acquired by larger
public technology firms. Technology innovation that is lost due to acquisitions may
result in a decrease of the economic environment by reducing job creation in the United

States. K. S. Christensen (2006) noted that an acquisition in the technology industry
destroys value; the price paid for an acquisition does not justify the subsequent
performance of the acquired company and subjects the organization to unfavorable future
economic conditions. The independent variable was large public technology
organizations, and the dependent variable in the study was small innovative technology
start-ups, and. The control variables used to measure if innovation lessons exist before
and after the acquisitions are patent generation, stock price trends, and stakeholder
retention. The quantitative research questions and hypotheses were determined through
experiments utilizing data from historical documents and from data mining for statistical
analysis. Through the data analysis, the researcher was able to determine if innovation
was lost in acquired organizations by measuring the control variables. The results of
losing innovation were then studied and analyzed by organizational leaders to implement
the methodologies needed to drive successful acquisition strategies for economic and
social sustainability.
Role of the Researcher
The role of the researcher throughout the data collection process was to collect,
organize, analyze, and interpret the data. The researcher had extensive knowledge, over
20 years, in the high-tech industry as a business owner and partner with the public
organizations that were researched. The researcher was also proficient with the data
collection process by having the knowledge on where to locate information with the
subject public organizations and their acquisitions. The data sets were also standardized

to determine the significance of the data to make conclusions about the entire population.
In the analysis of data, the statistical program SPSS Statistics 17 was used to perform the
complex computations needed to test the data statistically. The researcher‘s significant
knowledge and experience in the technology industry was able to interpret the results for
clarity if innovative continued after an acquisition occurred of entrepreneurial start-up
firm by public technology organizations.
Participants
The participants were purposefully selected from the U.S. stock market within the
technology industry and were limited to companies that made many acquisitions between
2006 and 2010. Nonrandom assignment in quasi-experiments is important because the
groups may be intact and available to the researcher (Creswell, 2009). The organizations
were manufacturers of computer hardware and software that have global tendencies. The
participants were the top 10 U.S. public technology companies in the standardized
industrial code (SIC) of 357, which is the U.S. system for classifying industries, and their
acquisitions over a 5-year period. A total of 213 data points were analyzed during the
period chosen.
Research Method and Design
The objective of the study was to determine if innovation decreases after larger
public technology organizations acquire smaller entrepreneurial innovative firms. The
best way to measure if innovation fails after an acquisition is through quantitative
analysis of the variables. In quantitative research, researchers rely on objective theories

that can measure variables so that numbered data can be analyzed (Creswell, 2009). This
approach uses a postpositivist worldview that includes a focus on determination,
reductionism, empirical observation and measurement, and theory verification (Creswell,
2009). In quantitative research methods, the researcher isolates variables and applies
analytics to associate conditions to generate trends.
The quantitative nonequivalent quasi-experimental (pretest and posttest) design
was most appropriate for the study because measuring variables to decide if innovation
decreases after the acquisition of a start-up entrepreneurial firm by a larger public
technology organization required an analysis of historical data. Historical data are
required for manipulating one or more independent variables against a dependent
variable, with the control variables tested for clear continuity (Simon, 2010). The three
major categories of quasi-experimental designs are the nonequivalent-groups, cohort, and
time-series methods, but the most frequently used and subjected to pretest and posttest
conditions toward control variables is the nonequivalent design (Simon, 2010). The
control variables in the study were the core measurements for data analysis and produced
the valid and reliable results for the study.
Method
The quantitative methodology in the study was based on the following research
questions, and the null hypotheses were tested using a p value less than .05 to reject the
null hypotheses.

1. For the entire sample, what is the patent generation rate before and after an
acquisition?
H10: Patent generation rate of the target firm was greater before acquisition.
H1a: Patent generation rate of the surviving firm was greater after acquisition.
2. For the entire sample, what is the stakeholder retention after an acquisition?
H20: Stakeholder acquisition decreased after acquisition.
H2a: Stakeholder acquisition increased after acquisition.
3. For the entire sample, what is the stock price or CAR value fluctuation during
the 5-day period 2 days before and 2 days after the acquisition?
H30: Stock price trend decreased after acquisition.
H3a: Stock price trend increased after acquisition.
The quantitative methodology was appropriate based on the measurements of the
independent, dependent, and control variables that predicted the outcome of innovation
loss in technology acquisitions. A qualitative methodology was not appropriate in the
study because whereas quantitative methodologies rely on statistical procedures toward
the relationships to the variables, qualitative methodologies rely on the analysis of
individuals or groups in the participants‘ setting (Creswell, 2009). The mixed methods
methodology was considered for the study but presented challenges based on the
magnitude of interviewing the CEOs or the top stakeholders of the 10 technology
corporations selected. The mixed methods methodology is becoming increasingly

proficient, but is the third approach behind quantitative and qualitative analysis (Johnson
et al., 2007).
Research Design
The study included a quasi-experimental nonequivalent (pretest and posttest)
control-group research design to address the innovation trends between target start-up
entrepreneurial firms and acquiring public technology corporations. According to Simon
(2010), the quasi-experimental method includes a sample of convenience and is treated
before and after to determine if any significant difference exists. The quasi-experimental
nonequivalent (pretest and posttest) control-group research design is a popular
quasiexperimental design where Experimental Group A and Control Group B are selected
without random assignment, and both groups take a pretest and a posttest, but only the
experimental group receives treatment (Creswell, 2009). With regard to measuring
performance of the control variables against Firms A and B, quasi-experiments capture
empirically the performance of the research questions by measuring the resources
transferred in the strategic factor market resource acquisition (Clougherty & Moliterno,
2010). The quasi-experimental design was more appropriate than other experimental
methods because quasi-experimental designs are not randomly assigned, which was a
requirement for the analysis portion of the study.
Population and Sampling
The population consisted of public technology organizations and their
acquisitions located in the United States. The organizations were chosen through the

researcher‘s investigative efforts and solicitations of various trade magazines, industry
and business knowledge, and professional communities. Random assignment was not
appropriate in the selection process because of the need of similar organizations in the
high-technology industry for consistency in innovation measurement. The intent of the
study was to analyze the acquisitions made by these organizations between 2006 and
2010 to determine whether the organizations were successful and to determine if
innovation was lost.
The sampling was based on the 10 largest technology companies within the data
center technology industry in 2010. The sample was from SIC 357 (Computer and Office
Equipment) within the U.S. Census Bureau and was based on market capitalization.
Defining a firm‘s valuation on market capitalization is important because the valuation is
proportional to stock price and encompasses the true value of a firm (Ko, 2009).
Determining a firm‘s true value aided in the analysis of the results.
The focus of the study was to determine if innovation was lost due to inadequate
integration of an acquired firm by the acquirer. The measurements to support if
innovation was lost were from a statistical analysis in three areas: (a) stock price
fluctuation during a window of time, (b) patent trend before and after acquisition, and (c)
stakeholder retention of the acquired firm. The organizations analyzed were all public
entities; therefore, the data extracted were public information. Gathering the data from
public documents ensured the validity and the reliability of the information analyzed.

Data Collection
The data for the study consisted of archival data collected from public
information. The data collection process set parameters for the study by establishing a
methodology for extracting data. This section includes a description of the instruments,
the data collection techniques, and the data organization techniques for the study.
Because this study is quantitative collecting public data, does not require a consenting
process, describe how participants may withdraw, provide any incentives, data
maintained in a safe place to protect the rights of the participants, no names of
individuals, and finally a narrative of using an organization to collect data.
Instruments
The study included a quantitative quasi-experimental design. The quantitative
quasi-experimental research design was more appropriate than other designs because the
design provides a baseline of statistical historical data for sufficient power or structure to
generate rigorous statistical data in a pretest and posttest format (Creswell & Plano Clark,
2007). The instrument used in the study was data mining historical documents from
various websites for continuity of the population. The population or organizations
selected were designated through organizations such as Yahoo! Finance and comprised
the top 10 technology organizations based on market capitalization in 2010.
The 10 technology organizations chosen for analysis were subjected to an intense
data mining process from Web-based software resources such as Capital IQ and other
Web-based financial software packages. The description of each organization was based

on high-technology firms that focus on acquiring smaller technology start-ups. The data
acquired were then subjected to the variables in the study, which were (a) disruptive
technology start-up firms that provide innovation, (b) acquiring larger public
organizations, (c) patent generation before and after an acquisition methodology
(Appendix B), (d) stock price fluctuation during an acquisition, and (e) stakeholder
retention after an acquisition. This information was public knowledge and could only be
compromised if the researcher transposed the information incorrectly.
Data Collection Techniques
The technique chosen for collecting data in the study was sampling existing data
that encompassed the statistical analysis of public merger and acquisition data between
2006 and 2010. Due to rapid technological change and in order to obtain an unbiased
representation of the true current technology industry landscape, Tassey (2008)
recommended that data should not be collected beyond 5 years prior to a study.
Generating data over a 5-year period provided conclusive evidence for optimal results.
Data Organization Techniques
Data organization in the study was analytic in nature and a cataloging system was
used to keep track of the data and emerging understanding. The cataloging system used
for the study involved a spreadsheet and filed documents, with all documents being
scanned into a database. The data were secured at the home of the researcher, at the
researcher‘s office that has redundant backup, and to compact disk. The term for storing
the data will be indefinite.

Data Analysis Techniques
Quantitative statistical analysis lies in the process of presenting and interpreting
numerical data pertaining to the questions and hypotheses in a study. Techniques behind
quantitative data analysis during an experiment require intensive statistical computation
to provide optimal results. Due to the complexities of quantitative analysis in an
experiment, rigorous data points, statistical expertise, and data fluency are needed and
can be formalized in the following steps (Creswell, 2009):
1. Report the descriptive statistics.
2. Indicate the inferential statistical tests.
3. Use line graphics for baseline and treatment observations.
4. Report both statistical results of hypotheses testing, confidence intervals, and
effect size.
The data collected from Capital IQ, Yahoo Finance, and other Web-based
resources were imported from an Excel spreadsheet into PASW GradPack Version 18,
previously known as SPSS, for statistical analysis. Analysis performed logically and
sequentially addressed all research questions and hypotheses. The study included a
Pearson correlation to examine the relationship of the variables between innovative target
firms and larger acquiring public technology corporations. The Pearson correlation
assesses the linear relationship between quantitative variables in a sample (Green &
Salkind, 2008). The choice of the Pearson correlation was primarily based on the
purpose of the study and the nature of the variables.

The data analysis was consistent with the research questions, hypotheses, and
underlying theoretical framework of the study. Consistency throughout the sectors
increased the validity and reliability of the study. The researcher answered the research
questions and hypotheses following the data analysis, which indicated whether larger
public technology corporations lose innovation due to acquisitions of entrepreneurial
start-ups.
Reliability
The measurement of the continuation of innovation after the acquisition of an
entrepreneurial technology firm by a publicly traded organization was the main theme of
the study. The control variables were the patent generation, stock price fluctuation, and
stockholder retention statistics before and after an acquisition. Patent generation can be a
viable measurement tool because the number of patents generated by an entrepreneurial
start-up before it was acquired may decrease after an acquisition and will determine if
innovation has stalled (Zhao, 2009). Stock price fluctuation was measured by an event
study using CARs, a widely used and accepted technique in which the results are
estimated and statistically analyzed to determine the magnitude of an acquisition (Lee &
Connolly, 2010). Stakeholder retention was measured by analyzing the length of time the
founders and critical management were retained after 2 years of the acquisition.
Schlange (2009) noted losing any support from the stakeholders or a critical group in an
acquisition over the first 2 years compromise the venture. The combined measurement of
the control variables brought a strong level of reliability to the study.

To uphold the integrity of the study, an additional reliability measure was
conducted through examining intercoder reliability. Intercoder reliability is a procedure
in which a researcher utilizes a second person to cross-check codes for agreement or
reliability regarding the concepts of the codes (Creswell, 2009). The procedure increased
the reliability of the study by creating an additional layer of testing that held the variables
as credible sources for analysis.
Validity
Statistical methods using t tests and correlation analysis helped to verify the
speculative relationships between the independent, dependent, and control variables in
the study. Many studies in technology acquisitions employ rigorous statistical
computation. Adavikolanu (2008) conducted a study using aggressive regression and
correlation analyses on multiple hypotheses to determine the value creation in serial
acquisitions of technology firms. External validity was based on the credible sources of
the data, and internal validity depended on statistical analysis of the variables under
analysis.
Transition and Summary
The study involved investigating the impact of acquisitions on entrepreneurial
technical organizations. The quantitative method of research using structured record
reviews was the best method to approach the study. Section 2 contained the purpose
statement, the role of the researcher, the research method and design, the population and
sampling method, the data collection process and implementation, and a discussion on the

reliability and validity of the study. The study involved statistical analysis using the
Pearson correlation method in the PASW GradPack Version 18 software to validate the
study. Section 3 contains the results obtained from the data analysis.
Section 3: Application to Professional Practice and Implications for Change
The purpose of the quantitative quasi-experimental study was to test the theory that
transcending innovation is lost due to the acquisition strategies of larger public
technological organizations acquiring smaller start-up innovative entrepreneurial
organizations, controlling for patent generation, stock price trend, and stakeholder
retention. The problem addressed was that new start-up companies with innovative ideas
do not mature when they are acquired by larger companies and do not fully articulate
potential industry-transcending innovation. The impediment of innovation may
eventually jeopardize the U.S. economic condition, resulting in decreasing technological
advantage against emerging global economies.
Section 3 includes a detailed account of how the study was conducted, the
presentation of the findings, discussions of the ability of those findings with respect to the
professional practice of business, and the implications for social change. The
recommendations for action by stating who needs to pay attention to the results are
addressed in this section. Finally, the researcher provides recommendations for further
study and a summary and conclusions for the study.

Overview of the Study
The current quantitative study involved examining the innovation that was lost
when start-up entrepreneurial firms were acquired by public technology organizations.
The study included two statistical approaches, a paired t test and subscripted statistics, to
understand the patent generation, stakeholder retention, and stock price fluctuation of 71
acquisitions by 10 public corporations.
The three research questions addressed in the study were as follows:
1. For the entire sample, what is the patent generation rate before and after an
acquisition?
2. For the entire sample, what is the stakeholder retention after an acquisition?
3. For the entire sample, what is the stock price or CAR value fluctuation during
the 5-day period 2 days before and 2 days after the acquisition?
The following null hypotheses and alternative hypotheses were tested using a p
value less than .05 to reject the null hypotheses.
H10: Patent generation rate of the target firm was greater before acquisition.
H10: Patent generation rate of the surviving firm was greater after acquisition.
H20: Stakeholder acquisition decreased after acquisition.
H2a: Stakeholder acquisition increased after acquisition.
H30: Stock price trend decreased after acquisition.
H3a: Stock price trend increased after acquisition.
H10 and H20 were both rejected, which holds favorable to the study. In addition,
H30 held true, which also holds favorable to the study. The next section provides a
detailed presentation of the findings of the study.
Presentation and Findings
The purpose of the quantitative quasi-experimental study was to test the theory
that transcending innovations are lost due to the acquisition strategies of larger public
technological organizations acquiring smaller start-up innovative entrepreneurial
organizations, controlling for patent generation, stock price trend, and stakeholder
retention. Public data sources for 71 acquired technology companies were examined.
Table 1 contains the frequency counts for the 10 parent companies that acquired
those 71 companies. Parent companies that acquired the most companies were Cisco
(28.2%), Microsoft (21.1%), and EMC (11.3%). A complete list of all the names of the
71 acquired companies appears in Appendix C.
Table 1
Frequency Distribution for Number of Companies Acquired (N = 71)
Parent company n %
Apple 6 8.5
Brocade 1 1.4
Cisco 20 28.2
Citrix 5 7.0
Dell 2 2.8
EMC 8 11.3
HP 7 9.9
Microsoft 15 21.1
Net App 3 4.2
VMWare 4 5.6
Table 2 displays the descriptive statistics for selected variables. The length of
time these acquired companies were incorporated ranged between 0.5 years and 10 years
(M = 4.89, SD = 2.06). In addition, Table 2 provides summary statistics for patents,
stakeholders, and the company‘s CAR value (M = -0.33).
Table 2
Descriptive Statistics for Selected Variables (N = 71)
Variable M SD Low High
Incorporation year 2002.55 2.31 1997.00 2007.00
Years incorporated before acquisition 4.89 2.06 0.50 10.00
Number of patents before 9.38 18.85 0.00 122.00
Number of patents after 1.03 3.04 0.00 18.00
CAR value (expressed as percentage) -0.33 3.66 -13.61 9.25
Stakeholders before 3.97 1.13 1.00 6.00
Number of stakeholders after 1.63 1.28 0.00 5.00
Percentage of stakeholder retained 41.47 31.27 0.00 100.00
Patents per year before a 2.07 3.52 0.00 18.77
Patents per year after b 0.51 1.52 0.00 9.00

Note. a Calculated based on the number of patents divided by number of years
incorporated.b Calculated based on the mean number of patents in the 2 years after
acquisition.
Research Question and Hypotheses
The primary research question for this study was as follows: How do start-up
entrepreneurial technical firms lose innovation when acquired by larger global public
entities? The three related null hypotheses were as follows:
H10: Patent generation rate of the target firm was greater before acquisition.
H20: Stakeholder acquisition decreased after acquisition.
H30: Stock price trend decreased after acquisition.
To address Hypothesis 1, paired t tests were used to compare the number of
patents generated before and after acquisition. The dependent variable was calculated
two ways: unadjusted patents were calculated using the number of patents for the years
incorporated before being acquired (M = 4.89) and for the 2 years after being acquired.
For patents per year, the before acquisition number was calculated by dividing the
number of patents generated by the number of years incorporated. Patents per year after
acquisition was calculated by dividing the number of patents generated in the 2 years
after acquisition by two. Inspection of Table 3 for both metrics indicated that significant
declines occurred (p = .001) from before to after acquisition. This combination of
findings provided support to reject Null Hypothesis 1.
To address Hypothesis 2, a paired t test was used to compare the number of
stakeholders in the acquired company before and after the acquisition (see Table 3). A
significant decline (p = .001) was noted (M = 3.97 vs. M = 1.63) where only 41% of the
original stakeholders were still with the company 2 years after acquisition. This finding
provided support to reject Null Hypothesis 2.
Table 3
Paired t Tests Comparing Number of Patents and Stakeholders Before and After the
Acquisition (N = 71)
Variable and time period M SD t p
Unadjusted patents a 4.05 .001
Before 9.38 18.85
After 1.03 3.04
Patents per year 4.11 .001
Before 2.07 3.52
After 0.51 1.52
Stakeholders 14.03 .001
Before 3.97 1.13
After 1.63 1.28
Note. a Unadjusted patents were the number of patents for the years incorporated before
being acquired (M = 4.89) and for the 2 years after being acquired. b Patents per year
before acquisition was calculated by dividing the number of patents by the number of
years incorporated. Patents per year after acquisition was calculated by dividing the
number of patents generated in the 2 years after acquisition by two.
For CAR values, a significant change was considered any gain greater than 1% or
any decline greater than -1% (Ma et al., 2009). Inspection of Table 4 revealed 25
companies (35.2%) had CAR values considered to be random fluctuations (between
-0.99% and +0.99%). Also, 31% had significant or important gains in their CAR values
while another 33.8% had significant or important declines. Given that 69.0% of the
acquired companies had CAR values considered to have only random fluctuation or a
significant or important decline, the findings provided support to retain Null Hypothesis 3
(see Table 4).
Table 4
Distribution of Cumulative Abnormal Return (CAR) Categories (N = 71)
CAR category (% included) n %
Important decline (-13.61 to -3.00) 9 12.7
Significant decline (-1.00 to -2.99) 15 21.1
Random fluctuation (-0.99 to +0.99) 25 35.2
Significant gain (+1.00 to +2.99) 12 16.9
Important gain (+3.00 to +9.25) 10 14.1
Note. CAR values expressed as percentages.
In summary, public data sources for 71 acquired technology companies were
examined to test the theory that transcending innovations are lost due to the acquisition
strategies of larger public technological organizations acquiring smaller start-up

innovative entrepreneurial organizations. For these acquired companies, the number of
patents generated and stakeholders retained significantly declined in the 2 years after
acquisition (see Table 3). In addition, CAR values either remained essentially the same
(random fluctuation) or had significant declines for 69% of the acquisitions (see Table 4).
Applications to Professional Practice
The current quantitative study involved examining if innovation was lost due to
acquisitions by examining the patent generation, stakeholder retention, and CAR values
before and after the acquisition of 71 entrepreneurial innovative firms by 10 large public
technology organizations. The results were consistent with the majority of the previous
studies on the topic, showing a negative effect on acquisitions. The 71 target firms
analyzed were start-up entrepreneurial firms incorporated in the United States, 10 years
old or less, and purchased between 2006 and 2010. The 10 acquiring public firms were
from the information technology sector and were computing, networking, storage, and
software enterprises all incorporated in the United States.
The patent generation results statistically in the sample indicated a significant
decrease in patents generated 2 years after the acquisition from 2 years before. The
findings are important because patent generation is a strong indicator of whether
innovation is prevalent in an organization. The innovative nature of a technology
organization is to create transecting implications that enable economies to expand, and
patent generation is a key determinant for this argument.
Stakeholder retention of the key employees of the target firm after 2 years
indicated a significant decline. The stakeholders researched were the founders, CEOs,

chief operating officers, chief technology officers, presidents, and vice presidents of
engineering or other equivalent titles organizations may use. The majority of the target
firms‘ founders and cofounders are considered the technical lead and operational stability
of the innovative nature of the organization. Whether the technical founders maintain
employment after acquisition is a key determinant of whether innovation fails. Because
the findings support a significant loss of stakeholders, the founders‘ employment
retention can only be determined equivalent and innovation will not continue. The
impact on the stock value fluctuation after acquisition had a substantial decrease
according to the results. The acquiring firms‘ stock price percentage fluctuation CAR
value was compared to the Vanguard Information Technology Index CAR value. The
acquiring technology firms were compared to the index to get a stronger perspective
because all the public firms selected are included in the index portfolio. Having a
substantial drop in the CAR values of these acquisitions over a 5-year period provides
businesses the ability to compare the price paid for the target firm with the stock price
lost and determine if the acquisition was favorable. The next section includes a
discussion on the implications for change.
Implications for Social Change
The economic conditions in the United States, along with increased competition
from foreign emerging markets, have had a profound effect on the prosperity of
Americans and future generations, as discussed in section 1. The technology industry has
the ability to transcend and create whole new industries, as Apple has done, which is now

the second largest valued company in the world. But serial acquisition strategies by large
public technology firms involve continually acquiring innovative organizations before
they mature. If entrepreneurial firms are able to transcend and create new industries,
many new opportunities would be available for individuals in the United States.
Many of the founders from the target companies were of foreign descent, and
although these entities were incorporated in the United States, the organizations used
technical resources from their home countries to outsource jobs not found in the United
States. Furthermore, many of the foreign entrepreneurs become serial entrepreneurs
because they understand the current technology venture capital investment system in the
United States. Therefore, a need exists for sovereign U.S. individuals to follow these
steps but continue to innovate without being acquired. The implication for social change
is to provide Americans with the ability to innovate through technology education and let
those entities transcend to create greater economic prosperity for Americans in the United
States.
Recommendations for Action
The research findings provided significant recommendations for action by looking
at how the U.S. economy can succeed for generations to come. For this to happen, the
U.S. government must partner with private and nonprofit organizations and create an
infrastructure for innovation, creativity, and ideas, which can involve supporting K-12
education and inspiring kids and teachers; providing incentives to universities that
encourage practical innovation and entrepreneurship both inside and outside the

classroom; creating inspired leadership; and supporting small business and
microenterprise. The space race and the Apollo program happened because the project
had a clear objective, inspired leadership, and significant investment in technology and
the sciences that created the technology revolution from the 1960s. The U.S. government
departments that would best serve in creating innovation are the Office of Innovation and
Improvement, the U.S. Department of Education, the U.S. Economic Development
Administration, and the U.S. Department of Commerce.
Acquisitions of entrepreneurial innovative firms will continue, but corporate
business strategies must consider the findings in the current study. The audience for the
study will be corporate heads, business strategists, and entrepreneurs. To reach the
appropriate audience, the results of the study will be disseminated through publications,
with the entire study being published in the ProQuest/UMI dissertation database. The
researcher also plans to publish parts of the study in several scholarly articles and publish
a book on the subject studied.
Recommendations for Further Study
Based on the literature and current findings, in the high-technology industry
acquisitions of start-up entrepreneurial innovative firms by larger public corporations
measured for patent generation, stakeholder retention, and stock price fluctuation
innovation is lost. However, the sample selected only included an acquisition window of
5 years, which may not define the complete story of the selected acquiring firms‘ history
toward acquisition behavior or the integration success of the target firm. Because the

selected corporations had long life cycles, meaning they had been incorporated for more
than 10 years with an average of 29 years in business, encompasses many years and
multiple business strategies that corporate heads had to execute acquisitions. Therefore, a
recommendation for future study should include a longer acquisition window of at least
10 years to achieve a stronger indication of whether innovation is lost over multiple
business strategies and leadership. Additionally, interviews of corporate heads will lend
greater credibility to the study and add insight to the habits of the business strategies, as
well as valuable consideration on why acquiring target firms is more beneficial to that
organization than internal research and development initiatives.
Reflections
As a founder and CEO of an information solutions partner of all the acquiring
organizations in this study, the researcher began the study with the preconceived notion
that innovation would be lost following the acquisitions by large public high-technology
corporations of innovative entrepreneurial start-up companies. The expectation was to
find scholarly literature closely related to the high-technology industry, although
informative journal articles was analyzed, what was found did not provide much specific
information on the acquiring firms and their target acquisitions. The researcher used his
extensive experience with high technology to facilitate the data collection techniques
utilizing online web resources to bridge this gap. Experience is important because on a
business level as a practitioner, the researcher will be able to provide scholarly-based
solutions to the business community in the high-technology industry. Furthermore, the

knowledge gained from writing and collecting data during this doctoral study will be
valuable and will aid in his company‘s growth and provide leadership toward
technological innovative economic growth for U.S. society in the years to come.
Summary and Study Conclusions
Transcending technological innovation has been the cornerstone of American
prosperity, but acquisitions of entrepreneurial start-up innovative firms by larger public
technology organizations are jeopardizing innovation. The goal of the current research
was to determine if innovation is lost by examining 71 acquisitions of entrepreneurial
start-up innovative firms by 10 larger public technology corporations, controlling for
patent generation, stakeholder retention, and stock price fluctuation. The purpose of the
data analysis was to determine if innovation decreased by examining if patent generation
decreased, stakeholder retention decreased, and stock price fluctuation decreased after the
acquisition of an innovative entrepreneurial firm. The results indicated that patents
decreased after acquisitions, stockholder retention decreased, and stock price fluctuation
decreased after acquisition. The outcomes indicated that the majority of acquisitions by
public technology corporations‘ shows that innovation declines, but there may be
additional research that can add to this study by increasing the number of years. Based
on the results of this study addressing whether innovation decreases after acquisition,
significant decline in innovation was shown. The Walden University Institutional
Review Board (IRB) approval number for this doctoral study is 08-10-11-0189730.

