


Introduction A merger or acquisition
A merger or acquisition represents one of the most important strategic decisions
made by managers as well as shareholders of the engaged firms. Any merger or acquisition
deal involves at least one of two separate yet equally important sets of negotiations. The
first set puts the managers and/or the shareholders of the acquiring and target firms face to
face to discuss issues related to the terms of the merger, including target firm’s valuation,
while the second set resolves disputes between the merging parties and the government
regulatory agency over the potential anticompetitive impact of the merger. A breakdown in
either set of negotiations would render the merger attempt unsuccessful and, therefore, an
announcement of merger does not necessarily mean it will eventually be completed.
Early theoretical and empirical research on the success of merger attempt
(Walkling, 1985; Samuelson and Rosenthal, 1986; Hirshleifer and Titman, 1990) finds that
the bid premium, the acquirer’s ownership of the target prior to the actual acquisition offer
(i.e., acquirer’s toehold), and target managements’ opposition are important factors in
predicting the acquisition deal outcome. More recent research (Officer, 2003; Bates and
Lemmon, 2003; Hotchkiss, Qian, and Song, 2005) focuses basically on the role of bidder
and target termination fees in acquisition deal completion. The evidence is that termination
fees serve as an efficient contracting device in the sense that they mitigate information
asymmetries between the merger parties, rather than their being an attempt by target
managers to deter competitive bidding.
Although the previous literature presents useful analyses of how a merger
completion decision is made, the regulatory role in a merger completion process has

escaped researchers’ attention. Thus, several interesting questions relevant to this issue
remain unanswered. These questions include the following:
1- What role, if any, do merger regulations and antitrust requirements play in
a firm’s decision to complete an acquisition deal?
2- What role do other factors play in a firm’s decision to successfully complete
an acquisition deal, conditioned upon regulatory approval or disapproval?
Specifically, there are two opposite issues that beg to be addressed in this
respect: a) what factors will motivate merging parties to complete the
merger in spite of a regulatory challenge? b) what factors will motivate the
parties to cancel the merger even in the absence of a regulatory challenge?
and
3- What, if any, is the actual cost of a merger facilitating divestiture? How does
it affect the acquirer’s future growth needs and internal capital allocation
efficiency?
These questions are intriguing in light of the evidence that the impact of
government intervention is not uniform across firms seeking mergers. At first glance, it
appears that government intervention has a deterring impact on acquisitions proposed by
some firms but not on those proposed by other firms. Similarly, the cost of compliance with
regulatory requirements appears to be different across merger-seeking firms. For example,
Barnes & Noble Inc. withdrew its proposal to buy Ingram Book Group, a closely held unit
of Ingram Industries Inc., following the Federal Trade Commission’s opposition although
both companies believed that the merger would be ultimately approved, while Albertson’s
Inc. chose to complete its merger with American Stores Co. although it was required to
divest more stores than it had expected. These two examples pose two opposite rationales:

Barnes & Noble case implies that if the merger had gone through, the government
requirements would have made it ex-ante infeasible, while Albertson’s case implies that
even after divesting some assets, the merger was still exante feasible. Thus, the bases on
which these firms made their deal completion or cancellation decision seem to be different
and the assets that these firms are required to divest seem to have different impact on their
future growth needs.
In this first essay, I investigate the first two issues raised above. More specifically,
I study the factors that explain the decision to cancel or complete a merger deal, conditioned
on the regulatory approval.
1. Literature Review:
The literature pertaining to mergers and acquisitions is abundant. Below I provide a brief
summary of the research that is immediately relevant to the question I address in this essay.
This provides a perspective on where my research contributes to the literature, while it also
motivates my analysis.
2.1. Motives behind Mergers and Acquisitions:
Since 1980, the U.S corporate market has been witnessing huge restructuring activities
that culminated in the largest merger wave in the U.S history in the 1990s. Most of the
acquisitions of the 1980s were hostile, paid for with cash, and played a significant role in
disciplining managers, while most of those of the 1990s were friendly, paid for with stock,
and played a trivial role as a corporate governance mechanism (Andrade, Mitchell, and
Stafford, 2001; Kini, Kracaw, and Mian, 2004). During 1998-2001 many mergers have also
been most value destroying (Moeller, Schlingemann, and Stulz, 2005).

Extant literature has thoroughly investigated the announcement effect of mergers
and acquisitions. An overwhelming conclusion of this line of research can be summarized
as follows: the targets return is positive and statistically significant, while for the acquirer
it is insignificant. Travlos (1987) notes that the announcement return to the acquirer is
affected by the method of payment (i.e., positive reaction to cash mergers and negative
reaction to stock exchange offers), and argues that the negative reaction for stock offers is
consistent with signaling hypothesis implying that stock offers convey information that the
bidding firm is overvalued. Brown and Ryngaert (1991) present empirical evidence
consistent with this argument and further argue that bidders offer stock in order to avoid
the tax consequences of cash offers. Berkovitch and Narayanan (1990) also present an
asymmetric information model that implies that in takeovers financed with mixture of cash
and equity, the higher the amount of cash, the higher the abnormal returns to stockholders
of both the acquirer and target. Huang and Walkling (1987) present empirical evidence
consistent with this implication.
The literature provides both theoretical and empirical explanations as to why firms
engage in mergers and acquisitions. The first explanation suggested in the literature is the
market (or the monopolistic) power hypothesis. It is argued that a takeover may be driven
by the acquiring firm’s desire to gain larger market share by acquiring rival firms so that it
could control output prices. However, such clear motivation is scrutinized and prohibited
by the federal government for its potential anticompetitive impact. Ellert (1976) presents
finds that enforcement of antimerger law does not dislodge monopolistic concentration of
corporate wealth. Eckbo (983); Stillman (1983); and Trembplay and Trembplay (1988),
test the effectiveness of this policy and find little or no evidence of anticompetitive effects
for firms prosecuted by the FTC. Most recently, Fee and Thomas (2004) and Sharur (2005)

find that horizontal mergers (i.e. mergers between competitors) challenged by the FTC, are
primarily motivated by efficiency considerations.
The hubris hypothesis, coined by Roll (1986) is another explanation for takeovers.
It asserts that the decision makers of the acquiring firm suffer from hubris, so they
mistakenly believe that the target firm value is above its market price and consequently
overpay. Roll (1986) argues that the hubris hypothesis assumes that markets are strongform
efficient but may imply that the market for corporate control is inefficient.
Therefore, hubris alone cannot explain the takeover phenomenon. Berkovitch and
Narayanan (1993) test the hubris hypothesis and document that they cannot reject it in spite
of their finding that the primary motive behind takeovers is the synergetic gains.
Given the conflict of interest between managers and shareholders, an acquisition
may be one way by which managers spend firm’s resources on nonpositive or even negative
net present value projects. However, if the market for corporate control is efficient, such a
firm will become a takeover target rather than being an acquiring firm. As a result, a
takeover is both an evidence of conflict of interest between managers and shareholders and
a solution of the problem. This is the free cash flow theory of takeovers formalized in
Jensen (1986). It predicts that managers of firms with unused borrowing power and large
free cash flows are more likely to undertake value-destroying mergers. Furthermore, these
mergers are more likely to be diversifying mergers. Harford (1999) provides empirical
evidence supportive of the Free Cash Flow theory. He finds that cashrich firms are more
likely to make diversifying, value destroying acquisitions. The prediction that
diversification does destroy value has been empirically supported by
Berger and Ofek (1995) and Lang and Stulz (1994) show that firms that undertake
diversifying mergers are poor performers. More recently, Aggrawal and Samwick (2003)

provide theoretical and empirical evidence that, in equilibrium, firms in which managers
experience an increase in private benefits of diversification will diversify more. Matsusaka
(1996) finds that diversification is not driven by tough antitrust enforcement that may have
prevented firms from growing in their industries, and that smaller firms are as likely to
diversify as larger ones.
More recent explanations for mergers include market misvaluation and the
industry shocks. Theoretical models of Shleifer and Vishny (2003) and Rhodes-Kropf and
Vishwanathan (2003) predict that merger waves occur as managers time acquisitions when
the market overvalues their firms. Empirically, Rhodes-Kropf, Robinson, and Viswanathan
(2003) and Dong, Hirshleifer, Richardson, and Teoh (2005) find evidence supportive of
this prediction. Mitchell and Mulherin (1996) show that merger waves are the result of
firms’ adaptation to industry shocks. However, whether an economic, regulatory, or
technological shock leads to a merger wave depends on whether there is sufficient liquidity
in capital markets (Harford, 2004).
2.2. The success of a merger or acquisition attempt:
The interest in modeling a takeover outcome has been propelled by the observation
of asymmetric reactions to news of bid success and bid failure. Dodd (1980) shows that
merger success announcement is greeted by positive market reaction while merger
cancellation announcement is perceived as bad news. This may imply that information
pertaining to the outcome of takeover was not fully incorporated in the stock price at the
initial announcement of the takeover. Alternatively, the asymmetric stock price reaction to
merger failure and success can be explained by new information released by the acquiring
and/or target firms during the time between the initial announcement date of a merger and

its eventual outcome date. A merger is a lengthy process that may take more than one year
to be concluded (completed or canceled). Research shows that, on average, the length of
time between the announcement date and completion or termination date is six months.
During this time period new information might be released about the acquirer and target
firms, consequently changing shareholders’ estimates about the post-merger value of the
combined firm and possibly the likelihood of completing the merger deal. Consistent with
this latter implication, Samuelson and Rosenthal (1986) find that target stock price changes
can predict the deal outcome and Luo (2005) finds that merging companies use information
extracted from market reaction in closing a merger deal. However, Jennings and Mazzeo
(1991) find that managers do not learn from changes in their stock prices when completing
or canceling their acquisition deal. Additionally, the new information allows competitors
reevaluate the initial bidder’s assessment of the target value, influencing their decision as
to whether or not they should make competitive bids. Walkling (1985) finds that the
existence of a competing bid and target management resistance decrease probability of
takeover success while increased bid premium and payment of solicitation fees increase it.
Hirshleifer and
Titman (1990) provide theoretical perspective that supports these results.
2.3. Cost of a failed merger attempt:
The failure of a merger attempt can entail significant direct and indirect costs to the
acquirer, target, or both firms. From the time of a merger announcement to the time when
it is completed or canceled, the acquiring firm discloses information that it would not

otherwise disclose, incurs substantial legal expenses, and faces production activity
disruptions as well as management distraction. If the deal falls through, then competitors
are in a better position to use such information to their advantage. Ekbo and Wier (1985)
find evidence that rival firms benefit from the news of a merger proposal and that a delay
in completion of the deal gives rival firms additional time to exploit the news. Bates and
Lemmon (2003) find that the inclusion of target termination fees is more frequent in merger
deals where the potential for information expropriation by third parties is significant. The
target, on the other hand, has to seek other means of restructuring, including being taken
over by a different firm, which may not be possible within a short period of time. The
literature overwhelmingly suggests that the target firm’s stock price reacts favorably at the
acquisition announcement date, with the average abnormal return exceeding 10%.
However, Wier (1983) finds that between the merger announcement date and the date when
the deal is canceled following antitrust challenge, targets lose all the announcement period
gains. She interprets this result as the cost of antitrust lawsuit to acquisition targets.
Moreover, the party that reneges on a merger deal bears the risk of having to compensate
the other party for damages stemming from the abandoned deal.
3. Hypotheses Development:
Based on the empirical evidence presented earlier, it seems that the likelihood of success
or failure of a merger depends on whether or not the regulatory agencies challenge the deal.
Thus, the determinants of completion or cancellation decision may be different when it is
conditioned on the regulatory approval. I, therefore, visualize the merger completion or
cancellation decision as in figure I where the merger parties get to choose between
completing and canceling the deal after they observe the government decision as to whether
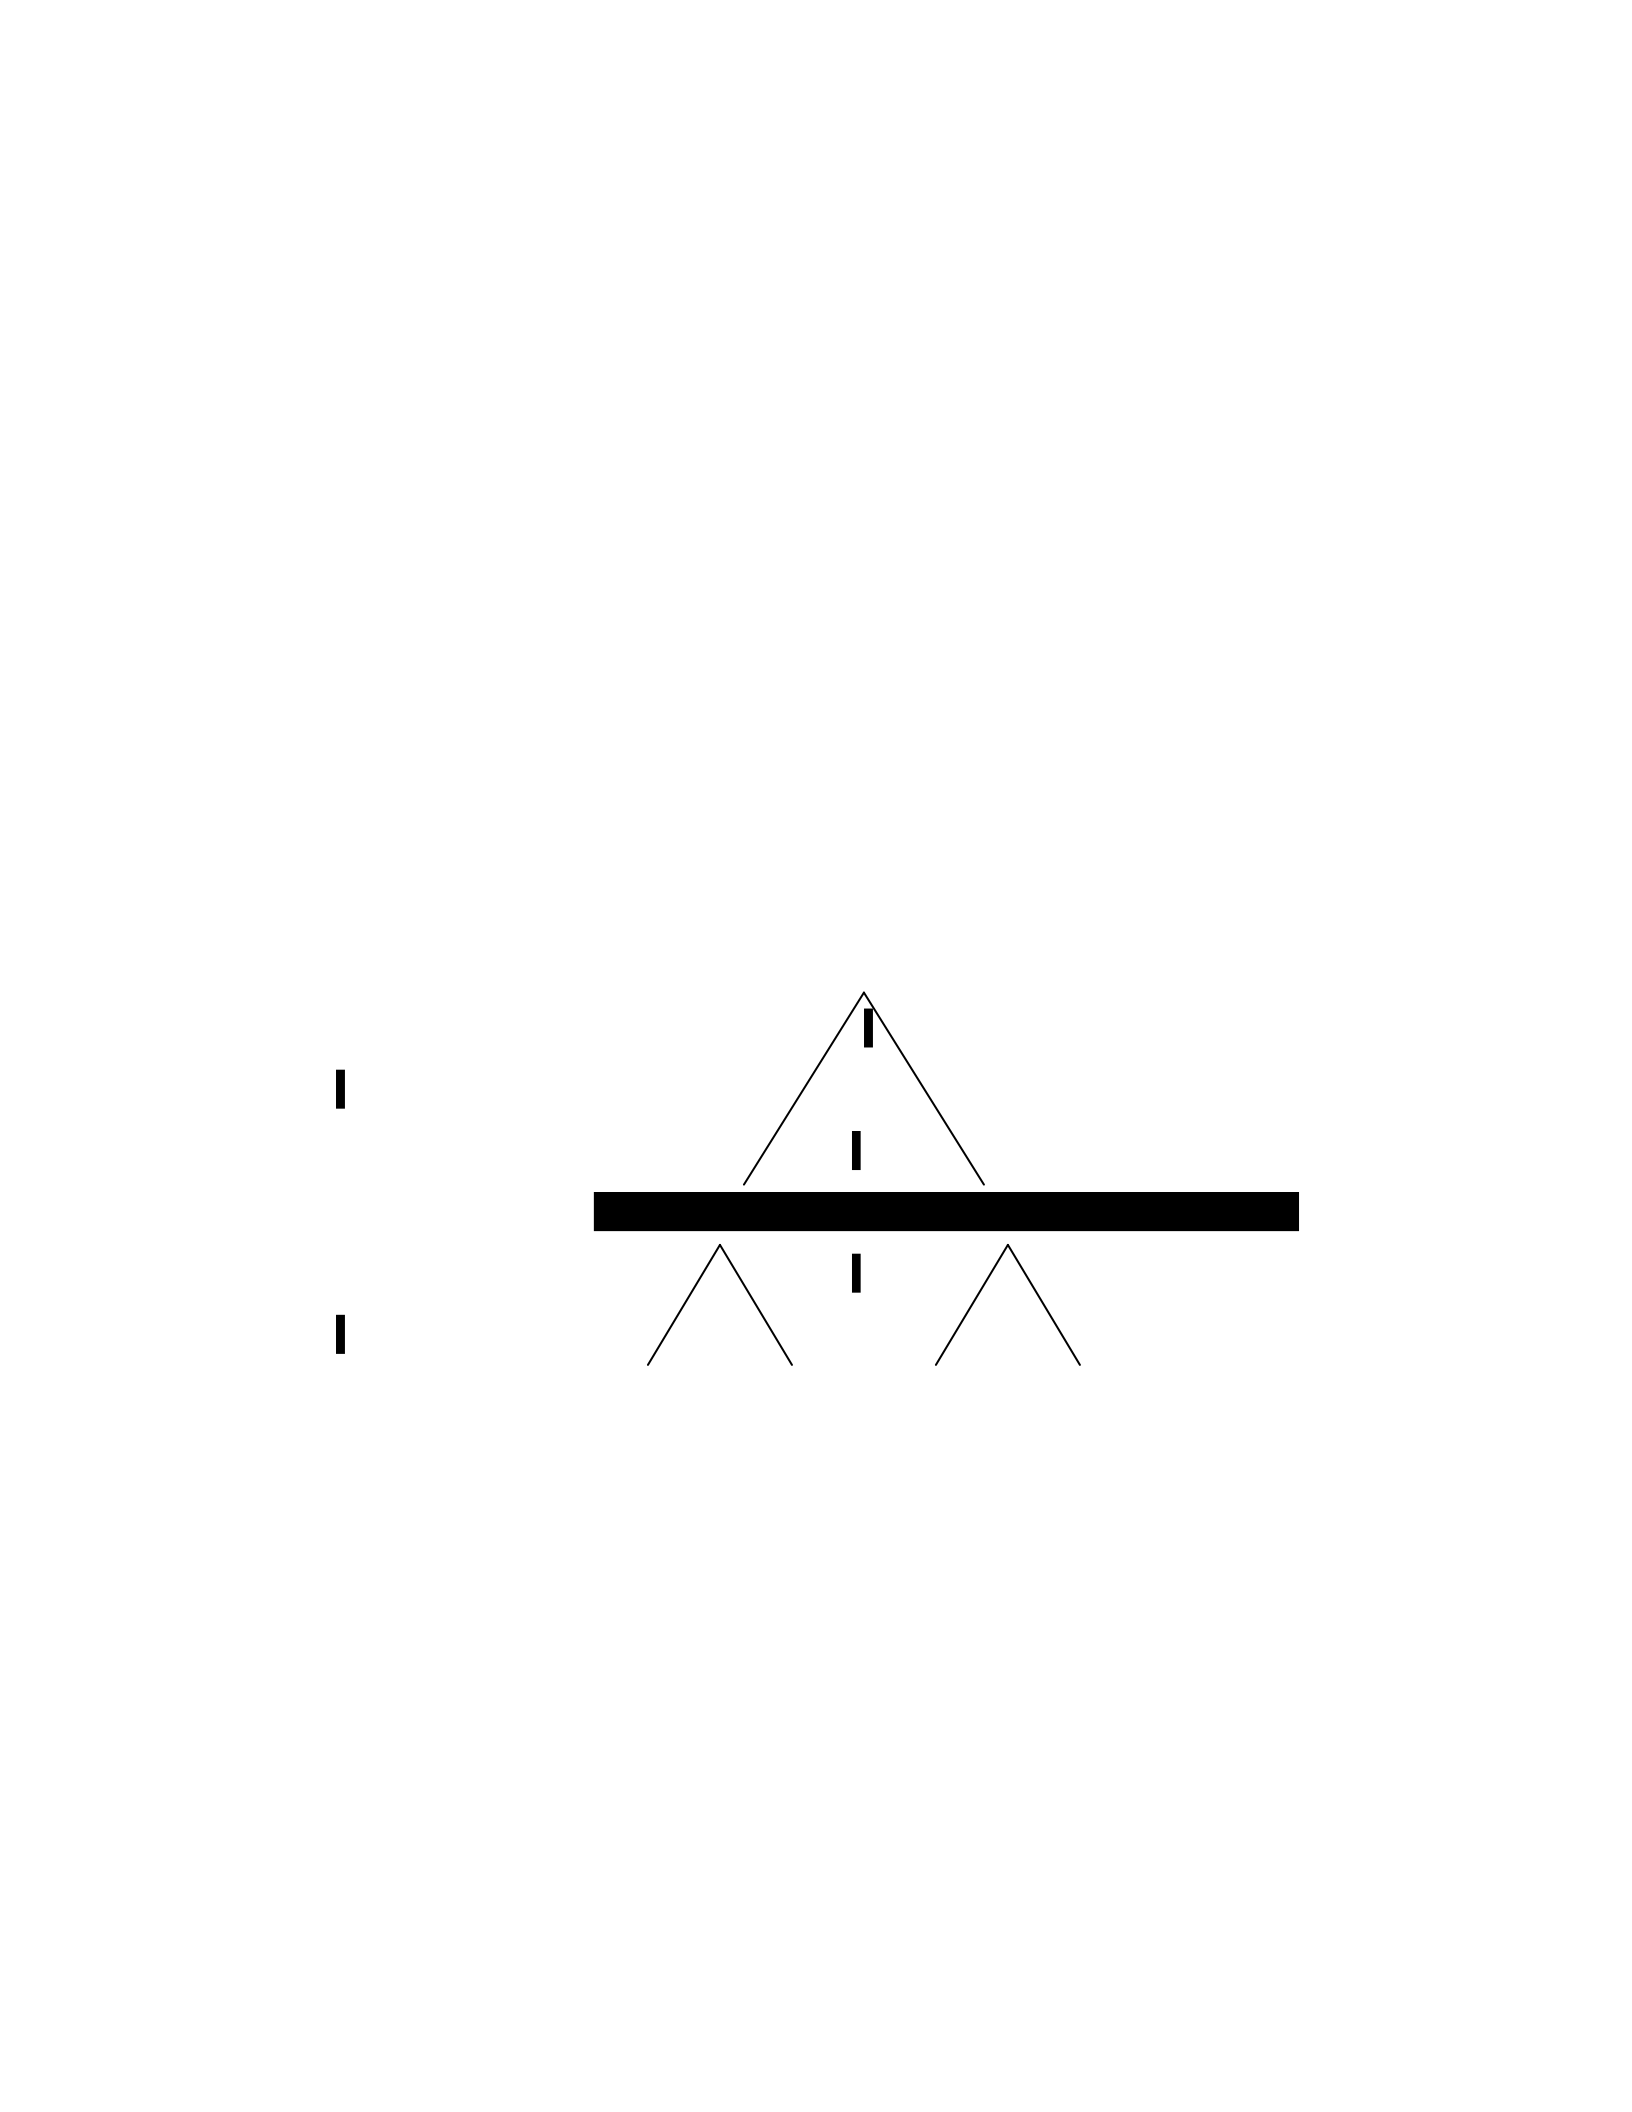
or not the deal is challenged. I develop two sets of hypotheses that capture intricacies of
the merger process path. The first set of the hypotheses is in regard to the regulatory
agency’s decision to challenge (or not challenge) the acquisition deal, while the second set
concerns merger parties’ decision to complete (or cancel) the acquisition conditional on the
regulatory agency’s approval.
Figure I: The path of a merger or acquisition proposal
Merger or acquisition proposal
Completed Cancelled Completed Cancelled
3.1. Factors Influencing Regulatory Challenge:
3.1.1. Market Concentration:
The regulatory investigation process of a merger begins once the merger parties accurately
complete the forms required for notifying the Federal Trade Commission (FTC) and
Challenged Not Challenged

Department of Justice (DOJ). The HSR Act requires both the acquiring and the acquired
entities to file notification if all the following conditions are met: (a) one entity has sales
or assets of at least $100 million; (b) the other entity has sales or assets of at least $10
million; and (c) as a result of the transaction, the acquiring entity will hold an aggregate
amount of stock and assets of the acquired entity valued at more than $50 million; or (d)
as a result of the transaction, the acquiring entity will hold an aggregate amount of stock
and assets of the acquired entity valued at more than $200 million, regardless of the sales
or assets of the acquiring and acquired entity. The parties must then wait a specified period,
usually 30 days (15 days in the case of a cash tender or a bankruptcy sale), before they may
complete the transaction.
The DOJ issued its merger guidelines in 1984 in order to describe the general principles
and specific standards normally used by the department in analyzing mergers to decide
whether or not they violate Section 7 of Clayton Act. These guidelines are also among other
undisclosed criteria that the FTC uses in its antitrust investigations. Coate, Higgins, and
McChesney (1990) find that the FTC’s decision to file an antitrust complaint against
particular acquisitions is determined by these guidelines beside political factors. In 1992
the DOJ and FTC jointly issued horizontal merger guidelines to clarify certain aspects that
proved to be ambiguous in the previous guidelines. Mergerinduced increase in market
concentration is the primary basis for the DOJ and the FTC in deciding whether or not to
challenge a merger or acquisition. Since horizontal mergers (mergers between competitors)
have the greatest potential for increasing market concentration, these proposals are primary
targets for regulatory challenges. Additionally, vertical mergers (merger between producer
and customer) that have the potential to increase concentration (measured by the

Herfindahl Hirshman Index) in the market in which the merger parties operate trigger
regulatory scrutiny.
Eckbo (1985) models the government’s decision to successfully challenge a proposed
merger deal and finds that merger-induced increase in market concentration increases the
probability of challenging a merger while the number of rival firms decreases it. Coate et
al (1990) model the FTC’s decision to challenge merger proposals and examine a sample
of cases for which the FTC issued a second request between 1982 and 1987. They find that
increase in HHI, the existence of barriers to entry, and the possibility of collusion as a result
of the merger can significantly predict the FTC’s decision to challenge a merger deal. Coate
(2005) finds that the probability that the FTC would file a complaint against a proposed
merger increases with the post-merger HHI and the number of consumer complaints. The
importance of the market share and concentration as determinants of challenging merger
proposals is not limited to the U.S.A. Governments of many other countries use them as a
basis on which
anticompetitive impacts of mergers are determined.
Based on the procedures and decision rules that the government follows in analyzing
and challenging mergers and the evidence presented by Eckbo (1985), Coate et al (1990)
and Coate (2005) I hypothesize that
H1: The greater the expected increase in the HHI in the relevant industry, the greater is
the chance that the merger proposal will be challenged.

The strategic importance to the economy of the industry in which a merger is
attempted may determine how severely the merger is scrutinized by the government. Also,
if the major player in the market is a foreign firm, the government may more likely allow
the merger to go through. Therefore, when testing the above hypothesis, I control for the
industry in which the merger is attempted and for the market share held by foreign firm (s).
3.2. Factors affecting merger Completion Decision conditioned on the
Regulatory Decision:
3.2.1. Target Termination Fees:
The literature presents two opposing arguments in explaining the role of the target
termination fees in merger or acquisition deals: The managerial entrenchment hypothesis
and the efficiency hypothesis. The managerial entrenchment hypothesis asserts that
incumbent target management agrees to pay termination fees in order to lock their firms
with bidders that promise them job security should the deal be completed. The efficiency
hypothesis argues that termination fees reflect target managers’ attempts to increase their
shareholders’ wealth. It asserts that target firm managers offer termination fees to the bidder
in order to encourage it to reveal information about its post-merger plans for target assets
that the bidder may be reluctant to disclose in order to prevent competitors from free riding
on this information. Such information would enhance target manager’s bargaining power
to ask for higher premium, which will eventually benefit target shareholders. Officer (2003)
and Bates and Lemmon (2003) find that target termination fees are associated with higher
bid premiums and higher probability of deal success, a result that supports the efficiency
hypothesis.
In merger deals that are challenged by the government, there are, at least, two
reasons to believe that the target firm’s agreement to pay termination fees is unlikely to

serve as an incentive for the acquirer to reveal private information. First, challenged
mergers are mergers in the same industry or related industries and, therefore, both the
acquirer and the target firms have less information asymmetries about each other’s values
as well as about how each others assets can be used. Second, in challenged mergers the
HSR Act prohibits the acquirer and the target from sharing information about each other’s
operations, pricing mechanisms, or future plans until the government agency concludes the
investigation process lasting well beyond 30 days. This suggests that termination fees in
challenged mergers are more likely to be used to deter competition rather than as a means
to encourage the bidder to disclose information about the target’s value.
Another reason for including target termination fees in merger deals is presented
by Hotchkiss et al (2005). They model the contracting and negotiation process in mergers
allowing for new information arrival subsequent to the signing of an initial merger
agreement. The model implies that including target termination fees in a merger contract
increases the expected merger synergy if the deal is completed by giving the acquirer the
incentive to exert deal-specific effort with less concern about the possibility that the target
would walk away from the deal after realizing the synergy. The acquirer has greater
incentive in a challenged merger (than in an unchallenged one) to be involved in deal-
specific efforts as it has to sign a consent decree requiring it to divest some assets or
preventing it from forming business combinations in the future. Thus, I hypothesize the
following,
H2: Conditional on the merger being challenged, the existence of target termination fees
increases the probability that the merger will be completed by deterring competitive
bidding.

3.2.2. Method of Payment:
Huang and Walkling (1987) state,
“The form of payment will influence bidding strategy if it affects the anticipated net present
value of an acquisition. Payment methods can affect net present values through
interrelations with either acquisition cost (i.e., size of premium) or the probability of
success, or both”.
They argue that in stock offers, the target will have time to implement a defensive strategy
because stock offers take more time to get the approval of the Securities and Exchange
relative to cash offers. Therefore, stock offers may have a lower probability of success than
that of cash offers. They do not directly test this prediction. However, they report a
statistically significant positive relation between target’s cumulative abnormal returns and
cash payment. As for the bidder’s abnormal returns, Travlos (1987) finds that it is positive
for cash offers and negative for stock offers and that this result is robust to the type (tender
offer or merger) and outcome (successful or unsuccessful) of the deal.
Travlos (1987) interprets the robustness of the negative (positive) reaction of stock offers
(cash offers) to the deal outcome as evidence against the possibility that stock offers may
be less likely to be completed. However, the negative abnormal return in stock offers is
greater for unsuccessful than for successful deals. Therefore, the possibility that the market
may be perceiving mergers paid with stock to be less likely to be completed cannot be ruled
out.
The literature offers several explanations for the asymmetric shareholder reaction across
cash and stock offers. Hansen (1987) develops a model of bargaining under asymmetric
information where the acquirer and target know their values but neither knows the value of

the other. He shows that equilibrium can develop whereby the acquirer offers stock when
it is overvalued and offers cash when it is undervalued. If either is the case, target
shareholders lose: if they had accepted stock, they would have purchased shares for more
than what they are worth, and if they had accepted cash, they would have lost the
opportunity to gain from expected increase in bidder’s post-takeover value. Thus, the
model predicts that target share price will decrease if the offer is accepted and increase if
it is rejected. In Fishman (1987) model, cash is used to signal bidder’s high valuation of
target assets rather than being an indication of bidder’s stock undervaluation as in Hansen
(1987). Fishman (1987) concludes that the probability of a competing bid consequent to a
stock offer is higher than that of a cash offer and that target shareholders are more likely to
accept a cash offer rather than a stock offer. Consistent with this latter result, Jennings and
Mazzeo (1993) find empirical evidence of negative relation between target resistance and
percentage of offer represented by cash.
The theoretical models of Hansen (1987) and Fishman (1987) do not allow for
mixed offers (only some percentage of the offer is made with cash). The implications of
this type of offers are theoretically addressed by Eckbo, Giammarino, and Heinkel (1990).
In the model, they derive a separating equilibrium in which the value of the bidder is
revealed by the mix of cash and securities used as payment for the target. The prediction is
that the value of the bidder is monotonically increasing and convex in the fraction of the
total offer that consists of cash. This prediction is in line with Hansen’s (1987) prediction
that cash offers signal bidder undervaluation and empirical tests fail to support the
implications of the Eckbo, Giammarino, and Heinkel model. Berkovitch and Narayanan
(1990) also model a setting that allows for mixed offers and predict that as competition to
acquire the target firm increases, the amount of cash used in financing takeovers increases.

This prediction is consistent with Fishman (1987) prediction in that cash payment deters
competition. Empirically, Walkling (1985) and Jennings and Mazzeo (1993) find some
evidence that the use of cash increases the probability of
takeover offer success.
The theoretical arguments and the empirical evidence presented above may imply
that acquisition deals paid in cash (or with some cash) are more likely to be completed than
those paid entirely in stock. This implication applies to both challenged and unchallenged
deals. However, I argue that cash payment is especially significant in completing
unchallenged deals. My reasoning follows.
Recall that previously, it was argued that the existence of target termination fees is
likely to deter competition (the managerial entrenchment hypothesis) in merger proposals,
and even more so when the deal is challenged by antitrust agencies, increasing the
likelihood of merger completion. Here, I posit the same competition deterrence role of the
cash offers as predicted by Fishman (1987) and empirically supported by Walkling (1985)
and Jennings and Mazzeo (1993). In other words, target termination fees and payment with
cash may serve as substitutes for each other. Officer (2003) finds evidence of negative
relation between payment in cash and the existence of target termination fees.
He reports that a larger percentage of deals without target termination fees are paid fully or
partly with cash than deals with target termination fees. Consequently, it is difficult to
predict ex-ante which of these two variables (target termination fees vs. cash offer) will
dominate in explaining acquisition deal completion. However, the success of challenged
deal is contingent on, among other things, the cost of fulfilling government requirements
as well as the acquirer’s willingness to comply with these requirements. Therefore, from
the perspective of both acquirer’s and target’s shareholders a challenged deal is more

uncertain than an unchallenged deal. From the view point of the acquirer of an challenged
deal, the target termination fees may serve as a better substitute as deterrent to competitive
offers than cash offers. This proposition leads me to hypothesize the following,
H3: Conditional on the merger not being challenged, a merger paid in cash (or a
combination of cash and stock) is more likely to be completed.
3.2.3. Investment Opportunities:
Tobin’s Q, measured as the ratio of the firm value to its replacement cost, has been
used in the literature as a metric of firm’s investment opportunities, management efficiency,
and information asymmetry. For the purpose of this dissertation, I use it as a measure of
firm’s investment opportunities. Viewed in this sense, Tobin’s Q is a forward looking
measure of a firm’s future growth opportunities that may justify its investments, including
acquisitions. Consistent with this conjecture, Lang, Stulz, and Walkling (1989) argue that
Tobin’s Q is an increasing function of the quality of a firm’s current and anticipated projects
under existing management. They investigate announcement returns by dividing merger
partners in terms of their Tobin’s Q. They find that bidder, target, and total returns are the
highest when a high Q bidder takes over a low Q target in tender offers and Servaes (1991)
finds that this result holds not only for tender offers but also for merger parties as well.
Jovanovic and Rousseau (2002) present a model that predicts that firms with high
investment opportunities will acquire those will low investment opportunities and that
merger waves occur during times when dispersion in investment opportunities among firms
increases. These results imply that Tobin’s Q also proxies for the improvements that
acquirer is expected to introduce in managing target firm’s assets. Such improvements are

predicted by Hirshleifer and Titman (1990) to increase the probability of deal success.
Thus, I hypothesize
H4: The higher the investment opportunities of the acquirer relative to those of the target,
the higher is the probability of a merger completion irrespective of whether the
merger is challenged or unchallenged.
4. Variables Definitions:
The existence of target termination fees, the method of payment for the
acquisition, and the final outcome of the deal are collected from the Securities Database
Corporation (SDC) and verified by Lexis-Nexis search except for target termination fees.
The SDC identifies an acquisition event as having target termination fees if the merger
parties have signed a merger agreement containing a statement that requires the target firm
to pay certain amount of money to the acquiring firm if it chooses to cancel the deal. The
merger deals that are challenged by the government are identified by Lexis-Nexis search.
A deal is defined as challenged if the FTC, FCC, or DOJ required the merger parties to
pursue a remedial action, if the merger parties cancelled the deal because of concerns about
antitrust investigation, or if the regulatory agency succeeded in obtaining a preliminary
injunction to block the deal.
The firm’s investment opportunities is measured by Tobin’s q and is calculated
as,
Tobin’s q = (market value of equity - book value of equity + total assets)/total assets
The Herfindahl Hirshman Index (henceforth, HHI) is calculated as,
n
H
i=1
where αi is the market share of firm i and n is the number of firms operating in the
relevant market. The relevant market is defined as the SIC code that is determined as
follows
1.Primary SIC code of the acquirer and target if they match on the 4- digit or 3-digit
level and the HHI is calculated using the sales of all firms that have such primary SIC
code. To determine the merger impact on HHI, the HHI is recalculated after summing
up the acquirer and target sales at the end of the year preceding the merger
announcement year; or
2.If the acquirer and target primary SIC codes do not match, the relevant market is the
acquirer and target divisional SIC code that matches on the 4-digit or 3-digit level. If
the acquirer and target have more than one similar divisional SIC codes, the relevant
market is the SIC code in which the HHI is the highest, and the HHI is calculated
using the segment sales of all firms that operate a segment with such SIC code. The
impact of HHI is determined by recalculating the HHI after summing up the acquirer
and target relevant segment sales; or
3.If neither the primary nor divisional SIC codes of the acquirer and target match on
the 4-digit or 3-digit level, the relevant market is the target firm’s primary SIC code.
The impact of the merger is determined by recalculating the HHI after dropping the
target firm from its primary market.

5. Methodology:
Almost every announcement of a merger or acquisition contains a clause that conditions
the completion of the deal on the regulatory approval, among other things. Therefore, the
decision making process of a merger deal completion can be viewed as a tree form as in
Figure I, where the merger parties have to get the regulatory approval on the first stage and
then decide the final outcome of the deal on the second stage. Such a decision making
process can be modeled using a nested logit model. The nested logit model has the
additional property of relaxing the Independence of Irrelevant Alternatives assumption
(IIA) that underlies the standard logit model. This assumption means that the decision to
make a particular choice is not affected by the existence of other choices.
Therefore, if the IIA assumption fails to hold, the ratio of the probabilities of any two
choices will not be independent from the remaining probabilities. Consequently, using a
standard logit model will produce inefficient parameter estimates. The IIA assumption is
unlikely to hold in an acquisition completion decision setting because an acquiring (or
target) firm that is involved in a challenged merger may choose to cancel the deal and seek
acquiring (or getting acquired by) a different firm that is unlikely to raise antitrust concerns.
Thus, the decision to cancel a challenged acquisition deal may be affected by the existence
of other firms that can be acquired (or get acquired by) without being challenged. In fact,
some acquiring and target firms that cancelled the merger attempt due to regulatory
concerns actually announced that they will be seeking mergers with other firms.
I assume that both the acquiring and target firms have a common (combined) utility
function and that both will jointly choose the final outcome of the deal (complete or cancel)
that maximizes the common utility function. This assumption holds, at least, for friendly
mergers where both parties are willing to do what it takes to facilitate the process (including
complying with regulatory requirements, should there be any). Although the upper level
choice in Figure I is made by the government and the lower level choice is made by the
merger parties, the whole decision making process can still be assumed solely the merger
parties’ because, first, merger guidelines have become so transparent that merger parties
can predict with reasonable accuracy whether or not a proposed merger attempt will be
challenged by the government (Johnson and Parkman, 1991). Second, even if the merger
was challenged, merger parties can still complete the merger provided that they comply
with the regulatory requirements.
The acquiring and target firms’ common utility function is assumed to take the
following form,
U Vij = ij +εij (1)
i∈{1,2,...,C} j∈{1,2,...,
Ni}
where Uij is the utility function from choice j from the choice set i, Vij is a function of all
measured characteristics and εij is a residual that captures the effects of unmeasured
variables and is independently and identically distributed with extreme value distribution.
Then, the probability Pij that the alternative (i, j) will be chosen is given by,
C Nm
=eVij∑∑eVmn (2) Pij
m= =1 n 1
I assume that,
Vij =β' Xij +α'Yi (3)
where Xij is the vector of explanatory variables for the final outcome of the deal and Yi is
the vector of explanatory variables for the regulatory decision.
Under these assumptions, the joint probability can be written as,
Pij = Pj│i . Pi (4)
where Pi is the marginal probability of choosing the regulatory reaction and Pj│i is the
conditional probability of choosing the final outcome conditional on the regulatory
decision.
The conditional probability Pj│i is
Pj│i = eβ’Xij ⁄ eλIi (5)
and the marginal probability Pi is, 20
C
Ii∑eα λ'Ym + Im (6) Pi = eα λ'Yi+
m=1
where
log ⎛⎜∑Ni eβ' Xij ⎞⎟ (7)
Ii =
⎝ j=1 ⎠
is the inclusive value and represents the expected value of the subset i. λ is the coefficient
of the inclusive value and reflects the dissimilarity of the lower level choice. Modeling the
decision making process as in figure I and using the nested logit model is appropriate if the
coefficient of the inclusive value is different from 1.21 If λ=1, the nested logit model reduces
to a multinomial model. For 0<λ< 1, the model fails to satisfy the IIA property but it does
satisfy the properties required for random utility. For
20 Another way to write equations (5) and (6) is, Ni
Pj | i = eβ' Xij ∑eβ' Xik (5)’
k=1
Ni C Nm
Pi =eα'Yi ∑ ∑ ∑eβ' Xij eα'Ym eα' Xnm (6)’
j=1 m=1 n=1
If Yi and/or Xij contain (s) firm specific terms that are the same for the same firm across all choices, they drop
out of the probability function. Therefore, to allow for firm specific variables, I use a method suggested by
Greene (2003) by adding an indicator variable for one choice on each subset and interacting it with the firm
specific variable.
21 See Maddala (1983) page 70.
λ outside the unit interval, the probabilities are still well defined (Hausman and McFadden,
1984). The parameter vectors α' and β'in equation (3) can be estimated by full information
maximum likelihood or sequentially by limited information maximum likelihood. I use the
full information maximum likelihood because it produces more efficient parameter
estimates.
6. Data and sample:
The initial sample of mergers and acquisitions is obtained from the Securities Database
Corporation (SDC) over the period 1990-2002. I select the mergers and acquisitions where
the acquirer and target are U.S public firms and exclude firms in the financial industry (i.e.
firms with SIC code 6000-6999) because the financial variables of these firms are not
directly comparable to those of other firms. I include only those acquisitions where the
acquirer seeks to end up controlling the target firm by holding more than 50% of its
outstanding shares after the transaction and exclude acquisitions where the acquirer had a

controlling stake in the target prior to the merger. Leverage buyouts, management buyouts,
and cases where the target firm ends up a private firm are excluded. To be in the sample,
both the acquiring and target firms must have data on the COMPUSTAT and CRSP
databases. Finally, only acquisition deals that are reportable under the HSR Act are
included and, therefore, acquisition cases where the sum of the acquirer and target assets
(sales) at the end of the year preceding the announcement year is less than $110 million
and acquisitions where the transactions value is less than $50 million are excluded. This
screening process results in 1416 acquisition deals. These deals are, then, searched on
Lexis-Nexis to verify the incidence of acquisition event, the announcement date of the deal,
its final outcome, the method of payment, and whether the acquisition parties had signed a
definitive merger or acquisition agreement before deciding the final outcome of the deal.
From the Lexis-Nexis search, I find that some of the deals that the SDC reports as
acquisitions are not actually acquisition deals. Instead, those cases are: strategic alliances,
sales of convertible debt, sales of series B stock or preferred stock, purchasing an option to
purchase target firm’s stock, or some kind of business combinations between the acquirer
and target firms. After excluding those observations the final sample drops to 1139
completed and cancelled acquisition deals. To identify acquisition deals challenged by the
government, I search the newswires compiled in Lexis-Nexis for announcements of such
deals.27 I define a deal as challenged if the FTC, FCC, or DOJ required the acquisition
parties to pursue a remedial action, if the merger parties cancelled the deal because of
concerns about antitrust investigation, or if the regulatory agency succeeded in obtaining
preliminary injunction to block the deal. The inclusion of target termination fees in a
merger deal is determined from the SDC. Articles published around the acquisition

announcement date are collected by searching the Wall Street Journal and Lexis-Nexis
news wires.
Panel A of Table I shows that the sample is dominated by mergers that were
completed without being challenged and that the percentage of cancelled mergers among
challenged deals is higher than that among unchallenged deals. The sample period has been
ended in 2002 because in 2002 the assets and/or sales thresholds have been amended for
the acquisition to qualify for merger notification under the HSR Act. Also, acquisitions of
foreign entities by U.S firms or foreign entity’s acquisition of U.S firm have become
qualified for notification provided that they satisfy the required thresholds. Panel B of Table
I shows the distribution of the sample acquisitions across the sample period of 1990-2002.
The sharp increase in the number of acquisitions during the second half of the 1990s is
consistent with the documented merger wave of the 1990s which starts to dissipate after
the turn of the century. The challenged deals do not include acquisition deals where the
FTC granted early termination of the HSR waiting period or terminated its investigation
after a second review had been issued. The peak of the number of challenged deals in 1998
is consistent with reports released by the Bureau of competition of the FTC that year 1998
was the most active year in terms of the number of merger cases reviewed by the FTC. Of
the 93 merger attempts that were challenged, 62 are challenged by the FTC, 18 by the DOJ,
10 by the FCC, one by both the DOJ and FCC, and one by the pentagon. In 52 challenged
and completed cases, merger parties are
Table I: Panel A shows the distribution of 1139 challenged and unchallenged acquisitions between completed and
cancelled deals. Panel B shows the distribution of these deals across the period 1990-2002 broken down into completed
and cancelled deals. The acquisition deals are obtained from the Securities Database Corporation (SDC). Challenged
deals are identified by searching the newswires compiled in Lexis-Nexis. A deal is defined as challenged if the FTC,
FCC, or DOJ required the acquisition parties to pursue a remedial action, if the merger parties cancelled the deal because
of concerns about antitrust investigation, or if the regulatory agency succeeded in obtaining preliminary injunction to
block the deal. Panel C shows the distribution of acquisitions across industries where the industry is defined at the two
digit SIC level and the acquisition is classified as same industry if the acquirer and targets firms have the same two digit
primary SIC code. Panel D shows mean and median values for transaction value, Herfindahl Hirschman Index (HHI) in
the year preceding the announcement date, and change in HHI that the acquisition results in, and percentage of deals that
fall in the classification shown in the first column. Dollar amounts are denominated in millions.
Panel A: Distribution of acquisitions between completed and cancelled
Deal outcome
Unchallenged acquisitions
Challenged acquisitions
N
%
N
%
Completed
904
86.42
72
77.42
Cancelled
142
13.58
21
22.58
Total
1046
100.00
93
100.00
Panel B: Distribution of acquisitions across sample period
Number of acquisitions
Unchallenged acquisitions Challenged acquisitions
Year Completed Cancelled Completed Cancelled
1990
16
4
1
0
1991
16
3
0
0
1992
17
2
0
0
1993
30
12
3
1
1994
33
14
9
1
1995
62
12
5
1
1996
74
13
8
3
1997
111
10
5
4
1998
131
16
15
1
1999
155
24
12
5
2000
123
17
8
1
2001
85
11
3
3
2002
51
4
3
1
Total
904
142
72
21

required to actually sell selected assets, in 8 cases parties have to sell rights to produce
some products or license patents to a third party named by the government, and in 5 cases
the acquirer or the resulting firm is restricted from acquiring interests in selected industries.
Other remedial actions include delegating voting rights or transferring holdings in another
firm to a trustee appointed by the FTC to sell those holding to a third party (2 cases),
creating a new competitor (2 cases), terminating selected business agreements (1 case),
making changes in internal operations (1 case), and canceling some business agreements
and allowing a target’s competitor equal access to cable (Time Warner’s acquisition of
Turner Broadcasting).
7. Descriptive Statistics:
The distribution of the same industry acquisition deals across industries in Panel C of Table
I does not show any clear industry clustering except for the business services industry that
went through a relatively huge consolidation activity. This pattern continues to be seen
when the deal is not challenged. Mergers in the communications, chemicals and allied
products, petroleum and coal products, and retail trade industries show more prevalent
government involvement as these industries have relatively higher percentage of
challenged deals. Only the communication industry is regulated, thus, there is no sufficient
indication that mergers in regulated industries may be subject to heavier government
scrutiny. Most of the acquisitions take place between parties in the same industry and a
larger percentage of deals are challenged by the government when the merger parties are
in the same industry than when they are in different industries.
Panel D of Table I shows that the median transaction value of a challenged and
completed deal is more than ten times higher than that of an unchallenged and completed
deal while the transaction value of a challenged and cancelled deal is only five times higher
than that of an unchallenged and cancelled deal. The larger transaction value of a
challenged deal may be due to larger size targets, higher bid premium offered by the
acquirer, or both. Following Officer (2003), I use two measures of the bid premium because
the premiums computed using SDC data are noisy containing large outliers. The first
measure is the total compensation paid to the target deflated by the target’s market value
42 days prior to the bid announcement day less one. The second measure is the share price
paid to the target as reported by SDC deflated by the target’s share price 42 days prior to
the bid announcement less one. The bid premium is equal to the first measure if it is greater
than zero and less than two and equal to the second measure if the first is missing and the
value of the second measure is between zero and two. The median bid premium is about
70% of the target firm’s value for completed deals whether the deal was challenged or not
while it is more than 90% for a challenged and cancelled deal compared to less than 50%
for an unchallenged and cancelled deal. The market concentration in which a merger is
attempted is low (median HHI is 0.123 for completed acquisitions and 0.130 for cancelled
acquisitions) and is expected to result in either no change or very small change in market
concentration (median change in HHI is 0.00 for completed acquisitions and 0.002 for
cancelled acquisitions). However, classifying the mergers into challenged and
unchallenged deals reveals that challenged mergers are
Panel C: Distribution of acquisitions across industries
Industry Name (2-digit SIC)
All acquisitions
Unchallenged
acquisitions
Challenged
acquisitions
N
%
Agricultural services (07)
1
0.09
1
0
Oil and gas extraction (13)
36
3.17
36
0
Other Mining (10 and 14)
4
0.35
4
0
General building contractors (15)
7
0.62
7
0
Food and kindred products (20)
21
1.85
20
1
Other manufacturing (22, 23, 24, 25, 30, 32, and 34)
23
2.02
22
1
Paper and allied products (26)
10
0.88
8
2
Printing and publishing (27)
10
0.88
9
1
Chemicals and allied products (28)
61
5.35
52
9
Petroleum and coal products (29)
6
0.52
1
5
Primary metal industries (33)
16
1.41
15
1
Industrial machinery and equipment (35)
49
4.31
47
2
Electronic and other electric equipment (36)
52
4.57
50
2
Transportation equipment (37)
17
1.50
14
3
Instruments and related products (38)
55
4.84
50
5
Miscellaneous manufacturing industries (39)
9
0.79
8
1
Other transportation (40, 42, 45, and 47)
18
1.58
17
1
Communication (48)
73
6.41
59
14
Electric, gas, and sanitary services (49)
50
4.40
46
4
Wholesale trade (50, and 51)
21
1.85
19
2
Retail trade (52, 53, 54, 56, 57, 58, and 59)
46
4.05
39
7
Other services (70, 72, 75, 78, 82, 83, and 87)
16
1.41
15
1
Business services (73)
152
13.37
144
8
Amusement and recreation services (79)
13
1.14
13
0
Health services (80)
30
2.64
27
3
Total same industry acquisitions
796
70
723
73
Cross industry acquisitions
343
30
323
20
Total
1139
100
1046
93
Panel D: Mean and median values for transaction value, HHI in the year preceding the announcement date, and change
in HHI that the acquisition results in, and percentage of deals that fall in the classification shown in the first column.
All acquisitions Unchallenged acquisitions Challenged acquisitions
Completed Cancelled Completed Cancelled Completed Cancelled
Mean transaction value
1874.39
1972.77
1081.36
1902.03
11787.25
2420.75
Median transaction value
339.57
402.77
303.73
356.86
4169.07
1905.36
Mean bid premium
0.7880
0.6189
0.7845
0.5733
0.8326
0.8829
Median bid premium
0.7169
0.4799
0.7171
0.4660
0.7007
0.9162
Mean HHI before merger
0.164
0.177
0.167
0.176
0.130
0.190
Median HHI before merger
0.123
0.130
0.124
0.125
0.099
0.160
Mean change in HHI
0.009
0.018
0.009
0.011
0.016
0.064
Median change in HHI
0
0.002
0
0.002
0.007
0.020
Percentage of deals paid with
cash only
22.8%
27.6%
23.8%
28.2%
11.1%
23.8%
Percentage of deals paid with
stock only
40.4%
39.9%
40.5%
42.3%
38.9%
23.8%
Percentage of deals with target
termination fess
75.4%
30.7%
75.3%
25.4%
76.4%
66.7%
Percentage of deals with
multiple bidders
5.1%
25.8%
5.1%
28.9%
5.6%
4.8%
Percentage of targets firms with
poison pill in place
0.9%
7.4%
1.0%
8.5%
0
0
Percentage of deals with lock up
option
16.5%
9.8%
16.6%
8.5%
15.3%
19.0%
expected to result in greater change in market concentration relative to unchallenged
mergers as the median change in HHI is 0.007 for completed acquisitions and 0.02 for
cancelled acquisitions. The mean and median values of the merger-induced change in HHI
for all the challenged cases are 0.0078 and 0.0266, respectively. These values confirm
Eckbo (1985) results who finds that challenged horizontal mergers induce a mean and
median change in HHI of 0.01 and 0.033, respectively. The stock is more prevalent method
of payment than pure cash payment as about 40% of the deals are paid for with only stock
regardless of whether the deal is challenged or not. Target termination fees are included in
more than 70% of merger deals with the exception of unchallenged yet cancelled deals
where only 25.4% of them include termination fess payable by the target. This observation
is consistent with the results of the empirical research that finds that acquisition deals that
include target termination fees are more likely to be completed. The unchallenged and
cancelled deals also represent the highest percentage of contested ones and the lowest
percentage of deals with target termination fees or lock up option. A lock up option gives
the acquirer the right to buy target firm’s shares at a specified price if the deal fails. It is
another mechanism beside target termination fees that the acquirer can use to lock the target
firm in the deal. The poison pill is rarely used by the target firm as an antitakeover measure
as less than 10% of targets involved in unchallenged mergers and none of the targets
involved in challenged merger has a poison pill in place.
Because the number of challenged deals is smaller than that of unchallenged deals, the
following discussion is based on median differences rather than mean differences. Panels
A and B of Table II show the descriptive statistics for acquirers and targets of unchallenged
and challenged acquisitions and median difference tests of selected variables. Acquirers
and targets of challenged deals are much larger than their counterparts of unchallenged
acquisition deals and have higher sales. This result is expected since the government is
more likely to challenge acquisitions proposed by parties whose sum of sales or assets
would result in increasing market concentration.
Acquirers of challenged acquisitions have significantly higher free cash flows but
significantly lower leverage ratio, lower investment opportunities, and lower market-to-
book ratio than acquirers of unchallenged acquisitions. Targets of challenged acquisitions,
on the other hand, are more levered and have significantly higher investment opportunities
and market- to-book ratio than targets of unchallenged mergers. In Panels C and D of Table
II, I classify the unchallenged deals into completed and cancelled deals.
Table II: Panels A and B present the summary statistics for acquirers and targets involved in unchallenged
and challenged acquisitions. Panels C and D present the summary statistics for acquirers and targets involved
in unchallenged completed and cancelled acquisitions. Panels E and F present the summary statistics for
acquirers and targets involved in challenged completed and cancelled acquisitions. All summary statistics are
calculated at the end of the year preceding the year of acquisition announcement date. Free cash flow (FCF)
is calculated as operating income before depreciation – interest expense – income taxes – capital
expenditures. Leverage is calculated as (long term debt + current portion of long term debt) / (total assets +
book value of equity + market value of common equity). Market value of common equity is calculated as the
product of number of shares outstanding and the fiscal year closing stock price. Tobin’s q is calculated as
(market value of common equity – book value of equity + total assets)/(total assets). PPE is the plant, property,
and equipment. Dollar amounts are denominated in millions.
Panel A: Acquirers
Variables
Unchallenged acquisitions
Challenged acquisitions
p-value for
median
difference
Mean
Median
Mean
Median
Total assets
7064.86
1259.04
11764.25
4096.10
0.00
Sales
5402.74
1046.15
10361.02
3797.00
0.00
FCF/Total assets
1.85%
3.96%
2.78%
4.81%
0.007
Leverage
14.34%
10.42%
13.48%
10.85%
0.014
PPE/Total assets
28.89%
21.09%
30.29%
25.30%
0.593
Tobin’s Q
3.25
1.96
3.11
2.31
0.00
M/B
7.98
3.22
4.60
3.44
0.003
Panel B: Targets
Total assets
800.55
170.08
4723.49
1476.00
0.00
Sales
762.65
170.44
4476.00
1001.56
0.00
FCF/Total assets
-2.56%
1.73%
0.78%
2.76%
0. 484
Leverage
17.12%
11.65%
18.66%
18.18%
0.052
PPE/Total asset
28.66%
20.52%
30.34%
24.73%
0.728
Tobin’s Q
2.42
1.54
2.45
1.63
0.00
M/B
3.54
2.09
4.13
2.59
0.00
Acquirers of unchallenged and completed deals have significantly higher sales than
acquirers of unchallenged and cancelled deals but are comparable in terms of their
assets,free cash flows, leverage, plant property and equipment, investment opportunities,
Table II continued,
Panel C: Acquirers of unchallenged acquisitions
Variables
Completed acquisitions
Cancelled acquisitions
p-value for
median
difference
Mean
Median
Mean
Median
Total Assets
7261.53
1342.16
5812.85
782.21
0.597
Sales
5759.64
1127.44
3130.62
637.84
0.00
FCF/Total assets
2.41%
4.24%
0.13%
2.02%
0.165
Leverage
13.69%
9.54%
18.48%
16.67%
0.143
PPE/Total assets
28.34%
20.65%
32.44%
24.75%
0.294
Tobin’s Q
3.35
2.02
2.56
1.68
0.303
M/B
8.56
3.29
4.30
2.72
0.250
Panel D: Targets of unchallenged acquisitions
Total assets
615.17
157.91
1926.56
305.61
0.00
Sales
575.96
155.37
1951.15
310.47
0.00
FCF/Total assets
-3.14%
1.73%
0.88%
1.73%
0.422
Leverage
16.64%
10.71%
20.13%
16.90%
0.235
PPE/Total assets
27.95%
19.75%
32.17%
27.340
0.045
Tobin’s Q
2.45
1.56
2.24
1.46
0.089
M/B
3.50
2.12
3.81
1.95
0.073
and market-to-book ratios. Targets of unchallenged and completed deals have significantly
less assets and sales and lower plant property and equipment and investment opportunities
than those of targets of unchallenged and cancelled deals.
Panels E and F of Table II classify the challenged deals into completed and
cancelled acquisitions. Both acquirers and targets of challenged and completed deals are
not significantly different from their counter parts of challenged and cancelled deals in
terms of assets, sales, free cash flows, leverage, investment opportunities, plant, property,
Table II continued,
Panel E: Acquirers of challenged acquisitions
Variables
Completed acquisitions
Cancelled acquisitions
p-value for
median
difference
Mean
Median
Mean
Median
Total assets
13744.98
5309.10
4973.17
2472.61
0.181
Sales
11723.52
4353.07
5689.62
3638.81
0.106
FCF/Total assets
1.35%
3.75%
8.23%
6.96%
0.136
Leverage
13.15%
11.12%
14.64%
8.33%
0.765
PPE/Total assets
32.92%
27.35%
21.27%
16.20%
0.575
Tobin’s Q
3.19
2.31
2.86
2.26
0.232
M/B
4.62
3.43
4.53
4.09
0.823
Panel F: Targets of challenged acquisitions
Total assets
5592.39
1718.55
1744.41
1187.96
0.903
Sales
5040.44
1007.48
2540.77
721.35
0.289
FCF/Total assets
0.92%
2.01%
0.34%
3.82%
0.145
Leverage
19.20%
17.88%
16.80%
17.79%
0.911
PPE/Total asset
32.48%
27.71%
23.02%
17.45%
0.391
Tobin’s Q
2.46
1.65
2.45
1.57
0.550
M/B
4.78
2.62
1.92
2.25
0.911
and equipment, or market-to-book ratio. The reason why the target firm is larger in a
cancelled deal than in a completed deal for the unchallenged deals may be due to the fact
that larger targets are harder to acquire.
8. Market Reaction:
Panel A of Table III shows that when an unchallenged deal that is eventually
completed is announced, acquirers lose a median value of less than 1% while the targets
gain about 15% over one day period before announcement. However, when an
unchallenged merger that is eventually cancelled is announced, acquirers lose 1.52% and
targets gain 7.58%. Lower gains to targets of cancelled deals may be attributed to market’s
ability to anticipate that the deal would fail. Panel B of Table III shows that the
Table III: Panels A and C show the cumulative abnormal returns (CAR) around the announcement of
unchallenged and challenged acquisition deals, respectively, for the event windows shown in the second
column and classified according to the final outcome of the deal. Panels B and D show the CARs around the
announcement of the final outcome of the deal for unchallenged and challenged deals, respectively. CAR is
calculated using the standard event study methodology of Brown and Warner (1985) with the value-weighted
portfolio of all CRSP firms is used as a proxy for the market portfolio. The market model parameters are
estimated using returns of 155 days ending 45 days before the date of announcement.
Panel A: Stock price reaction at the announcement of an unchallenged acquisition deal
Deal outcome Event window
Acquirer CAR
Target CAR
Mean (%)
Median (%)
Mean (%)
Median (%)
Completed
(-1,0)
-1.75a
-0.98a
19.94a
14.90 a
(-5,0)
-1.53a
-1.25 a
22.90 a
18.61 a
Cancelled
(-1,0)
-2.29 a
-1.52 a
9.58 a
7.58 a
(-5,0)
-1.72 a
-1.43b
12. 37 a
8.78 a
Panel B: Stock price reaction at the announcement of the final outcome for unchallenged acquisition deal
Deal outcome Event window
Acquirer CAR
Target CAR
Mean (%)
Median (%)
Mean (%)
Median (%)
Completed
(-1,0)
0.48 a
0.28 b
0.31 b
-0.17
(-5,0)
0.22
0.08
-0.20
-0.34
Cancelled
(-1,0)
0.53 b
-0.18
-3.74 a
-1.09 a
(-5,0)
-1.67 b
-0.69
-5.60 a
-1.59 b
a Significant at 1% level.
b Significant at 5% level. c
Significant at 10% level.
Table III continued,
Panel C: Stock price reaction at the announcement of a challenged acquisition deal
Deal outcome Event window
Acquirer CAR
Target CAR
Mean (%)
Median (%)
Mean (%)
Median (%)
Completed
(-1,0)
-2.26
-1.98a
15.89a
7.75 a
(-5,0)
-2.59a
-2.69 a
18.23 a
12.80 a
Cancelled
(-1,0)
-0.17
0.52
14.53 a
11.60 a
(-5,0)
1.40 b
3.95
15.48 a
14.21 a
Panel D: Stock price reaction at the announcement of the final outcome for a challenged acquisition deal
Deal outcome Event window
Acquirer CAR
Target CAR
Mean (%)
Median (%)
Mean (%)
Median (%)
Completed
(-1,0)
0.25
0.51
0
0.17
(-5,0)
0.36
0.53
0.16
0.02
Cancelled
(-1,0)
0.45
1.09
-11.82 a
-7.29 a
(-5,0)
-1.68
-0.61
-18.17 a
-12.21 a
challenged deal does not bring about any significant market reaction. When cancellation
of a challenged deal is announced, targets lose 7.29% of their stock value that represents
61.78% of what they gained when the deal was announced compared to the loss of only
14.38% by targets when the cancellation of an unchallenged deal is announced. Thus,
canceling an acquisition deal due to regulatory reason appears to be less anticipated by
investors than canceling an acquisition deal for other reasons.
Whether the merger was challenged or not, the market reaction of target stock upon
announcing completing or canceling the deal does not support Hansen’s (1986) predictions
that target firms lose if the deal is completed and gain if it is cancelled. In fact, upon
canceling a merger deal target stock price reacts negatively and shows no significant
change when the deal is completed whether the deal is challenged or not. Thus, these results
do not support the argument that the method of payment signals the bidder’s stock under-
or overvaluation.
In Table IV, I investigate the sources of value gains around the announcement of an
acquisition. The dependent variable is the combined two-day cumulative abnormal return
for the acquirer and target firms calculated as the sum of the market value weighted
cumulative abnormal return for the acquirer and target. As shown in model 1, merger deals
that end up being completed, paid for in cash, and deals that are expected to increase market
share have higher value gains while the higher the acquiring firm’s size relative to the target
firm’s size the lower is the value gain. The market reaction is not different between
challenged and unchallenged deals including target termination fees or whether the merger
is between firms in the same industry or different industries does not affect the combined
value change at the announcement. In models 2, 3, and 4, I include
Table IV: OLS regression of the determinants of the combined value change of the acquiring and target firms
at the announcement of the merger. The dependent variable is the two-day combined cumulative abnormal
return (-1,0) of the acquiring and target firms calculated as the sum of market value weighted cumulative
abnormal returns of the acquirer and target where the market value is calculated at the end of the year
preceding the announcement date. Deal completed dummy is a dummy variable that is equal to 1 if the deal
has been completed and zero otherwise, Challenged deal dummy is a dummy variable that is equal to 1 if the
deal has been challenged and zero otherwise. Cash merger dummy is a dummy variable if the method of
payment is only cash. Same industry is a dummy variable that is equal to 1 if the acquirer and target have the
same 2-digit primary SIC code and zero otherwise. Challenged_Cash merger is the interaction term for the
challenged deal that are paid with only cash. Challenged_Per_change in HHI is the interaction term for the
challenged deals and the percentage change in HHI. Challenged_Target termination fees is the interaction
term for the challenged deals that include target termination fees. All other variables are as defined earlier.
The standard errors are corrected for heteroskedasticity.
Variable
Model 1
Model 2
Model 3
Model 4
Constant
0.009
0.009
0.009
0.009
Deal completed dummy
0.012 c
0.012 c
0.012 c
0.013 c
Deal challenged dummy
-0.002
-0.004
-0.003
-0.013
Cash merger dummy
0.022 a
0.022 a
0.022 a
0.023 a
Relative size
-0.006 a
-0.006 a
-0.006 a
-0.006 a
Percentage change in HHI
0.059 a
0.059 a
0.059 a
0.060a
Same industry dummy
-0.001
-0.001
-0.001
-0.001
Target termination fees dummy
-0.007
-0.007
-0.007
-.0.008
Challenged_Cash nerger
0.011
Challenged_Per_change in HHI
0.036
Challenged_Target termination fees
0.015
a Significant at 1% level.
b Significant at 5% level. c
Significant at 10% level.
an interaction term for the challenged deals that are paid in cash, challenged and the change
in HHI, and challenged deals and the inclusion of target termination fees. The positive
impact of cash mergers and increase in HHI on the announcement returns is not different
for challenged deals.
9. Results:
9.1. Explaining the choice between completing and canceling an acquisition deal
conditional on regulatory decision:
The most important factor that the government employs when deciding whether or not to
challenge an acquisition attempt is the change in HHI that the merger is expected to result

in especially when the relevant market is highly concentrated. Therefore, when testing for
the effect of the change in HHI on the first stage, I use the percentage change in HHI and
control for the acquiring firm’s size. In addition, I control for regulated industries because
a regulated industry may be subject to more government scrutiny and for the industry in
which the merger is attempted because some industries may be more scrutinized than
others. The government may be more lenient towards acquisitions by U.S firms when the
relevant industry is dominated by foreign firms. Thus, I control for the market share held
by foreign firms. As shown in Panel A of Table V model 1, the percentage change in HHI
and the acquirer’s size are positively related to the probability of challenging the deal
controlling for acquirer industry, regulated industry, and market share held by foreign
firms. In other words, mergers attempted by larger acquirers that are expected to result in
larger increase in market concentration are more likely to be challenged. Furthermore, the
government’s decision to challenge a merger deal is not affected by the type of the industry
in which the merger is attempted, whether the industry is regulated, and the market share
held by foreign firms. Conditional on the acquisition not being challenged, the percentage
of cash paid by the acquirer, the
Table V: Nested Logit Regression Estimates estimated by full information maximum likelihood. Regulated industry dummy is 1 if the relevant market is a regulated
industry and zero otherwise. Relative size is the natural logarithm of the ratio of acquirer assets to target assets. Market share held by foreign firms is the market
share held by firms not incorporated in the U.S operating in the relevant market. All other variables are as defined previously.
Panel A
Challenged Vs. unchallenged
(Challenged =1; Unchallenged=0)
Challenged & completed Vs. challenged &
cancelled
(Challenged & completed=1;
Challenged & cancelled=0)
Unchallenged & completed Vs.
unchallenged & cancelled
(Unchallenged & completed=1;
unchallenged & cancelled=0)
Explanatory variable
Model 1
Model 2
Model 3
Model 1
Model 2
Model 3
Model 1
Model 2
Model 3
Constant
-5.8611a
-5.9652a
-5.9849 a
Percentage change in HHI
2.7620 a
2.7403 a
2.7221 a
Acquirer size
0.5372 a
0.5429 a
0.5532 a
Regulated industry dummy
0.1797
0.1582
Market share held by foreign firms
-0.3319
-0.2728
-0.2998
Acquirer industry
-0.0020
-0.0010
-0.0010
Target termination fees
2.1178 a
2.1201b
2.0466 a
2.0323 a
Percentage cash paid
0.0037
0.0005
0.0047 b
0.0021
Acquirer Tobin’s q
0.3359a
0.0997b
0.0914c
0.3399a
0.1070b
0.0997 b
Target Tobin’s q
-0.0104
-0.0249
-0.0230
-0.1018 b
-0.1215 a
-0.1162 a
Multiple bidders dummy
-1.5503 a
-1.7882 a
-1.8198 a
-1.3002 a
-1.4438 a
-1.5146 a
Relative size
0.1063
-0.0731
-0.0833
0.7539a
0.6187 a
0.5945 a
Inclusive value
LR
1.0859 a
1771.4
1.0514 a
1916.2
1.0705 a
1917
McFadden’s LRI
0.5610
0.6069
0.6071
a
Significant at 1% level. b
Significant at 5% level.
c
Significant at 10% level.
43
Table V continued,
Panel B
Challenged Vs. unchallenged (Challenged
=1; Unchallenged=0)
Challenged & completed Vs.
challenged & cancelled
(Challenged & completed=1;
Challenged & cancelled=0)
Unchallenged & completed Vs.
unchallenged & cancelled
(Unchallenged & completed=1;
unchallenged & cancelled=0)
Explanatory variable
Model 4
Model 5
Model 4
Model 5
Model 4
Model 5
Constant
-5.8928 a
-5.9121a
Percentage change in HHI
2.7848 a
2.7505 a
Acquirer size
0.5381 a
0.5573 a
Acquirer industry
-0.0015
-0.0013
Regulated industry dummy
0.1737
0.2328
Market share held by foreign firms
-0.3003
-0.4088
Target termination fees
2.1270 a
2.1533a
2.0329 a
1.9548 a
Percentage cash paid
0.0004
0.0002
0.0020
0.0010
Acquirer Tobin’s q
0.0971c
0.0710
0.0963 b
0.0845 b
Target Tobin’s q
-0.0248
-0.0279
-0.1175 a
-0.1057 a
Multiple bidders dummy
-1.8132 a
-1.8796 a
-1.5126 a
-1.5025 a
Relative size
-0.0870
-0.0093
0.5956 a
0.5868 a
Acquirer M/B
-0.0055
0.0016
Target M/B
0.0027
0.0005
Acquirer leverage
-2.3684 c
-0.9433
Target leverage
1.6718 c
1.5128 a
Inclusive value
LR
McFadden’s LRI
1.0426 a
1918.7
0.6077
1.2937 b
1925.4
0.6098
44

44
acquirer’s investment opportunities, and relative size are positively related to the
probability of completing the deal while the target firm’s investment opportunities and the
existence of multiple bidders are negatively related to the probability of completing the
deal. When the merger is challenged, the acquirer’s investment opportunities have a
positive and significant impact on the probability of completing the deal while the existence
of multiple bidders is significantly negatively related to the probability of completing the
deal. In model 2, I replace the percentage of cash paid by a dummy variable that indicates
whether the merger agreement includes target termination fees because the payment in cash
and the inclusion of target termination fees could be used as substitutes for preventing
competitive bidding. Including target termination fees is positively related to the
probability of completing the deal for both the challenged and unchallenged deals. This
result supports Officer (2003) and Bates and Lemmon (2003) empirical finding that target
termination fees do increase the probability of completing an acquisition deal and here I
document that this result holds even when the deal is challenged by the government. The
acquirer investment opportunities and the relative size are still positively related to the
probability of completing the deal and the existence of multiple bidders and target firm’s
investment opportunities are still negatively related to the probability of completion for the
unchallenged deals. For the challenged deals, the acquirer investment opportunities still
significantly increases the probability of completing the deal while the existence of
multiple bidders decreases it. When both the target termination fees and percentage of cash
paid are included in model 3, the inclusion of target termination fees (but not the percentage
of cash paid) is still positively related to the probability of completion regardless of whether
the merger is challenged or not. In model 4, I control for the acquirer and target firms’ M/B
ratios and in Model 5, I control for acquirer and target leverage ratios. The results presented

45
in the first three models do not change as a result of controlling for these variables for the
unchallenged deals while for the challenged deals the acquirer’s investment opportunities
lose significance when controlled for leverage ratios.
The parameters of inclusive values for all models are significantly different from 1 and the
McFadden’s LRI, which is one of the measures of the model’s explanatory power, ranges
from 56.1% to 60.98%.
Although the above analysis shows that the target termination fees are positively related
to the probability of completing an acquisition deal, it does not show whether this positive
impact is due to the target termination fees being an efficient contracting device (efficiency
hypothesis) or to their competition deterrence impact (managerial entrenchment
hypothesis). In what follows, I perform several tests that investigate these two issues.
The efficiency hypothesis of target termination fees argues that termination fees are an
efficient contracting device that benefits the target firm shareholders because by agreeing
to pay termination fees the target manager induces the acquirer to reveal information that
helps her to negotiate higher bid premium. Thus, the efficiency hypothesis implies that the
existence of target termination fees is positively related to bid premium and does not
discourage competitive bidding. The managerial entrenchment hypothesis argues that
target manager who agrees to pay termination fees does so in order to lock his shareholders
with acquiring firms that promise him job security. Thus, according to this hypothesis
including target termination fees would make the target firm more expensive to acquirer
and consequently discourage competitive bidding. Thus, the managerial entrenchment
hypothesis implies that the existence of target termination fees is negatively related to the
appearance of competitive bids and is not related to bid premium.
Table VI: OLS regression of the determinants of bid premium. The dependent variable is the bid premium.
Target (Acquirer) TF is a dummy variable that is equal to 1 for deals that include termination fees payable by
46
the target (acquiring) firm and zero otherwise. Percentage cash is the cash percentage of the cash paid by the
acquirer. Same industry is a dummy variable that is equal to 1 if the acquirer and target firms are in the same
industry where the industry is defined as 4-digit SIC. Hostile is a dummy variable that is equal to one for
deals classified by SDC as hostile and zero otherwise. Tender is a dummy variable that is equal to one if the
acquisition is a tender offer and zero otherwise. Lockup is a dummy variable if the target gave the acquirer a
lockup option and zero otherwise. Poison pill is a dummy variable if the target has a poison pill in place and
zero otherwise. PreComp is a dummy variable that is equal to 1 if the target firm received takeover offer
within six months prior to the acquisition announcement date and zero otherwise. Log Tar (Aqc) MV is the
natural logarithm of the target (acquiring) firm market capitalization one day before the acquisition
announcement day. The standard errors are corrected for heteroskedasticity.
Unchallenged mergers Challenged mergers
Variable Model 1 Model 2 Model 3 Model 4
Constant
0.864
0.842 a
1.055 a
0.798 a
Target TF
0.129a
0.122 a
0.110
0.152
Acquirer TF
-0.033
-0.024
Percentage cash
-0.001 b
0.003
Same industry
0.033
-0.052
Hostile
-0.007
0.035
Tender
0.127 a
-0.148
Lockup
-0.047
0.105
Poison pill
-0.002
PreComp
-0.008
-0.209
Log Tar MV
-0.049 a
-0.048 a
-0.048
-0.028
Log Aqc MV
0.010 a
0.012
0.005
0.011
Table VI shows OLS regression results for the determinants of the bid premium for
challenged and challenged deals separately using both successful and unsuccessful deals.
Model 1 shows that target termination fees are positively related to bid premium for the
unchallenged deals while for the unchallenged deals no significant relation exists between
target termination fees and bid premium. These results persist even after controlling for the
47
existence of acquirer termination fees, type of the deal (tender offer or not), and the attitude
by which the acquisition took place (hostile or friendly) as shown in models 2 and 4. Thus,
target termination fess result in higher bid premium for targets only when the deal is not
challenged.
The regressions in Table VI include three variables (percentage cash, target
termination fees, and lockup option) that can be related to competitive bidding. To
investigate the competition deterrence role of these three variables, I perform a probit
analysis of post announcement competition of a merger. The dependent variable in the
probit analysis in Table VII is an indicator variable that is equal to one if a competitive bid
is made within six months following the merger announcement date. Model 1 shows that
including target termination fees is negatively related to the probability of observing a
competitive bid following the announcement of an unchallenged merger. However, this
may be due to the omitted variable bias. Therefore, I control for other variables that may
be related to the appearance of a competitive bid especially the payment in cash and the
lockup option in Model 2. After controlling for other variables, target termination fees are
no longer related to the post announcement competition. In Models 3 and 4, I replicate the
same analysis for the challenged deals controlling for the variables for which enough data
is available. Model 3 shows that target termination fees do deter competitive bidding
Table VII: Probit regression of the determinants of the post announcement competition. The dependent
variable is a dummy variable that is equal to one if the target firm received a takeover offer within six months
following the announcement of the acquisition and zero otherwise All other variables are as defined earlier.
Unchallenged mergers Challenged mergers
Model 1 Model 2 Model 3 Model 4
Constant
-1.483a
-1.988 a
-4.785 a
7.225c
Target TF
-0.379a
-0.215
-1.447 b
-2.078 b
48
Acquirer TF
0.348 c
Bid premium
0.336
0.001
PreComp
-0.293
Poison pill
-0.223
Cash merger
0.564
0.416
Same industry
0.264
0.865
Hostile
0.944 a
-0. 408
Tender
0.180
0.979
Lockup
0.489
Log Tar MV
-0.001
-0.758
0.393
0.664
Log Aqc MV
-0.001
-0.840
0.638
0.838
a Significant at 1% level.
b Significant at 5% level. c
Significant at 10% level.
for challenged mergers as the inclusion of target termination fees in such mergers is
significantly negatively related to receiving a competitive bid following the merger
announcement and Model 4 shows that target termination fees continue playing
competition deterrence role even after controlling for other relevant variables.
Overall, the results indicate that the government’s antitrust policy plays a
significant role in shaping the structure of markets for products and services by monitoring
and preventing acquisition attempts that may result in giving few firms excessive control
over production factors. The implementation of such policy is mainly based on predicting
the post acquisition market concentration measured by the salesbased HHI. No evidence is
found here that mergers in regulated industries may be subject to heavier government
scrutiny and no evidence that the government would allow U.S firms to complete an alleged

49
anticompetitive acquisition transaction when non U.S firms hold a high market share in a
particular industry.
The fact that not any acquisition deal is approved by the government, at least not before
the merger parties agree to pursue the remedial action mandated by the government, is not
irrelevant of merger-seeking firms’ decision to complete or cancel the deal. The results
presented here show that merger parties as well as the deal characteristics of challenged
deals are systematically different from those of unchallenged deals. In unchallenged
mergers, targets are smaller than the acquirers and have lower investment opportunities and
both of these factors significantly increase the probability of completing the deal while in
challenged mergers, the relative size of the acquirer and target firms or the investment
opportunities of the target firm has no impact on the probability of completing the deal.
More importantly, the reason why the target firms would agree to paying termination fees
if the deal falls through is different between challenged and unchallenged deals. In
unchallenged deals, target termination fees result in higher bid premium for the target firm
without deterring competitive bidding while in challenged deals target termination fees
deter competitive bidding and do not result in higher bid premium.
10. Specification tests:
If the nested logit model is the appropriate specification for modeling the merger
completion decision as in figure I, then the parameter estimates of the inclusive value (λ)
must lie in the unit interval. The λ estimates in Table V are significantly different from zero
but lie outside the unit interval. Hausman and McFadden (1984) argue that in this case, the
50
probabilities are still well defined but the interpretation of the model as choice model is not
clear cut. They further suggest that the reason behind λ estimate taking a value outside the
unit interval might be that the IIA property is satisfied in any sub branch of the tree. For
the purpose of modeling merger completion decision, relaxing the IIA assumption across
the branches and not within a branch is sufficient. To further investigate this issue, I test
the IIA assumption using the likelihood ratio test and reestimate the parameters of the
different models in Table V by conditional logit that assumes that the IIA property holds.
The dependent variable in the conditional logit regressions in Table VII is a
4element choice variable (unchallenged and completed, unchallenged and cancelled,
challenged and competed, and challenged and cancelled) and the independent variables are
interacted with a dummy variable for the challenged and/or challenged and completed deals
in order to allow for the firm specific effects across the different choices. The results from
estimating model 1 in Table VII are qualitatively similar to those of model 1 in Table V and
the based on likelihood ratio test , the null hypothesis that the IIA assumption holds can be
rejected. In untabulted results, I reestimate the conditional logit for all the models on Table
V and find virtually similar results.
Table VIII: Conditional logit model estimates. The dependent variable is a choice variable that indicates
whether the acquisition is challenged and completed, challenged and canceled, unchallenged and completed,
or unchallenged and canceled. Challenged and completed dummy is a dummy variable that is equal to 1 if
the acquisition is challenged and completed and zero otherwise. Unchallenged and completed dummy is a
dummy variable if the acquisition is unchallenged and completed. All other variables are as defined earlier
except the challenged means that variables has been interacted with a dummy variable that is equal to 1 if the
acquisition is challenged and zero otherwise. Challenged_completed means that the variables has been
interacted with the challenged and completed dummy variable. Unchallenged_completed means that the
variable has been interacted with the unchallenged and completed dummy variable.
Model 1 Model 3
Constant
-6.0779 a
-6.0672 a
Challenged_acquirer industry
-0.0021
-0.0018
51
Challenged_percentage change in HHI
2.7630 a
2.7107 a
Challenged_regulated industry dummy
0.1878
0.1603
Challenged_ Market share held by foreign firms
-0.3674
-0.3431
Challenged_acquirer size
0.5412 a
0.5474 a
Challenged completed dummy
1.7040 a
0.7793 b
Challenged completed_target termination fees
1.7647 a
Challenged_completed percentage cash
-0.0052
-0.0031
Challenged_completed acquirer Tobin’s q
0.0874 c
0.0499
Challenged_completed target Tobin’s q
-0.0204
-0.0191
Challenged_completed multiple bidders
-1.9080 a
-1.9306 a
Challenged_completed relative size
-0.1505
-0.1782
Unchallenged completed dummy
1.3265 a
0.3988 b
Unchallenged_completed_target termination fees
1.8807 a
Unchallenged_completed percentage cash
-0.0024
-0.0031
Unchallenged_completed acquirer Tobin’s q
0.0981 b
0.0603
Unchallenged_completed target Tobin’s q
-0.1186 a
-0.1194 a
Unchallenged_completed multiple bidders
-1.6138 a
-1.6069 a
Unchallenged_completed relative size
-0.5687 a
0.5483 a
LR
McFadden’s LRI
1828.4 a
0.579
1923.4 a
0.6091
a
Significant at 1% level. b
Significant at 5% level.
c
Significant at 10% level.
10. Conclusions:

52
In this essay, I investigate the probability of completing an acquisition deal
conditional on the government approval. Mergers that satisfy certain jurisdictional the
merger parties to pursue a remedial action to restore competition as a condition for
thresholds require notifying the FTC and can not be completed unless they are approved
by the FTC, DOJ, or FCC which investigates the anticompetitive impact of the attempted
merger. Mergers that are challenged by the government are either disapproved or require
merger approval.
I model merger parties’ decision to complete or cancel an acquisition deal using the nested
logit model because it allows the completion decision to be made as getting the regulatory
approval on the first stage and then deciding to complete or cancel the deal on the second
stage. Also, the nested logit model allows the completion decision to be affected by the
existence of other choices.
Consistent with evidence presented by Eckbo (1985), Coate et al (1990), and Coate
(2005), the expected change in market concentration measured by the HHI is significantly
positively related to the probability that the government will challenge an acquisition deal.
Mergers that are expected to result in a concentrated market are more likely to be
challenged even if the market was fairly competitive before the attempted acquisition.
Consistent with Officer (2003) and Bates and Lemmon (2003), we find that
including target termination fees in merger deals is significantly positively related to the
probability of completing the deal whether it was challenged or not. However, we
document that including target termination fees deters competitive bidding only if the deal
was challenged and leads to higher bid premium to the target firm only if the deal was not
challenged. Conditional on not being challenged, acquirer’s investment opportunities and
the relative size of acquirer and target firms are significantly positively related to the

53
probability of completing the deal while target investment opportunities and the existence
of multiple bidders are significantly negatively related to the probability of completing the
deal. Finally, canceling an unchallenged merger attempt has more significant impact on
target firm value. Targets of failed unchallenged merger attempts keep most of the value
gains they had made at the merger announcement date while targets of failed challenged
merger attempts lose most of it.
Essay 2

54
The Divorce before a Merger: Value Consequences and Capital Allocation Efficiency
of Merger Facilitating Asset Divestitures
1. Introduction:
Extant empirical research shows that since the early 80s, U.S corporations have been
witnessing a trend toward firm specialization or focus, reversing the multidivisional
structure of U.S corporations that prevailed during the 60s and 70s. Comment and Jarrell
(1995) attribute this trend toward corporate focus to firms’ inability to exploit the
efficiencies that motivate diversification. In fact, Berger and Ofek (1995) show that
diversified firms sell at a discount compared to single segment firms and argue that one
reason for the discount is the inefficiency of investment policy of these firms. More
specifically, they argue that diversified firms do not efficiently allocate funds to their
divisions based on their divisional investment opportunities. Therefore, multisegment
firms do not seem to have efficient internal capital markets that would allow a financially
constrained division to undertake positive net present value investments.
Consistent with the notion of inefficient internal capital markets in diversified
firms, empirical research shows that firms that voluntarily divest assets that are not related
to their core business, experience improved operating performance of the remaining assets
(John and Ofek, 1995; Cusatis, Miles, and Wooldridge, 1993), higher stock returns
(Comment and Jarrell, 1995), lower information asymmetries between management and
investors (Krishnaswami amd Subramaniam, 1999), more efficient investment policy (Ahn
and Denis, 2004), and decrease in diversification discount (Dittmar and Shivdasani, 2003)
post divestiture .

55
Whether to divest an asset or not and, given that the firm has decided to divest an
asset, which asset to divest are decisions that the firm usually makes voluntarily. In some
cases, however, divesting an asset is mandated by regulators if the firm is simultaneously
involved in a merger attempt that is likely to increase market concentration in the relevant
industry or if the firm had gained excessive market power over its life. From the regulatory
point of view, an asset sale constitutes the most common remedial action that the Federal
Trade Commission (FTC), Federal Communications Commission (FCC), or the
Department of Justice (DOJ) recommends to prevent firms that acquire other firms from
gaining monopolistic (or monoposonistic) power following the acquisition. The assets that
the regulatory agency requires the acquirer to divest are those that overlap those of the
acquired firm in case of horizontal acquisitions (acquisitions between competitors). In
vertical acquisitions (acquisitions between firms in different industries), the federal
government requires the acquirer to divest assets that are likely to enhance its buying
power. In these cases, a firm would be giving up assets (or even a whole division) in order
to facilitate its acquisition plans. Empirical research finds no evidence that acquisition
attempts where the government required such kind of divestitures would have enhanced
the acquirer’s monopolistic power, and little evidence that they would have increased
acquirer’s buying power. This implies that merger facilitating assets
divestitures may be costly to divesting firms.
A merger facilitating asset divestiture need not be always formally mandated by the
government. Johnson and Parkman (1991) find that after the passage of the HSR Act,
merger regulations have become dramatically transparent eliminating much of the
uncertainty as to whether the government would challenge an acquisition deal. An example
that is consistent with this result is Texaco’s divestiture of some of its refining assets to

56
ease its merger with Chevron. Such a divestiture was proposed upfront in order to preempt
government challenge of the merger deal. Thus, another reason for asset divestitures is to
satisfy a regulatory requirement. Unlike for voluntary asset divestitures, the literature does
not clearly show whether merger facilitating sales are associated with changes in firm value
and what, if any, do these divestitures cost the divesting firm.
In this essay, I aim at contributing to the literature by investigating firm value
changes around merger facilitating asset divestitures. More specifically, I compare between
merger facilitating asset divestitures and other asset divestitures in terms of their
announcement impacts and changes in divesting firm’s operating performance and focus.
2. Literature Review:
In this section I present a brief review of the theoretical and empirical literature that
directly relates to gains from asset divestitures and capital market efficiency changes
around asset divestitures.
2.1. Explanations for gains from asset divestitures:
It is well documented in the literature that asset divestitures are positively associated
with firm value. One explanation for the gain from asset divestitures is that the
firm becomes more focused following the asset sale (John and Ofek, 1995; Comment and
Jarrell, 1995; Hite, Owers, and Rogers, 1987). According to this focus hypothesis, firms sell
assets that do not fit into their business to buyers whose assets have similar characteristics to
those assets being divested. Firms sell assets that interrupt the operations of other divisions
and create negative synergies. The corporate focus hypothesis predicts that following the
asset divestiture the firm will reduce investment in less efficient divisions and increase

57
investment in more efficient divisions. John and Ofek (1995) find empirical evidence that
the operating performance of asset sellers’ significantly improves following the divestiture.
Another explanation for gains from asset divestitures, presented by Lang, Poulsen,
and Stulz (1996), is the financing hypothesis. Lang et al. (1995) argue that firms that are
financially constrained and cannot issue external securities due to information asymmetries
find asset sales a less costly way to raise funds required to make new investments. The
financing hypothesis implicitly assumes that management values firm size and control and,
therefore, may not be willing to sell assets unless that was the last resort to raise funds for
new projects. Using a sample of asset sales that management deems significant and
unexpected, Lang et al. (1995) find that sellers who payout the cash proceeds from asset
sales are poor performers and have less investment opportunities than sellers who retain
the proceeds. Bates (2005) provides recent evidence consistent with this result.
Specifically, he finds that the probability of retaining sale proceeds is positively related to
firm’s investment opportunities. However, retaining firms invest significantly more than
their industry benchmarks. Therefore, although firms with more investment opportunities
are more likely to retain sale proceeds, the existence of agency considerations cannot be
ruled out.
Schlingmann, Stulz, Walkling (2002) present evidence consistent with both the
focusing and the financing explanations for divestitures. However, they show that firms
that refocus their operations by decreasing the number of their reported segments do not
necessarily do so by divesting the segment that the firm stopped reporting. Some firms
actually divest a segment while others restructure the segment internally. Schilngmann et
al. (2002) show that firm asset liquidity can explain why some focusing firms actually
divest an asset while others do not. They find that firms that have more liquid assets are

58
more likely to divest and given that a firm is divesting a segment, more liquid assets are
more likely to be divested. Dittmar and Shivdasani (2003) also find supporting evidence
for focusing and financing hypotheses and further document that the diversification
discount deceases following the asset divestiture.
2.2. Efficiency of internal capital allocation:
Proponents of the efficient internal capital market theory argue that the multidivisional
structure of diversified firms relaxes the external financing constraints that arise as a result
of information asymmetries between the firm and its capital suppliers. Because resources
could be transferred among divisions of a diversified firm, these firms can finance positive
NPV projects that would be forgone had the firm been a focused single division firm.
Consistent with this argument, Lamont (1997) finds that oil companies reduced investment
in non-oil divisions when the oil prices rose at the beginning of the 80s, an observation that
points at the interdependence among the different divisions of a multidivisional firm.
Stein (1997) theoretically models the circumstances under which an internal capital
market can function efficiently in a credit constrained firm whose headquarters has the
incentive to engage in winner-picking (because it can better assess the relative merits of
the firm’s divisions). He argues that diversification enhances the efficiency of the internal
capital market because it increases the resources available to headquarters and prevents
mistakes made about a project’s outcomes from affecting assessments of other projects. A
focused corporate structure would work better if there are errors in assessing projects and
those errors are correlated.
The classical internal capital markets theory assumes that the incentives of the
headquarters and divisional managers are aligned. If this is not the case, then, divisional

59
managers will act to extract rents from the headquarters. Scharfstein and Stein (2000)
model a setting that assumes such behavior and show that divisional managers may extract
greater compensation not in higher cash wages but rather in preferential capital budget
allocations. This leads to cross subsidization among divisions, which, in turn, results in the
resources being drained away from divisions with good investment opportunities to
divisions with poor investment opportunities. Therefore, contrary to the predictions of the
efficient capital markets theory, Scharfstein and Stein (2000) predict that diversified firms
will have an inefficient capital market.
Another reason for the possibility that the internal markets may not work efficiently
is presented by Rajan, Serveas, and Zingales (2000). They present a model where the
divisional manager can choose between two investments, one efficient and the other is not,
and show that as diversity between the resource-weighted investment opportunities (not
relative investment opportunities) of firm’s divisions increases, divisional managers have
less incentive to choose the efficient investment. Headquarters that understand this will try
to induce divisional managers to choose the efficient investment by giving them control
over more resources. According to the Rajan et al. (2000) model’s predictions, this will
lead to resources being transferred from divisions with high resource-weighted investment
opportunities to divisions with low-resource weighted investment opportunities. The model
also relates the value of the firm to the degree of its diversification and implies that there
is a level of diversification where the value of the firm peaks and then starts to decrease.
Matsusaka and Nanda (2002) also present a model that shows that a firm’s optimal level of
focus in operations is a trade off between the transaction costs of raising external financing
and the cost of overinvestment as the firm diversifies.

60
2.3. Empirical evidence on the efficiency of internal capital allocation:
The earliest evidence on the inefficiency of internal capital markets is presented by Berger
and Ofek (1995) who show that multidivisional (diversified) firms trade at a discount while
single division (focused) firms trade at a premium relative to the sum of their parts. They
show that diversified firms invest more in divisions with low investment opportunities than
in divisions with high investment opportunities. More recent empirical research finds
mixed evidence on the efficiency of internal capital markets in diversified firms. For
example, Shin and Stulz (1998) find that in highly diversified firms, segment investment
is less sensitive to its cash flow than for comparable single segment firms and that segment
investment increases with its investment opportunities but is not related to other segments’
investment opportunities. Billet and Mauer (2003) relate the efficiency of internal capital
markets to firm’s value and find that efficient subsidies to financially constrained segments
increase firm value while inefficient subsidies to unconstrained segments do not affect firm
value. This result is consistent with the internal capital markets being efficient.
Another line of empirical research tests changes in internal capital market efficiency
around corporate divestitures. This strand of literature unanimously shows that asset
divestitures are related to improvements in diversified firm’s investment policy but finds
mixed results when testing internal capital market efficiency around these divestitures.
Gertner, Powers, and Scharfstein (2002) find that firms that spin-off an unrelated division
experience increased sensitivity of investment to investment opportunities. By
reconstructing the parent firm after spinoff, Burch and Nanda (2003) find that firm value
improvement following the spinoff is related to decreases in diversity and not solely a result
of selection bias or measurement errors. Finally, Ahn and Denis (2004) more directly link
61
the inefficiency of investment with the incidence of spin off event. They find that following
a spin off firm’s value increases due improvement in investment efficiency.
3. Hypotheses Development:
In this section, I present hypotheses that investigate the difference between merger
facilitating asset divestitures and other divestitures. In addition, I compare the efficiency
of internal capital allocation prior to both of these asset divestitures.
3.1. Market reaction to merger facilitating asset divestitures:
Figure II below shows the sequences of event dates in a challenged acquisition deal. The
length of the time period that elapses between the acquisition announcement date and the
announcement of merger facilitating divestiture depends on how fast the merger parties
and the FTC, FCC, or DOJ officials agree on the assets to be divested.
Figure II: The sequence of event dates in a challenged acquisition deal.
Acquisition announcement Merger facilitating divestiture Acquisition completion
date announcement date or cancellation date
The announcement of an acquisition usually precedes the announcement of
regulatory mandated asset sale. Here, a question may be raised as to whether the market
reaction to the merger announcement reflects the impending possibility of the asset sale for
acquisitions that are likely to enhance acquirer’s monopolistic (or monopsonistic) power.

62
The announcement impacts of these two events are assumed to be independent although if
investors were able to anticipate government decision as to whether it would challenge the
acquisition, then, that anticipated reaction is likely to feed back in the acquisition
announcement impact. Therefore, to the extent that this assumption holds, the
announcement impact of the acquisition announcement will reflect the expected true value
change of the acquirer. A similar argument also applies for the announcement impacts of
the acquisition and its completion or cancellation.
Empirical research documents a positive market reaction to the announcement of
voluntary corporate asset sell offs. Hite et al. (1987) explain this positive reaction as
evidence that asset sell offs are movements of resources to those who can use them more
efficiently. Such argument implies that asset sellers sell those assets that fit more into the
buyers business than into their own business. John and Ofek (1995) provide consistent
evidence with this argument. Lang, Poulsen, Stulz (1995) show that the market reaction
depends on the purpose for which the proceeds from the sale are going to be used. They
find that when the management announces that the proceeds will be used for debt
retirement or as dividends then an asset sale is good news while if it is announced that the
proceeds will be retained in the firm then the market reaction becomes negative.
The assets that are divested in order to facilitate a merger are chosen by the regulatory
agency and are usually assets from the division whose assets overlap those of the target
firm. For example, in Tribune Co.’s acquisition of Renaissance Communication Corp., the
FCC required Tribune to divest its WDZL-TV because FCC rules prohibit ownership of
two or more TV stations whose signals overlap. Another example is Albertson’s Inc., which
had to divest its stores that overlapped with those of American Stores Co. Such divestitures
represent a loss of revenue which may not be easy to recover at least within a short period

63
of time. In fact, Albertson’s was expected to lose 6% of the combined company’s sales due
to this divestiture. Therefore, a merger facilitating divestiture is likely to be perceived by
the market as bad news. Thus, I hypothesize that,
H1: The announcement of a merger facilitating asset sale will have a negative or less positive
market reaction than that of non merger related asset sale.
3.2. Relatedness of assets divested in a merger facilitating divestiture to the
acquirer’s remaining business lines and the acquirer’s operating performance
following the asset sale:
Recent empirical literature documents an increasing trend toward corporate focus. Berger
and Ofek (1995) find that diversified firms trade at discount while single segment firms
trade at premium. Consistent with this result, Comment and Jarrell (1995) show that
increase in focus is positively related to firm stock performance. John and Ofek (1996)
show that increase in focus is also positively related to the operating performance of firm’s
remaining assets because it eliminates the negative synergies between the divested assets
and seller’s remaining assets. Dittmar and Shivdasani (2003) further show that diversified
firms that divest a segment experience increase in their value.
A regulatory mandated divestiture is a divestiture that would prevent the acquirer from
having a monopolistic power following the acquisition. Increasing monopolistic power
would be a concern when a firm acquires one of its competitors whose core business is the
same as that of the acquiring firm. Therefore, when required to divest assets, the acquirer
will have to divest assets that overlap those of the target firm. Thus, I hypothesize that,

64
H2: Firms that sell assets for non merger related reasons will experience increase in focus
while firms that sell assets to facilitate a merger will experience no change or even a
decrease in focus.
In the absence of agency problem that results from the information asymmetry between
managers and stockholders, the focus hypothesis predicts that the operating performance
of firms that sell assets that result in the firm becoming focused will increase. Since a
merger facilitating asset sale is not driven by firm’s willingness to become more focused,
the focus hypothesis would predict that firms that sell related (for example, merger-
facilitating) assets to have better operating performance than that of firms that sell related
assets. Thus, according to the focus hypothesis,
H3: Firms that sell assets to facilitate a merger attempt have better operating performance
prior to the sale than that of firms that sell assets for non-merger related reasons.
3.3. Internal Capital allocation efficiency:
Assuming that headquarters and divisional mangers’ interests are aligned, the classical
internal capital market theory predicts that as firm’s diversity decreases the internal capital
market will function less efficiently. In other words, divisions that have high investment
opportunities will become less able to finance new projects. In contrast, Scharfestein and
Stein (2000) model makes the opposite prediction assuming that headquarters and
divisional mangers’ interests are not aligned. Rajan et al. argue that divisional investment
opportunities should be compared relative to the resources available to them (i.e. not in
absolute terms) because the headquarters will induce the divisional mangers to choose

65
efficient investment by granting them enough resources to do so. They predict that the
higher are the division’s relative investment opportunities, the less will the firm invest in
that division, and vice versa. Thus, according to these three theories, if asset divestitures
are driven by inefficient internal capital market, firms that sell an asset only for the purpose
of facilitating an acquisition should have efficient internal capital market before the actual
sale of the asset compared to that of firms that sell for non regulatory reasons. Therefore, I
hypothesize that
H4: Before the asset sale, firms that sell assets to facilitate an acquisition deal have more
efficient internal capital market than that of firms that sell assets voluntarily.
4. Variables Definitions:
An asset sale is defined as merger-facilitating if the firm is selling the asset in order
to satisfy a regulatory requirement for approving an acquisition attempt that it is involved
in at the same time.
4.1. Corporate Focus:
To measure corporate focus, I use the following measures. First, the number of SIC
codes reported by COMPUSTAT. Second, whether or not the divested division is related
to the seller’s core business. An asset sale is classified as related if the 3-digit SIC code of
the assets or the segment to which the sold assets belong is the same as that of the segment
that has the highest sales. Third, sales-based Herfindahl Hirschman index (HHI). The HHI
is calculated as,
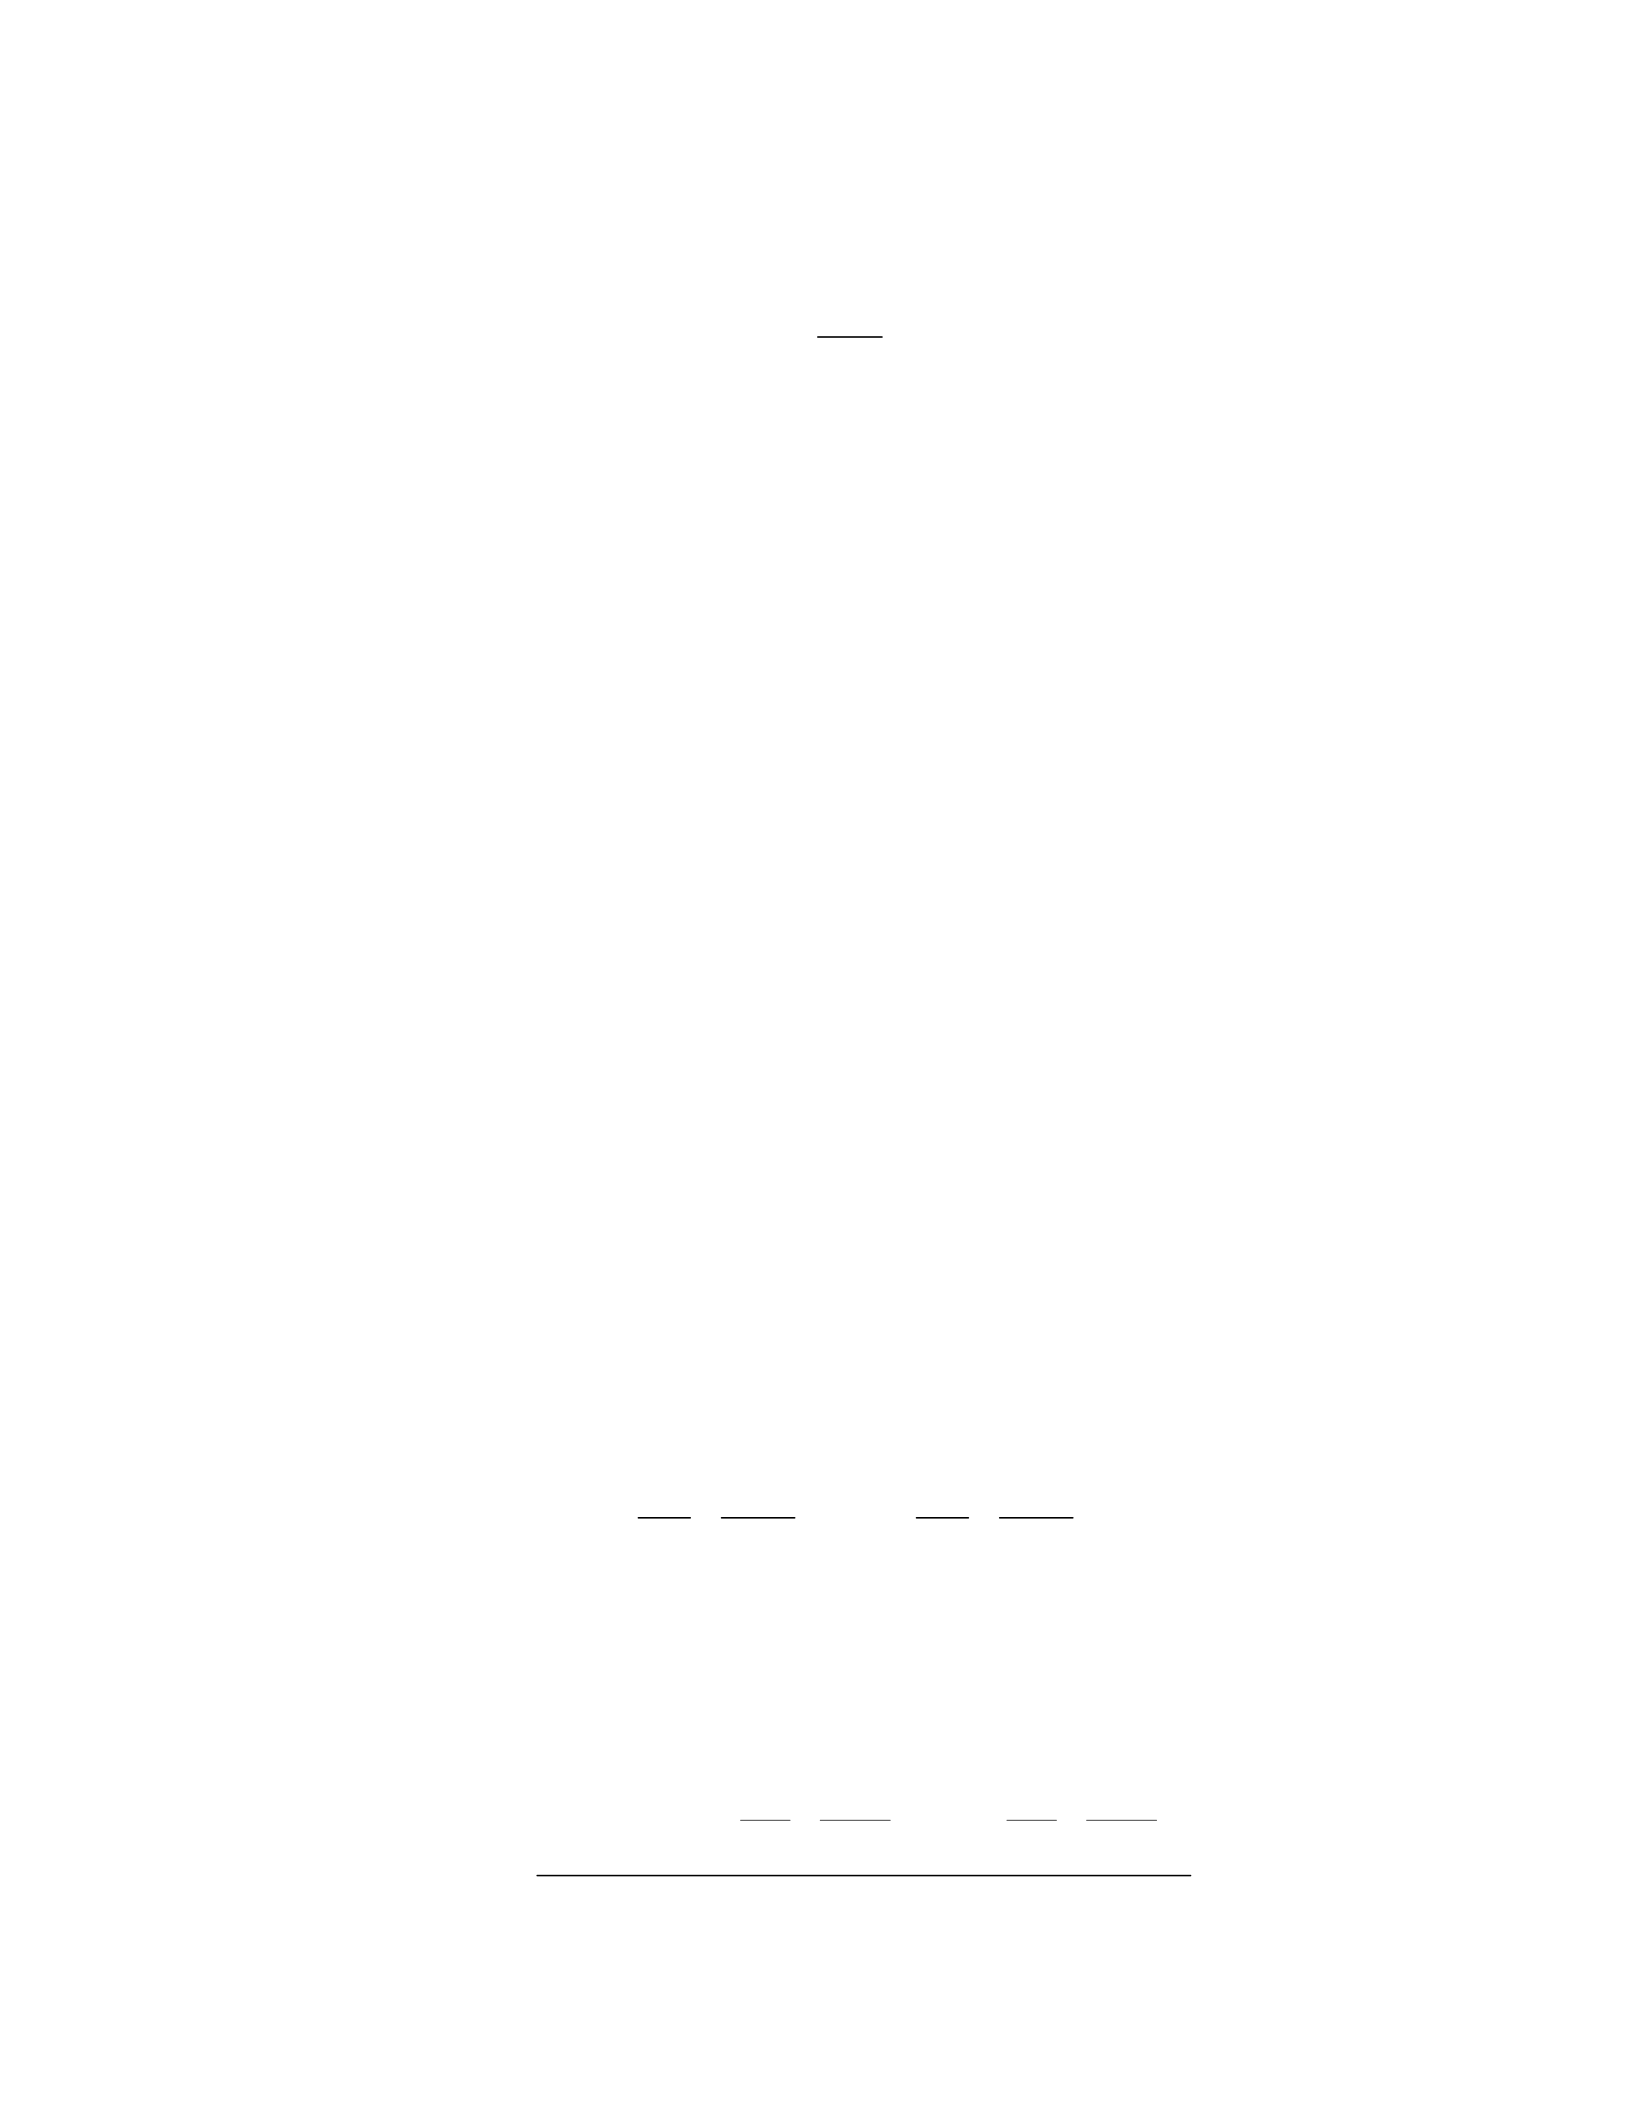
66
2
⎛
⎞ n ⎜ Si ⎟
H =∑⎜ n ⎟
i=1 ⎜∑Si ⎟⎟
⎜
⎝ i=1 ⎠
where Si is firm’s segment i’s sales or assets.
4.2. Operating performance:
As in John and Ofek (1995), I measure firm’s operating performance as (1)
earnings before interest, taxes, and depreciation to sales and (2) earnings before interest,
taxes, and depreciation to book value of assets.
4.3. Internal capital market efficiency:
To measure the internal capital market efficiency, I use Rajan et al. (2000) measures
of funds transferred to/from a segment and the relative value added by
allocation.
Rajan et al. (2000) proxy for the transfers the segment makes (if negative) or receives
(if positive) is computed as,
Ij Ijss n ⎛ Ij Ijss ⎞ − ss −∑ wj ⎜⎜ − ⎟
BAj BAj j=1 ⎝ BAj BAjss ⎟⎠
and the relative value added by allocation is,
n ⎛ Ij Ijss n ⎛ Ij Ijss ⎞⎞
∑j=1 BA qj ( j −q)⎜⎝ − ss −∑wj ⎜⎜ BAj − BAjss ⎟⎟⎠⎟⎟⎠
67
⎜ BAj BAj j=1 ⎝
BA
where ss refers to single-segment firms, wj is segment j’s share of total firm assets.
q is the asset-weighted average of segment qs for the firm, qj is the asset-weighted Q ratio
of single segment firms that operate exclusively in segment j, Ij is the capital
expenditure of segment j, BAj is the book value of assets of segment j, Ij is the
assetBAj
weighted average capital expenditures to assets ratio for the single segment firms in the
corresponding industry where the industry is defined at the 3-digit level of the segment
SIC, and BA in the firm’s book value of assets.
5. Methodology:
The market reaction to the announcement of asset sales will be tested using the
standard event study methodology of Brown and Warner (1985) with the CRSP value
weighted portfolio as proxy for the market portfolio. To test for the operating performance
and focus level changes, I use parametric and non parametric tests. I also use the ordinary
least regressions to relate the changes in operating performance to the change in a firm’s
focus level. .
6. Data and sample:
The initial sample of asset divestitures is obtained from the Securities Database
Corporation (SDC) over the period 1990-2002. The SDC database includes divestitures of
assets and divestitures of a whole subsidiary. When a firm sells an asset, the SDC records
the name of the divesting firm as the parent firm and the type of the assets divested as the
68
name of the target. Therefore, I treat the target parent firm rather than the target firm as the
asset divesting firm. I exclude spin off and equity carve-out transactions and transactions
where the asset divesting parent firm is not U.S public firm or is operating in the financial
industry (SIC 6000-6999). To verify the incidence of the asset sale transaction, its
announcement date, and reason for the sale, I search the transactions in Newswires
compiled in Lexis-Nexis. Finally, to be in the sample, the selling firms must have data on
the CRSP and COMPUSTAT databases. The final sample consists of 1240 asset and
subsidiary sale transactions including 51 merger facilitating sales where the transaction
value is $10 million or more and the reason for selling the asset is disclosed in 477 asset
sale announcements. Other disclosed reasons for the sale include: increasing firm’s focus,
reducing debt, selling non core or non strategic assets, among other reasons.
Panel A of Table I shows the distribution of asset sales over the sample period 1990-2002
classified into merger-facilitating and non merger-related asset sales. The number of asset
sales increases steadily until 1998, a pattern that is consistent with the documented
restructuring activity that U.S corporations went through during the 1990s.
Table I: Panel A shows the distribution of 1240 non-merger related and merger related asset sales over the
period 1990-2002. The initial sample of asset divestitures is obtained from the Securities Database
Corporation (SDC). The purpose of the asset sales is identified by searching the newswires compiled in Lexis-
Nexis. Panel B shows the distribution of the asset sales across industries where the industry defined on the 2-
digit SIC code.
Panel A: Distribution over the sample period.
Year All asset sales
Non-merger related
Merger-facilitating
1990
52
51
1
1991
33
33
0
1992
53
53
0
1993
59
58
1
1994
62
60
2
69
1995
91
85
6
1996
123
116
7
1997
123
122
1
1998
163
157
6
1999
126
115
11
2000
128
114
14
2001
110
109
1
2002
117
116
1
Total
1240
1189
51
Panel B: Distribution across industries.
Industry Name (2-digit SIC)
All asset sales
Non-merger related
Merger-facilitating
Mining (10-14)
101
98
3
Construction (15-17)
4
4
0
Manufacturing (20-39)
610
589
21
Transportation & public utilities (40-49)
232
212
20
Wholesale trade (50-51)
39
39
0
Retail trade (52-59)
55
50
5
Services (70-89)
190
188
2
Other (99)
9
9
0
Total
1240
1189
51
As similar patter is also seen in the government involvement as more and more firms divest
assets for regulatory reasons. Panel B shows the distribution of the asset sales across the
different industries. Most of both non merger related and merger facilitating asset sales take
70
place in the manufacturing and transportation and public utilities industries and no assets
are exchanged in the construction and wholesale trade industries to facilitate a merger
transaction.
7. Market reaction results:
Table II shows the market reaction to the announcement of an asset sale for both
merger-facilitating and non merger-related reasons over different event windows. Upon the
announcement of non merger-related asset sale, the stock price of the seller significantly
increases by 2.06% compared to no significant reaction for firms selling assets to facilitate
an acquisition transaction. The announcement day return documented in the literature
ranges from 0.014% to 1.66%. Over 4 day period (two days before to two days after)
around the announcement date, firms selling assets to facilitate a merger lose 1.84% of
their value while firms selling assets for non merger related reasons gain 2.79%. Thus,
announcement of selling asset to facilitate a merger is unfavorable news to investors while
selling an asset for non merger-related reasons is greeted as good news. For merger
facilitating asset sales, the announcement of an acquisition attempt is usually separate from
the announcement of the asset sale and therefore the announcement reaction of the asset
sales is not contaminated by the announcement impact of the acquisition attempt. However,
if the acquisition attempt is challenged by the government, investors may expect the
announcement of the asset sale. Thus, to the extent that investors are able to anticipate the
asset sale, the announcement reaction of that sale understates the true market reaction.
Table II: Cumulative abnormal returns (CAR) around the announcement of non merger-related and
mergerfacilitating. CAR is calculated using the standard event study methodology of Brown and Warner
(1985) where the value-weighted portfolio of all CRSP firms is used as a proxy for the market portfolio. The
market model parameters are estimated using returns of 155 days ending 45 days before the date of
announcement.
71
Non-merger related Merger-facilitating
Event window Mean(%) Median(%) Mean(%) Median(%)
(-1,0)
2.06a
0.56 a
0.41
-0.58
(-5,0)
2.84a
1.03 a
-1.97a
-1.52c
(-5,5)
2.75 a
1.19 a
-3.71a
-1.81b
(-2,2)
2.79 a
1.27 a
-1.84b
-1.709 b
a Significant at 1% level.
b Significant at 5% level. c
Significant at 10% level.
8. Descriptive statistics:
Panel A of table III shows the descriptive statistics for asset sellers at the end of the fiscal
year preceding the asset sale. Firms that are selling assets to facilitate an acquisition
transaction have significantly higher total assets, sales, and intangible assets than those of
firms selling assets for non merger related reasons. Firms that are selling assets to facilitate
a merger have significantly higher investment opportunities compared to their industry
peers and compared to firms that are selling assets for non merger related reasons as their
Tobin’s q (0.1640) is significantly higher than zero and significantly higher than that of
firms that are selling assets for non merger related reasons. One reason cited in the financial
press for undertaking an asset is the need for financing when the firm has low internally
generated funds or has high debt in its capital structure. This may
Table III: Panel A shows the summary statistics for asset selling firms calculated at the end of the year
preceding the year of the asset sale announcement date. Panel B shows measures of information asymmetry,
operating performance, focus, and internal capital market efficiency calculated at the end of the fiscal year
preceding the announcement date. Free cash flow (FCF) is calculated as operating income before depreciation
– interest expense – income taxes – capital expenditures. Leverage is calculated as (long term debt + current
portion of long term debt) / (total assets + book value of equity + market value of common equity). Market
value of common equity is calculated as the product of number of shares outstanding and the fiscal year
closing stock price. Tobin’s q is calculated as (market value of common equity – book value of equity + total
assets)/(total assets). MV assets is the market value of assets and is calculated as the market value of equity
+ book of debt. PPE is the plant, property, and equipment. EBITD is the earnings before interest, tax, and
depreciation. ROA is the return of assets and is calculated as net income/book value of assets. The Tobin’s q,
72
Leverage, EBITD/Sales, ROA, and EBITD/MV of assets are adjusted for industry by subtracting the industry
median value where the industry is defined as the 4 digit SIC code provided that there are at least three firms
in the industry, otherwise the industry is the defined as the 3 digit SIC code. Residual standard deviation in
year t is the standard deviation of the residuals of the market model regression using the daily returns from
year t-1. HHI is the Herfindahl Hirschman index calculated using segment sales. RVA is the Rajan et al.
(2000) measure of relative value added by allocation and is calculated as
n ⎛ Ij Ijss n ⎛ Ij Ijss ⎞⎞
∑j=1BA q qj ( j − )⎜⎝⎜BAj −BAjss −∑j=1wj⎜⎜⎝BAj −BAjss ⎟⎟⎠⎟⎟⎠
BA
where ss refers to single-segment firms, wj is segment j’s share of total firm assets. q is the asset-weighted
average of segment qs for the firm, qj is the asset-weighted Q ratio of single segment firms that operate
exclusively in segment j, Ij is the capital expenditure of segment j, BAj is the book value of assets of segment
j, Ij is the asset-weighted average capital expenditures to assets ratio for the single segment BAj
firms in the corresponding industry where the industry is defined at the 3-digit level of the segment SIC, and
BA in the firm’s book value of assets. Dollar amounts are denominated in millions. The median tests are
performed using the Wilcoxon signed rank test.
Panel A: summary statistics for asset selling firms calculated at the end of the year preceding the year of the
asset sale announcement date.
Non-merger related
Merger-facilitating
Mean
Median
Mean
Median
p-value for the
median difference
Assets
8744.09
1879.02
17125.32
11065.90
0.000
Sales
6536.84
1568.97
13516.38
3146.00
0.002
Intangibles/Total assets
0.1453
0.0696
0.2685
0.1927
0.000
PPE/Total assets
0.3754
0.3252
0.3728
0.2826
0.415
R&D expenses/sales
0.0705
0.0249
0.1709
0.0194
0.683
FCF/assets
-0.0072
0.0137
-0.0884
0.0233
0.085
Tobin’s q
0.0400
-0.0280 a
1.2965 a
0.1640 a
0.020
Leverage
0.0788 a
0.0430 a
0.0025
-0.0080
0.019
Panel B: Measures of information asymmetry, operating performance, focus, and internal capital market
efficiency.
Non-merger related
Merger-facilitating
73
Mean
Median
Mean
Median
p-value for the
median difference
Residual Standard deviation
0.0298 a
0.0242 a
0.0226 a
0.0204 a
0.435
EBITD/Sales
0.0102
0.0042
-0.0774
0.0136
0.626
ROA
0.0075
0.0014
-0.0681
0.0005
0.530
EBITD/MV of assets
-0.0108
0.0064 b
-0.0067
-0.0144
0.600
Number of segments
reported
2.82
3.00
3.19
2.00
0.176
HHI
0.6834
06594
0.6341
0.5111
0.203
RVA
0.0040c
0.00
-0.0089a
-0.0046a
0.00
a Significant at 1% level.
b Significant at 5% level. c
Significant at 10% level.
be a reason for the significantly high leverage ratio of firms selling assets for non merger
related reasons compared to their industry peers and compared to firms that are selling
assets to facilitate a merger transaction.
Panel B of table III shows measures of information asymmetry, operating performance,
focus, and internal capital market efficiency of asset selling firms. The operating
performance, measured by EBITD/sales or ROA, of asset selling firms is not different from
that of their industry peers irrespective of the announced reason for the asset sale.
Furthermore, the operating performance of firms selling assets to facilitate a merger is not
different from that of firms selling assets for non merger related reasons. However, asset
selling firms have significantly higher information asymmetry than their industry peers
regardless of the announced reason for the asset sale. The HHI is calculated using segment

74
sales and, therefore, it can only be calculated for firms that have segment data. As a result,
the sample reduces to 1153 asset sales including 42 merger facilitating asset sales. The
relative value added by allocation (RVA) in Table III is the Rajan et al. (2000) measure of
internal capital market efficiency which can only be calculated for diversified firms that
report multiple segments. Due to this restriction the RVA is calculated in 766 asset sales
including 29 merger facilitating asset sales. Firms selling assets to facilitate a merger are
not different from firms selling for other reasons in terms of their focus level whether it is
measured by the number of segments reported or their HHI calculated using segment sales.
Finally, firms that sell assets to facilitate a merger have significantly less efficient internal
capital market than that of firms selling assets for non merger related reasons.
9. Results:
9.2. Operating Performance Changes following an Asset Sale:
The pair wise comparisons of operating performance and focus in Table III do not show
whether the improvement in operating performance or increase in focus level may have
been a motive for selling an asset. Therefore, I examine the change in operating
performance and focus level from the year before to the year after the asset sale. Panel A
of Table IV shows that the operating performance of firms that sell assets for non merger
related reasons significantly increases regardless of how the operating performance is
measured while firms that sell assets to facilitate a merger do not experience any change in
operating performance following the asset sale as shown in panel B of Table III. Also, firms
that sell assets to facilitate a merger experience significant decrease in focus as the number
of segments that those firms report after the asset sale increases from 2 to 4 and their HHI
75
decreases from 0.5111 to 0.5015 and both of these changes are significant at the 1% and
10% levels, respectively. Thus, as a result of the asset sale, firms that sell
Table IV: Panel A shows measures of operating performance and focus for firms that sell assets for non
merger-related reasons in the year preceding and following the asset sale announcement and the mean and
median change tests from the year before to the year after the asset sale. Panel B shows measures of operating
performance for firms that sell assets for merger facilitating reason and the mean and median change tests
from the year before to the year after the asset sale. All the variables are as defined previously and dollar
amounts are denominated in millions
Panel A: Non merger-related asset sales
Variable
One year before
event
One year after event
p-value for
difference
Mean
Median
Mean
Median
Mean
Median
Residual standard deviation
Measures of operating
performance:
0.0301
0.0245
0.0320
0.0243
0.00
0.009
EBITD/sales
0.0097
0.0041
0.0236
0.0154
0.172
0.012
ROA
0.0078
0.0007
0.0154
0.0100
0.143
0.053
EBITD/ MV of assets
-0.0120
0.0066
-0.1094
0.0083
0.343
0.046
Measures of focus:
Number of segments reported
2.84
3.00
3.00
3.00
0.001
0.927
Segment-based HHI
0.6814
0.6577
0.6875
0.6596
0.234
0.001
Panel B: Merger facilitating asset sales
Residual standard deviation
Measures of operating performance:
0.0224
0.0227
0.0301
0.0249
0.010
0.004
EBITD/sales
0.0431
0.333
0.0310
0.0054
0.487
0.464
ROA
0.243
0.0005
0.0143
-0.0031
0.363
0.279
EBITD/ MV of assets
0.0008
0.0037
0.0095
0.0019
0.268
0.561
76
Measures of focus:
Number of segments reported
3.19
2.00
3.92
4.00
0.004
0.005
Segment-based HHI
0.6341
0.5111
0.5992
0.5015
0.068
0.096
assets to facilitate a merger become more diversified while firm that sell assets for other
reasons become more focused.
Next, I investigate the relationship between the change in operating
performance and the change in focus following an asset sale. Prior research shows that
firms that sell assets that are not related to their core business experience improved
operating performance of the remaining assets following the asset sale. The dependent
Table V: OLS regression of the determinants of change in operating performance following an asset sale. The
dependent variable is EBITD/sales. Change in HHI is the difference between HHI in the year before the asset
sale and HHI in the year after the asset sale. Firm size is the natural logarithm of the firm’s total assets.
Industry dummy is a dummy variable that indicates the firm’s 2-digit primary SIC code. Merger facilitating
dummy is a dummy variable that is equal to 1 if the announced reason for the asset sale is to facilitate a
merger. Merger_HHI is the interaction term of the merger facilitating asset and the change in HHI. Log MV
is the natural logarithm of the firm’s market value one day before the asset sale announcement day. After
1997 dummy is a dummy variable that is equal to 1 if the asset sale is announced after the end 1997. The
standard errors are corrected for heteroskedasticity.
Variable Model 1 Model 2 Model 3 Model 4
Constant
0.200 b
0.200 b
0.198 b
0.194
Change in HHI
0.146 b
0.145 b
0.151 b
0.150 b
Firm size
-0.014
-0.014
-0.016
-0.016
Industry dummy
-0.001 c
-0.001 c
-0.001 c
-0.001 c
Log MV
-0.005
-0.005
-0.003
-0.003
Merger facilitating dummy
-0.013
-0.021
Merger_HHI
0.025
0.027
After 1997 dummy
0.029
0.029

77
different between firms that sell assets to facilitate a merger and firms that sell assets for
other reasons by including a dummy variable for asset sales that are undertaken to facilitate
a merger and an interaction term with the change in focus. Both of these variables are not
significant indicating that the positive relationship between change in focus and change on
operating performance holds regardless of the announced reason for the asset sale. Since
the HHI is calculated using segment sales and because of the change in accounting
requirements for reporting segment data, I control for this change in models 3 and 4. The
results in Models 3 and 4 show that the change in reporting requirements does not change
the positive relation between change in operating performance and change in focus.
Overall, the results indicate that firms that sell assets to facilitate a merger have high
growth opportunities and do not seem to be financially constrained compared to their
industry peers. Although these firms are as diversified as the firms that sell assets for other
reasons, increase in focus does not represent a motive for them to sell assets as these firms
become more diversified following the asset sale. However, no evidence in found here to
indicate that the positive relationship between operating performance and change in focus
does not hold for firm that sell assets to facilitate a merger.
10. Conclusion:
In this essay, I compare between firms that sell assets to facilitate a merger and firms that
sell assets for other reasons in term of their and firm focus level changes. Merger
facilitating asset are those undertaken in order to satisfy a regulatory condition for
approving an acquisition transaction that the firm is involved in at the same time.

78
For a sample of 1250 asset sales obtained from the SDC, I study the value consequences
of asset sales that took place during the period 1990-2002 as well as the selling firm’s
operating and focus levels.
The results show that firms that sell assets to facilitate a merger are significantly larger
and have higher sales than those of firms that sell assets for other reasons. They also have
significantly higher growth opportunities and lower leverage ratio. The announcement of
an asset sale to facilitate a merger is perceived as bad news while selling an asset for other
reason is greeted as good news by investors.
Consistent with the evidence presented by John and Ofek (1995), Comment and Jarrell
(1995), and more recently, Bates (2005), I find that firms that sell assets for non merger
related reasons experience increase in focus and improved operating performance
following the asset sale. Furthermore, the change in focus is positively related to the change
in operating performance. In contrast, firms that sell assets to facilitate a merger become
more diversified and do not show any change on operating performance following the asset
sale. However, the positive relationship between the change in focus and the change in
operating performance is not different between firma that sell assets to facilitate a merger
and firms that sell assets for other reasons.

