


`
Climate Finance in the Global Context
In 2015, the Paris Agreement was ratified and signed during the Conference of Parties
(COP21), with 195 countries committing to intensifying actions and investments to develop a
global low-carbon economy (UN, 2015). This was an historic moment as it shifted the conversation
to how countries are expected to finance the execution of climate targets and the Sustainable
Development Goals (SDGs) Agenda from "billions" to "trillions," signifying a significant funding
shortfall (Doumbia & Lauridsen, 2019). Following Prasad et al. (2022), in order to meet the SDGs
within the set timeframe of 2030, there is a need to invest from 5-7 trillion dollars annually on the
global basis. Furthermore, the UNCTAD (2014) indicated an annual global investment gap of at
least $ 2.5 trillion, where developing countries face a wider gap between $3.3 trillion and $4.5
trillion annually.
Moreover, the recent global pandemic has had a profound socio-economic impact
worldwide, particularly in emerging economies. According to an OECD report (2022), following
the surge of the COVID-19 pandemic, there has been a 56% rise in the disparity towards attaining
the Sustainable Development Goals (SDGs) in developing nations, equating to a total of USD 3.9
trillion in the year 2020. As stated by Shulla & Leal Filho (2023), the global financial gap to attain
the SDGs has risen from USD 2.5 trillion to USD 3.5 trillion as a consequence of the pandemic.
Similarly, the OECD report (2020) indicated that developing countries are confronted with a
shortfall of 1.7 trillion USD in the financing required to remain on track for the 2030 SDGs as the
health and socio-economic consequences of the COVID-19 crisis have posed challenges for
governments and investors alike.

`
To bridge the investment gap and accomplish the SDGs, alternative climate financing
channels was created that included grants to low-carbon and climate resilient-related activities,
low-cost project debts, guarantees, capital instruments and private equity and finally result based
payments (Celikyilmaz & Arguello, 2021). The capital instruments and private equity related
financial tools, including green bonds, are gaining prominence, given that the necessary
investments exceed the limits of existing development funding.
1.2. Climate Finance in the Local Context:
The urgency of green bonds is derived from the criticality of the UN 2030 and its localized
Egyptian version, “Egypt National Climate Change Agenda 2050 (NCCA)”. The cost of green
transition in Egypt is massive and requires $211 billion to implement the mitigation program and
$113 billion for the adaptation program (MOE, 2022). The agenda recognizes five main goals with
twenty-two objectives, each containing several directions and enabling policies and tools that will
contribute to achieving the objectives, besides several KPIs that serve as performance measures.
The strategy is established in a way that recognizes the first and second goals as the primary goals
that contribute significantly to the mitigation and adaptation of climate change, where the other
three goals serve as implementation guidance to achieve the first two goals. However, the fourth
goal of the strategy is the one that discusses the green finance structure in Egypt and the role that
the financial tools can play in financing the NCCA agenda. This goal focuses on enhancing the
climate financing infrastructure, particularly within the local context as well as outlining five key
objectives, with the initial two objectives aimed at showcasing climate financing mechanisms
within both the banking and non-banking sectors. These objectives encompass:
1. Promoting the adoption of local green banking and green credit lines.

`
2. Advocating for innovative financing mechanisms, with a focus on prioritizing adaptation
actions, such as the utilization of green bonds.
A noteworthy aspect of the second objective is the recognition of green bonds as a vital
financial tool, essential for funding the climate change agenda. Green bonds are seen as pivotal in
involving all stakeholders and directing attention towards vulnerable sectors, primarily
emphasizing renewable energy, energy efficiency, waste management, clean transportation, climate
change adaptation, and other projects linked to environmental, social, and governance concerns.
However, in alignment with this strategy which underscores the role of the private sector in
climate finance as a key player in the Egyptian market, the Financial Regulatory Authority in Egypt
(FRA), has created the regulatory landscape for corporate green issuances to support the private
sector’s contribution in achieving the national agenda.
1.3. Significance of The Study
The significance of green bonds lies in their ability to secure financing for environmentally
friendly projects and stimulate private-sector investment in sustainable development. By providing
transparent and standardized investment opportunities, green bonds unlock new sources of capital
and promote the transition to a low-carbon economy (Wang et al., 2022). Furthermore, green
bonds, as conventional bonds, also can have a significant impact in achieving a lower rate of the
weighted average cost of capital (WACC) for Low carbon and climate resilience (LCR)
infrastructure projects financed or re-financed by green bonds (OECD, 2015) and thus, provide a
financing method that is exclusively targeting LCR projects.
Accordingly, and given the global commitment to the sustainable development agenda and
the need for financing, countries worldwide are increasingly accelerating green bond issuances to
`
secure the necessary funds, primarily via the private sector where the role of the private sector as
a leading green bond issuer has increased significantly and become a key market player on the
global scale in the last few years (CBI, 2023).
However, in the national context, although the thrive in the green bonds market worldwide
and the urgency of this market, Egypt has had only two green bond issuances since becoming a
signatory of the Paris Agreement in 2015. Notably, only one of these issuances is a corporate bond
issuance, occurring in 2021, two years after the establishment of the regulatory framework. Thus,
understanding the green bond market in Egypt and the main challenges will result in fostering the
green bond market in Egypt and supporting the national agenda and helping transform the Egyptian
economy into a more sustainable one.
1.4. Research Problem
Ever since the inception of green bonds to the global market, nations have been
progressively issuing these bonds to fund their pursuit of more environmentally sustainable
economies. However, Egypt has shown an intermediate level of green bond issuances compared to
other regional and global emerging markets if the Egyptian commitments towards the 2030 agenda
are to be considered. According to the IFC report (2022), Egypt ranked 24th among all emerging
economies in terms of green bonds issuance, with $850 million total issuance for both sovereign
and corporate green issuances. This rank is led mainly by sovereign issuance, which comprises
88.2% of the total Egyptian issuance, with corporate bonds comprising only 11.8%.
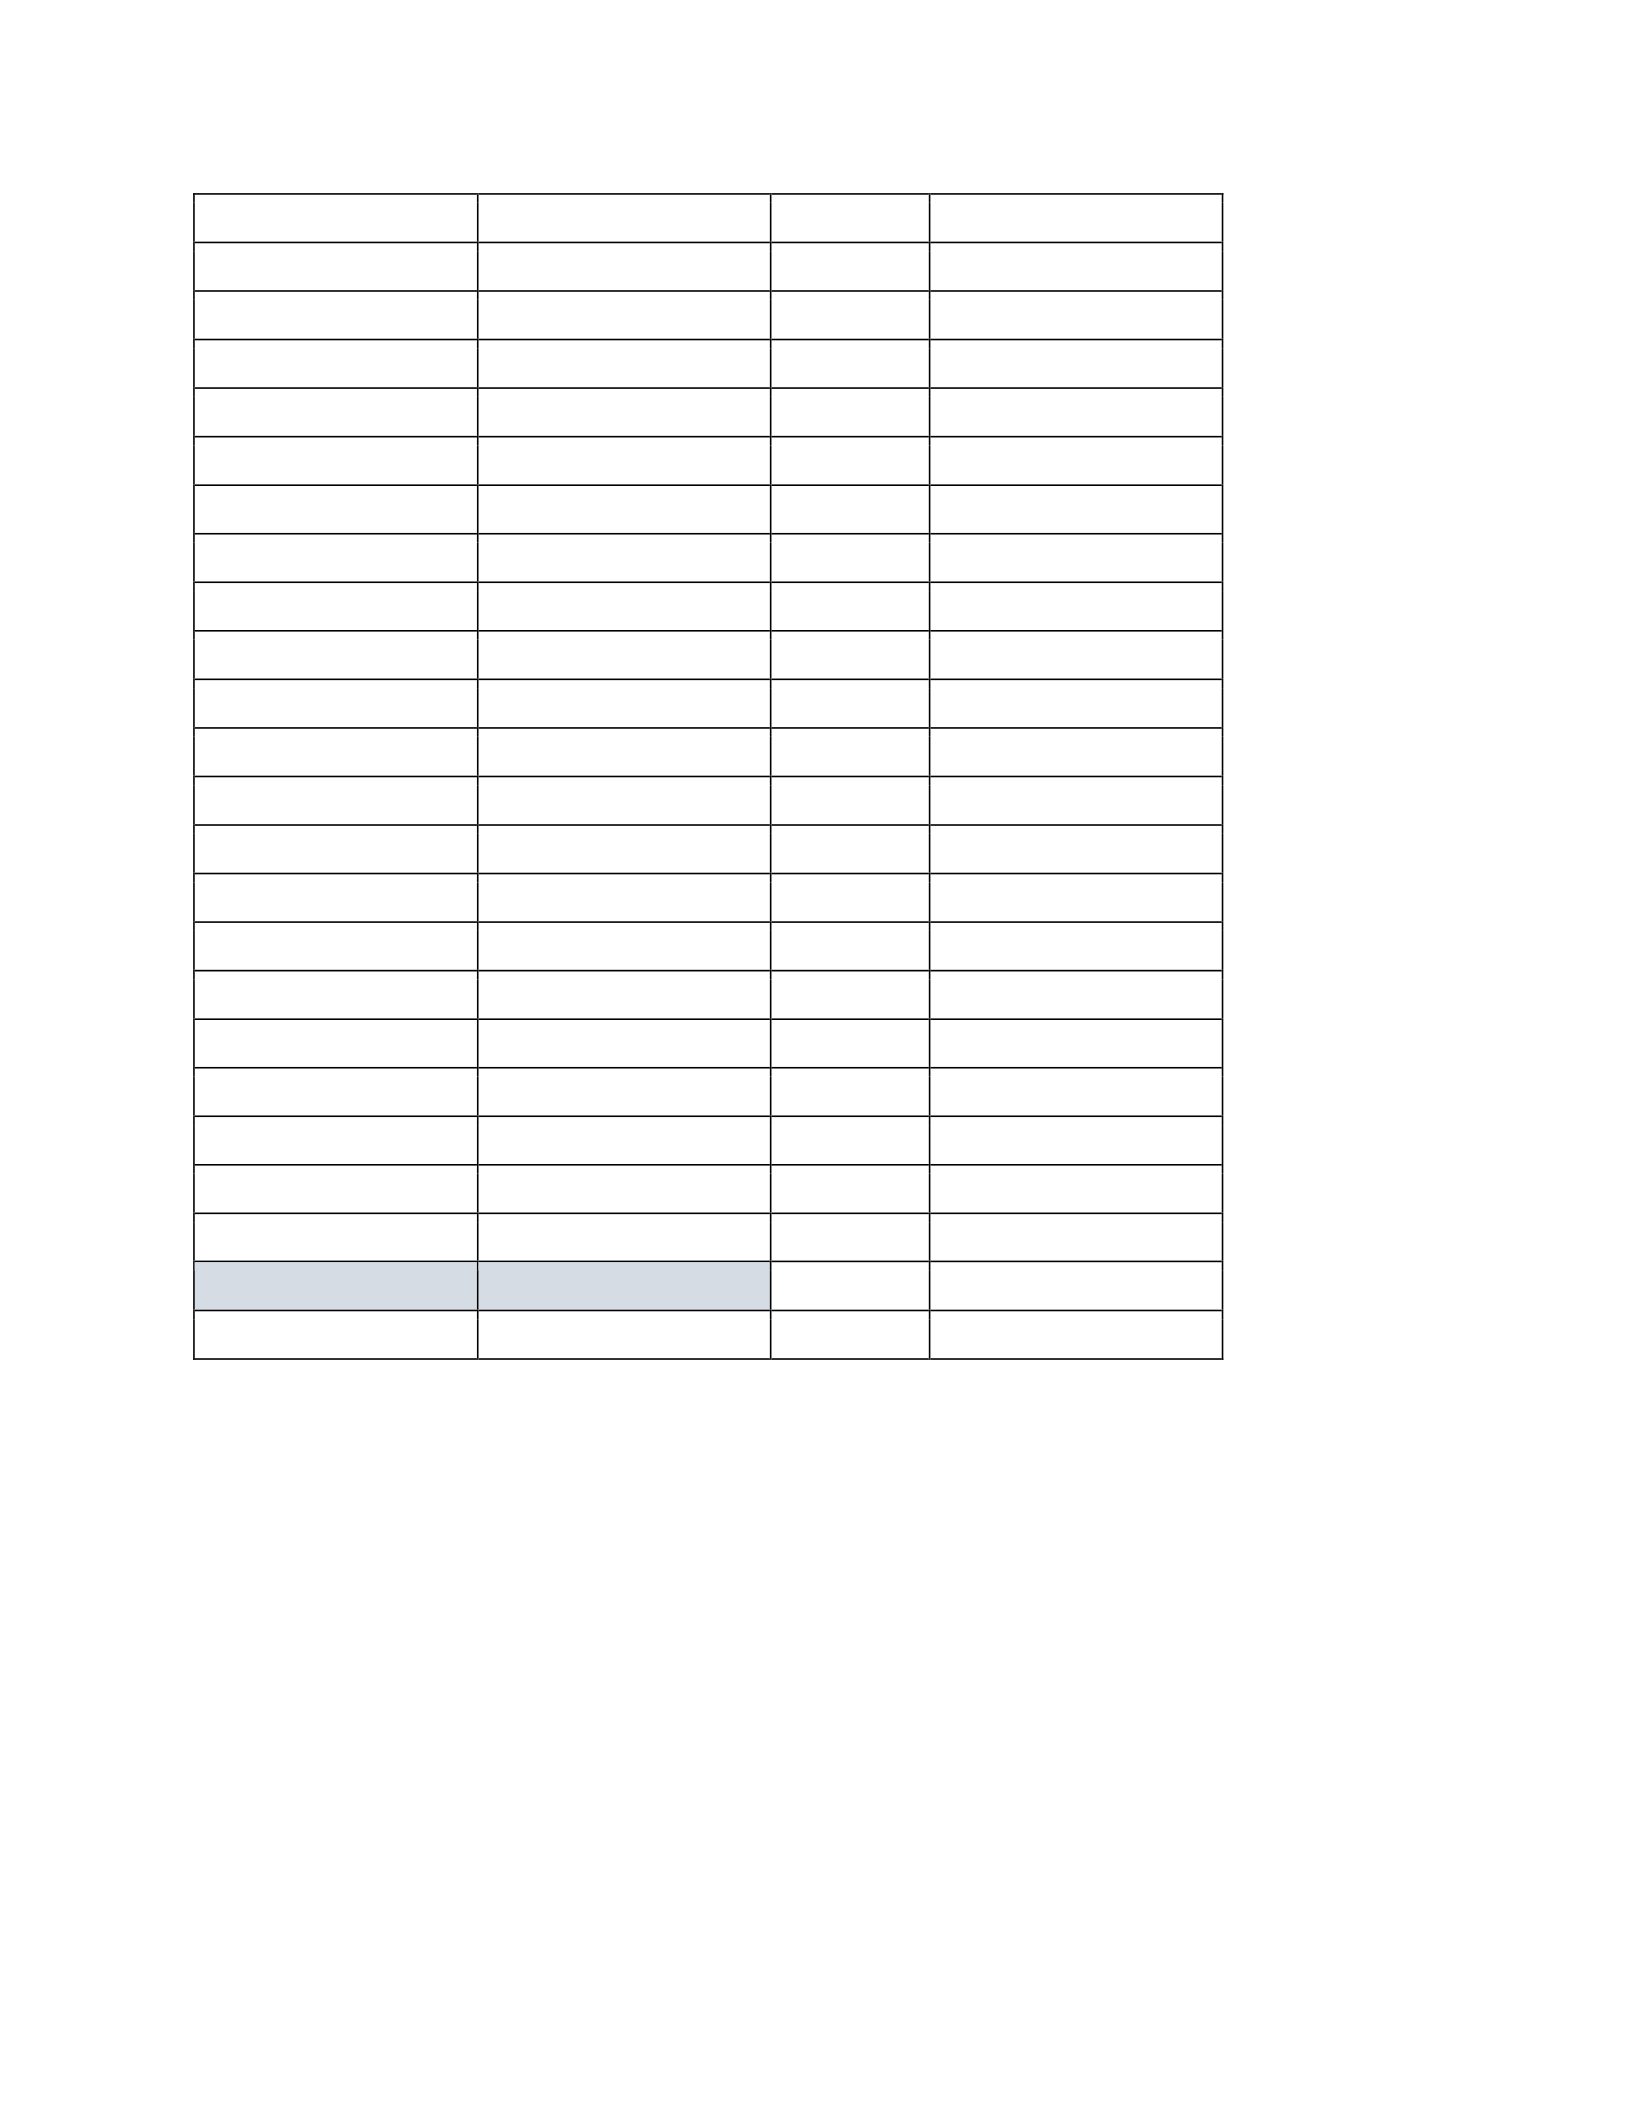
Table one: Emerging Market Green Bond Issuance Cumulative Issuance, 2012-21 (US$ million)
Country
Volume (US$ million)
Country
Volume (US$ million)
China
221,267
Georgia
750
`
India
17,750
Guatemala
700
Chile
13,584
Slovak Repu
b 520
Brazil
10,207
Costa Rica
504
Poland
7,374
Pakistan
500
Czech Republic
7,318
Uruguay
361
Indonesia
5,462
Morocco
356
Mexico
3,599
Panama
315
Hungary
3,354
Latvia
314
Philippines
2,946
Vietnam
227
South Africa
2,828
Nigeria
155
Thailand
2,778
Ecuador
150
United Arab Emirates
2,554
Slovenia
100
Russian Federation
2,552
Lebanon
60
Romania
1,926
Kenya
58
Malaysia
1,838
Estonia
56
Peru
1,686
Armenia
50
Turkey
1,440
Fiji
48
Saudi Arabia
1,300
Bangladesh
29
Ukraine
1,183
Dominican R
20
Serbia
1,174
Barbados
19
Argentina
1,165
Côte d’Ivoire
18
Colombia
1,067
Seychelles
15
Egypt, Arab Rep
850
Namibia
5
Lithuania
822
Kazakhstan
0.5
Author: IFC - Emerging Market Green Bonds Report 2021 (2022).
The total green bond volume in Egypt is comprised of only two green bond issuances. The
first was a sovereign issuance, which took place in September 2020 and establishing Egypt as the
inaugural nation in the Middle East and North Africa region to issue a sovereign green bond. The
initial announcement for a five-year green bond was set at US$500 million, carrying an interest
rate of 5.75 percent. Due to overwhelming demand, the bond was oversubscribed, prompting the

`
government to raise the bond's size to US$750 million and reduce the interest rate to 5.25 percent.
This rate is even beneath the level of Egypt's benchmark traditional bonds
(World Bank, 2022). The second issuance is a corporate green bonds issue that was announced in
2021, where the CIB Bank cooperated with the IFC to issue USD 100 million in green bonds
(Enterprise, 2021). To date, this marks the only corporate green bond issuance in the Egyptian
market.
Although the legal and regulatory framework of the green bond had existed since 2019,
when green bonds and green sukuk were considered as debt financial tools, the CIB issuance is the
only corporate green bond issuance in the Egyptian market to this date. Given the importance of
the private sector as a key player in financing the green transition and securing the required funds
to finance green projects, the low level of corporate bond issuances opens the door for questioning
the obstacles that companies face in issuing green bonds. It is essential to understand these issues
from the perspectives of market participants to accurately identify the exact policies to incentivize
and accelerate the issuance of green bond in the Egyptian market. In this light, this paper discusses
the obstacles that face corporate green bond issuance in the Egyptian market.
1.5. Research Objective
The study intends to provide a substantial addition to the current understanding of the green
bond market, particularly in emerging markets. It is evident from the literature review that there
are prominent gaps in various aspects of the global green bond market, emphasizing the necessity
for further research to enhance our understanding of this innovative financial instrument and its
overall impact on the economy. Therefore, this research addresses a crucial void in the literature
by providing a comprehensive analysis of the Egyptian bond market, with a specific focus on the

`
green bond market, and by identifying the barriers that impede the expansion of the local market
from the perspective of market experts. To the best of our knowledge, this research represents one
of the early attempts to examine the corporate green bond market in the Egyptian context, making
it a significant milestone for future studies. Accordingly, understanding the corporate green bond
market mechanism and identifying the expansion barriers will be essential for policymakers to
identify the most critical parameters affecting green bond issuance volume. This would help the
Egyptian market to accelerate issuances in Egypt, which, in turn, will serve as a driving force for
the green transition of the local economy. Accordingly, this study holds significant importance in
relation to the current global and national agendas, which are interconnected with boosting the
issuance of green bonds and facilitating the shift towards environmentally friendly initiatives.
1.6. Research Question
Since 2021, the private sector has started to play a critical role in the global bond market,
and its participation in 2022 contributed to more than 54% of the total global issuances (CBI,
2023). According to the same report of the CBI, the same trend is taking place on the emerging
market scale, with the private sector taking the lead in green issuances, where financial and
nonfinancial corporations comprise 73% of total issuances. However, this case is not the same for
the Egyptian market. Considering Egypt's commitment to the sustainability agenda and the urgent
need to fund the 2030 agenda, the low level of corporate green bond issuance is a concerning issue
that requires immediate attention. Corporate green bonds play a crucial role in driving Egypt's
green transition, making addressing the challenges hindering their issuance imperative.

`
The primary focus of this study is to develop an extensive comprehension of the Egyptian
corporate bond market while identifying the principal hurdles encountered within the realm of the
green bond market.
The main research question guiding this study is:
- "What are the challenges encountered by corporations when issuing green
bonds? And what policies are needed to overcome those challenges?
The sub-questions to be explored include:
- What are the structural challenges affecting the overall corporate bond
market?
- Why does the Egyptian corporate green bond market have lower issuances
than other emerging economies? What are the policy and implementation
gaps that need to be addressed?
- What factors influence green bond issuance from both the issuers' and
investors' perspectives?
Through the exploration of these research inquiries, this investigation seeks to offer
valuable understandings into the challenges the corporate green bond market faces in Egypt and
propose policy recommendations to foster its growth and development.
1.7. Organization of the Study:

`
This study is organized into eight chapters, which focus on the following matters: Chapter
One, which gives an overview of the topic and its background. It also explains the problem
statement and the significance of the research and highlights the main and sub-research questions
that will be discussed throughout the research. Furthermore, the section demonstrates the corporate
green bond issuance and the related regulations from a domestic lens.
Chapter Two discusses the background of the green bond and its main concepts and framework.
This section provides an international overview of the green bond market and its recent growth
trends to demonstrate the importance of the tool on a global scale.
Chapter Three demonstrates the conceptual framework used to evaluate and assess the thesis topic
and explain the relationships between the study variables.
Chapter Four discusses the literature review of green bonds. The literature review section
comprises three main themes. The first theme demonstrates green bonds’ impact on the economic
growth of the issuing countries. The second theme discusses the determinants of green bond
issuances. The third theme scans the global challenges facing the green bond market expansion.
Chapter Five presents the research methodology and design, where the data collection
methodology is explained, ethical considerations and research limitations.
Chapter Six demonstrates the analysis of the collected data. The data is presented into two main
themes; the first discusses the general challenges they face in the corporate bonds market in Egypt,
which directly impacted bond issuance. The second theme demonstrates the greenspecific
challenges related to the green element that the green bond requires to satisfy the unique
requirements of green bond issuances.
Chapter Seven discusses the conclusion of the thesis. It concludes the entire study by providing a
general concluding overview of the main findings of the analysis.

`
Chapter Eight is the closing chapter that presents analysis-based policy recommendations based
on the previous chapter's findings. These recommendations are applicable solutions to address the
gaps and alleviate the green bond market in Egypt.
2. Chapter Two: Background
2.1. What are Green Bonds?
There exists a multiplicity over the definition of a green bond, in the sense that The
International Capital Market Association ICMA (2021) defines green bonds as: "Green Bonds
are any type of bond instrument where the proceeds or an equivalent amount will be exclusively
applied to finance or re-finance, in part or in full, new and/or existing eligible Green Projects and
which are aligned with the four core components of the GBP". Whereas the World Bank (WB)

`
defines the green bond as a debt security issued to raise capital specifically to support
climaterelated or environmental projects (World Bank, 2015). Meanwhile, the Egyptian Financial
Regulatory Authority defines green Bonds as "A fixed-income instrument explicitly designed to
support specific climate-related or environmental projects (FRA, 2021). Ultimately, The WB
definition is preferred due to its comprehensiveness and because it specifically earmarks the
collected proceeds to the specific account, allowing more control over the green proceeds.
Therefore, green bonds differ from regular bonds in being labeled as "green" by the issuer
of the bond. This label entails a specific and certain commitment from the issuer to use the proceeds
exclusively to finance or refinance, in part or in full, new and/or existing eligible green Projects,
which are aligned with internationally acknowledged standards such as the four core components
of the Green Bond Principles (GBP) and or the Climate Bonds Initiative (CBI) (Kaminker, 2015;
OECD, 2015).
Nevertheless, the CBI functions as a global non-profit entity with a focus on investors.
Established in 2010, the CBI introduces a systematic framework that underlies the specifications
regarding the projects and assets that align with the attainment of the Paris Climate Agreement
objectives. This framework serves as the basis for determining the eligibility for inclusion in a
Certified Climate Bond, Certified Climate Loan, or Certified Climate Debt Instrument.
The Green Bond Principles (GBP) were introduced in 2014 as a set of voluntary guidelines
for best practices. This initiative was spearheaded by a consortium of investment banks, including
Bank of America Merrill Lynch, Citi Bank, Crédit Agricole Corporate and
Investment Bank, JPMorgan Chase, BNP Paribas, Daiwa, Deutsche Bank, Goldman Sachs, HSBC,
Mizuho Securities, Morgan Stanley, Rabobank, and SEB. Subsequent supervision and refinement

`
of these guidelines have been transitioned to an autonomous secretariat under the oversight of the
International Capital Market Association (ICMA).
However, it is noteworthy that green bonds are classified based on the type of issuers
including Sovereign bonds, Supranational, sub-sovereign and agency (SSA) bond, Municipal
bond, and corporate bonds. Only sovereign bonds, which are bonds issued by the governments,
and corporate bonds, which are bonds issued by corporates, exist in the Egyptian context.
2.2. Green Bonds Principles:
According to the green bonds principles (2021), four core components are identifies:
1. Use of Proceed:
The use of proceeds to be used to finance specific green projects is a cornerstone
for green bonds where all the designated projects should demonstrate clear,
assessable, and quantifiable (when possible) environmental benefits. The categories
of eligible green projects encompass a range of areas, including renewable energy,
energy efficiency, pollution prevention and control, sustainable management of
natural resources and land use, preservation of terrestrial and aquatic biodiversity,
clean transportation, responsible water and wastewater management, adaptation to
climate change, products and processes aligned with circular economy principles,
and environmentally friendly building initiatives.
2. Project Evaluation and Selection Process:
The issuer of green bonds is required to transparently declare:

`
- The sustainability objectives linked to environmental concerns for the green
projects.
- The methodology employed by the issuer to ascertain the alignment of the
project with the predetermined categories.
- Supplementary details pertaining to the methodologies utilized by the issuer
for recognizing and addressing environmental and social risks associated
with the projects.
3. Management of Proceeds:
Green bonds proceeds are recommended to be credited to sub-account or to be
moved to sub-portfolio or any other manner to ensure a transparent manner to track
the proceeds. During the duration of the Green Bond, it is necessary to regularly
adjust the balance of tracked net proceeds to align with allocations towards eligible
Green Projects made within that time frame. The issuer is responsible for informing
investors about the planned temporary placement options for the remaining
unallocated net proceeds.
4. Reporting:
Issuers are required to provide and maintain up-to-date information on the
utilization of proceeds, which should be renewed annually until full allocation.
Additionally, in the event of significant developments, issuers should promptly
disclose relevant information in a timely manner.

`
These core principles are widely adopted across the world and present a set of principles that ensure
high-quality green bonds issuances and reduced possibility of greenwashing. However, the
greenwashing phenomena was identified according to the International Organization of Securities
Commissions (IOSCO) as “the practice by asset managers of misrepresenting their own
sustainability-related practices or the sustainability-related features of their investment products”
(IOSCO, 2021). This definition is mainly specific to the financial markets, which make it of high
relevance to the topic of the study.
2.3. The Rise of the Green Bond Global Market:
In 2007, the inaugural issuance of green bonds took place through collaborative efforts
between the World Bank and the European Bank for Reconstruction and Development (EBRD).
This initiative was initiated from a consortium of Swedish pension funds advocating for their
investments to be directed toward climate change initiatives. This pioneering concept served as the
catalyst for the establishment of the global green bonds market. Subsequent to this groundbreaking
issuance, numerous similar offerings emerged worldwide, leading to a substantial and sustained
growth of the green bonds sector (World Bank, 2021). In 2012, a total of USD 2.6 billion worth of
green bonds were issued on a global scale. By 2015, the cumulative value of the green debt capital
market had escalated to USD 104 billion. Fast forward five years to 2020, the market achieved a
significant milestone, surpassing the cumulative USD 1 trillion mark in early December,
culminating the year with a total of USD 1.05 trillion. Furthermore, the cumulative sum of green,
social, and sustainability (GSS+) issuances collectively reached USD 3.7 trillion by the close of
2022. Despite the increasing prominence of other bond categories such as social, sustainability,
socially linked, and transition bonds, green bonds continue to maintain their prominent position as
`
the predominant financial instrument, constituting 58% of the overall total issuances and
amounting to USD 487.1 billion on a global scale.
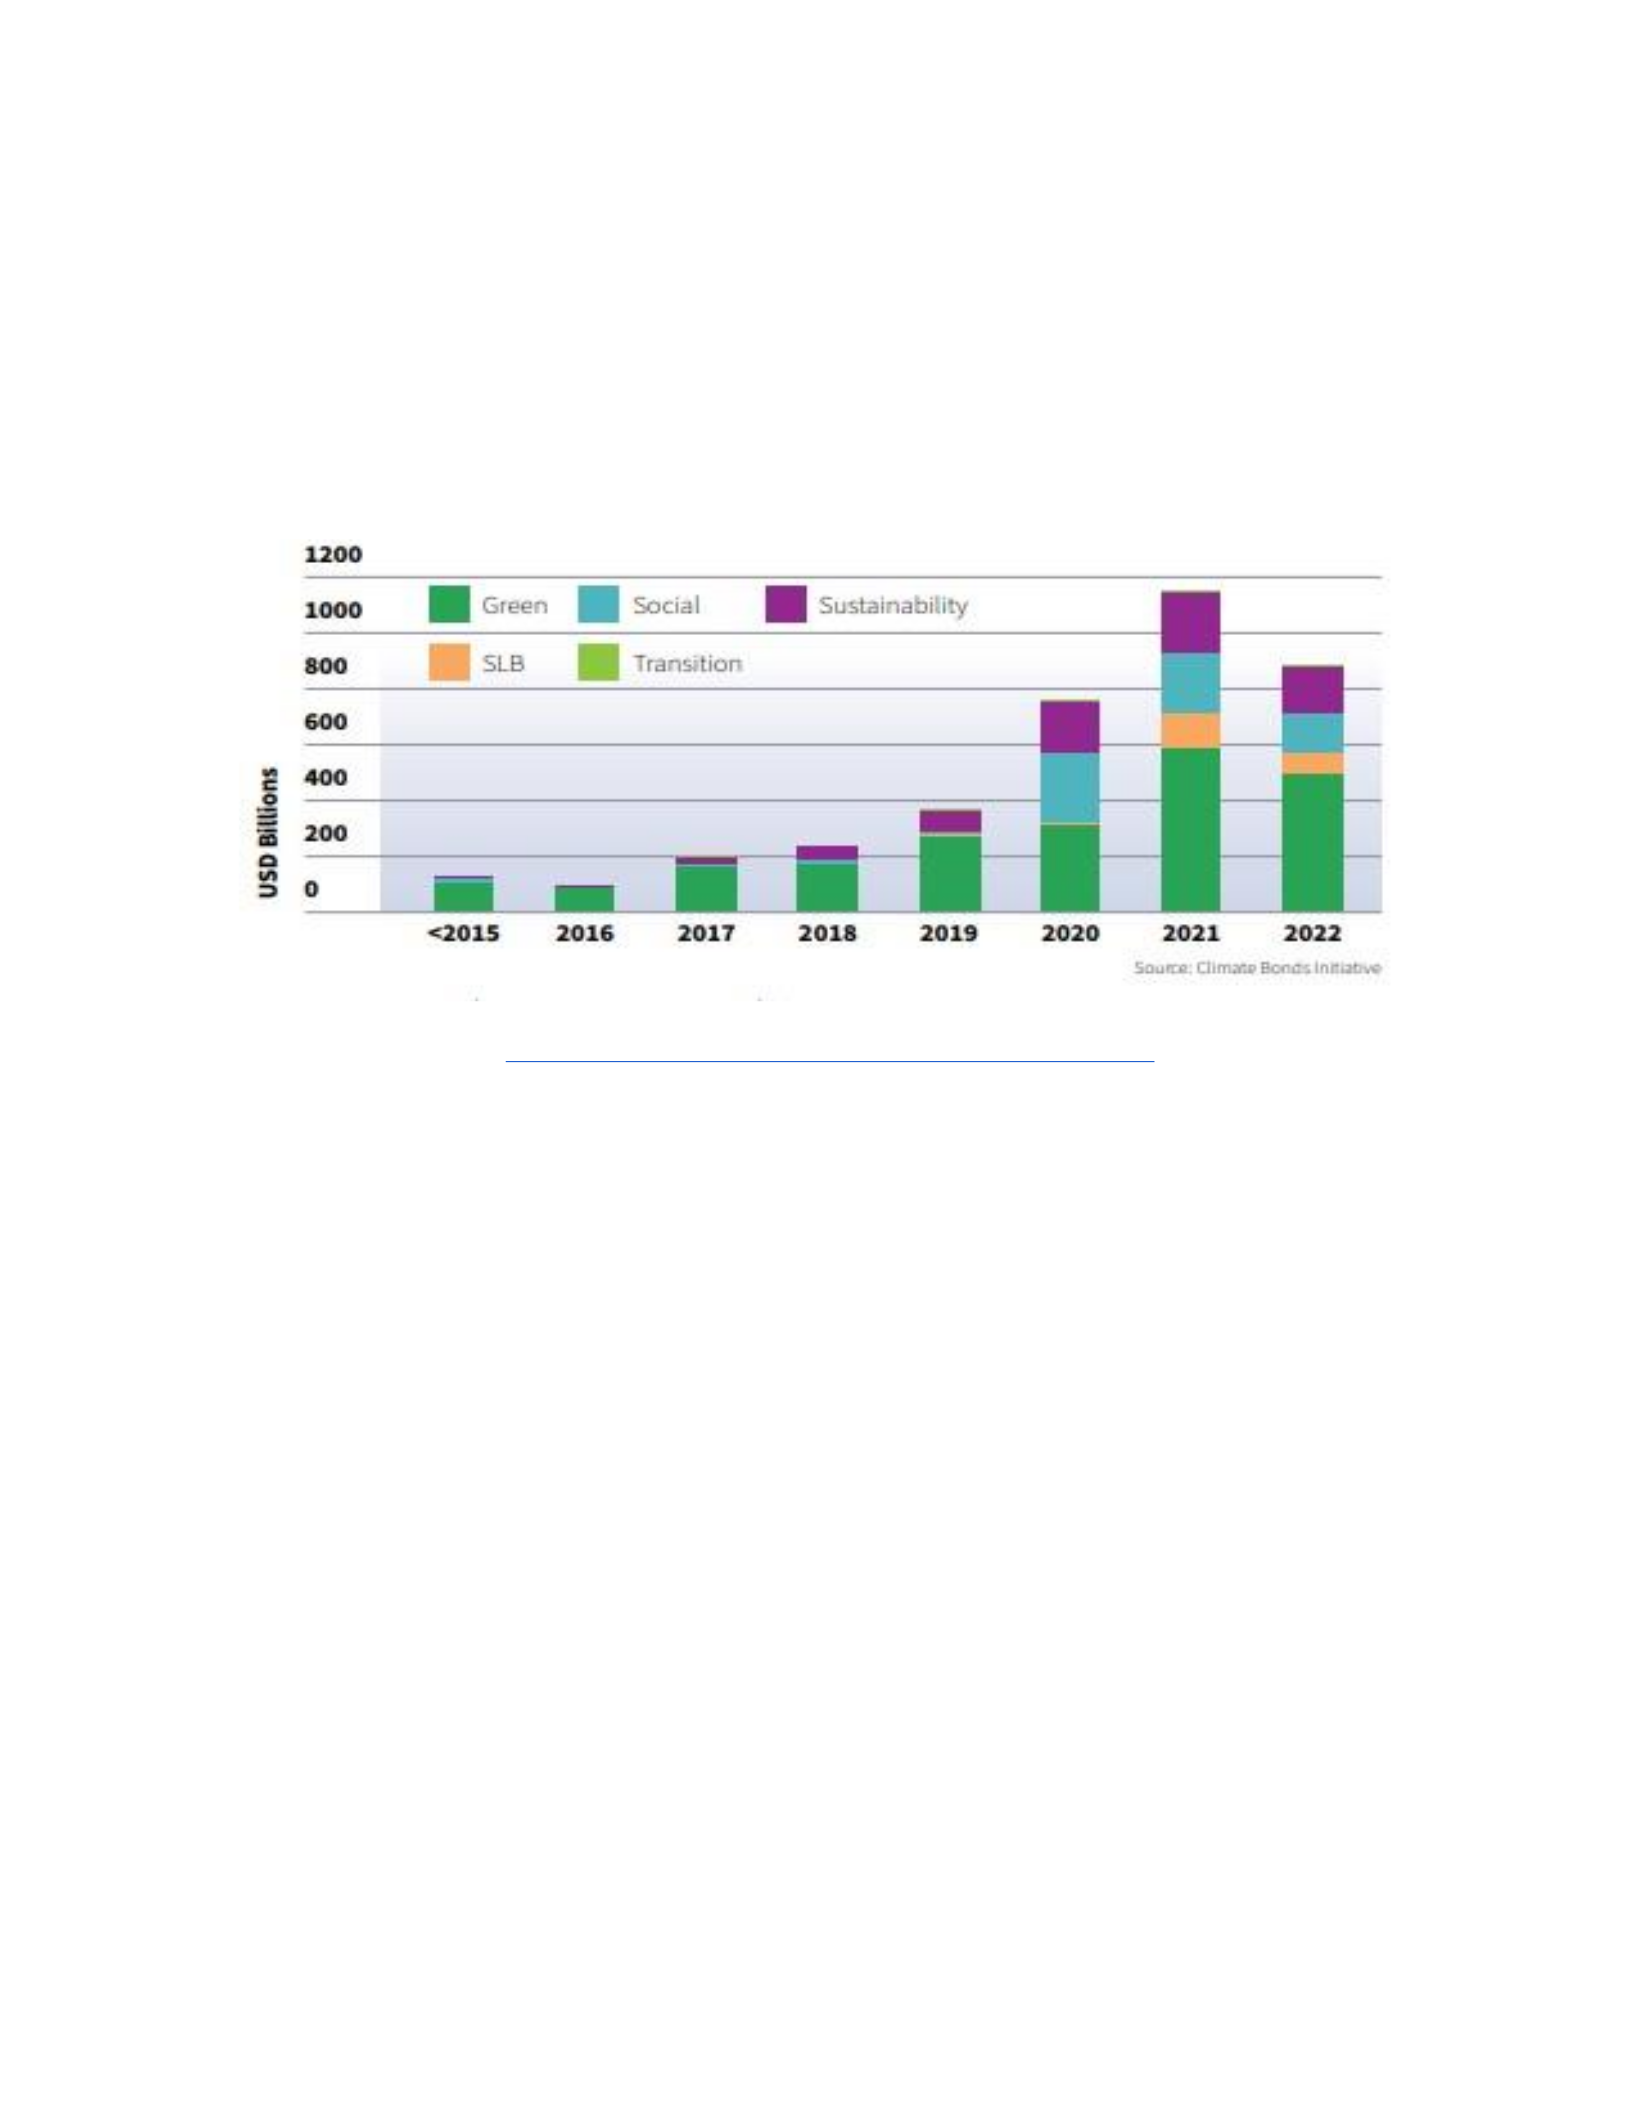
Figure Two: GSS+ Issuance Volumes (2015-2022).
Author: Climate Bond Initiative https://www.climatebonds.net/files/reports/cbi_sotm_2022_03d.pdf
The above chart shows the gradual increase of the green bond volumes over the years since
2015 and reflects the attractiveness of the green bonds and the high global demand for it as a major
financial tool.
2.4. Green Bond Issuances by Issuers’ Type:
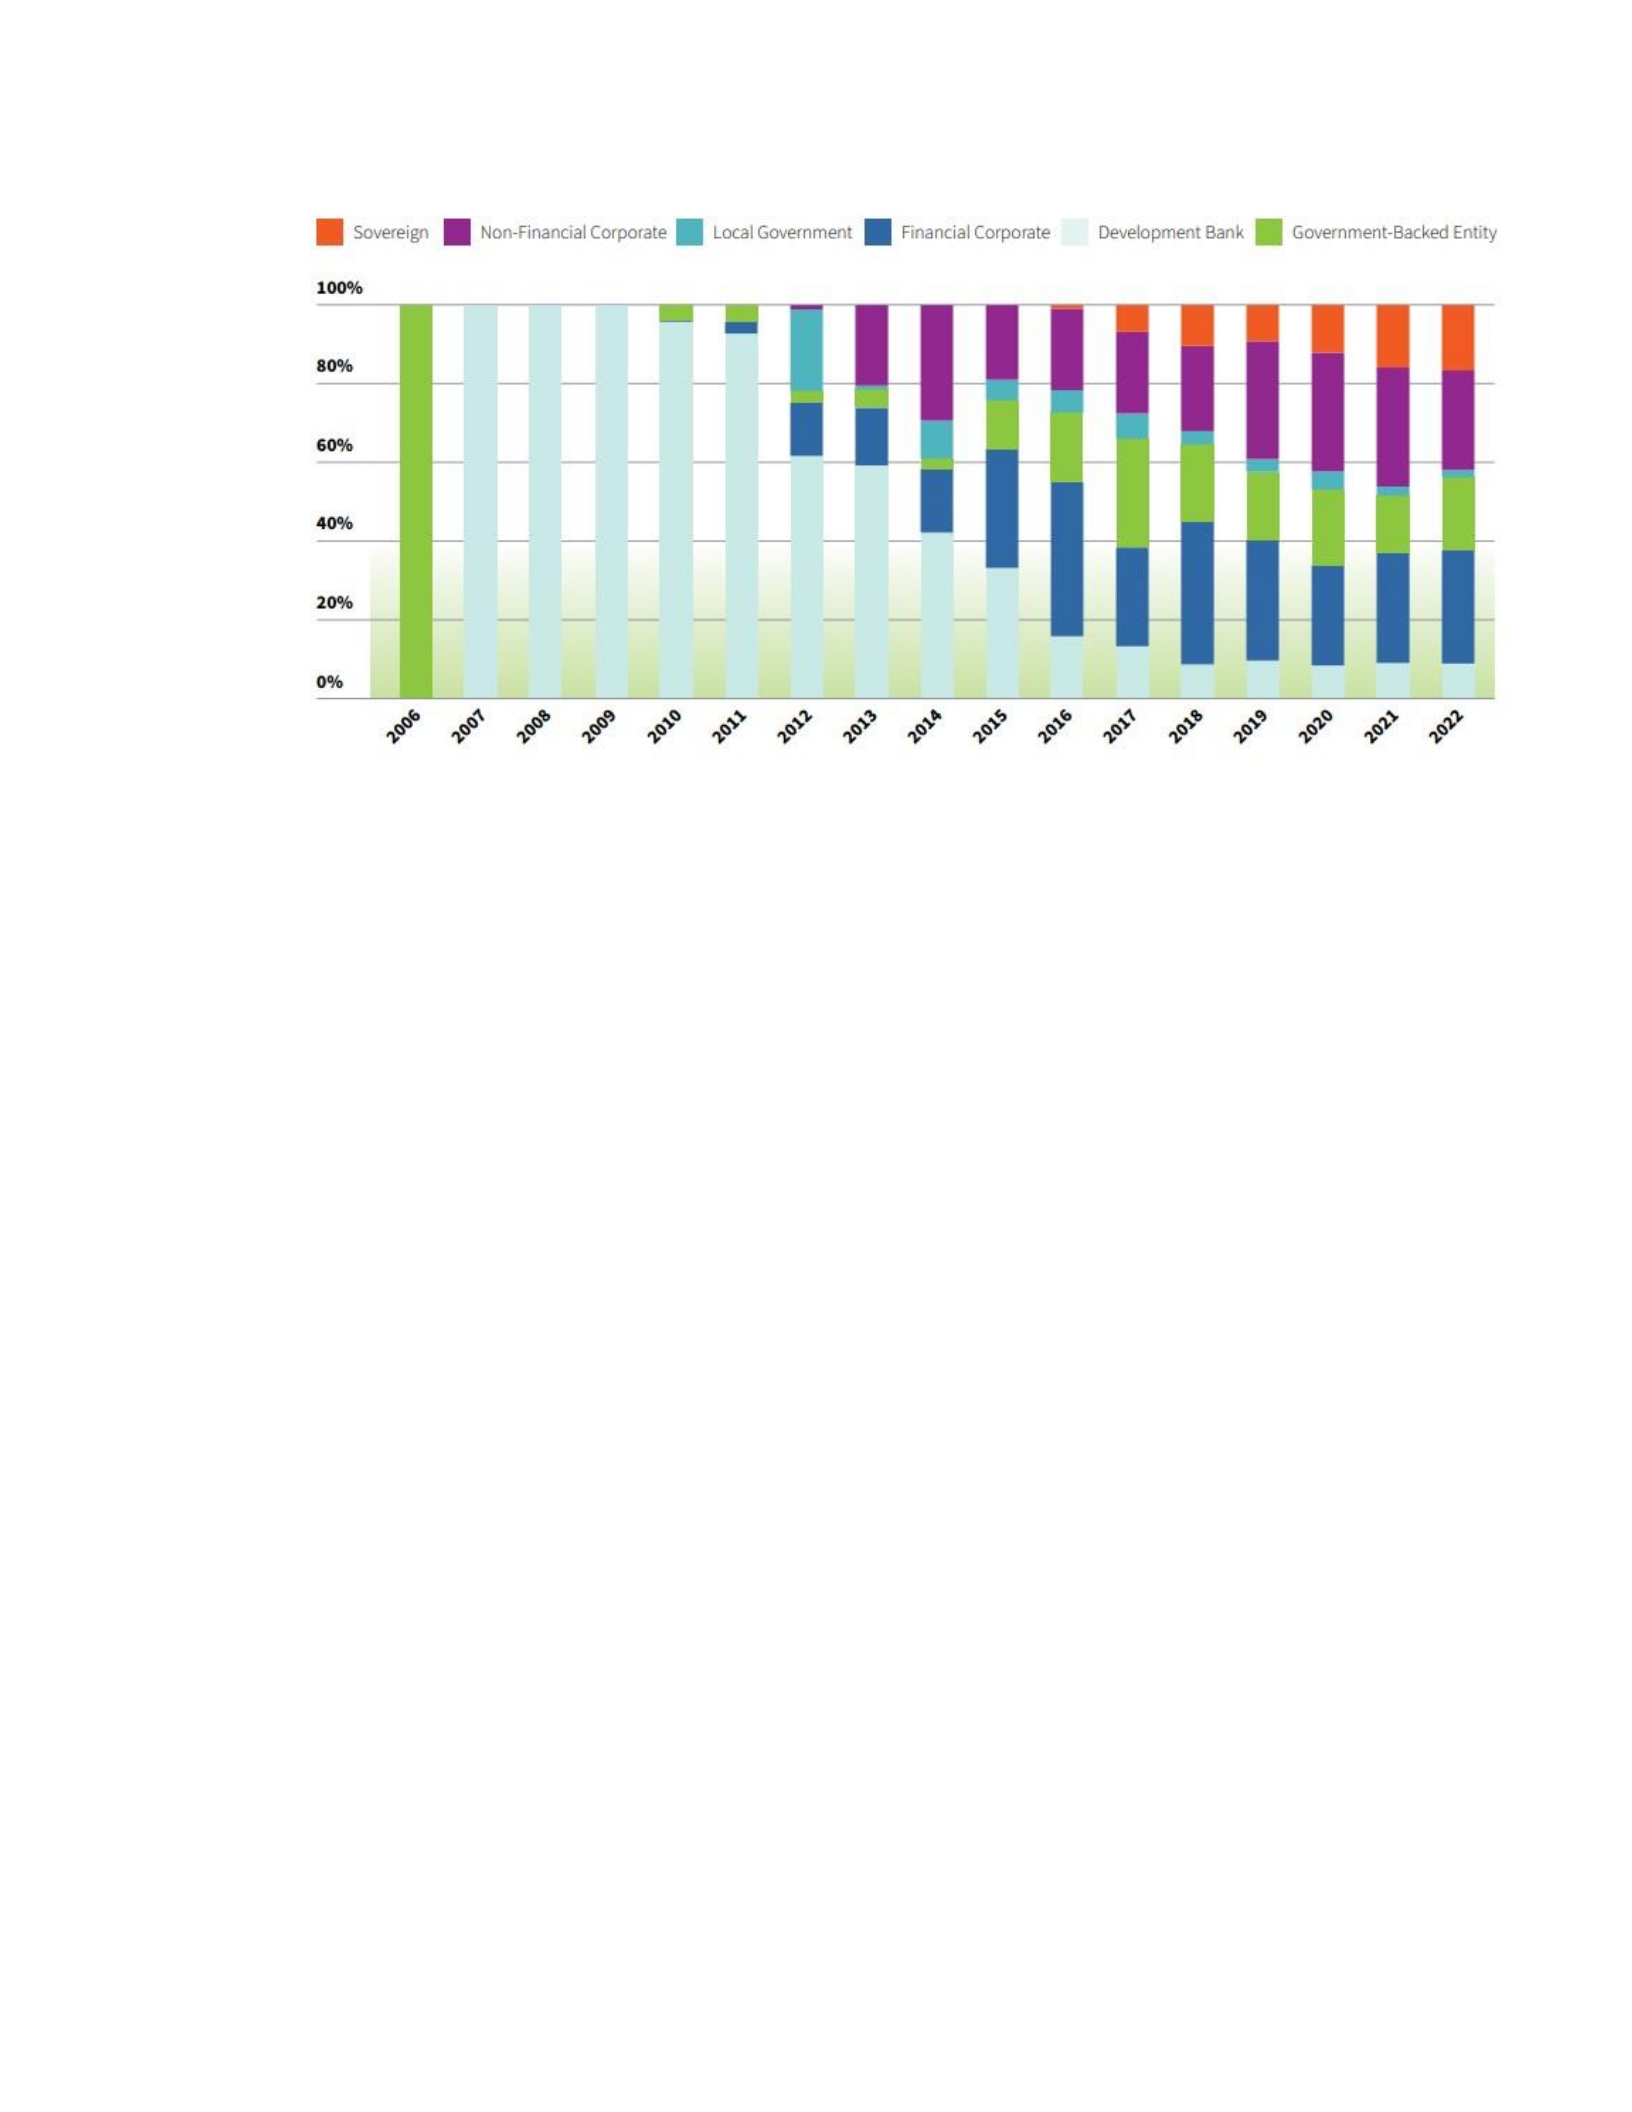
According to the latest report by the CBI (2023), the private sector issuers continued to
dominate the market and comprised 54% of total issuances. Financial corporations made the largest
contribution with 29% of volumes, while 25% originated from non-financial corporations. Only
about 19% are issued by government-backed entities.
Figure Three: Issuance Volumes Per Issuers (2015 - 2022).
`
Author: CBI - SUSTAINABLE DEBT GLOBAL STATE OF THE MARKET 2022 (2023)
The same trend occurred in the emerging markets, where financial and non-financial
institutions comprise 73% of total issuances based on the latest analysis conducted by the CBI
(2023). This indicates the importance of the private sector as a key player in the green bonds market
in the emerging economies and also poses the question of the role of private sector issuances in the
domestic market.
This section gave an overall idea about the main concepts behind the green bonds, with an
indication of the tools’ history and a glimpse at the latest international market trends.
Nevertheless, the following section discusses the conceptual framework of the study and draws the
line between the status of the green bond market and the associated challenges that face this market.
2.5. Why Focusing on green Bonds on the local context?
While the climate finance landscape is undeniably diverse, encompassing various bond
types like social, sustainability, sustainability-linked, and transition bonds, it's evident that green
bonds remain the prevailing force in the global financing universe. According to the Climate Bonds

`
Initiative's recent report (2023), green bonds maintain a remarkable stronghold, constituting a
substantial 58% of the overall issuance volumes on a global scale. This steadfast prominence
underscores their pivotal role in channeling funds towards environmentally impactful projects.
It's important to highlight that on a local level, the regulatory landscape of the green bonds
has undergone a transformative journey. The emergence of the regulatory framework for green
bonds in 2019 marked a significant stride forward, acknowledging these bonds as a potent
instrument within the realm of debt finance. However, the tides of progress surged even higher
towards the end of 2022. The Financial Regulatory Authority (FRA) catalyzed a remarkable
transformation by enacting Decree No. 3456 of 2022. This forward-looking decree wielded the
power to reshape the climate finance landscape by expanding its horizons to encompass a
comprehensive array of climate finance-related bonds. These new entrants, including sustainability
bonds, sustainability-linked bonds, social bonds, women empowerment bonds, climate bonds, and
even transition bonds (also known as brown bonds), have been ushered into the fold. However, it's
noteworthy to acknowledge that despite these exciting developments, the Egyptian market has yet
to witness the issuance of these newly introduced climate finance instruments. In this dynamic
landscape, green bonds not only maintain their status as the dominant player but also underscore
the complex nature of market adoption. Their longevity and efficacy as a tried-and-true mechanism
for climate-related financing are a testament to their relevance and reliability.

`
3. Chapter Three: Conceptual Framework
The conceptual framework section in this thesis focuses on exploring the challenges related to
green bonds in the context of Egypt and visualizing the relations between the dependent and
independent variables. This section aims to identify the specific challenges that face issuers,
investors, and policymakers in indorsing and adopting green bonds as an effective tool for
sustainable finance in Egypt.
However, it may be of a critical important to identify what are the bonds as a financial tool and
their types, issuers and how they differ from other equity financial tools such as shares. Bonds are
identified as debt instruments utilized by entities seeking financial resources to fund their diverse
needs associated with their core activities, or to finance a specific operation. Consequently, bonds
represent debt certificates issued by the entity, through which it commits to fully repay the bond's
nominal value to the bondholders after a specified period, along with regular payments such as the
accruing coupons (yield) due on the bond during a defined time frame. They also constitute tradable
or redeemable financial instruments, subject to early redemption or any bond-specific optional
provisions. These bonds can carry either a fixed or variable yield and may be convertible into
shares according to the terms specified in the prospectus or offering memorandum, in alignment
with the legislative regulations governing such bonds (FRA, 2021). Bonds Can be issued by states
/ governments, supernational institutions which are ranked below states including European
Investment Bank, European Financial Stability Facility etc., and finally enterprises and
corporations (Quintet Luxembourg Private Bank, 2020)
The main types of bonds are:
- Fixed rate bonds: The entity issuing a fixed-rate bond will compensate the
holder consistently at an unchanging rate that is predetermined upon

`
issuance, continuing until the bond reaches maturity. Upon maturity, the
issuer will repay the bondholder the borrowed principal amount.
- Variable (or floating) rate bonds: In contrast to fixed-rate bonds, the coupon
for these bonds fluctuates based on the benchmark rate, which could be the
inflation rate, the money market rate, or the bond rate. Similarly, the
borrowed principal amount is also repaid upon reaching maturity.
- Zero coupon bonds: This type of bond does not provide interest payments
throughout its lifespan. Instead, the initial issuance price is notably lower
than the redemption price upon maturity, which includes the accrued
interest.
However, the conceptual framework encompasses various interconnected factors that influence
the development and growth of this market. These factors revolve around three main variables:
● corporate bonds issuance volume
● the regulatory framework
● the general challenges facing the bond market as a whole.
● the green bonds' specific challenges attributed only to the green bonds in the market.
All of these dimensions include one or more variables that create the conceptual framework of
this research.
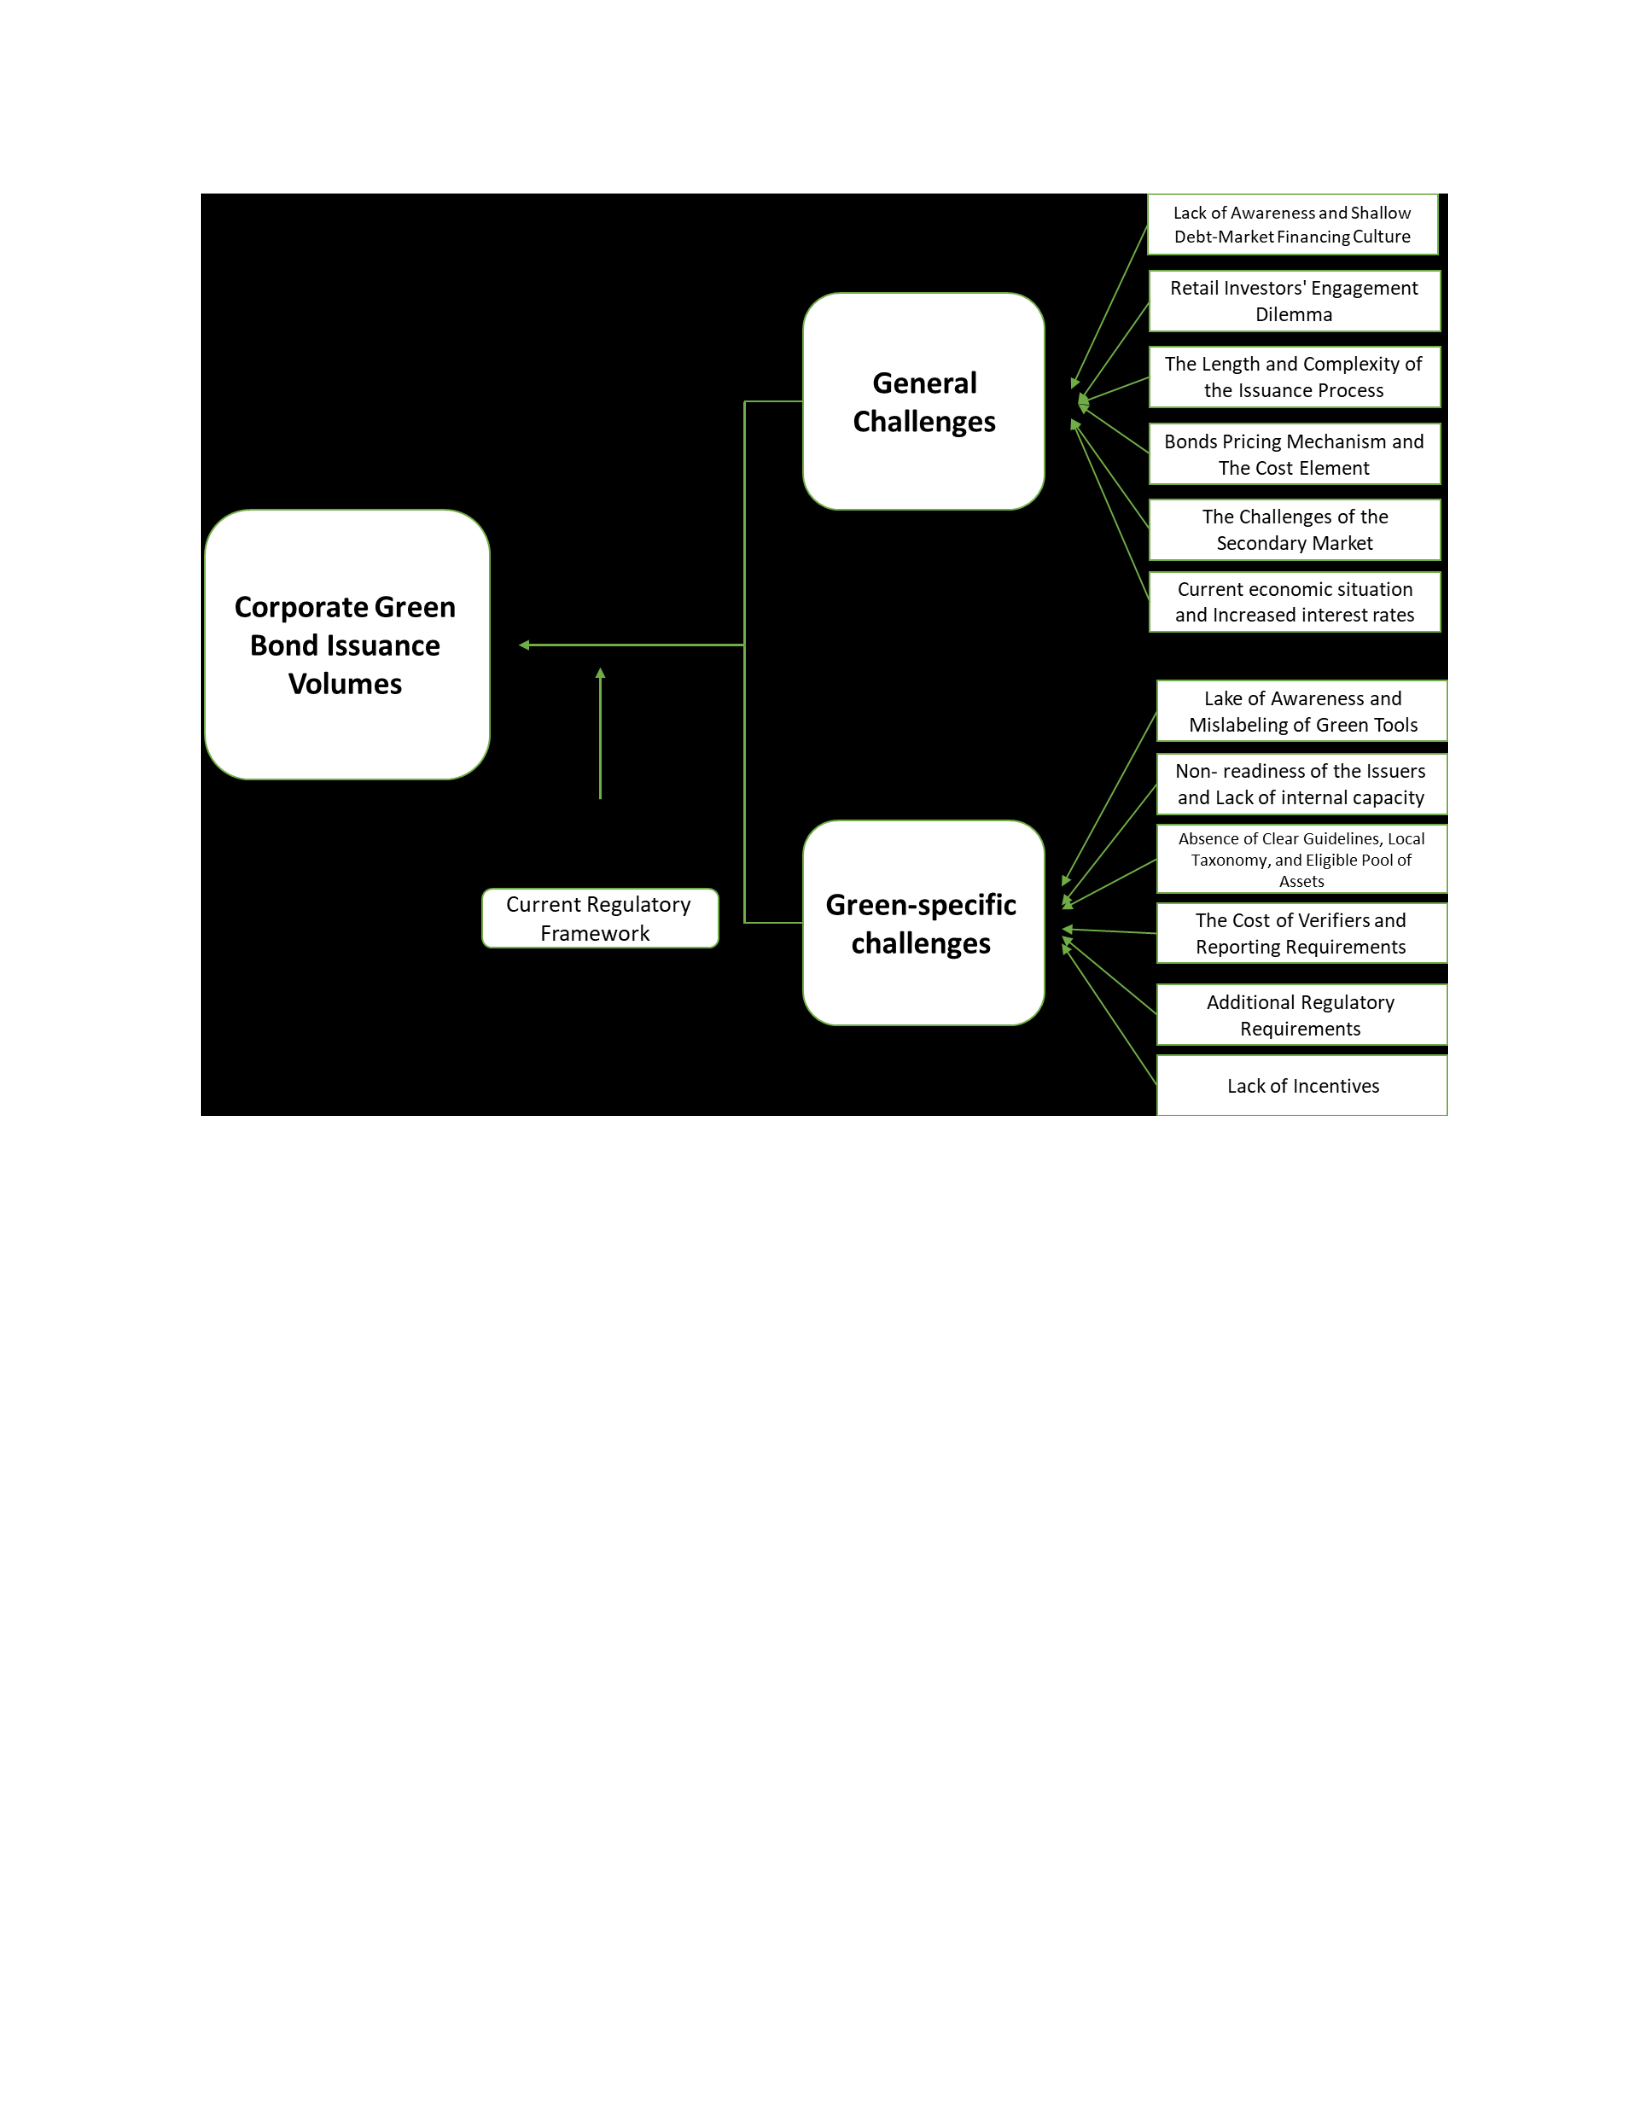
The following graph shows the underlined variables and the relationship between them.
Figure Four: Conceptual Framework Figure.
`
Source: The Author – Based on the literature review and the study field findings.
1. Corporate Green Bond Issuance Volume: This is the dependent variable of the study as the
primary research question tries to identify what factors and challenges contribute
significantly to the low volume of green bonds. This variable discusses the volumes of
corporate green bond issuance in the Egyptian market.
2. The regulatory framework: This dimension is perceived to be a moderating variable for the
study as it has a significant impact on both the dependent and independent variables. The
regulatory framework is a foundational and cornerstone element of the green bond market.

`
2.1 Corporate Green Bonds National Regulatory Framework in Egypt: As a
moderating variable that significantly impacts both the dependent and independent
variables, the green bonds issuance falls under the regulatory landscape of the Financial
Regulatory Authority (FRA). However, the regulatory framework and all the related
decrees that govern corporate green bonds are summarized as follows:
a. The FRA has established regulations recognizing green bonds and sukuk as debt
financial tools in the Egyptian market. The Capital Market Executive Regulation
was amended in 2018 through Prime Minister Decision No. 2479 of 2018,
providing the legal framework for issuing green instruments. According to Article
35 bis 3 of the executive regulations, green bonds are considered a type of bond,
and their proceeds are allocated to financing and refinancing environmentally
friendly projects.
b. To ensure the credibility of green projects, the FRA introduced Board Decree No.
113 of 2019, which lists international third-party verifiers authorized to verify green
projects in the Egyptian market. This initial list includes 11 globally recognized and
prominent institutions, with the possibility of adding additional institutions upon
the approval of the FRA.
c. Furthermore, FRA Board Decree No. 127 of 2019 establishes registration
requirements for local third-party verifiers in the FRA's registry. This decree aims
to develop the local market and create a list of efficient verifiers to support green
bond issuance with lower costs.
d. FRA Board Decree No. 141 of 2019 exempts green bond issuers from 50% of the
total cost of FRA's inspection services to incentivize the local green bond market.

`
e. In 2022, and based on the FRA drafts, Prime Minister Decree No. 3456/2022
introduced amendments to the executive regulation of the capital market law. These
amendments include introducing six new financial instruments: Sociallinked
Bonds, Sustainable Development Bonds, Sustainable Development-linked bonds,
Climate Bonds, Women's Empowerment Bonds and Transition Bonds (Brown
Bonds). The proceeds from these instruments are designated for financing and
refinancing sustainable development, social causes, women's empowerment, eco-
friendly projects, and transition projects.
These decrees construct the legal and regulatory landscape for corporate green bonds in the
Egyptian context.
3. The general challenges are considered the first independent variable that incorporates a set
of sub-variables, each affecting the corporate green bond issuance volume. These variables
include:
1. Lack of Awareness and Shallow Debt-Market Financing Culture: This discusses the impact
of the level of awareness among market participants on the bonds’ issuance in the domestic
market.
2. Retail Investors' Engagement Dilemma: This variable indicates the importance of the
diversified investors' base and the engagement of the retail investors in the debt market and
its relationship with corporate bonds issuances.
3. The Length and Complexity of the Issuance Process: This variable demonstrates the impact
that the duration and the level of complexity of the issuance process have on the issuers'
decision to issue corporate bonds.

`
4. The Challenges of the Secondary Market: This variable explains the challenges on the
secondary market in relation to bonds trading and the associated impact on bond issuance.
5. The current economic situation and increased interest rates: This variable discusses the
macroeconomic indicator's impact on the debt market, specifically the corporate bond
market.
4. The Green-specific Challenges: This is the second independent variable that embraces the
second set of sub-variables that directly impact the corporate green bond issuance volume.
These following variables are a green-specific set of challenges that exist only due to the
additional requirements of the green bonds. These underlined variables include:
1. Lake of Awareness and Mislabeling of Green Tools: This variable discusses the
impact of the low level of green bonds’-related awareness for and its impact on the
green bond issuance in the domestic bond. Furthermore, it illustrates the associated
risk of mislabeling eligible projects and assets resulting from the lack of awareness.
2. The unpreparedness of the Issuers and Lack of internal capacity: This variable
expresses the impact of the level of readiness of the issuers and their previous
familiarity with the green investment mechanism and the ESG-related governance
and its impact on the green corporate bond issuances.
3. The Absence of Clear Guidelines, Local Taxonomy, and Eligible Pool of Assets:
This variable demonstrates the importance of the clear definition and the existence
of a local taxonomy on paving the way for green issuances, along with the
importance of creating a diversified pool of eligible green projects and assets that
fits the green bond financing criteria.

`
4. The Cost of Verifiers and Reporting Requirements: Discuss the cost element
associated with the rigorous reporting process required for green bond issuance.
5. Additional Regulatory Requirements: This variable discusses other regulatory
requirements that oblige the issuers it keeps the green bonds' proceeds in
subaccount and the impact of this regulation on the market from the issuers' point
of view.
6. Lack of Incentives: This final variable indicates the impact of the lack of intensive
bundles on green bonds issuance from the market perspective.
However, this conceptual framework provides a structured approach to understanding the
challenges facing the green bond market in Egypt by considering the interplay between the green
bond issuance volumes, regulatory framework, general challenges and green-specific challenges
from market participants' perspectives. It helps identify the key barriers and opportunities within
each dimension and their interconnections, guiding further research and analysis to develop
strategies for overcoming challenges and fostering the growth of Egypt's vibrant and sustainable
green bond market.
4. Chapter Four: Literature Review
The green bonds market has experienced exponential growth in recent years, with issuances
reaching 500 billion since its inception in 2007 (Kumar & Chaturvedi, 2020). This growth is
initially supported by investors’ demand for environmentally friendly investments and the
recognition of green bonds as an effective financing instrument that facilitates green transitions.

`
Thus, there has been a growing interest in understanding the impacts of green bonds from many
angles. The literature review section delves into the dynamic landscape of the green bond market.
This section critically examines a range of scholarly works, industry reports, international
institutions’ reports to provide a comprehensive understanding of the current state and future
prospects of the green bond market.
Accordingly, the literature review address four main themes including the association
between green bonds and economic expansion in order to understand the macro effect of the green
bonds’ issuances, the impact of corporate green bonds on the issuing corporations, green bonds
issuances determinants from both demand side, supply sides, and finally, the macroeconomic
factors, and finally barriers to green bonds market expansion from a global point of view.
4.1 Green Bond and Economic Growth:
Extensive research within the realm of sustainable finance and economics has illuminated
the potential for green bonds to wield a considerable and multi-faceted impact on the overall
economic growth of the countries that issue them. On the economic and investment levels,
countries that are recognized with their green bond issuance abundance are proven to experience
faster GDP growth than those with lower issuance levels (Kumar & Chaturvedi, 2020).
Additionally, green bonds can have a notable long-term economic and social impact (Lichtenberger
et al., 2022) by providing additional financing for sustainable development projects. Besides, green
bonds can help to reduce poverty and inequality, which are key drivers of long-term economic
growth Blanchard et al. (2017). Green bonds also serve as a portfolio stabilizer, contributing to
`
overall economic stability through reduced volatility and enhanced Sharpe ratios
1
. This
characteristic helps safeguard investors and portfolios against fluctuations in oil prices and the
business cycle. (Lichtenberger, 2022). Furthermore, the green bond offers an alternative avenue
for funding risk-free securities, replacing high-interest debt schemes that come with unpredictable
equity expenses. This positions green bonds as an appealing financing instrument that fosters the
expansion of sustainable growth (Maltais & Nykvist, 2019).
On the other hand, green bond issuances may significantly impact specific sectors of the
economy, which spells over on real economic growth of the countries issuing these bonds. The
energy and technology sectors have dragged the researchers' attention and comprised a sizable
portion of the studies connecting green bond issuances to economic growth through channeling
investments in those sectors. In the research undertaken by Karras et al. (2020), the researchers
confirmed the positive relationship between green bond issuances and a higher level of private
investment in the renewable energy sector, which led to a notable increase in the overall GDP
growth rate. Similarly, Pindyck & Rubinfeld (2012) argued that investments in clean technology
can increase productivity, leading to higher economic growth rates over time. Furthermore, green
bonds exert a notable influence on broader economic green growth, facilitating the funding and
oversight of environmental and growth-oriented dimensions, thereby aiding economies in
maintaining and expanding their growth through environmentally sustainable means, particularly
within the energy sector (Ning et al., 2021). Moreover, issuance of the green bond also is claimed
to hold a significant influence on the employment rate growth of the renewable energy sectors,
including wind power and solar generation (Zhang et al. 2019). Besides, it also has a noteworthy

`
effect on the issuing country's increased foreign direct investments (FDI) into specific sectors
related to green transition, including clean technology industries such as electric vehicles and smart
grids (Huang et al. 2018). These findings imply that green bonds can exert a substantial impact not
just on overall economic expansion but also on specific sectors within the economy.
On the national level, a recent study was conducted aiming to identify the impact of green
bonds on the Egyptian green economy and the quest to the transition to greener economy. The
study recognized set of indicators including the GDP per capita, employment rate, poverty level,
and inflation. The results showed a significant potential for the Egyptian economy to transform to
a greener economy with the acceleration in addition to the continuous rise in the volume of green
investments including green bonds. Furthermore, the study also may shed the light on one of the
reasons of the low level of green bonds issuances which is the external financing which hurts green
bonds and the Egyptian green economy (Mohamed, et al. 2023).
However, the forthcoming section of the literature will engage in a detailed exploration at
the firm level, delving into the intricate relationship between the corporate green bond issuance
and the associated outcomes that is realized due to this green issuance.
4.2 The Impact of Corporate Green Bonds on the Issuing Corporations
Private green bond issuance is becoming more and more present on the global scale and on
the regional scale as well. On the African level, many corporate green bonds issuances are being
issued by private institutions in the recent years and showed notable success. In Kenya, the first
corporate green bonds took place in 2019. The 40 million USD issuance was a Climate
Bond Certified and aimed to construct ecologically conscious 5000 student housing (Ngwenya &
Simetale, 2020). The issuance for very successful and indicated the potential of the private sector

`
to participate in the green transition in the African continent. Furthermore, both Nigeria and South
Africa also have a successful corporate green bond issuance and are (FSD Africa; Ngwenya &
Simetale, 2020). These corporate green bond issuances marks the significance of the private sector
engagement and its important in the green transition.
However, as studying the impact of the green bonds issuances on the issuing countries is
important, it is also significant to shed the light on the importance of the green bonds on the firm
levels and how it is impacting the overall issuing corporations on different scales. The corporate
green bonds may have a several impacts that may affect the issuer companies.
In her study of the corporate green bonds, Flammer (2018) highlighted the impact of the
corporate green bond issuance on the public corporations. The results of the study showed that
issuing corporate green bonds have multiple positive impacts including the improved
environmental performance of the issuer corporations post the issuance where the companies have
scored improved environmental rating on Thomson Reuters’ ASSET4 and also companies
decreased their CO2 emissions. Other realized benefits are related to ownership equity where issuer
companies experienced an increase in long term investors as well as green investors. The study
also draws a relationship between the green bond issuance and positive financial performance in
sectors where natural environment is material on the financial scale. However, the same researcher
expanded her study (Flammer, 2020) by adding the third-party accreditation as an additional factor
to the bonds issuance and showed that companies that release green bonds demonstrate superior
financial performance compared to their counterparts issuing non-green bonds. The same results
were also reported by Yeow & Ng (2021) examining corporate issuances from different sectors and
countries, where green bonds were also reported to improve the environmental performance of the

`
issuer corporations. The study also examined the association between green bond issuance and
financial performance where no significant association between both variables was stated. The
difference in results between Flammer (2018) and Yeow & Ng (2021) is that the first and the later
studies may be attributed to the different corporate issuer type (public Vs private) and the sectors
under the study.
Additionally, the announcement green bonds were recognized as being galvanizing factor
that resulted in better financial performance for the issuing companies, better stock prices,
profitability, and operational performance for the Chinese listed companies. Furthermore, the green
bonds issuance was also reported to have a positive effect on the innovation capacity and the
corporate social responsibility performance of the issuing companies (Zhou & Cui, 2019). Another
study by Khurram, et al. (2023) also focused on the Chines market also showed the same results
in terms of enhancing the corporate innovation. In addition, the study suggests a significant positive
relationship between corporate green bond issuance and perceived corporate value.
In conclusion, the collective analysis of the literature underscores the intricate relationship
between green bond issuance and the performance of issuing corporations. The studies reviewed
consistently highlight the potential positive outcomes that arise from green bonds issuance and the
whole corporate performance.
However, it is critically imperative to recognize the determinants of green bonds issuance
decision and the factors that stimulate this decision. Accordingly, the following section discusses
the green bonds issuance determinants from both the demand and the supply sides and throughout
the macroeconomic lens.

`
4.3 Green Bonds Issuance Determinants
Green bonds issuance determinants have been analyzed through different lenses in the
literature. The demand side, the supply side and other macro and institutional factors.
Understanding what influences green issuance size from both the demand and supply sides is vital
to encourage green bond issuances, especially corporate issuances.
4.3.1 Demand Side Analysis
Studying the demand side is vital in terms of understanding the green bond determinants
as well as the market dynamics to understand what incentivizes the market profoundly.
Pricing is a primary element that affects the green bonds investing decision, where different
scholars have identified it as a primary factor. However, mixed results have been reported on the
association between green bonds issuance and the pricing element. The HSBC report (2016) and
the Climate Bond initiative (2017) both examined the variance in yields during issuance between
conventional and green bonds through samples comprising 14 and 30 bonds, respectively. Both
studies showed no disparity in terms of premiums at issuance between these two types of bonds,
indicating that investors are not inclined to pay an extra amount to acquire a green bond. However,
the outcomes of the HSBC report further indicated a positive performance factor associated with
green bonds in comparison to conventional bonds, tighter pricing, and a higher ability to attract a
broader spectrum of investors. However, conventional and green bonds performed similarly in
average oversubscription and spread performance factors. The study also suggested that many
green bonds are underpriced at issuance, which may lead to tighter pricing in the future. The same
results were identified by Zeribab (2016), confirming the lack of significant green bond premium.
Conversely, Nanayakkara & Colombage (2019) discussed the pricing difference between
conventional bonds and green Bonds in capital markets globally and how these factors affect the

`
demand side. the findings indicated that green bonds are traded at a premium when compared to
conventional bonds within the same timeframe. Additionally, the outcomes underscored that a
distinct green label on the bonds acts as a catalyst for investors, encouraging them to secure funds
through green bonds. This approach not only aids investors in diversifying their investment returns
but also contributes to the overall appeal of green bonds as a sustainable financial instrument. This
suggests that investors are inclined to pay an additional amount to acquire green bonds, attributed
to the advantages associated with investments tied to green bonds. The same results were reported
by Ehlers & Packer (2017) regarding green bond pricing at negative premiums of 18 basis points
at issuance for green bonds between 2014 and 2017 across a selection of 21 Euro- and USD-
denominated bonds. Besides, the findings indicated that despite the observed premium, the
performance of green bonds in the secondary market aligns closely with that of other bonds when
currency risks are effectively hedged. Barclays (2015) demonstrated a negative premium of 17
basis points (bps) between March 2014 and August 2015 at the secondary market level.
Correspondingly, Bloomberg's report (2017) presented a negative premium of 25 bps for Euro-
denominated green bonds related to government entities.
In addition, other factors may affect the demand side. The sector and the green bond rating
are among the main factors affecting investors' investment decisions and result in higher pricing
of green bonds. Furthermore, the investor type also affects the pricing of the bonds, where
institutional investors are more concerned with environmental performance than individual
investors (Zeirbab, 2019). However, the results suggest that although investors can absorb a yield
slightly lower than the conventional curve at issuance, reconsidering pricing methods is still
needed. The data quality is the study's primary limitation, requiring additional research.

`
This section has illuminated the factors impacting the demand side, encompassing the green
bonds' pricing model, bond ratings, and investor types. The subsequent section, however, will dive
into the aspects influencing the supply side, thus offering a well-rounded perspective of the market
dynamics. This section showed the elements that are affecting the demand side, including the
pricing model of the green bonds, the rating of the bonds, and the type of investors. However, the
next section will discuss the factors affecting the demand side to provide a comprehensive view of
the market.
4.3.2 The Supply-side Analysis
Comprehending the development pattern of the green bond market facilitates a deeper
insight into the significance of the supply side and its pivotal role as a driving force within the
market. The green bonds market is mainly “supply-pushed than demand-pulled” type of market.
Though the investor’s increased demand for green bonds, yet the traded volume mostly resulted
from issuers' need to finance green projects (Barua & Chiesa, 2019). Thus, understanding the
dynamics of the green bond supply side is just as, if not more, crucial than understanding the
demand side (Kidney, 2012).
The supply side, measured by issuance volume, is mainly sensitive to many factors,
including coupon offered, bond and issuer rating, sector of the issuer, financial health, and
collateral availability. These factors are all positively associated with higher issuance volumes,
besides the merging market material effects where emerging markets that are globally oriented and
denominated in the EURO currency have a larger size which led by currency effects (Chiesa
& Barua, 2019). Additionally, the bond issuer’s attributes can exert a notable influence on the
premium associated with green bonds. Notably, green bonds issued by institutional issuers tend to

`
have greater liquidity and a negative premium in comparison to their conventional bond
counterparts. Conversely, green bonds originating from private issuers display a positive premium
and a narrower liquidity advantage, a discrepancy that can potentially be offset through the
implementation of green verification measures for the bonds (Bachelet et al., 2019).
In their study, Barua & Chiesa (2019) studied the supply side by studying both bonds’
issuers and market characteristics and their impact on bond issuance volume. Among all the bond-
related parameters', coupon rate (with adverse effects), security collaterals (positive effect), and
bond credit rating (positive effect) showed significance. On the issuer-related characteristics level,
growth rates measured by the revenue growth rate (positive effect) and the profitability of
the firm, measured by “the return on assets ROA” are the most significant.
Conversely, issuer rating has an adverse impact on both high and medium‐grade bonds, which the
financial independence can justify that highly rated issuers have. Regarding market-related
characteristics, bonds with higher credit ratings issued in emerging markets tend to exhibit a greater
issuance volume compared to those issued in non-emerging markets. The same results are proved
by Chiesaa & Baruab (2019). The difference between the two studies is that the first conducted a
year‐wise estimation analysis to profoundly understand the development and
enduring nature of the impacts across various time periods.
4.3.3 The Macroeconomic Factors
On the national scale, state-level macroeconomic factors also examined the green bond
issuance volume determinants. ESG index, Credit rating, inflation rate, population, and fiscal
balance play a significant role in influencing and contributing to an increased level of green bond
issuances (Dan & Tiron-Tudor, 2021). In addition, some institutional factors that directly affect the

`
macroeconomic factors have indirect positive effects on green issuances, which include the
openness of the capital account, quality of the regulatory framework, and the rule of law. Moreover,
the “National Determined Contributions NDCs” also profoundly influences the green bond
issuance volumes. Finally, capitalization of the stock market, the economy size, and the degree of
trade openness also drive green bond market growth and, therefore, the green bond market (Tolliver
et al., 2019).
Nevertheless, as understanding the market mechanism and the factors that affect the supply
and demand sides, along with the impact of the macroeconomic factor, is essential to perceive the
complete picture of the green bonds market determinants, as the full realization of the market
obstacles is also fundamental to comprehend this market.
4.4 Obstacles to the Expansion of the Green Bond Market
As a green-oriented financial instrument, green bonds endorse specific characteristics and
require certain imperatives that may be perceived by issuers as hindering elements and may hinder
numerous issuers from participating in this market, thereby intensifying supply shortages.
Reviewing the growing literature on green bonds showed four main barriers and risks associated
with green bonds that may hurdle the market's future expansion.
4.4.1 Green Bond Conformity and Standardization Barriers
Conformity barriers arise from the lack of universal conformity around the main
terminologies and definitions of green financial tools. The absence of a global agreement on what
is green serves as an investment blocker and opens the door for greenwashing phenomenon where
the lack of a consistent definition among investors regarding the concept and scope of green

`
investing represents a significant obstacle (Chiange, 2017; OECD, 2017; G20, 2016). The absence
of a standardized reference framework has led to the emergence of various guidelines and best
practices, each with distinct definitions, being issued by different stakeholders in the global market.
Moreover, different issuers are issuing their own tailored green bond frameworks with no unified
standards being followed, where developing their own methodology is recognized by issuers as the
most common and convenient approach (Deschryver & Mariz, 2019). On the investors level,
investors in green bonds suffer from the inconsistency of the certification system compared to the
vanilla bond's (conventional bonds) credit rating system. ESG ratings and scoring vary
significantly between different data providers. Each data provider uses a different unannounced
methodology that prevents investors from reconciling the differences between the different scoring
and rating systems. The work of Deschryver & Mariz (2019) stands out for its comprehensive
approach, which integrates in-depth literature review, thorough market data analysis, and
interviews with a diverse range of participants in the green bond market.
Furthermore, although the importance of reporting to the green bond structure, there are no
legally binding standards for disclosing how proceeds are used or reporting on the environmental
impact of green bond projects on a global basis. (Berensmann et al., 2018: Chiange, 2017). The
lack of an enforceable code makes the proceeds hard to track and increases the risk of
greenwashing, which remains a major concern for investors. Besides, the fragmentation and
fragility of the third-party verifiers and second-opinion providers, given the absence of precise
identification of the green concepts, also consider a critical challenge to the green bond market
(Chiang, 2017).
4.4.2 Integrity and Legal Risk Barriers:

`
The market of the green bond is basically based on the ability to offer a methodology by
which green transition can be financed, which requires a high level of market integrity and
credibility. The reputational and integrity risks arise primarily from the potential of greenwashing.
Greenwashing can take place when generated proceeds from green bonds are channeled into
channels that do not align with environmentally friendly objectives. This can be observed when
core business practices are deemed unsustainable, the utilization of proceeds lacks proper
monitoring and transparent reporting, and there is inadequate substantiation that the projects have
genuinely contributed to environmental enhancement. (Shishlov et al., 2016).
Furthermore, greenwashing is a phenomenon that has been gaining a global snowballing
attention over the past few decades. Jay Westervelt first introduced the concept in 1986 (Westervelt,
1986), and lately was defined as “the practice of making unsubstantiated or misleading claims
about the environmental benefits of a product, service, technology or company practice” (García
& Ballester, 2017). Since its inception, a growing number of literatures has discussed its
implications and associated risks especially investigating the legal and reputational risks as it can
have a destructive impact on the organizations’ reputation and leads to serious legal consequences
in the longer term once realized (Srivastava et al. 2019; Hahn et al. 2016).
Greenwashing can cause investors to be skeptical about a company’s actual commitment towards
sustainability (Köhler et al. 2016), which can undermine their efforts by creating confusion among
consumers about what constitutes genuine sustainability initiatives, thus making it difficult for
them to differentiate between true progress and false claims made by companies (Wilcox et al.
2018). However, Jansen et al. (2020) investigated how governmental interventions can mitigate
the greenwashing phenomenon through enhancing the existing regulatory frameworks can offer
greater protection against deceptive marketing practices against violators.

`
Legal risk is interconnected with integrity risk and presented by what's called "green
default", where issuers provide inadequate or deceptive information that is significant to investors'
choices to invest in green bonds. When an investor purchases green bonds that fail to meet their
environmentally sustainable criteria, this could potentially lead to a legal situation where the
customer is misled through the use of inaccurate information and may require a full payment of
the bonds by the issuers (Shishlov et al., 2016).
However, the lack of enforcement mechanisms towards green bond verification systems
that hold the issuers accountable for green bond framework application and provide guarantees for
investors leads to aggravating the asymmetric information and greenwashing risks. Thirdparty
verification systems can have an essential influence on enhancing green bond performance and
may result in a positive premium (Bachelet, et al. 2019).
4.4.3 Complexity Risk Barriers
On the opposite side, the complexity of the issuance process is a double-edged weapon.
While this process may ensure the integrity of the market, it is also considered a deterrent to the
market in the long run. Before the issuance, issuers need to get prepared by hiring expert teams in
“Environmental, social and governance issues”, developing a solid green bond framework that is
aligned with the GBP, obtaining a third-party verification / second opinion to analyze the ESG risks
associated with the issuer and their strategies to mitigate these risks, assess and endorse the
selection of projects and allocation of funds, and review the reporting procedures before and after
the issuance. All these processes have to be closely combined with a robust and comprehensive
sustainability and ESG profile of the issuer to achieve a successful green bond issuance

`
(Deschryver & Mariz, 2019). This complexity risks are aggravating the obstacles that green bonds
still face in the market.
4.4.4 Financial and Structural Barriers.
Improving green bonds' financial performance is claimed to support and enhance their
environmental impact and expand their effects. For green bonds to be effective in green transition,
it has to achieve additionality, which entails financing new projects that would be funded more
expensively otherwise (Jones et al., 2020). Thus, three elements have been identified for green
bonds to achieve additionality and avoid the acquisition of “repackaging” the conventional bonds
and still be able to financially compete with regular bonds. The first is lowering the cost of
borrowing for the issuers, which is a core issue that needs to be recognized (Chiang, 2017;
Shishlov et al., 2016). The green bonds are commonly perceived to come with elevated costs
resulting from additional external verification, underwriting, monitoring proceeds, and reporting
requirements, which add to the expense and administrative burden of issuing green bonds. These
additional costs are not reflected in the pricing processes by having price benefits but rather are
reflected in requiring additional interest rates in some markets for green bonds (Bachelet et al.,
2019) with mixed evidence of realizing green bonds premium (Chiang, 2017). This means that
issuers face elevated transactional costs and higher interest rates in return for ensuring green bonds'
integrity which may result in increased cost of capital, which hinders achieving the additionality
that green bonds aim to achieve (Jones et al., 2020). These factors may drive investment decisions
towards financing even climate-friendly projects with unlabeled bonds to avoid the associated
risks. However, lowering capital cost is tricky due to some existing contradictions between
attracting new investment, lowering interest rates, and safeguarding bond integrity, which may

`
increase the pricing of green bonds and prevent it from being as attractive as conventional bonds
(Jones et al., 2020). Nevertheless, in the absence of higher returns, as of the green bonds case,
investors' demand would be supported by higher bond liquidity that allows investors to buy and
sell the bond with no change in its price (Chen, 2020). Liquidity risk in some markets is tied to
small issuances that do not rise to attract institutional investors with a
“hold to maturity” mandate. The offering size needs to reach $ 250 - 500 million for green bonds
to be able to achieve acceptable liquidity in the US market (Chiang, 2017). If bonds are traded at
small volumes, liquidity risk persists and making it challenging to buy or sell them during favorable
market conditions. The restricted secondary markets for green bond trading, which reduce liquidity
for investors and complicate the selling process, are therefore recognized as a constraint on demand
and contribute to the perception of this issue (OECD, 2017). Finally, the lack of green bonds rating,
indices, listings, and the necessity of incorporating environmental risk into credit ratings and
fixed-income indices are among the most critical financial barriers.
Green credit rating can help investors to identify the effect of “Environmental, Social and
Governance (ESG)” on the issuers’ risk profile as well as help investors to identify bonds that meet
their investment criteria which may potentially result in higher demand for green bonds and
subsequently lower the associated financing expenses (OECD, 2017). Until recently, although the
existence of many ESG-based indices aims to capture many sustainability and climate
considerations, yet the penetration of green bonds and ESG indices into conventional portfolio
allocation remains insignificant (HLEGSF, 2018). In addition, the lack of reliable ESG data
prevents credit rating agencies from considering ESG elements in their analysis and blocks fixed-
income investors from integrating climate change in their investment strategies (Hurley, 2019).

`
4.5 Research Gap:
The literature review analyzed the four main themes that identify the importance of green
bonds on the macro level of the countries issuing these bonds, understanding the impact of the
green bonds on the issuing corporations, recognize the determinants of green bonds issuances from
both demand and supply sides and finally identify the challenges that face the market of the green
bond from a global angle. Given that the green bond is still a comparatively novel financial
instrument, additional research needs to be undertaken to further realize the real effect of green
bonds and the opportunities and risks associated with them.
However, by reviewing the literature on the local scale focusing on the corporate green
bond market, the research results identified limited academic studies that cover either the structure
or the obstacles that face the corporate green bond market in Egypt. This reveals a significant
gap in literature in the domestic level that discusses the Egyptian market in particular.
Accordingly, this research significantly contributes to the current literature that addresses “the
corporate green bond market” in the Egyptian context and adds to the current literature about the
conventional corporate bond by explaining the main obstacles that face this market. Furthermore,
the research can add to the literature on green bonds in relation to emerging economies where
similar challenges may also persist.

`
5 Chapter Five: Research Methodology & Design
5.1 Research Methodology
This research is based on qualitative analysis methodology (Marshall & Rossman, 2011).
This methodology is mainly needed when researchers aim to understand how a system works or
why it fails. Therefore, the research topic decided for this project depended on qualitative research
methodology. Qualitative methods were identified to be more suitable for examining the low level
of corporate green bond issuances phenomenon in Egypt due to the existence of only one corporate
issuance, especially given that the research scope aims to review the obstacles that face the market
expansion, which entails market experts’ engagement. The questions raised in this research demand
analysis that goes beyond numerical data as shown in the literature review, which uses both
methods to analyze the topic.
In-depth interviews were conducted with eleven relevant stakeholders, which involved
Egyptian and International key players in the financial sector in Egypt.
5.2 Research Design and Data Collection
5.2.1 In-depth interviews:
The information presented in this article is based on comprehensive interviews conducted using
semi-structured methods. These methods were employed to facilitate open and insightful
discussions with the interviewees, allowing them to share their perspectives and ideas. The
statements obtained from these interviews were carefully analyzed using coding and decoding
techniques to address the research inquiries. The semi-structured approach to questioning was
designed to avoid simple 'yes' or 'no' responses and instead encouraged participants to provide
detailed insights, covering various dimensions of the interview subject. The interviews were

`
conducted over the course of four months, from February to May 2023, with a total of eleven
interviewees. The sample choice was based on an experience-based selection approach rather than
random sampling due to the research need for policy-making and managerial-level regulators along
with market experts with a certain level of experience. Accordingly, the sample included bank
managers, underwriters, international institutions participants, regulators from the Financial
Regulatory Authority and the Egyptian Commission Exchange, and finally, the executive manager
of the Egyptian Institute of Directors (EIOD) training center. The main aim behind this endeavor
was to achieve a diversified database of interviewees allowing for the collection, analysis, and
comparison of the insights from as many related and affected layers as possible.
The interviewees from the non-banking financial sector included three underwriters with
managerial levels specialized in the debt market as well as an investment Bank board CEO. In
comparison, the participants from the banking sector include three sustainable finance department
heads and strategy managers. Furthermore, the interviewees' sample included the head of the
Egyptian Institute Of Director, one of the most prominent training centers in the financial sector to
gain insights into their organization's perspective and role in shaping and overseeing the debt
market, including green bond policies and issuances. The participants were a total of three
participants. Two participants were from the Financial Regulatory Authority, and two were from
the Egyptian Exchange. Finally, participants from international institutions included one
participant from the “European Bank for Reconstruction and Development
(EBRD)”, who has previous experience working for development banks, including International
Finance Corporation (IFC).
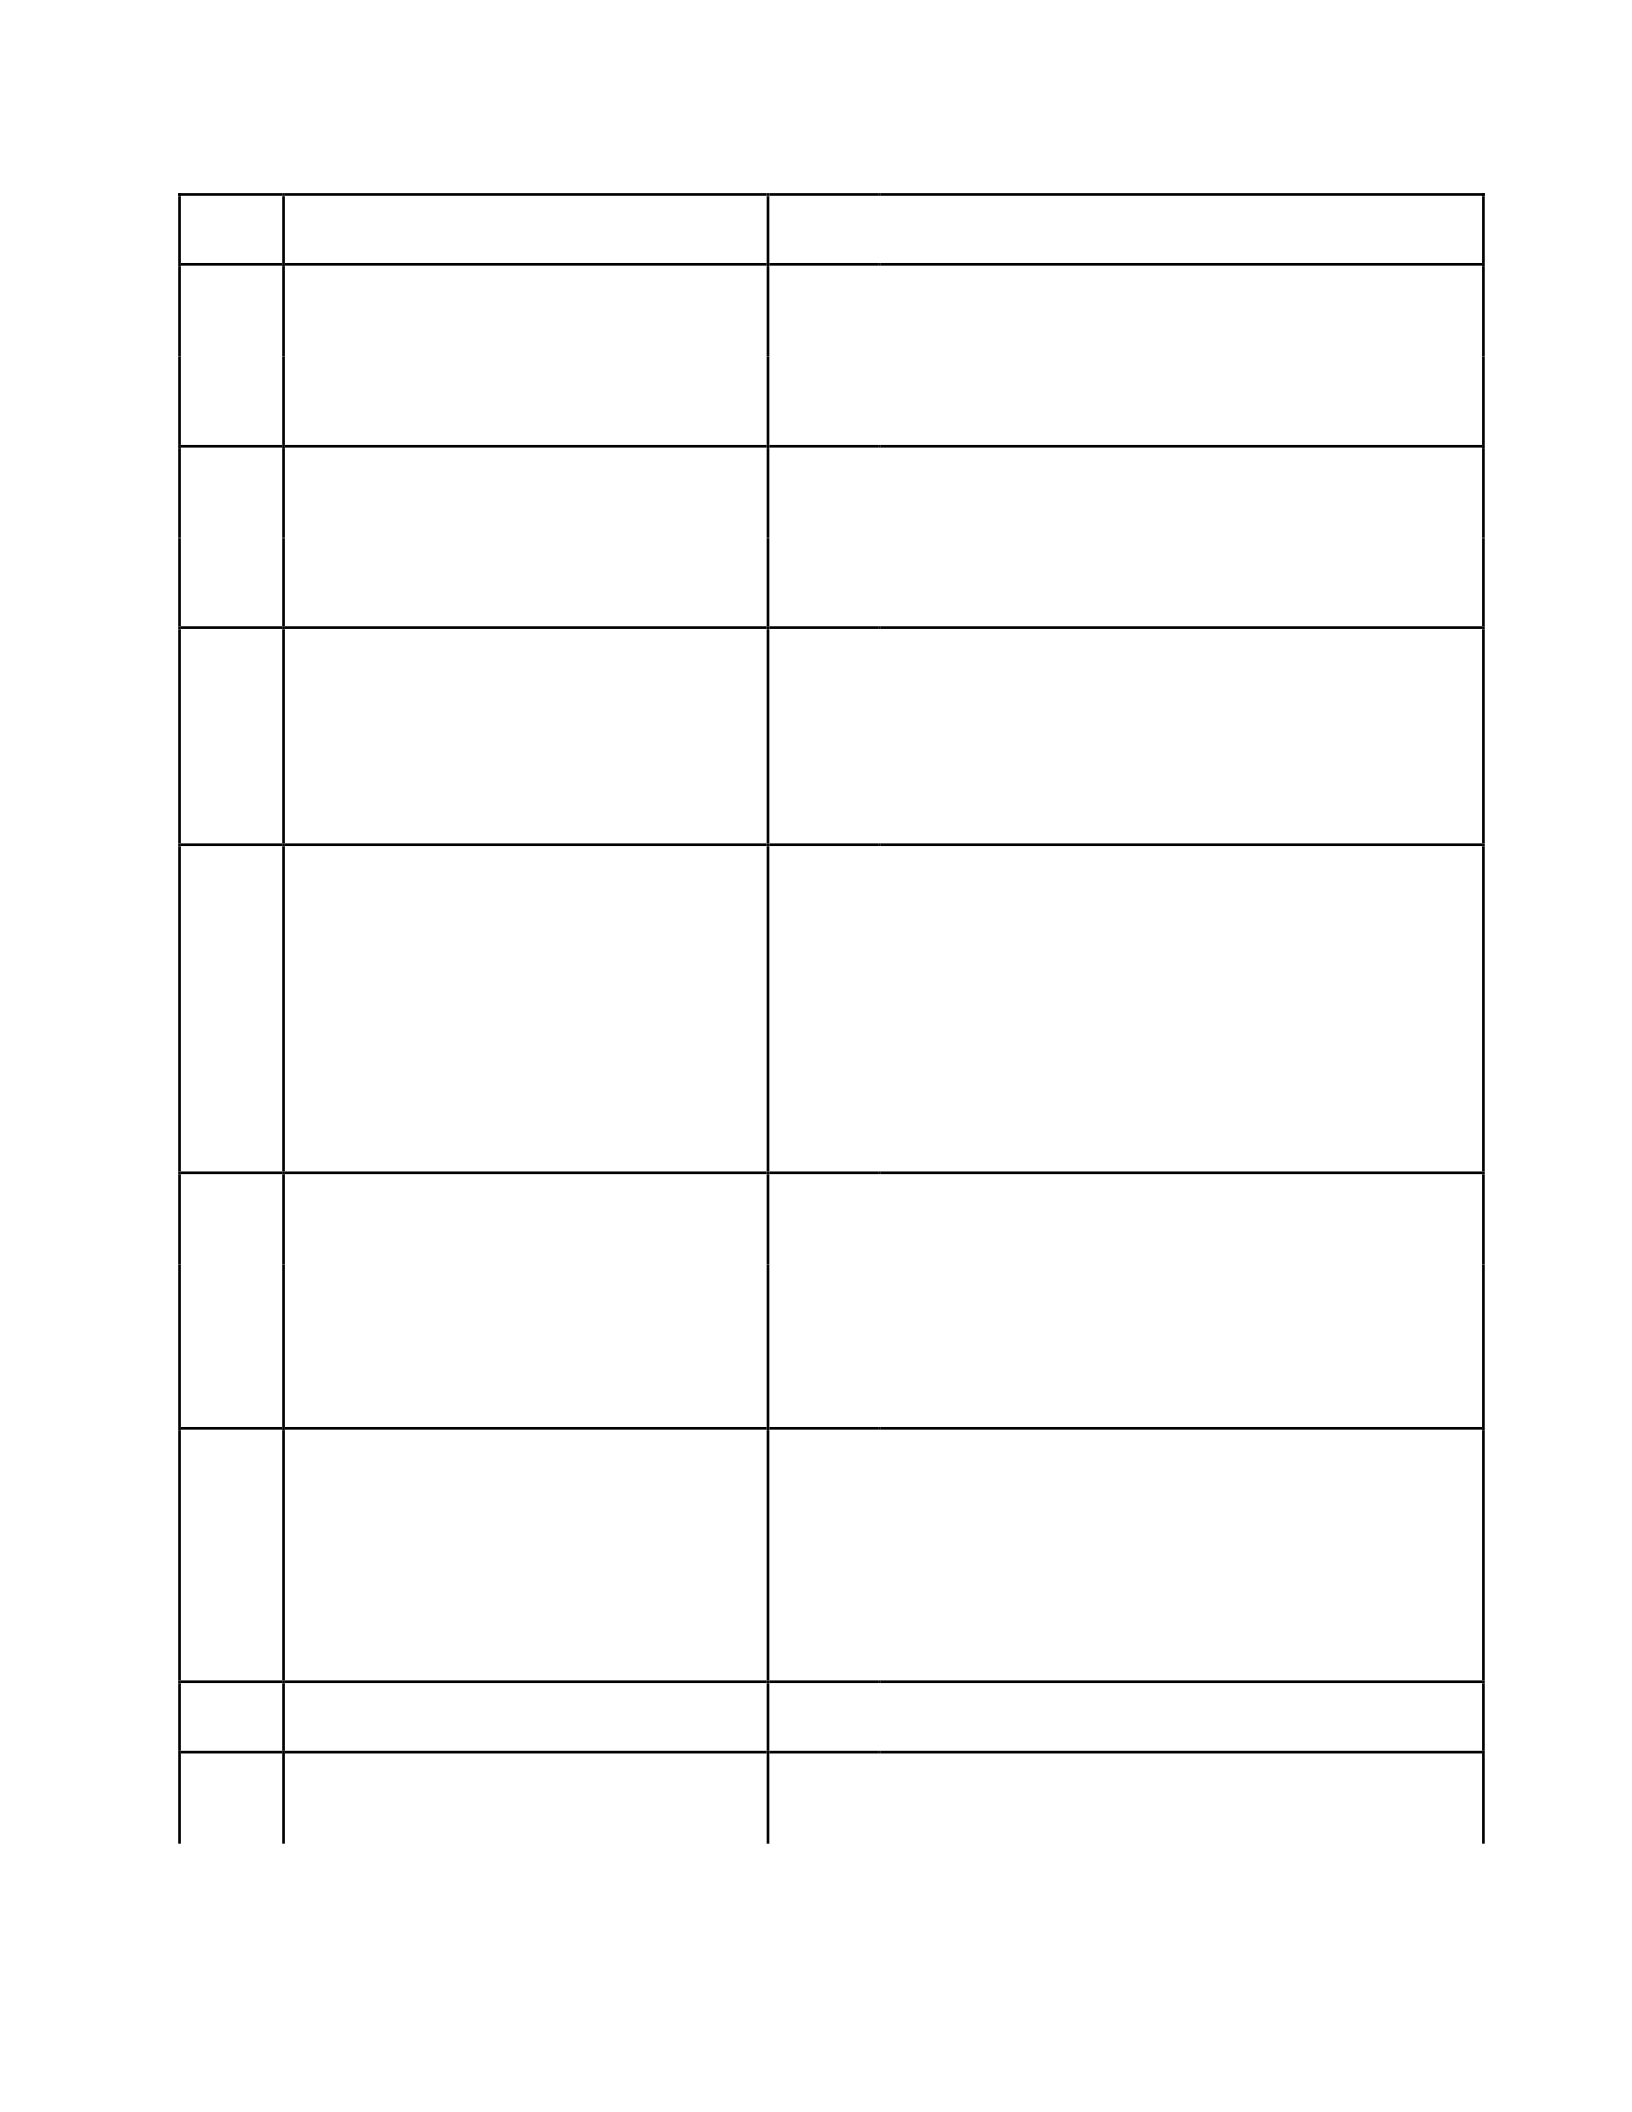
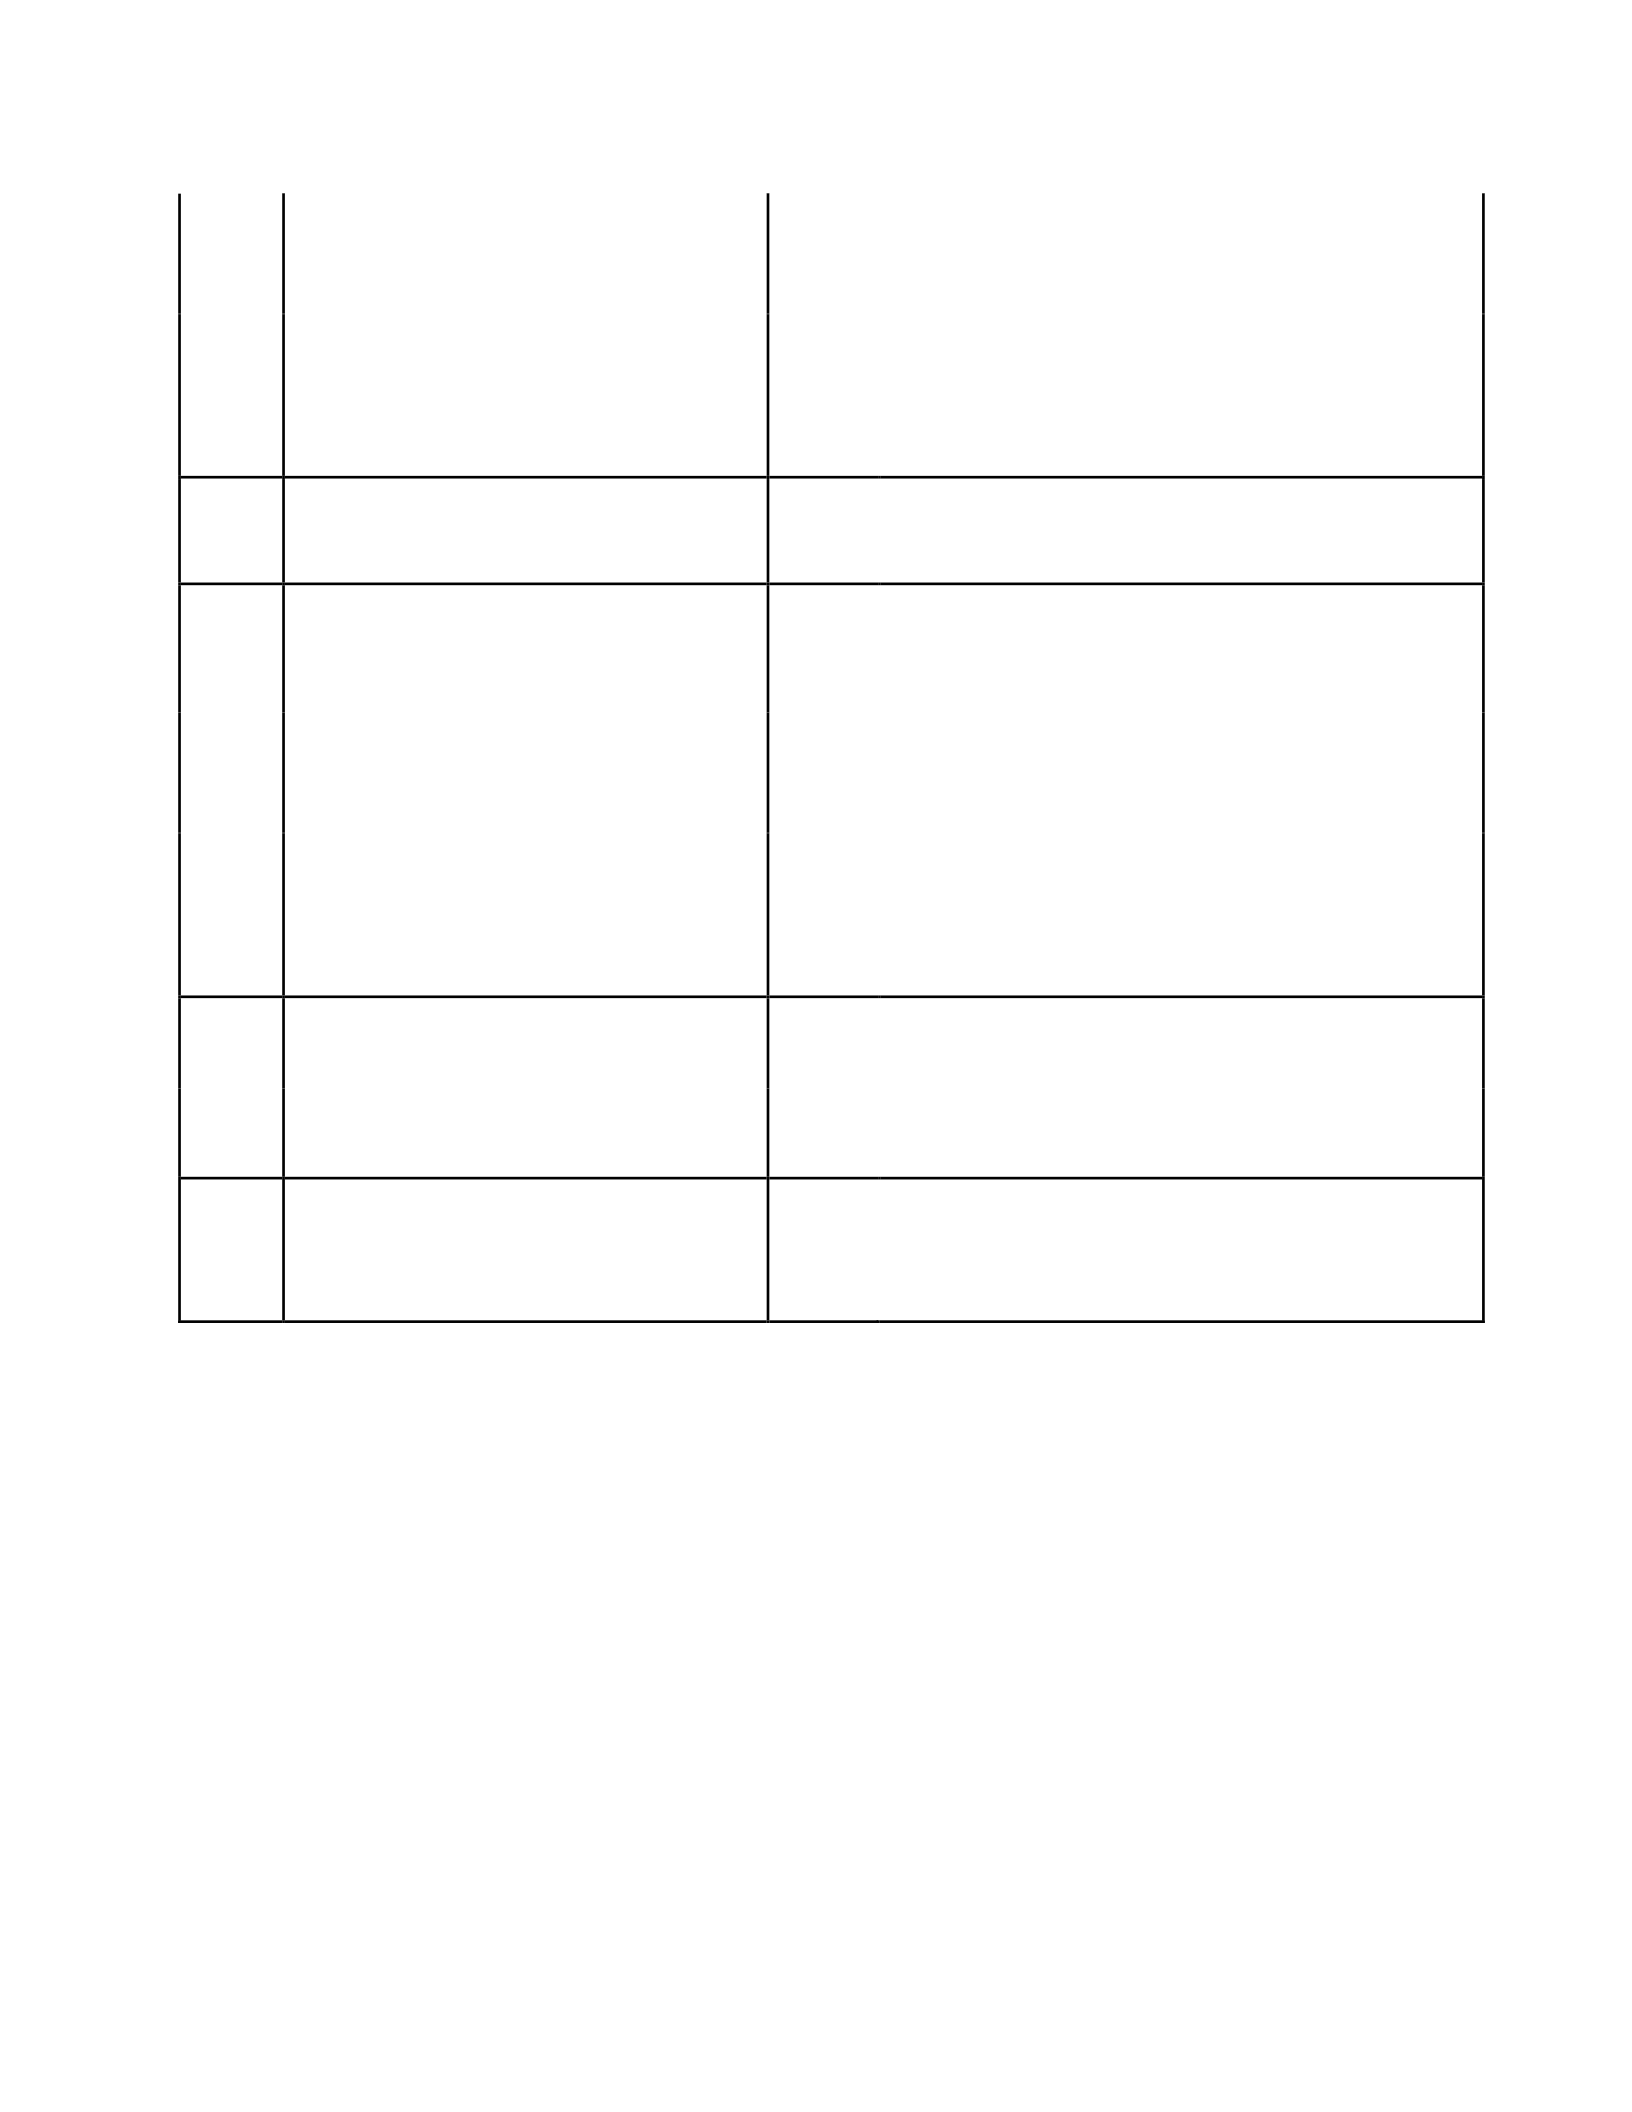
The following table demonstrates the interviewees' titles along with their main job descriptions:
Figure Five: Interviewees’ Titles and Job Descriptions
`
No.
Interviewee’s Title
Main Job Description
1.
Corporate Finance Head -
Regulatory Body
-
Monitor and supervise the capital market for
the non-banking financial sector.
-
Suggest and formulate related financial market
policies and regulatory
2.
Debt Market Head - Regulatory
Body
-
Supervise the debt market for the nonbanking
financial sector.
-
Monitor issuance processes of debt financial
tools.
3.
Sustainability Head - Regulatory
Body
-
-
Design all sustainability-related strategies.
Embeds sustainability imperatives within the
business model to manage its risks and
exposure to business impacts and
opportunities.
4.
CEO - Investment Bank
-
Provides guidance to the Executive Board
regarding matters related to investment
management and holds the responsibility of
offering thoroughly substantiated and
documented recommendations on the
comprehensive investment strategy of the
fund, as well as other facets of investment
management, to the Executive Board.
5.
Debt Capital Markets Head -
Investment Bank
-
Conduct an evaluation and assessment of the
debt capital market.
-
Take charge of initiating, designing, and
carrying out bond offerings, encompassing the
creation of materials, documentation, due
diligence, and the execution process.
6.
Debt Market Head - Investment
Bank
-
-
Examine and analyze the debt capital market.
Take on the role of initiating, designing, and
completing bond offerings, encompassing
tasks such as preparing materials,
documenting, conducting due diligence, and
managing the execution process.
7.
Sustainable finance Department
-
Executing strategies and procedures related to
Head - Bank
Environmental, Social, and
Governance aspects.
`
-
Creating tools for managing sustainable
finance risks and establishing frameworks for
ESG risks.
-
Ensuring the effective incorporation of ESG
data and tools throughout wealth and asset
management, insurance, banking, and capital
markets.
8.
Strategy Manager - Bank
-
developing long-term business strategies to
support growth and revenue.
9.
Sustainable finance Department -
Bank
-
Executing strategies and procedures related to
Environmental, Social, and
Governance aspects.
-
Creating tools for managing sustainable
finance risks and establishing frameworks for
ESG risks.
-
Ensuring the effective incorporation of ESG
data and tools throughout wealth and asset
management, insurance, banking, and capital
markets.
10.
Financial Institutions Manager -
International institution
-
Design programs to support the financial
markets in the Emerging Economies.
-
Cooperate with stakeholders to implement the
designed programs
11.
Executive Manager - financial
training center
-
Design and offer a wide set of training offered
for the financial sector institutions including
ESG training courses.
The interviews were designed to be predetermined and theme-based manner, where each
set of interview questions are individually tailored to optimize the desired outcome from each
participant’s particular sector. Each interviewee was allowed to express his/her full opinions and
perspectives. These interviews functioned as a primary data source to trace and respond to the
research question. The study also is data-driven and follows the grounded theory in building the
study structure and the presented outcomes (Glaser & Strauss, 1967). Furthermore, the data
collection and analysis processes systematically followed two main phases: interviews and content

`
analysis. Thus, the triangulation of that data ensured the validity and reliability of this research.
While interviewing the participants, identifying common themes, and analyzing literature are
considered to be the backbone of the research.
5.3 Research Timeframe
Egypt did not start to formulate the regulatory landscape of the corporate green bonds until
2019, when the Financial Regulatory Authority (FRA), in cooperation with the IFC, amended the
capital market executive regulations to recognize green bonds and green sukuk as financial tools
and to create the regulatory framework. Accordingly, the research time frame covers the period
since 2019 and incorporates the progress of the domestic policies represented by legislation and
ministerial decrees related to the capital market. Furthermore, the interviews were conducted
within a timeframe of four months. From February to May 2023.
5.4 Ethical Consideration:
Following the classification presented by Ghaniem (2023), this research process involved all
ethical considerations discussed in Babbie (2012).
1. Voluntary participation: The participants were explicitly made aware of the voluntary
character of their participation and had the full right to accept or reject the participation
without any related consequences.
2. Clarity and Transparency: The interviews were conducted in simple Egyptian-Arabic
language with some English expressions in accordance with the interviewee's choice to
ensure a high level of understanding.
3. Confidentiality: All participants signed the consent forms. In addition, before any
interviews took place, the interviewees were clearly informed that their interviews would

`
be recorded, and if rejected, the researcher settled for taking notes. The anonymity of the
participants' identities was prioritized unless otherwise approved by the participants both
verbally and via the consent form.
4. Causing No Harm: During the interviewees, it was fully committed not to cause any harm
to any of the participants. The researcher was keen to stop and withdraw from any particular
interview if the interviewee showed rejection at any stage.
5. Institutional Review Board: IRB approval on the research proposal and research question
was obtained before the study's inception to safeguard the rights of participants and to
ensure that the research adheres to the ethical standards set by the university and the
academic community.
5.5 Research Limitation:
The present study has key limitations that need be recognized. First of all, this study follows
a primary data collection methodology to obtain the needed information about the green bond
market in Egypt since secondary sources were not available owing to the singularity of corporate
green bond issuance took place the Egyptian market. While interviews provide valuable insights
from industry professionals, they represent a limited sample size and may not capture the
perspectives of all relevant stakeholders in the market. Therefore, the findings may not represent
the entire bond market perspective and should be interpreted cautiously. In addition, the study's
duration of four months for data collection may impose limitations on the comprehensiveness of
the collected data. Market dynamics and challenges can evolve over time, and a longer study
duration could have provided further inclusive comprehending of the challenges faced by the bond
market in Egypt.

`
Furthermore, the researcher has been a full-time employee of the financial regulatory
authority for four years as a sustainable finance specialist. These years of professional experience
added to the researcher's knowledge about the market limitation regarding the green bond in the
domestic market. Although all the ethical considerations to ensure the voluntary participation of
the interviewees were considered and unbiased content analysis was conducted, the interviewees
might have been affected by the professional background of the researcher.
Lastly, the limited available literature specifically focused on the corporate green bond
market in Egypt poses a limitation to this study. The absence of literature review that focuses on
the local status limits the ability to compare the findings to existing knowledge in the field. Future
research should aim to bridge this research gap by conducting a more extensive review of relevant
studies and reports to provide a stronger foundation for understanding the challenges of the
corporate green bond market in Egypt.
Overall, while this study offers insightful perspectives regarding the challenges facing the bond
market in Egypt, the limitations outlined above suggest the need for further research with larger
sample sizes, longer study durations, and a more comprehensive literature review on the local level
if available. These steps will significantly contribute to create a profound understanding of the
challenges and potential solutions for developing and enhancing the green bond markets in Egypt.
6 Chapter Six: Research Findings:
First and foremost, green bonds, same as any other bond, is a type of fixed-income financial
tool utilized to raise capital from investors within the debt capital market. Accordingly, what is
applied to conventional bonds is also applied to green bonds as green bonds are conventional
bonds, in essence, with additional requirements that ensure the use of the proceeds is allocated to

`
finance or refinance only green projects and with additional requirements to ensure the
transparency of reporting. Exploring the green bond market entails a profound comprehending of
the structures and unique features of the bond market in Egypt from a holistic point of view, as the
green bond market is severely affected by the debt market health as a whole. The data analysis
followed two main themes in discussing the research question to further understand and present a
reflective image of the market's current status. The first theme is the characteristics and obstacles
that face the bond market in Egypt in general, which affect the green bond market by association,
and the second theme discusses the obstacles that are greenspecific to the green bond market.
6.1 General Challenges and Observations:
6.1.1 General Observations -Fluctuated Growth Model:
The characteristics of the bonds’ growth model was one of the main highlights of the
analysis, where the historic and current status of the market are displayed to give a full picture of
the current market and the expected future trends.
A main observation of the Egyptian corporate bond market is the volatile performance,
where it has had a fluctuating growth model in the last two decades. Many ups and downs in terms
of issuance volumes, issuance models, and active trading were identified over the years.
Historically, the bond issuance model was diversified and embraced both public and private
placements. Many bond issuances were offered for public subscriptions, which allowed individuals
and retail investors to invest in the issued bond. However, in the last decade, corporate bond
issuances have been severely affected by the socioeconomic circumstances that took place during
this decade. The macroeconomic indicators’ volatility and the increased interest rates combined

`
with the unstable political scene resulted in investors being reluctant to use the fixed-income debt
market tools. However, since the inception of the comprehensive economic reforms in 2016, the
market started to show growth, and more issuers were eager to issue corporate bonds. The CEO of
one of the leading investment banks in the market explained:
“If we go back in time to 2010, we will find that the corporate bond market was very promising.
Where from 2011 to 2015, companies refrained from issuing corporate bonds due to the economic
and political situation. Starting from 2016 with the starting of the IMF program and the associated
economic growth, investors became more interested, and we received more requests from the clients
for corporate bonds, then, Covid-19 took place and again resulted in declining the bonds market
again.” (Interview, CEO, Investment Bank 1, March 2023)
The quote explains the historical growth patterns of the corporate bond market in the last
decade where it goes through a fluctuated growth model due to many market-related factors along
with macrolevel factors including the comprehensive economic reform and the emergence of
Covid-19 pandemic. However, the aftermath of the Covid-19 pandemic had an adverse impact and
led to slow the growth rate of the debt market and led the central bank of Egypt to heavily intervene
offering credit facilities initiatives, especially for the growing sectors. These interventions shifted
issuers’ attention towards the banking system as a primary source of funds.
An investment banks’ CEO in the market added:
“I am an investment consultant and all i care about is the best interest of my clients, so when the
central bank announced those initiatives, we advised our clients to prioritize it when applicable”
(Interview, CEO, Investment Bank 1, March 2023)
The quote explained how the Central Bank of Egypt credit facilitating initiatives during the
pandemic influenced the investment banks to direct the issuers to address the banking sector as a
main source of fund. However, the impact of these socioeconomic factors in the last decade and
`
the vast waves of uncertainty regarding the future of business and even humanity, caused by the
pandemic outbreak, affected the bond market and the willingness of issuers to issue bonds and
participated in creating the volatile theme of this market. Currently, although corporate bond is
witnessing a notable growth rate, the current market momentum and accelerated growth rate are
mainly derived by securitization
2
bonds issuances’ volume. Although corporate bond issuance
volume is expected to grow in the near future and flourish even more, securitization bonds are
expected to grow much faster in the upcoming years. This distinctive growth of the securitization
bonds and the comparison between the corporate bonds issuance and
securitizations issuances was highlighted by a regulator as follows:
“The main focus now is on the securitization field, which considers being a structured debt market
product recently. As for the corporate bond issuances, it is nearly three to four issuances per year
in comparison with 26 securitization issuances for the same period of time.” (Interview,
Corporate Finance Department Head, FRA, February 2023)
The expert shed light on the remarkable growth that the securitization market is
experiencing and show the differences between the growth of bond market to the securitization
market explaining that although the superiority of the securitization bond market. This booming
may be achieved due to many reasons, including the companies’ aspiration to support the
institution’s financial position and achieve higher liquidity via off-balance-sheet financing
among other factors.
However, the fluctuating growth model of the bond market poses questions about the
possible factors that may challenge the market growth and the obstacles that this market may be

`
facing. The following section will shed light on the main challenges that face this market from
market stakeholders’ viewpoints.
6.2 Corporate Bond General Obstacles:
The debt market, generally and the corporate bond specifically, is facing multidimensional
challenges. Some challenges are related to the issuance processes; others are related to the issuers
of the bonds, and others are related to the secondary market and trading. Additionally, other specific
challenges are tangled with the green element of the bonds posed in the case of green bond
issuances. However, the following challenges highlight the general challenges facing the whole
bond market with its conventional and green types.
6.2.1. Lack of Awareness and Shallow Debt-Market Financing Culture:
The lack of awareness was highlighted as a significant market setback in the local context,
which is wider than one stakeholder and extended to embrace almost all market players.
A key characteristic of the local bond market is that it is a "supply‐pushed market" where issuers
are the main drivers, and the demand is minimal. This dynamic means that issuers are the market
drivers, and investors play a minimal role in stimulating the issuance decisions. On the issuers'
scale, many of the market potential issuer companies are not very familiar with the debt market
financial tools, especially the corporate bond, and most issuers do not know its regulatory
framework and the associated incentive bundles that include the tax exemption for the listed
corporate bond, which significantly reduces the cost of issuance. This lack of knowledge from
companies turns their focus on the banking sector as a primary fund source and deprives their
institutions of a diversified credit portfolio.

`
On the investors' scale, the low level of awareness regarding the importance of the debt
market financial tools and the associated financial returns of the debt market financial tools creates
a sort of reluctance from investors to invest in tools unfamiliar to their best knowledge. The
investors do not know much about bonds and the advantages of being bond investors, which
deprive them of potentially higher returns investments and diversified investment portfolios.
However, the banks, both financial intermediaries and investors, are currently the primary bonds
investors due to the banks' extensive credit management experiences, which leads the corporate
bond market to be a "banks-dominant" sector. Nevertheless, other potential investors, including
both corporates and individuals, may not have the same experience, which keeps them away from
accessing the debt market. Accordingly, the lack of awareness is a critical factor that has an adverse
impact on the growth of the bond market. The impact of this factor on the market was elaborated
by investment bank’s CEO saying:
“One major factor is increasing the companies’ awareness about the capital market. Companies
need to shift to the capital market as an alternative finance for many reasons including a cheaper
finance, which will reduce their cost besides reasons related to the profitability as well. There are
many reasons why corporations should shift to the capital market as a financing channel, and it
should be well communicated to the companies. To be honest, the regulator is cooperating in
building the capacity of the market and enhancing the market participants’ awareness level in a
way that I have never witnessed from a regulator before. Yet, much more needs to be done in terms
of awareness spreading. The awareness exists in the banking sector because they are credit masters,
I will be honest, but other investors, including private insurance funds, pension funds and all other
players, are not credit experts, which deters them from being bond issuers” (Interview, CEO,
Investment Bank 1, March 2023)
The quote discussed the urgency of the companies to expand their knowledge about the
debt market along with other market participants show, the lack of knowledge from both issuers
and investors is a setback towards the more expanded market. Potential investors, whether

`
institutional or retail investors, are in great need of awareness regarding debt market investment
opportunities due to the many advantages that the debt market is able to offer. Even with the
regulatory initiatives, a lot needs to be done.
Furthermore, the lack of awareness may also be considered from another angle based on
the issuers’ geographic bases. Most of the bond issuances are issued by only Cairo and Alexandria-
located issuers. The corporations in other governorates in Egypt are even more poorly familiar with
the capital market mechanism and especially the debt market financial tools. There is a pressing
need for intensive awareness campaigns regarding the other finance channels, including debt
market financial tools, bonds and sukuk, that target other governorates. The geographical
distribution of the awareness campaign is also an essential element to be considered when
designing the awareness campaigns. These campaigns will increase and diversify the issuer’s pool
away from the traditional issuers. A debt market regulator in the FRA highlighted
the importance of such classification explaining:
“Geographical bases awareness is very important. We need awareness campaigns in the
governorates other than Cairo and Alexanderia where most of the issuers are located. Do you
remember how microfinance started when awareness campaigns from the regulator targeted the
governorates? We need to do the same for the bonds.” (Interview, Debt Market Manager, FRA,
March 2023)
The regulator emphasized the significance of geographical-based targeting in
capacitybuilding programs and cited the inception phase of the microfinance industry in Egypt as
an illustrative example. The interviewee highlighted the importance of replicating the
geographicalbased capacity-building model of microfinance, which is one of the fastest-growing
financial sectors, specifically regarding the design and implementation of awareness campaigns
for the whole debt market financial tools, especially corporate bonds. However, the lack of

`
awareness was not only limited to the issuers and investors but also largely relegated to the
brokerage firms as well. Most brokerage firms’ experience in the market is equity-tied and not
debt-related, where their experience in trading debt market financial tools is minimal. Brokerage
firms are critical market players, and being fully aware of the debt market's essentiality and
regulations is critically important to the debt market expansion and the diversification of its
investors’ pool. The CEO of a leading investment bank indicated that:
“Most of the brokers, no not most of them, let’s say 99.999% are only equity-experienced brokers,
not debt-experienced, which of course affects the bond market investments.” (Interview, CEO,
Investment Bank 1, March 2023)
The quote shows the unbalance of the brokerage firms’ knowledge base in regard to the
equity financing and debt financing which is mostly oriented towards the equity financing.
Accordingly, the brokerage firms’ lack of awareness is a timely and essential problem that
considered a market barrier. The disproportionate experience of both equity and debt markets and
the equity-related accumulated experience of the brokers directs a considerable portion of investors
away from investing in debt market tools, including corporate bonds, which resulted in a lower and
minimally diversified investors’ pool.
6.2.2. Retail Investors' Engagement Dilemma
The issuance model can have two forms, whether to be public or private placement. Private
placement involves a predetermined set of institutional investors that do not include retail
investors, whereas public placement is open to any investor to invest in the bonds. The type of
issuance model is significant to the market diversity and severely affects the level of investors'

`
engagement in the market. Public subscription resulted in the flourishing of the secondary bond
market and diversified the investor pool, which consequently positively impacted the secondary
market's activeness, but it entails a longer issuance process. However, recently, most of the
issuances in the market are privately subscribed where the investors are mature institutions with a
"buy-and-hold" mandate, which results in a sluggish secondary market for the bond issuances. The
secondary market is where the investors are trading the securities after the initial buying occurs in
the primary market. Accordingly, the institutional investors' "buy-and-hold" mandate severely
affects the secondary market activity. However, the current market is mainly private placement
oriented, with banks being the dominant player. It is worth mentioning that a healthy debt market
should have both issuances based on the issuers' business needs and not be dominated by a single
type of placement.
However, the minimal engagement and the slight presence of retail investors in the debt
market were interpreted differently across market participants based on their role in the market.
From financial institutions' and underwriters' perspectives, the bond market is a more "financial
institutions" oriented universe than retailer investors' universe for many reasons. Bonds are
highscale financial tools that are used to finance countries and other financial and non-financial
institutions. Thus, the engagement of retail investors in the local context exists through financial
institutions such as asset managers. The FRA’s corporate finance department head added the
following:
“All along, bonds are mainly financial institutions’ financial tool. Not in our market nor other
developed ones will you find a significant engagement of retail investors. This is due to the nature
of the bonds as a bulky financial tool used for large-scale finance, starting from financing countries
until we reach the financial institutions. Thus, it is not a retail investor-targeting tool.” (Interview,
Corporate Finance Department Head, FRA, March 2023)

`
The quote underlines the nature of the bond as a financial tool as a large-scale financing
tool used to finance different stakeholders, where the engagement of retail investors is not a
common practice in many well-developed and emerging markets across the globe. However, from
the issuer's point of view, retailer investors' engagement is applicable. However, it requires a public
placement issuance model, which entails a longer process and additional regulatory requirements
than that of a private placement issuance model, which is not favorable for most issuers. Thus,
adopting a private placement issuance model shortens the issuance time frame and results in fewer
regulatory requirements than a public placement. These insights were demonstrated by the debt
market manager in the FRA:
"The first problem is the private placement. In the last decade, the bond market was robust market
with multiple public placements taking place in the market. However, recently and starting from
2014, maybe, I cannot remember the exact dates, all the debt tools issuances, whether sukuk or
bonds, became private placement where the bond investors are institutions with strong financial
solvency profiles, including Banks as a primary investor, investment funds, insurance companies
etc. All these institutions will buy the bond and wait till the maturity date and do not actively trade
the securities. In contrast, when there was a public subscription with the engagement of retail
investors, they had a different mandate, and they tended to buy and sell and actively trade the bond
in the secondary market". (Interview, Debt Market Manager, FRA, March 2023)
The quote shed light on the historical bond issuance using the public placement model and
how the market moved to be a private placement dominant market with specific investors including
the banks as key players in the market. It also demonstrated how having a single model market
may negatively affect the market and results in eroding the investors’ base. However, the choice of
the financing model may comprise many factors including the length of the issuance and the
complexity of the process among other factors and given the length and uncertainty of the public
subscription issuance model, private subscriptions where institutional investors are pre-identified
themed better options for issuers The debt market manager in the FRA indicated:

`
"The issuers want the money as fast as possible; they want to avoid going through the lengthy
process of public issuance and the related regulatory requirements, including publication maturity
of at least two months and additional fifteen days’ time lag to start the issuance. This is almost two
months and a half to issue the bonds." (Interview, Debt Market Manager, FRA, March 2023).
The quote highlighted the priorities of the issuers and how the duration of the issuance is a
critical factor when choosing the issuance model by the investors. The public subscription requires
additional regulatory requirements that aim mainly to protect the retail investors that may not have
the required knowledge and needs more time to assess the investment decision and to rigorously
read the memorandum of information. Although the logic behind the additional regulatory
requirements for publicly subscribed issuance, the long process is perceived as a market barrier.
However, to avoid this barrier, the FRA tried to find a solution to engage the retail investor
by issuing board decree no. 57 of 2021 to allow at least 10% of the private subscriptions to retail
investors to underwrite with no threshold for underwriting. Although the importance of this
decision, no retail investors have invested in corporate bonds so far. The reason may be associated
with the delinquency and the lack of experience of the brokers to disseminate the knowledge to the
investors regarding the corporate bonds’ issuances and the investment opportunities of it or related
to the first challenge related to the low level of knowledge of the debt market tools specifically
corporate bonds. The brokerage firms have a substantial corporate client base, which they can use
to channel the investors' focus towards debt market financial tools, and thus, these firms are to play
a substantial role in the market. The debt market manager in the FRA explained:
“We tried to solve the retail investor issue by issuing a facilitating decree. We said fine, if the
problem is the lengthy process of the public subscription, then we will allow the issuers to issue
private subscriptions while allocating 10% at least for any investors to underwrite, including retail
investors, without the minimum requirement for underwriting Issuers will still have their shorter
issuance cycle, and we open for retail investors. Yet, no retail investors showed up! Why? Because
the brokers are lazy!” (Interview, Debt Market Manager, FRA, March 2023).

`
The quote underlined the regulator’s efforts to engagement retail investors throughout
issuing a decree that allow issuers to issue private issuance while being able to involve retail
investors simultaneously. However, the failure to communicate a complete data about the
investment opportunities throughout primarily debt market financial tools, primarily bond
investments, whether caused by laziness or unfamiliarity, is a significant market liability resulting
in an inefficient primary market. This combined with the lengthy process of public placements,
may lead many issuers to refrain from adopting this model and instead focus on private placement
issuances. Consequently, the market is deprived of a diversified pool of investors, and the retail
investors need to be more engaged in the process. Although regulators justify the lengthy nature
of the public subscription as a protection layer for non-experienced investors to have the time to
read the prospectus and to have financial consultancy if needed, market participants marked the
lengthy process of public subscription timeframe still to be considered as a market barrier.
However, the length and complexity of the issuance process are not limited only to public
placement expressly but also expanded to include private placement. Although having relatively
more relaxed regulations and issuance processes than public placement, it is still a complicated
process from the market perspective.
6.2.3. The Length and Complexity of the Issuance Process
The length of the issuance process for debt securities, in comparison with other sources of finance,
is identified as a significant market barrier that has a multidimensional effect. The required time
frame is too long and may cause significant harm to both issuers and investors, given that this tool's
nature depends on calculating the daily-accrued interest rates of the bond. Thus, any additional
delays may be of decisive impact. The reasons for the complexity and the delays may embrace

`
many factors, including the regulatory requirements and the credit rating agencies' related delays
as the fatal causes, among other factors.
Firstly, the regulatory requirements to issue bonds are fairly complicated for both the
public and private placement issuance models, although being more complicated for the public
subscription. Investors mostly need the fund as fast as possible, while the issuance process may
extend to six months or more for first-time issuers and at least two months for the regular issuer.
Those lengthy issuance processes delay the required funds, which may not be in the best interest
of the issuers, especially if the fund is urgently needed. However, it is worth mentioning that
although public subscriptions are available for any investors to invest in, whether institutions or
retailers involve more regulatory requirements and more time for the issuance to take place than
private placement, yet both were identified as lengthy. This was noted by a CEO of investment
bank operating in the Egyptian market:
“There was many project finance that might fit the bond and sukuk or bonds issuance requirements
and can be financed through bonds or sukuk perfectly, but companies refrained from issuing it due
to the length of the process, and companies needed the fund in a time frame that is shorter than the
issuance cycle timeframe, especially for a first-time issuer which may take about six month, and
this is too long.” (Interview, CEO, Investment Bank 1, March 2023)
The quote showed how the length of the process is resulting in shrinking the bond market
in Egypt and how it considers to be a critical and leading factor in financing decision. Bond issuers
require faster access to the funds that are offered by the bond issuance model. The same point was
raised and explained by another interviewee. A debt market manager in investment bank added:
“The most important element for companies is the time element. It is not logical to keep the company
waiting for three or four months to get the funds. In some cases, the issuer is willing to pay a
premium of 1 -2 % to get the fund fast” (Interview, Debt Market Manager 2, Investment Bank 2,
March 2023)

`
The interviewee demonstrated how the length of the funding process is a critical factor that
directs the issuer funding decision where a lengthy process may result in issuers being reluctant to
issue bonds even with financial preferences that offered by the bond if compared to other faster
funding channels. However, the second main challenge that results in expanding the issuance time
frame is the scarcity of credit rating agencies. This is another factor that contributes to increasing
the issuance process and distorting the market dynamics. The existence of only one credit rating
company, which significantly increases the processing time and causes additional delays to the
bond issuance process. Increasing the number of credit rating agencies will have multiple benefits,
including reducing any delays that may be caused due to lack of competition in the market. A debt
capital market of an investment bank indicated:
“For sure, having only one credit rating agency for the whole market slow down the issuance
process significantly due to the business rush, it causes significant additional delays.” (Interview,
Debt Capital Market Manager, Investment Bank 1, March 2023).
The quote shed light on the scarcity of the credit rating agencies and the impact on the local
market. The existence of only one active credit rating agency required to serve the whole market
efficiently was identified by many market participants as one factor adding significantly to the
length of the issuance process. However, in addition to the scarcity of credit rating agencies, the
methodology that credit rating agencies use and comparing all issuers to the top tier issuers in term
of firm size are considered to be limiting to the market and does not allow small issuers to grow
given the consistent comparison to the top performers in the market. A debt market manager in an
investment bank shared the following:
“Sometimes we have clients that are fairly new to a specific industry and have operated for only 3
to 4 years, and they are doing an excellent job and have good numbers, but they still have to be

`
compared to the industry’s top tier institution in terms of rating. Unfortunately, a crucial factor of
the issuers’ rating is based mainly on the size of the firms.” (Interview, Debt market manager,
Investment Bank 1, March 2023)
The quote showed how the regular credit rating methodology allows top-tier institutions to
remain market leaders. It does not give the other industry participant a chance to have a healthy
growth pattern by being compared to the top tier institutions which deprive these smaller
companies from obtaining a strong rating that opens the doors for more fund opportunities. Thus,
classifying the market firms and having firm size-related evaluation criteria may result in more
firms with different sizes being encouraged to issue more bonds.
However, the issuance process's length and complexity are tied closely to bond pricing,
where time is a critical factor in determining bond pricing.
6.2.4. Bonds Pricing Mechanism and The Cost Element:
However, the lengthy process not only affects the issuers in terms of delaying the required
fund, but it also has a noteworthy impact on the efficiency of the pricing model adopted by the
issuer, especially in the presence of unstable economic status and changing monetary policies. The
prolonged duration of the process can potentially result in fluctuations in the corridor interest rates
or lending pricing, which are key factors that issuers rely on when determining the bond yields,
they offer. Consequently, this extended timeframe between the issuance announcement and the
bond's actual offering can lead to inefficiencies in bond pricing. Ultimately, this can make the bond
yields less attractive for investors compared to the prevailing banking interest rates, resulting in
the failure of the issuance. A debt market manager in an investment bank explained:

`
“Pricing is very critical. Given the long period that it takes for the issuance to be launched and the
acceleration of the interest rates in the whole world as well as the local situation, the issuance may be
priceless when it is issued. It is extremely hard to be marketed because of distorted pricing and other tools
may be more financially viable for investors.” (Interview, Debt Capital Market Manager, Investment Bank
2, March 2023)
In this quote, the expert discusses how the long issuance duration and pricing are
interconnecting and how this duration may affect the pricing and result in adding additional risks
to the issuers. Given the changing monetary policies and the accelerated increase in the interest
rates as well as the associated uncertainties regarding the future of the businesses, the long process
of bond issuance can have more fatal financial consequences on the issuers in the recent times and
may lead to the failure of the issuance due to the non-appealing prices to the investors compared
to other investment opportunities once the issuance is launched. Furthermore, this long duration
results in channeling the focus of corporations to the banking system as the primary source of funds
and reducing the debt securities issuances volumes in general. A CEO of an investment bank
explained:
“Many large corporations were bond issuers before. But now, given the long process and the cost
of bond issuance, it is easier for corporations to get funds from the banks, especially corporations
with strong financial solvency. Say the corporation needs one billion, with all the regulations and
the costs related to the issuance of bonds, the issuer finds it easier to go to the bank to get the
finance.” (Interview, CEO, Investment Bank 1, March 2023)
The quote explained how the cost and time elements are crucial for the companies in
deciding the funding channel and how the banking system is offering a faster funding source which
affects the debt market in the local domain. Accordingly, facilitating the issuance of the bonds and
significantly reducing the issuance time frame can be a critical step in activating the debt market
and creating a substitute funding channel for corporations. However, in addition to the process

`
length, the cost element was also recognized by market participants as a key challenging factor to
be considered.
Costs of corporate bond issuance are divided to include many items, which include the
following as the main items. However, some of these costs can be avoided based on the issuance
model:
● Credit Rating for the issuance, which involves annual reporting cost.
● Stamp tax.
● Central depository and Clearing fees.
● Risk insurance fund fees ● EGX listing fees.
● FRA Inspection Fees.
● Brokerage, Auditing and Underwriters fees.
These are the required costs to issue the bonds and trade them in the secondary market. The
costs associated with bond issuance are high variable costs that are calculated based on the public
or private issuance model and based on the trading of bonds. A financial institution manager in the
EBRD added:
“To simplify the issuance process and mainstream it is the most important element, thus, any issuer
wants to issue bonds, one week should be enough time to kick the issue, not in 6 months which may
be extended to reach one year and without these costs as well!” (Interview, FIs Manager, EBRD,
April 2023).
The quote highlighted many challenges that face the bond market and underlined the
importance of shortening the issuance process along with decreasing the associated costs as a main
solution for supporting the bond market. However, besides the issuance model, costs also may be
variable based on the issuer type. The local market comprises two types of bonds based on the
issuers. Corporate bonds are issued by corporations, and treasury bonds, which governments issue.

`
Although being the same asset class, corporate and treasury bonds in the national context are not
on the same footing regarding trading and the associated costs in the secondary market.
The issuing cost of the corporate bonds is significantly higher than the issuing costs of the
sovereign bonds. The transactional cost is also significantly higher, which reduces the realized
accrued interests realized to the corporate bonds’ investors, and thus, results in corporate bonds
becoming an unappealing financial tool to be traded efficiently in the secondary market and direct
most of the investors’ finance towards the governmental channels. The cost elements for the
treasury bonds comprise the following elements:
● Stamp tax (which is lower than the corporate bond).
● Clearing fees.
Comparing the fees of the corporate and treasury bonds, additional elements that are only
specific to the corporate bonds issuance and trading are identified, which significantly result in
increasing the cost of the corporate bonds in comparison to the treasury bonds and result in
corporate bond to be in a less competitive position than that of treasury bonds. Furthermore, given
that treasury bonds are issued by the Ministry of Finance, which means that they are
governmentally collateralized bonds, they have a minimal credit risk associated with them. This
risk-free nature of treasury bonds should result in lower yields compared to other corporate bonds,
as per the principle of "the higher the risk, the higher the return.". Accordingly, in order for the
corporate bond to compete with the treasury bonds and to be an attractive financial tool for
investors, considerably higher yields that reflect the corporate bonds' credit risk premium should
be provided by the issuers. However, the domestic debt market has a different functioning
mechanism where treasury bonds are traded in a high interest, competing fiercely with corporate
bonds. Accordingly, the current market status of the high-interest rates that are offered on investing
treasury bonds, along with the low transactional costs of treasury bonds, serve as a blocker for

`
investors to consider investing in corporate bonds and leads to directing their investments to
treasury bonds. The CEO of a leading investment bank explained:
“Theoretically, risk-free products must have the lowest interest rate and the more the risk, the higher
the return. This is what we have learnt in the economic books, but this is not the case in our market,
where risk-free products rates are among the highest in the market. The equation is distorted.”
(Interview, CEO, Investment Bank 1, March 2023)
The interviewee indicated that the interest rate associated with treasury bonds is supposed
to be among the lowest in the market as the risk associated with treasury bonds is minimal, given
that risk is one major factor in bonds pricing, while corporate bonds’ Interest rates should reflect
the market risk premium, which is higher in the corporate bonds’ case. Thus, the pricing of
corporate bonds should be higher than any risk-free financial products in the market. This distortion
in the pricing mechanism results in treasury bonds being of a significant competitive advantage
over corporate bonds and weakens the investors’ interest in investing in this tool.
In addition to the cost element, treasury bonds are also advantaged over corporate bonds
by the trading system that is specific only to Treasury bond trading. The Primary Dealers System
is characterized by being linked electronically to the primary dealer’s custodians and Misr for
Central Clearing, Depository and Registry (MCDR) Company. This connected system results in
much easier trading of the treasury bonds and gives the treasury bonds an additional market
advantage not offered to the corporate bond. The corporate finance department head in the FRA
demonstrated:
“The problem of the bond market is the secondary market where the transaction cost in the
secondary market for treasury bonds is different than that of the corporate bond due to many
reasons including the utilization of The Primary Dealers' System.” (Interview, Corporate Finance
Department Head, FRA, March 2023)

`
The quote discusses the obstacles that face the bond market due to the challenges related to
the secondary market and specifically the cost of transaction which is affected by the trading
system used. The absence of a parallel system for private traders capable of automatically
calculating the traded bonds or sukuk prices, yields, and accrued interest, is a significant setback
in the market. Addressing this issue is crucial to create a level playing field and achieve parity
between the two financial instruments.
However, all the challenges mentioned above are issues that need to be addressed,
especially if combined with the long duration of the issuance process, which doubles the risks for
the issuers. These issuance-related challenges need to be addressed to help the debt market thrive.
However, in addition to the issuance-related challenges, the trading-related challenges related to
the secondary market also stand as a substantial challenge according to the market participants'
perspectives.
6.2.5. The Challenges of the Secondary Market:
The secondary market, often referred to as the aftermarket, is where financial instruments
are exchanged among various investors. However, the main challenge that was reported by the
market participants in relation to the secondary market is the inactive trading of the debt financial
tools as a whole and the corporate bonds in particular. Poor liquidity in the bond market generally
and green bonds specifically reinforce the bond market’s toward buy-and-hold investors and away
from active traders (Chiang, 2017), which was identified as a central challenge in the domestic
context. The interviewees used the “Dead trading” term to demonstrate the inactive status of the
secondary market in terms of buying and selling, where the trading is minimal. The inactive trading
status hardens the resale of the bond. It results in a higher commission for the selling process and

`
market exit, which reduces the accrued interest for the investor, and leads investors away from
investing in the debt financial tools. A debt market manager in an investment bank shared:
“Do you think that the companies operating in the market currently do not want additional finance
and don’t have expansion plans? Of course, they do, but the lengthy process and the issues cost,
plus the “dead trading” and the inactivity of the secondary market, kill the debt market. And for
retail investors, CDs and the current interest rates provided is also killing the bond market.”
(Interview, Debt market manager, Investment Bank 2, April 2023)
The quote explained some of the major challenges that faces the secondary market including the
cost and inactive trading and their impact on the bond market as the inactive secondary market is
a market risk that overlaps with other challenges, including the investors' base and the pricing of
the bonds. It significantly exacerbates the challenge of an undiversified investor base in the debt
market, as it restricts investor participation mainly to institutional investors with a "buy-and-hold"
approach. To diversify the investor base, it is crucial to activate the secondary market, enabling
retail investors to engage in the market actively.
Furthermore, the inactive status of the secondary market may also overlap with the pricing
process of the corporate bonds and alter the offered interest rates. To be an attractive financial tool
for investors, given this inactive status, notably higher yields should be offered by the issuers to
reflect the inability of investors to actively trade the bonds and exit the bond market if needed and
sell the bonds at good reasonable prices. This is an additional risk that is linked directly to the
secondary market and results in an increase in the cost of funds to the issuers. The FRA’s corporate
finance department head explain that:
“The problem of the bond in the secondary market is that the pricing should reflect also the market
risk premium due to the inability of the investors to exit the market and resell the bonds without
realizing losses” (Interview, Corporate Finance Department Head, FRA, March 2023)

`
The quote highlighted how the secondary market activity status impact the bond pricing
where inactive secondary market is considered to be additional risk that is should be reflected in
the bond pricing and result in bonds to be offered to investors with higher yields. This may
significantly increase the cost of capital to the issuer and present the bonds as a high-cost financial
tool.
6.2.6. Current economic situation and Increased interest rates
The current economic situation and interest rate volatility is a macro-level policy. It may
not be perceived as an issuance-related or market-related challenge, yet it significantly impacts the
capital market and the corporate bonds’ issuance. Increased inflation, slower economic growth,
and unstable progressive interest rates resulted in increasing the cost of funds. It resulted in
companies being more hesitant to commit to long-term debts and to issue long-term bond
issuances, given the high level of uncertainty and the future of businesses. Unstable economic
status leads to slower lending growth which in return affects all capital market dynamics, including
bond issuances. The FI manager in the EBRD and the sustainability managers of the EGX refer to
these points as follows:
“It's a tough time now. The current economic situation is translated into slow GDP growth, interest
rate hikes, volatility in foreign exchange, etc., which translates to slower lending, shrunk
investments and lower numbers of projects. No projects mean no demand. No demand means no
bonds, whether green or conventional. It is a cycle!” (Interview, FI Manager, EBRD, April 2023).
“Given the current local economic situation and the global scale as well, many companies
refraining from taking the risk of debt financing in the first place, let alone green finance with
additional requirements.” (Interview, Sustainability Manager, EGX, April 2023).

`
The two quotes are together explaining how the economic status affects the whole market
and results in decreasing the companies’ appetite to expand and to be involved in long-term debts
that they may be unable to fulfil where the second quote further explain that more complicated
requirements harden the financing decision specially for long term debt tools. The current debt
market status faces many challenges that are related to the market structure, yet the macroeconomic
policies have a significant impact on the demand and supply of the bonds, which significantly
affect the issuance volumes. A more stable economic scene will result in more company expansion
plans and more demand for additional funding.
However, all the challenges that have been discussed so far are considered to be general
challenges that face both conventional and green bond markets. In the next section, green-related
challenges specific to green bonds will be demonstrated. These challenges are unique to the green
bond market and require special attention and consideration.
6.3 Green Bonds Market Observations:
Green bonds draw their strength mainly because they finance the global green transition
trend as among the most groundbreaking financial instruments (World Bank, 2021). The green
bonds specify the bonds proceeds to be allocated only to green projects, with additional reporting
required to ensure the implementation of the green framework set by the issuers. However, the
domestic green bonds market is subject to all the challenges of conventional bonds besides the
setbacks that are merely specific to the green element of the bonds and the associated requirements
of this element. Besides the mentioned challenges, a specific observation that is related specifically
to the green bond market was also highlighted within the analysis framework as a main finding.
6.3.1. Issuance Motive: Recognition and Realized Brand Value:

`
Despite the green bond significance and the urgency for financing green projects, this
importance is not the main driver for local issuers to issue corporate bonds. Many interviewees
stressed that green issuances in the current market status and given the higher cost associated with
it, issuances are derived mainly from the aspiration of the issuer to be a market leader in the green
investment field, utilize it to enhance brand value, and to realize the national and international
recognition that would be obtained from issuing green tools. The sustainability manager in the
EGX added:
“Currently, what motivates issuers to issue green bonds, given the lack of incentives and the high
cost, is being market leaders, having a brand value, and comprising a market share of a new
financial product even if it is not very rewarding as a business model right now; eventually it will.”
(Interview, Sustainability Department Manager, EGX, April 2023).
The quote shed light on the motivations that may push the green bond issuers to issue green
bonds given the lack of incentives. Being a market leader and possessing a market share of a green
products stands among the most prominent motivations of the green bond issuances.
These were the same views offered by strategy manager in a local bank adding:
“To be frank with you, green issuance is not financially viable given the extra costs associated, i
wanted to go through this issuance for the publicity and to be the first bank and a market leader in
a fairly new field.” (Interview, Strategy Manager, Bank 2, May 2023).
The quote also explained that the positive publicity behind the green bond issuances is the
main driver for green bond issuances. However, the motive of being a market leader is not enough
driving force to be of a critical mass to incentives and to create a momentum for the green bond
issuances in Egypt. The willingness to invest in green projects needs to be accompanied by realized

`
financial gains in order to create sustained market moves towards higher scale green investments
and green finance.
Conversely, the green bond market faces a set of unique constraints that some of them are
uniquely attributed to the local market and others are shared with other emerging markets.
6.4 Green Bonds-related Challenges:
6.4.1 Lack of Awareness and Mislabeling of Green Tools:
The lack of awareness was mentioned to be a problem that persists and affects both the
conventional and green corporate bonds market in equal measures, not only on the local market
but also on the international level as well. According to a survey conducted by the G20 Green
Finance Study Group (2016), the delayed green bonds issuance may be attributed to two key
factors: lack of awareness and bias. The survey revealed that 74% of participants were unaware of
the benefits associated with green bonds, while 41% perceived an additional cost burden associated
with green issuances. It themes that the same challenge may linger in the local context. Although
the regulatory foundation has been created since 2019, the awareness of green bonds in 2023 is
almost the same as in 2019, where most investors lack basic knowledge about corporate green
bonds. A debt market manager in the FRA explained:
“People don’t know. Again, the lack of awareness problem keeps on popping up continuously.
Investors don’t know much about the green bonds and don’t know how it how it works.” (Interview,
Debt Market Manager, FRA, March 2023)

`
The quote explained how the lack of awareness persists as being among the top challenges
that faces the green bond market and how this challenge affects the demand and supply of the green
bond. This challenge is not only limited to a specific group but extends to embrace all market
players. The managing director of the Egyptian Institute of Directors, one of the most prominent
training centers added:
“Awareness for the different investors, traders, asset managers and brokers are especially critical
for the green bond market in Egypt. For all levels, I don't see anyone who is less important than
the others.” (Interview, Managing Director, EIOD, May 2023).
The quote highlighted the fact that the lack of awareness is a challenge that face the whole
market and not limited to specific segment of the market as it poses a significant obstacle to the
market, not only leading to a low level of green issuances but also causing mislabeling of existing
issuances that qualify for green classification. The limited understanding of green investing
principles and financial tools in the green debt market further contributes to misclassifying
products as conventional instead of recognizing their alignment with green requirements. Many
issuers lack the knowledge needed to properly classify their issuances as green, resulting in the
issuance of bonds and sukuk as conventional instruments rather than as green issuances. A
corporate finance department of the FRA explained:
“Let me tell you something, many of the issuers do not even know that their investments are coping
with green investments criteria, and the only thing they need to do is to label their investments as
green.” (Interview, Corporate Finance Department Head, FRA, March 2023).
The quote explained the association between the level of awareness and the right labeling
of the investments where accurate labelling of green investments requires issuers to be aware of
the green tools and the requirement of green issuances. However, the lack of awareness endures as

`
a primary barrier that faces the local market and results in low levels of green issuances in the local
market as well as mislabeling for eligible green issuances.
6.4.2 Unpreparedness of the Issuers and Lack of internal capacity:
Green bonds issuance requires a specific level of awareness about the green investment
mechanisms and the identification of the ESG standards within the issuer's governance structure.
Corporations issuing green bonds typically exhibit elevated environmental ratings, reduced CO2
emissions, boards with increased female representation, and established sustainability committees.
(García et al., 2023). This indicates the criticality of the ESG full integration within the
organizational structure that led the corporations to issue successful green bonds. These
considerations and ESG-related expertise are significant for the issuers to be able to commit to the
green bond framework that the issuer identified to finance or refinance certain green projects. The
more the issuer is committed to the green investments standards and endorses a high level of
experience among its staff, the more the issuer is ready to issue green bonds and able to reduce the
needed time to be ready for the green issuances. A sustainable finance head of a bank added:
“One of the main advantages that the CIB had that qualified the bank to be the issuer of the green
bond issuer in Egypt is the existence of green governance within the bank. The bank originally
endorsed ESG-related governance as a core value and has a pool of qualified assets financed by
the green bonds’ proceeds.” (Interview, Sustainable Finance Head, Bank 1, May 2023)
The quote cited the CIB bank green bond issuance experience and explains how some
elements such as the level of green-related governance and ESG consideration that the institutions
adopt have a significant impact on the and institution’s ability to issue green bonds. Furthermore,
having appropriate pool of eligible assets or projects in the pipeline that fits the green bond criteria
and fall into the taxonomy, as well as ESG-related lending criteria, all together determine the level

`
of readiness that issuer have and consider to be one of the critical factors that enable the issuers to
maintain a successful issuance and avoid the greenwashing practices. These prerequisites require
a profound understanding of the green investment standards, which is not the case for many
potential issuers in Egypt, whether within or outside the financial sector. The financial institutions
manager in the EBRD explained:
“Enhancing the capabilities of the financial sector, including the banking sector is still under
development, and we are still working on it. However, with the new regulations, whether from the
CBE or the FRA, I believe the financial sector in Egypt will acquire the required experience soon.”
(Interview, FI Manager, EBRD, April 2023).
The quote shed the light on the urgency of the capacity building within the financial sector
in Egypt and how the regulator of this sector is working to disseminate the knowledge about the
green investment mechanisms within the sector by issuing a set of supporting regulations in
cooperation with the international financing institutions. The financial market’ regulators in Egypt;
the Central Bank of Egypt and the Financial Regulatory Authority, both have identified the lack of
awareness as a major challenge and issued a set of regulations requiring the financial sector
companies and banks to recognize the ESG factors and to report on these factors. These regulations
are expected to support the financial sector in Egypt to move towards a more sustainable business
model and to acquire the required expertise in this scope. However, the lack of awareness is closely
tied to the absence of clear definitions of green terminologies and national taxonomy, a significant
barrier to green financial tools in the national domain.
6.4.3 Absence of Clear Guidelines, Local Taxonomy, and Eligible Pool of Assets and
Projects

`
The absence of clear and unified definitions of what constitutes “green” and what green
investment entails is not only a local barrier but persists to be a global concern, as highlighted by
the OECD (2015) and the G20 report (2016). The lack of global agreement on what is considered
green poses challenges in both global and local markets. Within the national context, there is a
dearth of clear guidance and definitions regarding green investments and their requirements. The
FRA’s corporate finance department head explained:
“A clear guideline and definitions that clarify the investment nature under any green or
sustainability-related labels are the most important to Egypt’s green bond and sustainabilityrelated
market. In addition, green bonds issuances require additional transparency and reporting, but how
will you trace what you barely identify?” (Interview, Corporate Finance Department Head, FRA,
March 2023)
This quote emphasizes the critical need for transparent and well-defined guidelines to
facilitate green bond growth and sustainability-related market growth. Furthermore, among the
central challenges facing in the Egyptian market in relation to the standardization challenge is the
lack of a national taxonomy. The absence of a national taxonomy identifying the qualified sectors
and economic activities for green investments hinders progress towards aggregating resources for
sustainable projects. The taxonomy refers to a classification system that identifies a set of economic
activities that is considered green. A sustainable finance manager in a local bank shared:
“Of course, one of the central challenges is the absence of national taxonomy. This is a serious
block to green investments and reduces the eligible assets and projects to be financed through green
investments.’’ (Interview, Sustainable finance Manager, Bank 1, May 2023).
The quote expressed how the absence of a clear national taxonomy that identifies the green
projects and precise definition of what constitutes “green” holds significant relevance in the local
context, where clear distinctions between green and conventional investments are not apparent.
However, due to the absence of a local taxonomy, a limited number of eligible assets and projects
meet the criteria for green investments. This lack of a concrete pool of eligible green assets and

`
projects, which fulfil the requirements for the proceeds distribution to green projects, poses a
significant barrier in the market that needs to be addressed. The sustainability manager in the EGX
explained:
“The lack of a pool of eligible assets is a critical setback. If I am a bank or any issuer, and I have
eligible investments, and I have the potential, what will prevent me from investing? The lack of
such a pool is a hindrance element for sure.” (Interview, Sustainability Manager, EGX, April
2023)
The quote shed light on the importance of having an eligible pool of green investments and
assets that allow investors to be able to identify their best green investment opportunities.
However, creating this pool is identifies to among the responsibilities of the Egyptian government
to support green transition within the Egyptian economy. A debt market manager of an investment
bank explained:
“The Egyptian government is the only institution capable of creating the green project. And here I
don’t mean only the ministry of finance, I mean all the economic government institutions in all
economic sectors” (Interview, Debt market manager, Investment Bank 2, April 2023)
While the current economic situation and sluggish economic growth may contribute to the
absence of a pool of eligible green assets for investments, it is vital to prioritize the creation of
such a pool. The Egyptian economical governmental institutions’ identification of a list of eligible
green projects is decisive for the development of the market and to the successful implementation
of the green transition agenda. The Ministry of Environment should be heavily engaged in the
identification process and should coordinate with all the related governmental institutions in this
regard. This endeavor requires a concerted effort from all governmental entities to cover all the

`
economic sectors and to ensure that the absence of a green assets pool no longer hampers investors
and issuers and instead fosters opportunities for green investments.
6.4.4 The Cost of Verifiers and Reporting Requirements:
The green bonds issuance usually involves additional costs due to the additional reporting
and regulations required to satisfy the bonds' green element and ensure the transparency and proper
allocation of the proceeds. These additional costs involve the cost of third-party verification, which
is assigned as an independent body to ensure that green bonds proceeds’ usage are to be used in
financing green projects and also provide annual reports on proceeds until the bonds’ redemption.
This process increases the cost of issuance compared to the conventional bonds and adds an
additional burden on the issuers' shoulders. Even with the FRA reduction of the green bonds’
inspection and service fees to green instruments' issuers, the cost is considerably higher than the
conventional bonds, given the absence of a local verifiers market that would lower the cost for
third-party verification. The cost issue was frequently persisted as a major market barrier by many
interviewees. The FRA’s debt market manager explained:
“Green bonds require additional verification, which leads to cost increase. The solution is to create
a local market to reduce verification costs. Till now, no local verifiers have been registered in the
FRA’s registry.” (Interview, Debt market manager, FRA, April 2023).
The quote showed that although third-party verification is a pivotal step in the green bond issuance
process, it involves a considerable additional cost, especially with the absence of local verification
firms to conduct the verification process, which in return direct the issuers towards international
verifiers and significantly increase the cost of verification processes. These thirdparty verification
costs can be significantly reduced if the assigned verifier is a local verifier and not an international

`
one. Accordingly, establishing a local verifiers’ market in Egypt is recognized as a pivotal step to
bolster the market. The EGX’s sustainability manager indicated:
“Creating a local market of third-party verifiers is a must to activate the green bond market in
Egypt. FRA has started already by providing the requirements of local third-party verifiers, yet, a
lot needs to be done, and many elements need to be considered simultaneously.” (Interview,
Sustainability Manager, EGX, April 2023).
The quote stressed on the importance of creating a local market for verifiers and further
explained that although the FRA has already set the regulations governing the green bond verifiers
requirements for individuals and corporations, no local verifier has been recognized by the FRA
so far. This indicates that issuing the related regulations is not the only supporting action that the
local market needs to incentivize the local firms to be registered. Raising the awareness of the
market, among other factors can create a demand for these firms and thus help in creating a robust
pool of local verifiers.
Nevertheless, in addition to the third-party verification and the associated costs, other
additional regulatory requirements regarding the proceeds keeping may also result in a more
complex and costly issuance process, which is also recognized as one of the reported challenges.
6.4.5 Additional Regulatory Requirements
While reporting is recognized as a challenging aspect of green bonds, it is not the sole
bottleneck. Green bond issuance involves additional regulations prohibiting issuers from
reinvesting the proceeds in non-green investments throughout the bond's duration. Essentially, the
funds must be held in a sub-account and cannot be reinvested in any non-green investment until it
is allocated to the outlined green projects. Although being a globally recognized best practice

`
(ICMA, 2021), this poses a problem in the context of Egypt, where the level of green investments
is fairly low. This implies that the proceeds are confined in the sub-accounts, which results in
increasing the cost of capital for the issuer. Furthermore, the establishment of a subaccount
introduces an additional reporting requirement. The financial auditor is additionally responsible
for monitoring every transaction within the sub-account to ensure compliance with the Green
Investments regulation. This monitoring process incurs additional costs for the bond issuers. These
complications tied to the issuance process and the associated costs often make issuers more hesitant
to issue green bonds. The financial institutions manager in the EBRD indicated:
“Green bond issuance is a very hectic process. Dr. Omran, the former FRA’s chairman, helped a
lot in the solo corporate green issuance that took place in Egypt. I doubt it would ever have been
launched if it was not for his assistance. For example, one of the bottlenecks was conditioning to
allocate the green proceeds in a separate account that must be reinvested in only green projects. It
was a barrier given the low level of eligible assets.” (Interview, FI Manager, EBRD, April 2023)
The quote discusses one of the requirements of the green bond issuance which is creating
a subaccount for the green bonds’ proceeds. Although these regulations are mainly compliant with
the best practices were framed to guarantee the credibility of the green bond market, which is an
integral pillar of this market and to mitigate the greenwashing risks, it is still perceived as a market
barrier as it hardens the reinvestment of these proceeds given the low level of green investments
that is qualified to be green and the absence of a eligible pool of assets. The highlighted challenges
are considered market challenges in terms of complexity level, cost and time. Accordingly, issuers
may prefer to issue conventional bonds even with the project's eligibility to be financed through
green bonds to avoid the extra costs of verifiers and reporting requirements (Jones et al., 2020),
which is a common practice on both international and domestic levels. However, there is a crucial

`
need for a balanced regulatory framework that ensures the market's credibility while maintaining
the process as quickly as possible.
6.4.6 Lack of Incentives:
A final barrier that is reported to be associated with green bonds issuance and identified as
a primary barrier is the lack of incentives. Currently, there is an absence of motivation for issuers
to issue green bonds and for also for investors to invest in these green issuances at the domestic
level. These incentives serve as a form of compensation that helps issuers offset the extra expenses
linked with green bonds, thereby motivating issuers to prioritize green financing and incentivizing
the investors to know more and invest in green bonds. While the Financial
Regulatory Authority (FRA) has taken a further step by reducing its service fees by 50% for green
issuances, this measure alone is insufficient to reconcile all the additional costs that the issuers
bear. A CEO of an investment bank explained:
“There is no incentive for issuers to issue green bonds. FRA has done a good job reducing its
service fees by 50% to green issuances. However, FRA fees are already minimal and are not a
bottleneck in the first place. Additional incentives are still urgently needed to make green issuances
appealing for bond issuers.” (Interview, CEO, Investment Bank 1, March 2023).
The quote showed how the market is in a great need for a high scale incentive bundle to
incentivize the issuers to issue green bonds as market participants highlighted the lack of incentives
as crucial hinder for the green bond market development even with the latest FRA’s incentivizing
decrees. However, as a direct result of the lack of financial support, issuers may not be able to
provide competing interest rates with conventional bonds. Although some impact investors may
pay any premium for green bonds due its importance and the morals behind them, as reported in

`
the literature, yet, if green bonds are traded at a considerably lower rate resulting from the
additional associated costs of capital, no investor will be willing to invest in such a tool.
A debt capital market of an investment bank indicated:
“Green bonds are great, but when it comes to offering considerably lower yields, investors will say,
“give me the higher yield now and let us discuss the green economy latter on.” (Interview, Debt
Capital Market Manager, Investment Bank 2, March 2023)
The quote showed how the investors will react if the green bonds are traded in a lower rate
than of the market and it shows again the importance of financial incentives to the green bond
market. A bundle of incentives to the issuers of the green bonds and any other green tools that will
allow the issuers to offer green tools with a competing interest rate is essential element that is
required to support the market and to lead to more active green financing mechanisms in the
domestic level.
However, having explored the multifaceted challenges and intricacies surrounding the
development of the green bond market in Egypt, it becomes clear that tackling these challenges
holds paramount importance in realizing the complete potential of sustainable finance within the
nation. The challenges identified have shed light on the areas that require concerted efforts and
strategic interventions. However, it is important to recognize that these challenges should not
overshadow the immense opportunities and benefits that lie within the realm of green bond market
development.

`
7 Chapter Seven: Conclusion and Policy Recommendations
Green bonds have appeared as a significant green financing instrument that plays a vital
role in advancing “sustainable development” and addressing the pressing environmental challenges
outlined in “the 2030 Agenda for Sustainable Development”. In pursuit of attaining the Sustainable
Development Goals (SDGs) by 2030, green bonds have gained prominence as an effective
mechanism to mobilize capital for environmentally friendly projects (World Bank, 2021). These
bonds empower issuers to secure financing for initiatives with favorable environmental effects,
such as renewable energy projects, energy-efficient buildings, sustainable transportation, and
climate change mitigation initiatives (ICMA, 2017).
The urgency of green bonds lies in their potential to bridge the gap between financial
markets and sustainable development objectives. By channelling investments towards
climatefriendly and socially responsible projects, green bonds aggregate the transition to a low-

`
carbon and more sustainable economy. They offer an avenue for investors to align their portfolios
with environmental goals while generating financial returns. Furthermore, green bonds facilitate
the mobilization of private sector capital, leveraging additional funding sources for sustainable
projects that participate in attainment of the SDGs.
On the national level, green bonds are of a special importance as a primary funding
mechanism to support the financing of Egypt's 2030 agenda (MOE, 2022). However, despite their
critical need, green issuances in Egypt have remained at a low level compared to other emerging
economies. Till now, Egypt has only issued one corporate green bond, raising concerns about the
challenges hindering the development and acceleration of green issuances in the domestic market.
The limited number of green bond issuances prompts further examination of the obstacles that
impede market growth and the facilitation of increased green bond issuance.
However, this paper aspires to inspect the challenges faced by the green bond market in
Egypt and highlighting the essential areas that require attention to foster its development. The
analysis has revealed several key general challenges in relation to the whole bond market in Egypt
that affects both conventional and green bonds alike. These challenges include the low level of
awareness of the bond market, low level of retail investors' engagement, length and complexity of
the bond issuance process, Bond pricing and cost of issuance-related, trading and secondary market
challenges, besides the effects that the current economic situation poses to the debt market
generally and bond market specifically. On the other hand, the analysis revealed a set of green
bond-related challenges that are specific to the green element in the bond. These challenges
included a lack of awareness and mislabeling of green issuances, the unpreparedness of the issuers
and lack of green investment-related internal capacity, reporting and verification complexities, the

`
need for a robust green project pipeline and assets pool, regulatory barriers, and severe lack of
incentives.
Addressing these challenges requires a comprehensive approach involving collaboration
among various stakeholders, including policymakers, regulators, issuers, investors, and financial
institutions. Our findings indicate that a balanced regulatory framework is needed to ensure market
transparency and credibility while minimizing complexity and costs. Furthermore, enhancing
market awareness and perception through targeted educational initiatives and communication
campaigns can play a pivotal role in driving demand for green bonds.

