


Introduction During the decades of the 1980s
During the decades of the 1980s and 1990s, the world of the Seventh-day
Adventist Church in the United States was greatly disturbed by the events surrounding
the bankruptcy cases of Dr. Donald Davenport and Harris Pine Mills (Wilson, 1983a,
1983c, 1983b, 1987). In the mid-1980s, the Davenport affair revived questions about
transparency, ethics, and integrity due to the perceived conflict of interest on the part of
some leaders who invested church and personal funds in Dr. Davenport’s real estate
ventures. In addition, the bankruptcy and closure of operations of Harris Pine Mills, a
wood furniture company which had been donated to the church, led to questioning the
leaders’ stewardship and financial management (Hackleman, 2008; Wilson, 1987).
A complete picture of the damage caused by these events was not limited to the
financial losses involved. It included a negative impact on the church constituency who
expected their leaders to be above reproach, efficient, and effective. The publicity these
events generated from the loss of leaders who were, despite the best of intentions, either
reprimanded or dismissed from employment for acting misguidedly presented a negative
image of the church to the community.
The public image of the church suffered when in March of 1999, Robert S.
Folkenberg, then President of the General Conference of Seventh-day Adventists brought
his presidency to an end by tendering his resignation due to personal financial concerns
(Medley, 1999; Thompson, 1999). Episodes like these contribute to the skepticism and
distrust of many toward church leadership. The erosion of trust in church leadership
touches particularly those who are responsible for fulfilling the church’s financial duties.
This perceived erosion of trust moved me to explore the leadership values of financial
officers of local Adventist conferences in the United States. This study is the second

dissertation study on record involving the local conference treasurers in the United States.
The first study was written by Theodore Brown (2005). As it is, local conference
treasurers in the United States guide in the financial affairs of thousands of congregations,
hundreds of schools, and multiple other church programs and projects. The knowledge
regarding the development of these leaders is limited, and yet they are responsible to
administer an approximate collective gross income above $1.5 billion per year. This study
contributes to the closure of the knowledge gap, and hopefully will contribute to planning
their development as financial leaders in the church.
As I endeavored to find an appropriate theoretical framework for this study, the
search guided me to consider positive forms of leadership (Avolio & Gardner, 2005;
Mazutis, 2007) as a desirable family of constructs, from where Authentic Leadership
seemed to be an appropriate fit given the current state of societal affairs.
The lack of trust experienced today by some church members is in harmony with
the American societal attitude developed over the last four decades as governmental and
corporate events have shaken trust and confidence, fomenting skepticism and distrust
(Halberstam, 1972; Reeves, 1982; Walsh, 1997). In the last decade alone we have
witnessed how financial scandals and business failures impacted investors, employees,
board members, corporate leaders and ultimately the general public. The stories of Enron,
WorldCom, Adelphia, Tyco, Arthur Andersen, HealthSouth, Sunbeam and others speak
eloquently about the values and attitudes that led to their malfunction. It is worth noting
that two non-profit organizations, the United Way and the Baptist Foundation of Arizona,
were also included perhaps to show that organizations established to benefit humanity
and to uphold high moral and religious values experience the same need for good

financial management, ethical and moral values, transparency, and guidance (Jennings,
2006).
As a result of the cases commented above there has been a reformulation of
leadership concepts to address more effectively moral and ethical issues faced today by
leaders and followers alike. This redefinition seems particularly apt at present, in our
post-Sarbanes-Oxley Act of 2002 era; an era in which corporate transparency, ethical
responsibility and accountability are frequently invoked (AICPA, 2002).
The Seventh-day Adventist Church depends on quality managers and leaders. The
church is organized into numerous geographical entities, institutions, and agencies, which
are structural instruments to help accomplish its mission. In this context, reassuring the
members and the general public is important in helping it prosper and attract donor gifts.
Above all, the church is in need of leaders with sterling character values that will
not create embarrassing situations and financial losses that motivate some members to
question the values and decision-making processes of all church leaders (Hackleman,
2008, p. 367). Obviously the need is ever present for leaders who preserve integrity, work
harmoniously with their peers, and guide church entities into acting transparently,
ethically, and morally because the name of the church is associated with the name and
character of its leaders and followers (Turknett & Turknett, 2005, p. 191).
The dimensions proposed by authentic leadership theory are an appropriate match
to focus our concerns about church leadership. Authentic leadership is a theoretical
construct that focuses on self-awareness, relational transparency, ethical/moral behavior,
and the balanced processing of others’ opinions. These aspects overlap with the
dimensions of leadership called for by Adventist leaders. These constructs have not been

tested in the church arena, thus little is known if they fit the current search for a higher
level of leadership. This study focuses on the authentic leadership qualities of Seventhday
Adventist Chief Financial Officers in the US.
Paulsen’s Statements on Leadership
Dr. Jan Paulsen, President of the General Conference of Seventh-day Adventists
between 1999 and 2010, in his address to the plenary assembly of church delegates on
July 4, 2005, in St. Louis, Missouri, declared that leadership development is a church
priority. He explained that the expansion of Adventist membership around the world is
expected to reach 50 million by the year 2020, and the proliferation of local conferences,
missions, and institutions will require that a deliberate effort be placed on the definition
of the values to be instilled in church leaders (Paulsen, 2005, p. 33).
Paulsen asked, “What are the qualities which the community of faith can
reasonably be expected to look for in electing a leader?” He identified (a) transparency,
defined as the filter through which humility and integrity are seen; (b) self-awareness, or
relating to our past experiences in order to learn from them; (c) ethical/moral integrity, as
greed and self-seeking do not belong in any leadership assignment in our church; and (d)
the ability of a leader to seek unity; inclusiveness of culture, gender, and opinions; and
consideration to having the same manual, policies, statement of fundamental beliefs, and
integrated resource support system which in essence makes the church ‘one united global
family of faith.’ In his latest book Paulsen reiterated that “an Adventist leader is a person
of integrity” (Paulsen, 2011, p. 5). Paulsen (2005) further indicated that
what is critical is to have a clear identification of what constitutes the core
personality, the spiritual ‘DNA,’ of Seventh-day Adventism, which transcends
cultures and traditions and must be retained, treasured, nurtured, and passed on to
our children and the next generation of church members. And this is a leadership

issue. It is leadership’s responsibility, with discipline and love to look after the
heart and the mind of this church. (p. 33)
The denomination restated its need for quality leadership at the 2011 Spring
Council meeting of the Executive Committee with the approval of the document entitled
“Transparency and Accountability in Financial Reporting” (Lemon, Evans, Douglas, &
Kajiura, 2011). They asked church leaders to address administrative and leadership
matters from a well-defined ethical perspective.
Context of the Study
The Authentic Leadership Development construct defines authenticity in both
leaders and followers using four variables: Self-awareness, Relational Transparency,
Ethical/Moral Behavior, and Balanced Processing of other peoples’ opinions (Avolio &
Gardner, 2005; Gardner, Avolio, Luthans, May, & Walumbwa, 2005; Walumbwa, Avolio,
Gardner, Wernsing, & Peterson, 2008). This study evaluates these variables among
Adventist local conference treasurers and their associates. They correlate closely with the
values expressed by Paulsen.
Local conference treasurers in the Seventh-day Adventist Church are financial
managers/leaders (CFOs) in a geographic entity that includes local congregations,
schools, and community service agencies. Their functions include budgeting, finances,
administration, auditing, and personnel (T. Brown, 2005, pp. 37-44). Their leadership
development needs are important as the denomination rests heavily on them to lead out in
entities that are clearing points for funds and to provide input that ultimately becomes
financial policy and practice. Also critical to the life of the church is the fact that local
conference treasurers constitute a pool of candidates for more specialized assignments.

The official by-laws of the church indicate that these financial officers “shall be
responsible to provide financial leadership” (General Conference of SDA, 2014, p. 176).
The Seventh-day Adventist Church in the United States has 50 local entities
known as conferences functioning as centers of church governance, administration, and
leadership to local congregations, schools, and to a diversity of community-based
programs with approximately 1 million members, an estimated $1.5 billion in unrestricted
donations per year, and about 6,000 employees (General Conference of SDA, 2013).
Conferences offer an array of managerial services that include, but are not limited
to, (a) hiring and supervising ministers and teachers; (b) training officers of local
congregations and schools; (c) implementing of school curriculum; (d) providing
guidance to the institutions serving in the territory; and (e) providing financial, payroll,
human resource management, auditing, planned giving, trust management, and legal
services (T. Brown, 2005). It was to individuals such as these managers and leaders that
Calvin Rock, General Vice President 1985-2005, wrote an inspiring book encouraging
them to seek virtue, integrity and holiness, proposing a desired set of qualities that
included self-confidence, courage, trust, self-control, versatility, honesty, decisiveness,
loyalty and disinterested love (Rock, 1990). The central theme of his book was “the
correlation between personal integrity and institutional effectiveness” (p. 7).
Jan Paulsen, President of the General Conference 1999-2010, appealed to the
delegates assembled in the General Conference Session of 2005 for a change in Adventist
leadership practices (Paulsen, 2005). He identifies outstanding Adventist leaders as
having transparent motives, who show balance as they consider everyone’s opinion
before deciding, act selflessly, are guided by scriptural principles, and seek the guidance

of the Holy Spirit to know themselves better and to be able to sense the pulse of the
community they have been asked to lead, have the humility to be led, and are able to
handle change (pp. 30-35).
Cindy Tutsch, in her book Ellen White on Leadership: Guidance for Those Who
Influence Others, gives the reader a glimpse of the impact of Adventist religious values
following a process of spiritual awakening, similar to the self-awareness process that
brings self-knowledge, spiritual guidance, and character development to the leader
(Tutsch, 2008). In 2011, the Spring Council meeting of the Executive Committee of the
General Conference approved the document entitled “Transparency and Accountability in
Financial Reporting” (Lemon et al., 2011). The document issued a call to church leaders
to address administrative and leadership matters from a well-defined ethical perspective.
It raised questions that resonate with the corporate ethical failures of recent years and the
impact that such matters have on the denomination, and it also pointed to leadership
qualities that have been contained in authentic leadership.
How do leaders, and more specifically leaders entrusted with the financial
leadership of a denomination, develop the values that undergird their expertise as leaders?
At the moment little is known about this question in the context of the Seventhday
Adventist Church. This study is an answer to the need to understand these leadership
development aspects of local conference treasurers, with the goal of developing suitable
ideas to provide a better understanding for their continued growth as leaders.
Statement of the Problem
Treasurers are trusted by church members to manage the finances and provide
financial leadership according to the highest moral and ethical principles, and best

professional practices. They are at the center of trust, effectiveness, and efficiency of
denominational activities. How do these financial administrators develop the values that
guide them as leaders?
The Seventh-day Adventist Church as a denomination exercises care and due
diligence in selecting its financial officers from individuals who show experience,
maturity, and professional knowledge. However, to date there have been no studies
written of how their values compare with leadership values of ethics, morality, integrity,
and fairness that are prevalent in today’s positive and ethical leadership theories, and in
Authentic Leadership theory specifically. Conference treasurers are professionals who
combine business and accounting knowledge with leadership. These Chief Financial
Officers (CFOs) exert a significant influence in the administration the church; they are an
important voice among the executive officers, and provide input into the policies
governing church entities. In this study I was able to see their values through their eyes,
and through the eyes of their peers and subordinates.
Purpose of the Study
The purpose of this study was to explore the perceptions of Adventist local
conference treasurers in the continental United States as authentic leaders and assess how
their perceptions either agree or disagree with the perceptions of their followers. This
study compares their self-assessment responses with the rating that their associates and
team members (followers) provide of their leadership. It will help us to know what their
leadership values are, as seen by the people that work the closest to them.
Research Questions
This study is guided by three research questions. They are:

Research Question 1
Are the self-perceptions of local conference treasurers (leaders) significantly
different from the perceptions of their followers in what refers to their authentic
leadership values (relational transparency, internalized moral and ethical values, balanced
processing of others’ opinions and self-awareness)?
Research Question 2
Are the personal characteristics of the local conference treasurers (their gender,
age, years of experience in administration, years of denominational service, and education
level) significantly related to their own self-perception as authentic leaders as expressed
in their relational transparency, internalized moral and ethical values, balanced processing
of others’ opinions, and self-awareness?
Research Question 3
Are the personal characteristics of the associates in treasury and academy
treasurers (their gender, age, years of experience in administration, years of
denominational service and education level) significantly related to the perceptions of the
local conference treasurers as authentic in their relational transparency, internalized moral
perspective, balanced processing of others’ opinions, and self-awareness?
Research Hypotheses
This research is based on the following hypotheses:
Hypothesis 1

The first research hypothesis (Ha1) of this study is the expectation that a local
conference treasurer’s self-perceptions of relational transparency, moral/ethical, balanced
processing, and self-awareness values are significantly different from the perceptions
followers expressed of their leaders in the same four ALD factors already indicated.
Hypothesis 2
The second hypothesis (Ha2) states that the treasurer’s gender, age, years of
professional service, years of service to the Seventh-day Adventist Church, and academic
level are significantly related to their own self-perception of relational transparency,
moral/ethical values, balanced processing, and self-awareness.
Hypothesis 3
The third hypothesis (Ha3) states that the follower’s gender, age, years of professional
service, years of service to the Seventh-day Adventist Church, and academic level are
significantly related to their perception of relational transparency, moral/ethical,
balanced processing, and self-awareness of their leaders, the local conference treasurers.
Methodology
This study approached the population directly, instead of through a random
sampling or any other statistical technique. The participants responded to the Authentic
Leadership Questionnaire 1.0 (ALQ) obtained through Mind Garden, Inc. (Avolio,
Gardner, & Walumbwa, 2007). Given the nature of church work, the Authentic
Leadership construct provides a viable instrument from which a foundational and
comprehensive knowledge of their perception of leadership is possible through the
variables tested (Avolio & Luthans, 2006).

In the religious Protestant denomination of Seventh-day Adventists, treasurers are
Chief Financial Officers (CFOs) and they offer a business/financial voice to their entity,
and they also serve in an important subservient or secondary leadership role. Their
responses to the ALQ allowed me to understand how they see themselves. The responses
of their followers, the associates in treasury and the academy treasurers, provided a
window view into the values of the leaders as they either ratified or denied the CFO’s
responses.
The ALQ was developed by Bruce J. Avolio, William L. Gardner, and Fred O.
Walumbwa (2007) and is a theory-driven leadership-validated survey instrument designed
to measure the components or dimensions that together offer a measure of authentic
leadership. The ALQ is a validated research questionnaire that is reliable, has valid
construction, and has been used in a number of projects around the globe
(Walumbwa et al., 2008). It consists of 16 questions asked of the leader and 16 questions
asked of the follower. In the current study, the leader’s group consists of 50 leaders (Self)
currently working as local conference treasurers, and the 148 followers’ (raters) group is
composed of 120 serving as associates in treasury (undertreasurer, associate treasurer,
assistant treasurer, controller, and accountant), and 28 serving as academy treasurers for
selected secondary-level boarding institutions. These academies were identified by the
Office of Education of the North American Division of the Seventh-day Adventist
Church.
Conceptual Framework
This study was framed through the lens of Authentic Leadership Development
theory. The leadership theories that incorporate a moral/ethical component, Authentic

Leadership and its four distinctive constructs of self-awareness, ethical/moral values,
relational transparency, and balanced processing of others’ opinions, offer an approach to
measuring authentic leadership development. These variables are unique to the version of
the theory presented by the studies of Avolio, Gardner, Luthans and Walumbwa (Avolio
& Gardner, 2005; Walumbwa et al., 2008). Although many of the elements found in the
theory can also be found in other positive leadership theories, Authentic Leadership
claims to be a leadership development theory positioned “at the root of positive forms of
leadership” (Avolio & Gardner, 2005, p. 316).
Authenticity in leaders is grounded in values of morality and character. Gardner,
Avolio, Luthans, et al. (2005) define authentic leaders as “genuine leaders who lead by
example in fostering ethical climates characterized by transparency, trust, integrity, and
high moral standards, and these authentic leaders are both true to themselves and lead
others to achieve authenticity” (p. 344).
Significance of the Study
This study is relevant to the leaders and followers of the Seventh-day Adventist
Church in the United States of America, as it will provide information that was not
previously available, and better plans for leadership growth may be elaborated. Although
the study involves chief financial officers and their followers, the research design can be
applied to other leaders and followers as well. The Seventh-day Adventist Church around
the world will reap the benefit of this study as the research design can be replicated
elsewhere depending on the geographic, cultural, and social milieu. This study may prove
of interest to the financial sector of religious and secular non-profit entities, as there are
relatively few academic studies that provide information that is framed in Authentic
Leadership theory. And, it is ultimately important to me as a researcher, because this is a

subject of deep interest to me personally because of my study of positive forms of
leadership and authentic leadership in particular.
Assumptions
This study assumed that the local conference treasurers and other participant
groups were willing to share their responses by participating in the study. In May 2011 I
met with the Treasurer’s Council and presented the proposal, inviting them to participate
in the study. It was a time to answer their questions and reservations about the study.
They took an action at that meeting, affirming their participation. This action indicated
their willingness, and also their eagerness to participate because they realized this study
would provide light on their role as leaders. We met with the group again in August 2013,
receiving an affirming response. Therefore, this study rightfully assumes that respondents
took the time to answer questions in a sincere and honest way.
Limitations of the Study
The limitations of the study are (a) the participants’ potential willingness to
answer the questionnaire online, and (b) the ability to answer the questions asked by the
Authentic Leadership Questionnaire honestly and sincerely. The population under study is
composed of individuals who have multiple time-demands and some may have
considered this study unnecessary, or perhaps an unwelcome task.
Delimitations
This study is delimited to a population composed of Adventist local conference
treasurers in the United States and their treasury teams. The Seventh-day Adventist
Church (SDA) is a worldwide religious not-for-profit entity established originally in 1863
in the United States of America to carry on a dynamic work in religious, educational,

humanitarian, publishing, health-care, and food-production areas. Of the 58 official local
conferences in the territory of North America requiring the services of treasurers or
financial managers, seven of them operate in Canada, one in the Bermuda Islands, and 50
in the territory of the United States of America (General Conference of SDA, 2014, pp.
165-229). The administrative units located in Canada and the Bermuda Islands have not
been included in this study. Only the 50 entities serving in the United States are a part of
the population studied.
Definition of Terms
The terms defined below will be used repeatedly throughout the study:
Academy Treasurers (Followers): Financial officers of secondary schools. In this
study I included the academies operated by the local conferences in the United States, or
Local Conference-Operated Academies. They were selected by the Office of Education of
the North American Division located on 12501 Old Columbia Pike, Silver Spring, MD
20904.
Adventist: Refers to the Seventh-day Adventist Church, its beliefs, mission,
structure, organization, and philosophical values.
Associates in Treasury (Followers): The treasury personnel who provide
professional support to the local conference treasurer; a participant group of local
conference employees working in the treasury departments composed of Undertreasurers,
Associate Treasurers, Assistant Treasurers and Accountants.
Authentic Leadership Values: Values advocated by Authentic Leadership
practitioners and believers as advocated by Avolio, Gardner, and Walumbwa.

Church: Term used mostly to identify Adventist local congregations. In this
dissertation the terms “churches” or “local churches” are used to identify local
congregations; the term “Church” (with capitalized “C”), depending on the context, is
used to identify the Seventh-day Adventist Church as a denomination or the Christian
Church in general.
Constituent Academies: Secondary schools operated by either a single local
congregation, or by a group of congregations that have agreed to operate it. Usually the
board elects the chair, and the local conference superintendent is an invitee serving in an
advisory role as the school is operated by the constituency of the local congregations,
rather than the conference office. Board membership includes a representative group of
pastors and members from the constituent congregations.
Denominational Culture: Adventist organizational way of thinking.
Followers: Participant group of associates in treasury and academy treasurers of
local conference-operated academies.
Inauthenticity: Considered the opposite of authenticity.
Leaders: Participant group of chief financial officers of the local conference, or
conference treasurer.
Local Conference Treasurer (Leader): The chief financial officer of the local
conference who is responsible to provide financial leadership, property ownership issues,
routing of funds, and other general financial and personnel matters.
Local Conference: An administrative unit composed of local congregations,
schools, and institutions. It is a center of church governance, the clearinghouse for the
routing of funds, holds title of church properties, and is the personnel employer.

Local Conference-Operated Academies: Secondary schools that have their direct
governance structure connected to the local conference office. Usually the local
conference president is the board chair, and the local conference treasurer is a member of
the board, and may chair the finance committee. The local conference superintendent is a
member of the board and is fully involved with personnel and classroom supervision.
Major decisions are made by the K-12 Board of Education, or the local conference
executive committee.
Working Policy: A compilation of mutual operational agreements guiding
organizational Adventist administrative practice for organizations and institutions, and
that establishes the norms of personnel behavior.
Mind Garden, Inc.: A company that administers the use of the Authentic
Leadership Questionnaire 1.0 (ALQ 1.0), and offers online data collection services at
www.mindgarden.com.
Overview of the Study
This study explores the authentic leadership values of the local conference
treasurers in the United States by observing whether their self-assessment responses agree
or disagree with the assessment their followers provide of them as authentic leaders. Both
groups, leaders and followers, responded to the same questionnaire (ALQ 1.0), but each
from a different perspective. In the following chapter I review the literature that provides
a theoretical framework to this study.

CHAPTER 2
REVIEW OF THE LITERATURE
Introduction
This review of the literature is focused on authentic leadership. The chapter is
organized into four sections: (a) brief historical overview of authentic leadership; (b) the
philosophical and theoretical foundations of authentic leadership; (c) ethical leadership
and positive forms of leadership, and (d) issues from the current research environment.
These four sections describe the authentic leader as a better kind of person, whose
character and behavior agree, who shows consistency in values and actions, in beliefs and
behavior, and one who is capable of inspiring others to follow, or lead.
Brief Historical Overview of Authentic Leadership
Authenticity, sincerity, and integrity are virtues that man has pursued for centuries.
Authenticity was understood by Chester Barnard in 1938 as the capacity of a leader to
balance responsibilities such as private freedom and public obligation, and this capacity is
“a litmus test of executive quality” (Novicevic, Harvey, Ronald, & BrownRadford, 2006,
p. 64).
Erickson (1995) notes that authenticity is “a centuries old problem that in its
modern conception emerged within the past eight decades” (p. 123). C. Taylor (1992)
notes that being authentic “is recovering our own ‘sentiment de l’existence,’ that perhaps
we can only achieve integrally if we recognize that this sentiment connects us to a wider

whole” (p. 91). Bill George (2003) defines authenticity as being yourself; being the
person you were created to be (George, 2003, p. 11). Goleman, Boyatzis, and McKee
(2004) understand the modern concept of authenticity as a re-statement of a human
emotion in a new context, as “acting from one’s genuine feelings” (Goleman, Boyatzis, &
McKee, 2004, p. 51).
Walumbwa et al. (2008) indicate that authenticity is found “at the intersection of
the leadership, ethics, positive organizational behavior and scholarship literatures, and it
is achieved by owning one’s personal experiences be they thoughts, emotions, needs,
preferences, or beliefs, all processes captured by the injunction to know oneself.” He
further states that there is “growing evidence that an authentic approach to leading is
desirable and effective for advancing human enterprise, achieving positive outcomes, and
achieving enduring results” (Walumbwa et al., 2008, p. 92). Ideas on authentic leadership
espoused by other scholars are found in the literature (Cooper, Scandura, & Schriesheim,
2005; Gardner, Cogliser, Davis, & Dickens, 2011; Ilies, Morgeson, & Nahrgang, 2005;
Neider & Schriesheim, 2011; Shamir & Eilam, 2005).
The need for authenticity in leadership has been present in society from Bible
times, even prior to the Israelite exodus (Herskovitz & Klein, 1999, pp. 87-93). Socrates
is said to have advocated for an examined life, and more than 300 years ago Niccolo
Machiavelli was in search of a prudent man (Stackhouse, McCann, Roels, & Williams,
1995). During the last half of the 19th century and the first part of the 20th century, in
the days of Henry Fayol, Frederick Taylor, Max Weber, Elton Mayo, and Mary Parker
Follett, the economic emphasis shifted from an agrarian to an industrial society, and with
it came the need to reevaluate management and conform to new realities (Thompson,

Heames, & Harvey, 2006). Later into the 20th century Barnard looked at the personal
qualities of managers in his seminal work The Functions of the Executive and provided a
backdrop for the historic representation of the necessary qualities of successful managers
and leaders (Barnard, 1938). The evolution of management to conform to actual realities,
and the search for authenticity, integrity and transparency in leaders in general have
continued resonating in subsequent decades (Caro, 1982; Halberstam, 1972; Tuchman,
1984).
Until 2003 there were two practical approaches to authentic leadership. The
approach to authentic leadership developed by Robert W. Terry in 1993 with his
actioncentered Authentic Action Wheel comprised six elements. These elements are (a)
Mission, (b) Power, (c) Structure, (d) Resources, (e) Existence, and (f) Meaning, with the
center labeled Fulfillment. Terry helps distinguish between authentic and unauthentic
actions. As problems are diagnosed, the six elements of the wheel assist in finding a
solution.
The second practical approach was developed by Bill George in 2003 and
indicated that authentic leaders (a) have a genuine desire to serve others through their
leadership; (b) are interested in empowering the people they lead; (c) are guided by
qualities of the heart, by passion and compassion, as well as by qualities of the mind; (d)
lead with purpose, meaning, and values; (e) build enduring relationships with people; (f)
refuse to compromise their principles; and (g) are dedicated to developing themselves
because they know that becoming a leader takes a lifetime of personal growth (George,
2003; Northouse, 2013). The quest for integrity and ethical leadership values in
leadership was in part fueled by historical events.

After the conclusion of the Watergate Affair some theorists began writing about
adding an ethical and moral dimension to leadership (Burns, 2005), and others sought to
introduce a moral perspective to transformational leadership (Bass & Steidlmeier, 1999;
Bass & Stogdill, 1990; Bennis, 2004, 2009). These different voices proclaimed the need
for the rise of integrity, sincerity, and transparency even when the term “authenticity”
may not have been used.
The Approach of This Study
The theoretical orientation used in this study owes its direction and focus to the
contributions of Bruce J. Avolio, William L. Gardner, Fred Luthans, and Fred O.
Walumbwa. They defined and operationalized Authentic Leadership theory (AL), and in
collaboration with other scholars reinterpreted authenticity, identified and tested its
variables nationally and internationally, and defined Authentic Leadership Development
(ALD) among positive leadership theories (Avolio & Gardner, 2005; Walumbwa et al.,
2008).
The approach proposed by Avolio, Gardner, Luthans, and Walumbwa, even
though it is not the only interpretation of Authentic Leadership to be found in the
literature (Gardner et al., 2011; Neider & Schriesheim, 2011), provides four identifiable
constructs and a tested measurement instrument. The constructs are Self-Awareness,
Balanced Processing, Ethical/Moral, and Relational Transparency. The instrument called
the Authentic Leadership Questionnaire (ALQ 1.0) was given in this study to the
Adventist chief financial officers in the United States, to their associates in treasury, and
to selected academy treasurers.

These four constructs or measurable variables, when measured together, define
authentic leadership. Thus authentic leadership is viewed as being composed of related
and substantive dimensions that are needed for individuals to be considered authentic
leaders (Walumbwa et al., 2008).
After the conclusion of the Watergate Affair some theorists began writing about
adding an ethical and moral dimension to leadership (Burns, 2005), and others sought to
introduce a moral perspective to transformational leadership (Bass & Steidlmeier, 1999;
Bass & Stogdill, 1990; Bennis, 2004, 2009).
A New Awareness in Society
Although the need for authenticity in leadership has surfaced repeatedly, the
corporate failures of Enron, WorldCom, and other companies at the beginning of the new
millennium showcased the need to redefine leadership on an ethical and moral platform
(Jennings, 2006). As Sparrowe stated, “Authenticity—or, more precisely the lack thereof
—lies near the heart of the crisis of confidence in contemporary corporate leadership”
(Sparrowe, 2005, p. 419). A new awareness was created in society.
McCall and Hollenbeck (2002) identified the qualities needed by leaders in the
new environment as (a) being open-minded and flexible in thought and tactics, (b) having
value-added technical and business skills, (c) having cultural interest and sensitivity, (d)
being resilient, resourceful, optimistic, and energetic, (e) being able to deal with
complexity, (f) having a stable personal life, and (g) possessing and engendering honesty
and integrity (p. 35). Managers and leaders today, and financial managers in particular,
are aware of existing ethical rules as governmental regulations have given ethics and
morality more prominence in leadership development (Brown & Trevino, 2006;

Sarbanes, 2002). Novicevic et al. (2006) indicate that “the capacity of moral creativity is
a crucial quality of executives that have a genuine sense of self, are adaptive to situational
and organizational demands, but do not sacrifice their personal moral code” (p. 72). This
change represents a variation in professional outlook, as management transitioned from
an industrial-base profession to more individual oriented (Wren, 1972). It is observable
that this change in society has affected not only industrial but also corporate not-forprofit
and governmental organizations (Dresner, 2000, p. 33), integrating the perceptions of
both leader and follower (M. Taylor, 2009; Zhu, 2006) on a platform of ethics and
morality (M. E. Brown & Trevino, 2006).
Novicevic et al. (2006) indicated that “the capacity of moral creativity is a crucial
quality of executives that have a genuine sense of self, are adaptive to situational and
organizational demands, but do not sacrifice their personal moral code” (p. 72).
T. Brown (2005), in his study of Adventist treasurers, observed that the research
participants of his study agreed that the treasurer’s roles and responsibilities were
changing from accounting to financial leadership, thus confirming that the trend
perceived in the financial world in general also affects Adventist financial managers. This
element has a potential effect on the leadership development as it is to be implemented
within the Adventist Church. Local conference treasurers are leaders who have a
subservient leadership function (Bonem & Patterson, 2005). While in past times the role
of the financial officer was seen mostly as accountant, in the 1980s the corporate role of
the Chief Financial Officer (CFO) became more prominent, outgrowing the traditional
accountant/bookkeeper concept, and rising to an executive status with leadership
influence (Vames, 1988). T. Brown (2005) described the functions of the financial

manager as servant, diplomat, accounting manager, and financial leader (T. Brown, 2005,
p. 91), pointing to the mixing of regular financial responsibilities with non-financial
duties, which makes the function fit the organizational climate the Church provides.
The Quest for Authenticity
The foundation of Authentic Leadership theory is grounded in the quest for
authenticity of society in general (Novicevic et al., 2006; Novicevic, Heames, Paolillo, &
Buckley, 2009). More recently the concept of authenticity—being true to oneself—
became a central focus of the post-Enron era, and the need for authenticity, executive
quality, or executive authenticity led to “reinventing theory, reinterpreting evidence, and
rediscovering voices and issues” attributing a new meaning to existing facts, as proposed
by Mark Bevir in his post-analytic philosophy approach (Novicevic et al., 2006, p. 64).
Considered an ethical theory, together with Ethical, Spiritual, and Servant
leadership (Yukl, 2010, p. 409). The Ethical, Servant, Spiritual and Authentic Leadership
category “reflects an eclectic mix of theories that emerged and/or rose in prominence
during the past decade and share a common focus on the moral component of leadership”
(Gardner, Lowe, Moss, Mahoney, & Cogliser, 2010, p. 937). A decade after its inception
we have a better view of Authentic Leadership’s theoretical foundations, its research
history, and its place in the field of leadership development (Gardner et al., 2011).
Shamir and Eilam (2005) note that the value of authenticity in leadership springs
from the fact that leaders exhibiting authenticity “lead from a conviction,” “do not fake
their leadership,” and “have a value-based cause or a mission they want to promote.”
They show they are eudaimonic—true to themselves—when people’s life activities are
congruent with the deeply held values, what they believe and what they do, work

harmoniously together. They want to reach their potential and make a difference—all for
a greater good. Shamir and Eilam elaborate that when people are eudaimonically
motivated, they are fully engaged in their own self-actualization, and make use of their
virtues, talents, and skills. They affirm that being authentic is being personal, original,
and unique although similar to others, but characterized by having a high level of
integrity and transparency. They write that “authenticity is personal, and develops from
personal reflections and personal learning,” and it takes place when talk and actions are
consistent with beliefs and values (Shamir & Eilam, 2005, pp. 3, 4). The need for these
values was made evident during the corporate malfeasance of the last decade documented
by Marianne Jennings (2006). As the concept of authenticity found its way to center
stage, the theory of Authentic Leadership appeared, and authentic leadership development
took its place among ethical and other positive forms of leadership.
The Positive Approach to Leadership
Positive psychology originated in the work of Martin Seligman. His philosophical
position is an objectivist view of life, explaining that there is no greater moral goal than
achieving happiness (Seligman, 2002). Positive psychology is in contrast with the views
presented in clinical psychology and places its emphasis on positive behavior, valuing the
strengths and virtues of people (Seligman, 2002; Seligman & Csikszentmihalyi, 2000;
Whitney & Trosten-Bloom, 2010). Luthans (Avolio & Luthans, 2006) considered that
positive psychology offered a better theoretical platform for leadership development than
did traditional clinical psychology. His participation in a positive psychology summit
inspired him to apply its concepts to leadership development. His ideas connected well
with Avolio’s work on transformational leadership (Avolio, 2005; Avolio & Luthans,

2006, p. 147), and with these basic elements, authentic leadership became a full-fledged
theoretical approach to leadership.
The beginning of Authentic Leadership took place when Bruce Avolio and Fred
Luthans (2006) published an essay on Authentic Leadership Development in a book about
Positive Organizational Scholarship (POS), also known as Positive Organizational
Behavior (POB) (Cameron, Dutton, & Quinn, 2003, pp. 241-258). Avolio and Luthans
(2006) identified POS as foundational to positive psychological capital (PsyCap). The
component parts of PsyCap are hope, confidence, optimism, and resilience. In the very
first publications these PsyCap components were considered additional dimensions of the
Authentic Leadership theory, but now they are considered preliminary leadership
character qualities, foundational to positive forms of leadership (Avolio & Luthans, 2006,
p. 149). On this point Avolio and Luthans (2006) explain that traditionally
business schools and the implicit theories of business leaders have been almost
solely based on the perspective of the value of economic and financial capital:
how to invest it and gain a return from it. The vast majority of this education and
the resulting practice of capitalism is concerned with how to raise financial
capital, account for it, budget it, leverage it, and impact the ‘bottom line’;
however, such economic and financial capital is finally being recognized as not
entirely sufficient. Both business and authentic leaders recognize the value of
financial capital as a necessary foundation for today’s and for future
organizations, but they now also understand that financial and economic capital is
not the only consideration impacting sustained growth and competitive
advantage. (Avolio & Luthans, 2006, p. 143)
They further elaborate that the term capital “refers to the resources that are withdrawn
from consumption and invested for future anticipated returns” (p. 144). Table 1
consolidates Avolio and Luthans’ (2006) comprehensive view on the capital package of
leaders, which is a perspective of what a corporate leader provides. The items shown in
Table 1 are prioritized in order of importance from Economic/Financial to Psychological
(Avolio & Luthans, 2006).
Table 1
Comprehensive Capital Package
Capital Resources Definitions
4. Psychological (PsyCap) – Who you are
(the actual self) and what you intend to
become (your possible self) (p. 144).
Based on the positive psychology movement developed by
Martin Seligman that emphasizes what is right, and not what
is wrong with people (p.147).
3. Social – Who you know – Relationships Estimated based on years of education and experience, and
and the network of contacts and friends the expertise and qualifications people possess for completing
that can facilitate getting done what needs the mission and critical tasks. Calculated on network analysis
to be accomplished (p. 144). and the quality of the relationships that exist in the organization.
Associated with mutual trust, transparency, support, openness, etc. (p. 147).
2. Human – What you know – Employees
are the assets that walk home every night
(p. 144).
Made up of education, skills, experience, and tacit knowledge
that cannot be imitated or easily duplicated or purchased (p.
144).
1. Economic/Financial – What you have –
resources withdrawn from consumption
and invested for future anticipated returns
(p. 144).
Tangible assets such as plant, equipment, inventories,
technological processes, data of all kinds, and even
intellectual property like patents, copyrights, and trademarks
(p. 144).
Table 2 contains a summary explanation of the four components of Psychological
Capital (PsyCap)—Hope, Optimism, Confidence, and Resiliency—that Avolio and
Luthans (2006) consider embedded into the four variables of Authentic Leadership
Development: Relational Transparency, Self-Awareness, Balanced Processing of
Opinions and Ethical/Moral Values (Avolio & Luthans, 2006). The elements of PsyCap
shown in Table 2 are expected personal character qualities of an individual pursuing a
positive practice of leadership.
The contributions of Positive Psychology and Positive Psychological Capital (Psy
Cap), the new awareness in society about the need of integrity, honesty, and ethical
behavior, were incorporated into a new view of leadership that Avolio and Luthans (2006)
proposed with Authentic Leadership Theory.
Table 2
Elements of Psychological Capital (PsyCap)
Character Qualities Definitions
PsyCap – Hope
Defined by positive psychologist Rick Snyder as constituting the “will” and the “way.” The
Will represents a strong belief and sense of confidence that one will succeed, while the Way
represents what Snyder calls “pathway thinking.”
PsyCap – Optimism
Positive psychology treats optimism as expecting a positive outcome. Optimists do not take
failure personally, and view it as a temporary set-back that does not shatter their
selfawareness, while pessimists take failures personally. Provides a higher level for setting
your level of confidence, kicks into action your will power and ways to accomplish it.
PsyCap – Confidence
Confidence, or self-efficacy, refers to the probability that you will be successful in taking on
a particular task or challenge. ALD has a trickle-down or cascading effect through the
mechanism of self-efficacy (p. 71).
PsyCap – Resiliency
Exhibited by those who are hit hard by a particular problem or challenge but still find some
way to keep moving ahead. Resilient people bounce back and even beyond, never
bemoaning the past or the present.
Philosophical and Theoretical Foundations of Authentic
Leadership
A Post-Analytic View
During the first half of the 20th century, existential thinkers like Heidegger, Sartre,
Camus, Kierkegaard, and Maslow explored issues of inauthenticity, elevating honesty
and truthfulness in individuals above other existential values (Park, 1983; Seeman, 1966;

Trilling, 1972). Philosopher Mark Bevir (1999) participated in the philosophical
foundation by offering his voice to the theoretical framers of authentic leadership and
adopting “a (post) analytic view of philosophy drawing on the later work of
Wittgenstein” (p. 6). He writes, “I adopted a version of Wittgenstein’s view of analytic
philosophy as the grammar of our concepts, and then explored the forms of reasoning
appropriate to the history of ideas” (Bevir, 1999, p. 310). Providing a new philosophical
interpretation to already existing views, he treated “analytic philosophy, phenomenology,
and hermeneutics as compatible activities” (Bevir, 1999, p. 3), and argued that
while philosophers construct the logic of a discipline on the basis of the concepts
deployed within it, not the data uncovered by it, they do so to examine what
these concepts imply about the nature of the world, not to record how we use the
words that embody these concepts. (p. 13)
Novicevic et al. (2006) affirm that this new discipline studies cultural meanings
from a historical perspective. By seeking a normative reasoning and not pursuing the
uncovering of historical facts, the new discipline and the post-analytic view advocated by
Bevir provides us with a rationale to explain the uncovered meanings of past events
(Novicevic et al., 2006, p. 65). Grenz (1996) offers the perspective that
no experience occurs in the vacuum; no transformation comes to us apart from an
interpretation facilitated by the concepts—the ‘web of belief’—we bring to it.
To the contrary, experience and interpretive concepts are reciprocally related. Our
concepts facilitate our understanding of the experiences we have in life, and our
experience shapes the interpretive concepts we employ to speak about our lives.
(p. 170)
Novicevic et al. (2006) also observed that Bevir (1999) carved a middle-of-
theroad path to connect shared traditions in the process of discovering historical meanings
(Novicevic et al., 2006, p. 65). Bevir (1999) declared that “historians cannot have direct
access to the past, in the way we can to the present, simply because it has gone. . . .

Historians of ideas study relics from the past in order to recover historical meanings.
They seek to reconstruct ideas or meanings from the past” (p. 31). One would ask, What
does this philosophical intertwining have to do with authentic leadership? The answer is
simple, there is nothing new under the sun, and authenticity, authentic leadership,
authentic followership, and authentic leadership development are not an exception. The
terms may sound like new ideas, but their philosophical and historical origins declare
them to be a resurrection, a reincarnation, and a recasting of concepts that existed in a
different time and historical context. Bevir makes that point clear.
Other Contributions to Authentic Leadership
The perspective advanced by Avolio and Gardner (2005) and by Illies et al. (2005)
is firmly rooted in social psychology theory and research on authenticity; also the
perspective of Avolio and Gardner (2005) did not include either an inductive or a
philosophical approach (Deci & Ryan, 2000; Kernis, 2003). They were seeking a simpler
way to explain authentic leadership (Shamir & Eilam, 2005; Sparrowe, 2005). It is also
important to note the influence of self-determination theory (Deci & Ryan, 2000, pp.
227268) on various facets of leader and follower self-awareness (such as values, identity,
emotions, goals, and motives), as well as the relationships between the follower outcomes
of trust, engagement, and well-being; and the attainment of a verifiable and sustainable
performance (Gardner, Avolio, & Walumbwa, et al., 2005).
Self-awareness is the capacity for self-reflection and introspection required for a
true understanding of the self or others. It is needed because an authentic leader needs to
know himself/herself, in order to be true to himself/herself. This process of
selfknowledge “frequently begins with some sort of a trigger moment, a moment that

activates an internal review of core ideas and values” (Avolio & Luthans, 2006, p. 228).
“Self-awareness is not a destination point, but rather an emerging process where one
continually comes to understand his or her unique talents, strengths, sense of purpose,
core values, beliefs and desires” (Avolio & Gardner, 2005, p. 324).
Self-awareness is defined as “an emerging process where one continually comes
to understand his or her unique talents, strengths, sense of purpose, core values, beliefs
and desires” (Avolio & Gardner, 2005, p. 324).
Other writers indicate that self-awareness, self-reflection, and storytelling develop
self-concept clarity, helping a leader to become mature and able to relate better to
complexity (Denning, 2007; Nehls, 2012; Shamir & Eilam, 2005; Simmons, 2007).
The process of self-awareness shows similarities with the experiential learning
and development model advocated by D. A. Kolb’s content and process reflection cycle,
that encompasses the stages of Concrete Experience (CE), Reflective Observation (RO),
Abstract Conceptualization (AC), Active Experimentation (AE), with the cycle repeating
itself (Kolb, 1984). The process of self-awareness is very much in line with the lifelong
process of self-development taught by several developmental psychologists and
leadership educators (Andenoro, Popa, Bletscher, & Albert, 2012; Clinton, 1988;
Levinson, 1978; Merriam, Caffarella, & Baumgartner, 2007; Rothstein, 2010; Shamir &
Eilam, 2005; Sheehy, 1995).
Through self-awareness, “followers develop greater clarity about their values,
identity, and emotions and, in turn move towards internalized regulatory processes,
balanced information processing, transparent relations with the leader and associates, and
authentic behavior” (Avolio & Gardner, 2005, p. 326). Other more recent contributors to

authentic leadership theory are discussed in the following segments of this review of the
literature (Kernis & Goldman, 2006; Kernis, 2003; Mruk, 2006, 2008), and these
variables measure the degree of authenticity of leaders and followers (Ilies et al., 2005;
Walumbwa et al., 2008). Shamir and Eilam (2005) observed that in authentic leadership
“the role of leaders is central to their self-concept, they have achieved a high level of
selfresolution or self-concept clarity, their goals are self-concordant, and their behavior is
self-expressive” (Shamir & Eilam, 2005, p. 399).
Consistent with Kernis’s developmental model of “optimal” levels of self-esteem,
Walumbwa indicates that authentic leaders display high levels of self-esteem and
consistency between their values, beliefs, and actions (Walumbwa et al., 2008, p. 93). To
that effect Walumbwa et al. defined authentic leadership as
a pattern of leader behavior that draws upon and promotes both positive
psychological capacities and a positive ethical climate, to foster greater
selfawareness, an internalized moral perspective, balanced processing of
information, and relational transparency on the part of leaders working with
followers, fostering positive self-development. (p. 94)
As the four dimensions of the developmental model authored by Kernis (2003)
became the four measurable components of authentic leadership, Walumbwa et al. (2008)
argued that the four areas proposed by Shamir and Eilam (2005) are integrated in the
selfbased model of authentic leaders and follower development of Gardner, Avolio, and
Luthans, et al. ( 2005).
According to Guasta (2012), the meaning of self-awareness is highly complex and
multifaceted, as expressed in Leading in Complex Worlds. “Self-awareness may be
considered to be personal and subjective, although equally connected to relationship and
community” (p. 11) and, as she suggests, “dialogue helps to develop self-awareness as
well as the relational connection that exists among all humans.” She identifies
“selfawareness as a fluid process” and as “a journey involving courage, vulnerability,
confusion, reflection, relation, discovery, and deepened awareness” (p. 12).
In Table 3 I present theorists, philosophers, researchers, and visionaries who have
contributed in varying measures to the origination and early understanding of Authentic
Leadership theory, as discussed in this review of the literature.
Table 3
Theorists, Philosophers, Researchers, and Visionaries
Philosophers Psychologists Theoreticians &
Researchers
Historians &
Visionaries
Bevir, Sartre,
Wittgenstein,
Heidegger
Seligman, Deci &
Ryan, Kernis,
Kolb
Avolio, Gardner, Luthans,
Kernis, Walumbwa, Ilies,
Cooper, Scandura,
Schriesheim, Shamir &
Eilam, Goleman
Novicevic, Barnard,
George, Terry
Existentialist,
Objectivist, Social
Constructionism,
Post-Analytic
Positive,
Social
Psychology
Psychological Capital,
Positive Leadership
theories, Emotional
Intelligence
Ethical Leadership, Positive Forms of Leadership, and
Authentic Leadership
Optimal Self-Esteem
In line with the interpretation of Authentic Leadership theory endorsed by Avolio,
Gardner and Luthans, the variables that define authentic leadership development are:
selfawareness, relational transparency, ethical/moral values, and balanced decision-

making involving others. These are adopted from the model of optimal self-esteem
offered by Kernis. The four dimensions of authentic leadership were originally introduced
by psychologist M. H. Kernis, as the component parts of what constitutes optimal
selfesteem (Kernis, 2003; Mruk, 2006, 2008), and he stated that optimal self-esteem “is
characterized by qualities associated with genuine, true, stable, and congruent high
selfesteem” (Kernis, 2003, p. 1). As Kernis establishes his rationale to achieve optimal
selfesteem, he expresses the reasons why he selected the four variables as follows:
I propose that authenticity as an individual difference construct may be
particularly important in delineating the adaptive features of optimal self-esteem.
Authenticity can be characterized as reflecting the unobstructed operation of
one’s true, or core, self in one’s daily enterprise. As I describe, authenticity has at
least four discriminable components: awareness, unbiased processing, action, and
relational orientation. (p. 13)
Kernis (2003) believed that “experiencing oneself as authentic provides the basis
for experiencing optimal self-esteem” (p. 16), and visualized authenticity as “useful in
advancing our understanding of optimal, or secure self-esteem” (p. 23). He identified
self-awareness as “having awareness of, and trust in, one’s motives, feelings, desires, and
self-relevant cognitions,” including, but not limited to, “being aware of one’s strengths
and weaknesses, trait characteristics and emotions” (p. 13) He further clarified that the
“awareness component of authenticity involves knowledge of one’s needs, values,
feelings, figure-ground personality aspects, and their roles in behavior” (p. 13).
Kernis’s (2003) second component “involves the unbiased processing of
selfrelevant information. In other words, it involves not denying, distorting, exaggerating,
or ignoring private knowledge, internal experiences, and externally based evaluative
information” (p. 14). Third is an ethical/moral element that involves behavior, and
“whether people act in accord with their true self . . . acting in accord with one’s values,

preferences, and needs as opposed to acting merely to please others or to attain rewards or
avoid punishments through acting ‘falsely’” (p. 14). In Kernis’s view transparency is
“relational in nature, inasmuch as it involves valuing and achieving openness and
truthfulness in one’s close relationships. Relational authenticity involves endorsing the
importance for close others to see the real you, good and bad” (p. 15). He attributes his
conception of authenticity to anthropologist Carlos Castaneda (Castaneda, 1971).
Kernis (2003) believed there is no single physical, social, or psychological reality,
but multiple realities coexist, and it is up to the individual to learn about and accept these
multiple realities. Kernis points out that Castaneda’s (1971) central argument is that
individuals are free to choose their own reality; they must trust in it and, at the same time,
recognize that it is not the only reality. He further argues that “this awareness provides a
sense of freedom and responsibility that promotes authenticity” (Kernis, 2003, p. 13).
Authentic Leadership Development
The most significant ideas of leadership development affecting authentic
leadership are found in the book The High Impact Leader (Avolio & Luthans, 2006). In
this work Avolio and Luthans brought authenticity to leadership development.
In an earlier work Avolio and Gardner (2005) identified the constructs guiding
how to do Authentic Leadership Development as (a) practicing transparency, (b) using a
balanced decision-making process, (c) growing moral/ethical perspectives, and (d)
developing self-awareness. These four constructs became the quantifiable variables of
authentic leadership, and they were placed at the foundation of authentic leadership, and
therefore are “at the root of positive forms of leadership” (Avolio & Gardner, 2005, pp.
322-324).

Authentic Leadership follows a developmental process identified as self-based,
where the individual owns his or her experiences, whether they are values, thoughts,
emotions, and/or beliefs. Through a process of self-awareness these past experiences are
revisited, sometimes repeatedly, and lessons are extracted from them bringing “the actual
self” to become “the possible self,” helping connect the past, the present, and the future
(Gardner, Avolio, Luthans, et al., 2005, p. 344).
Social constructivism (Bruner, 1996; Dewey, 1916; Vygotsky & Cole, 1978)
offers Authentic Leadership and Authentic Leadership Development a philosophical
dwelling, as individuals learn as they work and understand their experiences, create
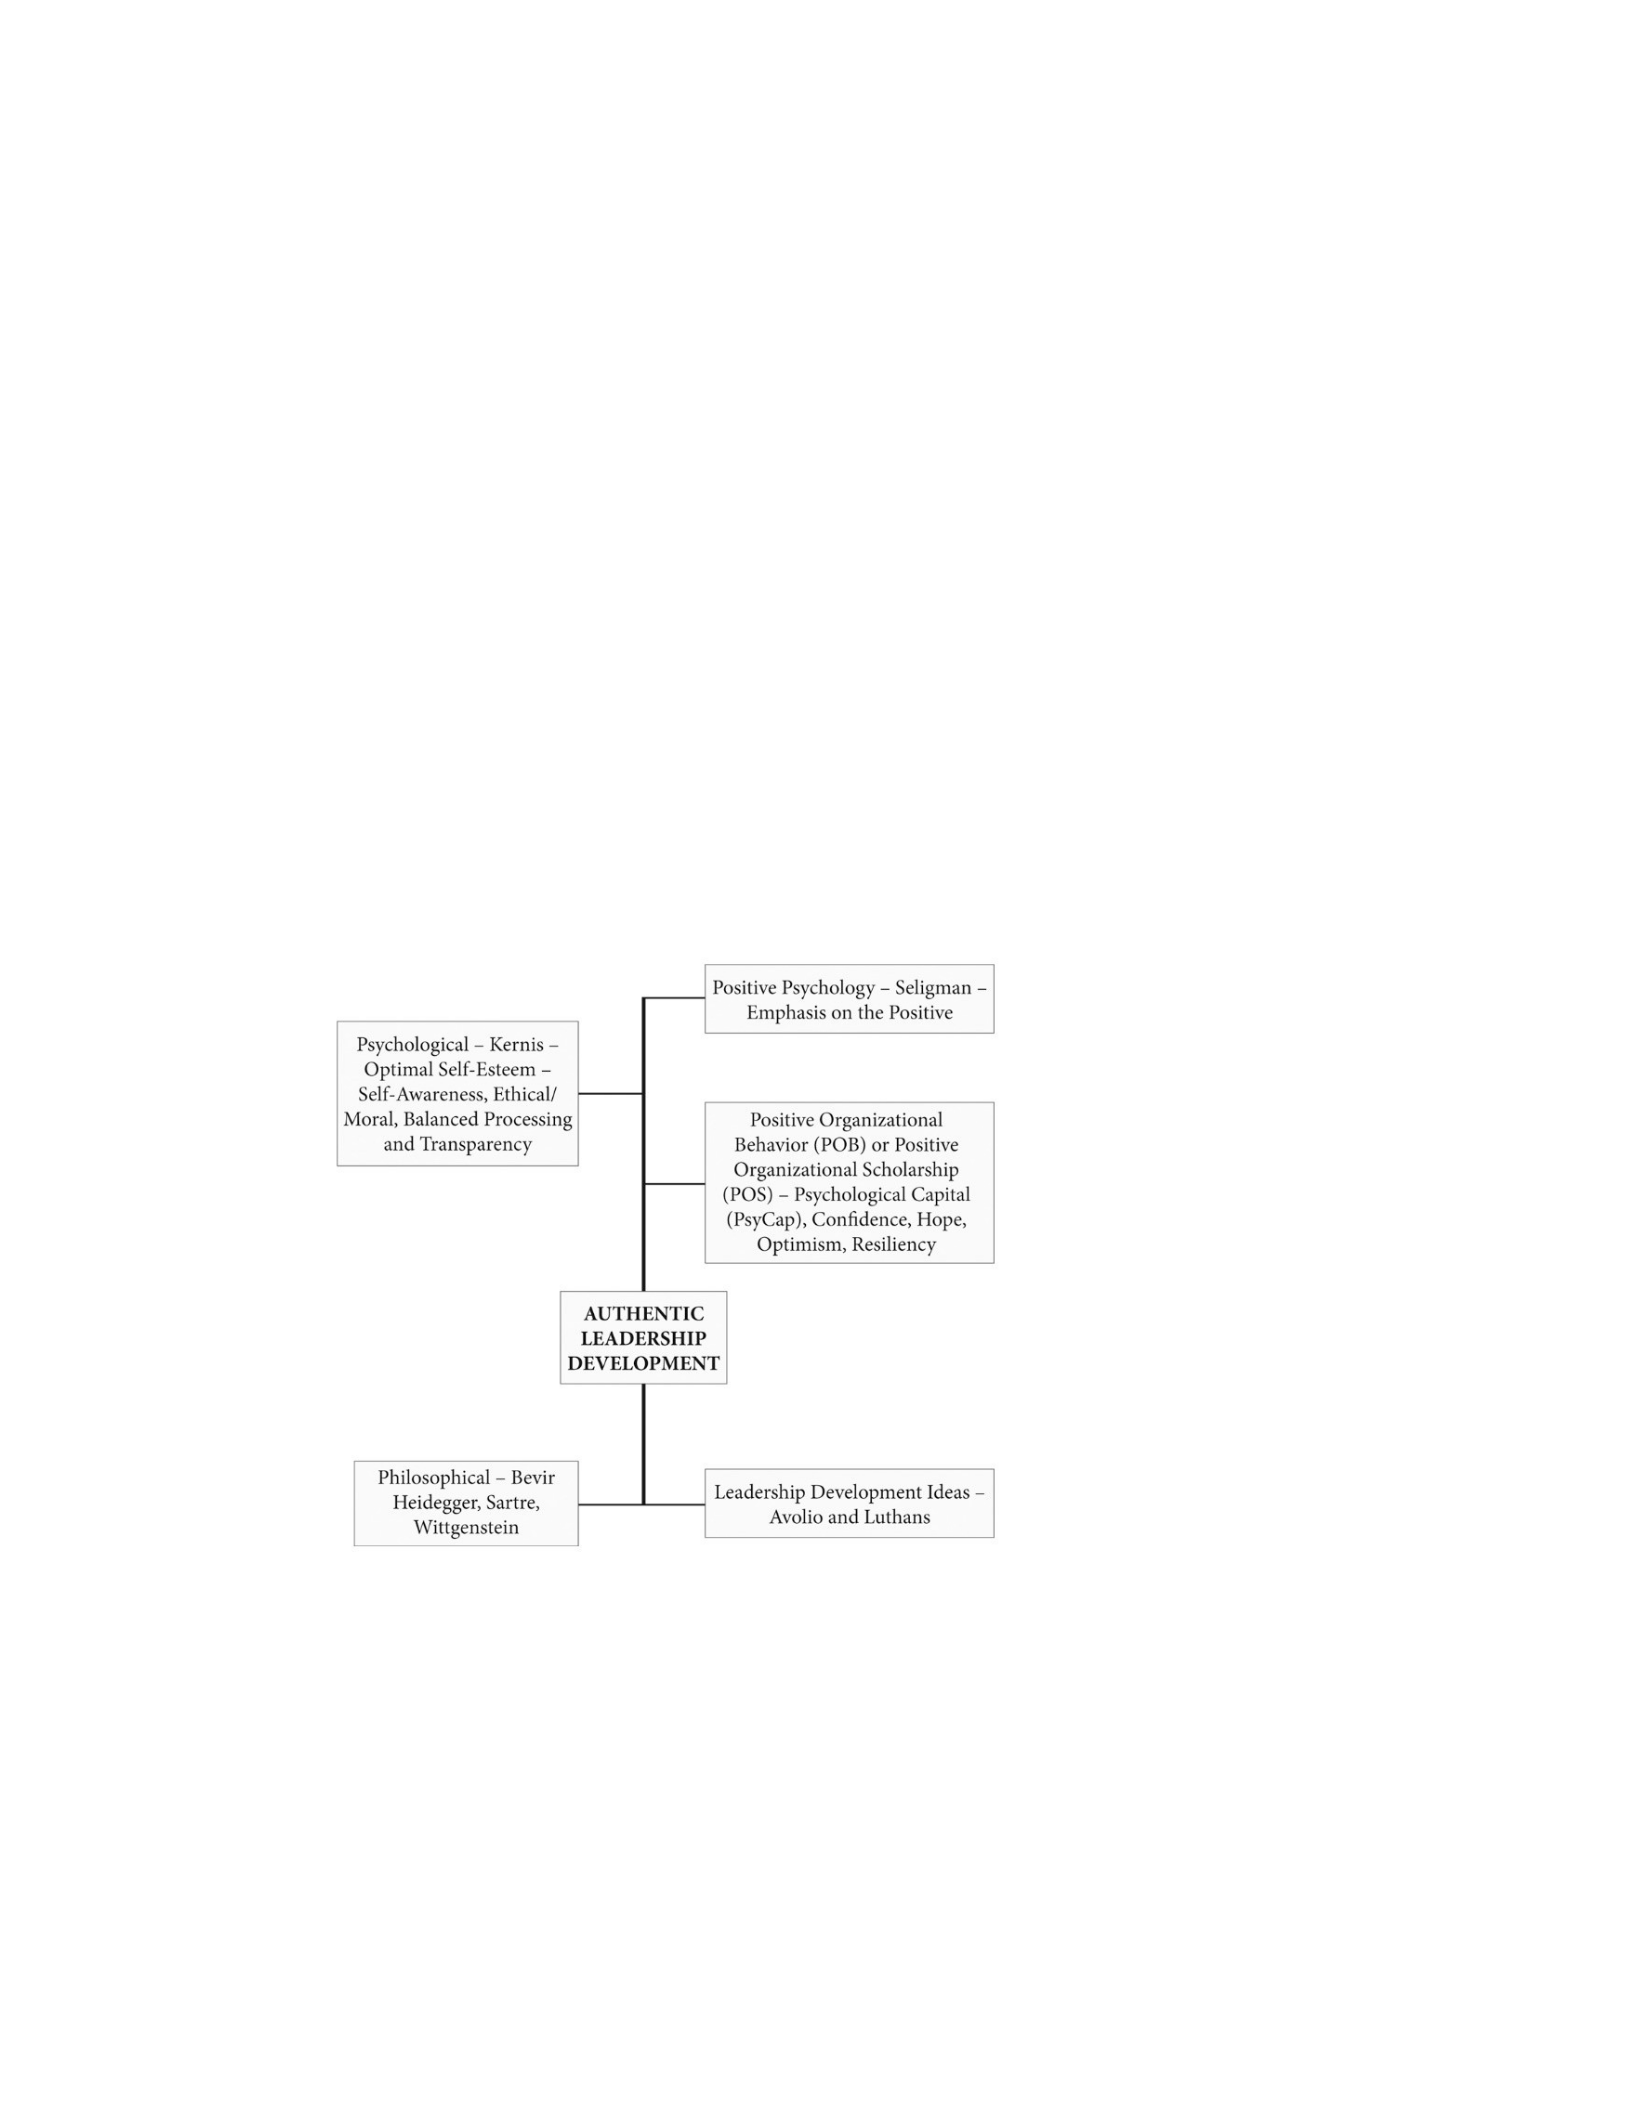
meaning, and learn from them. Figure 1 depicts the different theoretical influences I have
found in Authentic Leadership Development.
The PsyCap components—Confidence, Hope, Optimism and Resiliency—are
considered inherent to authentic leaders, and ultimately, the leadership development ideas
extracted from developmental psychology introduced by Bruce Avolio and Fred Luthans.
These different components serve as a framework that holds this theory together. Central
to Authentic Leadership are the measurable variables contributed by the Kernis studies on
Optimal Self-Esteem. Figure 1 depicts these influences.
Avolio and Gardner (2005) consider ALD to be “at the root of positive forms of
leadership” (pp. 322-324). Theories classified as positive forms of leadership include
Ethical, Transformational, Charismatic, Servant and Spiritual leadership (Avolio &
Gardner, 2005, p. 315; Walumbwa et al., 2008).
Yukl (2010) acknowledges the ambiguity that exists among theorists about
Transformational and Charismatic when he writes about “conceptual ambiguity and lack
of consistency in definitions,” indicating that “even among theorists who view the two
types of leadership as distinct processes, there remains disagreement about whether it is
possible to be both transformational and charismatic at the same time” (Yukl, 2010, p.
285). Yukl also classifies Authentic Leadership together with Ethical, Servant and
Spiritual leadership and considers these theories as “different conceptions of ethical
leadership” (p. 409). He treats Charismatic and Transformational leadership as two
separate theories, and compares Transformational with four charismatic leadership
constructs (Attributed Charisma, Self-Concept Theory, Psycho-Dynamic and Social
Contagion) (pp. 267-269).
Figure 1. Summary of philosophical, psychological, and theoretical influences on
authentic leadership development.
A comparison of the variables of Authentic, Transformational and Ethical
leadership theories by Walumbwa et al. (2008) shows that seven out of ten theoretical
components of transformational leadership are present in authentic leadership, most of
them treated as major focal components of the theory. Table 4 describes the components
of Authentic Leadership Development theory as compared with other positive forms of
Table 4
Components of Authentic Leadership Development Theory
TL SP
1. Positive psychological capital ○ ○ ○ - ○
2. Positive moral perspective ● ● ● ● ●
3. Leader self-awareness - - - - -
Values ● ● ● ● ●
Cognitions ● ● ● ● ●
Emotions ● ● ● ● ●
4. Leader self-regulation - - - - -
Internalized ● - ● - ● Balanced processing ● - - - -
Relational transparency ● - - - -
Authentic behavior ○ ○ ○ ● -
5. Leadership processes/behaviors - - - - -
Positive modeling ● ● ● ● ○
Personal and social identification ● ● ● ○ ○
Emotional Contagion - - - - -
Supporting self-determination ● ● ○ ● ● Positive social
exchanges ● ○ ○ ○ ○
6. Follower self-awareness - - - - -
Values ● - ● ● ●
Cognitions ● - ● - ●
Emotions ● - ● - ●
7. Follower self-regulation - - - - -
Internalized ● ● ● ○ ●
Balanced processing ● - - - -
Relational transparency ○ - ○ - - Authentic behavior
○ - ○ - ○
8. Follower development - - - ● ● 9. Organizational context - - - - -
CL (B) CL (SC) SVT
Uncertainty ● ● ● - - Inclusion ● - - - ●
Ethical ● - - - -
Positive, strengths-based - - - ○ -
Table 4—Continued.
TL CL (B) CL (SC) SVT SP
10. Performance - - - - -
- - - -
Sustained ● ● - - -
Beyond expectations ● ● - - ●
Total
○ ○ ○ ○ ○
25 14 18 13 18
Note. Focal component = ●; Discussed = ○; Not discussed = - .
TL=Transformational Leadership Theory; CL (B)=Behavioral Theory of Charismatic
Leadership; CL (SC)=Self-Concept Based Theory of Charismatic Leadership;
SVT=Servant Leadership Theory; SP=Spiritual Leadership Theory. From “Authentic
Leadership Development: Getting to the Root of Positive Forms of Leadership,” by B. J.
Avolio and W. L. Gardner, 2005, The Leadership Quarterly, 16, 315-338.
doi:10.1016/j.leaqua.2005.03.001
leadership. The comparison shown on Table 4 also shows that five of the main factors in
transformational leadership are found in ethical leadership theory (Walumbwa et al.,
2008).
Authentic Leadership Among Ethical and Positive Forms of
Leadership
Ethical leaders seek to do the right thing personally and professionally and have
the attributes of honesty, fairness, integrity, and openness. This dimension is the moral

person aspect of ethical leadership (M. E. Brown & Treviño, 2006, p. 597). In their
pursuit of clear standards, ethical leaders show self-discipline and consistency in their
pursuit of clear standards, and consider these standards to be not negotiable. This
dimension is what M. Brown, Treviño, and Harrison (2005) identify as the moral manager
aspect of ethical leadership. Walumbwa et al. (2008) comment that of the two constructs
(authentic leadership and ethical leadership), authentic leadership reflects more fully the
moral person aspect, and reflect only partially the moral manager aspect of ethical
leadership (p. 103).
Authentic Leadership likewise contains components that are not considered by
ethical leadership theory, such as the focus on self-awareness, relational transparency, and
balanced processing (Walumbwa et al., 2008, p. 103). Avolio and Gardner (2005) do not
include Ethical Leadership in their comparison with theories that bear similar components
of authentic leadership.
Transformational and Charismatic leadership theories have elements that are also
found in Authentic Leadership. According to the comparative analysis done by Avolio
and Gardner (2005), the foundational elements of transformational leadership theory can
be found in Authentic Leadership. The positive psychological capital, positive moral
perspective, leader self-awareness, leader self-regulation, leadership processes/behaviors,
follower self-awareness, follower self-regulation, follower development, organizational
context, and performance are identified in both theories. The emphasis, major or minor,
varies for both theories (Avolio & Gardner, 2005, p. 323). Yukl (2010) identifies
charismatic leadership as having influenced processes, leader behaviors and facilitating
conditions, and according to his analysis, of the four modalities of charismatic leadership
(Attributed charisma, Self-Concept theory, Psycho-Dynamic, and Social Contagion), only
Self-Concept and Social Contagion were included in the comparison, indicating that these
two versions of charismatic leadership keep closer similarities with authentic leadership
(Avolio & Gardner, 2005, p. 323).
Avolio and Gardner (2005) point out that transformational and authentic
leadership theories remain the closest due to the number of similarities between them (see
Table 4 above). Avolio and Gardner also indicate that an authentic leader does not
necessarily mean the leader is transformational. They write, “We believe the key
distinction is that authentic leaders are anchored by their own deep sense of self; they
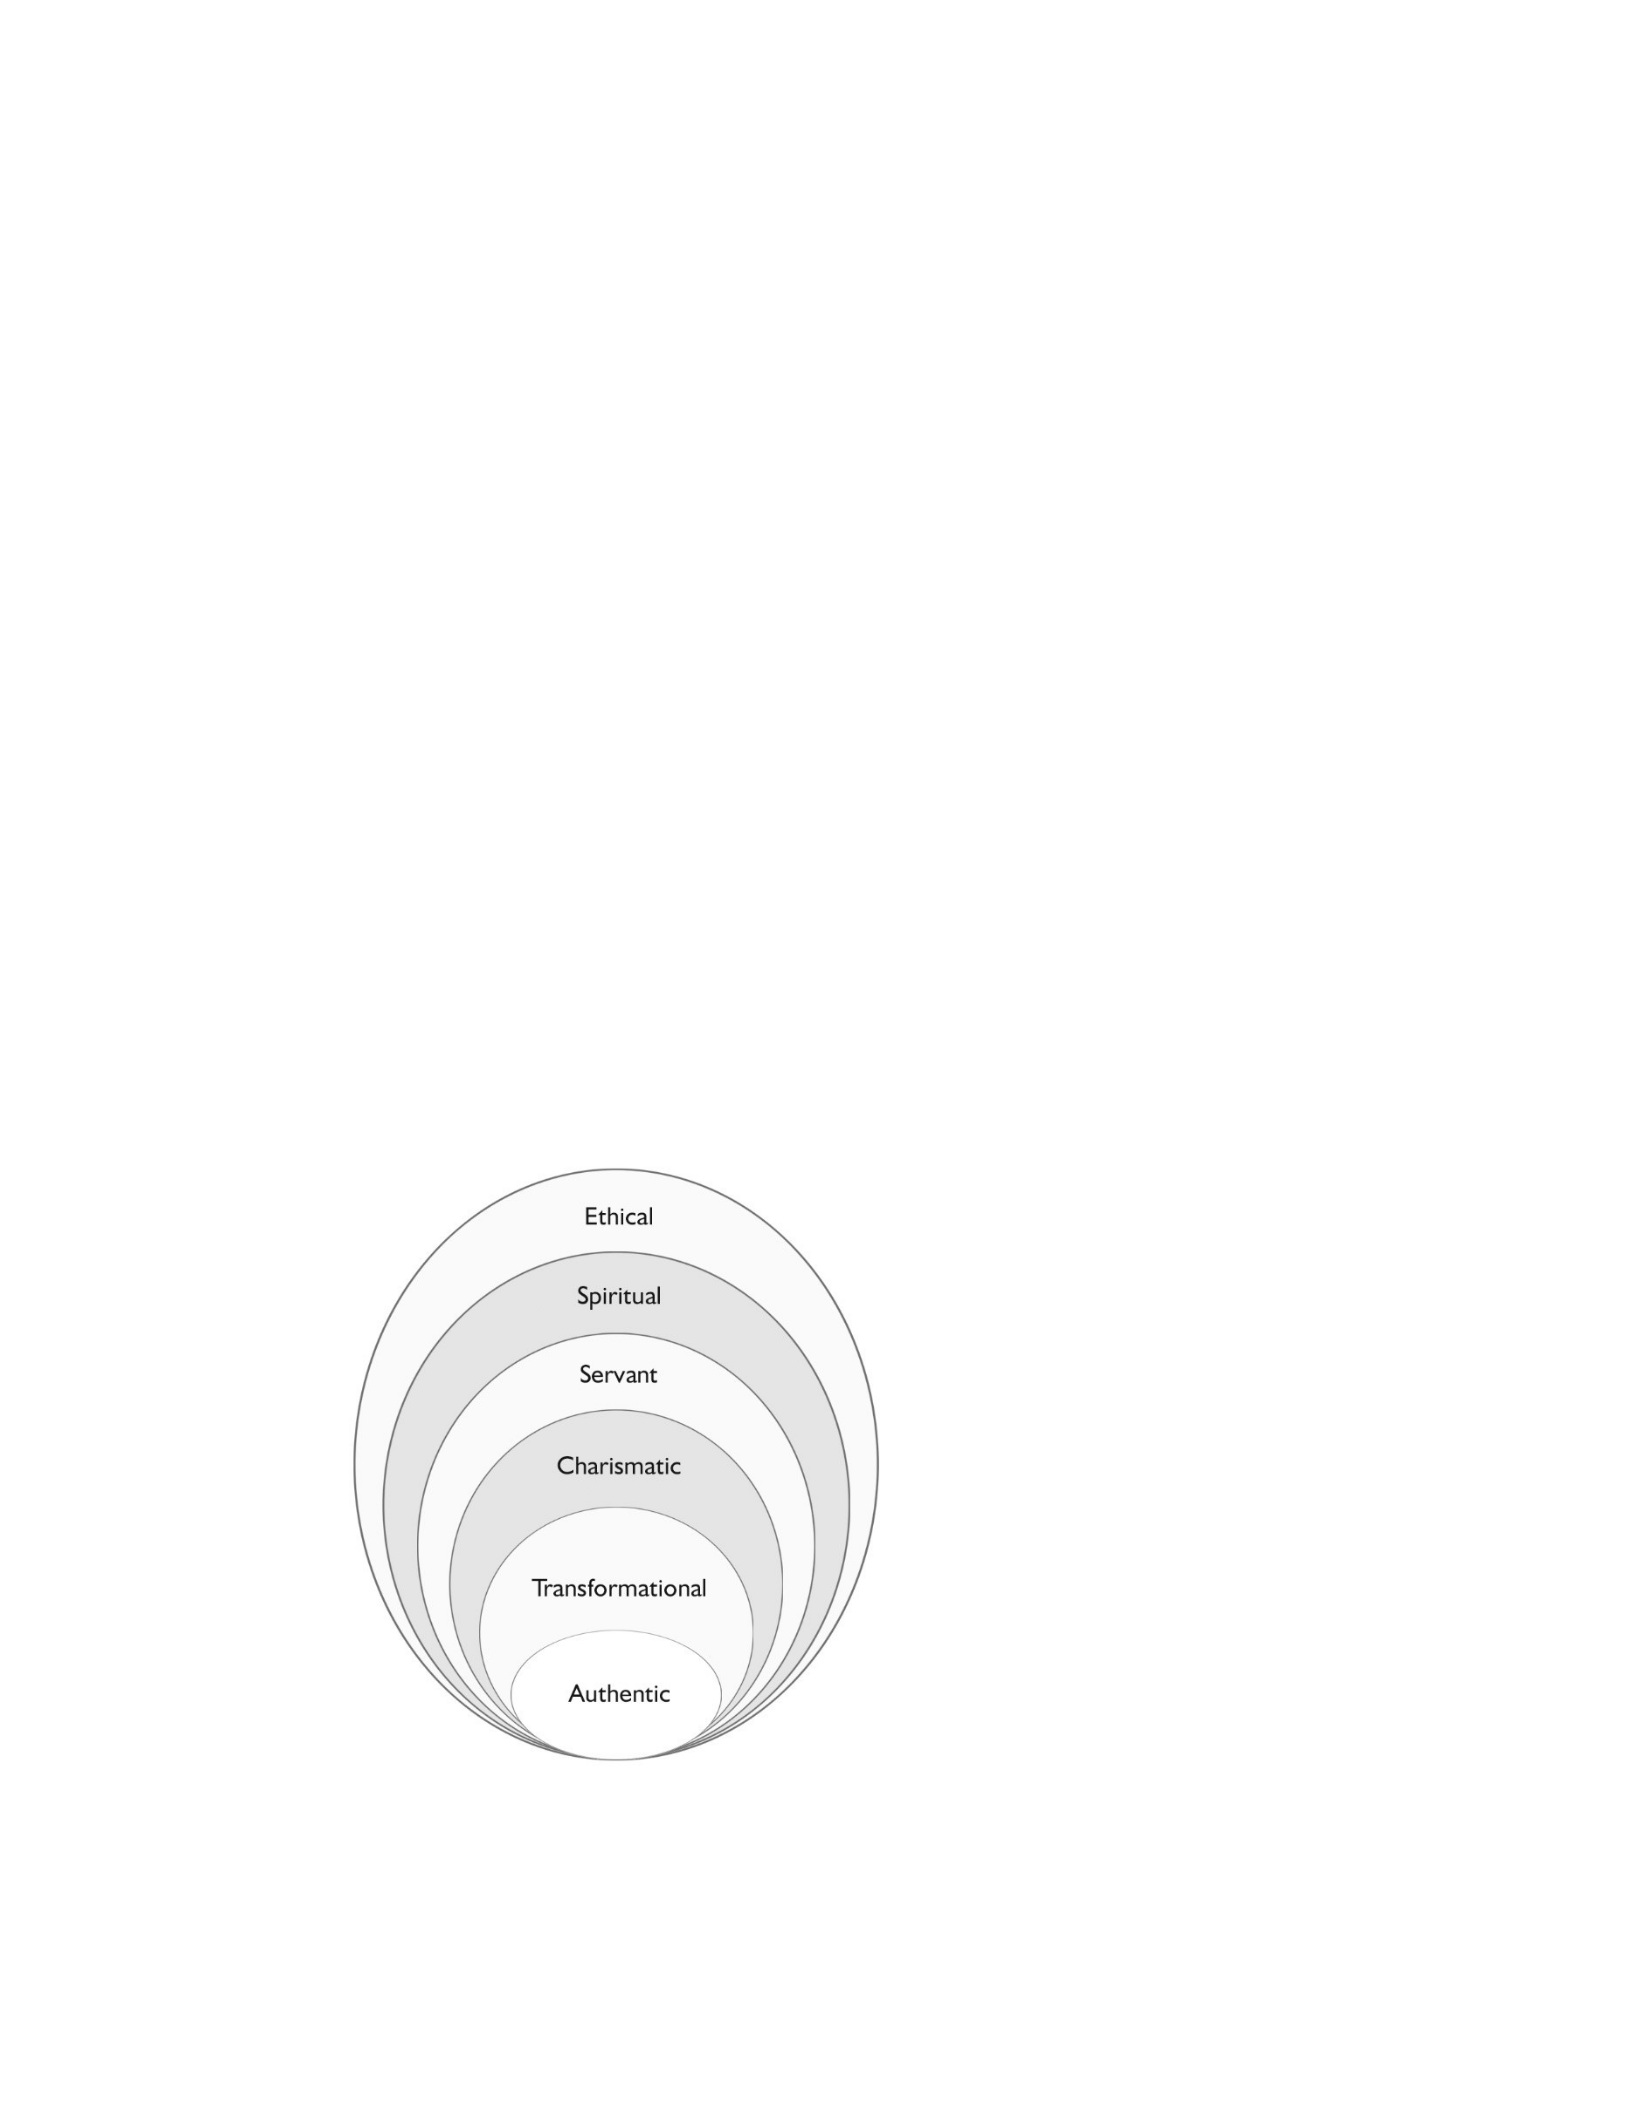
know where they stand on important issues, values and beliefs” (p. 329). Figure 2
describes the place of authentic leadership and its relationship among these closely
related theories, based on the assessment of Avolio and Gardner (2005).

Figure 2. Authentic leadership among ethical theories of leadership. Based on “Authentic
Leadership Development: Getting to the Root of Positive Forms of
Leadership,” by B. J. Avolio and W. L. Gardner, 2005, The Leadership Quarterly, 16,
315-338. doi:10.1016/j.leaqua.2005.03.001
The fields of Ethical Leadership, Transformational Leadership, Leadership
Development, and other positive forms of leadership that preceded it, provided a rich
literature field in which Authentic Leadership and Authentic Leadership Development
started and grew. Just as the voices of practitioners claimed morality, ethics, integrity,
transparency, and self-based development to be central to leadership, likewise the field of
research in ethical theories has been actively contributing to leadership (Gardner et al.,
2011; Gardner et al., 2010).
These positive forms of leadership place moral values at the foundation,
emphasize “leader traits, skills, values, and behaviors; follower values, perceptions and
needs” and together with ethical leadership, are classified as the group of ethical theories
(Yukl, 2010, p. 431). Authentic Leadership came to light after these other theories existed,
and was conceived to integrate their common foundational elements. “A key
differentiation of Authentic Leadership Development from currently popular leadership
theories is that authentic leadership is more generic and represents what we would term ‘a
root construct’” (Avolio & Gardner, 2005, p. 328).
Algera and Lips-Wiersma (2012) indicate that Authentic Leadership and Authentic
Leadership Development, as they are currently theorized, contain paradoxes that
challenge the original objectives. They also indicate that the process of selfawareness,
self-development and self-regulation elevate Authentic Leadership theory above a mere
technique, as it brings the concept of existential authenticity to the heart of what is
human.
Table 5 is a summary of the measuring instruments and variables used to test
authentic, ethical, and positive forms of leadership theories. It also shows the comparison
of Authentic Leadership Development theory with transformational, charismatic, servant,
and spiritual leadership developed by Avolio and Gardner (2005, p. 323).
Table 5
Measuring Instruments for Authentic Leadership and Other
Theories of Leadership
Theory Authentic Transformational Charismatic Servant Spiritual Ethical
Measuring
Instruments
Authentic
Leadership
Questionnaire
ALQ (Walumbwa
& Avolio, 2008)
Authentic
Leadership
Inventory (ALI)
(Neider &
Schriesheim, 2011)
Multifactor
Leadership
Questionnaire
MLQ (Bass &
Avolio, 1996, 2003)
Transformational
Leadership Inventory
(TLI) (Podsaskoff,
1996)
Transformational Servant
Leadership Leadership
Questionnaire Questionnaire
TLQ-I (Conger, SLQ (Barbuto
1989) & Wheeler,
2006)
Spiritual Ethical
Leadership Leadership
On Line at Work,
Survey ELW
SLQ
Avolio and Gardner (2005) point to the fact that Authentic Leadership theory
shows more similarities with Transformational Leadership theory (see the 25 matching
concepts found in Table 4) than with any other positive form of leadership. Authentic
Leadership is growing into adulthood, and the academic community has responded in
diverse ways to it. The next section will provide a glimpse of the variety of issues and
questions still seeking answers.

Issues From the Current Research Environment
It has been 10 years since the first essays and journal articles on authenticity and
authentic leadership were published, and the new ideas began infiltrating the business
world. The young and untested construct journeyed into the spotlight, bringing a new
perspective and a new promise to be examined and tested because authentic leadership “is
about the authenticity of leaders and their leadership” (Northouse, 2013, p. 215). Avolio,
in the foreword he wrote to the book edited by Donna Ladkin and Chellie Spiller, has
referred to the response of the academic community as follows:
Simply put, I have truly marveled at how an idea in any field can become a study,
an article, a conference, the foundation for creating a network of scholars, a
collaborative relationship, a grant, a research contract, and indeed in some case
even institutionalized in the literature. . . . In sum, we started with a simple
definition offered initially by Avolio et al. (2004, p. 806), who stated that
authentic leaders ‘act in accordance with deep personal values and convictions,
to build credibility and win the respect and trust of followers by encouraging
diverse viewpoints and building networks of collaborative relationships with
followers, and thereby lead in a manner that followers recognize as authentic.’
(Avolio, 2013, p. xxvi)
A Complex Process
Despite the progress of the development of Authentic Leadership (AL) theory, a
number of issues need to be highlighted to show how AL theory relates to the continual
struggle to understand leadership. Northouse (2013) acknowledges that Authentic
Leadership “is a complex process that is difficult to characterize, and that can be seen
from an intrapersonal, developmental, and interpersonal perspective” (p. 215). Defined
from an intrapersonal viewpoint, it focuses on the leader and what goes on within the
leader, that is, the leader’s self-knowledge, self-regulation, and self-concept. From a
developmental perspective, Authentic Leadership is viewed as something that can be
nurtured in a leader over a lifetime, and can be triggered by life events. The interpersonal

perspective views Authentic Leadership as an interpersonal process, a relational process
created by leaders and followers (Northouse, 2013). These three aspects are seen in the
research material that has been produced in the last 10 years. This study in particular fits
into the interpersonal perspective, as authentic leadership is seen not only as the result of
the leader’s efforts but also from the response of followers. Authenticity emerges from the
interactions between leaders and their followers, with both groups affecting each other.
A Leader-Follower Process
Multiple statements from noted authors identify the leader-follower relationship as
the epicenter of Authentic Leadership (AL). In fact, the theory was conceived around the
concept that leadership is a relationship, and that it takes place as a result of the
interaction of the leader and the follower in the context of a mutual task. Küpers and
Weibler (2008) raised questions about the integral understanding of leadership as a series
of complex and interrelated processes, rather than isolated or mutually exclusive
paradigms lacking a more inclusive orientation and enfoldment of leadership (p. 444).
The role of followers has been researched and studied before AL appeared (Kelley, 1992),
and the understanding of the relationship leader-follower was established from the outset
by the framers of AL (Gardner, Avolio, & Walumbwa, et al., 2005; Walumbwa et al.,
2008; Walumbwa, Wang, Wang, Schaubroeck, & Avolio, 2010).
Until 2003 there were two practical approaches to Authentic Leadership. The first
was developed Robert W. Terry in 1993, and the second was developed by Bill George in
2003 (George, 2003; Northouse, 2013). Since 2003 the studies on AL have been mostly
theoretical (Avolio, Gardner, Walumbwa, Luthans, & May, 2004; Cooper et al., 2005;
Gardner, Avolio, & Walumbwa, et al., 2005; Walumbwa et al., 2008).

Authentic Leadership has been formulated as a practical and also as a theoretical
approach to a trustworthy, morally guided leadership. Northouse (2013) identified the
practical approach as evolving “from real life examples and training and development
literature,” and the theoretical approach as “based on findings from social science
research” (p. 208).
The practical approach found its voice with Bill George and Robert Terry
(George, 2003; George, Sims, McLean, & Mayer, 2007; Terry, 1998). The Authentic
Leadership Institute (ALI) and the Authentic Leadership Institute in Action (ALIA) are
pursuing the practical approach, providing mentoring to managers and leaders. ALI has
developed the Authentic Leadership Inventory, a research questionnaire that guides a
practical application of authenticity. Northouse notes that (a) AL is still in the formative
stages of development, and there are questions that still need to be addressed about the
theory; (b) the moral component of AL is not fully explained; (c) some researchers have
questioned whether positive psychological capacities (PsyCap) should be included as
components as they broadened the construct of AL too much and make measuring it
difficult; and (d) it is unclear how AL results in positive organizational outcomes
(Cameron et al., 2003; Cooper et al., 2005; Northouse, 2013).
Clashes, Convergences, and Coalescences
The issues and opinions on Authentic Leadership that have accumulated over a
period of 10 years have become a part of this new field of study, and research is discussed
in a useful summary of those who agree, disagree, or simply gravitate towards accepting
the current arguments in favor of AL published by Ladkin and Spiller (2013). At the
outset they dismissed the idea that authentic leadership is a repackaging of
transformational leadership, and proceeded to frame the book with a summary of the
clashes or inharmonious areas existing among scholars, presented the concepts in which
the scholars converge, and the areas of clear agreement or coalescence that form a body
of agreements uniting the participating authentic leadership scholars. Ladkin and Spiller
presented two overarching premises in their introduction. They are (a) leadership is a
relational phenomenon, and (b) the nature of the “self” is formed in relationships and is
considered a work in process (p. 1). The summary of their concepts is presented in Table
6.
Table 6
Summary of Ladkin and Spiller (2013)
Clashes Convergences Coalescences
The nature of the self marginalizes
relationships and contexts. The
notion that the ‘true self’ operates
at its best when unencumbered by
the world of others denies the
forces that interplay to forge a
person.
Letting go – leaders need the
capacity to act selflessly in order
to provide leadership. There is
potential for reciprocity between
leaders and followers. The
orchestra conductor needs to let
the musicians play.
Authenticity in the context of
institutions – fitting in to the
dominant discourse, rather than
being “true” can be a key to
career advancement. Followers
need a leader who is prototypical
of them.
Performing authentically and the
requirements of leading as leaders
can hide behind abusive and
dysfunctional behavior by
claiming to be authentic.
Power and status – being fully in
each moment produces a genuine,
live and unplanned response to
what happens on stage. Followers
may lower their status in order to
experience the safety of having a
higher status leader around.
Relational nature of authenticity –
who is authenticity for? A sense of
acting with one’s own values and
beliefs is key to an individual’s
experience of operating with a
healthy sense of well-being.
Authenticity is a social, rather
than personal virtue.
Too good to be true, as leaders are
idealized and portrayed as more
god-like despite the realities of
being human.
Working it – the idea that
authenticity is a process to be
“worked” rather than a quality of
self to be dipped to. It is not
enough being yourself, if you are
not at your best.
The value of authenticity –
shareholders observe leader’s
commitment to a longer term and
broader interests. Direct
experience, reflection and
discovery forge authentic
responses in the face of the
unknown.
Leadership as “a relational phenomenon is not something that can be distilled
down to one leader, whether authentic or not” (Ladkin & Spiller, 2013, p. 1). Instead, they
observed that “it involves taking up the leader role—a part required by a particular socio-
historic moment—rather than being something that a person is” (p. 1). This position
seems to be partial to the interpersonal and apparent denial of the intrapersonal and
developmental perspectives of authentic leadership (Northouse, 2013).
Ladkin and Spiller (2013) believe that much of authentic leadership focuses on the
individual leader, although, they admit, the self is formed in relationships. Even when the
notion that the “true self” operates at its best when unencumbered by others, that in itself
is a denial of forces that interplay to forge a person, and many authors speak of the
benefits and the drawbacks in understanding the self primarily through self-reflection.
Ladkin and Spiller (2013) also questioned how authentic leadership, with its focus on the
self, can produce the selfless and enlightened leaders that it claims. Furthermore, with
some scholars questioning self-other rating comparison for measuring self-awareness, the
question becomes open as to the measuring statistical technique that could be applied to
the groups studied (S. N. Taylor, Wang, & Yujie, 2012). As scholarly research in the area
of authentic leadership proliferated during the last decade, its impact on our
understanding of leadership development has also grown (Gardner et al., 2011).

Inauthentic Leaders
Leaders are not perfect, and most of them present a measure of inauthentic beliefs
and behavior. They may be found less than open, reliable, and accountable; not following
principles, and less than upright and honest. They could be openly biased, partial, unfair,
and unable to understand the world and the meaning of its realities, simply being
inauthentic (Algera & Lips-Wiersma, 2012; Dasborough & Ashkanasy, 2005; Seeman,
1966). Even the most classic examples of leaders with widely recognized integrity and
authenticity, like Mohandas Gandhi in India, Nelson Mandela in South Africa, or Aung
San Suu Kyi in Myanmar, are found to be inauthentic in some aspect of their leadership.
Leaders are complex and may show less than their authentic self. Ciulla (2013)
sees that a construct of authenticity that centers on self-knowledge is too simplistic to
explain leaders like Mandela. Ciulla describes him as less than authentic when his public
behavior was at odds with his true personal emotions. Mandela, she concludes,
gives up some of his freedom and autonomy to become a part of the project of
the anti-apartheid movement. Mandela is attentive to what he is in the context of
others, but whether he acts as he really is or fakes it is irrelevant to what he
actually does. The assumption that morality is a quality of an authentic leader and
the result of being an authentic leader is circular and too simplistic to stand up to
real examples in history. Mandela is not a moral leader because he is authentic,
nor is he an authentic leader because he is moral. (p. 37)
She concluded, “Mandela the man got lost in Mandela the movement” (Ciulla, 2013, p.
37).
Issues of inauthenticity have been implied also in research done on toxic,
despotic, destructive, tyrannical or simply systemic anomalies that have crept into the
system and make leaders fail (Einarsen, Aasland, & Skogstad, 2007; Krasikova, Green, &

LeBreton, 2013; Padilla, Hogan, & Kaiser, 2007; Popper, 2011; Schyns & Schilling,
2013; Thoroughgood, Padilla, Hunter, & Tate, 2012).
A View of Adventist Leaders
Before concluding this chapter, it is of critical importance to emphasize the need
of authenticity among Adventist leaders, and to revisit Jan Paulsen’s remarks in 2005
already commented on previously. A harmony exists between his description of the
leadership dimensions needed by church leaders and the constructs of Authentic
Leadership theory. During his public address Paulsen asked, “What are the qualities
which the community of faith can reasonably be expected to look for in electing a
leader?” (p. 37). He identified (a) transparency, defined as the filter through which
humility and integrity are seen; (b) self-awareness, or relating to our past experiences in
order to learn from them; (c) ethical/moral integrity, as greed and self-seeking do not
belong in any leadership assignment in our church; and (d) the ability of a leader to seek
unity, inclusiveness of culture, gender and opinions, and consideration to having the same
manual, policies, statement of fundamental beliefs and integrated resource support system
which in essence makes the church ‘one united global family of faith.’ Paulsen (2005)
further indicated,
what is critical is to have a clear identification of what constitutes the core
personality, the spiritual ‘DNA,’ of Seventh-day Adventism, which transcends
cultures and traditions and must be retained, treasured, nurtured, and passed on to
our children and the next generation of church members. And this is a leadership
issue. It is leadership’s responsibility, with discipline and love to look after the
heart and the mind of this church. (p. 33)
The Authentic Leadership construct defines authenticity in both leaders and
followers in four variables that impact their development: Self-Awareness, Relational
Transparency, Ethical/Moral Behavior, and Balanced Processing of other peoples’

opinions (Avolio & Gardner, 2005; Gardner, Avolio, Luthans, et al., 2005; Walumbwa et
al., 2008). They correlate closely with the values expressed by Paulsen (2005). As I
evaluate these variables among Adventist local conference treasurers and their associates
in this study, I believe that I am also addressing needs the church has already articulated.
In his latest book (2011), Paulsen reiterated that “an Adventist leader is a person
of integrity” (p. 29), and identified outstanding Adventist leaders as (a) having transparent
motives, (b) showing balance as they consider everyone’s opinion before deciding and
acting selflessly, (c) should be guided by scriptural principles, (d) seek the guidance of
the Holy Spirit to know themselves better, (e) to be able to sense the pulse of the
community they have been asked to lead, (f) having the humility to be led, and (g) being
able to handle change (pp. 30-35).
Before I conclude this literature review it is fair to mention a less intentional, and
yet generalized problem existing in the administration of the structures of the Adventist
denomination. The systemic, perhaps an imperceptible hint at inequity in the distribution
leadership tasks among administrative officers that renders my target group, the local
conference treasurers, unable to function as the leaders they are (Patterson, 2012). The
reader of this study should be made aware of the fact that when leaders are unable to
exercise leadership effectively in their assigned areas, they forfeit the possibility of
becoming authentic leaders.
Summary
This review of the literature was divided into four major sections: (a) a historical
overview of Authentic Leadership (AL); (b) the philosophical and theoretical foundations
of AL; (c) ethical, positive forms of leadership and AL/Authentic Leadership

Development (ALD), and (d) issues and questions from the current research environment.
These four sections describe the origin and development of AL as a leadership theory, its
different philosophical and theoretical influences, and the most recent trends of the theory
given its relatively short life. Authentic leadership was eclectically conceived to be at the
root of positive forms of leadership with the purpose of developing a leader who is a
better kind of person, whose character and behavior agree, who shows consistency in
values and actions, in beliefs and behavior, and who is capable of inspiring others to
follow, or lead. The local conference treasurers, or chief financial officers, function in a
church environment and culture. T. Brown (2005) indicates that the perception of the
treasurer has moved from accounting to financial leadership. The review of the literature
framing this study provides a platform to help understand their perceptions and that of
their followers within the context of authentic leadership, which converges with the stated
desires expressed by the church. In the following chapter I address the research design,
the methodology, and the limitations of the study.

CHAPTER 3
RESEARCH DESIGN, METHODOLOGY, AND
LIMITATIONS
Introduction
The purpose of the study is to explore the perceptions of Adventist local
conference treasurers in the continental United States as Authentic Leaders and assess
how their perceptions either agree or disagree with the perceptions of their followers. I
will accomplish this by relating the answers of the local conference treasurers with the
answers of their subordinates or followers to the Authentic Leadership Questionnaire
(ALQ 1.0) (Avolio et al., 2007).
The chapter includes (a) a description of the sample/population under study; (b)
the survey procedure; (c) a description of the Authentic Leadership Questionnaire (ALQ);
(d) the methodology used for data collection and analysis; and (e) notes the limitations of
the research design and methodology of this study. I seek to explore how the treasurers
relate to the values proposed by “a root construct at the base of transformational
leadership” (Gardner, Avolio, Luthans, et al., 2005, p. 350), and if their perception is
either confirmed or denied by the responses of their followers.
This is a quantitative correlational, comparative, cross-sectional survey. It seeks to
explore and measure the relationship between leaders and followers (Creswell, 2008, pp.
133-135). The study seeks to explain the relationship of two sets of measurable variables

(relational transparency, balanced processing of opinions, ethical/moral values and self-
awareness), and it has a cross-sectional survey design (pp. 389-391).
Population and Sample
The populations studied compose the conference-level financial personnel of the
Seventh-day Adventist Church in the United States. In this study the Authentic
Leadership values, in four measurable dimensions, are tested for the local conference
treasurers or financial managers/leaders, as the “leaders,” and their responses will be
measured and compared with the responses of their “followers,” their associates in
financial management (local conference undertreasurers, associate treasurers, assistant
treasurers, accountants, and association or corporation treasurers working under their
immediate and direct supervision). These are identified in Table 7 as Follower 1. The
treasurers of secondary boarding school institutions operating under the direct local
conference financial supervision are identified under Follower 2. The table groups them
by Union Conferences, which are geographic areas where the conferences operate.
Based on the information shown in Table 7, the number of participants from the
Leader group was 50, from Follower 1 group were 120, and from Follower 2 group were
28, for a total number of 198 possible participants. This study is considered to be a census
study, as it studies the data directly from the population; therefore, a random sample was
not taken, and hypothesis probability testing procedures were not required (Creswell,
2008, p. 394).
Hypotheses
For this quantitative inferential study the first research hypothesis (Ha1) is the
expectation that the local conference treasurers’ self-perceptions of transparency, Table 7
Leaders and Followers Participants
Union
Conference
Local Conference Leader Follower 1 Follower 2 Total
Atlantic
(North East, New
York)
Greater New York
New York
Northeastern
Northern New England
Southern New England
1
1
1
1
1
2 2
4
2 3
1
-
-
- -
5 13 1 19
Columbia
(Middle Atlantic)
Allegheny East
Allegheny West
Chesapeake
Mountain View
New Jersey
Ohio
Pennsylvania
Potomac
1
1
1
1
1
1
1
1
3 3
3
1
2
2
2 5
1
- 1
-
- 1
1
8 21 5 34
Lake
(Great Lakes)
Illinois
Indiana
Lake Region
Michigan
Wisconsin
1
1
1
1
1
3 1
2
3 3
- 1
- 1
1
5 12 3 20
Mid-America
(US center region)
Central States
Dakota
Iowa-Missouri
Kansas-Nebraska
Minnesota
Rocky Mountain
1
1
1
1
1
1
1 1
2
2
2 2
- 1
1
- 1
1
6 10 4 20
North Pacific
(Pacific North
West)
Alaska
Idaho
Montana
Oregon
Upper Columbia
Washington
1
1
1
1
1
1
1 1
1
1
1 4
- 1
1
1
1
-
6 9 5 20
Pacific
(Arizona,
California,
Hawaii, Nevada
and Utah)
Arizona
Central California
Hawaii
Nevada-Utah
Northern California
Southeastern California
Southern California
1
1
1
1
1
1
1
1 5
1
1
1
4
3 4
1 1
1
- 1
-
-
7 20 4 31 Table 7—Continued.
Union Conference Local Conference Leader Follower 1 Follower 2 Total
Southern
(South East and
South Central
States)
Carolina
Florida
Georgia-Cumberland
Gulf States
Kentucky-Tennessee
South Atlantic
South Central
Southeastern
1 1
1
1
1
1
1
1
4 4
4
1
2
2
2
3 2
1 1
1
1
1
-
-
-
8 24 5 37
Southwestern
(South West)
Arkansas-Louisiana
Oklahoma
Southwest Region
Texas
Texico
1 1
1
1 1
1 3
2
4 1
1
-
-
-
-
5 11 1 17
Total 50 120 28 198
moral/ethical values, balanced processing, and self-awareness are significantly different
from followers’ perceptions of their leaders in the same four factors already indicated.
This expectation stands in contrast with the null hypothesis (Ha1) that the treasurer’s self-
perceptions of relational transparency, moral/ethical values, balanced processing, and
self-awareness are not significantly different from followers’ perceptions of their leaders
in the same four constructs.
The second hypothesis (Ha2) states that the treasurers’ gender, age, years of
professional service, years of service to the Seventh-day Adventist Church, and academic

level are significantly related to their own self-perception of relational transparency,
moral/ethical values, balanced processing, and self-awareness. This expectation stands in
contrast with the null hypothesis (Ha2) that the treasurers’ gender, age, years of
professional service, years of service to the Seventh-day Adventist Church, and the
academic level are not significantly related to their own self-perceptions of relational
transparency, moral/ethical, balanced processing, and self-awareness.
The third hypothesis (Ha3) states that the followers’ gender, age, years of
professional service, years of service to the Seventh-day Adventist Church, and academic
level are significantly related to their perception of relational transparency, moral/ethical,
balanced processing, and self-awareness of their leaders, the local conference treasurers.
This expectation stands in contrast with the null hypothesis (Ha3) that the treasurers’
gender, age, years of professional service, years of service to the Seventh-day Adventist
Church, and academic level are not significantly related to the followers’ perception of
relational transparency, moral/ethical, balanced processing, and self-awareness of their
leaders.
Definition of Variables
This section includes the conceptual, instrumental, and operational definitions of
the variables included in this study, namely (a) relational transparency; (b) balanced
processing of opinions; (c) ethical/moral values, and (d) self-awareness. These variables
are defined and described below. The reader also finds definitions for these variables in
the Table of Variable Definitions in Appendix A.
Relational Transparency

In this study, following Avolio and Gardner (2005) and Walumbwa et al. (2008),
the Leader (Self) concept of relational transparency is expressed as the leaders present
authentic self to others, promoting trust through disclosures, openly sharing information,
and expressing true thoughts and feelings while trying to minimize displays of
inappropriate emotions. This concept will be operationalized via the Authentic
Leadership Questionnaire (ALQ 1.0) constituted by five items like leaders “Encourage
everyone to speak their mind,” and “Admit their mistakes when they are made.” A
fivescore Likert scale type (from “Not at all” to “Frequently if not always”) is used to
answer the items. An addition of the scores from items 1 to 5 divided by 5 will be a 0 to 4
value of the exact interval. The same measure will apply to followers with similar
instrumental and operational definition.
Ethical/Moral Values
The Leader concept of moral/ethical values is expressed as the leaders have an
internalized and integrated form of self-regulation guided by internal moral standards and
values versus group organizational and societal pressures that result in expressed decision
making and behavior consistent with the internalized values. This concept will be
operationalized via the Authentic Leadership Questionnaire (ALQ 1.0) constituted by
four items such as leaders “Demonstrate beliefs that are consistent with actions,” and
“Make difficult decisions based on high standards of ethical conduct.” A five-score
Likert scale type (“Not at all,” to “Frequently if not always”) is used to answer the items.
An addition of the scores from items 6 to 9 divided by 4 will be a 0 to 4 value of the exact
interval scale. A similar measure will apply to followers with a similar instrumental and
operational definition.

Balanced Processing
The Leader concept of balanced processing of the opinions of others is expressed
as they objectively analyze all relevant data before coming to a decision, and solicit views
that challenge their deeply held positions. This concept will be operationalized via the
Authentic Leadership Questionnaire (ALQ 1.0) constituted by three items such as leaders
“Solicit views that challenge my deeply held positions,” and “Listen carefully to different
points of view before coming to conclusions.” A five-score Likert scale type (from “Not
at all” to “Frequently if not always”) is used to answer the items. An addition of the
scores from items 10 to 12 divided by 3 will be a 0 to 4 value of the exact interval scale.
A similar measure will apply to followers with similar instrumental and operational
definition.
Self-Awareness
The Leader concept of self-awareness is expressed as the leaders demonstrate an
understanding of how one derives and makes meaning of the world and how that
meaning-making process impacts the way one views himself or herself over time. It also
refers to showing an understanding of one’s strengths and weaknesses and the
multifaceted nature of the self, which includes gaining insight into the self through
exposure to others. This concept will be operationalized via the Authentic Leadership
Questionnaire (ALQ 1.0) constituted by four items such as leaders “Seek feedback to
improve interactions with others,” “Accurately describe how others view my
capabilities,” “Know when it is time to reevaluate my position on important issues,” and
“Shows he or she understands how specific actions impact others.” A five-score Likert
scale type (“Not at all,” to “Frequently if not always”) is used to answer the items. An

addition of the scores from items 13 to 16 divided by 4 will be a 0 to 4 value of the exact
interval scale. A similar measure will apply to followers with similar instrumental and
operational definition.
Demographic Variables
In addition to the variables defined above, I collected other pertinent information
to describe the population under study. These variables include age, defined as the time
from birth to the present. The age of the respondent was determined by asking the year
when he/she was born, and subtracting the year reported from 2011. Gender is defined as
the respondent’s sexual biological condition. The responses seek to identify whether the
respondent is a male or a female with a 1 for male, and 0 for a female, which is to be
treated as a dummy variable. Educational level is defined as the highest academic degree
obtained. It provides an operational definition of 1 for High School, 2 for Associate
College Degree, 3 for Bachelor of Arts/Bachelor of Science, 4 for Master of Arts, Master
of Science or Master of Business Administration, and 5 for PhD or equivalent.
Professional affiliations involve collecting information of professional certifications such
as Certified Public Accountant (CPA), Certified Management Accountant (CMA),
Certified Internal Auditor (CIA), or any other equivalent professional certification. The
operational definitions are 1 for CPA, 2 for CMA, 3 for CIA, and 4 for other.
I also sought information about the total number of years of professional work of
the respondent in either a financial and/or administrative area such as managerial,
investments, treasury, accounting, etc. These will be operationalized based on actual
number reported. The years reported in this section should be the total number of years of
work regardless of whether they worked for Adventist denomination or not. The Years of

Denominational Service variable seeks to obtain the information of the years of service
the individual served for the Seventh-day Adventist denomination in treasury or
treasuryrelated work. This could include any time served in financial management,
investment, management, treasury, and accounting as an employee of a Seventh-day
Adventist entity.
The information is defined as the total number of years of service for the SDA Church,
and is operationalized as the actual number reported by the respondent.
Instrumentation
The instrument chosen for this study is the Authentic Leadership Questionnaire
(ALQ) version 1.0, developed by the theorists who originated Authentic Leadership
Development (Avolio et al., 2007). It is available through www.mindgarden.com, with the
following physical address: Mind Garden, Inc., 855 Oak Grove Ave., Suite 215,
Menlo Park, CA 94025 ([email protected]). The questionnaire was introduced by
Walumbwa et al. (2008) and “has undergone significant validation efforts to demonstrate
that it is both reliable and construct valid that gave Authentic Leadership Development a
quantitative foundation” (Avolio et al., 2007, p. 1). It was tested with samples in The
Republic of China, Kenya, and the United States (p. 92). The ALQ consists of 16
questions to the leaders (self), and 16 questions to the followers, (rater). Each statement
was judged using the following scale: 0 = Not at all; 1 = Once in a while; 2 = Sometimes;
3 = Fairly often; 4 = Frequently, if not always. The constructs are measured with the
following questions: Transparency (1, 2, 3, 4, 5); Moral/Ethical (6, 7, 8, 9); Balanced
Processing (10, 11, 12); and Self-Awareness (13, 14, 15, 16) for both leaders and
followers.

Validity and reliability of the instrument ALQ 1.0 are established as
confirmatory factor analyses [that] supported a higher order, multidimensional model
of the construct comprising leader self-awareness, relational transparency,
internalized moral perspective, and balanced processing. Structural equation
modeling (SEM) demonstrated the predictive validity for the ALQ measure for
important work-related attitudes and behaviors, beyond what ethical and
transformational leadership offered. (Walumbwa et al., 2008, pp. 97)
Finally, the instrument provided to the participants included three open-ended
questions addressed to the local conference treasurers. These answers were used as the
foundation of a separate qualitative study not related to this dissertation.
Data Collection
On April 13, 2011, a presentation of the research project was made to the leaders,
the group of local conference treasurers. They collectively and voluntarily agreed to
participate in the study. The Institutional Review Board (IRB) approved the application
under AU Protocol Number 11-142, and upon receiving the approval I contacted the
participants by email to reestablish contact with the leader group, and to establish contact
with the follower groups. I contacted Mind Garden, Inc., and received their permission
for the use of the Authentic Leadership Questionnaire, ALQ 1.0, for data collection. Their
message contained a web line that required the Informed Consent Form to be answered
first by the participant, and only after they extended their consent did the web page allow
them to have access to the ALQ for them to respond to the survey questions. Each
participant was given electronic access to the portion of the ALQ that applied to them.
Their responses were received by Mind Garden, Inc., through an encrypted line, thus
protecting the anonymity of the respondents and the confidentiality of the data.

Data Analysis
The data were processed without names to protect the anonymity of the
participants, and in line with the methodology I used the SPSS statistical package. This is
a census study and descriptive statistics was applied to the data collected. The population
was studied in its entirety due to its size and identity, and as such it permits conclusions to
be drawn about the entire population (Creswell, 2008, p. 394). The application of
MANOVA in order to test Hypothesis 1 (Ha1), and Canonical Regression (Rc) to
Hypotheses 2 and 3 (Ha2, Ha3) afforded a valuable opportunity to understand the
responses of the groups appropriately.
Summary
This chapter has presented a complete description of the methodology, including
the type of research, population and sample, hypotheses, definition of variables,
instrumentation, data collection, and data analysis.

CHAPTER 4
PRESENTATION AND ANALYSIS OF DATA
Introduction
The purpose of this study was to explore the Authentic Leadership values of
Adventist local conference treasurers or Chief Financial Officers (CFOs) in the
continental United States by comparing their self-evaluating input with the input their
followers provide of them. This study used the Authentic Leadership Development
Questionnaire 1.0 (ALQ 1.0) as the measuring instrument (Avolio et al., 2007). This
chapter presents how the leaders and the followers relate to the four variables defining
Authentic Leadership Development (ALD), which are relational transparency,
selfawareness, ethical/moral values, and balanced processing of other people’s opinions.
ALD is considered “a root construct at the base of transformational leadership” (Gardner,
Avolio, Luthans, et al., 2005, p. 350).
The data describe the demographic characteristics of the population and were
tested using multivariate statistical analyses. Because of this, it should be clarified that
the statistical mean (ẋ) is to be considered the population mean (µ). The data are a
description of the population studied, and are not a sample (Heiman, 2004; Hinkle,
Wiersma, & Jurs, 1998). The individuals studied are the population of local conference
treasurers (the leaders), and the associates in treasurers and academy treasurers (the

followers). The first research hypothesis in this study was tested with MANOVA, and the
second and third hypotheses were tested by means of canonical correlation, using the
statistical software SPSS, version 22.
Description of the Population
The group studied consisted of 50 Adventist local conference treasurers, who are
also referred to in this study as leaders, CFOs, and self who are serving in the United
States. A total of 45 individuals answered the Authentic Leadership Questionnaire 1.0
(ALQ 1.0) anonymously via web, using the services of Mind Garden, Inc. for data
collection, and four (4) decided not to participate in the study. In order to protect their
anonymity, as well as the identities of the group of respondents who evaluated the 45
participating local conference treasurers, Mind Garden, Inc., made the data available to
my advisor, who made them available to me without individual names, but only with
code numbers. The second group is a total of 102 respondents composed of 84 Associates
in Treasury in Adventist local conferences, and 18 Academy Treasurers directly
administered by local conferences, as provided by the Education Department of the
Seventh-day Adventist Church in North America. It should be noted that one participant
leader (CFO, Local Conference Treasurer) chose to answer only part of the questions and
because of this the number of respondents varies from 45 to 46. This fluctuation is noted
in Table 8. This study is a census of the population.
The first group, Self, is a group of financial leaders consisting of 35 males and 10
females who self-evaluated, with ages ranging from their 30s to their 70s, with 71% of
them in age groups ranging from 50 to 69 years of age, and with an educational level of
BA, BS, MA, or MBA totaling 95.6% of the participant leaders. The second group

(Raters) represents a total of 102 participants composed of two kinds of followers. The
Associates in Treasury work group (R1) consists of 84 participants, and the Academy
Treasurers group (R2) consists of 18 participants. The number of raters who decided not to
participate was 45, of which 35 are Associates in Treasury and 10 are Academy
Treasurers. The groups together included 37% females and 63% males, with ages ranging
between 25 and 74 years of age. This population group of employees responded to the
same ALQ 1.0 questions to which the first group responded. The results are detailed in
Table 8.
Description of the Variables
The four dependent variables tested as the core of Authentic Leadership
Development (ALD) are the leader’s (a) Relational Transparency in dealing with others,
(b) adherence to Moral/Ethical standards and values, (c) understanding of his/her own
self through Self-Awareness, and (d) Balanced Processing weighing the opinions of
others in making decisions.
These four dependent variables taken together provide a measure of the leader’s
view of his/her own authentic values. The measurement of authenticity is completed
when their followers add their own views about their leader’s self-rating. Both sets of
responses taken in combination provide the view of authentic leadership of this study.
The three independent or demographic metric variables are (a) Years of Work for
the Denomination, (b) Years in Administration, and (c) Age of the participants. The
summary of results of the Mean and Standard Deviation for all groups (Self, R1, and R2) is
presented in Table 9. The total number of independent variables increases to five (5) with
the addition of two categorical variables, Educational Level and Gender.

Table 8
1–9
10–19
20–29
30–39
40–50
6
15
5
13.3
15.5
33.4
26.7
11.1
21
20
26
4
25.0
24.0
31.0
15.0
5.0
6
2
1
33.0
33.0
11.0
17.0
6.0
33
33
43
28
10
22.0
22.0
29.0
19.0
7.0
Years in Denominational Work
1–9
10–19
20–29
30–39
40–50
4
16
3
8.9
15.5
35.5
33.4
6.7
29
30
5
1
67
35.0
36.0
23.0
6.0
1.0
7
2
1
-
44.0
39.0
11.0
6.0
-
41
44
37
4
28.0
30.0
25.0
14.0
3.0
Variables Local Conference Treasurers N=45 Associates in Treasury N=84 Academy Treasurers N=18 Total
N=147
Frequency Percentage Frequency Percentage Frequency Percentage Frequency Percentage
Demographic Information of Participants
Gender
Male
Female 35
10
77.8
22.2
49
35
58.3
41.7
9 9 50.0
50.0
93
54
63.0
37.0
Age
25–29
30–39
40–49
50–59
60–69
70–74
0 6
5
20
12 2
0
13.0
11.0
44.0
27.0
5.0
2
20
17
30
15
-
2.0
24.0
20.0
36.0
18.0
-
2 4
4
5
2 1
11.0
22.0
22.0
28.0
11.0
6.0
4
30
26
55
29 3
3.0
20.0
18.0
37.0
20.0
2.0
Educational Level
High School
Associate
Degree BA or BS
MA or MBA
0
1
22
21
0
2.2
48.9
46.7
8
5
42
29
10.0
6.0
50.0
34.0
1
0
12 5
6.0
0
66.0
28.0
9
6 76
55
6.0
4.0
52.0
37.0
67
CPA
OTHER
None
12
4
29
26.7
8.9
64.4
- 5
-
-
6.0
-
- -
-
- -
-
12
9
29
8.0
7.0
85.0
Years in Administration
PhD or Equivalent 1 2.2 -
- - - 1 1
Professional Affiliation
Table 9
Summary of Means and Standard Deviations
Years of DEN
Years of ADM 24.30 19.85 17.94 11.42 11.01 11.87
Age 54.60 48.60 46.39 9.67 11.19 12.37
Transparency 3.07 2.86 3.43 0.49 0.91 0.57
Self-Awareness 2.99 2.64 3.26 0.54 1.04 0.80
Ethical Moral 3.56 3.21 3.61 0.43 0.94 0.64
Balanced Processing 3.24 2.82 3.26 0.50 0.99 0.85
Note. DEN = Denomination Service; ADM = Administrative Experience.
The five independent and the four dependent variates were used to test the
hypotheses described in the following paragraphs. The results are detailed in the
following tables and paragraphs.
Testing
This section describes the tests applied to each of the research hypotheses and the
results of the tests. It includes descriptive statistical tables and comments on the results.
Hypothesis 1
The first research hypothesis (Ha1) of this study is the expectation that a local
conference treasurer’s self-perceptions of relational transparency, moral/ethical, balanced
processing, and self-awareness values are significantly different from the perceptions
69
Variables
Mean SD
Self R1 R2 Self R1 R2
(N=45) (N=84) (N=18) (N=45) (N=84) (N=18)
25.62 14.93 11.78 10.03 9.46 9.59

followers expressed of their leaders in the same four ALD factors already indicated. This
expectation stands in contrast with the null hypothesis (Ho1) that the treasurer’s
selfperceptions of relational transparency, moral/ethical, balanced processing, and
selfawareness are not significantly different from those of followers on the same four
constructs.
A three group one-way between-subjects multivariate analysis of variance was
performed on the four authentic leadership dependent variables indicated above. The
independent variable was the role of the participant, namely the local conference
treasurer, the associates in treasury, and the academy treasurer. A total of 148 participants
were distributed in 46 Treasurers, 84 Associates in Treasury, and 18 Academy Treasurers
(see Table 8). A statistically significant Box’s M test (p<.001) indicated unequal variance-
covariance matrices of the dependent variables across levels of participant role, and thus
necessitated the use of Pillai’s trace in assessing the multivariate effect.
By using Pillai’s trace as the criterion, the dependent variate mean was
significantly different by participant’s role. Pillai’s trace is equal to .126, F (8,286) = 2.40,
p=.016, 1 minus the Wilks’s Lambda value = .122. Univariate ANOVAs were conducted
in each dependent variable separately to determine the locus of the statistically significant
multivariate difference. Against this alpha level, the participant’s role was statistically
significantly different for transparency F (2,145) = 4.97, sig. = .013; SelfAwareness F (2,
145) = 4.720, sig. = .010; Ethical/Moral F (2, 145) = 3.935, sig. = .022; and Balanced
Processing F (2, 145) = 4.671, sig. = .011.
The Tamhane test suggested that the Academy raters (R2, Followers) value
transparency slightly higher than do the Associates in Treasury (R1, Followers), with sig. =
70

.004, but remain closer to the treasurer’s self-evaluation (see Table 9). The SelfAwareness
mean is significantly lower for Associates in Treasury than the Academy Treasurers and
Treasurers, with sig. = .027 for Academy Treasurers, and sig. = .040 for Treasurers (see
Table 9).
Ethical/Moral mean of Associates in Treasury is significantly lower in comparison
with the Treasurers mean, sig. = .013, than with the mean of Academy Treasurers, and the
difference is not significant. Balanced Processing mean of Associates in Treasury is
significantly lower in comparison with the Treasurer’s mean, sig. = .004, than with the
mean of Academy Treasurers, and the difference is not significant. The Treasurers and the
Academy Treasurers show no significant difference among themselves.
Hypothesis 2
The hypothesis that was examined stated that the treasurer’s personal
characteristics of gender, age, years of professional service, years of service to the
Seventh-day Adventist Church, and academic level are significantly related to his or her
own self-perception of authentic leadership as expressed in transparency, moral/ethical
values, balanced processing, and self-awareness. This expectations stand in contrast with
null hypothesis 2 (Ho2) that the treasurer’s personal characteristics of gender, age, years
of professional service, years of service to the Seventh-day Adventist Church, and
academic level are not significantly related to his or her own self-perception of authentic
leadership as expressed in transparency, moral/ethical values, balanced processing, and
self-awareness. Table 10 describes the zero/order correlation coefficient of dependent and
independent variables for Treasurers.
71
Table 10
Zero/Order Correlation Coefficient of Dependent and
Independent Variables for Treasurers*
Variables 1 2 3 4 5 6 7 8
Years DEN
Years ADM
.519
Educational Level -.280 -.312
Gender .228 .082 -.194
Age .651 .631 -.324 -.089
Transparency .192 .121 .121 -.303 .155
Self-Awareness -.329 -.079 .372 -.253 -.129 .480
Ethical/Moral -.079 .081 .138 -.142 .255 .455 .436
Balanced Process -.387 -.243 .209 .064 -.247 .374 .731 .356
Note. DEN = Denominational Service; ADM = Administrative Experience. *Self-Rated,
Leaders, Local Conference Treasurers, CFOs.
A canonical correlational analysis was conducted to test the multivariate
relationship between the variables of the dependent variate authentic leadership (relational
transparency, moral/ethical values, balanced processing, and self-awareness) and the
variables of the independent variate personal characteristics (gender, age, years of
professional service, years of service to the Seventh-day Adventist Church, and academic
level). The relationship between authentic leadership and personal characteristics was
statistically significant using the Wilks’s λ =.446 criterion (F [20,120] =1.65), p =.051, Rc
= .581, Rc2 = .338, and RI =.175. The significance of this relationship, canonical
72
correlation, canonical correlation squared (shared variance), and redundancy index
provided the basis for the rejection of the null hypothesis.
Canonical loadings were examined to measure the correlation between the
variables with the respective canonical variables (authentic leadership and personal
characteristics). Table 11 presents the canonical loadings as a measure of the correlation
and shared variance between each variate with the respective canonical variables.
Table 11
Canonical Correlation Analysis Between Treasurers’ Personal
Characteristics and Authentic Leadership Self-evaluation (N=45)
Variables Ba rb r2c
Correlations between dependent variable AL and
its canonical variables
Transparency .514 .776 .602
Self-Awareness .728 .641 .411
Ethical/Moral .374 .679 .461
Balanced Processing
-.678
.179
.032
Rc .581 .338
Correlations between independent variable PC
and its canonical variables
Variables Ba rb r2c
Years DEN -.653 -.180 .032
Years ADM .410 .343 .118
Education .551 .424 .180
Gender -.311 -.600 .360
Age
.745
.428
.183
73

Note. AL = authentic leadership and PC = personal characteristics; DEN = Denominational Service; ADM =
Administrative Experience.
aStandardized function coefficients. bCanonical correlation coefficients/Canonical loadings. cSquared
canonical coefficients/Canonical loadings.
The correlation between each variable and the respective canonical variate is
organized in a range from highest to lowest. The following relationships between the
variables in the canonical variate authentic leadership were observed: transparency (.776),
ethical moral (.679), self-awareness (.641), and balance processing (.179). The correlation
between the variables and the canonical variate personal characteristics was observed:
gender (-.600), age (.428), education (.424), years administration (.343), years
denominational (-.180).
In Table 12 the Beta (β) coefficients of Treasurers, their personal characteristics,
serve as predictors of the AL variables (Relational Transparency, Self-Awareness,
Ethical/Moral behavior, and Balanced Processing of others’ opinions). The highest
coefficients for Relational Transparency are predicted by the Years of Denominational
Service (-.45) and Age (.36). The highest coefficients for Self-Awareness are predicted by
the Years of Denominational Service (-.36) and Education (.34). The highest ones for
Ethical/Moral Behavior are predicted by Years of Denominational Service (-.42) and by
Age (.62), and the highest coefficients for Balanced Processing are predicted by Years of
Denominational Service (-.40), with the other levels showing no significance. The (R)
correlation levels show low β coefficients ranging from .17 to .25, with the highest one for
Self-Awareness.
Hypothesis 3
74
The hypothesis that was examined stated that the followers’ (raters) personal
characteristics of gender, age, years of professional service, years of service to the
Seventh-day Adventist Church, and academic level are significantly related to their
perception of authentic leadership as expressed in transparency, moral/ethical values,
Table 12
β Coefficients of Treasurers’ Personal Characteristics Variables as
Predictors of Authentic Leadership Variables (N=46)
Variables Transparency Self-Awareness Ethical/Moral Balanced
Processing
Years DEN -.45 -.36 -.42 -.40
Years ADM .18 .15 -.03 -.06
Education .14 .34 .22 .12
Gender -.16 -.11 .05 .06
Age .36 .11 .62 .10
R .23 .25 .21 .17
Note. DEN = Denominational Service; ADM = Administrative Experience.
balanced processing, and self-awareness of their leaders, the local treasurers. This
expectation stands in contrast with null hypothesis 2 (Ho2) that the followers’ (raters)
personal characteristics of gender, age, years of professional service, years of service to
the Seventh-day Adventist Church, and academic level are not significantly related to
their perception of authentic leadership as expressed in transparency, moral/ethical values,
balanced processing, and self-awareness of their leaders, the local treasurers.
Table 13 describes the zero/order correlation coefficient for raters.
A canonical correlational analysis was conducted to test the multivariate
relationship between the variables of the dependent variate authentic leadership
75
(transparency, moral/ethical values, balanced processing and self-awareness) and the
variables of the independent variate personal characteristics (gender, age, years of
professional service, years of service to the Seventh-day Adventist Church, and academic
level). The relationship between authentic leadership and personal characteristics was
statistically significant using the Wilks’s λ =.694 criterion (F [20,309] =1.79), p =.020, Rc
Table 13
Zero/Order Correlation Coefficients of Raters
Variables 1 2 3 4 5 6 7 8
Years DEN
Years ADM
.586
Education -.179 -.285
Gender .064 -.017 .332
Age .571 .763 -.418 .191
Transparency -.111 .005 -.102 .162 -.053
Self-
Awareness .021 .085 -.087 .076 -.045 .787
Ethical/Moral -.067 -.053 -.146 .069 -.035 .822 .743
Balanced
Processing
-.021 -.008 -.016 .095 -.020 .774 .855 .774
Note. DEN = Denominational Service; ADM = Administrative Experience.
= .408, Rc2 = .167, and RI =.078. The significance of this relationship, canonical
correlation, canonical correlation squared (shared variance), and redundancy index helped
in making the decision to reject the null hypothesis.
Canonical loadings were examined to measure the correlation between the
variables with the respective canonical variables (authentic leadership and personal
76
characteristics). Table 14 presents the canonical loadings as a measure of the correlation
and shared variance between each variate with the respective canonical variables.
The correlation between each variable and the respective canonical variate is
organized in a range from highest to lowest. The following relationships between the
variables in the canonical variate authentic leadership were observed: self-awareness
(-.470), transparency (-.048), ethical moral (.048), and balance processing (.022). The
correlation between the variables and the canonical variate personal characteristics was
observed: years in administration (-.496), years denominational (-.304), education (.195),
age (.098), and gender (.088).
Table 14
Correlation Analysis Between Raters’ Personal Characteristics and
Authentic Leadership Perception (N=102)
Variables Ba rb r2c
Correlations between dependent variable AL and
its canonical variables
Transparency .292 -.048 .002
Self-Awareness 2.056 -.470 .229
Ethical/Moral .334 .048 .002
Balanced Processing
1.295
.022
.000
Rc .408 .167
Correlations between independent variable PC
and its canonical variables
Variables Ba rb r2c
Years DEN -.330 -.304 .092
77
Years ADM -1.356 -.496 .246
Education .281 .195 .038
Gender .278 .088 .007
Age
1.492
.098
.009
Note. AL = authentic leadership perception and PC = personal characteristics; DEN = Denominational
Service; ADM = Administrative Experience.
aStandardized function coefficients. bCanonical correlation coefficients/Canonical loadings. cSquared
canonical coefficients/Canonical loadings.
In Table 15 the Beta (β) coefficients shown are the results of the personal
characteristics variables of the raters (Associates in Treasury and Academy Treasurers)
predicting the ALD variables (Relational Transparency, Self-Awareness, Ethical/Moral
behavior, and Balanced Processing) of the leaders, the local conference treasurers. The
strongest predictors for Relational Transparency are Education (-.21) and Gender (.23).
Table 15
β Coefficients of Raters’ Personal Characteristics Variables as
Predictors of Authentic Leadership Variables (N=102)
Variables Transparency Self-Awareness Ethical/Moral
Balanced
Processing
Years DEN -.18 .00 -.07 -.04
Years ADM .10 .27 -.06 .00
Education -.21 -.16 -.23 -.06
Gender .23 .07 .15 .11
Age -.07 -.31 -.01 .00
.08 .06 .05 .01
Note. DEN = Denominational Service; ADM = Administrative Experience.
78

The predictors of Self-Awareness are indicated by the scores in Years of
Administrative Experience (.27) and Age (-.31). The Ethical/Moral variable is predicted
by Education (-.45), and the Balanced Processing scores are not significant to indicate an
impact on the variable. The correlation (R) levels show very low beta (β) coefficients
ranging from .08 to .01, with the highest level indicated for Relational Transparency.
Summary
In this study I measured the authentic leadership values of local conference
treasurers as tested by their followers, their associates in treasury and academy treasurers.
Three hypotheses were tested using MANOVA (on Ha1) and Canonical correlation (on
Ha2 and Ha3) on the dependent variables (Self-Awareness, Relational Transparency,
Ethical/Moral behavior, and Balanced Processing of others’ opinions) that taken together
provide the view of authentic leadership. In the case of hypothesis 1 (Ha1) the null
hypothesis was rejected. The demographic data of the participants indicate a frequency of
male ages ranging from 50 to 59, an educational level of BA or BS, with a significant
number of years of experience in administration, and years in denominational service.
The summary of means and standard deviations (Table 9) points to a higher mean
and a lower standard deviation for age among leaders (Self) than for followers (R1, R2),
which indicate a stronger concurrence of opinion and a lower data variability. Among the
dependent variables, the leaders also indicated a higher mean (3.56) and a lower standard
deviation (0.43), pointing to higher agreement and low data variability in their responses
on Ethical/Moral behavior. Testing hypothesis 1 (Ha1) with Pillai’s trace, and with
79

Tamhane’s and Levene’s tests, provides a higher alpha, with a .01 level used for
transparency.
In the case of the second and third hypotheses (Ha2, Ha3) the null hypotheses
(Ho2, Ho3) were rejected. The canonical correlation analysis for Ha2 indicates that the
stronger predictors among personal characteristics were Gender (-.600), and (equally
significant) Age and Education (.428, .424, respectively). And the highest correlations
were found with variables Relational Transparency (.776) and Ethical/Moral (.679). The
canonical correlation analysis for Ha3 (in which the personal characteristics of the
followers predict the authentic leadership variables of the leaders) points to the Years of
Experience in Administration (-.496) and the Years of Denominational Service (-.304) as
significant predictors of Self-Awareness (-.470). The scores of other dependent variables
do not show significance. These factors are analyzed in the next and final chapter of this
study.
80

CHAPTER 5
DISCUSSION OF FINDINGS, CONCLUSIONS, AND
RECOMMENDATIONS
Introduction
This chapter provides a summary of the study, a brief review of the methodology
and the research design, a discussion of the study’s key findings, the conclusions, and
recommendations. The findings are interpreted in the light of the literature and my
personal experience.
Summary
The purpose of this study was to explore the authentic leadership values of
Adventist local conference treasurers in the United States. I accomplished this task by
observing whether the self-assessment responses agree or disagree with the assessment
their followers provided of them as authentic leaders. The followers are the associates in
treasury and academy treasurers. This study is categorized as a self-rater, correlational,
cross-sectional exploration survey of a population of business leaders working in a
religious organizational structure. Through the application of the Authentic Leadership
Questionnaire 1.0 I sought answers to the following questions:
1. Are local conference treasurers’ self-perceptions as authentic leaders
significantly different from the perceptions of their followers in their relational
81

transparency, their internalized moral and ethical values, their balanced processing of
followers’ opinions, and their self-awareness?
2. Are personal characteristics of the local conference treasurers significantly
related to their own self-perception as authentic leaders in their relational transparency,
their internalized moral and ethical values, their balanced processing of followers’
opinions and their self-awareness?
3. Are personal characteristics of the followers (gender, age, years of
professional work, years of service to the church and education) significantly related to
the perceptions of the local conference treasurers as authentic leaders in their relational
transparency, internalized moral and ethical values, balanced processing of followers’
opinions, and their self-awareness?
Authentic Leadership is an intrapersonal, developmental, and interpersonal
process, depending on whether the focus is (a) on what goes on within the leader, (b) on
the nurturing of the leader, or (c) on the relational part of leadership (Northouse, 2013). In
this research study, the responses of the participants touch on all three aspects, but they
especially connect with authentic leadership as an interpersonal or relational process. For
the purposes of answering Research Question 1, I tested a group of leaders and two
groups of followers, totaling 148 participants. I used a one-way MANOVA to compare
their responses to the four dimensions of authentic leadership, relational transparency,
self-awareness, internalized moral and ethical values, and balanced processing of their
followers’ opinions. Figure 3 shows a graphic description of Research Question 1, testing
Hypothesis 1 with MANOVA.
82
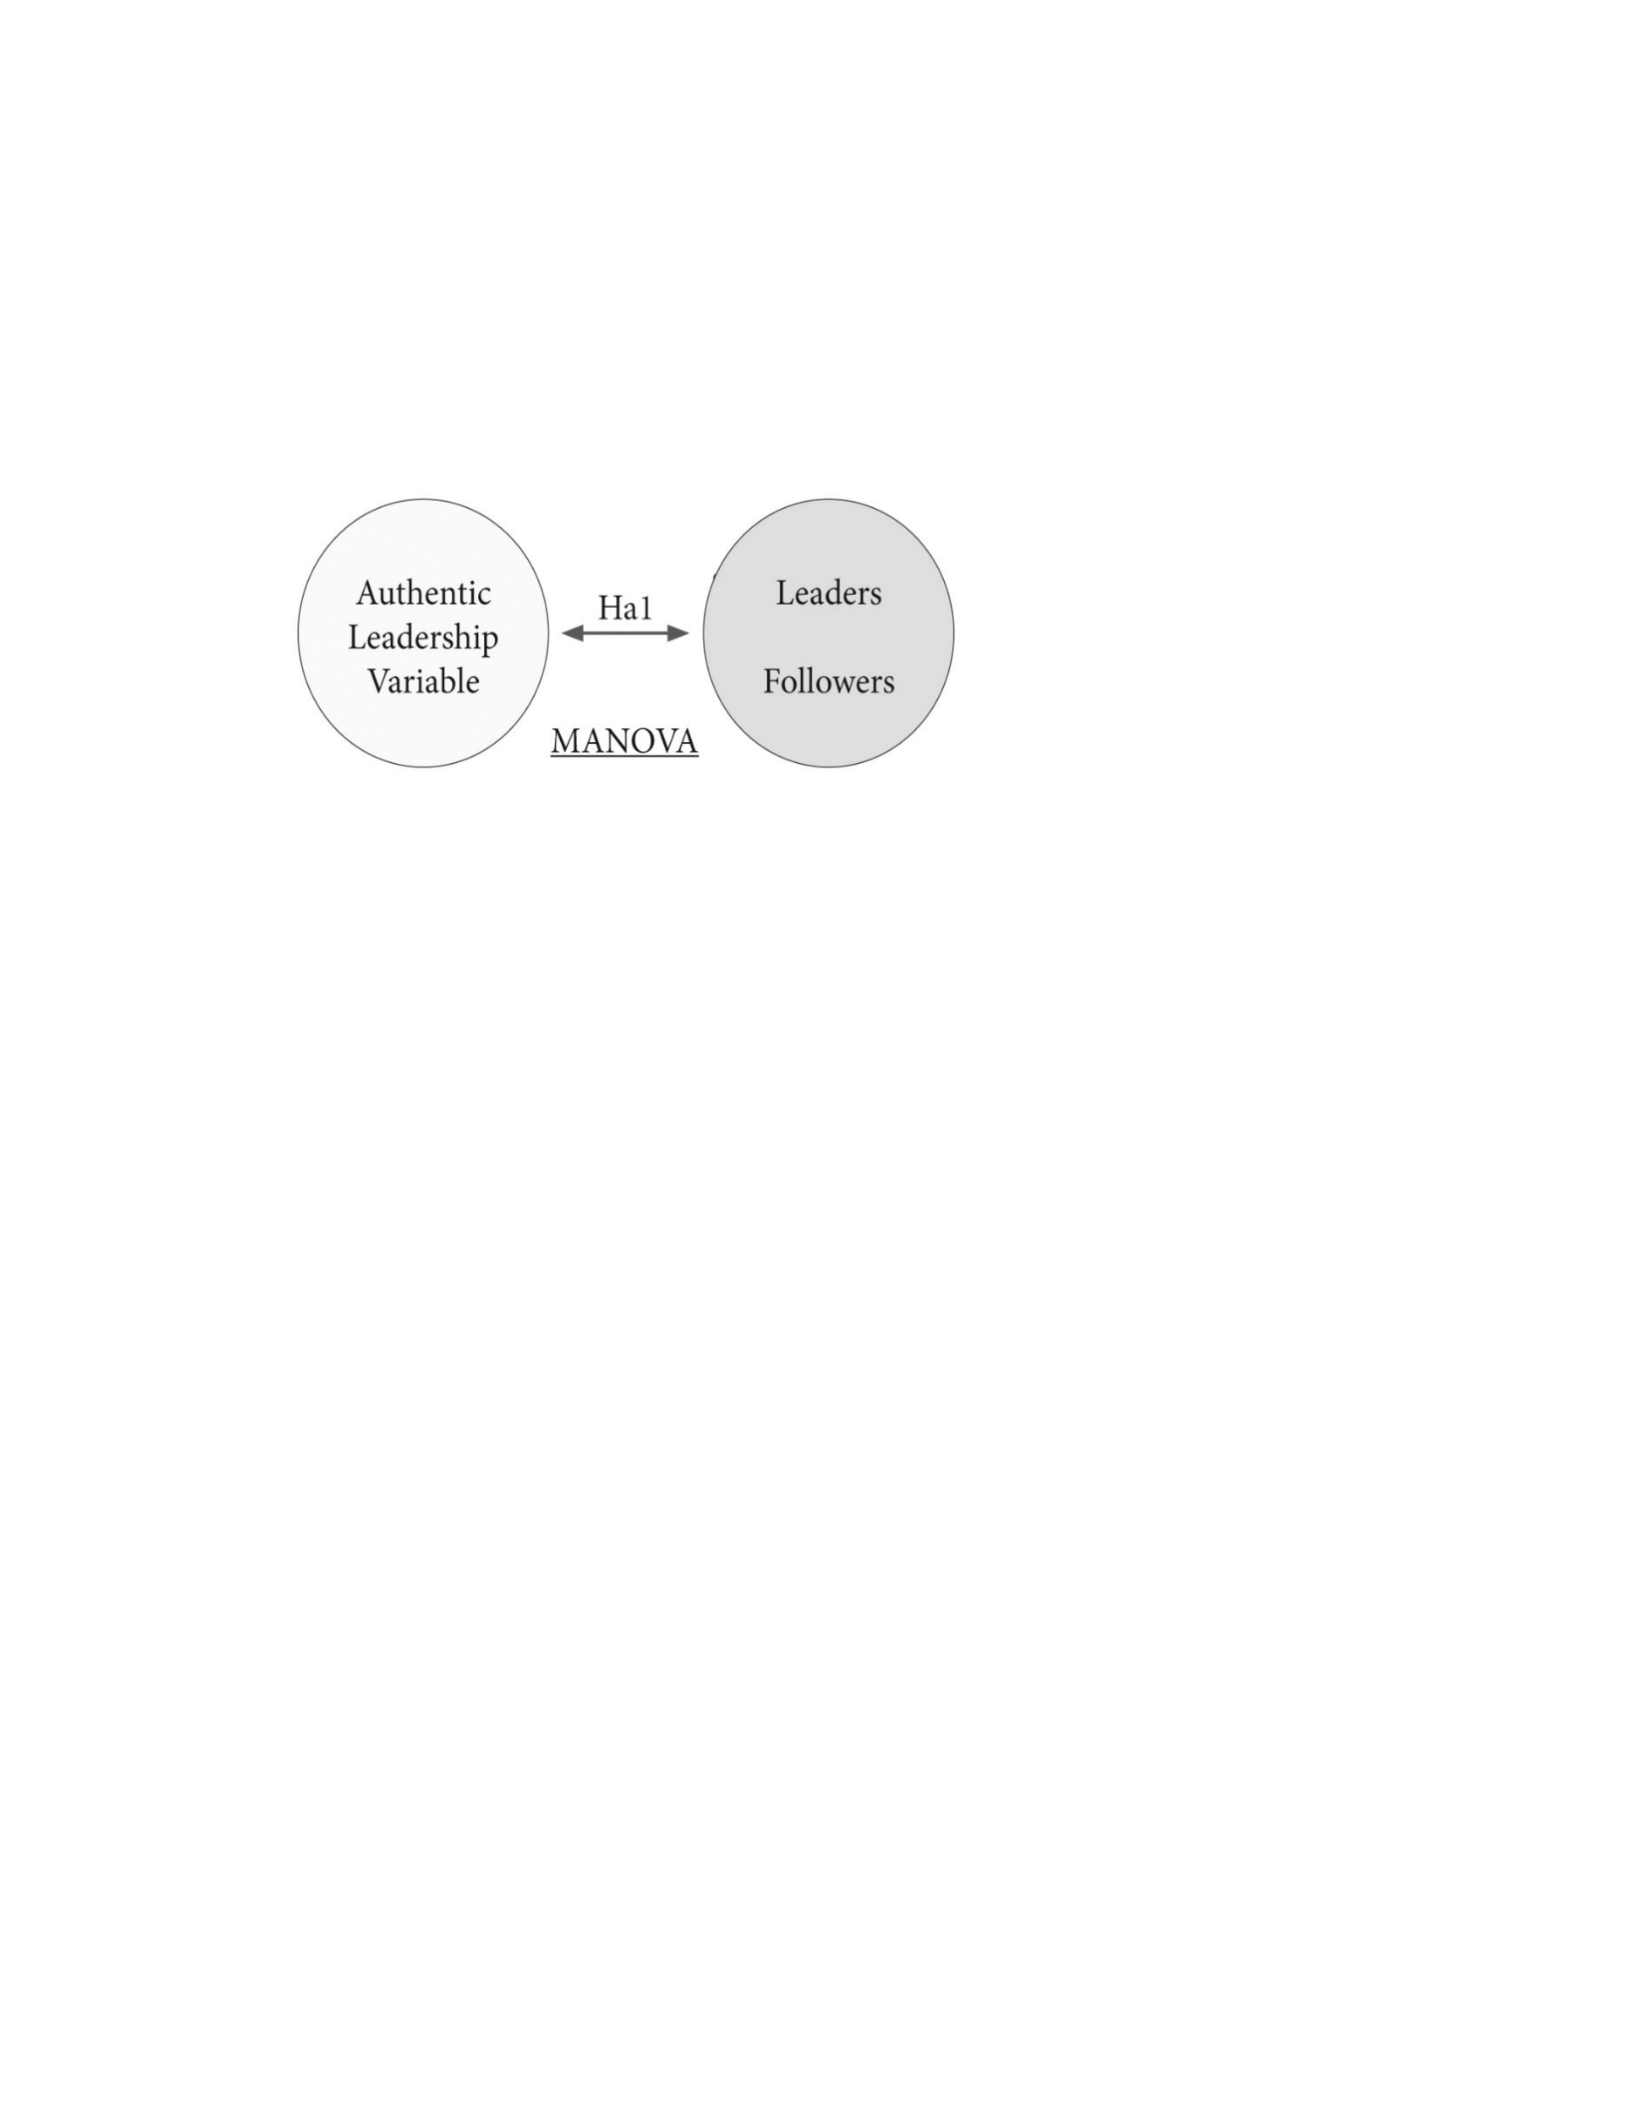
Answering Research Question 2 involved exploring the group of local conference
treasurers’ personal characteristics (years of denominational service, years of
administrative experience, educational level, gender and age) through canonical
Figure 3. Graphic description of the study—Hypothesis 1 (Ha1).
regression (Rc) as predictors of their responses to the four dimensions of authentic
leadership (relational transparency, self-awareness, internalized moral and ethical values,
and balanced processing of their followers’ opinions). Answering Research Question 3
involved applying canonical regression to identify how the followers’ personal
characteristics (years of denominational service, years of experience in administration,
educational level, gender and age) are related to their understanding of the local
conference treasurers’ view of the four dimensions of (relational transparency,
selfawareness, internalized moral and ethical values, and the balanced processing of their
followers’ opinions) authentic leadership. Figure 4 shows a graphic description of
Research Questions 2 and 3 testing Hypotheses 2 and 3 with canonical regressions (Rc).
83
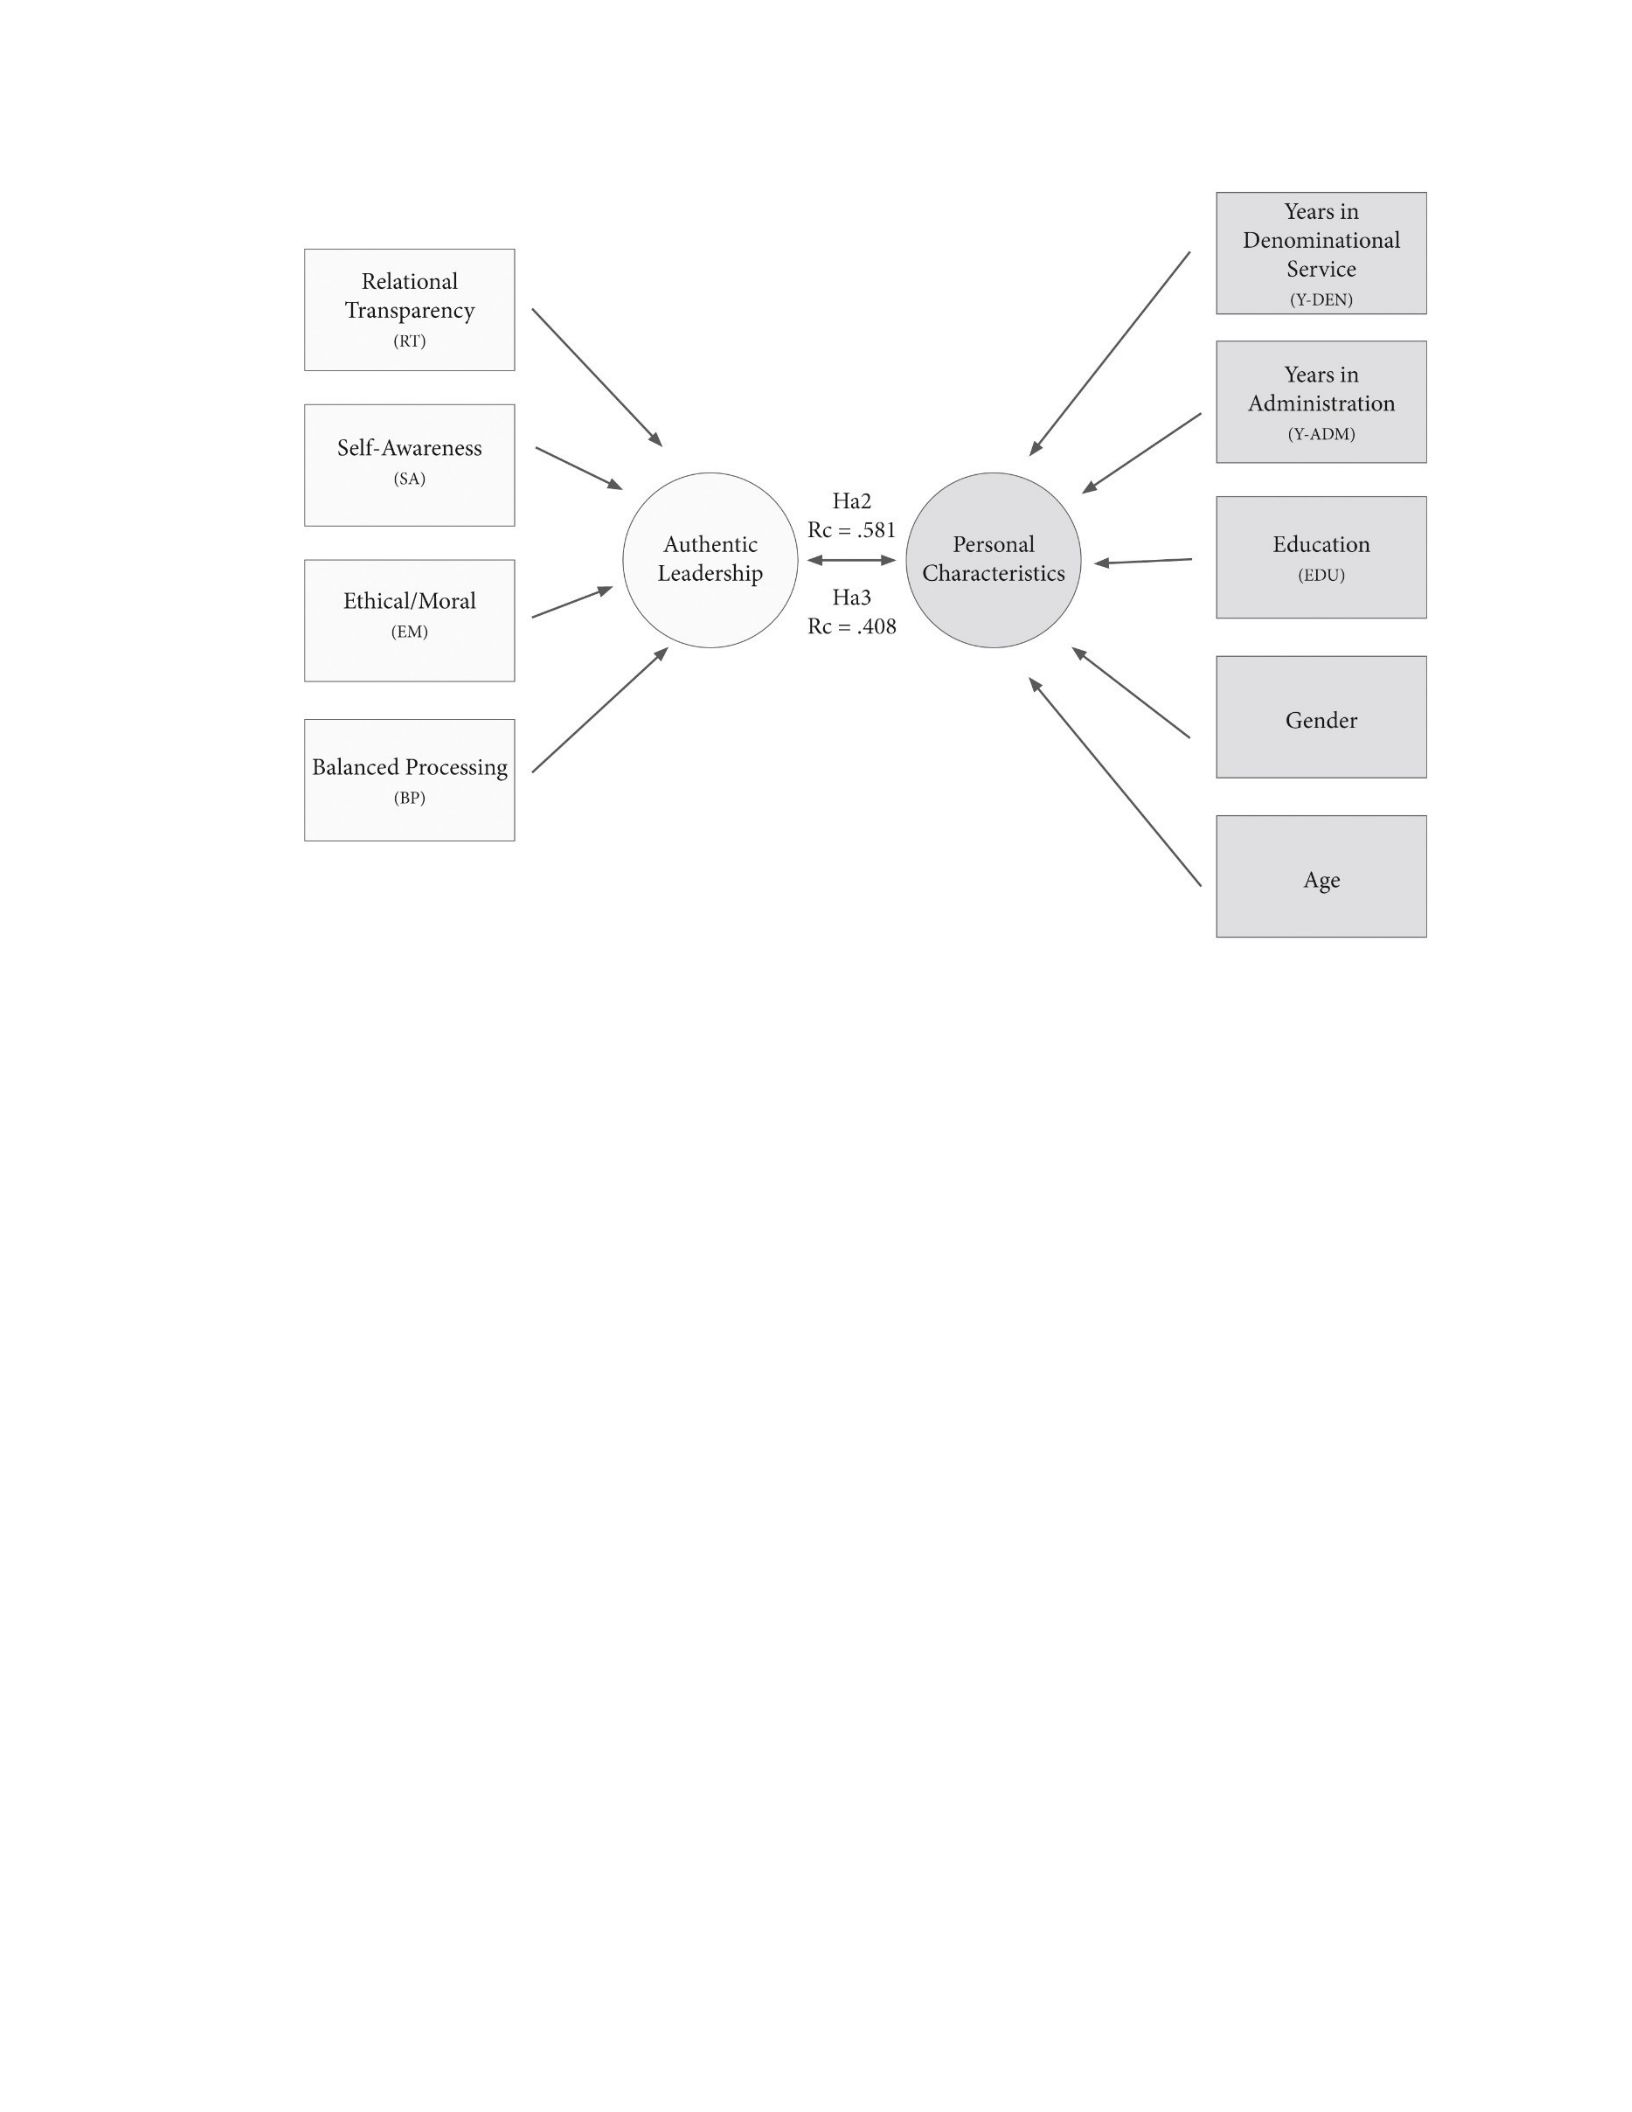
Figure 4. Graphic description of the study—Hypothesis 2 (Ha2) and Hypothesis 3 (Ha3).
Findings
Findings From MANOVA Test
The results of the MANOVA test and the Canonical Regressions are presented and
discussed in the following paragraphs. There are three results of the MANOVA test that
point to the main findings of this study. These are:
1. The self-perceptions of the leaders are significantly higher than the
perception expressed by the followers. This result helped set aside null hypothesis Ho1.
2. The group of associates in treasury consistently gave lower means (µ) than
did the academy treasurers.
84

3. The role played by the participants (local conference treasurers, associates
in treasury, and academy treasurers) was significantly related to the responses they
provided.
The first finding addressed whether the perceptions of local conference treasurers
agreed with the perceptions of their followers. The simplest answer is that they do not
agree. Local conference treasurers rate themselves higher than the rating they received
from their followers. A degree of discomfort, possibly distrust, skepticism or
dissatisfaction can be inferred by the lower statistical means of the raters (followers). The
local conference treasurers are not viewed as the open, reliable, principle-guided,
unbiased, even-handed, self-aware and understanding leaders they believe themselves to
be. This answer also means that local conference treasurers tend to view themselves as
accountants, not as CFOs, thus leaving their leadership role unfulfilled. They do not
inspire confidence when they are challenged; generate hope when facing obstacles;
inspire optimism when they interact with their associates; or show resilience when facing
discouragement.
Because the demographic information shows that the majority of local conference
treasurer’ ages fall between 50 and 69, it leads one to conjecture whether they received
their graduate education without a proper emphasis in business leadership, or whether the
age factor is proving to be a sign of vulnerability. One could also conjecture about the fact
that local conference treasuries in the Adventist structure are elective positions, and the
treasurers may be showing themselves sensitive to the effect of a combination of these
previously mentioned factors in the way they lead. One thing seems clear: The difference
in the means of the participating groups shows that conference treasurers are leaving their
85

leadership chair vacant. This conclusion is on the opposite side of Brown (2005) who saw
them functioning more as Chief Financial Officers. The other side of the issue is the
systemic conundrum that the Seventh-day Adventist Church structure with regard to
administration may have become more presidential than perhaps it was intended to be,
and that power has gravitated towards the position of the president, as happens often in
corporate business structures (Patterson, 2012).
The second finding indicates that of the two groups of followers, the group of the
associates in treasury consistently provided lower means (µ) than did the academy
treasurers. This finding gives us an opportunity to question the reasons why the closest
group of collaborators consistently gives low ratings to the conference treasurers as
leaders. This finding compounds the first issue I already discussed because it suggests that
the reality that is lived in the treasury may be a silent crisis, showing a destructive and
insidious toxicity that has become the normal way of operating. It seems to be that local
conference treasurers are rated lower by their closest associates, and a bit higher by their
more distant ones. This scenario is unacceptable, and points to an erosion of influence,
power, and authority, which leaves the treasurers open to the question, What is it that their
people in the office headquarters seem to object about their leading? What do these
followers see that the academy treasurers don’t? These and other questions are addressed
in the following sections.
The third finding points to the fact that the positions held by each group tested and
the role they play were significantly related to the responses they shared. Local
conference treasurers rated themselves higher, as compared to the rating they received
from their associates in treasury. Perhaps local conference treasurers were generous in
86

their own self-rating because they need to have a clearer view of what leaders are about.
Under normal circumstances people protect themselves, particularly if their identity is
involved. It seems that in this study the closest associates to the treasurers expressed
themselves freely regardless of any potential risk to their jobs. This is also evidence that
the protocol that was arranged to protect their identity was considered to be effective and
trustworthy.
Associates in treasury constitute a tier of followers who work directly under the
guidance of the leaders, and these leaders set the tone for their organizations. The
relationship of these followers and their leaders is expected to be close, their
communication flow is intense, and they depend much on each other. From that
perspective, is it that academy treasurers have a totally different point of view from where
they evaluate their leaders? Or is it simply that academy treasurers do not see enough of
their leaders to perceive them as less than open, reliable, accountable, principle-guided,
upright, honest, unbiased, impartial, even-handed, and understanding? Even though this
study was not designed to focus on the difference in perception between the two groups of
followers, the difference in the statistical means of their responses indicates a need for
further study of the factors that motivate both groups to answer as they did. The
importance of this finding is simple: Leaders cannot afford to have their closest group of
followers doubt their leadership values.
The understanding of the leader-follower relationship as it was understood by the
framers of authentic leadership advises this research study about the importance of the
interpersonal or relational process. In the next findings we look into additional discoveries
that build on the idea of leader-follower interpersonal process.
87

