


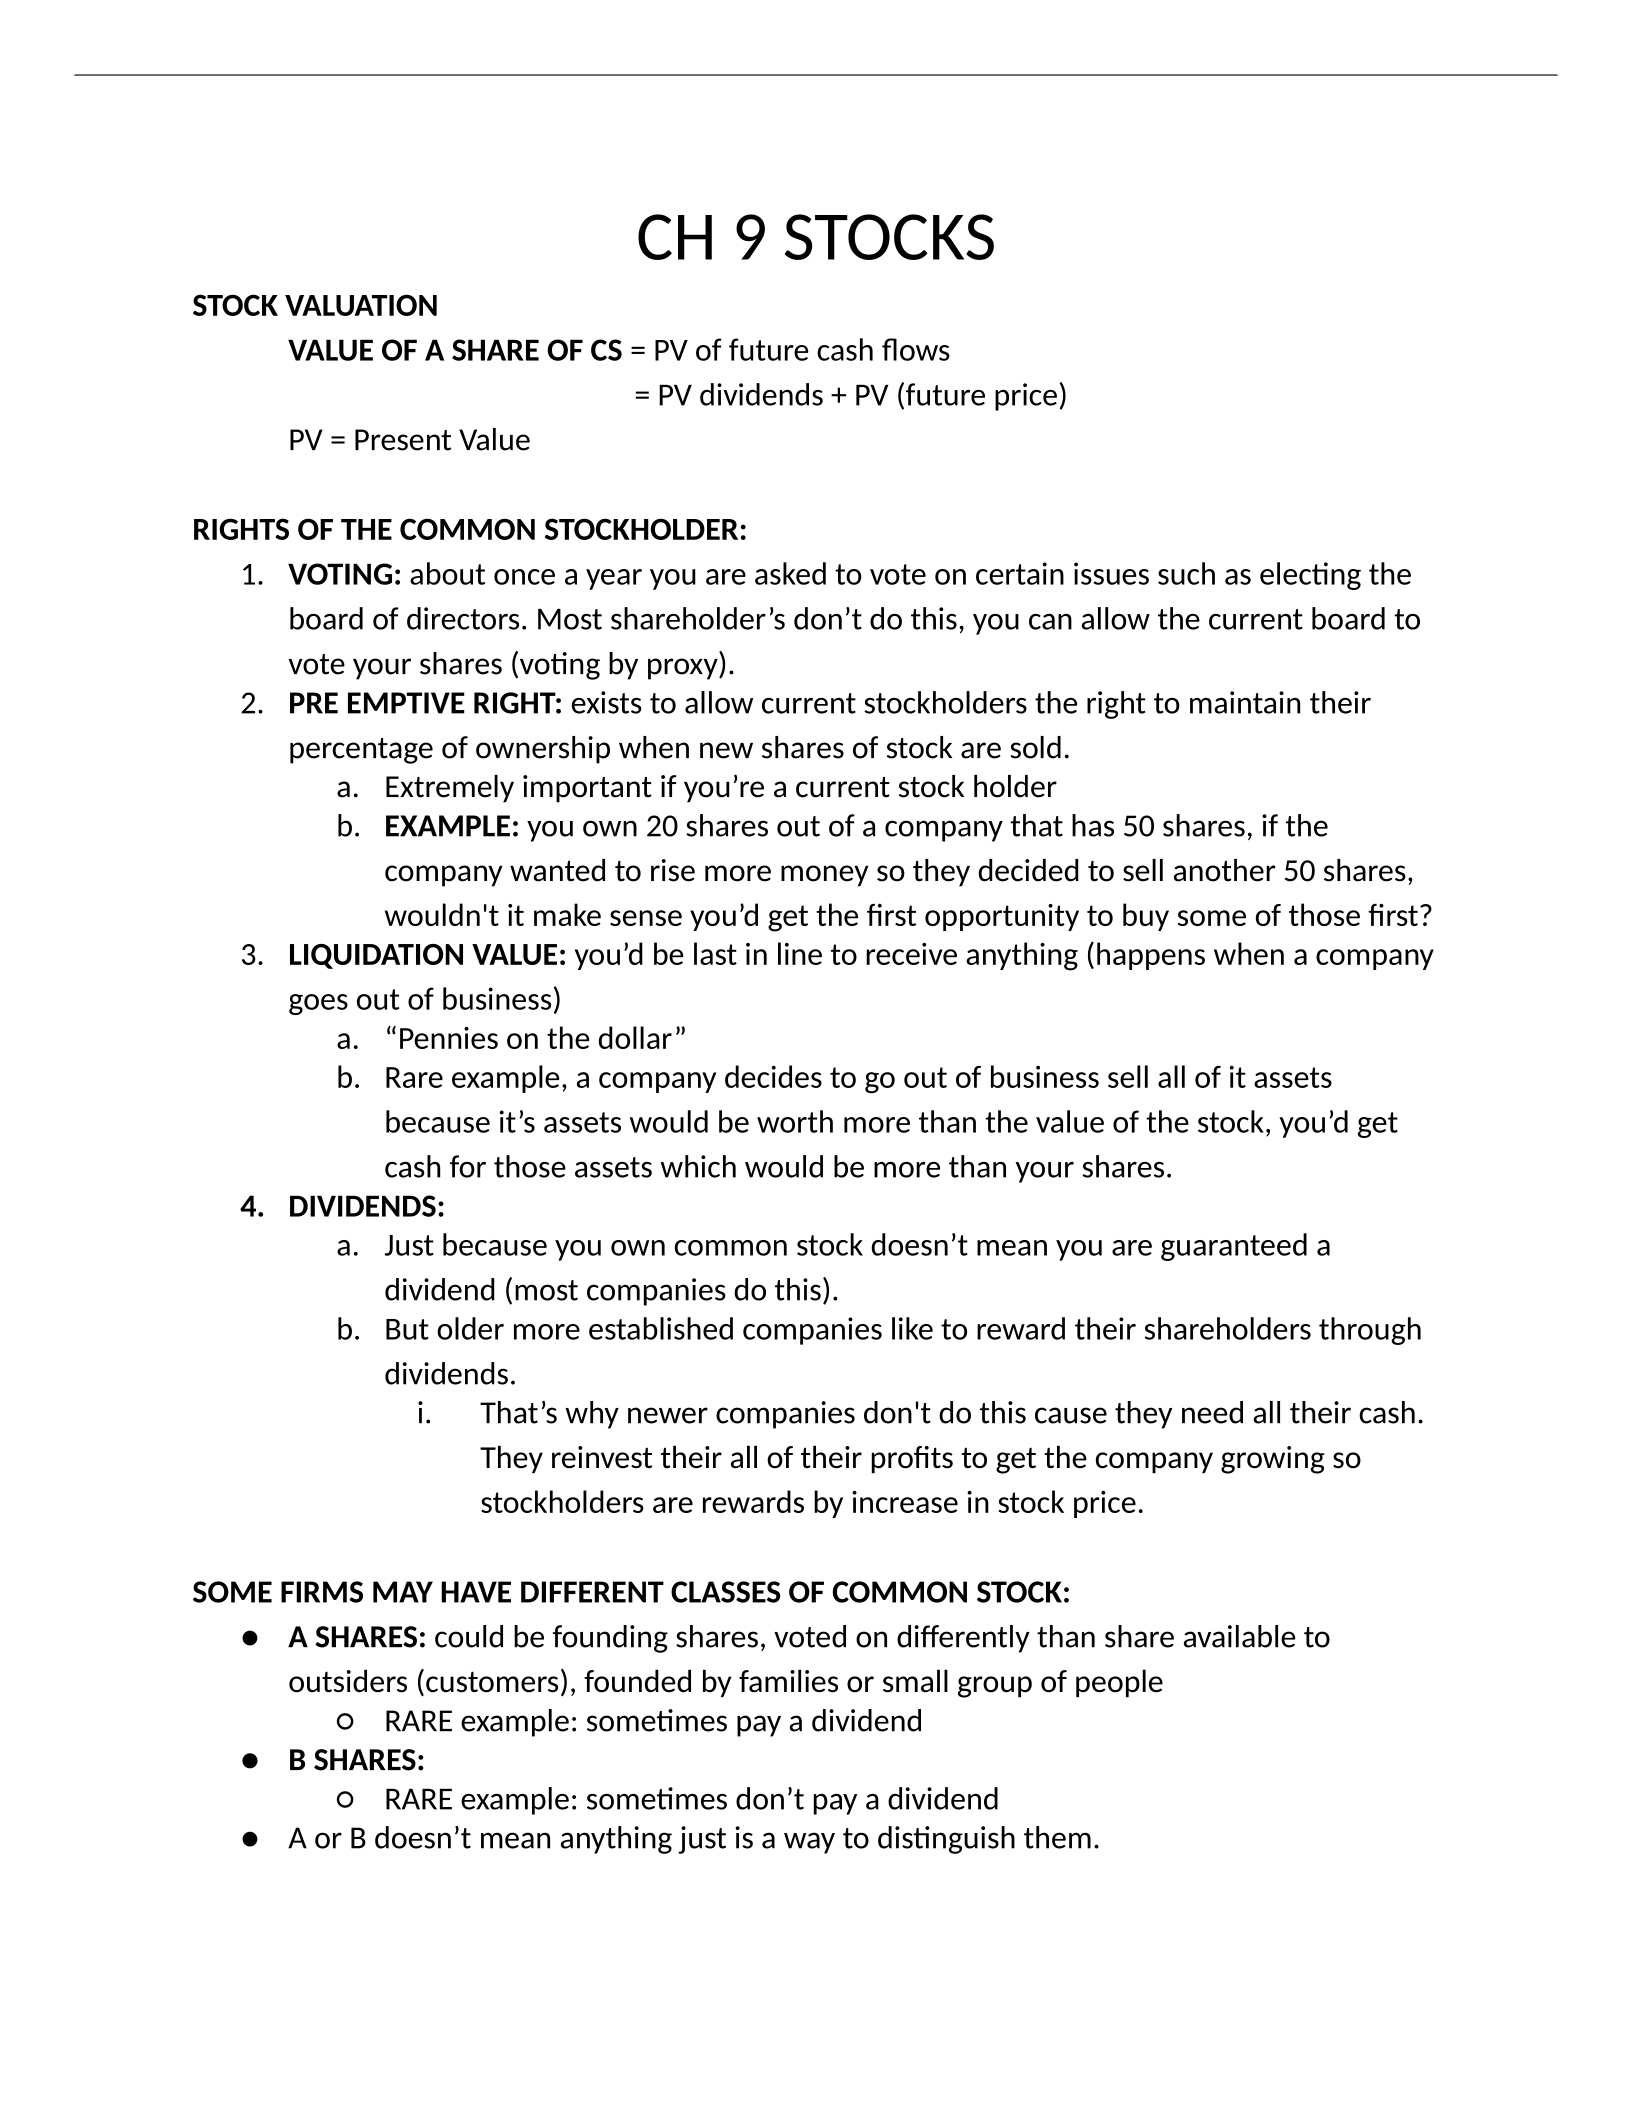
CH 9 STOCKS
STOCK VALUATION
VALUE OF A SHARE OF CS = PV of future cash flows
= PV dividends + PV (future price)
PV = Present Value
RIGHTS OF THE COMMON STOCKHOLDER:
1. VOTING: about once a year you are asked to vote on certain issues such as electing the
board of directors. Most shareholder’s don’t do this, you can allow the current board to
vote your shares (voting by proxy).
2. PRE EMPTIVE RIGHT: exists to allow current stockholders the right to maintain their
percentage of ownership when new shares of stock are sold.
a. Extremely important if you’re a current stock holder
b. EXAMPLE: you own 20 shares out of a company that has 50 shares, if the
company wanted to rise more money so they decided to sell another 50 shares,
wouldn't it make sense you’d get the first opportunity to buy some of those first?
3. LIQUIDATION VALUE: you’d be last in line to receive anything (happens when a company
goes out of business)
a. “Pennies on the dollar”
b. Rare example, a company decides to go out of business sell all of it assets
because it’s assets would be worth more than the value of the stock, you’d get
cash for those assets which would be more than your shares.
4. DIVIDENDS:
a. Just because you own common stock doesn’t mean you are guaranteed a
dividend (most companies do this).
b. But older more established companies like to reward their shareholders through
dividends.
i. That’s why newer companies don't do this cause they need all their cash.
They reinvest their all of their profits to get the company growing so
stockholders are rewards by increase in stock price.
SOME FIRMS MAY HAVE DIFFERENT CLASSES OF COMMON STOCK:
●A SHARES: could be founding shares, voted on differently than share available to
outsiders (customers), founded by families or small group of people
○ RARE example: sometimes pay a dividend
● B SHARES:
○ RARE example: sometimes don’t pay a dividend
● A or B doesn’t mean anything just is a way to distinguish them.
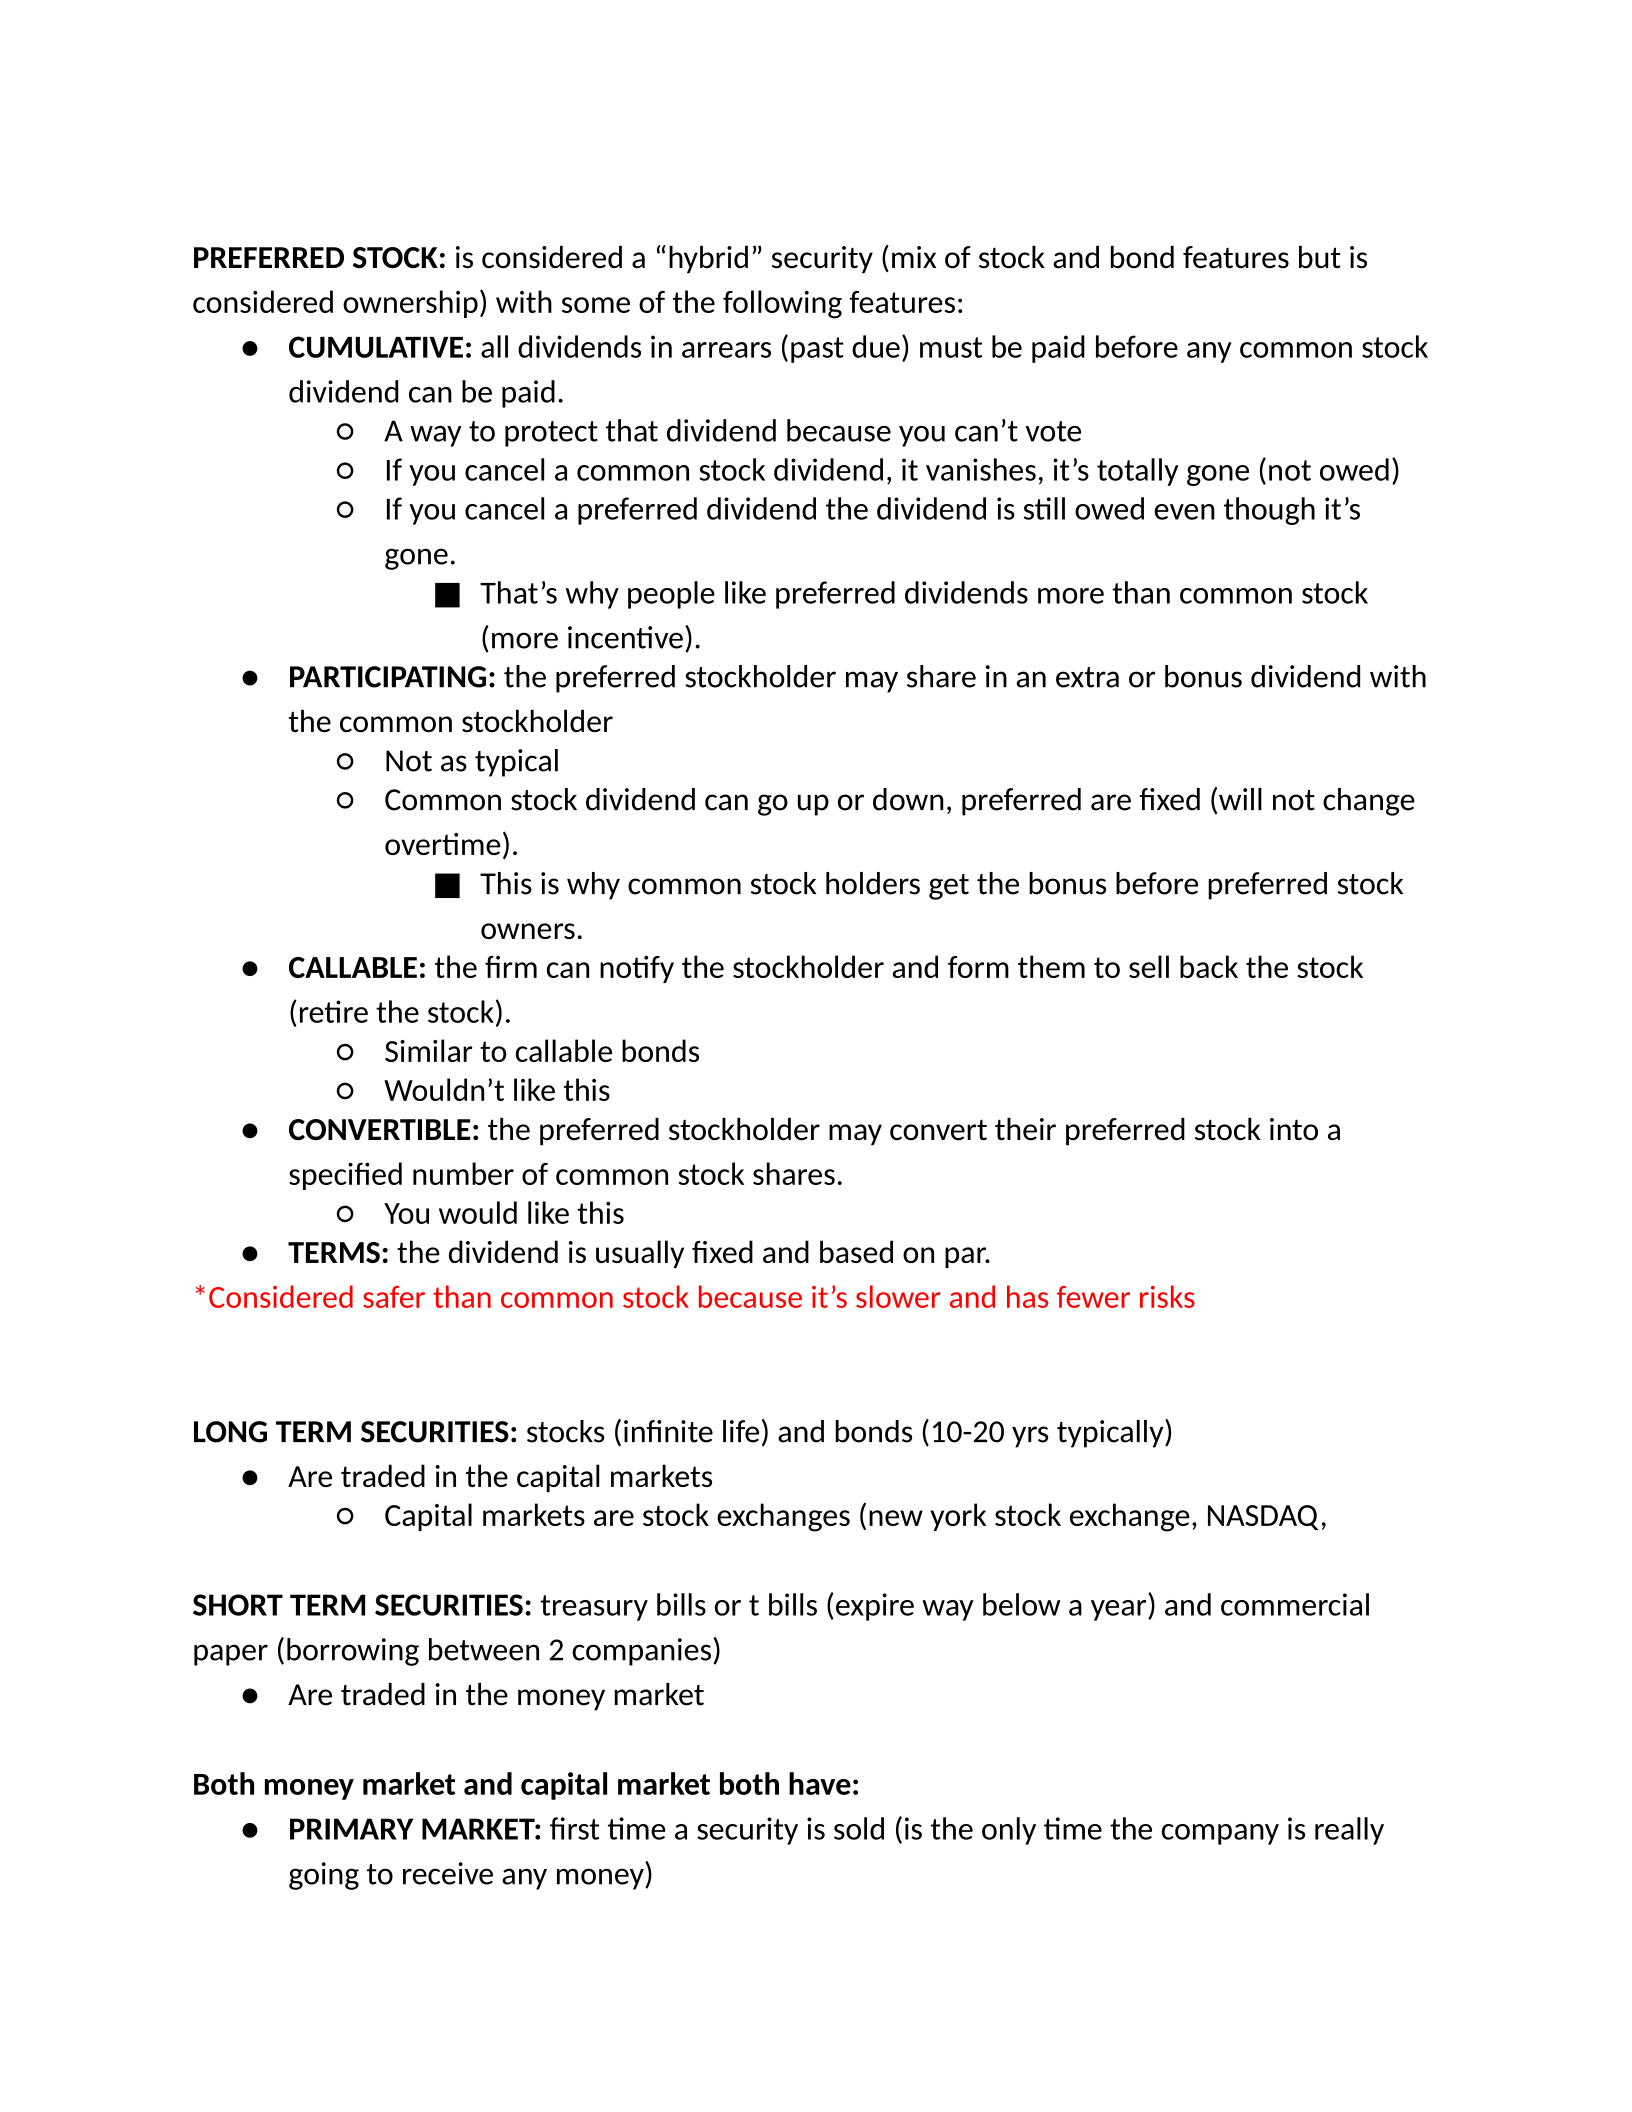
PREFERRED STOCK: is considered a “hybrid” security (mix of stock and bond features but is
considered ownership) with some of the following features:
●CUMULATIVE: all dividends in arrears (past due) must be paid before any common stock
dividend can be paid.
○ A way to protect that dividend because you can’t vote
○ If you cancel a common stock dividend, it vanishes, it’s totally gone (not owed)
○ If you cancel a preferred dividend the dividend is still owed even though it’s
gone.
■That’s why people like preferred dividends more than common stock
(more incentive).
●PARTICIPATING: the preferred stockholder may share in an extra or bonus dividend with
the common stockholder
○ Not as typical
○ Common stock dividend can go up or down, preferred are fixed (will not change
overtime).
■This is why common stock holders get the bonus before preferred stock
owners.
●CALLABLE: the firm can notify the stockholder and form them to sell back the stock
(retire the stock).
○ Similar to callable bonds
○ Wouldn’t like this
●CONVERTIBLE: the preferred stockholder may convert their preferred stock into a
specified number of common stock shares.
○ You would like this
●TERMS: the dividend is usually fixed and based on par.
*Considered safer than common stock because it’s slower and has fewer risks
LONG TERM SECURITIES: stocks (infinite life) and bonds (10-20 yrs typically)
● Are traded in the capital markets
○ Capital markets are stock exchanges (new york stock exchange, NASDAQ,
SHORT TERM SECURITIES: treasury bills or t bills (expire way below a year) and commercial
paper (borrowing between 2 companies)
● Are traded in the money market
Both money market and capital market both have:
●PRIMARY MARKET: first time a security is sold (is the only time the company is really
going to receive any money)
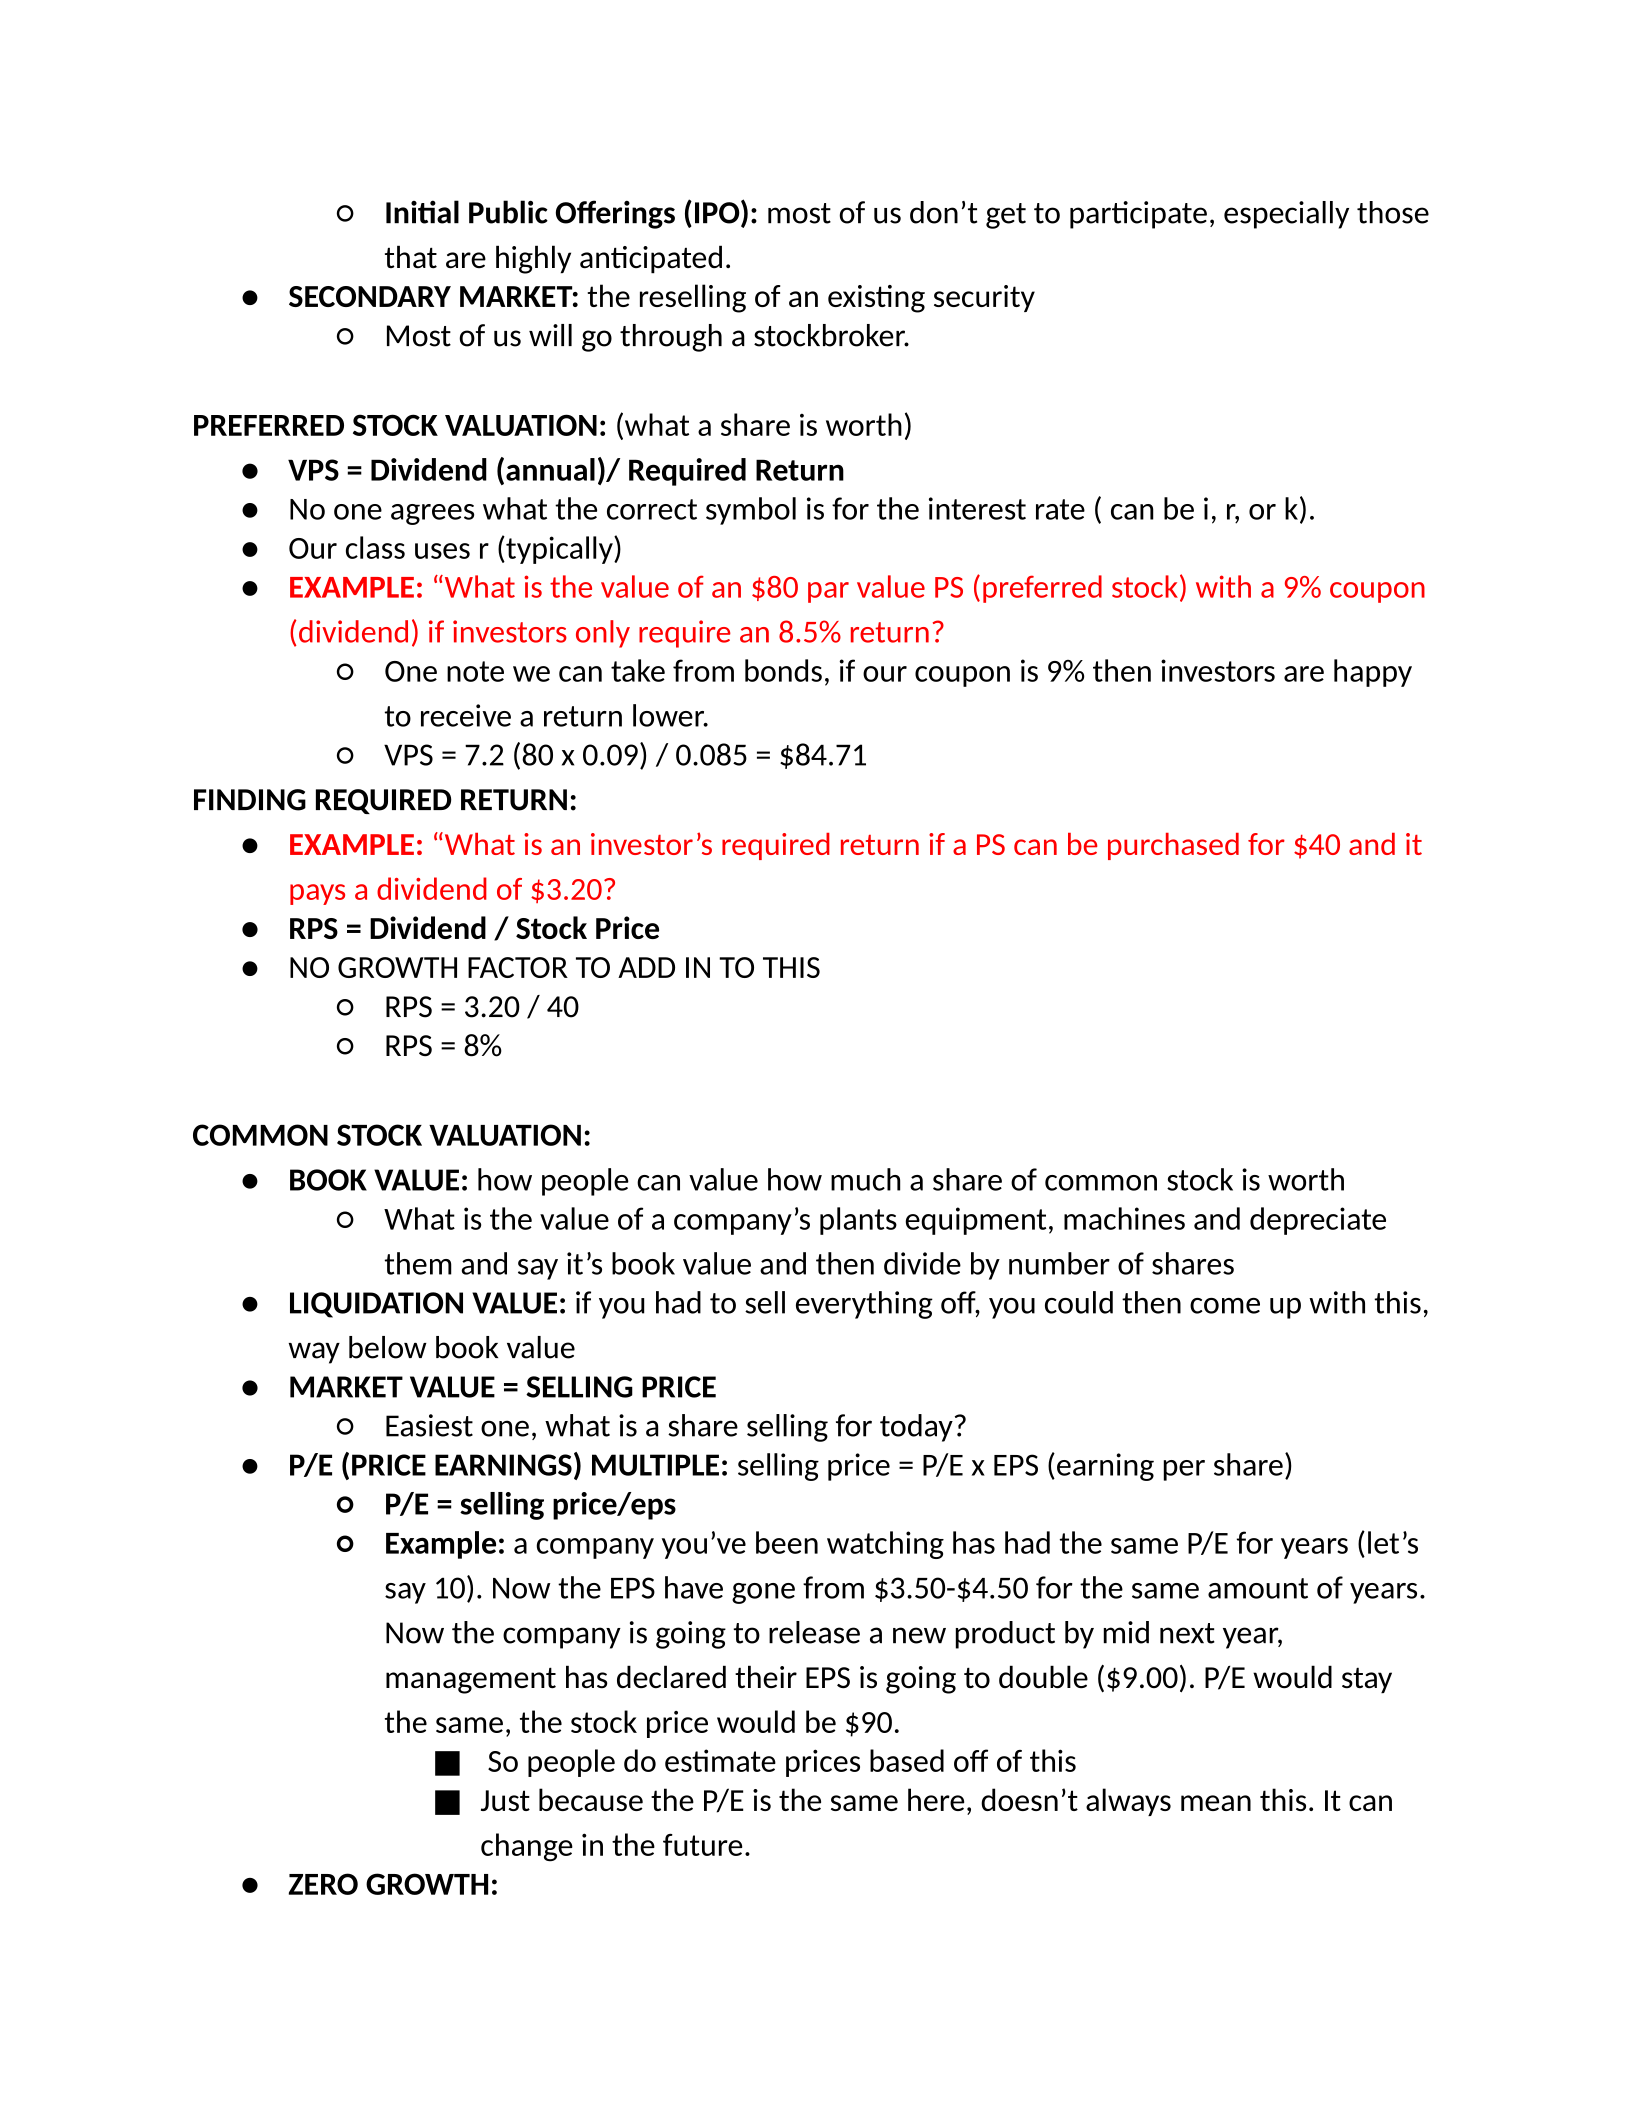
○Initial Public Offerings (IPO): most of us don’t get to participate, especially those
that are highly anticipated.
●SECONDARY MARKET: the reselling of an existing security
○ Most of us will go through a stockbroker.
PREFERRED STOCK VALUATION: (what a share is worth)
● VPS = Dividend (annual)/ Required Return
● No one agrees what the correct symbol is for the interest rate ( can be i, r, or k).
● Our class uses r (typically)
●EXAMPLE: “What is the value of an $80 par value PS (preferred stock) with a 9% coupon
(dividend) if investors only require an 8.5% return?
○ One note we can take from bonds, if our coupon is 9% then investors are happy
to receive a return lower.
○ VPS = 7.2 (80 x 0.09) / 0.085 = $84.71
FINDING REQUIRED RETURN:
●EXAMPLE: “What is an investor’s required return if a PS can be purchased for $40 and it
pays a dividend of $3.20?
● RPS = Dividend / Stock Price
● NO GROWTH FACTOR TO ADD IN TO THIS
○ RPS = 3.20 / 40
○ RPS = 8%
COMMON STOCK VALUATION:
●BOOK VALUE: how people can value how much a share of common stock is worth
○ What is the value of a company’s plants equipment, machines and depreciate
them and say it’s book value and then divide by number of shares
●LIQUIDATION VALUE: if you had to sell everything off, you could then come up with this,
way below book value
● MARKET VALUE = SELLING PRICE
○ Easiest one, what is a share selling for today?
●P/E (PRICE EARNINGS) MULTIPLE: selling price = P/E x EPS (earning per share)
○ P/E = selling price/eps
○ Example: a company you’ve been watching has had the same P/E for years (let’s
say 10). Now the EPS have gone from $3.50-$4.50 for the same amount of years.
Now the company is going to release a new product by mid next year,
management has declared their EPS is going to double ($9.00). P/E would stay
the same, the stock price would be $90.
■ So people do estimate prices based off of this
■Just because the P/E is the same here, doesn’t always mean this. It can
change in the future.
● ZERO GROWTH:
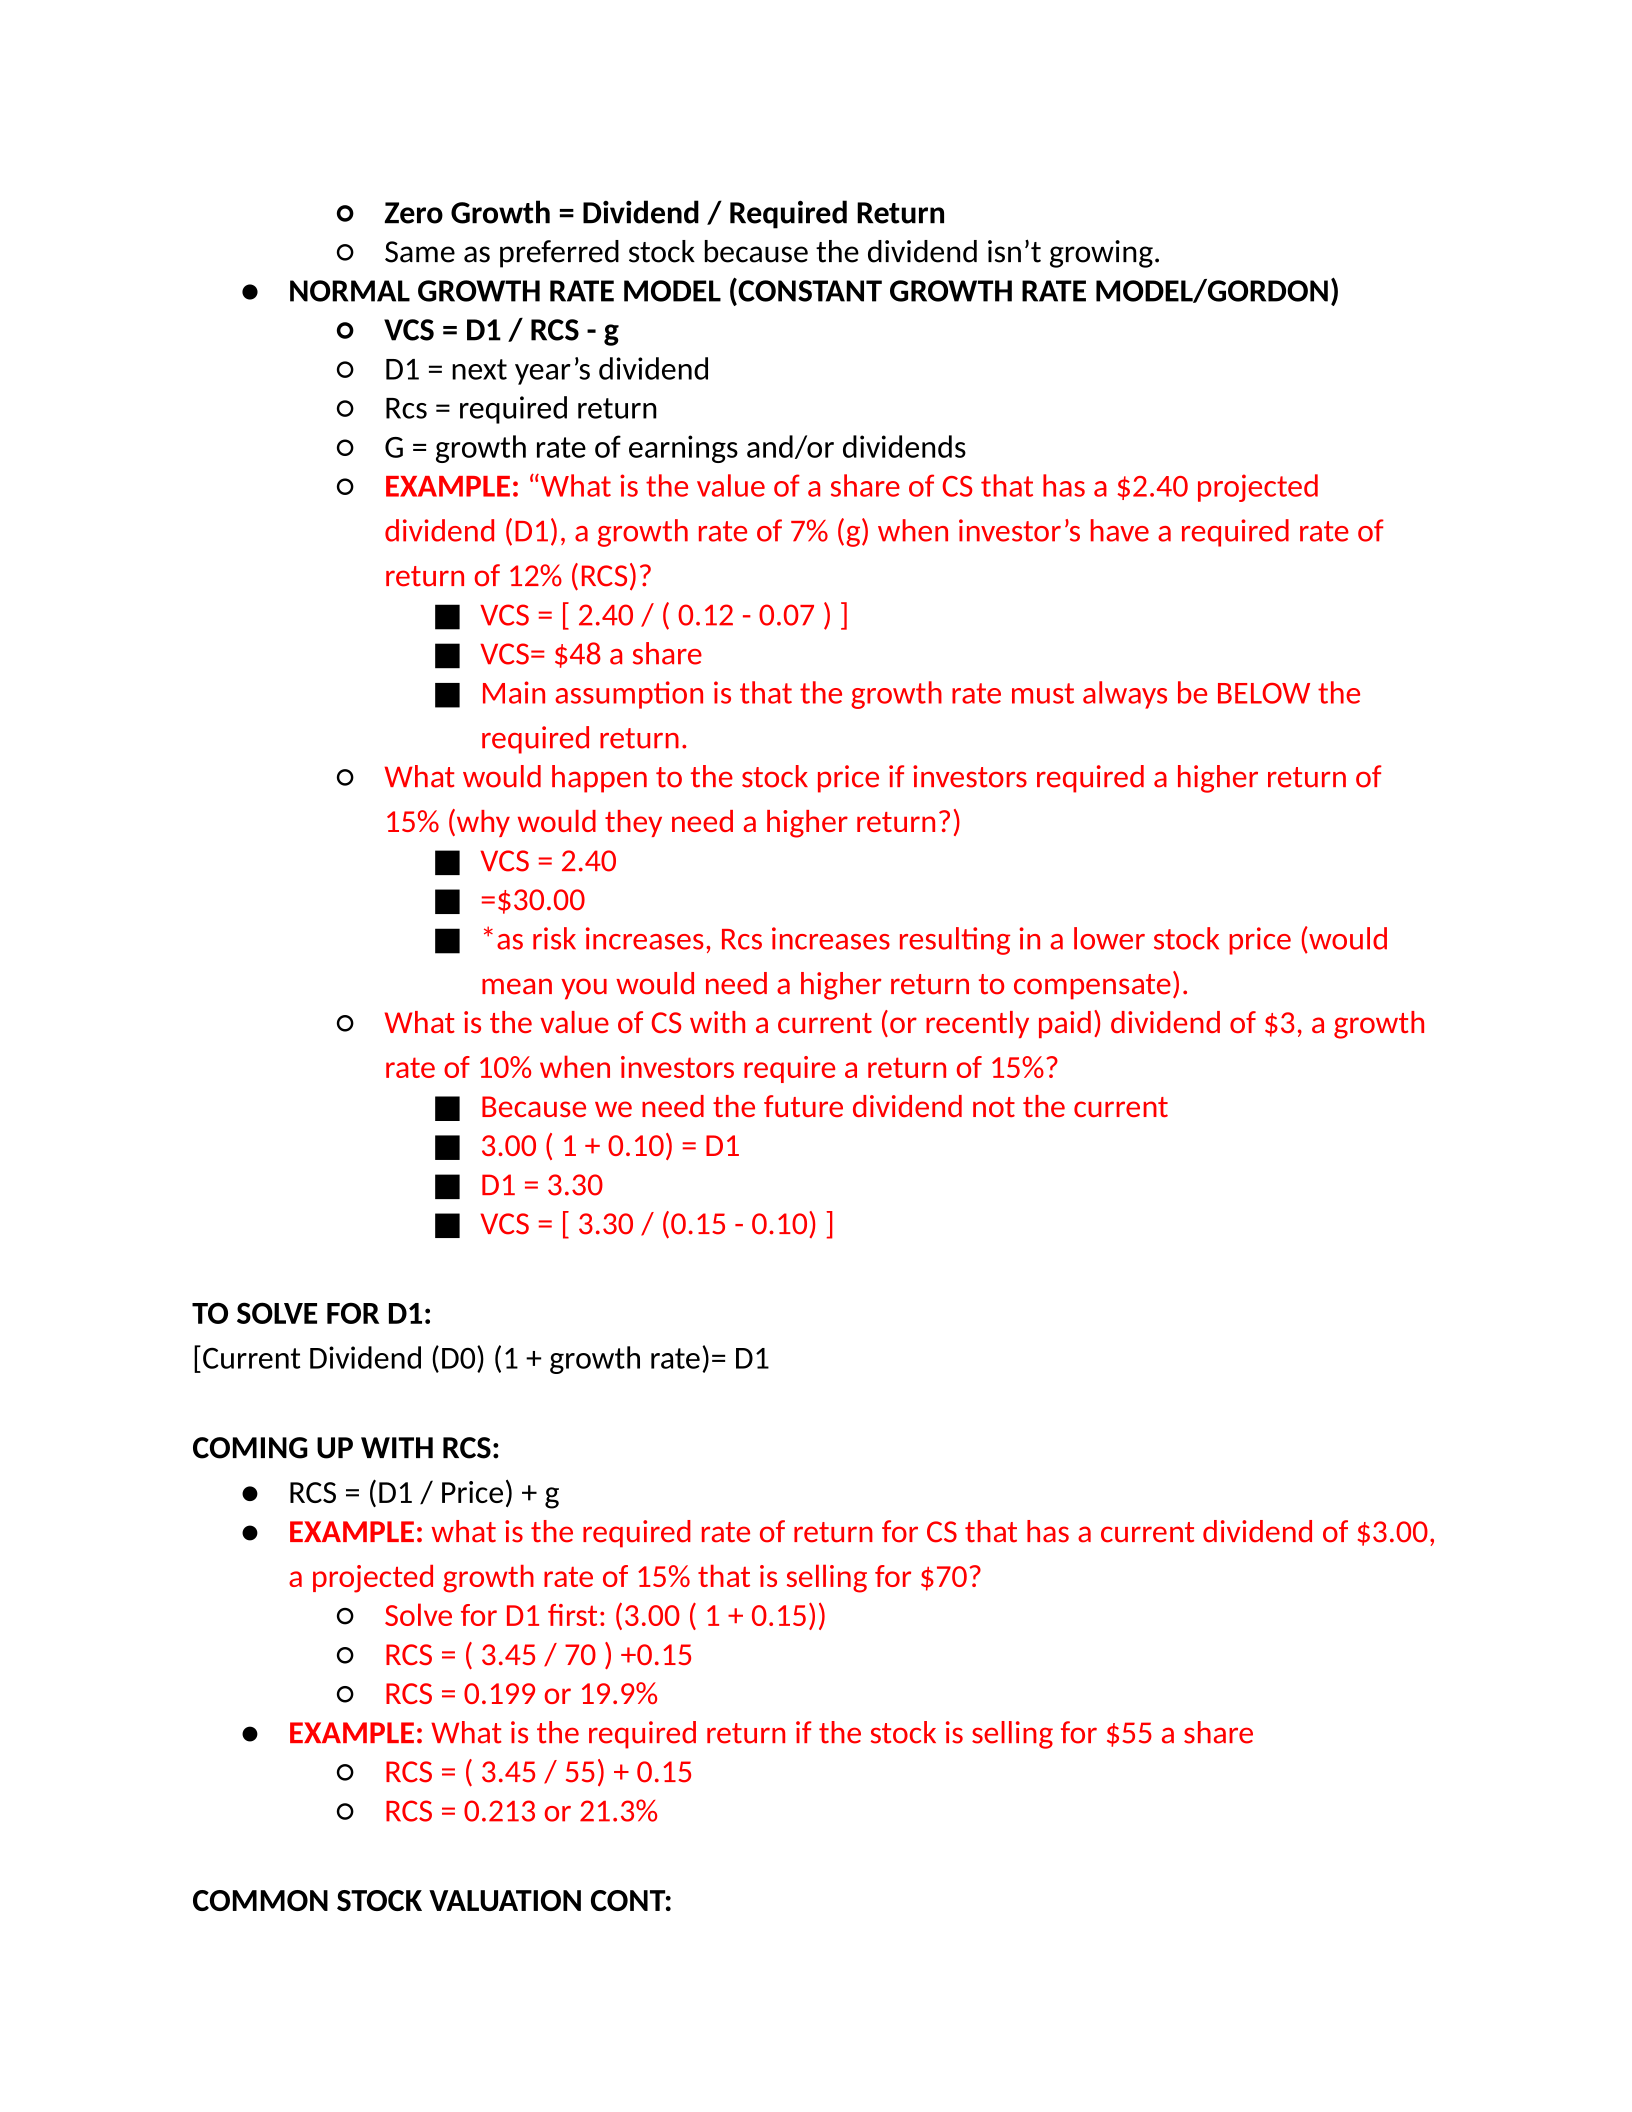
○ Zero Growth = Dividend / Required Return
○ Same as preferred stock because the dividend isn’t growing.
● NORMAL GROWTH RATE MODEL (CONSTANT GROWTH RATE MODEL/GORDON)
○ VCS = D1 / RCS - g
○ D1 = next year’s dividend
○ Rcs = required return
○ G = growth rate of earnings and/or dividends
○EXAMPLE: “What is the value of a share of CS that has a $2.40 projected
dividend (D1), a growth rate of 7% (g) when investor’s have a required rate of
return of 12% (RCS)?
■VCS = [ 2.40 / ( 0.12 - 0.07 ) ]
■VCS= $48 a share
■Main assumption is that the growth rate must always be BELOW the
required return.
○What would happen to the stock price if investors required a higher return of
15% (why would they need a higher return?)
■VCS = 2.40
■=$30.00
■*as risk increases, Rcs increases resulting in a lower stock price (would
mean you would need a higher return to compensate).
○What is the value of CS with a current (or recently paid) dividend of $3, a growth
rate of 10% when investors require a return of 15%?
■Because we need the future dividend not the current
■3.00 ( 1 + 0.10) = D1
■D1 = 3.30
■VCS = [ 3.30 / (0.15 - 0.10) ]
TO SOLVE FOR D1:
[Current Dividend (D0) (1 + growth rate)= D1
COMING UP WITH RCS:
● RCS = (D1 / Price) + g
●EXAMPLE: what is the required rate of return for CS that has a current dividend of $3.00,
a projected growth rate of 15% that is selling for $70?
○Solve for D1 first: (3.00 ( 1 + 0.15))
○RCS = ( 3.45 / 70 ) +0.15
○RCS = 0.199 or 19.9%
●EXAMPLE: What is the required return if the stock is selling for $55 a share
○RCS = ( 3.45 / 55) + 0.15
○RCS = 0.213 or 21.3%
COMMON STOCK VALUATION CONT:
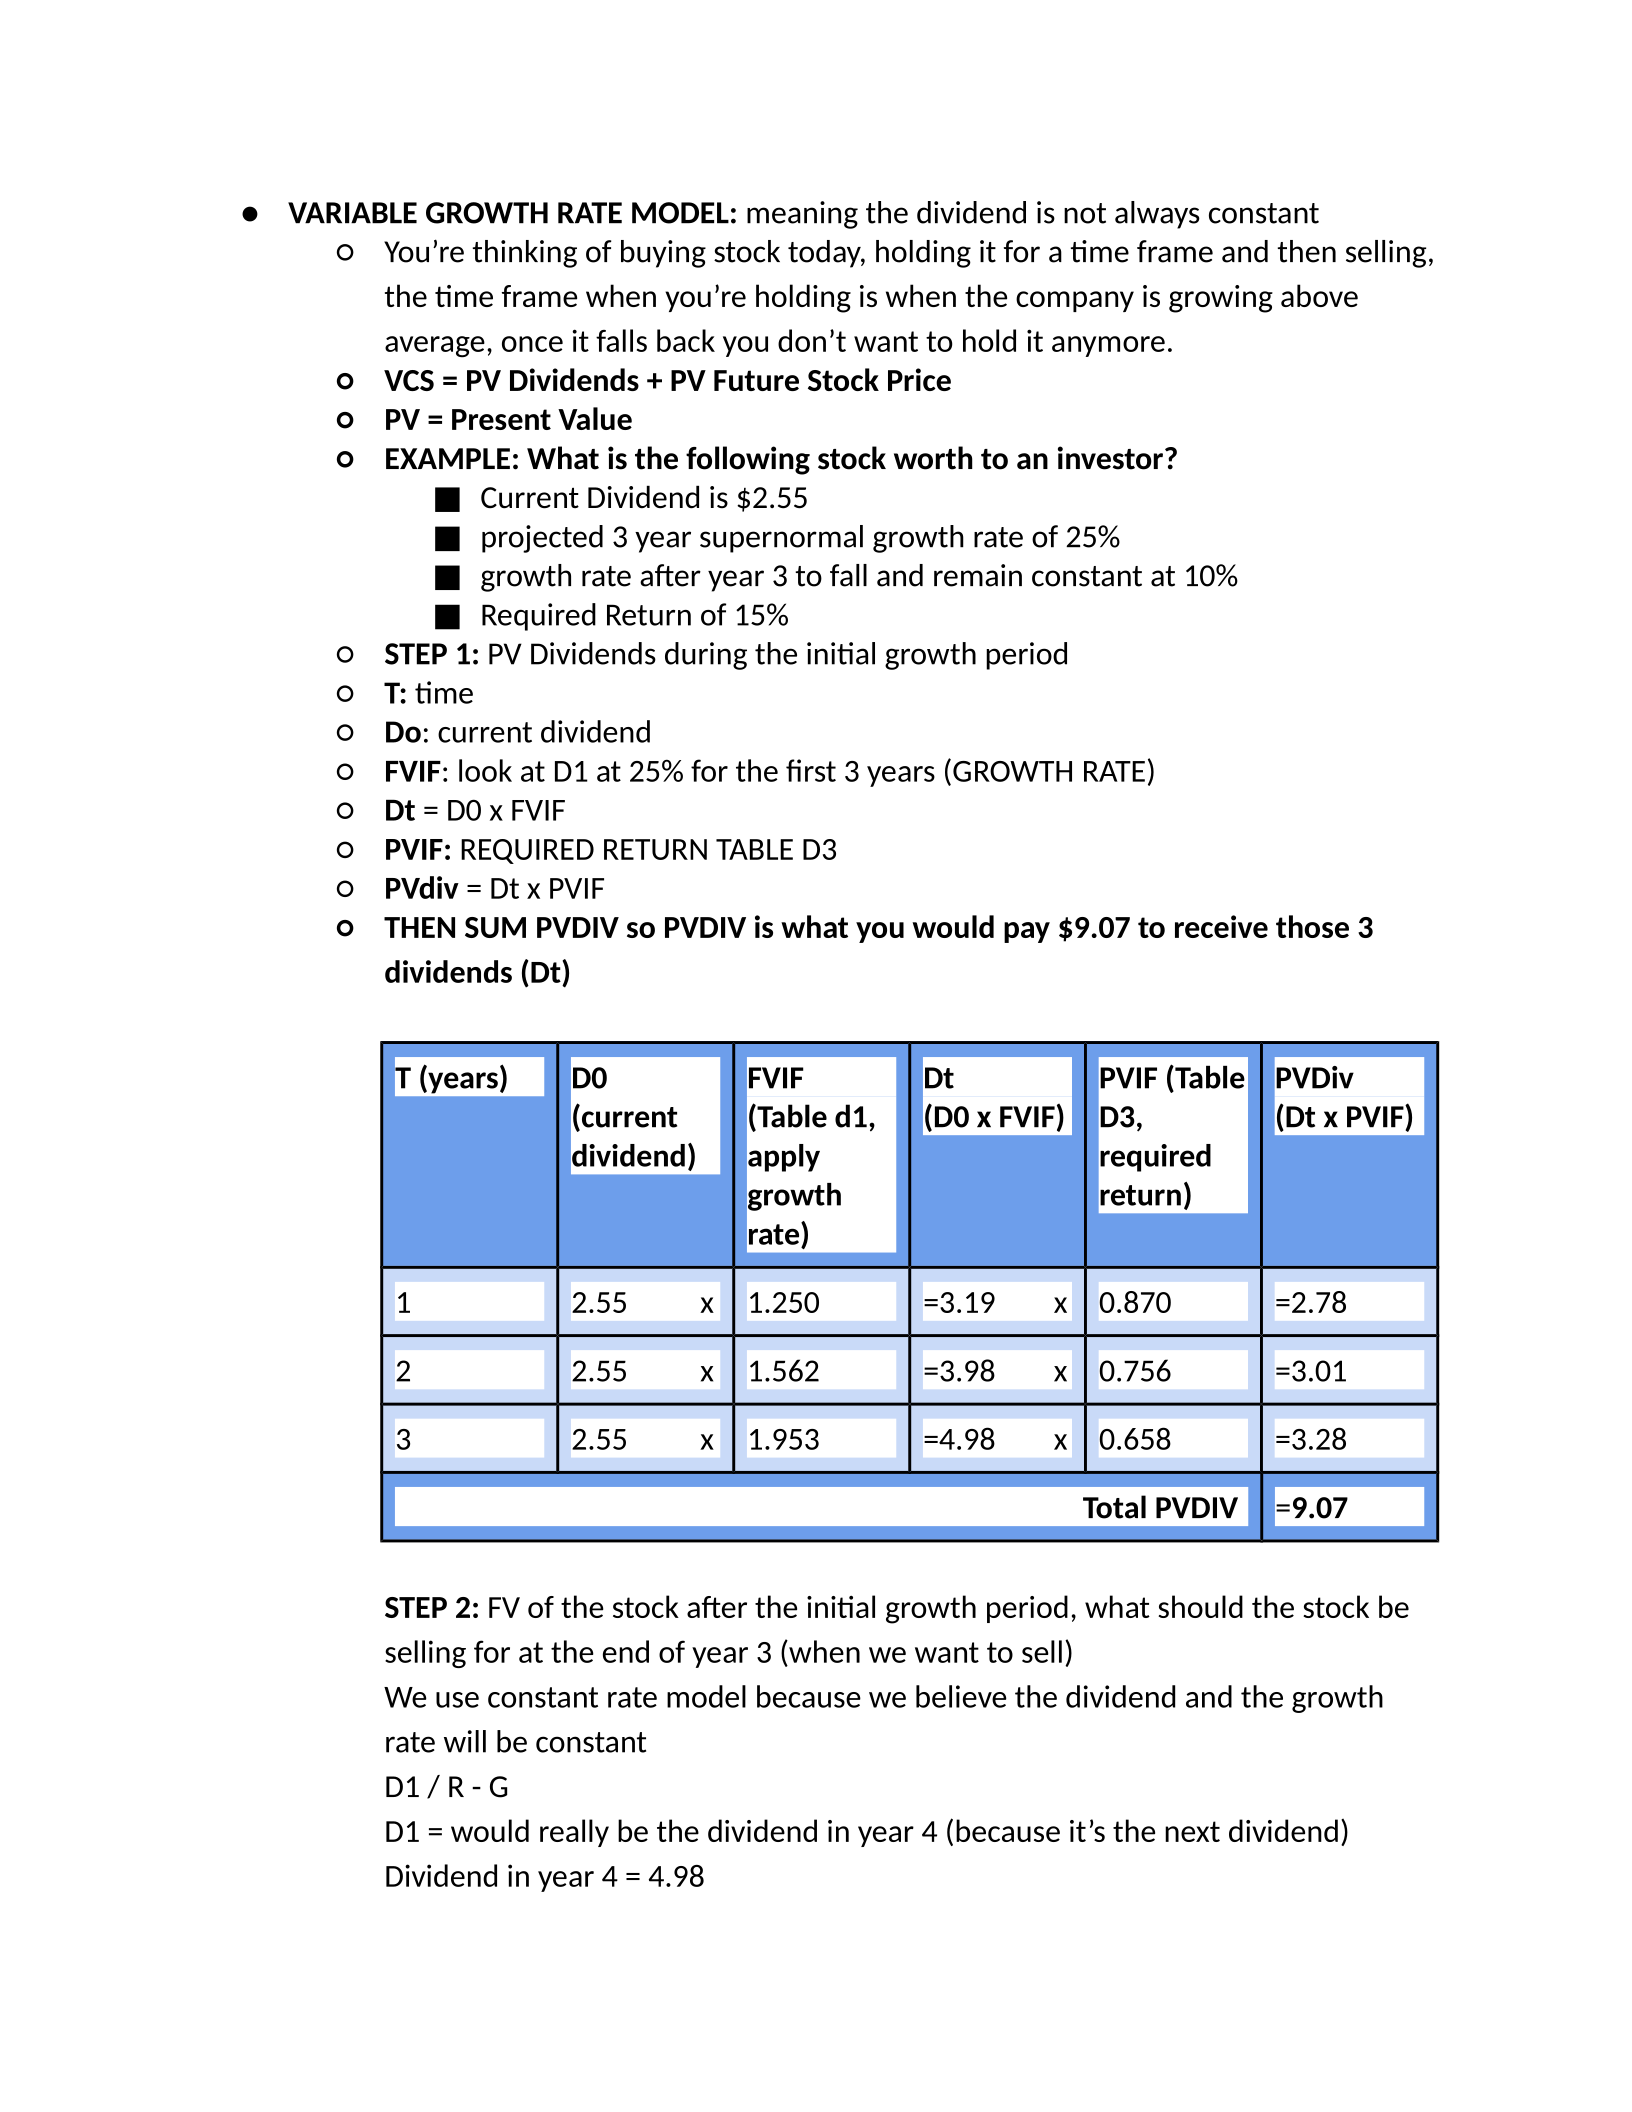
●VARIABLE GROWTH RATE MODEL: meaning the dividend is not always constant
○ You’re thinking of buying stock today, holding it for a time frame and then selling,
the time frame when you’re holding is when the company is growing above
average, once it falls back you don’t want to hold it anymore.
○ VCS = PV Dividends + PV Future Stock Price
○ PV = Present Value
○ EXAMPLE: What is the following stock worth to an investor?
■Current Dividend is $2.55
■projected 3 year supernormal growth rate of 25%
■growth rate after year 3 to fall and remain constant at 10%
■Required Return of 15%
○STEP 1: PV Dividends during the initial growth period
○T: time
○Do: current dividend
○FVIF: look at D1 at 25% for the first 3 years (GROWTH RATE)
○Dt = D0 x FVIF
○PVIF: REQUIRED RETURN TABLE D3
○PVdiv = Dt x PVIF
○ THEN SUM PVDIV so PVDIV is what you would pay $9.07 to receive those 3
dividends (Dt)
T (years) D0
(current
dividend)
FVIF
(Table d1,
apply
growth
rate)
Dt
(D0 x FVIF)
PVIF (Table
D3,
required
return)
PVDiv
(Dt x PVIF)
1 2.55 x 1.250 =3.19 x 0.870 =2.78
2 2.55 x 1.562 =3.98 x 0.756 =3.01
3 2.55 x 1.953 =4.98 x 0.658 =3.28
Total PVDIV =9.07
STEP 2: FV of the stock after the initial growth period, what should the stock be
selling for at the end of year 3 (when we want to sell)
We use constant rate model because we believe the dividend and the growth
rate will be constant
D1 / R - G
D1 = would really be the dividend in year 4 (because it’s the next dividend)
Dividend in year 4 = 4.98
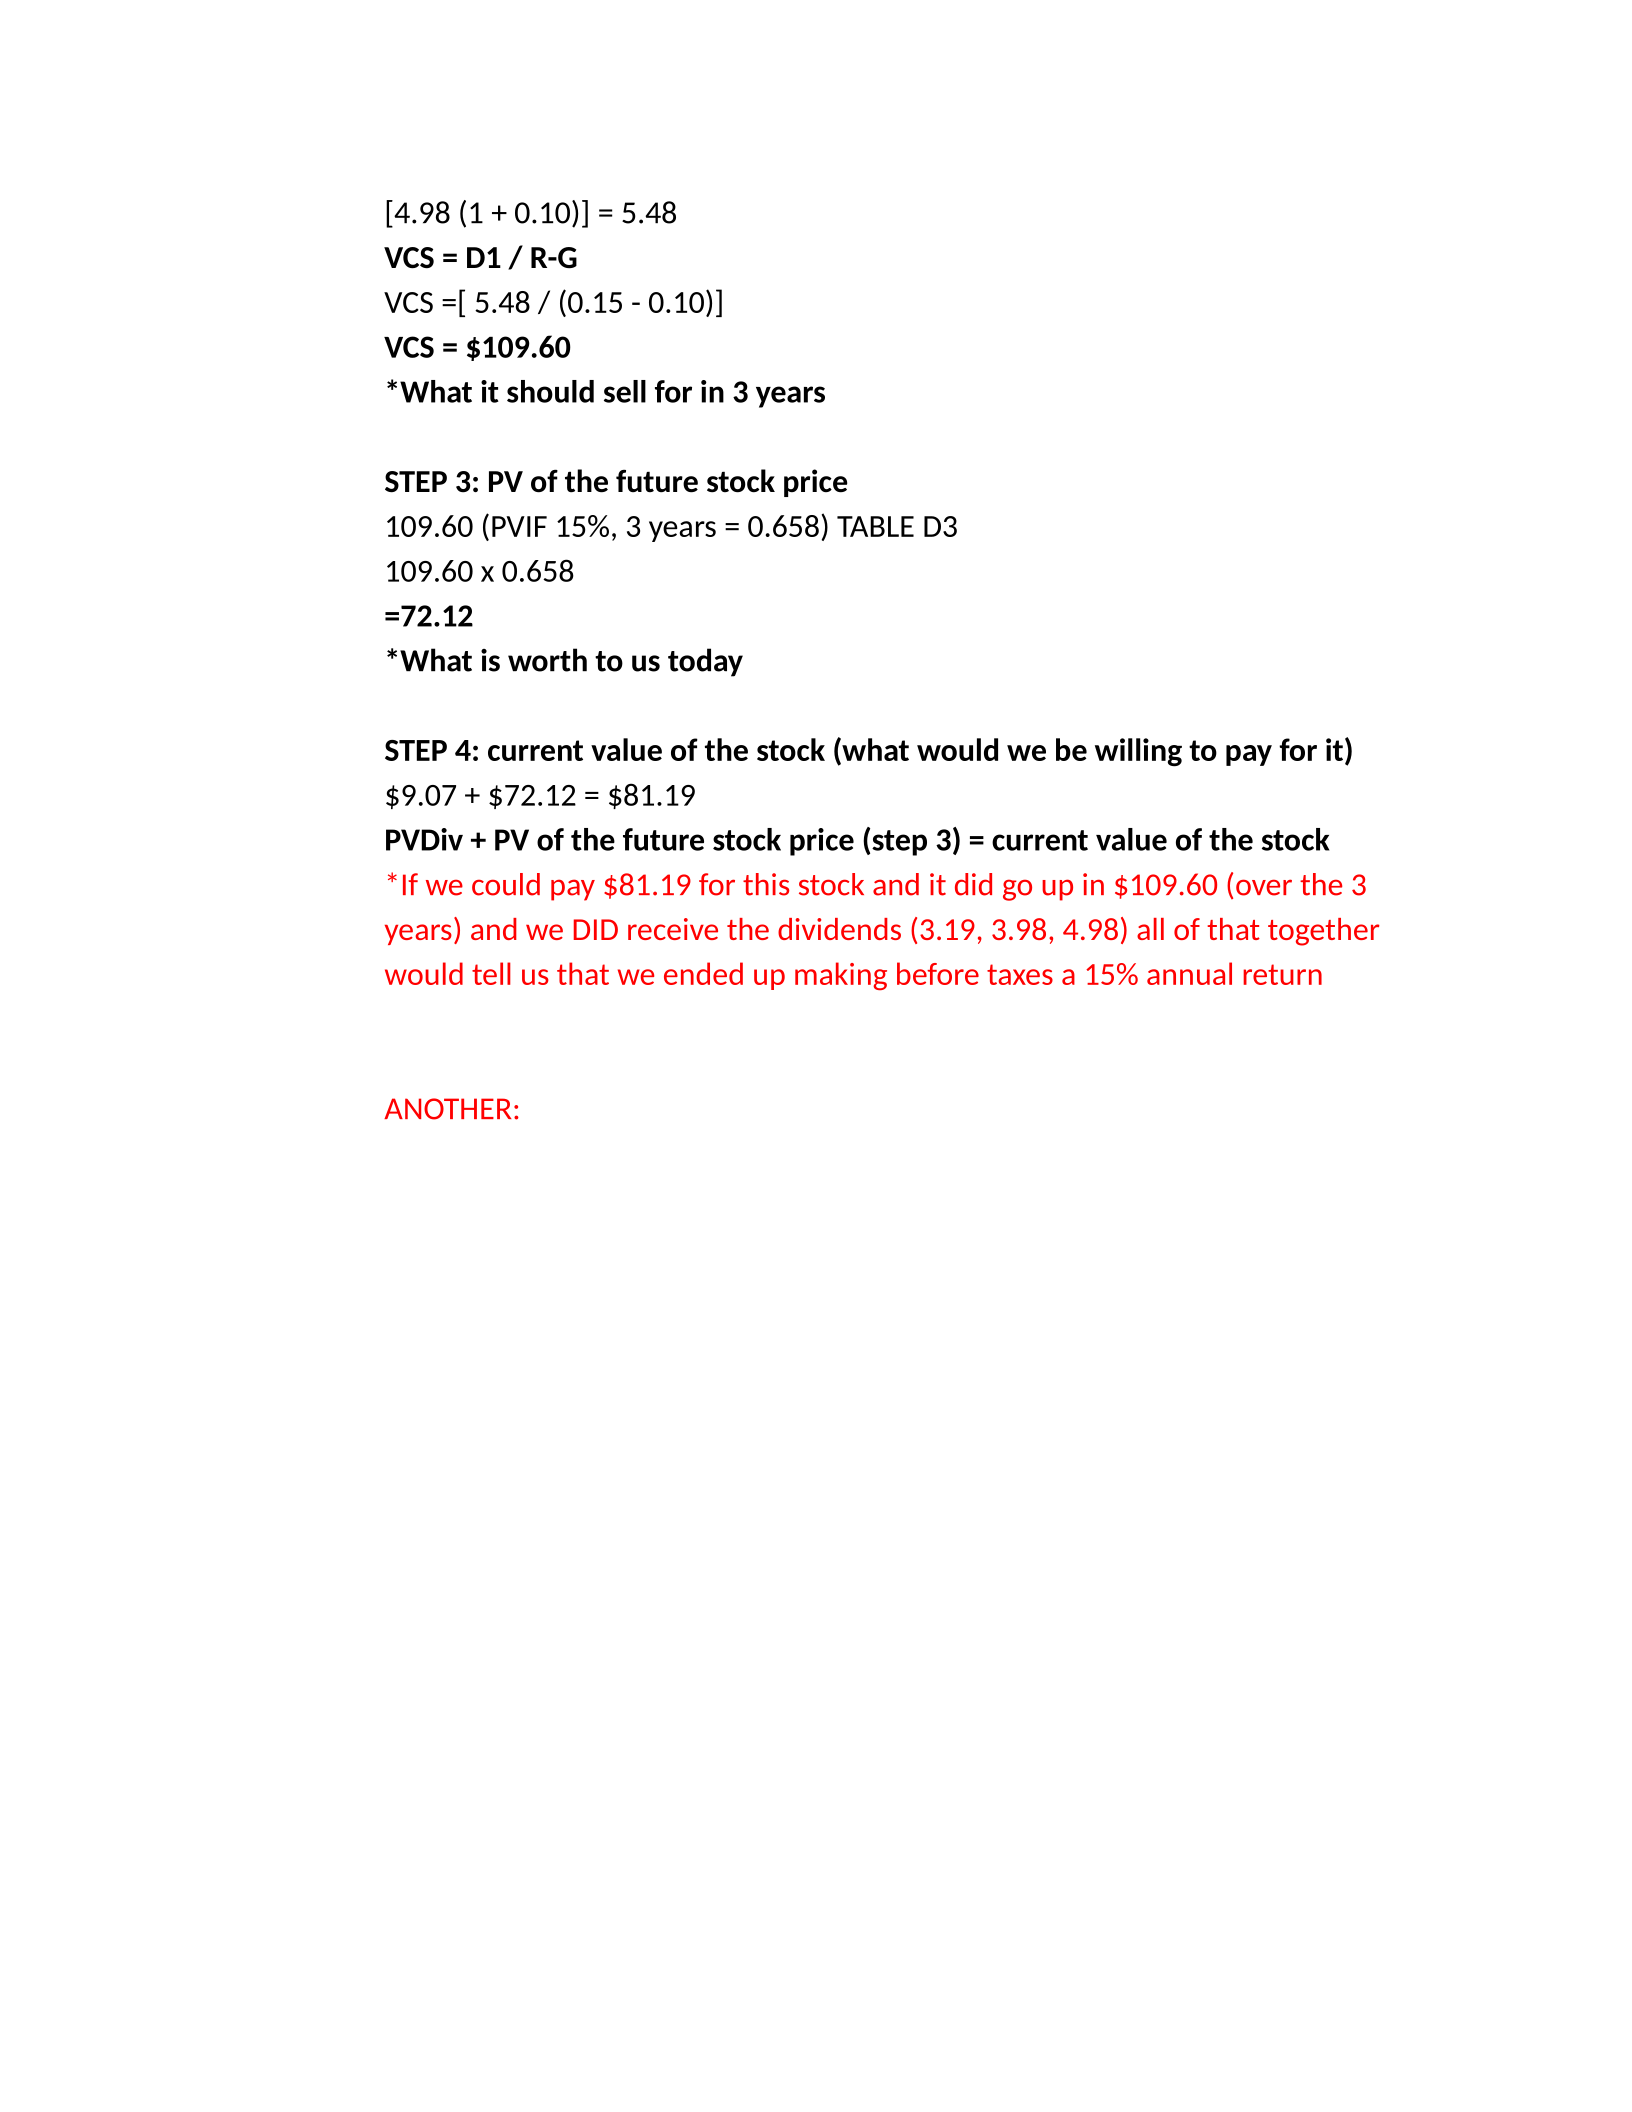
[4.98 (1 + 0.10)] = 5.48
VCS = D1 / R-G
VCS =[ 5.48 / (0.15 - 0.10)]
VCS = $109.60
*What it should sell for in 3 years
STEP 3: PV of the future stock price
109.60 (PVIF 15%, 3 years = 0.658) TABLE D3
109.60 x 0.658
=72.12
*What is worth to us today
STEP 4: current value of the stock (what would we be willing to pay for it)
$9.07 + $72.12 = $81.19
PVDiv + PV of the future stock price (step 3) = current value of the stock
*If we could pay $81.19 for this stock and it did go up in $109.60 (over the 3
years) and we DID receive the dividends (3.19, 3.98, 4.98) all of that together
would tell us that we ended up making before taxes a 15% annual return
ANOTHER:
Powered by TCPDF (www.tcpdf.org)

