


BANK VALUATION METHODS
Before the global crisis, the topic of bank valuation had been
discussed relatively few in the academic world and mainly in the real-life,
some bank valuation techniques were offered to be used by analysts &
professionals. After the crisis, the importance of banks have been noticed
and since then academic studies in bank valuation techniques also
increased.
Valuation attained its place and importance in Western literature in
the 1960s and it is sloganised that the main objective of the corporation is
to maximise the value rather than maximise the profit. It is started to
emphasize on the importance of valuation in Turkey since the 1990s in
both academic and practical studies (Küçükkaplan, 2008: 1). In the past,
in US finance books the main objective of the firm was mentioned as
profit maximisation but later it is lost its significance since profit
maximisation is subjective. For example, as mentioned in Ercan and
Üreten (2000), in the article of Robert Antony in Harvard Business
Review in December 1960 with the name of “The Trouble with Profit
Maximisation” it is mentioned that profit does not have a meaning in
solitary sense and it is not clear whether the profit to be maximised is
short term, long term, profitability ratio or profit amount. In today’s
world, the objective of a corporation is defined as maximising the value in
shareholder perspective (Küçükkaplan, 2008: 4).
According to Damodaran (2009) analyst having the purpose of
valuing a bank faces three main difficulties. Firstly, the character of
banks’ facilities create obstacles to specify re-investment (net capital
expenditure and working capital) and debt and this makes it tough to
estimate cash flows (banks’ debts are more close to staple rather than a
capital source). Secondly, banks are usually under intemperate regulations
and this may cause notable outcome on value. Thirdly, accounting
principles governing banks are quite dissimilar from the accounting
principles applied in other non-financial corporations and assets of the
banks are mostly marked to the market-place. Assets of banks are usually
financial instruments such as securitised obligations, bonds and they
usually have dynamic marketplace. Accounting standards are built up by
considering the fact & tendency that banks usually achieve a profit for
long intervals and usually have heavy losses for short intervals.
The intention of valuing an investment instrument is determining
its price. Market price does not always reflect the true value of an asset.
Investors need to find the true value which has to be. Different techniques
are employed in the valuation process. In the literature, these techniques
are used easily for manufacturing and commercial firms but they are quite

difficult to employ for financial corporations (banks, insurance, leasing,
factoring companies etc.). These difficulties arise from the different
structure of financial corporations’ financial statements and the excessive
sensitivity of these corporations to macro-economic decisions. It is quite
tough to value a bank for both theoretical and practical sense. For some
techniques, it is quite difficult to reach the required data needed for
valuation (Küçükkaplan, 2008: 1). Common conceptions like income
from operations and working capital happen to specify and account. As a
result of this, there is a need to value a bank from a quite different
perspective which has advantages and disadvantages (Dime Trader, 2012).
Valuing banks by internal bodies mostly focus on stockholders’ objective-
creating value, improving cash and profitability. However valuing banks
by external bodies is various-sided and mostly focuses on risk
(Strumickas & Valanclene, 2006: 22).
Banks are to a great extent controlled by regulations every place
in the world, although the size of the control changes from state to state.
Generally, this regularization happens in three kinds. Firstly, bank
corporations are expected to achieve some capital proportions which are
asked by the regulators and which are calculated according to their book
values of equities and their performance in order not to stretch beyond
their capacities and risk the position of the shareholders or depositors.
Secondly, banks are commonly restrained in terms of where they can
venture their reserves. For example, at the beginning of 2000s, the Glass
Steagall Act which is enacted in the USA, restrained banks operating in
commercial facilities from seizing effective equity-related places in non-
financial corporations and involving in investment banking facilities.
Thirdly, the entrance of new banks in the sector and merging requests
between the corporations are usually checked & controlled by the
regulatory bodies. All these issues affect valuation calculations because
suppositions related to growing are concatenated to suppositions
surrounding re-investment. In terms of banks, those suppositions must be
scrutinized to assure that they meet regulation restrictions. These issues
may also affect the framework where the risk of the bank is quantified. If
regulation related constraints are varying or they are expected to vary, this
then might increase the risk (uncertainty) for the future facilities and
affect the bank’s value. Simply, we must be conscious of the governing
regulatory forms in the valuation process (Damodaran, 2009: 5).
Beltrame and Previtali (2016) mention that usually bank regulators
impact several features of banks’ facilities both from asset and liability
perspective. They acknowledge that the Basel framework which imposes
some capital restraints is one of the most crucial components that impact

bank value. It is mentioned that the concentration is on bank capital due to
the undermentioned reasons:
•The character of bank facility that conducts with payments,
investments, credits and savings needs a stable type of safeguard
from market failure.
•Lofty level of capital shields claim holder from failure (default)
and they promote to strengthen bank sector’s resiliency to likely
systematic financial crisis.
•Bank capital possesses an unlike function in comparison with the
other non-financial corporations. In the banking sector, capital
hinges on the aggregate of asset and its risk.
These likely capital stipulations which are imposed by Basel are
peculiarly important in bank valuation process since capital additions and
their inner form may create an explicit restraint on growth chances. A
capital shortage diminishes the bank’s potential to extend assets or even to
handle their interior mixture by considering the inherent risk. This kind of
rigidness in asset and capital supervision may impact the bank’s capability
to achieve earning and to give out a dividend. Hence, it is believed that
when the bank is valued, in addition to asset growth and earning, also
bank’s plan to encounter the required increase in the capital should be
assessed (Beltrame & Previtali, 2016: 9-10).
Cash flows generated by banks are usually quite volatile and are
connected to macro-economic conditions. For this reason, it is quite
difficult to forecast cash flows of banks and it is easier to make a fault.
For most of the corporations, their balance sheets are heavily influenced
by presumptions made by the managers and past events. For instance, the
judgment made between FIFO (First in first out) and LIFO (Last in first
out) stock valuations may affect the results of a corporation with a high
level of stock and in high inflation environment. As a result of this, for
non-banks, equity of stockholders is quite gratuitous evaluation and it is
quite tough to contrast across corporations with divergent business tactics
& strategies, grand and ages. Fortunately, in most cases, this is not an
issue for banks. Banks utilise accountancy of mark to market and this
enables us to see almost assets and liabilities at a valuation which are at a
fair level determined by the market rather than historical cost. By this
way, unrealized gains and losses are in actuality recognised. The
stockholders’ equity on the balance sheet of the bank becomes to a greater
extent of net deviation between the existing marketplace of assets and
liabilities (Dime Trader, 2012).
Another notable point which should be considered is the loan loss
provision (LLP). Banks make loan loss provisions to confront a possible

twisting in the quality of their credit portfolio and this can be noted as one
of the primary accrual expenses. Usually, loan loss provisions are
discretional and they should be normalised when the analyst calculates the
expected earning of the bank. The main targets of provision can be listed
as below (Beltrame & Previtali, 2016: 14-15):
•Taxes: Executives can modify provision with the purpose to
report a targeted net profit (when more provision is made, yearly
tax expense is lowered).
•Capital adequacy: Executives may utilise provision to achieve
the capital requirement.
•Income smoothing: When there is an intention to stabilise net
profit over time-period, this pursuit is made.
•Signalling: Substantial loan loss provisions are thought to be a
signal to the market that profitability will increase in the future
rather than a credit loss.
When we examine capital expenditures in banks, it is noticed that
since mostly the bank’s investment is not a tangible asset, banks have a
low grade of amortization. Bank’s investment in a brand name, I&T
technology, process and procedure improvement and human capital are
usually accounted as operational cost (rather than fixed investment).
Some academicians defend that to estimate capitalisation, the primary
difficulty faced by an external analyser is to distinguish distinct elements
of investment from operational cost. Therefore, adjustments made in
capital expenditure in nonfinancial corporations are not suitable for banks
due to the unlikeness in fixed investment concept (Beltrame and Previtali
2016, 16).
To obtain efficiency and reliability in capital markets one of the
crucial issues is to value the firm correctly. At first, determining the value
of the firm correctly is needed in the initial public offering and at the time
when the decision to buy the stock is made. The degree of reflecting the
true price in the market is very important for investors. On the other hand,
it is crucial to determine the value of the corporation that is in the
privatisation process in a true way (Küçükkaplan, 2008: 1).
Assets can be marked to market but despite this, the analyst
should carefully and independently assess the value. Otherwise, there are
two reasons for failure in precise value estimation. Firstly; believing that
the market will form accurately can be misleading, it can make mistakes
and these mistakes will then pass to the book value. For example, after the
crisis in 2008, it was understood that markets overvalued the assets.
Secondly, assets are usually valued by the market by the use of models
utilised by appraisers and this evidently causes the lag in noticing the
change in the value and sometimes causes to overvalue (Damodaran,
2009: 12).
EXCESS RETURN MODEL
Because of the reason that banks’ equities’ book values are to a
greater extent true and cash flows of banks are quite volatile and to a
lesser extent precise for measuring the managers’ performance due to
larger effect of macro-economic factors rather than micro-economic
factors) compared to other types of firms, some of the analysts who are
interested in the value of banks, depend on stockholders’ equities. This
technique is known as ‘Excess Return Model’ and reaches to equities’
values by summing the existing equities capitals and present economic
values of expected excess returns to equities (Dime Trader, 2012). Also
discounted cash flow measures do not provide any info about the value
created. Therefore to examine if banks accomplish higher return than the
cost of capital, this model; the excess return model is quite practical and is
a different approach to value measurement. This model is also known as
residual income model or abnormal earnings model in the literature. This
approach originates from the study of Marshall in 1890 and at that date,
he mentioned that value concept is measured by the excess profit after we
deduct a capital charge. By the help of this model, we measure the value
of the bank on the capability of the bank to accomplish a flow of return
higher than the return which will be achieved by the invested capital with
the same risk level (i.e. opportunity cost). When this model is examined
from an academic perspective, it is noticed that the model’s measures
abide by Feltham and Ohlson model. The bank’s value stringently hinges
upon whether the return is more than the capital cost (i.e. excess return).
If this stipulation is not accomplished in the forecast term, then bank
value is simply net asset value. The model can be calculated as below
(Beltrame & Previtali, 2016: 23-25):
Residual Income (ROEre)*EquityCapitalt1 Residual
Income Net Income( *re EquityCapitalt1)
EquityValue EquityBookValue
t nt1 (1RIrt ) TV
t(1
ere )n
RIt1
TV
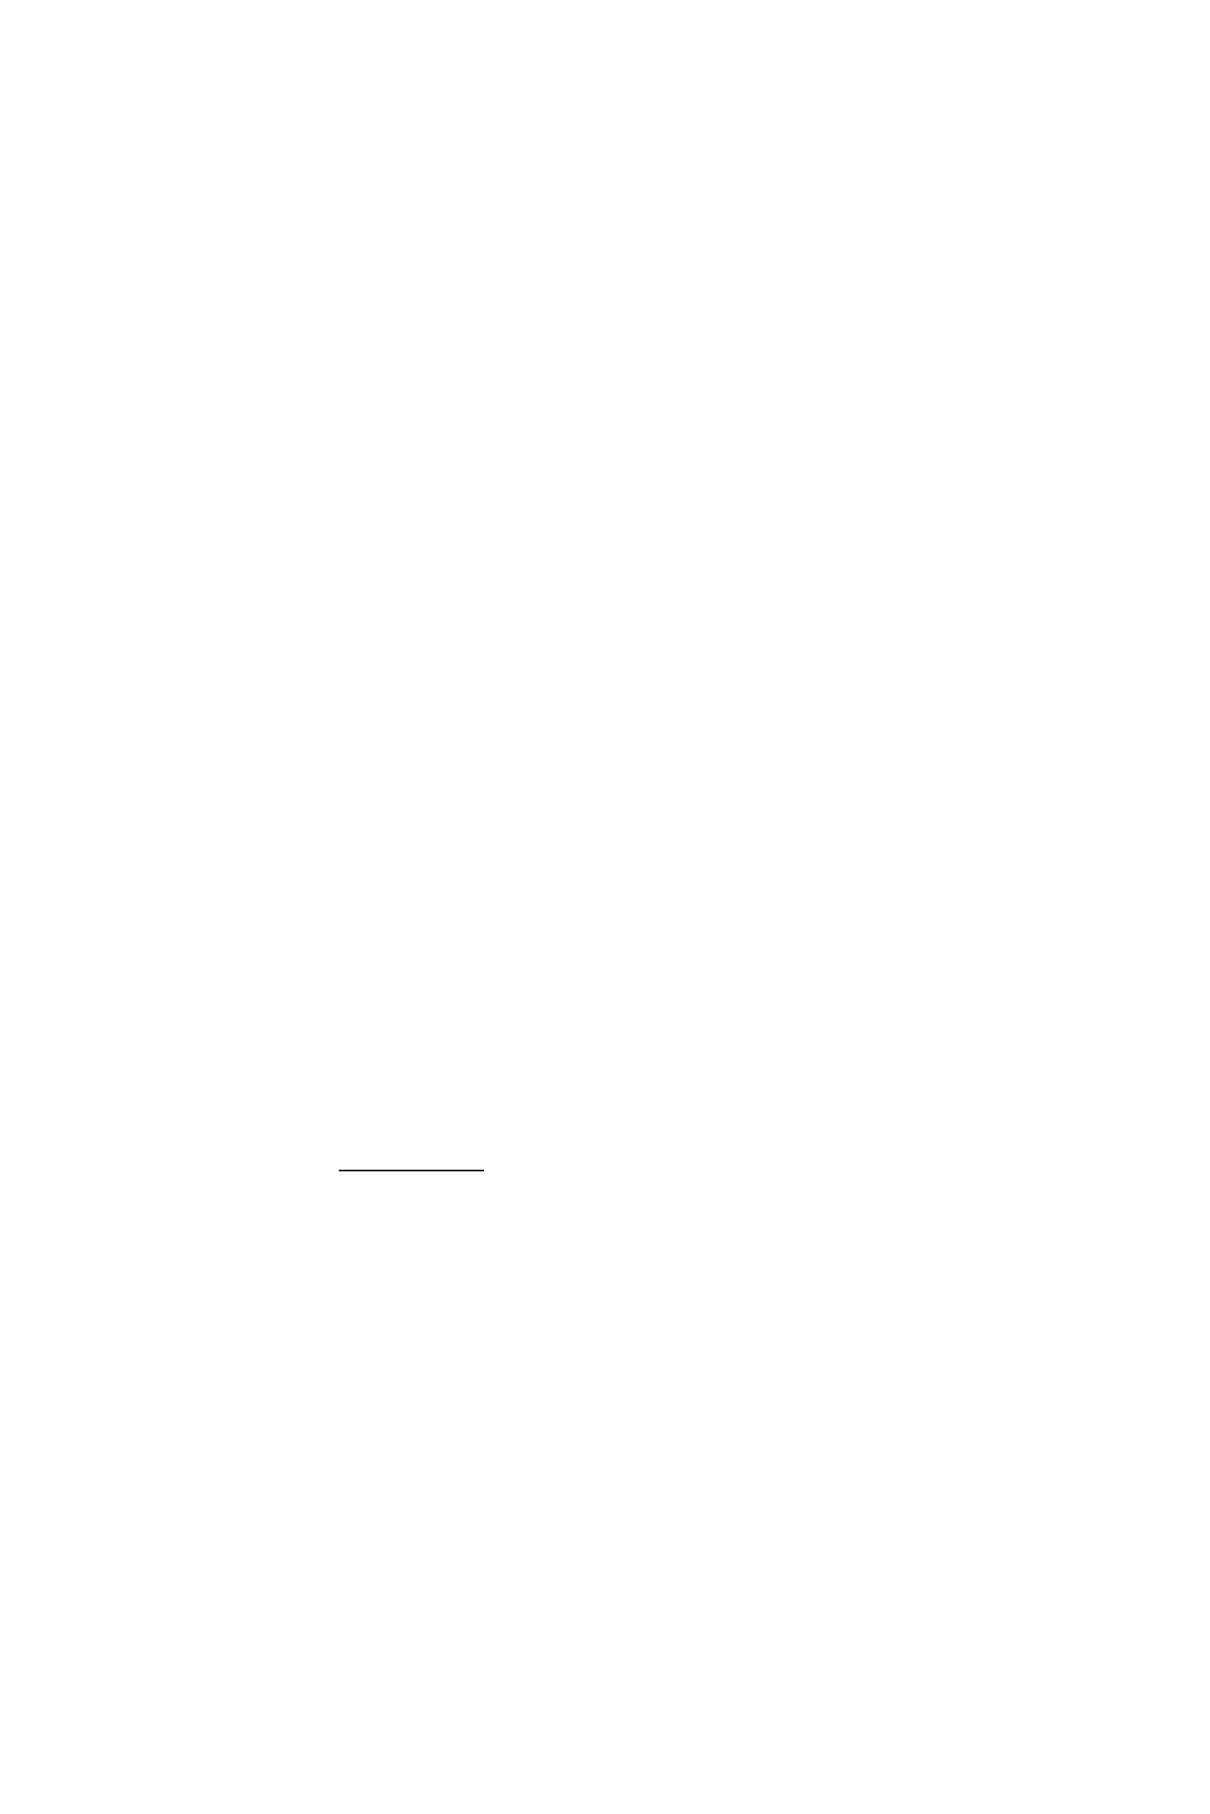
(re g)
In other words, in the excess return technique, cash flows are
separated into normal return cash flows and excess return cash flows.
When the bank earns a risk-adjusted required return, this is recognized
as cash flow of normal return but when the bank creates cash flow above
or below this figure, and then it is called an excess return. This excess
return may be positive or negative. Excess return technique originates
from the concept of capital budgeting and NPV (net present value). As
long as bank achieves positive NPV, the regarding investment improves
the value (the prior estimated profitability of the investment does not
matter). This means that if the excess return is achieved then cash flow
growth and earnings matter value (equity return>cost of equity).
Therefore this technique values the bank as a function of estimated
excess returns (Damodaran, 2006: 37).
DISCOUNTED CASH FLOW MODELS
As it is usually applied, the discounted cash flow (DCF)
approaching is built on the theory that we estimate the asset’s price by
discounting back the expected cash flows in a period. In bank valuations,
mainly two discounted cash flow models are utilised: Dividend Discount
Model (with excess capital adjustment) and Cash Flow to Equity Model
(CFE). When these models are examined, it is seen that they give the
same results when banks pay out all distributable earning. This happens
when the pay-out ratio is equal to 100% (Beltrame & Previtali, 2016: 19-
22).
CashFlowt
Value (1re)t
t 0
Estimation of profit evolvement for banks can be accomplished
by regression analysis or by analysing the plan in terms of finance from
data prepared from profit & loss account and balance sheet. The
regression analysis technique is suitable in developed countries where
there exists long term stability. Secondly, this technique is more
appropriate for banks rather than nonfinancial corporations since banks
usually operate under strict regulations and there is not chief
unsteadiness. However, if it is available to the bank’s financial plan is
the best and most accurate way to estimate future performance (dividend
etc.). An analyst should be able to examine the critical features of a
bank’s profits and future projections. It should be usually reasonable if
estimations are performed for the next 5 years. Loans and other earning

assets which are main profit creators and income from fees should be
very carefully assessed in the analysis (Horvatova, 2010: 57).
Nevertheless, calculating a value from cash flows can be
problematic. In terms of cash flow, there is not a well-defined value
creation procedure, since, for example, the dividend represents a synthetic
amplitude of cash. By some academicians, it is advocated that equity side
perspective can be imperfect technique since this technique does not
permit to analyse cash formed by the use of asset and liability (Beltrame
& Previtali, 2016: 1).
According to Damodaran (2009) two main figures that affect bank
value are the ‘cost of equity’, which is the function related to the risk that
originates from the banks’ investment, and ‘the return on equity’, that is
settled by banks’ business choosings and regulatory stipulations.
For a bank, in comparison with other nonfinancial corporation
there exists a substantial difference in terms of the portion of own and
foreign fund sources. Due to the characteristics of bank, it usually has a
high gearing ratio. Cost of capital stands for the investors’ expected rate
of return considering the investment risk grade. Expected rate of return
should be higher than the bank interest rates (bank deposit) since any kind
of business facility represents a higher risk than risk-free investment.
Riskfree rate(rf) may be calculated from government bond interest rates or
these government bonds’ yield to maturity. Cost of capital is higher than
the riskfree rate considering the tax shield. Some techniques for
estimating the cost of equity can be listed as below (Horvatova, 2010: 53-
54):
•Gordon Growth Model
•Capital Assets Pricing Model (CAPM)
•APT (Arbitrage Pricing Theory) Model
•The foreign funds’ cost
•Average profitability
CASH FLOW TO EQUITY MODEL
Aggelopoulos (2017) argues that when a bank’s cash flow model
is tried to be built outside the bank, Cash Flow to Equity technique rather
than the Discounted Cash Flow technique should be utilised. Because the
financing and operating judgement can not be segregated in banks
(interest expense and income (financing judgements’ elements) are crucial
factors of operating income) (Aggelopoulos, 2017: 2). In this technique,
rather than free cash flows provided to debt and equity holders are used,
only cash flows expected to be provided to equity holders are utilised.
Since the expected cash flows are only for equity holders, when the

present value of these cash flows is calculated, the equity cost of the bank
should be used. The sum of discounted values of equity cash flows
estimates the value of a bank’s equity. When equity value is divided by
the stock number, the price of each bank stock is estimated. Stock price in
the market can be compared to the required value of the stock estimated
by the model and buy-sell decisions are given by examining the difference
(Bozacı, 2012: 34-38).
CashFlow EBIT *(1T)
(Capital Expenditure AmortisationExpense)
NetWorkingCapital
EBIT EarningsBeforeInterestandTax
DIVIDEND DISCOUNT MODEL
Damodaran(2009) mentions that some analysts believe that
the estimation of value by cash flows for banks is not applicable and
only depend on the sole discernible cash flows: dividend. This can be
thought to be sensible, these analysts inherently assume that the
dividend which is paid by banks is reasonable and sustainable.
Nevertheless, this assumption is not always correct. It is known that
some banks are paying dividend too much and afterwards they issue
new shares to recompense and some pay too little and utilise the
remaining amount to improve their capital proportion(ratio). When the
valuation is performed depending on paid out dividends by
considering the scenarios mentioned, in the former case we will
overvalue the value of the bank and in the latter case, we will
undervalue the value of the bank. The use of present dividends can be
problematic; for example, the bank can have high growth potential
and pay a very little dividend for a very long time compared to the
mature banks. This time we can again undervalue the bank. If the
bank pays no dividend, we can even conclude that the value of the
bank is zero!
Horvatora (2010) believes that in utilising cash flow to
estimate value from the perspective of bank shareholders below issues
should be taken into consideration:
•For banks, statement of cash flows is not appropriate for
deciding owners’ sources because dividend related to the bank
shareholders can be reimbursed only from real net income
after tax and not from the cash flow activity.
•Banks’ and nonfinancial corporations’ profits are not evenly
come-at-able because there is not a problem in terms of cash
available to bank shareholders due to the character of most of

the assets&liabilities, whereas in nonfinancial corporations
substantial deviations exist between profits and cash flows
(some businesses may create profit but not enough cash
flow).
•The primary income generators for banks are service fees and
the balance between interest income and expense. i) Gordon
Growth Model
As mentioned by Damodaran(2002), the Gordon Growth Model is
utilised usually to value corporations which have steady growth and
which have dividend growth rate preserved in an infinite time. Because of
the reason that it is assumed in the model that the corporation’s growth
rate in dividends is anticipated to continue eternally, in literature the title
‘steady growth rate’ is extensively argued and queried. One of the
viewpoints of the Gordon Growth Model and the model’s steady growth is
that other functioning rates (for example ‘earnings’) have the identical
yearly growing rate as a dividend. For this reason, in the case that
corporation’s earning is developing quicker than its ‘dividend payout
ratio’ in the longterm, than the corporation’s ‘payout ratio’ is going to
tardily come close to zero and this isn’t a characteristic of a corporation
which has a stable growing structure. Moreover, a corporation which is in
‘steady state’ can not possess a growing rate which surpasses the growth
rate of the sector & economy where the corporation functions. It is
pellucid that ‘growing rate’ has an important function in this model and if
we utilise inappropriate rate, this will result as improper valuations. It can
be seen in the regarding the formulation of the model that when the
corporation’s ‘growth rate’ approaches the ‘cost of equity’, the value will
become infinite and when the ‘growth rate’ passes the ‘cost of equity’
then the value will become negative (Charumathi & Suraj, 2014: 39).
Regarding the payout ratios issue; the ‘expected dividend per
share’ may be calculated by finding the product of EPS (Earning per
Share) and ‘Expected Payout Ratio’. There are two gains when we derive
dividends from ‘expected earnings’. Firstly this enables the analyst to
concentrate on ‘expected growth rate in earnings’, that is more credible
and obtainable than ‘growth in dividends’. Secondly, ‘payout ratio may
vary in due course and this shows that investment possibilities and growth
are changing. We can calculate the bank’s ‘payout ratio’ dividing the
dividend by the earning (same calculation with the corporations in other
sectors). When the dividend performances of banks are examined it is
noticed that banks usually pay more dividends in comparison with the
other corporations in the market. The ‘dividend yield’ and ‘dividend
payout ratio’ for banks are mostly higher than the results of the
corporations in different sectors. This happens firstly because banks
facilitate in much more ripe field in comparison with the corporations in
other fields such as software and telecommunication. Secondly, even the
differences in the expected ‘growing rate’ are controlled, banks usually
pay more in dividends compared to non-financial corporations for two
causes: banks customarily have fewer invesments in the ‘capital
expenditures’ than nonfinancial corporations (so more dividend from
more net income can be paid and as a dividend) and when the historical
performances are analysed it is seen that banks are stable and high
performance in dividend payment (so they earned the reputation of being
reliable dividend payers) and they appealed investors who prefer dividend
and by this way, it has become more arduous to modify their dividend
payment scheme (Charumathi & Suraj, 2014: 40).
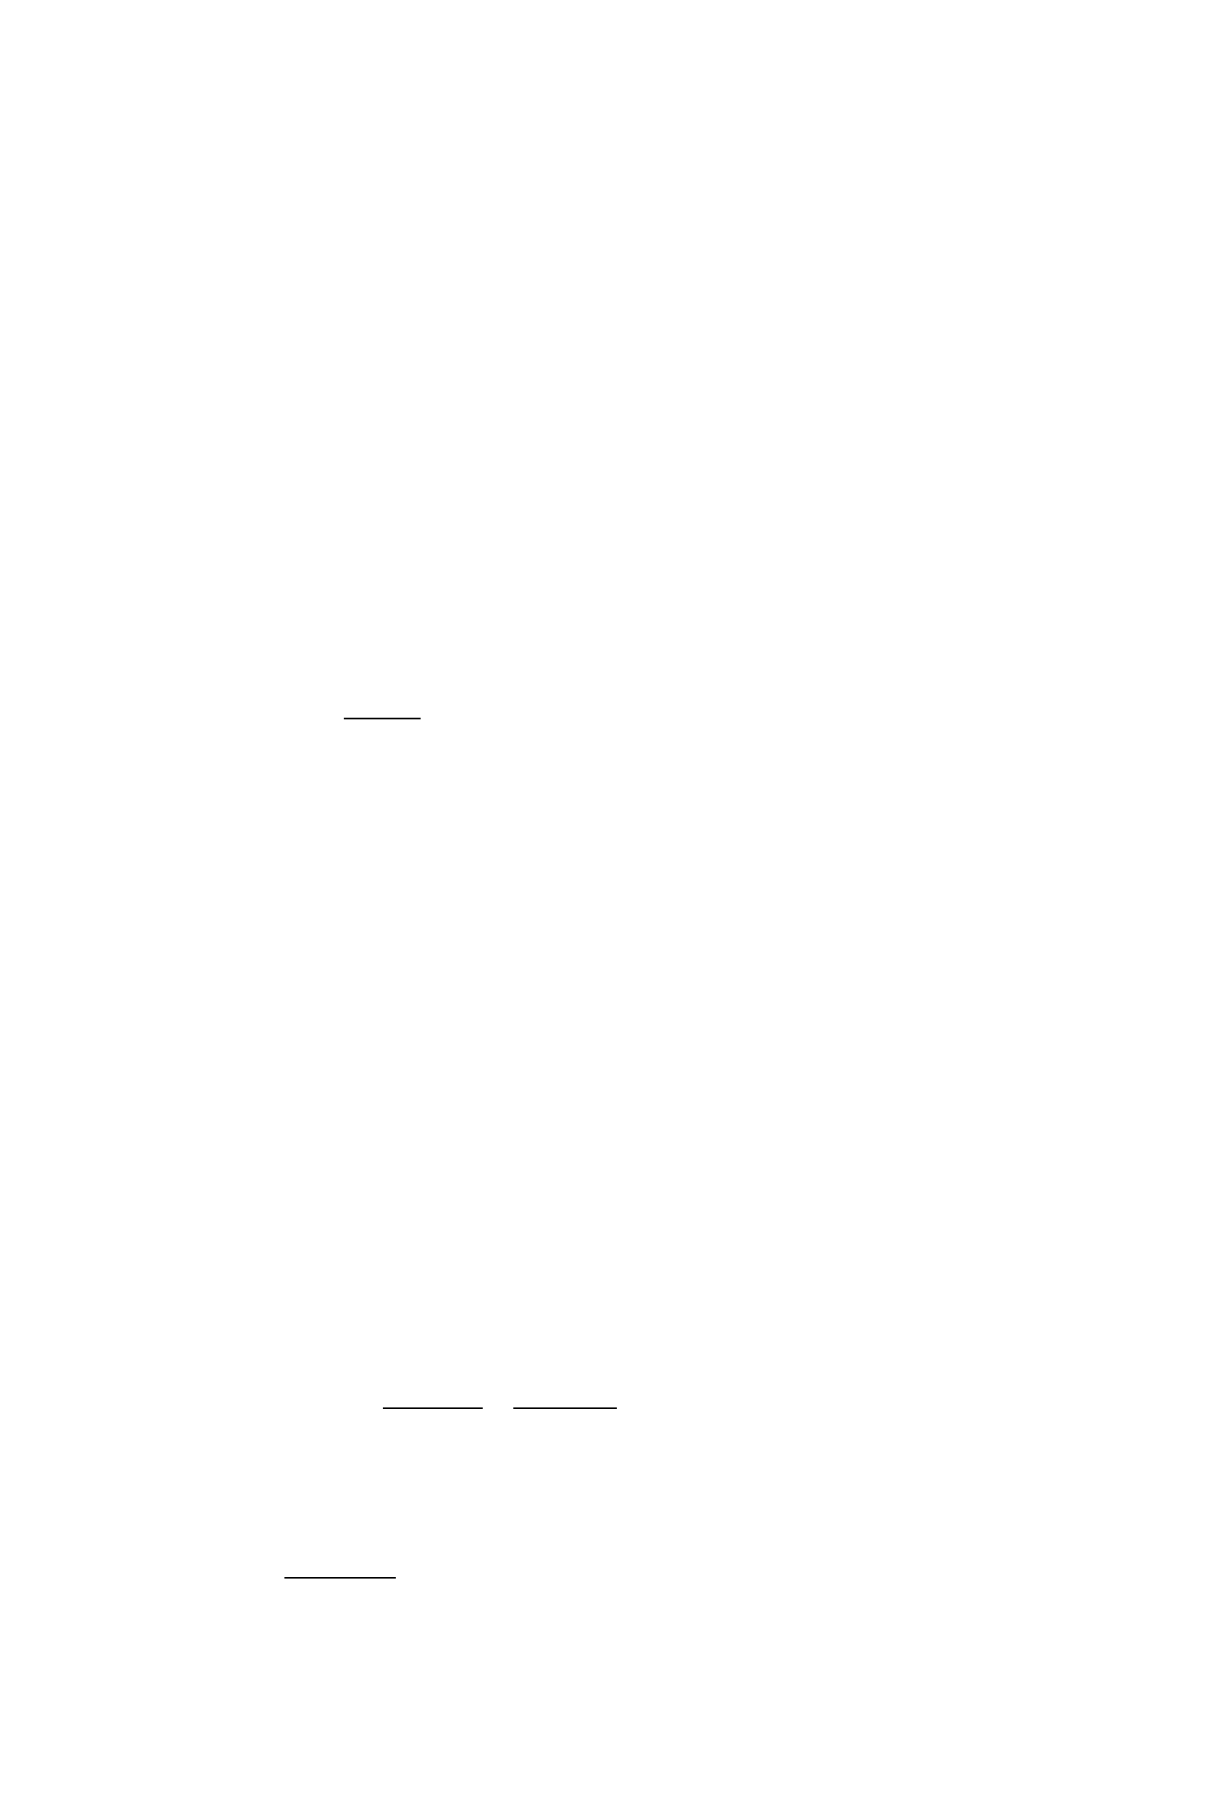
The formulation is as below:
D1
Value ke g
ke Costof Equity
g GrowthRateof Dividend
ii) Two-Stage Dividend Discount Model
This model allows us to use two different growth rates for two
different periods. Firstly, a growth rate is decided for the suitable first
period (this rate does not need to be constant). Secondly, a constant
growth rate is used for the second period which is assumed to continue
eternally. In most cases, it is expected that the growth rate is higher than
the constant growth rate. However, this is not a necessity. This model can
also be applied to the banks which have low growth rates initially
however which are expected to grow fast afterwards. (Bozacı, 2012: 41-
42). The formulations are as below:
Value tn1 (1Dkt e)t (1Vkne)n
Dn1
V
n
(ke gn )
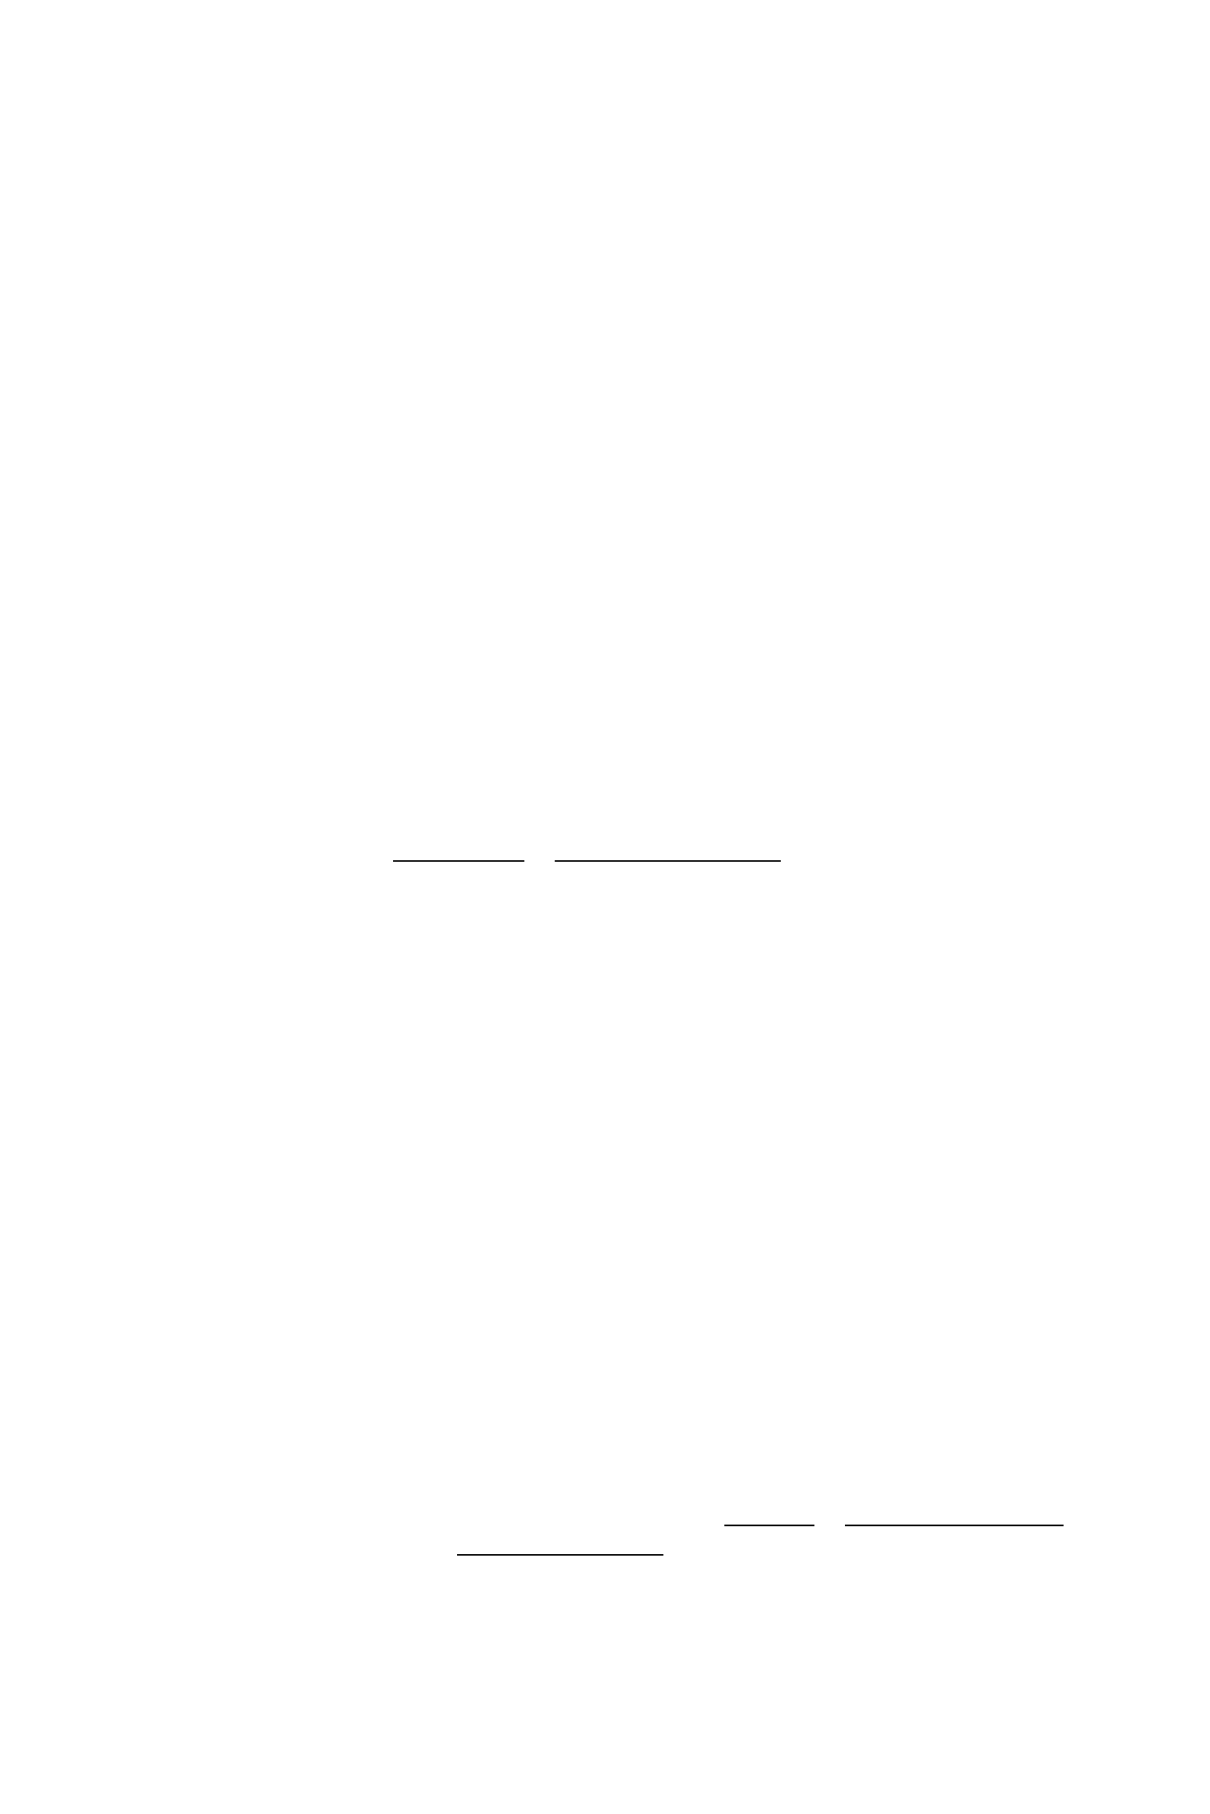
Dt expected dividend in yeart
ke costof equity
Vn valuein yearn g
growthrateatthebeginning gn
unchanging growthrate
iii) H Model
H Model is another quantitative method which can be used in the
dividend discount model. This technique is quite alike as the two-stage
dividend discount model. The difference is that growth rate is attempted
to be smoothed out over time and it does not suddenly change from high
to a low value. In this model, it is assumed that the growth rate falls
linearly towards the final growth rate. For most of the corporations,
dividends fall or rise gradually rather than suddenly changing. This model
was created for the corporations whose growth rates change over time
(“What is the HModel?”,t.y.)
The formulations are as below:
Value D0(1 gn ) D0 * H *(ga gn )
ke gn ke gn
Dt e xpected dividendin yeart
ke c ostof equity
H the durationof thedecline incompany s growth'
ga growthrateatthebeginning gn unchanging
growthrateafter H years2
iv) Three-Stage Dividend Discount Model
This model is created by combining the two-stage dividend
discount model with the H model. This is the most flexible dividend
discount model. In this model, it is assumed that the corporation will
grow at a constant high rate, afterwards, it will decline gradually and
finally, it will remain at a lower constant rate and continue eternally in
this constant growth rate (Bozacı, 2012: 44-45).
Value tn11 E0 *(1(1gkea))t a t n n12 1
(1Dkt e) E(kne2 *gnn)(1*(1kge)nn)
Dt expected dividend in
yeart Et earningin yeart ke
costof equity
a dividend payoutratioinhighgrowthrate period n
dividend payoutratioinunchanging growthrate period ga
growthrate forn period1 gn unchanging growthrate
expected growthrate
1
equity profitability
Below primary propositions can be made when discounted cash
flow models are considered as a whole (Beltrame & Previtali, 2016:
2223):
•Dividend discount model is easier to be performed in practical
life since free cash flows to equity can not be calculated for banks
unless we make some strong suppositions. Moreover, a bank
usually does not pay out all of its yearly earning and it tries to
smooth stockholder’s cash flow in time. Dividends can be
regarded as the best substitute for the free cash flows available to
stockholders.
•From the viewpoint of an external analyser, it can be quite tough
to estimate the dividends in the long-term since dividends are the
outcome of banks’ dispersion policies. It can be advocated that
historical performance can be a useful benchmark, however,
valuation is made for the future. When it is tough to estimate the
future (for example in case of crisis) dividend discount model can
be untrustworthy. In such occasions, it would be convenient to
perform probabilistic sensitivity review or asset-side technique of
valuation.
RELATIVE MARKET VALUATION MODEL
Relative market valuation model takes its roots from the
presumption that financial markets are efficient and have liquidity. When
the financial markets are efficient, then alike assets that have the same
risk and return properties should be traded with close prices to each other.
Value and market multiples are usually used to value the firm by
assuming the above presumption and the bank’s value is estimated in the
context of banks’ which have close properties. To able to apply the above
methods, we have to have similar banks that are close to each other in
terms of growth, efficiency, profitability, diversification, size and
commercial plan. But it is a quite tough task to find similar banks. For this
reason, the criteria are loosened to achieve a tradeoff between the number
of the banks in the list and the closeness of the banks in terms of
properties and a counterbalance between data quality and precision is
tried to be accomplished. Since there is a risk to misprice the bank and a
risk to be inaccurate, this technique is advised to be used only as a control
method (ie not the chief method) (Beltrame & Previtali, 2016: 31).
Damodaran (2006) mentions that corporate value multiples such
as Value to EBIT or Value to EBITDA can not be simply used for the
valuation of banks, because we can not simply estimate operating income
and value for banks. Therefore it is advised that equity multiplies should
be utilised in the valuation process. Mostly, in practice, price to sales
ratio, price to book value ratio and price-earnings ratio are used. It is
believed that from these ratios, price-earnings ratio and price to book
value ratio should be preferred since sales are not easy to be measured for
banks and it is more difficult to use price to sales ratio.
i) Price Earnings Ratio:
Price-earnings ratio is among the most favourite valuation
techniques for analysts who are interested in the values of firms. It is quite
useful since the price-earnings ratio seizes stock’s growth rate and risk.
Therefore we can evaluate the bank’s value by utilising the price-earnings
ratio of corresponding banks that have the same growth and risk. This
technique is particularly handy when we can not observe the value of a
bank. The functioning of this technique relies on the way we choose
comparable banks. Alford (1992) inspects many explications of
comparable corporations (for example sector membership, return on
equity, size) (Cheng & McNamara, 2000: 349-350).
Price per share Earnings per share
Price Earnings Ratio
Value Price arning atio Bank snet profit e r * '
ii)Price to Book Value Ratio:
If we keep other factors same, higher price to book ratio will
occur when return on equity, earnings growth rate or payout ratio
increases or equity cost decreases. Among these four ratios, return on
equity has the greatest impact on the price to book value ratio, therefore
this ratio can be identified as the associate variable for the price to book
value ratio. It can be said that the association of return on equity and price
to book value ratio is stronger for the banks in comparison with the firms
in other industries & sectors. The reason for this is the fact that equity’s
book value is closer to the equity’s market value. Additionally, accounting
facilities affect the return on equity less for banks (Damodaran, 2009: 30).
Price per share
Price to Book Ratio
Bookvalueof theequity per share
Value PricetoBook Ratio Bank sEquity*
ASSET MARK-DOWN MODEL
Beltrame & Previtali (2016) proposed a new model which is
based on bank-specific theoretical valuation perspective and a novel asset
side model. It is an adjusted PV(Present Value) model and it aims to
calculate chief value creator originators which are identified as mark-
down on deposit, tax benefit on bearing liability (deposit and non-deposit
debt) and free cash flow from assets (FCFA). Unlike industrial companies,
bank deposit creates value. To estimate value created by banks, model
formulates an association between WACC and cost of assets and suggests
a restatement of the Modigliani Miller proposition utilising bank-specific
adjustments.

