


Chapter I Introduction
Financing guarantee companies (FGCs) mainly serve small and medium-sized
private enterprises (SMEs). Firstly, the current financial system in China, which mainly
focuses on direct financing and debt financing, is taken as the logical starting point of
the theoretical analysis. Then, the external and internal causes of financing difficulties
of private SMEs are analyzed. Finally, from the point of view of credit risk
management, financing guarantee is regarded as a special kind of credit risk
management instruments, which provides a clear perspective and focus for the
subsequent chapters.
1.1 Main Topics of the Background
China's indirect financing system and debt financing system aggravate the
financing difficulties of SMEs. The financing guarantee of SMEs can be analyzed from
the perspective of credit risk transferring instruments. At present, China's SMEs
financing guarantee system needs to be improved urgently. These pre-existing
conditions constitute the financial background and logical starting point of this study.
I. China's Financial System and Financing Difficulties of SMEs
The financing difficulty of SMEs is a worldwide problem. In China's traditional
financial system, which is characterized by indirect financing and creditor's rights
financing, imperfect credit system and lack of credit risk transfer tools, the financing
problem of SMEs is more severe.

i Characteristics of China's Financial System
At present, China's financial system is characterized by indirect financing is
dominant while direct financing is weak, debt financing as the main component while
equity financing lags behind, lack of market-oriented credit risk management
instruments, lagging credit information system and high credit risks.
1. Dominant Indirect Financing and Weak Direct Financing
At present, China's finance is still a separate mode, mainly including banking,
trust, insurance and securities. As shown in Figure 1-1, the total assets of banking
financial institutions reached 261.4 trillion yuan at the end of 2018, trust financial
institutions reached 23.14 trillion yuan, and insurance financial institutions reached
18.33 trillion yuan, the market value of stocks, which represents the securities industry,
with a scale of 43.03 trillion yuan at the end of 2018. The above four sectors accounted
for 75.6%, 6.7%, 5.3% and 12.4% respectively. Banking financial institutions were in
the leading position. The market value of the stock market, which represents direct
financing, only accounted for 12.4% of the stock of major
financial assets.
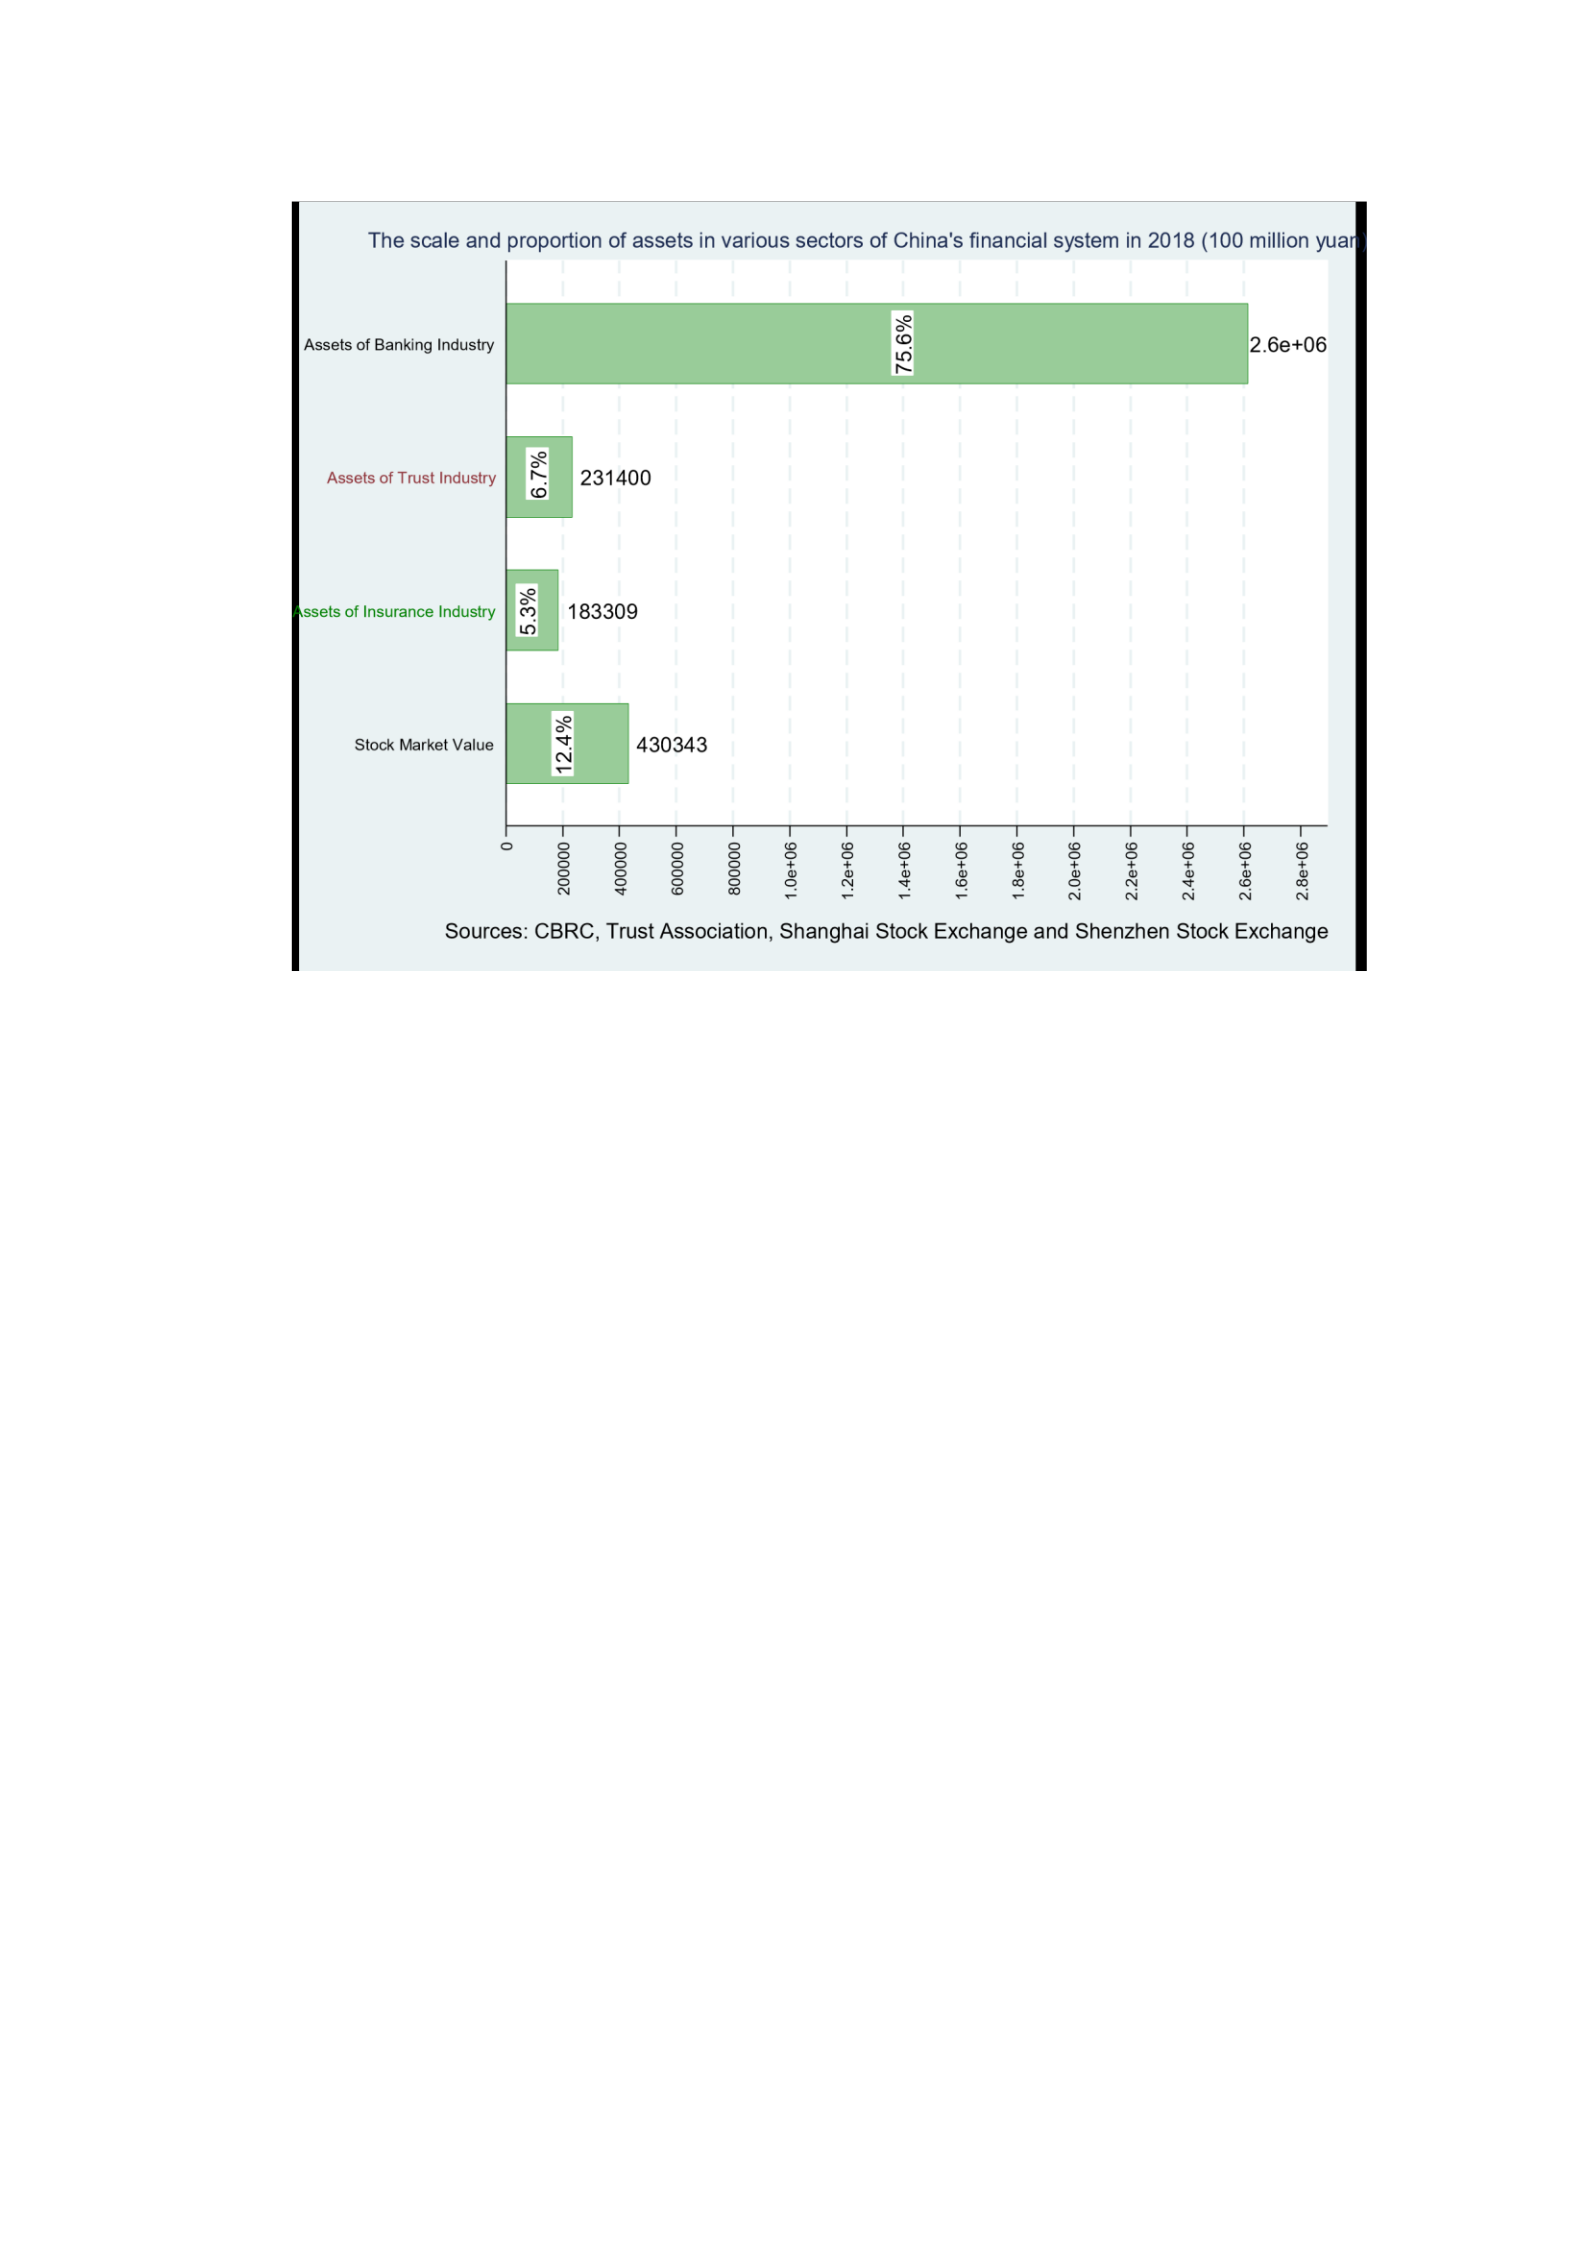
Figure 1-1 Scale and proportion of assets in various sectors of China's financial
system in 2018
Commercial banks, insurance institutions and trust companies are typical
financial intermediaries with indirect financing as the main business, and their
financial liabilities and assets are mainly debt instruments rather than equity. The
financial system dominated by indirect financing, on the one hand, creates the
dominant position of financial intermediaries; on the other hand, it makes it difficult
for financial risks to be spread in the whole society by means of market-oriented
methods. These concentrated risks bring heavy pressure on financial intermediaries
and further strengthen financial intermediaries’ conservative character in business
operation. In short, the dominant position of indirect financing and the imperfect risk
spreading mechanism result in the inadequate service of financial intermediaries to
private enterprises, especially SMEs, which lack implicit guarantee from the
government.
2. Dominant Debt Financing and Backward Equity Financing
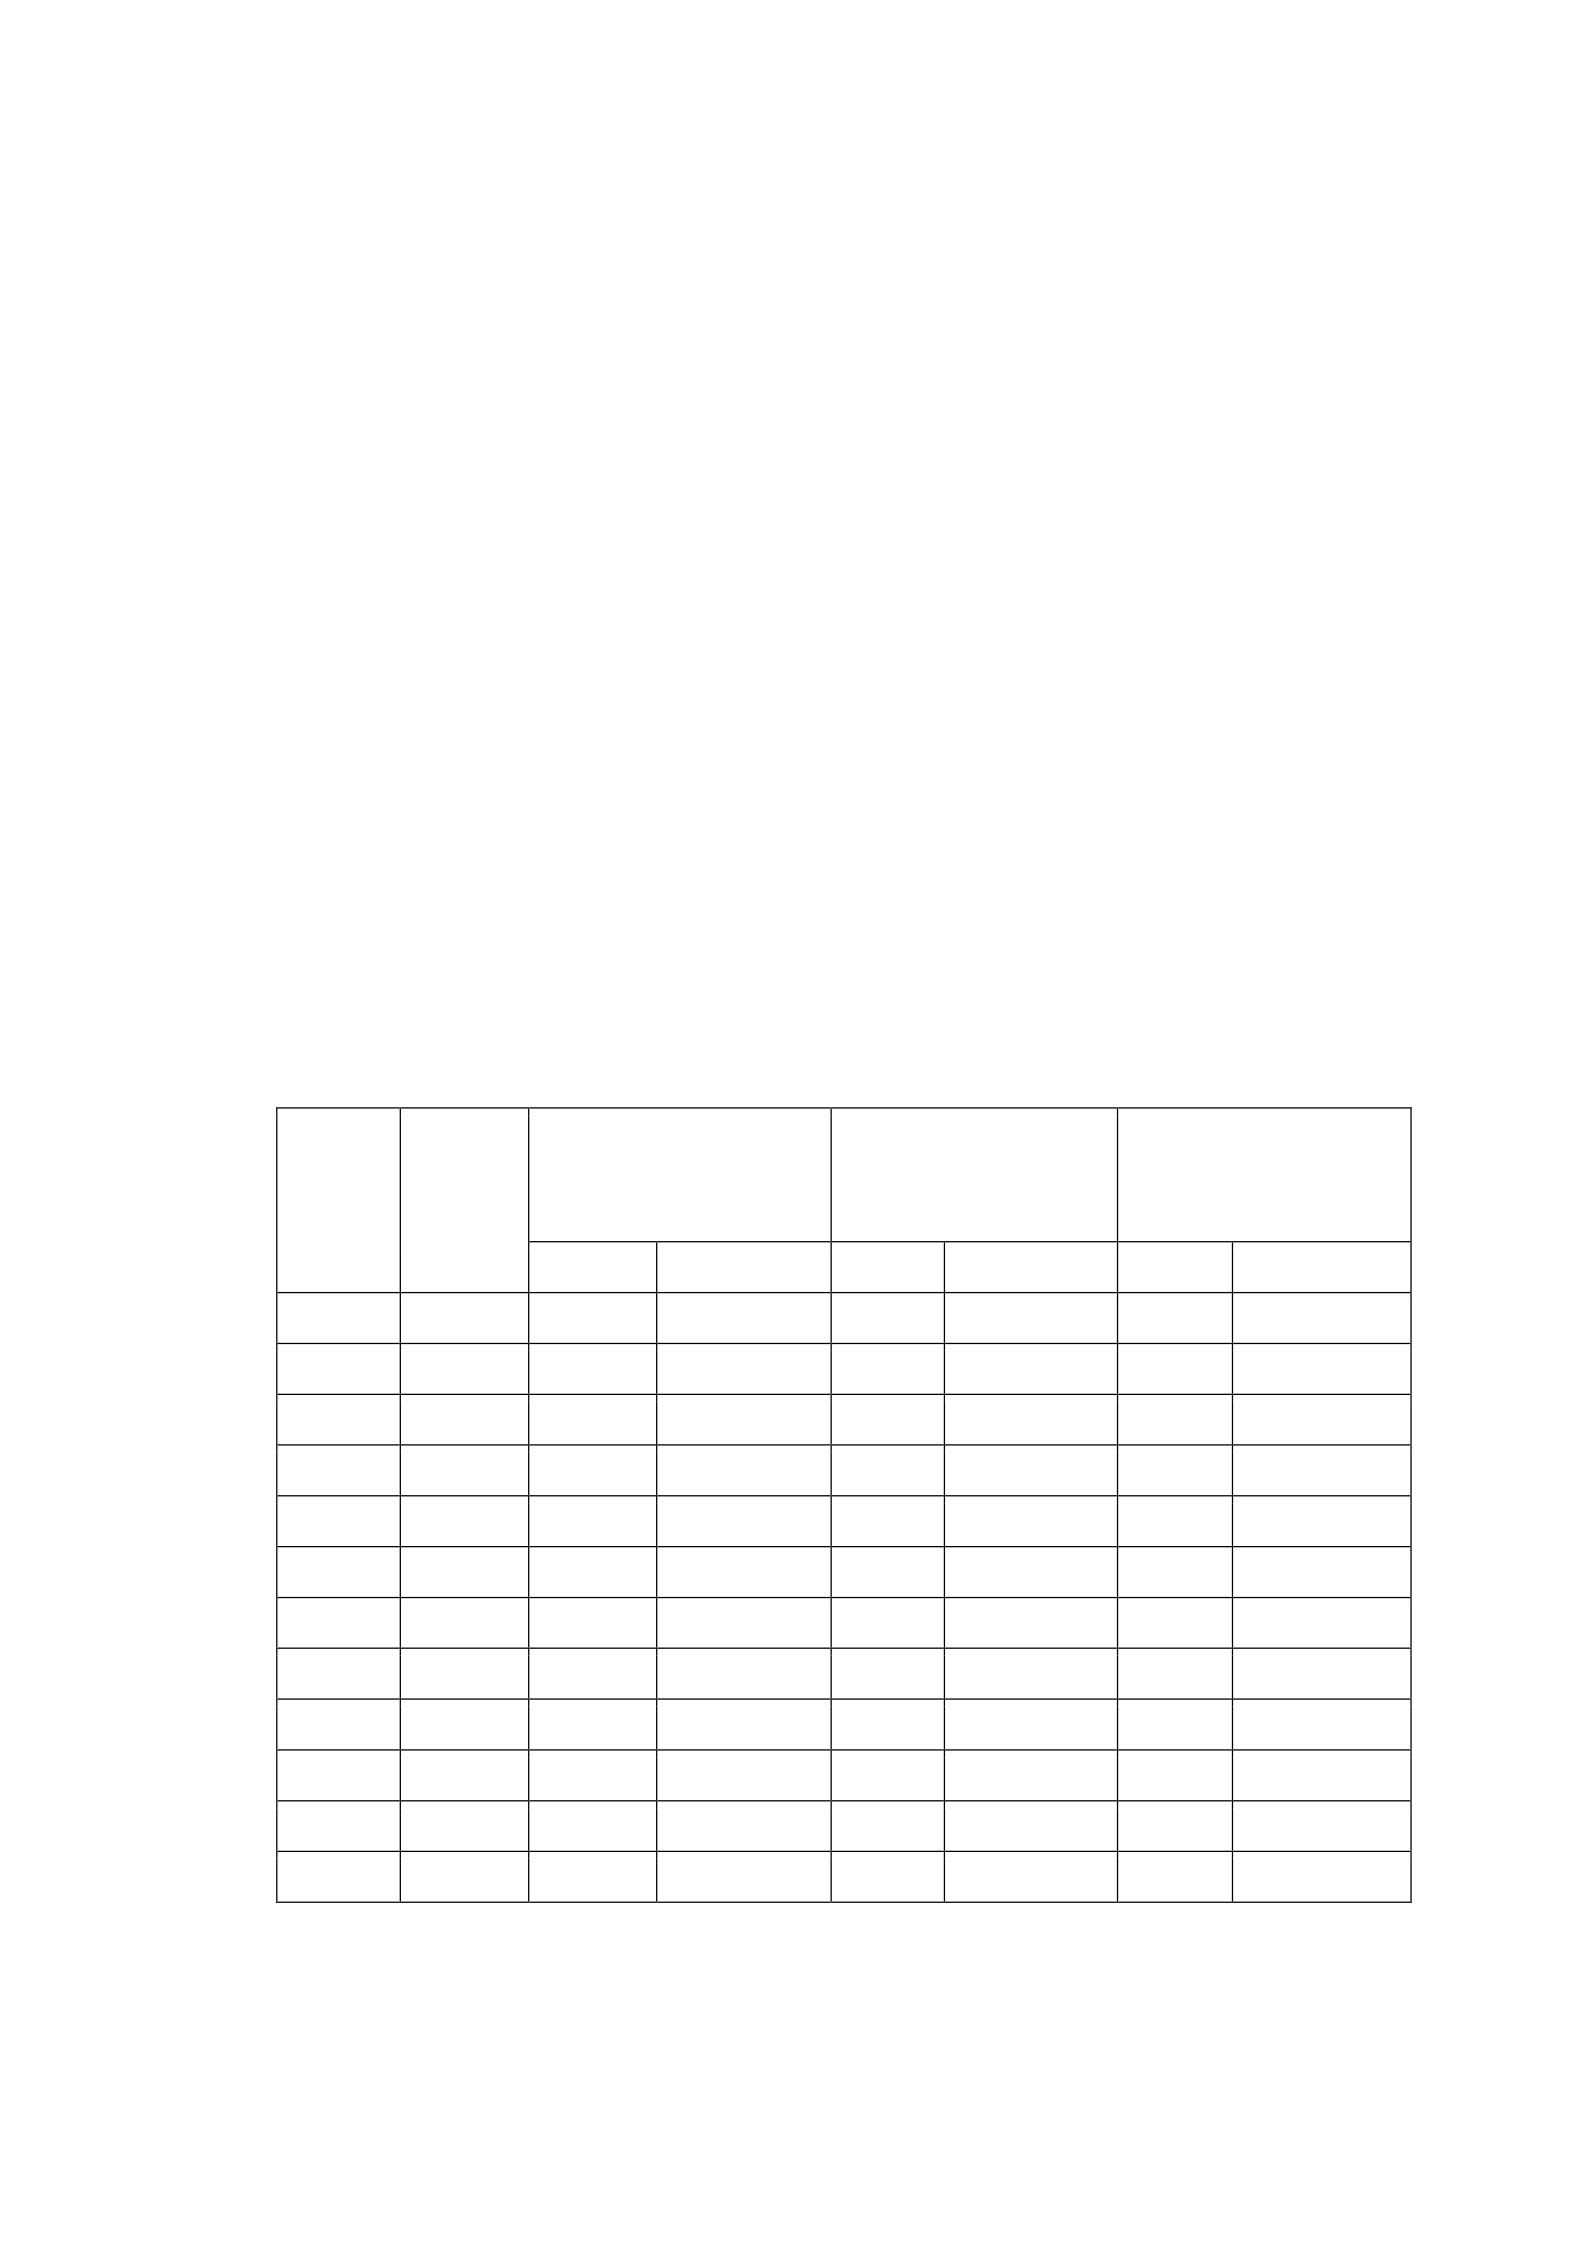
As shown in Table 1-1, according to the National Bureau of Statistics, the increase
of social financing in 2018 was 19259.8 billion yuan, of which: RMB loan was 15,671
billion yuan, accounting for 81.37%; corporate bond financing was 2,485.3 billion
yuan, accounting for 12.90%; stock financing of non-financial enterprises was only
36.6 billion yuan, accounting for only 1.87%. From the nature of financing
instruments, debt financing is dominant, and the proportion of equity financing is too
low.
Table 1-1 Structure of China's Social Financing in 2008 -2018 (RMB 100 million)
year
amount
Renminbi loan
Enterprise bonds
Domestic Stocks of
Non-financial
Enterprises
amount
share(%)
amount
share(%)
amount
share(%)
2018
192598
156710
81.37
24853
12.90
3606
1.87
2017
194445
138432
71.19
4421
2.27
8759
4.50
2016
178159
124372
69.81
30025
16.85
12416
6.97
2015
154063
112693
73.15
29388
19.08
7590
4.93
2014
158761
97452
61.38
24329
15.32
4350
2.74
2013
173169
88916
51.35
18111
10.46
2219
1.28
2012
157631
82038
52.04
22551
14.31
2508
1.59
2011
128286
74715
58.24
13658
10.65
4377
3.41
2010
140191
79451
56.67
11063
7.89
5786
4.13
2009
139104
95942
68.97
12367
8.89
3350
2.41
2008
69802
49041
70.26
5523
7.91
3324
4.76
Average
153292
99978
65.22
17844
11.64
5299
3.46
Source: National Bureau of Statistics

From the legal and financial point of view, the creditor's right is a put option, and
the lender (creditor) is the seller of the put option. Interest income constitutes the
creditor's limited return, while potential principal loss constitutes the risk it may
encounter. The interest rate is only a small fraction of principal, so creditors are facing
a severe return-risk asymmetry. Considering the asymmetric characteristics of
creditor's rights with limited return and risk of nearly limitless potential loss, the lender
should first consider downside risks of the prospective project and strictly follow the
principles of soundness, safety and prudence. In general, the priority clients for the
lenders are enterprises with long operating history, large scale, stable performance,
good corporate governance, sufficient solvency and adequate collateral, especially
state-owned enterprises with implicit government guarantee. Private SMEs are at a
disadvantage in the above aspects, and naturally, they are not the
favorite clients for the lenders.
From the fact of China's financial development in recent years, credit institutions
represented by commercial banks naturally have the characteristics of preferring to
large enterprises, mature industries and state-owned enterprises with implicit
government guarantee. These organizations control China's financial resources mainly,
which aggravates the financing difficulties of private SMEs in China. Especially in the
period when the economy encounters external shocks or disturbances, such as the
decline of economic growth, uncertain economic prospects or the background of de-
leveraging, this feature is particularly pronounced.
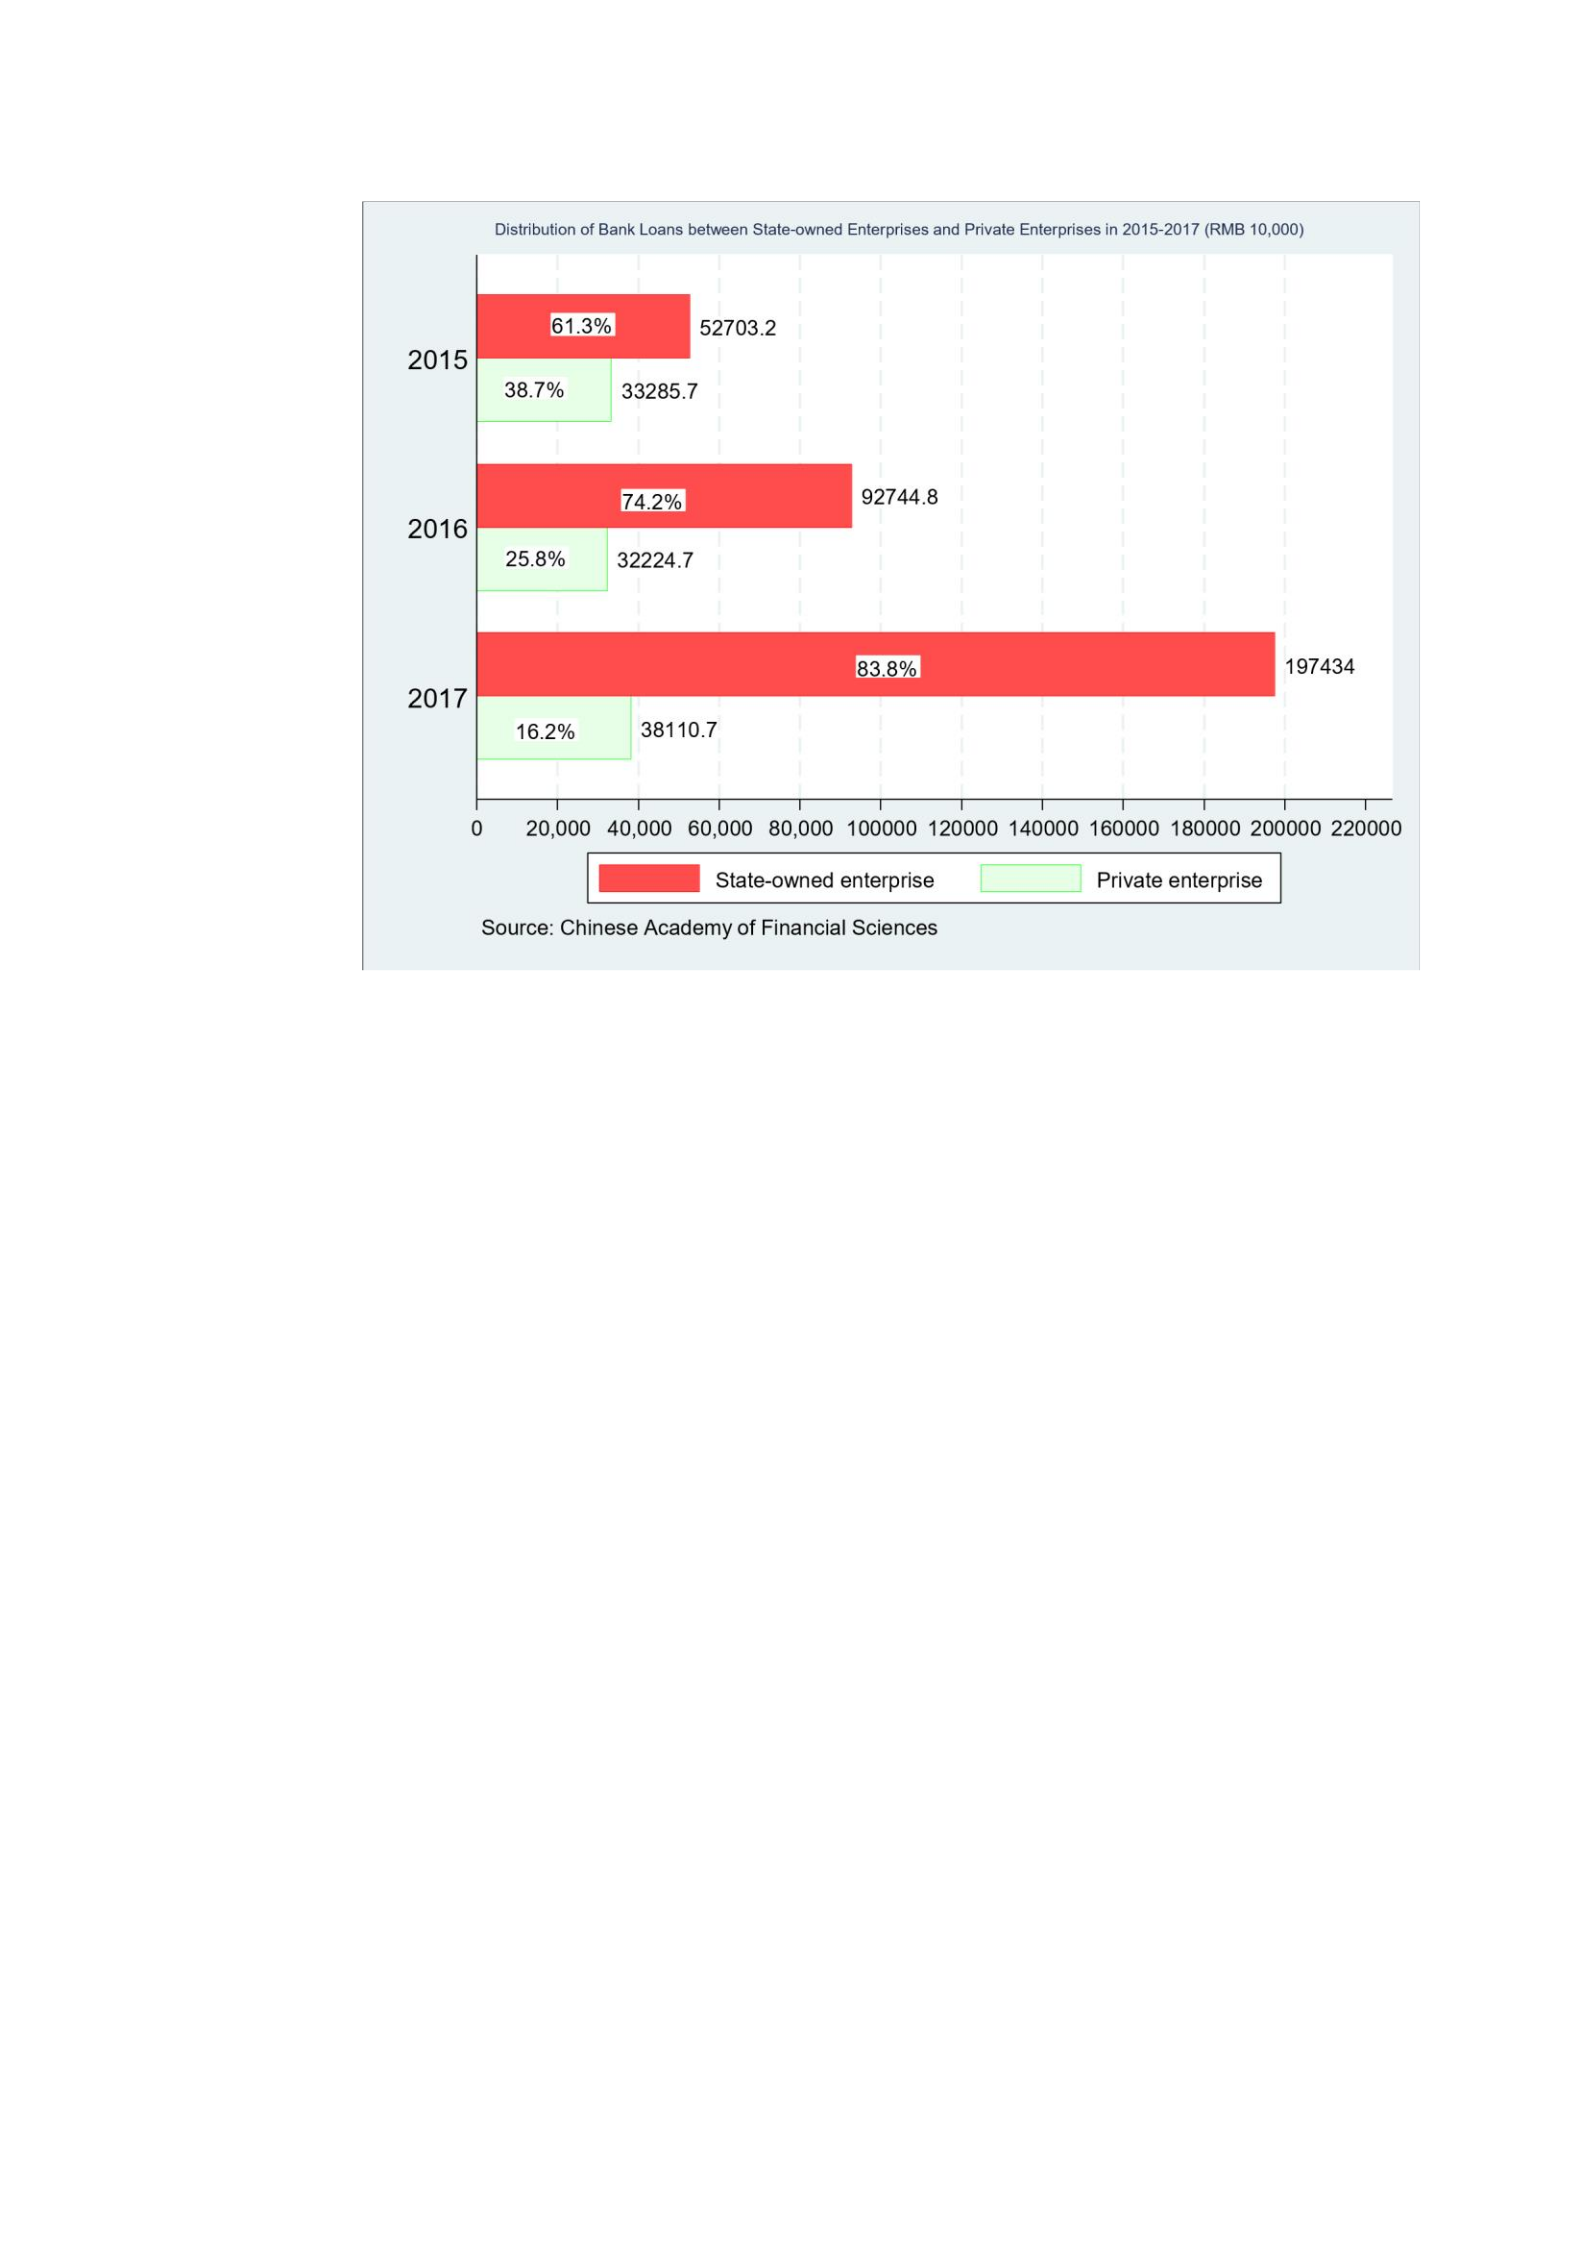
Figure 1-2 Distribution of Bank Loans in State-owned Enterprises and Private
Enterprises in 2015 - 2017
As shown in Figure 1-2, since the implementation of the supply-side structural
reform policy in 2016, the share of bank loans to state-owned enterprises has increased
sharply from 61.3% in 2015 to 83.8% in 2017. While the share of bank loans to private
enterprises has dropped rapidly from 38.7% in 2015 to 16.2% in 2017 which has
dropped by more than half (-58.2%). This trend makes the private enterprises facing
financing difficulties undoubtedly worse. It also makes the financing guarantee
business of the FGC decline sharply and the quality of the financing guarantee business
decrease tremendously.
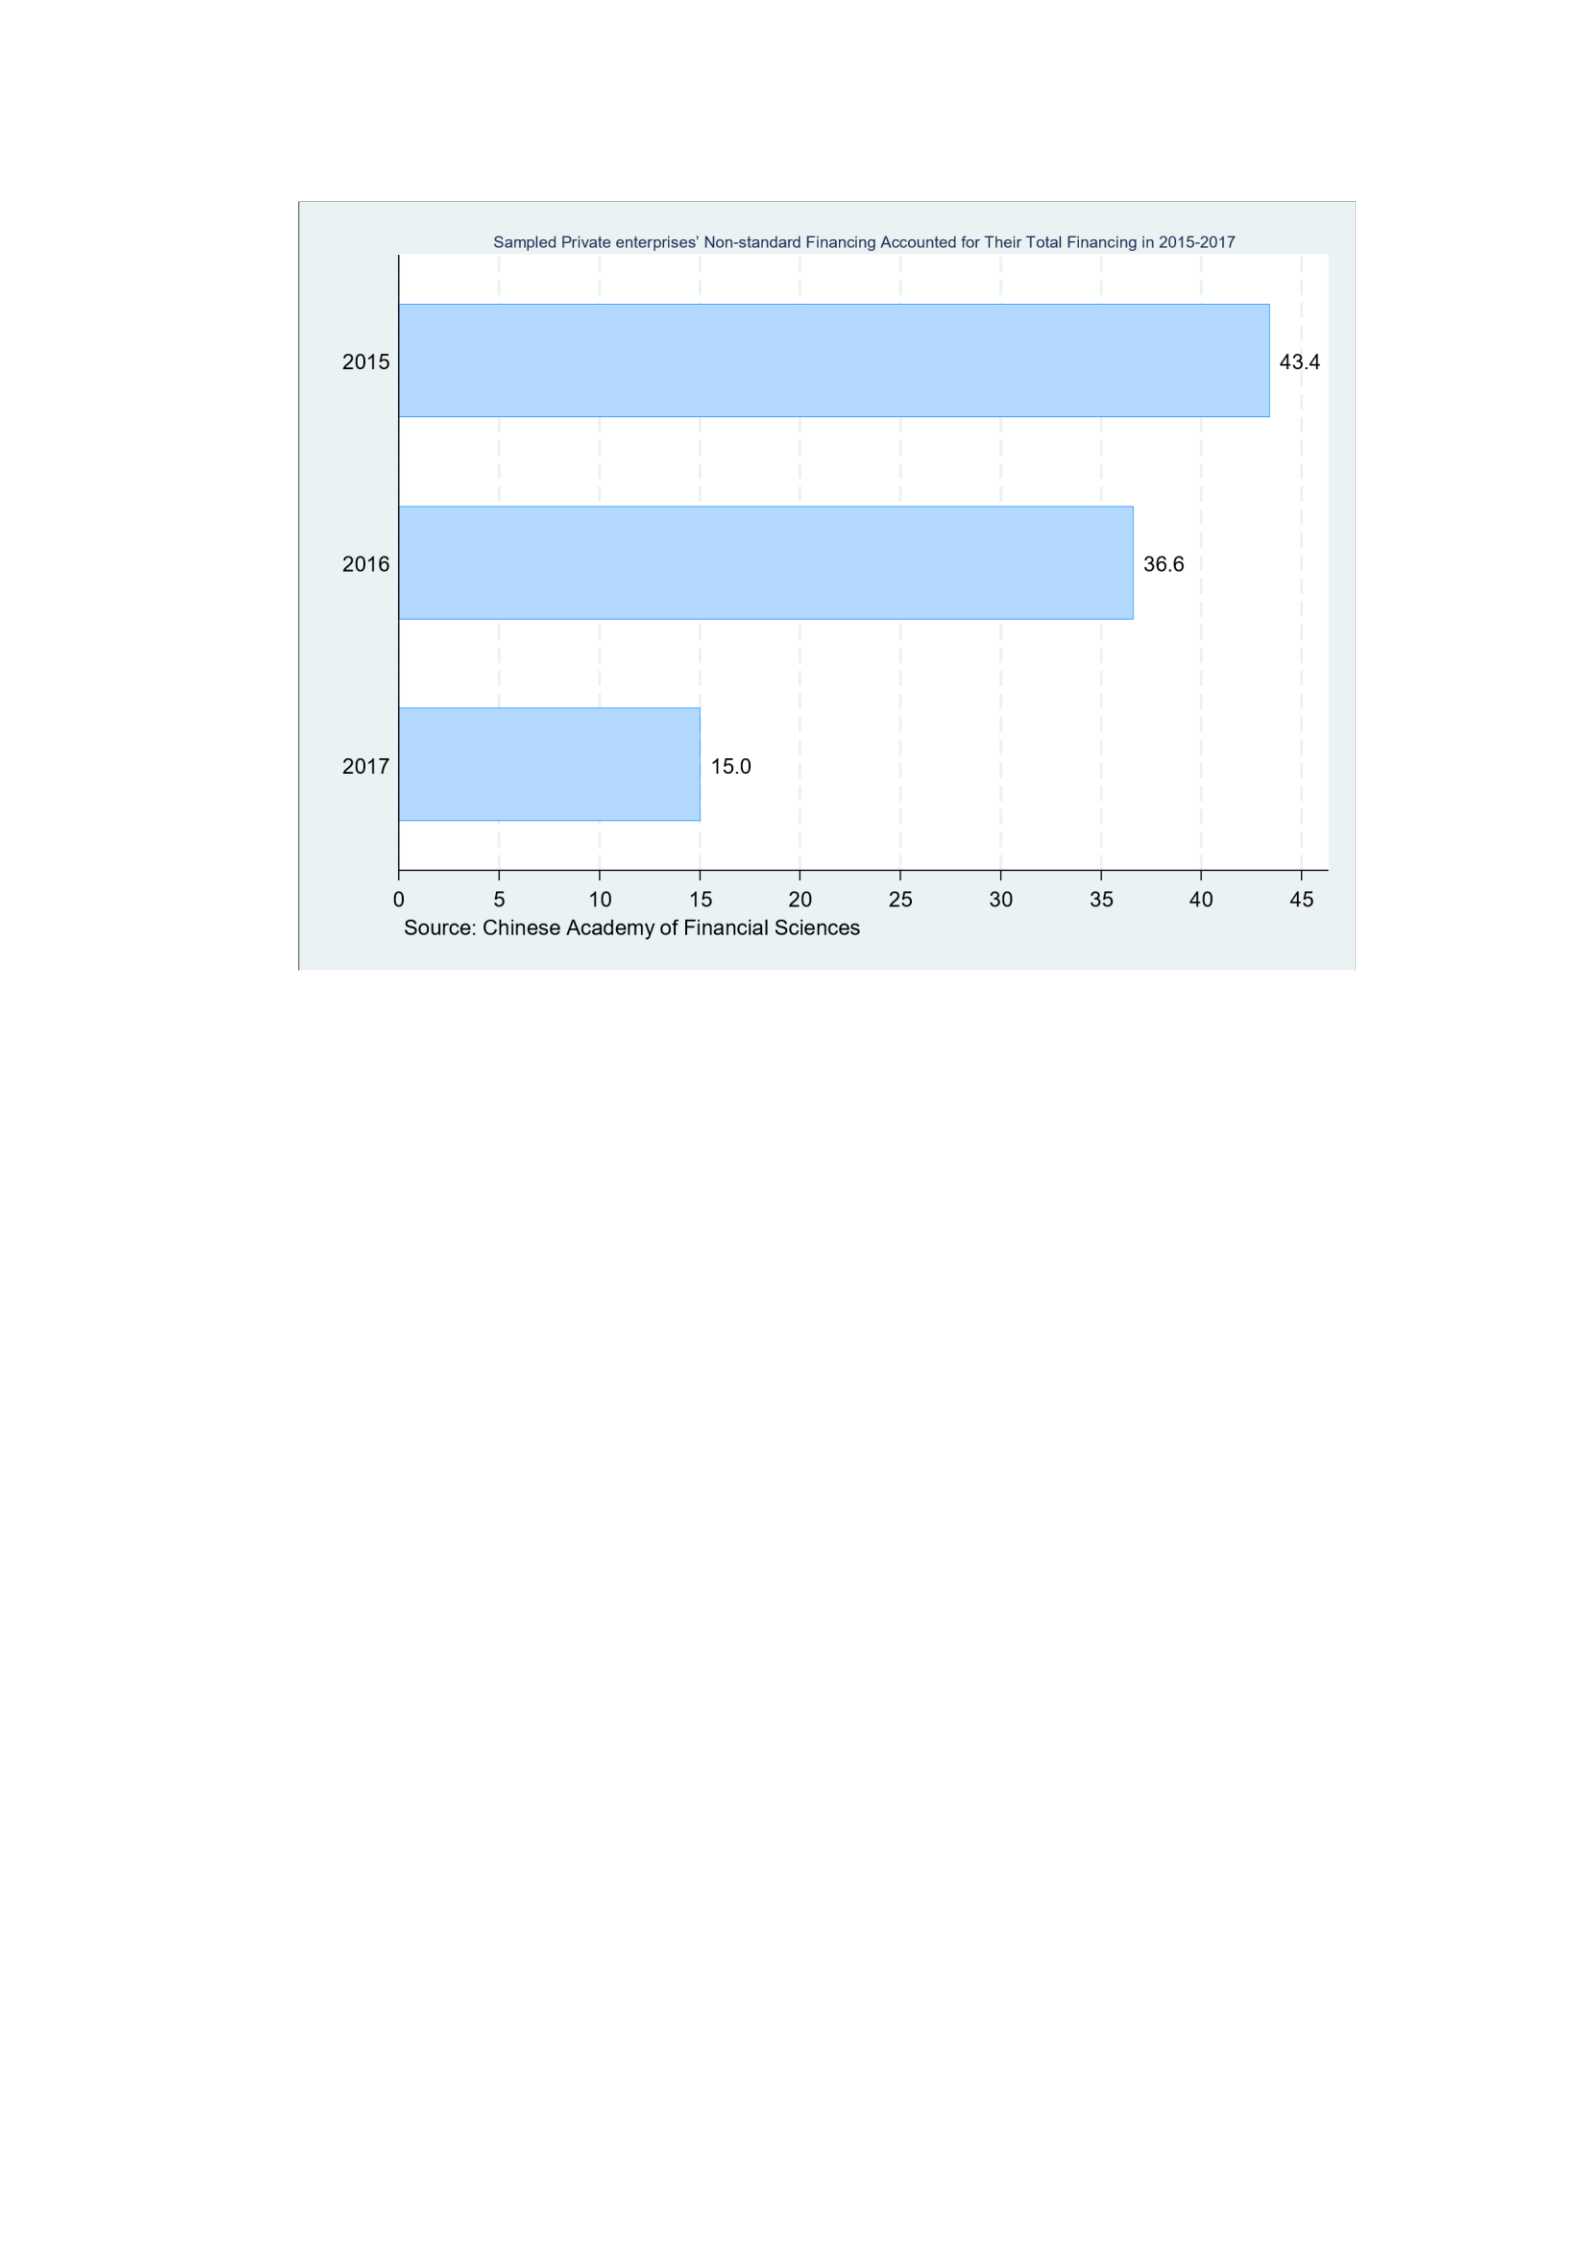
Figure 1-3 Sampled Private enterprises’ Non-standard Financing Accounted for
Their Total Financing in 2015-2017
As shown in Figure 1-3, under the background of strict financial supervision, non-
standard financing relied on by private enterprises has also contracted sharply. The
proportion of non-standard financing to the total financing of sampled private
enterprises has decreased from 43.4% to 15.0%, while the increase in bank credit
cannot cancel out the decrease in non-standard financing, resulting in the decline of
the total financing scale of private enterprises. Inadequate traditional loans and
tightened non-standard financing make the financing problem of private enterprises
very noticeable.
3. Deficient Market-oriented Credit Risk Management Instruments
China's low proportion of direct financing seriously distresses the full
development of the financial market, and it cannot provide effective risk transferring

instruments for financial institutions operating indirect financing, thus seriously
restrict the development of indirect financing.
Asset securitization started late and CDS developed slowly.
Asset securitization refers to the process of dividing and reorganizing the assets
expected to produce stable cash flow but with poor liquidity through a series of
structural arrangements, and transforming the expected cash flow of assets into more
competitive financial products with the help of credit enhancement. For banks and
other credit institutions, the main functions of asset securitization include: revitalizing
assets, alleviating mismatches between assets and liabilities; dispersing risks and
reducing credit risk concentration; increasing intermediary business income,
improving the return on assets of banks; enlarging business, strengthening and
consolidating customer relations. China's credit asset securitization sprouted in the
1990s. It was not until 2005 that the Central Bank and the Banking Regulatory
Commission officially promulgated the "Measures for the Pilot Management of Credit
Asset Securitization". The pilot work of credit asset securitization officially opened,
and a system of issuing and circulating of credit asset-backed securities
(ABS) in the interbank market was set up, with the central bank and the Banking
Regulatory Commission as the leading force. In 2017, 62 sponsors in the credit ABS
market successfully issued 133 single products with a total amount of 597.229 billion
yuan. Banking financial institutions, as the main initiator, account for 75.91% of the
total amount issued. At present, the main problems of asset securitization in
China are simple structure, limited profit margin, difficult pricing and valuation, single
investor structure, weak liquidity, etc.

In fact, as early as 2010, the China Traders Association issued the "Interbank
Market Credit Risk Mitigation Instruments Pilot Business Guidelines", outlining the
relevant framework of credit risk mitigation instruments, but the development of the
mitigation instruments in the exchange market is relatively slow. On September 23,
2016, in order to enrich the means of risk management for market participants and
improve the mechanism of credit risk transferring and sharing, the China Traders
Association issued the revised "Pilot Business Rules for Credit Risk Mitigation
Instruments in Interbank Markets". On October 22, 2018, the People's Bank of China
issued the "Establishment of Bond Financing Support Instruments for Private
Enterprises to Support the Development of Private Economy Unwavering". It requires
that the credit risk mitigating instruments and credit enhancement should support
private enterprises with market, prospect and competitive technology.
However, up to now, the trading volume and application scope are very limited.
Credit Insurance Develops Slowly and Needs to Be Improved Urgently.
On July 11, 2017, the CIRC promulgated the Interim Measures for the Supervision
of Credit Guarantee Insurance Business. In April of 2018, the credit insurance market
changed dramatically. Suddenly, insurance companies issuing credit insurance policies
informed clients that they could no longer issue insurance policies for financing
businesses. Foreign banks notified customers one after another that the financing
would be stopped because insurance could not be renewed. The utilization of credit
insurance by Chinese banks has been popular for several years, but in recent years, due
to the internal management problems of banks and banks liking to use simple means

of risk controlling such as mortgage and guarantee, the application scale of credit
insurance has gradually declined. At the same time, due to the narrow variety of credit
insurance in China, product introduction and innovation are practically absent, which
cannot meet the diversified financing needs.
4. Behindhand Credit System and the High Credit Risk
The Development of Credit Reporting System Lags Behind.
Social credit system is a kind of social governance mechanism. It takes credit laws
and regulations as the basis of system, credit professional service institutions as the
main body, legal and effective credit information as the basis. It aims at reducing the
information asymmetry among market participants, encouraging the trustworthy,
making the dishonest pay the price, and ensuring the fairness and efficiency of market
economy. The purpose of social credit system is to establish a market soft environment
and efficient market rules suitable for the development of credit transactions, and to
ensure the smooth transition from market economy to credit economy, that is, to
replace the primary means of payment by credit transactions as the main mode of
market transactions. A perfect social credit system is the premise for credit to play its
role, the institutional assurance for the development of market economy to an advanced
stage, and the infrastructure for the development of credit economy. The perfection of
social credit system has become a remarkable symbol of the maturity of market
economy.
In 1999, China put forward the concept of social credit system as a fundamental
measure to rectify and standardize the market economic order. However, it was not

until 15 years later, that is, June 2014, that the first national top-level design
document, the Outline of Social Credit System Planning (2014-2020), was issued. In
recent years, great progress has taken place in the construction of China's social
credit system, which has attracted wide attention of the international communities.
However, the lack of social credit has not been fundamentally reversed, mainly
including: the lack of social integrity and credit transaction risks are still prominent,
the development of public credit mechanism and market credit mechanism is very
unbalanced, and the institutional mechanism of social credit system building is
facing challenges. Compared with developed countries, the main problems in the
construction of China's social credit system are: laws and regulations on credit
management need to be established urgently, the construction of social credit system
lacks overall planning, and the supply and demand of credit service market is
seriously insufficient.
Credit Risk Remains High.
Since the reform and opening up, under the impetus of industrialization and
urbanization, Chinese society has changed dramatically from a traditional
acquaintance society to a modern anonymous society. With the imperfection of social
credit system and legal system, there inevitably exist opportunists who betray their
faith in market transactions: as long as the cost of default is much lower than the
benefits, the existence of such opportunists is the result of rational game. This kind of
opportunistic transaction acts on the financing market, which significantly increases
the burden and cost of the creditors' screening, and aggravates the financing difficulties

of private SMEs. State-owned enterprises usually have implicit guarantees from the
government, and there are no serious financing constraints. However, private SMEs
have to pay for the high credit risk, so there are always difficulties in SMEs financing.
ii Financing Difficulties of SMEs
1. Embodiment of Financing Difficulties
Private economy plays an important role in the whole economic system. It
contributes more than 50% of tax revenue, 60% of GDP, 70% of technological
innovation, 80% of urban employment, 90% of new employment and the number of
enterprises. Private enterprises are mainly SMEs. It is very difficult for private SMEs
to finance indirectly or directly.
Indirect financing of private SMEs is difficult. At present, indirect financing is
the main financing approach of Chinese enterprises. However, depositary financial
institutions are inherently reluctant to lend, which is difficult to meet the financing
needs of the whole society and seriously underserves private SMEs. Depositary
financial institutions are very special investors, whose funds mainly come from deposit
liabilities. Depositary financial institutions essentially absorb short-term liabilities and
then use them to grant loans with relatively long maturities through the term mismatch.
According to Article 7 of the Bankruptcy Law, if the debtor is unable to pay the debts
that are due, the creditor may propose to the court the bankruptcy liquidation of the
debtor. As deposit liabilities of depositary financial institutions are essentially matured
debts, it can be said that they are born on the start line of bankruptcy liquidation. This

means that compared with other financial institutions or investors, depositary financial
institutions tend to be vigilant and conservative in their investment behavior.
Because the amount of collateral is difficult to meet the bank's credit
requirements, and the lack of government "implicit guarantee", financing problems of
private SMEs are prominent. According to the sample survey data of the Chinese
Academy of Financial Sciences, from 2015 to 2017, the ratio of bank loans of private
enterprises to those of state-owned enterprises in the sampled enterprises declined
rapidly from 63% to only 15%. Credit resources incline obviously to state-owned
enterprises. At the same time, under the background of strict financial supervision,
non-standard financing relied on by private enterprises has contracted sharply. The
proportion of non-standard financing in the total financing of sampled private
enterprises has decreased from 43% to 15%, while the increase of bank credit cannot
offset the contraction of non-standard financing, which leads to the decline of the total
financing scale of private enterprises. Traditional loans are inadequate and non-
standard financing is tightened, which makes it difficult for private enterprises to raise
funds.
It is difficult for private SMEs to obtain direct financing. Financing by issuing
stocks and bonds is very demanding in China. According to the current Company Law
of China, Joint Stock Company can be listed to raise funds from the whole society.
However, the minimum registered capital for the establishment of a joint stock
company shall not be less than 10 million RMB. With such a high threshold, most
SMEs can only stand back. At present, China's capital market is mainly inclined to

large enterprises. The SME board, Growth Enterprise Market (GEM) board and the
new three boards are still in the early stage of development, with small scale and
narrow industry coverage, which are far from meeting the direct financing needs of
SMEs. Although the newly established joint venture board in China provides a
platform for direct financing for SMEs, the listed enterprises are a small number of
large-scale SMEs, and most SMEs are difficult to access to the fund stock market. If
SMEs have higher credit, they can obtain financing through commercial paper.
However, due to the late start and imperfection of China's credit rating system, this
financing channel is obviously not feasible.
According to the data of the 2012 World Bank questionnaire on Chinese
enterprises, compared with the surrounding countries, Chinese enterprises are facing
higher levels of credit constraints. Specifically, among the sources of funds needed by
Chinese enterprises, endogenous financing provides most of the funds for enterprise
investment, up to 90%, and bank loans provide only 5% of the total funds needed for
investment, compared with 70% and 15% in the Asia-Pacific region, respectively. In
addition, from the point of view of the availability of corporate loans, only 25% of
Chinese enterprises can obtain bank loans, which is far below the average level in the
Asia-Pacific region (40%). Among them, the ratio of the value of collateral to the
amount of bank loans provided by enterprises receiving bank mortgages reaches 200%,
which is much higher than the average collateral coverage of 170% in the Asia-Pacific
region. It can be said that over-reliance on endogenous financing and lack of bank loan

support have become serious obstacles to the development of SMEs in the context of
China's slowdown in economic growth and
supply-side structural reform.
2. Reasons for Financing Difficulties of SMEs
The financing problem of SMEs has always been the focus of policy makers and
researchers. The economic importance of the SMEs sector has been widely recognized
in academic and policy literature. They acknowledge that SMEs are under-served,
especially in the financial sector. The difficulty and high cost of financing for SMEs is
a worldwide problem. As early as early as 1931, the McMillan Commission Report
insisted that relatively small capital investment is riskier and more expensive for the
lenders, which makes the conditions for SMEs to seek loans extremely unfavorable.
Banks are unwilling to grant loans on the terms proposed by SMEs, so that in the
process of SMEs development, the total amount of money invested is riskier and more
expensive. There is a financing gap, i.e. the Macmillan gap.
In addition to the deficiencies that the enterprises themselves cannot eradicate, the
factors that cause the financing difficulties of Chinese private SMEs are also related to
the imperfection of the external environment and financing policy of the
enterprises.
(a) Changes in the external environment are not conducive to the
development of SMEs. In recent years, the basic wages of on-the-job workers have
been increasing year by year. Prices have risen, consumption expenditure has
increased, and labor costs of SMEs have risen sharply. On the contrary, the profit

margin of SMEs is decreasing year by year, and the survival risk of SMEs is increasing.
At the same time, banks are facing such huge financial pressure, SMEs financing is
worse. These difficulties include a substantial increase in overall costs and a huge
shortfall in operating capital. At the same time, some industries are experiencing a
decline in profits and even losses.
(b) The credit information system is not yet all encompassing. China's
credit information system started late, and the People's Bank of China and commercial
banks have not jointly established credit files for SMEs. It is difficult for the credit
information system to provide sufficient credit information support for commercial
banks to grant loans to SMEs. Commercial banks rely too much on mortgage
guarantees for loans to SMEs.
(c) The return-risk of SMEs loans is asymmetric. With small business
scale, small assets, weak brand effect, lack of market stability, weak competitiveness
and ability to withstand external shocks, SMEs are easy to bring greater risks to
investors. With the establishment of strict credit risk management accountability
system in banks, it will obviously increase the difficulty of SME loans.
(d) The assets that SMEs can use for mortgage loans are inadequate. For
the sake of risk factors, bank loans to SMEs are mainly guaranteed or mortgage loans.
However, the size of SMEs is not large. They have neither fixed assets to be mortgaged
nor negotiable securities. Some of them even rely on leasing equipment and factory
buildings. It is difficult to meet the preconditions that the borrower must have certain
capital strength.

(e) The financial system of SMEs is not perfect, and the authenticity of
financial information is difficult to verify. A considerable number of SMEs have not
standardized financial systems and sound accounting departments. There are many
doubts about the authenticity of financial statements provided by SMEs. Financial
institutions can get little valuable operational and financial information of SMEs.
Consequently, in order to control risks, banks are unwilling to grant loans to
SMEs.
II. Financing Guarantee as Credit Risk Transfer Instrument
1. Regulatory Requirements on Credit Risk of
Various versions of the Basel Accord require banks to bear credit risk with a
corresponding proportion of capital, which constitutes a regulatory constraint on the
amount of credit risk that banks bear under certain capital conditions. The Basel Accord
I of July 1988 regards the capital adequacy ratio as the core of the regulatory
framework to assess the bank's coverage and resistance to credit risk. The main
contents include: concretizing the calculation of capital adequacy ratio, dividing the
capital into core capital and subsidiary capital, and unifying the standard of capital
composition; dividing the risky assets into the risky assets in the statement and the
risky assets outside the statement, and stipulating different credit conversion
coefficients for the off-balance sheet business, and classifying the inside and outside
of the statement according to the asset classification. The risk weight is divided into
five categories, and the minimum capital adequacy ratio is proposed, in which the core
Basel Accord

capital adequacy ratio is not less than 4%, and the capital adequacy ratio is not less
than 8%.
In June 2004, the Basel II Accord for the first time established three pillars of the
international banking regulatory framework. On the basis of strengthening the
minimum capital regulatory requirements, the second and third pillars based on
supervision, inspection and market discipline were proposed. To expand the coverage
of risk measurement, a banking risk system covering credit risk, operational risk and
market risk was established for the first time. At the same time, counterparty credit
risk, asset securitization credit risk and risk mitigation were included in bank risk
measurement. Introducing internal model measurement for the first time allows banks
with high risk management level to construct internal model to calculate capital
through historical data.
In December 2010, Basel III focused on improving the "minimum capital
requirements" of the first pillar. On the one hand, the requirements for capital quality
and quantity have been further improved, including restoring the leading role of core
capital, improving the criteria for identifying capital instruments, and stringent capital
deduction projects; on the other hand, the scope of risk coverage has been expanded,
and the minimum capital requirements for asset securitization and counterparty credit
risk have been raised. At the same time, a broader level of macro-prudential capital has
been achieved, including increasing the reserve capital requirement of no less than
2.5% consisting of common equity interests; establishing counter-cyclical capital of 0-

2.5% associated with excessive credit growth; and putting forward additional capital
requirement of 1% for systemically important banks.
2. Financing Guarantee as a Credit Risk Transfer Instrument
Credit risk transfer (CRT) refers to financial institutions, generally commercial
banks using various financial instruments to transfer credit risk to other banks or other
financial institutions. At present, the participants in the credit risk transfer market are
mainly various financial institutions, including: commercial banks, institutional
investors and securities companies. Those who transfer credit risk are called credit risk
transferors, and those who accept credit risk are called the recipient of credit risk.
CRT can be divided into financing CRT and non-financing CRT. Financing CRT
refers to the transfer of credit risk to financial markets or financial institutions, while
achieving the financing of funds, including loan sales, asset securitization and so on.
The means of CRT separated from financing are credit guarantee, credit insurance and
credit derivatives (CD). Credit guarantee is a flexible tool for credit risk transfer.
Through bilateral contracts, the guarantor, as the undertaker of credit risk, assumes the
corresponding obligation of compensation or payment on behalf of the third party
(debtor) when it fails to fulfill its obligations. The amount is limited to the loss exposed
to potential risks. Credit insurance refers to the insurance contract signed by an
enterprise and an insurance institution to pay a certain premium so as to obtain
compensation for losses incurred within the specified credit risk range. Credit
derivatives refer to a bilateral financial contractual arrangement in which both parties
agree to swap the pre-agreed or formula-based cash flow, which depends on the pre-

determined occurrence of credit events in the future. Credit events are usually
associated with default, bankruptcy registration, credit rating decline or price decline
considerably.
III. Financing Guarantee System in Urgent Need of Perfection
1. The Position of SMEs in the Economic System
SMEs are often seen as the backbone of the economy. Their significant
contributions to economic growth, employment creation, social cohesion, poverty
alleviation and local and regional development have won wide consensus. In China,
according to official statistics in 2015, SMEs contributed more than 65% of GDP, more
than 50% of tax revenue, more than 68% of exports and more than 75% of employment
in 2014. According to Yi Gang, governor of the Central Bank, by the end of 2017, there
were 28 million small and micro enterprises as legal persons, more than 65 million
individual businesses, accounting for more than 90% of the total market participants;
small and micro enterprises contributed more than 60% of GDP, more than 50% of tax
revenue and 80% of employment posts; small and micro enterprises completed 65% of
invention patents and 80% of employment posts. The above new product development
is an important carrier of mass entrepreneurship and innovation.
2. Quasi-public Nature of Financing Guarantee for SMEs
The important role of SMEs in economic development and their financial
weakness characteristics determine that the development of SMEs must rely on
government policy support. To this end, countries around the world generally adopt

active fiscal and taxation support policies to promote the growth and development of
SMEs. Practice in various countries has proved that because SMEs have the
characteristics of large quantity, small scale, wide distribution and many kinds, only
using financial support cannot avoid the problems of low efficiency, small coverage
and poor fairness. The introduction of SMEs financing guarantee can effectively
improve the efficiency and fairness of government support. At the same time, through
the establishment of a guarantee group, the government can increase the support to the
guaranteed, and use the leverage effect of guarantee to guide more SMEs and funds
into the areas encouraged by the national industrial policy. From the practical effect,
the government's intention to establish and develop SMEs financing guarantee is
mainly to alleviate the financing difficulties of SMEs, at the same time to help achieve
other macro-policy objectives, such as industrial policy guidance, supporting SMEs
technological upgrading, and promoting the rapid development of high-tech
enterprises. This reflects the quasi-public nature of SMEs financing guarantee. If it is
fully commercialized, it will inevitably lead to insufficient supply.
Over the past 100 years, the development history of foreign guarantee industry
and the actual operation mode of guarantee business in various countries have clearly
shown that the financing guarantee business of SMEs has the characteristics of high
risk and low return. It must rely on government financial funds. It belongs to the
government's behavior to achieve specific policy objectives, and it is difficult to
universally implement profit-making business model.

3. Development status of SMEs financing guarantee system
The development of China's financing guarantee industry began in 1993. With the
rapid development of the national economy, the financing guarantee industry has
developed rapidly. By the end of 2014, when the momentum of the development of
financing guarantee companies was at its peak, there were 7898 financing guarantee
companies in China, with a guarantee balance of 2.74 trillion yuan, including 2.34
trillion yuan in the guarantee balance, 1.28 trillion yuan in the guarantee loan balance
of SMEs financing, and 2514,000 small and medium-sized customers. The industry's
paid-in capital is 925.5 billion yuan, of which 75 institutions have registered capital of
more than 1 billion yuan, with an average registered capital of 117 million yuan. Since
2015, the growth rate of the number of financing guarantee companies has decreased
by an average of 5% annually, and the growth rate of the scale of financing guarantee
business has also slowed down.
The relevant policies on SMEs financing guarantee have been issued in
succession throughout the country, which makes the financing guarantee industry
standardized and provides practical guarantee for its stable development. At present,
the CBRC and relevant departments have continuously strengthened the reform of the
financing guarantee industry. The State Council has also issued a series of guidance on
the development of financing guarantee companies. The financing guarantee industry
is developing towards a scientific and effective model. However, there are still many
problems in financing guarantee for SMEs, and it is necessary to constantly improve
the financing guarantee system.

1.2 Significance and Potential Innovation of Selection of Topics
I. Significance of Selecting Topics
At present, financing difficulty is still one of the basic problems that perplex the
development of SMEs in China. The government and industry are also trying to
alleviate or solve this problem through various institutional mechanism innovations.
For example, to solve the difficulties of SMEs by increasing the credit of financing
guarantee companies, but its institutional mechanism is still in the exploratory stage
and needs to be further improved. The company I lead (China Success Finance Group
Holding Co., Ltd.) has also been engaged in financing guarantee services for SMEs for
a long time, and has accumulated rich first-hand materials and business experience.
Based on the business cases of FGC, focusing on the zero-loss-principle of financing
guarantee business operation under the mode of profit-making business in China, this
paper tries to summarize the credit enhancement of financing guarantee company from
three aspects: entrepreneur factor, market factor and technology factor inherent in the
borrowing enterprise. It is expected that the conclusions of this study will be helpful to
guide FCGs to carry out financing guarantee services more effectively, and to add new
research perspectives and empirical conclusions to the theory of SMEs credit
enhancement.
II. Potential Innovation Points
At present, China's financing guarantee system has not yet
been unified as quasi-public nature and the national support system has not
yet been established. Under the condition that the FCG operates the financing

guarantee business according to the principle of commercial operation, it should not
only conform to the changes of the economic and social development situation, but
also properly deal with the asymmetry of return-risk in financing guarantee business.
FCGs must implement the zero-loss-principle in their business operations, and they
must select their clients very harshly and carefully. This selection rule for financing
guarantee customers is the basis of FCG's business operation, which is worthy of in-
depth study. Following the logical thinking of enterprise fundamentals analysis,
starting from the essential source of credit risk and taking the guaranteed enterprise
as the analysis object, this paper incorporates the characteristics of entrepreneurs, the
market competitiveness and the technological suitability of enterprises into the
framework of credit enhancement model, and tries to simplify the traditional credit
analysis methods as far as possible on the basis of refining the essential elements of
credit enhancement of FGCs.
Summary
Financing difficulties of SMEs are a worldwide problem, which is more serious
in China. This chapter first analyses the characteristics of China's financial system:
indirect financing is dominant, direct financing is weak; debt financing is dominant,
equity financing lags behind; market-oriented credit risk management instruments are
scarce; credit reporting system lags behind, and credit risk is high. This is the basic
financial environment for China’s FGCs to carry out credit enhancement business.
Then it introduces the main manifestations of SMEs financing difficulties, and
preliminarily analyses the internal and external causes of SMEs' financing difficulties.

Then, from the perspective of credit risk transfer instruments, the paper examines the
financing guarantee system of SMEs in China, which needs to be improved urgently.
Finally, the significance and potential innovations of the topic are introduced.
According to the first-hand documents of the company's long-term financing guarantee
business, this paper tries to summarize the credit enhancement model of FGC from
three aspects: entrepreneurs, market and technology factors inherent in the borrowing
enterprise.

Chapter II Literature Review
The credit enhancement business of FGC mainly serves for the financing of
SMEs. In nature, it is a credit enhancement instrument, which belongs to credit risk
management in theory and technology. The following is a review of the main literature
on SMEs financing, credit enhancement and credit risk management.
1.1 Literature Review of SMEs Financing
I. Foreign Literature on Financing of SMEs
i. Credit Rationing and Relational Financing
1. Bank Credit Rationing
Credit rationing theory of Stiglitz and Weiss (1981) explains that SMEs are more
difficult to obtain credit support. Information asymmetry in credit market will
inevitably lead to adverse selection and moral hazard, which will make banks face
higher credit risk. In order to reduce credit risk, banks will lower the interest rate below
the equilibrium interest rate level to encourage enterprises with high creditworthiness
to borrow, and limit those enterprises with low creditworthiness to borrow. For various
reasons, SMEs often have low creditworthiness and are difficult to obtain loans from
banks. This theory provides a good idea for the analysis of financing obstacles of SMEs
from another angle, that is, from the perspective of information economics. It is
generally believed that the characteristics of small enterprises determine that bank
credit is one of the important sources of financing in its development process.
Therefore, the discussion on credit rationing of small enterprises is also an important
branch of financing theory of SMEs.

Equilibrium credit rationing refers to the phenomenon that the credit market
cannot be cleared under general interest rate conditions, not because of the monetary
authority's control over the interest rate ceiling, but because of the bank's profit
maximization motive. There are many theoretical explanations about the generation
mechanism of credit rationing, among which Stiglitz et al. (1981) have the most
influence on the theoretical model based on information asymmetry in credit market.
Stiglitz and Weiss (1981, 1986, 1992 ) point out in the classical literature on credit
rationing that adverse selection and moral hazard caused by information asymmetry
are the basic reasons for balanced credit rationing. When facing the excess demand for
loans, in order to avoid adverse selection, banks will not raise interest rates to clear the
market, but allocate loan applicants at a level lower than the competitive equilibrium
interest rate.
Whette (1983) extends Stiglitz's theory, pointing out that the collateral
requirement of banks may also become an endogenous mechanism of credit rationing
under the condition of borrower's risk neutrality. Bester (1987) further discusses the
role of collateral in credit rationing. He believes that collateral and interest rate can be
used as the screening mechanism for banks to separate the risk types of loan projects,
that is, banks can separate high-risk and low-risk loan projects through the sensitivity
of enterprises to the changes in the number of collateral.
Williamson (1986) discusses the supervisory cost in the process of credit rationing.
He also attributed the non-monotonic change between bank expected returns and
interest rates to information asymmetry.

2. Relationship Lending
Credit rationing is an endogenous mechanism of credit market. However,
theoretical research and empirical evidence show that the rejected in credit rationing
are mainly SMEs. The main problem of SMEs credit is that the information of SMEs
is seriously opaque. Unlike standard contracts provided by banks, SMEs credit is more
carried out through relationship loans. As an important means to solve the financing
problem of SMEs, relational loan has attracted extensive attention of foreign sectors
and scholars. The decision-making of such bank loans is mainly based on the
accumulated information about borrowing enterprises and entrepreneurs through long-
term and multi-channel contacts. Under the relational loan, the bank's information
accumulation can be acquired not only incidentally through the deposit, settlement and
consulting business of the enterprise, but also from the stakeholders of the enterprise
and the community where the enterprise is located. The "soft information" which is
difficult to quantify and transmit on the basis of relational loan partly makes up for the
credit gap caused by SMEs inability to provide qualified financial information and
collateral, and helps to increase their unfavorable credit conditions. Empirical research
shows that the strengthening of long-term cooperation between banks and enterprises
is conducive to reducing the loan interest rate of SMEs, reducing the loan guarantee
and mortgage requirements, reducing the dependence on commercial credit, and
mitigating the impact of interest rate fluctuations on the loan interest rate of SMEs.
Boot and Greenbaum (1993) argue that when small businesses cannot obtain
formal loan commitments from banks or unconditional loan contracts, they will seek

alternatives. One way is to resort to market mechanisms, by purchasing long-term
implicit contracts with commissions, firms and banks can build closer relationships.
With the expansion of the length and scope of the relationship, banks can better
supervise enterprises. Nakamura (1993) emphasizes that the comparative advantage of
banks in information production is particularly strong for small, relatively unknown
enterprises that rely on a bank to provide services, so banks are willing to maintain
credit relations with the original enterprises. The relationship theory generally agrees
that the benefits of relationship-based credit are multifaceted, including increasing the
supply of credit, but there are differences on whether it will reduce the cost of credit.
Boot and Thakor (1994) show that for the best credit contract, borrowers initially pay
a higher interest rate than the market and provide collateral. When a project succeeds,
the interest rate for unsecured loans is lower than the market rate. Many scholars
believe that a stronger "relationship" can enable small businesses to obtain lower
lending rates (Berger and Udell, 1995).
As for the comparative advantage of banks in information production, Petersen
and Rajan (1994, 1995) believe that banks can solve the problems of adverse selection
and moral hazard, thus reducing interest rates. However, in a centralized credit market,
the bank capture effect has little possibility of reducing interest rates. Others believe
that firms may get worse credit conditions from their lending banks in the future.
Sharpe (1990) and Rajan (1992) argue that the problem of information possession
allows banks to monopolize the market. Lenders gain information monopoly after the

event. If successful enterprises want to find new banks, they may have to pay
conversion costs.
In fact, high-quality borrowers are not necessarily mobile, and they are captured
by information. Santomero (1982) argues that banks are allowed to extract additional
rents from businesses because they have a cost burden in finding loans. However,
Greenbaum (1989) emphasizes that when firms can afford such search costs,
competitive banks will capture firms at low initial interest rates, so borrowing rates
will not increase over time. Grace O. Kim (2001) argues that small businesses are
willing to pay higher interest rates as credit commissions in the initial stage to ensure
better credit conditions in the future. According to the relational investment model,
unless small businesses default in the first phase, they will not get worse loan
conditions in the second phase regardless of the number of lending institutions. In
addition, in the aspect of cost-benefit analysis, the return on investment of small
enterprises in relation is negative in the initial stage. After a certain period of time,
small businesses may also gain the monopoly position of buyers in the credit market,
because they can choose to suspend or not suspend the credit relationship, invest or not
invest in the credit relationship of other banks. This may be because small businesses
evolve in the financing life cycle and build creditworthiness without being captured by
banks. However, since small businesses are already investing in their relationships with
banks, there is no need for them to give up financing from them. This model not only
explains the value of "relationship" to small enterprises, but also explains the
development of "relationship" itself when small enterprises develop.

ii. Structural Response Theory
1. Credit Policy Shocks.
There are two channels of credit shock: bank loan channel and balance sheet
channel. The bank loan channel refers to the reduction of bank reserve accompanied
by monetary tightening, which leads to the decrease of loan supply. In this case,
enterprises tend to reduce their real expenditure level due to the lack of alternative
sources of funds. This means that monetary policy may have a greater impact on firms
that rely on bank loans while lacking alternative sources of capital, and small
businesses tend to have these characteristics. The balance sheet channel means that
monetary tightening impairs the value of corporate collateral by raising interest rates,
reduces the credit rating of enterprises, and thus weakens the ability of enterprises to
obtain loans. From this point of view, it can be concluded that small businesses are
more impacted by the adjustment of monetary policy, because mortgage loan plays a
more important role in financing of small enterprises than large enterprises. Gertler
and Gilchrist (1994) show that small manufacturing enterprises are not only directly
sensitive to interest rates, but also indirectly affected by the economic cycle. Therefore,
the impact of monetary tightening on small enterprises is greater than that on large
enterprises.
2. Scale Matching Theory
According to the theory of scale matching, there is a strong negative correlation
between bank loans to SMEs and bank size. Through the empirical analysis of banks
with different scales, Strahan and Weston (1998) find that there is an inverted U-

shaped non-monotonic function relationship between bank M& A scale and SMEs
loan ratio. The ratio of loan to SMEs increases first and then decreases with the asset
scale of bank M& A. Peek and Rosongren (1997) argue that mergers between big
banks and small banks or between big banks tend to reduce lending to SMEs.
Banerjee et al.(2014) discuss the information advantages of small and medium-
sized financial institutions in providing financial services for SMEs. They put forward
two hypotheses: one is the long-term interaction hypothesis. The hypothesis holds that
small and medium-sized financial institutions are generally local, specially serving
local SMEs. Through long-term cooperation, the understanding of local SMEs is
gradually increasing. Another hypothesis is the co-supervision hypothesis. This
hypothesis is especially suitable for cooperative small and medium-sized financial
institutions. Even if small and medium-sized financial institutions cannot really
understand the operation of SMEs, for the common interests, SMEs in cooperative
organizations will implement
self-supervision, which is even more than the supervision of financial institutions. The
enlightenment of this theory is that it is a feasible choice to develop small and medium-
sized financial institutions to meet the financing needs of SMEs.
3. Growth Cycle Theory
Berger et al. (2003) put forward the theory of enterprise financial growth cycle by
combining enterprise life cycle with financing. They believe that there is a financial
growth cycle in the course of enterprise development. With the development of
enterprises, the accumulation of business records and performance, and the

improvement of information transparency, the financing needs and financing options
of enterprises will also change. Michaelas et al. (1998) believe that enterprises used
debt financing more in the period of establishment and growth, and their dependence
on debt financing would gradually decrease when enterprises gradually matured.
Berger and Udell (1998) point out that small, young and opaque enterprise depend on
initial internal financing, trade credit or angel financing; indirect financing can be
obtained when enterprises develop gradually; and finally, if enterprises continue to
grow, they have the opportunity to finance through the public equity and debt markets.
Berger and Udell (1998) point out that the growth cycle theory mentioned above is
only a general description of the financing path of enterprises. It does not apply to all
small enterprises, because the size, age and information opacity of enterprises are not
completely related.
The empirical test results also show the difference with this theoretical
expectation. Fluck et al. (1997) find that the external financing (mainly debt financing)
of Wisconsin enterprises in the initial stage exceeded the internal financing. From 7 to
8 years before the development of enterprises, the proportion of external financing in
the total financing gradually declined, after the proportion of external financing
gradually declined the proportion tends to rise again. This reflects that with the passage
of time, the use of external capital by enterprises is not simply from a minimum to a
maximum, but presents a "U" shaped development trend. The combination of the two
theories reflects that in the early stage of enterprise development, internal funds are
always used first, while external funds are used only when internal funds are

insufficient and conditions permit. Even in the initial stage, there are external financing
channels to choose. Enterprises often choose debt financing firstly, and equity
financing secondly. In equity financing, angel financing or venture capital is the first
step. It is possible and reasonable to raise funds through the open equity market only
when the enterprise develops to a considerable extent.
II. Domestic Literature on Financing of SMEs
i.Reasons for the Financing Difficulties of SMEs
1. Defects of Financial System Theory
Lin Yifu (2000) focuses on solving the financing problems of SMEs at the
institutional levels. He believes that we should vigorously develop SMEs, reform state-
owned enterprises, reform state-owned banks, open the market of non-state-owned
SMEs, and establish financing institutions especially for SMEs; strengthen the
function of market supervision, and strive to solve the financing difficulties of SMEs
in essence. Lin Yifu (2014) believes that the current financial system cannot fully meet
the financing needs of SMEs. Farmers, SMEs, although the proportion of the employed
population is as high as 70%, and the proportion of gross domestic product is more
than 60%, the financial services provided to them are still
scarce.
Wu Jinglian (2012) believes that the financing difficulties of SMEs are directly or
indirectly related to the discriminatory economic policies to a certain extent. In the
planned economy era, there is little possibility for SMEs to survive. Since the 1980s,
individual households business, private enterprises have emerged. The initial stage of

private enterprises is SMEs. These enterprises have been facing a disadvantageous
market environment for a long time. Only by eliminating discriminatory standards,
improving the financing environment, lowering the access threshold of the financial
industry, allowing and supporting the establishment and development of various types
of private small financial institutions, and matching SMEs with small and medium-
sized financial institutions, can the problem of financing be alleviated.。
Xu Honghong (2001) believes that the financial gap is fundamentally caused by
the financial depression in China. Real interest rates do not reflect the real supply and
demand of funds, resulting in the coexistence of excessive demand for funds and
insufficient effective supply, resulting in a financial gap. At the same time, because of
the asymmetric information between banks and enterprises, the effective supply of
funds is reduced and the financial gap is aggravated. Yu Xuehua and Luan Jingzong
(2005) argue that China's credit rationing is not a single credit rationing subject to
market constraints, but also one subject to the inertia of the traditional planned
economic system, namely the so-called "double credit rationing". Under this condition,
the financing difficulties of SMEs mainly lie in three aspects: information asymmetry,
excessive government involvement and endogenous financing constraints of SMEs.
Zhang Jie (1998, 2000) believes that the financing difficulties of SMEs stem
from the financial support of the state-owned financial system for large state-owned
enterprises, the rigid dependence of state-owned enterprises on such support and the
resulting credit capitalization. Therefore, the financing problem of SMEs is
fundamentally a credit dilemma caused by the financing system. Liu Xiuli et al. (2006)
believe that state-owned commercial banks occupy an absolute position in the national

financial system. If private enterprises cannot get its support, it will be difficult to solve
the problem of financing, the credit policy of state-owned commercial banks and
should be adjusted and a certain proportion of funds should be allocated to SMEs
2. Theory of Enterprise Defects
Li Yang and Yang Siqun (2001) believe that the financing difficulties of SMEs are
due to their high failure rate and closure rate, low credit rating, poor asset condition,
lack of effective guarantee or collateral for loans, and insufficient creditworthiness for
their own assets. Yang Qianyuan et al. (2000) and Li Changyou
(2004) think that the basic reason for financing difficulties is the quality of Chinese
SMEs themselves - the financial system is not perfect, which leads to their low credit.
When the operation is difficult, most SMEs try to prolong the interest on loans, which
poses a great threat to the security of credit funds of financial institutions and
aggravates the difficulty of SMEs loan. Yang Junlong and Yang Jun (2003) believe that
the main causes of financing difficulties are unclear property rights structure, credit
barriers and risk variables of SMEs. SMEs should start from improving their own
creditworthiness to solve the financing difficulties. Hu Naiwu et al. (2006) point out
that SMEs have a lower reputation than large enterprises, their management style and
behavioral characteristics are highly uncertain, and the moral hazard of lending to
SMEs is relatively more serious.
3. Theory of Market Matching Failure
Hu Naiwu et al. (2006) emphasize that in the face of the financing demand of
SMEs characterized by of privatization, diversification and serious information

blockage, financial intermediaries with scale advantage in lending have failed, so it may
be contrary to economic theory and not sustainable forcing large commercial banks to
grant loans to SMEs. Zhang Qinggeng et al. (2006) point out that the lack of experience
in credit analysis of SMEs and the poor ability of risk management of banks are also
one of the reasons for financing difficulties of SMEs. Chen Jian (2006) summarizes the
practical experience of Korean Bank in developing SMEs credit business, points out
that the biggest problem faced by Chinese commercial banks is the lack of basic data.
The data model of commercial banks is mainly based on account center, not customer
center. This makes it possible for Chinese commercial banks to establish their own data
model based on account center rather than customer center. Commercial banks cannot
fully understand the overall situation of enterprises, and the weak risk management
foundation of SMEs makes it difficult to control
risks.
Liu Juntao (2004) argues that the structure of China's financial market is
unbalanced, the long-term lending and property rights markets of banks are
underdeveloped, while the debt security and stock markets are much more developed;
there are also imbalances in the capital market, where debt security issuance is
relatively large while stock issuance is relatively small, while the opposite is true in
the trading market; and it is the imbalance in the debt security market itself, that is, the
bond market is relatively developed, while the corporate bond market are relatively
lagging behind. Yang Fenglai et al. (2006) point out that the lack of financial innovation
makes the financial system lack of new financial products to support SMEs. Chen

Hanwen (2006) points out that the lack of capital market hierarchy, second board
market and over-the-counter market, as well as strict market access rules and lack of a
variety of trading instruments in capital market make SMEs unable to use capital
market to raise funds in their own way.
ii.Solutions to the Financing Problem of SMEs
1. Improving the Loanability of SMEs
Ye Qian et al. (2003) examine the specific content of the expansion of Hodgmann
model of default risk through model analysis, including four types of credit rationing
and eliminating ideas, and believe that credit rationing existed objectively for a long
time and credit risk classification for enterprises was an effective incentive mechanism.
The guarantee effect should be exerted by establishing a borrower alliance and a
supervision alliance. Tang Luyuan (2003) analyzes the significance of introducing
external institutional constraints to change the game equilibrium from the perspective
of bank-enterprise game, and put forward some countermeasures, such as establishing
a credit legal system, punishing enterprise's dishonesty and establishing enterprise's
credit information system. Tang Ping (2006) believes that credit intermediaries should
give full play to the role of credit supervision of SMEs. Credit intermediaries providing
credit guarantee for
SMEs should regularly or irregularly inspect and supervise the credit and finance of
SMEs in order to prevent the irregularities in the operation of SMEs. Li Dan (2006)
believes that SMEs should not only establish a standardized property rights system and
credit system, but also establish a standardized financial system, improve the level of

financial management, and enhance the authenticity and transparency of financial
information. At the same time, the enterprise financial agency system has been proved
to be an effective measure in market economy countries, and China should gradually
implement it.
2. Perfecting the Financing Guarantee System
Lin Yifu et al. (2001) based on the function and effective allocation of the financial
system, believe that the premise of SMEs financing is to establish national credit
system, credit investigation institutions, guarantee system, government and market
mechanism. Duan Weiping et al.(2003) through game analysis, propose that the
solution to non-cooperation between banks and enterprises is to develop credit
guarantee and small and medium-sized financial institutions. Ou Xinqian (2004)
believes that, with the necessary policy support, it is unavoidable to focus on
supporting a number of guaranty institutions with outstanding business performance
and sound management system to speed up the establishment of SMEs credit re-
guarantee institutions. Zhang Qinggeng et al. (2006) believe that state-owned
commercial banks should gradually formulate and improve their internal "Credit Grade
Evaluation Measures of Credit Guarantee Institutions", promote the development of
guarantee business of FGCs, and promote the smooth financing channels of SMEs. To
solve the problem of information asymmetry, the development of credit guarantee
institutions can effectively reduce the problem of information asymmetry. Jin Lihong
et al. (2006) believe that the re-guarantee system should be established. While
undertaking the responsibility of guarantee, the guarantee institutions should

reinsurance the risks already assumed in accordance with a certain proportion, and then
the insurance institutions should take part of the risks. In this way, insurance companies
can update products, and guarantee agencies can relieve worries and avoid risks.
2.1 Literature Review of Credit Enhancement
According to the Business Standards for Credit Enhancing Institutions and Risk
Management Standards for Credit Enhancing Institutions issued by the People's Bank
of China in 2001, credit enhancement refers to the effective forms that are clearly
defined in the documents of guarantee, credit derivatives, structured financial products
or other effective forms defined in laws, regulations, policies and industry self-
regulatory documents that can improve the credit rating of debts and enhance the level
of debt performance guarantee, thereby dispersing and transferring credit risks to
professional financial services. The way to achieve credit enhancement is to design the
product structure and specific agreement arrangements, or use various effective means
and financial instruments to ensure that debtors pay the principal and interest of
corporate bonds on time, so as to make corporate bonds have higher credit rating,
increase the probability of successful bond issuance, and reduce the cost of bond
issuance.
According to the principle of credit enhancement, the ways of credit enhancement
can be divided into basic credit enhancement, derivatives credit enhancement and
structured credit enhancement. Among them: basic credit enhancement, including
guarantee and pledge, has been widely used in various types of corporate bonds, mainly
for improving the credit rating of bonds before issuance; credit derivatives credit

enhancement includes credit default swaps, credit risk mitigation instruments, mainly
for short-term financing bills, medium-term bills and other bonds. By purchasing credit
derivatives, securities investors can transfer their credit risks and slow down their
capital regulatory constraints. Structured credit enhancement includes senior-junior
structure, which is mainly used for investors with different risk preferences to share
bond risks through bond stratification and increase structured credit. Structured credit
enhancement is generally used in conjunction with other credit enhancement methods.
I. Foreign Credit Enhancement Literature
Steven (2002) believes that credit enhancement is a unique technological
approach. When credit rating is insufficient, the initiator sacrifices part of the capital
cost to purchase additional credit support from the other party. John, Lynch and Puri
(2003) believe that there is a strong negative correlation between bond spreads and
credit rating, and that higher-level bonds have smaller spreads, so credit enhancement
can effectively reduce financing costs. Ambuose (2001) believes that there are many
aspects of risk in the process of asset securitization issuance, and credit enhancement
can effectively increase the confidence of investors, which is a practical strategy. This
slight concession to income can promote the project to produce cash flow redistribution
and achieve a small and broad effect. Van Son Lai and Issouf Soumare (2010) establish
contingent claim analysis models for continuous time to analyze the impact of credit
insurance on investment, and find that under the premise of maximizing the interests
of investors, the existence of credit insurance has greatly increased the attractiveness
of investment, and there is a relationship between investment duration and investment

scale. Acharya (2002) analyzes all aspects of the credit enhancement mode and finds
that there is the most suitable design in each specific situation, but each design has its
advantages and disadvantages, and the combination of internal and external upgrading
is a
reasonable solution.
II. Domestic Credit Enhancement Literature
Xue Shirong (2009) points out that credit enhancement technology can effectively
reduce the financing costs of securities issuers and improve the credit rating of assets,
thereby increasing the liquidity of assets in the economy, improving the flow of funds
and turnover speed. Peng Jiangbo and Geng Xin (2011) believe that credit
enhancement improves the allocation efficiency of funds and the financing efficiency
of financial markets by reducing the credit risk and financing cost of SMEs. Liao
Xiaoyun (2007) compares the effects of various credit derivatives, believing that credit
derivatives have the characteristics of off-balance-sheet management instruments, and
the effectiveness of their correction results has been recognized by the banking
industry. The application of credit derivatives can simplify legal procedures, save
transaction costs, and effectively and reasonably adjust the capital adequacy ratio and
risk weight of banks and expand the scope of credit risk protection. Zhang Xuetao and
Hu Wei (2012) use the method of combining theory with demonstration to explore and
study the effect of credit derivative instrument-credit risk mitigation instrument in the
credit risk mitigation of commercial banks. They believe that the use of credit risk
mitigation instrument could increase the target loan amount by about 63% while

maintaining the risk-weighted assets unchanged. At the same time, the use of credit
risk mitigation instruments will generate excessive investment demand, and ultimately
increase the target loan amount by about 74%.
2.3 Review of Credit Risk Management Literature
Credit risk refers to the risk that the borrower defaults and fails to fulfill his
obligation to pay debts. This may happen when the other party fails to pay or fails to
pay on time. As far as the essence of banking activities is concerned, credit risk is the
most obvious risk of banks. As far as potential losses are concerned, this is usually the
biggest category of risk for banks. The default of a few customers may cause great
losses to banks. McKinsey, a well-known consulting firm, has studied the actual
allocation of risk capital in international banking industry and finds that credit risk
accounts for 60% of the total risk exposure of banks, while market risk and operational
risk only account for 20%. According to the definition of Basel II, credit risk is a
function of the probability distribution of expected results of bank loans and risk
exposure and it can be decomposed into three elements: default probability, default
exposure and specific default loss rate. According to the Criteria for Credit Rating in
Credit Market and Interbank Bond Market (People's Bank of China, 2006), credit risk
refers to the possibility of loss caused by default of borrowers or market counterparties;
in a broad sense, credit risk also includes the possibility of loss caused by the change
of borrower's credit rating and fulfilling capability, which leads to the change of market
value of borrower's debt.

The main purpose of risk management is to reduce income volatility and avoid
major losses. In the proper risk management process, it is necessary to identify risks,
measure and quantify risks, and formulate risk management strategies. Risk can be
dealt with by one of the following four methods: risk aversion, risk mitigation, risk
retention and risk transfer. Credit risk is managed in various ways. The most important
credit risk management technologies include selection, limit, diversification and credit
enhancement. Selection - A good credit risk management begins with a good choice of
counterparties and products. Limit - Limit the bank's exposure to specific counterparts,
avoiding a loss or a limited number of losses that endanger the bank's solvency.
Diversification - The allocation process of banks will provide good risk diversification
for different borrowers of different types, sectors and regions. Credit enhancement -
When a bank finds that it is exposed to a certain type of counterparty, it can purchase
financing guarantees or credit derivatives to obtain credit protection. Through
protection, the credit quality of the secured assets can be improved, which is also called
credit risk mitigation. I. Foreign Credit Risk Management Literature
i. Credit Risk Management Thought
Western commercial banks have a history of more than 300 years, which has laid
a solid theoretical foundation and effective institutional arrangements for bank credit
risk management. From Adam Smith's theory of asset management, the theory of
liability management in the 1960s, the theory of integrated asset-liability management
in the 1970s to the theory of off-balance sheet management and risky asset
management in the 1980s, as well as the emergence and rapid development of financial

engineering, the formation and continuous improvement of the Basel system. After
more than two centuries of development, the theory of bank credit risk management
has become a more systematic scientific system.
1. Asset Management Theory
Since the emergence of banking industry until the 1960s, the focus of asset-
liability management of commercial banks has been on asset management. The
representative theories mainly include reserve theory, commercial loan theory,
anticipated income theory, super money supply theory and asset shiftability theory.
Firstly, the Reserve Theory. That is to say, in order to cope with liquidity risk,
banks must maintain a certain level of cash assets or some short-term securities, which
is the traditional way for commercial banks to maintain liquidity.
Secondly, the Commercial Loan Theory, also known as the Real Bill Theory,
originated from the 18th century British economist Adam Smith's the Wealth of
Nations. The theory holds that in order to cope with the unforeseen cash withdrawal
risk of depositors, banks must maintain the high liquidity of assets in the use of funds,
and loans must be short-term and self-repayment. For quite a long time, the real bill
theory has dominated the asset management theory of commercial banks.
Thirdly, the Shiftability Theory. After World War I, Moulton, an American
scholar, first proposed it in 1919 and it developed rapidly in the 1930s and 1940s. The
theory of asset convertibility is the product of the development of financial market to
certain extent, that is, the products of the more developed security exchange market.
Convertibility theory provides a theoretical basis for the

diversification of bank financial assets.
Fourthly, the Anticipated Theory. Anticipated theory is an important turning point
in the evolution of bank risk management theory. In 1949, Prochow, an American
scholar, published the theory of anticipated income on loan liquidity, which marked
the birth of the anticipated theory.
Fifthly, the Theory of Super-money Supply. With the diversification of money
forms and the increasing pressure of competition in bank credit market, the theory of
excess money supply appeared in the 1960s and 1970s. The theory holds that the
provision of money by bank credit is only one of the means by which banks achieve
the business objectives. In addition, banks have not only a variety of alternative means,
but also a wide range of objectives that can be achieved simultaneously.
2. Liability Management Theory
This theory is based on the vague definition of liabilities. Banks can give a variety of
explanations on the issue of liabilities. Liability management can be divided into two
categories: one is to compensate for withdrawal deposits by short-term borrowings,
the other is to borrow money to meet increased borrowing requirements, and to
expand liabilities by borrowing from the Eurodollar market, federal funds and so on.
The purpose of liability management is to increase the
possibility of profit by expanding liabilities.
3. Integrated Asset-Liability Management Theory
Backe (1977), an American economist, put forward the theory of integrated asset-
liability management. This theory is a comprehensive one, which aims to managing

the risk of assets and liabilities of banks as a whole, and in a flexible and changeable
way. It can make corresponding policy adjustments with the change of operating
environment, collocates reasonably in the aspects of interest rate, term, risk and
liquidity, and organically combines various assets and liabilities to ensure the
profitability and assets of banks safety and liquidity. The goal of this kind of
management is to maximize the profit and to develop steadily in the long run under the
condition of the established risk tolerance. Interest rate risk management is only a
means to achieve the goal. The main contents of the management include interest
spread management, non-interest expenditure management, capital flow supervision,
loan quality control and so on.
4. Intermediary Business Management Theory
In the context of deregulation in the 1980s, the competition in banking industry
intensified unprecedentedly, and industrial and commercial enterprises began to
participate in the competition of financial industry on a large scale, forcing commercial
banks to find new management ideas to get out of the predicament. It is under this
condition that the theory of intermediate business management, also known as off-
balance sheet business theory, has sprung up. The theory advocates looking for new
business areas beyond traditional bank liabilities and assets business, and opening up
new sources of profit. This theory holds that banks are institutions that produce
financial products and provide financial services, and also engage in business activities
that provide information services. Banks should join in all areas related to information
services.

5. Risk Asset Management Theory
The theory originated from the promulgation and implementation of Basel Accord
in July 1988. The accord unifies the understanding of capital composition, introduces
the ratio of risky assets, classifies assets and off-balance-sheet business items with risk
weights, familiarizes the concept of minimum capital adequacy ratio to control the
credit expansion of banks, and alerts banks to strictly control the quality of credit
assets.
ii.Credit Risk Management Method
In recent years, there have been a large number of empirical studies on corporate
credit risk abroad. Fitzpatrick (1932) compares the financial ratios of bankrupt and
non-bankrupt enterprises, and finds that the financial ratios of bankrupt enterprises are
poor. Fisher (1936), who originally proposes the discriminant analysis method, has a
simple idea: select a certain number of groupings from the data you want to separate,
such as default and non-default, and then find out the explanatory variables from the
two categorizations and find the combination of these explanatory variables. Durand
(1941) first applies Fisher's method to economic and financial fields. The Z-score
model of Altman (1968) is the earliest and most famous
application of discriminant analysis in credit scoring. A multivariate analysis method
is used to discriminate the operating conditions of 66 manufacturing enterprises in the
United States. The explanatory variables include: working capital to assets, retained
earnings to assets, EBIT to assets, net value to liability and sales income to assets. The
model has strong discriminant ability and soon becomes a mainstream technique to

measure enterprise risk. Eisenbeis (1977) criticizes this method, believing that it is only
suitable for small sample distribution data, and it is difficult to define the boundaries
of data classification, such as good or bad. Nevertheless, because of its simplicity and
ease of estimation, this method is favored by banks. Mester (1997) believes that 70%
of the world's banks use the scoring model to analyze small commercial loans.
On the basis of Altman (1968), many scholars, such as Fernandez of Spain (1988),
Altman, Marco and Varetto of Italy (1994), Izan of Australia (1984), Gloubos and
Grammatikos of Greece (1988), Ta and Seah of Singapore (1981), Altman and
Lavallee of Canada (1981), Ko of Japan (1982), Baetge, Huss and Niehaus of Germany
(1988) have studied the credit risk of enterprises by using different financial ratios in
different quantities and forms in the frameworks of linear discriminant analysis,
quadratic discriminant analysis and linear regression analysis.
Since the 1980s, logistic regression analysis has gradually replaced the traditional
discriminant analysis method. Martin (1977) uses logistic method and discriminant
analysis to predict 23 bankruptcy banks from 1975 to 1976, and finds that the results
of the two methods are similar. Lawrence and Ashadi (1995) use logit model to analyze
the management of problematic loans, and use a series of borrowers and bank variables
to analyze the choice of solutions. Campbell and Dietrich (1983) use logit model to
study mortgage loan and show that the age of mortgage, the ratio of mortgage to loan
value, interest rate and unemployment rate have strong explanatory power in
explaining the repayment, default and negligence of mortgage loan. Laitinen (2000)
applies Taylor series to logistic regression analysis to predict corporate default and

bankruptcy and finds that cash ratio, shareholder equity ratio and cash flow ratio are
important indicators to determine the level of default risk. Gardner and Mills (1989)
use logit model to estimate the default probability of the current negligent loan, find
that the default of the negligent borrower is not necessarily the end of default, and
suggest that the bank use this method to determine the seriousness of the loan problem
and establish the corresponding response mechanism. Empirical study by Charitou,
Neophytou and Charalambous (2004) shows that logit model has stronger predictive
ability than other methods for predicting default risk.
The development of credit risk measurement technology as a symbol of modern
credit risk management has its characteristics and general development trend: from
qualitative analysis to quantitative analysis; from indicator form to modeled form or
combination of the two; from the analysis of individual assets (or loans) to combining-
angle analysis; from the method of book value to the method of market value; the
transformation of variables describing risk from discrete form to continuous form;
considering not only the micro-characteristics of single borrower and single lender, but
also the impact of the macroeconomic environment; from a single risk measurement
model to a diversified and customized one. The change in risk measurement mode also
draws on the latest research results in related fields such as econometrics, insurance
actuarial science, optimization theory, simulation technology, and so on, so as to
continuously improve the precision and accuracy of credit risk measurement.
The common practice adopted by western commercial banks is to

comprehensively control the assets and liabilities of banks. In addition, it is worth
mentioning that in the selection of specific strategies, attention is not only paid to the
management of various risks, but also to the management of portfolio risk, and the
diversification of risk portfolio is fully considered. In the choice of management
methods, the main characteristics are: to unify management of various risks, to use
more quantitative analysis with appropriate qualitative analysis, to transform the
previous indicator evaluation into model quantitative analysis gradually, and to achieve
a systematic and comprehensive assessment of the risk of credit portfolio, and to apply
advanced concepts in the financial field to practice timely.
II. Domestic Credit Risk Management Literature
The research on bank credit risk management in China started in the late 1980s.
Since the 1990s, the government, practitioners and theorists have shown great interest
in financial risk, such as the translation of foreign credit risk theory, the writing of
books or the trial implementation of Western risk management methods, which have
achieved great results. From the theoretical point of view, a large number of academic
papers and works on financial risks, including credit risks of commercial banks, are
emerging at an unprecedented rate. Scholars have conducted in-depth discussions from
different perspectives, and the research contents, scope and methods are becoming
increasingly rich and mature.
i. Credit Risk Management of Commercial Banks
Xue Feng (1995) makes a systematic analysis of the credit risk from the macro-
environment, economic subject and economic system, and makes an empirical

description of the credit risk in China's actual economic and financial operation, and
puts forward some ideas and countermeasures to solve the problem of bank credit risk.
Zhong Wei and Li Xindan (1998) explain the formation mechanism of credit risk from
the internal risk of financial system. Zheng Yaodong et al. (1998) discuss the role of
the five-level classification of credit assets in preventing credit risks. Han Ping and Xi
Youmin (1999) analyze the characteristics, concrete appearances and generating
mechanism of credit risk of commercial banks in China during the period of economic
transition.
Gao Ling (2000) believes that the key to the management of bank credit risk lies
in the control of default risk of borrowing enterprises. By using the analytic hierarchy
process (AHP), an early warning model of bank credit risk in China is established,
which playes a guiding role in the management of bank credit risk. Liang Qi and Huang
Gonghao (2002) make a tentative discussion on the construction of credit risk
management system of commercial banks in China. Shi Hanxiang (2003) believes that
the main reasons for the formation of credit risk in state-owned commercial banks were
the external factors such as administrative intervention, enterprises escaping the
financial obligations, the lagging development of financial market, and the internal
factors such as the low level of bank risk management, the imperfect mechanism and
the low quality of employees.
To manage the credit risk, banks must introduce the concept of integrated risk
management, and implement integrated risk management in all aspects from the
external environment governance and internal management. Jiang Fangming (2003)

analyzes the inherent mechanism of credit risk caused by the backward risk
management of commercial banks, and puts forward countermeasures and suggestions
from five aspects: risk culture, risk monitoring mode, risk monitoring process, risk
measurement and risk transfer. Ouyang Weimin (2003) considers the basic principles
and evolution of commercial bank risk management, analyzes the current situation and
characteristics of commercial bank risk in China and the problems in risk management,
and proposes means and suggestions to speed up the modernization of commercial
bank risk management in China.
Based on the impact of economic and financial globalization on credit risk
management of state-owned commercial banks, the Research Team of Shanghai
Branch of ICBC (2004) proposes that state-owned commercial
banks should establish right risk management concepts, and designs several
principles, overall framework and strategic steps of credit risk management. The
Project Team of Hangzhou Institute of Finance Studies (2005) believes that in order to
improve the risk management system of credit assets of modern commercial banks in
China, three key elements must be focused on: system, culture and people. At the same
time, many principles should be grasped, namely the advanced principle, hierarchical
principle, dynamic principle, gradual principle, contingency principle and humanity
principle.
Zhao Zongjun et al. (2005) use the theory of asymmetric information as an
analytical tool, discourse the formation mechanism of credit risk management of
commercial banks, and put forward suggestions to improve the credit risk management

of commercial banks aiming at the credit risk caused by asymmetric information. Sun
Lingyun and Wu Baohong (2006) point out that due to the rapid development of market
economy and the serious inadaptability of financial property right system reform,
authorized operation of management and internal control and self-discipline system,
many banks still have serious deficiencies in the concept of credit risk control and
behavioral deviation, so that the rate of non-performing credit assets is still at a high
level. They also put forward specific suggestions on credit risk management and
optimization of credit risk control.
ii. Quantification of Credit Risk
Since the latest credit risk quantitative management model was developed by
international financial institutions and major western banks in recent years, the current
domestic research and analysis on credit risk quantitative management mainly focuses
on the introduction, evaluation and reference of foreign models. Some scholars have
done some research on these models, and revised and perfected the credit risk
measurement models suitable for China.
Lu Yaoming et al. (1998) introduce some technical methods of credit risk
management of western commercial banks, including credit derivative transactions,
asset securitization and so on. Pong Sulin et al. (2001) aim at the credit market with
asymmetric information, analyze several common cases of loss of credit funds or loss
of opportunity and their mathematical principles, establish a decision-making model
of bank credit risk, and draw the following conclusions by giving Kuhn-Tucker
conditions: when collateral fails as a means of identifying the type of enterprise risk,

banks will have special requirements for the value of collateral provided by enterprises
in order to avoid credit risk.
Hao Liping et al. (2001) discuss the feasibility of artificial neural network and its
application in credit risk analysis, emphasis the construction of artificial neural
network model for credit risk analysis of commercial banks. A feasible neural network
model for credit risk assessment is obtained, which provides a scientific basis for credit
decision-making. Liang Shidong and Guo Zhong (2002) analyze the reasons for the
development of new credit risk models, and make a comparative analysis of the
representative modern credit risk models in the West. Pan Weilin (2002) introduces in
detail how to use VaR method to calculate the credit risk of commercial banks. Wang
Qiong and Chen Jinxian (2002) introduce credit risk pricing and KMV credit risk
pricing model. Xiao Dongmei and Li Tao (2002) make a systematic analysis of credit
risk based on H ∞ control theory in view of the uncertainty of bank credit risk system
model. Liu Wei and Chen Xiangzhi (2002) establish a more scientific and feasible
credit asset management model which can meet the market requirements by using the
methods of principal component analysis, cluster analysis, discriminant analysis,
multiple regression, random sampling and statistical test of modern multivariate
statistical theory.。
Wang Yuanyue et al. (2003) introduce the most popular credit risk model
construction method in the West - factor method, and briefly analyze its application in
the popular risk management models such as Basel Accord internal rating method,
Creditmetrics, CreditRisk Plus. Fan Nan (2003) believes that Creditmetrics is a typical

quantitative method which can be compared among different industries, and it is a good
supplement to the traditional methods of credit risk management of commercial banks
in China. Yuan Guiqiu (2003) analyzes the credit risk measurement based on RAROC
principle and believes that it is a feasible method for China's financial institutions to
study and apply credit risk at the present stage by adjusting the credit grade transferring
matrix which has been used publicly and establishing credit risk pricing model. Zhou
Chunxi (2003) introduces the method of multi-level fuzzy mathematics into bank
performance rating to make a
comprehensive evaluation, combining qualitative and quantitative analysis. Liu Fang
(2003) proposes to use the principal component analysis method to evaluate the bank's
operating performance, trying to avoid the problem that the comprehensive evaluation
method is difficult to achieve fairness and objectivity in the setting of weights, and
strive to objectively and impartially evaluate the results. Ge Chaohao and Ge Xuejian
(2005) use cluster analysis and Fisher discriminant analysis to measure and evaluate
the credit risk of banks. The mathematical principle of the model, indicators and data
pre-processing are introduced in detail, and the
discriminant function of credit rating is established.
Liang Qi (2005) studies the measurement of credit loss of commercial banks'
portfolio on the basis of defining the relationship between bank loan loss and default
loss, elaborates the asset-related method of measuring default loss, and gives the
specific process of the additional method of enterprise asset return rate. Fu Qiang and
Li Yongtao (2005) establish a logistic model of the credit situation of listed companies

based on the annual report data and find that the multiple of interest guarantee and the
turnover of inventory are the key determinants of the credit of listed companies, and
use the model to evaluate the credit risk of listed companies one year later. Zou Xinyue
(2005) makes an empirical analysis of the credit risk of 184 listed companies in China,
and clearly finds that the typical linear discriminant model is effective in Chinese
market and can provide investors with scientific decision-making.
Guo Zhanqin and Zhou Zongfang (2006) set up a parametric programming model
based on interval number to deal with the uncertainty of credit risk and return. By
choosing the risk loss parameter alpha, banks can determine the optimal portfolio
weights of different risky credit projects under the equilibrium state of risk-return, so
as to obtain the maximum return under the given risk. Long Haiming and Deng Taixing
(2006) set up a solvency model to discuss the quantitative relationship between
consumer debt ratio and expected default rate of consumer credit, and compare the
return and risk loss of non-performing loan rate with the actual default rate, and
provides a new idea for the management of consumer credit in commercial banks.
Wang Naijing and Youyonghua (2006) use the comprehensive financial data of 100
listed companies as samples, and use principal component analysis and Fisher
discriminant analysis to evaluate the risk of enterprises. Zhai Dongsheng and Cao
Yunfa (2006) use Fisher discriminant analysis model to analyze the credit status of
listed companies in China and show that the overall discriminant accuracy of the model
is 90.38%.

After the promulgation of the new Basel Accord, many scholars have carried out
research. Xu Zhendong (2002) analyzes the capital requirements for bank credit risk
under the new standard method and internal evaluation method. Zhang Shi (2002)
introduces the main contents of the internal rating method proposed by the new Basel
Accord and the specific requirements for its implementation, and then analyzes the
ways to construct the internal rating of credit risk of commercial banks management
in China. Zhang Zhang (2002) describes the credit risk management system and related
technologies from the perspective of the internal rating method of the new Basel
Capital Accord, and organically combined the advanced risk concepts with the actual
operation of commercial banks in China. Chen Jianhua and Tang Libo
(2003) start with the analysis of the characteristics of IRB and the minimum standard
of use, and proceed from the angle of risk management of commercial banks, analyze
the difference between the risk management system based on asset classification and
the risk management system based on IRB, and put forward the business under the
current conditions ,and point out that in order to establish risk management system
based on IRB law, commercial banks should reform and improve the loan risk
classification system. Yu Liyong and Cao Fengqi (2004) analyze the impact of the new
Basel Accord on the capital adequacy of Chinese banks. Tan Ying (2005) introduces
the internal allocation method of economic capital commonly used in foreign
commercial banks, and uses three methods of economic capital allocation to compare
the hypothetical data, thus found some problems in China.

To sum up, the domestic theoretical research on bank credit risk management
mainly stays on introducing and drawing lessons from foreign advanced models.
Domestic research on bank credit risk management and model-building lacks initiative
and innovation. The main signs are as follows:
(1) The framework of integrated management of credit risk in commercial
banks is not complete enough. Many scholars only study and analyze some local
problems. Although some scholars try to use some mathematical methods to measure
bank credit risk, their ideas are not in line with international standards and are difficult
to be recognized.
(2) There is no reasonable and complete construction of bank credit risk
management system from the perspective of modern commercial bank system. In the
analysis of existing credit risk problems of state-owned commercial banks, most
papers generally confine their research direction in external factors such as
macroeconomic system, and seldom pay attention to the bank's own imperfect risk
management system, weak implementation, backward means and other internal
factors.
(3) Quantitative analysis is less. Several copy the western models, neglect
the different accounting systems and national conditions and non-financial statement
factors, and lack of analysis from the technical level.
(4) The research on bank credit risk is mainly about credit risk, but the
research on credit market risk and internal control is insufficient.

(5) The analysis and construction of credit risk management system lay
particular emphasis on qualitative analysis, lacking of theoretical research combining
qualitative and quantitative analysis, and empirical research is even scarcer.
Summary
Credit enhancement of FGCs serves the financing of SMEs, which is a credit
enhancement instrument in nature and belongs to the scope of credit risk management
in terms of theoretical origin and technology. This chapter reviews the main literature
in three areas. On the financing difficulties of SMEs, foreign literatures mainly include
bank credit rationing, relationship lending, asymmetric response to credit policy
shocks, scale matching theory and growth cycle theory under the condition of
asymmetric information; domestic literatures mainly include system defect theory,
enterprise self-defect theory, matching failure theory. The main countermeasures and
suggestions are to improve the loanability of SMEs funds and improve the financing
guarantee system. As for the literature on credit enhancement, domestic and foreign
literature focuses on discussing its function from the perspective of financial
instruments and financial markets.
Credit risk management is the core of bank operation, which has accumulated
abundant literature in its 300-year development process. The credit risk management
thoughts of foreign banks have gone through the stages of asset management theory,
liability management theory, integrated asset-liability management theory,
intermediary business management theory and risk asset management theory. Credit

risk management method is mainly quantitative analysis, supplemented by qualitative
analysis. From the previous indictors evaluation, it gradually transforms into model
measurement analysis, and realizes a systematic and comprehensive assessment of the
risk of credit portfolio. Domestic research on bank credit risk management started in
the late 1980s, or translated and introduced western credit risk theory, or wrote books,
or tried out western risk management methods, which have achieved great results.
From the theoretical point of view, a large number of academic papers and works on
financial risks, including credit risks of commercial banks, are emerging at an
unprecedented rate. Scholars have conducted in-depth discussions from different
perspectives, and the research contents, scope and methods are becoming increasingly
rich and mature.
Chapter III Essence of Credit Enhancement of FGC
Financing guarantee is a special kind of creditor's rights. First, the economic
characteristics of creditor's rights are analyzed. It is deduced that creditor's rights
investors (lenders and bond investors) should abide by the conservative principle.
Then, from the perspective of credit risk management instruments, the connection and
difference among financing guarantee and CDS, credit insurance are analyzed.
3.1 Economic Analysis of Creditor's Rights
This section analyses the nature of creditor's rights and the conservative criteria
that creditor's rights investors should follow. As a special creditor's right, financing
guarantee should strictly abide by the conservative criterion, namely
zero-loss-principle.
I. Creditor's Rights Are Essentially Put Options
Black and Scholes (1973) not only give option BS pricing formula, but also extend
it to the valuation of corporate equity and creditor's rights. They think that the value of
equity is such a call option, the execution price is the par value of unliquidated debt,
the maturity price of basic assets is the value of the company assets, and the creditor is
the seller of put options, allowing shareholders to buy company assets at the par value
of creditor's rights at maturity.
Merton (1974) uses the option pricing principle to give the pricing method of
corporate debt, which is used to price credit risk. Merton (1974) gives the parabolic
partial differential equation of stock market value: 0= ⺁
⺁ , among them, V refers to the enterprise value, refers to
instantaneous variance for enterprise returns,C is the amount paid by the enterprise
per unit time and F is the market value of the securities, ⺁ is the amount of payment
per unit time, r is the risk-free rate of return and t is the time.。
For creditor's rights, if B is the face value of creditor's rights, F is the market value
of creditor's rights and τ is the term of creditor's rights, then there are: 0,
0, <0, <0, <0。Then it demonstrates that the risk premium of
creditor's rights increases with the increase in the ratio of the present value of debt to
the value of enterprise, increases with the fluctuation rate of enterprise value; and the
volatility of the value of creditor's rights increases with the increase of the ratio of the
present value of debt to the value of enterprise, and with the increase of the
volatility of enterprise's value.
Figure 3-1 Equity Rights Income versus Creditor's Rights Income
The profit models of creditor's rights and equity vary with the behavior of
creditors and shareholders. Figure 3-1 shows the income function of the creditor and
the shareholder in relation to the enterprise value V when the debt matures. B is the
principal of the debt. The creditor's income is capped by the principal returned at
maturity. But if the value of the enterprise is below the principal amount of the debt
(V<B), the creditor takes priority over the shareholder to get the whole value of the
company V, while the shareholder gets zero payment. However, if the value of the
company exceeds the repayable debt (V > B), the excess value (V-B) will be shared by
the shareholders. As a result, the shareholder's income increases with the increase of
B
B
V
V
Income increases with the increase of enterprise value V
and income potential tends to be infinite
After reaching point B, the profit no longer increases with the
increase of enterprise value V,and with limited revenue potential
Equity Rights Income versus Creditor's Rights Income

enterprise value, and the earning potential is infinite; after the creditor's income reaches
a certain point (B), it is restricted and will not increase with the increase of enterprise
value. In short, the shareholder is in the position of buyer of call options, while the
creditor is in the position of seller of put options. In reality, because the ratio of
creditor's interest income to principal (interest rate) is far less than 1, under the limited
liability institutional arrangements, creditors always face the situation of limited
income (pre-agreed interest income) and huge potential loss (total principal).
Therefore, creditors should pay special attention to the downside risks of the investee
enterprises. Creditors should pay special attention to enterprise value because the
downside risks have a reverse relationship with enterprise value.
II. Conservative Principle of Creditor's Rights Investment
i. Conservative Principles of Bank Loans
The practice of long-term business operation shows that the general principles of
ensuring the safety of principal, maintaining the liquidity and striving for maximum
profits should be adhered to in the operation of banks. Banks must try their best to
make the loans repaid in a timely and complete manner. If the loan cannot be recovered
in time, it will inevitably affect the liquidity of the bank. If bad loans occur, the bank
will suffer losses of funds and even shake the bank's credit. Therefore, ensuring the
safety of bank loan funds is the first principle that banks must follow when loaning. In
order to maintain the liquidity, commercial banks must also rationally arrange the types
and term structure of loans according to the types and term structure of the sources of
funds. On the premise of ensuring the safety of funds, banks strive for maximum

profits, seizing opportunities in loan business, paying attention to the art and skills of
loan pricing, aiming at obtain higher interest income. Safety, liquidity and profitability
are often contradictory in the specific implementation of loans. In general, banks
always consider the safety and liquidity of funds first. But in order to make full use of
bank funds and increase profit opportunities, they usually take into account by
strengthening pre-loan review.
In the pre-loan review, banks act according to some specific loan principles. For
example, the "5Ws" principle was a set of specific lending principles once very popular
in the western banking industry. Banks must examine every loan application from five
aspects: who, why, what, when and how. Because these five words all contain "W",
they are also called "5Ws" principle. For example, the "5Cs" principle is another set of
specific rules commonly used in the loan review of western commercial banks, which
refers to the character, capital, capacity, collateral and condition of borrowers.
1. The 5Ws Principle
Who is the borrower? This requires that focus should be placed on the situation
of the borrowers (including enterprises and individuals), including the credit status of
the borrowers, the ability to repay the loans, and the operation status of the enterprises
(or personal wealth). This is the most basic one of the "5Ws" principles. If this one
does not meet the standard, then there is no need to review other factors.
Why does the potential debtor borrow money? This requires a clear understanding
of the purpose of borrowing. Generally speaking, banks are more willing to meet the
demand for capital revolving loan or productive loans, especially for working capital

loans, which are mostly short-term, with commodity guarantees and relatively safe.
For consumption or speculative borrowing, banks have strict control, especially those
with high risk of speculative borrowing. Banks are particularly cautious when
examining applications for such loans.
What is the borrower's guarantee? This requires determining how or in what way
the borrower mortgages or guarantees the loan. Although banks also carry out credit
loans, more often than not they ask borrowers for collateral, so that when borrowers
cannot repay the loan on time, they can sell the collateral to compensate for the loss.
In implementing this principle, banks strive to accurately grasp the quality and quantity
of the collaterals.
When can the borrower repay the loan? This requires determining the term or
duration of the loan. Banks generally consider the borrower's requirements in terms of
the duration and structure of the source of funds. The main purpose is to maintain the
solvency and liquidity of the bank.
How does the borrower repay the loan? This requires knowing whether the
borrower repays the loan at one time or in installments, and what kind of income the
borrower uses to repay the loan, whether the debt is repaid with normal income or with
liabilities. For those who pay off the loan at one time with normal income, the bank
can give a reasonable discount in the pricing of the loan, because the repayment of
such borrowers is more reliable. For loan installment borrowers, the interest rate can
be increased appropriately when the loan is priced, because the borrower's economic
situation is often not very good and the loan risk is habitually high.

2. The 5Cs Principle
Character, mainly refers to the willingness of borrower to pay their debts, is the
most important factor in 5Cs. It is reflected in the borrower's past record of repayment
of debts, and banks generally have files on customers for inquiry. In addition, western
countries generally have institutions specializing in investigating the credit position of
individuals and enterprises. Banks basically know the credit status of their new
customers through such institutions. Therefore, in western countries, whether
individuals, enterprises or governments, they must maintain a good record of debt
servicing. If there is a forcible recourse by the court because of the debt relationship,
whoever will lose the opportunity to obtain loans.
Capital refers to the value, nature and quantity of borrower's capital. The bank
pays special attention to the stability and liquidity of the borrower's capital value in the
loan review. At the same time, great attention is paid to the borrower's net capital value
and its structure, as well as the amount and structure of borrower's liabilities. All these
are related to the safety of bank loans. Banks will agree to provide loans only if they
are sure that the credit is risk-free.
Capacity refers to the ability of the borrower to make extensive use of their
abilities and to make good use of their borrowed funds and make profits. The bank
judges the borrower's ability mainly by his/her age, business experience, business
ability, education level, adaptability, forecasting ability and ideology. No matter how
good a company's debt-servicing record and capital is, if there are no smart
entrepreneurs and managers, it is also likely to fail in the fierce competition, which

will lead to the loss of bank loans. As a result, banks are particularly careful in
examining borrower’s capacity.
Collateral refers to the collateral that the borrower provides as a guarantee of
repayment. Banks usually require that such collateral be stable in value, insured by
insurance companies, and used as a widely marketable asset. In case the borrower fails
to repay the loan, the bank can quickly dispose of the collateral and sell it for cash to
mitigate the risk and loss of the loan.
The condition of an enterprise refers to its operation and external operating
environment. The bank mainly judges whether the enterprise's own operation is good
or not according to the enterprise's operation characteristics, operation methods,
technology conditions and labor relations. The assessment of the external business
environment of enterprises is based on factors such as political changes, social
environment, business cycle, seasonal changes, national income level, etc., as well as
the development trend of the industry and the level of competition in the same industry,
almost all the factors that the enterprises themselves cannot control. The banks think it
is necessary to know the conditions in advance and take measures to ensure the safety
of bank loans.
3. Three Core Factors
Whether "5Ws" principle or "5Cs" principle, we can sum up three elements:
human factors (such as "who" in the 5Ws principle, character and capacity in the 5Cs
principle, etc.), financial factors (such as "what" in the 5Ws principle, capital and
collateral in the 5Cs principle, etc.), economic factors (such as "why", "when", "how"

in the "5Ws" principle, and "conditions" in the "5Cs" principle, etc.). So when banks
implement the loan principles, the key points of its implementation are formulated
around these three elements.
Human factors. Banks always know as much as possible about the number of
shareholders of borrowing enterprises, the proportion structure of common
shareholders and preferred shareholders, and the status of private property of
shareholders. If necessary, they can conduct enquiries through credit investigation
agencies. The top managers of enterprise generally participate in decision-making.
Some of the leading managers themselves are shareholders of enterprises. Their
experience, educational background, ability and social relations have a significant
impact on the operation of enterprises. In addition, business operators with good social
relations tend to have a lot of convenience in purchasing, marketing and utilizing new
technologies and raising funds, while those with bad social relations are not only
difficult to get outside help when they encounter difficulties, but also tend to fall into
the situation of being pushed down by others.
Financial factors. Banks mainly use financial statements to analyze a series of
financial ratios, such as liquidity ratio, quick ratio, cash ratio, profitability, debt ratio
and so on. Banks usually require collateral from borrowers, such as goods purchased
with loans, or houses, land, and securities. Banks review of these collateral focuses on
legitimacy, safety and convenience。
Economic factors. The core of economic factor analysis is to evaluate the nature
of the enterprise, the market of the enterprise, the characteristics and development

trend of the industry in which the borrowing enterprise is located, to understand the
borrowing purpose of the enterprise and the time and mode of repayment, and to make
a proper choice when pricing the loan according to the international and domestic
political and economic situation.
ii. Conservative Principle of Debt Security Investment
Debt security is an investment instrument with restricted returns. The correct way
to select debt security is to find specific and convincing safety factors that can support
the sacrifices made in terms of earnings. Debt security investment is an art of negation.
The focus of debt security investment is to avoid losses, so choosing debt securities is
a negating process. What need to do is to exclude and reject the prospect bad investee,
not to seek and accept them. In the field of debt security investment, there is no such a
thing as being overly critical or calculating. The correct process of debt security
investment should be to select a strong company, and then select the highest yield of
the debt security issued by the company. Debt securities that worth buying should be
able to withstand the test of recession. The more stable the nature of the enterprise, the
better the safety of its debt security. The debt securities of very small enterprises do
not qualify as fixed-value investment instruments. Of course, large-scale per se is not
enough to ensure safety, which must be built on the basis of sufficient value of
enterprises. The pursuit of yield at the cost of safety often results in a loss. A prudent
debt security investor should not allow himself to play the role of an insurance
company and risk losing money in order to earn extra profits.
3.2 Economic Analysis of Financing Guarantee

I. Relations among Participants in Financing Guarantee
Because of the high degree of information asymmetry, high risk of adverse selection
and low credit rating of SMEs, banks are generally reluctant to grant loans to SMEs.
In order to improve their credit rating and obtain bank loans, SMEs need the
guarantee from third parties with higher credit rating. The existence of guarantor
reduces the degree of information asymmetry between credit parties. Guarantor
provides financing guarantee for SMEs with its own credit, promises banks that
when SMEs cannot repay loans on time as stipulated in the contract, and in case of
breach of contract, the guarantor will repay the loans for SMEs. In this way, the risk
of credit default of banks is greatly reduced, and it is easier for banks to choose to
lend to SMEs with guarantors. The guarantor who provides the financing guarantee
service charges the guarantee fee from the SMEs. Therefore, in financing guarantee
transactions, the main function of the guarantor is to enhance credit of the
guaranteed, and for the beneficiary (lending bank), the risk of the guaranteed has
been spread out to a large extent.
Figure 3-2 Relations among SMEs Financing Guarantee Participants
According to the Guarantee Law of the People's Republic of China (1995),
financing guarantee is a kind of guarantee. The guarantee refers to the act that the
guarantor and the creditor agree that when the debtor fails to perform the debt, the
guarantor performs the debt or assumes responsibility according to the agreement.
Guarantee has the characteristics of equality, voluntariness, subordination, security and
complementarity. According to the Regulations on the Supervision and Administration
of Financing Guarantee Companies (2017), financing guarantee refers to the
guarantor's act of providing guarantee for the guaranteed borrowing, issuing bonds and
other debt financing; the so-called financing guarantee company (FGC) refers to a
limited liability company or an incorporated company which has established and
operated financing guarantee business according to law. The main functions of
financing guarantee include safeguarding the realization of creditor's rights, reducing
Bank
SMEs
The participation of the guarantor reduces the degree of information asymmetry,
the risk of adverse selection, and makes the transaction easier to achieve.
Financing Guarantee Company (Guarantor)
Once an enterprise fails to pay its principal and interest due,
the guarantor performs the contract on behalf of the debtor
Paying Guarantee Fees
Providing financing guarantee services
Relations among Participants in Financing Guarantee for Small and Medium-sized Enterprises

information asymmetry, decreasing market transaction costs, enhancing credit, risk
management and economic leverage.
II. Economic Characteristics of Financing Guarantee
From the point of view of risk-return structure, financing guarantee is a kind of
non-standard debt securities. As an investor of this kind of debt securities, the FGC can
obtain a certain amount of premium income in advance, and its potential risk
(the possibility of loss) is the guaranteed amount which is tens of times the premium.
To be exact, every guarantee business can be regarded as a put option. FGC is in the
position of seller of put options, with restricted profits and unrestricted potential losses.
Generally, the risk of financing guarantee is the residual risk transferred by banks and
other credit institutions. Although it usually represents the risk of breach of contract by
the guaranteed, it is essentially a combination of various risks from the guaranteed.
Under the imperfect conditions of China's social credit system, financing guarantee
system, laws and regulations, financial supervision and financial market, any
unfavorable change of any variable will evolve into the residual risk to FGCs.
According to risk sources, the residual risk can be divided into: risks from guaranteed
enterprises, from government departments, from FGCs themselves, from banks, from
the guarantee system, and so on.
From the perspective of return-risk structure, financing guarantee business has all
the economic characteristics of debt security investment. Therefore, the FGC should
strictly follow the conservative principle of debt security investment in its process of
operation, and strictly regulate the process and rules of "negating and excluding".

Moreover, almost all the clients of FGCs, namely the guaranteed enterprises, are
SMEs, who are usually not qualified to issue debt securities in the capital market,
because their credit rating is far lower than that of issuing debt securities. This means
that compared with debt security investments, financing guarantees generally have
greater risks. Therefore, for each financing guarantee business, the FGC must take risk
control as the core. The operating criteria are more conservative than the "safe margin"
principle of debt security investment, and should be defined as the zero-loss-principle.
The zero-loss-principle refers to that the whole process of financing guarantee business
follows the most stringent excluding and screening rules, and in case of any suspicious
situation, timely to take remedial measures or terminate the business to control losses.
If the zero-loss-principle is violated, the financing guarantee business is not worth
doing at all. Especially in the case that China regards financing guarantee as a profit-
making business at present, FGC must strictly screen clients and strictly implement
counter-guarantee measures in accordance with the principle of zero loss; in the case
of adverse macroeconomic situation, even to suspend the guarantee business rather
than to easily relaxes the rules of conservative operation to result in huge compensation
losses.
III. Case Study of Asymmetric Risk-Return Structure
On August 31, 2016, J Guarantee Company provided HY Company with a loan
guarantee contract with a period of one year and amount of 2.7 million yuan to P Bank.
The guarantee rate was 2%, and the guarantee fee was 54,000 yuan. On

September 9, 2016, P Bank granted loans totaling 2.7 million yuan to HY Company,
agreeing to repay 1.7 million yuan in one time and 1 million yuan in monthly equal
amount. On September 20, 2017, P Bank served J Guarantee Company with the Notice
of Performance of Compensation. Because HY Company failed to repay the principal
and interest of the loan due on September 9, 2017. On the expiration date of the loan
contract, P Bank required J Guarantee Company to fulfill its guarantee responsibility
and repay the principal of the loan on behalf of the Guaranteed HY Company of
2210186.43 yuan and the overdue interest of 860.74 yuan, totalling
RMB 2296187.17 yuan. On the day of receipt of the P Bank's notification, J
Guarantee Company fulfills its guarantee responsibility in accordance with the contract
and repays the loan principal and overdue interest to P Bank on behalf of the
guaranteed, totaling RMB 2,296,187.17 yuan.
Although there are various counter-guarantee clauses and penalties for breach of
contract in the guarantee contract, the negotiation failed. The guaranteed HY company
and three individuals did not recoup J Guarantee Company. After resorting to the court,
the counter-guarantor did not appear in court. Court default judgment was: HY
company repays the amount of compensation 2,296,187.17 yuan, and interest (229
6187.17 yuan as capital, according to the loan interest rate of the
People's Bank of China during the same period, from September 20, 2017 to September
23, 2017) and fine for breach of contract (the principal is 229687.17 yuan, with an
annual interest rate of 24%, which is calculated from September 24, 2017 to the date
of actual liquidation).

After the judgment came into effect, the guaranteed HY Company refused to comply
with the court judgment. On April 27, 2018, J Guarantee Company applied to the
court for enforcement. As a result, the bank deposit account of the executed person
was 25.72 yuan, and the property allocated by the court was 423,170.34 yuan. The
total amount of the executed money was 423,196.06 yuan. After withholding the
execution fee of 26,941 yuan, the balance was 396,255.06 yuan. On April 27 and 28,
2018, the court announced the Restriction of High Consumption Order, against legal
person and natural persons of the guaranteed company. This is the end of the
guarantee business.
Even if we do not consider the troubles and costs of auditing, signing, litigation
and other activities, only calculate the income of guarantee fees, compensation losses
and recovery gains, then according to this business case, the results are as follows: In
the absence of breach of contract by the guaranteed, the income of the guarantee fee is
54,000 yuan. In fact, the guaranteed breached the contract and J Guarantee Company
compensated 2296,187.17 yuan, then recovered 396,255.06 yuan through court
judgment and enforcement, and finally lost 1899,932.11 yuan. This case calculates the
real return-risk ratio of 1:35.2. That is to say, once the financing guarantee business
fails, the actual loss is 35.2 times the income of the guarantee fee. Therefore, financing
guarantee is a special debt security with strong asymmetry of return-risk. FGC must
strictly follow the principle of zero loss in its operation.

3.3 Comparisons between Financing Guarantee and CDS
I. Brief Introduction to Credit Default Swaps
Credit default swaps (CDS) is also called loan default insurance.
The International Swap and Derivatives Association (ISDA) established
standardized credit default swap contracts in 1998. Since then, CDS transactions
have developed rapidly. In CDS transactions, one party wishing to avoid credit risk is
called the purchaser of credit protection, while the other party who is willing to bear
credit risk and provides credit protection to the risk transferring party is called the
seller of credit protection. The purchaser of CDS pays a certain fee to the seller on a
regular basis. Once a credit event occurs (mainly refers to the insolvency of the debt
security issuer), the CDS purchaser has the right to deliver the debt security to the
CDS seller at face value, thus effectively avoiding credit risk. The emergence of
CDS solves the liquidity problem of credit risk, makes credit risk trade and transfer
like price risk, and reduces the difficulty and cost of issuing debt securities.
In CDS contracts, the buyer of CDS pays the seller a certain fee on a regular basis,
which is generally expressed by a fixed basis point based on face value. If there is no
default event, the CDS seller will not have any cash outflow. Once the default event
occurs, the CDS seller is obliged to compensate the difference between the face value
of the debt security and the market value after the default event, or to purchase the debt
security held by the CDS buyer at the face value. Characteristically, CDS belongs to
options. Because the characteristics of options are that the buyer has only rights but no
obligations, while the seller has only obligations but no rights, so once the debtor

defaults, the buyer can ask for implementing CDS contract to pass on credit risk. And
the CDS point difference reflects the option premium.
CDS is transaction in which the credit risk of reference assets is transferred
from the buyer of credit protection to the seller. The CDS buyer pays a fixed fee to the
seller who is willing to take risk protection during the contract period; while the CDS
seller accepts the fee, he undertakes to compensate the buyer for the loss of default
within the contract period when the corresponding credit default occurs. The credit
corresponding to the reference assets is either a certain credit or a basket of credit. If
any default occurs in a basket of credit, the seller must compensate the other party for
the loss.
II. Linkage between Financing Guarantee and CDS
Both are instruments for creditors to transfer the debtor's credit risk, and they
belong to credit risk derivatives in a broad sense. For creditors, the effect of divesting
and transferring credit risk is the same, which can protect the principal of creditor's
rights. For product pricing, the pricing principle of credit risk is the same. Because of
the large volume of CDS market transactions, financing guarantee can effectively refer
to the pricing of CDS under the same system, and adjust the guarantee fee rate
according to the degree of credit risk of the guaranteed enterprise. III. Difference
between Financing Guarantee and CDS
1. The legal status of the debtor is different.
Under CDS, the seller of credit protection can issue, create and trade CDS without
any relationship with the debtor and without the request or consent of the debtor. CDS
credit protection seller collects insurance premium from creditors

(credit protection buyer), and has no right to collect insurance premium from debtors.
Under CDS, the reference enterprise (debtor) does not
need to sign a counter-guarantee contract with the seller of credit protection.
Even if the debtor defaults and causes the seller to compensate the buyer, the seller of
credit protection has no right to recover from the debtor.
In the financing guarantee business, the FGC provides guarantee to the creditor at
the request of the debtor. FGC collects guarantee fee from debtors, and usually has no
right to collect guarantee fee from the creditor. Both FGC and the guaranteed enterprise
must sign the counter-guarantee contract. Once the debtor defaults and causes the FGC
to fulfill its obligation of compensation according to the financing guarantee contract,
it can recover according to the counter-guarantee contract.
2. The degree of standardization of contracts varies.
CDS contracts have a higher degree of standardization, which is conducive to
reducing transaction costs; financing guarantee contracts have a lower degree of
standardization and higher transaction costs. Under CDS, the number of buyers is
usually uncertain, and the actual creditor-debtor relationship is not required. In
financing guarantee business, creditors and debtors are usually specific and have real
lending relationship in reality. Under CDS, the amount of CDS issued or created by
financial institutions is not limited by the size of the reference debt; in financing
guarantee business, the maximum amount of guarantee is the amount of the primary
creditor's rights. Under CDS, the amount of CDS issued or created by financial
institutions may be higher or lower than the amount of reference debt; in the guarantee

business, the amount usually guaranteed by FGC is the same as or less than the amount
of the principal claim. The buyer of CDS is not necessarily the creditor of the reference
debt; the beneficiary of the financing guarantee must be the creditor of the debt under
the primary contract.
Under CDS, the precondition for credit protection seller to pay the buyer is the
credit events stipulated in CDS agreement. In the guarantee business, the factors
leading to the payment by the guarantee company include all default events stipulated
in the guarantee contract, and the scope of default events is often much larger than that
of credit events. The validity of CDS agreement is not affected by the reference debt
relationship. Even though the reference debt relationship is invalid, the CDS agreement
is still valid. Generally, the validity of the guarantee contract is affected by the validity
of the primary contract, the primary contract is invalid, and the guarantee contract is
invalid. CDS can be transferred separately from the reference debt relationship, thus
promoting the prosperity and development of the financial derivatives market. It is
conducive for banks to obtain profits linked to the reference debt without capital
investment when no credit event occurs. It is also conducive to dispersing the risk
concentration of banks. Guarantee contracts cannot be transferred separately from the
primary contract.
3. The final effect of risk management is different.
CDS, as the most widely used credit derivatives in the international financial
market, plays an important role in innovative financial business such as asset

securitization. It can optimize asset allocation actively, hedge risks and carry out active
risk management. CDS is an important part of innovative financial business.
In the financing guarantee business, the FGC is in a passive position in dealing with
the risk, and financing guarantee does not have the function of dispersing credit risk in
a large scale. Therefore, FGC must operate the financing guarantee business in line
with the prudent principle of zero loss.
3.4 Comparisons between Financing Guarantee and Credit Insurance
I. Links between Financing Guarantee and Credit Insurance
1. The Same Basis for Production
Reducing credit risk is the common foundation of financing guarantee and credit
insurance. Credit risk exists in economic and social exchanges. In order to protect the
rights and interests and reduce losses caused by risks, it is badly need to avoid risks
and make up for losses. Both financing guarantee and credit insurance arise because of
the existence of risks.
2. The Same as Risk Management Instruments
In a mature market economy, both financing guarantee and credit insurance are
effective means for market transaction participants to manage and disperse risks. They
play an important role in protecting the rights and interests of market transaction
participants and reducing risks. In order to maximize their own interests, market
participants usually combine financing guarantee with credit insurance.
II. Differences between Financing Guarantee and Credit Insurance

1. Different Functions
The primary function of financing guarantee is to guarantee the realization of
creditor's rights and promote the financing. The function of insurance is to compensate
the insured when the loss agreed upon in the insurance contract occurs.
The function of financing guarantee is firstly to promote financing, secondly to
compensate the creditor when the debtor defaults.
2. Different Operating Mechanism
For financing guarantee, the carrier of financial guarantee liability is generally the
property of the guarantor itself; for insurance, the carrier of compensation
responsibility is mainly the insurance fund formed by policyholders paying premiums.
Guarantee fund has the characteristics of closeness, while the composition of insurance
fund has the characteristics of openness.
The operation concept of financing guarantee is the principle of zero loss which
means that the premise of providing financing guarantee is to avoid compensation as
far as possible. Financing guarantee carries out risk measurement and business
operation according to the principle of zero loss and the guarantee-all-the way means.
It must track and monitor the change of risks, and takes corresponding measures to
deal the existing and potential risk factors, so as to reduce the risk of customer default
and ensure the interests of FGC. Insurance calculates and collects premiums according
to the probability of loss and does not need to track and monitor the risk of customers.
Insurance only needs to measure the risk according to the probability and provide
compensation when the risk occurs. The premise of insurance is that there must be

compensation behavior, as long as the compensation does not exceed the estimated
rate, it can make profits.
Generally, financing guarantee cannot operate in accordance with "law of large
numbers" as insurance does. The number of guarantees provided by FGC is limited by
its financial resources and ability to disperse risks, and the amount of compensation
often exceeds the guarantee fee income. Therefore, the law of large numbers is
generally not applicable to guarantee business, and the principle of zero loss must be
implemented in guarantee business.
The insurance compensation is due to the proximate causes, and the financing
guarantee compensation is due to the default results. Insurance follows the principle of
proximate cause, and only the loss proximately caused by insured perils can be
compensated. Generally, the guarantee liability should be fulfilled as long as the
consequences of the loss occur, no matter what causes the loss.
3. Different Legal Relations
The legal relationship of financing guarantee is subordinate. Guarantee contract
is the subordinate contract of the main contract according to the Guarantee Law, while
insurance contract is an independent legal relationship. The legal relationship of
guarantee is restrictive, and the guarantor has the right to restrict the property rights of
the guaranteed, which derives that the guarantor has the right to supervise the
production and business activities of the guaranteed. While the insurer generally has
no right to restrict the property of the insured and has no right to supervise its business
activities. Guarantee is based on the principle of general good faith, and the risk of

dishonesty is borne by the guarantor, that is, the guarantor can't cancel the guarantee
contract because of fault and general dishonesty of the guaranteed unless the
guaranteed and the creditor collude to defraud the guarantor to provide the guarantee.
Insurance is based on the principle of utmost good faith. The risk of dishonesty is
generally borne by the insured.
4. Different Characteristics of Economic Relations
Guarantee has significant personalization characteristics, while insurance does
not. Financing guarantee is not only the proof of ability of the guaranteed to perform
the contract, but also the recognition and guarantee of credit quality of the guaranteed.
It is a significant personalized social relationship. The guarantor should conduct a
comprehensive examination and evaluation of the quality and ability of the guaranteed.
Insurance is a relatively simple economic relationship. Only when there is a possibility
of claims settlement in the event of an insurance accident, can the insurer conduct in-
depth examination and evaluation of the insured and the insurance accident. This
occasion accounts for a very small proportion of the overall insurance business.
Summary
Financing guarantee is a special kind of creditor's rights, so this chapter first
analyses the economic characteristics of creditor's rights. According to the analysis of
Black and Scholes (1973), Merton (1974), the essence of creditor's rights is put options.
Creditor is in the position of seller. Its return-risk portfolio is characterized by:
restricted income and the almost unlimited potential loss (whole principal is subject to
loss). Creditor (lender and debt security investor) should abide by the principle of

conservatism. In order to ensure the safety of funds, banks usually strictly abide by
conservative principles of loan review, such as the "5Ws" principle
(who, why, what, when, how), the "5Cs" principle (Character, Capital, Capacity,
Collateral, Condition), aiming at making a detailed assessment of the human, financial
and economic factors of borrowing enterprises. The key point of debt security
investment is to avoid loss, and the pursuit of yield at the cost of safety is often not
worth the loss. Therefore, debt security selection is a negating process. In the field of
debt security investment, there is no behavior that can be called excessive criticism or
haggling.
Financing guarantee means that the guarantor provides guarantee for the
guaranteed borrowing, issuing bonds and other debt financing. From the point of view
of return- risk structure, financing guarantee product is a kind of non-standard debt
security. As an investor of this kind of debt security, FGC can obtain a certain amount
of premium in advance, and its potential risk (the possibility of loss) is tens of times
that of premium. Every guarantee business can be regarded as a put option, and FGC
is in the position of seller of put options, with limited return and unlimited potential
losses. The financing guarantee business has all the economic characteristics of debt
security investment, and FGC should follow the conservative principle of debt security
investment in its operation. FGC must take risk control as the core in handling every
financing guarantee business. The operating criteria are more conservative than the
"safe margin" principle of debt security investment, and they should follow the zero-

loss- principle. If the principle of zero loss is violated, the financing guarantee business
is not worth operating.
As a credit risk management tool, financing guarantee has both commons and
difference with CDS. For creditors, the effect of divesting and transferring credit risk
is the same, both of which can protect the principal of creditor's rights; for product
pricing, the pricing principle of credit risk is the same. The difference between the two
is that the legal status of the debtor, the degree of standardization of the contract, and
the final effect of risk treatment.
Financing guarantee and credit insurance are both based on the existence of credit
risk. They are effective means for market transaction participants to manage and
disperse risks, and play an important role in protecting the rights and interests of market
transaction participants and reducing risks. The main differences between them are:
different functions, different operating mechanisms, different legal relations and
different characteristics of economic relations.

Chapter IV Spirit of Doer and Enterprise Credit Enhancement
Firstly, this chapter defines the spirit of doer, analyses the matching between the
spirit of doer and the principle of zero loss of financing guarantee. Then, through the
case analysis of Mr. A, it is found that FGC must resolutely reject the financing
guarantee applications of those opportunist owners who lack professional and
dedicated spirit.
4.1 Zero-Loss-Principle and Doer Spirit
I. Doer and Doer Spirit
Financing guarantee is a special kind of creditor's rights, and its asymmetry of
return-risk is very pronounced. Generally, the guaranteed enterprises are usually
SMEs, and their credit risk is usually much greater than that of the large enterprises
qualified to issue normal debt securities. Therefore, for each financing guarantee
business, the FGC must take strict control of downside risk as the core and fully
implement the principle of zero loss. Especially under the condition that China regards
the financing guarantee business as a profit-making business which means FGC bears
profits and losses with its own account. That is to say, if any financing guarantee
business does not conform to the principle of zero loss, it is not worth
trying at all.
In addition, financing guarantee is the proof of the ability of the guaranteed to
perform the contract, the recognition and guarantee of the reputation quality of the
guaranteed and it is a remarkable personalized social relationship. The guarantor
should conduct an all-round examination and evaluation of the quality, ability and

social relations of the guaranteed. The principle of zero loss not only requires the FGC
to implement strict counter-guarantee measures for every guarantee business,
surmount the relevant restrictions of the current company law on limited liability, and
let the owner or actual controller of the guaranteed enterprise bear joint liabilities
through the counter-guarantee agreement. That is, once the guaranteed enterprise
breaches the contract, it must be liable for joint liabilities and FGC can recover the
compensation from the owners or actual controllers according to the counter-guarantee
agreement. And more importantly, FGC must choose the right person from the
beginning, because the key to the success or failure of SMEs lies in the owners and
actual controllers. Financing guarantee business will be far more critical on the
selection criteria for business owners than bank loan business, because the credit risk
of SMEs depends largely on their business owners or actual controllers. Only through
the factor of owner or actual controller, can FGC
effectively identify, measure and control the financing guarantee risk.
Taking Foshan financing guarantee as an example, Foshan is mainly a private
economy. In 2016, the private economy accounted for 63.5% of the whole economy.
There are more than 200,000 private enterprises and private SMEs constitute the main
service clients of Foshan FGCs. In theory, the zero-loss-principle implemented by the
FGC should match the actual controllers of the guaranteed enterprise with stable and
conservative personality traits, such as prudence and low-keyed, keen and flexible,
practical and tenacious, honesty and trustworthiness, and good social reputation.
Through text analysis of sampled business documents, it is found that the main

characteristics of the actual controllers of the guaranteed enterprises are: (1) rich
industry experience, 10-30 years of industry experience, most have 15-20 years of
industry experience; (2) low-keyed and pragmatic, stable operation; (3) insight, quick
thinking; (4) stable source of customers, the abundant human relations, good
reputation. The above characteristics are different from the entrepreneurship defined
by the current academic community. The core of entrepreneurship is innovation. The
above characteristics mainly emphasize focus, experience and sound operation.
Essentially, equity investment emphasizes entrepreneurship, because the return-risk of
equity investment instruments is symmetric, and entrepreneurship with innovation and
risk as its core features can bring huge upside profit space for equity investors.
However, for the financing guarantee business, because of the asymmetry of return-
risk, FGC emphasizes the principle of zero loss and the overall control of the downside
risk, so it prefers the steady and continuous operation of enterprises and prudent and
pragmatic entrepreneurs. Therefore, the above characteristics of financing guarantee
clients are summarized as the spirit of doer.
A doer is a concept contrary to a visionary or a theorist. The core characteristic of
doer is to seek the sustained survival and development of enterprises and undertakings
with a go-getter attitude. In reality, the concept of doer is broader than that of
entrepreneur. In fact, entrepreneur is also a special kind of doers. Doers pay more
attention to cherishing the present, doing practical work well, focusing on areas of
expertise, striving for ambition, and beginning well and ending well.

When referring to the spirit of doer, it is necessary to mention the background of
the slogan "empty talk misleads the nation, practical work rejuvenates the country". In
1992, during the mid-term of China's reform and opening-up, Deng Xiaoping's speech
on the Southern Tour mentioned that "empty talk misleads the country and practical
work to rejuvenate the country". Shenzhen Shekou Industrial Zone resolutely erected
it as a sign on Shekou Industrial Avenue, which not only inspired Shenzhen people to
build special economic zones and strive for reform, but also quickly became the
catchwords and mottos that inspired people of the whole nation to be enterprising and
ambitious. After the Eighteenth National Congress of the Communist Party of China,
"empty talk misleads the nation, practical work rejuvenates the country " once again
appeared in the prominent position of newspapers, television and the Internet. From
the perspective of societal culture and historical background, the essence of doer is a
person who pursues wealth and career through vigorous efforts and step-by-step
stability. The typical groups of doers are usually well-managed SMEs owners.
Some people generalize that the characteristics of a doer are bearing
accountability, enduring loneliness, tolerating solitude, withstanding pressure,
surviving the pain, resisting temptation, standing up to ups and downs, weathering
humiliation, holding out the blow and preserving vitality. The core of the doer spirit is
to practice the law of value in the market by focusing, specializing and sticking to what
is determined to do. In short, the spirit of doer is the dedicated character of being
practical, deep-going, persistent, capable and excellent.

II. Roles of Doer Spirit
The spirit of doer accords with the inherent requirements of law of value and law
of competition. According to the principle of Marxist economics, SMEs run by doers
are commodity producers, while commodities are labor products for exchange, which
have two attributes of use value and value. The value of a commodity is determined by
the socially necessary labor time consumed in the production of the commodity.
Commodity exchange is based on the amount of value. The spirit of doer can promote
enterprises to improve production, management, labor productivity, and to reduce
individual working time in unit commodities, thereby improving the market
competition status and profit opportunities of enterprises.
The spirit of doer usually pursues the enterprising philosophy of "if others succeed
by exerting one ounce of effort, I will exert a hundred times as much effort". The
Doctrine of the Mean records: "If another man succeeds by one effort, he will use a
hundred efforts. If another man succeeds by ten efforts, he will use a thousand. Let a
man proceed in this way, and, though dull, he will surely become intelligent; though
weak, he will surely become strong. "Mr. Inamori once summarized the results of life
and career as a formula: the results of life or career = thinking mode * enthusiasm *
ability, in which the values of enthusiasm and ability range from 0 to 100 points, and
the values of thinking mode range from negative 100 to positive 100 points (-100,100).
Mr. Inamori believes that even people with ordinary abilities can be very successful as
long as s/he has a good way of thinking and devotes enough enthusiasm. Actually, from
the dynamic point of view, the spirit of doer will directly affect the two elements of

enthusiasm and thinking mode in the equation, and in the long run, it will also increase
the ability in the equation, thus promoting the doer to achieve sustainable success in
his career.
In terms of entrepreneurs' human capital, the doer spirit can make up for the
shortcomings of low educational background to a certain extent. After all, the practice
produces true knowledge and achievements. According to the analysis of the sampled
business documents, only 9 of the actual controllers of the guaranteed enterprises have
college or higher education, accounting for 30%, while the other 70% have education
of high school or below. In view of the especially historical and social background of
China at that time, Foshan entrepreneurs in their 50s generally have low educational
background, but entire period of actual operation since their start-up is 6-31 years,
averaging 16.5 years. Their long-term work in the industry has enabled them to
accumulate considerable experience and a certain scale of market and wealth.
In addition, doer spirit helps to accumulate social capital. The entrepreneur's
social capital is characterized by his/her personal attachment, and is the sum of the
network system, social reputation and trust centered on the entrepreneur's individual.
On the one hand, the spirit of doer can maintain, consolidate and expand the reputation
of entrepreneurs in the industry and in the region, and accumulate market social capital;
on the other hand, the spirit of doer can help entrepreneur establish and maintain
various (direct or indirect) links with government functional departments, and
accumulate institutional social capital. Social capital can provide enterprise with key
knowledge and resources, thus helping enterprise to integrate internal and external
resources, and to obtain development opportunities from the external environment. In
so doing, the doer spirit favors SMEs to gain competitive advantage and improve
enterprise performance and enterprise value.
4.2 Doer Spirit and Enterprise Value
I. Enterprise Value and Its Determinants
According to financial economics theory, enterprise value (EV) is the discounted
value of all future cash flows generated by the enterprise, which is expressed by
formula as follows: = =h⺁鳰 ,among them, t is the future time point, CFt is the
profit of t time, k is the discount rate, and ∑ is the summation sign. This formula
reveals four factors that affect the value of an enterprise: (a) the number of times of
earnings persistence (N), (b) the size of each return (CFt), (c) the discounted interest
rate (k) and, (d) the time-point distribution of earnings (t). Keeping other conditions
unchanged, the number of times (N) and the size of each return (CFt) are positively
associated with EV, and the discounted interest rate (k) and the time distribution (t)
positively associated with EV.
As a special creditor's right, the risk of financing guarantee is inversely
proportional to the value of the guaranteed enterprise. In other words, other conditions
remain unchanged, the greater the value of the guaranteed enterprise, the smaller the
possibility of default and the lower the risk of financing guarantee business; on the
contrary, the smaller the value of the guaranteed enterprise, the greater the possibility
of default and the higher the risk of financing guarantee business. Therefore, the
aforementioned four factors that determine EV will affect the risk of financing

guarantee business through the EV. According to this logic, the following chapters will
directly analyze the impact of the factors discussed on EV when discussing the credit
enhancement model of FGC. In theory, as long as the minimum boundary of the
guaranteed enterprise EV is far greater than 0, the guaranteed client has no motive for
breach of contract, and the financing guarantee business can achieve zero-loss.
II. Doer Spirit and Enterprise Value
i. Learning Curve Effect and Enterprise Value
1. Learning Curve Effect
Learning curve is a dynamic production function, which is first summarized in
the aircraft manufacturing industry. Dr. Wright of Cornell University (1936)
summarizes the experience of aircraft manufacturing and find that when the cumulative
output of aircraft doubled, the average working hours decreased by about 20%, that is
to say, to 80% before the output doubled. For the first time, the relationship between
average working hours and cumulative output is called learning curve. The learning
curve function can be described by the following models: y=
,Among them, y is the man-hour needed to produce unit x, k is the man-hour
needed to produce unit 1, and is the learning rate index, 0 < < 1. The above formula
can be visualized in Figure 4-1 below.
Learning curve effect is helpful to intuitively understand the economic meaning
of doer spirit from the aspect of cost. If there is an obvious learning effect in the
production process, the product cost will decrease with the increase of accumulated
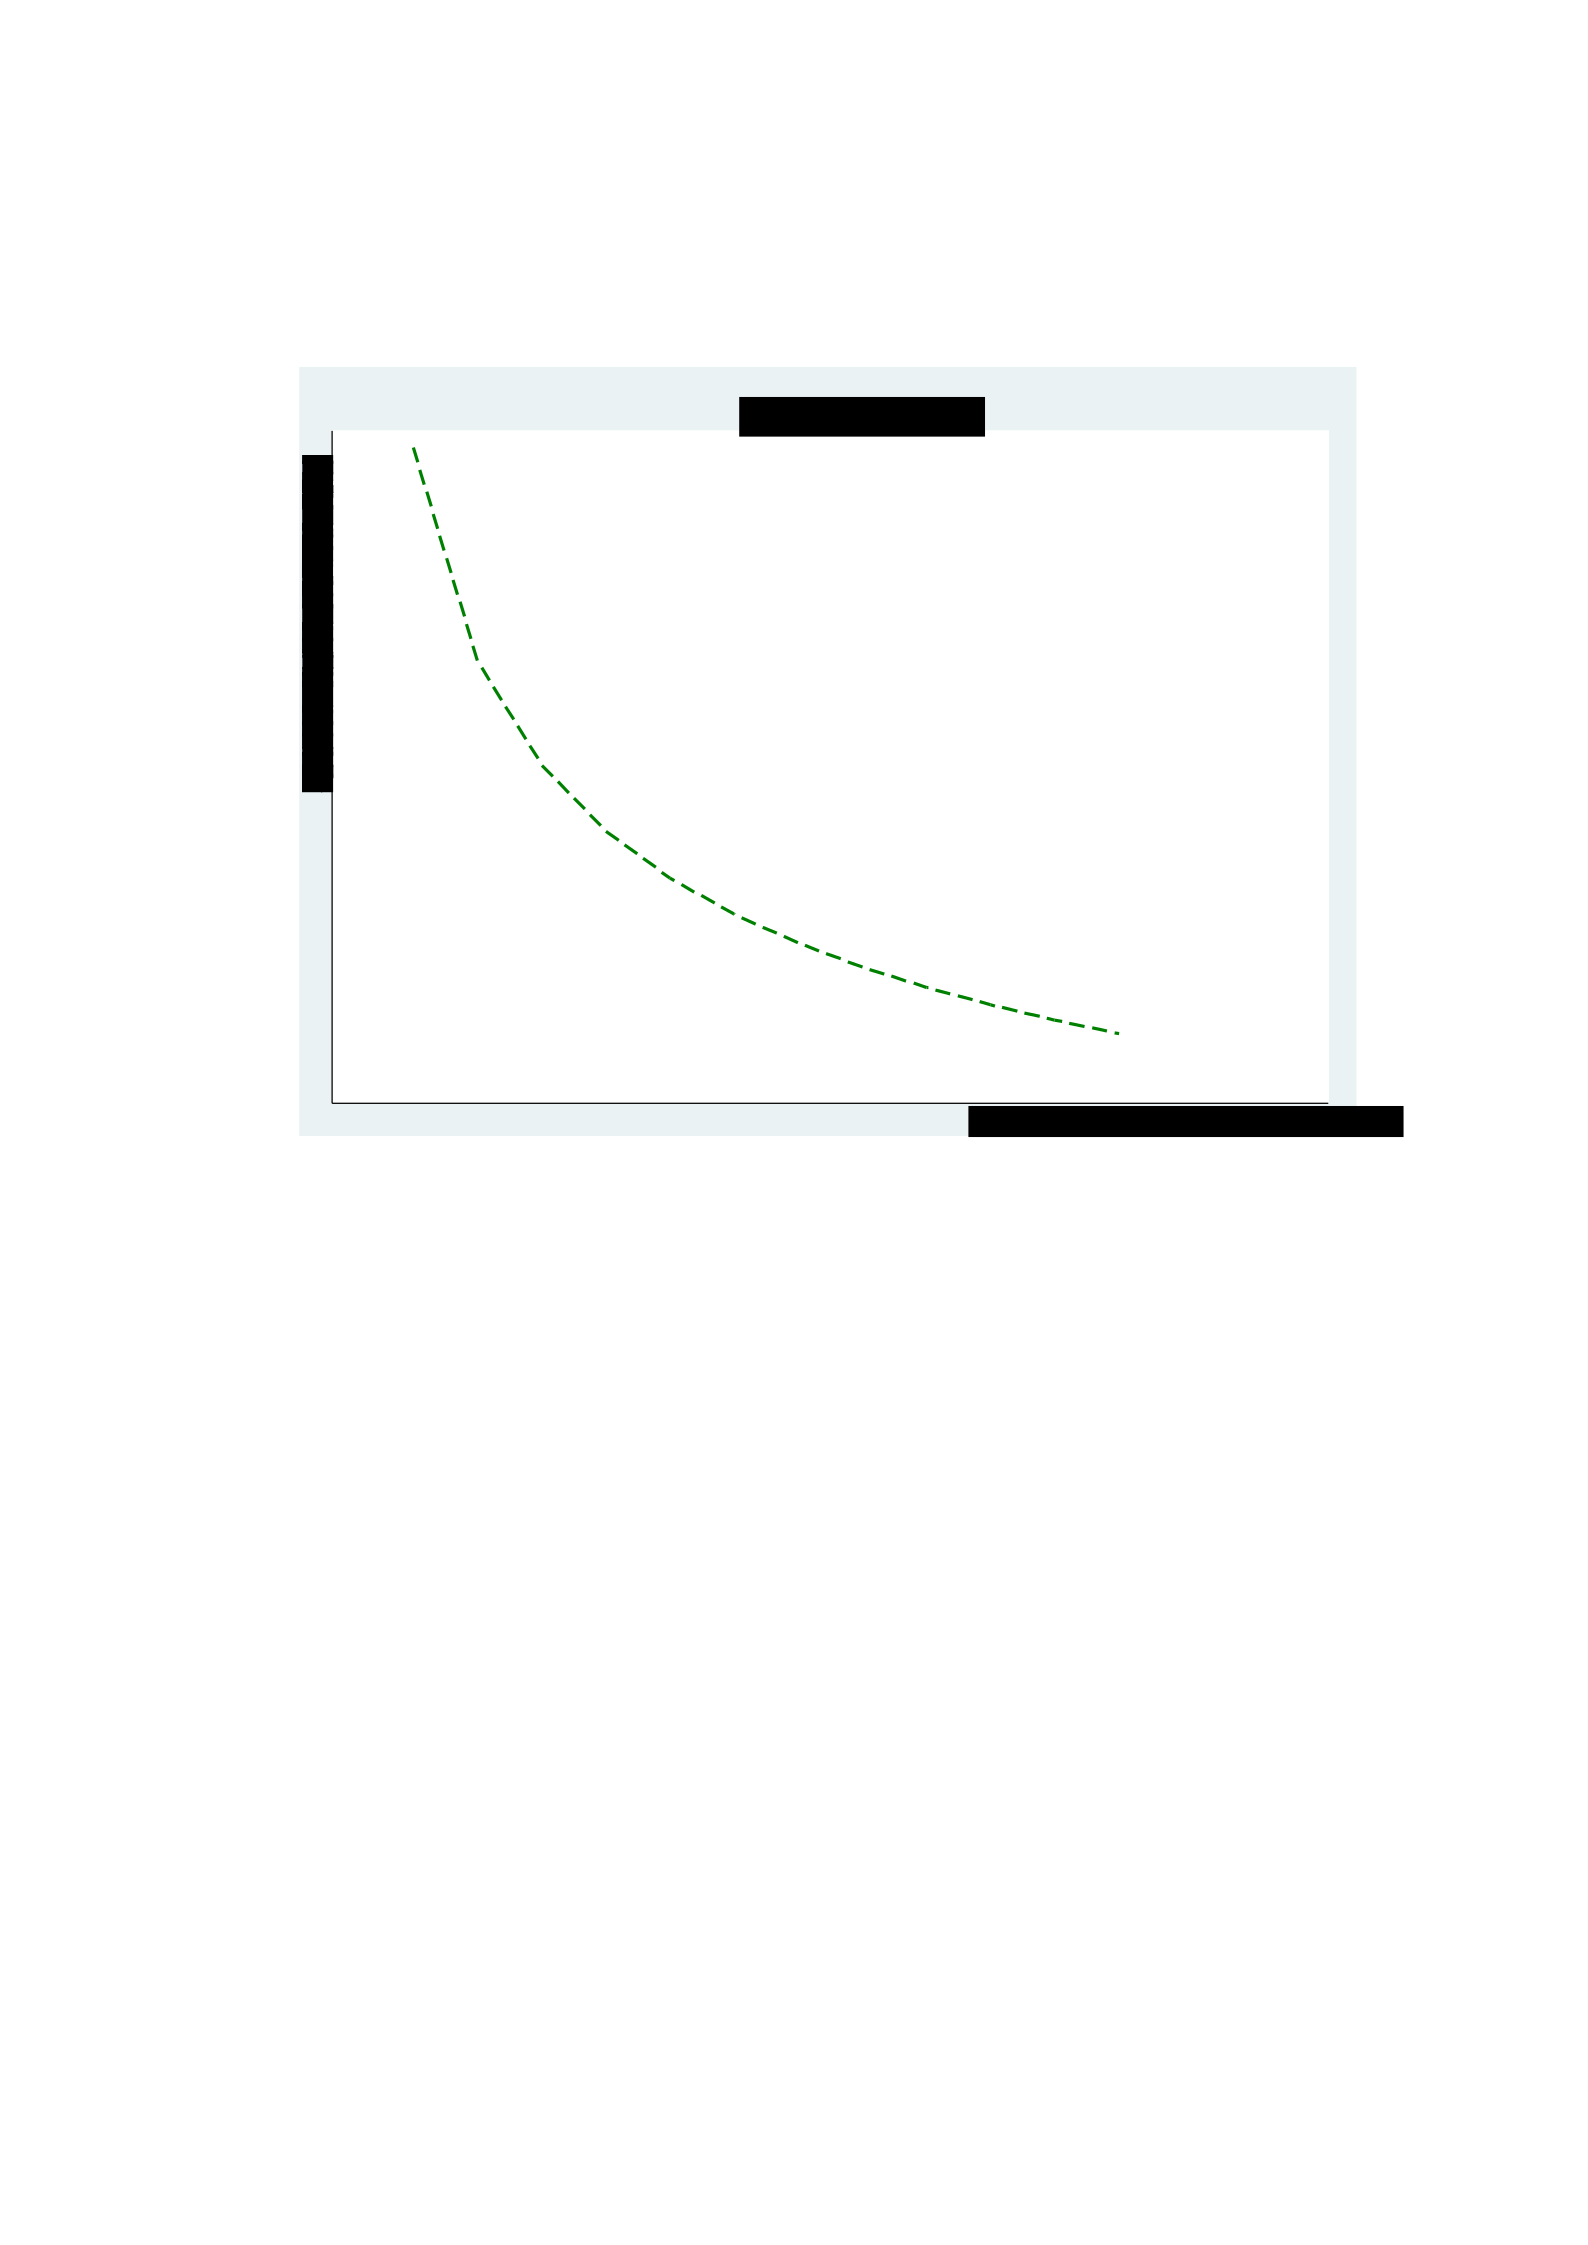
output, and then enterprise can use the learning curve to establish cost advantage and
competitive advantage by focusing and sticking to what is determined to do.
Figure 4-1 Learning Curve
Although the learning curve effect is summarized from the manufacturing
process, it can be easily extended to other activities involving skill accumulation and
knowledge accumulation. The learning curve effect brought about by concentration
and experience accumulation is not only reflected in reducing operating costs, but also
in expanding sales opportunities, optimizing sales markets and increasing sales
revenue, which ultimately results in the improvement of net profit of enterprise.
2. Learning Curve Effect and Enterprise Value
As before, the spirit of doer can ensure that enterprise and entrepreneur get
sufficient learning curve effect. The learning curve effect can enhance EV by
increasing the size of the return (CFt) and the number of times the return lasts (N) in
Learning Curve
Cumulative Production Quantity (x)
the enterprise valuation formula. The main mechanisms are as follows: (1) the spirit of
doer helps to expand revenues by learning curve effect; (2) the spirit of doer helps to
reduce average operating costs by learning curve effect; (3) the spirit of doer itself can
improve the number of net income perseverance.
If d is used to express the spirit of doer, substituting d into the formula of
enterprise valuation, we can get following formula:
䖘 = =0䖘 ⺁ 䖘 ,
⺁ 䖘 䖘
where, 0, 0, 䖘 䖘
Thus, 䖘 0,that is, the spirit of doer is conducive to improving EV.
䖘
ii. Social Capital and Enterprise Value
Social capital refers to the collection of social relations network of entrepreneur,
which plays the roles of resource grabbing and ability endowing. According to the
nature of social network, it can be divided into two categories: market-oriented social
capital and institutional-oriented social capital. Market-oriented social capital refers to
the social network established by entrepreneur and their main business partners (such
as middlemen-suppliers and strategic partners). Institutional-oriented social capital
refers to the societal networking among entrepreneur, government agencies and
industry authorities (such as industry, commerce, taxation and other government
administrative agencies, and trade associations, etc.).
The entrepreneur with the spirit of doer can accumulate not only abundant human
capital, but also extensive and profound social capital in the process of doing

businesses that they recognize as practical, deep-going, long-term, capable and
excellent. In the process of mutual promotion of human capital, social capital and
physical capital, the capability of doers to identify and capture market opportunities is
gradually improved, and the ability of enterprises to create and realize value is
constantly enriched, which ultimately leads to the enlarging EV.
According to the relationship between the risk of financing guarantee business
and EV, it can be inferred that: the spirit of doer is conducive to reducing
the risk of financing guarantee business.
4.2 Case Study of Doer Spirit and Enterprise Credit Enhancement
II. Background note
The asymmetric nature of return-risk of financing guarantee business determines
that the distribution of the successful cases versus the failure ones is also extremely
asymmetric. From the perspective of compensation rate indicator, the compensation
rate of Foshan financing guarantee during 2015 to 2017 were 3.16%,
1.77% and 2.00% respectively, which belonged to the typical small probability.
Compensation means that there is a problem in the financing guarantee business. If the
compensatory business is deducted from the entire business, it will be successful
business. From 2015 to 2017, the success rates of Foshan financing guarantee business
were 96.84%, 98.23% and 98.00%, respectively. Because successful cases play an
absolute dominant role in financing guarantee business, the failure ones are small
probability events. Because the distribution of successful samples versus failure ones
in financing guarantee business is severely asymmetrical, the commonly used

quantitative methods cannot be used to carry out regression analysis, in this instance
only case study method can be used.
In addition, considering the return-risk asymmetry of financing guarantee and the
principle of zero loss in business operation, it is more meaningful and feasible to select
typical cases from a limited number of failure business to focused research. Therefore,
the case studies in this chapter and subsequent chapters are all compensatory business,
i.e. failure cases. As far as the average situation of Foshan FGCs is concerned, the
number of guaranteed clients of each FGC is less than 200 per year, and the number of
failure business per year is less than 5. Whether from the perspective of each FGC or
the whole financing guarantee industry, the failure cases are more scarce and precious.
In view of the inherent requirement of the principle of zero loss in business operation,
failure cases are worth studying in order to fully and comprehensively draw lessons
from them.
II. Basic Situation of Guarantee Business Case
Mr. A, born in 1965, is the actual controller of YH Company. YH Company was
founded on July 30, 1996. Its registered capital was 1 million yuan, and Mr. A paid
700,000 yuan, accounting for 70% of the shares. The weaving business of YH
Company was under the responsibility of Mr. A, while hardware products business was
in the charge of the other shareholder. In 1997, the hardware business ceased
production and withdrew. The other shareholder did not participate in the management
of YH Company. Since then, the company only operated the weaving business, and its
actual controller was Mr. A. After the amendment of the Company Law in October

2005, in order to improve the organizational structure of YH Company, on September
3, 2006, the shareholders meeting passed a resolution, and the other shareholder
transferred all his shares to Mr. A, and the nature of the enterprise was changed to
limited liability company wholly owned by natural person. Mr. A continued to be the
executive director and his wife was the supervisor.
YH Company set up a new shoe factory at the end of 2010 and put into
production after the Spring Festival of 2011. Because shoe manufacturing involved
environmental protection approval and export licenses of new company, it was decided
not to set up new company, and continue to operate in the name of YH Company and
expand its business scope. In February 2012, HY Company was approved by the
Bureau of Industry and Commerce to change its business scope. Shoe factory was
closed in the second half of 2014. Because shoe market was depressed, the order of
shoe factory declined, and the cost of manpower increased, which caused the profit of
shoe factory to decline, Mr. A decided to stop the production and operation of the shoe
factory.
On September 5, 2011, Mr. A established HS restaurant, which operates in the
form of individual business. His wife was the individual operator and ran the catering
business, which was mainly featuring fish. Up to the time of applying for financing
guarantee, the average monthly revenue reached more than 2.8 million yuan, and HS
restaurant had about 150 employees. The monthly cost was composed of 450,000 yuan
of labor cost, 100,000 yuan of water and electricity cost, 60,000 yuan of tax and fee,

130,000 yuan of rent; and 45% of the revenue went to raw materials, totaling about 1.8
million yuan.
At the end of 2011, another limited liability company, HS Restaurant Co., Ltd.
(HS Company for short) was set up in another town's commercial complex, which
rented 1-3 storeys of the office buildings. HS Company invested 26 million yuan in
renovation, started trial operation at the end of 2012, and formally obtained a business
license on March 29, 2013, and had 50 waiters and 30 cooks. Mr. A. was the legal
representative and actual controller of HS Company. With the gradual expansion of
business, the original HS restaurant could no longer meet the daily business needs,
therefore the company and its Hong Kong partners re-upgraded the canteen and
planned to invest 12 million yuan. The initial investment of 5.5 million yuan was
funded by Hong Kong partner. Later, the partner applied for share withdrawal.
Therefore, the initial investment of 5.5 million yuan, together with half of the profit of
5 million yuan of the old HS restaurant, i.e. 2.5 million yuan, totaling 8 million yuan,
was returned to the Hong Kong partner.
In August 2016, YH Company applied to J Guarantee Company for loan
guarantee. The nature of the loan was working capital loan, the application amount was
2.7 million yuan, and the period was 12 months, agreeing to repay the loan in the
following manner: one-time repay 1 .7 million yuan, and equally repay the other
1 million yuan on monthly basis. At that time, the family assets and liabilities of 51-
year-old Mr. A were: real estate with appraisal value of 2.8448 million yuan; loans with
a total amount of 900,000 yuan and outstanding balance of 644,000 yuan.

And monthly repayment of 74,143 yuan went to micro-credit company. Loans from
micro-credit company were used to repay due loans from Z Bank at the beginning of
the year.
YH Company, the guaranteed enterprise, mainly dealt in the hosiery industry, and
most of its products were exported. After more than 10 years of development, it had
become a hosiery company with a certain scale and distinct product characteristics. By
2016, the company had more than 100 modern hosiery looms, and could independently
complete all hosiery weaving processes including knitting, stitching, setting, hot
stamping, finishing and packaging.
In credit assessment, J Guarantee Company considered that besides the real estate
of the actual controller (28,448,000 yuan) as counter-guarantee collateral, a batch of
machinery and equipment under YH Company's name had an appraised value of about
3 million yuan as counter-collateral; in addition, it provided land and ground buildings
to be subleased to the guarantee company with an appraised value of 5.07 million yuan.
The original lease contract was kept by J Guarantee Company and a batch of inventory
was used as collateral. The final credit rating was rated B, with a qualitative score of
64.49.
On August 31, 2016, J Guarantee Company signed a guarantee contract with YH
Company, which agreed to provide guarantee for YH Company to P Bank for a sum of
2.7 million yuan. On September 20, 2017, P Bank served "Notice of Performance of
Compensation" to J Guarantee Company. Because YH Company failed to repay the
principal and interest on the date of maturity of the loan, J

Guarantee Company was required to fulfill the guarantor liability in accordance with
the contract. J Guarantee Company repaid the principal and overdue interest of
2,210,186.43 yuan and 86,000.74 yuan on behalf of YH Company, totaling
2,296,187.17 yuan.
III. Controller's Doer Spirit Analysis
1. Every Cooperation Ends with the Withdrawal of Minority Shareholders.
The organizational form of a limited liability company provides a legal basis for
long-term cooperation between shareholders. In theory, as long as the relationship
among shareholders is harmonious and the business of the company is blameless, the
cooperative shareholders usually stick to the growth and development of the company.
However, due to numerous reasons, there are flaws in the relationship among
shareholders, and the minor shareholders eventually choose to withdraw from the
operation and shares. From the perspective of corporate information transmission, even
minor shareholders know more about inside information than external creditors. There
are two causes for minor shareholders to withdraw: voluntarily or forcibly.
If the minor shareholders withdraw voluntarily, it usually means that the business
prospects of the company or/and the major shareholders are not optimistic, and they
want to stop losses by the foot vote in time. If the minor shareholders are forced to
withdraw from the company, it means that the major shareholders have moral
problems. Therefore, whether minor shareholders voluntarily or forcibly withdraw
from the company, it is the very alert signal when evaluating the company and its actual
controllers. Especially when evaluating the creditworthiness of the actual controlling
shareholder, if each cooperation relationship ends with the ultimate departure of the

minor shareholders, it can be undoubtedly suspected that the personality of the
controlling shareholders is questionable. It's hard to imagine that an entrepreneur with
doer spirit will end up barren wherever s/he goes. Logically, if the minor shareholders
who cooperate with the actual controller end up with withdrawal or failure, it is
difficult to prevent the controller from taking opportunistic actions against the interests
of lenders and guarantors.
In the above case, Mr. A was the actual controller of YH Company. The
guaranteed enterprise was established in 1996 and the minor shareholder withdrew
from management in the following year (1997). Ten years later (2006), the minor
shareholder transferred all the shares of YH Company and the controller Mr. A wholly
owned YH Company.
At the end of 2011, Mr. A and his Hong Kong partner re-upgraded the restaurant,
and the initial investment of 5.5 million yuan was funded by Hong Kong partners. In
2013, the partner applied for withdrawal. Mr. A returned 5.5 million yuan of pre-
investment funds and half of the original HS restaurant's profits of 5 million yuan (2.5
million yuan) to the minor shareholder and ended the cooperative
relationship.
2. Lack of Focus and Cross-border Operation
In 2016, when applying for guarantee, YH Company, the guaranteed enterprise,
was mainly engaged in hosiery industry. Before or at that time, the actual controller
Mr. A tried many times to operate across borders. Mr. A had a severely opportunistic

mentality and lacked the necessary dedication and professionalism. YH Company set
up a new shoe factory at the end of 2010, which was engaged in production after the
Spring Festival of 2011 and closed in the second half of 2014. In September 2011, Mr.
A set up HS restaurant. In late 2011, he rented 1-3 floors of the office buildings in
another town to set up HS Restaurant company. He invested 26 million yuan in
decoration and began trial operation in late 2012. As of September 20, 2017, when Mr.
A defaulted, HS Restaurant and HS Restaurant Co., Ltd. all ended in failures.
According to the first section of this chapter, the spirit of doer is a kind of
dedicated character with the philosophy of " If others succeed by exerting one ounce
of effort, I will exert a hundred times as much effort". A doer will do things that are
recognized as practical, deep-going, long-term, capable and excellent as possible. In
this case, Mr. A had a completely speculative mindset. It is difficult to imagine that
such a person can begin well and end well. Whether dealing with interpersonal
relationships or business economy, he just tasted it and ended up fruitless.
Summary
The zero-loss-principle of financing guarantee requires that FGC should first
strictly screen clients in credit enhancement business, and systematically evaluate the
owners and actual controllers of guaranteed enterprise. According to the business files
of the China Success Guarantee Company, this chapter summarizes the assessment
factors in the credit enhancement model for the owner or actual controller as the spirit
of doer. Doers refer to those who pursue wealth and career through vigorous efforts
and stepwise stability. Typical groups of doers are usually well-managed small and

medium-sized business owners. The spirit of doer refers to the enterprising concept of
" If others succeed by exerting one ounce of effort, I will exert a hundred times as much
effort", which makes sure that the right things are done in a practical, deep, long-term,
capable and excellent way.
The spirit of doer can promote enterprise to do anything possible to improve
production, management, labor productivity, and to reduce individual labor time in unit
commodities, thereby to improve the position of the enterprise in the market
competition and profit opportunities. To a certain extent, the spirit of doer can make
up for the shortcomings of low educational background and realize the accumulation
of entrepreneur’s human capital. The spirit of doer helps to accumulate social capital.
Therefore, the doer spirit can directly improve the enterprise value through the learning
curve effect and the social capital accumulation effect. The increase in enterprise value
can reduce the credit risk of financing guarantee business. From the essential and long-
term point of view, the spirit of doer matches systematically with the zero-loss-
principle of credit enhancement business. Through the case study of Mr. A, the major
shareholder and controller of YH Company, this chapter verifies the principle and
mechanism of the spirit of doers reducing the credit risk of financing guarantee
business.
ChapterV Market Competitiveness and Enterprise Credit Enhancement
Firstly, this chapter analyses the implication of market competitiveness, and the
relation between market competitiveness and enterprise value. Secondly, the case study
of B Company shows that the enterprise market competitiveness can be measured

objectively and accurately by two indicators: customer concentration and net profit
margin.
5.1 Market Competitiveness and Enterprise Value
I. Meaning of Market Competitiveness
Market competitiveness means that enterprise provides the right goods or services
with the right quality at the right price on the right time. This means that the
competitive enterprise satisfies customer needs more efficiently and effectively than
others do. Usually in the competitory environment, only by relying on their own
resources or strategic advantages to provide products or services for the market, and
on the basis of optimizing and integrating the market and their own resources, can
enterprise form a market competitiveness characterized by market impact and market
power to achieve profits and sustainable development.
From the financial point of view, enterprise can reduce product cost and improve
product quality by refining production process and technological level, which not only
helps to increase market shares, but also benefits to improve sales profit margin. The
financial performance of enterprise market competitiveness is good sales trend and
high profit margin. In the same market, faced with similar customer groups, when
enterprise can win higher profit margins than others in the same industry, it means that
it has competitive advantages in the market. Generally speaking, the larger the market
share and the stronger the profitability, the stronger the market competitiveness. Hence,
market competitiveness can improve the
profitability, solvency and sustainability of the enterprise.

According to the 30 selected business archives, 8 of them have a clear evaluation
of the competitiveness of enterprises in the market: 6 of them have strong
competitiveness in the market, one has competitiveness in the market, and another has
been evaluated as having ordinary competitiveness in the market. The other 22 files do
not make a clear evaluation of market competitiveness. It can be seen that in practice,
market competitiveness evaluation is a relatively complex process. Only when the
relevant conditions are clear and sufficient, can the enterprise market competitiveness
be evaluated.
In the actual market competition, the development trend of the subdividing
industry has a direct impact on the enterprise market competitiveness. The enterprise
market competitiveness is closely related to market potential and market structure. For
FGC as outsider, market potential and market structure are easier to evaluate to some
extent. Among the 30 files selected, 15 have definite evaluation conclusions on the
market potential, 12 of them have positive evaluation on the market potential of
enterprises. They are commented with "fast growth", "good prospect", "rising trend",
"great potential", "great" and so on. In conclusion, only 2 files give the evaluation
conclusion of "overcapacity" and "transformation" respectively, while the other 15
materials do not give the conclusion of market potential. As for the evaluation of
market structure, 8 files have evaluation conclusion: 3 of them are competitive,
differentiated or uncertain, 5 of them are centralized and marketed; the other 22 files
don’t have evaluation conclusions.
II. Market Competitiveness and Enterprise Value
Because financing guarantee business is usually short-term business, the focus of
business evaluation is mainly on the impact of enterprise market competitiveness on
business income and profit in the short term, at the same time taking into account its
impact on enterprise value. Financial short-term analysis model is mainly cost-volume-
profit analysis model. According to this model, the enterprise market competitiveness
directly affects the unit price and sales volume in the short term, thus affecting
EBITDA and the net profit, and ultimately influencing EV. The model is constructed
as follows:
Supposing that in the relevant range, enterprise cost can be divided into two parts:
variable versus fixed. And fixed cost is expressed as a, and unit variable cost expressed
as b; assuming unit price is expressed as p, sales volume expressed as x, and sales
revenue expressed as y, then y = px; presuming that total cost function is c, then c = a
+ bx. Assuming that enterprise has market competitiveness, its products always have
market for sale and a balance between production and marketing can be achieved, that
is to say, its inventory level remains unchanged for a period of time.
The profit is π, and the model can be expressed as:
π=y-c=px-(a+bx)=(p-b)x-a (5-1)
According to Formula 5-1, the enterprise market competitiveness can act on profit
π through two variables of p and x, and derive the profit function to p and x,
respectively:
′
=x (5-2)
Form 5-2 reveals that if an enterprise with sufficient market competitiveness
increases its profits by raising its price, it can increase the EBITDA of x units per unit
of price increase, and the leverage effect of price increase on EBITDA is x. As shown
in Fig. 5-1, a price increase not only reduces the position of break-even point, but also
increases EBITDA in an equal proportion based on sales volume. See the shadow area
of the figure.
′
= (5-3)
Form 5-3 reveals that if a competitive enterprise increases its profits by expanding
its sales, the EBITDA of (p-b) units can be increased with each additional unit of sales
volume, and the leverage effect of expanding sales volume on EBITDA is p-b. In the
cost-volume-profit analysis model, p-b is called unit contribution margin (CM for
short), i.e. EBITDA increases with each additional sales volume. As shown in Figure
5-2, when sales volume increase from x0 to x1, EBITDA increases from EBITDA0 to
EBITDA1 with a leverage factor of p-b.
Figure 5-1 Impact of Price Rise on EBITDA

Figure 5-2 Impact of Expanding Sales on EBITDA If the other
conditions remain unchanged, the increase of EBITDA will
increase the net profit, that is to say, the numerator in the enterprise
valuation formula will rise, and thus EV will be increased.
According to the relationship between the risk of financing
guarantee business and EV, it can be inferred that: the enterprise
market competitiveness is conducive to reducing the risk of
financing guarantee business.
5.2 Case Study on Market Competitiveness and Credit Enhancement
I. Basic Situation of Guarantee Business Case
1. Status of the Guaranteed Enterprise
B Ceramics Company was founded in November 2006. In June 2007, natural
person Mr. H and natural person Mr. T invested 300,000 yuan respectively to acquire
all shares of the company, and each accounted for 50% shares. In November 2008, Mr.
H's cousin invested 300,000 yuan to acquire Mr. T's equity. Mr. T was a
registered shareholder and the real controller was Mr. H.
In 1990, Mr. H began to work in a ceramics factory in Nanzhuang Town of
Foshan, and engaged in the sales of ceramics and chemical raw materials from 1995 to
2003. In 2003, Mr. H went to Heshan to set up F Ceramics Company to engage in brick
production and marketing. F Ceramics Company closed its business in October 2009
due to other reasons. At the end of 2006, Mr. H acquired B Ceramics Company to
engage in brick polishing, processing and marketing.

In July 2008, it established Xinxing County Y Ceramics Company to engage in
brick production and marketing. Y Ceramic Company employed about 1000 people,
and the legal representative and actual controller was natural person Mr. H.
Another affiliated enterprise, Xinxing J Building Material Company was
registered and established on April 11, 2013. Its business scope was sales of building
materials, processing and sales of building ceramics, and its legal representative and
actual controller was Mr. H.
After nearly seven years of development, B Ceramics Company had three
polishing production lines, 40, 42, 48, respectively, with more than 300 employees.
Products were mainly high-grade dark Bratti polishing bricks. Because dark brick was
mainly used in decoration engineering and building materials, its market and sales
channels were stable, and were not affected by the real estate regulation policy.
Moreover, there were few competitors in the market of high-grade dark brick
subdivision in the industry, and its sales channel was more stable than others in the
same industry.
Compared with 2012, the ceramic industry showed signs of recovery in 2013, and
market orders increased. In order to adapt to the changing market demand, enterprises
produced white polycrystalline stone in 2013. The product structure was half of dark
brick and half of light brick. About 40% of B company's ceramics products were sold
abroad to the Middle East, Southeast Asia and other regions, mainly 600 dark Bratti.
For domestic sales, at that time, four brands had been
registered.

B Ceramics Company is essentially an industrial extension project added by the
actual controller, Mr. H, on the basis of managing Y Company ceramics brick
production. On the one hand, this "private polishing factory" could achieve new
economic benefits; on the other hand, it could solve the problem of quality degradation
through deep processing and polishing of brick billets with quality problems to
maximize current benefits. At that time, more than 90% of the bricks purchased by B
Company came from Y Ceramics Company.
For ceramic industry, the upgrading of production line and technical improvement
were the key to development. Starting in 2012, the company had completed two
polishing line equipment upgrading; and the remaining one had also been upgraded by
half. Through the renewal of equipment technology, the production efficiency and
product quality were improved, and the competitiveness of was further enhanced. In
2013, the actual controller Mr. H set up the second affiliated company in Xinxing
County. At that time, the first polishing production line was being ordered. It was
planned to relocate the production line of B Ceramics
Company to factories in Xinxing County one after another, and B Ceramics
Company had no investment plan.
2. The Process of Guarantee Business
B Ceramic Company was the old customer of J Guarantee Company, and the two
parties had been cooperating for 4 years. This business is a continuation. B
Ceramic Company applied for 10 million yuan guarantee to J Guarantee Company.

After credit rating, J Guarantee Company gave the applicant a good credit rating of BB
ratings and qualitative rating of 70.73.
On February 14, 2014, J Guarantee Company signed a guarantee contract with
B Ceramics Company, which stipulated that 7 million yuan of loans and other expenses
under the Working Capital Loan Contract signed by B Ceramics Company and Z Bank
would be guaranteed by J Guarantee Company. At the same time, it was agreed that if
the breach of contract of B Ceramic Company results in the compensation of J
Guarantee Company, it should repay the full amount of money to the J Guarantee
Company within three days from the date of compensation, as well as the interest and
penalty on the bank loan of the same period. In case of overdue liquidation, J Guarantee
Company had the right to collect liquidated damages from B Ceramics Company at
0.2% of the compensation amount per day from the date of
overdue liquidation.
At the same time, J Guarantee Company and B Ceramics Company, the two
affiliated enterprises, the actual controller, the affiliated enterprise shareholders signed
the "Maximum Counter-Guarantee Contract", which agreed that B Ceramics
Company provided machinery and equipment and existing and future inventory, and
the affiliated enterprise provided machinery and equipment as collaterals. A number of
real estates under the name of the actual controller and the shareholders of the affiliated
enterprises and the buildings of the guaranteed enterprise were mortgaged
to J Guarantee Company. On the same day, J Guarantee Company signed a

Guarantee Contract with Z Bank to undertake joint guarantee liability for the loan of
B Ceramics Company from Z Bank.
On February 19, 2014, Z Bank granted the loan of 7 million yuan to B Ceramics
Company. The borrowing period was 24 months, and the repayment method was to
repay according to the plan. It was agreed that the principal and interest should be
repaid on a quarterly basis starting from the sixth month.
On December 18 of 2015, December 21 and January 26 of 2016, Z Bank issued a
Notice of Claim for Compensation to J Guarantee Company. Because B Ceramic
Company could not repay the principal and interest of the matured loan, J Guarantee
Company was required to repay the principal and interest of the loan on behalf of B
Ceramic Company, totaling 2,022,001.23 yuan. J Guarantee Company repaid
202,2001.23 yuan to Z Bank on the same day.
After compensation, B Ceramics Company did not return the full amount to J
Guarantee Company as contracted. J Guarantee Company sued the guaranteed
enterprise, the affiliated enterprises and the actual controller and associated individuals
under counter-guarantee contract to the court. On May 18 of 2016, the court made a
default judgment:
Demanding that B Ceramics Company pay J Guarantee Company the
principal amount of compensation of 2,022,001.23 yuan, as well as interest, penalty
and liquidated damages; the actual controller, affiliated enterprises and affiliated
shareholders bear joint liability for the above debts; J Guarantee Company has
priority of claim in the collaterals under the counter-guarantee contract.

From February 22 to 23 of 2018, the court auctioned a house and three parking
spaces of collaterals. The total revenue from the auction is 5,738,080 yuan. So far, after
four years, the guarantee business was closed.
II. Market Competitiveness Analysis
1. Market Situation of Construction Ceramics Industry
Since the second half of 2010, great changes have taken place in the pattern of
China's ceramics industry. From the industrial base to the sales market, from brand
management to channel access, a new market pattern has taken shape. Since the state
promulgated energy saving and emission reduction policies in 2010, the governments
of Foshan, Shandong and other ceramics producing areas have implemented shutdown
and transfer of enterprises with high energy consumption and heavy pollution. The
large-scale migration of Foshan building ceramics had shocked the whole ceramic
industry.
As building ceramics industry has always been a labor-intensive industry, it has
always been unable to get rid of the ultimate destiny of relocating to poor areas. With
the rising costs of raw materials, energy, human resources, logistics, environment and
so on, the development of building ceramics industry in Guangdong coastal areas had
reached a limit. According to incomplete statistics, from March 2007 to the first half
of 2013, Foshan ceramics enterprises had migrated to the following areas: Qingyuan,
Deqing, Gaoyao, Gaoan, Fengcheng, Pingxiang, Jingdezhen and Jiujiang. The total
investment was over 25 billion yuan, the total area of the new plan was close to 40,000
mu (about 26,666,640 square meters) and there were more than 350 designed

production lines. In the process of northward migration, Qingyuan and Xinxing were
the earliest regions to undertake the transfer, and also the regions to take shape firstly
in emerging industrial bases.
Judging from the situation at that time (2013), the industry had gradually formed
a number of strong ceramic brands. Among them, Xinzhongyuan was unique scenery
in the field of polished tiles, Jinyitao was invincible in the field of antique tiles,
Dongpeng had successfully spanned the two fields of architectural ceramics and
bathroom, Wrigley led the trend in the field of bathroom, Huida was exceptional in the
field of bathroom export. And Xinmingzhu, Smick and Marco Polo, Oxonor,
Irvine, Nobel, etc., all were excellent brands.
2. Market Competitiveness Analysis
B Ceramic Company was commonly known as "Private Polishing Factory" in the
industry. It produced dark Bratti bricks and white polycrystalline bricks. Its mode was
similar to other polishing bricks factories. Brick billets are polished into polished
bricks through a series of polishing and grinding processes. After compressive strength
test and damage test, the finished products are packed out of the factory. After nearly
seven years of development, B Ceramic Company had three polishing production lines,
40, 42, 48 respectively, and had more than 300 employees. The products were mainly
high-grade dark polished Bratti bricks. Because dark bricks were mainly used in
decoration engineering and building materials, their market and sales channels were
stable, and they were not affected by real estate regulation policies.

There were few competitors in the market of high-grade dark brick sector in the
industry, and its sales channel was more stable. In 2013, the ceramic industry showed
signs of recovery and market orders increased. In order to adapt to the changing market
demand, the company produced white polycrystalline stone. The product structure was
half of dark brick and half of light brick. In 2012, the company realized sales revenue
of 252.12 million yuan and net profit of 12.92 million yuan. By August 2013, it had
realized sales revenue of 158.48 million yuan and net profit of 7.7 million yuan.
About 40% of the products of B Ceramics Company, mainly 600 dark Bratti, were
sold to the Middle East, Southeast Asia and other regions. For domestic sales, four
brands had been registered. The company had carried out general contracting sales on
these brands, and introduced powerful distributors as their general agents for external
sales. More than 90% of the bricks purchased by B Ceramics Company came from the
affiliated enterprise of Y Ceramics Company. The settlement method was prepaid, and
the bills of promissory notes were paid for 2 months after the bricks were shipped.
Both sides had fair purchasing price and independent accounting. They were closely
related to each other to ensure timely supply of bricks and billets.
In 2012, the company's top four sales customers were all natural persons. Their
total sales volume and sales revenue were 387,000 square meters and 232,870,000
yuan, respectively. The top four sales accounted for 92.4% of the sales volume of B
Ceramics Company. The top four customers’ sales accounted for 33.11%, 27.68%,
17.42% and 13.84% of sales respectively. The high customer concentration reflected
that the sales channel was too single and the market competitiveness was weak. After

all, for the enterprise in building ceramics industry with low industry concentration,
the profit division between suppliers and distributors was inconsistent. In order to
maximize their profits, the distributors with market power would inevitably depress
the prices and profits of the suppliers.
Referring to the financial statements provided by B Ceramic Company from 2011
to 2013, the net profit margins of sales, as the final result of the market
competitiveness, were 5.23%, 5.12% and 4.76% respectively. The minute and
deteriorating net profit margin reflected the weak market competitiveness of B
Ceramic Company.
Summery
Market competitiveness means that enterprise provides the right goods or services
with the right quality at the right price on the right time. Market competitiveness means
that enterprise meets the customer needs more efficiently and more effectively. Market
competitiveness can improve the profitability, solvency and sustainability. Competitive
enterprise, whether by raising prices or expanding sales, can improve EBITDA,
thereby improve the short-term solvency and reduce the risk of financing guarantee
business. Most financing guarantee businesses are short-term, and market
competitiveness can significantly improve the short-term performance indicators,
therefore market competitiveness and the zero-loss-principle of credit enhancement
business form a key match. Through the case analysis of B Ceramics Company, it is
found that the enterprise market competitiveness can be measured objectively and
accurately by two indicators of customer concentration and net profit margin.

Chapter VI Technology Suitability and Enterprise Credit Enhancement
6.1 Technology Suitability and Enterprise Value
I. Meaning of Technical Suitability
From an economics point of view, technology refers to the means of converting
input into output in the production process, including hard technology (means of labor)
and soft technology (design, manufacturing methods, technical information). Technical
suitability is the organic unity of technological advancement and economic efficiency.
Technology is a means to improve economic benefits, and the purpose of developing
technology is to improve economic benefits. To achieve the unity of technological
advancement and economic efficiency, that is, to improve technological suitability is
the fundamental direction when enterprises choose or develop technology.
Technological suitability is the physical basis for linking doer spirit and market
competitiveness. In order to give full play to the role of doer spirit, it must be put into
practice on technology suitability and technology most suitable for enterprise
environmental conditions. Market competitiveness will not arise out of thin air. Its
realistically solid basis is the enterprise technology suitability.
According to the files of guarantee business, the items of evaluating technical
suitability mainly include technical equipment, quality management, technical
certification and management level. As for technical equipment, 18 out of 30 files have
definite evaluation conclusions, including "advanced" (15), "breakthrough" (1),
"complete" (1), "high-tech" (1); the remaining 12 do not have any conclusion. As for
quality management and technical argumentation, 15 out of 30 files have definite

conclusions, which are "conformity" (11), "medium" (1), "specification" (1), "more
than 30 patents" (1), "brand value" (1). The remaining 15 files don’t have any
evaluation conclusion. As for the management level, 21 of the 30 files have clear
conclusions, which are "normative" (6), "normal" (3), "medium" (1), "robust" (2),
"efficient" (2), "advanced" (5), "skilled" (1), "main research, development and sales,
manufacturing outsourcing" (1).
II. Technical Suitability and Enterprise Value
According to the basic principles of technological economics or engineering
economics, enterprises should evaluate the economic effect of each technology project
they choose. The technological project will be adopted when its net present value
(NPV) is greater than zero or when the highest internal rate of return (IRR) is achieved.
Selecting the technology project of which the financial net present value is positive
and maximized means that the technology project can contribute the maximized value
to enterprise value (EV). Because the method of evaluating the technology suitability
is completely consistent with the method of evaluating the enterprise value, the
technological suitability is directly unified with EV maximization. In theory, enterprise
value is the sum of the net present value of all technological projects. For FGC, each
client-enterprise can be regarded as a technology project, and the potential enterprises
can be screened according to the principles and methods of engineering economics for
screening technology projects, so as to provide impartial basis for credit risk
assessment and financing guarantee business decision-making.

Enterprise operation activities are inseparable from capital investment and labor
investment. Under the new normal conditions of China's economy, the suitable
technology can improve the return on assets (ROA) and the wage level of employees
from the perspective of business performance. Return on assets measures how much
net profit is generated from one unit of assets. The formula is: return on assets = net
profit after tax / total assets. The higher the return on assets, the better the effect of
asset utilization, indicating that the enterprise has achieved decent results in increasing
income and saving the use of funds, and vice versa.
In competitive labor market, the wage level directly reflects the quality of
employees. Generally, with the updating of technological equipment and the
improvement of technological level in enterprises, low-quality workers tend to be
replaced by machines. When the number of high-quality workers who operate
advanced machinery and equipment increases and that of high-quality workers
decreases, the proportion of high-quality workers will increase. In addition to the long-
term trend of rising wage level in China, technologically suitable enterprise can
provide higher salary for their employees. Therefore, the return on asset and wage level
are the two basic indicators to measure enterprise technology suitability.
6.2 Case Study on Technology Suitability and Credit Enhancement
I. Basic Situation of Guarantee Business Case
1. Basic Situation of C Clothing Company
C Clothing Company (C Company for short) was established in January 2004.

It mainly produced and managed various kinds of knitted clothing products. Actual
Controller Mr. L, diligent and willing to specialize, in 1996, when he had one-year
apprenticeship experience in garment craft factories after graduation from middle
school, tried to run garment factory. In the early days of its establishment, due to the
lack of in-depth understanding of the garment industry, C Company once fell into a
slow stage of development. To make up for its shortcomings, Mr. L stationed in
garment factory day and night, from a layman to C company's chief designer and
testing officer. Since its establishment, C company had been growing steadily in the
fierce market competition with its indomitable pioneering spirit. Especially after 2011,
advanced JIT single-piece production line and hanging equipment had been introduced
to ensure better product quality and delivery time.
Company C enjoyed a high reputation among its peers. After a good pace of
adjustment, the company had obtained IS09001 quality system certification with
strong technical force and standardized operation process. At the same time, it had won
the favor of domestic and foreign brands. Yishion, Zhenweisi, Birchmei, Beibei
Bear, 361, Delphi and so on are its main partners, among which Yishion and Baiqimei
account for more than 50% of all orders of C Company. Having a fixed sales channel
did not stop the pace of its progress, C company continued to introduce a number of
semi-automatic equipment, in order to ensure the quality of the premises of further
shortening the delivery period, and further expand the production scale.
C Company had developed from a small workshop with only a dozen people to
a private enterprise with more than 300 people. In addition to having good production
technology and sales channels, it was also closely related to the innovative and

forward-looking thinking of managers. Firstly, the company paid attention to effective
communication between management and grass-roots level, realizing that the grass-
roots feedback could help enterprise correct errors in time; secondly, the company
attached great importance to the training of staff skills, and carried out a series of
training courses from time to time, so that employees could better adapt to their own
work. C Company's performance was relatively stable, in the medium position in the
same industry. Especially in 2011, the introduction of new computer equipment,
effective decomposition process, and control production speed, offset the regret of
slowing the process due to lack of skilled craftsmen.
After China's economy entered a new normal, young people willing to work in
factories were becoming more and more difficult to recruit. Enterprises once fell into
a situation of shortage of manpower. They clearly had endless orders, but had to cancel
them. In view of this situation, Mr. L, the actual controller, believed that only by
constantly replacing manpower with machines could the enterprise have long-term
development. So C Company planned to continue to introduce semi-automated
equipment, in addition to the original four automated production lines, it was estimated
that 50-100 employees could be saved.
Furthermore, due to the buyer's settlement period of 30-60 days, and garment
manufacturing industry needed a large amount of capital to be prepare, once the capital
chain was broken, the company would fall into the awkward situation of prolonging
the supply period. As a result, in July 2012, the company borrowed a working capital

loan amounted 3 million yuan from local financial institutions for a period of two years,
mainly to supplement the liquidity.
From the domestic demand of the industry, by the end of 2012, with the
stabilization of China's economy, the growth rate of domestic garment sales had
rebounded gradually. According to China Garment Association's understanding of
some garment enterprises order meeting in spring and summer of 2013, due to the
slowdown in demand, the willingness of agents to order declined, and the total order
volume was generally lower than expected. In the second half of 2013, with the
recovery of the economy and the gradual improvement of consumption stimulus
policy, domestic garment consumption would also show a gradual upward trend.
Three-year enterprise data show that sales revenue increased by 15.7741 million
yuan in the same period of 2012 compared with 2011, an increase of 21.5%, and net
profit increased by 35.3 million yuan, an increase of 0.8%. The large increase in sales
revenue had not caused a significant increase in net profit. Firstly, the main reason was
that the price of raw materials and the cost of labor increased, which led to the increase
in sales cost. Secondly, because the profit margin of the apparel industry was generally
not high, small profits and more sales were the usual methods used by many
enterprises. The comprehensive financial indicators were still within the normal range.
Clothing industry belongs to labor-intensive industry. In 2013, the number of
employees in C Company was 292-301, with the average wage ranging from 2716.7
to 3239.6 yuan per capita per month. In 2013, the minimum wage in Foshan was 1310
yuan, and the average wage of on-the-job employees was of 4196 yuan. It could be

seen that C company was facing a difficult choice: there was no room to depress the
wages, because it had already faced the situation of difficult recruitment; the machine
replacement scheme would consume a lot of investment, fixed cost would be raised
after a substantial increase in operating leverage, and the sales volume and sales
revenue at the break-even-point would increase rapidly.
Mr. L, the actual controller, also had an associated enterprise, JC Glass Machinery
Company. JC Glass Machinery Company, founded on June 6, 2008, was a sole
proprietorship company. The company mainly produced glass edge grinders, and the
models produced were all general purpose machines. Therefore, the company could
prepare materials before they received orders, and the process of
preparing materials required sufficient liquidity.
According to the information provided, the main business revenue in 2010 was
15.89 million yuan, and the net profit was 2.48 million yuan; in 2011, the main business
revenue was 19.83 million yuan, and the net profit was 2.93 million yuan; in 2012, the
main business income was 31.27 million yuan, and the net profit was
4.42 million yuan.
2. The Process of Guarantee Business
In June 2013, C Company filed a loan guarantee application to J Guarantee
Company. The application amounted 10 million yuan and the period was 36 months.
The repayment methodwas to repay the principal as
planned (paying interest monthly, repaying the principal in the first year
was 2 million yuan, repaying 500,000 yuan quarterly; repaying the remaining 4 million

yuan in the second and third year respectively, namely repaying 1 million yuan
quarterly for the last two years). After credit evaluation, on July 25, 2013, J Guarantee
Company gave C Company a BBB rating with good credit and a qualitative score of
78.86. It agreed to provide guarantee for C Company to apply for liquidity loan of 10
million yuan from
Z Bank. The guarantee fee was calculated at 6% of the guaranteed amount, as was
600,000 yuan.
On September 25, 2013, J Guarantee Company and C Company signed the
Guarantee Contract, which stipulated that J Guarantee Company would provide joint
guarantees for loans of 10 million yuan and other expenses under the Working Capital
Loan Contract signed by C Company and Z Bank on September 25, 2013. If the default
of C Company resulted in the compensation of J Guarantee Company, C Company
should repay the full amount of money to J Guarantee Company within three days from
the date of compensation, as well as the interest and penalty on the bank loan of the
same period from the date of compensation. In case of overdue liquidation, J Guarantee
Company had the right to collect liquidated damages from C Company at 0.2% of the
compensation amount per day from the date of overdue liquidation. On the same day,
J Guarantee Company signed a Guarantee Contract with Z Bank to provide joint
guarantee liability for the loan of C Company. On October 8 of the same year, Z Bank
granted a loan of 10 million yuan to C Company.

In order to protect rights and interests, J Guarantee
Company signed the following counter-guarantee contracts with the
actual controllers and other stakeholders of C Company:
(1) On September 25, 2013, J Guarantee Company
signed the
"Counter-guarantee Contract" with C Company and five shareholders, which agreed
to provide joint liability guarantees for the debts of C Company to J Guarantee
Company;
(2) On September 25, 2013, signed the "Maximum Counter-Guarantee Contract"
with the actual controller and his spouse, and agreed to mortgage four shops and five
parking spaces under their name to J Guarantee Company, which had been registered
for mortgage;
(3) on September 17, 2013, signed the "Maximum Counter-Guarantee Contract"
with C Company, which stipulated that C Company should mortgage its existing and
future inventories to J Guarantee Company;
(4) on October 30, 2014, signed the Contract of Maximum Counter-Guarantee
with C Company, which stipulated that C Company would provide J Guarantee
Company with the Maximum Counter-Guarantee Mortgage for the batch of machinery
and equipment under its name, and had already registered the mortgage;
(5) On October 30, 2014, signed the Contract of Maximum Counter-guarantee
with the actual controller and his spouse, which stipulated that two of them would
mortgage their real estate to J Guarantee Company;

(6) On September 25, 2013, signed a "Maximum Counter-Guarantee Contract"
with Company C, stipulating that the existing and future accounts receivable and other
accounts receivable generated by the production and operation of C Company within
the next five years from the date of issuance of the loans referred to in the contract
would provide counter-guarantee to J Guarantee Company, and the
registration had been completed.
On June 5, 2015, Z Bank issued a Notice of Claim for Compensation to J
Guarantee Company, requesting J Guarantee Company to compensate the borrowing
principal of C Company amounted 890,430.69 yuan and the fine interest of 3,623.56
yuan, totaling 894,054.25 yuan. J Guarantee Company compensated Z Bank the
amount on the same day.
According to the counter-guarantee contract, if the recovery is failed, J Guarantee
Company would sue the parties of the counter-guarantee contracts to the court. On July
9, 2015, the court rendered a default judgment:
(1) C Company should repay the principal of compensation and interest, penalty
and liquidation damages to J Guarantee Company within three days from the effective
date of this judgment; (2) Other guarantors under the
counter-guarantee contract should bear joint liability for the above-mentioned debts;
(3) J Guarantee Company, as the first creditor, had the priority right to be repaid for
the price of the collateral (the current assets of shops, garages, houses, affiliated
enterprises, machinery and equipment of C Company and accounts receivable) after
discount, auction or sale.

After the judgment comes into effect, the execution process of the judgment
becomes tortuous. On May 26, 2017, the court received an execution objection from
the outsider LYZ, who believed that he had acquired 20% of the property rights of the
mortgaged property. The court's auction of the property damaged his legitimate rights
and interests. On May 23, 2018, the outsider filed suits in the Intermediate Court.
Finally, on July 19, 2018 and February 25, 2019, the court issued notice of the auction
of the mortgaged shops respectively. On December 31, 2018, some collateral
(parking spaces, shops) began to be auctioned online, with a total amount of
3,998,890 yuan. The guarantee business started in June 2013 and ended in March 2019.
It had spanned six years and gone through many setbacks. This profoundly shows that
the occurrence of compensation and breaking the zero-loss-principle is undoubtedly a
nightmare for FGCs.
II. Technology Suitability Analysis
1. Hardware Equipment
As shown in Table 6-1, in 2013 C Company had 816 machines and equipment of
various types, with a total value of more than 71.0 million yuan. According to the
relevant announcement of the Market Supervision and Administration, the 816
machines and equipment were registered as mortgages on October 30, 2014, and the
mortgagee was J Guarantee Company. From the aspect of purchasing unit price, the
highest price of a single piece of equipment was 35,000 yuan. Background information
showed that all equipment did not have invoices, at least it could be explained that
there were no invoices when purchasing equipment, or the invoice management was
not prudent. Regardless of which case, it showed that the company did not attach
enough importance to machinery and equipment management. The low value of
machinery and equipment and insufficient attention easily led to the lag of hardware
and equipment technology and the development hindrances. After introducing the new
computer equipment in 2011, the company continued to introduce semi-automation
equipment in the second half of 2013. The fact proved that this kind of passive
adjustment to the problem of rising labor costs and difficulty in recruiting workers on
hardware equipment was too late.
Table 6-1 Hardware Equipment List of C Company (2013)
No.
Hardware Equipment
Quantity
Unit price
(yuan)
Total value (yuan)
1
Hang System
150
19,600
2,940,000
2
Computerized flat car
356
4,300
1,530,800
3
Cart Style-1
84
13,500
1,134,000
4
Cart Style-2
115
5,500
632,500
5
Double needle car
10
5,000
50,000
6
Double Needle Chain Bottom
6
3,000
18,000
7
Knife cart
6
2,490
14,940
8
Zigzag Sewing Machine
15
2,500
37,500
9
Five-lane Car
5
6,500
32,500
10
Third-lane car
2
5,500
11,000
11
Double Needle and Trouser Head Car
10
13,800
138,000
12
Button Car
8
6,500
52,000
13
Knob Car
4
30,000
120,000
14
Injection truck
8
600
4,800
15
Jujube cart
5
28,000
140,000
16
Zhanggen Car
2
20,000
40,000
17
Paper press
1
29,990
29,990
18
Wire blower
3
5,000
15,000
19
Needle tester
1
35,000
35,000
20
Cloth inspecting machine
2
28,000
56,000
21
Loosening machine
3
11,000
33,000
22
Hot bed
20
2,000
40,000
summation
7,105,030
Source: J Guarantee Company Guarantee Business Survey Report.
2. Management Technology
Financial management lost efficacy. The idea of borrowing short-term debt to
support equipment-update in the context of continued declines in return on asset
(ROA) was wrong in itself. According to the data, the ROA of C Company in 2011 was
23.9%, which dropped to 11.0% in 2012. The downward trend of C Company in 2013
was not meaningfully improved. Given the high financing costs of SMEs, in the case
of declining ROA, enterprises should have acted prudently and could not easily borrow
and increase financial leverage. The graver mistake was that C Company intended to
add automation equipment with part of short-term loans. This mismatch strategy of
"short-term borrowing and long-term using" easily led to bankruptcy due to the
breakdown of funds chains once the company ran into some unfavorable shocks.
Outsourcing management was backward. C Company took most of orders for
their own production. Generally, about 30% of the orders needed to be outsourced in
summer. According to the owner, Mr. L, it was difficult to control the quality of
outgoing parts. Some manufacturers were unwilling to assume after-sales
responsibility, resulting in the re-processing of returned parts, which wasted both
resources and time. Therefore, the company planned to increase production capacity
and reduce outsourcing.

Personnel management failed. C Company was charged with unprovoked arrears
in the remuneration of eight employees in August 2015. C Company refused to attend
the lawsuit without justifiable reasons, and the court made a default judgment: C
Company should pay 86,380 yuan of wages owed to the eight plaintiffs; C Company
should pay 12,9880 yuan of economic compensation for the termination of labor
relations with the two plaintiffs; and C Company should bear the litigation expenses.
3. Indicator Evaluation
The return on assets of C Company was 23.9% in 2011, 11.0% in 2012 and 9.9%
in the first five months of 2013, showing a continuous declining trend. The average
wage in March 2013 was 3239.6 yuan, which was basically the same as the average
annual wage of urban private sector employees in China in 2013 (32706 yuan). This
indicated that most employees were ordinary workers with low technical
literacy.
Summary
Technology is a means of converting input into output in the production process.
Achieving the unity of technological advancement and economic efficiency is the
fundamental direction when enterprises choose and develop technology. Technical
suitability is the physical basis of connecting doer spirit and market competitiveness.
According to the basic principles of technological economics or engineering
economics, enterprise should evaluate the economic effect of each technology project
they choose. In theory, enterprise value is the sum of the net present value of all

technological projects of the enterprise. Therefore, technology suitability and the
maximization of enterprise value are directly unified.
Under the new normal conditions of China's economy, the technology suitability
can improve the return on assets and the wage level of employees from the perspective
of business performance. Return on assets and wage level are two straightforward
indicators to measure the technological suitability. Through the case study of C
Company, it is found that enterprise without technology suitability displays signs of
imbalance in many aspects of machinery and equipment, financial management,
personnel management, outsourcing management. The imbalance directly increases
enterprise vulnerability and risk level. The ultimate consequences of technology
imbalance are the reduced return on assets and low average wage

level.

Chapter VI Concluding Remarks and Research Prospects
7.1 Concluding Remarks
Under China's current financial system, which is dominated by indirect financing
and creditor's rights financing, combining with underdeveloped social credit system
and imperfect credit risk management instruments, SMEs financing is very difficult.
Financing guarantee can alleviate the SMEs financing problem to a certain extent, and
it has the nature of quasi-public service. At present, China defines financing guarantee
as profit-making business and encourages private capital and private enterprises to
develop financing guarantee business. Private financing guarantee company (FGC)
must strictly follow the zero-loss-principle to carry out business, otherwise they will
not survive.
The principle of zero loss essentially requires the financing guarantee company to
give special attention to the key value driving factors of client-enterprises, such as
human factors, market competition factors and technological factors. Combining with
the business cases of China Success Guarantee Company, this paper summarizes the
above three factors as doer spirit, market competitiveness and
technology suitability.
As shown in Figure 7-1, the principle of zero loss is the core of financing
guarantee business, while the spirit of doer, market competitiveness and technology
suitability are the realistic assurance of implementing the principle. Among them, the
spirit of doer is the commander-in-chief, technology suitability is the means, and
market competitiveness is the driving force and guidance.
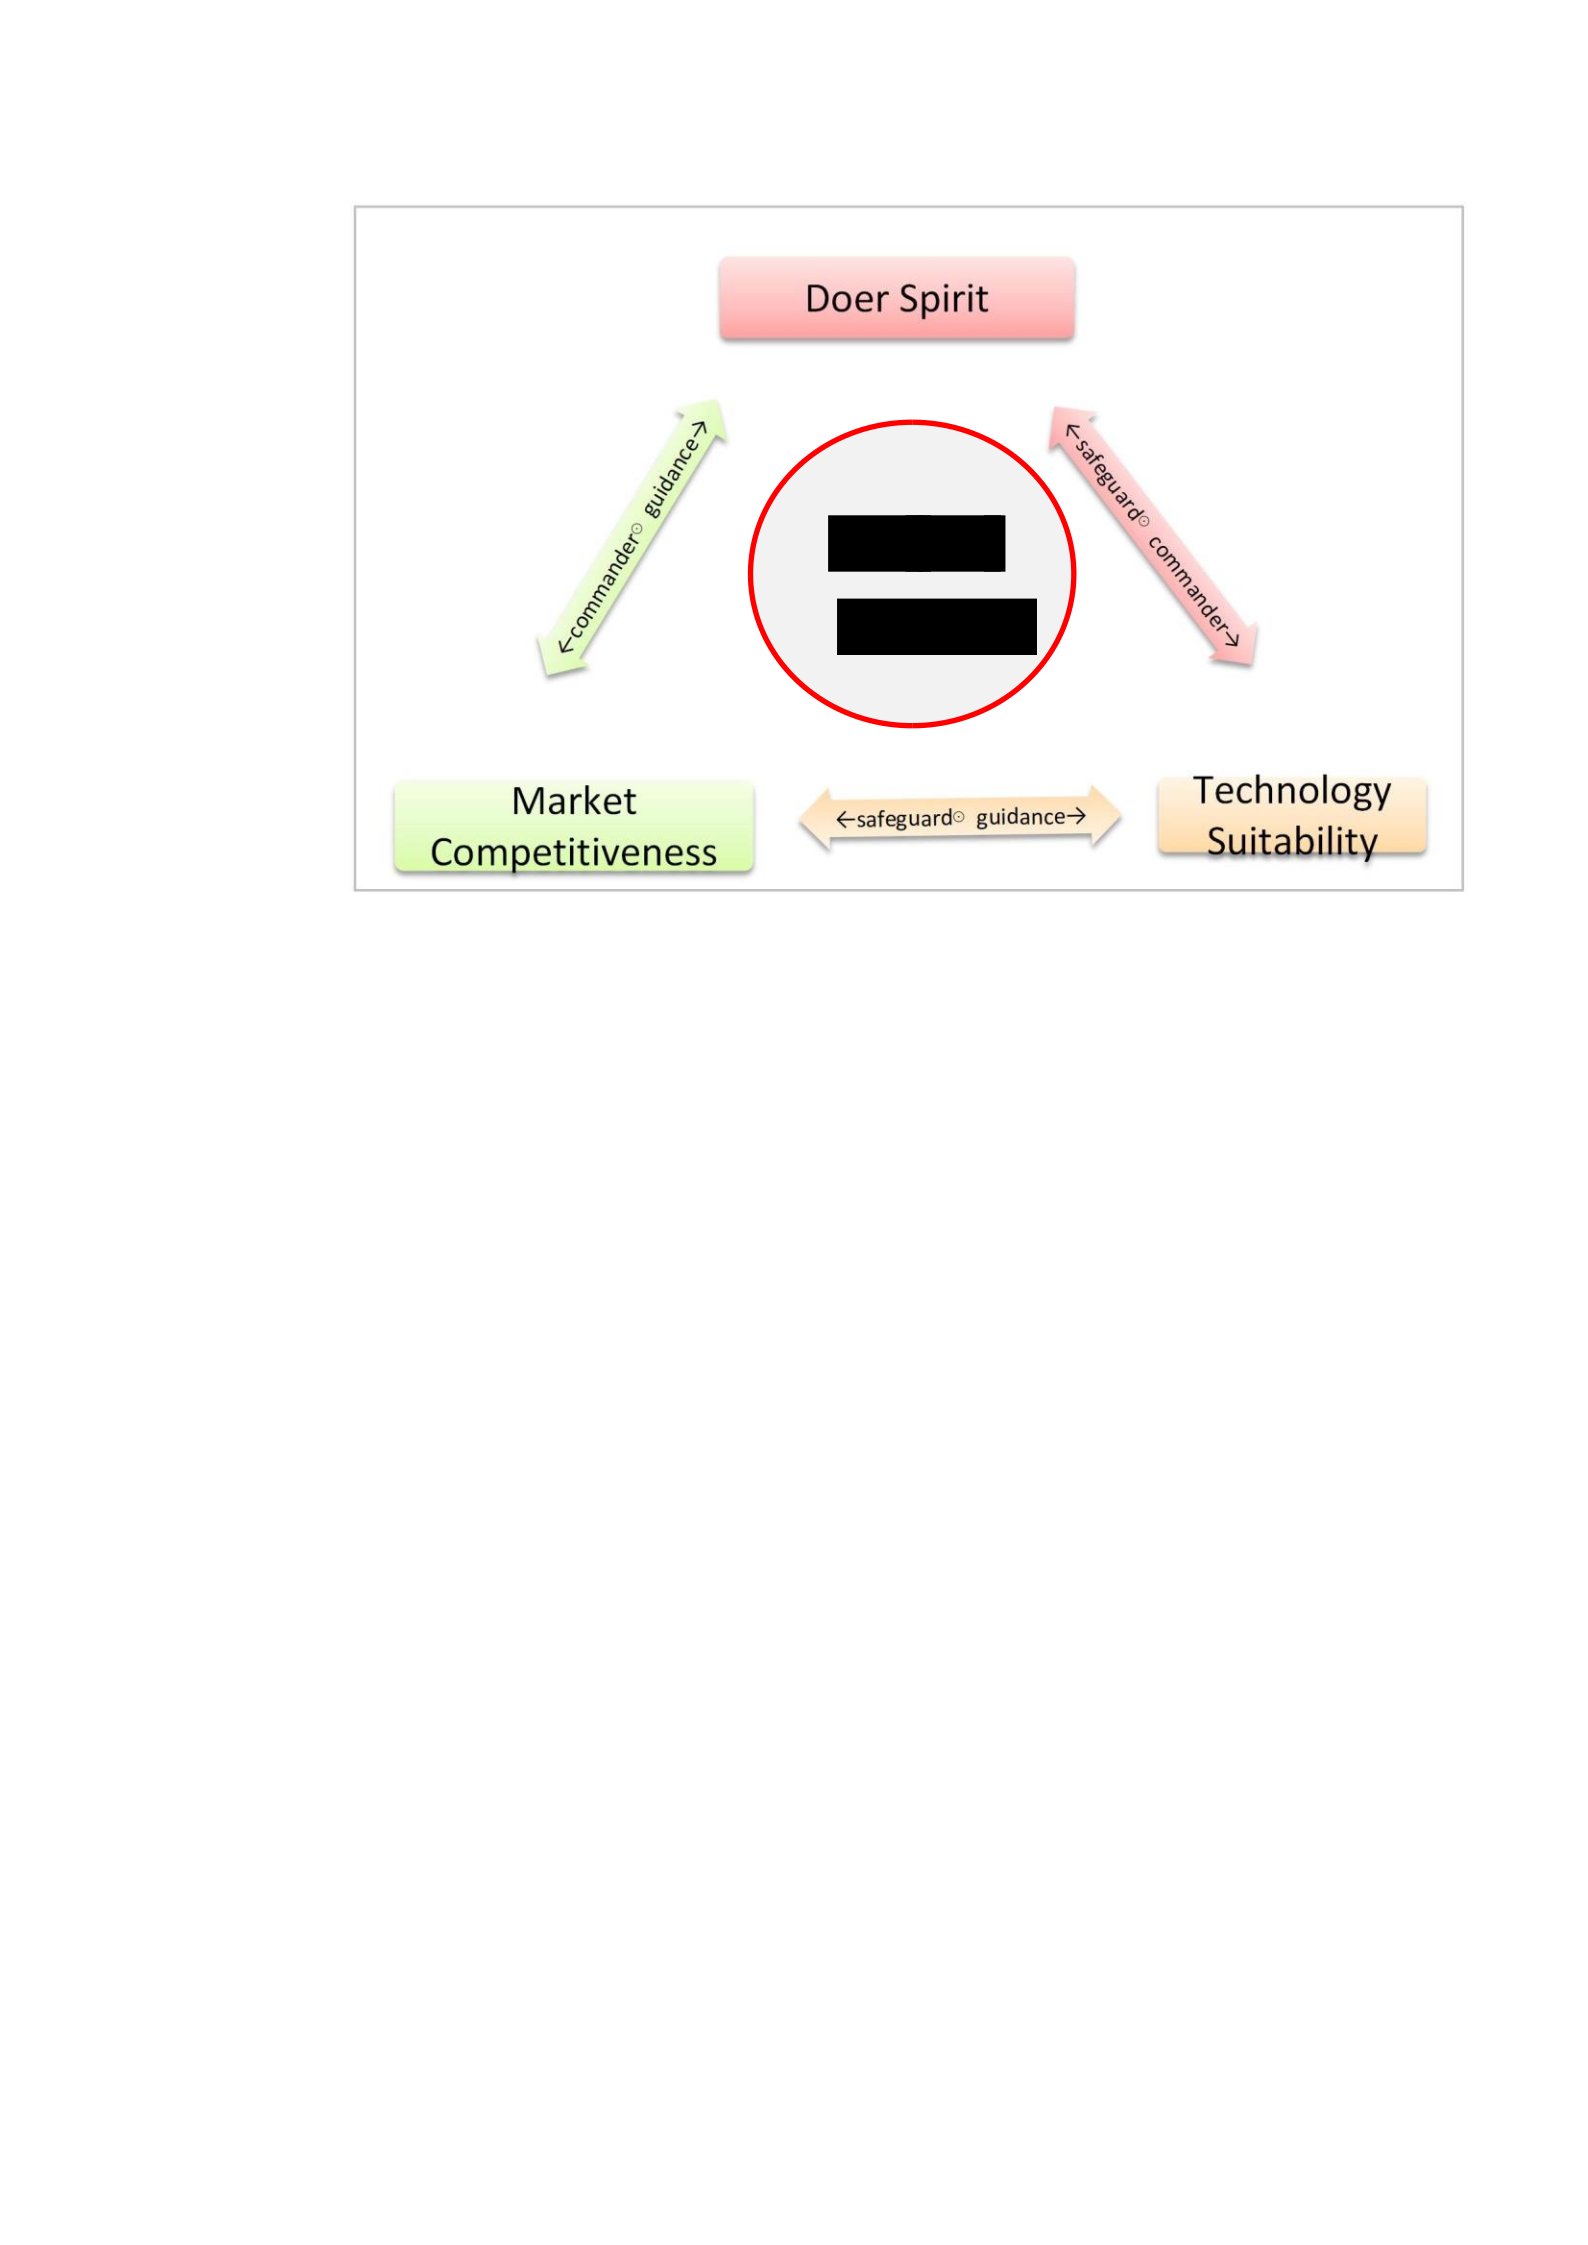
Figure 7-1 Three Factors of Financing Guarantee Credit Enhancement Model
The principle of zero loss does not deny the existence value of FGC; on the
contrary, it highlights the service value of FGC. Financing guarantee companies are
professional service organizations providing credit rating, credit enhancement and
certification services, etc. Taking the principle of zero loss as the core, it is of great
significance to establish and improve the service-oriented FGCs, financing guarantee
system and financing guarantee business aiming at alleviating financing difficulties of
SMEs and perfecting social credit system.
7.2 Research Prospects
Through thorough analysis, this paper argues that the credit enhancement business
of FGC is a "pure service", and the principle of zero loss must be fully implemented in
its business operation process. Whether in the future the Chinese government still
defines the financing guarantee as a profit-making business or redefines it as non-profit
Zero
-
loss
-
Principle

quasi-public service, the private FGCs that run the financing guarantee business should
fully implement the zero-loss-principle. Understandably, the three-factor credit
enhancement model summarized in this paper only proves some directions. The focus
of future research is to build and improve the evaluation indicator system for each
factor according to the actual needs of economic and social development, so as to make
the indicator system compatible with big data technology and keep synchronous
development.
Although the present study gives a preliminary evaluation framework, it can well
explain the ups and downs of China's financing guarantee industry. Especially from
the second half of 1995 to 2014, China's financing guarantee industry entered a stage
of coexistence of growth and disorder. The main reason for the growth and disorder is
that neither the government nor the FGC has clarified that the essence of financing
guarantee is "pure service" rather than insurance business, and the principle of zero
loss must be fully implemented in the course of business operation. As a result, after
China's economy entered a new normal stage, the default rate and the compensation
rate of FGCs increased sharply, and a large number of private FGCs went bankrupt or
suspended business. So did the loan risk of commercial banks. Originally, the financing
guarantee system aimed at dispersing risks, on the contrary it led to the accumulation
of risks.
Since 2015, in the context of economic downturn and reduced export demand,
the survival pressure of SMEs has increased sharply, and the non-performing rate of
bank loans has continued to rise. Under these conditions, FGCs are cautious about
business development and take the initiative to reduce the loan guarantee scale for fear

of sharp rise in compensation rates. According to the credit enhancement model, the
equilibrium between supply of and demand for financing guarantee business is a circle,
along which the principle of zero loss can be observed. Those enterprises that do not
meet the requirements of credit enhancement model are excluded from the circle
(financing guarantee supply screening mechanism), and those that fully meet the
requirements of credit enhancement model but can also meet the loan conditions of
credit institutions are inside the circle because they have no financing guarantee
demand (financing guarantee demand screening mechanism). The equilibrium
boundary between supply and demand of financing guarantee varies with the change
in business cycle and has strong pro-cyclicality. Hence, the financing guarantee
industry, like the credit industry, does not have counter-cyclical balancing mechanism.
Taking Guangdong Province as an example, according to the "Development
Report of Guangdong Credit Guarantee Industry 2015", by the end of December 2014,
126 legal entities of FGCs (including 10 state-owned and state-owned holding
guarantee institutions) had submitted data through the information reporting system of
SMEs credit guarantee institutions. At the end of 2014, the total registered capital was
18.799 billion yuan. 116 FGCs, accounting for 92.06% of the provincial guarantee
institutions, had registered capital of more than 100 million yuan. The government
finance or state-owned holding enterprises contributed 2.038 billion yuan, accounting
for 10.84% of the total registered capital. The rest were invested by natural persons
and private enterprises. In 2014, the operating income of FGCs was 1.198 billion yuan,
down by 57.51% from the same period last year. In 2014, assets totaled 2.354 billion
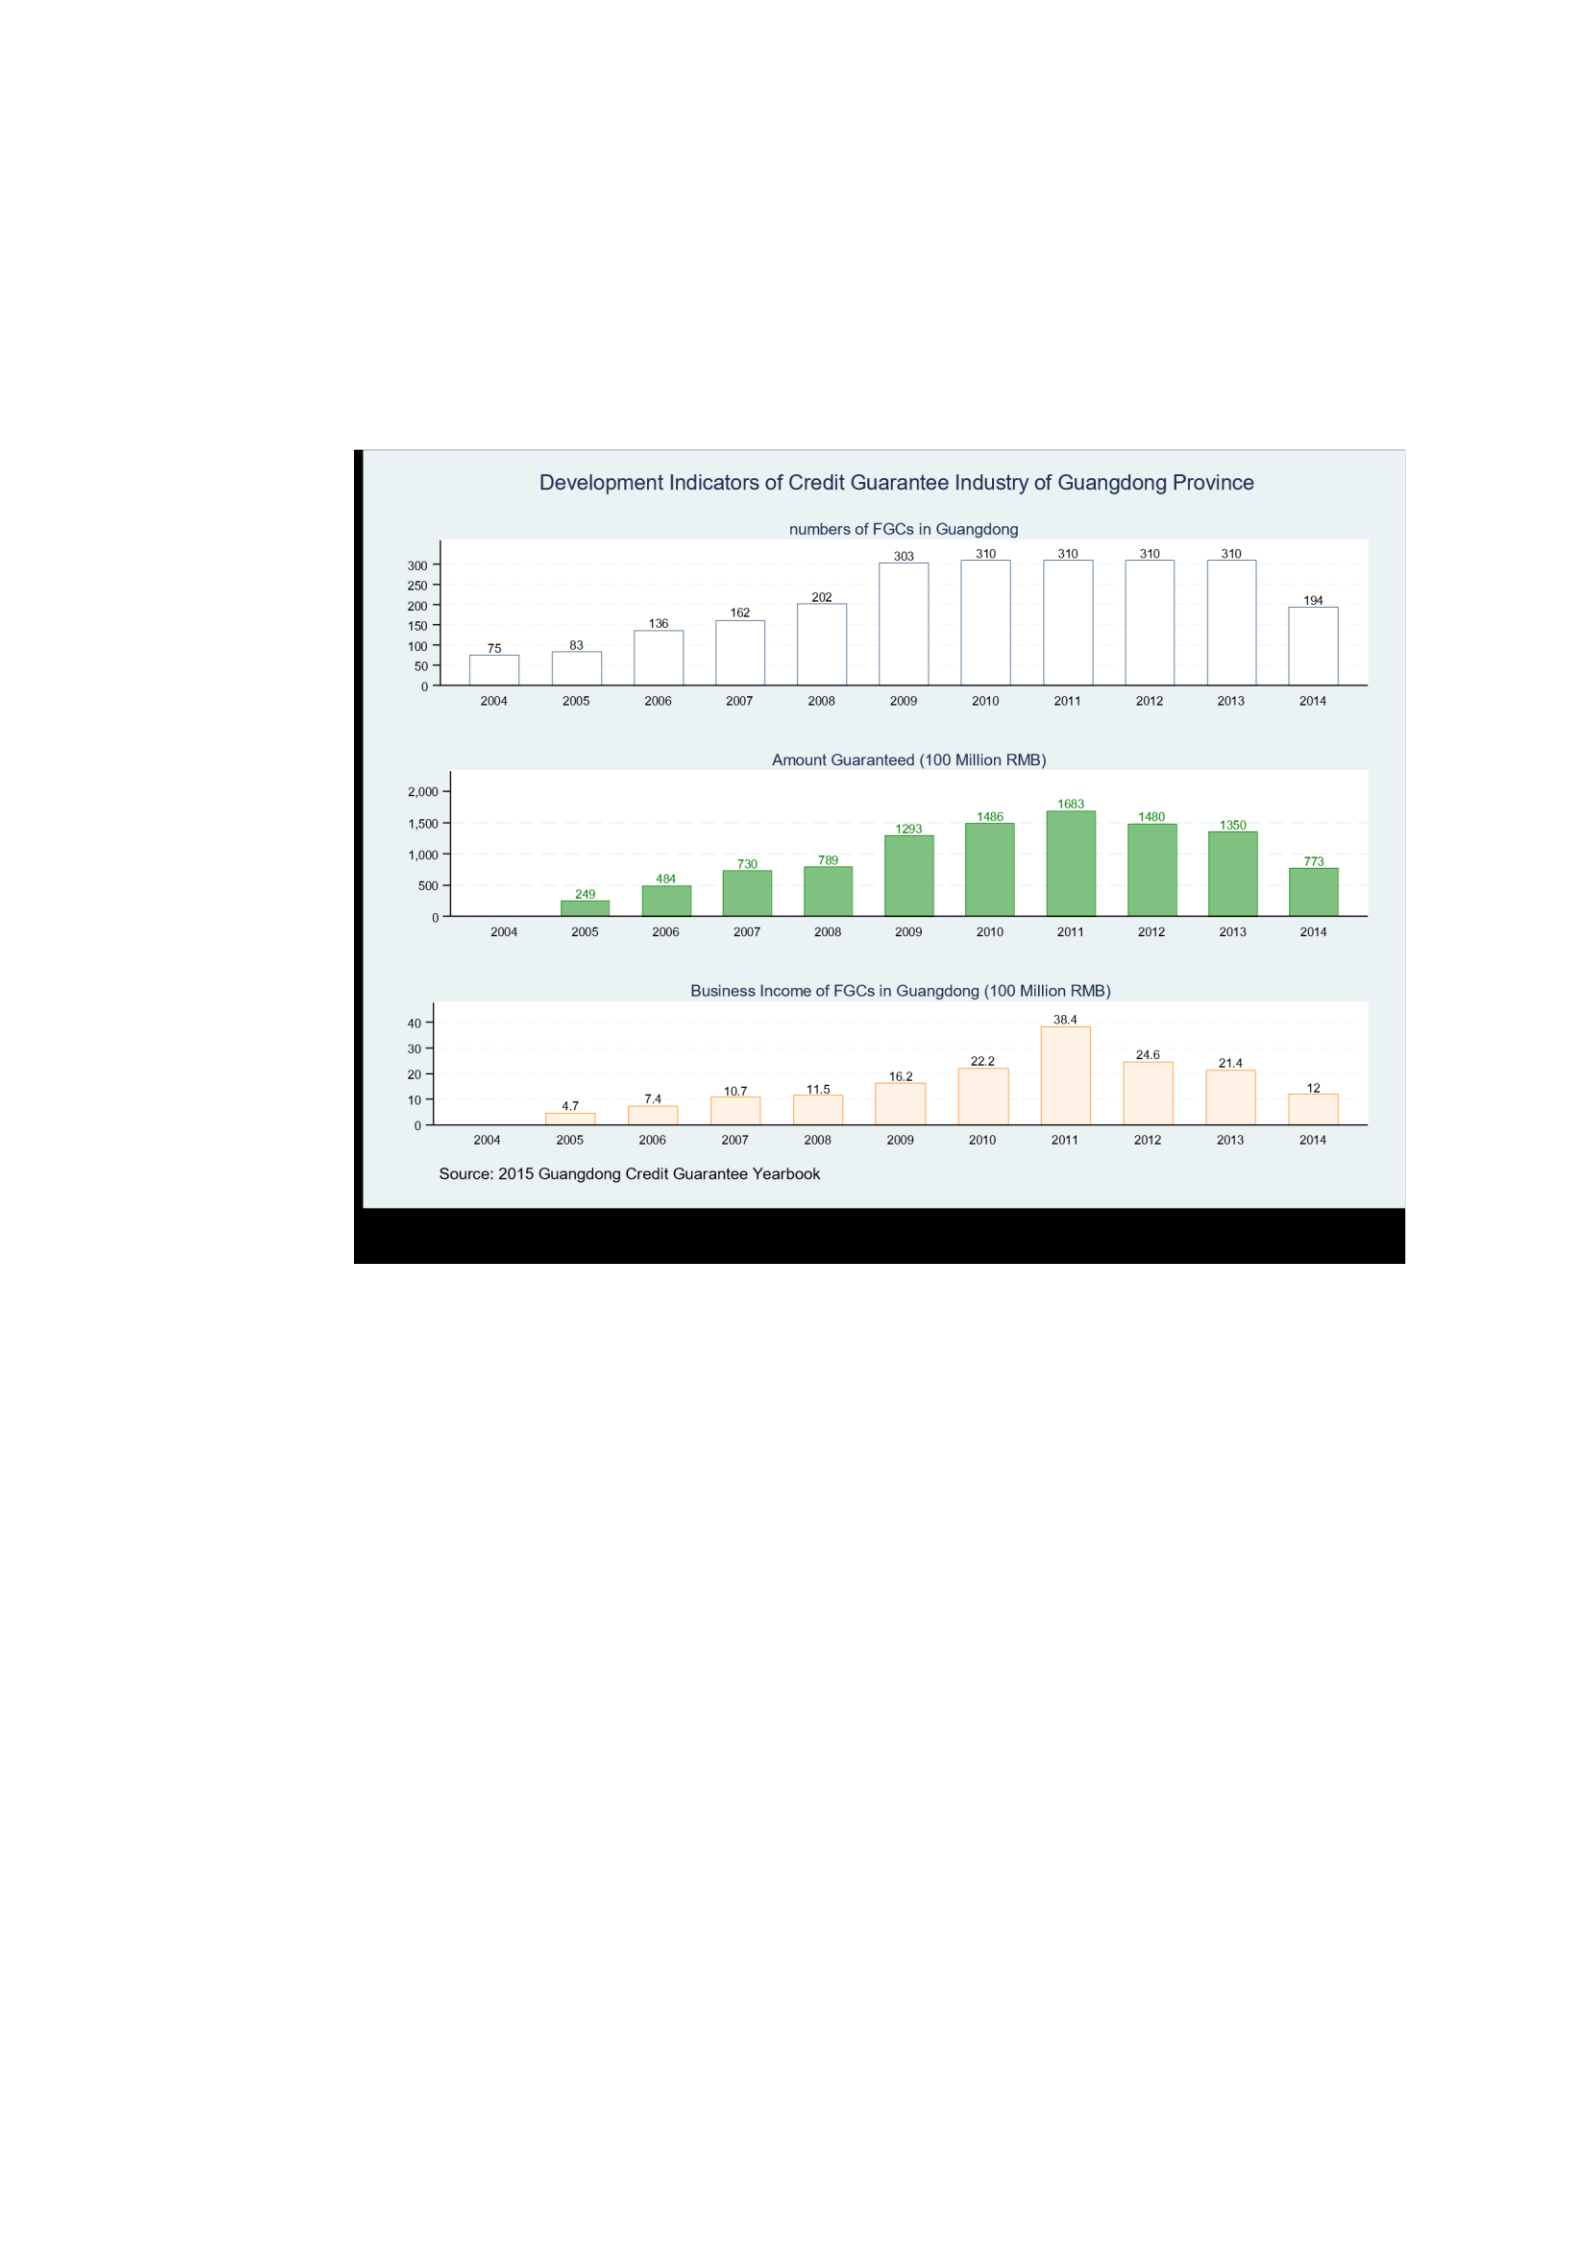
yuan, down by 50.94% from the same period last year; liabilities totaled 3.267 billion
yuan, down by 64.56% from the same period last year; owner's equity 2.027 billion
yuan, down by 47.71% from the same period last year.
Guangdong Province, 2004-2014
As shown in Figure 7-2, from 2004 to 2014, Guangdong credit guarantee industry
had experienced a rapid development stage and a sharp adjustment and modification
stage. The number of FGCs increased from 75 in 2004 to 310 in 2010, increasing 3.1
times in six years, with an average annual growth rate of 26.7%.
However, by 2014, the number of FGCs decreased to 194, decreased by 37.4% from
2010. The amount guaranteed increased from 24.9 billion yuan in 2005 to 268.3 billion
yuan in 2011, an increase of 98.8 times in six years, with an average annual growth
rate of 48.6%, but it dropped to 77.3 billion yuan in 2014, a decrease of 71.2%

compared with 2011. The revenue of guarantee business increased from 470 million
yuan in 2005 to 3.84 billion yuan in 2011, which increased by 7.2 times in six years
with an average annual growth rate of 41.9%, but it dropped to 1.2 billion yuan in
2014, 68.8% decrease compared with 2011.
Looking forward, with the zero-loss principle as the core, the three-factor credit
enhancement model of FGC discussed in this paper needs to be further studied in the
future. Besides the improvement of the three-factor indicators, more research space
exists in the research, discussion and redefinition of the implications and content of
credit enhancement service of FGC. Under the background of Internet plus, big data
and service economy, it is of great significance and profound influence to further study
and explore the industry boundary, business mode and empowerment technology of
FGC credit enhancement service.

