


1
THE INFLUENCE OF FINANCIAL PERFORMANCE AND
ACROECONOMICS ON
FINANCIAL DISTRESS
IN THE ENERGY
SECTOR
INTRODUCTION:
Financial distress is a condition where the company's finances are not in good condition which
then becomes an early indicator of bankruptcy or as an early warning system for the company to
anticipate or restructure so that the company does not experience bankruptcy and liquidation (Ardi et
al. 2020; Ashraf et al. 2019). Fitzpatrick (1932) defines financial distress as the company's inability
to meet its financial obligations to creditors, and according to Plat and Plat (2002) financial distress is
the final stage of financial decline before bankruptcy occurs. Financial difficulties or financial
distress can occur due to influences from within the company (internal) or from outside the company
(external) (Kristianti in Wangsih et al. 2021; Putri 2021).
The company's inability to manage and maintain stable financial performance can cause
financial distress so that the company experiences losses, therefore financial distress can be predicted
by observing the financial performance of a company by analyzing financial ratios in financial
statements (Suidarma et al. 2022; Pratiwi et al. 2019; Restianti and Agustina 2018). According to
Dirman (2020) and Suidarma et al. (2022) financial ratios can describe past, present, and future
circumstances as useful indicators to estimate the survival of the company or the level of bankruptcy
of the company. Some financial ratios that can affect the company's financial distress include
liquidity, profitability, leverage, company activity, cash flow, and sales growth (Ariska et al., 2021;
Permana & Serly, 2021). 2021; Permana & Serly 2021; Wangsih et al. 2021; Dirman 2020; Restianti
& Agustina 2018). There are also external factors that can affect financial distress with a broader
scope, namely macroeconomic conditions, such as economic growth experiencing inflation as well as
policies to increase loan interest rates which cause the interest burden that companies must bear to
increase so that this will affect the financial condition of the company (Kristianti in Wangsih et al.
2021; Putri 2021).
In Indonesia, the phenomenon of financial distress occurred in several energy companies. The
energy sector includes companies that sell products and services related to energy generation,
including non-renewable energy (fossil fuels), the sector's revenue is directly influenced by global
energy commodity prices, such as natural gas, petroleum mining, and coal, as well as companies that
provide services to support the industry (idx.co.id 2021).

2
The energy sector is different from other sectors because this sector requires large capital,
technological innovation and renewable energy resources, and has high risks (Fadila et al. 2021). The
energy sector plays an important role in the Indonesian economy. Based on data from IHS Markit,
Indonesia is predicted to remain the largest exporter of coal until 2050. It can be seen in Figure 1.1
that Indonesia is the third largest contributor to coal production in the world after China and India.
According to data from the Ministry of Energy and Mineral Resources, coal production in
Indonesia reached 562.5 million tons in 2020. The largest coal producer, PT Bumi Resources Tbk, in
2021 recorded coal production of 78.8 million tons, then the second largest producer with production
of 52.7 million tons, PT Adaro Energy Indonesia Tbk, and PT Bayan Resources Tbk ranked third
with production of 37.6 million tons (katadata.co.id 2022). After the Covid-19 pandemic, the GDP of
the energy sector decreased compared to the contribution of GDP in the energy sector to the National
GDP in previous years. It can be seen in Figure 1.2 which shows the graph of GDP in the energy
sector from 2010 to 2021.
According to the Agency for the Assessment and Application of Technology, the policy of
limiting social interaction has caused a decline in industrial activity, especially the service industry,
as well as disruptions to the supply chain including energy supply and demand, and disruptions to
global trade. The global economic shock caused by the Covid-19 pandemic pushed most commodity
prices down. The commodities most affected by the halt in economic activity are energy
commodities, especially petroleum as it is directly related to the transportation sector which
experienced the sharpest decline (BPPT 2020). The Covid-19 pandemic has left the world faced with
triple challenges: high inflation, high interest rates, and high inflation. risk of economic downturn.
There are two economic issues to watch out for, namely rising energy prices and rising food prices.
The sectors most affected by the global crisis are those that rely on external demand (tradables), such
as manufacturing, agriculture and mining (kompas.com). For companies in the energy sector, the high
cost of exports will be a big problem because this sector relies on exports so that the increase in costs
will shrink the company's profits so that if it cannot be anticipated, it will lead to financial distress.
The energy sector is experiencing a number of challenges due to geopolitical uncertainty and the
introduction of measures and policies to strengthen energy sustainability, efficiency, security, and
address climate change concerns. At the same time, major investments are required to meet growing
energy needs. The International Energy Agency estimates that, under its baseline scenario, a 30%
global increase in energy demand by 2040 (Doumpos et al. 2017).

3
The amount of debt of a company is also one of the factors in the occurrence of financial distress in a
company (Nurhayati 2021), companies that have difficulty in fulfilling their obligations to debtors and
failure or inability to pay debts are also factors in the occurrence of financial distress in companies
(Permana and Serly 2021; Pratiwi et al. 2019). The impact of the Covid-19 pandemic can be seen in
the increase in non-performing loan (NPL) ratios in almost all sectors, the energy sector is the sector
with the highest NPL ratio compared to other sectors which are also above the national NPL.
Based on Bank Indonesia data, the gross NPL of national banks was 3.24% in the second
quarter of 2021. This number increased compared to December 2019 or before the Covid-19
pandemic which amounted to 2.53%. By sector, NPLs in mining rose to 5.8% in the second quarter
of 2021 compared to December 2019 position of 3.58% (katadata.co.id 2022).
Prediction of financial distress conditions is important to do as an early detection step so that
both companies and investors can Knowing the possibility of company bankruptcy in the future and
also useful for companies to evaluate the company's financial condition and be able to think as soon
as possible the right steps to avoid bankruptcy. Therefore, the importance of a bankruptcy prediction
model for a company is something that is needed by various parties such as lenders, investors,
government, accountants, and management. Most of the existing studies on corporate failure
prediction models focus on sectors such as banking, manufacturing, trade, and services, usually in the
context of a single country. However, this study uses the energy sector. In addition, the researcher
adopts a broad approach that covers all subsectors within the energy industry. With this background,
this study aims to analyze the effect of financial performance, cash flow from operating activities,
sales growth and interest rates, economic growth, as well as covid 19 on the financial distress of
energy companies listed on the Indonesia Stock Exchange. Financial performance variables in this
study use liquidity ratios, profitability ratios, solvency/leverage ratios, company activity ratios, cash
flow, and sales growth. Then macroeconomic variables are measured through interest rates, economic
growth, and Covid-19.
Problem
Formulation:
Financial distress is a situation where the company faces financial problems, financial distress
occurs before bankruptcy occurs in the company. Financial distress prediction needs to be done to
detect the company's financial condition early on and is expected to anticipate conditions that lead to
bankruptcy. Financial difficulties or financial distress can occur due to influences from within the
company (internal) and from outside the company (external) (Kristianti in Wangsih et al. 2021; Putri
2021).

4
The phenomenon of financial distress has occurred in several energy companies. The mining
sector is a sector that is different from other sectors because this sector requires large capital,
technological innovation and renewable energy resources, and has high risks (Fadila et al. 2021).
In general, the energy sector contributes significantly to the Gross Domestic Product (GDP).
However, the global financial crisis allows companies in this sector to experience financial
difficulties, making it difficult to continue their business sustainability. The impact of this financial
difficulty has caused companies in this sector to be delisted from the Indonesia Stock Exchange
(Nurhayati 2021). Over the past five years, there have been five energy sector companies that have
had to delist from the Indonesia Stock Exchange:
Companies that experience delisting are a sign that the company will experience financial
difficulties (Nurhayati 2021). There are five companies over the past five years in the energy sector
that have declared delisting from the Indonesia Stock Exchange, this is one sign that companies in
this sector are experiencing financial difficulties. The energy sector has an important role in the
Indonesian economy. From the explanation of the problem formulation above, this research question
is:
1. What are the financial distress, financial performance, and macroeconomic conditions before and
during the Covid-19 pandemic in energy companies listed on the Indonesia Stock Exchange
2. How does financial performance and macroeconomics affect financial distress before and during
the Covid-19 pandemic in energy companies listed on the Indonesia Stock Exchange?
Research Objectives
Based on the formulation of the problem, the objectives of this study are:
1. Analyzing financial distress before and during the Covid-19 pandemic in energy companies listed
on the Indonesia Stock Exchange.
2. Analyzing the effect of financial performance and macroeconomics on financial distress before
and during the Covid-19 pandemic in energy companies listed on the Indonesia Stock Exchange.

5
Signal Theory:
Signaling Theory stems from pragmatic accounting theory where the effect of information is
centered on changes in the behavior of information users and signal theory is an effect due to
information asymmetry (Aviannie et al. 2020). Signaling theory explains the actions taken by company
management to provide clues to investors about how management views the prospects of a company.
Signaling theory can help companies (agents), owners (principals), and outsiders reduce information
asymmetry by producing quality or integrated financial statement information (Dirman 2020;
Restianti and Agustina 2018).
Financial distress is defined as a company that is experiencing a decline in performance due to
poor management or a financial crisis, the company's reported profits will increasingly provide a
good signal, or good news but on the other hand when profits decrease, the resulting signal from the
financial statements is spotty or bad news (Dirman 2020). This theory supports the research because
companies experiencing financial distress tend to be more secretive in disclosing their financial
statements than healthy companies and also interpret that the financial statements published by a
company or issuer are used to provide positive signals as good news or negative signals as bad news
in both financial and non-financial aspects.
Financial distress
Financial distress is a stage of deterioration in the company's financial condition before
bankruptcy or liquidation occurs, from the description of the company's financial status in the
company's financial statements. (Permana and Serly 2021; Aminah et al. in Suidarma et al. 2022;
Pratiwi et al. 2019; Platt & Platt 2002). An indication that a company is experiencing financial
distress is if the company has difficulty in fulfilling its obligations to debtors and carrying out
operational activities due to insufficient funds. failure or inability to pay debt, negative financial
performance, and liquidity problems. (Permana and Serly 2021; Pratiwi et al. 2019). According to
Joseph and Mensah; Weston and Copeland in Gunawan et al. (2017), there are two types of
bankruptcy, namely:
a.
Economic distress, means that the company's income is no longer able to cover its own costs because
the level of profit is less than the cost of capital or the present value and cash flow of the company is
less than its liabilities. Failure occurs when the company's actual cash flows are far below expected
cash flows or the rate of return on historical costs and investments is less than the company's cost of
capital spent on an investment.
b.
Financial distress, means the difficulty of funds to cover the company's obligations or the occurrence
of liquidation starting with mild financial difficulties to more serious financial difficulties, namely if
debts are greater than assets. Financial failure can be caused by two things. The first is technical
insolvency, a situation in which the company fails to pay its maturing obligations but its assets are

6
inadequate. is greater than the total amount of debt it has. The second is bankruptcy, a situation where the
company is no longer able to fulfill its obligations to debtors because the company has insufficient or
insufficient funds to continue its business so that the company's economic goals cannot be achieved.
In addition, in heading towards bankruptcy there are several stages that will be experienced by
a company but there are also companies that do not experience these stages, according to Kordestani
in Sudarman et al. (2020) the stages of bankruptcy in the company are as follows:
a. Latency, a situation where Return on Asset (ROA) has decreased.
b. Shortage of Cash, where the company lacks cash or the company does not have enough cash
resources to fulfill obligations, and at this stage the company has no source of funds.
c. Financial distress, at this stage financial difficulties can be considered an emergency. But
many researchers consider it to be somewhere between bankruptcy and an emergency.
d. Bankrupty, at this stage the company is unable to cure the symptoms of financial difficulties
and then the company goes bankrupt.
The causes of financial distress can be classified into internal (firm-specific factors) and
external (industry-specific and macro factors). Internal factors include financial factors, corporate
governance factors and productivity factors. External factors from the industry consist of customers,
suppliers, new entrants, substitutes, and the competitive environment. External factors from the
macro are political, economic, social, and technological (Ceylan 2021; Putri 2021).
Financial Performance:
According to IAI (2007) financial performance is the company's ability to manage and control
its resources. In analyzing financial performance measured through financial ratios, it can provide
information about the good or bad condition of a company. Financial performance can be seen
through several ratios, namely profitability ratios, liquidity ratios, solvency/leverage ratios, company
activity ratios, cash flow, and sales growth.
Profitability Ratio:
Profitability is defined as a company's ability to generate profits by maximizing company assets and
certain share capital (Ardi et al. 2020). The main goal of the company is to earn high profits. High
profits will increase the welfare of its shareholders and will increase investor interest in investing in
the company. High profits will also illustrate the company's success rate in carrying out its company's
operational activities (Rohmadini et al. in Dirman 2020). Profitability is an indicator of the
performance carried out by management in managing the company's assets as indicated by the profit
generated (Kristi 2020).
Liquidity Ratio:
Liquidity is a ratio to measure the company's ability to meet its short-term obligations (Fadila et al.
2021). Liquidity is fundamental to the company, liquidity will be reflected in the form of the

7
company's ability to pay creditors. on time or pay their employees' salaries on time (Dirman 2020).
1.
Solvency/Leverage Ratio
Leverage is known as the solvency ratio, where the ratio is used to measure the extent to
which the company's assets are financed with debt (Dirman 2020). The leverage ratio shows the
ability of an entity to pay off its current and long-term debt (Gunawan et al. 2017). The company is
said to be solvable if the company has sufficient wealth to fulfill all its obligations. Conversely,
companies that do not have the wealth to pay off all their obligations are categorized as insolvable
companies (Alfianto 2017).
2.
Activity Ratio
The activity ratio is used to measure the company's ability to use existing assets effectively
to generate sales, this ratio shows a measure of how effective the company is in utilizing all the
resources in the company (Lumbantobing 2019; Restianti & Agustina 2018).
3.
Cash flow from operating activities
The cash flow statement is a summary of cash flows for a certain period, the source of this
report comes from the use of the company's operating, investment, and financing cash flows and this
report shows the company's cash and securities during the period. The cash flow statement can help
users to see how the balance of cash and cash equivalents in the company's balance sheet changes
from the beginning to the end of the accounting period. If the cash flow statement continuously
shows negative achievements, it will have an impact on the company's financial condition (Liahmad
et al. 2021). Cash flow is widely recognized to estimate the value of a business that is able to meet
business continuity and is financially viable (Karas and Reznakova 2020). Cash flow from operating
activities shows the large amount of cash obtained and used by the company from its operating
activities (Giarto and Fachrurrozie 2020). According to Gentry et al. in Sayari and Mugan (2013)
cash flow from operating activities has more information than investment and financing cash flows in
explaining the financial success or failure of a company. Operating activities are profit-related
activities, operating activities also include cash inflows and net cash outflows from operating
activities such as investing in inventory, obtaining credit from suppliers, and providing loans to
customers (Putri 2021).
4.
Sales growth
Sales growth is used to measure how stable sales are and how successful the company is
from each period, it is also used to predict future company growth and reflects the successful
implementation of investments made by the company in the past period which can be used as a
prediction of future company growth (Simanjuntak in Putri 2021; Wangsih et al. 2021).

8
Macroeconomics
Dornbusch et al. (2018) explains that macroeconomics is concerned with the nature of the
economy as a whole, regarding growth and economic development. economic slowdown, growth of
economic products and services, inflation and unemployment rates, balance of payments and
currency exchange rates. Macroeconomics focuses on the nature of the economy and the policies that
affect consumption and investment, currency and the balance of payments, the determinants of wage
and price changes, monetary and fiscal policy, the stock of money, the budget, interest rates and
sovereign debt. So the macroeconomics of a country is the condition of a country's economy as a
whole, including income growth, price changes and unemployment rates. According to Fahmi in
Priyatnasari (2019) the macroeconomic conditions that occur in the country concerned will have an
impact on the industry as a whole to influence the policies or actions of a company. So that
macroeconomic sensitivity will be very important for the welfare and ability of the company to manage
its business.
1.
Economic Growth
Economic growth is a process of changing economic conditions that occur in a country on
an ongoing basis towards a situation that is considered better over a certain period of time
(kemenkeu.go.id). Gross Domestic Product (GDP) is considered the best indicator to describe the
economic condition of a country because it represents the overall level of economic activity in a
country, namely the amount of goods and services produced for a market. This suggests that GDP is
an important growth indicator for economic performance measures (Ummah et al. 2020). The
purpose of GDP is to summarize all data into a single value that represents the value of a country's
economic activity at a point in time. The components of gross domestic product are income,
expenditure/investment, government expenditure and export-import differences (Ummah et al.
2020).
2.
Interest Rate
There are several types of interest rates, when viewed from their use, namely consumption
credit, investment credit and working capital credit. Consumption loans are loans whose funds are
used for consumption purposes, while investment loans are loans whose funds will be used for
medium to long-term investment purposes such as relocation and procurement of goods/services.
Finally, working capital loans are loans whose funds will be used for working capital purposes with
a relatively short term (BI 2022). The interest rate or BI rate is a monetary policy formalized by
Bank Indonesia and announced to the public and the Indonesian Interest Certificate (SBI) is an
interest rate imposed by Bank Indonesia (Nurriadianis and Ardi 2021). According to Case and Fair
in Priyatnasari (2019) interest rates are annual overvalue payments on a loan expressed in
percentage form. Bank Indonesia has strengthened the monetary operating framework by

9
implementing a new benchmark interest rate or policy rate, the BI 7-Day (Reverse) Repo Rate,
which has been effective since August 19, 2016, replacing the BI Rate. This strengthening of the
monetary operating framework is a common practice in various central banks and is an
international best practice in the implementation of monetary operations. The monetary operating
framework is constantly being refined to strengthen the monetary policy.
Covid-19 Pandemic:
The Covid-19 pandemic has impacted the food system, the economy, and even the world of
work. The uncertainty regarding economic policies due to the Covid-19 pandemic has hampered
investment and burdened international trade. Many business sectors have been affected during the
Covid-19 pandemic, forcing them to stop operating. Indirectly, the Covid-19 pandemic can affect
the effectiveness of the business world which can reduce financial performance and lead companies
to financial distress (Hasanat et al. 2020). The Covid-19 pandemic has resulted in uncertain
economic conditions in Indonesia and poses a high risk for companies to experience financial
difficulties or even bankruptcy. Errors in predicting the continuity of company operations in the
future can be fatal. Therefore, the importance of a bankruptcy prediction model for a company is
something that is needed by various parties such as lenders, investors, governments, accountants,
and management (Suidarma et al. 2022). The Covid-19 pandemic itself is not one of the
macroeconomic indicators, but the Covid-19 pandemic has a huge impact on the world economy
including Indonesia.
Review of Previous Research:
This study refers to several previous studies. In this study, financial distress is measured using
the probit model developed by Zmijewski (1984), Ashraf et al. (2019) and Husein & Pambekti
(2014) found that the probit model developed by Zmijewski (1984) has a higher overall prediction
accuracy than all other models, namely Z-score, O-score, Hazard, and d-score as the best predictor of
financial distress. Profitability is proxied by return on assets (ROA). Based on research by Dirman
(2020) and Lumbantobing (2019) found profitability proxied by return on assets (ROA) has an
influence on financial distress. However, Mahaningrum & Merkusiwati (2020) and Nurhayati (2022)
did not find any effect of the profitability ratio proxied through return on assets (ROA) on financial
distress. The liquidity ratio is proxied through the current ratio, based on research conducted by
Suherman et al. (2022) liquidity ratio affects financial distress. Meanwhile, the results of research by
Putri and Hendayana (2022) found that the liquidity ratio did not affect financial distress.

10
The leverage ratio is proxied through the debt to asset ratio (DAR), based on research
conducted by Lumbantobing (2019) suggests that the leverage ratio affects financial distress.
Meanwhile, Ariska et al. (2021) and Ardi et al. (2020) found that the leverage ratio does not affect
financial distress. The activity ratio is proxied through total asset turnover, based on research
conducted by Faizatullail (2019) the activity ratio affects financial distress. However, Restianti &
Agustina's research (2018) found that the activity ratio did not affect financial distress. Cash flow
ratio is calculated through changes in the amount of cash that occurs in a company during a certain
period (Julius 2017). Based on research conducted by Putri (2021) and Giarto and Fachrurrozie
(2020) cash flow has an influence on financial distress. Meanwhile, the results of research by
Liahmad et al. (2021) found that cash flow has no effect on financial distress. Sales growth is used to
measure how stable sales are and how successful the company is from each period, based on research
conducted by Elviana and Ali (2022) and Putri (2021) sales growth has an influence on financial
distress. However, Wangsih et al. (2021) and Giarto and Fachrurrozie (2020) found that sales growth
has no effect on financial distress. The macroeconomic variable interest rate is based on data on the
value of interest rates available at Bank Indonesia (Kholisoh Dwiarti 2020), based on Kriswanto's
research (2019) interest rates have an influence on financial distress. However, Kholisoh and Dwiarti
(2020) found that interest rates have no influence on financial distress. Economic growth can be seen
through GDP, research by Inekwe and Valenzuela (2017) found that economic growth has an
influence on financial distress. However, Ceylan (2021) found that economic growth has no effect on
financial distress.
Framework of Thought:
The energy sector has an important role in the Indonesian economy, in general the energy sector
contributes greatly to the formation of Gross Domestic Product (GDP). According to the Agency for
the Assessment and Application of Technology, the policy of limiting social interaction caused
disruptions in the supply chain including energy supply and demand, it also pushed most commodity
prices down and the commodities most affected by the suspension of economic activity were energy
commodities, especially petroleum because it was directly related to the transportation sector which
experienced the sharpest decline (BPPT 2020). The occurrence of the global financial crisis allows
companies in this sector to experience financial difficulties, making it difficult to continue their
business sustainability. The impact of this financial difficulty has caused companies in this sector to
be delisted from the Indonesia Stock Exchange (Nurhayati 2021). Prediction of financial distress
conditions is very important as an early detection step so that both companies and investors can
determine the possibility of company bankruptcy in the future.

11
Relationship between profitability and
financial distress:
A high level of profitability makes the company further away from financial distress because
profitability is an indicator of how well the company is performing. Conversely, if the level of
profitability is lower, the more likely the company will experience financial distress. Research
conducted by Dirman (2020) and Lumbantobing (2019) states that profitability proxied through ROA
has an influence on financial distress. However, Mahaningrum & Merkusiwati (2020) and Nurhayati
(2022) in their research found the opposite, that there was no effect of the profitability ratio with
proxies through ROA on financial distress.
H11 :β1>0 ; Profitability ratios affect financial distress conditions
Liquidity relationship with
financial distress
Large liquidity indicates that the company is able to utilize current assets to be liquid so that
the company can pay its short-term obligations. If the company experiences a decrease in liquidity,
the risk of financial distress conditions in the company is greater (Ardi et al. 2020). The greater the
liquidity ratio indicates that the better the company's financial performance, the lower the risk of
financial distress in the company (Dirman 2020; Lumbantobing 2019). Research conducted by
Suherman et al. (2022) found that the liquidity ratio with the current ratio proxy can affect the
company's financial performance.
financial distress. Meanwhile, the results of Putri & Hendayana's research (2022) found that the
liquidity ratio with the current ratio proxy did not affect financial distress.
H12 :β2>0 ; Liquidity ratio affects the condition of financial distress
1.
Leverage/Solvency relationship with
financial distress
A higher debt ratio will result in high financial risk, when there is an increase in financial risk
it will endanger the company because it is funding too many assets. The lower the debt ratio, the
smaller the financial risk, the less likely the company will experience financial distress
(Lumbantobing 2019). Research conducted by Lumbantobing (2019) suggests that the leverage ratio
with proxies through the debt to asset ratio can affect financial distress. Meanwhile, the results of
research by Ariska et al. (2021) and Ardi et al. (2020) that the leverage ratio with a proxy through the
debt to asset ratio does not affect financial distress.
H13 :β3>0 ; Leverage ratio affects the condition of financial distress
2.
The relationship between activity and
financial distress
The activity ratio can be seen through total asset turnover. The higher the total asset turnover,
the more effectively the company uses its assets and can also provide greater profits for the company
so that the further the company is in financial distress (Restianti & Agustina 2018). Research
conducted by Faizatullail (2019) suggests that the activity ratio with proxies through total asset
turnover can affect financial distress.

12
Meanwhile, the results of research by Restianti & Agustina (2018) that the activity ratio with
proxies through total asset turnover does not affect financial distress.
H14 :β4>0 ; Activity ratio affects the condition of financial distress
3.
Relationship between
Cash Flow
from Operating Activities and
financial distress
Cash flow difficulties are caused by the imbalance between revenue sourced from sales and
expenditures for spending and the mismanagement of cash flow by management in financing the
company's operations so that the company's cash flow is in a deficit condition (Gunawan et al. 2017).
The higher operating activity cash flow obtained by the company indicates that the company has a
good performance that is able to manage cash to meet the company's internal needs so that the less
likely the company will experience financial difficulties (Giarto & Fachrurrozie 2020). The higher
the operating cash flow, the less likely the company will experience financial distress (Giarto &
Fachrurrozie 2020). Research conducted by Putri (2021) and Giarto & Fachrurrozie (2020) suggests
that cash flow has an influence on financial distress. Meanwhile, the results of research by Liahmad
et al. (2021) found that cash flow has no effect on financial distress.
H15 :β5>0 ; Cash flow from operating activities affects the condition of financial distress
4.
The relationship between
sales growth
and
financial distress
Every company wants to maintain and increase its sales from year to year and a company that
continues to run will increase sales growth, the better the prospects. they have. Conversely, if the
company's sales growth decreases, the greater the potential for the company to experience financial
distress (Wangsih et al. 2021). A low sales growth value illustrates that the company's ability to
create sales has decreased, which will affect the company's financial distress condition. Research
conducted by Elviana and Ali (2022); Putri (2021) suggests that sales growth has an influence on
financial distress. Meanwhile, the results of research by Wangsih et al. (2021); Giarto and
Fachrurrozie (2020) found that sales growth has no effect on financial distress.
H16 :β6>0 ; Sales growth affects the condition of financial distress
5.
The relationship between interest rates and
financial distress
Higher interest rates will increase interest expense so that it has an impact on revenue deficits
which result in additional costs and interest so that it will have an impact on the company's financial
condition (Kholisoh and Dwiarti 2020) or a decrease in interest rates will result in lower borrowing
costs and low borrowing costs have a good impact on the company because it reduces the cost of its
loan expenses and increases its profits and vice versa (Alifiah and Tahir 2018). Research conducted
by Kriswanto (2019) found that interest rates have an influence on financial distress. Meanwhile, the
results of research by Kholisoh & Dwiarti (2020) found that interest rates have no effect on financial
distress.
13
H17 :β7>0 ; Interest rates affect the condition of financial distress
6.
Relationship between Economic Growth and financial distress
Gross Domestic Product (GDP) is used as a proxy for economic growth and represents the
general condition of the country's economy. Companies tend to have good conditions when the
economy is good which causes the company to be less likely to experience financial distress in this
condition and face financial problems when the economy is bad which further increases the
possibility of the company experiencing financial distress (Alifiah and Tahir 2021). Research
conducted by Inekwe and Valenzuela (2017) found that economic growth through GDP has an
influence on financial distress. Meanwhile, the results of Ceylan's research (2021) found that
economic growth through GDP has no effect on financial distress.
H18 :β8>0 ; Economic growth affects the condition of financial distress
7.
The relationship between Covid-19 and
financial distress
The occurrence of the Covid-19 pandemic has not only had an impact on public health, but has
also had an impact on the economic sector. As a result of the Covid-19 pandemic, it has certainly put
enormous pressure on the real sector and the business world. Several business sectors have suffered
losses, so many companies have cut back or reduced their business activities. This will certainly put
pressure on the ability to fulfill its obligations or reduce the ability to pay debts, so that the company
will experience financial difficulties (financial distrees) (Dini et al. 2023).
H19 :β9>0 ; Covid-19 affects the condition of financial distress
Time and Research Approach
This research began in August 2022. The research object used in this study is the energy sector
listed on the Indonesia Stock Exchange (IDX) for the 2017-2021 period. This study did not use data
for 2022 because at the time the research was conducted, there was still a lot of company financial
report data in the energy sector that had not been published so that if it was still included, a lot of
sample data would be wasted and would significantly reduce the sample size. This study uses a
quantitative approach by collecting data to be analyzed in the form of descriptive statistical analysis
and econometrics as well as using certain populations and samples that aim to test predetermined
hypotheses.
Sampling Technique
The sample determination in this study is based on the number of energy sector companies in
Indonesia in 2017-2021, totaling 265 samples consisting of 53 companies. This study uses one of the
non-probability sampling methods, namely purposive sampling in the sampling process.

14
Purposive sampling is a data source sampling technique with certain considerations or criteria
(Sugiyono 2018). The criteria that are the basis for sample selection, namely:
1.
Energy sector companies in Indonesia listed on the Indonesia Stock Exchange (IDX) in the period
2017-2021
2.
Have complete financial statement data for the period 2017-2021
3.
No relisting or delisting and no mergers, acquisitions or other business changes during the 2017-2021
period.
Research Variables:
The variables in this study consist of two variables, namely the independent variable (free)
and the dependent variable (bound). The dependent variable in this study is financial distress. The
independent variables in this study are profitability ratio, liquidity ratio, leverage / solvency ratio,
activity ratio, cash flow from operating activities, sales growth, interest rates, economic growth and
the Covid-19 pandemic.
Dependent Variable:
Financial distress in this study uses a probit model developed by Zmijewski (1984), which is
calculated through three variables, namely net income/total assets, total liabilities/total assets, and
current assets/current liabilities (Ashraf et al. 2019). Zavgren in Hassan et al. (2017) stated that in
predicting bankruptcy, logit and probit conditional probability models are more helpful because these
models do not always have linearity assumptions. Ashraf et al. (2019) and Husein & Pambekti (2014)
found that the probit model developed by Zmijewski (1984) has higher overall prediction accuracy
than all other models namely Z-score, O-score, Hazard, and d-score as the best predictor of financial
distress. Zmijewski X-Score does not have a criterion threshold value to compare results. According
to the results of Özparlak's research (2022), the Zmijewski model is the best predictor of financial
distress.
The most appropriate model to predict bankruptcy of companies in the energy sector in the
United States is the same as Özparlak's research (2022) in this study analyzing the condition of
companies in the energy sector during the Covid-19 pandemic, Zmijewski can also be used as a
model to predict companies that experience financial decline 1-3 years before bankruptcy occurs.
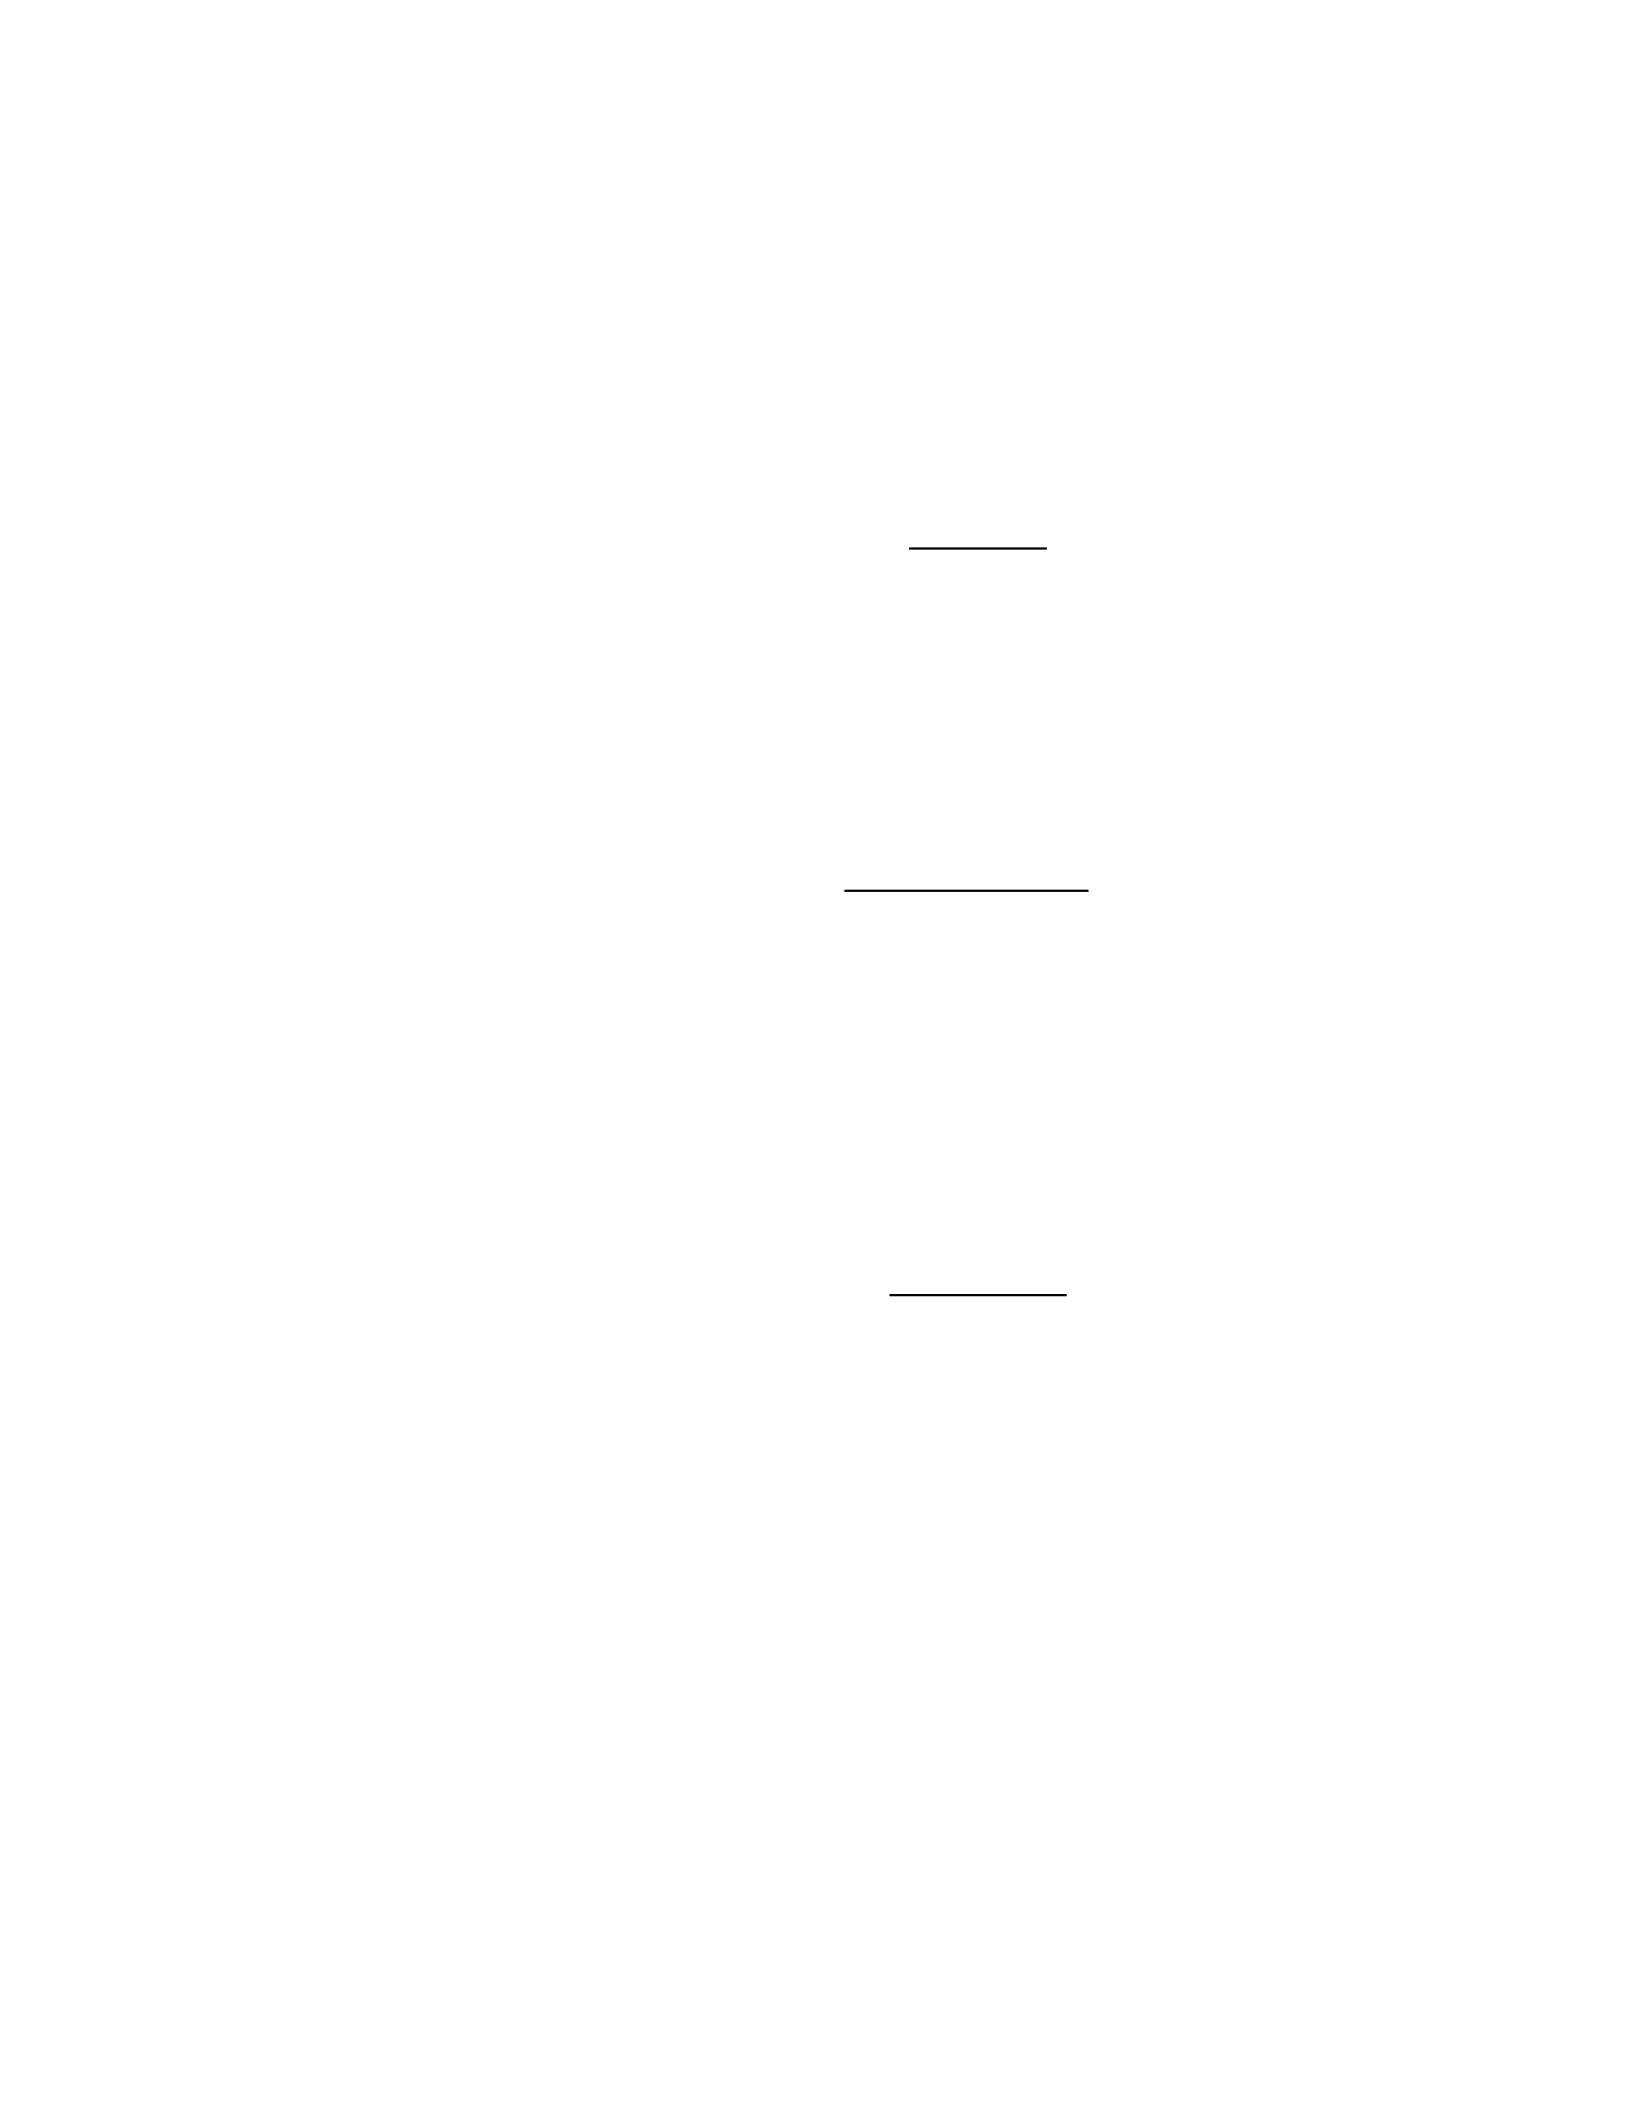
The following is the Zmijewski (1984) model:
15
Independent Variable
a.
Profitability Ratio
Profitability is defined as a company's ability to generate profits by maximizing company assets
and certain share capital (Ardi et al. 2020). In this study, the profitability ratio is proxied by the
return on assets (ROA) ratio, return on assets (ROA) is used to measure the ability of a company to
earn net income on the assets used (Ariska et al. 2021).
EBIT
b.
Liquidity Ratio
ROA
=
Total
Assets
Liquidity ratio is a ratio to measure the company's ability to meet its short-term obligations. In
this study, the liquidity ratio is proxied by the current ratio. Current ratio is a ratio to measure how far
current assets can pay off their short-term liabilities (Ariska et al. 2021).
Current
Assets
c.
Leverage Ratio
CR
=
Current
Liabilities
Leverage is also known as the solvency ratio, where the ratio is used to measure the extent to
which the company's assets are financed with debt (Dirman 2020). In this study, the leverage ratio is
proxied using the debt ratio (debt to asset ratio), the debt ratio (debt to asset ratio) is used to measure
how much funding comes from debt to asset financing companies (Ariska et al. 2021).
Total
Debt
d.
Activity Ratio
DAR
=
Total
Assets
The activity ratio is used to measure the company's ability to use existing assets effectively to
generate sales (Lumbantobing 2019). The activity ratio is a ratio that shows the size
16
how effective the company is in utilizing all the resources in the company (Restianti and Agustina
2018). The activity ratio considers that there should be a proper balance between sales and various
elements of assets.
Sales
Asset Turnover Ratio =
e.
Cash Flow from operating activities
Total
Assets
Cash flow from operating activities shows the large amount of cash obtained and used by the
company from its operating activities (Giarto & Fachrurrozie 2020). According to Gentry et al. in
Sayari & Mugan (2013) cash flow from operating activities has more information than investment
and financing cash flows in explaining the financial success or failure of a company.
f.
Sales Growth
asℎ Flow =
Operating Cash Flow
Total
Assets
Sales growth is used to predict future company growth, the sales growth ratio reflects the
successful application of investments made by the company in the past period which can be used as a
prediction of future company growth (Simanjuntak in Putri 2021; Wangsih et al. 2021). The sales
growth ratio describes the comparison of the difference between total net sales for the current year
and the previous year (Elviana & Ali 2021; Wangsih et al. 2021).
(Sales t) - (Sales t - 1)
g.
Interest Rate
Sales Grow ℎ
=
(Sales t - 1)
The interest rate is the price of using investment funds or loan funds (Kholisoh and Dwiarti
2020). The interest rate or BI rate is a monetary policy formalized by bank Indonesia (Nurriadianis
and Ardi 2021). According to Case and Fair in Priyatnasari (2019) interest rates are annual overvalue
payments on a loan expressed in percentage form. From the company's side, interest rates are
considered a burden that must be borne by the company for a certain nominal debt borrowed from the
bank. The interest rate is based on data on the value of interest rates available at Bank Indonesia
(Dwiarti 2020).
h.
Economic Growth
Economic growth is a process of changing economic conditions that occur in a country on an
ongoing basis towards a situation that is considered better over a certain period of time
(kemenkeu.go.id). According to Iskandar in Halim (2020) to calculate how much economic growth a
country has, the data used is the national income of a country, for developing countries using Gross
Domestic Product (GDP), while for developed countries using Gross National Product (GNP). So in
this study economic growth is measured through Gross Domestic Product (GDP).

17
This method is conducted to determine between the common effect or fixed effect model that
will be used in this study. The criterion with this test is the hypothesis:
H0 = Common Effect Model
H1 = Fixed Effect Model
With decision-making criteria (α = 0.05)
a)
If the cross section chi-square probability value <0.05 then H0 is rejected, so the fixed
effect method will be used.
b)
If the cross section chi-square probability value > 0.05 then H0 is accepted, so we will
use the common effect method.
Fixed Effect or Random Effect Significance Test (Hausman Test)
Hausman has developed a statistical test to choose whether to use a fixed effect or random effect
model. The criteria for this test are as follows:
H0 = Random Effect Model
H1 = Fixed Effect Model
a.
If the probability value of cross-section random <0.05 then H0 is rejected, so the fixed effect
model will be used.
b.
If the cross-section random probability value > 0.05 then H0 is accepted, so we will use the
random effect model.
Significant Test of Common Effect or Random Effect (Lagrange Multiplier Test)
To determine whether the random effect model is better than the common effect model, the
Lagrange Multiplier (LM) test is used. The random effect significance test was developed by Breusch
Pagan. The Bruesch Pagan method for testing the significance of the random effect model is based on
the residuals from the OLS method. This test is based on the residual value of the PLS model. to
perform the LM test, use the following hypothesis:
H0 = Common effect model
H1 = Random effect model
With the decision-making criteria that is if:
c.
If the LM statistic value is smaller than <0.05 then H0 is accepted, meaning that the common
effect model is more appropriate in this study.
d.
If the LM statistic is greater than > 0.05 then H0 is rejected, meaning that the model
Random effects are more appropriate in this study.

18
1.
Classical Assumption Testing
The classical assumption tests used in linear regression analysis are linearity, normality,
autocorrelation, heteroscedasticity, and multicollinearity tests. However, not all classic assumption
tests need to be performed on the panel data model (Basuki and Prawoto 2016). The eligibility tests
used in this study are only multicollinearity test and heteroscedasticity test with the following
explanation:
a.
Multicollinearity Test
According to Ghozali (2016) the multicollinearity test aims to test whether the regression model
found a correlation between independent variables. The method that can be used to test for
multicollinearity can be seen from the correlation matrix of the independent variables. For Testing for
multicollinearity problems can look at the matrix of independent variables. If there is a correlation
coefficient> 0.90 then there is a multicollinearity problem. Conversely, if the correlation coefficient
<0.90 then there is no multicollinearity problem.
b.
Heteroskedasticity Test
According to Ghozali (2016) the heteroscedasticity test aims to test whether in the regression model
there is an inequality of variance from the residuals of one observation to another. To test the
problem of heteroscedasticity, the provisions used are, if the probability value is <0.05 then there is a
heteroscedasticity problem. Conversely, if the probability value is > 0.05 then there is no
heteroscedasticity problem. In addition, the heteroscedasticity test can be seen through the graph, if
the data graph does not form a certain pattern, there is no heteroscedasticity problem.
1.
Hypothesis Testing
In this study, hypothesis testing aims to obtain a comprehensive picture of the relationship between
the independent variable and the dependent variable. The hypothesis tests carried out in this study are
the coefficient of determination test, simultaneous test (F test), and partial test (T test).
a.
Coefficient of Determination
The coefficient of determination is used to determine the percentage of changes in the dependent
variable caused by the independent variable. If the coefficient of determination is greater, the
percentage of changes in the dependent variable caused by the independent variable is higher and
vice versa (Sujarweni 2015). In other words, the coefficient of determination is used to determine how
much the independent variable (independent) affects the dependent variable (dependent).
b.
Simultaneous Hypothesis Testing (F Test)
The F test is an equation significance test used to determine how much influence the independent
variables in this study, namely profitability, liquidity, solvency / leverage, activity, cash flow, and
sales growth together on the dependent variable, namely financial distress (Sujarweni 2015). The
19
testing criteria carried out in this research F test are (Ghozali 2016):
1)
Significance level of 0.05 (α = 0.05)
2)
If the probability is greater than the significance level (Sig. > 0.05), then H0 is accepted or Ha is
rejected, this means that all independent variables (profitability, liquidity, solvency/leverage, activity,
cash flow, and sales growth) simultaneously have no effect on the dependent variable (financial
distress).
3)
If the probability is smaller than the significance level (Sig. <0.05), then H0 is rejected or Ha is
accepted, this means that all independent variables (profitability, liquidity, solvency/leverage,
activity, cash flow, and sales growth) simultaneously affect the dependent variable (financial
distress).
e.
Partial Hypothesis Testing (T Test)
The T test is an individual partial regression coefficient test used to determine whether the
independent variable individually affects the dependent variable (Sujarweni 2015). In other words,
whether each independent variable affects the dependent variable. The test criteria carried out in this
research T test are (Ghozali 2016):
1)
Significance level of 0.05 (α = 0.05)
2)
If the probability is greater than the significance level (Sig. > 0.05), then H0 is accepted or Ha is
rejected, this means that the independent variables (profitability, liquidity, solvency / leverage,
activity, cash flow, and sales growth) have no effect on the dependent variable (financial distress).
3)
If the probability is smaller than the significance level (Sig. <0.05), then H0 is rejected or Ha is
accepted, this means that the independent variables (profitability, liquidity, solvency / leverage,
activity, cash flow, and sales growth) affect the dependent variable (financial distress).
Descriptive Statistical Analysis
The energy sector includes companies that sell products and services related to energy
generation, including non-renewable energy (fossil fuels). Based on the classification of the
Indonesia Stock Exchange, as of 2021 there are 71 companies in the energy sector (BEI 2021) listed
on the Indonesia Stock Exchange. However, there are 18 companies that do not have complete sample
selection criteria in the observation period, so the number of samples used in this study is 53
companies so that there are 265 research samples.

20
Financial distress in 2017 shows an average of -1.39% with a maximum value of 4.89% and a
minimum value of -4.63%. Financial distress in 2018 shows an average of -1.24% with a maximum
value of 5.12% and a minimum value of -4.06%. Financial distress in 2019 shows an average of -
1.17% with a maximum value of 5.91% and a minimum value of -3.97%. Financial distress in 2020
shows an average of -1.05% with a maximum value of 8.30% and a minimum value of -4.42%.
Financial distress in 2021 shows an average of -1.24% with a maximum value of 8.11% and a
minimum value of -4.42%.
-5,36%. The highest average value is in 2020 where the Covid-19 pandemic has just emerged and
cannot be controlled.
Profitability in 2017 shows an average of 0.08% with a maximum value of 0.53% and a
minimum value of -0.62%. Profitability in 2018 shows an average of 0.07% with a maximum value
of 0.60% and a minimum value of - 0.38%. Profitability in 2019 shows an average of 0.06% with a
maximum value of 0.25% and a minimum value of -0.19%. Profitability in 2020 shows an average of
0.05% with a maximum value of 0.54% and a minimum value of - 0.20%. Profitability in 2021 shows
an average of 0.09% with a value of The maximum value is 0.68% and the minimum value is -0.18%.
The highest average value is in 2021 where the Covid-19 pandemic has just emerged and cannot be
controlled.
Liquidity in 2017 shows an average of 1.61% with a maximum value of 6.73% and a minimum
value of 0.07%. Liquidity in 2018 shows an average of 1.38% with a maximum value of 4.55% and a
minimum value of 0.02%. Liquidity in 2019 shows an average of 1.60% with a maximum value of
9.22% and a minimum value of 0.04%. Liquidity in 2020 shows an average of 1.91% with a
maximum value of 10.07% and a minimum value of 0.04%. Liquidity in 2021 shows an average of
1.98% with a maximum value of 7.41% and a minimum value of 0.01%. The highest average value is
in 2021 where the Covid-19 pandemic has appeared.
Leverage in 2017 shows an average of 0.54% with a maximum value of 1.10% and a minimum
value of 0.13%. Leverage in 2018 shows an average of 0.571% with a maximum value of 1.30% and
a minimum value of 0.16%. Leverage in 2019 shows an average of 0.577% with a maximum value of
1.77% and a minimum value of 0.10%. Leverage in 2020 shows an average of 0.575% with a
maximum value of 2.03% and a minimum value of 0.08%. Leverage in 2021 shows an average of
0.579% with a maximum value of 2.13% and a minimum value of 0.04%. The highest average value
is in 2021 where the Covid-19 pandemic has appeared.

21
Activity in 2017 shows an average of 0.642% with a maximum value of 2.06% and a minimum
value of 0.002%. Activity in 2018 shows an average of 0.641% with a maximum value of 1.80% and
a minimum value of 0.01%. Activity in 2019 shows an average of 0.67% with a maximum value of
2.24% and a minimum value of 0.02%. Activity in 2020 shows an average of 0.54% with a maximum
value of 2.22% and a minimum value of 0.0004%. Activity in 2021 shows an average of 0.60% with
a maximum value of 1.91% and a minimum value of 0.003%. The highest average value was in 2019
where the Covid-19 pandemic had not yet emerged.
Cash flow from operating activities (CFO) in 2017 showed an average of 0.10% with a
maximum value of 0.48% and a minimum value of -0.30%. CFO in 2018 shows an average of 0.09%
with a maximum value of 0.49% and a minimum value of -0.05%. CFO in 2019 shows an average of
0.06% with a maximum value of 0.26% and a minimum value of -0.25%. CFO in 2020 shows an
average of 0.09% with a maximum value of 0.30% and a minimum value of -0.14%. CFO in 2021
shows an average of 0.13% with a maximum value of 0.62% and a minimum value of -0.04%. The
highest average value is in 2021 where the Covid-19 pandemic has appeared.
Sales growth in 2017 shows an average of 0.27% with a maximum value of 1.73% and a
minimum value of -0.78%. Sales growth in 2018 shows an average of 0.69% with a maximum value
of 67.65% and a minimum value of -0.57%. Sales growth in 2019 shows an average of 0.23% with a
maximum value of 8.3% and a minimum value of -0.52%. Sales growth in 2020 shows an average of
-0.19% with a maximum value of 0.94% and a minimum value of -0.99%. Sales growth in 2021
shows an average of 0.37% with a maximum value of 26.67% and a minimum value of -0.82%. The
highest average value is in 2018 where the Covid-19 pandemic has not yet emerged.
Interest rates in 2017-2021 show an average of 4.61% with a maximum value of 5.62% in 2019
and a minimum value of 3.52% in 2021. The decline in the BI benchmark interest rate during the
pandemic has become a stimulus and encouragement for business people as well as lower interest
rates to encourage the movement of the Indonesian economy to develop further. GDP in 2017-2021
shows an average of 10,626,202.48 with a maximum value of 11,120,078.00 in 2021 and a minimum
value of 9,912,928.10 in 2019. It can be seen in the table that Indonesia's GDP generally continues to
increase even though in 2020 GDP has decreased where in this year Covid-19 appeared in Indonesia.
1. Financial distress, financial performance, and macroeconomic conditions before and during the Covid-
19 pandemic
Financial distress is indicated by the Zm value, if the Zm value is greater than or equal to 0.5,
the company is predicted to experience financial distress. Conversely, companies that have a Zm
value smaller than the predicted 0.5 are not experiencing financial distress (Ashraf et al. 2019; Habib
et al. 2018; Hirawati & Arifin 2015). The following are companies that indicated financial distress in
the study:

22
Based on the analysis, there are 12 out of 53 companies in the energy sector that are indicated
to experience financial distress. Of the total sample, 12.83% indicated financial distress consisting of
four subsectors, namely mining, distribution of oil, gas and coal storage, as well as trade, energy
services and investment and basic and chemical industries. The following is the percentage of
companies that indicate financial distress.
There are five mining subsector companies indicated financial distress, namely Apexindo
Pratama Duta Tbk (APEX), Ratu Prabu Energi Tbk (ARTI), Borneo Olah Sarana Sukses Tbk
(BOSS), Energi Mega Persada Tbk (ENRG), and SMR Utama Tbk (SMRU). When viewed from the
financial condition of the five coal subsector companies, they have almost the same financial
condition, namely having a small and even minus profitability value, minus sales growth value
except APEX 2018, BOSS 2017, and SMRU 2021, liquidity value less than 1, high leverage value,
activity ratio value and cash flow from small operating activities.
In the oil & gas storage and coal distribution subsectors, four companies indicated financial
difficulties, namely Bina Buana Raya National Shipping Tbk (BBRM), Buana Lintas Lautan Tbk
(BULL), Capitol Nusantara Indonesia Tbk (CANI), and Logindo Samudramakmur Tbk (LEAD). The
sectors most affected by the global crisis are sectors that rely on external demand (tradable) and one
of the commodities affected by the cessation of economic activity is energy commodities because it is
directly related to the transportation sector which experienced the sharpest decline (BPPT 2020).
BBRM, CANI, and BULL indicated financial distress during the covid-19 pandemic, namely the
2020 and 2021 periods, these issuers are included in transportation service companies that support the
energy sector. Meanwhile, LEAD indicated financial distress in 2018, this happened because the
company had assets that were not productive and efficient to use, so the company could not utilize
assets and convert them into cash.
There are two companies in the trade, services & investment subsector indicated financial
distress, namely Exploitasi Energi Indonesia Tbk (CNKO) and Dwi Guna Laksana Tbk (DWGL).
During the research period (2017-2021) CNKO indicated financial distress for five years, based on the
condition that the stock value did not move or was often called sleeping stock, in addition to financial
performance.

23
CNKO also experienced technical problems that hampered the production process. In addition, there
are internal problems in the company, namely a change in management due to the dismissal of
commissioners and directors. DWGL indicated financial distress in 2017-2020, the company's
financial performance improved during the Covid-19 pandemic this occurred due to increased energy
demand, the company also posted profits during the covid period, namely in 2020 and 2021.
In the basic and chemical industry subsector, Eterindo Wahanatama Tbk (ETWA) indicated
financial distress, ETWA indicated financial distress during the study period, namely for five years.
ETWA consistently has a negative profitability value during 2017-2021.
Apart from having poor financial performance, several companies that indicated financial
distress in the study were also subject to sanctions from the IDX for being late in submitting their
financial reports so that the IDX suspended several stock issuers who committed violations and this
could cause the company to go bankrupt and delisting from the Indonesian stock exchange. The
following are consistent companies from 2017-2021 that experienced financial distress:
There are three companies, namely Capitol Nusantara Indonesia Tbk (CANI), Exploitation
Energi Indonesia Tbk (CNKO), and Eterindo Wahanatama Tbk (ETWA) which indicated financial
distress during the research period, namely 2017-2021, these companies have special notations on the
stock exchange, notation E (financial statements show negative equity), notation X (equity securities
under special monitoring), as well as notation S (the last financial report does not show operating
profit). In addition, the Indonesia Stock Exchange (IDX) also temporarily suspends trading or
suspends stock trading. This shows that these companies do not have a healthy financial condition
and are vulnerable to bankruptcy if this financial distress problem cannot be corrected.
In 2020, the Covid-19 pandemic emerged which had a direct and indirect impact on the
financial condition of a company. The following is a comparison of financial distress conditions,
financial performance and macroeconomic conditions before and during the Covid-19 pandemic:
Based on Figure 4.2, the value of financial distress is higher during a pandemic which
illustrates that the company is getting closer to financial distress, based on Figure 4.2 significant
difference is in the liquidity value, the liquidity value is higher during the pandemic than before the
pandemic, this can be explained that the company's ability to pay off its short-term obligations
through current assets is higher during the Covid-19 pandemic, companies can take advantage of
credit restructuring policies, namely lowering interest rates, extending the term of payment, reducing

24
principal arrears, adding credit / financing facilities, and converting credit / financing into Temporary
Capital Participation (OJK Regulation No. 11 / POJK.03 / 2020)./2020). Then there is profitability
whose value is not much different, this means that the company can take advantage of the use of its
assets to generate maximum profit, energy demand also increases sharply in 2021 so that companies
can take advantage of opportunities to take maximum advantage and restore the situation due to the
impact of the Covid-19 pandemic.
In the midst of the Covid-19 pandemic, several companies in the energy sector experienced
profits, marked by the value of shares that soared and provided profits for the Company, this gave
rise to biased behavior in the stock market, the link between domestic financial markets and the
higher global financial markets. Rising demand as well as energy prices caused financial market
participants to engage in panic buying. Shocks that occur in global financial markets will be more
quickly transmitted to domestic financial markets. This condition causes financial market participants
to do panic selling/buying (Kuantan et al. 2019). Drastic changes in the structure of the domestic
economy have caused the risk of instability to increase even though economic fundamentals are
maintained. This is also why financial ratio values have increased during the Covid-19 pandemic in
the energy sector. The condition of misvaluation and behavioral bias in financial markets is indicated
by the formation of prices in financial markets that tend to be biased towards fundamentals (Kuantan
et al. 2019).
Financial distress conditions during the pandemic are generally higher than before the Covid-19
pandemic. Where the average before the pandemic was -1.27% and the average during the pandemic
was -1.14%. In the period before
Liquidity conditions during the pandemic are generally higher than before the Covid-19
pandemic. Where the average before the pandemic was 1.53% and the average during the pandemic
was 1.94%. The largest liquidity value both before and during the pandemic was in the Harum
Energy Tbk company in 2019 and 2020, this happened because the company continued the work of
the contract obtained the previous year as well as the company regained a new contract of IDR 8.668
billion, in 2020 there was a surge in the amount of cash, even the Company was in a net cash
position, namely the Company has currently paid off all bank debts. This can be explained that the
company's ability to pay debts is higher during the Covid-19 pandemic.
Leverage conditions during the pandemic are generally higher than before the Covid-19
pandemic. Where the average before the pandemic was 0.56% and the average during the pandemic
was 0.57%.

25
The largest leverage value before the pandemic and during the pandemic was in the company
Perdana Capitol Nusantara Indonesia Tbk in 2019 and 2021, this happened because in 2019 there was
a decrease in company revenue and a decrease in cargo volume, be it exports or imports as well as a
substantial decrease in freight rates and transportation volumes, which increased credit risk on trade
receivables thereby increasing the company's total debt. This can be explained that the global
economic slowdown increases the credit risk on trade receivables, thus increasing the company's total
debt.
Activity conditions before the pandemic were generally higher than during the Covid-19
pandemic. Where the average before the pandemic was 0.65% and the average during the pandemic
was 0.57%. During the period before the pandemic, the largest activity value was in the Perdana Alfa
Energi Investama Tbk company in 2019, this occurred due to an increase in sales and a significant
decrease in total assets and during the pandemic the largest activity value was in the Dwi Guna
Laksana Tbk company in 2020, this occurred due to a decrease in total assets. This can be explained
that the company's ability to use its assets effectively is higher when the Covid-19 pandemic has not
occurred.
Cash flow from operating activities (CFO) during the pandemic is generally higher than before
the Covid-19 pandemic. Where the average before the pandemic was 0.08% and the average during
the pandemic was 0.11%. The largest cash flow from operating activities (CFO) value both before
and during the pandemic was in the Bayan Resources Tbk company in 2018 and 2021, this happened
because there was an increase in revenue from customers as well as a decrease in interest expense
payments. In 2021, there was an increase in revenue from customers and an increase in tax refund
revenue.
Sales growth before the pandemic was generally higher than during the Covid-19 pandemic.
Where the average before the pandemic was 0.40% and the average during the pandemic was 0.08%.
During the pre-pandemic period, the largest sales growth value was in the Bumi Resources Tbk
company in 2018, this occurred due to an increase in coal sales volume as well as the achievement of
higher average selling prices due to better coal market conditions. During the pandemic, the largest
sales value was in the Atlas Resources Tbk company in 2021, this occurred due to an increase in
sales volume.
Indonesia's economic structure has not changed significantly in 2017-2021. Indonesia's
economic growth remains strong amid the global economic slowdown. In addition, Indonesia's
economic development shows an increasingly positive trend of improvement amid global economic
uncertainty. The GDP value showed an increase in 2017-2019 then in 2020 it decreased due to the
Covid-19 pandemic which resulted in a slowdown in the national economy. The following is a graph
of GDP growth from 2017-2021:
Source: Data processed 2023

26
In 2020 the value of GDP decreased, this occurred due to the Covid-19 pandemic, but the
decline that occurred was not significant, Indonesia's GDP in 2019 amounted to 10,949,155.40 and in
2020 it decreased to 10,722,999 then in 2021 there was a significant increase in economic growth with
a GDP value of 11,120,078 this happened because it was supported by good handling of the
pandemic by the government, the government, and the government.
Indonesia has a strategic role in driving the acceleration and effectiveness of national economic
recovery. In addition to Indonesia's main export commodities such as coal, crude palm oil (CPO), and
crude oil have also experienced price increases, increasing state revenue from taxes and non-taxes so
that Indonesia benefits from high energy prices.
In addition to economic growth, Indonesia's interest rates in 2020 also fell and continued to fall
until 2021. The cut in the benchmark interest rate is the monetary authority's response to economic
conditions affected by the Covid-19 pandemic. BI has cut interest rates 5 times in 2020. The
following is a graph of Indonesia's interest rates from 2017-2021:
Interest rates continued to rise from 2017-2019 then during the Covid-19 pandemic there was
a decrease in interest rates to 4.25 and continued to decline in 2021 with a value of 3.52. During the
Covid-19 pandemic, the government lowered interest rates to ease the burden on companies and
boost economic productivity (Dini et al. 2023). The decision to reduce interest rates was taken to
restore the slumping economy that contracted due to the Covid-19 pandemic.
Panel Data Regression Analysis Results
The research technique in this study uses panel data regression analysis with EViews 12
software. In the research technique, there are several panel data regression models that can be used,
namely the common effect model, fixed effect model, and random effect model. There are three tests
that can be done to determine the right technique in estimating panel data regression. The three tests
are: 1. Chow test, used to choose between common effect or fixed effect models. 2. Hausman test,
used to choose between fixed effect or random effect models. 3. Lagrange Multiplier (LM) test, used
to choose between the common effect or random effect model.
1.
Fixed Effect or common effect Significance Test (Chow Test)
The chow test was conducted to determine whether the common effect or fixed effect model was
more appropriate to use in the study.
27
2.
Fixed Effect or Random Effect Significance Test (Hausman Test)
After knowing that the result of the chow test is fixed effect, the next hausman test is conducted
to choose between regression models with fixed effect or random effect.
a.
If the number of individuals is greater than the number of coefficients including the intercept REM
can be used.
b.
If in panel data, the number of times is larger than the number of individuals, FEM can be used.
c.
If in panel data, the number of times is smaller than the number of individuals, REM can be used.
After knowing that the result of the hausman test is random effect, there is no need to do the
lagrange multiplier (LM) test because this test is used to choose between the common effect or
random effect model while in the chow test it is known that the common effect model is not chosen.
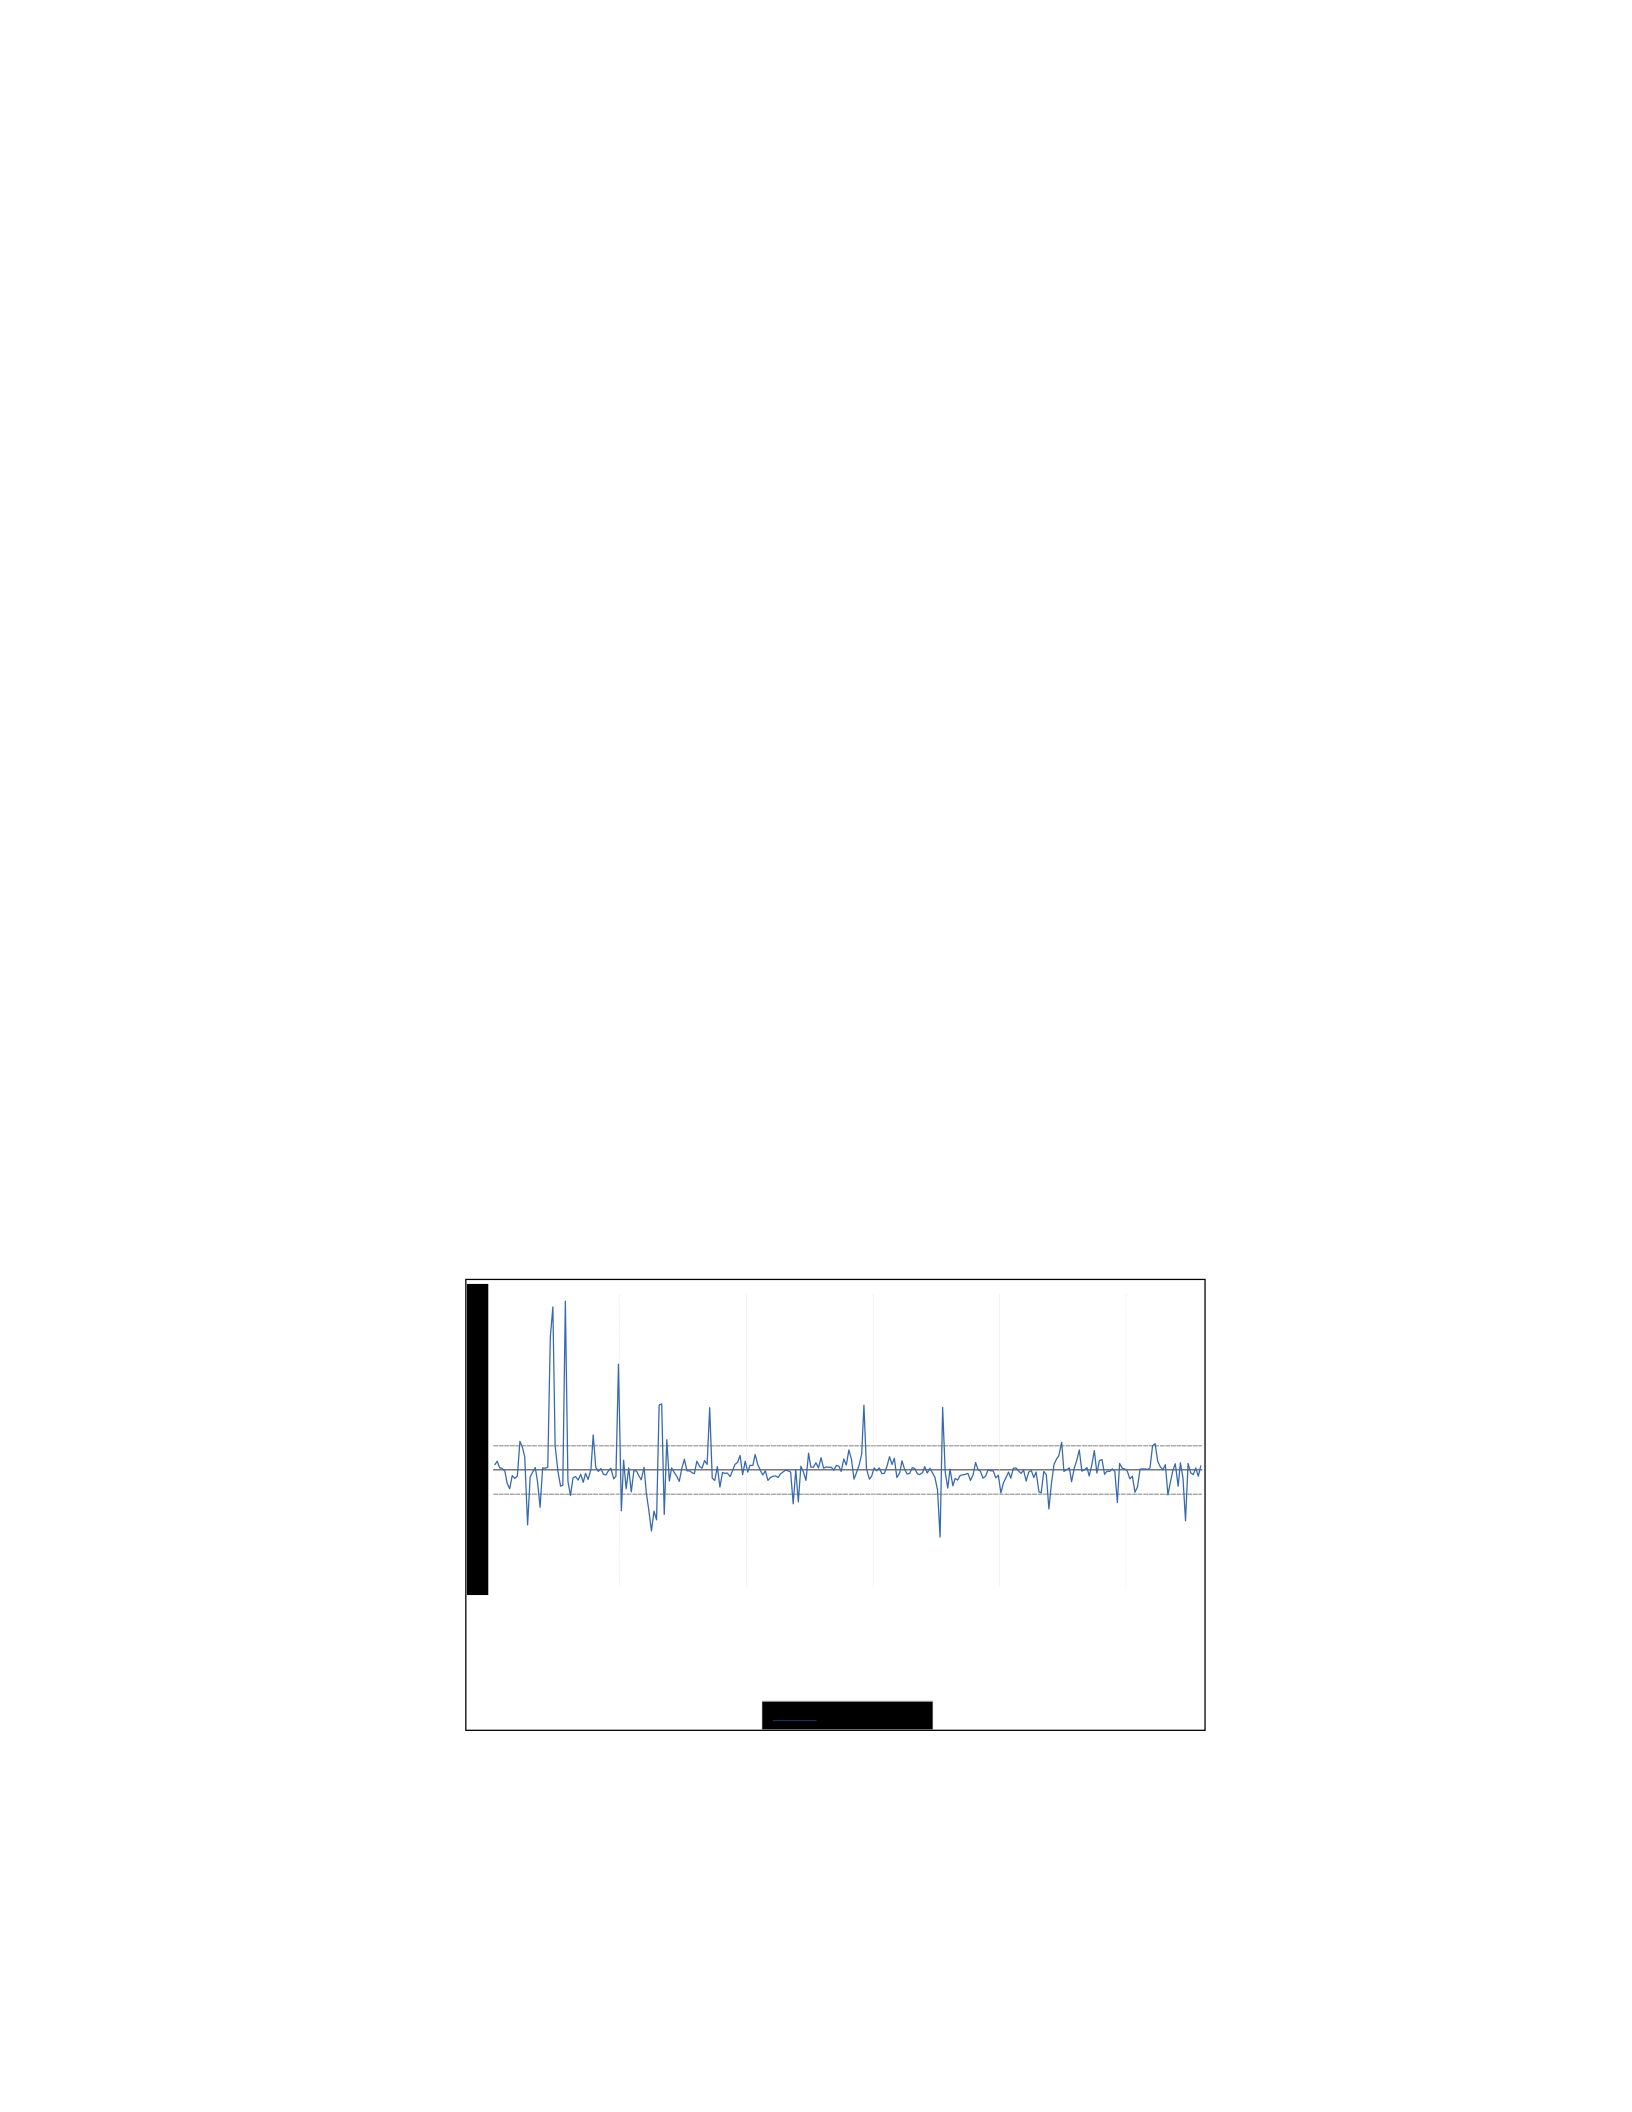
Based on the results of the tests that have been carried out, namely the chow test and the Hausman
test, the random effect model is the right and appropriate model for this study. The following are the
results of random effect testing using EViews 12 software:
1.
Heteroskedasticity Test
The heteroscedasticity test aims to test whether in the regression model there is an inequality of
variance from the residuals of one observation to another. heteroscedasticity test can be seen through
the graph, if the data graph does not form a certain pattern, there is no heteroscedasticity problem. The
following are the results of the heteroscedasticity test:
Figure 4.7 Heteroscedasticity test results
Based on Figure 4.7, it can be seen that the data graph does not form a certain pattern, it can be
concluded that there is no heteroscedasticity problem in the regression model so that the regression
model is suitable for use to predict financial distress based on the input of the independent variables.
ADRO - 17
ARII - 17
BIPI - 17
BULL - 17
CANI - 17
DOID - 17
ELSA - 17
FIRE - 17
HRUM - 17
ITMG - 17
COFFEE -
17
MBSS - 17
PGAS - 17
PTBA - 17
KING - 17
SMMT - 17
SURE - 17
TEBE - 17
WINS - 17

28
1.1
Analysis and Discussion
In the perspective of signal theory, the value of good financial ratios reflects the condition of a
healthy company and as one of the actions and choices made by management to show investors that
the company's performance is in good condition or the company is suitable to be chosen.
In addition to good financial performance, management actions to distribute dividends which
then become one of the signals to investors that the company is in a healthy financial state because it
is able to distribute its dividends. Dividends can be an indicator of the company's financial stability
because the company will pay dividends if the profits earned are indeed quite feasible.
Based on the partial significance test results in table 4.8, profitability has a probability value of
0.00 <0.05. The significance value is smaller than the required significance level, which is 0.05 so it
can be concluded that profitability proxied by ROA (Return on Asset) has an effect on financial
distress. Thus it can be said that the results of this study are in accordance with the hypothesis. The
profitability ratio is measured using the ROA (Return on Asset) proxy, this measurement measures
how well the company uses its assets to generate maximum profit. The higher the profitability figure,
it will make the company avoid financial distress because the company has been able to use its assets
to generate large profits so as to avoid bankruptcy. Based on the research results, the profitability
value of companies that indicate financial distress is negative, this means that companies cannot
maximize asset utilization in order to generate profits, even companies that indicate financial distress
cannot generate profits. Based on signal theory, a low ROA will provide a bad signal for investors
because it proves that the company is in an unhealthy state and is not suitable for investing. The
results of this study are consistent with Lumantobing's research (2019) which states that profitability
affects financial distress as well as the results of Rahma's research (2020). According to Rahma
(2020), the lower the profitability, the higher the possibility of the company experiencing financial
distress. Companies that have a low profitability ratio will have a signal that the company cannot turn
incoming cash into a profit.
Based on the partial significance test results in Table 4.8, liquidity has a probability value of
0.0009 <0.05. The significance value is smaller than the required significance level, which is 0.05 so
it can be concluded that liquidity proxied by the current ratio has an effect on financial distress. The
main components in calculating the current ratio are current assets such as cash, inventory, accounts
receivable and also current debt such as accounts payable, salaries, taxes and others. Almost all
companies in the study that indicated financial distress had a low current ratio value or a value of
less than one. A low current ratio value indicates that the company is unable to manage assets
properly and is unable to pay off short-term liabilities in accordance with the specified time period so
that the possibility that the company will experience financial distress is higher.

29
The results of this study are in line with Suherman's research (2022) which states that liquidity
with the current ratio proxy affects financial distress conditions.
Based on the partial significance test results in Table 4.8 leverage has a probability value of
0.00 <0.05. The significance value is smaller than the required significance level, which is 0.05 so it
can be concluded that the leverage has a probability value of 0.00 <0.05.
Leverage proxied by DAR (Debt to Asset Ratio) affects financial distress. Debt to Asset Ratio
(DAR) measures how much debt affects a company's assets. The higher the DAR value owned by the
company means that the company has more debt and there is potential for the company not to be able
to pay the debt and result in default which triggers financial distress. Every debt owned by the
company will affect the risk and return of a company. In general, a healthy or good DAR value is
smaller than 1 time or (<100%) but the results in the resulting DAR research are worth more than one
or the value is high, this results in the company experiencing financial distress. Financial distress
begins with a situation where a company fails to settle its debts, the more debt the company has, the
greater the company's responsibility in paying its debts. The results of this study are consistent with
Lumantobing's research (2019) which states that the leverage ratio affects financial distress.
Based on the partial significance test results in table 4.8, the activity ratio has a probability
value of 0.9588> 0.05. The significance value is greater than the required significance level, which is
0.05 so it can be concluded that the activity ratio proxied by TATO (Total Asset Turnover) has no
effect on financial distress. The activity ratio explains the optimal management of assets so that the
company can generate maximum sales and profits. Profitable profits will make the company avoid
financial distress. However, high sales are not only obtained from asset utilization. If the costs
incurred by the company increase, it will result in erratic net sales each year so that the profits
generated are erratic or experience losses which will lead the company to financial distress. Based on
the research results, almost all companies in the study have a low TATO value, so that the low TATO
value is still included in the category of companies that are not experiencing financial difficulties. So
that the size of the TATO value does not affect the condition of financial difficulties in the company
in the study. The results of this study are in line with the research of Restianti & Agustina (2018)
which states that if the sales of a company are high, the liabilities owned by the company will also be
high, so it is not certain that a large TATO value will make the company avoid financial distress.
Based on the partial significance test results in table 4.8 cash flow operation has a probability
value of 0.2608> 0.05. The significance value is greater than the required significance level, which is
0.05 so it can be concluded that cash flow from operating activities has no effect on financial distress.
The cash flow statement is one of the important components for external users to see the company
utilize its cash in operational activities. Such as creditors who want to lend their credit and investors
who will inject their funds for the company, the higher the cash flow operation means that the

30
company has used cash well in carrying out its operational activities so that the company does not
experience financial distress. In this study, it can be said that cash flow from operating activities. If the
value is low, it does not necessarily mean that the company is experiencing financial distress. A high
value of cash flow from operating activities does not necessarily explain that the company can pay its
obligations to creditors. Other causes can occur when the value of cash outflows from operating
activities is high. Although the value of operating cash flow is high but followed by expenses from
operational activities such as payment of raw materials, tax payments are large, it does not
necessarily make the company experience financial distress. The results of this study are consistent
with the research of Liahmad et al. (2021) which states that cash flow operations have no effect on
financial distress. In contrast to Giarto & Fachrurrozie's research (2020) which states that cash flow
operations affect financial distress.
Based on the partial significance test results in table 4.8 sales growth has a probability value of
0.0362 <0.05. The significance value is smaller than the required significance level, which is 0.05 so
it can be concluded that sales growth has an effect on financial distress. High sales reflect a company
in good condition because it can be said that high sales will generate high profits as well so that it can
avoid financial distress. In the results of the study, companies that indicated financial distress were
dominated by negative sales growth values, this indicates that companies that indicated financial
distress did not have the ability to maintain their economic position in the midst of the economy and
their business sector. Based on signal theory, the higher the sales growth, it will give a positive signal
to external parties such as creditors because the company can pay its obligations and also give a
positive signal to investors because the injection of funds is successful in the company. The results of
this study are consistent with research by Elviana & Ali (2022) and Putri (2021) suggesting that sales
growth has an influence on financial distress.
Based on the partial significance test results in table 4.8, the interest rate has a probability value
of 0.9679> 0.05. The significance value is greater than the required significance level, which is 0.05
so it can be concluded that interest rates have no effect on financial distress. This can happen because
when there is an increase in interest rates, the interest costs incurred by the company do not affect the
amount of interest costs borne by the company, because the interest rate on debt has been agreed
upon at the beginning of the loan contract, so it does not affect the company's financial stability. In
addition, it was found that in the energy sector companies studied, the value of short-term debt is
more than long-term debt, this has an impact on interest rates. The following is the percentage of debt
in the energy sector in the study:

31
From the company's side, interest rates are considered a burden that must be borne by the company
for a certain nominal debt borrowed from the bank, long-term debt interest or loans are costs charged
to the company because they will reduce the tax burden, but in research the percentage of short-term
debt in energy companies is more than long-term debt. In addition, changes in interest rates when
viewed from an investor's point of view are more likely to be used to control inflation and exchange
rates (Ningsih et al. 2021). So that the interest rate cannot be used as a measure of a company in
assessing the condition of the company experiencing financial distress, because not all companies are
affected by an increase or decrease in interest rates. This is in line with Sandi and Aman (2019) who
state that interest rates have no effect on financial distress.
Based on the results of testing economic growth calculated through
GDP has a probability value of 0.4593, which means that the value of 0.4593> 0.05, it is concluded
that the economic growth variable has no partial effect on financial distress. Indonesia is one of the
world's largest coal exporters, so Indonesia benefits from high energy prices so that the condition of
companies in the energy sector is not affected by good or bad economic growth. So that economic
growth cannot be used as a measure of a company in assessing the condition of the company
experiencing financial distress. This is in line with Ceylan (2021) which states that economic growth
has no effect on financial distress.
Based on the results of testing the Covid-19 pandemic has a probability value of 0.3707, which
means that the value of 0.3707> 0.05, it is concluded that the Covid-19 variable has no partial effect
on financial distress. This can happen because of the increase in commodity prices during the
pandemic, the increase in prices is driven by strong demand amidst efforts to recover from the
pandemic and supply chain disruptions that are still continuing. In addition, this is supported by the
good handling of the pandemic by the government, the Indonesian government has a strategic role in
encouraging the acceleration and effectiveness of national economic recovery. The government
formed 3 (three) policies that will be carried out including increasing domestic consumption,
increasing business activity and maintaining economic stabilization and monetary expansion.
1.2
Managerial
Implications
Early indicators of bankruptcy or as an early warning system for companies when the
company's financial condition is not good can be anticipated by early detection by predicting
financial distress through the company's financial performance. As for the research results, several
managerial implications are obtained that can be shared for various parties, including:

32
1.
` The information obtained from the research results can be used by companies in the energy
sector that want to protect themselves and avoid financial distress, company management must be
able to use and manage assets properly to increase sales so that profit margins can increase. Good
asset management can be utilized to cover company debt. In addition to asset management, debt
management also needs to be done so that it is not too large and can still be controlled. Maintaining
high sales is important because it reflects the company's good financial condition. After all, high sales
will generate high profits and can avoid financial difficulties. If the company has indications of
financial distress, the company can restructure bank debt to strengthen the capital structure and
improve the overall cash position, as well as carry out cost efficiency. In unfavorable market
conditions due to declining demand for energy commodities, cost burden management as well as cost
efficiency is one of the crucial things so that companies in the energy sector can avoid financial
distress.
2.
Investors in evaluating companies to determine investment targets
Based on the research results, investors can consider the value of return on assets which can
describe how well the company uses its assets to generate maximum profit, investors can also
consider the value of liquidity by looking at the current ratio where the value should not be too small.
Based on the research results, investors can consider the return on assets value which can describe
how well the company uses its assets to generate maximum profit, investors can also consider the
value of liquidity by looking at the current ratio value where the value should not be too small
because it can be said that the company is having difficulty paying its obligations on time because its
assets cannot cover large debts, besides that investors can consider leverage by looking at the debt to
asset ratio if the value is too high indicating that the company has a large debt ratio so it is not
suitable for investing. Poor financial performance will have an impact on the value of the company's
shares, either the value of the shares continues to decline or the company has shares that do not move
so that investors are trapped in a bad investment.
3.
The Indonesia Stock Exchange (IDX) and the Financial Services Authority (OJK) can review
The Indonesian Stock Exchange and the Financial Services Authority as the authority of the
stock market cannot allow the dormant stocks to become a market risk, so it is necessary to take
preventive measures to protect investors and make rules regarding investor protection in the stock
market. The Indonesia Stock Exchange and the Financial Services Authority as authorities in the
capital market cannot allow these dormant stocks to become market risks, so it is necessary to take
preventive steps to protect investors and make rules regarding investor protection in the capital
market. This is expected to filter out companies with increasingly poor performance.

33
worsen before entering the shortage of cash stage which then leads to financial distress and will
harm investors. The Indonesia Stock Exchange (IDX) and the Financial Services Authority (OJK)
also need to enforce the code of ethics related to information disclosure to keep the market
mechanism running properly.

