


When we complete this chapter, you should:
1. Understand the various components of the standard FS audit report.
2. Know the situations that result in the addition of explanatory.
3. Be able to explain the conditions that lead to a departure from the standard report.
4. Know the types of FS audit reports other than unqualified/unmodified.
5. Be able to explain the effect of materiality on the auditor’s choice of audit reports.
6. Understand the situations that require different types of reports on comparative FS.
7. Know the auditor’s responsibility for other info in documents containing audited FS.
8. Understand the auditor’s responsibility when FS are prepared on non-GAAP basis.
9. Understand the auditor’s responsibility for reporting on specified elements,
accounts, or items of a FS.
10. Understand the auditor’s reporting responsibility when compliance with contractual
agreements or regulatory requirements related to FS.
11. Understand the changes to the auditor reporting model coming soon.
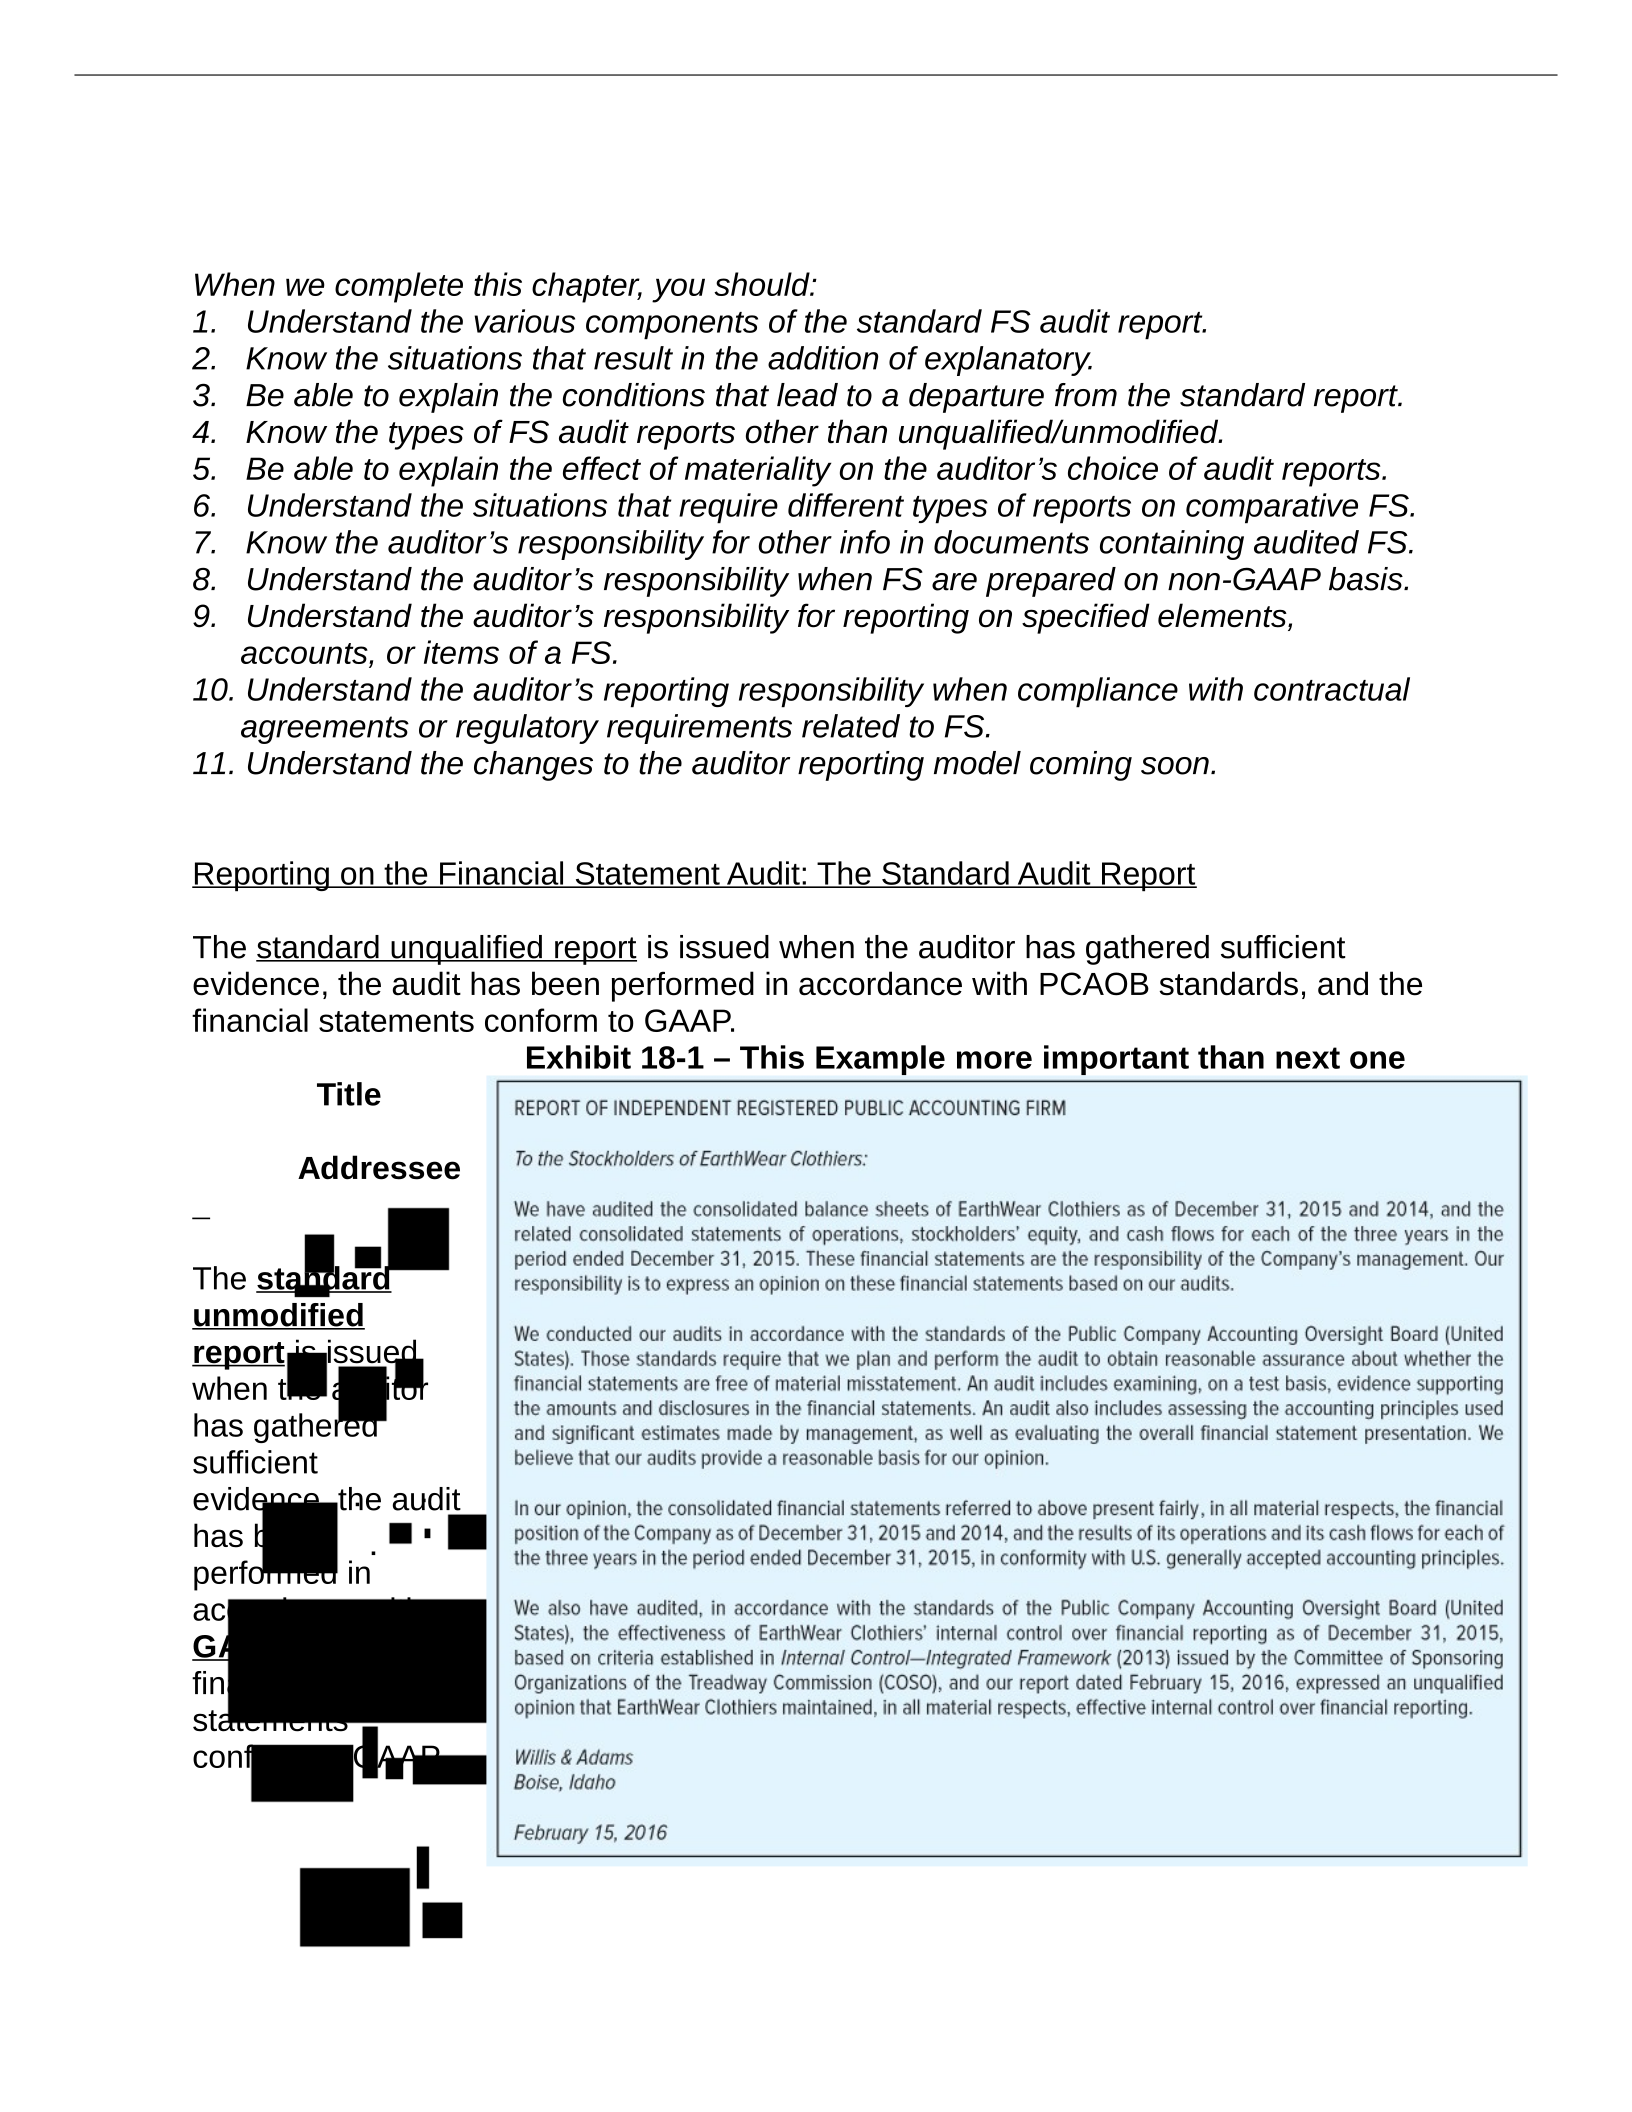
Reporting on the Financial Statement Audit: The Standard Audit Report
The standard unqualified report is issued when the auditor has gathered sufficient
evidence, the audit has been performed in accordance with PCAOB standards, and the
financial statements conform to GAAP.
Exhibit 18-1 – This Example more important than next one
Title
Addressee
The standard
unmodified
report is issued
when the auditor
has gathered
sufficient
evidence, the audit
has been
performed in
accordance with
GAAS, and the
financial
statements
conform to GAAP.
Chapter 18: Reports on Audited Financial Statements
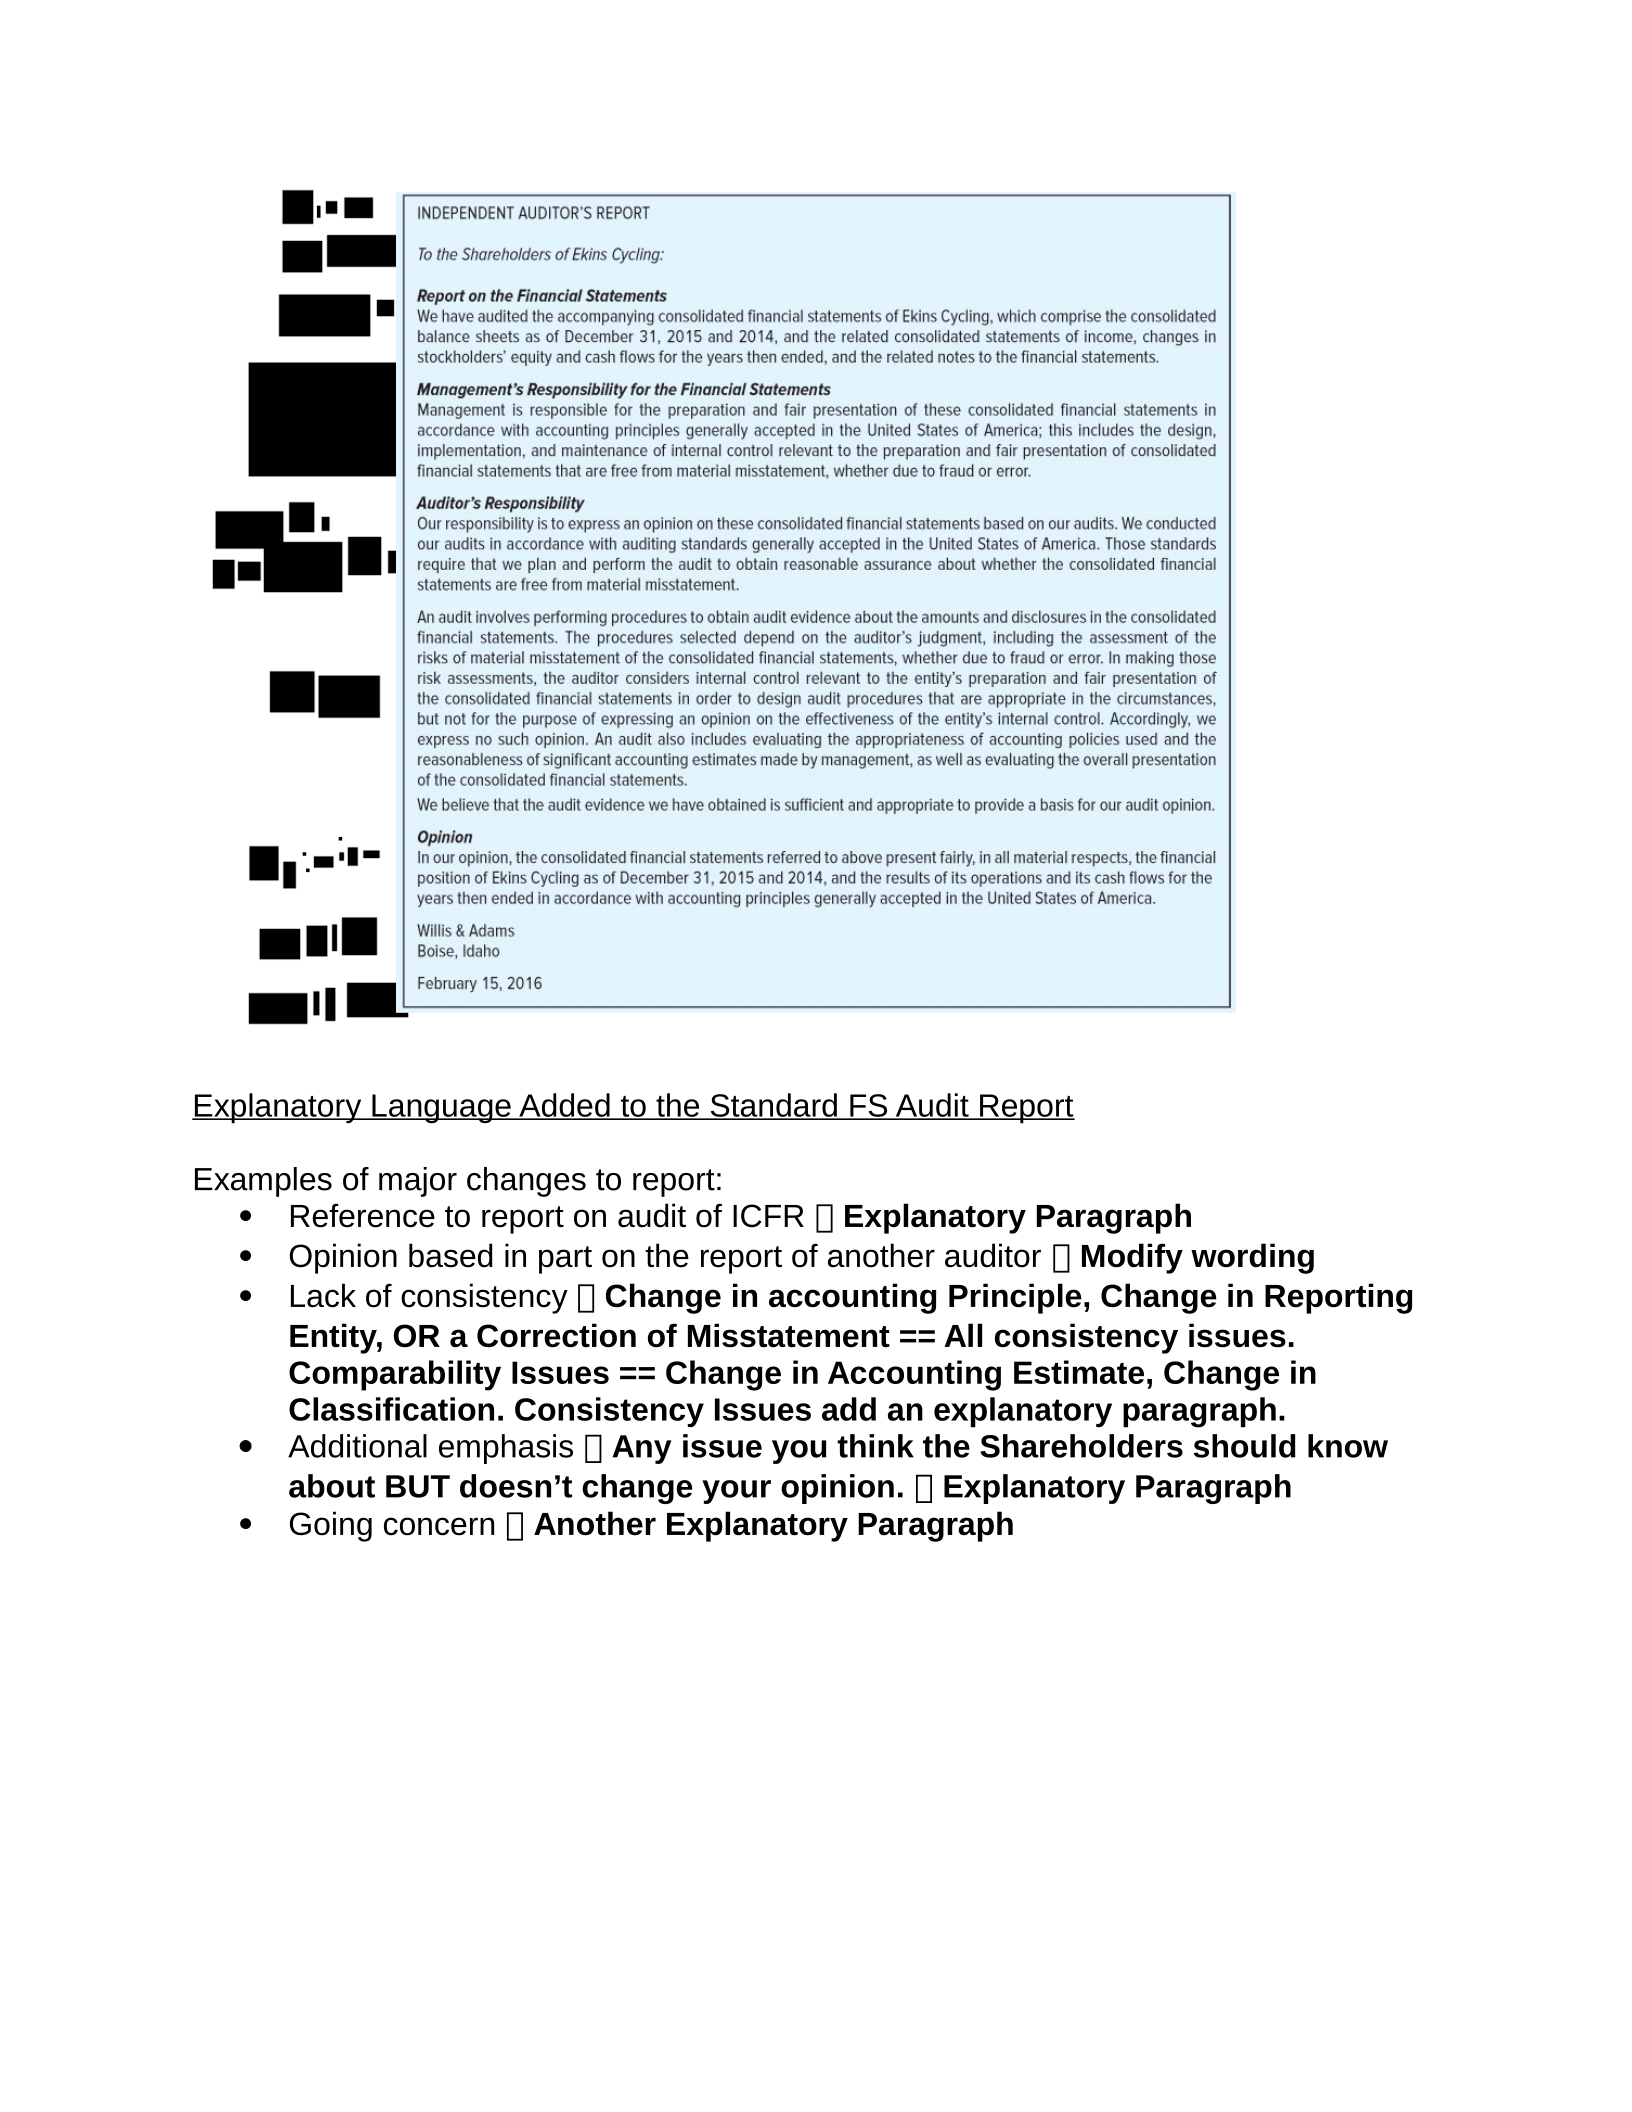
Explanatory Language Added to the Standard FS Audit Report
Examples of major changes to report:
Reference to report on audit of ICFR Explanatory Paragraph
Opinion based in part on the report of another auditor Modify wording
Lack of consistency Change in accounting Principle, Change in Reporting
Entity, OR a Correction of Misstatement == All consistency issues.
Comparability Issues == Change in Accounting Estimate, Change in
Classification. Consistency Issues add an explanatory paragraph.
Additional emphasis Any issue you think the Shareholders should know
about BUT doesn’t change your opinion. Explanatory Paragraph
Going concern Another Explanatory Paragraph
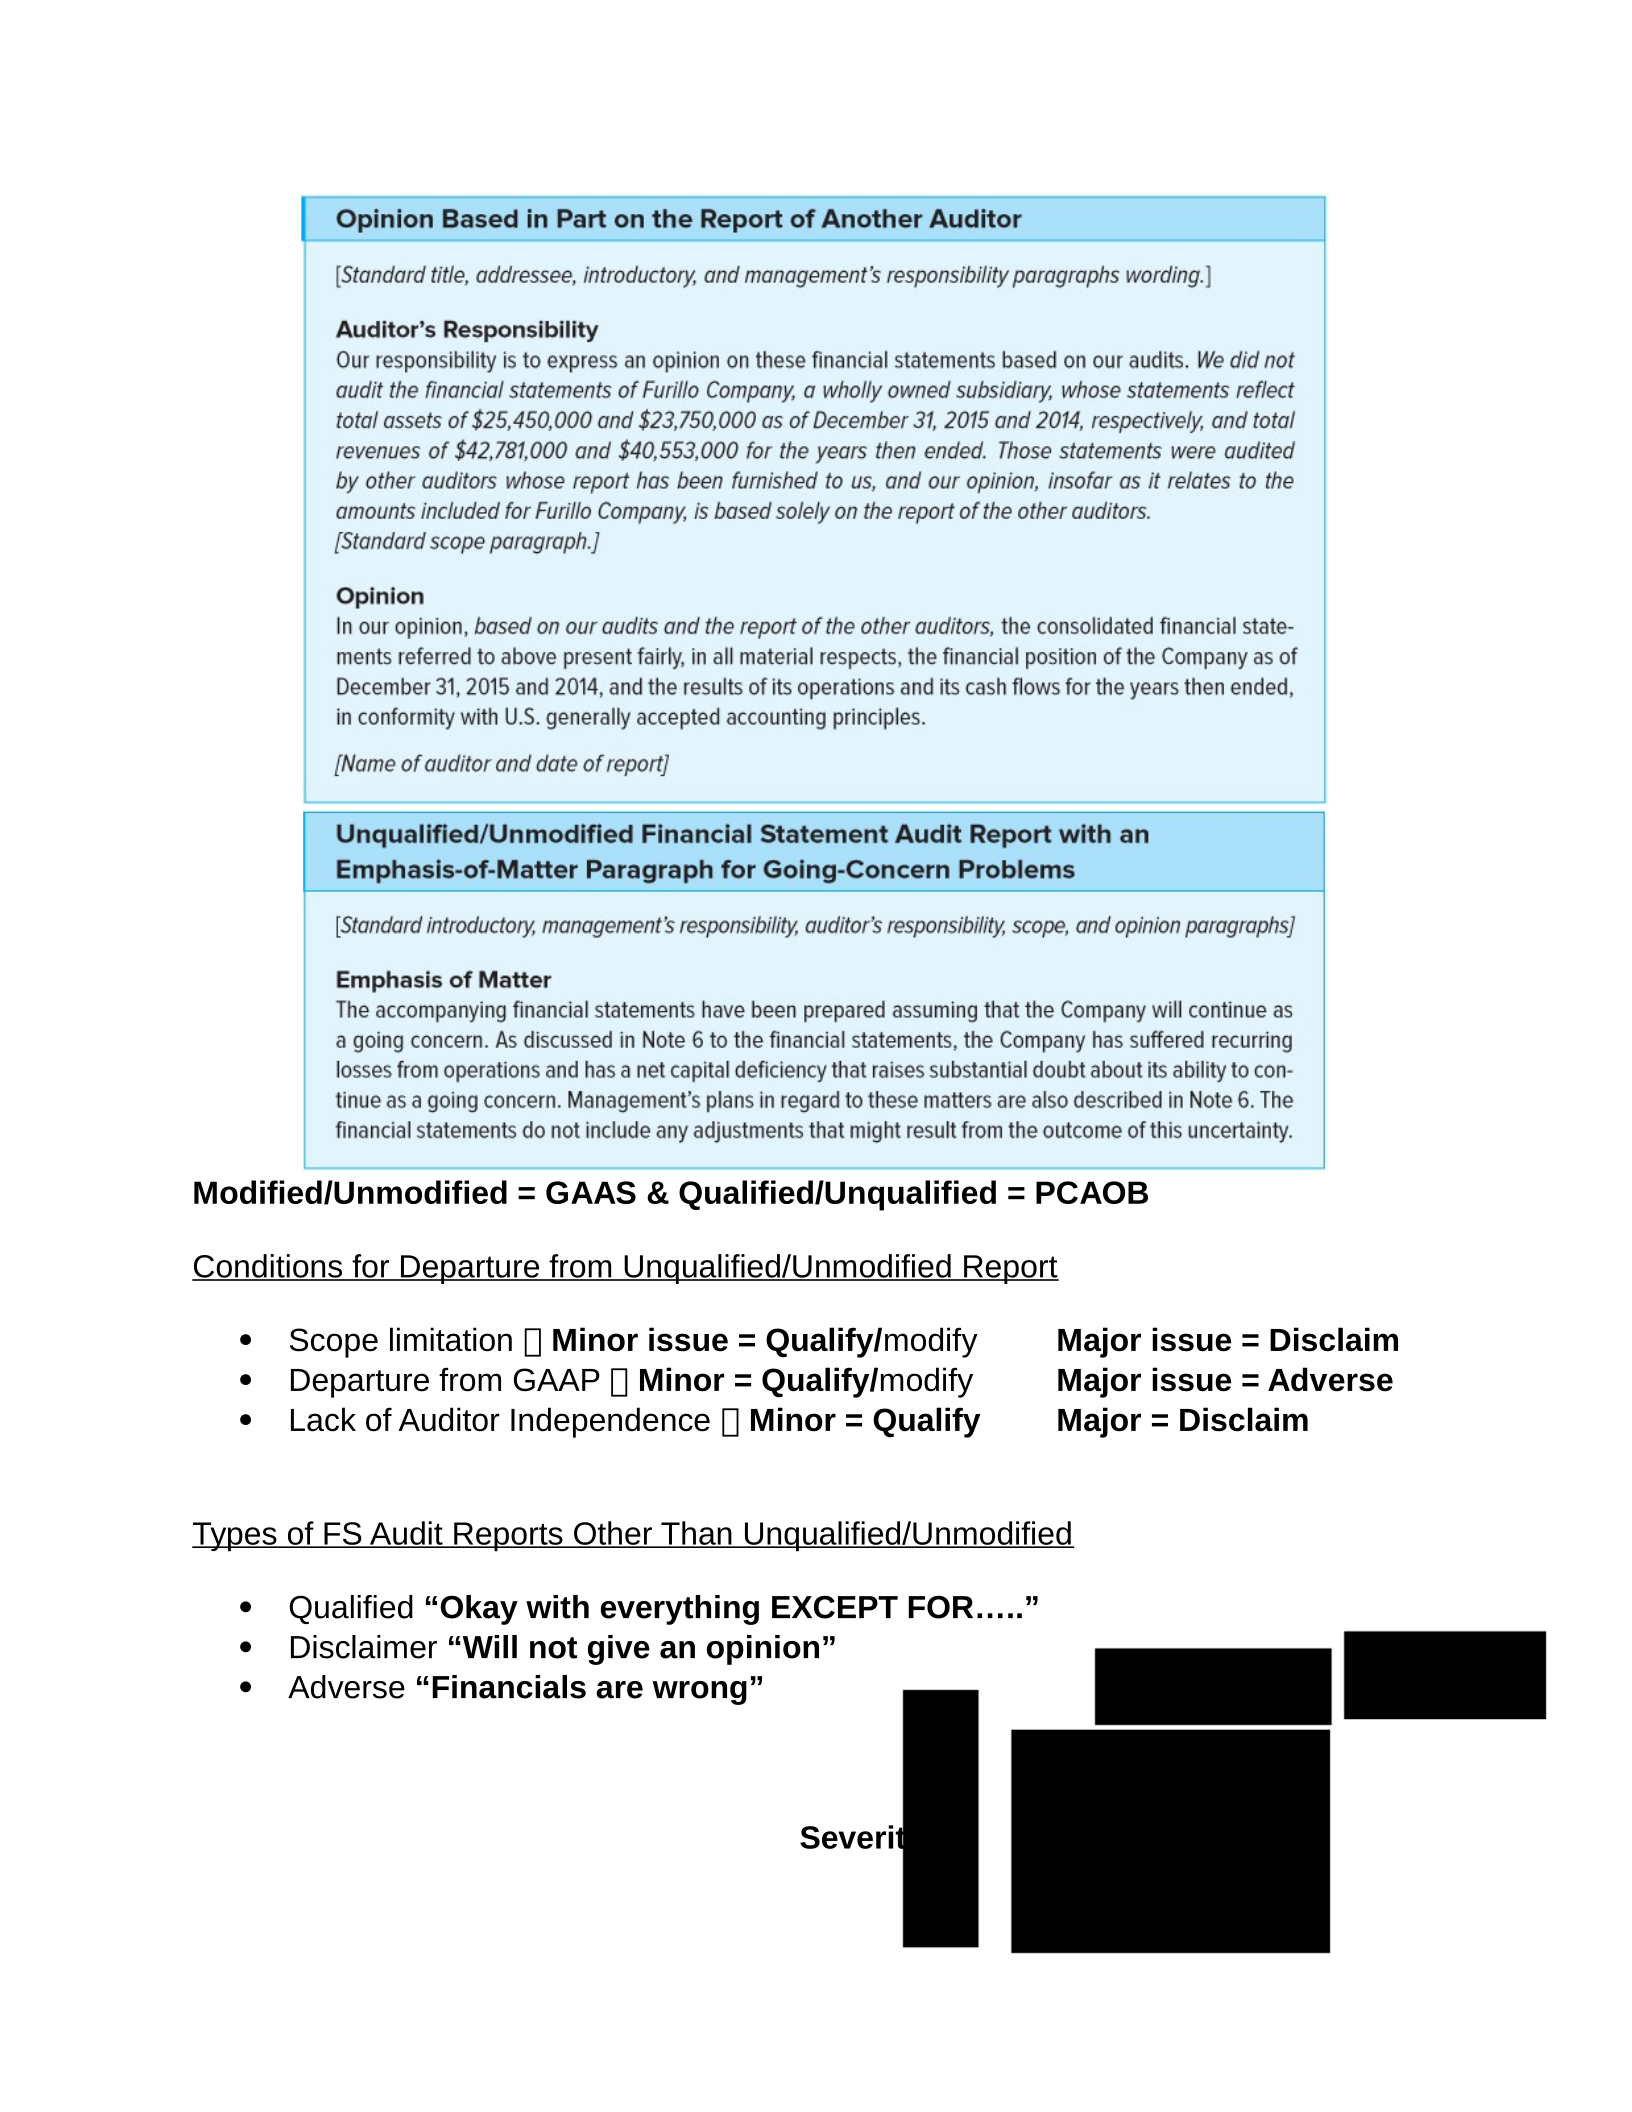
Modified/Unmodified = GAAS & Qualified/Unqualified = PCAOB
Conditions for Departure from Unqualified/Unmodified Report
Scope limitation Minor issue = Qualify/modify Major issue = Disclaim
Departure from GAAP Minor = Qualify/modify Major issue = Adverse
Lack of Auditor Independence Minor = Qualify Major = Disclaim
Types of FS Audit Reports Other Than Unqualified/Unmodified
Qualified “Okay with everything EXCEPT FOR…..”
Disclaimer “Will not give an opinion”
Adverse “Financials are wrong”
Severity
The Effect of Materiality on Financial Statement Reporting
Pervasive effects on the FS are those that:
Are not confined to specific elements, accounts, or items
If so confined, represent or could represent a substantial proportion
With regard to disclosures, are fundamental to users’ understanding
Conditions Requiring Other Types of Audit Reports
Scope Limitation: Results from an inability to obtain sufficient appropriate
evidence about some component of the financial statements.
Not in Conformity with GAAP: Results when financial statements are materially
affected by a departure from GAAP.
Auditor not Independent: Results when auditor has some form of prohibited
relationship with the entity (see Ch. 19).
Special Reporting Issues
Different reports on comparative financial statements
Change in report on prior-period financial statements
Report by a predecessor auditor
Other Information in Documents Containing Audited Financial Statements
The auditor has no responsibility beyond the financial information contained in the
report, and he or she has no obligation to perform any audit procedures to corroborate
the other information. However, the auditor is required to read the other
information and consider whether it is consistent with the information contained
in the audited financial statements.
Special Reports
Financial statements prepared on a basis of accounting other than GAAP
Specified elements, accounts, or items of a financial statement
Compliance with aspects of contractual agreements or regulatory requirements
Financial Statements Prepared According to a Special Purpose Framework
Regulatory Basis
Tax Basis
Cash (or modified cash) basis
Contractual Basis
Specific Elements, Accounts, or Items of a Financial Statement
In some situations, an auditor may be engaged to report on only specific parts of the
FS. Rather than auditing specified elements, accounts, or items, an auditor may be
engaged to apply only agreed-upon procedures.
Compliance Reports Related to Audited Financial Statements
The auditor provides negative assurance as to compliance with the provisions of
contractual agreements or regulatory requirements. The auditor does not use the words
“In our opinion…”
Big Changes Coming to Audit Reporting
IAASB has adopted new standards that will increase the amount of subjective
information conveyed by the auditor to financial statement users. The new standards
are effective for periods ending after December 15, 2016.
PCAOB and ASB standards have not been finalized, however, it appears that the
substance of the US audit reporting standards under development likely will be very
similar to those adopted by the IAASB.
New IAASB requirements for “listed” entities:
A new section in the report to communicate key audit matters
Disclosure of the name of the engagement partner in the audit report
New IAASB requirements for all entities:
Auditor reporting on going concern will be enhanced
The audit report will include a statement that the auditor is independent and has
fulfilled all relevant ethical responsibilities
The audit report will include an enhanced description of the responsibilities of the
auditor and the key features of an audit
Powered by TCPDF (www.tcpdf.org)

