


IMPLICIT TAXES AND TAX CLIENTELES
The earlier leasing example and the municipal bond example both illustrate two
very important concepts we will encounter time and time again throughout the text:
1. Implicit taxes
2. Tax clienteles
Implicit taxes arise because the before-tax investment returns available on tax-
favored assets are less than those available on tax-disfavored assets. In the rent-or-
buy example, a reduction in the rental rate is required to induce renters to forego the
tax benefits of ownership, and this decreases the pretax investment return garnered
by property lessors. Another example of implicit taxes is our example of the reduced
yield available on tax-exempt municipal bonds in the United States relative to taxable
corporate bonds of equal risk. Here, the reduced yield represents an implicit tax paid
to the issuing municipalities rather than to the federal government.
As an example of the common misunderstanding of implicit taxes, consider an
article published by the Wall Street Journal when John Kerry was running for president
and his wife, Teresa Heinz Kerry, released her tax returns. The article stated that
because Mrs. Kerry had $2.78 million in tax-exempt interest from municipal bonds that
she was not paying her fair share of taxes because her tax rate was below other
wealthy Americans and also below many in the middle class.1 What the author of the
article was incorrectly ignoring is the implicit taxes that Mrs. Kerry was paying by
accepting a lower pretax rate of return on the municipal bond investment. Once the
implicit tax (lower pretax return) is taken into account, her total tax rate was much
higher than the 12.4% computed in the article.
The tax clienteles and implicit tax concepts are closely related. Tax clienteles
arise because of cross-sectional differences in tax rates. Certain taxpayers are more
likely than others to own various kinds of assets or to organize production in particular
ways. Examples of tax clienteles are high-tax-bracket taxpayers who are more likely
to hold tax-exempt municipal bonds rather than taxable corporate bonds and who are
more likely to be lessors and owners of depreciable equipment rather than lessees. In
our previous example, Teresa Heinz Kerry is more likely to own a municipal bond

because she is a high-explicit-rate taxpayer, and the after-tax return on the municipal
bond is likely higher than the after-tax rate of return on fully taxed bonds and assets.
Mrs. Kerry, as someone in the highest income tax bracket, bears implicit taxes on
municipal bonds at a rate slightly lower than the explicit tax rate she would otherwise
be subject to on fully taxable income. With every topic we cover throughout the book
we will encounter implicit taxes, tax clienteles, or both concepts.
Tax Planning as a Tax-Favored Activity
One reason governments use tax policy to encourage (or discourage) a variety
of economic activities is that tax planning itself is a tax-favored activity. Specifically,
money spent on tax planning is tax deductible, whereas any tax savings arising from
the tax planning are effectively tax exempt because they reduce taxes payable.
Suppose a taxpayer could invest $10,000 in fully taxable corporate bonds for 1 year
that yield 10% per annum before taxes. If the taxpayer faces a marginal tax rate of
28%, the after-tax rate of return is 7.2% (calculated as .10 × [1 – .28]). Alternatively,
suppose the taxpayer could invest in tax-planning services for $10,000 to save
$11,000 in taxes in the current year. The pretax rate of return is 10%. However, the
after-tax rate of return is 13.89%, calculated as the tax savings net of the tax-planning
cost, $1,000, divided by the after-tax cost of the tax-planning services, $10,000 × (1 –
.28) or $1,000/$7,200. Note that the tax-favored treatment of tax planning results here
in an after-tax rate of return higher than the pretax rate of return. In this case, tax
planning is more tax favored than is tax exemption (a situation in which an asset
escapes explicit taxation such that the after-tax rate of return equals the pretax rate of
return). Note also that the aftertax return to tax planning depends on the taxpayer’s
marginal tax rate. For a taxpayer facing a marginal tax rate of 15%, the after-tax rate
of return is 11.76%, calculated as $1,000/[$10,000 × (1 – .15)]. For a taxpayer facing
a 35% tax rate, the after-tax rate of return is 15.38%, or $1,000/ [$10,000 × (1 – .35)].
The after-tax returns are largest for high-tax-rate investors, so these taxpayers tend to
be most responsive to tax-rule changes and tend to spend the most on the services of
tax accountants and tax lawyers.
Why Study Tax Planning?
We answer this question with the following simple example. Suppose there were
two skills that you could acquire: tax-planning and investing expertise. Further
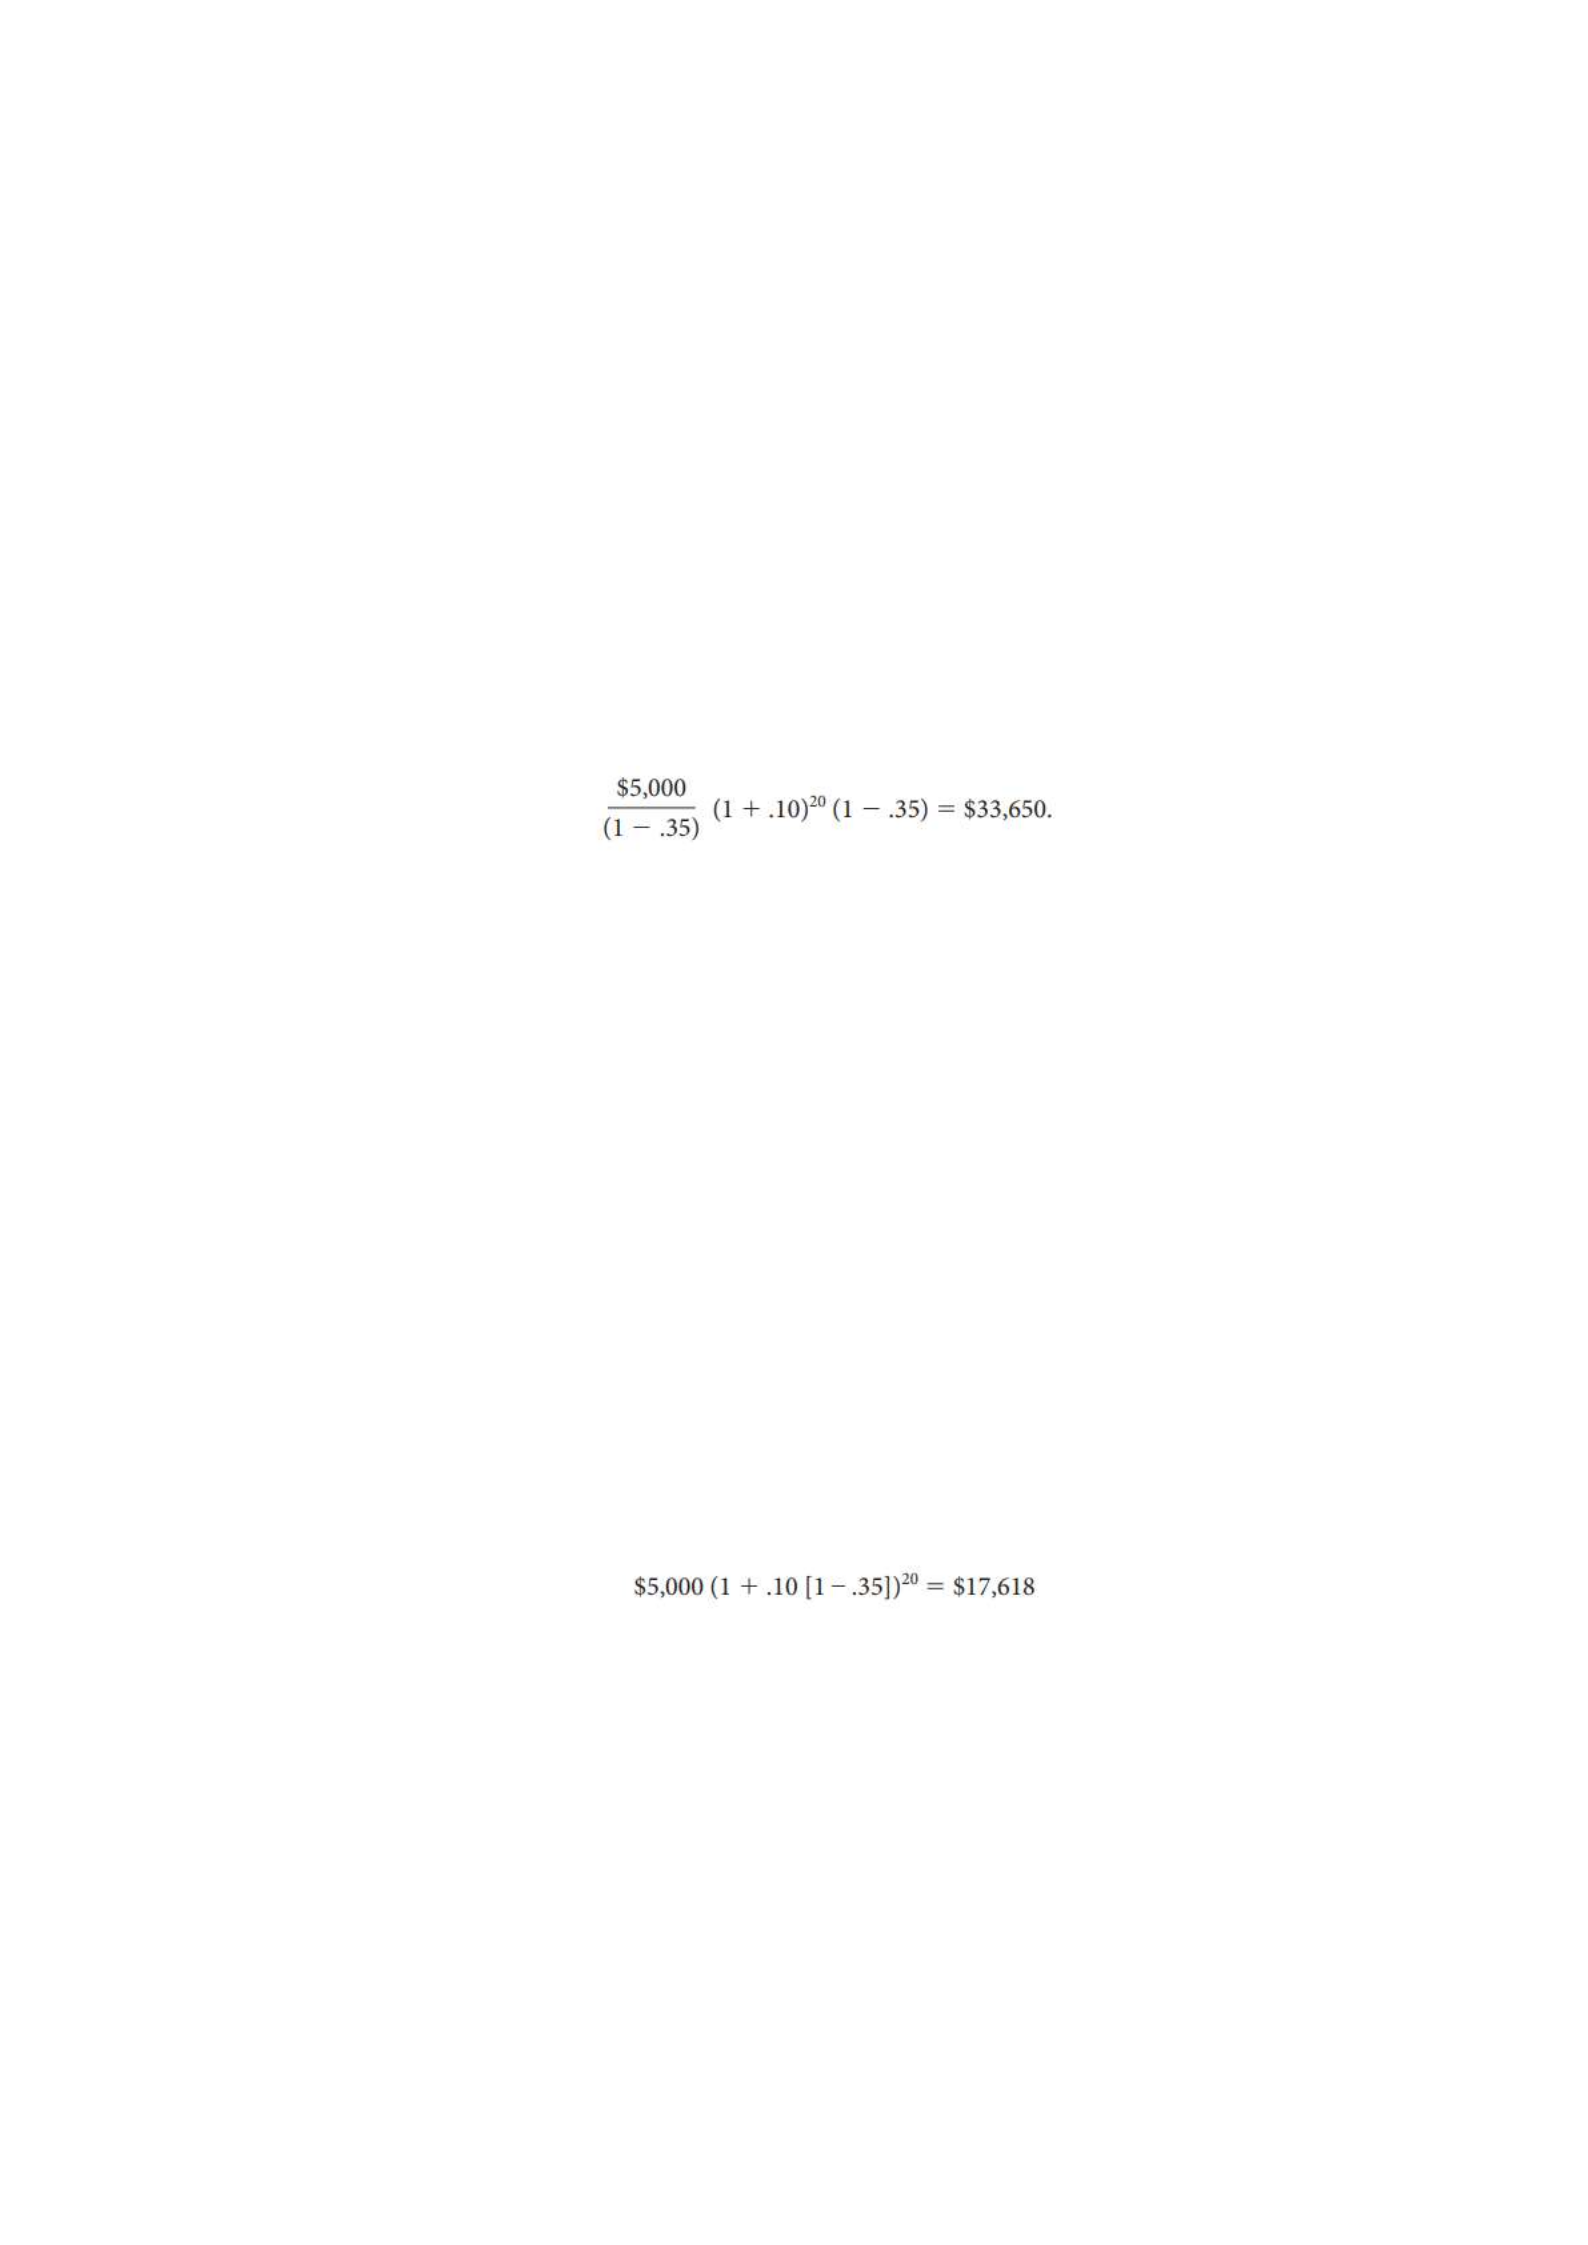
suppose you could only learn one. You are faced with the following fact pattern. You
are endowed with $5,000 of after-tax cash, have a 20-year investment horizon, and
face a current marginal tax rate of 35%, which also is the rate you expect to face over
the next 20 years. You expect that investing passively in an index fund will generate a
10% pretax return each year for the next 20 years. You choose to learn tax-planning
skills and invest passively. You invest in a pension plan (such as a 401[k] plan,
discussed in more detail in Chapter 3) such that the after-tax cost of the investment is
$5,000. The investment is tax deductible, whereas tax on the returns in this plan is
deferred until the end of the investment horizon. The after-tax accumulation from this
investment is:
Suppose instead you choose investing expertise and behave as a day trader,
actively moving in and out of stocks. You hold stock no longer than 1 month and thus
there is no deferral of taxes on your annual returns. How much would you have to earn
pretax to match the returns to the basic tax-planning example just presented? Because
the basic tax planning example earns 10% after-tax per year, you would need to earn
15.38% pretax per year on your actively managed portfolio to earn 10% after-tax per
year (15.38% [1 – .35] = 10%).
But what if, more realistically for most taxpayers, you just thought you could beat
the market but really could not, and your active portfolio management yielded a 10%
pretax return per year? In this case you would accumulate after-tax after 20 years as
follows:
which is substantially less than the return to basic tax planning.
But, of course, tax planning and investing expertise are not mutually exclusive.
Consider now what happens if you can beat the market and be a good tax planner.
That is, you invest in a pension plan such as a 401(k) plan and actively manage the
investment in the plan, earning a 14% annual pretax rate of return for the next 20
years. Because the investment is in a 401(k) plan, the tax on the annual returns is
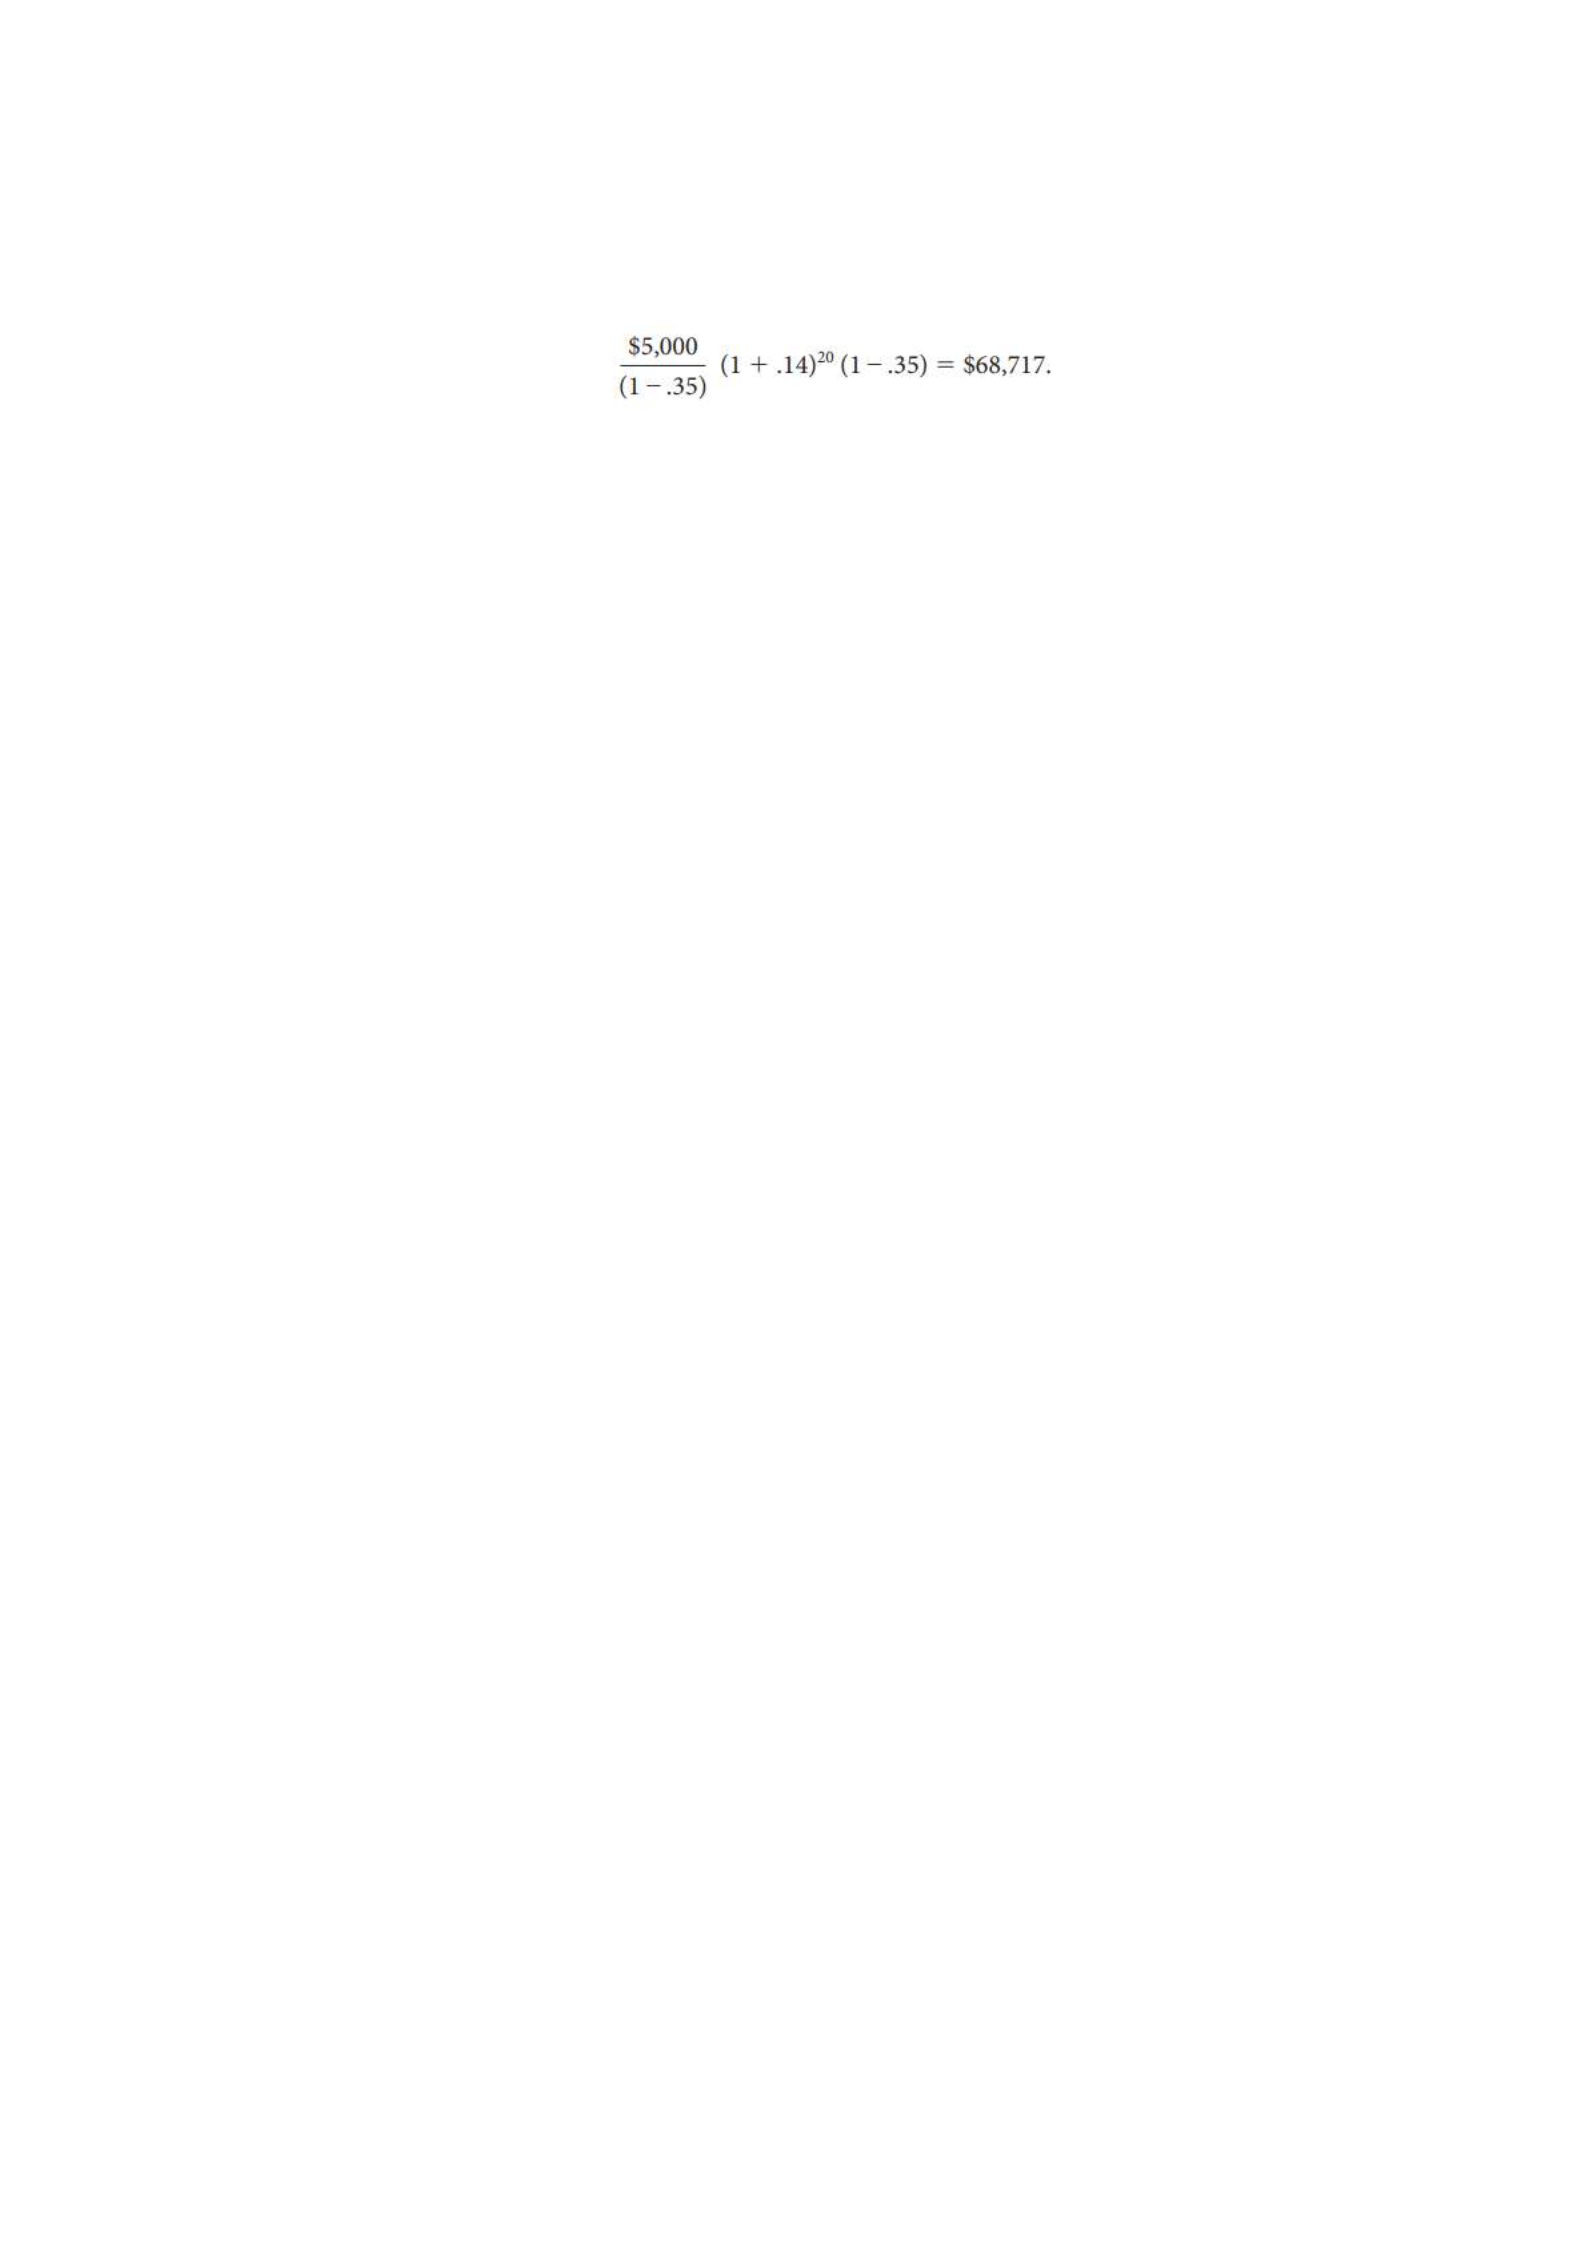
deferred until the funds are withdrawn in 20 years. The after-tax accumulation at the
end of 20 years is now

