


Chapter 1: Introduction to the Study
Introduction
Participants in the 2019 Personal Finance (P-Fin) Index survey, an annual measure
of financial literacy within the U.S. adult population, answered an average of 14 out of 28
questions correctly (Yakoboski, Lusardi, Hasler, et al., 2019). As troubling as this number
may appear, the implications extend well beyond a failing score. Individuals who lack
financial education are more likely to make late credit-card payments, to carry a card
balance each month, to be compulsive buyers, and are ill-equipped to navigate the
complex and evolving financial landscape, which can further exacerbate socioeconomic
inequality (Lin et al., 2019). It is against this complex backdrop of deficient financial
knowledge, negative behaviors and outcomes, and emotion-laden attitudes toward money
that adult-parents implicitly transfer these imprints to their children (Kim, Gutter, &
Spangler, 2017). For the 31% of parents who are comfortable and explicit in their
attempts to educate their 8-14 year-old children about financial matters, their
effectiveness may also fall short (T. Rowe Price, 2017). According the results of the 9th
Annual Parents, Kids, and Money Survey commissioned by T. Rowe Price (2017), 50% of
the respondents’ children noted that their parents confuse them or convey information
about finances that differs from what they may learn at school.
Therefore, it comes as no surprise that the financial literacy statistics associated
with 15-year-old teenagers are equally sobering. Across the 20 countries participating in
the 2018 Programme for International Student Assessment (PISA) financial literacy
survey, only one in seven 15-year-old students recognized the value of a rudimentary

budget and could apply common financial concepts to perfunctory, money-centered
situations that are of immediate relevance to their daily life (Organisation for Economic
Cooperation and Development [OECD], 2020). Accordingly, this group is not well
positioned to make impending significant and complex monetary decisions regarding
transportation, housing, employment, and post-secondary education that will affect their
future financial wellbeing (OECD, 2020).
There is, however, promising anecdotal evidence that expanding the role of
transaction-based financial technology (fintech) to include financial education may be an
affordable, scalable, and effective solution to the cross-generational financial literacy gap.
Arnold and Rhyne (2016) noted that the shift to fintech allows financial institutions to
reach a broader, more remote, yet technology-enabled client base. Access, however, is
only one lever in the addressing financial literacy gap. A natural extension of these
fintech services would include an authentic-learning component that accounts for the
knowing-doing gap, psychological considerations, life stages, and cultural factors that
shape financial behavior (Arnold & Rhyne, 2016). This assertion is further supported by
the Brookings Institution team of Kasman, Heuberger, and Hammond (2018), who also
highlighted the strong positive impact that experiential learning and informed parental
involvement may have on financial literacy and behaviors.
The clarion call for financial education combined with the promising research on
leveraging fintech applications to support authentic financial literacy experiences within
the family construct should not be ignored. Through this study, I sought to understand the
parents’ experience with and perceptions of using a private mobile budgeting and

banking application to support family financial socialization and the financial literacy
levels of the parent and child-users. The results of this study may expand on the
frameworks of family financial socialization and situated cognition theory and serve to
inform the role of parents, caregivers, and financial technology tools in the
personalfinance education space.
In the remaining sections of this chapter, I offer a background context for the
research topic including a summary of select literature, introduce the problem statement,
discuss the purpose of the study, state the research questions, and outline the conceptual
framework that is elaborated on in Chapter 3. I also summarize the nature of this study,
provide working definitions of unique terms used in the study, explore assumptions
within the context of the study, explain the scope and associated delimitations of the
study, and identify limitations related to the design and methodology. I close the section
by highlighting the significance of this research and summarizing the most salient points.
Background
In this study, I addressed a gap in the research related to fintech’s role in
supporting family financial socialization, situated cognition, and associated financial
literacy levels. I focused on how parents perceive fintech in terms of promoting
conversations, facilitating authentic learning opportunities, and supporting financial
literacy levels within the family construct. The following selection of peer-reviewed
articles related to financial literacy, the use of financial technology to support situation
cognition and education programs, and parental and family influence on financial
attitudes and behaviors speaks to the relevance of this study.

Existing research and media coverage is replete with dueling perspectives on the
effectiveness of classroom-based financial literacy education, the value of which is mired
by contrasting definitions of what constitutes literacy, inconsistent measurement systems,
varying levels of instructional rigor, and differences in teacher confidence and capability
with personal finance matters and content instruction (see Consumer Financial Protection
Bureau, 2019; Kaiser, Lusardi, Menkhoff, & Urban, 2020; Kaiser & Menkhoff, 2017;
Kasman et al., 2018; Walstad et al., 2017; Yakoboski et al., 2018). In their 2019 review of
the effects of youth financial education, the Consumer Financial Protection Bureau
(2019) stated that it is difficult to make priori assumptions about the effects of
classroombased efforts when the application of that knowledge may not be immediate or
measured. In effect, their review of school-based programs illustrates the disconnect
between financial knowledge acquisition and situated cognition whereby the personal
finance concepts learned in the classroom would be assessed through their authentic
application to financial transactions and decisions (see Consumer Financial Protection
Bureau, 2019).
What researchers do agree upon is that financial education begins in early
childhood and financial literacy imprints are imparted intentionally or tacitly by parents
through their narrative and behaviors (see Batty, Collins, & Odder-White, 2015; Hubler et
al., 2016; LeBaron, Rosa-Holyoak, Bryce, & Hill, 2018; Smith et al., 2018). Also, despite
the mired record of financial literacy efforts as evidenced by disparate grades ascribed to
state performance and comparative rankings among states and countries, there are some
common, positive inputs across school, home, and community-based curricula and

programs that support measured progress in financial literacy (Lin et al., 2019; OECD,
2020; Pelletier, 2017). Specifically, the purposeful and informed involvement of family
members, access to financial services and products, and the experiential learning
opportunities associated with handling money that are now ubiquitous on mobile and
digital devices have been collectively shown to support financial confidence,
responsibility, and efficacy (Aber, Morris, Wolf, & Berg, 2016; Amagir, Groot, Maassen
van den Brink, & Wilschut, 2018; Batty et al., 2015; Bosch, Serido, Card, Shim, &
Barber, 2016; Brown & Taylor, 2016; Fraczek & Klimontowicz, 2015; LeBaron et al.,
2019; LeBaron, Hill, Rosa, et al., 2018; Lusardi et al., 2017; Moreno-Herrero,
SalasVelasco, & Sanchez-Campillo, 2018; Smith, Echelbarger, Gelman, & Rick, 2018).
Financial literacy cognition begins in the home, may be augmented with
classroom curricula, but it is contextually and situationally applied and experienced
through in-person, and more often, online transactions using frictionless payment
systems. Arnold and Rhyne (2016), in a qualitative, multicase study, documented the
global shift from brick-and-mortar financial institutions to technology-based service
models. They discussed the potential implications of a parallel shift in financial education
delivery models away from classroom-based financial literacy toward an authentic,
technology-facilitated approach to building financial capability. Their prognostication that
fintech is positioned to play a pivotal role in supporting informed financial decisions and
associated literacy levels provided a perspective and lens for this study.
Similarly, Gudmunson and Danes (2011) noted that future expansion of their
family financial socialization theory could extend the definition of the family-social

environment to include digital media and schools. The development of this model and the
suggestion to include technology as an element of the family-social environment
acknowledges, by extension, the role of fintech in supporting financial literacy, which
was the basis of this study. Moreover, Hanson and Olson (2018) found that financial
literacy is positively influenced by individuals’ subjective assessment of their knowledge,
experience, and money-related conversations within the family construct. These results
supported my examination of parental perceptions, which served as a subjective measure
of differences in the nature and content of parent-child communication surrounding
financial transactions, and differences in financial literacy levels, which they attributed to
the fintech application.
In a meta-analysis, Kaiser, Lusardi, Menkoff, and Urban (2020) showed a
positive, measurable effect of financial education on financial behaviors. This research
suggested a linkage between behaviors and education, a relationship that I explored by
garnering perceived changes in financial literacy levels related to the transaction- and
communication-based activity on a fintech platform between parents and children. In a
complementary study, Kim et al. (2017) conducted a systematic literature review
designed to isolate research that focused on the process associated with family financial
decisions. Their summary analysis highlighted the opportunities for older children to
resocialize their parents’ financial behavior and literacy levels through the use of
technology applications (Kim et al., 2017). This finding pointed to the potential reciprocal
benefits of family financial socialization and fintech on the financial literacy levels of the
parent(s) and their child(ren), which helped inform my research questions.

Through a quantitative, developmental study, Smith, Echelbarger, Gelman, and
Rick (2018) identified the early-life stages during which attitudes about money are
shaped and whether those orientations can predict a child’s future spending behaviors.
Likewise, Kasman et al. (2018) noted that participating in or observing financial
transactions during childhood, such as accompanying a parent to a bank or hearing family
members talk about money, provide what they call “context and familiarity” that can
inform a child’s financial literacy levels and his or her facility managing money a decade
or more later as an emerging adult (p. 5). An age-appropriate, staged approach to
authentic learning is also advocated for by Mattar (2018) who cited Brown et al.’s (1989)
situated cognition theory as evidence for the need to account for the “social context of
interactions and tools” to create an environment for knowledge acquisition and learning
and, in turn, their systematic application (p. 6). In combination, this research aligned with
my premise that purposeful, money-centered conversations, involvement in
developmentally appropriate financial transactions, and financial literacy can be
supported through and facilitated by a fintech tool.
The existing body of literature points to the potential value of fintech in
supporting financial socialization processes within the family construct, promoting
productive money-oriented attitudes and behaviors, and elevating financial literacy levels.
This study connected the disparate research on family financial socialization; situated,
experiential learning; and financial literacy facilitated through and by financial
technology. Equally important, it may inform future policy and programmatic initiatives
related to purposeful parental involvement in financial education and the use of financial

technology to promote financial socialization, experiential financial learning, and literacy
levels in the home, classroom, and congregate care environments.
Problem Statement
The problem is that there is limited research exploring parent perceptions of the
use of fintech tools to support family financial socialization and the associated financial
literacy levels of parents and children. Researchers acknowledge that family socialization
during the formative childhood and adolescent years has an enduring effect on financial
attitudes and behaviors—positive or negative, intentional or unintentional
(MorenoHerrero, Salas-Velasco, & Sanchez-Campillo, 2018; Shim, Serido, Tang, & Card,
2015; Serido & Deenanath, 2016; Sundarasen, Rahman, Othman, & Danaraj, 2016).
Meanwhile, technology is redefining those socialization agents, and fintech is expanding
access to financial products and making their use frictionless (Blumenthal & Shanks,
2019; Fraczek & Klimontowicz, 2015; Sundarasen et al., 2016).
A long-standing body of research substantiates the pivotal role of parents in the
financial socialization process, and present-day studies warn that easy access to money
and credit, which fintech affords, may yield negative balances and outcomes for the
financially illiterate (Aber, Morris, Wolf, & Berg, 2016; Agnew, 2018; OECD, 2020;
Yakoboski & Lusardi, 2018). Accordingly, this study acknowledged the role of parents
and fintech in the financial socialization process. As recorded by Deenanath, Danes, and
Jang (2019), most of the existing literature on family financial socialization uses
retrospective data gathered from students’ experiences and interactions with parents
rather than from the parents themselves. In contrast to historic, student-centered

recollections captured in the prevailing literature, I gathered present-day perceptions of
differences in financial literacy levels that parents attributed to use of fintech in support
of conversations and situated, authentic learning.
Purpose of the Study
The purpose of this basic qualitative study was to explore parents’ experience with
and perceptions of the use of a fintech tool to support family financial socialization and
the associated financial literacy levels of parents and children. An open-ended set of
interview questions that focused on family financial literacy and money-based
conversations, interactions, and decisions between the parent and child(ren) was used to
capture differences in financial literacy levels that parents perceive as a result of using of
a family-managed, virtual bank (FMVB). The study site, hereafter referred to by the
pseudonym of FMVB, is an integrated mobile banking, budgeting, and payment
application that parents comanage with their child(ren), which is designed to develop
financial skills through hands-on experience.
FMVB markets itself as an educational prepaid card. The cards are used in tandem
with the FMVB mobile and web-based virtual family banking software where parent(s)
and child(ren) can establish budgets, manage chores, request and send money, split
payments, set and reward savings goals with interest, and view balances and activity.
Individually and collectively, the authentic functionality, educational objectives, and
family engagement that are foundational to this fintech platform align with the situated
cognition, authentic learning, and family financial socialization theories that underpinned
this study.

Research Questions
RQ1: What are parents’ experiences with the use of a fintech tool to interact with
their child(ren) about financial concepts and decisions?
RQ2: What are parents’ perceptions of how the use of a fintech tool supports
conversation and transaction-based financial socialization activities between a parent and
child?
RQ3: What differences in financial literacy levels do parents perceive based on
their tandem use of a financial technology application with their child(ren)?
Conceptual Framework
As captured in Figure 1, the conceptual framework for this study was rooted in
components of Gudmunson and Danes' family financial socialization theory (2011),
specifically how financial attitudes, behaviors, and associated financial literacy levels are
shaped intentionally and unintentionally through family dynamics and experiences. In
addition, situated cognition theory (Brown et al., 1989) undergirds the authentic,
digitalbased financial learning and decision-making context of the study. In effect, the
FMVB fintech tool was a proxy for the “cognitive apprenticeship” advocated for by
Brown et al. (1989, p. 18). Under this construct, students or child-subscribers in the
context of this study were enculturated into authentic activities (i.e., financial transactions
and decisions) and social interactions (Mattar, 2018). This socialization component
included moneycentered conversations with parents that were facilitated and necessitated
by the shared use of the FMVB platform. In combination, parent-child social interactions
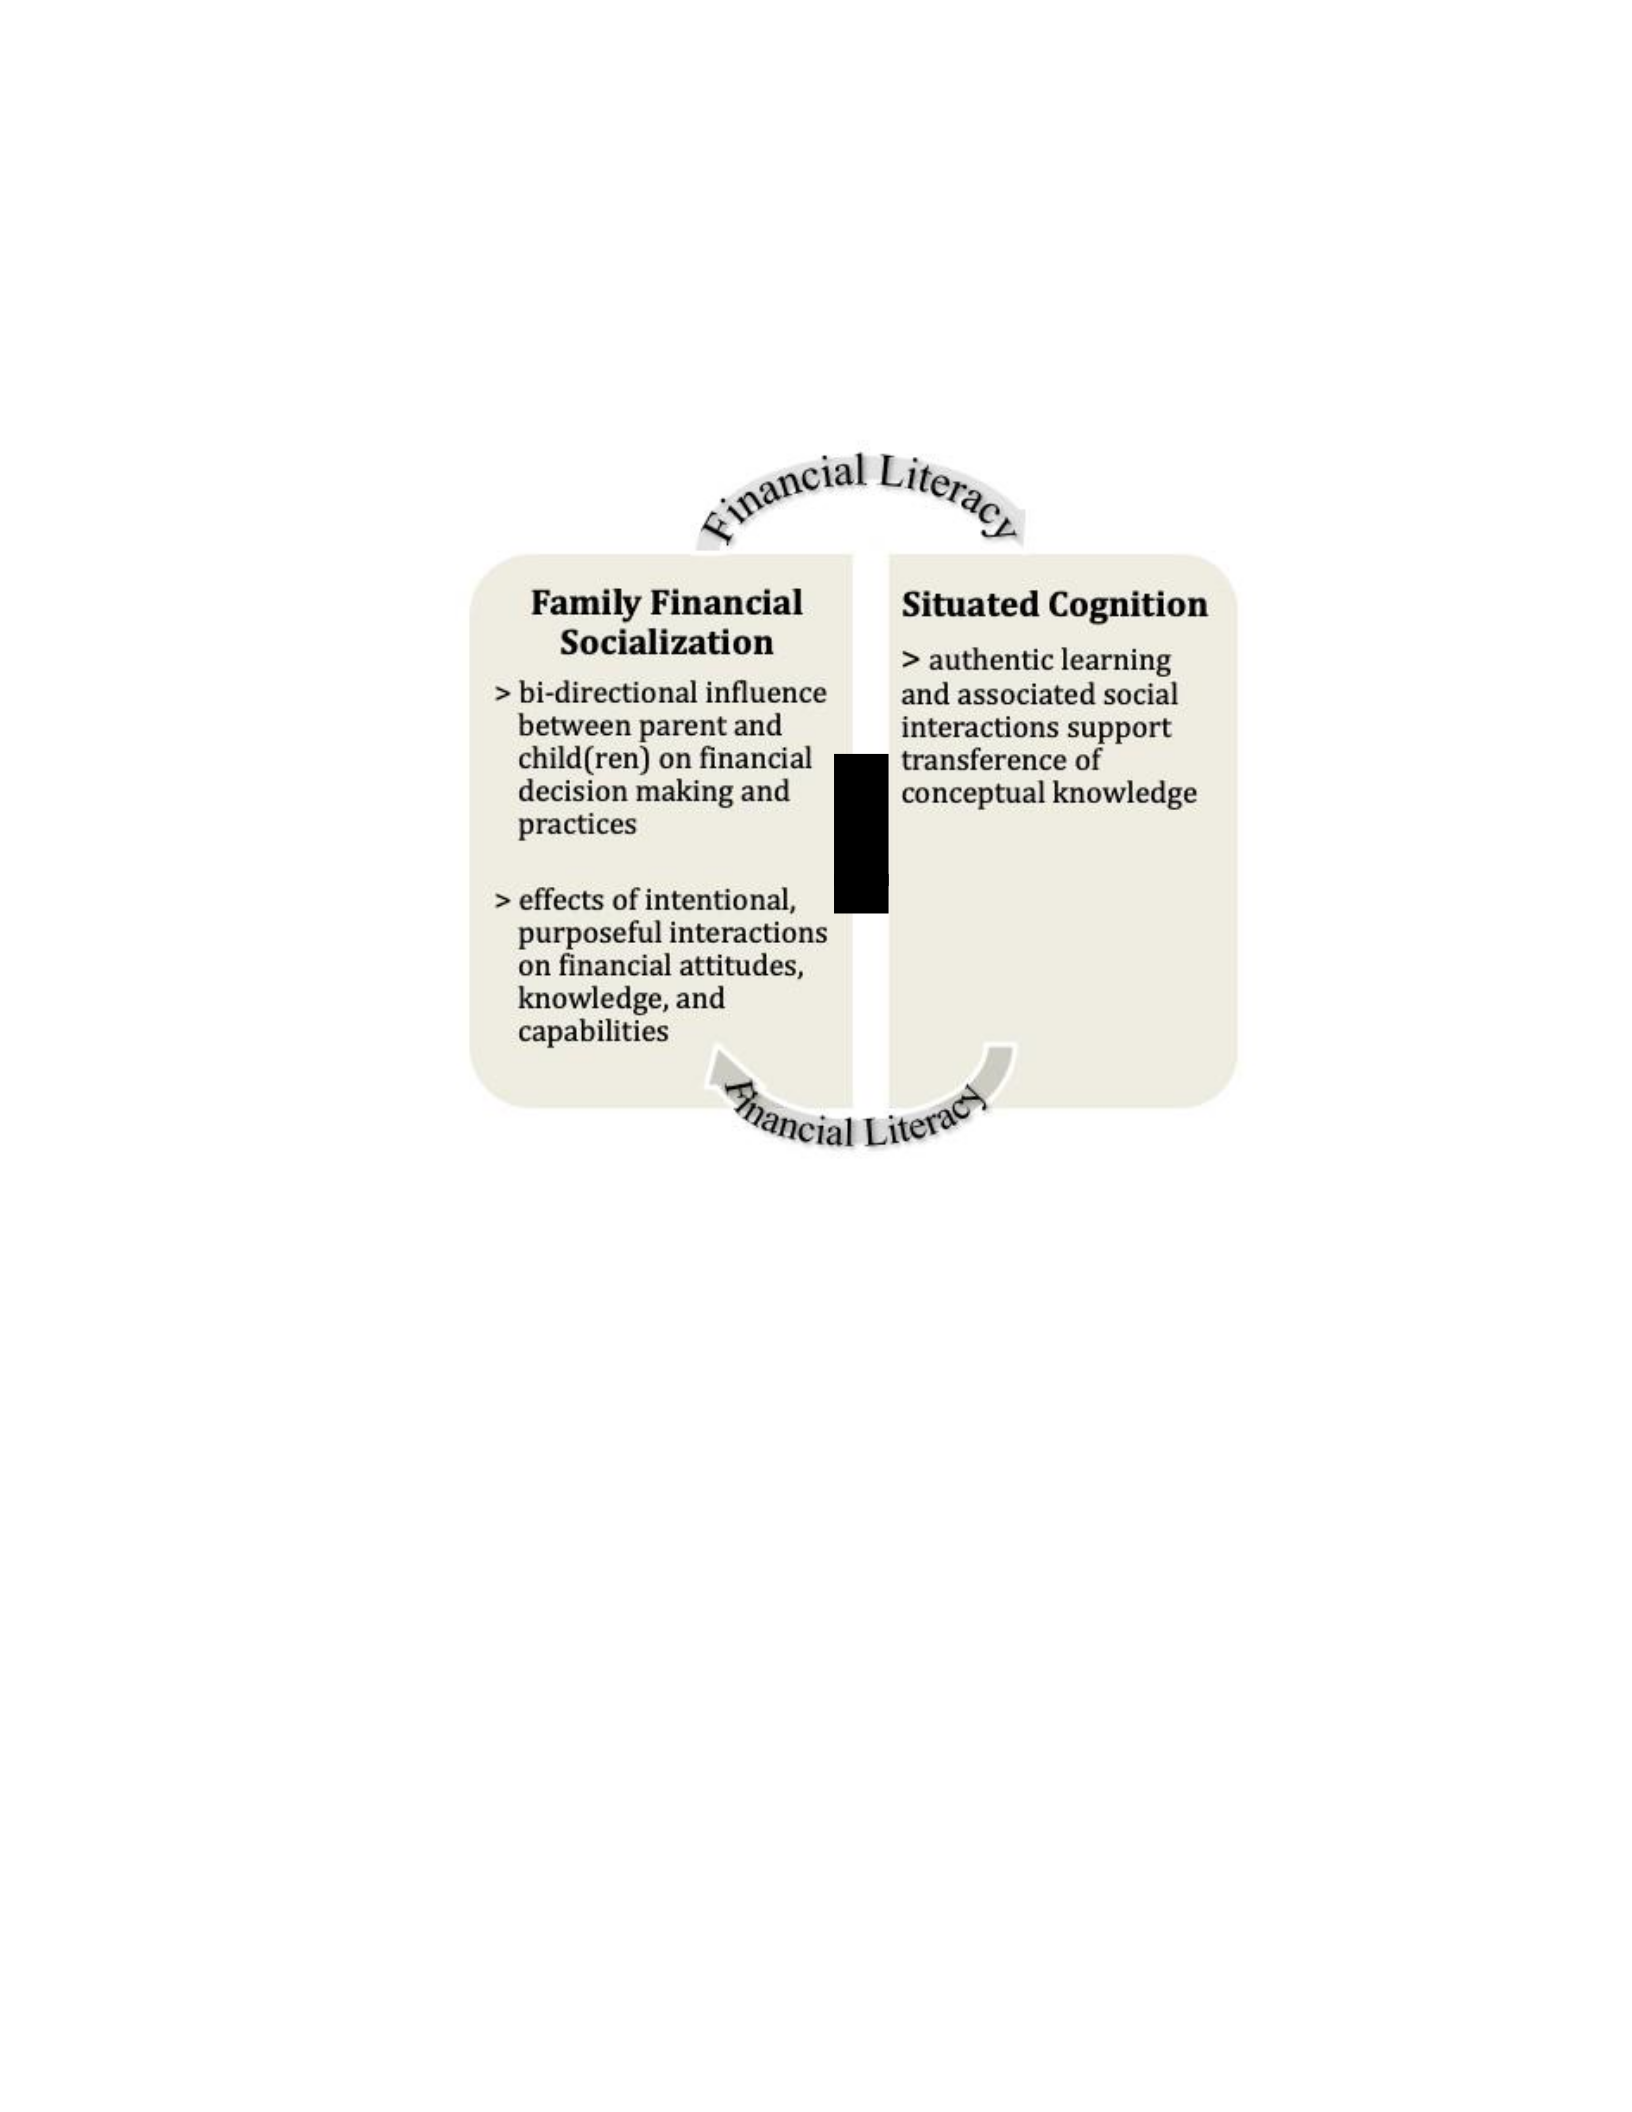
situated in real-time and technology-supported financial decisions have the potential to
promote financial literacy levels.
Figure 1. Study’s conceptual framework. Fintech’s role in bridging, informing, and
supporting components of family financial socialization and situated cognition theories
and associated financial literacy levels. Adapted from Gudmunson and Danes (2011) and
Brown, Collins, and Duguid (1989).
I used this framework of family financial socialization and situated cognition to
examine and describe how parent-subscribers to the fintech tool operationalize these
theories through conversations, financial decisions, and transactions with their child(ren).
In Chapter 2, I more thoroughly explain this conceptual framework in relation to the
existing body of research and my study. The composite conceptual framework of family

financial socialization and situated cognition informed the basic qualitative approach.
Using this framework, I sought to describe the parents’ perceptions of a contemporary
phenomenon, the use of fintech as a socialization and education tool. The information
gathered through in-depth interviews was interpreted against this conceptual framework
and compiled into a rich narrative that showcases the distinct but analogous ways in
which financial socialization and situational cognition were operationalized by the fintech
subscribers in the study group.
The family financial socialization and situated cognition components of this
framework helped structure the research questions, which focused on conversations,
behaviors, and literacy levels. Specifically, financial socialization was explored in
research question RQ2. I asked the parents about their thoughts on and experiences with
the fintech tool in terms of supporting money-centered conversations and activities with
their children. The theory of situation cognition informed elements of RQ1 and RQ3,
which were framed to elicit perceptions about financial concepts, transactional decisions,
and differences in literacy levels attributed to the use of the fintech tool.
Nature of the study
This study employed a basic qualitative approach. As noted by Li (2018), the
strength of qualitative inquiry lies in its ability to provide meaning and context to the
perceptions and experiences of the study participants in relation to the phenomenon of
interest. Similarly, Clancey (1993) contended that perceptions are the precursor to
situated cognition since changes that individuals perceive in knowledge acquisition and
learning are socially and contextually constructed. For the parents in the study, their

perceptions served as a social- and situation-constructed measure of differences in
financial literacy levels they perceived in their child(ren) and themselves as a result of the
family-financial socialization and authentic, experiential learning facilitated by the shared
use the FMVB platform. The perceptions that were captured through in-depth, responsive
interviews and the resultant analysis and findings may inform future policies and
practices related to financial literacy education and the use of fintech.
Moreover, Ravitch and Carl (2015) asserted that qualitative inquiry is descriptive
and analytic. It seeks “complexity and contextualization,” which allows for an integrated
analysis of social, cognitive, and behavioral connections that influence, inform, and
potentially reform habitudes (Ravitch & Carl, 2015, p. 9). Given that the conceptual
framework for this study was based on socialization and situated cognition theories—the
interplay between people and context on financial literacy levels—a basic qualitative
approach accounted for these connections.
The research setting for this study was a parent-managed mobile and web-based
virtual-banking system. A small, purposeful, random sample of volunteers from the
subscriber base, 16 participants in total, served as the study group. This approach helped
ensure that the study was manageable and credible since participants were randomly
selected from the volunteer pool (see Patton, 2015; Ravitch & Carl, 2015). To ascertain
parents’ experiences with and perceptions of using this fintech tool to interact with their
child(ren) regarding financial concepts and decisions, I conducted in-depth, online
interviews.

The interview questions were informed by the theoretical framework and
emanated from the three research questions. The interview data helped discern parents’
perceptions of how or if the use of a fintech tool supports conversation- and
transactionbased financial socialization activities with their child(ren) and/or contributes
to perceived differences in financial-literacy levels.
I also used the conceptual framework for this study to interpret, categorize, and
summarize the data collected using a variation of a word table (see Baxter & Jack, 2005;
Yin, 2009). To mitigate bias, I kept a reflective journal of the rationale behind key
decisions throughout the design, implementation, interpretation, and reporting phases.
Also, as suggested by Yin (2009), I maintained a chain of evidence that captures the
progression from research questions to reporting.
Definitions
The following terms are uniquely defined in the context of this study:
Adolescent: Ages vary within the respective studies cited in this document. In
general, adolescents are 11–17 years old or U.S. middle- and high-school students.
Authentic or Experiential Learning: Authentic or experiential learning
encompasses discrete tasks and complex processes that replicate and are situated in
reallife activities which, as noted by Mattar (2018), blurs the distinction between learning
and application.
Emerging Adults: Emerging adults includes individuals ages 18-24 (Bosch et al.,
2016).

Family Financial Socialization: Family financial socialization encompasses the
financial attitudes, behaviors, and literacy levels that are shaped through money-related
conversations, transactions, and decisions that may be intentional, unintentional,
informed and/or misinformed that occur within the family construct during the formative
adolescent years and influence future financial behaviors during adulthood (Bosch et al.,
2016; Gudmunson & Danes, 2011).
Financial Literacy: Financial literacy, within the context of this study, extended
beyond personal finance content knowledge. It encompassed the attitudes, values, and
motivation to confidently apply knowledge, skills, and strategies to make informed
financial transactions and decisions in a variety of contexts (OECD, 2019).
Fintech or Financial Technology: Fintech includes companies such as FMVB that
provide financial payment, banking, and/or lending services to the consumer through
mobile and online platforms (Magnuson, 2018). However that definition is being
extended to encompass any technology innovation in the personal finance sector
including financial literacy and education( Kagan, n.d.; Lee, 2017).
Situated or Situation Cognition: A constructivist learning theory that stresses
authentic learning, context, and social interaction as the path toward constructing and
applying knowledge (Mattar, 2018).
Young Adults: Individuals ages 25-35, but the range is study dependent.
Assumptions
Following are two assumptions or beliefs that I as the researcher held to be true in
this study. First, I assumed that study participants answered the interview questions

honestly, which helped ensure that the data I collected accurately reflected their
perceptions. According to Walston and Lissitz (2000), as cited by (Patton, 2015), the fact
that I conducted online interviews may have reduced participant anxiety making it easier
to openly and accurately share information. In addition, study participants were advised
that any personally-identifiable information would be and is being kept secure and
anonymous, which should have allayed concerns about confidentiality and supported an
open discourse.
My second assumption was that parents subscribed to the FMVB platform to
promote responsible financial transactions and decision making within their child(ren).
Although this objective may have been one of the reasons, I acknowledged that parents
may have additional or perhaps higher-priority motivations for subscribing. Therefore, I
ensured that my open-ended questions examined my suppositions and parents’ objectives
related to this phenomenon.
Scope and Delimitations
The scope of this study was limited to the perceptions of parent-subscribers to the
FMVB fintech platform. It focused on perceived differences in factors related to financial
socialization and situational cognition (i.e., the conversations, behaviors, decisions, and
attitudes around money-related matters and literacy levels), which the parents attributed
to the use of the fintech platform. It did not focus on ancillary products or programs that
may have contributed to the differences noted by parents. Accordingly, questions were
framed explicitly and exclusively within the context of the fintech platform.

I identified two delimitations to this study. First, I confined this study to the
subscribers of the FMVB platform only. Although parents and children may be engaging
in financial socialization practices facilitated by other mobile budgeting and payment
platforms, securing site approval from a start-up entrant into this market was not viable.
New entrants into this fintech market niche may not have an established subscriber base
at the time of this study. Second, to help ensure the resultant study group was
manageable, I restricted the number of participants to 16.
Limitations
Some of the challenges associated with this study were inherent to the
datacollection method. As pointed out by Patton (2015), interviews are time-intensive,
and the “quality of the information obtained during an interview is largely dependent on
the interviewer” (p. 427). Accordingly, I devoted the requisite time to develop and test
questions, and to define and practice associated interview protocols to ensure my format,
engagement style, and questions elicited responses aligned to the research questions.
I also took proactive steps to mitigate any positive bias in my approach to this
study and the associated data analysis. Given that my volunteer work centers on
promoting financial literacy in the K-16 and underserved populations, I am optimistic that
fintech may be part of the solution to financial illiteracy. Accordingly, I disclosed my
commitment to financial education to the study participants, which also illustrated my
commitment to the study. I also kept a reflective journal in which I recorded my rationale
for key decisions I made related to data analysis and interpretation. My objective was to
memorialize my thought process and make it transparent.

Moreover, the context for this study was restricted to one fintech tool, which may
limit the generalization of this study’s findings to other contexts. Nevertheless, the
resultant findings, as they relate to the perceived value of fintech to support financial
literacy, may apply beyond the boundaries of this study.
Significance
Financial literacy is an economic and social imperative that underpins individual
and societal well-being. One in five 15-year-olds does not have the fundamental skills
and knowledge needed to perform and understand the implications of everyday financial
activities (OECD, 2017). Some researchers attribute this growing trend to the lack of
physical connection to money (Lusardi, Scheresberg, & Avery, 2018). In fact,
kindergarteners, children as young as age five, are making cashless transactions. They
buy lunch daily in school cafeterias by scanning a card or entering a code, and make
purchases on their mobile and gaming devices that result in microtransactions that show
up on a parent’s credit card (“Economics of Microtransactions in Video Games,” 2017).
Among 8-14 year-olds, 18% carry a credit card as an authorized user on a parent’s
account and that percentage is expected to continue to rise as online transactions and the
number of cashless stores and restaurants grows (T. Rowe Price, 2017).
The low level of financial literacy among the Millennial and Generation Z
population and the growth in cashless mobile transactions reinforces, according to
Yakoboski and Lusardi (2018), the importance of equipping this large generation with the
knowledge and skills that are needed to make financial decisions in the digital era.

Fintech, according to Maurer, Wrapp, Middleton, Dzokoto, and Fan (2019), may be the
gateway that acknowledges end-user preference for digital mobility, provides access to
financial management tools, and supports financial stability. In effect, this evolving
digital landscape presents an opportunity for fintech developers to address the literacy
gap by redefining the content, form, and access modality to financial education
(Yakoboski & Lusardi, 2018).
Gudmunson and Danes' (2011) family financial socialization theory supports the
contention that the financial literacy deficit needs to be addressed in the formative
childhood and adolescent years when financial attitudes and behaviors are shaped
intentionally and unintentionally through family dynamics and experiences. Equally
noteworthy was Agnew’s (2018) assertion that having children engage in routine financial
transactions may facilitate parent-child, money-based conversations. Therefore, a
comprehensive approach to addressing financial literacy, which my study represents,
acknowledges that children are making cashless transactions at a young age, affirms the
parents’ role in the financial education and socialization process, and supports the
development of foundational financial concepts and productive behaviors that will
transcend life stages.
In addition to expanding on the theoretical framework of family financial
socialization, this study may also provide some level of validation to Brown et al.’s
(1989) theory of situated cognition. Situated cognition theorists posited that authentic
activities and associated social interactions, those that occur outside the classroom
learning environment, support deeper learning and the transference of conceptual

knowledge to alternative situations (Brown et al., 1989). Within the context of this study,
the use of a financial technology application coupled with parental involvement provided
an authentic learning context and social interaction deemed by Brown et al. to support
improvements in learning which, is this instance, centered on financial literacy.
Accordingly, the insights from this study have the potential to define the role of fintech in
the personal-finance education space and add to the existing research on financial
socialization (Gudmunson & Danes, 2011).
Although Lusardi et al. (2018) stressed that fintech is not a substitute for financial
literacy they, alongside Serido and Deenanth (2018), acknowledged that fintech’s
potential to support financial parenting and literacy levels does holds promise. Students
who engage in conversations with their parents about money-related matters and who feel
their academic efforts are supported by their parents tend to have higher financial literacy
scores (OECD, 2017). These findings indicate that parents can play an important role in
addressing the financial literacy gap, and harnessing fintech to support financial
conversations and applied learning opportunities may be the lever that makes a
statistically-significant and sustained impact on financial literacy levels (Kasman et al.,
2018; Lusardi, Yakoboski, et al., 2018).
Summary
In this section, I outlined the social and economic implications of financial
illiteracy, which was the genesis of this study. I highlighted that the prevailing research
recognizes the pivotal role of parents in the financial socialization process and alludes to
fintech’s potential role in promoting financial inclusion and literacy levels. I noted that

despite these acknowledgements, the problem remains that there is limited research
exploring parents’ present-day perceptions of the use of fintech tools to support family
financial socialization and the associated financial literacy levels of parents and children.
Accordingly, this study may add to the existing literature associated with the family
financial socialization and situated cognition framework while promoting conversations
around the use of fintech to advance financial literacy levels. In Chapter 2, I provide an
in-depth analysis and synthesis of the literature and the conceptual framework.

Chapter 2: Literature Review
Introduction
Chapter 2 provides a comprehensive analysis and synthesis of the prevailing
literature related to the central topic of this study, the use of fintech to support financial
socialization and literacy levels within the family construct. The chapter begins with an
explanation of the approach to the literature search. It is followed by a discussion of the
challenges associated with defining and measuring financial literacy, which segues into
an examination of the conceptual framework. Finally, I provide a detailed review of the
relevant research, including a discussion of family financial socialization processes
alongside associated, resultant, and supporting factors which include life-stage and
intergenerational considerations, authentic/ experiential learning, financial confidence,
financial inclusion, financial education, and fintech.
The prevailing problem is that there is limited research exploring the role of
fintech in supporting family financial socialization and literacy levels. The purpose of this
qualitative study was to explore parents’ experience with and perceptions of the use of a
fintech tool to support family financial socialization and the associated financial literacy
levels of the parent(s) and child(ren). Current research points to promising outcomes
associated with the expanded use of transaction-based fintech as an experiential learning
tool to bridge the cross-generational financial literacy gap. However, much of the existing
research centers on a retrospective analysis of personal accounts of financial socialization
practices that parents and their emerging-adult children recall from the adolescent years.
Moreover, much of the research related to fintech focuses on financial inclusion, scaling

access to banking and financial markets through technology, and on the saving and
spending behaviors of those currently using fintech applications. There is gap in the
literature regarding the tandem use of fintech by family members to support present-day
financial socialization practices and literacy levels.
Literature Search Strategy
I restricted my search primarily to peer-reviewed journal articles that were written
in English, published in the last 5 years, focused on financial literacy, highlighted parental
and family influence on financial attitudes and behaviors, and referenced the use of
financial technology to support personal finance education. The keywords of financial
literacy, money management, personal finance separate from and coupled with family
education, parent education and technology, applications were combined into search
strings and used within Education Source, Academic Search Complete, ERIC and
ABI/INFORM. To secure research articles related to my conceptual framework, I used
the same databases and entered the following search strings: family financial
socialization, situated cognition, and situation cognition, including and excluding the
word theory.
Conceptual Framework
The combined theories of situated cognition and family financial socialization, as
reflected in Figure 1, captured the reciprocal- and social-learning opportunities that may
be facilitated by the FMVB fintech platform (see Brown et al., 1989; Gudmunson &

Danes, 2011). The sections that follow examine the existing research in relation to this
conceptual framework and how it applies to the purpose, significance, data interpretation,
and reporting associated with this study.
The Formative Years of Financial Socialization and Literacy
Family climate, money scripts, and childhood involvement in money-based
decisions have a cumulative effect on financial attitudes and long-term behaviors. In a
longitudinal study of 1,511 college students at a public U.S. university, Bosch, Serido,
Card, Shim, and Barber (2016) administered the Financial Identify Scale survey during
the students’ first and final years of enrollment. The goal was to isolate contextual
predictors of the financial identity of this study group. Specifically, the research team
examined and found that socialization agents (e.g., parents, friends, colleagues at school
and work) affect financial attitudes and perceived levels of control over finances in
emerging adults (Bosch et al., 2016). They also suggested that future researchers might
focus on early and middle adolescence to more fully understand how identification
formation in these pivotal years shapes an individual’s financial self-efficacy as an
emerging adult (Bosch et al., 2016). This recommendation informed the types of
questions I posed to the parent study-participants to capture their perceptions of their
adolescent child’s current level of self-efficacy and confidence.
Bamforth, Jebarajakirthy, and Geursen (2018), during focus groups with 47
students in three Australian universities, noted that students’ observations of how their
parents managed money, the mantras they heard about savings and spending growing up,

and their involvement in and autonomy to make financial decisions as a child influenced
the students’ money-management behavior and attitudes throughout their college years.
Hubler, Burr, Gardner, Larzelere, and Busby's (2016) survey work with 715 couples
further illustrated the long parental reach on financial dispositions. The researchers found
that current family financial stressors within the study group had carried over from
childhood and will likely be passed from one generation to the next despite improvements
in income and education levels (p. 385).
Similarly, Jorgensen et al. (2019) found that of all the early influencers on a
child’s financial vision including formal education, media, and friends, parents have the
greatest effect in three areas: setting financial goals, planning and acting, and
understanding the time value of money. These findings resulted from semistructured
qualitative interviews with a convenience sample of 128 undergraduate students ages
1830 who were enrolled in a family finance course and 17 of their parents and eight
grandparents. Moreover, Bosch et al. (2016) confirmed their hypothesis that a wellformed
financial identity during childhood years facilitates the transition from
“adolescent financial dependency to adult financial self-sufficiency” (p. 417).
Interestingly, Smith et al., (2018) found the level of child’s frugality, even at a
young age, affected their purchasing decisions more than the desire for a given item.
These findings were based on responses from 225 children, 5-10 years of age, and one of
their parents to a questionnaire designed to determine the children’s frugality orientation,
which the researchers termed spendthrift-tightwad. Collectively, these representative
findings reinforce the extant literature that marks early-childhood through adolescent

years as the formative period when parent communication, behaviors, and the child’s
level of involvement in financial decisions serves to shape attitudes about money and
future, adult financial self-sufficiency (see Bosch et al., 2016).
Parents as Financial Socialization Agents
Parents, intentionally or not, exert the most influence on their child(ren)’s
financial behavior development (Moreno-Herrero, Salas-Velasco, & Sánchez-Campillo,
2018; Shim, Serido, Tang, & Card, 2015). Underscoring the gravity of this role,
Sundarasen, Rahman, Othman, and Danaraj (2016) positioned parents as the primary
socialization proxy for their adolescent child’s financial knowledge accumulation and
habitual patterns (p. 143). Serido and Deenanath (2016) defined the shape and form in
which parents influence financial knowledge and skills under the following contexts:
• Financial socialization – what parents do and say to convey information.
• Parenting style – the way financial information is conveyed.
• Social class – the range of opportunities and experiences parents provide that
involve financial decision making.
In fact, students who consider their parents as their primary source of financial
information outperformed their counterparts by 27 points on the PISA financial literacy
assessment (OECD, 2020).
However, not all financial socialization modeling, which affects financial
knowledge, behaviors, and well-being is intentional and positive, and the quality of the
relationship with the child affects that dynamic (Gudmunson & Danes, 2011; Jorgensen,
Rappleyea, Schweichler, Fang, & Moran, 2017). Compounding this potential challenge is

the fact that there are no clear strategies to strengthen family financial socialization and
normalize the taboo surrounding money discussions, which transcends socioeconomic
and ethnic/cultural backgrounds (Gudmunson et al., 2016; Palakvangsa-Na-Ayudhya,
Pongchandaj, Kriangsakdachai, & Sunthornwutthikrai, 2017).
Explicit Financial Socialization
When parents are intentional in their financial instruction and provide purposeful
opportunities to engage their children in money-centered decisions and transactions, their
efforts can yield positive and sustained financial orientations, behaviors, and literacy
levels. Kagotho, Nabunya, Ssewamala, Mwangi, and Njenga (2017), as part of a
randomized control trial, analyzed data from 90-minute interviews with 3,965 lowincome
Kenyan students enrolled in Grades 5-7. Their objective was to determine the relationship
across financial socialization, financial management skills, and savings. They found that
children in a household where the parent/caregiver engaged them in financial decision-
making were more likely to save. Perhaps more noteworthy, the researchers identified
that the process of engaging in financial decisions and activities may partially offset low
family financial socialization (Kagotho et al., 2017).
To identify how or if financial literacy levels are affected by parental involvement
and communication, Hanson and Olson (2018) conducted a correlation and regression
analysis on responses from 96 college students to a composite survey comprised of
questions from the Revised Family Communication Pattern survey (Ritchie & Fitzpatrick,
1990) and the 2015 National Personal Finance Index. They analyzed the family
communication patterns for those participants who answered “do not know” rather than

guess the answer to a financial literacy question (Hanson & Olson, 2018). Their findings
suggested that financial literacy confidence levels and formal financial education may be
enhanced by direct parental involvement. On a cautionary note, Fraczek and
Klimontowicz (2015) asserted that “only educated young parents can show their children
a correct attitude to family finance and an appropriate way of making financial decisions”
(p.77). However, they did add that financial education can help to change habits and
orientations.
As part of their Emerging Adult Financial Capability Study (EAFCS), Jorgensen
et al., (2017) examined the role of attachment insecurity, locus of control, and parental
financial communication on the financial behavior of 321 emerging-adult college students
through the lens of family financial socialization theory. Their findings were consistent
with their prediction that a decrease in purposive financial communication with parents
reduced a student’s sense of control and aligned with their increased level of insecurity.
Expanding on the role of explicit financial parenting in relation to knowledge, skill, and
confidence levels, Serido and Deenanath's (2016) literature review touted the need for
parents to consciously involve children in daily transactions such as buying groceries and
paying bills. By explicitly modeling the norms, attitudes, and behaviors associated with
financial decisions, parents are supporting the development of their child’s financial
values (Serido & Deenanath, 2016).
As part of the rationale for their qualitative, multigenerational study, LeBaron et
al. (2019) highlighted that existing research on parental influence has focused almost
exclusively on discussions and modeling, which they deem implicit teaching. The

researchers suggested that parent-facilitated experiential learning is the third potential
method of financial socialization that parents are using (LeBaron et al., 2019). Through
line-item open coding of interviews with 90 families, with a least one emerging adult
“child” enrolled in a college family finance class, the team identified consistent themes.
The first group of themes included observed behaviors: working hard, managing money,
and spending wisely. The second category centered on knowledge and dispositions:
learning financial skills, acquiring financial values, and becoming independent (LeBaron
et al., 2019). The researchers advocated that experiential learning supports the transfer of
observed behaviors and attitudes, translates discussion and knowledge into practice, and
builds financial confidence through the learning opportunities inherent in handling money
(LeBaron et al., 2019).
As part of their analysis of a subset of questions from the 10-wave Flourishing
Families Project, researchers LeBaron, Holmes, Jorgensen, and Bean (2020) found that
the now emerging adults, who were overtly financially educated by their parents as
children during the initial years of the study, reported a greater frequency of healthy
financial-management behaviors. The team did note that this finding was based on a
retrospective response to one question that allowed for multiple, overlapping answers and
that future research should include a more precise measure of what constitutes overt
financial education (LeBaron et al., 2020).
Deenanath et al. (2019), in a study they heralded as unique in its examination of
the present-day effect of purposive and unintentional financial socialization on the
financial knowledge and behavior of high-school students, found that students who

communicated with parents about money and who were confident in making money
decisions tended to display a greater number of healthy financial behaviors. Interestingly,
the researchers considered communication with parents about money as an unintentional
socialization factor since it does not involve the tangible exchange of money. Whereas,
earned income and access to money from parents are considered purposive attempts at
financial socialization (Deenanath et al., 2019).
However, their findings suggest that the common, purposive attempt to
indoctrinate children to money management through allowances may not be effective in
supporting financial knowledge and healthy financial decisions. They posited that since
the money transfer from parent to child happens outside of the financial marketplace and
excludes the experience of earning money, the resultant lack of situated cognition
negatively affects students’ self-reported financial knowledge (Deenanath et al., 2019).
Similarly, Lanz, Sorgente, and Danes (2019), as part of multi-informant study with 160
college-age emerging adults and their parent(s), found that economic enmeshment, the
implicitly transferred sense that the family’s money and assets belong to everyone,
actually discouraged the emerging adult from pursuing employment and negatively
affected their financial well-being.
The challenge of translating financial cognition and conceptual knowledge into
action was also cited by Riach, McDonald, and Grant-Smith (2017) in their findings from
semistructured interviews with 123 university students during which they explored the
interrelated themes of education, employment, relationship, and finances. They found that

authentic, real-time financial transactions and decisions had more influence on financial
behavior than abstract concepts that parents may attempt to explain (Riach et al., 2017).
As defined through the aforementioned studies, explicit, parent-guided financial
socialization is intentional, purpose-driven, and activity-based, which is in direct contrast
to the unintentional, implicit transfer of financial knowledge, skills, and values. Yet,
regardless of intent, these socialization behaviors–overt or tacit, observed or experienced–
have a lasting effect, positive or negative, on a child’s financial well-being.
Unintended Consequences
Financial parenting happens explicitly and implicitly on a daily basis through
observation, conversation, and dollar-driven decisions that may or may not involve the
children. The implicit socialization, which is likely unintentional, occurs more frequently
versus conversation-based, overt teaching and may be more impactful than parental
attempts to teach financial concepts (Britt, 2016). In fact, parental attempts to provide
direct financial guidance and instruction to children may be thwarted by the quality of the
relationship between the parent and child. In their seminal work on family financial
socialization, Gudmunson and Danes (2011) suggested that family conflict that is
unrelated to finances will leach into attempts to engage children in learning opportunities
related to personal finance. Accordingly, the resultant attitudes and behaviors from those
exchanges may create a negative imprint.
Building on this notion that financial imprints are engrained at young age, Britt,
Klontz, and Archuleta (2015) in their conceptual framework for financial therapy called
for a conscious change in the scripts between the primary financial influencer, which is

the parent, and the child. Similarly, Serido and Deenanath (2016) noted that this implicit
transfer of money scripts and the associated knowledge, skills, and values is subject to
misinterpretation by young children and misapplication in adolescent and emerging-adult
years. In fact, Riach et al. (2017) found that emerging adults may overtly reject their
parents attempts to influence their spending habits and intentionally act counter to the
financial values the parents were attempting to impart. Although the students in their
study acknowledged that this behavior may be counterproductive to their financial
wellbeing, they characterized their parents’ financial lessons as nagging, which generated
an emotional trigger and justified an oppositional response (Riach et al., 2017).
Gudmunson et al. (2016) explained that financial socialization is a process that everyone
experiences; it is the collective tone and behaviors, coupled with the accuracy of that
indoctrination that can have a positive or detrimental effect on the individual and the
larger financial and economic ecosystem.
Not surprising, a parent’s self-perception of their financial knowledge and overall
confidence level may inhibit or support their willingness to engage in explicit teaching
opportunities with their children. Serido and Deenanath (2016) recommended that one
way to change the narrative around money is to help parents understand that “good
decision-making transcends content knowledge,” which may bolster their self-confidence
and efficacy (p. 297). This prevailing belief system among parents that they need to be a
financial content expert perpetuates the taboo nature of the topic which, according to
Jorgensen et al. (2017), results in parents underestimating what their 9-17-year-olds are
cognitively ready to process (LeBaron, Hill, et al., 2018).

Holding a contrary opinion, Moreno-Herrero et al. (2018), based on their analysis
of the OECD data associated with the countries participating the 2015 PISA assessment
on financial literacy, stated that the opportunity to improve financial literacy among youth
is predicated in part on the average level of financial knowledge of the family members.
Conflicting positions are also evident in the work of Bamforth et al. (2018) and Brown
and Taylor (2016). The former posited that the money-management behavior of parents is
mirrored by their children, while the latter reported that parental saving behavior does not
influence the decisions to save by their children. Perhaps LeBaron, Rosa-Holyoak, Bryce,
Hill, & Marks (2018) have found the middle ground between these opposing positions—
children learn financial practices and attitudes by watching and imitating their parents,
but they also learn financial principles through the consequences of their own decisions
and experiences.
Financial Socialization Agents Expand with Age
Within the sphere of financial education, parents, by default, are the primary
educator, lead influencer, and decision-maker for emerging adults. In particular, a child’s
financial values and future orientation as it relates to college are indelibly shaped by
parents and their implicit and explicit modeling of values and behaviors (Blumenthal &
Shanks, 2019; Brown & Taylor, 2016; Jorgensen et al., 2019). As Bosch et al. (2016)
found during their bookend survey of college students as freshmen and seniors, the
subjective norms instilled by parents alongside explicit communication remained the
primary influence on students’ financial behaviors.

Similar results were recorded by Sundarasen et al. (2016) who analyzed responses
from 200 post-graduate students to a questionnaire measuring financial literacy and
parental norms. They found that parental involvement, passive or active, was of greater
influence on an adult-child’s approach to money management more so than financial
experience (Sundarasen et al., 2016). Likewise, Batty, Collins, and Odders-White (2015)
noted that the financial attitudes that children develop early are based on observations of
their parents, which serve to inform their financial behaviors over their lifetime.
Combined, these findings illustrate the engrained effect that parents have during the
formative adolescent years on their child(ren)’s lifelong dispositions toward and decisions
regarding money.
Financial socialization can be viewed as an assimilation and learning process that
evolves over life stages with socialization agents shifting from lead to supporting roles.
Gudmunson and Danes (2011) contended that social interactions at any given point in
one's life—whether it be with parents, caregivers, friends, teachers—had implications for
financial socialization. More important, these agents of socialization did so pervasively
and with long-lasting effects. Shim et al. (2015) supported Gudmunson and Danes’
socialization theory and expanded the scope of financial agents to include the social
constructs of the classroom, self-directed learning, and media.
Te’eni-Harari (2016) as part of his interviews with 103 first-grade children
determined a positive correlation between a child’s involvement in saving money (ISM)
and parent and peers’ attitudes toward saving. Te’eni-Harari also noted that the influence
these socialization agents had on the elementary children was not necessarily focused on

financial behavior but on the more nuanced process of socialization and involvement. The
complex nature of socialization in relation to money was also discussed in Jorgensen et
al.'s 2019 study, which was designed to determine the influence of parents on the
development of a child's healthy financial vision for life. Jorgensen’s team emphasized
that children emulate the behavior of those with whom they socialize, and it is the
reinforcement of those behaviors that shapes learning (Jorgensen et al., 2019). Using
a structural equation model to analyze the objective and open-ended responses to a
questionnaire administered to 530 tenth-grade students, Rudeloff (2019) found that of all
the informal financial learning opportunities involving various socialization agents (i.e.,
parents, siblings, financial institutions, media, and personal experience), those provided
by parents resulted in higher student-child financial literacy levels. Test scores across
daily money-management areas related to saving, payments, loans, and insurance were
positively correlated to the intensity level that the studentparticipants assigned to their
parents’ informal financial lessons (Rudeloff, 2019). Learning from siblings, however,
resulted in lower scores in the dimensions measuring saving, payments, and loans
(Rudeloff, 2019). Rudeloff surmises that this pronounced negative correlation is a product
of comparable deficits in financial knowledge between the study participants and their
sibling(s).
Fraczek and Klimontowicz (2015) undertook a questionnaire-based, quantitative
study involving 181 business and economic students that yielded complementary
findings. Using students’ responses to two questionnaires, they correlated factors
associated with financial literacy levels and decision-making processes to the students’

actual behavior in the banking market. The researchers found that when making a
decision involving complex banking products, young adults defer to their social network
of family and friends, individuals who may be ill-equipped to provide informed guidance
(Fraczek & Klimontowicz, 2015).
This tendency to defer to social networks was also identified by Sundarasen et al.
(2016). This research team stated that without a strong foundation, young adults may
succumb to peer pressure in attempt to keep up with a financially unsustainable lifestyle
(Sundarasen et al., 2016). To offset the potential deleterious effects of peer-based,
uniformed advice, LeBaron, Rosa-Holyoak, et al. (2018) emphasized that children,
throughout their lives, need regular and relevant financial conversations. Reinforcing that
position, Serido and Deenanath (2016) suggested that parents should capitalize on
opportunities to shift into a peer-advising role with their older children that “encourages
deeper thinking about the role of finances” (p. 294). As noted by LeBaron, RosaHolyoak,
et al. (2018), parents end up paying literally for their children’s financial illiteracy, and
the historic notion of learning from mistakes is not a viable option in today’s economy.
Xiao and Porto (2017) advanced a compensatory strategy that involves tailoring
educational materials to a particular life stage thus augmenting or offsetting the quality of
socialized financial learning.
Also related are the findings from Hubler, Burr, Gardner, Larzelere, and Busby
(2016), who used structural equation modeling to analyze the intergenerational transfer of
financial stress in a sample of 715 couples. Their findings supported the hypothesis that
family stressors including finance do “spill over onto the child” (p. 385). Perhaps more

disconcerting is the assertion that a predisposition toward stressing about finances, even
with a strong personal balance sheet, carries forward through multiple generations, along
with latent attitudes about risk and trust (Bhattacharya, Gill, & Stanley, 2016; Hubler et
al., 2016).
Recommendations from numerous studies dating back to the foundational work of
Gudmunson and Danes (2011) and as recent Britt (2016) and Moreno-Herrero et al.
(2018) highlighted the potential of cross-generational, reciprocal learning whereby family
members engage together in financial education and decision-making processes that are
designed to support sustained, positive socialization. Also noteworthy and directly
supporting this study is the limited research exploring the real-time effects of the
intergenerational transfer of money dispositions and behaviors, and the recurring question
as to why formal financial education and applied learning opportunities fail to include the
family (Bhattacharya et al., 2016; Britt, 2016).
Situated Learning, Social Interaction, and Financial Literacy
The value of providing children with age-appropriate opportunities to practice and
apply financial decision-making as part of an explicit and holistic approach to financial
socialization is a recurring theme in the literature. Brown et al. (1989) in the formation of
their theory of situated cognition maintained that knowledge is inextricably situated in the
activity and the social construct through which is it developed and applied. Their
assertion that applied knowledge and learning, versus knowing sets of discrete
information, can only take shape in the context in which it is used is supported by leading
and emerging researchers in the financial socialization and financial education sphere

(Brown et al., 1989).
To better understand how children applied metacognition to daily money
decisions, Lee, Koh, Cai, and Quek (2012) asked 136 fifth-grade students to describe
their own life experiences and the nonlinear process they used to navigate financial
scenarios with multiple alternatives. This approach, as highlighted by Lee et al. (2012),
aligned with Brown, Collins, and Duguid’s (1989) theory of situated cognition, since it
elicited the children’s financial reasoning in context. In affirming studies, Gudmunson
and Danes (2011), Gudmunson, Ray, and Xiao (2016), and LeBaron et al. (2019) stressed
that experiential learning supports the transfer of observed financial behavior and
attitudes and translates discussion into practice. In effect, knowledge or cognition may be
individually or socially constructed, but learning is situationally based.
Supporting this contention, are the findings and recommendations from the
research work of Shim et al. (2015), and Tang, Ning, and Peter (2015). The latter team, as
part of their regression analysis of the 3597 young adults who participated in a national
longitudinal survey, identified a positive correlation between and across financial
experience, knowledge developed through financial education, and the parents’ “financial
sophistication” (p. 135). They emphasized that it is hard to determine the direction of the
causality and therefore the effectiveness of any one of the co-determinants of financial
literacy cannot be evaluated in isolation. Fraczek and Klimontowicz (2015) also
underscored the combined importance of positive family financial socialization and
experiential learning that supports informed conversations and systematic decision
making.

The design of these life-stage-informed experiential learning opportunities is key
to ensuring that children develop self-reliance and individual responsibility when it
comes to money. As part of their expansive literature review, Gudmunson et al. (2016)
emphasized that applied learning opportunities need to mirror the experience that children
will have as part of the larger financial and economic systems, which is not the case with
most household allowance and grade-based financial reward systems. Serido and
Deenanath (2016) also mentioned in their literature review of financial parenting
practices that young children who have experience with handling money show a greater
understanding of pricing and credit models in comparison to their counterparts with no
money management or transaction experience.
Similarly, LeBaron, Hill, et al. (2018) and LeBaron, Rosa-Holyoak, Bryce, Hill,
and Marks (2018), stated that students need to be given opportunities to manage their
own finances in order to develop self-confidence, internalize the money scripts they hear,
and apply the practices they were taught. However, unlike Gudmunson et al. (2016),
LeBaron, Rosa-Holyoak, et al. suggested that payment for academic performance may be
appropriate, as it does reflect the pay-for-performance systems found in the workplace.
On an aggregate basis, these studies speak to the value of introducing authentic learning
opportunities in the family financial socialization process — experiences that reflect the
digital saving, spending, and borrowing environments that children are and will be
navigating.
Not surprising, the multi-generational and millennial participants in the studies
conducted by LeBaron, Hill, et al. (2018) wished they had been given more financial

responsibility during their formative childhood years, reinforcing the position that
knowledge without application is not effective. Participants also indicated they would
benefited from more candor about finances and the family’s financial situation and vowed
to break the cone of silence that stifles open conversations about money with their own
children (LeBaron, Hill, et al., 2018). Hanson and Olson (2018) alluded to the potential
benefits of multi-generational and reciprocal learning between adults and children that is
facilitated through experiential learning. However, Moreno-Herrero et al. (2018)
cautioned that parents socialize their children differently and limited experience, financial
resources, and/or access to financial products and services can hinder the financial
literacy development of the children.
As part of a longitudinal study dating back to 1979, Tang (2017) examined the
intergenerational transfer of explicit modeling of financial behaviors among 2,520 young
adults. This sample included the children of females who initially participated in the
Bureau of Labor Statistics NLSY79 study as 10-17 year-old adolescents (Tang, 2017).
Using a generalized structural equation model, Tang found that parents directly affect the
financial behaviors of young adults through purposeful practice and modeling of
productive behaviors related to managing credit, debt, and cash flow. Tang invited future
studies to explore the interplay among financial socialization efforts that include
purposeful practice. Teng’s recommendation bolstered my rationale for discussing
reciprocal differences in financial literacy levels that the parent-participants in my study
perceived based on their tandem use of the FMVB fintech platform with their child(ren).

Experiential Financial Learning and Situation Cognition
As part of an analysis of effective financial capability interventions and
schoolbased education programs, Amagir, Groot, Maassen van den Brink, and Wilschut
(2018) alongside Arnold and Rhyne (2016), determined that active learning and practice
makes financial behaviors habitual, and the effectiveness of those practice sessions and
resultant financial literacy levels can be amplified with parental involvement. Likewise,
Bosch et al. (2016) encouraged parents to include practical opportunities to involve their
children in financial decisions, thus creating a path toward self-sufficiency. Several
researchers have identified the effectiveness of experiential learning as the mechanism
through which students can develop and apply financial knowledge (Batty et al., 2015;
Gudmunson et al., 2016; LeBaron et al., 2019). However, the long-term impact of just-in-
time and experiential approaches to financial socialization, alongside the aggregate value
of multiple hands-on activities versus discrete financial activities, has yet to be fully
examined.
Amagir et al. (2018) highlighted several studies that showed the
statisticallysignificant effect that multiple instructional methods supplemented by take-
home activities had on the financial knowledge of elementary-age children. Farinella,
Bland, and Franco (2017), in their regression analysis of the 2012 OECD financial
literacy survey results for the 15-year-old student-participants, found that students
benefitted more when money management is learned outside of school or embedded in an
existing course, versus a stand-alone class. Their finding stands in contrast to the results

of a pre- and post-evaluation of a financial literacy camp conducted by Bhattacharya et al.
(2016).
They found that direct financial instruction raised financial literacy scores approximately
12% points in a group of 93 eighth-grade students from Title I schools that are eligible for
free and reduced-lunch funding. Equally noteworthy is the fact that their study yielded no
evidence showing that the use of incentivized or prefunded saving plan, which all the
participant-families had, affected the campers’ test scores (Bhattacharya et al., 2016).
Further confounding the discussion about the effectiveness of formal financial
education interventions vis-à-vis purposeful parental socialization efforts are two articles
from Zhu (2019) and Zhu, Yu, and Chou (2019). The experimental study associated with
these published works involved 247 fifteen-year-old students, 59 of whom were in the
control group and did not participate in the 10-week financial education course. The
objective was to investigate the effect that formal, school-based financial education has
on implicit and explicit parental socialization practices and financial knowledge (Zhu et
al., 2019). The results, as reported by Zhu, Yu, and Chou indicated that the financial
knowledge acquired during the course, specifically information related to spending and
saving, topics that are most relevant to high-school students, did not alter behaviors.
Moreover, the school-delivered financial education had a mixed effect on financial
parenting, yielding a positive effect on tacitly promoted financial norms and a negative
effect on financial concepts parents conveyed through intentional teaching (Zhu et al.,
2019).

Smith et al. (2018) proffered one explanation of these contradictory findings on
the interplay of financial socialization, inclusion, education, and literacy levels. They
suggested that children’s responses to questions about spending and saving may be
sensitive to the context in which they are framed and the unique opportunity cost they
assign to a given financial decision (Smith et al., 2018). Addressing this need to consider
the situational construct in which financial knowledge is applied and measured, Prevett,
Pampaka, Farnsworth, Kalambouka, and Shi (2020) developed a framework for assessing
financial self-efficacy in practice that may serve as a proxy of financial literacy levels.
Their two-phase, mixed-methods study with a subset of 171, 16-19 year-old students
highlighted the faulty link between classroom-resultant financial knowledge and
confidence and its anticipated transfer to financial capability and actual practice (Prevett
et al., 2020.). These conflicting studies speak to the ambiguous definitions of financial
literacy and the inconsistency in evaluation tools. Albeit unintentionally, they serve as a
testimonial to the need to situate financial literacy assessments in its applied context.
Situation Cognition Facilitated by Fintech
Clancey, a foremost researcher and pioneer at the nucleus of constructivism,
systems theory, situated cognition, and artificial intelligence contends that learning
processes are neural, social, and bidirectional (Clancey, 2008). He asserts that relationship
dynamics, such as those found within the family structure, influence perceptions,
knowledge conception, and actions indicative of applied learning (Clancey, 2008). He
also argues that constructivist epistemology is the basis of situated cognition in that all
learning is a complex interplay among memory, perception, and the social environment

(Brown et al., 1989; Clancey, 1993). In parallel, this study acknowledged that the
conception and application of financial literacy knowledge and skills is a reciprocal
process that occurs within the social, family environment. Moreover, the basic qualitative
methodology of this study drew forth and accounted for parents’ perceptions as a
representative measure of reciprocal changes in money-centered interactions and personal
finance knowledge and skills that they attributed to the use of FMVB. Li (2018), in
his study of financial instruction through situation simulation technology, used what was
characterized as a “highly-simulated experimental environment” to replicate the
authentic, interrelated contexts in which students will apply finance and accounting
principles (p. 73). Noteworthy and relevant to this study are his conclusions that an
authentic, technology-based environment allows learners to situate and apply their
knowledge to moral dilemmas and unexpected events inherent in the world of finance
where judgment needs to be practiced and exercised (Li, 2018). Similarly, the family-
centered, authentic financial technology that FMVB represents aligns with the goals of
artificial intelligence knowledge acquisition and situated simulation technology through
which learning is construed as an active, willful process and whereby knowledge is
constructed, experienced, and guided in stages (Clancey, 2008; Li, 2018).
Fintech may serve as the gateway that transitions users from acknowledging
financial capability gaps to seeking out personal finance education resources (Maurer,
Wrapp, Middleton, Dzokoto, & Fan, 2019). In a pilot study of 27 Millennial and Gen Z
participants ages 18-34, who were asked to use one of five budgeting and investing apps,
Maurer et al. sought to gain insight on the “use and usability of the apps…, the
educational strategies or curricula of the apps…, and the apps’ effectiveness with regard
to people’s financial practices” (p. 7). Though pre- and post-use interviews and a
voluntary focus group, the researchers found that the apps raised participants’ awareness
of their budgeting or investing behavior, may not have changed it, but did spur the
participants to see out financial education resources, which included YouTube videos or a
bank representative (Maurer et al., 2019). The researchers noted that Millennials, their
children, and Gen Z are the target market for this category of personal finance
management apps, which may serve as the singular source of financial education that
young consumers have or will receive (Maurer et al., 2019).
In this study, the FMVB child-subscriber may seek financial information from the
parent, reinforcing the socialization and reciprocal learning processes. For the parent,
personal finance resources within the FMVB platform include the collateral education
materials on the website, blog, or the extended financial socialization agents on the
subscriber Facebook page. When fintech is positioned as a personal finance management
and education platform it may serve as or facilitate the dynamic feedback loop that
Kasman et al. (2018) use to describe the interrelationship across core financial concepts,
psychological/social factors, experiential learning, and financial behaviors. Although
fintech is poised to encompass all the components of a comprehensive and relevant
financial education experience, including fostering family socialization and positive
money-management strategies using leading-edge digital tools and products, its potential
and impact has not been fully examined.
Literature Review Related to Key Concepts

Financial Literacy
The distinction between the often-interchanged terms of financial literacy and
financial capability extends beyond semantics. It dictates the focus and scope of
associated research. Historically, the definition of financial literacy focused on knowledge
and dispositions—separate from, but in relation to, financial behaviors and decisions.
This behavioral-focused construction of financial literacy was used by Te’eniHarari in his
2016 interview-based study of 100 first-grade students where he explored their
involvement in savings activities and associated attitudes, intentions, and behaviors.
Fraczek and Klimontowicz (2015), in their study of 181 business and economic students,
examined the correlation between financial knowledge and resultant financial behaviors
in the banking market. In this instance, conceptual knowledge of personal finance or
financial literacy was a precursor to application. Similarly, Kaiser and Menkhoff (2017)
in their meta-analysis of 126 studies, investigated the effect of financial education on
improvements in literacy and behavior, two distinct factors. Once again, financial
conceptual knowledge was segregated from its use.
In contrast, Amagir, Groot, Maassen van den Brink, and Wilschut (2018) took an
all-encompassing view of financial literacy. As part of their systematic literature review
of financial-literacy education programs for children and adolescents, they defined
financial literacy in terms of three components: knowledge and understanding of
concepts; skill or behavior associated with applying that knowledge; and the attitudes,
confidence, and self-efficacy to act (Amagir et al., 2018). However, Xiao and O’Neill
(2016), in their analysis of the 2012 data from the National Financial Capability Study,

emphasized that unlike financial literacy, financial capability is a more comprehensive
term that accounts for financial knowledge and overlays behavior and self-efficacy.
Against this backdrop of conflicting, inconsistent, and interchangeable use of
financial literacy versus capability, Xiao and Porto (2017) also noted the subjectivity
involved in identifying and measuring what constitutes financial knowledge, literacy,
behavior, capability, and well-being. As part of their mediation analyses of the 2012
National Financial Capability Index, which was designed to determine the effect of
financial education on financial capability factors, the researchers identified the
cumulative and symbiotic relationship of the component elements of financial literacy
and capability and the challenge associated with isolating and examining one dimension
(Xiao & Porto, 2017).
The lack of a standard operating definition of financial literacy makes it difficult
to isolate what drives financial behaviors and decision making. Is it beliefs, attitudes,
knowledge, skill, confidence, access to financial products, cultural and social norms – or
some composite thereof that is situation specific? This inconsistency also makes it
challenging to compare results across measurement instruments and research studies
(Allgood & Walstad, 2016; Kaiser et al., 2020).
Echoing the call from the OECD to collect high-quality, comparable data on
international financial-literacy levels in the young an emerging-adult populations, Hanson
and Olson (2018) advocated for measuring the effectiveness of financial education efforts
by focusing on application, behavior modeling, and cross-generational family

interactions. Further extending the list of measurement factors, Tang and Peter (2015)
asserted that financial education, personal experience, and parents’ financial experiences
are co-determinants of financial knowledge acquisition and that you cannot evaluate the
effect of one factor independent of the others.
For measurements that account for participation in formal financial-education
programs, Kaiser and Menkhoff (2017) and Xiao and O’Neill (2016) recommended that
the quality of the inputs—e.g., teacher training, curriculum, and implementation—be
included in financial-literacy assessment criteria. Likewise, Xiao and Porto (2017)
suggested that an accurate measure of financial knowledge acquisition needs to include
objective and subjective or self-reported measures of literacy, behavior, capability, and
satisfaction to determine the impact of financial education programs on their intended
audience. Although Shim et al. (2015) conducted a longitudinal study of 1,511 college
students during their first and fourth years, which was a self-reported survey of
socialization factors, they called for a more balanced approach that includes an objective
set of measures of financial behavior beyond perceptions and self-identification.
Morgan, Huang, and Trinh (2019) advocated for an even more expansive
definition that considers the medium through which much present-day financial
knowledge is constructed and applied—that being technology. They highlighted the fact
that most definitions of financial literacy or capability fail to account for the digital
component, specifically an individual’s confidence with and skill in using fintech, which
is rapidly replacing cash- and brick-and-mortar-based money transactions (Morgan et al.,

2019). This team suggested that surveys should include aspects of digital financial
literacy, which were not found in widely-used financial-literacy questionnaires prior to
the May 2020 release of the 2018 PISA financial literacy assessment (Morgan et al.,
2019; OECD, 2020). Likewise, Grohmann and Menkhoff (2017) contended that
aggregate measures of financial literacy ought to account for and be weighted according
to financial-inclusion levels, or access to and use of financial systems including digital
access and platforms.
Irrespective of the label, the financial literacy and/or capability research landscape
is replete with conflicting definitions that do not fully acknowledge nor account for the
evolving digital financial landscape. The application of these inconsistent and limited
definitions to the research environment serves to exacerbate the challenge of measuring
financial competency and the effectiveness of education and interventions designed to
bolster factors that contribute to financial literacy. Accordingly, a comprehensive
operating definition and measurement of financial literacy would include all
codeterminants—the external and internal factors influencing knowledge, skill, attitude,
confidence levels, and resultant money-management behaviors. Operationalizing that
definition, however, poses another challenge, particularly as it relates to measuring the
effect that financial education has on youth financial behavior (Amagir et al., 2018).
Granted, my research could not and did not identify or encompass all the variables that
affect financial literacy. Nevertheless, the purposeful focus on parents’ perceptions of
changes in the nature and content of money-centered conversations and financial literacy
levels attributable to the use of fintech tool was responsive to the call for a more holistic,

digitally-supported, and socially-situated approach to financial measurement and
education.
Family Financial Discussions, Activities, and Literacy Levels
Financial literacy levels are not clinically derived metrics devoid of social,
situation-specific, and affective influences. They are a composite of the long-term effects
of spoken and unspoken family truths surrounding money, formal education, peer and
media influence, and the situational factors and learned behaviors surrounding financial
decisions. Agnew (2018) selected three experiences captured in existing financial literacy
questionnaires that could be considered contributing factors to financial knowledge and
behavior—allowance, savings accounts, and conversations with a parent. His findings,
from a sample of 1,247 children ages 14 and 15, pointed to the discussions among the
parent and child as being the most influential on savings behavior and financial literacy
scores (Agnew, 2018). Alekam, Salleh, and Mokhtar (2018) in their analysis of the
relationship between behavior, family/parent effects, and peer influence on the financial
literacy levels of 500 Malaysians ages 18-34 found a positive effect, not causal, between
the three factors and literacy levels.
The pivotal role of parents in relation to financial literacy levels was also
validated in three separate studies published in 2018. The results reinforced prior research
showing that emerging adults who talked to their parents about money at a young age
have higher levels of financial independence, financial awareness, and overall
capability/literacy levels. (Bamforth et al., 2018; LeBaron, Rosa-Holyoak, et al., 2018;

Moreno-Herrero et al., 2018). Nevertheless, what students learn from these interactions is
not equally accurate, productive, or positive. These representative studies point to the need
to identify financial topics not sufficiently taught or modeled by parents; to influence the
nature and content of family socialization recognizing the social and emotional components
of those conversations; and to acknowledge that family, as defined by the emerging adult,
is the primary lever to lift financial literacy.
Effects of Education and Parental Involvement
Although the majority of classroom-based financial education efforts and the
wealth of free curriculum resources target high-school and college-level students, those
efforts may be too late. Based on pre- and post-assessment literacy scores associated with
700 fourth and fifth graders, 380 of whom participated in a personal-finance-curriculum
intervention and 320 who were part of the control group, Batty et al. (2015) found a .77
effect size, almost of full standard deviation, in the number of additional correct answers
logged by those in the personal finance class. In their findings, Batty et al. noted that
financial habits are formed early and family influences have already taken hold by age 7,
the point at which children begin to experience growth in the areas of planning,
decisionmaking, and self-control. Te’eni-Harari (2016) also noted that it is between the
ages of 6 and 12 that a child begins to understand the value of saving and its link to future
opportunity.
Meanwhile, children as young as age four are being socialized through money
scripts and observations, and are influencing or engaging in purchases especially those on
or related to digital and gaming devices (Fraczek & Klimontowicz, 2015; Kim et al.,

2017). When reporting what they termed “novel findings”, Smith et al. (2018) found that
children as young as age five could articulate their feelings about saving and spending
and relate their personal dispositions to their money behaviors (p. 455). Teaching
earlyelementary children about the value of money has the added benefit of working with
a blank slate, rather than attempting to reshape an emerging adult’s financial identity and
poor financial habits, which were established more than a decade earlier (Batty et al.,
2015; Bosch et al., 2016; Farinella et al., 2017). These conversations about the proper
timing, content, format, and delivery mechanism for financial education are further
confounded by the same set of considerations surrounding financial inclusion or access to
monetary resources and products.
Financial Inclusion Has Mixed Effect on Financial Knowledge
Financial inclusion is the banking and financial-market equivalent of situated
cognition. At its most fundamental level, financial inclusion is measured by access to and
use of a bank account and debit card (Grohmann & Menkhoff, 2017; Moreno-Herrero et
al., 2018). For adolescents, financial inclusion provides a contextually-relevant
opportunity to apply the financial knowledge, habits, and dispositions fostered through
financial socialization and formal education. In the countries of Belgium, Canada, and
Spain, Moreno-Herrero et al. (2018) identified a causal, positive influence between
financial inclusion and financial literacy. Students who had a bank account scored 10
points above peers who did not, thus supporting the idea that giving children access to
financial services at a young age supports experiential learning and measurable changes
in literacy levels (Moreno-Herrero et al., 2018).

Grohmann and Menkhoff (2017) in their analysis of the S&P Global Financial
Literacy Data determined that high financial literacy levels had a causal relationship with
financial inclusion with the reverse effect also plausible. On a micro-level, Te’eni-Harari
(2016) indicated that providing children access to financial products gives them the
hands-on experience that will contribute positively to their savings orientation and future
financial behaviors. Jorgensen et al. (2019) showcased instances where parents created
their own family bank to help their children learn to save and plan for their future. These
are powerful examples of the how financial inclusion on a micro- and macro-level can
shape individual and aggregate literacy levels alongside access to and design of financial
products.
The use of banking products facilitates concrete financial discussions within
families, while low financial inclusion limits the conversations about finance-related
opportunities and potentially undermines a child’s financial confidence and vision
(Blumenthal & Shanks, 2019; LeBaron, Rosa-Holyoak, et al., 2018; Serido & Deenanath,
2016). Supporting this contention, Kagotho et al. (2017) and Sinha, Tan, and Zhan (2018)
emphasized the negative compounding effects of low financial literacy and banking
system participation rates within financially at-risk classes, which limit financial
socialization opportunities across generations.
Even though historic studies have shown a positive relationship between bank
accounts and financial literacy, Moreno-Herrero et al. (2018) noted an area for future
exploration centers on the association between experience with money matters, financial
products, and students’ financial literacy levels. It is this void in the current research that I

partially addressed through my research. I reported on parents’ experience with the use of
a mobile budgeting, banking, and payment application (FMVB) in tandem with their
children and perceived changes in the nature and level of family financial socialization
and financial literacy.
Financial Inclusion and Socialization with Fintech
The proliferation of mobile-banking, payment, investing, and peer-lending
applications signals what is likely the inevitable transition to a predominantly cashless
society. It also points to the potential of positioning fintech as the cognitively-situated
learning environment for children and parents that can support positive financial
socialization and literacy levels. Fintech provides parents the opportunity to model
productive money-management and decision-making behaviors for their children (Kim et
al., 2017; Rosa-Holyoak, Marks, LeBaron, & Hill, 2018). That however, must be a
conscious decision, since the electronic nature of these processes does not allow children
to visibly see their parents setting aside physical currency for saving or using checks to
pay bills (Rosa-Holyoak et al., 2018).
Expanded financial inclusion enabled through technology does present
implications related to financial behaviors and literacy levels (EY FinTech Adoption
Index, 2017). Elsinger et al. (2018) as part of their literature review sought to determine
whether fintech will redefine financial literacy. They concluded, as did Arnold and Rhyne
(2016), that fintech may exacerbate financial literacy deficiencies, making gaps more
problematic given the lack of face-to-face advice to support transactions (Elsinger et al.,
2018). Equally concerning are the cautions repeated by researchers who stressed that

frictionless transactions, those not involving physical currency, make it easy to engage in
impulse spending, overspend, and consequently overdraw accounts and carry excessive
credit balances (Aber et al., 2016; Agnew, 2018; Yakoboski & Lusardi, 2018).
Yet, Aber et al. (2016) in their study of 511 students and parents using a digital
cash-transfer program also noted that students actually reduced their spending on
discretionary items while parents increased their spending. Perhaps that finding is a
product of the parents purchasing those discretionary items for their student-child;
however, it may also reflect children embracing ownership of those funds and adjusting
their spending habits accordingly. Regardless, improved access to financial services via
fintech requires higher digital-financial-literacy and overall financial-literacy levels to
support productive behaviors and decisions on these platforms (Brown & Taylor, 2016;
Grohmann & Menkhoff, 2017; Morgan et al., 2019; Yakoboski & Lusardi, 2018).
The case for financial technology, not only as a complement to literacy programs
but as a mechanism to maximize the scale and effect of education efforts, was extolled by
Agnew (2018), Arnold and Rhyne (2016), and Bamforth et al. (2018). In fact, Bamforth
et al. and Kim et al. (2017) not only encouraged the use of fintech to foster prudent
money-management behaviors between the parent(s) and child(ren), they noted that
fintech may be the vehicle through which children “resocialize” their parents as they
learn together about personal finance concepts and the functionality of the digital
platform. This concept of reciprocal socialization, learning, and leveraging fintech to
break the stigma of openly discussing money, informed the content and focus of my
interviews with parent-subscribers to the FMVB platform.

Fintech in Financial Education
Lusardi et al. (2017) studied the effect that online-delivered education programs
has on self-efficacy, financial literacy, and decision making through a sample of 892
participants in the American Life Panel. The results spoke to the ability of web and
mobile-based tools to bring educational materials to users quickly and efficiently.
Although videos appeared to be most effective at improving financial literacy scores and
confidence levels, the study did not assess the viewers ability to transfer and apply this
enhanced conceptual knowledge, to situate the cognition within the context of actual
financial decisions (Lusardi et al., 2017). Warder et al. (2018), as part of his team’s
development and implementation of a computer-based application to teach financial
decision-making, noted the potential for computer-aided instruction to support and scale
literacy.
In a qualitative explorative study, Lee (2019) asked 20 Texas-based bank and
credit union leaders, who had experience delivering financial education, what their
perceptions were of using online education technology to foster financial literacy. Most
interviewees noted that their websites included financial calculators and links to external
government and commercial resources that students and consumers could access. They
also alluded to gamification and edutainment as ways to engage learners and supplement
in-person financial education. Yet, these sensory-stimulating, one-directional, digital
delivery methods do place the onus on the learner—first to access the tools and then to
interpret and apply game-based results and general web-based information to their own
financial circumstances. One financial leader, however, did emphasize that personal

finance education needs to be concrete, not gamified, with real-life financial practice
supported by parents and technology (Lee, 2019).
The above examples that focus on the use of technology to deliver content are not
representative of the emerging application of fintech through which financial transactions
and experiential learning can be supported. There is a common call among researchers,
including Yakoboski and Lusardi (2018) for baseline and longitudinal studies tracking
fintech use and literacy levels. Bolognesi, Hasler, and Lusardi (2020) contend that the
design of financial education programs needs to account for the increased use of fintech
tools among financially illiterate Millennials and their Gen Z successors. Moreno-Herrero
et al. (2018) also noted that it would be interesting to further study how fintech can
provide the vehicle for “conscious creation of opportunities that allow young people to
participate in financial practices” (p. 337).
As discussed in the 2017 EY FinTech Adoption Index, fintech companies have
excelled at capitalizing on the tech-literate but financially illiterate and underserved
populations. Fintech firms are also emerging specifically to target children, under the
auspices of starting them on the path to financial acumen and regular fintech use with
mobile tools for savings, investments, and payments” (EY FinTech Adoption Index,
2017). Palakvangsa-Na-Ayudhya et al. (2017) in their case study of recently-launched,
family-centered fintech applications commented that most applications fail to focus on
interactions between the parent and child. Also noteworthy, Carlin, Olafsson, and Pagel
(2017), who analyzed the consumer-credit behavior of more than 13,000 active users of
an online banking platform, discussed that the expansion of social learning and electronic

access to information reinforces the relevance and importance of future research in the
area of fintech and financial literacy. Although fintech is poised to encompass all the
components of a comprehensive and relevant financial education, including fostering
family socialization and positive money-management strategies using leading-edge
digital tools and products, its potential and impact have not been fully examined.
Leading researchers may dispute the effectiveness of traditional financial
education in the media; however, they do share a common area of agreement with
policymakers, which centers on the need to revisit the role of family and personal
experience in supporting financial knowledge and learning (Farinella et al., 2017; Kaiser
& Menkhoff, 2017; Tang & Peter, 2015; Xiao & Porto, 2017). The complexity of the
evolving financial services market and the recognition that social influences and
technology can add or subtract from financial literacy levels signals the need for a
recursive and holistic approach to financial education. This comprehensive model
includes quality formal education across grade levels, involves family members and
social service agencies, and promotes the use of technology to support prudent
moneymanagement behaviors (Agnew, 2018; Arnold & Rhyne, 2016; Bamforth et al.,
2018; Gudmunson et al., 2016; Kaiser & Menkhoff, 2017).
LeBaron, Rosa-Holyoak, et al. (2018) promoted systemic parental involvement to
inform and reinforce school-based personal finance content that includes authentic
practice opportunities and shifts financial decision-making responsibility to the student.
Moreno-Herrero et al. (2018) alongside Sundarasen et al. (2016), and Tang and Peter

(2015) collectively acknowledged and advocated for parental guidance at early life
stages, formal financial education, and applied opportunities to use financial tools. Also
worth noting is the common call for additional studies that test the effect of parental
communication on child saving and spending behaviors, include broader social networks
and financial institutions as part of the financial-education process, and assess existing
and proposed delivery methods of financial education (Blumenthal & Shanks, 2019;
Brown & Taylor, 2016; Kagotho et al., 2017; LeBaron, Rosa-Holyoak, et al., 2018; Sinha
et al., 2018; Xiao & Porto, 2017).
Financial Confidence and Literacy
Financial education in isolation from the home environment and which fails to
embrace the evolving fintech landscape as an applied-learning sandbox cannot adequately
enhance financial attitudes, self-efficacy, and confidence, which are precursors to and
products of financial behaviors and actions. Studies suggest that implicit and explicit
financial socialization and formal financial education may have a more direct and
pronounced effect on financial attitudes, identity formation, and confidence, which
encourage financial action rather than on financial behaviors themselves (Bosch et al.,
2016; Shim et al., 2015; Xiao & Porto, 2017). A key finding in the analysis of family
communication patterns and literacy levels by Hanson and Olson (2018) affirmed the
contention that subjective knowledge, or one’s perceived financial literacy level, has a
stronger impact on behavior than objective knowledge transmitted through family
interactions. This relationship between self-reported confidence and financial literacy
levels was measured in the PISA 2018 financial literacy assessment (OECD, 2020).

Fifteen-year-olds who are confident using cashless payment systems and tracking account
balances online had statistically greater financial literacy levels, scoring 29 points higher
than those without access to these digital products (OECD, 2020).
Allgood and Walstad (2016) positioned financial confidence as a proxy for
perceived financial literacy, which serves as a potential determinant and measure of actual
behaviors. Although they noted the value of self-assessment in comparison to an
objective measure of what financial knowledge people do know and can apply, Allgood
and Walstad recounted the dangers of acting on overconfidence characterized by a high
perceived financial literacy level when the actual level is statistically lower. This
cautionary note was also identified by Bolognesi et al. (2020) in their analysis of the
financial behavior and literacy levels of millennials ages 18-37 who participated in the
2018 National Financial Capability Study. They found that 62% of the study participants
rated their financial knowledge as high or very high, yet only 19% of these respondents
could correctly answer three questions about the time value of money, inflation, and risk
(Bolognesi et al., 2020.) Clearly, confidence may not in all instances account for
competence.
Yakoboski and Lusardi (2018) spotlighted the disconnect between self-reported
confidence levels and objective measures of financial literacy among millennial
smartphone users who used fintech for transaction and information purposes. When
technology-enabled overconfidence is acted upon, it leads to a pattern of irresponsible
financial behavior, which is one of the leading causes of debt among emerging adults and
other vulnerable groups (Amagir et al., 2018). Conversely, a child’s lack of financial

confidence could be attributed to limited parental presence in the household, which
negatively affects family-based financial education and money-management opportunities
(LeBaron, Rosa-Holyoak, et al., 2018). Thankfully, children’s expectations for themselves
and their self-confidence may change based on their education grade level and exposure
to accurate financial information (Bannier & Schwarz, 2018; Blumenthal & Shanks,
2019). Perhaps, individuals who are financially assimilated through multiple touch
points—e.g., school, parents, digital media—begin to realize just how little they know as
a result of additional education and financial experiences.
Summary and Conclusions
Financial literacy is a multi-faceted construct that encompasses conceptual
knowledge, family and expanded social influences, access to and experience with
financial products via technology, confidence levels, and behavior patterns. In the studies
referenced in this literature review, efforts to measure literacy levels and compare results
were confounded by the inconsistency across and within operating and research
definitions of the term. Moreover, much of the existing research centered on established
indices, which were designed as meta-assessments to reflect aggregate levels of financial
literacy. However, many of the quantitative research studies related to financial literacy
isolated line-item responses within these existing indices. They drew correlations between
categories of answers that may not accurately represent the factors associated with
financial literacy that the researchers intended to analyze.
Qualitative efforts also had their challenges. Attempts to capture the longstanding
effect of family financial socialization during the impressionable childhood years

typically occurred a decade or more later as a retrospective account from emergingadults
and their family members. Although these impressions were likely shaping present-day
behaviors, they did not reflect the real-time nature and purpose of those interactions and
their perceived effect on financial literacy. In addition, technology’s legacy in this turbid
landscape is still evolving as fintech further refines financial socialization, streamlines
access to financial products, and supports both productive and damaging cashless
financial transactions and behaviors.
Support for Study and Social Implications
The purpose of this study, to explore parents’ experience with and perceptions of
the use of fintech tools to support family financial socialization, was consistent with the
following recurring recommendations that emanated from the studies referenced in this
literature review:
• Capture a more expansive set of financial literacy inputs and influences,
including social agents and technology, with the goal of determining effect
level and informing financial education interventions.
• Conduct qualitative studies that collect real-time versus retrospective accounts
of the nature and content of family financial socialization.
• Include alternative perspectives beyond self-reporting of financial
socialization activities and literacy levels.
These gaps were also articulated in a post-study reflective analysis conducted by
Marks, Rosa, LeBaron, and Hill (2019). They mentioned the substantial body of research

that references parents’ pivotal role in their child’s financial socialization and capability,
including the work of Serido and Deenanath (2016), yet acknowledged that there is little
research-based discussion on what and how parents should teach their students about
finances (Marks et al., 2019). Serido (personal communication, January 23, 2020)
suggests that there is a distinction between shoulds versus shows that needs to be further
explored. What are the specific financial behaviors and decision-making strategies
parents should model that may be supported through fintech, versus what are they
actually showing and inculcating through their actions (J. Serido, personal
communication, January 23, 2020)?
This study did not position fintech as an intervention through which its effect on
financial literacy can be measured. It was designed, however, to address recurring gaps
and recommendations in the literature by providing a lens into the parents’ intentions
behind introducing a mobile payment and budgeting system to their child(ren); the nature
of the conversations with their child(ren) surrounding money that were prompted and/or
facilitated by the FMVB fintech tool; and insight on perceived changes in financial
confidence, self-efficacy, and literacy levels that the parents attributed to its use.
The effects of financial illiteracy on a micro- and macro- level cannot be ignored.
Burgeoning credit card and student loan debt shackles emerging and young adults.
Uninformed and misinformed financial decisions undermine their participation in and
contributions to social and economic growth. The findings from this study are not the
panacea for these global challenges. But perhaps, they will serve as the catalyst that
illustrates how scaling fintech to support family financial socialization in the formative

adolescent years can alter the financial identity, literacy, and behaviors of the next
generation.
Chapter 3: Research Method
Introduction
In this basic qualitative study I explored parents’ experience with and perceptions
of the use of a fintech tool to support family financial socialization and the associated
financial literacy levels of the parents and child(ren). In this chapter, I delve into the
rationale for a qualitative research design and the associated basic qualitative
methodology that I employed in this study. I also discuss my role as researcher and the
position I assumed within the study itself and associated considerations. In addition, I
describe the methodology, the study participants and selection process, and the data
collection and analysis method I used. I conclude by examining factors that support the
trustworthiness of this study.
Research Design and Rationale
The following central questions shaped the focus of my study:
RQ1: What are parents’ experiences with the use of a fintech tool to interact with
their child(ren) about financial concepts and decisions?
RQ2: What are parents’ perceptions of how the use of a fintech tool supports
conversation and transaction-based financial socialization activities between a parent and
child?
RQ3: What differences in financial literacy levels do parents perceive based on
their tandem use of a financial technology application with their child(ren)?

The central phenomena of this qualitative study were parents’ perceptions,
specifically as they related to their experience using a fintech tool to interact with their
child(ren) about financial concepts and decisions in support of financial literacy levels.
Accordingly, I employed qualitative research since its design and associated approaches
provide a descriptive frame and contextualized meaning to interactions among individuals
and their environment. In the instance of the current study, these interactions occurred
between the parent and child(ren) with and through the use of technology, specifically the
FMVB fintech tool.
One key distinguishing factor among the various approaches to qualitative
research is the associated foundational theory. For example, a basic qualitative approach
seeks to describe and understand a phenomenon, whereas an approach rooted in realism
strives to “move beyond description to explanation” (Patton, 2015, p. 112). Also, the data
collection methods, which are informed by the associated theory, vary by the approach.
For example, observation and retrospective interviews are the preferred data sources for
phenomenology and heuristic inquiry, while the interplay among focus groups members,
supports the synergistic relationship among phenomena found in a systems theory
approach (Howard & Hirani, 2013; Pallan, Parry, Cheng, & Adab, 2013). Moreover, the
study participants’ position relative to the time and place of the phenomenon being
studied (i.e., present-day engagement in the activity versus reflective perspective) informs
the approach, the research questions, and the data collection and analysis methods.
The use of a qualitative methodology is further supported by Caelli, Ray, and Mill
(2016), and Basias and Pollalis (2018). They emphasized that basic or generic qualitative

research blends established theory and epistemology with emerging fields of study.
(Basias & Pollalis, 2018; Caelli et al., 2016). For this study, the recognized theories of
family financial socialization and situated cognition, which are rooted in a constructivist
epistemology, served as the framework for the iterative design, implementation, and
analysis phases associated with the study-participants’ use of an emerging financial
technology. Further, Basias and Pollalis purported that a basic qualitative approach is
suitable to meeting the objectives of a study related to technology particularly where there
is “interaction of key factors,” which in this study included parent-child financial
interactions and reciprocal differences in literacy levels that may be facilitated through
the FMVB fintech tool (p. 98).
Given the existing theoretical foundation of this study (i.e., family financial
socialization and situated cognition) and the context-specific focus of the research
questions (i.e., perceptions related to the use of fintech tool), a basic qualitative approach
was the preferred and implemented method of inquiry for this study. As emphasized by
Percy, Kostere, and Kostere (2015), basic qualitative inquiry focuses on the outward or
contextual application of perceptions, reflections, and opinions. In contrast,
phenomenological inquiry focuses on the study participants’ isolated act of experiencing
feelings and beliefs, not on the context or outward manifestation of those cognitive and
emotional processes (Percy et al., 2015). Accordingly, the latter approach would not been
appropriate for the present study.
Also, a multicase study methodology and method would not have been applicable
to this research study. A multiple case study would have necessitated that the study cases

or units be bounded using criteria or a common context beyond that of being a subscriber
to the FMVB platform (see Miles, 2015). Since the commonality for this study is based
on the collective use of a fintech tool, there was no apparent subunit that would have lent
itself to within and across-case analysis (Miles, 2015). Moreover, the comparative
analysis associated with a multi-case study approach uses established variables, which are
neither present nor relevant to the research questions, to understand and explain predicted
versus resultant similarities between cases (Baxter & Jack, 2005).
Unlike quantitative studies, which typically use some form of questionnaire with
answers that can be quantified to test or verify what Ravitch and Carl (2015) would call a
singular “objective or immutable truth” (p. 9), a qualitative study acknowledges that the
phenomena being studied occurs in a broader context. Since I did not intend to confirm an
existing theory or prove/disprove a hypothesis, a quantitative approach did not support
the purpose of this study. Rather, this study explored perceptions and experiences of
parents within the dynamic fintech and family context in which money-based interactions
occur. Given that there is an existing body of “pre-knowledge/pre-understandings” (Percy
et al., 2015, p. 78) relative to family financial socialization, which I expanded upon in the
applied context of financial technology, a basic qualitative inquiry was the appropriate
methodological approach (see Percy et al., 2015).
Role of the Researcher
In keeping with the tenets of a basic qualitative study, I personally collected,
analyzed, and interpreted the data compiled from the interviews. This role, as
characterized by Patton (2015), required me to assume an objective but empathetic and

reflective stance in relation to the study participants and throughout the transformation of
data into meaningful information. Since I did not have any personal or professional
connections to any study members, I was able to maintain objectivity throughout the
process.
Bias, however, is almost inevitable in this type of people-centric research study
and needs to be acknowledged and accepted (Burkholder, Cox, & Crawford, 2016).
Accordingly, I kept a reflective journal that identified any predispositions I had towards
key elements of the conceptual framework. To further mitigate bias, I recorded the
rationale behind key decisions throughout the design, implementation, interpretation, and
reporting phases. Also, as suggested by Yin (2009), I maintained a chain of evidence that
captured the progression from the formulation and refinement of the research questions
through to the reporting phase.
Methodology
As stressed by Caelli et al. (2016), a qualitative researcher must be able to clearly
distinguish and articulate the relationship between a qualitative research methodology, the
theories that inform the research approach, and the methods themselves, which include
data collection and analyses techniques. Accordingly, the considerations and rationale
associated with how I approached, implemented, and interpreted this study were informed
by the conceptual framework and tenets inherent in the foundational theories.
Participant Selection
The participants in my study were active parent/guardian-users of the FMVB
fintech mobile banking, budgeting, and payment platform. The criteria for inclusion in the

study were all active parent users of the fintech tool. The criteria for exclusion were those
who may have purchased a subscription but were not actively engaged in regular
transactions at the time of the study. This latter subset of subscribers was self-excluded
from the potential pool of participants since they did not respond to recruitment
communication distributed through channels populated with active subscribers.
As noted by Patton (2015), qualitative sampling needs to be flexible and
pragmatic. The objective is to create a contextually rich analysis of the given
phenomenon, which typically warrants depth with a minimal number of study participants
versus breadth with a larger sample (Patton, 2015). Ideally, as noted by Patton (2015), the
sample size will be adjusted during the fieldwork to achieve a reasonable level of
saturation. As anticipated, I reached a proxy of saturation as evidenced by redundant
themes with 16 participants (see Caelli et al., 2016).
In terms of sequence, once I secured institution review board (IRB) approval
(0317-20-0578234), I sent the founder-developer of FMVB a recruitment announcement
to disseminate in a biweekly newsletter and monthly blog post. I also received
authorization to post the recruitment announcement on the site’s closed subscriber
Facebook Group. Interested participants were directed to a linked form where they
reviewed the informed consent documentation that detailed the purpose of the study, the
interview procedures, the voluntary nature of the study, the risks and benefits, and privacy
considerations.
Individuals who formally consented to be part of the interview, as evidenced by
selecting the “I consent” form on the informed consent document, were then directed to a

digital appointment scheduling dashboard (i.e., Calendly) that limited the number of
interviews to 18, and notified subsequent visitors that they may be contacted in the near
future. Setting the threshold at 18, which was eight above my proposed number of 10,
allowed me to account for potential cancellations and withdrawals within the interviewee
pool. The final number of interviewees was 16, and I interviewed each subject once. Each
scheduled interviewee received an electronic link to the Zoom videoconference room and
digital reminders through the Calendly application.
Instrumentation
To create my initial set of interview questions and probes, which are included in
Appendix A, I reviewed Rubin and Rubin’s (2012) components of a responsive interview
and incorporated guidance from DiCicco-Bloom and Crabtree (2006) for creating
semistructured, in-depth interviews that allow the interviewer and interviewee to cocreate
meaning. This interview technique was consistent with the conceptual framework and
research questions, which focused on experiences and perceptions, factors that Evans and
Lewis (2018) characterized as the realities and meanings that study participants connect
to their assumptions or ideas within a given context. The context for this study was the
authentic learning and family-based financial experiences embedded in the FMVB fintech
tool that were explored in relation to financial literacy levels through the interview
process.
To ensure I honored and built on the evolving body of research on how fintech
may facilitate family financial socialization, support situated financial cognition, and
further financial literacy, I secured permission for and drew upon the interview guide

from the longitudinal research of Serido related to financial parenting and financial
selfreliance of young consumers (J. Serido, personal communication, January 23, 2020). I
also reviewed the work of Lusardi and Hasler at the Global Financial Literacy Excellence
Center (A. Hasler, personal communication, January 22, 2020). Specifically, I reviewed
the code tables and survey items related to parental support and encouragement, and
technology use in financial education. My objective was to identify any facets of these
financial literacy levers that I had not accounted for in my interview questions.
In addition, to promote alignment, content validity, and credibility, I made certain
that the focus of each question emanated from the conceptual framework. This step
ensured I addressed issues of “congruence or commensurability” that may occur when a
researcher borrows components of previous resource methods from studies that had a
different theoretical foundation (see Caelli et al., 2016, p. 9). Also, without compromising
their denotative and connotative meaning, I substituted keywords found in the conceptual
framework and research questions with layperson synonyms in the interview questions.
Procedures for Recruitment, Participation, and Data Collection
For this study I conducted one interview with 16 subjects over the course of 6
consecutive days to achieve saturation. Interviewees scheduled a convenient, 40-minute
videoconference time through the digital platform Calendly. Each videoconference was
conducted on and the audio recorded through the Zoom videoconferencing platform with
expressed written and oral consent from the study participants. Given that the subscribers
to FMVB are dispersed throughout the U.S., in-person interviews were not an option.

Since the study participants are using a mobile and web-based banking and payment
application, they were, as expected, comfortable using a videoconference platform.
Videoconferencing, as noted by Irani (2019), affords study participants the
comfort of being interviewed in a familiar setting, and allows the interviewer to read and
respond to verbal and non-verbal cues. Granted, I, as the video-conference host, did not
have the same visual range of the interviewee’s body language as I would have had in
person; nevertheless, it was a superior alternative to a phone-only modality or an
asynchronous email exchange.
At the conclusion of the interviews, I thanked the participants for their time and
input. I advised the interviewees that they may contact me with additional questions and
to anticipate a copy of the transcript for their review. Although this form of
memberchecking affords a study participant the opportunity to review collected and/or
analyzed data, it may be, according to Caelli et al. (2016), “incommensurable with a
constructivist epistemology” (p. 7). My reasoning for allowing member-checking aligned,
in part, with Dervin’s (1997) position on elevating trustworthiness. I did, however, use
memberchecking judiciously and limited it to transcript review. My goal was to ensure
the accuracy of a transcript and afford the research participant the opportunity to provide
additional clarification and context, which several did. The intent was to increase
trustworthiness in the data collection process but not abdicate or diminish my role as a
researcher (Dervin, 1997).

Data Analysis Plan
I used theoretical analysis, a form of thematic analysis, to examine the data
collected in this study. This approach honored the theoretical and epistemological
underpinnings of the research questions and afforded me the opportunity to analyze the
data through the lens of a priori codes while acknowledging that new domains may
surface. First, I created a set of terms and preliminary categories that were grounded in
the study’s conceptual framework, research questions, and codes from related prior
research. I then proceeded to label and group the interview content (Patton, 2015). From
there, I employed an inductive approach as I identified recurring patterns based on
similarities, differences, frequency, sequence, or relationship among the categories
(Saldaña, 2016, p.7). For the final iteration, I overlaid a deductive approach using the
themes that emerged as part of the literature review to “affirm the appropriateness” of my
inductive analysis (Patton, 2015, p. 542).
Coding the interview data, even with the support of qualitative data analysis
software, was an iterative, time-intensive process (Caelli et al., 2016). It required me to
summarize transcripts and ascribe labels that captured the meaning and intent of the study
participant, in my case the interviewee, in relationship to the phenomenon being study.
These resultant labels or categories were then compared and combined into broader
categories. From there, I generalized these categories to reflect enduring themes that
illustrate how the findings apply beyond the construct of the current study (Rubin &
Rubin, 2012).

I began my data analysis by assigning initial codes based on concepts that are
associated with my theoretical framework and which appear in the other research studies
rooted in family financial socialization and/or situated cognition. In effect, I created what
Saldaña (2016) would call a provisional list of code using labels such as confident, social,
and intentional/unintentional to describe financial-socialization and literacy-related
factors that parents perceived were facilitated by or were a result of using the FMVB
fintech platform.
My second round of coding took into consideration the epistemological
orientation of my research questions, which sought to understand perceptions related to
financial behaviors and knowledge. Using the NVivo software, I employed pattern coding
to consolidate initial codes into more meaningful and theme-related concepts (Saldaña,
2016). My priori coding, as anticipated, affected the relevance and quality of my
subsequent cycles of work. Each successive phase required me to go beyond the mere
reporting of disparate coding schemes and apply meaning and relevance to each of
associated categories and candidate themes by clearly articulating how it supported and
extended components of the conceptual framework and research questions (Braun &
Clarke, 2006; Caelli et al., 2016; Evans & Lewis, 2018). Refer to Appendix B and Figure
4 for additional detail.
Specifically, Evans and Lewis (2018) citing the work of Braun and Clarke (2006)
identified two levels of thematic analysis that I employed. The first, which is semantic,
occurred simultaneous and subsequent to the conceptual-framework-based, a priori
coding. Here, I mapped explicit statements from interviews to existing coding schemes or

generated new ones. The second-stage, latent analysis honored the constructivist
principles associated with the study’s purpose and research questions, and required me to
looked at an interviewee’s statements in relation to the broader field of discourse (Braun
& Clarke, 2006). This phase necessitated that I acknowledge my assumptions and the lens
through which I was interpreting the content (Evans & Lewis, 2018). When employed in
a systematic and iterative manner, these two levels of analysis are designed to construct
meaning to and convey relevance about the data. Moreover, any disconfirming cases that
emerged (i.e., perceptions from the study participants that did not align with existing or
emerging themes) were reported and serve to support the trustworthiness of this study
(Patton, 2015).
Issues of Trustworthiness
The trustworthiness of a qualitative study is a product of four dimensions:
credibility, transferability, dependability, conformity, and overall quality (Shenton, 2004).
The credibility of this research study, which was designed to elicit parents’ perceptions of
and experiences with a fintech tool to interact with their child(ren) about financial
concepts and decisions, was supported with accurate, descriptive excerpts from the
interviews. I wove together a coherent, contextualized, and comprehensive narrative of
the study participants’ individual and collective experiences and perceptions. I also
employed member-checking to ensure the accuracy of my transcription and to afford
study participants the opportunity to clarify and/or provide additional context to their
interview responses.

The dependability and confirmability of the categories and themes I identified
were enhanced through the use of existing codes and themes from credible research
studies, alongside the iterative review process I undertook with each successive phase of
data analysis and interpretation. To promote the dependability of this study, I clearly
described in my reflective journal and associated documentation the rationale for the
research design, how it was implemented in terms of actual practice, and the effectiveness
of the data collection and interpretation protocols (Shenton, 2004).
Notably, Patton (2015) questions the existence of true objectivity, a hallmark of
quantitative studies, since human skill and perception influence the objectivity, or in the
case of qualitative studies the confirmability, of both bodies of research. To that end,
Shenton (2004) emphasizes the need for an “audit trail” that maps out steps in the data
collection, interpretation, and reporting processes. Alongside these key process and
decision stages, Shenton encourages a more theoretical track that captures the ontological
underpinnings of the study and the predispositions of the researcher. Therefore, I created
a graphical representation of a decision-and-event tree as part of my reflective journal.
As noted earlier, relevant themes not only bring meaning to the information
collected, they support the transferability of the results beyond the construct of the data
set (Rubin & Rubin, 2012). To further promote transferability, I focused on developing
rich, deep descriptions of the study participants’ perceptions and experiences. Ideally, the
narrative contained in this study might inform the use of technology to promote and
support family engagement in relation to student growth across multiple literacy metrics,
not just financial.

The responsive approach that I took to each phase of the data collection process
helped me to create thick descriptions. Although not necessary in the present study, this
technique would have compensated for potentially low thematic saturation and any limits
on contextual and cultural appreciation that are inherent in a remote interview process. As
Ravitch and Carl (2015) recommended, I clearly explained to prospective study
participants and actual interviewees the objective of the study and how the interview
would be used as a medium to collect data. I explained how the data will be recorded and
used, emphasizing how anonymity is maintained. I also afforded interviewees an
opportunity to ask questions about the study and protocols before and after our dialogue.
Ethical Procedures
The human-centric nature of qualitative research is fraught with ethical
considerations, what Ravitch and Carl (2015) citing Sharon refer to as “micro-design
choices” (p. 379). Ravitch and Carl encourage researchers to be conservative, to model
ethical, respectful, and transparent behavior by seeking informed consent in those
instances where it is unclear whether participants have an expectation of privacy. Beyond
strict adherence to Walden University’s IRB requirements, a conservative orientation
guided my actions throughout this research project.
Ethical procedures and protocols were followed throughout the recruiting, data
collection, and debriefing process. I did not begin the study, nor did I begin to recruit
potential participants until I received IRB approved. At that point, I began to actively
solicit study participants. My communication explained the purpose of the study, format,
risks, and benefits related to voluntary participation, alongside the steps taken to ensure

confidentiality and to protect personally-identifiable information. I afforded each
prospective participant the opportunity to ask questions before executing the informed
consent agreement.
I also advised study participants that they may elect to withdraw at any time in the
process and that any data collected prior to their withdrawal will be kept confidential and
excluded from the final report. I clearly delineated steps that would be taken, in
accordance with Walden IRB, to maintain the participants’ privacy and to safeguard any
data that was collected. Digital transcriptions and notes related to the interviews are
secured in a password-protected folder. Related written documents are filed in a locked
cabinet and will remain there for five years, at which time I will shred them.
Participants were advised and reminded that their names and any potential
personally-identifiable information are masked in the written study, that participation was
voluntary, and that they may have withdrawn at any time. I provided study participants
with my contact information and that of the Research Participant Advocate at Walden
University.
Summary
Chapter 3 provided a detailed description of the research design and supporting
rationale, my role as the researcher, the research methodology, and the data collection and
analysis plan that I implemented. I also addressed considerations related to
trustworthiness and ethics. This basic qualitative study used semistructured interviews
that were transcribed using thematic coding. The goal was to create a rich, deep narrative
that reflects the parents’ perceptions regarding the use of a fintech tool to promote and

support family financial socialization and financial literacy levels. The results of this
study may help connect the disparate research on financial technology, family financial
socialization, and financial literacy. As noted earlier, the findings may inform future
policy and programmatic initiatives related to purposeful parental involvement in
financial education and the use of financial technology to promote financial socialization
and literacy levels in the home and classroom environments. Chapter 4 presents the
results of the study through the lens of existing scholarship and the conceptual
framework, which is grounded in the theories of family financial socialization and
situated cognition (Brown et al., 1989; Gudmunson & Danes, 2011).

Chapter 4: Results
Introduction
The purpose of this basic qualitative study was to explore parents’ experience with
and perceptions of the use of a fintech tool to support family financial socialization and
the associated financial literacy levels of parents and children. The following research
questions guided my data collection, analysis, and interpretation:
RQ1: What are parents’ experiences with the use of a fintech tool to interact with
their child(ren) about financial concepts and decisions?
RQ2: What are parents’ perceptions of how the use of a fintech tool supports
conversation and transaction-based financial socialization activities between a parent and
child?
RQ3: What differences in financial literacy levels do parents perceive based on
their tandem use of a financial technology application with their child(ren)?
Organization
In this chapter, I will present the results of my dissertation study. I will describe
the setting for the study, provide relevant descriptive statistics associated with the study
participants, explain the data collection and analysis processes, and discuss evidence of
trustworthiness. I will then present the results of my research, organizing the data
according to the themes I distilled, and conclude this chapter with a summary.
Setting
The site for this research study was FMVB, which markets itself as an educational
prepaid card. As noted earlier, the cards are used in tandem with the FMVB mobile and

web-based virtual family banking software where parent(s) and child(ren) can establish
budgets, request and send money, split payments, set and reward savings goals with
interest, and view balances and activity. This integrated mobile banking, budgeting, and
payment application that parents comanage with their child(ren) is designed to develop
financial skills through hands-on experience.
All study participants were active adult-subscribers to FMVB. Each of the 16
participants engaged in an in-depth interview that lasted a minimum of 40 minutes. It
should be noted that approximately two weeks prior to the start of these interviews, the
United States had declared a national emergency related to the Coronavirus pandemic.
That announcement, however, did not temper participation in my study, which was
oversubscribed. Naturally, the interviewees noted concerns around the financial fragility
of the economy and the physical and financial wellbeing of their family moving forward.
Most commented on the timeliness and relevance of our conversation given the financial
uncertainty that many Americans would likely face depending on the duration and
severity of the crisis. The parent’s foreboding was recapitulated in the OECD’s May 2020
release of the 2018 PISA financial literacy results:
The Covid-19 pandemic has also made evident the uncertain and precarious
financial employment situations in which many people find themselves. Financial
literacy may improve citizens’ financial resiliency, thereby preparing them to
manage and weather such unexpected shocks. Many 15-year-olds face financial
decisions and are already consumers of financial services. They are likely to face

growing complexity and risks in the financial marketplace as they move into
adulthood (OECD, 2020, p.34).
Demographics
Participants were recruited through the FMVB subscriber Facebook page and a
listserve mailing sent by the study site’s CEO. At the time of the interviews, seven of the
16 participants had been using the platform for 3 or fewer months, and 13 had been using
it for 1 year or less. The longest subscriber had been using FMVB for 4 years. Of the 16
interviewees, 14 had two children currently on the platform. Two of the parents had four
children using FMVB. The average and median age of a child-subscriber was 13 and split
between gender with 14 females and 15 males. At the time of this study, none of the
children had taken a personal finance class or had explicit classroom-based instruction in
personal-finance-related topics. Figure 2 captures the descriptive data associated with the
participants in this study.
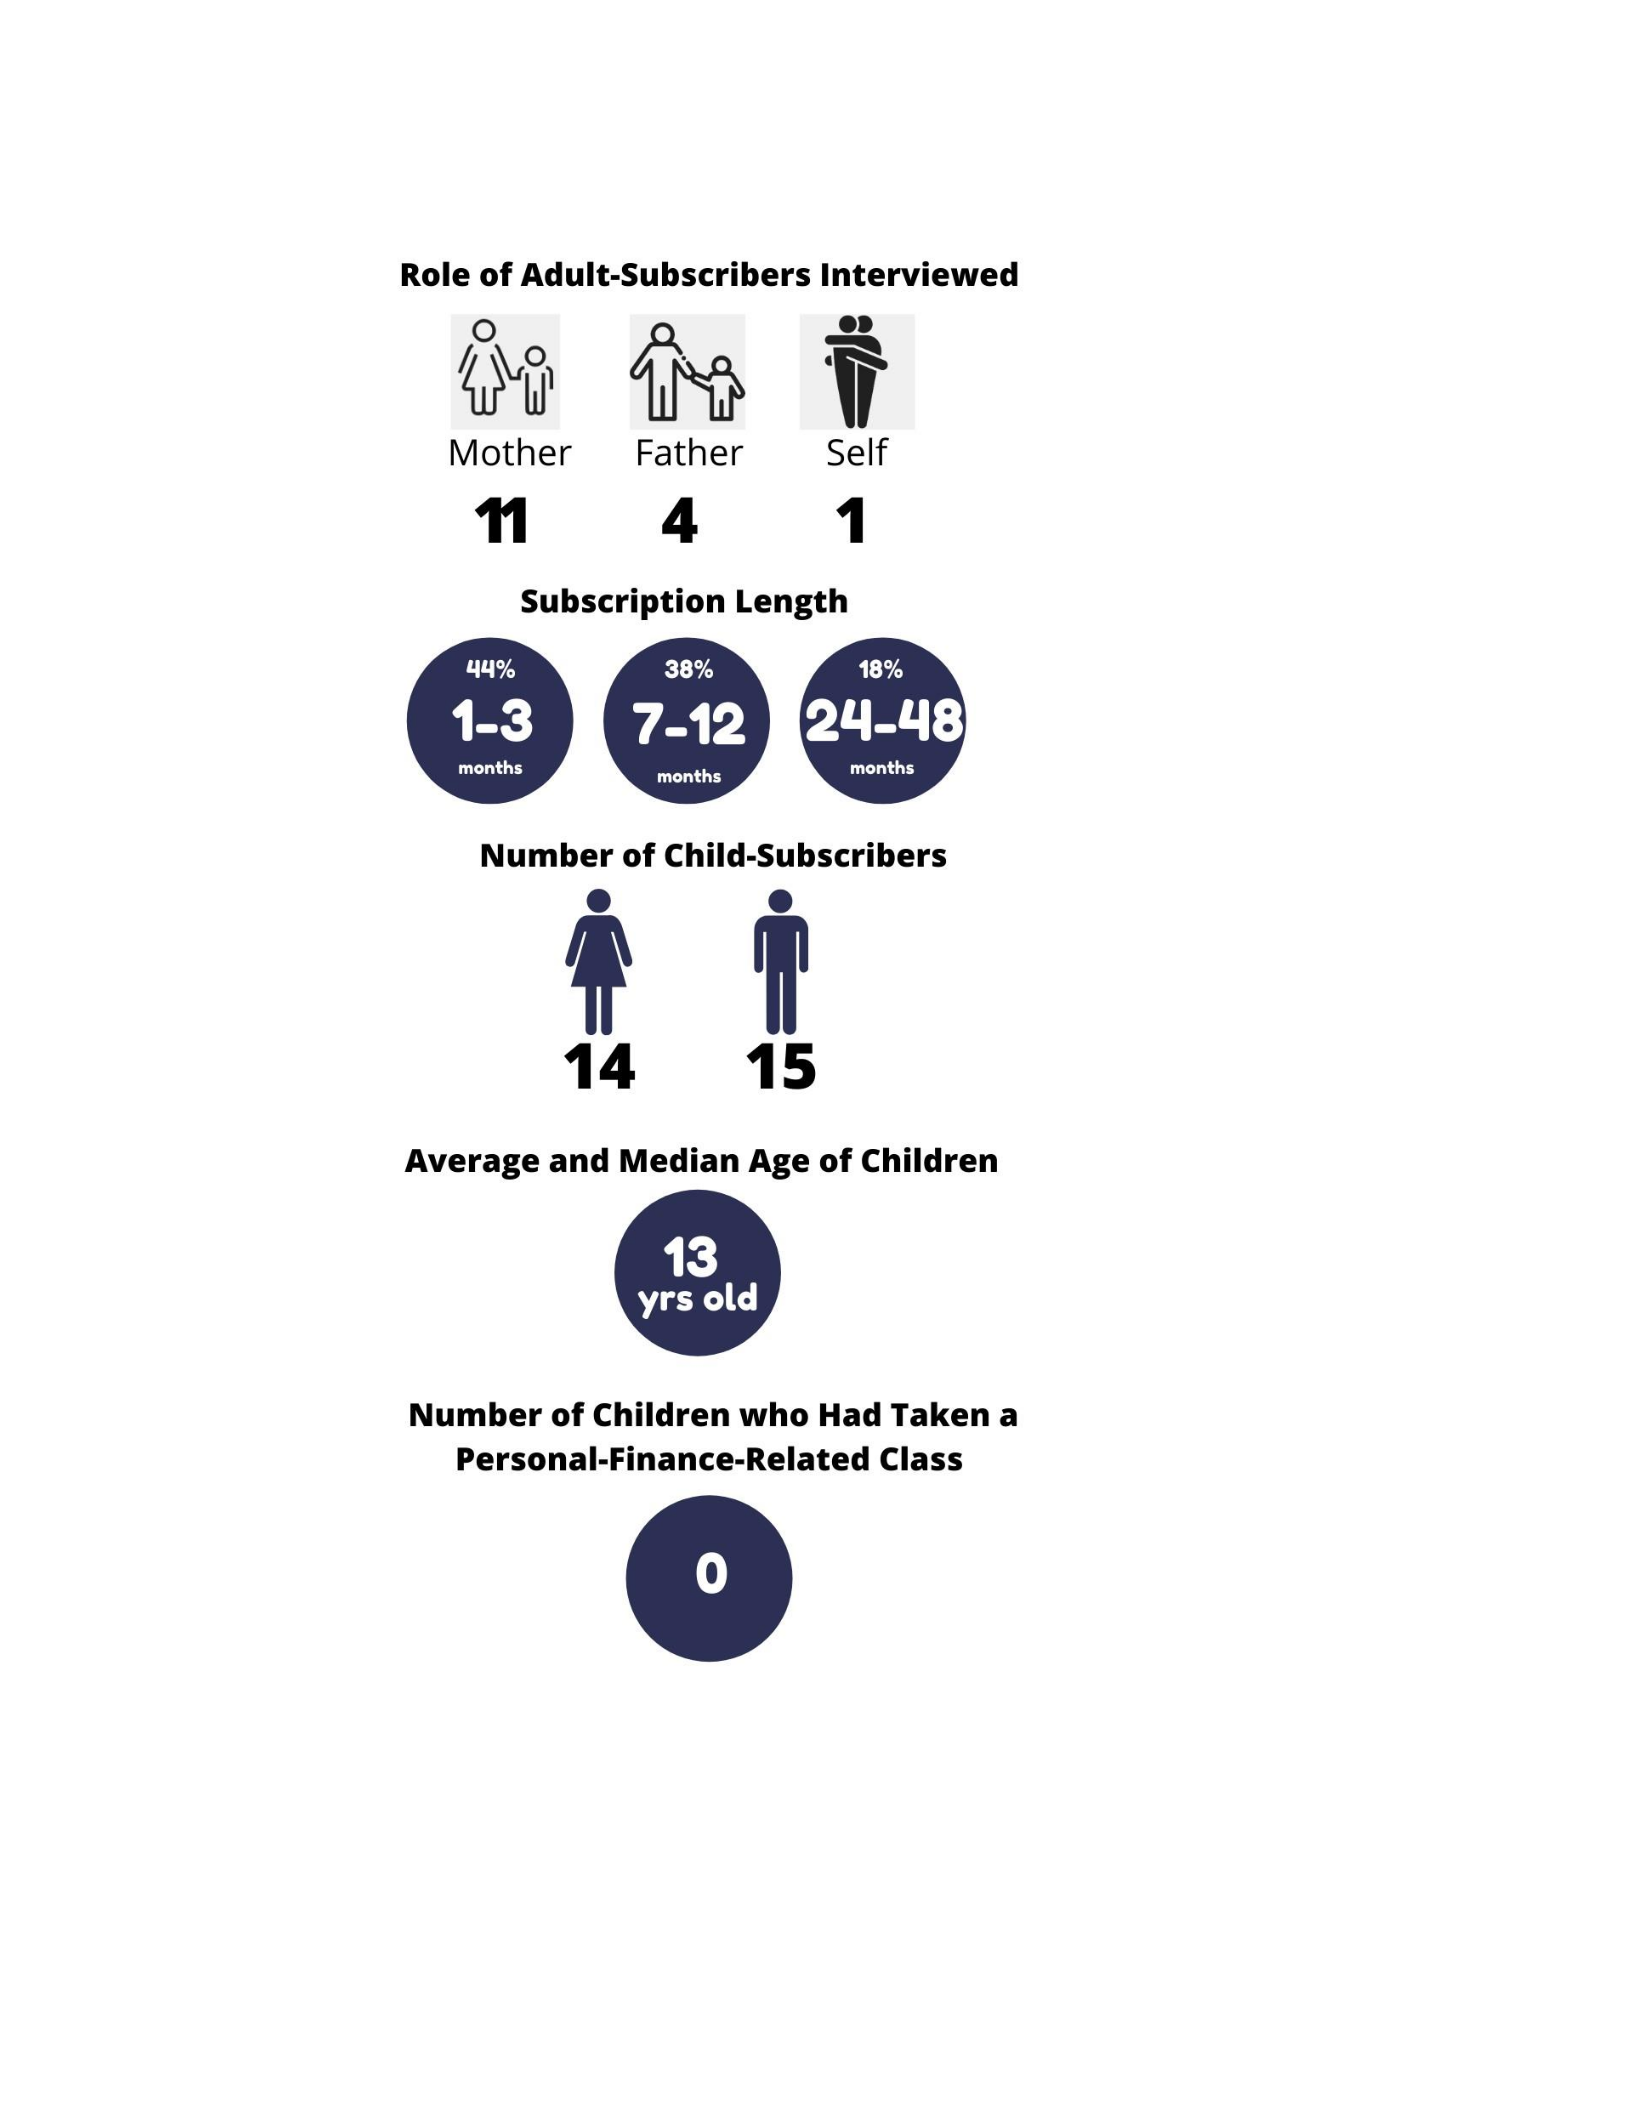
Figure 2. Descriptive data associated with study participants.

Data Collection
I interviewed a total of 16 adult-subscribers to FMVB and assigned each an
alphanumeric pseudonym P01–P16. Each interview lasted approximately 40 minutes and
was conducted over the course of six consecutive days. I recorded the audio portion of the
interview using Zoom. See Appendix A for a representative sample of the questions asked
during these semistructured interviews.
Although technical challenges occurred at times, unstable internet connections on
the Zoom video-conferencing platform, each interview yielded a complete and usable
audio recording. I transcribed each recording. During the process, I eliminated verbal
disfluencies and addressed most of the grammatical issues without compromising the
tone or content. I also excluded side conversations that included personally sensitive
information that was not germane to the study. I emailed each study participant a copy of
the edited transcript and requested they review it for accuracy, completeness, and
adequate context. I also asked them to share any additional examples or post interview
thoughts, which several did. My data collection process did not vary from the proposed
form and format, and I did not encounter any unusual circumstances as I collected the
data.
Data Analysis
I used a form of thematic analysis whereby I actively engaged with the written
interview transcripts, reading them several times to identify excerpts that appeared
consistent with components of my conceptual framework and annotating sections that
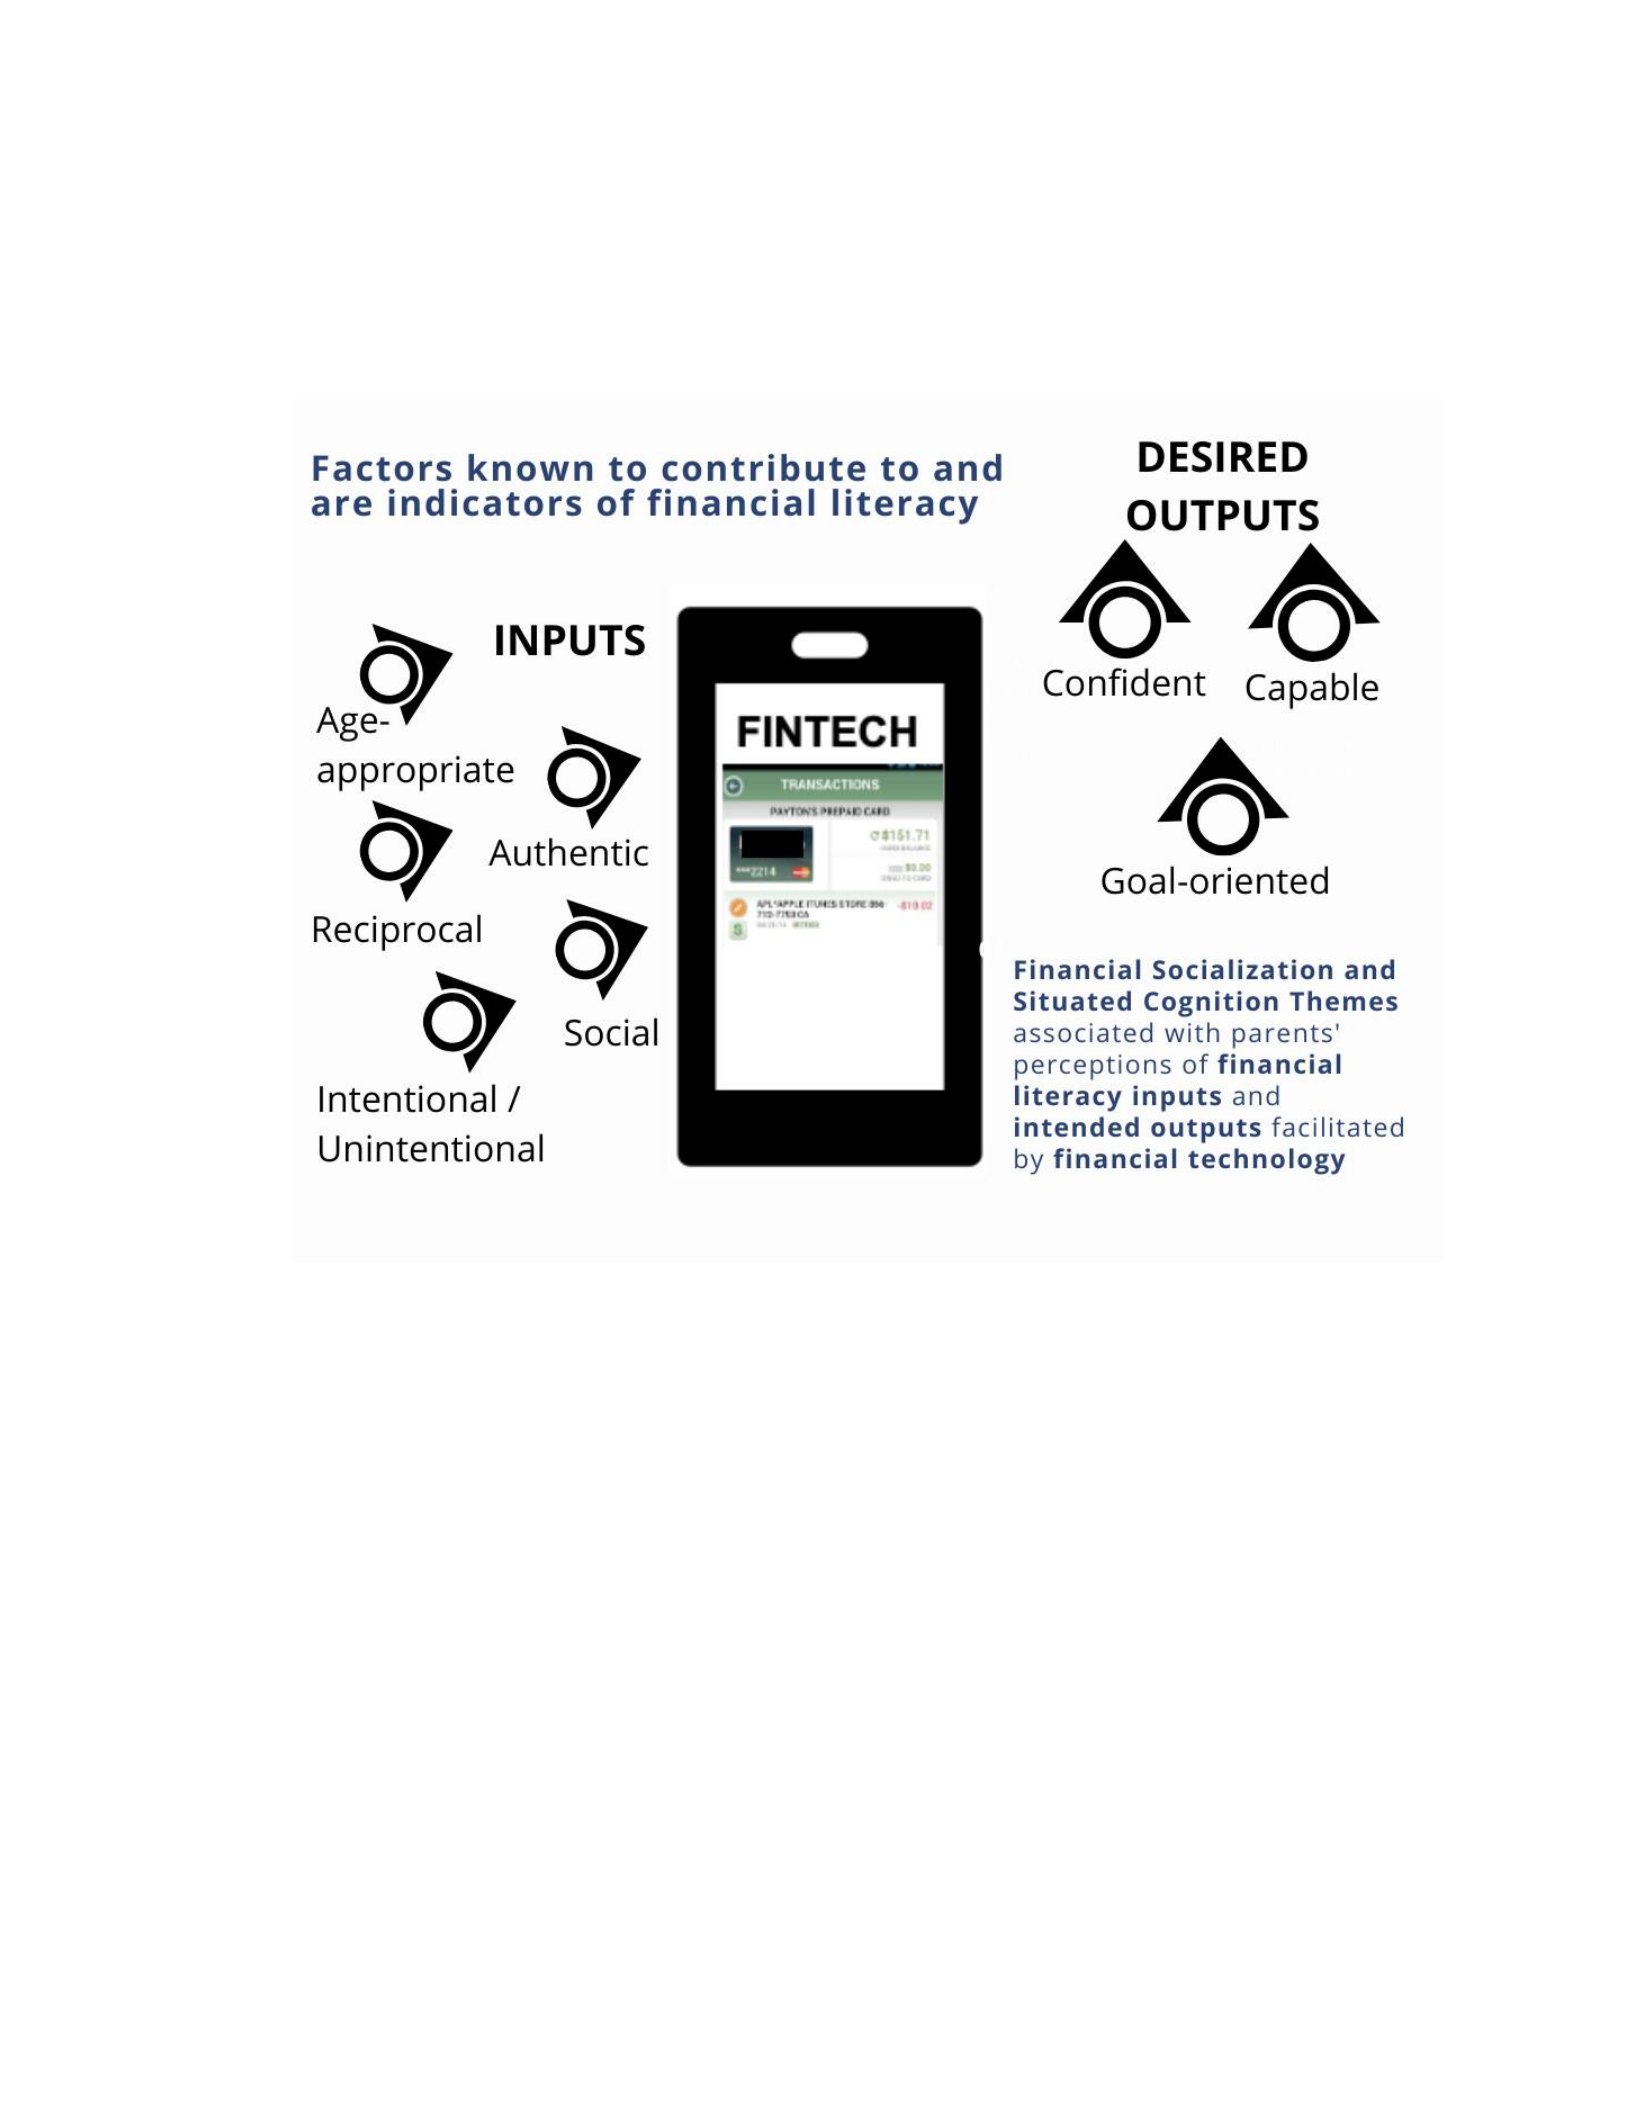
could form potential new codes (Braun & Clarke, 2006). Refer to Figure 3 for the a priori
codes and Appendix B for associated descriptors.
Figure 3. A priori codes adapted from research studies related to Gudmunson and Danes’
(2011) family financial socialization processes and Brown et al.’s (1989) theory of
situated cognition.
I uploaded the transcripts to NVivo, created nodes based on the preliminary a
priori codes, and systematically coded the interview data. I added new topical codes that
were rooted in segments of the transcripts and related to the study’s phenomenon, but
were not accounted for in the conceptual, a priori codes. To ensure I provided ample
context for the data interview segments that I coded, I included surrounding text. As
applicable, I also assigned multiple codes to excerpts with the intent of illustrating
potential relationships between codes of information during the advanced stages of my
analysis (see Braun & Clarke, 2006).
During the next phase of my analysis, I reviewed the descriptors associated with
each code with the objective of combining redundant codes and identifying
complementary and conflicting patterns across the codes. I then proceeded to group the
codes into categories that emanated from the conceptual framework and extant literature
while also capturing the relationship among the codes as expressed by the participants
(see Vaismoradi, Jones, Turunen, & Snelgrove, 2016). Equally important, I created what
Vaismoradi et al. (2016) have termed participant-perspective and setting codes, which
align with the perspective-taking focus of the research questions and account for FMVB’s
role as the research setting and financial socialization facilitator. As one parent-subscriber
(P9) expressed, in a sentiment echoed across most of the study participants, “FMVB is a
learning environment. We talk about it [finances] a lot more” The results of that category-
and code-building process and the associated number of references from the interviews
are reflected in Figure 4.
CODE
DESCRIPTION
REFS
CATEGORY: PERSONAL FINANCE EXPERIENCES AND LESSONS
Cash or Credit Alternative
Need for cashless payment option.
27
Decisions and Transparency
Conceptual and transactional understanding of the value of money including comparison
shopping and opportunity costs. Illustrates patterns of spending. Makes spending visual.
66
Lessons and Messages
Financial concepts, skills, and attitudes that parents attempt to share through direct
communication, teaching, and daily money-centered activities.
30
Intentional or Unintentional
Explicit modeling and teaching versus tacit scripts, modeling, and behaviors. May be
productive and/or counter-productive.
36
Age-appropriate
Money-centered conversations, transactions, and decisions that parents perceive their
child is ready to engage in and understand. May include use of fintech and cashless
financial products.
13
Authentic
Learning opportunities, including everyday experiences that may be facilitated by
technology and may include consequences.
33
Manual Systems
Non-technology systems parents had or would need to put in place in lieu of fintech.
17
Reciprocal
Interpersonal and intergenerational exchanges and learning that occurs through
moneycentered conversations, shared experiences/mutual learning, and modeling.
14
Structured vs Adhoc
Systems and mechanisms for promoting contributions toward family responsibilities and
ensuring commensurate and timely compensation.
31
CATEGORY: FINANCIAL SOCIALIZATION COMPONENTS
Conflict and Objectivity
Instances of how fintech has made interactions centered on family responsibilities (i.e.
chores) and spending patterns less contentious and emotion laden given the data on
spending and saving patterns.
13
Conversations
Examples of mutually-initiated, money-centered conversations. Identifies instances where
fintech has deepened the level of sophistication of the conversations.
41
Different Abilities and Attitudes
Use of fintech to support differently-abled family members and those with different
attitudes and orientations regarding money management and goals.
9
Socialization Agents &
Influencers
Expanded socialization agents as influencers—e.g., social media and peers.
Longstanding influence of parental messages.
16
Norms: Generational,
Social, Cultural
Generational, societal, and cultural unwritten rules surrounding the topic of money
18
Adult-subscriber’s
Childhood Socialization
Recount of how the parents / adult-subscribers learned about personal finance.
23
Value(s)
Financial orientations that the parents’ want to instill in their children. Includes the
monetary-based concept of “value,” and underlying tenets of family values.
22
Orientation and Attitude
Same financial socialization experiences but different attitudes and behaviors.
30
CATEGORY: FINANCIAL LITERACY INDICATORS AND OBJECTIVES
Accountability and Autonomy
Instances where fintech has supported mutual responsibility for money-based decisions and
transactions while promoting a sense of independence and ownership.
56
Financially literate
Perceived financial-literacy level that parents ascribe to their child(ren) in comparison with
child(ren)’s peers.
16
Capable
Subjective assessment that combines personal finance conceptual knowledge, productive
financial behavior, and self-efficacy that may be attributed to the use of fintech.
5
Confident
Parents’ subjective measure of their child(ren)’s comfort level to make financial decisions and
transactions based on personal finance knowledge and skill.
10
Goal oriented
Future financial independence; values and aspirations parents have for children.
39
Savings
Systematically setting aside money for a long-term purchase.
21
Figure 4. Resultant categories, codes, descriptors, and number of references.
From the categories, I then proceeded to develop what Braun and Clarke (2006)
characterized as a “set of candidate themes” that are rooted in the data, honor the
conceptual framework, speak separately to the study’s phenomenon of interest, and
weave a concise story that speaks to the relevance and implications of a theme in relation
to the study’s purpose (p. 20). Figure 5 reflects the progression and refinement from
categories to candidate themes.
CODE
REFS
THEME
RESEARCH QUESTION
CATEGORY: Personal Finance Experiences and Lessons
Cash or Credit Alternative
27
Parents use fintech to
facilitate timeless
financial lessons
RQ1: What are parents’
experiences with the use of
a fintech tool to interact
with their child(ren) about
financial concepts and
decisions?
Decisions and Transparency
66
Lessons and Messages
30
Intentional or Unintentional
36
Age-appropriate
13
Authentic
33
Manual Systems
17
Reciprocal
14
Structured vs Adhoc
31
CATEGORY: Financial Socialization Components
Conflict and Objectivity
13
Perceived shifts in family
financial interactions
that parents attribute to
FMVB
RQ2: What are parents’
perceptions of how the use
of a fintech tool supports
conversation and
transaction-based financial
socialization activities
between a parent and
child?
Conversations
41
Different Abilities and Attitudes
9
Socialization Agents & Influencers
16
Norms: Generational, Social, Cultural
18
Adult-subscriber’s Childhood Socialization
23
Value(s)
22
Orientation and Attitude
30
CATEGORY: Financial Literacy Indicators and Objectives
Accountability and Autonomy
56
Parents’ proxy measures
of financial literacy
RQ3: What differences in
financial literacy levels do
Financially literate
16
Capable
5
parents perceive based on
their tandem use of a
financial technology
application with their
child(ren)?
Confident
10
Goal oriented
39
Savings
21
Figure 5. Categories, themes, and associated research questions.
One discrepant case did emerge within the participant group and expanded the
description of a typical and now seemingly restrictive definition of the characteristics of
an FMVB subscriber. P16, a long-term subscriber, was not using the fintech platform in
tandem with children. P16 had self-subscribed with a spouse to curb gambling behaviors:
[The spouse] pretty much acted as the quote parent, and I acted with a card as the child. I
will tell you that it solved the problem. I had access to funds…and [my spouse] got an
alert every time I was using it…It gave [my spouse] some observation of what I was
using it for, and it put a lot of accountability on me, which was the idea.
This use of the platform to support the financial component of addiction recovery,
coupled with expanded application of the platform to support elder-care and individuals
with developmental, behavioral, and social challenges expanded the “story line that gives
a holistic view on the study phenomenon,” which centers on the use of fintech as a
socialization and education tool (Vaismoradi et al., 2016, p. 107).
Evidence of Trustworthiness
I addressed credibility by crafting categories and resultant themes that honor the
extant literature while speaking to the singular and collective perceptions and experiences
of the study participants. I also employed member-checking to afford study participants
the opportunity to clarify and/or expand on their responses, which several participants

did. To support the transferability of the results, I included detailed, nuanced descriptions
of the study participants’ perceptions and experiences using FMVB that may inform the
personal finance education efforts of caregivers, educators, policy makers, and the
financial industry.
Likewise, I used multiple strategies to promote the dependability and
confirmability of my codes, categories, and themes. Initially, I undertook a deductive
process to identify interview excerpts that may support or refute codes derived from the
conceptual framework and associated literature. Next, I completed an exploratory review
of the data using a semantic lens to identify codes embedded in the participants’ words. In
the subsequent iterations, I evoked a more latent approach as I refined, merged, and
categorized codes that reflect a more contextual understanding of the participants
perceptions and experiences (Braun & Clarke, 2006). As I repeatedly cycled through the
data, I kept a reflective journal that serves as a working document and audit trail of my
approach to labeling, defining, and interpreting the data. My goal was to forge a balance
between immersion in and distancing from the data, staying true to the established
research while legitimizing the participants’ narrative and my related analysis and
interpretation (Vaismoradi et al., 2016).
Results
In this section, I will report study results organized by themes. This approach is
consistent with the objective of highlighting the relevance and transferability of the
findings beyond the scope this study.
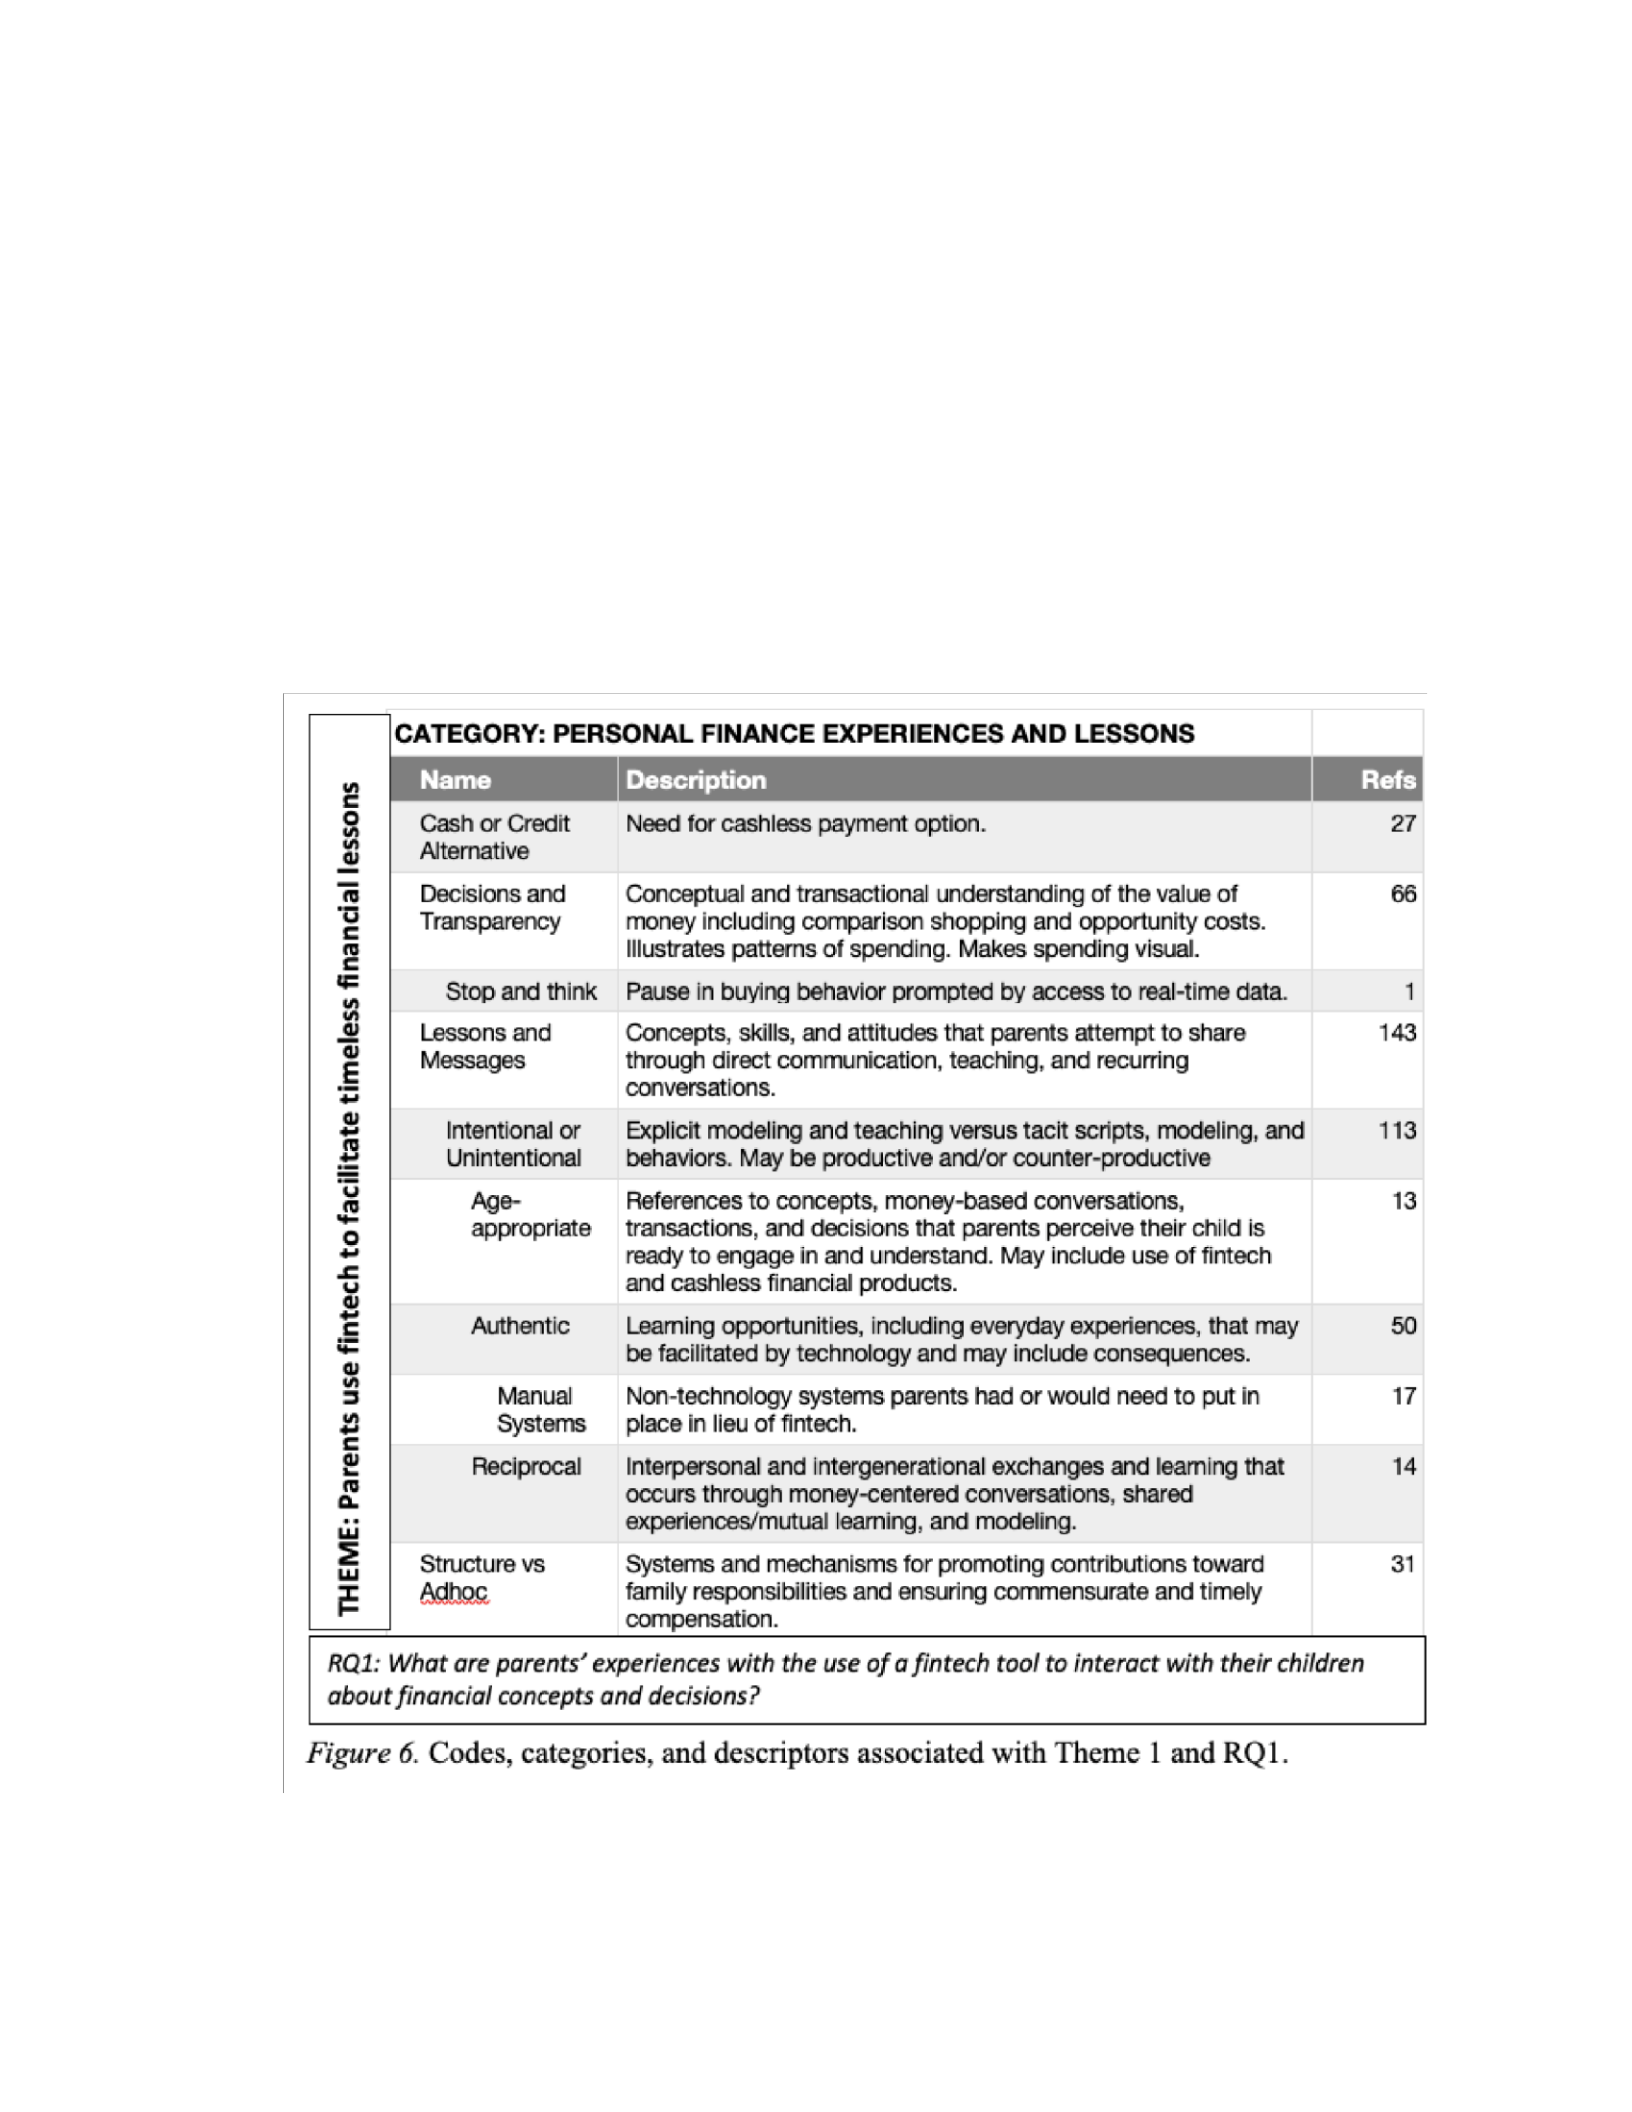
Theme 1: Parents use fintech to facilitate timeless financial lessons
This theme, which supports RQ1: What are parents’ experiences with the use of a
fintech tool to interact with their child(ren) about financial concepts and decisions?,
encompasses how the study participants have positioned and used FMVB to support
conversations, modeling, and systems that form the basis of the finance-related
interactions among family members. See Figure 6 for additional detail.

On a transactional level, FMVB fulfilled a defined need for all the study
participants—a cash or credit alternative. P06 captured the general sentiment of the
FMVB subscribers that I interviewed when stating, “Cash isn’t practical anymore.” All the
participants cited that as adults they rarely carry cash. So, oftentimes they do not have the
cash on-hand to give to their child to go out with friends or as part of an allowance. P11
recounted another recurring challenge that the use of this fintech tool addressed. “It’s been
almost 180 degree turn since we changed [to FMVB] because they [the children] never
knew where they put their cash or how much they had. They would just fold it up, throw it
in a bag.” Also, participants with teenagers noted that FMVB solved the problem of not
wanting to hand over their debit or credit card or as P06 framed it “a wad of bills” when
their children travel for sports, school, or on a separate trip.
What started as a tool to fulfill the practical need for a non-cash alternative has
become for many participants a structure to promote a sense of shared responsibility
between the parent and child, while supporting the parents’ efforts to deepen their child’s
understanding of the concept of value. A recurring commentary was perhaps best
expressed by P03, “To be honest, I [subscribed to FMVB] as a way to given them money
they needed it. But it’s turned into more than that. I now think that I was really looking
for structure.” “This platform is something that I can manage from phone at 10 p.m. when
I’m thinking about it and can actually make it happen,” stated P10, “…and so it’s been a
real enabler for us.”
Structure brings value. The ability to set up a chore chart and assign a price to
each task was one feature to FMVB highlighted by most of the parent-participants. In

addition to promoting shared responsibility and accountability—on the child’s side to
complete the task and on the parent to issue prompt payment—the act of earning money
in exchange for work underscored the connotative meaning of value. The concept of
value, in terms of money and as a family ideal related to work ethic, was discussed
repeatedly by the parent-participants including P15 who commented that [FMVB]
“reinforces what we do here–earn your money and save it when you can.” P10 shared that
FMVB supplemented but did not supplant existing norms. “It’s our family philosophy
that you have responsibilities around the home and that is not something that we give a
monetary reward for…If you want to do more than what your regular responsibilities are,
we can talk about what that’s worth.” P14 recounted,
I think the one thing that I have liked about [FMVB] and the reason why we
started to use it in the first place was because of the chores. So, we are able to
have that whole value of money thing. You do something, you get something in
return, which I think has helped them understand value. It’s not just that money all
of a sudden shows up. Or, if you want something, it just shows up on the
doorstep. There’s a tit for tat. You do this, you get this, and then you can go get
this.
P08 discussed how he was not trying to “school [his child] morally and ethically
all at once,” but was hopeful that eventually those conversations alongside the use of
FMVB would translate into his child thinking more empirically about value in terms of
money and time. P15 commented that the lessons associated with FMVB are “just basic

responsibility. Having a debit card, keeping track of it, knowing how much money you
have on it. Just that basic.”
Context and consistency matter. The parent-subscribers shared ways in which
they try to educate their children about saving, spending, and borrowing. The format of
those explicit and implicit lessons included: conversations, active participation in daily
activities that involve the exchange of money, observations of parents negotiating the
price of large purchases, and lecturing. P05 indicated that conversations among family
members about funds can be “very real and raw particularly with what is happening right
now with the virus and people losing their jobs.” P03 recounted, “I went off my soapbox
about not buying more than you can afford…and there are a lot of examples around me of
people who are doing that. So, it’s like you can’t do that. You need to be careful. You
need to pay attention.” The effectiveness of these lectures came into question for several
of the participants including P11, “But it would be just us talking and questioning. What
are you buying? What do you need? Is there something you want to save up for?”
Most participants discussed how they supplemented those conversations by
engaging their child(ren) in age-appropriate activities that involve the exchange of
money. P12 conveyed, “So, we’ve tried to be intentional about making those learning
experiences out of things that come up in everyday life.” P06 also noted how
homeschooling lends itself to more real-life money experiences including the “errands
that everyone hates.”
I take him with me for that purpose, so that he can learn that life isn’t all just fun
things. Sometimes we have responsibilities. When you do these responsibilities,

there are questions you have to ask yourself. When we go to the store, we have
this much money. What are we going to spend it on? And how can we shop
around and get the best bang for our buck? It’s that kind of organic learning.
In addition to introducing financial concepts through daily activities, participants
also highlighted some of the non-technology-based systems they have used, with mixed
success, including: chore and goal charts, maintaining a mock check register to track cash
received and spent, and envelope and jar systems to allocate money for specific purposes.
As P14 relayed, which holds true for all the study participants, cash and check
transactions were the norm growing up. Now, “it will always be a credit card or it’s even
just with my phone.”
Upon reflection, P07, P09, P10, P12, P14 and additional participants quoted
below questioned what their conversations and inconsistent use of paper systems were
really showing their children. “I was not imparting all the things that I have learned to my
kids in a relevant manner because things have changed since I was younger,” P09 relayed.
“Although I like the idea of using an envelope system…it’s just not practical...We don’t
keep money like that.” Parents also lamented over their failed attempts to maintain an
allowance system, noting that they and the children weren’t consistent on following
through. “Everything was sporadic, P11 explained, “and it meant keeping cash around,
which neither of us [reference to children and parents] were good
at.”
Participants asserted that children cannot learn financial concepts and practices
abstractly and remotely by just listening and watching. P03 explained,

I would always try to tell them that’s expensive or you have to pay for that, but
it’s hard to have those kinds of conversations... So, I think [FMVB] gives them
the starter program…It makes the conversations a little more concrete.
P09 shared an example of how her two children were shopping with their newly-issued
FMVB prepaid debit cards and had to come get the adult parents because they did not
know how to use it. “It was just weird. They needed help with that, but they’ve seen us do
it a million times.” P13 underscored, “They need to know how to swipe a card, enter their
pin number, sign for it.” P06 took a more balanced approached to the digital versus paper
paradigm. She noted that although she does not carry cash anymore and relies heavily on
technology, she still thinks it is important to have children “learn about things the old
way.”
Digital makes it visible. The notion that a digital platform and prepaid card can
make money and the concept of value more tangible seemed initially counter-intuitive to
a majority of the study participants. However, this group found that the value-centered
lessons that they were attempting to convey through conversations, explanations of
financial transactions, manual systems, and lecturing were not positively affecting their
child’s approach to financial decisions or their spending and saving habits.
“FMVB gives them the tools to see how they are doing financially, what they’re
spending on,” explained P01. “It’s not me telling them. They can see it…It makes
spending visible and transparent.” P02 emphasized,
It is more concrete, It is more concrete. He can see it more openly. We’ve always
told him that your bank account gives you interest. But I think even being able to

see the interest amount [makes it] a little more tangible. Giving him 1% per
month, rather than .01% annually, allows him to feel it now.
P04 equated FMVB to a visual tool, an analogy echoed by P12 who indicated that there is
“no guessing game and hiding.” As P13 stated, “It is all laid out. You don’t have to think,
‘Oh! Where did I spend that $5?’ It’s all there for you and a little more controllable to
look at and see.” P02 stressed, “In a cash environment, there is no visibility.” One
subscriber P03 did, however, voice some caution. “It’s easy to spend money you can’t
see, and you don’t have in hand.”
Data informs decisions. Since using FMVB, the parent-subscribers I interviewed
have witnessed a shift in their children’s approach to spending and saving. They and their
children can now see the pattern and cumulative effect of routine expenditures ranging
from Legos to Frapuccinos to Uber rides. Two parents, one who has a child with ADHD,
shared how the use of FMVB affords their children the opportunity to “pause and think”
(P05) and “give it a minute” (P13). P05 shared,
Instead of buying [the Lego set] immediately, which he would have [with physical
cash], he now thinks about it, makes sure, figures out why he wants it…which I
know seems silly because it’s only a Lego set, but I’m hoping that process will
transfer over later in life.
P14 recounted how her son wanted to buy his girlfriend a gift for their one-year
anniversary, which he saved up for and purchased himself with his FMVB card. “He’s
making the decisions…he’s learning by doing it on his own.” Similarly, P13 noted how

the account balance that is displayed on FMVB app helps shape the children’s buying
decisions:
It’s a good visual to show them. Oh, this what I have, and if I spend it on that it’s
going to go down, unlike when they are holding money, which they sometimes
lose. And if they aren’t losing the money, then it becomes just as elusive – “Oh, I
have this money somewhere out in the world,” but it’s not as concrete. And it’s
very real when they make that transaction, and the money comes out, and they can
see it right on the app.
The parents I spoke with also noted how readily their children would ask them for
money or how quickly their child’s pocket money would disappear before they became
FMVB subscribers. P7 noted how much “more thoughtful” her children are with their
decisions, including their middle child who is “happy to spend more money.” P10
discussed how they wanted to put their children in charge of having a budget for
Christmas gifts that included making the list for people they wanted to buy for and do the
actual purchases themselves, which was a departure from previous years.
We gave them a budgeted amount [in FMVB]. It was very interesting to see the
two different ways they approached it. The younger daughter allocated $20 to
each person. And she’d identify things [online or in a store] that she thought a
person would like. But she would say, “I still have $5, what else could I find for
$5 to meet that $20 budget per person?” Whereas, my other daughter searched for
things that people would really like, but if it didn’t go to the full $20, she knew
she would have extra [in the account].

As P01 summarized, “Now when my son shops, it becomes a process. He consciously
asks, ‘Do I really want that action figure? Do I really want that game?’” For these FMVB
subscribers, the sense of ownership, accountability, transparency, and independence that
FMVB provides appears to be shaping their children’s spending decisions. Yet, the
benefits, as several parents explained, are not restricted to just the children.
Reaping reciprocal benefits. According to participants P04, P05, P06, P09, P10,
P12 and P16, the benefits of using FMVB to support productive financial lessons and
practices were not restricted to just the children. As P09 explained,
It’s helped our financial literacy. It’s helped me to be able to verbalize it and think
more long-term for my kids as well. [Prior to FMVB], I was on a short-term plan
with my kids…I was just trying to get them to understand what was going on
right now. [FMVB] is allowing us to take [our] planning to the longer-term goals,
which has really helped the financial literacy in our household.
P10 discussed that as she and her spouse began thinking about how best to support their
daughters’ financial education, it prompted them [the adult parents] to “get together our
finances.” It was around the same time that P04 and P12 signed up for FMVB that they
signed up for budgeting software. As P12 relayed,
It’s been a year of really intense sort of learning. And it’s been fun…I had never
thought about financial literacy being fun before. It’s like a whole new world now.
I need to get on the ball so that I could help my kids to make better decisions and
learn more. So, I think it’s been beneficial all around.

P05 discussed how she has earmarked the fourth FMVB prepaid card for savings, which
has allowed her to streamline the flow of money with her husband and son, both of whom
have ADHD.
So, if there’s an extra purchase that my husband needs to make…he’ll say, “Can
you just transfer some money over to my card?’ So he can do what he needs
to…without going to the ATM…It’s made it easier for him to kind of understand
what’s going on and to keep track of his money. I think [FMVB] is really going to
help our family stay on point. Having it separate from our bank account is really
helpful because…it’s compartmentalized.
Summary of Theme 1, RQ1.
• Parents found that FMVB makes the concepts of value and responsibility
more tangible, visible, and concrete.
• Parents experienced the shared benefits, alongside their child[ren], from
the structure and consistency that FMVB brought to household
responsibilities and the transactional and decision-making processes
associated with budgeting, spending, and saving.
Theme 2: Perceived shifts in family financial interactions attributed to FMVB
This theme is a product of the relationship dynamics and nuanced influence that
individuals and factors within and outside the nuclear family, including technology, had
on the financial socialization processes of the parents and children. As reflected in Figure
7, the theme addresses RQ2: What are parents’ perceptions of how the use of a fintech
tool supports conversation and transaction-based socialization activities between a parent
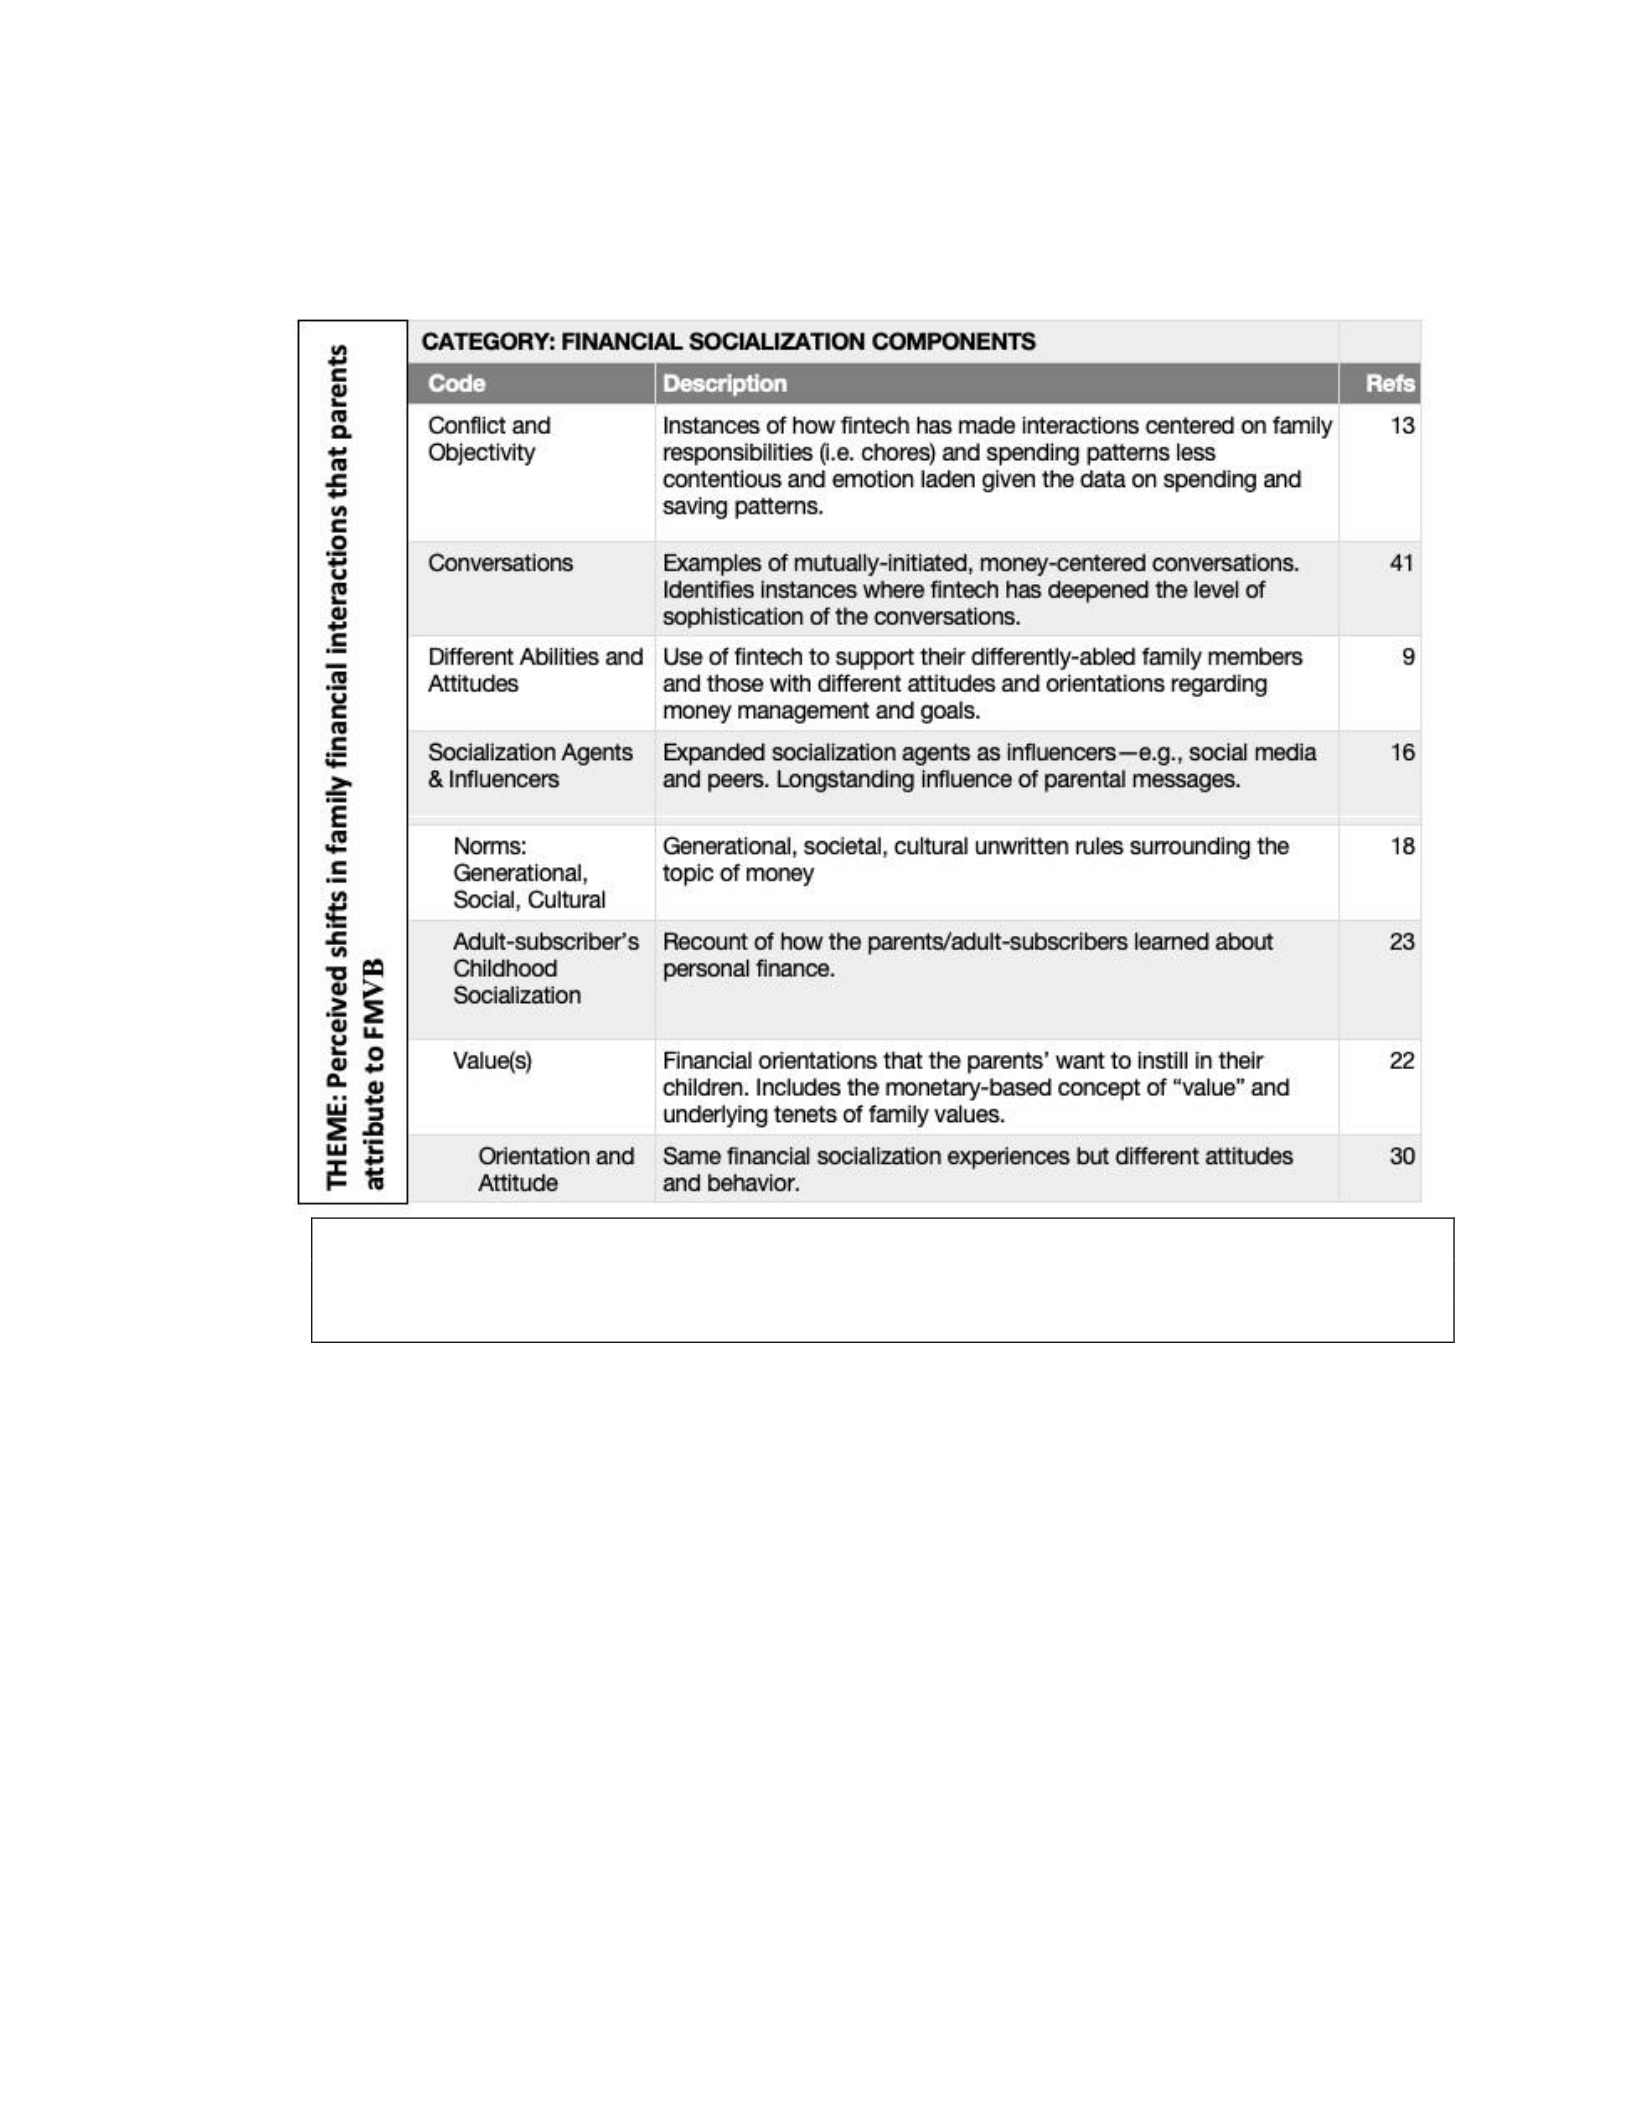
and child?
RQ2: What are parents’ perceptions of h ow the use of a fintech tool supports conversation and
transaction-based financial socialization activities between a parent and child?
Figure 7. Codes, categories, and descriptors associated with Theme 2 and RQ2.
Childhood shapes parents’ approach to financial socialization. The financial
socialization process that the parent-participants experienced themselves, productive or
counterproductive, provided insight on the rationale behind and approach to the practices
they are using with their own children. Several participants noted that their parents were
quiet on the subject of finances. P05 recounted, “I didn’t have any idea growing up. Other
than being told I should tithe on Sunday, and it’s good save…my parents didn’t really

share anything with me about their financial dealings.” P13 conveyed a similar
experience, “Growing up…my parents didn’t really talk about it. Nobody really talked to
me about saving money or how to responsibly spend my money.” Others, including P11,
discussed the mantras and warnings that they regularly heard.
I was definitely taught by my dad, who was obsessed and shared all his feelings
about how much we should spend and not spend, and to constantly save and buy
real estate….Every little thing we did, he would explain his philosophy on what
we buy or not buy, or how you handle things.
As P11 described it, “I definitely would not call it a dialogue [about finances]. It more of
a lecture.”
Most participants recalled that their hands-on experience with money growing up
was limited to the occasional small purchase (e.g., candy bar or ice cream) and the typical
way they learned about personal finance matters, other than listening, was by watching.
For P05 it was—
Basically seeing it [financial decisions and transactions]. Not so much to teach us
really, but seeing it in action. Seeing [my mother] budget, and comment to us as the store
that we only have such and such money. We don’t have extra this week. P09 reported,
“We were very poor, but mother was stellar with every penny she had. So she slowly built
herself up. I watched her do that and then I did the same thing for myself.” P15 disclosed
that her parents grew up in the Depression Era and used the envelope system for
budgeting. “So, that’s how I was brought up. Budget, budget, budget.” Others like P08
revealed, “I didn’t become educated [in personal finances] until

I was an adult.”
Many participants, including P10, recounted how they learned from there financial
mistakes. “When I finally got my own checking account and was doing the real work of
balancing and it was all on paper…my very first rent check bounced,” because she did
not know that the bank processes payments before deposits. Like P10, P11 had
professional parents, “but even with that they never taught me anything about financials.”
The approach, not the values, becomes time-worn. The prevalent feeling
among this group is that the long-standing maxims including, “Don’t live beyond your
means,” and “Save for a rainy day,” remain part of the values and lessons that they want
to instill in their children. However, how they support the development and application of
these values, even with FMVB, is challenging. As P15 emphasized, “I have all [my
children] so far, except for one, who seem to understand that you need to save money for
a rainy day. We’ve raised them all the same way. And her [approach to money] is not
something that you learn from FMVB or that we taught her…” Several parents bemoaned
that broader social influences are affecting their child’s financial orientation and habits.
P07 elaborated:
There’s a bit more material focus nowadays, at least in the environment that I’m
in, versus when I was younger. Their [children’s] social status is based on how much their
family has. So, there’s also just anxiety about self-worth and how you feel about your
family, and how you fit in the world in comparison to your peers. As P08 voiced,
I don’t care what generation that you’re from, there’s an enormous pressure to be
part of the “good” group…and I think that social media has hugely exacerbated

this problem. Unlike when I went the school, the only comparison was with the
kids in your classroom or hallway. Nowadays with social media, you can see what
the whole world is wearing, driving, and the kind of houses they live in. And this
kind of increased awareness puts our lifestyle and theirs (reference to children)
under a microscope.
P06, P07, and P10 were among a number of parents who noted the positive effect
that both responsible and comparatively extravagant behaviors among peers had on their
own children. P06 shared that her child’s best friend has a card similar to FMVB. “My
daughter sees her saving. So it pushes her to do the same.” P07 mentioned that unlike her
children, who have their own money on FMVB, their friends are “spending their mom
and dad’s money…and it doesn’t register for them like it does [my child]. She makes
thoughtful decisions now [with FMVB] that I don’t know she would have before
[FMVB].” P10 characterized her child as being a discerning consumer, which she
attributes in part to FMVB.
My younger daughter has a couple of friends who really glom onto trends…and
their parents will often get them…high-profile, brand-name items. My daughter
will look at those things a more critically and be like, “I’m not paying that much
for a pair of shoes.” So there’s some discernment there.
Fintech facilitates conversations. All parent-subscribers noted change in the
frequency, depth, and/or tone of the finance-centered conversations with their child(ren)
since they started using FMVB. As expressed by P09, who is navigating the challenges of
newly-formed blended family,

It surprises me how frequently now we talk about money, and how infrequently
before [FMVB} we weren’t talking about it, when we need to be. And it’s not a
point of contention anymore. I feel absolutely no frustration. It’s a learning
environment. They’re stimulated. They ask a ton of questions.
In a similar vein, P10 noted that because of FMVB, “You have a platform, a structure to
talk around, and clear examples that you can use. The tools that are offered with the
platform give parents ways to talk about money beyond managing it. It’s a tool for
creating those conversations.” P11 also indicated that the conversations are not only
happening more frequently, but they are more casual and less parent-directed, since they
occur in tandem with the transactions that occur routinely within the accounts.
Particularly noteworthy for several of the parents, including P10, was the fact that
FMVB is providing a bridge from talking about financial topics—to applying them using
the FMVB platform, calculators, and accounts—and extending the conversation to
longer-term decisions about employment and college.
It’s opened up conversations about future employment…They ask us. It’s not us
telling them or asking, “What do you want to do in the future?” They are starting
to realize the impact of career decisions [on their future financial state]. Without
those foundational conversations, it would be harder to make the leap…to your
goals.
P11 noted that as her family is starting to have more conversations about college and
what they could likely afford in three or four years, it is “filtering down to the smaller
purchases” and affecting the children’s short-term saving and spending decisions.

Parents manage attitudes through fintech. Money can be an emotion-laden
topic, as many of the parent-subscribers expressed, which the use of FMVB has helped
temper. “We’re on the same page [parents and children]. Everyone can open up the app
and see who has done what chores and if they have any money,” shared P09. “It’s not
personal…and I think it’s curbed some emotional spending habits.” P12 indicated, “It
[FMVB] has been a positive…for our family dynamics and well as for financial literacy.”
One parent who struggles with letting her children spend money on items she considers
frivolous said, “It’s [FMVB] caused a lot less arguments for the family, even in terms of
telling [the children] how to spend their money.”
The adult-subscribers to FMVB shared that despite their children growing up in
the same household with the same narrative and modeling around financial habits, their
children’s individual orientation toward money is as unique as their personality. My
middle child has the most conservative outlook, explained P01. She has an interesting
relationship with money and will stress over it. My oldest daughter is the opposite. Not
that she is frivolous, but she does have a huge heart. No amount is too great when it
comes to buying a gift for someone close. [Before FMVB] she went into debt buying a
dog for her boyfriend. She would spend beyond her means.
Other parents, including P02, discussed how FMVB has supported the different
orientations their children have toward spending and saving.
My youngest just piles up the money…Her [FMVB] is more like a savings
account, and she doesn’t really want to spend it very often. But my older one
wants every single thing under the sun. She’s a bit more materialist. [With

FMVB] she plots things out and understands how much things cost now in a
different way than before [FMVB]. She can see how much she has and she’s
paying for it herself, which gives that feeling of ownership. And I think that she’s
understanding the value of money, which can be lost on kids.
P03 also highlighted how FMVB helps manage the different timeline orientations and
spending mentalities of her children. “The younger one…is a little bit better with saving.
She’s thinking ahead to college and a car. And the older one, she’s more into what she
wants now.” P05 shared a similar perspective on her children.
He lives week-to-week like paycheck-to-paycheck. He just wants to spend. That’s
just the way he is. My daughter is more…I’m going to save because I have
plans…In my eyes, he doesn’t care. That’s just his personality. I don’t know if it’s
like a boy thing?
P02, the mother of three girls, conveyed that her younger one “likes to see the FMVB
balance going up. The middle one can spend all the time.” Another parent, P13, described
how she is positioning FMVB to support “the ideas of saving for a goal and not impulse
buying. That’s something I really would like to stick with them especially one of my kids
is very ‘right now, what’s the newest, the best, the latest.’ And I think that’s a really hard
way to live in life—to always want newer, better, and more right now.”
Summary of Theme 2, RQ2.
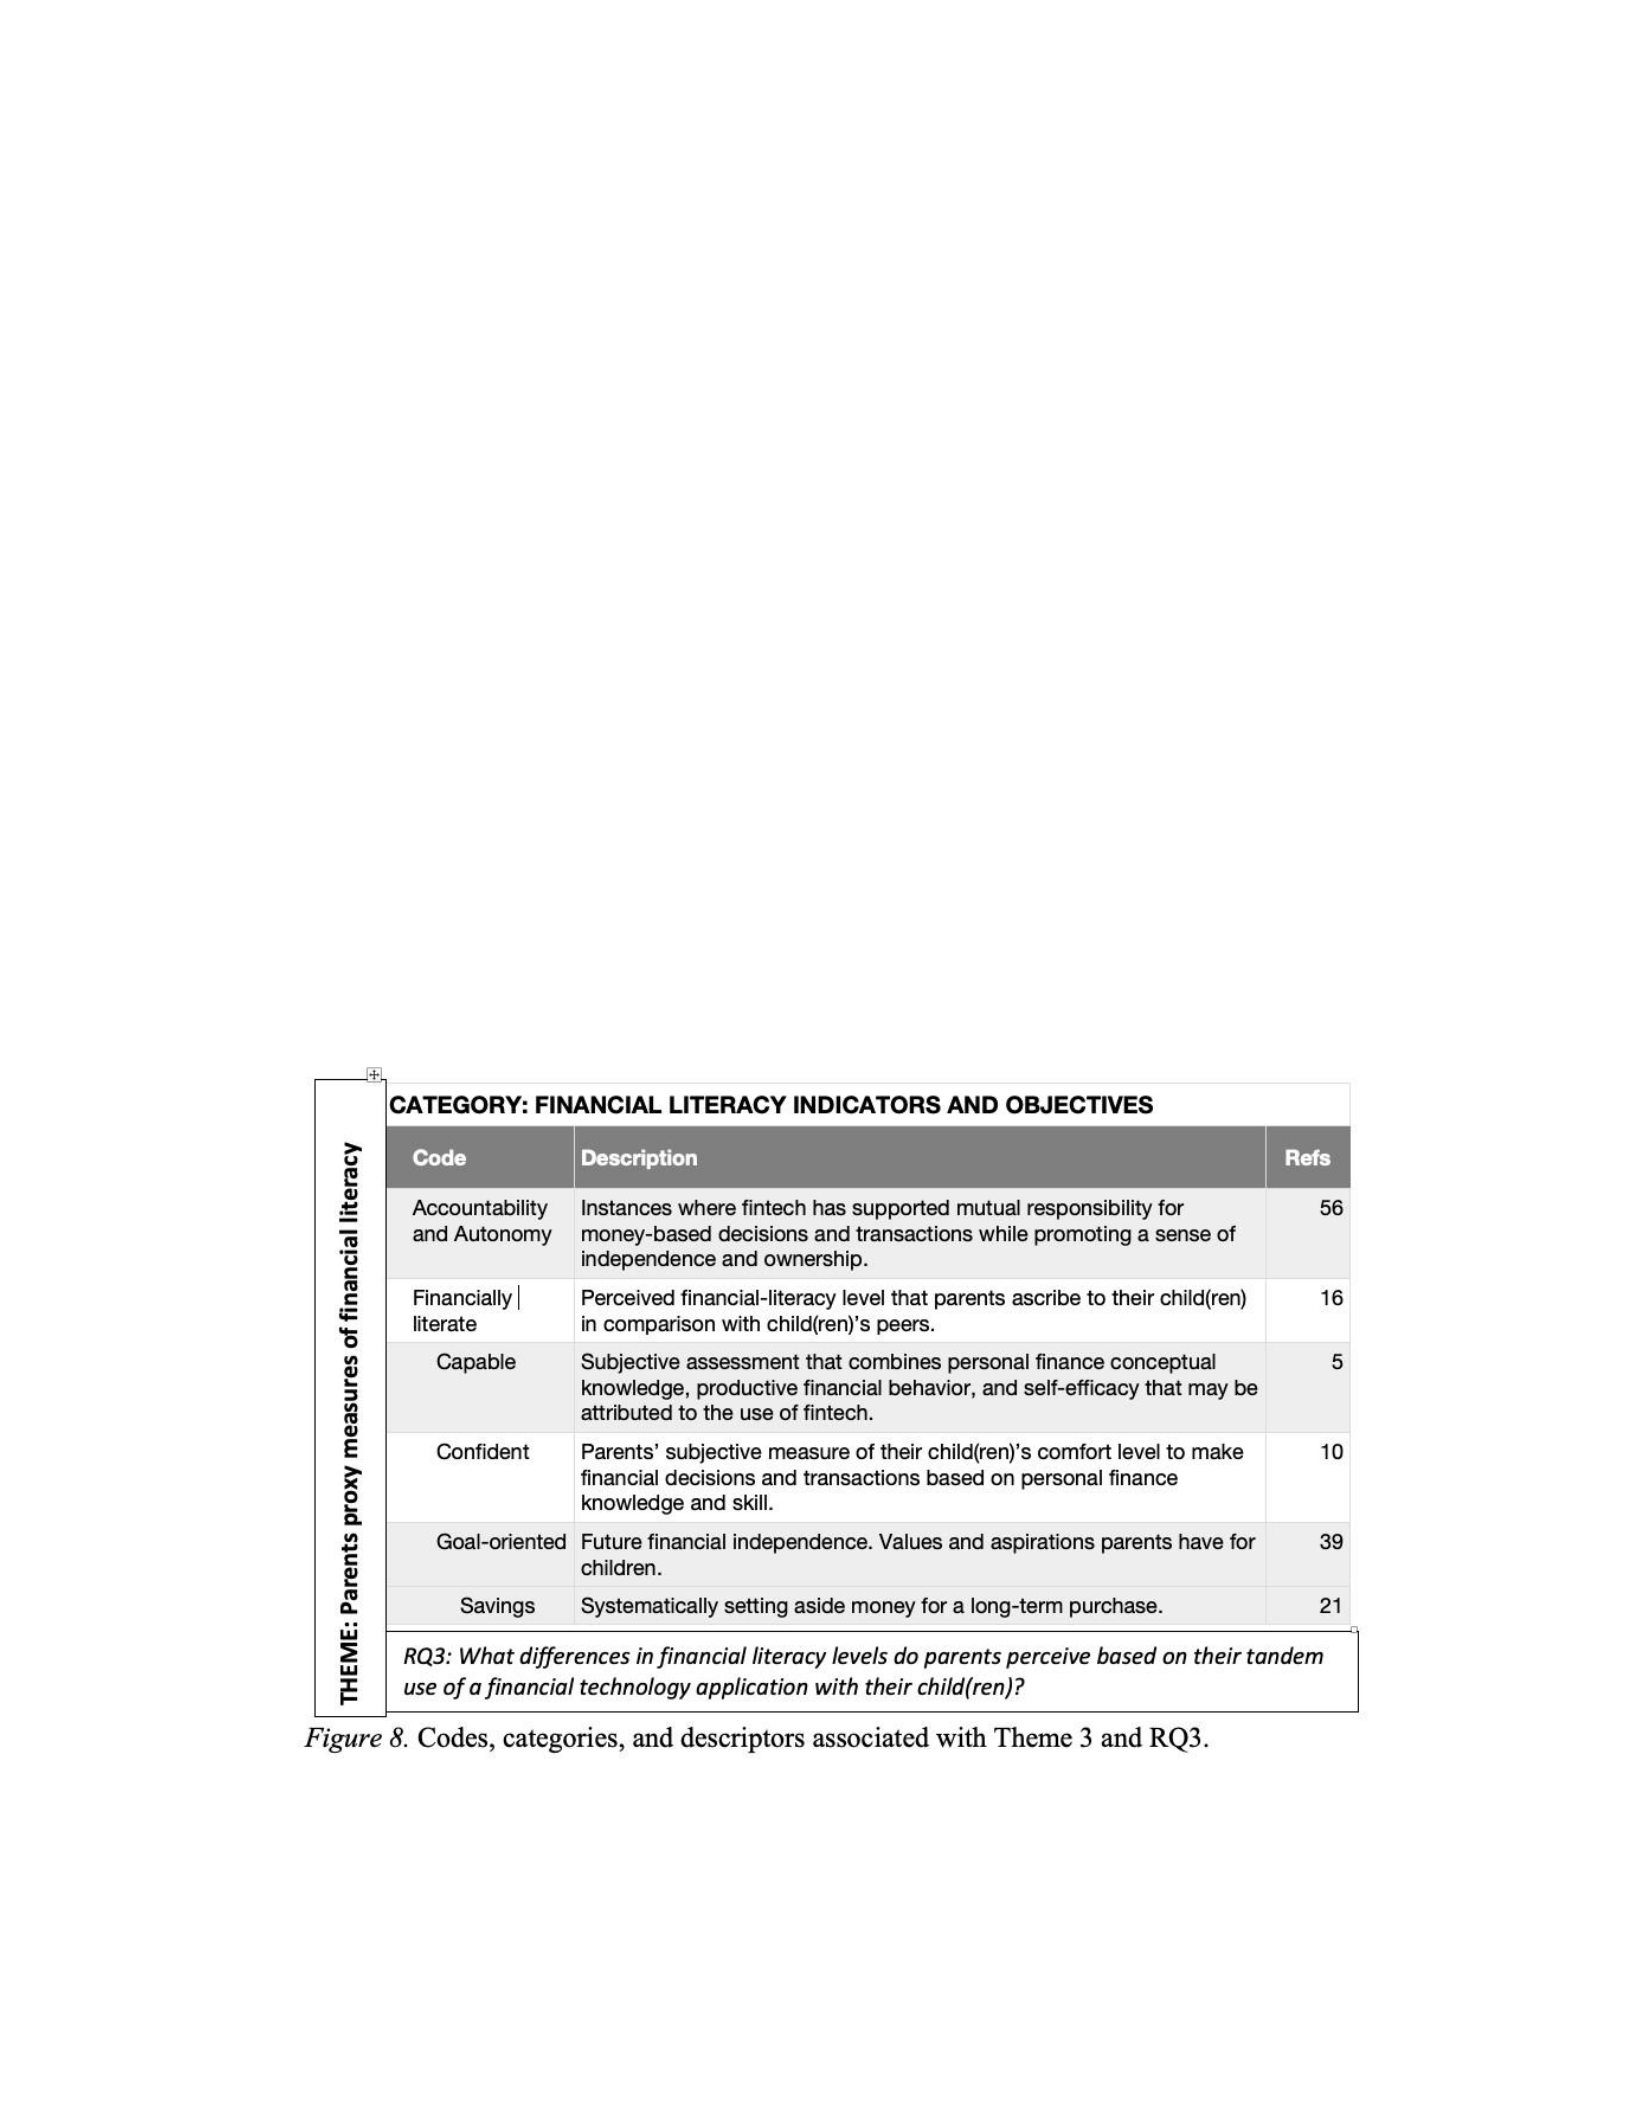
• Parents perceive that the use of FMVB has increased the frequency,
objectivity, productivity, and depth of personal finance conversations with
their child[ren].
• Parents perceive that FMVB helps align the unique and differing
individual attitudes and approaches toward money management that are
present within the family construct.
Theme 3: Parents’ proxy measures of financial literacy
This final theme accounts for the subjective indicators that parent-participants
used to assess differences in their child[ren]’s financial literacy level, which may be
attributed to the use of FMVB. See Figure 8 for additional detail on the factors associated
with the theme.

The parent-participants had well-defined, observable, and demarcated criteria for
what financial literacy, confidence, and capability looked like in their children. They also
qualified their subjective assessments of their child’s financial literacy levels using
comparisons to peers alongside their own expectations and observations as a
measurement standard. Most parents used the term financial literacy to explain their
child(ren)’s conceptual understanding of financial topics. “I feel like he’s got a better
grasp, in general, that money is a thing,” explained P02. “I think that some of his peers
don’t think that way. Goods and services just appear at the doorstep because mommy
made them.” Similarly, P05 noted, “I think the knowledge is there. It’s just that [financial
transactions and decisions] haven’t happened enough in his life yet for him to produce
that thought process himself yet.”
In terms of confidence, several parents noted reciprocal benefits to using FMVB
for the child(ren) and the adult-parent(s) in the household. P03 conveyed,
I know that both of them [children] really enjoy being able to go to the mall and
have their own debit card. And I think they feel sense of “I’m an adult. I’m kind
of grown up when I get to walk up the register with a card that has my name on it.
And I can buy things with the money that I’ve earned.” So, I think they’re very
confident in that.
P06 framed her assessment of children’s financial confidence this way:
Their confidence has increased because with all three of them, they will use their
own card to buy things that they want. When one daughter wanted a sweatshirt
from a concert…but didn’t get there…but wanted to get it online. [She said] “I’ll

pay for it myself. This is something I want to pay for myself…I’ve got enough
money. I’ll do it myself.” I think [their confidence] is more because they know
they have the money that they’ve earned themselves, and then they’ll find ways to
purchase on their own, and then they may just need a little bit of help in how to
exactly do the transaction [online].
P12 shared, “I’m feeling pretty confident about what my kids know and are able to do.
And I feel like FMVB in conjunction with [budget app that she and spouse are using]
made me feel more confident and able to teach my sons.” P06 conveyed that with FMVB,
“I’m very confident in knowing that I can talk to my kids, and I know as much as I need
to know.” P08 added a different perspective on how his son’s lack of financial confidence
is serving to motivate him to learn more.
His interest in money is because there is less security there. In other words, there
more of competitive insecurity in him. There’s this measurement between how
much [he knows about financial matters] and how he compares [himself] against
the rest of the world.
Capability yields confidence. Confidence as defined by this group of parents is a
product of capability, the children being able to conduct age-appropriate transactions
independently through FMVB. “My son is better grounded,” remarked P01. “FMVB
created a space for him to be in control and for us to have conversations.” P06 relayed, I
don’t have any involvement in their purchases. My son uses it to buy computer and
gaming things online. My daughter uses it socially…when they go out to eat or to the
movies. My kids are more self-reliant in that way ever since I had them

help me complete some things online. And I like for them to feel like they are
growing up and get that independence of where they don’t need my permission
for what they buy.
Several parents discussed how FMVB provided a managed-level of independence
and autonomy that resulted in their child[ren] feeling empowered yet accountable.
“[FMVB] gave them so much more control and autonomy over their own
decisionmaking,” explained P07. Perhaps P05 most succinctly captured that transfer of
control and accountability from parent to child that other parents alluded to: “Once I
throw the money on your card, that’s it. It’s your job to track that. You know that’s what
you have. It’s all there.” P07 emphasized, “It [FMVB] has given them so much more
control… They feel like they have much more voice in how they are spending their
money. It gave them so much more control and autonomy over their own decision
making.” Parents release control. Others alluded to their child’s management of the
FMVB debit card and associated accounts as providing a rite of passage with guardrails.
“It’s a very adult thing to have a debit card,” explained P07. “It’s like a rite of passage
that shows your children that they are responsible enough to possess something like that
and to deal with what it entails, which is money.” P08 echoed those sentiments: There
are two aspects to it [use of FMVB]. One is giving [the child] the buying power that the
debit card affords…[Second] he’s empowered. It’s his decision…and choice to make. He
has the tool and the mechanism to buy that Frapuccino. I just want him to be empowered
to make these little choices…All of the other stuff [reference to financial capability] will
come later. I hope.

Accountability accompanies empowerment. As the parents discussed this shift
in control and the resultant empowerment that the children may feel, several framed and
qualified their comments in terms of the associated accountability including P09: Here’s
what I love about FMVB. They get a reminder on their phone to do their chores, and if it
doesn’t get done, they get charged, and it’s not personal. There are no hurt feelings
involved. If you didn’t do it, there’s a monetary penalty…And when they’re bored, and
don’t have money to do anything, they [are experiencing] the consequences.
FMVB also serves as an accountability gatekeeper, as several parents noted, for
themselves. P13 explained,
Whenever my two sons get money, they hand it to me right away and say, “Put
this on my card.” Before they would try to put in their pocket...or give it to us, and we’d
throw it our pocket, and then we’re like, “Shoot, where did we put that?” So now, they
give their money right away to me always, and I put it on their card. Another parent, P10,
conveyed how her daughter sent her an invoice through the FMVB mobile application
because the parent failed to make a timely deposit based on a verbal request:
She said, “Mom, did you make that deposit to my FMVB account yet for those
chores?” And I said, “Oh, well I know we talked about it, but if you could write
down what you did and how much you think that’s worth.” But instead of writing
it on a piece of paper, she sent me a request through the FMVB app with an
invoice and in the details wrote this is what I did, and this is how much its worth.

P15 also noted that her children know that if she buys something for them, “I’m going to
take that money out of their FMVB account instantly when I get in the car. Other times
before [FMVB], maybe I might forget.”
Short-term practices segue to a long-term orientation. Understanding the value
of money coupled with the decision-making skills developed through FMVB will,
according to these parents, provide the springboard for longer-term, financiallysignificant
goals and decisions.
I want my children to have some sort of understanding of the value of money.
That’s my biggest goal overall, P14 relayed. I don’t want them to think that
everything is just going to be handed to them…I want them to understand how
they can go about acquiring it, but do it a way that makes them happy…Succeed
at school, go to college, get a job, and be able to support themselves.
Several others, including P5, discussed how they position the FMVB prepaid card as their
child[ren]’s “training wheels” for a credit card:
My husband and I tossed around the idea of not just getting [FMVB] for my son’s
allowance, but for him to learn how to use a card more responsibly than getting a
credit card for the first time and all the woes that come with that.
Most every parent stated that their primary, long-term financial education
objective with their child[ren] is to teach them the importance of saving for a future goal.
As P02 expressed, “The long term hasn’t pieced together for [his son] yet...I think [the
savings account in FMVB] is going to help open up the conversation when he wants to
save for something bigger.” P03 stated, “I would like for them [the children] to learn the

importance of saving and be in a better position than my husband and I are…I just want
them to be wise with their money and be savers.”
Several parents conveyed how they are using FMVB to develop that savings
orientation in their children. P07 shared,
We just started their savings accounts [in FMVB]. The little one wants a computer
and the middle one wants a car. I think this is really helpful for them as young
kids to be able to set a goal and then work towards it.
P11 shared that any money the children are gifted goes directly into the FMVB savings
account. “Whenever that happens, I always try to talk to them. ‘What’s your next big
thing you’re saving for right now.” P05 shared a comparable approach,
My goal is to have them [the children] let me know what is that one thing that you
want to buy. “Okay, well, let’s work towards it. Is there a way you can make extra
money so you can get to that goal?” I really think that it’s [reference to FMVB
and the goal setting] going to help them be independent and hopefully learn to
care about their finances.
Several parents noted how their children are using the interest and savings
contribution calculators on FMVB to establish saving targets and timelines. P07 relayed
an example with her child, “Mom, I just the calculations and at $13 a week, it’s going to
take me three years to get the computer I want. That’s too long.” This parent decided to
match their child’s monthly contribution and summarized her objective:
So now I think they’re going to be much more willing to do that [save], because
they have some goal in mind…But the whole idea of focusing on a goal and then

achieving it financially, I think it’s going to be really important for them now, so
that when they become adults, it’s easier to do, hopefully.
Summary of Theme 3, RQ3.
• Parents perceive that the use of FMVB has bolstered their children’s
agecommensurate financial autonomy, accountability, knowledge,
capability and confidence to make informed financial transactions and
decisions.
• Parents revealed that the tandem use of the FMVB platform and access to
common, real-time data have increased their confidence and comfort level
initiating and discussing immediate and long-term financial transactions,
decisions, and goals with their children.
Summary
In this chapter, I recapped the purpose of this study and associated research
questions. I presented the setting for the study and included summary, descriptive data
about the participants. I also discussed the steps taken to promote the trustworthiness of
this study. A discussion of how I collected the data and the method I used to analyze it
was also included. I presented the findings in a format consistent with thematic analysis
and addressed each of the research questions that served as the basis of this study.
In Chapter 5, I will interpret the findings and their potential value for stakeholders
including educators, public policy officials, and families. I will also outline
recommendations for future research and realistic implications for positive social change.

Chapter 5: Discussion, Conclusions, and Recommendations
Introduction
This chapter begins with an overview of the rationale for this study, summarizes
relevant research that anchored this work, recaps the research questions that informed and
guided the data collection, and introduces the resultant findings. From there, I interpret
the findings within the context of the extant literature and conceptual framework and
revisit the limitations to trustworthiness that I experienced during the study. To conclude
the chapter, I identify opportunities for future research and discuss potential implications
for actionable social change by stakeholder group.
The purpose of this basic qualitative study was to explore parents’ experience with
and perceptions of the use of a fintech tool to support family financial socialization and
the associated financial literacy levels of parents and children. It was designed to address
a gap in the research related to fintech’s potential to bolster factors that contribute to
financial literacy.
The prevailing scholarship on the present and prospective value of financial
literacy efforts is mired by conflicting definitions of what financial literacy looks and
sounds like, inconsistent measurement systems, varying levels of instructional rigor, and
differences in teacher confidence and capability with personal finance matters and content
instruction (Consumer Financial Protection Bureau, 2019; Kaiser et al., 2020; Kaiser &
Menkhoff, 2016; Kasman et al., 2018; Lusardi et al., 2018; Walstad et al., 2017). Yet,
within this ambiguous research base, there are proof points of factors that consistently
and positively affect financial literacy levels. Those factors include the purposeful and

informed involvement of family members, access to financial services and products, and
the experiential learning opportunities associated with handling money that are now
ubiquitous on mobile and digital devices (Aber et al., 2016; Amagir et al., 2018; Batty et
al., 2015; Bosch et al., 2016; Brown & Taylor, 2016; Fraczek & Klimontowicz, 2015;
LeBaron et al., 2019; LeBaron, et al., 2018; Lusardi et al., 2017; Moreno-Herrero et al.,
2018; OEDC, 2020; Smith et al., 2018). This study acknowledges the pivotal role of
parents and fintech’s potential to redefine financial socialization and authentic learning
processes, which are key levers to financial literacy.
Through a series of semistructured, in-depth interviews with 16 adult-subscribers
to FMVB, I delved into a specific set of financial-literacy-related factors that emanated
from the following research questions:
RQ1: What are parents’ experiences with the use of a fintech tool to interact with
their child(ren) about financial concepts and decisions?
RQ2: What are parents’ perceptions of how the use of a fintech tool supports
conversation and transaction-based financial socialization activities between a parent and
child?
RQ3: What differences in financial literacy levels do parents perceive based on
their tandem use of a financial technology application with their child(ren)?
The adult-participants and I discussed the content and nature of finance-related
conversations among their family members, alongside explicit and tacit modeling of
financial behaviors and decisions that occurred prior to and since subscribing to FMVB. I
also inquired about the situational contexts, separate from, and facilitated by FMVB, in
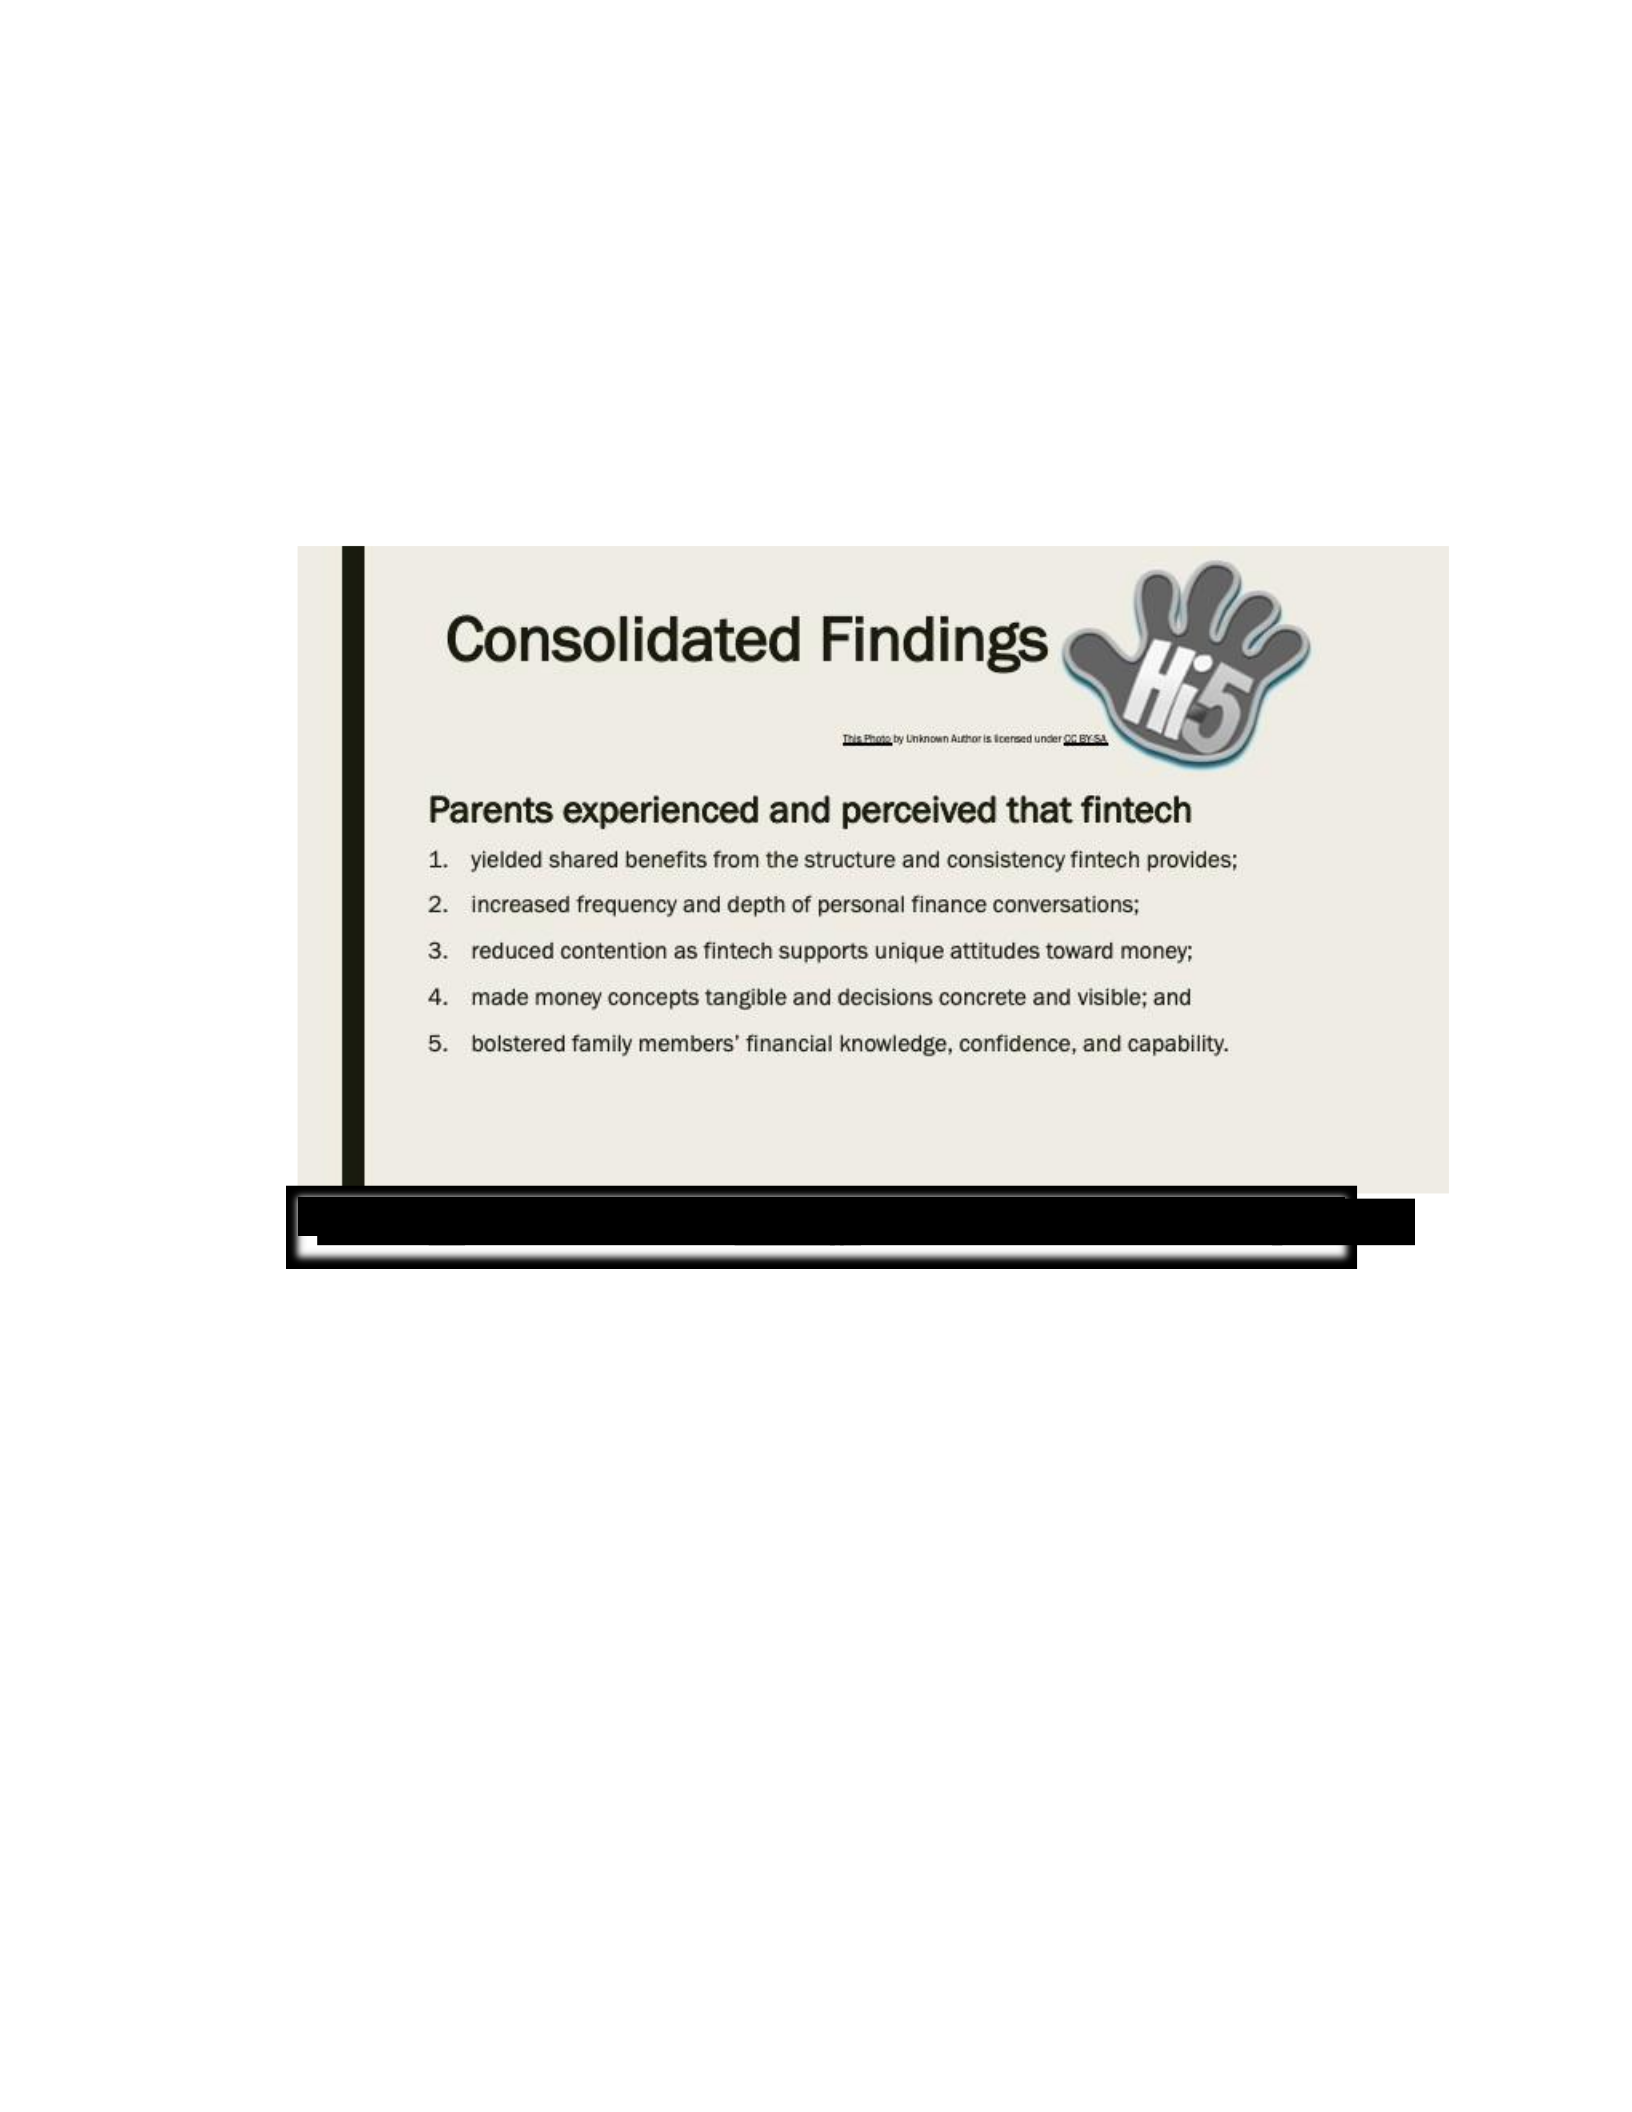
which the adults and their children applied financial knowledge and skills. The high-level
findings from these interviews, which will be further qualified in the context of the
study’s research questions and examined in relation to extant literature and the study’s
conceptual framework, are summarized in Figure 9.
Interpretation of the Findings
Answers in Relation to the Literature
RQ1: What are parents’ experiences with the use of a fintech tool to interact
with their child(ren) about financial concepts and decisions? The parent-subscribers I
interviewed first experienced the FMVB platform as a solution to an existing problem
(e.g., the arguments around chores, limited accountability or accounting for spending, and
no mechanism to access funds safely). They subsequently found that FMVB’s
functionality lends itself to facilitating broader conversations and financial literacy
Figure 9
. Consolidated findings
from in
-
depth, semistructured interviews.

lessons centered on the concept of value and longer-term savings. Parents noted that the
app-accessible, real-time data tied to savings, payments, and allowances/chores makes the
seemingly nebulous and complex concepts of value and budgeting more visible and
tangible. The emphasis that the parents in this study placed on indoctrinating their
children to the time value of money is validated in the literature. Researchers, including
Bosch et al. (2016) and Jorgensen et al. (2019), highlight the connection between
presentday, money-management patterns and orientations in relation to future financial
independence and well-being.
All the FMVB subscribers I interviewed asserted that the digital payment and
tracking system makes money more visible. This finding and the study participants’
collective experience does stand in contrast to the caution raised by Rosa-Holyoak et al.
(2018) and Lusardi et al. (2018). The former research team contended that with electronic
transactions children do not see their parents setting aside physical currency for savings
or writing checks to pay bills, which may hinder the parents’ attempts to explicitly model
positive financial socialization and decision-making behaviors (Rosa-Holyoak et al.,
2018). Lusardi et al. also warned that the lack of physical connection to money may
exacerbate deleterious financial behaviors. P04’s commentary reflected the general
sentiment of the parents regarding these concerns:
I've gone back and forth between do they [children] really understand how much
they have [on the FMVB prepaid debit card]. And although I do agree [with the
concerns raised by researchers] to a point, that’s someone talking about a credit

card situation. With [FMVB], you’re basically walking around with your bank
account, and you’re able to see at any given point what is available to you.
There is agreement, however, among researchers and the parent-participants in
this study on the value of having children be responsible for their money, engaging in
financial transactions, and experiencing the benefits and consequences of the decisions
they make during their childhood and adolescent years. Parents explained that FMVB’s
prepaid debit card and app give their children authority, autonomy, and accountability in
relation to their money. Researchers including Bamforth et al. (2018), Riach et al. (2017),
Gudmunson et al. (2016), LeBaron et al. (2019), and Rudeloff (2019) concurred that the
experiential learning opportunities initiated by parents not only allow children to apply
the money scripts they have heard, but also to develop the foundational financial
decision-making strategies that will carry forward to adulthood.
The structure and transparency that FMVB brought to daily payment transactions
and money transfers by and between family members also created an opening for parents
to focus on their own financial planning and goals. Many of the parents in the study
found that through their use of FMVB they now had the motivation and foundational
skills to better manage their own spending patterns, formulate a household budget, and
focus long term. These parents, including P12, experienced the reciprocal benefits of
family-centered, financial socialization practices. “It’s a whole new world now...I needed
to get on the ball so that I could help my kids to make better decisions and to learn more.
So, I think it's been beneficial all around.” This positive cross-generational effect of
purposeful family financial socialization is corroborated by the research teams of

Bhattacharya et al. (2016), Britt (2016), Gudmunson and Danes, (2011) and
MorenoHerrero et al. (2018), whose members have also questioned why most financial
education programs fail to include the family.
RQ 2: What are parents’ perceptions of how the use of a fintech tool supports
conversation and transaction-based financial socialization activities between a
parent and child? Parent-participants admitted that the content of their conversation-
based lessons, which in many instances transitioned into one-sided lectures, either
reflected or attempted to compensate for their childhood introduction to personal finance.
This group also acknowledged that the enduring lessons on sound financial practices may
be timeless but maintained that the sit-and-listen and paper-and-pen approach to
conveying those lessons is outdated and ineffective with their children. All the parents in
this study noted and acquiesced to the fact that their children, unlike when they were
growing up, are subjected to an expansive set of influencers, in-person and media-based.
The money messages displayed by these influencers often conflict with the conservative
orientation toward spending that the parents in this study are attempting to instill in their
children.
Although the parent-participants often felt that external financial socialization
agents, in particular peers and social-media influencers, were undermining their efforts,
researchers have suggested otherwise. They indicated that parents have the greatest and
lasting influence on their child’s future financial practices and orientations starting at a
young age and continuing through adulthood (Bamforth et al., 2018; Jorgensen et al.,

2019; LeBaron, Rosa-Holyoak, et al., 2018; Serido & Deenanath, 2016). However, as the
parent-participants mentioned and researchers concede, the effect of the parents’ attempts
to positively socialize a child into a productive financial mindset and behavior pattern are
tempered by the quality of their overall relationship with that child (Gudmunson &
Danes, 2011; Jorgensen et al., 2017; Riach et al., 2017).
That being said, the parents in this study experienced and researchers contend that
the process of engaging in financial activities, which in this instance is through the
FMVB fintech tool, may compensate for and improve parent-child dynamics, limited
family financial socialization, and the parents’ lack of confidence with financial content
(Kagotho et al., 2017; Serido & Deenanath, 2016). One of the most candid accounts of
the negative interplay between family dynamics and finances that a parent abated by
FMVB was conveyed by P09:
You know what is sad though, we were, I was, having trouble instilling those
same [financial] values in my kids, and it was really affecting our relationship in a
very negative way. They were a complete irritant to me, which is terrible to say,
but it's the truth. I was so tired. I was so tired of repeating myself and asking my
children to do the same thing over and over and over. And it's the “I'll do it later
attitude.” And while their intentions were great, it would never get done. And it
was making me bonkers. And that's what I love about FMVB. I mean, they [the
children] get a reminder on their phone. And if it doesn't get done, they get
charged and it's not personal. There are no hurt feelings involved. It's, “You didn't
do it.” I don't have to ask them repeatedly.

The research is replete with examples of and evidence supporting the benefits of
parents engaging children early and often in authentic, hands-on, personal-finance-related
learning opportunities (Amagir et al., 2018; Arnold & Rhyne, 2016; LeBaron et al., 2019;
Serido & Deenanath, 2016; Tang, 2017; Xiao & Porto, 2017). Yet, as the
parentparticipants expressed, comparison-shopping and making small purchases with
cash, fails to place these discrete transactions in the broader context of assessing spending
patterns or forgoing a purchase to save for a future goal. Palakvangsa-Na-Ayudhya et al.
(2017) and Carlin et al. (2017) alluded to the potential, as in the case of FMVB, of fintech
that combines a data dashboard and user interface to support both family-centered
interactions and financial literacy objectives, the multiple factors researchers know and
parents perceived influence financial literacy levels.
RQ3: What differences in financial literacy levels do parents perceive based
on their tandem use of a financial technology application with their child(ren)? In
this study, parents used their subjective assessment of the following factors as a
composite benchmark for perceived short-term differences in financial literacy levels,
which they attribute to the use of FMVB:
• Depth of financial conversations.
• Demonstrated capability to use the data and calculators on FMVB to make
financial decisions.
• Confidence in the current level of financial knowledge and skill to support
an informed decision-making process.

All the parent-participants highlighted positive differences they perceived, from
both the parent and child side, in relation to the data-driven content and complexity of the
conversations facilitated by FMVB. Yet, responses from the parent-participants did vary
when they discussed factors that they perceive contribute to financial confidence. For
several parents, their renewed financial confidence was the anthesis of conflict avoidance
given the pre-FMVB history of contentious conversations around household
responsibilities, money earned and owed, and spending. Other parents alluded to how the
shared used of the platform gave them the confidence and information they need to be
able to teach their children age-appropriate, accurate information on topics such as
budgeting.
The differences in confidence levels that parents perceive in their children and
attribute to FMVB varied in terms of direction and origin. Most related their child(ren)’s
increased confidence to the autonomy and accountability their child(ren) now have over
their money. This assertion is consistent with the 2018 PISA financial literacy assessment,
which found that students who reported they were more independent in their spending
decisions scored 30 points higher (OECD, 2020). Moreover, studentparticipants who had
a payment or debit card scored 21 higher than their 15-year-old counterparts who did not
have or know what a debit or prepaid card is (OECD, 2020).
Strikingly, P08 described his child’s diminished financial confidence as a positive
outgrowth of using FMVB, which has motivated his son to learn more about financial
markets:

[FMVB] has engendered these other discussions...this larger discussion, “Do you
think we should take a portion of your savings and invested in equities or in
bonds?” He doesn't know what those things are, but he knows that there's a
mechanism out there. He knows that there's something called the stock market.
He knows that it exists, and he's already come back to ask me questions. “Well,
what is a share? How does the stock market work?” We haven't done anything yet.
I'm waiting for him to kind of get there, but I can see already, I can see the little
wheels of his mind turning. He understands that just like you're saving your
allowance, just because you buy a share of Apple stock, or whatever it is, it
doesn't mean that you're going to make a lot of money next week, or even next
month, or even next year.
The subjectivity and challenge of isolating and measuring the contributing factors
to, codeterminants of, and proxies for financial literacy is also acknowledged in the
literature (Tang, Ning & Peter, 2015; Xiao & Porto, 2017). One outstanding question
centered on the combination of subjective and objective factors (i.e., financial
socialization practices, application, attitudes and orientations, education, confidence) that
has the most effect on resultant literacy levels and future financial behaviors. Several
researchers, including Xiao and Porto (2017), assert that an accurate, holistic measure of
financial literacy needs to include self-reported measures such as confidence. Yet, false
financial confidence enabled by and acted upon through untethered access to technology
can foster and form irresponsible financial behavior patterns in adolescents (Amagir et
al., 2018; Yakoboski & Lusardi, 2018).

Parents in this study did qualify their assessment of present-day differences in
financial literacy levels in terms of longer-term objectives backed by the use of FMVB.
They spoke of their intention to foster responsible money management skills through
FMVB that hopefully carry forward to more complex decisions and translate into a
lifelong orientation toward saving for goals. The research literature is mixed as to how
childhood or proximal financial socialization activities and orientations shape distal
financial attitudes and behaviors. Several parents in this study worried that their child’s
apathetic or contrary attitude toward money would carry forth despite their current efforts
to reshape their behaviors through the use of FMVB. As P15 explained,
I have all of them so far, except for one, who seem to understand that you need to
save money for a rainy day. And that was not something learned from FMVB or
that we taught her. We raised them all the same way. The same amount of
influence on finance, and we have one that cannot save money. She’s horrible
[managing money].
One possibility, as reported by Smith et al. (2018), is that a child’s
spending/saving orientation has formed as early as age five. Most researchers concur that
childhood, family-based financial socialization activities, in particular active engagement
in financial activities, do shape the financial behaviors of emerging adults (Deenanath et
al., 2019; Fraczek & Klimontowicz, 2015; Jorgensen et al., 2017; Kagotho et al., 2017).
Perhaps, the findings from the present research study, coupled with the extant literature
on factors that contribute to sustainable changes in financial behaviors and associated
literacy levels, speak to the value of exposing children to consistent, accurate, and
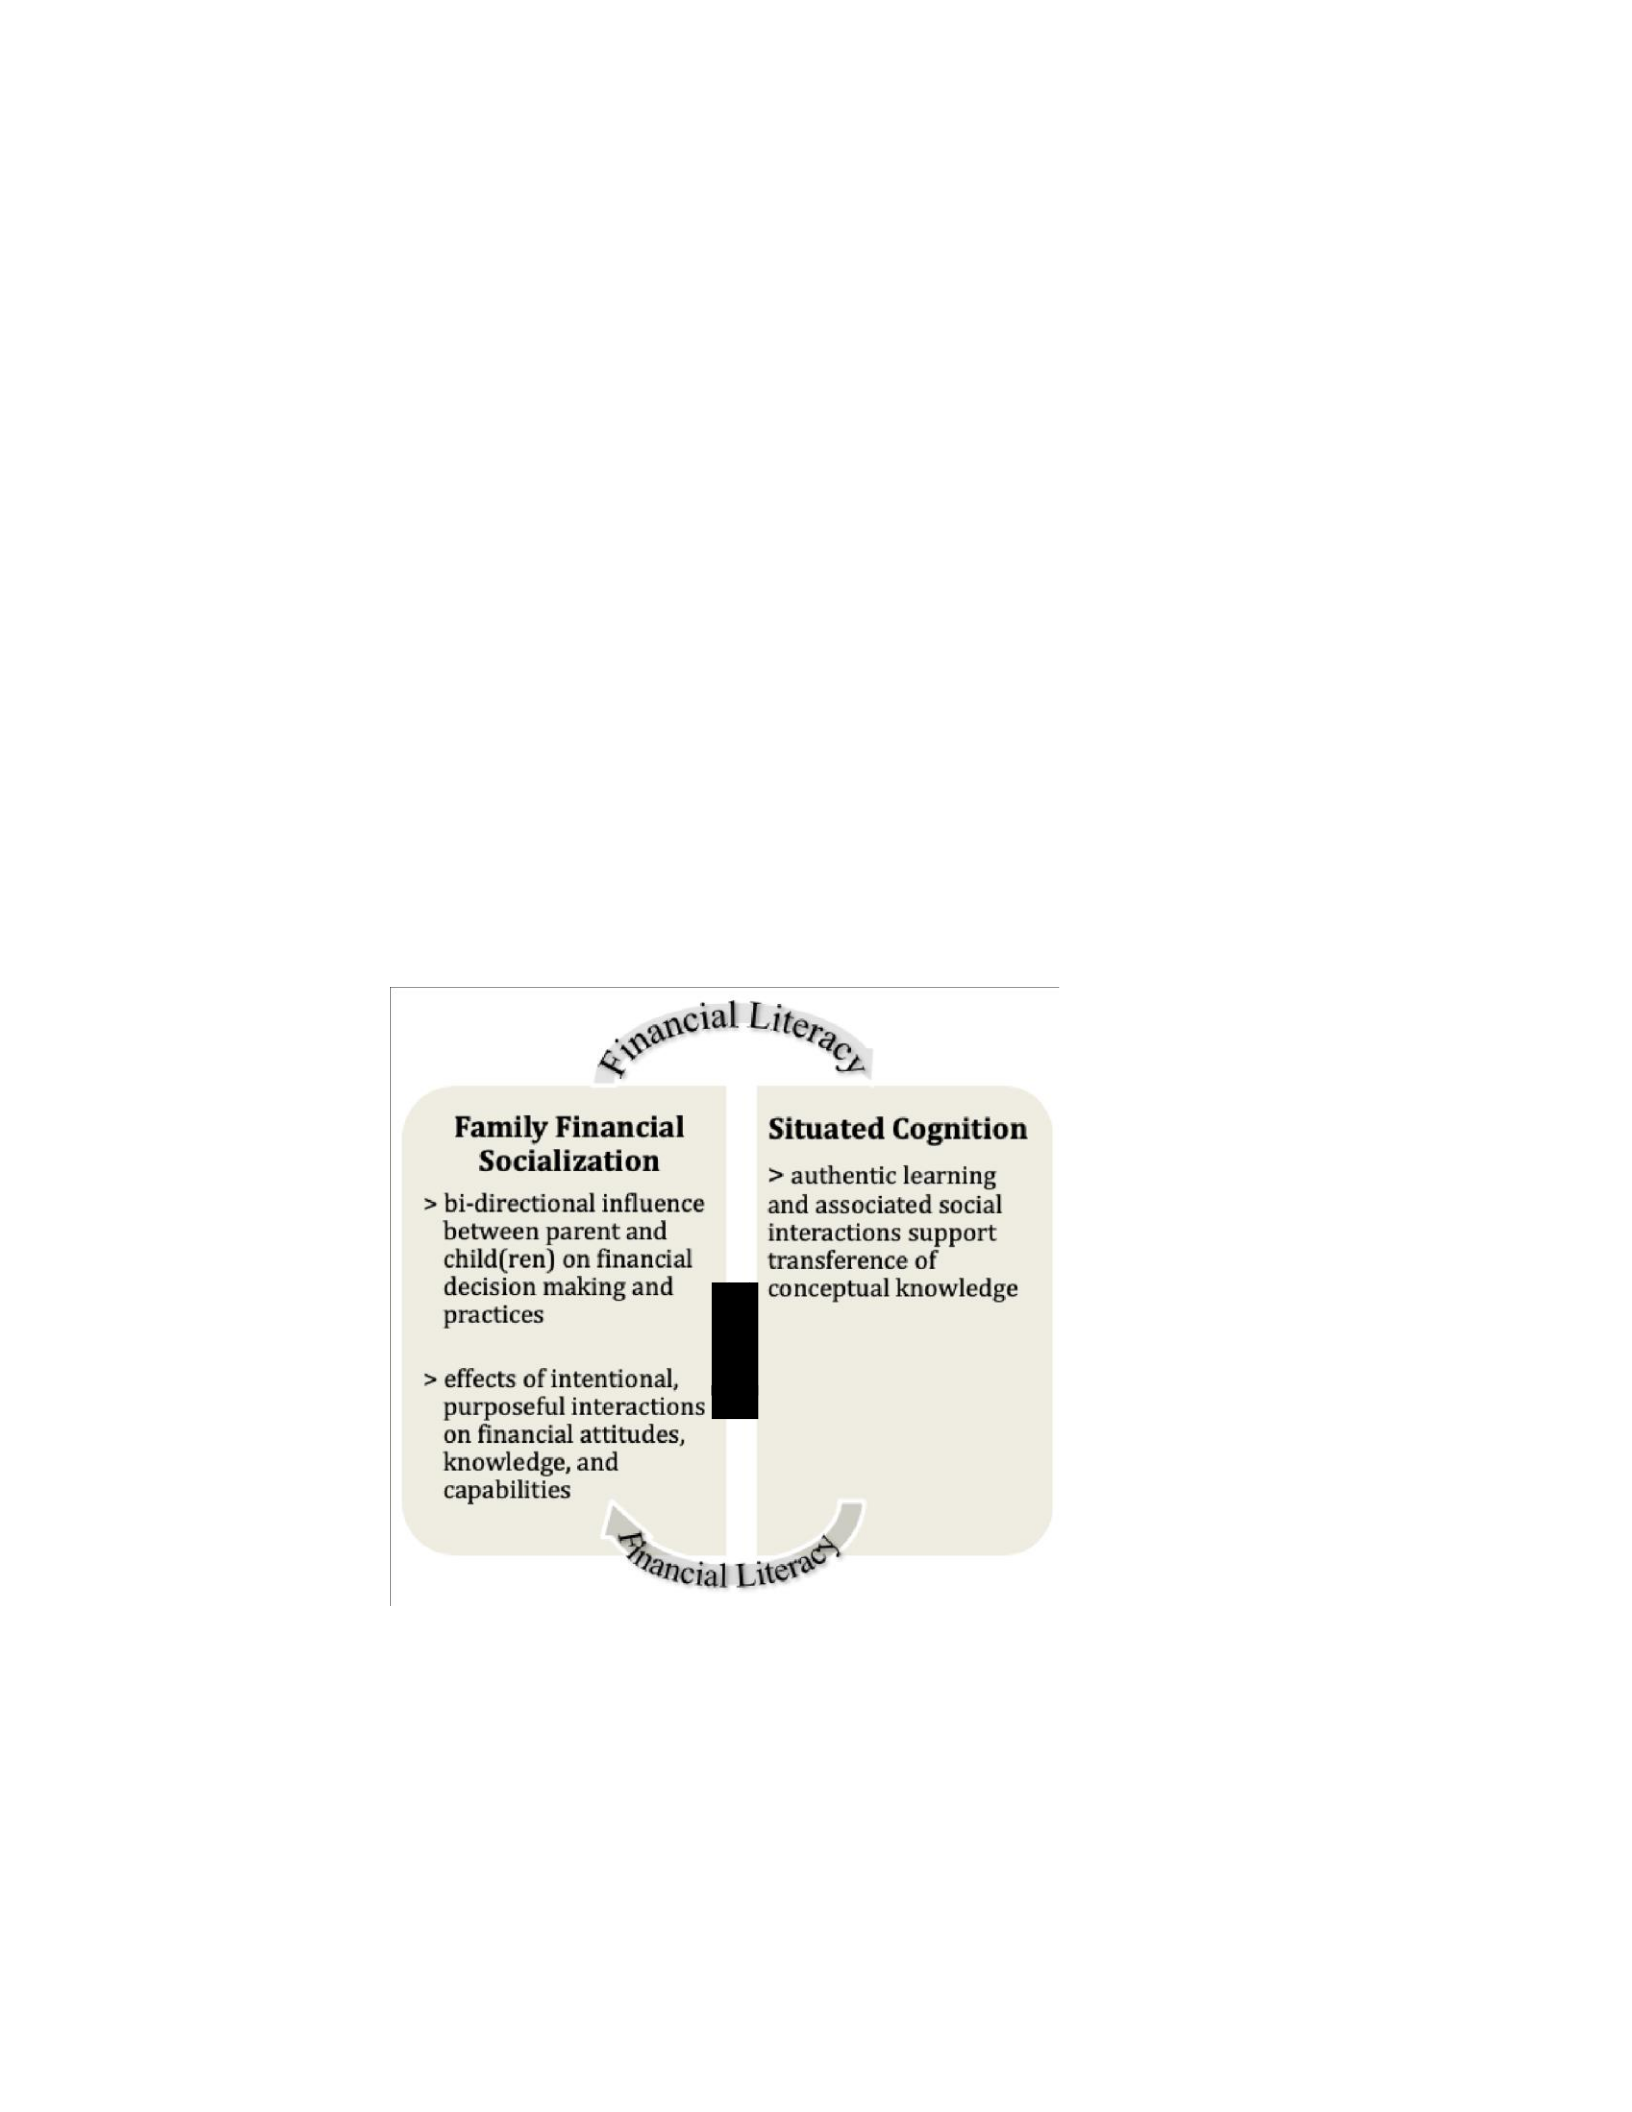
multiple financial socialization touchpoints throughout their childhood and adolescence
years that include, but are not relegated to, the authentic financial experiences that fintech
can provide.
Framing the Findings
The conceptual framework for this study, as depicted in Figure 10, positioned
fintech, specifically FMVB, as the facilitator of family financial socialization practices
and the authentic learning platform through which subscribers apply their financial
knowledge and skills and engage in financial transactions. It is this combination of
financial socialization and application, orchestrated through the FMVB fintech tool, that I
wanted to examine in relation to perceived differences in financial literacy levels.
Figure 10. Study’s conceptual framework. Fintech’s role in bridging, informing, and
supporting components of family financial socialization and situated cognition theories
and associated financial literacy levels. Adapted from Gudmunson and Danes (2011) and
Brown et al. (1989). (This figure originally appeared as Figure 1 in Chapter 1.)

I explored the applicability of Gudmunson and Danes' (2011) financial
socialization theory through RQ2 and the related interview questions that centered on the
parents’ thoughts and experiences with the type and level of support that FMVB provided
to money-centered conversations and activities with their children. Through interview
questions aligned to RQ1 and RQ3, I explored parents’ perceptions and experiences with
how or if FMVB served as the apprentice platform described by Brown et al. (1989) in
their theory of situation cognition. Specifically, I sought to understand how the
socialization-related practices and outcomes associated with financial messages and
conceptual knowledge were applied in the context of FMVB and in relation to perceived
differences in financial literacy levels.
Technology enabled family financial socialization. FMVB’s role in supporting
productive family financial socialization practices was evident in my research.
Parentsubscribers consistently cited how the objective data generated by the shared use of
FMVB with their child(ren) changed some combination of the tone, content, and depth of
their personal-finance related interactions. Gudmunson and Danes’ (2011) socialization
theory surmised that most socialization practices undertaken by the family would be
nonpurposive and be part of perfunctory daily activities. Their supposition stands in
contrast to the findings from this study in which the parents highlighted how the real-time
data and tools embedded in FMVB shifted their intentional money-centered conversations
and lessons from a one-sided, compartmentalized exchange about a singular transaction
or decision to a more purposive, goal-oriented interaction that was now often initiated by
the child.

Although technology as a socialization practice or platform was not specifically
addressed in Gudmunson and Danes’ (2011) initial family financial socialization
conceptual model, subsequent application of the model did account for changes in
financial socialization agents (i.e., friends, teachers, and media) that occur across life
stages (Shim et al., 2015). In effect, the introduction of family-managed financial
technology in the context of this study serves to expand the list of socialization agents
and anchors the relevance of family financial socialization in the evolving digital
financial landscape.
My findings also speak to how FMVB was positioned by the parents as a
transitional tool. It provided needed structured, made abstract money messages more
tangible, and helped adult and child-subscribers consider the value and cost of
discretionary purchases in the context of longer-term goals. For example, P01 stated that
her objective in subscribing to FMVB centered on “helping them [her children] to
establish goals. Giving them the tools to see how they are doing financially, where their
spending habits are. Not me telling them. They can see it.”
The tenets of family financial socialization assert that family relationships and the
lesser-seen purposive, finance-centered interactions contribute to “financial attitudes,
knowledge, and capability, which in turn contribute to distal outcomes, financial behavior
and financial wellbeing” (Gudmunson et al., 2016, p. 64). By extension, applying this
theory to the present study and positioning FMVB and comparably-gated fintech products
as financial socialization agents may illustrate fintech’s potential to facilitate sustained
changes in financial attitudes and behaviors, which underpin financial literacy goals.

Situating financial learning in the context of fintech. In their theory of situated
cognition, Brown et al. (1989) profess that knowledge or cognition is constructed
individually or socially. Consistent with Gudmunson and Danes’ (2011) model, the
FMVB children and their parents may acquire some or all of their financial knowledge as
part of the family financial socialization process facilitated by this fintech tool. Parent
responses, nevertheless, suggested that knowing discrete personal finance concepts is not
their intended goal. Rather, their objective is to have their child(ren) learn how to apply
that knowledge to increasingly complex financial situations that accompany each life
stage. The parents have, in effect, situated that content knowledge within the learning
environment of FMVB to support the transition from decontextualized financial
definitions and mantras to authentic application. Parents have positioned FMVB as a
cognitive apprenticeship through which they are assimilating the family members into
social interactions and authentic financial practices that form the basis of applied
financial literacy (Brown et al., 1989).
Similarly, Clancey (2008) argues from a constructivist epistemology that situated
cognition and learning needs to account for the social, dynamic environment in which
those cognitions are formed and eventually applied. In the present study, FMVB was the
parallel authentic, social, and constructivist environment in which financial literacy is
learned and financial behaviors are shaped. The effectiveness of attempting to simulate
authentic learning environments was called into question by Brown et al. (1989):
“When authentic activities are transferred to the classroom, their context is inevitably
transmuted; they become classroom tasks and part of the school culture” (“Authentic

Activity,” para. 5).
Parents in this study extolled the perceived value of school-based personal finance
courses, and noted despondently that neither their child(ren) nor they had taken one.
Although the prevailing design of these courses may support knowledge construction and
facilitate transference, they cannot, in accordance with situated cognition theory, fully
replicate the authentic, family-influenced context in which financial decisions are made
and executed. This incongruence between classroom-based applied learning and authentic
learning may explain, in part, the mixed reviews on the effectiveness of financial
education (Kaiser et al., 2020; Zhu et al., 2019).
The FMVB archetype facilitates family financial socialization and provides the
authentically-situated, digital context to apply financial knowledge and skills. It supports,
as depicted in Figure 10, the organic interplay of family and situational factors that
account for the differences in financial literacy that parent-participants perceived.
Limitations to the Study
During the proposal phase for this study, I identified the following limitations to
this study:
• The quality and relevance of the information obtained through the interview
process depends, in part, on the interview techniques and the construct of the
questions.
To compensate for this potential limitation, I outreached to leading researchers in
the personal finance field to solicit their input on interview questions. I also conducted
practice interviews with two researchers and two parent-educators who teach personal

finance. From there, I refined the interview questions based on their feedback and my
analysis of the mock interview findings in relation to the research questions.
• My volunteer work centers on promoting financial literacy in the K-16 student
and underserved populations, and I also teach personal finance classes. So, I
am optimistic about the potential for fintech to address the transference gap
between classroom-based financial education, actual financial behaviors, and
resultant literacy levels.
To offset this limitation, I disclosed my personal-finance-related work in the study
recruitment material; kept a reflective journal of my coding nodes, descriptors, and
rationale; and actively looked for contrary data as I interpreted my findings.
• The setting for this study and participant pool was limited to the subscriber
base of one fintech tool, FMVB, which may call into question the
generalizability of the findings.
To promote the application of my findings beyond this study, I did not address the
features and functions of FMVB in my research and interview questions. Instead, I
focused on personal finance concepts, conversations, skills, behaviors, and attitudes
associated with financial literacy and that are rooted in extant literature and the
conceptual framework. I asked parent-subscribers about their experiences and perceptions
of using FMVB in relation to these broader, transferrable components of financialliteracy.
As I conducted the study, I did not encounter any additional limitations.

Recommendations
The role of fintech in relation to the broader base of research on personal finance
education and the effectiveness of financial literacy interventions is an emerging area of
research. According, the following recommendations are based on my findings, the
limitations of this present study, and related recommendations from the literature.
Although this study included short-term subscribers to FMVB, 13 of the 15 families with
children had been using it for less than 1 year, and none of the children had taken a
formal personal finance class, I could not fully account for additional factors that may
have influenced the parents’ perceptions of differences in financial literacy levels that
they attributed to FMVB. Accordingly, I would recommend that future studies include a
randomized controlled trial in which FMVB or a comparable fintech tool is positioned as
an intervention with the objective of measuring its effectiveness to support changes in
financial literacy levels.
I would also suggest that future studies explore the potential application of FMVB
and similar fintech tools to support the elderly, individuals with addiction, and those with
developmental, behavioral, and social challenges, who would benefit from fintechenabled
and managed autonomy in their daily financial transactions. This recommendation
emanates in part from this study’s one, previously-identified, discrepant case, which
involved an adult FMVB subscriber who had positioned his spouse as the parent to
provide accountability and oversight of his spending as part of his ongoing recovery from
a gambling addiction. This recommendation also honors a request made by several
parent-participants who have a spouse and/or child with ADHD or Asperger’s. They

asked that I convey their positive experience with FMVB in hopes of helping others in
comparable situations who are trying to bring routines, structure, and consistency to
financial lessons and transactions.
Another phenomenon worthy of further research would build upon the work of
Batty et al. (2018) and Smith et al. (2018) and examine how early-childhood orientations
toward money may be shaped through family-centered, technology-supported,
authenticlearning opportunities that are facilitated by a platform such as FMVB. Within
this present study, most parents noted that their child(ren)’s attitude toward money
differed from their own or that of their sibling(s). They wondered how or if the use of
FMVB would influence those tendencies long term. Accordingly, a longitudinal study
that explores the effect of FMVB or a comparable tool on financial attitudes and
associated behaviors would provide additional evidence-based insight on when, how, or if
fintech may be best positioned to support productive spending and saving orientations.
Implications
The findings and recommendations from this study may inform future policy and
programmatic initiatives related to purposeful parental involvement in financial education
and the use of financial technology to support the financial well-being of the next
generation of emerging adults and the vulnerable members of our population. The
following implications identify fintech-enabled opportunities on a national, state,
classroom, and family level to support financial literacy. The opportunities are informed
by this body of research and my work across these sectors. Equally important, I account

for the fact that any policy or programmatic shift needs to include a funding stream,
which is where I begin my discussion.
On a federal level, Title IV of the Elementary and Secondary Education Act
(ESSA) includes grant funding for financial literacy programs, a portion of which could
be earmarked for research and pilot studies related to fintech and financial literacy. (Title
IV 21’st Century Schools, 2019). This legislative change could be initiated by members of
the bi-partisan Financial Literacy Caucus who were responsible for the initial expansion
of Title IV and would support broader national objectives of identifying quality, effective,
and scalable approaches to financial education.
State treasurers, in concert with their national association, continue to champion a
personal finance requirement at the high-school level (National Association of State
Treasurers (NAST), n.d.). This advocacy work is rooted in the broader social objective of
enabling access to financial products and developing financially-literate citizens who can
“avoid pitfalls and navigate the financial world with success” (Office of RI General
Treasurer, 2018, p. 7). State treasury officials are positioned to encourage and partner
with their post-secondary institutions to support pilot programs designed to measure the
effect of FMVB or comparable product on financial literacy levels, behaviors, and distal
objectives across varied populations and programs.
Specifically, FMVB may be positioned as a complementary product to
statesupported child and individual development accounts (CDAs and IDAs), which are
designed to help individuals save for a financial goal (e.g., college, car, starting a
business). Within state-affiliated congregate care settings including group homes,

residential treatment programs, and correctional facilities that house members of our most
vulnerable populations, FMVB or similar fintech tool can provide managed-access to a
digital financial product while promoting financial literacy and inclusion for these
citizens. As suggested by several FMVB study participations, the traditional profile of a
subscriber—parent and child—fails to account for its more inclusive application and
value to a broader base of individuals who need the structure, scaffolding, and access to
financial products that FMVB can provide.
At the level of the Local Education Agency (LEA), parent-teacher organizations
with support from post-secondary researchers can position FMVB as an extension of the
classroom-based instruction related to financial topics. For families, FMVB may promote
productive, informed financial conversations and practices similar to those experienced
by the parents in this study. FMVB can also support the application of
classroomconstructed financial knowledge, which is the critical transference component
that school-based experiential learning cannot replicate (Brown et al., 1989; Gudmunson
& Danes, 2011). For the administrators and teachers, this undertaking may produce the
playbook of strategies that promote meaningful parental engagement in support of student
literacy and achievement across content areas (OECD, 2020).
Conclusion
Casting fintech as a financial literacy tool is not the panacea for financial inequity
and insecurity on a family and community level. However, positioning a family-managed
virtual bank and prepaid debit card service (FMVB) as an applied learning environment,
where individuals can experience autonomy and accountability while developing the

confidence and capability to manage their own finances, can be empowering. Through
further studies and use in settings outside the traditional family construct, FMVB’s
potential to facilitate the transfer of financial education, support productive
moneycentered socialization activities and decisions, and scale financial capability may
be validated. Technology is driving expanded access to financial products. FMVB may
the platform that drives a deeper examination of fintech’s complementary potential—to
elevate financial literacy, resilience, and social responsibility.

