


FUND ACCOUNTING PRINCIPLES FOR NON-PROFIT ORGANIZATIONS
1. Question: A non-profit organization has total indirect costs of 10,000forthemonth.Iftheorganization′sprogramAincurred4,000
in direct costs and program B incurred 6,000indirectcosts, howmuchindirectcostsshouldbeallocatedtoprogramA?
Solution: To allocate indirect costs to program A, we need to determine the proportion of total direct
costs incurred by program A compared to the total direct costs incurred by both programs A and B.
Total direct costs = Direct costs of program A + Direct costs of program B Total direct costs = 4,000+6,000
=10,000
Proportion of total direct costs allocated to program A: = (Direct costs of program A / Total direct costs)
* Total indirect costs = (4,000/10,000) * 10,000 = 0.4∗10,000 = 4,000
Therefore, 4,000ofthetotalindirectcostsshouldbeallocatedtoprogramA.
2. Question: A non-profit organization has three funds: Fund A, Fund B, and Fund C. The organization
incurred total expenses of 60,000intheyear.F undAisresponsiblef or40
Solution: 1. Calculate the amount of expenses allocated to each fund: - Fund A: 60,000 ∗40 −
F undB :60,000 * 30- Fund C: 60,000 ∗30
2. Therefore, the expenses allocated to Fund A are 24,000.
3. Question: A non-profit organization has received donations totaling 50,000f oraspecif icprogram.T heorganizationspent12,000
on the program during the fiscal year. What is the balance of the restricted fund for this program at the end
of the fiscal year?
Solution: To determine the balance of the restricted fund for this program at the end of the fiscal year,
we need to subtract the amount spent on the program from the total donations received.
Restricted fund balance = Total donations received - Amount spent on the program
Restricted fund balance = 50,000−12,000 Restricted fund balance = 38,000
Therefore, the balance of the restricted fund for this program at the end of the fiscal year is 38,000.
4. Question: A non-profit organization has total overhead costs of 50,000fortheyear.If40
Solution: Total Overhead Costs = 50,000P ercentageof OverheadCostsattributabletoRestrictedF und =
40
Calculating the portion of overhead costs attributable to the specific restricted fund: Restricted Fund
Overhead Costs = Total Overhead Costs x Percentage for Restricted Fund Restricted Fund Overhead Costs
=50,000x40RestrictedF undOverheadCosts =20,000
Now, to find the amount of overhead costs to be allocated to the unrestricted funds: Unrestricted Fund
Overhead Costs = Total Overhead Costs - Restricted Fund Overhead Costs Unrestricted Fund Overhead
Costs = 50,000−20,000 Unrestricted Fund Overhead Costs = 30,000
Therefore, 30,000ofthetotaloverheadcostsshouldbeallocatedtotheunrestrictedfunds.
5. Question: A non-profit organization receives a restricted donation of 10,000designatedforaspecif icprogram.T heorganizationalsoincurs2,000
in indirect costs related to managing the program. How much of the restricted funds can be allocated directly
to the program after accounting for the indirect costs?
Solution: The total amount of restricted funds received is 10,000.T heorganizationincurs2,000 in
indirect costs related to managing the program. Therefore, the amount of restricted funds available for
direct allocation to the program is: 10,000−2,000 = 8,000.
Thus, after accounting for the indirect costs, 8,000oftherestrictedf undscanbeallocateddirectlytothespecificprogram.
6. Question: A non-profit organization incurred 20,000intotalindirectcostsf ortheyear, ofwhich30
Solution: To find the amount of indirect costs allocated to unrestricted funds, we first need to determine
the portion of indirect costs allocated to the restricted funds. Restricted funds share of indirect costs = Total
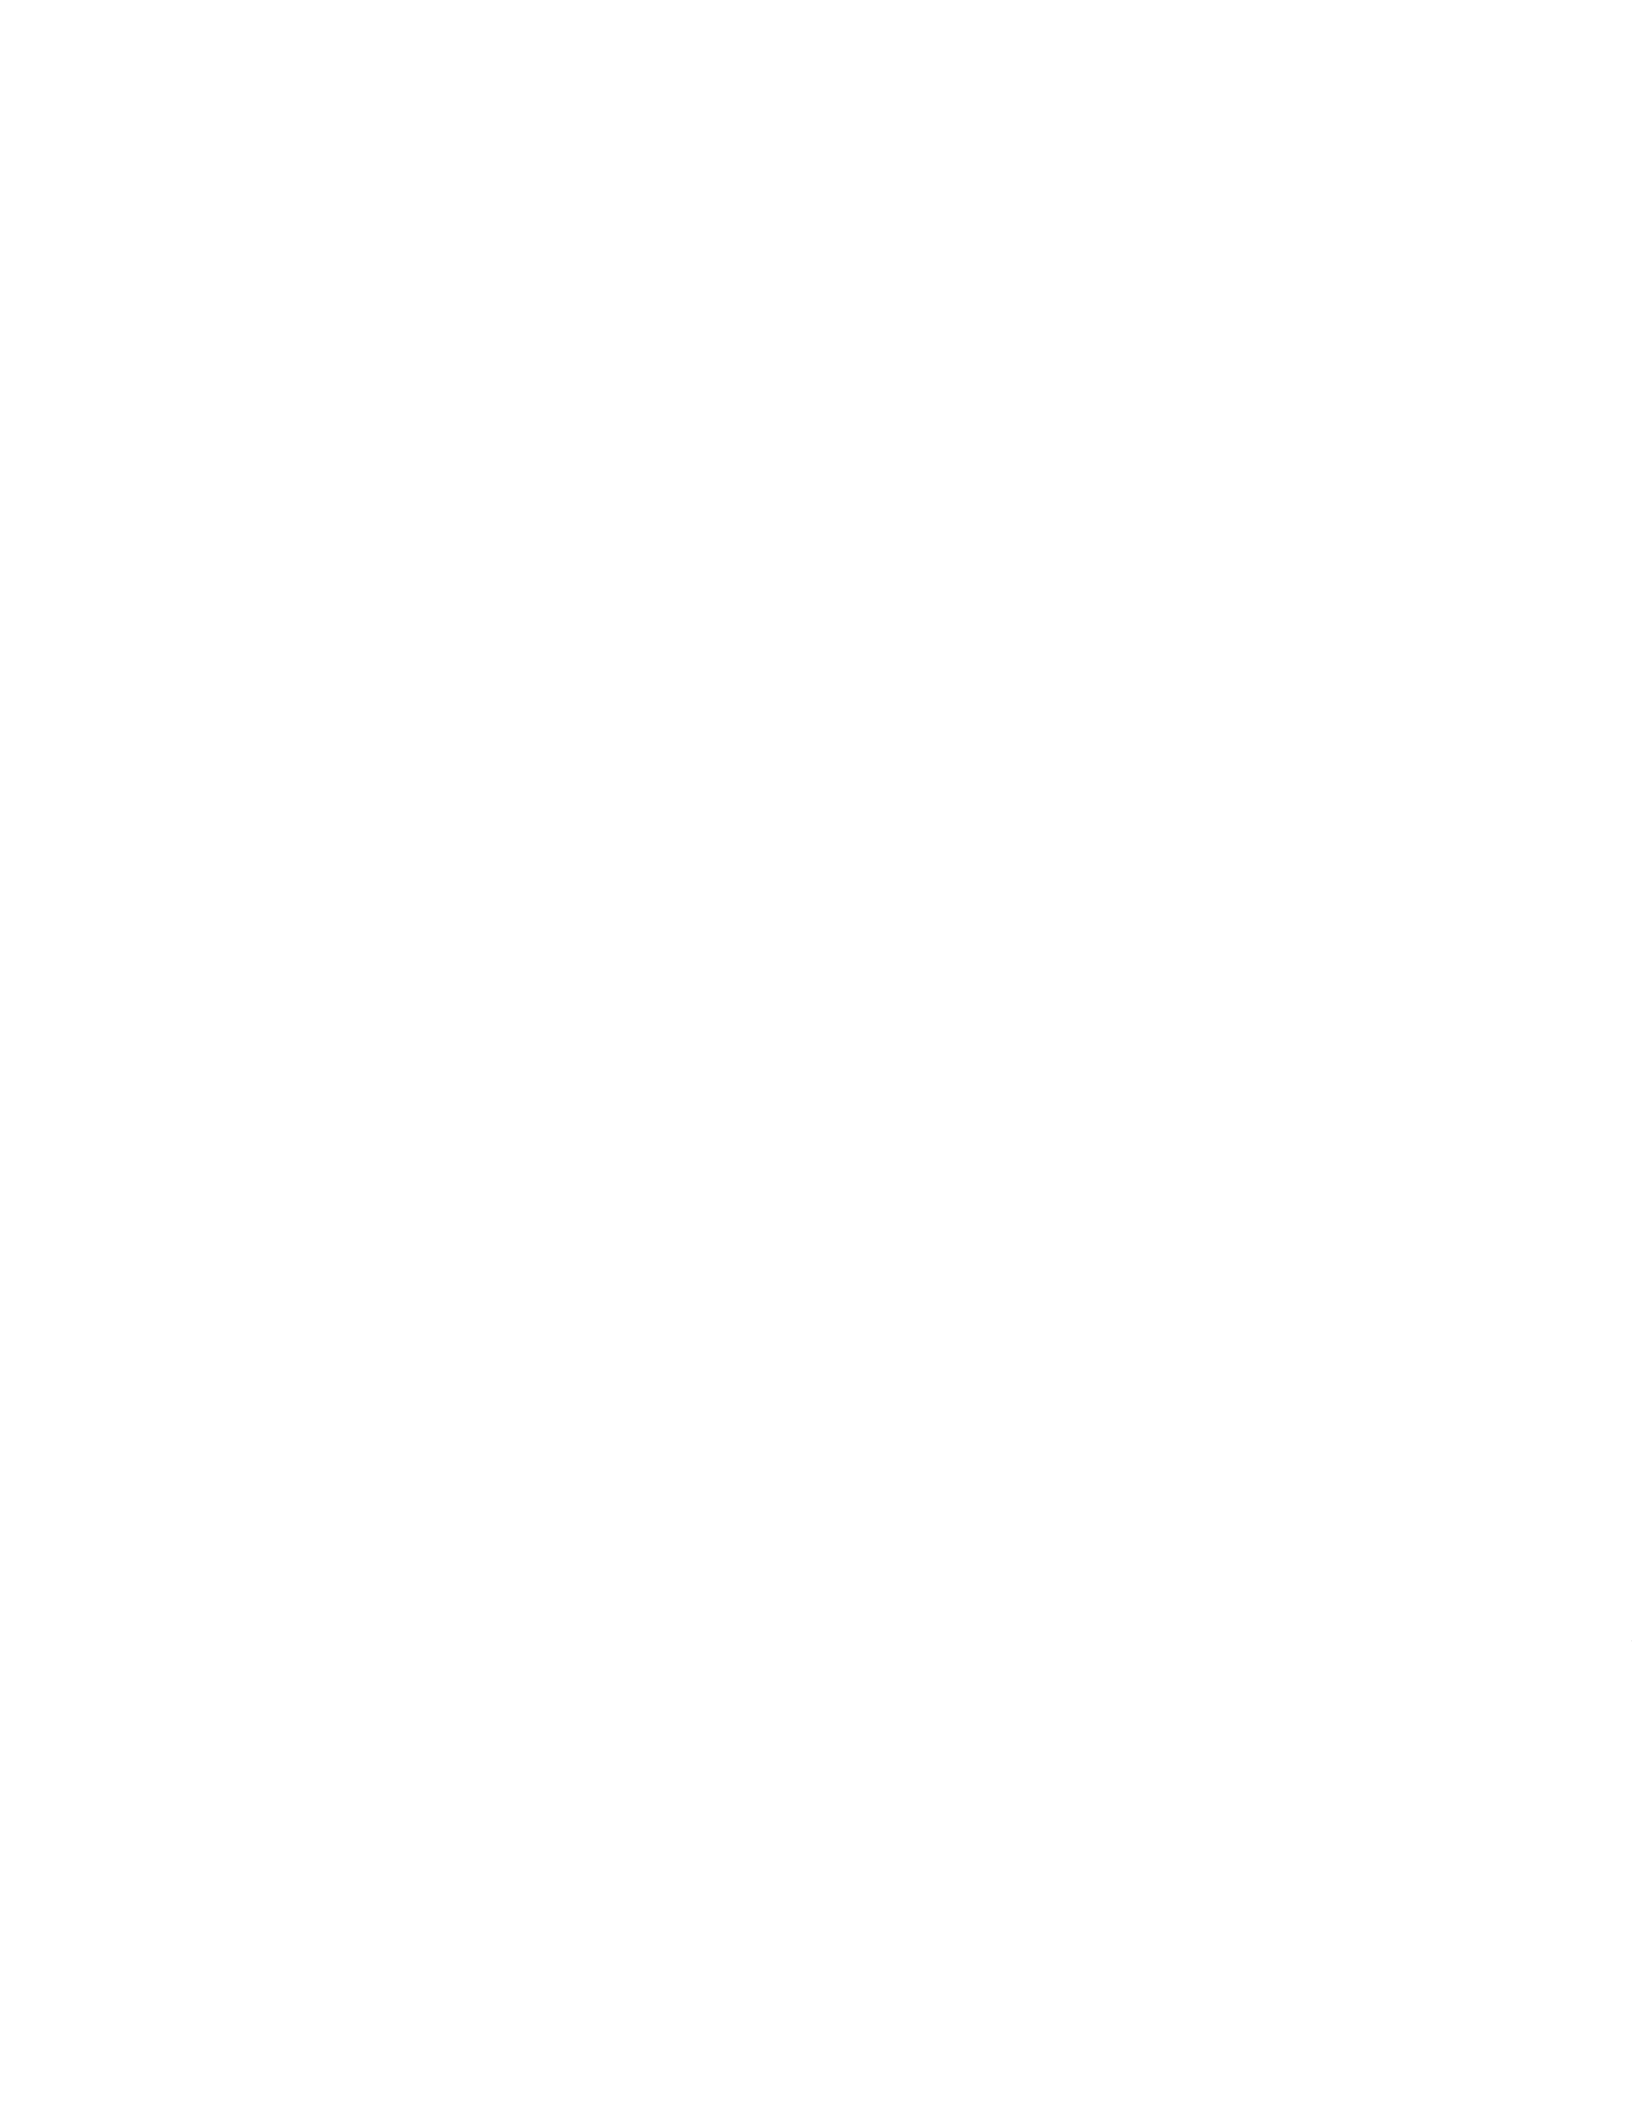
indirect costs * Restricted funds share of indirect costs = 20,000 ∗30
Now, the remaining indirect costs will be allocated to the unrestricted funds. Unrestricted funds share
of indirect costs = Total indirect costs - Restricted funds share of indirect costs Unrestricted funds share of
indirect costs = 20,000−6,000 = 14,000
Therefore, the amount of the indirect costs allocated to the unrestricted funds is 14,000.
7. Question: A non-profit organization has three separate funds: Fund A, Fund B, and Fund C. Fund
A incurred expenses of 10,000, F undBincurredexpensesof 15,000, and Fund C incurred expenses of
20,000.T heorganization′stotalindirectcostsf ortheyearare5,000. If the organization wants to allocate
indirect costs based on the proportion of expenses in each fund, how much indirect cost should be allocated
to Fund A?
Solution: To allocate indirect costs based on the proportion of expenses in each fund, we need to calcu-
late the total expenses across all funds first.
Total Expenses = 10,000(F undA)+15,000 (Fund B) + 20,000(F undC)T otalExpenses =45,000
Next, we calculate the proportion of expenses for each fund:
Proportion of Fund A’s Expenses = Fund A’s Expenses / Total Expenses Proportion of Fund A’s Expenses
=10,000/45,000 Proportion of Fund A’s Expenses = 1/4 or 0.25
Now, we allocate the total indirect costs to Fund A based on its proportion of expenses:
Indirect Cost Allocated to Fund A = Proportion of Fund A’s Expenses * Total Indirect Costs Indirect
Cost Allocated to Fund A = 0.25 * 5,000IndirectCostAllocatedtoF undA =1,250
Therefore, 1,250ofindirectcostsshouldbeallocatedtoF undA.
8. Question: A non-profit organization receives a donation of 10,000thatisrestrictedtobeusedforaspecif icprogram.T heorganizationincursexpensesof6,000
directly related to this program. How much is the remaining balance of the restricted fund for this program?
Solution: The remaining balance of the restricted fund for the specific program can be found by sub-
tracting the expenses incurred from the total donation amount.
Remaining Balance = Total Donation - Program Expenses Remaining Balance = 10,000−6,000 Re-
maining Balance = 4,000
Therefore, the remaining balance of the restricted fund for this program is 4,000.
9. Question: A non-profit organization receives a donation of 10,000specif icallydesignatedforabuildingrenovationproject.Duringthecurrentfiscalyear, theorganizationuses5,000
of the donation for the project. At the end of the fiscal year, what are the balances of the temporarily re-
stricted fund and the amount available for general use in the unrestricted fund?
Solution: 1. Temporary Restricted Fund Balance: - Initial donation: 10,000−Amountusedf ortheproject :5,000
- Balance of temporarily restricted fund = Initial donation - Amount used - Balance of temporarily restricted
fund = 10,000−5,000 - Balance of temporarily restricted fund = 5,000
2. Unrestricted Fund Balance: - Any part of the donation not used for the project remains in the tem-
porarily restricted fund. - Amount available for general use in the unrestricted fund = Initial donation -
Amount in temporarily restricted for the project - Amount available for general use in the unrestricted fund
=10,000−5,000 - Amount available for general use in the unrestricted fund = 5,000
Therefore, at the end of the fiscal year, the balance of the temporarily restricted fund is 5,000, andtheamountavailableforgeneraluseintheunrestrictedfundisalso5,000.
10. Question: A non-profit organization incurred total operating expenses of 50,000.F romthatamount,12,000
expenses were incurred specifically for the education fund, 8,000forthehealthcaref und, andtheremainingexpensesweregeneraloperatingexpenses.W hatpercentageof thetotaloperatingexpenseswereallocatedtotheeducationf und?
Solution: To find the percentage of total operating expenses allocated to the education fund, we first
need to calculate the total specific allocations for the education fund:
Total specific allocation for education fund = 12,000
Then, we calculate the total operating expenses allocated to the education fund:

Total operating expenses allocated to the education fund = Total specific allocation for education fund +
General operating expenses Total operating expenses allocated to the education fund = 12,000 + (50,000 -
12,000−8,000) Total operating expenses allocated to the education fund = 12,000+30,000 Total operating
expenses allocated to the education fund = 42,000
Finally, we calculate the percentage of total operating expenses allocated to the education fund:
Percentage allocated to education fund = (Total operating expenses allocated to education fund / To-
tal operating expenses) * 100Percentage allocated to education fund = (42,000/50,000) * 100Percentage
allocated to education fund = 0.84 * 100Percentage allocated to education fund = 84
Therefore, 84
11. Question: A non-profit organization receives a donation of 10,000restrictedforaspecif icpurpose.T heorganizationspends4,000
on the designated program and incurs 1,500infundraisingexpensesrelatedtothesameprogram.Howmuchoftherestrictedfundsarestillavailableforthedesignatedpurpose?
Solution: Initially, the organization received 10,000asarestricteddonation.Af terspending4,000 on
the designated program, the remaining amount is 10,000−4,000 = 6,000.However, theyalsoincurred1,500
in fundraising expenses related to the designated program. This amount needs to be subtracted from the re-
maining funds. Therefore, the total amount available for the designated purpose is 6,000−1,500 = 4,500.
Final Answer: 4,500
12. Question: A non-profit organization received a grant of 50,000thatisrestrictedforaspecif icprogram.Duringthefiscalyear, theorganizationspent20,000
on the program. Calculate the amount of restricted funds remaining at the end of the fiscal year.
Solution: Restricted funds remaining = Grant amount - Expenditure on the program Restricted funds
remaining = 50,000−20,000 Restricted funds remaining = 30,000
Therefore, the amount of restricted funds remaining at the end of the fiscal year is 30,000.
13. Question: A non-profit organization has total expenses of 100,000, anditincurred20,000 in fundrais-
ing expenses, 30,000inprogramAexpenses, and25,000 in program B expenses. Calculate the percentage
of total expenses allocated to program A.
Solution: To calculate the percentage of total expenses allocated to program A, we need to first find the
total expenses allocated to program A.
Total expenses allocated to program A = fundraising expenses + program A expenses Total expenses
allocated to program A = 20,000+30,000 Total expenses allocated to program A = 50,000
Now, we can calculate the percentage of total expenses allocated to program A by dividing the total
expenses allocated to program A by the total expenses and multiplying by 100.
Percentage of total expenses allocated to program A = (Total expenses allocated to program A / Total
expenses) * 100 Percentage of total expenses allocated to program A = (50,000/100,000) * 100 Percentage
of total expenses allocated to program A = 0.5 * 100 Percentage of total expenses allocated to program A =
50
Therefore, 50
14. Question: A non-profit organization has total funds of 100,000.40
Solution: Total funds = 100,000Restrictedfunds = 40Unrestrictedfunds =T otalfunds−RestrictedfundsUnrestrictedfunds =100,000
-40,000Unrestrictedfunds =60,000
Therefore, 60,000isallocatedtotheunrestrictedaccount.
15. Question: In a non-profit organization, if the total indirect costs amount to 50,000andaretobeallocatedtotwodifferentprogramsbasedonthedirectcostsincurredbyeachprogram, withP rogramAhavingdirectcostsof30,000
and Program B having direct costs of 20,000, whatistheallocationof indirectcostsf orP rogramA?
Solution: To allocate the indirect costs to each program based on their direct costs, we need to find the
proportion of each program’s direct costs to the total direct costs of both programs.

Total direct costs = Direct costs of Program A + Direct costs of Program B Total direct costs = 30,000+20,000
Total direct costs = 50,000
Now, find the proportion of direct costs for Program A: Proportion of direct costs for Program A =
Direct costs of Program A / Total direct costs Proportion of direct costs for Program A = 30,000/50,000
Proportion of direct costs for Program A = 0.6 or 60
Next, allocate the total indirect costs based on the proportion of direct costs for Program A: Indirect
costs allocated to Program A = Proportion of direct costs for Program A * Total indirect costs Indirect costs
allocated to Program A = 0.6 * 50,000IndirectcostsallocatedtoP rogramA =30,000
Therefore, the allocation of indirect costs for Program A would be 30,000.
16. Question: A non-profit organization receives a grant of 10,000specif icallydesignatedf oraspecialprogram.T heorganizationincurs2,000
in administrative expenses that benefit multiple programs, including the special program funded by the grant.
How much of the administrative expenses should be allocated to the special program using a proportional
allocation method based on the grant amount?
Solution: 1. Calculate the percentage of the grant amount relative to the total funds received: Grant
Percentage = (Grant Amount / Total Funds Received) * 100 = (10,000/10,000) * 100 = 100
2. Allocate the administrative expenses to the special program based on the grant percentage: Adminis-
trative Expenses Allocated = Grant Percentage * Total Administrative Expenses = 100= 1.00 * 2,000 =2,000
Therefore, using the proportional allocation method based on the grant amount, 2,000oftheadministrativeexpensesshouldbeallocatedtothespecialprogram.
17. Question: A non-profit organization incurred total administrative costs of 50,000f ortheyear.Ofthisamount,10,000
relates to a program funded by restricted funds. How much of the administrative costs should be allocated
to the restricted funds?
Solution: To determine the allocation of costs to restricted funds, we need to calculate the proportion of
administrative costs that relate to the program funded by restricted funds.
Proportion of administrative costs allocated to restricted funds = (Costs related to restricted funds / Total
administrative costs) Proportion of administrative costs allocated to restricted funds = (10,000/50,000) =
0.2 or 20
Now, we can calculate the specific amount of administrative costs that should be allocated to the re-
stricted funds:
Administrative costs allocated to restricted funds = Proportion of administrative costs allocated to re-
stricted funds * Total administrative costs Administrative costs allocated to restricted funds = 0.2 * 50,000 =10,000
Therefore, 10,000ofthetotaladministrativecostsshouldbeallocatedtotheprogramfundedbyrestrictedfunds.
18. Question: A non-profit organization has total restricted funds of 50,000.If40
Solution: To find the amount allocated to the specific project, we need to calculate 40
Amount allocated to project = 40Amount allocated to project = 0.40 * 50,000Amountallocatedtoproject =20,000
Therefore, 20,000isallocatedtothespecificprojectwithinthenon −profitorganization.
19. Question: A non-profit organization has total funds of 500,000, ofwhich100,000 is restricted for a
specific program. If the organization spends 30,000ontherestrictedprogram, whatistheremainingbalanceintherestrictedfund?
Solution: 1. Total funds = 500,0002.Restrictedfunds =100,000 3. Amount spent on restricted pro-
gram = 30,000
To find the remaining balance in the restricted fund after spending on the program, we subtract the
amount spent from the initial restricted funds:
Remaining balance = Restricted funds - Amount spent Remaining balance = 100,000−30,000 Remain-
ing balance = 70,000
Therefore, the remaining balance in the restricted fund is 70,000.

20. Question: A non-profit organization has total funds of 500,000.Outofthisamount,150,000 is
classified as restricted funds and the rest as unrestricted funds. What is the percentage of the organization’s
total funds that are classified as restricted funds?
Solution: To find the percentage of restricted funds out of the total funds, we first need to calculate the
proportion of restricted funds to total funds.
Restricted funds / Total funds = 150,000/500,000 = 0.3
Now, to convert this proportion to a percentage, we multiply by 100.
Percentage of restricted funds = 0.3 * 100 = 30
Therefore, 30
21. Question: A non-profit organization receives a donation of 10,000thatisrestrictedforaspecif icprogram.If theorganizationspends5,000
from this restricted donation on the program, how much remains in the restricted fund?
Solution: To determine how much remains in the restricted fund after spending 5,000ontheprogram, wesimplysubtracttheamountspentfromtheinitialrestricteddonation.
Initial restricted donation = 10,000Amountspentontheprogram =5,000
Remaining amount in the restricted fund = 10,000−5,000 = 5,000
Therefore, the remaining amount in the restricted fund is 5,000.
22. Question: A non-profit organization has a total of 50,000infunds.T heyallocate40
Solution: To find the amount allocated to the restricted account, we first calculate 4050,000∗0.40 =20,000
Therefore, 20,000isallocatedtotherestrictedaccount.
23. Question: A non-profit organization has total funds of 100,000.40
Solution: 1. Calculate the current amount of funds in the restricted account: Restricted funds = Total
funds * Percentage restricted Restricted funds = 100,000 ∗40
2. Since the organization needs to allocate an additional 30,000totherestrictedfunds, thenewamountintherestrictedaccountwillbe :
Newrestrictedfunds =40,000 + 30,000 =70,000
3. To find the new amount in the unrestricted funds, simply subtract the new amount in the restricted
funds from the total funds: New unrestricted funds = Total funds - New restricted funds New unrestricted
funds = 100,000−70,000 New unrestricted funds = 30,000
Therefore, the new amount in the unrestricted funds will be 30,000.
24. Question: A non-profit organization has total unrestricted net assets of 100,000andtotalrestrictednetassetsof50,000.
If the organization designates 20,000fromtheunrestrictednetassetstoanewdonor−restrictedfund, whatwillbethenewbalanceofunrestrictednetassets?
Solution: Total Unrestricted Net Assets = 100,000T otalRestrictedN etAssets =50,000 Amount des-
ignated to new donor-restricted fund from Unrestricted Net Assets = 20,000
New Unrestricted Net Assets = Total Unrestricted Net Assets - Amount designated to new fund New
Unrestricted Net Assets = 100,000−20,000 New Unrestricted Net Assets = 80,000
Therefore, the new balance of unrestricted net assets after designating 20,000toanewdonor−restrictedfundwouldbe80,000.
25. Question: A non-profit organization has three funds: Fund A, Fund B, and Fund C. Fund A
incurred 10,000inexpensesthatwereallocabletoallthreef unds, F undBincurred5,000 in expenses that
were specific to Fund B only, and Fund C incurred 8,000inexpensesthatwereallocabletoF undAandF undC.If theorganizationwantstoallocatetheexpensesproportionallybasedonthetotalrevenueofeachfund, andthetotalrevenueforF undA, F undB, andF undCis100,000,
50,000, and80,000 respectively, what would be the total amount of expenses allocated to Fund A?
Solution: 1. Calculate the total revenue for all funds: 100,000(F undA)+50,000 (Fund B) + 80,000(F undC) =230,000
2. Calculate the proportion of total revenue for each fund: - Fund A: 100,000/230,000 = 0.4348 - Fund B:
50,000/230,000 = 0.2174 - Fund C: 80,000/230,000 = 0.3478 3. Allocate the shared expenses to each fund
proportionally: - Fund A: 10,000 ∗0.4348 =4,348 - Fund B: 10,000 ∗0.2174 =2,174 - Fund C: 10,000 ∗

0.3478 =3,478 4. Allocate Fund B’s expenses to Fund B: 5,0005.AllocateF undC′sexpensestoF undAandF undCproportionally :
−F undA :8,000 * 0.4348 = 3,478 −F undC :8,000 * 0.3478 = 2,784
Total expenses allocated to Fund A = 4,348(sharedexpenses)+3,478 (expenses from Fund C) = 7,826
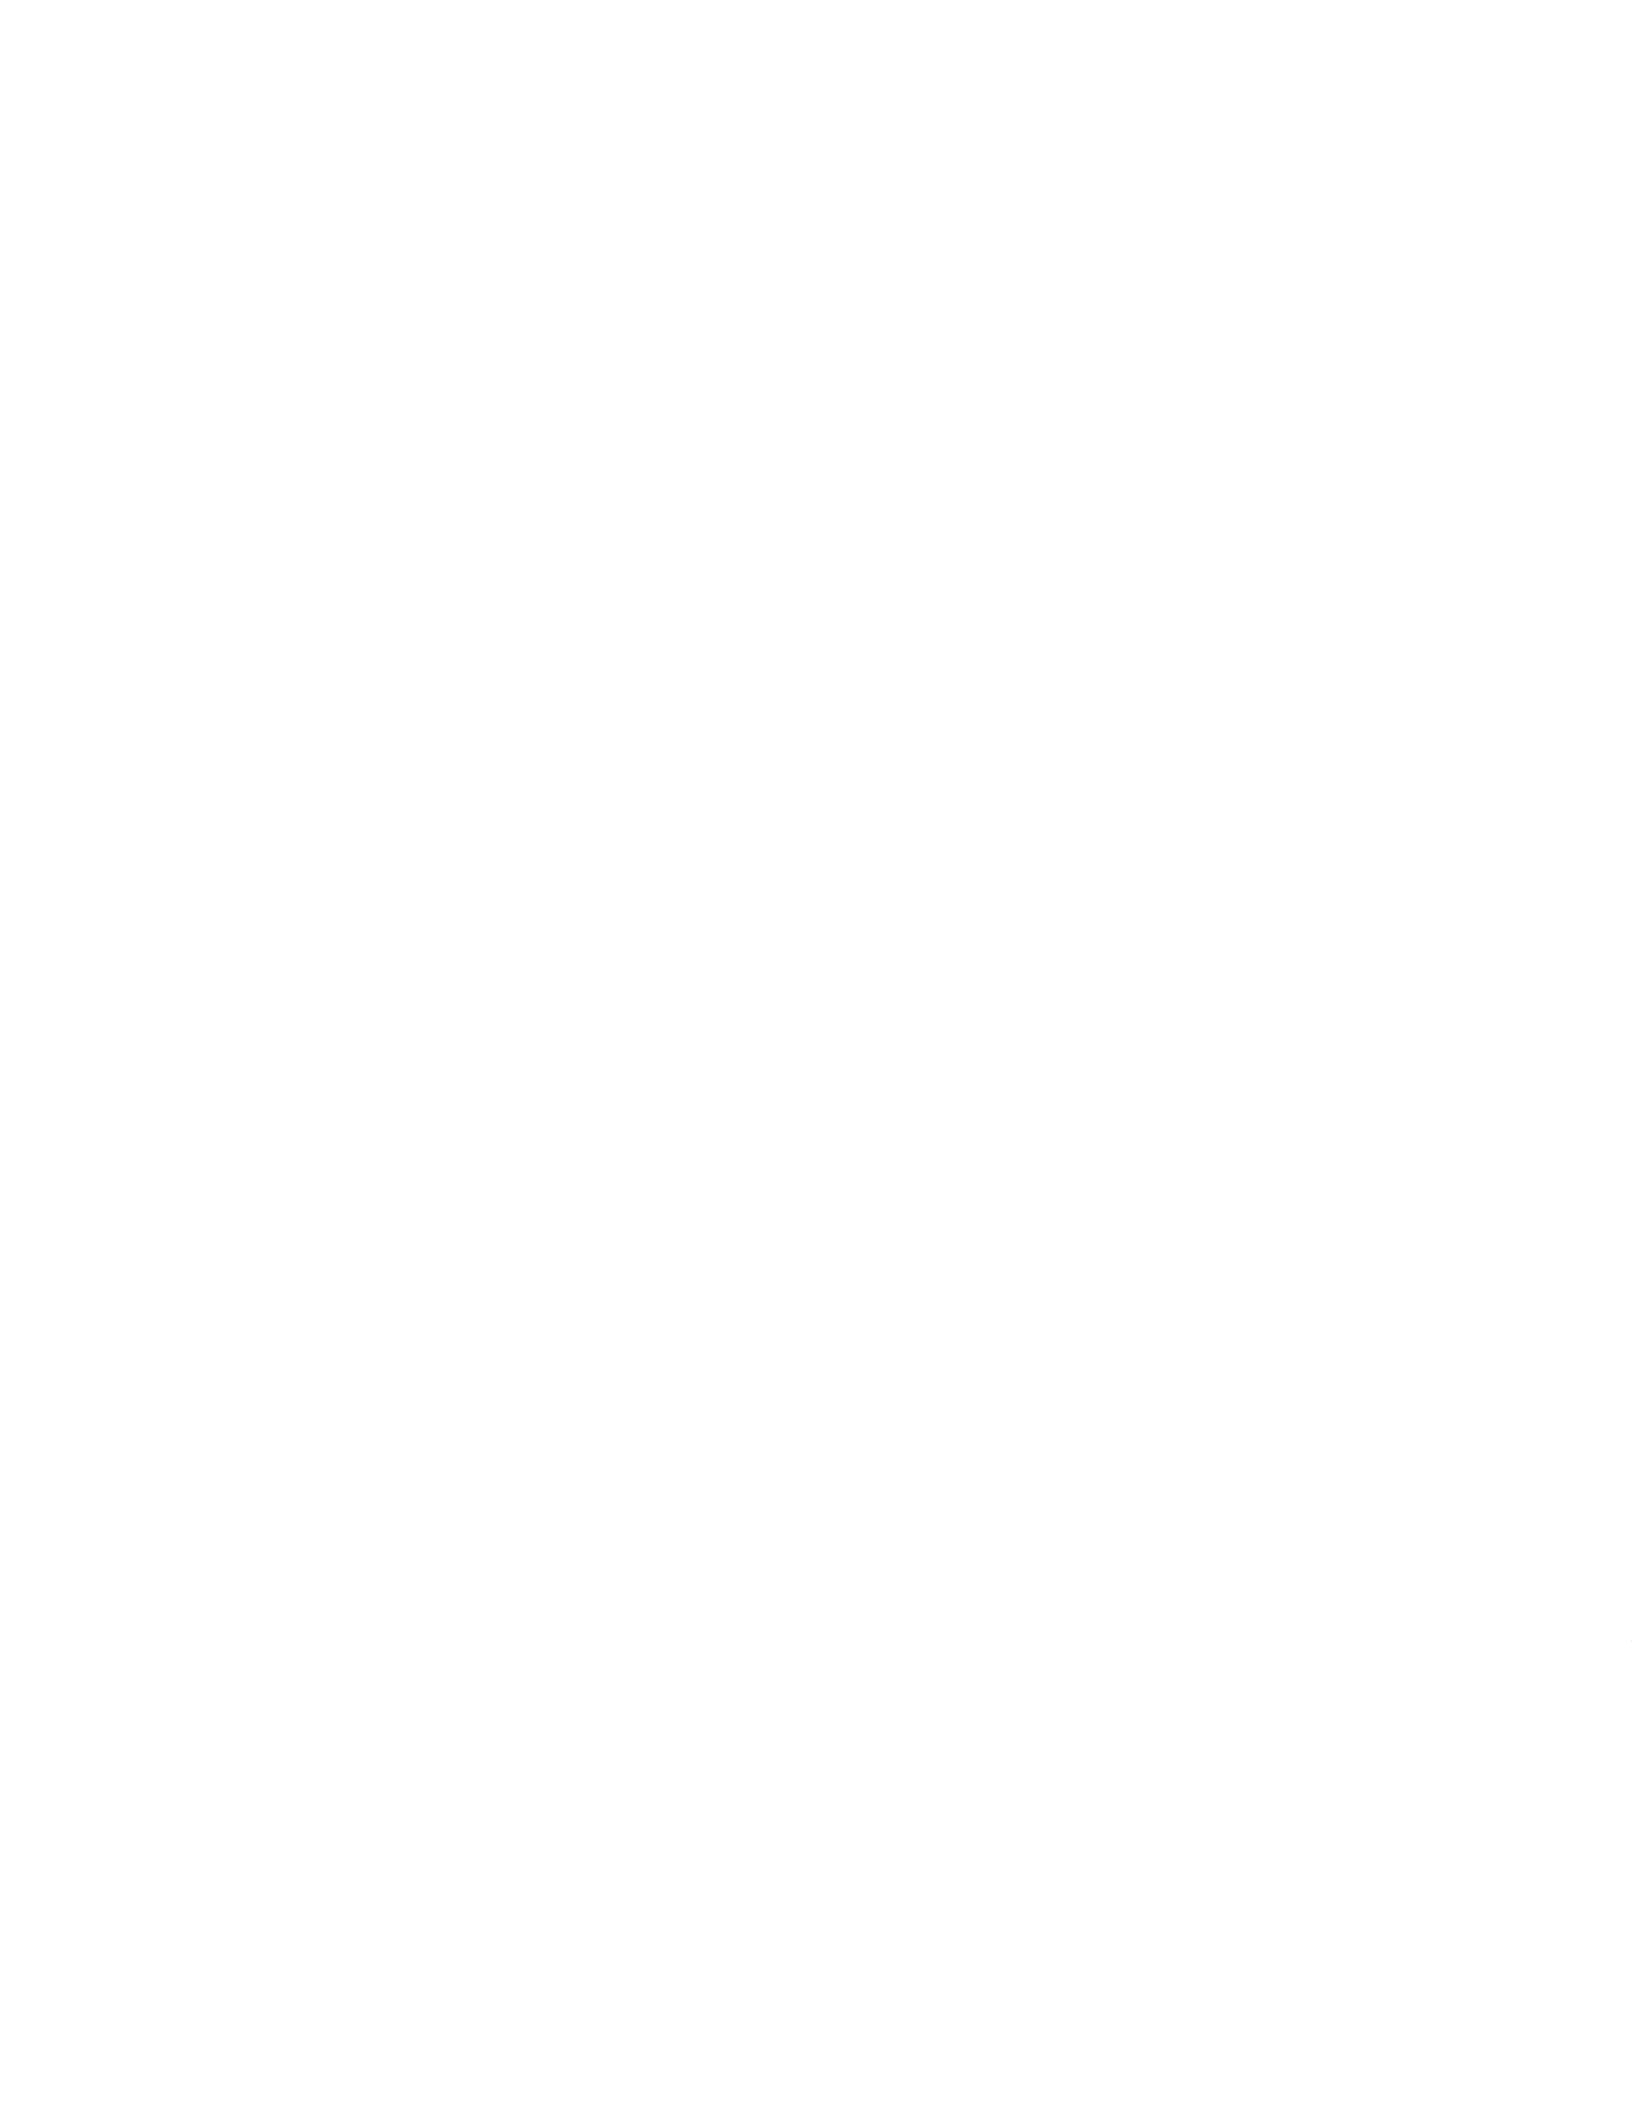
indirect costs * Restricted funds share of indirect costs = 20,000 ∗30
Now, the remaining indirect costs will be allocated to the unrestricted funds. Unrestricted funds share
of indirect costs = Total indirect costs - Restricted funds share of indirect costs Unrestricted funds share of
indirect costs = 20,000−6,000 = 14,000
Therefore, the amount of the indirect costs allocated to the unrestricted funds is 14,000.
7. Question: A non-profit organization has three separate funds: Fund A, Fund B, and Fund C. Fund
A incurred expenses of 10,000, F undBincurredexpensesof 15,000, and Fund C incurred expenses of
20,000.T heorganization′stotalindirectcostsf ortheyearare5,000. If the organization wants to allocate
indirect costs based on the proportion of expenses in each fund, how much indirect cost should be allocated
to Fund A?
Solution: To allocate indirect costs based on the proportion of expenses in each fund, we need to calcu-
late the total expenses across all funds first.
Total Expenses = 10,000(F undA)+15,000 (Fund B) + 20,000(F undC)T otalExpenses =45,000
Next, we calculate the proportion of expenses for each fund:
Proportion of Fund A’s Expenses = Fund A’s Expenses / Total Expenses Proportion of Fund A’s Expenses
=10,000/45,000 Proportion of Fund A’s Expenses = 1/4 or 0.25
Now, we allocate the total indirect costs to Fund A based on its proportion of expenses:
Indirect Cost Allocated to Fund A = Proportion of Fund A’s Expenses * Total Indirect Costs Indirect
Cost Allocated to Fund A = 0.25 * 5,000IndirectCostAllocatedtoF undA =1,250
Therefore, 1,250ofindirectcostsshouldbeallocatedtoF undA.
8. Question: A non-profit organization receives a donation of 10,000thatisrestrictedtobeusedforaspecif icprogram.T heorganizationincursexpensesof6,000
directly related to this program. How much is the remaining balance of the restricted fund for this program?
Solution: The remaining balance of the restricted fund for the specific program can be found by sub-
tracting the expenses incurred from the total donation amount.
Remaining Balance = Total Donation - Program Expenses Remaining Balance = 10,000−6,000 Re-
maining Balance = 4,000
Therefore, the remaining balance of the restricted fund for this program is 4,000.
9. Question: A non-profit organization receives a donation of 10,000specif icallydesignatedforabuildingrenovationproject.Duringthecurrentfiscalyear, theorganizationuses5,000
of the donation for the project. At the end of the fiscal year, what are the balances of the temporarily re-
stricted fund and the amount available for general use in the unrestricted fund?
Solution: 1. Temporary Restricted Fund Balance: - Initial donation: 10,000−Amountusedf ortheproject :5,000
- Balance of temporarily restricted fund = Initial donation - Amount used - Balance of temporarily restricted
fund = 10,000−5,000 - Balance of temporarily restricted fund = 5,000
2. Unrestricted Fund Balance: - Any part of the donation not used for the project remains in the tem-
porarily restricted fund. - Amount available for general use in the unrestricted fund = Initial donation -
Amount in temporarily restricted for the project - Amount available for general use in the unrestricted fund
=10,000−5,000 - Amount available for general use in the unrestricted fund = 5,000
Therefore, at the end of the fiscal year, the balance of the temporarily restricted fund is 5,000, andtheamountavailableforgeneraluseintheunrestrictedfundisalso5,000.
10. Question: A non-profit organization incurred total operating expenses of 50,000.F romthatamount,12,000
expenses were incurred specifically for the education fund, 8,000forthehealthcaref und, andtheremainingexpensesweregeneraloperatingexpenses.W hatpercentageof thetotaloperatingexpenseswereallocatedtotheeducationf und?
Solution: To find the percentage of total operating expenses allocated to the education fund, we first
need to calculate the total specific allocations for the education fund:
Total specific allocation for education fund = 12,000
Then, we calculate the total operating expenses allocated to the education fund:

Total operating expenses allocated to the education fund = Total specific allocation for education fund +
General operating expenses Total operating expenses allocated to the education fund = 12,000 + (50,000 -
12,000−8,000) Total operating expenses allocated to the education fund = 12,000+30,000 Total operating
expenses allocated to the education fund = 42,000
Finally, we calculate the percentage of total operating expenses allocated to the education fund:
Percentage allocated to education fund = (Total operating expenses allocated to education fund / To-
tal operating expenses) * 100Percentage allocated to education fund = (42,000/50,000) * 100Percentage
allocated to education fund = 0.84 * 100Percentage allocated to education fund = 84
Therefore, 84
11. Question: A non-profit organization receives a donation of 10,000restrictedforaspecif icpurpose.T heorganizationspends4,000
on the designated program and incurs 1,500infundraisingexpensesrelatedtothesameprogram.Howmuchoftherestrictedfundsarestillavailableforthedesignatedpurpose?
Solution: Initially, the organization received 10,000asarestricteddonation.Af terspending4,000 on
the designated program, the remaining amount is 10,000−4,000 = 6,000.However, theyalsoincurred1,500
in fundraising expenses related to the designated program. This amount needs to be subtracted from the re-
maining funds. Therefore, the total amount available for the designated purpose is 6,000−1,500 = 4,500.
Final Answer: 4,500
12. Question: A non-profit organization received a grant of 50,000thatisrestrictedforaspecif icprogram.Duringthefiscalyear, theorganizationspent20,000
on the program. Calculate the amount of restricted funds remaining at the end of the fiscal year.
Solution: Restricted funds remaining = Grant amount - Expenditure on the program Restricted funds
remaining = 50,000−20,000 Restricted funds remaining = 30,000
Therefore, the amount of restricted funds remaining at the end of the fiscal year is 30,000.
13. Question: A non-profit organization has total expenses of 100,000, anditincurred20,000 in fundrais-
ing expenses, 30,000inprogramAexpenses, and25,000 in program B expenses. Calculate the percentage
of total expenses allocated to program A.
Solution: To calculate the percentage of total expenses allocated to program A, we need to first find the
total expenses allocated to program A.
Total expenses allocated to program A = fundraising expenses + program A expenses Total expenses
allocated to program A = 20,000+30,000 Total expenses allocated to program A = 50,000
Now, we can calculate the percentage of total expenses allocated to program A by dividing the total
expenses allocated to program A by the total expenses and multiplying by 100.
Percentage of total expenses allocated to program A = (Total expenses allocated to program A / Total
expenses) * 100 Percentage of total expenses allocated to program A = (50,000/100,000) * 100 Percentage
of total expenses allocated to program A = 0.5 * 100 Percentage of total expenses allocated to program A =
50
Therefore, 50
14. Question: A non-profit organization has total funds of 100,000.40
Solution: Total funds = 100,000Restrictedfunds = 40Unrestrictedfunds =T otalfunds−RestrictedfundsUnrestrictedfunds =100,000
-40,000Unrestrictedfunds =60,000
Therefore, 60,000isallocatedtotheunrestrictedaccount.
15. Question: In a non-profit organization, if the total indirect costs amount to 50,000andaretobeallocatedtotwodifferentprogramsbasedonthedirectcostsincurredbyeachprogram, withP rogramAhavingdirectcostsof30,000
and Program B having direct costs of 20,000, whatistheallocationof indirectcostsf orP rogramA?
Solution: To allocate the indirect costs to each program based on their direct costs, we need to find the
proportion of each program’s direct costs to the total direct costs of both programs.

Total direct costs = Direct costs of Program A + Direct costs of Program B Total direct costs = 30,000+20,000
Total direct costs = 50,000
Now, find the proportion of direct costs for Program A: Proportion of direct costs for Program A =
Direct costs of Program A / Total direct costs Proportion of direct costs for Program A = 30,000/50,000
Proportion of direct costs for Program A = 0.6 or 60
Next, allocate the total indirect costs based on the proportion of direct costs for Program A: Indirect
costs allocated to Program A = Proportion of direct costs for Program A * Total indirect costs Indirect costs
allocated to Program A = 0.6 * 50,000IndirectcostsallocatedtoP rogramA =30,000
Therefore, the allocation of indirect costs for Program A would be 30,000.
16. Question: A non-profit organization receives a grant of 10,000specif icallydesignatedf oraspecialprogram.T heorganizationincurs2,000
in administrative expenses that benefit multiple programs, including the special program funded by the grant.
How much of the administrative expenses should be allocated to the special program using a proportional
allocation method based on the grant amount?
Solution: 1. Calculate the percentage of the grant amount relative to the total funds received: Grant
Percentage = (Grant Amount / Total Funds Received) * 100 = (10,000/10,000) * 100 = 100
2. Allocate the administrative expenses to the special program based on the grant percentage: Adminis-
trative Expenses Allocated = Grant Percentage * Total Administrative Expenses = 100= 1.00 * 2,000 =2,000
Therefore, using the proportional allocation method based on the grant amount, 2,000oftheadministrativeexpensesshouldbeallocatedtothespecialprogram.
17. Question: A non-profit organization incurred total administrative costs of 50,000f ortheyear.Ofthisamount,10,000
relates to a program funded by restricted funds. How much of the administrative costs should be allocated
to the restricted funds?
Solution: To determine the allocation of costs to restricted funds, we need to calculate the proportion of
administrative costs that relate to the program funded by restricted funds.
Proportion of administrative costs allocated to restricted funds = (Costs related to restricted funds / Total
administrative costs) Proportion of administrative costs allocated to restricted funds = (10,000/50,000) =
0.2 or 20
Now, we can calculate the specific amount of administrative costs that should be allocated to the re-
stricted funds:
Administrative costs allocated to restricted funds = Proportion of administrative costs allocated to re-
stricted funds * Total administrative costs Administrative costs allocated to restricted funds = 0.2 * 50,000 =10,000
Therefore, 10,000ofthetotaladministrativecostsshouldbeallocatedtotheprogramfundedbyrestrictedfunds.
18. Question: A non-profit organization has total restricted funds of 50,000.If40
Solution: To find the amount allocated to the specific project, we need to calculate 40
Amount allocated to project = 40Amount allocated to project = 0.40 * 50,000Amountallocatedtoproject =20,000
Therefore, 20,000isallocatedtothespecificprojectwithinthenon −profitorganization.
19. Question: A non-profit organization has total funds of 500,000, ofwhich100,000 is restricted for a
specific program. If the organization spends 30,000ontherestrictedprogram, whatistheremainingbalanceintherestrictedfund?
Solution: 1. Total funds = 500,0002.Restrictedfunds =100,000 3. Amount spent on restricted pro-
gram = 30,000
To find the remaining balance in the restricted fund after spending on the program, we subtract the
amount spent from the initial restricted funds:
Remaining balance = Restricted funds - Amount spent Remaining balance = 100,000−30,000 Remain-
ing balance = 70,000
Therefore, the remaining balance in the restricted fund is 70,000.

20. Question: A non-profit organization has total funds of 500,000.Outofthisamount,150,000 is
classified as restricted funds and the rest as unrestricted funds. What is the percentage of the organization’s
total funds that are classified as restricted funds?
Solution: To find the percentage of restricted funds out of the total funds, we first need to calculate the
proportion of restricted funds to total funds.
Restricted funds / Total funds = 150,000/500,000 = 0.3
Now, to convert this proportion to a percentage, we multiply by 100.
Percentage of restricted funds = 0.3 * 100 = 30
Therefore, 30
21. Question: A non-profit organization receives a donation of 10,000thatisrestrictedforaspecif icprogram.If theorganizationspends5,000
from this restricted donation on the program, how much remains in the restricted fund?
Solution: To determine how much remains in the restricted fund after spending 5,000ontheprogram, wesimplysubtracttheamountspentfromtheinitialrestricteddonation.
Initial restricted donation = 10,000Amountspentontheprogram =5,000
Remaining amount in the restricted fund = 10,000−5,000 = 5,000
Therefore, the remaining amount in the restricted fund is 5,000.
22. Question: A non-profit organization has a total of 50,000infunds.T heyallocate40
Solution: To find the amount allocated to the restricted account, we first calculate 4050,000∗0.40 =20,000
Therefore, 20,000isallocatedtotherestrictedaccount.
23. Question: A non-profit organization has total funds of 100,000.40
Solution: 1. Calculate the current amount of funds in the restricted account: Restricted funds = Total
funds * Percentage restricted Restricted funds = 100,000 ∗40
2. Since the organization needs to allocate an additional 30,000totherestrictedfunds, thenewamountintherestrictedaccountwillbe :
Newrestrictedfunds =40,000 + 30,000 =70,000
3. To find the new amount in the unrestricted funds, simply subtract the new amount in the restricted
funds from the total funds: New unrestricted funds = Total funds - New restricted funds New unrestricted
funds = 100,000−70,000 New unrestricted funds = 30,000
Therefore, the new amount in the unrestricted funds will be 30,000.
24. Question: A non-profit organization has total unrestricted net assets of 100,000andtotalrestrictednetassetsof50,000.
If the organization designates 20,000fromtheunrestrictednetassetstoanewdonor−restrictedfund, whatwillbethenewbalanceofunrestrictednetassets?
Solution: Total Unrestricted Net Assets = 100,000T otalRestrictedN etAssets =50,000 Amount des-
ignated to new donor-restricted fund from Unrestricted Net Assets = 20,000
New Unrestricted Net Assets = Total Unrestricted Net Assets - Amount designated to new fund New
Unrestricted Net Assets = 100,000−20,000 New Unrestricted Net Assets = 80,000
Therefore, the new balance of unrestricted net assets after designating 20,000toanewdonor−restrictedfundwouldbe80,000.
25. Question: A non-profit organization has three funds: Fund A, Fund B, and Fund C. Fund A
incurred 10,000inexpensesthatwereallocabletoallthreef unds, F undBincurred5,000 in expenses that
were specific to Fund B only, and Fund C incurred 8,000inexpensesthatwereallocabletoF undAandF undC.If theorganizationwantstoallocatetheexpensesproportionallybasedonthetotalrevenueofeachfund, andthetotalrevenueforF undA, F undB, andF undCis100,000,
50,000, and80,000 respectively, what would be the total amount of expenses allocated to Fund A?
Solution: 1. Calculate the total revenue for all funds: 100,000(F undA)+50,000 (Fund B) + 80,000(F undC) =230,000
2. Calculate the proportion of total revenue for each fund: - Fund A: 100,000/230,000 = 0.4348 - Fund B:
50,000/230,000 = 0.2174 - Fund C: 80,000/230,000 = 0.3478 3. Allocate the shared expenses to each fund
proportionally: - Fund A: 10,000 ∗0.4348 =4,348 - Fund B: 10,000 ∗0.2174 =2,174 - Fund C: 10,000 ∗

0.3478 =3,478 4. Allocate Fund B’s expenses to Fund B: 5,0005.AllocateF undC′sexpensestoF undAandF undCproportionally :
−F undA :8,000 * 0.4348 = 3,478 −F undC :8,000 * 0.3478 = 2,784
Total expenses allocated to Fund A = 4,348(sharedexpenses)+3,478 (expenses from Fund C) = 7,826
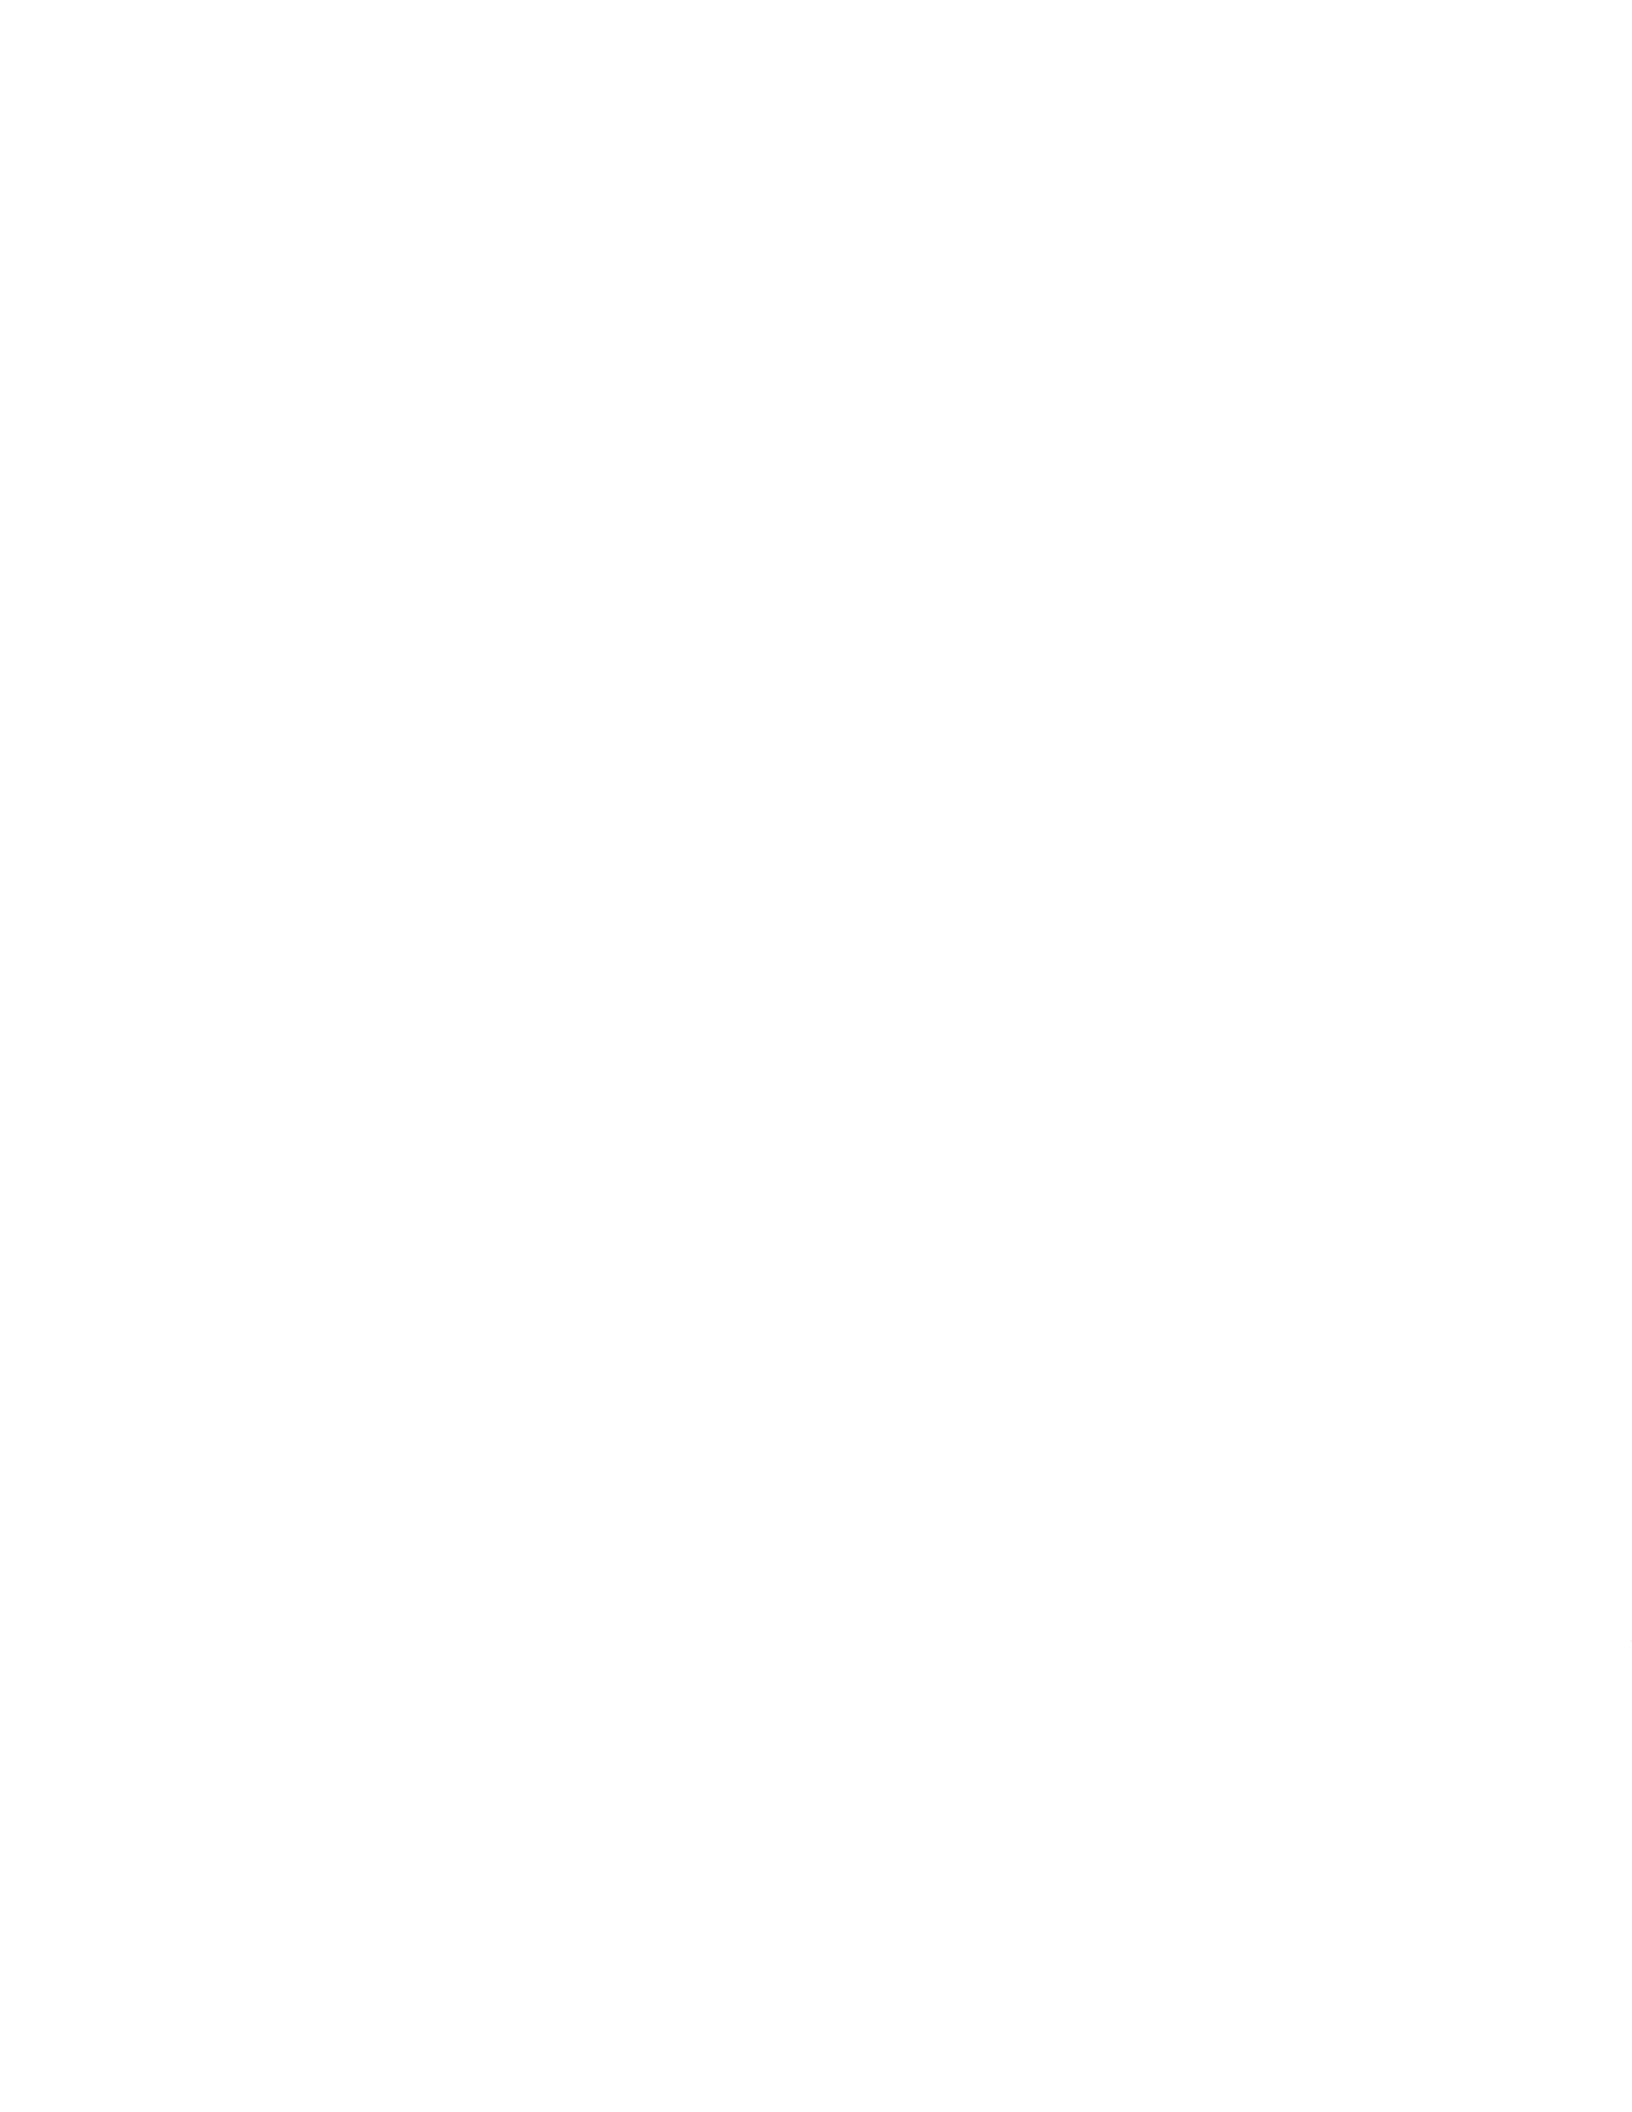
indirect costs * Restricted funds share of indirect costs = 20,000 ∗30
Now, the remaining indirect costs will be allocated to the unrestricted funds. Unrestricted funds share
of indirect costs = Total indirect costs - Restricted funds share of indirect costs Unrestricted funds share of
indirect costs = 20,000−6,000 = 14,000
Therefore, the amount of the indirect costs allocated to the unrestricted funds is 14,000.
7. Question: A non-profit organization has three separate funds: Fund A, Fund B, and Fund C. Fund
A incurred expenses of 10,000, F undBincurredexpensesof 15,000, and Fund C incurred expenses of
20,000.T heorganization′stotalindirectcostsf ortheyearare5,000. If the organization wants to allocate
indirect costs based on the proportion of expenses in each fund, how much indirect cost should be allocated
to Fund A?
Solution: To allocate indirect costs based on the proportion of expenses in each fund, we need to calcu-
late the total expenses across all funds first.
Total Expenses = 10,000(F undA)+15,000 (Fund B) + 20,000(F undC)T otalExpenses =45,000
Next, we calculate the proportion of expenses for each fund:
Proportion of Fund A’s Expenses = Fund A’s Expenses / Total Expenses Proportion of Fund A’s Expenses
=10,000/45,000 Proportion of Fund A’s Expenses = 1/4 or 0.25
Now, we allocate the total indirect costs to Fund A based on its proportion of expenses:
Indirect Cost Allocated to Fund A = Proportion of Fund A’s Expenses * Total Indirect Costs Indirect
Cost Allocated to Fund A = 0.25 * 5,000IndirectCostAllocatedtoF undA =1,250
Therefore, 1,250ofindirectcostsshouldbeallocatedtoF undA.
8. Question: A non-profit organization receives a donation of 10,000thatisrestrictedtobeusedforaspecif icprogram.T heorganizationincursexpensesof6,000
directly related to this program. How much is the remaining balance of the restricted fund for this program?
Solution: The remaining balance of the restricted fund for the specific program can be found by sub-
tracting the expenses incurred from the total donation amount.
Remaining Balance = Total Donation - Program Expenses Remaining Balance = 10,000−6,000 Re-
maining Balance = 4,000
Therefore, the remaining balance of the restricted fund for this program is 4,000.
9. Question: A non-profit organization receives a donation of 10,000specif icallydesignatedforabuildingrenovationproject.Duringthecurrentfiscalyear, theorganizationuses5,000
of the donation for the project. At the end of the fiscal year, what are the balances of the temporarily re-
stricted fund and the amount available for general use in the unrestricted fund?
Solution: 1. Temporary Restricted Fund Balance: - Initial donation: 10,000−Amountusedf ortheproject :5,000
- Balance of temporarily restricted fund = Initial donation - Amount used - Balance of temporarily restricted
fund = 10,000−5,000 - Balance of temporarily restricted fund = 5,000
2. Unrestricted Fund Balance: - Any part of the donation not used for the project remains in the tem-
porarily restricted fund. - Amount available for general use in the unrestricted fund = Initial donation -
Amount in temporarily restricted for the project - Amount available for general use in the unrestricted fund
=10,000−5,000 - Amount available for general use in the unrestricted fund = 5,000
Therefore, at the end of the fiscal year, the balance of the temporarily restricted fund is 5,000, andtheamountavailableforgeneraluseintheunrestrictedfundisalso5,000.
10. Question: A non-profit organization incurred total operating expenses of 50,000.F romthatamount,12,000
expenses were incurred specifically for the education fund, 8,000forthehealthcaref und, andtheremainingexpensesweregeneraloperatingexpenses.W hatpercentageof thetotaloperatingexpenseswereallocatedtotheeducationf und?
Solution: To find the percentage of total operating expenses allocated to the education fund, we first
need to calculate the total specific allocations for the education fund:
Total specific allocation for education fund = 12,000
Then, we calculate the total operating expenses allocated to the education fund:

Total operating expenses allocated to the education fund = Total specific allocation for education fund +
General operating expenses Total operating expenses allocated to the education fund = 12,000 + (50,000 -
12,000−8,000) Total operating expenses allocated to the education fund = 12,000+30,000 Total operating
expenses allocated to the education fund = 42,000
Finally, we calculate the percentage of total operating expenses allocated to the education fund:
Percentage allocated to education fund = (Total operating expenses allocated to education fund / To-
tal operating expenses) * 100Percentage allocated to education fund = (42,000/50,000) * 100Percentage
allocated to education fund = 0.84 * 100Percentage allocated to education fund = 84
Therefore, 84
11. Question: A non-profit organization receives a donation of 10,000restrictedforaspecif icpurpose.T heorganizationspends4,000
on the designated program and incurs 1,500infundraisingexpensesrelatedtothesameprogram.Howmuchoftherestrictedfundsarestillavailableforthedesignatedpurpose?
Solution: Initially, the organization received 10,000asarestricteddonation.Af terspending4,000 on
the designated program, the remaining amount is 10,000−4,000 = 6,000.However, theyalsoincurred1,500
in fundraising expenses related to the designated program. This amount needs to be subtracted from the re-
maining funds. Therefore, the total amount available for the designated purpose is 6,000−1,500 = 4,500.
Final Answer: 4,500
12. Question: A non-profit organization received a grant of 50,000thatisrestrictedforaspecif icprogram.Duringthefiscalyear, theorganizationspent20,000
on the program. Calculate the amount of restricted funds remaining at the end of the fiscal year.
Solution: Restricted funds remaining = Grant amount - Expenditure on the program Restricted funds
remaining = 50,000−20,000 Restricted funds remaining = 30,000
Therefore, the amount of restricted funds remaining at the end of the fiscal year is 30,000.
13. Question: A non-profit organization has total expenses of 100,000, anditincurred20,000 in fundrais-
ing expenses, 30,000inprogramAexpenses, and25,000 in program B expenses. Calculate the percentage
of total expenses allocated to program A.
Solution: To calculate the percentage of total expenses allocated to program A, we need to first find the
total expenses allocated to program A.
Total expenses allocated to program A = fundraising expenses + program A expenses Total expenses
allocated to program A = 20,000+30,000 Total expenses allocated to program A = 50,000
Now, we can calculate the percentage of total expenses allocated to program A by dividing the total
expenses allocated to program A by the total expenses and multiplying by 100.
Percentage of total expenses allocated to program A = (Total expenses allocated to program A / Total
expenses) * 100 Percentage of total expenses allocated to program A = (50,000/100,000) * 100 Percentage
of total expenses allocated to program A = 0.5 * 100 Percentage of total expenses allocated to program A =
50
Therefore, 50
14. Question: A non-profit organization has total funds of 100,000.40
Solution: Total funds = 100,000Restrictedfunds = 40Unrestrictedfunds =T otalfunds−RestrictedfundsUnrestrictedfunds =100,000
-40,000Unrestrictedfunds =60,000
Therefore, 60,000isallocatedtotheunrestrictedaccount.
15. Question: In a non-profit organization, if the total indirect costs amount to 50,000andaretobeallocatedtotwodifferentprogramsbasedonthedirectcostsincurredbyeachprogram, withP rogramAhavingdirectcostsof30,000
and Program B having direct costs of 20,000, whatistheallocationof indirectcostsf orP rogramA?
Solution: To allocate the indirect costs to each program based on their direct costs, we need to find the
proportion of each program’s direct costs to the total direct costs of both programs.

Total direct costs = Direct costs of Program A + Direct costs of Program B Total direct costs = 30,000+20,000
Total direct costs = 50,000
Now, find the proportion of direct costs for Program A: Proportion of direct costs for Program A =
Direct costs of Program A / Total direct costs Proportion of direct costs for Program A = 30,000/50,000
Proportion of direct costs for Program A = 0.6 or 60
Next, allocate the total indirect costs based on the proportion of direct costs for Program A: Indirect
costs allocated to Program A = Proportion of direct costs for Program A * Total indirect costs Indirect costs
allocated to Program A = 0.6 * 50,000IndirectcostsallocatedtoP rogramA =30,000
Therefore, the allocation of indirect costs for Program A would be 30,000.
16. Question: A non-profit organization receives a grant of 10,000specif icallydesignatedf oraspecialprogram.T heorganizationincurs2,000
in administrative expenses that benefit multiple programs, including the special program funded by the grant.
How much of the administrative expenses should be allocated to the special program using a proportional
allocation method based on the grant amount?
Solution: 1. Calculate the percentage of the grant amount relative to the total funds received: Grant
Percentage = (Grant Amount / Total Funds Received) * 100 = (10,000/10,000) * 100 = 100
2. Allocate the administrative expenses to the special program based on the grant percentage: Adminis-
trative Expenses Allocated = Grant Percentage * Total Administrative Expenses = 100= 1.00 * 2,000 =2,000
Therefore, using the proportional allocation method based on the grant amount, 2,000oftheadministrativeexpensesshouldbeallocatedtothespecialprogram.
17. Question: A non-profit organization incurred total administrative costs of 50,000f ortheyear.Ofthisamount,10,000
relates to a program funded by restricted funds. How much of the administrative costs should be allocated
to the restricted funds?
Solution: To determine the allocation of costs to restricted funds, we need to calculate the proportion of
administrative costs that relate to the program funded by restricted funds.
Proportion of administrative costs allocated to restricted funds = (Costs related to restricted funds / Total
administrative costs) Proportion of administrative costs allocated to restricted funds = (10,000/50,000) =
0.2 or 20
Now, we can calculate the specific amount of administrative costs that should be allocated to the re-
stricted funds:
Administrative costs allocated to restricted funds = Proportion of administrative costs allocated to re-
stricted funds * Total administrative costs Administrative costs allocated to restricted funds = 0.2 * 50,000 =10,000
Therefore, 10,000ofthetotaladministrativecostsshouldbeallocatedtotheprogramfundedbyrestrictedfunds.
18. Question: A non-profit organization has total restricted funds of 50,000.If40
Solution: To find the amount allocated to the specific project, we need to calculate 40
Amount allocated to project = 40Amount allocated to project = 0.40 * 50,000Amountallocatedtoproject =20,000
Therefore, 20,000isallocatedtothespecificprojectwithinthenon −profitorganization.
19. Question: A non-profit organization has total funds of 500,000, ofwhich100,000 is restricted for a
specific program. If the organization spends 30,000ontherestrictedprogram, whatistheremainingbalanceintherestrictedfund?
Solution: 1. Total funds = 500,0002.Restrictedfunds =100,000 3. Amount spent on restricted pro-
gram = 30,000
To find the remaining balance in the restricted fund after spending on the program, we subtract the
amount spent from the initial restricted funds:
Remaining balance = Restricted funds - Amount spent Remaining balance = 100,000−30,000 Remain-
ing balance = 70,000
Therefore, the remaining balance in the restricted fund is 70,000.

20. Question: A non-profit organization has total funds of 500,000.Outofthisamount,150,000 is
classified as restricted funds and the rest as unrestricted funds. What is the percentage of the organization’s
total funds that are classified as restricted funds?
Solution: To find the percentage of restricted funds out of the total funds, we first need to calculate the
proportion of restricted funds to total funds.
Restricted funds / Total funds = 150,000/500,000 = 0.3
Now, to convert this proportion to a percentage, we multiply by 100.
Percentage of restricted funds = 0.3 * 100 = 30
Therefore, 30
21. Question: A non-profit organization receives a donation of 10,000thatisrestrictedforaspecif icprogram.If theorganizationspends5,000
from this restricted donation on the program, how much remains in the restricted fund?
Solution: To determine how much remains in the restricted fund after spending 5,000ontheprogram, wesimplysubtracttheamountspentfromtheinitialrestricteddonation.
Initial restricted donation = 10,000Amountspentontheprogram =5,000
Remaining amount in the restricted fund = 10,000−5,000 = 5,000
Therefore, the remaining amount in the restricted fund is 5,000.
22. Question: A non-profit organization has a total of 50,000infunds.T heyallocate40
Solution: To find the amount allocated to the restricted account, we first calculate 4050,000∗0.40 =20,000
Therefore, 20,000isallocatedtotherestrictedaccount.
23. Question: A non-profit organization has total funds of 100,000.40
Solution: 1. Calculate the current amount of funds in the restricted account: Restricted funds = Total
funds * Percentage restricted Restricted funds = 100,000 ∗40
2. Since the organization needs to allocate an additional 30,000totherestrictedfunds, thenewamountintherestrictedaccountwillbe :
Newrestrictedfunds =40,000 + 30,000 =70,000
3. To find the new amount in the unrestricted funds, simply subtract the new amount in the restricted
funds from the total funds: New unrestricted funds = Total funds - New restricted funds New unrestricted
funds = 100,000−70,000 New unrestricted funds = 30,000
Therefore, the new amount in the unrestricted funds will be 30,000.
24. Question: A non-profit organization has total unrestricted net assets of 100,000andtotalrestrictednetassetsof50,000.
If the organization designates 20,000fromtheunrestrictednetassetstoanewdonor−restrictedfund, whatwillbethenewbalanceofunrestrictednetassets?
Solution: Total Unrestricted Net Assets = 100,000T otalRestrictedN etAssets =50,000 Amount des-
ignated to new donor-restricted fund from Unrestricted Net Assets = 20,000
New Unrestricted Net Assets = Total Unrestricted Net Assets - Amount designated to new fund New
Unrestricted Net Assets = 100,000−20,000 New Unrestricted Net Assets = 80,000
Therefore, the new balance of unrestricted net assets after designating 20,000toanewdonor−restrictedfundwouldbe80,000.
25. Question: A non-profit organization has three funds: Fund A, Fund B, and Fund C. Fund A
incurred 10,000inexpensesthatwereallocabletoallthreef unds, F undBincurred5,000 in expenses that
were specific to Fund B only, and Fund C incurred 8,000inexpensesthatwereallocabletoF undAandF undC.If theorganizationwantstoallocatetheexpensesproportionallybasedonthetotalrevenueofeachfund, andthetotalrevenueforF undA, F undB, andF undCis100,000,
50,000, and80,000 respectively, what would be the total amount of expenses allocated to Fund A?
Solution: 1. Calculate the total revenue for all funds: 100,000(F undA)+50,000 (Fund B) + 80,000(F undC) =230,000
2. Calculate the proportion of total revenue for each fund: - Fund A: 100,000/230,000 = 0.4348 - Fund B:
50,000/230,000 = 0.2174 - Fund C: 80,000/230,000 = 0.3478 3. Allocate the shared expenses to each fund
proportionally: - Fund A: 10,000 ∗0.4348 =4,348 - Fund B: 10,000 ∗0.2174 =2,174 - Fund C: 10,000 ∗

0.3478 =3,478 4. Allocate Fund B’s expenses to Fund B: 5,0005.AllocateF undC′sexpensestoF undAandF undCproportionally :
−F undA :8,000 * 0.4348 = 3,478 −F undC :8,000 * 0.3478 = 2,784
Total expenses allocated to Fund A = 4,348(sharedexpenses)+3,478 (expenses from Fund C) = 7,826
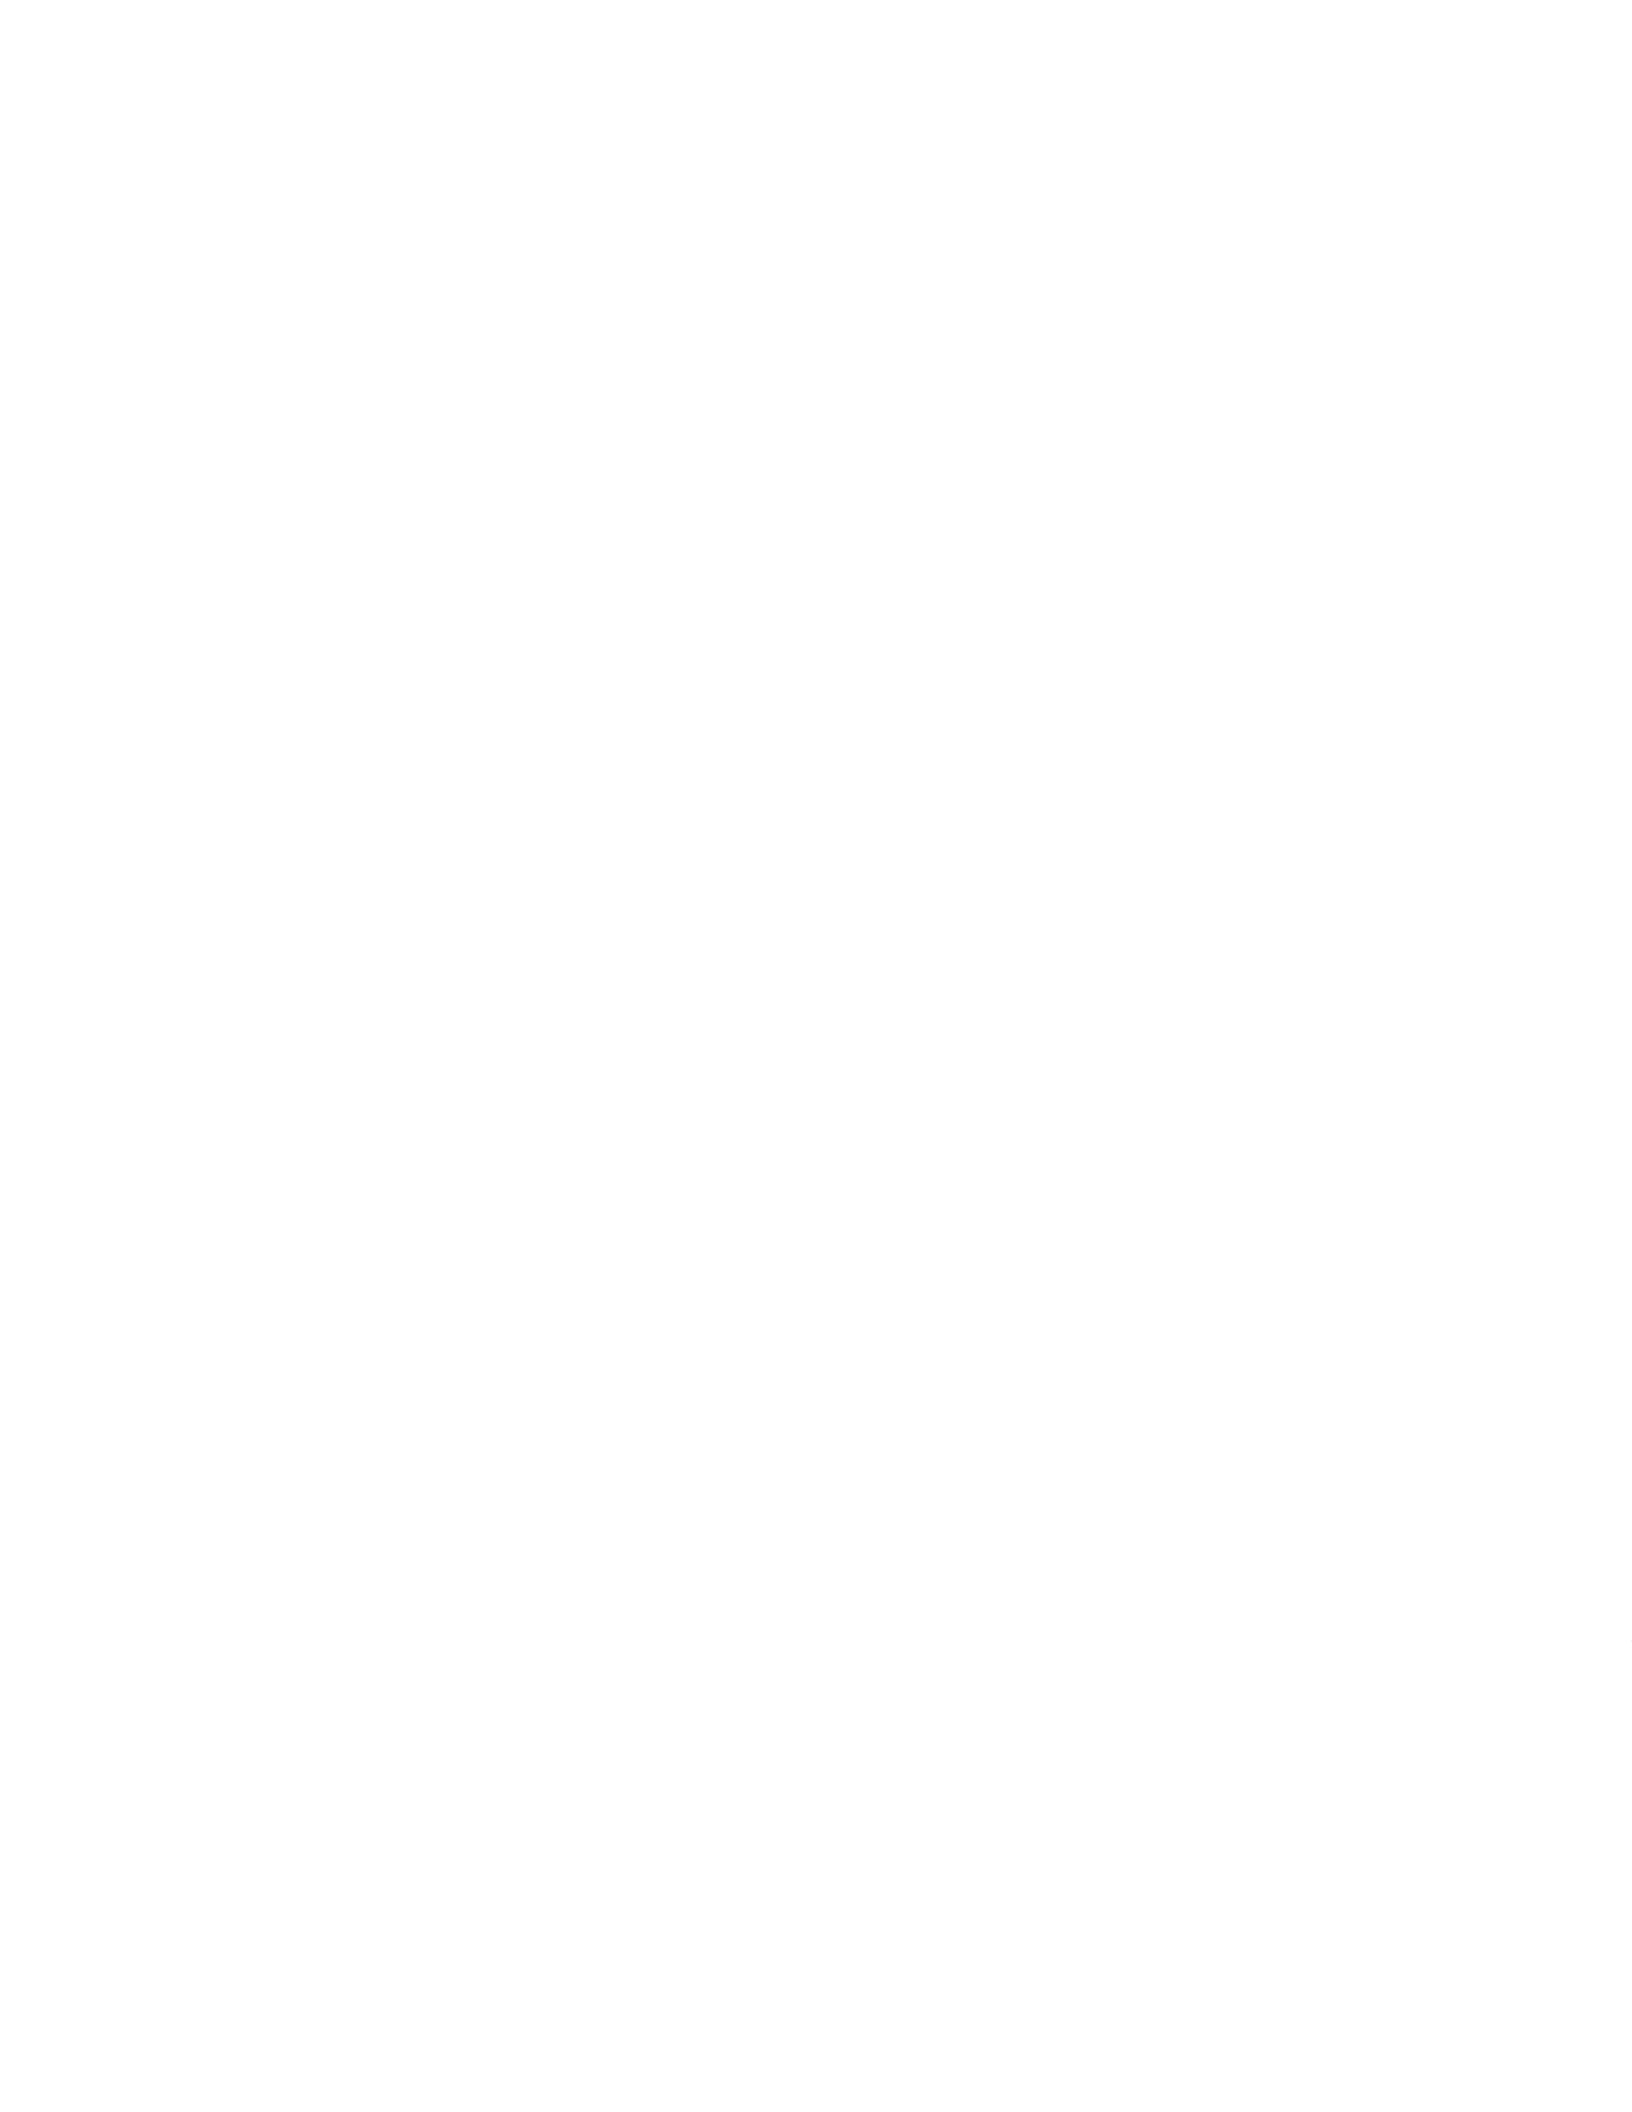
indirect costs * Restricted funds share of indirect costs = 20,000 ∗30
Now, the remaining indirect costs will be allocated to the unrestricted funds. Unrestricted funds share
of indirect costs = Total indirect costs - Restricted funds share of indirect costs Unrestricted funds share of
indirect costs = 20,000−6,000 = 14,000
Therefore, the amount of the indirect costs allocated to the unrestricted funds is 14,000.
7. Question: A non-profit organization has three separate funds: Fund A, Fund B, and Fund C. Fund
A incurred expenses of 10,000, F undBincurredexpensesof 15,000, and Fund C incurred expenses of
20,000.T heorganization′stotalindirectcostsf ortheyearare5,000. If the organization wants to allocate
indirect costs based on the proportion of expenses in each fund, how much indirect cost should be allocated
to Fund A?
Solution: To allocate indirect costs based on the proportion of expenses in each fund, we need to calcu-
late the total expenses across all funds first.
Total Expenses = 10,000(F undA)+15,000 (Fund B) + 20,000(F undC)T otalExpenses =45,000
Next, we calculate the proportion of expenses for each fund:
Proportion of Fund A’s Expenses = Fund A’s Expenses / Total Expenses Proportion of Fund A’s Expenses
=10,000/45,000 Proportion of Fund A’s Expenses = 1/4 or 0.25
Now, we allocate the total indirect costs to Fund A based on its proportion of expenses:
Indirect Cost Allocated to Fund A = Proportion of Fund A’s Expenses * Total Indirect Costs Indirect
Cost Allocated to Fund A = 0.25 * 5,000IndirectCostAllocatedtoF undA =1,250
Therefore, 1,250ofindirectcostsshouldbeallocatedtoF undA.
8. Question: A non-profit organization receives a donation of 10,000thatisrestrictedtobeusedforaspecif icprogram.T heorganizationincursexpensesof6,000
directly related to this program. How much is the remaining balance of the restricted fund for this program?
Solution: The remaining balance of the restricted fund for the specific program can be found by sub-
tracting the expenses incurred from the total donation amount.
Remaining Balance = Total Donation - Program Expenses Remaining Balance = 10,000−6,000 Re-
maining Balance = 4,000
Therefore, the remaining balance of the restricted fund for this program is 4,000.
9. Question: A non-profit organization receives a donation of 10,000specif icallydesignatedforabuildingrenovationproject.Duringthecurrentfiscalyear, theorganizationuses5,000
of the donation for the project. At the end of the fiscal year, what are the balances of the temporarily re-
stricted fund and the amount available for general use in the unrestricted fund?
Solution: 1. Temporary Restricted Fund Balance: - Initial donation: 10,000−Amountusedf ortheproject :5,000
- Balance of temporarily restricted fund = Initial donation - Amount used - Balance of temporarily restricted
fund = 10,000−5,000 - Balance of temporarily restricted fund = 5,000
2. Unrestricted Fund Balance: - Any part of the donation not used for the project remains in the tem-
porarily restricted fund. - Amount available for general use in the unrestricted fund = Initial donation -
Amount in temporarily restricted for the project - Amount available for general use in the unrestricted fund
=10,000−5,000 - Amount available for general use in the unrestricted fund = 5,000
Therefore, at the end of the fiscal year, the balance of the temporarily restricted fund is 5,000, andtheamountavailableforgeneraluseintheunrestrictedfundisalso5,000.
10. Question: A non-profit organization incurred total operating expenses of 50,000.F romthatamount,12,000
expenses were incurred specifically for the education fund, 8,000forthehealthcaref und, andtheremainingexpensesweregeneraloperatingexpenses.W hatpercentageof thetotaloperatingexpenseswereallocatedtotheeducationf und?
Solution: To find the percentage of total operating expenses allocated to the education fund, we first
need to calculate the total specific allocations for the education fund:
Total specific allocation for education fund = 12,000
Then, we calculate the total operating expenses allocated to the education fund:

Total operating expenses allocated to the education fund = Total specific allocation for education fund +
General operating expenses Total operating expenses allocated to the education fund = 12,000 + (50,000 -
12,000−8,000) Total operating expenses allocated to the education fund = 12,000+30,000 Total operating
expenses allocated to the education fund = 42,000
Finally, we calculate the percentage of total operating expenses allocated to the education fund:
Percentage allocated to education fund = (Total operating expenses allocated to education fund / To-
tal operating expenses) * 100Percentage allocated to education fund = (42,000/50,000) * 100Percentage
allocated to education fund = 0.84 * 100Percentage allocated to education fund = 84
Therefore, 84
11. Question: A non-profit organization receives a donation of 10,000restrictedforaspecif icpurpose.T heorganizationspends4,000
on the designated program and incurs 1,500infundraisingexpensesrelatedtothesameprogram.Howmuchoftherestrictedfundsarestillavailableforthedesignatedpurpose?
Solution: Initially, the organization received 10,000asarestricteddonation.Af terspending4,000 on
the designated program, the remaining amount is 10,000−4,000 = 6,000.However, theyalsoincurred1,500
in fundraising expenses related to the designated program. This amount needs to be subtracted from the re-
maining funds. Therefore, the total amount available for the designated purpose is 6,000−1,500 = 4,500.
Final Answer: 4,500
12. Question: A non-profit organization received a grant of 50,000thatisrestrictedforaspecif icprogram.Duringthefiscalyear, theorganizationspent20,000
on the program. Calculate the amount of restricted funds remaining at the end of the fiscal year.
Solution: Restricted funds remaining = Grant amount - Expenditure on the program Restricted funds
remaining = 50,000−20,000 Restricted funds remaining = 30,000
Therefore, the amount of restricted funds remaining at the end of the fiscal year is 30,000.
13. Question: A non-profit organization has total expenses of 100,000, anditincurred20,000 in fundrais-
ing expenses, 30,000inprogramAexpenses, and25,000 in program B expenses. Calculate the percentage
of total expenses allocated to program A.
Solution: To calculate the percentage of total expenses allocated to program A, we need to first find the
total expenses allocated to program A.
Total expenses allocated to program A = fundraising expenses + program A expenses Total expenses
allocated to program A = 20,000+30,000 Total expenses allocated to program A = 50,000
Now, we can calculate the percentage of total expenses allocated to program A by dividing the total
expenses allocated to program A by the total expenses and multiplying by 100.
Percentage of total expenses allocated to program A = (Total expenses allocated to program A / Total
expenses) * 100 Percentage of total expenses allocated to program A = (50,000/100,000) * 100 Percentage
of total expenses allocated to program A = 0.5 * 100 Percentage of total expenses allocated to program A =
50
Therefore, 50
14. Question: A non-profit organization has total funds of 100,000.40
Solution: Total funds = 100,000Restrictedfunds = 40Unrestrictedfunds =T otalfunds−RestrictedfundsUnrestrictedfunds =100,000
-40,000Unrestrictedfunds =60,000
Therefore, 60,000isallocatedtotheunrestrictedaccount.
15. Question: In a non-profit organization, if the total indirect costs amount to 50,000andaretobeallocatedtotwodifferentprogramsbasedonthedirectcostsincurredbyeachprogram, withP rogramAhavingdirectcostsof30,000
and Program B having direct costs of 20,000, whatistheallocationof indirectcostsf orP rogramA?
Solution: To allocate the indirect costs to each program based on their direct costs, we need to find the
proportion of each program’s direct costs to the total direct costs of both programs.

Total direct costs = Direct costs of Program A + Direct costs of Program B Total direct costs = 30,000+20,000
Total direct costs = 50,000
Now, find the proportion of direct costs for Program A: Proportion of direct costs for Program A =
Direct costs of Program A / Total direct costs Proportion of direct costs for Program A = 30,000/50,000
Proportion of direct costs for Program A = 0.6 or 60
Next, allocate the total indirect costs based on the proportion of direct costs for Program A: Indirect
costs allocated to Program A = Proportion of direct costs for Program A * Total indirect costs Indirect costs
allocated to Program A = 0.6 * 50,000IndirectcostsallocatedtoP rogramA =30,000
Therefore, the allocation of indirect costs for Program A would be 30,000.
16. Question: A non-profit organization receives a grant of 10,000specif icallydesignatedf oraspecialprogram.T heorganizationincurs2,000
in administrative expenses that benefit multiple programs, including the special program funded by the grant.
How much of the administrative expenses should be allocated to the special program using a proportional
allocation method based on the grant amount?
Solution: 1. Calculate the percentage of the grant amount relative to the total funds received: Grant
Percentage = (Grant Amount / Total Funds Received) * 100 = (10,000/10,000) * 100 = 100
2. Allocate the administrative expenses to the special program based on the grant percentage: Adminis-
trative Expenses Allocated = Grant Percentage * Total Administrative Expenses = 100= 1.00 * 2,000 =2,000
Therefore, using the proportional allocation method based on the grant amount, 2,000oftheadministrativeexpensesshouldbeallocatedtothespecialprogram.
17. Question: A non-profit organization incurred total administrative costs of 50,000f ortheyear.Ofthisamount,10,000
relates to a program funded by restricted funds. How much of the administrative costs should be allocated
to the restricted funds?
Solution: To determine the allocation of costs to restricted funds, we need to calculate the proportion of
administrative costs that relate to the program funded by restricted funds.
Proportion of administrative costs allocated to restricted funds = (Costs related to restricted funds / Total
administrative costs) Proportion of administrative costs allocated to restricted funds = (10,000/50,000) =
0.2 or 20
Now, we can calculate the specific amount of administrative costs that should be allocated to the re-
stricted funds:
Administrative costs allocated to restricted funds = Proportion of administrative costs allocated to re-
stricted funds * Total administrative costs Administrative costs allocated to restricted funds = 0.2 * 50,000 =10,000
Therefore, 10,000ofthetotaladministrativecostsshouldbeallocatedtotheprogramfundedbyrestrictedfunds.
18. Question: A non-profit organization has total restricted funds of 50,000.If40
Solution: To find the amount allocated to the specific project, we need to calculate 40
Amount allocated to project = 40Amount allocated to project = 0.40 * 50,000Amountallocatedtoproject =20,000
Therefore, 20,000isallocatedtothespecificprojectwithinthenon −profitorganization.
19. Question: A non-profit organization has total funds of 500,000, ofwhich100,000 is restricted for a
specific program. If the organization spends 30,000ontherestrictedprogram, whatistheremainingbalanceintherestrictedfund?
Solution: 1. Total funds = 500,0002.Restrictedfunds =100,000 3. Amount spent on restricted pro-
gram = 30,000
To find the remaining balance in the restricted fund after spending on the program, we subtract the
amount spent from the initial restricted funds:
Remaining balance = Restricted funds - Amount spent Remaining balance = 100,000−30,000 Remain-
ing balance = 70,000
Therefore, the remaining balance in the restricted fund is 70,000.

20. Question: A non-profit organization has total funds of 500,000.Outofthisamount,150,000 is
classified as restricted funds and the rest as unrestricted funds. What is the percentage of the organization’s
total funds that are classified as restricted funds?
Solution: To find the percentage of restricted funds out of the total funds, we first need to calculate the
proportion of restricted funds to total funds.
Restricted funds / Total funds = 150,000/500,000 = 0.3
Now, to convert this proportion to a percentage, we multiply by 100.
Percentage of restricted funds = 0.3 * 100 = 30
Therefore, 30
21. Question: A non-profit organization receives a donation of 10,000thatisrestrictedforaspecif icprogram.If theorganizationspends5,000
from this restricted donation on the program, how much remains in the restricted fund?
Solution: To determine how much remains in the restricted fund after spending 5,000ontheprogram, wesimplysubtracttheamountspentfromtheinitialrestricteddonation.
Initial restricted donation = 10,000Amountspentontheprogram =5,000
Remaining amount in the restricted fund = 10,000−5,000 = 5,000
Therefore, the remaining amount in the restricted fund is 5,000.
22. Question: A non-profit organization has a total of 50,000infunds.T heyallocate40
Solution: To find the amount allocated to the restricted account, we first calculate 4050,000∗0.40 =20,000
Therefore, 20,000isallocatedtotherestrictedaccount.
23. Question: A non-profit organization has total funds of 100,000.40
Solution: 1. Calculate the current amount of funds in the restricted account: Restricted funds = Total
funds * Percentage restricted Restricted funds = 100,000 ∗40
2. Since the organization needs to allocate an additional 30,000totherestrictedfunds, thenewamountintherestrictedaccountwillbe :
Newrestrictedfunds =40,000 + 30,000 =70,000
3. To find the new amount in the unrestricted funds, simply subtract the new amount in the restricted
funds from the total funds: New unrestricted funds = Total funds - New restricted funds New unrestricted
funds = 100,000−70,000 New unrestricted funds = 30,000
Therefore, the new amount in the unrestricted funds will be 30,000.
24. Question: A non-profit organization has total unrestricted net assets of 100,000andtotalrestrictednetassetsof50,000.
If the organization designates 20,000fromtheunrestrictednetassetstoanewdonor−restrictedfund, whatwillbethenewbalanceofunrestrictednetassets?
Solution: Total Unrestricted Net Assets = 100,000T otalRestrictedN etAssets =50,000 Amount des-
ignated to new donor-restricted fund from Unrestricted Net Assets = 20,000
New Unrestricted Net Assets = Total Unrestricted Net Assets - Amount designated to new fund New
Unrestricted Net Assets = 100,000−20,000 New Unrestricted Net Assets = 80,000
Therefore, the new balance of unrestricted net assets after designating 20,000toanewdonor−restrictedfundwouldbe80,000.
25. Question: A non-profit organization has three funds: Fund A, Fund B, and Fund C. Fund A
incurred 10,000inexpensesthatwereallocabletoallthreef unds, F undBincurred5,000 in expenses that
were specific to Fund B only, and Fund C incurred 8,000inexpensesthatwereallocabletoF undAandF undC.If theorganizationwantstoallocatetheexpensesproportionallybasedonthetotalrevenueofeachfund, andthetotalrevenueforF undA, F undB, andF undCis100,000,
50,000, and80,000 respectively, what would be the total amount of expenses allocated to Fund A?
Solution: 1. Calculate the total revenue for all funds: 100,000(F undA)+50,000 (Fund B) + 80,000(F undC) =230,000
2. Calculate the proportion of total revenue for each fund: - Fund A: 100,000/230,000 = 0.4348 - Fund B:
50,000/230,000 = 0.2174 - Fund C: 80,000/230,000 = 0.3478 3. Allocate the shared expenses to each fund
proportionally: - Fund A: 10,000 ∗0.4348 =4,348 - Fund B: 10,000 ∗0.2174 =2,174 - Fund C: 10,000 ∗

0.3478 =3,478 4. Allocate Fund B’s expenses to Fund B: 5,0005.AllocateF undC′sexpensestoF undAandF undCproportionally :
−F undA :8,000 * 0.4348 = 3,478 −F undC :8,000 * 0.3478 = 2,784
Total expenses allocated to Fund A = 4,348(sharedexpenses)+3,478 (expenses from Fund C) = 7,826
indirect costs * Restricted funds share of indirect costs = 20,000 ∗30
Now, the remaining indirect costs will be allocated to the unrestricted funds. Unrestricted funds share
of indirect costs = Total indirect costs - Restricted funds share of indirect costs Unrestricted funds share of
indirect costs = 20,000−6,000 = 14,000
Therefore, the amount of the indirect costs allocated to the unrestricted funds is 14,000.
7. Question: A non-profit organization has three separate funds: Fund A, Fund B, and Fund C. Fund
A incurred expenses of 10,000, F undBincurredexpensesof 15,000, and Fund C incurred expenses of
20,000.T heorganization′stotalindirectcostsf ortheyearare5,000. If the organization wants to allocate
indirect costs based on the proportion of expenses in each fund, how much indirect cost should be allocated
to Fund A?
Solution: To allocate indirect costs based on the proportion of expenses in each fund, we need to calcu-
late the total expenses across all funds first.
Total Expenses = 10,000(F undA)+15,000 (Fund B) + 20,000(F undC)T otalExpenses =45,000
Next, we calculate the proportion of expenses for each fund:
Proportion of Fund A’s Expenses = Fund A’s Expenses / Total Expenses Proportion of Fund A’s Expenses
=10,000/45,000 Proportion of Fund A’s Expenses = 1/4 or 0.25
Now, we allocate the total indirect costs to Fund A based on its proportion of expenses:
Indirect Cost Allocated to Fund A = Proportion of Fund A’s Expenses * Total Indirect Costs Indirect
Cost Allocated to Fund A = 0.25 * 5,000IndirectCostAllocatedtoF undA =1,250
Therefore, 1,250ofindirectcostsshouldbeallocatedtoF undA.
8. Question: A non-profit organization receives a donation of 10,000thatisrestrictedtobeusedforaspecif icprogram.T heorganizationincursexpensesof6,000
directly related to this program. How much is the remaining balance of the restricted fund for this program?
Solution: The remaining balance of the restricted fund for the specific program can be found by sub-
tracting the expenses incurred from the total donation amount.
Remaining Balance = Total Donation - Program Expenses Remaining Balance = 10,000−6,000 Re-
maining Balance = 4,000
Therefore, the remaining balance of the restricted fund for this program is 4,000.
9. Question: A non-profit organization receives a donation of 10,000specif icallydesignatedforabuildingrenovationproject.Duringthecurrentfiscalyear, theorganizationuses5,000
of the donation for the project. At the end of the fiscal year, what are the balances of the temporarily re-
stricted fund and the amount available for general use in the unrestricted fund?
Solution: 1. Temporary Restricted Fund Balance: - Initial donation: 10,000−Amountusedf ortheproject :5,000
- Balance of temporarily restricted fund = Initial donation - Amount used - Balance of temporarily restricted
fund = 10,000−5,000 - Balance of temporarily restricted fund = 5,000
2. Unrestricted Fund Balance: - Any part of the donation not used for the project remains in the tem-
porarily restricted fund. - Amount available for general use in the unrestricted fund = Initial donation -
Amount in temporarily restricted for the project - Amount available for general use in the unrestricted fund
=10,000−5,000 - Amount available for general use in the unrestricted fund = 5,000
Therefore, at the end of the fiscal year, the balance of the temporarily restricted fund is 5,000, andtheamountavailableforgeneraluseintheunrestrictedfundisalso5,000.
10. Question: A non-profit organization incurred total operating expenses of 50,000.F romthatamount,12,000
expenses were incurred specifically for the education fund, 8,000forthehealthcaref und, andtheremainingexpensesweregeneraloperatingexpenses.W hatpercentageof thetotaloperatingexpenseswereallocatedtotheeducationf und?
Solution: To find the percentage of total operating expenses allocated to the education fund, we first
need to calculate the total specific allocations for the education fund:
Total specific allocation for education fund = 12,000
Then, we calculate the total operating expenses allocated to the education fund:

Total operating expenses allocated to the education fund = Total specific allocation for education fund +
General operating expenses Total operating expenses allocated to the education fund = 12,000 + (50,000 -
12,000−8,000) Total operating expenses allocated to the education fund = 12,000+30,000 Total operating
expenses allocated to the education fund = 42,000
Finally, we calculate the percentage of total operating expenses allocated to the education fund:
Percentage allocated to education fund = (Total operating expenses allocated to education fund / To-
tal operating expenses) * 100Percentage allocated to education fund = (42,000/50,000) * 100Percentage
allocated to education fund = 0.84 * 100Percentage allocated to education fund = 84
Therefore, 84
11. Question: A non-profit organization receives a donation of 10,000restrictedforaspecif icpurpose.T heorganizationspends4,000
on the designated program and incurs 1,500infundraisingexpensesrelatedtothesameprogram.Howmuchoftherestrictedfundsarestillavailableforthedesignatedpurpose?
Solution: Initially, the organization received 10,000asarestricteddonation.Af terspending4,000 on
the designated program, the remaining amount is 10,000−4,000 = 6,000.However, theyalsoincurred1,500
in fundraising expenses related to the designated program. This amount needs to be subtracted from the re-
maining funds. Therefore, the total amount available for the designated purpose is 6,000−1,500 = 4,500.
Final Answer: 4,500
12. Question: A non-profit organization received a grant of 50,000thatisrestrictedforaspecif icprogram.Duringthefiscalyear, theorganizationspent20,000
on the program. Calculate the amount of restricted funds remaining at the end of the fiscal year.
Solution: Restricted funds remaining = Grant amount - Expenditure on the program Restricted funds
remaining = 50,000−20,000 Restricted funds remaining = 30,000
Therefore, the amount of restricted funds remaining at the end of the fiscal year is 30,000.
13. Question: A non-profit organization has total expenses of 100,000, anditincurred20,000 in fundrais-
ing expenses, 30,000inprogramAexpenses, and25,000 in program B expenses. Calculate the percentage
of total expenses allocated to program A.
Solution: To calculate the percentage of total expenses allocated to program A, we need to first find the
total expenses allocated to program A.
Total expenses allocated to program A = fundraising expenses + program A expenses Total expenses
allocated to program A = 20,000+30,000 Total expenses allocated to program A = 50,000
Now, we can calculate the percentage of total expenses allocated to program A by dividing the total
expenses allocated to program A by the total expenses and multiplying by 100.
Percentage of total expenses allocated to program A = (Total expenses allocated to program A / Total
expenses) * 100 Percentage of total expenses allocated to program A = (50,000/100,000) * 100 Percentage
of total expenses allocated to program A = 0.5 * 100 Percentage of total expenses allocated to program A =
50
Therefore, 50
14. Question: A non-profit organization has total funds of 100,000.40
Solution: Total funds = 100,000Restrictedfunds = 40Unrestrictedfunds =T otalfunds−RestrictedfundsUnrestrictedfunds =100,000
-40,000Unrestrictedfunds =60,000
Therefore, 60,000isallocatedtotheunrestrictedaccount.
15. Question: In a non-profit organization, if the total indirect costs amount to 50,000andaretobeallocatedtotwodifferentprogramsbasedonthedirectcostsincurredbyeachprogram, withP rogramAhavingdirectcostsof30,000
and Program B having direct costs of 20,000, whatistheallocationof indirectcostsf orP rogramA?
Solution: To allocate the indirect costs to each program based on their direct costs, we need to find the
proportion of each program’s direct costs to the total direct costs of both programs.

Total direct costs = Direct costs of Program A + Direct costs of Program B Total direct costs = 30,000+20,000
Total direct costs = 50,000
Now, find the proportion of direct costs for Program A: Proportion of direct costs for Program A =
Direct costs of Program A / Total direct costs Proportion of direct costs for Program A = 30,000/50,000
Proportion of direct costs for Program A = 0.6 or 60
Next, allocate the total indirect costs based on the proportion of direct costs for Program A: Indirect
costs allocated to Program A = Proportion of direct costs for Program A * Total indirect costs Indirect costs
allocated to Program A = 0.6 * 50,000IndirectcostsallocatedtoP rogramA =30,000
Therefore, the allocation of indirect costs for Program A would be 30,000.
16. Question: A non-profit organization receives a grant of 10,000specif icallydesignatedf oraspecialprogram.T heorganizationincurs2,000
in administrative expenses that benefit multiple programs, including the special program funded by the grant.
How much of the administrative expenses should be allocated to the special program using a proportional
allocation method based on the grant amount?
Solution: 1. Calculate the percentage of the grant amount relative to the total funds received: Grant
Percentage = (Grant Amount / Total Funds Received) * 100 = (10,000/10,000) * 100 = 100
2. Allocate the administrative expenses to the special program based on the grant percentage: Adminis-
trative Expenses Allocated = Grant Percentage * Total Administrative Expenses = 100= 1.00 * 2,000 =2,000
Therefore, using the proportional allocation method based on the grant amount, 2,000oftheadministrativeexpensesshouldbeallocatedtothespecialprogram.
17. Question: A non-profit organization incurred total administrative costs of 50,000f ortheyear.Ofthisamount,10,000
relates to a program funded by restricted funds. How much of the administrative costs should be allocated
to the restricted funds?
Solution: To determine the allocation of costs to restricted funds, we need to calculate the proportion of
administrative costs that relate to the program funded by restricted funds.
Proportion of administrative costs allocated to restricted funds = (Costs related to restricted funds / Total
administrative costs) Proportion of administrative costs allocated to restricted funds = (10,000/50,000) =
0.2 or 20
Now, we can calculate the specific amount of administrative costs that should be allocated to the re-
stricted funds:
Administrative costs allocated to restricted funds = Proportion of administrative costs allocated to re-
stricted funds * Total administrative costs Administrative costs allocated to restricted funds = 0.2 * 50,000 =10,000
Therefore, 10,000ofthetotaladministrativecostsshouldbeallocatedtotheprogramfundedbyrestrictedfunds.
18. Question: A non-profit organization has total restricted funds of 50,000.If40
Solution: To find the amount allocated to the specific project, we need to calculate 40
Amount allocated to project = 40Amount allocated to project = 0.40 * 50,000Amountallocatedtoproject =20,000
Therefore, 20,000isallocatedtothespecificprojectwithinthenon −profitorganization.
19. Question: A non-profit organization has total funds of 500,000, ofwhich100,000 is restricted for a
specific program. If the organization spends 30,000ontherestrictedprogram, whatistheremainingbalanceintherestrictedfund?
Solution: 1. Total funds = 500,0002.Restrictedfunds =100,000 3. Amount spent on restricted pro-
gram = 30,000
To find the remaining balance in the restricted fund after spending on the program, we subtract the
amount spent from the initial restricted funds:
Remaining balance = Restricted funds - Amount spent Remaining balance = 100,000−30,000 Remain-
ing balance = 70,000
Therefore, the remaining balance in the restricted fund is 70,000.

20. Question: A non-profit organization has total funds of 500,000.Outofthisamount,150,000 is
classified as restricted funds and the rest as unrestricted funds. What is the percentage of the organization’s
total funds that are classified as restricted funds?
Solution: To find the percentage of restricted funds out of the total funds, we first need to calculate the
proportion of restricted funds to total funds.
Restricted funds / Total funds = 150,000/500,000 = 0.3
Now, to convert this proportion to a percentage, we multiply by 100.
Percentage of restricted funds = 0.3 * 100 = 30
Therefore, 30
21. Question: A non-profit organization receives a donation of 10,000thatisrestrictedforaspecif icprogram.If theorganizationspends5,000
from this restricted donation on the program, how much remains in the restricted fund?
Solution: To determine how much remains in the restricted fund after spending 5,000ontheprogram, wesimplysubtracttheamountspentfromtheinitialrestricteddonation.
Initial restricted donation = 10,000Amountspentontheprogram =5,000
Remaining amount in the restricted fund = 10,000−5,000 = 5,000
Therefore, the remaining amount in the restricted fund is 5,000.
22. Question: A non-profit organization has a total of 50,000infunds.T heyallocate40
Solution: To find the amount allocated to the restricted account, we first calculate 4050,000∗0.40 =20,000
Therefore, 20,000isallocatedtotherestrictedaccount.
23. Question: A non-profit organization has total funds of 100,000.40
Solution: 1. Calculate the current amount of funds in the restricted account: Restricted funds = Total
funds * Percentage restricted Restricted funds = 100,000 ∗40
2. Since the organization needs to allocate an additional 30,000totherestrictedfunds, thenewamountintherestrictedaccountwillbe :
Newrestrictedfunds =40,000 + 30,000 =70,000
3. To find the new amount in the unrestricted funds, simply subtract the new amount in the restricted
funds from the total funds: New unrestricted funds = Total funds - New restricted funds New unrestricted
funds = 100,000−70,000 New unrestricted funds = 30,000
Therefore, the new amount in the unrestricted funds will be 30,000.
24. Question: A non-profit organization has total unrestricted net assets of 100,000andtotalrestrictednetassetsof50,000.
If the organization designates 20,000fromtheunrestrictednetassetstoanewdonor−restrictedfund, whatwillbethenewbalanceofunrestrictednetassets?
Solution: Total Unrestricted Net Assets = 100,000T otalRestrictedN etAssets =50,000 Amount des-
ignated to new donor-restricted fund from Unrestricted Net Assets = 20,000
New Unrestricted Net Assets = Total Unrestricted Net Assets - Amount designated to new fund New
Unrestricted Net Assets = 100,000−20,000 New Unrestricted Net Assets = 80,000
Therefore, the new balance of unrestricted net assets after designating 20,000toanewdonor−restrictedfundwouldbe80,000.
25. Question: A non-profit organization has three funds: Fund A, Fund B, and Fund C. Fund A
incurred 10,000inexpensesthatwereallocabletoallthreef unds, F undBincurred5,000 in expenses that
were specific to Fund B only, and Fund C incurred 8,000inexpensesthatwereallocabletoF undAandF undC.If theorganizationwantstoallocatetheexpensesproportionallybasedonthetotalrevenueofeachfund, andthetotalrevenueforF undA, F undB, andF undCis100,000,
50,000, and80,000 respectively, what would be the total amount of expenses allocated to Fund A?
Solution: 1. Calculate the total revenue for all funds: 100,000(F undA)+50,000 (Fund B) + 80,000(F undC) =230,000
2. Calculate the proportion of total revenue for each fund: - Fund A: 100,000/230,000 = 0.4348 - Fund B:
50,000/230,000 = 0.2174 - Fund C: 80,000/230,000 = 0.3478 3. Allocate the shared expenses to each fund
proportionally: - Fund A: 10,000 ∗0.4348 =4,348 - Fund B: 10,000 ∗0.2174 =2,174 - Fund C: 10,000 ∗

0.3478 =3,478 4. Allocate Fund B’s expenses to Fund B: 5,0005.AllocateF undC′sexpensestoF undAandF undCproportionally :
−F undA :8,000 * 0.4348 = 3,478 −F undC :8,000 * 0.3478 = 2,784
Total expenses allocated to Fund A = 4,348(sharedexpenses)+3,478 (expenses from Fund C) = 7,826
indirect costs * Restricted funds share of indirect costs = 20,000 ∗30
Now, the remaining indirect costs will be allocated to the unrestricted funds. Unrestricted funds share
of indirect costs = Total indirect costs - Restricted funds share of indirect costs Unrestricted funds share of
indirect costs = 20,000−6,000 = 14,000
Therefore, the amount of the indirect costs allocated to the unrestricted funds is 14,000.
7. Question: A non-profit organization has three separate funds: Fund A, Fund B, and Fund C. Fund
A incurred expenses of 10,000, F undBincurredexpensesof 15,000, and Fund C incurred expenses of
20,000.T heorganization′stotalindirectcostsf ortheyearare5,000. If the organization wants to allocate
indirect costs based on the proportion of expenses in each fund, how much indirect cost should be allocated
to Fund A?
Solution: To allocate indirect costs based on the proportion of expenses in each fund, we need to calcu-
late the total expenses across all funds first.
Total Expenses = 10,000(F undA)+15,000 (Fund B) + 20,000(F undC)T otalExpenses =45,000
Next, we calculate the proportion of expenses for each fund:
Proportion of Fund A’s Expenses = Fund A’s Expenses / Total Expenses Proportion of Fund A’s Expenses
=10,000/45,000 Proportion of Fund A’s Expenses = 1/4 or 0.25
Now, we allocate the total indirect costs to Fund A based on its proportion of expenses:
Indirect Cost Allocated to Fund A = Proportion of Fund A’s Expenses * Total Indirect Costs Indirect
Cost Allocated to Fund A = 0.25 * 5,000IndirectCostAllocatedtoF undA =1,250
Therefore, 1,250ofindirectcostsshouldbeallocatedtoF undA.
8. Question: A non-profit organization receives a donation of 10,000thatisrestrictedtobeusedforaspecif icprogram.T heorganizationincursexpensesof6,000
directly related to this program. How much is the remaining balance of the restricted fund for this program?
Solution: The remaining balance of the restricted fund for the specific program can be found by sub-
tracting the expenses incurred from the total donation amount.
Remaining Balance = Total Donation - Program Expenses Remaining Balance = 10,000−6,000 Re-
maining Balance = 4,000
Therefore, the remaining balance of the restricted fund for this program is 4,000.
9. Question: A non-profit organization receives a donation of 10,000specif icallydesignatedforabuildingrenovationproject.Duringthecurrentfiscalyear, theorganizationuses5,000
of the donation for the project. At the end of the fiscal year, what are the balances of the temporarily re-
stricted fund and the amount available for general use in the unrestricted fund?
Solution: 1. Temporary Restricted Fund Balance: - Initial donation: 10,000−Amountusedf ortheproject :5,000
- Balance of temporarily restricted fund = Initial donation - Amount used - Balance of temporarily restricted
fund = 10,000−5,000 - Balance of temporarily restricted fund = 5,000
2. Unrestricted Fund Balance: - Any part of the donation not used for the project remains in the tem-
porarily restricted fund. - Amount available for general use in the unrestricted fund = Initial donation -
Amount in temporarily restricted for the project - Amount available for general use in the unrestricted fund
=10,000−5,000 - Amount available for general use in the unrestricted fund = 5,000
Therefore, at the end of the fiscal year, the balance of the temporarily restricted fund is 5,000, andtheamountavailableforgeneraluseintheunrestrictedfundisalso5,000.
10. Question: A non-profit organization incurred total operating expenses of 50,000.F romthatamount,12,000
expenses were incurred specifically for the education fund, 8,000forthehealthcaref und, andtheremainingexpensesweregeneraloperatingexpenses.W hatpercentageof thetotaloperatingexpenseswereallocatedtotheeducationf und?
Solution: To find the percentage of total operating expenses allocated to the education fund, we first
need to calculate the total specific allocations for the education fund:
Total specific allocation for education fund = 12,000
Then, we calculate the total operating expenses allocated to the education fund:

Total operating expenses allocated to the education fund = Total specific allocation for education fund +
General operating expenses Total operating expenses allocated to the education fund = 12,000 + (50,000 -
12,000−8,000) Total operating expenses allocated to the education fund = 12,000+30,000 Total operating
expenses allocated to the education fund = 42,000
Finally, we calculate the percentage of total operating expenses allocated to the education fund:
Percentage allocated to education fund = (Total operating expenses allocated to education fund / To-
tal operating expenses) * 100Percentage allocated to education fund = (42,000/50,000) * 100Percentage
allocated to education fund = 0.84 * 100Percentage allocated to education fund = 84
Therefore, 84
11. Question: A non-profit organization receives a donation of 10,000restrictedforaspecif icpurpose.T heorganizationspends4,000
on the designated program and incurs 1,500infundraisingexpensesrelatedtothesameprogram.Howmuchoftherestrictedfundsarestillavailableforthedesignatedpurpose?
Solution: Initially, the organization received 10,000asarestricteddonation.Af terspending4,000 on
the designated program, the remaining amount is 10,000−4,000 = 6,000.However, theyalsoincurred1,500
in fundraising expenses related to the designated program. This amount needs to be subtracted from the re-
maining funds. Therefore, the total amount available for the designated purpose is 6,000−1,500 = 4,500.
Final Answer: 4,500
12. Question: A non-profit organization received a grant of 50,000thatisrestrictedforaspecif icprogram.Duringthefiscalyear, theorganizationspent20,000
on the program. Calculate the amount of restricted funds remaining at the end of the fiscal year.
Solution: Restricted funds remaining = Grant amount - Expenditure on the program Restricted funds
remaining = 50,000−20,000 Restricted funds remaining = 30,000
Therefore, the amount of restricted funds remaining at the end of the fiscal year is 30,000.
13. Question: A non-profit organization has total expenses of 100,000, anditincurred20,000 in fundrais-
ing expenses, 30,000inprogramAexpenses, and25,000 in program B expenses. Calculate the percentage
of total expenses allocated to program A.
Solution: To calculate the percentage of total expenses allocated to program A, we need to first find the
total expenses allocated to program A.
Total expenses allocated to program A = fundraising expenses + program A expenses Total expenses
allocated to program A = 20,000+30,000 Total expenses allocated to program A = 50,000
Now, we can calculate the percentage of total expenses allocated to program A by dividing the total
expenses allocated to program A by the total expenses and multiplying by 100.
Percentage of total expenses allocated to program A = (Total expenses allocated to program A / Total
expenses) * 100 Percentage of total expenses allocated to program A = (50,000/100,000) * 100 Percentage
of total expenses allocated to program A = 0.5 * 100 Percentage of total expenses allocated to program A =
50
Therefore, 50
14. Question: A non-profit organization has total funds of 100,000.40
Solution: Total funds = 100,000Restrictedfunds = 40Unrestrictedfunds =T otalfunds−RestrictedfundsUnrestrictedfunds =100,000
-40,000Unrestrictedfunds =60,000
Therefore, 60,000isallocatedtotheunrestrictedaccount.
15. Question: In a non-profit organization, if the total indirect costs amount to 50,000andaretobeallocatedtotwodifferentprogramsbasedonthedirectcostsincurredbyeachprogram, withP rogramAhavingdirectcostsof30,000
and Program B having direct costs of 20,000, whatistheallocationof indirectcostsf orP rogramA?
Solution: To allocate the indirect costs to each program based on their direct costs, we need to find the
proportion of each program’s direct costs to the total direct costs of both programs.

Total direct costs = Direct costs of Program A + Direct costs of Program B Total direct costs = 30,000+20,000
Total direct costs = 50,000
Now, find the proportion of direct costs for Program A: Proportion of direct costs for Program A =
Direct costs of Program A / Total direct costs Proportion of direct costs for Program A = 30,000/50,000
Proportion of direct costs for Program A = 0.6 or 60
Next, allocate the total indirect costs based on the proportion of direct costs for Program A: Indirect
costs allocated to Program A = Proportion of direct costs for Program A * Total indirect costs Indirect costs
allocated to Program A = 0.6 * 50,000IndirectcostsallocatedtoP rogramA =30,000
Therefore, the allocation of indirect costs for Program A would be 30,000.
16. Question: A non-profit organization receives a grant of 10,000specif icallydesignatedf oraspecialprogram.T heorganizationincurs2,000
in administrative expenses that benefit multiple programs, including the special program funded by the grant.
How much of the administrative expenses should be allocated to the special program using a proportional
allocation method based on the grant amount?
Solution: 1. Calculate the percentage of the grant amount relative to the total funds received: Grant
Percentage = (Grant Amount / Total Funds Received) * 100 = (10,000/10,000) * 100 = 100
2. Allocate the administrative expenses to the special program based on the grant percentage: Adminis-
trative Expenses Allocated = Grant Percentage * Total Administrative Expenses = 100= 1.00 * 2,000 =2,000
Therefore, using the proportional allocation method based on the grant amount, 2,000oftheadministrativeexpensesshouldbeallocatedtothespecialprogram.
17. Question: A non-profit organization incurred total administrative costs of 50,000f ortheyear.Ofthisamount,10,000
relates to a program funded by restricted funds. How much of the administrative costs should be allocated
to the restricted funds?
Solution: To determine the allocation of costs to restricted funds, we need to calculate the proportion of
administrative costs that relate to the program funded by restricted funds.
Proportion of administrative costs allocated to restricted funds = (Costs related to restricted funds / Total
administrative costs) Proportion of administrative costs allocated to restricted funds = (10,000/50,000) =
0.2 or 20
Now, we can calculate the specific amount of administrative costs that should be allocated to the re-
stricted funds:
Administrative costs allocated to restricted funds = Proportion of administrative costs allocated to re-
stricted funds * Total administrative costs Administrative costs allocated to restricted funds = 0.2 * 50,000 =10,000
Therefore, 10,000ofthetotaladministrativecostsshouldbeallocatedtotheprogramfundedbyrestrictedfunds.
18. Question: A non-profit organization has total restricted funds of 50,000.If40
Solution: To find the amount allocated to the specific project, we need to calculate 40
Amount allocated to project = 40Amount allocated to project = 0.40 * 50,000Amountallocatedtoproject =20,000
Therefore, 20,000isallocatedtothespecificprojectwithinthenon −profitorganization.
19. Question: A non-profit organization has total funds of 500,000, ofwhich100,000 is restricted for a
specific program. If the organization spends 30,000ontherestrictedprogram, whatistheremainingbalanceintherestrictedfund?
Solution: 1. Total funds = 500,0002.Restrictedfunds =100,000 3. Amount spent on restricted pro-
gram = 30,000
To find the remaining balance in the restricted fund after spending on the program, we subtract the
amount spent from the initial restricted funds:
Remaining balance = Restricted funds - Amount spent Remaining balance = 100,000−30,000 Remain-
ing balance = 70,000
Therefore, the remaining balance in the restricted fund is 70,000.

20. Question: A non-profit organization has total funds of 500,000.Outofthisamount,150,000 is
classified as restricted funds and the rest as unrestricted funds. What is the percentage of the organization’s
total funds that are classified as restricted funds?
Solution: To find the percentage of restricted funds out of the total funds, we first need to calculate the
proportion of restricted funds to total funds.
Restricted funds / Total funds = 150,000/500,000 = 0.3
Now, to convert this proportion to a percentage, we multiply by 100.
Percentage of restricted funds = 0.3 * 100 = 30
Therefore, 30
21. Question: A non-profit organization receives a donation of 10,000thatisrestrictedforaspecif icprogram.If theorganizationspends5,000
from this restricted donation on the program, how much remains in the restricted fund?
Solution: To determine how much remains in the restricted fund after spending 5,000ontheprogram, wesimplysubtracttheamountspentfromtheinitialrestricteddonation.
Initial restricted donation = 10,000Amountspentontheprogram =5,000
Remaining amount in the restricted fund = 10,000−5,000 = 5,000
Therefore, the remaining amount in the restricted fund is 5,000.
22. Question: A non-profit organization has a total of 50,000infunds.T heyallocate40
Solution: To find the amount allocated to the restricted account, we first calculate 4050,000∗0.40 =20,000
Therefore, 20,000isallocatedtotherestrictedaccount.
23. Question: A non-profit organization has total funds of 100,000.40
Solution: 1. Calculate the current amount of funds in the restricted account: Restricted funds = Total
funds * Percentage restricted Restricted funds = 100,000 ∗40
2. Since the organization needs to allocate an additional 30,000totherestrictedfunds, thenewamountintherestrictedaccountwillbe :
Newrestrictedfunds =40,000 + 30,000 =70,000
3. To find the new amount in the unrestricted funds, simply subtract the new amount in the restricted
funds from the total funds: New unrestricted funds = Total funds - New restricted funds New unrestricted
funds = 100,000−70,000 New unrestricted funds = 30,000
Therefore, the new amount in the unrestricted funds will be 30,000.
24. Question: A non-profit organization has total unrestricted net assets of 100,000andtotalrestrictednetassetsof50,000.
If the organization designates 20,000fromtheunrestrictednetassetstoanewdonor−restrictedfund, whatwillbethenewbalanceofunrestrictednetassets?
Solution: Total Unrestricted Net Assets = 100,000T otalRestrictedN etAssets =50,000 Amount des-
ignated to new donor-restricted fund from Unrestricted Net Assets = 20,000
New Unrestricted Net Assets = Total Unrestricted Net Assets - Amount designated to new fund New
Unrestricted Net Assets = 100,000−20,000 New Unrestricted Net Assets = 80,000
Therefore, the new balance of unrestricted net assets after designating 20,000toanewdonor−restrictedfundwouldbe80,000.
25. Question: A non-profit organization has three funds: Fund A, Fund B, and Fund C. Fund A
incurred 10,000inexpensesthatwereallocabletoallthreef unds, F undBincurred5,000 in expenses that
were specific to Fund B only, and Fund C incurred 8,000inexpensesthatwereallocabletoF undAandF undC.If theorganizationwantstoallocatetheexpensesproportionallybasedonthetotalrevenueofeachfund, andthetotalrevenueforF undA, F undB, andF undCis100,000,
50,000, and80,000 respectively, what would be the total amount of expenses allocated to Fund A?
Solution: 1. Calculate the total revenue for all funds: 100,000(F undA)+50,000 (Fund B) + 80,000(F undC) =230,000
2. Calculate the proportion of total revenue for each fund: - Fund A: 100,000/230,000 = 0.4348 - Fund B:
50,000/230,000 = 0.2174 - Fund C: 80,000/230,000 = 0.3478 3. Allocate the shared expenses to each fund
proportionally: - Fund A: 10,000 ∗0.4348 =4,348 - Fund B: 10,000 ∗0.2174 =2,174 - Fund C: 10,000 ∗

0.3478 =3,478 4. Allocate Fund B’s expenses to Fund B: 5,0005.AllocateF undC′sexpensestoF undAandF undCproportionally :
−F undA :8,000 * 0.4348 = 3,478 −F undC :8,000 * 0.3478 = 2,784
Total expenses allocated to Fund A = 4,348(sharedexpenses)+3,478 (expenses from Fund C) = 7,826
indirect costs * Restricted funds share of indirect costs = 20,000 ∗30
Now, the remaining indirect costs will be allocated to the unrestricted funds. Unrestricted funds share
of indirect costs = Total indirect costs - Restricted funds share of indirect costs Unrestricted funds share of
indirect costs = 20,000−6,000 = 14,000
Therefore, the amount of the indirect costs allocated to the unrestricted funds is 14,000.
7. Question: A non-profit organization has three separate funds: Fund A, Fund B, and Fund C. Fund
A incurred expenses of 10,000, F undBincurredexpensesof 15,000, and Fund C incurred expenses of
20,000.T heorganization′stotalindirectcostsf ortheyearare5,000. If the organization wants to allocate
indirect costs based on the proportion of expenses in each fund, how much indirect cost should be allocated
to Fund A?
Solution: To allocate indirect costs based on the proportion of expenses in each fund, we need to calcu-
late the total expenses across all funds first.
Total Expenses = 10,000(F undA)+15,000 (Fund B) + 20,000(F undC)T otalExpenses =45,000
Next, we calculate the proportion of expenses for each fund:
Proportion of Fund A’s Expenses = Fund A’s Expenses / Total Expenses Proportion of Fund A’s Expenses
=10,000/45,000 Proportion of Fund A’s Expenses = 1/4 or 0.25
Now, we allocate the total indirect costs to Fund A based on its proportion of expenses:
Indirect Cost Allocated to Fund A = Proportion of Fund A’s Expenses * Total Indirect Costs Indirect
Cost Allocated to Fund A = 0.25 * 5,000IndirectCostAllocatedtoF undA =1,250
Therefore, 1,250ofindirectcostsshouldbeallocatedtoF undA.
8. Question: A non-profit organization receives a donation of 10,000thatisrestrictedtobeusedforaspecif icprogram.T heorganizationincursexpensesof6,000
directly related to this program. How much is the remaining balance of the restricted fund for this program?
Solution: The remaining balance of the restricted fund for the specific program can be found by sub-
tracting the expenses incurred from the total donation amount.
Remaining Balance = Total Donation - Program Expenses Remaining Balance = 10,000−6,000 Re-
maining Balance = 4,000
Therefore, the remaining balance of the restricted fund for this program is 4,000.
9. Question: A non-profit organization receives a donation of 10,000specif icallydesignatedforabuildingrenovationproject.Duringthecurrentfiscalyear, theorganizationuses5,000
of the donation for the project. At the end of the fiscal year, what are the balances of the temporarily re-
stricted fund and the amount available for general use in the unrestricted fund?
Solution: 1. Temporary Restricted Fund Balance: - Initial donation: 10,000−Amountusedf ortheproject :5,000
- Balance of temporarily restricted fund = Initial donation - Amount used - Balance of temporarily restricted
fund = 10,000−5,000 - Balance of temporarily restricted fund = 5,000
2. Unrestricted Fund Balance: - Any part of the donation not used for the project remains in the tem-
porarily restricted fund. - Amount available for general use in the unrestricted fund = Initial donation -
Amount in temporarily restricted for the project - Amount available for general use in the unrestricted fund
=10,000−5,000 - Amount available for general use in the unrestricted fund = 5,000
Therefore, at the end of the fiscal year, the balance of the temporarily restricted fund is 5,000, andtheamountavailableforgeneraluseintheunrestrictedfundisalso5,000.
10. Question: A non-profit organization incurred total operating expenses of 50,000.F romthatamount,12,000
expenses were incurred specifically for the education fund, 8,000forthehealthcaref und, andtheremainingexpensesweregeneraloperatingexpenses.W hatpercentageof thetotaloperatingexpenseswereallocatedtotheeducationf und?
Solution: To find the percentage of total operating expenses allocated to the education fund, we first
need to calculate the total specific allocations for the education fund:
Total specific allocation for education fund = 12,000
Then, we calculate the total operating expenses allocated to the education fund:

Total operating expenses allocated to the education fund = Total specific allocation for education fund +
General operating expenses Total operating expenses allocated to the education fund = 12,000 + (50,000 -
12,000−8,000) Total operating expenses allocated to the education fund = 12,000+30,000 Total operating
expenses allocated to the education fund = 42,000
Finally, we calculate the percentage of total operating expenses allocated to the education fund:
Percentage allocated to education fund = (Total operating expenses allocated to education fund / To-
tal operating expenses) * 100Percentage allocated to education fund = (42,000/50,000) * 100Percentage
allocated to education fund = 0.84 * 100Percentage allocated to education fund = 84
Therefore, 84
11. Question: A non-profit organization receives a donation of 10,000restrictedforaspecif icpurpose.T heorganizationspends4,000
on the designated program and incurs 1,500infundraisingexpensesrelatedtothesameprogram.Howmuchoftherestrictedfundsarestillavailableforthedesignatedpurpose?
Solution: Initially, the organization received 10,000asarestricteddonation.Af terspending4,000 on
the designated program, the remaining amount is 10,000−4,000 = 6,000.However, theyalsoincurred1,500
in fundraising expenses related to the designated program. This amount needs to be subtracted from the re-
maining funds. Therefore, the total amount available for the designated purpose is 6,000−1,500 = 4,500.
Final Answer: 4,500
12. Question: A non-profit organization received a grant of 50,000thatisrestrictedforaspecif icprogram.Duringthefiscalyear, theorganizationspent20,000
on the program. Calculate the amount of restricted funds remaining at the end of the fiscal year.
Solution: Restricted funds remaining = Grant amount - Expenditure on the program Restricted funds
remaining = 50,000−20,000 Restricted funds remaining = 30,000
Therefore, the amount of restricted funds remaining at the end of the fiscal year is 30,000.
13. Question: A non-profit organization has total expenses of 100,000, anditincurred20,000 in fundrais-
ing expenses, 30,000inprogramAexpenses, and25,000 in program B expenses. Calculate the percentage
of total expenses allocated to program A.
Solution: To calculate the percentage of total expenses allocated to program A, we need to first find the
total expenses allocated to program A.
Total expenses allocated to program A = fundraising expenses + program A expenses Total expenses
allocated to program A = 20,000+30,000 Total expenses allocated to program A = 50,000
Now, we can calculate the percentage of total expenses allocated to program A by dividing the total
expenses allocated to program A by the total expenses and multiplying by 100.
Percentage of total expenses allocated to program A = (Total expenses allocated to program A / Total
expenses) * 100 Percentage of total expenses allocated to program A = (50,000/100,000) * 100 Percentage
of total expenses allocated to program A = 0.5 * 100 Percentage of total expenses allocated to program A =
50
Therefore, 50
14. Question: A non-profit organization has total funds of 100,000.40
Solution: Total funds = 100,000Restrictedfunds = 40Unrestrictedfunds =T otalfunds−RestrictedfundsUnrestrictedfunds =100,000
-40,000Unrestrictedfunds =60,000
Therefore, 60,000isallocatedtotheunrestrictedaccount.
15. Question: In a non-profit organization, if the total indirect costs amount to 50,000andaretobeallocatedtotwodifferentprogramsbasedonthedirectcostsincurredbyeachprogram, withP rogramAhavingdirectcostsof30,000
and Program B having direct costs of 20,000, whatistheallocationof indirectcostsf orP rogramA?
Solution: To allocate the indirect costs to each program based on their direct costs, we need to find the
proportion of each program’s direct costs to the total direct costs of both programs.

Total direct costs = Direct costs of Program A + Direct costs of Program B Total direct costs = 30,000+20,000
Total direct costs = 50,000
Now, find the proportion of direct costs for Program A: Proportion of direct costs for Program A =
Direct costs of Program A / Total direct costs Proportion of direct costs for Program A = 30,000/50,000
Proportion of direct costs for Program A = 0.6 or 60
Next, allocate the total indirect costs based on the proportion of direct costs for Program A: Indirect
costs allocated to Program A = Proportion of direct costs for Program A * Total indirect costs Indirect costs
allocated to Program A = 0.6 * 50,000IndirectcostsallocatedtoP rogramA =30,000
Therefore, the allocation of indirect costs for Program A would be 30,000.
16. Question: A non-profit organization receives a grant of 10,000specif icallydesignatedf oraspecialprogram.T heorganizationincurs2,000
in administrative expenses that benefit multiple programs, including the special program funded by the grant.
How much of the administrative expenses should be allocated to the special program using a proportional
allocation method based on the grant amount?
Solution: 1. Calculate the percentage of the grant amount relative to the total funds received: Grant
Percentage = (Grant Amount / Total Funds Received) * 100 = (10,000/10,000) * 100 = 100
2. Allocate the administrative expenses to the special program based on the grant percentage: Adminis-
trative Expenses Allocated = Grant Percentage * Total Administrative Expenses = 100= 1.00 * 2,000 =2,000
Therefore, using the proportional allocation method based on the grant amount, 2,000oftheadministrativeexpensesshouldbeallocatedtothespecialprogram.
17. Question: A non-profit organization incurred total administrative costs of 50,000f ortheyear.Ofthisamount,10,000
relates to a program funded by restricted funds. How much of the administrative costs should be allocated
to the restricted funds?
Solution: To determine the allocation of costs to restricted funds, we need to calculate the proportion of
administrative costs that relate to the program funded by restricted funds.
Proportion of administrative costs allocated to restricted funds = (Costs related to restricted funds / Total
administrative costs) Proportion of administrative costs allocated to restricted funds = (10,000/50,000) =
0.2 or 20
Now, we can calculate the specific amount of administrative costs that should be allocated to the re-
stricted funds:
Administrative costs allocated to restricted funds = Proportion of administrative costs allocated to re-
stricted funds * Total administrative costs Administrative costs allocated to restricted funds = 0.2 * 50,000 =10,000
Therefore, 10,000ofthetotaladministrativecostsshouldbeallocatedtotheprogramfundedbyrestrictedfunds.
18. Question: A non-profit organization has total restricted funds of 50,000.If40
Solution: To find the amount allocated to the specific project, we need to calculate 40
Amount allocated to project = 40Amount allocated to project = 0.40 * 50,000Amountallocatedtoproject =20,000
Therefore, 20,000isallocatedtothespecificprojectwithinthenon −profitorganization.
19. Question: A non-profit organization has total funds of 500,000, ofwhich100,000 is restricted for a
specific program. If the organization spends 30,000ontherestrictedprogram, whatistheremainingbalanceintherestrictedfund?
Solution: 1. Total funds = 500,0002.Restrictedfunds =100,000 3. Amount spent on restricted pro-
gram = 30,000
To find the remaining balance in the restricted fund after spending on the program, we subtract the
amount spent from the initial restricted funds:
Remaining balance = Restricted funds - Amount spent Remaining balance = 100,000−30,000 Remain-
ing balance = 70,000
Therefore, the remaining balance in the restricted fund is 70,000.

20. Question: A non-profit organization has total funds of 500,000.Outofthisamount,150,000 is
classified as restricted funds and the rest as unrestricted funds. What is the percentage of the organization’s
total funds that are classified as restricted funds?
Solution: To find the percentage of restricted funds out of the total funds, we first need to calculate the
proportion of restricted funds to total funds.
Restricted funds / Total funds = 150,000/500,000 = 0.3
Now, to convert this proportion to a percentage, we multiply by 100.
Percentage of restricted funds = 0.3 * 100 = 30
Therefore, 30
21. Question: A non-profit organization receives a donation of 10,000thatisrestrictedforaspecif icprogram.If theorganizationspends5,000
from this restricted donation on the program, how much remains in the restricted fund?
Solution: To determine how much remains in the restricted fund after spending 5,000ontheprogram, wesimplysubtracttheamountspentfromtheinitialrestricteddonation.
Initial restricted donation = 10,000Amountspentontheprogram =5,000
Remaining amount in the restricted fund = 10,000−5,000 = 5,000
Therefore, the remaining amount in the restricted fund is 5,000.
22. Question: A non-profit organization has a total of 50,000infunds.T heyallocate40
Solution: To find the amount allocated to the restricted account, we first calculate 4050,000∗0.40 =20,000
Therefore, 20,000isallocatedtotherestrictedaccount.
23. Question: A non-profit organization has total funds of 100,000.40
Solution: 1. Calculate the current amount of funds in the restricted account: Restricted funds = Total
funds * Percentage restricted Restricted funds = 100,000 ∗40
2. Since the organization needs to allocate an additional 30,000totherestrictedfunds, thenewamountintherestrictedaccountwillbe :
Newrestrictedfunds =40,000 + 30,000 =70,000
3. To find the new amount in the unrestricted funds, simply subtract the new amount in the restricted
funds from the total funds: New unrestricted funds = Total funds - New restricted funds New unrestricted
funds = 100,000−70,000 New unrestricted funds = 30,000
Therefore, the new amount in the unrestricted funds will be 30,000.
24. Question: A non-profit organization has total unrestricted net assets of 100,000andtotalrestrictednetassetsof50,000.
If the organization designates 20,000fromtheunrestrictednetassetstoanewdonor−restrictedfund, whatwillbethenewbalanceofunrestrictednetassets?
Solution: Total Unrestricted Net Assets = 100,000T otalRestrictedN etAssets =50,000 Amount des-
ignated to new donor-restricted fund from Unrestricted Net Assets = 20,000
New Unrestricted Net Assets = Total Unrestricted Net Assets - Amount designated to new fund New
Unrestricted Net Assets = 100,000−20,000 New Unrestricted Net Assets = 80,000
Therefore, the new balance of unrestricted net assets after designating 20,000toanewdonor−restrictedfundwouldbe80,000.
25. Question: A non-profit organization has three funds: Fund A, Fund B, and Fund C. Fund A
incurred 10,000inexpensesthatwereallocabletoallthreef unds, F undBincurred5,000 in expenses that
were specific to Fund B only, and Fund C incurred 8,000inexpensesthatwereallocabletoF undAandF undC.If theorganizationwantstoallocatetheexpensesproportionallybasedonthetotalrevenueofeachfund, andthetotalrevenueforF undA, F undB, andF undCis100,000,
50,000, and80,000 respectively, what would be the total amount of expenses allocated to Fund A?
Solution: 1. Calculate the total revenue for all funds: 100,000(F undA)+50,000 (Fund B) + 80,000(F undC) =230,000
2. Calculate the proportion of total revenue for each fund: - Fund A: 100,000/230,000 = 0.4348 - Fund B:
50,000/230,000 = 0.2174 - Fund C: 80,000/230,000 = 0.3478 3. Allocate the shared expenses to each fund
proportionally: - Fund A: 10,000 ∗0.4348 =4,348 - Fund B: 10,000 ∗0.2174 =2,174 - Fund C: 10,000 ∗

0.3478 =3,478 4. Allocate Fund B’s expenses to Fund B: 5,0005.AllocateF undC′sexpensestoF undAandF undCproportionally :
−F undA :8,000 * 0.4348 = 3,478 −F undC :8,000 * 0.3478 = 2,784
Total expenses allocated to Fund A = 4,348(sharedexpenses)+3,478 (expenses from Fund C) = 7,826
indirect costs * Restricted funds share of indirect costs = 20,000 ∗30
Now, the remaining indirect costs will be allocated to the unrestricted funds. Unrestricted funds share
of indirect costs = Total indirect costs - Restricted funds share of indirect costs Unrestricted funds share of
indirect costs = 20,000−6,000 = 14,000
Therefore, the amount of the indirect costs allocated to the unrestricted funds is 14,000.
7. Question: A non-profit organization has three separate funds: Fund A, Fund B, and Fund C. Fund
A incurred expenses of 10,000, F undBincurredexpensesof 15,000, and Fund C incurred expenses of
20,000.T heorganization′stotalindirectcostsf ortheyearare5,000. If the organization wants to allocate
indirect costs based on the proportion of expenses in each fund, how much indirect cost should be allocated
to Fund A?
Solution: To allocate indirect costs based on the proportion of expenses in each fund, we need to calcu-
late the total expenses across all funds first.
Total Expenses = 10,000(F undA)+15,000 (Fund B) + 20,000(F undC)T otalExpenses =45,000
Next, we calculate the proportion of expenses for each fund:
Proportion of Fund A’s Expenses = Fund A’s Expenses / Total Expenses Proportion of Fund A’s Expenses
=10,000/45,000 Proportion of Fund A’s Expenses = 1/4 or 0.25
Now, we allocate the total indirect costs to Fund A based on its proportion of expenses:
Indirect Cost Allocated to Fund A = Proportion of Fund A’s Expenses * Total Indirect Costs Indirect
Cost Allocated to Fund A = 0.25 * 5,000IndirectCostAllocatedtoF undA =1,250
Therefore, 1,250ofindirectcostsshouldbeallocatedtoF undA.
8. Question: A non-profit organization receives a donation of 10,000thatisrestrictedtobeusedforaspecif icprogram.T heorganizationincursexpensesof6,000
directly related to this program. How much is the remaining balance of the restricted fund for this program?
Solution: The remaining balance of the restricted fund for the specific program can be found by sub-
tracting the expenses incurred from the total donation amount.
Remaining Balance = Total Donation - Program Expenses Remaining Balance = 10,000−6,000 Re-
maining Balance = 4,000
Therefore, the remaining balance of the restricted fund for this program is 4,000.
9. Question: A non-profit organization receives a donation of 10,000specif icallydesignatedforabuildingrenovationproject.Duringthecurrentfiscalyear, theorganizationuses5,000
of the donation for the project. At the end of the fiscal year, what are the balances of the temporarily re-
stricted fund and the amount available for general use in the unrestricted fund?
Solution: 1. Temporary Restricted Fund Balance: - Initial donation: 10,000−Amountusedf ortheproject :5,000
- Balance of temporarily restricted fund = Initial donation - Amount used - Balance of temporarily restricted
fund = 10,000−5,000 - Balance of temporarily restricted fund = 5,000
2. Unrestricted Fund Balance: - Any part of the donation not used for the project remains in the tem-
porarily restricted fund. - Amount available for general use in the unrestricted fund = Initial donation -
Amount in temporarily restricted for the project - Amount available for general use in the unrestricted fund
=10,000−5,000 - Amount available for general use in the unrestricted fund = 5,000
Therefore, at the end of the fiscal year, the balance of the temporarily restricted fund is 5,000, andtheamountavailableforgeneraluseintheunrestrictedfundisalso5,000.
10. Question: A non-profit organization incurred total operating expenses of 50,000.F romthatamount,12,000
expenses were incurred specifically for the education fund, 8,000forthehealthcaref und, andtheremainingexpensesweregeneraloperatingexpenses.W hatpercentageof thetotaloperatingexpenseswereallocatedtotheeducationf und?
Solution: To find the percentage of total operating expenses allocated to the education fund, we first
need to calculate the total specific allocations for the education fund:
Total specific allocation for education fund = 12,000
Then, we calculate the total operating expenses allocated to the education fund:

Total operating expenses allocated to the education fund = Total specific allocation for education fund +
General operating expenses Total operating expenses allocated to the education fund = 12,000 + (50,000 -
12,000−8,000) Total operating expenses allocated to the education fund = 12,000+30,000 Total operating
expenses allocated to the education fund = 42,000
Finally, we calculate the percentage of total operating expenses allocated to the education fund:
Percentage allocated to education fund = (Total operating expenses allocated to education fund / To-
tal operating expenses) * 100Percentage allocated to education fund = (42,000/50,000) * 100Percentage
allocated to education fund = 0.84 * 100Percentage allocated to education fund = 84
Therefore, 84
11. Question: A non-profit organization receives a donation of 10,000restrictedforaspecif icpurpose.T heorganizationspends4,000
on the designated program and incurs 1,500infundraisingexpensesrelatedtothesameprogram.Howmuchoftherestrictedfundsarestillavailableforthedesignatedpurpose?
Solution: Initially, the organization received 10,000asarestricteddonation.Af terspending4,000 on
the designated program, the remaining amount is 10,000−4,000 = 6,000.However, theyalsoincurred1,500
in fundraising expenses related to the designated program. This amount needs to be subtracted from the re-
maining funds. Therefore, the total amount available for the designated purpose is 6,000−1,500 = 4,500.
Final Answer: 4,500
12. Question: A non-profit organization received a grant of 50,000thatisrestrictedforaspecif icprogram.Duringthefiscalyear, theorganizationspent20,000
on the program. Calculate the amount of restricted funds remaining at the end of the fiscal year.
Solution: Restricted funds remaining = Grant amount - Expenditure on the program Restricted funds
remaining = 50,000−20,000 Restricted funds remaining = 30,000
Therefore, the amount of restricted funds remaining at the end of the fiscal year is 30,000.
13. Question: A non-profit organization has total expenses of 100,000, anditincurred20,000 in fundrais-
ing expenses, 30,000inprogramAexpenses, and25,000 in program B expenses. Calculate the percentage
of total expenses allocated to program A.
Solution: To calculate the percentage of total expenses allocated to program A, we need to first find the
total expenses allocated to program A.
Total expenses allocated to program A = fundraising expenses + program A expenses Total expenses
allocated to program A = 20,000+30,000 Total expenses allocated to program A = 50,000
Now, we can calculate the percentage of total expenses allocated to program A by dividing the total
expenses allocated to program A by the total expenses and multiplying by 100.
Percentage of total expenses allocated to program A = (Total expenses allocated to program A / Total
expenses) * 100 Percentage of total expenses allocated to program A = (50,000/100,000) * 100 Percentage
of total expenses allocated to program A = 0.5 * 100 Percentage of total expenses allocated to program A =
50
Therefore, 50
14. Question: A non-profit organization has total funds of 100,000.40
Solution: Total funds = 100,000Restrictedfunds = 40Unrestrictedfunds =T otalfunds−RestrictedfundsUnrestrictedfunds =100,000
-40,000Unrestrictedfunds =60,000
Therefore, 60,000isallocatedtotheunrestrictedaccount.
15. Question: In a non-profit organization, if the total indirect costs amount to 50,000andaretobeallocatedtotwodifferentprogramsbasedonthedirectcostsincurredbyeachprogram, withP rogramAhavingdirectcostsof30,000
and Program B having direct costs of 20,000, whatistheallocationof indirectcostsf orP rogramA?
Solution: To allocate the indirect costs to each program based on their direct costs, we need to find the
proportion of each program’s direct costs to the total direct costs of both programs.

Total direct costs = Direct costs of Program A + Direct costs of Program B Total direct costs = 30,000+20,000
Total direct costs = 50,000
Now, find the proportion of direct costs for Program A: Proportion of direct costs for Program A =
Direct costs of Program A / Total direct costs Proportion of direct costs for Program A = 30,000/50,000
Proportion of direct costs for Program A = 0.6 or 60
Next, allocate the total indirect costs based on the proportion of direct costs for Program A: Indirect
costs allocated to Program A = Proportion of direct costs for Program A * Total indirect costs Indirect costs
allocated to Program A = 0.6 * 50,000IndirectcostsallocatedtoP rogramA =30,000
Therefore, the allocation of indirect costs for Program A would be 30,000.
16. Question: A non-profit organization receives a grant of 10,000specif icallydesignatedf oraspecialprogram.T heorganizationincurs2,000
in administrative expenses that benefit multiple programs, including the special program funded by the grant.
How much of the administrative expenses should be allocated to the special program using a proportional
allocation method based on the grant amount?
Solution: 1. Calculate the percentage of the grant amount relative to the total funds received: Grant
Percentage = (Grant Amount / Total Funds Received) * 100 = (10,000/10,000) * 100 = 100
2. Allocate the administrative expenses to the special program based on the grant percentage: Adminis-
trative Expenses Allocated = Grant Percentage * Total Administrative Expenses = 100= 1.00 * 2,000 =2,000
Therefore, using the proportional allocation method based on the grant amount, 2,000oftheadministrativeexpensesshouldbeallocatedtothespecialprogram.
17. Question: A non-profit organization incurred total administrative costs of 50,000f ortheyear.Ofthisamount,10,000
relates to a program funded by restricted funds. How much of the administrative costs should be allocated
to the restricted funds?
Solution: To determine the allocation of costs to restricted funds, we need to calculate the proportion of
administrative costs that relate to the program funded by restricted funds.
Proportion of administrative costs allocated to restricted funds = (Costs related to restricted funds / Total
administrative costs) Proportion of administrative costs allocated to restricted funds = (10,000/50,000) =
0.2 or 20
Now, we can calculate the specific amount of administrative costs that should be allocated to the re-
stricted funds:
Administrative costs allocated to restricted funds = Proportion of administrative costs allocated to re-
stricted funds * Total administrative costs Administrative costs allocated to restricted funds = 0.2 * 50,000 =10,000
Therefore, 10,000ofthetotaladministrativecostsshouldbeallocatedtotheprogramfundedbyrestrictedfunds.
18. Question: A non-profit organization has total restricted funds of 50,000.If40
Solution: To find the amount allocated to the specific project, we need to calculate 40
Amount allocated to project = 40Amount allocated to project = 0.40 * 50,000Amountallocatedtoproject =20,000
Therefore, 20,000isallocatedtothespecificprojectwithinthenon −profitorganization.
19. Question: A non-profit organization has total funds of 500,000, ofwhich100,000 is restricted for a
specific program. If the organization spends 30,000ontherestrictedprogram, whatistheremainingbalanceintherestrictedfund?
Solution: 1. Total funds = 500,0002.Restrictedfunds =100,000 3. Amount spent on restricted pro-
gram = 30,000
To find the remaining balance in the restricted fund after spending on the program, we subtract the
amount spent from the initial restricted funds:
Remaining balance = Restricted funds - Amount spent Remaining balance = 100,000−30,000 Remain-
ing balance = 70,000
Therefore, the remaining balance in the restricted fund is 70,000.

20. Question: A non-profit organization has total funds of 500,000.Outofthisamount,150,000 is
classified as restricted funds and the rest as unrestricted funds. What is the percentage of the organization’s
total funds that are classified as restricted funds?
Solution: To find the percentage of restricted funds out of the total funds, we first need to calculate the
proportion of restricted funds to total funds.
Restricted funds / Total funds = 150,000/500,000 = 0.3
Now, to convert this proportion to a percentage, we multiply by 100.
Percentage of restricted funds = 0.3 * 100 = 30
Therefore, 30
21. Question: A non-profit organization receives a donation of 10,000thatisrestrictedforaspecif icprogram.If theorganizationspends5,000
from this restricted donation on the program, how much remains in the restricted fund?
Solution: To determine how much remains in the restricted fund after spending 5,000ontheprogram, wesimplysubtracttheamountspentfromtheinitialrestricteddonation.
Initial restricted donation = 10,000Amountspentontheprogram =5,000
Remaining amount in the restricted fund = 10,000−5,000 = 5,000
Therefore, the remaining amount in the restricted fund is 5,000.
22. Question: A non-profit organization has a total of 50,000infunds.T heyallocate40
Solution: To find the amount allocated to the restricted account, we first calculate 4050,000∗0.40 =20,000
Therefore, 20,000isallocatedtotherestrictedaccount.
23. Question: A non-profit organization has total funds of 100,000.40
Solution: 1. Calculate the current amount of funds in the restricted account: Restricted funds = Total
funds * Percentage restricted Restricted funds = 100,000 ∗40
2. Since the organization needs to allocate an additional 30,000totherestrictedfunds, thenewamountintherestrictedaccountwillbe :
Newrestrictedfunds =40,000 + 30,000 =70,000
3. To find the new amount in the unrestricted funds, simply subtract the new amount in the restricted
funds from the total funds: New unrestricted funds = Total funds - New restricted funds New unrestricted
funds = 100,000−70,000 New unrestricted funds = 30,000
Therefore, the new amount in the unrestricted funds will be 30,000.
24. Question: A non-profit organization has total unrestricted net assets of 100,000andtotalrestrictednetassetsof50,000.
If the organization designates 20,000fromtheunrestrictednetassetstoanewdonor−restrictedfund, whatwillbethenewbalanceofunrestrictednetassets?
Solution: Total Unrestricted Net Assets = 100,000T otalRestrictedN etAssets =50,000 Amount des-
ignated to new donor-restricted fund from Unrestricted Net Assets = 20,000
New Unrestricted Net Assets = Total Unrestricted Net Assets - Amount designated to new fund New
Unrestricted Net Assets = 100,000−20,000 New Unrestricted Net Assets = 80,000
Therefore, the new balance of unrestricted net assets after designating 20,000toanewdonor−restrictedfundwouldbe80,000.
25. Question: A non-profit organization has three funds: Fund A, Fund B, and Fund C. Fund A
incurred 10,000inexpensesthatwereallocabletoallthreef unds, F undBincurred5,000 in expenses that
were specific to Fund B only, and Fund C incurred 8,000inexpensesthatwereallocabletoF undAandF undC.If theorganizationwantstoallocatetheexpensesproportionallybasedonthetotalrevenueofeachfund, andthetotalrevenueforF undA, F undB, andF undCis100,000,
50,000, and80,000 respectively, what would be the total amount of expenses allocated to Fund A?
Solution: 1. Calculate the total revenue for all funds: 100,000(F undA)+50,000 (Fund B) + 80,000(F undC) =230,000
2. Calculate the proportion of total revenue for each fund: - Fund A: 100,000/230,000 = 0.4348 - Fund B:
50,000/230,000 = 0.2174 - Fund C: 80,000/230,000 = 0.3478 3. Allocate the shared expenses to each fund
proportionally: - Fund A: 10,000 ∗0.4348 =4,348 - Fund B: 10,000 ∗0.2174 =2,174 - Fund C: 10,000 ∗

0.3478 =3,478 4. Allocate Fund B’s expenses to Fund B: 5,0005.AllocateF undC′sexpensestoF undAandF undCproportionally :
−F undA :8,000 * 0.4348 = 3,478 −F undC :8,000 * 0.3478 = 2,784
Total expenses allocated to Fund A = 4,348(sharedexpenses)+3,478 (expenses from Fund C) = 7,826
indirect costs * Restricted funds share of indirect costs = 20,000 ∗30
Now, the remaining indirect costs will be allocated to the unrestricted funds. Unrestricted funds share
of indirect costs = Total indirect costs - Restricted funds share of indirect costs Unrestricted funds share of
indirect costs = 20,000−6,000 = 14,000
Therefore, the amount of the indirect costs allocated to the unrestricted funds is 14,000.
7. Question: A non-profit organization has three separate funds: Fund A, Fund B, and Fund C. Fund
A incurred expenses of 10,000, F undBincurredexpensesof 15,000, and Fund C incurred expenses of
20,000.T heorganization′stotalindirectcostsf ortheyearare5,000. If the organization wants to allocate
indirect costs based on the proportion of expenses in each fund, how much indirect cost should be allocated
to Fund A?
Solution: To allocate indirect costs based on the proportion of expenses in each fund, we need to calcu-
late the total expenses across all funds first.
Total Expenses = 10,000(F undA)+15,000 (Fund B) + 20,000(F undC)T otalExpenses =45,000
Next, we calculate the proportion of expenses for each fund:
Proportion of Fund A’s Expenses = Fund A’s Expenses / Total Expenses Proportion of Fund A’s Expenses
=10,000/45,000 Proportion of Fund A’s Expenses = 1/4 or 0.25
Now, we allocate the total indirect costs to Fund A based on its proportion of expenses:
Indirect Cost Allocated to Fund A = Proportion of Fund A’s Expenses * Total Indirect Costs Indirect
Cost Allocated to Fund A = 0.25 * 5,000IndirectCostAllocatedtoF undA =1,250
Therefore, 1,250ofindirectcostsshouldbeallocatedtoF undA.
8. Question: A non-profit organization receives a donation of 10,000thatisrestrictedtobeusedforaspecif icprogram.T heorganizationincursexpensesof6,000
directly related to this program. How much is the remaining balance of the restricted fund for this program?
Solution: The remaining balance of the restricted fund for the specific program can be found by sub-
tracting the expenses incurred from the total donation amount.
Remaining Balance = Total Donation - Program Expenses Remaining Balance = 10,000−6,000 Re-
maining Balance = 4,000
Therefore, the remaining balance of the restricted fund for this program is 4,000.
9. Question: A non-profit organization receives a donation of 10,000specif icallydesignatedforabuildingrenovationproject.Duringthecurrentfiscalyear, theorganizationuses5,000
of the donation for the project. At the end of the fiscal year, what are the balances of the temporarily re-
stricted fund and the amount available for general use in the unrestricted fund?
Solution: 1. Temporary Restricted Fund Balance: - Initial donation: 10,000−Amountusedf ortheproject :5,000
- Balance of temporarily restricted fund = Initial donation - Amount used - Balance of temporarily restricted
fund = 10,000−5,000 - Balance of temporarily restricted fund = 5,000
2. Unrestricted Fund Balance: - Any part of the donation not used for the project remains in the tem-
porarily restricted fund. - Amount available for general use in the unrestricted fund = Initial donation -
Amount in temporarily restricted for the project - Amount available for general use in the unrestricted fund
=10,000−5,000 - Amount available for general use in the unrestricted fund = 5,000
Therefore, at the end of the fiscal year, the balance of the temporarily restricted fund is 5,000, andtheamountavailableforgeneraluseintheunrestrictedfundisalso5,000.
10. Question: A non-profit organization incurred total operating expenses of 50,000.F romthatamount,12,000
expenses were incurred specifically for the education fund, 8,000forthehealthcaref und, andtheremainingexpensesweregeneraloperatingexpenses.W hatpercentageof thetotaloperatingexpenseswereallocatedtotheeducationf und?
Solution: To find the percentage of total operating expenses allocated to the education fund, we first
need to calculate the total specific allocations for the education fund:
Total specific allocation for education fund = 12,000
Then, we calculate the total operating expenses allocated to the education fund:

Total operating expenses allocated to the education fund = Total specific allocation for education fund +
General operating expenses Total operating expenses allocated to the education fund = 12,000 + (50,000 -
12,000−8,000) Total operating expenses allocated to the education fund = 12,000+30,000 Total operating
expenses allocated to the education fund = 42,000
Finally, we calculate the percentage of total operating expenses allocated to the education fund:
Percentage allocated to education fund = (Total operating expenses allocated to education fund / To-
tal operating expenses) * 100Percentage allocated to education fund = (42,000/50,000) * 100Percentage
allocated to education fund = 0.84 * 100Percentage allocated to education fund = 84
Therefore, 84
11. Question: A non-profit organization receives a donation of 10,000restrictedforaspecif icpurpose.T heorganizationspends4,000
on the designated program and incurs 1,500infundraisingexpensesrelatedtothesameprogram.Howmuchoftherestrictedfundsarestillavailableforthedesignatedpurpose?
Solution: Initially, the organization received 10,000asarestricteddonation.Af terspending4,000 on
the designated program, the remaining amount is 10,000−4,000 = 6,000.However, theyalsoincurred1,500
in fundraising expenses related to the designated program. This amount needs to be subtracted from the re-
maining funds. Therefore, the total amount available for the designated purpose is 6,000−1,500 = 4,500.
Final Answer: 4,500
12. Question: A non-profit organization received a grant of 50,000thatisrestrictedforaspecif icprogram.Duringthefiscalyear, theorganizationspent20,000
on the program. Calculate the amount of restricted funds remaining at the end of the fiscal year.
Solution: Restricted funds remaining = Grant amount - Expenditure on the program Restricted funds
remaining = 50,000−20,000 Restricted funds remaining = 30,000
Therefore, the amount of restricted funds remaining at the end of the fiscal year is 30,000.
13. Question: A non-profit organization has total expenses of 100,000, anditincurred20,000 in fundrais-
ing expenses, 30,000inprogramAexpenses, and25,000 in program B expenses. Calculate the percentage
of total expenses allocated to program A.
Solution: To calculate the percentage of total expenses allocated to program A, we need to first find the
total expenses allocated to program A.
Total expenses allocated to program A = fundraising expenses + program A expenses Total expenses
allocated to program A = 20,000+30,000 Total expenses allocated to program A = 50,000
Now, we can calculate the percentage of total expenses allocated to program A by dividing the total
expenses allocated to program A by the total expenses and multiplying by 100.
Percentage of total expenses allocated to program A = (Total expenses allocated to program A / Total
expenses) * 100 Percentage of total expenses allocated to program A = (50,000/100,000) * 100 Percentage
of total expenses allocated to program A = 0.5 * 100 Percentage of total expenses allocated to program A =
50
Therefore, 50
14. Question: A non-profit organization has total funds of 100,000.40
Solution: Total funds = 100,000Restrictedfunds = 40Unrestrictedfunds =T otalfunds−RestrictedfundsUnrestrictedfunds =100,000
-40,000Unrestrictedfunds =60,000
Therefore, 60,000isallocatedtotheunrestrictedaccount.
15. Question: In a non-profit organization, if the total indirect costs amount to 50,000andaretobeallocatedtotwodifferentprogramsbasedonthedirectcostsincurredbyeachprogram, withP rogramAhavingdirectcostsof30,000
and Program B having direct costs of 20,000, whatistheallocationof indirectcostsf orP rogramA?
Solution: To allocate the indirect costs to each program based on their direct costs, we need to find the
proportion of each program’s direct costs to the total direct costs of both programs.

Total direct costs = Direct costs of Program A + Direct costs of Program B Total direct costs = 30,000+20,000
Total direct costs = 50,000
Now, find the proportion of direct costs for Program A: Proportion of direct costs for Program A =
Direct costs of Program A / Total direct costs Proportion of direct costs for Program A = 30,000/50,000
Proportion of direct costs for Program A = 0.6 or 60
Next, allocate the total indirect costs based on the proportion of direct costs for Program A: Indirect
costs allocated to Program A = Proportion of direct costs for Program A * Total indirect costs Indirect costs
allocated to Program A = 0.6 * 50,000IndirectcostsallocatedtoP rogramA =30,000
Therefore, the allocation of indirect costs for Program A would be 30,000.
16. Question: A non-profit organization receives a grant of 10,000specif icallydesignatedf oraspecialprogram.T heorganizationincurs2,000
in administrative expenses that benefit multiple programs, including the special program funded by the grant.
How much of the administrative expenses should be allocated to the special program using a proportional
allocation method based on the grant amount?
Solution: 1. Calculate the percentage of the grant amount relative to the total funds received: Grant
Percentage = (Grant Amount / Total Funds Received) * 100 = (10,000/10,000) * 100 = 100
2. Allocate the administrative expenses to the special program based on the grant percentage: Adminis-
trative Expenses Allocated = Grant Percentage * Total Administrative Expenses = 100= 1.00 * 2,000 =2,000
Therefore, using the proportional allocation method based on the grant amount, 2,000oftheadministrativeexpensesshouldbeallocatedtothespecialprogram.
17. Question: A non-profit organization incurred total administrative costs of 50,000f ortheyear.Ofthisamount,10,000
relates to a program funded by restricted funds. How much of the administrative costs should be allocated
to the restricted funds?
Solution: To determine the allocation of costs to restricted funds, we need to calculate the proportion of
administrative costs that relate to the program funded by restricted funds.
Proportion of administrative costs allocated to restricted funds = (Costs related to restricted funds / Total
administrative costs) Proportion of administrative costs allocated to restricted funds = (10,000/50,000) =
0.2 or 20
Now, we can calculate the specific amount of administrative costs that should be allocated to the re-
stricted funds:
Administrative costs allocated to restricted funds = Proportion of administrative costs allocated to re-
stricted funds * Total administrative costs Administrative costs allocated to restricted funds = 0.2 * 50,000 =10,000
Therefore, 10,000ofthetotaladministrativecostsshouldbeallocatedtotheprogramfundedbyrestrictedfunds.
18. Question: A non-profit organization has total restricted funds of 50,000.If40
Solution: To find the amount allocated to the specific project, we need to calculate 40
Amount allocated to project = 40Amount allocated to project = 0.40 * 50,000Amountallocatedtoproject =20,000
Therefore, 20,000isallocatedtothespecificprojectwithinthenon −profitorganization.
19. Question: A non-profit organization has total funds of 500,000, ofwhich100,000 is restricted for a
specific program. If the organization spends 30,000ontherestrictedprogram, whatistheremainingbalanceintherestrictedfund?
Solution: 1. Total funds = 500,0002.Restrictedfunds =100,000 3. Amount spent on restricted pro-
gram = 30,000
To find the remaining balance in the restricted fund after spending on the program, we subtract the
amount spent from the initial restricted funds:
Remaining balance = Restricted funds - Amount spent Remaining balance = 100,000−30,000 Remain-
ing balance = 70,000
Therefore, the remaining balance in the restricted fund is 70,000.

20. Question: A non-profit organization has total funds of 500,000.Outofthisamount,150,000 is
classified as restricted funds and the rest as unrestricted funds. What is the percentage of the organization’s
total funds that are classified as restricted funds?
Solution: To find the percentage of restricted funds out of the total funds, we first need to calculate the
proportion of restricted funds to total funds.
Restricted funds / Total funds = 150,000/500,000 = 0.3
Now, to convert this proportion to a percentage, we multiply by 100.
Percentage of restricted funds = 0.3 * 100 = 30
Therefore, 30
21. Question: A non-profit organization receives a donation of 10,000thatisrestrictedforaspecif icprogram.If theorganizationspends5,000
from this restricted donation on the program, how much remains in the restricted fund?
Solution: To determine how much remains in the restricted fund after spending 5,000ontheprogram, wesimplysubtracttheamountspentfromtheinitialrestricteddonation.
Initial restricted donation = 10,000Amountspentontheprogram =5,000
Remaining amount in the restricted fund = 10,000−5,000 = 5,000
Therefore, the remaining amount in the restricted fund is 5,000.
22. Question: A non-profit organization has a total of 50,000infunds.T heyallocate40
Solution: To find the amount allocated to the restricted account, we first calculate 4050,000∗0.40 =20,000
Therefore, 20,000isallocatedtotherestrictedaccount.
23. Question: A non-profit organization has total funds of 100,000.40
Solution: 1. Calculate the current amount of funds in the restricted account: Restricted funds = Total
funds * Percentage restricted Restricted funds = 100,000 ∗40
2. Since the organization needs to allocate an additional 30,000totherestrictedfunds, thenewamountintherestrictedaccountwillbe :
Newrestrictedfunds =40,000 + 30,000 =70,000
3. To find the new amount in the unrestricted funds, simply subtract the new amount in the restricted
funds from the total funds: New unrestricted funds = Total funds - New restricted funds New unrestricted
funds = 100,000−70,000 New unrestricted funds = 30,000
Therefore, the new amount in the unrestricted funds will be 30,000.
24. Question: A non-profit organization has total unrestricted net assets of 100,000andtotalrestrictednetassetsof50,000.
If the organization designates 20,000fromtheunrestrictednetassetstoanewdonor−restrictedfund, whatwillbethenewbalanceofunrestrictednetassets?
Solution: Total Unrestricted Net Assets = 100,000T otalRestrictedN etAssets =50,000 Amount des-
ignated to new donor-restricted fund from Unrestricted Net Assets = 20,000
New Unrestricted Net Assets = Total Unrestricted Net Assets - Amount designated to new fund New
Unrestricted Net Assets = 100,000−20,000 New Unrestricted Net Assets = 80,000
Therefore, the new balance of unrestricted net assets after designating 20,000toanewdonor−restrictedfundwouldbe80,000.
25. Question: A non-profit organization has three funds: Fund A, Fund B, and Fund C. Fund A
incurred 10,000inexpensesthatwereallocabletoallthreef unds, F undBincurred5,000 in expenses that
were specific to Fund B only, and Fund C incurred 8,000inexpensesthatwereallocabletoF undAandF undC.If theorganizationwantstoallocatetheexpensesproportionallybasedonthetotalrevenueofeachfund, andthetotalrevenueforF undA, F undB, andF undCis100,000,
50,000, and80,000 respectively, what would be the total amount of expenses allocated to Fund A?
Solution: 1. Calculate the total revenue for all funds: 100,000(F undA)+50,000 (Fund B) + 80,000(F undC) =230,000
2. Calculate the proportion of total revenue for each fund: - Fund A: 100,000/230,000 = 0.4348 - Fund B:
50,000/230,000 = 0.2174 - Fund C: 80,000/230,000 = 0.3478 3. Allocate the shared expenses to each fund
proportionally: - Fund A: 10,000 ∗0.4348 =4,348 - Fund B: 10,000 ∗0.2174 =2,174 - Fund C: 10,000 ∗

0.3478 =3,478 4. Allocate Fund B’s expenses to Fund B: 5,0005.AllocateF undC′sexpensestoF undAandF undCproportionally :
−F undA :8,000 * 0.4348 = 3,478 −F undC :8,000 * 0.3478 = 2,784
Total expenses allocated to Fund A = 4,348(sharedexpenses)+3,478 (expenses from Fund C) = 7,826
indirect costs * Restricted funds share of indirect costs = 20,000 ∗30
Now, the remaining indirect costs will be allocated to the unrestricted funds. Unrestricted funds share
of indirect costs = Total indirect costs - Restricted funds share of indirect costs Unrestricted funds share of
indirect costs = 20,000−6,000 = 14,000
Therefore, the amount of the indirect costs allocated to the unrestricted funds is 14,000.
7. Question: A non-profit organization has three separate funds: Fund A, Fund B, and Fund C. Fund
A incurred expenses of 10,000, F undBincurredexpensesof 15,000, and Fund C incurred expenses of
20,000.T heorganization′stotalindirectcostsf ortheyearare5,000. If the organization wants to allocate
indirect costs based on the proportion of expenses in each fund, how much indirect cost should be allocated
to Fund A?
Solution: To allocate indirect costs based on the proportion of expenses in each fund, we need to calcu-
late the total expenses across all funds first.
Total Expenses = 10,000(F undA)+15,000 (Fund B) + 20,000(F undC)T otalExpenses =45,000
Next, we calculate the proportion of expenses for each fund:
Proportion of Fund A’s Expenses = Fund A’s Expenses / Total Expenses Proportion of Fund A’s Expenses
=10,000/45,000 Proportion of Fund A’s Expenses = 1/4 or 0.25
Now, we allocate the total indirect costs to Fund A based on its proportion of expenses:
Indirect Cost Allocated to Fund A = Proportion of Fund A’s Expenses * Total Indirect Costs Indirect
Cost Allocated to Fund A = 0.25 * 5,000IndirectCostAllocatedtoF undA =1,250
Therefore, 1,250ofindirectcostsshouldbeallocatedtoF undA.
8. Question: A non-profit organization receives a donation of 10,000thatisrestrictedtobeusedforaspecif icprogram.T heorganizationincursexpensesof6,000
directly related to this program. How much is the remaining balance of the restricted fund for this program?
Solution: The remaining balance of the restricted fund for the specific program can be found by sub-
tracting the expenses incurred from the total donation amount.
Remaining Balance = Total Donation - Program Expenses Remaining Balance = 10,000−6,000 Re-
maining Balance = 4,000
Therefore, the remaining balance of the restricted fund for this program is 4,000.
9. Question: A non-profit organization receives a donation of 10,000specif icallydesignatedforabuildingrenovationproject.Duringthecurrentfiscalyear, theorganizationuses5,000
of the donation for the project. At the end of the fiscal year, what are the balances of the temporarily re-
stricted fund and the amount available for general use in the unrestricted fund?
Solution: 1. Temporary Restricted Fund Balance: - Initial donation: 10,000−Amountusedf ortheproject :5,000
- Balance of temporarily restricted fund = Initial donation - Amount used - Balance of temporarily restricted
fund = 10,000−5,000 - Balance of temporarily restricted fund = 5,000
2. Unrestricted Fund Balance: - Any part of the donation not used for the project remains in the tem-
porarily restricted fund. - Amount available for general use in the unrestricted fund = Initial donation -
Amount in temporarily restricted for the project - Amount available for general use in the unrestricted fund
=10,000−5,000 - Amount available for general use in the unrestricted fund = 5,000
Therefore, at the end of the fiscal year, the balance of the temporarily restricted fund is 5,000, andtheamountavailableforgeneraluseintheunrestrictedfundisalso5,000.
10. Question: A non-profit organization incurred total operating expenses of 50,000.F romthatamount,12,000
expenses were incurred specifically for the education fund, 8,000forthehealthcaref und, andtheremainingexpensesweregeneraloperatingexpenses.W hatpercentageof thetotaloperatingexpenseswereallocatedtotheeducationf und?
Solution: To find the percentage of total operating expenses allocated to the education fund, we first
need to calculate the total specific allocations for the education fund:
Total specific allocation for education fund = 12,000
Then, we calculate the total operating expenses allocated to the education fund:

Total operating expenses allocated to the education fund = Total specific allocation for education fund +
General operating expenses Total operating expenses allocated to the education fund = 12,000 + (50,000 -
12,000−8,000) Total operating expenses allocated to the education fund = 12,000+30,000 Total operating
expenses allocated to the education fund = 42,000
Finally, we calculate the percentage of total operating expenses allocated to the education fund:
Percentage allocated to education fund = (Total operating expenses allocated to education fund / To-
tal operating expenses) * 100Percentage allocated to education fund = (42,000/50,000) * 100Percentage
allocated to education fund = 0.84 * 100Percentage allocated to education fund = 84
Therefore, 84
11. Question: A non-profit organization receives a donation of 10,000restrictedforaspecif icpurpose.T heorganizationspends4,000
on the designated program and incurs 1,500infundraisingexpensesrelatedtothesameprogram.Howmuchoftherestrictedfundsarestillavailableforthedesignatedpurpose?
Solution: Initially, the organization received 10,000asarestricteddonation.Af terspending4,000 on
the designated program, the remaining amount is 10,000−4,000 = 6,000.However, theyalsoincurred1,500
in fundraising expenses related to the designated program. This amount needs to be subtracted from the re-
maining funds. Therefore, the total amount available for the designated purpose is 6,000−1,500 = 4,500.
Final Answer: 4,500
12. Question: A non-profit organization received a grant of 50,000thatisrestrictedforaspecif icprogram.Duringthefiscalyear, theorganizationspent20,000
on the program. Calculate the amount of restricted funds remaining at the end of the fiscal year.
Solution: Restricted funds remaining = Grant amount - Expenditure on the program Restricted funds
remaining = 50,000−20,000 Restricted funds remaining = 30,000
Therefore, the amount of restricted funds remaining at the end of the fiscal year is 30,000.
13. Question: A non-profit organization has total expenses of 100,000, anditincurred20,000 in fundrais-
ing expenses, 30,000inprogramAexpenses, and25,000 in program B expenses. Calculate the percentage
of total expenses allocated to program A.
Solution: To calculate the percentage of total expenses allocated to program A, we need to first find the
total expenses allocated to program A.
Total expenses allocated to program A = fundraising expenses + program A expenses Total expenses
allocated to program A = 20,000+30,000 Total expenses allocated to program A = 50,000
Now, we can calculate the percentage of total expenses allocated to program A by dividing the total
expenses allocated to program A by the total expenses and multiplying by 100.
Percentage of total expenses allocated to program A = (Total expenses allocated to program A / Total
expenses) * 100 Percentage of total expenses allocated to program A = (50,000/100,000) * 100 Percentage
of total expenses allocated to program A = 0.5 * 100 Percentage of total expenses allocated to program A =
50
Therefore, 50
14. Question: A non-profit organization has total funds of 100,000.40
Solution: Total funds = 100,000Restrictedfunds = 40Unrestrictedfunds =T otalfunds−RestrictedfundsUnrestrictedfunds =100,000
-40,000Unrestrictedfunds =60,000
Therefore, 60,000isallocatedtotheunrestrictedaccount.
15. Question: In a non-profit organization, if the total indirect costs amount to 50,000andaretobeallocatedtotwodifferentprogramsbasedonthedirectcostsincurredbyeachprogram, withP rogramAhavingdirectcostsof30,000
and Program B having direct costs of 20,000, whatistheallocationof indirectcostsf orP rogramA?
Solution: To allocate the indirect costs to each program based on their direct costs, we need to find the
proportion of each program’s direct costs to the total direct costs of both programs.

Total direct costs = Direct costs of Program A + Direct costs of Program B Total direct costs = 30,000+20,000
Total direct costs = 50,000
Now, find the proportion of direct costs for Program A: Proportion of direct costs for Program A =
Direct costs of Program A / Total direct costs Proportion of direct costs for Program A = 30,000/50,000
Proportion of direct costs for Program A = 0.6 or 60
Next, allocate the total indirect costs based on the proportion of direct costs for Program A: Indirect
costs allocated to Program A = Proportion of direct costs for Program A * Total indirect costs Indirect costs
allocated to Program A = 0.6 * 50,000IndirectcostsallocatedtoP rogramA =30,000
Therefore, the allocation of indirect costs for Program A would be 30,000.
16. Question: A non-profit organization receives a grant of 10,000specif icallydesignatedf oraspecialprogram.T heorganizationincurs2,000
in administrative expenses that benefit multiple programs, including the special program funded by the grant.
How much of the administrative expenses should be allocated to the special program using a proportional
allocation method based on the grant amount?
Solution: 1. Calculate the percentage of the grant amount relative to the total funds received: Grant
Percentage = (Grant Amount / Total Funds Received) * 100 = (10,000/10,000) * 100 = 100
2. Allocate the administrative expenses to the special program based on the grant percentage: Adminis-
trative Expenses Allocated = Grant Percentage * Total Administrative Expenses = 100= 1.00 * 2,000 =2,000
Therefore, using the proportional allocation method based on the grant amount, 2,000oftheadministrativeexpensesshouldbeallocatedtothespecialprogram.
17. Question: A non-profit organization incurred total administrative costs of 50,000f ortheyear.Ofthisamount,10,000
relates to a program funded by restricted funds. How much of the administrative costs should be allocated
to the restricted funds?
Solution: To determine the allocation of costs to restricted funds, we need to calculate the proportion of
administrative costs that relate to the program funded by restricted funds.
Proportion of administrative costs allocated to restricted funds = (Costs related to restricted funds / Total
administrative costs) Proportion of administrative costs allocated to restricted funds = (10,000/50,000) =
0.2 or 20
Now, we can calculate the specific amount of administrative costs that should be allocated to the re-
stricted funds:
Administrative costs allocated to restricted funds = Proportion of administrative costs allocated to re-
stricted funds * Total administrative costs Administrative costs allocated to restricted funds = 0.2 * 50,000 =10,000
Therefore, 10,000ofthetotaladministrativecostsshouldbeallocatedtotheprogramfundedbyrestrictedfunds.
18. Question: A non-profit organization has total restricted funds of 50,000.If40
Solution: To find the amount allocated to the specific project, we need to calculate 40
Amount allocated to project = 40Amount allocated to project = 0.40 * 50,000Amountallocatedtoproject =20,000
Therefore, 20,000isallocatedtothespecificprojectwithinthenon −profitorganization.
19. Question: A non-profit organization has total funds of 500,000, ofwhich100,000 is restricted for a
specific program. If the organization spends 30,000ontherestrictedprogram, whatistheremainingbalanceintherestrictedfund?
Solution: 1. Total funds = 500,0002.Restrictedfunds =100,000 3. Amount spent on restricted pro-
gram = 30,000
To find the remaining balance in the restricted fund after spending on the program, we subtract the
amount spent from the initial restricted funds:
Remaining balance = Restricted funds - Amount spent Remaining balance = 100,000−30,000 Remain-
ing balance = 70,000
Therefore, the remaining balance in the restricted fund is 70,000.

20. Question: A non-profit organization has total funds of 500,000.Outofthisamount,150,000 is
classified as restricted funds and the rest as unrestricted funds. What is the percentage of the organization’s
total funds that are classified as restricted funds?
Solution: To find the percentage of restricted funds out of the total funds, we first need to calculate the
proportion of restricted funds to total funds.
Restricted funds / Total funds = 150,000/500,000 = 0.3
Now, to convert this proportion to a percentage, we multiply by 100.
Percentage of restricted funds = 0.3 * 100 = 30
Therefore, 30
21. Question: A non-profit organization receives a donation of 10,000thatisrestrictedforaspecif icprogram.If theorganizationspends5,000
from this restricted donation on the program, how much remains in the restricted fund?
Solution: To determine how much remains in the restricted fund after spending 5,000ontheprogram, wesimplysubtracttheamountspentfromtheinitialrestricteddonation.
Initial restricted donation = 10,000Amountspentontheprogram =5,000
Remaining amount in the restricted fund = 10,000−5,000 = 5,000
Therefore, the remaining amount in the restricted fund is 5,000.
22. Question: A non-profit organization has a total of 50,000infunds.T heyallocate40
Solution: To find the amount allocated to the restricted account, we first calculate 4050,000∗0.40 =20,000
Therefore, 20,000isallocatedtotherestrictedaccount.
23. Question: A non-profit organization has total funds of 100,000.40
Solution: 1. Calculate the current amount of funds in the restricted account: Restricted funds = Total
funds * Percentage restricted Restricted funds = 100,000 ∗40
2. Since the organization needs to allocate an additional 30,000totherestrictedfunds, thenewamountintherestrictedaccountwillbe :
Newrestrictedfunds =40,000 + 30,000 =70,000
3. To find the new amount in the unrestricted funds, simply subtract the new amount in the restricted
funds from the total funds: New unrestricted funds = Total funds - New restricted funds New unrestricted
funds = 100,000−70,000 New unrestricted funds = 30,000
Therefore, the new amount in the unrestricted funds will be 30,000.
24. Question: A non-profit organization has total unrestricted net assets of 100,000andtotalrestrictednetassetsof50,000.
If the organization designates 20,000fromtheunrestrictednetassetstoanewdonor−restrictedfund, whatwillbethenewbalanceofunrestrictednetassets?
Solution: Total Unrestricted Net Assets = 100,000T otalRestrictedN etAssets =50,000 Amount des-
ignated to new donor-restricted fund from Unrestricted Net Assets = 20,000
New Unrestricted Net Assets = Total Unrestricted Net Assets - Amount designated to new fund New
Unrestricted Net Assets = 100,000−20,000 New Unrestricted Net Assets = 80,000
Therefore, the new balance of unrestricted net assets after designating 20,000toanewdonor−restrictedfundwouldbe80,000.
25. Question: A non-profit organization has three funds: Fund A, Fund B, and Fund C. Fund A
incurred 10,000inexpensesthatwereallocabletoallthreef unds, F undBincurred5,000 in expenses that
were specific to Fund B only, and Fund C incurred 8,000inexpensesthatwereallocabletoF undAandF undC.If theorganizationwantstoallocatetheexpensesproportionallybasedonthetotalrevenueofeachfund, andthetotalrevenueforF undA, F undB, andF undCis100,000,
50,000, and80,000 respectively, what would be the total amount of expenses allocated to Fund A?
Solution: 1. Calculate the total revenue for all funds: 100,000(F undA)+50,000 (Fund B) + 80,000(F undC) =230,000
2. Calculate the proportion of total revenue for each fund: - Fund A: 100,000/230,000 = 0.4348 - Fund B:
50,000/230,000 = 0.2174 - Fund C: 80,000/230,000 = 0.3478 3. Allocate the shared expenses to each fund
proportionally: - Fund A: 10,000 ∗0.4348 =4,348 - Fund B: 10,000 ∗0.2174 =2,174 - Fund C: 10,000 ∗

0.3478 =3,478 4. Allocate Fund B’s expenses to Fund B: 5,0005.AllocateF undC′sexpensestoF undAandF undCproportionally :
−F undA :8,000 * 0.4348 = 3,478 −F undC :8,000 * 0.3478 = 2,784
Total expenses allocated to Fund A = 4,348(sharedexpenses)+3,478 (expenses from Fund C) = 7,826
indirect costs * Restricted funds share of indirect costs = 20,000 ∗30
Now, the remaining indirect costs will be allocated to the unrestricted funds. Unrestricted funds share
of indirect costs = Total indirect costs - Restricted funds share of indirect costs Unrestricted funds share of
indirect costs = 20,000−6,000 = 14,000
Therefore, the amount of the indirect costs allocated to the unrestricted funds is 14,000.
7. Question: A non-profit organization has three separate funds: Fund A, Fund B, and Fund C. Fund
A incurred expenses of 10,000, F undBincurredexpensesof 15,000, and Fund C incurred expenses of
20,000.T heorganization′stotalindirectcostsf ortheyearare5,000. If the organization wants to allocate
indirect costs based on the proportion of expenses in each fund, how much indirect cost should be allocated
to Fund A?
Solution: To allocate indirect costs based on the proportion of expenses in each fund, we need to calcu-
late the total expenses across all funds first.
Total Expenses = 10,000(F undA)+15,000 (Fund B) + 20,000(F undC)T otalExpenses =45,000
Next, we calculate the proportion of expenses for each fund:
Proportion of Fund A’s Expenses = Fund A’s Expenses / Total Expenses Proportion of Fund A’s Expenses
=10,000/45,000 Proportion of Fund A’s Expenses = 1/4 or 0.25
Now, we allocate the total indirect costs to Fund A based on its proportion of expenses:
Indirect Cost Allocated to Fund A = Proportion of Fund A’s Expenses * Total Indirect Costs Indirect
Cost Allocated to Fund A = 0.25 * 5,000IndirectCostAllocatedtoF undA =1,250
Therefore, 1,250ofindirectcostsshouldbeallocatedtoF undA.
8. Question: A non-profit organization receives a donation of 10,000thatisrestrictedtobeusedforaspecif icprogram.T heorganizationincursexpensesof6,000
directly related to this program. How much is the remaining balance of the restricted fund for this program?
Solution: The remaining balance of the restricted fund for the specific program can be found by sub-
tracting the expenses incurred from the total donation amount.
Remaining Balance = Total Donation - Program Expenses Remaining Balance = 10,000−6,000 Re-
maining Balance = 4,000
Therefore, the remaining balance of the restricted fund for this program is 4,000.
9. Question: A non-profit organization receives a donation of 10,000specif icallydesignatedforabuildingrenovationproject.Duringthecurrentfiscalyear, theorganizationuses5,000
of the donation for the project. At the end of the fiscal year, what are the balances of the temporarily re-
stricted fund and the amount available for general use in the unrestricted fund?
Solution: 1. Temporary Restricted Fund Balance: - Initial donation: 10,000−Amountusedf ortheproject :5,000
- Balance of temporarily restricted fund = Initial donation - Amount used - Balance of temporarily restricted
fund = 10,000−5,000 - Balance of temporarily restricted fund = 5,000
2. Unrestricted Fund Balance: - Any part of the donation not used for the project remains in the tem-
porarily restricted fund. - Amount available for general use in the unrestricted fund = Initial donation -
Amount in temporarily restricted for the project - Amount available for general use in the unrestricted fund
=10,000−5,000 - Amount available for general use in the unrestricted fund = 5,000
Therefore, at the end of the fiscal year, the balance of the temporarily restricted fund is 5,000, andtheamountavailableforgeneraluseintheunrestrictedfundisalso5,000.
10. Question: A non-profit organization incurred total operating expenses of 50,000.F romthatamount,12,000
expenses were incurred specifically for the education fund, 8,000forthehealthcaref und, andtheremainingexpensesweregeneraloperatingexpenses.W hatpercentageof thetotaloperatingexpenseswereallocatedtotheeducationf und?
Solution: To find the percentage of total operating expenses allocated to the education fund, we first
need to calculate the total specific allocations for the education fund:
Total specific allocation for education fund = 12,000
Then, we calculate the total operating expenses allocated to the education fund:

Total operating expenses allocated to the education fund = Total specific allocation for education fund +
General operating expenses Total operating expenses allocated to the education fund = 12,000 + (50,000 -
12,000−8,000) Total operating expenses allocated to the education fund = 12,000+30,000 Total operating
expenses allocated to the education fund = 42,000
Finally, we calculate the percentage of total operating expenses allocated to the education fund:
Percentage allocated to education fund = (Total operating expenses allocated to education fund / To-
tal operating expenses) * 100Percentage allocated to education fund = (42,000/50,000) * 100Percentage
allocated to education fund = 0.84 * 100Percentage allocated to education fund = 84
Therefore, 84
11. Question: A non-profit organization receives a donation of 10,000restrictedforaspecif icpurpose.T heorganizationspends4,000
on the designated program and incurs 1,500infundraisingexpensesrelatedtothesameprogram.Howmuchoftherestrictedfundsarestillavailableforthedesignatedpurpose?
Solution: Initially, the organization received 10,000asarestricteddonation.Af terspending4,000 on
the designated program, the remaining amount is 10,000−4,000 = 6,000.However, theyalsoincurred1,500
in fundraising expenses related to the designated program. This amount needs to be subtracted from the re-
maining funds. Therefore, the total amount available for the designated purpose is 6,000−1,500 = 4,500.
Final Answer: 4,500
12. Question: A non-profit organization received a grant of 50,000thatisrestrictedforaspecif icprogram.Duringthefiscalyear, theorganizationspent20,000
on the program. Calculate the amount of restricted funds remaining at the end of the fiscal year.
Solution: Restricted funds remaining = Grant amount - Expenditure on the program Restricted funds
remaining = 50,000−20,000 Restricted funds remaining = 30,000
Therefore, the amount of restricted funds remaining at the end of the fiscal year is 30,000.
13. Question: A non-profit organization has total expenses of 100,000, anditincurred20,000 in fundrais-
ing expenses, 30,000inprogramAexpenses, and25,000 in program B expenses. Calculate the percentage
of total expenses allocated to program A.
Solution: To calculate the percentage of total expenses allocated to program A, we need to first find the
total expenses allocated to program A.
Total expenses allocated to program A = fundraising expenses + program A expenses Total expenses
allocated to program A = 20,000+30,000 Total expenses allocated to program A = 50,000
Now, we can calculate the percentage of total expenses allocated to program A by dividing the total
expenses allocated to program A by the total expenses and multiplying by 100.
Percentage of total expenses allocated to program A = (Total expenses allocated to program A / Total
expenses) * 100 Percentage of total expenses allocated to program A = (50,000/100,000) * 100 Percentage
of total expenses allocated to program A = 0.5 * 100 Percentage of total expenses allocated to program A =
50
Therefore, 50
14. Question: A non-profit organization has total funds of 100,000.40
Solution: Total funds = 100,000Restrictedfunds = 40Unrestrictedfunds =T otalfunds−RestrictedfundsUnrestrictedfunds =100,000
-40,000Unrestrictedfunds =60,000
Therefore, 60,000isallocatedtotheunrestrictedaccount.
15. Question: In a non-profit organization, if the total indirect costs amount to 50,000andaretobeallocatedtotwodifferentprogramsbasedonthedirectcostsincurredbyeachprogram, withP rogramAhavingdirectcostsof30,000
and Program B having direct costs of 20,000, whatistheallocationof indirectcostsf orP rogramA?
Solution: To allocate the indirect costs to each program based on their direct costs, we need to find the
proportion of each program’s direct costs to the total direct costs of both programs.

Total direct costs = Direct costs of Program A + Direct costs of Program B Total direct costs = 30,000+20,000
Total direct costs = 50,000
Now, find the proportion of direct costs for Program A: Proportion of direct costs for Program A =
Direct costs of Program A / Total direct costs Proportion of direct costs for Program A = 30,000/50,000
Proportion of direct costs for Program A = 0.6 or 60
Next, allocate the total indirect costs based on the proportion of direct costs for Program A: Indirect
costs allocated to Program A = Proportion of direct costs for Program A * Total indirect costs Indirect costs
allocated to Program A = 0.6 * 50,000IndirectcostsallocatedtoP rogramA =30,000
Therefore, the allocation of indirect costs for Program A would be 30,000.
16. Question: A non-profit organization receives a grant of 10,000specif icallydesignatedf oraspecialprogram.T heorganizationincurs2,000
in administrative expenses that benefit multiple programs, including the special program funded by the grant.
How much of the administrative expenses should be allocated to the special program using a proportional
allocation method based on the grant amount?
Solution: 1. Calculate the percentage of the grant amount relative to the total funds received: Grant
Percentage = (Grant Amount / Total Funds Received) * 100 = (10,000/10,000) * 100 = 100
2. Allocate the administrative expenses to the special program based on the grant percentage: Adminis-
trative Expenses Allocated = Grant Percentage * Total Administrative Expenses = 100= 1.00 * 2,000 =2,000
Therefore, using the proportional allocation method based on the grant amount, 2,000oftheadministrativeexpensesshouldbeallocatedtothespecialprogram.
17. Question: A non-profit organization incurred total administrative costs of 50,000f ortheyear.Ofthisamount,10,000
relates to a program funded by restricted funds. How much of the administrative costs should be allocated
to the restricted funds?
Solution: To determine the allocation of costs to restricted funds, we need to calculate the proportion of
administrative costs that relate to the program funded by restricted funds.
Proportion of administrative costs allocated to restricted funds = (Costs related to restricted funds / Total
administrative costs) Proportion of administrative costs allocated to restricted funds = (10,000/50,000) =
0.2 or 20
Now, we can calculate the specific amount of administrative costs that should be allocated to the re-
stricted funds:
Administrative costs allocated to restricted funds = Proportion of administrative costs allocated to re-
stricted funds * Total administrative costs Administrative costs allocated to restricted funds = 0.2 * 50,000 =10,000
Therefore, 10,000ofthetotaladministrativecostsshouldbeallocatedtotheprogramfundedbyrestrictedfunds.
18. Question: A non-profit organization has total restricted funds of 50,000.If40
Solution: To find the amount allocated to the specific project, we need to calculate 40
Amount allocated to project = 40Amount allocated to project = 0.40 * 50,000Amountallocatedtoproject =20,000
Therefore, 20,000isallocatedtothespecificprojectwithinthenon −profitorganization.
19. Question: A non-profit organization has total funds of 500,000, ofwhich100,000 is restricted for a
specific program. If the organization spends 30,000ontherestrictedprogram, whatistheremainingbalanceintherestrictedfund?
Solution: 1. Total funds = 500,0002.Restrictedfunds =100,000 3. Amount spent on restricted pro-
gram = 30,000
To find the remaining balance in the restricted fund after spending on the program, we subtract the
amount spent from the initial restricted funds:
Remaining balance = Restricted funds - Amount spent Remaining balance = 100,000−30,000 Remain-
ing balance = 70,000
Therefore, the remaining balance in the restricted fund is 70,000.

20. Question: A non-profit organization has total funds of 500,000.Outofthisamount,150,000 is
classified as restricted funds and the rest as unrestricted funds. What is the percentage of the organization’s
total funds that are classified as restricted funds?
Solution: To find the percentage of restricted funds out of the total funds, we first need to calculate the
proportion of restricted funds to total funds.
Restricted funds / Total funds = 150,000/500,000 = 0.3
Now, to convert this proportion to a percentage, we multiply by 100.
Percentage of restricted funds = 0.3 * 100 = 30
Therefore, 30
21. Question: A non-profit organization receives a donation of 10,000thatisrestrictedforaspecif icprogram.If theorganizationspends5,000
from this restricted donation on the program, how much remains in the restricted fund?
Solution: To determine how much remains in the restricted fund after spending 5,000ontheprogram, wesimplysubtracttheamountspentfromtheinitialrestricteddonation.
Initial restricted donation = 10,000Amountspentontheprogram =5,000
Remaining amount in the restricted fund = 10,000−5,000 = 5,000
Therefore, the remaining amount in the restricted fund is 5,000.
22. Question: A non-profit organization has a total of 50,000infunds.T heyallocate40
Solution: To find the amount allocated to the restricted account, we first calculate 4050,000∗0.40 =20,000
Therefore, 20,000isallocatedtotherestrictedaccount.
23. Question: A non-profit organization has total funds of 100,000.40
Solution: 1. Calculate the current amount of funds in the restricted account: Restricted funds = Total
funds * Percentage restricted Restricted funds = 100,000 ∗40
2. Since the organization needs to allocate an additional 30,000totherestrictedfunds, thenewamountintherestrictedaccountwillbe :
Newrestrictedfunds =40,000 + 30,000 =70,000
3. To find the new amount in the unrestricted funds, simply subtract the new amount in the restricted
funds from the total funds: New unrestricted funds = Total funds - New restricted funds New unrestricted
funds = 100,000−70,000 New unrestricted funds = 30,000
Therefore, the new amount in the unrestricted funds will be 30,000.
24. Question: A non-profit organization has total unrestricted net assets of 100,000andtotalrestrictednetassetsof50,000.
If the organization designates 20,000fromtheunrestrictednetassetstoanewdonor−restrictedfund, whatwillbethenewbalanceofunrestrictednetassets?
Solution: Total Unrestricted Net Assets = 100,000T otalRestrictedN etAssets =50,000 Amount des-
ignated to new donor-restricted fund from Unrestricted Net Assets = 20,000
New Unrestricted Net Assets = Total Unrestricted Net Assets - Amount designated to new fund New
Unrestricted Net Assets = 100,000−20,000 New Unrestricted Net Assets = 80,000
Therefore, the new balance of unrestricted net assets after designating 20,000toanewdonor−restrictedfundwouldbe80,000.
25. Question: A non-profit organization has three funds: Fund A, Fund B, and Fund C. Fund A
incurred 10,000inexpensesthatwereallocabletoallthreef unds, F undBincurred5,000 in expenses that
were specific to Fund B only, and Fund C incurred 8,000inexpensesthatwereallocabletoF undAandF undC.If theorganizationwantstoallocatetheexpensesproportionallybasedonthetotalrevenueofeachfund, andthetotalrevenueforF undA, F undB, andF undCis100,000,
50,000, and80,000 respectively, what would be the total amount of expenses allocated to Fund A?
Solution: 1. Calculate the total revenue for all funds: 100,000(F undA)+50,000 (Fund B) + 80,000(F undC) =230,000
2. Calculate the proportion of total revenue for each fund: - Fund A: 100,000/230,000 = 0.4348 - Fund B:
50,000/230,000 = 0.2174 - Fund C: 80,000/230,000 = 0.3478 3. Allocate the shared expenses to each fund
proportionally: - Fund A: 10,000 ∗0.4348 =4,348 - Fund B: 10,000 ∗0.2174 =2,174 - Fund C: 10,000 ∗

0.3478 =3,478 4. Allocate Fund B’s expenses to Fund B: 5,0005.AllocateF undC′sexpensestoF undAandF undCproportionally :
−F undA :8,000 * 0.4348 = 3,478 −F undC :8,000 * 0.3478 = 2,784
Total expenses allocated to Fund A = 4,348(sharedexpenses)+3,478 (expenses from Fund C) = 7,826
indirect costs * Restricted funds share of indirect costs = 20,000 ∗30
Now, the remaining indirect costs will be allocated to the unrestricted funds. Unrestricted funds share
of indirect costs = Total indirect costs - Restricted funds share of indirect costs Unrestricted funds share of
indirect costs = 20,000−6,000 = 14,000
Therefore, the amount of the indirect costs allocated to the unrestricted funds is 14,000.
7. Question: A non-profit organization has three separate funds: Fund A, Fund B, and Fund C. Fund
A incurred expenses of 10,000, F undBincurredexpensesof 15,000, and Fund C incurred expenses of
20,000.T heorganization′stotalindirectcostsf ortheyearare5,000. If the organization wants to allocate
indirect costs based on the proportion of expenses in each fund, how much indirect cost should be allocated
to Fund A?
Solution: To allocate indirect costs based on the proportion of expenses in each fund, we need to calcu-
late the total expenses across all funds first.
Total Expenses = 10,000(F undA)+15,000 (Fund B) + 20,000(F undC)T otalExpenses =45,000
Next, we calculate the proportion of expenses for each fund:
Proportion of Fund A’s Expenses = Fund A’s Expenses / Total Expenses Proportion of Fund A’s Expenses
=10,000/45,000 Proportion of Fund A’s Expenses = 1/4 or 0.25
Now, we allocate the total indirect costs to Fund A based on its proportion of expenses:
Indirect Cost Allocated to Fund A = Proportion of Fund A’s Expenses * Total Indirect Costs Indirect
Cost Allocated to Fund A = 0.25 * 5,000IndirectCostAllocatedtoF undA =1,250
Therefore, 1,250ofindirectcostsshouldbeallocatedtoF undA.
8. Question: A non-profit organization receives a donation of 10,000thatisrestrictedtobeusedforaspecif icprogram.T heorganizationincursexpensesof6,000
directly related to this program. How much is the remaining balance of the restricted fund for this program?
Solution: The remaining balance of the restricted fund for the specific program can be found by sub-
tracting the expenses incurred from the total donation amount.
Remaining Balance = Total Donation - Program Expenses Remaining Balance = 10,000−6,000 Re-
maining Balance = 4,000
Therefore, the remaining balance of the restricted fund for this program is 4,000.
9. Question: A non-profit organization receives a donation of 10,000specif icallydesignatedforabuildingrenovationproject.Duringthecurrentfiscalyear, theorganizationuses5,000
of the donation for the project. At the end of the fiscal year, what are the balances of the temporarily re-
stricted fund and the amount available for general use in the unrestricted fund?
Solution: 1. Temporary Restricted Fund Balance: - Initial donation: 10,000−Amountusedf ortheproject :5,000
- Balance of temporarily restricted fund = Initial donation - Amount used - Balance of temporarily restricted
fund = 10,000−5,000 - Balance of temporarily restricted fund = 5,000
2. Unrestricted Fund Balance: - Any part of the donation not used for the project remains in the tem-
porarily restricted fund. - Amount available for general use in the unrestricted fund = Initial donation -
Amount in temporarily restricted for the project - Amount available for general use in the unrestricted fund
=10,000−5,000 - Amount available for general use in the unrestricted fund = 5,000
Therefore, at the end of the fiscal year, the balance of the temporarily restricted fund is 5,000, andtheamountavailableforgeneraluseintheunrestrictedfundisalso5,000.
10. Question: A non-profit organization incurred total operating expenses of 50,000.F romthatamount,12,000
expenses were incurred specifically for the education fund, 8,000forthehealthcaref und, andtheremainingexpensesweregeneraloperatingexpenses.W hatpercentageof thetotaloperatingexpenseswereallocatedtotheeducationf und?
Solution: To find the percentage of total operating expenses allocated to the education fund, we first
need to calculate the total specific allocations for the education fund:
Total specific allocation for education fund = 12,000
Then, we calculate the total operating expenses allocated to the education fund:

Total operating expenses allocated to the education fund = Total specific allocation for education fund +
General operating expenses Total operating expenses allocated to the education fund = 12,000 + (50,000 -
12,000−8,000) Total operating expenses allocated to the education fund = 12,000+30,000 Total operating
expenses allocated to the education fund = 42,000
Finally, we calculate the percentage of total operating expenses allocated to the education fund:
Percentage allocated to education fund = (Total operating expenses allocated to education fund / To-
tal operating expenses) * 100Percentage allocated to education fund = (42,000/50,000) * 100Percentage
allocated to education fund = 0.84 * 100Percentage allocated to education fund = 84
Therefore, 84
11. Question: A non-profit organization receives a donation of 10,000restrictedforaspecif icpurpose.T heorganizationspends4,000
on the designated program and incurs 1,500infundraisingexpensesrelatedtothesameprogram.Howmuchoftherestrictedfundsarestillavailableforthedesignatedpurpose?
Solution: Initially, the organization received 10,000asarestricteddonation.Af terspending4,000 on
the designated program, the remaining amount is 10,000−4,000 = 6,000.However, theyalsoincurred1,500
in fundraising expenses related to the designated program. This amount needs to be subtracted from the re-
maining funds. Therefore, the total amount available for the designated purpose is 6,000−1,500 = 4,500.
Final Answer: 4,500
12. Question: A non-profit organization received a grant of 50,000thatisrestrictedforaspecif icprogram.Duringthefiscalyear, theorganizationspent20,000
on the program. Calculate the amount of restricted funds remaining at the end of the fiscal year.
Solution: Restricted funds remaining = Grant amount - Expenditure on the program Restricted funds
remaining = 50,000−20,000 Restricted funds remaining = 30,000
Therefore, the amount of restricted funds remaining at the end of the fiscal year is 30,000.
13. Question: A non-profit organization has total expenses of 100,000, anditincurred20,000 in fundrais-
ing expenses, 30,000inprogramAexpenses, and25,000 in program B expenses. Calculate the percentage
of total expenses allocated to program A.
Solution: To calculate the percentage of total expenses allocated to program A, we need to first find the
total expenses allocated to program A.
Total expenses allocated to program A = fundraising expenses + program A expenses Total expenses
allocated to program A = 20,000+30,000 Total expenses allocated to program A = 50,000
Now, we can calculate the percentage of total expenses allocated to program A by dividing the total
expenses allocated to program A by the total expenses and multiplying by 100.
Percentage of total expenses allocated to program A = (Total expenses allocated to program A / Total
expenses) * 100 Percentage of total expenses allocated to program A = (50,000/100,000) * 100 Percentage
of total expenses allocated to program A = 0.5 * 100 Percentage of total expenses allocated to program A =
50
Therefore, 50
14. Question: A non-profit organization has total funds of 100,000.40
Solution: Total funds = 100,000Restrictedfunds = 40Unrestrictedfunds =T otalfunds−RestrictedfundsUnrestrictedfunds =100,000
-40,000Unrestrictedfunds =60,000
Therefore, 60,000isallocatedtotheunrestrictedaccount.
15. Question: In a non-profit organization, if the total indirect costs amount to 50,000andaretobeallocatedtotwodifferentprogramsbasedonthedirectcostsincurredbyeachprogram, withP rogramAhavingdirectcostsof30,000
and Program B having direct costs of 20,000, whatistheallocationof indirectcostsf orP rogramA?
Solution: To allocate the indirect costs to each program based on their direct costs, we need to find the
proportion of each program’s direct costs to the total direct costs of both programs.

Total direct costs = Direct costs of Program A + Direct costs of Program B Total direct costs = 30,000+20,000
Total direct costs = 50,000
Now, find the proportion of direct costs for Program A: Proportion of direct costs for Program A =
Direct costs of Program A / Total direct costs Proportion of direct costs for Program A = 30,000/50,000
Proportion of direct costs for Program A = 0.6 or 60
Next, allocate the total indirect costs based on the proportion of direct costs for Program A: Indirect
costs allocated to Program A = Proportion of direct costs for Program A * Total indirect costs Indirect costs
allocated to Program A = 0.6 * 50,000IndirectcostsallocatedtoP rogramA =30,000
Therefore, the allocation of indirect costs for Program A would be 30,000.
16. Question: A non-profit organization receives a grant of 10,000specif icallydesignatedf oraspecialprogram.T heorganizationincurs2,000
in administrative expenses that benefit multiple programs, including the special program funded by the grant.
How much of the administrative expenses should be allocated to the special program using a proportional
allocation method based on the grant amount?
Solution: 1. Calculate the percentage of the grant amount relative to the total funds received: Grant
Percentage = (Grant Amount / Total Funds Received) * 100 = (10,000/10,000) * 100 = 100
2. Allocate the administrative expenses to the special program based on the grant percentage: Adminis-
trative Expenses Allocated = Grant Percentage * Total Administrative Expenses = 100= 1.00 * 2,000 =2,000
Therefore, using the proportional allocation method based on the grant amount, 2,000oftheadministrativeexpensesshouldbeallocatedtothespecialprogram.
17. Question: A non-profit organization incurred total administrative costs of 50,000f ortheyear.Ofthisamount,10,000
relates to a program funded by restricted funds. How much of the administrative costs should be allocated
to the restricted funds?
Solution: To determine the allocation of costs to restricted funds, we need to calculate the proportion of
administrative costs that relate to the program funded by restricted funds.
Proportion of administrative costs allocated to restricted funds = (Costs related to restricted funds / Total
administrative costs) Proportion of administrative costs allocated to restricted funds = (10,000/50,000) =
0.2 or 20
Now, we can calculate the specific amount of administrative costs that should be allocated to the re-
stricted funds:
Administrative costs allocated to restricted funds = Proportion of administrative costs allocated to re-
stricted funds * Total administrative costs Administrative costs allocated to restricted funds = 0.2 * 50,000 =10,000
Therefore, 10,000ofthetotaladministrativecostsshouldbeallocatedtotheprogramfundedbyrestrictedfunds.
18. Question: A non-profit organization has total restricted funds of 50,000.If40
Solution: To find the amount allocated to the specific project, we need to calculate 40
Amount allocated to project = 40Amount allocated to project = 0.40 * 50,000Amountallocatedtoproject =20,000
Therefore, 20,000isallocatedtothespecificprojectwithinthenon −profitorganization.
19. Question: A non-profit organization has total funds of 500,000, ofwhich100,000 is restricted for a
specific program. If the organization spends 30,000ontherestrictedprogram, whatistheremainingbalanceintherestrictedfund?
Solution: 1. Total funds = 500,0002.Restrictedfunds =100,000 3. Amount spent on restricted pro-
gram = 30,000
To find the remaining balance in the restricted fund after spending on the program, we subtract the
amount spent from the initial restricted funds:
Remaining balance = Restricted funds - Amount spent Remaining balance = 100,000−30,000 Remain-
ing balance = 70,000
Therefore, the remaining balance in the restricted fund is 70,000.

20. Question: A non-profit organization has total funds of 500,000.Outofthisamount,150,000 is
classified as restricted funds and the rest as unrestricted funds. What is the percentage of the organization’s
total funds that are classified as restricted funds?
Solution: To find the percentage of restricted funds out of the total funds, we first need to calculate the
proportion of restricted funds to total funds.
Restricted funds / Total funds = 150,000/500,000 = 0.3
Now, to convert this proportion to a percentage, we multiply by 100.
Percentage of restricted funds = 0.3 * 100 = 30
Therefore, 30
21. Question: A non-profit organization receives a donation of 10,000thatisrestrictedforaspecif icprogram.If theorganizationspends5,000
from this restricted donation on the program, how much remains in the restricted fund?
Solution: To determine how much remains in the restricted fund after spending 5,000ontheprogram, wesimplysubtracttheamountspentfromtheinitialrestricteddonation.
Initial restricted donation = 10,000Amountspentontheprogram =5,000
Remaining amount in the restricted fund = 10,000−5,000 = 5,000
Therefore, the remaining amount in the restricted fund is 5,000.
22. Question: A non-profit organization has a total of 50,000infunds.T heyallocate40
Solution: To find the amount allocated to the restricted account, we first calculate 4050,000∗0.40 =20,000
Therefore, 20,000isallocatedtotherestrictedaccount.
23. Question: A non-profit organization has total funds of 100,000.40
Solution: 1. Calculate the current amount of funds in the restricted account: Restricted funds = Total
funds * Percentage restricted Restricted funds = 100,000 ∗40
2. Since the organization needs to allocate an additional 30,000totherestrictedfunds, thenewamountintherestrictedaccountwillbe :
Newrestrictedfunds =40,000 + 30,000 =70,000
3. To find the new amount in the unrestricted funds, simply subtract the new amount in the restricted
funds from the total funds: New unrestricted funds = Total funds - New restricted funds New unrestricted
funds = 100,000−70,000 New unrestricted funds = 30,000
Therefore, the new amount in the unrestricted funds will be 30,000.
24. Question: A non-profit organization has total unrestricted net assets of 100,000andtotalrestrictednetassetsof50,000.
If the organization designates 20,000fromtheunrestrictednetassetstoanewdonor−restrictedfund, whatwillbethenewbalanceofunrestrictednetassets?
Solution: Total Unrestricted Net Assets = 100,000T otalRestrictedN etAssets =50,000 Amount des-
ignated to new donor-restricted fund from Unrestricted Net Assets = 20,000
New Unrestricted Net Assets = Total Unrestricted Net Assets - Amount designated to new fund New
Unrestricted Net Assets = 100,000−20,000 New Unrestricted Net Assets = 80,000
Therefore, the new balance of unrestricted net assets after designating 20,000toanewdonor−restrictedfundwouldbe80,000.
25. Question: A non-profit organization has three funds: Fund A, Fund B, and Fund C. Fund A
incurred 10,000inexpensesthatwereallocabletoallthreef unds, F undBincurred5,000 in expenses that
were specific to Fund B only, and Fund C incurred 8,000inexpensesthatwereallocabletoF undAandF undC.If theorganizationwantstoallocatetheexpensesproportionallybasedonthetotalrevenueofeachfund, andthetotalrevenueforF undA, F undB, andF undCis100,000,
50,000, and80,000 respectively, what would be the total amount of expenses allocated to Fund A?
Solution: 1. Calculate the total revenue for all funds: 100,000(F undA)+50,000 (Fund B) + 80,000(F undC) =230,000
2. Calculate the proportion of total revenue for each fund: - Fund A: 100,000/230,000 = 0.4348 - Fund B:
50,000/230,000 = 0.2174 - Fund C: 80,000/230,000 = 0.3478 3. Allocate the shared expenses to each fund
proportionally: - Fund A: 10,000 ∗0.4348 =4,348 - Fund B: 10,000 ∗0.2174 =2,174 - Fund C: 10,000 ∗

0.3478 =3,478 4. Allocate Fund B’s expenses to Fund B: 5,0005.AllocateF undC′sexpensestoF undAandF undCproportionally :
−F undA :8,000 * 0.4348 = 3,478 −F undC :8,000 * 0.3478 = 2,784
Total expenses allocated to Fund A = 4,348(sharedexpenses)+3,478 (expenses from Fund C) = 7,826
indirect costs * Restricted funds share of indirect costs = 20,000 ∗30
Now, the remaining indirect costs will be allocated to the unrestricted funds. Unrestricted funds share
of indirect costs = Total indirect costs - Restricted funds share of indirect costs Unrestricted funds share of
indirect costs = 20,000−6,000 = 14,000
Therefore, the amount of the indirect costs allocated to the unrestricted funds is 14,000.
7. Question: A non-profit organization has three separate funds: Fund A, Fund B, and Fund C. Fund
A incurred expenses of 10,000, F undBincurredexpensesof 15,000, and Fund C incurred expenses of
20,000.T heorganization′stotalindirectcostsf ortheyearare5,000. If the organization wants to allocate
indirect costs based on the proportion of expenses in each fund, how much indirect cost should be allocated
to Fund A?
Solution: To allocate indirect costs based on the proportion of expenses in each fund, we need to calcu-
late the total expenses across all funds first.
Total Expenses = 10,000(F undA)+15,000 (Fund B) + 20,000(F undC)T otalExpenses =45,000
Next, we calculate the proportion of expenses for each fund:
Proportion of Fund A’s Expenses = Fund A’s Expenses / Total Expenses Proportion of Fund A’s Expenses
=10,000/45,000 Proportion of Fund A’s Expenses = 1/4 or 0.25
Now, we allocate the total indirect costs to Fund A based on its proportion of expenses:
Indirect Cost Allocated to Fund A = Proportion of Fund A’s Expenses * Total Indirect Costs Indirect
Cost Allocated to Fund A = 0.25 * 5,000IndirectCostAllocatedtoF undA =1,250
Therefore, 1,250ofindirectcostsshouldbeallocatedtoF undA.
8. Question: A non-profit organization receives a donation of 10,000thatisrestrictedtobeusedforaspecif icprogram.T heorganizationincursexpensesof6,000
directly related to this program. How much is the remaining balance of the restricted fund for this program?
Solution: The remaining balance of the restricted fund for the specific program can be found by sub-
tracting the expenses incurred from the total donation amount.
Remaining Balance = Total Donation - Program Expenses Remaining Balance = 10,000−6,000 Re-
maining Balance = 4,000
Therefore, the remaining balance of the restricted fund for this program is 4,000.
9. Question: A non-profit organization receives a donation of 10,000specif icallydesignatedforabuildingrenovationproject.Duringthecurrentfiscalyear, theorganizationuses5,000
of the donation for the project. At the end of the fiscal year, what are the balances of the temporarily re-
stricted fund and the amount available for general use in the unrestricted fund?
Solution: 1. Temporary Restricted Fund Balance: - Initial donation: 10,000−Amountusedf ortheproject :5,000
- Balance of temporarily restricted fund = Initial donation - Amount used - Balance of temporarily restricted
fund = 10,000−5,000 - Balance of temporarily restricted fund = 5,000
2. Unrestricted Fund Balance: - Any part of the donation not used for the project remains in the tem-
porarily restricted fund. - Amount available for general use in the unrestricted fund = Initial donation -
Amount in temporarily restricted for the project - Amount available for general use in the unrestricted fund
=10,000−5,000 - Amount available for general use in the unrestricted fund = 5,000
Therefore, at the end of the fiscal year, the balance of the temporarily restricted fund is 5,000, andtheamountavailableforgeneraluseintheunrestrictedfundisalso5,000.
10. Question: A non-profit organization incurred total operating expenses of 50,000.F romthatamount,12,000
expenses were incurred specifically for the education fund, 8,000forthehealthcaref und, andtheremainingexpensesweregeneraloperatingexpenses.W hatpercentageof thetotaloperatingexpenseswereallocatedtotheeducationf und?
Solution: To find the percentage of total operating expenses allocated to the education fund, we first
need to calculate the total specific allocations for the education fund:
Total specific allocation for education fund = 12,000
Then, we calculate the total operating expenses allocated to the education fund:

Total operating expenses allocated to the education fund = Total specific allocation for education fund +
General operating expenses Total operating expenses allocated to the education fund = 12,000 + (50,000 -
12,000−8,000) Total operating expenses allocated to the education fund = 12,000+30,000 Total operating
expenses allocated to the education fund = 42,000
Finally, we calculate the percentage of total operating expenses allocated to the education fund:
Percentage allocated to education fund = (Total operating expenses allocated to education fund / To-
tal operating expenses) * 100Percentage allocated to education fund = (42,000/50,000) * 100Percentage
allocated to education fund = 0.84 * 100Percentage allocated to education fund = 84
Therefore, 84
11. Question: A non-profit organization receives a donation of 10,000restrictedforaspecif icpurpose.T heorganizationspends4,000
on the designated program and incurs 1,500infundraisingexpensesrelatedtothesameprogram.Howmuchoftherestrictedfundsarestillavailableforthedesignatedpurpose?
Solution: Initially, the organization received 10,000asarestricteddonation.Af terspending4,000 on
the designated program, the remaining amount is 10,000−4,000 = 6,000.However, theyalsoincurred1,500
in fundraising expenses related to the designated program. This amount needs to be subtracted from the re-
maining funds. Therefore, the total amount available for the designated purpose is 6,000−1,500 = 4,500.
Final Answer: 4,500
12. Question: A non-profit organization received a grant of 50,000thatisrestrictedforaspecif icprogram.Duringthefiscalyear, theorganizationspent20,000
on the program. Calculate the amount of restricted funds remaining at the end of the fiscal year.
Solution: Restricted funds remaining = Grant amount - Expenditure on the program Restricted funds
remaining = 50,000−20,000 Restricted funds remaining = 30,000
Therefore, the amount of restricted funds remaining at the end of the fiscal year is 30,000.
13. Question: A non-profit organization has total expenses of 100,000, anditincurred20,000 in fundrais-
ing expenses, 30,000inprogramAexpenses, and25,000 in program B expenses. Calculate the percentage
of total expenses allocated to program A.
Solution: To calculate the percentage of total expenses allocated to program A, we need to first find the
total expenses allocated to program A.
Total expenses allocated to program A = fundraising expenses + program A expenses Total expenses
allocated to program A = 20,000+30,000 Total expenses allocated to program A = 50,000
Now, we can calculate the percentage of total expenses allocated to program A by dividing the total
expenses allocated to program A by the total expenses and multiplying by 100.
Percentage of total expenses allocated to program A = (Total expenses allocated to program A / Total
expenses) * 100 Percentage of total expenses allocated to program A = (50,000/100,000) * 100 Percentage
of total expenses allocated to program A = 0.5 * 100 Percentage of total expenses allocated to program A =
50
Therefore, 50
14. Question: A non-profit organization has total funds of 100,000.40
Solution: Total funds = 100,000Restrictedfunds = 40Unrestrictedfunds =T otalfunds−RestrictedfundsUnrestrictedfunds =100,000
-40,000Unrestrictedfunds =60,000
Therefore, 60,000isallocatedtotheunrestrictedaccount.
15. Question: In a non-profit organization, if the total indirect costs amount to 50,000andaretobeallocatedtotwodifferentprogramsbasedonthedirectcostsincurredbyeachprogram, withP rogramAhavingdirectcostsof30,000
and Program B having direct costs of 20,000, whatistheallocationof indirectcostsf orP rogramA?
Solution: To allocate the indirect costs to each program based on their direct costs, we need to find the
proportion of each program’s direct costs to the total direct costs of both programs.

Total direct costs = Direct costs of Program A + Direct costs of Program B Total direct costs = 30,000+20,000
Total direct costs = 50,000
Now, find the proportion of direct costs for Program A: Proportion of direct costs for Program A =
Direct costs of Program A / Total direct costs Proportion of direct costs for Program A = 30,000/50,000
Proportion of direct costs for Program A = 0.6 or 60
Next, allocate the total indirect costs based on the proportion of direct costs for Program A: Indirect
costs allocated to Program A = Proportion of direct costs for Program A * Total indirect costs Indirect costs
allocated to Program A = 0.6 * 50,000IndirectcostsallocatedtoP rogramA =30,000
Therefore, the allocation of indirect costs for Program A would be 30,000.
16. Question: A non-profit organization receives a grant of 10,000specif icallydesignatedf oraspecialprogram.T heorganizationincurs2,000
in administrative expenses that benefit multiple programs, including the special program funded by the grant.
How much of the administrative expenses should be allocated to the special program using a proportional
allocation method based on the grant amount?
Solution: 1. Calculate the percentage of the grant amount relative to the total funds received: Grant
Percentage = (Grant Amount / Total Funds Received) * 100 = (10,000/10,000) * 100 = 100
2. Allocate the administrative expenses to the special program based on the grant percentage: Adminis-
trative Expenses Allocated = Grant Percentage * Total Administrative Expenses = 100= 1.00 * 2,000 =2,000
Therefore, using the proportional allocation method based on the grant amount, 2,000oftheadministrativeexpensesshouldbeallocatedtothespecialprogram.
17. Question: A non-profit organization incurred total administrative costs of 50,000f ortheyear.Ofthisamount,10,000
relates to a program funded by restricted funds. How much of the administrative costs should be allocated
to the restricted funds?
Solution: To determine the allocation of costs to restricted funds, we need to calculate the proportion of
administrative costs that relate to the program funded by restricted funds.
Proportion of administrative costs allocated to restricted funds = (Costs related to restricted funds / Total
administrative costs) Proportion of administrative costs allocated to restricted funds = (10,000/50,000) =
0.2 or 20
Now, we can calculate the specific amount of administrative costs that should be allocated to the re-
stricted funds:
Administrative costs allocated to restricted funds = Proportion of administrative costs allocated to re-
stricted funds * Total administrative costs Administrative costs allocated to restricted funds = 0.2 * 50,000 =10,000
Therefore, 10,000ofthetotaladministrativecostsshouldbeallocatedtotheprogramfundedbyrestrictedfunds.
18. Question: A non-profit organization has total restricted funds of 50,000.If40
Solution: To find the amount allocated to the specific project, we need to calculate 40
Amount allocated to project = 40Amount allocated to project = 0.40 * 50,000Amountallocatedtoproject =20,000
Therefore, 20,000isallocatedtothespecificprojectwithinthenon −profitorganization.
19. Question: A non-profit organization has total funds of 500,000, ofwhich100,000 is restricted for a
specific program. If the organization spends 30,000ontherestrictedprogram, whatistheremainingbalanceintherestrictedfund?
Solution: 1. Total funds = 500,0002.Restrictedfunds =100,000 3. Amount spent on restricted pro-
gram = 30,000
To find the remaining balance in the restricted fund after spending on the program, we subtract the
amount spent from the initial restricted funds:
Remaining balance = Restricted funds - Amount spent Remaining balance = 100,000−30,000 Remain-
ing balance = 70,000
Therefore, the remaining balance in the restricted fund is 70,000.

20. Question: A non-profit organization has total funds of 500,000.Outofthisamount,150,000 is
classified as restricted funds and the rest as unrestricted funds. What is the percentage of the organization’s
total funds that are classified as restricted funds?
Solution: To find the percentage of restricted funds out of the total funds, we first need to calculate the
proportion of restricted funds to total funds.
Restricted funds / Total funds = 150,000/500,000 = 0.3
Now, to convert this proportion to a percentage, we multiply by 100.
Percentage of restricted funds = 0.3 * 100 = 30
Therefore, 30
21. Question: A non-profit organization receives a donation of 10,000thatisrestrictedforaspecif icprogram.If theorganizationspends5,000
from this restricted donation on the program, how much remains in the restricted fund?
Solution: To determine how much remains in the restricted fund after spending 5,000ontheprogram, wesimplysubtracttheamountspentfromtheinitialrestricteddonation.
Initial restricted donation = 10,000Amountspentontheprogram =5,000
Remaining amount in the restricted fund = 10,000−5,000 = 5,000
Therefore, the remaining amount in the restricted fund is 5,000.
22. Question: A non-profit organization has a total of 50,000infunds.T heyallocate40
Solution: To find the amount allocated to the restricted account, we first calculate 4050,000∗0.40 =20,000
Therefore, 20,000isallocatedtotherestrictedaccount.
23. Question: A non-profit organization has total funds of 100,000.40
Solution: 1. Calculate the current amount of funds in the restricted account: Restricted funds = Total
funds * Percentage restricted Restricted funds = 100,000 ∗40
2. Since the organization needs to allocate an additional 30,000totherestrictedfunds, thenewamountintherestrictedaccountwillbe :
Newrestrictedfunds =40,000 + 30,000 =70,000
3. To find the new amount in the unrestricted funds, simply subtract the new amount in the restricted
funds from the total funds: New unrestricted funds = Total funds - New restricted funds New unrestricted
funds = 100,000−70,000 New unrestricted funds = 30,000
Therefore, the new amount in the unrestricted funds will be 30,000.
24. Question: A non-profit organization has total unrestricted net assets of 100,000andtotalrestrictednetassetsof50,000.
If the organization designates 20,000fromtheunrestrictednetassetstoanewdonor−restrictedfund, whatwillbethenewbalanceofunrestrictednetassets?
Solution: Total Unrestricted Net Assets = 100,000T otalRestrictedN etAssets =50,000 Amount des-
ignated to new donor-restricted fund from Unrestricted Net Assets = 20,000
New Unrestricted Net Assets = Total Unrestricted Net Assets - Amount designated to new fund New
Unrestricted Net Assets = 100,000−20,000 New Unrestricted Net Assets = 80,000
Therefore, the new balance of unrestricted net assets after designating 20,000toanewdonor−restrictedfundwouldbe80,000.
25. Question: A non-profit organization has three funds: Fund A, Fund B, and Fund C. Fund A
incurred 10,000inexpensesthatwereallocabletoallthreef unds, F undBincurred5,000 in expenses that
were specific to Fund B only, and Fund C incurred 8,000inexpensesthatwereallocabletoF undAandF undC.If theorganizationwantstoallocatetheexpensesproportionallybasedonthetotalrevenueofeachfund, andthetotalrevenueforF undA, F undB, andF undCis100,000,
50,000, and80,000 respectively, what would be the total amount of expenses allocated to Fund A?
Solution: 1. Calculate the total revenue for all funds: 100,000(F undA)+50,000 (Fund B) + 80,000(F undC) =230,000
2. Calculate the proportion of total revenue for each fund: - Fund A: 100,000/230,000 = 0.4348 - Fund B:
50,000/230,000 = 0.2174 - Fund C: 80,000/230,000 = 0.3478 3. Allocate the shared expenses to each fund
proportionally: - Fund A: 10,000 ∗0.4348 =4,348 - Fund B: 10,000 ∗0.2174 =2,174 - Fund C: 10,000 ∗

0.3478 =3,478 4. Allocate Fund B’s expenses to Fund B: 5,0005.AllocateF undC′sexpensestoF undAandF undCproportionally :
−F undA :8,000 * 0.4348 = 3,478 −F undC :8,000 * 0.3478 = 2,784
Total expenses allocated to Fund A = 4,348(sharedexpenses)+3,478 (expenses from Fund C) = 7,826
indirect costs * Restricted funds share of indirect costs = 20,000 ∗30
Now, the remaining indirect costs will be allocated to the unrestricted funds. Unrestricted funds share
of indirect costs = Total indirect costs - Restricted funds share of indirect costs Unrestricted funds share of
indirect costs = 20,000−6,000 = 14,000
Therefore, the amount of the indirect costs allocated to the unrestricted funds is 14,000.
7. Question: A non-profit organization has three separate funds: Fund A, Fund B, and Fund C. Fund
A incurred expenses of 10,000, F undBincurredexpensesof 15,000, and Fund C incurred expenses of
20,000.T heorganization′stotalindirectcostsf ortheyearare5,000. If the organization wants to allocate
indirect costs based on the proportion of expenses in each fund, how much indirect cost should be allocated
to Fund A?
Solution: To allocate indirect costs based on the proportion of expenses in each fund, we need to calcu-
late the total expenses across all funds first.
Total Expenses = 10,000(F undA)+15,000 (Fund B) + 20,000(F undC)T otalExpenses =45,000
Next, we calculate the proportion of expenses for each fund:
Proportion of Fund A’s Expenses = Fund A’s Expenses / Total Expenses Proportion of Fund A’s Expenses
=10,000/45,000 Proportion of Fund A’s Expenses = 1/4 or 0.25
Now, we allocate the total indirect costs to Fund A based on its proportion of expenses:
Indirect Cost Allocated to Fund A = Proportion of Fund A’s Expenses * Total Indirect Costs Indirect
Cost Allocated to Fund A = 0.25 * 5,000IndirectCostAllocatedtoF undA =1,250
Therefore, 1,250ofindirectcostsshouldbeallocatedtoF undA.
8. Question: A non-profit organization receives a donation of 10,000thatisrestrictedtobeusedforaspecif icprogram.T heorganizationincursexpensesof6,000
directly related to this program. How much is the remaining balance of the restricted fund for this program?
Solution: The remaining balance of the restricted fund for the specific program can be found by sub-
tracting the expenses incurred from the total donation amount.
Remaining Balance = Total Donation - Program Expenses Remaining Balance = 10,000−6,000 Re-
maining Balance = 4,000
Therefore, the remaining balance of the restricted fund for this program is 4,000.
9. Question: A non-profit organization receives a donation of 10,000specif icallydesignatedforabuildingrenovationproject.Duringthecurrentfiscalyear, theorganizationuses5,000
of the donation for the project. At the end of the fiscal year, what are the balances of the temporarily re-
stricted fund and the amount available for general use in the unrestricted fund?
Solution: 1. Temporary Restricted Fund Balance: - Initial donation: 10,000−Amountusedf ortheproject :5,000
- Balance of temporarily restricted fund = Initial donation - Amount used - Balance of temporarily restricted
fund = 10,000−5,000 - Balance of temporarily restricted fund = 5,000
2. Unrestricted Fund Balance: - Any part of the donation not used for the project remains in the tem-
porarily restricted fund. - Amount available for general use in the unrestricted fund = Initial donation -
Amount in temporarily restricted for the project - Amount available for general use in the unrestricted fund
=10,000−5,000 - Amount available for general use in the unrestricted fund = 5,000
Therefore, at the end of the fiscal year, the balance of the temporarily restricted fund is 5,000, andtheamountavailableforgeneraluseintheunrestrictedfundisalso5,000.
10. Question: A non-profit organization incurred total operating expenses of 50,000.F romthatamount,12,000
expenses were incurred specifically for the education fund, 8,000forthehealthcaref und, andtheremainingexpensesweregeneraloperatingexpenses.W hatpercentageof thetotaloperatingexpenseswereallocatedtotheeducationf und?
Solution: To find the percentage of total operating expenses allocated to the education fund, we first
need to calculate the total specific allocations for the education fund:
Total specific allocation for education fund = 12,000
Then, we calculate the total operating expenses allocated to the education fund:

Total operating expenses allocated to the education fund = Total specific allocation for education fund +
General operating expenses Total operating expenses allocated to the education fund = 12,000 + (50,000 -
12,000−8,000) Total operating expenses allocated to the education fund = 12,000+30,000 Total operating
expenses allocated to the education fund = 42,000
Finally, we calculate the percentage of total operating expenses allocated to the education fund:
Percentage allocated to education fund = (Total operating expenses allocated to education fund / To-
tal operating expenses) * 100Percentage allocated to education fund = (42,000/50,000) * 100Percentage
allocated to education fund = 0.84 * 100Percentage allocated to education fund = 84
Therefore, 84
11. Question: A non-profit organization receives a donation of 10,000restrictedforaspecif icpurpose.T heorganizationspends4,000
on the designated program and incurs 1,500infundraisingexpensesrelatedtothesameprogram.Howmuchoftherestrictedfundsarestillavailableforthedesignatedpurpose?
Solution: Initially, the organization received 10,000asarestricteddonation.Af terspending4,000 on
the designated program, the remaining amount is 10,000−4,000 = 6,000.However, theyalsoincurred1,500
in fundraising expenses related to the designated program. This amount needs to be subtracted from the re-
maining funds. Therefore, the total amount available for the designated purpose is 6,000−1,500 = 4,500.
Final Answer: 4,500
12. Question: A non-profit organization received a grant of 50,000thatisrestrictedforaspecif icprogram.Duringthefiscalyear, theorganizationspent20,000
on the program. Calculate the amount of restricted funds remaining at the end of the fiscal year.
Solution: Restricted funds remaining = Grant amount - Expenditure on the program Restricted funds
remaining = 50,000−20,000 Restricted funds remaining = 30,000
Therefore, the amount of restricted funds remaining at the end of the fiscal year is 30,000.
13. Question: A non-profit organization has total expenses of 100,000, anditincurred20,000 in fundrais-
ing expenses, 30,000inprogramAexpenses, and25,000 in program B expenses. Calculate the percentage
of total expenses allocated to program A.
Solution: To calculate the percentage of total expenses allocated to program A, we need to first find the
total expenses allocated to program A.
Total expenses allocated to program A = fundraising expenses + program A expenses Total expenses
allocated to program A = 20,000+30,000 Total expenses allocated to program A = 50,000
Now, we can calculate the percentage of total expenses allocated to program A by dividing the total
expenses allocated to program A by the total expenses and multiplying by 100.
Percentage of total expenses allocated to program A = (Total expenses allocated to program A / Total
expenses) * 100 Percentage of total expenses allocated to program A = (50,000/100,000) * 100 Percentage
of total expenses allocated to program A = 0.5 * 100 Percentage of total expenses allocated to program A =
50
Therefore, 50
14. Question: A non-profit organization has total funds of 100,000.40
Solution: Total funds = 100,000Restrictedfunds = 40Unrestrictedfunds =T otalfunds−RestrictedfundsUnrestrictedfunds =100,000
-40,000Unrestrictedfunds =60,000
Therefore, 60,000isallocatedtotheunrestrictedaccount.
15. Question: In a non-profit organization, if the total indirect costs amount to 50,000andaretobeallocatedtotwodifferentprogramsbasedonthedirectcostsincurredbyeachprogram, withP rogramAhavingdirectcostsof30,000
and Program B having direct costs of 20,000, whatistheallocationof indirectcostsf orP rogramA?
Solution: To allocate the indirect costs to each program based on their direct costs, we need to find the
proportion of each program’s direct costs to the total direct costs of both programs.

Total direct costs = Direct costs of Program A + Direct costs of Program B Total direct costs = 30,000+20,000
Total direct costs = 50,000
Now, find the proportion of direct costs for Program A: Proportion of direct costs for Program A =
Direct costs of Program A / Total direct costs Proportion of direct costs for Program A = 30,000/50,000
Proportion of direct costs for Program A = 0.6 or 60
Next, allocate the total indirect costs based on the proportion of direct costs for Program A: Indirect
costs allocated to Program A = Proportion of direct costs for Program A * Total indirect costs Indirect costs
allocated to Program A = 0.6 * 50,000IndirectcostsallocatedtoP rogramA =30,000
Therefore, the allocation of indirect costs for Program A would be 30,000.
16. Question: A non-profit organization receives a grant of 10,000specif icallydesignatedf oraspecialprogram.T heorganizationincurs2,000
in administrative expenses that benefit multiple programs, including the special program funded by the grant.
How much of the administrative expenses should be allocated to the special program using a proportional
allocation method based on the grant amount?
Solution: 1. Calculate the percentage of the grant amount relative to the total funds received: Grant
Percentage = (Grant Amount / Total Funds Received) * 100 = (10,000/10,000) * 100 = 100
2. Allocate the administrative expenses to the special program based on the grant percentage: Adminis-
trative Expenses Allocated = Grant Percentage * Total Administrative Expenses = 100= 1.00 * 2,000 =2,000
Therefore, using the proportional allocation method based on the grant amount, 2,000oftheadministrativeexpensesshouldbeallocatedtothespecialprogram.
17. Question: A non-profit organization incurred total administrative costs of 50,000f ortheyear.Ofthisamount,10,000
relates to a program funded by restricted funds. How much of the administrative costs should be allocated
to the restricted funds?
Solution: To determine the allocation of costs to restricted funds, we need to calculate the proportion of
administrative costs that relate to the program funded by restricted funds.
Proportion of administrative costs allocated to restricted funds = (Costs related to restricted funds / Total
administrative costs) Proportion of administrative costs allocated to restricted funds = (10,000/50,000) =
0.2 or 20
Now, we can calculate the specific amount of administrative costs that should be allocated to the re-
stricted funds:
Administrative costs allocated to restricted funds = Proportion of administrative costs allocated to re-
stricted funds * Total administrative costs Administrative costs allocated to restricted funds = 0.2 * 50,000 =10,000
Therefore, 10,000ofthetotaladministrativecostsshouldbeallocatedtotheprogramfundedbyrestrictedfunds.
18. Question: A non-profit organization has total restricted funds of 50,000.If40
Solution: To find the amount allocated to the specific project, we need to calculate 40
Amount allocated to project = 40Amount allocated to project = 0.40 * 50,000Amountallocatedtoproject =20,000
Therefore, 20,000isallocatedtothespecificprojectwithinthenon −profitorganization.
19. Question: A non-profit organization has total funds of 500,000, ofwhich100,000 is restricted for a
specific program. If the organization spends 30,000ontherestrictedprogram, whatistheremainingbalanceintherestrictedfund?
Solution: 1. Total funds = 500,0002.Restrictedfunds =100,000 3. Amount spent on restricted pro-
gram = 30,000
To find the remaining balance in the restricted fund after spending on the program, we subtract the
amount spent from the initial restricted funds:
Remaining balance = Restricted funds - Amount spent Remaining balance = 100,000−30,000 Remain-
ing balance = 70,000
Therefore, the remaining balance in the restricted fund is 70,000.

20. Question: A non-profit organization has total funds of 500,000.Outofthisamount,150,000 is
classified as restricted funds and the rest as unrestricted funds. What is the percentage of the organization’s
total funds that are classified as restricted funds?
Solution: To find the percentage of restricted funds out of the total funds, we first need to calculate the
proportion of restricted funds to total funds.
Restricted funds / Total funds = 150,000/500,000 = 0.3
Now, to convert this proportion to a percentage, we multiply by 100.
Percentage of restricted funds = 0.3 * 100 = 30
Therefore, 30
21. Question: A non-profit organization receives a donation of 10,000thatisrestrictedforaspecif icprogram.If theorganizationspends5,000
from this restricted donation on the program, how much remains in the restricted fund?
Solution: To determine how much remains in the restricted fund after spending 5,000ontheprogram, wesimplysubtracttheamountspentfromtheinitialrestricteddonation.
Initial restricted donation = 10,000Amountspentontheprogram =5,000
Remaining amount in the restricted fund = 10,000−5,000 = 5,000
Therefore, the remaining amount in the restricted fund is 5,000.
22. Question: A non-profit organization has a total of 50,000infunds.T heyallocate40
Solution: To find the amount allocated to the restricted account, we first calculate 4050,000∗0.40 =20,000
Therefore, 20,000isallocatedtotherestrictedaccount.
23. Question: A non-profit organization has total funds of 100,000.40
Solution: 1. Calculate the current amount of funds in the restricted account: Restricted funds = Total
funds * Percentage restricted Restricted funds = 100,000 ∗40
2. Since the organization needs to allocate an additional 30,000totherestrictedfunds, thenewamountintherestrictedaccountwillbe :
Newrestrictedfunds =40,000 + 30,000 =70,000
3. To find the new amount in the unrestricted funds, simply subtract the new amount in the restricted
funds from the total funds: New unrestricted funds = Total funds - New restricted funds New unrestricted
funds = 100,000−70,000 New unrestricted funds = 30,000
Therefore, the new amount in the unrestricted funds will be 30,000.
24. Question: A non-profit organization has total unrestricted net assets of 100,000andtotalrestrictednetassetsof50,000.
If the organization designates 20,000fromtheunrestrictednetassetstoanewdonor−restrictedfund, whatwillbethenewbalanceofunrestrictednetassets?
Solution: Total Unrestricted Net Assets = 100,000T otalRestrictedN etAssets =50,000 Amount des-
ignated to new donor-restricted fund from Unrestricted Net Assets = 20,000
New Unrestricted Net Assets = Total Unrestricted Net Assets - Amount designated to new fund New
Unrestricted Net Assets = 100,000−20,000 New Unrestricted Net Assets = 80,000
Therefore, the new balance of unrestricted net assets after designating 20,000toanewdonor−restrictedfundwouldbe80,000.
25. Question: A non-profit organization has three funds: Fund A, Fund B, and Fund C. Fund A
incurred 10,000inexpensesthatwereallocabletoallthreef unds, F undBincurred5,000 in expenses that
were specific to Fund B only, and Fund C incurred 8,000inexpensesthatwereallocabletoF undAandF undC.If theorganizationwantstoallocatetheexpensesproportionallybasedonthetotalrevenueofeachfund, andthetotalrevenueforF undA, F undB, andF undCis100,000,
50,000, and80,000 respectively, what would be the total amount of expenses allocated to Fund A?
Solution: 1. Calculate the total revenue for all funds: 100,000(F undA)+50,000 (Fund B) + 80,000(F undC) =230,000
2. Calculate the proportion of total revenue for each fund: - Fund A: 100,000/230,000 = 0.4348 - Fund B:
50,000/230,000 = 0.2174 - Fund C: 80,000/230,000 = 0.3478 3. Allocate the shared expenses to each fund
proportionally: - Fund A: 10,000 ∗0.4348 =4,348 - Fund B: 10,000 ∗0.2174 =2,174 - Fund C: 10,000 ∗

0.3478 =3,478 4. Allocate Fund B’s expenses to Fund B: 5,0005.AllocateF undC′sexpensestoF undAandF undCproportionally :
−F undA :8,000 * 0.4348 = 3,478 −F undC :8,000 * 0.3478 = 2,784
Total expenses allocated to Fund A = 4,348(sharedexpenses)+3,478 (expenses from Fund C) = 7,826
indirect costs * Restricted funds share of indirect costs = 20,000 ∗30
Now, the remaining indirect costs will be allocated to the unrestricted funds. Unrestricted funds share
of indirect costs = Total indirect costs - Restricted funds share of indirect costs Unrestricted funds share of
indirect costs = 20,000−6,000 = 14,000
Therefore, the amount of the indirect costs allocated to the unrestricted funds is 14,000.
7. Question: A non-profit organization has three separate funds: Fund A, Fund B, and Fund C. Fund
A incurred expenses of 10,000, F undBincurredexpensesof 15,000, and Fund C incurred expenses of
20,000.T heorganization′stotalindirectcostsf ortheyearare5,000. If the organization wants to allocate
indirect costs based on the proportion of expenses in each fund, how much indirect cost should be allocated
to Fund A?
Solution: To allocate indirect costs based on the proportion of expenses in each fund, we need to calcu-
late the total expenses across all funds first.
Total Expenses = 10,000(F undA)+15,000 (Fund B) + 20,000(F undC)T otalExpenses =45,000
Next, we calculate the proportion of expenses for each fund:
Proportion of Fund A’s Expenses = Fund A’s Expenses / Total Expenses Proportion of Fund A’s Expenses
=10,000/45,000 Proportion of Fund A’s Expenses = 1/4 or 0.25
Now, we allocate the total indirect costs to Fund A based on its proportion of expenses:
Indirect Cost Allocated to Fund A = Proportion of Fund A’s Expenses * Total Indirect Costs Indirect
Cost Allocated to Fund A = 0.25 * 5,000IndirectCostAllocatedtoF undA =1,250
Therefore, 1,250ofindirectcostsshouldbeallocatedtoF undA.
8. Question: A non-profit organization receives a donation of 10,000thatisrestrictedtobeusedforaspecif icprogram.T heorganizationincursexpensesof6,000
directly related to this program. How much is the remaining balance of the restricted fund for this program?
Solution: The remaining balance of the restricted fund for the specific program can be found by sub-
tracting the expenses incurred from the total donation amount.
Remaining Balance = Total Donation - Program Expenses Remaining Balance = 10,000−6,000 Re-
maining Balance = 4,000
Therefore, the remaining balance of the restricted fund for this program is 4,000.
9. Question: A non-profit organization receives a donation of 10,000specif icallydesignatedforabuildingrenovationproject.Duringthecurrentfiscalyear, theorganizationuses5,000
of the donation for the project. At the end of the fiscal year, what are the balances of the temporarily re-
stricted fund and the amount available for general use in the unrestricted fund?
Solution: 1. Temporary Restricted Fund Balance: - Initial donation: 10,000−Amountusedf ortheproject :5,000
- Balance of temporarily restricted fund = Initial donation - Amount used - Balance of temporarily restricted
fund = 10,000−5,000 - Balance of temporarily restricted fund = 5,000
2. Unrestricted Fund Balance: - Any part of the donation not used for the project remains in the tem-
porarily restricted fund. - Amount available for general use in the unrestricted fund = Initial donation -
Amount in temporarily restricted for the project - Amount available for general use in the unrestricted fund
=10,000−5,000 - Amount available for general use in the unrestricted fund = 5,000
Therefore, at the end of the fiscal year, the balance of the temporarily restricted fund is 5,000, andtheamountavailableforgeneraluseintheunrestrictedfundisalso5,000.
10. Question: A non-profit organization incurred total operating expenses of 50,000.F romthatamount,12,000
expenses were incurred specifically for the education fund, 8,000forthehealthcaref und, andtheremainingexpensesweregeneraloperatingexpenses.W hatpercentageof thetotaloperatingexpenseswereallocatedtotheeducationf und?
Solution: To find the percentage of total operating expenses allocated to the education fund, we first
need to calculate the total specific allocations for the education fund:
Total specific allocation for education fund = 12,000
Then, we calculate the total operating expenses allocated to the education fund:

Total operating expenses allocated to the education fund = Total specific allocation for education fund +
General operating expenses Total operating expenses allocated to the education fund = 12,000 + (50,000 -
12,000−8,000) Total operating expenses allocated to the education fund = 12,000+30,000 Total operating
expenses allocated to the education fund = 42,000
Finally, we calculate the percentage of total operating expenses allocated to the education fund:
Percentage allocated to education fund = (Total operating expenses allocated to education fund / To-
tal operating expenses) * 100Percentage allocated to education fund = (42,000/50,000) * 100Percentage
allocated to education fund = 0.84 * 100Percentage allocated to education fund = 84
Therefore, 84
11. Question: A non-profit organization receives a donation of 10,000restrictedforaspecif icpurpose.T heorganizationspends4,000
on the designated program and incurs 1,500infundraisingexpensesrelatedtothesameprogram.Howmuchoftherestrictedfundsarestillavailableforthedesignatedpurpose?
Solution: Initially, the organization received 10,000asarestricteddonation.Af terspending4,000 on
the designated program, the remaining amount is 10,000−4,000 = 6,000.However, theyalsoincurred1,500
in fundraising expenses related to the designated program. This amount needs to be subtracted from the re-
maining funds. Therefore, the total amount available for the designated purpose is 6,000−1,500 = 4,500.
Final Answer: 4,500
12. Question: A non-profit organization received a grant of 50,000thatisrestrictedforaspecif icprogram.Duringthefiscalyear, theorganizationspent20,000
on the program. Calculate the amount of restricted funds remaining at the end of the fiscal year.
Solution: Restricted funds remaining = Grant amount - Expenditure on the program Restricted funds
remaining = 50,000−20,000 Restricted funds remaining = 30,000
Therefore, the amount of restricted funds remaining at the end of the fiscal year is 30,000.
13. Question: A non-profit organization has total expenses of 100,000, anditincurred20,000 in fundrais-
ing expenses, 30,000inprogramAexpenses, and25,000 in program B expenses. Calculate the percentage
of total expenses allocated to program A.
Solution: To calculate the percentage of total expenses allocated to program A, we need to first find the
total expenses allocated to program A.
Total expenses allocated to program A = fundraising expenses + program A expenses Total expenses
allocated to program A = 20,000+30,000 Total expenses allocated to program A = 50,000
Now, we can calculate the percentage of total expenses allocated to program A by dividing the total
expenses allocated to program A by the total expenses and multiplying by 100.
Percentage of total expenses allocated to program A = (Total expenses allocated to program A / Total
expenses) * 100 Percentage of total expenses allocated to program A = (50,000/100,000) * 100 Percentage
of total expenses allocated to program A = 0.5 * 100 Percentage of total expenses allocated to program A =
50
Therefore, 50
14. Question: A non-profit organization has total funds of 100,000.40
Solution: Total funds = 100,000Restrictedfunds = 40Unrestrictedfunds =T otalfunds−RestrictedfundsUnrestrictedfunds =100,000
-40,000Unrestrictedfunds =60,000
Therefore, 60,000isallocatedtotheunrestrictedaccount.
15. Question: In a non-profit organization, if the total indirect costs amount to 50,000andaretobeallocatedtotwodifferentprogramsbasedonthedirectcostsincurredbyeachprogram, withP rogramAhavingdirectcostsof30,000
and Program B having direct costs of 20,000, whatistheallocationof indirectcostsf orP rogramA?
Solution: To allocate the indirect costs to each program based on their direct costs, we need to find the
proportion of each program’s direct costs to the total direct costs of both programs.

Total direct costs = Direct costs of Program A + Direct costs of Program B Total direct costs = 30,000+20,000
Total direct costs = 50,000
Now, find the proportion of direct costs for Program A: Proportion of direct costs for Program A =
Direct costs of Program A / Total direct costs Proportion of direct costs for Program A = 30,000/50,000
Proportion of direct costs for Program A = 0.6 or 60
Next, allocate the total indirect costs based on the proportion of direct costs for Program A: Indirect
costs allocated to Program A = Proportion of direct costs for Program A * Total indirect costs Indirect costs
allocated to Program A = 0.6 * 50,000IndirectcostsallocatedtoP rogramA =30,000
Therefore, the allocation of indirect costs for Program A would be 30,000.
16. Question: A non-profit organization receives a grant of 10,000specif icallydesignatedf oraspecialprogram.T heorganizationincurs2,000
in administrative expenses that benefit multiple programs, including the special program funded by the grant.
How much of the administrative expenses should be allocated to the special program using a proportional
allocation method based on the grant amount?
Solution: 1. Calculate the percentage of the grant amount relative to the total funds received: Grant
Percentage = (Grant Amount / Total Funds Received) * 100 = (10,000/10,000) * 100 = 100
2. Allocate the administrative expenses to the special program based on the grant percentage: Adminis-
trative Expenses Allocated = Grant Percentage * Total Administrative Expenses = 100= 1.00 * 2,000 =2,000
Therefore, using the proportional allocation method based on the grant amount, 2,000oftheadministrativeexpensesshouldbeallocatedtothespecialprogram.
17. Question: A non-profit organization incurred total administrative costs of 50,000f ortheyear.Ofthisamount,10,000
relates to a program funded by restricted funds. How much of the administrative costs should be allocated
to the restricted funds?
Solution: To determine the allocation of costs to restricted funds, we need to calculate the proportion of
administrative costs that relate to the program funded by restricted funds.
Proportion of administrative costs allocated to restricted funds = (Costs related to restricted funds / Total
administrative costs) Proportion of administrative costs allocated to restricted funds = (10,000/50,000) =
0.2 or 20
Now, we can calculate the specific amount of administrative costs that should be allocated to the re-
stricted funds:
Administrative costs allocated to restricted funds = Proportion of administrative costs allocated to re-
stricted funds * Total administrative costs Administrative costs allocated to restricted funds = 0.2 * 50,000 =10,000
Therefore, 10,000ofthetotaladministrativecostsshouldbeallocatedtotheprogramfundedbyrestrictedfunds.
18. Question: A non-profit organization has total restricted funds of 50,000.If40
Solution: To find the amount allocated to the specific project, we need to calculate 40
Amount allocated to project = 40Amount allocated to project = 0.40 * 50,000Amountallocatedtoproject =20,000
Therefore, 20,000isallocatedtothespecificprojectwithinthenon −profitorganization.
19. Question: A non-profit organization has total funds of 500,000, ofwhich100,000 is restricted for a
specific program. If the organization spends 30,000ontherestrictedprogram, whatistheremainingbalanceintherestrictedfund?
Solution: 1. Total funds = 500,0002.Restrictedfunds =100,000 3. Amount spent on restricted pro-
gram = 30,000
To find the remaining balance in the restricted fund after spending on the program, we subtract the
amount spent from the initial restricted funds:
Remaining balance = Restricted funds - Amount spent Remaining balance = 100,000−30,000 Remain-
ing balance = 70,000
Therefore, the remaining balance in the restricted fund is 70,000.

20. Question: A non-profit organization has total funds of 500,000.Outofthisamount,150,000 is
classified as restricted funds and the rest as unrestricted funds. What is the percentage of the organization’s
total funds that are classified as restricted funds?
Solution: To find the percentage of restricted funds out of the total funds, we first need to calculate the
proportion of restricted funds to total funds.
Restricted funds / Total funds = 150,000/500,000 = 0.3
Now, to convert this proportion to a percentage, we multiply by 100.
Percentage of restricted funds = 0.3 * 100 = 30
Therefore, 30
21. Question: A non-profit organization receives a donation of 10,000thatisrestrictedforaspecif icprogram.If theorganizationspends5,000
from this restricted donation on the program, how much remains in the restricted fund?
Solution: To determine how much remains in the restricted fund after spending 5,000ontheprogram, wesimplysubtracttheamountspentfromtheinitialrestricteddonation.
Initial restricted donation = 10,000Amountspentontheprogram =5,000
Remaining amount in the restricted fund = 10,000−5,000 = 5,000
Therefore, the remaining amount in the restricted fund is 5,000.
22. Question: A non-profit organization has a total of 50,000infunds.T heyallocate40
Solution: To find the amount allocated to the restricted account, we first calculate 4050,000∗0.40 =20,000
Therefore, 20,000isallocatedtotherestrictedaccount.
23. Question: A non-profit organization has total funds of 100,000.40
Solution: 1. Calculate the current amount of funds in the restricted account: Restricted funds = Total
funds * Percentage restricted Restricted funds = 100,000 ∗40
2. Since the organization needs to allocate an additional 30,000totherestrictedfunds, thenewamountintherestrictedaccountwillbe :
Newrestrictedfunds =40,000 + 30,000 =70,000
3. To find the new amount in the unrestricted funds, simply subtract the new amount in the restricted
funds from the total funds: New unrestricted funds = Total funds - New restricted funds New unrestricted
funds = 100,000−70,000 New unrestricted funds = 30,000
Therefore, the new amount in the unrestricted funds will be 30,000.
24. Question: A non-profit organization has total unrestricted net assets of 100,000andtotalrestrictednetassetsof50,000.
If the organization designates 20,000fromtheunrestrictednetassetstoanewdonor−restrictedfund, whatwillbethenewbalanceofunrestrictednetassets?
Solution: Total Unrestricted Net Assets = 100,000T otalRestrictedN etAssets =50,000 Amount des-
ignated to new donor-restricted fund from Unrestricted Net Assets = 20,000
New Unrestricted Net Assets = Total Unrestricted Net Assets - Amount designated to new fund New
Unrestricted Net Assets = 100,000−20,000 New Unrestricted Net Assets = 80,000
Therefore, the new balance of unrestricted net assets after designating 20,000toanewdonor−restrictedfundwouldbe80,000.
25. Question: A non-profit organization has three funds: Fund A, Fund B, and Fund C. Fund A
incurred 10,000inexpensesthatwereallocabletoallthreef unds, F undBincurred5,000 in expenses that
were specific to Fund B only, and Fund C incurred 8,000inexpensesthatwereallocabletoF undAandF undC.If theorganizationwantstoallocatetheexpensesproportionallybasedonthetotalrevenueofeachfund, andthetotalrevenueforF undA, F undB, andF undCis100,000,
50,000, and80,000 respectively, what would be the total amount of expenses allocated to Fund A?
Solution: 1. Calculate the total revenue for all funds: 100,000(F undA)+50,000 (Fund B) + 80,000(F undC) =230,000
2. Calculate the proportion of total revenue for each fund: - Fund A: 100,000/230,000 = 0.4348 - Fund B:
50,000/230,000 = 0.2174 - Fund C: 80,000/230,000 = 0.3478 3. Allocate the shared expenses to each fund
proportionally: - Fund A: 10,000 ∗0.4348 =4,348 - Fund B: 10,000 ∗0.2174 =2,174 - Fund C: 10,000 ∗

0.3478 =3,478 4. Allocate Fund B’s expenses to Fund B: 5,0005.AllocateF undC′sexpensestoF undAandF undCproportionally :
−F undA :8,000 * 0.4348 = 3,478 −F undC :8,000 * 0.3478 = 2,784
Total expenses allocated to Fund A = 4,348(sharedexpenses)+3,478 (expenses from Fund C) = 7,826
indirect costs * Restricted funds share of indirect costs = 20,000 ∗30
Now, the remaining indirect costs will be allocated to the unrestricted funds. Unrestricted funds share
of indirect costs = Total indirect costs - Restricted funds share of indirect costs Unrestricted funds share of
indirect costs = 20,000−6,000 = 14,000
Therefore, the amount of the indirect costs allocated to the unrestricted funds is 14,000.
7. Question: A non-profit organization has three separate funds: Fund A, Fund B, and Fund C. Fund
A incurred expenses of 10,000, F undBincurredexpensesof 15,000, and Fund C incurred expenses of
20,000.T heorganization′stotalindirectcostsf ortheyearare5,000. If the organization wants to allocate
indirect costs based on the proportion of expenses in each fund, how much indirect cost should be allocated
to Fund A?
Solution: To allocate indirect costs based on the proportion of expenses in each fund, we need to calcu-
late the total expenses across all funds first.
Total Expenses = 10,000(F undA)+15,000 (Fund B) + 20,000(F undC)T otalExpenses =45,000
Next, we calculate the proportion of expenses for each fund:
Proportion of Fund A’s Expenses = Fund A’s Expenses / Total Expenses Proportion of Fund A’s Expenses
=10,000/45,000 Proportion of Fund A’s Expenses = 1/4 or 0.25
Now, we allocate the total indirect costs to Fund A based on its proportion of expenses:
Indirect Cost Allocated to Fund A = Proportion of Fund A’s Expenses * Total Indirect Costs Indirect
Cost Allocated to Fund A = 0.25 * 5,000IndirectCostAllocatedtoF undA =1,250
Therefore, 1,250ofindirectcostsshouldbeallocatedtoF undA.
8. Question: A non-profit organization receives a donation of 10,000thatisrestrictedtobeusedforaspecif icprogram.T heorganizationincursexpensesof6,000
directly related to this program. How much is the remaining balance of the restricted fund for this program?
Solution: The remaining balance of the restricted fund for the specific program can be found by sub-
tracting the expenses incurred from the total donation amount.
Remaining Balance = Total Donation - Program Expenses Remaining Balance = 10,000−6,000 Re-
maining Balance = 4,000
Therefore, the remaining balance of the restricted fund for this program is 4,000.
9. Question: A non-profit organization receives a donation of 10,000specif icallydesignatedforabuildingrenovationproject.Duringthecurrentfiscalyear, theorganizationuses5,000
of the donation for the project. At the end of the fiscal year, what are the balances of the temporarily re-
stricted fund and the amount available for general use in the unrestricted fund?
Solution: 1. Temporary Restricted Fund Balance: - Initial donation: 10,000−Amountusedf ortheproject :5,000
- Balance of temporarily restricted fund = Initial donation - Amount used - Balance of temporarily restricted
fund = 10,000−5,000 - Balance of temporarily restricted fund = 5,000
2. Unrestricted Fund Balance: - Any part of the donation not used for the project remains in the tem-
porarily restricted fund. - Amount available for general use in the unrestricted fund = Initial donation -
Amount in temporarily restricted for the project - Amount available for general use in the unrestricted fund
=10,000−5,000 - Amount available for general use in the unrestricted fund = 5,000
Therefore, at the end of the fiscal year, the balance of the temporarily restricted fund is 5,000, andtheamountavailableforgeneraluseintheunrestrictedfundisalso5,000.
10. Question: A non-profit organization incurred total operating expenses of 50,000.F romthatamount,12,000
expenses were incurred specifically for the education fund, 8,000forthehealthcaref und, andtheremainingexpensesweregeneraloperatingexpenses.W hatpercentageof thetotaloperatingexpenseswereallocatedtotheeducationf und?
Solution: To find the percentage of total operating expenses allocated to the education fund, we first
need to calculate the total specific allocations for the education fund:
Total specific allocation for education fund = 12,000
Then, we calculate the total operating expenses allocated to the education fund:

Total operating expenses allocated to the education fund = Total specific allocation for education fund +
General operating expenses Total operating expenses allocated to the education fund = 12,000 + (50,000 -
12,000−8,000) Total operating expenses allocated to the education fund = 12,000+30,000 Total operating
expenses allocated to the education fund = 42,000
Finally, we calculate the percentage of total operating expenses allocated to the education fund:
Percentage allocated to education fund = (Total operating expenses allocated to education fund / To-
tal operating expenses) * 100Percentage allocated to education fund = (42,000/50,000) * 100Percentage
allocated to education fund = 0.84 * 100Percentage allocated to education fund = 84
Therefore, 84
11. Question: A non-profit organization receives a donation of 10,000restrictedforaspecif icpurpose.T heorganizationspends4,000
on the designated program and incurs 1,500infundraisingexpensesrelatedtothesameprogram.Howmuchoftherestrictedfundsarestillavailableforthedesignatedpurpose?
Solution: Initially, the organization received 10,000asarestricteddonation.Af terspending4,000 on
the designated program, the remaining amount is 10,000−4,000 = 6,000.However, theyalsoincurred1,500
in fundraising expenses related to the designated program. This amount needs to be subtracted from the re-
maining funds. Therefore, the total amount available for the designated purpose is 6,000−1,500 = 4,500.
Final Answer: 4,500
12. Question: A non-profit organization received a grant of 50,000thatisrestrictedforaspecif icprogram.Duringthefiscalyear, theorganizationspent20,000
on the program. Calculate the amount of restricted funds remaining at the end of the fiscal year.
Solution: Restricted funds remaining = Grant amount - Expenditure on the program Restricted funds
remaining = 50,000−20,000 Restricted funds remaining = 30,000
Therefore, the amount of restricted funds remaining at the end of the fiscal year is 30,000.
13. Question: A non-profit organization has total expenses of 100,000, anditincurred20,000 in fundrais-
ing expenses, 30,000inprogramAexpenses, and25,000 in program B expenses. Calculate the percentage
of total expenses allocated to program A.
Solution: To calculate the percentage of total expenses allocated to program A, we need to first find the
total expenses allocated to program A.
Total expenses allocated to program A = fundraising expenses + program A expenses Total expenses
allocated to program A = 20,000+30,000 Total expenses allocated to program A = 50,000
Now, we can calculate the percentage of total expenses allocated to program A by dividing the total
expenses allocated to program A by the total expenses and multiplying by 100.
Percentage of total expenses allocated to program A = (Total expenses allocated to program A / Total
expenses) * 100 Percentage of total expenses allocated to program A = (50,000/100,000) * 100 Percentage
of total expenses allocated to program A = 0.5 * 100 Percentage of total expenses allocated to program A =
50
Therefore, 50
14. Question: A non-profit organization has total funds of 100,000.40
Solution: Total funds = 100,000Restrictedfunds = 40Unrestrictedfunds =T otalfunds−RestrictedfundsUnrestrictedfunds =100,000
-40,000Unrestrictedfunds =60,000
Therefore, 60,000isallocatedtotheunrestrictedaccount.
15. Question: In a non-profit organization, if the total indirect costs amount to 50,000andaretobeallocatedtotwodifferentprogramsbasedonthedirectcostsincurredbyeachprogram, withP rogramAhavingdirectcostsof30,000
and Program B having direct costs of 20,000, whatistheallocationof indirectcostsf orP rogramA?
Solution: To allocate the indirect costs to each program based on their direct costs, we need to find the
proportion of each program’s direct costs to the total direct costs of both programs.

Total direct costs = Direct costs of Program A + Direct costs of Program B Total direct costs = 30,000+20,000
Total direct costs = 50,000
Now, find the proportion of direct costs for Program A: Proportion of direct costs for Program A =
Direct costs of Program A / Total direct costs Proportion of direct costs for Program A = 30,000/50,000
Proportion of direct costs for Program A = 0.6 or 60
Next, allocate the total indirect costs based on the proportion of direct costs for Program A: Indirect
costs allocated to Program A = Proportion of direct costs for Program A * Total indirect costs Indirect costs
allocated to Program A = 0.6 * 50,000IndirectcostsallocatedtoP rogramA =30,000
Therefore, the allocation of indirect costs for Program A would be 30,000.
16. Question: A non-profit organization receives a grant of 10,000specif icallydesignatedf oraspecialprogram.T heorganizationincurs2,000
in administrative expenses that benefit multiple programs, including the special program funded by the grant.
How much of the administrative expenses should be allocated to the special program using a proportional
allocation method based on the grant amount?
Solution: 1. Calculate the percentage of the grant amount relative to the total funds received: Grant
Percentage = (Grant Amount / Total Funds Received) * 100 = (10,000/10,000) * 100 = 100
2. Allocate the administrative expenses to the special program based on the grant percentage: Adminis-
trative Expenses Allocated = Grant Percentage * Total Administrative Expenses = 100= 1.00 * 2,000 =2,000
Therefore, using the proportional allocation method based on the grant amount, 2,000oftheadministrativeexpensesshouldbeallocatedtothespecialprogram.
17. Question: A non-profit organization incurred total administrative costs of 50,000f ortheyear.Ofthisamount,10,000
relates to a program funded by restricted funds. How much of the administrative costs should be allocated
to the restricted funds?
Solution: To determine the allocation of costs to restricted funds, we need to calculate the proportion of
administrative costs that relate to the program funded by restricted funds.
Proportion of administrative costs allocated to restricted funds = (Costs related to restricted funds / Total
administrative costs) Proportion of administrative costs allocated to restricted funds = (10,000/50,000) =
0.2 or 20
Now, we can calculate the specific amount of administrative costs that should be allocated to the re-
stricted funds:
Administrative costs allocated to restricted funds = Proportion of administrative costs allocated to re-
stricted funds * Total administrative costs Administrative costs allocated to restricted funds = 0.2 * 50,000 =10,000
Therefore, 10,000ofthetotaladministrativecostsshouldbeallocatedtotheprogramfundedbyrestrictedfunds.
18. Question: A non-profit organization has total restricted funds of 50,000.If40
Solution: To find the amount allocated to the specific project, we need to calculate 40
Amount allocated to project = 40Amount allocated to project = 0.40 * 50,000Amountallocatedtoproject =20,000
Therefore, 20,000isallocatedtothespecificprojectwithinthenon −profitorganization.
19. Question: A non-profit organization has total funds of 500,000, ofwhich100,000 is restricted for a
specific program. If the organization spends 30,000ontherestrictedprogram, whatistheremainingbalanceintherestrictedfund?
Solution: 1. Total funds = 500,0002.Restrictedfunds =100,000 3. Amount spent on restricted pro-
gram = 30,000
To find the remaining balance in the restricted fund after spending on the program, we subtract the
amount spent from the initial restricted funds:
Remaining balance = Restricted funds - Amount spent Remaining balance = 100,000−30,000 Remain-
ing balance = 70,000
Therefore, the remaining balance in the restricted fund is 70,000.

20. Question: A non-profit organization has total funds of 500,000.Outofthisamount,150,000 is
classified as restricted funds and the rest as unrestricted funds. What is the percentage of the organization’s
total funds that are classified as restricted funds?
Solution: To find the percentage of restricted funds out of the total funds, we first need to calculate the
proportion of restricted funds to total funds.
Restricted funds / Total funds = 150,000/500,000 = 0.3
Now, to convert this proportion to a percentage, we multiply by 100.
Percentage of restricted funds = 0.3 * 100 = 30
Therefore, 30
21. Question: A non-profit organization receives a donation of 10,000thatisrestrictedforaspecif icprogram.If theorganizationspends5,000
from this restricted donation on the program, how much remains in the restricted fund?
Solution: To determine how much remains in the restricted fund after spending 5,000ontheprogram, wesimplysubtracttheamountspentfromtheinitialrestricteddonation.
Initial restricted donation = 10,000Amountspentontheprogram =5,000
Remaining amount in the restricted fund = 10,000−5,000 = 5,000
Therefore, the remaining amount in the restricted fund is 5,000.
22. Question: A non-profit organization has a total of 50,000infunds.T heyallocate40
Solution: To find the amount allocated to the restricted account, we first calculate 4050,000∗0.40 =20,000
Therefore, 20,000isallocatedtotherestrictedaccount.
23. Question: A non-profit organization has total funds of 100,000.40
Solution: 1. Calculate the current amount of funds in the restricted account: Restricted funds = Total
funds * Percentage restricted Restricted funds = 100,000 ∗40
2. Since the organization needs to allocate an additional 30,000totherestrictedfunds, thenewamountintherestrictedaccountwillbe :
Newrestrictedfunds =40,000 + 30,000 =70,000
3. To find the new amount in the unrestricted funds, simply subtract the new amount in the restricted
funds from the total funds: New unrestricted funds = Total funds - New restricted funds New unrestricted
funds = 100,000−70,000 New unrestricted funds = 30,000
Therefore, the new amount in the unrestricted funds will be 30,000.
24. Question: A non-profit organization has total unrestricted net assets of 100,000andtotalrestrictednetassetsof50,000.
If the organization designates 20,000fromtheunrestrictednetassetstoanewdonor−restrictedfund, whatwillbethenewbalanceofunrestrictednetassets?
Solution: Total Unrestricted Net Assets = 100,000T otalRestrictedN etAssets =50,000 Amount des-
ignated to new donor-restricted fund from Unrestricted Net Assets = 20,000
New Unrestricted Net Assets = Total Unrestricted Net Assets - Amount designated to new fund New
Unrestricted Net Assets = 100,000−20,000 New Unrestricted Net Assets = 80,000
Therefore, the new balance of unrestricted net assets after designating 20,000toanewdonor−restrictedfundwouldbe80,000.
25. Question: A non-profit organization has three funds: Fund A, Fund B, and Fund C. Fund A
incurred 10,000inexpensesthatwereallocabletoallthreef unds, F undBincurred5,000 in expenses that
were specific to Fund B only, and Fund C incurred 8,000inexpensesthatwereallocabletoF undAandF undC.If theorganizationwantstoallocatetheexpensesproportionallybasedonthetotalrevenueofeachfund, andthetotalrevenueforF undA, F undB, andF undCis100,000,
50,000, and80,000 respectively, what would be the total amount of expenses allocated to Fund A?
Solution: 1. Calculate the total revenue for all funds: 100,000(F undA)+50,000 (Fund B) + 80,000(F undC) =230,000
2. Calculate the proportion of total revenue for each fund: - Fund A: 100,000/230,000 = 0.4348 - Fund B:
50,000/230,000 = 0.2174 - Fund C: 80,000/230,000 = 0.3478 3. Allocate the shared expenses to each fund
proportionally: - Fund A: 10,000 ∗0.4348 =4,348 - Fund B: 10,000 ∗0.2174 =2,174 - Fund C: 10,000 ∗

0.3478 =3,478 4. Allocate Fund B’s expenses to Fund B: 5,0005.AllocateF undC′sexpensestoF undAandF undCproportionally :
−F undA :8,000 * 0.4348 = 3,478 −F undC :8,000 * 0.3478 = 2,784
Total expenses allocated to Fund A = 4,348(sharedexpenses)+3,478 (expenses from Fund C) = 7,826
indirect costs * Restricted funds share of indirect costs = 20,000 ∗30
Now, the remaining indirect costs will be allocated to the unrestricted funds. Unrestricted funds share
of indirect costs = Total indirect costs - Restricted funds share of indirect costs Unrestricted funds share of
indirect costs = 20,000−6,000 = 14,000
Therefore, the amount of the indirect costs allocated to the unrestricted funds is 14,000.
7. Question: A non-profit organization has three separate funds: Fund A, Fund B, and Fund C. Fund
A incurred expenses of 10,000, F undBincurredexpensesof 15,000, and Fund C incurred expenses of
20,000.T heorganization′stotalindirectcostsf ortheyearare5,000. If the organization wants to allocate
indirect costs based on the proportion of expenses in each fund, how much indirect cost should be allocated
to Fund A?
Solution: To allocate indirect costs based on the proportion of expenses in each fund, we need to calcu-
late the total expenses across all funds first.
Total Expenses = 10,000(F undA)+15,000 (Fund B) + 20,000(F undC)T otalExpenses =45,000
Next, we calculate the proportion of expenses for each fund:
Proportion of Fund A’s Expenses = Fund A’s Expenses / Total Expenses Proportion of Fund A’s Expenses
=10,000/45,000 Proportion of Fund A’s Expenses = 1/4 or 0.25
Now, we allocate the total indirect costs to Fund A based on its proportion of expenses:
Indirect Cost Allocated to Fund A = Proportion of Fund A’s Expenses * Total Indirect Costs Indirect
Cost Allocated to Fund A = 0.25 * 5,000IndirectCostAllocatedtoF undA =1,250
Therefore, 1,250ofindirectcostsshouldbeallocatedtoF undA.
8. Question: A non-profit organization receives a donation of 10,000thatisrestrictedtobeusedforaspecif icprogram.T heorganizationincursexpensesof6,000
directly related to this program. How much is the remaining balance of the restricted fund for this program?
Solution: The remaining balance of the restricted fund for the specific program can be found by sub-
tracting the expenses incurred from the total donation amount.
Remaining Balance = Total Donation - Program Expenses Remaining Balance = 10,000−6,000 Re-
maining Balance = 4,000
Therefore, the remaining balance of the restricted fund for this program is 4,000.
9. Question: A non-profit organization receives a donation of 10,000specif icallydesignatedforabuildingrenovationproject.Duringthecurrentfiscalyear, theorganizationuses5,000
of the donation for the project. At the end of the fiscal year, what are the balances of the temporarily re-
stricted fund and the amount available for general use in the unrestricted fund?
Solution: 1. Temporary Restricted Fund Balance: - Initial donation: 10,000−Amountusedf ortheproject :5,000
- Balance of temporarily restricted fund = Initial donation - Amount used - Balance of temporarily restricted
fund = 10,000−5,000 - Balance of temporarily restricted fund = 5,000
2. Unrestricted Fund Balance: - Any part of the donation not used for the project remains in the tem-
porarily restricted fund. - Amount available for general use in the unrestricted fund = Initial donation -
Amount in temporarily restricted for the project - Amount available for general use in the unrestricted fund
=10,000−5,000 - Amount available for general use in the unrestricted fund = 5,000
Therefore, at the end of the fiscal year, the balance of the temporarily restricted fund is 5,000, andtheamountavailableforgeneraluseintheunrestrictedfundisalso5,000.
10. Question: A non-profit organization incurred total operating expenses of 50,000.F romthatamount,12,000
expenses were incurred specifically for the education fund, 8,000forthehealthcaref und, andtheremainingexpensesweregeneraloperatingexpenses.W hatpercentageof thetotaloperatingexpenseswereallocatedtotheeducationf und?
Solution: To find the percentage of total operating expenses allocated to the education fund, we first
need to calculate the total specific allocations for the education fund:
Total specific allocation for education fund = 12,000
Then, we calculate the total operating expenses allocated to the education fund:

Total operating expenses allocated to the education fund = Total specific allocation for education fund +
General operating expenses Total operating expenses allocated to the education fund = 12,000 + (50,000 -
12,000−8,000) Total operating expenses allocated to the education fund = 12,000+30,000 Total operating
expenses allocated to the education fund = 42,000
Finally, we calculate the percentage of total operating expenses allocated to the education fund:
Percentage allocated to education fund = (Total operating expenses allocated to education fund / To-
tal operating expenses) * 100Percentage allocated to education fund = (42,000/50,000) * 100Percentage
allocated to education fund = 0.84 * 100Percentage allocated to education fund = 84
Therefore, 84
11. Question: A non-profit organization receives a donation of 10,000restrictedforaspecif icpurpose.T heorganizationspends4,000
on the designated program and incurs 1,500infundraisingexpensesrelatedtothesameprogram.Howmuchoftherestrictedfundsarestillavailableforthedesignatedpurpose?
Solution: Initially, the organization received 10,000asarestricteddonation.Af terspending4,000 on
the designated program, the remaining amount is 10,000−4,000 = 6,000.However, theyalsoincurred1,500
in fundraising expenses related to the designated program. This amount needs to be subtracted from the re-
maining funds. Therefore, the total amount available for the designated purpose is 6,000−1,500 = 4,500.
Final Answer: 4,500
12. Question: A non-profit organization received a grant of 50,000thatisrestrictedforaspecif icprogram.Duringthefiscalyear, theorganizationspent20,000
on the program. Calculate the amount of restricted funds remaining at the end of the fiscal year.
Solution: Restricted funds remaining = Grant amount - Expenditure on the program Restricted funds
remaining = 50,000−20,000 Restricted funds remaining = 30,000
Therefore, the amount of restricted funds remaining at the end of the fiscal year is 30,000.
13. Question: A non-profit organization has total expenses of 100,000, anditincurred20,000 in fundrais-
ing expenses, 30,000inprogramAexpenses, and25,000 in program B expenses. Calculate the percentage
of total expenses allocated to program A.
Solution: To calculate the percentage of total expenses allocated to program A, we need to first find the
total expenses allocated to program A.
Total expenses allocated to program A = fundraising expenses + program A expenses Total expenses
allocated to program A = 20,000+30,000 Total expenses allocated to program A = 50,000
Now, we can calculate the percentage of total expenses allocated to program A by dividing the total
expenses allocated to program A by the total expenses and multiplying by 100.
Percentage of total expenses allocated to program A = (Total expenses allocated to program A / Total
expenses) * 100 Percentage of total expenses allocated to program A = (50,000/100,000) * 100 Percentage
of total expenses allocated to program A = 0.5 * 100 Percentage of total expenses allocated to program A =
50
Therefore, 50
14. Question: A non-profit organization has total funds of 100,000.40
Solution: Total funds = 100,000Restrictedfunds = 40Unrestrictedfunds =T otalfunds−RestrictedfundsUnrestrictedfunds =100,000
-40,000Unrestrictedfunds =60,000
Therefore, 60,000isallocatedtotheunrestrictedaccount.
15. Question: In a non-profit organization, if the total indirect costs amount to 50,000andaretobeallocatedtotwodifferentprogramsbasedonthedirectcostsincurredbyeachprogram, withP rogramAhavingdirectcostsof30,000
and Program B having direct costs of 20,000, whatistheallocationof indirectcostsf orP rogramA?
Solution: To allocate the indirect costs to each program based on their direct costs, we need to find the
proportion of each program’s direct costs to the total direct costs of both programs.

Total direct costs = Direct costs of Program A + Direct costs of Program B Total direct costs = 30,000+20,000
Total direct costs = 50,000
Now, find the proportion of direct costs for Program A: Proportion of direct costs for Program A =
Direct costs of Program A / Total direct costs Proportion of direct costs for Program A = 30,000/50,000
Proportion of direct costs for Program A = 0.6 or 60
Next, allocate the total indirect costs based on the proportion of direct costs for Program A: Indirect
costs allocated to Program A = Proportion of direct costs for Program A * Total indirect costs Indirect costs
allocated to Program A = 0.6 * 50,000IndirectcostsallocatedtoP rogramA =30,000
Therefore, the allocation of indirect costs for Program A would be 30,000.
16. Question: A non-profit organization receives a grant of 10,000specif icallydesignatedf oraspecialprogram.T heorganizationincurs2,000
in administrative expenses that benefit multiple programs, including the special program funded by the grant.
How much of the administrative expenses should be allocated to the special program using a proportional
allocation method based on the grant amount?
Solution: 1. Calculate the percentage of the grant amount relative to the total funds received: Grant
Percentage = (Grant Amount / Total Funds Received) * 100 = (10,000/10,000) * 100 = 100
2. Allocate the administrative expenses to the special program based on the grant percentage: Adminis-
trative Expenses Allocated = Grant Percentage * Total Administrative Expenses = 100= 1.00 * 2,000 =2,000
Therefore, using the proportional allocation method based on the grant amount, 2,000oftheadministrativeexpensesshouldbeallocatedtothespecialprogram.
17. Question: A non-profit organization incurred total administrative costs of 50,000f ortheyear.Ofthisamount,10,000
relates to a program funded by restricted funds. How much of the administrative costs should be allocated
to the restricted funds?
Solution: To determine the allocation of costs to restricted funds, we need to calculate the proportion of
administrative costs that relate to the program funded by restricted funds.
Proportion of administrative costs allocated to restricted funds = (Costs related to restricted funds / Total
administrative costs) Proportion of administrative costs allocated to restricted funds = (10,000/50,000) =
0.2 or 20
Now, we can calculate the specific amount of administrative costs that should be allocated to the re-
stricted funds:
Administrative costs allocated to restricted funds = Proportion of administrative costs allocated to re-
stricted funds * Total administrative costs Administrative costs allocated to restricted funds = 0.2 * 50,000 =10,000
Therefore, 10,000ofthetotaladministrativecostsshouldbeallocatedtotheprogramfundedbyrestrictedfunds.
18. Question: A non-profit organization has total restricted funds of 50,000.If40
Solution: To find the amount allocated to the specific project, we need to calculate 40
Amount allocated to project = 40Amount allocated to project = 0.40 * 50,000Amountallocatedtoproject =20,000
Therefore, 20,000isallocatedtothespecificprojectwithinthenon −profitorganization.
19. Question: A non-profit organization has total funds of 500,000, ofwhich100,000 is restricted for a
specific program. If the organization spends 30,000ontherestrictedprogram, whatistheremainingbalanceintherestrictedfund?
Solution: 1. Total funds = 500,0002.Restrictedfunds =100,000 3. Amount spent on restricted pro-
gram = 30,000
To find the remaining balance in the restricted fund after spending on the program, we subtract the
amount spent from the initial restricted funds:
Remaining balance = Restricted funds - Amount spent Remaining balance = 100,000−30,000 Remain-
ing balance = 70,000
Therefore, the remaining balance in the restricted fund is 70,000.

20. Question: A non-profit organization has total funds of 500,000.Outofthisamount,150,000 is
classified as restricted funds and the rest as unrestricted funds. What is the percentage of the organization’s
total funds that are classified as restricted funds?
Solution: To find the percentage of restricted funds out of the total funds, we first need to calculate the
proportion of restricted funds to total funds.
Restricted funds / Total funds = 150,000/500,000 = 0.3
Now, to convert this proportion to a percentage, we multiply by 100.
Percentage of restricted funds = 0.3 * 100 = 30
Therefore, 30
21. Question: A non-profit organization receives a donation of 10,000thatisrestrictedforaspecif icprogram.If theorganizationspends5,000
from this restricted donation on the program, how much remains in the restricted fund?
Solution: To determine how much remains in the restricted fund after spending 5,000ontheprogram, wesimplysubtracttheamountspentfromtheinitialrestricteddonation.
Initial restricted donation = 10,000Amountspentontheprogram =5,000
Remaining amount in the restricted fund = 10,000−5,000 = 5,000
Therefore, the remaining amount in the restricted fund is 5,000.
22. Question: A non-profit organization has a total of 50,000infunds.T heyallocate40
Solution: To find the amount allocated to the restricted account, we first calculate 4050,000∗0.40 =20,000
Therefore, 20,000isallocatedtotherestrictedaccount.
23. Question: A non-profit organization has total funds of 100,000.40
Solution: 1. Calculate the current amount of funds in the restricted account: Restricted funds = Total
funds * Percentage restricted Restricted funds = 100,000 ∗40
2. Since the organization needs to allocate an additional 30,000totherestrictedfunds, thenewamountintherestrictedaccountwillbe :
Newrestrictedfunds =40,000 + 30,000 =70,000
3. To find the new amount in the unrestricted funds, simply subtract the new amount in the restricted
funds from the total funds: New unrestricted funds = Total funds - New restricted funds New unrestricted
funds = 100,000−70,000 New unrestricted funds = 30,000
Therefore, the new amount in the unrestricted funds will be 30,000.
24. Question: A non-profit organization has total unrestricted net assets of 100,000andtotalrestrictednetassetsof50,000.
If the organization designates 20,000fromtheunrestrictednetassetstoanewdonor−restrictedfund, whatwillbethenewbalanceofunrestrictednetassets?
Solution: Total Unrestricted Net Assets = 100,000T otalRestrictedN etAssets =50,000 Amount des-
ignated to new donor-restricted fund from Unrestricted Net Assets = 20,000
New Unrestricted Net Assets = Total Unrestricted Net Assets - Amount designated to new fund New
Unrestricted Net Assets = 100,000−20,000 New Unrestricted Net Assets = 80,000
Therefore, the new balance of unrestricted net assets after designating 20,000toanewdonor−restrictedfundwouldbe80,000.
25. Question: A non-profit organization has three funds: Fund A, Fund B, and Fund C. Fund A
incurred 10,000inexpensesthatwereallocabletoallthreef unds, F undBincurred5,000 in expenses that
were specific to Fund B only, and Fund C incurred 8,000inexpensesthatwereallocabletoF undAandF undC.If theorganizationwantstoallocatetheexpensesproportionallybasedonthetotalrevenueofeachfund, andthetotalrevenueforF undA, F undB, andF undCis100,000,
50,000, and80,000 respectively, what would be the total amount of expenses allocated to Fund A?
Solution: 1. Calculate the total revenue for all funds: 100,000(F undA)+50,000 (Fund B) + 80,000(F undC) =230,000
2. Calculate the proportion of total revenue for each fund: - Fund A: 100,000/230,000 = 0.4348 - Fund B:
50,000/230,000 = 0.2174 - Fund C: 80,000/230,000 = 0.3478 3. Allocate the shared expenses to each fund
proportionally: - Fund A: 10,000 ∗0.4348 =4,348 - Fund B: 10,000 ∗0.2174 =2,174 - Fund C: 10,000 ∗

0.3478 =3,478 4. Allocate Fund B’s expenses to Fund B: 5,0005.AllocateF undC′sexpensestoF undAandF undCproportionally :
−F undA :8,000 * 0.4348 = 3,478 −F undC :8,000 * 0.3478 = 2,784
Total expenses allocated to Fund A = 4,348(sharedexpenses)+3,478 (expenses from Fund C) = 7,826
indirect costs * Restricted funds share of indirect costs = 20,000 ∗30
Now, the remaining indirect costs will be allocated to the unrestricted funds. Unrestricted funds share
of indirect costs = Total indirect costs - Restricted funds share of indirect costs Unrestricted funds share of
indirect costs = 20,000−6,000 = 14,000
Therefore, the amount of the indirect costs allocated to the unrestricted funds is 14,000.
7. Question: A non-profit organization has three separate funds: Fund A, Fund B, and Fund C. Fund
A incurred expenses of 10,000, F undBincurredexpensesof 15,000, and Fund C incurred expenses of
20,000.T heorganization′stotalindirectcostsf ortheyearare5,000. If the organization wants to allocate
indirect costs based on the proportion of expenses in each fund, how much indirect cost should be allocated
to Fund A?
Solution: To allocate indirect costs based on the proportion of expenses in each fund, we need to calcu-
late the total expenses across all funds first.
Total Expenses = 10,000(F undA)+15,000 (Fund B) + 20,000(F undC)T otalExpenses =45,000
Next, we calculate the proportion of expenses for each fund:
Proportion of Fund A’s Expenses = Fund A’s Expenses / Total Expenses Proportion of Fund A’s Expenses
=10,000/45,000 Proportion of Fund A’s Expenses = 1/4 or 0.25
Now, we allocate the total indirect costs to Fund A based on its proportion of expenses:
Indirect Cost Allocated to Fund A = Proportion of Fund A’s Expenses * Total Indirect Costs Indirect
Cost Allocated to Fund A = 0.25 * 5,000IndirectCostAllocatedtoF undA =1,250
Therefore, 1,250ofindirectcostsshouldbeallocatedtoF undA.
8. Question: A non-profit organization receives a donation of 10,000thatisrestrictedtobeusedforaspecif icprogram.T heorganizationincursexpensesof6,000
directly related to this program. How much is the remaining balance of the restricted fund for this program?
Solution: The remaining balance of the restricted fund for the specific program can be found by sub-
tracting the expenses incurred from the total donation amount.
Remaining Balance = Total Donation - Program Expenses Remaining Balance = 10,000−6,000 Re-
maining Balance = 4,000
Therefore, the remaining balance of the restricted fund for this program is 4,000.
9. Question: A non-profit organization receives a donation of 10,000specif icallydesignatedforabuildingrenovationproject.Duringthecurrentfiscalyear, theorganizationuses5,000
of the donation for the project. At the end of the fiscal year, what are the balances of the temporarily re-
stricted fund and the amount available for general use in the unrestricted fund?
Solution: 1. Temporary Restricted Fund Balance: - Initial donation: 10,000−Amountusedf ortheproject :5,000
- Balance of temporarily restricted fund = Initial donation - Amount used - Balance of temporarily restricted
fund = 10,000−5,000 - Balance of temporarily restricted fund = 5,000
2. Unrestricted Fund Balance: - Any part of the donation not used for the project remains in the tem-
porarily restricted fund. - Amount available for general use in the unrestricted fund = Initial donation -
Amount in temporarily restricted for the project - Amount available for general use in the unrestricted fund
=10,000−5,000 - Amount available for general use in the unrestricted fund = 5,000
Therefore, at the end of the fiscal year, the balance of the temporarily restricted fund is 5,000, andtheamountavailableforgeneraluseintheunrestrictedfundisalso5,000.
10. Question: A non-profit organization incurred total operating expenses of 50,000.F romthatamount,12,000
expenses were incurred specifically for the education fund, 8,000forthehealthcaref und, andtheremainingexpensesweregeneraloperatingexpenses.W hatpercentageof thetotaloperatingexpenseswereallocatedtotheeducationf und?
Solution: To find the percentage of total operating expenses allocated to the education fund, we first
need to calculate the total specific allocations for the education fund:
Total specific allocation for education fund = 12,000
Then, we calculate the total operating expenses allocated to the education fund:

Total operating expenses allocated to the education fund = Total specific allocation for education fund +
General operating expenses Total operating expenses allocated to the education fund = 12,000 + (50,000 -
12,000−8,000) Total operating expenses allocated to the education fund = 12,000+30,000 Total operating
expenses allocated to the education fund = 42,000
Finally, we calculate the percentage of total operating expenses allocated to the education fund:
Percentage allocated to education fund = (Total operating expenses allocated to education fund / To-
tal operating expenses) * 100Percentage allocated to education fund = (42,000/50,000) * 100Percentage
allocated to education fund = 0.84 * 100Percentage allocated to education fund = 84
Therefore, 84
11. Question: A non-profit organization receives a donation of 10,000restrictedforaspecif icpurpose.T heorganizationspends4,000
on the designated program and incurs 1,500infundraisingexpensesrelatedtothesameprogram.Howmuchoftherestrictedfundsarestillavailableforthedesignatedpurpose?
Solution: Initially, the organization received 10,000asarestricteddonation.Af terspending4,000 on
the designated program, the remaining amount is 10,000−4,000 = 6,000.However, theyalsoincurred1,500
in fundraising expenses related to the designated program. This amount needs to be subtracted from the re-
maining funds. Therefore, the total amount available for the designated purpose is 6,000−1,500 = 4,500.
Final Answer: 4,500
12. Question: A non-profit organization received a grant of 50,000thatisrestrictedforaspecif icprogram.Duringthefiscalyear, theorganizationspent20,000
on the program. Calculate the amount of restricted funds remaining at the end of the fiscal year.
Solution: Restricted funds remaining = Grant amount - Expenditure on the program Restricted funds
remaining = 50,000−20,000 Restricted funds remaining = 30,000
Therefore, the amount of restricted funds remaining at the end of the fiscal year is 30,000.
13. Question: A non-profit organization has total expenses of 100,000, anditincurred20,000 in fundrais-
ing expenses, 30,000inprogramAexpenses, and25,000 in program B expenses. Calculate the percentage
of total expenses allocated to program A.
Solution: To calculate the percentage of total expenses allocated to program A, we need to first find the
total expenses allocated to program A.
Total expenses allocated to program A = fundraising expenses + program A expenses Total expenses
allocated to program A = 20,000+30,000 Total expenses allocated to program A = 50,000
Now, we can calculate the percentage of total expenses allocated to program A by dividing the total
expenses allocated to program A by the total expenses and multiplying by 100.
Percentage of total expenses allocated to program A = (Total expenses allocated to program A / Total
expenses) * 100 Percentage of total expenses allocated to program A = (50,000/100,000) * 100 Percentage
of total expenses allocated to program A = 0.5 * 100 Percentage of total expenses allocated to program A =
50
Therefore, 50
14. Question: A non-profit organization has total funds of 100,000.40
Solution: Total funds = 100,000Restrictedfunds = 40Unrestrictedfunds =T otalfunds−RestrictedfundsUnrestrictedfunds =100,000
-40,000Unrestrictedfunds =60,000
Therefore, 60,000isallocatedtotheunrestrictedaccount.
15. Question: In a non-profit organization, if the total indirect costs amount to 50,000andaretobeallocatedtotwodifferentprogramsbasedonthedirectcostsincurredbyeachprogram, withP rogramAhavingdirectcostsof30,000
and Program B having direct costs of 20,000, whatistheallocationof indirectcostsf orP rogramA?
Solution: To allocate the indirect costs to each program based on their direct costs, we need to find the
proportion of each program’s direct costs to the total direct costs of both programs.

Total direct costs = Direct costs of Program A + Direct costs of Program B Total direct costs = 30,000+20,000
Total direct costs = 50,000
Now, find the proportion of direct costs for Program A: Proportion of direct costs for Program A =
Direct costs of Program A / Total direct costs Proportion of direct costs for Program A = 30,000/50,000
Proportion of direct costs for Program A = 0.6 or 60
Next, allocate the total indirect costs based on the proportion of direct costs for Program A: Indirect
costs allocated to Program A = Proportion of direct costs for Program A * Total indirect costs Indirect costs
allocated to Program A = 0.6 * 50,000IndirectcostsallocatedtoP rogramA =30,000
Therefore, the allocation of indirect costs for Program A would be 30,000.
16. Question: A non-profit organization receives a grant of 10,000specif icallydesignatedf oraspecialprogram.T heorganizationincurs2,000
in administrative expenses that benefit multiple programs, including the special program funded by the grant.
How much of the administrative expenses should be allocated to the special program using a proportional
allocation method based on the grant amount?
Solution: 1. Calculate the percentage of the grant amount relative to the total funds received: Grant
Percentage = (Grant Amount / Total Funds Received) * 100 = (10,000/10,000) * 100 = 100
2. Allocate the administrative expenses to the special program based on the grant percentage: Adminis-
trative Expenses Allocated = Grant Percentage * Total Administrative Expenses = 100= 1.00 * 2,000 =2,000
Therefore, using the proportional allocation method based on the grant amount, 2,000oftheadministrativeexpensesshouldbeallocatedtothespecialprogram.
17. Question: A non-profit organization incurred total administrative costs of 50,000f ortheyear.Ofthisamount,10,000
relates to a program funded by restricted funds. How much of the administrative costs should be allocated
to the restricted funds?
Solution: To determine the allocation of costs to restricted funds, we need to calculate the proportion of
administrative costs that relate to the program funded by restricted funds.
Proportion of administrative costs allocated to restricted funds = (Costs related to restricted funds / Total
administrative costs) Proportion of administrative costs allocated to restricted funds = (10,000/50,000) =
0.2 or 20
Now, we can calculate the specific amount of administrative costs that should be allocated to the re-
stricted funds:
Administrative costs allocated to restricted funds = Proportion of administrative costs allocated to re-
stricted funds * Total administrative costs Administrative costs allocated to restricted funds = 0.2 * 50,000 =10,000
Therefore, 10,000ofthetotaladministrativecostsshouldbeallocatedtotheprogramfundedbyrestrictedfunds.
18. Question: A non-profit organization has total restricted funds of 50,000.If40
Solution: To find the amount allocated to the specific project, we need to calculate 40
Amount allocated to project = 40Amount allocated to project = 0.40 * 50,000Amountallocatedtoproject =20,000
Therefore, 20,000isallocatedtothespecificprojectwithinthenon −profitorganization.
19. Question: A non-profit organization has total funds of 500,000, ofwhich100,000 is restricted for a
specific program. If the organization spends 30,000ontherestrictedprogram, whatistheremainingbalanceintherestrictedfund?
Solution: 1. Total funds = 500,0002.Restrictedfunds =100,000 3. Amount spent on restricted pro-
gram = 30,000
To find the remaining balance in the restricted fund after spending on the program, we subtract the
amount spent from the initial restricted funds:
Remaining balance = Restricted funds - Amount spent Remaining balance = 100,000−30,000 Remain-
ing balance = 70,000
Therefore, the remaining balance in the restricted fund is 70,000.

20. Question: A non-profit organization has total funds of 500,000.Outofthisamount,150,000 is
classified as restricted funds and the rest as unrestricted funds. What is the percentage of the organization’s
total funds that are classified as restricted funds?
Solution: To find the percentage of restricted funds out of the total funds, we first need to calculate the
proportion of restricted funds to total funds.
Restricted funds / Total funds = 150,000/500,000 = 0.3
Now, to convert this proportion to a percentage, we multiply by 100.
Percentage of restricted funds = 0.3 * 100 = 30
Therefore, 30
21. Question: A non-profit organization receives a donation of 10,000thatisrestrictedforaspecif icprogram.If theorganizationspends5,000
from this restricted donation on the program, how much remains in the restricted fund?
Solution: To determine how much remains in the restricted fund after spending 5,000ontheprogram, wesimplysubtracttheamountspentfromtheinitialrestricteddonation.
Initial restricted donation = 10,000Amountspentontheprogram =5,000
Remaining amount in the restricted fund = 10,000−5,000 = 5,000
Therefore, the remaining amount in the restricted fund is 5,000.
22. Question: A non-profit organization has a total of 50,000infunds.T heyallocate40
Solution: To find the amount allocated to the restricted account, we first calculate 4050,000∗0.40 =20,000
Therefore, 20,000isallocatedtotherestrictedaccount.
23. Question: A non-profit organization has total funds of 100,000.40
Solution: 1. Calculate the current amount of funds in the restricted account: Restricted funds = Total
funds * Percentage restricted Restricted funds = 100,000 ∗40
2. Since the organization needs to allocate an additional 30,000totherestrictedfunds, thenewamountintherestrictedaccountwillbe :
Newrestrictedfunds =40,000 + 30,000 =70,000
3. To find the new amount in the unrestricted funds, simply subtract the new amount in the restricted
funds from the total funds: New unrestricted funds = Total funds - New restricted funds New unrestricted
funds = 100,000−70,000 New unrestricted funds = 30,000
Therefore, the new amount in the unrestricted funds will be 30,000.
24. Question: A non-profit organization has total unrestricted net assets of 100,000andtotalrestrictednetassetsof50,000.
If the organization designates 20,000fromtheunrestrictednetassetstoanewdonor−restrictedfund, whatwillbethenewbalanceofunrestrictednetassets?
Solution: Total Unrestricted Net Assets = 100,000T otalRestrictedN etAssets =50,000 Amount des-
ignated to new donor-restricted fund from Unrestricted Net Assets = 20,000
New Unrestricted Net Assets = Total Unrestricted Net Assets - Amount designated to new fund New
Unrestricted Net Assets = 100,000−20,000 New Unrestricted Net Assets = 80,000
Therefore, the new balance of unrestricted net assets after designating 20,000toanewdonor−restrictedfundwouldbe80,000.
25. Question: A non-profit organization has three funds: Fund A, Fund B, and Fund C. Fund A
incurred 10,000inexpensesthatwereallocabletoallthreef unds, F undBincurred5,000 in expenses that
were specific to Fund B only, and Fund C incurred 8,000inexpensesthatwereallocabletoF undAandF undC.If theorganizationwantstoallocatetheexpensesproportionallybasedonthetotalrevenueofeachfund, andthetotalrevenueforF undA, F undB, andF undCis100,000,
50,000, and80,000 respectively, what would be the total amount of expenses allocated to Fund A?
Solution: 1. Calculate the total revenue for all funds: 100,000(F undA)+50,000 (Fund B) + 80,000(F undC) =230,000
2. Calculate the proportion of total revenue for each fund: - Fund A: 100,000/230,000 = 0.4348 - Fund B:
50,000/230,000 = 0.2174 - Fund C: 80,000/230,000 = 0.3478 3. Allocate the shared expenses to each fund
proportionally: - Fund A: 10,000 ∗0.4348 =4,348 - Fund B: 10,000 ∗0.2174 =2,174 - Fund C: 10,000 ∗

0.3478 =3,478 4. Allocate Fund B’s expenses to Fund B: 5,0005.AllocateF undC′sexpensestoF undAandF undCproportionally :
−F undA :8,000 * 0.4348 = 3,478 −F undC :8,000 * 0.3478 = 2,784
Total expenses allocated to Fund A = 4,348(sharedexpenses)+3,478 (expenses from Fund C) = 7,826
indirect costs * Restricted funds share of indirect costs = 20,000 ∗30
Now, the remaining indirect costs will be allocated to the unrestricted funds. Unrestricted funds share
of indirect costs = Total indirect costs - Restricted funds share of indirect costs Unrestricted funds share of
indirect costs = 20,000−6,000 = 14,000
Therefore, the amount of the indirect costs allocated to the unrestricted funds is 14,000.
7. Question: A non-profit organization has three separate funds: Fund A, Fund B, and Fund C. Fund
A incurred expenses of 10,000, F undBincurredexpensesof 15,000, and Fund C incurred expenses of
20,000.T heorganization′stotalindirectcostsf ortheyearare5,000. If the organization wants to allocate
indirect costs based on the proportion of expenses in each fund, how much indirect cost should be allocated
to Fund A?
Solution: To allocate indirect costs based on the proportion of expenses in each fund, we need to calcu-
late the total expenses across all funds first.
Total Expenses = 10,000(F undA)+15,000 (Fund B) + 20,000(F undC)T otalExpenses =45,000
Next, we calculate the proportion of expenses for each fund:
Proportion of Fund A’s Expenses = Fund A’s Expenses / Total Expenses Proportion of Fund A’s Expenses
=10,000/45,000 Proportion of Fund A’s Expenses = 1/4 or 0.25
Now, we allocate the total indirect costs to Fund A based on its proportion of expenses:
Indirect Cost Allocated to Fund A = Proportion of Fund A’s Expenses * Total Indirect Costs Indirect
Cost Allocated to Fund A = 0.25 * 5,000IndirectCostAllocatedtoF undA =1,250
Therefore, 1,250ofindirectcostsshouldbeallocatedtoF undA.
8. Question: A non-profit organization receives a donation of 10,000thatisrestrictedtobeusedforaspecif icprogram.T heorganizationincursexpensesof6,000
directly related to this program. How much is the remaining balance of the restricted fund for this program?
Solution: The remaining balance of the restricted fund for the specific program can be found by sub-
tracting the expenses incurred from the total donation amount.
Remaining Balance = Total Donation - Program Expenses Remaining Balance = 10,000−6,000 Re-
maining Balance = 4,000
Therefore, the remaining balance of the restricted fund for this program is 4,000.
9. Question: A non-profit organization receives a donation of 10,000specif icallydesignatedforabuildingrenovationproject.Duringthecurrentfiscalyear, theorganizationuses5,000
of the donation for the project. At the end of the fiscal year, what are the balances of the temporarily re-
stricted fund and the amount available for general use in the unrestricted fund?
Solution: 1. Temporary Restricted Fund Balance: - Initial donation: 10,000−Amountusedf ortheproject :5,000
- Balance of temporarily restricted fund = Initial donation - Amount used - Balance of temporarily restricted
fund = 10,000−5,000 - Balance of temporarily restricted fund = 5,000
2. Unrestricted Fund Balance: - Any part of the donation not used for the project remains in the tem-
porarily restricted fund. - Amount available for general use in the unrestricted fund = Initial donation -
Amount in temporarily restricted for the project - Amount available for general use in the unrestricted fund
=10,000−5,000 - Amount available for general use in the unrestricted fund = 5,000
Therefore, at the end of the fiscal year, the balance of the temporarily restricted fund is 5,000, andtheamountavailableforgeneraluseintheunrestrictedfundisalso5,000.
10. Question: A non-profit organization incurred total operating expenses of 50,000.F romthatamount,12,000
expenses were incurred specifically for the education fund, 8,000forthehealthcaref und, andtheremainingexpensesweregeneraloperatingexpenses.W hatpercentageof thetotaloperatingexpenseswereallocatedtotheeducationf und?
Solution: To find the percentage of total operating expenses allocated to the education fund, we first
need to calculate the total specific allocations for the education fund:
Total specific allocation for education fund = 12,000
Then, we calculate the total operating expenses allocated to the education fund:

Total operating expenses allocated to the education fund = Total specific allocation for education fund +
General operating expenses Total operating expenses allocated to the education fund = 12,000 + (50,000 -
12,000−8,000) Total operating expenses allocated to the education fund = 12,000+30,000 Total operating
expenses allocated to the education fund = 42,000
Finally, we calculate the percentage of total operating expenses allocated to the education fund:
Percentage allocated to education fund = (Total operating expenses allocated to education fund / To-
tal operating expenses) * 100Percentage allocated to education fund = (42,000/50,000) * 100Percentage
allocated to education fund = 0.84 * 100Percentage allocated to education fund = 84
Therefore, 84
11. Question: A non-profit organization receives a donation of 10,000restrictedforaspecif icpurpose.T heorganizationspends4,000
on the designated program and incurs 1,500infundraisingexpensesrelatedtothesameprogram.Howmuchoftherestrictedfundsarestillavailableforthedesignatedpurpose?
Solution: Initially, the organization received 10,000asarestricteddonation.Af terspending4,000 on
the designated program, the remaining amount is 10,000−4,000 = 6,000.However, theyalsoincurred1,500
in fundraising expenses related to the designated program. This amount needs to be subtracted from the re-
maining funds. Therefore, the total amount available for the designated purpose is 6,000−1,500 = 4,500.
Final Answer: 4,500
12. Question: A non-profit organization received a grant of 50,000thatisrestrictedforaspecif icprogram.Duringthefiscalyear, theorganizationspent20,000
on the program. Calculate the amount of restricted funds remaining at the end of the fiscal year.
Solution: Restricted funds remaining = Grant amount - Expenditure on the program Restricted funds
remaining = 50,000−20,000 Restricted funds remaining = 30,000
Therefore, the amount of restricted funds remaining at the end of the fiscal year is 30,000.
13. Question: A non-profit organization has total expenses of 100,000, anditincurred20,000 in fundrais-
ing expenses, 30,000inprogramAexpenses, and25,000 in program B expenses. Calculate the percentage
of total expenses allocated to program A.
Solution: To calculate the percentage of total expenses allocated to program A, we need to first find the
total expenses allocated to program A.
Total expenses allocated to program A = fundraising expenses + program A expenses Total expenses
allocated to program A = 20,000+30,000 Total expenses allocated to program A = 50,000
Now, we can calculate the percentage of total expenses allocated to program A by dividing the total
expenses allocated to program A by the total expenses and multiplying by 100.
Percentage of total expenses allocated to program A = (Total expenses allocated to program A / Total
expenses) * 100 Percentage of total expenses allocated to program A = (50,000/100,000) * 100 Percentage
of total expenses allocated to program A = 0.5 * 100 Percentage of total expenses allocated to program A =
50
Therefore, 50
14. Question: A non-profit organization has total funds of 100,000.40
Solution: Total funds = 100,000Restrictedfunds = 40Unrestrictedfunds =T otalfunds−RestrictedfundsUnrestrictedfunds =100,000
-40,000Unrestrictedfunds =60,000
Therefore, 60,000isallocatedtotheunrestrictedaccount.
15. Question: In a non-profit organization, if the total indirect costs amount to 50,000andaretobeallocatedtotwodifferentprogramsbasedonthedirectcostsincurredbyeachprogram, withP rogramAhavingdirectcostsof30,000
and Program B having direct costs of 20,000, whatistheallocationof indirectcostsf orP rogramA?
Solution: To allocate the indirect costs to each program based on their direct costs, we need to find the
proportion of each program’s direct costs to the total direct costs of both programs.

Total direct costs = Direct costs of Program A + Direct costs of Program B Total direct costs = 30,000+20,000
Total direct costs = 50,000
Now, find the proportion of direct costs for Program A: Proportion of direct costs for Program A =
Direct costs of Program A / Total direct costs Proportion of direct costs for Program A = 30,000/50,000
Proportion of direct costs for Program A = 0.6 or 60
Next, allocate the total indirect costs based on the proportion of direct costs for Program A: Indirect
costs allocated to Program A = Proportion of direct costs for Program A * Total indirect costs Indirect costs
allocated to Program A = 0.6 * 50,000IndirectcostsallocatedtoP rogramA =30,000
Therefore, the allocation of indirect costs for Program A would be 30,000.
16. Question: A non-profit organization receives a grant of 10,000specif icallydesignatedf oraspecialprogram.T heorganizationincurs2,000
in administrative expenses that benefit multiple programs, including the special program funded by the grant.
How much of the administrative expenses should be allocated to the special program using a proportional
allocation method based on the grant amount?
Solution: 1. Calculate the percentage of the grant amount relative to the total funds received: Grant
Percentage = (Grant Amount / Total Funds Received) * 100 = (10,000/10,000) * 100 = 100
2. Allocate the administrative expenses to the special program based on the grant percentage: Adminis-
trative Expenses Allocated = Grant Percentage * Total Administrative Expenses = 100= 1.00 * 2,000 =2,000
Therefore, using the proportional allocation method based on the grant amount, 2,000oftheadministrativeexpensesshouldbeallocatedtothespecialprogram.
17. Question: A non-profit organization incurred total administrative costs of 50,000f ortheyear.Ofthisamount,10,000
relates to a program funded by restricted funds. How much of the administrative costs should be allocated
to the restricted funds?
Solution: To determine the allocation of costs to restricted funds, we need to calculate the proportion of
administrative costs that relate to the program funded by restricted funds.
Proportion of administrative costs allocated to restricted funds = (Costs related to restricted funds / Total
administrative costs) Proportion of administrative costs allocated to restricted funds = (10,000/50,000) =
0.2 or 20
Now, we can calculate the specific amount of administrative costs that should be allocated to the re-
stricted funds:
Administrative costs allocated to restricted funds = Proportion of administrative costs allocated to re-
stricted funds * Total administrative costs Administrative costs allocated to restricted funds = 0.2 * 50,000 =10,000
Therefore, 10,000ofthetotaladministrativecostsshouldbeallocatedtotheprogramfundedbyrestrictedfunds.
18. Question: A non-profit organization has total restricted funds of 50,000.If40
Solution: To find the amount allocated to the specific project, we need to calculate 40
Amount allocated to project = 40Amount allocated to project = 0.40 * 50,000Amountallocatedtoproject =20,000
Therefore, 20,000isallocatedtothespecificprojectwithinthenon −profitorganization.
19. Question: A non-profit organization has total funds of 500,000, ofwhich100,000 is restricted for a
specific program. If the organization spends 30,000ontherestrictedprogram, whatistheremainingbalanceintherestrictedfund?
Solution: 1. Total funds = 500,0002.Restrictedfunds =100,000 3. Amount spent on restricted pro-
gram = 30,000
To find the remaining balance in the restricted fund after spending on the program, we subtract the
amount spent from the initial restricted funds:
Remaining balance = Restricted funds - Amount spent Remaining balance = 100,000−30,000 Remain-
ing balance = 70,000
Therefore, the remaining balance in the restricted fund is 70,000.

20. Question: A non-profit organization has total funds of 500,000.Outofthisamount,150,000 is
classified as restricted funds and the rest as unrestricted funds. What is the percentage of the organization’s
total funds that are classified as restricted funds?
Solution: To find the percentage of restricted funds out of the total funds, we first need to calculate the
proportion of restricted funds to total funds.
Restricted funds / Total funds = 150,000/500,000 = 0.3
Now, to convert this proportion to a percentage, we multiply by 100.
Percentage of restricted funds = 0.3 * 100 = 30
Therefore, 30
21. Question: A non-profit organization receives a donation of 10,000thatisrestrictedforaspecif icprogram.If theorganizationspends5,000
from this restricted donation on the program, how much remains in the restricted fund?
Solution: To determine how much remains in the restricted fund after spending 5,000ontheprogram, wesimplysubtracttheamountspentfromtheinitialrestricteddonation.
Initial restricted donation = 10,000Amountspentontheprogram =5,000
Remaining amount in the restricted fund = 10,000−5,000 = 5,000
Therefore, the remaining amount in the restricted fund is 5,000.
22. Question: A non-profit organization has a total of 50,000infunds.T heyallocate40
Solution: To find the amount allocated to the restricted account, we first calculate 4050,000∗0.40 =20,000
Therefore, 20,000isallocatedtotherestrictedaccount.
23. Question: A non-profit organization has total funds of 100,000.40
Solution: 1. Calculate the current amount of funds in the restricted account: Restricted funds = Total
funds * Percentage restricted Restricted funds = 100,000 ∗40
2. Since the organization needs to allocate an additional 30,000totherestrictedfunds, thenewamountintherestrictedaccountwillbe :
Newrestrictedfunds =40,000 + 30,000 =70,000
3. To find the new amount in the unrestricted funds, simply subtract the new amount in the restricted
funds from the total funds: New unrestricted funds = Total funds - New restricted funds New unrestricted
funds = 100,000−70,000 New unrestricted funds = 30,000
Therefore, the new amount in the unrestricted funds will be 30,000.
24. Question: A non-profit organization has total unrestricted net assets of 100,000andtotalrestrictednetassetsof50,000.
If the organization designates 20,000fromtheunrestrictednetassetstoanewdonor−restrictedfund, whatwillbethenewbalanceofunrestrictednetassets?
Solution: Total Unrestricted Net Assets = 100,000T otalRestrictedN etAssets =50,000 Amount des-
ignated to new donor-restricted fund from Unrestricted Net Assets = 20,000
New Unrestricted Net Assets = Total Unrestricted Net Assets - Amount designated to new fund New
Unrestricted Net Assets = 100,000−20,000 New Unrestricted Net Assets = 80,000
Therefore, the new balance of unrestricted net assets after designating 20,000toanewdonor−restrictedfundwouldbe80,000.
25. Question: A non-profit organization has three funds: Fund A, Fund B, and Fund C. Fund A
incurred 10,000inexpensesthatwereallocabletoallthreef unds, F undBincurred5,000 in expenses that
were specific to Fund B only, and Fund C incurred 8,000inexpensesthatwereallocabletoF undAandF undC.If theorganizationwantstoallocatetheexpensesproportionallybasedonthetotalrevenueofeachfund, andthetotalrevenueforF undA, F undB, andF undCis100,000,
50,000, and80,000 respectively, what would be the total amount of expenses allocated to Fund A?
Solution: 1. Calculate the total revenue for all funds: 100,000(F undA)+50,000 (Fund B) + 80,000(F undC) =230,000
2. Calculate the proportion of total revenue for each fund: - Fund A: 100,000/230,000 = 0.4348 - Fund B:
50,000/230,000 = 0.2174 - Fund C: 80,000/230,000 = 0.3478 3. Allocate the shared expenses to each fund
proportionally: - Fund A: 10,000 ∗0.4348 =4,348 - Fund B: 10,000 ∗0.2174 =2,174 - Fund C: 10,000 ∗

0.3478 =3,478 4. Allocate Fund B’s expenses to Fund B: 5,0005.AllocateF undC′sexpensestoF undAandF undCproportionally :
−F undA :8,000 * 0.4348 = 3,478 −F undC :8,000 * 0.3478 = 2,784
Total expenses allocated to Fund A = 4,348(sharedexpenses)+3,478 (expenses from Fund C) = 7,826
indirect costs * Restricted funds share of indirect costs = 20,000 ∗30
Now, the remaining indirect costs will be allocated to the unrestricted funds. Unrestricted funds share
of indirect costs = Total indirect costs - Restricted funds share of indirect costs Unrestricted funds share of
indirect costs = 20,000−6,000 = 14,000
Therefore, the amount of the indirect costs allocated to the unrestricted funds is 14,000.
7. Question: A non-profit organization has three separate funds: Fund A, Fund B, and Fund C. Fund
A incurred expenses of 10,000, F undBincurredexpensesof 15,000, and Fund C incurred expenses of
20,000.T heorganization′stotalindirectcostsf ortheyearare5,000. If the organization wants to allocate
indirect costs based on the proportion of expenses in each fund, how much indirect cost should be allocated
to Fund A?
Solution: To allocate indirect costs based on the proportion of expenses in each fund, we need to calcu-
late the total expenses across all funds first.
Total Expenses = 10,000(F undA)+15,000 (Fund B) + 20,000(F undC)T otalExpenses =45,000
Next, we calculate the proportion of expenses for each fund:
Proportion of Fund A’s Expenses = Fund A’s Expenses / Total Expenses Proportion of Fund A’s Expenses
=10,000/45,000 Proportion of Fund A’s Expenses = 1/4 or 0.25
Now, we allocate the total indirect costs to Fund A based on its proportion of expenses:
Indirect Cost Allocated to Fund A = Proportion of Fund A’s Expenses * Total Indirect Costs Indirect
Cost Allocated to Fund A = 0.25 * 5,000IndirectCostAllocatedtoF undA =1,250
Therefore, 1,250ofindirectcostsshouldbeallocatedtoF undA.
8. Question: A non-profit organization receives a donation of 10,000thatisrestrictedtobeusedforaspecif icprogram.T heorganizationincursexpensesof6,000
directly related to this program. How much is the remaining balance of the restricted fund for this program?
Solution: The remaining balance of the restricted fund for the specific program can be found by sub-
tracting the expenses incurred from the total donation amount.
Remaining Balance = Total Donation - Program Expenses Remaining Balance = 10,000−6,000 Re-
maining Balance = 4,000
Therefore, the remaining balance of the restricted fund for this program is 4,000.
9. Question: A non-profit organization receives a donation of 10,000specif icallydesignatedforabuildingrenovationproject.Duringthecurrentfiscalyear, theorganizationuses5,000
of the donation for the project. At the end of the fiscal year, what are the balances of the temporarily re-
stricted fund and the amount available for general use in the unrestricted fund?
Solution: 1. Temporary Restricted Fund Balance: - Initial donation: 10,000−Amountusedf ortheproject :5,000
- Balance of temporarily restricted fund = Initial donation - Amount used - Balance of temporarily restricted
fund = 10,000−5,000 - Balance of temporarily restricted fund = 5,000
2. Unrestricted Fund Balance: - Any part of the donation not used for the project remains in the tem-
porarily restricted fund. - Amount available for general use in the unrestricted fund = Initial donation -
Amount in temporarily restricted for the project - Amount available for general use in the unrestricted fund
=10,000−5,000 - Amount available for general use in the unrestricted fund = 5,000
Therefore, at the end of the fiscal year, the balance of the temporarily restricted fund is 5,000, andtheamountavailableforgeneraluseintheunrestrictedfundisalso5,000.
10. Question: A non-profit organization incurred total operating expenses of 50,000.F romthatamount,12,000
expenses were incurred specifically for the education fund, 8,000forthehealthcaref und, andtheremainingexpensesweregeneraloperatingexpenses.W hatpercentageof thetotaloperatingexpenseswereallocatedtotheeducationf und?
Solution: To find the percentage of total operating expenses allocated to the education fund, we first
need to calculate the total specific allocations for the education fund:
Total specific allocation for education fund = 12,000
Then, we calculate the total operating expenses allocated to the education fund:

Total operating expenses allocated to the education fund = Total specific allocation for education fund +
General operating expenses Total operating expenses allocated to the education fund = 12,000 + (50,000 -
12,000−8,000) Total operating expenses allocated to the education fund = 12,000+30,000 Total operating
expenses allocated to the education fund = 42,000
Finally, we calculate the percentage of total operating expenses allocated to the education fund:
Percentage allocated to education fund = (Total operating expenses allocated to education fund / To-
tal operating expenses) * 100Percentage allocated to education fund = (42,000/50,000) * 100Percentage
allocated to education fund = 0.84 * 100Percentage allocated to education fund = 84
Therefore, 84
11. Question: A non-profit organization receives a donation of 10,000restrictedforaspecif icpurpose.T heorganizationspends4,000
on the designated program and incurs 1,500infundraisingexpensesrelatedtothesameprogram.Howmuchoftherestrictedfundsarestillavailableforthedesignatedpurpose?
Solution: Initially, the organization received 10,000asarestricteddonation.Af terspending4,000 on
the designated program, the remaining amount is 10,000−4,000 = 6,000.However, theyalsoincurred1,500
in fundraising expenses related to the designated program. This amount needs to be subtracted from the re-
maining funds. Therefore, the total amount available for the designated purpose is 6,000−1,500 = 4,500.
Final Answer: 4,500
12. Question: A non-profit organization received a grant of 50,000thatisrestrictedforaspecif icprogram.Duringthefiscalyear, theorganizationspent20,000
on the program. Calculate the amount of restricted funds remaining at the end of the fiscal year.
Solution: Restricted funds remaining = Grant amount - Expenditure on the program Restricted funds
remaining = 50,000−20,000 Restricted funds remaining = 30,000
Therefore, the amount of restricted funds remaining at the end of the fiscal year is 30,000.
13. Question: A non-profit organization has total expenses of 100,000, anditincurred20,000 in fundrais-
ing expenses, 30,000inprogramAexpenses, and25,000 in program B expenses. Calculate the percentage
of total expenses allocated to program A.
Solution: To calculate the percentage of total expenses allocated to program A, we need to first find the
total expenses allocated to program A.
Total expenses allocated to program A = fundraising expenses + program A expenses Total expenses
allocated to program A = 20,000+30,000 Total expenses allocated to program A = 50,000
Now, we can calculate the percentage of total expenses allocated to program A by dividing the total
expenses allocated to program A by the total expenses and multiplying by 100.
Percentage of total expenses allocated to program A = (Total expenses allocated to program A / Total
expenses) * 100 Percentage of total expenses allocated to program A = (50,000/100,000) * 100 Percentage
of total expenses allocated to program A = 0.5 * 100 Percentage of total expenses allocated to program A =
50
Therefore, 50
14. Question: A non-profit organization has total funds of 100,000.40
Solution: Total funds = 100,000Restrictedfunds = 40Unrestrictedfunds =T otalfunds−RestrictedfundsUnrestrictedfunds =100,000
-40,000Unrestrictedfunds =60,000
Therefore, 60,000isallocatedtotheunrestrictedaccount.
15. Question: In a non-profit organization, if the total indirect costs amount to 50,000andaretobeallocatedtotwodifferentprogramsbasedonthedirectcostsincurredbyeachprogram, withP rogramAhavingdirectcostsof30,000
and Program B having direct costs of 20,000, whatistheallocationof indirectcostsf orP rogramA?
Solution: To allocate the indirect costs to each program based on their direct costs, we need to find the
proportion of each program’s direct costs to the total direct costs of both programs.

Total direct costs = Direct costs of Program A + Direct costs of Program B Total direct costs = 30,000+20,000
Total direct costs = 50,000
Now, find the proportion of direct costs for Program A: Proportion of direct costs for Program A =
Direct costs of Program A / Total direct costs Proportion of direct costs for Program A = 30,000/50,000
Proportion of direct costs for Program A = 0.6 or 60
Next, allocate the total indirect costs based on the proportion of direct costs for Program A: Indirect
costs allocated to Program A = Proportion of direct costs for Program A * Total indirect costs Indirect costs
allocated to Program A = 0.6 * 50,000IndirectcostsallocatedtoP rogramA =30,000
Therefore, the allocation of indirect costs for Program A would be 30,000.
16. Question: A non-profit organization receives a grant of 10,000specif icallydesignatedf oraspecialprogram.T heorganizationincurs2,000
in administrative expenses that benefit multiple programs, including the special program funded by the grant.
How much of the administrative expenses should be allocated to the special program using a proportional
allocation method based on the grant amount?
Solution: 1. Calculate the percentage of the grant amount relative to the total funds received: Grant
Percentage = (Grant Amount / Total Funds Received) * 100 = (10,000/10,000) * 100 = 100
2. Allocate the administrative expenses to the special program based on the grant percentage: Adminis-
trative Expenses Allocated = Grant Percentage * Total Administrative Expenses = 100= 1.00 * 2,000 =2,000
Therefore, using the proportional allocation method based on the grant amount, 2,000oftheadministrativeexpensesshouldbeallocatedtothespecialprogram.
17. Question: A non-profit organization incurred total administrative costs of 50,000f ortheyear.Ofthisamount,10,000
relates to a program funded by restricted funds. How much of the administrative costs should be allocated
to the restricted funds?
Solution: To determine the allocation of costs to restricted funds, we need to calculate the proportion of
administrative costs that relate to the program funded by restricted funds.
Proportion of administrative costs allocated to restricted funds = (Costs related to restricted funds / Total
administrative costs) Proportion of administrative costs allocated to restricted funds = (10,000/50,000) =
0.2 or 20
Now, we can calculate the specific amount of administrative costs that should be allocated to the re-
stricted funds:
Administrative costs allocated to restricted funds = Proportion of administrative costs allocated to re-
stricted funds * Total administrative costs Administrative costs allocated to restricted funds = 0.2 * 50,000 =10,000
Therefore, 10,000ofthetotaladministrativecostsshouldbeallocatedtotheprogramfundedbyrestrictedfunds.
18. Question: A non-profit organization has total restricted funds of 50,000.If40
Solution: To find the amount allocated to the specific project, we need to calculate 40
Amount allocated to project = 40Amount allocated to project = 0.40 * 50,000Amountallocatedtoproject =20,000
Therefore, 20,000isallocatedtothespecificprojectwithinthenon −profitorganization.
19. Question: A non-profit organization has total funds of 500,000, ofwhich100,000 is restricted for a
specific program. If the organization spends 30,000ontherestrictedprogram, whatistheremainingbalanceintherestrictedfund?
Solution: 1. Total funds = 500,0002.Restrictedfunds =100,000 3. Amount spent on restricted pro-
gram = 30,000
To find the remaining balance in the restricted fund after spending on the program, we subtract the
amount spent from the initial restricted funds:
Remaining balance = Restricted funds - Amount spent Remaining balance = 100,000−30,000 Remain-
ing balance = 70,000
Therefore, the remaining balance in the restricted fund is 70,000.

20. Question: A non-profit organization has total funds of 500,000.Outofthisamount,150,000 is
classified as restricted funds and the rest as unrestricted funds. What is the percentage of the organization’s
total funds that are classified as restricted funds?
Solution: To find the percentage of restricted funds out of the total funds, we first need to calculate the
proportion of restricted funds to total funds.
Restricted funds / Total funds = 150,000/500,000 = 0.3
Now, to convert this proportion to a percentage, we multiply by 100.
Percentage of restricted funds = 0.3 * 100 = 30
Therefore, 30
21. Question: A non-profit organization receives a donation of 10,000thatisrestrictedforaspecif icprogram.If theorganizationspends5,000
from this restricted donation on the program, how much remains in the restricted fund?
Solution: To determine how much remains in the restricted fund after spending 5,000ontheprogram, wesimplysubtracttheamountspentfromtheinitialrestricteddonation.
Initial restricted donation = 10,000Amountspentontheprogram =5,000
Remaining amount in the restricted fund = 10,000−5,000 = 5,000
Therefore, the remaining amount in the restricted fund is 5,000.
22. Question: A non-profit organization has a total of 50,000infunds.T heyallocate40
Solution: To find the amount allocated to the restricted account, we first calculate 4050,000∗0.40 =20,000
Therefore, 20,000isallocatedtotherestrictedaccount.
23. Question: A non-profit organization has total funds of 100,000.40
Solution: 1. Calculate the current amount of funds in the restricted account: Restricted funds = Total
funds * Percentage restricted Restricted funds = 100,000 ∗40
2. Since the organization needs to allocate an additional 30,000totherestrictedfunds, thenewamountintherestrictedaccountwillbe :
Newrestrictedfunds =40,000 + 30,000 =70,000
3. To find the new amount in the unrestricted funds, simply subtract the new amount in the restricted
funds from the total funds: New unrestricted funds = Total funds - New restricted funds New unrestricted
funds = 100,000−70,000 New unrestricted funds = 30,000
Therefore, the new amount in the unrestricted funds will be 30,000.
24. Question: A non-profit organization has total unrestricted net assets of 100,000andtotalrestrictednetassetsof50,000.
If the organization designates 20,000fromtheunrestrictednetassetstoanewdonor−restrictedfund, whatwillbethenewbalanceofunrestrictednetassets?
Solution: Total Unrestricted Net Assets = 100,000T otalRestrictedN etAssets =50,000 Amount des-
ignated to new donor-restricted fund from Unrestricted Net Assets = 20,000
New Unrestricted Net Assets = Total Unrestricted Net Assets - Amount designated to new fund New
Unrestricted Net Assets = 100,000−20,000 New Unrestricted Net Assets = 80,000
Therefore, the new balance of unrestricted net assets after designating 20,000toanewdonor−restrictedfundwouldbe80,000.
25. Question: A non-profit organization has three funds: Fund A, Fund B, and Fund C. Fund A
incurred 10,000inexpensesthatwereallocabletoallthreef unds, F undBincurred5,000 in expenses that
were specific to Fund B only, and Fund C incurred 8,000inexpensesthatwereallocabletoF undAandF undC.If theorganizationwantstoallocatetheexpensesproportionallybasedonthetotalrevenueofeachfund, andthetotalrevenueforF undA, F undB, andF undCis100,000,
50,000, and80,000 respectively, what would be the total amount of expenses allocated to Fund A?
Solution: 1. Calculate the total revenue for all funds: 100,000(F undA)+50,000 (Fund B) + 80,000(F undC) =230,000
2. Calculate the proportion of total revenue for each fund: - Fund A: 100,000/230,000 = 0.4348 - Fund B:
50,000/230,000 = 0.2174 - Fund C: 80,000/230,000 = 0.3478 3. Allocate the shared expenses to each fund
proportionally: - Fund A: 10,000 ∗0.4348 =4,348 - Fund B: 10,000 ∗0.2174 =2,174 - Fund C: 10,000 ∗

0.3478 =3,478 4. Allocate Fund B’s expenses to Fund B: 5,0005.AllocateF undC′sexpensestoF undAandF undCproportionally :
−F undA :8,000 * 0.4348 = 3,478 −F undC :8,000 * 0.3478 = 2,784
Total expenses allocated to Fund A = 4,348(sharedexpenses)+3,478 (expenses from Fund C) = 7,826

