


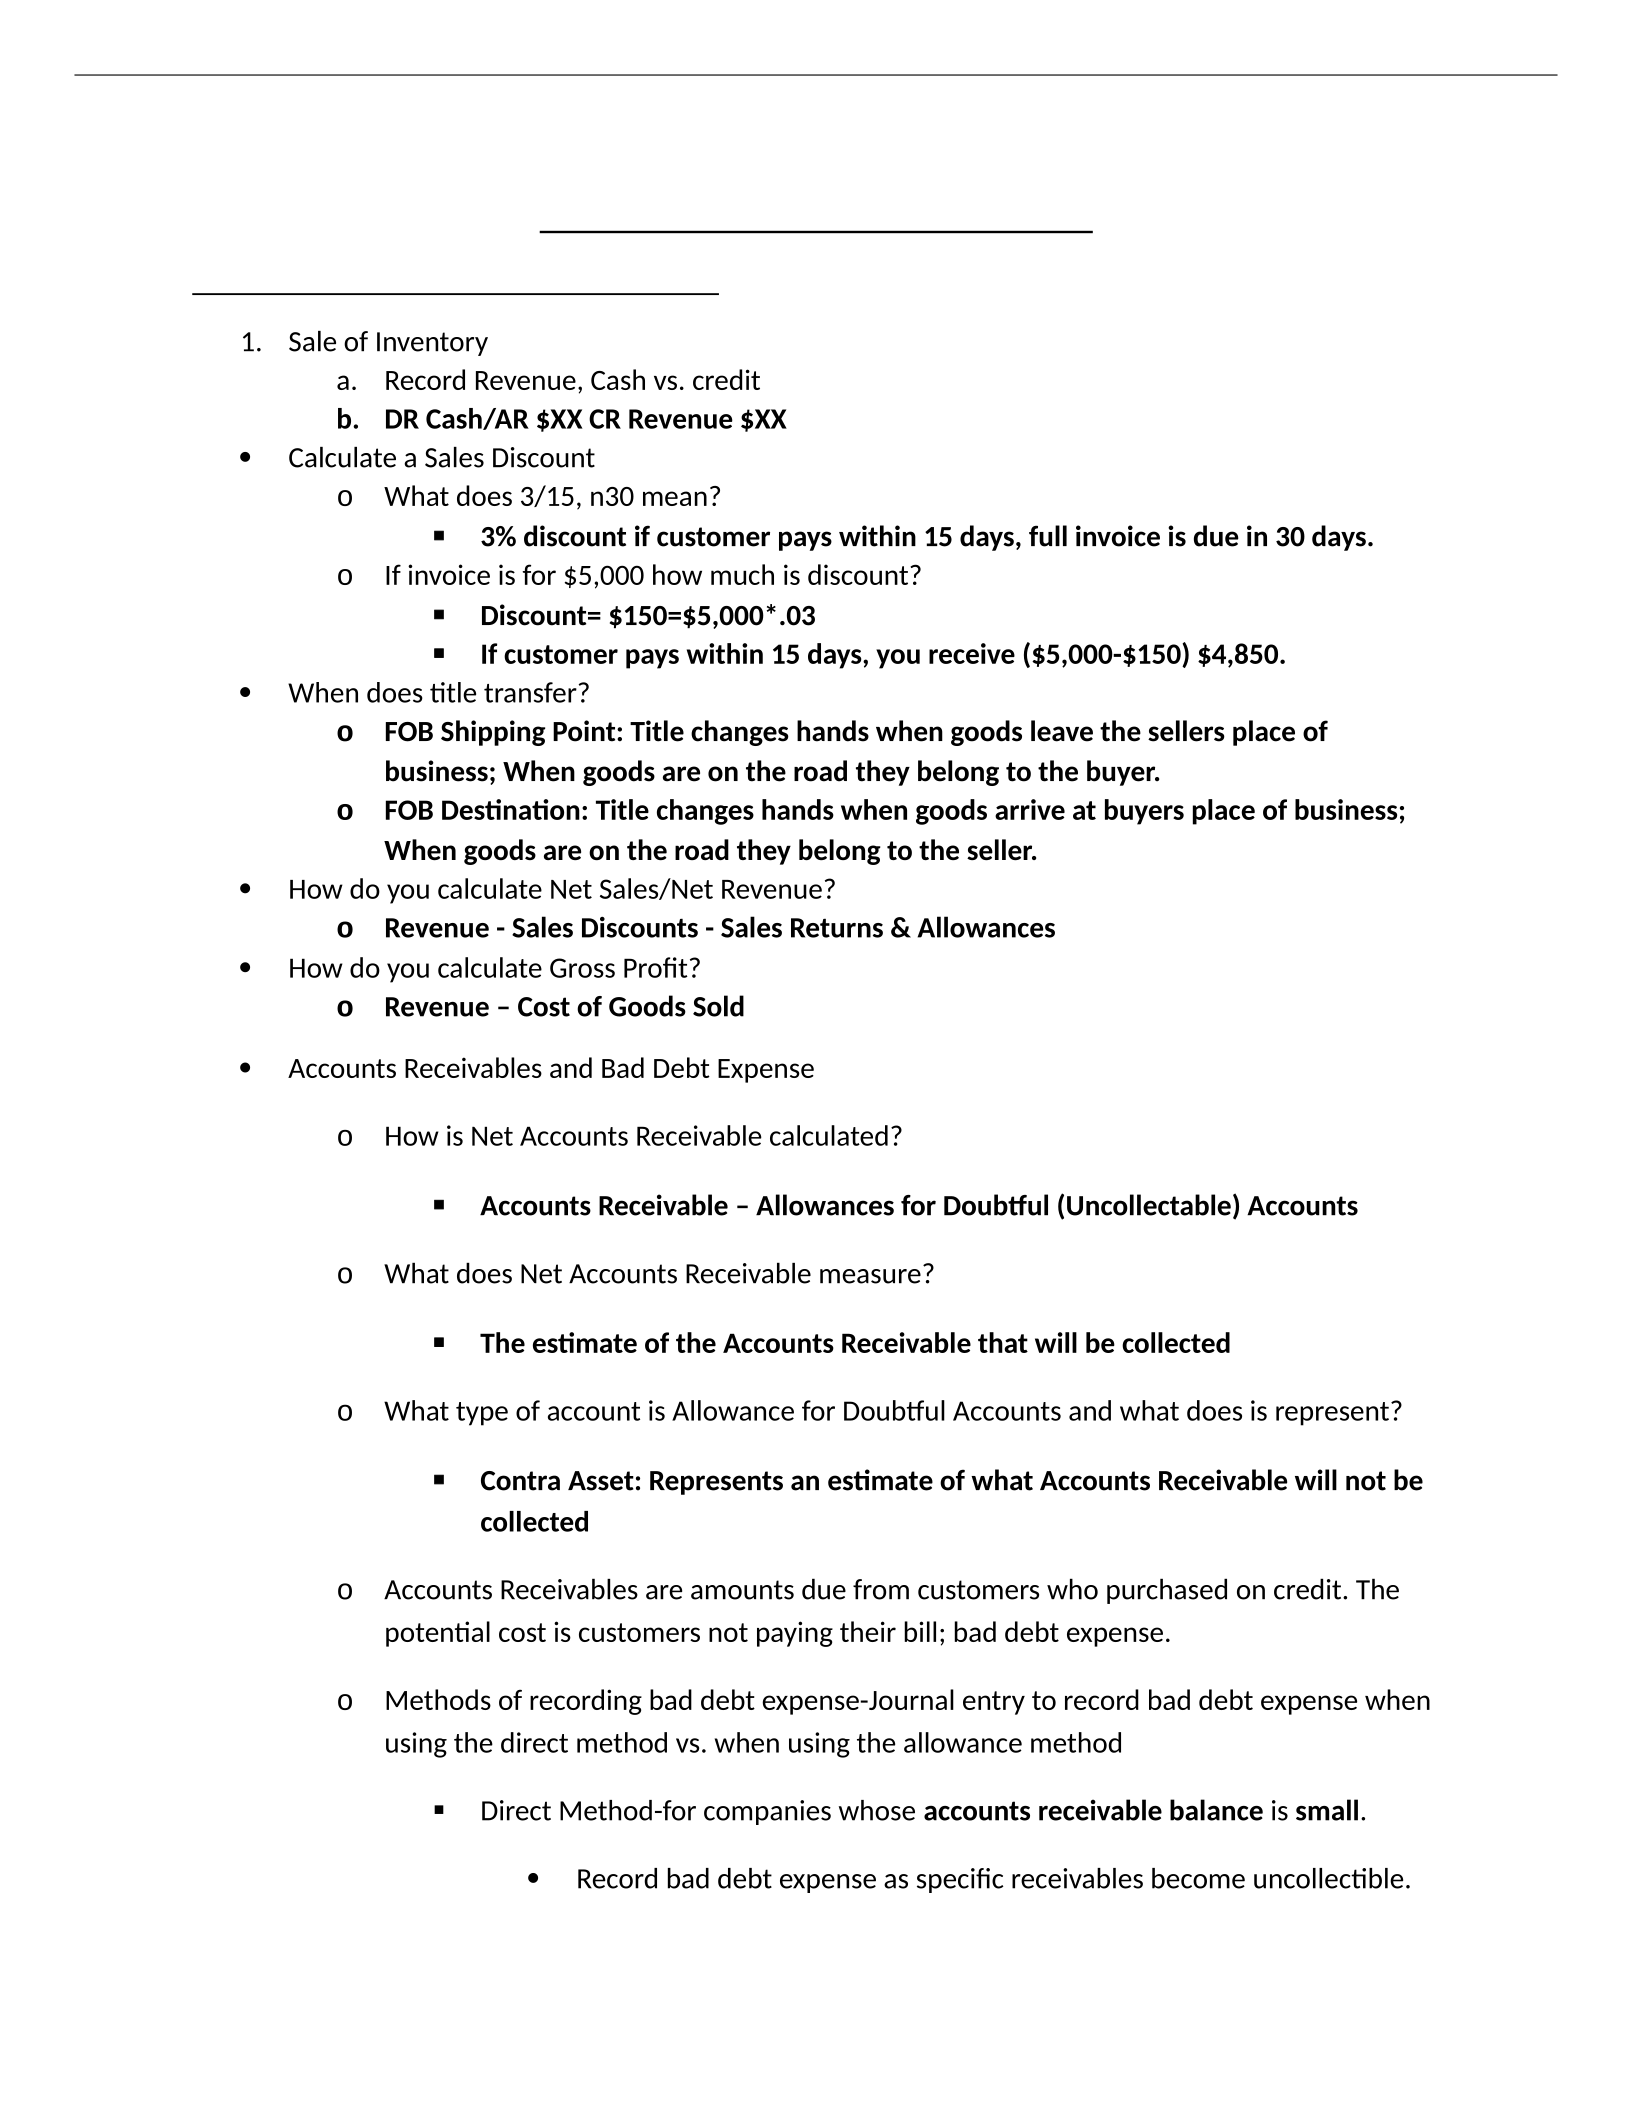
1. Sale of Inventory
a. Record Revenue, Cash vs. credit
b. DR Cash/AR $XX CR Revenue $XX
Calculate a Sales Discount
oWhat does 3/15, n30 mean?
3% discount if customer pays within 15 days, full invoice is due in 30 days.
oIf invoice is for $5,000 how much is discount?
Discount= $150=$5,000*.03
If customer pays within 15 days, you receive ($5,000-$150) $4,850.
When does title transfer?
oFOB Shipping Point: Title changes hands when goods leave the sellers place of
business; When goods are on the road they belong to the buyer.
oFOB Destination: Title changes hands when goods arrive at buyers place of business;
When goods are on the road they belong to the seller.
How do you calculate Net Sales/Net Revenue?
oRevenue - Sales Discounts - Sales Returns & Allowances
How do you calculate Gross Profit?
oRevenue – Cost of Goods Sold
Accounts Receivables and Bad Debt Expense
oHow is Net Accounts Receivable calculated?
Accounts Receivable – Allowances for Doubtful (Uncollectable) Accounts
oWhat does Net Accounts Receivable measure?
The estimate of the Accounts Receivable that will be collected
oWhat type of account is Allowance for Doubtful Accounts and what does is represent?
Contra Asset: Represents an estimate of what Accounts Receivable will not be
collected
oAccounts Receivables are amounts due from customers who purchased on credit. The
potential cost is customers not paying their bill; bad debt expense.
oMethods of recording bad debt expense-Journal entry to record bad debt expense when
using the direct method vs. when using the allowance method
Direct Method-for companies whose accounts receivable balance is small.
Record bad debt expense as specific receivables become uncollectible.
Exam #2 - Outline of Topics Covered
Chapter 5 Accounts Receivable and Revenue
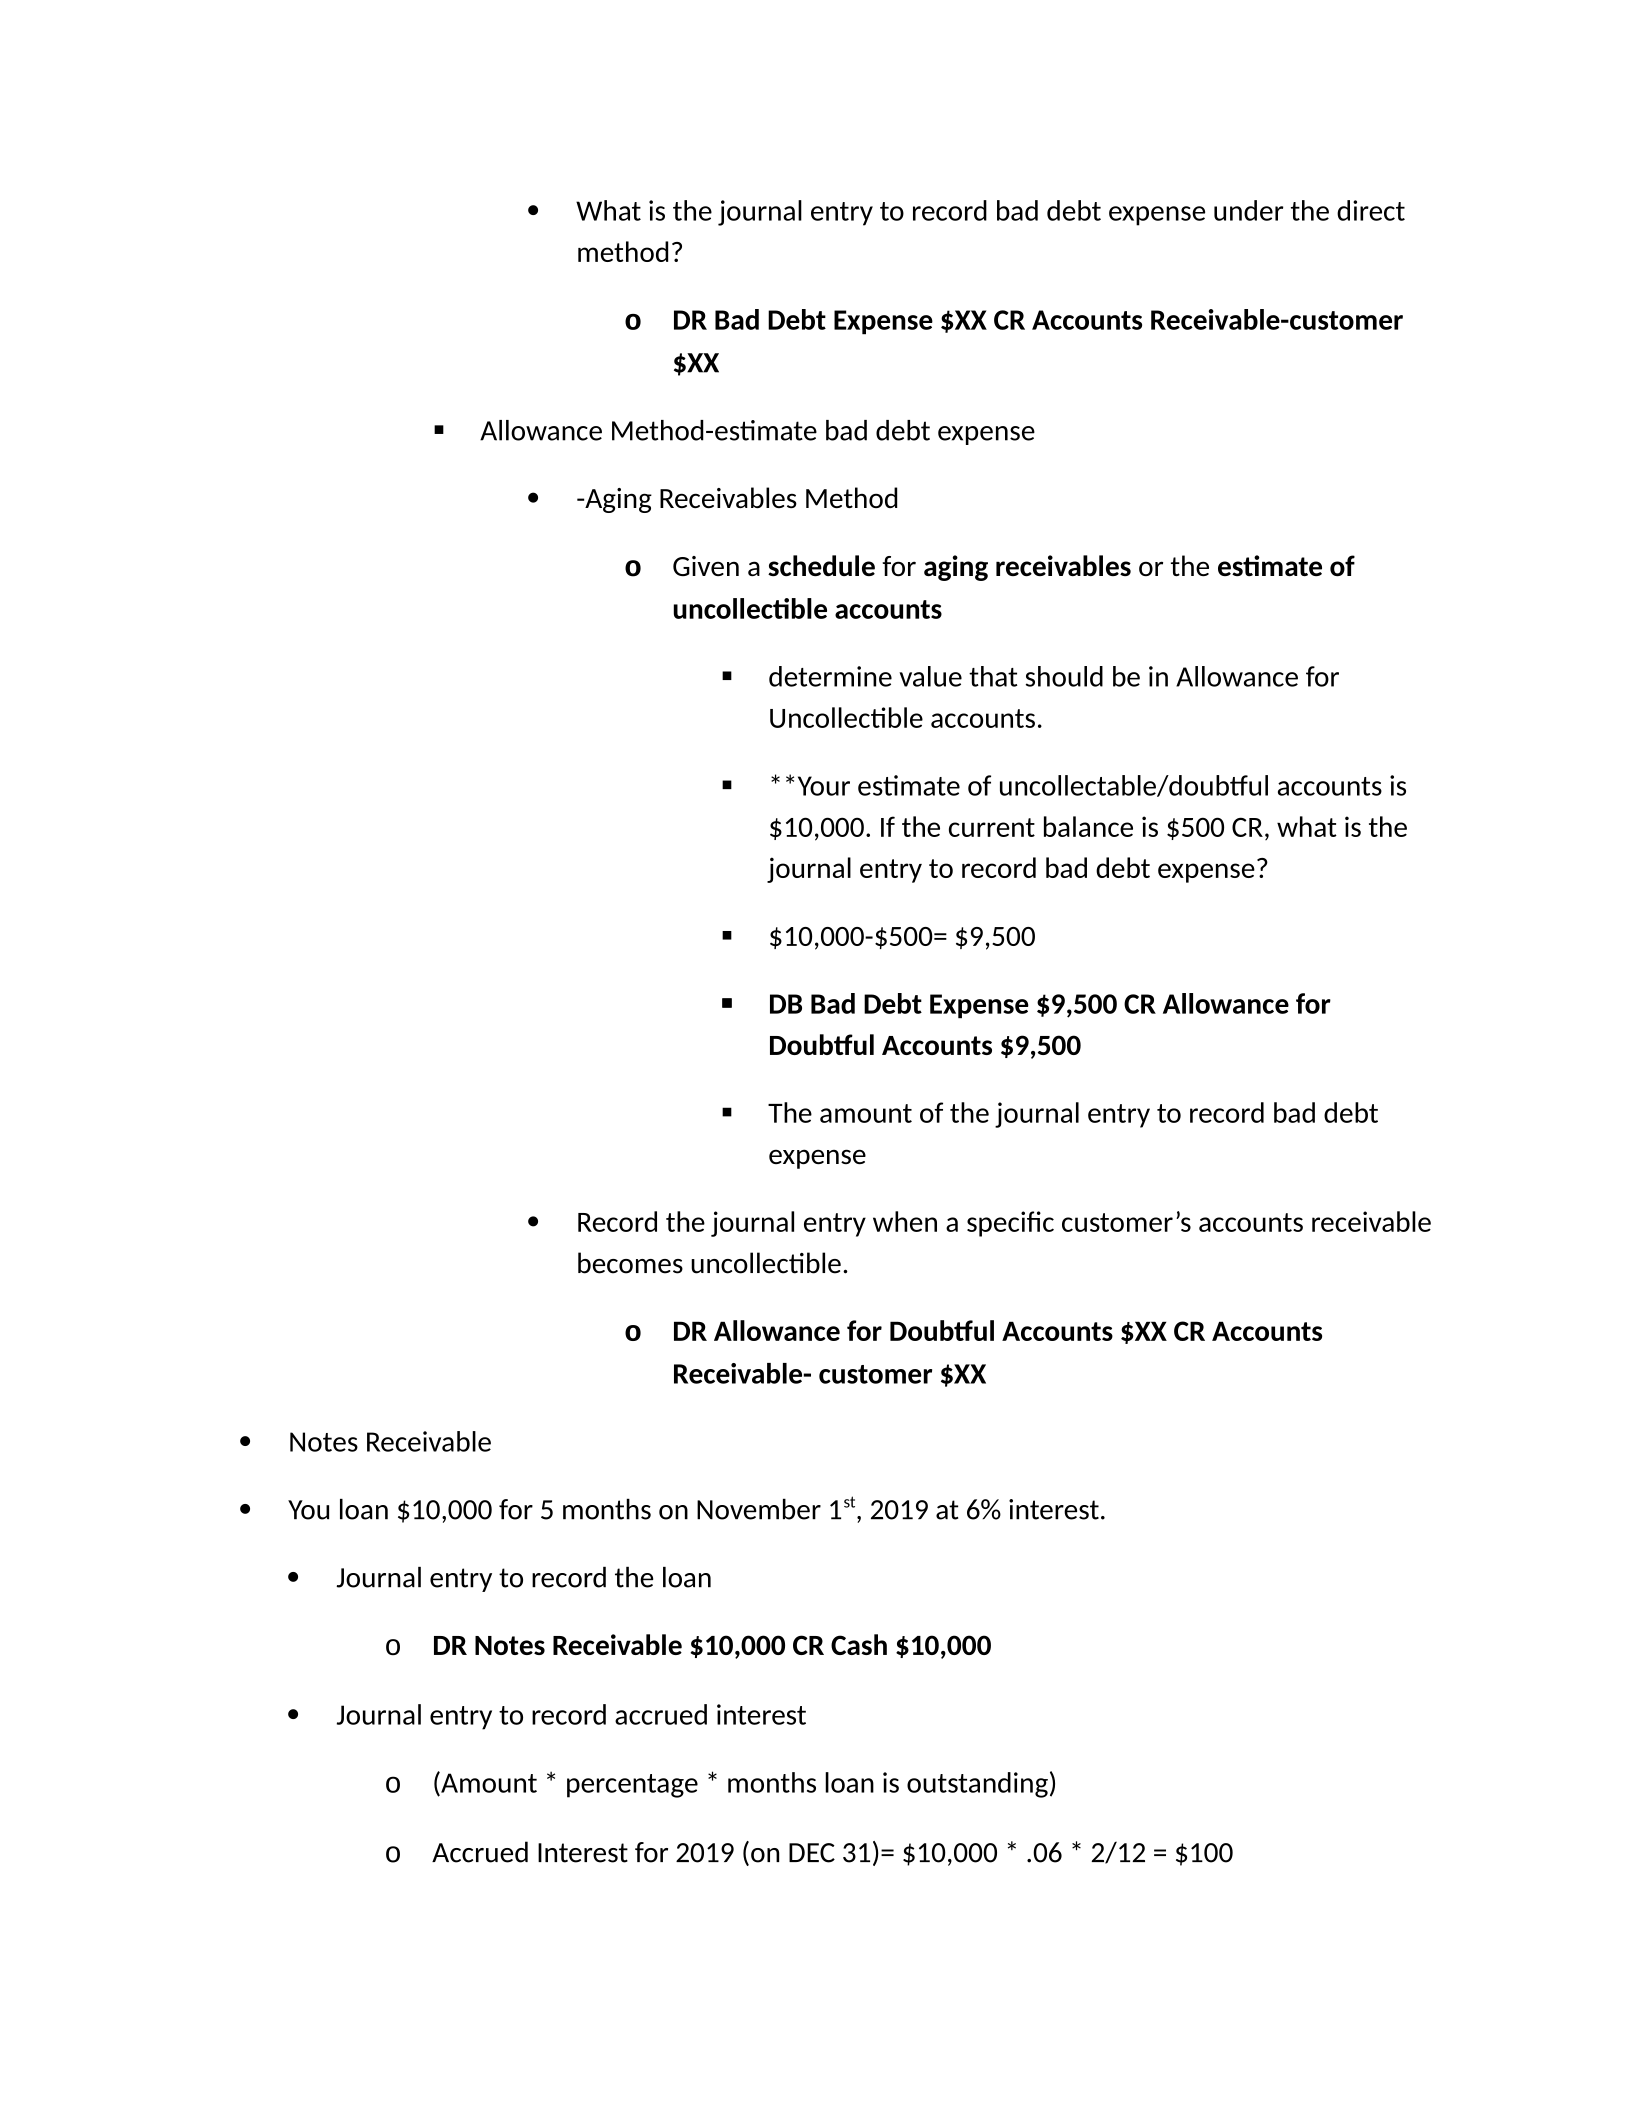
What is the journal entry to record bad debt expense under the direct
method?
oDR Bad Debt Expense $XX CR Accounts Receivable-customer
$XX
Allowance Method-estimate bad debt expense
-Aging Receivables Method
oGiven a schedule for aging receivables or the estimate of
uncollectible accounts
determine value that should be in Allowance for
Uncollectible accounts.
**Your estimate of uncollectable/doubtful accounts is
$10,000. If the current balance is $500 CR, what is the
journal entry to record bad debt expense?
$10,000-$500= $9,500
DB Bad Debt Expense $9,500 CR Allowance for
Doubtful Accounts $9,500
The amount of the journal entry to record bad debt
expense
Record the journal entry when a specific customer’s accounts receivable
becomes uncollectible.
oDR Allowance for Doubtful Accounts $XX CR Accounts
Receivable- customer $XX
Notes Receivable
You loan $10,000 for 5 months on November 1st, 2019 at 6% interest.
Journal entry to record the loan
oDR Notes Receivable $10,000 CR Cash $10,000
Journal entry to record accrued interest
o(Amount * percentage * months loan is outstanding)
oAccrued Interest for 2019 (on DEC 31)= $10,000 * .06 * 2/12 = $100
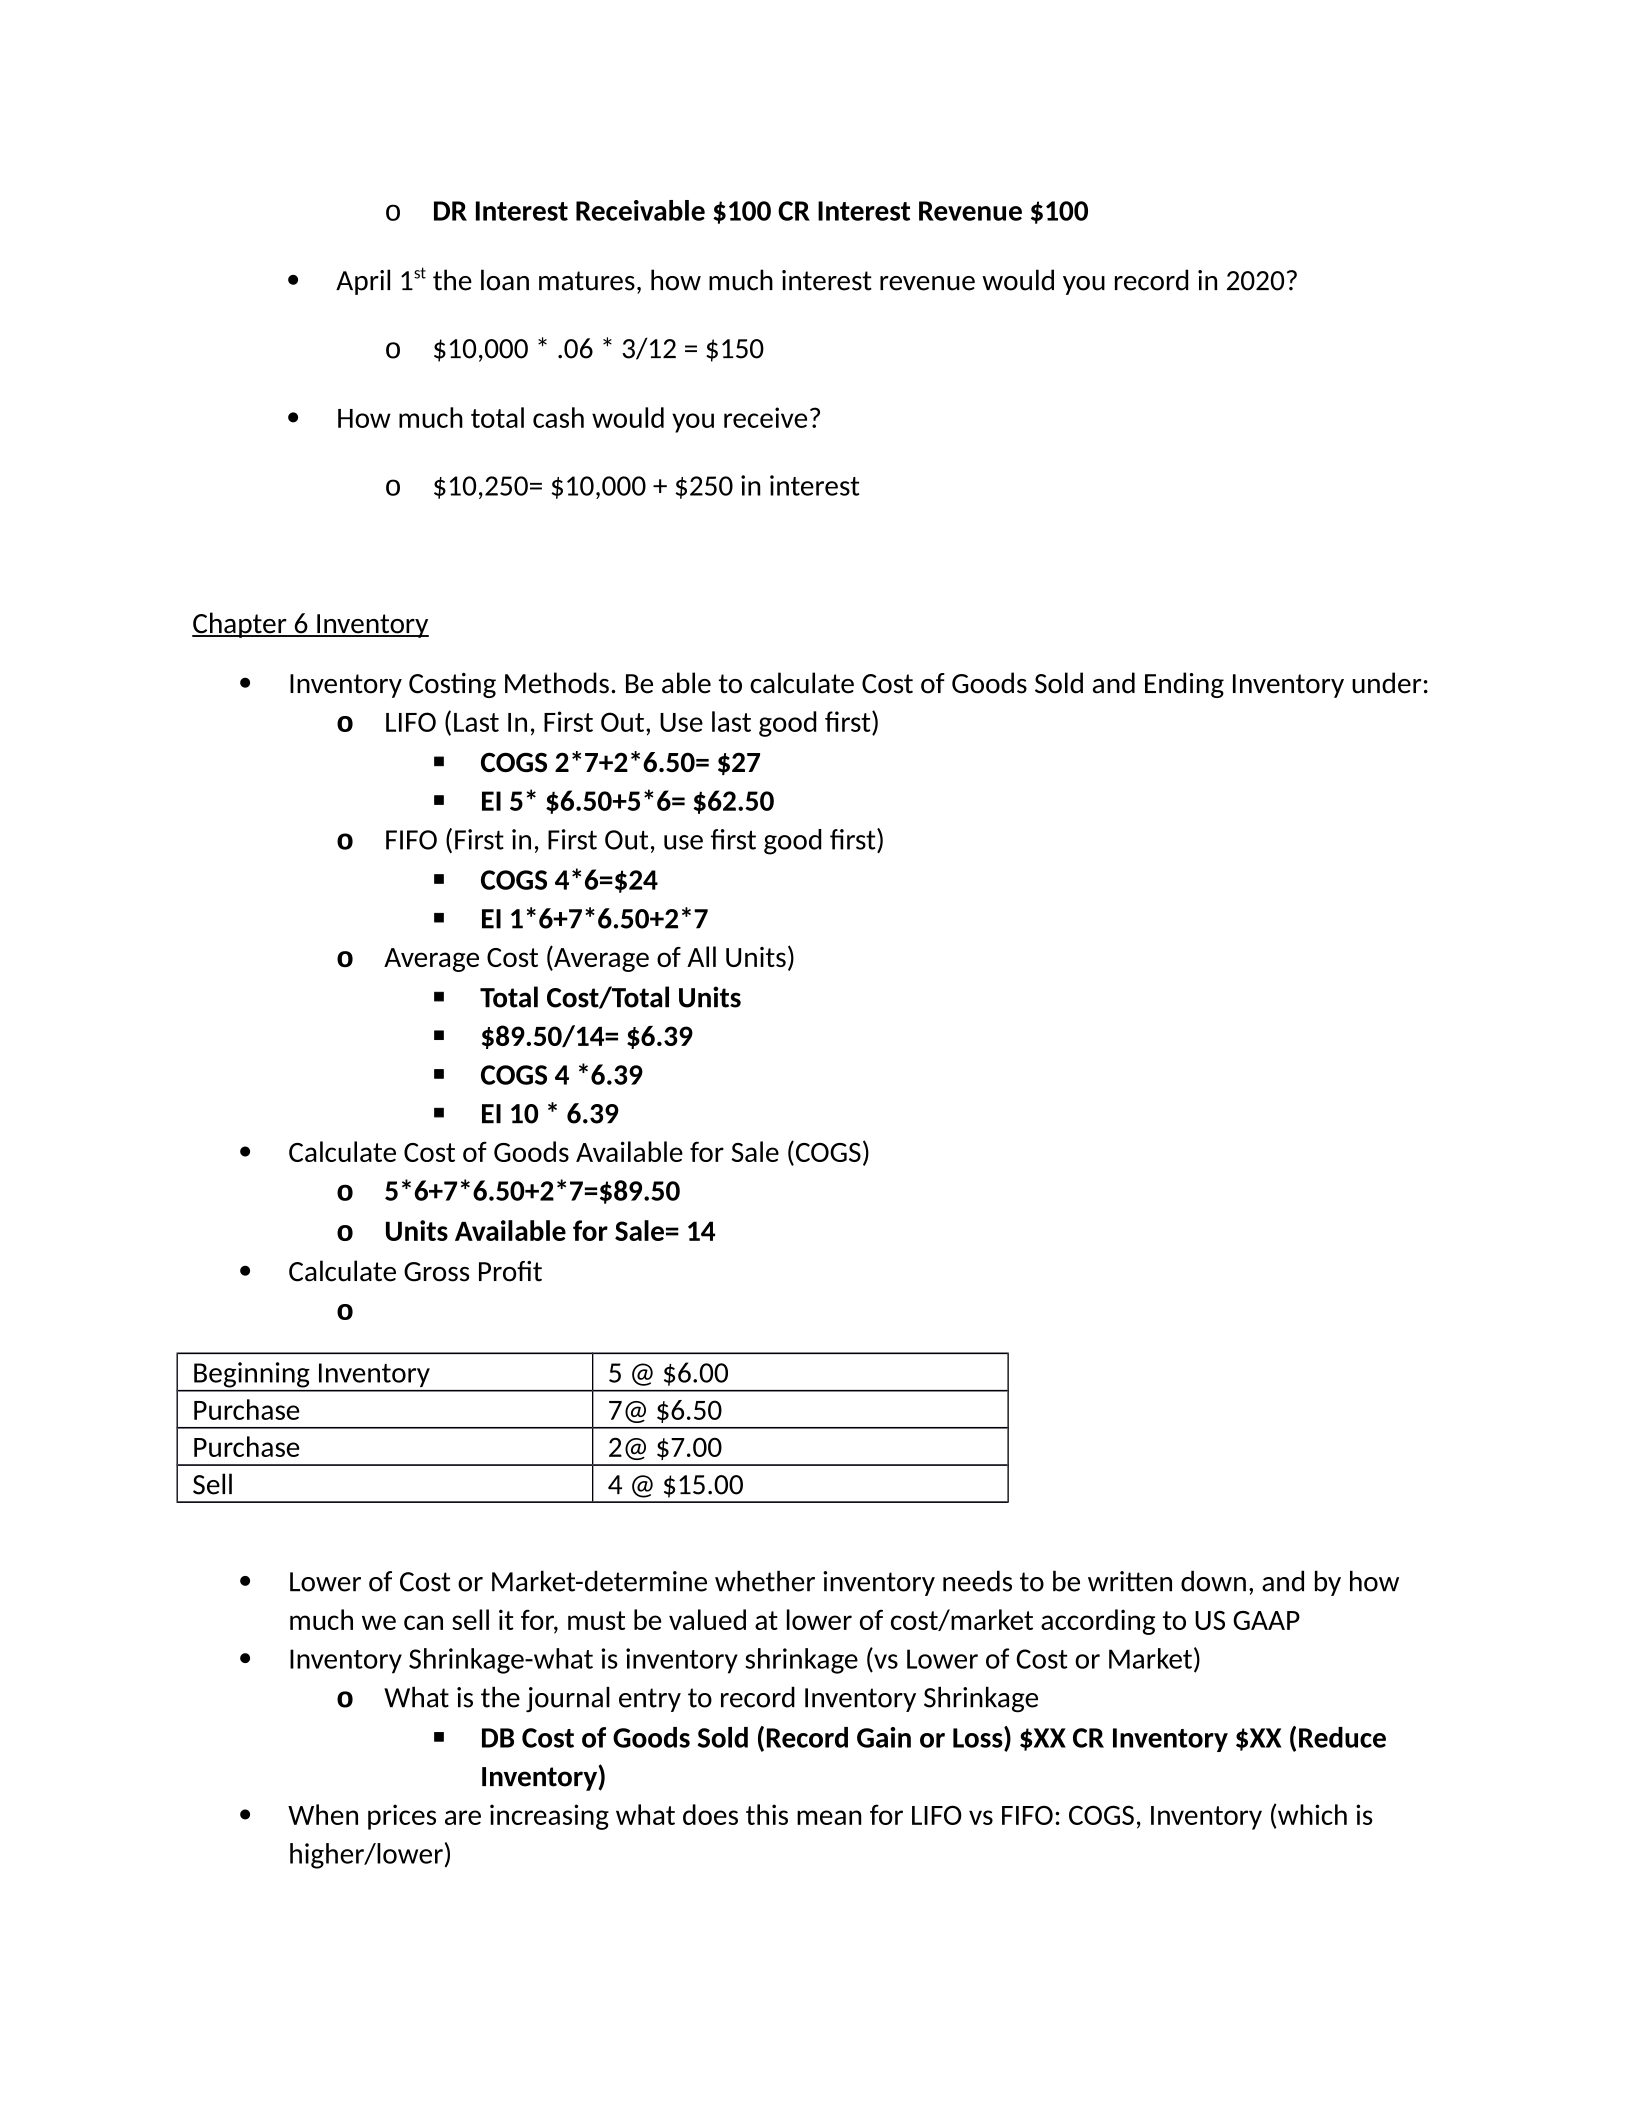
oDR Interest Receivable $100 CR Interest Revenue $100
April 1st the loan matures, how much interest revenue would you record in 2020?
o$10,000 * .06 * 3/12 = $150
How much total cash would you receive?
o$10,250= $10,000 + $250 in interest
Chapter 6 Inventory
Inventory Costing Methods. Be able to calculate Cost of Goods Sold and Ending Inventory under:
oLIFO (Last In, First Out, Use last good first)
COGS 2*7+2*6.50= $27
EI 5* $6.50+5*6= $62.50
oFIFO (First in, First Out, use first good first)
COGS 4*6=$24
EI 1*6+7*6.50+2*7
oAverage Cost (Average of All Units)
Total Cost/Total Units
$89.50/14= $6.39
COGS 4 *6.39
EI 10 * 6.39
Calculate Cost of Goods Available for Sale (COGS)
o5*6+7*6.50+2*7=$89.50
oUnits Available for Sale= 14
Calculate Gross Profit
o
Beginning Inventory 5 @ $6.00
Purchase 7@ $6.50
Purchase 2@ $7.00
Sell 4 @ $15.00
Lower of Cost or Market-determine whether inventory needs to be written down, and by how
much we can sell it for, must be valued at lower of cost/market according to US GAAP
Inventory Shrinkage-what is inventory shrinkage (vs Lower of Cost or Market)
oWhat is the journal entry to record Inventory Shrinkage
DB Cost of Goods Sold (Record Gain or Loss) $XX CR Inventory $XX (Reduce
Inventory)
When prices are increasing what does this mean for LIFO vs FIFO: COGS, Inventory (which is
higher/lower)
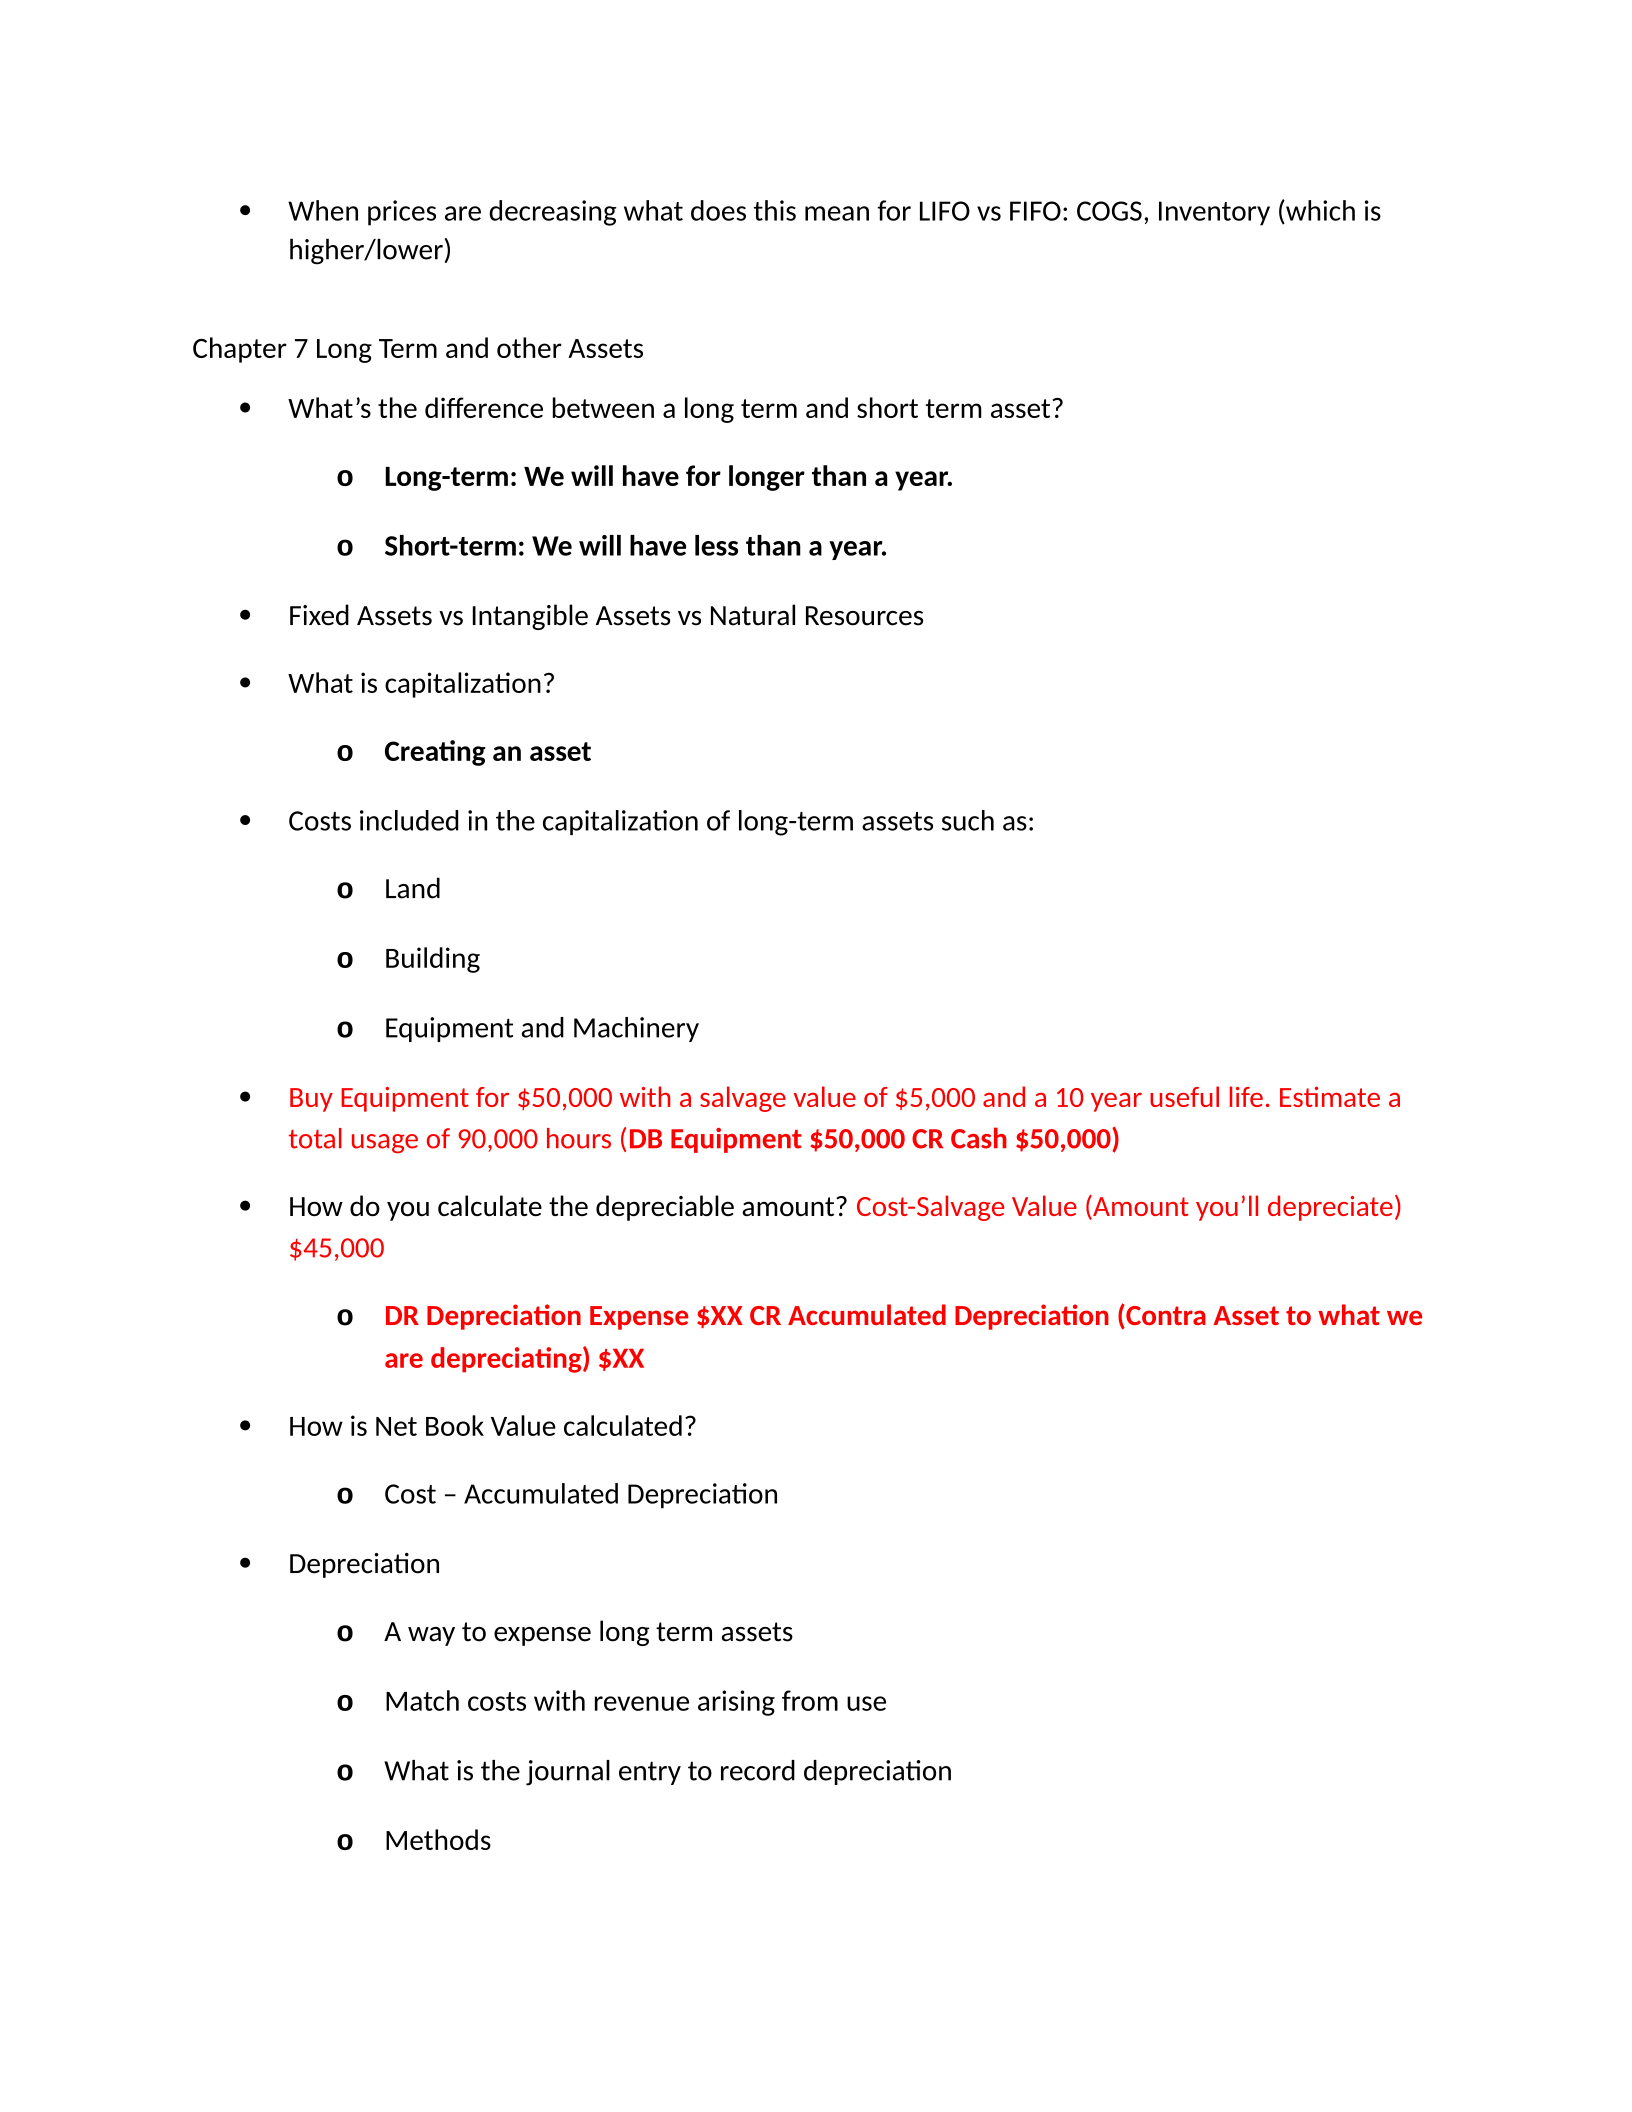
When prices are decreasing what does this mean for LIFO vs FIFO: COGS, Inventory (which is
higher/lower)
Chapter 7 Long Term and other Assets
What’s the difference between a long term and short term asset?
oLong-term: We will have for longer than a year.
oShort-term: We will have less than a year.
Fixed Assets vs Intangible Assets vs Natural Resources
What is capitalization?
oCreating an asset
Costs included in the capitalization of long-term assets such as:
oLand
oBuilding
oEquipment and Machinery
Buy Equipment for $50,000 with a salvage value of $5,000 and a 10 year useful life. Estimate a
total usage of 90,000 hours (DB Equipment $50,000 CR Cash $50,000)
How do you calculate the depreciable amount? Cost-Salvage Value (Amount you’ll depreciate)
$45,000
oDR Depreciation Expense $XX CR Accumulated Depreciation (Contra Asset to what we
are depreciating) $XX
How is Net Book Value calculated?
oCost – Accumulated Depreciation
Depreciation
oA way to expense long term assets
oMatch costs with revenue arising from use
oWhat is the journal entry to record depreciation
oMethods
Straight-line: ($50,000-$5,000)/10 years= $4,500
Decreases by the same amount every year
Double Declining Balance
Net book value *2 * 1/useful life (Decreases every yr)
oYear 1: $50,000 *2 *1/10 yrs = $10,000
oYear 2: $40,000 *2 *1/10= $8,000
Units of production
Cost per Unit ($50,000-$5,000)/90,000 hrs= $0.50/hr
Units of production for Natural Resources
oDetermine the Gain or Loss on the Sale of a long term asset
We use straight line and we sell the asset for $44,500 after year 1
After YR 1 Net book value: $50,000-$4,500= $45,500
oProceeds (Cash we received) – Net Book Value = Gain/Loss
o> Book Value = GAIN
o< Book Value = LOSS
$44,500 - $45,500= LOSS OF $1,000 (Less than Book Value)
Intangible Assets-What are intangible assets
oAn intangible asset is an asset that lacks physical substance
Most internally developed intangibles are expensed as incurred.
When is goodwill recorded?
When we buy a company
How is the value of goodwill determined?
Amount we paid over and above fair value of net assets; Purchase
price – Net Fair Value of Assets (FV Assets – FV Liabilities)
Powered by TCPDF (www.tcpdf.org)

